3 days ago
On September 9, 2026, Reuters reported that Stellantis N.V. (NYSE:STLA) is recalling 201,976 Jeep vehicles in the U.S., including certain Grand Cherokee, Wagoneer and Grand Wagoneer models. It happened after the National Highway Traffic Safety Administration found a software error that can prevent the tire-pressure monitoring system from detecting low tire pressure or alerting the driver, raising crash risk.
Dealers will update the affected radio-frequency hub software free of charge. The recall is the latest in a year that has already included a 1.5-million-vehicle Ram seat-belt recall, a 955,000-vehicle camera-glitch recall in August, and more than 1 million Wranglers and Gladiators recalled in June for fire risk.
The recall should carry a relatively limited direct financial burden because Stellantis N.V. (NYSE:STLA) can fix the defect with a software update. The recall covers 201,976 Jeep vehicles, but Stellantis does not need to replace a physical component. A software-based remedy should reduce parts and labor costs and allow dealers to complete the repair relatively quickly, limiting the recall's immediate impact on earnings and cash flow.
Stellantis has already begun rebuilding its financial performance, giving investors a stronger foundation to absorb another recall. Second-quarter net profit reached €293 million compared with a €1.87 billion loss a year earlier. Revenue surged 13% to €43.5 billion. The business also generated €1 billion in industrial free cash flow during the quarter, showing real improvement as CEO Antonio Filosa executes his turnaround plan.
Strong North American demand shows the recall has not yet undermined demand for Stellantis' key Jeep and Ram products. Second-quarter North American shipments increased 38% to 445,000 vehicles. It was backed up by refreshed models, including the Jeep Grand Wagoneer and Grand Cherokee and the Ram 1500. So the company enters this recall with improving volumes and strong demand for several of the brands that matter most to its North American turnaround.
#software
Dealers will update the affected radio-frequency hub software free of charge. The recall is the latest in a year that has already included a 1.5-million-vehicle Ram seat-belt recall, a 955,000-vehicle camera-glitch recall in August, and more than 1 million Wranglers and Gladiators recalled in June for fire risk.
The recall should carry a relatively limited direct financial burden because Stellantis N.V. (NYSE:STLA) can fix the defect with a software update. The recall covers 201,976 Jeep vehicles, but Stellantis does not need to replace a physical component. A software-based remedy should reduce parts and labor costs and allow dealers to complete the repair relatively quickly, limiting the recall's immediate impact on earnings and cash flow.
Stellantis has already begun rebuilding its financial performance, giving investors a stronger foundation to absorb another recall. Second-quarter net profit reached €293 million compared with a €1.87 billion loss a year earlier. Revenue surged 13% to €43.5 billion. The business also generated €1 billion in industrial free cash flow during the quarter, showing real improvement as CEO Antonio Filosa executes his turnaround plan.
Strong North American demand shows the recall has not yet undermined demand for Stellantis' key Jeep and Ram products. Second-quarter North American shipments increased 38% to 445,000 vehicles. It was backed up by refreshed models, including the Jeep Grand Wagoneer and Grand Cherokee and the Ram 1500. So the company enters this recall with improving volumes and strong demand for several of the brands that matter most to its North American turnaround.
#software

3 days ago
Trip.com Group Limited (NASDAQ:TCOM) reported second-quarter 2026 net revenue of RMB15.7 billion, up 6% year over year, in results released September 15. Revenue on its international platform increased more than 50%, highlighting a promising source of expansion against slower group growth.
Trip.com Group Limited (NASDAQ:TCOM) also recognized a RMB5.2 billion antimonopoly penalty in general and administrative expenses. The investment question extends beyond that charge: can international expansion generate enough profitable growth to offset pressure on domestic monetization?
International expansion gives Trip.com Group Limited (NASDAQ:TCOM) a potential route to reducing dependence on revenue earned from domestic travel. A broader customer base could make growth less reliant on a single market's commercial practices and regulatory environment.
The opportunity is especially attractive if new customers become repeat users. Over time, repeat bookings could reduce acquisition spending per transaction and allow technology and service costs to be spread across more revenue. That would turn international scale into operating leverage, with profits growing faster than sales.
Trip.com Group Limited (NASDAQ:TCOM) also grew accommodation revenue 6% year over year despite a regulator-imposed revenue reduction. That result offers some evidence of resilience, although reservation growth and the revenue earned from those reservations remain separate considerations.
#NASDAQ
Trip.com Group Limited (NASDAQ:TCOM) also recognized a RMB5.2 billion antimonopoly penalty in general and administrative expenses. The investment question extends beyond that charge: can international expansion generate enough profitable growth to offset pressure on domestic monetization?
International expansion gives Trip.com Group Limited (NASDAQ:TCOM) a potential route to reducing dependence on revenue earned from domestic travel. A broader customer base could make growth less reliant on a single market's commercial practices and regulatory environment.
The opportunity is especially attractive if new customers become repeat users. Over time, repeat bookings could reduce acquisition spending per transaction and allow technology and service costs to be spread across more revenue. That would turn international scale into operating leverage, with profits growing faster than sales.
Trip.com Group Limited (NASDAQ:TCOM) also grew accommodation revenue 6% year over year despite a regulator-imposed revenue reduction. That result offers some evidence of resilience, although reservation growth and the revenue earned from those reservations remain separate considerations.
#NASDAQ


3 days ago
LifeMD, Inc. (NASDAQ:LFMD) announced an exclusive healthcare collaboration on September 15 that initially makes virtual-health membership benefits available to approximately 29 million eligible AT&T wireless and fiber customers across 11 states. Customers must be 18 or older, and some services have additional eligibility and state restrictions. A nationwide expansion planned for January 2027 would extend eligibility beyond 100 million customers.
The $19 monthly membership fee is waived, but customers must enroll. Visits, prescriptions, and other services remain separately payable. For LifeMD, Inc. (NASDAQ:LFMD), the opportunity is converting access to a large audience into recurring demand for paid care.
The partnership gives LifeMD, Inc. (NASDAQ:LFMD) a distribution channel through the website, mobile app and customer-benefits program of AT&T Inc. (NYSE:T). Reaching customers through an established relationship could reduce reliance on advertising and lower acquisition costs per paying patient.
Removing the membership charge also reduces the financial commitment required to try the service. Announced visit prices start at $29 for message-based care, $49 for urgent and primary care video visits, and $79 for specialty care. Customers may use insurance, Medicare, or discounted cash-pay rates for visits and prescriptions.
LifeMD, Inc. (NASDAQ:LFMD) could benefit from repeat consultations and prescription fulfillment when clinically appropriate. Primary care, chronic-condition management and other services create opportunities for continuing patient relationships. If satisfied patients return, the revenue earned over those relationships could exceed the cost of acquiring and serving them.
#Services
The $19 monthly membership fee is waived, but customers must enroll. Visits, prescriptions, and other services remain separately payable. For LifeMD, Inc. (NASDAQ:LFMD), the opportunity is converting access to a large audience into recurring demand for paid care.
The partnership gives LifeMD, Inc. (NASDAQ:LFMD) a distribution channel through the website, mobile app and customer-benefits program of AT&T Inc. (NYSE:T). Reaching customers through an established relationship could reduce reliance on advertising and lower acquisition costs per paying patient.
Removing the membership charge also reduces the financial commitment required to try the service. Announced visit prices start at $29 for message-based care, $49 for urgent and primary care video visits, and $79 for specialty care. Customers may use insurance, Medicare, or discounted cash-pay rates for visits and prescriptions.
LifeMD, Inc. (NASDAQ:LFMD) could benefit from repeat consultations and prescription fulfillment when clinically appropriate. Primary care, chronic-condition management and other services create opportunities for continuing patient relationships. If satisfied patients return, the revenue earned over those relationships could exceed the cost of acquiring and serving them.
#Services


4 days ago
On September 16, Air Products (NYSE:APD) said it had signed a long-term deal to supply high-purity gases to a leading chipmaker, backed by roughly $250 million of its own money in Arizona. It is the company's second semiconductor supply win, and the two projects together carry more than $900 million of investment. That is a notable turn for a company that has been pulling back from big clean-energy projects.
The Arizona project plays to what Air Products already does. It will build, own, and operate the equipment, from hydrogen generation units and carbon dioxide purification to bulk supply for three gases: helium, hydrogen, and carbon dioxide. That means the customer's gas supply runs through equipment Air Products owns. Supply is targeted to start in phases, so the buildout can move alongside the customer's expansion plans. And this is familiar ground. Air Products has supplied electronics makers for more than 40 years, and its Chandler facility has served the Phoenix chip cluster since 1981, with a pipeline system carrying ultra-high purity nitrogen around the area.
The core business gives the deal a solid floor. In the fiscal third quarter, reported on July 30, adjusted earnings per share rose 12% to $3.47, and management lifted its full-year outlook to an adjusted $13.39 to $13.49 per share. Margins widened as well, so growth is showing up as profit. Chips appear elsewhere in the results too, since the company announced a deal to build four large air separation units to serve a chipmaker's growth in Taiwan.
The cost of the pivot is hard to ignore. On June 30, Air Products announced it would not go ahead with its Louisiana Clean Energy Complex and would discontinue a zero-carbon liquid hydrogen facility in Casa Grande, Arizona, plus other smaller clean energy distribution projects. The exits triggered roughly $2.9 billion in pre-tax charges, which is why the company posted a GAAP loss of $6.47 per share in the third quarter even as its underlying earnings grew. Adjusted results leave that hit out, but the GAAP numbers show what the retreat cost.
Owning the ****** ets also means funding them. Air Products expects about $3.5 billion of capital spending in fiscal 2026, and the Arizona plant alone is a commitment of approximately $250 million, with supply arriving in phases. The release also leaves gaps: it does not name the customer or say how long the contract runs, so the length of the revenue stream is unclear. Elsewhere, Europe's operating income rose only 2% as costs climbed, and management says it is still cautious about the economic backdrop.
#clean #adjusted
The Arizona project plays to what Air Products already does. It will build, own, and operate the equipment, from hydrogen generation units and carbon dioxide purification to bulk supply for three gases: helium, hydrogen, and carbon dioxide. That means the customer's gas supply runs through equipment Air Products owns. Supply is targeted to start in phases, so the buildout can move alongside the customer's expansion plans. And this is familiar ground. Air Products has supplied electronics makers for more than 40 years, and its Chandler facility has served the Phoenix chip cluster since 1981, with a pipeline system carrying ultra-high purity nitrogen around the area.
The core business gives the deal a solid floor. In the fiscal third quarter, reported on July 30, adjusted earnings per share rose 12% to $3.47, and management lifted its full-year outlook to an adjusted $13.39 to $13.49 per share. Margins widened as well, so growth is showing up as profit. Chips appear elsewhere in the results too, since the company announced a deal to build four large air separation units to serve a chipmaker's growth in Taiwan.
The cost of the pivot is hard to ignore. On June 30, Air Products announced it would not go ahead with its Louisiana Clean Energy Complex and would discontinue a zero-carbon liquid hydrogen facility in Casa Grande, Arizona, plus other smaller clean energy distribution projects. The exits triggered roughly $2.9 billion in pre-tax charges, which is why the company posted a GAAP loss of $6.47 per share in the third quarter even as its underlying earnings grew. Adjusted results leave that hit out, but the GAAP numbers show what the retreat cost.
Owning the ****** ets also means funding them. Air Products expects about $3.5 billion of capital spending in fiscal 2026, and the Arizona plant alone is a commitment of approximately $250 million, with supply arriving in phases. The release also leaves gaps: it does not name the customer or say how long the contract runs, so the length of the revenue stream is unclear. Elsewhere, Europe's operating income rose only 2% as costs climbed, and management says it is still cautious about the economic backdrop.
#clean #adjusted


4 days ago
On September 17, Ferrari N.V. (NYSE:RACE) announced a partnership with the technology company Rakuten Group, Inc., effective January 1, 2027. The announcement gives no scope and no price tag, so it works better as a signal than as a number. The real substance sits in the results Ferrari posted on July 30, when it raised its 2026 guidance because buyers are ordering more personalization than the company expected.
In the second quarter, revenue rose 8%, but operating profit rose 10%, which means each euro of sales is leaving more behind. Ferrari credits a richer mix of cars, with the F80 helping, along with more buyers paying up for personalization. Strip out currency swings, and the gap widens, with revenue up 11% and operating profit up 16%. Deliveries of the Purosangue and the 296 Speciale family grew even in the middle of a planned model changeover.
Cash and demand back that up. Industrial free cash flow jumped 39% to €276 million, and Ferrari also returned more than €800 million to shareholders through a dividend and buybacks. Racing helped too, as higher sponsorships and engine rentals to other Formula 1 teams lifted revenue. Meanwhile, the order book covers 2027 in full, and the new 12Cilindri Manuale is already fully allocated, which is about as strong a demand signal as a carmaker can send. Those trends are why revenue guidance moved up to about €7.60 billion from about €7.50 billion.
Part of the strength is timing. Operating profit got a boost from temporarily lower depreciation and amortization while Ferrari swaps out models, and the company says those charges will climb once the new cars enter production. Net profit also leaned on a 23.0% tax rate, which reflects an estimated benefit from the new Patent Box. Neither says much about how profitable the cars themselves are.
Costs are climbing too. Higher industrial and marketing expenses weighed on operating profit, EBITDA margin slipped to 39.0% from 39.7% a year earlier, and management expects heavier brand, racing and digital spending for the year. Currency is a drag as well, mostly from the dollar and the yen, which is why 11% growth at constant currency shrank to 8% as reported. Deliveries totaled 3,366 cars while the 296 GTS, Roma Spider and SF90 XX family wound down, and sponsorship, commercial and brand revenue grew just 2%. And the whole outlook leans on current visibility into the Middle East crisis, which Ferrari cannot control.
#Ferrari
In the second quarter, revenue rose 8%, but operating profit rose 10%, which means each euro of sales is leaving more behind. Ferrari credits a richer mix of cars, with the F80 helping, along with more buyers paying up for personalization. Strip out currency swings, and the gap widens, with revenue up 11% and operating profit up 16%. Deliveries of the Purosangue and the 296 Speciale family grew even in the middle of a planned model changeover.
Cash and demand back that up. Industrial free cash flow jumped 39% to €276 million, and Ferrari also returned more than €800 million to shareholders through a dividend and buybacks. Racing helped too, as higher sponsorships and engine rentals to other Formula 1 teams lifted revenue. Meanwhile, the order book covers 2027 in full, and the new 12Cilindri Manuale is already fully allocated, which is about as strong a demand signal as a carmaker can send. Those trends are why revenue guidance moved up to about €7.60 billion from about €7.50 billion.
Part of the strength is timing. Operating profit got a boost from temporarily lower depreciation and amortization while Ferrari swaps out models, and the company says those charges will climb once the new cars enter production. Net profit also leaned on a 23.0% tax rate, which reflects an estimated benefit from the new Patent Box. Neither says much about how profitable the cars themselves are.
Costs are climbing too. Higher industrial and marketing expenses weighed on operating profit, EBITDA margin slipped to 39.0% from 39.7% a year earlier, and management expects heavier brand, racing and digital spending for the year. Currency is a drag as well, mostly from the dollar and the yen, which is why 11% growth at constant currency shrank to 8% as reported. Deliveries totaled 3,366 cars while the 296 GTS, Roma Spider and SF90 XX family wound down, and sponsorship, commercial and brand revenue grew just 2%. And the whole outlook leans on current visibility into the Middle East crisis, which Ferrari cannot control.
#Ferrari

4 days ago
Americans are increasingly falling victim to so-called "ghost charges": small, frictionless payment purchases at Starbucks or McDonald's, or digital subscription deductions from your bank account you forgot about. The costs may only be $5 or $10 a pop, but they add up, and before you know it, $200 has disappeared from your savings every month.
Jeff Bezos backs a platform that lets anyone invest in rental homes for as little as $100 — 6 ways to build wealth like a landlord without actually being one
Dave Ramsey warns nearly 50% of Americans are making 1 big Social Security mistake. Here's what it is and 3 simple steps to fix it ASAP
The tax breaks in Trump's 'big beautiful bill' expire after 2028. Here are 4 moves to make before the window closes
A recent study from Cashews, a digital bank tracking platform for serial small recurring charges, shows that 61% of people have more than $50 a month in these small charges; 38.7% have more than $100 a month; and 14.5% have more than $200 a month in charges where no single charge is over $100. Additionally, three of the median person's four small recurring monthly charges go to merchants they never otherwise interact with.
#charges #digital #bank #platform
Jeff Bezos backs a platform that lets anyone invest in rental homes for as little as $100 — 6 ways to build wealth like a landlord without actually being one
Dave Ramsey warns nearly 50% of Americans are making 1 big Social Security mistake. Here's what it is and 3 simple steps to fix it ASAP
The tax breaks in Trump's 'big beautiful bill' expire after 2028. Here are 4 moves to make before the window closes
A recent study from Cashews, a digital bank tracking platform for serial small recurring charges, shows that 61% of people have more than $50 a month in these small charges; 38.7% have more than $100 a month; and 14.5% have more than $200 a month in charges where no single charge is over $100. Additionally, three of the median person's four small recurring monthly charges go to merchants they never otherwise interact with.
#charges #digital #bank #platform

4 days ago
If you're trying to choose between the Vanguard S&P 500 ETF (NYSEMKT: VOO) and the State Street SPDR S&P 500 ETF (NYSEMKT: SPY), it might seem they're essentially interchangeable. They're both huge and track the same index.
At a high level, that's probably true. But if you want to dive deep and get picky, a few factors set them apart.
Missed AI's "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our **** ysts, we're only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
The State Street SPDR S&P 500 ETF has an expense ratio of 0.0945%. The Vanguard S&P 500 ETF charges just 0.03%. Given that the index has historically returned about 10% per year, this fee difference may seem immaterial. But I will take any advantage I can get.
Because of their sizes, trading spreads (the difference between the buying (ask) price and the selling (bid) price of a stock) are virtually nothing, so spreads aren't really a consideration here. But if you can own the exact same index for a third of the cost, why not?
#index #same
At a high level, that's probably true. But if you want to dive deep and get picky, a few factors set them apart.
Missed AI's "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our **** ysts, we're only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
The State Street SPDR S&P 500 ETF has an expense ratio of 0.0945%. The Vanguard S&P 500 ETF charges just 0.03%. Given that the index has historically returned about 10% per year, this fee difference may seem immaterial. But I will take any advantage I can get.
Because of their sizes, trading spreads (the difference between the buying (ask) price and the selling (bid) price of a stock) are virtually nothing, so spreads aren't really a consideration here. But if you can own the exact same index for a third of the cost, why not?
#index #same

4 days ago
Some offers on this page are from advertisers who pay us, which may affect which products we write about, but not our recommendations. See our Advertiser Disclosure.
The FOMC began a new interest rate cycle, raising the federal funds rate a quarter point on Sept. 16. Wall Street traders expect at least one more rate increase before the end of 2026.
The federal funds rate. The Fed. The FOMC. No doubt you've heard and read these terms before. But what do they mean? How does this impact your financial life?
The federal funds rate is the interest rate the government sets for one bank to charge another bank for ultra-short-term loans, usually just overnight. It's actually an interest rate range. Banks negotiate a specific rate with each other within that range set by the Federal Reserve.
The current federal funds rate is now 3.75% to 4.00%.
#advertiser #disclosure
The FOMC began a new interest rate cycle, raising the federal funds rate a quarter point on Sept. 16. Wall Street traders expect at least one more rate increase before the end of 2026.
The federal funds rate. The Fed. The FOMC. No doubt you've heard and read these terms before. But what do they mean? How does this impact your financial life?
The federal funds rate is the interest rate the government sets for one bank to charge another bank for ultra-short-term loans, usually just overnight. It's actually an interest rate range. Banks negotiate a specific rate with each other within that range set by the Federal Reserve.
The current federal funds rate is now 3.75% to 4.00%.
#advertiser #disclosure



4 days ago
FleetCor and CEO Ronald Clarke agreed to a $100 million payment resolving Federal Trade Commission litigation. The settlement follows years of court action over hidden charges involving commercial fuel cards. Harm reached tens of thousands among small-business customers seeking lower operating costs. Regulators say promised savings disappeared beneath undisclosed billing practices.
Federal regulators accused FleetCor, which now operates as Corpay, of imposing unauthorized fees totaling hundreds of millions. Investigators found improper late penalties despite timely remittance or company barriers that prevented payment. Officials cited misleading claims about gas savings, fraud controls, plus card-related expenses. Those practices harmed operators across the United States, according to a 2019 complaint.
Regulators found FleetCor often waited several billing cycles before adding many charges. Delayed timing made extra costs harder for customers to notice. Invoices omitted fee disclosures, pushing account holders toward separate management reports. Even those documents obscured some amounts among unrelated details or excluded them entirely.
"FleetCor deceived its small business customers by promising fuel savings that never materialized," Christopher Mufarrige said. He directs FTC's Bureau of Consumer Protection. Agency officials also criticized hidden and unauthorized charges. Settlement terms channel restitution toward harmed account holders.
In 2023, one federal district court granted summary judgment to the FTC on every count. Its ruling found hidden charges and false representations involving savings, fees, plus fraud-control features. Permanent injunction terms barred FleetCor from billing without informed consent alongside clear disclosures. That order also prohibited deceptive fuel-card claims or hiding material information behind hyperlinks.
#fleetcor #savings
Federal regulators accused FleetCor, which now operates as Corpay, of imposing unauthorized fees totaling hundreds of millions. Investigators found improper late penalties despite timely remittance or company barriers that prevented payment. Officials cited misleading claims about gas savings, fraud controls, plus card-related expenses. Those practices harmed operators across the United States, according to a 2019 complaint.
Regulators found FleetCor often waited several billing cycles before adding many charges. Delayed timing made extra costs harder for customers to notice. Invoices omitted fee disclosures, pushing account holders toward separate management reports. Even those documents obscured some amounts among unrelated details or excluded them entirely.
"FleetCor deceived its small business customers by promising fuel savings that never materialized," Christopher Mufarrige said. He directs FTC's Bureau of Consumer Protection. Agency officials also criticized hidden and unauthorized charges. Settlement terms channel restitution toward harmed account holders.
In 2023, one federal district court granted summary judgment to the FTC on every count. Its ruling found hidden charges and false representations involving savings, fees, plus fraud-control features. Permanent injunction terms barred FleetCor from billing without informed consent alongside clear disclosures. That order also prohibited deceptive fuel-card claims or hiding material information behind hyperlinks.
#fleetcor #savings


4 days ago
Two years of Synopsys (SNPS) earnings calls show management changing what it explains. The company used to open on problems, some outside its control and some its own. The August 2026 call is built around a joint product with Ansys, agentic AI, and a new way to charge for its design IP. Most of that switch is earned, but parts of it are still a promise.
Synopsys Once Opened Its Calls With Bad News
Management used to point to underperformance in the IP business, where expected deals did not arrive, and to challenges at a major foundry customer that were having a sizable impact. The CEO said it plainly on an earlier call: "new export restrictions disrupted design starts in China."
None of that comes up on the August 2026 call. China does not come up. The closest thing to the old worry is that design starts outside AI have stopped declining.
Synopsys Now Leads With Multiphysics Fusion And Agentic AI
#China
Synopsys Once Opened Its Calls With Bad News
Management used to point to underperformance in the IP business, where expected deals did not arrive, and to challenges at a major foundry customer that were having a sizable impact. The CEO said it plainly on an earlier call: "new export restrictions disrupted design starts in China."
None of that comes up on the August 2026 call. China does not come up. The closest thing to the old worry is that design starts outside AI have stopped declining.
Synopsys Now Leads With Multiphysics Fusion And Agentic AI
#China

4 days ago
Volkswagen announced a steep cut to its full-year profit outlook on Friday, citing roughly €10 billion ($11.5 billion) in one-time charges concentrated at its troubled Porsche division, amid mounting pressure from U.S. tariffs and a weakening Chinese auto market on the world's second-largest automaker.
The company said it now expects an operating return on sales of up to 1% for 2026, down from its previous guidance of 4% to 5.5%. Volkswagen also said full-year revenue is expected to fall to about €315 billion, from €321.9 billion in 2025.
The bulk of the charges — about €6 billion — stem from revised mid-term ******* umptions for Porsche, in which Volkswagen holds a 75.4% stake. The sports car brand has been hit by U.S. tariffs and a collapse in demand for foreign luxury vehicles in China. On top of that, Volkswagen said it would book a further €2 billion in impairments in the second half of the year, covering China-related writedowns as well as restructuring charges such as costs from early-retirement schemes and the pending divestiture of its Osnabrück plant in Germany, according to The Wall Street Journal.
Volkswagen stock closed down 5.6% following the announcement. Shares of Porsche and Volkswagen's top shareholder Porsche SE fell 3.3% and 4.9%, respectively.
The company cautioned that "further deterioration in the market environment, especially in China, as well as an accelerated shift in demand in favour of battery-electric vehicles" would drag down results, with its Audi and Volkswagen passenger car brands bearing the brunt. Volkswagen noted that its outlook ******* umes tariffs remain unchanged and does not account for possible future effects from the war in the Middle East.
#charges #tariffs #full
The company said it now expects an operating return on sales of up to 1% for 2026, down from its previous guidance of 4% to 5.5%. Volkswagen also said full-year revenue is expected to fall to about €315 billion, from €321.9 billion in 2025.
The bulk of the charges — about €6 billion — stem from revised mid-term ******* umptions for Porsche, in which Volkswagen holds a 75.4% stake. The sports car brand has been hit by U.S. tariffs and a collapse in demand for foreign luxury vehicles in China. On top of that, Volkswagen said it would book a further €2 billion in impairments in the second half of the year, covering China-related writedowns as well as restructuring charges such as costs from early-retirement schemes and the pending divestiture of its Osnabrück plant in Germany, according to The Wall Street Journal.
Volkswagen stock closed down 5.6% following the announcement. Shares of Porsche and Volkswagen's top shareholder Porsche SE fell 3.3% and 4.9%, respectively.
The company cautioned that "further deterioration in the market environment, especially in China, as well as an accelerated shift in demand in favour of battery-electric vehicles" would drag down results, with its Audi and Volkswagen passenger car brands bearing the brunt. Volkswagen noted that its outlook ******* umes tariffs remain unchanged and does not account for possible future effects from the war in the Middle East.
#charges #tariffs #full

4 days ago
Merck (MRK) stock returned about 87% over the past twelve months, climbing from roughly $79 to about $147. Nothing in the year's results looks like that. The medicines Merck sells today grew at their usual pace. Investors spent the year repricing what comes next.
Revenue over the trailing twelve months was $66.6 billion, up 4.6% and in line with its own three-year pace. Profitability did not follow. Its operating margin over the same twelve months was 10.5%, versus a three-year average of 22.4%.
Most of that gap is one purchase. Merck took a $5.7 billion charge in the second quarter of 2026, about 9% of a year's sales. It bought Terns Pharmaceuticals, and with it MK-4208, a candidate for chronic myeloid leukemia. The bill hits earnings now and the medicine arrives later.
The proof matters because of the risk hanging over this stock. The KEYTRUDA family was just over half of Merck's revenue in the second quarter of 2026. The company is openly planning for the end of that exclusivity when Keytruda loses primary U.S. patent protection in 2028. Management describes the stretch as more of a hill than a cliff, with a shallow dip and a fast return to growth.
Johnson & Johnson (JNJ) returned 56% over the same twelve months and Pfizer (PFE) 23%, so a good year for pharmaceuticals explains some of this but not Merck's lead. What separated Merck was evidence. The FDA approved LIPFENDRA, the first and only oral PCSK9 inhibitor. In the CORALreef Lipids trial it lowered LDL cholesterol by up to 60% when added to a statin.
#year #johnson
Revenue over the trailing twelve months was $66.6 billion, up 4.6% and in line with its own three-year pace. Profitability did not follow. Its operating margin over the same twelve months was 10.5%, versus a three-year average of 22.4%.
Most of that gap is one purchase. Merck took a $5.7 billion charge in the second quarter of 2026, about 9% of a year's sales. It bought Terns Pharmaceuticals, and with it MK-4208, a candidate for chronic myeloid leukemia. The bill hits earnings now and the medicine arrives later.
The proof matters because of the risk hanging over this stock. The KEYTRUDA family was just over half of Merck's revenue in the second quarter of 2026. The company is openly planning for the end of that exclusivity when Keytruda loses primary U.S. patent protection in 2028. Management describes the stretch as more of a hill than a cliff, with a shallow dip and a fast return to growth.
Johnson & Johnson (JNJ) returned 56% over the same twelve months and Pfizer (PFE) 23%, so a good year for pharmaceuticals explains some of this but not Merck's lead. What separated Merck was evidence. The FDA approved LIPFENDRA, the first and only oral PCSK9 inhibitor. In the CORALreef Lipids trial it lowered LDL cholesterol by up to 60% when added to a statin.
#year #johnson


4 days ago
Volkswagen cut its 2026 operating-margin forecast to no more than 1 per cent, down from a previous range of 4 to 5.5 per cent.
Approximately €10 billion in special charges includes a €6 billion non-cash impairment connected with Porsche.
Volkswagen maintained its cash-flow outlook, but the downgrade highlights deeper pressure from China, restructuring costs and lower-margin electric vehicles.
Volkswagen AG (OTC:VWAGY) shares suffered their sharpest decline in months after the German automaker warned that Porsche's deteriorating outlook and additional restructuring costs would substantially reduce its 2026 profit.
Volkswagen's preferred shares fell as much as 7.5 per cent in Frankfurt on Friday before closing 5.6 per cent lower. Shares of Porsche AG declined 3.3 per cent, while Volkswagen's largest shareholder, Porsche Automobil Holding SE, lost 4.9 per cent.
#volkswagen #Margin #billion
Approximately €10 billion in special charges includes a €6 billion non-cash impairment connected with Porsche.
Volkswagen maintained its cash-flow outlook, but the downgrade highlights deeper pressure from China, restructuring costs and lower-margin electric vehicles.
Volkswagen AG (OTC:VWAGY) shares suffered their sharpest decline in months after the German automaker warned that Porsche's deteriorating outlook and additional restructuring costs would substantially reduce its 2026 profit.
Volkswagen's preferred shares fell as much as 7.5 per cent in Frankfurt on Friday before closing 5.6 per cent lower. Shares of Porsche AG declined 3.3 per cent, while Volkswagen's largest shareholder, Porsche Automobil Holding SE, lost 4.9 per cent.
#volkswagen #Margin #billion
4 days ago
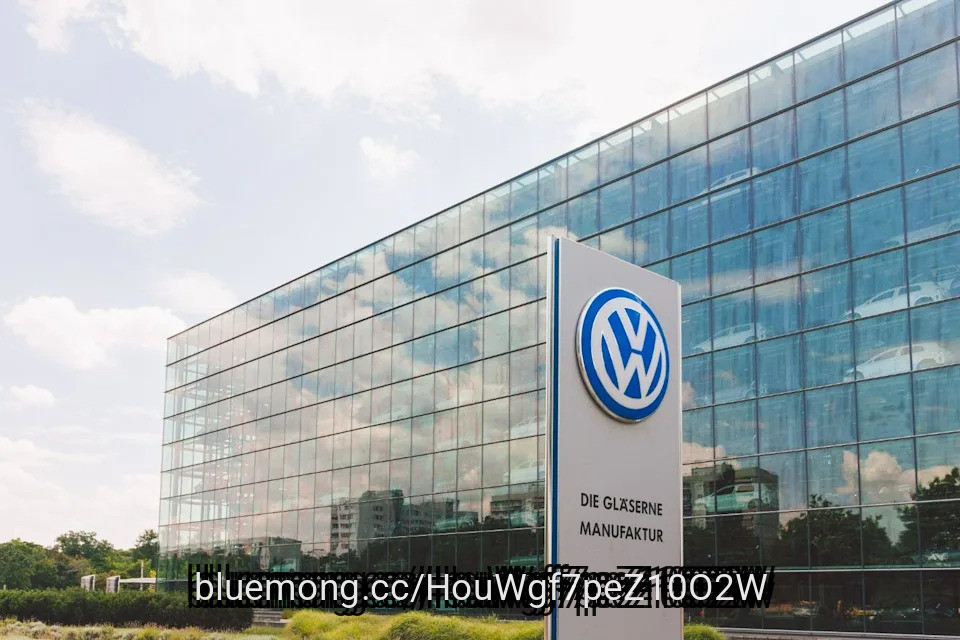
Volkswagen has dramatically cut its 2026 profit outlook as deteriorating business in China, restructuring costs and a multibillion-euro writedown at Porsche pile pressure on Europe's largest automaker.
The German carmaker now expects an operating margin of no more than 1% this year, down from its previous forecast of at least 4%, according to Bloomberg. Volkswagen shares fell more than 7% following the announcement, dragging other automakers lower.
VW expects around €10 billion ($11.5 billion) in charges this year, including restructuring costs ****** ociated with workforce reductions and writedowns on Chinese ****** ets. The total includes a €6-billion writedown related to Porsche, reflecting revised long-term expectations for the sports-car maker.
Excluding the exceptional charges, Volkswagen said its operating margin would be around 4%.
China represents one of the biggest challenges. Volkswagen CFO Arno Antlitz said the market has contracted by around 20%, with no stabilization currently in sight. Chinese automakers are simultaneously taking domestic market share and expanding into Europe with competitively priced electric vehicles.
#porsche
The German carmaker now expects an operating margin of no more than 1% this year, down from its previous forecast of at least 4%, according to Bloomberg. Volkswagen shares fell more than 7% following the announcement, dragging other automakers lower.
VW expects around €10 billion ($11.5 billion) in charges this year, including restructuring costs ****** ociated with workforce reductions and writedowns on Chinese ****** ets. The total includes a €6-billion writedown related to Porsche, reflecting revised long-term expectations for the sports-car maker.
Excluding the exceptional charges, Volkswagen said its operating margin would be around 4%.
China represents one of the biggest challenges. Volkswagen CFO Arno Antlitz said the market has contracted by around 20%, with no stabilization currently in sight. Chinese automakers are simultaneously taking domestic market share and expanding into Europe with competitively priced electric vehicles.
#porsche


4 days ago
On September 18, Prudential Financial (NYSE:PRU) announced it will sell every share it holds in Alexforbes, a company listed on the Johannesburg Stock Exchange. Two buyers are splitting the stake. Alexforbes will repurchase roughly 372.8 million shares itself, and ARC AF Holdings will take about 74.1 million more. The package is worth about $185 million, a small number for a company managing $1.642 trillion. But the message matters more than the money. A plan Prudential laid out in August is now turning into signed agreements.
The logic is easy to follow. Prudential wants to operate in fewer places and put its money, people and attention where it thinks it can win for years. Andy Sullivan, the chief executive, says the aim is to lean harder on ***** et management, retirement and protection, and get those units working together more closely. David Legher, who leads emerging markets, called Alexforbes a successful investment, so this reads as a planned exit rather than a retreat from a problem.
The core business is giving management room to be choosy. On August 4, Prudential reported second-quarter net income of $985 million, up from $533 million a year earlier. That happened even though a charge from the yearly ***** umption update grew to $299 million from $134 million, so the underlying engine ran strong enough to absorb a bigger hit. The company also returned $743 million to shareholders in the quarter and held $4.2 billion in highly liquid ***** ets at the parent level. That does not look like a seller in a hurry.
Start with what has not happened yet. The deals are expected to close in the first half of 2027, and they still need Alexforbes shareholders to approve the buyback, along with regulatory sign-off. Until then, $185 million is an agreed price, not cash in the bank. Prudential also said New Veld's involvement continues before completion, so the company stays tied to the ***** et for now.
Then there is the size. Set against those trillions in ***** ets, this sale will not move results either way. Its value is strategic, and strategy takes years to judge. Prudential is giving up a foothold in a partnership it called important, and its remaining businesses have their own snags. Sales in Prudential of ***** an are suspended, and management said that weighed on international results even as earnings held up.
#august #money
The logic is easy to follow. Prudential wants to operate in fewer places and put its money, people and attention where it thinks it can win for years. Andy Sullivan, the chief executive, says the aim is to lean harder on ***** et management, retirement and protection, and get those units working together more closely. David Legher, who leads emerging markets, called Alexforbes a successful investment, so this reads as a planned exit rather than a retreat from a problem.
The core business is giving management room to be choosy. On August 4, Prudential reported second-quarter net income of $985 million, up from $533 million a year earlier. That happened even though a charge from the yearly ***** umption update grew to $299 million from $134 million, so the underlying engine ran strong enough to absorb a bigger hit. The company also returned $743 million to shareholders in the quarter and held $4.2 billion in highly liquid ***** ets at the parent level. That does not look like a seller in a hurry.
Start with what has not happened yet. The deals are expected to close in the first half of 2027, and they still need Alexforbes shareholders to approve the buyback, along with regulatory sign-off. Until then, $185 million is an agreed price, not cash in the bank. Prudential also said New Veld's involvement continues before completion, so the company stays tied to the ***** et for now.
Then there is the size. Set against those trillions in ***** ets, this sale will not move results either way. Its value is strategic, and strategy takes years to judge. Prudential is giving up a foothold in a partnership it called important, and its remaining businesses have their own snags. Sales in Prudential of ***** an are suspended, and management said that weighed on international results even as earnings held up.
#august #money


4 days ago
Some offers on this page are from advertisers who pay us, which may affect which products we write about, but not our recommendations. See our Advertiser Disclosure.
Visa and Mastercard ATM cash withdrawals spanning roughly 19 years are part of a class-action lawsuit settlement totaling $167.5 million.
The case, known as Burke v. Visa Inc., involves independent ATMs often found in convenience stores, gas stations, grocery stores, hotels, and bars — non-bank locations that often levy surcharges on cash withdrawals.
Here's who is eligible for a cash payment as part of the settlement.
Read more: Just received a settlement? 5 smart ways to use the money.
#advertiser
Visa and Mastercard ATM cash withdrawals spanning roughly 19 years are part of a class-action lawsuit settlement totaling $167.5 million.
The case, known as Burke v. Visa Inc., involves independent ATMs often found in convenience stores, gas stations, grocery stores, hotels, and bars — non-bank locations that often levy surcharges on cash withdrawals.
Here's who is eligible for a cash payment as part of the settlement.
Read more: Just received a settlement? 5 smart ways to use the money.
#advertiser

5 days ago
Interested in Ally Financial Inc.? Here are five stocks we like better.
Ally Financial reaffirmed its full-year net interest margin guidance of 3.6% to 3.7%, supported by balance-sheet growth in higher-yielding retail auto and Corporate Finance loans. However, about $20 million in third-quarter lease losses tied to recalled Stellantis vehicles is expected to keep sequential margin growth roughly flat.
Stellantis-related lease pressure is expected to persist through 2026 but ease in 2027 as Ally's lease portfolio becomes more diversified and protected leases begin to mature. Ally also reaffirmed its 2026 retail auto net charge-off guidance of 1.8% to 2%.
Ally reported growth across its core businesses, including a 7% year-over-year increase in deposit customers and roughly 25% loan growth in Corporate Finance since launching Focus Forward. The company maintained guidance for 3% to 5% average earning-asset growth and approximately 1% operating-expense growth while continuing capital returns.
OneMain's Yield Comes With a Catch
#year #stellantis
Ally Financial reaffirmed its full-year net interest margin guidance of 3.6% to 3.7%, supported by balance-sheet growth in higher-yielding retail auto and Corporate Finance loans. However, about $20 million in third-quarter lease losses tied to recalled Stellantis vehicles is expected to keep sequential margin growth roughly flat.
Stellantis-related lease pressure is expected to persist through 2026 but ease in 2027 as Ally's lease portfolio becomes more diversified and protected leases begin to mature. Ally also reaffirmed its 2026 retail auto net charge-off guidance of 1.8% to 2%.
Ally reported growth across its core businesses, including a 7% year-over-year increase in deposit customers and roughly 25% loan growth in Corporate Finance since launching Focus Forward. The company maintained guidance for 3% to 5% average earning-asset growth and approximately 1% operating-expense growth while continuing capital returns.
OneMain's Yield Comes With a Catch
#year #stellantis


5 days ago
Saudi Arabia warned of a "hostile aerial threat" and issued a string of emergency alerts across the kingdom, including in its capital, late Friday and early Saturday.
Also Saturday, Iran's state TV reported that a man was executed after being convicted on charges of spying for Israel's intelligence agency Mossad.
Here is the latest news from the Middle East on Saturday. Full coverage is available here.
Saudi Arabia warned of a "hostile aerial threat" after issuing emergency alerts, and at least one explosion was heard in Riyadh.
The alert in Riyadh was the first for the Saudi capital since the latest escalation with Yemen's Iran-backed Houthi rebels.
#arabia #riyadh
Also Saturday, Iran's state TV reported that a man was executed after being convicted on charges of spying for Israel's intelligence agency Mossad.
Here is the latest news from the Middle East on Saturday. Full coverage is available here.
Saudi Arabia warned of a "hostile aerial threat" after issuing emergency alerts, and at least one explosion was heard in Riyadh.
The alert in Riyadh was the first for the Saudi capital since the latest escalation with Yemen's Iran-backed Houthi rebels.
#arabia #riyadh



5 days ago
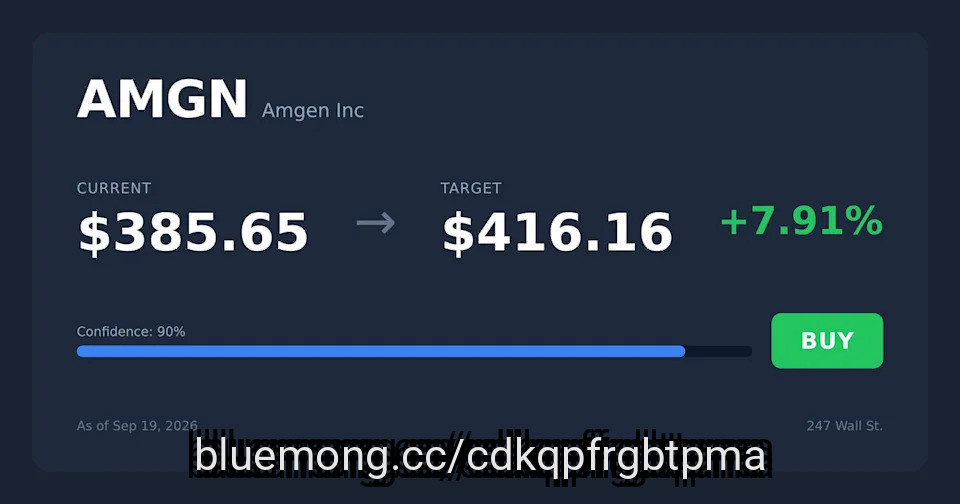
Amgen (AMGN) yields 2.6% with a $10.08 annualized payout, topping Merck (MRK) at 2.29%, and has raised its dividend 6% annually versus Merck's smaller step-ups.
Amgen's 17 billion-dollar products and $3.5B quarterly free cash flow dwarf Merck's reliance on a single Keytruda franchise facing peak penetration.
Merck absorbed a $5.7B acquisition charge that pushed Q2 earnings to a loss, while Amgen raised 2026 EPS guidance to as high as $23.50.
Just released. Our ***** ysts combed the entire stock market and named the ten best stocks to buy right now, and Merck didn't make the cut. Enter your email to see the names that beat MRK. The report is free. Enter your email and see if any of your stocks made the cut.
For a retirement portfolio that leans on pharma dividends, the choice between Amgen (NASDAQ:AMGN) and Merck (NYSE:MRK) comes down to one question: which check is more likely to keep getting bigger through the next wave of patent expirations? Both companies deliver quarterly income today. Only one has the coverage, the growth cadence, and the portfolio breadth to keep raising through the cliff.
#merck #amgen
Amgen's 17 billion-dollar products and $3.5B quarterly free cash flow dwarf Merck's reliance on a single Keytruda franchise facing peak penetration.
Merck absorbed a $5.7B acquisition charge that pushed Q2 earnings to a loss, while Amgen raised 2026 EPS guidance to as high as $23.50.
Just released. Our ***** ysts combed the entire stock market and named the ten best stocks to buy right now, and Merck didn't make the cut. Enter your email to see the names that beat MRK. The report is free. Enter your email and see if any of your stocks made the cut.
For a retirement portfolio that leans on pharma dividends, the choice between Amgen (NASDAQ:AMGN) and Merck (NYSE:MRK) comes down to one question: which check is more likely to keep getting bigger through the next wave of patent expirations? Both companies deliver quarterly income today. Only one has the coverage, the growth cadence, and the portfolio breadth to keep raising through the cliff.
#merck #amgen


5 days ago
The State Department's approval of two potential arms sales to Saudi Arabia totaling $5.75 billion, including JDAM-ER munitions and AGT-1500 tank engines, offers a modest but meaningful data point for two very different defense players. For The Boeing Company (NYSE:BA), the potential sale represents an additional international defense opportunity as the company continues working through margin pressure elsewhere. For Honeywell Aerospace Inc. (NASDAQ:HONA), the package reinforces a stable business line while the firm tackles its first quarter as a standalone public company.
The State Department approved a potential $5 billion sale of JDAM-ER guidance kits and bombs to Saudi Arabia, along with a separate potential $750 million deal for AGT-1500 tank engines. The JDAM package consists of 5,004 KMU-572 and 5,000 KMU-556 JDAM guidance kits and 5,004 BLU-111 and 5,000 BLU-117 bombs. Boeing has been identified as the principal contractor for the JDAM-ERs, with Honeywell handling the engines. The State Department said the sales would strengthen Saudi Arabia's airborne defense capabilities and improve interoperability with U.S. and Gulf partner forces.
Boeing stands to gain only modestly from the deal, given its roughly $85 billion Defense, ******* e and Security backlog. International orders already account for 27% of that total. The segment reported a second-quarter operating loss, largely due to charges tied to the VC-25B (Air Force One) program. That makes mature, lower-risk munitions programs such as JDAM-ER a more dependable part of the portfolio, though the deal is unlikely to have a meaningful impact on margins. For Honeywell Aerospace, the contract is smaller, but the AGT-1500 fits within its established defense propulsion business. It also adds to the company's international defence business, which makes up about 30% of its total Defense and ******* e revenue.
Honeywell Aerospace is owned by 74 hedge funds as of Q2 2026, which is consistent with Honeywell (NASDAQ:HON) hedge fund ownership prior to the spinoff. Unlike Honeywell, the number of hedge funds holding Boeing stock dropped from 99 at the end of the first quarter of fiscal 2026 to 90 at the end of Q2 2026.
Neither potential sale is large enough to have a meaningful impact on either company's short-term results by itself. Still, each supports a different investment story. For Boeing, the potential sales add to international defense exposure if finalized, as its defense unit continues dealing with fixed-price losses. For Honeywell, they support the steady flow of high-margin legacy revenue across its broader defense franchise.
#international #saudi
The State Department approved a potential $5 billion sale of JDAM-ER guidance kits and bombs to Saudi Arabia, along with a separate potential $750 million deal for AGT-1500 tank engines. The JDAM package consists of 5,004 KMU-572 and 5,000 KMU-556 JDAM guidance kits and 5,004 BLU-111 and 5,000 BLU-117 bombs. Boeing has been identified as the principal contractor for the JDAM-ERs, with Honeywell handling the engines. The State Department said the sales would strengthen Saudi Arabia's airborne defense capabilities and improve interoperability with U.S. and Gulf partner forces.
Boeing stands to gain only modestly from the deal, given its roughly $85 billion Defense, ******* e and Security backlog. International orders already account for 27% of that total. The segment reported a second-quarter operating loss, largely due to charges tied to the VC-25B (Air Force One) program. That makes mature, lower-risk munitions programs such as JDAM-ER a more dependable part of the portfolio, though the deal is unlikely to have a meaningful impact on margins. For Honeywell Aerospace, the contract is smaller, but the AGT-1500 fits within its established defense propulsion business. It also adds to the company's international defence business, which makes up about 30% of its total Defense and ******* e revenue.
Honeywell Aerospace is owned by 74 hedge funds as of Q2 2026, which is consistent with Honeywell (NASDAQ:HON) hedge fund ownership prior to the spinoff. Unlike Honeywell, the number of hedge funds holding Boeing stock dropped from 99 at the end of the first quarter of fiscal 2026 to 90 at the end of Q2 2026.
Neither potential sale is large enough to have a meaningful impact on either company's short-term results by itself. Still, each supports a different investment story. For Boeing, the potential sales add to international defense exposure if finalized, as its defense unit continues dealing with fixed-price losses. For Honeywell, they support the steady flow of high-margin legacy revenue across its broader defense franchise.
#international #saudi


5 days ago
On September 15, Jazz Pharmaceuticals plc (NASDAQ:JAZZ) completed its acquisition of privately held Actio Biosciences for $820 million upfront, adding a clinical-stage epilepsy drug called ABS-1230 to its rare disease pipeline. The deal lands weeks after Jazz posted its highest quarterly revenue ever on August 3, and raised its full-year guidance, so a fresh acquisition now sits on top of a business that was already accelerating. The question for investors is whether that combination adds up to durable growth or just a bigger bill.
ABS-1230 targets KCNT1-related epilepsy, a rare and hard-to-treat form of the disease. In an early clinical proof-of-concept trial, children who received the drug experienced meaningful seizure reductions, and preclinical testing showed it inhibited KCNT1 across every pathogenic mutation researchers evaluated, hinting it could work across the whole patient population rather than a narrow subset. The FDA has already granted ABS-1230 Orphan Drug, Rare Pediatric Disease and Fast Track designations, and accepted it into the agency's Rare Disease Evidence Principles process, a set of regulatory advantages that can speed a drug toward approval.
The acquisition also arrives while Jazz's existing business is firing on multiple cylinders. Second-quarter revenue climbed 16% year over year to $1.2 billion, the company's highest quarterly total on record, and management raised full-year 2026 revenue guidance to a range of $4.6 billion to $4.75 billion. Growth was not confined to one product. Xywav sales rose 13% to $471 million on 525 net new patients, Epidiolex grew 16% to $292 million, and Zepzelca jumped 42% to $106 million. Zanidatamab, sold as Ziihera in biliary tract cancer, also received Breakthrough Therapy designation from the FDA for a form of colorectal cancer, adding another avenue for the oncology franchise Jazz has been building beyond its epilepsy and sleep businesses.
None of that came free. The $820 million upfront payment for Actio lands on top of $4.4 billion in long-term debt that Jazz already carried as of June 30, even after the company used part of its cash to repay $1.0 billion of exchangeable notes that matured this year. Cash, equivalents and investments stood at $2.2 billion at that point, meaning the Actio payment alone accounts for a meaningful share of the company's liquid resources.
Jazz's recent history also shows how acquisitions can distort the bottom line before they pay off. A $905.4 million in-process research and development charge tied to the 2025 Chimerix acquisition pushed second-quarter 2025 GAAP earnings to a loss of $11.74 per share, and a smaller $77 million IPR&D charge from the AbCellera and Werewolf deals still dented second-quarter 2026 results. ABS-1230 itself remains early, with only proof-of-concept data in hand and no late-stage trial results yet. The portfolio is not without setbacks, either. Jazz is moving to voluntarily drop the second-line indication for Zepzelca in meta
ABS-1230 targets KCNT1-related epilepsy, a rare and hard-to-treat form of the disease. In an early clinical proof-of-concept trial, children who received the drug experienced meaningful seizure reductions, and preclinical testing showed it inhibited KCNT1 across every pathogenic mutation researchers evaluated, hinting it could work across the whole patient population rather than a narrow subset. The FDA has already granted ABS-1230 Orphan Drug, Rare Pediatric Disease and Fast Track designations, and accepted it into the agency's Rare Disease Evidence Principles process, a set of regulatory advantages that can speed a drug toward approval.
The acquisition also arrives while Jazz's existing business is firing on multiple cylinders. Second-quarter revenue climbed 16% year over year to $1.2 billion, the company's highest quarterly total on record, and management raised full-year 2026 revenue guidance to a range of $4.6 billion to $4.75 billion. Growth was not confined to one product. Xywav sales rose 13% to $471 million on 525 net new patients, Epidiolex grew 16% to $292 million, and Zepzelca jumped 42% to $106 million. Zanidatamab, sold as Ziihera in biliary tract cancer, also received Breakthrough Therapy designation from the FDA for a form of colorectal cancer, adding another avenue for the oncology franchise Jazz has been building beyond its epilepsy and sleep businesses.
None of that came free. The $820 million upfront payment for Actio lands on top of $4.4 billion in long-term debt that Jazz already carried as of June 30, even after the company used part of its cash to repay $1.0 billion of exchangeable notes that matured this year. Cash, equivalents and investments stood at $2.2 billion at that point, meaning the Actio payment alone accounts for a meaningful share of the company's liquid resources.
Jazz's recent history also shows how acquisitions can distort the bottom line before they pay off. A $905.4 million in-process research and development charge tied to the 2025 Chimerix acquisition pushed second-quarter 2025 GAAP earnings to a loss of $11.74 per share, and a smaller $77 million IPR&D charge from the AbCellera and Werewolf deals still dented second-quarter 2026 results. ABS-1230 itself remains early, with only proof-of-concept data in hand and no late-stage trial results yet. The portfolio is not without setbacks, either. Jazz is moving to voluntarily drop the second-line indication for Zepzelca in meta


5 days ago
Interested in Capital One Financial Corporation? Here are five stocks we like better.
Consumer credit remains resilient: Capital One reported strong spending, stable delinquencies and better-than-seasonal charge-offs, including among lower-income customers in its portfolio. Auto lending is also growing while the company maintains underwriting and margin standards.
Discover integration is progressing toward 2027 completion: New Discover card originations have moved to Capital One's platform, with the existing portfolio conversion expected to finish in January 2027 and broader integration substantially complete by mid-2027. Capital One has achieved about one-third of its targeted $1.5 billion in operating-expense synergies.
Capital One is expanding beyond lending: The company sees Brex as a strategic commercial-payments platform and plans to leverage its technology, marketing reach and small-business customer base. With a 13.7% common equity tier 1 ratio, management says it can fund investments while maintaining conservative capital and shareholder returns.
These 4 Earnings Reports Expose the Market's Growing Economic Divide
#company #integration #interested
Consumer credit remains resilient: Capital One reported strong spending, stable delinquencies and better-than-seasonal charge-offs, including among lower-income customers in its portfolio. Auto lending is also growing while the company maintains underwriting and margin standards.
Discover integration is progressing toward 2027 completion: New Discover card originations have moved to Capital One's platform, with the existing portfolio conversion expected to finish in January 2027 and broader integration substantially complete by mid-2027. Capital One has achieved about one-third of its targeted $1.5 billion in operating-expense synergies.
Capital One is expanding beyond lending: The company sees Brex as a strategic commercial-payments platform and plans to leverage its technology, marketing reach and small-business customer base. With a 13.7% common equity tier 1 ratio, management says it can fund investments while maintaining conservative capital and shareholder returns.
These 4 Earnings Reports Expose the Market's Growing Economic Divide
#company #integration #interested


5 days ago
Advanced Micro Devices (NASDAQ: AMD) stock rose 6.3% on Thursday, Sept. 17, 2026, after a neocloud operator said a price hike was coming for the use of chips across its stack, with AMD CPUs seeing a substantial **** p.
The S&P 500 and the Nasdaq Composite rose 1.1% and 1.7%, respectively, on Thursday.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Nebius, which rents out the use of chips from AMD and Nvidia, told customers it would soon charge a higher rate. Nebius said that Nvidia GPU prices would increase from 17% to 21%, while AMD's EPYC Genoa CPU rates will increase 25%, while supply constrained memory offerings would see a 41% **** p.
The announcement helps reassure investors that compute demand is still strong across AI, including demand for CPUs, which AMD has pushed in recent months. The company's stock was also rising amid a broader rally across the stock market.
#signal #thursday
The S&P 500 and the Nasdaq Composite rose 1.1% and 1.7%, respectively, on Thursday.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Nebius, which rents out the use of chips from AMD and Nvidia, told customers it would soon charge a higher rate. Nebius said that Nvidia GPU prices would increase from 17% to 21%, while AMD's EPYC Genoa CPU rates will increase 25%, while supply constrained memory offerings would see a 41% **** p.
The announcement helps reassure investors that compute demand is still strong across AI, including demand for CPUs, which AMD has pushed in recent months. The company's stock was also rising amid a broader rally across the stock market.
#signal #thursday

5 days ago
Medicare's two-year income lookback makes age 63 the last year a Roth conversion won't directly raise your Medicare premiums at 65.
Married couples can convert roughly $133,000 annually within the 22% bracket, but crossing the $218,000 IRMAA threshold triggers surcharges for both spouses.
Delaying Social Security to 70 preserves low-income years for conversions, since every dollar of benefits claimed adds an invisible marginal rate on top of conversion income.
Read More: Learn 7 secret wealth tips high net worth investors use that most investors miss (sponsor)
A 63-year-old with $1.4 million in a traditional 401(k) has a narrower Roth conversion window than the calendar suggests. Medicare enrollment at 65 uses a two-year lookback on modified adjusted gross income, which means the conversion executed at 63 is the one that sets Medicare premiums at 65. The real deadline arrives earlier than most people expect.
#income #roth #lookback
Married couples can convert roughly $133,000 annually within the 22% bracket, but crossing the $218,000 IRMAA threshold triggers surcharges for both spouses.
Delaying Social Security to 70 preserves low-income years for conversions, since every dollar of benefits claimed adds an invisible marginal rate on top of conversion income.
Read More: Learn 7 secret wealth tips high net worth investors use that most investors miss (sponsor)
A 63-year-old with $1.4 million in a traditional 401(k) has a narrower Roth conversion window than the calendar suggests. Medicare enrollment at 65 uses a two-year lookback on modified adjusted gross income, which means the conversion executed at 63 is the one that sets Medicare premiums at 65. The real deadline arrives earlier than most people expect.
#income #roth #lookback


5 days ago
Hub Group, Inc. (NASDAQ:HUBG) disclosed on September 14 that preliminary, unaudited first-half 2026 revenue was expected to reach $1.7 billion to $1.8 billion, near management's expectations. Yet management anticipated an operating loss before one-time charges. This non-GAAP presentation excludes those charges, but neither the loss nor the exclusions were quantified.
Hub Group, Inc. (NASDAQ:HUBG) identified higher fuel, rail, and drayage costs, excess warehouse capacity, and accounting-review and restatement expenses. The central issue is whether pricing and efficiency improvements can restore profitability on the revenue already moving through the business.
Hub Group, Inc. (NASDAQ:HUBG) began implementing rate increases in the third quarter, after transportation costs had pressured first-half results. Relatively stable intermodal volume trends suggest an existing customer base on which better pricing could improve margins. If increases hold without significant volume losses, revenue could become more profitable without requiring a broad freight recovery.
Hub Group, Inc. (NASDAQ:HUBG) also launched additional efficiency initiatives in the second quarter, including warehouse consolidation and improvements in driver and warehouse-worker productivity. These actions address specific weaknesses: underused ***** e spreads fixed costs across fewer orders, while low productivity raises the cost of each shipment or handling task. Better utilization could reinforce the benefit of higher rates.
Hub Group, Inc. (NASDAQ:HUBG) is also targeting order-to-cash processes, which cover the steps from taking orders through billing and collection. Improvements could reduce administrative friction and accelerate cash collection. That would support liquidity while operational changes take effect, although faster collections alone would not repair an operating loss.
#improvements #better
Hub Group, Inc. (NASDAQ:HUBG) identified higher fuel, rail, and drayage costs, excess warehouse capacity, and accounting-review and restatement expenses. The central issue is whether pricing and efficiency improvements can restore profitability on the revenue already moving through the business.
Hub Group, Inc. (NASDAQ:HUBG) began implementing rate increases in the third quarter, after transportation costs had pressured first-half results. Relatively stable intermodal volume trends suggest an existing customer base on which better pricing could improve margins. If increases hold without significant volume losses, revenue could become more profitable without requiring a broad freight recovery.
Hub Group, Inc. (NASDAQ:HUBG) also launched additional efficiency initiatives in the second quarter, including warehouse consolidation and improvements in driver and warehouse-worker productivity. These actions address specific weaknesses: underused ***** e spreads fixed costs across fewer orders, while low productivity raises the cost of each shipment or handling task. Better utilization could reinforce the benefit of higher rates.
Hub Group, Inc. (NASDAQ:HUBG) is also targeting order-to-cash processes, which cover the steps from taking orders through billing and collection. Improvements could reduce administrative friction and accelerate cash collection. That would support liquidity while operational changes take effect, although faster collections alone would not repair an operating loss.
#improvements #better

5 days ago
Become a CEO after your MBA: that's the promise some private equity firms are using to recruit top operating talent.
This promise propels the best and brightest into top executive roles without requiring them to climb the corporate ladder, underpinned by the belief that cultivating talent is a better bet than making semi-blind bets on external hires.
Alpine Investors and Shore Capital Partners have each built separate pipelines to funnel operational talent, aiming to equip executives to take charge of their portfolio companies.
Lower-middle-market buyout firm Shore Capital Partners runs what it calls its CXO program, a two-year training scheme that places early- to mid-career talent and recent MBA grads into C-suite-adjacent roles at its portfolio companies—typically chief of staff or vice president of business operations or strategic initiatives.
Top-performing CXO graduates then have the chance to be promoted to C-level positions. So far, Shore has produced four CEOs from the CXO program. This includes Mark Larsen, who has been CEO of medical software business Connexure since 2024.
#Companies
This promise propels the best and brightest into top executive roles without requiring them to climb the corporate ladder, underpinned by the belief that cultivating talent is a better bet than making semi-blind bets on external hires.
Alpine Investors and Shore Capital Partners have each built separate pipelines to funnel operational talent, aiming to equip executives to take charge of their portfolio companies.
Lower-middle-market buyout firm Shore Capital Partners runs what it calls its CXO program, a two-year training scheme that places early- to mid-career talent and recent MBA grads into C-suite-adjacent roles at its portfolio companies—typically chief of staff or vice president of business operations or strategic initiatives.
Top-performing CXO graduates then have the chance to be promoted to C-level positions. So far, Shore has produced four CEOs from the CXO program. This includes Mark Larsen, who has been CEO of medical software business Connexure since 2024.
#Companies


5 days ago
DANA POINT, California – Natalie Driessen drove down Beach Road on a mission, past neighbors whose houses fell into the sea and others now scrambling to prevent their property from collapsing next.
She had a video from March that she wanted everyone to see. When she spotted an Orange County supervisor outside what was left of one mangled kitchen and living room, Driessen pulled out her phone to play the clip of the California Coastal Commission — the powerful state agency tasked with preserving beaches — discussing a home in her gated community.
California beaches are considered public beyond a certain high tide line, the commissioners warned, and that waterline was rising. “I wonder,” one of the commissioners said, “how many years before I’m allowed to just pull up a chair — sit in their, you know, front deck porch and watch TV because it’s public land. … I don’t think we’re that far away from this, right?”
Storms and high tides — fueled by a near record-breaking El Niño — have battered the California coast in recent weeks, destroying homes and eroding beaches. The fallout has supercharged years-long tensions between the owners of coveted oceanfront property and the authorities they say aren’t doing enough to protect them.
The damage has intensified a bigger debate playing out around the coast: What can or should be done to save private property in the most vulnerable communities?
#years
She had a video from March that she wanted everyone to see. When she spotted an Orange County supervisor outside what was left of one mangled kitchen and living room, Driessen pulled out her phone to play the clip of the California Coastal Commission — the powerful state agency tasked with preserving beaches — discussing a home in her gated community.
California beaches are considered public beyond a certain high tide line, the commissioners warned, and that waterline was rising. “I wonder,” one of the commissioners said, “how many years before I’m allowed to just pull up a chair — sit in their, you know, front deck porch and watch TV because it’s public land. … I don’t think we’re that far away from this, right?”
Storms and high tides — fueled by a near record-breaking El Niño — have battered the California coast in recent weeks, destroying homes and eroding beaches. The fallout has supercharged years-long tensions between the owners of coveted oceanfront property and the authorities they say aren’t doing enough to protect them.
The damage has intensified a bigger debate playing out around the coast: What can or should be done to save private property in the most vulnerable communities?
#years

5 days ago
Some offers on this page are from advertisers who pay us, which may affect which products we write about, but not our recommendations. See our Advertiser Disclosure.
Visa and Mastercard ATM cash withdrawals spanning roughly 19 years are part of a class-action lawsuit settlement totaling $167.5 million.
The case, known as Burke v. Visa Inc., involves independent ATMs often found in convenience stores, gas stations, grocery stores, hotels, and bars — non-bank locations that often levy surcharges on cash withdrawals.
Here's who is eligible for a cash payment as part of the settlement.
Read more: Just received a settlement? 5 smart ways to use the money.
#Visa #part #stores #mastercard
Visa and Mastercard ATM cash withdrawals spanning roughly 19 years are part of a class-action lawsuit settlement totaling $167.5 million.
The case, known as Burke v. Visa Inc., involves independent ATMs often found in convenience stores, gas stations, grocery stores, hotels, and bars — non-bank locations that often levy surcharges on cash withdrawals.
Here's who is eligible for a cash payment as part of the settlement.
Read more: Just received a settlement? 5 smart ways to use the money.
#Visa #part #stores #mastercard


5 days ago
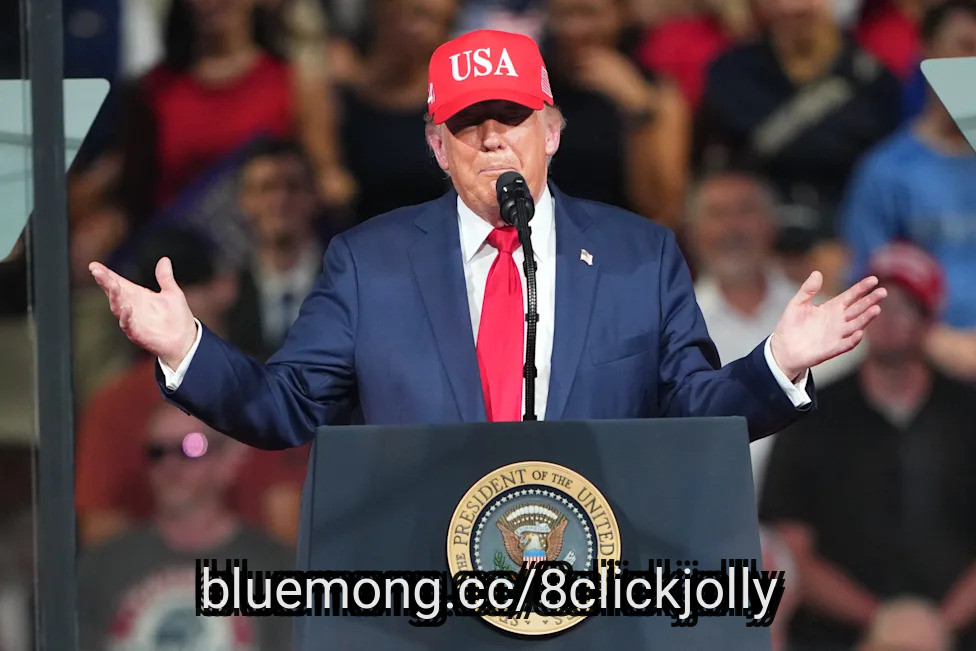
As President Donald Trump tries to convince voters that Democrats have let crime run amok, he's digging into the country's political past to cite one of the most controversial campaign advertisements that relied heavily on racist tropes.
During a campaign stop Wednesday in Gastonia, North Carolina, to stump for Republican U.S. Senate candidate Michael Whatley, Trump resurrected a 1988 George H.W. Bush presidential campaign ad featuring Willie Horton, a Black man convicted of rape and ****** ault after his release through a Massachusetts prison furlough program.
A grainy black-and-white prison photo of Horton was used in the ad targeting then-Massachusetts Gov. Michael Dukakis, who was ahead of Bush in the polls. On Wednesday, Trump evoked the Horton ad in an effort to convince voters Democratic former Gov. Roy Cooper, Whatley's opponent in the Senate race, is soft on crime.
"Willie Horton was a bad guy, really bad guy," Trump said, before comparing Dukakis's release of Horton to the pretrial release of a Black man who faces a murder charge for last year's killing of a white Ukrainian refugee in Charlotte, North Carolina.
But Cooper was not the governor when the man was released or when he was later charged with killing the refugee.
#black
During a campaign stop Wednesday in Gastonia, North Carolina, to stump for Republican U.S. Senate candidate Michael Whatley, Trump resurrected a 1988 George H.W. Bush presidential campaign ad featuring Willie Horton, a Black man convicted of rape and ****** ault after his release through a Massachusetts prison furlough program.
A grainy black-and-white prison photo of Horton was used in the ad targeting then-Massachusetts Gov. Michael Dukakis, who was ahead of Bush in the polls. On Wednesday, Trump evoked the Horton ad in an effort to convince voters Democratic former Gov. Roy Cooper, Whatley's opponent in the Senate race, is soft on crime.
"Willie Horton was a bad guy, really bad guy," Trump said, before comparing Dukakis's release of Horton to the pretrial release of a Black man who faces a murder charge for last year's killing of a white Ukrainian refugee in Charlotte, North Carolina.
But Cooper was not the governor when the man was released or when he was later charged with killing the refugee.
#black


5 days ago
A woman from a low-income family in China crossed over into Hong Kong to get to a concert she had spent months saving up for.
It was a trip that Beijing’s vast surveillance apparatus didn’t miss. Now her family face the prospect of losing their government benefits for splurging on “high-end consumption.”
The incident has sparked massive debate across Chinese social media over whether those receiving benefits are also entitled to small luxuries. It’s also a reminder of the staggering extent of the Chinese government’s surveillance system, one turbocharged by advances in AI and the embrace of digital payments.
The story first surfaced in a post on popular site Red Note in early September by a user who said they were the young woman’s cousin.
The woman, surnamed Huang, had “worked hard doing manual labor and saved up from the subsidies” to pay for the concert ticket and expenses of traveling to Hong Kong, around 235 miles (380 kilometers) from her home in Jiangxi province, the post said.
#hong #family #government #benefits
It was a trip that Beijing’s vast surveillance apparatus didn’t miss. Now her family face the prospect of losing their government benefits for splurging on “high-end consumption.”
The incident has sparked massive debate across Chinese social media over whether those receiving benefits are also entitled to small luxuries. It’s also a reminder of the staggering extent of the Chinese government’s surveillance system, one turbocharged by advances in AI and the embrace of digital payments.
The story first surfaced in a post on popular site Red Note in early September by a user who said they were the young woman’s cousin.
The woman, surnamed Huang, had “worked hard doing manual labor and saved up from the subsidies” to pay for the concert ticket and expenses of traveling to Hong Kong, around 235 miles (380 kilometers) from her home in Jiangxi province, the post said.
#hong #family #government #benefits