16 hours ago
For an average single person planning to stop working at 64, a $1.2 million 401(k) account and $2,800 Social Security benefit could provide enough income to make ends meet during retirement. Widely used guidelines suggest your annual income may be around $81,600, which may or may not be more than your annual expenses. Much depends on individual circumstances, including the kind of retirement lifestyle you desire, your location and future trends of inflation, taxes and investment returns. To get a comprehensive workup of your retirement budget, take the question to a financial advisor.
Income and expenses represent the two sides of your retirement budget. Both are equally important and decisions you make regarding either can affect the overall accuracy and dependability of the budget.
You can estimate expenses by using averages for typical retirees or by considering specifics of your situation with estimate for categories such as housing, healthcare and taxes. Similarly, you can estimate future income with general guidelines or by accounting for specifics such as your personal investment preferences.
In your case, we'll start with income since we have information about that. Despite the possibility that Social Security benefits will be cut by about 20% after 2035, your $2,800 Social Security benefit can probably be relied upon. And benefits are indexed to a cost-of-living benchmark, providing protection against inflation.
Note, however, that if you wait to claim benefits, your monthly amount will increase every year until you are 70. By claiming at age 64 rather than waiting until your full retirement age of 67, you are receiving 20% less. If you wait until age 70, you'll get 24% more than at 67. And you'll receive the higher amount, adjusted annually for cost of living, as long as you live.
#Retirement #benefits

1 day ago
A Medicaid divorce lets the at-home spouse keep the house and up to $162,660 while Medicaid covers the nursing home's $9,277 monthly bill.
The strategy requires a real court-ordered divorce, since Medicaid's five-year look-back treats uneven transfers as gifts and penalizes them.
Before filing, families should exhaust spousal refusal, Medicaid-compliant annuities, and exempt-asset conversions, since a divorce strips survivor benefits and medical decision rights.
Just released. Our ***** ysts combed the entire stock market and named the ten best stocks to buy right now. The report is free. Enter your email and see if any of your stocks made the cut.
A Medicaid divorce, involves a long-married couple legally ending their marriage as part of a long-term care strategy. He enters a nursing home that Medicaid may cover, while she keeps the house and a larger share of their savings to protect her retirement. It's a real but uncommon strategy. State laws may vary, and many attorneys consider it a last resort.
#medicaid #real #since #stocks
1 day ago
Michael Dell, philanthropist and founder of Dell Technologies, pushed back against critics who argue that allowing wealthy investors to donate individual company stocks to Trump Accounts could have a nefarious impact.
Under new rules that took effect last week, charities can put individual stocks into kids' accounts as a donation. Trump Accounts are tax-advantaged investment vehicles that can be used for education expenses, starting a business, or saving for retirement. They were authorized in last year's One Big Beautiful Tax bill. Previously, the money was required to be invested in low-cost index funds.
Read more: Trump Accounts expand to stock donations. What are the benefits and risks?
So far, ***** eX President Gwynne Shotwell is the only donor to announce a major stock contribution, pledging more than 2 million shares to benefit lower-income children ages 11 to 17 living in lower-income areas.
"It's kind of hard for me to believe that's a bad thing, right?" Dell said Wednesday in an interview with Yahoo Finance. "That these children are going to somehow be negatively influenced because they now have one share of ***** eX, but they didn't have before, right? The alternative is they didn't have it, right?"
#last #lower

1 day ago
Michael Dell, philanthropist and founder of Dell Technologies, pushed back against critics who argue that allowing wealthy investors to donate individual company stocks to Trump Accounts could have a nefarious impact.
Under new rules that took effect last week, charities can put individual stocks into kids' accounts as a donation. Trump Accounts are tax-advantaged investment vehicles that can be used for education expenses, starting a business, or saving for retirement. They were authorized in last year's One Big Beautiful Tax bill. Previously, the money was required to be invested in low-cost index funds.
Read more: Trump Accounts expand to stock donations. What are the benefits and risks?
So far, **** eX President Gwynne Shotwell is the only donor to announce a major stock contribution, pledging more than 2 million shares to benefit lower-income children ages 11 to 17 living in lower-income areas.
"It's kind of hard for me to believe that's a bad thing, right?" Dell said Wednesday in an interview with Yahoo Finance. "That these children are going to somehow be negatively influenced because they now have one share of **** eX, but they didn't have before, right? The alternative is they didn't have it, right?"
#accounts

2 days ago
Moneywise and Yahoo Finance LLC may earn commission or revenue through links in the content below.
The annual Social Security cost-of-living adjustment (COLA) can make or break the finances of retirees, as it determines how much benefits will increase to keep pace with inflation.
Since COLAs are very important to beneficiaries, advocacy groups make predictions throughout the year, offering insight into how much extra money (if any) Social Security recipients will collect in the coming year.
Jeff Bezos backs a platform that lets anyone invest in rental homes for as little as $100 — 6 ways to build wealth like a landlord without actually being one
A single line on your car insurance policy could be inflating your premium by up to 30% — here's what to change
#make #moneywise #since

2 days ago
When a farm sells for a lump sum, IRS rules split proceeds across five ******* et types, and only market cattle profits count as Social Security self-employment earnings.
In a hypothetical sale generating $500,000 in gains, only $100,000 from market cattle counts toward Social Security's earnings test, while land and equipment gains register $0.
Land gains escape the Social Security earnings test but still raise adjusted gross income, potentially making up to 85% of benefits taxable.
Read More: Learn 7 ways to generate income with a $1,000,000+ portfolio (sponsor)
Freeman Family Ranches covered 87,953 acres across the North Texas and Oklahoma panhandles. The three properties, in the family for four generations, sold in late July after being listed at nearly $128 million.
#Social #gains #family #market
2 days ago
Social Security acts as a financial safety net for many retirees, but it's not enough for most. These government checks were never designed to cover all living expenses. Social Security is a supplemental income source that can keep up with expenses if you combine it with savings.
That's why many people are encouraged to save up before retirement, and the math proves it. Your life in retirement will be very different if you just live on Social Security compared to having $500,000 in savings alongside your government checks. Let's break it all down below.
The average monthly Social Security benefit for retired workers as of mid-2026 was $2,085.98, according to the Social Security Administration (SSA). At that rate, you will not pay any taxes on Social Security, ******* uming you do not have any other income sources. You won't even have to worry about state income taxes.
However, that's where the advantages end if you rely exclusively on Social Security. Per Apartment List data, the national median rent was $1,390 in August. That median rent leaves you with less than $700 for groceries, transportation, healthcare, utilities, insurance, debt and miscellaneous purchases.
For most people, the average Social Security is not enough. High-earners can max out their benefits at $5,181 per month if they earned a high salary for most or all of their 35 highest-earning years and wait until 70 to tap into Social Security, per the SSA. That monthly amount offers more room for financial flexibility, but the average is insufficient for most people unless their spouse earns a similar check or they live very frugally.
#income #financial

2 days ago
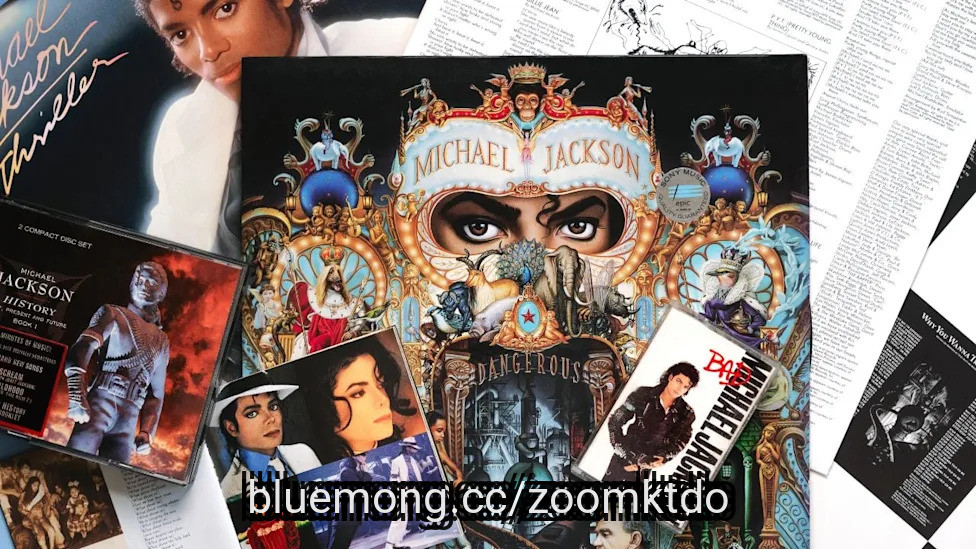
Michael Jackson's estate reported about $20 million in benefits for his three children and his mother during 2024, according to an annual accounting obtained by TMZ.
The filing, submitted by executor John Branca, details spending for Prince Jackson, Paris Jackson, Bigi Jackson and Katherine Jackson, including bills paid on their behalf.
Prince's approximately $4.9 million tax bill accounted for most of his reported benefits.
Katherine's entries included $145 at Cordie Cakes, $242 for balloons and $400 for cleaning services.
Prince had the largest reported benefits total at approximately $6.4 million. Payments connected to a Chevron gas card were also listed among his expenses.
#million #prince #approximately
2 days ago
EPR Properties (NYSE: EPR) is a company focused on properties designed for experiential and educational purposes. One of the benefits of owning its stock has been its dividend, which has increased for four consecutive years.
EPR is a real estate investment trust (REIT), which means it must pay out at least 90% of its taxable net income as dividends to retain that status. That makes it highly likely that payouts will continue. As the dividend has become more generous, it might surprise investors how little it takes to generate more than $1,000 in annual dividends in this stock.
Missed AI's "Act 1"? Act 2 Could Be 14x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our **** ysts, we're only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
Working with whole shares, 269 shares purchased for $15,182 will generate $1,001 in annual dividends.
This amounts to an annual dividend of $3.72 per share with a yield of about 6.6%. That is far above the S&P 500 average of 1.1%. Moreover, it is one of the few stocks paying monthly dividends, which might make it especially appealing to income investors.
#Dividend #annual #missed
3 days ago
SmartAsset and Yahoo Finance LLC may earn commission or revenue through links in the content below.
During most of the decades you are preparing financially for retirement, you are likely focused on saving as close as you can get to the recommended amount, without worrying too much about the details. As you approach retirement, however, it's a good idea to look more closely at what might be a realistic retirement budget. At age 62, with $890,000 in a 401(k) account, $115,000 in a Roth IRA and accounting for Social Security benefits, you can likely generate enough income to cover typical retiree lifestyle expenses. Your individual needs may vary, of course, but there are likely moves you can make now and in retirement to give you the flexibility you'll need to fund a comfortable and secure retirement.
Consider speaking with a financial advisor for help building an effective retirement strategy.
A typical retirement budget starts with the income side and Social Security benefits represent an important part of that for a large majority of retirees. Social Security is lifelong, guaranteed by the U.S. government and includes annual cost-of-living adjustments to keep up with inflation. The amount of your specific benefit is controlled by your work history and age at claiming. ****** uming your current income is $90,000 annually, here are estimates of your annual Social Security benefit based on your age when you start claiming benefits:
Age
#annual
3 days ago
Some offers on this page are from advertisers who pay us, which may affect which products we write about, but not our recommendations. See our Advertiser Disclosure.
Social Security is the retirement income lifeline for millions of Americans and garners its share of confusing headlines. From the full retirement age and cost-of-living adjustment to the rules for claiming benefits while still working, here is what's expected to change in 2027.
A common concern among those planning for retirement is an ever-increasing Social Security "full retirement age."
Geoffrey Schmidt, a certified public accountant and founder of Holy Schmidt!, a retirement education resource, told Yahoo Finance that many seniors ****** ume the full retirement age keeps climbing.
"It doesn't. It has finished its long, slow climb to 67. Anyone born in 1960 or later has a full retirement age of exactly 67, and that group reaches it in 2027," Schmidt said. "Under current law, it does not go any higher. So if you've been worried they'll keep moving the goalposts on you, at least on the retirement age, that increase is over."
#Retirement #schmidt #Social #holy


3 days ago
In late September 2026, Huntington Ingalls Industries' Newport News Shipbuilding division secured a US$5.10 billion contract to conduct the refueling and complex overhaul of USS Harry S. Truman (CVN 75), while also advancing carrier programs and expanding unmanned production capacity across its U.S. facilities.
Together with the Navy order for 10 ROMULUS unmanned surface vessels and the Pocasset unmanned systems campus expansion, these developments highlight how HII is tying long-duration carrier work to growing autonomous maritime capabilities within its Mission Technologies division.
We'll now examine how the Truman overhaul award, alongside new ROMULUS unmanned vessel production, could influence Huntington Ingalls Industries' investment narrative.
Rare earth metals are an input to most high-tech devices, military and defence systems and electric vehicles. The global race is on to secure supply of these critical minerals. Beat the pack to uncover the 33 best rare earth metal stocks of the very few that mine this essential strategic resource.
To own Huntington Ingalls Industries, you need to believe that its multi decade carrier, submarine and unmanned systems backlog can be converted into steadier margins and free cash flow despite current back end loaded cash expectations. The Truman refueling and complex overhaul award reinforces that backlog, but does not remove the near term risk that 2026 free cash flow could miss if contract advances or tax benefits arrive later or smaller than management hopes.
#unmanned #truman #romulus


3 days ago
The size of your Social Security check changes the nest egg you need more than any differences between states.
Under the 4% rule, each additional $100 a month in benefits cuts the savings a single retiree needs by about $30,000, regardless of state.
A maximum earner who delays to 70 can cover the average comfortable budget on Social Security alone, with essentially nothing saved—but very few qualify for the maximum benefit.
For a single retiree, your monthly Social Security benefit shapes the savings you need more than your address does—there's no second check to fall back on.
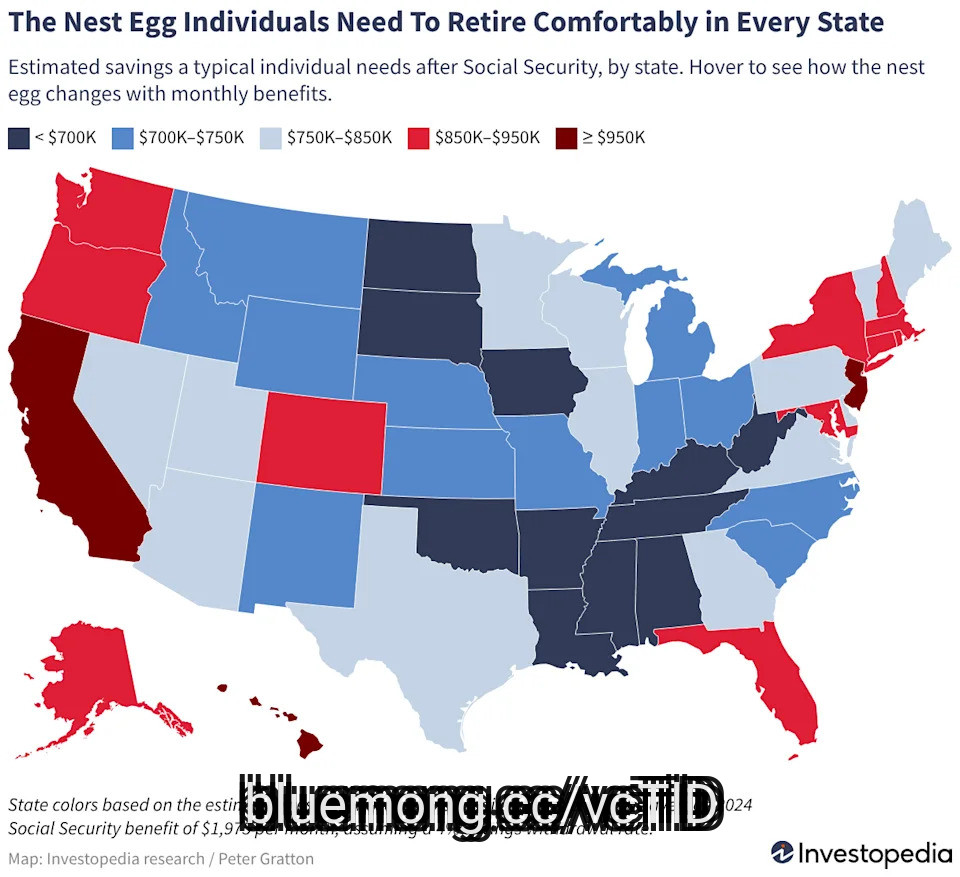
But regional costs of living matter, too. An Investopedia ******* ysis of federal cost and benefit data found that the savings a typical single American age 65 or older needs for a comfortable retirement is about $898,000. The least expensive state, North Dakota, runs about $644,000, while the priciest, New Jersey, costs about $1.02 million—a spread of about $375,000.
#security #check #retiree

3 days ago
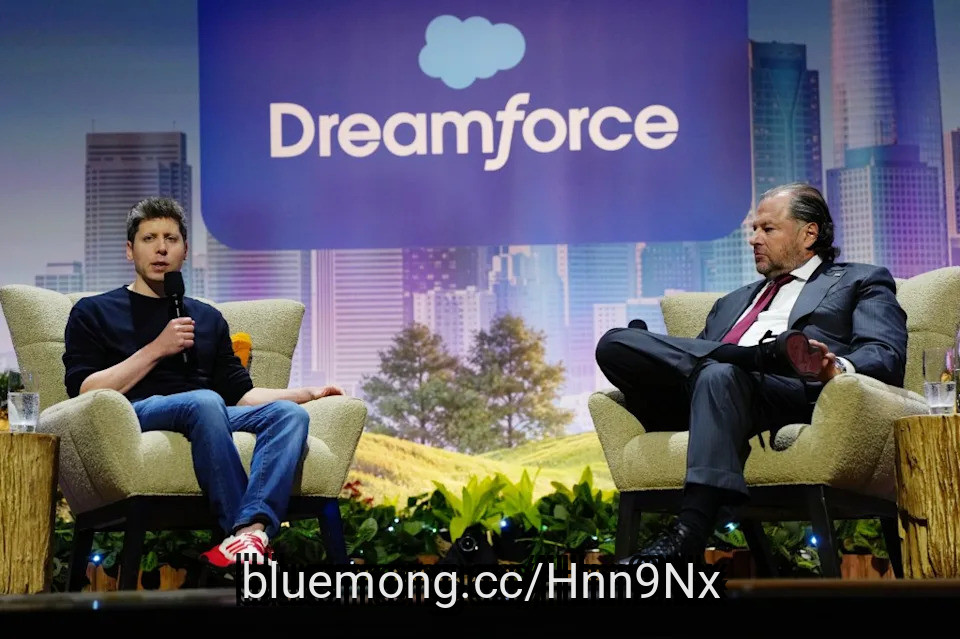
OpenAI CEO Sam Altman admits "something's clearly not working" with the artificial intelligence money that has flooded the midterm elections — and he doesn't expect President Donald Trump's rebrand of the technology to improve his industry's image with the American public, either.
"I get why AI has a really negative perception right now," Altman told Brendan Bordelon in an exclusive interview marking the launch of Decoded by POLITICO. "I don't think spending money on politics is what's going to make people feel better about it. The industry needs to figure out a way to address what the actual concerns are, and right now, a lot of people in the industry are being quite tone deaf."
In the wide-ranging conversation, Altman offered a window into how OpenAI is confronting new political pressures and intensified competition with Anthropic, its corporate archrival run by former employee Dario Amodei.
Altman says OpenAI is more tolerant than Anthropic of less-than-catastrophic harms from AI, drawing out what he sees as a fundamental split in worldview between the two leading labs even as they converge on tougher rules in the wake of high-profile autonomous hacking incidents.
"We believe that the world should accept some bad things happening for the benefits of this technology and people having the agency," said Altman, who characterized those harms as linked to "the lighter touch regulatory stance that we advocate for."
#openai #money #president
4 days ago
The OpenAI CEO sought to distinguish his policy stance from rival developer Anthropic.
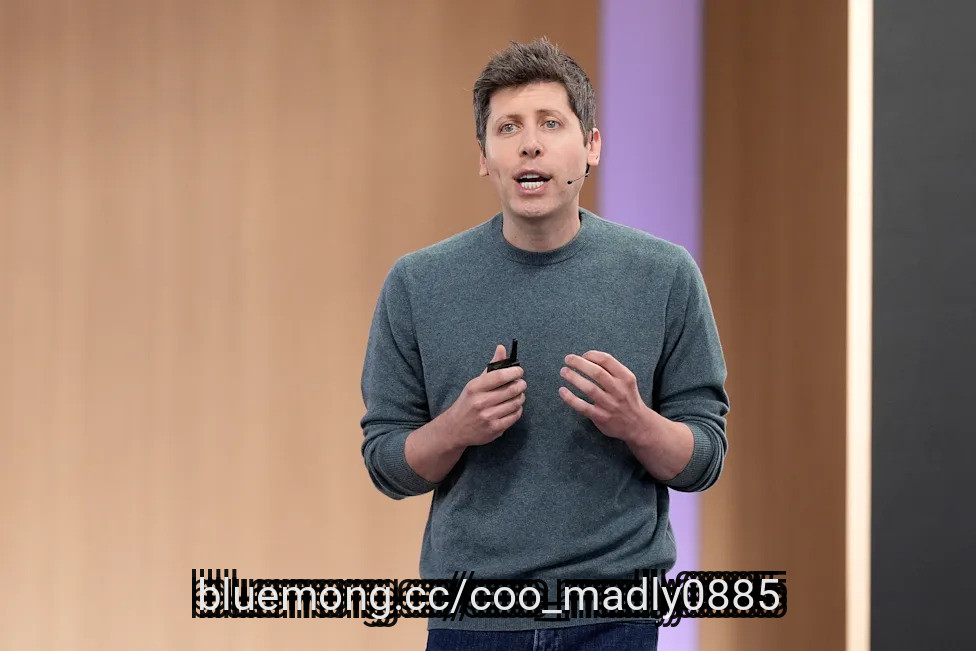
OpenAI CEO Sam Altman argued in an exclusive interview with Decoded by POLITICO that AI’s benefits justify accepting some risks. | Heather Diehl/Getty Images
10/05/2026 05:55 AM GMT+9
OpenAI CEO Sam Altman said there remains a fundamental difference in worldview between his company and rival Anthropic on artificial intelligence regulation, arguing in an exclusive interview with Decoded by POLITICO that the technology’s benefits justify accepting some risks — and that AI should remain broadly accessible to the public.
#anthropic #decoded #benefits #justify
18 days ago
On August 6, Aflac (NYSE:AFL) reported second-quarter numbers that point in opposite directions. Net earnings climbed to $825 million, helped along by investment losses that shrank to $153 million from $421 million a year ago. Adjusted earnings, though, fell 7.7% to $883 million. Both numbers are real, but they answer different questions. Which measure you trust changes the story, so here is what sits underneath.
Start with the yen, because it is muddying the picture. The average rate was 159.45 to the dollar, 9.3% weaker than a year earlier, and that cost adjusted earnings $0.05 a share. Take the currency out of the first half and adjusted earnings per share rose 4.1% to $3.57. ******* an is also running more profitably. Its pretax adjusted margin widened to 34.3% from 32.0% as claims took a smaller bite out of premiums, and yen-based pretax adjusted earnings rose 3.4%. So part of the decline in ******* an's dollar-reported profit is currency, not operations.
The US business is still growing at the top line. Net earned premiums rose 2.3% to $1.5 billion, and sales climbed 2.6% to $349 million, led by group voluntary benefits along with dental and vision plans. In ******* an, the refreshed Tsumitasu life policy and the new Anshin Palette medical product grew strongly in the quarter, and first-half sales rose 7.0% to ¥37.3 billion. Then there is the cash. Aflac returned $1.3 billion to shareholders in the quarter, $983 million of it through buybacks, and declared a $0.61 third-quarter dividend, payable September 1 to holders of record on August 19, 2026. Management notes 43 straight years of dividend increases through 2025 and says the board is on a path to extend that in 2026.
The catch is that ******* an's profit gains came from lower claims, not a bigger business. Net earned premiums in yen fell 3.7%, mainly because of a new external reinsurance deal and older limited-pay policies reaching paid-up status. Premium persistency, the share of policies customers keep, slipped to 92.7% from 93.7%. ******* an's pretax adjusted earnings still fell 2.1% once currency is stripped out, and new sales dipped 5.6% in the quarter against a tough comparison for the Miraito cancer product, which launched in March 2025.
The US segment has its own soft spot. Pretax adjusted earnings fell 4.6% to $370 million, and the margin narrowed to 20.9% from 22.5% as claims and benefits took a bigger share of premiums. Corporate and Other swung to a $10 million pretax adjusted loss from a $20 million gain a year earlier, with interest expense up 21.6% to $62 million. And adjusted book value per share, excluding foreign currency remeasurement, slid to $41.22 at June 30 from $42.97 a year earlier.
#earnings #fell
18 days ago
On September 9, 2026, Chewy, Inc. (NYSE:CHWY) reported fiscal second-quarter net sales of $3.33 billion, up 7.3% year over year, and adjusted earnings per share of $0.36, nearly double the roughly $0.18 ******* ysts had expected, prompting the company to raise its full-year revenue and profitability outlook. CEO Sumit Singh said the broader pet market did not meaningfully recover during the quarter but also did not deteriorate further, with Chewy continuing to outperform the category by two to three times through share gains across its established and newer businesses.
Chewy, Inc. (NYSE:CHWY)'s recurring revenue base is solid. It gives the company greater visibility into future sales. Autoship sales jumped by 9.3% year over year to $2.82 billion and represented 84.6% of total net sales. The growing contribution from subscription-based purchases gives Chewy a more predictable revenue stream and reduces its exposure to fluctuations in discretionary pet spending.
Chewy is also building growth engines beyond its core retail business. Chewy Health, which includes veterinary care and pharmacy services, delivered triple-digit revenue growth. Specialty categories such as equine and exotics recorded a seventh consecutive quarter of mid-double-digit growth. These businesses give Chewy additional opportunities to increase customer spending and diversify its sources of revenue as the overall pet market matures.
Chewy is combining customer growth with stronger profitability and shareholder returns. The firm added 208,000 net active customers during the quarter. It takes its customer base to 21.7 million while returning $200 million to shareholders through share repurchases. Management also noted structural SG&A leverage, automation, and AI-driven cost reductions as contributors to margin expansion. It shows that Chewy can improve earnings while investing in customer acquisition and growth.
Part of Chewy, Inc. (NYSE:CHWY)'s profitability improvement came from benefits that may not recur. CFO Chris Deppe said the quarter's profitability upside included about $10 million from timing benefits and more than $5 million from discrete benefits. Those items boosted the latest results but do not provide a recurring earnings contribution. It means investors may need to lower their expectations for the pace of margin expansion in future quarters.
#customer
18 days ago
LifeMD, Inc. (NASDAQ:LFMD) announced an exclusive healthcare collaboration on September 15 that initially makes virtual-health membership benefits available to approximately 29 million eligible AT&T wireless and fiber customers across 11 states. Customers must be 18 or older, and some services have additional eligibility and state restrictions. A nationwide expansion planned for January 2027 would extend eligibility beyond 100 million customers.
The $19 monthly membership fee is waived, but customers must enroll. Visits, prescriptions, and other services remain separately payable. For LifeMD, Inc. (NASDAQ:LFMD), the opportunity is converting access to a large audience into recurring demand for paid care.
The partnership gives LifeMD, Inc. (NASDAQ:LFMD) a distribution channel through the website, mobile app and customer-benefits program of AT&T Inc. (NYSE:T). Reaching customers through an established relationship could reduce reliance on advertising and lower acquisition costs per paying patient.
Removing the membership charge also reduces the financial commitment required to try the service. Announced visit prices start at $29 for message-based care, $49 for urgent and primary care video visits, and $79 for specialty care. Customers may use insurance, Medicare, or discounted cash-pay rates for visits and prescriptions.
LifeMD, Inc. (NASDAQ:LFMD) could benefit from repeat consultations and prescription fulfillment when clinically appropriate. Primary care, chronic-condition management and other services create opportunities for continuing patient relationships. If satisfied patients return, the revenue earned over those relationships could exceed the cost of acquiring and serving them.
#Services

19 days ago
On September 14, NextEra Energy, Inc. (NYSE:NEE) and Dominion Energy, Inc. (NYSE:D) announced a "transformational" Virginia benefits package to address concerns regarding their proposed $66.8 billion merger. The Virginia supplier program, worth up to $1 billion annually for five years, will direct spending toward contractors, suppliers, and service providers in the state.
Additionally, the companies also proposed doubling residential bill credits to four years, protecting retail customers from grid costs tied to Northern Virginia's rapidly expanding AI data centers, and committing $100 million toward directly supporting workforce development in the Commonwealth. NextEra also stated that it plans to add 600 new energy jobs in Virginia, while expecting suppliers to create another 400 positions.
The updated package comes after the proposed merger attracted a great deal of political scrutiny due to the impact it can have on everyday consumers. Virginia Governor Abigail Spanberger also stated last month that she would formally intervene in the regulatory review to press for commitments on electric bill affordability, job protections, and clean-energy investments.
John Ketchum, Chairman, President, and CEO of NextEra Energy, commented:
"This is a Virginia-first package, and it starts with customers. We are proposing to double residential bill relief from two years to four years, along with expanded low-income financial ******* istance and long-term affordability benefits. We are also reaffirming our support for the State Corporation Commission, Governor and General ******* embly's efforts to protect residential and small business customers from costs ******* ociated with serving data centers. Just as important, this package would help Virginia build more of the clean energy and infrastructure it needs faster, so the Commonwealth can reduce its reliance on expensive imported power. And it would do that while positioning Virginia as a major energy leader, bringing NextEra Energy jobs, good-paying supplier jobs, workforce investment, economic development and national-scale energy technology and innovation to Virginia. This is the kind of customer-focused, job-creating package this combination makes possible."
#energy #years #Jobs

19 days ago
Moneywise and Yahoo Finance LLC may earn commission or revenue through links in the content below.
The Social Security trust fund is projected to be depleted by the end of 2032 — at which point benefits could be automatically cut by as much as 22% on average, according to the 2026 Trustees Report (1) put out by the Social Security Administration (SSA).
Now, two Democrat lawmakers have proposed a solution that would not only avoid the cut but also boost benefits for some older Americans on the program.
Jeff Bezos backs a platform that lets anyone invest in rental homes for as little as $100 — 6 ways to build wealth like a landlord without actually being one
A single line on your car insurance policy could be inflating your premium by up to 30% — here's what to change
#Social #benefits #democrat
19 days ago
Moneywise and Yahoo Finance LLC may earn commission or revenue through links in the content below.
The future of America's social safety net is hanging in limbo as the underlying trust fund reserves for Social Security benefits will be depleted in just six years.
And not only is the U.S. government not offering solutions for the funding crisis, it's actually making the problem worse — even if there's money on the table for retirees as a result.
Jeff Bezos backs a platform that lets anyone invest in rental homes for as little as $100 — 6 ways to build wealth like a landlord without actually being one
A single line on your car insurance policy could be inflating your premium by up to 30% — here's what to change
#actually #moneywise #bezos #commission
19 days ago
GDEV Inc. (NASDAQ:GDEV) saw a year-on-year drop in bookings from both its in-app purchases and advertising, during the second quarter fiscal 2026. Consequently, the quarterly revenue figure of $94 million was down 22% compared to Q2 FY25. On the flip side, SG&A expenses and costs related to platform commissions were lower relative to the corresponding period last year. Along with other factors, the lower cost base helped GDEV report $20 million in net profit, up from $17 million in the second quarter of 2025.
Copyright: artush / 123RF Stock Photo
Breaking down the expenses, selling and marketing costs came down by 38% compared to the same quarter last year, clocking in at $33 million. It reflects on management's continued focus on deploying an efficient approach for its user acquisition initiatives. The approach is based on a more targeted performance marketing across certain channels that lead to durable high-value users, instead of broader campaigns for near-term benefits.
The reported quarter marked a turnaround related to the equity accounted ******* ociates. These contributed a $2 million profit share, which was a reversal from a $2 million loss share in Q2 FY25. Most notably, cash flows from operating activities turned from negative $10 million in Q2 FY25 to positive $10 million in the reported period.
Several operating metrics weakened during the reported quarter. Monthly paying users dropped by 23% year-over-year, along with a 15% decline for the entire first half. This was the major underlying reason for a sluggish performance in bookings, which stood at $73 million and $156 million for the second quarter and first half of the year, respectively. These fell short in comparison to $92 million and $173 million recorded in the corresponding periods last year. GDEV also said the decline in first-half platform commissions was driven by lower revenues recognized from PC platforms, while PC's share of bookings fell to 36% from 39%.
#million #lower
19 days ago
Claiming Social Security at 62 gives you three extra years of payments, but each monthly check is permanently smaller than it would be if you had waited until 65. Delaying benefits means giving up that early income in exchange for a larger monthly payment later. The break-even point shows when those larger checks catch up to the benefits collected by claiming early. Comparing that crossover age with your income needs, life expectancy and other retirement resources can help put the tradeoff in context.
A financial advisor can review a range of retirement strategies with you, including your optimum retirement age.
Social Security benefits can generally begin at age 62. However, starting before full retirement age (FRA) permanently reduces the monthly amount you receive. FRA depends on your birth year and ranges from 66 to 67 for workers approaching retirement today. For anyone born in 1960 or later, FRA is 67.
The Social Security Administration calculates early-claiming reductions based on how many months before FRA you begin collecting benefits. For the first 36 months before FRA, the benefit is generally reduced by 5/9 of 1% for each month. If you claim more than 36 months early, the reduction for those additional months is generally 5/12 of 1% per month.1
For a worker with an FRA of 67, claiming at 62 generally results in a 30% reduction. This means the worker receives about 70% of the benefit they would have received at FRA. Someone entitled to $2,500 per month at 67, for example, would receive approximately $1,750 per month by claiming at 62.
#Retirement

19 days ago
Choosing between claiming Social Security at 62 or waiting until 70 can create a wide gap in your monthly income. Starting early gives you more years of payments, while delaying may increase the amount of each check. The tradeoff comes down to how long you expect to collect benefits and how much income you need along the way. Comparing the break-even point can help show when waiting may produce more ****** ulative benefits.
A financial advisor can help you plan for retirement at any age.
The size of your monthly retirement check largely depends on the age at which you start collecting. Your earnings history establishes the foundation for your payment, but when you claim affects the portion you receive each month.
Age 62 is generally the earliest you can begin collecting Social Security retirement benefits. Claiming that early comes with a permanent reduction in your monthly payment. Social Security calculates the reduction based on how many months before your full retirement age (FRA) you begin receiving benefits.
For people born in 1960 or later, FRA is 67. In that case, claiming at 62 means starting benefits 60 months early. This generally reduces a worker's retirement benefit by 30% compared with the amount available at FRA. For example, someone entitled to $2,000 per month at FRA would receive approximately $1,400 at 62, before considering other adjustments.1
#monthly #early #starting #income

19 days ago
Comparing iShares National Muni Bond ETF (NYSEMKT:MUB) and Vanguard Intermediate-Term Treasury ETF (NASDAQ:VGIT) reveals a choice between tax-advantaged municipal income and the federal credit safety of intermediate-term U.S. government securities.
Both funds serve as core fixed-income holdings. The iShares fund tracks high-quality municipal bonds, which may provide tax benefits for certain investors. The Vanguard fund targets Treasury notes with maturities between three and 10 years, offering a refuge from credit risk during periods of market uncertainty.
Metric
MUB
VGIT
#income
19 days ago
TIPS held in taxable brokerage accounts generate phantom income from inflation-adjusted principal, potentially pushing up to 85% of Social Security benefits into taxable income.
30-year TIPS currently yield 2.96% above inflation, but account placement determines how much of that real return retirees actually keep after taxes.
Holding TIPS inside a traditional IRA defers inflation-adjustment taxation until withdrawal, shielding annual principal increases from the Social Security provisional income formula.
Two retirees, same $1 million, same 4% rule, buy one finished with $1.4 million, the other hit $0 in 12 years. Our free reader guide explains the flaw that separated them, and the income-first method built to avoid it.
A 71-year-old retiree did what the textbooks suggest. He built a ladder of Treasury Inflation-Protected Securities in his brokerage account to keep inflation from quietly eating away at retirement. The timing looks unusually attractive. As of August 28, Treasury's real-yield curve put 10-year TIPS at 2.42% and 30-year TIPS at 2.96%. Those are yields above inflation for an investor buying at current market prices and holding to maturity. That 2.96% is a real yield, meaning it sits on top of the inflation adjustment rather than competing with the inflation rate itself.
#real #taxable
19 days ago
On September 16, IDEXX Laboratories (NASDAQ:IDXX) announced it had bought CoVetAI, a fast-growing veterinary software company whose tool listens during appointments and organizes what gets said and done. It sounds like a productivity gadget. But IDEXX is pitching it as a way to put the right patient details in front of a vet at the moment they decide what to test. The price was not disclosed, so the strategy is the story.
Start with the customer base IDEXX already has. More than 10,000 clinics worldwide run on its cloud practice software, and CoVet will plug into that system, including a link to IDEXX VetConnect PLUS. That hands a new product a ready audience. CoVet also works with practice systems IDEXX does not make, and IDEXX plans to keep supporting rival scribes, so the tool can reach clinics and regions the company does not serve today.
Then there is the engine this could feed. On August 4, IDEXX reported second-quarter revenue growth of 10%, and its recurring diagnostics business grew 11%, powered by higher volumes. That says vets are already running more tests, which is the behavior a smarter workflow tool is meant to encourage. The company also placed more than 1,600 inVue Dx ****** yzers in the quarter, lifting the installed base past 9,000, and it counts that instrument among its AI-driven products. Software and hardware are pointing in the same direction.
The biggest problem is what we can't see. Without deal terms, there is no way to judge what IDEXX paid or how much CoVet matters to earnings. And the company describes the payoff in future tense, saying these capabilities can raise diagnostic use over time. That is a hope, not a result yet. CoVet's openness to other systems cuts both ways too. It widens reach, but it also means a clinic can use CoVet without going deeper into IDEXX's ecosystem.
The second quarter also needs a careful read. Earnings per share rose 18%, but that included tax benefits from stock-based pay and a currency boost, and growth on a comparable basis was 15%. Some of the gain, in other words, did not come from selling more to vets. IDEXX also says it is spending more on commercial and innovation priorities, so its higher full-year earnings outlook comes with added costs attached.
#company #software #earnings #already

20 days ago
On August 6, Aflac (NYSE:AFL) reported second-quarter numbers that point in opposite directions. Net earnings climbed to $825 million, helped along by investment losses that shrank to $153 million from $421 million a year ago. Adjusted earnings, though, fell 7.7% to $883 million. Both numbers are real, but they answer different questions. Which measure you trust changes the story, so here is what sits underneath.
Start with the yen, because it is muddying the picture. The average rate was 159.45 to the dollar, 9.3% weaker than a year earlier, and that cost adjusted earnings $0.05 a share. Take the currency out of the first half and adjusted earnings per share rose 4.1% to $3.57. **** an is also running more profitably. Its pretax adjusted margin widened to 34.3% from 32.0% as claims took a smaller bite out of premiums, and yen-based pretax adjusted earnings rose 3.4%. So part of the decline in **** an's dollar-reported profit is currency, not operations.
The US business is still growing at the top line. Net earned premiums rose 2.3% to $1.5 billion, and sales climbed 2.6% to $349 million, led by group voluntary benefits along with dental and vision plans. In **** an, the refreshed Tsumitasu life policy and the new Anshin Palette medical product grew strongly in the quarter, and first-half sales rose 7.0% to ¥37.3 billion. Then there is the cash. Aflac returned $1.3 billion to shareholders in the quarter, $983 million of it through buybacks, and declared a $0.61 third-quarter dividend, payable September 1 to holders of record on August 19, 2026. Management notes 43 straight years of dividend increases through 2025 and says the board is on a path to extend that in 2026.
The catch is that **** an's profit gains came from lower claims, not a bigger business. Net earned premiums in yen fell 3.7%, mainly because of a new external reinsurance deal and older limited-pay policies reaching paid-up status. Premium persistency, the share of policies customers keep, slipped to 92.7% from 93.7%. **** an's pretax adjusted earnings still fell 2.1% once currency is stripped out, and new sales dipped 5.6% in the quarter against a tough comparison for the Miraito cancer product, which launched in March 2025.
The US segment has its own soft spot. Pretax adjusted earnings fell 4.6% to $370 million, and the margin narrowed to 20.9% from 22.5% as claims and benefits took a bigger share of premiums. Corporate and Other swung to a $10 million pretax adjusted loss from a $20 million gain a year earlier, with interest expense up 21.6% to $62 million. And adjusted book value per share, excluding foreign currency remeasurement, slid to $41.22 at June 30 from $42.97 a year earlier.
#adjusted #pretax
20 days ago
Des Moines, Iowa-based Principal Financial Group, Inc. (PFG) provides retirement, ******* et management, and insurance products and services to businesses, individuals, and institutional clients worldwide. The company has a market cap of $25 billion and operates through Retirement and Income Solutions, Principal ******* et Management, and Benefits and Protection segments.
Companies with a market cap of $10 billion or more are typically called "large-cap stocks." PFG fits squarely into that category, with a market cap above this threshold that reflects its substantial size and influence in the ******* et management industry.
Mark Cuban Says He Was Dizzy for Months, So He Built a VR Fix That Does at Home 'Much Of What A 180k Machine' Does
Bank of America Just Declared a 'Generational Entry Point' in U.S. Bonds. Why Investors Should Be Backing Up the Truck on Treasuries Here.
Nvidia, OpenAI, and Oracle's $745B Financing Circle Just Hit Its First Stress Test: A Fed Rate Hike
#asset #management #market #moines

20 days ago
Moneywise and Yahoo Finance LLC may earn commission or revenue through links in the content below.
The CEO of Anthropic, one of the most valuable pure-play AI companies in the world, has some reservations about AI.
In a post (1) to his personal website, Anthropic CEO Dario Amodei called for companies to slow the development of increasingly capable AI models so safety measures can catch up. After listing some of the potential future benefits of AI — including his belief that it could "cure most major diseases" — Amodei acknowledged that it also "brings risks."
Jeff Bezos backs a platform that lets anyone invest in rental homes for as little as $100 — 6 ways to build wealth like a landlord without actually being one
A single line on your car insurance policy could be inflating your premium by up to 30% — here's what to change
#anthropic #amodei #Companies #moneywise