

9 hours ago
Following an impressive second quarter FY27, Navan Inc. (NASDAQ:NAVN) announced its acquisition of BoomPop, an AI-powered meetings and events platform that has been recognized by Inc. as one of the fastest-growing private companies in America. Launched in 2023, BoomPop offers end-to-end event management solutions to enterprises, by leveraging artificial intelligence capabilities. Its offerings cover the entire spectrum of event management procedures including venue selection, vendor sourcing, contractual agreement, payments, and more. For Navan, this deal build on an existing alliance between the two entities, which was announced earlier in February. It marks the company's strategic push to expand its footprint across the meetings and events segment, where a large chunk of the spending is still done outside managed platforms.
LStockStudio/Shutterstock.com
The BoomPop acquisition follows a persistent enterprise market momentum reported by the company in its second quarter results, allowing Navan to enter into collaborative agreements with several leading companies during the quarter. These included Enbridge, Ingersoll Rand, ****** mins, and Evotec. Navan also concluded the deal to acquire Smartrips, a well-reputed travel management business, with the aim of bolstering its presence across a rapidly-growing Latin American market.
Notably, Navan registered adjusted net income of $14 million during the second quarter compared to an $8 million loss in Q2 FY26. It came at the back of year-over-year growth figures of 39% and 35% for subscription revenue and usage revenue, respectively.
Through full integration of BoomPop's staff and technology, Navan intends to expand its current meetings and events operations, accelerate its product development timeline, and satisfy growing customer interest. The company aims to deliver a more seamless experience covering travel, expense, meetings, and events.
#navan
LStockStudio/Shutterstock.com
The BoomPop acquisition follows a persistent enterprise market momentum reported by the company in its second quarter results, allowing Navan to enter into collaborative agreements with several leading companies during the quarter. These included Enbridge, Ingersoll Rand, ****** mins, and Evotec. Navan also concluded the deal to acquire Smartrips, a well-reputed travel management business, with the aim of bolstering its presence across a rapidly-growing Latin American market.
Notably, Navan registered adjusted net income of $14 million during the second quarter compared to an $8 million loss in Q2 FY26. It came at the back of year-over-year growth figures of 39% and 35% for subscription revenue and usage revenue, respectively.
Through full integration of BoomPop's staff and technology, Navan intends to expand its current meetings and events operations, accelerate its product development timeline, and satisfy growing customer interest. The company aims to deliver a more seamless experience covering travel, expense, meetings, and events.
#navan


15 hours ago
We now know what time and how to watch the Homecoming clash between Penn State and Wisconsin on Saturday, September 26th. Earlier today, it was announced via the official PSU Football social media accounts that the Nittany Lions will face the Badgers at Beaver Stadium in a 5:00 PM EST kickoff that will be streaming on Peacock.
Understandably, this is frustrating news for those who don't already have a Peacock subscription and don't feel like plunking down additional money for another monthly streaming subscription just to watch one game. That being said, games that air on Peacock also air simultaneously on NBC Sports Network, a channel that is readily available on Comcast Xfinity, YouTubeTV, and Fubo. So, if you already are a subscriber to one of those aforementioned streaming services, you should be good to go.
The last time these two teams collided was on October 26th, 2024, when PSU went into Camp Randall Stadium for a nighttime showdown that saw Beau Pribula step in for an injured Drew Allar after halftime and along with a pick-six by Jaylen Reed and some strong running from Kaytron Allen, help guide the Nittany Lions to a 28-13 win to keep their College Football Playoff hopes intact.
#Football #already
Understandably, this is frustrating news for those who don't already have a Peacock subscription and don't feel like plunking down additional money for another monthly streaming subscription just to watch one game. That being said, games that air on Peacock also air simultaneously on NBC Sports Network, a channel that is readily available on Comcast Xfinity, YouTubeTV, and Fubo. So, if you already are a subscriber to one of those aforementioned streaming services, you should be good to go.
The last time these two teams collided was on October 26th, 2024, when PSU went into Camp Randall Stadium for a nighttime showdown that saw Beau Pribula step in for an injured Drew Allar after halftime and along with a pick-six by Jaylen Reed and some strong running from Kaytron Allen, help guide the Nittany Lions to a 28-13 win to keep their College Football Playoff hopes intact.
#Football #already

15 hours ago
An AI ****** istant that orders your groceries and renews subscriptions on its own might hit the market soon.
Visa (V) and Mastercard (MA) want to make sure that payment still runs through their networks when that happens.
This week, the two card giants said they are working with global fintech Ant International to build a shared way to identify and trust AI shopping agents.
For anyone holding the two stocks or considering them, this plan gives a hint on how both companies could grow in the future.
It also raises a fair question. If software does your spending, who makes sure it spends wisely?
#mastercard #subscriptions
Visa (V) and Mastercard (MA) want to make sure that payment still runs through their networks when that happens.
This week, the two card giants said they are working with global fintech Ant International to build a shared way to identify and trust AI shopping agents.
For anyone holding the two stocks or considering them, this plan gives a hint on how both companies could grow in the future.
It also raises a fair question. If software does your spending, who makes sure it spends wisely?
#mastercard #subscriptions

22 hours ago
Sep. 14—The term sabermetrics was first coined by Bill James in 1980. It took quite a bit longer, however, for the idea to catch on with the baseball populace, but eventually acronyms like WAR, VORP and UZR caught on as a way to ****** yze the sport.
Analytics are equally as important these days in college basketball. It's why you hear Illinois coach Brad Underwood constantly referencing his team's adjusted offensive efficiency and offensive rebounding rate. Paid services like Synergy give coaching staffs an ****** ytical breakdown of their team to the finest detail.
Publicly available sites like , and , however, have broadened the usage and acceptance of a different way to follow and break down the sport. (KenPom and CBBAnalytics do have a subscription piece but are drastically cheaper than Synergy).
It's through those sites Illinois fans could track one of the most efficient offenses in the modern era during the 2025-26 season. The Illini eventually finished second in adjusted offensive efficiency behind Purdue last season. That particular metric was helped by the Illini not turning the ball over (eighth in turnover rate) and dominating the offensive glass (third in offensive rebounding rate).
One particular metric Illinois tracks is shot volume.
#like #rate #synergy
Analytics are equally as important these days in college basketball. It's why you hear Illinois coach Brad Underwood constantly referencing his team's adjusted offensive efficiency and offensive rebounding rate. Paid services like Synergy give coaching staffs an ****** ytical breakdown of their team to the finest detail.
Publicly available sites like , and , however, have broadened the usage and acceptance of a different way to follow and break down the sport. (KenPom and CBBAnalytics do have a subscription piece but are drastically cheaper than Synergy).
It's through those sites Illinois fans could track one of the most efficient offenses in the modern era during the 2025-26 season. The Illini eventually finished second in adjusted offensive efficiency behind Purdue last season. That particular metric was helped by the Illini not turning the ball over (eighth in turnover rate) and dominating the offensive glass (third in offensive rebounding rate).
One particular metric Illinois tracks is shot volume.
#like #rate #synergy

23 hours ago
When you buy through links on our articles, Future and its syndication partners may earn a commission.
Credit: Sony Pictures
Over the last decade and change, The Marvel Cinematic Universe has grown into a behemoth franchise that spans both movies and TV shows that air with a Disney+ subscription. Fans who have watched the Marvel movies in order have seen how Tom Holland got a reputation for accidentally spoiling movies, often going viral in the process. But how does the 30 year-old actor feel about this perception?
Holland is a beloved part of the MCU, with Spider-Man: Brand New Day beating out even Avengers: Endgame's box office haul. But aside from his A+ performances as Peter Parker, he's also known for repeatedly spoiling movies, despite Marvel's tight security. In a video from the Happy Sad Confused podcast, the Odyssey actor was asked about how folks are constantly dunking on him about spoilers, responding with:
There's part of me that loves it. My dad's a comedian. So having thick skin and growing up with people taking the mick out of you is like part of our upbringing, you know? My love language, I think, is taking the ****** out of me. I just love it.
#marvel #future #credit
Credit: Sony Pictures
Over the last decade and change, The Marvel Cinematic Universe has grown into a behemoth franchise that spans both movies and TV shows that air with a Disney+ subscription. Fans who have watched the Marvel movies in order have seen how Tom Holland got a reputation for accidentally spoiling movies, often going viral in the process. But how does the 30 year-old actor feel about this perception?
Holland is a beloved part of the MCU, with Spider-Man: Brand New Day beating out even Avengers: Endgame's box office haul. But aside from his A+ performances as Peter Parker, he's also known for repeatedly spoiling movies, despite Marvel's tight security. In a video from the Happy Sad Confused podcast, the Odyssey actor was asked about how folks are constantly dunking on him about spoilers, responding with:
There's part of me that loves it. My dad's a comedian. So having thick skin and growing up with people taking the mick out of you is like part of our upbringing, you know? My love language, I think, is taking the ****** out of me. I just love it.
#marvel #future #credit

2 days ago
Navan Inc. (NASDAQ:NAVN), a global AI-enabled business travel and expense management solutions provider, announced its second quarter results on September 9. The company registered a 45% growth in its gross booking volume (GBV), which reached more than $3 billion. Such growth was fueled by cohort expansion, customer additions and increase in its existing install base. Total revenue for the quarter was $233 million, representing a 35% year-over-year jump. The company's adjusted operating income more than doubled compared to Q2 FY26, and the quarter also saw positive cash flow generation.
Copyright: kentoh / 123RF Stock Photo
Navan delivered robust performance during the recently concluded quarter, driven by a 35% increase in usage revenue which clocked in at $211 million. Subscription revenue was also up 39%, reaching $21 million. Apart from the 45% GBV expansion, a 34% growth was witnessed in Q2 Payment Volume which stood at $1.3 billion. One of the highlights of this quarter was a turnaround in adjusted net income, which jumped from an $8 million loss in Q2 FY26 to a $14 million profit for the reported period.
Enterprise market momentum remained persistent during the period, as the company established partnerships with leading names such as Evotec, Enbridge, ****** mins, and Ingersoll Rand. Significant progress was made around the Navan's proprietary AI agent, Ava, which managed roughly 60% of the total customer interactions. More than 50% of AI calls are now being managed through the company's in-house AI models, compared to 30% for the previous quarter.
Additionally, the company finalized its acquisition of a leading travel management business, Smartrips. This will enable Navan to expand its presence within the swiftly expanding Latin American market. Navan also acquired an AI-led meetings and events management platform, BoomPop.
#volume
Copyright: kentoh / 123RF Stock Photo
Navan delivered robust performance during the recently concluded quarter, driven by a 35% increase in usage revenue which clocked in at $211 million. Subscription revenue was also up 39%, reaching $21 million. Apart from the 45% GBV expansion, a 34% growth was witnessed in Q2 Payment Volume which stood at $1.3 billion. One of the highlights of this quarter was a turnaround in adjusted net income, which jumped from an $8 million loss in Q2 FY26 to a $14 million profit for the reported period.
Enterprise market momentum remained persistent during the period, as the company established partnerships with leading names such as Evotec, Enbridge, ****** mins, and Ingersoll Rand. Significant progress was made around the Navan's proprietary AI agent, Ava, which managed roughly 60% of the total customer interactions. More than 50% of AI calls are now being managed through the company's in-house AI models, compared to 30% for the previous quarter.
Additionally, the company finalized its acquisition of a leading travel management business, Smartrips. This will enable Navan to expand its presence within the swiftly expanding Latin American market. Navan also acquired an AI-led meetings and events management platform, BoomPop.
#volume

2 days ago
CrowdStrike (CRWD) stock rose about 97% over the past year, against 18% for the S&P 500, as growth in the recurring revenue it adds each quarter sped up. Management was forecasting that speed-up by March 2025 and named one mechanism: Falcon Flex customers using up their contracts early and coming back for more. The direction was public. The size of the fiscal 2027 speed-up was not.
How Early Did CrowdStrike Forecast The Speed-Up?
The earliest sign came with the fiscal Q4 2025 report in March 2025. After its July 19 outage, CrowdStrike had given affected clients customer commitment packages, mostly extra product and Falcon Flex subscriptions. The CEO said that uptake underpinned an expected speed-up in net new annual recurring revenue (ARR) in the second half of fiscal 2026. He added that Flex demand plans were running ahead of schedule and expected contracts to be upsized and renewed. The CFO expected more acceleration in fiscal 2027.
The fiscal Q1 2026 report in early June 2025 put numbers on the mechanism: 39 Flex customers had deployed initial plans signed for 35 months on average and came back for more within five months, a step the company calls a reflex.
What Could You See Just Before The Run Began?
#speed #crowdstrike
How Early Did CrowdStrike Forecast The Speed-Up?
The earliest sign came with the fiscal Q4 2025 report in March 2025. After its July 19 outage, CrowdStrike had given affected clients customer commitment packages, mostly extra product and Falcon Flex subscriptions. The CEO said that uptake underpinned an expected speed-up in net new annual recurring revenue (ARR) in the second half of fiscal 2026. He added that Flex demand plans were running ahead of schedule and expected contracts to be upsized and renewed. The CFO expected more acceleration in fiscal 2027.
The fiscal Q1 2026 report in early June 2025 put numbers on the mechanism: 39 Flex customers had deployed initial plans signed for 35 months on average and came back for more within five months, a step the company calls a reflex.
What Could You See Just Before The Run Began?
#speed #crowdstrike

3 days ago
SailPoint Inc. (NASDAQ:SAIL), a leading player within the enterprise identity security ***** e, released its fiscal second-quarter 2027 on September 9. The company registered a 25% growth in its annual recurring revenue compared to the same period last year, with figures of $1.231 billion. This was driven by a 36% expansion in SaaS ARR which clocked in at $847 million. SailPoint generated $45 million in operating cash flow during the quarter, along with $37 million in free cash flow.
Burben/Shutterstock.com
Topline for the quarter hit $309 million, exhibiting 17% growth compared to Q2 FY26, amid several underlying factors. The company's subscription revenue reached $295 million, up 19% from a year earlier. SaaS customer base increased by 16%, with net new SaaS ARR jumping 34% year-over-year. It contributed around 97% to overall net new ARR for the business, with AI-driven ARR crossing $70 million mark.
SailPoint's existing customer base showed highly encouraging trends in adopting the company's AI-enabled solutions, with a 60% increase in their annual spend during the second quarter. These solutions were incorporated within more than two-thirds of the completed migrations during the quarter. Quarterly adjusted operating income increased from $54 million a year prior to $63 million, translating into an adjusted margin of 20%.
The quarter also saw key strategic moves by the management. It introduced the SailPoint Identity Security solution, which integrates SailPoint Agentic Fabric with SailPoint Human Fabric to deliver a real-time cycle for discovering and securing intricate digital ecosystems. The company also launched its Cursor Enterprise connector, which enables enterprises to manage both autonomous AI agents and human developers through an integrated control plane.
#year #SaaS #fabric #identity
Burben/Shutterstock.com
Topline for the quarter hit $309 million, exhibiting 17% growth compared to Q2 FY26, amid several underlying factors. The company's subscription revenue reached $295 million, up 19% from a year earlier. SaaS customer base increased by 16%, with net new SaaS ARR jumping 34% year-over-year. It contributed around 97% to overall net new ARR for the business, with AI-driven ARR crossing $70 million mark.
SailPoint's existing customer base showed highly encouraging trends in adopting the company's AI-enabled solutions, with a 60% increase in their annual spend during the second quarter. These solutions were incorporated within more than two-thirds of the completed migrations during the quarter. Quarterly adjusted operating income increased from $54 million a year prior to $63 million, translating into an adjusted margin of 20%.
The quarter also saw key strategic moves by the management. It introduced the SailPoint Identity Security solution, which integrates SailPoint Agentic Fabric with SailPoint Human Fabric to deliver a real-time cycle for discovering and securing intricate digital ecosystems. The company also launched its Cursor Enterprise connector, which enables enterprises to manage both autonomous AI agents and human developers through an integrated control plane.
#year #SaaS #fabric #identity

3 days ago
On September 10, Piper Sandler **** yst Bill Carcache initiated coverage of Q2 Holdings, Inc. (NYSE:QTWO), giving the stock an Overweight rating and setting the price target at $82.
The research firm started coverage on companies in the payments and consumer finance group and named Q2 Holdings, Inc. (NYSE:QTWO) as its preferred name in the sector.
According to Piper Sandler, the company offers the "clearest combination" of subscription revenue growth, visibility into annual recurring revenue, and improving free cash flow conversion. The firm also highlighted the company's growing margins and debt-free balance sheet. Piper Sandler said these factors support what it sees as the clearest path toward durable growth among the payments and consumer finance group.
Q2 Holdings, Inc. (NYSE:QTWO) delivered strong financial performance in Q2 2026. The company reported revenue of $219.8 million, an increase of 13% year-over-year and 2% sequentially. GAAP gross margin improved to 59.2% from 53.6% in the prior-year quarter, while GAAP net income rose to $29.9 million from $11.8 million.
Adjusted EBITDA reached a record $62.8 million, up 37% year-over-year. The company said it delivered another quarter of consistent execution, with strong bookings across its solutions.
#year #NYSE #revenue
The research firm started coverage on companies in the payments and consumer finance group and named Q2 Holdings, Inc. (NYSE:QTWO) as its preferred name in the sector.
According to Piper Sandler, the company offers the "clearest combination" of subscription revenue growth, visibility into annual recurring revenue, and improving free cash flow conversion. The firm also highlighted the company's growing margins and debt-free balance sheet. Piper Sandler said these factors support what it sees as the clearest path toward durable growth among the payments and consumer finance group.
Q2 Holdings, Inc. (NYSE:QTWO) delivered strong financial performance in Q2 2026. The company reported revenue of $219.8 million, an increase of 13% year-over-year and 2% sequentially. GAAP gross margin improved to 59.2% from 53.6% in the prior-year quarter, while GAAP net income rose to $29.9 million from $11.8 million.
Adjusted EBITDA reached a record $62.8 million, up 37% year-over-year. The company said it delivered another quarter of consistent execution, with strong bookings across its solutions.
#year #NYSE #revenue


3 days ago
New Mexico vs. Mercyhurst
When and where: 2 p.m. Saturday at University Stadium.
How to watch/listen: MW+ – the Mountain West's new subscription-based streaming service – will carry UNM-Mercyhurst with Robert Portnoy (play-by-play) and DonTrell Moore (analyst) on the call. J.J. Buck (play-by-play) and Ned James (analyst) will broadcast the game via radio on the Lobo Radio Network (770 AM/96.3 FM).
Who's favored: UNM is listed as a 41.5-point favorite, per bet365. The over/under is set at 51.5 points.
Every year, more than a few coaches say it: The biggest improvement a team makes in any given season is from its first game to its second.
#radio #analyst #saturday #university
When and where: 2 p.m. Saturday at University Stadium.
How to watch/listen: MW+ – the Mountain West's new subscription-based streaming service – will carry UNM-Mercyhurst with Robert Portnoy (play-by-play) and DonTrell Moore (analyst) on the call. J.J. Buck (play-by-play) and Ned James (analyst) will broadcast the game via radio on the Lobo Radio Network (770 AM/96.3 FM).
Who's favored: UNM is listed as a 41.5-point favorite, per bet365. The over/under is set at 51.5 points.
Every year, more than a few coaches say it: The biggest improvement a team makes in any given season is from its first game to its second.
#radio #analyst #saturday #university



4 days ago
When you buy through links on our articles, Future and its syndication partners may earn a commission.
Credit: Peacock
Actor Zac Efron grew up before our eyes, becoming a household name thanks to starring in the High School Musical movies (which are streaming with a Disney+ subscription). But in recent years his younger brother Dylan Efron has also become a celebrity, largely thanks to winning The Traitors Season 3 and showing off his fitness on Dancing with the Stars. Zac's own fitness is the stuff of legend, and recently his trainer posted a photo showing off his huge bicep. Naturally, Dylan took to social media to drop his own very buff photo dump.
Dylan Efron's star power has been steadily growing in recent years. After The Traitors (streaming with a Peacock subscription), he also competed on Dancing with The Stars. Not one to be left of out of thirsty discourse, Efron posted on Instagram, including some shirtless pictures on a boat. Check it out for yourself below:
Holy abs. I guess there's a reason why Dylan Efron was nominated for ******* iest Man Alive, because he's looking absolutely ripped. And who doesn't love a little healthy competition between two famous brothers? We'll just have to wait and see if Zac posts his own set of ab-oriented photos in response.
#peacock #stars
Credit: Peacock
Actor Zac Efron grew up before our eyes, becoming a household name thanks to starring in the High School Musical movies (which are streaming with a Disney+ subscription). But in recent years his younger brother Dylan Efron has also become a celebrity, largely thanks to winning The Traitors Season 3 and showing off his fitness on Dancing with the Stars. Zac's own fitness is the stuff of legend, and recently his trainer posted a photo showing off his huge bicep. Naturally, Dylan took to social media to drop his own very buff photo dump.
Dylan Efron's star power has been steadily growing in recent years. After The Traitors (streaming with a Peacock subscription), he also competed on Dancing with The Stars. Not one to be left of out of thirsty discourse, Efron posted on Instagram, including some shirtless pictures on a boat. Check it out for yourself below:
Holy abs. I guess there's a reason why Dylan Efron was nominated for ******* iest Man Alive, because he's looking absolutely ripped. And who doesn't love a little healthy competition between two famous brothers? We'll just have to wait and see if Zac posts his own set of ab-oriented photos in response.
#peacock #stars


4 days ago
Two cybersecurity heavyweights, Rubrik, Inc. (NYSE:RBRK) and CrowdStrike Holdings, Inc. (NASDAQ:CRWD), both released Q2 FY2027 earnings in late August/early September while deepening their strategic alliance. On September 1, the companies announced a joint agentic identity resilience workflow orchestrated by CrowdStrike's Charlotte Agentic SOAR. By uniting CrowdStrike's Falcon Next-Gen Identity Security with Rubrik's Identity Resilience, joint customers can now detect, investigate, and recover from compromised identity environments in hours instead of days.
Den Rise/Shutterstock.com
CrowdStrike continues to operate at a massive scale with strong cash generation and expanding margins. For Q2 FY2027, CrowdStrike reported total revenue of $1.47 billion, up 26% year-over-year, with annual recurring revenue (ARR) reaching $5.84 billion (up 25%) after adding a record $333 million in net new ARR. GAAP net income turned positive at $5.3 million ($0.01 per diluted share), while non-GAAP net income reached $322.9 million ($0.31 per diluted share). Operating cash flow hit a Q2 record of $530.3 million, with free cash flow reaching $377.4 million. Expanding its momentum, CrowdStrike announced a partnership with OpenAI on September 2 to secure Codex agents and integrate GPT-5.6 Cyber into Falcon, prompting Raymond James to raise its price target to $250 from $240 on September 3, citing an "AI double whammy."
Rubrik, meanwhile, represents the hyper-growth challenger outperforming Wall Street's top-line expectations. For Q2 FY2027, Rubrik's total revenue surged 38% year-over-year to $427.3 million (up 43% when normalized for material rights), while Subscription ARR grew 33% to $1.66 billion. While GAAP net loss per share narrowed to $(0.30), Rubrik achieved non-GAAP net income per share of $0.20 ($0.47–$0.53 guidance for full FY27). Operating cash flow reached $76.8 million, generating $65.7 million in free cash flow. While CrowdStrike holds the stronger overall financial profile given its $5.84 billion ARR scale and $377.4 million free cash flow generation, Rubrik leads in top-line growth velocity.
CrowdStrike's bull case rests on its leadership in endpoint and identity security, proven GAAP and non-GAAP profitability, and deep AI integrations with platforms such as OpenAI and Charlotte AI, which could drive further platform consolidation and high-margin ARR growth. However, slower percentage growth compared with younger peers, elevated valuation multiples, and lingering customer scrutiny following past software update disruptions remain key risks.
#flow
Den Rise/Shutterstock.com
CrowdStrike continues to operate at a massive scale with strong cash generation and expanding margins. For Q2 FY2027, CrowdStrike reported total revenue of $1.47 billion, up 26% year-over-year, with annual recurring revenue (ARR) reaching $5.84 billion (up 25%) after adding a record $333 million in net new ARR. GAAP net income turned positive at $5.3 million ($0.01 per diluted share), while non-GAAP net income reached $322.9 million ($0.31 per diluted share). Operating cash flow hit a Q2 record of $530.3 million, with free cash flow reaching $377.4 million. Expanding its momentum, CrowdStrike announced a partnership with OpenAI on September 2 to secure Codex agents and integrate GPT-5.6 Cyber into Falcon, prompting Raymond James to raise its price target to $250 from $240 on September 3, citing an "AI double whammy."
Rubrik, meanwhile, represents the hyper-growth challenger outperforming Wall Street's top-line expectations. For Q2 FY2027, Rubrik's total revenue surged 38% year-over-year to $427.3 million (up 43% when normalized for material rights), while Subscription ARR grew 33% to $1.66 billion. While GAAP net loss per share narrowed to $(0.30), Rubrik achieved non-GAAP net income per share of $0.20 ($0.47–$0.53 guidance for full FY27). Operating cash flow reached $76.8 million, generating $65.7 million in free cash flow. While CrowdStrike holds the stronger overall financial profile given its $5.84 billion ARR scale and $377.4 million free cash flow generation, Rubrik leads in top-line growth velocity.
CrowdStrike's bull case rests on its leadership in endpoint and identity security, proven GAAP and non-GAAP profitability, and deep AI integrations with platforms such as OpenAI and Charlotte AI, which could drive further platform consolidation and high-margin ARR growth. However, slower percentage growth compared with younger peers, elevated valuation multiples, and lingering customer scrutiny following past software update disruptions remain key risks.
#flow



4 days ago
Braze Inc. (NASDAQ:BRZE) turned in a strong second quarter. The reputed customer engagement platform showcased continued momentum across both its product strategy and financial performance. The company generated topline figure of $227.2 million, an impressive 26.2% increase compared to the same period last year. This revenue growth was fueled by upselling gains, customer additions and renewals. The company posted $24.2 million in cash flow from operating activities, a monumental growth relative to $7 million in the same period a year ago. This was paired with $21.7 million in free cash flow, against $3.5 million during Q2 FY26.
Jirsak/Shutterstock.com
The quarter brought several meaningful strategic moves. Braze broadened its BrazeAI Operator tool, which allows users to build new Canvas steps straight from conversational prompts. The company also signed a three-year Strategic Collaboration Agreement with AWS to support collaborative co-selling and go-to-market initiatives. The arrangement will incentivize AWS sellers for integrating Braze within their accounts.
For the latest quarter, subscription revenue jumped to $207.7 million from $171.8 million a year prior, while professional services and other revenue more than doubled, reaching $19.6 million. Dollar-based net retention among larger accounts, defined as those with annual recurring revenue of $500,000 or more, edged up to 112% in comparison to 111% a year earlier. Profitability metrics improved considerably as well, with adjusted operating income jumping to $22 million from $6 million, and adjusted diluted EPS increasing from $0.15 to $0.19.
Management cited growing demand for measurable return on investment as the primary force behind faster uptake of Braze's AI product lineup, which includes BrazeAI Operator, BrazeAI Agent Console, and BrazeAI Decisioning Studio.
#revenue
Jirsak/Shutterstock.com
The quarter brought several meaningful strategic moves. Braze broadened its BrazeAI Operator tool, which allows users to build new Canvas steps straight from conversational prompts. The company also signed a three-year Strategic Collaboration Agreement with AWS to support collaborative co-selling and go-to-market initiatives. The arrangement will incentivize AWS sellers for integrating Braze within their accounts.
For the latest quarter, subscription revenue jumped to $207.7 million from $171.8 million a year prior, while professional services and other revenue more than doubled, reaching $19.6 million. Dollar-based net retention among larger accounts, defined as those with annual recurring revenue of $500,000 or more, edged up to 112% in comparison to 111% a year earlier. Profitability metrics improved considerably as well, with adjusted operating income jumping to $22 million from $6 million, and adjusted diluted EPS increasing from $0.15 to $0.19.
Management cited growing demand for measurable return on investment as the primary force behind faster uptake of Braze's AI product lineup, which includes BrazeAI Operator, BrazeAI Agent Console, and BrazeAI Decisioning Studio.
#revenue


4 days ago
On September 2, F5, Inc. (NASDAQ:FFIV) announced a key integration with MuleSoft, a Salesforce, Inc. (NYSE:CRM) company, federating F5 AI Guardrails directly into MuleSoft's Agent Fabric Omni Gateway. As enterprises rapidly scale agentic AI capabilities, security teams face growing governance gaps and risks from prompt injection, data leakage, and toxic outputs. This native integration gives security and platform engineering teams centralized policy enforcement, proactive threat mitigation, and low-touch policy tuning without forcing organizations to re-architect existing infrastructure.
While the partnership strengthens both ecosystems, examining their latest financials reveals two enterprise software giants moving at distinctly different scales and growth trajectories.
F5, Inc. (NASDAQ:FFIV) reported strong Q3 FY26 results, generating $865 million in revenue (up 11% year-over-year). Revenue growth was anchored by a 19% jump in product revenue, led by a 32% surge in systems revenue ($240 million). F5's bottom line remained exceptionally robust, expanding non-GAAP operating margin to 35.0% and delivering non-GAAP net income of $272 million ($4.73 per diluted share, up from $4.16).
Salesforce operated at a much larger scale in its record Q2 FY27, generating $11.3 billion in quarterly revenue (up 11% year-over-year). Growth was fueled by subscription and support revenue of $10.8 billion and expanding adoption of its Agentforce platform, whose annual recurring revenue (ARR) neared $3.9 billion. Salesforce posted a non-GAAP operating margin of 34.1%, and non-GAAP diluted EPS of $5.90, while raising its full-year FY27 revenue guidance to $46.1B–$46.4B.
While both companies run near-identical, highly profitable non-GAAP operating margins (~34%–35%), Salesforce leads overall financial health due to its massive free cash flow generation, cRPO backlog of $33.5 billion, and broader ecosystem dominance.
#Growth
While the partnership strengthens both ecosystems, examining their latest financials reveals two enterprise software giants moving at distinctly different scales and growth trajectories.
F5, Inc. (NASDAQ:FFIV) reported strong Q3 FY26 results, generating $865 million in revenue (up 11% year-over-year). Revenue growth was anchored by a 19% jump in product revenue, led by a 32% surge in systems revenue ($240 million). F5's bottom line remained exceptionally robust, expanding non-GAAP operating margin to 35.0% and delivering non-GAAP net income of $272 million ($4.73 per diluted share, up from $4.16).
Salesforce operated at a much larger scale in its record Q2 FY27, generating $11.3 billion in quarterly revenue (up 11% year-over-year). Growth was fueled by subscription and support revenue of $10.8 billion and expanding adoption of its Agentforce platform, whose annual recurring revenue (ARR) neared $3.9 billion. Salesforce posted a non-GAAP operating margin of 34.1%, and non-GAAP diluted EPS of $5.90, while raising its full-year FY27 revenue guidance to $46.1B–$46.4B.
While both companies run near-identical, highly profitable non-GAAP operating margins (~34%–35%), Salesforce leads overall financial health due to its massive free cash flow generation, cRPO backlog of $33.5 billion, and broader ecosystem dominance.
#Growth

4 days ago
Braze, Inc. (NASDAQ:BRZE) reported strong Q2 results on September 8, but investors appeared more focused on the company's outlook. Despite the solid performance, the company's shares had fallen sharply following the earnings report, declining nearly 20% in the September 9 session.
In its second quarter of fiscal 2027, the company generated $227.2 million in revenue, up 26.2% year-over-year. Braze, Inc. (NASDAQ:BRZE) said growth was mainly driven by new customers, along with upsells and renewals from existing customers. Subscription revenue increased 21% to reach $207.7 million.
Non-GAAP net income also improved 26% to more than $21.23 million, or $0.19 per share. Revenue and adjusted earnings were ahead of Wall Street expectations. **** ysts were expecting Braze, Inc. (NASDAQ:BRZE) to report revenue of slightly more than $220 million and adjusted earnings of $0.15 per share.
The company also showed improvement in its cash generation as it reported record second-quarter cash flow from operations of $24 million and free cash flow of $22 million.
Guidance Becomes the Main Concern
#september
In its second quarter of fiscal 2027, the company generated $227.2 million in revenue, up 26.2% year-over-year. Braze, Inc. (NASDAQ:BRZE) said growth was mainly driven by new customers, along with upsells and renewals from existing customers. Subscription revenue increased 21% to reach $207.7 million.
Non-GAAP net income also improved 26% to more than $21.23 million, or $0.19 per share. Revenue and adjusted earnings were ahead of Wall Street expectations. **** ysts were expecting Braze, Inc. (NASDAQ:BRZE) to report revenue of slightly more than $220 million and adjusted earnings of $0.15 per share.
The company also showed improvement in its cash generation as it reported record second-quarter cash flow from operations of $24 million and free cash flow of $22 million.
Guidance Becomes the Main Concern
#september

4 days ago
Good morning everyone and welcome to Fitzie's gaming corner, where your hoddler-in-chief talks about video and **** ogue games.
There's an exciting new PC game coming out soon: Guild Wars 3.
It's official. #GW3 is a thing – we are developing Guild Wars 3! https://t.co/yKMu6euKg2 pic.twitter.com/7nkR6TBt8v
Guild Wars is what is called an MMORPG – or "massively multiplayer online role-playing game" – that's like a cooler version of World of Warcraft. It's got these cool characters and no subscription model, which means it's far more accessible.
Your hoddler-in-chief used to play Guild Wars all the time. First the OG when it came out in 2007 and then when Guild Wars 2 was released in 2012. I spent a tonne of hours playing it until it reached a point where my computer's RAM could no longer support it.
#game #playing #mmorpg #World
There's an exciting new PC game coming out soon: Guild Wars 3.
It's official. #GW3 is a thing – we are developing Guild Wars 3! https://t.co/yKMu6euKg2 pic.twitter.com/7nkR6TBt8v
Guild Wars is what is called an MMORPG – or "massively multiplayer online role-playing game" – that's like a cooler version of World of Warcraft. It's got these cool characters and no subscription model, which means it's far more accessible.
Your hoddler-in-chief used to play Guild Wars all the time. First the OG when it came out in 2007 and then when Guild Wars 2 was released in 2012. I spent a tonne of hours playing it until it reached a point where my computer's RAM could no longer support it.
#game #playing #mmorpg #World


4 days ago
Adobe Inc. (NASDAQ:ADBE) is asking designers who use Figma, Inc. (NYSE:FIG) and similar tools to help test Project Oasis, a web-based graphic-design tool with brand-aware AI. The September 7 community invitation seeks feedback under a nondisclosure agreement before public launch. That makes it an early competitive signal, with neither customer wins nor meaningful revenue established.
The investment question is whether easier AI design draws marketing budgets toward Adobe or encourages customers to do more inside Figma. Both already serve people creating branded visual material. Winning that workflow could support subscriptions and paid AI usage, but another tool also gives customers another reason to compare prices.
Copyright: photogearch / 123RF Stock Photo
Adobe Inc. (NASDAQ:ADBE) reported fiscal second-quarter revenue of $6.62 billion, up 13%, for the period ended May 29. Its AI-first annualized recurring revenue exceeded $500 million and more than tripled year over year. Those figures give its AI strategy substance beyond a product invitation. Its established creative customer base could also make testing and distribution easier.
The risk is that product experimentation fails to produce additional spending. Adobe must persuade customers that new capabilities deserve payment while competitors make basic ******* et creation easier. Oasis currently provides no disclosed conversion rate or financial contribution with which investors can test that proposition. Its invitation targets brand-identity and marketing workflows, so success would need to solve repeatable production problems. Generating an attractive demonstration is a different hurdle from becoming the tool a team pays to use every week.
#tool #easier
The investment question is whether easier AI design draws marketing budgets toward Adobe or encourages customers to do more inside Figma. Both already serve people creating branded visual material. Winning that workflow could support subscriptions and paid AI usage, but another tool also gives customers another reason to compare prices.
Copyright: photogearch / 123RF Stock Photo
Adobe Inc. (NASDAQ:ADBE) reported fiscal second-quarter revenue of $6.62 billion, up 13%, for the period ended May 29. Its AI-first annualized recurring revenue exceeded $500 million and more than tripled year over year. Those figures give its AI strategy substance beyond a product invitation. Its established creative customer base could also make testing and distribution easier.
The risk is that product experimentation fails to produce additional spending. Adobe must persuade customers that new capabilities deserve payment while competitors make basic ******* et creation easier. Oasis currently provides no disclosed conversion rate or financial contribution with which investors can test that proposition. Its invitation targets brand-identity and marketing workflows, so success would need to solve repeatable production problems. Generating an attractive demonstration is a different hurdle from becoming the tool a team pays to use every week.
#tool #easier


5 days ago
OpenAI launched a product on Thursday called ChatGPT for Financial Services, a version of its enterprise tool tailored to handle tasks traditionally performed by entry-level investment bankers, including company research, financial data ***** ysis, and pitchbook creation.
According to CNBC, the product was developed alongside Morgan Stanley and Evercore as design partners, is built on top of ChatGPT Work, and is powered by GPT-6 Astra, the most capable model in OpenAI's current lineup. It is initially aimed at investment banking and equity research teams.
"We're effectively teaching ChatGPT to research like an ***** yst and back up its conclusions like an ***** yst as well," Nick Turley, OpenAI's vice president of product, told CNBC during a briefing announcing the product.
Unlike the standard ChatGPT Work offering, the financial services version connects directly to data from LSEG, Daloopa, and Pitchbook — giving the system ready access to financial statements and earnings transcripts — and can also tap into a firm's existing data subscriptions automatically, according to CNBC. The product also includes sourcing tools that link figures directly to underlying filings, chart verification functionality, and permission controls designed to safeguard confidential deal information.
In a live demo, Turley walked through the platform's capabilities as it examined a prospective M&A target, drew financial figures from industry-standard data sources, and generated a formatted PowerPoint presentation styled to a bank's existing template, according to CNBC.
#according
According to CNBC, the product was developed alongside Morgan Stanley and Evercore as design partners, is built on top of ChatGPT Work, and is powered by GPT-6 Astra, the most capable model in OpenAI's current lineup. It is initially aimed at investment banking and equity research teams.
"We're effectively teaching ChatGPT to research like an ***** yst and back up its conclusions like an ***** yst as well," Nick Turley, OpenAI's vice president of product, told CNBC during a briefing announcing the product.
Unlike the standard ChatGPT Work offering, the financial services version connects directly to data from LSEG, Daloopa, and Pitchbook — giving the system ready access to financial statements and earnings transcripts — and can also tap into a firm's existing data subscriptions automatically, according to CNBC. The product also includes sourcing tools that link figures directly to underlying filings, chart verification functionality, and permission controls designed to safeguard confidential deal information.
In a live demo, Turley walked through the platform's capabilities as it examined a prospective M&A target, drew financial figures from industry-standard data sources, and generated a formatted PowerPoint presentation styled to a bank's existing template, according to CNBC.
#according

0.00$ raised of 0.00$ goal
0 donations
0.00$
to go
5 days ago
Palo Alto Networks, Inc. (NASDAQ:PANW) reported fiscal fourth-quarter revenue of $3.41 billion, up 34% year over year. Next-Generation Security annual recurring revenue, or NGS ARR, increased 63% to $9.10 billion, while remaining performance obligations rose 34% to $21.2 billion. Remaining performance obligations represent contracted revenue not yet recognized.
NGS ARR is a company-reported operating metric measuring annualized allocated revenue from active contracts, excluding hardware, legacy attached subscriptions and support, and professional services. The current portfolio includes acquired identity and observability businesses absent from the prior-year base, so the 63% increase is not an organic growth rate. Palo Alto Networks, Inc. (NASDAQ:PANW) also reported a $282 million GAAP net loss after earning $254 million a year earlier.
The commercial indicators support greater customer consolidation onto the expanded platform. Palo Alto Networks, Inc. (NASDAQ:PANW) added approximately $970 million of net new NGS ARR. The $21.2 billion RPO balance provides visibility as contracted revenue is recognized over time.
Cash generation also remained strong despite the GAAP loss. Palo Alto Networks, Inc. (NASDAQ:PANW) produced $1.36 billion of operating cash flow, up from $1.02 billion a year earlier. That cash supports integration work.
Management expects fiscal 2027 revenue of $14.10 billion to $14.20 billion, representing growth of 23% to 24%. NGS ARR is expected to reach $11.075 billion to $11.175 billion, up 22% to 23%. Palo Alto Networks, Inc. (NASDAQ:PANW) also acquired Console, an AI-native platform intended to add agentic workflows to Cortex and extend automated investigation and remediation across enterprise operations.
#billion #networks #NASDAQ
NGS ARR is a company-reported operating metric measuring annualized allocated revenue from active contracts, excluding hardware, legacy attached subscriptions and support, and professional services. The current portfolio includes acquired identity and observability businesses absent from the prior-year base, so the 63% increase is not an organic growth rate. Palo Alto Networks, Inc. (NASDAQ:PANW) also reported a $282 million GAAP net loss after earning $254 million a year earlier.
The commercial indicators support greater customer consolidation onto the expanded platform. Palo Alto Networks, Inc. (NASDAQ:PANW) added approximately $970 million of net new NGS ARR. The $21.2 billion RPO balance provides visibility as contracted revenue is recognized over time.
Cash generation also remained strong despite the GAAP loss. Palo Alto Networks, Inc. (NASDAQ:PANW) produced $1.36 billion of operating cash flow, up from $1.02 billion a year earlier. That cash supports integration work.
Management expects fiscal 2027 revenue of $14.10 billion to $14.20 billion, representing growth of 23% to 24%. NGS ARR is expected to reach $11.075 billion to $11.175 billion, up 22% to 23%. Palo Alto Networks, Inc. (NASDAQ:PANW) also acquired Console, an AI-native platform intended to add agentic workflows to Cortex and extend automated investigation and remediation across enterprise operations.
#billion #networks #NASDAQ

0.00$ raised of 0.00$ goal
0 donations
0.00$
to go

5 days ago
GitLab Inc. (NASDAQ:GTLB) reported fiscal second-quarter revenue of $286.3 million, up 21% year over year, as gross bookings reached a company record. Annual recurring revenue, or ARR, is the annualized run rate of subscription revenue at period end and excludes professional services. GitLab Inc. (NASDAQ:GTLB) defines Net ARR as the change in ARR between periods on a bookings basis, measured by opportunity close date. Quarterly Net ARR grew more than 40%, which does not mean total ending ARR grew at that rate.
Dollar-based net retention was 117%, the same rounded figure as the first quarter. GitLab Inc. (NASDAQ:GTLB) said the underlying rate accelerated sequentially, although it declined from 121% one year earlier. Customers generating more than $100,000 of ARR increased 17% to 1,571. Current remaining performance obligations, or contracted revenue expected to be recognized within 12 months, rose 20% to $744.7 million. Total remaining performance obligations increased 16% to $1.2 billion.
Record bookings and management-reported sequential improvement in dollar-based net retention create a credible path to future subscription revenue. First orders more than doubled, while first-order Net ARR grew nearly 40%. Deals worth at least $500,000 increased more than 150%, and the Ultimate tier reached 59% of ARR after growing approximately 35%.
AI and consumption products are gaining early traction. Duo Agent Platform paid consumption run rate grew roughly 50% sequentially. GitLab Inc. (NASDAQ:GTLB) defines paid consumption run rate as a point-in-time annualized measure of credit and Flex commitments plus paid on-demand consumption, excluding trials and promotional credits. It exceeded $40 million, up from $15 million entering the quarter, but is not revenue or ARR. The increase included Flex, where existing subscription dollars can enter the commitment pool, so it was not necessarily incremental consumption demand.
GitLab Flex attracted more than 130 customers and over $20 million of commitments during its first six weeks, with most occurring at renewal. Flex lets customers allocate one commitment across seats, credits, and eligible consumption products, potentially reducing procurement friction as AI-driven activity grows.
#revenue #consumption #gtlb #first
Dollar-based net retention was 117%, the same rounded figure as the first quarter. GitLab Inc. (NASDAQ:GTLB) said the underlying rate accelerated sequentially, although it declined from 121% one year earlier. Customers generating more than $100,000 of ARR increased 17% to 1,571. Current remaining performance obligations, or contracted revenue expected to be recognized within 12 months, rose 20% to $744.7 million. Total remaining performance obligations increased 16% to $1.2 billion.
Record bookings and management-reported sequential improvement in dollar-based net retention create a credible path to future subscription revenue. First orders more than doubled, while first-order Net ARR grew nearly 40%. Deals worth at least $500,000 increased more than 150%, and the Ultimate tier reached 59% of ARR after growing approximately 35%.
AI and consumption products are gaining early traction. Duo Agent Platform paid consumption run rate grew roughly 50% sequentially. GitLab Inc. (NASDAQ:GTLB) defines paid consumption run rate as a point-in-time annualized measure of credit and Flex commitments plus paid on-demand consumption, excluding trials and promotional credits. It exceeded $40 million, up from $15 million entering the quarter, but is not revenue or ARR. The increase included Flex, where existing subscription dollars can enter the commitment pool, so it was not necessarily incremental consumption demand.
GitLab Flex attracted more than 130 customers and over $20 million of commitments during its first six weeks, with most occurring at renewal. Flex lets customers allocate one commitment across seats, credits, and eligible consumption products, potentially reducing procurement friction as AI-driven activity grows.
#revenue #consumption #gtlb #first
0.00$ raised of 0.00$ goal
0 donations
0.00$
to go

7 days ago
In 2026, sports highlights should be accessible to anyone, anytime, anywhere. Unless you're Georgia Bulldogs football that is.
College football fans are among the most passionate in all of sports. And we have seen media companies and streaming platforms use that passion to drive subscriptions. There's a reason why there's at least one Ohio State Buckeyes game on Big Ten Network and Peacock each year, it helps to drive subscriptions for those outlets. But there has certainly been anger and disenchantment from fans and even legislators knowing that they are being forced to pay up to watch their team.
But Georgia may be taking it to an entirely new and absurd level.
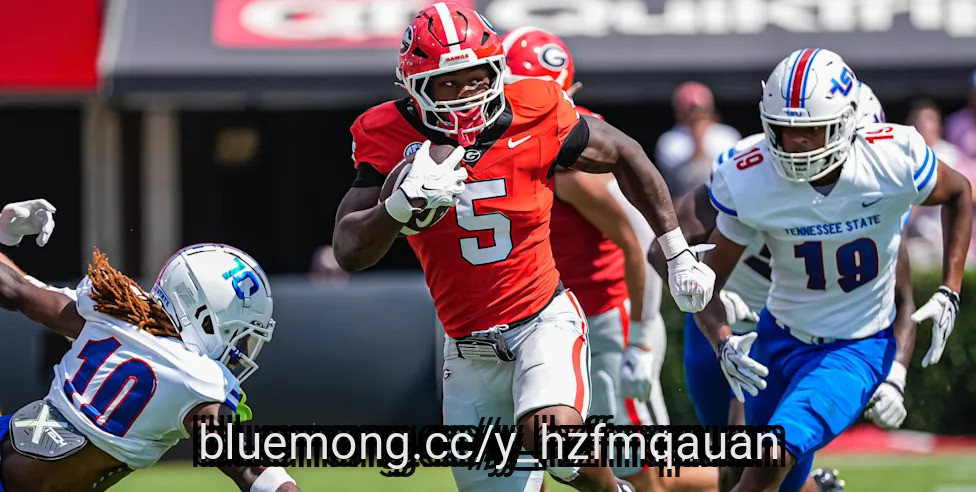
The third-ranked Bulldogs began their season with a 63-3 victory over Tennessee State on Saturday in what amounted to a glorified preseason game. And on Monday evening, they posted a teaser trailer for the program's official highlight video… with a catch. The full highlights were only available on the Glory Glory Georgia website and app. And access requires a minimum $20 monthly subscription fee.
As you might expect, the replies and quote tweets to the post are filled with fans in disbelief over having to pay a monthly subscription to watch a highlights video.
#highlights #state #glory
College football fans are among the most passionate in all of sports. And we have seen media companies and streaming platforms use that passion to drive subscriptions. There's a reason why there's at least one Ohio State Buckeyes game on Big Ten Network and Peacock each year, it helps to drive subscriptions for those outlets. But there has certainly been anger and disenchantment from fans and even legislators knowing that they are being forced to pay up to watch their team.
But Georgia may be taking it to an entirely new and absurd level.
The third-ranked Bulldogs began their season with a 63-3 victory over Tennessee State on Saturday in what amounted to a glorified preseason game. And on Monday evening, they posted a teaser trailer for the program's official highlight video… with a catch. The full highlights were only available on the Glory Glory Georgia website and app. And access requires a minimum $20 monthly subscription fee.
As you might expect, the replies and quote tweets to the post are filled with fans in disbelief over having to pay a monthly subscription to watch a highlights video.
#highlights #state #glory

7 days ago
Reuters and Bloomberg reported that Blackstone Inc. (NYSE:BX) offered to sell up to 25% of India's Knowledge Realty Trust, a real estate investment trust it backs alongside local partner Sattva Group, in a deal that could raise as much as $1.25 billion to $1.3 billion.
The floor price of 108 rupees per unit represented a 4.7% discount to the prior close and a 13% discount to net ******* et value. The sale ran August 31 for institutional investors and September 1 for retail investors. Bloomberg later reported the offering was fully subscribed and upsized to raise about $1.3 billion, the largest share sale by a private shareholder in India via this method. Blackstone's stake will fall to about 21.5% from 46.5% if the oversubscription option is fully exercised, making Sattva Group the trust's largest shareholder at 32%. Knowledge Realty Trust owns 29 properties across six Indian cities and has gained roughly 10% since its August 2025 listing.
Strong investor demand validates the quality of the portfolio Blackstone built. The offering attracted enough demand to sell out and even allowed Blackstone to increase the size of the transaction. That strong response gives Blackstone confidence that institutional and retail investors want exposure to Knowledge Realty Trust and India's commercial real estate market.
The sale also lets Blackstone recycle capital after generating gains on its investment. Knowledge Realty Trust has gained about 10% since its August 2025 listing. Blackstone can now redeploy proceeds into new investments rather than keep as much capital concentrated in one real estate ******* et and market. The transaction shows Blackstone's ability to monetize mature investments and redeploy capital into new opportunities.
Blackstone Inc. (NYSE:BX) still retains exposure to Knowledge Realty Trust after the sale. Its remaining stake of about 21.5% gives the firm substantial economic exposure to the trust's future performance alongside Sattva Group, which holds about 32%. Blackstone can continue to participate in India's commercial real estate growth while securing a significant amount of liquidity from the partial exit.
#trust #real #sale
The floor price of 108 rupees per unit represented a 4.7% discount to the prior close and a 13% discount to net ******* et value. The sale ran August 31 for institutional investors and September 1 for retail investors. Bloomberg later reported the offering was fully subscribed and upsized to raise about $1.3 billion, the largest share sale by a private shareholder in India via this method. Blackstone's stake will fall to about 21.5% from 46.5% if the oversubscription option is fully exercised, making Sattva Group the trust's largest shareholder at 32%. Knowledge Realty Trust owns 29 properties across six Indian cities and has gained roughly 10% since its August 2025 listing.
Strong investor demand validates the quality of the portfolio Blackstone built. The offering attracted enough demand to sell out and even allowed Blackstone to increase the size of the transaction. That strong response gives Blackstone confidence that institutional and retail investors want exposure to Knowledge Realty Trust and India's commercial real estate market.
The sale also lets Blackstone recycle capital after generating gains on its investment. Knowledge Realty Trust has gained about 10% since its August 2025 listing. Blackstone can now redeploy proceeds into new investments rather than keep as much capital concentrated in one real estate ******* et and market. The transaction shows Blackstone's ability to monetize mature investments and redeploy capital into new opportunities.
Blackstone Inc. (NYSE:BX) still retains exposure to Knowledge Realty Trust after the sale. Its remaining stake of about 21.5% gives the firm substantial economic exposure to the trust's future performance alongside Sattva Group, which holds about 32%. Blackstone can continue to participate in India's commercial real estate growth while securing a significant amount of liquidity from the partial exit.
#trust #real #sale

7 days ago
Workday, Inc. (NASDAQ:WDAY) reported fiscal second-quarter revenue of $2.65 billion, up nearly 13% year over year and above the $2.64 billion ***** ysts expected, Reuters reported, citing LSEG data. Subscription revenue rose 13.9% to $2.471 billion. Chief Commercial Officer Rob Enslin said, "Over half of our net new wins in the second quarter signed up for one or more AI solutions," and AI products drove more than $100 million in new annual contract value, over 25% of all new ACV closed in the quarter. Non-GAAP operating margin expanded to 31.1%, up 212 basis points year over year. CFO Zane Rowe said Workday expects fiscal 2028 subscription revenue to grow by nearly 11%, in line with the pace expected for the second half of fiscal 2027.
The beat came with quantified AI monetization behind it. AI products already account for more than 25% of new annual contract value and are approaching $600 million in annual recurring revenue. It is evidence that customers are paying for AI capabilities today rather than Workday simply promising future upside.
Profitability is expanding at the same time growth continues, not at growth's expense. Non-GAAP operating margin rose to 31.1%, up 212 basis points from a year earlier. It shows Workday's AI investment is being absorbed without eroding the bottom line, a combination that strengthens the case that AI is additive rather than just a cost center.
Workday, Inc. (NASDAQ:WDAY)'s reporting is directly countering the disruption narrative that has weighed on enterprise software stocks. Reuters described the results as "easing investor fears of artificial intelligence disruption," and Enslin's comment that AI is now "a key reason companies are modernizing their core on Workday" shows AI is pulling customers toward Workday's platform rather than away from it.
Forward revenue visibility is improving, not just this quarter's headline number. The 12-month subscription revenue backlog grew 14.2% to $9.03 billion. It gives Workday a larger, growing pipeline of already-contracted future revenue to draw on.
#revenue #year #fiscal #rather
The beat came with quantified AI monetization behind it. AI products already account for more than 25% of new annual contract value and are approaching $600 million in annual recurring revenue. It is evidence that customers are paying for AI capabilities today rather than Workday simply promising future upside.
Profitability is expanding at the same time growth continues, not at growth's expense. Non-GAAP operating margin rose to 31.1%, up 212 basis points from a year earlier. It shows Workday's AI investment is being absorbed without eroding the bottom line, a combination that strengthens the case that AI is additive rather than just a cost center.
Workday, Inc. (NASDAQ:WDAY)'s reporting is directly countering the disruption narrative that has weighed on enterprise software stocks. Reuters described the results as "easing investor fears of artificial intelligence disruption," and Enslin's comment that AI is now "a key reason companies are modernizing their core on Workday" shows AI is pulling customers toward Workday's platform rather than away from it.
Forward revenue visibility is improving, not just this quarter's headline number. The 12-month subscription revenue backlog grew 14.2% to $9.03 billion. It gives Workday a larger, growing pipeline of already-contracted future revenue to draw on.
#revenue #year #fiscal #rather
8 days ago
Jack Doherty has been accused of targeting women described as "young and vulnerable" with promises of a glamorous lifestyle before allegedly taking a substantial share of the money they generated. Former employees claim the controversial YouTuber used his massive social media following to promote women selling adult content while exercising considerable control over their businesses. The allegations have resurfaced as Doherty faces heightened scrutiny following his recent arrest on a misdemeanor domestic battery charge in Florida.
Doherty built his online following through confrontational pranks, livestreams and increasingly outrageous public stunts. As his operation expanded, luxury cars, private jets and scantily clad models became a regular part of his content.
Former employee Matthew Gonzalez, a content creator who has worked with Jake Paul and MrBeast, reportedly spent approximately six months working for Doherty in 2023. "He did whatever he had to do to get views," Gonzalez told the Daily Mail.
Gonzalez claimed Doherty's controversial behavior helped him build a large audience of young viewers. According to the former employee, that following was later used to promote models who sold adult content.
The arrangement allegedly allowed Doherty to profit from both the public videos featuring the women and their separate subscription-based accounts.
#content #allegedly
Doherty built his online following through confrontational pranks, livestreams and increasingly outrageous public stunts. As his operation expanded, luxury cars, private jets and scantily clad models became a regular part of his content.
Former employee Matthew Gonzalez, a content creator who has worked with Jake Paul and MrBeast, reportedly spent approximately six months working for Doherty in 2023. "He did whatever he had to do to get views," Gonzalez told the Daily Mail.
Gonzalez claimed Doherty's controversial behavior helped him build a large audience of young viewers. According to the former employee, that following was later used to promote models who sold adult content.
The arrangement allegedly allowed Doherty to profit from both the public videos featuring the women and their separate subscription-based accounts.
#content #allegedly


8 days ago
On September 2, ChargePoint Holdings, Inc (NYSE:CHPT) reported stronger-than-expected results for the second quarter of fiscal 2027. Revenue and the company's loss per share both came in better than Wall Street expectations and the company also reported record non-GAAP gross margin while also highlighting continued progress across its charging business.
Q2 revenue increased 18% year-over-year to $116.1 million, exceeding the $105.2 million ****** yst estimate. ChargePoint Holdings, Inc (NYSE:CHPT) reported an adjusted loss of 35 cents per share, compared with ****** ysts' expectations for a loss of 85 cents per share, according to average estimates compiled by LSEG.
The company also benefited from higher North American home-charging sales, which helped push revenue above expectations. Networked charging systems revenue was up 25% year-over-year as it reached $62.9 million. Subscription revenue increased 10% to $43.7 million. Additionally, the company reported a 78% improvement in its non-GAAP adjusted EBITDA loss, which narrowed sharply to $4.8 million from $22.1 million in the same quarter last year.
ChargePoint Holdings, Inc (NYSE:CHPT) expanded its commercial relationships during the quarter as it extended its long-standing partnership with Mercedes-Benz through a new agreement covering charging solutions for fleet operators in the UK and Germany. The company also announced agreements with Optimus Energy Solutions and Onvo that are expected to add hundreds of new charging ports across the eastern US.
The company also appointed automotive industry veteran John Saffrett as Executive Vice President and Managing Director for Europe, where he will be overseeing sales, customer relationships, partnerships, and market expansion.
#revenue #holdings #chpt
Q2 revenue increased 18% year-over-year to $116.1 million, exceeding the $105.2 million ****** yst estimate. ChargePoint Holdings, Inc (NYSE:CHPT) reported an adjusted loss of 35 cents per share, compared with ****** ysts' expectations for a loss of 85 cents per share, according to average estimates compiled by LSEG.
The company also benefited from higher North American home-charging sales, which helped push revenue above expectations. Networked charging systems revenue was up 25% year-over-year as it reached $62.9 million. Subscription revenue increased 10% to $43.7 million. Additionally, the company reported a 78% improvement in its non-GAAP adjusted EBITDA loss, which narrowed sharply to $4.8 million from $22.1 million in the same quarter last year.
ChargePoint Holdings, Inc (NYSE:CHPT) expanded its commercial relationships during the quarter as it extended its long-standing partnership with Mercedes-Benz through a new agreement covering charging solutions for fleet operators in the UK and Germany. The company also announced agreements with Optimus Energy Solutions and Onvo that are expected to add hundreds of new charging ports across the eastern US.
The company also appointed automotive industry veteran John Saffrett as Executive Vice President and Managing Director for Europe, where he will be overseeing sales, customer relationships, partnerships, and market expansion.
#revenue #holdings #chpt
9 days ago
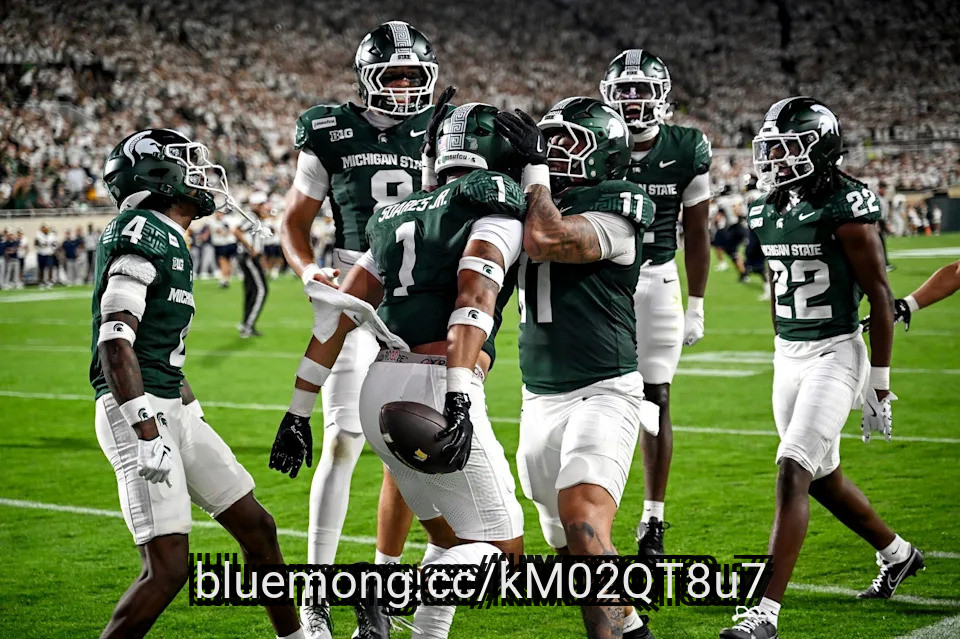
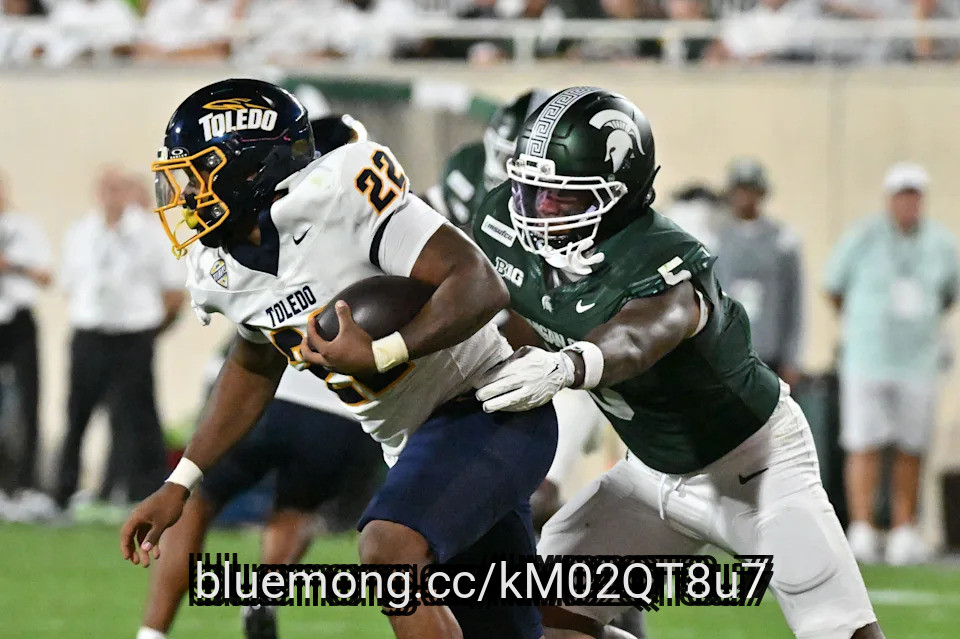
Michigan State football got the 2026 season started with a 30-20 win over Toledo. The Spartans, playing their first game under new head coach Pat Fitzgerald, got the tenure started right with a victory.
While it was a double digit victory, things were not always pretty for the Spartans, who needed to overcome a small deficit in the fourth quarter after having a very disappointing third quarter. In the end, though, the Spartans were victorious and are 1-0 on the season.
On defense, it is an interesting unit to evaluate. The Spartans did give up 20 points, and 273 yards of offense, but most of that damage was done on five individual plays that accounted for over 75-percent of the Rockets offensive output. All in all, the Spartans got the job done, and got stops when they mattered most.
After the game, and evaluating the film, Pro Football Focus (Subscription Required) gave out their grades for the Spartans in the game.
Check out the top five defenders for the Spartans, according to PFF:
#spartans #quarter #done
While it was a double digit victory, things were not always pretty for the Spartans, who needed to overcome a small deficit in the fourth quarter after having a very disappointing third quarter. In the end, though, the Spartans were victorious and are 1-0 on the season.
On defense, it is an interesting unit to evaluate. The Spartans did give up 20 points, and 273 yards of offense, but most of that damage was done on five individual plays that accounted for over 75-percent of the Rockets offensive output. All in all, the Spartans got the job done, and got stops when they mattered most.
After the game, and evaluating the film, Pro Football Focus (Subscription Required) gave out their grades for the Spartans in the game.
Check out the top five defenders for the Spartans, according to PFF:
#spartans #quarter #done

10 days ago
This story was originally published on Payments Dive. To receive daily news and insights, subscribe to our free daily Payments Dive newsletter.
As consumers spend more on goods and services through subscriptions, retail and entertainment categories are attracting a lot of their payments. Those two categories comprised roughly 43% of consumers' overall subscription spending in the past 12 months ending in July, a greater share than 41% in 2025 and 2024, according to a new Bank of America report. Food, fitness and fashion was the next highest category (26%) among the non-utility spending.
The growth in subscription spending by U.S. consumers at 7.7% outpaced the expansion of total card spending for the second consecutive year, also for the 12-month period through July, according to the report issued Wednesday, which is based on the bank's transaction data.
While subscription spending among Gen Xers and Baby Boomers grew modestly during that 12-month period at 3% and 5%, respectively, Gen Z subscription spending surged by about 14%, surpassing that of younger Millennials (about 10%) and older Millennials (nearly 8%), per the report.
While subscription spending on reading and information was the smallest category of spending (7%), per the bank's report, those payments grew the most year-over-year, especially among the Gen Z group.
#spending #daily
As consumers spend more on goods and services through subscriptions, retail and entertainment categories are attracting a lot of their payments. Those two categories comprised roughly 43% of consumers' overall subscription spending in the past 12 months ending in July, a greater share than 41% in 2025 and 2024, according to a new Bank of America report. Food, fitness and fashion was the next highest category (26%) among the non-utility spending.
The growth in subscription spending by U.S. consumers at 7.7% outpaced the expansion of total card spending for the second consecutive year, also for the 12-month period through July, according to the report issued Wednesday, which is based on the bank's transaction data.
While subscription spending among Gen Xers and Baby Boomers grew modestly during that 12-month period at 3% and 5%, respectively, Gen Z subscription spending surged by about 14%, surpassing that of younger Millennials (about 10%) and older Millennials (nearly 8%), per the report.
While subscription spending on reading and information was the smallest category of spending (7%), per the bank's report, those payments grew the most year-over-year, especially among the Gen Z group.
#spending #daily

10 days ago
Jim Cramer questioned the reaction to Rubrik, Inc.'s (NYSE:RBRK) latest earnings report during the September 2 episode of Mad Money, as he said:
What just happened to the stock of Rubrik? That's the data security company, reported a seemingly very strong quarter last week... The stock dropped 13% the next day. Darn thing's been drifting lower ever since. Now, this is kind of crazy, people. Rubrik posted a big revenue beat. Earned 20 cents per share when the ***** ysts were looking for 4 cents. They raised their full-year forecast for revenue. Annual recurring revenue was sensational. Margins, free cash flow good too. Stock got hurt. Now some of that's because Rubrik's billings, some people say, came in a little light. I think it's supposedly because the stock had run up like crazy in the month before the quarter. It just came in maybe too hot. The stock's up 14% for the year.
Rubrik, Inc. (NYSE:RBRK) reported revenue of $427.3 million for the second quarter fiscal year 2027, up 38% year over year and above Wall Street's roughly $396 million estimate. Non-GAAP diluted earnings were $0.20 per share, compared with a non-GAAP loss of $(0.03) per share a year earlier and a $0.04 consensus estimate. Subscription ARR increased 33% to $1.66 billion, while net new subscription ARR rose 35% to approximately $96 million.
Management raised its fiscal 2027 outlook. Revenue is now expected at $1.685 billion to $1.693 billion, subscription ARR at $1.880 billion to $1.885 billion and free cash flow at $323 million to $333 million. Third-quarter revenue guidance of $429 million to $431 million also implies continued strong growth.
Moreover, management said demand is being driven by cyber resilience, platform consolidation and expansion into identity resilience. Customers with at least $100,000 of subscription ARR increased 23% to 3,084, while customers generating more than $1 million grew by more than 57%. Rubrik's newer Agent Cloud product remains early, with more than 15 paying customers and only a minimal ARR contribution included in the fiscal-year outlook.
#billion #Stock
What just happened to the stock of Rubrik? That's the data security company, reported a seemingly very strong quarter last week... The stock dropped 13% the next day. Darn thing's been drifting lower ever since. Now, this is kind of crazy, people. Rubrik posted a big revenue beat. Earned 20 cents per share when the ***** ysts were looking for 4 cents. They raised their full-year forecast for revenue. Annual recurring revenue was sensational. Margins, free cash flow good too. Stock got hurt. Now some of that's because Rubrik's billings, some people say, came in a little light. I think it's supposedly because the stock had run up like crazy in the month before the quarter. It just came in maybe too hot. The stock's up 14% for the year.
Rubrik, Inc. (NYSE:RBRK) reported revenue of $427.3 million for the second quarter fiscal year 2027, up 38% year over year and above Wall Street's roughly $396 million estimate. Non-GAAP diluted earnings were $0.20 per share, compared with a non-GAAP loss of $(0.03) per share a year earlier and a $0.04 consensus estimate. Subscription ARR increased 33% to $1.66 billion, while net new subscription ARR rose 35% to approximately $96 million.
Management raised its fiscal 2027 outlook. Revenue is now expected at $1.685 billion to $1.693 billion, subscription ARR at $1.880 billion to $1.885 billion and free cash flow at $323 million to $333 million. Third-quarter revenue guidance of $429 million to $431 million also implies continued strong growth.
Moreover, management said demand is being driven by cyber resilience, platform consolidation and expansion into identity resilience. Customers with at least $100,000 of subscription ARR increased 23% to 3,084, while customers generating more than $1 million grew by more than 57%. Rubrik's newer Agent Cloud product remains early, with more than 15 paying customers and only a minimal ARR contribution included in the fiscal-year outlook.
#billion #Stock


10 days ago
C3.ai's fiscal first-quarter results replaced a speculative earnings setup with a mixed turnaround test. The company reported $52.4 million of revenue, within its $50 million to $54 million guidance but down 25% from $70.3 million a year earlier. Subscription revenue was $49.2 million, or 94% of total revenue, compared with $60.3 million in the prior-year quarter. C3.ai, Inc. (NYSE:AI) therefore stabilized within management's lowered expectations, without yet returning to growth.
There were encouraging operating signals. Bookings increased 73% sequentially, the company signed 22 agreements, and free cash flow improved to positive $2.1 million from negative $34.3 million a year earlier. Its non-GAAP operating loss narrowed 33% sequentially to $36.2 million. Management guided fiscal second-quarter revenue to $51 million to $55 million and maintained full-year revenue guidance of $210 million to $240 million. Still, both ranges imply that a rapid return to the prior year's scale is unlikely.
Those figures complicate, rather than erase, DA Davidson ***** yst Lucky Schreiner's bearish case. In a September 1 note, Schreiner reiterated an Underperform rating and a $7 target, while seeing possible professional-services upside and stabilization in subscription trends. Revenue landed near the middle of guidance, and subscription revenue represented a larger share of the mix. However, stabilization at a much lower level is not the same as renewed expansion.
The bearish evidence remains substantial. GAAP gross margin was only 32%, and the company posted a $92.8 million GAAP net loss, or $0.60 per share. C3.ai, Inc. (NYSE:AI) still competes against cloud providers, data platforms, and customers building applications internally. Better bookings and cash flow must translate into durable subscription growth and improving margins before the results demonstrate an economic turnaround.
Hedge funds showed cautious improvement rather than conviction. Insider Monkey counted 29 hedge funds holding the shares in Q2, up from 25 in Q1. Point72 ***** et Management increased its position 154% to 568,406 shares. That is notable, but 13F filings reveal positions rather than investment rationales.
#gaap #company #guidance #NYSE
There were encouraging operating signals. Bookings increased 73% sequentially, the company signed 22 agreements, and free cash flow improved to positive $2.1 million from negative $34.3 million a year earlier. Its non-GAAP operating loss narrowed 33% sequentially to $36.2 million. Management guided fiscal second-quarter revenue to $51 million to $55 million and maintained full-year revenue guidance of $210 million to $240 million. Still, both ranges imply that a rapid return to the prior year's scale is unlikely.
Those figures complicate, rather than erase, DA Davidson ***** yst Lucky Schreiner's bearish case. In a September 1 note, Schreiner reiterated an Underperform rating and a $7 target, while seeing possible professional-services upside and stabilization in subscription trends. Revenue landed near the middle of guidance, and subscription revenue represented a larger share of the mix. However, stabilization at a much lower level is not the same as renewed expansion.
The bearish evidence remains substantial. GAAP gross margin was only 32%, and the company posted a $92.8 million GAAP net loss, or $0.60 per share. C3.ai, Inc. (NYSE:AI) still competes against cloud providers, data platforms, and customers building applications internally. Better bookings and cash flow must translate into durable subscription growth and improving margins before the results demonstrate an economic turnaround.
Hedge funds showed cautious improvement rather than conviction. Insider Monkey counted 29 hedge funds holding the shares in Q2, up from 25 in Q1. Point72 ***** et Management increased its position 154% to 568,406 shares. That is notable, but 13F filings reveal positions rather than investment rationales.
#gaap #company #guidance #NYSE

10 days ago
Updated Sept 03, 2026, 1:17 pm EDT / Original Sept 03, 2026, 12:27 pm EDT
Count me among those who believe we are in an artificial-intelligence bubble.
Copyright ©2026 Dow Jones & Company, Inc. All Rights Reserved. 87990cbe856818d5eddac44c7b1cdeb8
The software maker said annual recurring revenue, a closely watched measure of its subscription business, rose 30%.
#rights #believe
Count me among those who believe we are in an artificial-intelligence bubble.
Copyright ©2026 Dow Jones & Company, Inc. All Rights Reserved. 87990cbe856818d5eddac44c7b1cdeb8
The software maker said annual recurring revenue, a closely watched measure of its subscription business, rose 30%.
#rights #believe



