20 mins. ago
On September 15, CareTrust REIT (NYSE:CTRE) announced it had closed on a $400 million skilled nursing portfolio in the Southwest, effective September 1, and unveiled a reloaded $600 million investment pipeline behind it. The deal covers 2,622 licensed beds triple net leased back to the existing operator, sourced off-market and structured through a joint venture that put roughly $380 million of CareTrust's own capital to work. It is the latest entry in a buying spree that has now pushed the company's 2026 investment total past $1.9 billion.
The new portfolio is expected to generate a stabilized yield of about 8.6%, in line with the 8.7% blended yield CareTrust has posted across two dozen deals closed so far in 2026. That consistency matters more than any single transaction. The company has now closed roughly $710 million in investments in the third quarter alone, including a small UK care home purchase in mid-August, on top of the $899.6 million it closed in the second quarter at an 8.9% yield.
Management says the $600 million pipeline of near-term, actionable deals, about half of it aimed at the senior housing operating portfolio, does not even include a set of larger transactions still being pursued, so the deal flow may not be finished. The balance sheet backs up that ambition. CareTrust ended the second quarter, on June 30, 2026, with net debt to annualized normalized EBITDA of just 1.01x, and as of the September announcement it still had $725 million available under its revolver plus $612 million of remaining ATM capacity. That combination let the company raise its full year 2026 guidance on August 6 to normalized FFO of $2.03 to $2.06 per share, an increase of 16.2% at the midpoint over 2025, even before this latest acquisition was on the books.
This growth has come with a real cost to existing shareholders. Diluted weighted average shares outstanding rose from about 192.9 million in the second quarter of 2025 to 234.2 million a year later, as CareTrust leaned on forward equity offerings and its ATM program to fund the buying spree. The company still had $439 million of expected net proceeds sitting in unsettled forward equity contracts as of September 15, meaning more shares are still coming.
The second quarter also carried a $4.7 million provision for loan losses, a line that did not appear in the prior year period and is worth watching as the loan and financing receivable book grows alongside the property portfolio. Interest expense rose to $15.3 million in the quarter from $13.0 million a year earlier, and 2026 guidance leans on rent escalators of just 2.5% a year, a modest built-in growth rate once the acquisition pace eventually slows. The company's own risk disclosures flag reliance on tenants to keep meeting their lease obligations, along with exposure to healthcare reform, staffing requirements, and currency swings tied to its UK operations.
#still
The new portfolio is expected to generate a stabilized yield of about 8.6%, in line with the 8.7% blended yield CareTrust has posted across two dozen deals closed so far in 2026. That consistency matters more than any single transaction. The company has now closed roughly $710 million in investments in the third quarter alone, including a small UK care home purchase in mid-August, on top of the $899.6 million it closed in the second quarter at an 8.9% yield.
Management says the $600 million pipeline of near-term, actionable deals, about half of it aimed at the senior housing operating portfolio, does not even include a set of larger transactions still being pursued, so the deal flow may not be finished. The balance sheet backs up that ambition. CareTrust ended the second quarter, on June 30, 2026, with net debt to annualized normalized EBITDA of just 1.01x, and as of the September announcement it still had $725 million available under its revolver plus $612 million of remaining ATM capacity. That combination let the company raise its full year 2026 guidance on August 6 to normalized FFO of $2.03 to $2.06 per share, an increase of 16.2% at the midpoint over 2025, even before this latest acquisition was on the books.
This growth has come with a real cost to existing shareholders. Diluted weighted average shares outstanding rose from about 192.9 million in the second quarter of 2025 to 234.2 million a year later, as CareTrust leaned on forward equity offerings and its ATM program to fund the buying spree. The company still had $439 million of expected net proceeds sitting in unsettled forward equity contracts as of September 15, meaning more shares are still coming.
The second quarter also carried a $4.7 million provision for loan losses, a line that did not appear in the prior year period and is worth watching as the loan and financing receivable book grows alongside the property portfolio. Interest expense rose to $15.3 million in the quarter from $13.0 million a year earlier, and 2026 guidance leans on rent escalators of just 2.5% a year, a modest built-in growth rate once the acquisition pace eventually slows. The company's own risk disclosures flag reliance on tenants to keep meeting their lease obligations, along with exposure to healthcare reform, staffing requirements, and currency swings tied to its UK operations.
#still


5 hours ago
On August 5, Kinetik Holdings Inc. (NYSE:KNTK) reported the strongest quarterly results in company history and raised its full-year 2026 guidance. The Permian-focused midstream operator posted net income, including noncontrolling interest, of $123.1 million for the quarter ended June 30, while Adjusted EBITDA climbed to $280.8 million. Management didn't stop at celebrating the number. It used the quarter as the launchpad for a string of expansion decisions that stretch out to 2028.
The Midstream Logistics segment, Kinetik's largest, grew Adjusted EBITDA 35% year over year to $204.8 million in the second quarter, even though processed natural gas volumes held flat at 1.74 Bcf/d. That flat number actually undersells the quarter. It came despite roughly 250 million cubic feet per day of gas that had been shut in because of weak Waha-area pricing, with stronger natural gas liquid recoveries, condensate yields, and favorable commodity spreads carrying the segment instead.
Management is betting the growth continues well past 2026. In May, Kinetik reached a final investment decision on Kings Landing II, a roughly $260 million project that will lift sour gas processing capacity across the company's Delaware North complex above 700 MMcf/d and push total system capacity to 2.7 Bcf/d when it comes online in mid-2028, earlier than previously communicated. The ECCC Pipeline, which links the system's northern and southern halves between Eddy and Culberson Counties, is now in service, and right-of-way work has already begun on a follow-on expansion for 2027.
Kinetik also locked in new firm Gulf Coast access for residue gas starting in 2027 and signed fresh natural gas liquids transport agreements, both aimed at getting better prices for the gas it moves. On the back of that momentum, Kinetik raised its full-year 2026 Adjusted EBITDA guidance to a range of $1.04 billion to $1.1 billion, a 7% ***** p from the guidance it issued in February.
Not every part of the business is moving in the same direction. The Pipeline Transportation segment posted Adjusted EBITDA of $83.0 million in the quarter, down 14% year over year, a decline the company attributes to last year's divestiture of its equity stake in EPIC Crude Holdings. That sale removed a source of cash flow the rest of the business now has to make up for. Kinetik also expects gas curtailments to keep running at an average of 25 million cubic feet per day through the second half of 2026, on top of the Waha-driven shut-ins that already weighed on the quarter. Its own pricing ***** umptions underline the regional problem: the company is now modeling Waha Hub natural gas at negative $0.26 per MMBtu for the full year, meaning gas in parts of the Permian is priced so low that moving it out of the basin is the whole game.
#quarter
The Midstream Logistics segment, Kinetik's largest, grew Adjusted EBITDA 35% year over year to $204.8 million in the second quarter, even though processed natural gas volumes held flat at 1.74 Bcf/d. That flat number actually undersells the quarter. It came despite roughly 250 million cubic feet per day of gas that had been shut in because of weak Waha-area pricing, with stronger natural gas liquid recoveries, condensate yields, and favorable commodity spreads carrying the segment instead.
Management is betting the growth continues well past 2026. In May, Kinetik reached a final investment decision on Kings Landing II, a roughly $260 million project that will lift sour gas processing capacity across the company's Delaware North complex above 700 MMcf/d and push total system capacity to 2.7 Bcf/d when it comes online in mid-2028, earlier than previously communicated. The ECCC Pipeline, which links the system's northern and southern halves between Eddy and Culberson Counties, is now in service, and right-of-way work has already begun on a follow-on expansion for 2027.
Kinetik also locked in new firm Gulf Coast access for residue gas starting in 2027 and signed fresh natural gas liquids transport agreements, both aimed at getting better prices for the gas it moves. On the back of that momentum, Kinetik raised its full-year 2026 Adjusted EBITDA guidance to a range of $1.04 billion to $1.1 billion, a 7% ***** p from the guidance it issued in February.
Not every part of the business is moving in the same direction. The Pipeline Transportation segment posted Adjusted EBITDA of $83.0 million in the quarter, down 14% year over year, a decline the company attributes to last year's divestiture of its equity stake in EPIC Crude Holdings. That sale removed a source of cash flow the rest of the business now has to make up for. Kinetik also expects gas curtailments to keep running at an average of 25 million cubic feet per day through the second half of 2026, on top of the Waha-driven shut-ins that already weighed on the quarter. Its own pricing ***** umptions underline the regional problem: the company is now modeling Waha Hub natural gas at negative $0.26 per MMBtu for the full year, meaning gas in parts of the Permian is priced so low that moving it out of the basin is the whole game.
#quarter


5 hours ago
On September 11, Elastic (NYSE:ESTC) rolled out Elasticsearch Vector Database, a new serverless offering the company says lets developers ship large-scale vector search and AI applications without stitching together the usual pile of infrastructure themselves. The launch landed less than three weeks after Elastic posted first-quarter fiscal 2027 results on August 27, for the period ended July 31, giving investors a fresh product story to weigh against a quarter that already showed accelerating growth.
The new database automates what used to require manual **** embly: chunking documents, hosting embedding and reranking models, configuring indexes, and wiring query-time retrieval. Elastic built in expert-tuned defaults, a single field type that handles indexing, embeddings, and chunking together, and hybrid search that combines full-text and vector retrieval in one query. The system scales to hundreds of billions of vectors using Elastic's Better Binary Quantization, which the company says shrinks vector memory by up to 32 times while keeping recall high, and pricing is based on data and search capacity rather than the opaque compute units the company says define most pure-play vector database pricing.
That product push follows a quarter that was already running hot. Total revenue reached $478 million in the first quarter of fiscal 2027, up 15% year over year, while current remaining performance obligations grew 21% and remaining performance obligations grew 27%. Sales-led subscription revenue, which strips out Monthly Elastic Cloud, grew 18% year over year to $399 million, outpacing the company's overall subscription growth.
Elastic added more customers with annual contract value above $100,000 than in any prior quarter, pushing that cohort past 1,800 from over 1,720 in the fourth quarter of fiscal 2026 and over 1,550 a year earlier. Net expansion rate held around 111%, and the company generated $143 million in adjusted free cash flow during the quarter. Guidance for the second quarter of fiscal 2027, ending October 31, calls for revenue of $486 million to $487 million and a swing to positive GAAP operating margin, with full fiscal 2027 non-GAAP operating margin guided to roughly 19.4%, up from 16.2% in the quarter just reported.
Growth came with a reminder that Elastic has not fully crossed into GAAP profitability. The company posted a GAAP operating loss of $24 million in the first quarter of fiscal 2027, a -5% operating margin, and a GAAP net loss per share of $0.16. Non-GAAP figures told a healthier story, with $77 million in non-GAAP operating income and $0.70 in non-GAAP diluted earnings per share, but the gap between the two measures shows how much of Elastic's reported profitability still depends on excluding real costs like stock-based compensation.
#elastic #vector #company
The new database automates what used to require manual **** embly: chunking documents, hosting embedding and reranking models, configuring indexes, and wiring query-time retrieval. Elastic built in expert-tuned defaults, a single field type that handles indexing, embeddings, and chunking together, and hybrid search that combines full-text and vector retrieval in one query. The system scales to hundreds of billions of vectors using Elastic's Better Binary Quantization, which the company says shrinks vector memory by up to 32 times while keeping recall high, and pricing is based on data and search capacity rather than the opaque compute units the company says define most pure-play vector database pricing.
That product push follows a quarter that was already running hot. Total revenue reached $478 million in the first quarter of fiscal 2027, up 15% year over year, while current remaining performance obligations grew 21% and remaining performance obligations grew 27%. Sales-led subscription revenue, which strips out Monthly Elastic Cloud, grew 18% year over year to $399 million, outpacing the company's overall subscription growth.
Elastic added more customers with annual contract value above $100,000 than in any prior quarter, pushing that cohort past 1,800 from over 1,720 in the fourth quarter of fiscal 2026 and over 1,550 a year earlier. Net expansion rate held around 111%, and the company generated $143 million in adjusted free cash flow during the quarter. Guidance for the second quarter of fiscal 2027, ending October 31, calls for revenue of $486 million to $487 million and a swing to positive GAAP operating margin, with full fiscal 2027 non-GAAP operating margin guided to roughly 19.4%, up from 16.2% in the quarter just reported.
Growth came with a reminder that Elastic has not fully crossed into GAAP profitability. The company posted a GAAP operating loss of $24 million in the first quarter of fiscal 2027, a -5% operating margin, and a GAAP net loss per share of $0.16. Non-GAAP figures told a healthier story, with $77 million in non-GAAP operating income and $0.70 in non-GAAP diluted earnings per share, but the gap between the two measures shows how much of Elastic's reported profitability still depends on excluding real costs like stock-based compensation.
#elastic #vector #company


5 hours ago
Alluvium ******* et Management, an ******* et management company, released its "Conventum – Alluvium Global Fund" second-quarter 2026 investor letter. The letter can be downloaded here. The second quarter reflected a sharp shift from geopolitical uncertainty and oil market volatility to a powerful equity rally led by semiconductor companies. Despite the broader market strength, the Fund declined 1.4% in EUR terms, 2.2% in USD terms, and 3.9% in AUD terms. Portfolio results were mixed, with Alphabet benefiting from strong Cloud growth, while Robert Half, H&R Block, and other holdings posted solid gains. However, cable businesses and several healthcare and consumer holdings weighed on performance. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Conventum – Alluvium Global Fund highlighted McKesson Corporation (NYSE:MCK). McKesson Corporation (NYSE:MCK) is a leading healthcare services company headquartered in Irving, Texas. On September 15, 2026, McKesson Corporation (NYSE:MCK) closed at $899.56 per share. Over the past month. McKesson Corporation (NYSE:MCK) returned 5.37% and its shares gained 29.95% over the past 52 weeks. McKesson Corporation (NYSE:MCK) has a market capitalization of $106.21 billion, and its stock has traded with a range of $687.68 and $999.00.
Conventum – Alluvium Global Fund stated the following regarding McKesson Corporation (NYSE:MCK) in its Q2 2026 investor letter:
"Our two healthcare companies had a poor quarter (in terms of share price performance, not business fundamentals). McKesson Corporation (NYSE:MCK), the drug distributor (down 12.6%), reported its full year results which were perfectly in-line with our expectations. Management provided strong guidance for its next year's earnings, and reiterated its 13%-16% long term growth expectations. After feeding the numbers through our model, our valuation increased by 18%, and with the share price trading below it, we bought a little more such that it accounts for 6.8% of the Fund."
McKesson Corporation (NYSE:MCK) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 77 hedge fund portfolios held McKesson Corporation (NYSE:MCK) at the end of the second quarter which was 73 in the previous quarter. While we acknowledge the potential of McKesson Corporation (NYSE:MCK) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#mckesson #alluvium #global
In its second-quarter 2026 investor letter, Conventum – Alluvium Global Fund highlighted McKesson Corporation (NYSE:MCK). McKesson Corporation (NYSE:MCK) is a leading healthcare services company headquartered in Irving, Texas. On September 15, 2026, McKesson Corporation (NYSE:MCK) closed at $899.56 per share. Over the past month. McKesson Corporation (NYSE:MCK) returned 5.37% and its shares gained 29.95% over the past 52 weeks. McKesson Corporation (NYSE:MCK) has a market capitalization of $106.21 billion, and its stock has traded with a range of $687.68 and $999.00.
Conventum – Alluvium Global Fund stated the following regarding McKesson Corporation (NYSE:MCK) in its Q2 2026 investor letter:
"Our two healthcare companies had a poor quarter (in terms of share price performance, not business fundamentals). McKesson Corporation (NYSE:MCK), the drug distributor (down 12.6%), reported its full year results which were perfectly in-line with our expectations. Management provided strong guidance for its next year's earnings, and reiterated its 13%-16% long term growth expectations. After feeding the numbers through our model, our valuation increased by 18%, and with the share price trading below it, we bought a little more such that it accounts for 6.8% of the Fund."
McKesson Corporation (NYSE:MCK) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 77 hedge fund portfolios held McKesson Corporation (NYSE:MCK) at the end of the second quarter which was 73 in the previous quarter. While we acknowledge the potential of McKesson Corporation (NYSE:MCK) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#mckesson #alluvium #global


6 hours ago
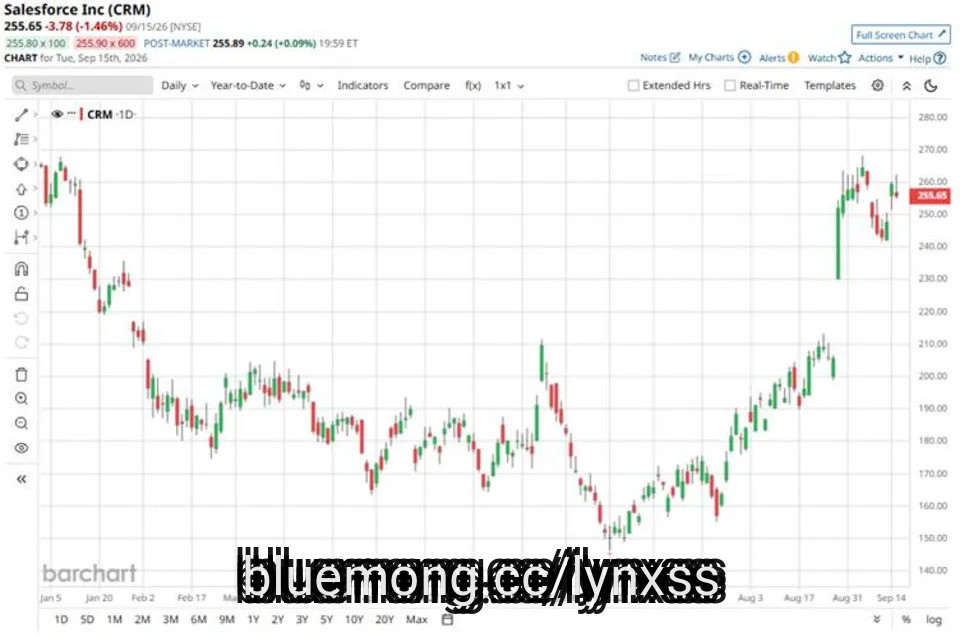
Salesforce (CRM) investors have an important date to watch as the company prepares to host its Investor & ****** yst Session on Wednesday, Sept. 16, during Dreamforce 2026. The event comes at a critical time for Salesforce as investors look for greater clarity on how the company plans to turn rapid artificial intelligence (AI) adoption into sustainable revenue growth. Salesforce recently delivered a strong second-quarter fiscal 2027 report, with current remaining performance obligations rising 14% and management raising its full-year revenue guidance.
Against this backdrop, the Investor Day session could provide additional insight into Salesforce's long-term financial position, Agentforce, Data 360, and AI monetization. The company has increasingly positioned AI agents as a major growth opportunity, while its recent partnership with Anthropic has further expanded its AI ecosystem.
Billionaire Charlie Munger, Who Died at 99, Skipped Insurance on His Mansion Since He Could Just Write a Check to Rebuild — 'All Intelligent People Do It My Way'
The Case for Selling CrowdStrike Stock
Nvidia CEO Jensen Huang Just Dropped Huge News for This Cybersecurity Stock
#company #revenue
Against this backdrop, the Investor Day session could provide additional insight into Salesforce's long-term financial position, Agentforce, Data 360, and AI monetization. The company has increasingly positioned AI agents as a major growth opportunity, while its recent partnership with Anthropic has further expanded its AI ecosystem.
Billionaire Charlie Munger, Who Died at 99, Skipped Insurance on His Mansion Since He Could Just Write a Check to Rebuild — 'All Intelligent People Do It My Way'
The Case for Selling CrowdStrike Stock
Nvidia CEO Jensen Huang Just Dropped Huge News for This Cybersecurity Stock
#company #revenue


6 hours ago
Ciena stock rebounds 4% as investors reprice CEO Gary Smith's projection of a $10B backlog by fiscal year-end, despite a 19% monthly slide.
Arista rises just 2% and Cisco barely moves at 0.4%, confirming today's surge is Ciena's own order book story, not a broad networking rally.
CFO Marc Graff guided for at least 30% revenue growth next fiscal year, backed by backlog that extends beyond that period.
Read More: Learn 7 secret wealth tips high net worth investors use that most investors miss (sponsor)
Ciena (NYSE:CIEN) stock is climbing early Wednesday, up 4% to $347.60. The advance is a rebound rather than a breakout, since Ciena stock is down 19% over the past month. No fresh company news landed this morning, and the market is re-pricing disclosures Ciena made at the start of September, when the company reported record quarterly results with revenue at the top end of guidance.
#backlog
Arista rises just 2% and Cisco barely moves at 0.4%, confirming today's surge is Ciena's own order book story, not a broad networking rally.
CFO Marc Graff guided for at least 30% revenue growth next fiscal year, backed by backlog that extends beyond that period.
Read More: Learn 7 secret wealth tips high net worth investors use that most investors miss (sponsor)
Ciena (NYSE:CIEN) stock is climbing early Wednesday, up 4% to $347.60. The advance is a rebound rather than a breakout, since Ciena stock is down 19% over the past month. No fresh company news landed this morning, and the market is re-pricing disclosures Ciena made at the start of September, when the company reported record quarterly results with revenue at the top end of guidance.
#backlog



7 hours ago
Walmart and SCAN Health Plan announced a partnership on Wednesday to offer co-branded Medicare Advantage plans in two states, targeting a pool of more than two million Medicare enrollees.
The plans, pending regulatory approval, may include pharmacy, vision, food, and over-the-counter benefits, the companies said. Open enrollment for Medicare Advantage begins Oct. 15, according to MarketWatch.
A central feature of the partnership is Walmart's Everyday Health Signals platform, an AI tool designed to provide personalized nutrition and wellness guidance based on members' shopping preferences and self-reported wellness goals. The companies said they plan to make that capability available to participating plan members as part of broader coaching and wellness support.
"By combining Walmart's technology capabilities and consumer retail expertise with SCAN's Medicare product experience, we have an opportunity to develop products that translate those insights into meaningful support that helps members make more informed choices about their health and well-being," said Zack Myers, national general manager of SCAN Health Plan, in a statement.
Walmart Group Director for Consumer Health and Data Solutions Pravene Nath said the collaboration is distinct because of Walmart's role in customers' everyday lives. "Because customers regularly turn to Walmart for groceries and other everyday essentials, we have an opportunity for those who choose to participate, to use insights from their shopping experiences to make nutrition guidance more relevant and actionable," Nath said in a statement.
#Wellness #members #scan #advantage
The plans, pending regulatory approval, may include pharmacy, vision, food, and over-the-counter benefits, the companies said. Open enrollment for Medicare Advantage begins Oct. 15, according to MarketWatch.
A central feature of the partnership is Walmart's Everyday Health Signals platform, an AI tool designed to provide personalized nutrition and wellness guidance based on members' shopping preferences and self-reported wellness goals. The companies said they plan to make that capability available to participating plan members as part of broader coaching and wellness support.
"By combining Walmart's technology capabilities and consumer retail expertise with SCAN's Medicare product experience, we have an opportunity to develop products that translate those insights into meaningful support that helps members make more informed choices about their health and well-being," said Zack Myers, national general manager of SCAN Health Plan, in a statement.
Walmart Group Director for Consumer Health and Data Solutions Pravene Nath said the collaboration is distinct because of Walmart's role in customers' everyday lives. "Because customers regularly turn to Walmart for groceries and other everyday essentials, we have an opportunity for those who choose to participate, to use insights from their shopping experiences to make nutrition guidance more relevant and actionable," Nath said in a statement.
#Wellness #members #scan #advantage


8 hours ago
Alluvium ******* et Management, an ******* et management company, released its "Conventum – Alluvium Global Fund" second-quarter 2026 investor letter. The letter can be downloaded here. The second quarter reflected a sharp shift from geopolitical uncertainty and oil market volatility to a powerful equity rally led by semiconductor companies. Despite the broader market strength, the Fund declined 1.4% in EUR terms, 2.2% in USD terms, and 3.9% in AUD terms. Portfolio results were mixed, with Alphabet benefiting from strong Cloud growth, while Robert Half, H&R Block, and other holdings posted solid gains. However, cable businesses and several healthcare and consumer holdings weighed on performance. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Conventum – Alluvium Global Fund highlighted HCA Healthcare, Inc. (NYSE:HCA). HCA Healthcare, Inc. (NYSE:HCA) owns and operates hospitals and related healthcare entities. On September 15, 2026, HCA Healthcare, Inc. (NYSE:HCA) closed at $423.04 per share. HCA Healthcare, Inc. (NYSE:HCA) returned 3.93% over the past month, and its shares are up 5.92% over the past year. HCA Healthcare, Inc. (NYSE:HCA) has a market capitalization of $91.76 billion.
Conventum – Alluvium Global Fund stated the following regarding HCA Healthcare, Inc. (NYSE:HCA) in its Q2 2026 investor letter:
"Our two healthcare companies had a poor quarter (in terms of share price performance, not business fundamentals). HCA Healthcare, Inc. (NYSE:HCA), the hospital operator, fell 17.5%. The share price fell 8.8% immediately following its first quarter results (despite management reaffirming its 2026 guidance). We suspect this is a (over) reaction to poorer than expected respiratory volumes due to a mild flu season. With the shares trading at a discount to our valuation we bought a little more to bring the Fund's position to 6.4%."
HCA Healthcare, Inc. (NYSE:HCA) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 75 hedge fund portfolios held HCA Healthcare, Inc. (NYSE:HCA) at the end of the second quarter which was 70 in the previous quarter. While we acknowledge the potential of HCA Healthcare, Inc. (NYSE:HCA) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#quarter #fund #alluvium #conventum
In its second-quarter 2026 investor letter, Conventum – Alluvium Global Fund highlighted HCA Healthcare, Inc. (NYSE:HCA). HCA Healthcare, Inc. (NYSE:HCA) owns and operates hospitals and related healthcare entities. On September 15, 2026, HCA Healthcare, Inc. (NYSE:HCA) closed at $423.04 per share. HCA Healthcare, Inc. (NYSE:HCA) returned 3.93% over the past month, and its shares are up 5.92% over the past year. HCA Healthcare, Inc. (NYSE:HCA) has a market capitalization of $91.76 billion.
Conventum – Alluvium Global Fund stated the following regarding HCA Healthcare, Inc. (NYSE:HCA) in its Q2 2026 investor letter:
"Our two healthcare companies had a poor quarter (in terms of share price performance, not business fundamentals). HCA Healthcare, Inc. (NYSE:HCA), the hospital operator, fell 17.5%. The share price fell 8.8% immediately following its first quarter results (despite management reaffirming its 2026 guidance). We suspect this is a (over) reaction to poorer than expected respiratory volumes due to a mild flu season. With the shares trading at a discount to our valuation we bought a little more to bring the Fund's position to 6.4%."
HCA Healthcare, Inc. (NYSE:HCA) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 75 hedge fund portfolios held HCA Healthcare, Inc. (NYSE:HCA) at the end of the second quarter which was 70 in the previous quarter. While we acknowledge the potential of HCA Healthcare, Inc. (NYSE:HCA) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#quarter #fund #alluvium #conventum


21 hours ago
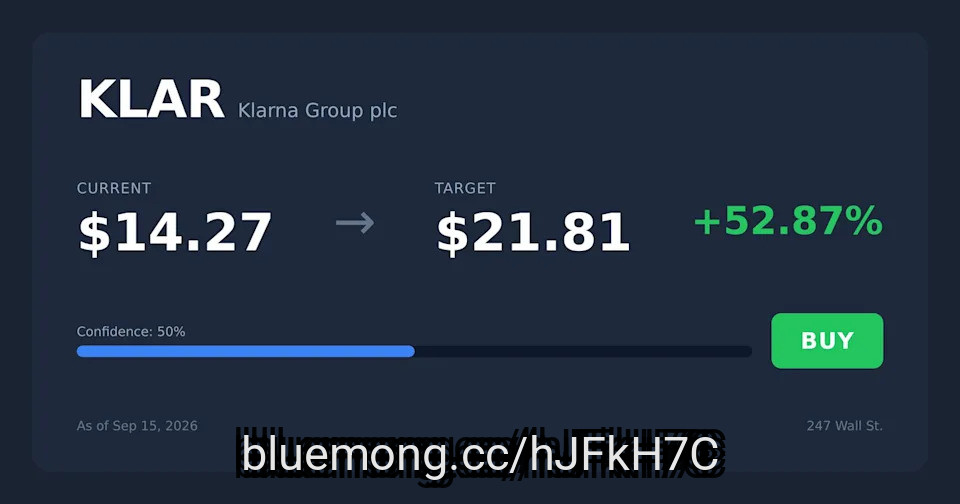
Klarna stock has cratered 51% year to date and 32% in just the past month, trading near its 52-week low of $12.
While KLAR collapsed, Sezzle surged 87% and Affirm slipped just 3%, signaling Klarna's pain is company-specific, not a BNPL sector rout.
Klarna's Q2 showed transaction margin up 42% and a swing to $9M net profit, but a guidance cut and accounting changes cloud the Q3 outlook.
Just released. Our ****** ysts combed the entire stock market and named the ten best stocks to buy right now, and Klarna Group plc didn't make the cut. Enter your email to see the names that beat KLAR. The report is free. Enter your email and see if any of your stocks made the cut.
Shares of Klarna (NYSE:KLAR) are trading at $14.23 on Tuesday afternoon, leaving the buy now, pay later (BNPL) lender down 51% year to date. Klarna stock is also down 32% over the past month, meaning much of the damage has landed recently rather than fading out.
#klar #year #month
While KLAR collapsed, Sezzle surged 87% and Affirm slipped just 3%, signaling Klarna's pain is company-specific, not a BNPL sector rout.
Klarna's Q2 showed transaction margin up 42% and a swing to $9M net profit, but a guidance cut and accounting changes cloud the Q3 outlook.
Just released. Our ****** ysts combed the entire stock market and named the ten best stocks to buy right now, and Klarna Group plc didn't make the cut. Enter your email to see the names that beat KLAR. The report is free. Enter your email and see if any of your stocks made the cut.
Shares of Klarna (NYSE:KLAR) are trading at $14.23 on Tuesday afternoon, leaving the buy now, pay later (BNPL) lender down 51% year to date. Klarna stock is also down 32% over the past month, meaning much of the damage has landed recently rather than fading out.
#klar #year #month



21 hours ago
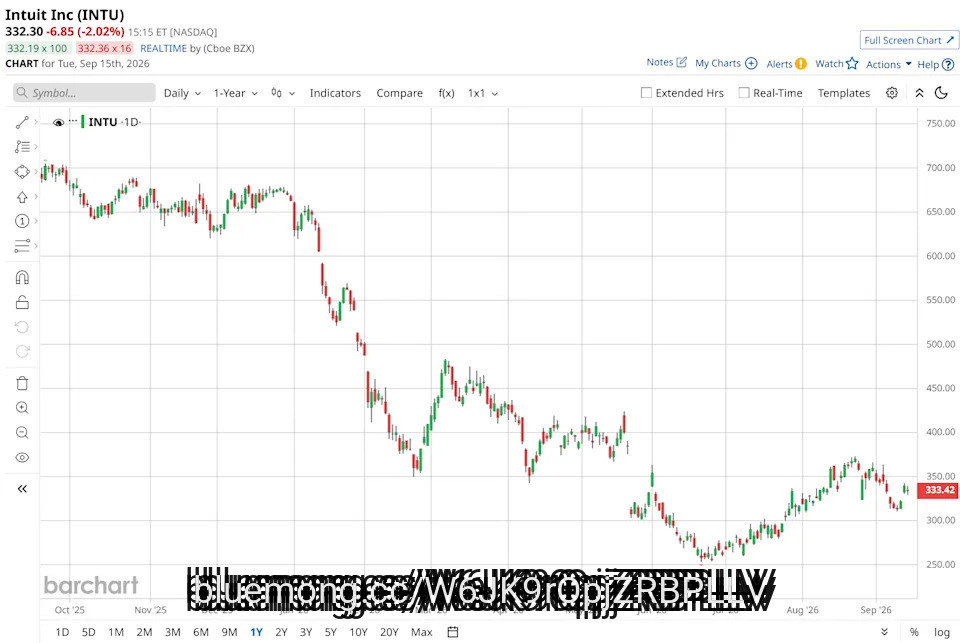
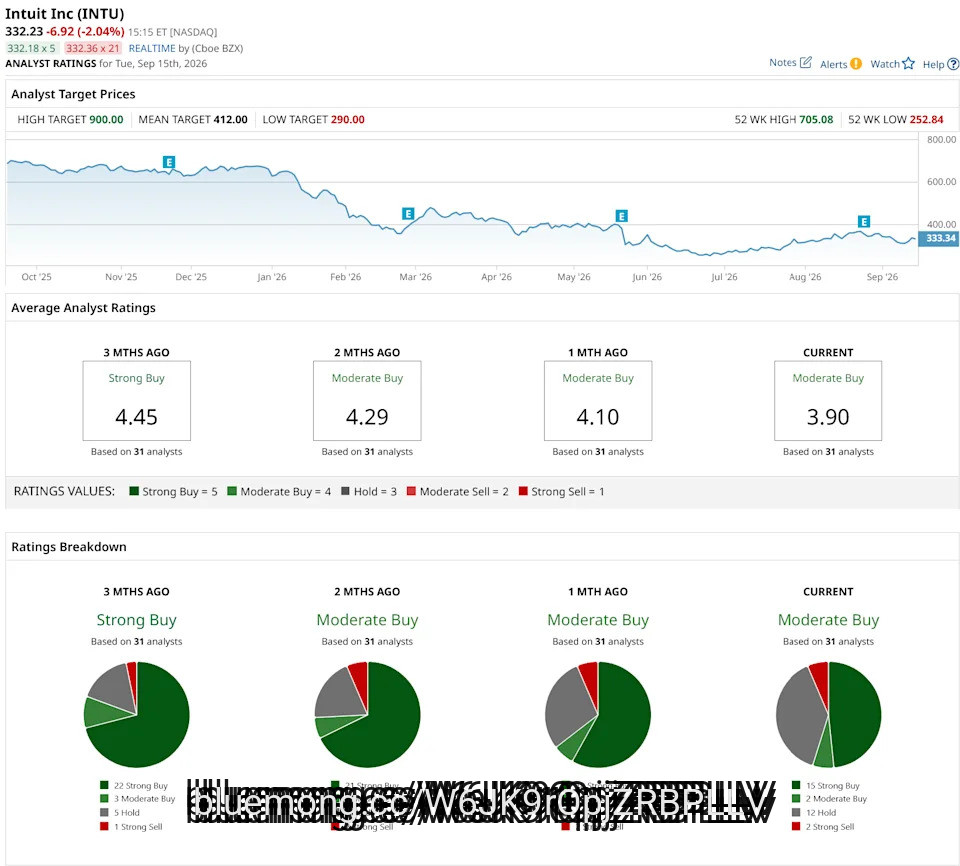
Intuit (INTU) remains a financial technology powerhouse, with roughly 100 million customers across its platforms. Its biggest advantage is the breadth of financial workflows it brings together, spanning everything from tax preparation to business software. But that strength has not protected the stock from a changing market narrative.
Wall Street is increasingly concerned that the rapid adoption and advancement of artificial intelligence (AI) could chip away at Intuit's core tax and business software offerings. These concerns intensified after Intuit delivered slightly disappointing FY2027 sales guidance with its Q4 FY2026 results.
1 'Strong Buy' Dividend Stock Offering a 6.3% Yield Right Now
A $90 Billion Reason to Buy Oracle Stock Now
This High-Yield Construction Stock Just Raised Its Dividend by 40%
#Dividend #yield #intu
Wall Street is increasingly concerned that the rapid adoption and advancement of artificial intelligence (AI) could chip away at Intuit's core tax and business software offerings. These concerns intensified after Intuit delivered slightly disappointing FY2027 sales guidance with its Q4 FY2026 results.
1 'Strong Buy' Dividend Stock Offering a 6.3% Yield Right Now
A $90 Billion Reason to Buy Oracle Stock Now
This High-Yield Construction Stock Just Raised Its Dividend by 40%
#Dividend #yield #intu


22 hours ago
Our **** ysts just identified a stock with the potential to be the next Nvidia. Tell us how you invest and we'll show you why it's our #1 pick. Tap here.
Trustpilot's underlying business is still growing quickly, with revenue up 23%, bookings up 22% and adjusted EBITDA climbing 46% in the first half. But investors instead focused on a surprise statutory loss, several one-off charges and management's decision to leave full-year guidance unchanged after a huge run in the shares.
Trustpilot shares fell as much as 20% after the online review platform reported strong first-half growth but delivered a messier bottom line than investors had expected.
Revenue increased 23% to $151.4 million in the six months to June, equivalent to 19% growth at constant currencies, while bookings rose 22% to $171.2 million.
Adjusted EBITDA climbed 46% to a record $26.3 million and the margin expanded to 17.4%, although the profit figure came in slightly below the $27 million company-compiled consensus.
#ebitda #bookings #investors
Trustpilot's underlying business is still growing quickly, with revenue up 23%, bookings up 22% and adjusted EBITDA climbing 46% in the first half. But investors instead focused on a surprise statutory loss, several one-off charges and management's decision to leave full-year guidance unchanged after a huge run in the shares.
Trustpilot shares fell as much as 20% after the online review platform reported strong first-half growth but delivered a messier bottom line than investors had expected.
Revenue increased 23% to $151.4 million in the six months to June, equivalent to 19% growth at constant currencies, while bookings rose 22% to $171.2 million.
Adjusted EBITDA climbed 46% to a record $26.3 million and the margin expanded to 17.4%, although the profit figure came in slightly below the $27 million company-compiled consensus.
#ebitda #bookings #investors

23 hours ago
During the September 10 episode of Mad Money, a caller inquired about Mad Money host Jim Cramer's confidence that Arista Networks, Inc. (NYSE:ANET) will not go down the same path as Ciena Corporation. He replied:
Okay, so let me just tell you, Arista is up a lot this year. My confidence is with Jayshree Ullall. I think she's amazing and I think it every time the stock has dipped, if you've noticed it. Since her tenure began, you have to buy it, and I'm not backing away from that. I feel the same way I do now, the way I did, oh man, how many years ago when we first met her. She is money, and the company's fantastic.
In its second quarter, the company shattered records by delivering its first-ever $3 billion quarter, reporting $3.036 billion in revenue, a 38% year-over-year and over 12% sequential increase. Management lifted its full-year 2026 revenue guidance to approximately $12.6 billion, representing roughly 40% annual top-line growth. The acceleration is supported by deep integration into cloud architectures, where Arista Networks, Inc. (NYSE:ANET) expects its dedicated AI fabrics revenue to reach at least $3.5 billion in 2026, supported by more than 100 **** ulative Etherlink customers.
Bottom-line performance remains equally strong, with non-GAAP diluted earnings per share reaching $1.02, driven by a 49.9% non-GAAP operating margin and $1.3 billion in non-GAAP quarterly net income. Arista Networks, Inc. (NYSE:ANET) ended the quarter with roughly $13.3 billion in cash and marketable securities, offering substantial liquidity. However, its $9.7 billion of non-cancellable purchase commitments also increase working-capital and inventory risk as the company secures components ahead of expected AI demand.
The company's financial results remain heavily tied to two hyperscale customers. According to its 10-K filings, Microsoft accounted for 26%, and Meta Platforms generated 16% of total revenue in fiscal 2025, bringing combined spending from these two cloud giants to 42%. It leaves Arista Networks, Inc. (NYSE:ANET) vulnerable to sudden capital expenditure adjustments, vendor diversification shifts, or project delays by its core buyers.
#billion #NYSE #year
Okay, so let me just tell you, Arista is up a lot this year. My confidence is with Jayshree Ullall. I think she's amazing and I think it every time the stock has dipped, if you've noticed it. Since her tenure began, you have to buy it, and I'm not backing away from that. I feel the same way I do now, the way I did, oh man, how many years ago when we first met her. She is money, and the company's fantastic.
In its second quarter, the company shattered records by delivering its first-ever $3 billion quarter, reporting $3.036 billion in revenue, a 38% year-over-year and over 12% sequential increase. Management lifted its full-year 2026 revenue guidance to approximately $12.6 billion, representing roughly 40% annual top-line growth. The acceleration is supported by deep integration into cloud architectures, where Arista Networks, Inc. (NYSE:ANET) expects its dedicated AI fabrics revenue to reach at least $3.5 billion in 2026, supported by more than 100 **** ulative Etherlink customers.
Bottom-line performance remains equally strong, with non-GAAP diluted earnings per share reaching $1.02, driven by a 49.9% non-GAAP operating margin and $1.3 billion in non-GAAP quarterly net income. Arista Networks, Inc. (NYSE:ANET) ended the quarter with roughly $13.3 billion in cash and marketable securities, offering substantial liquidity. However, its $9.7 billion of non-cancellable purchase commitments also increase working-capital and inventory risk as the company secures components ahead of expected AI demand.
The company's financial results remain heavily tied to two hyperscale customers. According to its 10-K filings, Microsoft accounted for 26%, and Meta Platforms generated 16% of total revenue in fiscal 2025, bringing combined spending from these two cloud giants to 42%. It leaves Arista Networks, Inc. (NYSE:ANET) vulnerable to sudden capital expenditure adjustments, vendor diversification shifts, or project delays by its core buyers.
#billion #NYSE #year

24 hours ago
On September 10, Canaccord cut its price target for The Lovesac Company (NASDAQ:LOVE) from $22 to $20 but maintained its Buy rating on the stock. This update came after the company reported its financial results for the second quarter of fiscal 2027, which ended August 2, 2026.
Canaccord noted that the company's fiscal Q2 results were in line with expectations. Revenue and adjusted EBITDA were both within the company's guidance and close to consensus estimates. The company received $21 million in IEEPA tariff refunds, which helped lift gross margins and earnings above consensus.
The Lovesac Company (NASDAQ:LOVE) reported net sales 0.4% higher than the prior-year period. This slight increase was mainly driven by 14 net new showrooms, although this was partly offset by a 1.9% decline in omni-channel comparable net sales and the closure of the company's Best Buy shop-in-shop locations. During the quarter, the company opened five additional showrooms and closed two.
The company reported net income of $7.4 million in the second quarter, compared with a net loss of $6.7 million in the same period last year. Operating income also improved to $10.9 million from an operating loss of $8.8 million a year earlier.
Gross profit rose 21.7% year-over-year while gross margin expanded to 68.4% of net sales from 56.4%, an increase of 1,200 basis points. The improvement was largely driven by IEEPA tariff recoveries, which contributed 1,240 basis points to gross margin. Excluding those recoveries, gross margin was 56.0%, down 40 basis points from the prior-year period.
#year #sales #period
Canaccord noted that the company's fiscal Q2 results were in line with expectations. Revenue and adjusted EBITDA were both within the company's guidance and close to consensus estimates. The company received $21 million in IEEPA tariff refunds, which helped lift gross margins and earnings above consensus.
The Lovesac Company (NASDAQ:LOVE) reported net sales 0.4% higher than the prior-year period. This slight increase was mainly driven by 14 net new showrooms, although this was partly offset by a 1.9% decline in omni-channel comparable net sales and the closure of the company's Best Buy shop-in-shop locations. During the quarter, the company opened five additional showrooms and closed two.
The company reported net income of $7.4 million in the second quarter, compared with a net loss of $6.7 million in the same period last year. Operating income also improved to $10.9 million from an operating loss of $8.8 million a year earlier.
Gross profit rose 21.7% year-over-year while gross margin expanded to 68.4% of net sales from 56.4%, an increase of 1,200 basis points. The improvement was largely driven by IEEPA tariff recoveries, which contributed 1,240 basis points to gross margin. Excluding those recoveries, gross margin was 56.0%, down 40 basis points from the prior-year period.
#year #sales #period

24 hours ago
On September 10, Zumiez Inc. (NASDAQ:ZUMZ) reported weaker-than-expected results for its second quarter ended August 1, 2026, with the results falling short of Wall Street estimates and sending the stock lower.
For the second quarter of fiscal 2026, Zumiez Inc. (NASDAQ:ZUMZ) reported net sales of $209 million, down 2.5% year-over-year. Comparable sales declined 2.1%, with the weakness mainly coming from the US. Canada, Europe, and Australia all had positive comparable sales growth for the quarter. The company said it saw strong sales growth across its international markets, but softer domestic sales and lower foot traffic weighed on overall results.
The company also posted a net loss of $2.7 million, or $0.17 per share, compared with a net loss of $1.0 million, or $0.06 per share, in the second quarter of fiscal 2025.
Third-Quarter Outlook Disappoints, But Is It All Bad?
Zumiez Inc. (NASDAQ:ZUMZ) introduced third-quarter guidance, which also failed to provide much relief as it came in below Wall Street expectations. For the three months ending October 31, 2026, the company expects net sales of $222 million to $226 million, while earnings per share are projected to range from $0.00 to $0.10.
#quarter #sales
For the second quarter of fiscal 2026, Zumiez Inc. (NASDAQ:ZUMZ) reported net sales of $209 million, down 2.5% year-over-year. Comparable sales declined 2.1%, with the weakness mainly coming from the US. Canada, Europe, and Australia all had positive comparable sales growth for the quarter. The company said it saw strong sales growth across its international markets, but softer domestic sales and lower foot traffic weighed on overall results.
The company also posted a net loss of $2.7 million, or $0.17 per share, compared with a net loss of $1.0 million, or $0.06 per share, in the second quarter of fiscal 2025.
Third-Quarter Outlook Disappoints, But Is It All Bad?
Zumiez Inc. (NASDAQ:ZUMZ) introduced third-quarter guidance, which also failed to provide much relief as it came in below Wall Street expectations. For the three months ending October 31, 2026, the company expects net sales of $222 million to $226 million, while earnings per share are projected to range from $0.00 to $0.10.
#quarter #sales
1 day ago
Fidelity Investments, an investment management company, recently released its second-quarter 2026 investor letter for the "Fidelity Dividend Growth Fund". The letter can be downloaded here. The Fidelity Dividend Growth Fund is a diversified large-cap equity strategy focused on capital appreciation through investments in large- and mid-cap stocks with strong dividend growth prospects. The fund returned 17.05% in the quarter, outperforming the S&P 500 Index, which gained 15.20%. U.S. stocks experienced significant gains in Q2, driven by increased spending on artificial intelligence. Technology stocks gained 31.79%, mainly driven by semiconductor companies, while the index faced a slight decline in June as investors considered the sustainability of AI-related profits amidst rising interest rates. Despite recent turbulence from the Middle East conflict, the fund remains optimistic about key investment themes, particularly in artificial intelligence. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Fidelity Dividend Growth Fund highlighted Western Digital Corporation (NASDAQ:WDC). Western Digital Corporation (NASDAQ:WDC) is a data storage company that engages in the manufacturing and distribution of data storage devices and solutions based on hard disk drive (HDD) technology. On September 14, 2026, Western Digital Corporation (NASDAQ:WDC) closed at $426.94 per share. Over the past month, Western Digital Corporation (NASDAQ:WDC) declined 13.95%, and its shares are up 314.14% over the past year. Western Digital Corporation (NASDAQ:WDC) has a market capitalization of $153.93 billion, and its stock has traded within a 52-week range of $93.92 to $799.87.
Fidelity Dividend Growth Fund stated the following regarding Western Digital Corporation (NASDAQ:WDC) in its Q2 2026 investor letter:
"Among individual holdings, a sizable overweight in Western Digital Corporation (NASDAQ:WDC) (+140%) topped the list of relative contributors. In late April, the data-storage maker reported better-than-expected quarterly financial results, including higher earnings and gross profit margin. In its report, management said brisk demand for the firm's storage solutions for AI capabilities contributed to the solid quarter. Also, the company raised its financial guidance."
Western Digital Corporation (NASDAQ:WDC) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 98 hedge fund portfolios held Western Digital Corporation (NASDAQ:WDC) at the end of the second quarter, up from 83 in the previous quarter. While we acknowledge the potential of Western Digital Corporation (NASDAQ:WDC) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-te
In its second-quarter 2026 investor letter, Fidelity Dividend Growth Fund highlighted Western Digital Corporation (NASDAQ:WDC). Western Digital Corporation (NASDAQ:WDC) is a data storage company that engages in the manufacturing and distribution of data storage devices and solutions based on hard disk drive (HDD) technology. On September 14, 2026, Western Digital Corporation (NASDAQ:WDC) closed at $426.94 per share. Over the past month, Western Digital Corporation (NASDAQ:WDC) declined 13.95%, and its shares are up 314.14% over the past year. Western Digital Corporation (NASDAQ:WDC) has a market capitalization of $153.93 billion, and its stock has traded within a 52-week range of $93.92 to $799.87.
Fidelity Dividend Growth Fund stated the following regarding Western Digital Corporation (NASDAQ:WDC) in its Q2 2026 investor letter:
"Among individual holdings, a sizable overweight in Western Digital Corporation (NASDAQ:WDC) (+140%) topped the list of relative contributors. In late April, the data-storage maker reported better-than-expected quarterly financial results, including higher earnings and gross profit margin. In its report, management said brisk demand for the firm's storage solutions for AI capabilities contributed to the solid quarter. Also, the company raised its financial guidance."
Western Digital Corporation (NASDAQ:WDC) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 98 hedge fund portfolios held Western Digital Corporation (NASDAQ:WDC) at the end of the second quarter, up from 83 in the previous quarter. While we acknowledge the potential of Western Digital Corporation (NASDAQ:WDC) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-te
1 day ago
Fidelity Investments, an investment management company, recently released its second-quarter 2026 investor letter for the "Fidelity Dividend Growth Fund". The letter can be downloaded here. The Fidelity Dividend Growth Fund is a diversified large-cap equity strategy focused on capital appreciation through investments in large- and mid-cap stocks with strong dividend growth prospects. The fund returned 17.05% in the quarter, outperforming the S&P 500 Index, which gained 15.20%. U.S. stocks experienced significant gains in Q2, driven by increased spending on artificial intelligence. Technology stocks gained 31.79%, mainly driven by semiconductor companies, while the index faced a slight decline in June as investors considered the sustainability of AI-related profits amidst rising interest rates. Despite recent turbulence from the Middle East conflict, the fund remains optimistic about key investment themes, particularly in artificial intelligence. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Fidelity Dividend Growth Fund highlighted Seagate Technology Holdings plc (NASDAQ:STX) as a notable performance contributor. Seagate Technology Holdings plc (NASDAQ:STX) is a data storage company providing data storage technology and infrastructure solutions. On September 14, 2026, Seagate Technology Holdings plc (NASDAQ:STX) closed at $805.55 per share. Over the past month, Seagate Technology Holdings plc (NASDAQ:STX) declined 10.86%, but its shares are up 281.54% over the past year. Seagate Technology Holdings plc (NASDAQ:STX) has a market capitalization of $183.18 billion, and its stock has traded within a 52-week range of $206.26 to $1,145.00.
Fidelity Dividend Growth Fund stated the following regarding Seagate Technology Holdings plc (NASDAQ:STX) in its Q2 2026 investor letter:
"Shares of Seagate Technology Holdings plc (NASDAQ:STX) gained about 147% the past three months. Seagate is one of the world's largest producers of digital storage and, along with Western Digital, one of two dominant makers of hard-disk drives. Exploding demand for HDDs used in AI capable data centers has led to surging sales and strong pricing power for the company. In its most recent quarterly filing in April, Seagate reported revenue, earnings and profitability that all exceeded consensus expectations, while raising financial guidance."
Seagate Technology Holdings plc (NASDAQ:STX) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 131 hedge fund portfolios held Seagate Technology Holdings plc (NASDAQ:STX) at the end of the second quarter, compared to 93 in the previous quarter. While we acknowledge the potential of Seagate Technology Holdings plc (NASDAQ:STX) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly f
In its second-quarter 2026 investor letter, Fidelity Dividend Growth Fund highlighted Seagate Technology Holdings plc (NASDAQ:STX) as a notable performance contributor. Seagate Technology Holdings plc (NASDAQ:STX) is a data storage company providing data storage technology and infrastructure solutions. On September 14, 2026, Seagate Technology Holdings plc (NASDAQ:STX) closed at $805.55 per share. Over the past month, Seagate Technology Holdings plc (NASDAQ:STX) declined 10.86%, but its shares are up 281.54% over the past year. Seagate Technology Holdings plc (NASDAQ:STX) has a market capitalization of $183.18 billion, and its stock has traded within a 52-week range of $206.26 to $1,145.00.
Fidelity Dividend Growth Fund stated the following regarding Seagate Technology Holdings plc (NASDAQ:STX) in its Q2 2026 investor letter:
"Shares of Seagate Technology Holdings plc (NASDAQ:STX) gained about 147% the past three months. Seagate is one of the world's largest producers of digital storage and, along with Western Digital, one of two dominant makers of hard-disk drives. Exploding demand for HDDs used in AI capable data centers has led to surging sales and strong pricing power for the company. In its most recent quarterly filing in April, Seagate reported revenue, earnings and profitability that all exceeded consensus expectations, while raising financial guidance."
Seagate Technology Holdings plc (NASDAQ:STX) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 131 hedge fund portfolios held Seagate Technology Holdings plc (NASDAQ:STX) at the end of the second quarter, compared to 93 in the previous quarter. While we acknowledge the potential of Seagate Technology Holdings plc (NASDAQ:STX) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly f

1 day ago
Citigroup Inc. (NYSE:C)'s CFO Gonzalo Luchetti said the bank expects return on tangible common equity (RoTCE) to come in slightly above 11% in 2026, while also indicating that Citi will increase stock buybacks from the $13 billion repurchased in 2025. The bank plans to accelerate roughly $500 million of investment by year-end, including spending on severance and marketing intended to expand its credit-card and wealth-management businesses. Citi also expects to remove Banamex from its balance sheet in 2027, which will create an estimated $9 billion currency-translation adjustment loss.
The 11%+ target is meaningful because Citi's profitability has already improved materially. In the second quarter, Citi generated $24.8 billion of revenue, up 14% year over year, while net income rose 45% to $5.8 billion. Investment-banking revenue increased 44% to $1.55 billion, and net interest income increased 13%. Citi's SEC filing shows second-quarter RoTCE of 13.0%, versus 8.7% a year earlier, while the first half of 2026 produced a 13.1% RoTCE. The new guidance therefore suggests management believes profitability can remain above the longer-term 11%-13% RoTCE range Citi established for 2027-28, despite additional investment spending.
Kiev.Victor / Shutterstock.com
The bullish argument is that Citigroup Inc. (NYSE:C) appears to be converting its multiyear restructuring into higher returns while simultaneously returning more capital to shareholders. The move from 8.7% RoTCE in the second quarter of 2025 to 13.0% in the second quarter of 2026 represents a substantial improvement in capital efficiency. Citi's efficiency ratio also improved to 57.4% from 62.7%, indicating that revenue growth is increasingly translating into operating leverage rather than being absorbed by expenses. That is particularly relevant because management now intends to spend another roughly $500 million on severance, marketing, and growth initiatives; if these investments produce the intended expansion in cards and wealth management, they could support revenue growth without derailing the profitability trajectory.
Capital returns provide another positive lever. Citi repurchased $13 billion of stock in 2025 and now expects to increase that amount, while its June 2026 CET1 ratio remained 12.78%, comfortably above its 11.6% standardized regulatory requirement. Buybacks can reduce tangible common equity and shares outstanding, potentially supporting both RoTCE and per-share earnings when executed below intrinsic value. Citi's tangible book value per share had already risen 7% year over year to $100.89 by June 30, 2026. The combination of higher operating profitability, shrinking share count, and improving capital efficiency strengthens the case for a valuation re-rating if Citi can sustain returns above 11%.
#rotce #citi #management
The 11%+ target is meaningful because Citi's profitability has already improved materially. In the second quarter, Citi generated $24.8 billion of revenue, up 14% year over year, while net income rose 45% to $5.8 billion. Investment-banking revenue increased 44% to $1.55 billion, and net interest income increased 13%. Citi's SEC filing shows second-quarter RoTCE of 13.0%, versus 8.7% a year earlier, while the first half of 2026 produced a 13.1% RoTCE. The new guidance therefore suggests management believes profitability can remain above the longer-term 11%-13% RoTCE range Citi established for 2027-28, despite additional investment spending.
Kiev.Victor / Shutterstock.com
The bullish argument is that Citigroup Inc. (NYSE:C) appears to be converting its multiyear restructuring into higher returns while simultaneously returning more capital to shareholders. The move from 8.7% RoTCE in the second quarter of 2025 to 13.0% in the second quarter of 2026 represents a substantial improvement in capital efficiency. Citi's efficiency ratio also improved to 57.4% from 62.7%, indicating that revenue growth is increasingly translating into operating leverage rather than being absorbed by expenses. That is particularly relevant because management now intends to spend another roughly $500 million on severance, marketing, and growth initiatives; if these investments produce the intended expansion in cards and wealth management, they could support revenue growth without derailing the profitability trajectory.
Capital returns provide another positive lever. Citi repurchased $13 billion of stock in 2025 and now expects to increase that amount, while its June 2026 CET1 ratio remained 12.78%, comfortably above its 11.6% standardized regulatory requirement. Buybacks can reduce tangible common equity and shares outstanding, potentially supporting both RoTCE and per-share earnings when executed below intrinsic value. Citi's tangible book value per share had already risen 7% year over year to $100.89 by June 30, 2026. The combination of higher operating profitability, shrinking share count, and improving capital efficiency strengthens the case for a valuation re-rating if Citi can sustain returns above 11%.
#rotce #citi #management
1 day ago
Broyhill **** et Management, a Charlotte-based firm, issued its second-quarter 2026 investor letter, which is available for download here. The Broyhill Equity Composite gained 8.8% in Q2, trailing the MSCI All Country World Index's 15.1% and the MSCI ACWI Value Index's 10.8%. For the first half, the Composite returned 2.3%, versus 11.5% for the Index. The letter highlights that a significant portion of the shortfall occurred in April due to market dynamics and geopolitical events, with tech, particularly semiconductors, driving recent gains. Broyhill notes its lack of direct semiconductor exposure but acknowledges potential interest in the sector if opportunities arise, maintaining its investment philosophy focused on capital protection in fragile market conditions. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Broyhill **** et Management highlighted Valvoline Inc. (NYSE:VVV) as a leading performance contributor. Valvoline Inc. (NYSE:VVV) is a US-based automotive preventive maintenance company that offers oil changes, battery, bulb, and wiper replacements; tire rotations; and other maintenance services. On September 14, 2026, Valvoline Inc. (NYSE:VVV) closed at $30.37 per share. Over the past month, Valvoline Inc. (NYSE:VVV) declined 9.69%, and its shares lost 25.33% over the past 52 weeks. Valvoline Inc. (NYSE:VVV) has a market capitalization of $3.87 billion.
Broyhill **** et Management stated the following regarding Valvoline Inc. (NYSE:VVV) in its Q2 2026 investor letter:
"Valvoline Inc. (NYSE:VVV) gained 18%, having also led the first quarter. Comparable sales grew 8.2% against consensus near 5.4%, adjusted EBITDA grew 28%, and guidance was raised across comparable sales, EBITDA, and earnings. The company added 31 stores and now operates 2,409 stores, with ticket sales driving roughly two-thirds of the gain."
Valvoline Inc. (NYSE:VVV) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 44 hedge fund portfolios held Valvoline Inc. (NYSE:VVV) at the end of the second quarter, compared to 39 in the previous quarter. While we acknowledge the potential of Valvoline Inc. (NYSE:VVV) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#broyhill #investor
In its second-quarter 2026 investor letter, Broyhill **** et Management highlighted Valvoline Inc. (NYSE:VVV) as a leading performance contributor. Valvoline Inc. (NYSE:VVV) is a US-based automotive preventive maintenance company that offers oil changes, battery, bulb, and wiper replacements; tire rotations; and other maintenance services. On September 14, 2026, Valvoline Inc. (NYSE:VVV) closed at $30.37 per share. Over the past month, Valvoline Inc. (NYSE:VVV) declined 9.69%, and its shares lost 25.33% over the past 52 weeks. Valvoline Inc. (NYSE:VVV) has a market capitalization of $3.87 billion.
Broyhill **** et Management stated the following regarding Valvoline Inc. (NYSE:VVV) in its Q2 2026 investor letter:
"Valvoline Inc. (NYSE:VVV) gained 18%, having also led the first quarter. Comparable sales grew 8.2% against consensus near 5.4%, adjusted EBITDA grew 28%, and guidance was raised across comparable sales, EBITDA, and earnings. The company added 31 stores and now operates 2,409 stores, with ticket sales driving roughly two-thirds of the gain."
Valvoline Inc. (NYSE:VVV) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 44 hedge fund portfolios held Valvoline Inc. (NYSE:VVV) at the end of the second quarter, compared to 39 in the previous quarter. While we acknowledge the potential of Valvoline Inc. (NYSE:VVV) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#broyhill #investor

1 day ago
Broyhill ***** et Management, a Charlotte-based firm, issued its second-quarter 2026 investor letter, which is available for download here. The Broyhill Equity Composite gained 8.8% in Q2, trailing the MSCI All Country World Index's 15.1% and the MSCI ACWI Value Index's 10.8%. For the first half, the Composite returned 2.3%, versus 11.5% for the Index. The letter highlights that a significant portion of the shortfall occurred in April due to market dynamics and geopolitical events, with tech, particularly semiconductors, driving recent gains. Broyhill notes its lack of direct semiconductor exposure but acknowledges potential interest in the sector if opportunities arise, maintaining its investment philosophy focused on capital protection in fragile market conditions. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Broyhill ***** et Management highlighted The Middleby Corporation (NASDAQ:MIDD). The Middleby Corporation (NASDAQ:MIDD), a leading player in the foodservice industry, contributed positively to performance during the quarter. On September 14, 2026, The Middleby Corporation (NASDAQ:MIDD) closed at $109.72 per share. Over the past month, The Middleby Corporation (NASDAQ:MIDD) declined 3.75%, but its shares are up 1.27% over the past year. The Middleby Corporation (NASDAQ:MIDD) has a market capitalization of $78.51 billion, and its stock has traded within a 52-week range of $89.14 to $148.55.
Broyhill ***** et Management stated the following regarding The Middleby Corporation (NASDAQ:MIDD) in its Q2 2026 investor letter:
"The Middleby Corporation (NASDAQ:MIDD) gained 31%. Commercial Foodservice grew organic revenue 8% as chains returned to growth and management raised full-year guidance by roughly 4%. More important was the structural progress: the Food Processing separation was confirmed at the May investor day (which our investment team attended) and completed on July 6th, creating Midera. Following the majority sale of the residential business earlier this year, what remains is a cleaner business with leverage approaching 2.5x."
The Middleby Corporation (NASDAQ:MIDD) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 42 hedge fund portfolios held The Middleby Corporation (NASDAQ:MIDD) at the end of the second quarter which was 35 in the previous quarter. While we acknowledge the potential of The Middleby Corporation (NASDAQ:MIDD) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#middleby #corporation #broyhill #quarter
In its second-quarter 2026 investor letter, Broyhill ***** et Management highlighted The Middleby Corporation (NASDAQ:MIDD). The Middleby Corporation (NASDAQ:MIDD), a leading player in the foodservice industry, contributed positively to performance during the quarter. On September 14, 2026, The Middleby Corporation (NASDAQ:MIDD) closed at $109.72 per share. Over the past month, The Middleby Corporation (NASDAQ:MIDD) declined 3.75%, but its shares are up 1.27% over the past year. The Middleby Corporation (NASDAQ:MIDD) has a market capitalization of $78.51 billion, and its stock has traded within a 52-week range of $89.14 to $148.55.
Broyhill ***** et Management stated the following regarding The Middleby Corporation (NASDAQ:MIDD) in its Q2 2026 investor letter:
"The Middleby Corporation (NASDAQ:MIDD) gained 31%. Commercial Foodservice grew organic revenue 8% as chains returned to growth and management raised full-year guidance by roughly 4%. More important was the structural progress: the Food Processing separation was confirmed at the May investor day (which our investment team attended) and completed on July 6th, creating Midera. Following the majority sale of the residential business earlier this year, what remains is a cleaner business with leverage approaching 2.5x."
The Middleby Corporation (NASDAQ:MIDD) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 42 hedge fund portfolios held The Middleby Corporation (NASDAQ:MIDD) at the end of the second quarter which was 35 in the previous quarter. While we acknowledge the potential of The Middleby Corporation (NASDAQ:MIDD) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#middleby #corporation #broyhill #quarter

1 day ago
Carter's unveiled a new brand identity and marketing campaign on Tuesday, as the children's clothing company works to attract a younger generation of parents and build on a recent business turnaround.
The rebrand centers on a new brand promise — "Let every child's light shine" — and a refreshed logo in which a shooting star replaces the apostrophe in the Carter's wordmark, the company said. A new 60-second film called "Watch Them Glow" will debut across connected television as the first major marketing expression of the new direction.
Chief Marketing Officer Sarah Crockett told CNBC that the company sees a significant shift in its core customer base. Gen Z is expected to account for a large share of new parents over the next several years, according to Carter's, and those parents tend to let children make their own clothing choices and turn to social media for guidance.
"We had an opportunity to really tap into the values that parents are bringing into the household," Crockett told CNBC.
The new identity will begin rolling out across Carter's channels in 2026, with additional retail, product, and packaging elements to follow in 2027, the company said. Carter's is also launching a creator program called Light Makers, featuring voices across North America, and expanding partnerships with organizations including Outward Bound and Boys & Girls Clubs of America.
#parents #Marketing #cnbc #America
The rebrand centers on a new brand promise — "Let every child's light shine" — and a refreshed logo in which a shooting star replaces the apostrophe in the Carter's wordmark, the company said. A new 60-second film called "Watch Them Glow" will debut across connected television as the first major marketing expression of the new direction.
Chief Marketing Officer Sarah Crockett told CNBC that the company sees a significant shift in its core customer base. Gen Z is expected to account for a large share of new parents over the next several years, according to Carter's, and those parents tend to let children make their own clothing choices and turn to social media for guidance.
"We had an opportunity to really tap into the values that parents are bringing into the household," Crockett told CNBC.
The new identity will begin rolling out across Carter's channels in 2026, with additional retail, product, and packaging elements to follow in 2027, the company said. Carter's is also launching a creator program called Light Makers, featuring voices across North America, and expanding partnerships with organizations including Outward Bound and Boys & Girls Clubs of America.
#parents #Marketing #cnbc #America

1 day ago
Broyhill ******* et Management, a Charlotte-based firm, issued its second-quarter 2026 investor letter, which is available for download here. The Broyhill Equity Composite gained 8.8% in Q2, trailing the MSCI All Country World Index's 15.1% and the MSCI ACWI Value Index's 10.8%. For the first half, the Composite returned 2.3%, versus 11.5% for the Index. The letter highlights that a significant portion of the shortfall occurred in April due to market dynamics and geopolitical events, with tech, particularly semiconductors, driving recent gains. Broyhill notes its lack of direct semiconductor exposure but acknowledges potential interest in the sector if opportunities arise, maintaining its investment philosophy focused on capital protection in fragile market conditions. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Broyhill ******* et Management highlighted Sotera Health Company (NASDAQ:SHC). Sotera Health Company (NASDAQ:SHC), a US-based company that provides sterilization solutions, lab testing, and advisory services for the healthcare industry, contributed positively to the portfolio's performance this quarter. On September 14, 2026, Sotera Health Company (NASDAQ:SHC) closed at $18.52 per share, reflecting a market capitalization of $5.29 billion. Sotera Health Company (NASDAQ:SHC) posted a one-month return of 0.05%, while its shares gained 13.62% over the past 52 weeks.
Broyhill ******* et Management stated the following regarding Sotera Health Company (NASDAQ:SHC) in its Q2 2026 investor letter:
"Sotera Health Company (NASDAQ:SHC) was our largest contributor, with shares gaining 25%. We bought it in the first quarter, when the litigation docket was the only thing anyone wanted to discuss, and the price gave no weight to the fact that there are only two companies of scale doing this work. Results beat on revenue, adjusted EBITDA, and earnings per share; guidance was reaffirmed across every line, and management described March as its best volume month in three to four years. The EPA has proposed a full repeal of the 2024 ethylene oxide standard. At the time, the shares traded at roughly 14x forward earnings against 20x for the closest comparable."
Sotera Health Company (NASDAQ:SHC) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 43 hedge fund portfolios held Sotera Health Company (NASDAQ:SHC) at the end of the second quarter, compared to 42 in the previous quarter. While we acknowledge the potential of Sotera Health Company (NASDAQ:SHC) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#sotera #broyhill #second
In its second-quarter 2026 investor letter, Broyhill ******* et Management highlighted Sotera Health Company (NASDAQ:SHC). Sotera Health Company (NASDAQ:SHC), a US-based company that provides sterilization solutions, lab testing, and advisory services for the healthcare industry, contributed positively to the portfolio's performance this quarter. On September 14, 2026, Sotera Health Company (NASDAQ:SHC) closed at $18.52 per share, reflecting a market capitalization of $5.29 billion. Sotera Health Company (NASDAQ:SHC) posted a one-month return of 0.05%, while its shares gained 13.62% over the past 52 weeks.
Broyhill ******* et Management stated the following regarding Sotera Health Company (NASDAQ:SHC) in its Q2 2026 investor letter:
"Sotera Health Company (NASDAQ:SHC) was our largest contributor, with shares gaining 25%. We bought it in the first quarter, when the litigation docket was the only thing anyone wanted to discuss, and the price gave no weight to the fact that there are only two companies of scale doing this work. Results beat on revenue, adjusted EBITDA, and earnings per share; guidance was reaffirmed across every line, and management described March as its best volume month in three to four years. The EPA has proposed a full repeal of the 2024 ethylene oxide standard. At the time, the shares traded at roughly 14x forward earnings against 20x for the closest comparable."
Sotera Health Company (NASDAQ:SHC) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 43 hedge fund portfolios held Sotera Health Company (NASDAQ:SHC) at the end of the second quarter, compared to 42 in the previous quarter. While we acknowledge the potential of Sotera Health Company (NASDAQ:SHC) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#sotera #broyhill #second
1 day ago
Our ****** ysts just identified a stock with the potential to be the next Nvidia. Tell us how you invest and we'll show you why it's our #1 pick. Tap here.
Saleable coal production grew 8% to 11.5 million tonnes, exceeding guidance due to the successful ramp-up of New Acland and Bengalla returning to nameplate capacity.
Management attributed the 10% decline in average realized price to $145 per tonne to broader market cyclicality, though low-cost ****** ets maintained a resilient $45 per tonne margin.
Bengalla's performance was impacted by a temporary increase in strip ratio and pit resequencing following significant weather events late in the 2025 financial year.
The group shifted its primary safety metric to High Potential Event Frequency Rate (HPEFR) to focus on preventing fatal or life-altering risks rather than just traditional injury counts.
#tell #Event
Saleable coal production grew 8% to 11.5 million tonnes, exceeding guidance due to the successful ramp-up of New Acland and Bengalla returning to nameplate capacity.
Management attributed the 10% decline in average realized price to $145 per tonne to broader market cyclicality, though low-cost ****** ets maintained a resilient $45 per tonne margin.
Bengalla's performance was impacted by a temporary increase in strip ratio and pit resequencing following significant weather events late in the 2025 financial year.
The group shifted its primary safety metric to High Potential Event Frequency Rate (HPEFR) to focus on preventing fatal or life-altering risks rather than just traditional injury counts.
#tell #Event
1 day ago
Fidelity Investments, an investment management company, recently released its second-quarter 2026 investor letter for the "Fidelity Dividend Growth Fund". The letter can be downloaded here. The Fidelity Dividend Growth Fund is a diversified large-cap equity strategy focused on capital appreciation through investments in large- and mid-cap stocks with strong dividend growth prospects. The fund returned 17.05% in the quarter, outperforming the S&P 500 Index, which gained 15.20%. U.S. stocks experienced significant gains in Q2, driven by increased spending on artificial intelligence. Technology stocks gained 31.79%, mainly driven by semiconductor companies, while the index faced a slight decline in June as investors considered the sustainability of AI-related profits amidst rising interest rates. Despite recent turbulence from the Middle East conflict, the fund remains optimistic about key investment themes, particularly in artificial intelligence. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Fidelity Dividend Growth Fund highlighted Seagate Technology Holdings plc (NASDAQ:STX) as a notable performance contributor. Seagate Technology Holdings plc (NASDAQ:STX) is a data storage company providing data storage technology and infrastructure solutions. On September 14, 2026, Seagate Technology Holdings plc (NASDAQ:STX) closed at $805.55 per share. Over the past month, Seagate Technology Holdings plc (NASDAQ:STX) declined 10.86%, but its shares are up 281.54% over the past year. Seagate Technology Holdings plc (NASDAQ:STX) has a market capitalization of $183.18 billion, and its stock has traded within a 52-week range of $206.26 to $1,145.00.
Fidelity Dividend Growth Fund stated the following regarding Seagate Technology Holdings plc (NASDAQ:STX) in its Q2 2026 investor letter:
"Shares of Seagate Technology Holdings plc (NASDAQ:STX) gained about 147% the past three months. Seagate is one of the world's largest producers of digital storage and, along with Western Digital, one of two dominant makers of hard-disk drives. Exploding demand for HDDs used in AI capable data centers has led to surging sales and strong pricing power for the company. In its most recent quarterly filing in April, Seagate reported revenue, earnings and profitability that all exceeded consensus expectations, while raising financial guidance."
Seagate Technology Holdings plc (NASDAQ:STX) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 131 hedge fund portfolios held Seagate Technology Holdings plc (NASDAQ:STX) at the end of the second quarter, compared to 93 in the previous quarter. While we acknowledge the potential of Seagate Technology Holdings plc (NASDAQ:STX) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly f
In its second-quarter 2026 investor letter, Fidelity Dividend Growth Fund highlighted Seagate Technology Holdings plc (NASDAQ:STX) as a notable performance contributor. Seagate Technology Holdings plc (NASDAQ:STX) is a data storage company providing data storage technology and infrastructure solutions. On September 14, 2026, Seagate Technology Holdings plc (NASDAQ:STX) closed at $805.55 per share. Over the past month, Seagate Technology Holdings plc (NASDAQ:STX) declined 10.86%, but its shares are up 281.54% over the past year. Seagate Technology Holdings plc (NASDAQ:STX) has a market capitalization of $183.18 billion, and its stock has traded within a 52-week range of $206.26 to $1,145.00.
Fidelity Dividend Growth Fund stated the following regarding Seagate Technology Holdings plc (NASDAQ:STX) in its Q2 2026 investor letter:
"Shares of Seagate Technology Holdings plc (NASDAQ:STX) gained about 147% the past three months. Seagate is one of the world's largest producers of digital storage and, along with Western Digital, one of two dominant makers of hard-disk drives. Exploding demand for HDDs used in AI capable data centers has led to surging sales and strong pricing power for the company. In its most recent quarterly filing in April, Seagate reported revenue, earnings and profitability that all exceeded consensus expectations, while raising financial guidance."
Seagate Technology Holdings plc (NASDAQ:STX) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 131 hedge fund portfolios held Seagate Technology Holdings plc (NASDAQ:STX) at the end of the second quarter, compared to 93 in the previous quarter. While we acknowledge the potential of Seagate Technology Holdings plc (NASDAQ:STX) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly f

1 day ago
Fidelity Investments, an investment management company, recently released its second-quarter 2026 investor letter for the "Fidelity Dividend Growth Fund". The letter can be downloaded here. The Fidelity Dividend Growth Fund is a diversified large-cap equity strategy focused on capital appreciation through investments in large- and mid-cap stocks with strong dividend growth prospects. The fund returned 17.05% in the quarter, outperforming the S&P 500 Index, which gained 15.20%. U.S. stocks experienced significant gains in Q2, driven by increased spending on artificial intelligence. Technology stocks gained 31.79%, mainly driven by semiconductor companies, while the index faced a slight decline in June as investors considered the sustainability of AI-related profits amidst rising interest rates. Despite recent turbulence from the Middle East conflict, the fund remains optimistic about key investment themes, particularly in artificial intelligence. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Fidelity Dividend Growth Fund highlighted Western Digital Corporation (NASDAQ:WDC). Western Digital Corporation (NASDAQ:WDC) is a data storage company that engages in the manufacturing and distribution of data storage devices and solutions based on hard disk drive (HDD) technology. On September 14, 2026, Western Digital Corporation (NASDAQ:WDC) closed at $426.94 per share. Over the past month, Western Digital Corporation (NASDAQ:WDC) declined 13.95%, and its shares are up 314.14% over the past year. Western Digital Corporation (NASDAQ:WDC) has a market capitalization of $153.93 billion, and its stock has traded within a 52-week range of $93.92 to $799.87.
Fidelity Dividend Growth Fund stated the following regarding Western Digital Corporation (NASDAQ:WDC) in its Q2 2026 investor letter:
"Among individual holdings, a sizable overweight in Western Digital Corporation (NASDAQ:WDC) (+140%) topped the list of relative contributors. In late April, the data-storage maker reported better-than-expected quarterly financial results, including higher earnings and gross profit margin. In its report, management said brisk demand for the firm's storage solutions for AI capabilities contributed to the solid quarter. Also, the company raised its financial guidance."
Western Digital Corporation (NASDAQ:WDC) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 98 hedge fund portfolios held Western Digital Corporation (NASDAQ:WDC) at the end of the second quarter, up from 83 in the previous quarter. While we acknowledge the potential of Western Digital Corporation (NASDAQ:WDC) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-te
In its second-quarter 2026 investor letter, Fidelity Dividend Growth Fund highlighted Western Digital Corporation (NASDAQ:WDC). Western Digital Corporation (NASDAQ:WDC) is a data storage company that engages in the manufacturing and distribution of data storage devices and solutions based on hard disk drive (HDD) technology. On September 14, 2026, Western Digital Corporation (NASDAQ:WDC) closed at $426.94 per share. Over the past month, Western Digital Corporation (NASDAQ:WDC) declined 13.95%, and its shares are up 314.14% over the past year. Western Digital Corporation (NASDAQ:WDC) has a market capitalization of $153.93 billion, and its stock has traded within a 52-week range of $93.92 to $799.87.
Fidelity Dividend Growth Fund stated the following regarding Western Digital Corporation (NASDAQ:WDC) in its Q2 2026 investor letter:
"Among individual holdings, a sizable overweight in Western Digital Corporation (NASDAQ:WDC) (+140%) topped the list of relative contributors. In late April, the data-storage maker reported better-than-expected quarterly financial results, including higher earnings and gross profit margin. In its report, management said brisk demand for the firm's storage solutions for AI capabilities contributed to the solid quarter. Also, the company raised its financial guidance."
Western Digital Corporation (NASDAQ:WDC) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 98 hedge fund portfolios held Western Digital Corporation (NASDAQ:WDC) at the end of the second quarter, up from 83 in the previous quarter. While we acknowledge the potential of Western Digital Corporation (NASDAQ:WDC) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-te

1 day ago
Citigroup Inc. (NYSE:C)'s CFO Gonzalo Luchetti said the bank expects return on tangible common equity (RoTCE) to come in slightly above 11% in 2026, while also indicating that Citi will increase stock buybacks from the $13 billion repurchased in 2025. The bank plans to accelerate roughly $500 million of investment by year-end, including spending on severance and marketing intended to expand its credit-card and wealth-management businesses. Citi also expects to remove Banamex from its balance sheet in 2027, which will create an estimated $9 billion currency-translation adjustment loss.
The 11%+ target is meaningful because Citi's profitability has already improved materially. In the second quarter, Citi generated $24.8 billion of revenue, up 14% year over year, while net income rose 45% to $5.8 billion. Investment-banking revenue increased 44% to $1.55 billion, and net interest income increased 13%. Citi's SEC filing shows second-quarter RoTCE of 13.0%, versus 8.7% a year earlier, while the first half of 2026 produced a 13.1% RoTCE. The new guidance therefore suggests management believes profitability can remain above the longer-term 11%-13% RoTCE range Citi established for 2027-28, despite additional investment spending.
Kiev.Victor / Shutterstock.com
The bullish argument is that Citigroup Inc. (NYSE:C) appears to be converting its multiyear restructuring into higher returns while simultaneously returning more capital to shareholders. The move from 8.7% RoTCE in the second quarter of 2025 to 13.0% in the second quarter of 2026 represents a substantial improvement in capital efficiency. Citi's efficiency ratio also improved to 57.4% from 62.7%, indicating that revenue growth is increasingly translating into operating leverage rather than being absorbed by expenses. That is particularly relevant because management now intends to spend another roughly $500 million on severance, marketing, and growth initiatives; if these investments produce the intended expansion in cards and wealth management, they could support revenue growth without derailing the profitability trajectory.
Capital returns provide another positive lever. Citi repurchased $13 billion of stock in 2025 and now expects to increase that amount, while its June 2026 CET1 ratio remained 12.78%, comfortably above its 11.6% standardized regulatory requirement. Buybacks can reduce tangible common equity and shares outstanding, potentially supporting both RoTCE and per-share earnings when executed below intrinsic value. Citi's tangible book value per share had already risen 7% year over year to $100.89 by June 30, 2026. The combination of higher operating profitability, shrinking share count, and improving capital efficiency strengthens the case for a valuation re-rating if Citi can sustain returns above 11%.
#year #management
The 11%+ target is meaningful because Citi's profitability has already improved materially. In the second quarter, Citi generated $24.8 billion of revenue, up 14% year over year, while net income rose 45% to $5.8 billion. Investment-banking revenue increased 44% to $1.55 billion, and net interest income increased 13%. Citi's SEC filing shows second-quarter RoTCE of 13.0%, versus 8.7% a year earlier, while the first half of 2026 produced a 13.1% RoTCE. The new guidance therefore suggests management believes profitability can remain above the longer-term 11%-13% RoTCE range Citi established for 2027-28, despite additional investment spending.
Kiev.Victor / Shutterstock.com
The bullish argument is that Citigroup Inc. (NYSE:C) appears to be converting its multiyear restructuring into higher returns while simultaneously returning more capital to shareholders. The move from 8.7% RoTCE in the second quarter of 2025 to 13.0% in the second quarter of 2026 represents a substantial improvement in capital efficiency. Citi's efficiency ratio also improved to 57.4% from 62.7%, indicating that revenue growth is increasingly translating into operating leverage rather than being absorbed by expenses. That is particularly relevant because management now intends to spend another roughly $500 million on severance, marketing, and growth initiatives; if these investments produce the intended expansion in cards and wealth management, they could support revenue growth without derailing the profitability trajectory.
Capital returns provide another positive lever. Citi repurchased $13 billion of stock in 2025 and now expects to increase that amount, while its June 2026 CET1 ratio remained 12.78%, comfortably above its 11.6% standardized regulatory requirement. Buybacks can reduce tangible common equity and shares outstanding, potentially supporting both RoTCE and per-share earnings when executed below intrinsic value. Citi's tangible book value per share had already risen 7% year over year to $100.89 by June 30, 2026. The combination of higher operating profitability, shrinking share count, and improving capital efficiency strengthens the case for a valuation re-rating if Citi can sustain returns above 11%.
#year #management
1 day ago
Broyhill ***** et Management, a Charlotte-based firm, issued its second-quarter 2026 investor letter, which is available for download here. The Broyhill Equity Composite gained 8.8% in Q2, trailing the MSCI All Country World Index's 15.1% and the MSCI ACWI Value Index's 10.8%. For the first half, the Composite returned 2.3%, versus 11.5% for the Index. The letter highlights that a significant portion of the shortfall occurred in April due to market dynamics and geopolitical events, with tech, particularly semiconductors, driving recent gains. Broyhill notes its lack of direct semiconductor exposure but acknowledges potential interest in the sector if opportunities arise, maintaining its investment philosophy focused on capital protection in fragile market conditions. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Broyhill ***** et Management highlighted Valvoline Inc. (NYSE:VVV) as a leading performance contributor. Valvoline Inc. (NYSE:VVV) is a US-based automotive preventive maintenance company that offers oil changes, battery, bulb, and wiper replacements; tire rotations; and other maintenance services. On September 14, 2026, Valvoline Inc. (NYSE:VVV) closed at $30.37 per share. Over the past month, Valvoline Inc. (NYSE:VVV) declined 9.69%, and its shares lost 25.33% over the past 52 weeks. Valvoline Inc. (NYSE:VVV) has a market capitalization of $3.87 billion.
Broyhill ***** et Management stated the following regarding Valvoline Inc. (NYSE:VVV) in its Q2 2026 investor letter:
"Valvoline Inc. (NYSE:VVV) gained 18%, having also led the first quarter. Comparable sales grew 8.2% against consensus near 5.4%, adjusted EBITDA grew 28%, and guidance was raised across comparable sales, EBITDA, and earnings. The company added 31 stores and now operates 2,409 stores, with ticket sales driving roughly two-thirds of the gain."
Valvoline Inc. (NYSE:VVV) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 44 hedge fund portfolios held Valvoline Inc. (NYSE:VVV) at the end of the second quarter, compared to 39 in the previous quarter. While we acknowledge the potential of Valvoline Inc. (NYSE:VVV) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#valvoline #asset
In its second-quarter 2026 investor letter, Broyhill ***** et Management highlighted Valvoline Inc. (NYSE:VVV) as a leading performance contributor. Valvoline Inc. (NYSE:VVV) is a US-based automotive preventive maintenance company that offers oil changes, battery, bulb, and wiper replacements; tire rotations; and other maintenance services. On September 14, 2026, Valvoline Inc. (NYSE:VVV) closed at $30.37 per share. Over the past month, Valvoline Inc. (NYSE:VVV) declined 9.69%, and its shares lost 25.33% over the past 52 weeks. Valvoline Inc. (NYSE:VVV) has a market capitalization of $3.87 billion.
Broyhill ***** et Management stated the following regarding Valvoline Inc. (NYSE:VVV) in its Q2 2026 investor letter:
"Valvoline Inc. (NYSE:VVV) gained 18%, having also led the first quarter. Comparable sales grew 8.2% against consensus near 5.4%, adjusted EBITDA grew 28%, and guidance was raised across comparable sales, EBITDA, and earnings. The company added 31 stores and now operates 2,409 stores, with ticket sales driving roughly two-thirds of the gain."
Valvoline Inc. (NYSE:VVV) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 44 hedge fund portfolios held Valvoline Inc. (NYSE:VVV) at the end of the second quarter, compared to 39 in the previous quarter. While we acknowledge the potential of Valvoline Inc. (NYSE:VVV) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#valvoline #asset

1 day ago
Broyhill ***** et Management, a Charlotte-based firm, issued its second-quarter 2026 investor letter, which is available for download here. The Broyhill Equity Composite gained 8.8% in Q2, trailing the MSCI All Country World Index's 15.1% and the MSCI ACWI Value Index's 10.8%. For the first half, the Composite returned 2.3%, versus 11.5% for the Index. The letter highlights that a significant portion of the shortfall occurred in April due to market dynamics and geopolitical events, with tech, particularly semiconductors, driving recent gains. Broyhill notes its lack of direct semiconductor exposure but acknowledges potential interest in the sector if opportunities arise, maintaining its investment philosophy focused on capital protection in fragile market conditions. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Broyhill ***** et Management highlighted The Middleby Corporation (NASDAQ:MIDD). The Middleby Corporation (NASDAQ:MIDD), a leading player in the foodservice industry, contributed positively to performance during the quarter. On September 14, 2026, The Middleby Corporation (NASDAQ:MIDD) closed at $109.72 per share. Over the past month, The Middleby Corporation (NASDAQ:MIDD) declined 3.75%, but its shares are up 1.27% over the past year. The Middleby Corporation (NASDAQ:MIDD) has a market capitalization of $78.51 billion, and its stock has traded within a 52-week range of $89.14 to $148.55.
Broyhill ***** et Management stated the following regarding The Middleby Corporation (NASDAQ:MIDD) in its Q2 2026 investor letter:
"The Middleby Corporation (NASDAQ:MIDD) gained 31%. Commercial Foodservice grew organic revenue 8% as chains returned to growth and management raised full-year guidance by roughly 4%. More important was the structural progress: the Food Processing separation was confirmed at the May investor day (which our investment team attended) and completed on July 6th, creating Midera. Following the majority sale of the residential business earlier this year, what remains is a cleaner business with leverage approaching 2.5x."
The Middleby Corporation (NASDAQ:MIDD) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 42 hedge fund portfolios held The Middleby Corporation (NASDAQ:MIDD) at the end of the second quarter which was 35 in the previous quarter. While we acknowledge the potential of The Middleby Corporation (NASDAQ:MIDD) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#NASDAQ #midd #asset
In its second-quarter 2026 investor letter, Broyhill ***** et Management highlighted The Middleby Corporation (NASDAQ:MIDD). The Middleby Corporation (NASDAQ:MIDD), a leading player in the foodservice industry, contributed positively to performance during the quarter. On September 14, 2026, The Middleby Corporation (NASDAQ:MIDD) closed at $109.72 per share. Over the past month, The Middleby Corporation (NASDAQ:MIDD) declined 3.75%, but its shares are up 1.27% over the past year. The Middleby Corporation (NASDAQ:MIDD) has a market capitalization of $78.51 billion, and its stock has traded within a 52-week range of $89.14 to $148.55.
Broyhill ***** et Management stated the following regarding The Middleby Corporation (NASDAQ:MIDD) in its Q2 2026 investor letter:
"The Middleby Corporation (NASDAQ:MIDD) gained 31%. Commercial Foodservice grew organic revenue 8% as chains returned to growth and management raised full-year guidance by roughly 4%. More important was the structural progress: the Food Processing separation was confirmed at the May investor day (which our investment team attended) and completed on July 6th, creating Midera. Following the majority sale of the residential business earlier this year, what remains is a cleaner business with leverage approaching 2.5x."
The Middleby Corporation (NASDAQ:MIDD) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 42 hedge fund portfolios held The Middleby Corporation (NASDAQ:MIDD) at the end of the second quarter which was 35 in the previous quarter. While we acknowledge the potential of The Middleby Corporation (NASDAQ:MIDD) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#NASDAQ #midd #asset

1 day ago
Broyhill ****** et Management, a Charlotte-based firm, issued its second-quarter 2026 investor letter, which is available for download here. The Broyhill Equity Composite gained 8.8% in Q2, trailing the MSCI All Country World Index's 15.1% and the MSCI ACWI Value Index's 10.8%. For the first half, the Composite returned 2.3%, versus 11.5% for the Index. The letter highlights that a significant portion of the shortfall occurred in April due to market dynamics and geopolitical events, with tech, particularly semiconductors, driving recent gains. Broyhill notes its lack of direct semiconductor exposure but acknowledges potential interest in the sector if opportunities arise, maintaining its investment philosophy focused on capital protection in fragile market conditions. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Broyhill ****** et Management highlighted Sotera Health Company (NASDAQ:SHC). Sotera Health Company (NASDAQ:SHC), a US-based company that provides sterilization solutions, lab testing, and advisory services for the healthcare industry, contributed positively to the portfolio's performance this quarter. On September 14, 2026, Sotera Health Company (NASDAQ:SHC) closed at $18.52 per share, reflecting a market capitalization of $5.29 billion. Sotera Health Company (NASDAQ:SHC) posted a one-month return of 0.05%, while its shares gained 13.62% over the past 52 weeks.
Broyhill ****** et Management stated the following regarding Sotera Health Company (NASDAQ:SHC) in its Q2 2026 investor letter:
"Sotera Health Company (NASDAQ:SHC) was our largest contributor, with shares gaining 25%. We bought it in the first quarter, when the litigation docket was the only thing anyone wanted to discuss, and the price gave no weight to the fact that there are only two companies of scale doing this work. Results beat on revenue, adjusted EBITDA, and earnings per share; guidance was reaffirmed across every line, and management described March as its best volume month in three to four years. The EPA has proposed a full repeal of the 2024 ethylene oxide standard. At the time, the shares traded at roughly 14x forward earnings against 20x for the closest comparable."
Sotera Health Company (NASDAQ:SHC) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 43 hedge fund portfolios held Sotera Health Company (NASDAQ:SHC) at the end of the second quarter, compared to 42 in the previous quarter. While we acknowledge the potential of Sotera Health Company (NASDAQ:SHC) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#letter
In its second-quarter 2026 investor letter, Broyhill ****** et Management highlighted Sotera Health Company (NASDAQ:SHC). Sotera Health Company (NASDAQ:SHC), a US-based company that provides sterilization solutions, lab testing, and advisory services for the healthcare industry, contributed positively to the portfolio's performance this quarter. On September 14, 2026, Sotera Health Company (NASDAQ:SHC) closed at $18.52 per share, reflecting a market capitalization of $5.29 billion. Sotera Health Company (NASDAQ:SHC) posted a one-month return of 0.05%, while its shares gained 13.62% over the past 52 weeks.
Broyhill ****** et Management stated the following regarding Sotera Health Company (NASDAQ:SHC) in its Q2 2026 investor letter:
"Sotera Health Company (NASDAQ:SHC) was our largest contributor, with shares gaining 25%. We bought it in the first quarter, when the litigation docket was the only thing anyone wanted to discuss, and the price gave no weight to the fact that there are only two companies of scale doing this work. Results beat on revenue, adjusted EBITDA, and earnings per share; guidance was reaffirmed across every line, and management described March as its best volume month in three to four years. The EPA has proposed a full repeal of the 2024 ethylene oxide standard. At the time, the shares traded at roughly 14x forward earnings against 20x for the closest comparable."
Sotera Health Company (NASDAQ:SHC) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 43 hedge fund portfolios held Sotera Health Company (NASDAQ:SHC) at the end of the second quarter, compared to 42 in the previous quarter. While we acknowledge the potential of Sotera Health Company (NASDAQ:SHC) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#letter

1 day ago
Our **** ysts just identified a stock with the potential to be the next Nvidia. Tell us how you invest and we'll show you why it's our #1 pick. Tap here.
Saleable coal production grew 8% to 11.5 million tonnes, exceeding guidance due to the successful ramp-up of New Acland and Bengalla returning to nameplate capacity.
Management attributed the 10% decline in average realized price to $145 per tonne to broader market cyclicality, though low-cost **** ets maintained a resilient $45 per tonne margin.
Bengalla's performance was impacted by a temporary increase in strip ratio and pit resequencing following significant weather events late in the 2025 financial year.
The group shifted its primary safety metric to High Potential Event Frequency Rate (HPEFR) to focus on preventing fatal or life-altering risks rather than just traditional injury counts.
#tonne #saleable #acland
Saleable coal production grew 8% to 11.5 million tonnes, exceeding guidance due to the successful ramp-up of New Acland and Bengalla returning to nameplate capacity.
Management attributed the 10% decline in average realized price to $145 per tonne to broader market cyclicality, though low-cost **** ets maintained a resilient $45 per tonne margin.
Bengalla's performance was impacted by a temporary increase in strip ratio and pit resequencing following significant weather events late in the 2025 financial year.
The group shifted its primary safety metric to High Potential Event Frequency Rate (HPEFR) to focus on preventing fatal or life-altering risks rather than just traditional injury counts.
#tonne #saleable #acland

1 day ago
All eyes will be on the September Federal Open Market Committee (FOMC) meeting. Unless there is extraordinary news, like collapsing crude oil prices, I am fully expecting a key Fed interest rate hike.
The Fed never fights market rates. Since market rates have risen globally due to higher energy prices, and after the ECB hike, more central banks are expected to follow and raise key interest rates.
The big news is expected to be the FOMC statement that may signal whether or not the Fed is "one and done" or signal that more key interest rate hikes will be forthcoming. Under new Fed Chairman Warsh, the Fed may not provide good guidance, since Warsh wants Wall Street to take its cue from market rates.
Related: Louis Navellier is buying 3 headline-making stocks, including Google
The good news is that with a hike already baked into the cake, there shouldn't be a negative market reaction on September 16. In other words, don't fear the reaper because even if interest rates rise and market volatility increases, fundamentally superior stocks continue to outperform. Ahead of the meeting, however, I suspect the stock market will trade sideways.
#rates #warsh
The Fed never fights market rates. Since market rates have risen globally due to higher energy prices, and after the ECB hike, more central banks are expected to follow and raise key interest rates.
The big news is expected to be the FOMC statement that may signal whether or not the Fed is "one and done" or signal that more key interest rate hikes will be forthcoming. Under new Fed Chairman Warsh, the Fed may not provide good guidance, since Warsh wants Wall Street to take its cue from market rates.
Related: Louis Navellier is buying 3 headline-making stocks, including Google
The good news is that with a hike already baked into the cake, there shouldn't be a negative market reaction on September 16. In other words, don't fear the reaper because even if interest rates rise and market volatility increases, fundamentally superior stocks continue to outperform. Ahead of the meeting, however, I suspect the stock market will trade sideways.
#rates #warsh