7 days ago
Joe Manganiello says Sofía Vergara refused to hug him when he pleaded for affection during his long health battle. According to PEOPLE's Oct. 7 report, he writes in his memoir that their marriage had "become devoid of any emotionality whatsoever."
The 49-year-old True Blood actor discusses that period in Bloodlines, his memoir arriving Oct. 13 from Avid Reader Press/Simon & Schuster.
Manganiello and Vergara married in November 2015, announced their separation in July 2023 and finalized their divorce in April 2024.
Vergara had not addressed the memoir allegations when Us Weekly published its Oct. 7 report. The outlet said it had contacted her for comment.
Manganiello says his symptoms began shortly after the wedding. Abdominal pain sometimes left him unable to walk, while digestive ulcers, fevers, blistering rashes, bleeding and exhaustion became recurring problems.
#memoir #blood

7 days ago
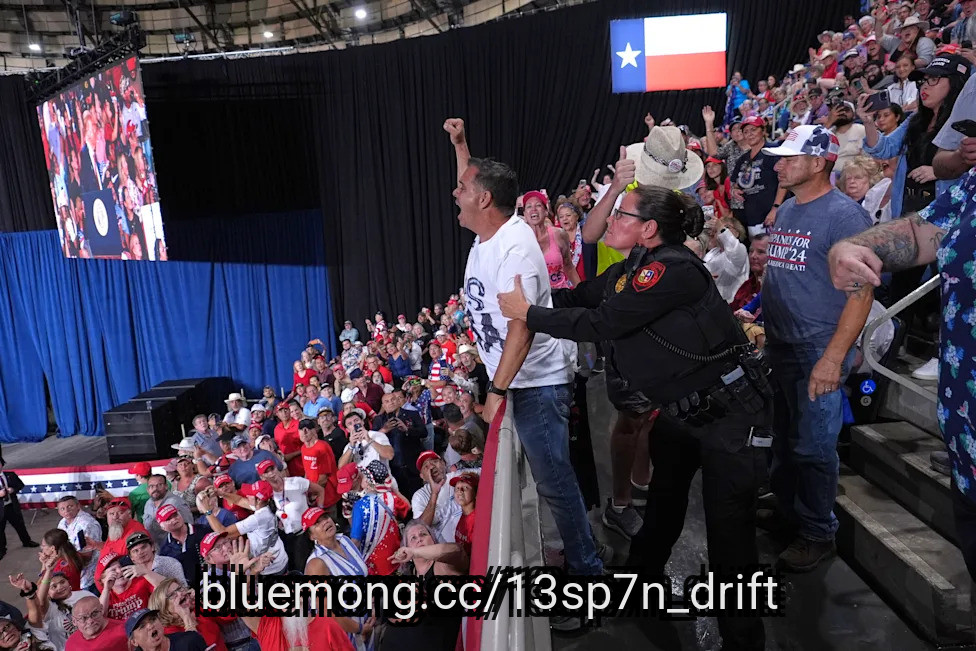
SAN ANTONIO (AP) — President Donald Trump, facing protesters and a poor political climate, fought to rally Texas voters behind Senate candidate Ken Paxton on Wednesday night in a bid to stave off sweeping Democratic victories in the nation's most populous red state.
But Trump's remarks were not focused solely on Paxton.
Speaking to a packed Freeman Coliseum, Trump also pledged to award retired baseball star Roger Clemens the Presidential Medal of Freedom, restated his support for the death penalty for drug dealers and clarified recent comments in which he talked about the possibility of Iran bombing American cities as part of a recurring riff about how high fuel costs are "a small price to pay" for the war.
"You want to see problems? Let them hit San Diego, let them hit Los Angeles," Trump said. "We're not going to let that happen. We protect our cities. We protect our country."
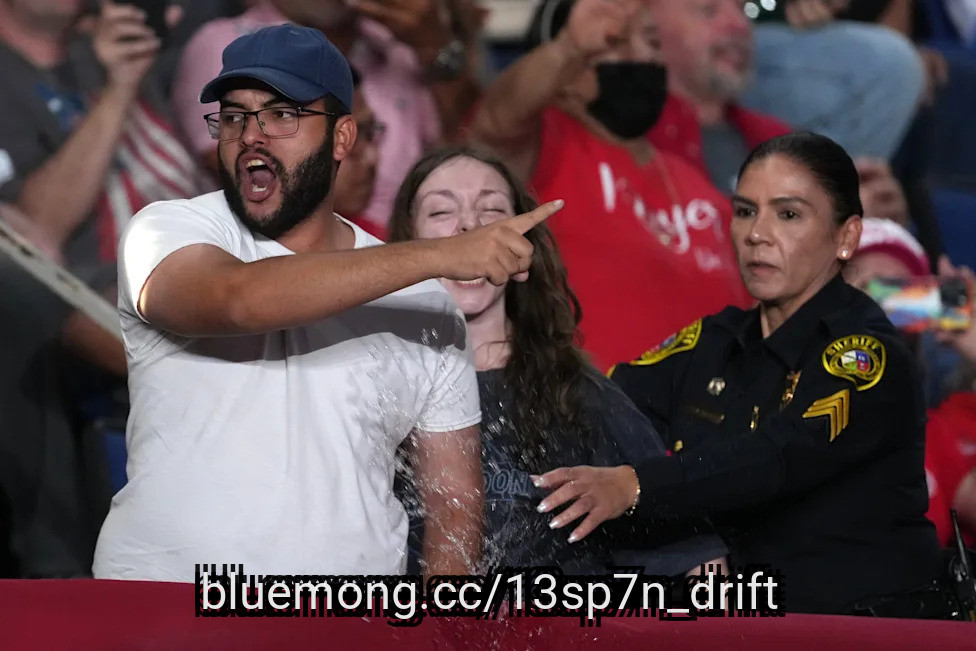
The president's message was interrupted repeatedly by protesters, including by one who appeared to be close to the stage. In all, at least a dozen demonstrators interrupted the president. Some were led away by police.
#president #cities #antonio
9 days ago
FYEE beat JEPI on a $100,000 investment in 2026, paying $7,023 versus $6,070, but FYEE's quarterly payout has fallen from $0.82 to $0.56 per share.
JEPI's monthly distributions better match recurring expenses for retirees, while FYEE's quarterly schedule suits investors who reinvest or can wait between payments.
FYEE's lower share price ($30 vs. JEPI's $56) means $100,000 buys nearly twice as many shares, which is why it delivers more cash despite lower per-share payouts.
Building a portfolio and living off one are two completely different skills, and almost ***** ody teaches the second. This problem is what The Definitive Guide to Retirement Income helps, and it is free today. Read more here. (Sponsor)
The JPMorgan Equity Premium Income ETF (NYSEARCA:JEPI) built its following on a simple promise. It holds lower-volatility U.S. stocks, adds income from S&P 500 call-option premium, and sends a check every month. JEPI holders value that rhythm, and JEPI remains the default name in covered-call income. On an identical $100,000 investment this year, though, the Fidelity Yield Enhanced Equity ETF (CBOE:FYEE) has paid more cash while writing far fewer checks.
#income #quarterly
25 days ago
On September 9, 2026, Chewy, Inc. (NYSE:CHWY) reported fiscal second-quarter net sales of $3.33 billion, up 7.3% year over year, and adjusted earnings per share of $0.36, nearly double the roughly $0.18 ******* ysts had expected, prompting the company to raise its full-year revenue and profitability outlook. CEO Sumit Singh said the broader pet market did not meaningfully recover during the quarter but also did not deteriorate further, with Chewy continuing to outperform the category by two to three times through share gains across its established and newer businesses.
Chewy, Inc. (NYSE:CHWY)'s recurring revenue base is solid. It gives the company greater visibility into future sales. Autoship sales jumped by 9.3% year over year to $2.82 billion and represented 84.6% of total net sales. The growing contribution from subscription-based purchases gives Chewy a more predictable revenue stream and reduces its exposure to fluctuations in discretionary pet spending.
Chewy is also building growth engines beyond its core retail business. Chewy Health, which includes veterinary care and pharmacy services, delivered triple-digit revenue growth. Specialty categories such as equine and exotics recorded a seventh consecutive quarter of mid-double-digit growth. These businesses give Chewy additional opportunities to increase customer spending and diversify its sources of revenue as the overall pet market matures.
Chewy is combining customer growth with stronger profitability and shareholder returns. The firm added 208,000 net active customers during the quarter. It takes its customer base to 21.7 million while returning $200 million to shareholders through share repurchases. Management also noted structural SG&A leverage, automation, and AI-driven cost reductions as contributors to margin expansion. It shows that Chewy can improve earnings while investing in customer acquisition and growth.
Part of Chewy, Inc. (NYSE:CHWY)'s profitability improvement came from benefits that may not recur. CFO Chris Deppe said the quarter's profitability upside included about $10 million from timing benefits and more than $5 million from discrete benefits. Those items boosted the latest results but do not provide a recurring earnings contribution. It means investors may need to lower their expectations for the pace of margin expansion in future quarters.
#customer
25 days ago
On September 9, 2026, Reuters reported that AI music startup Suno launched a new suite of models, including its flagship v6 and exploratory v6-Wild, built in partnership with Warner Music Group Corp. (NASDAQ:WMG) and BMG. It lets users make new music inspired by licensed recordings from participating artists. The launch follows Warner Music's copyright lawsuit settlement with Suno in November 2025, under which artists and songwriters can opt in to have their names, voices, and compositions used in AI-generated music in exchange for compensation.
Warner Music Group Corp. (NASDAQ:WMG) can turn the Suno litigation dispute into a new licensing revenue opportunity. Suno has now launched its v6 models in partnership with Warner Music and BMG. It allows users to make music inspired by licensed works from participating artists. Warner previously sued Suno over copyright issues before reaching a licensing agreement. This gives the label a direct path to monetize AI-generated music rather than relying solely on litigation. The deal could create a new revenue stream as consumers increasingly adopt AI music tools.
Warner enters the AI-music market from a position of financial strength. The firm reported fiscal third-quarter revenue of $5.44 billion, up 9% year over year. Adjusted OIBDA increased 16% to $433 million, and its adjusted OIBDA margin expanded to 23.2%. Warner also said it had met or exceeded its financial targets for five consecutive quarters. That basic growth gives the company greater flexibility to invest in AI initiatives while using licensing agreements to add another potential growth driver to its existing streaming and publishing businesses.
Warner could help establish a more sustainable commercial model for AI-generated music. Suno said future products will include opt-in experiences that allow individual artists to participate and receive payment when users generate music around them. So Warner has an opportunity to help shape licensing and compensation practices as Spotify and other platforms develop their own AI-music products. If the industry increasingly adopts licensed models, Warner's large catalog and relationships with artists could solidify its negotiating position and create recurring AI-related revenue.
Suno's new licensing model does not eliminate the overall legal risks surrounding AI music. Warner Music Group Corp. (NASDAQ:WMG) has reached an agreement with Suno, but other copyright owners are challenging the firm's technology. Independent publisher Round Hill sued Suno in August, alleging that the company used copyrighted songs to train its AI system. Suno also faces separate litigation from Universal Music Group and Sony Music. Hence, lawsuits could increase legal costs and create uncertainty over the licensing framework that Warner hopes to monetize.
#music #licensing #corp #revenue

25 days ago
LifeMD, Inc. (NASDAQ:LFMD) announced an exclusive healthcare collaboration on September 15 that initially makes virtual-health membership benefits available to approximately 29 million eligible AT&T wireless and fiber customers across 11 states. Customers must be 18 or older, and some services have additional eligibility and state restrictions. A nationwide expansion planned for January 2027 would extend eligibility beyond 100 million customers.
The $19 monthly membership fee is waived, but customers must enroll. Visits, prescriptions, and other services remain separately payable. For LifeMD, Inc. (NASDAQ:LFMD), the opportunity is converting access to a large audience into recurring demand for paid care.
The partnership gives LifeMD, Inc. (NASDAQ:LFMD) a distribution channel through the website, mobile app and customer-benefits program of AT&T Inc. (NYSE:T). Reaching customers through an established relationship could reduce reliance on advertising and lower acquisition costs per paying patient.
Removing the membership charge also reduces the financial commitment required to try the service. Announced visit prices start at $29 for message-based care, $49 for urgent and primary care video visits, and $79 for specialty care. Customers may use insurance, Medicare, or discounted cash-pay rates for visits and prescriptions.
LifeMD, Inc. (NASDAQ:LFMD) could benefit from repeat consultations and prescription fulfillment when clinically appropriate. Primary care, chronic-condition management and other services create opportunities for continuing patient relationships. If satisfied patients return, the revenue earned over those relationships could exceed the cost of acquiring and serving them.
#Services

25 days ago
Americans are increasingly falling victim to so-called "ghost charges": small, frictionless payment purchases at Starbucks or McDonald's, or digital subscription deductions from your bank account you forgot about. The costs may only be $5 or $10 a pop, but they add up, and before you know it, $200 has disappeared from your savings every month.
Jeff Bezos backs a platform that lets anyone invest in rental homes for as little as $100 — 6 ways to build wealth like a landlord without actually being one
Dave Ramsey warns nearly 50% of Americans are making 1 big Social Security mistake. Here's what it is and 3 simple steps to fix it ASAP
The tax breaks in Trump's 'big beautiful bill' expire after 2028. Here are 4 moves to make before the window closes
A recent study from Cashews, a digital bank tracking platform for serial small recurring charges, shows that 61% of people have more than $50 a month in these small charges; 38.7% have more than $100 a month; and 14.5% have more than $200 a month in charges where no single charge is over $100. Additionally, three of the median person's four small recurring monthly charges go to merchants they never otherwise interact with.
#charges #digital #bank #platform
26 days ago
ResMed Inc. (NYSE:RMD) is well positioned to benefit from the long-term growth of the global obstructive sleep apnea (OSA) treatment market. Likewise, the company remains well positioned to benefit from growing awareness and penetration in the global market, backed by a robust product portfolio.
The company's OSA portfolio includes CPAP and APAP machines, led by the AirSense platform. The AirSense 10 series is one of the most widely used CPAP and APAP machine series. Beyond sleep therapy machines, it also offers nasal, nasal-pillow, and full-face masks, along with a wide range of accessories and related products.
The broad product portfolio offers multiple avenues for generating recurring revenue beyond the initial sale of a sleep therapy device.
Monkey Business Images/Shutterstock.com
In the fourth quarter of fiscal 2026, ResMed's revenue increased 9% year over year to $1.5 billion, supported by strong demand for sleep devices, masks, and accessories. Americas device revenue increased 6%, while total Americas Sleep and Breathing Health revenue rose 8%. Americas masks and other revenue increased 10%. The stronger performance is particularly important as it highlights the ability to monetize the installed patient base beyond the initial device purchase.
#sleep #increased
26 days ago
Affirm Holdings, Inc. (NASDAQ:AFRM) has underperformed the broader market year to date, but the tide is slowly turning. Robust growth in interest-bearing loans, a strategic partnership with Shopify in Australia, and accelerating volumes at Amazon provide multiple avenues for continued growth.
On September 12, Goldman Sachs raised its price target to $115 from $106, citing improving underlying fundamentals. The hike follows the company's impressive fourth-quarter fiscal 2026 results, with revenues surging 33% to $1.2 billion and operating income rising $89 million to $147 million.
The robust revenue growth came as the company continued to attract more business interest-bearing loans. Interest income rose 35% in the fourth quarter, in line with a 33% increase in average net loans held for investment partners. More importantly, 80% of Affirm's direct-to-consumer product loans carried interest at quarter-end, giving the company an increasingly meaningful source of recurring interest income.
The investment bank has also touted the growth opportunity around Affirm Card, which is helping the company expand its relationship with consumers beyond individual BNPL transactions. Active cardholders more than doubled to 5.2 million, resulting in a 124% increase in Card GMV to $2.8 billion.
Management has already hinted at continued upside momentum by estimating a massive increase in GMV to $64 billion in fiscal 2027 and an adjusted operating margin of 30.5%. Against this backdrop, Wolfe Research ****** yst Darrin Peller upgraded the stock to Outperform with a $90 price target. According to the ****** yst, Affirm Holdings is a winner in the point-of-sale financing ****** e.
#interest #billion #company

26 days ago
Cybersecurity provider CrowdStrike Holdings, Inc. (NASDAQ:CRWD)'s shares are up by more than 100% year to date. With AI continuing to dominate the market narrative, the firm has found itself at the center of the industry's concerns about cybersecurity. While some, such as Anthropic's Dario Amodei, have claimed that their AI software is sufficient for cybersecurity purposes, others have argued that firms such as CrowdStrike Holdings, Inc. (NASDAQ:CRWD) will play a key role in the industry. Cramer is in the latter camp, and in his morning appearance on September 15th, the CNBC TV host discussed the recent discussions about AI being a threat:
"I had George Kurtz last night, who has partnered both with OpenAI and Anthropic. And he encouraged me to say look, they are doing a lot of things about safeguards. I think he was so much surprised, that there was so much doomsaying, of course, doomsaying being heavily refuted. Now there's a stock, remember that stock was up the most of any stock in the S&P."
While Cramer believes CrowdStrike Holdings, Inc. (NASDAQ:CRWD) will play an important role in cybersecurity in the AI era, the broader debate about the firm is about its AI-driven cybersecurity initiatives and whether they are sufficient to stay competitive and justify the eye-watering share price performance. On this front, the firm's annual recurring revenue (ARR) grew by 25% and net new ARR grew by 55% in its fiscal second quarter. Additionally, CrowdStrike Holdings, Inc. (NASDAQ:CRWD)'s net new ARR set a new record of $333 million. Cramer's bullishness on the firm is also matched by others, such as ******* ysts from Argus. Argus has set a $425 share price target for CrowdStrike Holdings, Inc. (NASDAQ:CRWD) and argued that growth in agentic AI use presents a major tailwind for the firm.
Yet, in a classic case of the bigger you are, the harder you fall, CrowdStrike Holdings, Inc. (NASDAQ:CRWD)'s massive growth creates risk. For its fiscal second quarter, the firm has guided net new ARR to range between $343 million and $347 million to imply growth ranging between 29% to 31%. Considering that the metric grew by 55% in Q1, the new figures do indicate a slowdown. As for catalysts from agentic AI, CrowdStrike Holdings, Inc. (NASDAQ:CRWD)'s next-gen SIEM (Security Information and Event Management) ending ARR grew by 60% to $695 million in the second quarter.
Hedge fund interest in CrowdStrike Holdings, Inc. (NASDAQ:CRWD) grew in Q2. According to Insider Monkey's data, 89 out of 1,006 funds had held a stake in the firm during the period. This marked a jump over the 89 out of the 1,022 funds in Q1. As for valuation, CrowdStrike Holdings, Inc. (NASDAQ:CRWD)'s forward P/E ratio of 188 is significantly higher than peer firm Palo Alto's 89 which should increase the pressure to maintain growth. Short interest as a percentage of float is 2.41% for CrowdStrike Holdings, Inc. (NASDAQ:CRWD) compared to 2.65% for Palo Alto.
#NASDAQ #firm #grew

26 days ago
SailPoint Inc. (NASDAQ:SAIL), a leading player within the enterprise identity security ****** e, recently expanded its strategic alliance with CrowdStrike. As part of the revised arrangement, the company's SailPoint SecOps Identity Intelligence will be integrated with CrowdStrike Falcon Next-Gen SIEM. This will help in expediting threat detection procedures, and will also incorporate access data and identity governance into the overall investigation process. The expanded partnership will facilitate security teams in lining up the identity insights with Falcon's existing security telemetry.
Copyright: franckito / 123RF Stock Photo
The announcement aligns strongly with SailPoint's broader strategic narrative revealed in its Q2 FY27 print. It builds upon several recent initiatives undertaken by the management, such as introduction of the SailPoint Identity Security solution. This is aimed toward integrating SailPoint Agentic Fabric with SailPoint Human Fabric for real-time discovery and security of complex digital ecosystems. The company also launched its Cursor Enterprise connector, which helps organizations to leverage a highly-integrated control plane to manage human developers and autonomous AI agents.
The recently released financials also back this narrative as the company delivered a 25% year-over-year growth in its annual recurring revenue, which stood at $1.231 billion. SailPoint generated $45 million in operating cash flow during the second quarter, along with $37 million in free cash flow.
By weaving SailPoint's identity intelligence into Falcon Next-Gen SIEM, customers gain extra context inside workflows they already rely on, making it easier to probe identity-related risks. The integration augments SailPoint's position at a time when identity threats are on a rise. This leads to an opportunity for SailPoint to cement itself as a leading provider of advanced security solutions.
#sailpoint #falcon #next

26 days ago
On September 16, IDEXX Laboratories (NASDAQ:IDXX) announced it had bought CoVetAI, a fast-growing veterinary software company whose tool listens during appointments and organizes what gets said and done. It sounds like a productivity gadget. But IDEXX is pitching it as a way to put the right patient details in front of a vet at the moment they decide what to test. The price was not disclosed, so the strategy is the story.
Start with the customer base IDEXX already has. More than 10,000 clinics worldwide run on its cloud practice software, and CoVet will plug into that system, including a link to IDEXX VetConnect PLUS. That hands a new product a ready audience. CoVet also works with practice systems IDEXX does not make, and IDEXX plans to keep supporting rival scribes, so the tool can reach clinics and regions the company does not serve today.
Then there is the engine this could feed. On August 4, IDEXX reported second-quarter revenue growth of 10%, and its recurring diagnostics business grew 11%, powered by higher volumes. That says vets are already running more tests, which is the behavior a smarter workflow tool is meant to encourage. The company also placed more than 1,600 inVue Dx ****** yzers in the quarter, lifting the installed base past 9,000, and it counts that instrument among its AI-driven products. Software and hardware are pointing in the same direction.
The biggest problem is what we can't see. Without deal terms, there is no way to judge what IDEXX paid or how much CoVet matters to earnings. And the company describes the payoff in future tense, saying these capabilities can raise diagnostic use over time. That is a hope, not a result yet. CoVet's openness to other systems cuts both ways too. It widens reach, but it also means a clinic can use CoVet without going deeper into IDEXX's ecosystem.
The second quarter also needs a careful read. Earnings per share rose 18%, but that included tax benefits from stock-based pay and a currency boost, and growth on a comparable basis was 15%. Some of the gain, in other words, did not come from selling more to vets. IDEXX also says it is spending more on commercial and innovation priorities, so its higher full-year earnings outlook comes with added costs attached.
#company #software #earnings #already

26 days ago
Without a signed, prospective contract, Medicaid treats family caregiver payments as gifts, exposing $60,000 in payments to a six-month nursing home ineligibility penalty.
A defensible care agreement must be signed before services begin, specify duties and market-rate pay, and be backed by time sheets and traceable payments.
At 20 documented hours per week, $2,500 monthly works out to roughly $29 per hour, defensible against the 2025 national median caregiver rate of $35.
Two retirees, same $1 million, same 4% rule, buy one finished with $1.4 million, the other hit $0 in 12 years. Our free reader guide explains the flaw that separated them, and the income-first method built to avoid it.
Picture a widow in her 80s who pays her adult daughter $2,500 a month for two years to handle bathing, meals, medications, driving to appointments, and overnight supervision. The care is real. The daughter cuts back her own job to provide it. One year later, mom breaks a hip, lands in a nursing home, and applies for institutional Medicaid. The caseworker pulls five years of bank statements, spots $60,000 in recurring payments to the daughter, and finds no signed agreement, no time sheets, no invoices. In that state, the agency treats every dollar as an uncompensated transfer, effectively a gift.
#signed #daughter
27 days ago
While he stepped down as CEO of Berkshire Hathaway at the end of last year, Warren Buffett's wealth, and thus his portfolio, is still tied to the conglomerate and its stock portfolio. On that end, Berkshire's top-three positions -- consisting of Apple (NASDAQ: AAPL), American Express (NYSE: AXP), and Alphabet (NASDAQ: GOOG) (NASDAQ: GOOGL) (Nasdaq) -- make up more than half of its equity portfolio.
All three are strong compounding businesses with wide moats, but which looks like the best of the group to buy today? Let's take a look at each.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Apple is Berkshire's largest holding, making up about 22% of its portfolio. The stock is a Buffett favorite because it has one of the best compounding business models out there.
Apple, of course, is best known for its iPhone and other devices. Smartphones and computers tend to have very predictable replacement cycles, which creates an almost recurring type of revenue stream for the company. However, the beauty of the business stems from its closed-garden ecosystem that helps lock in consumers, from which it then collects high-margin service revenue. This revenue comes from a variety of sources, including a search revenue-sharing deal with Alphabet, commissions on app downloads, Apple Pay, and subscriptions for things like cloud storage.
#NASDAQ #revenue #best #alphabet

27 days ago
On September 14, L3Harris Technologies, Inc. (NYSE:LHX) said it had secured a $60 million contract from the U.S. Air Force to continue producing sensors that let aircrews choose the precise detonation altitude.
SpaceKris/Shutterstock.com
The DSU-43/B ******* pit Selectable Height of Burst Sensors (C-HOBS) allow crews to adjust the munition's effect to different targets and mission environments. The system will provide enhanced radar-guided performance, advanced sensing features, and manual and ******* pit-selectable burst heights, the company said in a press release.
The production will take place at L3Harris' Cincinnati facility. The order comes at a time when the defense contractor is expanding the output capacity of proximity fuzes and sensors for the U.S. military to support a wartime footing.
Investors should view the C-HOBS contract as evidence of the company's recurring business with the Air Force on precision-guidance electronics. Despite being small in magnitude, such low-risk and steady order flow underpins the bull thesis for the stock.
#cockpit

27 days ago
Starting the lightning round on September 14, when a caller inquired about SentinelOne, Inc. (NYSE:S), Mad Money host Jim Cramer remarked:
No, look, I think you don't need, look, my Charitable Trust owns both Palo Alto and CrowdStrike. It's already too many. I think either one of those two is superior to letter S.
The latest results show a large difference in scale. SentinelOne's fiscal second-quarter 2027 revenue rose 21% year over year to $292 million, while annualized recurring revenue increased 22% to $1.218 billion. Palo Alto Networks, Inc.'s (NASDAQ:PANW) fiscal fourth-quarter 2026 revenue rose 34% to $3.41 billion, while Next-Generation Security ARR increased 63% to $9.10 billion. Additionally, we have discussed CRWD in our recent article, "Jim Cramer Highlights CrowdStrike (CRWD) as AI Security Concerns Lift Cybersecurity Stocks."
SentinelOne, Inc. (NYSE:S) non-GAAP operating margin reached 10% in fiscal Q2 2027, up from 2% a year earlier, while its GAAP operating margin improved to negative 31% from negative 33%. The company guided for fiscal third-quarter revenue of $309 million to $311 million and full-year revenue of $1.202 billion to $1.207 billion.
Palo Alto Networks, Inc. (NASDAQ:PANW) reported approximately $1 billion of non-GAAP operating income in its fiscal fourth quarter of 2026, compared with $768 million a year earlier. Adjusted free cash flow reached approximately $1.3 billion, while GAAP operating income was $172 million versus $497 million a year earlier. Palo Alto CEO Nikesh Arora said in the September 1 earnings release that the latest advances in AI are "elevating cybersecurity to the top of the CIO priority list."
#billion #year #gaap #operating

27 days ago
On September 14, during the episode of Mad Money, Jim Cramer said CrowdStrike Holdings, Inc. (NASDAQ:CRWD) is emerging as a beneficiary of growing concerns over the cybersecurity risks created by artificial intelligence, as he said:
Over the weekend, the co-founder and CEO of Anthropic published an essay where he pushed for a slowdown among the frontier AI labs in order to handle newfound security concerns. In response to that, the cybersecurity cohort just went crazy because there are the companies that can prevent AI agents from randomly hacking into networks all over the world, and it's the cybersecurity companies. Take CrowdStrike, which shot up nearly 14% today, leading the S&P 500, something I feel great about, of course, because we own it big for the Charitable Trust. These guys have been adamant that AI represented a great opportunity for their business, and now Wall Street's finally gotten the memo.
CrowdStrike Holdings, Inc.'s (NASDAQ:CRWD) second-quarter fiscal 2027 revenue increased 26% year over year to $1.47 billion, while ending annual recurring revenue rose 25% to $5.84 billion. Net new ARR reached a record $332.8 million, and free cash flow was $377.4 million. The company also raised its full-year fiscal 2027 net new ARR growth outlook to 34% at the midpoint, up 630 basis points. CEO George Kurtz said the company believes securing AI is its "largest market opportunity in our history."
Kurtz said on September 14 that AI-driven threats are already operating at machine speed, describing the emerging threat as autonomous campaigns rather than individual hackers. He identified endpoints, cloud workloads and SaaS as key battlegrounds and said "enforcement at machine speed" is needed to stop AI agents in motion. CrowdStrike has responded by expanding into AI-agent, model and infrastructure protection, including Continuous Identity for AI Agents and Falcon AI Detection and Response.
CrowdStrike Holdings, Inc.'s (NASDAQ:CRWD) valuation leaves little room for a meaningful slowdown in growth. Yahoo Finance currently shows a forward P/E of approximately 188.7 times and a price-to-sales ratio of roughly 44.6 times. Those multiples leave little room for a material slowdown in ARR growth, weaker adoption of newer products, or greater competitive pressure. The company also remains much less profitable on a GAAP basis than its adjusted results suggest. The company reported a $33.2 million GAAP operating loss in the latest quarter against $371.6 million of non-GAAP operating income, while stock-based compensation and related employer payroll taxes totaled $399 million.
#crwd

27 days ago
Crane Company (NYSE:CR) announced a definitive agreement on September 14 to acquire Trillium Flow Technologies' U.S. pump business for approximately $240 million. The operations primarily serve municipal water and wastewater customers and are expected to generate approximately $115 million in full-year revenue. Closing is expected in the fourth quarter, subject to regulatory approvals and customary conditions.
The acquisition would add Floway, Wemco, Roto-Jet and WSP to Process Flow Technologies. Their installed equipment base supports service, repair, retrofit and replacement demand, giving the transaction a recurring-revenue rationale.
Crane Company (NYSE:CR) disclosed a price of approximately 14.6 times estimated 2026 adjusted EBITDA. Adjusted EBITDA is a company-defined non-GAAP measure based on earnings before interest, taxes, depreciation, and amortization, with further adjustments. The announcement did not specify the target's adjustments or provide a GAAP reconciliation.
Water and wastewater systems require reliable pumping equipment throughout their operating lives. An established installed base creates opportunities to sell replacement parts, restore equipment, and upgrade performance long after the original sale.
For Crane Company (NYSE:CR), those customer relationships could make revenue less dependent on winning entirely new projects. Service capability and product familiarity may also help retain customers when equipment eventually needs replacement.
#NYSE

27 days ago
Realty Income Corporation (NYSE:O) announced on September 14 a European property venture in which capital accounts advised by KKR & Co. Inc. (NYSE:KKR) intend to invest €528 million for a 49% interest. Closing is expected September 30, subject to customary conditions.
Realty Income Corporation (NYSE:O) would receive approximately €528 million in gross proceeds while retaining 51% ownership and day-to-day ******* et management. The contributed portfolio carries a 5.9% effective initial capitalization rate after recurring management fees. The question is whether redeploying the capital and earning fees can more than offset the rental economics transferred to the partner.
The venture could provide another funding source for acquisitions. Selling a minority interest in existing properties can release capital while preserving operational continuity. It also gives management an alternative when public equity or debt financing offers less attractive terms.
Management fees add a second source of income alongside retained property earnings. Realty Income Corporation (NYSE:O) could use its existing European operating platform to manage the venture, potentially spreading overhead across a broader pool of investor capital. The benefit depends on fee revenue exceeding the incremental costs of providing those services.
The structure includes a further source of potential upside. Realty Income Corporation (NYSE:O) would have an option to redeem the partner's interest after year 10 and through year 17. The redemption price would provide a capped internal rate of return, an annualized return accounting for cash-flow timing, expected at 6.3% to 6.5% and finalized at closing.
#NYSE #corporation #management #source

27 days ago
Alcoa Corporation (NYSE:AA) priced $2.6 billion of acquisition financing on September 9, 2026, through two wholly owned subsidiaries. Alumina Pty Ltd will issue $1.5 billion of 6.625% notes due 2034, while Alcoa Nederland Holding B.V. will issue $1.1 billion of 6.875% notes due 2036. Alcoa Corporation (NYSE:AA) and certain subsidiaries will guarantee the notes on a senior unsecured basis.
The tranches imply annual coupons of $99.375 million and $75.625 million, respectively, totaling exactly $175 million. Settlement is expected on September 23. Net proceeds and cash on hand would fund the approximately $3.1 billion cash portion of the South32 Limited (ASX:S32) ****** et acquisition, plus related fees and expenses.
For Alcoa Corporation (NYSE:AA), successful settlement would secure longer-dated funding and allow termination of the remaining 364-day bridge commitments. Maturities in 2034 and 2036 give management time to integrate the ****** ets before principal comes due.
The operating opportunity lies in linking additional bauxite resources, alumina refining and aluminum production. Better coordination could strengthen feedstock security and improve purchasing, logistics and plant economics. Acquired earnings and operating improvements could produce recurring cash to service the debt while funding reinvestment.
Fixed coupons also make the interest burden predictable. Strong ****** et performance could support debt reduction and give shareholders a growing share of incremental cash generation.
#notes #september

27 days ago
Cognyte Software Ltd. (NASDAQ:CGNT) reported on September 9 that revenue for the fiscal second quarter ended July 31, 2026, increased 12.0% to $109.2 million. Total software revenue, comprising software and software services, rose 20.9% to $100.8 million.
Company-defined non-GAAP adjusted EBITDA increased 35.7% to $14.9 million. The measure adds depreciation, amortization, stock-based compensation, restructuring costs, and other specified adjustments to GAAP operating income. Yet quarterly billings fell to $76.3 million from $93.0 million. The central question is whether a more profitable revenue mix can produce stronger cash generation while sustaining future growth.
The portfolio transition is visible in the revenue base. Total software revenue represented more than 92% of sales. Recurring revenue, primarily support contracts and subscription offerings, reached $56.2 million, or 51.4% of total revenue.
For Cognyte Software Ltd. (NASDAQ:CGNT), a larger recurring base could make revenue more predictable and support continued product investment. Renewals also create opportunities to expand customer relationships without rebuilding the sales pipeline from scratch. The benefit depends on retention and expansion within those accounts.
Profitability improved under both accounting measures. GAAP operating margin increased to 4.3% from 2.8%, while adjusted EBITDA margin expanded to 13.6% from 11.3%. That combination strengthens the case that the transition is improving operating economics, even after recognizing expenses excluded from adjusted results.
#gaap #NASDAQ

27 days ago
Oddity Tech Ltd. (NASDAQ:ODD) reported second-quarter revenue of approximately $181 million on September 9, down 25% from $241 million a year earlier. Company-defined non-GAAP adjusted EBITDA fell to $13 million from $70 million. This measure excludes net financial income, income taxes, depreciation and amortization, share-based compensation, and certain unusual or nonrecurring items from net income.
Management attributed the disruption primarily to an advertising-algorithm problem affecting IL MAKIAGE. Oddity Tech Ltd. (NASDAQ:ODD) expects third-quarter revenue to decline approximately 5% year over year, with adjusted EBITDA of $18 million to $20 million. The sequential improvement describes a narrowing year-over-year revenue decline.
Management's diagnosis centers on distorted advertising signals that impair IL MAKIAGE's ability to reach suitable customers at acceptable acquisition costs. Oddity Tech Ltd. (NASDAQ:ODD) is testing changes with its largest advertising partner to retrain the algorithm. If those changes restore profitable customer acquisition, the existing brand could recover without a fundamental overhaul of its products.
Other brands provide operating evidence beyond that hypothesis. SpoiledChild delivered double-digit quarterly revenue growth, and management expects at least 35% growth for 2026, approaching $350 million in revenue. Management expects METHODIQ's first-year revenue to exceed SpoiledChild's first-year result.
These results support the argument that Oddity Tech Ltd. (NASDAQ:ODD) can build additional brands using its technology platform. A broader sales base could gradually reduce dependence on IL MAKIAGE, while successful customer retention would help recover upfront advertising spending over multiple purchases.
#revenue #NASDAQ #advertising #expects

28 days ago
Wealthfront Corporation (NASDAQ:WLTH) reported on September 9 that fiscal second-quarter revenue increased 1% to $91.9 million, despite platform ***** ets rising 12% to $99 billion. The quarter ended July 31, 2026. Funded clients increased 14% to 1.51 million, and platform ***** ets surpassed $100 billion by the end of August.
Platform ***** ets measure financial ***** ets held in client accounts. Their growth reflects both net deposits and market movements, so the headline increase does not represent new client money alone.
Adjusted EBITDA declined 15% to $38.1 million, with its margin falling to 41% from 49%. Wealthfront Corporation (NASDAQ:WLTH) defines this non-GAAP measure as net income excluding interest expense, income taxes, depreciation and amortization, stock-based compensation, fair-value changes in convertible notes, warrant liabilities and simple agreements for future equity, and nonrecurring expenses. Adjusted EBITDA margin divides that figure by revenue.
The advisory business is translating ***** et growth into revenue. Investment advisory ***** ets increased 30% to $54.1 billion, while advisory revenue rose 31% to $28.8 million. Those results show that the expanding investment business is generating a larger recurring fee stream.
For Wealthfront Corporation (NASDAQ:WLTH), this creates an opportunity to deepen client relationships as savings move toward longer-term investment goals. A growing advisory base could support more durable relationships, provided clients remain invested and continue contributing.
#wealthfront #revenue #platform #investment

28 days ago
Sunbelt Rentals Holdings, Inc. (NYSE:SUNB) reported on September 9 that fiscal first-quarter revenue increased 11.2% to $3.115 billion, including $2.927 billion of rental revenue, up 12.5%. The quarter ended July 31, 2026.
Management raised fiscal 2027 rental-revenue growth guidance to 7% through 10%, while increasing planned net rental-equipment capital expenditures to $2.4 billion through $2.8 billion. Demand supports expansion, but investors need to ****** s how much cash remains after funding the fleet.
North America Specialty rental revenue grew 25.3%, giving Sunbelt Rentals Holdings, Inc. (NYSE:SUNB) a strong source of growth beyond general equipment rentals. Specialized services can deepen customer relationships and create opportunities to supply several needs on the same project.
The company estimated that the FIFA World Cup contributed 2.5 percentage points to quarterly rental-revenue growth. Serving complex events demonstrates the commercial value of a broad equipment network. The investment opportunity is to turn that capability into recurring work across industrial, energy and construction customers.
Adjusted EBITDA increased 8.7% to $1.315 billion. This company-defined non-GAAP measure adds taxes, net interest, depreciation, amortization, stock-based compensation and specified restructuring costs to net income. Its margin is adjusted EBITDA divided by revenue.
#rentals

28 days ago
York Water holds the longest dividend streak in US public markets at 27 consecutive years, while WTW's $1.775B operating cash flow dwarfs its $358M dividend obligation.
Amdocs and Ituran both run near-recession-proof revenue models, with DOX posting near-100% managed services renewal rates and ITRN carrying zero debt alongside $103.7M in net cash.
All five stocks fund dividends from contracted or recurring revenue streams such as regulated rates, fee income, or subscriptions, insulating payouts from economic cycles.
Read More: Learn 7 secret wealth tips high net worth investors use that most investors miss (sponsor)
Income investors heading into the fourth quarter want payouts that don't wobble with the business cycle. The five names below share one thing: dividends funded by recurring, contracted, or fee-based revenue streams that keep flowing whether or not the macro cooperates. Each has raised its payout recently, and each trades on Nasdaq. As a grounding data point, Willis Towers Watson (NASDAQ:WTW) alone generated $360 million of first-half free cash flow, roughly double the prior-year period, giving the broker ample room to keep funding both dividends and buybacks.
#revenue #NASDAQ #Dividend

28 days ago
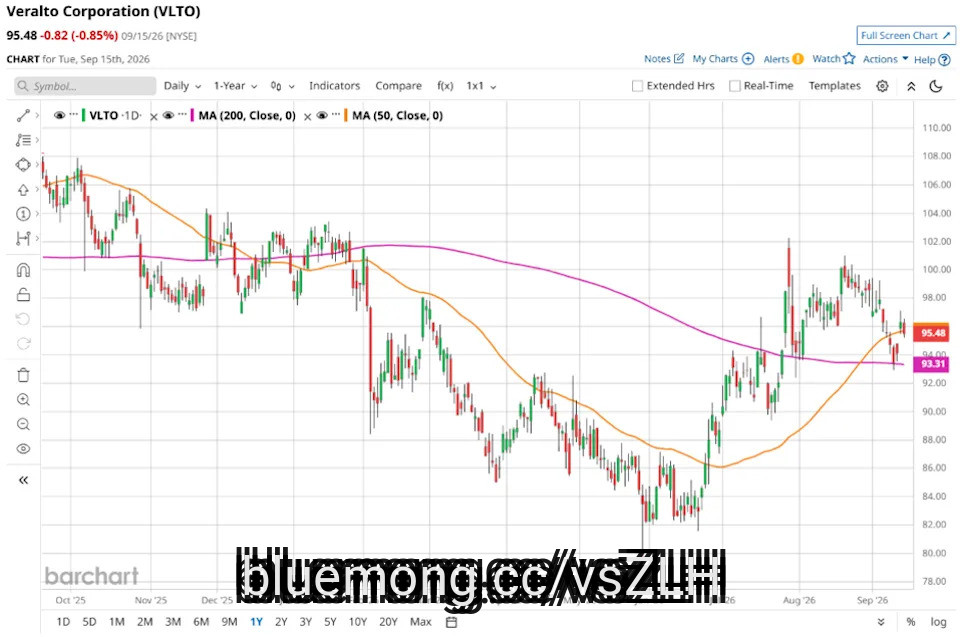
Veralto Corporation (VLTO), headquartered in Waltham, Massachusetts, provides water ******* ytics, water treatment, marking and coding, and packaging and color services. Valued at $23.3 billion by market cap, the company offers product quality control systems and water purification equipment.
Companies worth $10 billion or more are generally described as "large-cap stocks," and VLTO perfectly fits that description, with its market cap exceeding this mark, underscoring its size, influence, and dominance within the pollution & treatment controls industry. VLTO leads water quality and product quality & innovation with iconic brands like Hach, Trojan, ChemTreat, Videojet, Linx, Esko, X-Rite and Pantone, leveraging a large installed base to drive recurring consumables and software sales.
Billionaire Charlie Munger, Who Died at 99, Skipped Insurance on His Mansion Since He Could Just Write a Check to Rebuild — 'All Intelligent People Do It My Way'
Nvidia CEO Jensen Huang Just Dropped Huge News for This Cybersecurity Stock
How to Play GME Stock as GameStop CEO Ryan Cohen Buys $20.3 Million in Shares
#treatment #market #veralto


29 days ago
Adobe (ADBE) reported a record fiscal Q3 2026 and raised its fiscal 2026 revenue and earnings targets. Revenue rose 13% as reported to $6.76 billion, above the $6.70 billion the company had guided. But the key figure that did not move is the one to hold the quarter against: the fiscal 2026 target for growth in ending annualized recurring revenue, or ARR, still 10.2%.
The fiscal 2026 revenue target moved to $26.576 billion to $26.626 billion from $26.55 billion. The interim CFO sized that at around $50 million at the midpoint, a little less than the $60 million revenue beat in fiscal Q3. The gap is a slight currency headwind in fiscal Q4, and the interim CFO said nothing in the business changed. Non-GAAP earnings per share of $6.13 cleared the $6.08 guide, and the fiscal 2026 non-GAAP EPS target moved to $24.45 to $24.50.
Total ending ARR was $27.5 billion, up 11.2% year over year at the end of fiscal Q3, and the fiscal 2026 year-end growth target for it stayed at 10.2%. Remaining performance obligations, or RPO, grew 8% year over year. One ***** yst called that the first single-digit reading since early fiscal 2023, and down from the prior quarter. The interim CFO tied the RPO figure to the push to acquire new users through the freemium model, and said RPO typically steps up in fiscal Q4 and then stays roughly flat for three quarters.
Another ***** yst put net new ARR down 36% to 37% year over year. Management's answer: Adobe has sent a portion of its traffic into the freemium path to acquire users, and will calibrate when to convert them into paying ARR. The CEO said the company was happy to skip pricing actions that might have brought short-term relief but matter less than new user adoption. Creative freemium monthly active users, which include Firefly, Express and the web and mobile versions of Photoshop, crossed 100 million, growing more than 70% year over year.
So far the paying signal is small against the book. AI-first ending ARR passed $650 million, growing more than 150% year over year, which is about 2.4% of the $27.5 billion total. Management says credit consumption is accelerating quarter on quarter across Creative Cloud and the Firefly app, and Acrobat AI ***** istant monthly active users doubled from the prior quarter. Management gave no date for resuming the pricing actions it deferred in Creative Cloud, and said it is constantly calibrating the best conversion point.
#year #revenue #target #creative
29 days ago
Entrepreneur Media LLC and Yahoo Finance LLC may earn commission or revenue on some products and services through the links below.
Break a proposed role into its recurring tasks and sort them into four categories — judgment, relationship, repetition and coordination — to determine whether you truly need to hire another person.
If the bottleneck is mostly judgment or relationship work, hiring or developing a person is probably the right answer. If the bottleneck is mostly repetition, test automation before adding permanent headcount.
If the bottleneck is mostly coordination, redesign the process first. If the job contains all three, separate the workflow so the human role is built around the work that deserves a human.
Before you approve the next hire, write down the 10 things you expect that person to do.
#role
29 days ago
Apollo Global Management, Inc. (NYSE:APO) is reportedly in talks to acquire Johnson & Johnson (NYSE:JNJ) DePuy Synthes orthopedics business in a transaction that could value the unit at close to $20 billion, according to Bloomberg, as reported by Reuters. J&J generated $9.3 billion of revenue from the orthopedics business in 2025, making the potential transaction material for both companies. The discussions could reach an agreement within weeks, although J&J is also considering a public-market spin-off. This is consistent with J&J's October 2025 decision to separate DePuy Synthes within an expected 18-to-24-month timeframe and shift its MedTech portfolio toward higher-growth, higher-margin businesses.
For Apollo Global Management, Inc. (NYSE:APO), the attraction is the opportunity to acquire a large, established medical-device franchise with substantial recurring demand from joint-replacement and surgical procedures. A roughly $20 billion valuation against $9.3 billion of 2025 revenue implies a price-to-sales multiple of about 2.2x, giving Apollo room to pursue operational improvements, portfolio rationalization, and margin expansion if the business is acquired at an attractive valuation.
DePuy Synthes also has meaningful scale and leading positions across major orthopedics categories, while J&J has recently invested in technologies that could strengthen the franchise, including an agreement covering Gemtrack tracking technology for robotic and navigation-assisted joint procedures and the acquisition of Expanding Innovations for expandable spine implants. Apollo is also entering the potential deal from a position of considerable financial scale: it had approximately $1.05 trillion of ***** ets under management as of June 30, 2026, with $198 billion in equity strategies and $849 billion in credit strategies. Its second-quarter results included $111 billion of gross capital deployment, demonstrating the capacity to execute large transactions.
For Johnson & Johnson (NYSE:JNJ), a sale could accelerate the portfolio transformation that management has already identified as a strategic priority while potentially delivering a sizeable upfront cash inflow. J&J explicitly said its planned orthopedics separation should increase the company's top-line growth and operating margins by allowing it to concentrate on Oncology, Immunology, Neuroscience, Cardiovascular, Surgery and Vision.
The company has also been restructuring orthopedics, with $307 million of restructuring expense in 2025, following $167 million in 2024 and $319 million in 2023, primarily tied to market and product exits. A sale could therefore remove a business that has required restructuring resources while allowing J&J to redeploy capital toward areas it views as higher growth and higher margin.
#billion #depuy
29 days ago
Rocket Lab surged 3% after a $1.944 billion equity offering eliminated the need for a $3.6 billion bridge loan to fund its Iridium acquisition.
The Iridium deal adds recurring satellite communications revenue to Rocket Lab's launch and ***** ecraft businesses, creating a more vertically integrated ***** e company.
The offering added 29.3 million shares, raising dilution concerns as Rocket Lab integrates Iridium while developing Neutron and awaiting mid-2027 regulatory approval.
Read More: Avoid these 13 retirement mistakes before they derail your future (sponsor)
Rocket Lab Corporation (NASDAQ:RKLB) stock is rising 3% to $64.14 in Tuesday morning trading as investors respond to progress on the company's planned acquisition of Iridium Communications. Rocket Lab completed a $1.944 billion at-the-market equity offering, giving Rocket Lab enough financing to cover the cash portion of the roughly $8 billion transaction and related costs.
#iridium #billion #offering