

18 hours ago
If you had only ever seen Katie Holmes as tomboy-adjacent Joey Potter from "Dawson's Creek," which is arguably the actor's most famous role, then you might be surprised to look up and witness the gorgeous, style-forward woman that Holmes has become in the years since. From Katie Holmes' stunning hair transformation to her trend-setting street style — you can take notes from Katie Holmes on nailing denim-on-denim — this former girl-next-door has established herself as a fashionable member of the A-list.
However, there is one thing that Katie Holmes still has in common with her years portraying Joey: a minimalist approach to cosmetics. Surprised? This may seem like a big shift from the woman who told Redbook in 2013 that while some celebs don't need makeup, "But I do! I need it!" and confessed to British Vogue, "I don't always take off my makeup before bed."
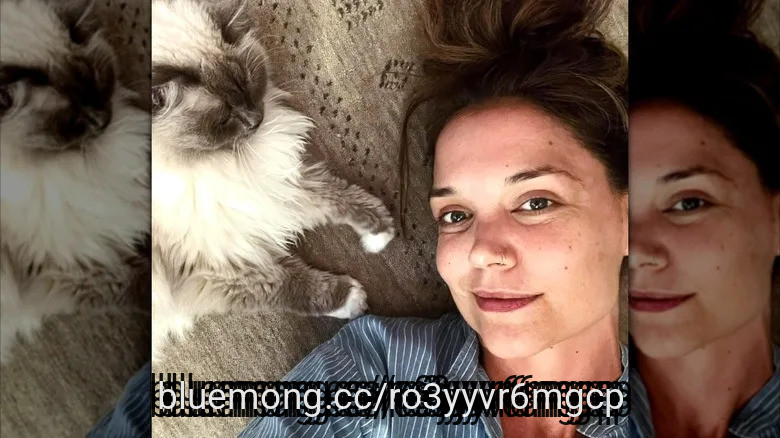
Today's Katie Holmes is a skincare-conscious queen who prioritizes a healthy glow. And while she enjoys her time in the makeup chair, she doesn't feel that a full-face look is necessary armor for day-to-day life. She even filmed an entire movie — 2015's "Touched with Fire" — wearing basically no makeup on camera. This translates into many moments in the actor's off-screen existence, as well. From grocery shopping and posting selfies without cosmetics to scaling back her event makeup wherever she can, Katie Holmes prefers to embrace her inherent beauty.
Read more: Dolly Parton's Natural Hair Was Gorgeous But Her Reason For Wearing Wigs Is So Relatable
katieholmes / Instagram
#joey
However, there is one thing that Katie Holmes still has in common with her years portraying Joey: a minimalist approach to cosmetics. Surprised? This may seem like a big shift from the woman who told Redbook in 2013 that while some celebs don't need makeup, "But I do! I need it!" and confessed to British Vogue, "I don't always take off my makeup before bed."
Today's Katie Holmes is a skincare-conscious queen who prioritizes a healthy glow. And while she enjoys her time in the makeup chair, she doesn't feel that a full-face look is necessary armor for day-to-day life. She even filmed an entire movie — 2015's "Touched with Fire" — wearing basically no makeup on camera. This translates into many moments in the actor's off-screen existence, as well. From grocery shopping and posting selfies without cosmetics to scaling back her event makeup wherever she can, Katie Holmes prefers to embrace her inherent beauty.
Read more: Dolly Parton's Natural Hair Was Gorgeous But Her Reason For Wearing Wigs Is So Relatable
katieholmes / Instagram
#joey
1 day ago
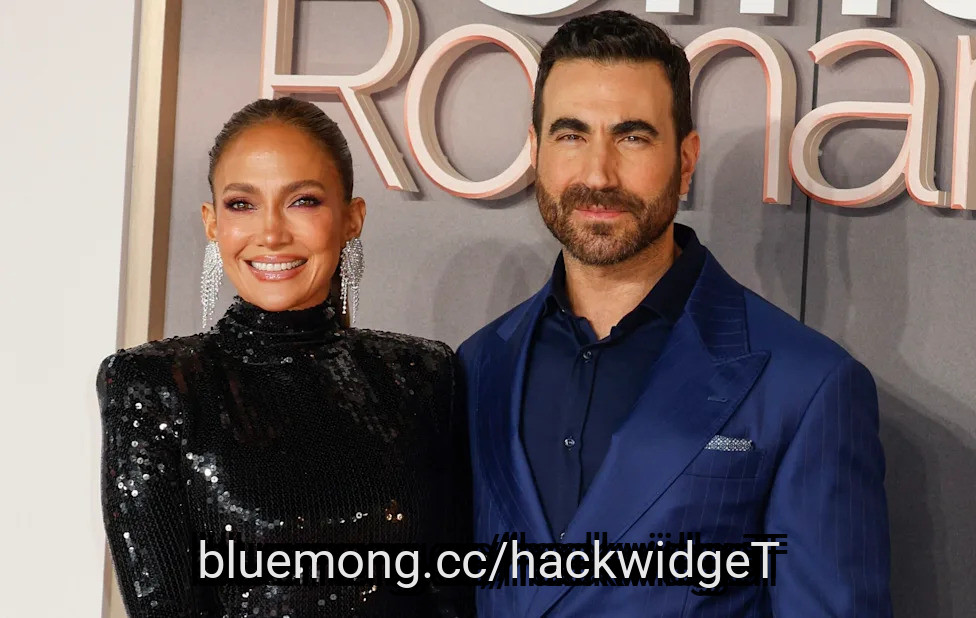
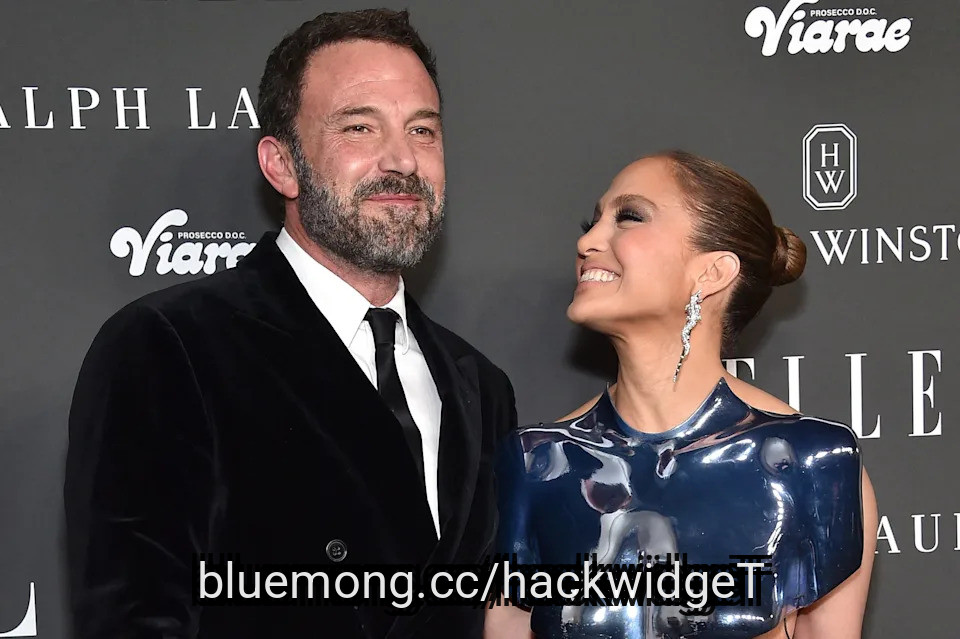
Jennifer Lopez is raising eyebrows among her friend group by giving new man Brett Goldstein a very Ben Affleck-esque makeover, a source tells Star.
"When she looks in the mirror, she sees every little detail and how it could be improved and she tends to do the same thing with the men she dates," reveals the source. "She's not mean about it, she just helps them to look their best, and there's no denying her men always get a glow-up when they start dating her."
And her former Office Romance costar, 46, is no different.
"She's picking his clothes, advising him on how to style his hair and his beard, even his trademark eyebrows have gotten way less bushy since they got together," the source notes. "The funny thing is, her idea of his best look is getting closer and closer to Ben's. She's choosing all the same styles she likes on Ben. Even the way she's got him grooming his beard is the way she likes Ben's beard."
Lisa OConnor/AFF-USA.com / MEGA
#beard
"When she looks in the mirror, she sees every little detail and how it could be improved and she tends to do the same thing with the men she dates," reveals the source. "She's not mean about it, she just helps them to look their best, and there's no denying her men always get a glow-up when they start dating her."
And her former Office Romance costar, 46, is no different.
"She's picking his clothes, advising him on how to style his hair and his beard, even his trademark eyebrows have gotten way less bushy since they got together," the source notes. "The funny thing is, her idea of his best look is getting closer and closer to Ben's. She's choosing all the same styles she likes on Ben. Even the way she's got him grooming his beard is the way she likes Ben's beard."
Lisa OConnor/AFF-USA.com / MEGA
#beard

7 days ago
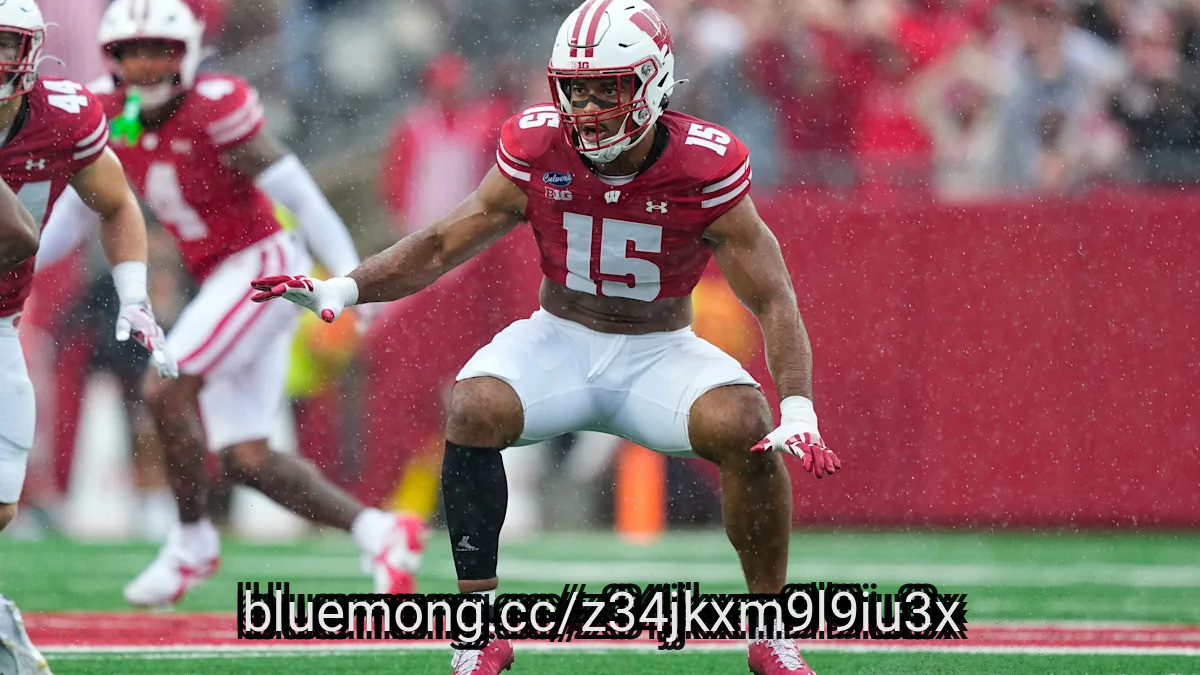
Sebastian Cheeks has spearheaded one of the best defenses in the nation this season. The Wisconsin Badgers rank inside the top 10 in total yards allowed per game at 276.5, all while allowing a stout 16.3 points per game, which ranks 13th-best in the country. Cheeks joined the Badgers ahead of the 2024 season after spending two seasons at UNC. Cheeks' first two seasons saw him flash at times, but overall, he never jumped out as one of the Big Ten's biggest stars.That was until now. So far this season, Cheeks has tallied 26 total tackles, seven tackles for loss, five sacks, and two forced fumbles.In Wisconsin's upset 24-7 win over USC this past weekend, Cheeks pulled together five tackles and 2.5 sacks, earning him conference acclaim.
Cheeks was recently tipped as a potential NFL draft pick by draft expert Mel Kiper thanks to his do-it-all archetype.
Luke Fickell's squad has just five games on the season; up next is the 5-2 Iowa Hawkeyes inside what is bound to be an electric Kinnick Stadium. Kickoff is set for 12 PM ET and is the Big Noon Kickoff game for FOX.
Contact/FollowTheBadgersWire on X (formerly Twitter) and like our page on Facebook to follow ongoing coverage of Wisconsin Badgers news, notes and opinion.
This article originally appeared on Badgers Wire: Wisconsin OLB finally named Big Ten Defensive Player of the Week
#cheeks #badgers #follow
Cheeks was recently tipped as a potential NFL draft pick by draft expert Mel Kiper thanks to his do-it-all archetype.
Luke Fickell's squad has just five games on the season; up next is the 5-2 Iowa Hawkeyes inside what is bound to be an electric Kinnick Stadium. Kickoff is set for 12 PM ET and is the Big Noon Kickoff game for FOX.
Contact/FollowTheBadgersWire on X (formerly Twitter) and like our page on Facebook to follow ongoing coverage of Wisconsin Badgers news, notes and opinion.
This article originally appeared on Badgers Wire: Wisconsin OLB finally named Big Ten Defensive Player of the Week
#cheeks #badgers #follow

7 days ago
The Arizona Cardinals have made one trade already. As the trade deadline approaches, many believe they could make at least one other deal.
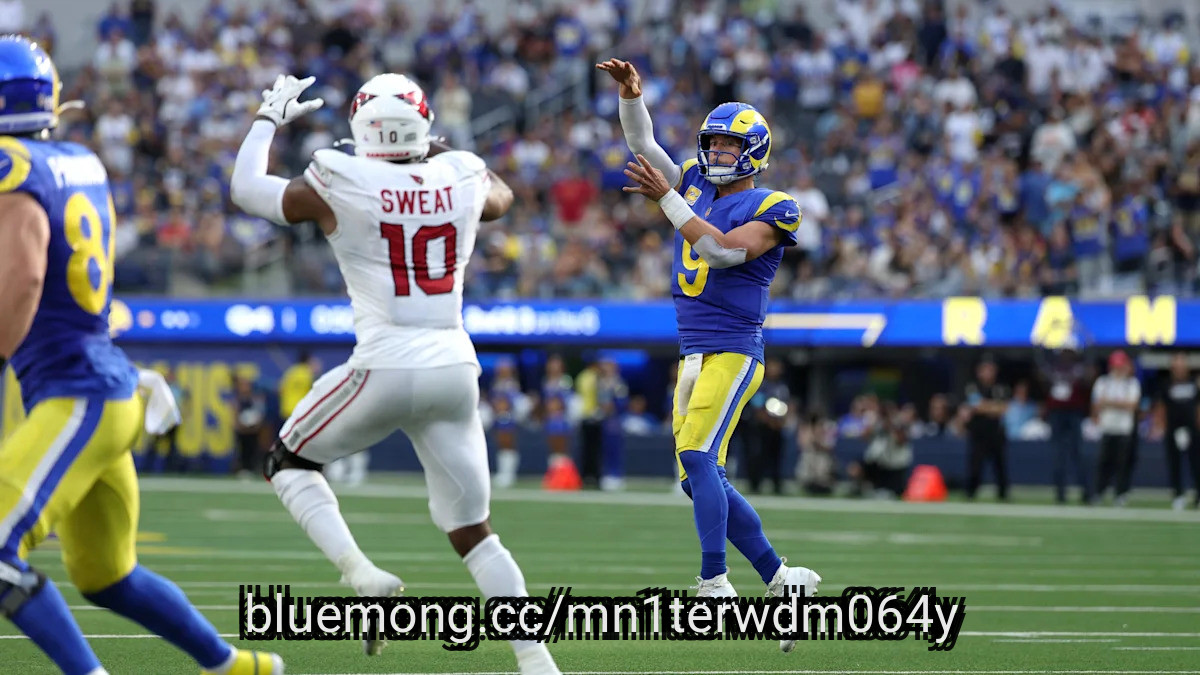
Outside linebacker Josh Sweat has been the subject of rumors since the offseason. Those rumors are heating up, although it is no more than people speculating fit.
ESPN's Jeremy Fowler is hearing that rivals see the Cardinals moving Sweat. One source considers the Dallas Cowboys, whom the Cardinals play this weekend, a good fit.
Fowler gives a Sweat trade about 40% odds and notes the Cowboys, San Francisco 49ers and Chicago Bears as teams to watch.
With the Bears acquiring defensive tackle Jeffery Simmons from the Tennessee ******* ans, they likely aren't a possibility now. It seems unlikely the Cardinals would send their best edge rusher to a division rival like the 49ers, so the Cowboys make the most sense.
#cardinals #outside
Outside linebacker Josh Sweat has been the subject of rumors since the offseason. Those rumors are heating up, although it is no more than people speculating fit.
ESPN's Jeremy Fowler is hearing that rivals see the Cardinals moving Sweat. One source considers the Dallas Cowboys, whom the Cardinals play this weekend, a good fit.
Fowler gives a Sweat trade about 40% odds and notes the Cowboys, San Francisco 49ers and Chicago Bears as teams to watch.
With the Bears acquiring defensive tackle Jeffery Simmons from the Tennessee ******* ans, they likely aren't a possibility now. It seems unlikely the Cardinals would send their best edge rusher to a division rival like the 49ers, so the Cowboys make the most sense.
#cardinals #outside

28 days ago
Sydney Sweeney's blonde bombshell aesthetic just might be hereditary.
The "Euphoria" actress and the late Marilyn Monroe are distant relatives, according to a new MyHeritage study shared with USA TODAY.
The genealogy research site notes the actresses are ninth cousins, once removed, meaning that there is a one-generation gap between them.
The Hollywood darlings share the common ancestors Ezra Perry and Elizabeth Burgess, 17th-century British settlers in Massachusetts, through Sweeney's father, Steven Sweeney, and Monroe's biological father, Charles Stanley Gifford, according to the online genealogy company.
The Perry-Burgess lineage also includes former President Franklin D. Roosevelt and Gen. Douglas MacArthur.
#monroe #myheritage
The "Euphoria" actress and the late Marilyn Monroe are distant relatives, according to a new MyHeritage study shared with USA TODAY.
The genealogy research site notes the actresses are ninth cousins, once removed, meaning that there is a one-generation gap between them.
The Hollywood darlings share the common ancestors Ezra Perry and Elizabeth Burgess, 17th-century British settlers in Massachusetts, through Sweeney's father, Steven Sweeney, and Monroe's biological father, Charles Stanley Gifford, according to the online genealogy company.
The Perry-Burgess lineage also includes former President Franklin D. Roosevelt and Gen. Douglas MacArthur.
#monroe #myheritage



29 days ago
Russell Brand appeared in court with his wife, Laura, ahead of his upcoming rape and ****** ual ****** ault trial. The comedian, who denied the charges, faced allegations from six women over a 10-year period between 1999 and 2009.
The case involved seven charges in total: three counts of rape, three charges of ****** ual ****** ault and one allegation of indecent ****** ault. Brand pleaded not guilty to all the charges, which related to allegations involving six women.
According to Metro, Brand arrived at Southwark Crown Court with Laura and a security guard for the first of two pre-trial hearing days. Laura wore a yellow suit and sunglasses, while Brand wore a grey suit, black trousers, a collarless shirt and brown boots, along with sunglasses. The couple did not speak as they entered the court.
Meanwhile, his trial was scheduled to begin on Monday, October 12, and could continue for up to 10 weeks. Brand remained on bail as the criminal proceedings moved forward.
Brand pleaded not guilty in February. As he arrived at court at the time, he told Sky News that he was feeling "blessed" and carried a blue book bearing the words "Holy Bible," with post-it notes attached inside.
#laura #charges
The case involved seven charges in total: three counts of rape, three charges of ****** ual ****** ault and one allegation of indecent ****** ault. Brand pleaded not guilty to all the charges, which related to allegations involving six women.
According to Metro, Brand arrived at Southwark Crown Court with Laura and a security guard for the first of two pre-trial hearing days. Laura wore a yellow suit and sunglasses, while Brand wore a grey suit, black trousers, a collarless shirt and brown boots, along with sunglasses. The couple did not speak as they entered the court.
Meanwhile, his trial was scheduled to begin on Monday, October 12, and could continue for up to 10 weeks. Brand remained on bail as the criminal proceedings moved forward.
Brand pleaded not guilty in February. As he arrived at court at the time, he told Sky News that he was feeling "blessed" and carried a blue book bearing the words "Holy Bible," with post-it notes attached inside.
#laura #charges


29 days ago
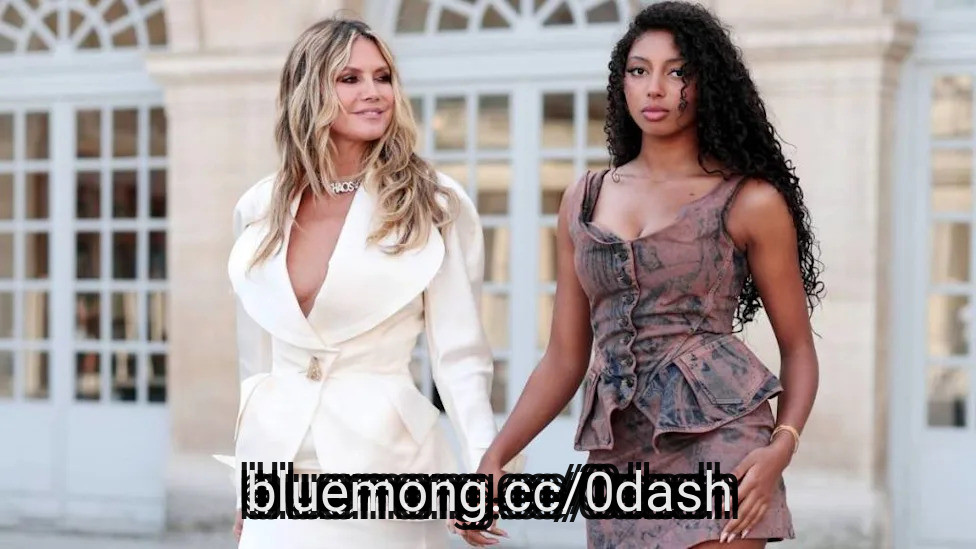
Heidi Klum just brought a very special plus-one to Paris Fashion Week, and the mother-daughter duo is turning heads. The supermodel, 53, stepped out with her youngest child, 16-year-old daughter Lou, for the Vivienne Westwood show. It was the teen's Fashion Week debut, and she proved that she's been taking notes from her stylish mom. The pair coordinated in chic peplum silhouettes and towering platforms.
Heidi Klum and daughter Lou coordinated in peplum looks at the Vivienne Westwood show. Lou, whose dad is singer Seal, usually stays out of the spotlight, which makes this sweet outing even more special. A video from the event shows the two posing side by side in front of a white backdrop splashed with bold orange and red brushstrokes. They look relaxed, happy, and completely in sync.
Heidi went for a glamorous all-white moment. Her ivory satin blazer features a deep plunging neckline, sculpted shoulders, and a single gold ******* on at the waist. She paired it with a matching floor-length satin skirt that skimmed the ground. The model mom finished the look with a sparkling statement necklace and her golden blonde waves styled loose and tousled.
Lou, on the other hand, brought a warm and earthy twist. The teen wore a ******* on-front, corset-style mini dress in a washed brown print. The fitted bodice features thin straps and a scooped neckline, while the flared peplum waist adds a playful touch of movement. The design is a perfect nod to Westwood's famous love for dramatic corsetry and tailoring. She accessorized with a gold bangle and let her dark, voluminous curls fall naturally around her shoulders.
The most eye-catching part of both outfits is the footwear. Lou towers in patterned platform sandals with ankle straps, done in rich brown and red tones that match her dress. Heidi's blue platform shoes peek out from beneath her skirt in a closing shot, adding a fun pop of color to her neutral outfit.
#heidi #klum
Heidi Klum and daughter Lou coordinated in peplum looks at the Vivienne Westwood show. Lou, whose dad is singer Seal, usually stays out of the spotlight, which makes this sweet outing even more special. A video from the event shows the two posing side by side in front of a white backdrop splashed with bold orange and red brushstrokes. They look relaxed, happy, and completely in sync.
Heidi went for a glamorous all-white moment. Her ivory satin blazer features a deep plunging neckline, sculpted shoulders, and a single gold ******* on at the waist. She paired it with a matching floor-length satin skirt that skimmed the ground. The model mom finished the look with a sparkling statement necklace and her golden blonde waves styled loose and tousled.
Lou, on the other hand, brought a warm and earthy twist. The teen wore a ******* on-front, corset-style mini dress in a washed brown print. The fitted bodice features thin straps and a scooped neckline, while the flared peplum waist adds a playful touch of movement. The design is a perfect nod to Westwood's famous love for dramatic corsetry and tailoring. She accessorized with a gold bangle and let her dark, voluminous curls fall naturally around her shoulders.
The most eye-catching part of both outfits is the footwear. Lou towers in patterned platform sandals with ankle straps, done in rich brown and red tones that match her dress. Heidi's blue platform shoes peek out from beneath her skirt in a closing shot, adding a fun pop of color to her neutral outfit.
#heidi #klum

29 days ago
By Ann Saphir
Oct 7 (Reuters) - The interest rate on the most common US home loan jumped last week to its highest in almost three years, worsening affordability for buyers four weeks before elections that will decide if President Donald Trump's Republicans keep control of Congress.
The average 30-year fixed-rate mortgage surged 19 basis points to 7.49% in the week ended October 2, the Mortgage Bankers **** ociation said on Wednesday. It was last higher in November 2023.
Mortgage rates are tied closely to the yield on US 10-year Treasury notes, which earlier this week hit a 24-year high, driven by worries over inflationary pressures from soaring oil prices and data showing stronger US economic growth.
The cost of living is the top issue on Americans' minds as they decide how they will vote on November 3, a Reuters/Ipsos poll completed on Monday showed, and is one reason why Trump's approval rating is at a record low of 32%.
#week #rate
Oct 7 (Reuters) - The interest rate on the most common US home loan jumped last week to its highest in almost three years, worsening affordability for buyers four weeks before elections that will decide if President Donald Trump's Republicans keep control of Congress.
The average 30-year fixed-rate mortgage surged 19 basis points to 7.49% in the week ended October 2, the Mortgage Bankers **** ociation said on Wednesday. It was last higher in November 2023.
Mortgage rates are tied closely to the yield on US 10-year Treasury notes, which earlier this week hit a 24-year high, driven by worries over inflationary pressures from soaring oil prices and data showing stronger US economic growth.
The cost of living is the top issue on Americans' minds as they decide how they will vote on November 3, a Reuters/Ipsos poll completed on Monday showed, and is one reason why Trump's approval rating is at a record low of 32%.
#week #rate
1 month ago
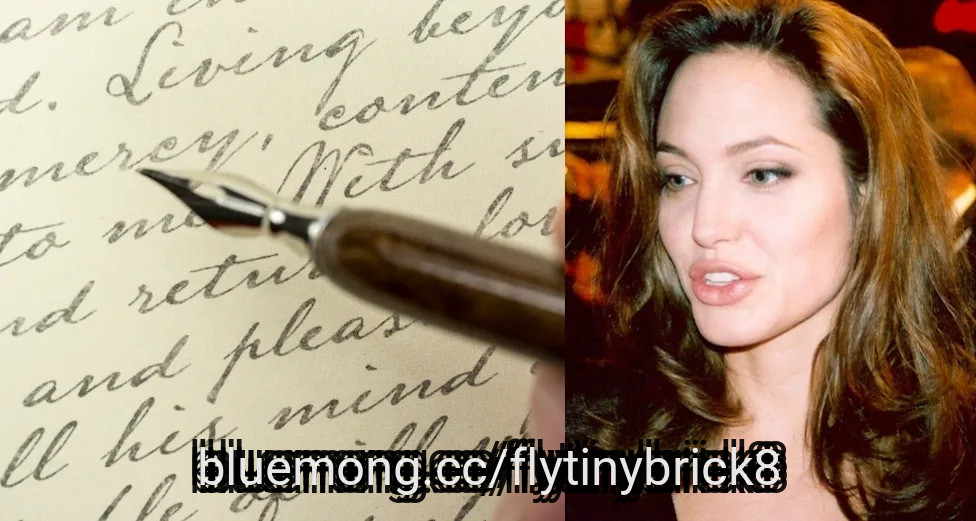
Like most Gen X-ers, 51-year-old Angelina Jolie likely had to study penmanship in elementary school. (As a fellow Gen X-er, I can attest that this particular class often lowered my grade point average.) But now that many schools place less emphasis on cursive, younger generations might struggle not only to write it, but to read it, too.
A recent post on the How Everything Works Instagram page shared a thank-you note reportedly written by Jolie for hotel staff. As the note goes viral, many have weighed in, calling it mostly illegible. This is causing quite a stir between generations, with some blaming a lack of education on this subject as the culprit.
The original poster added, for context, "Angelina Jolie left a handwritten thank you note for the staff after staying at a luxury hotel, but the internet quickly became more interested in trying to read it. Her distinctive cursive proved so difficult to decipher that people began sharing their guesses about what the note actually said, turning a simple message into an unexpected online puzzle. Some words were easier to make out than others, but the handwriting became the main attraction, with fans collectively trying to decode the entire note. What started as a thoughtful gesture from Jolie ended up becoming a viral guessing game over her handwriting."
Many commenters tried to transcribe the letter, which appears to have first been shared back in October, 2023. One commenter immediately notes how difficult it might be for Gen Z to read it. She first shares her take on what the note says. "'Thank you for a restful stay at your beautiful resort. The 'Maria' crew had a lovely time here. With love, Angelina Jolie' — With some context and if you know cursive, you can make most of it out. I don't think any GenZ's would know what this said."
Others suggested it was some kind of medical professional "script." This Instagrammer explains, in part, " This is NOT script. It's just her sloppy 'style' of writing. Yes. I'm a nurse."
#angelina #cursive #others
A recent post on the How Everything Works Instagram page shared a thank-you note reportedly written by Jolie for hotel staff. As the note goes viral, many have weighed in, calling it mostly illegible. This is causing quite a stir between generations, with some blaming a lack of education on this subject as the culprit.
The original poster added, for context, "Angelina Jolie left a handwritten thank you note for the staff after staying at a luxury hotel, but the internet quickly became more interested in trying to read it. Her distinctive cursive proved so difficult to decipher that people began sharing their guesses about what the note actually said, turning a simple message into an unexpected online puzzle. Some words were easier to make out than others, but the handwriting became the main attraction, with fans collectively trying to decode the entire note. What started as a thoughtful gesture from Jolie ended up becoming a viral guessing game over her handwriting."
Many commenters tried to transcribe the letter, which appears to have first been shared back in October, 2023. One commenter immediately notes how difficult it might be for Gen Z to read it. She first shares her take on what the note says. "'Thank you for a restful stay at your beautiful resort. The 'Maria' crew had a lovely time here. With love, Angelina Jolie' — With some context and if you know cursive, you can make most of it out. I don't think any GenZ's would know what this said."
Others suggested it was some kind of medical professional "script." This Instagrammer explains, in part, " This is NOT script. It's just her sloppy 'style' of writing. Yes. I'm a nurse."
#angelina #cursive #others
1 month ago
Sophia Bush is married to Ashlyn Harris.
The One Tree Hill actress reveals in her memoir And I Will Tell You Mine: Notes from a Life in Progress that she secretly wed the former professional soccer player last summer in upstate New York.
The couple, who have been together for three years, opened up to Vogue about why they decided in favor of a private, intimate ceremony.
"When you get to this stage in your life, you begin to unpack what's yours and what's always sort of been for everyone else," Bush tells Vogue.
Harris says a smaller wedding was also perfect for her children, Sloane and Ocean, to whom Bush is a stepmom.
#bush #vogue #tree #tell
The One Tree Hill actress reveals in her memoir And I Will Tell You Mine: Notes from a Life in Progress that she secretly wed the former professional soccer player last summer in upstate New York.
The couple, who have been together for three years, opened up to Vogue about why they decided in favor of a private, intimate ceremony.
"When you get to this stage in your life, you begin to unpack what's yours and what's always sort of been for everyone else," Bush tells Vogue.
Harris says a smaller wedding was also perfect for her children, Sloane and Ocean, to whom Bush is a stepmom.
#bush #vogue #tree #tell



2 months ago
On August 5, Cencora (NYSE:COR) reported results for its fiscal third quarter, which closed on June 30, and the headline numbers looked clean. Revenue rose 5.1% to $84.8 billion, adjusted earnings per share climbed 12.0% to $4.48, and management raised its full-year adjusted EPS outlook to $17.75 to $17.95. The company also repurchased $1 billion of its own stock during the quarter. But the profit story has moving parts, and a few of them pull in opposite directions.
Start with the gap between profit growth and sales growth. Adjusted operating income rose 17.0% while revenue grew only 5.1%. Much of the help came from gross profit, which jumped 23.2% on an adjusted basis as both segments contributed and the OneOncology acquisition in February lifted margins in the US business. In plain terms, adjusted gross margin widened 61 basis points to 4.16%, so the company keeps more gross profit from every dollar it sells.
The strength was not confined to one corner, either. US Healthcare Solutions grew operating income 15.9% on higher pharmaceutical sales and the OneOncology deal, while specialty volume to health systems and physician groups lifted its revenue. International Healthcare Solutions did better still, with operating income up 20.8% on strength in European distribution and global specialty logistics. Management also put cash to work, completing in one quarter the $1 billion of buybacks it had expected to finish by the close of calendar 2026. The board declared a $0.60 quarterly dividend as well, payable August 31, to holders of record on August 14.
Growth is costing more than it first appears. Adjusted operating expenses jumped 26.8%, faster than adjusted gross profit, because OneOncology brought expenses along with its profits. Even so, adjusted operating income amounts to just 1.46% of revenue, a thin cushion on a business this large. Financing adds weight too. Cencora funded part of the purchase with new senior notes plus variable-rate term loans, and net interest expense rose $58.9 million from a year earlier.
The sales mix carries its own drag. GLP-1 drugs for diabetes and weight loss are adding to revenue, but they earn lower gross margins, so each dollar of that growth is worth less to profit. Meanwhile, an oncology customer Cencora lost in 2025, and lower sales to a large mail order customer both held back US revenue, as did lower manufacturer prices on some brand pharmaceuticals. Cencora is also exploring strategic alternatives for a group of other businesses, and its April divestiture of US Consulting Services trimmed consulting sales.
#adjusted #revenue #august
Start with the gap between profit growth and sales growth. Adjusted operating income rose 17.0% while revenue grew only 5.1%. Much of the help came from gross profit, which jumped 23.2% on an adjusted basis as both segments contributed and the OneOncology acquisition in February lifted margins in the US business. In plain terms, adjusted gross margin widened 61 basis points to 4.16%, so the company keeps more gross profit from every dollar it sells.
The strength was not confined to one corner, either. US Healthcare Solutions grew operating income 15.9% on higher pharmaceutical sales and the OneOncology deal, while specialty volume to health systems and physician groups lifted its revenue. International Healthcare Solutions did better still, with operating income up 20.8% on strength in European distribution and global specialty logistics. Management also put cash to work, completing in one quarter the $1 billion of buybacks it had expected to finish by the close of calendar 2026. The board declared a $0.60 quarterly dividend as well, payable August 31, to holders of record on August 14.
Growth is costing more than it first appears. Adjusted operating expenses jumped 26.8%, faster than adjusted gross profit, because OneOncology brought expenses along with its profits. Even so, adjusted operating income amounts to just 1.46% of revenue, a thin cushion on a business this large. Financing adds weight too. Cencora funded part of the purchase with new senior notes plus variable-rate term loans, and net interest expense rose $58.9 million from a year earlier.
The sales mix carries its own drag. GLP-1 drugs for diabetes and weight loss are adding to revenue, but they earn lower gross margins, so each dollar of that growth is worth less to profit. Meanwhile, an oncology customer Cencora lost in 2025, and lower sales to a large mail order customer both held back US revenue, as did lower manufacturer prices on some brand pharmaceuticals. Cencora is also exploring strategic alternatives for a group of other businesses, and its April divestiture of US Consulting Services trimmed consulting sales.
#adjusted #revenue #august

2 months ago
On August 6, Aflac (NYSE:AFL) reported second-quarter numbers that point in opposite directions. Net earnings climbed to $825 million, helped along by investment losses that shrank to $153 million from $421 million a year ago. Adjusted earnings, though, fell 7.7% to $883 million. Both numbers are real, but they answer different questions. Which measure you trust changes the story, so here is what sits underneath.
Start with the yen, because it is muddying the picture. The average rate was 159.45 to the dollar, 9.3% weaker than a year earlier, and that cost adjusted earnings $0.05 a share. Take the currency out of the first half and adjusted earnings per share rose 4.1% to $3.57. ******* an is also running more profitably. Its pretax adjusted margin widened to 34.3% from 32.0% as claims took a smaller bite out of premiums, and yen-based pretax adjusted earnings rose 3.4%. So part of the decline in ******* an's dollar-reported profit is currency, not operations.
The US business is still growing at the top line. Net earned premiums rose 2.3% to $1.5 billion, and sales climbed 2.6% to $349 million, led by group voluntary benefits along with dental and vision plans. In ******* an, the refreshed Tsumitasu life policy and the new Anshin Palette medical product grew strongly in the quarter, and first-half sales rose 7.0% to ¥37.3 billion. Then there is the cash. Aflac returned $1.3 billion to shareholders in the quarter, $983 million of it through buybacks, and declared a $0.61 third-quarter dividend, payable September 1 to holders of record on August 19, 2026. Management notes 43 straight years of dividend increases through 2025 and says the board is on a path to extend that in 2026.
The catch is that ******* an's profit gains came from lower claims, not a bigger business. Net earned premiums in yen fell 3.7%, mainly because of a new external reinsurance deal and older limited-pay policies reaching paid-up status. Premium persistency, the share of policies customers keep, slipped to 92.7% from 93.7%. ******* an's pretax adjusted earnings still fell 2.1% once currency is stripped out, and new sales dipped 5.6% in the quarter against a tough comparison for the Miraito cancer product, which launched in March 2025.
The US segment has its own soft spot. Pretax adjusted earnings fell 4.6% to $370 million, and the margin narrowed to 20.9% from 22.5% as claims and benefits took a bigger share of premiums. Corporate and Other swung to a $10 million pretax adjusted loss from a $20 million gain a year earlier, with interest expense up 21.6% to $62 million. And adjusted book value per share, excluding foreign currency remeasurement, slid to $41.22 at June 30 from $42.97 a year earlier.
#earnings #fell
Start with the yen, because it is muddying the picture. The average rate was 159.45 to the dollar, 9.3% weaker than a year earlier, and that cost adjusted earnings $0.05 a share. Take the currency out of the first half and adjusted earnings per share rose 4.1% to $3.57. ******* an is also running more profitably. Its pretax adjusted margin widened to 34.3% from 32.0% as claims took a smaller bite out of premiums, and yen-based pretax adjusted earnings rose 3.4%. So part of the decline in ******* an's dollar-reported profit is currency, not operations.
The US business is still growing at the top line. Net earned premiums rose 2.3% to $1.5 billion, and sales climbed 2.6% to $349 million, led by group voluntary benefits along with dental and vision plans. In ******* an, the refreshed Tsumitasu life policy and the new Anshin Palette medical product grew strongly in the quarter, and first-half sales rose 7.0% to ¥37.3 billion. Then there is the cash. Aflac returned $1.3 billion to shareholders in the quarter, $983 million of it through buybacks, and declared a $0.61 third-quarter dividend, payable September 1 to holders of record on August 19, 2026. Management notes 43 straight years of dividend increases through 2025 and says the board is on a path to extend that in 2026.
The catch is that ******* an's profit gains came from lower claims, not a bigger business. Net earned premiums in yen fell 3.7%, mainly because of a new external reinsurance deal and older limited-pay policies reaching paid-up status. Premium persistency, the share of policies customers keep, slipped to 92.7% from 93.7%. ******* an's pretax adjusted earnings still fell 2.1% once currency is stripped out, and new sales dipped 5.6% in the quarter against a tough comparison for the Miraito cancer product, which launched in March 2025.
The US segment has its own soft spot. Pretax adjusted earnings fell 4.6% to $370 million, and the margin narrowed to 20.9% from 22.5% as claims and benefits took a bigger share of premiums. Corporate and Other swung to a $10 million pretax adjusted loss from a $20 million gain a year earlier, with interest expense up 21.6% to $62 million. And adjusted book value per share, excluding foreign currency remeasurement, slid to $41.22 at June 30 from $42.97 a year earlier.
#earnings #fell

2 months ago
On August 20, Royal Caribbean Group (NYSE:RCL) said it had completed a sale of $1.25 billion of notes that carry a 5.55% coupon and come due on January 20, 2034. The money is earmarked first for floating-rate term loans, with anything left over used to repay or refinance other debt, and the offering rode on a shelf registration filed on February 29, 2024. That sounds like routine upkeep. But next to an earnings beat and a flat third-quarter pricing outlook, the deal gives you a handy lens on where the company stands.
Start with the debt itself. Swapping floating-rate borrowings for notes with a stated 5.550% coupon takes some interest-rate guesswork out of the picture, and the notes don't mature until January 20, 2034. That matters because $2.7 billion comes due in 2027 and $3.4 billion in 2028. Against those bills, the company held $6.9 billion of liquidity as of June 30, and it added $250 million to its revolving credit line in July.
The business generating the cash is running well. On July 28, Royal Caribbean reported second-quarter adjusted earnings of $4.21 per share, ahead of its own guidance on stronger last-minute demand, lower costs, and better results from joint ventures. Management then raised full-year adjusted EPS guidance to a range of $17.73 to $17.87, which implies 14% growth. It also kept returning cash to shareholders in the second quarter, through $404 million of dividends and $199 million of buybacks. Booking volumes are running above last year, and 2027 bookings are tracking ahead of past years, even on routes that geopolitical events hit in 2026.
Beat or not, that $4.21 is still below the $4.38 from the same quarter in 2025. Costs excluding fuel per passenger cruise day rose 4.4%, and the cost beat came largely from the timing of expenses. Then there is pricing, where the story gets less rosy. Third-quarter net yields are guided to roughly flat against 2025 while capacity grows 8.5%, so the expected 8% revenue growth comes from more capacity, not from better yields. Management also says prolonged geopolitical activity has dented bookings on select itineraries. It calls the hit modest, but it is now built into guidance.
The refinancing also doesn't shrink the debt pile. New notes pay off old borrowings, so the total owed stays roughly where it was, and the company still expects net interest of $980 million to $990 million this year. Add roughly $4.7 billion of capital spending in 2026, mostly for new ships and destination projects, and it is clear this business needs a steady supply of capital. The April ship orders, Icon VI and Icon VII, extend that appetite, though their financing is already committed.
#billion #quarter #company #year
Start with the debt itself. Swapping floating-rate borrowings for notes with a stated 5.550% coupon takes some interest-rate guesswork out of the picture, and the notes don't mature until January 20, 2034. That matters because $2.7 billion comes due in 2027 and $3.4 billion in 2028. Against those bills, the company held $6.9 billion of liquidity as of June 30, and it added $250 million to its revolving credit line in July.
The business generating the cash is running well. On July 28, Royal Caribbean reported second-quarter adjusted earnings of $4.21 per share, ahead of its own guidance on stronger last-minute demand, lower costs, and better results from joint ventures. Management then raised full-year adjusted EPS guidance to a range of $17.73 to $17.87, which implies 14% growth. It also kept returning cash to shareholders in the second quarter, through $404 million of dividends and $199 million of buybacks. Booking volumes are running above last year, and 2027 bookings are tracking ahead of past years, even on routes that geopolitical events hit in 2026.
Beat or not, that $4.21 is still below the $4.38 from the same quarter in 2025. Costs excluding fuel per passenger cruise day rose 4.4%, and the cost beat came largely from the timing of expenses. Then there is pricing, where the story gets less rosy. Third-quarter net yields are guided to roughly flat against 2025 while capacity grows 8.5%, so the expected 8% revenue growth comes from more capacity, not from better yields. Management also says prolonged geopolitical activity has dented bookings on select itineraries. It calls the hit modest, but it is now built into guidance.
The refinancing also doesn't shrink the debt pile. New notes pay off old borrowings, so the total owed stays roughly where it was, and the company still expects net interest of $980 million to $990 million this year. Add roughly $4.7 billion of capital spending in 2026, mostly for new ships and destination projects, and it is clear this business needs a steady supply of capital. The April ship orders, Icon VI and Icon VII, extend that appetite, though their financing is already committed.
#billion #quarter #company #year

2 months ago
Accenture plc (NYSE:ACN) investors are having a rough year, with the shares down more than 25%. Now Wall Street is divided over the company's outlook.
Morgan Stanley raised its price target on Accenture to $175 from $130 on September 14. Accenture shares soared more than 6% in afternoon trading following the price target increase, even though the firm reiterated its Equal weight rating on the stock.
Meanwhile, UBS recently maintained a Buy rating on the stock with a price target of $275. The bank pointed to confidence in the company's positioning around AI and, in separate notes, its acquisition strategy. However, Wells Fargo downgraded Accenture to Equal Weight. According to Wells Fargo, macroeconomic pressures could weigh on fiscal 2027 growth expectations.
The question is whether Accenture's expanding AI capabilities and acquisitions can translate into long-term growth.
Accenture's AI fortunes are tied to enterprise deployment of the technology. The company has formed a joint business group with Google Cloud to deploy AI engineers across enterprise clients. That arrangement gives Accenture another channel through which AI adoption can create demand for consulting, implementation, and integration services.
#fargo
Morgan Stanley raised its price target on Accenture to $175 from $130 on September 14. Accenture shares soared more than 6% in afternoon trading following the price target increase, even though the firm reiterated its Equal weight rating on the stock.
Meanwhile, UBS recently maintained a Buy rating on the stock with a price target of $275. The bank pointed to confidence in the company's positioning around AI and, in separate notes, its acquisition strategy. However, Wells Fargo downgraded Accenture to Equal Weight. According to Wells Fargo, macroeconomic pressures could weigh on fiscal 2027 growth expectations.
The question is whether Accenture's expanding AI capabilities and acquisitions can translate into long-term growth.
Accenture's AI fortunes are tied to enterprise deployment of the technology. The company has formed a joint business group with Google Cloud to deploy AI engineers across enterprise clients. That arrangement gives Accenture another channel through which AI adoption can create demand for consulting, implementation, and integration services.
#fargo


2 months ago
The first full week of trading in September didn't give Zscaler (NASDAQ: ZS) investors much to celebrate. During the shortened trading week that followed Labor Day, Zscaler dropped about 3%. This week, however, is a very different story, thanks to a firm providing an auspicious outlook for the cybersecurity stock.
According to data provided by S&P Global Market Intelligence, Zscaler shares were up 20.7% from the end of trading last Friday through 3:37 p.m. today.
Missed AI's "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our ******* ysts, we're only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
Maintaining its outperform rating, Bernstein hiked its price target on Zscaler stock to $298 from $224 on Thursday morning. Based on Zscaler's closing price of $191.58 on Wednesday, the Bernstein price target implies 56% upside.
According to Thefly.com, Bernstein based its improved outlook on the belief that there's growing positive market sentiment toward cybersecurity stocks. In addition, Bernstein notes that cybersecurity stocks it had previously identified as "too cheap" are now reasonable valued, yet Zscaler is one option that still provides material upside.
#week
According to data provided by S&P Global Market Intelligence, Zscaler shares were up 20.7% from the end of trading last Friday through 3:37 p.m. today.
Missed AI's "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our ******* ysts, we're only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
Maintaining its outperform rating, Bernstein hiked its price target on Zscaler stock to $298 from $224 on Thursday morning. Based on Zscaler's closing price of $191.58 on Wednesday, the Bernstein price target implies 56% upside.
According to Thefly.com, Bernstein based its improved outlook on the belief that there's growing positive market sentiment toward cybersecurity stocks. In addition, Bernstein notes that cybersecurity stocks it had previously identified as "too cheap" are now reasonable valued, yet Zscaler is one option that still provides material upside.
#week

2 months ago
Comparing iShares National Muni Bond ETF (NYSEMKT:MUB) and Vanguard Intermediate-Term Treasury ETF (NASDAQ:VGIT) reveals a choice between tax-advantaged municipal income and the federal credit safety of intermediate-term U.S. government securities.
Both funds serve as core fixed-income holdings. The iShares fund tracks high-quality municipal bonds, which may provide tax benefits for certain investors. The Vanguard fund targets Treasury notes with maturities between three and 10 years, offering a refuge from credit risk during periods of market uncertainty.
Metric
MUB
VGIT
#income
Both funds serve as core fixed-income holdings. The iShares fund tracks high-quality municipal bonds, which may provide tax benefits for certain investors. The Vanguard fund targets Treasury notes with maturities between three and 10 years, offering a refuge from credit risk during periods of market uncertainty.
Metric
MUB
VGIT
#income

2 months ago
On August 10, Ferguson Enterprises Inc. (NYSE:FERG) reported results for the quarter ended June 30, and the numbers show a company growing straight through a soft housing market. Sales rose 4.6% to $8.8 billion, and management lifted its outlook for the full year. But profit grew more slowly than sales, and that gap is what makes this report worth a closer look.
The strongest engine was non-residential work, where US revenue jumped 8% on share gains in what management called a mixed market. Large capital projects are part of the story, with open order volumes growing and bidding activity strong, so there is a pipeline behind the current numbers. Housing, roughly half of revenue, is the weak spot. Yet residential sales still rose 2% in the US even though new construction is weak and repair work is soft, which means Ferguson is beating its markets rather than riding them.
Capital deployment is the second pillar. Ferguson closed five acquisitions in the quarter, and on July 13, it announced a deal for FWI Holdings, known as FloWorks, an industrial distributor of valves and flow-control products that is expected to close in the third quarter. The eight deals announced this year carry about $1.4 billion in annualized revenue, a second growth path alongside organic sales. Net debt sits at 1.3 times adjusted EBITDA, a level management calls strong. The company also returned cash, buying back $202 million of stock in the quarter and declaring a $0.89 dividend payable October 7 to holders of record on August 21. Management raised its full-year sales outlook to mid-single-digit growth, before counting FloWorks.
Start with the gap between sales and profit. Adjusted operating profit rose 2.9%, behind the 4.6% sales gain, and gross margin slipped 20 basis points to 31.0%. Ferguson notes that last year's gross margin was temporarily lifted by the timing of supplier price increases, which is fair context, but the direction is still down. Reported earnings per share of $3.43 rose 6.9%, while the adjusted figure of $3.39 grew a slower 5.3%.
Then there are the soft spots. About half of revenue comes from residential markets that management describes as subdued, so a 2% gain there is modest. Canada's sales slipped 1.9%, with a business divestment outweighing organic growth, and management calls the market there challenging, especially in residential. Management also describes the economic environment as uncertain, and the margin part of the guidance raise is small. The low end of the adjusted operating margin range moved from 9.4% to 9.5%, while the top stayed at 9.8%. The guidance also leaves out FloWorks, and net debt to adjusted EBITDA is 1.3 times, against 1.2 times a year ago.
#management
The strongest engine was non-residential work, where US revenue jumped 8% on share gains in what management called a mixed market. Large capital projects are part of the story, with open order volumes growing and bidding activity strong, so there is a pipeline behind the current numbers. Housing, roughly half of revenue, is the weak spot. Yet residential sales still rose 2% in the US even though new construction is weak and repair work is soft, which means Ferguson is beating its markets rather than riding them.
Capital deployment is the second pillar. Ferguson closed five acquisitions in the quarter, and on July 13, it announced a deal for FWI Holdings, known as FloWorks, an industrial distributor of valves and flow-control products that is expected to close in the third quarter. The eight deals announced this year carry about $1.4 billion in annualized revenue, a second growth path alongside organic sales. Net debt sits at 1.3 times adjusted EBITDA, a level management calls strong. The company also returned cash, buying back $202 million of stock in the quarter and declaring a $0.89 dividend payable October 7 to holders of record on August 21. Management raised its full-year sales outlook to mid-single-digit growth, before counting FloWorks.
Start with the gap between sales and profit. Adjusted operating profit rose 2.9%, behind the 4.6% sales gain, and gross margin slipped 20 basis points to 31.0%. Ferguson notes that last year's gross margin was temporarily lifted by the timing of supplier price increases, which is fair context, but the direction is still down. Reported earnings per share of $3.43 rose 6.9%, while the adjusted figure of $3.39 grew a slower 5.3%.
Then there are the soft spots. About half of revenue comes from residential markets that management describes as subdued, so a 2% gain there is modest. Canada's sales slipped 1.9%, with a business divestment outweighing organic growth, and management calls the market there challenging, especially in residential. Management also describes the economic environment as uncertain, and the margin part of the guidance raise is small. The low end of the adjusted operating margin range moved from 9.4% to 9.5%, while the top stayed at 9.8%. The guidance also leaves out FloWorks, and net debt to adjusted EBITDA is 1.3 times, against 1.2 times a year ago.
#management

2 months ago
On August 5, Cencora (NYSE:COR) reported results for its fiscal third quarter, which closed on June 30, and the headline numbers looked clean. Revenue rose 5.1% to $84.8 billion, adjusted earnings per share climbed 12.0% to $4.48, and management raised its full-year adjusted EPS outlook to $17.75 to $17.95. The company also repurchased $1 billion of its own stock during the quarter. But the profit story has moving parts, and a few of them pull in opposite directions.
Start with the gap between profit growth and sales growth. Adjusted operating income rose 17.0% while revenue grew only 5.1%. Much of the help came from gross profit, which jumped 23.2% on an adjusted basis as both segments contributed and the OneOncology acquisition in February lifted margins in the US business. In plain terms, adjusted gross margin widened 61 basis points to 4.16%, so the company keeps more gross profit from every dollar it sells.
The strength was not confined to one corner, either. US Healthcare Solutions grew operating income 15.9% on higher pharmaceutical sales and the OneOncology deal, while specialty volume to health systems and physician groups lifted its revenue. International Healthcare Solutions did better still, with operating income up 20.8% on strength in European distribution and global specialty logistics. Management also put cash to work, completing in one quarter the $1 billion of buybacks it had expected to finish by the close of calendar 2026. The board declared a $0.60 quarterly dividend as well, payable August 31, to holders of record on August 14.
Growth is costing more than it first appears. Adjusted operating expenses jumped 26.8%, faster than adjusted gross profit, because OneOncology brought expenses along with its profits. Even so, adjusted operating income amounts to just 1.46% of revenue, a thin cushion on a business this large. Financing adds weight too. Cencora funded part of the purchase with new senior notes plus variable-rate term loans, and net interest expense rose $58.9 million from a year earlier.
The sales mix carries its own drag. GLP-1 drugs for diabetes and weight loss are adding to revenue, but they earn lower gross margins, so each dollar of that growth is worth less to profit. Meanwhile, an oncology customer Cencora lost in 2025, and lower sales to a large mail order customer both held back US revenue, as did lower manufacturer prices on some brand pharmaceuticals. Cencora is also exploring strategic alternatives for a group of other businesses, and its April divestiture of US Consulting Services trimmed consulting sales.
#profit #operating #Growth #august
Start with the gap between profit growth and sales growth. Adjusted operating income rose 17.0% while revenue grew only 5.1%. Much of the help came from gross profit, which jumped 23.2% on an adjusted basis as both segments contributed and the OneOncology acquisition in February lifted margins in the US business. In plain terms, adjusted gross margin widened 61 basis points to 4.16%, so the company keeps more gross profit from every dollar it sells.
The strength was not confined to one corner, either. US Healthcare Solutions grew operating income 15.9% on higher pharmaceutical sales and the OneOncology deal, while specialty volume to health systems and physician groups lifted its revenue. International Healthcare Solutions did better still, with operating income up 20.8% on strength in European distribution and global specialty logistics. Management also put cash to work, completing in one quarter the $1 billion of buybacks it had expected to finish by the close of calendar 2026. The board declared a $0.60 quarterly dividend as well, payable August 31, to holders of record on August 14.
Growth is costing more than it first appears. Adjusted operating expenses jumped 26.8%, faster than adjusted gross profit, because OneOncology brought expenses along with its profits. Even so, adjusted operating income amounts to just 1.46% of revenue, a thin cushion on a business this large. Financing adds weight too. Cencora funded part of the purchase with new senior notes plus variable-rate term loans, and net interest expense rose $58.9 million from a year earlier.
The sales mix carries its own drag. GLP-1 drugs for diabetes and weight loss are adding to revenue, but they earn lower gross margins, so each dollar of that growth is worth less to profit. Meanwhile, an oncology customer Cencora lost in 2025, and lower sales to a large mail order customer both held back US revenue, as did lower manufacturer prices on some brand pharmaceuticals. Cencora is also exploring strategic alternatives for a group of other businesses, and its April divestiture of US Consulting Services trimmed consulting sales.
#profit #operating #Growth #august


2 months ago
On August 6, Aflac (NYSE:AFL) reported second-quarter numbers that point in opposite directions. Net earnings climbed to $825 million, helped along by investment losses that shrank to $153 million from $421 million a year ago. Adjusted earnings, though, fell 7.7% to $883 million. Both numbers are real, but they answer different questions. Which measure you trust changes the story, so here is what sits underneath.
Start with the yen, because it is muddying the picture. The average rate was 159.45 to the dollar, 9.3% weaker than a year earlier, and that cost adjusted earnings $0.05 a share. Take the currency out of the first half and adjusted earnings per share rose 4.1% to $3.57. **** an is also running more profitably. Its pretax adjusted margin widened to 34.3% from 32.0% as claims took a smaller bite out of premiums, and yen-based pretax adjusted earnings rose 3.4%. So part of the decline in **** an's dollar-reported profit is currency, not operations.
The US business is still growing at the top line. Net earned premiums rose 2.3% to $1.5 billion, and sales climbed 2.6% to $349 million, led by group voluntary benefits along with dental and vision plans. In **** an, the refreshed Tsumitasu life policy and the new Anshin Palette medical product grew strongly in the quarter, and first-half sales rose 7.0% to ¥37.3 billion. Then there is the cash. Aflac returned $1.3 billion to shareholders in the quarter, $983 million of it through buybacks, and declared a $0.61 third-quarter dividend, payable September 1 to holders of record on August 19, 2026. Management notes 43 straight years of dividend increases through 2025 and says the board is on a path to extend that in 2026.
The catch is that **** an's profit gains came from lower claims, not a bigger business. Net earned premiums in yen fell 3.7%, mainly because of a new external reinsurance deal and older limited-pay policies reaching paid-up status. Premium persistency, the share of policies customers keep, slipped to 92.7% from 93.7%. **** an's pretax adjusted earnings still fell 2.1% once currency is stripped out, and new sales dipped 5.6% in the quarter against a tough comparison for the Miraito cancer product, which launched in March 2025.
The US segment has its own soft spot. Pretax adjusted earnings fell 4.6% to $370 million, and the margin narrowed to 20.9% from 22.5% as claims and benefits took a bigger share of premiums. Corporate and Other swung to a $10 million pretax adjusted loss from a $20 million gain a year earlier, with interest expense up 21.6% to $62 million. And adjusted book value per share, excluding foreign currency remeasurement, slid to $41.22 at June 30 from $42.97 a year earlier.
#adjusted #pretax
Start with the yen, because it is muddying the picture. The average rate was 159.45 to the dollar, 9.3% weaker than a year earlier, and that cost adjusted earnings $0.05 a share. Take the currency out of the first half and adjusted earnings per share rose 4.1% to $3.57. **** an is also running more profitably. Its pretax adjusted margin widened to 34.3% from 32.0% as claims took a smaller bite out of premiums, and yen-based pretax adjusted earnings rose 3.4%. So part of the decline in **** an's dollar-reported profit is currency, not operations.
The US business is still growing at the top line. Net earned premiums rose 2.3% to $1.5 billion, and sales climbed 2.6% to $349 million, led by group voluntary benefits along with dental and vision plans. In **** an, the refreshed Tsumitasu life policy and the new Anshin Palette medical product grew strongly in the quarter, and first-half sales rose 7.0% to ¥37.3 billion. Then there is the cash. Aflac returned $1.3 billion to shareholders in the quarter, $983 million of it through buybacks, and declared a $0.61 third-quarter dividend, payable September 1 to holders of record on August 19, 2026. Management notes 43 straight years of dividend increases through 2025 and says the board is on a path to extend that in 2026.
The catch is that **** an's profit gains came from lower claims, not a bigger business. Net earned premiums in yen fell 3.7%, mainly because of a new external reinsurance deal and older limited-pay policies reaching paid-up status. Premium persistency, the share of policies customers keep, slipped to 92.7% from 93.7%. **** an's pretax adjusted earnings still fell 2.1% once currency is stripped out, and new sales dipped 5.6% in the quarter against a tough comparison for the Miraito cancer product, which launched in March 2025.
The US segment has its own soft spot. Pretax adjusted earnings fell 4.6% to $370 million, and the margin narrowed to 20.9% from 22.5% as claims and benefits took a bigger share of premiums. Corporate and Other swung to a $10 million pretax adjusted loss from a $20 million gain a year earlier, with interest expense up 21.6% to $62 million. And adjusted book value per share, excluding foreign currency remeasurement, slid to $41.22 at June 30 from $42.97 a year earlier.
#adjusted #pretax

2 months ago
On August 6, James Hardie Industries (NYSE:JHX) reported results for the quarter ended June 30 and beat its own numbers by enough to raise guidance just three months into the fiscal year. Net sales jumped 64% year over year to $1.475 billion, adjusted EBITDA climbed 79% to $422.1 million, and both figures came in ahead of what management had originally guided investors to expect. For a company that closed a transformative acquisition less than a year earlier, that kind of overshoot forces a reassessment of the growth story ahead.
The headline growth number is inflated by the AZEK Exteriors deal folded into the base, so the more telling figure is the 12% pro forma net sales growth, which also beat original guidance. Siding & Trim, the core fiber cement business, posted organic net sales growth of 20% as North American fiber cement volumes returned to growth for the first time in several quarters. CEO Aaron Erter tied that to share gains against vinyl and other competing materials, along with programs like ColorPlus and Expanded Statement drawing more of the higher-end repair and remodel market. Adjusted EBITDA margin in that segment expanded 140 basis points to 33.5%, powered by favorable pricing, cheaper raw materials, and continued savings from the company's Hardie Manufacturing Operating System even as freight costs rose.
Management also said cost synergies from the AZEK integration are running ahead of schedule and revenue synergies are on track, evidenced by newly expanded nationwide distribution partnerships with Boise Cascade and other regional distributors. In Deck, Rail & Accessories, sell-through accelerated every month of the quarter and outpaced shipments, pulling channel inventory back to normal levels and setting up a cleaner back half of the year. Free cash flow more than doubled to $254.2 million, and the company used the cash to pay down $400 million of senior unsecured notes.
Erter was careful to frame the beat as execution rather than a healthier market, telling investors the company is "not ***** uming a housing market improvement" for the rest of fiscal 2027. Part of the quarter's strength came from an easy comparison, since channel inventory was deliberately reduced a year earlier, and management said that benefit is expected to moderate as the year goes on. Deck, Rail & Accessories net sales actually fell 5% on a pro forma basis because the company intentionally cut production to work down channel inventory, leaving the segment with an operating loss of $3.3 million for the quarter.
#Growth #sales #management
The headline growth number is inflated by the AZEK Exteriors deal folded into the base, so the more telling figure is the 12% pro forma net sales growth, which also beat original guidance. Siding & Trim, the core fiber cement business, posted organic net sales growth of 20% as North American fiber cement volumes returned to growth for the first time in several quarters. CEO Aaron Erter tied that to share gains against vinyl and other competing materials, along with programs like ColorPlus and Expanded Statement drawing more of the higher-end repair and remodel market. Adjusted EBITDA margin in that segment expanded 140 basis points to 33.5%, powered by favorable pricing, cheaper raw materials, and continued savings from the company's Hardie Manufacturing Operating System even as freight costs rose.
Management also said cost synergies from the AZEK integration are running ahead of schedule and revenue synergies are on track, evidenced by newly expanded nationwide distribution partnerships with Boise Cascade and other regional distributors. In Deck, Rail & Accessories, sell-through accelerated every month of the quarter and outpaced shipments, pulling channel inventory back to normal levels and setting up a cleaner back half of the year. Free cash flow more than doubled to $254.2 million, and the company used the cash to pay down $400 million of senior unsecured notes.
Erter was careful to frame the beat as execution rather than a healthier market, telling investors the company is "not ***** uming a housing market improvement" for the rest of fiscal 2027. Part of the quarter's strength came from an easy comparison, since channel inventory was deliberately reduced a year earlier, and management said that benefit is expected to moderate as the year goes on. Deck, Rail & Accessories net sales actually fell 5% on a pro forma basis because the company intentionally cut production to work down channel inventory, leaving the segment with an operating loss of $3.3 million for the quarter.
#Growth #sales #management


2 months ago
While it's extremely difficult to predict a stock market pullback, there are certainly harbingers that the market could be in for a rough ride over the coming month. The September-October period ahead of U.S. mid-term elections is historically a volatile one. In fact, Cantor Fitzgerald notes that the S&P 500 index has fallen by 5% or more during these two months in 15 of the past 24 midterm election cycles.
At the same time, two major market valuation indicators point to stocks being at extremely frothy valuations. The S&P 500 Shiller CAPE (cyclically adjusted price-to-earnings) ratio is at over 40 times for the first time since before the dot.com market crash. The so-called Buffett indicator (U.S. stock market value divided by gross domestic product), named after Warren Buffett, is over 230%, well above the 120% where the market is considered overvalued. Throw in a war and a stressed consumer, and the ingredients for a market pullback are there.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
There is no guarantee of a big market dip, and even if there were one, I wouldn't panic. Instead, I'd view it as a strong buying opportunity. AI has changed the equation, leading to big productivity gains that are just beginning, and stocks are generally cheap on a forward basis. The market today is very different than in the past. The S&P 500 is no longer led by cyclical and financial companies. Instead, it's dominated by large tech companies with strong balance sheets that produce enormous operating cash flow.
Let's look at five exchange-traded funds (ETFs) to scoop up if the market dips in the coming month.
#NVIDIA #time #pullback
At the same time, two major market valuation indicators point to stocks being at extremely frothy valuations. The S&P 500 Shiller CAPE (cyclically adjusted price-to-earnings) ratio is at over 40 times for the first time since before the dot.com market crash. The so-called Buffett indicator (U.S. stock market value divided by gross domestic product), named after Warren Buffett, is over 230%, well above the 120% where the market is considered overvalued. Throw in a war and a stressed consumer, and the ingredients for a market pullback are there.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
There is no guarantee of a big market dip, and even if there were one, I wouldn't panic. Instead, I'd view it as a strong buying opportunity. AI has changed the equation, leading to big productivity gains that are just beginning, and stocks are generally cheap on a forward basis. The market today is very different than in the past. The S&P 500 is no longer led by cyclical and financial companies. Instead, it's dominated by large tech companies with strong balance sheets that produce enormous operating cash flow.
Let's look at five exchange-traded funds (ETFs) to scoop up if the market dips in the coming month.
#NVIDIA #time #pullback

2 months ago
On September 15, Jazz Pharmaceuticals plc (NASDAQ:JAZZ) completed its acquisition of privately held Actio Biosciences for $820 million upfront, adding a clinical-stage epilepsy drug called ABS-1230 to its rare disease pipeline. The deal lands weeks after Jazz posted its highest quarterly revenue ever on August 3, and raised its full-year guidance, so a fresh acquisition now sits on top of a business that was already accelerating. The question for investors is whether that combination adds up to durable growth or just a bigger bill.
ABS-1230 targets KCNT1-related epilepsy, a rare and hard-to-treat form of the disease. In an early clinical proof-of-concept trial, children who received the drug experienced meaningful seizure reductions, and preclinical testing showed it inhibited KCNT1 across every pathogenic mutation researchers evaluated, hinting it could work across the whole patient population rather than a narrow subset. The FDA has already granted ABS-1230 Orphan Drug, Rare Pediatric Disease and Fast Track designations, and accepted it into the agency's Rare Disease Evidence Principles process, a set of regulatory advantages that can speed a drug toward approval.
The acquisition also arrives while Jazz's existing business is firing on multiple cylinders. Second-quarter revenue climbed 16% year over year to $1.2 billion, the company's highest quarterly total on record, and management raised full-year 2026 revenue guidance to a range of $4.6 billion to $4.75 billion. Growth was not confined to one product. Xywav sales rose 13% to $471 million on 525 net new patients, Epidiolex grew 16% to $292 million, and Zepzelca jumped 42% to $106 million. Zanidatamab, sold as Ziihera in biliary tract cancer, also received Breakthrough Therapy designation from the FDA for a form of colorectal cancer, adding another avenue for the oncology franchise Jazz has been building beyond its epilepsy and sleep businesses.
None of that came free. The $820 million upfront payment for Actio lands on top of $4.4 billion in long-term debt that Jazz already carried as of June 30, even after the company used part of its cash to repay $1.0 billion of exchangeable notes that matured this year. Cash, equivalents and investments stood at $2.2 billion at that point, meaning the Actio payment alone accounts for a meaningful share of the company's liquid resources.
Jazz's recent history also shows how acquisitions can distort the bottom line before they pay off. A $905.4 million in-process research and development charge tied to the 2025 Chimerix acquisition pushed second-quarter 2025 GAAP earnings to a loss of $11.74 per share, and a smaller $77 million IPR&D charge from the AbCellera and Werewolf deals still dented second-quarter 2026 results. ABS-1230 itself remains early, with only proof-of-concept data in hand and no late-stage trial results yet. The portfolio is not without setbacks, either. Jazz is moving to voluntarily drop the second-line indication for Zepzelca in meta
ABS-1230 targets KCNT1-related epilepsy, a rare and hard-to-treat form of the disease. In an early clinical proof-of-concept trial, children who received the drug experienced meaningful seizure reductions, and preclinical testing showed it inhibited KCNT1 across every pathogenic mutation researchers evaluated, hinting it could work across the whole patient population rather than a narrow subset. The FDA has already granted ABS-1230 Orphan Drug, Rare Pediatric Disease and Fast Track designations, and accepted it into the agency's Rare Disease Evidence Principles process, a set of regulatory advantages that can speed a drug toward approval.
The acquisition also arrives while Jazz's existing business is firing on multiple cylinders. Second-quarter revenue climbed 16% year over year to $1.2 billion, the company's highest quarterly total on record, and management raised full-year 2026 revenue guidance to a range of $4.6 billion to $4.75 billion. Growth was not confined to one product. Xywav sales rose 13% to $471 million on 525 net new patients, Epidiolex grew 16% to $292 million, and Zepzelca jumped 42% to $106 million. Zanidatamab, sold as Ziihera in biliary tract cancer, also received Breakthrough Therapy designation from the FDA for a form of colorectal cancer, adding another avenue for the oncology franchise Jazz has been building beyond its epilepsy and sleep businesses.
None of that came free. The $820 million upfront payment for Actio lands on top of $4.4 billion in long-term debt that Jazz already carried as of June 30, even after the company used part of its cash to repay $1.0 billion of exchangeable notes that matured this year. Cash, equivalents and investments stood at $2.2 billion at that point, meaning the Actio payment alone accounts for a meaningful share of the company's liquid resources.
Jazz's recent history also shows how acquisitions can distort the bottom line before they pay off. A $905.4 million in-process research and development charge tied to the 2025 Chimerix acquisition pushed second-quarter 2025 GAAP earnings to a loss of $11.74 per share, and a smaller $77 million IPR&D charge from the AbCellera and Werewolf deals still dented second-quarter 2026 results. ABS-1230 itself remains early, with only proof-of-concept data in hand and no late-stage trial results yet. The portfolio is not without setbacks, either. Jazz is moving to voluntarily drop the second-line indication for Zepzelca in meta


2 months ago
CoreWeave (NASDAQ: CRWV) stock was rocked on Thursday. The artificial intelligence (AI) cloud company's shares closed down more than 5% on news of two fundraising measures it announced that morning.
CoreWeave announced an at-the-market (ATM) issue of its publicly traded Class A common stock. Up to 35 million shares are to be sold in a public offering by a large syndicate of sales agents.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
The company said it will use its share of the proceeds "to provide ongoing financing flexibility and to support CoreWeave's objective of migrating its enterprise credit profile toward investment grade."
The company also announced an issue of convertible senior notes. It will float $3 billion worth of the securities, which mature in 2033 if not converted, in a private offering. The company intends to offer the initial purchasers of the note up to a total of $500 million in additional aggregate principal amount of notes.
#shares
CoreWeave announced an at-the-market (ATM) issue of its publicly traded Class A common stock. Up to 35 million shares are to be sold in a public offering by a large syndicate of sales agents.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
The company said it will use its share of the proceeds "to provide ongoing financing flexibility and to support CoreWeave's objective of migrating its enterprise credit profile toward investment grade."
The company also announced an issue of convertible senior notes. It will float $3 billion worth of the securities, which mature in 2033 if not converted, in a private offering. The company intends to offer the initial purchasers of the note up to a total of $500 million in additional aggregate principal amount of notes.
#shares
2 months ago
Burford Capital Limited (NYSE:BUR) announced on September 14 that its indirect, wholly owned subsidiary, Burford Capital Global Finance LLC, priced $300 million of 8% senior secured notes due 2029. Closing is expected September 17, subject to customary conditions.
Net proceeds and existing cash are intended to redeem the subsidiary's 6.25% unsecured notes due in 2028. The transaction would move this maturity into 2029, with a coupon 175 basis points higher.
The September 14 offering announcement confirmed $400 million of outstanding 2028 notes, making the cash contribution central to the refinancing. Burford Capital Limited (NYSE:BUR) said it expected to issue a conditional notice targeting September 24, 2026, for redemption of all $400 million, subject to successful completion of the $300 million financing.
For Burford Capital Limited (NYSE:BUR), refinancing ahead of maturity creates more room for litigation investments to generate cash. Court proceedings, settlements, and collections follow uncertain schedules. Reducing dependence on a particular realization date could help management preserve investment value.
Redeeming the confirmed $400 million balance with $300 million of replacement notes would reduce gross principal by $100 million. Calculated annual coupons would fall from $25 million to $24 million, before fees and other financing costs.
#capital #september #NYSE
Net proceeds and existing cash are intended to redeem the subsidiary's 6.25% unsecured notes due in 2028. The transaction would move this maturity into 2029, with a coupon 175 basis points higher.
The September 14 offering announcement confirmed $400 million of outstanding 2028 notes, making the cash contribution central to the refinancing. Burford Capital Limited (NYSE:BUR) said it expected to issue a conditional notice targeting September 24, 2026, for redemption of all $400 million, subject to successful completion of the $300 million financing.
For Burford Capital Limited (NYSE:BUR), refinancing ahead of maturity creates more room for litigation investments to generate cash. Court proceedings, settlements, and collections follow uncertain schedules. Reducing dependence on a particular realization date could help management preserve investment value.
Redeeming the confirmed $400 million balance with $300 million of replacement notes would reduce gross principal by $100 million. Calculated annual coupons would fall from $25 million to $24 million, before fees and other financing costs.
#capital #september #NYSE

2 months ago
Seagate Technology Holdings plc (NASDAQ:STX) announced on September 9 that its subsidiary, Seagate HDD Cayman, completed the redemption and exchange of its remaining 3.50% exchangeable senior notes due 2028 on September 8. Approximately $150.7 million of principal was retired through a settlement involving approximately $150.97 million in cash and 1,647,862 ordinary shares.
For notes submitted for exchange, principal was paid in cash, and the exchange obligation above principal was settled in shares, with cash for fractional shares where applicable. The share delivery therefore satisfied an existing contractual obligation.
Seagate Technology Holdings plc (NASDAQ:STX) has removed a 2028 maturity and the remaining settlement uncertainty attached to this instrument. Based on the approximately $150.7 million principal balance and 3.50% coupon, the transaction eliminates roughly $5.3 million of annual stated interest. That is a calculated annualized saving before taxes and any interest income lost on the cash used.
Recent cash generation supports the ability to absorb the payment. As of July 3, 2026, Seagate Technology Holdings plc (NASDAQ:STX) reported $1.704 billion in cash and cash equivalents. Fiscal fourth-quarter free cash flow was $1.118 billion. This company-defined non-GAAP measure is operating cash flow less acquisitions of property, equipment, and leasehold improvements.
The settlement cash payment equals approximately 8.9% of that reported cash balance. Although the July figure predates settlement, it provides a useful measure of the transaction's scale.
#technology #million #exchange
For notes submitted for exchange, principal was paid in cash, and the exchange obligation above principal was settled in shares, with cash for fractional shares where applicable. The share delivery therefore satisfied an existing contractual obligation.
Seagate Technology Holdings plc (NASDAQ:STX) has removed a 2028 maturity and the remaining settlement uncertainty attached to this instrument. Based on the approximately $150.7 million principal balance and 3.50% coupon, the transaction eliminates roughly $5.3 million of annual stated interest. That is a calculated annualized saving before taxes and any interest income lost on the cash used.
Recent cash generation supports the ability to absorb the payment. As of July 3, 2026, Seagate Technology Holdings plc (NASDAQ:STX) reported $1.704 billion in cash and cash equivalents. Fiscal fourth-quarter free cash flow was $1.118 billion. This company-defined non-GAAP measure is operating cash flow less acquisitions of property, equipment, and leasehold improvements.
The settlement cash payment equals approximately 8.9% of that reported cash balance. Although the July figure predates settlement, it provides a useful measure of the transaction's scale.
#technology #million #exchange

2 months ago
American Tower Corporation (NYSE:AMT) priced $1.6 billion of senior notes on September 9: $500 million at 5.300% due 2031, $500 million at 5.560% due 2033, and $600 million at 5.750% due 2036. Once issued, the three tranches would carry combined annual coupons of $88.8 million, equivalent to a weighted average coupon of 5.55%.
American Tower Corporation (NYSE:AMT) expects approximately $1.580 billion in net proceeds. It intends to use $600 million to repay 1.450% notes due in 2026, with additional proceeds designated for revolving-credit debt and general corporate purposes. The financing exchanges a near-term repayment requirement and some revolving debt for longer fixed-rate obligations.
The investment question is whether greater funding certainty compensates for the higher cash-interest commitment.
American Tower Corporation (NYSE:AMT) would remove a $600 million maturity falling due this year once the planned repayment occurs. That reduces exposure to having to refinance the obligation closer to its deadline, when borrowing conditions could be less favorable.
The new maturities also distribute principal repayments across 2031, 2033 and 2036. For American Tower Corporation (NYSE:AMT), a spread of repayment dates can support financial planning across its communications-site and data-center portfolio. Fixed coupons make the cost of this funding predictable.
#tower
American Tower Corporation (NYSE:AMT) expects approximately $1.580 billion in net proceeds. It intends to use $600 million to repay 1.450% notes due in 2026, with additional proceeds designated for revolving-credit debt and general corporate purposes. The financing exchanges a near-term repayment requirement and some revolving debt for longer fixed-rate obligations.
The investment question is whether greater funding certainty compensates for the higher cash-interest commitment.
American Tower Corporation (NYSE:AMT) would remove a $600 million maturity falling due this year once the planned repayment occurs. That reduces exposure to having to refinance the obligation closer to its deadline, when borrowing conditions could be less favorable.
The new maturities also distribute principal repayments across 2031, 2033 and 2036. For American Tower Corporation (NYSE:AMT), a spread of repayment dates can support financial planning across its communications-site and data-center portfolio. Fixed coupons make the cost of this funding predictable.
#tower

2 months ago
Alcoa Corporation (NYSE:AA) priced $2.6 billion of acquisition financing on September 9, 2026, through two wholly owned subsidiaries. Alumina Pty Ltd will issue $1.5 billion of 6.625% notes due 2034, while Alcoa Nederland Holding B.V. will issue $1.1 billion of 6.875% notes due 2036. Alcoa Corporation (NYSE:AA) and certain subsidiaries will guarantee the notes on a senior unsecured basis.
The tranches imply annual coupons of $99.375 million and $75.625 million, respectively, totaling exactly $175 million. Settlement is expected on September 23. Net proceeds and cash on hand would fund the approximately $3.1 billion cash portion of the South32 Limited (ASX:S32) ****** et acquisition, plus related fees and expenses.
For Alcoa Corporation (NYSE:AA), successful settlement would secure longer-dated funding and allow termination of the remaining 364-day bridge commitments. Maturities in 2034 and 2036 give management time to integrate the ****** ets before principal comes due.
The operating opportunity lies in linking additional bauxite resources, alumina refining and aluminum production. Better coordination could strengthen feedstock security and improve purchasing, logistics and plant economics. Acquired earnings and operating improvements could produce recurring cash to service the debt while funding reinvestment.
Fixed coupons also make the interest burden predictable. Strong ****** et performance could support debt reduction and give shareholders a growing share of incremental cash generation.
#notes #september
The tranches imply annual coupons of $99.375 million and $75.625 million, respectively, totaling exactly $175 million. Settlement is expected on September 23. Net proceeds and cash on hand would fund the approximately $3.1 billion cash portion of the South32 Limited (ASX:S32) ****** et acquisition, plus related fees and expenses.
For Alcoa Corporation (NYSE:AA), successful settlement would secure longer-dated funding and allow termination of the remaining 364-day bridge commitments. Maturities in 2034 and 2036 give management time to integrate the ****** ets before principal comes due.
The operating opportunity lies in linking additional bauxite resources, alumina refining and aluminum production. Better coordination could strengthen feedstock security and improve purchasing, logistics and plant economics. Acquired earnings and operating improvements could produce recurring cash to service the debt while funding reinvestment.
Fixed coupons also make the interest burden predictable. Strong ****** et performance could support debt reduction and give shareholders a growing share of incremental cash generation.
#notes #september
2 months ago
Wealthfront Corporation (NASDAQ:WLTH) reported on September 9 that fiscal second-quarter revenue increased 1% to $91.9 million, despite platform ***** ets rising 12% to $99 billion. The quarter ended July 31, 2026. Funded clients increased 14% to 1.51 million, and platform ***** ets surpassed $100 billion by the end of August.
Platform ***** ets measure financial ***** ets held in client accounts. Their growth reflects both net deposits and market movements, so the headline increase does not represent new client money alone.
Adjusted EBITDA declined 15% to $38.1 million, with its margin falling to 41% from 49%. Wealthfront Corporation (NASDAQ:WLTH) defines this non-GAAP measure as net income excluding interest expense, income taxes, depreciation and amortization, stock-based compensation, fair-value changes in convertible notes, warrant liabilities and simple agreements for future equity, and nonrecurring expenses. Adjusted EBITDA margin divides that figure by revenue.
The advisory business is translating ***** et growth into revenue. Investment advisory ***** ets increased 30% to $54.1 billion, while advisory revenue rose 31% to $28.8 million. Those results show that the expanding investment business is generating a larger recurring fee stream.
For Wealthfront Corporation (NASDAQ:WLTH), this creates an opportunity to deepen client relationships as savings move toward longer-term investment goals. A growing advisory base could support more durable relationships, provided clients remain invested and continue contributing.
#wealthfront #revenue #platform #investment
Platform ***** ets measure financial ***** ets held in client accounts. Their growth reflects both net deposits and market movements, so the headline increase does not represent new client money alone.
Adjusted EBITDA declined 15% to $38.1 million, with its margin falling to 41% from 49%. Wealthfront Corporation (NASDAQ:WLTH) defines this non-GAAP measure as net income excluding interest expense, income taxes, depreciation and amortization, stock-based compensation, fair-value changes in convertible notes, warrant liabilities and simple agreements for future equity, and nonrecurring expenses. Adjusted EBITDA margin divides that figure by revenue.
The advisory business is translating ***** et growth into revenue. Investment advisory ***** ets increased 30% to $54.1 billion, while advisory revenue rose 31% to $28.8 million. Those results show that the expanding investment business is generating a larger recurring fee stream.
For Wealthfront Corporation (NASDAQ:WLTH), this creates an opportunity to deepen client relationships as savings move toward longer-term investment goals. A growing advisory base could support more durable relationships, provided clients remain invested and continue contributing.
#wealthfront #revenue #platform #investment

2 months ago
MercadoLibre, Inc. (NASDAQ:MELI) priced $1 billion of senior unsecured notes on September 9, 2026, with settlement scheduled for September 14 and maturity on September 14, 2036. As of September 10, the transaction had not settled.
The notes carry a 5.85% coupon, with proceeds intended for general corporate purposes. Once settled, they would require $58.5 million in annual coupon payments on the full principal outstanding, alongside repayment of $1 billion at maturity.
Management retains discretion over deployment. Logistics, payments, credit and commerce represent potential uses within the business, rather than disclosed allocations of this particular offering.
Ten-year funding can better match investments whose benefits emerge over several years. Logistics facilities need time to attract shipment volume, while financial-services products require investment in technology, customer acquisition and risk management before reaching scale.
For MercadoLibre, Inc. (NASDAQ:MELI), that longer horizon could reduce dependence on repeated short-term refinancing. A fixed coupon also makes contractual dollar interest payments more predictable if market borrowing rates rise.
#payments
The notes carry a 5.85% coupon, with proceeds intended for general corporate purposes. Once settled, they would require $58.5 million in annual coupon payments on the full principal outstanding, alongside repayment of $1 billion at maturity.
Management retains discretion over deployment. Logistics, payments, credit and commerce represent potential uses within the business, rather than disclosed allocations of this particular offering.
Ten-year funding can better match investments whose benefits emerge over several years. Logistics facilities need time to attract shipment volume, while financial-services products require investment in technology, customer acquisition and risk management before reaching scale.
For MercadoLibre, Inc. (NASDAQ:MELI), that longer horizon could reduce dependence on repeated short-term refinancing. A fixed coupon also makes contractual dollar interest payments more predictable if market borrowing rates rise.
#payments


2 months ago
(Bloomberg) -- When Aon Inc. on Monday priced $2 billion of notes maturing in 2056 as part of a debt package to fund an acquisition, investors rushed to buy it, placing orders more than seven times the size of the offering.
Most Read from Bloomberg
Zuckerberg Has an AI Empire to Build. Meet the Adviser Who Handles the Details
EU Proposes Canada Become the Bloc's First 'Associate Member'
Bond Market's 'Extreme' Short Counts on Fed to Deliver Hike
#bloomberg #zuckerberg #details #proposes
Most Read from Bloomberg
Zuckerberg Has an AI Empire to Build. Meet the Adviser Who Handles the Details
EU Proposes Canada Become the Bloc's First 'Associate Member'
Bond Market's 'Extreme' Short Counts on Fed to Deliver Hike
#bloomberg #zuckerberg #details #proposes




