

5 days ago
FDRR beat JEPI by nearly 12 points over the past year, returning 19% versus JEPI's 7%.
A $100,000 investment in FDRR five years ago grew to $180,650 versus $141,220 for JEPI, a $39,430 gap.
JEPI pays monthly while FDRR pays quarterly, giving retirees who need regular cash a reason to stay put.
Building a portfolio and living off one are two completely different skills, and almost ****** ody teaches the second. This problem is what The Definitive Guide to Retirement Income helps, and it is free today. Read more here. (Sponsor)
#versus #guide #income #sponsor

22 days ago
A TikTok video posted by ciearratati, which has amassed close to 815,000 views and 3,364 comments, describes a woman's preference for high-maintenance friendships. She explained that she believes real friendships are supposed to involve that level of closeness. Ciearra said her friends' needs and concerns are never too much for her to handle, and she would much rather have close, familiar friendships than distant ones.
Ciearra began by saying that once she considers someone a friend, they're never too high-maintenance for her because she will make time for them if they need to talk or video chat. Even if she just met someone the day before and they want to see her again, she doesn't mind because, in her view, that's what friends are for.
She said, "No, you're not acting like I'm your boyfriend. No, it's not too high-maintenance. No, I don't feel like you're smothering me." Ciearra continued by explaining that this level of closeness is exactly what she wants in a friendship because she thrives on the connection she has with the people she considers friends.
She explained, "This is literally what I want. I literally want to do life with human beings." She went on to say that she doesn't consider a friendship one where you barely see each other throughout the year. Instead, she believes real friends should naturally see each other more often, and she said she actually looks forward to spending time with her friends.
Ciearra stated, "No, I don't want to see you every quarter of the year. I wanna see you way more than that, actually. Why are we doing quarterly meetings? What is this, a business or a friendship?" Ciearra believes many people view real friendships as "high-maintenance" because they are used to giving and accepting the bare minimum.
#want #friendship #close



23 days ago
Rich Americans are getting richer, but not all equally. The K-shaped split that let high earners pull away from low earners now cuts through the top 1% too, with the ultra-rich far ahead of the rest.
The average household in the top 0.1% is now worth about $204 million, or 7.7 times as much as one in the rest of the top 1%, according to a Fortune ******* ysis of Federal Reserve data. That ratio is the highest in the Fed's quarterly series going back to 1989, up from 6.2 times at the end of 2019. Currently, the Fed counts 136,779 households in the top 0.1%
The top 0.1%'s wealth has more than doubled since the end of 2019, from $13.4 trillion to nearly $28 trillion in the second quarter of 2026. Over the same period, the rest of the top 1% saw its wealth grow 68%, from $19.3 trillion to $32.5 trillion. The top 0.1% now holds 15% of the nation's household wealth, up 0.5 percentage point since the first quarter.
"We are talking about continued redistribution upward and further concentration of wealth at the top," Markus Schneider, an ******* ociate professor of economics at the University of Denver, told Fortune.
The clearest difference between the two groups is what they own.
#earners


24 days ago
AGNC's Q2 spread income of 40 cents per share covered its 36-cent dividend, but the payout has been cut three times since 2015.
Annaly raised its quarterly dividend from $0.70 to $0.75, while Dynex rebounded to 6.4% economic return after both posted Q1 losses.
If Q3 spread income falls below 36 cents or book value drops below $8.38, shareholders' own capital funds the dividend and a cut becomes likely.
Read More: Learn 7 ways to generate income with a $1,000,000+ portfolio (sponsor)
AGNC Investment (NASDAQ:AGNC) is a mortgage REIT that borrows short-term money in the repo market, buys agency mortgage-backed securities, and keeps the spread between bond yields and borrowing costs. Leverage of 7.4 times tangible equity magnifies both gains and losses.
#times

24 days ago
JPMorgan just raised its dividend 10% while still paying out only 28% of earnings, and Visa's even lower 23% payout fuels years of double-digit raises.
Cisco's AI infrastructure orders hit $9.3 billion, lifting earnings faster than its dividend, while T. Rowe Price yields 5% at just 10 times earnings.
Building a portfolio and living off one are two completely different skills, and almost ******* ody teaches the second. This problem is what The Definitive Guide to Retirement Income helps, and it is free today. Read more here. (Sponsor)
The best dividend raises come from companies that pay out a small piece of what they earn. JPMorgan Chase (NYSE:JPM) just showed how that works: it lifted its quarterly dividend from $1.50 to $1.65, a 10% increase, and the new annual rate still matches only 28.3% of trailing earnings. The five companies below all fit that pattern. Each has strong earnings and a payout ratio low enough to fund many more raises. A long streak of past increases supports the case for some of them, but the reason they're here is how much room each has to keep advancing.
Visa (NYSE:V) yields only about 0.72% on its $2.68 annualized dividend at a share price of $370.97. That's a small yield, but the dividend has a lot of room to grow. The payout uses about 22.8% of trailing diluted EPS of $11.75, and Visa's trailing operating margin is 66.1%.
#payout #trailing

24 days ago
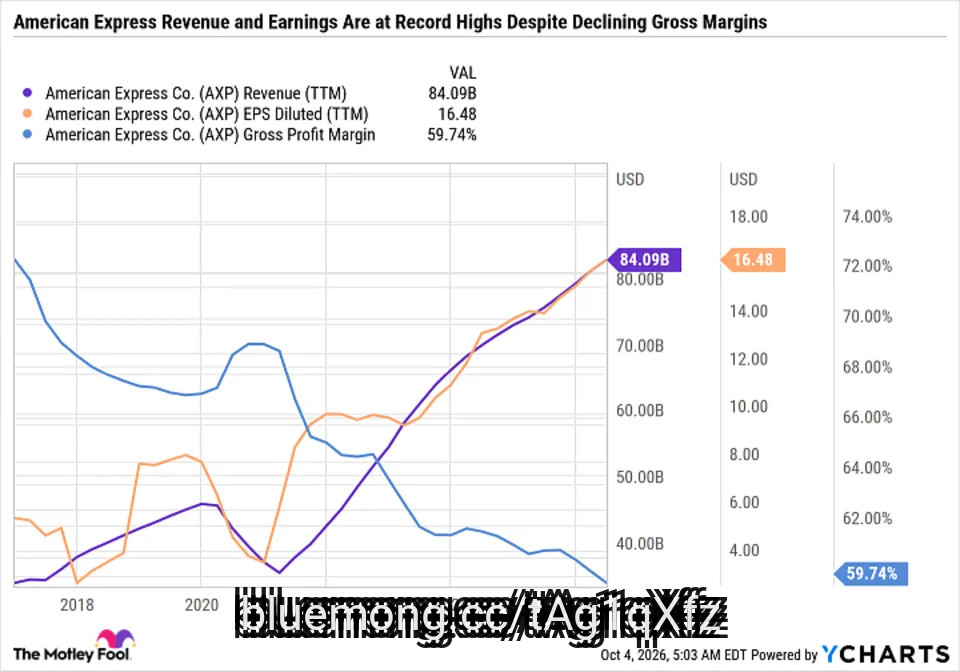
American Express (NYSE: AXP) has been a staple of Berkshire Hathaway's (NYSE: BRKA) (NYSE: BRKB) portfolio for decades -- with Warren Buffett essentially completing purchases of the stock by 1995. Buffett's hand-picked successor -- Greg Abel -- expects American Express to remain a long-term compounder and a core Berkshire holding because it's a business Berkshire understands well and trusts its management team.
American Express also features a growing dividend. It doesn't raise it every year, but even during the 2008 financial crisis, when many banks and financial services companies were slashing their payouts, American Express held its quarterly dividend steady at $0.18 per share.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
American Express has substantially increased its dividend since then. The next payment of $0.95 per share is payable on Nov. 10 to shareholders on record as of Oct. 9.
Here's how many shares of American Express you'd need to generate $1,000 in yearly dividends, and the three levers American Express pulls to reward long-term shareholders.
#signal



24 days ago
XOM has raised its dividend for 43 straight years, while CVX yields 3.45% with Hess acquisition synergies running 50% above initial targets.
EPD's distributable cash flow covered its 6% distribution 1.9x last quarter, with a trailing payout ratio of just 56% on adjusted cash flow.
Read More: Learn 7 ways to generate income with a $1,000,000+ portfolio (sponsor)
Energy has a reputation for boom and bust, yet the sector's largest companies have turned volatile commodities into some of the market's most reliable income. Exxon Mobil (NYSE:XOM) alone has grown its annual dividend per share for 43 consecutive years. The four large caps below split into two integrated oil majors and two midstream toll-road operators. Each pairs a well-covered payout with strong cash generation, making them natural candidates for a long-term income portfolio.
At a recent price of $163.83, Exxon's annualized forward dividend of $4.12 per share works out to a 2.51% yield. The quarterly payout is $1.03, up from $0.99 after a 4% raise late last year.
#income

24 days ago
Pfizer paid $9.8B in dividends in 2025 while earning only $7.7B in net income, marking the third straight year its payout exceeded its profit.
Icahn Enterprises yields near 30% but lost money every year from 2021 to 2025 and has already slashed its quarterly payout from $2.00 to $0.50.
Dow halved its dividend yet still failed to cover it from operating cash in 2025, posting a $2.6B net loss the same year.
Building a portfolio and living off one are two completely different skills, and almost **** ody teaches the second. This problem is what The Definitive Guide to Retirement Income helps, and it is free today. Read more here. (Sponsor)
Pfizer (NYSE:PFE) paid $9.771 billion in dividends in 2025 and earned net income of $7.746 billion. That was the third straight year the payout ran ahead of profit. When this repeats year after year, it is company policy. A high yield lasts only as long as the cash behind it does.
#year #pfizer #only

24 days ago
FYEE beat JEPI on a $100,000 investment in 2026, paying $7,023 versus $6,070, but FYEE's quarterly payout has fallen from $0.82 to $0.56 per share.
JEPI's monthly distributions better match recurring expenses for retirees, while FYEE's quarterly schedule suits investors who reinvest or can wait between payments.
FYEE's lower share price ($30 vs. JEPI's $56) means $100,000 buys nearly twice as many shares, which is why it delivers more cash despite lower per-share payouts.
Building a portfolio and living off one are two completely different skills, and almost ***** ody teaches the second. This problem is what The Definitive Guide to Retirement Income helps, and it is free today. Read more here. (Sponsor)
The JPMorgan Equity Premium Income ETF (NYSEARCA:JEPI) built its following on a simple promise. It holds lower-volatility U.S. stocks, adds income from S&P 500 call-option premium, and sends a check every month. JEPI holders value that rhythm, and JEPI remains the default name in covered-call income. On an identical $100,000 investment this year, though, the Fidelity Yield Enhanced Equity ETF (CBOE:FYEE) has paid more cash while writing far fewer checks.
#income #quarterly

25 days ago
GNL paid out more in dividends than it earned in operating cash for four straight years and has already slashed its quarterly dividend from $0.53 to $0.19; PSEC's NAV fell from $6.56 to $5.71 while distributions exceeded net investment income.
IEP carries a 30% yield but posted net losses every year from 2019 through 2025 and slashed distributions from $2 to $0.50 per quarter while units dropped 66% over five years.
BEP and CWEN both rely on billions in annual financing inflows to fund distributions, with BEP's 2025 capex hitting $6.7 billion against just $1.5 billion in operating cash flow.
Building a portfolio and living off one are two completely different skills, and almost ******* ody teaches the second. This problem is what The Definitive Guide to Retirement Income helps, and it is free today. Read more here. (Sponsor)
One stock on this list has a forward yield of about 30%. For a retiree, a number like that looks like a solid paycheck. A high yield only means something if the payout is sustainable, and each of the five names below has spent years sending out more cash than the business brought in.
#distributions #operating #slashed


25 days ago
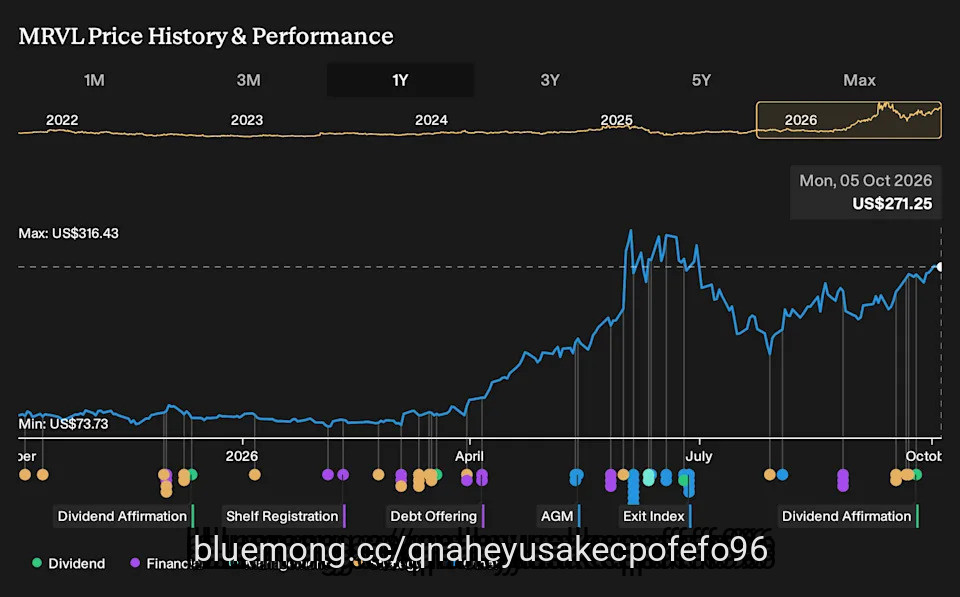
In late September 2026, AT&S Austria Technologie & Systemtechnik AG announced an expanded collaboration with Marvell Technology to increase advanced IC substrate capacity for next-generation AI and cloud infrastructure, while Marvell also affirmed a quarterly dividend of US$0.06 per share payable on October 29, 2026.
This deeper manufacturing partnership gives Marvell greater access to complex packaging technologies that are increasingly critical for high-performance AI chips and data center hardware.
Next, we'll examine how this expanded AT&S manufacturing capacity could influence Marvell's AI-focused growth story and longer-term investment narrative.
The future of work is here. Discover the 89 top robotics and automation stocks leading the charge in AI-driven automation and industrial transformation.
To own Marvell, you need to believe its AI and data center franchises can justify today's rich valuation and eventually translate into stronger, more consistent earnings power. The expanded AT&S IC substrate deal directly supports Marvell's near term AI optics and custom silicon ramp, while also amplifying the existing risk that long term supplier prepayments and capacity commitments could weigh on margins and free cash flow if AI demand or customer ramps slow.
#term #substrate #Manufacturing #data

25 days ago
Energy Transfer (NYSE: ET) is one of the largest U.S.-listed master limited partnerships (MLPs) specializing in the ownership of pipelines and other midstream energy ***** ets. Based on current prices, Energy Transfer has a forward distribution yield of 6.64%.
In other words, add up its quarterly cash distributions and divide by the current stock price, and you'll get approximately this figure. Considering this, let's run the numbers and see how many shares of this pipeline stock you'd need to own in order to earn $250 monthly.
Missed AI's "Act 1"? Act 2 Could Be 14x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our ***** ysts, we're only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
Considering the complexities of MLPs and taxation, we will focus on a gross dividend income of $250 per month from an Energy Transfer position, for purposes of our calculation. A monthly payout of $250 comes out to $3,000 per year. Energy Transfer pays $1.36 per share in annual distributions.
Divide $3,000 by $1.36, and you get 2,205 shares, worth around $45,136 based on Energy Transfer's current stock price. From this position, you'd generate around $2,998.80 in dividend income annually, or just under $250 per month.
#transfer #mlps #considering


1 month ago
For the recently reported second quarter, PicS N.V. (NASDAQ:PICS) outperformed relative to its previous guidance across all profitability metrics. The total account base for the company went up to 70.4 million during the second quarter, showcasing a 10% jump from the prior year. Moving on to the bottom line figures, the adjusted earnings before tax, without factoring in costs ******* ociated with stock-based compensation came in at R$291 million for the quarter. This represented a 2.1% outperformance relative to the company's R$285 million guidance. Similarly, compared to the R$245 million projection, adjusted net income for the period actually stood 15.5% higher at R$283 million.
welcomia/Shutterstock.com
The second quarter concluded with strong financial and operating momentum for PicS. The company recorded a 9% annual and 2% sequential growth in its client base, which went up to 45.4 million active users. The total credit portfolio jumped to R$31.9 billion, exceeding management's guidance by 3%. This outperformance came due to a higher number of mature credit card cohorts, and accelerated origination within secured and partly secured categories. An additional factor that accounted for the credit portfolio growth was management's measured expansion into higher risk areas such as newer platform credit and private payroll lending.
Managerial revenue rose to R$3,730 million, topping guidance by 3.6%, and net interest income reached R$2,002 million, 5.4% above projections, boosted by growing credit income. Total cash in totaled R$136.4 billion, up 17% from a year earlier and 9% from the previous quarter, with customers bringing in an average of approximately R$45.4 billion to the platform each month. Total deposits climbed to R$35.8 billion, a 45% yearly jump and 10% quarterly rise.
Some concerns related to the company's loan portfolio emerged during the quarter. Non-performing loans more than 90 days overdue increased to 9.8% of the credit portfolio during the quarter, up 93 basis points sequentially. Stage 3 exposure, which includes a broader set of credit-impaired loans, reached 12.9% of the total credit portfolio.
#million #credit #quarter #Portfolio
1 month ago
On September 14, Evercore ISI raised its price target for Netflix, Inc. (NASDAQ:NFLX) from $100 to $110 while maintaining its Outperform rating. The research firm rolled its valuation framework forward to 2028 and applied a multiple of 25 times its 2028 EPS estimate.
The new price target represents more than 40% upside from the share price of $76.41 as of September 16. However, the stock has declined about 16% year-to-date and remains well below its 52-week high of $124.86.
Evercore ISI conducted its 58th quarterly US survey and 12th semi-annual ****** an survey on Netflix, Inc. (NASDAQ:NFLX), which showed multi-year high penetration of 63% in the US and a record-high 22% penetration in ****** an.
Japan also showed strong subscriber engagement as 58% of subscribers said they were slightly or not at all likely to cancel. Subscriber satisfaction in ****** an also reached 67%.
The company's new ads plan also showed encouraging signs in ****** an. About 66% of new ads plan subscribers were either former Netflix users or people who were new to Netflix.
#high

1 month ago
On August 5, Cencora (NYSE:COR) reported results for its fiscal third quarter, which closed on June 30, and the headline numbers looked clean. Revenue rose 5.1% to $84.8 billion, adjusted earnings per share climbed 12.0% to $4.48, and management raised its full-year adjusted EPS outlook to $17.75 to $17.95. The company also repurchased $1 billion of its own stock during the quarter. But the profit story has moving parts, and a few of them pull in opposite directions.
Start with the gap between profit growth and sales growth. Adjusted operating income rose 17.0% while revenue grew only 5.1%. Much of the help came from gross profit, which jumped 23.2% on an adjusted basis as both segments contributed and the OneOncology acquisition in February lifted margins in the US business. In plain terms, adjusted gross margin widened 61 basis points to 4.16%, so the company keeps more gross profit from every dollar it sells.
The strength was not confined to one corner, either. US Healthcare Solutions grew operating income 15.9% on higher pharmaceutical sales and the OneOncology deal, while specialty volume to health systems and physician groups lifted its revenue. International Healthcare Solutions did better still, with operating income up 20.8% on strength in European distribution and global specialty logistics. Management also put cash to work, completing in one quarter the $1 billion of buybacks it had expected to finish by the close of calendar 2026. The board declared a $0.60 quarterly dividend as well, payable August 31, to holders of record on August 14.
Growth is costing more than it first appears. Adjusted operating expenses jumped 26.8%, faster than adjusted gross profit, because OneOncology brought expenses along with its profits. Even so, adjusted operating income amounts to just 1.46% of revenue, a thin cushion on a business this large. Financing adds weight too. Cencora funded part of the purchase with new senior notes plus variable-rate term loans, and net interest expense rose $58.9 million from a year earlier.
The sales mix carries its own drag. GLP-1 drugs for diabetes and weight loss are adding to revenue, but they earn lower gross margins, so each dollar of that growth is worth less to profit. Meanwhile, an oncology customer Cencora lost in 2025, and lower sales to a large mail order customer both held back US revenue, as did lower manufacturer prices on some brand pharmaceuticals. Cencora is also exploring strategic alternatives for a group of other businesses, and its April divestiture of US Consulting Services trimmed consulting sales.
#adjusted #revenue #august
1 month ago
On September 9, 2026, Jersey Mike's Subs Inc. (NYSE:JMKE) reported its first quarterly results as a public company, with total revenue up 10% year over year to $208 million and same-store sales accelerating to 2.3% growth from 1.7% in the prior quarter. It was primarily driven by transaction growth even as the restaurant industry faced weak traffic trends. Net income fell to $37 million from $59 million a year earlier. It showed non-routine expenses, advertising fund timing, and higher interest costs following the company's July initial public offering, partially offset by a $14 million gain on the sale of corporate-owned stores.
Jersey Mike's Subs Inc. (NYSE:JMKE) is gaining customers while its brand remains a major competitive advantage. The firm added 83 stores in the second quarter. It grew its customer base and increased systemwide sales 10% to $1.21 billion. Jersey Mike's also earned the No. 1 ranking among U.S. quick-service restaurant brands in the 2026 American Customer Satisfaction Index, surpassing Chick-fil-A after 11 consecutive years at the top. It gives the newly public company a strong foundation for continued customer and franchisee growth.
The business has substantial whitespace for long-term unit growth. Jersey Mike's ended the quarter with 3,378 locations and maintains a domestic development pipeline of more than 1,600 stores, with more than 90% of that pipeline coming from existing franchisees. Management estimates that the U.S. market could eventually support roughly 7,500 locations and sees potential to reach approximately 15,000 stores globally. It gives the business a long runway for franchise-led revenue and royalty growth.
Digital engagement and transaction growth give Jersey Mike's more avenues to increase sales. Digital sales represented 43% of systemwide sales in the second quarter, up from 41% a year earlier. Same-store sales increased 2.3% mainly because customers placed more transactions. Jersey Mike's also had more than 12.5 million active MyMike's loyalty members in 2025. It provides the company with a large customer database that it can use to increase frequency and personalize marketing as it expands.
Jersey Mike's Subs Inc. (NYSE:JMKE) still faces a significant profitability challenge despite its revenue growth. Second-quarter revenue jumped 10% to $208 million. However, net income fell 37% to $37 million from $59 million a year earlier. Management attributed part of the decline to advertising-fund timing and higher interest expense. It shows that revenue growth has not yet translated into comparable bottom-line growth for shareholders.
#million #customer

1 month ago
Toward the end of the lightning round on September 17, a caller asked for Mad Money's host Jim Cramer's thoughts on Iron Mountain Incorporated (NYSE:IRM), and he replied:
It's been an incredible stock. It's a real estate investment trust, basically. And you know, we know that they shred, 3% yield, down 20 points from its high. I think it's a buy.
Iron Mountain Incorporated (NYSE:IRM) operates a highly durable business model centered on physical records management, secure document destruction, and expanding digital infrastructure. In Q2, total revenue reached $2.03 billion, representing an 18.7% increase year-over-year and 16.8% organic growth. The core physical storage business provides reliable cash flow, with storage rental revenue expanding 11.5% year-over-year excluding foreign-exchange effects across a global customer base of 240,000. Adjusted funds from operations grew 17% to $432.7 million, or $1.44 per share.
At the same time, management has channeled capital into scaling higher-growth segments, including digital solutions, ***** et lifecycle management, and data center operations. The data center segment posted 39% revenue growth during the second quarter, securing 110 megawatts in new leases through July and increasing power capacity across major enterprise markets. Operating as a real estate investment trust, the company maintains a quarterly dividend of $0.864 per share, offering shareholders a forward yield of over 3%.
On the other hand, Iron Mountain Incorporated (NYSE:IRM) faces risks inherent to capital-intensive real estate infrastructure expansion. Rapid buildouts of data center power capacity demand substantial capital expenditure, leading to elevated leverage across the balance sheet. Long-term debt, net of the current portion, reached approximately $17.1 billion at the end of the second quarter, increasing sensitivity to interest rate fluctuations and refinancing costs.
#revenue #Growth

1 month ago
RF Industries, Ltd. (NASDAQ:RFIL) reported stronger fiscal third-quarter results on September 14. Revenue increased 21% to $23.96 million for the quarter ended July 31, 2026, while operating income reached approximately $1.8 million, compared with $720,000 a year earlier.
The next question is whether new orders can sustain that performance. Quarterly bookings totaled $22.5 million, below revenue. Backlog stood at $18.6 million at quarter-end and increased to $19.8 million by September 14.
Bookings measure new orders, including modifications or cancellations of earlier orders. Backlog represents orders received for which revenue has yet to be recognized.
RF Industries, Ltd. (NASDAQ:RFIL) improved both sales and profitability. Gross margin increased to 35.6% from 34% a year earlier, helping operating income grow much faster than revenue.
Management attributes the margin expansion to a shift toward customized cabling and integrated systems. These offerings involve more engineering and larger projects than traditional component sales. Competing on technical capability and customer requirements could support stronger relationships and repeat business.
#earlier

1 month ago
Forgent Power Solutions, Inc. (NYSE:FPS) reported fiscal fourth-quarter revenue of approximately $462 million on September 15, up 94% year over year. Bookings reached $1.503 billion, increasing 375%, while backlog stood at $3.0 billion as of June 30, 2026.
The reported 3.3 times book-to-bill ratio compares quarterly bookings with quarterly revenue. Bookings and backlog are operating measures of order activity and outstanding contractual work, respectively. Neither represents cash collected, and backlog does not guarantee the timing of future revenue.
Forgent Power Solutions, Inc. (NYSE:FPS) expects fiscal 2027 revenue of $2.4 billion to $2.6 billion, implying 76% growth at the midpoint. The question is whether factories, employees, and working capital can support that expansion while preserving cash generation.
Forgent Power Solutions, Inc. (NYSE:FPS) already has evidence of stronger production economics. Fourth-quarter operating income reached $91.9 million, compared with $8.3 million a year earlier. Operating cash flow was $74 million, exceeding the quarter's $31 million of capital expenditures.
Those results suggest that rising output is beginning to cover the costs of expansion. Management attributed stronger profitability partly to revenue growing faster than operating costs as new campuses approached target production levels.
#operating #power #solutions #NYSE

1 month ago
On August 6, Targa Resources Corp. (NYSE:TRGP) reported a record second quarter. Adjusted EBITDA reached $1.60 billion, a 38% jump from the same period a year earlier, and management now expects full-year results near the top of its guidance range. Targa moves and processes natural gas and natural gas liquids out of the Permian Basin, and these numbers suggest that system is running fuller than ever.
The strength came from volume, not just price. Adjusted EBITDA also climbed 14% from the first quarter, helped by Permian gas volumes that added over 450 million cubic feet of daily throughput. Some producers held back output because Waha gas prices went negative, and Targa still set a volume record. Volumes for NGL pipelines, fractionation, and LPG exports also hit records, helped by Train 11, a new fractionator in Mont Belvieu, Texas, that started up early in the quarter.
Construction is also landing on time. East Driver, a new processing plant serving the Midland side of the Permian, started up late in the quarter and ahead of schedule, and the other gathering and logistics projects are tracking their plans. Shareholders get a cut too. On July 16, Targa declared a $1.25 per share quarterly dividend, 25% above the payout for the second quarter of 2025, payable August 14 to holders of record on July 31. It also spent $80 million buying back shares during the quarter.
Growth at this pace costs real money. Targa plans about $4.5 billion in net growth spending this year, and its consolidated debt stood at $19,578 million on June 30. About $3.2 billion of liquidity gives it a cushion. In July, it also extended its receivables securitization facility to July 30, 2027 and raised the size to as much as $800 million. More borrowing capacity helps, but it is still borrowing.
Not every dollar of the profit surge is as steady as a pipeline volume. Management tied the higher outlook partly to strong marketing margin and optimization work in the first two quarters, and the quarter's jump in marketing margin came from greater optimization opportunities. That kind of income can be lumpy. Meanwhile, lower natural gas prices trimmed margins in the gathering business, and the Waha curtailments showed that producers can pull back when local prices turn ugly.
#record
1 month ago
On August 6, Republic Services (NYSE:RSG) reported earnings of $1.84 per diluted share for the quarter that closed on June 30, up from $1.75 a year earlier, and lifted most of its full-year targets. Here is the odd part. The company moved less volume than it did a year ago and still grew profit. Understanding how that works, and how long it can last, is the whole story.
Start with pricing, because that is the engine. Core price on total revenue added 5.3% to growth, which helped lift total revenue by 4.6%. Inside the related business, price contributed 4.1% in the restricted portion and 7.8% in the open market. Management says price beat cost inflation, and the margin backs that up. Adjusted EBITDA reached $1.42 billion at a 32.1% margin, matching the prior year even after Republic absorbed a 50 basis point drag from event-driven landfill volumes it received in 2025.
Cash generation is just as sturdy. Through the first half of 2026, operations produced $2.38 billion, and adjusted free cash flow came to $1.58 billion. That paid for $860 million of acquisitions and $1.04 billion returned to shareholders, so Republic is buying growth and rewarding owners from the same pool. The board added 4.5 cents to the quarterly dividend, setting it at $0.670 per share with an October 2 record date and payment on October 15. Management also raised full-year revenue, adjusted EBITDA, and free cash flow guidance, and set adjusted earnings at $7.23 to $7.28 per share.
The catch is that volume is moving the wrong way. Average yield added 3.4% to total revenue, while volume took away 1.6%, and the related business gave up 1.9% to volume. That makes this a price-led story, and price can only carry so much weight if volumes keep shrinking. Acquisitions also supplied 1.1% of the 4.6% total growth, so organic growth is smaller than the headline suggests.
Other lines were softer too. The environmental solutions business slipped 0.2%, so it added no lift. Recycled commodities sold for an average of $136 per ton at Republic's recycling centers, which is $13 lower than a year earlier. Margin only matched last year's level, and adjusted earnings per share rose 4.5%, just under revenue growth, so profit grew in step with sales rather than faster.
#year

1 month ago
GDEV Inc. (NASDAQ:GDEV) saw a year-on-year drop in bookings from both its in-app purchases and advertising, during the second quarter fiscal 2026. Consequently, the quarterly revenue figure of $94 million was down 22% compared to Q2 FY25. On the flip side, SG&A expenses and costs related to platform commissions were lower relative to the corresponding period last year. Along with other factors, the lower cost base helped GDEV report $20 million in net profit, up from $17 million in the second quarter of 2025.
Copyright: artush / 123RF Stock Photo
Breaking down the expenses, selling and marketing costs came down by 38% compared to the same quarter last year, clocking in at $33 million. It reflects on management's continued focus on deploying an efficient approach for its user acquisition initiatives. The approach is based on a more targeted performance marketing across certain channels that lead to durable high-value users, instead of broader campaigns for near-term benefits.
The reported quarter marked a turnaround related to the equity accounted ******* ociates. These contributed a $2 million profit share, which was a reversal from a $2 million loss share in Q2 FY25. Most notably, cash flows from operating activities turned from negative $10 million in Q2 FY25 to positive $10 million in the reported period.
Several operating metrics weakened during the reported quarter. Monthly paying users dropped by 23% year-over-year, along with a 15% decline for the entire first half. This was the major underlying reason for a sluggish performance in bookings, which stood at $73 million and $156 million for the second quarter and first half of the year, respectively. These fell short in comparison to $92 million and $173 million recorded in the corresponding periods last year. GDEV also said the decline in first-half platform commissions was driven by lower revenues recognized from PC platforms, while PC's share of bookings fell to 36% from 39%.
#million #lower

1 month ago
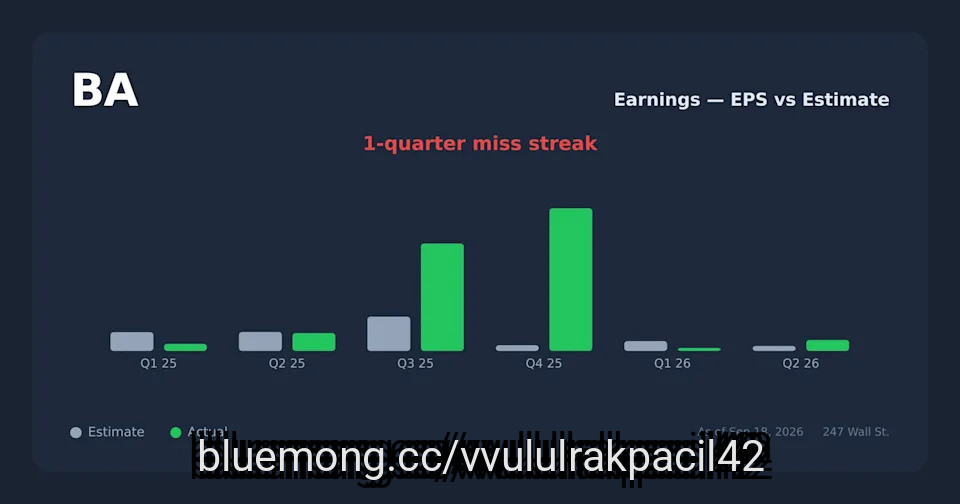
Boeing locked Korean Air into a $36.2 billion order spanning 737 MAX, 787-10, and 777X variants, but no deliveries arrive until the early 2030s.
Lockheed Martin posts steady profits while Boeing burns cash lifting production rates, carrying $600 million in quarterly interest expense that pressures GAAP results.
Just released. Our ******* ysts combed the entire stock market and named the ten best stocks to buy right now, and Boeing didn't make the cut. Enter your email to see the names that beat BA. The report is free. Enter your email and see if any of your stocks made the cut.
Boeing (NYSE:BA) confirmed a firm Korean Air order for the stretched 737 MAX, 787-10, and 777X in passenger and freighter variants, valued at $36.2 billion. Deliveries begin in the early 2030s.
These aircraft were previously logged as unidentified orders from a commitment announced last summer, so this is existing backlog getting a customer name rather than fresh demand.
#boeing #deliveries



1 month ago
Meta Platforms (META) has spent most of 2026 trading near $648 while the business behind it delivered record quarterly revenue. That growing mismatch has drawn a wave of ******* ysts who believe the stock is meaningfully underpriced.
Second-quarter revenue reached $60.8 billion, up 28% year over year, with a 31% operating margin, Meta's earnings press release confirmed.
At a forward price-to-earnings (P/E) ratio of 19, the stock trades below the S&P 500's approximately 22 times forward earnings.
Reaching $900 would require roughly 39% upside from current levels. Whether the target is realistic depends on how quickly Meta's artificial intelligence spending produces revenue beyond its advertising business.
Meta's advertising technology is producing gains that rival any growth story in big tech. Internal model upgrades drove an 8.3% lift in ad clicks and a 15.7% conversion gain on Facebook last quarter, 24/7 Wall St reported.
#business #year
1 month ago
On September 14, Evercore ISI raised its price target for Netflix, Inc. (NASDAQ:NFLX) from $100 to $110 while maintaining its Outperform rating. The research firm rolled its valuation framework forward to 2028 and applied a multiple of 25 times its 2028 EPS estimate.
The new price target represents more than 40% upside from the share price of $76.41 as of September 16. However, the stock has declined about 16% year-to-date and remains well below its 52-week high of $124.86.
Evercore ISI conducted its 58th quarterly US survey and 12th semi-annual **** an survey on Netflix, Inc. (NASDAQ:NFLX), which showed multi-year high penetration of 63% in the US and a record-high 22% penetration in **** an.
Japan also showed strong subscriber engagement as 58% of subscribers said they were slightly or not at all likely to cancel. Subscriber satisfaction in **** an also reached 67%.
The company's new ads plan also showed encouraging signs in **** an. About 66% of new ads plan subscribers were either former Netflix users or people who were new to Netflix.
#netflix #price #september #evercore

1 month ago
For the recently reported second quarter, PicS N.V. (NASDAQ:PICS) outperformed relative to its previous guidance across all profitability metrics. The total account base for the company went up to 70.4 million during the second quarter, showcasing a 10% jump from the prior year. Moving on to the bottom line figures, the adjusted earnings before tax, without factoring in costs ****** ociated with stock-based compensation came in at R$291 million for the quarter. This represented a 2.1% outperformance relative to the company's R$285 million guidance. Similarly, compared to the R$245 million projection, adjusted net income for the period actually stood 15.5% higher at R$283 million.
welcomia/Shutterstock.com
The second quarter concluded with strong financial and operating momentum for PicS. The company recorded a 9% annual and 2% sequential growth in its client base, which went up to 45.4 million active users. The total credit portfolio jumped to R$31.9 billion, exceeding management's guidance by 3%. This outperformance came due to a higher number of mature credit card cohorts, and accelerated origination within secured and partly secured categories. An additional factor that accounted for the credit portfolio growth was management's measured expansion into higher risk areas such as newer platform credit and private payroll lending.
Managerial revenue rose to R$3,730 million, topping guidance by 3.6%, and net interest income reached R$2,002 million, 5.4% above projections, boosted by growing credit income. Total cash in totaled R$136.4 billion, up 17% from a year earlier and 9% from the previous quarter, with customers bringing in an average of approximately R$45.4 billion to the platform each month. Total deposits climbed to R$35.8 billion, a 45% yearly jump and 10% quarterly rise.
Some concerns related to the company's loan portfolio emerged during the quarter. Non-performing loans more than 90 days overdue increased to 9.8% of the credit portfolio during the quarter, up 93 basis points sequentially. Stage 3 exposure, which includes a broader set of credit-impaired loans, reached 12.9% of the total credit portfolio.
#million #total
1 month ago
Whirlpool already cut its dividend 49% then skipped a payment entirely, while KHC's yield is inflated by a 55% decade-long price collapse with frozen payouts since 2019.
IEP's 29% yield masks two prior cuts and a 68% cash drop year over year, while UPS's quarterly operating cash flow fell $469 million short of its dividend payout.
A collapsing share price mechanically inflates yield, making high-yield stocks look attractive precisely when the underlying business is deteriorating most.
Just released. Our ******* ysts combed the entire stock market and named the ten best stocks to buy right now, and Kraft Heinz didn't make the cut. Enter your email to see the names that beat KHC. The report is free. Enter your email and see if any of your stocks made the cut.
Yield is a promise, not a payment. When a stock advertises a payout that looks two or three times the market average, it usually means the market has already decided something is wrong. The screen below flags six US-listed names where the numbers behind the yield show real strain: shrinking cash flow, stretched coverage, or a share price that collapsed and inflated the yield mechanically. None of these companies has announced a cut. Each has warning signs a retirement-focused reader should understand before buying the yield.
#inflated


1 month ago
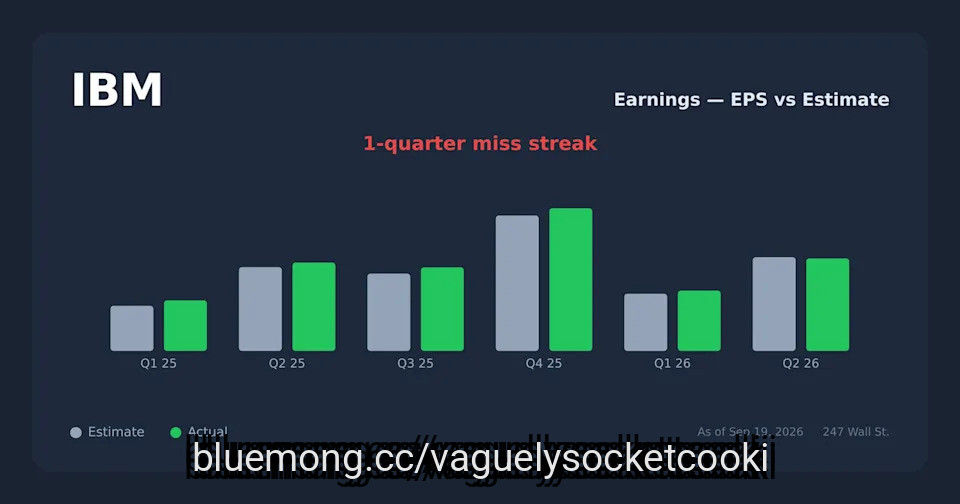
IBM raised its quarterly dividend a single penny, from $1.68 to $1.69, marking its 31st consecutive increase but delivering just $0.04 more annually to shareholders.
Microsoft grew its quarterly dividend from $0.13 to $0.98 since 2010, making it the stronger pick for investors seeking real income growth over IBM's 2.83% yield.
IBM's dividend appears safe, with $14.7B in free cash flow comfortably covering its $6.3B payout, though capital is flowing toward acquisitions, $62B in debt, and quantum computing bets.
Just released. Our ******* ysts combed the entire stock market and named the ten best stocks to buy right now, and IBM didn't make the cut. Enter your email to see the names that beat IBM. The report is free. Enter your email and see if any of your stocks made the cut.
The headline is easy to sell. IBM (NYSE:IBM) has paid consecutive quarterly dividends every year since 1916 and, with the April declaration, notched its 31st consecutive year of dividend increases. The reality a retiree actually banks is smaller. Much smaller.
#Dividend #year


1 month ago
Amgen (AMGN) yields 2.6% with a $10.08 annualized payout, topping Merck (MRK) at 2.29%, and has raised its dividend 6% annually versus Merck's smaller step-ups.
Amgen's 17 billion-dollar products and $3.5B quarterly free cash flow dwarf Merck's reliance on a single Keytruda franchise facing peak penetration.
Merck absorbed a $5.7B acquisition charge that pushed Q2 earnings to a loss, while Amgen raised 2026 EPS guidance to as high as $23.50.
Just released. Our ***** ysts combed the entire stock market and named the ten best stocks to buy right now, and Merck didn't make the cut. Enter your email to see the names that beat MRK. The report is free. Enter your email and see if any of your stocks made the cut.
For a retirement portfolio that leans on pharma dividends, the choice between Amgen (NASDAQ:AMGN) and Merck (NYSE:MRK) comes down to one question: which check is more likely to keep getting bigger through the next wave of patent expirations? Both companies deliver quarterly income today. Only one has the coverage, the growth cadence, and the portfolio breadth to keep raising through the cliff.
#merck #amgen

1 month ago
On August 5, Cencora (NYSE:COR) reported results for its fiscal third quarter, which closed on June 30, and the headline numbers looked clean. Revenue rose 5.1% to $84.8 billion, adjusted earnings per share climbed 12.0% to $4.48, and management raised its full-year adjusted EPS outlook to $17.75 to $17.95. The company also repurchased $1 billion of its own stock during the quarter. But the profit story has moving parts, and a few of them pull in opposite directions.
Start with the gap between profit growth and sales growth. Adjusted operating income rose 17.0% while revenue grew only 5.1%. Much of the help came from gross profit, which jumped 23.2% on an adjusted basis as both segments contributed and the OneOncology acquisition in February lifted margins in the US business. In plain terms, adjusted gross margin widened 61 basis points to 4.16%, so the company keeps more gross profit from every dollar it sells.
The strength was not confined to one corner, either. US Healthcare Solutions grew operating income 15.9% on higher pharmaceutical sales and the OneOncology deal, while specialty volume to health systems and physician groups lifted its revenue. International Healthcare Solutions did better still, with operating income up 20.8% on strength in European distribution and global specialty logistics. Management also put cash to work, completing in one quarter the $1 billion of buybacks it had expected to finish by the close of calendar 2026. The board declared a $0.60 quarterly dividend as well, payable August 31, to holders of record on August 14.
Growth is costing more than it first appears. Adjusted operating expenses jumped 26.8%, faster than adjusted gross profit, because OneOncology brought expenses along with its profits. Even so, adjusted operating income amounts to just 1.46% of revenue, a thin cushion on a business this large. Financing adds weight too. Cencora funded part of the purchase with new senior notes plus variable-rate term loans, and net interest expense rose $58.9 million from a year earlier.
The sales mix carries its own drag. GLP-1 drugs for diabetes and weight loss are adding to revenue, but they earn lower gross margins, so each dollar of that growth is worth less to profit. Meanwhile, an oncology customer Cencora lost in 2025, and lower sales to a large mail order customer both held back US revenue, as did lower manufacturer prices on some brand pharmaceuticals. Cencora is also exploring strategic alternatives for a group of other businesses, and its April divestiture of US Consulting Services trimmed consulting sales.
#profit #operating #Growth #august



