

28 days ago
Generating $6,550 a month requires $2.25M at a 3.5% yield, $1.31M at 6%, or just $786,000 at 10%.
A blended portfolio of VYM, DIVO, VICI, JEPQ, ARCC, and SGOV yields 5.6%, requiring $1.4M while preserving some dividend growth.
A 3.5% yield growing 8% annually reaches $249,000 in income by year 15, while a static 10% yield stays flat and loses ground to inflation.
Read More: Learn 7 ways to generate income with a $1,000,000+ portfolio (sponsor)
A target of $6,550 a month equals $78,600 a year. For a 66-year-old, that income must cover housing, healthcare premiums, travel, and decades of other retirement expenses. The amount you need to invest to generate $78,600 from portfolio income alone varies widely by yield. Here's what the numbers look like at three yield levels, using six income holdings as examples.
#yield
A blended portfolio of VYM, DIVO, VICI, JEPQ, ARCC, and SGOV yields 5.6%, requiring $1.4M while preserving some dividend growth.
A 3.5% yield growing 8% annually reaches $249,000 in income by year 15, while a static 10% yield stays flat and loses ground to inflation.
Read More: Learn 7 ways to generate income with a $1,000,000+ portfolio (sponsor)
A target of $6,550 a month equals $78,600 a year. For a 66-year-old, that income must cover housing, healthcare premiums, travel, and decades of other retirement expenses. The amount you need to invest to generate $78,600 from portfolio income alone varies widely by yield. Here's what the numbers look like at three yield levels, using six income holdings as examples.
#yield



28 days ago
Selling appreciated stock and donating cash still leaves the full capital gain in Medicare's MAGI, potentially triggering IRMAA surcharges two years later.
A couple adding a $90,000 gain to $200,000 in normal income can face $5,770 in extra annual Medicare premiums, even after donating every dollar to charity.
Donating appreciated shares held over a year directly to charity keeps the gain out of MAGI entirely, avoiding IRMAA; those over 70.5 can also use a QCD up to $111,000.
Building a portfolio and living off one are two completely different skills, and almost ***** ody teaches the second. This problem is what The Definitive Guide to Retirement Income helps, and it is free today. Read more here. (Sponsor)
A 72-year-old retiree has held Berkshire Hathaway (NYSE:BRK-B) shares for decades. This fall he sells $100,000 worth of stock he bought for $10,000, then writes a check for the full amount to his church's building fund. He ***** umes the gift wipes out the income Medicare sees. For his income tax bill, the gift helps. For Medicare, the $90,000 gain stays on his return, and it will raise his premiums two years from now.
#medicare #magi #Stock
A couple adding a $90,000 gain to $200,000 in normal income can face $5,770 in extra annual Medicare premiums, even after donating every dollar to charity.
Donating appreciated shares held over a year directly to charity keeps the gain out of MAGI entirely, avoiding IRMAA; those over 70.5 can also use a QCD up to $111,000.
Building a portfolio and living off one are two completely different skills, and almost ***** ody teaches the second. This problem is what The Definitive Guide to Retirement Income helps, and it is free today. Read more here. (Sponsor)
A 72-year-old retiree has held Berkshire Hathaway (NYSE:BRK-B) shares for decades. This fall he sells $100,000 worth of stock he bought for $10,000, then writes a check for the full amount to his church's building fund. He ***** umes the gift wipes out the income Medicare sees. For his income tax bill, the gift helps. For Medicare, the $90,000 gain stays on his return, and it will raise his premiums two years from now.
#medicare #magi #Stock

28 days ago
If you're bracing for higher health insurance premiums as the end of the year creeps up, keep bracing: The news might be worse than you think.
Health insurance premiums have been skyrocketing, rising by around 20% over the past three years. Now, some consumers could see premium increase by nearly 10% in 2027.
Dave Ramsey warns nearly 50% of Americans are making 1 big Social Security mistake. Here's what it is and 3 simple steps to fix it ASAP
The tax breaks in Trump's 'big beautiful bill' expire after 2028. Here are 4 reasons why retirees can't afford to waste time
Jeff Bezos backs a platform that lets anyone invest in rental homes for as little as $100 — 6 ways to build wealth like a landlord without actually being one
#bracing #nearly #dave #security
Health insurance premiums have been skyrocketing, rising by around 20% over the past three years. Now, some consumers could see premium increase by nearly 10% in 2027.
Dave Ramsey warns nearly 50% of Americans are making 1 big Social Security mistake. Here's what it is and 3 simple steps to fix it ASAP
The tax breaks in Trump's 'big beautiful bill' expire after 2028. Here are 4 reasons why retirees can't afford to waste time
Jeff Bezos backs a platform that lets anyone invest in rental homes for as little as $100 — 6 ways to build wealth like a landlord without actually being one
#bracing #nearly #dave #security


29 days ago
Giving out checks to Americans has emerged as one of President Trump's major messages in the final weeks of the campaign season.
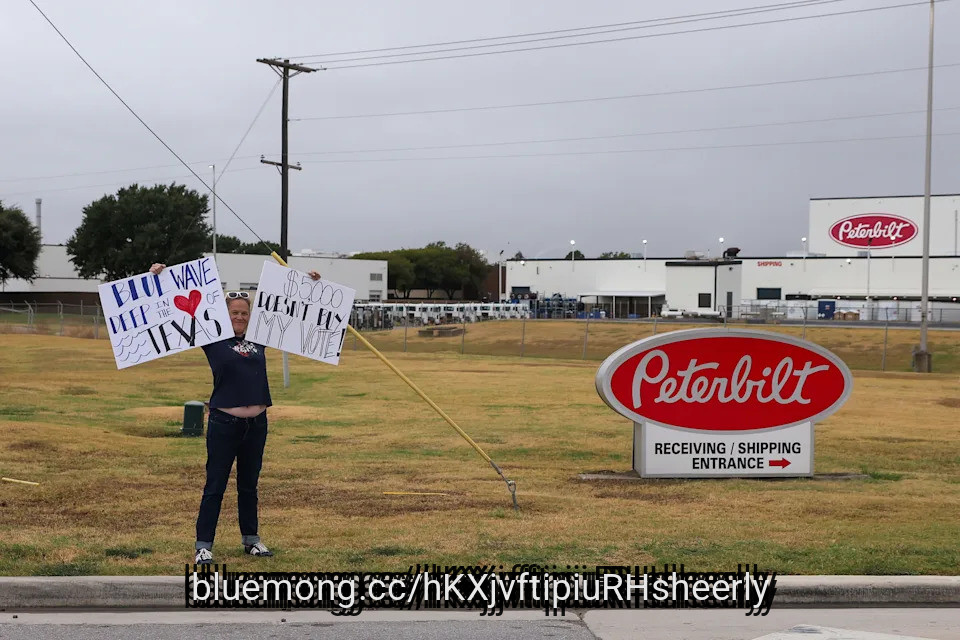
But Americans are skeptical, as multiple polls show voters harbor serious doubts about whether Trump will deliver and whether the cost would hurt the economy.
The president is nevertheless determined to escalate the issue with 29 days until the midterm elections. This past weekend, he mentioned checks at every campaign stop and made a new pledge to send $90 to millions of seniors enrolled in Medicare Part B.
The payment is intended to offset October Medicare premiums and will be deposited this month, but Trump emphasized that it will come in the form of cash.
"Over 20 million seniors on Medicare will soon be receiving a deposit of nearly $100 directly into their bank accounts," he announced on Truth Social. "You'll get your money almost immediately."
#medicare #Trump #whether #part
But Americans are skeptical, as multiple polls show voters harbor serious doubts about whether Trump will deliver and whether the cost would hurt the economy.
The president is nevertheless determined to escalate the issue with 29 days until the midterm elections. This past weekend, he mentioned checks at every campaign stop and made a new pledge to send $90 to millions of seniors enrolled in Medicare Part B.
The payment is intended to offset October Medicare premiums and will be deposited this month, but Trump emphasized that it will come in the form of cash.
"Over 20 million seniors on Medicare will soon be receiving a deposit of nearly $100 directly into their bank accounts," he announced on Truth Social. "You'll get your money almost immediately."
#medicare #Trump #whether #part

29 days ago
President Trump has announced that the administration will send a one-time $90 payment to 21 million people enrolled in Medicare Part B coverage. The payments will be issued automatically to qualified Medicare beneficiaries starting this week.
Not everyone enrolled in Medicare Part B will be paid. There are over 70 million people enrolled in Medicare, with almost 63 million in Part B, which covers general medical care and preventive health services.
In a White House statement, the president said the "premium rebates" are intended to help "enrollees pay for their Medicare Part B premiums."
The standard Part B premium is $202.90 for 2026, up from $185 in 2025.
Read more: Medicare changes coming in 2027: What to know before open enrollment
#part #president #premium #House
Not everyone enrolled in Medicare Part B will be paid. There are over 70 million people enrolled in Medicare, with almost 63 million in Part B, which covers general medical care and preventive health services.
In a White House statement, the president said the "premium rebates" are intended to help "enrollees pay for their Medicare Part B premiums."
The standard Part B premium is $202.90 for 2026, up from $185 in 2025.
Read more: Medicare changes coming in 2027: What to know before open enrollment
#part #president #premium #House


1 month ago
By Kanishka Singh
WASHINGTON, Oct 2 (Reuters) - President Donald Trump said the US government will send a one-time $90 payment to more than 20 million Americans enrolled in Medicare, a health insurance program for the elderly, to help offset the cost of their monthly medical insurance premiums.
Trump said on social media late on Friday the payments will come from the Medicare Improvement Fund, which he said was given $2 billion by Congress to improve the Medicare fee-for-service program.
The announcement is the latest in a series of financial promises the Republican leader has made to voters heading into the November midterm elections where control of Congress is at stake.
Trump's Republican Party currently has a narrow majority in both the Senate and the House of Representatives but his approval rating has been low over his handling of the high cost of living for Americans during the US-Israeli war on Iran that has spiked oil and gas prices.
#americans #insurance #program #singh
WASHINGTON, Oct 2 (Reuters) - President Donald Trump said the US government will send a one-time $90 payment to more than 20 million Americans enrolled in Medicare, a health insurance program for the elderly, to help offset the cost of their monthly medical insurance premiums.
Trump said on social media late on Friday the payments will come from the Medicare Improvement Fund, which he said was given $2 billion by Congress to improve the Medicare fee-for-service program.
The announcement is the latest in a series of financial promises the Republican leader has made to voters heading into the November midterm elections where control of Congress is at stake.
Trump's Republican Party currently has a narrow majority in both the Senate and the House of Representatives but his approval rating has been low over his handling of the high cost of living for Americans during the US-Israeli war on Iran that has spiked oil and gas prices.
#americans #insurance #program #singh


1 month ago
On August 6, Aflac (NYSE:AFL) reported second-quarter numbers that point in opposite directions. Net earnings climbed to $825 million, helped along by investment losses that shrank to $153 million from $421 million a year ago. Adjusted earnings, though, fell 7.7% to $883 million. Both numbers are real, but they answer different questions. Which measure you trust changes the story, so here is what sits underneath.
Start with the yen, because it is muddying the picture. The average rate was 159.45 to the dollar, 9.3% weaker than a year earlier, and that cost adjusted earnings $0.05 a share. Take the currency out of the first half and adjusted earnings per share rose 4.1% to $3.57. ******* an is also running more profitably. Its pretax adjusted margin widened to 34.3% from 32.0% as claims took a smaller bite out of premiums, and yen-based pretax adjusted earnings rose 3.4%. So part of the decline in ******* an's dollar-reported profit is currency, not operations.
The US business is still growing at the top line. Net earned premiums rose 2.3% to $1.5 billion, and sales climbed 2.6% to $349 million, led by group voluntary benefits along with dental and vision plans. In ******* an, the refreshed Tsumitasu life policy and the new Anshin Palette medical product grew strongly in the quarter, and first-half sales rose 7.0% to ¥37.3 billion. Then there is the cash. Aflac returned $1.3 billion to shareholders in the quarter, $983 million of it through buybacks, and declared a $0.61 third-quarter dividend, payable September 1 to holders of record on August 19, 2026. Management notes 43 straight years of dividend increases through 2025 and says the board is on a path to extend that in 2026.
The catch is that ******* an's profit gains came from lower claims, not a bigger business. Net earned premiums in yen fell 3.7%, mainly because of a new external reinsurance deal and older limited-pay policies reaching paid-up status. Premium persistency, the share of policies customers keep, slipped to 92.7% from 93.7%. ******* an's pretax adjusted earnings still fell 2.1% once currency is stripped out, and new sales dipped 5.6% in the quarter against a tough comparison for the Miraito cancer product, which launched in March 2025.
The US segment has its own soft spot. Pretax adjusted earnings fell 4.6% to $370 million, and the margin narrowed to 20.9% from 22.5% as claims and benefits took a bigger share of premiums. Corporate and Other swung to a $10 million pretax adjusted loss from a $20 million gain a year earlier, with interest expense up 21.6% to $62 million. And adjusted book value per share, excluding foreign currency remeasurement, slid to $41.22 at June 30 from $42.97 a year earlier.
#earnings #fell
Start with the yen, because it is muddying the picture. The average rate was 159.45 to the dollar, 9.3% weaker than a year earlier, and that cost adjusted earnings $0.05 a share. Take the currency out of the first half and adjusted earnings per share rose 4.1% to $3.57. ******* an is also running more profitably. Its pretax adjusted margin widened to 34.3% from 32.0% as claims took a smaller bite out of premiums, and yen-based pretax adjusted earnings rose 3.4%. So part of the decline in ******* an's dollar-reported profit is currency, not operations.
The US business is still growing at the top line. Net earned premiums rose 2.3% to $1.5 billion, and sales climbed 2.6% to $349 million, led by group voluntary benefits along with dental and vision plans. In ******* an, the refreshed Tsumitasu life policy and the new Anshin Palette medical product grew strongly in the quarter, and first-half sales rose 7.0% to ¥37.3 billion. Then there is the cash. Aflac returned $1.3 billion to shareholders in the quarter, $983 million of it through buybacks, and declared a $0.61 third-quarter dividend, payable September 1 to holders of record on August 19, 2026. Management notes 43 straight years of dividend increases through 2025 and says the board is on a path to extend that in 2026.
The catch is that ******* an's profit gains came from lower claims, not a bigger business. Net earned premiums in yen fell 3.7%, mainly because of a new external reinsurance deal and older limited-pay policies reaching paid-up status. Premium persistency, the share of policies customers keep, slipped to 92.7% from 93.7%. ******* an's pretax adjusted earnings still fell 2.1% once currency is stripped out, and new sales dipped 5.6% in the quarter against a tough comparison for the Miraito cancer product, which launched in March 2025.
The US segment has its own soft spot. Pretax adjusted earnings fell 4.6% to $370 million, and the margin narrowed to 20.9% from 22.5% as claims and benefits took a bigger share of premiums. Corporate and Other swung to a $10 million pretax adjusted loss from a $20 million gain a year earlier, with interest expense up 21.6% to $62 million. And adjusted book value per share, excluding foreign currency remeasurement, slid to $41.22 at June 30 from $42.97 a year earlier.
#earnings #fell

2 months ago
JEPI, DIVO, and GPIX each pay near 8% monthly yields while growing share price by writing calls on only a portion of holdings.
GPIX has beaten SPY with an 80% return since its 2023 launch by capping its options overlay at just 25 to 75% of the portfolio.
DIVO's tactical options sleeve delivers a lower 6% yield but drives 72% five-year price appreciation, nearly matching SPY's gains.
Two retirees, same $1 million, same 4% rule, buy one finished with $1.4 million, the other hit $0 in 12 years. Our free reader guide explains the flaw that separated them, and the income-first method built to avoid it.
Covered call ETFs have a reputation problem. For years, the category was defined by funds like QYLD and XYLD that wrote at-the-money calls on entire index portfolios, harvested rich premiums, and quietly bled principal every time markets rallied. Investors got their monthly check and watched their share price drift lower. That is the trap worth avoiding.
#gpix #calls #lower #years
GPIX has beaten SPY with an 80% return since its 2023 launch by capping its options overlay at just 25 to 75% of the portfolio.
DIVO's tactical options sleeve delivers a lower 6% yield but drives 72% five-year price appreciation, nearly matching SPY's gains.
Two retirees, same $1 million, same 4% rule, buy one finished with $1.4 million, the other hit $0 in 12 years. Our free reader guide explains the flaw that separated them, and the income-first method built to avoid it.
Covered call ETFs have a reputation problem. For years, the category was defined by funds like QYLD and XYLD that wrote at-the-money calls on entire index portfolios, harvested rich premiums, and quietly bled principal every time markets rallied. Investors got their monthly check and watched their share price drift lower. That is the trap worth avoiding.
#gpix #calls #lower #years
2 months ago
My husband, 59, and I, 55, are planning to retire over the next few years, and this is one of the biggest unknowns I'm struggling with. My mom had Alzheimer's disease and spent seven years in a really nice memory-care facility in a smaller town. It cost about $7,000 a month. Thankfully, my parents had purchased long-term-care insurance and had paid premiums for about 12 years.
My dad died shortly after being diagnosed with cancer, so his policy was never used. But my mom's policy ended up being worth its weight in gold. It essentially covered all of her care. By the time my mother died, the insurance company had paid out almost $600,000. We only paid about $100 a month for some extras. Needless to say, that experience has made me think.
The 10-year Treasury is having its worst run in over 100 years. Why investors are buying bonds anyway.
'I'm burned out': I'm constantly helping my cousin who is running out of money. Is it too much to expect his sister to help?
I've looked into long-term-care insurance, but the premiums are so incredibly expensive, and I worry about what they'll cost by the time it makes sense for me to seriously consider a policy. We're fortunate financially. After 35 years in the corporate grind, we'll have substantial retirement savings; we've always saved carefully; and we have no debt or mortgage.
#insurance #paid #term
My dad died shortly after being diagnosed with cancer, so his policy was never used. But my mom's policy ended up being worth its weight in gold. It essentially covered all of her care. By the time my mother died, the insurance company had paid out almost $600,000. We only paid about $100 a month for some extras. Needless to say, that experience has made me think.
The 10-year Treasury is having its worst run in over 100 years. Why investors are buying bonds anyway.
'I'm burned out': I'm constantly helping my cousin who is running out of money. Is it too much to expect his sister to help?
I've looked into long-term-care insurance, but the premiums are so incredibly expensive, and I worry about what they'll cost by the time it makes sense for me to seriously consider a policy. We're fortunate financially. After 35 years in the corporate grind, we'll have substantial retirement savings; we've always saved carefully; and we have no debt or mortgage.
#insurance #paid #term


2 months ago
On August 6, Aflac (NYSE:AFL) reported second-quarter numbers that point in opposite directions. Net earnings climbed to $825 million, helped along by investment losses that shrank to $153 million from $421 million a year ago. Adjusted earnings, though, fell 7.7% to $883 million. Both numbers are real, but they answer different questions. Which measure you trust changes the story, so here is what sits underneath.
Start with the yen, because it is muddying the picture. The average rate was 159.45 to the dollar, 9.3% weaker than a year earlier, and that cost adjusted earnings $0.05 a share. Take the currency out of the first half and adjusted earnings per share rose 4.1% to $3.57. **** an is also running more profitably. Its pretax adjusted margin widened to 34.3% from 32.0% as claims took a smaller bite out of premiums, and yen-based pretax adjusted earnings rose 3.4%. So part of the decline in **** an's dollar-reported profit is currency, not operations.
The US business is still growing at the top line. Net earned premiums rose 2.3% to $1.5 billion, and sales climbed 2.6% to $349 million, led by group voluntary benefits along with dental and vision plans. In **** an, the refreshed Tsumitasu life policy and the new Anshin Palette medical product grew strongly in the quarter, and first-half sales rose 7.0% to ¥37.3 billion. Then there is the cash. Aflac returned $1.3 billion to shareholders in the quarter, $983 million of it through buybacks, and declared a $0.61 third-quarter dividend, payable September 1 to holders of record on August 19, 2026. Management notes 43 straight years of dividend increases through 2025 and says the board is on a path to extend that in 2026.
The catch is that **** an's profit gains came from lower claims, not a bigger business. Net earned premiums in yen fell 3.7%, mainly because of a new external reinsurance deal and older limited-pay policies reaching paid-up status. Premium persistency, the share of policies customers keep, slipped to 92.7% from 93.7%. **** an's pretax adjusted earnings still fell 2.1% once currency is stripped out, and new sales dipped 5.6% in the quarter against a tough comparison for the Miraito cancer product, which launched in March 2025.
The US segment has its own soft spot. Pretax adjusted earnings fell 4.6% to $370 million, and the margin narrowed to 20.9% from 22.5% as claims and benefits took a bigger share of premiums. Corporate and Other swung to a $10 million pretax adjusted loss from a $20 million gain a year earlier, with interest expense up 21.6% to $62 million. And adjusted book value per share, excluding foreign currency remeasurement, slid to $41.22 at June 30 from $42.97 a year earlier.
#adjusted #pretax
Start with the yen, because it is muddying the picture. The average rate was 159.45 to the dollar, 9.3% weaker than a year earlier, and that cost adjusted earnings $0.05 a share. Take the currency out of the first half and adjusted earnings per share rose 4.1% to $3.57. **** an is also running more profitably. Its pretax adjusted margin widened to 34.3% from 32.0% as claims took a smaller bite out of premiums, and yen-based pretax adjusted earnings rose 3.4%. So part of the decline in **** an's dollar-reported profit is currency, not operations.
The US business is still growing at the top line. Net earned premiums rose 2.3% to $1.5 billion, and sales climbed 2.6% to $349 million, led by group voluntary benefits along with dental and vision plans. In **** an, the refreshed Tsumitasu life policy and the new Anshin Palette medical product grew strongly in the quarter, and first-half sales rose 7.0% to ¥37.3 billion. Then there is the cash. Aflac returned $1.3 billion to shareholders in the quarter, $983 million of it through buybacks, and declared a $0.61 third-quarter dividend, payable September 1 to holders of record on August 19, 2026. Management notes 43 straight years of dividend increases through 2025 and says the board is on a path to extend that in 2026.
The catch is that **** an's profit gains came from lower claims, not a bigger business. Net earned premiums in yen fell 3.7%, mainly because of a new external reinsurance deal and older limited-pay policies reaching paid-up status. Premium persistency, the share of policies customers keep, slipped to 92.7% from 93.7%. **** an's pretax adjusted earnings still fell 2.1% once currency is stripped out, and new sales dipped 5.6% in the quarter against a tough comparison for the Miraito cancer product, which launched in March 2025.
The US segment has its own soft spot. Pretax adjusted earnings fell 4.6% to $370 million, and the margin narrowed to 20.9% from 22.5% as claims and benefits took a bigger share of premiums. Corporate and Other swung to a $10 million pretax adjusted loss from a $20 million gain a year earlier, with interest expense up 21.6% to $62 million. And adjusted book value per share, excluding foreign currency remeasurement, slid to $41.22 at June 30 from $42.97 a year earlier.
#adjusted #pretax
2 months ago
Property and casualty insurer Progressive (NYSE: PGR) is probably best known for selling auto insurance. That's a highly competitive segment of the industry, but the company has proven its chops, reporting a strong combined ratio of 87.3% in the second quarter of 2026. Is the roughly 10% pullback from the 52-week high, and about 25% drawdown from 2025's peak, as of this writing, enough to make the stock a buy? Probably not if you are a value investor.
The combined ratio is a measure of profitability in the insurance sector, with numbers below 100% indicating that a company is earning more from premiums than it costs to support those premiums and cover claims. Progressive has a strong history of running its business well on this front. Basically, it is a good business. But paying too much for a good business can turn it into a bad investment, as Benjamin Graham was fond of saying (Graham notably helped train Warren Buffett).
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
So the real question here is whether the drawdowns noted above were sufficient to make Progressive's valuation attractive. The answer there isn't clean cut. For example, the price-to-sales ratio of 1.4x is in the middle of the historical range of roughly 0.5x to 2.2x. If anything, the P/S ratio is kind of toward the high side. The same general story holds with the price-to-book ratio. So these two metrics hint at a stock that isn't expensive, but it also isn't trading at bargain-basement prices.
The price-to-earnings ratio is a bit more positive, with the 11.1x P/E toward the lower end of its historical range. And the average insurance company has a P/E ratio of around 11.8x, so this makes Progressive look reasonably priced. Only Progressive's P/B ratio is 3.7x compared to the industry average of 1.7x, so the broader industry comparison still isn't a clear-cut win.
#ratio #progressive
The combined ratio is a measure of profitability in the insurance sector, with numbers below 100% indicating that a company is earning more from premiums than it costs to support those premiums and cover claims. Progressive has a strong history of running its business well on this front. Basically, it is a good business. But paying too much for a good business can turn it into a bad investment, as Benjamin Graham was fond of saying (Graham notably helped train Warren Buffett).
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
So the real question here is whether the drawdowns noted above were sufficient to make Progressive's valuation attractive. The answer there isn't clean cut. For example, the price-to-sales ratio of 1.4x is in the middle of the historical range of roughly 0.5x to 2.2x. If anything, the P/S ratio is kind of toward the high side. The same general story holds with the price-to-book ratio. So these two metrics hint at a stock that isn't expensive, but it also isn't trading at bargain-basement prices.
The price-to-earnings ratio is a bit more positive, with the 11.1x P/E toward the lower end of its historical range. And the average insurance company has a P/E ratio of around 11.8x, so this makes Progressive look reasonably priced. Only Progressive's P/B ratio is 3.7x compared to the industry average of 1.7x, so the broader industry comparison still isn't a clear-cut win.
#ratio #progressive


2 months ago
Medicare's two-year income lookback makes age 63 the last year a Roth conversion won't directly raise your Medicare premiums at 65.
Married couples can convert roughly $133,000 annually within the 22% bracket, but crossing the $218,000 IRMAA threshold triggers surcharges for both spouses.
Delaying Social Security to 70 preserves low-income years for conversions, since every dollar of benefits claimed adds an invisible marginal rate on top of conversion income.
Read More: Learn 7 secret wealth tips high net worth investors use that most investors miss (sponsor)
A 63-year-old with $1.4 million in a traditional 401(k) has a narrower Roth conversion window than the calendar suggests. Medicare enrollment at 65 uses a two-year lookback on modified adjusted gross income, which means the conversion executed at 63 is the one that sets Medicare premiums at 65. The real deadline arrives earlier than most people expect.
#income #roth #lookback
Married couples can convert roughly $133,000 annually within the 22% bracket, but crossing the $218,000 IRMAA threshold triggers surcharges for both spouses.
Delaying Social Security to 70 preserves low-income years for conversions, since every dollar of benefits claimed adds an invisible marginal rate on top of conversion income.
Read More: Learn 7 secret wealth tips high net worth investors use that most investors miss (sponsor)
A 63-year-old with $1.4 million in a traditional 401(k) has a narrower Roth conversion window than the calendar suggests. Medicare enrollment at 65 uses a two-year lookback on modified adjusted gross income, which means the conversion executed at 63 is the one that sets Medicare premiums at 65. The real deadline arrives earlier than most people expect.
#income #roth #lookback

2 months ago
Five covered-call ETFs yield 8% to 14% monthly by writing options against large-cap U.S. equity portfolios, putting them at double to triple the 10-year Treasury rate near 5%.
Nasdaq-100 funds post higher yields than S&P 500 funds because greater implied volatility generates fatter option premiums, but they cap upside during rallies.
QQQI delivers the group's top 14% yield with roughly 99% of 2025 distributions classified as return of capital, deferring taxes rather than creating current income.
Read More: Learn 7 secret wealth tips high net worth investors use that most investors miss (sponsor)
Income investors heading into the fourth quarter face a market where the 10-year Treasury yield is near 5%, yet a cluster of options-income ETFs still pays roughly double to triple that rate every month. The five funds on this list — JPMorgan Equity Premium Income ETF (NYSEARCA:JEPI), Global X S&P 500 Covered Call ETF (NYSEARCA:XYLD), Goldman Sachs Nasdaq-100 Premium Income ETF (NASDAQ:GPIQ), NEOS S&P 500 High Income ETF (NYSEARCA:SPYI), and NEOS Nasdaq-100 High Income ETF (NASDAQ:QQQI), all sit in an 8% to 14% trailing yield band while distributing cash monthly.
#NASDAQ #high #etfs #treasury
Nasdaq-100 funds post higher yields than S&P 500 funds because greater implied volatility generates fatter option premiums, but they cap upside during rallies.
QQQI delivers the group's top 14% yield with roughly 99% of 2025 distributions classified as return of capital, deferring taxes rather than creating current income.
Read More: Learn 7 secret wealth tips high net worth investors use that most investors miss (sponsor)
Income investors heading into the fourth quarter face a market where the 10-year Treasury yield is near 5%, yet a cluster of options-income ETFs still pays roughly double to triple that rate every month. The five funds on this list — JPMorgan Equity Premium Income ETF (NYSEARCA:JEPI), Global X S&P 500 Covered Call ETF (NYSEARCA:XYLD), Goldman Sachs Nasdaq-100 Premium Income ETF (NASDAQ:GPIQ), NEOS S&P 500 High Income ETF (NYSEARCA:SPYI), and NEOS Nasdaq-100 High Income ETF (NASDAQ:QQQI), all sit in an 8% to 14% trailing yield band while distributing cash monthly.
#NASDAQ #high #etfs #treasury

2 months ago
When planning for retirement, most people account for housing, travel, daily living expenses and general healthcare costs. However, it's easy to overlook one retirement expense: the Income-Related Monthly Adjustment Amount, commonly known as IRMAA.
If you have a large pension, substantial tax-deferred retirement accounts, or other variables that may elevate your retirement income, IRMAA is a factor you may encounter starting in your mid-60s. While it is unlikely to derail a well-constructed financial plan, failing to understand IRMAA and how to plan ahead for it can lead to frustrating annual surprises.
In the United States, most adults become eligible for Medicare when they turn 65. Medicare is divided into several parts, but IRMAA specifically applies to two of them: Part B (which covers doctor visits, outpatient care and preventive services) and Part D (prescription drug coverage).
For the average retiree, Medicare Part B carries a standard monthly base premium ($202.90 per month in 2026). Part D coverage varies depending on the specific private plan selected, but carries a national average base premium of roughly $38.99 per month. Combined, a standard retiree pays roughly $242 per month for basic Part B and Part D coverage, per Medicare.
However, Medicare premiums are not one-size-fits-all. If your income exceeds specific threshold limits set by the federal government, you will be required to pay an additional surcharge on top of your base monthly premiums. That additional surcharge is IRMAA.
#income #base
If you have a large pension, substantial tax-deferred retirement accounts, or other variables that may elevate your retirement income, IRMAA is a factor you may encounter starting in your mid-60s. While it is unlikely to derail a well-constructed financial plan, failing to understand IRMAA and how to plan ahead for it can lead to frustrating annual surprises.
In the United States, most adults become eligible for Medicare when they turn 65. Medicare is divided into several parts, but IRMAA specifically applies to two of them: Part B (which covers doctor visits, outpatient care and preventive services) and Part D (prescription drug coverage).
For the average retiree, Medicare Part B carries a standard monthly base premium ($202.90 per month in 2026). Part D coverage varies depending on the specific private plan selected, but carries a national average base premium of roughly $38.99 per month. Combined, a standard retiree pays roughly $242 per month for basic Part B and Part D coverage, per Medicare.
However, Medicare premiums are not one-size-fits-all. If your income exceeds specific threshold limits set by the federal government, you will be required to pay an additional surcharge on top of your base monthly premiums. That additional surcharge is IRMAA.
#income #base


2 months ago
Oscar Health (OSCR) raised its full-year earnings outlook while lowering its expected medical costs to cover benefits for its nearly 3 million Affordable Care Act exchange members. OSCR stock climbed in early Wednesday stock market action ahead of its 9 a.m. ET investor conference.
Oscar, which made an aggressive play to gain ACA market share, has seen enrollment surge 47% from a year ago as of June 30, even as overall enrollment has plunged due to the expiration of enhanced premium subsidies. As of now, it looks like the bet is paying off in a big way, with shares up 126% this year through Tuesday. But it's still a bit early to know, because Oscar's earnings depend not only on its own members' costs, but also those of other ACA insurers.
The ACA's No. 2 insurer by membership behind Centene (CNC) said that it now expects its medical loss ratio, or benefit costs as a share of premiums, to be in the 81% to 82% range, down from the prior outlook of 81.5% to 82.5%.
Oscar boosted its outlook for earnings from operations by $100 million at both ends to a range of $600 million to $800 million. The unchanged revenue outlook, between $18.7 billion and $19 billion, implies that no additional customer churn is expected.
Here is what investors should keep in mind. Compared to the overall ACA risk pool, Oscar's enrollment is relatively young, healthy and more likely to sign up for very-high-deductible bronze plans. Yet based on its relatively healthy risk pool, Oscar expects about 20% of its premiums will be paid out via risk adjustment to other carriers under ACA rules. That means results in the second half of this year depend to a large degree on the level of healthcare utilization by non-Oscar members. As of now, it's a bit early to tell, since healthcare spending tends to rise as the year progresses and insured members exhaust their deductibles.
#oscar #year
Oscar, which made an aggressive play to gain ACA market share, has seen enrollment surge 47% from a year ago as of June 30, even as overall enrollment has plunged due to the expiration of enhanced premium subsidies. As of now, it looks like the bet is paying off in a big way, with shares up 126% this year through Tuesday. But it's still a bit early to know, because Oscar's earnings depend not only on its own members' costs, but also those of other ACA insurers.
The ACA's No. 2 insurer by membership behind Centene (CNC) said that it now expects its medical loss ratio, or benefit costs as a share of premiums, to be in the 81% to 82% range, down from the prior outlook of 81.5% to 82.5%.
Oscar boosted its outlook for earnings from operations by $100 million at both ends to a range of $600 million to $800 million. The unchanged revenue outlook, between $18.7 billion and $19 billion, implies that no additional customer churn is expected.
Here is what investors should keep in mind. Compared to the overall ACA risk pool, Oscar's enrollment is relatively young, healthy and more likely to sign up for very-high-deductible bronze plans. Yet based on its relatively healthy risk pool, Oscar expects about 20% of its premiums will be paid out via risk adjustment to other carriers under ACA rules. That means results in the second half of this year depend to a large degree on the level of healthcare utilization by non-Oscar members. As of now, it's a bit early to tell, since healthcare spending tends to rise as the year progresses and insured members exhaust their deductibles.
#oscar #year


2 months ago
Retiring at 62 and living off a 401(k) until 70 keeps a couple in the 12% tax bracket, with an effective federal rate near 8% on roughly $133,000 in annual withdrawals.
Delaying Social Security to 70 grows each spouse's benefit by 8% per year, producing roughly $6,200 combined monthly in guaranteed, inflation-adjusted income plus a maximized survivor benefit.
Medicare's two-year income lookback means couples must keep joint MAGI below $218,000 or face IRMAA surcharges that add over $160 per month in Part B premiums.
Read More: Learn 7 secret wealth tips high net worth investors use that most investors miss (sponsor)
A 62-year-old couple with $1.8 million in a traditional 401(k) and matching $3,100 monthly Social Security benefits available at full retirement age is looking at one of the most tax-efficient windows in the entire retirement code. The plan: retire now, live off the 401(k) for eight years, and switch to two delayed Social Security checks totaling roughly $6,200 a month at 70. It sounds aggressive. The math says it is close to optimal.
#security #year #benefit
Delaying Social Security to 70 grows each spouse's benefit by 8% per year, producing roughly $6,200 combined monthly in guaranteed, inflation-adjusted income plus a maximized survivor benefit.
Medicare's two-year income lookback means couples must keep joint MAGI below $218,000 or face IRMAA surcharges that add over $160 per month in Part B premiums.
Read More: Learn 7 secret wealth tips high net worth investors use that most investors miss (sponsor)
A 62-year-old couple with $1.8 million in a traditional 401(k) and matching $3,100 monthly Social Security benefits available at full retirement age is looking at one of the most tax-efficient windows in the entire retirement code. The plan: retire now, live off the 401(k) for eight years, and switch to two delayed Social Security checks totaling roughly $6,200 a month at 70. It sounds aggressive. The math says it is close to optimal.
#security #year #benefit


2 months ago
Unlike Medicare Advantage, Medigap offers no recurring annual shopping window, so health conditions can permanently lock policyholders into higher premiums.
The one-time federal Medigap Open Enrollment Period lasts just six months starting at age 65; after that, most states allow medical underwriting.
Never cancel an existing Medigap policy before a replacement is confirmed in writing, since a declined application leaves the original coverage intact.
Are you ahead, or behind on retirement? SmartAsset's free tool can match you with a financial advisor in minutes to help you answer that today. Each advisor has been carefully vetted, and must act in your best interests. Don't waste another minute; learn more here.
A 72-year-old in Ohio opens a December rate notice and finds that her Medigap Plan G premium is rising again in January, the fourth increase in four years. Her broker finds a competitor charging $40 less each month.
#finds #period
The one-time federal Medigap Open Enrollment Period lasts just six months starting at age 65; after that, most states allow medical underwriting.
Never cancel an existing Medigap policy before a replacement is confirmed in writing, since a declined application leaves the original coverage intact.
Are you ahead, or behind on retirement? SmartAsset's free tool can match you with a financial advisor in minutes to help you answer that today. Each advisor has been carefully vetted, and must act in your best interests. Don't waste another minute; learn more here.
A 72-year-old in Ohio opens a December rate notice and finds that her Medigap Plan G premium is rising again in January, the fourth increase in four years. Her broker finds a competitor charging $40 less each month.
#finds #period

2 months ago
CVS Health (NYSE: CVS) dealt with significant headwinds after the COVID-19 pandemic. The company's financial results suffered as sales of coronavirus-related products (such as diagnostic tests) declined, while expenses in its insurance business rose substantially, resulting in lower profits and margins. However, CVS Health has done a good job of addressing those problems, and the stock has rebounded. Shares are up 31% over the past 12 months. Wall Street thinks there may be even more upside on the horizon. CVS Health's average price target is $116.04 (according to Yahoo! Finance), implying a meaningful 20% upside from current levels. Is now a great time to buy the stock?
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Over the past 18 months (or so), CVS Health has implemented several initiatives that have helped improve its business. For instance, the company closed dozens of stores, many of which were unprofitable. The pharmacy chain specialist also scaled back its insurance division, notably by exiting the Affordable Care Act marketplace. The results have been pretty impressive. Consider the company's second-quarter results. CVS Health's revenue increased by a healthy 7.3% year over year to $106.1 billion.
Adjusted earnings per share were $2.58, 42.5% higher than the year-ago period. Note the improvement in CVS Health's healthcare benefits segment, which offers health insurance services. Operating expenses as a percentage of revenue declined slightly to 12.4%, down from 12.5% in the prior-year quarter, even as revenue grew 3.5% year over year. And operating margins within this unit came in at 5.8%, up from the 2.8% reported in the year-ago period. Also, CVS Health's medical benefits ratio -- the percentage of insurance premiums the company spent on medical care (the lower the better) -- declined to 87.4% in the second quarter, down from 89.9% in Q2 2025.
CVS Health also increased its guidance for the full fiscal year 2026. The company now expects its adjusted EPS to fall between $7.90 and $8.10, up from its previous range of between $7.30 to $7.50. The company is also now projecting cash flow from operations of at least $11.5 billion, up from the previous lower bound of $9.5 billion. These are signs of a much-improved business.
#insurance
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Over the past 18 months (or so), CVS Health has implemented several initiatives that have helped improve its business. For instance, the company closed dozens of stores, many of which were unprofitable. The pharmacy chain specialist also scaled back its insurance division, notably by exiting the Affordable Care Act marketplace. The results have been pretty impressive. Consider the company's second-quarter results. CVS Health's revenue increased by a healthy 7.3% year over year to $106.1 billion.
Adjusted earnings per share were $2.58, 42.5% higher than the year-ago period. Note the improvement in CVS Health's healthcare benefits segment, which offers health insurance services. Operating expenses as a percentage of revenue declined slightly to 12.4%, down from 12.5% in the prior-year quarter, even as revenue grew 3.5% year over year. And operating margins within this unit came in at 5.8%, up from the 2.8% reported in the year-ago period. Also, CVS Health's medical benefits ratio -- the percentage of insurance premiums the company spent on medical care (the lower the better) -- declined to 87.4% in the second quarter, down from 89.9% in Q2 2025.
CVS Health also increased its guidance for the full fiscal year 2026. The company now expects its adjusted EPS to fall between $7.90 and $8.10, up from its previous range of between $7.30 to $7.50. The company is also now projecting cash flow from operations of at least $11.5 billion, up from the previous lower bound of $9.5 billion. These are signs of a much-improved business.
#insurance
0.00$ raised of 0.00$ goal
0 donations
0.00$
to go

2 months ago
Medicare calculates Part B and Part D surcharges using income from two years prior, so a profitable ***** et sale can trigger higher premiums long after the money is spent.
IRMAA resets annually, so a one-time income spike typically raises premiums for only one or two years before fading as normal income returns.
Voluntary ***** et sales don't qualify for SSA-44 relief, making pre-sale income planning the only real tool to minimize Medicare surcharges.
Many financial professionals are salespeople paid on what they push, not whether you end up wealthier. A fiduciary is the opposite. The SEC legally requires them to put your interests first. Advisor.com's free matching tool pairs you with vetted fiduciaries from major national firms, all in under three minutes. See who you match with today.
Picture a longtime fan who bought a personal seat license two decades ago, giving him the right to buy the same season tickets year after year. He has climbed the same stadium stairs every fall, watched his knees start to complain and finally decided the ticket rights were worth more to him as cash than as seats he uses a handful of times each season.
#income #medicare #premiums #tool
IRMAA resets annually, so a one-time income spike typically raises premiums for only one or two years before fading as normal income returns.
Voluntary ***** et sales don't qualify for SSA-44 relief, making pre-sale income planning the only real tool to minimize Medicare surcharges.
Many financial professionals are salespeople paid on what they push, not whether you end up wealthier. A fiduciary is the opposite. The SEC legally requires them to put your interests first. Advisor.com's free matching tool pairs you with vetted fiduciaries from major national firms, all in under three minutes. See who you match with today.
Picture a longtime fan who bought a personal seat license two decades ago, giving him the right to buy the same season tickets year after year. He has climbed the same stadium stairs every fall, watched his knees start to complain and finally decided the ticket rights were worth more to him as cash than as seats he uses a handful of times each season.
#income #medicare #premiums #tool

2 months ago
On August 5, Primerica (NYSE:PRI) reported second-quarter results that read as two different companies bolted together. Net income climbed 13% to $202 million, and earnings per diluted share jumped 19% to $6.45, pushing return on stockholders' equity to 32.1%. Total revenue reached $865 million, up 9% from a year earlier. But those headline figures obscure a split story. The investment arm is sprinting to record highs while the life insurance sales force is quietly getting smaller. Here is what is actually moving the numbers.
Investment and savings product sales hit a record $4.4 billion in the quarter, up 23% from a year ago, while client ***** et values ended the period at an all-time high of $140 billion, up 16%. Net inflows added another $397 million. That growth translated directly into profit. ISP segment revenue rose 21% to $361 million, and pretax income jumped 31% to $104 million, meaning the segment's margin expanded even as it grew. The reason: ***** et-based commission revenue climbed 28%, outpacing the 19% rise in average client ***** ets, thanks to a shift toward higher-margin US managed accounts and Canadian mutual funds.
Primerica also returned $172 million to shareholders in the quarter through $135 million in buybacks and roughly $37 million in dividends, bringing year-to-date capital returns to $352 million. Its effective tax rate improved to 21.7% from 23.9% a year earlier, and its life insurer's statutory risk-based capital ratio stood at approximately 440%, a cushion most insurers would envy.
The company's distribution engine tells a rougher story. The life-licensed sales force fell 3% year over year to 148,612 representatives. Recruiting rose 2% to 82,346 recruits, but far fewer of them actually got licensed: new life-licensed representatives dropped 15% to 11,020. That gap between recruiting and licensing shows up directly in output. The company issued 78,904 life insurance policies, down 12%, with total face amount issued falling 8% to $27.7 billion.
Term Life revenue was roughly flat at $444 million even as adjusted direct premiums rose 3%, and segment pretax income fell 4% to $148 million. Part of that came from cost creep rather than claims: the benefits and claims ratio held steady at 57.9%, but the insurance expense ratio rose to 8.4% from 7.6% a year earlier, eating into a segment that is supposed to be Primerica's stable, predictable cash generator.
#million #year #rose #sales
Investment and savings product sales hit a record $4.4 billion in the quarter, up 23% from a year ago, while client ***** et values ended the period at an all-time high of $140 billion, up 16%. Net inflows added another $397 million. That growth translated directly into profit. ISP segment revenue rose 21% to $361 million, and pretax income jumped 31% to $104 million, meaning the segment's margin expanded even as it grew. The reason: ***** et-based commission revenue climbed 28%, outpacing the 19% rise in average client ***** ets, thanks to a shift toward higher-margin US managed accounts and Canadian mutual funds.
Primerica also returned $172 million to shareholders in the quarter through $135 million in buybacks and roughly $37 million in dividends, bringing year-to-date capital returns to $352 million. Its effective tax rate improved to 21.7% from 23.9% a year earlier, and its life insurer's statutory risk-based capital ratio stood at approximately 440%, a cushion most insurers would envy.
The company's distribution engine tells a rougher story. The life-licensed sales force fell 3% year over year to 148,612 representatives. Recruiting rose 2% to 82,346 recruits, but far fewer of them actually got licensed: new life-licensed representatives dropped 15% to 11,020. That gap between recruiting and licensing shows up directly in output. The company issued 78,904 life insurance policies, down 12%, with total face amount issued falling 8% to $27.7 billion.
Term Life revenue was roughly flat at $444 million even as adjusted direct premiums rose 3%, and segment pretax income fell 4% to $148 million. Part of that came from cost creep rather than claims: the benefits and claims ratio held steady at 57.9%, but the insurance expense ratio rose to 8.4% from 7.6% a year earlier, eating into a segment that is supposed to be Primerica's stable, predictable cash generator.
#million #year #rose #sales

2 months ago
No withdrawal order eliminates RMDs from a traditional IRA. Only Roth conversions, qualified charitable distributions, or never owning one in the first place can genuinely shrink them.
IRMAA surcharges hit Medicare premiums two years after the income that triggers them, jumping joint filers from $203 to $284 monthly by crossing $218,000 MAGI.
Letting an IRA compound untouched through your 60s forces larger RMDs at 73, often pushing retirees into higher brackets and through IRMAA cliffs simultaneously.
Read More: Avoid these 13 retirement mistakes before they derail your future (sponsor)
A $2.1 million nest egg split evenly between a taxable brokerage account and a traditional IRA can throw off a six-figure income. What most retirees miss is that where each holding sits and when each dollar comes out determine whether Medicare surcharges and a swollen required minimum distribution eat that income a decade later.
#medicare #surcharges #retirees #magi
IRMAA surcharges hit Medicare premiums two years after the income that triggers them, jumping joint filers from $203 to $284 monthly by crossing $218,000 MAGI.
Letting an IRA compound untouched through your 60s forces larger RMDs at 73, often pushing retirees into higher brackets and through IRMAA cliffs simultaneously.
Read More: Avoid these 13 retirement mistakes before they derail your future (sponsor)
A $2.1 million nest egg split evenly between a taxable brokerage account and a traditional IRA can throw off a six-figure income. What most retirees miss is that where each holding sits and when each dollar comes out determine whether Medicare surcharges and a swollen required minimum distribution eat that income a decade later.
#medicare #surcharges #retirees #magi

2 months ago
On August 5, Primerica (NYSE:PRI) reported second-quarter results that read as two different companies bolted together. Net income climbed 13% to $202 million, and earnings per diluted share jumped 19% to $6.45, pushing return on stockholders' equity to 32.1%. Total revenue reached $865 million, up 9% from a year earlier. But those headline figures obscure a split story. The investment arm is sprinting to record highs while the life insurance sales force is quietly getting smaller. Here is what is actually moving the numbers.
Investment and savings product sales hit a record $4.4 billion in the quarter, up 23% from a year ago, while client ****** et values ended the period at an all-time high of $140 billion, up 16%. Net inflows added another $397 million. That growth translated directly into profit. ISP segment revenue rose 21% to $361 million, and pretax income jumped 31% to $104 million, meaning the segment's margin expanded even as it grew. The reason: ****** et-based commission revenue climbed 28%, outpacing the 19% rise in average client ****** ets, thanks to a shift toward higher-margin US managed accounts and Canadian mutual funds.
Primerica also returned $172 million to shareholders in the quarter through $135 million in buybacks and roughly $37 million in dividends, bringing year-to-date capital returns to $352 million. Its effective tax rate improved to 21.7% from 23.9% a year earlier, and its life insurer's statutory risk-based capital ratio stood at approximately 440%, a cushion most insurers would envy.
The company's distribution engine tells a rougher story. The life-licensed sales force fell 3% year over year to 148,612 representatives. Recruiting rose 2% to 82,346 recruits, but far fewer of them actually got licensed: new life-licensed representatives dropped 15% to 11,020. That gap between recruiting and licensing shows up directly in output. The company issued 78,904 life insurance policies, down 12%, with total face amount issued falling 8% to $27.7 billion.
Term Life revenue was roughly flat at $444 million even as adjusted direct premiums rose 3%, and segment pretax income fell 4% to $148 million. Part of that came from cost creep rather than claims: the benefits and claims ratio held steady at 57.9%, but the insurance expense ratio rose to 8.4% from 7.6% a year earlier, eating into a segment that is supposed to be Primerica's stable, predictable cash generator.
#sales
Investment and savings product sales hit a record $4.4 billion in the quarter, up 23% from a year ago, while client ****** et values ended the period at an all-time high of $140 billion, up 16%. Net inflows added another $397 million. That growth translated directly into profit. ISP segment revenue rose 21% to $361 million, and pretax income jumped 31% to $104 million, meaning the segment's margin expanded even as it grew. The reason: ****** et-based commission revenue climbed 28%, outpacing the 19% rise in average client ****** ets, thanks to a shift toward higher-margin US managed accounts and Canadian mutual funds.
Primerica also returned $172 million to shareholders in the quarter through $135 million in buybacks and roughly $37 million in dividends, bringing year-to-date capital returns to $352 million. Its effective tax rate improved to 21.7% from 23.9% a year earlier, and its life insurer's statutory risk-based capital ratio stood at approximately 440%, a cushion most insurers would envy.
The company's distribution engine tells a rougher story. The life-licensed sales force fell 3% year over year to 148,612 representatives. Recruiting rose 2% to 82,346 recruits, but far fewer of them actually got licensed: new life-licensed representatives dropped 15% to 11,020. That gap between recruiting and licensing shows up directly in output. The company issued 78,904 life insurance policies, down 12%, with total face amount issued falling 8% to $27.7 billion.
Term Life revenue was roughly flat at $444 million even as adjusted direct premiums rose 3%, and segment pretax income fell 4% to $148 million. Part of that came from cost creep rather than claims: the benefits and claims ratio held steady at 57.9%, but the insurance expense ratio rose to 8.4% from 7.6% a year earlier, eating into a segment that is supposed to be Primerica's stable, predictable cash generator.
#sales

2 months ago
A large land-sale gain can push Medicare Part B premiums from $203 to $690 monthly, with the IRMAA impact arriving two years after closing.
Federal installment-sale rules let sellers spread gain recognition across multiple years, softening Medicare surcharges and Social Security tax exposure.
Taking the full lump sum eliminates buyer default risk, but installment sales may only reduce years spent at peak IRMAA tiers, not avoid them entirely.
Just released. Our ***** ysts combed the entire stock market and named the ten best stocks to buy right now. The report is free. Enter your email and see if any of your stocks made the cut.
A retired man in his late sixties owns rural land that suddenly sits in the path of a data center developer. The offer runs into seven figures. He is ready to sell, but instead of taking every dollar at closing, he negotiates payments over several years.
#irmaa #gain
Federal installment-sale rules let sellers spread gain recognition across multiple years, softening Medicare surcharges and Social Security tax exposure.
Taking the full lump sum eliminates buyer default risk, but installment sales may only reduce years spent at peak IRMAA tiers, not avoid them entirely.
Just released. Our ***** ysts combed the entire stock market and named the ten best stocks to buy right now. The report is free. Enter your email and see if any of your stocks made the cut.
A retired man in his late sixties owns rural land that suddenly sits in the path of a data center developer. The offer runs into seven figures. He is ready to sell, but instead of taking every dollar at closing, he negotiates payments over several years.
#irmaa #gain


2 months ago
Delaying the first RMD to April 1 stacks two distributions on one tax return, potentially bundling over $150,000 in income for a $2 million IRA.
Medicare sets 2028 premiums using 2026 income, so a bunched RMD year can trigger IRMAA surcharges costing a married couple nearly $5,770 extra annually.
Taking the first RMD by December 31 instead of April 1 keeps both distributions on separate returns and eliminates the income-stacking problem entirely.
Read More: Learn 7 ways to generate income with a $1,000,000+ portfolio (sponsor)
A retiree turned 73 in 2025 and used the option Congress left him. Instead of taking his first required minimum distribution (RMD) by December 31, he delayed it until April 1, 2026. The second RMD was still due December 31, 2026. Two withdrawals landed on one tax return, and Medicare does not care that the first one "belonged" to 2025. Both dollars became 2026 income. The April deadline bought three months. It did not buy another tax year.
#taking #instead
Medicare sets 2028 premiums using 2026 income, so a bunched RMD year can trigger IRMAA surcharges costing a married couple nearly $5,770 extra annually.
Taking the first RMD by December 31 instead of April 1 keeps both distributions on separate returns and eliminates the income-stacking problem entirely.
Read More: Learn 7 ways to generate income with a $1,000,000+ portfolio (sponsor)
A retiree turned 73 in 2025 and used the option Congress left him. Instead of taking his first required minimum distribution (RMD) by December 31, he delayed it until April 1, 2026. The second RMD was still due December 31, 2026. Two withdrawals landed on one tax return, and Medicare does not care that the first one "belonged" to 2025. Both dollars became 2026 income. The April deadline bought three months. It did not buy another tax year.
#taking #instead

2 months ago
PPLI's annual fees ranging from 2 to 4 percent erase most tax benefits unless you fund the policy with at least $5 million in premiums.
IRS investor-control rules bar policyholders from directing any trades or pre-arranging investments, surrendering full portfolio control to their adviser.
The same ***** et-location logic that PPLI sells for between 2% and 4% annually is available free through existing 401(k), IRA, and Roth accounts.
Read More: Learn 7 ways to generate income with a $1,000,000+ portfolio (sponsor)
The pitch is seductive. Put your hedge funds, private credit, and private real estate inside a life insurance policy, let it compound tax-free for decades, then pass the proceeds to your kids income-tax-free at death. Jim White, founder of Great Oak Wealth Management, told The Wall Street Journal it is "a Roth IRA on steroids for people who can afford it and want to leave it to their heirs."
#control #Portfolio
IRS investor-control rules bar policyholders from directing any trades or pre-arranging investments, surrendering full portfolio control to their adviser.
The same ***** et-location logic that PPLI sells for between 2% and 4% annually is available free through existing 401(k), IRA, and Roth accounts.
Read More: Learn 7 ways to generate income with a $1,000,000+ portfolio (sponsor)
The pitch is seductive. Put your hedge funds, private credit, and private real estate inside a life insurance policy, let it compound tax-free for decades, then pass the proceeds to your kids income-tax-free at death. Jim White, founder of Great Oak Wealth Management, told The Wall Street Journal it is "a Roth IRA on steroids for people who can afford it and want to leave it to their heirs."
#control #Portfolio


2 months ago
Selling an inherited rental home triggers a large taxable gain since depreciation reduces basis and the Section 121 home-sale exclusion doesn't apply.
IRMAA uses income from two years prior, so a large 2026 gain can push both spouses into Medicare's $649 monthly Part B tier by 2028.
A voluntary property sale disqualifies sellers from SSA-44 relief, but IRMAA resets annually, so higher premiums should last only one affected year.
Read More: Learn 7 ways to generate income with a $1,000,000+ portfolio (sponsor)
A 68-year-old retiree in Ohio inherited his parents' three-bedroom colonial when his mother died in 2006. He never moved in. Instead, he rented it for 20 years before selling it this spring for a price that felt like a lottery win. He and his wife are both on Medicare. What they may not realize is that the sale can come back two years later in the form of substantially higher premiums.
#selling #inherited #home #large
IRMAA uses income from two years prior, so a large 2026 gain can push both spouses into Medicare's $649 monthly Part B tier by 2028.
A voluntary property sale disqualifies sellers from SSA-44 relief, but IRMAA resets annually, so higher premiums should last only one affected year.
Read More: Learn 7 ways to generate income with a $1,000,000+ portfolio (sponsor)
A 68-year-old retiree in Ohio inherited his parents' three-bedroom colonial when his mother died in 2006. He never moved in. Instead, he rented it for 20 years before selling it this spring for a price that felt like a lottery win. He and his wife are both on Medicare. What they may not realize is that the sale can come back two years later in the form of substantially higher premiums.
#selling #inherited #home #large

2 months ago
First Eagle Investment Management, an investment management company, released its Q2 2026 investor update for "First Eagle Global Fund". The letter can be downloaded here. Easing tensions in the Middle East led to a strong rally in risk markets in Q2. The S&P 500 Index rose 15.2%, while the MSCI EAFE Index gained 10.8%. Growth stocks outperformed, with the MSCI World Growth Index significantly exceeding value returns. A notable shift in U.S. interest rate expectations followed Kevin Warsh's appointment as chair of the Federal Open Market Committee, pushing Treasury yields higher and strengthening the dollar. Despite the optimistic market environment, concerns about fiscal constraints and limited policy flexibility remain. Tighter credit spreads and elevated equity valuations reflect strong demand for financial ***** ets, with household wealth in equities at a post-WWII high. Earnings expectations are buoyant, driven by AI infrastructure developments. Against this backdrop, Global Fund A Shares returned 2.86% in Q2 2026, with emerging markets and developed Europe as the primary contributors. Developed Asia (excluding ***** an) was the only detractor, and ***** an lagged. Information technology and financials led among equity sectors, while materials and energy detracted. The fund underperformed relative to the MSCI World Index during this period. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, First Eagle Global Fund highlighted Elevance Health, Inc. (NYSE:ELV) as a notable contributor. Elevance Health, Inc. (NYSE:ELV) is a US-based health benefits company. On August 31, 2026, Elevance Health, Inc. (NYSE:ELV) closed at $392.54 per share. Over the past month, Elevance Health, Inc. (NYSE:ELV) reported 3.85%, but its shares are up 21.78% over the past year. Elevance Health, Inc. (NYSE:ELV) has a market capitalization of $85.13 billion, and its stock has traded within a 52-week range of $274.84 to $436.24.
First Eagle Global Fund stated the following regarding Elevance Health, Inc. (NYSE:ELV) in its Q2 2026 investor letter:
"Shares of Elevance Health, Inc. (NYSE:ELV), the health insurer and healthcare-services provider formerly known as Anthem, rallied during the quarter as margins expanded—after a protracted decline—due to declining medical costs, stronger pricing and increased utilization with higher premiums."
Elevance Health, Inc. (NYSE:ELV) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 84 hedge fund portfolios held Elevance Health, Inc. (NYSE:ELV) at the end of the second quarter, which was 87 in the previous quarter. While we acknowledge the potential of Elevance Health, Inc. (NYSE:ELV) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring tr
In its second-quarter 2026 investor letter, First Eagle Global Fund highlighted Elevance Health, Inc. (NYSE:ELV) as a notable contributor. Elevance Health, Inc. (NYSE:ELV) is a US-based health benefits company. On August 31, 2026, Elevance Health, Inc. (NYSE:ELV) closed at $392.54 per share. Over the past month, Elevance Health, Inc. (NYSE:ELV) reported 3.85%, but its shares are up 21.78% over the past year. Elevance Health, Inc. (NYSE:ELV) has a market capitalization of $85.13 billion, and its stock has traded within a 52-week range of $274.84 to $436.24.
First Eagle Global Fund stated the following regarding Elevance Health, Inc. (NYSE:ELV) in its Q2 2026 investor letter:
"Shares of Elevance Health, Inc. (NYSE:ELV), the health insurer and healthcare-services provider formerly known as Anthem, rallied during the quarter as margins expanded—after a protracted decline—due to declining medical costs, stronger pricing and increased utilization with higher premiums."
Elevance Health, Inc. (NYSE:ELV) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 84 hedge fund portfolios held Elevance Health, Inc. (NYSE:ELV) at the end of the second quarter, which was 87 in the previous quarter. While we acknowledge the potential of Elevance Health, Inc. (NYSE:ELV) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring tr


2 months ago
Riverwater Partners, an investment management company, released its 'Small Cap Strategy' Q2 2026 investor letter. The letter can be downloaded here. The Small Cap Strategy underperformed the Russell 2000 in the second quarter as the benchmark experienced one of its strongest risk-on rallies in recent memory, although the strategy remained ahead year-to-date. The quarter was defined by accelerating AI investment, energy market disruptions, and renewed investor appetite for higher-beta stocks, creating headwinds for the firm's quality-focused approach and healthcare positioning. Despite this, stock selection contributed positively in energy, materials, and financials, while healthcare and consumer discretionary detracted due to the fund's disciplined avoidance of speculative businesses. Looking ahead, the firm remains cautiously optimistic, focusing on opportunities created by market dislocations, including AI infrastructure enablers, select consumer companies, healthcare innovators, and energy businesses trading below intrinsic value. The strategy continues to emphasize high-quality companies with strong management teams and attractive valuations, positioning the portfolio for a potential rotation away from speculative market leadership. In addition, please check the Strategy's top five holdings to know its best picks in 2026.
In its second-quarter 2026 investor letter, Riverwater Partners Small Cap Strategy highlighted NetScout Systems, Inc. (NASDAQ:NTCT) as a new addition. NetScout Systems, Inc. (NASDAQ:NTCT) provides carrier service ****** urance, cybersecurity, and Distributed Denial-of-Service (DDoS) solutions to protect digital business services against disruptions. On August 31, 2026, NetScout Systems, Inc. (NASDAQ:NTCT) closed at $38.83 per share. The one-month return of NetScout Systems, Inc. (NASDAQ:NTCT) was -8.01% and its shares gained 57.59% over the past 52 weeks. NetScout Systems, Inc. (NASDAQ:NTCT) has a market capitalization of $2.82 billion with a 52-week trading range between $24.27 - $45.28.
Riverwater Partners Small Cap Strategy stated the following regarding NetScout Systems, Inc. (NASDAQ:NTCT) in its Q2 2026 investor letter:
"We initiated a position in NetScout Systems, Inc. (NASDAQ:NTCT) in April. Founded in 1984, NetScout Systems, Inc. (NTCT), with a stated mission of "Guardians of A Connected World," has been a technology innovator providing service ****** urance and cybersecurity solutions based on its pioneering deep packet inspection technology at scale. While high-growth competitors trade at significant premiums, NetScout offers a more attractive valuation for what we view as a durable software business with deeply embedded customer relationships among the Fortune 500. Its deep packet inspection technology is increasingly critical as enterprises navigate complex digital transformations, cloud migrations, and a heightened threat landscape. We view NTCT as a disciplined way to gain exposure to secular technology tail
In its second-quarter 2026 investor letter, Riverwater Partners Small Cap Strategy highlighted NetScout Systems, Inc. (NASDAQ:NTCT) as a new addition. NetScout Systems, Inc. (NASDAQ:NTCT) provides carrier service ****** urance, cybersecurity, and Distributed Denial-of-Service (DDoS) solutions to protect digital business services against disruptions. On August 31, 2026, NetScout Systems, Inc. (NASDAQ:NTCT) closed at $38.83 per share. The one-month return of NetScout Systems, Inc. (NASDAQ:NTCT) was -8.01% and its shares gained 57.59% over the past 52 weeks. NetScout Systems, Inc. (NASDAQ:NTCT) has a market capitalization of $2.82 billion with a 52-week trading range between $24.27 - $45.28.
Riverwater Partners Small Cap Strategy stated the following regarding NetScout Systems, Inc. (NASDAQ:NTCT) in its Q2 2026 investor letter:
"We initiated a position in NetScout Systems, Inc. (NASDAQ:NTCT) in April. Founded in 1984, NetScout Systems, Inc. (NTCT), with a stated mission of "Guardians of A Connected World," has been a technology innovator providing service ****** urance and cybersecurity solutions based on its pioneering deep packet inspection technology at scale. While high-growth competitors trade at significant premiums, NetScout offers a more attractive valuation for what we view as a durable software business with deeply embedded customer relationships among the Fortune 500. Its deep packet inspection technology is increasingly critical as enterprises navigate complex digital transformations, cloud migrations, and a heightened threat landscape. We view NTCT as a disciplined way to gain exposure to secular technology tail


2 months ago
Aon plc (NYSE:AON) has agreed to acquire USI Insurance Services from KKR and other shareholders for $17 billion in cash, making it one of the largest insurance-brokerage acquisitions in recent years. USI generates roughly $3 billion in annual revenue, has more than 10,500 employees, and operates nearly 200 offices across the U.S.
The strategic focus is clear: Aon wants to significantly strengthen its position in the U.S. middle-market insurance segment, which Aon estimates at more than $40 billion and more than one-third of U.S. commercial P&C premiums. The acquisition also expands Aon's exposure to the excess & surplus (E&S) market, one of the faster-growing parts of commercial insurance. The deal builds on Aon's $13 billion acquisition of NFP in 2024, giving the company another major middle-market platform. Aon expects the USI transaction to generate approximately $395 million of annual run-rate net adjusted EBITDA synergies and become accretive to adjusted EPS in 2028.
The market's initial reaction was negative. Aon shares fell roughly 6% in early trading, reflecting investor concerns about the size of the transaction, leverage, and the time required for the deal to become earnings accretive.
Photo by Scott Graham on Unsplash
The biggest positive is that Aon plc (NYSE:AON) is buying into a large and attractive part of the insurance market. USI gives Aon considerably more scale among middle-market customers, while adding capabilities in employee benefits, P&C, personal risk and retirement services. This could allow Aon to sell more products to existing customers and use USI's relationships to cross-sell Aon's broader services.
#market #middle
The strategic focus is clear: Aon wants to significantly strengthen its position in the U.S. middle-market insurance segment, which Aon estimates at more than $40 billion and more than one-third of U.S. commercial P&C premiums. The acquisition also expands Aon's exposure to the excess & surplus (E&S) market, one of the faster-growing parts of commercial insurance. The deal builds on Aon's $13 billion acquisition of NFP in 2024, giving the company another major middle-market platform. Aon expects the USI transaction to generate approximately $395 million of annual run-rate net adjusted EBITDA synergies and become accretive to adjusted EPS in 2028.
The market's initial reaction was negative. Aon shares fell roughly 6% in early trading, reflecting investor concerns about the size of the transaction, leverage, and the time required for the deal to become earnings accretive.
Photo by Scott Graham on Unsplash
The biggest positive is that Aon plc (NYSE:AON) is buying into a large and attractive part of the insurance market. USI gives Aon considerably more scale among middle-market customers, while adding capabilities in employee benefits, P&C, personal risk and retirement services. This could allow Aon to sell more products to existing customers and use USI's relationships to cross-sell Aon's broader services.
#market #middle
2 months ago
Medicare drug plans can silently shift on January 1, moving drugs to costlier tiers, adding prior authorization, or dropping coverage entirely without notice.
A $0-premium plan can cost more annually than a higher-premium plan if it places your maintenance drugs on unfavorable tiers.
Check your Annual Notice of Change each fall and compare total annual drug costs in Medicare Plan Finder, not just premiums, to avoid January surprises.
Read More: Learn 7 ways to generate income with a $1,000,000+ portfolio (sponsor)
A 72-year-old walks into her pharmacy on January 5 and hands over the same prescription she has filled every month for three years. The copay was $12 in December. Now the pharmacist is asking for $87.
#january #plan #drugs #check
A $0-premium plan can cost more annually than a higher-premium plan if it places your maintenance drugs on unfavorable tiers.
Check your Annual Notice of Change each fall and compare total annual drug costs in Medicare Plan Finder, not just premiums, to avoid January surprises.
Read More: Learn 7 ways to generate income with a $1,000,000+ portfolio (sponsor)
A 72-year-old walks into her pharmacy on January 5 and hands over the same prescription she has filled every month for three years. The copay was $12 in December. Now the pharmacist is asking for $87.
#january #plan #drugs #check




