7 days ago
On September 17, Lucid Group, Inc. (NASDAQ:LCID) and Bolt, a leading European shared mobility platform, announced a strategic partnership to develop and deploy autonomous mobility services across Europe. This sent shares of Lucid Group, Inc. (NASDAQ:LCID) higher, and the stock ended the trading session with gains of nearly 6%.
The partnership will combine Lucid Group, Inc.'s (NASDAQ:LCID) software-defined vehicle platform with Bolt's European data, operating infrastructure, and mobility expertise. The companies will be looking to develop and launch autonomous mobility services at scale, using vehicles based on Lucid Group, Inc.'s (NASDAQ:LCID) upcoming Midsize platform.
Bolt plans to deploy at least 25,000 fully autonomous vehicles across multiple European cities and countries, supporting its ambitious goal of having 100,000 autonomous vehicles on its platform by 2035.
The financial details of the partnership were not disclosed.
The deal comes as Lucid Group, Inc. (NASDAQ:LCID) continues to face significant financial pressure. The company has been pursuing an ambitious expansion strategy. However, its revenue growth has not yet been enough to offset substantial operating losses and the high costs ****** ociated with building its global factories.
#lcid #european #platform #partnership
7 days ago
For younger generations, the idea of living a life of leisure in retirement — playing golf, pursuing hobbies, going on bucket-list trips — seems increasingly out of reach.
At least one expert is saying they're right — and the new retirement plan is to "keep your job." Cultural historian Lawrence Samuel told Marketwatch he believes the modern idea of a leisurely retirement has come and gone.
Indeed, he says it's a powerful myth — just like the American dream. "But most Americans don't realize their American dream. The odds are against you," he told MarketWatch.
Jeff Bezos backs a platform that lets anyone invest in rental homes for as little as $100 — 6 ways to build wealth like a landlord without actually being one
Dave Ramsey warns nearly 50% of Americans are making 1 big Social Security mistake. Here's what it is and 3 simple steps to fix it ASAP
#like #cultural #lawrence

7 days ago
On September 17, shares of Marvell Technology, Inc. (NASDAQ:MRVL) and GLOBALFOUNDRIES Inc. (NASDAQ:GFS) moved sharply higher, with Marvell Technology, Inc. (NASDAQ:MRVL) gaining more than 4% and GLOBALFOUNDRIES Inc. (NASDAQ:GFS) rising more than 6% by the end of the trading session.
Reuters reported that the two companies have expanded their agreement to increase production capacity for silicon germanium (SiGe), a semiconductor technology used in high-speed optical connections for data centers. The multi-year agreement will expand capacity for GLOBALFOUNDRIES Inc.'s (NASDAQ:GFS) SiGe technology at its facility in Burlington, Vermont. SiGe allows semiconductor devices to operate at higher speeds while using less energy, making it increasingly important as data centers handle larger volumes of data.
Robb Johnson, Vice President, Foundry Technology at Marvell Technology, Inc. (NASDAQ:MRVL) said the expanded collaboration will help ensure that the company has the "SiGe technology and manufacturing capacity to support the significant growth" it expects ahead.
According to the report, the increased manufacturing capacity will help Marvell Technology, Inc. (NASDAQ:MRVL) meet growing demand for optical networking products, including pluggable optical transceivers, near-packaged optics, and co-packaged optics.
GlobalFoundries Is Seeing Strong SiGe Demand
#sige #globalfoundries #optical #data


7 days ago
For the past couple of decades, the so-called "American Dream" has followed a pretty linear pathway. You finish high school, go to a four-year university, and then graduate straight into a corporate office that comes with a slick 401(k).
That bachelor's degree was the golden ticket that made everything possible, and your parents probably told you that earning a diploma was critical to your success, right? Well, new labor market data has turned that decades-old playbook upside down.
Here's Another Little-Known Firm Jensen Huang's Nvidia Is Quietly Backing
MediaTek Is Stepping Up Competition Against Qualcomm With a New 2-Nanometer Chip. What This Means for QCOM Stock.
1 Year Into the Microsoft Deal, IREN Is Delivering and a Rally May Follow Soon
#firm #jensen
7 days ago
I'll admit that like many economists and market commentators, I have warned about more market calamities than have actually come to pass. I'll say this in my defense:
If you ignore risk, you take your chances with what the market does next. If you always seek to account for risk, you can ride the highs without being pummeled by all the lows. Over time, that's a more gratifying investment experience.
Here's Another Little-Known Firm Jensen Huang's Nvidia Is Quietly Backing
MediaTek Is Stepping Up Competition Against Qualcomm With a New 2-Nanometer Chip. What This Means for QCOM Stock.
1 Year Into the Microsoft Deal, IREN Is Delivering and a Rally May Follow Soon
#little


7 days ago
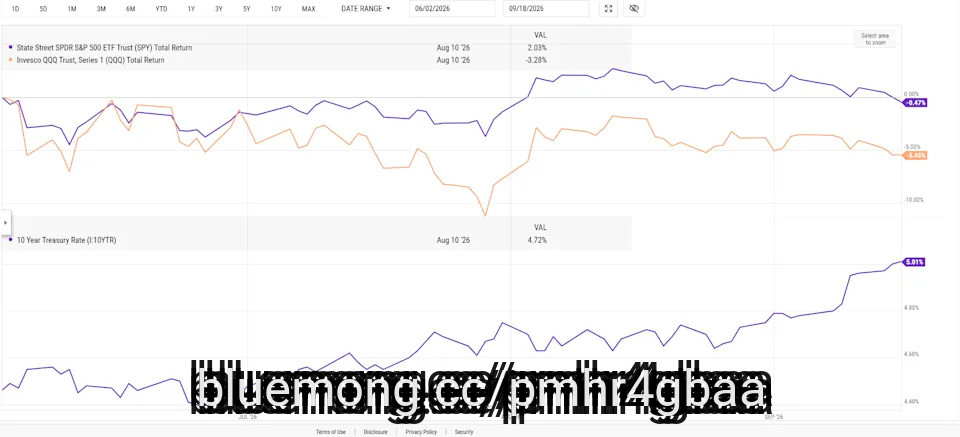
Just over a year ago, investors largely viewed IREN (IREN) as a bitcoin mining company. Today, the company supplies AI infrastructure to Microsoft (MSFT) and signs billion-dollar contracts with some of the biggest names in the AI market, including Nvidia (NVDA) and Dell Technologies (DELL). These developments provide evidence that IREN's shift toward AI infrastructure is translating into actual business activity, and the market has responded strongly to that progress. IREN shares have been rewarded with two strong moves over the last two months.
IREN's AI transformation centers on a major five-year agreement with Microsoft. The company entered into a $9.7 billion cloud services agreement with Microsoft, with 20% of the contract value paid upfront. Once fully commissioned, the deal is expected to generate nearly $1.94 billion in annualized run-rate revenue. That gives IREN a significant source of contracted business as it builds out its AI cloud operations.
Here's Another Little-Known Firm Jensen Huang's Nvidia Is Quietly Backing
MediaTek Is Stepping Up Competition Against Qualcomm With a New 2-Nanometer Chip. What This Means for QCOM Stock.
JPMorgan Changed Its Mind on Meta Stock After This Major AI Breakthrough
#NVIDIA

7 days ago
One of the top companies I'm keeping my eye on right now happens to be among the leading quantum computing companies in North America, and globally.
Shares of Infleqtion (INFQ) have been on a roller coaster ride lately, partly due to the volatility we've seen across this sector.
Here's Another Little-Known Firm Jensen Huang's Nvidia Is Quietly Backing
MediaTek Is Stepping Up Competition Against Qualcomm With a New 2-Nanometer Chip. What This Means for QCOM Stock.
'Even Though It's Bad for Berkshire' Billionaire Charlie Munger Said to Skip Insurance Because 'You're Paying for the Other Fellow's Frauds'
#shares #infleqtion #known #firm


7 days ago
Risk management is my number one priority. As I see it, you can't get where you want to be as an investor if you don't control the risk you take.
That ranges from the use of cash, incorporation of hedging techniques, and a whole lot more. Here, I want to draw your attention to one of the less research intensive aspects of risk management.
Here's Another Little-Known Firm Jensen Huang's Nvidia Is Quietly Backing
MediaTek Is Stepping Up Competition Against Qualcomm With a New 2-Nanometer Chip. What This Means for QCOM Stock.
1 Year Into the Microsoft Deal, IREN Is Delivering and a Rally May Follow Soon
#risk #known #jensen #quietly



7 days ago
With a market cap of $19.5 billion, Best Buy Co., Inc. (BBY) is a leading technology retailer focused on enriching lives through technology by combining tech expertise with personalized customer service. The company serves customers through its online platform, stores, and in-home services, addressing a wide range of everyday technology needs.
Companies valued at more than $10 billion are generally considered "large-cap" stocks, and Best Buy fits this criterion perfectly. Best Buy operates more than 1,000 stores across the United States and Canada and employs more than 85,000 people.
Here's Another Little-Known Firm Jensen Huang's Nvidia Is Quietly Backing
MediaTek Is Stepping Up Competition Against Qualcomm With a New 2-Nanometer Chip. What This Means for QCOM Stock.
1 Year Into the Microsoft Deal, IREN Is Delivering and a Rally May Follow Soon
#stores #known



7 days ago
On August 6, Aflac (NYSE:AFL) reported second-quarter numbers that point in opposite directions. Net earnings climbed to $825 million, helped along by investment losses that shrank to $153 million from $421 million a year ago. Adjusted earnings, though, fell 7.7% to $883 million. Both numbers are real, but they answer different questions. Which measure you trust changes the story, so here is what sits underneath.
Start with the yen, because it is muddying the picture. The average rate was 159.45 to the dollar, 9.3% weaker than a year earlier, and that cost adjusted earnings $0.05 a share. Take the currency out of the first half and adjusted earnings per share rose 4.1% to $3.57. ******* an is also running more profitably. Its pretax adjusted margin widened to 34.3% from 32.0% as claims took a smaller bite out of premiums, and yen-based pretax adjusted earnings rose 3.4%. So part of the decline in ******* an's dollar-reported profit is currency, not operations.
The US business is still growing at the top line. Net earned premiums rose 2.3% to $1.5 billion, and sales climbed 2.6% to $349 million, led by group voluntary benefits along with dental and vision plans. In ******* an, the refreshed Tsumitasu life policy and the new Anshin Palette medical product grew strongly in the quarter, and first-half sales rose 7.0% to ¥37.3 billion. Then there is the cash. Aflac returned $1.3 billion to shareholders in the quarter, $983 million of it through buybacks, and declared a $0.61 third-quarter dividend, payable September 1 to holders of record on August 19, 2026. Management notes 43 straight years of dividend increases through 2025 and says the board is on a path to extend that in 2026.
The catch is that ******* an's profit gains came from lower claims, not a bigger business. Net earned premiums in yen fell 3.7%, mainly because of a new external reinsurance deal and older limited-pay policies reaching paid-up status. Premium persistency, the share of policies customers keep, slipped to 92.7% from 93.7%. ******* an's pretax adjusted earnings still fell 2.1% once currency is stripped out, and new sales dipped 5.6% in the quarter against a tough comparison for the Miraito cancer product, which launched in March 2025.
The US segment has its own soft spot. Pretax adjusted earnings fell 4.6% to $370 million, and the margin narrowed to 20.9% from 22.5% as claims and benefits took a bigger share of premiums. Corporate and Other swung to a $10 million pretax adjusted loss from a $20 million gain a year earlier, with interest expense up 21.6% to $62 million. And adjusted book value per share, excluding foreign currency remeasurement, slid to $41.22 at June 30 from $42.97 a year earlier.
#earnings #fell
7 days ago
On the Sept. 3, 2026 episode of The Ramsey Show, a Houston caller named Nathan asked whether he should use his savings to clear a mortgage he described as a "whatever, 2% mortgage or something." He had about $280,000 left on it and roughly $346,000 in liquid ******* ets, most of it cash and the rest in a taxable brokerage account. Dave Ramsey told him to do it, and to do it that night.
Five months earlier, Ramsey had told a caller in almost the same position the opposite. On April 1, 2026, a web engineer earning around $600,000 a year called in about three weeks after being laid off, sitting on enough cash to clear a San Francisco, California mortgage. "When you're in the middle of a storm, you do temporary things," Ramsey said. "Hold on to the cash. We're not gonna pay off the house because we may not be staying in the house."
Here's Another Little-Known Firm Jensen Huang's Nvidia Is Quietly Backing
MediaTek Is Stepping Up Competition Against Qualcomm With a New 2-Nanometer Chip. What This Means for QCOM Stock.
1 Year Into the Microsoft Deal, IREN Is Delivering and a Rally May Follow Soon
#mortgage #told

7 days ago
Today, I'm kicking off a new risk management series here at Barchart called "Look Both Ways Before You Cross Wall Street."
Instead of hitting you with my topical trade ideas, I'll get a little more nitty-gritty and into the weeds – explaining the what, why, how, and the real risk/reward math you need to know as a DIY manager of your own wealth.
Here's Another Little-Known Firm Jensen Huang's Nvidia Is Quietly Backing
MediaTek Is Stepping Up Competition Against Qualcomm With a New 2-Nanometer Chip. What This Means for QCOM Stock.
1 Year Into the Microsoft Deal, IREN Is Delivering and a Rally May Follow Soon
#look

7 days ago
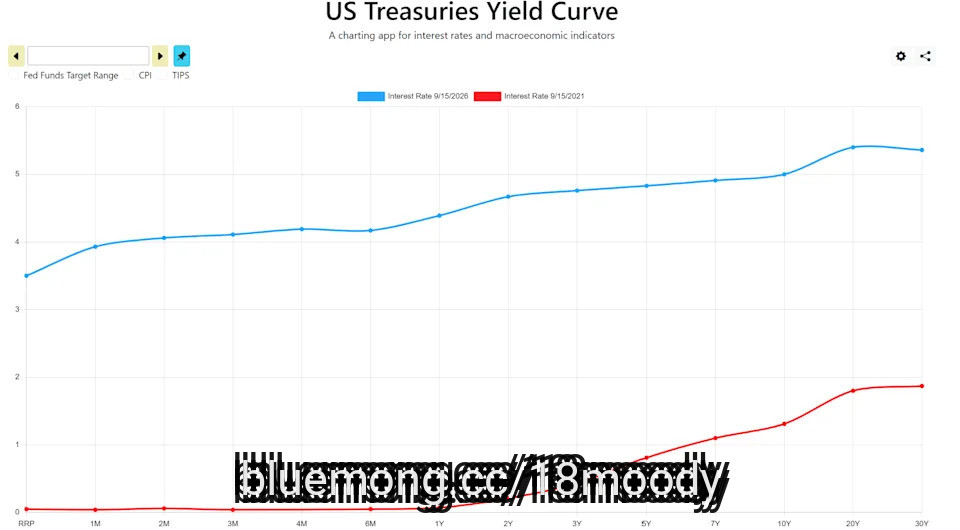
Huntington Bancshares Incorporated (NASDAQ:HBAN) dropped 5.55% to $15.82 on September 16, 2026, close to its 52-week low. The price movement was triggered by a profit warning at a Barclays conference. Huntington brought down its 2027 EPS guidance from above $1.90 to the range of $1.75-$1.83, and its 2026 net interest income growth from 39%-43% to roughly 35%. What matters more than these numbers is the reason behind them. Deposit costs are rising, and loan pricing is tightening, and it landed on the day the Fed delivered its first interest rate hike since 2023. The drop therefore raises the question: is this an oversold bank or the opening crack in regional-bank margins?
A well-run bank has just lowered its guidance, citing intense competition for deposits and loans. If Huntington feels the margin pressure, then it is likely that its peers feel the same. This explains why Fifth Third shares slid 4.1% on the same afternoon alongside the whole financials group. The Fed's new hike makes the environment more unfavorable for the group in the near term. While rate increases eventually lift ***** et yields, banks must immediately offer higher deposit yields to retain balances, squeezing net interest margins in the near term. Furthermore, accelerated commercial real estate loan payoffs reduced total earning ***** ets, though these early payoffs lower credit risk on the loan book.
The selloff leans too much into the reset. A move to $1.75-$1.83 from above $1.90 is a modest single-digit trim. Huntington sustains its profit as well as its operational performance. Loans reached $189 billion from $50 billion in 2015. Deposits touched $222 billion. And one of the company's biggest growth engines, value-added fee income, compounded at a 14% annual rate since mid-2024, with year-to-date growth near 32%. The income helps offset a notable portion of the spread pressure and offers a competitive edge against pure spread lenders.
A higher-for-longer rate environment carries trade-offs for commercial banks. It drives up deposit expenses, reflecting the margin pressure Huntington reported. It also expands loan yields as credit ***** ets reprice. Deposit beta determines the net effect by measuring how much of each benchmark rate increase the bank transfers to depositors. After the rate hikes, deposit costs typically rise further, so betting on a near-term peak takes some faith. A lower beta allows fee revenue to support earnings, whereas a higher beta keeps the squeeze sustained over multiple quarters.
#bank #interest #Growth
7 days ago
On September 9, 2026, Chewy, Inc. (NYSE:CHWY) reported fiscal second-quarter net sales of $3.33 billion, up 7.3% year over year, and adjusted earnings per share of $0.36, nearly double the roughly $0.18 ******* ysts had expected, prompting the company to raise its full-year revenue and profitability outlook. CEO Sumit Singh said the broader pet market did not meaningfully recover during the quarter but also did not deteriorate further, with Chewy continuing to outperform the category by two to three times through share gains across its established and newer businesses.
Chewy, Inc. (NYSE:CHWY)'s recurring revenue base is solid. It gives the company greater visibility into future sales. Autoship sales jumped by 9.3% year over year to $2.82 billion and represented 84.6% of total net sales. The growing contribution from subscription-based purchases gives Chewy a more predictable revenue stream and reduces its exposure to fluctuations in discretionary pet spending.
Chewy is also building growth engines beyond its core retail business. Chewy Health, which includes veterinary care and pharmacy services, delivered triple-digit revenue growth. Specialty categories such as equine and exotics recorded a seventh consecutive quarter of mid-double-digit growth. These businesses give Chewy additional opportunities to increase customer spending and diversify its sources of revenue as the overall pet market matures.
Chewy is combining customer growth with stronger profitability and shareholder returns. The firm added 208,000 net active customers during the quarter. It takes its customer base to 21.7 million while returning $200 million to shareholders through share repurchases. Management also noted structural SG&A leverage, automation, and AI-driven cost reductions as contributors to margin expansion. It shows that Chewy can improve earnings while investing in customer acquisition and growth.
Part of Chewy, Inc. (NYSE:CHWY)'s profitability improvement came from benefits that may not recur. CFO Chris Deppe said the quarter's profitability upside included about $10 million from timing benefits and more than $5 million from discrete benefits. Those items boosted the latest results but do not provide a recurring earnings contribution. It means investors may need to lower their expectations for the pace of margin expansion in future quarters.
#customer

7 days ago
Morgan Stanley has cut Novo Nordisk A/S (NYSE:NVO) to Underweight on September 11, 2026. Semaglutide, the underlying molecule for Wegovy and Ozempic, generates roughly 75% of 2026 revenue. Morgan Stanley models that it will still represent 59% of total sales when its patent protection expires in 2031. And according to the firm, the valuation does not price in the impact it has on Novo's terminal value. The stock, currently trading at 10.6x earnings and down 33% from its 52-week high, slipped another 2% following the call. At this point, the question isn't about whether the patent cliff is real or not, but whether the 10x multiple reflects an actual bargain.
Semaglutide loses exclusivity in Europe in 2031 and the US in 2032. And Morgan Stanley believes Novo's oral-obesity business, projected to reach $10 billion by 2031, could not offset the pricing collapse after the arrival of generics. Growth decelerates to a 4% compound rate between 2027 and 2030. If the deceleration continues, it will justify 10x earnings as a fair price instead of a cheap one.
The 10.6x multiple already prices aggressive pessimism into a market leader of one of the fastest-growing drug classes in history. Morgan Stanley fueled the pessimism by discounting a 2031 cliff five years earlier. However, pharmaceutical patent expirations frequently face extensions and prove difficult to time. Second, the ***** umption that oral obesity treatments cannot offset patent losses relies on oral semaglutide being the bridge. But Novo's next-generation portfolio, including CagriSema and amycretin, offers a significant defense against the patent cliff. This remains unproven, however, specifically after CagriSema's earlier weight-loss data failed to impress, yet Morgan Stanley's terminal-value model discounts this pipeline almost entirely. The company is also expanding its franchise. On September 7, the STEP Young trial hit its endpoint in children aged six to twelve, strengthening the base its successors inherit.
The smart money is leaning in. As per the Insider Monkey database, 59 hedge funds held NVO in the second quarter of 2026, up from 55 in the first, indicating a slight increase in the modest institutional interest in the stock. Short interest on the ADR is negligible at about 0.7%. The positioning reflects a beaten-down value stock quietly seeing institutional accumulation while Wall Street turns increasingly bearish.
#semaglutide #oral

7 days ago
On September 9, 2026, Jersey Mike's Subs Inc. (NYSE:JMKE) reported its first quarterly results as a public company, with total revenue up 10% year over year to $208 million and same-store sales accelerating to 2.3% growth from 1.7% in the prior quarter. It was primarily driven by transaction growth even as the restaurant industry faced weak traffic trends. Net income fell to $37 million from $59 million a year earlier. It showed non-routine expenses, advertising fund timing, and higher interest costs following the company's July initial public offering, partially offset by a $14 million gain on the sale of corporate-owned stores.
Jersey Mike's Subs Inc. (NYSE:JMKE) is gaining customers while its brand remains a major competitive advantage. The firm added 83 stores in the second quarter. It grew its customer base and increased systemwide sales 10% to $1.21 billion. Jersey Mike's also earned the No. 1 ranking among U.S. quick-service restaurant brands in the 2026 American Customer Satisfaction Index, surpassing Chick-fil-A after 11 consecutive years at the top. It gives the newly public company a strong foundation for continued customer and franchisee growth.
The business has substantial whitespace for long-term unit growth. Jersey Mike's ended the quarter with 3,378 locations and maintains a domestic development pipeline of more than 1,600 stores, with more than 90% of that pipeline coming from existing franchisees. Management estimates that the U.S. market could eventually support roughly 7,500 locations and sees potential to reach approximately 15,000 stores globally. It gives the business a long runway for franchise-led revenue and royalty growth.
Digital engagement and transaction growth give Jersey Mike's more avenues to increase sales. Digital sales represented 43% of systemwide sales in the second quarter, up from 41% a year earlier. Same-store sales increased 2.3% mainly because customers placed more transactions. Jersey Mike's also had more than 12.5 million active MyMike's loyalty members in 2025. It provides the company with a large customer database that it can use to increase frequency and personalize marketing as it expands.
Jersey Mike's Subs Inc. (NYSE:JMKE) still faces a significant profitability challenge despite its revenue growth. Second-quarter revenue jumped 10% to $208 million. However, net income fell 37% to $37 million from $59 million a year earlier. Management attributed part of the decline to advertising-fund timing and higher interest expense. It shows that revenue growth has not yet translated into comparable bottom-line growth for shareholders.
#million #customer

7 days ago
On September 4, 2026, the Wall Street Journal reported that Starbucks Corporation (NASDAQ:SBUX)' longtime chai latte devotees have turned against the company's reformulated recipe, introduced in March. It reduced sweetener and shifted from a pre-made concentrate to a new base with just two grams of sugar.
Customers have signed petitions, flooded Starbucks' corporate lines, and taken to Reddit and store review sites demanding the original formula back. Starbucks says the change gives customers more control over sweetness and has introduced new variations like Mango Cream Chai and Pumpkin Cream Chai.
Starbucks Corporation (NASDAQ:SBUX)' broader turnaround remains intact despite the backlash over its chai reformulation. Global comparable sales increased 7.9% in fiscal Q3, with comparable transactions rising 4.2%. The company raised its fiscal 2026 adjusted EPS guidance to $2.55-$2.65 from $2.25-$2.45. Stronger customer traffic and higher earnings give investors evidence that one unpopular menu change has not derailed the recovery.
The chai backlash appears concentrated among loyal customers of one product rather than across Starbucks' broader customer base. The business introduced the new chai formula as part of a personalization strategy. Customers can customize sweetness and other ingredients. If Starbucks keeps transaction growth across its wider menu, the business could improve its product economics without materially damaging overall customer demand.
Starbucks is improving profitability while it executes its turnaround. Non-GAAP operating margin expanded 430 basis points year over year to 14.4% in fiscal Q3, while North America revenue increased 7% to $7.4 billion. These results give investors evidence that the company can improve margins and sales even as it experiments with its menu and customer experience.
#customer
7 days ago
On September 9, 2026, Reuters reported that Alphabet Inc. (NASDAQ:GOOGL)'s Google will invest at least €13 billion, or about $15.1 billion, in AI infrastructure in Finland over the next two years, its biggest European investment, including three new data centers and a 22-year deal for up to 50% of the output of one of Finland's two nuclear power plants. The agreement with Finnish utility Fortum is Google's first nuclear energy deal outside the United States, and Fortum's stock jumped as much as 15.5% on the news, its biggest gain in Europe that day.
Finland gives Alphabet Inc. (NASDAQ:GOOGL) a potentially more cost-efficient location for its expanding AI infrastructure. Google plans to invest at least €13 billion ($15.1 billion) in three new data centers and related infrastructure in Finland during 2027 and 2028. The country's cold climate can reduce the need for energy-intensive cooling. The investment will also help grid improvements, clean-energy projects and battery storage.
The 22-year nuclear power agreement gives Google greater control over a critical input for AI infrastructure. Google will purchase up to 50% of the electricity generated by Finland's Loviisa nuclear plant, providing a long-term source of low-carbon power for its data-center operations. The agreement also gives Fortum greater economic certainty to extend and upgrade the plant through 2050. Google and Fortum plan to explore more nuclear and renewable projects.
Alphabet has strong demand drivers that can justify investment in AI capacity. The firm has increased its 2026 global capital investment target to $195 billion-$205 billion as it seeks to capture growing AI computing demand. Google is using the additional infrastructure to support Gemini, Search, Maps, and YouTube. It gives Alphabet multiple major products through which it can monetize greater AI capacity over time.
The Finland project adds another major commitment to Alphabet Inc. (NASDAQ:GOOGL)'s already enormous AI spending program. Alphabet expects to spend $195 billion-$205 billion on capital investment globally in 2026. The Finnish project will require at least another €13 billion during 2027 and 2028. Investors need Alphabet to make enough incremental revenue and cash flow from AI services to justify an infrastructure buildout that is rapidly increasing the company's capital requirements.
#billion #Google #investment #googl
7 days ago
On September 8, 2026, Reuters reported that Paramount Skydance Corporation (NASDAQ:PSKY) said California Attorney General Rob Bonta made television statements that contradict his own legal arguments against Paramount's request for a $1.88 billion bond in the ongoing court fight over its roughly $110 billion acquisition of Warner Bros. Discovery, Inc. (NASDAQ:WBD).
Bonta's office has argued the bond is unnecessary because Paramount voluntarily agreed to pause the deal's closing rather than wait for a court injunction. But Paramount described that same pause as equivalent to an injunction in media interviews, which it argues legally requires the states to post a bond under antitrust law. A hearing is scheduled for September 24.
Paramount Skydance Corporation (NASDAQ:PSKY) could protect a significant portion of its financial position if the court grants its $1.88 billion bond request. Paramount says the delay could cost it about $1.3 billion in fees to Warner Bros. Discovery shareholders by the time the case concludes in April 2027. A bond would give Paramount a potential path to recover those losses if it ultimately defeats the states' challenge. It reduces the financial damage from a prolonged legal process.
Warner Bros. Discovery, Inc. (NASDAQ:WBD) is receiving financial protection from the transaction's delay through Paramount's ticking fees. Paramount agreed to pay WBD shareholders approximately $7 million per day starting October 1 if the transaction does not close, creating a growing payment obligation for Paramount. It is also providing WBD shareholders with compensation for waiting. The arrangement gives WBD a financial benefit from the prolonged closing process even as the companies await a final legal resolution.
The legal dispute has not eliminated the strategic rationale for combining the two media companies. Paramount argues that the merger would strengthen the film and television industry and lead to more content while giving the combined company greater scale to compete with Netflix and Disney. For Paramount, completing the acquisition would speed up David Ellison's plan to build a larger media competitor. WBD shareholders would receive the transaction consideration rather than remain exposed to the company's standalone turnaround.
#paramount

7 days ago
On September 9, 2026, Reuters reported that CEO Brian Niccol's first two years as Starbucks Corporation (NASDAQ:SBUX) CEO have succeeded in bringing customers back to the coffee chain. Comparable sales rose 7.9% in the fiscal third quarter for a fourth straight quarter of improvement, but his "Back to Starbucks" restructuring has raised costs and squeezed margins along the way. Global operating margin has fallen to 12.9% from 15.8% two years earlier. Niccol, who marks his second anniversary in the role, now faces pressure to convert the sales recovery into the sustainable profit growth investors are demanding.
Niccol's turnaround strategy has already restored customer momentum at Starbucks Corporation (NASDAQ:SBUX). The "Back to Starbucks" strategy reversed six consecutive quarters of declining comparable sales as the company focused on reducing wait times, simplifying menus, improving store ambiance, and increasing staffing. Starbucks has moved beyond the sales deterioration that preceded Niccol's tenure. It gives investors a stronger foundation for the next phase of the turnaround. If management can sustain traffic gains while improving productivity, the sales recovery could provide a path toward stronger earnings growth.
The China joint venture with Boyu Capital gives Starbucks a more capital-efficient way to participate in China's growth. Starbucks sold control of its China retail operations to Boyu. It retained a 40% stake and continues to own and license its brand and intellectual property. The structure reduces Starbucks' direct capital requirements while allowing it to retain economic exposure to the Chinese market. Reuters cited ****** ysts who said the arrangement leaves Starbucks well positioned to convert stronger organic sales growth into profit growth, which could support returns as the recovery progresses.
Starbucks now has an opportunity to turn its customer investments into margin expansion. The firm committed at least $500 million toward labor as part of the restructuring. Niccol prioritized staffing and store improvements to rebuild the customer experience. That spending helped help the sales recovery. But it also pushed global operating margins down to 12.9% from 15.8% over two years. With sales now improving, management can focus more heavily on productivity, cost control, and operating leverage. It creates an opportunity for stronger earnings if it can improve margins without damaging customer traffic.
Labor tensions could undermine Starbucks Corporation (NASDAQ:SBUX)' recovery and keep costs elevated. Starbucks has yet to reach a first contract with its U.S. barista union. The union called for a consumer boycott in August. Negotiations or labor actions could disrupt store operations, increase labor costs, and create reputational pressure just as Starbucks tries to improve profitability. Therefore, investors face a risk that labor issues could offset some of the productivity gains management needs to expand margins.
#

7 days ago
Former President Obama on Friday slammed President Trump over his handling of how to approach artificial intelligence amid “doomsday” warnings coming from some in the tech industry about the technology’s potential existential threat to humanity.
Obama said during an interview at Colgate University in New York that the federal government must regulate AI, before referring to comments made by one Trump adviser.
“I heard one of Donald Trump’s main advisers on this make the argument that, ‘The market will take care of AI,'” the former president said. “‘These companies will solve the safety issues because they have every incentive to do so — if it turns out to be dangerous, people will just sue them, and they’re worried about financial liability.'”
“That’s not how we treat airlines,” Obama added. “Or drug companies, or food companies.”
Obama continued to say that AI could become a threat at a human level if it falls into the clutches of “bad humans” and if self-improving AI models realize they no longer need humans. He referred to Trump again in that his successor has said regulations on AI are “for losers.”
#obama #president #university

7 days ago
Trip.com Group Limited (NASDAQ:TCOM) reported second-quarter 2026 net revenue of RMB15.7 billion, up 6% year over year, in results released September 15. Revenue on its international platform increased more than 50%, highlighting a promising source of expansion against slower group growth.
Trip.com Group Limited (NASDAQ:TCOM) also recognized a RMB5.2 billion antimonopoly penalty in general and administrative expenses. The investment question extends beyond that charge: can international expansion generate enough profitable growth to offset pressure on domestic monetization?
International expansion gives Trip.com Group Limited (NASDAQ:TCOM) a potential route to reducing dependence on revenue earned from domestic travel. A broader customer base could make growth less reliant on a single market's commercial practices and regulatory environment.
The opportunity is especially attractive if new customers become repeat users. Over time, repeat bookings could reduce acquisition spending per transaction and allow technology and service costs to be spread across more revenue. That would turn international scale into operating leverage, with profits growing faster than sales.
Trip.com Group Limited (NASDAQ:TCOM) also grew accommodation revenue 6% year over year despite a regulator-imposed revenue reduction. That result offers some evidence of resilience, although reservation growth and the revenue earned from those reservations remain separate considerations.
#NASDAQ

7 days ago
Though it's down by 33% over the last five years, Ethereum (CRYPTO: ETH) climbed from about $130 in early 2020 to over $4,800 in early November 2021, which would have been sufficient to turn an investment of $27,000 into about $1 million. It's natural for investors to wonder if another historic run is in the cards for the coin, given that it's more widely known now than it was then.
Today, with a market cap of $292 billion as of Sept. 15, Ethereum can still grow your wealth substantially, but it probably won't be a millionaire maker for those with small positions anytime soon. Let's first look at the math to see why, then examine its upcoming catalysts.
Missed AI's "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our **** ysts, we're only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
Ethereum isn't going to be a millionaire-maker investment from here, even if you're willing to pony up a lot more capital than most investors have on hand or are willing to allocate to a lottery ticket, and even if it becomes the next cryptocurrency to explode.
Turning $10,000 into $1 million requires a 100x gain, which would boost Ethereum's market cap to $29.2 trillion.
#even

7 days ago
Sen. John Barrasso, R-Wyo., on Sunday downplayed concerns that President Donald Trump may have violated the Constitution when reporters from Politico, MS NOW and CNN were banned from covering the White House on Saturday.
Asked directly whether the president had violated the Constitution, Barrasso said, “No, I believe the press has an obligation to report fairly.”
Pressed again on whether he agreed with Trump’s ban, Barrasso said, “We all respect and value the freedom of the press — it’s in the Constitution.”
“He was banned from Twitter. He was banned from Facebook, and I didn’t see people come to his defense,” the Wyoming senator told NBC News’ “Meet the Press.” “So it goes both ways. The press has an obligation to report fairly, and the president doesn’t see it happening that way.”
Pressed on whether the president’s decision to ban the reporters from White House coverage violated the First Amendment, Barrasso demurred, saying again, “I believe the press has an obligation to report fairly.”
#president #violated


7 days ago
Phillips 66 (NYSE:PSX) has been on a strong rally this year, posting gains of over 110% since the beginning of 2026. The outperformance has been driven by an unusually sharp surge in global refining margins amid the war in the Middle East, which has significantly tightened the world's refining capacity and reduced supplies of gasoline, diesel, and jet fuel.
Given Phillips 66's substantial outperformance compared to the wider market, investors may be questioning whether the stock's record-setting run has reached its peak. However, the ****** ysts over at BMO Capital see further upside ahead. On September 17, the firm raised its price target on PSX from $260 to $310, while maintaining an 'Outperform' rating on the shares. The target boost implies an upside of 13% from the current levels and even exceeds the stock's all-time high of over $274 achieved earlier this month.
BMO Capital highlighted Phillips 66's integrated business model, noting that it has gained momentum and outperformed its individual segments, supported by strong execution across the portfolio. While Refining and Renewables remain the cyclical leaders, BMO also sees a favorable medium-term growth outlook for the company's Midstream business.
BMO Capital's vote of confidence comes amid a broader optimism surrounding Phillips 66, with ****** ysts from Morgan Stanley, Raymon James, UBS, and several others also improving their respective outlooks on PSX. This suggests that Wall Street expects the ongoing refining upcycle to last longer than previously expected, particularly following the renewed escalations between Iran and the United States.
The supply disruptions now extend beyond the troubled region, as a recent wave of Ukrainian attacks on Russian refineries has further reduced global refining capacity and provided further support to margins.
#further #margins #amid
7 days ago
Veteran ******* yst Jim Cramer sees something in Apple's (AAPL) latest launch that is more than a reason for its customers to buy another replacement phone.
After visiting Apple's Manhattan store, the CNBC host praised the iPhone 18 but reserved his strongest enthusiasm for the foldable Duo. He plans to buy it as a second phone, a distinction that gives his excitement an intriguing business angle.
Apple shares have already gained around 23.6% this year through September 18, raising the stakes for turning product excitement into sales.
For context, Apple unveiled its iPhone 18 Pro lineup and first foldable iPhone on September 9. The Pro models reached stores on September 18; Duo availability follows on October 23.
For Cramer, the bigger opportunity goes beyond better cameras and battery life. His reaction suggests Apple could give loyal customers a fresh reason to spend, even when their existing phones still work perfectly well.
#reason #phone #veteran

7 days ago
Apple's (NASDAQ: AAPL) new iPhones are here, and this could be just the ticket to get the consumer tech ******* an back on top of the market cap throne. It doesn't have far to go to get there.
The stock's recent gains now place it within 2% of hitting a market cap of $5 trillion. Perhaps even more intriguingly, Apple is now less than 10% away from overtaking Nvidia (NASDAQ: NVDA) to become the market's most valuable company by market capitalization.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Apple's business isn't growing as quickly as Nvidia's these days, but it is closing the gap in market cap. Nvidia investors can't feel too bad, with the stock up 26% over the past year. It's just that Apple stock has soared by more than 40% in that time. Momentum is on its side, and that's before a bar-raising device hits the market.
For more than a dozen years, Apple has fallen into a predictable pattern. It delivers double-digit revenue growth in a fiscal year in which it rolls out a revolutionary iPhone model. Then it follows that with two -- and lately more than two -- years of single-digit or negative top-line growth, settling for merely evolutionary smartphone updates.
#NASDAQ
7 days ago
As a Californian, I can say this: If there are two industries that residents of the Golden State really don't like, it's insurance providers and utilities.
Interestingly, with the state considering wildfire reform legislation, those industries are at odds with one another. That's material for investors considering stocks such as PG&E (NYSE: PCG). The company known to California customers as Pacific Gas & Electric is one of the four major investor-owned utilities in the state, and due to the state having some of the highest utility rates in the U.S., PG&E and friends don't have a lot of fans in the state.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Of course, investing isn't a popularity contest. There are plenty of stocks that are often vilified in the court of public opinion that also deliver compelling returns. This year, oil equities certainly check that box. But the biggest risk to prospective PG&E investors isn't how Californians feel about the utility. It's the goings-on in Sacramento.
For those who are new to utility stocks, the primary reasons investors have embraced this sector over the years are above-average dividend yields, below-average risk profiles, and, more recently, inroads to the artificial intelligence (AI) trade.
#state #signal
7 days ago
It's been a disappointing couple of years for shareholders of biotechnology outfit CRISPR Therapeutics (NASDAQ: CRSP). This stock's barely up since the end of 2022, lagging the broad market's gains. It's not the performance that investors keeping tabs on this company were expecting, given its potential.
Don't be discouraged, though. While still speculative like most young biotech names, CRISPR Therapeutics remains a compelling prospect for investors who can stomach the risk and its inevitable volatility. Here's why.
Missed AI's "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our **** ysts, we're only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
On the off-chance you're reading this and aren't already familiar with the company, CRISPR Therapeutics is a drug developer that specializes in gene editing.
It's probably an area you've heard a great deal about. No gene-editing drugs were actually on the market in the United States until CRISPR Therapeutics' Casgevy was approved by the FDA as a treatment for sickle cell disease in late 2023. Any and all gene therapies currently on the market followed this pioneer's foray. Being first is a well-deserved accolade for the company, too, which was co-founded by Dr. Emmanuelle Charpentier, who was one of the co-discoverers of the CRISPR/Cas9 gene-editing mechanism that makes Casgevy work.
#crispr #gene #company
7 days ago
Targa Resources Corp. (NYSE:TRGP) has significantly outperformed the wider market this year, posting gains of over 56% since the beginning of 2026. A major catalyst behind this growth was the 20-year fee-based agreement that the company signed with ExxonMobil last month.
While there are concerns that the stock's rally may have topped out, the **** ysts over at TD Cowen see further growth ahead. On September 18, the firm upgraded TRGP from 'Hold' to Buy', while also boosting its price target from $275 to $350. The revised target implies an upside of almost 20% from the current levels and even exceeds the stock's record high of just under $308 achieved last month.
TD Cowen cited Targa's expected Permian Basin wet gas growth and peer-leading EBITDA growth for the upgrade. The **** yst expects the company's free cash flow yield to rise from 6% in 2026 to more than 10% in 2028, compared with an estimated 8.5% FCF yield for peers in 2030. The improvement is expected to be driven by EBITDA growth from new processing plants and the completion of a major capital project in the Speedway NGL pipeline.
According to TD Cowen, a key driver for Targa's growth is the rising wet gas production in the Permian, which means that the **** yst's thesis is tied to physical volume growth rather than simply a higher-commodity price **** umption.
Targa's recently announced deal with ExxonMobil provides greater visibility into future volumes and infrastructure demand. The company has also planned three new natural gas processing plants in the Permian Delaware as part of the deal, with an aggregate capacity of roughly 825 MMcf/day. Targa expects this agreement to add significantly to its "strong growth rate well into the next decade and bolster its outlook for durable and growing adjusted free cash flow over the long term".
#exxonmobil #ebitda