1 day ago
Pfizer (NYSE: PFE) is offering a dividend yield of roughly 6% today. That is well above the roughly 1% yield on offer from the S&P 500 index (SNPINDEX: ^GSPC) and the 1.4% average yield of pharmaceutical stocks. There are good reasons for the negative view of Pfizer, but investors may be ignoring the company's over 100-year history of success. Here's why you may want to consider buying this out-of-favor dividend stock while others are fearful.
Pfizer's stock rocketed higher during the coronavirus pandemic, as investors myopically focused on the company's COVID vaccine. When COVID turned out to be a less serious long-term threat than originally believed, Wall Street dumped Pfizer. At this point, the stock is down more than 50% from its 2021 high. That is a big part of the story behind the high yield.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
However, there's another piece that is more fundamental to the pharmaceutical industry. Like all drug makers, Pfizer's drugs receive time-limited patent protections. When patents expire, generic versions of the medications can be produced. That generally leads to a dramatic decline in revenue from Pfizer's drugs. Right now, Pfizer is facing down some notable patent expirations. This is a completely normal dynamic in the pharmaceutical sector.
Patent expirations are why drug companies are always on the lookout for new drugs. The problem is that patent expirations follow a set schedule, but drug development does not. Pfizer's drug pipeline isn't producing major new drugs right now, and it looks like it may have to work through a period in which new drugs won't fully offset revenue lost to patent expirations. This isn't uncommon, either, but investors are likely focusing on the short term rather than the long term when it comes to Pfizer.
#patent #yield #drug #expirations
3 days ago
Procter & Gamble has raised its dividend for 70 straight years while Johnson & Johnson covers its roughly $12.6 billion dividend run rate 1.56 times with free cash flow.
Coca-Cola posted its strongest Trademark volume growth in 17 years, and ADP's operating cash flow covers its dividend more than twice over while still funding buybacks.
Lowe's carries the lowest payout ratio in the group at 41% and trades at just 15 times earnings after falling 24% year to date.
Read More: Learn 7 ways to generate income with a $1,000,000+ portfolio (sponsor)
Yield is relatively easy to find. A dividend that keeps arriving through recessions, patent cliffs and housing slumps is much harder to find, and that kind of reliability is the hook for this group. Every name below covers its payout with real cash flow, has a long record of raises and keeps its payout ratio at a level that leaves room for mistakes. Procter & Gamble (NYSE:PG) sets the standard: management says its latest increase marks the 70th consecutive year of dividend increases and 136th consecutive year of dividend payments, putting it firmly in the Dividend Kings club (we ranked ten of them by valuation in a free report here). The other four pair long dividend records with cash flow that covers the payout.
#cash #year #procter #gamble
5 days ago
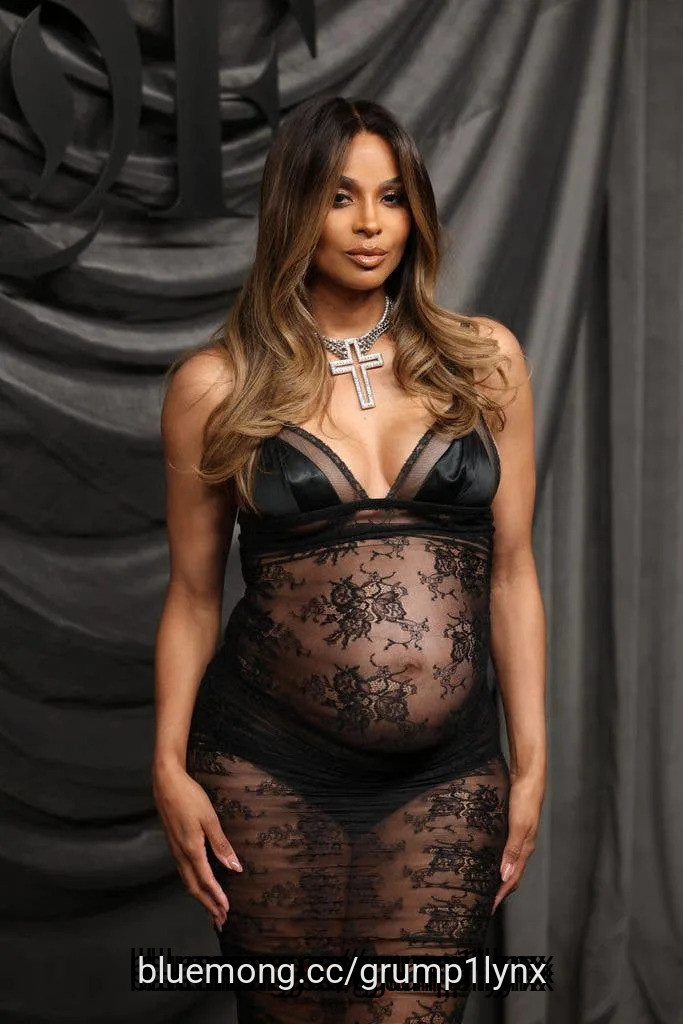
Ciara showcased her growing baby ******* p in a sheer black lace dress at the BoF 500 gala in Paris, following a surprise appearance on the runway earlier that day.
The singer, 40, chose a fitted design with a plunging neckline and delicate straps for the October 3 celebration, revealing her ******* p beneath the floral lace. Her evening appearance followed a turn modelling Junya Watanabe's spring/summer 2027 collection during Paris Fashion Week.
Ciara's dress featured black satin bra panels and matching briefs beneath its transparent fabric, with gathered detailing around the waist and hips.
Ciara stuns in naked lace dress (@ Getty Images for The Business of)
The lace skirt fell below her knees, leaving her pointed black patent heels on display. An oversized sparkling cross pendant, layered chains and a statement ring completed the look.
#lace #black #beneath #october



19 days ago
Morgan Stanley has cut Novo Nordisk A/S (NYSE:NVO) to Underweight on September 11, 2026. Semaglutide, the underlying molecule for Wegovy and Ozempic, generates roughly 75% of 2026 revenue. Morgan Stanley models that it will still represent 59% of total sales when its patent protection expires in 2031. And according to the firm, the valuation does not price in the impact it has on Novo's terminal value. The stock, currently trading at 10.6x earnings and down 33% from its 52-week high, slipped another 2% following the call. At this point, the question isn't about whether the patent cliff is real or not, but whether the 10x multiple reflects an actual bargain.
Semaglutide loses exclusivity in Europe in 2031 and the US in 2032. And Morgan Stanley believes Novo's oral-obesity business, projected to reach $10 billion by 2031, could not offset the pricing collapse after the arrival of generics. Growth decelerates to a 4% compound rate between 2027 and 2030. If the deceleration continues, it will justify 10x earnings as a fair price instead of a cheap one.
The 10.6x multiple already prices aggressive pessimism into a market leader of one of the fastest-growing drug classes in history. Morgan Stanley fueled the pessimism by discounting a 2031 cliff five years earlier. However, pharmaceutical patent expirations frequently face extensions and prove difficult to time. Second, the ***** umption that oral obesity treatments cannot offset patent losses relies on oral semaglutide being the bridge. But Novo's next-generation portfolio, including CagriSema and amycretin, offers a significant defense against the patent cliff. This remains unproven, however, specifically after CagriSema's earlier weight-loss data failed to impress, yet Morgan Stanley's terminal-value model discounts this pipeline almost entirely. The company is also expanding its franchise. On September 7, the STEP Young trial hit its endpoint in children aged six to twelve, strengthening the base its successors inherit.
The smart money is leaning in. As per the Insider Monkey database, 59 hedge funds held NVO in the second quarter of 2026, up from 55 in the first, indicating a slight increase in the modest institutional interest in the stock. Short interest on the ADR is negligible at about 0.7%. The positioning reflects a beaten-down value stock quietly seeing institutional accumulation while Wall Street turns increasingly bearish.
#semaglutide #oral


19 days ago
Morgan Stanley met privately with Gilead Sciences (GILD) leadership at its 2026 Global Healthcare Conference this month, and the feedback strengthened the bank's positive view on the stock.
Morgan Stanley's biopharma team hosted a meeting and a management dinner with Gilead Chairman and CEO Daniel O'Day and Chief Commercial and Corporate Affairs Officer Johanna Mercier. According to a Morgan Stanley research note shared with me, the discussion reinforced its Overweight rating on Gilead and singled out one franchise as the biggest reason to stay positive.
Gilead trades around $150.89, up about 24% year to date and roughly 111% over five years. That kind of run in a biotech stock usually needs a catalyst, and Morgan Stanley points to HIV prevention. The bigger question for investors now is whether the new HIV prevention business built around Yeztugo can keep growing at the pace of the last few quarters.
Terence Flynn, a Morgan Stanley equity **** yst who covers Gilead and other healthcare stocks has held an Overweight rating on the stock since January 2025.
According to the note, Gilead management described the company as being at "an important inflection point, supported by what it views as the most robust portfolio in the company's history," with no patent expiring until 2036.
#gilead #healthcare #management #note
19 days ago
On September 17, Ferrari N.V. (NYSE:RACE) announced a partnership with the technology company Rakuten Group, Inc., effective January 1, 2027. The announcement gives no scope and no price tag, so it works better as a signal than as a number. The real substance sits in the results Ferrari posted on July 30, when it raised its 2026 guidance because buyers are ordering more personalization than the company expected.
In the second quarter, revenue rose 8%, but operating profit rose 10%, which means each euro of sales is leaving more behind. Ferrari credits a richer mix of cars, with the F80 helping, along with more buyers paying up for personalization. Strip out currency swings, and the gap widens, with revenue up 11% and operating profit up 16%. Deliveries of the Purosangue and the 296 Speciale family grew even in the middle of a planned model changeover.
Cash and demand back that up. Industrial free cash flow jumped 39% to €276 million, and Ferrari also returned more than €800 million to shareholders through a dividend and buybacks. Racing helped too, as higher sponsorships and engine rentals to other Formula 1 teams lifted revenue. Meanwhile, the order book covers 2027 in full, and the new 12Cilindri Manuale is already fully allocated, which is about as strong a demand signal as a carmaker can send. Those trends are why revenue guidance moved up to about €7.60 billion from about €7.50 billion.
Part of the strength is timing. Operating profit got a boost from temporarily lower depreciation and amortization while Ferrari swaps out models, and the company says those charges will climb once the new cars enter production. Net profit also leaned on a 23.0% tax rate, which reflects an estimated benefit from the new Patent Box. Neither says much about how profitable the cars themselves are.
Costs are climbing too. Higher industrial and marketing expenses weighed on operating profit, EBITDA margin slipped to 39.0% from 39.7% a year earlier, and management expects heavier brand, racing and digital spending for the year. Currency is a drag as well, mostly from the dollar and the yen, which is why 11% growth at constant currency shrank to 8% as reported. Deliveries totaled 3,366 cars while the 296 GTS, Roma Spider and SF90 XX family wound down, and sponsorship, commercial and brand revenue grew just 2%. And the whole outlook leans on current visibility into the Middle East crisis, which Ferrari cannot control.
#Ferrari
20 days ago
Merck (MRK) stock returned about 87% over the past twelve months, climbing from roughly $79 to about $147. Nothing in the year's results looks like that. The medicines Merck sells today grew at their usual pace. Investors spent the year repricing what comes next.
Revenue over the trailing twelve months was $66.6 billion, up 4.6% and in line with its own three-year pace. Profitability did not follow. Its operating margin over the same twelve months was 10.5%, versus a three-year average of 22.4%.
Most of that gap is one purchase. Merck took a $5.7 billion charge in the second quarter of 2026, about 9% of a year's sales. It bought Terns Pharmaceuticals, and with it MK-4208, a candidate for chronic myeloid leukemia. The bill hits earnings now and the medicine arrives later.
The proof matters because of the risk hanging over this stock. The KEYTRUDA family was just over half of Merck's revenue in the second quarter of 2026. The company is openly planning for the end of that exclusivity when Keytruda loses primary U.S. patent protection in 2028. Management describes the stretch as more of a hill than a cliff, with a shallow dip and a fast return to growth.
Johnson & Johnson (JNJ) returned 56% over the same twelve months and Pfizer (PFE) 23%, so a good year for pharmaceuticals explains some of this but not Merck's lead. What separated Merck was evidence. The FDA approved LIPFENDRA, the first and only oral PCSK9 inhibitor. In the CORALreef Lipids trial it lowered LDL cholesterol by up to 60% when added to a statin.
#year #johnson

20 days ago
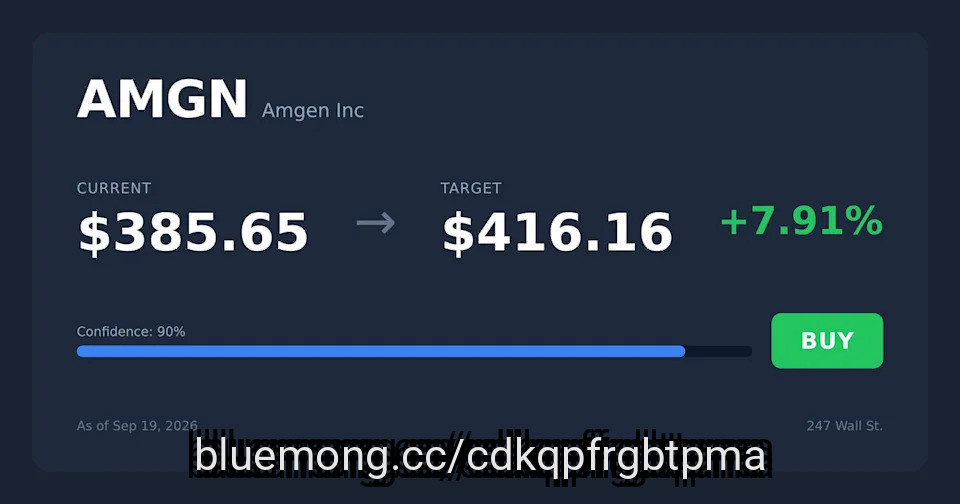
Amgen (AMGN) yields 2.6% with a $10.08 annualized payout, topping Merck (MRK) at 2.29%, and has raised its dividend 6% annually versus Merck's smaller step-ups.
Amgen's 17 billion-dollar products and $3.5B quarterly free cash flow dwarf Merck's reliance on a single Keytruda franchise facing peak penetration.
Merck absorbed a $5.7B acquisition charge that pushed Q2 earnings to a loss, while Amgen raised 2026 EPS guidance to as high as $23.50.
Just released. Our ***** ysts combed the entire stock market and named the ten best stocks to buy right now, and Merck didn't make the cut. Enter your email to see the names that beat MRK. The report is free. Enter your email and see if any of your stocks made the cut.
For a retirement portfolio that leans on pharma dividends, the choice between Amgen (NASDAQ:AMGN) and Merck (NYSE:MRK) comes down to one question: which check is more likely to keep getting bigger through the next wave of patent expirations? Both companies deliver quarterly income today. Only one has the coverage, the growth cadence, and the portfolio breadth to keep raising through the cliff.
#merck #amgen

22 days ago
Wolfe Research upgraded two prominent pharmaceutical companies to Outperform on August 13. The firm upgraded both Biogen Inc. (NASDAQ:BIIB) and AbbVie Inc. (NYSE:ABBV)'s ratings from Peer Perform, with Wolfe ***** igning them similar $300 price targets. The firm's logic in each case was based on a comparable set of factors: pipelines that the market appears to undervalue, and valuations that Wolfe believes are too low given each company's growth track.
Wolfe's thesis for Biogen Inc. (NASDAQ:BIIB) is mainly based on late-stage clinical programs, which it believes the stock has yet to reflect. The firm focused on two experimental therapies in particular, both of which have key late-stage clinical readouts expected over the coming year: litifilimab, which Wolfe believes could be the first biologic approved for cutaneous lupus erythematosus, and felzartamab, which the firm claims represents a bigger commercial opportunity in antibody-mediated transplant rejection than Wall Street currently thinks.
Wolfe also cited Biogen's acquisition of Apellis Pharmaceuticals as strengthening its near-term revenue base through the FDA-approved drugs Empaveli and Syfovre. That move is part of an overall pattern of Biogen Inc. (NASDAQ:BIIB) diversifying beyond its core neurology brand, with the company completing its acquisition of RayThera on August 6, adding another early-stage immunology platform to its pipeline.
Wolfe's Biogen Inc. (NASDAQ:BIIB) thesis is incomplete without valuation. The firm believes the stock is trading at a discount to the broader market, despite the company's development on Leqembi, its Alzheimer's medication, and what Wolfe described as solid commercial execution overall.
AbbVie's upgrade is based on a slightly different premise: patent strength and cash generation rather than simple clinical events. Wolfe stated that AbbVie's 2027 earnings multiple of 14.6x seemed too low for a company that forecasts high-single-digit revenue growth for the rest of the decade. AbbVie's patent position, according to Wolfe, sets the company apart from its competitors in a way that the market has yet to completely price in.
#wolfe #firm #market #clinical

23 days ago
When it comes to long-term success with dividend investing, you need to focus on criteria beyond just yield. While some high yield dividend stocks can be worth the risk, there are plenty that are trading at a high yield for a good reason.
That is, either they are at risk of cutting or suspending their payouts, and/or other risks may lead to stock price declines that outweigh the returns generated by their large payouts. So, instead of focusing on yield alone, consider criteria such as dividend coverage and dividend growth, along with metrics like valuation.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Taking all of these into account, three blue chip dividend stocks stand out as strong, dare I say, "no brainer," buys right now: AbbVie (NYSE: ABBV), Realty Income (NYSE: O), and Procter & Gamble (NYSE: PG).
Several years ago, uncertainty ran high about AbbVie, mostly due to concerns about the impact of losing patent exclusivity for its flagship drug product, the rheumatoid arthritis treatment Humira. Yet while this did hurt AbbVie's revenue and earnings after exclusivity ended in 2023, the company has staged a comeback, largely thanks to the success of the anti-inflammatory drugs Skyrizi and Rinvoq.
#NYSE #abbvie #flashing

23 days ago
Novo Nordisk A/S (NYSE:NVO)'s decision to rebrand its day-to-day identity as "Novo" and launch a cultural reset is primarily a strategic response to the company's loss of momentum in the obesity-drug market, rather than a financial restructuring in itself. Reuters reports that the company is trying to regain competitiveness as pressure from Eli Lilly intensifies. The move comes as Novo prepares to unveil new strategic ambitions at its September 21 Capital Markets Day, making the cultural reset potentially important if it leads to faster decision-making, stronger commercial execution and a more aggressive R&D approach.
The underlying business still has substantial scale to protect. Novo generated DKK 309.1 billion of 2025 sales and DKK 127.7 billion of operating profit, while obesity-care sales rose 31% at constant exchange rates to DKK 82.3 billion. However, the company also spent around DKK 8 billion on its transformation in 2025, and its diabetes value-market share fell 3.6 percentage points to 30.1%. The reset therefore comes at a critical point: Novo remains the global obesity-market leader, with a 59.6% branded-volume share in 2025, but Lilly is rapidly narrowing the competitive gap.
A successful cultural reset could improve Novo Nordisk A/S (NYSE:NVO)'s execution at a time when the company needs to convert its scientific and commercial ******* ets into faster growth. Reuters reported that CEO Mike Doustdar is already seeking to accelerate R&D and streamline decision-making following investor concerns about the pipeline and competition from Lilly. If the reorganization reduces internal bureaucracy and improves the speed of clinical, regulatory and commercial decisions, it could help Novo extract more value from its existing obesity portfolio while advancing next-generation treatments before the semaglutide patent cliff expected early next decade.
The company also has ******* ets that give a cultural and operational reset something concrete to build around. Wegovy was available in 52 countries by the end of 2025, while the company's higher-dose Wegovy achieved 20.7% weight loss in Phase 3 studies and its oral Wegovy achieved 16.6% weight loss. More recently, Wegovy received approval in China for MASH, expanding its potential beyond weight management and cardiovascular benefits into another large metabolic-disease market. If Novo Nordisk A/S (NYSE:NVO) can combine these products with better execution, the reset could support higher patient volumes and extend the commercial life of its GLP-1 franchise, helping defend revenue and cash flow despite pricing pressure.
#nordisk #lilly
23 days ago
Novo Nordisk A/S (NYSE:NVO)'s decision to rebrand its day-to-day identity as "Novo" and launch a cultural reset is primarily a strategic response to the company's loss of momentum in the obesity-drug market, rather than a financial restructuring in itself. Reuters reports that the company is trying to regain competitiveness as pressure from Eli Lilly intensifies. The move comes as Novo prepares to unveil new strategic ambitions at its September 21 Capital Markets Day, making the cultural reset potentially important if it leads to faster decision-making, stronger commercial execution and a more aggressive R&D approach.
The underlying business still has substantial scale to protect. Novo generated DKK 309.1 billion of 2025 sales and DKK 127.7 billion of operating profit, while obesity-care sales rose 31% at constant exchange rates to DKK 82.3 billion. However, the company also spent around DKK 8 billion on its transformation in 2025, and its diabetes value-market share fell 3.6 percentage points to 30.1%. The reset therefore comes at a critical point: Novo remains the global obesity-market leader, with a 59.6% branded-volume share in 2025, but Lilly is rapidly narrowing the competitive gap.
A successful cultural reset could improve Novo Nordisk A/S (NYSE:NVO)'s execution at a time when the company needs to convert its scientific and commercial ***** ets into faster growth. Reuters reported that CEO Mike Doustdar is already seeking to accelerate R&D and streamline decision-making following investor concerns about the pipeline and competition from Lilly. If the reorganization reduces internal bureaucracy and improves the speed of clinical, regulatory and commercial decisions, it could help Novo extract more value from its existing obesity portfolio while advancing next-generation treatments before the semaglutide patent cliff expected early next decade.
The company also has ***** ets that give a cultural and operational reset something concrete to build around. Wegovy was available in 52 countries by the end of 2025, while the company's higher-dose Wegovy achieved 20.7% weight loss in Phase 3 studies and its oral Wegovy achieved 16.6% weight loss. More recently, Wegovy received approval in China for MASH, expanding its potential beyond weight management and cardiovascular benefits into another large metabolic-disease market. If Novo Nordisk A/S (NYSE:NVO) can combine these products with better execution, the reset could support higher patient volumes and extend the commercial life of its GLP-1 franchise, helping defend revenue and cash flow despite pricing pressure.
#cultural #company #lilly
25 days ago
NEW YORK – If there's anyone who knows how to command a room, it's Nene Leakes.
The "Real Housewives" OG brought a little Atlanta to New York Fashion Week, attending Sergio Hudson's spring/summer 2027 show on Sunday, Sept. 13. Hudson brought the glamour to NYFW, hosting his show at one of New York's most iconic venues — the Rainbow Room.
Guests including Mickey Guyton, Muni Long and Sunny Hostin ventured to top of Rockefeller Center for Hudson, but it was Leakes who stole the show. The "Real Housewives of Atlanta" star entered the glittering ballroom moments before the first model took to the runway, but that didn't stop a swarm of photographers and fans from trying to get a snap of the Bravo star. Leakes took her seat next to "Beauty in Black" actress Crystle Stewart as the two posed for front-row photos.
Leakes showed off a classic Hudson creation, donning a bodycon little black dress from the designer's fall-winter '24 collection. The sleeveless LBD featured an extra-long gold zipper extending from the neckline to the hem. The reality star styled the look with black patent pumps and a gold-embellished clutch.
"Me and Nene go way back … When I met her, I was a little ****** ody, and she always treated me really well, so I take care of her, 'cause she always took care of me," Hudson told USA TODAY backstage after his show. "She's a superstar."
#leakes #nene


28 days ago
Amanda Seyfried went for an earthy color palette while attending the Tory Burch spring 2027 show during New York Fashion Week on Thursday. For the event, the actress paired one of the brand's most popular shoes with a fall-ready brown-and-green look. Amanda Seyfried attends the Tory Burch spring 2027 show. Getty Images for Tory Burch She opted for the Tory Burch Peep Toe pump, which has been a favored choice among celebrities in recent years. The peep-toe pump riffs on the classic style with a twisted, sculptural heel, designed to look as if it is in motion. Rather than reveal several toes like a traditional peep-toe silhouette, the cutout frames only the hallux, or big toe — a highly specific footwear trend that surfaced at Copenhagen Fashion Week at the end of August. Grosgrain details and side seaming borrow from balletic pointe shoes. The pumps were made in partnership with a Leather Working Group-certified tannery, which supports high standards in leather manufacturing and chemical management. Their twisted heels measure 90mm, or approximately 3.54 inches, while a cushioned leather footbed offers comfort. The shoes also boast a patent leather upper and grosgrain binding. Napa leather lining and a buffed leather sole complete the construction. A closeup
Follow Footwear News on Twitter or become a fan on Facebook.
#burch #peep #fashion #footwear
Follow Footwear News on Twitter or become a fan on Facebook.
#burch #peep #fashion #footwear

28 days ago
The pharmaceutical sector was hit with major pipeline news on September 1 when Novartis AG (NYSE:NVS) paused eight clinical trials of rap-cel, its experimental CAR-T cell therapy targeting autoimmune and neurological disorders. The suspension, effective August 24, followed three patient deaths caused by severe, life-threatening immune reactions (immune effector cell-associated hemophagocytic syndrome). Novartis is currently conducting a safety review alongside independent monitoring boards. Following the news, Bristol-Myers Squibb Company (NYSE:BMY) voluntarily paused trials for its competing CAR-T treatment, zola-cel, as a precautionary measure after detecting transient inflammatory side effects.
Looking at Q2 2026 earnings, Bristol Myers Squibb is currently demonstrating stronger financial momentum. Bristol-Myers Squibb Company (NYSE:BMY) reported total revenue of $13.0 billion, up 6% year over year, driven by a 15% increase in its Growth Portfolio to $7.6 billion, led by Opdivo, Qvantig, Reblozyl, and Camzyos. Non-GAAP EPS reached $2.04, while net income totaled $3.3 billion, or $4.2 billion on a non-GAAP basis. The company also raised its full-year 2026 revenue guidance from approximately $46.0–$47.5 billion to $49.0–$50.0 billion and increased its non-GAAP EPS outlook to $6.75–$7.00.
Novartis AG (NYSE:NVS), meanwhile, reported Q2 net sales of $14.4 billion, up 3% in U.S. dollars and 1% at constant currencies, supported by Kisqali and Kesimpta, which grew 43% and 32% at constant currencies, respectively. However, generic competition reduced growth by 14 percentage points, while core operating income remained flat at $5.9 billion and GAAP net income fell 19% to $3.3 billion. Novartis reaffirmed rather than raised its full-year guidance, calling for low single-digit sales growth and a low single-digit decline in core operating income.
Overall, Bristol Myers stands out as the stronger financial story this quarter, with its Growth Portfolio offsetting legacy patent-cliff pressures and supporting a guidance increase, while Novartis continues to contend with generic erosion weighing on earnings.
Novartis' bull case rests on strong double-digit growth from high-margin blockbusters such as Kisqali, Kesimpta, and Scemblix, supporting robust Q2 free cash flow of $5.6 billion. However, CAR-T safety setbacks could threaten a key pipeline platform, while intense generic competition has already reduced top-line growth by 14 percentage points.
#billion #novartis

29 days ago
Our ****** ysts just identified a stock with the potential to be the next Nvidia. Tell us how you invest and we'll show you why it's our #1 pick. Tap here.
Management attributes the 25% revenue decline primarily to a technical 'algorithm dislocation' with its largest advertising partner, causing an audience drift that sharply increased customer acquisition costs (CPA) for IL MAKIAGE.
The company is prioritizing technical remediation over immediate growth for IL MAKIAGE, shifting resources toward intensive testing to retrain the ad algorithm rather than executing its planned product pipeline.
SpoiledChild is demonstrating operational resilience, on track for $350 million in 2026 revenue by maintaining strong unit economics and 12-month net revenue repeat rates exceeding 100% despite broader platform headwinds.
The launch of METHODIQ signals a strategic pivot toward the 'beauty and medicine' convergence, leveraging computer vision and ODDITY Labs' patented molecules to capture higher-intent medical-grade customers.
#tell #management
29 days ago
Is it better to own a company already selling drugs or one with a potential blockbuster in testing? Investors are weighing Axsome Therapeutics (NASDAQ:AXSM) against Viking Therapeutics (NASDAQ:VKTX) to decide.
Axsome focuses on commercializing treatments for depression and sleep disorders, showing significant revenue growth. Viking is a clinical-stage developer targeting the massive obesity market but has no products on the market yet. Both represent different stages of growth within the biotech world, making them popular choices for healthcare-minded portfolios.
Axsome develops and sells treatments for central nervous system conditions such as depression, migraines, and narcolepsy. It is a prominent name among biotech stocks, with a portfolio that includes Auvelity, Sunosi, and Symbravo. The company recently entered a settlement that grants license rights to five generic manufacturers for Sunosi starting in 2040, providing long-term clarity on its patent life and market position. In its latest annual report, filed in early 2026, the company noted it had over 900 full-time employees to support its commercial reach.
In FY 2025, revenue reached nearly $638.5 million, marking growth of close to 65.5% compared to the prior year. This increase was driven by the continued expansion of its key central nervous system treatments into new geographic markets. The company reported a net loss of approximately $183.2 million, resulting in a negative net margin, which is the percentage of revenue left after all expenses are paid, of roughly 28.7%. Some investors focus on the P/S ratio to value the business relative to this growing revenue.
As of December 2025, the debt-to-equity ratio was nearly 2.7x, meaning the company uses significant debt relative to its equity. The current ratio of approximately 1.6x indicates it has $1.60 in ****** ets for every $1.00 in liabilities due within a year. Free cash flow, or cash from operations minus capital spending, was nearly negative $93.9 million as the company continues to invest in its commercial pipeline. This spending is intended to support the long-term growth of its approved products and the development of new candidates.
#ratio #therapeutics
0.00$ raised of 0.00$ goal
0 donations
0.00$
to go
1 month ago
Amanda Seyfried brought easy, breezy glamour to the 83rd Venice Film Festival. She arrived by water taxi in a cornflower-blue minidress that slipped playfully off her shoulders. The actress waved to photographers, embracing a look that felt right at home against Venice's striped poles and golden light.
Amanda Seyfried stuns in off-shoulder Miu Miu minidress at the 83rd Venice Film Festival. Seyfried wore Miu Miu's Poplin Mini Dress, a vivid blue design cut from crisp cotton poplin. The dress featured a ruched, off-the-shoulder neckline and short puffed sleeves. This gave it a relaxed, vacation-ready silhouette that still held its own on a red carpet-adjacent occasion. A subtle logo tag peeked out from the sleeve, a quiet nod to the house's signature detailing.
She paired the dress with Miu Miu's Satin Ballerinas in black, keeping the footwear simple and low-key. For her bag, Seyfried chose the label's Solitaire Patent Leather Bag, also in black, a structured top-handle silhouette that added a polished, glossy contrast to the dress's soft, matte fabric.
The jewelry came courtesy of Tiffany & Co. Seyfried wore the brand's Victoria Pearl and Diamond Earrings, featuring a single pearl drop beneath a diamond-studded star motif, along with the Knot Double Row Ring, a sculptural design finished in diamonds. Both pieces added a delicate sparkle without competing with the dress's bold color.
Her hair was pulled back into a sleek, low updo, drawing attention to the dress's statement neckline, while her makeup stayed soft and dewy, fitting for a daytime festival appearance.
#seyfried #venice #film #blue

1 month ago
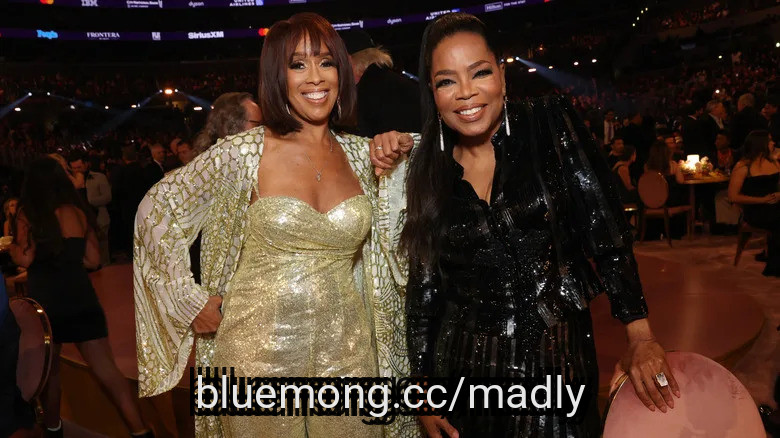
Gayle King took nothing away from the bride but certainly captivated guests with her mother-of-the-groom style at her son's June 2024 wedding. The "CBS Mornings" host was all smiles in photos and videos she shared from the event, including a stunning snap with her son, William "Will" **** pus Jr., and longtime best friend, Oprah Winfrey, who hosted the lavish oceanside nuptials at her home in Montecito, California. "Favorite son Will found the girl of his dreams and now lovely elisemariesmith is an official member of the family," King captioned an Instagram post. "It was truly a spectacular family wedding!"
gayleking/instagram
Considering how Gayle King's best on-air looks are a colorful masterclass in fun fashion, she brought that same flair when selecting her mother-of-the-groom attire. The morning news anchor looked radiant in a graceful powder-blue gown by designer Amsale, who also created the bride Elise Smith's wedding dress, King revealed in her Instagram post. King completed the elegant look with a matching light blue shawl and sequined clutch. **** pus looked dashing in a classic tuxedo, finished with a black bowtie and patent leather shoes. Meanwhile, Winfrey embraced her role as the ultimate wedding host in a light pink ruched gown and salmon-colored clutch. Oprah Winfrey and Gayle King proved they're the ultimate BFFs when King praised her best friend for putting together such a beautiful setting for her son's big day. "Thanks to oprah—the wedding was magical in her 'backyard!' She pulled out all the stops," King wrote.
Read more: The 20 Most Expensive Celebrity Engagement Rings In The World
Monica Schipper/Getty Images
#bumpus

1 month ago
Amal Clooney infused her sartorial agenda with a dose of flapper-girl charm as she stepped out for an evening in Venice, Italy.
The international human rights lawyer was photographed exiting her private boat with her husband, George Clooney, on September 3. The 48-year-old looked incredible in an archival Prada mini dress adorned with turquoise fringed sequins and silver gems. The garment featured a strapless design with a bandeau neckline and a figure-hugging silhouette. The look was styled with silver pumps and a pair of matching diamond-encrusted drop earrings.
Amal's luscious brunette locks were left down in soft waves while her makeup oozed glam, courtesy of a bronze eye and a nude lip. Meanwhile, George looked suave in a navy suit layered over a simple black T-shirt.
Amal Clooney wore a vintage Prada dress (@ GC Images)
The evening came after Amal graced the red carpet alongside her husband at the 83rd Venice International Film Festival. For the event, she slipped into a chic Tom Ford number by Haider Ackermann. The custom-made black gown was crafted in black silk taffeta and featured sculptural panels with delicate pleating. The square neckline was adorned in patent leather while the dress fell into a figure-hugging silhouette that looked so sleek.
#dress #black #george


1 month ago
On August 6, Peloton Interactive (NASDAQ:PTON) reported results for its fiscal fourth quarter and full year ended June 30, and the headline number is one the company has chased for years: a full year of positive net income. Total revenue for fiscal 2026 came in at $2.446 billion, and quarterly revenue of $608 million ticked up $1 million from a year earlier. The bigger story sits beneath the top line, in a business that finally converted cost cuts into cash while its subscriber base kept shrinking.
Fiscal 2026 marked the first time in Peloton's history that the company posted positive net income and operating income for a full year, with GAAP net income landing at $63 million. Adjusted EBITDA rose 16% year over year to $468 million, even after absorbing a $23.8 million nonrecurring legal accrual tied to patent litigation in the fourth quarter. Free cash flow climbed to $378 million, up $54 million, and management used that cash to cut net debt by 80% to just $93 million from $459 million a year earlier. CEO Peter Stern credited the turnaround to an improved revenue trajectory paired with cost restructuring, and the company said it exceeded its own target of more than $100 million in run-rate savings by the end of the fiscal year.
Growth is showing up outside the core bike and treadmill business too. The Commercial Business Unit grew revenue by double digits for the year, Peloton expanded its digital footprint through a partnership with Spotify, and it closed the acquisition of Skōp to push further into connected Pilates. Microstores beat their internal sales goals as an efficient in-person retail channel, and Peloton plans to double that store fleet in fiscal 2027. New training programs also drove engagement, with the Pace Your Race Marathon Training Program and a Live Spring Cross-Training Plan generating more than 850,000 completed workouts in the fourth quarter alone.
The profitability story cannot hide what is happening to the customer base. Ending Paid Connected Fitness Subscriptions fell 8.8% year over year to 2.553 million, and monthly churn rose to 2.2% in the fourth quarter from 1.8% a year earlier. Hardware sales are choppy too. Connected Fitness Products revenue dropped 14% year over year in the quarter to $171 million, and gross margin on that hardware segment swung to 13.4% from 17.3% a year ago before recovering some ground quarter over quarter. Peloton's own guidance signals the subscriber slide is not over.
#year #revenue #fourth #connected

1 month ago
Pfizer (NYSE: PFE) has faced several issues in recent years that have weighed on its share price. First, the company's coronavirus business isn't nearly as strong as it once was. Second, Pfizer is racing toward important patent cliffs, including that of Eliquis, an anticoagulant. Third, the pharmaceutical giant has faced clinical setbacks with otherwise promising pipeline candidates, including some it acquired. This problem has led to billions in impairment charges. Because of these headwinds (and others), Pfizer's shares have lagged broader equities over the past two years and have hovered below $30 apiece. Is it finally time to invest in the company? Let's see whether there is a rebound on the horizon.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Let's start with Pfizer's recent second-quarter update. The company's revenue increased by 1% year over year to $15 billion. While that top-line growth doesn't look impressive, it beat ***** yst estimates. On the bottom line, Pfizer's adjusted earnings per share were $0.77, slightly lower than the $0.78 reported in the prior-year quarter. Here too, Pfizer beat expectations. And it's important to highlight what drove the revenue and earnings beat.
The company noted that non-COVID revenue increased 5% year over year, while sales from launched and acquired products jumped 18%. This is great news for Pfizer. It suggests that newer (and acquired) products will help pull sales in the right direction over the medium term, while older medicines, especially within its coronavirus business, continue to lose steam.
Even with the progress Pfizer is making with relatively new launches, upcoming patent cliffs will be a major problem for the company. Consider, for instance, that Eliquis was the drugmaker's best-selling therapy during the second quarter. Pfizer's revenue from Eliquis came in at $2.4 billion, up 21% year over year. So, it arguably remains its single most important growth driver. Pfizer will have to launch more new drugs to fill the gap Eliquis will leave behind as it faces generic competition by the end of the decade. Can the company pull it off? My view is that it can.
#company #revenue #years
1 month ago
By Mary Guzman
Apple's July 10, 2026 lawsuit against OpenAI, filed in the Northern District of California just five weeks after OpenAI's confidential Form S‑1 targeted a trillion‑dollar valuation, presents a governance case study with implications far beyond Silicon Valley. In Apple Inc. v. Liu, No. 5:26‑cv‑07078, Apple alleges that OpenAI Group PBC, OpenAI Foundation, io Products LLC, former Apple vice president Tang Yew Tan, and former Apple engineer Chang Liu engaged in a coordinated effort to obtain confidential Apple hardware designs, supply‑chain intelligence, and unreleased product specifications. Apple claims the misappropriation reached every level of OpenAI's hardware organization and seeks preliminary and permanent injunctions, compensatory damages, a reasonable royalty in the alternative, exemplary damages for willful misappropriation, and attorneys' fees*. OpenAI denies all allegations and points to Apple's allegedly lax exit procedures as the key negating factor.
From a governance perspective, the case highlights a recurring pattern: trade‑secret disputes that appear straightforward to the public often reveal deeper structural weaknesses inside the victim organization. The industry has seen versions of this before—emails encouraging departing employees to "bring what you know," or the more extreme mole scenario, as in Deel v. Rippling. These are not just operational failures; they are governance failures that should alarm any board member or investor expecting a clean exit or a stable competitive position.
The risk is accelerating. More than 1,500 federal trade‑secret cases were filed in 2025 – the highest ever – and still only a fraction of the true number. AI proliferation, high employee mobility, and limits on non‑competes ensure that trade‑secret litigation will continue to rise. Meanwhile, companies increasingly rely on trade‑secret protection (surpassing the long-favored patent-or-die approach) recognizing that patents disclose the playbook to competitors and nation‑state adversaries. In a world where competitive advantage is often driven by a process rather than the output it creates, trade secrets are often the most valuable and strategic IP ******* et.
But the governance question is always the same: Did the company actually have protectable trade secrets? That requires: a) legal ownership of the innovation, b) demonstrable uniqueness that creates value, and c) "reasonable measures" to protect it.
#confidential #case

1 month ago
Olivia Rodrigo leaned into edgy glamour for her latest look, pairing a skeleton micro minidress with Stuart Weitzman pumps. The "deja vu" singer turned heads at the Grammy Museum in Los Angeles, California, on September 1 for the "An Evening with Olivia Rodrigo" event. The museum's official Instagram page shared her photos from the event.
Olivia Rodrigo wore a vintage Undercover Fall/Winter 2013 Silk Skeleton Top in Orange/Black to the Grammy Museum. Styled as a micro minidress, the top featured cap sleeves and a black Peter Pan collar that rested wide across her shoulders. The garment's most eye-catching detail was the centrally printed black skeletal ribcage graphic. The goth-inspired anatomical graphic contrasted with the soft peach color of the fabric, creating a playful and edgy juxtaposition.
Styled by Chloe and Chenelle, the Grammy winner paired the lightweight dress with black sheer Wolford tights. For footwear, she opted for Stuart Weitzman Babette Patent Leather Mary Jane Pumps in black colorway. The high-shine patent finish caught the light, elevating the dark tights beneath and bringing a sleek, liquid-like **** re to her look.
The $495 shoes featured an almond-shaped toe and a slender instep strap with a metallic buckle. The 85 mm block heel elongated her frame while maintaining a retro silhouette that balanced the breezy drape of her tunic. Furthermore, its black color kept the look cohesive along her leg line.
Rodrigo wore her dark brown hair in voluminous, glossy waves parted down the side, softly framing her face. Meanwhile, her makeup was fresh and radiant. It featured a natural flush, defined lashes, and a pink lip that echoed the peach tones of her dress.
#black #rodrigo #olivia #look

1 month ago
Pop superstar Olivia Rodrigo continues to showcase her passion for edgy vintage fashion. Recently, the singer attended the "An Evening with Olivia Rodrigo" event at the Grammy Museum in Los Angeles. Naturally, her stylish appearance captured everyone's attention. She cleverly repurposed an archival designer top into a thigh-skimming micro minidress. Ultimately, her unique outfit seamlessly blended spooky graphic elements with classic preppy aesthetic details.
For the special museum appearance on September 1, 2026, Olivia Rodrigo selected an iconic archival piece from ***** anese brand Undercover's Fall/Winter 2013 collection. Specifically, the vintage silk top showcases a soft peachy-orange shade with short sleeves. Furthermore, a contrasting black rounded collar and dark shoulder cap trims give the top a neat, structured silhouette. However, rather than pairing the top with pants or a skirt, Rodrigo wore the piece as a teeny tiny micro minidress.
The front of the dress features a detailed black ribcage and spine print running down the middle. Consequently, this bold skeleton graphic adds a rebellious, punk-rock twist to her sweet look. Moreover, celebrity stylists Chloe and Chenelle elevated the leggy silhouette by pairing the dress with semi-sheer black Wolford tights. The dark tights created a striking contrast against the bright orange silk fabric.
In addition, Rodrigo chose shiny black patent leather Stuart Weitzman "Babette" Mary Jane pumps ($495) for her footwear. The block-heel shoes featured delicate straps across her feet, injecting a dainty vintage charm into the edgy outfit. Furthermore, she kept her jewelry very subtle so the graphic vintage dress could remain the main focus.
Her beauty team complemented the look with effortless styling. Hairstylist Mary Kendall brushed her long dark locks into soft, glossy waves that fell over her shoulders. Meanwhile, makeup artist Karissa O'Hanlon gave her glowing skin, rosy flushed cheeks, and a glossy berry-pink lip. Overall, Rodrigo perfectly demonstrated her ability to turn a vintage top into an iconic micro-dress.
#olivia #black #dress

1 month ago
On August 12, Royalty Pharma (NASDAQ:RPRX) agreed to pay Zealand Pharma $100 million for the rights to future royalties on rusfertide, an experimental treatment for a rare blood disorder called polycythemia vera. It is Royalty Pharma's second collaboration with Zealand, and it arrives just as rusfertide awaits a decision from the FDA. For a company that makes its living buying pieces of other companies' drugs, the timing says a lot about how it weighs risk against reward before a regulatory verdict even lands.
Royalty Pharma's business depends on picking the right moment to buy into a drug's future, and this deal fits that pattern. Under the agreement, $50 million changes hands at closing and the remaining $50 million arrives on the first anniversary, in exchange for a 1% royalty on rusfertide's global sales plus any regulatory and commercial milestones. Rusfertide, a once-weekly self-injected therapy that mimics the hormone hepcidin to control iron levels in polycythemia vera patients, already has an FDA goal date set for the third quarter of 2026, with Takeda lined up to handle commercialization worldwide. That is a near-term catalyst most royalty purchases do not carry.
The broader portfolio backs up the confidence. Royalty Receipts grew 14% to $768 million in the second quarter of 2026, lifted by Tremfya, Voranigo, Imdelltra and Evrysdi, and the company raised its full-year 2026 guidance for Portfolio Receipts to a range of $3.4 billion to $3.5 billion, the second increase this year. Capital deployment has already topped $1 billion in 2026, including a July 2026 royalty purchase tied to AstraZeneca's cliramitug, pushing the development-stage pipeline to 19 potential therapies. Even after repaying a $380 million term loan in July 2026, Royalty Pharma still paid a quarterly dividend of $0.235 per share and bought back $45 million of stock in the second quarter alone.
Not every royalty ages well, and Royalty Pharma's own numbers show it. Promacta royalties fell 75% in the second quarter of 2026 to just $8 million as US generic competition took hold, and Imbruvica payments slipped 16% to $36 million, a reminder that patent cliffs eventually catch up to even the steadiest cash flows. That same risk sits underneath every new deal the company signs, including the one with Zealand.
The rusfertide agreement carries its own strings. Royalty Pharma's 1% royalty stops scaling once global sales pass $1.5 billion, at which point Zealand keeps a 0.25% cut and Royalty Pharma only 0.75%, so the largest commercial outcomes get split rather than fully captured. And rusfertide still has not cleared the FDA. The agency's goal date only falls in the third quarter of 2026, meaning the second $50 million payment is committed before regulators finish their review. Layer that onto a balance sheet carrying $9.2 billion in total debt principal against $812 million of cash as of June 30, 2026, and it becomes clear this is a company funding new bets with borrowed as w
1 month ago
Investment management company First Pacific Advisors recently released its "FPA Queens Road Small Cap Value Fund" second-quarter 2026 investor letter. A copy of the letter can be downloaded here. The Fund returned 27.02% in the first half of 2026, outperforming the Russell 2000 Value Index's 22.99% gain and the S&P 600 Index's 23.90% return. Small-cap earnings growth also began accelerating relative to large caps, while the small-cap technology sector surged nearly 100% in 26H1. The fund's technology holdings gained 72.39%, contributing 14.87 percentage points, compared with a 95.27% return and 7.10-point contribution from the benchmark's technology sector. Excluding IT and cash, the Fund contributed 12.73% versus 15.89% for the Russell 2000 Value Index; on a fully invested basis, the figures were 16.62% and 17.59%, respectively. The portfolio continued to trim appreciated technology holdings amid the AI-driven rally, while maintaining a bottom-up approach and avoiding beaten-down SaaS stocks due to the widening range of AI-related outcomes. The fund also eliminated about $62 million in capital gains during Q2 and approximately $140 million year-to-date through July, while ending the quarter with 10.2% in cash. In addition, please check the Fund's top five holdings to know its best picks in 2026.
In its second-quarter 2026 investor letter, FPA Queens Road Small Cap Value Fund highlighted stocks like InterDigital (NASDAQ:IDCC). InterDigital (NASDAQ:IDCC) develops wireless and video technologies and generates licensing revenue from its portfolio of cellular and digital communications patents. The one-month return of InterDigital (NASDAQ:IDCC) was 3.67% while its shares traded between $249.14 and $412.60 over the last 52 weeks. On August 31, 2026, InterDigital (NASDAQ:IDCC) stock closed at approximately $335.15 per share, with a market capitalization of about $8.65 billion.
FPA Queens Road Small Cap Value Fund stated the following regarding InterDigital (NASDAQ:IDCC) in its Q2 2026 investor letter:
"Interdigital (NASDAQ:IDCC) owns an expansive collection of wireless patents. Most of their revenue comes from licensing agreements with smart phone manufacturers, but the company has also started licensing to consumer electronics, auto, industrial and media companies. CEO Liren Chen joined in 2021 from Qualcomm and has done an exceptional job ramping up the pace of licensing deals. The stock price has followed earnings growth higher and IDCC was a top performer for the Fund in 2023, 2024 and 2025. We have trimmed all the way up but still hold a less than 2% position in IDCC."
#fund #small #road

1 month ago
Intercontinental Exchange (ICE) (NYSE: $ICE), the parent company of the New York Stock Exchange, has partnered with blockchain infrastructure firm tZERO to build the systems behind its planned market for tokenized securities.
On Monday, the companies announced that tZERO will work with ICE on transfer-agent and broker-dealer infrastructure designed to support the onchain settlement of tokenized securities on ICE's upcoming NYSE-affiliated digital trading platform.
ICE will also invest in tZERO's latest funding round and license its portfolio of 103 blockchain patents. The size of the investment was not disclosed.
More From Cryptoprowl:
MEXC Launches Earn Plus With Limited-Time Event Offering Up to 800% APR Booster
#Blockchain #infrastructure

1 month ago
Rahway, New Jersey-based Merck & Co., Inc. (MRK) is a global research-driven biopharmaceutical company focused on developing medicines, vaccines, and animal-health products. Known as MSD outside the U.S. and Canada, Merck operates through two main businesses: Pharmaceuticals and Animal Health. Valued at a market cap of $297 billion, its pharmaceutical portfolio spans oncology, vaccines, cardiometabolic disease, infectious diseases, and other therapeutic areas.
Companies with a market cap of $200 billion or more are typically referred to as "mega-cap stocks." It fits right into that category, with its market cap exceeding this threshold, reflecting its substantial size and influence in the general drug manufacturers industry. Merck combines a dominant oncology franchise, a broad vaccine portfolio, an expanding pipeline of newer medicines, and a large animal-health business. Its key investment consideration is balancing the continued strength of Keytruda and newer products against pressure on mature franchises such as Gardasil and the eventual impact of Keytruda's patent expiry.
Wu-Tang Clan Member Raekwon Is a Palantir 'OG,' Visiting Headquarters 16 Years After Receiving His Custom PLTR Jacket
Tesla Just Killed Its Solar Roof After Years of Struggling to Scale. What It Means for TSLA Stock.
Tesla Stock Could Benefit as Trump Locks Down the U.S. Power Grid
#animal #medicines #products


1 month ago
Uncrowned has Duel: Arena live results, round-by-round updates, highlights and start time for the Mike Perry vs. Brandon Jenkins fight card on Saturday night at the Kia Center in Orlando, Florida. Bare-knuckle boxing superstar Mike Perry is sticking with MMA and staying on the inaugural Duel: Arena card, despite the last-minute withdrawal of his original opponent, Dillon Danis. Taking Danis' place will be UFC veteran Brandon Jenkins.
Perry (15-8) returned to the win column in MMA when he took on fellow veteran Nate Diaz at the MVP MMA card in May on Netflix. In a lopsided effort, Perry battered Diaz with his patented aggression, ****** ing Diaz en route to a second-round TKO via doctor's stoppage. Since his UFC departure in 2021, Perry has gone undefeated across bare-knuckle boxing matches and MMA, with his lone combat sports loss coming in a boxing match against Jake Paul in July 2024.
Jenkins (17-11) steps in on short notice, having last fought the same night as Perry. In his MVP MMA bout, Jenkins scored a split decision nod over Chris Avila to snap a two-fight losing skid. It's been a journey of ups and downs for Jenkins after he left the UFC in 2022, fighting across MMA, bare-knuckle MMA and Karate Combat.
Duel Arena: Perry vs. Jenkins begins at 6 p.m. ET on DuelArena.TV pay-per-view.
Follow along with Uncrowned's live Mike Perry vs. Brandon Jenkins results, highlights and live blog below, including round-by-round play-by-play of the main event.
#duel #mike #diaz