

8 days ago
Bear markets are a normal part of investing in the stock market. **** ody knows when the next one will arrive, but it will eventually arrive with 100% certainty. The time to prepare is before you face the fear that comes with big market downturns. That's why you should consider owning companies like Johnson & Johnson (NYSE: JNJ), Medtronic (NYSE: MDT), Coca-Cola (NYSE: KO), and Procter & Gamble (NYSE: PG).
But there are two pieces to the story here. First, they all operate in economically resilient industries. Second, they all have incredible dividend track records. Here's a quick look at each one.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
To be fair, you may not be happy about paying for healthcare, since it can be expensive. But you will still pay for it because, in the most extreme cases, it can be the difference between life and death. In less extreme cases, the difference is between a better and worse quality of life, and you'll still probably pay up. The risk of not paying simply isn't worth it.
Johnson & Johnson is a good choice if you are worried about a bear market and are looking for a safe-haven investment. It is a major player in both the pharmaceutical and medical device sectors, providing diversification. It is a Dividend King, having rewarded shareholders with more than 50 consecutive annual dividend increases. And while its yield isn't exactly huge at 2%, it is roughly twice what you'd collect from an S&P 500 index (SNPINDEX: ^GSPC) fund. J&J isn't exactly an exciting company, but it is a reliable one.
#signal
But there are two pieces to the story here. First, they all operate in economically resilient industries. Second, they all have incredible dividend track records. Here's a quick look at each one.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
To be fair, you may not be happy about paying for healthcare, since it can be expensive. But you will still pay for it because, in the most extreme cases, it can be the difference between life and death. In less extreme cases, the difference is between a better and worse quality of life, and you'll still probably pay up. The risk of not paying simply isn't worth it.
Johnson & Johnson is a good choice if you are worried about a bear market and are looking for a safe-haven investment. It is a major player in both the pharmaceutical and medical device sectors, providing diversification. It is a Dividend King, having rewarded shareholders with more than 50 consecutive annual dividend increases. And while its yield isn't exactly huge at 2%, it is roughly twice what you'd collect from an S&P 500 index (SNPINDEX: ^GSPC) fund. J&J isn't exactly an exciting company, but it is a reliable one.
#signal



1 month ago
Procter & Gamble has raised its dividend for 70 straight years while Johnson & Johnson covers its roughly $12.6 billion dividend run rate 1.56 times with free cash flow.
Coca-Cola posted its strongest Trademark volume growth in 17 years, and ADP's operating cash flow covers its dividend more than twice over while still funding buybacks.
Lowe's carries the lowest payout ratio in the group at 41% and trades at just 15 times earnings after falling 24% year to date.
Read More: Learn 7 ways to generate income with a $1,000,000+ portfolio (sponsor)
Yield is relatively easy to find. A dividend that keeps arriving through recessions, patent cliffs and housing slumps is much harder to find, and that kind of reliability is the hook for this group. Every name below covers its payout with real cash flow, has a long record of raises and keeps its payout ratio at a level that leaves room for mistakes. Procter & Gamble (NYSE:PG) sets the standard: management says its latest increase marks the 70th consecutive year of dividend increases and 136th consecutive year of dividend payments, putting it firmly in the Dividend Kings club (we ranked ten of them by valuation in a free report here). The other four pair long dividend records with cash flow that covers the payout.
#cash #year #procter #gamble
Coca-Cola posted its strongest Trademark volume growth in 17 years, and ADP's operating cash flow covers its dividend more than twice over while still funding buybacks.
Lowe's carries the lowest payout ratio in the group at 41% and trades at just 15 times earnings after falling 24% year to date.
Read More: Learn 7 ways to generate income with a $1,000,000+ portfolio (sponsor)
Yield is relatively easy to find. A dividend that keeps arriving through recessions, patent cliffs and housing slumps is much harder to find, and that kind of reliability is the hook for this group. Every name below covers its payout with real cash flow, has a long record of raises and keeps its payout ratio at a level that leaves room for mistakes. Procter & Gamble (NYSE:PG) sets the standard: management says its latest increase marks the 70th consecutive year of dividend increases and 136th consecutive year of dividend payments, putting it firmly in the Dividend Kings club (we ranked ten of them by valuation in a free report here). The other four pair long dividend records with cash flow that covers the payout.
#cash #year #procter #gamble

1 month ago
Before we get worried about recessions or market crashes, let's put a 10% drop in context. Going back to 1980, the S&P 500 has fallen 10% or more in roughly half of all calendar years, and a correction of that size has historically shown up about once every 12 to 18 months.
What makes a 10% decline packed into a single month unusual isn't the size of the drop, it's the speed: that kind of compressed move tends to show up during sudden shocks rather than the slower grind most corrections take. Even so, it's happened before, and the market has recovered every time.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
My goal here isn't to predict whether October brings one. It's to point to three consumer businesses whose underlying demand doesn't particularly care what the stock market does that month.
Procter & Gamble (NYSE: PG) makes Tide, Pampers, Crest, and Gillette. These products are the kind of household basics people buy again almost automatically, recession or not. That steadiness shows up in the numbers. P&G generated more than $87 billion in revenue in its 2026 fiscal year and returned over $15 billion to shareholders through dividends and buybacks.
#market #flashing #every #month
What makes a 10% decline packed into a single month unusual isn't the size of the drop, it's the speed: that kind of compressed move tends to show up during sudden shocks rather than the slower grind most corrections take. Even so, it's happened before, and the market has recovered every time.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
My goal here isn't to predict whether October brings one. It's to point to three consumer businesses whose underlying demand doesn't particularly care what the stock market does that month.
Procter & Gamble (NYSE: PG) makes Tide, Pampers, Crest, and Gillette. These products are the kind of household basics people buy again almost automatically, recession or not. That steadiness shows up in the numbers. P&G generated more than $87 billion in revenue in its 2026 fiscal year and returned over $15 billion to shareholders through dividends and buybacks.
#market #flashing #every #month

1 month ago
JNJ and PG both trade at 21x forward earnings, but J&J's 46% payout ratio versus P&G's 62% signals stronger long-term dividend coverage.
P&G carries a $1.4 billion after-tax earnings headwind into fiscal 2027, while J&J has already absorbed its Stelara biosimilar competition.
J&J's 10-year share price gain of 181% nearly doubled P&G's 117%, with management targeting double-digit earnings growth by decade's end.
Read More: Learn 7 ways to generate income with a $1,000,000+ portfolio (sponsor)
Johnson & Johnson (NYSE:JNJ) orProcter & Gamble (NYSE:PG): If someone saving for retirement could hold only one Dividend King for the next 20 years, which one should it be? My pick is Johnson & Johnson, and the gap is wider than the yields suggest. Both stocks trade near 21 times forward earnings (P&G at 21), so valuation is effectively a tie. The decision comes down to three things that matter more to a retiree: dividend coverage, durability and structural risk.
#trade
P&G carries a $1.4 billion after-tax earnings headwind into fiscal 2027, while J&J has already absorbed its Stelara biosimilar competition.
J&J's 10-year share price gain of 181% nearly doubled P&G's 117%, with management targeting double-digit earnings growth by decade's end.
Read More: Learn 7 ways to generate income with a $1,000,000+ portfolio (sponsor)
Johnson & Johnson (NYSE:JNJ) orProcter & Gamble (NYSE:PG): If someone saving for retirement could hold only one Dividend King for the next 20 years, which one should it be? My pick is Johnson & Johnson, and the gap is wider than the yields suggest. Both stocks trade near 21 times forward earnings (P&G at 21), so valuation is effectively a tie. The decision comes down to three things that matter more to a retiree: dividend coverage, durability and structural risk.
#trade



2 months ago
One of the biggest stories in markets this year has been how stubborn inflation remains. Geopolitical tension in the Middle East spurred the Consumer Price Index (CPI) in March, which rose 3.4% year over year in August. However, even before this conflict, the CPI was still well above the Federal Reserve's 2% target.
The market is starting to believe that inflation will stick around for a lot longer than initially expected. This could explain why Treasury yields, particularly for 10-, 20-, and 30-year terms, have risen significantly in the past 12 months. The **** umption is that interest rates will stay elevated for an extended time, at least compared to most of the 2010s.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Income investors looking to allocate capital are now faced with a crucial decision, one that might have been easier to make in the past. Is it smart to put money in dividend stalwarts, such as Coca-Cola (NYSE: KO) and Procter & Gamble (NYSE: PG)? Or should U.S. government bonds be on your shopping list?
As of this writing on the morning of Sept. 16, the 10-year Treasury yields just under 5%. At the same time, investors can earn more than 5.3% on 20-year and 30-year bonds. For the sake of this **** ysis, I believe it's best to focus on the 10-year Treasury, as this is a reasonable holding period that's also comparable to long-term stock investing.
#time #flashing
The market is starting to believe that inflation will stick around for a lot longer than initially expected. This could explain why Treasury yields, particularly for 10-, 20-, and 30-year terms, have risen significantly in the past 12 months. The **** umption is that interest rates will stay elevated for an extended time, at least compared to most of the 2010s.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Income investors looking to allocate capital are now faced with a crucial decision, one that might have been easier to make in the past. Is it smart to put money in dividend stalwarts, such as Coca-Cola (NYSE: KO) and Procter & Gamble (NYSE: PG)? Or should U.S. government bonds be on your shopping list?
As of this writing on the morning of Sept. 16, the 10-year Treasury yields just under 5%. At the same time, investors can earn more than 5.3% on 20-year and 30-year bonds. For the sake of this **** ysis, I believe it's best to focus on the 10-year Treasury, as this is a reasonable holding period that's also comparable to long-term stock investing.
#time #flashing

2 months ago
Consumer confidence decreased in August, according to The Conference Board's Consumer Confidence Index. This was the second straight month in decline. If September's report shows the same trend, investors might start looking for stocks that can prove resilient through tough economic times.
Procter & Gamble (NYSE: PG) fits the bill about as well as a company can. Let's have a look.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
P&G has raised its dividend for 70 consecutive years. Not many businesses can claim that. Among Dividend Kings, or companies that have raised dividends for 50 years straight, only P&G and five other members qualify for that ultra-elite group. The dividend is also well-funded, as P&G's earnings per share and free cash flow comfortably exceed the amount needed. The company's payout ratio is around 64%.
P&G is diversified within its products. Everything consumers need, ranging from diapers to toothpaste, razors, and detergents, is held within its portfolio of everyday household staples. These are products that people will continue to buy regardless of macroeconomic conditions.
#same
Procter & Gamble (NYSE: PG) fits the bill about as well as a company can. Let's have a look.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
P&G has raised its dividend for 70 consecutive years. Not many businesses can claim that. Among Dividend Kings, or companies that have raised dividends for 50 years straight, only P&G and five other members qualify for that ultra-elite group. The dividend is also well-funded, as P&G's earnings per share and free cash flow comfortably exceed the amount needed. The company's payout ratio is around 64%.
P&G is diversified within its products. Everything consumers need, ranging from diapers to toothpaste, razors, and detergents, is held within its portfolio of everyday household staples. These are products that people will continue to buy regardless of macroeconomic conditions.
#same

2 months ago
Answering a caller's query about The Procter & Gamble Company (NYSE:PG) during the lightning round of the September 10 episode of Mad Money, Jim Cramer said:
It's a tough stock. It's a tough stock because they don't have the growth that I want. They do have the 3% yield, but that's not enough. So, I'm going to say, you know, we sold it for the club. Don't look back.
The Procter & Gamble Company's (NYSE:PG) upside relies on elite operational execution and pricing power in high-margin categories. Continuous supply chain savings and an aggressive premiumization push toward items like Tide PODS help protect profitability. Combined with strong free cash flow productivity, management returned roughly $15 billion in FY 2026 through dividends and share buybacks, ensuring a steady earnings floor despite slow top-line growth.
The primary headwind is weak top-line momentum, with organic sales flat in the second quarter as challenging consumer trends, particularly in the U.S., weighed on growth. Foreign exchange friction and cost pressures further cap near-term earnings acceleration. Additionally, while the stock offers a reliable 3% dividend yield, that income profile creates a steep opportunity cost when risk-free ******* ets and higher-growth stocks offer attractive returns. We recently discussed what Cramer thinks is the ideal valuation for a good entry point in our article, "Jim Cramer Discusses Procter & Gamble (PG) Valuation and Growth."
According to Insider Monkey's data, 83 hedge funds had a stake in The Procter & Gamble Company (NYSE:PG) in Q2 compared to 78 in the prior quarter. Short percentage of the float is 1.21%, showing its status as a defensive holding rather than a short target. While the company provides exceptional balance sheet stability and reliable cash returns for defensive portfolios, its modest top-line growth trajectory and premium valuation continue to test investor patience, validating Cramer's decision to reallocate capital toward faster-moving opportunities.
#company
It's a tough stock. It's a tough stock because they don't have the growth that I want. They do have the 3% yield, but that's not enough. So, I'm going to say, you know, we sold it for the club. Don't look back.
The Procter & Gamble Company's (NYSE:PG) upside relies on elite operational execution and pricing power in high-margin categories. Continuous supply chain savings and an aggressive premiumization push toward items like Tide PODS help protect profitability. Combined with strong free cash flow productivity, management returned roughly $15 billion in FY 2026 through dividends and share buybacks, ensuring a steady earnings floor despite slow top-line growth.
The primary headwind is weak top-line momentum, with organic sales flat in the second quarter as challenging consumer trends, particularly in the U.S., weighed on growth. Foreign exchange friction and cost pressures further cap near-term earnings acceleration. Additionally, while the stock offers a reliable 3% dividend yield, that income profile creates a steep opportunity cost when risk-free ******* ets and higher-growth stocks offer attractive returns. We recently discussed what Cramer thinks is the ideal valuation for a good entry point in our article, "Jim Cramer Discusses Procter & Gamble (PG) Valuation and Growth."
According to Insider Monkey's data, 83 hedge funds had a stake in The Procter & Gamble Company (NYSE:PG) in Q2 compared to 78 in the prior quarter. Short percentage of the float is 1.21%, showing its status as a defensive holding rather than a short target. While the company provides exceptional balance sheet stability and reliable cash returns for defensive portfolios, its modest top-line growth trajectory and premium valuation continue to test investor patience, validating Cramer's decision to reallocate capital toward faster-moving opportunities.
#company


2 months ago
When it comes to long-term success with dividend investing, you need to focus on criteria beyond just yield. While some high yield dividend stocks can be worth the risk, there are plenty that are trading at a high yield for a good reason.
That is, either they are at risk of cutting or suspending their payouts, and/or other risks may lead to stock price declines that outweigh the returns generated by their large payouts. So, instead of focusing on yield alone, consider criteria such as dividend coverage and dividend growth, along with metrics like valuation.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Taking all of these into account, three blue chip dividend stocks stand out as strong, dare I say, "no brainer," buys right now: AbbVie (NYSE: ABBV), Realty Income (NYSE: O), and Procter & Gamble (NYSE: PG).
Several years ago, uncertainty ran high about AbbVie, mostly due to concerns about the impact of losing patent exclusivity for its flagship drug product, the rheumatoid arthritis treatment Humira. Yet while this did hurt AbbVie's revenue and earnings after exclusivity ended in 2023, the company has staged a comeback, largely thanks to the success of the anti-inflammatory drugs Skyrizi and Rinvoq.
#NYSE #abbvie #flashing
That is, either they are at risk of cutting or suspending their payouts, and/or other risks may lead to stock price declines that outweigh the returns generated by their large payouts. So, instead of focusing on yield alone, consider criteria such as dividend coverage and dividend growth, along with metrics like valuation.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Taking all of these into account, three blue chip dividend stocks stand out as strong, dare I say, "no brainer," buys right now: AbbVie (NYSE: ABBV), Realty Income (NYSE: O), and Procter & Gamble (NYSE: PG).
Several years ago, uncertainty ran high about AbbVie, mostly due to concerns about the impact of losing patent exclusivity for its flagship drug product, the rheumatoid arthritis treatment Humira. Yet while this did hurt AbbVie's revenue and earnings after exclusivity ended in 2023, the company has staged a comeback, largely thanks to the success of the anti-inflammatory drugs Skyrizi and Rinvoq.
#NYSE #abbvie #flashing


2 months ago
On August 6, PureCycle Technologies (NASDAQ:PCT) reported second-quarter results for the period ended June 30, and buried in the numbers was something the plastics recycler has chased for years: an actual branded product on store shelves. Select Downy detergent caps made with PureCycle's PureFive resin entered commercial production for Procter & Gamble during the quarter, the first tangible sign the company's purification technology can clear a major consumer brand's supply chain. Revenue came in at $4.5 million, up roughly 173% from a year earlier and the sixth straight quarter of sequential growth.
The Downy win was not an isolated event. PureCycle said select Tide caps are scheduled for retail production in the third quarter, with Vicks ZzzQuil PURE Zzzs child-resistant lids targeted for the fourth quarter of 2026. Seven customer conversions took place during the quarter, alongside six new commercial partnerships spanning closures, automotive, film, and food packaging, including Amcor, Motherson, and Innovia Films. Regulation is doing real work here too. New Jersey's Department of Environmental Protection approved PureFive as post-consumer recycled content, a decision that arrives as the state's food contact exemption expires in January 2027 and its recycled content requirement climbs to 20%, while California's SB54 is already in effect.
Operationally, the Ironton facility's planned turnaround finished ahead of schedule and under budget, with more than 170 reliability and rate projects completed and inspections showing no corrosion on major equipment. On-site compounding, commissioned in April, is now running 24 hours a day, five days a week, with plans to expand to seven by the fourth quarter. PureCycle also picked up ISO 9001:2015 certification in May and closed the quarter with $236.9 million in total liquidity after a June capital raise.
The other side of the ledger is harder to ignore. PureCycle posted a net loss of $142.2 million for the quarter, and adjusted EBITDA actually widened to a loss of $31.7 million from a loss of $27.8 million a year earlier, a shift the company attributes to smaller non-cash addbacks rather than weaker operations. PureFive production fell to 4.5 million pounds for the quarter, a direct result of the planned turnaround, even though output was still up about 32% from a year ago. Growth is not coming cheap either. Full-year 2026 project spending guidance was raised to a range of $45 million to $50 million, up from the prior $39 million to $45 million.
#year #loss
The Downy win was not an isolated event. PureCycle said select Tide caps are scheduled for retail production in the third quarter, with Vicks ZzzQuil PURE Zzzs child-resistant lids targeted for the fourth quarter of 2026. Seven customer conversions took place during the quarter, alongside six new commercial partnerships spanning closures, automotive, film, and food packaging, including Amcor, Motherson, and Innovia Films. Regulation is doing real work here too. New Jersey's Department of Environmental Protection approved PureFive as post-consumer recycled content, a decision that arrives as the state's food contact exemption expires in January 2027 and its recycled content requirement climbs to 20%, while California's SB54 is already in effect.
Operationally, the Ironton facility's planned turnaround finished ahead of schedule and under budget, with more than 170 reliability and rate projects completed and inspections showing no corrosion on major equipment. On-site compounding, commissioned in April, is now running 24 hours a day, five days a week, with plans to expand to seven by the fourth quarter. PureCycle also picked up ISO 9001:2015 certification in May and closed the quarter with $236.9 million in total liquidity after a June capital raise.
The other side of the ledger is harder to ignore. PureCycle posted a net loss of $142.2 million for the quarter, and adjusted EBITDA actually widened to a loss of $31.7 million from a loss of $27.8 million a year earlier, a shift the company attributes to smaller non-cash addbacks rather than weaker operations. PureFive production fell to 4.5 million pounds for the quarter, a direct result of the planned turnaround, even though output was still up about 32% from a year ago. Growth is not coming cheap either. Full-year 2026 project spending guidance was raised to a range of $45 million to $50 million, up from the prior $39 million to $45 million.
#year #loss


2 months ago
Coca-Cola (NYSE: KO) is one of the best-known companies in the world, thanks to its namesake beverage brand, so it needs little introduction. However, what's most impressive right now is the stock's performance. It is up 28% over the past year, as of this writing. The average consumer staples stock is only up 5% over that span. Even the S&P 500 index (SNPINDEX: ^GSPC) is "only" up 20%. After a run like that, is Coca-Cola a buy, hold, or sell?
Coca-Cola is a well-run business. It is one of the world's largest consumer staples companies. It is globally diversified and has industry-leading capabilities in distribution, marketing, and innovation. The company's fundamental strength is evident in its status as a Dividend King, with 64 consecutive annual dividend increases. The only consumer staples peer with a better record is Procter & Gamble (NYSE: PG), but P&G doesn't make food. So, Coca-Cola is the food company with the best dividend record.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
If you want to own industry-leading businesses, Coca-Cola should be on your short list. And, with an above-market yield of 2.4%, you could easily justify adding it to your portfolio. That's particularly true given recent results, with organic revenue growth of 6% in the second quarter of 2026, even as consumers tighten their belts. In fact, Coca-Cola raised its full-year guidance despite the broader food industry's struggles.
Certainly, if you have owned Coca-Cola for years, selling it right when it is performing so well as a business probably isn't something you should be considering. Unless, of course, the stock's valuation was running ahead of its historical norms. But that's not the case.
#staples
Coca-Cola is a well-run business. It is one of the world's largest consumer staples companies. It is globally diversified and has industry-leading capabilities in distribution, marketing, and innovation. The company's fundamental strength is evident in its status as a Dividend King, with 64 consecutive annual dividend increases. The only consumer staples peer with a better record is Procter & Gamble (NYSE: PG), but P&G doesn't make food. So, Coca-Cola is the food company with the best dividend record.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
If you want to own industry-leading businesses, Coca-Cola should be on your short list. And, with an above-market yield of 2.4%, you could easily justify adding it to your portfolio. That's particularly true given recent results, with organic revenue growth of 6% in the second quarter of 2026, even as consumers tighten their belts. In fact, Coca-Cola raised its full-year guidance despite the broader food industry's struggles.
Certainly, if you have owned Coca-Cola for years, selling it right when it is performing so well as a business probably isn't something you should be considering. Unless, of course, the stock's valuation was running ahead of its historical norms. But that's not the case.
#staples


2 months ago
If it's strong capital appreciation that you're after, then Procter & Gamble (NYSE: PG) isn't the best investment candidate. Its shares are up just 67% in the past decade (as of Sept. 3), drastically underperforming the S&P 500 index.
But if you're seeking a blue chip dividend stock, then Procter & Gamble is hard to beat. Its dividend yield of nearly 3% is almost triple the benchmark average.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Here's how many shares of this company you'd need for $15,000 in yearly dividends.
Procter & Gamble currently pays an annual dividend of about $4.34 per share. This means you would have to own 3,456 shares to generate $15,000 in yearly passive income. Based on the stock price of $147.51, investors would be required to pay $510,000 to buy enough shares.
#NVIDIA #Stock #company
But if you're seeking a blue chip dividend stock, then Procter & Gamble is hard to beat. Its dividend yield of nearly 3% is almost triple the benchmark average.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Here's how many shares of this company you'd need for $15,000 in yearly dividends.
Procter & Gamble currently pays an annual dividend of about $4.34 per share. This means you would have to own 3,456 shares to generate $15,000 in yearly passive income. Based on the stock price of $147.51, investors would be required to pay $510,000 to buy enough shares.
#NVIDIA #Stock #company

2 months ago
Valued at a market cap of $343.4 billion, The Procter & Gamble Company (PG) is one of the world's largest consumer goods companies, selling a broad portfolio of everyday household, personal care, health, beauty, and grooming products in about 180 countries and territories. The Cincinnati, Ohio-based company has built its business around globally recognized brands such as Tide, Pampers, Gillette, Head & Shoulders, Pantene, Olay, Oral-B, Always, Dawn, Bounty, and Crest.
Companies worth $200 billion or more are typically classified as "mega-cap stocks," and PG fits the label perfectly, with its market cap exceeding this threshold, underscoring its size, influence, and dominance within the household & personal products industry. The company's scale, powerful brands, extensive distribution network, and consistent product innovation give it a formidable position in the global fast-moving consumer goods industry.
Sandisk Stock Could Nearly Double to $3,000, According to Wall Street
Jeff Bezos' Heartfelt Tribute to Dolly Parton Drew Brutal Backlash: 'Nobody Wanted to Hear This From You' — He Once Gave Her $100 Million for Charity
Warren Buffett's Granddaughter Says He Disowned Her and Twin Sister in a Letter —'I Have Not Emotionally or Legally Adopted You as a Grandchild…'
#Companies #Consumer #personal #brands
Companies worth $200 billion or more are typically classified as "mega-cap stocks," and PG fits the label perfectly, with its market cap exceeding this threshold, underscoring its size, influence, and dominance within the household & personal products industry. The company's scale, powerful brands, extensive distribution network, and consistent product innovation give it a formidable position in the global fast-moving consumer goods industry.
Sandisk Stock Could Nearly Double to $3,000, According to Wall Street
Jeff Bezos' Heartfelt Tribute to Dolly Parton Drew Brutal Backlash: 'Nobody Wanted to Hear This From You' — He Once Gave Her $100 Million for Charity
Warren Buffett's Granddaughter Says He Disowned Her and Twin Sister in a Letter —'I Have Not Emotionally or Legally Adopted You as a Grandchild…'
#Companies #Consumer #personal #brands

2 months ago
If you're looking for a well-proven dividend stock, consumer goods name Procter & Gamble (NYSE: PG) is about as good as they come, with 70 consecutive years of annual dividend hikes to its credit. Indeed, only one other company has a longer track record of uninterrupted yearly dividend increases. That streak isn't apt to end anytime soon, if ever.
But reliable dividend growth is only half the story. How much are income investors actually making with their positions in P&G?
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Procter & Gamble's forward-looking dividend yield currently stands at 3%, based on a quarterly payment of $1.0885 per share. A $25,000 position in the stock -- about 172 shares -- would produce just over $187 in dividend income per quarter, or just under $750 per year. That's not earth-shattering, but it's not bad either.
But those numbers arguably understate the total long-term potential that Procter & Gamble offers to patient investors. This company also boasts one of the better rates of dividend growth among blue chip dividend payers. Over the past 10 completed fiscal years, Procter's annual dividend payout has grown from $2.66 to $4.26 per share, and is currently running at an annualized pace of $4.35 per share. That's annualized growth of right around 4.8%, easily outpacing inflation as well as most other Dividend Kings' payment increase rates.
#Dividend #signal #Growth #flashing
But reliable dividend growth is only half the story. How much are income investors actually making with their positions in P&G?
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Procter & Gamble's forward-looking dividend yield currently stands at 3%, based on a quarterly payment of $1.0885 per share. A $25,000 position in the stock -- about 172 shares -- would produce just over $187 in dividend income per quarter, or just under $750 per year. That's not earth-shattering, but it's not bad either.
But those numbers arguably understate the total long-term potential that Procter & Gamble offers to patient investors. This company also boasts one of the better rates of dividend growth among blue chip dividend payers. Over the past 10 completed fiscal years, Procter's annual dividend payout has grown from $2.66 to $4.26 per share, and is currently running at an annualized pace of $4.35 per share. That's annualized growth of right around 4.8%, easily outpacing inflation as well as most other Dividend Kings' payment increase rates.
#Dividend #signal #Growth #flashing


3 months ago
KO is up 32% year to date on record Trademark volume growth, while PEP yields 4% at a discounted 17x forward P/E.
PG has paid dividends for 136 consecutive years and trades at a rare 20x forward P/E after falling 6% over the past year.
Act now: the ***** yst who called NVIDIA in 2010 just named his top 10 AI stocks — and P&G didn't make the cut. Grab the names FREE today.
August is closing on a market that has rewarded speculation and punished patience, which is exactly when the boring compounders start looking interesting again. The three names below are all Dividend Kings, each with more than 50 consecutive years of dividend increases, and each has just delivered results that reinforce why long-term holders keep showing up (we ranked our ten favorite Dividend Kings by valuation right now in a free report here). Two of them are trading well off their 52-week highs, and one is running hot into a World Cup catalyst. For investors thinking about positioning income portfolios before the calendar flips to September, this trio deserves a serious look.
Procter & Gamble (NYSE:PG) is the definition of forever-hold. The consumer staples giant just closed out fiscal 2026 with its 70th consecutive year of dividend increases and has now paid dividends for 136 straight years, going back to 1890. That is a streak that has become an institution.
#consecutive #dividends
PG has paid dividends for 136 consecutive years and trades at a rare 20x forward P/E after falling 6% over the past year.
Act now: the ***** yst who called NVIDIA in 2010 just named his top 10 AI stocks — and P&G didn't make the cut. Grab the names FREE today.
August is closing on a market that has rewarded speculation and punished patience, which is exactly when the boring compounders start looking interesting again. The three names below are all Dividend Kings, each with more than 50 consecutive years of dividend increases, and each has just delivered results that reinforce why long-term holders keep showing up (we ranked our ten favorite Dividend Kings by valuation right now in a free report here). Two of them are trading well off their 52-week highs, and one is running hot into a World Cup catalyst. For investors thinking about positioning income portfolios before the calendar flips to September, this trio deserves a serious look.
Procter & Gamble (NYSE:PG) is the definition of forever-hold. The consumer staples giant just closed out fiscal 2026 with its 70th consecutive year of dividend increases and has now paid dividends for 136 straight years, going back to 1890. That is a streak that has become an institution.
#consecutive #dividends


3 months ago
Are you shopping for a dividend stock you can comfortably buy and hold forever? It's not as easy as it used to be. Yesteryear's stalwart companies aren't guaranteed survivors anymore. The advent of the internet -- and, more recently, artificial intelligence -- is making it easier than ever to compete with **** ans in any industry.
There's one well-known dividend-paying blue chip stock, however, that's still as attractive as it ever was because its competitive moat is as wide today as it's ever been. That's consumer goods behemoth Procter & Gamble (NYSE: PG).
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Even if you don't use any of them (which is unlikely), you know the company's products. Procter & Gamble is the parent company of Tide laundry detergent, Charmin toilet paper, Gillette razors, Crest toothpaste, and more. Several of its goods are either the first- or second-best sellers in their particular product categories.
That's not just due to luck, though, or even the direct result of being around for longer. In fact, the three reasons so many of P&G's brands dominate their respective categories are the same reasons that income-seeking investors can comfortably buy and hold this consumer staples name forever.
#NVIDIA #ever #procter #Dividend
There's one well-known dividend-paying blue chip stock, however, that's still as attractive as it ever was because its competitive moat is as wide today as it's ever been. That's consumer goods behemoth Procter & Gamble (NYSE: PG).
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Even if you don't use any of them (which is unlikely), you know the company's products. Procter & Gamble is the parent company of Tide laundry detergent, Charmin toilet paper, Gillette razors, Crest toothpaste, and more. Several of its goods are either the first- or second-best sellers in their particular product categories.
That's not just due to luck, though, or even the direct result of being around for longer. In fact, the three reasons so many of P&G's brands dominate their respective categories are the same reasons that income-seeking investors can comfortably buy and hold this consumer staples name forever.
#NVIDIA #ever #procter #Dividend

3 months ago
Personal care products provider Kimberly-Clark Corporation (NYSE:KMB)'s shares are down by 17% over the past year and are up by 9% year-to-date. It is currently undergoing a major transformation through acquiring Kenvue. Cramer has discussed Kimberly-Clark Corporation (NYSE:KMB)'s acquisition several times and linked its performance with consumer goods giant Procter & Gamble. In his morning appearance on August 6th, the CNBC TV host discussed Kimberly-Clark Corporation (NYSE:KMB)'s earnings and the tailwinds from the acquisition:
"I like the way Kimberly acted, even though they had a asterisk China diaper problem which I did not know about. The stock started down and then finished up nicely. I think that Chu is doing is a nice job. I think that Kenvue acquisition's going to be very good. Proctor was not as good, so I think that maybe you're going to start seeing, even though Proctor's much bigger than Kimberly, maybe we're going to have a new colossus."
On the 4th, Kimberly-Clark Corporation (NYSE:KMB) had reported its second quarter earnings to post $4.19 billion in revenue that missed **** yst estimates of $4.22 billion. Yet, the firm also cut its organic sales growth and earnings forecasts. Yet, the shares close 3.7% higher on the 4th, exhibiting solid momentum after the report hit the wires before market open.
Kimberly-Clark Corporation (NYSE:KMB)'s business model, i.e., selling personal care products, is resistant in a tough economy as consumers continue to spend on its products even if they reduce discretionary spending. Cramer's previous comments about the firm have also noted this, but the firm's sluggish revenue performance in the second quarter opens up concerns about its growth. Additionally, turmoil in the oil market stemming from the Iran war and other factors can stress its margins. This stress, at a time when Kimberly-Clark Corporation (NYSE:KMB) might have to deal with high debt levels as well. Consequently, 15% of the float being short as of July-end is unsurprising.
On the other hand, the difference between Kimberly-Clark Corporation (NYSE:KMB) and Procter & Gamble Company (NYSE:PG) is visible when we compare their forward P/E. While the former has a multiple of 14.93, the latter is valued better through a 20.9 multiple. Procter & Gamble Company (NYSE:PG)'s ability to sustain high prices courtesy of its brand strength and market share (60% in blades and razors and 45% to 50% in fabric) is one of its strongest suits. It enables the firm to deliver stable revenue growth, as evidenced by a 2% jump in its June quarter sales. Additionally, Procter & Gamble Company (NYSE:PG)'s stable defensive market lead it to commit to stable stock buybacks ($6 billion to $7 billion in FY27) and stable dividends (2.48% yield). Naturally, the P/E is higher, and the short interest is negligible at 1.17% of the float.
#company
"I like the way Kimberly acted, even though they had a asterisk China diaper problem which I did not know about. The stock started down and then finished up nicely. I think that Chu is doing is a nice job. I think that Kenvue acquisition's going to be very good. Proctor was not as good, so I think that maybe you're going to start seeing, even though Proctor's much bigger than Kimberly, maybe we're going to have a new colossus."
On the 4th, Kimberly-Clark Corporation (NYSE:KMB) had reported its second quarter earnings to post $4.19 billion in revenue that missed **** yst estimates of $4.22 billion. Yet, the firm also cut its organic sales growth and earnings forecasts. Yet, the shares close 3.7% higher on the 4th, exhibiting solid momentum after the report hit the wires before market open.
Kimberly-Clark Corporation (NYSE:KMB)'s business model, i.e., selling personal care products, is resistant in a tough economy as consumers continue to spend on its products even if they reduce discretionary spending. Cramer's previous comments about the firm have also noted this, but the firm's sluggish revenue performance in the second quarter opens up concerns about its growth. Additionally, turmoil in the oil market stemming from the Iran war and other factors can stress its margins. This stress, at a time when Kimberly-Clark Corporation (NYSE:KMB) might have to deal with high debt levels as well. Consequently, 15% of the float being short as of July-end is unsurprising.
On the other hand, the difference between Kimberly-Clark Corporation (NYSE:KMB) and Procter & Gamble Company (NYSE:PG) is visible when we compare their forward P/E. While the former has a multiple of 14.93, the latter is valued better through a 20.9 multiple. Procter & Gamble Company (NYSE:PG)'s ability to sustain high prices courtesy of its brand strength and market share (60% in blades and razors and 45% to 50% in fabric) is one of its strongest suits. It enables the firm to deliver stable revenue growth, as evidenced by a 2% jump in its June quarter sales. Additionally, Procter & Gamble Company (NYSE:PG)'s stable defensive market lead it to commit to stable stock buybacks ($6 billion to $7 billion in FY27) and stable dividends (2.48% yield). Naturally, the P/E is higher, and the short interest is negligible at 1.17% of the float.
#company


3 months ago
I've been writing about Procter & Gamble (NYSE: PG) for years, and my conviction has never been higher, because the company keeps doing the boring, hard things that compound over time: It protects its brands, invests in innovation, and quietly returns a lot of cash to shareholders even when the environment is rough.
Fiscal 2026 was not a blowout year for Procter & Gamble. Net sales grew 3%, organic sales rose 1%, and core earnings per share increased 1%. That's the kind of result many investors would shrug at. What matters to me is that those numbers landed right inside the company's guidance in a year that featured currency swings, higher energy and transportation costs, and uneven demand across regions.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
P&G's strategy is deliberately simple. It focuses on daily use categories where performance drives brand choice and seeks to deliver superiority in product, packaging, communication, retail execution, and value. It pairs that with what it calls "constructive disruption" and a heavy dose of productivity, meaning it constantly looks for ways to do the same work with fewer resources. The result is a business that rarely looks spectacular quarter to quarter but, over many years, keeps nudging growth and margins in the right direction.
This is not a sleepy soap company. In April, Procter & Gamble was named the top household products company on Fortune's America's Most Innovative Companies list for the third year in a row, with product innovation singled out as its biggest strength.
#signal #conviction #flashing
Fiscal 2026 was not a blowout year for Procter & Gamble. Net sales grew 3%, organic sales rose 1%, and core earnings per share increased 1%. That's the kind of result many investors would shrug at. What matters to me is that those numbers landed right inside the company's guidance in a year that featured currency swings, higher energy and transportation costs, and uneven demand across regions.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
P&G's strategy is deliberately simple. It focuses on daily use categories where performance drives brand choice and seeks to deliver superiority in product, packaging, communication, retail execution, and value. It pairs that with what it calls "constructive disruption" and a heavy dose of productivity, meaning it constantly looks for ways to do the same work with fewer resources. The result is a business that rarely looks spectacular quarter to quarter but, over many years, keeps nudging growth and margins in the right direction.
This is not a sleepy soap company. In April, Procter & Gamble was named the top household products company on Fortune's America's Most Innovative Companies list for the third year in a row, with product innovation singled out as its biggest strength.
#signal #conviction #flashing

3 months ago
Procter & Gamble (NYSE:PG) is buying its way into wellness. On August 4, L Catterton announced it had signed a definitive agreement to sell Thorne, a science-backed health and wellness brand, to Procter & Gamble for $3.8 billion in cash. The deal lands a day after an August 3 ****** ysis flagged a fiscal 2027 earnings guide that came in below expectations, weighed down by roughly $1 billion in new cost headwinds. Investors now have two stories to weigh at once: fresh expansion and a tougher near-term cost picture.
The Thorne acquisition gives Procter & Gamble entry into a category built on clinical credibility rather than shelf ****** e. Thorne has spent 40 years building relationships with healthcare practitioners, and L Catterton's announcement noted the company developed a proprietary AI wellness advisor to help consumers navigate its supplement lineup, a tool practitioners can point their patients to directly.
The transaction is expected to close in the fourth quarter of 2026, an all-cash deal with no debt or equity swapped into the mix. Procter & Gamble isn't skimping on shareholders while it shops, either. The company returned $10.2 billion in dividends and $5.0 billion in share repurchases during fiscal 2026, and it plans roughly the same combination, about $10 billion in dividends and $5 billion in buybacks, for fiscal 2027. There's a case buried inside the company's own guidance, too. Strip out the roughly $1 billion in commodity, energy, and transportation costs management expects to absorb next year, and core EPS would be growing at about 10% instead of the 0% to 3% baked into the outlook.
The numbers behind the fiscal 2027 outlook explain the caution. Management guided core EPS to $6.89 to $7.11, implying growth of just 0% to 3%, and pointed to roughly $1 billion in after-tax commodity, energy, and transportation costs as the main culprit. Add higher net interest expense, lower non-operating income, and unfavorable currency, and the total drag reaches $0.56 per share, wiping out about 8 percentage points of core earnings growth before the year even starts.
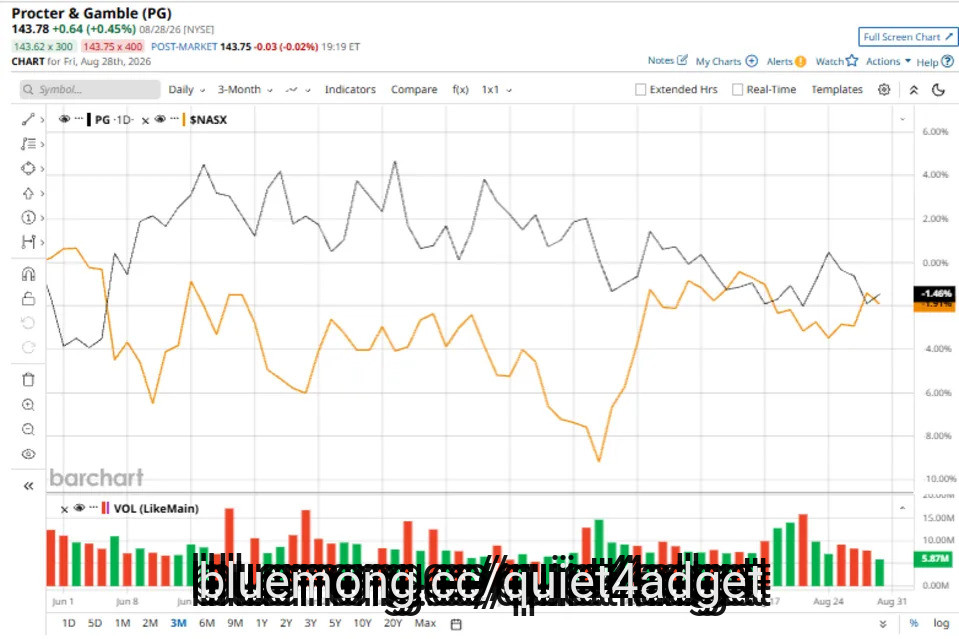
The trend already shows up in recent results. In the fiscal fourth quarter, net sales rose 2% year-over-year to $21.2 billion while organic sales were flat, and core EPS fell 3% to $1.43. For the full fiscal year, net sales grew 3% to $87.0 billion, but organic sales rose only 1%, and every bit of that growth came from higher prices rather than more units sold. Volume and mix didn't move. Shares trade near $144, about 5% above their 52-week low of $137.62, or roughly 21 times fiscal 2026 core earnings of $6.89. That's not an expensive multiple, but it isn't cheap for a business guiding to low-single-digit growth.
#gamble #thorne
The Thorne acquisition gives Procter & Gamble entry into a category built on clinical credibility rather than shelf ****** e. Thorne has spent 40 years building relationships with healthcare practitioners, and L Catterton's announcement noted the company developed a proprietary AI wellness advisor to help consumers navigate its supplement lineup, a tool practitioners can point their patients to directly.
The transaction is expected to close in the fourth quarter of 2026, an all-cash deal with no debt or equity swapped into the mix. Procter & Gamble isn't skimping on shareholders while it shops, either. The company returned $10.2 billion in dividends and $5.0 billion in share repurchases during fiscal 2026, and it plans roughly the same combination, about $10 billion in dividends and $5 billion in buybacks, for fiscal 2027. There's a case buried inside the company's own guidance, too. Strip out the roughly $1 billion in commodity, energy, and transportation costs management expects to absorb next year, and core EPS would be growing at about 10% instead of the 0% to 3% baked into the outlook.
The numbers behind the fiscal 2027 outlook explain the caution. Management guided core EPS to $6.89 to $7.11, implying growth of just 0% to 3%, and pointed to roughly $1 billion in after-tax commodity, energy, and transportation costs as the main culprit. Add higher net interest expense, lower non-operating income, and unfavorable currency, and the total drag reaches $0.56 per share, wiping out about 8 percentage points of core earnings growth before the year even starts.
The trend already shows up in recent results. In the fiscal fourth quarter, net sales rose 2% year-over-year to $21.2 billion while organic sales were flat, and core EPS fell 3% to $1.43. For the full fiscal year, net sales grew 3% to $87.0 billion, but organic sales rose only 1%, and every bit of that growth came from higher prices rather than more units sold. Volume and mix didn't move. Shares trade near $144, about 5% above their 52-week low of $137.62, or roughly 21 times fiscal 2026 core earnings of $6.89. That's not an expensive multiple, but it isn't cheap for a business guiding to low-single-digit growth.
#gamble #thorne


3 months ago
Procter & Gamble (PG) shares extended gains on Aug. 4 after the company announced a definitive agreement to acquire premium wellness and dietary supplement maker Thorne. The $3.8 billion all-cash transaction equips the NYSE-listed consumer staple giant with immediate scale in the rapidly expanding health and self-care market.
Despite recent gains, Procter & Gamble stock is down roughly 12% versus its year-to-date high in late February.
Jeff Bezos Says He's Selling $1 Billion In Amazon Stock Every Year to Fund Blue Origin — 'It's The Most Important Work I'm Doing'
Apple's New CEO Is Bringing a Familiar Face Back From Retirement. The Shift Is Happening.
Nasdaq Futures Climb as Tech Rally Continues on Palantir Boost, U.S. JOLTS Report and ***** eX Earnings on Tap
#procter #Stock #year #despite
Despite recent gains, Procter & Gamble stock is down roughly 12% versus its year-to-date high in late February.
Jeff Bezos Says He's Selling $1 Billion In Amazon Stock Every Year to Fund Blue Origin — 'It's The Most Important Work I'm Doing'
Apple's New CEO Is Bringing a Familiar Face Back From Retirement. The Shift Is Happening.
Nasdaq Futures Climb as Tech Rally Continues on Palantir Boost, U.S. JOLTS Report and ***** eX Earnings on Tap
#procter #Stock #year #despite



3 months ago
Procter & Gamble Co (NYSE:PG, XETRA:PRG) shares fell more than 3% on Wednesday after the consumer goods giant reported fourth-quarter revenue that missed ***** yst estimates, even as it topped profit expectations.
The maker of Tide detergent and Pampers diapers posted revenue of $21.2 billion for the quarter, up 2% from a year earlier but below ***** ysts' estimate of $21.38 billion. Organic sales were flat year-over-year.
Adjusted earnings per share came in at $1.43, above the $1.41 estimate, though down 3% from the prior year. Diluted EPS fell 15% to $1.26, while net earnings dropped 16% to $3.04 billion.
Both operating and gross margins contracted during the quarter, while SG&A costs rose as a share of sales.
By segment, Beauty led growth, with Grooming, Health Care and Fabric & Home Care also posting modest increases. Baby, Feminine & Family Care was the only segment to decline.
#care
The maker of Tide detergent and Pampers diapers posted revenue of $21.2 billion for the quarter, up 2% from a year earlier but below ***** ysts' estimate of $21.38 billion. Organic sales were flat year-over-year.
Adjusted earnings per share came in at $1.43, above the $1.41 estimate, though down 3% from the prior year. Diluted EPS fell 15% to $1.26, while net earnings dropped 16% to $3.04 billion.
Both operating and gross margins contracted during the quarter, while SG&A costs rose as a share of sales.
By segment, Beauty led growth, with Grooming, Health Care and Fabric & Home Care also posting modest increases. Baby, Feminine & Family Care was the only segment to decline.
#care


3 months ago
Stock market investors on Wednesday were spooked by the prospect of an interest rate hike by the Federal Reserve while flaring U.S.-Iran tensions propelled oil prices. GE HealthCare (GEHC) soared on the stock market today after its earnings report. Meanwhile, Meta Platforms (META) and Microsoft (MSFT) reports are on deck.
The Dow Jones Industrial Average dropped more than 800 points, or 1.6%, amid mixed reactions to earnings reports from Visa (V) and Procter & Gamble (PG). The S&P 500 flopped 0.8%. The tech-heavy Nasdaq composite fell 1.1%. The Nasdaq-100 (NDX) dropped 1% and once again stumbled into correction territory, falling 10% from its June highs. Small caps were hit as well, pulling the Russell 2000 index lower by 1.1%.
In the face of heightened hostilities between the U.S. and Iran, West Texas intermediate crude oil futures spiked more than 7%, trading around $84.90 per barrel. Brent crude futures also jumped more than 7%, trading at $88 per barrel.
Also, ahead of the Fed's announcement on the fed funds rate, the 10-year Treasury yield rose 2 basis to 4.62%. Bitcoin slid near $63,990.
GE Healthcare (GEHC) soared more than 10%, rebounding from a downward-sloping 50-day moving average. It was the best performer on the Nasdaq composite Wednesday, and was on track for its largest percentage increase on record, according to Dow Jones Markets Data.
#wednesday #gehc #average
The Dow Jones Industrial Average dropped more than 800 points, or 1.6%, amid mixed reactions to earnings reports from Visa (V) and Procter & Gamble (PG). The S&P 500 flopped 0.8%. The tech-heavy Nasdaq composite fell 1.1%. The Nasdaq-100 (NDX) dropped 1% and once again stumbled into correction territory, falling 10% from its June highs. Small caps were hit as well, pulling the Russell 2000 index lower by 1.1%.
In the face of heightened hostilities between the U.S. and Iran, West Texas intermediate crude oil futures spiked more than 7%, trading around $84.90 per barrel. Brent crude futures also jumped more than 7%, trading at $88 per barrel.
Also, ahead of the Fed's announcement on the fed funds rate, the 10-year Treasury yield rose 2 basis to 4.62%. Bitcoin slid near $63,990.
GE Healthcare (GEHC) soared more than 10%, rebounding from a downward-sloping 50-day moving average. It was the best performer on the Nasdaq composite Wednesday, and was on track for its largest percentage increase on record, according to Dow Jones Markets Data.
#wednesday #gehc #average


4 months ago
With artificial intelligence fueling upside, Taiwan Semiconductor (TSM) is still one of the hottest tech giants to buy and hold long-term. Furthermore, the company just posted strong earnings. EPS of $4.31 beat by $0.37. Revenue of $40.2 billion rocketed 33.7% higher year-over-year (YOY), beating estimates by $300 million. And ***** ysts are still incredibly bullish. For example, Wedbush reiterated an "Outperform" rating on the stock, with a price target of NT$3,000 from NT$2,900, thanks to strong, growing demand for artificial intelligence chips.
And while the stock did pull back on the company's plans to increase its 2026 capital expenditures to between $60 billion and $64 billion, up from $52 billion to $56 billion, I'd use recent weakness as an opportunity to buy for the long haul.
This Dividend King Could Be One of the Safest Stocks to Own Right Now
AI Startup Moonshot Just Launched Its Record-Setting Kimi K3 Model. Buy Alibaba Stock to Benefit.
As the AI Selloff Worsens, Time-Tested Procter & Gamble Stock Could Be the Biggest Winner
#artificial #still #year #semiconductor
And while the stock did pull back on the company's plans to increase its 2026 capital expenditures to between $60 billion and $64 billion, up from $52 billion to $56 billion, I'd use recent weakness as an opportunity to buy for the long haul.
This Dividend King Could Be One of the Safest Stocks to Own Right Now
AI Startup Moonshot Just Launched Its Record-Setting Kimi K3 Model. Buy Alibaba Stock to Benefit.
As the AI Selloff Worsens, Time-Tested Procter & Gamble Stock Could Be the Biggest Winner
#artificial #still #year #semiconductor


4 months ago
Procter & Gamble (NYSE: PG) raised its quarterly dividend 3% in April to $1.0885 per share, marking its 70th consecutive year of dividend increases. Only five other publicly traded companies have raised their payouts for that many years in a row.
The streak is even more remarkable when you zoom out. P&G has paid a dividend every year since its incorporation in 1890 -- 136 straight years. And the payments are enormous in absolute terms, too. The company behind Tide, Pampers, and Gillette expects to pay around $10 billion in dividends in fiscal 2026, plus roughly $5 billion in share repurchases on top of it.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
A streak like this is only possible because of what P&G sells. Detergent, diapers, razors, and paper towels get bought in good economies and bad ones, and the company's latest results show that durability at work. In its fiscal 2026 third quarter (the period ended March 31), P&G's organic sales, which exclude currency moves, acquisitions, and divestitures, grew 3% year over year, and core earnings per share rose 3% to $1.59. Management also maintained its full-year outlook even while absorbing tariff-related costs.
With shares trading near $148, P&G stock yields about 2.9% as of this writing. The payout consumes about 63% of the company's earnings over the past 12 months, a level that leaves room for the increases to continue. And the valuation looks arguably reasonable, too. Shares trade at about 21 times earnings -- not a bargain, but hardly a demanding price for a business this durable.
The streak is even more remarkable when you zoom out. P&G has paid a dividend every year since its incorporation in 1890 -- 136 straight years. And the payments are enormous in absolute terms, too. The company behind Tide, Pampers, and Gillette expects to pay around $10 billion in dividends in fiscal 2026, plus roughly $5 billion in share repurchases on top of it.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
A streak like this is only possible because of what P&G sells. Detergent, diapers, razors, and paper towels get bought in good economies and bad ones, and the company's latest results show that durability at work. In its fiscal 2026 third quarter (the period ended March 31), P&G's organic sales, which exclude currency moves, acquisitions, and divestitures, grew 3% year over year, and core earnings per share rose 3% to $1.59. Management also maintained its full-year outlook even while absorbing tariff-related costs.
With shares trading near $148, P&G stock yields about 2.9% as of this writing. The payout consumes about 63% of the company's earnings over the past 12 months, a level that leaves room for the increases to continue. And the valuation looks arguably reasonable, too. Shares trade at about 21 times earnings -- not a bargain, but hardly a demanding price for a business this durable.

4 months ago
By Nate Raymond
BOSTON, July 7 (Reuters) - The founder and chief executive of an AI startup secretly pleaded guilty last year to participating in a vast scheme in which attorneys at major law firms tipped traders about mergers their employers were advising on.
Court records unsealed on Monday show that Arya Bolurfrushan, a former Goldman Sachs banker who founded Abu Dhabi-based AppliedAI, pleaded guilty in June 2025 after striking a deal with federal prosecutors in Boston who were working to build cases against dozens of other people accused of participating in the long-running insider trading scheme.
Those individuals include Nicolo Nourafchan, who had worked at the law firms Sidley Austin, Latham & Watkins and Goodwin Procter before prosecutors in May unveiled charges against him and 29 other people accused of engaging in a scheme to profit from confidential information about mergers underway.
Bolurfrushan pleaded guilty to conspiring to commit securities fraud in a plea agreement where prosecutors agreed to recommend that he be sentenced to two years in prison and forfeit $954,496 he derived from the scheme.
BOSTON, July 7 (Reuters) - The founder and chief executive of an AI startup secretly pleaded guilty last year to participating in a vast scheme in which attorneys at major law firms tipped traders about mergers their employers were advising on.
Court records unsealed on Monday show that Arya Bolurfrushan, a former Goldman Sachs banker who founded Abu Dhabi-based AppliedAI, pleaded guilty in June 2025 after striking a deal with federal prosecutors in Boston who were working to build cases against dozens of other people accused of participating in the long-running insider trading scheme.
Those individuals include Nicolo Nourafchan, who had worked at the law firms Sidley Austin, Latham & Watkins and Goodwin Procter before prosecutors in May unveiled charges against him and 29 other people accused of engaging in a scheme to profit from confidential information about mergers underway.
Bolurfrushan pleaded guilty to conspiring to commit securities fraud in a plea agreement where prosecutors agreed to recommend that he be sentenced to two years in prison and forfeit $954,496 he derived from the scheme.

4 months ago
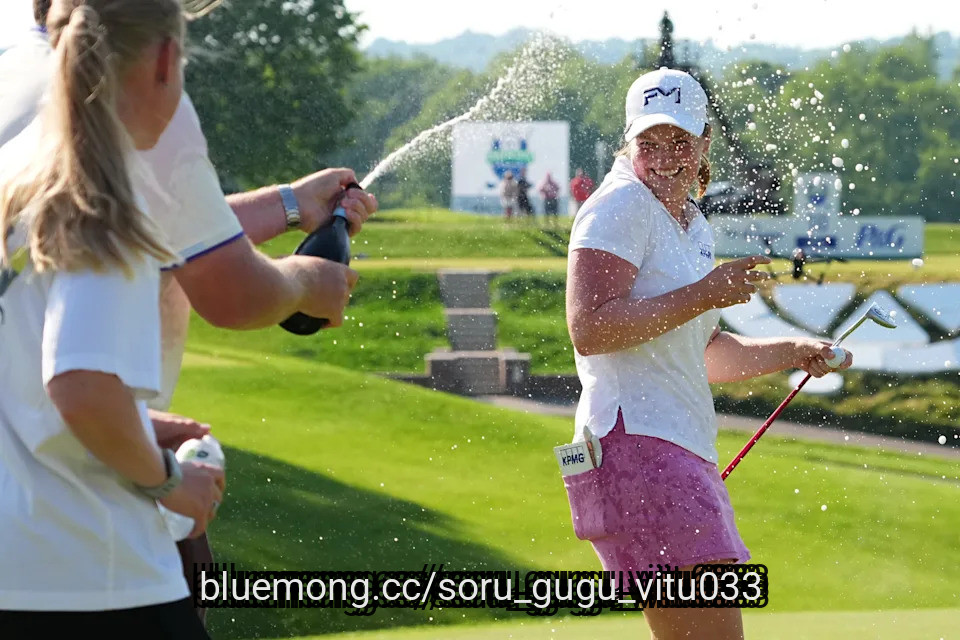
The Cincinnati Business Courier has reported that Kroger Co. and Procter & Gamble Co. will no longer sponsor the LPGA’s Cincinnati stop.
The Kroger Queen City Championship presented by P&G was on the LPGA's schedule for five years. The event was strongly attended, with roughly 50,000 fans, and held over three different courses, most recently at Maketewah Country Club, where Lottie Woad held off Haeran Ryu for the ***** le. Typically held in the fall, the event moved to mid-May in 2026.
“After thoughtful consideration, we’ve made the difficult decision to focus our efforts in other areas that align with our long-term priorities," a Kroger spokesperson told the Cincinnati Business Courier.
In February, Kroger appointed Greg Foran as its new Chief Executive Officer.
The 2026 LPGA schedule includes 31 official events. LPGA commissioner Craig Kessler, who has been in the position for a full year now, is working toward a revamp of the tour’s schedule, though details of a future blueprint have yet to be shared. Sources say the tour is expected to announce at least one new event in the coming months.
The Kroger Queen City Championship presented by P&G was on the LPGA's schedule for five years. The event was strongly attended, with roughly 50,000 fans, and held over three different courses, most recently at Maketewah Country Club, where Lottie Woad held off Haeran Ryu for the ***** le. Typically held in the fall, the event moved to mid-May in 2026.
“After thoughtful consideration, we’ve made the difficult decision to focus our efforts in other areas that align with our long-term priorities," a Kroger spokesperson told the Cincinnati Business Courier.
In February, Kroger appointed Greg Foran as its new Chief Executive Officer.
The 2026 LPGA schedule includes 31 official events. LPGA commissioner Craig Kessler, who has been in the position for a full year now, is working toward a revamp of the tour’s schedule, though details of a future blueprint have yet to be shared. Sources say the tour is expected to announce at least one new event in the coming months.
5 months ago
P&G (PG) tops Colgate (CL) for dividend investors with 70 straight annual hikes, a 2.83% yield, and a cheaper 22x trailing P/E.
Colgate's North America sales fell 1.8% with volume off 3%, as private label competition erodes shelf ****** e for Speed Stick and core Colgate brands.
P&G absorbed $400 million in tariff drag while executing over $600 million in buybacks and maintaining 85% to 90% free cash flow productivity.
Act now: the ****** yst who called NVIDIA in 2010 just named his top 10 AI stocks — and P&G didn't make the cut. Grab the names FREE today.
Procter & Gamble (NYSE:PG) and Colgate-Palmolive (NYSE:CL) both just reported, and the earnings reports sharpened a debate dividend investors have been having for years.
Colgate's North America sales fell 1.8% with volume off 3%, as private label competition erodes shelf ****** e for Speed Stick and core Colgate brands.
P&G absorbed $400 million in tariff drag while executing over $600 million in buybacks and maintaining 85% to 90% free cash flow productivity.
Act now: the ****** yst who called NVIDIA in 2010 just named his top 10 AI stocks — and P&G didn't make the cut. Grab the names FREE today.
Procter & Gamble (NYSE:PG) and Colgate-Palmolive (NYSE:CL) both just reported, and the earnings reports sharpened a debate dividend investors have been having for years.



