3 hours ago
AbbVie Inc. (NYSE:ABBV) was trading at around $263 on October 5, up 14.18% over twelve months. Its payout ratio is 190.40%. The company distributes nearly twice what it reports as profit.
A dividend that large is either about to be cut or is being paid out of something the earnings line does not show.
READ ALSO: Here is Why Tripadvisor (TRIP) is a Bad Investment at Today's Price
AbbVie reported net income of $6.27 billion and generated $16.87 billion of free cash flow. Dividends are paid from the second number, so a ratio measured against the first is describing depressed earnings rather than a company living beyond its means.
The margins show what depresses them. Operating margin is 40.04%. Net margin is 9.80%. Thirty points vanish between those lines, and where they vanish matters. Costs that high sitting below the operating line are not the business failing to earn. They are the amortization of a drug portfolio AbbVie bought rather than discovered, plus interest on the debt that bought it.
#paid

1 day ago
A Florida woman is facing 14 felony charges in connection with a shooting at Rihanna's Los Angeles home earlier this year.
Ivanna Lisette Ortiz, 36, was indicted on one count of attempted murder, 10 counts of **** ault with an **** ault weapon, and three counts of shooting at an inhabited dwelling or camper, according to the Los Angeles County District Attorney's Office.
Prosecutors allege Ortiz drove to the property on March 8 and fired an **** ault weapon multiple times at the home in broad daylight while Rihanna, A$AP Rocky, their children and others were on the property or nearby.
Ortiz pleaded not guilty after the grand jury indictment was unsealed Wednesday, with bail set at $2.65 million. Los Angeles County District Attorney Nathan J. Hochman said it was fortunate **** ody was killed or injured during the shooting.
COMPLEX SHOP: Shop the brands you love, anytime and anywhere. Uncover what's next. Buy. Collect. Obsess.
#ortiz #district #counts #weapon

16 days ago
On September 17, Coherent Corp. (NYSE:COHR) announced an upgraded Pluggable Optical Line System that covers the full C-band and fits in a compact QSFP module, the same slot ordinary transceivers use. That is a lot of networking gear shrunk into a plug, and it follows a quarter of 34% revenue growth. Here is what the launch means, and where the stock's story gets harder to read.
Start with what the product does. The upgraded system can pack 32 wavelengths onto a single pair of fibers, which Coherent says adds up to as much as 25.6Tbps of traffic on links running 2km to 200km. It is designed for the latest 800G coherent optics, and it configures itself, handling link setup and laser safety without a technician tuning each connection. Coherent also says the system is generally available and already shipping in high volume, in 400G and 800G versions that work with existing network setups. Madhu Krishnaswamy, who runs the company's telecom transport unit, describes the goal as easing the usual trade-off between raw performance and operational simplicity.
The launch also sits on top of a business that is already moving. On August 12, Coherent reported results for its fiscal fourth quarter, which ended June 30: revenue of $2.05 billion, up 34% from a year earlier. Non-GAAP earnings per share rose to $1.74 from $1.00, and CEO Jim Anderson noted that for the full year, that measure grew more than twice as fast as revenue. Management guided to revenue of $2.2 billion to $2.4 billion for the first quarter of fiscal 2027, and Anderson says AI data centers are increasingly moving from copper to optical links.
Now look at the two versions of profit. Coherent's non-GAAP earnings came to $1.74 per share, but under GAAP the figure was $1.19. The gap comes from items management leaves out, including stock-based pay, amortization on acquired intangibles, and restructuring and integration costs. Operating margin shows it more clearly, at 21.8% on a non-GAAP basis and 12.4% under GAAP. Some of those costs are non-cash, but they are real, and anyone anchoring on the higher figure is skipping them.
Then there is how much weight this launch can carry. The announcement puts no sales figure on the product, so its contribution to a company that booked $2.05 billion in a quarter cannot be sized from what has been published. The bullish story also rests on management's own read of where AI networks are headed, and on a capacity build-out that CFO Sherri Luther says gets priority in spending. Money spent on capacity only pays off if the demand management describes keeps arriving.
#gaap #revenue #launch #anderson
17 days ago
On September 17, Ferrari N.V. (NYSE:RACE) announced a partnership with the technology company Rakuten Group, Inc., effective January 1, 2027. The announcement gives no scope and no price tag, so it works better as a signal than as a number. The real substance sits in the results Ferrari posted on July 30, when it raised its 2026 guidance because buyers are ordering more personalization than the company expected.
In the second quarter, revenue rose 8%, but operating profit rose 10%, which means each euro of sales is leaving more behind. Ferrari credits a richer mix of cars, with the F80 helping, along with more buyers paying up for personalization. Strip out currency swings, and the gap widens, with revenue up 11% and operating profit up 16%. Deliveries of the Purosangue and the 296 Speciale family grew even in the middle of a planned model changeover.
Cash and demand back that up. Industrial free cash flow jumped 39% to €276 million, and Ferrari also returned more than €800 million to shareholders through a dividend and buybacks. Racing helped too, as higher sponsorships and engine rentals to other Formula 1 teams lifted revenue. Meanwhile, the order book covers 2027 in full, and the new 12Cilindri Manuale is already fully allocated, which is about as strong a demand signal as a carmaker can send. Those trends are why revenue guidance moved up to about €7.60 billion from about €7.50 billion.
Part of the strength is timing. Operating profit got a boost from temporarily lower depreciation and amortization while Ferrari swaps out models, and the company says those charges will climb once the new cars enter production. Net profit also leaned on a 23.0% tax rate, which reflects an estimated benefit from the new Patent Box. Neither says much about how profitable the cars themselves are.
Costs are climbing too. Higher industrial and marketing expenses weighed on operating profit, EBITDA margin slipped to 39.0% from 39.7% a year earlier, and management expects heavier brand, racing and digital spending for the year. Currency is a drag as well, mostly from the dollar and the yen, which is why 11% growth at constant currency shrank to 8% as reported. Deliveries totaled 3,366 cars while the 296 GTS, Roma Spider and SF90 XX family wound down, and sponsorship, commercial and brand revenue grew just 2%. And the whole outlook leans on current visibility into the Middle East crisis, which Ferrari cannot control.
#Ferrari
18 days ago
On September 15, Arthur J. Gallagher & Co. (NYSE:AJG) announced that it had bought McMillan Insurance & Bonding Inc., an Englewood, Colorado, firm that operates as Innovise Business Consultants. Gallagher did not say what it paid. On its own, the deal is a footnote. But it is one of many, and the way those deals show up in earnings is where the debate over this stock really lives.
On July 30, Gallagher reported results for the quarter ended June 30, and the top line was hard to argue with. Revenue from its combined Brokerage and Risk Management businesses grew 24%, and organic growth, which leaves out acquisitions, was 6%. That second number shows clients are staying and spending. It was not confined to one corner, either, since organic fees in the risk management arm rose 12%. Management adds that retention is strong and customers want broader help from the platform. Adjusted earnings per share climbed to $2.84 from $2.30, which means growth is reaching profit once one-time acquisition costs are set aside.
Innovise fits the pattern. It sells surety bonds and commercial insurance brokerage with a focus on manufacturing, energy, construction and real estate, and Chairman and CEO J. Patrick Gallagher, Jr. said that niche expertise adds depth in Colorado. Jason McMillan's team will move into Gallagher's Denver office and work under Bret VanderVoort, who oversees retail property/casualty brokerage for the Western Zone. Buying specialists and folding them into existing offices is a repeatable playbook, and Gallagher closed 14 brokerage acquisitions in the first six months of 2026.
Now look at reported earnings, because that is where you see the cost. Diluted earnings per share fell to $1.25, from $1.40 in the second quarter of 2025, even though revenue jumped. Much of the gap between reported and adjusted results is the price of buying growth. Amortization of acquired intangibles alone weighs on brokerage net earnings by $218 million, up from $130 million a year ago, and integration costs rose as well. Adjusted figures set those aside, but they are real expenses, and they keep landing as long as Gallagher keeps buying.
Margins tell a similar story. The brokerage segment's adjusted EBITDAC margin, a stand-in for operating profit, slipped to 33.3% from 36.1%. Gallagher points to last year's interest income on cash raised for the ***** uredPartners deal, which closed in the third quarter of 2025, plus seasonality and newly added tuck-ins. That is a fair explanation. But the debt behind the deal is still here, including $9.55 billion of public debt, plus more in private placements and on a credit line. And the deal flow is thinner: brokerage acquisitions closed in the first six months of 2026 carried $107 million of annualized revenue, versus $354 million a year earlier, which puts more weight on organic growth.
#Growth

18 days ago
On September 17, Coherent Corp. (NYSE:COHR) announced an upgraded Pluggable Optical Line System that covers the full C-band and fits in a compact QSFP module, the same slot ordinary transceivers use. That is a lot of networking gear shrunk into a plug, and it follows a quarter of 34% revenue growth. Here is what the launch means, and where the stock's story gets harder to read.
Start with what the product does. The upgraded system can pack 32 wavelengths onto a single pair of fibers, which Coherent says adds up to as much as 25.6Tbps of traffic on links running 2km to 200km. It is designed for the latest 800G coherent optics, and it configures itself, handling link setup and laser safety without a technician tuning each connection. Coherent also says the system is generally available and already shipping in high volume, in 400G and 800G versions that work with existing network setups. Madhu Krishnaswamy, who runs the company's telecom transport unit, describes the goal as easing the usual trade-off between raw performance and operational simplicity.
The launch also sits on top of a business that is already moving. On August 12, Coherent reported results for its fiscal fourth quarter, which ended June 30: revenue of $2.05 billion, up 34% from a year earlier. Non-GAAP earnings per share rose to $1.74 from $1.00, and CEO Jim Anderson noted that for the full year, that measure grew more than twice as fast as revenue. Management guided to revenue of $2.2 billion to $2.4 billion for the first quarter of fiscal 2027, and Anderson says AI data centers are increasingly moving from copper to optical links.
Now look at the two versions of profit. Coherent's non-GAAP earnings came to $1.74 per share, but under GAAP the figure was $1.19. The gap comes from items management leaves out, including stock-based pay, amortization on acquired intangibles, and restructuring and integration costs. Operating margin shows it more clearly, at 21.8% on a non-GAAP basis and 12.4% under GAAP. Some of those costs are non-cash, but they are real, and anyone anchoring on the higher figure is skipping them.
Then there is how much weight this launch can carry. The announcement puts no sales figure on the product, so its contribution to a company that booked $2.05 billion in a quarter cannot be sized from what has been published. The bullish story also rests on management's own read of where AI networks are headed, and on a capacity build-out that CFO Sherri Luther says gets priority in spending. Money spent on capacity only pays off if the demand management describes keeps arriving.
#quarter #launch #anderson


18 days ago
Crane Company (NYSE:CR) announced a definitive agreement on September 14 to acquire Trillium Flow Technologies' U.S. pump business for approximately $240 million. The operations primarily serve municipal water and wastewater customers and are expected to generate approximately $115 million in full-year revenue. Closing is expected in the fourth quarter, subject to regulatory approvals and customary conditions.
The acquisition would add Floway, Wemco, Roto-Jet and WSP to Process Flow Technologies. Their installed equipment base supports service, repair, retrofit and replacement demand, giving the transaction a recurring-revenue rationale.
Crane Company (NYSE:CR) disclosed a price of approximately 14.6 times estimated 2026 adjusted EBITDA. Adjusted EBITDA is a company-defined non-GAAP measure based on earnings before interest, taxes, depreciation, and amortization, with further adjustments. The announcement did not specify the target's adjustments or provide a GAAP reconciliation.
Water and wastewater systems require reliable pumping equipment throughout their operating lives. An established installed base creates opportunities to sell replacement parts, restore equipment, and upgrade performance long after the original sale.
For Crane Company (NYSE:CR), those customer relationships could make revenue less dependent on winning entirely new projects. Service capability and product familiarity may also help retain customers when equipment eventually needs replacement.
#NYSE

19 days ago
Cognyte Software Ltd. (NASDAQ:CGNT) reported on September 9 that revenue for the fiscal second quarter ended July 31, 2026, increased 12.0% to $109.2 million. Total software revenue, comprising software and software services, rose 20.9% to $100.8 million.
Company-defined non-GAAP adjusted EBITDA increased 35.7% to $14.9 million. The measure adds depreciation, amortization, stock-based compensation, restructuring costs, and other specified adjustments to GAAP operating income. Yet quarterly billings fell to $76.3 million from $93.0 million. The central question is whether a more profitable revenue mix can produce stronger cash generation while sustaining future growth.
The portfolio transition is visible in the revenue base. Total software revenue represented more than 92% of sales. Recurring revenue, primarily support contracts and subscription offerings, reached $56.2 million, or 51.4% of total revenue.
For Cognyte Software Ltd. (NASDAQ:CGNT), a larger recurring base could make revenue more predictable and support continued product investment. Renewals also create opportunities to expand customer relationships without rebuilding the sales pipeline from scratch. The benefit depends on retention and expansion within those accounts.
Profitability improved under both accounting measures. GAAP operating margin increased to 4.3% from 2.8%, while adjusted EBITDA margin expanded to 13.6% from 11.3%. That combination strengthens the case that the transition is improving operating economics, even after recognizing expenses excluded from adjusted results.
#gaap #NASDAQ

19 days ago
Oddity Tech Ltd. (NASDAQ:ODD) reported second-quarter revenue of approximately $181 million on September 9, down 25% from $241 million a year earlier. Company-defined non-GAAP adjusted EBITDA fell to $13 million from $70 million. This measure excludes net financial income, income taxes, depreciation and amortization, share-based compensation, and certain unusual or nonrecurring items from net income.
Management attributed the disruption primarily to an advertising-algorithm problem affecting IL MAKIAGE. Oddity Tech Ltd. (NASDAQ:ODD) expects third-quarter revenue to decline approximately 5% year over year, with adjusted EBITDA of $18 million to $20 million. The sequential improvement describes a narrowing year-over-year revenue decline.
Management's diagnosis centers on distorted advertising signals that impair IL MAKIAGE's ability to reach suitable customers at acceptable acquisition costs. Oddity Tech Ltd. (NASDAQ:ODD) is testing changes with its largest advertising partner to retrain the algorithm. If those changes restore profitable customer acquisition, the existing brand could recover without a fundamental overhaul of its products.
Other brands provide operating evidence beyond that hypothesis. SpoiledChild delivered double-digit quarterly revenue growth, and management expects at least 35% growth for 2026, approaching $350 million in revenue. Management expects METHODIQ's first-year revenue to exceed SpoiledChild's first-year result.
These results support the argument that Oddity Tech Ltd. (NASDAQ:ODD) can build additional brands using its technology platform. A broader sales base could gradually reduce dependence on IL MAKIAGE, while successful customer retention would help recover upfront advertising spending over multiple purchases.
#revenue #NASDAQ #advertising #expects

19 days ago
Core & Main, Inc. (NYSE:CNM) reported quarterly sales of $2.145 billion on September 9, up 2.5%. Company-defined non-GAAP adjusted EBITDA reached $274 million. The measure adjusts consolidated net income for interest, taxes, depreciation and amortization, equity compensation, debt modification and extinguishment losses, offering expenses, and specified other income or expenses.
Consolidated net income rose 6.4% to $150 million, while GAAP diluted earnings per share increased 10% to $0.77. Diluted weighted-average shares declined approximately 2.5% to 193.4 million. Buybacks amplified an improvement that also had an operating foundation.
The company repurchased $169 million of equity during the quarter, against $62 million of operating cash flow. The investment question is whether cash generation can sustain capital returns alongside the spending needed to grow.
Core & Main, Inc. (NYSE:CNM) benefits from demand for essential infrastructure products. Management highlighted municipal demand, fire protection, treatment plants, and data centers as areas of strength. These end markets provide several sources of business even when construction demand is uneven.
Expense discipline also helped. Quarterly selling, general and administrative expenses declined to $301 million from $302 million. Controlling overhead allows modest sales growth to contribute more to earnings. Stronger volumes would make further earnings gains easier to sustain.
#income #main #quarterly

19 days ago
AeroVironment, Inc. (NASDAQ:AVAV) reported on September 9, 2026, that revenue for fiscal Q1 2027, ended August 1, 2026, increased 6% to $480.5 million. Funded backlog reached approximately $1.5 billion at quarter-end, up from $1.2 billion at April 30, 2026. This represents remaining work under firm customer orders with funding already appropriated, providing a concrete base for future revenue.
Non-GAAP adjusted diluted earnings were $0.59 per share, excluding acquired-intangible amortization, purchase-accounting adjustments, acquisition expenses, and net gains and losses on equity-method and equity-security investments. Adjusted EPS retains net interest income. The GAAP result was a $5.1 million net loss, or $0.10 per diluted share. The question is whether the expanding order base can produce stronger operating earnings and cash generation.
Bookings reached $683 million, producing a book-to-bill ratio of 1.4, calculated as bookings divided by revenue. Bookings measure authorized contract awards and modifications and can include work whose funding has not yet been obligated. The ratio indicates that new business exceeded revenue recognized during the quarter.
AeroVironment, Inc. (NASDAQ:AVAV) is also translating demand into sales in Autonomous Systems, where revenue rose 21% to $346 million. That provides operating evidence behind the opportunity in unmanned aircraft and precision-strike systems.
Management maintained fiscal 2027 revenue guidance of $2.125 billion to $2.225 billion, and non-GAAP adjusted EBITDA of $305 million to $325 million. Adjusted EBITDA excludes net interest income or expense, taxes, depreciation and amortization from net income and further adjusts for stock compensation, acquisition expenses, cloud-computing amortization, net gains and losses on equity-method and equity-security investments, and other specified items.
#Equity

19 days ago
Wealthfront Corporation (NASDAQ:WLTH) reported on September 9 that fiscal second-quarter revenue increased 1% to $91.9 million, despite platform ***** ets rising 12% to $99 billion. The quarter ended July 31, 2026. Funded clients increased 14% to 1.51 million, and platform ***** ets surpassed $100 billion by the end of August.
Platform ***** ets measure financial ***** ets held in client accounts. Their growth reflects both net deposits and market movements, so the headline increase does not represent new client money alone.
Adjusted EBITDA declined 15% to $38.1 million, with its margin falling to 41% from 49%. Wealthfront Corporation (NASDAQ:WLTH) defines this non-GAAP measure as net income excluding interest expense, income taxes, depreciation and amortization, stock-based compensation, fair-value changes in convertible notes, warrant liabilities and simple agreements for future equity, and nonrecurring expenses. Adjusted EBITDA margin divides that figure by revenue.
The advisory business is translating ***** et growth into revenue. Investment advisory ***** ets increased 30% to $54.1 billion, while advisory revenue rose 31% to $28.8 million. Those results show that the expanding investment business is generating a larger recurring fee stream.
For Wealthfront Corporation (NASDAQ:WLTH), this creates an opportunity to deepen client relationships as savings move toward longer-term investment goals. A growing advisory base could support more durable relationships, provided clients remain invested and continue contributing.
#wealthfront #revenue #platform #investment


19 days ago
Sunbelt Rentals Holdings, Inc. (NYSE:SUNB) reported on September 9 that fiscal first-quarter revenue increased 11.2% to $3.115 billion, including $2.927 billion of rental revenue, up 12.5%. The quarter ended July 31, 2026.
Management raised fiscal 2027 rental-revenue growth guidance to 7% through 10%, while increasing planned net rental-equipment capital expenditures to $2.4 billion through $2.8 billion. Demand supports expansion, but investors need to ****** s how much cash remains after funding the fleet.
North America Specialty rental revenue grew 25.3%, giving Sunbelt Rentals Holdings, Inc. (NYSE:SUNB) a strong source of growth beyond general equipment rentals. Specialized services can deepen customer relationships and create opportunities to supply several needs on the same project.
The company estimated that the FIFA World Cup contributed 2.5 percentage points to quarterly rental-revenue growth. Serving complex events demonstrates the commercial value of a broad equipment network. The investment opportunity is to turn that capability into recurring work across industrial, energy and construction customers.
Adjusted EBITDA increased 8.7% to $1.315 billion. This company-defined non-GAAP measure adds taxes, net interest, depreciation, amortization, stock-based compensation and specified restructuring costs to net income. Its margin is adjusted EBITDA divided by revenue.
#rentals


24 days ago
A horse named Coach Pope, after Kentucky basketball head coach Mark Pope, picked up his first win in a Maiden Special Weight race at Churchill Downs during the first weekend of the track's September Meet.
The 2-year-old colt, who entered the race as a 1/1 favorite, pulled away to win by 1½ lengths. Coach Pope completed the one-mile race on a fast track in 1:35.77.
Ridden by Jose Ortiz — who won the Kentucky Derby and Belmont Stakes aboard Golden Tempo, as well as the Kentucky Oaks with Always a Runner — Coach Pope broke well and raced close before breaking away after the final turn, passing Fullback and Justification.
Congrats to KennyMcPeek & jose93_ortiz & Coach Pope sired by the legendary Tapit on a massive 12.5 length victory ChurchillDowns today!
AND CATS up by 4 at half! Let's Go! pic.twitter.com/lG7GxRomh9
The colt is trained by Kenny McPeek and owned by Gainsway Stable, Shamrock Stables and Michael J. Mackin.
#coach #race

25 days ago
Oxford Industries, Inc. (NYSE:OXM) reported fiscal second-quarter net sales of $394.4 million, down 2.2%. Full-price direct-to-consumer sales declined 1%, while wholesale sales fell 14%, primarily reflecting lower off-price sales.
GAAP gross margin increased to 73.8% from 61.4% after Oxford Industries, Inc. (NYSE:OXM) recognized approximately $42 million of tariff refund claims as a reduction of cost of goods sold. Company-defined non-GAAP adjusted gross margin, excluding tariff refunds and LIFO effects, still improved to 63.1% from 61.7%. Updated **** ortment, sourcing, and pricing strategies increased initial markups, while lower off-price wholesale sales improved the sales mix.
Oxford Industries, Inc. (NYSE:OXM) lowered full-year sales guidance to $1.43 billion to $1.47 billion from $1.475 billion to $1.505 billion. Company-defined non-GAAP adjusted EPS guidance fell to $1.60 to $2.00 from $2.30 to $2.70, reducing the midpoint by 28%. Adjusted EPS excludes LIFO effects, tariff refunds and related interest, Johnny Was amortization, distribution-center relocation costs, merchandising initiatives, store-closure impairments and related taxes.
Underlying margin expansion suggests Oxford Industries, Inc. (NYSE:OXM) improved product economics beyond the one-time refund. Company-defined non-GAAP adjusted operating income, which excludes LIFO effects, tariff refunds and related interest, Johnny Was amortization, and specified distribution-center, merchandising, and store-closure costs, increased to $29.3 million from $28.3 million. Adjusted operating margin rose to 7.4% from 7.0%.
Tommy Bahama remained the strongest major brand for Oxford Industries, Inc. (NYSE:OXM), with sales increasing 0.8% and adjusted gross margin rising to 63.6% from 60.7%. FIFO inventory fell $9 million, or 4%, from one year earlier, reducing markdown exposure.
#gaap

25 days ago
XPO, Inc. (NYSE:XPO) reported that preliminary August 2026 North American less-than-truckload, or LTL, tonnage per day increased 3.7% from a year earlier. Shipments per day rose 5.7%, while average weight per shipment declined 1.8%. Final July figures showed tonnage per day increasing 5.8%, shipments per day rising 5.9%, and weight per shipment slipping 0.2%.
The two months indicate stronger shipment activity, but August's wider gap between shipment and tonnage growth points to lighter freight. The investment question is whether XPO, Inc. (NYSE:XPO) can convert additional shipments into better network density and fixed-cost absorption without allowing extra handling costs to dilute margins.
Higher shipment counts can improve the utilization of routes, service centers, dock doors, and equipment. XPO, Inc. (NYSE:XPO) operates an ****** et-based North American LTL network that moves approximately 16 billion pounds of freight annually. More shipments moving through that infrastructure can spread terminal, technology, and equipment costs across a larger revenue base.
The second quarter provides evidence that XPO, Inc. (NYSE:XPO) has recently translated volume and pricing growth into stronger economics. North American LTL revenue increased 15.2% to $1.43 billion. Fuel-surcharge revenue accounted for part of that increase, rising to $314 million from $183 million. Separately, yield excluding fuel increased 4.4%, shipments per day rose 2.8%, and tonnage per day increased 1.0%.
XPO, Inc. (NYSE:XPO) reported a company-defined non-GAAP adjusted operating ratio of 79.9%, an improvement of 300 basis points. XPO, Inc. (NYSE:XPO) calculates adjusted operating ratio as one minus adjusted operating income divided by segment revenue, using unrounded amounts. Adjusted operating income removes amortization and restructuring costs and adjusts for gains on real estate transactions. XPO, Inc. (NYSE:XPO) also reported a damage claims ratio below 0.2%.
#adjusted #north #operating

26 days ago
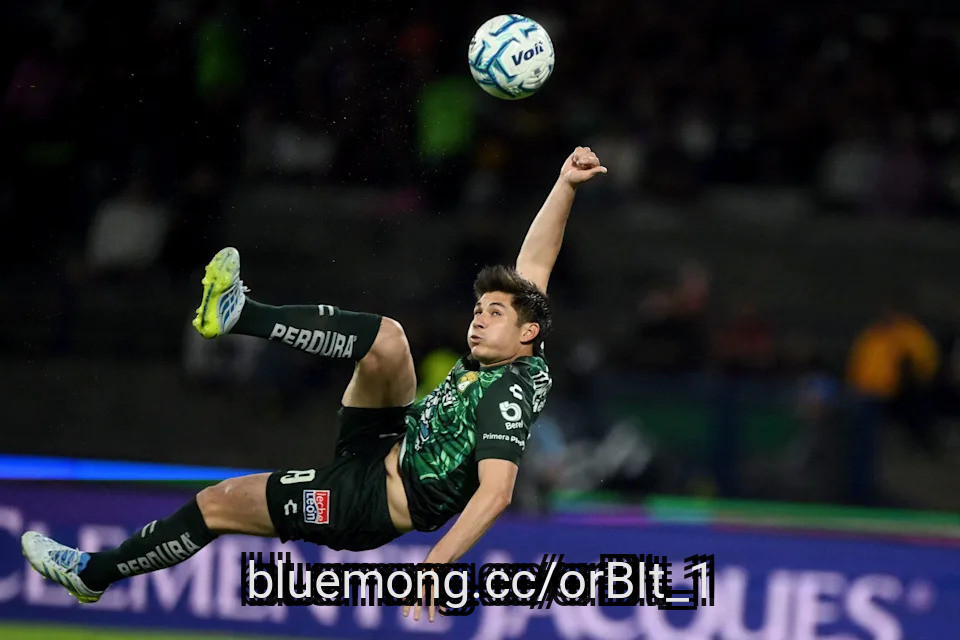
Pumas got their first home win of the Apertura 2026 after beating Leon by a 3-1 score. Pumas played a solid match and were able to recover after giving up the tying goal to get a solid three points and climb into the Liguilla zone with the victory. Leon battled hard but it wasn't enough. They will return home to host Atletico San Luis on Monday while Pumas will have a tough away match on Sunday when they visit Guadalajara to face off against Chivas.
The 1st half started with Pumas coming out with their usual starting 11 and without Cesar Huerta, who was expected to make his return to Pumas but was rule out because of an injury. Off a counter, Jordi Cortizo got off a left footed shot that would go just wide. Ismael Diaz got off a right footed shot from outside the area that went just wide. A left footed shot in the area from Cristian Calderon would go wide. Off a counter, Luciano Herrera would get off a left footed shot from outside the area that would be saved by Leon's goalkeeper, Oscar Garcia. Cristian Calderon had hurt himself when he got off his left footed shot and had to be subbed out because of that injury. Angel Azuaje was subbed in his place. In the middle of the half, an incredible rain storm started to fall which would probably have a big impact in the match. A cross into the area found Diaz, who whiffed on his close range shot and wasted a great opportunity. A great thru pass found Uriel Antuna but the ball was cleared off his feet by Leon's defense. After a cross into the area was bouncing in the area, Antuna would get off a right footed shot that went wide. From outside the area, Ivan Moreno got off a great right footed shot that forced a wonderful save from Pumas' goalkeeper, Keylor Navas. A great cross into the area by Rodrigo Lopez was beautifully headed by Juninho past Garcia to give Pumas the 1-0 lead. It was a deserved goal as Pumas had been the better team after a slow start. A cross into the area was headed from close range by Diaz but Navas made a good save. The halftime whistle blew and after a good first 45 minutes, Pumas took the deserved lead to their dressing room.
The 2nd half started with Leon subbing out Juan Pablo Dominguez for Diber Cambindo. A cross into the area was headed wide by Herrera. A cross into the area would get to a wide open Jose Alvarado, who got off a great half bicycle kick past Navas to score and tie the match at 1-1. It was a bad mistake by Pumas' defense in leaving Alvarado wide open but he made a great goal with the opportunity. Diaz got off a right footed shot in the area that went wide. Off a counter, the ball would eventually reach Herrera, whose right footed shot went wide. Leon subbed out Ivan Rodriguez for Rodrigo Echeverria. A lob into the area found a wide open Juninho but his right footed volley went wide in a terrible miss. Pumas subbed out Uriel Antuna for Alan Medina. Off a good run, the pass into the area found Cambindo, whose left footed shot went past Navas but hit the post. A


26 days ago
An illegal immigrant from El Salvador was returned to his home country this week after the Department of Homeland Security took him into custody in sanctuary Fairfax County, Virginia, where he had just served an abbreviated jail sentence, and deported him.
The case is the latest in a string of controversies involving illegal immigrants plaguing the Democrat-led county adjacent to Washington, D.C., where sanctuary policies run up against the Trump administration's heavy-handed approach to removing people who do not belong in the U.S.
"This groper is gone," an ICE spokesperson told Fox News Digital.
Illegal Immigrant Israel Flores-ortiz Gets 360 Days For Groping Girls At Fairfax County Va. High School
A photo of the Fairfax High School campus in Fairfax, Va., from March 15, 2022. At right is a mugshot of Israel Flores-Ortiz, accused of groping girls at Fairfax High School, taken in March 2025.
#county #Israel #immigrant


0.00$ raised of 0.00$ goal
0 donations
0.00$
to go
26 days ago
Arcosa, Inc. (NYSE:ACA) shareholders approved the proposed acquisition by CRH plc (NYSE:CRH) on September 4. The merger agreement received 39,595,867 votes in favor, compared with 66,113 against and 16,786 abstentions. Approximately 39.7 million shares, representing 80.8% of shares outstanding as of the record date, were present or represented by proxy.
The vote satisfies a major condition for the all-cash transaction. CRH plc (NYSE:CRH) agreed to pay $150 per share, valuing Arcosa, Inc. (NYSE:ACA) at an enterprise value of approximately $8.5 billion. The companies continue to expect a first-quarter 2027 closing, subject to required regulatory approvals and other customary conditions.
CRH plc (NYSE:CRH) described the valuation as 11.5 times estimated 2026 adjusted EBITDA, a company-defined non-GAAP measure, including $175 million of targeted annual run-rate cost synergies expected by year three. CRH plc (NYSE:CRH) defines adjusted EBITDA as earnings from continuing operations before interest, taxes, depreciation, depletion and amortization, with exclusions for impairments, divestitures and investments, equity-method results, substantial acquisition costs and specified pension items.
The result removes the principal seller-side approval risk. The merger no longer depends on another shareholder meeting, and support was decisive among the shares represented. Financing appears less exposed than regulatory clearance: CRH plc (NYSE:CRH) plans to use available cash and committed debt financing, while completion is not subject to a financing condition.
The strategic rationale is tangible. Arcosa, Inc. (NYSE:ACA) would add 109 quarries and yards, nine asphalt plants, 19 terminals and approximately 35 million tons of 2025 aggregates shipments. CRH plc (NYSE:CRH) expects more than 265 million tons of combined annualized aggregates production. Arcosa, Inc. (NYSE:ACA) also brings engineered structures serving grid modernization, electrification and data-center construction.
#NYSE #represented

0.00$ raised of 0.00$ goal
0 donations
0.00$
to go
29 days ago
Shares of Chime Financial (NASDAQ: CHYM) rallied 44% in August, according to data from S&P Global Market Intelligence.
Chime delivered an excellent second-quarter earnings report, showing stronger-than-expected growth and a significant inflection in profitability. With the stock having sold off since going public a little over a year ago, it's no surprise to see a rally in response to the strong numbers one year later.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
In the second quarter, Chime's revenue grew 27% to $670 million, with earnings per share swinging from a loss in the prior-year quarter to a positive $0.07. Both figures handily beat **** yst expectations. Chime also raised its full-year revenue guidance to between $2.725 and $2.745 billion, up from the prior quarter's range of $2.66 billion to $2.69 billion, and adjusted EBITDA (earnings before interest, taxes, and depreciation, and amortization) between $465 and $475 million, up from the prior quarter's guidance between $416 million and $431 million.
While revenue growth came in ahead of expectations, the real story appeared to be the company's skyrocketing profit margins. Second quarter adjusted EBITDA margins of 15% marked a more than 12 percentage point improvement relative to the year-ago quarter.
#year #chime #signal
29 days ago
Atlético de Madrid face Liverpool this Wednesday at 9 p.m., and they will do so without two attacking players.
The 24 players selected by Diego Pablo Simeone:
Sorloth, who is still injured, and Arnau Ortiz, through suspension, will miss the match.
The young Atlético forward misses out because of an old suspension dating back to his time playing in Poland.
Otherwise, Jonathan David, Cuti Romero and Julián Álvarez are all included in the squad as normal.
#players #suspension #simeone

1 month ago
On August 5, Southwest Gas Holdings (NYSE:SWX) reported second quarter results for the period ended June 30 and reaffirmed its full year 2026 guidance. Net income attributable to the company reached $42.1 million, a sharp turnaround from a $40.2 million loss in the same quarter of 2025. But the number that stood out was the Great Basin 2028 Expansion Project, where contracted demand has grown enough that management now expects capital costs of $2.3 billion instead of the $1.7 billion baked into current five year guidance.
Southwest Gas's growth story increasingly runs through Nevada. Binding precedent agreements for the Great Basin 2028 Expansion Project have grown to roughly 1 billion cubic feet per day of contracted demand, and the company has fielded another 1.8 billion cubic feet of expressions of interest for phases running from 2029 through 2035. Based on that demand, management now projects an annual margin of $270 million to $300 million once the pipeline is in service, on capital investment of about $2.3 billion.
Regulators have been cooperating too. California's Public Utilities Commission approved the non-cost-of-capital pieces of Southwest Gas's rate case, adding roughly $40 million of incremental annual revenue and triggering recognition of $9.7 million of previously deferred first-quarter income. Nevada regulators approved a Triennial Resource Plan with prudency pre-determinations for about $186 million of capital spending, and the company filed for a general rate case increase of roughly $74 million.
Arizona's new System Integrity Mechanism, effective April 1 this year, lets Southwest Gas recover safety and reliability spending faster, up to a $50 million annual cap. The company put $520 million into its network in the first six months of 2026, including $115 million toward Great Basin, and closed the quarter with $270.5 million in cash and nearly $1 billion in available liquidity.
Look past the headline swing to profit, and the picture gets murkier. The core natural gas distribution segment actually earned less this quarter, with its contribution to net income falling from $45.6 million a year earlier to $40.8 million, and its adjusted net income slipping from $33.7 million to $31 million. Depreciation and amortization rose $8.7 million, or 13%, as gas plant in service grew 7% year over year, a reminder that heavy pipeline spending shows up in expenses well before it shows up in rates.
#million #company #basin

1 month ago
On September 1, Rezolve AI (NASDAQ:RZLV) reported first-half revenue of $130.8 million, up from just $6.3 million a year earlier, a jump of roughly 1,970%. The AI commerce and payments company also said its enterprise customer base grew to 1,640 accounts. Numbers like that demand attention, but the same report showed losses widening even faster than sales. Here's what's really going on underneath the headline growth rate.
Rezolve's enterprise base grew from 950 customers at the end of the prior fiscal year to 1,640 by June 30, and management is leaning on partnerships with Microsoft, Google, Tata Consultancy Services, and Tech Mahindra to keep that pipeline filling without building out its own global sales force. That distribution strategy got a notable vote of confidence after the quarter closed: Google selected Rezolve's proprietary distributed database technology following a technical evaluation of 24 competing companies, and the system is now indexing roughly 100 terabytes of data across 10 blockchain networks inside Google Cloud's infrastructure.
The platform also proved it can handle real traffic. During the FIFA 2026 World Cup measurement window from June 1 through July 31, Rezolve's technology logged about 103 million app opens from 9.86 million unique devices across 16 stadiums, along with 5.84 million geofence events. On the loyalty and payments side, the recently completed acquisition of Reward Loyalty expanded Rezolve's footprint to more than 15 markets, and a partnership with Zilch now touches almost 6 million customers, driving over $3.3 billion a year to partner merchants. Management reaffirmed guidance for approximately $360 million in full-year 2026 revenue, implying second-half sales near $229 million, and reiterated a target of at least $500 million in annual recurring revenue by year-end.
Growth this fast has come at a steep price. Rezolve's operating loss widened to $128.1 million in the first half of 2026, compared with $32.4 million a year earlier, and net loss grew to $139.5 million from $57.9 million. Some of that reflects noncash items, including $41.5 million in share-based compensation and $20.4 million in depreciation and amortization, but cash is also going out the door faster. Net cash used in operating activities jumped to $96.1 million from $19.8 million in the prior-year period, and investing activities consumed another $148.3 million, largely tied to acquisitions and platform development.
#million #revenue #grew #june


1 month ago
CHICAGO (AP) — Christian Yelich capped Milwaukee's four-run sixth inning with a tiebreaking two-run homer, helping the Brewers beat the Chicago Cubs 9-4 on Tuesday night.
Milwaukee used a 13-hit attack to restore its eight-game lead in the NL Central over Chicago, bouncing back nicely after losing 17-3 to the Cubs in the opener of the four-game series. The top three hitters in the Brewers' lineup — Jackson Chourio, Brice Turang and William Contreras — went 6 for 14 and scored four times.
A day after hitting a franchise-record nine homers, Chicago was held to three singles and three doubles on a muggy night at Wrigley Field. Tyrone Taylor drove in two runs, and BJ Murray Jr. singled in the sixth for his first hit in his major league debut.
Milwaukee went ahead to stay in the sixth. Turang scored on a balk by Daniel Palencia, and Andrew Vaughn's RBI double tied it at 3. Yelich then drove an 0-2 slider from Palencia (2-2) to right-center for his 10th homer.
Yelich also walked and scored on Joey Ortiz's eighth homer in the eighth, a two-run shot to center field off Tyler Ferguson that lifted the Brewers to a 9-4 lead.
#scored #milwaukee


1 month ago
The Chargers announced their initial 53-man roster for the 2026 season.
While it's unlikely to be exactly like this come Week 1, let alone within 48 hours, I have plenty of thoughts after general manager Joe Hortiz and the coaching staff's moves to reach the roster limit on Sunday.
Here are eight takeaways:
The Chargers placed offensive lineman Branson Taylor on injured reserve with a designation to return, meaning he will miss at least the first four games. To maintain depth, the team opted to roster 11 offensive linemen, including Trevor Penning and rookies Alex Harkey and Logan Taylor. Rookie Jake Slaughter has already been elevated to the starting center role following a season-ending ACL injury to Tyler Biadasz earlier in training camp.
General manager Joe Hortiz flipped bubble players for future draft **** ets rather than letting them hit the waiver wire for free. The Chargers traded defensive tackle TeRah Edwards to the Panthers and sent cornerback Avery Smith to the Seahawks in exchange for late-round draft picks in 2027 and 2028. Additionally, it freed up a roster spot to retain safety Tony Jefferson, who initially seemed like he was on his way out.
#season

1 month ago
The Chargers concluded their training camp and preseason. Now, coach Jim Harbaugh, general manager Joe Hortiz, and company must reduce the roster to 53 players by Sunday's deadline at 3 p.m. PT.
That said, we are here to keep you updated on the latest news and reports about Los Angeles' roster cuts and potential trades, so make sure to bookmark this page.
Final Chargers 53-man roster prediction by Chargers Wire
The Chargers must have their roster trimmed down to 53 players by 3:00 p.m. (Pacific time) on Sunday.
Week 1: Sunday, Sept. 13, vs. Arizona Cardinals, 1:25 p.m., CBS
#final

1 month ago
CLEVELAND — Last summer, the Guardians found themselves embroiled in one of the wildest storylines around baseball, as closer Emmanuel Clase and starter Luis Ortiz were placed on leave for their alleged roles in a gambling scheme.
It's possible the Guardians might end up being involved in one of the oddest stories around the league in 2026 as well.
Major League Baseball reportedly opened an investigation and then suspended a sought-after Dominican prospect for an alleged scheme that included a fake name, age, birth certificate and even gravestone in order to falsify his identity and make him appear to be younger, according to an ESPN report.
David Severino was purportedly a switch-hitting infielder around the age of 14. He reportedly agreed to a $2.8 million deal with the Guardians that would be finalized in 2029, when he'd turn 17 and be eligible to sign.
But, it turns out his real name is Daury David Severino Damaso, and he's actually 16 years old, according to the reported investigation. Allegedly, with the consent of his parents and with the help of a trainer, the identity of David Severino Damaso was created to appear to be Daury's younger brother. A fake, late-filed birth registration was made under that name, along with falsified medical records.
#name #league


1 month ago
Tuniu Corporation's (NASDAQ:TOUR) ADSs closed lower after the company reported its second-quarter results. Net revenue increased 3.0% year over year to RMB138.9 million, while packaged-tour revenue rose 6.8% to RMB121.1 million as organized tours continued to grow.
However, cost of revenue increased 27.9% to RMB62.5 million, substantially outpacing the top line. Gross profit declined 11.1% to RMB76.4 million, and gross margin contracted to 55.0% from 63.8%. Tuniu consequently swung to a RMB6.1 million operating loss from RMB7.1 million of operating income a year earlier.
Packaged-tour growth indicates that demand for Tuniu's core travel products remains intact. The company has been expanding small-group, private and customized tour offerings in response to demand for more personalized and flexible travel options.
Tuniu also remained marginally profitable below the operating line. GAAP net income attributable to ordinary shareholders was RMB0.7 million. Company-defined non-GAAP net income attributable to ordinary shareholders was RMB2.2 million after excluding share-based compensation and amortization of acquired intangible **** ets.
Liquidity provides additional room to absorb uneven travel demand. Tuniu ended June with approximately RMB1.0 billion in cash and cash equivalents, restricted cash, short-term investments, and long-term deposits. Management said during the earnings call that Tuniu generated RMB46.9 million of operating cash flow while recording RMB1.4 million of capital expenditures.
#tuniu #company #revenue #demand

1 month ago
LSI Industries Inc. (NASDAQ:LYTS) reported fiscal fourth-quarter net sales of $234.6 million, up 51% year over year. Company-defined adjusted diluted earnings reached $0.38 per share, compared with $0.34 a year earlier. The adjusted measure excludes acquisition costs, acquired-intangible amortization, long-term performance compensation, lease step-up costs and restructuring or severance costs. Shares closed lower following the results.
The headline growth reflected Royston's first full-quarter contribution. Royston generated $66.9 million of revenue, accounting for roughly 84% of LSI Industries Inc. (NASDAQ:LYTS)'s $79.6 million year-over-year sales increase. Excluding acquisitions, company-defined organic sales rose 8% to $167.7 million. The central question is whether Royston is creating durable per-share value or simply making the company larger.
Display Solutions sales at LSI Industries Inc. (NASDAQ:LYTS) nearly doubled to $164.2 million, including company-defined organic growth of 18%. Segment adjusted EBITDA margin expanded 180 basis points to 12.4%. Grocery sales increased 21%, while refueling and convenience-store sales rose 16%.
Royston adds store fixtures, signage and refrigerated displays to LSI Industries Inc. (NASDAQ:LYTS)'s lighting and retail-branding portfolio. That broader offering helped the company win an approximately $30 million program to renovate roughly 2,500 sites for a large oil company. The award was excluded from the quarter's approximately 1.0-times Display Solutions book-to-bill because customer releases and timing were still being finalized.
Full-year revenue reached a record $689.4 million, up 20%. Company-defined adjusted EBITDA rose 27% to $69.7 million, while its margin increased 50 basis points to 10.1%. Company-defined free cash flow, calculated as operating cash flow less capital expenditures, increased 13% to $39.0 million. Continued cash generation could support debt reduction.
#million #sales #NASDAQ #defined
1 month ago
OSI Systems, Inc. (NASDAQ:OSIS) ended fiscal 2026 with record operating cash flow and backlog, but its fourth-quarter revenue result was materially below expectations. Revenue declined 4% to $484.1 million, approximately $45.6 million below the $529.7 million consensus estimate. Full-year revenue of $1.786 billion also finished about $39 million below the $1.825 billion floor of the company's prior guidance. Company-defined non-GAAP diluted EPS of $3.78 was essentially in line with the $3.77 consensus estimate.
Shares closed lower following the revenue miss, Middle Eastern delivery delays, and fiscal 2027 guidance. The central question is whether the delayed sales represent a temporary shift or evidence that the record backlog will convert unevenly.
Fiscal 2026 GAAP diluted EPS increased 3% to $8.95, while company-defined non-GAAP diluted EPS rose 11% to $10.35. The non-GAAP measure excludes impairment, restructuring, and other charges, acquired-intangible amortization, a $4.359 million former-CEO retirement expense, related tax effects, and discrete tax items.
Management said Middle Eastern conflicts and site-access constraints shifted approximately $50 million of planned Security deliveries beyond June 30. OSI Systems, Inc. (NASDAQ:OSIS) said the orders were deferred rather than lost and remain in backlog under revised delivery schedules.
Backlog increased to approximately $1.9 billion from $1.8 billion a year earlier. Fiscal 2027 guidance calls for revenue of $1.875 billion to $1.930 billion, representing growth of 5% to 8.1%. Company-defined non-GAAP diluted EPS is expected between $11.13 and $11.49, implying growth of 7.5% to 11%.
#million #company