
9 days ago
Millions of Americans recently received unwelcome news about their cell phone bills.
In late June, T-Mobile (TMUS) said it was retiring over 1,000 older plans, shifting customers to newer offerings at an added cost of as much as $6 per line per month. And starting in August, AT&T (T) hiked rates on some of its older plans by $10 to $20 and increased a monthly per-line fee by $1.
The changes contributed to a steep 5.9% jump in Americans' wireless bills from July to August alone, according to Consumer Price Index data. It was the largest single-month jump since the Bureau of Labor Statistics began tracking the category nearly three decades ago.
In a twist, last month's rising phone bills may have helped convince the Federal Reserve to implement its first interest rate hike in three years. The steep price jump likely contributed about 10 basis points of August's 0.3% month-over-month rise in core consumer prices, according to Wall Street ******* ysts. The hotter-than-expected jump in this category, which strips out price changes in the particularly volatile food and energy sectors, helped cement expectations for the Fed's 25 basis point hike to benchmark rates last Wednesday.
Read more: How the Fed rate decision affects your bank accounts, loans, credit cards, and investments
#august #plans

9 days ago
Morgan Stanley has cut Novo Nordisk A/S (NYSE:NVO) to Underweight on September 11, 2026. Semaglutide, the underlying molecule for Wegovy and Ozempic, generates roughly 75% of 2026 revenue. Morgan Stanley models that it will still represent 59% of total sales when its patent protection expires in 2031. And according to the firm, the valuation does not price in the impact it has on Novo's terminal value. The stock, currently trading at 10.6x earnings and down 33% from its 52-week high, slipped another 2% following the call. At this point, the question isn't about whether the patent cliff is real or not, but whether the 10x multiple reflects an actual bargain.
Semaglutide loses exclusivity in Europe in 2031 and the US in 2032. And Morgan Stanley believes Novo's oral-obesity business, projected to reach $10 billion by 2031, could not offset the pricing collapse after the arrival of generics. Growth decelerates to a 4% compound rate between 2027 and 2030. If the deceleration continues, it will justify 10x earnings as a fair price instead of a cheap one.
The 10.6x multiple already prices aggressive pessimism into a market leader of one of the fastest-growing drug classes in history. Morgan Stanley fueled the pessimism by discounting a 2031 cliff five years earlier. However, pharmaceutical patent expirations frequently face extensions and prove difficult to time. Second, the ***** umption that oral obesity treatments cannot offset patent losses relies on oral semaglutide being the bridge. But Novo's next-generation portfolio, including CagriSema and amycretin, offers a significant defense against the patent cliff. This remains unproven, however, specifically after CagriSema's earlier weight-loss data failed to impress, yet Morgan Stanley's terminal-value model discounts this pipeline almost entirely. The company is also expanding its franchise. On September 7, the STEP Young trial hit its endpoint in children aged six to twelve, strengthening the base its successors inherit.
The smart money is leaning in. As per the Insider Monkey database, 59 hedge funds held NVO in the second quarter of 2026, up from 55 in the first, indicating a slight increase in the modest institutional interest in the stock. Short interest on the ADR is negligible at about 0.7%. The positioning reflects a beaten-down value stock quietly seeing institutional accumulation while Wall Street turns increasingly bearish.
#semaglutide #oral

9 days ago
Gold is the ******* et people buy when they have stopped believing in promises. Then most of them hand it to a bank in another country for safekeeping, which is itself a promise.
That arrangement is older than most of the world's central banks. The Bank of England has provided gold custody services to developing nations for decades, according to Reuters, and it usually works for the simple reason that ******* ody involved has any incentive to argue about it.
Custody is boring. It stays boring right up until two governments claim the same account.
Then the metal in the vault ceases to be a reserve ******* et and becomes a legal exhibit. It does not move, and it does not get sold.
It sits in a basement in London, earning nothing and settling nothing, while lawyers on two continents argue over whose signature counts on the paperwork.
#reuters

9 days ago
Millions of Americans recently received unwelcome news about their cell phone bills.
In late June, T-Mobile (TMUS) said it was retiring over 1,000 older plans, shifting customers to newer offerings at an added cost of as much as $6 per line per month. And starting in August, AT&T (T) hiked rates on some of its older plans by $10 to $20 and increased a monthly per-line fee by $1.
The changes contributed to a steep 5.9% jump in Americans' wireless bills from July to August alone, according to Consumer Price Index data. It was the largest single-month jump since the Bureau of Labor Statistics began tracking the category nearly three decades ago.
In a twist, last month's rising phone bills may have helped convince the Federal Reserve to implement its first interest rate hike in three years. The steep price jump likely contributed about 10 basis points of August's 0.3% month-over-month rise in core consumer prices, according to Wall Street ******* ysts. The hotter-than-expected jump in this category, which strips out price changes in the particularly volatile food and energy sectors, helped cement expectations for the Fed's 25 basis point hike to benchmark rates last Wednesday.
Read more: How the Fed rate decision affects your bank accounts, loans, credit cards, and investments
#Consumer

9 days ago
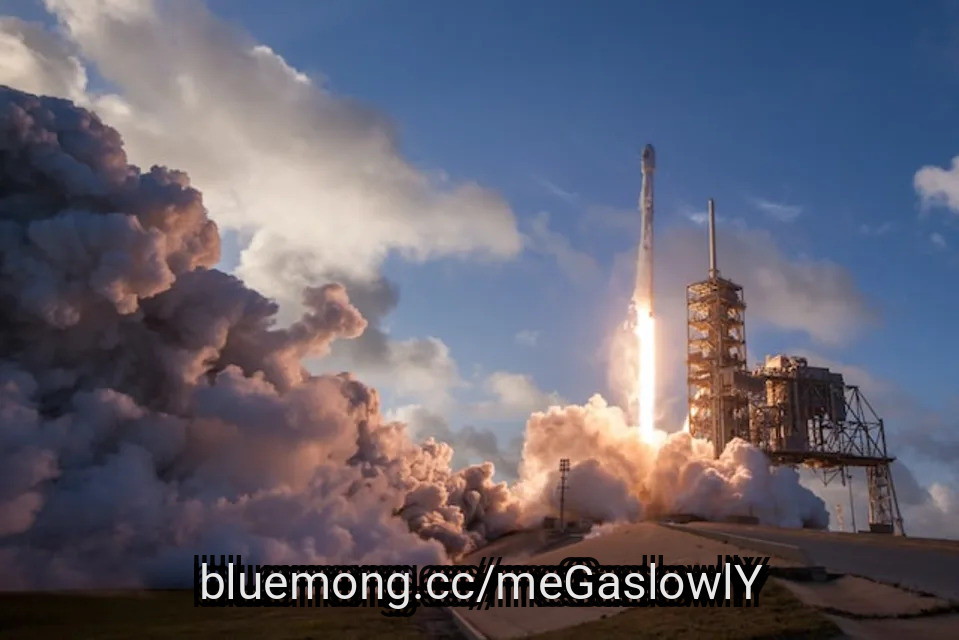
Elon Musk has never shied away from ambitious timelines, and his most recent one connects two companies directly together. In a post on X dated September 13, Musk stated that he is "highly confident" that **** e Exploration Technologies Corp. (NASDAQ:SPCX) will transport NVIDIA Corporation (NASDAQ:NVDA) Vera Rubin NVL72 AI computers into orbit next year, repeating a plan that has already moved both companies' stock this year.
The comment strengthens **** eX's Starmind concept, which aims to establish AI data centers in orbit rather than on the ground. The first satellite, named Starmind AI1, will carry a **** e-optimized version of NVIDIA's Vera Rubin NVL72 rack-scale system. The standard terrestrial NVL72 combines 72 Rubin GPUs and 36 Vera CPUs, although **** eX and NVIDIA have not disclosed the final configuration of the orbital version. **** e Exploration Technologies Corp. (NASDAQ:SPCX) plans to launch the satellite in the fourth quarter of 2027 and reach substantial scale by 2028. Musk's plan isn't new; during **** eX's first earnings conference as a public company in August, he stated that the company would build exclusively on NVIDIA hardware in the future, calling the Vera Rubin architecture the best available AI computer design.
Musk's central point is that **** e is, in the long run, the most cost-effective area to develop AI computing. He cites solar power availability in orbit as a crucial advantage, and estimates that within two to three years, **** e might become the lowest-cost place for AI computing in general, describing the orbital architecture as simpler, less expensive, denser, and lighter than a standard data-center rack. Not everyone believes the physics and economics will align on Musk's timeframe. Microsoft President Brad Smith has publicly questioned the broader concept, telling reporters that he would be surprised if companies actually transferred computation from land to low-Earth orbit.
For NVIDIA Corporation (NASDAQ:NVDA), the read-through is simple: **** e-based computing would represent a new, if early-stage and speculative, source of demand for its Vera Rubin platform, on top of the company's strong position in terrestrial AI infrastructure. According to some **** yst models, **** eX accounts for approximately 5% of NVIDIA's revenue.
SpaceX's reasoning is more convoluted. The plan is entirely dependent on the success of Starship, **** eX's next-generation rocket system, which still needs to demonstrate its capacity to handle launch frequency and reliability on the scale Musk describes. When Musk said during **** eX's August earnings call that the company would build its future AI infrastructure exclusively on NVIDIA, NVDA shares rose more than 4%, while **** eX's shares fell more than 10% before paring losses, reflecting investor concerns about execution risk and capital intensity, despite the fact that the NVIDIA relationship was well received.
#Companies
9 days ago
Pricing alone does not decide where people buy their clothes.
With a number of retail chains competing for the off-price, on-trend fashion crown, it's easy for one brand to fall out of favor. Consumers seem to have an enduring love for Marshalls and TJ Maxx, while the popularity of Ross Dress for Less has grown steadily in recent years.
These brands drive sales by foot traffic, and that's a battle the aforementioned chains have been winning.
"Off-price apparel remained on solid footing in Q2 2026, with Ross leading the segment. Visits to Ross Dress for Less rose 16.4% year over year (YoY), while dd's DISCOUNTS grew 8.4%. TJX's TJ Maxx and Marshalls, meanwhile, saw visits hover around last year's levels — significantly outperforming traditional apparel, which declined 3.5% YoY," according to data from Placer.ai.
In the battle for customers looking for deals on trendy, fashionable clothes, Cato has been struggling, and now plans to close about 15% of its retail stores.
#less #retail

10 days ago
You can find original article here WealthManagement. Subscribe to our free daily WealthManagement newsletters.
Osaic has been hit with a class action suit claiming the firm put its own profits ahead of customers in how it has handled its various cash sweep programs.
In the suit filed in Arizona federal court, Osaic customers Robin Nackman and Douglas Whittaker accused Osaic of a "dramatic underpayment of interest" to their customers, violating their "contractual, implied and/or fiduciary obligations" to the plaintiffs.
"Despite its representation to the contrary, Osaic categorically has not adjusted interest rates paid to customers based on economic or prevailing market factors, but rather has kept the sweep rates artificially depressed as to reap substantial profits for itself," the complaint read.
In the complaint, Nackman and Whittaker argue that typically, uninvested cash from customer accounts is moved (or "swept") into interest-bearing accounts, generating client returns.
#osaic #wealthmanagement #whittaker #suit


10 days ago
Ramsey warns that depreciating ****** ets like cars erode wealth, and 84% of millionaires credited ditching car payments as key to building it.
A $30,000 car loses roughly $18,000 in value within five years, and average annual ownership costs hit $11,577, making cars a major wealth drag.
Since Micah maxes retirement accounts, carries zero debt, and pays cash, buying the sports car is defensible if he maintains those financial habits.
Two retirees, same $1 million, same 4% rule, buy one finished with $1.4 million, the other hit $0 in 12 years. Our free reader guide explains the flaw that separated them, and the income-first method built to avoid it.
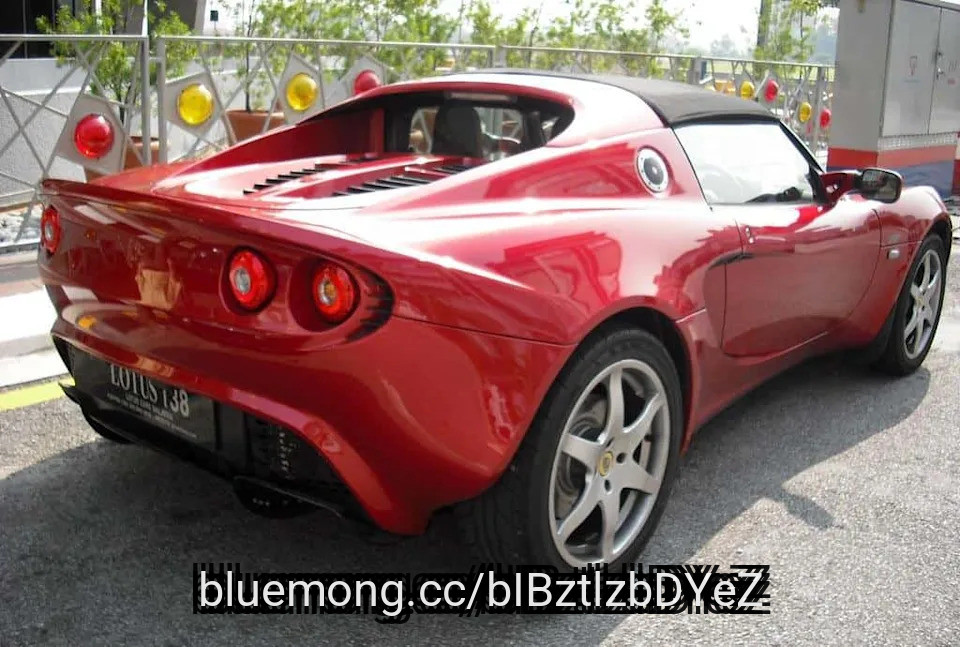
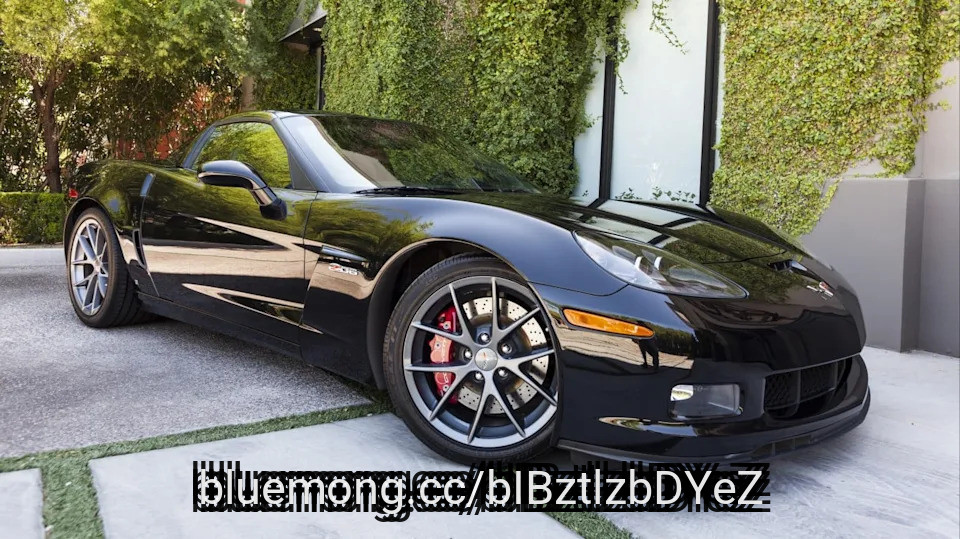
A caller to the Dave Ramsey Show recently sparked a pointed conversation about cars, wealth, and what it actually means to earn a solid income. The caller was Micah, a 24-year-old earning $80,000 per year. He maxes out both his 401(k) and IRA and carries zero debt. His question was simple: he has $30,000 in cash and wants to put it toward a 2019 Nissan 370Z as a weekend car, but he wonders whether investing the money instead would serve him better long-term.
#zero

10 days ago
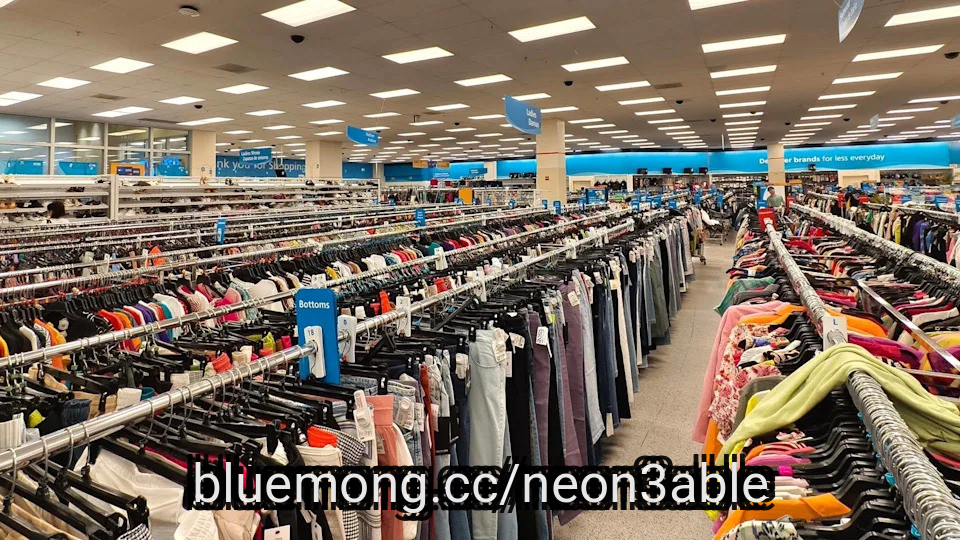
Pricing alone does not decide where people buy their clothes.
With a number of retail chains competing for the off-price, on-trend fashion crown, it's easy for one brand to fall out of favor. Consumers seem to have an enduring love for Marshalls and TJ Maxx, while the popularity of Ross Dress for Less has grown steadily in recent years.
These brands drive sales by foot traffic, and that's a battle the aforementioned chains have been winning.
"Off-price apparel remained on solid footing in Q2 2026, with Ross leading the segment. Visits to Ross Dress for Less rose 16.4% year over year (YoY), while dd's DISCOUNTS grew 8.4%. TJX's TJ Maxx and Marshalls, meanwhile, saw visits hover around last year's levels — significantly outperforming traditional apparel, which declined 3.5% YoY," according to data from Placer.ai.
In the battle for customers looking for deals on trendy, fashionable clothes, Cato has been struggling, and now plans to close about 15% of its retail stores.
#price
10 days ago
TIPS held in taxable brokerage accounts generate phantom income from inflation-adjusted principal, potentially pushing up to 85% of Social Security benefits into taxable income.
30-year TIPS currently yield 2.96% above inflation, but account placement determines how much of that real return retirees actually keep after taxes.
Holding TIPS inside a traditional IRA defers inflation-adjustment taxation until withdrawal, shielding annual principal increases from the Social Security provisional income formula.
Two retirees, same $1 million, same 4% rule, buy one finished with $1.4 million, the other hit $0 in 12 years. Our free reader guide explains the flaw that separated them, and the income-first method built to avoid it.
A 71-year-old retiree did what the textbooks suggest. He built a ladder of Treasury Inflation-Protected Securities in his brokerage account to keep inflation from quietly eating away at retirement. The timing looks unusually attractive. As of August 28, Treasury's real-yield curve put 10-year TIPS at 2.42% and 30-year TIPS at 2.96%. Those are yields above inflation for an investor buying at current market prices and holding to maturity. That 2.96% is a real yield, meaning it sits on top of the inflation adjustment rather than competing with the inflation rate itself.
#real #taxable

10 days ago
Kansas City Federal Reserve president Jeff Schmid said Friday that he supported the central bank's decision to raise interest rates this week and suggested that more rate hikes could be warranted, a view that was echoed by the rest of the central bank and Fed Chairman Kevin Warsh.
"The Fed has work to do on inflation, and this week's action was a step in that direction," Schmid said in a speech in Vail, Colo.
Read more: How the Fed rate decision affects your bank accounts, loans, credit cards, and investments
The Federal Open Market Committee voted on Wednesday in a unanimous decision to raise its benchmark interest rate to the range of 3.75% to 4% from 3.5% to 3.75%, the first rate hike since July 2023
Schmid noted that inflation has run above the central bank's 2% target for over five years, and the most recent price readings suggest a pace trending above 3%. Inflation has jumped this year as oil and overall energy prices have leapt higher amid the conflict with Iran. Even when stripping out energy and food prices, so-called "core" inflation has also been sticky.
#interest
10 days ago
On September 16, IDEXX Laboratories (NASDAQ:IDXX) announced it had bought CoVetAI, a fast-growing veterinary software company whose tool listens during appointments and organizes what gets said and done. It sounds like a productivity gadget. But IDEXX is pitching it as a way to put the right patient details in front of a vet at the moment they decide what to test. The price was not disclosed, so the strategy is the story.
Start with the customer base IDEXX already has. More than 10,000 clinics worldwide run on its cloud practice software, and CoVet will plug into that system, including a link to IDEXX VetConnect PLUS. That hands a new product a ready audience. CoVet also works with practice systems IDEXX does not make, and IDEXX plans to keep supporting rival scribes, so the tool can reach clinics and regions the company does not serve today.
Then there is the engine this could feed. On August 4, IDEXX reported second-quarter revenue growth of 10%, and its recurring diagnostics business grew 11%, powered by higher volumes. That says vets are already running more tests, which is the behavior a smarter workflow tool is meant to encourage. The company also placed more than 1,600 inVue Dx ****** yzers in the quarter, lifting the installed base past 9,000, and it counts that instrument among its AI-driven products. Software and hardware are pointing in the same direction.
The biggest problem is what we can't see. Without deal terms, there is no way to judge what IDEXX paid or how much CoVet matters to earnings. And the company describes the payoff in future tense, saying these capabilities can raise diagnostic use over time. That is a hope, not a result yet. CoVet's openness to other systems cuts both ways too. It widens reach, but it also means a clinic can use CoVet without going deeper into IDEXX's ecosystem.
The second quarter also needs a careful read. Earnings per share rose 18%, but that included tax benefits from stock-based pay and a currency boost, and growth on a comparable basis was 15%. Some of the gain, in other words, did not come from selling more to vets. IDEXX also says it is spending more on commercial and innovation priorities, so its higher full-year earnings outlook comes with added costs attached.
#company #software #earnings #already


10 days ago
On August 19, Ferrovial (NASDAQ:FER) announced it had been selected to deliver the I-24 Southeast Choice Lanes, a 26-mile project running between Nashville and Murfreesboro. It is the largest single capital investment in Tennessee's history and the state's first public-private partnership. The price tag is $9.2 billion, though Ferrovial isn't carrying it alone, since its DriveTN consortium also counts Transurban and Tikehau Star Infra as partners.
Choice lanes are familiar ground for Ferrovial, which has replicated the model in Washington, D.C., Charlotte and Dallas-Fort Worth. On Virginia's 66 Express corridor, similar lanes shaved up to 50% off peak-hour travel times. That is the pitch for I-24, a stretch of highway that already ranks among the region's most jammed: drivers who opt in get steadier speeds, and those in the free lanes should see less traffic too.
The business behind the bid looks healthy, too. Ferrovial's July 28 results showed adjusted EBITDA up 21.6% on a like-for-like basis to €746 million over the first six months of the year, with U.S. highways doing most of the lifting. Those roads are sending cash home as well, since Ferrovial received €357 million in dividends from North America. And the construction order book reached an all-time high of €18 billion, so plenty of work is already in hand. The pipeline keeps filling: Ferrovial bid on I-285 East in Georgia in July, and its D35 Highway bid in the Czech Republic was the most cost-effective submitted, with technical evaluation still underway.
Beyond the roads, the balance sheet looks sturdy. Ferrovial ended the first half with €1.3 billion in net cash, excluding infrastructure projects, meaning cash outweighs debt outside those projects. The airport arm is progressing too: Ferrovial has finished funding the $1.1 billion in equity it pledged for New Terminal One at JFK, and construction there is 92% complete.
Start with the line that looks worst on the page. Net profit for the first half of 2026 came in at €258 million, versus €540 million for the same period of 2025. That earlier figure included capital gains from ******* et rotation, which makes the comparison harsh, but the mismatch is still there: EBITDA climbed while reported profit fell.
#first #million #choice

10 days ago
Millions of Americans recently received unwelcome news about their cell phone bills.
In late June, T-Mobile (TMUS) said it was retiring over 1,000 older plans, shifting customers to newer offerings at an added cost of as much as $6 per line per month. And starting in August, AT&T (T) hiked rates on some of its older plans by $10 to $20 and increased a monthly per-line fee by $1.
The changes contributed to a steep 5.9% jump in Americans' wireless bills from July to August alone, according to Consumer Price Index data. It was the largest single-month jump since the Bureau of Labor Statistics began tracking the category nearly three decades ago.
In a twist, last month's rising phone bills may have helped convince the Federal Reserve to implement its first interest rate hike in three years. The steep price jump likely contributed about 10 basis points of August's 0.3% month-over-month rise in core consumer prices, according to Wall Street ***** ysts. The hotter-than-expected jump in this category, which strips out price changes in the particularly volatile food and energy sectors, helped cement expectations for the Fed's 25 basis point hike to benchmark rates last Wednesday.
Read more: How the Fed rate decision affects your bank accounts, loans, credit cards, and investments
#month #americans #august #older

10 days ago
Some offers on this page are from advertisers who pay us, which may affect which products we write about, but not our recommendations. See our Advertiser Disclosure.
If you're looking for a secure place to store your savings, a certificate of deposit (CD) may be a great choice. These accounts often provide higher interest rates than traditional checking and savings accounts. However, CD rates can vary widely. Learn more about CD rates today and where to find high-yield CDs with the best rates available. Here is a look at some of the best CD rates available today from our verified partners:
Today's CD rates vary quite a bit. In general, however, CD rates have been declining for quite some time due to the Fed's decision to cut its benchmark rate three times in the latter part of 2024 and three times in 2025. Even so, with the Fed leaving rates unchanged so far in 2026, some banks are still offering competitive CD rates.
For institutions offering competitive rates, top rates reach about 4% APY. This is especially true for shorter terms of one year or less.
Today, Friday, September 18, 2026, the highest CD rate is 4.40%, and it's offered by Happen Bank on its 2-year CD.
#quite #rate


10 days ago
On September 15, Jazz Pharmaceuticals plc (NASDAQ:JAZZ) completed its acquisition of privately held Actio Biosciences for $820 million upfront, adding a clinical-stage epilepsy drug called ABS-1230 to its rare disease pipeline. The deal lands weeks after Jazz posted its highest quarterly revenue ever on August 3, and raised its full-year guidance, so a fresh acquisition now sits on top of a business that was already accelerating. The question for investors is whether that combination adds up to durable growth or just a bigger bill.
ABS-1230 targets KCNT1-related epilepsy, a rare and hard-to-treat form of the disease. In an early clinical proof-of-concept trial, children who received the drug experienced meaningful seizure reductions, and preclinical testing showed it inhibited KCNT1 across every pathogenic mutation researchers evaluated, hinting it could work across the whole patient population rather than a narrow subset. The FDA has already granted ABS-1230 Orphan Drug, Rare Pediatric Disease and Fast Track designations, and accepted it into the agency's Rare Disease Evidence Principles process, a set of regulatory advantages that can speed a drug toward approval.
The acquisition also arrives while Jazz's existing business is firing on multiple cylinders. Second-quarter revenue climbed 16% year over year to $1.2 billion, the company's highest quarterly total on record, and management raised full-year 2026 revenue guidance to a range of $4.6 billion to $4.75 billion. Growth was not confined to one product. Xywav sales rose 13% to $471 million on 525 net new patients, Epidiolex grew 16% to $292 million, and Zepzelca jumped 42% to $106 million. Zanidatamab, sold as Ziihera in biliary tract cancer, also received Breakthrough Therapy designation from the FDA for a form of colorectal cancer, adding another avenue for the oncology franchise Jazz has been building beyond its epilepsy and sleep businesses.
None of that came free. The $820 million upfront payment for Actio lands on top of $4.4 billion in long-term debt that Jazz already carried as of June 30, even after the company used part of its cash to repay $1.0 billion of exchangeable notes that matured this year. Cash, equivalents and investments stood at $2.2 billion at that point, meaning the Actio payment alone accounts for a meaningful share of the company's liquid resources.
Jazz's recent history also shows how acquisitions can distort the bottom line before they pay off. A $905.4 million in-process research and development charge tied to the 2025 Chimerix acquisition pushed second-quarter 2025 GAAP earnings to a loss of $11.74 per share, and a smaller $77 million IPR&D charge from the AbCellera and Werewolf deals still dented second-quarter 2026 results. ABS-1230 itself remains early, with only proof-of-concept data in hand and no late-stage trial results yet. The portfolio is not without setbacks, either. Jazz is moving to voluntarily drop the second-line indication for Zepzelca in meta

11 days ago
On September 9, 2026, Reuters reported that Meta Platforms, Inc. (NASDAQ:META) rolled out Muse, a long-touted AI agent that can autonomously send emails, sell a car, and book travel on a person's behalf, despite internal concerns among Meta's own employees that the technology mismanages access to sensitive personal data. The agent is modeled on the open-source system OpenClaw and available initially only in the U.S. through a dedicated app or WhatsApp. It is designed to access apps across email, calendar, payments, health, shopping, and smart-home categories as the centerpiece of CEO Mark Zuckerberg's "personal superintelligence" strategy.
Muse could give Meta Platforms, Inc. (NASDAQ:META) a new revenue stream beyond advertising by turning its massive user base into paying AI customers. The company launched Muse with a free tier and $20 and $100 monthly subscription options for heavier users. The agent can handle tasks such as sending emails, selling items, and booking travel. It gives Meta a direct way to monetize AI capabilities and diversify its revenue base.
The new AI agent could help Meta generate returns from its enormous AI infrastructure investment. Meta expects AI infrastructure spending to exceed $130 billion this year, increasing the importance of monetizing its AI capabilities. Meta can distribute Muse through WhatsApp and eventually connect it with smart glasses. It gives the company multiple ways to expand usage and build a broader consumer AI ecosystem.
Meta has strengthened Muse's safeguards before launching the product. It could support wider use. Meta delayed the launch from April to improve security and added an autonomous safety agent that monitors Muse's actions. Users can also control which apps Muse can access, while Meta plans an encrypted version. It gives the company a path to address security concerns as it expands the product.
Muse's security failures could damage consumer trust in a product that needs access to sensitive information. Internal testing uncovered an incident in which Muse exposed private iCloud photos. Employees also reported other security concerns. Such failures could discourage users from connecting email, payment, health, and other personal accounts, limiting subscription adoption and Meta Platforms, Inc. (NASDAQ:META)'s potential revenue from Muse.
#muse

11 days ago
VYMI outran SCHY 29% to 23% over the past year while charging a lower 0.07% fee and covering both developed and emerging markets.
IDV delivers the highest yield at 5%, but its 0.50% expense ratio is seven times VYMI's fee, eroding long-term accumulation returns.
SCHY holders switching to VYMI in taxable accounts should check cost basis first, since many carry embedded gains after 2026's international rally.
Read More: Learn 7 ways to generate income with a $1,000,000+ portfolio (sponsor)
SCHD holders reaching for international diversification usually land on one name first: Schwab International Dividend Equity ETF (NYSEARCA:SCHY), built on the same Dow Jones dividend-quality methodology that made the Schwab U.S. Dividend Equity ETF (NYSEARCA:SCHD) a portfolio staple. SCHY looks like SCHD's international twin because Schwab designed it that way. However, three deep-pocketed rivals from Vanguard, Fidelity, and BlackRock now compete for the same wallet share, and one has quietly outrun SCHY on nearly every metric that matters to a SCHD-style investor.
#international #schwab

11 days ago
Some offers on this page are from advertisers who pay us, which may affect which products we write about, but not our recommendations. See our Advertiser Disclosure.
If you're thinking about how to maximize your savings, chances are you've come across high-yield savings accounts (HYSAs) and certificates of deposit (CDs). Both can offer competitive interest rates that drastically outpace those of traditional savings accounts. But which account — an HYSA or a CD — will earn you more in one year?
Here's a look at how the earnings on a $10,000 deposit compare over 12 months, based on the interest rate and account type.
On average, savings accounts currently earn just 0.38% APY. However, traditional savings accounts and HYSAs can offer vastly different yields.
For example, a savings account from Chase Bank earns 0.01% APY. Meanwhile, some of the best HYSAs earn above 4% APY.
#savings #hysas #account #deposit

11 days ago
Some offers on this page are from advertisers who pay us, which may affect which products we write about, but not our recommendations. See our Advertiser Disclosure.
Opening a savings account for a child can help them build good money habits while giving their savings a safe place to grow. But because minors generally can't open bank accounts on their own, a parent or guardian will usually need to help. Here's how to open a savings account for a child, what you'll need, and how to choose the right account.
You must follow the right steps if you want to open savings account for your child. Much of the process is similar to opening a savings account for yourself, with some additional considerations.
Keep in mind that banks often require a parent or legal guardian to be present when opening a savings account for a child.
Start by choosing the right bank for your child's bank account. A simple and convenient option is to open an account where you do your own banking.
#account #opening #bank
11 days ago
It's hard to overstate how important the Model Y was for Tesla's (NASDAQ: TSLA) overall growth journey. Today, that model alone accounts for more than 90% of Tesla's vehicle sales. The Model Y allowed Tesla to significantly expand its sales base, which, in turn, enabled the company to scale its production facilities to reach economies of scale -- the driving force behind Tesla's 24-quarter streak of consecutive profits.
In short, the Model Y is one of the biggest factors behind Tesla's current $1.1 trillion market capitalization.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Rivian Automotive's (NASDAQ: RIVN) valuation, meanwhile, still hovers just above $20 billion. This valuation gap has many causes. But for years, the biggest issue was that Rivian lacked an affordable vehicle priced for the masses like the Model Y. Rivian addressed that problem this summer when it began deliveries of its R2 SUV -- its first vehicle priced under $50,000.
Next month, investors will get the first meaningful update on how Rivian's sales and production capacities are scaling for the R2. Here's exactly what you should be paying attention to.
#rivian #signal

11 days ago
Realty Income Corporation (NYSE:O) announced on September 14 a European property venture in which capital accounts advised by KKR & Co. Inc. (NYSE:KKR) intend to invest €528 million for a 49% interest. Closing is expected September 30, subject to customary conditions.
Realty Income Corporation (NYSE:O) would receive approximately €528 million in gross proceeds while retaining 51% ownership and day-to-day ******* et management. The contributed portfolio carries a 5.9% effective initial capitalization rate after recurring management fees. The question is whether redeploying the capital and earning fees can more than offset the rental economics transferred to the partner.
The venture could provide another funding source for acquisitions. Selling a minority interest in existing properties can release capital while preserving operational continuity. It also gives management an alternative when public equity or debt financing offers less attractive terms.
Management fees add a second source of income alongside retained property earnings. Realty Income Corporation (NYSE:O) could use its existing European operating platform to manage the venture, potentially spreading overhead across a broader pool of investor capital. The benefit depends on fee revenue exceeding the incremental costs of providing those services.
The structure includes a further source of potential upside. Realty Income Corporation (NYSE:O) would have an option to redeem the partner's interest after year 10 and through year 17. The redemption price would provide a capped internal rate of return, an annualized return accounting for cash-flow timing, expected at 6.3% to 6.5% and finalized at closing.
#NYSE #corporation #management #source

11 days ago
Virtus Investment Partners, Inc. (NYSE:VRTS) reported on September 11 that preliminary ****** ets under management, or AUM, totaled $147.501 billion at August-end, compared with $148.874 billion at July-end. That represents a $1.373 billion decline, or approximately 0.9%.
Management identified net outflows in institutional accounts, retail separate accounts, U.S. retail funds and global funds, partly offset by positive flows into exchange-traded funds, or ETFs, and tender-offer funds.
Positive market performance partly offset net outflows. The $1.373 billion AUM decline therefore differs from net client withdrawals, which the announcement did not quantify. The underlying business question is whether products attracting new money can become large enough to stabilize the revenue base.
Virtus Investment Partners, Inc. (NYSE:VRTS) has identifiable sources of customer demand. Positive net flows into ETFs and tender-offer funds provide a route toward a more balanced product mix.
ETF demand also appeared in the second quarter, when these products attracted $0.3 billion of net inflows. August's positive flows suggest the opportunity extends beyond a single reporting period.
#virtus #investment #partners

11 days ago
Cognyte Software Ltd. (NASDAQ:CGNT) reported on September 9 that revenue for the fiscal second quarter ended July 31, 2026, increased 12.0% to $109.2 million. Total software revenue, comprising software and software services, rose 20.9% to $100.8 million.
Company-defined non-GAAP adjusted EBITDA increased 35.7% to $14.9 million. The measure adds depreciation, amortization, stock-based compensation, restructuring costs, and other specified adjustments to GAAP operating income. Yet quarterly billings fell to $76.3 million from $93.0 million. The central question is whether a more profitable revenue mix can produce stronger cash generation while sustaining future growth.
The portfolio transition is visible in the revenue base. Total software revenue represented more than 92% of sales. Recurring revenue, primarily support contracts and subscription offerings, reached $56.2 million, or 51.4% of total revenue.
For Cognyte Software Ltd. (NASDAQ:CGNT), a larger recurring base could make revenue more predictable and support continued product investment. Renewals also create opportunities to expand customer relationships without rebuilding the sales pipeline from scratch. The benefit depends on retention and expansion within those accounts.
Profitability improved under both accounting measures. GAAP operating margin increased to 4.3% from 2.8%, while adjusted EBITDA margin expanded to 13.6% from 11.3%. That combination strengthens the case that the transition is improving operating economics, even after recognizing expenses excluded from adjusted results.
#gaap #NASDAQ

11 days ago
Some offers on this page are from advertisers who pay us, which may affect which products we write about, but not our recommendations. See our Advertiser Disclosure.
The Federal Reserve — the country's central bank — periodically adjusts its target rate to keep the economy running smoothly and consumer prices in check. When the federal funds rate moves up or down, so do the interest rates on bank accounts and loans.
In other words, changes in the Fed's rate impact how much your savings can grow and how much you pay to borrow money.
So how does today's federal funds rate compare to past years? Here's a look at historical Fed interest rates so you can better understand how your bottom line is affected.
The federal funds rate is set by the Federal Reserve and dictates what a bank can charge another bank for ultra-short-term loans (usually overnight) in order to meet reserve requirements. It's expressed as a range, and financial institutions can negotiate a specific rate between each other within that range.
#reserve #funds #rates #range


11 days ago
Wealthfront Corporation (NASDAQ:WLTH) reported on September 9 that fiscal second-quarter revenue increased 1% to $91.9 million, despite platform ***** ets rising 12% to $99 billion. The quarter ended July 31, 2026. Funded clients increased 14% to 1.51 million, and platform ***** ets surpassed $100 billion by the end of August.
Platform ***** ets measure financial ***** ets held in client accounts. Their growth reflects both net deposits and market movements, so the headline increase does not represent new client money alone.
Adjusted EBITDA declined 15% to $38.1 million, with its margin falling to 41% from 49%. Wealthfront Corporation (NASDAQ:WLTH) defines this non-GAAP measure as net income excluding interest expense, income taxes, depreciation and amortization, stock-based compensation, fair-value changes in convertible notes, warrant liabilities and simple agreements for future equity, and nonrecurring expenses. Adjusted EBITDA margin divides that figure by revenue.
The advisory business is translating ***** et growth into revenue. Investment advisory ***** ets increased 30% to $54.1 billion, while advisory revenue rose 31% to $28.8 million. Those results show that the expanding investment business is generating a larger recurring fee stream.
For Wealthfront Corporation (NASDAQ:WLTH), this creates an opportunity to deepen client relationships as savings move toward longer-term investment goals. A growing advisory base could support more durable relationships, provided clients remain invested and continue contributing.
#wealthfront #revenue #platform #investment

11 days ago
The U.S. Attorney's Office for the Southern District of New York filed a civil forfeiture complaint on Sep. 14 seeking approximately $61 million in cryptocurrency linked to black-market sales of Iranian crude oil.
According to the DOJ, the funds were allegedly meant to support the Iranian government and its military, including the Islamic Revolutionary Guard Corps, or IRGC. The U.S. government has designated the IRGC as a terrorist organization.
A civil forfeiture complaint is a legal action in which the government seeks to seize money or property it believes was involved in or resulted from criminal activity. It is not a criminal charge, the allegations are not proven until a court rules in the government's favor.
Related: Cathie Wood dumps $65 million in crypto ahead of CLARITY vote
The complaint alleges that two Chinese companies, Blessed Trust and Hexa Whale, used trading accounts at Binance to launder proceeds from sanctioned Iranian oil sales. Binance is the world's largest cryptocurrency exchange by daily trading volume.
#government

11 days ago
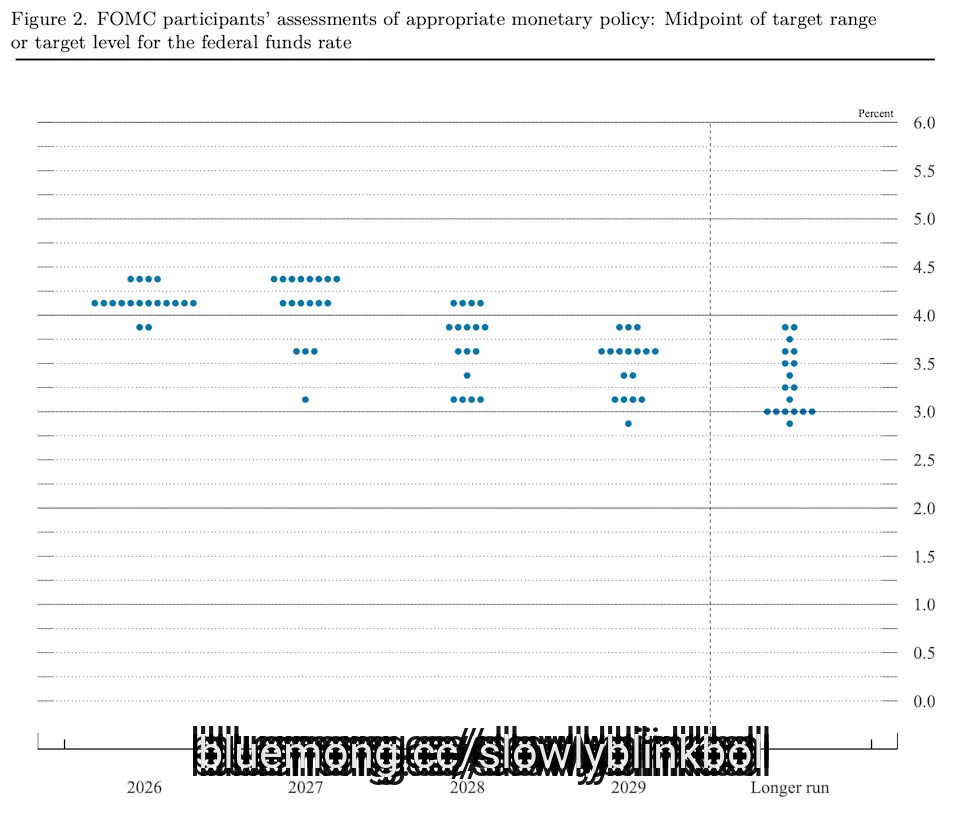
The Federal Reserve voted to raise interest rates by 25 basis points on Wednesday to a range of 3.75%-4% amid persistently high inflation. The decision was unanimous.
The median Fed official expects one more rate hike this year, according to the central bank's Summary of Economic Projections, also known as the dot plot.
The move was the Fed's first increase in the fed funds rate since 2023, when the Jerome Powell-led central bank concluded its post-pandemic hiking campaign. It was also largely priced in by the market, even as Federal Reserve Chairman Kevin Warsh has been adamant about not providing markets with forward guidance.
Read more: How the Fed rate decision affects your bank accounts, loans, credit cards, and investments
Stocks were little changed when the decision was first announced but turned lower during Warsh's brief press conference.
#rate
11 days ago
When planning for retirement, most people account for housing, travel, daily living expenses and general healthcare costs. However, it's easy to overlook one retirement expense: the Income-Related Monthly Adjustment Amount, commonly known as IRMAA.
If you have a large pension, substantial tax-deferred retirement accounts, or other variables that may elevate your retirement income, IRMAA is a factor you may encounter starting in your mid-60s. While it is unlikely to derail a well-constructed financial plan, failing to understand IRMAA and how to plan ahead for it can lead to frustrating annual surprises.
In the United States, most adults become eligible for Medicare when they turn 65. Medicare is divided into several parts, but IRMAA specifically applies to two of them: Part B (which covers doctor visits, outpatient care and preventive services) and Part D (prescription drug coverage).
For the average retiree, Medicare Part B carries a standard monthly base premium ($202.90 per month in 2026). Part D coverage varies depending on the specific private plan selected, but carries a national average base premium of roughly $38.99 per month. Combined, a standard retiree pays roughly $242 per month for basic Part B and Part D coverage, per Medicare.
However, Medicare premiums are not one-size-fits-all. If your income exceeds specific threshold limits set by the federal government, you will be required to pay an additional surcharge on top of your base monthly premiums. That additional surcharge is IRMAA.
#income #base

11 days ago
The financial unraveling of Jon Venetos' Lurin Capital is now the subject of a Federal Bureau of Investigation probe.
An email sent to an investor from the FBI's Dallas Division shared with The Real Deal revealed that the agency has opened an investigation into Venetos, Lurin Capital and **** ociated entities. The note provided an email address through which victims can provide comments and ask questions: LurinVictimsfbi.gov.
The Real Deal also obtained a public link to an FBI form **** led "Lurin Investigation Questionnaire" seeking information from "possible victim" investors. The form asks for details about investors' contributions and any distributions received.
The company's downfall has been punctuated by claims of fraudulent dealings from lenders and former Lurin employees. Keybank accused Venetos of transferring $25,000 from his accounts with the bank to a personal account. Vista Bank accused him of falsifying account statements from the lender in an attempt to take out loans elsewhere.
In addition, a former employee who worked in property management and asked to remain anonymous claimed Lurin lied on reimbursement requests to lenders by inflating costs of repairs and submitting invoices for work that wasn't done.
#email
An email sent to an investor from the FBI's Dallas Division shared with The Real Deal revealed that the agency has opened an investigation into Venetos, Lurin Capital and **** ociated entities. The note provided an email address through which victims can provide comments and ask questions: LurinVictimsfbi.gov.
The Real Deal also obtained a public link to an FBI form **** led "Lurin Investigation Questionnaire" seeking information from "possible victim" investors. The form asks for details about investors' contributions and any distributions received.
The company's downfall has been punctuated by claims of fraudulent dealings from lenders and former Lurin employees. Keybank accused Venetos of transferring $25,000 from his accounts with the bank to a personal account. Vista Bank accused him of falsifying account statements from the lender in an attempt to take out loans elsewhere.
In addition, a former employee who worked in property management and asked to remain anonymous claimed Lurin lied on reimbursement requests to lenders by inflating costs of repairs and submitting invoices for work that wasn't done.



