

1 day ago
Investors are worried. CNN's Fear and Greed Index is at "extreme fear." Inflation remains persistently high, with the ongoing Iran war and tariffs not helping matters. Stock market valuations are frothy by most metrics.
In times of uncertainty, many investors look to safe havens. Utility stocks rank high on the list. But if the stock market crashes, will utility stocks really protect your portfolio?
Missed AI's "Act 1"? Act 2 Could Be 16x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our ***** ysts, we're only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
Arguments for buying utility stocks as a defensive portfolio move make sense. Consumers don't stop using electricity, natural gas, or water during an economic downturn or stock market sell-off.
There's also historical precedent for utility stocks protecting against a market crash. For example, the S&P 500 (SNPINDEX: ^GSPC) sank almost 50% from its peak in early 2000 by October 2002 when the dot-com bubble burst. The Nasdaq-100 index plunged more than 80%. Meanwhile, shares of NextEra Energy (NYSE: NEE) and The Southern Company (NYSE: SO), both large electric utility providers, jumped more than 20% during the same period.
#utility #Stock #fear #high
In times of uncertainty, many investors look to safe havens. Utility stocks rank high on the list. But if the stock market crashes, will utility stocks really protect your portfolio?
Missed AI's "Act 1"? Act 2 Could Be 16x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our ***** ysts, we're only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
Arguments for buying utility stocks as a defensive portfolio move make sense. Consumers don't stop using electricity, natural gas, or water during an economic downturn or stock market sell-off.
There's also historical precedent for utility stocks protecting against a market crash. For example, the S&P 500 (SNPINDEX: ^GSPC) sank almost 50% from its peak in early 2000 by October 2002 when the dot-com bubble burst. The Nasdaq-100 index plunged more than 80%. Meanwhile, shares of NextEra Energy (NYSE: NEE) and The Southern Company (NYSE: SO), both large electric utility providers, jumped more than 20% during the same period.
#utility #Stock #fear #high

1 day ago
Dutch Bros Executive Chairman Travis Boersma sold 2.39 million shares worth about $106.4 million.
Dutch Bros' Q3 revenue rose 30% to $549.8 million, but EPS missed Street estimates.
On Stocktwits, retail sentiment jumped to 'extremely bullish' from 'bearish'.
Dutch Bros Inc. (BROS) stock plunged overnight as third-quarter (Q3) earnings miss and a $106.4 million stock sale by Executive Chairman Travis Boersma rattled investors, overshadowing revenue growth even as retail traders doubled down on the coffee chain's long-term potential.
Dutch Bros stock traded over 15% lower overnight. The stock had registered gains for the past three weeks.
#bros #Stock #executive #travis
Dutch Bros' Q3 revenue rose 30% to $549.8 million, but EPS missed Street estimates.
On Stocktwits, retail sentiment jumped to 'extremely bullish' from 'bearish'.
Dutch Bros Inc. (BROS) stock plunged overnight as third-quarter (Q3) earnings miss and a $106.4 million stock sale by Executive Chairman Travis Boersma rattled investors, overshadowing revenue growth even as retail traders doubled down on the coffee chain's long-term potential.
Dutch Bros stock traded over 15% lower overnight. The stock had registered gains for the past three weeks.
#bros #Stock #executive #travis
2 days ago
Stocks soared Wednesday as investors reacted to a clean sweep by Democrats in the midterm election.
Stocks were initially down when results started to roll in Tuesday night, in part due to fears of a data center crackdown, but futures turned green later in the evening, and all three major indexes soared on Wednesday.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
It wasn't immediately clear why stocks jumped on the results, though it appeared to be a combination of several factors. Investors were glad to see pushback on the Trump administration validated, including on inflation and the war in Iran. Investors tend to like a divided government, and with Democrats gaining solid control of both houses of Congress, they clearly have that. Finally, President Trump was surprisingly conciliatory, saying he would "absolutely accept the results of the election," and was willing to work with Democrats, which could pave the way to a productive Congressional term.
Among the winning sectors today was housing, which has languished over the last two years due to high mortgage rates and weak housing turnover. The State Street SPDR S&P Homebuilders ETF (NYSEMKT:XHB) closed up 5.4%, reaching its highest point in more than two months, while Home Depot (NYSE:HD) and Lowe's (NYSE:LOW), the two leading home improvement retailers, were up as well. Home Depot finished up 6.5%, and Lowe's jumped 7.5%.
#home
Stocks were initially down when results started to roll in Tuesday night, in part due to fears of a data center crackdown, but futures turned green later in the evening, and all three major indexes soared on Wednesday.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
It wasn't immediately clear why stocks jumped on the results, though it appeared to be a combination of several factors. Investors were glad to see pushback on the Trump administration validated, including on inflation and the war in Iran. Investors tend to like a divided government, and with Democrats gaining solid control of both houses of Congress, they clearly have that. Finally, President Trump was surprisingly conciliatory, saying he would "absolutely accept the results of the election," and was willing to work with Democrats, which could pave the way to a productive Congressional term.
Among the winning sectors today was housing, which has languished over the last two years due to high mortgage rates and weak housing turnover. The State Street SPDR S&P Homebuilders ETF (NYSEMKT:XHB) closed up 5.4%, reaching its highest point in more than two months, while Home Depot (NYSE:HD) and Lowe's (NYSE:LOW), the two leading home improvement retailers, were up as well. Home Depot finished up 6.5%, and Lowe's jumped 7.5%.
#home

2 days ago
US stocks jumped on Wednesday after Democrats won control of both chambers of Congress in a seismic midterm election, paving the way for a divided government.
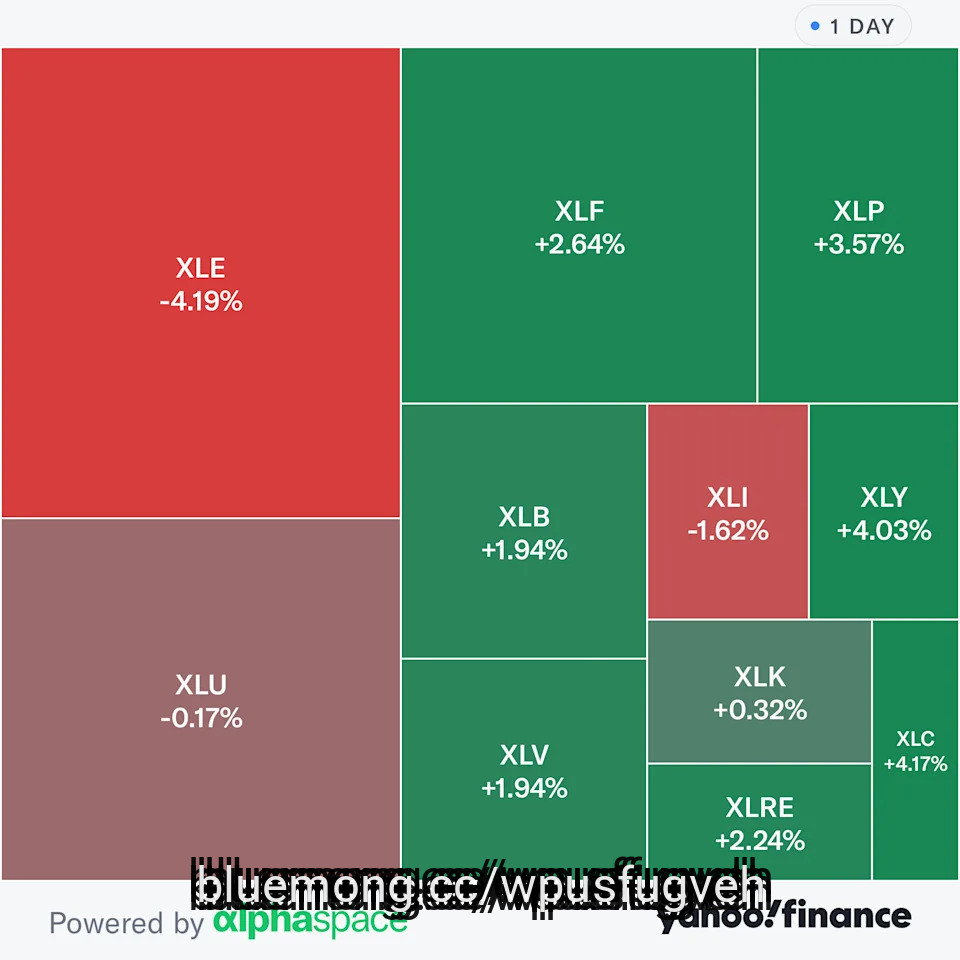
The Dow Jones Industrial Average (^DJI) rose 3%, or over 1,500 points, while the S&P 500 (^GSPC) climbed 1.7%. The Nasdaq Composite (^IXIC) traded up by 1.6% amid a post-election relief rally.
Markets swiftly repriced a Democratic sweep of the House and Senate — and the potential for ballot measures and newly elected officials to restrict data center construction. Chip stocks, including Nvidia (NVDA) and Micron (MU), fell. Meanwhile, other parts of the tech sector offset some of those losses, with Apple (AAPL) and Microsoft (MSFT) each hitting all-time highs.
Investors will also be watching for policy actions on housing and pharmaceuticals in the aftermath of the election. As Yahoo Finance's Jared Blikre pointed out on Tuesday, midterm elections have a history of shaping stock performance in the near term but don't tend to move markets much over the long term.
On the economic front, ISM and S&P data showed that US services activity expanded at a slower pace in October as businesses continued to grapple with elevated costs. Private-sector hiring, meanwhile, continued to show strength in October as an ADP report indicated "pretty solid job growth."
#election #october #continued
The Dow Jones Industrial Average (^DJI) rose 3%, or over 1,500 points, while the S&P 500 (^GSPC) climbed 1.7%. The Nasdaq Composite (^IXIC) traded up by 1.6% amid a post-election relief rally.
Markets swiftly repriced a Democratic sweep of the House and Senate — and the potential for ballot measures and newly elected officials to restrict data center construction. Chip stocks, including Nvidia (NVDA) and Micron (MU), fell. Meanwhile, other parts of the tech sector offset some of those losses, with Apple (AAPL) and Microsoft (MSFT) each hitting all-time highs.
Investors will also be watching for policy actions on housing and pharmaceuticals in the aftermath of the election. As Yahoo Finance's Jared Blikre pointed out on Tuesday, midterm elections have a history of shaping stock performance in the near term but don't tend to move markets much over the long term.
On the economic front, ISM and S&P data showed that US services activity expanded at a slower pace in October as businesses continued to grapple with elevated costs. Private-sector hiring, meanwhile, continued to show strength in October as an ADP report indicated "pretty solid job growth."
#election #october #continued

2 days ago
US stocks jumped on Wednesday after Democrats won control of both chambers of Congress in a seismic midterm election, paving the way for a divided government.
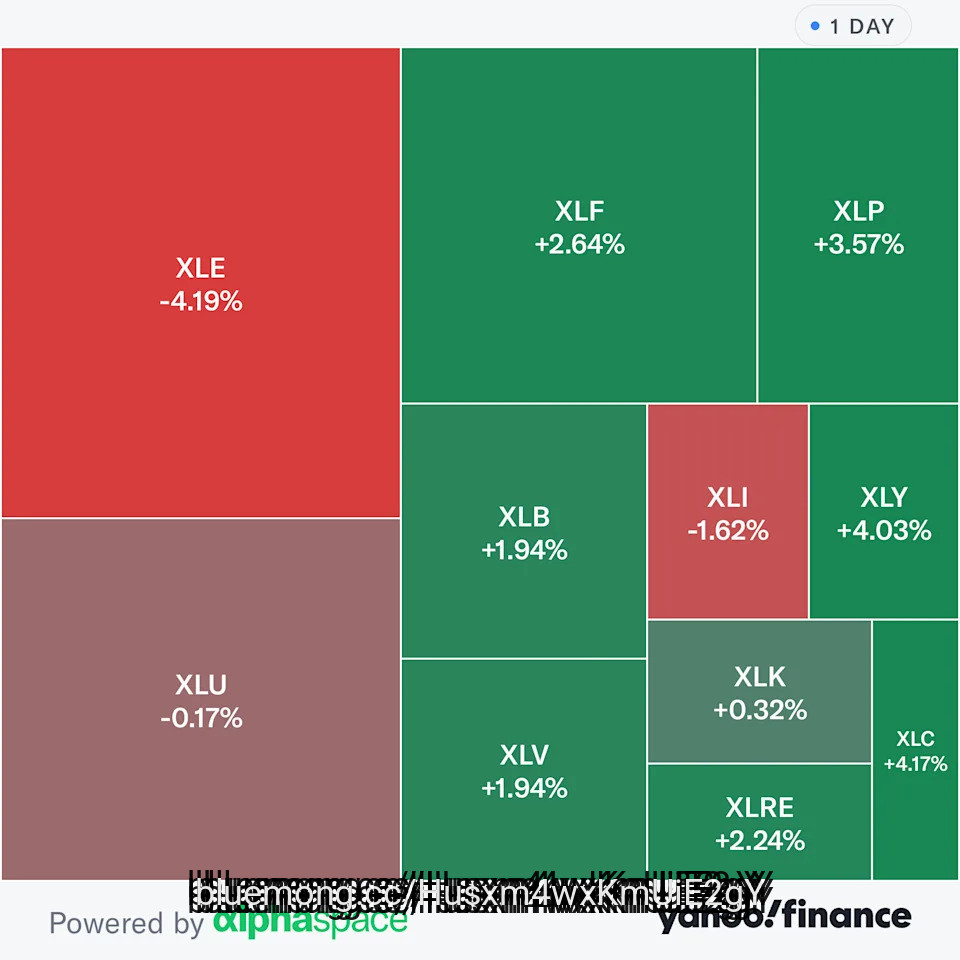
The Dow Jones Industrial Average (^DJI) rose 2.8%, or around 1,400 points, while the S&P 500 (^GSPC) climbed 1.7%. The Nasdaq Composite (^IXIC) traded up by 1.8% as Apple (AAPL) and Microsoft (MSFT) stocks touched record highs.
Markets swiftly repriced a Democratic sweep of the House and Senate — and the potential for ballot measures and newly elected officials to restrict data center construction. Chip stocks, including Nvidia (NVDA) and Micron (MU), fell more than 1%. Meanwhile, other parts of the tech sector offset some of those losses with Apple (AAPL) and Microsoft (MSFT) each hitting all-time highs.
Investors will also be watching for policy actions on housing and pharmaceuticals in the aftermath of the election.
As Yahoo Finance's Jared Blikre pointed out on Tuesday, midterm elections have a history of shaping stock performance in the near term but don't tend to move markets much over the long term.
#midterm #highs
The Dow Jones Industrial Average (^DJI) rose 2.8%, or around 1,400 points, while the S&P 500 (^GSPC) climbed 1.7%. The Nasdaq Composite (^IXIC) traded up by 1.8% as Apple (AAPL) and Microsoft (MSFT) stocks touched record highs.
Markets swiftly repriced a Democratic sweep of the House and Senate — and the potential for ballot measures and newly elected officials to restrict data center construction. Chip stocks, including Nvidia (NVDA) and Micron (MU), fell more than 1%. Meanwhile, other parts of the tech sector offset some of those losses with Apple (AAPL) and Microsoft (MSFT) each hitting all-time highs.
Investors will also be watching for policy actions on housing and pharmaceuticals in the aftermath of the election.
As Yahoo Finance's Jared Blikre pointed out on Tuesday, midterm elections have a history of shaping stock performance in the near term but don't tend to move markets much over the long term.
#midterm #highs
2 days ago
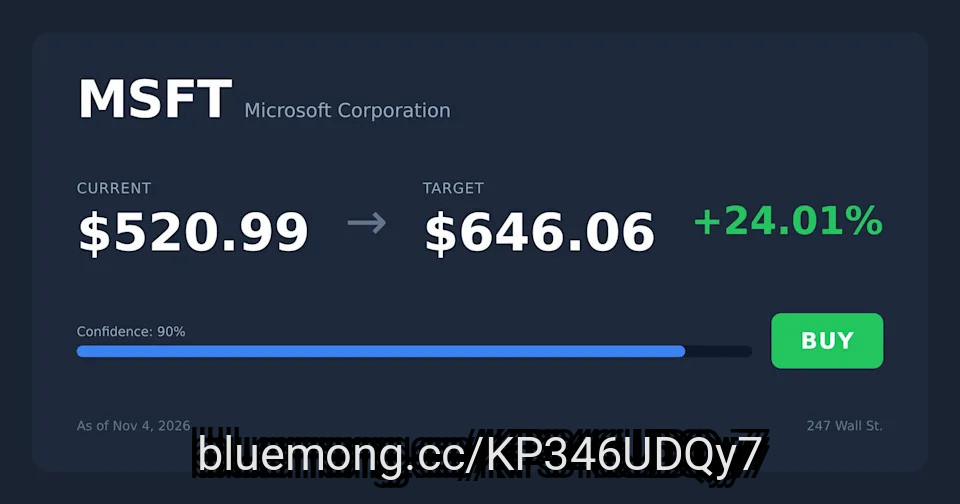
A $1,000 investment in MSFT today could reach $1,587 by 2029 under the base case, or as high as $1,911 in a bull scenario.
Azure revenue surged 48% last quarter, and CFO Amy Hood guided next-quarter growth of between 49% and 50% in constant currency.
Microsoft's contracted backlog jumped 73% to $677 billion, with Copilot daily users up over 5x year over year.
Just released. Our ***** ysts combed the entire stock market and named the ten best stocks to buy right now, and Microsoft didn't make the cut. Enter your email to see the names that beat MSFT. The report is free. Enter your email and see if any of your stocks made the cut.
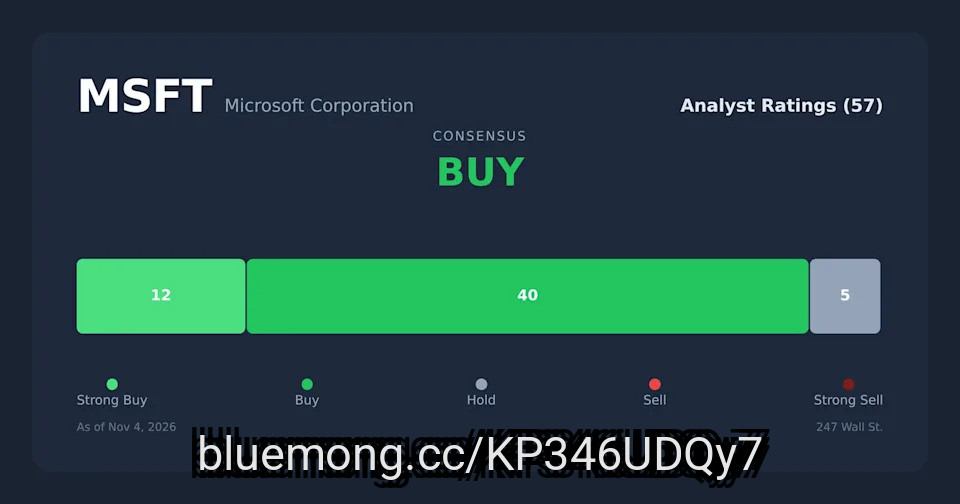
Microsoft (NASDAQ:MSFT) is one of the biggest stocks you can own to get exposure to enterprise AI, so it makes sense to ask what $1,000 put in today could grow into by 2029. Our price-prediction model uses a reference price of $525.63 per share.
#year #email #price
Azure revenue surged 48% last quarter, and CFO Amy Hood guided next-quarter growth of between 49% and 50% in constant currency.
Microsoft's contracted backlog jumped 73% to $677 billion, with Copilot daily users up over 5x year over year.
Just released. Our ***** ysts combed the entire stock market and named the ten best stocks to buy right now, and Microsoft didn't make the cut. Enter your email to see the names that beat MSFT. The report is free. Enter your email and see if any of your stocks made the cut.
Microsoft (NASDAQ:MSFT) is one of the biggest stocks you can own to get exposure to enterprise AI, so it makes sense to ask what $1,000 put in today could grow into by 2029. Our price-prediction model uses a reference price of $525.63 per share.
#year #email #price

6 days ago
Buying a new car is getting harder just as Ford Motor's stock is having one of its best days of the year.
Ford (F) shares jumped 12.4% Thursday after the automaker delivered better-than-expected adjusted earnings and raised the bottom end of its annual profit outlook.
For shareholders, that was welcome news.
For someone walking into a dealership, Ford's results revealed a less comfortable trend.
From a previous forecast of around $2 billion, Ford now anticipates increased commodity expenses of nearly $2.5 billion this year. The cost of steel, copper, computer chips, gasoline, and transportation is all rising.
#ford
Ford (F) shares jumped 12.4% Thursday after the automaker delivered better-than-expected adjusted earnings and raised the bottom end of its annual profit outlook.
For shareholders, that was welcome news.
For someone walking into a dealership, Ford's results revealed a less comfortable trend.
From a previous forecast of around $2 billion, Ford now anticipates increased commodity expenses of nearly $2.5 billion this year. The cost of steel, copper, computer chips, gasoline, and transportation is all rising.
#ford


7 days ago
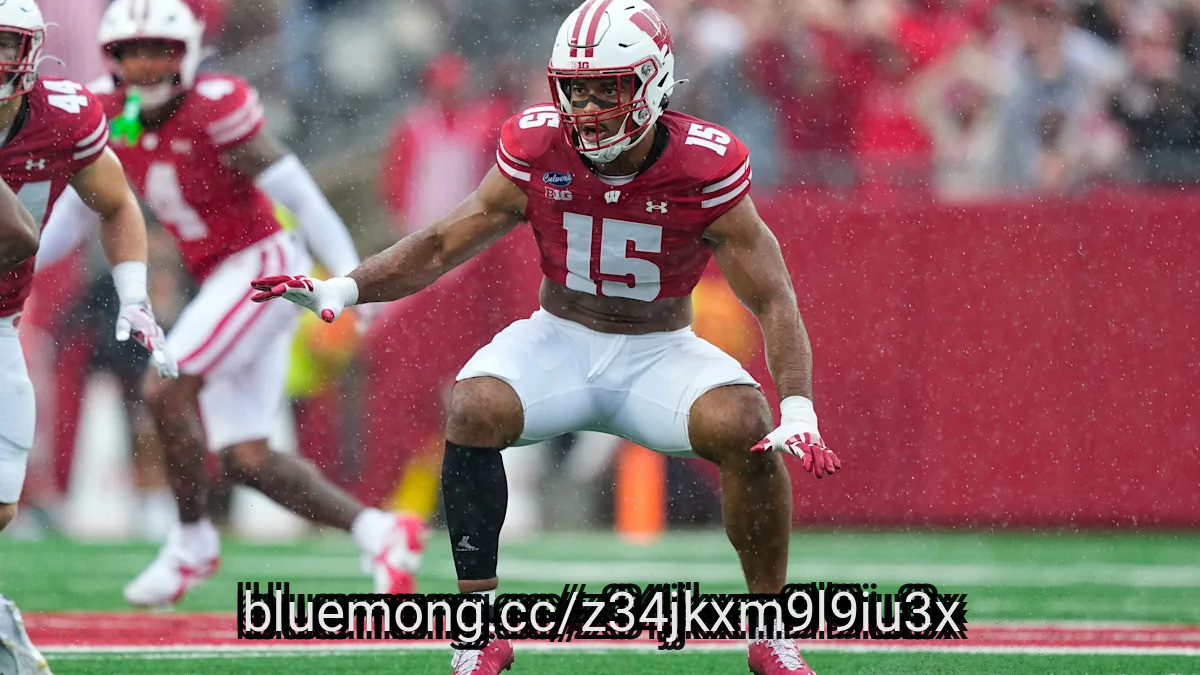
Sebastian Cheeks has spearheaded one of the best defenses in the nation this season. The Wisconsin Badgers rank inside the top 10 in total yards allowed per game at 276.5, all while allowing a stout 16.3 points per game, which ranks 13th-best in the country. Cheeks joined the Badgers ahead of the 2024 season after spending two seasons at UNC. Cheeks' first two seasons saw him flash at times, but overall, he never jumped out as one of the Big Ten's biggest stars.That was until now. So far this season, Cheeks has tallied 26 total tackles, seven tackles for loss, five sacks, and two forced fumbles.In Wisconsin's upset 24-7 win over USC this past weekend, Cheeks pulled together five tackles and 2.5 sacks, earning him conference acclaim.
Cheeks was recently tipped as a potential NFL draft pick by draft expert Mel Kiper thanks to his do-it-all archetype.
Luke Fickell's squad has just five games on the season; up next is the 5-2 Iowa Hawkeyes inside what is bound to be an electric Kinnick Stadium. Kickoff is set for 12 PM ET and is the Big Noon Kickoff game for FOX.
Contact/FollowTheBadgersWire on X (formerly Twitter) and like our page on Facebook to follow ongoing coverage of Wisconsin Badgers news, notes and opinion.
This article originally appeared on Badgers Wire: Wisconsin OLB finally named Big Ten Defensive Player of the Week
#cheeks #badgers #follow
Cheeks was recently tipped as a potential NFL draft pick by draft expert Mel Kiper thanks to his do-it-all archetype.
Luke Fickell's squad has just five games on the season; up next is the 5-2 Iowa Hawkeyes inside what is bound to be an electric Kinnick Stadium. Kickoff is set for 12 PM ET and is the Big Noon Kickoff game for FOX.
Contact/FollowTheBadgersWire on X (formerly Twitter) and like our page on Facebook to follow ongoing coverage of Wisconsin Badgers news, notes and opinion.
This article originally appeared on Badgers Wire: Wisconsin OLB finally named Big Ten Defensive Player of the Week
#cheeks #badgers #follow
8 days ago
COLUMBUS — Pleasant continues to make it look easy.
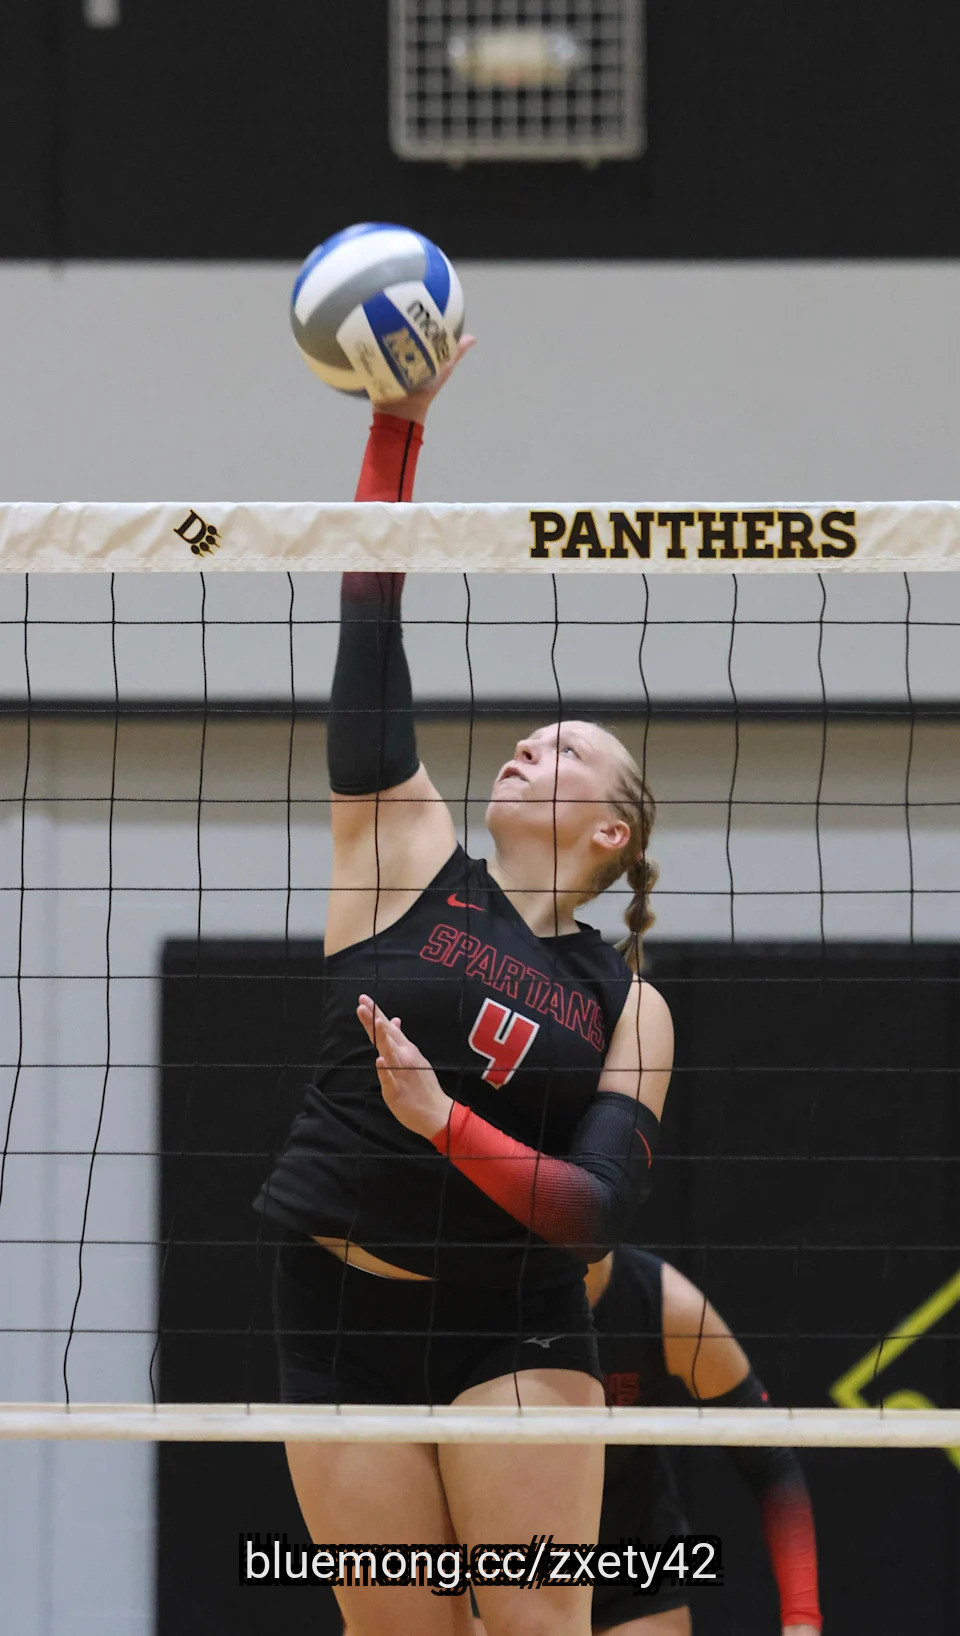
Yet to drop a set this season, the top-seeded Spartans continued that streak with a 3-0 victory over No. 4 seed Utica to win the Division V volleyball district championship Oct. 29 at Ohio Dominican University's Alumni Hall.
It is Pleasant's fourth straight district ***** le, and the victory puts them in the regional semifinals in the familiar O-rena at Ontario High School with a 6 p.m. start Wednesday, Nov. 4. The Spartans (25-0) will face Centerburg (23-2) after the third-seeded Trojans got by No. 7 North Union 3-1 in the first match at ODU Oct. 29.
"We're leaving everything out on the court. We know this is our last chance to do it. We haven't done it the past two years (which is win a state championship)," Pleasant senior libero Kam Roberts said. "I think we're hungry for it this year. We're working hard for it in practice, and it's really showing on the court."
Pleasant jumped out to an 8-0 lead in the first set, ***** ping it to 13-2 and 19-5 before finishing it with a 25-10 victory. It set the tone for the night.
#pleasant #championship #court
Yet to drop a set this season, the top-seeded Spartans continued that streak with a 3-0 victory over No. 4 seed Utica to win the Division V volleyball district championship Oct. 29 at Ohio Dominican University's Alumni Hall.
It is Pleasant's fourth straight district ***** le, and the victory puts them in the regional semifinals in the familiar O-rena at Ontario High School with a 6 p.m. start Wednesday, Nov. 4. The Spartans (25-0) will face Centerburg (23-2) after the third-seeded Trojans got by No. 7 North Union 3-1 in the first match at ODU Oct. 29.
"We're leaving everything out on the court. We know this is our last chance to do it. We haven't done it the past two years (which is win a state championship)," Pleasant senior libero Kam Roberts said. "I think we're hungry for it this year. We're working hard for it in practice, and it's really showing on the court."
Pleasant jumped out to an 8-0 lead in the first set, ***** ping it to 13-2 and 19-5 before finishing it with a 25-10 victory. It set the tone for the night.
#pleasant #championship #court

8 days ago
Sean Brady won't be competing in the main event of UFC Fight Night 293 due to a gnarly knee injury that forced him to stay in the hospital for multiple days.
Brady (19-2 MMA, 9-2 UFC) was set to face Gabriel Bonfim in the Nov. 7 headliner at the Meta APEX in Las Vegas, but was forced out due to an infection and fluid buildup in his knee. The welterweight contender hopes to keep the matchup with Bonfim (20-1 MMA, 7-1 UFC) together, but isn't certain what will happen just yet.
Brady detailed the reasons for the fight's cancellation on "The BradyBags Show".
"So last week, Tuesday, I practiced in the morning," Brady explained. "Everything was going completely fine. By nighttime, I was going to do my next workout. I jumped on my bike. My knee was a little bit swollen afterwards. By 9 o'clock at night, I couldn't walk. So, that's Tuesday. Wednesday morning, I already knew because I've been in this situation before, like I've dealt with bursitis and sh*t, and I knew this wasn't bursitis – I knew it was an infection.
"So, I knew right away from dealing with my arm and my leg, the feeling that you get, it's just different. It's just a different pain. Like, I could barely walk. So, Wednesday morning, 6 a.m., first thing I do, I got to the hospital, and they start drawing blood, doing everything. They put me on IV antibiotics."
#knee #i 've
Brady (19-2 MMA, 9-2 UFC) was set to face Gabriel Bonfim in the Nov. 7 headliner at the Meta APEX in Las Vegas, but was forced out due to an infection and fluid buildup in his knee. The welterweight contender hopes to keep the matchup with Bonfim (20-1 MMA, 7-1 UFC) together, but isn't certain what will happen just yet.
Brady detailed the reasons for the fight's cancellation on "The BradyBags Show".
"So last week, Tuesday, I practiced in the morning," Brady explained. "Everything was going completely fine. By nighttime, I was going to do my next workout. I jumped on my bike. My knee was a little bit swollen afterwards. By 9 o'clock at night, I couldn't walk. So, that's Tuesday. Wednesday morning, I already knew because I've been in this situation before, like I've dealt with bursitis and sh*t, and I knew this wasn't bursitis – I knew it was an infection.
"So, I knew right away from dealing with my arm and my leg, the feeling that you get, it's just different. It's just a different pain. Like, I could barely walk. So, Wednesday morning, 6 a.m., first thing I do, I got to the hospital, and they start drawing blood, doing everything. They put me on IV antibiotics."
#knee #i 've

8 days ago
I reached out to the folks at Black Shoe Diaries to talk about this weekend's game between their Nittany Lions and our Purdue Boilermakers. They were kind enough to respond with some informative answers to my questions. Make sure to go check them out.
Penn State has not won a Big Ten game yet this year. The schedule to start the year has turned out to be a lot tougher than most people probably thought going in. Given the turnover at the top, what was expected of Penn State by fans coming into this season?
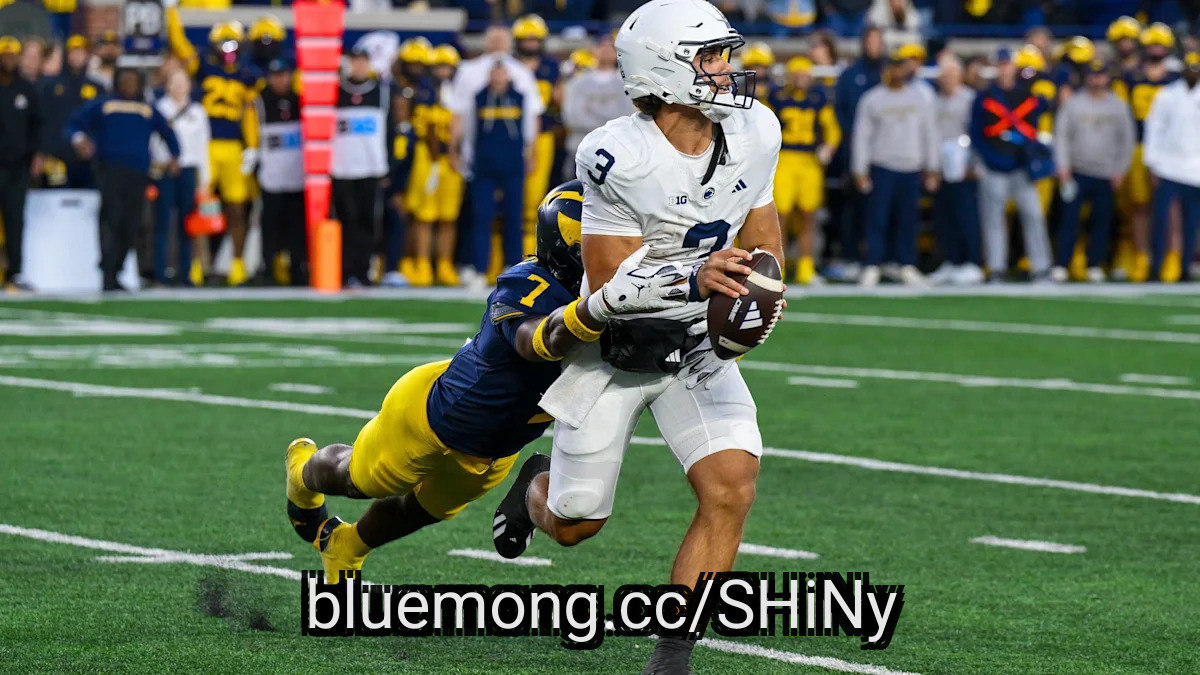
I predicted a 9-3 season. Some others on our site were at least mentioning the word playoff in the offseason. Personally, I thought Penn State would have enough experience with Matt Campbell's system considering that there would be so much continuity with so many players making the move from Iowa State. A lot of that optimism was tied to the schedule. Unlike 2025 where Penn State jumped right into the deep end with a showdown against Oregon in conference play, this year seemed like it would give some runway for the Lions to work things out before a Whiteout matchup against USC. That seemed to be the plan until halftime of the Wisconsin game. From that 17-0 lead against the Badgers, the Lions have struggled mightily.
Three of the four Big Ten losses have come by 8 or fewer points. Is this a situation where Penn State may be 0-4 but they could very easily be 3-1? I guess the crux of my question is, is Penn State better than their record reflects?
I think it should be at least 1-3. The Wisconsin loss was egregious. Penn State led from the start. They could never quite put away the Badgers, had to settle for field goals, committed a brutal turnover, and then allowed a couple of long conversions in the loss. This team isn't as talented as last year's Penn State team, but there are some similarities. They've had second half leads in three of the four losses, just as last year's Penn State team lost fourth quarter/overtime leads to Oregon, Indiana, Iowa, and Northwestern.
#game #team #iowa #oregon
Penn State has not won a Big Ten game yet this year. The schedule to start the year has turned out to be a lot tougher than most people probably thought going in. Given the turnover at the top, what was expected of Penn State by fans coming into this season?
I predicted a 9-3 season. Some others on our site were at least mentioning the word playoff in the offseason. Personally, I thought Penn State would have enough experience with Matt Campbell's system considering that there would be so much continuity with so many players making the move from Iowa State. A lot of that optimism was tied to the schedule. Unlike 2025 where Penn State jumped right into the deep end with a showdown against Oregon in conference play, this year seemed like it would give some runway for the Lions to work things out before a Whiteout matchup against USC. That seemed to be the plan until halftime of the Wisconsin game. From that 17-0 lead against the Badgers, the Lions have struggled mightily.
Three of the four Big Ten losses have come by 8 or fewer points. Is this a situation where Penn State may be 0-4 but they could very easily be 3-1? I guess the crux of my question is, is Penn State better than their record reflects?
I think it should be at least 1-3. The Wisconsin loss was egregious. Penn State led from the start. They could never quite put away the Badgers, had to settle for field goals, committed a brutal turnover, and then allowed a couple of long conversions in the loss. This team isn't as talented as last year's Penn State team, but there are some similarities. They've had second half leads in three of the four losses, just as last year's Penn State team lost fourth quarter/overtime leads to Oregon, Indiana, Iowa, and Northwestern.
#game #team #iowa #oregon

19 days ago
Yandy Díaz knows how close they are. And he's not going to let the ALCS run to a Game 7.
"It's a great opportunity," Díaz said in Spanish on Sunday night after the Tampa Bay Rays beat the Cleveland Guardians, via the Tampa Bay Times' Mark Topkin. "All of us are thinking of it.
"But it all ends tomorrow. We're going to win tomorrow."
The Rays are just a single win away from reaching the World Series, thanks to Sunday's convincing 3-1 win over the Guardians at Progressive Field. They jumped out to a 3-0 lead in the first three innings in Game 5 on Sunday afternoon, and then held on the rest of the way to take a 3-2 lead in the series.
Díaz opened the contest up with a double, and was hit in later that inning after Parker Messick walked Jonny DeLuca. Díaz ended up with three hits in the win.
#game
"It's a great opportunity," Díaz said in Spanish on Sunday night after the Tampa Bay Rays beat the Cleveland Guardians, via the Tampa Bay Times' Mark Topkin. "All of us are thinking of it.
"But it all ends tomorrow. We're going to win tomorrow."
The Rays are just a single win away from reaching the World Series, thanks to Sunday's convincing 3-1 win over the Guardians at Progressive Field. They jumped out to a 3-0 lead in the first three innings in Game 5 on Sunday afternoon, and then held on the rest of the way to take a 3-2 lead in the series.
Díaz opened the contest up with a double, and was hit in later that inning after Parker Messick walked Jonny DeLuca. Díaz ended up with three hits in the win.
#game



29 days ago
(Bloomberg) -- Chipotle Mexican Grill Inc. (CMG) shares jumped after the Financial Times reported that Starbucks Corp. has worked with advisers in recent months on a takeover proposal for the burrito chain.
Most Read from Bloomberg
UPS Worker Missed Email, Letting China Get F-35 Parts
Apple to Launch Doorbell, Lock, Thermostat Developed With LG
Dalio Says We're Nearing Point Where AI Bubble May Burst
#missed
Most Read from Bloomberg
UPS Worker Missed Email, Letting China Get F-35 Parts
Apple to Launch Doorbell, Lock, Thermostat Developed With LG
Dalio Says We're Nearing Point Where AI Bubble May Burst
#missed

29 days ago
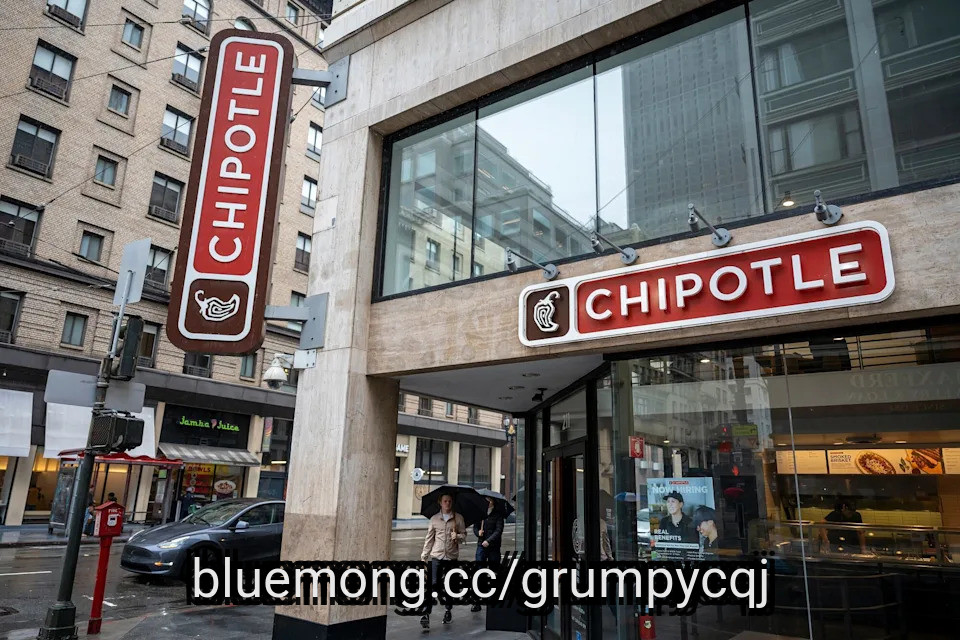
Investing.com -- Shares of Chipotle Mexican Grill (NYSE: CMG) and Starbucks (NASDAQ: SBUX) swung sharply Thursday following a Financial Times report that Starbucks has explored a potential acquisition of the burrito chain.
Before you buy NVIDIA: our AI model's stock picks are beating the market by 120%+. See the list now »
Chipotle shares initially jumped as much as 8% following the report, while Starbucks fell as much as 6%. Both stocks later pared those moves as investors weighed the potential implications of a deal.
Whispers of a potential tie-up had circulated previously, including a report from Semafor, but the speculation was largely dismissed by the market at the time. The Financial Times report carries greater weight, indicating that Starbucks has worked with advisers in recent months on a potential proposal for Chipotle, which currently has a market value of nearly $39 billion.
The sharp divergence in the stocks, however, could complicate the financial mechanics of a potential transaction. Starbucks' declining share price would reduce the value of any equity used as consideration, while Chipotle's rally increases the price Starbucks would need to pay for the company. The status of Starbucks' plans, including whether it has made a formal offer, remains unclear.
#starbucks #market #shares
Before you buy NVIDIA: our AI model's stock picks are beating the market by 120%+. See the list now »
Chipotle shares initially jumped as much as 8% following the report, while Starbucks fell as much as 6%. Both stocks later pared those moves as investors weighed the potential implications of a deal.
Whispers of a potential tie-up had circulated previously, including a report from Semafor, but the speculation was largely dismissed by the market at the time. The Financial Times report carries greater weight, indicating that Starbucks has worked with advisers in recent months on a potential proposal for Chipotle, which currently has a market value of nearly $39 billion.
The sharp divergence in the stocks, however, could complicate the financial mechanics of a potential transaction. Starbucks' declining share price would reduce the value of any equity used as consideration, while Chipotle's rally increases the price Starbucks would need to pay for the company. The status of Starbucks' plans, including whether it has made a formal offer, remains unclear.
#starbucks #market #shares

1 month ago
WASHINGTON (AP) — Most Federal Reserve officials expect that another interest rate increase will likely be needed this year to combat inflation, according to minutes released Wednesday from the central bank's most recent meeting.
The officials unanimously agreed that inflation was still elevated and had not made much progress toward their 2% target in recent months, the minutes said. The Fed increased its key interest rate at the Sept. 15-16 meeting by a quarter-point to about 3.9%, its first increase in three years.
The increase defied President Donald Trump's repeated calls for the Fed to cut rates and prompted the president to criticize the Fed's rate-setting committee, though he still expressed support for Chairman Kevin Warsh, whom he appointed earlier this year. The rate increase comes as Americans are already struggling with high costs for groceries, gas and housing, and as affordability has taken on a leading role in the upcoming midterm elections, just seven weeks away.
Longer-term interest rates for mortgages and other borrowing have also jumped in the past few months for a range of reasons, including rising government debt, heavy borrowing by tech firms to finance data center construction, climbing oil and gas prices, and signs that growth and inflation remain elevated. The Fed's rate hike has likely played only a limited role in the increase.
Still, key policymakers have said since the meeting that the Fed can take some time to monitor the economy and the impact of last month's rate hike before making another move. Wall Street investors now forecast the Fed will keep its rate unchanged at its next meeting Oct. 28-29, according to futures pricing, and raise it when they meet in December.
#officials
The officials unanimously agreed that inflation was still elevated and had not made much progress toward their 2% target in recent months, the minutes said. The Fed increased its key interest rate at the Sept. 15-16 meeting by a quarter-point to about 3.9%, its first increase in three years.
The increase defied President Donald Trump's repeated calls for the Fed to cut rates and prompted the president to criticize the Fed's rate-setting committee, though he still expressed support for Chairman Kevin Warsh, whom he appointed earlier this year. The rate increase comes as Americans are already struggling with high costs for groceries, gas and housing, and as affordability has taken on a leading role in the upcoming midterm elections, just seven weeks away.
Longer-term interest rates for mortgages and other borrowing have also jumped in the past few months for a range of reasons, including rising government debt, heavy borrowing by tech firms to finance data center construction, climbing oil and gas prices, and signs that growth and inflation remain elevated. The Fed's rate hike has likely played only a limited role in the increase.
Still, key policymakers have said since the meeting that the Fed can take some time to monitor the economy and the impact of last month's rate hike before making another move. Wall Street investors now forecast the Fed will keep its rate unchanged at its next meeting Oct. 28-29, according to futures pricing, and raise it when they meet in December.
#officials



1 month ago
By Ann Saphir
Oct 7 (Reuters) - The interest rate on the most common US home loan jumped last week to its highest in almost three years, worsening affordability for buyers four weeks before elections that will decide if President Donald Trump's Republicans keep control of Congress.
The average 30-year fixed-rate mortgage surged 19 basis points to 7.49% in the week ended October 2, the Mortgage Bankers **** ociation said on Wednesday. It was last higher in November 2023.
Mortgage rates are tied closely to the yield on US 10-year Treasury notes, which earlier this week hit a 24-year high, driven by worries over inflationary pressures from soaring oil prices and data showing stronger US economic growth.
The cost of living is the top issue on Americans' minds as they decide how they will vote on November 3, a Reuters/Ipsos poll completed on Monday showed, and is one reason why Trump's approval rating is at a record low of 32%.
#week #rate
Oct 7 (Reuters) - The interest rate on the most common US home loan jumped last week to its highest in almost three years, worsening affordability for buyers four weeks before elections that will decide if President Donald Trump's Republicans keep control of Congress.
The average 30-year fixed-rate mortgage surged 19 basis points to 7.49% in the week ended October 2, the Mortgage Bankers **** ociation said on Wednesday. It was last higher in November 2023.
Mortgage rates are tied closely to the yield on US 10-year Treasury notes, which earlier this week hit a 24-year high, driven by worries over inflationary pressures from soaring oil prices and data showing stronger US economic growth.
The cost of living is the top issue on Americans' minds as they decide how they will vote on November 3, a Reuters/Ipsos poll completed on Monday showed, and is one reason why Trump's approval rating is at a record low of 32%.
#week #rate
1 month ago
Taylor Swift is reportedly generating nearly twice as much jersey search demand as her husband, Travis Kelce. This is according to a new study conducted across the US. The findings highlight how strongly Swift's connection to the NFL star continues to influence interest in football merchandise.
A new ******* ysis by Casino.guru found that searches for a "Taylor Swift jersey" account for around 77% of the search demand recorded for the most-searched NFL player jersey in the country. The figure would place Taylor Swift among the five most in-demand jersey searches if her name were compared directly with NFL players, the study said.
The research also found a notable gap between Swift and Travis Kelce. Searches for Swift's jersey were nearly twice as high as searches for Kelce's jersey across the US. "Search demand for Taylor Swift jerseys is also nearly twice as high as it is for husband Travis Kelce jerseys across the U.S.," Casino.guru data ******* yst Max Barlow wrote in the study. He added that the search volume would "place her inside the top five most in-demand jerseys if compared directly with NFL players."
According to the ******* ysis, Swift also generated more than twice the jersey interest of the state's leading NFL player, Jaxson Dart. However, the study measured online search volume to estimate potential sales interest rather than using audited retail sales figures.
The latest figures contrast sharply with the surge in Kelce's jersey sales after Swift attended one of his games in 2023. Swift watched Kelce play from a suite at Arrowhead Stadium on September 24, 2023. After her appearance, Fanatics told the ******* ociated Press that Kelce entered the NFL's top five jersey sellers. His merchandise sales jumped nearly 400% across Fanatics' sites, according to NPR. Before the surge, Kelce ranked around 19th among NFL jersey sellers.
#jersey #taylor #twice #travis
A new ******* ysis by Casino.guru found that searches for a "Taylor Swift jersey" account for around 77% of the search demand recorded for the most-searched NFL player jersey in the country. The figure would place Taylor Swift among the five most in-demand jersey searches if her name were compared directly with NFL players, the study said.
The research also found a notable gap between Swift and Travis Kelce. Searches for Swift's jersey were nearly twice as high as searches for Kelce's jersey across the US. "Search demand for Taylor Swift jerseys is also nearly twice as high as it is for husband Travis Kelce jerseys across the U.S.," Casino.guru data ******* yst Max Barlow wrote in the study. He added that the search volume would "place her inside the top five most in-demand jerseys if compared directly with NFL players."
According to the ******* ysis, Swift also generated more than twice the jersey interest of the state's leading NFL player, Jaxson Dart. However, the study measured online search volume to estimate potential sales interest rather than using audited retail sales figures.
The latest figures contrast sharply with the surge in Kelce's jersey sales after Swift attended one of his games in 2023. Swift watched Kelce play from a suite at Arrowhead Stadium on September 24, 2023. After her appearance, Fanatics told the ******* ociated Press that Kelce entered the NFL's top five jersey sellers. His merchandise sales jumped nearly 400% across Fanatics' sites, according to NPR. Before the surge, Kelce ranked around 19th among NFL jersey sellers.
#jersey #taylor #twice #travis

1 month ago
The S&P 500 hit a record Tuesday as it rose for a fourth straight day, supported by rising technology stocks, hopes for a positive earnings season and a pause in oil’s recent surge.
The broad-based index closed higher by 0.58%, its first record closing high since Aug. 13. The Nasdaq Composite also jumped 0.45%. It also hit a record high for the second time this week.
The S&P 500 and the Nasdaq’s gains were overwhelmingly powered by gains in tech companies, such as chipmakers Marvell and Broadcom.
Nvidia, the world’s largest public company, also rose and moved closer to becoming the first company to ever reach $6 trillion in market value. Other trillion-dollar tech stocks also rose Tuesday. Microsoft, Amazon, **** eX, Meta Platforms and Tesla shares all traded in the green.
Investors are also looking forward to the start of the third quarter’s earnings season, which begins in earnest next week with the country’s biggest banks reporting their results.
#rose
The broad-based index closed higher by 0.58%, its first record closing high since Aug. 13. The Nasdaq Composite also jumped 0.45%. It also hit a record high for the second time this week.
The S&P 500 and the Nasdaq’s gains were overwhelmingly powered by gains in tech companies, such as chipmakers Marvell and Broadcom.
Nvidia, the world’s largest public company, also rose and moved closer to becoming the first company to ever reach $6 trillion in market value. Other trillion-dollar tech stocks also rose Tuesday. Microsoft, Amazon, **** eX, Meta Platforms and Tesla shares all traded in the green.
Investors are also looking forward to the start of the third quarter’s earnings season, which begins in earnest next week with the country’s biggest banks reporting their results.
#rose


1 month ago
The US trade deficit jumped to more than $100 billion in August as importers wrestled with a new round of President Trump's tariffs and continued to bring in billions of dollars' worth of components for AI data centers.
The total gap: $105.6 billion, a 13.8% increase from July's revised $92.8 billion deficit, the highest level since early 2025, when importers stocked up ahead of Trump's "Liberation Day" and a later four-month surge in imports that pushed average monthly trade deficits north of $120 billion.
Imports rose in August by 4.3%, compared with a 1.4% increase in exports. The US brought in $420.8 billion in total imports in August against $315.2 billion in exports.
In an **** ysis, Capital Economics said the "sharp rise in imports suggests third quarter GDP growth will be well below our current forecast of 4.0%," suggesting that the final annualized figure could be closer to 2.5%."
"The relatively broad-based rise in goods imports mean net trade was still a drag overall," the group added.
#billion #imports #total #increase
The total gap: $105.6 billion, a 13.8% increase from July's revised $92.8 billion deficit, the highest level since early 2025, when importers stocked up ahead of Trump's "Liberation Day" and a later four-month surge in imports that pushed average monthly trade deficits north of $120 billion.
Imports rose in August by 4.3%, compared with a 1.4% increase in exports. The US brought in $420.8 billion in total imports in August against $315.2 billion in exports.
In an **** ysis, Capital Economics said the "sharp rise in imports suggests third quarter GDP growth will be well below our current forecast of 4.0%," suggesting that the final annualized figure could be closer to 2.5%."
"The relatively broad-based rise in goods imports mean net trade was still a drag overall," the group added.
#billion #imports #total #increase

1 month ago
When AI stocks rebounded last week, optical networking companies did not rebound equally.
Lumentum Holdings Inc. (NASDAQ:LITE) jumped nearly 10% in Wednesday trading and led the S&P 500, while Coherent rose 6.9%. Corning Incorporated (NYSE:GLW) managed only a 0.4% gain and remained down sharply for the week.
All three sit inside the same broad AI-connectivity buildout. The divergence suggests investors are beginning to distinguish between different pieces of that infrastructure rather than buying every optics name together.
Photo from Lumentum Holdings website
AI clusters increasingly need optical connections as more accelerators communicate across larger physical distances. That drives demand for high-speed transceivers, lasers and other photonic components.
#NASDAQ #lite #wednesday #coherent
Lumentum Holdings Inc. (NASDAQ:LITE) jumped nearly 10% in Wednesday trading and led the S&P 500, while Coherent rose 6.9%. Corning Incorporated (NYSE:GLW) managed only a 0.4% gain and remained down sharply for the week.
All three sit inside the same broad AI-connectivity buildout. The divergence suggests investors are beginning to distinguish between different pieces of that infrastructure rather than buying every optics name together.
Photo from Lumentum Holdings website
AI clusters increasingly need optical connections as more accelerators communicate across larger physical distances. That drives demand for high-speed transceivers, lasers and other photonic components.
#NASDAQ #lite #wednesday #coherent
2 months ago
For the recently reported second quarter, PicS N.V. (NASDAQ:PICS) outperformed relative to its previous guidance across all profitability metrics. The total account base for the company went up to 70.4 million during the second quarter, showcasing a 10% jump from the prior year. Moving on to the bottom line figures, the adjusted earnings before tax, without factoring in costs ******* ociated with stock-based compensation came in at R$291 million for the quarter. This represented a 2.1% outperformance relative to the company's R$285 million guidance. Similarly, compared to the R$245 million projection, adjusted net income for the period actually stood 15.5% higher at R$283 million.
welcomia/Shutterstock.com
The second quarter concluded with strong financial and operating momentum for PicS. The company recorded a 9% annual and 2% sequential growth in its client base, which went up to 45.4 million active users. The total credit portfolio jumped to R$31.9 billion, exceeding management's guidance by 3%. This outperformance came due to a higher number of mature credit card cohorts, and accelerated origination within secured and partly secured categories. An additional factor that accounted for the credit portfolio growth was management's measured expansion into higher risk areas such as newer platform credit and private payroll lending.
Managerial revenue rose to R$3,730 million, topping guidance by 3.6%, and net interest income reached R$2,002 million, 5.4% above projections, boosted by growing credit income. Total cash in totaled R$136.4 billion, up 17% from a year earlier and 9% from the previous quarter, with customers bringing in an average of approximately R$45.4 billion to the platform each month. Total deposits climbed to R$35.8 billion, a 45% yearly jump and 10% quarterly rise.
Some concerns related to the company's loan portfolio emerged during the quarter. Non-performing loans more than 90 days overdue increased to 9.8% of the credit portfolio during the quarter, up 93 basis points sequentially. Stage 3 exposure, which includes a broader set of credit-impaired loans, reached 12.9% of the total credit portfolio.
#million #credit #quarter #Portfolio
welcomia/Shutterstock.com
The second quarter concluded with strong financial and operating momentum for PicS. The company recorded a 9% annual and 2% sequential growth in its client base, which went up to 45.4 million active users. The total credit portfolio jumped to R$31.9 billion, exceeding management's guidance by 3%. This outperformance came due to a higher number of mature credit card cohorts, and accelerated origination within secured and partly secured categories. An additional factor that accounted for the credit portfolio growth was management's measured expansion into higher risk areas such as newer platform credit and private payroll lending.
Managerial revenue rose to R$3,730 million, topping guidance by 3.6%, and net interest income reached R$2,002 million, 5.4% above projections, boosted by growing credit income. Total cash in totaled R$136.4 billion, up 17% from a year earlier and 9% from the previous quarter, with customers bringing in an average of approximately R$45.4 billion to the platform each month. Total deposits climbed to R$35.8 billion, a 45% yearly jump and 10% quarterly rise.
Some concerns related to the company's loan portfolio emerged during the quarter. Non-performing loans more than 90 days overdue increased to 9.8% of the credit portfolio during the quarter, up 93 basis points sequentially. Stage 3 exposure, which includes a broader set of credit-impaired loans, reached 12.9% of the total credit portfolio.
#million #credit #quarter #Portfolio

2 months ago
On August 5, Cencora (NYSE:COR) reported results for its fiscal third quarter, which closed on June 30, and the headline numbers looked clean. Revenue rose 5.1% to $84.8 billion, adjusted earnings per share climbed 12.0% to $4.48, and management raised its full-year adjusted EPS outlook to $17.75 to $17.95. The company also repurchased $1 billion of its own stock during the quarter. But the profit story has moving parts, and a few of them pull in opposite directions.
Start with the gap between profit growth and sales growth. Adjusted operating income rose 17.0% while revenue grew only 5.1%. Much of the help came from gross profit, which jumped 23.2% on an adjusted basis as both segments contributed and the OneOncology acquisition in February lifted margins in the US business. In plain terms, adjusted gross margin widened 61 basis points to 4.16%, so the company keeps more gross profit from every dollar it sells.
The strength was not confined to one corner, either. US Healthcare Solutions grew operating income 15.9% on higher pharmaceutical sales and the OneOncology deal, while specialty volume to health systems and physician groups lifted its revenue. International Healthcare Solutions did better still, with operating income up 20.8% on strength in European distribution and global specialty logistics. Management also put cash to work, completing in one quarter the $1 billion of buybacks it had expected to finish by the close of calendar 2026. The board declared a $0.60 quarterly dividend as well, payable August 31, to holders of record on August 14.
Growth is costing more than it first appears. Adjusted operating expenses jumped 26.8%, faster than adjusted gross profit, because OneOncology brought expenses along with its profits. Even so, adjusted operating income amounts to just 1.46% of revenue, a thin cushion on a business this large. Financing adds weight too. Cencora funded part of the purchase with new senior notes plus variable-rate term loans, and net interest expense rose $58.9 million from a year earlier.
The sales mix carries its own drag. GLP-1 drugs for diabetes and weight loss are adding to revenue, but they earn lower gross margins, so each dollar of that growth is worth less to profit. Meanwhile, an oncology customer Cencora lost in 2025, and lower sales to a large mail order customer both held back US revenue, as did lower manufacturer prices on some brand pharmaceuticals. Cencora is also exploring strategic alternatives for a group of other businesses, and its April divestiture of US Consulting Services trimmed consulting sales.
#adjusted #revenue #august
Start with the gap between profit growth and sales growth. Adjusted operating income rose 17.0% while revenue grew only 5.1%. Much of the help came from gross profit, which jumped 23.2% on an adjusted basis as both segments contributed and the OneOncology acquisition in February lifted margins in the US business. In plain terms, adjusted gross margin widened 61 basis points to 4.16%, so the company keeps more gross profit from every dollar it sells.
The strength was not confined to one corner, either. US Healthcare Solutions grew operating income 15.9% on higher pharmaceutical sales and the OneOncology deal, while specialty volume to health systems and physician groups lifted its revenue. International Healthcare Solutions did better still, with operating income up 20.8% on strength in European distribution and global specialty logistics. Management also put cash to work, completing in one quarter the $1 billion of buybacks it had expected to finish by the close of calendar 2026. The board declared a $0.60 quarterly dividend as well, payable August 31, to holders of record on August 14.
Growth is costing more than it first appears. Adjusted operating expenses jumped 26.8%, faster than adjusted gross profit, because OneOncology brought expenses along with its profits. Even so, adjusted operating income amounts to just 1.46% of revenue, a thin cushion on a business this large. Financing adds weight too. Cencora funded part of the purchase with new senior notes plus variable-rate term loans, and net interest expense rose $58.9 million from a year earlier.
The sales mix carries its own drag. GLP-1 drugs for diabetes and weight loss are adding to revenue, but they earn lower gross margins, so each dollar of that growth is worth less to profit. Meanwhile, an oncology customer Cencora lost in 2025, and lower sales to a large mail order customer both held back US revenue, as did lower manufacturer prices on some brand pharmaceuticals. Cencora is also exploring strategic alternatives for a group of other businesses, and its April divestiture of US Consulting Services trimmed consulting sales.
#adjusted #revenue #august
2 months ago
On September 9, 2026, Casey's General Stores, Inc. (NASDAQ:CASY) reported fiscal first-quarter revenue of $5.68 billion, up 24.3% year over year, and earnings per share of $7.37, beating the $6.78 ******* yst consensus. Yet shares fell roughly 10-15% after same-store sales grew just 3.2%, below the 3.8% Wall Street had expected.
CEO Darren Rebelez described a "volatile" fuel environment during the quarter. Same-store fuel gallons sold declined 0.3% as elevated prices pushed customers toward fewer gallons per visit, more frequent trips, and cheaper fuel grades.
Fuel profitability more than offset softer gallon volumes. Fuel gross profit jumped 19.6% to $446.9 million as the fuel margin expanded to 47.8 cents per gallon from 41.0 cents a year earlier. It shows Casey's General Stores, Inc. (NASDAQ:CASY)'s pricing discipline can protect profitability even when customers buy fewer gallons. Prepared food added another source of margin strength, with same-store sales rising 4.8% and margins expanding to 59.3% from 58.0%.
Strong earnings growth gives Casey's a solid start to fiscal 2027. EBITDA grew 17.1% to $485.1 million, while net income rose 27.1% to $273.7 million. It shows that Casey's can grow earnings despite softer same-store sales. The firm also delivered $5.68 billion of revenue, up 24% year over year and above the $5.56 billion ******* yst estimate. It gives investors evidence that the overall business remains capable of producing strong growth.
Casey's is expanding its store base and integrating Fikes. The business said the Fikes integration remains ahead of schedule and maintained its plan to open at least 120 stores in fiscal 2027 through construction and acquisitions. Ongoing unit growth can expand Casey's geographic reach, increase purchasing scale, and support long-term revenue growth even if mature-store sales remain uneven.
#fuel #revenue
CEO Darren Rebelez described a "volatile" fuel environment during the quarter. Same-store fuel gallons sold declined 0.3% as elevated prices pushed customers toward fewer gallons per visit, more frequent trips, and cheaper fuel grades.
Fuel profitability more than offset softer gallon volumes. Fuel gross profit jumped 19.6% to $446.9 million as the fuel margin expanded to 47.8 cents per gallon from 41.0 cents a year earlier. It shows Casey's General Stores, Inc. (NASDAQ:CASY)'s pricing discipline can protect profitability even when customers buy fewer gallons. Prepared food added another source of margin strength, with same-store sales rising 4.8% and margins expanding to 59.3% from 58.0%.
Strong earnings growth gives Casey's a solid start to fiscal 2027. EBITDA grew 17.1% to $485.1 million, while net income rose 27.1% to $273.7 million. It shows that Casey's can grow earnings despite softer same-store sales. The firm also delivered $5.68 billion of revenue, up 24% year over year and above the $5.56 billion ******* yst estimate. It gives investors evidence that the overall business remains capable of producing strong growth.
Casey's is expanding its store base and integrating Fikes. The business said the Fikes integration remains ahead of schedule and maintained its plan to open at least 120 stores in fiscal 2027 through construction and acquisitions. Ongoing unit growth can expand Casey's geographic reach, increase purchasing scale, and support long-term revenue growth even if mature-store sales remain uneven.
#fuel #revenue

2 months ago
On September 9, 2026, Chewy, Inc. (NYSE:CHWY) reported fiscal second-quarter net sales of $3.33 billion, up 7.3% year over year, and adjusted earnings per share of $0.36, nearly double the roughly $0.18 ******* ysts had expected, prompting the company to raise its full-year revenue and profitability outlook. CEO Sumit Singh said the broader pet market did not meaningfully recover during the quarter but also did not deteriorate further, with Chewy continuing to outperform the category by two to three times through share gains across its established and newer businesses.
Chewy, Inc. (NYSE:CHWY)'s recurring revenue base is solid. It gives the company greater visibility into future sales. Autoship sales jumped by 9.3% year over year to $2.82 billion and represented 84.6% of total net sales. The growing contribution from subscription-based purchases gives Chewy a more predictable revenue stream and reduces its exposure to fluctuations in discretionary pet spending.
Chewy is also building growth engines beyond its core retail business. Chewy Health, which includes veterinary care and pharmacy services, delivered triple-digit revenue growth. Specialty categories such as equine and exotics recorded a seventh consecutive quarter of mid-double-digit growth. These businesses give Chewy additional opportunities to increase customer spending and diversify its sources of revenue as the overall pet market matures.
Chewy is combining customer growth with stronger profitability and shareholder returns. The firm added 208,000 net active customers during the quarter. It takes its customer base to 21.7 million while returning $200 million to shareholders through share repurchases. Management also noted structural SG&A leverage, automation, and AI-driven cost reductions as contributors to margin expansion. It shows that Chewy can improve earnings while investing in customer acquisition and growth.
Part of Chewy, Inc. (NYSE:CHWY)'s profitability improvement came from benefits that may not recur. CFO Chris Deppe said the quarter's profitability upside included about $10 million from timing benefits and more than $5 million from discrete benefits. Those items boosted the latest results but do not provide a recurring earnings contribution. It means investors may need to lower their expectations for the pace of margin expansion in future quarters.
#customer
Chewy, Inc. (NYSE:CHWY)'s recurring revenue base is solid. It gives the company greater visibility into future sales. Autoship sales jumped by 9.3% year over year to $2.82 billion and represented 84.6% of total net sales. The growing contribution from subscription-based purchases gives Chewy a more predictable revenue stream and reduces its exposure to fluctuations in discretionary pet spending.
Chewy is also building growth engines beyond its core retail business. Chewy Health, which includes veterinary care and pharmacy services, delivered triple-digit revenue growth. Specialty categories such as equine and exotics recorded a seventh consecutive quarter of mid-double-digit growth. These businesses give Chewy additional opportunities to increase customer spending and diversify its sources of revenue as the overall pet market matures.
Chewy is combining customer growth with stronger profitability and shareholder returns. The firm added 208,000 net active customers during the quarter. It takes its customer base to 21.7 million while returning $200 million to shareholders through share repurchases. Management also noted structural SG&A leverage, automation, and AI-driven cost reductions as contributors to margin expansion. It shows that Chewy can improve earnings while investing in customer acquisition and growth.
Part of Chewy, Inc. (NYSE:CHWY)'s profitability improvement came from benefits that may not recur. CFO Chris Deppe said the quarter's profitability upside included about $10 million from timing benefits and more than $5 million from discrete benefits. Those items boosted the latest results but do not provide a recurring earnings contribution. It means investors may need to lower their expectations for the pace of margin expansion in future quarters.
#customer

2 months ago
On September 9, 2026, Jersey Mike's Subs Inc. (NYSE:JMKE) reported its first quarterly results as a public company, with total revenue up 10% year over year to $208 million and same-store sales accelerating to 2.3% growth from 1.7% in the prior quarter. It was primarily driven by transaction growth even as the restaurant industry faced weak traffic trends. Net income fell to $37 million from $59 million a year earlier. It showed non-routine expenses, advertising fund timing, and higher interest costs following the company's July initial public offering, partially offset by a $14 million gain on the sale of corporate-owned stores.
Jersey Mike's Subs Inc. (NYSE:JMKE) is gaining customers while its brand remains a major competitive advantage. The firm added 83 stores in the second quarter. It grew its customer base and increased systemwide sales 10% to $1.21 billion. Jersey Mike's also earned the No. 1 ranking among U.S. quick-service restaurant brands in the 2026 American Customer Satisfaction Index, surpassing Chick-fil-A after 11 consecutive years at the top. It gives the newly public company a strong foundation for continued customer and franchisee growth.
The business has substantial whitespace for long-term unit growth. Jersey Mike's ended the quarter with 3,378 locations and maintains a domestic development pipeline of more than 1,600 stores, with more than 90% of that pipeline coming from existing franchisees. Management estimates that the U.S. market could eventually support roughly 7,500 locations and sees potential to reach approximately 15,000 stores globally. It gives the business a long runway for franchise-led revenue and royalty growth.
Digital engagement and transaction growth give Jersey Mike's more avenues to increase sales. Digital sales represented 43% of systemwide sales in the second quarter, up from 41% a year earlier. Same-store sales increased 2.3% mainly because customers placed more transactions. Jersey Mike's also had more than 12.5 million active MyMike's loyalty members in 2025. It provides the company with a large customer database that it can use to increase frequency and personalize marketing as it expands.
Jersey Mike's Subs Inc. (NYSE:JMKE) still faces a significant profitability challenge despite its revenue growth. Second-quarter revenue jumped 10% to $208 million. However, net income fell 37% to $37 million from $59 million a year earlier. Management attributed part of the decline to advertising-fund timing and higher interest expense. It shows that revenue growth has not yet translated into comparable bottom-line growth for shareholders.
#million #customer
Jersey Mike's Subs Inc. (NYSE:JMKE) is gaining customers while its brand remains a major competitive advantage. The firm added 83 stores in the second quarter. It grew its customer base and increased systemwide sales 10% to $1.21 billion. Jersey Mike's also earned the No. 1 ranking among U.S. quick-service restaurant brands in the 2026 American Customer Satisfaction Index, surpassing Chick-fil-A after 11 consecutive years at the top. It gives the newly public company a strong foundation for continued customer and franchisee growth.
The business has substantial whitespace for long-term unit growth. Jersey Mike's ended the quarter with 3,378 locations and maintains a domestic development pipeline of more than 1,600 stores, with more than 90% of that pipeline coming from existing franchisees. Management estimates that the U.S. market could eventually support roughly 7,500 locations and sees potential to reach approximately 15,000 stores globally. It gives the business a long runway for franchise-led revenue and royalty growth.
Digital engagement and transaction growth give Jersey Mike's more avenues to increase sales. Digital sales represented 43% of systemwide sales in the second quarter, up from 41% a year earlier. Same-store sales increased 2.3% mainly because customers placed more transactions. Jersey Mike's also had more than 12.5 million active MyMike's loyalty members in 2025. It provides the company with a large customer database that it can use to increase frequency and personalize marketing as it expands.
Jersey Mike's Subs Inc. (NYSE:JMKE) still faces a significant profitability challenge despite its revenue growth. Second-quarter revenue jumped 10% to $208 million. However, net income fell 37% to $37 million from $59 million a year earlier. Management attributed part of the decline to advertising-fund timing and higher interest expense. It shows that revenue growth has not yet translated into comparable bottom-line growth for shareholders.
#million #customer

2 months ago
On September 9, 2026, Reuters reported that Alphabet Inc. (NASDAQ:GOOGL)'s Google will invest at least €13 billion, or about $15.1 billion, in AI infrastructure in Finland over the next two years, its biggest European investment, including three new data centers and a 22-year deal for up to 50% of the output of one of Finland's two nuclear power plants. The agreement with Finnish utility Fortum is Google's first nuclear energy deal outside the United States, and Fortum's stock jumped as much as 15.5% on the news, its biggest gain in Europe that day.
Finland gives Alphabet Inc. (NASDAQ:GOOGL) a potentially more cost-efficient location for its expanding AI infrastructure. Google plans to invest at least €13 billion ($15.1 billion) in three new data centers and related infrastructure in Finland during 2027 and 2028. The country's cold climate can reduce the need for energy-intensive cooling. The investment will also help grid improvements, clean-energy projects and battery storage.
The 22-year nuclear power agreement gives Google greater control over a critical input for AI infrastructure. Google will purchase up to 50% of the electricity generated by Finland's Loviisa nuclear plant, providing a long-term source of low-carbon power for its data-center operations. The agreement also gives Fortum greater economic certainty to extend and upgrade the plant through 2050. Google and Fortum plan to explore more nuclear and renewable projects.
Alphabet has strong demand drivers that can justify investment in AI capacity. The firm has increased its 2026 global capital investment target to $195 billion-$205 billion as it seeks to capture growing AI computing demand. Google is using the additional infrastructure to support Gemini, Search, Maps, and YouTube. It gives Alphabet multiple major products through which it can monetize greater AI capacity over time.
The Finland project adds another major commitment to Alphabet Inc. (NASDAQ:GOOGL)'s already enormous AI spending program. Alphabet expects to spend $195 billion-$205 billion on capital investment globally in 2026. The Finnish project will require at least another €13 billion during 2027 and 2028. Investors need Alphabet to make enough incremental revenue and cash flow from AI services to justify an infrastructure buildout that is rapidly increasing the company's capital requirements.
#billion #Google #investment #googl
Finland gives Alphabet Inc. (NASDAQ:GOOGL) a potentially more cost-efficient location for its expanding AI infrastructure. Google plans to invest at least €13 billion ($15.1 billion) in three new data centers and related infrastructure in Finland during 2027 and 2028. The country's cold climate can reduce the need for energy-intensive cooling. The investment will also help grid improvements, clean-energy projects and battery storage.
The 22-year nuclear power agreement gives Google greater control over a critical input for AI infrastructure. Google will purchase up to 50% of the electricity generated by Finland's Loviisa nuclear plant, providing a long-term source of low-carbon power for its data-center operations. The agreement also gives Fortum greater economic certainty to extend and upgrade the plant through 2050. Google and Fortum plan to explore more nuclear and renewable projects.
Alphabet has strong demand drivers that can justify investment in AI capacity. The firm has increased its 2026 global capital investment target to $195 billion-$205 billion as it seeks to capture growing AI computing demand. Google is using the additional infrastructure to support Gemini, Search, Maps, and YouTube. It gives Alphabet multiple major products through which it can monetize greater AI capacity over time.
The Finland project adds another major commitment to Alphabet Inc. (NASDAQ:GOOGL)'s already enormous AI spending program. Alphabet expects to spend $195 billion-$205 billion on capital investment globally in 2026. The Finnish project will require at least another €13 billion during 2027 and 2028. Investors need Alphabet to make enough incremental revenue and cash flow from AI services to justify an infrastructure buildout that is rapidly increasing the company's capital requirements.
#billion #Google #investment #googl
2 months ago
Microsoft's (NASDAQ:MSFT) fiscal 2026, which ended June 30, was arguably the strongest year in the software giant's history. Revenue grew 18% to $331.8 billion. Net income jumped 31% year over year, to $133.7 billion.
Micron Technology (NASDAQ:MU) is approaching that number from a different direction. The memory specialist earned $8.5 billion in its fiscal 2025.
Missed AI's "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our ***** ysts, we're only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
But for the fiscal fourth quarter of 2026, which ended in early September, management guided to earnings of $30.73 per diluted share, plus or minus $1.00, on a generally accepted accounting principles (GAAP) basis. On about 1.15 billion diluted shares, the guidance works out to about $35 billion of profit in one quarter (about four times what the whole prior fiscal year produced).
Here's my prediction: In fiscal 2027, Micron will earn more than Microsoft. That means beating the year Microsoft is now in, not the one it just reported. It's a bold call, and it relies almost entirely on the price of memory.
#Microsoft #quarter
Micron Technology (NASDAQ:MU) is approaching that number from a different direction. The memory specialist earned $8.5 billion in its fiscal 2025.
Missed AI's "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our ***** ysts, we're only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
But for the fiscal fourth quarter of 2026, which ended in early September, management guided to earnings of $30.73 per diluted share, plus or minus $1.00, on a generally accepted accounting principles (GAAP) basis. On about 1.15 billion diluted shares, the guidance works out to about $35 billion of profit in one quarter (about four times what the whole prior fiscal year produced).
Here's my prediction: In fiscal 2027, Micron will earn more than Microsoft. That means beating the year Microsoft is now in, not the one it just reported. It's a bold call, and it relies almost entirely on the price of memory.
#Microsoft #quarter

2 months ago
On September 17, Ferrari N.V. (NYSE:RACE) announced a partnership with the technology company Rakuten Group, Inc., effective January 1, 2027. The announcement gives no scope and no price tag, so it works better as a signal than as a number. The real substance sits in the results Ferrari posted on July 30, when it raised its 2026 guidance because buyers are ordering more personalization than the company expected.
In the second quarter, revenue rose 8%, but operating profit rose 10%, which means each euro of sales is leaving more behind. Ferrari credits a richer mix of cars, with the F80 helping, along with more buyers paying up for personalization. Strip out currency swings, and the gap widens, with revenue up 11% and operating profit up 16%. Deliveries of the Purosangue and the 296 Speciale family grew even in the middle of a planned model changeover.
Cash and demand back that up. Industrial free cash flow jumped 39% to €276 million, and Ferrari also returned more than €800 million to shareholders through a dividend and buybacks. Racing helped too, as higher sponsorships and engine rentals to other Formula 1 teams lifted revenue. Meanwhile, the order book covers 2027 in full, and the new 12Cilindri Manuale is already fully allocated, which is about as strong a demand signal as a carmaker can send. Those trends are why revenue guidance moved up to about €7.60 billion from about €7.50 billion.
Part of the strength is timing. Operating profit got a boost from temporarily lower depreciation and amortization while Ferrari swaps out models, and the company says those charges will climb once the new cars enter production. Net profit also leaned on a 23.0% tax rate, which reflects an estimated benefit from the new Patent Box. Neither says much about how profitable the cars themselves are.
Costs are climbing too. Higher industrial and marketing expenses weighed on operating profit, EBITDA margin slipped to 39.0% from 39.7% a year earlier, and management expects heavier brand, racing and digital spending for the year. Currency is a drag as well, mostly from the dollar and the yen, which is why 11% growth at constant currency shrank to 8% as reported. Deliveries totaled 3,366 cars while the 296 GTS, Roma Spider and SF90 XX family wound down, and sponsorship, commercial and brand revenue grew just 2%. And the whole outlook leans on current visibility into the Middle East crisis, which Ferrari cannot control.
#Ferrari
In the second quarter, revenue rose 8%, but operating profit rose 10%, which means each euro of sales is leaving more behind. Ferrari credits a richer mix of cars, with the F80 helping, along with more buyers paying up for personalization. Strip out currency swings, and the gap widens, with revenue up 11% and operating profit up 16%. Deliveries of the Purosangue and the 296 Speciale family grew even in the middle of a planned model changeover.
Cash and demand back that up. Industrial free cash flow jumped 39% to €276 million, and Ferrari also returned more than €800 million to shareholders through a dividend and buybacks. Racing helped too, as higher sponsorships and engine rentals to other Formula 1 teams lifted revenue. Meanwhile, the order book covers 2027 in full, and the new 12Cilindri Manuale is already fully allocated, which is about as strong a demand signal as a carmaker can send. Those trends are why revenue guidance moved up to about €7.60 billion from about €7.50 billion.
Part of the strength is timing. Operating profit got a boost from temporarily lower depreciation and amortization while Ferrari swaps out models, and the company says those charges will climb once the new cars enter production. Net profit also leaned on a 23.0% tax rate, which reflects an estimated benefit from the new Patent Box. Neither says much about how profitable the cars themselves are.
Costs are climbing too. Higher industrial and marketing expenses weighed on operating profit, EBITDA margin slipped to 39.0% from 39.7% a year earlier, and management expects heavier brand, racing and digital spending for the year. Currency is a drag as well, mostly from the dollar and the yen, which is why 11% growth at constant currency shrank to 8% as reported. Deliveries totaled 3,366 cars while the 296 GTS, Roma Spider and SF90 XX family wound down, and sponsorship, commercial and brand revenue grew just 2%. And the whole outlook leans on current visibility into the Middle East crisis, which Ferrari cannot control.
#Ferrari

2 months ago
On August 6, Wheaton Precious Metals (NYSE:WPM) reported second-quarter net earnings of $543 million on $929 million of revenue, both records. Through the first half, net earnings rose 106% to $1.1 billion. During the quarter, the company also made net upfront cash payments of $4.5 billion relative to mineral stream interests, and it now carries $2.0 billion of total debt against $100 million of cash on hand. Here is what that trade looks like up close.
Start with what the streaming model does when prices climb. Wheaton sold 14% more gold equivalent ounces than a year ago, but the average realized gold equivalent price jumped 61% in Q2, and that higher price explains most of the revenue surge. Costs per ounce rose from $406 to $568, yet the cash operating margin per ounce still grew 65% to $3,875, faster than gold itself appreciated. Operating cash flow hit $650 million in the quarter and $1.4 billion for the half.
The second argument is that plenty of growth hasn't arrived yet. Only about 3% of this year's production comes from **** ets still in construction or ramp-up, and the company forecasts a rise of roughly 50% to 1,200,000 gold equivalent ounces by 2030. Some of that ramp has dates attached. Ivanhoe now expects commercial production at Platreef in the fourth quarter of 2026, and Montage Gold is targeting first gold at Koné in late Q4. Effective April 1, Wheaton expanded its share of silver production from Antamina from 33.75% to 67.5% through the newly acquired BHP Antamina PMPA.
Growth on this scale wasn't free. Wheaton had no bank debt at the end of 2025. On April 1, it drew $1.5 billion on a new two-year term loan to help pay for Antamina, and finance costs that were negligible a year ago now take a real bite. Net debt stands at $1.9 billion. Taxes are heavier too. Wheaton paid $109 million of global minimum tax on June 24, and another Cdn$346 million is due around March 31, 2027.
Operations also gave investors a few reasons for caution. Gold ounces produced slipped 2.6% year over year, so the 6% rise in gold equivalent production leaned heavily on the Antamina purchase. Gold output at Salobo fell 11% on lower grades. At Constancia, it fell 35% after mining at the higher-grade Pampacancha pit finished in the fourth quarter of 2025. Hemlo Mining said on July 20 that its second-quarter output fell below the first quarter's, and Rio2 said on May 15 that Fenix missed planned tonnes and grade in Q1. And because the revenue jump came mainly from price, the same leverage works in reverse if metals slip.
#wheaton
Start with what the streaming model does when prices climb. Wheaton sold 14% more gold equivalent ounces than a year ago, but the average realized gold equivalent price jumped 61% in Q2, and that higher price explains most of the revenue surge. Costs per ounce rose from $406 to $568, yet the cash operating margin per ounce still grew 65% to $3,875, faster than gold itself appreciated. Operating cash flow hit $650 million in the quarter and $1.4 billion for the half.
The second argument is that plenty of growth hasn't arrived yet. Only about 3% of this year's production comes from **** ets still in construction or ramp-up, and the company forecasts a rise of roughly 50% to 1,200,000 gold equivalent ounces by 2030. Some of that ramp has dates attached. Ivanhoe now expects commercial production at Platreef in the fourth quarter of 2026, and Montage Gold is targeting first gold at Koné in late Q4. Effective April 1, Wheaton expanded its share of silver production from Antamina from 33.75% to 67.5% through the newly acquired BHP Antamina PMPA.
Growth on this scale wasn't free. Wheaton had no bank debt at the end of 2025. On April 1, it drew $1.5 billion on a new two-year term loan to help pay for Antamina, and finance costs that were negligible a year ago now take a real bite. Net debt stands at $1.9 billion. Taxes are heavier too. Wheaton paid $109 million of global minimum tax on June 24, and another Cdn$346 million is due around March 31, 2027.
Operations also gave investors a few reasons for caution. Gold ounces produced slipped 2.6% year over year, so the 6% rise in gold equivalent production leaned heavily on the Antamina purchase. Gold output at Salobo fell 11% on lower grades. At Constancia, it fell 35% after mining at the higher-grade Pampacancha pit finished in the fourth quarter of 2025. Hemlo Mining said on July 20 that its second-quarter output fell below the first quarter's, and Rio2 said on May 15 that Fenix missed planned tonnes and grade in Q1. And because the revenue jump came mainly from price, the same leverage works in reverse if metals slip.
#wheaton
2 months ago
For custom chip designer Broadcom Inc. (NASDAQ:AVGO), the debate is all about whether the demand for AI products will sustain and grow. It is among the few firms capable of designing custom AI chips that big technology firms rely on to supplement NVIDIA's high-power and expensive AI chips. Anthropic CEO Dario Amodei's latest remarks about the need to slow down AI development due to safety concerns have generated quite a buzz, and Cramer discussed what Broadcom Inc. (NASDAQ:AVGO)'s CEO told him when asked about AI infrastructure development losing traction:
"What's refuted by Hock Tan, of course, maybe Hock Tan is one of the biggest providers of semis, other than NVIDIA, and when I asked him about, give me a prediction about the AI slowdown, would there be one, he said, not in the least. We see the demand for compute infrastructure for development of AI and inference as extremely strong and durable. So I know those stocks were the most heavily hammered, other than the fiber stocks. But David, when you listen to what Hock Tan said last night on Mad Money, you are inclined to do buying.
"I think David, you recognize, and a lot of people don't, when you're speaking about Hock Tan, whom I had on, you're talking about a 1.6 trillion dollar company. This isn't just someone. . .worried about what orders are going to be. . .this man has more orders than almost anybody other than Jensen Huang. So I think Carl, when we get very, very negative we still have to rely on the facts And the facts do not support there are some people who are very worried about mankind, I did not get the mankind worry when I spoke yesterday."
The CNBC TV host's remarks about Broadcom Inc. (NASDAQ:AVGO) sit right at the center of the debate for the firm. This debate is about whether it will be able to continue to capture additional orders for custom AI chips. Looking at the third quarter earnings, released on September 2nd, the growth narrative appears to be quite strong.
It boosts Cramer's claims of Broadcom Inc. (NASDAQ:AVGO) experiencing strong orders, as during the quarter, the firm's revenue grew by 86%, AI semiconductor revenue jumped by 221% and fiscal year 2026 guidance implied 186% annual AI revenue growth. Not to mention, CEO Tan reaffirmed that Broadcom Inc. (NASDAQ:AVGO) could pull in $115 billion in annual AI chip sales in 2027 and a whopping $230 billion in 2028.
#orders #debate #strong
"What's refuted by Hock Tan, of course, maybe Hock Tan is one of the biggest providers of semis, other than NVIDIA, and when I asked him about, give me a prediction about the AI slowdown, would there be one, he said, not in the least. We see the demand for compute infrastructure for development of AI and inference as extremely strong and durable. So I know those stocks were the most heavily hammered, other than the fiber stocks. But David, when you listen to what Hock Tan said last night on Mad Money, you are inclined to do buying.
"I think David, you recognize, and a lot of people don't, when you're speaking about Hock Tan, whom I had on, you're talking about a 1.6 trillion dollar company. This isn't just someone. . .worried about what orders are going to be. . .this man has more orders than almost anybody other than Jensen Huang. So I think Carl, when we get very, very negative we still have to rely on the facts And the facts do not support there are some people who are very worried about mankind, I did not get the mankind worry when I spoke yesterday."
The CNBC TV host's remarks about Broadcom Inc. (NASDAQ:AVGO) sit right at the center of the debate for the firm. This debate is about whether it will be able to continue to capture additional orders for custom AI chips. Looking at the third quarter earnings, released on September 2nd, the growth narrative appears to be quite strong.
It boosts Cramer's claims of Broadcom Inc. (NASDAQ:AVGO) experiencing strong orders, as during the quarter, the firm's revenue grew by 86%, AI semiconductor revenue jumped by 221% and fiscal year 2026 guidance implied 186% annual AI revenue growth. Not to mention, CEO Tan reaffirmed that Broadcom Inc. (NASDAQ:AVGO) could pull in $115 billion in annual AI chip sales in 2027 and a whopping $230 billion in 2028.
#orders #debate #strong


