

2 days ago
A $1,000 investment in MSFT today could reach $1,587 by 2029 under the base case, or as high as $1,911 in a bull scenario.
Azure revenue surged 48% last quarter, and CFO Amy Hood guided next-quarter growth of between 49% and 50% in constant currency.
Microsoft's contracted backlog jumped 73% to $677 billion, with Copilot daily users up over 5x year over year.
Just released. Our ***** ysts combed the entire stock market and named the ten best stocks to buy right now, and Microsoft didn't make the cut. Enter your email to see the names that beat MSFT. The report is free. Enter your email and see if any of your stocks made the cut.
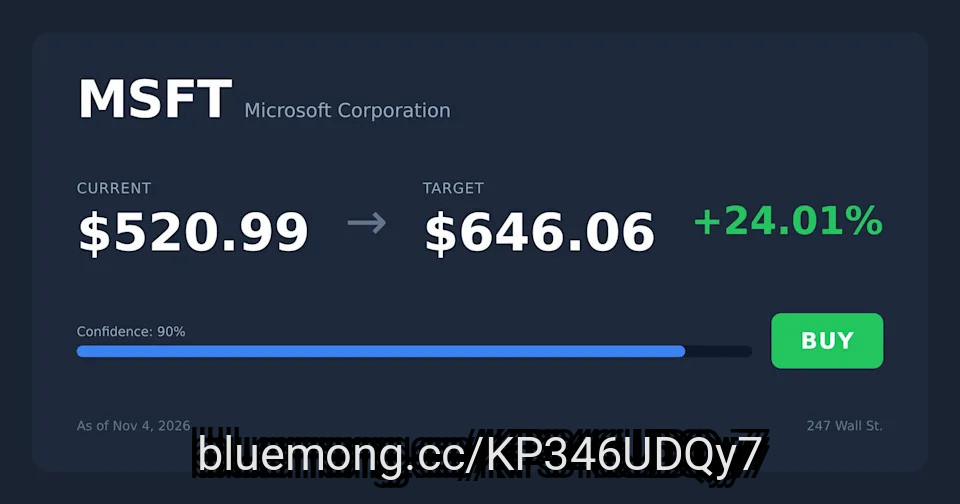
Microsoft (NASDAQ:MSFT) is one of the biggest stocks you can own to get exposure to enterprise AI, so it makes sense to ask what $1,000 put in today could grow into by 2029. Our price-prediction model uses a reference price of $525.63 per share.
#year #email #price
Azure revenue surged 48% last quarter, and CFO Amy Hood guided next-quarter growth of between 49% and 50% in constant currency.
Microsoft's contracted backlog jumped 73% to $677 billion, with Copilot daily users up over 5x year over year.
Just released. Our ***** ysts combed the entire stock market and named the ten best stocks to buy right now, and Microsoft didn't make the cut. Enter your email to see the names that beat MSFT. The report is free. Enter your email and see if any of your stocks made the cut.
Microsoft (NASDAQ:MSFT) is one of the biggest stocks you can own to get exposure to enterprise AI, so it makes sense to ask what $1,000 put in today could grow into by 2029. Our price-prediction model uses a reference price of $525.63 per share.
#year #email #price

1 month ago
JERUSALEM (AP) — A dentist and other passengers wrestled with a violent copilot. A plumber seized the controls as the plane plunged towards the desert. And the captain, despite being stabbed, managed to open the ***** pit door — helping save all 182 people aboard the Israel-bound flight.
"Hollywood isn't creative enough to come up with stories like this!" said Mike Huckabee, the U.S. ambassador to Israel.
Although major questions remained unanswered on Thursday about the attacker and his motive, the story of ordinary passengers saving the FlyDubai flight from disaster has quickly become the stuff of legend.
Israeli Prime Minister Benjamin Netanyahu warmly embraced plumber Yaniv Hayoun shortly after the passengers arrived in Tel Aviv late on Wednesday. He later posted a five-star review of Hayoun's professional services, calling him "a hero who has saved many lives."
"He can help you too — I highly recommend him!" Netanyahu added on X.
#passengers #Israel #jerusalem
"Hollywood isn't creative enough to come up with stories like this!" said Mike Huckabee, the U.S. ambassador to Israel.
Although major questions remained unanswered on Thursday about the attacker and his motive, the story of ordinary passengers saving the FlyDubai flight from disaster has quickly become the stuff of legend.
Israeli Prime Minister Benjamin Netanyahu warmly embraced plumber Yaniv Hayoun shortly after the passengers arrived in Tel Aviv late on Wednesday. He later posted a five-star review of Hayoun's professional services, calling him "a hero who has saved many lives."
"He can help you too — I highly recommend him!" Netanyahu added on X.
#passengers #Israel #jerusalem



2 months ago
MSFT's new government AI suite goes on sale October 1, but agencies must commit annual budgets before all features clear security accreditation.
Microsoft hasn't disclosed per-seat pricing or paid conversion rates from earlier no-cost federal Copilot deployments, making any government revenue forecast impossible.
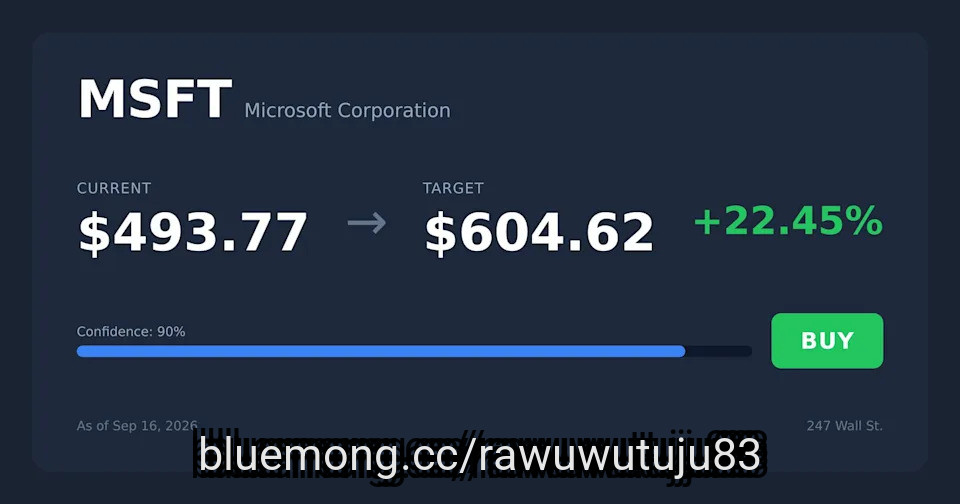
With $116 billion in capex and free cash flow falling 23%, Microsoft's AI monetization curve in government remains unproven against a $573 ***** yst price target.
Just released. Our ***** ysts combed the entire stock market and named the ten best stocks to buy right now, and Microsoft didn't make the cut. Enter your email to see the names that beat MSFT. The report is free. Enter your email and see if any of your stocks made the cut.
Microsoft (NASDAQ:MSFT) has told federal buyers that a new top government tier of its productivity suite, plus a companion agent-management product, will be available for Government Community Cloud customers to purchase on October 1. Individual capabilities will light up in phases as each workload clears its required government security accreditation, and additional Copilot features are slated for the months after general availability.
#government #features
Microsoft hasn't disclosed per-seat pricing or paid conversion rates from earlier no-cost federal Copilot deployments, making any government revenue forecast impossible.
With $116 billion in capex and free cash flow falling 23%, Microsoft's AI monetization curve in government remains unproven against a $573 ***** yst price target.
Just released. Our ***** ysts combed the entire stock market and named the ten best stocks to buy right now, and Microsoft didn't make the cut. Enter your email to see the names that beat MSFT. The report is free. Enter your email and see if any of your stocks made the cut.
Microsoft (NASDAQ:MSFT) has told federal buyers that a new top government tier of its productivity suite, plus a companion agent-management product, will be available for Government Community Cloud customers to purchase on October 1. Individual capabilities will light up in phases as each workload clears its required government security accreditation, and additional Copilot features are slated for the months after general availability.
#government #features


2 months ago
This story was originally published on CFO Dive. To receive daily news and insights, subscribe to our free daily CFO Dive newsletter.
Business executives consider artificial intelligence a leading tool for decision-making, with 61% citing large language models such as ChatGPT, Claude, Gemini and Copilot among the sources that most influence their strategic decisions, AI enterprise planning platform Board said in a report released Wednesday.
The finding was most ***** ounced among CFOs, with 69% citing LLMs among the resources that inform their decisions, compared with 58% of chief operating officers and 56% of chief information officers.
"CFOs, by nature, are typically a little bit more conservative and skeptical, so I think what this shows is that the AI wave is so strong that it can't be ignored," Board CFO Gordon Pothier said in an interview.
The findings come just a few years after ChatGPT burst onto the market, highlighting how quickly advanced AI tools have reshaped the way businesses operate and make decisions.
#decisions #daily #officers #business
Business executives consider artificial intelligence a leading tool for decision-making, with 61% citing large language models such as ChatGPT, Claude, Gemini and Copilot among the sources that most influence their strategic decisions, AI enterprise planning platform Board said in a report released Wednesday.
The finding was most ***** ounced among CFOs, with 69% citing LLMs among the resources that inform their decisions, compared with 58% of chief operating officers and 56% of chief information officers.
"CFOs, by nature, are typically a little bit more conservative and skeptical, so I think what this shows is that the AI wave is so strong that it can't be ignored," Board CFO Gordon Pothier said in an interview.
The findings come just a few years after ChatGPT burst onto the market, highlighting how quickly advanced AI tools have reshaped the way businesses operate and make decisions.
#decisions #daily #officers #business


2 months ago
During the September 3 episode of Mad Money, Jim Cramer mentioned Microsoft Corporation (NASDAQ:MSFT) for its unconventional approach to powering hyperscale data centers in partnership with Chevron Corporation (NYSE:CVX). He said:
How about Microsoft? Look, Mr. Softee is getting religion. They've realized that by giving us more disclosure on Azure, their cloud infrastructure business, we'll find more things to like. They're right. In the end, I come to praise Microsoft CFO Amy Hood, not bury her. They've been very clever getting power for the data centers, pumping it right out of the Permian. They got this deal with Chevron as a partner… 2.67 gigawatts. No one's talking about it. It's the cleanest behind the meter plan for power I have seen yet. People even, and this is not a stretch, I'm not kidding, people even like Copilot.
CFO Amy Hood provided Wall Street with a much clearer look at actual cloud demand by breaking down detailed Azure growth metrics and data center capacity constraints. At the same time, enterprise adoption of Microsoft 365 Copilot is moving past initial trials, with major corporations deploying the AI ***** istant across workforce segments.
A major highlight of the company's infrastructure strategy is a twenty-year agreement with Chevron Corporation (NYSE:CVX) for a proposed 2.67-gigawatt natural gas power plant in West Texas. Designed to supply dedicated off-grid electricity directly to a hyperscale data center in the Permian Basin, the project bypasses regional grid transmission queues to secure reliable power for continuous AI workloads. Microsoft Corporation's (NASDAQ:MSFT) president of Cloud Operations + Innovation, Noelle Walsh, commented:
Our agreement with Chevron helps ensure we'll have dedicated, large-scale power to support the evolution and reliability of advanced compute. Through this partnership, we're delighted to grow with and become a deeper part of the West Texas community.
#chevron #power #they 've
How about Microsoft? Look, Mr. Softee is getting religion. They've realized that by giving us more disclosure on Azure, their cloud infrastructure business, we'll find more things to like. They're right. In the end, I come to praise Microsoft CFO Amy Hood, not bury her. They've been very clever getting power for the data centers, pumping it right out of the Permian. They got this deal with Chevron as a partner… 2.67 gigawatts. No one's talking about it. It's the cleanest behind the meter plan for power I have seen yet. People even, and this is not a stretch, I'm not kidding, people even like Copilot.
CFO Amy Hood provided Wall Street with a much clearer look at actual cloud demand by breaking down detailed Azure growth metrics and data center capacity constraints. At the same time, enterprise adoption of Microsoft 365 Copilot is moving past initial trials, with major corporations deploying the AI ***** istant across workforce segments.
A major highlight of the company's infrastructure strategy is a twenty-year agreement with Chevron Corporation (NYSE:CVX) for a proposed 2.67-gigawatt natural gas power plant in West Texas. Designed to supply dedicated off-grid electricity directly to a hyperscale data center in the Permian Basin, the project bypasses regional grid transmission queues to secure reliable power for continuous AI workloads. Microsoft Corporation's (NASDAQ:MSFT) president of Cloud Operations + Innovation, Noelle Walsh, commented:
Our agreement with Chevron helps ensure we'll have dedicated, large-scale power to support the evolution and reliability of advanced compute. Through this partnership, we're delighted to grow with and become a deeper part of the West Texas community.
#chevron #power #they 've

2 months ago
On August 24, ePlus (NASDAQ:PLUS) announced it had completed the acquisition of the **** ets of Daymark Solutions, a Massachusetts-based IT services provider, with the deal having closed three days earlier on August 21. The announcement landed three weeks after the company posted first-quarter fiscal 2027 results on August 4, showing sales climbing even as profit slipped. Together, the two headlines capture where ePlus stands right now: reaching for new growth in cloud and security while working through pressure on its existing business.
Daymark, founded in 2001, built its business serving highly regulated, data-intensive industries including energy and utilities, healthcare, life sciences, defense, and financial services. Its core capabilities span modern data center infrastructure, cloud, Microsoft 365, Microsoft 365 Copilot, and cybersecurity, and its status as a Microsoft Tier 1 Cloud Solution Provider slots directly alongside ePlus' existing Azure and Microsoft 365 professional and managed services work. The acquisition also gives ePlus a deeper foothold in the New England region, particularly metropolitan Boston. CEO Mark Marron framed it as a way to gain a specialized Microsoft team that could serve as a catalyst for growth across Azure, Microsoft 365, security, and Copilot.
The timing lines up with what was already ePlus' fastest-growing segment. Managed services revenue rose 15.1% to $51.3 million in the first quarter, the segment's first quarter above $50 million, with gross profit up 11.3% on that growth. The balance sheet backs further moves like this one: cash and equivalents reached $448.9 million as of June 30, up from $410.8 million three months earlier, giving ePlus room for additional acquisitions, dividends, and buybacks. Management also pointed to record sales and a significant rise in booked and open orders, positioning the company for what it called a stronger second half.
The first quarter numbers show a company growing on top but shrinking underneath. Net earnings from continuing operations fell 5.4% to $30.3 million, adjusted EBITDA dropped 9.2% to $47.8 million, and operating income declined 9.6% to $38.8 million. Gross margin slipped to 23.3% from 23.9% a year earlier, with margin compression showing up across all three business segments rather than just one.
The professional services segment, the part of the business closest to the consulting and implementation work Daymark specializes in, fell 5.1% to $68.1 million, and its margin dropped to 36.9% from 39.2%. The product segment saw its own margin decline, to 21.0% from 21.3%, as an ongoing memory chip shortage extended lead times and delayed shipments. Terms of the Daymark transaction were not disclosed, leaving no visibility into what ePlus paid or how the deal affects near-term results.
#Microsoft #million #august #first
Daymark, founded in 2001, built its business serving highly regulated, data-intensive industries including energy and utilities, healthcare, life sciences, defense, and financial services. Its core capabilities span modern data center infrastructure, cloud, Microsoft 365, Microsoft 365 Copilot, and cybersecurity, and its status as a Microsoft Tier 1 Cloud Solution Provider slots directly alongside ePlus' existing Azure and Microsoft 365 professional and managed services work. The acquisition also gives ePlus a deeper foothold in the New England region, particularly metropolitan Boston. CEO Mark Marron framed it as a way to gain a specialized Microsoft team that could serve as a catalyst for growth across Azure, Microsoft 365, security, and Copilot.
The timing lines up with what was already ePlus' fastest-growing segment. Managed services revenue rose 15.1% to $51.3 million in the first quarter, the segment's first quarter above $50 million, with gross profit up 11.3% on that growth. The balance sheet backs further moves like this one: cash and equivalents reached $448.9 million as of June 30, up from $410.8 million three months earlier, giving ePlus room for additional acquisitions, dividends, and buybacks. Management also pointed to record sales and a significant rise in booked and open orders, positioning the company for what it called a stronger second half.
The first quarter numbers show a company growing on top but shrinking underneath. Net earnings from continuing operations fell 5.4% to $30.3 million, adjusted EBITDA dropped 9.2% to $47.8 million, and operating income declined 9.6% to $38.8 million. Gross margin slipped to 23.3% from 23.9% a year earlier, with margin compression showing up across all three business segments rather than just one.
The professional services segment, the part of the business closest to the consulting and implementation work Daymark specializes in, fell 5.1% to $68.1 million, and its margin dropped to 36.9% from 39.2%. The product segment saw its own margin decline, to 21.0% from 21.3%, as an ongoing memory chip shortage extended lead times and delayed shipments. Terms of the Daymark transaction were not disclosed, leaving no visibility into what ePlus paid or how the deal affects near-term results.
#Microsoft #million #august #first


2 months ago
Microsoft announced a new financial reporting structure on Wednesday, collapsing its three operating segments into two as artificial intelligence reshapes how the company organizes its business. The change takes effect in fiscal year 2027.
The two new segments are Agents and Infra, and Devices and Consumer. Those three categories — Productivity and Business Processes, Intelligent Cloud, and More Personal Computing — dated to 2015, according to CNBC.
Agents and Infra will include Azure cloud infrastructure, Microsoft 365, GitHub, productivity and server licensing, industry solutions, and frontier and support services. Devices and Consumer will cover search and advertising, Xbox, Windows operating system licenses, and device sales. The restructuring brings Microsoft's advertising businesses together under one segment, the company said.
"There's no question AI represents a profound shift in both technology and business," Chairman and Chief Executive Officer Satya Nadella wrote in the presentation. "It is changing what we build and how we operate, and it is blurring the boundaries between our products and reshaping our business models."
As part of the changes, Microsoft will begin reporting quarterly Azure revenue figures — a disclosure it has not previously made. Under the new, narrower definition of Azure, which excludes GitHub cloud services, developer cloud services, the Security Copilot **** istant, and healthcare and life sciences cloud products, Azure revenue grew 42% to $29.42 billion in the June quarter. That compares with 43% growth under the old Azure and other cloud services metric. Azure represented roughly 33% of Microsoft's total revenue in that period.
#Services #agents
The two new segments are Agents and Infra, and Devices and Consumer. Those three categories — Productivity and Business Processes, Intelligent Cloud, and More Personal Computing — dated to 2015, according to CNBC.
Agents and Infra will include Azure cloud infrastructure, Microsoft 365, GitHub, productivity and server licensing, industry solutions, and frontier and support services. Devices and Consumer will cover search and advertising, Xbox, Windows operating system licenses, and device sales. The restructuring brings Microsoft's advertising businesses together under one segment, the company said.
"There's no question AI represents a profound shift in both technology and business," Chairman and Chief Executive Officer Satya Nadella wrote in the presentation. "It is changing what we build and how we operate, and it is blurring the boundaries between our products and reshaping our business models."
As part of the changes, Microsoft will begin reporting quarterly Azure revenue figures — a disclosure it has not previously made. Under the new, narrower definition of Azure, which excludes GitHub cloud services, developer cloud services, the Security Copilot **** istant, and healthcare and life sciences cloud products, Azure revenue grew 42% to $29.42 billion in the June quarter. That compares with 43% growth under the old Azure and other cloud services metric. Azure represented roughly 33% of Microsoft's total revenue in that period.
#Services #agents


2 months ago
MSFT earns a BUY with a $590 price target as Azure crosses $100B in annual revenue and Copilot surpasses 30 million paid seats.
AMZN trades at P/E 36 versus MSFT's 27 despite AWS growing slower than Azure's 43%, making the $590 target look conservative.
Full-year capex hit $116B while free cash flow fell 23%, but net income still grew 31%, making demand normalization the lone bear-case risk.
Act now: the ******* yst who called NVIDIA in 2010 just named his top 10 AI stocks — and Microsoft didn't make the cut. Grab the names FREE today.
Microsoft has become the quiet outlier in the AI trade. While NVIDIA (NASDAQ:NVDA) absorbs the spotlight and hyperscaler rivals chase headlines, Microsoft (NASDAQ:MSFT) is quietly compounding the deepest enterprise AI moat in software.
#Microsoft #free #making #azure
AMZN trades at P/E 36 versus MSFT's 27 despite AWS growing slower than Azure's 43%, making the $590 target look conservative.
Full-year capex hit $116B while free cash flow fell 23%, but net income still grew 31%, making demand normalization the lone bear-case risk.
Act now: the ******* yst who called NVIDIA in 2010 just named his top 10 AI stocks — and Microsoft didn't make the cut. Grab the names FREE today.
Microsoft has become the quiet outlier in the AI trade. While NVIDIA (NASDAQ:NVDA) absorbs the spotlight and hyperscaler rivals chase headlines, Microsoft (NASDAQ:MSFT) is quietly compounding the deepest enterprise AI moat in software.
#Microsoft #free #making #azure



3 months ago
The score is Machines 1-0 Humans - at least when it comes to predicting football results, anyway.
AI - in this case Microsoft chatbot CoPilot - finished top of the BBC predictions league at the first attempt last season, but will it stay there?
BBC Sport football expert Chris Sutton, his guests and the BBC readers will be hoping to strike back, and land a blow for the human race.
"It was a final-day defeat for me, that is how close I came to the **** le," Sutton said.
"But I keep reading how AI models are going rogue and attacking each other.
#Football
AI - in this case Microsoft chatbot CoPilot - finished top of the BBC predictions league at the first attempt last season, but will it stay there?
BBC Sport football expert Chris Sutton, his guests and the BBC readers will be hoping to strike back, and land a blow for the human race.
"It was a final-day defeat for me, that is how close I came to the **** le," Sutton said.
"But I keep reading how AI models are going rogue and attacking each other.
#Football

3 months ago
Sam Altman's push for a $1 trillion OpenAI IPO is on a collision course with SoftBank's need to repay a $40 billion bridge loan early next year, creating real tension around the deal's timing and valuation. All this tension matters for Microsoft (NASDAQ: MSFT) and Nvidia (NASDAQ: NVDA) shareholders, because both companies have meaningful OpenAI exposure on their balance sheets and in their narratives.
OpenAI filed a confidential S‑1 with the Securities and Exchange Commission in June and sits at a private post‑money valuation of around $852 billion after its March 2026 funding round. Reports put its 2025 revenue near $13 billion and its 2026 revenue near $2 billion per month, numbers that support a high valuation multiple, but not a stress‑free one. Altman has told investors he will not take the company public below $1 trillion, so the IPO must clear that bar, or the listing will stay on hold.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
To fund its expanded stake in OpenAI, SoftBank arranged an unsecured $40 billion bridge loan that matures in March 2027. Bridge paper exists to carry a borrower into a specific liquidity moment, which in this case lines up with a fourth-quarter 2026 or first-quarter 2027 window for OpenAI's IPO. If public markets balk at putting a $1 trillion valuation on the ChatGPT developer, SoftBank will either have to refinance at tougher terms or the company will have to accept a lower market cap -- an outcome that could ripple through its broader AI story.
Microsoft owns roughly 27% of OpenAI after committing about $13 billion to it a few years ago, and it's in talks to add a bit under $10 billion more to its stake in the new funding round. A trillion-dollar IPO would turn that stake into one of the most valuable strategic holdings in corporate history, which supports the long‑term AI infrastructure thesis around Azure and Copilot. The risk here is that SoftBank's need for speed will push OpenAI to go public before the economics of enterprise AI are stable, leaving Microsoft with headline valuation gains but more scrutiny on capital intensity and on an AI partner whose stock could swing hard.
#bridge #signal
OpenAI filed a confidential S‑1 with the Securities and Exchange Commission in June and sits at a private post‑money valuation of around $852 billion after its March 2026 funding round. Reports put its 2025 revenue near $13 billion and its 2026 revenue near $2 billion per month, numbers that support a high valuation multiple, but not a stress‑free one. Altman has told investors he will not take the company public below $1 trillion, so the IPO must clear that bar, or the listing will stay on hold.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
To fund its expanded stake in OpenAI, SoftBank arranged an unsecured $40 billion bridge loan that matures in March 2027. Bridge paper exists to carry a borrower into a specific liquidity moment, which in this case lines up with a fourth-quarter 2026 or first-quarter 2027 window for OpenAI's IPO. If public markets balk at putting a $1 trillion valuation on the ChatGPT developer, SoftBank will either have to refinance at tougher terms or the company will have to accept a lower market cap -- an outcome that could ripple through its broader AI story.
Microsoft owns roughly 27% of OpenAI after committing about $13 billion to it a few years ago, and it's in talks to add a bit under $10 billion more to its stake in the new funding round. A trillion-dollar IPO would turn that stake into one of the most valuable strategic holdings in corporate history, which supports the long‑term AI infrastructure thesis around Azure and Copilot. The risk here is that SoftBank's need for speed will push OpenAI to go public before the economics of enterprise AI are stable, leaving Microsoft with headline valuation gains but more scrutiny on capital intensity and on an AI partner whose stock could swing hard.
#bridge #signal
3 months ago
The 2026 NFL season is rapidly approaching, and prognosticators everywhere are beginning to release their predictions for how the campaign will unfold.
The exercise isn't an easy one given the league's general unpredictability. The 2025 season reminded fans of that, as few would have projected the Seattle Seahawks and New England Patriots to be the final teams standing in Super Bowl 60.
With that in mind, USA TODAY Sports decided to give Microsoft Copilot – an artificial intelligence (AI) chatbot – a crack at predicting the results of the 2026 NFL season.
2026 NFL RECORD PROJECTIONS: Win totals for all 32 teams, playoff predictions
Copilot was prompted to ***** s the upcoming NFL season with two simple queries. They were as follows.
#copilot #predictions #teams #Seattle
The exercise isn't an easy one given the league's general unpredictability. The 2025 season reminded fans of that, as few would have projected the Seattle Seahawks and New England Patriots to be the final teams standing in Super Bowl 60.
With that in mind, USA TODAY Sports decided to give Microsoft Copilot – an artificial intelligence (AI) chatbot – a crack at predicting the results of the 2026 NFL season.
2026 NFL RECORD PROJECTIONS: Win totals for all 32 teams, playoff predictions
Copilot was prompted to ***** s the upcoming NFL season with two simple queries. They were as follows.
#copilot #predictions #teams #Seattle



3 months ago
On August 4, Tenable Holdings (NASDAQ:TENB) announced that it now covers every major AI platform and developer tool through its Tenable One platform, adding Google Gemini to a list that already included Anthropic Claude, OpenAI's ChatGPT Enterprise, and Microsoft Copilot. It is a bet that as companies rush to adopt AI, someone needs to watch where the risk is hiding, and Tenable wants to be the company holding that flashlight.
The scale of the problem Tenable is chasing is hard to ignore. The company said it detected 457 million AI-related security issues across more than 7,000 organizations, averaging 62,000 exposures per organization over 30 days. That is the kind of number that makes the case for exposure management on its own. Tenable One AI Exposure now extends discovery to every major LLM, all major Model Context Protocol deployments, and AI-native development tools like Cursor, Windsurf, and Trae, roughly doubling its coverage of sanctioned and shadow AI in one release. Beyond just finding the exposures, the platform lets security teams act on them directly, creating tickets in Jira or ServiceNow (NYSE:NOW), or firing off alerts through email, Slack, or Teams. That combination of visibility and Tenable's Hexa AI engine, which automates remediation tasks, is what the company is positioning as a full loop rather than another dashboard ****** ody checks.
The business results back up the demand story. Tenable One made up half of the company's new sales in the second quarter, evidence that customers are consolidating onto the full platform instead of buying individual point tools. Second-quarter revenue came in at $268.5 million, ahead of management's guided range of $263 million to $266 million, while operating expenses fell to $195.8 million from $200.3 million a year earlier. That combination flipped a $14.7 million net loss into a $3.8 million net profit, and adjusted profit jumped 40% to $57.9 million. The stock is up more than 40% in 2026 on the back of that improvement, yet Tenable's market capitalization of $3.6 billion is still a fraction of CrowdStrike Holdings (NASDAQ:CRWD) and Palo Alto Networks (NASDAQ:PANW), whose combined market cap tops $450 billion.
That gap shows up in valuation too. Tenable trades at a price-to-sales ratio of 3.7, well below its own historical average of 7.1 since going public in 2018, and far cheaper than Palo Alto Networks at 22.9 times sales or CrowdStrike at 38.1 times. But cheap multiples usually come with a reason attached. Tenable's revenue grew 8.6% year over year in the quarter, modest next to CrowdStrike's annual recurring revenue growth of 24% to $5.5 billion. Some of Tenable's profit turnaround came from cutting costs, including in growth-oriented areas like marketing, rather than from accelerating sales. That is a reasonable way to prove discipline, but it raises the question of whether faster growth is coming or whether the company is simply managing a slower-growth business more efficiently.
The scale of the problem Tenable is chasing is hard to ignore. The company said it detected 457 million AI-related security issues across more than 7,000 organizations, averaging 62,000 exposures per organization over 30 days. That is the kind of number that makes the case for exposure management on its own. Tenable One AI Exposure now extends discovery to every major LLM, all major Model Context Protocol deployments, and AI-native development tools like Cursor, Windsurf, and Trae, roughly doubling its coverage of sanctioned and shadow AI in one release. Beyond just finding the exposures, the platform lets security teams act on them directly, creating tickets in Jira or ServiceNow (NYSE:NOW), or firing off alerts through email, Slack, or Teams. That combination of visibility and Tenable's Hexa AI engine, which automates remediation tasks, is what the company is positioning as a full loop rather than another dashboard ****** ody checks.
The business results back up the demand story. Tenable One made up half of the company's new sales in the second quarter, evidence that customers are consolidating onto the full platform instead of buying individual point tools. Second-quarter revenue came in at $268.5 million, ahead of management's guided range of $263 million to $266 million, while operating expenses fell to $195.8 million from $200.3 million a year earlier. That combination flipped a $14.7 million net loss into a $3.8 million net profit, and adjusted profit jumped 40% to $57.9 million. The stock is up more than 40% in 2026 on the back of that improvement, yet Tenable's market capitalization of $3.6 billion is still a fraction of CrowdStrike Holdings (NASDAQ:CRWD) and Palo Alto Networks (NASDAQ:PANW), whose combined market cap tops $450 billion.
That gap shows up in valuation too. Tenable trades at a price-to-sales ratio of 3.7, well below its own historical average of 7.1 since going public in 2018, and far cheaper than Palo Alto Networks at 22.9 times sales or CrowdStrike at 38.1 times. But cheap multiples usually come with a reason attached. Tenable's revenue grew 8.6% year over year in the quarter, modest next to CrowdStrike's annual recurring revenue growth of 24% to $5.5 billion. Some of Tenable's profit turnaround came from cutting costs, including in growth-oriented areas like marketing, rather than from accelerating sales. That is a reasonable way to prove discipline, but it raises the question of whether faster growth is coming or whether the company is simply managing a slower-growth business more efficiently.

3 months ago
LegalZoom.com (NASDAQ:LZ) had one of the roughest weeks in its history, and it happened almost right on top of a product launch. On August 4, the company announced a new agent integrated into Microsoft 365 Copilot, putting business formation, compliance filings, and attorney consultations directly inside the productivity tool millions of small businesses already use. Two days later, on August 6, the stock dropped 30% after second-quarter earnings revealed a guidance cut. Investors now have to decide which story matters more.
The Copilot integration is a meaningful distribution move. Instead of asking small business owners to leave their workflow and visit LegalZoom's site, the new agent lets Microsoft 365 Copilot users compare business structures like LLCs, corporations, nonprofits, and DBAs right where they are already working. A founder can ask Copilot how to start a business, get walked through a formation checklist covering state, name, and ownership, and see LLC packages with pricing, all backed by LegalZoom's 100% accuracy filing guarantee. The same agent connects users to attorneys in LegalZoom's network for consultations on contracts, intellectual property, and employment matters, complete with attorney bios and available appointment times for either async chat or scheduled calls. LegalZoom even generates an AI-powered briefing document so attorneys walk into each consultation with context on the client already in hand.
That product push lands on top of a subscription business that has actually been performing. Subscription revenue rose 11% in the second quarter, marking five consecutive quarters of double-digit growth in that category, the part of the business LegalZoom is leaning into most. Total revenue came in at $205.3 million, up 7% year over year and roughly in line with what ******* ysts expected. For investors willing to look past this week's news, the forward price-to-earnings ratio of 6.22 is strikingly cheap for a company still growing its highest-margin revenue line by double digits.
The reason the stock fell 30% is that the good subscription numbers came wrapped in bad news elsewhere. Management said abrupt changes to Google's search algorithm hurt the company's traffic from the world's largest search engine, a serious problem for a business that depends heavily on customers finding it online. In response, LegalZoom cut its full-year 2026 revenue guidance to a range of $795 million to $805 million, down from a prior range of $810 million to $830 million. The company also trimmed the top end of its adjusted EBITDA guidance to $195 million, down from a previous ceiling of $200 million. Adjusted net income, which excludes certain accounting items, actually fell 3% to $27.4 million, or $0.16 per share, even as revenue grew. Management is now taking what it calls a more cautious approach to customer acquisition while it works to offset the search disruption with subscription and specialized product growth, a pivot that will ta
The Copilot integration is a meaningful distribution move. Instead of asking small business owners to leave their workflow and visit LegalZoom's site, the new agent lets Microsoft 365 Copilot users compare business structures like LLCs, corporations, nonprofits, and DBAs right where they are already working. A founder can ask Copilot how to start a business, get walked through a formation checklist covering state, name, and ownership, and see LLC packages with pricing, all backed by LegalZoom's 100% accuracy filing guarantee. The same agent connects users to attorneys in LegalZoom's network for consultations on contracts, intellectual property, and employment matters, complete with attorney bios and available appointment times for either async chat or scheduled calls. LegalZoom even generates an AI-powered briefing document so attorneys walk into each consultation with context on the client already in hand.
That product push lands on top of a subscription business that has actually been performing. Subscription revenue rose 11% in the second quarter, marking five consecutive quarters of double-digit growth in that category, the part of the business LegalZoom is leaning into most. Total revenue came in at $205.3 million, up 7% year over year and roughly in line with what ******* ysts expected. For investors willing to look past this week's news, the forward price-to-earnings ratio of 6.22 is strikingly cheap for a company still growing its highest-margin revenue line by double digits.
The reason the stock fell 30% is that the good subscription numbers came wrapped in bad news elsewhere. Management said abrupt changes to Google's search algorithm hurt the company's traffic from the world's largest search engine, a serious problem for a business that depends heavily on customers finding it online. In response, LegalZoom cut its full-year 2026 revenue guidance to a range of $795 million to $805 million, down from a prior range of $810 million to $830 million. The company also trimmed the top end of its adjusted EBITDA guidance to $195 million, down from a previous ceiling of $200 million. Adjusted net income, which excludes certain accounting items, actually fell 3% to $27.4 million, or $0.16 per share, even as revenue grew. Management is now taking what it calls a more cautious approach to customer acquisition while it works to offset the search disruption with subscription and specialized product growth, a pivot that will ta


3 months ago
On August 4, Tenable Holdings (NASDAQ:TENB) announced that it now covers every major AI platform and developer tool through its Tenable One platform, adding Google Gemini to a list that already included Anthropic Claude, OpenAI's ChatGPT Enterprise, and Microsoft Copilot. It is a bet that as companies rush to adopt AI, someone needs to watch where the risk is hiding, and Tenable wants to be the company holding that flashlight.
The scale of the problem Tenable is chasing is hard to ignore. The company said it detected 457 million AI-related security issues across more than 7,000 organizations, averaging 62,000 exposures per organization over 30 days. That is the kind of number that makes the case for exposure management on its own. Tenable One AI Exposure now extends discovery to every major LLM, all major Model Context Protocol deployments, and AI-native development tools like Cursor, Windsurf, and Trae, roughly doubling its coverage of sanctioned and shadow AI in one release. Beyond just finding the exposures, the platform lets security teams act on them directly, creating tickets in Jira or ServiceNow (NYSE:NOW), or firing off alerts through email, Slack, or Teams. That combination of visibility and Tenable's Hexa AI engine, which automates remediation tasks, is what the company is positioning as a full loop rather than another dashboard ******* ody checks.
The business results back up the demand story. Tenable One made up half of the company's new sales in the second quarter, evidence that customers are consolidating onto the full platform instead of buying individual point tools. Second-quarter revenue came in at $268.5 million, ahead of management's guided range of $263 million to $266 million, while operating expenses fell to $195.8 million from $200.3 million a year earlier. That combination flipped a $14.7 million net loss into a $3.8 million net profit, and adjusted profit jumped 40% to $57.9 million. The stock is up more than 40% in 2026 on the back of that improvement, yet Tenable's market capitalization of $3.6 billion is still a fraction of CrowdStrike Holdings (NASDAQ:CRWD) and Palo Alto Networks (NASDAQ:PANW), whose combined market cap tops $450 billion.
That gap shows up in valuation too. Tenable trades at a price-to-sales ratio of 3.7, well below its own historical average of 7.1 since going public in 2018, and far cheaper than Palo Alto Networks at 22.9 times sales or CrowdStrike at 38.1 times. But cheap multiples usually come with a reason attached. Tenable's revenue grew 8.6% year over year in the quarter, modest next to CrowdStrike's annual recurring revenue growth of 24% to $5.5 billion. Some of Tenable's profit turnaround came from cutting costs, including in growth-oriented areas like marketing, rather than from accelerating sales. That is a reasonable way to prove discipline, but it raises the question of whether faster growth is coming or whether the company is simply managing a slower-growth business more efficiently
The scale of the problem Tenable is chasing is hard to ignore. The company said it detected 457 million AI-related security issues across more than 7,000 organizations, averaging 62,000 exposures per organization over 30 days. That is the kind of number that makes the case for exposure management on its own. Tenable One AI Exposure now extends discovery to every major LLM, all major Model Context Protocol deployments, and AI-native development tools like Cursor, Windsurf, and Trae, roughly doubling its coverage of sanctioned and shadow AI in one release. Beyond just finding the exposures, the platform lets security teams act on them directly, creating tickets in Jira or ServiceNow (NYSE:NOW), or firing off alerts through email, Slack, or Teams. That combination of visibility and Tenable's Hexa AI engine, which automates remediation tasks, is what the company is positioning as a full loop rather than another dashboard ******* ody checks.
The business results back up the demand story. Tenable One made up half of the company's new sales in the second quarter, evidence that customers are consolidating onto the full platform instead of buying individual point tools. Second-quarter revenue came in at $268.5 million, ahead of management's guided range of $263 million to $266 million, while operating expenses fell to $195.8 million from $200.3 million a year earlier. That combination flipped a $14.7 million net loss into a $3.8 million net profit, and adjusted profit jumped 40% to $57.9 million. The stock is up more than 40% in 2026 on the back of that improvement, yet Tenable's market capitalization of $3.6 billion is still a fraction of CrowdStrike Holdings (NASDAQ:CRWD) and Palo Alto Networks (NASDAQ:PANW), whose combined market cap tops $450 billion.
That gap shows up in valuation too. Tenable trades at a price-to-sales ratio of 3.7, well below its own historical average of 7.1 since going public in 2018, and far cheaper than Palo Alto Networks at 22.9 times sales or CrowdStrike at 38.1 times. But cheap multiples usually come with a reason attached. Tenable's revenue grew 8.6% year over year in the quarter, modest next to CrowdStrike's annual recurring revenue growth of 24% to $5.5 billion. Some of Tenable's profit turnaround came from cutting costs, including in growth-oriented areas like marketing, rather than from accelerating sales. That is a reasonable way to prove discipline, but it raises the question of whether faster growth is coming or whether the company is simply managing a slower-growth business more efficiently


3 months ago
LegalZoom.com (NASDAQ:LZ) had one of the roughest weeks in its history, and it happened almost right on top of a product launch. On August 4, the company announced a new agent integrated into Microsoft 365 Copilot, putting business formation, compliance filings, and attorney consultations directly inside the productivity tool millions of small businesses already use. Two days later, on August 6, the stock dropped 30% after second-quarter earnings revealed a guidance cut. Investors now have to decide which story matters more.
The Copilot integration is a meaningful distribution move. Instead of asking small business owners to leave their workflow and visit LegalZoom's site, the new agent lets Microsoft 365 Copilot users compare business structures like LLCs, corporations, nonprofits, and DBAs right where they are already working. A founder can ask Copilot how to start a business, get walked through a formation checklist covering state, name, and ownership, and see LLC packages with pricing, all backed by LegalZoom's 100% accuracy filing guarantee. The same agent connects users to attorneys in LegalZoom's network for consultations on contracts, intellectual property, and employment matters, complete with attorney bios and available appointment times for either async chat or scheduled calls. LegalZoom even generates an AI-powered briefing document so attorneys walk into each consultation with context on the client already in hand.
That product push lands on top of a subscription business that has actually been performing. Subscription revenue rose 11% in the second quarter, marking five consecutive quarters of double-digit growth in that category, the part of the business LegalZoom is leaning into most. Total revenue came in at $205.3 million, up 7% year over year and roughly in line with what **** ysts expected. For investors willing to look past this week's news, the forward price-to-earnings ratio of 6.22 is strikingly cheap for a company still growing its highest-margin revenue line by double digits.
The reason the stock fell 30% is that the good subscription numbers came wrapped in bad news elsewhere. Management said abrupt changes to Google's search algorithm hurt the company's traffic from the world's largest search engine, a serious problem for a business that depends heavily on customers finding it online. In response, LegalZoom cut its full-year 2026 revenue guidance to a range of $795 million to $805 million, down from a prior range of $810 million to $830 million. The company also trimmed the top end of its adjusted EBITDA guidance to $195 million, down from a previous ceiling of $200 million. Adjusted net income, which excludes certain accounting items, actually fell 3% to $27.4 million, or $0.16 per share, even as revenue grew. Management is now taking what it calls a more cautious approach to customer acquisition while it works to offset the search disruption with subscription and specialized product growth, a pivot that will take
The Copilot integration is a meaningful distribution move. Instead of asking small business owners to leave their workflow and visit LegalZoom's site, the new agent lets Microsoft 365 Copilot users compare business structures like LLCs, corporations, nonprofits, and DBAs right where they are already working. A founder can ask Copilot how to start a business, get walked through a formation checklist covering state, name, and ownership, and see LLC packages with pricing, all backed by LegalZoom's 100% accuracy filing guarantee. The same agent connects users to attorneys in LegalZoom's network for consultations on contracts, intellectual property, and employment matters, complete with attorney bios and available appointment times for either async chat or scheduled calls. LegalZoom even generates an AI-powered briefing document so attorneys walk into each consultation with context on the client already in hand.
That product push lands on top of a subscription business that has actually been performing. Subscription revenue rose 11% in the second quarter, marking five consecutive quarters of double-digit growth in that category, the part of the business LegalZoom is leaning into most. Total revenue came in at $205.3 million, up 7% year over year and roughly in line with what **** ysts expected. For investors willing to look past this week's news, the forward price-to-earnings ratio of 6.22 is strikingly cheap for a company still growing its highest-margin revenue line by double digits.
The reason the stock fell 30% is that the good subscription numbers came wrapped in bad news elsewhere. Management said abrupt changes to Google's search algorithm hurt the company's traffic from the world's largest search engine, a serious problem for a business that depends heavily on customers finding it online. In response, LegalZoom cut its full-year 2026 revenue guidance to a range of $795 million to $805 million, down from a prior range of $810 million to $830 million. The company also trimmed the top end of its adjusted EBITDA guidance to $195 million, down from a previous ceiling of $200 million. Adjusted net income, which excludes certain accounting items, actually fell 3% to $27.4 million, or $0.16 per share, even as revenue grew. Management is now taking what it calls a more cautious approach to customer acquisition while it works to offset the search disruption with subscription and specialized product growth, a pivot that will take


3 months ago
Microsoft (MSFT) is riding high. The company reported better-than-anticipated fourth quarter results after the bell last week, winning over investors who had soured on the Windows developer's stock.
Microsoft has been hounded for much of the year over questions about when its massive AI investments would begin to pay off and whether its Copilot AI software was gaining traction among its vast customer base.
Now it looks as though that's beginning to happen, with the company saying it now has more than 30 million paid Microsoft Copilot 365 seats. Azure revenue also grew 43% last quarter, and growth is expected to continue to accelerate through the first half of Microsoft's fiscal 2027.
However, Bloomberg reported on Wednesday that the bulk of Microsoft's AI growth came from OpenAI (OPAI.PVT), adding to concerns about too much revenue concentration around a small set of AI companies.
Despite that, Microsoft's results helped boost Wall Street's confidence in the company's AI plans. While shares of Microsoft underperformed the broader S&P 500, as well as peers Google and Amazon over the last 12 months, the stock turned positive year to date following the company's earnings announcement.
#Microsoft #results #Stock #year
Microsoft has been hounded for much of the year over questions about when its massive AI investments would begin to pay off and whether its Copilot AI software was gaining traction among its vast customer base.
Now it looks as though that's beginning to happen, with the company saying it now has more than 30 million paid Microsoft Copilot 365 seats. Azure revenue also grew 43% last quarter, and growth is expected to continue to accelerate through the first half of Microsoft's fiscal 2027.
However, Bloomberg reported on Wednesday that the bulk of Microsoft's AI growth came from OpenAI (OPAI.PVT), adding to concerns about too much revenue concentration around a small set of AI companies.
Despite that, Microsoft's results helped boost Wall Street's confidence in the company's AI plans. While shares of Microsoft underperformed the broader S&P 500, as well as peers Google and Amazon over the last 12 months, the stock turned positive year to date following the company's earnings announcement.
#Microsoft #results #Stock #year


3 months ago
This story was originally published on CIO Dive. To receive daily news and insights, subscribe to our free daily CIO Dive newsletter.
Agentic AI is exceeding expectations around productivity and satisfaction at work, according to data from Accenture's Pulse of Change report released last week, which surveyed 3,000 C-suite leaders and 3,000 non-C-suite employees. More than two-thirds of C-suite respondents said the effect of agentic AI has been greater than expected on employee productivity, and about the same number of employees said they're overall more satisfied with their jobs overall.
Though most companies are seeing some positive impact, fewer say they're seeing sustained business value — impact that can be reported to a company's board — from their AI investments. Just 23% of companies said they saw reportable business value in the July survey, down from 32% earlier this year.
The dip follows a theme executives are seeing in 2026, where companies are trying to apply the technology to as many places as possible, rather than in targeted ways, Muqsit Ashraf, industry and enterprise global lead at Accenture, told CIO Dive. "Companies have rolled out the tools and copilots, and that produces local productivity, but it doesn't produce enterprise-level PnL impact," he said.
Nearly every enterprise is using AI in some capacity, but only the organizations that redesign their work around it can recover the millions spent on the technology.
#dive #daily
Agentic AI is exceeding expectations around productivity and satisfaction at work, according to data from Accenture's Pulse of Change report released last week, which surveyed 3,000 C-suite leaders and 3,000 non-C-suite employees. More than two-thirds of C-suite respondents said the effect of agentic AI has been greater than expected on employee productivity, and about the same number of employees said they're overall more satisfied with their jobs overall.
Though most companies are seeing some positive impact, fewer say they're seeing sustained business value — impact that can be reported to a company's board — from their AI investments. Just 23% of companies said they saw reportable business value in the July survey, down from 32% earlier this year.
The dip follows a theme executives are seeing in 2026, where companies are trying to apply the technology to as many places as possible, rather than in targeted ways, Muqsit Ashraf, industry and enterprise global lead at Accenture, told CIO Dive. "Companies have rolled out the tools and copilots, and that produces local productivity, but it doesn't produce enterprise-level PnL impact," he said.
Nearly every enterprise is using AI in some capacity, but only the organizations that redesign their work around it can recover the millions spent on the technology.
#dive #daily


3 months ago
Microsoft's growth story is undeniable, but its latest earnings call revealed the one question that truly matters: who is paying for the large AI buildout, and what happens if they stop?
After a year of underperforming the S&P 500, Microsoft (MSFT) stock has been climbing again, powered by an AI narrative that seems unstoppable. But on its latest earnings call, the real story was not the impressive growth, but the large spending required to generate it. The entire Q&A session circled one central question: with the company investing at a historic pace, is the return on that capital both real and defensible?
The justification for the spending spree starts with Azure's stunning growth. Azure's revenue grew 43% this quarter, a figure that prompted ***** ysts to probe the underlying drivers. Management's response was clear: the growth is real, and it is constrained by supply, not demand. The company stated that "Customer demand continues to exceed available capacity." In fact, the better-than-expected results were partly driven by engineering teams getting more out of the existing infrastructure and bringing new capacity online faster. Every efficiency gain, the CFO noted, was "quickly monetized" because the demand was already there waiting. This paints a picture of a company racing to build factories for a product that sells before it even hits the shelf.
If the demand is so strong, what is the risk? That was the core of the sharpest challenge of the call, a direct question about the danger of overbuilding and the pressure of rising component prices. The concern is that Microsoft is spending billions on a gold rush, and could be left with expensive, empty data centers if demand normalizes. Management's answer focused on flexibility. The CFO explained that the majority of capital spending is on "short-lived ***** ets" like CPUs and GPUs, not the buildings themselves. If the demand environment changes, the company can simply slow down orders for those components. The response was a direct attempt to reframe the large CapEx number from a fixed risk to a variable, manageable cost. It was a solid, logical answer, though the real test of that flexibility has yet to come.
In the end, management projects confidence, guiding for another year of double-digit revenue and operating income growth. The adoption of services like Microsoft 365 Copilot, which now has over 30 million paid seats, supports that optimism. We recently looked at what investors are paying for at these levels in a separate piece. But the company also gave a crucial tell in its own guidance: for the full fiscal year, operating margins are expected to be "down less than 1 point." That single data point acknowledges the pressure from this investment cycle. The thing to watch next quarter is that margin figure. If it holds steady, it means the company is successfully navigating the costs of its AI ambition. If it slips, the question of who pays for all this will get much louder.
#microsof
After a year of underperforming the S&P 500, Microsoft (MSFT) stock has been climbing again, powered by an AI narrative that seems unstoppable. But on its latest earnings call, the real story was not the impressive growth, but the large spending required to generate it. The entire Q&A session circled one central question: with the company investing at a historic pace, is the return on that capital both real and defensible?
The justification for the spending spree starts with Azure's stunning growth. Azure's revenue grew 43% this quarter, a figure that prompted ***** ysts to probe the underlying drivers. Management's response was clear: the growth is real, and it is constrained by supply, not demand. The company stated that "Customer demand continues to exceed available capacity." In fact, the better-than-expected results were partly driven by engineering teams getting more out of the existing infrastructure and bringing new capacity online faster. Every efficiency gain, the CFO noted, was "quickly monetized" because the demand was already there waiting. This paints a picture of a company racing to build factories for a product that sells before it even hits the shelf.
If the demand is so strong, what is the risk? That was the core of the sharpest challenge of the call, a direct question about the danger of overbuilding and the pressure of rising component prices. The concern is that Microsoft is spending billions on a gold rush, and could be left with expensive, empty data centers if demand normalizes. Management's answer focused on flexibility. The CFO explained that the majority of capital spending is on "short-lived ***** ets" like CPUs and GPUs, not the buildings themselves. If the demand environment changes, the company can simply slow down orders for those components. The response was a direct attempt to reframe the large CapEx number from a fixed risk to a variable, manageable cost. It was a solid, logical answer, though the real test of that flexibility has yet to come.
In the end, management projects confidence, guiding for another year of double-digit revenue and operating income growth. The adoption of services like Microsoft 365 Copilot, which now has over 30 million paid seats, supports that optimism. We recently looked at what investors are paying for at these levels in a separate piece. But the company also gave a crucial tell in its own guidance: for the full fiscal year, operating margins are expected to be "down less than 1 point." That single data point acknowledges the pressure from this investment cycle. The thing to watch next quarter is that margin figure. If it holds steady, it means the company is successfully navigating the costs of its AI ambition. If it slips, the question of who pays for all this will get much louder.
#microsof


3 months ago
Benzinga and Yahoo Finance LLC may earn commission or revenue on some items through the links below.
Microsoft Corp. used its fiscal fourth-quarter earnings call to deliver upbeat updates on Azure, Copilot and AI spending. But one of the company's most consequential messages for investors wasn't about cloud growth or capital expenditures — it was about the future role of AI models themselves.
Throughout the call, CEO Satya Nadella emphasized that Microsoft's AI strategy is increasingly built around model choice rather than dependence on any single AI provider. Instead of betting exclusively on OpenAI, Microsoft is building a platform where customers can mix and match models based on cost, performance and use case.
Don't Miss:
A single bad hire can set a startup back years. Here are the 5 hires founders most often misjudge — and why
#models
Microsoft Corp. used its fiscal fourth-quarter earnings call to deliver upbeat updates on Azure, Copilot and AI spending. But one of the company's most consequential messages for investors wasn't about cloud growth or capital expenditures — it was about the future role of AI models themselves.
Throughout the call, CEO Satya Nadella emphasized that Microsoft's AI strategy is increasingly built around model choice rather than dependence on any single AI provider. Instead of betting exclusively on OpenAI, Microsoft is building a platform where customers can mix and match models based on cost, performance and use case.
Don't Miss:
A single bad hire can set a startup back years. Here are the 5 hires founders most often misjudge — and why
#models

3 months ago
Once again, Microsoft (NASDAQ: MSFT) delivered a strong quarter, driven by its cloud computing segment and growing adoption of Copilot. And for once, the stock surged higher on the news. However, it is still trading down year-to-date and off more than 10% over the past year.
Let's take a closer look at the company's fiscal Q4 results to see if its rally can continue.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Microsoft's cloud computing unit, Azure, once powered its growth, with revenue soaring 43% year over year. It was the 12th straight quarter in which Azure revenue rose by 30% or more, and it surpassed $100 billion for the fiscal year. Demand continues to outstrip capacity, and Azure revenue is projected to accelerate to 45% constant-currency growth in Q1.
Bookings rose 10% and were up 18% when excluding OpenAI. Remaining performance obligations (RPOs), which include future Azure commitments, surged 84% year over year to $678 billion. The company said about 30% of these commitments will be recognized as revenue over the next 12 months. Notably, it said all of the sequential growth it saw came from non-AI model companies.
#azure #once #Growth #down
Let's take a closer look at the company's fiscal Q4 results to see if its rally can continue.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Microsoft's cloud computing unit, Azure, once powered its growth, with revenue soaring 43% year over year. It was the 12th straight quarter in which Azure revenue rose by 30% or more, and it surpassed $100 billion for the fiscal year. Demand continues to outstrip capacity, and Azure revenue is projected to accelerate to 45% constant-currency growth in Q1.
Bookings rose 10% and were up 18% when excluding OpenAI. Remaining performance obligations (RPOs), which include future Azure commitments, surged 84% year over year to $678 billion. The company said about 30% of these commitments will be recognized as revenue over the next 12 months. Notably, it said all of the sequential growth it saw came from non-AI model companies.
#azure #once #Growth #down

3 months ago
Last Updated: July. 30, 2026 at 11:43pm ET
Updated 2026년 7월 30일 오후 6:18 New York 시간
By
WSJ Staff
↗️ Microsoft (MSFT): Shares of the tech giant jumped more than 15%, poised for their biggest one-day gain since 2008, after it reported a 31% jump in profit late yesterday. Microsoft also saw a boost in the number of paid users of Copilot.
#july #msft
Updated 2026년 7월 30일 오후 6:18 New York 시간
By
WSJ Staff
↗️ Microsoft (MSFT): Shares of the tech giant jumped more than 15%, poised for their biggest one-day gain since 2008, after it reported a 31% jump in profit late yesterday. Microsoft also saw a boost in the number of paid users of Copilot.
#july #msft


3 months ago
Microsoft (MSFT) AI business runs at $37 billion annually, up 123% year over year, yet shares sit down 21% year to date.
Microsoft's $190 billion 2026 infrastructure spend has investors worried returns will lag, creating a sell-the-news pattern across five straight earnings reports.
Reaching $900 by 2030 demands Azure hold 40% growth, Copilot scale beyond 20 million seats, and CapEx normalize sharply after 2027.
Act now: the ****** yst who called NVIDIA in 2010 just named his top 10 AI stocks — and Microsoft didn't make the cut. Grab the names FREE today.
Microsoft (NASDAQ:MSFT) has quietly become the most important AI infrastructure company on the planet, yet the stock is acting like ****** ody noticed.
#capex
Microsoft's $190 billion 2026 infrastructure spend has investors worried returns will lag, creating a sell-the-news pattern across five straight earnings reports.
Reaching $900 by 2030 demands Azure hold 40% growth, Copilot scale beyond 20 million seats, and CapEx normalize sharply after 2027.
Act now: the ****** yst who called NVIDIA in 2010 just named his top 10 AI stocks — and Microsoft didn't make the cut. Grab the names FREE today.
Microsoft (NASDAQ:MSFT) has quietly become the most important AI infrastructure company on the planet, yet the stock is acting like ****** ody noticed.
#capex


3 months ago
Microsoft (MSFT) stock rocketed 14% higher on Thursday after posting better-than-anticipated earnings results powered by strong growth in its Copilot and Azure offerings. The company also tamed its spending a hair, saying it is extending the useful life of some data centers and offices, helping to move that spending out of capex.
It's a different story for Meta (META), though. Shares of the social media giant fell more than 9% in early trading as the company failed to provide spending guidance for 2027 and its cash pile dwindled.
Qualcomm (QCOM) stock also slid despite beating expectations on revenue for the quarter, as slowing smartphone sales bit into its outlook.
Up next, Amazon (AMZN) and Apple (AAPL) will report their results after the bell today, as investors look for more insights into Amazon's spending and the impact of the memory shortage on Apple's bottom line.
Microsoft (MSFT) surged more than 15% in early trading on Thursday.
#thursday
It's a different story for Meta (META), though. Shares of the social media giant fell more than 9% in early trading as the company failed to provide spending guidance for 2027 and its cash pile dwindled.
Qualcomm (QCOM) stock also slid despite beating expectations on revenue for the quarter, as slowing smartphone sales bit into its outlook.
Up next, Amazon (AMZN) and Apple (AAPL) will report their results after the bell today, as investors look for more insights into Amazon's spending and the impact of the memory shortage on Apple's bottom line.
Microsoft (MSFT) surged more than 15% in early trading on Thursday.
#thursday



3 months ago
Microsoft Corporation (NASDAQ:MSFT) is seeking to position itself as the platform of choice for enterprise frontier AI adoption. It is part of the company's strategy of extending its cloud platform, Azure, beyond traditional infrastructure into the foundation for nmext-generation AI computing.
That was evident on July 21, as the software giant confirmed the expansion of its strategic partnership with Mistral. The collaboration is designed to give enterprises and regulated industries access to frontier AI models that they can deploy with greater control over security, governance, and compliance.
The expanded partnership reinforces Microsoft's ambition to become the trusted AI infrastructure provider for highly regulated industries, including financial services, healthcare, government, defense, energy, and manufacturing.
As part of this agreement, Microsoft will use Mistral's expanding European GPU infrastructure. Mistral, on the other hand, has added its AI models called Medium 3.5 and OCR 4 to Microsoft's app builder known as Foundry; while Microsoft Copilot Studio has brought on Medium 3.5 as well.
Photo by Microsoft 365 on Unsplash
#frontier
That was evident on July 21, as the software giant confirmed the expansion of its strategic partnership with Mistral. The collaboration is designed to give enterprises and regulated industries access to frontier AI models that they can deploy with greater control over security, governance, and compliance.
The expanded partnership reinforces Microsoft's ambition to become the trusted AI infrastructure provider for highly regulated industries, including financial services, healthcare, government, defense, energy, and manufacturing.
As part of this agreement, Microsoft will use Mistral's expanding European GPU infrastructure. Mistral, on the other hand, has added its AI models called Medium 3.5 and OCR 4 to Microsoft's app builder known as Foundry; while Microsoft Copilot Studio has brought on Medium 3.5 as well.
Photo by Microsoft 365 on Unsplash
#frontier


4 months ago
The AI boom is forcing some of technology's biggest cash machines to behave more like utilities. On July 22, Reuters reported that Microsoft Corporation (NASDAQ:MSFT), Oracle Corporation (NYSE:ORCL), and three other hyperscalers are expected to spend more on capital expenditures than they generate in combined free cash flow by 2027. From 2025 through 2027, their annual operating cash flow is projected to rise by $340 billion, versus a $534 billion increase in capex. Microsoft and Oracle, however, are not carrying the same risk.
Microsoft showed the squeeze in fiscal Q2. Operating cash flow was $35.8 billion, while capex including finance leases reached $37.5 billion. That does not mean the company burned cash: Microsoft reported $5.9 billion of conventional free cash flow because that measure deducts cash property and equipment purchases, not newly originated finance leases.
Carol Gauthier/Shutterstock.com
Fiscal Q3, however, was stronger. Operating cash flow rose to $46.7 billion and free cash flow reached $15.8 billion, even after $30.9 billion of cash property and equipment spending. Its AI business also passed a $37 billion annual revenue run rate. Microsoft can finance the buildout. The question is whether Azure and Copilot can generate nice returns before expensive GPUs depreciate or become obsolete.
Oracle has a more immediate cash problem. In fiscal 2026, it spent $55.7 billion on capex against $32 billion of operating cash flow, leaving free cash flow at negative $23.7 billion. Demand is real: cloud revenue grew 39% to $34 billion, and remaining performance obligations reached $638 billion. But backlog is not cash. Oracle must construct capacity before much of that revenue arrives, and plans to raise $45 billion to $50 billion through debt and equity.
#Microsoft #fiscal
Microsoft showed the squeeze in fiscal Q2. Operating cash flow was $35.8 billion, while capex including finance leases reached $37.5 billion. That does not mean the company burned cash: Microsoft reported $5.9 billion of conventional free cash flow because that measure deducts cash property and equipment purchases, not newly originated finance leases.
Carol Gauthier/Shutterstock.com
Fiscal Q3, however, was stronger. Operating cash flow rose to $46.7 billion and free cash flow reached $15.8 billion, even after $30.9 billion of cash property and equipment spending. Its AI business also passed a $37 billion annual revenue run rate. Microsoft can finance the buildout. The question is whether Azure and Copilot can generate nice returns before expensive GPUs depreciate or become obsolete.
Oracle has a more immediate cash problem. In fiscal 2026, it spent $55.7 billion on capex against $32 billion of operating cash flow, leaving free cash flow at negative $23.7 billion. Demand is real: cloud revenue grew 39% to $34 billion, and remaining performance obligations reached $638 billion. But backlog is not cash. Oracle must construct capacity before much of that revenue arrives, and plans to raise $45 billion to $50 billion through debt and equity.
#Microsoft #fiscal

4 months ago
OpenAI's $100B ad revenue target for 2030 is 20 times eMarketer's forecast for the whole chatbot market, threatening Oracle's $75B in AI-linked commitments.
ChatGPT's AI traffic share dropped from 87% to 65% as Alphabet's Gemini gains ground, making projections of chatbot ad dominance harder to justify.
Don't wait: the **** yst who called NVIDIA in 2010 just revealed his top 10 AI stocks. See the full list FREE now.
One of the load-bearing **** umptions behind the AI investment story just got a hard sanity check, and the numbers do not add up.
According to research firm eMarketer, OpenAI's advertising business is on pace to miss the company's own five-year revenue forecast by roughly 90%. OpenAI has projected $2.5 billion in OpenAI ad revenue in 2026, growing to $100 billion by 2030. eMarketer's data tells a different story: standalone AI chatbots, including ChatGPT, Microsoft Copilot, Google AI Mode, and Amazon's Alexa for Shopping combined, will generate less than $1 billion in ad revenue this year, and just $5.41 billion across the entire market by 2030.
#forecast #gemini #don 't
ChatGPT's AI traffic share dropped from 87% to 65% as Alphabet's Gemini gains ground, making projections of chatbot ad dominance harder to justify.
Don't wait: the **** yst who called NVIDIA in 2010 just revealed his top 10 AI stocks. See the full list FREE now.
One of the load-bearing **** umptions behind the AI investment story just got a hard sanity check, and the numbers do not add up.
According to research firm eMarketer, OpenAI's advertising business is on pace to miss the company's own five-year revenue forecast by roughly 90%. OpenAI has projected $2.5 billion in OpenAI ad revenue in 2026, growing to $100 billion by 2030. eMarketer's data tells a different story: standalone AI chatbots, including ChatGPT, Microsoft Copilot, Google AI Mode, and Amazon's Alexa for Shopping combined, will generate less than $1 billion in ad revenue this year, and just $5.41 billion across the entire market by 2030.
#forecast #gemini #don 't

4 months ago
The AI boom is forcing some of technology's biggest cash machines to behave more like utilities. On July 22, Reuters reported that Microsoft Corporation (NASDAQ:MSFT), Oracle Corporation (NYSE:ORCL), and three other hyperscalers are expected to spend more on capital expenditures than they generate in combined free cash flow by 2027. From 2025 through 2027, their annual operating cash flow is projected to rise by $340 billion, versus a $534 billion increase in capex. Microsoft and Oracle, however, are not carrying the same risk.
Microsoft showed the squeeze in fiscal Q2. Operating cash flow was $35.8 billion, while capex including finance leases reached $37.5 billion. That does not mean the company burned cash: Microsoft reported $5.9 billion of conventional free cash flow because that measure deducts cash property and equipment purchases, not newly originated finance leases.
Carol Gauthier/Shutterstock.com
Fiscal Q3, however, was stronger. Operating cash flow rose to $46.7 billion and free cash flow reached $15.8 billion, even after $30.9 billion of cash property and equipment spending. Its AI business also passed a $37 billion annual revenue run rate. Microsoft can finance the buildout. The question is whether Azure and Copilot can generate nice returns before expensive GPUs depreciate or become obsolete.
Oracle has a more immediate cash problem. In fiscal 2026, it spent $55.7 billion on capex against $32 billion of operating cash flow, leaving free cash flow at negative $23.7 billion. Demand is real: cloud revenue grew 39% to $34 billion, and remaining performance obligations reached $638 billion. But backlog is not cash. Oracle must construct capacity before much of that revenue arrives, and plans to raise $45 billion to $50 billion through debt and equity.
#operating #free
Microsoft showed the squeeze in fiscal Q2. Operating cash flow was $35.8 billion, while capex including finance leases reached $37.5 billion. That does not mean the company burned cash: Microsoft reported $5.9 billion of conventional free cash flow because that measure deducts cash property and equipment purchases, not newly originated finance leases.
Carol Gauthier/Shutterstock.com
Fiscal Q3, however, was stronger. Operating cash flow rose to $46.7 billion and free cash flow reached $15.8 billion, even after $30.9 billion of cash property and equipment spending. Its AI business also passed a $37 billion annual revenue run rate. Microsoft can finance the buildout. The question is whether Azure and Copilot can generate nice returns before expensive GPUs depreciate or become obsolete.
Oracle has a more immediate cash problem. In fiscal 2026, it spent $55.7 billion on capex against $32 billion of operating cash flow, leaving free cash flow at negative $23.7 billion. Demand is real: cloud revenue grew 39% to $34 billion, and remaining performance obligations reached $638 billion. But backlog is not cash. Oracle must construct capacity before much of that revenue arrives, and plans to raise $45 billion to $50 billion through debt and equity.
#operating #free

4 months ago
Haleon (NYSE:HLN) is one of the best up and coming stocks to invest in right now. On June 1, Haleon announced a five-year collaboration with Microsoft (NASDAQ:MSFT) to scale its digital, data, and AI capabilities. This partnership aims to accelerate the company's global "Win as One" strategy by integrating Microsoft's cloud and AI tools into Haleon's consumer health operations.
The initiative builds on existing uses of Microsoft 365 Copilot to automate tasks and boost productivity across the organization. By adopting advanced agentic AI, security, and identity features, Haleon intends to scale its AI infrastructure securely and responsibly while streamlining operations from supply chain to commercial execution.
Both companies will co-create high-impact AI use cases to enhance innovation, scientific research, and consumer insights. These efforts support Haleon's (NYSE:HLN) goal of reaching one billion more consumers by 2030, ultimately enabling the business to make faster, more data-driven decisions.
Haleon (NYSE:HLN), together with its subsidiaries, researches, develops, manufactures, and sells various consumer healthcare products in North America, Europe, the Middle East, Africa, Latin America, and the Asia Pacific.
While we acknowledge the risk and potential of HLN as an investment, our conviction lies in the belief that some AI stocks hold greater promise for delivering higher returns and doing so within a shorter time frame. If you are looking for an AI stock that is more promising than HLN and that has 10,000% upside potential, check out our report about the cheapest AI stock.
The initiative builds on existing uses of Microsoft 365 Copilot to automate tasks and boost productivity across the organization. By adopting advanced agentic AI, security, and identity features, Haleon intends to scale its AI infrastructure securely and responsibly while streamlining operations from supply chain to commercial execution.
Both companies will co-create high-impact AI use cases to enhance innovation, scientific research, and consumer insights. These efforts support Haleon's (NYSE:HLN) goal of reaching one billion more consumers by 2030, ultimately enabling the business to make faster, more data-driven decisions.
Haleon (NYSE:HLN), together with its subsidiaries, researches, develops, manufactures, and sells various consumer healthcare products in North America, Europe, the Middle East, Africa, Latin America, and the Asia Pacific.
While we acknowledge the risk and potential of HLN as an investment, our conviction lies in the belief that some AI stocks hold greater promise for delivering higher returns and doing so within a shorter time frame. If you are looking for an AI stock that is more promising than HLN and that has 10,000% upside potential, check out our report about the cheapest AI stock.

4 months ago
Argentina is looking to become the first country to win back-to-back World Cups since Brazil did so in 1958 and 1962.
To achieve that goal, La Albiceleste will first have to beat Switzerland in a quarterfinal at the 2026 World Cup.
Argentina is favored, but will Lionel Messi's squad be up to the task after close calls against Cape Verde and Egypt? USA TODAY decided to ask AI chatbot Microsoft Copilot to predict the outcome of the World Cup quarterfinal.
The chatbot was fed the following query to generate its ****** ysis for the match:
Can you predict the winner of the Argentina vs. Switzerland World Cup match?
To achieve that goal, La Albiceleste will first have to beat Switzerland in a quarterfinal at the 2026 World Cup.
Argentina is favored, but will Lionel Messi's squad be up to the task after close calls against Cape Verde and Egypt? USA TODAY decided to ask AI chatbot Microsoft Copilot to predict the outcome of the World Cup quarterfinal.
The chatbot was fed the following query to generate its ****** ysis for the match:
Can you predict the winner of the Argentina vs. Switzerland World Cup match?


4 months ago
Microsoft Corporation (NASDAQ:MSFT) is one of the top stocks to buy according to Whale Rock Capital Management. On June 29, Haleon, a consumer health company, announced a new five-year collaboration with Microsoft Corporation (NASDAQ:MSFT) to expand the use of cloud, data, and artificial intelligence tools across Haleon's global operations.
Ken Wolter / Shutterstock.com
Haleon said the deal builds on its current use of Microsoft 365 Copilot and is designed to speed up the company's wider "Win as One" strategy. The strategy is the company's global plan for growth and digital transformation. The expanded collaboration entails Haleon continuing to use Microsoft Azure as its main cloud platform and expanding its use of Copilot. As such, Haleon will get access to broader computing power, data **** ytics, and enterprise security tools.
A major focus of the partnership is agentic AI, where Haleon plans to use this technology to help teams manage and secure digital AI agents across the business. To that end, the two companies will jointly build AI applications across several parts of Haleon's operations. This includes consumer research, product innovation, supply chain management, marketing, and commercial execution. Microsoft will also provide stronger identity management, governance, and threat protection tools, which Haleon said will let it scale AI use safely across its systems and workflows.
Haleon framed the expanded AI push as supporting two long-term business goals: reaching one billion additional consumers by 2030 and improving shareholder returns.
Ken Wolter / Shutterstock.com
Haleon said the deal builds on its current use of Microsoft 365 Copilot and is designed to speed up the company's wider "Win as One" strategy. The strategy is the company's global plan for growth and digital transformation. The expanded collaboration entails Haleon continuing to use Microsoft Azure as its main cloud platform and expanding its use of Copilot. As such, Haleon will get access to broader computing power, data **** ytics, and enterprise security tools.
A major focus of the partnership is agentic AI, where Haleon plans to use this technology to help teams manage and secure digital AI agents across the business. To that end, the two companies will jointly build AI applications across several parts of Haleon's operations. This includes consumer research, product innovation, supply chain management, marketing, and commercial execution. Microsoft will also provide stronger identity management, governance, and threat protection tools, which Haleon said will let it scale AI use safely across its systems and workflows.
Haleon framed the expanded AI push as supporting two long-term business goals: reaching one billion additional consumers by 2030 and improving shareholder returns.




