1 day ago
Roth conversions count as income, so retirees over 65 near $75,000 can lose the new $6,000 senior deduction without warning.
A $40,000 conversion for a single retiree costs about 23% rather than the quoted 22%, while $100,000 nearly erases the deduction.
Converting only up to the income threshold, waiting until 2029, or paying conversion tax from taxable savings can protect the deduction.
Read More: Learn 7 ways to generate income with a $1,000,000+ portfolio (sponsor)
Congress handed people 65 and older a new tax break last year, and it comes with a tripwire that most of the articles celebrating it skipped. The deduction is worth up to $6,000 a person for tax years 2025 through 2028. It starts to shrink once your income passes $75,000 if you are single, or $150,000 if you file jointly, and it shrinks fast: 6 cents for every dollar over the line. At $175,000 single or $250,000 joint it is gone.
#income #single #converting #conversions
A $40,000 conversion for a single retiree costs about 23% rather than the quoted 22%, while $100,000 nearly erases the deduction.
Converting only up to the income threshold, waiting until 2029, or paying conversion tax from taxable savings can protect the deduction.
Read More: Learn 7 ways to generate income with a $1,000,000+ portfolio (sponsor)
Congress handed people 65 and older a new tax break last year, and it comes with a tripwire that most of the articles celebrating it skipped. The deduction is worth up to $6,000 a person for tax years 2025 through 2028. It starts to shrink once your income passes $75,000 if you are single, or $150,000 if you file jointly, and it shrinks fast: 6 cents for every dollar over the line. At $175,000 single or $250,000 joint it is gone.
#income #single #converting #conversions

2 days ago
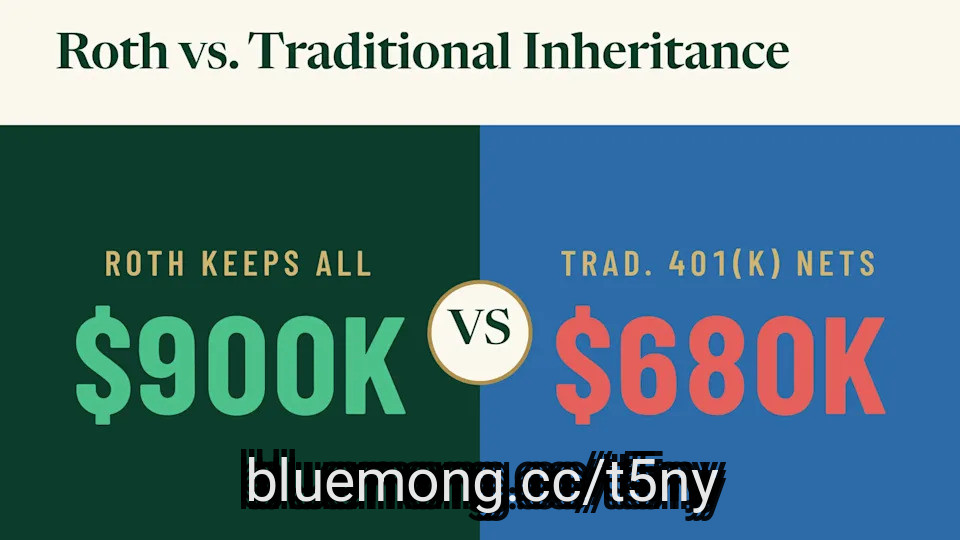
A $900,000 traditional 401(k) left to heirs yields roughly $684,000 after taxes, while a Roth passes the full $900,000 income-tax-free.
Heirs must empty inherited accounts within 10 years, potentially pushing a child earning $150,000 into the 32% or higher tax bracket.
Converting gradually during low-income retirement years keeps taxes in the 22 to 24 percent brackets and avoids Medicare surcharges above $218,000 in joint income.
The biggest 401k decisions tend to get made once and never revisited: when to roll it over, what to hold inside it, and when to start taking money out. That is exactly what the report: 401k & IRA Tips and Answers was created to address, and it is free today. Read more here. (Sponsor)
Picture a 66-year-old with $900,000 in a traditional 401(k) who has already decided the money goes to the adult children. The open question is whether to leave it alone or convert it to Roth first. That choice can change what the kids keep by six figures.
#traditional #free #medicare
Heirs must empty inherited accounts within 10 years, potentially pushing a child earning $150,000 into the 32% or higher tax bracket.
Converting gradually during low-income retirement years keeps taxes in the 22 to 24 percent brackets and avoids Medicare surcharges above $218,000 in joint income.
The biggest 401k decisions tend to get made once and never revisited: when to roll it over, what to hold inside it, and when to start taking money out. That is exactly what the report: 401k & IRA Tips and Answers was created to address, and it is free today. Read more here. (Sponsor)
Picture a 66-year-old with $900,000 in a traditional 401(k) who has already decided the money goes to the adult children. The open question is whether to leave it alone or convert it to Roth first. That choice can change what the kids keep by six figures.
#traditional #free #medicare

2 days ago
Converting your 401(k) to a Roth portfolio will allow you to entirely avoid RMDs. This is a legitimate form of tax planning. However, often there's a difference between whether you can do something and whether you should; whether it's allowed, and whether it's in your long-term best interest.
For example, say that you're 62 years old. You have $1.6 million in a 401(k). If you convert this portfolio to a Roth IRA 10% at a time, you can avoid required minimum distributions on your $1.6 million. However, particularly for households approaching retirement, a Roth conversion may result in a net-loss. There's a chance that the tax costs of making those conversions will outweigh the tax benefits of avoiding minimum distributions.
Here are some things to consider. Also consider matching with a fiduciary financial advisor who can help you weigh your options.
Starting at age 73 (or 75 starting in 2023), the IRS requires you to begin taking regular, minimum withdrawals from every pre-tax retirement account. This includes 401(k) and traditional IRA portfolios. These withdrawals are known as RMDs.
The exact amount you must take is based on the portfolio's total value on January 1 and your age. You have until the end of each year to make the withdrawal, so you can take your minimum distribution in any amount at any time by or before December 31. If you don't take your minimum distribution, the IRS charges a tax penalty typically worth 25% of the amount not withdrawn.
#rmds #avoid
For example, say that you're 62 years old. You have $1.6 million in a 401(k). If you convert this portfolio to a Roth IRA 10% at a time, you can avoid required minimum distributions on your $1.6 million. However, particularly for households approaching retirement, a Roth conversion may result in a net-loss. There's a chance that the tax costs of making those conversions will outweigh the tax benefits of avoiding minimum distributions.
Here are some things to consider. Also consider matching with a fiduciary financial advisor who can help you weigh your options.
Starting at age 73 (or 75 starting in 2023), the IRS requires you to begin taking regular, minimum withdrawals from every pre-tax retirement account. This includes 401(k) and traditional IRA portfolios. These withdrawals are known as RMDs.
The exact amount you must take is based on the portfolio's total value on January 1 and your age. You have until the end of each year to make the withdrawal, so you can take your minimum distribution in any amount at any time by or before December 31. If you don't take your minimum distribution, the IRS charges a tax penalty typically worth 25% of the amount not withdrawn.
#rmds #avoid
7 days ago
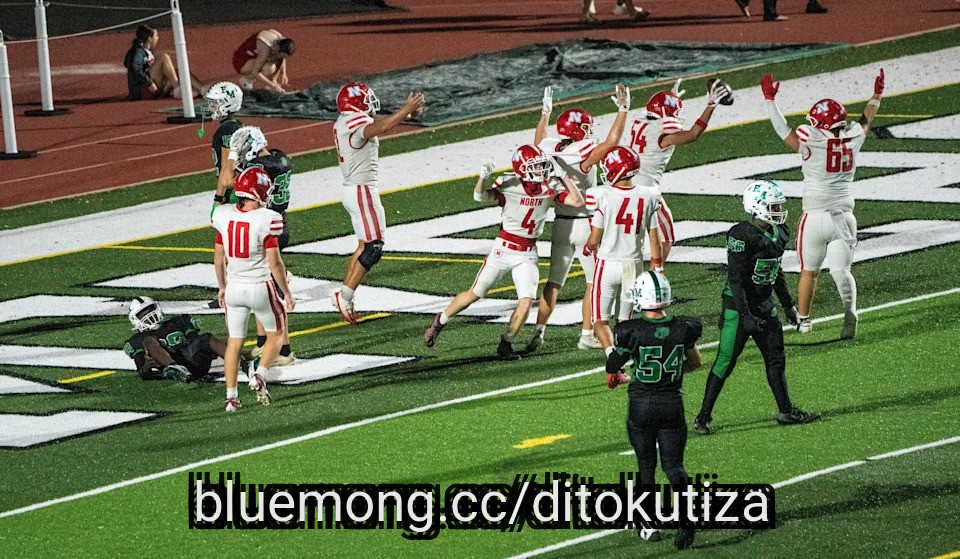
A roundup of Southwest Florida high school football games played in Week 11 on Thursday, Oct. 29 and Friday, Oct. 30, 2026.
After a challenging season with a young roster, the Red Knights went out on a high note.
Facing rival Fort Myers, North pounded the rock and came up with some key defensive scores for a running clock victory at Sam Sirianni Field on Thursday night.
"I feel great," North head coach Ira Riggins said. "This team has been through so much this year. It's just fun to see these guys come out and put it all together for the first time versus a very well-known team. Hat's off to Fort Myers – they've always been top notch in this area, and it's always good to get a win versus them."
The Greenies got on the board first, converting a successful onside kick into points on a 33-yard field goal by senior Brayden Russell.
#north #team
After a challenging season with a young roster, the Red Knights went out on a high note.
Facing rival Fort Myers, North pounded the rock and came up with some key defensive scores for a running clock victory at Sam Sirianni Field on Thursday night.
"I feel great," North head coach Ira Riggins said. "This team has been through so much this year. It's just fun to see these guys come out and put it all together for the first time versus a very well-known team. Hat's off to Fort Myers – they've always been top notch in this area, and it's always good to get a win versus them."
The Greenies got on the board first, converting a successful onside kick into points on a 33-yard field goal by senior Brayden Russell.
#north #team


18 days ago
The Green Bay Packers got a pair of first half touchdowns from Jordan Love to take a commanding lead, and Jonathan Gannon's aggressive defense confounded Dak Prescott the rest of the way, leading Matt LaFleur's team to a 23-13 win over the Dallas Cowboys on "Sunday Night Football" in Week 6. The Packers have now won three straight games since a 1-2 start.
Highlighting the good, the bad and the ugly coming out of the Packers' primetime win over the Cowboys:
The start on offense, and finish on defense: Jordan Love was picked off on Green Bay's second possession, but the Packers offense scored on three of the four first-half drives, all gaining at least 70 yards. The long, time-consuming drives helped the Packers keep the Dallas offense on the sideline and build a 17-0 lead at the half. But when the Packers offense sputtered over the final 30 minutes, Jonathan Gannon's defense had answers, producing a pair of stops on fourth down in the fourth quarter. The garbage time touchdown meant little. The Packers ended up holding the Cowboys to only 13 points, a winning performance 10 times out of 10.
Love under pressure: Jordan Love's passer rating finished at 74.8, a pedestrian number in today's NFL, but drops drastically affected his final stat line, and Love was excellent when pressured. He found completions on 11 pressured dropbacks. Many of his best throws came on third down against pressure. The Packers started the game converting nine of the first 10 opportunities on third down.
The offensive line: Sunday night was a step backwards for the offensive line, which allowed Jordan Love to be pressured on 45.5 percent of his dropbacks, per Next Gen Stats, and paved the way for a lifeless run game that averaged 2.2 yards per carry. Love was sacked three times, and the Cowboys were credited with eight quarterback hits. In the run game, the Packers didn't have a designed run over six yards, and the three running backs combined to rush 20 times for 36 yards. Matt LaFleur wants to build continuity up front, but it's probably time to see what Kevin Zeitler can do at right guard, and there will be a decision to make on who starts at left guard between Laken Tomlinson and Aaron Banks next week.
#packers #jordan
Highlighting the good, the bad and the ugly coming out of the Packers' primetime win over the Cowboys:
The start on offense, and finish on defense: Jordan Love was picked off on Green Bay's second possession, but the Packers offense scored on three of the four first-half drives, all gaining at least 70 yards. The long, time-consuming drives helped the Packers keep the Dallas offense on the sideline and build a 17-0 lead at the half. But when the Packers offense sputtered over the final 30 minutes, Jonathan Gannon's defense had answers, producing a pair of stops on fourth down in the fourth quarter. The garbage time touchdown meant little. The Packers ended up holding the Cowboys to only 13 points, a winning performance 10 times out of 10.
Love under pressure: Jordan Love's passer rating finished at 74.8, a pedestrian number in today's NFL, but drops drastically affected his final stat line, and Love was excellent when pressured. He found completions on 11 pressured dropbacks. Many of his best throws came on third down against pressure. The Packers started the game converting nine of the first 10 opportunities on third down.
The offensive line: Sunday night was a step backwards for the offensive line, which allowed Jordan Love to be pressured on 45.5 percent of his dropbacks, per Next Gen Stats, and paved the way for a lifeless run game that averaged 2.2 yards per carry. Love was sacked three times, and the Cowboys were credited with eight quarterback hits. In the run game, the Packers didn't have a designed run over six yards, and the three running backs combined to rush 20 times for 36 yards. Matt LaFleur wants to build continuity up front, but it's probably time to see what Kevin Zeitler can do at right guard, and there will be a decision to make on who starts at left guard between Laken Tomlinson and Aaron Banks next week.
#packers #jordan

30 days ago
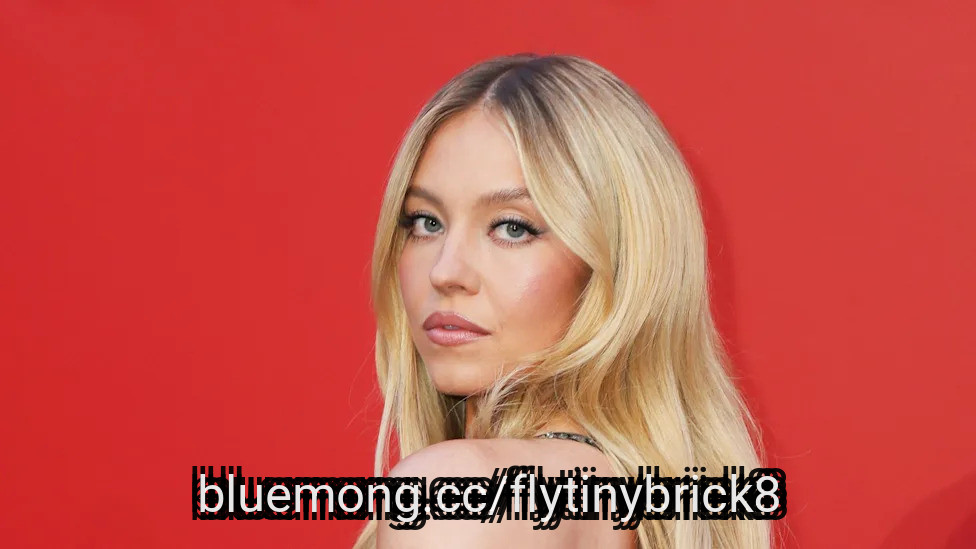
Sydney Sweeney and Scooter Braun may be thinking well beyond their next date night. The 29-year-old "Euphoria" and "The Housemaid" star has reportedly met with two rabbis as she considers converting to Judaism amid her increasingly serious relationship with Braun, according to Page Six. The reported meetings come as sources claim the couple has begun discussing marriage, children, and their future together.
Neither Sweeney nor Braun has publicly confirmed that she plans to convert.
Sweeney's reported interest in Judaism is connected to conversations she and Braun have been having about starting a family. (@ GC Images)
According to Page Six, Sweeney's reported interest in Judaism is connected to conversations she and Braun have been having about starting a family. "The couple is discussing having their own family, and Scooter feels strongly on the subject," an unnamed source told the outlet.
You may also like
#family #sweeney
Neither Sweeney nor Braun has publicly confirmed that she plans to convert.
Sweeney's reported interest in Judaism is connected to conversations she and Braun have been having about starting a family. (@ GC Images)
According to Page Six, Sweeney's reported interest in Judaism is connected to conversations she and Braun have been having about starting a family. "The couple is discussing having their own family, and Scooter feels strongly on the subject," an unnamed source told the outlet.
You may also like
#family #sweeney

1 month ago
Sydney Sweeney and Scooter Braun's reported relationship appears to be moving into more serious territory, with the couple now said to be discussing what a future family could look like.
The conversations reportedly extend beyond marriage, as Braun is said to feel strongly about having children.
That development has also been linked to Sweeney's reported interest in Judaism, following recent appearances with Braun at synagogue services and reports that she has already spoken with rabbis about potentially converting.
A billion-dollar net worth doesn't buy a better view than general admission.
Sydney Sweeney and Scooter Braun skipped the velvet ropes at Stagecoach this weekend. They dropped right into the dirt with the crowd for Ella Langley's set. No security walls. No hiding the PDA. Just… pic.twitter.com/0PVUG6DHku
— Desiree (DesireeAmerica4) April 26, 2026
#sweeney #scooter #reported #stagecoach
The conversations reportedly extend beyond marriage, as Braun is said to feel strongly about having children.
That development has also been linked to Sweeney's reported interest in Judaism, following recent appearances with Braun at synagogue services and reports that she has already spoken with rabbis about potentially converting.
A billion-dollar net worth doesn't buy a better view than general admission.
Sydney Sweeney and Scooter Braun skipped the velvet ropes at Stagecoach this weekend. They dropped right into the dirt with the crowd for Ella Langley's set. No security walls. No hiding the PDA. Just… pic.twitter.com/0PVUG6DHku
— Desiree (DesireeAmerica4) April 26, 2026
#sweeney #scooter #reported #stagecoach


1 month ago
A $700,000 inherited IRA forces the daughter to withdraw annually for 10 years, stacking on her salary and generating $182,580 in federal taxes.
If the father had converted at 22%, his $154,000 tax bill would have been $28,580 less than his daughter pays at her higher rate.
Converting only wins when the parent's rate is lower than the heir's, making a conversation about the child's income the essential first step.
Read More: Learn 7 ways to generate income with a $1,000,000+ portfolio (sponsor)
His plan was simple: leave the IRA invested, take only the required distributions, and let the rest pass to his daughter. When he died at 82, the account still held $700,000. His daughter inherited the money, but she also inherited the tax bill, with withdrawals taxed at her rate during her peak earning years.
#rate #income
If the father had converted at 22%, his $154,000 tax bill would have been $28,580 less than his daughter pays at her higher rate.
Converting only wins when the parent's rate is lower than the heir's, making a conversation about the child's income the essential first step.
Read More: Learn 7 ways to generate income with a $1,000,000+ portfolio (sponsor)
His plan was simple: leave the IRA invested, take only the required distributions, and let the rest pass to his daughter. When he died at 82, the account still held $700,000. His daughter inherited the money, but she also inherited the tax bill, with withdrawals taxed at her rate during her peak earning years.
#rate #income


2 months ago
LifeMD, Inc. (NASDAQ:LFMD) announced an exclusive healthcare collaboration on September 15 that initially makes virtual-health membership benefits available to approximately 29 million eligible AT&T wireless and fiber customers across 11 states. Customers must be 18 or older, and some services have additional eligibility and state restrictions. A nationwide expansion planned for January 2027 would extend eligibility beyond 100 million customers.
The $19 monthly membership fee is waived, but customers must enroll. Visits, prescriptions, and other services remain separately payable. For LifeMD, Inc. (NASDAQ:LFMD), the opportunity is converting access to a large audience into recurring demand for paid care.
The partnership gives LifeMD, Inc. (NASDAQ:LFMD) a distribution channel through the website, mobile app and customer-benefits program of AT&T Inc. (NYSE:T). Reaching customers through an established relationship could reduce reliance on advertising and lower acquisition costs per paying patient.
Removing the membership charge also reduces the financial commitment required to try the service. Announced visit prices start at $29 for message-based care, $49 for urgent and primary care video visits, and $79 for specialty care. Customers may use insurance, Medicare, or discounted cash-pay rates for visits and prescriptions.
LifeMD, Inc. (NASDAQ:LFMD) could benefit from repeat consultations and prescription fulfillment when clinically appropriate. Primary care, chronic-condition management and other services create opportunities for continuing patient relationships. If satisfied patients return, the revenue earned over those relationships could exceed the cost of acquiring and serving them.
#Services
The $19 monthly membership fee is waived, but customers must enroll. Visits, prescriptions, and other services remain separately payable. For LifeMD, Inc. (NASDAQ:LFMD), the opportunity is converting access to a large audience into recurring demand for paid care.
The partnership gives LifeMD, Inc. (NASDAQ:LFMD) a distribution channel through the website, mobile app and customer-benefits program of AT&T Inc. (NYSE:T). Reaching customers through an established relationship could reduce reliance on advertising and lower acquisition costs per paying patient.
Removing the membership charge also reduces the financial commitment required to try the service. Announced visit prices start at $29 for message-based care, $49 for urgent and primary care video visits, and $79 for specialty care. Customers may use insurance, Medicare, or discounted cash-pay rates for visits and prescriptions.
LifeMD, Inc. (NASDAQ:LFMD) could benefit from repeat consultations and prescription fulfillment when clinically appropriate. Primary care, chronic-condition management and other services create opportunities for continuing patient relationships. If satisfied patients return, the revenue earned over those relationships could exceed the cost of acquiring and serving them.
#Services


2 months ago
Picture a snowy mountain slope in France or an elite tennis court during a grand slam. Whether it is an Arc'teryx jacket designed for the harshest alpine conditions or a Wilson racket in the hands of a professional, Amer Sports (NYSE:AS) equips the world's most demanding athletes. The company functions as a global powerhouse in athletic gear and apparel, operating a premium multi-brand platform that spans from high-end technical clothing to specialized sports equipment. With its current stock price at $27.26 as of Sept. 16, 2026, the company has seen the stock decline 26% over the past year, reflecting the market's digestion of its rapid post-IPO scaling.
Our proprietary Hidden Gems scoring system **** igns Amer Sports an overall Superscore of 75 out of 100, placing it in the Above Average category. This score ranks the company in the Top ~21% of every company we evaluate, ahead of roughly 79 out of every 100 firms we score. The Superscore serves as a data-driven starting point, and this article examines both the operational momentum fueling its recent success and the structural hurdles that keep the company below top-tier rankings, helping you weigh these signals against your own research.
Strong revenue momentum: The company achieved 27% year-over-year revenue growth in 2025, reaching $6.6 billion as it successfully scaled its brand-led platform across global markets.
Effective channel pivot: Direct-to-consumer revenue surged 43% in 2025, allowing the company to capture higher margins and deepen its direct relationship with premium consumers.
Expanding operational efficiency: Adjusted EBITDA margins widened to 18% in 2025, demonstrating that the company's shared infrastructure strategy is successfully converting scale into bottom-line profitability.
#company #sports #global #premium
Our proprietary Hidden Gems scoring system **** igns Amer Sports an overall Superscore of 75 out of 100, placing it in the Above Average category. This score ranks the company in the Top ~21% of every company we evaluate, ahead of roughly 79 out of every 100 firms we score. The Superscore serves as a data-driven starting point, and this article examines both the operational momentum fueling its recent success and the structural hurdles that keep the company below top-tier rankings, helping you weigh these signals against your own research.
Strong revenue momentum: The company achieved 27% year-over-year revenue growth in 2025, reaching $6.6 billion as it successfully scaled its brand-led platform across global markets.
Effective channel pivot: Direct-to-consumer revenue surged 43% in 2025, allowing the company to capture higher margins and deepen its direct relationship with premium consumers.
Expanding operational efficiency: Adjusted EBITDA margins widened to 18% in 2025, demonstrating that the company's shared infrastructure strategy is successfully converting scale into bottom-line profitability.
#company #sports #global #premium


2 months ago
Citigroup Inc. (NYSE:C)'s CFO Gonzalo Luchetti said the bank expects return on tangible common equity (RoTCE) to come in slightly above 11% in 2026, while also indicating that Citi will increase stock buybacks from the $13 billion repurchased in 2025. The bank plans to accelerate roughly $500 million of investment by year-end, including spending on severance and marketing intended to expand its credit-card and wealth-management businesses. Citi also expects to remove Banamex from its balance sheet in 2027, which will create an estimated $9 billion currency-translation adjustment loss.
The 11%+ target is meaningful because Citi's profitability has already improved materially. In the second quarter, Citi generated $24.8 billion of revenue, up 14% year over year, while net income rose 45% to $5.8 billion. Investment-banking revenue increased 44% to $1.55 billion, and net interest income increased 13%. Citi's SEC filing shows second-quarter RoTCE of 13.0%, versus 8.7% a year earlier, while the first half of 2026 produced a 13.1% RoTCE. The new guidance therefore suggests management believes profitability can remain above the longer-term 11%-13% RoTCE range Citi established for 2027-28, despite additional investment spending.
Kiev.Victor / Shutterstock.com
The bullish argument is that Citigroup Inc. (NYSE:C) appears to be converting its multiyear restructuring into higher returns while simultaneously returning more capital to shareholders. The move from 8.7% RoTCE in the second quarter of 2025 to 13.0% in the second quarter of 2026 represents a substantial improvement in capital efficiency. Citi's efficiency ratio also improved to 57.4% from 62.7%, indicating that revenue growth is increasingly translating into operating leverage rather than being absorbed by expenses. That is particularly relevant because management now intends to spend another roughly $500 million on severance, marketing, and growth initiatives; if these investments produce the intended expansion in cards and wealth management, they could support revenue growth without derailing the profitability trajectory.
Capital returns provide another positive lever. Citi repurchased $13 billion of stock in 2025 and now expects to increase that amount, while its June 2026 CET1 ratio remained 12.78%, comfortably above its 11.6% standardized regulatory requirement. Buybacks can reduce tangible common equity and shares outstanding, potentially supporting both RoTCE and per-share earnings when executed below intrinsic value. Citi's tangible book value per share had already risen 7% year over year to $100.89 by June 30, 2026. The combination of higher operating profitability, shrinking share count, and improving capital efficiency strengthens the case for a valuation re-rating if Citi can sustain returns above 11%.
#rotce #citi #management
The 11%+ target is meaningful because Citi's profitability has already improved materially. In the second quarter, Citi generated $24.8 billion of revenue, up 14% year over year, while net income rose 45% to $5.8 billion. Investment-banking revenue increased 44% to $1.55 billion, and net interest income increased 13%. Citi's SEC filing shows second-quarter RoTCE of 13.0%, versus 8.7% a year earlier, while the first half of 2026 produced a 13.1% RoTCE. The new guidance therefore suggests management believes profitability can remain above the longer-term 11%-13% RoTCE range Citi established for 2027-28, despite additional investment spending.
Kiev.Victor / Shutterstock.com
The bullish argument is that Citigroup Inc. (NYSE:C) appears to be converting its multiyear restructuring into higher returns while simultaneously returning more capital to shareholders. The move from 8.7% RoTCE in the second quarter of 2025 to 13.0% in the second quarter of 2026 represents a substantial improvement in capital efficiency. Citi's efficiency ratio also improved to 57.4% from 62.7%, indicating that revenue growth is increasingly translating into operating leverage rather than being absorbed by expenses. That is particularly relevant because management now intends to spend another roughly $500 million on severance, marketing, and growth initiatives; if these investments produce the intended expansion in cards and wealth management, they could support revenue growth without derailing the profitability trajectory.
Capital returns provide another positive lever. Citi repurchased $13 billion of stock in 2025 and now expects to increase that amount, while its June 2026 CET1 ratio remained 12.78%, comfortably above its 11.6% standardized regulatory requirement. Buybacks can reduce tangible common equity and shares outstanding, potentially supporting both RoTCE and per-share earnings when executed below intrinsic value. Citi's tangible book value per share had already risen 7% year over year to $100.89 by June 30, 2026. The combination of higher operating profitability, shrinking share count, and improving capital efficiency strengthens the case for a valuation re-rating if Citi can sustain returns above 11%.
#rotce #citi #management

2 months ago
Investors choosing between Carnival (NYSE:CCL) and Uber Technologies (NYSE:UBER) must decide between a capital-intensive cruise leader and a high-growth technology platform. Both companies have shown resilience, but their financial structures offer very different risks.
Carnival operates as a global giant in the travel industry, managing a diverse fleet of ships that cater to millions of vacationers. Uber dominates the gig economy by connecting riders, diners, and shippers with service providers through its proprietary mobile applications and digital infrastructure.
As a major player among consumer discretionary stocks, Carnival operates a massive fleet of over 90 ships across eight distinct brands. In its latest annual report, the company highlighted a workforce of over 160,000 team members who served approximately 13.5 million guests throughout 2025. This scale allows the company to source passengers from major global markets, and notably, no single travel agency group accounted for more than 10% of total revenue during the year.
In FY 2025, revenue reached nearly $26.6 billion, representing a growth rate of roughly 6.4% compared to the prior year. This top-line expansion helped the company generate a net income of approximately $2.8 billion, a significant improvement over the $1.9 billion recorded in 2024. The net margin improved to 10.4%, indicating that the company is successfully converting a larger portion of its sales into actual profit.
Based on its November 2025 balance sheet, Carnival carries a debt-to-equity ratio of 2.3x, which is the total debt divided by shareholder equity. Its current ratio, a measure of current **** ets relative to current liabilities, is nearly 0.3x, suggesting tight short-term liquidity. However, the company generated close to $2.6 billion in free cash flow, which is cash from operations minus capital expenditures, providing capital for debt reduction and fleet maintenance.
#carnival #fleet #current
Carnival operates as a global giant in the travel industry, managing a diverse fleet of ships that cater to millions of vacationers. Uber dominates the gig economy by connecting riders, diners, and shippers with service providers through its proprietary mobile applications and digital infrastructure.
As a major player among consumer discretionary stocks, Carnival operates a massive fleet of over 90 ships across eight distinct brands. In its latest annual report, the company highlighted a workforce of over 160,000 team members who served approximately 13.5 million guests throughout 2025. This scale allows the company to source passengers from major global markets, and notably, no single travel agency group accounted for more than 10% of total revenue during the year.
In FY 2025, revenue reached nearly $26.6 billion, representing a growth rate of roughly 6.4% compared to the prior year. This top-line expansion helped the company generate a net income of approximately $2.8 billion, a significant improvement over the $1.9 billion recorded in 2024. The net margin improved to 10.4%, indicating that the company is successfully converting a larger portion of its sales into actual profit.
Based on its November 2025 balance sheet, Carnival carries a debt-to-equity ratio of 2.3x, which is the total debt divided by shareholder equity. Its current ratio, a measure of current **** ets relative to current liabilities, is nearly 0.3x, suggesting tight short-term liquidity. However, the company generated close to $2.6 billion in free cash flow, which is cash from operations minus capital expenditures, providing capital for debt reduction and fleet maintenance.
#carnival #fleet #current


2 months ago
Citigroup Inc. (NYSE:C)'s CFO Gonzalo Luchetti said the bank expects return on tangible common equity (RoTCE) to come in slightly above 11% in 2026, while also indicating that Citi will increase stock buybacks from the $13 billion repurchased in 2025. The bank plans to accelerate roughly $500 million of investment by year-end, including spending on severance and marketing intended to expand its credit-card and wealth-management businesses. Citi also expects to remove Banamex from its balance sheet in 2027, which will create an estimated $9 billion currency-translation adjustment loss.
The 11%+ target is meaningful because Citi's profitability has already improved materially. In the second quarter, Citi generated $24.8 billion of revenue, up 14% year over year, while net income rose 45% to $5.8 billion. Investment-banking revenue increased 44% to $1.55 billion, and net interest income increased 13%. Citi's SEC filing shows second-quarter RoTCE of 13.0%, versus 8.7% a year earlier, while the first half of 2026 produced a 13.1% RoTCE. The new guidance therefore suggests management believes profitability can remain above the longer-term 11%-13% RoTCE range Citi established for 2027-28, despite additional investment spending.
Kiev.Victor / Shutterstock.com
The bullish argument is that Citigroup Inc. (NYSE:C) appears to be converting its multiyear restructuring into higher returns while simultaneously returning more capital to shareholders. The move from 8.7% RoTCE in the second quarter of 2025 to 13.0% in the second quarter of 2026 represents a substantial improvement in capital efficiency. Citi's efficiency ratio also improved to 57.4% from 62.7%, indicating that revenue growth is increasingly translating into operating leverage rather than being absorbed by expenses. That is particularly relevant because management now intends to spend another roughly $500 million on severance, marketing, and growth initiatives; if these investments produce the intended expansion in cards and wealth management, they could support revenue growth without derailing the profitability trajectory.
Capital returns provide another positive lever. Citi repurchased $13 billion of stock in 2025 and now expects to increase that amount, while its June 2026 CET1 ratio remained 12.78%, comfortably above its 11.6% standardized regulatory requirement. Buybacks can reduce tangible common equity and shares outstanding, potentially supporting both RoTCE and per-share earnings when executed below intrinsic value. Citi's tangible book value per share had already risen 7% year over year to $100.89 by June 30, 2026. The combination of higher operating profitability, shrinking share count, and improving capital efficiency strengthens the case for a valuation re-rating if Citi can sustain returns above 11%.
#year #management
The 11%+ target is meaningful because Citi's profitability has already improved materially. In the second quarter, Citi generated $24.8 billion of revenue, up 14% year over year, while net income rose 45% to $5.8 billion. Investment-banking revenue increased 44% to $1.55 billion, and net interest income increased 13%. Citi's SEC filing shows second-quarter RoTCE of 13.0%, versus 8.7% a year earlier, while the first half of 2026 produced a 13.1% RoTCE. The new guidance therefore suggests management believes profitability can remain above the longer-term 11%-13% RoTCE range Citi established for 2027-28, despite additional investment spending.
Kiev.Victor / Shutterstock.com
The bullish argument is that Citigroup Inc. (NYSE:C) appears to be converting its multiyear restructuring into higher returns while simultaneously returning more capital to shareholders. The move from 8.7% RoTCE in the second quarter of 2025 to 13.0% in the second quarter of 2026 represents a substantial improvement in capital efficiency. Citi's efficiency ratio also improved to 57.4% from 62.7%, indicating that revenue growth is increasingly translating into operating leverage rather than being absorbed by expenses. That is particularly relevant because management now intends to spend another roughly $500 million on severance, marketing, and growth initiatives; if these investments produce the intended expansion in cards and wealth management, they could support revenue growth without derailing the profitability trajectory.
Capital returns provide another positive lever. Citi repurchased $13 billion of stock in 2025 and now expects to increase that amount, while its June 2026 CET1 ratio remained 12.78%, comfortably above its 11.6% standardized regulatory requirement. Buybacks can reduce tangible common equity and shares outstanding, potentially supporting both RoTCE and per-share earnings when executed below intrinsic value. Citi's tangible book value per share had already risen 7% year over year to $100.89 by June 30, 2026. The combination of higher operating profitability, shrinking share count, and improving capital efficiency strengthens the case for a valuation re-rating if Citi can sustain returns above 11%.
#year #management

2 months ago
Recent trade acquisition Jaylen Brown is preparing for the 2026-27 NBA season, his first with the Philadelphia 76ers. Ahead of training camp, the former Boston Celtics forward was seen working out with famous shooting instructor Chris "Lethal Shooter" Matthews. Before Matthews became a famous coach, he played for Washington State and St. Bonaventure and also spent time in the NBA G-League.
In a video posted to social media, Brown was knocking down consecutive long-range attempts, giving Philadelphia fans something to cheer about prior to the team's season opener in October. Brown, who led the league in two-pointers attempted last season, is a career 35.8% shooter from beyond the arc. Last season, Brown shot slightly below that figure, converting on 34.7% of 3-point attempts.
Following a top-six finish in MVP voting a season ago, increased shooting efficiency from Brown will help him benefit as an off-ball contributor when LeBron James, Tyrese Maxey or Joel Embiid is in possession.
For more NBA content, check out the BasketBaltes podcast:
https://www.youtube.com/@B...
#league
In a video posted to social media, Brown was knocking down consecutive long-range attempts, giving Philadelphia fans something to cheer about prior to the team's season opener in October. Brown, who led the league in two-pointers attempted last season, is a career 35.8% shooter from beyond the arc. Last season, Brown shot slightly below that figure, converting on 34.7% of 3-point attempts.
Following a top-six finish in MVP voting a season ago, increased shooting efficiency from Brown will help him benefit as an off-ball contributor when LeBron James, Tyrese Maxey or Joel Embiid is in possession.
For more NBA content, check out the BasketBaltes podcast:
https://www.youtube.com/@B...
#league


2 months ago
On August 10, Red Violet Inc. (NASDAQ:RDVT) reported second-quarter 2026 results for the period ended June 30 that showed the company converting growth into profit at an accelerating clip. Revenue rose 23% to $26.7 million, and net income nearly doubled to $5 million. For a company built on selling identity intelligence to businesses, watching net margin move from 12% to 19% says that growth is not costing more to produce.
Gross profit climbed 29% to $20.2 million, pushing gross margin to 76% from 72%, while adjusted EBITDA jumped 48% to $11.2 million as its margin widened to 42% from 35%. Adjusted net income rose 58% to $7.2 million. Cash generation told the same story: operating cash flow increased 42% to a record $10.6 million for the quarter. None of that came from adding customers who barely move the needle. Red Violet signed on 447 new IDI customers in the quarter, a company record, ending with 10,869 customers on the platform.
FOREWARN, its product built for real estate agents, picked up 25,493 new users to reach 443,173, and 660 REALTOR ****** ociations across the country are now under contract to use it. The company also closed an underwritten public offering in August that sold 1,916,667 shares, including 250,000 shares from the underwriters' full exercise of their option, generating net proceeds of about $109.0 million. Between the funds already on hand and this new raise, Red Violet says it holds over $160 million in cash and carries no debt, money earmarked for working capital and possible acquisitions.
CEO Derek Dubner called it what he described as "the strongest pipeline of strategic initiatives" in the company's history. The company also repurchased 74,500 shares by June 30, paying $41.87 per share on average, and had $15.5 million left on its buyback authorization.
The August offering that padded Red Violet's cash balance also added 1,916,667 new shares to the count, arriving in the same year that per-share profit is climbing fastest. Diluted earnings came in a penny below basic at $0.34, and adjusted diluted earnings landed at $0.50 versus $0.51 on a basic basis, a gap new shares will only widen going forward. There is also a timing tension worth sitting with: Red Violet spent part of the quarter buying back its own stock at an average of $41.87 a share, then turned around weeks later and sold new shares to the public.
#million
Gross profit climbed 29% to $20.2 million, pushing gross margin to 76% from 72%, while adjusted EBITDA jumped 48% to $11.2 million as its margin widened to 42% from 35%. Adjusted net income rose 58% to $7.2 million. Cash generation told the same story: operating cash flow increased 42% to a record $10.6 million for the quarter. None of that came from adding customers who barely move the needle. Red Violet signed on 447 new IDI customers in the quarter, a company record, ending with 10,869 customers on the platform.
FOREWARN, its product built for real estate agents, picked up 25,493 new users to reach 443,173, and 660 REALTOR ****** ociations across the country are now under contract to use it. The company also closed an underwritten public offering in August that sold 1,916,667 shares, including 250,000 shares from the underwriters' full exercise of their option, generating net proceeds of about $109.0 million. Between the funds already on hand and this new raise, Red Violet says it holds over $160 million in cash and carries no debt, money earmarked for working capital and possible acquisitions.
CEO Derek Dubner called it what he described as "the strongest pipeline of strategic initiatives" in the company's history. The company also repurchased 74,500 shares by June 30, paying $41.87 per share on average, and had $15.5 million left on its buyback authorization.
The August offering that padded Red Violet's cash balance also added 1,916,667 new shares to the count, arriving in the same year that per-share profit is climbing fastest. Diluted earnings came in a penny below basic at $0.34, and adjusted diluted earnings landed at $0.50 versus $0.51 on a basic basis, a gap new shares will only widen going forward. There is also a timing tension worth sitting with: Red Violet spent part of the quarter buying back its own stock at an average of $41.87 a share, then turned around weeks later and sold new shares to the public.
#million

2 months ago
Real Madrid closed out matchday five of La Liga with a 4-1 win over Rayo Vallecano at the Santiago Bernabéu, with Kylian Mbappé scoring twice against Rayo goalkeeper Emil Audero. The victory moved Real Madrid level on points with Barcelona at the top of the standings.
Mbappé opened the scoring from the penalty spot in the 14th minute after Florian Lejeune fouled Alvaro Carreras in the area. Three minutes later, Carreras exchanged passes with Mbappé and finished to double the lead after Lejeune had lost possession under pressure from Vinícius Júnior.
Jude Bellingham made it three before the interval, converting Vinícius Júnior's cut-back after the Brazilian had driven down the left. Real Madrid therefore took a commanding three-goal advantage into half-time, with Mbappé also hitting the post late in the first half.
Rayo Vallecano reduced the deficit in the 51st minute when Sergio Camello scored after a turnover, and the visitors created further openings as they tried to work their way back into the game. Thibaut Courtois made saves during Rayo's improved second-half spell, while Pedro Díaz struck the post.
Mbappé settled the contest in stoppage time, finishing a move created by Arda Güler to make it 4-1 and complete his brace, as detailed in the original match report. The second goal took Mbappé to seven goals in six appearances in all competitions.
#rayo #vallecano
Mbappé opened the scoring from the penalty spot in the 14th minute after Florian Lejeune fouled Alvaro Carreras in the area. Three minutes later, Carreras exchanged passes with Mbappé and finished to double the lead after Lejeune had lost possession under pressure from Vinícius Júnior.
Jude Bellingham made it three before the interval, converting Vinícius Júnior's cut-back after the Brazilian had driven down the left. Real Madrid therefore took a commanding three-goal advantage into half-time, with Mbappé also hitting the post late in the first half.
Rayo Vallecano reduced the deficit in the 51st minute when Sergio Camello scored after a turnover, and the visitors created further openings as they tried to work their way back into the game. Thibaut Courtois made saves during Rayo's improved second-half spell, while Pedro Díaz struck the post.
Mbappé settled the contest in stoppage time, finishing a move created by Arda Güler to make it 4-1 and complete his brace, as detailed in the original match report. The second goal took Mbappé to seven goals in six appearances in all competitions.
#rayo #vallecano

2 months ago
The deafening roar of Kroger Field that fueled a 17-13 halftime lead eventually gave way to a much heavier, quieter reality. When the final whistle blew on a 45-17 loss to Alabama, the scoreboard reflected a fractured dream of an upset, leaving players and fans alike processing the sting of what could have been yet again.
For Will Stein, the immediate aftermath wasn't about pointing fingers; it was about raw accountability and a profound gratitude for a fanbase that delivered a championship-level atmosphere.
The fans showed up in full force, selling out Kroger Field for Will Stein's SEC debut, creating an environment that Stein described as "unbelievable," "loud," and "energetic." Recognizing the massive emotional investment of the crowd, he didn't mince words. "I apologize to our fans for the way that we finished," he admitted, fully aware of the collective heartbreak echoing through the stands and the locker room. "I know our guys are hurting."
That hurt can't carry on too long; the SEC is an unforgiving league, and the 2nd-half performance against Alabama can't bleed over to next week.
The first half offered a vivid glimpse into the program's potential that Will Stein spoke on before the season started. The defense hunted the ball, securing three takeaways, while the offense capitalized to carry a lead into the locker room. But the second half brought stalled drives and exhausted defenders. Pinned back by short fields, the defense was asked to hold back the Tide a few too many times. "When you're defending a short field virtually the entire half, and we weren't converting on third downs, that was tough on our defense," Stein noted, acknowledging the brutal physical toll.
#field #defense #room
For Will Stein, the immediate aftermath wasn't about pointing fingers; it was about raw accountability and a profound gratitude for a fanbase that delivered a championship-level atmosphere.
The fans showed up in full force, selling out Kroger Field for Will Stein's SEC debut, creating an environment that Stein described as "unbelievable," "loud," and "energetic." Recognizing the massive emotional investment of the crowd, he didn't mince words. "I apologize to our fans for the way that we finished," he admitted, fully aware of the collective heartbreak echoing through the stands and the locker room. "I know our guys are hurting."
That hurt can't carry on too long; the SEC is an unforgiving league, and the 2nd-half performance against Alabama can't bleed over to next week.
The first half offered a vivid glimpse into the program's potential that Will Stein spoke on before the season started. The defense hunted the ball, securing three takeaways, while the offense capitalized to carry a lead into the locker room. But the second half brought stalled drives and exhausted defenders. Pinned back by short fields, the defense was asked to hold back the Tide a few too many times. "When you're defending a short field virtually the entire half, and we weren't converting on third downs, that was tough on our defense," Stein noted, acknowledging the brutal physical toll.
#field #defense #room

2 months ago
Two retirees with identical $1.65M portfolios face different tax outcomes based solely on withdrawal order and account placement, not holdings.
Drawing down or converting a traditional IRA to Roth before age 73 shrinks future RMDs and keeps income below IRMAA Medicare surcharge thresholds.
VTEB's tax-exempt municipal interest still counts fully toward IRMAA calculations, making it a hidden Medicare cost trap for retirees.
Read More: Learn 7 ways to generate income with a $1,000,000+ portfolio (sponsor)
Two retirees, same age, same $1.65 million balance, same seven holdings in identical weights. One will pay a Medicare premium surcharge stacked on top of a rising required withdrawal starting at 73. The other will not. Only the order they draw from, and the accounts those draws come from, separates the outcomes.
#medicare #irmaa #holdings
Drawing down or converting a traditional IRA to Roth before age 73 shrinks future RMDs and keeps income below IRMAA Medicare surcharge thresholds.
VTEB's tax-exempt municipal interest still counts fully toward IRMAA calculations, making it a hidden Medicare cost trap for retirees.
Read More: Learn 7 ways to generate income with a $1,000,000+ portfolio (sponsor)
Two retirees, same age, same $1.65 million balance, same seven holdings in identical weights. One will pay a Medicare premium surcharge stacked on top of a rising required withdrawal starting at 73. The other will not. Only the order they draw from, and the accounts those draws come from, separates the outcomes.
#medicare #irmaa #holdings


2 months ago
SmartAsset and Yahoo Finance LLC may earn commission or revenue through links in the content below.
I'm turning 68 shortly and plan to wait to claim my Social Security at age 70 to maximize the monthly benefit. I also plan to retire at the end of the year, if not sooner (so in three months or less). Does withdrawing from my traditional IRAs (current balance is $215,000) to reduce the income tax on my RMDs outweigh the benefit of keeping those withdrawals invested and growing tax-deferred? My understanding is that if I withdraw amounts up to my standard deduction, then those amounts would be tax-free.
– Austen
Retirement withdrawals, Social Security benefits, required minimum distribution (RMDs), taxes … there are a lot of moving parts when it comes to making decisions about your retirement income. Reducing the amount of money that's subject to RMDs can help minimize your taxes once they kick in. This may also help avoid taxes on your Social Security benefits.
If you don't need the money now, but want to reduce RMDs later, one of the best moves might be converting a portion of your IRA to a Roth IRA each year. That can help reduce future required withdrawals and allow your money to grow tax-free, though there can be tax consequences for certain withdrawals. (A financial advisor can help guide you through the Roth conversion process and potentially avoid unwanted tax consequences.)
#Help #taxes #roth #Retirement
I'm turning 68 shortly and plan to wait to claim my Social Security at age 70 to maximize the monthly benefit. I also plan to retire at the end of the year, if not sooner (so in three months or less). Does withdrawing from my traditional IRAs (current balance is $215,000) to reduce the income tax on my RMDs outweigh the benefit of keeping those withdrawals invested and growing tax-deferred? My understanding is that if I withdraw amounts up to my standard deduction, then those amounts would be tax-free.
– Austen
Retirement withdrawals, Social Security benefits, required minimum distribution (RMDs), taxes … there are a lot of moving parts when it comes to making decisions about your retirement income. Reducing the amount of money that's subject to RMDs can help minimize your taxes once they kick in. This may also help avoid taxes on your Social Security benefits.
If you don't need the money now, but want to reduce RMDs later, one of the best moves might be converting a portion of your IRA to a Roth IRA each year. That can help reduce future required withdrawals and allow your money to grow tax-free, though there can be tax consequences for certain withdrawals. (A financial advisor can help guide you through the Roth conversion process and potentially avoid unwanted tax consequences.)
#Help #taxes #roth #Retirement

0.00$ raised of 0.00$ goal
0 donations
0.00$
to go

2 months ago
The Baltimore Ravens reconstructed their coaching staff and strengthened several areas of the roster after falling short of the postseason. Those changes created renewed optimism, but they also increased the pressure on several returning players.
Baltimore's established stars will drive the team's championship pursuit. The Ravens' ability to close the gap in the AFC, however, could be determined by younger contributors becoming more consistent in expanded roles.
Here are five Ravens who must improve in 2026.
Simpson possesses the athletic tools to become a productive three-down linebacker, but Baltimore needs greater consistency from him alongside Roquan Smith. He must diagnose plays faster, take cleaner pursuit angles, and become more dependable in coverage. Teddye Buchanan and Jay Higgins IV give the Ravens additional options, placing even more importance on Simpson converting his physical ability into reliable production.
Rosengarten has gained valuable experience at right tackle, but the Ravens need him to take another step as a pass protector. His ability to handle speed rushers without consistent ****** istance would give Declan Doyle greater freedom with formations and route combinations. Baltimore cannot allow pressure from the right side to disrupt Lamar Jackson or force the offense away from deeper-developing concepts.
#Ravens
Baltimore's established stars will drive the team's championship pursuit. The Ravens' ability to close the gap in the AFC, however, could be determined by younger contributors becoming more consistent in expanded roles.
Here are five Ravens who must improve in 2026.
Simpson possesses the athletic tools to become a productive three-down linebacker, but Baltimore needs greater consistency from him alongside Roquan Smith. He must diagnose plays faster, take cleaner pursuit angles, and become more dependable in coverage. Teddye Buchanan and Jay Higgins IV give the Ravens additional options, placing even more importance on Simpson converting his physical ability into reliable production.
Rosengarten has gained valuable experience at right tackle, but the Ravens need him to take another step as a pass protector. His ability to handle speed rushers without consistent ****** istance would give Declan Doyle greater freedom with formations and route combinations. Baltimore cannot allow pressure from the right side to disrupt Lamar Jackson or force the offense away from deeper-developing concepts.
#Ravens


2 months ago
Bloomberg reported on August 25, 2026, that BlackRock, Inc. (NYSE:BLK) cut the minimum size for converting large Bitcoin holdings directly into shares of its iShares Bitcoin Trust ETF to $1 million in July, down from $25 million when the in-kind conversion process first became available. The fund has facilitated more than $5 billion of these conversions, up from more than $3 billion when Bloomberg first reported on the trend in October, according to Robbie Mitchnick, BlackRock's head of digital ******* ets. The process, which can take more than a week, lets holders move Bitcoin from private wallets into a regulated fund structure while retaining price exposure. Mitchnick said "kidnappings, ransom demands, and custody failures" motivate some holders to make the switch. Rival issuer Bitwise has cut its own minimum even further, from $100 million to $3 million, Bloomberg reported.
This is a fast-scaling new source of fee-generating ******* ets for BlackRock, Inc. (NYSE:BLK). The $5 billion processed through IBIT is up from $3 billion just months earlier. It shows accelerating adoption of a service that pulls previously self-custodied Bitcoin wealth directly into BlackRock's ******* et base rather than competing for ******* ets already inside the traditional financial system.
Cutting the minimum by 96% meaningfully widens who can use the service. Dropping the threshold from $25 million to $1 million brings the option within reach of family offices and wealthy individual holders, rather than limiting it to the largest Bitcoin holders. That gives BlackRock access to a substantially larger pool of potential conversions as the practice becomes more common.
IBIT's scale gives it a head start in capturing this migration. The fund already holds roughly 3.645% of Bitcoin's total supply and lists net ******* ets of $60.65 billion. It is scale advantage that likely makes it the default destination for holders deciding where to move their coins, reinforcing BlackRock's position as conversions boost industry-wide.
The process remains manual and slow despite the lower headline minimum. Bitwise chief investment officer Matt Hougan said the conversion process industry-wide is "still bespoke, from introducing a client to a market maker to working with the adviser, but it's becoming more standardized," and Mitchnick himself said conversions can take more than a week. That means BlackRock, Inc. (NYSE:BLK) has not yet turned this into a fully automated, scalable pipeline even as it markets lower minimums to a broader audience.
#blackrock #billion #minimum
This is a fast-scaling new source of fee-generating ******* ets for BlackRock, Inc. (NYSE:BLK). The $5 billion processed through IBIT is up from $3 billion just months earlier. It shows accelerating adoption of a service that pulls previously self-custodied Bitcoin wealth directly into BlackRock's ******* et base rather than competing for ******* ets already inside the traditional financial system.
Cutting the minimum by 96% meaningfully widens who can use the service. Dropping the threshold from $25 million to $1 million brings the option within reach of family offices and wealthy individual holders, rather than limiting it to the largest Bitcoin holders. That gives BlackRock access to a substantially larger pool of potential conversions as the practice becomes more common.
IBIT's scale gives it a head start in capturing this migration. The fund already holds roughly 3.645% of Bitcoin's total supply and lists net ******* ets of $60.65 billion. It is scale advantage that likely makes it the default destination for holders deciding where to move their coins, reinforcing BlackRock's position as conversions boost industry-wide.
The process remains manual and slow despite the lower headline minimum. Bitwise chief investment officer Matt Hougan said the conversion process industry-wide is "still bespoke, from introducing a client to a market maker to working with the adviser, but it's becoming more standardized," and Mitchnick himself said conversions can take more than a week. That means BlackRock, Inc. (NYSE:BLK) has not yet turned this into a fully automated, scalable pipeline even as it markets lower minimums to a broader audience.
#blackrock #billion #minimum
2 months ago
On August 4, Voya Financial (NYSE:VOYA) announced its second-quarter 2026 results, and the headline numbers tell an uncomfortable story. Net income available to common shareholders dropped to $90 million, or $0.97 per diluted share, down from $162 million and $1.66 a year earlier. Adjusted operating earnings fell just as sharply, to $140 million from $240 million. Yet look past the income statement and Voya's underlying businesses were adding client ******* ets, growing fee income, and returning cash to shareholders at a steady pace.
Voya's Retirement business crossed 10 million participant accounts during the quarter, a milestone that arrived alongside the completed integration of OneAmerica. Total client ******* ets in that segment reached $863 billion as of June 30, up 14% from $757 billion a year earlier, and fee-based revenues climbed 10% year over year. Investment Management told a similar story. Pre-tax adjusted operating earnings there rose 12% to $57 million, helped by $1.2 billion of net inflows during the quarter that pushed ******* ets under management to $377 billion, up from $360 billion a year ago.
Assets under advisory grew even faster, reaching $63 billion from $54 billion. Margins widened too, up 100 basis points on a trailing twelve-month basis to 29.0%. Employee Benefits, often the company's most volatile segment, showed real underwriting progress: the total aggregate loss ratio improved to 74% from 79% a year earlier, lifting its trailing twelve-month margin to 11.0% from just 3.7%. None of that came at the expense of shareholders. Voya generated roughly $150 million of excess capital in the quarter, more than fully converting its adjusted operating earnings into deployable cash, and returned about $200 million through dividends and buybacks, with $263 million still authorized for future repurchases.
The drop in profitability traces to specific, identifiable costs. Corporate reported pre-tax adjusted operating losses of $102 million, up from $67 million a year earlier, largely because of roughly $40 million in severance tied to efficiency actions. A $15 million pre-tax loss on alternative investments added further pressure. Those same alternative investment declines hit Retirement directly: pre-tax adjusted operating earnings there fell to $190 million from $235 million, even as fee revenue grew, because lower alternative investment income and planned strategic investment spending offset the gains. Employee Benefits saw the sharpest swing, with pre-tax adjusted operating earnings falling to $22 million from $69 million.
#year #earnings #assets #voya
Voya's Retirement business crossed 10 million participant accounts during the quarter, a milestone that arrived alongside the completed integration of OneAmerica. Total client ******* ets in that segment reached $863 billion as of June 30, up 14% from $757 billion a year earlier, and fee-based revenues climbed 10% year over year. Investment Management told a similar story. Pre-tax adjusted operating earnings there rose 12% to $57 million, helped by $1.2 billion of net inflows during the quarter that pushed ******* ets under management to $377 billion, up from $360 billion a year ago.
Assets under advisory grew even faster, reaching $63 billion from $54 billion. Margins widened too, up 100 basis points on a trailing twelve-month basis to 29.0%. Employee Benefits, often the company's most volatile segment, showed real underwriting progress: the total aggregate loss ratio improved to 74% from 79% a year earlier, lifting its trailing twelve-month margin to 11.0% from just 3.7%. None of that came at the expense of shareholders. Voya generated roughly $150 million of excess capital in the quarter, more than fully converting its adjusted operating earnings into deployable cash, and returned about $200 million through dividends and buybacks, with $263 million still authorized for future repurchases.
The drop in profitability traces to specific, identifiable costs. Corporate reported pre-tax adjusted operating losses of $102 million, up from $67 million a year earlier, largely because of roughly $40 million in severance tied to efficiency actions. A $15 million pre-tax loss on alternative investments added further pressure. Those same alternative investment declines hit Retirement directly: pre-tax adjusted operating earnings there fell to $190 million from $235 million, even as fee revenue grew, because lower alternative investment income and planned strategic investment spending offset the gains. Employee Benefits saw the sharpest swing, with pre-tax adjusted operating earnings falling to $22 million from $69 million.
#year #earnings #assets #voya
2 months ago
On August 13, TSS Inc. (NASDAQ:TSSI) reported second-quarter results that look worse on the top line and better underneath it. Revenue fell 20% year over year to $35.1 million, yet gross profit rose 11% and adjusted EBITDA climbed 12%. The company is deliberately walking away from lower-margin procurement work and leaning into systems integration for AI and HPC infrastructure, a business that grew 46% in the quarter. That trade-off is the whole story right now, and it cuts both ways.
Systems integration revenue reached $13.9 million in the quarter, up 46% from a year earlier, and now makes up 39% of revenue, versus just 22% in last year's second quarter. Facilities management grew even faster, up 84% to $2.7 million. CEO Darryll Dewan said systems integration is expected to keep outpacing the rest of the business given strong demand and the company's track record on complex technology projects.
TSS has started deploying capital toward a planned $17 million investment aimed at the next wave of AI data center technology, a buildout the company expects to start converting into higher systems integration revenue in the third quarter. The company has also put an idle **** et back to work: its former Round Rock integration facility began warehouse operations on May 1, generating $0.3 million in operating lease income during the quarter.
Management is also pointing to stronger months ahead. TSS expects the second half of 2026 to outperform the first half, with accelerated systems integration growth, and it maintained guidance for full-year adjusted EBITDA to land between $20 million and $22 million, at the high end of that band.
The revenue decline is not small. Procurement revenue, still TSS's largest segment by dollars, fell 45% to $18.2 million in the quarter and is down 53% to $58.2 million for the first six months of the year. That drop pulled total revenue down 20% in the quarter and 37% for the year to date, to $90.5 million, even as the higher-margin segments expanded.
#systems #procurement
Systems integration revenue reached $13.9 million in the quarter, up 46% from a year earlier, and now makes up 39% of revenue, versus just 22% in last year's second quarter. Facilities management grew even faster, up 84% to $2.7 million. CEO Darryll Dewan said systems integration is expected to keep outpacing the rest of the business given strong demand and the company's track record on complex technology projects.
TSS has started deploying capital toward a planned $17 million investment aimed at the next wave of AI data center technology, a buildout the company expects to start converting into higher systems integration revenue in the third quarter. The company has also put an idle **** et back to work: its former Round Rock integration facility began warehouse operations on May 1, generating $0.3 million in operating lease income during the quarter.
Management is also pointing to stronger months ahead. TSS expects the second half of 2026 to outperform the first half, with accelerated systems integration growth, and it maintained guidance for full-year adjusted EBITDA to land between $20 million and $22 million, at the high end of that band.
The revenue decline is not small. Procurement revenue, still TSS's largest segment by dollars, fell 45% to $18.2 million in the quarter and is down 53% to $58.2 million for the first six months of the year. That drop pulled total revenue down 20% in the quarter and 37% for the year to date, to $90.5 million, even as the higher-margin segments expanded.
#systems #procurement


2 months ago
A B Graphic International (ABG) has renamed Enprom Solutions as ABG Girona, as part of the continued integration of its Spain-based operation into the wider group.
The move follows the 2019 acquisition of the business by ABG and Kocher+Beck and affirms the site as the group's centre of excellence for flexible packaging.
Based in Girona, the operation designs and builds machinery, converting systems, sleeve products and automated production lines for the flexible packaging and label sectors.
Within the ABG group, the Girona business is set to take on a larger role in flexible packaging work, including the FlexPack range.
The name change is intended to clarify the Girona operation's position within the group for customers while retaining the technical knowledge developed by the existing team.
#packaging #based #business #international
The move follows the 2019 acquisition of the business by ABG and Kocher+Beck and affirms the site as the group's centre of excellence for flexible packaging.
Based in Girona, the operation designs and builds machinery, converting systems, sleeve products and automated production lines for the flexible packaging and label sectors.
Within the ABG group, the Girona business is set to take on a larger role in flexible packaging work, including the FlexPack range.
The name change is intended to clarify the Girona operation's position within the group for customers while retaining the technical knowledge developed by the existing team.
#packaging #based #business #international
2 months ago
The Wisconsin Badgers fell short 41-13 to the Notre Dame Fighting Irish in a competitive first game of the season at Lambeau Field, inspiring confidence for 2026 while showing the key areas of improvement needed.
The Badgers kept Notre Dame in check through the first 30 minutes, trailing 13-10 at halftime, and continued to fight throughout the game, although an early third-quarter stretch from the Fighting Irish was the leading force to them winning the game.
Wisconsin started with the ball, but had a quick three-and-out, as they were stuffed on first down and couldn't recover. The defense had a strong opening drive, though, as the run defense started off on a good note and Sebastian Cheeks got home on a strip sack on Notre Dame's first third down, but the Fighting Irish recovered.
Wisconsin blocked the punt, getting field position in plus territory, and that led to the first points of the game. Wisconsin had a nice Abu Sama III run on 3rd & 6 with good blocking and got to the red zone, where they eventually settled for a field goal.
Notre Dame overcame tough field position on its next drive, converting a fourth down, while finding a hole in Wisconsin's off coverage to the field side with a couple of short passes. They eventually got into field goal range and drilled a 52-yarder to tie the game up there after the defense got a stop.
#field #first #game
The Badgers kept Notre Dame in check through the first 30 minutes, trailing 13-10 at halftime, and continued to fight throughout the game, although an early third-quarter stretch from the Fighting Irish was the leading force to them winning the game.
Wisconsin started with the ball, but had a quick three-and-out, as they were stuffed on first down and couldn't recover. The defense had a strong opening drive, though, as the run defense started off on a good note and Sebastian Cheeks got home on a strip sack on Notre Dame's first third down, but the Fighting Irish recovered.
Wisconsin blocked the punt, getting field position in plus territory, and that led to the first points of the game. Wisconsin had a nice Abu Sama III run on 3rd & 6 with good blocking and got to the red zone, where they eventually settled for a field goal.
Notre Dame overcame tough field position on its next drive, converting a fourth down, while finding a hole in Wisconsin's off coverage to the field side with a couple of short passes. They eventually got into field goal range and drilled a 52-yarder to tie the game up there after the defense got a stop.
#field #first #game

2 months ago
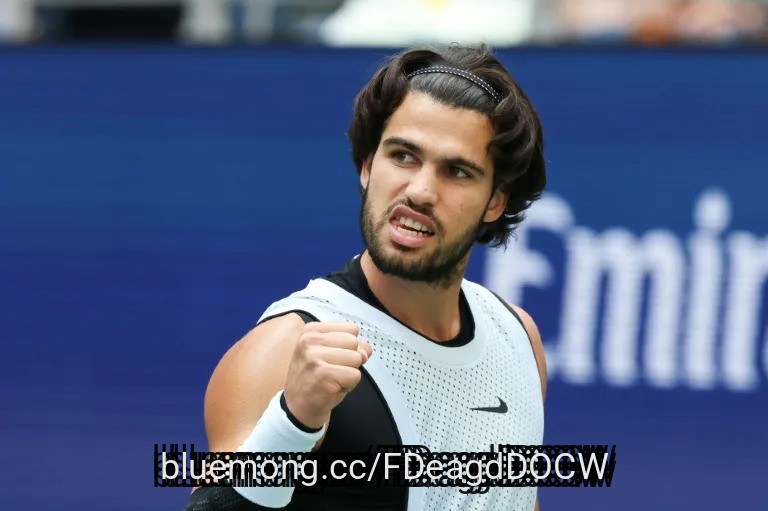
Defending champion Carlos Alcaraz, gaining confidence with every match, cruised into the US Open quarter-finals on Sunday with a comprehensive victory over Tommy Paul.
The second-seeded Spaniard, playing his first tournament after a four-month absence with a right wrist injury, beat Paul 6-4, 6-3, 6-4 to reach his fifth quarter-final at Flushing Meadows -- where he won the first of his seven Grand Slam **** les back in 2022.
The 23-year-old Spaniard will face either eighth-seeded American Ben Shelton or resurgent Greek Stefanos Tsitsipas for a place in the semi-finals.
In Paul, Alcaraz faced his first top-25 player of the tournament and he rose to the occasion, firing 33 winners in the two-hour, 20-minute victory and improving to 7-2 against the American.
Alcaraz finally broke through in a tight first set with the first break of the contest, earning three set points and converting the second.
#american #quarter #victory #second
The second-seeded Spaniard, playing his first tournament after a four-month absence with a right wrist injury, beat Paul 6-4, 6-3, 6-4 to reach his fifth quarter-final at Flushing Meadows -- where he won the first of his seven Grand Slam **** les back in 2022.
The 23-year-old Spaniard will face either eighth-seeded American Ben Shelton or resurgent Greek Stefanos Tsitsipas for a place in the semi-finals.
In Paul, Alcaraz faced his first top-25 player of the tournament and he rose to the occasion, firing 33 winners in the two-hour, 20-minute victory and improving to 7-2 against the American.
Alcaraz finally broke through in a tight first set with the first break of the contest, earning three set points and converting the second.
#american #quarter #victory #second
2 months ago
I get cautious when an artificial intelligence (AI) stock asks investors to pay today for profits that may not show up for years.
Nvidia (NASDAQ: NVDA) has been the dominant player in AI hardware for some time, but its stock still deserves a closer look even after gaining more than 360% over the past three years (as of Sept. 2, 2026). Is Nvidia stock now priced for distant hopes, or is it one of the tech sector's rare exceptions?
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Nvidia's results for its fiscal 2027 second quarter (which ended July 26) show how much the company is already benefiting from AI infrastructure spending. The company's revenue rose 106% year over year to $96.2 billion. The performance was mainly driven by the data center segment, where revenue increased 117% year over year to $89 billion. The company also generated $63.7 billion in generally accepted accounting principles (GAAP) operating income during the quarter. This pace of growth is particularly impressive considering Nvidia's massive size.
Nvidia is also converting a large portion of its revenues into cash. The company's free cash flow reached $69.9 billion, while the company returned roughly $46 billion to shareholders through share repurchases and dividends in the first half of its fiscal 2027. This shows that Nvidia has significant funds to invest in research and development, secure future supply, and return capital to shareholders.
#company
Nvidia (NASDAQ: NVDA) has been the dominant player in AI hardware for some time, but its stock still deserves a closer look even after gaining more than 360% over the past three years (as of Sept. 2, 2026). Is Nvidia stock now priced for distant hopes, or is it one of the tech sector's rare exceptions?
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Nvidia's results for its fiscal 2027 second quarter (which ended July 26) show how much the company is already benefiting from AI infrastructure spending. The company's revenue rose 106% year over year to $96.2 billion. The performance was mainly driven by the data center segment, where revenue increased 117% year over year to $89 billion. The company also generated $63.7 billion in generally accepted accounting principles (GAAP) operating income during the quarter. This pace of growth is particularly impressive considering Nvidia's massive size.
Nvidia is also converting a large portion of its revenues into cash. The company's free cash flow reached $69.9 billion, while the company returned roughly $46 billion to shareholders through share repurchases and dividends in the first half of its fiscal 2027. This shows that Nvidia has significant funds to invest in research and development, secure future supply, and return capital to shareholders.
#company
2 months ago
Duke (DUK) and Southern (SO) have secured a combined 25 gigawatts of data-center load commitments, converting electrification demand into recoverable regulated earnings.
Con Edison (ED) leads all S&P 500 utilities with 52 consecutive annual dividend increases, protected by New York State revenue decoupling that cushions volume swings.
Just released. Our **** ysts combed the entire stock market and named the ten best stocks to buy right now. The report is free. Enter your email and see if any of your stocks made the cut.
Regulated electric utilities are one of the few places income investors can find dividends backed by cash flows that don't rely on the economic cycle. Rate cases, riders, and long-term customer contracts turn capital spending into recoverable revenue, which is why payouts at these three names have kept climbing for decades. The clearest example: Con Edison's "50 straight years of dividend increases, a record unmatched among utilities in the S&P 500" was extended again this year to a 52nd consecutive annual increase. Here are three regulated-cash-flow utilities that income-focused portfolios can lean on.
Duke Energy (NYSE:DUK) is one of the largest fully regulated electric utilities in the country, serving roughly 8.73 million retail customers across the Carolinas, Florida, Indiana, Ohio, and Kentucky, plus Piedmont Natural Gas. The stock closed at $121.40 on September 3, 2026, with an annualized forward dividend of $4.34 after the July step-up to a $1.085 quarterly rate.
#duke #rate #recoverable
Con Edison (ED) leads all S&P 500 utilities with 52 consecutive annual dividend increases, protected by New York State revenue decoupling that cushions volume swings.
Just released. Our **** ysts combed the entire stock market and named the ten best stocks to buy right now. The report is free. Enter your email and see if any of your stocks made the cut.
Regulated electric utilities are one of the few places income investors can find dividends backed by cash flows that don't rely on the economic cycle. Rate cases, riders, and long-term customer contracts turn capital spending into recoverable revenue, which is why payouts at these three names have kept climbing for decades. The clearest example: Con Edison's "50 straight years of dividend increases, a record unmatched among utilities in the S&P 500" was extended again this year to a 52nd consecutive annual increase. Here are three regulated-cash-flow utilities that income-focused portfolios can lean on.
Duke Energy (NYSE:DUK) is one of the largest fully regulated electric utilities in the country, serving roughly 8.73 million retail customers across the Carolinas, Florida, Indiana, Ohio, and Kentucky, plus Piedmont Natural Gas. The stock closed at $121.40 on September 3, 2026, with an annualized forward dividend of $4.34 after the July step-up to a $1.085 quarterly rate.
#duke #rate #recoverable

2 months ago
On the September 2 episode of Mad Money, Jim Cramer called Cardinal Health, Inc. (NYSE:CAH) one of his "absolute favorites" and mentioned its growing exposure to specialty pharmaceuticals and higher-margin healthcare services.
Cardinal's been running circles around McKesson and Cencora. They consistently put up the best numbers because this company has gradually become less of a commoditized service provider and more of a specialized player.
Cardinal Health, Inc.'s (NYSE:CAH) fiscal fourth-quarter revenue rose 6% to $63.7 billion but missed estimates, while adjusted earnings per share came in at $2.91. Excluding a $0.31 per share tariff refund benefit, adjusted EPS was $2.60. Management forecast fiscal 2027 non-GAAP EPS of $12.40 to $12.60, a 13% to 15% growth, while adjusted free cash flow is expected at $3.5 billion to $4 billion.
The revenue miss is less significant if the company continues converting pharmaceutical volume into earnings. Lower branded-drug prices, including those affected by Medicare negotiations, can reduce reported sales without a proportional decline in distributor fees. The shift toward generics can have a similar effect because lower-priced drugs generate less revenue but can support attractive margins and high volumes. As Cramer said:
Remember, volume is where Cardinal really makes the money, volume, okay? That's why I keep shrugging off the revenue misses.
#cardinal #less #billion #NYSE
Cardinal's been running circles around McKesson and Cencora. They consistently put up the best numbers because this company has gradually become less of a commoditized service provider and more of a specialized player.
Cardinal Health, Inc.'s (NYSE:CAH) fiscal fourth-quarter revenue rose 6% to $63.7 billion but missed estimates, while adjusted earnings per share came in at $2.91. Excluding a $0.31 per share tariff refund benefit, adjusted EPS was $2.60. Management forecast fiscal 2027 non-GAAP EPS of $12.40 to $12.60, a 13% to 15% growth, while adjusted free cash flow is expected at $3.5 billion to $4 billion.
The revenue miss is less significant if the company continues converting pharmaceutical volume into earnings. Lower branded-drug prices, including those affected by Medicare negotiations, can reduce reported sales without a proportional decline in distributor fees. The shift toward generics can have a similar effect because lower-priced drugs generate less revenue but can support attractive margins and high volumes. As Cramer said:
Remember, volume is where Cardinal really makes the money, volume, okay? That's why I keep shrugging off the revenue misses.
#cardinal #less #billion #NYSE

2 months ago
Our ******* ysts just identified a stock with the potential to be the next Nvidia. Tell us how you invest and we'll show you why it's our #1 pick. Tap here.
Management is executing a deliberate pivot from a digital wealth management firm to a technology company focused on building specialized AI agents for high-stakes use cases.
The strategy follows a three-step pattern: operating a business vertical, converting that domain expertise into an AI agent, and then taking that agent to market.
Revenue growth of 39% sequentially was driven by the first quarter of recognition for A-MM, which management classifies as 'agentic' revenue rather than legacy financial services.
Gross margin expansion to 79.5% is attributed to a mix shift toward these agentic solutions, which carry structurally higher margins than the manual businesses they replace.
#agentic
Management is executing a deliberate pivot from a digital wealth management firm to a technology company focused on building specialized AI agents for high-stakes use cases.
The strategy follows a three-step pattern: operating a business vertical, converting that domain expertise into an AI agent, and then taking that agent to market.
Revenue growth of 39% sequentially was driven by the first quarter of recognition for A-MM, which management classifies as 'agentic' revenue rather than legacy financial services.
Gross margin expansion to 79.5% is attributed to a mix shift toward these agentic solutions, which carry structurally higher margins than the manual businesses they replace.
#agentic