

20 days ago
Amcor plc (NYSE:AMCR) isn't a flashy business. Most people probably don't know much about the company, even though they come across its products every day. The company makes the packaging used for food, drinks, healthcare products, beauty products, and plenty of other everyday items.
That gives the company an interesting quality from an investment perspective. Consumers may cut back on certain purchases when the economy gets tougher, but they still need to buy food, medicine, and other basic products. About 60% of Amcor's markets are tied to nutrition, while health, beauty, and wellness make up another 25%. Billionaires are gravitating towards another packaging company, and that has also returned nearly 20% in the past year. Find here.
The company's size is another advantage. Amcor operates across a large global manufacturing network and has relationships with major customers that have been built over many years. It also offers a wide range of packaging formats and materials. For a large multinational customer, being able to deal with one supplier across multiple markets can be a meaningful advantage. The Berry Global acquisition has made Amcor even larger, although it also brought more debt onto the balance sheet.
Amcor plc (NYSE:AMCR) pays $0.65 per share every quarter, giving investors an annual dividend of $2.60. At the October 7 closing price of $41.26, that works out to a yield of about 6.3%. That's a big yield for a company selling products that are tied to everyday consumption. However, a high yield doesn't automatically make a dividend attractive. What matters is whether the business can actually afford to keep paying it. Amcor's latest numbers offer some comfort. Its steady dividend growth is one reason the stock remains popular with income-focused investors.
The company generated $1.303 billion in free cash flow during fiscal 2026, while adjusted diluted EPS came in at $4.02, up 13% from the previous year. Amcor also increased its annual dividend to $2.60. On an adjusted earnings basis, the payout ratio is around 65%. That's not unusual for a mature company and doesn't immediately raise a red flag.
#NYSE

22 days ago
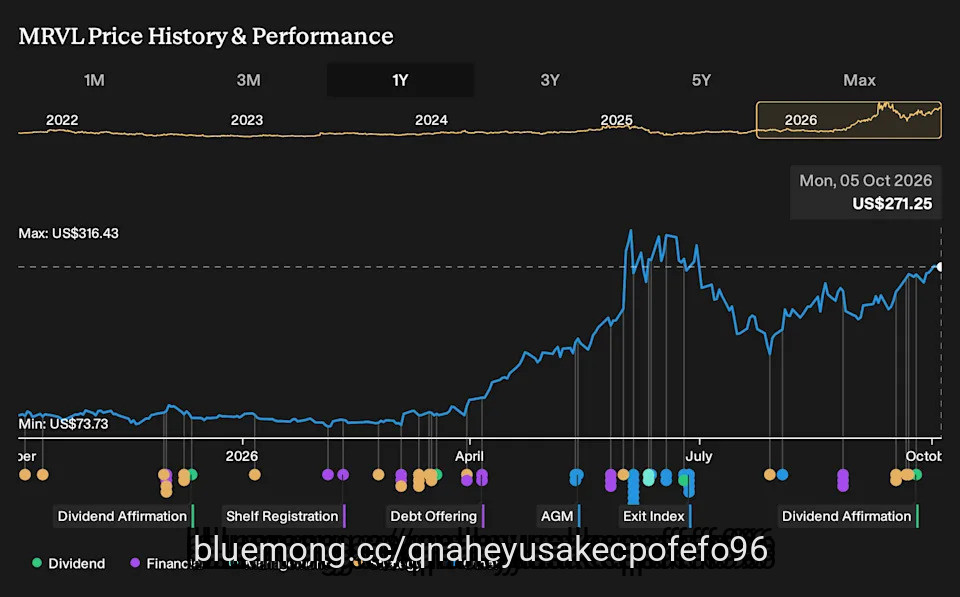
In late September 2026, AT&S Austria Technologie & Systemtechnik AG announced an expanded collaboration with Marvell Technology to increase advanced IC substrate capacity for next-generation AI and cloud infrastructure, while Marvell also affirmed a quarterly dividend of US$0.06 per share payable on October 29, 2026.
This deeper manufacturing partnership gives Marvell greater access to complex packaging technologies that are increasingly critical for high-performance AI chips and data center hardware.
Next, we'll examine how this expanded AT&S manufacturing capacity could influence Marvell's AI-focused growth story and longer-term investment narrative.
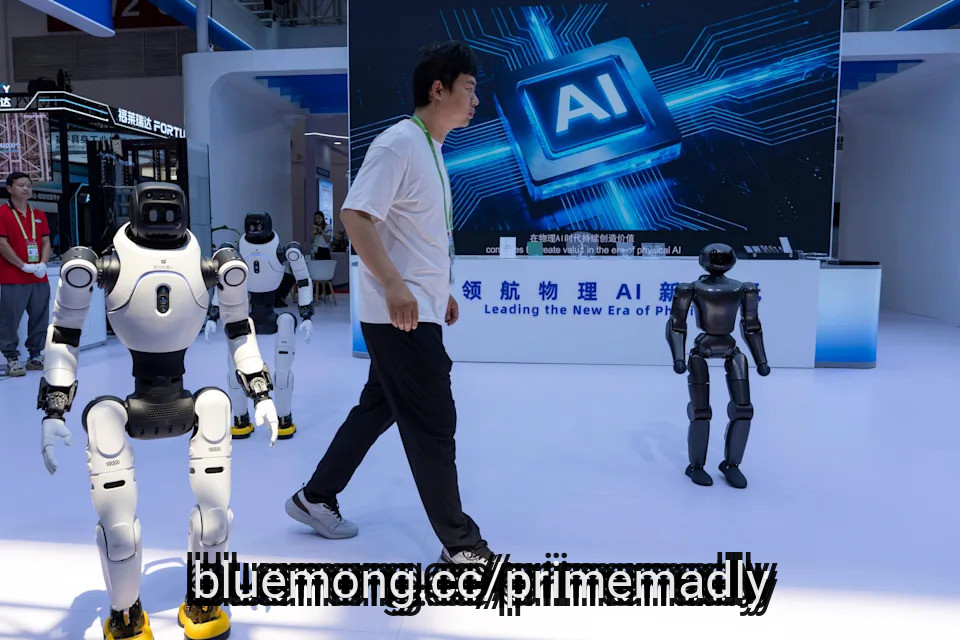
The future of work is here. Discover the 89 top robotics and automation stocks leading the charge in AI-driven automation and industrial transformation.
To own Marvell, you need to believe its AI and data center franchises can justify today's rich valuation and eventually translate into stronger, more consistent earnings power. The expanded AT&S IC substrate deal directly supports Marvell's near term AI optics and custom silicon ramp, while also amplifying the existing risk that long term supplier prepayments and capacity commitments could weigh on margins and free cash flow if AI demand or customer ramps slow.
#term #substrate #Manufacturing #data

1 month ago
Applied Materials (NASDAQ:AMAT) primarily generates its revenue by designing, developing, manufacturing, and selling the critical fabrication equipment, specialized factory automation software, and materials engineering solutions utilized to produce integrated circuits for customers globally.
While launching multiple new hardware systems to address technical production challenges in advanced memory scaling, it formalized a joint development agreement for augmented reality optics and reported a 34% operating margin for the quarter ended July 26, 2026.
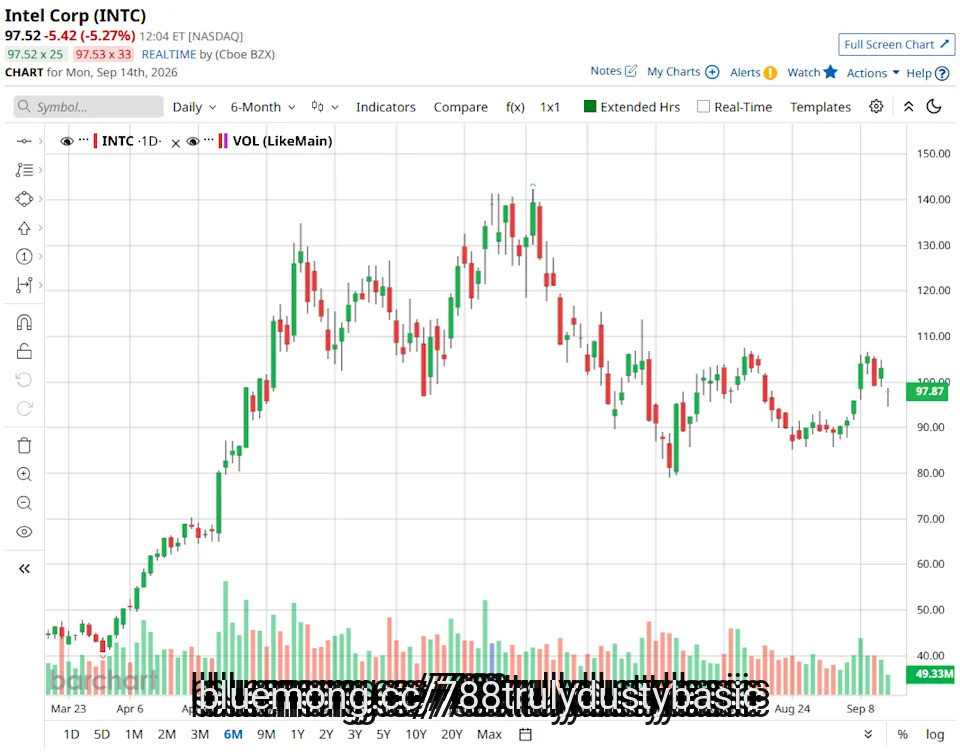
Intel (NASDAQ:INTC) primarily generates its revenue by designing, developing, and manufacturing commercial central processing units, discrete graphics processors, and edge computing components, alongside operating its independent wafer fabrication and advanced packaging services.
It finalized a large-scale public common stock offering and confirmed pending organizational workforce reductions within its data center operations, while reporting a 12% operating margin for the quarter ended June 27, 2026.
Revenue establishes a fundamental baseline for investors seeking to measure the total incoming capital a business generates before any operating expenses, interest, or taxes are deducted. This metric reveals whether an organization is successfully attracting customers and growing its overall business volume over time.
#generates #primarily


1 month ago
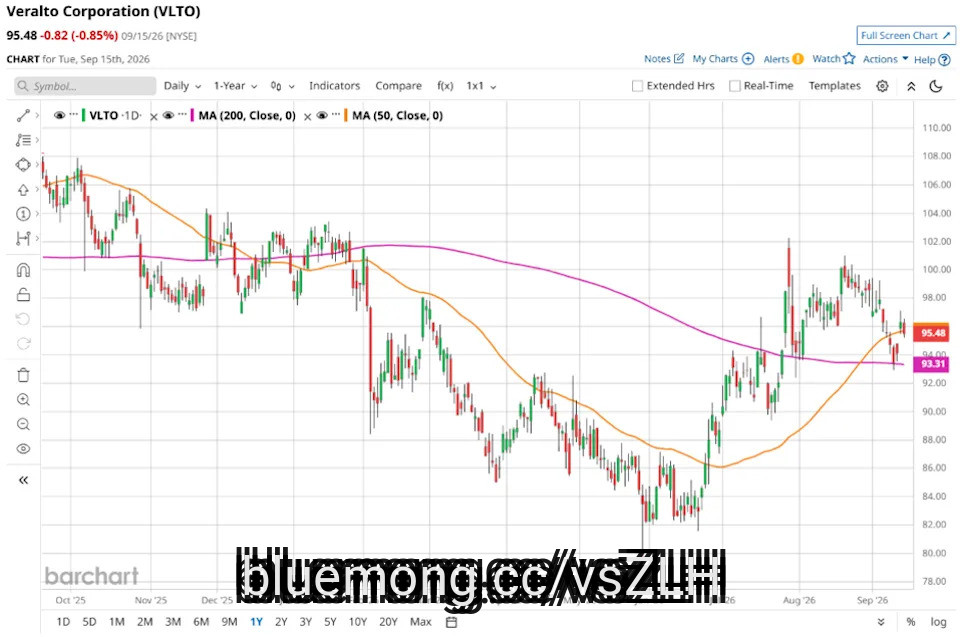
Veralto Corporation (VLTO), headquartered in Waltham, Massachusetts, provides water ******* ytics, water treatment, marking and coding, and packaging and color services. Valued at $23.3 billion by market cap, the company offers product quality control systems and water purification equipment.
Companies worth $10 billion or more are generally described as "large-cap stocks," and VLTO perfectly fits that description, with its market cap exceeding this mark, underscoring its size, influence, and dominance within the pollution & treatment controls industry. VLTO leads water quality and product quality & innovation with iconic brands like Hach, Trojan, ChemTreat, Videojet, Linx, Esko, X-Rite and Pantone, leveraging a large installed base to drive recurring consumables and software sales.
Billionaire Charlie Munger, Who Died at 99, Skipped Insurance on His Mansion Since He Could Just Write a Check to Rebuild — 'All Intelligent People Do It My Way'
Nvidia CEO Jensen Huang Just Dropped Huge News for This Cybersecurity Stock
How to Play GME Stock as GameStop CEO Ryan Cohen Buys $20.3 Million in Shares
#treatment #market #veralto



1 month ago
Exton, Pennsylvania-based West Pharmaceutical Services, Inc. (WST) designs, manufactures, and sells containment and delivery systems for injectable drugs and healthcare products. Valued at $25.7 billion by market cap, the company's technologies include the design and manufacture of packaging components, research and development of drug delivery systems, and contract laboratory services and other services.
Companies worth $10 billion or more are generally described as "large-cap stocks," and WST perfectly fits that description, with its market cap exceeding this mark, underscoring its size, influence, and dominance within the medical instruments & supplies industry. WST stands out as a market leader with a diversified portfolio serving pharma and healthcare.
Billionaire Charlie Munger, Who Died at 99, Skipped Insurance on His Mansion Since He Could Just Write a Check to Rebuild — 'All Intelligent People Do It My Way'
Nvidia CEO Jensen Huang Just Dropped Huge News for This Cybersecurity Stock
How to Play GME Stock as GameStop CEO Ryan Cohen Buys $20.3 Million in Shares
#Stock #billion


1 month ago
Cardinal Health, Inc. (CAH), headquartered in Dublin, Ohio, operates as a healthcare services and products company. Valued at $54.6 billion by market cap, the company's services include pharmaceutical distribution, health-care product manufacturing, distribution and consulting services, drug delivery systems development, pharmaceutical packaging, automated dispensing systems manufacturing, and retail pharmacy franchising.
Companies worth $10 billion or more are generally described as "large-cap stocks," and CAH perfectly fits that description, with its market cap exceeding this mark, underscoring its size, influence, and dominance within the medical distribution industry. As one of the top three U.S. pharma wholesalers, CAH holds a commanding market position. Its diversified pharmaceutical and medical distribution portfolio, broadens its customer base, adds resilience to market swings, and creates multiple revenue streams with cross-selling opportunities.
Billionaire Charlie Munger, Who Died at 99, Skipped Insurance on His Mansion Since He Could Just Write a Check to Rebuild — 'All Intelligent People Do It My Way'
Nvidia CEO Jensen Huang Just Dropped Huge News for This Cybersecurity Stock
How to Play GME Stock as GameStop CEO Ryan Cohen Buys $20.3 Million in Shares
#market #Health #Manufacturing #systems



1 month ago
Jim Cramer sees Seneca Foods Corporation (NASDAQ:SENEA) as an attractive food stock after its sharp rally, but he wants investors to leave room for a further pullback. During the September 10 episode of Mad Money, he noted that the shares had recently fallen about 11% from their high the previous week. He added:
Looking at the chart, you'd think this was an AI data center company. The stock's up 256% over the past three years, nearly 70% year to date.
Cramer said its appeal starts with its exposure to both branded and private-label products:
They don't care whether you're buying the premium nationally branded stuff or the cheap private-label knockoffs because they package everything.
Seneca reported fiscal first-quarter 2027 revenue of $405.2 million, up 36.2% year over year, while diluted EPS increased to $2.85 from $2.14. Management attributed the revenue growth to the Green Giant U.S. frozen acquisition, private-label growth and the timing of contract-packaging sales. Cramer credited the Green Giant transaction with helping drive the improvement after Seneca acquired B&G Foods' U.S. frozen business in March.
#seneca #giant

1 month ago
Mizuho has identified four clear tailwinds for Intel (INTC): ongoing CPU supply shortages, a stronger PC refresh cycle, accelerating demand for agentic AI, and growth in advanced packaging. Normally, such a setup would provide a reason to raise a price target. Instead, the firm cut its price target from $109 to $92, citing short-term multiple compression across Agentic AI stocks, and maintained a "Neutral" rating. The contradiction becomes more important because Intel's re-rating still depends on a foundry turnaround that has yet to prove itself.
Mizuho remains cautious on INTC stock despite outlining four separate tailwinds that could support the company's growth. The firm lowered its price target from $109 to $92 on Sept. 3, pointing to short-term multiple compression across agentic AI companies while keeping its "Neutral" rating unchanged. Mizuho **** yst Vijay Rakesh highlighted four developments that could support Intel's outlook. According to the **** yst, accelerating agentic AI demand could improve CPU-to-GPU ratios and drive additional server refreshers. Ongoing CPU supply constraints could also leave the company unable to fully meet demand through 2027. In addition, advanced packaging revenue is expected to reach $3.5 billion by 2029, with external foundry revenue potentially reaching a similar level through the 14A node. Finally, a stronger PC cycle could extend the upgrade cycle as corporate refreshes combine with ongoing memory tightness.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Billionaire Charlie Munger, Who Died at 99, Skipped Insurance on His Mansion Since He Could Just Write a Check to Rebuild — 'All Intelligent People Do It My Way'
The EV Bubble Has Burst. How to Play Rivian Stock Now.
#four


1 month ago
Carter's unveiled a new brand identity and marketing campaign on Tuesday, as the children's clothing company works to attract a younger generation of parents and build on a recent business turnaround.
The rebrand centers on a new brand promise — "Let every child's light shine" — and a refreshed logo in which a shooting star replaces the apostrophe in the Carter's wordmark, the company said. A new 60-second film called "Watch Them Glow" will debut across connected television as the first major marketing expression of the new direction.
Chief Marketing Officer Sarah Crockett told CNBC that the company sees a significant shift in its core customer base. Gen Z is expected to account for a large share of new parents over the next several years, according to Carter's, and those parents tend to let children make their own clothing choices and turn to social media for guidance.
"We had an opportunity to really tap into the values that parents are bringing into the household," Crockett told CNBC.
The new identity will begin rolling out across Carter's channels in 2026, with additional retail, product, and packaging elements to follow in 2027, the company said. Carter's is also launching a creator program called Light Makers, featuring voices across North America, and expanding partnerships with organizations including Outward Bound and Boys & Girls Clubs of America.
#parents #Marketing #cnbc #America

1 month ago
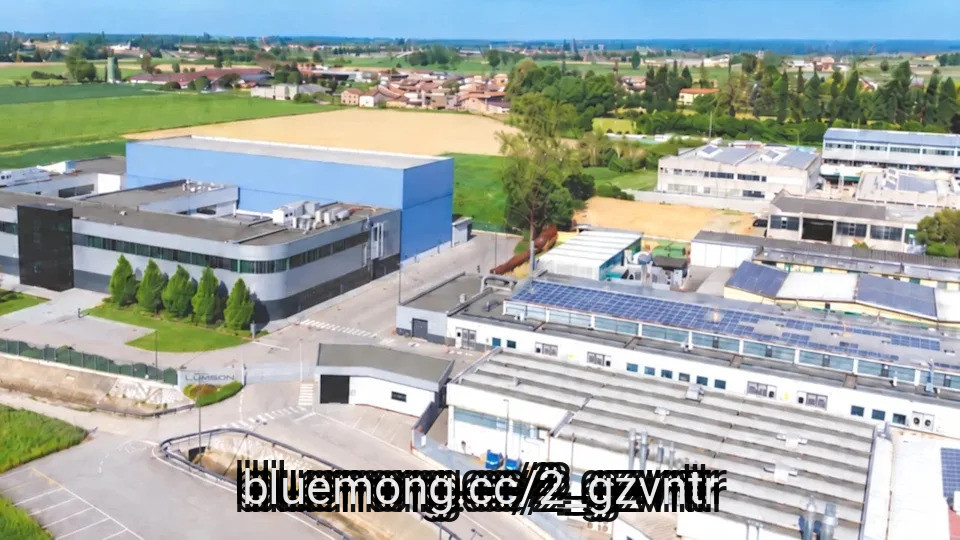
Lumson has purchased Lombardi Design and Manufacturing in the US, along with full ownership of Lombardi Design & MFG in Asia.
Financial terms of the deals remain undisclosed.
The deals form part of Lumson's wider international expansion plan and are intended to add to its industrial and technological capacity while extending its reach in primary packaging for the beauty and personal care sector.
With the two transactions, Lumson has a direct presence in Europe, North America and Asia.
The broader footprint will support work with international clients, help build industrial and commercial ties across markets, and open access to regions.
#financial #Europe

1 month ago
On August 6, PureCycle Technologies (NASDAQ:PCT) reported second-quarter results for the period ended June 30, and buried in the numbers was something the plastics recycler has chased for years: an actual branded product on store shelves. Select Downy detergent caps made with PureCycle's PureFive resin entered commercial production for Procter & Gamble during the quarter, the first tangible sign the company's purification technology can clear a major consumer brand's supply chain. Revenue came in at $4.5 million, up roughly 173% from a year earlier and the sixth straight quarter of sequential growth.
The Downy win was not an isolated event. PureCycle said select Tide caps are scheduled for retail production in the third quarter, with Vicks ZzzQuil PURE Zzzs child-resistant lids targeted for the fourth quarter of 2026. Seven customer conversions took place during the quarter, alongside six new commercial partnerships spanning closures, automotive, film, and food packaging, including Amcor, Motherson, and Innovia Films. Regulation is doing real work here too. New Jersey's Department of Environmental Protection approved PureFive as post-consumer recycled content, a decision that arrives as the state's food contact exemption expires in January 2027 and its recycled content requirement climbs to 20%, while California's SB54 is already in effect.
Operationally, the Ironton facility's planned turnaround finished ahead of schedule and under budget, with more than 170 reliability and rate projects completed and inspections showing no corrosion on major equipment. On-site compounding, commissioned in April, is now running 24 hours a day, five days a week, with plans to expand to seven by the fourth quarter. PureCycle also picked up ISO 9001:2015 certification in May and closed the quarter with $236.9 million in total liquidity after a June capital raise.
The other side of the ledger is harder to ignore. PureCycle posted a net loss of $142.2 million for the quarter, and adjusted EBITDA actually widened to a loss of $31.7 million from a loss of $27.8 million a year earlier, a shift the company attributes to smaller non-cash addbacks rather than weaker operations. PureFive production fell to 4.5 million pounds for the quarter, a direct result of the planned turnaround, even though output was still up about 32% from a year ago. Growth is not coming cheap either. Full-year 2026 project spending guidance was raised to a range of $45 million to $50 million, up from the prior $39 million to $45 million.
#year #loss


2 months ago
On August 13, a federal appeals court ruled in favor of Gilead Sciences, Inc. (NASDAQ:GILD), upholding a preliminary injunction that bars the defendants from importing or facilitating the sale of foreign-market Gilead-branded medications in the US. The US Court of Appeals for the Fourth Circuit found that the differences between Gilead's HIV medication for the US market and the foreign versions being imported were "material, not theoretical." The controversy began in December 2024 when Gilead Sciences, Inc. (NASDAQ:GILD) filed suit against a number of companies, including third-party administrator Meritain Health, pharmacy benefit manager ProAct, and pharmacies Rx Valet and Advanced Pharmacy, alleging illegal imports of its best-selling HIV drug Biktarvy.
The dispute dates back to December 2024, when Gilead Sciences, Inc. (NASDAQ:GILD) sued a group of companies, including third-party administrator Meritain Health, pharmacy benefit manager ProAct, and pharmacies Rx Valet and Advanced Pharmacy, alleging illegal imports of its top-selling HIV drug Biktarvy. The lawsuit arose from a specific instance in which a patient in Maryland received the medicine in the mail from Turkey, with label instructions written in Turkish.
A federal district court in Baltimore ruled in Gilead's favor and ordered a preliminary injunction, determining that the company was likely to succeed on its Lanham Act trademark violation and unfair competition arguments. As the case continued, the injunction was increased to include new sellers like CanaRx, ElectRx, and ScriptSourcing. The defendants filed an appeal with the Fourth Circuit, and the district judge declined to suspend the injunction while the appeal was pending, thus the import restriction has been in effect the entire time. The recent ruling maintains the order rather than overturning it.
In court documents, Rx Valet stated that the Turkish-sourced Biktarvy was chemically identical to the US version, which was offered at a significantly higher price. Meritain, for its part, said that it has never supported getting non-FDA-approved pharmaceuticals from outside the US and denies the claims, despite being named as a defendant.
The Fourth Circuit rejected the defendants' main argument that the imported and domestic versions of Biktarvy are interchangeable. The court's judgment that the two versions differ materially, not just in packaging or labeling, but also in the quality-control protocols that each version goes through before reaching a patient, challenges the basic argument that these alternative funding programs have used to support their business model.
#gild


2 months ago
Interested in Lam Research Corporation? Here are five stocks we like better.
Lam Research raised its 2026 wafer-fabrication equipment spending outlook to the low-$150 billion range from $135 billion-$140 billion, driven by sustained AI demand and expectations for eight to 10 new leading-edge fabs through 2027.
AI hardware is increasing equipment intensity, while advanced chip designs and packaging are expanding Lam's addressable market. The company cited growing opportunities in gate-all-around transistors, backside power delivery, advanced packaging and dry-resist technology.
Lam is accelerating capacity expansion, including a second Malaysia facility, as clean-room availability and supply-chain capacity constrain the industry. The company also expects NAND upgrades to accelerate, while targeting mid-50% gross margins and reporting record customer-support revenue.
From High Dividend Growth to High Yield, These 3 Stocks Just Boosted Dividend Payouts
#billion #Research #equipment #advanced

2 months ago
Christian Siriano teamed up with Alani Nu to create a one-of-a-kind couture gown inspired by the brand's cult-favorite Witch's Brew energy drink
The designer spoke to PEOPLE about the design process and how the gown was a "perfect" fit for his storybook-inspired spring/summer 2027 collection
The purple and green gown takes inspiration from the drink's iconic packaging
Christian Siriano's creativity knows no bounds.
As part of his spring/summer 2027 collection, which debuted at New York Fashion Week on Thursday, Sept. 10, the designer featured a one-of-a-kind couture gown inspired by Alani Nu's Witch's Brew — yes, the cult-favorite energy drink.
#gown #inspired #brew



2 months ago
Based in Midland, Michigan, Dow Inc. (DOW) is a global materials science leader that develops and manufactures chemicals, plastics, coatings, silicones, and other advanced materials used across industries ranging from packaging and construction to automotive, electronics, and consumer products.
Companies valued between $10 billion and $200 billion are typically classified as "large-cap stocks," and DOW, with a market capitalization of $21.4 billion, fits the label perfectly. Its key competitive advantage is its global scale, deep materials-science expertise, and broad portfolio of essential chemicals and advanced materials.
'Not Tens Of Billions, But Tens Of Trillions': Nvidia CEO Jensen Huang Says AI Is Like the New Electricity and the Scale Is Unlike Any Tech in History
What It Means for MSFT Stock Investors as Microsoft Switches to 2 Business Segments
RKLB Stock Jumps as Rocket Lab Debuts New Solar Cell for ******* e
#billion #science


2 months ago
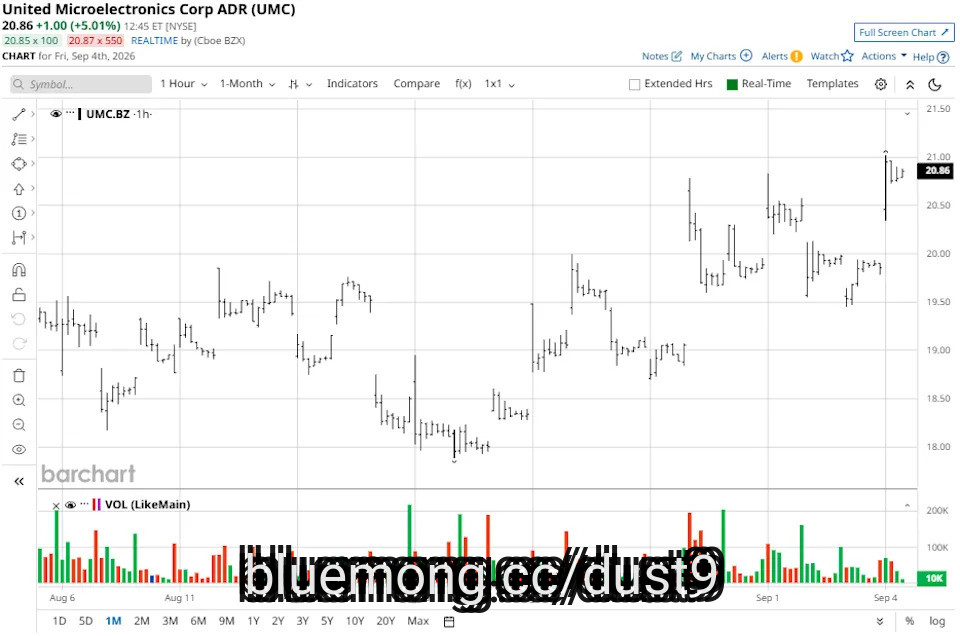
United Microelectronics (UMC) is a leading global semiconductor foundry founded in 1980 and headquartered in Hsinchu, Taiwan. The company specializes in advanced wafer fabrication, offering complementary metal-oxide semiconductor (CMOS) logic, mixed-signal, radiofrequency, embedded memory, high-voltage, and image sensor manufacturing services to a diverse global customer base. The company has increasingly focused on specialty semiconductor solutions spanning power management, connectivity, and advanced packaging, while expanding into silicon photonics to capture emerging demand related to artificial intelligence (AI).
UMC stock currently trades around $22, which is closer to the higher end of its 52-week range of $6.72 to $28.96, reflecting a dramatic rebound from multiyear lows earlier in the year. Shares have been volatile in recent sessions, popping on strong sales figures as investors weigh near-term margin pressures against long-term AI-driven capacity expansion plans.
Dear Nvidia Stock Fans, Mark Your Calendars for September 10
Rocket Lab Keeps Landing Defense Deals. Here's Why ***** ysts Aren't Getting More Bullish.
Why Stifel Just Revamped Its Price Target for Microsoft Stock
#semiconductor #united #taiwan



2 months ago
It looks like the American consumer has more to worry about than food recalls and cyclospora—a new study found that even the packaging the food comes in may pose some health concerns.
Out of over 15,000 food contact chemicals (FCCs), 1,222 or 8% can pose serious health risks, according to a recent study published in the peer-reviewed journal Environmental Science & Technology. Some of these FCCs, which in general are "substances that come into contact with food, such as through food packaging, processing, storage or other handling," per the FDA, were found to be hazardous to human health.
Researchers from the nonprofit Food Packaging Forum Foundation, which conducted the study, found at least 2,160 chemicals regularly contact food and "migrate into foodstuffs." Using guidelines from the UN's Globally Harmonized System of Classification and Labeling of Chemicals (GHS), researchers found some of the chemicals related to food packaging and other materials were "carcinogenic, mutagenic, toxic to reproduction, harmful to specific organs after repeated exposure, [and] endocrine disrupting."
That's not the only concerning part. The researchers found that 13,211 of the 15,159 known food-contact chemicals lacked harmonized hazard data. That means the scientists could not determine from the available data whether those chemicals met the study's criteria for being hazardous.
"There's a lot of ways of establishing whether something is hazardous or not, and some methods are based very much just on computer models, looking at the structure, predicting something. And others are based on in vitro tests," Dr. Helene Wiesinger, scientific communication officer at the nonprofit and one of the researchers on the study, told Fortune. "And in some sense, the data that we used?' So this is the data we used, and the problem we ran into at that point was that there were huge data lags."
#Food #study #contact

0.00$ raised of 0.00$ goal
0 donations
0.00$
to go

2 months ago
On August 6, Nova (NASDAQ:NVMI) reported second-quarter 2026 results for the three months ended June 30, and the numbers marked a new high point for the semiconductor metrology company. Revenue hit $255.0 million, up 8% from the first quarter of 2026 and 16% higher than the second quarter of 2025. GAAP net income reached $75 million, while non-GAAP net income climbed to $86.5 million. For a company built around measuring the tiniest details in chip manufacturing, the quarter itself was anything but small.
The headline figures tell part of the story, but the breakdown underneath is where the quarter gets interesting. GAAP earnings per diluted share reached $2.20 in the second quarter of 2026, up from $2.04 in the first quarter of 2026 and $2.14 a year earlier in the second quarter of 2025. Non-GAAP earnings per diluted share went further, hitting $2.51 in the second quarter of 2026 compared with $2.33 in the first quarter of 2026 and $2.20 in the second quarter of 2025. That is back-to-back sequential growth on both a GAAP and non-GAAP basis, not just a single strong quarter against an easy comparison.
Two product lines did the heavy lifting. Nova posted record revenue from its advanced logic devices business, which it tied to the industry's shift toward Gate-All-Around transistor architecture and rising demand for advanced process nodes. Advanced packaging solutions also hit a record, supported by capacity additions across both logic and memory manufacturing. Those are two distinct growth engines firing in the same quarter, which matters more than a single hot product line would.
Management is not treating this as a one-off. For the third quarter of 2026, the period ending September 30, Nova guided to revenue of $277 million to $287 million, GAAP diluted EPS of $2.46 to $2.61, and non-GAAP diluted EPS of $2.70 to $2.85. At the midpoint, that outlook points to another double-digit sequential jump in sales. President and CEO Gaby Waisman framed the quarter as validation of the company's long-term plan, citing broad-based customer demand, continued market share gains, and deeper engagement across leading-edge device segments as the drivers behind what he described as increased visibility into coming quarters.
The results were not clean across every line. Gross margin came in at 56.5% in the second quarter of 2026, down from 57.7% in the first quarter of 2026 and 57.8% in the second quarter of 2025. That is a decline on both a sequential and year-over-year basis even as revenue set records, which means the mix of what Nova sold this quarter carried lower profitability than what it sold a year ago.
#quarter #gaap

2 months ago
A B Graphic International (ABG) has renamed Enprom Solutions as ABG Girona, as part of the continued integration of its Spain-based operation into the wider group.
The move follows the 2019 acquisition of the business by ABG and Kocher+Beck and affirms the site as the group's centre of excellence for flexible packaging.
Based in Girona, the operation designs and builds machinery, converting systems, sleeve products and automated production lines for the flexible packaging and label sectors.
Within the ABG group, the Girona business is set to take on a larger role in flexible packaging work, including the FlexPack range.
The name change is intended to clarify the Girona operation's position within the group for customers while retaining the technical knowledge developed by the existing team.
#packaging #based #business #international
2 months ago
AMD gained 4.7% and Intel rose 4.5% on September 4, while Nvidia added only 0.8%. The one-session gap is consistent with investors widening the AI trade beyond Nvidia, but it cannot identify buyer motive or prove a lasting rotation. Advanced Micro Devices, Inc. (NASDAQ:AMD) and Intel Corporation (NASDAQ:INTC) each offer a route to AI spending that does not require Nvidia to lose outright.
AMD's second-quarter revenue reached a record $11.5 billion, up 50% year over year, and Data Center represented 58% of the company. Its portfolio includes MI450 accelerators, sixth-generation EPYC processors, Helios rack-scale systems, and Pensando networking. Customers seeking a credible second source and more negotiating leverage support the bull case. The countercase is software maturity, execution across a broad roadmap, and the capital required to challenge Nvidia's ecosystem.
Insider Monkey's database counted 164 hedge funds holding Advanced Micro Devices, Inc. (NASDAQ:AMD) in Q2 2026, up from 134 in Q1 2026. Marshall Wace reported 3,898,210 shares, about 3% more than in Q1. The quarter-end filings predate the September 4 rally and cannot show whether funds reacted to it.
Intel's second-quarter Data Center and AI revenue was $6.3 billion, up 59% year over year. A resilient CPU franchise, custom silicon, advanced packaging, and a domestic foundry network form the bull case. The cost and uncertain returns of rebuilding manufacturing leadership form the bear case. Intel generated $1.8 billion of GAAP operating income, while its $2.16 GAAP loss per share was driven largely by a $12.5 billion noncash mark-to-market loss on escrowed shares. Negative $8.4 billion adjusted free cash flow still makes capital efficiency a real concern.
The Q2 2026 database counted 138 hedge funds holding Intel Corporation (NASDAQ:INTC), up from 112 in Q1 2026. AQR Capital Management reported 10,742,567 shares after cutting its position by about 6% from Q1. That disclosure also predates the September rally, so it is historical positioning rather than a reaction.
#billion #advanced #quarter


2 months ago
On August 6, Nova (NASDAQ:NVMI) reported second-quarter 2026 results for the three months ended June 30, and the numbers marked a new high point for the semiconductor metrology company. Revenue hit $255.0 million, up 8% from the first quarter of 2026 and 16% higher than the second quarter of 2025. GAAP net income reached $75 million, while non-GAAP net income climbed to $86.5 million. For a company built around measuring the tiniest details in chip manufacturing, the quarter itself was anything but small.
The headline figures tell part of the story, but the breakdown underneath is where the quarter gets interesting. GAAP earnings per diluted share reached $2.20 in the second quarter of 2026, up from $2.04 in the first quarter of 2026 and $2.14 a year earlier in the second quarter of 2025. Non-GAAP earnings per diluted share went further, hitting $2.51 in the second quarter of 2026 compared with $2.33 in the first quarter of 2026 and $2.20 in the second quarter of 2025. That is back-to-back sequential growth on both a GAAP and non-GAAP basis, not just a single strong quarter against an easy comparison.
Two product lines did the heavy lifting. Nova posted record revenue from its advanced logic devices business, which it tied to the industry's shift toward Gate-All-Around transistor architecture and rising demand for advanced process nodes. Advanced packaging solutions also hit a record, supported by capacity additions across both logic and memory manufacturing. Those are two distinct growth engines firing in the same quarter, which matters more than a single hot product line would.
Management is not treating this as a one-off. For the third quarter of 2026, the period ending September 30, Nova guided to revenue of $277 million to $287 million, GAAP diluted EPS of $2.46 to $2.61, and non-GAAP diluted EPS of $2.70 to $2.85. At the midpoint, that outlook points to another double-digit sequential jump in sales. President and CEO Gaby Waisman framed the quarter as validation of the company's long-term plan, citing broad-based customer demand, continued market share gains, and deeper engagement across leading-edge device segments as the drivers behind what he described as increased visibility into coming quarters.
The results were not clean across every line. Gross margin came in at 56.5% in the second quarter of 2026, down from 57.7% in the first quarter of 2026 and 57.8% in the second quarter of 2025. That is a decline on both a sequential and year-over-year basis even as revenue set records, which means the mix of what Nova sold this quarter carried lower profitability than what it sold a year ago.
#second #diluted #advanced

2 months ago
Palantir shares gained 7.7% on September 3, the same day PwC US expanded an alliance built around enterprise AI, M&A, and ERP modernization. The companies described an AI-native deals platform intended to execute transactions up to 50% faster and cut one-time costs by as much as 45%, but disclosed no new contract value. The same day, Globant introduced a MuleSoft AI Pod for Salesforce integration. Palantir Technologies Inc. (NASDAQ:PLTR) and Globant S.A. (NYSE:GLOB) are packaging expertise around software in very different ways.
Palantir's bull case is productized delivery. PwC can bring industry relationships and implementation capacity, while Foundry and AIP remain the recurring platform. Palantir's Q2 revenue rose 93% to $1.94 billion, including 149% growth in U.S. commercial revenue, so the alliance lands on real momentum. Arrowstreet Capital held 20,517,115 shares at June 30 after increasing its stake by 97%.
The valuation is the obvious counterweight. A partnership announcement without disclosed revenue cannot by itself justify a large daily move. Receivables concentration, stock-based compensation, and competition from clouds and consultants deserve attention. Hedge-fund breadth had already weakened: Insider Monkey counted 86 funds holding Palantir at June 30, down from 96 at March 31.
Globant's AI Pod offers a more explicit delivery unit. Configurations support roughly six, 12, or 24 integration flows or APIs per month, and the company cited benchmarks including up to 80% automation and 15% to 25% faster time to value. That makes capacity tangible. Twenty-three hedge funds held Globant S.A. (NYSE:GLOB) in Q2, down from 25 in Q1. Pzena Investment Management reported 3,859,718 shares after adding 31%.
Globant's problem is that reusable pods can still be labor businesses. The service remains on a waitlist, the benchmark outcomes are not guaranteed customer results, and AI may pressure billing rates even as it improves productivity.
#glob

2 months ago
Palantir shares gained 7.7% on September 3, the same day PwC US expanded an alliance built around enterprise AI, M&A, and ERP modernization. The companies described an AI-native deals platform intended to execute transactions up to 50% faster and cut one-time costs by as much as 45%, but disclosed no new contract value. The same day, Globant introduced a MuleSoft AI Pod for Salesforce integration. Palantir Technologies Inc. (NASDAQ:PLTR) and Globant S.A. (NYSE:GLOB) are packaging expertise around software in very different ways.
Palantir's bull case is productized delivery. PwC can bring industry relationships and implementation capacity, while Foundry and AIP remain the recurring platform. Palantir's Q2 revenue rose 93% to $1.94 billion, including 149% growth in U.S. commercial revenue, so the alliance lands on real momentum. Arrowstreet Capital held 20,517,115 shares at June 30 after increasing its stake by 97%.
The valuation is the obvious counterweight. A partnership announcement without disclosed revenue cannot by itself justify a large daily move. Receivables concentration, stock-based compensation, and competition from clouds and consultants deserve attention. Hedge-fund breadth had already weakened: Insider Monkey counted 86 funds holding Palantir at June 30, down from 96 at March 31.
Globant's AI Pod offers a more explicit delivery unit. Configurations support roughly six, 12, or 24 integration flows or APIs per month, and the company cited benchmarks including up to 80% automation and 15% to 25% faster time to value. That makes capacity tangible. Twenty-three hedge funds held Globant S.A. (NYSE:GLOB) in Q2, down from 25 in Q1. Pzena Investment Management reported 3,859,718 shares after adding 31%.
Globant's problem is that reusable pods can still be labor businesses. The service remains on a waitlist, the benchmark outcomes are not guaranteed customer results, and AI may pressure billing rates even as it improves productivity.
#palantir #globant #shares #june

2 months ago
JBM Packaging has opened a 52,500ft² site in Lebanon, Ohio, US, approximately a mile from its main base, as it expands its contract packaging, kitting and filling activities.
The facility will support up to 50 additional jobs.
It will house operations that had previously been run from rented premises in Queensgate, where JBM began its contract packaging business in 2021.
The new building has 28ft clear-height ceilings, dense warehouse racking and a layout intended to improve the movement of materials and completed goods.
JBM said the move lifts total machine capacity by 50%, giving it scope to handle a larger share of customers' packaging requirements, including planning, production and distribution.
#contract
2 months ago
This story was originally published on QSR. To receive daily news and insights, subscribe to our free daily QSR AM Jolt.
SupplyCaddy has received growth investment from CEAS Investments, which is a partner in the business.
Established in 2020, SupplyCaddy supplies customised packaging and supply chain services to restaurant groups.
It currently works with more than 70 brands, among them sweetgreen, Dave's Hot Chicken, Huey Magoo's and Burger King, covering over 6,500 sites in North America and nine overseas markets.
The business collaborates with foodservice distribution groups such as Sysco, US Foods, Gordon Food Service, Performance Food Group, Imperial Dade and McLane.
#Food #groups #jolt #Investments
2 months ago
Freight broker FitzMark announced it has acquired United Transportation Services, a broker specializing in trade show logistics.
Founded in 1998, Aurora, Colorado-based UTS is a full-service 3PL focused on the retail and hospitality industries. It provides dry van, refrigerated, flatbed and specialty truckload transportation as well as packaging, warehousing and white-glove delivery services.
Financial terms of the transaction were not disclosed. The deal closed on Tuesday.
"Today marks an exciting new chapter— with the national support and strength of the FitzMark platform, we look forward to expanding capacity and service offerings while growing our shipper community together," said Bruce Parsons, CEO and president of UTS.
Indianapolis-based FitzMark provides brokerage services and a proprietary TMS to more than 3,000 shippers and 25,000 carriers. The company is backed by private equity firm Calera Capital.
#fitzmark #service #united


2 months ago
SK hynix (SKHY) is giving investors a fresh reason to watch its artificial intelligence (AI)-driven memory growth story as the South Korean chipmaker weighs expanding its manufacturing footprint into ****** an. The company is reportedly exploring a potential memory-chip joint venture, with Miyagi Prefecture among the locations seeking to attract the investment. SK hynix looks to capitalize on surging AI-driven demand while deepening relationships with ****** anese customers and suppliers, including through its indirect stake in Kioxia Holdings.
The potential ****** an expansion could become another important piece of SK hynix's global capacity strategy. The company is already investing heavily in South Korea and recently broke ground on a $4 billion advanced packaging facility in Indiana, underscoring its effort to secure supply as the memory shortage is expected to persist through 2030. Amid this, ****** an could be strategically attractive because it has an established semiconductor ecosystem, and its willingness to subsidize semiconductor investments could further support SK hynix's expansion plans.
Dear GameStop Stock Fans, Mark Your Calendars for September 8
SMCI vs. CoreWeave: 1 AI Infrastructure Model Has the Bigger Opportunity
Why ****** ysts Think Sellas Life Sciences Stock Can Gain 150% From Here
#Japan #driven



2 months ago
SK hynix (SKHY) is giving investors a fresh reason to watch its artificial intelligence (AI)-driven memory growth story as the South Korean chipmaker weighs expanding its manufacturing footprint into **** an. The company is reportedly exploring a potential memory-chip joint venture, with Miyagi Prefecture among the locations seeking to attract the investment. SK hynix looks to capitalize on surging AI-driven demand while deepening relationships with **** anese customers and suppliers, including through its indirect stake in Kioxia Holdings.
The potential **** an expansion could become another important piece of SK hynix's global capacity strategy. The company is already investing heavily in South Korea and recently broke ground on a $4 billion advanced packaging facility in Indiana, underscoring its effort to secure supply as the memory shortage is expected to persist through 2030. Amid this, **** an could be strategically attractive because it has an established semiconductor ecosystem, and its willingness to subsidize semiconductor investments could further support SK hynix's expansion plans.
Dear GameStop Stock Fans, Mark Your Calendars for September 8
SMCI vs. CoreWeave: 1 AI Infrastructure Model Has the Bigger Opportunity
Why **** ysts Think Sellas Life Sciences Stock Can Gain 150% From Here
#memory

2 months ago
Kaiser Aluminum Corporation (NASDAQ:KALU) has pulled back sharply from its recent highs, but UBS sees the weakness as a buying opportunity. On August 31, UBS upgraded Kaiser Aluminum from Neutral to Buy and raised its price target to $184 from $179. ******* yst Alex Stansbury argued that the selloff has created an attractive entry point into a business with improving earnings power.
UBS's upgrade to Buy from Neutral is based on the view that Kaiser Aluminum Corporation (NASDAQ:KALU)'s recent pullback has created an attractive entry point rather than signaling a deterioration in the company's long-term earnings outlook. ******* yst Alex Stansbury raised the price target to $184 from $179, arguing that the selloff has created an opportunity to buy a business with improving earnings power.
The most important part of UBS's argument is that several of the pressures weighing on Kaiser's shares appear temporary. Stansbury specifically pointed to scrap as a meaningful tailwind while also saying that the company's underlying fundamentals are strengthening. That is important because UBS is not relying solely on higher aluminum prices to support its bullish view. Instead, the bank sees operational improvements and stronger end-market demand contributing to earnings growth.
UBS also highlighted the benefits of Kaiser's investments at Warrick and Trentwood. Those investments are increasingly relevant to the earnings story. Kaiser says its Warrick investment is designed to increase capacity for higher-margin coated packaging products, while its Trentwood modernization has focused on improving efficiency, capacity and the quality of products serving aerospace and general engineering customers.
The aerospace recovery is another key part of UBS's thesis. Stansbury pointed to the end of aerospace destocking and accelerating build rates, suggesting that an important headwind for Kaiser is beginning to reverse. That view is supported by Kaiser's latest results: the company said aerospace demand was strengthening as destocking eased, while second-quarter aerospace shipments increased year over year.
#kaiser #earnings #created #view


2 months ago
MD Sass, a boutique **** et management firm, published its second-quarter investor update for its flagship, the "MD Sass Concentrated Value Strategy." The letter can be downloaded here. In the first half of 2026, AI infrastructure stocks led the market, with the Russell 1000 Value increasing by 16.3%, outpacing the S&P 500 (10.2%) and Russell 1000 Growth (5.3%). This growth was fueled by semiconductor, memory, and hardware companies benefiting from AI development, even though they are considered cyclical. These sectors, representing only 7.7% of the Russell 1000 Value at the start of the year, contributed nearly 70% of its returns. The portfolio gained 10.0% in the second quarter, net of fees, compared to 13.9% for the Russell 1000 Value Index. Year-to-date, the strategy returned 6.6%, net of fees, versus 16.3% for the Index. The portfolio faced challenges due to limited exposure to companies with the greatest upside from AI infrastructure investments. It also lacked exposure to the Energy sector, which returned about 20% in the first half amid geopolitical tensions with Iran that increased commodity prices, affecting performance. The firm recognizes the importance of adapting its strategies while maintaining core investment principles as it explores future opportunities in emerging technological themes. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, MD Sass Concentrated Value Strategy highlighted Primo Brands Corporation (NYSE:PRMB) as a notable contributor. Primo Brands Corporation (NYSE:PRMB) operates as a branded beverage company in North America. On August 28, 2026, Primo Brands Corporation (NYSE:PRMB) closed at $23.00 per share. Over the past month, Primo Brands Corporation (NYSE:PRMB) returned 3.00%, while its shares have declined 8.40% in the last 52 weeks. Primo Brands Corporation (NYSE:PRMB) has a market capitalization of $8.32 billion, and its stock has traded within a 52-week range of $14.36 to $26.21.
MD Sass Concentrated Value Strategy stated the following regarding Primo Brands Corporation (NYSE:PRMB) in its Q2 2026 investor letter:
"The largest positive contributors to performance in Q2 were Primo Brands Corporation (NYSE:PRMB), Micron Technology (MU), and Henry Schein (HSIC), which collectively contributed approximately 382 bps. PRMB, a leading North American branded water company with a significant retail and home and office delivery business, declined 23% from its March 3 year-to-date peak amid concerns about commodity inflation following the onset of the conflict in Iran. Prices for plastic resins and other oil-related inputs rose sharply from the end of February through mid-April, raising concerns that PRMB would need to cut guidance given its exposure to PET resin and other packaging costs. The company's May 7 financial results and earnings call provided a big sigh of relief. Management explained that a combination of hedging, forward purchase agreements





