

2 months ago
On September 15, Arthur J. Gallagher & Co. (NYSE:AJG) announced that it had bought McMillan Insurance & Bonding Inc., an Englewood, Colorado, firm that operates as Innovise Business Consultants. Gallagher did not say what it paid. On its own, the deal is a footnote. But it is one of many, and the way those deals show up in earnings is where the debate over this stock really lives.
On July 30, Gallagher reported results for the quarter ended June 30, and the top line was hard to argue with. Revenue from its combined Brokerage and Risk Management businesses grew 24%, and organic growth, which leaves out acquisitions, was 6%. That second number shows clients are staying and spending. It was not confined to one corner, either, since organic fees in the risk management arm rose 12%. Management adds that retention is strong and customers want broader help from the platform. Adjusted earnings per share climbed to $2.84 from $2.30, which means growth is reaching profit once one-time acquisition costs are set aside.
Innovise fits the pattern. It sells surety bonds and commercial insurance brokerage with a focus on manufacturing, energy, construction and real estate, and Chairman and CEO J. Patrick Gallagher, Jr. said that niche expertise adds depth in Colorado. Jason McMillan's team will move into Gallagher's Denver office and work under Bret VanderVoort, who oversees retail property/casualty brokerage for the Western Zone. Buying specialists and folding them into existing offices is a repeatable playbook, and Gallagher closed 14 brokerage acquisitions in the first six months of 2026.
Now look at reported earnings, because that is where you see the cost. Diluted earnings per share fell to $1.25, from $1.40 in the second quarter of 2025, even though revenue jumped. Much of the gap between reported and adjusted results is the price of buying growth. Amortization of acquired intangibles alone weighs on brokerage net earnings by $218 million, up from $130 million a year ago, and integration costs rose as well. Adjusted figures set those aside, but they are real expenses, and they keep landing as long as Gallagher keeps buying.
Margins tell a similar story. The brokerage segment's adjusted EBITDAC margin, a stand-in for operating profit, slipped to 33.3% from 36.1%. Gallagher points to last year's interest income on cash raised for the ***** uredPartners deal, which closed in the third quarter of 2025, plus seasonality and newly added tuck-ins. That is a fair explanation. But the debt behind the deal is still here, including $9.55 billion of public debt, plus more in private placements and on a credit line. And the deal flow is thinner: brokerage acquisitions closed in the first six months of 2026 carried $107 million of annualized revenue, versus $354 million a year earlier, which puts more weight on organic growth.
#Growth
On July 30, Gallagher reported results for the quarter ended June 30, and the top line was hard to argue with. Revenue from its combined Brokerage and Risk Management businesses grew 24%, and organic growth, which leaves out acquisitions, was 6%. That second number shows clients are staying and spending. It was not confined to one corner, either, since organic fees in the risk management arm rose 12%. Management adds that retention is strong and customers want broader help from the platform. Adjusted earnings per share climbed to $2.84 from $2.30, which means growth is reaching profit once one-time acquisition costs are set aside.
Innovise fits the pattern. It sells surety bonds and commercial insurance brokerage with a focus on manufacturing, energy, construction and real estate, and Chairman and CEO J. Patrick Gallagher, Jr. said that niche expertise adds depth in Colorado. Jason McMillan's team will move into Gallagher's Denver office and work under Bret VanderVoort, who oversees retail property/casualty brokerage for the Western Zone. Buying specialists and folding them into existing offices is a repeatable playbook, and Gallagher closed 14 brokerage acquisitions in the first six months of 2026.
Now look at reported earnings, because that is where you see the cost. Diluted earnings per share fell to $1.25, from $1.40 in the second quarter of 2025, even though revenue jumped. Much of the gap between reported and adjusted results is the price of buying growth. Amortization of acquired intangibles alone weighs on brokerage net earnings by $218 million, up from $130 million a year ago, and integration costs rose as well. Adjusted figures set those aside, but they are real expenses, and they keep landing as long as Gallagher keeps buying.
Margins tell a similar story. The brokerage segment's adjusted EBITDAC margin, a stand-in for operating profit, slipped to 33.3% from 36.1%. Gallagher points to last year's interest income on cash raised for the ***** uredPartners deal, which closed in the third quarter of 2025, plus seasonality and newly added tuck-ins. That is a fair explanation. But the debt behind the deal is still here, including $9.55 billion of public debt, plus more in private placements and on a credit line. And the deal flow is thinner: brokerage acquisitions closed in the first six months of 2026 carried $107 million of annualized revenue, versus $354 million a year earlier, which puts more weight on organic growth.
#Growth


2 months ago
Property and casualty insurer Progressive (NYSE: PGR) is probably best known for selling auto insurance. That's a highly competitive segment of the industry, but the company has proven its chops, reporting a strong combined ratio of 87.3% in the second quarter of 2026. Is the roughly 10% pullback from the 52-week high, and about 25% drawdown from 2025's peak, as of this writing, enough to make the stock a buy? Probably not if you are a value investor.
The combined ratio is a measure of profitability in the insurance sector, with numbers below 100% indicating that a company is earning more from premiums than it costs to support those premiums and cover claims. Progressive has a strong history of running its business well on this front. Basically, it is a good business. But paying too much for a good business can turn it into a bad investment, as Benjamin Graham was fond of saying (Graham notably helped train Warren Buffett).
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
So the real question here is whether the drawdowns noted above were sufficient to make Progressive's valuation attractive. The answer there isn't clean cut. For example, the price-to-sales ratio of 1.4x is in the middle of the historical range of roughly 0.5x to 2.2x. If anything, the P/S ratio is kind of toward the high side. The same general story holds with the price-to-book ratio. So these two metrics hint at a stock that isn't expensive, but it also isn't trading at bargain-basement prices.
The price-to-earnings ratio is a bit more positive, with the 11.1x P/E toward the lower end of its historical range. And the average insurance company has a P/E ratio of around 11.8x, so this makes Progressive look reasonably priced. Only Progressive's P/B ratio is 3.7x compared to the industry average of 1.7x, so the broader industry comparison still isn't a clear-cut win.
#ratio #progressive
The combined ratio is a measure of profitability in the insurance sector, with numbers below 100% indicating that a company is earning more from premiums than it costs to support those premiums and cover claims. Progressive has a strong history of running its business well on this front. Basically, it is a good business. But paying too much for a good business can turn it into a bad investment, as Benjamin Graham was fond of saying (Graham notably helped train Warren Buffett).
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
So the real question here is whether the drawdowns noted above were sufficient to make Progressive's valuation attractive. The answer there isn't clean cut. For example, the price-to-sales ratio of 1.4x is in the middle of the historical range of roughly 0.5x to 2.2x. If anything, the P/S ratio is kind of toward the high side. The same general story holds with the price-to-book ratio. So these two metrics hint at a stock that isn't expensive, but it also isn't trading at bargain-basement prices.
The price-to-earnings ratio is a bit more positive, with the 11.1x P/E toward the lower end of its historical range. And the average insurance company has a P/E ratio of around 11.8x, so this makes Progressive look reasonably priced. Only Progressive's P/B ratio is 3.7x compared to the industry average of 1.7x, so the broader industry comparison still isn't a clear-cut win.
#ratio #progressive


2 months ago
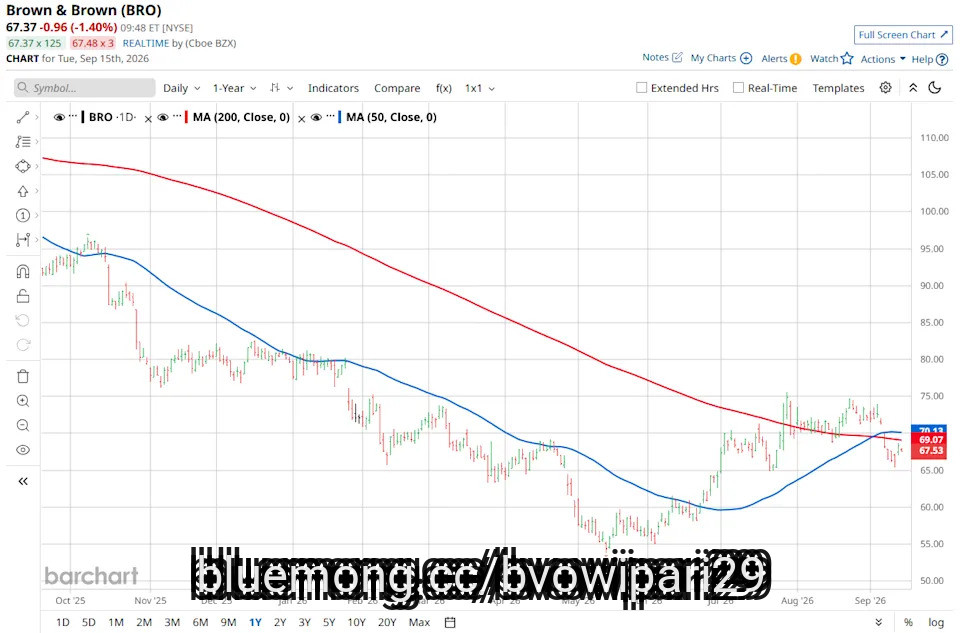
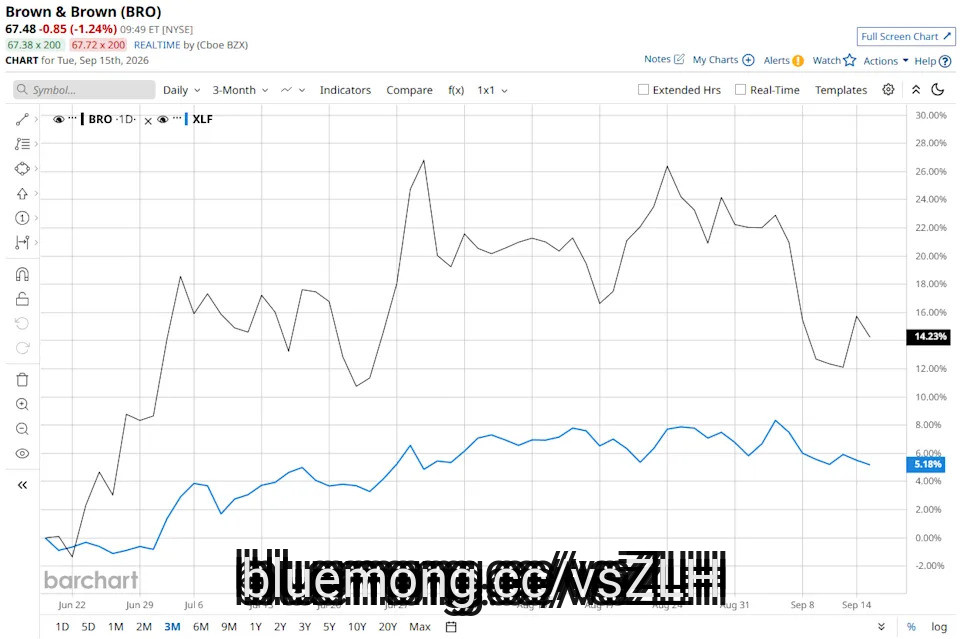
Daytona Beach, Florida-based Brown & Brown, Inc. (BRO) markets and sells insurance products and services in the United States and internationally. Valued at a market cap of $22.9 billion, the company operates through Retail and Specialty Distribution segments and provides property and casualty insurance, employee benefits insurance, personal insurance, specialty insurance, and more.
Companies with a market cap of $10 billion or more are typically called "large-cap stocks." BRO fits squarely into that category, with a market cap above this threshold that reflects its substantial size and influence in the insurance brokers industry.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Morgan Stanley Doubles Down on Apple Stock as New Offerings Become 'More Exciting'
The EV Bubble Has Burst. How to Play Rivian Stock Now.
#market #Stock #daytona #united
Companies with a market cap of $10 billion or more are typically called "large-cap stocks." BRO fits squarely into that category, with a market cap above this threshold that reflects its substantial size and influence in the insurance brokers industry.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Morgan Stanley Doubles Down on Apple Stock as New Offerings Become 'More Exciting'
The EV Bubble Has Burst. How to Play Rivian Stock Now.
#market #Stock #daytona #united

2 months ago
Daytona Beach, Florida-based Brown & Brown, Inc. (BRO) markets and sells insurance products and services in the United States and internationally. Valued at a market cap of $22.9 billion, the company operates through Retail and Specialty Distribution segments and provides property and casualty insurance, employee benefits insurance, personal insurance, specialty insurance, and more.
Companies with a market cap of $10 billion or more are typically called "large-cap stocks." BRO fits squarely into that category, with a market cap above this threshold that reflects its substantial size and influence in the insurance brokers industry.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Morgan Stanley Doubles Down on Apple Stock as New Offerings Become 'More Exciting'
The EV Bubble Has Burst. How to Play Rivian Stock Now.
#brown #beach #united
Companies with a market cap of $10 billion or more are typically called "large-cap stocks." BRO fits squarely into that category, with a market cap above this threshold that reflects its substantial size and influence in the insurance brokers industry.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Morgan Stanley Doubles Down on Apple Stock as New Offerings Become 'More Exciting'
The EV Bubble Has Burst. How to Play Rivian Stock Now.
#brown #beach #united


2 months ago
NFP, the Aon-owned property and casualty (P&C) broker and benefits consultant, has acquired Moores Insurance Management, a multi-disciplinary risk management company based in Minnesota, US.
Established in 1987, Moores works with high-net-worth (HNW) individuals and businesses in 43 states, offering P&C insurance services to both commercial and personal-risk clients.
Under the agreement, Moores CEO Mark Moores will take on the role of senior vice-president, commercial P&C at NFP, reporting to Amanda Ruback, the company's managing director of P&C for the central region.
NFP personal risk president Brett Woodward said: "Moores is a long-standing risk management firm and this addition further establishes our presence in the Minnesota market and positions us well to continue delivering P&C insurance solutions for high-net-worth and commercial clients."
Jack Moores, who serves as president of Moores, will join NFP as senior vice-president of personal lines.
#moores
Established in 1987, Moores works with high-net-worth (HNW) individuals and businesses in 43 states, offering P&C insurance services to both commercial and personal-risk clients.
Under the agreement, Moores CEO Mark Moores will take on the role of senior vice-president, commercial P&C at NFP, reporting to Amanda Ruback, the company's managing director of P&C for the central region.
NFP personal risk president Brett Woodward said: "Moores is a long-standing risk management firm and this addition further establishes our presence in the Minnesota market and positions us well to continue delivering P&C insurance solutions for high-net-worth and commercial clients."
Jack Moores, who serves as president of Moores, will join NFP as senior vice-president of personal lines.
#moores


2 months ago
On September 10, IBEX Limited (NASDAQ:IBEX) held its fourth-quarter and full fiscal year 2026 earnings call, and the numbers backed up a message management has been building toward for months. The company posted record full-year revenue, adjusted EBITDA, and free cash flow, all while pitching itself as a business that has flipped the AI narrative in its favor rather than becoming its next casualty. For a sector that has spent the last two years bracing for automation to gut it, that is a notable claim to back with actual client wins.
Full-year revenue hit $644.1 million, up 15.4% organically, and fourth-quarter revenue reached $164.3 million, up 11.6% from a year earlier. That marked the sixth straight quarter of double-digit growth, a streak that suggests the momentum is not a one-off. HealthTech led the charge, climbing 38.5% to $114 million for the year and blowing past the $100 million target management had set for the segment, driven largely by demand from large insurance payers. Technology grew 27.4% in the quarter, while travel and logistics added 17.8%, helped by a new AI agent partnership with Philippine Airlines.
That Philippine Airlines deal is the clearest evidence that IBEX's Sierra AI partnership, formalized in January and announced publicly in May, is more than a slide in an investor deck. During the proof of concept, the AI agent handled interactions in English, Tagalog, and Taglish, hit resolution rates above 20%, and scored a 4.7 out of 5.0 on customer satisfaction, on par with human agents. A separate deployment for BJ's Wholesale pushed resolution rates above 40% and matched that same satisfaction score, beating the marks the client's prior BPO vendor had put up with human agents alone. The company added 17 new trophy logo clients across the year, and its top five clients now make up 33% of revenue, down from 36%, a sign the business is not leaning on a shrinking handful of accounts to carry it.
Not every line moved in the right direction. Fourth quarter GAAP net income slipped to $8.7 million from $9.6 million a year earlier, and diluted EPS fell to $0.59 from $0.66. Management pointed to training costs tied to all those new client wins, a temporary hit from shifting work out of nearshore centers into offshore ones, and higher fuel prices hitting utility and transportation costs, particularly offshore. Adjusted EBITDA margin for the quarter slipped to 12.3% from 13.9%, the same set of pressures showing up in the profitability line rather than just net income.
#revenue #fourth
Full-year revenue hit $644.1 million, up 15.4% organically, and fourth-quarter revenue reached $164.3 million, up 11.6% from a year earlier. That marked the sixth straight quarter of double-digit growth, a streak that suggests the momentum is not a one-off. HealthTech led the charge, climbing 38.5% to $114 million for the year and blowing past the $100 million target management had set for the segment, driven largely by demand from large insurance payers. Technology grew 27.4% in the quarter, while travel and logistics added 17.8%, helped by a new AI agent partnership with Philippine Airlines.
That Philippine Airlines deal is the clearest evidence that IBEX's Sierra AI partnership, formalized in January and announced publicly in May, is more than a slide in an investor deck. During the proof of concept, the AI agent handled interactions in English, Tagalog, and Taglish, hit resolution rates above 20%, and scored a 4.7 out of 5.0 on customer satisfaction, on par with human agents. A separate deployment for BJ's Wholesale pushed resolution rates above 40% and matched that same satisfaction score, beating the marks the client's prior BPO vendor had put up with human agents alone. The company added 17 new trophy logo clients across the year, and its top five clients now make up 33% of revenue, down from 36%, a sign the business is not leaning on a shrinking handful of accounts to carry it.
Not every line moved in the right direction. Fourth quarter GAAP net income slipped to $8.7 million from $9.6 million a year earlier, and diluted EPS fell to $0.59 from $0.66. Management pointed to training costs tied to all those new client wins, a temporary hit from shifting work out of nearshore centers into offshore ones, and higher fuel prices hitting utility and transportation costs, particularly offshore. Adjusted EBITDA margin for the quarter slipped to 12.3% from 13.9%, the same set of pressures showing up in the profitability line rather than just net income.
#revenue #fourth

2 months ago
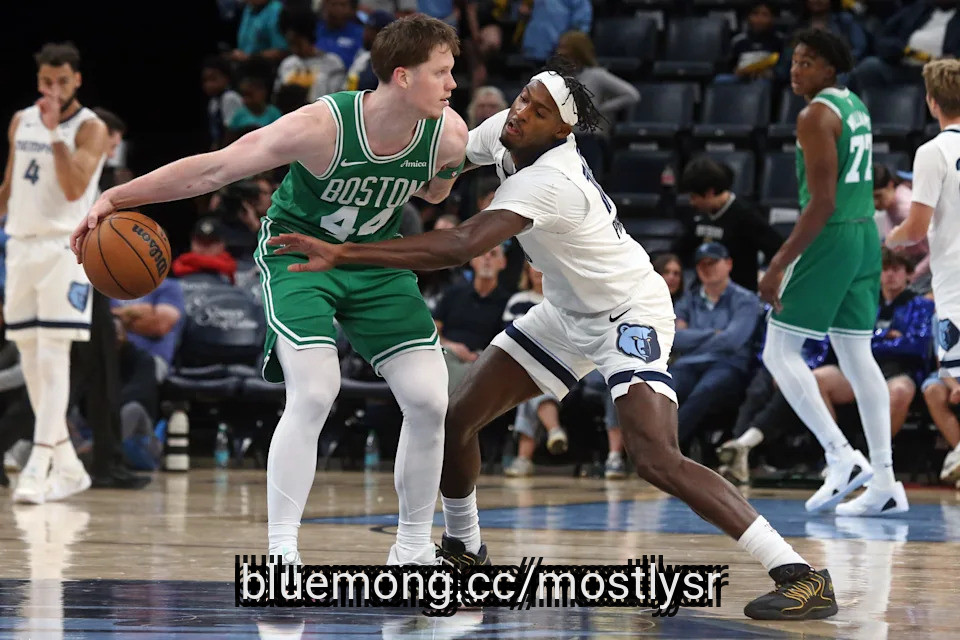
The Boston Celtics have reportedly signed Devin Carter to a training camp deal, per HoopsHype's Michael Scotto. Carter, 24, will have the opportunity to either earn a spot on Boston's main NBA roster or to join Amari Williams and Dillon Mitchell as one of the Celtics' three two-way talents. Should he sign a two-way deal, he would be expected to spend the majority of the season with the Maine Celtics. Still, it's fair to ******* ume he'd get a chance to impress with the NBA roster at some point, too.
Unfortunately, the decision to sign Carter doesn't come without a potential roster casualty. Milos Uzan has been with the Celtics since signing an Exhibit 10 contract earlier this summer. Uzan instantly impressed when suiting up for the Celtics during Las Vegas Summer League, where he averaged 9.2 points, 4.2 rebounds and 4 ******* ists per game, shooting 36.8 percent from 3-point range and 38.1 percent from the field.
Following John Tonje's decision to join the Portland Trail Blazers on a two-way deal earlier in the offseason, the path for Uzan to earn the final two-way spot with the Celtics appeared wide open. Sure, he'd have to impress during training camp and beat out Tucker DeVries, but given Boston's need for a depth piece at guard, everything seemed to be lining up.
Now, with Carter also in the mix, Uzan is facing a far tougher battle to prove himself and earn a two-way spot with the Celtics. Uzan is a talented young guard and should have no problem finding a home in the coming months if things do not go his way.
Hopefully, he remains in Maine regardless of whether he gets a two-way deal. After all, he could still work with the Celtics' developmental staff and potentially prove the front office wrong for signing Carter, should that come to pass. Of course, Uzan will likely draw interest from elsewhere if Carter does beat Uzan to the Celtics' final two-way spot, and unfortunately for Uzan, that's just part of trying to make it in the NBA.
#celtics #carter #deal #still
Unfortunately, the decision to sign Carter doesn't come without a potential roster casualty. Milos Uzan has been with the Celtics since signing an Exhibit 10 contract earlier this summer. Uzan instantly impressed when suiting up for the Celtics during Las Vegas Summer League, where he averaged 9.2 points, 4.2 rebounds and 4 ******* ists per game, shooting 36.8 percent from 3-point range and 38.1 percent from the field.
Following John Tonje's decision to join the Portland Trail Blazers on a two-way deal earlier in the offseason, the path for Uzan to earn the final two-way spot with the Celtics appeared wide open. Sure, he'd have to impress during training camp and beat out Tucker DeVries, but given Boston's need for a depth piece at guard, everything seemed to be lining up.
Now, with Carter also in the mix, Uzan is facing a far tougher battle to prove himself and earn a two-way spot with the Celtics. Uzan is a talented young guard and should have no problem finding a home in the coming months if things do not go his way.
Hopefully, he remains in Maine regardless of whether he gets a two-way deal. After all, he could still work with the Celtics' developmental staff and potentially prove the front office wrong for signing Carter, should that come to pass. Of course, Uzan will likely draw interest from elsewhere if Carter does beat Uzan to the Celtics' final two-way spot, and unfortunately for Uzan, that's just part of trying to make it in the NBA.
#celtics #carter #deal #still


2 months ago
Army dentists say war games omit dental emergencies that could strain wartime casualty evacuation.
Broken equipment and limited supplies can hinder field dental training opportunities.
Forward dental teams can treat patients quickly and return them to duty.
A painful toothache or an oral infection might not sound like an injury that could sideline a soldier in combat, but US Army dental leaders warn that in a future conflict, such easily overlooked conditions could take troops out of the fight, consume scarce evacuation capacity, and further stress a strained medical system.
Most of the Army's major exercises don't include dental emergencies in their casualty scenarios, dentists said in a recent professional article, leaving commanders with an incomplete picture of the medical and triage or evacuation demands they could face in large-scale combat.
#evacuation #army #casualty #combat
Broken equipment and limited supplies can hinder field dental training opportunities.
Forward dental teams can treat patients quickly and return them to duty.
A painful toothache or an oral infection might not sound like an injury that could sideline a soldier in combat, but US Army dental leaders warn that in a future conflict, such easily overlooked conditions could take troops out of the fight, consume scarce evacuation capacity, and further stress a strained medical system.
Most of the Army's major exercises don't include dental emergencies in their casualty scenarios, dentists said in a recent professional article, leaving commanders with an incomplete picture of the medical and triage or evacuation demands they could face in large-scale combat.
#evacuation #army #casualty #combat



2 months ago
LONDON, Sept 11 (Reuters) - Intelligence services must not dwell too much on past threats but accept that a new strategic shock along the lines of the 9/11 attacks could already be in preparation where they are not looking, the head of Britain's MI5 spy agency said.
In an opinion piece published on Friday to mark 25 years since al Qaeda militants crashed hijacked passenger jets into the World Trade Center in New York and the Pentagon, MI5's Director General Ken McCallum said security agencies had to be ready to adapt to current and future challenges.
"We know that the next strategic shock will, by definition, not resemble the last one. That is perhaps the most important lesson of all," McCallum wrote in the commentary for the Independent newspaper.
"We must of course always learn from the last attack – but must beware of preparing brilliantly to fight yesterday's enemy, using yesterday's methods, against yesterday's target ... The uncomfortable truth is that the next strategic shock may already be taking shape somewhere we are not yet looking."
Al Qaeda, though diminished, remains a threat, as does the aspiration of that group and other militants for mass casualty attacks, McCallum said.
#next
In an opinion piece published on Friday to mark 25 years since al Qaeda militants crashed hijacked passenger jets into the World Trade Center in New York and the Pentagon, MI5's Director General Ken McCallum said security agencies had to be ready to adapt to current and future challenges.
"We know that the next strategic shock will, by definition, not resemble the last one. That is perhaps the most important lesson of all," McCallum wrote in the commentary for the Independent newspaper.
"We must of course always learn from the last attack – but must beware of preparing brilliantly to fight yesterday's enemy, using yesterday's methods, against yesterday's target ... The uncomfortable truth is that the next strategic shock may already be taking shape somewhere we are not yet looking."
Al Qaeda, though diminished, remains a threat, as does the aspiration of that group and other militants for mass casualty attacks, McCallum said.
#next



2 months ago
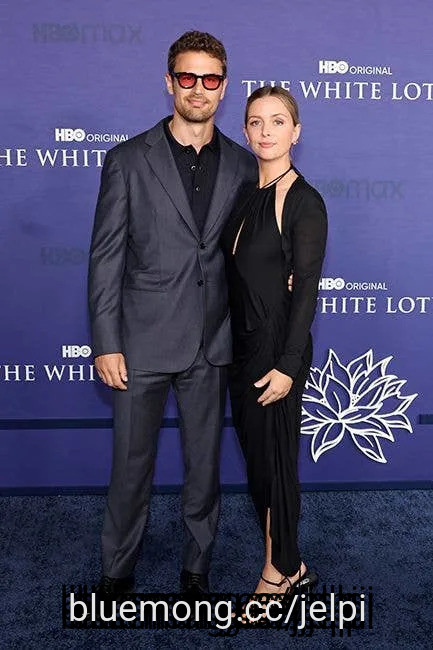
After a two-year wait, Theo James is back on our screens in the highly-anticipated second season of Netflix's The Gentlemen.
The 41-year-old actor stars as Eddie Horniman, the new Duke of Halstead who inherits the family's sweeping estate and discovers an industrial cannabis empire operating beneath it. The second season reunites viewers with faces old and new, including Kaya Scodelario, Vinnie Jones and newcomer Benedetta Porcaroli.
Theo has become a well-known face thanks to his roles in The Time Travellers Wife, Sanditon and plenty more – but did you know he has a wife who is pretty famous too? The actor married his wife six years ago and the pair are even proud parents. Here's all you need to know…
Ruth Kearney and Theo James in 2023 (@ Dave Benett, Getty)
Theo James is married to Irish actress Ruth Kearney. Ruth has a number of credits to her name that fans may recognise her from. In 2010, she began starring in ITV drama Primeval before going on to land parts in Casualty and American political drama Tyrant.
#james #wife
The 41-year-old actor stars as Eddie Horniman, the new Duke of Halstead who inherits the family's sweeping estate and discovers an industrial cannabis empire operating beneath it. The second season reunites viewers with faces old and new, including Kaya Scodelario, Vinnie Jones and newcomer Benedetta Porcaroli.
Theo has become a well-known face thanks to his roles in The Time Travellers Wife, Sanditon and plenty more – but did you know he has a wife who is pretty famous too? The actor married his wife six years ago and the pair are even proud parents. Here's all you need to know…
Ruth Kearney and Theo James in 2023 (@ Dave Benett, Getty)
Theo James is married to Irish actress Ruth Kearney. Ruth has a number of credits to her name that fans may recognise her from. In 2010, she began starring in ITV drama Primeval before going on to land parts in Casualty and American political drama Tyrant.
#james #wife


2 months ago
Eagle Capital Management, an investment management company, released its second quarter 2026 investor letter. A copy of the letter can be downloaded here. In the quarter, Eagle Capital Management discussed how enthusiasm around AI capital spending has driven strong S&P 500 earnings growth while also increasing risks from elevated valuations, concentrated demand, and aggressive investment ****** umptions. Eagle remains a strong believer in AI but prefers constructing a portfolio that can perform across multiple outcomes rather than relying on one forecast. The firm believes current earnings can overstate underlying economics because semiconductor equipment is depreciated over several years, while free cash flow growth remains much weaker. It also expects competition and additional capacity across AI labs, hyperscalers, and semiconductors to eventually create winners and losers. These dynamics are encouraging Eagle to recycle capital toward attractive opportunities outside the most crowded AI trades while maintaining selective exposure to high-quality beneficiaries. The portfolio trades at a 20% market discount with faster expected EPS growth. Please review the Strategy's top five holdings for key selections in 2026.
In its second-quarter 2026 investor letter, Eagle Capital Management highlighted Arthur J. Gallagher & Co. (NYSE:AJG). Arthur J. Gallagher & Co. (NYSE:AJG) provides insurance and reinsurance brokerage, consulting, and third-party property/casualty claims settlement and administration services to entities and individuals. On September 02, 2026, Arthur J. Gallagher & Co. (NYSE:AJG) closed at $264.46 per share. Over the past month, Arthur J. Gallagher & Co. (NYSE:AJG) was up 5.05%, while its shares lost 11.91% over the past 52 weeks. Arthur J. Gallagher & Co. (NYSE:AJG) has a market capitalization of $67.78 billion.
Eagle Capital Management stated the following regarding Arthur J. Gallagher & Co. (NYSE:AJG) in its Q2 2026 investor letter:
"High quality with low volatility (24% of capital): London Stock Exchange, Danaher, S&P Global, Mastercard, A.J. Gallagher: Approximately a quarter of Eagle's portfolio is spread across a handful of superb businesses that exhibit high and stable margins, strong returns on capital, wide competitive advantages, and well above GDP growth. We expect the group to deftly navigate the integration of AI into their markets. Most operate with a combination of oligopoly/monopoly ****** ets, network effects, or regulatory moats. A.J. Gallagher is a commercial insurance broker that continues to gain share in a consolidating industry.
A few years ago, these stocks were priced for perfection. Their attractive characteristics were prized, and the group traded at more than 30x earnings. Over the past five years, the businesses have grown significantly, while the stocks have de rated. Today, the group trades at a high teen multiple. In a market that is growing EPS at nearly 20%, their steady growth isn't scarce. Howev
In its second-quarter 2026 investor letter, Eagle Capital Management highlighted Arthur J. Gallagher & Co. (NYSE:AJG). Arthur J. Gallagher & Co. (NYSE:AJG) provides insurance and reinsurance brokerage, consulting, and third-party property/casualty claims settlement and administration services to entities and individuals. On September 02, 2026, Arthur J. Gallagher & Co. (NYSE:AJG) closed at $264.46 per share. Over the past month, Arthur J. Gallagher & Co. (NYSE:AJG) was up 5.05%, while its shares lost 11.91% over the past 52 weeks. Arthur J. Gallagher & Co. (NYSE:AJG) has a market capitalization of $67.78 billion.
Eagle Capital Management stated the following regarding Arthur J. Gallagher & Co. (NYSE:AJG) in its Q2 2026 investor letter:
"High quality with low volatility (24% of capital): London Stock Exchange, Danaher, S&P Global, Mastercard, A.J. Gallagher: Approximately a quarter of Eagle's portfolio is spread across a handful of superb businesses that exhibit high and stable margins, strong returns on capital, wide competitive advantages, and well above GDP growth. We expect the group to deftly navigate the integration of AI into their markets. Most operate with a combination of oligopoly/monopoly ****** ets, network effects, or regulatory moats. A.J. Gallagher is a commercial insurance broker that continues to gain share in a consolidating industry.
A few years ago, these stocks were priced for perfection. Their attractive characteristics were prized, and the group traded at more than 30x earnings. Over the past five years, the businesses have grown significantly, while the stocks have de rated. Today, the group trades at a high teen multiple. In a market that is growing EPS at nearly 20%, their steady growth isn't scarce. Howev

2 months ago
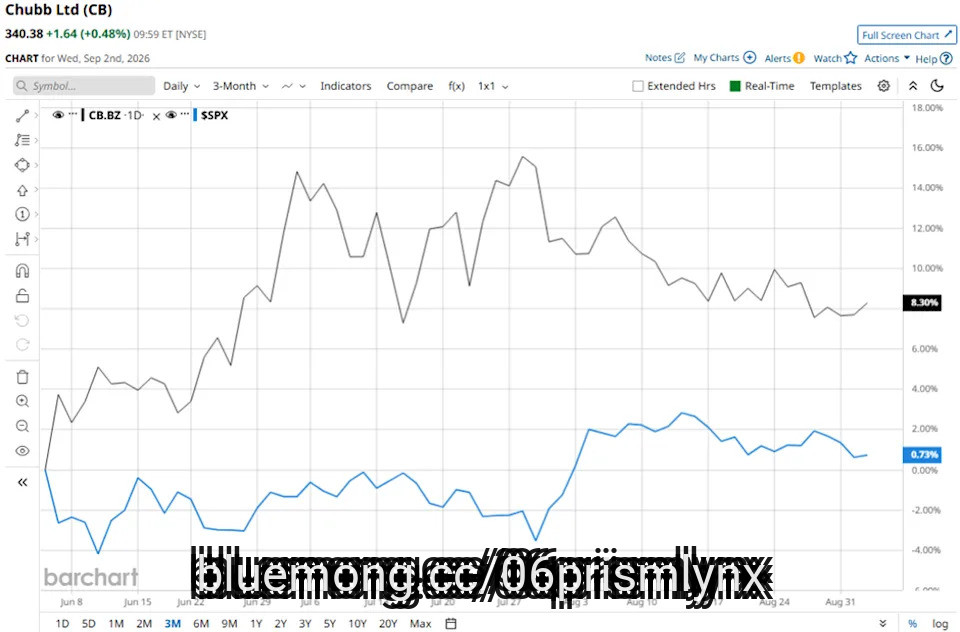
With a market cap of $130.7 billion, Chubb Limited (CB) is a global insurance leader providing a broad range of commercial and personal insurance solutions across 54 countries and territories. Its offerings span property and casualty, personal accident and supplemental health, reinsurance, and life insurance for a diverse range of customers.
Companies valued at more than $10 billion or more are generally considered "large-cap" stocks, and Chubb Limited fits this criterion perfectly. With strong financial capabilities, extensive distribution networks, and local operations worldwide, Chubb employs approximately 45,000 people globally.
Dear GameStop Stock Fans, Mark Your Calendars for September 8
SMCI vs. CoreWeave: 1 AI Infrastructure Model Has the Bigger Opportunity
Why **** ysts Think Sellas Life Sciences Stock Can Gain 150% From Here
#Stock #Companies
Companies valued at more than $10 billion or more are generally considered "large-cap" stocks, and Chubb Limited fits this criterion perfectly. With strong financial capabilities, extensive distribution networks, and local operations worldwide, Chubb employs approximately 45,000 people globally.
Dear GameStop Stock Fans, Mark Your Calendars for September 8
SMCI vs. CoreWeave: 1 AI Infrastructure Model Has the Bigger Opportunity
Why **** ysts Think Sellas Life Sciences Stock Can Gain 150% From Here
#Stock #Companies



2 months ago
Tampa Bay must trim its roster to 53 players by Sunday evening, and while many of the decisions will involve players who entered training camp fighting uphill battles, the Buccaneers' improved depth could also lead to a few surprising names being left off the initial roster. Here are three players who could find themselves on the wrong side of the numbers.
Of all the potential cuts, Sean Tucker would probably be the most surprising. Tucker has shown he can produce when given opportunities, and he led Tampa Bay with eight touchdowns last season. He also brings value on special teams and has averaged 5.1 yards per carry over his first three NFL seasons. The issue is Josh Williams's emergence and the $3.5 million price tag Tucker carries. That's quite the price for an RB3, especially with Bucky Irving and Kenny Gainwell firmly established as Tampa Bay's top two backs. Tucker and Williams are competing for one spot unless the Buccaneers keep four running backs. Todd Bowles admitted Saturday that the competition went "back and forth" throughout the preseason and called it a tough decision. Williams getting offensive snaps ahead of Tucker during the preseason finale was also noteworthy. Tucker's track record makes him difficult to move on from, but roster construction and cost could ultimately work against him.
Payne Durham has been a regular part of Tampa Bay's offense over the past three seasons, but the changing makeup of the tight end room could put him in a more vulnerable position than expected. Cade Otton remains entrenched as the starter, while rookie Bauer Sharp has continued to make a case for a role. Even though he has shown more than his more direct competition, Devin Culp, Ko Kieft being healthy adds another body to the room who contributes on both offense and special teams. Durham's biggest argument is his blocking. At 6'6 and 253 pounds, he has provided the Buccaneers with a physical presence at the position and has experience playing meaningful offensive snaps. But if Tampa Bay believes Sharp can eventually handle some of those responsibilities while offering more upside, Durham could become an unexpected casualty of the numbers game.
Josh Hayes has survived Tampa Bay's final cuts in each of the past three seasons largely because of his special teams ability, but this could finally be the year his roster spot becomes vulnerable. Hayes has been one of Tampa Bay's most consistent special teams contributors and has also provided emergency depth in the secondary. But Tampa Bay has added more young talent to its secondary, creating a situation where the Buccaneers could prioritize upside at cornerback rather than keep a player primarily for his special teams role. Ayden Garnes and "Pepe" Williams have made the most of their opportunities with the starting corners dealing with injuries and have turned conversations of the corner room being a weakness to being one of their strengths. Hayes' experience and value in the kicking game still giv
Of all the potential cuts, Sean Tucker would probably be the most surprising. Tucker has shown he can produce when given opportunities, and he led Tampa Bay with eight touchdowns last season. He also brings value on special teams and has averaged 5.1 yards per carry over his first three NFL seasons. The issue is Josh Williams's emergence and the $3.5 million price tag Tucker carries. That's quite the price for an RB3, especially with Bucky Irving and Kenny Gainwell firmly established as Tampa Bay's top two backs. Tucker and Williams are competing for one spot unless the Buccaneers keep four running backs. Todd Bowles admitted Saturday that the competition went "back and forth" throughout the preseason and called it a tough decision. Williams getting offensive snaps ahead of Tucker during the preseason finale was also noteworthy. Tucker's track record makes him difficult to move on from, but roster construction and cost could ultimately work against him.
Payne Durham has been a regular part of Tampa Bay's offense over the past three seasons, but the changing makeup of the tight end room could put him in a more vulnerable position than expected. Cade Otton remains entrenched as the starter, while rookie Bauer Sharp has continued to make a case for a role. Even though he has shown more than his more direct competition, Devin Culp, Ko Kieft being healthy adds another body to the room who contributes on both offense and special teams. Durham's biggest argument is his blocking. At 6'6 and 253 pounds, he has provided the Buccaneers with a physical presence at the position and has experience playing meaningful offensive snaps. But if Tampa Bay believes Sharp can eventually handle some of those responsibilities while offering more upside, Durham could become an unexpected casualty of the numbers game.
Josh Hayes has survived Tampa Bay's final cuts in each of the past three seasons largely because of his special teams ability, but this could finally be the year his roster spot becomes vulnerable. Hayes has been one of Tampa Bay's most consistent special teams contributors and has also provided emergency depth in the secondary. But Tampa Bay has added more young talent to its secondary, creating a situation where the Buccaneers could prioritize upside at cornerback rather than keep a player primarily for his special teams role. Ayden Garnes and "Pepe" Williams have made the most of their opportunities with the starting corners dealing with injuries and have turned conversations of the corner room being a weakness to being one of their strengths. Hayes' experience and value in the kicking game still giv


2 months ago
A teenage Georgia girl was convicted of brutally killing her mother after abandoning a plan to commit a school shooting, following an obsession with mass casualty events, authorities said.
Lilyana Rose Wagner, 16, was sentenced to life in prison after pleading guilty to murder and aggravated ****** ault in the November 2024 death of her mother Rachel Wagner, 51, Tifton District Attorney Patrick Warren said Tuesday.
The slaying was discovered after Wagner, then 14, crashed her mother's car. Wagner told responding officers that she lived alone with her mother.
The officers went to the home to perform a welfare check and discovered Rachel Wagner, who had not shown up for work and wasn't answering her phone, dead from a gunshot wound to the back of her head.
Georgia High School Shooting Suspect Colt Gray Changes Plea To Guilty, Now Faces Life In Prison
#wagner #mother #school #discovered
Lilyana Rose Wagner, 16, was sentenced to life in prison after pleading guilty to murder and aggravated ****** ault in the November 2024 death of her mother Rachel Wagner, 51, Tifton District Attorney Patrick Warren said Tuesday.
The slaying was discovered after Wagner, then 14, crashed her mother's car. Wagner told responding officers that she lived alone with her mother.
The officers went to the home to perform a welfare check and discovered Rachel Wagner, who had not shown up for work and wasn't answering her phone, dead from a gunshot wound to the back of her head.
Georgia High School Shooting Suspect Colt Gray Changes Plea To Guilty, Now Faces Life In Prison
#wagner #mother #school #discovered



2 months ago
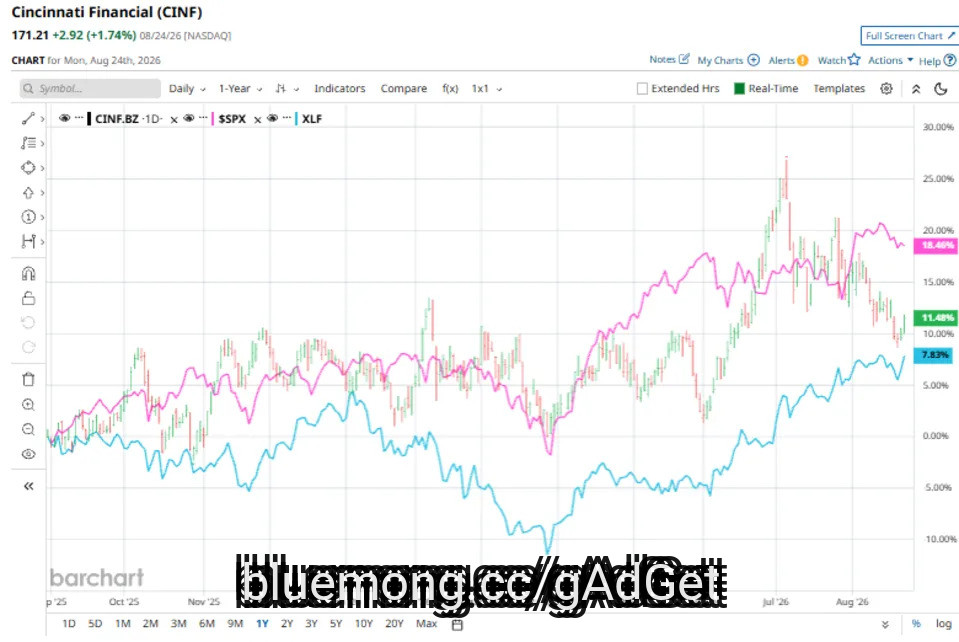
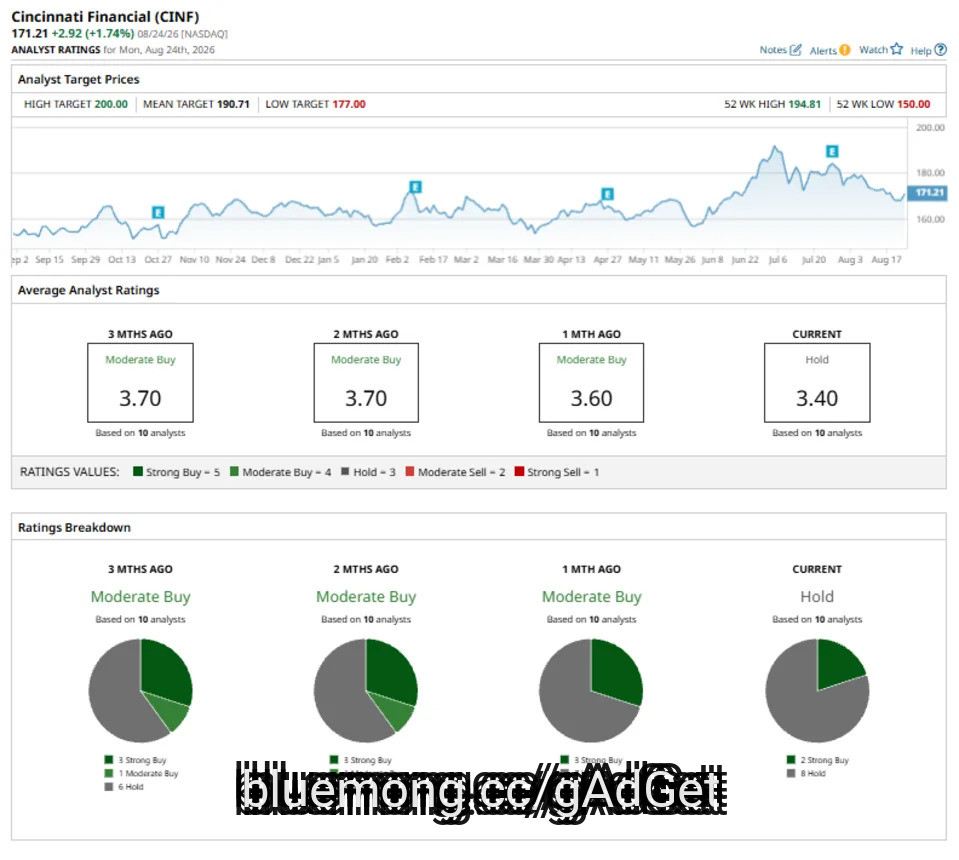
With a market cap of $25.8 billion, Cincinnati Financial Corporation (CINF) is a property and casualty insurance company that has built its business around a network of independent insurance agencies. Headquartered in Fairfield, Ohio, the company provides a broad range of commercial, personal, life, and specialty insurance products across 46 states. Its operations span commercial lines, personal lines, excess and surplus lines, life insurance, and investments, giving CINF a diversified insurance and investment portfolio.
Shares of the insurance ****** an have trailed the broader market over the past 52 weeks. CINF stock has increased 10.2% over this time frame, while the broader S&P 500 Index ($SPX) has rallied 18.3%. Moreover, shares of the company are up 4.8% on a YTD basis, lagging behind SPX's 11.8% gain.
IonQ vs. Rigetti: The Better Quantum Computing Stock for Long-Term Investors
QQQ is Still in a Negative Gamma Regime. Here's How a 'Put Wall' and Fibonacci Support Could Come Into Play.
Stocks Set to Open Lower as Chipmakers Get Hit, Nvidia Earnings and Warsh's Jackson Hole Speech Awaited
#Stock #personal #life
Shares of the insurance ****** an have trailed the broader market over the past 52 weeks. CINF stock has increased 10.2% over this time frame, while the broader S&P 500 Index ($SPX) has rallied 18.3%. Moreover, shares of the company are up 4.8% on a YTD basis, lagging behind SPX's 11.8% gain.
IonQ vs. Rigetti: The Better Quantum Computing Stock for Long-Term Investors
QQQ is Still in a Negative Gamma Regime. Here's How a 'Put Wall' and Fibonacci Support Could Come Into Play.
Stocks Set to Open Lower as Chipmakers Get Hit, Nvidia Earnings and Warsh's Jackson Hole Speech Awaited
#Stock #personal #life

2 months ago
The Cleveland Browns appear poised to make a difficult decision at quarterback, with Dillon Gabriel emerging as a potential casualty of a crowded position group. The former third-round pick faces an uncertain future as the team weighs its depth chart and prepares for the 2026 season.
Gabriel entered the NFL with significant expectations after Cleveland selected him in the third round of the 2025 draft. However, his standing within the organization has changed as competition has intensified, leaving him in a difficult position heading into final roster decisions.
Sep 14, 2025; Baltimore, Maryland, USA; Cleveland Browns quarterback Dillon Gabriel (8) drops back to pass during the second half against the Baltimore Ravens at M&T Bank Stadium. Mandatory Credit: Peter Casey-Imagn Images
The biggest obstacle is the number of quarterbacks competing for limited roster spots. Gabriel has reportedly fallen behind Deshaun Watson and Shedeur Sanders, while rookie Taylen Green has added another young option to the equation, making it increasingly difficult for Cleveland to justify keeping everyone.
The situation became even more complicated after the Browns made their decision regarding the starting quarterback. With Watson positioned to receive the starting opportunity and Sanders also ahead of Gabriel, the former Oregon standout could find himself without a clear path to meaningful playing time in Cleveland.
#cleveland #Browns #dillon
Gabriel entered the NFL with significant expectations after Cleveland selected him in the third round of the 2025 draft. However, his standing within the organization has changed as competition has intensified, leaving him in a difficult position heading into final roster decisions.
Sep 14, 2025; Baltimore, Maryland, USA; Cleveland Browns quarterback Dillon Gabriel (8) drops back to pass during the second half against the Baltimore Ravens at M&T Bank Stadium. Mandatory Credit: Peter Casey-Imagn Images
The biggest obstacle is the number of quarterbacks competing for limited roster spots. Gabriel has reportedly fallen behind Deshaun Watson and Shedeur Sanders, while rookie Taylen Green has added another young option to the equation, making it increasingly difficult for Cleveland to justify keeping everyone.
The situation became even more complicated after the Browns made their decision regarding the starting quarterback. With Watson positioned to receive the starting opportunity and Sanders also ahead of Gabriel, the former Oregon standout could find himself without a clear path to meaningful playing time in Cleveland.
#cleveland #Browns #dillon


2 months ago
Patriots Veteran Emerges As Potential Surprise Cut Candidate originally appeared on NESN. Add NESN as a Preferred Source by clicking here.
Chad Muma appeared to be closing in on a prominent role in the New England Patriots defense earlier this summer. Now, the veteran linebacker might be fighting for his roster spot.
Muma entered training camp as the apparent favorite to become New England's third off-ball linebacker behind Robert Spillane and Christian Elliss. He regularly wore the green-dot communication helmet during spring practices and continued seeing important defensive snaps when camp began.
The competition has changed considerably following two preseason games.
A new 53-man roster projection from Pats Pulpit predicts that New England will release Muma while retaining K.J. Britt and rookies Khalil Jacobs and Namdi Obiazor. It is only a projection, but Muma's rapid slide from presumed top backup to possible roster casualty has become one of the Patriots' more surprising late-summer developments.
#linebacker
Chad Muma appeared to be closing in on a prominent role in the New England Patriots defense earlier this summer. Now, the veteran linebacker might be fighting for his roster spot.
Muma entered training camp as the apparent favorite to become New England's third off-ball linebacker behind Robert Spillane and Christian Elliss. He regularly wore the green-dot communication helmet during spring practices and continued seeing important defensive snaps when camp began.
The competition has changed considerably following two preseason games.
A new 53-man roster projection from Pats Pulpit predicts that New England will release Muma while retaining K.J. Britt and rookies Khalil Jacobs and Namdi Obiazor. It is only a projection, but Muma's rapid slide from presumed top backup to possible roster casualty has become one of the Patriots' more surprising late-summer developments.
#linebacker

3 months ago
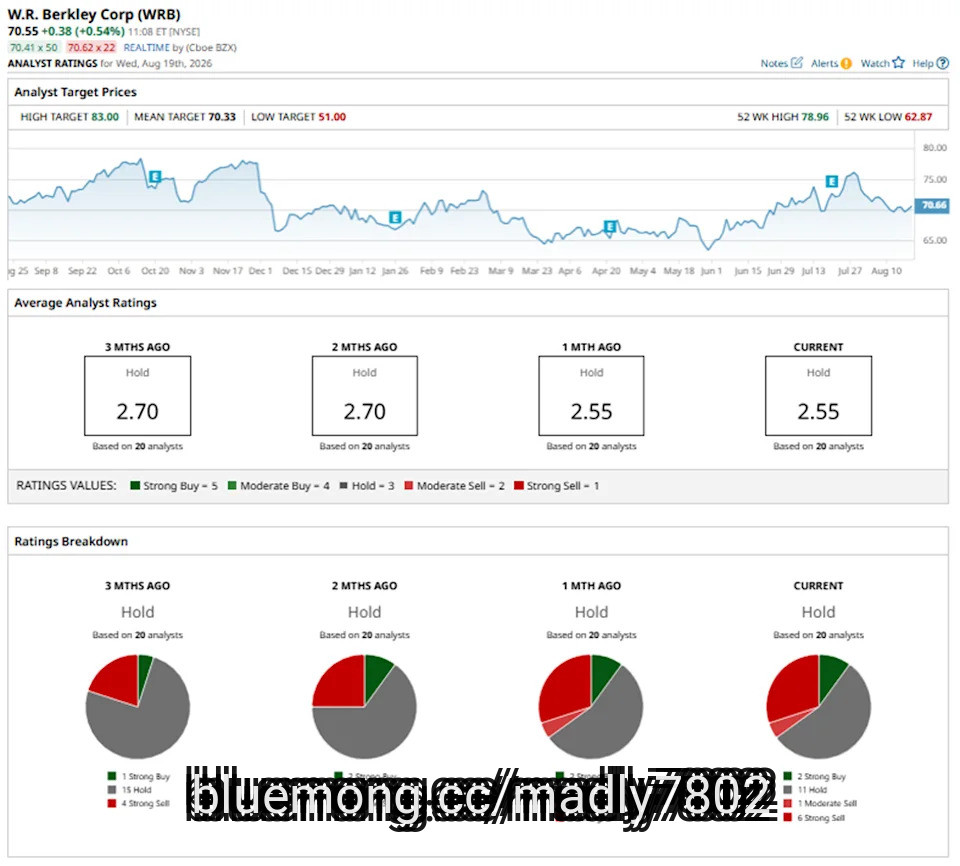
With a market cap of $26 billion, W. R. Berkley Corporation (WRB) is a leading insurance holding company and one of the largest commercial lines insurers in the United States, with operations spanning global markets. The company operates through two core property and casualty segments: Insurance and Reinsurance & Monoline Excess, providing a broad range of insurance solutions to its customers.
Shares of the Greenwich, Connecticut-based company have lagged behind the broader market over the past 52 weeks. WRB stock has fallen marginally over this time frame, while the broader S&P 500 Index ($SPX) has returned 20.4%. Moreover, shares of the company are up 1.5% on a YTD basis, compared to SPX's 12.7% gain.
Barron Trump, 20, Now Worth $150 Million — More Than Mom, Melania — From Crypto And $39 Energy Drink
Billionaire Michael Saylor Warns Against Buying a House Because 'Every 36 Years You Actually Pay the Cost of the House in Tax to the Government'
QQQ Just 'Gamma Flipped' as Market Makers Were Forced to Sell. Here's What Our Top Chart Expert is Tracking Next.
#insurance
Shares of the Greenwich, Connecticut-based company have lagged behind the broader market over the past 52 weeks. WRB stock has fallen marginally over this time frame, while the broader S&P 500 Index ($SPX) has returned 20.4%. Moreover, shares of the company are up 1.5% on a YTD basis, compared to SPX's 12.7% gain.
Barron Trump, 20, Now Worth $150 Million — More Than Mom, Melania — From Crypto And $39 Energy Drink
Billionaire Michael Saylor Warns Against Buying a House Because 'Every 36 Years You Actually Pay the Cost of the House in Tax to the Government'
QQQ Just 'Gamma Flipped' as Market Makers Were Forced to Sell. Here's What Our Top Chart Expert is Tracking Next.
#insurance


3 months ago
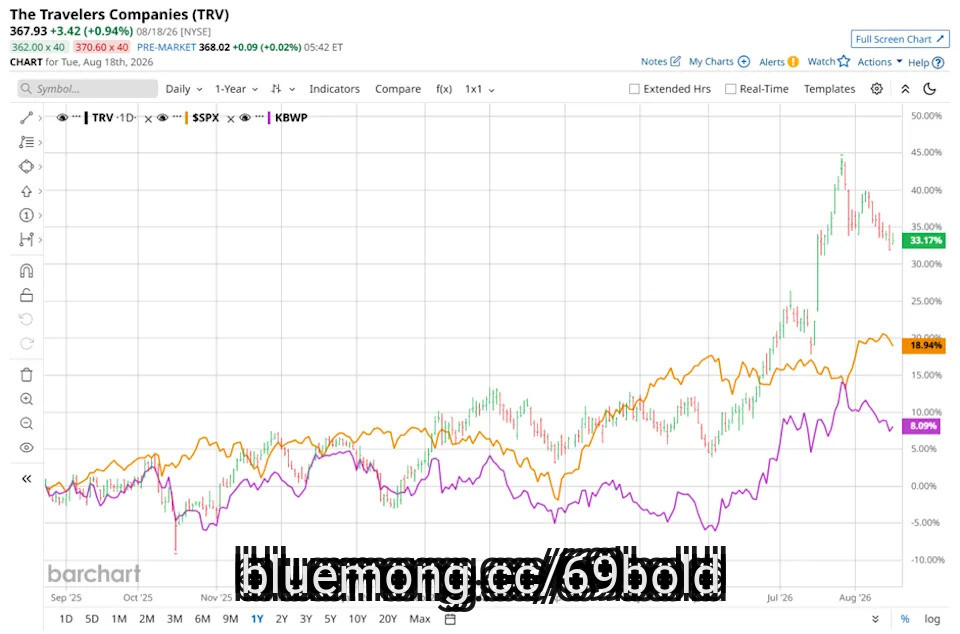
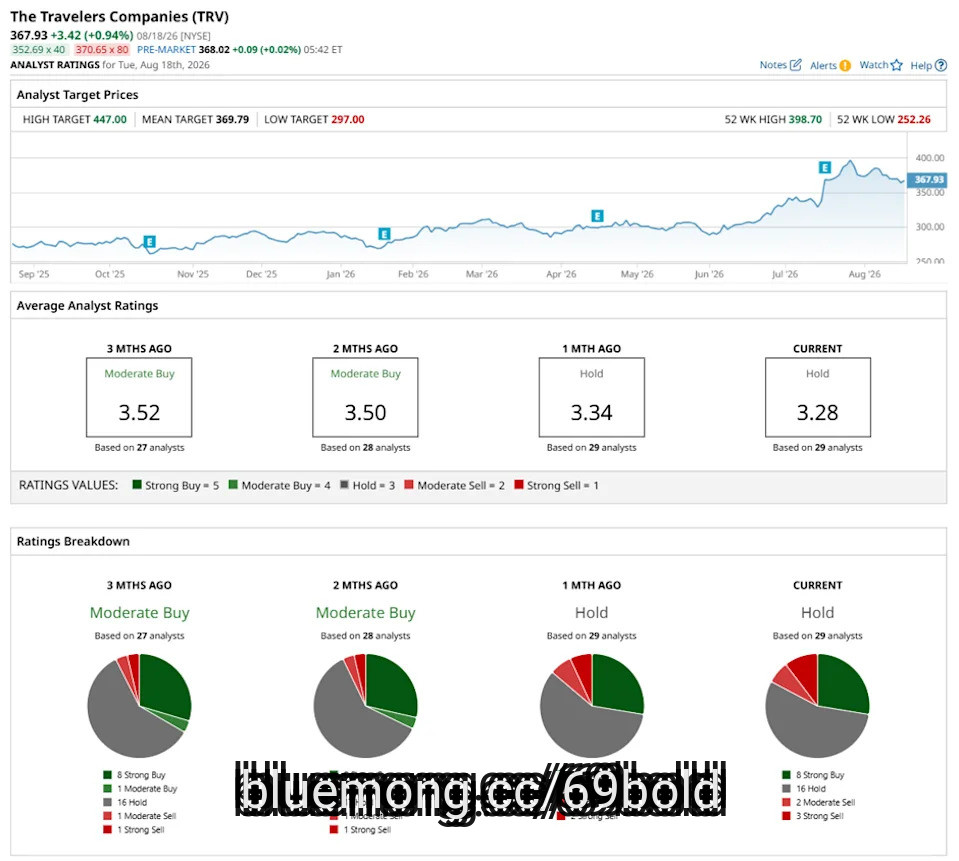
New York-based The Travelers Companies, Inc. (TRV) is a leading provider of commercial and personal property, and property casualty insurance for auto, home and business. Valued at $76.7 billion by market cap, the company's diverse business lines offer its global customers a wide range of coverage sold primarily through independent agents and brokers.
Shares of this insurance giant have outperformed the broader market over the past year. TRV has gained 38.9% over this time frame, while the broader S&P 500 Index ($SPX) has rallied nearly 19.3%. In 2026, TRV stock is up 26.9%, surpassing the SPX's 12.4% rise on a YTD basis.
Barron Trump, 20, Now Worth $150 Million — More Than Mom, Melania — From Crypto And $39 Energy Drink
Billionaire Michael Saylor Warns Against Buying a House Because 'Every 36 Years You Actually Pay the Cost of the House in Tax to the Government'
QQQ Just 'Gamma Flipped' as Market Makers Were Forced to Sell. Here's What Our Top Chart Expert is Tracking Next.
#market #House #property
Shares of this insurance giant have outperformed the broader market over the past year. TRV has gained 38.9% over this time frame, while the broader S&P 500 Index ($SPX) has rallied nearly 19.3%. In 2026, TRV stock is up 26.9%, surpassing the SPX's 12.4% rise on a YTD basis.
Barron Trump, 20, Now Worth $150 Million — More Than Mom, Melania — From Crypto And $39 Energy Drink
Billionaire Michael Saylor Warns Against Buying a House Because 'Every 36 Years You Actually Pay the Cost of the House in Tax to the Government'
QQQ Just 'Gamma Flipped' as Market Makers Were Forced to Sell. Here's What Our Top Chart Expert is Tracking Next.
#market #House #property


3 months ago
With a market cap of $26 billion, W. R. Berkley Corporation (WRB) is a leading insurance holding company and one of the largest commercial lines insurers in the United States, with operations spanning global markets. The company operates through two core property and casualty segments: Insurance and Reinsurance & Monoline Excess, providing a broad range of insurance solutions to its customers.
Shares of the Greenwich, Connecticut-based company have lagged behind the broader market over the past 52 weeks. WRB stock has fallen marginally over this time frame, while the broader S&P 500 Index ($SPX) has returned 20.4%. Moreover, shares of the company are up 1.5% on a YTD basis, compared to SPX's 12.7% gain.
Barron Trump, 20, Now Worth $150 Million — More Than Mom, Melania — From Crypto And $39 Energy Drink
Billionaire Michael Saylor Warns Against Buying a House Because 'Every 36 Years You Actually Pay the Cost of the House in Tax to the Government'
QQQ Just 'Gamma Flipped' as Market Makers Were Forced to Sell. Here's What Our Top Chart Expert is Tracking Next.
#House #shares #corporation
Shares of the Greenwich, Connecticut-based company have lagged behind the broader market over the past 52 weeks. WRB stock has fallen marginally over this time frame, while the broader S&P 500 Index ($SPX) has returned 20.4%. Moreover, shares of the company are up 1.5% on a YTD basis, compared to SPX's 12.7% gain.
Barron Trump, 20, Now Worth $150 Million — More Than Mom, Melania — From Crypto And $39 Energy Drink
Billionaire Michael Saylor Warns Against Buying a House Because 'Every 36 Years You Actually Pay the Cost of the House in Tax to the Government'
QQQ Just 'Gamma Flipped' as Market Makers Were Forced to Sell. Here's What Our Top Chart Expert is Tracking Next.
#House #shares #corporation

3 months ago
New York-based The Travelers Companies, Inc. (TRV) is a leading provider of commercial and personal property, and property casualty insurance for auto, home and business. Valued at $76.7 billion by market cap, the company's diverse business lines offer its global customers a wide range of coverage sold primarily through independent agents and brokers.
Shares of this insurance giant have outperformed the broader market over the past year. TRV has gained 38.9% over this time frame, while the broader S&P 500 Index ($SPX) has rallied nearly 19.3%. In 2026, TRV stock is up 26.9%, surpassing the SPX's 12.4% rise on a YTD basis.
Barron Trump, 20, Now Worth $150 Million — More Than Mom, Melania — From Crypto And $39 Energy Drink
Billionaire Michael Saylor Warns Against Buying a House Because 'Every 36 Years You Actually Pay the Cost of the House in Tax to the Government'
QQQ Just 'Gamma Flipped' as Market Makers Were Forced to Sell. Here's What Our Top Chart Expert is Tracking Next.
#market #property #business #Companies
Shares of this insurance giant have outperformed the broader market over the past year. TRV has gained 38.9% over this time frame, while the broader S&P 500 Index ($SPX) has rallied nearly 19.3%. In 2026, TRV stock is up 26.9%, surpassing the SPX's 12.4% rise on a YTD basis.
Barron Trump, 20, Now Worth $150 Million — More Than Mom, Melania — From Crypto And $39 Energy Drink
Billionaire Michael Saylor Warns Against Buying a House Because 'Every 36 Years You Actually Pay the Cost of the House in Tax to the Government'
QQQ Just 'Gamma Flipped' as Market Makers Were Forced to Sell. Here's What Our Top Chart Expert is Tracking Next.
#market #property #business #Companies


3 months ago
Brown Brothers Harriman, an investment management company, released its Q2 2026 investor letter for the "BBH Select Mid Cap ETF". A copy of the letter can be downloaded here. In the quarter, the fund increased 9.7% on a total return basis compared to the Russell Midcap Index's 13.8% return. Artificial intelligence is a key factor influencing market performance, with high-valuation and high-beta companies consistently outperforming others. The portfolio saw gains from being overweight in technology and industrials but missed opportunities due to underweighting more cyclical stocks. At the end of Q2 2026, the Fund held positions in 27 companies, with 48% of **** ets concentrated in the top 10 holdings. The Fund's strategy focuses on companies priced below intrinsic value to ensure a margin of safety, rather than on whether valuations are high or low. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its Q2 2026 investor letter, BBH Select Mid Cap ETF highlighted Guidewire Software, Inc. (NYSE:GWRE). Guidewire Software, Inc. (NYSE:GWRE) provides a platform for property and casualty (P&C) insurers. On August 19, 2026, Guidewire Software, Inc. (NYSE:GWRE) closed at $181.18 per share, reflecting a market capitalization of $15.08 billion. Guidewire Software, Inc. (NYSE:GWRE) posted a one‑month return of 37.91%, while its shares lost 14.98% over the past 52 weeks.
BBH Select Mid Cap ETF stated the following regarding Guidewire Software, Inc. (NYSE:GWRE) in its Q2 2026 investor letter:
"The Fund's largest detractors to performance in the quarter were Guidewire Software, Inc. (NYSE:GWRE) and Dar ling Ingredients Inc. (Darling). Guidewire declined -17.7% during the quarter, ending with a weight of 3.1%. Guidewire is the leading provider of core systems software to the property and casualty (P&C) insurance industry. Guidewire reported strong fiscal third quarter results (its fiscal year ends in July), with revenue growth of 27% and profitability well ahead of guidance, and management raised full-year guidance for both. The shares nevertheless declined because annual recurring revenue (ARR) growth of 19% finished at the midpoint of guidance, the first quarter since 2022 that ARR did not meet or exceed the high end of its guidance, as a couple of deals slipped past quarter end. We believe the slippage reflects timing rather than demand. The pipeline remains healthy, and management noted the fiscal fourth quarter is off to a good start and could be a record quarter. Fully ramped ARR continues to grow faster than reported ARR, and management expects it to grow above the 22% achieved in fiscal year 25, which supports continued growth into future years. While AI is perceived as a risk by the market, a modern core system is a prerequisite for insurers to deploy AI, and early customer pilots using AI tooling have reduced cloud migration costs by approximately 35%, lowering the largest cost barrier to modernizatio
In its Q2 2026 investor letter, BBH Select Mid Cap ETF highlighted Guidewire Software, Inc. (NYSE:GWRE). Guidewire Software, Inc. (NYSE:GWRE) provides a platform for property and casualty (P&C) insurers. On August 19, 2026, Guidewire Software, Inc. (NYSE:GWRE) closed at $181.18 per share, reflecting a market capitalization of $15.08 billion. Guidewire Software, Inc. (NYSE:GWRE) posted a one‑month return of 37.91%, while its shares lost 14.98% over the past 52 weeks.
BBH Select Mid Cap ETF stated the following regarding Guidewire Software, Inc. (NYSE:GWRE) in its Q2 2026 investor letter:
"The Fund's largest detractors to performance in the quarter were Guidewire Software, Inc. (NYSE:GWRE) and Dar ling Ingredients Inc. (Darling). Guidewire declined -17.7% during the quarter, ending with a weight of 3.1%. Guidewire is the leading provider of core systems software to the property and casualty (P&C) insurance industry. Guidewire reported strong fiscal third quarter results (its fiscal year ends in July), with revenue growth of 27% and profitability well ahead of guidance, and management raised full-year guidance for both. The shares nevertheless declined because annual recurring revenue (ARR) growth of 19% finished at the midpoint of guidance, the first quarter since 2022 that ARR did not meet or exceed the high end of its guidance, as a couple of deals slipped past quarter end. We believe the slippage reflects timing rather than demand. The pipeline remains healthy, and management noted the fiscal fourth quarter is off to a good start and could be a record quarter. Fully ramped ARR continues to grow faster than reported ARR, and management expects it to grow above the 22% achieved in fiscal year 25, which supports continued growth into future years. While AI is perceived as a risk by the market, a modern core system is a prerequisite for insurers to deploy AI, and early customer pilots using AI tooling have reduced cloud migration costs by approximately 35%, lowering the largest cost barrier to modernizatio

3 months ago
The Belgian forward arrived from Royal Antwerp for £4.5million last summer after being pursued by Celtic for more than a year, but has managed just 398 minutes of football despite being fit throughout the campaign.
Signed during Brendan Rodgers' final transfer window, Balikwisha struggled for opportunities under the former Hoops boss and Wilfried Nancy before again finding himself on the fringes under Martin O'Neill.
After some involvement during pre-season, the 24-year-old appears to have slipped back down the pecking order and interest is now emerging from across Europe.
According to Belgian journalist Sacha Tavolieri, the race for Balikwisha remains "wide open", with Bundesliga side SV Elversberg, Italian outfit Monza and Swiss giants Basel among the clubs interested.
The report describes Balikwisha as "a casualty of Martin O'Neill's tactical approach", although his lack of football predates O'Neill's return.
#balikwisha #martin #Football #celtic
Signed during Brendan Rodgers' final transfer window, Balikwisha struggled for opportunities under the former Hoops boss and Wilfried Nancy before again finding himself on the fringes under Martin O'Neill.
After some involvement during pre-season, the 24-year-old appears to have slipped back down the pecking order and interest is now emerging from across Europe.
According to Belgian journalist Sacha Tavolieri, the race for Balikwisha remains "wide open", with Bundesliga side SV Elversberg, Italian outfit Monza and Swiss giants Basel among the clubs interested.
The report describes Balikwisha as "a casualty of Martin O'Neill's tactical approach", although his lack of football predates O'Neill's return.
#balikwisha #martin #Football #celtic

3 months ago
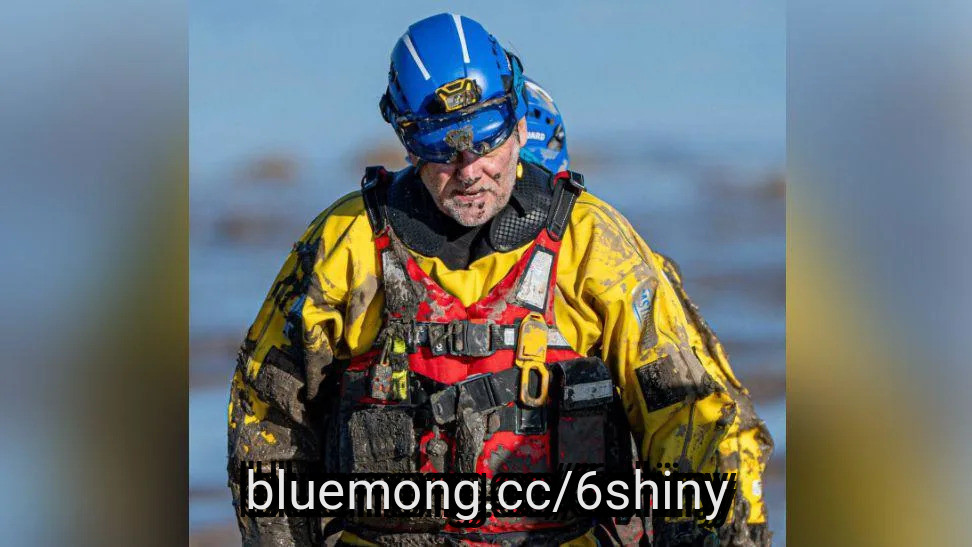
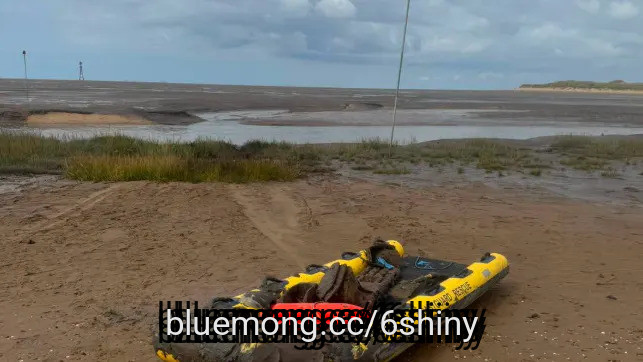
A man stuck in up to his knees in mud on the banks of a tidal river had to be rescued as rising waters almost engulfed him.
Coastguards were called to the incident at the River Alt close to Blundellsands Sailing Club in Sefton, Merseyside, on Sunday.
HM Coastguard Crosby said the terrain near the sailing club and river is "difficult to work in even in ideal conditions, never mind with a flooding tide quickly approaching the casualty".
With the help of the fire service, crews entered the mud and managed to free him.
He was ******* sed by paramedics and "luckily didn't require any further medical treatment", coastguards added.
#merseyside
Coastguards were called to the incident at the River Alt close to Blundellsands Sailing Club in Sefton, Merseyside, on Sunday.
HM Coastguard Crosby said the terrain near the sailing club and river is "difficult to work in even in ideal conditions, never mind with a flooding tide quickly approaching the casualty".
With the help of the fire service, crews entered the mud and managed to free him.
He was ******* sed by paramedics and "luckily didn't require any further medical treatment", coastguards added.
#merseyside
3 months ago
On August 14, autoworkers at Stellantis (NYSE:STLA) learned their union had been told the company is weighing the sale of its Brampton, Ontario plant, a move Unifor tied directly to US tariffs on Canadian goods. The timing is awkward. Days earlier, Stellantis had posted a swing back to profit, which looked like the first real evidence that its turnaround plan is working. Now investors have to weigh a genuine operational rebound against a labor and trade headache tangled up in the very North American market the company is counting on.
Stellantis reported a Q2 net profit of 293 million euros, a sharp reversal from a loss of 1.87 billion euros a year earlier, while adjusted operating income more than tripled to 773 million euros. North America, the region investors watch most closely, saw market share climb to 7.4% from a flat 7%, and Ram notched its fourth straight quarter of year-over-year sales growth, up 6%, breaking a seven-year losing streak. Renewed demand for the reintroduced Hemi V8 helped drive that gain, and Stellantis is leaning further into high-margin performance vehicles to extend it.
The Ram 1500 TRX SRT, priced at $102,590 with shipping, just reached dealerships only six months after its unveiling, and a lower-priced Rumble Bee variant is coming in the lower $60,000s. SRT trims carry margins two to three times higher than standard versions, and the automaker plans eleven SRT models across Ram, Jeep, and Dodge over the next five years. Combined with two all-new and three refreshed vehicles launched in the quarter, and nine more on the way, that product cycle backs up a stated goal of pushing North American margins to 8% to 10% within five years.
Wall Street was not impressed by the Q2 print. Adjusted operating income fell short of the 914 million euro estimate, and the stock dropped nearly 10% on the news before recovering part of that loss, a sign the turnaround still has to prove itself. That skepticism looks more justified given what surfaced on August 14, when Unifor said Stellantis notified the union it may close and sell its Brampton plant, ending decades of vehicle ***** embly there. Stellantis pointed to US tariffs on Canadian goods as the driver, and Brampton would not be the first casualty.
The plant was already idled for retooling in 2024, paused again in 2025, and lost its planned Jeep Compass production to a factory in Illinois once the tariffs hit. Brampton employed 2,200 workers before closing, and Canada's government, including Industry Minister Melanie Joly's office, has been pushing Stellantis to restart it. Stellantis has also previously discussed building electric vehicles in Canada with Chinese partner Zhejiang Leapmotor, an idea Unifor has openly opposed. All of this lands just as Unifor enters new contract talks covering Brampton and two other plants, with the current agreement expiring in September.
#north #plant #million #euros
Stellantis reported a Q2 net profit of 293 million euros, a sharp reversal from a loss of 1.87 billion euros a year earlier, while adjusted operating income more than tripled to 773 million euros. North America, the region investors watch most closely, saw market share climb to 7.4% from a flat 7%, and Ram notched its fourth straight quarter of year-over-year sales growth, up 6%, breaking a seven-year losing streak. Renewed demand for the reintroduced Hemi V8 helped drive that gain, and Stellantis is leaning further into high-margin performance vehicles to extend it.
The Ram 1500 TRX SRT, priced at $102,590 with shipping, just reached dealerships only six months after its unveiling, and a lower-priced Rumble Bee variant is coming in the lower $60,000s. SRT trims carry margins two to three times higher than standard versions, and the automaker plans eleven SRT models across Ram, Jeep, and Dodge over the next five years. Combined with two all-new and three refreshed vehicles launched in the quarter, and nine more on the way, that product cycle backs up a stated goal of pushing North American margins to 8% to 10% within five years.
Wall Street was not impressed by the Q2 print. Adjusted operating income fell short of the 914 million euro estimate, and the stock dropped nearly 10% on the news before recovering part of that loss, a sign the turnaround still has to prove itself. That skepticism looks more justified given what surfaced on August 14, when Unifor said Stellantis notified the union it may close and sell its Brampton plant, ending decades of vehicle ***** embly there. Stellantis pointed to US tariffs on Canadian goods as the driver, and Brampton would not be the first casualty.
The plant was already idled for retooling in 2024, paused again in 2025, and lost its planned Jeep Compass production to a factory in Illinois once the tariffs hit. Brampton employed 2,200 workers before closing, and Canada's government, including Industry Minister Melanie Joly's office, has been pushing Stellantis to restart it. Stellantis has also previously discussed building electric vehicles in Canada with Chinese partner Zhejiang Leapmotor, an idea Unifor has openly opposed. All of this lands just as Unifor enters new contract talks covering Brampton and two other plants, with the current agreement expiring in September.
#north #plant #million #euros


3 months ago
The ties between EuroLeague powerhouse Real Madrid and the Boston Celtics have reportedly grown thicker. Former Celtics two way guard Max Shulga has evidently made the trip to the other side of the proverbial pond to sign with the Spanish ball club according to recent reporting from Basket News Dot Com.
Shulga saw his two way contract with the Celtics converted to a full roster spot near the end of the 2025-26 NBA regular season, but found himself a casualty of Boston's moves around the margins, supplanted both as a member of the regular roster and a two way spot by the incoming cohort of rookies from the 2026 NBA Draft.
Now, Shulga has reportedly inked a two-year deal with Real Madrid that will have him with the team until the end of the 2027-28 season.
The Ukraine native did not have the best season with Boston at the NBA level in the 11 games he appeared in for the parent club, but had a solid season with the Maine Celtics in the G League.
There, the former No. 57 pick of the 2025 NBA Draft put up 15.7 points, 4.4 rebounds, and 6.7 ****** ists per game.
#celtics #reportedly #club
Shulga saw his two way contract with the Celtics converted to a full roster spot near the end of the 2025-26 NBA regular season, but found himself a casualty of Boston's moves around the margins, supplanted both as a member of the regular roster and a two way spot by the incoming cohort of rookies from the 2026 NBA Draft.
Now, Shulga has reportedly inked a two-year deal with Real Madrid that will have him with the team until the end of the 2027-28 season.
The Ukraine native did not have the best season with Boston at the NBA level in the 11 games he appeared in for the parent club, but had a solid season with the Maine Celtics in the G League.
There, the former No. 57 pick of the 2025 NBA Draft put up 15.7 points, 4.4 rebounds, and 6.7 ****** ists per game.
#celtics #reportedly #club
3 months ago
Brown Advisory, an investment management company, released its "Brown Advisory Global Leaders Strategy" for the second quarter of 2026 investor letter. A copy of the letter can be downloaded here. Brown Advisory's Global Leaders Strategy delivered a net return of 4.6% in the second quarter of 2026, underperforming its benchmark, the MSCI ACWI Net Index, which returned 14.9%. The relative weakness was driven mainly by underexposure to semiconductors and technology hardware, while software, cloud services, and financial holdings also weighed on performance. The strategy benefited from holdings in areas tied to AI infrastructure, with semiconductor exposure and AI-related investments gaining from strong demand. Looking ahead, Brown Advisory sees an attractive environment for active stock-picking, with its ready-to-buy list at its highest level since the COVID-19 period and an estimated 12%-13% average five-year base-case IRR, while maintaining a focus on quality, valuation discipline, and long-term cash-flow generation. In addition, please check the Fund's top five holdings to know its best picks in 2026.
In its second-quarter 2026 investor letter, Brown Advisory Global Leaders Strategy Fund highlighted stocks like The Progressive Corporation (NYSE:PGR). The Progressive Corporation (NYSE:PGR) is an insurance company offering auto, home, and commercial insurance products to consumers and businesses. The one-month return of The Progressive Corporation (NYSE:PGR) was -8.17% while its shares traded between $189.20 and $254.93 over the last 52 weeks. On August 7, 2026, The Progressive Corporation (NYSE:PGR) stock closed at approximately $215.34 per share, with a market capitalization of about $125.19 billion.
Brown Advisory Global Leaders Strategy Fund stated the following regarding The Progressive Corporation (NYSE:PGR) in its Q2 2026 investor letter:
We initiated a position in Progressive Corporation (NYSE:PGR) in June. Progressive is a dominant property and casualty (P&C) personal insurance carrier in the US and the leading auto insurance carrier. Its scale advantage is driven by its' low-cost offering to customers, which allows it to reinvest in product enhancements, offer more competitive prices, and benefit from marketing scale. In addition, Progressive's ability to leverage data for customer segmentation has resulted in consistent market share gains, in both hard and soft insurance pricing markets, and consistent profitability. The currently soft insurance market, characterized by generally lower premium levels and greater availability of insurance, has provided us with an attractive entry point to purchase the industry leader at a double-digit, five-year IRR. We expect the company to gain market share, drive 10% FCF growth, and offer a non-deferrable demand profile within the Strategy.
#progressive #strategy #insurance #letter
In its second-quarter 2026 investor letter, Brown Advisory Global Leaders Strategy Fund highlighted stocks like The Progressive Corporation (NYSE:PGR). The Progressive Corporation (NYSE:PGR) is an insurance company offering auto, home, and commercial insurance products to consumers and businesses. The one-month return of The Progressive Corporation (NYSE:PGR) was -8.17% while its shares traded between $189.20 and $254.93 over the last 52 weeks. On August 7, 2026, The Progressive Corporation (NYSE:PGR) stock closed at approximately $215.34 per share, with a market capitalization of about $125.19 billion.
Brown Advisory Global Leaders Strategy Fund stated the following regarding The Progressive Corporation (NYSE:PGR) in its Q2 2026 investor letter:
We initiated a position in Progressive Corporation (NYSE:PGR) in June. Progressive is a dominant property and casualty (P&C) personal insurance carrier in the US and the leading auto insurance carrier. Its scale advantage is driven by its' low-cost offering to customers, which allows it to reinvest in product enhancements, offer more competitive prices, and benefit from marketing scale. In addition, Progressive's ability to leverage data for customer segmentation has resulted in consistent market share gains, in both hard and soft insurance pricing markets, and consistent profitability. The currently soft insurance market, characterized by generally lower premium levels and greater availability of insurance, has provided us with an attractive entry point to purchase the industry leader at a double-digit, five-year IRR. We expect the company to gain market share, drive 10% FCF growth, and offer a non-deferrable demand profile within the Strategy.
#progressive #strategy #insurance #letter

3 months ago
Barcelona head coach Hansi Flick requested for six members of the current first-team setup in Catalunya's capital to train separately from the rest of his players on Tuesday.
That's according to Mundo Deportivo, who have provided an insight into the latest developments behind the scenes at the Ciutat Esportiva.
Barcelona are of course currently in the thick of pre-season preparations with a view to the fast-approaching 2026/27 campaign. Training drills and methods have therefore been ramped up a notch over recent days, as players inch towards full match fitness.
This step up gave rise to its first casualty on Monday, however, as Roony Bardghji was forced out of training with what was later revealed to be a torn ACL in his right knee.
In turn, it should not come as a major surprise to hear of cautionary measures since being taken by Hansi Flick and his staff. As per a report from MD, all of Marc Casadó, Héctor Fort, Jofre Torrents, Tommy Marqués, Toni Fernández, and Guille Fernández were put through their paces in training away from their teammates earlier today.
#training
That's according to Mundo Deportivo, who have provided an insight into the latest developments behind the scenes at the Ciutat Esportiva.
Barcelona are of course currently in the thick of pre-season preparations with a view to the fast-approaching 2026/27 campaign. Training drills and methods have therefore been ramped up a notch over recent days, as players inch towards full match fitness.
This step up gave rise to its first casualty on Monday, however, as Roony Bardghji was forced out of training with what was later revealed to be a torn ACL in his right knee.
In turn, it should not come as a major surprise to hear of cautionary measures since being taken by Hansi Flick and his staff. As per a report from MD, all of Marc Casadó, Héctor Fort, Jofre Torrents, Tommy Marqués, Toni Fernández, and Guille Fernández were put through their paces in training away from their teammates earlier today.
#training

3 months ago
NONTHABURI, Thailand (AP) — A student opened fire at a high school outside Bangkok on Friday, killing at least five people and wounding more than 20, according to authorities, who said he also appeared to have killed his two grandparents at the family home earlier in the morning.
The 14-year-old shooter took his own life at the school, officials said.
Five school staff members, including teachers and administrators, died in the shooting around 10 a.m. at Debsirin Nonthaburi School in Nonthaburi province northwest of Bangkok, Deputy Interior Minister Polapee Suwunchwee said at the scene.
The boy also killed his grandparents at the home he shared with them prior to the school shooting, Polapee said.
Bangyai Hospital, about 5 kilometers (3 miles) from the school, said 23 people were wounded, of whom 10 were in critical condition, with most suffering gunshot wounds. Earlier reports gave conflicting casualty numbers.
#polapee
The 14-year-old shooter took his own life at the school, officials said.
Five school staff members, including teachers and administrators, died in the shooting around 10 a.m. at Debsirin Nonthaburi School in Nonthaburi province northwest of Bangkok, Deputy Interior Minister Polapee Suwunchwee said at the scene.
The boy also killed his grandparents at the home he shared with them prior to the school shooting, Polapee said.
Bangyai Hospital, about 5 kilometers (3 miles) from the school, said 23 people were wounded, of whom 10 were in critical condition, with most suffering gunshot wounds. Earlier reports gave conflicting casualty numbers.
#polapee


3 months ago
Emerald Wealth Partners, an independent ***** et and wealth management firm based in Zurich, released its Q2 2026 investor letter for the "Focused Equity Strategy." A copy of the letter can be downloaded here. The Strategy reported a 0.8% gross return for the second quarter of 2026. Equity markets rallied after the first quarter's Iran shock faded and oil prices reversed their spike, but the advance remained narrow and concentrated in cyclical semiconductor and memory stocks benefiting from supply constraints. The letter warned that investors were treating peak-cycle earnings as durable, while FOMO, IPO demand, and a US cyclically adjusted P/E ratio near 40 pointed to late-cycle market behavior. Long-term fundamentals are currently undervalued by the market, leading to underperformance in the strategy, notably due to the portfolio's avoidance of low-quality momentum-driven semiconductor stocks, which boosted the benchmark this quarter. It remains focused on enterprise infrastructure, digital platforms, custom silicon, and networking businesses that hold customer relationships, workflow data, distribution, and efficiency advantages, which could allow them to monetize AI rather than be displaced by it. Please review the Strategy's top five holdings for its key selections.
In its second-quarter 2026 investor letter, Emerald Wealth Partners Focused Equity Strategy ServiceNow, Inc. (NYSE:NOW), noting its inclusion in the portfolio this quarter. ServiceNow, Inc. (NYSE:NOW) is a cloud-based software company that provides a platform for automating and managing digital workflows. On August 04, 2026, ServiceNow, Inc. (NYSE:NOW) closed at $118.14 per share. The one-month return of ServiceNow, Inc. (NYSE:NOW) was 9.61% and its shares lost 35.25% over the past 52 weeks. ServiceNow, Inc. (NYSE:NOW) has a market capitalization of $122.16 billion with a 52-week trading range between $81.24 - $194.73.
Emerald Wealth Partners Focused Equity Strategy stated the following regarding ServiceNow, Inc. (NYSE:NOW) in its Q2 2026 investor letter:
"Finally, we added to ServiceNow, Inc. (NYSE:NOW). As we explained last quarter, investors are drawing too few distinctions in the software sell-off. We believe businesses that sit at the operating core of large enterprises are far harder to displace than the market ***** umes, because what has to be replaced is not the code but everything built around it — years of configuration, shared investment and accumulated understanding of each customer's specificities. ServiceNow is the clearest illustration we own: its Now Platform has become the system of record for how large organizations manage work across IT, HR, finance, legal and customer operations, and the proprietary workflow data it holds is precisely what allows it to deliver AI tools that are immediately relevant — and what makes it a monetization vehicle for enterprise AI adoption rather than a casualty of it."
#wealth #focused #quarter #partners
In its second-quarter 2026 investor letter, Emerald Wealth Partners Focused Equity Strategy ServiceNow, Inc. (NYSE:NOW), noting its inclusion in the portfolio this quarter. ServiceNow, Inc. (NYSE:NOW) is a cloud-based software company that provides a platform for automating and managing digital workflows. On August 04, 2026, ServiceNow, Inc. (NYSE:NOW) closed at $118.14 per share. The one-month return of ServiceNow, Inc. (NYSE:NOW) was 9.61% and its shares lost 35.25% over the past 52 weeks. ServiceNow, Inc. (NYSE:NOW) has a market capitalization of $122.16 billion with a 52-week trading range between $81.24 - $194.73.
Emerald Wealth Partners Focused Equity Strategy stated the following regarding ServiceNow, Inc. (NYSE:NOW) in its Q2 2026 investor letter:
"Finally, we added to ServiceNow, Inc. (NYSE:NOW). As we explained last quarter, investors are drawing too few distinctions in the software sell-off. We believe businesses that sit at the operating core of large enterprises are far harder to displace than the market ***** umes, because what has to be replaced is not the code but everything built around it — years of configuration, shared investment and accumulated understanding of each customer's specificities. ServiceNow is the clearest illustration we own: its Now Platform has become the system of record for how large organizations manage work across IT, HR, finance, legal and customer operations, and the proprietary workflow data it holds is precisely what allows it to deliver AI tools that are immediately relevant — and what makes it a monetization vehicle for enterprise AI adoption rather than a casualty of it."
#wealth #focused #quarter #partners




