1 day ago
With a market cap of $19.5 billion, Best Buy Co., Inc. (BBY) is a leading technology retailer focused on enriching lives through technology by combining tech expertise with personalized customer service. The company serves customers through its online platform, stores, and in-home services, addressing a wide range of everyday technology needs.
Companies valued at more than $10 billion are generally considered "large-cap" stocks, and Best Buy fits this criterion perfectly. Best Buy operates more than 1,000 stores across the United States and Canada and employs more than 85,000 people.
Here's Another Little-Known Firm Jensen Huang's Nvidia Is Quietly Backing
MediaTek Is Stepping Up Competition Against Qualcomm With a New 2-Nanometer Chip. What This Means for QCOM Stock.
1 Year Into the Microsoft Deal, IREN Is Delivering and a Rally May Follow Soon
#stores #known
Companies valued at more than $10 billion are generally considered "large-cap" stocks, and Best Buy fits this criterion perfectly. Best Buy operates more than 1,000 stores across the United States and Canada and employs more than 85,000 people.
Here's Another Little-Known Firm Jensen Huang's Nvidia Is Quietly Backing
MediaTek Is Stepping Up Competition Against Qualcomm With a New 2-Nanometer Chip. What This Means for QCOM Stock.
1 Year Into the Microsoft Deal, IREN Is Delivering and a Rally May Follow Soon
#stores #known



1 day ago
On September 9, 2026, Reuters reported that CEO Brian Niccol's first two years as Starbucks Corporation (NASDAQ:SBUX) CEO have succeeded in bringing customers back to the coffee chain. Comparable sales rose 7.9% in the fiscal third quarter for a fourth straight quarter of improvement, but his "Back to Starbucks" restructuring has raised costs and squeezed margins along the way. Global operating margin has fallen to 12.9% from 15.8% two years earlier. Niccol, who marks his second anniversary in the role, now faces pressure to convert the sales recovery into the sustainable profit growth investors are demanding.
Niccol's turnaround strategy has already restored customer momentum at Starbucks Corporation (NASDAQ:SBUX). The "Back to Starbucks" strategy reversed six consecutive quarters of declining comparable sales as the company focused on reducing wait times, simplifying menus, improving store ambiance, and increasing staffing. Starbucks has moved beyond the sales deterioration that preceded Niccol's tenure. It gives investors a stronger foundation for the next phase of the turnaround. If management can sustain traffic gains while improving productivity, the sales recovery could provide a path toward stronger earnings growth.
The China joint venture with Boyu Capital gives Starbucks a more capital-efficient way to participate in China's growth. Starbucks sold control of its China retail operations to Boyu. It retained a 40% stake and continues to own and license its brand and intellectual property. The structure reduces Starbucks' direct capital requirements while allowing it to retain economic exposure to the Chinese market. Reuters cited ****** ysts who said the arrangement leaves Starbucks well positioned to convert stronger organic sales growth into profit growth, which could support returns as the recovery progresses.
Starbucks now has an opportunity to turn its customer investments into margin expansion. The firm committed at least $500 million toward labor as part of the restructuring. Niccol prioritized staffing and store improvements to rebuild the customer experience. That spending helped help the sales recovery. But it also pushed global operating margins down to 12.9% from 15.8% over two years. With sales now improving, management can focus more heavily on productivity, cost control, and operating leverage. It creates an opportunity for stronger earnings if it can improve margins without damaging customer traffic.
Labor tensions could undermine Starbucks Corporation (NASDAQ:SBUX)' recovery and keep costs elevated. Starbucks has yet to reach a first contract with its U.S. barista union. The union called for a consumer boycott in August. Negotiations or labor actions could disrupt store operations, increase labor costs, and create reputational pressure just as Starbucks tries to improve profitability. Therefore, investors face a risk that labor issues could offset some of the productivity gains management needs to expand margins.
#
Niccol's turnaround strategy has already restored customer momentum at Starbucks Corporation (NASDAQ:SBUX). The "Back to Starbucks" strategy reversed six consecutive quarters of declining comparable sales as the company focused on reducing wait times, simplifying menus, improving store ambiance, and increasing staffing. Starbucks has moved beyond the sales deterioration that preceded Niccol's tenure. It gives investors a stronger foundation for the next phase of the turnaround. If management can sustain traffic gains while improving productivity, the sales recovery could provide a path toward stronger earnings growth.
The China joint venture with Boyu Capital gives Starbucks a more capital-efficient way to participate in China's growth. Starbucks sold control of its China retail operations to Boyu. It retained a 40% stake and continues to own and license its brand and intellectual property. The structure reduces Starbucks' direct capital requirements while allowing it to retain economic exposure to the Chinese market. Reuters cited ****** ysts who said the arrangement leaves Starbucks well positioned to convert stronger organic sales growth into profit growth, which could support returns as the recovery progresses.
Starbucks now has an opportunity to turn its customer investments into margin expansion. The firm committed at least $500 million toward labor as part of the restructuring. Niccol prioritized staffing and store improvements to rebuild the customer experience. That spending helped help the sales recovery. But it also pushed global operating margins down to 12.9% from 15.8% over two years. With sales now improving, management can focus more heavily on productivity, cost control, and operating leverage. It creates an opportunity for stronger earnings if it can improve margins without damaging customer traffic.
Labor tensions could undermine Starbucks Corporation (NASDAQ:SBUX)' recovery and keep costs elevated. Starbucks has yet to reach a first contract with its U.S. barista union. The union called for a consumer boycott in August. Negotiations or labor actions could disrupt store operations, increase labor costs, and create reputational pressure just as Starbucks tries to improve profitability. Therefore, investors face a risk that labor issues could offset some of the productivity gains management needs to expand margins.
#

2 days ago
GOOG trades at a P/E of 14 versus META's 24, with Cloud revenue surging 82% while META's operating margins collapsed from 43% to 31%.
META's Reality Labs bleeds roughly $4B per quarter, 2026 capex is projected between $130B and $145B, and active litigation makes it a volatile aggressive-growth bet rather than a retirement hold.
Just released. Our ******* ysts combed the entire stock market and named the ten best stocks to buy right now, and Google didn't make the cut. Enter your email to see the names that beat GOOG. The report is free. Enter your email and see if any of your stocks made the cut.
Alphabet (NASDAQ:GOOG) and Meta Platforms (NASDAQ:META) just unleashed rival consumer AI agents (Google's family-focused CC, a shared agent supporting up to six family members, and Meta's single-user Muse, aiming for higher autonomy across a user's digital life, including commerce), and the retirement-focused investor writing one check today needs a clear answer: which mega-cap deserves the slot?
Both stocks are pouring tens of billions into AI infrastructure. Both consumer AI agents (not just chatbots) are designed to take real actions on a user's behalf rather than only answering questions. However, CC is a family-oriented productivity and logistics agent tightly tied to the Google ecosystem. Muse is a more general-purpose personal agent aiming for higher autonomy across a user's digital life, including commerce. They compete in the emerging "AI agent that actually does things" category, but target different use cases and user models.
#stocks #family
META's Reality Labs bleeds roughly $4B per quarter, 2026 capex is projected between $130B and $145B, and active litigation makes it a volatile aggressive-growth bet rather than a retirement hold.
Just released. Our ******* ysts combed the entire stock market and named the ten best stocks to buy right now, and Google didn't make the cut. Enter your email to see the names that beat GOOG. The report is free. Enter your email and see if any of your stocks made the cut.
Alphabet (NASDAQ:GOOG) and Meta Platforms (NASDAQ:META) just unleashed rival consumer AI agents (Google's family-focused CC, a shared agent supporting up to six family members, and Meta's single-user Muse, aiming for higher autonomy across a user's digital life, including commerce), and the retirement-focused investor writing one check today needs a clear answer: which mega-cap deserves the slot?
Both stocks are pouring tens of billions into AI infrastructure. Both consumer AI agents (not just chatbots) are designed to take real actions on a user's behalf rather than only answering questions. However, CC is a family-oriented productivity and logistics agent tightly tied to the Google ecosystem. Muse is a more general-purpose personal agent aiming for higher autonomy across a user's digital life, including commerce. They compete in the emerging "AI agent that actually does things" category, but target different use cases and user models.
#stocks #family



2 days ago
On September 14, NextEra Energy, Inc. (NYSE:NEE) and Dominion Energy, Inc. (NYSE:D) announced a "transformational" Virginia benefits package to address concerns regarding their proposed $66.8 billion merger. The Virginia supplier program, worth up to $1 billion annually for five years, will direct spending toward contractors, suppliers, and service providers in the state.
Additionally, the companies also proposed doubling residential bill credits to four years, protecting retail customers from grid costs tied to Northern Virginia's rapidly expanding AI data centers, and committing $100 million toward directly supporting workforce development in the Commonwealth. NextEra also stated that it plans to add 600 new energy jobs in Virginia, while expecting suppliers to create another 400 positions.
The updated package comes after the proposed merger attracted a great deal of political scrutiny due to the impact it can have on everyday consumers. Virginia Governor Abigail Spanberger also stated last month that she would formally intervene in the regulatory review to press for commitments on electric bill affordability, job protections, and clean-energy investments.
John Ketchum, Chairman, President, and CEO of NextEra Energy, commented:
"This is a Virginia-first package, and it starts with customers. We are proposing to double residential bill relief from two years to four years, along with expanded low-income financial ******* istance and long-term affordability benefits. We are also reaffirming our support for the State Corporation Commission, Governor and General ******* embly's efforts to protect residential and small business customers from costs ******* ociated with serving data centers. Just as important, this package would help Virginia build more of the clean energy and infrastructure it needs faster, so the Commonwealth can reduce its reliance on expensive imported power. And it would do that while positioning Virginia as a major energy leader, bringing NextEra Energy jobs, good-paying supplier jobs, workforce investment, economic development and national-scale energy technology and innovation to Virginia. This is the kind of customer-focused, job-creating package this combination makes possible."
#energy #years #Jobs
Additionally, the companies also proposed doubling residential bill credits to four years, protecting retail customers from grid costs tied to Northern Virginia's rapidly expanding AI data centers, and committing $100 million toward directly supporting workforce development in the Commonwealth. NextEra also stated that it plans to add 600 new energy jobs in Virginia, while expecting suppliers to create another 400 positions.
The updated package comes after the proposed merger attracted a great deal of political scrutiny due to the impact it can have on everyday consumers. Virginia Governor Abigail Spanberger also stated last month that she would formally intervene in the regulatory review to press for commitments on electric bill affordability, job protections, and clean-energy investments.
John Ketchum, Chairman, President, and CEO of NextEra Energy, commented:
"This is a Virginia-first package, and it starts with customers. We are proposing to double residential bill relief from two years to four years, along with expanded low-income financial ******* istance and long-term affordability benefits. We are also reaffirming our support for the State Corporation Commission, Governor and General ******* embly's efforts to protect residential and small business customers from costs ******* ociated with serving data centers. Just as important, this package would help Virginia build more of the clean energy and infrastructure it needs faster, so the Commonwealth can reduce its reliance on expensive imported power. And it would do that while positioning Virginia as a major energy leader, bringing NextEra Energy jobs, good-paying supplier jobs, workforce investment, economic development and national-scale energy technology and innovation to Virginia. This is the kind of customer-focused, job-creating package this combination makes possible."
#energy #years #Jobs


2 days ago
For the record:
1:38 p.m. Sept. 19, 2026: An earlier version of this article stated KCAL's helicopter is owned by Angel City Air. It is owned by Helicopters Inc.
Whether it's a brush fire, a mass shooting, a car chase or the aftermath of a major storm, viewers in Los Angeles are used to getting the news from above.
Television news helicopter coverage has become one of the most important elements of any local newscast, with the high-flying helicopters roaring overhead a common fixture of breaking news scenes.
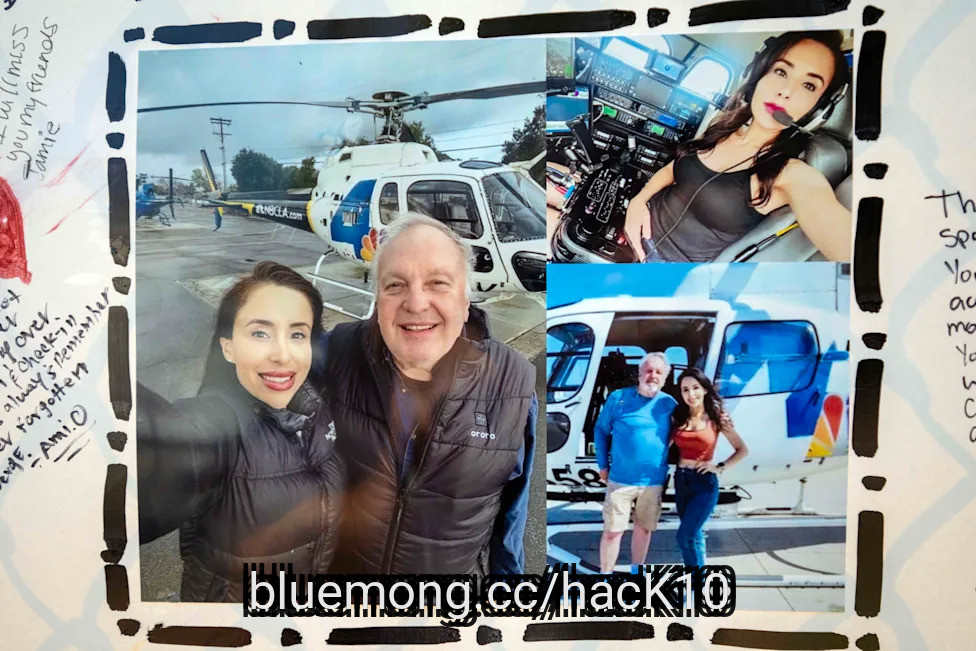
These images are so ubiquitous, it may have been easy to take them for granted, until Tuesday, when an NBC4 helicopter carrying reporter Eliana Moreno and pilot George Marciniw crashed while covering breaking news in Chatsworth. Both died, along with a bystander on the ground.
The tragedy has prompted soul-searching in the world of TV news helicopter pilots and focused attention on safety issues.
#city #whether #angeles
1:38 p.m. Sept. 19, 2026: An earlier version of this article stated KCAL's helicopter is owned by Angel City Air. It is owned by Helicopters Inc.
Whether it's a brush fire, a mass shooting, a car chase or the aftermath of a major storm, viewers in Los Angeles are used to getting the news from above.
Television news helicopter coverage has become one of the most important elements of any local newscast, with the high-flying helicopters roaring overhead a common fixture of breaking news scenes.
These images are so ubiquitous, it may have been easy to take them for granted, until Tuesday, when an NBC4 helicopter carrying reporter Eliana Moreno and pilot George Marciniw crashed while covering breaking news in Chatsworth. Both died, along with a bystander on the ground.
The tragedy has prompted soul-searching in the world of TV news helicopter pilots and focused attention on safety issues.
#city #whether #angeles

2 days ago
Intel Corporation (NASDAQ:INTC) is targeting a potentially significant opportunity through its strategic Terafab partnership with companies **** ociated with Elon Musk, including **** eX, Tesla, and xAI. The initiative is part of an ambitious semiconductor manufacturing project focused on producing advanced chips for artificial intelligence (AI), robotics, autonomous vehicles, and other compute-intensive applications.
On September 15, Tigress Financial highlighted the strategic importance of the alliance to Intel's turnaround prospects. The research firm reiterated its Buy rating on Intel and raised its price target to $145 from $118, citing the company's long-term growth opportunity.
The Terafab partnership could provide Intel's foundry business with exposure to customers that have substantial AI and high-performance computing requirements. Securing external customers could help Intel increase manufacturing scale while improving the utilization and economics of its foundry operations.
The partnership could also support Intel Corporation (NASDAQ:INTC)'s efforts to improve its semiconductor manufacturing technology. Greater production volumes and engagement with demanding customers could provide opportunities to improve manufacturing economics, yields, and scalability as Intel works to strengthen its competitive position in advanced chip manufacturing.
Beyond manufacturing scale, Terafab could expand Intel's role in the broader AI semiconductor supply chain. The company has historically been heavily **** ociated with CPUs, but growing its foundry business could give it greater exposure to AI accelerators, custom silicon, and other specialized compute applications. A relationship with major AI-focused customers could also help provide greater visibility into future manufacturing demand.
#Intel
On September 15, Tigress Financial highlighted the strategic importance of the alliance to Intel's turnaround prospects. The research firm reiterated its Buy rating on Intel and raised its price target to $145 from $118, citing the company's long-term growth opportunity.
The Terafab partnership could provide Intel's foundry business with exposure to customers that have substantial AI and high-performance computing requirements. Securing external customers could help Intel increase manufacturing scale while improving the utilization and economics of its foundry operations.
The partnership could also support Intel Corporation (NASDAQ:INTC)'s efforts to improve its semiconductor manufacturing technology. Greater production volumes and engagement with demanding customers could provide opportunities to improve manufacturing economics, yields, and scalability as Intel works to strengthen its competitive position in advanced chip manufacturing.
Beyond manufacturing scale, Terafab could expand Intel's role in the broader AI semiconductor supply chain. The company has historically been heavily **** ociated with CPUs, but growing its foundry business could give it greater exposure to AI accelerators, custom silicon, and other specialized compute applications. A relationship with major AI-focused customers could also help provide greater visibility into future manufacturing demand.
#Intel

2 days ago
If you're trying to build a consumer-focused corner of your portfolio that can grow through a lot of different economic backdrops, three names stand out right now: Church & Dwight Co. (NYSE: CHD), YETI Holdings (NYSE: YETI), and Newell Brands (NASDAQ: NWL). Each of these is making deliberate moves in 2026 and into 2027 that communicate to me more about their future than any single rocky quarter's earnings line.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Church & Dwight has built its identity on everyday products like baking soda, laundry detergents, and cleaners that quietly show up in millions of homes. In May 2026, it moved to deepen that footprint by buying the Miss Mouth's Messy Eater brand, a fast-growing, non-toxic stain remover built for parents. It's a small thing on paper, but it fits this successful company's patterns: Keep layering niche, repeat-use products into an existing distribution machine instead of chasing flashy new categories.
The company's first-quarter 2026 update backs that strategy up. Organic sales rose 5% even though reported net sales were basically flat due to past portfolio pruning, per company management. Management described 2026 as a year of "volume-driven" organic growth, meaning they're focused on selling more units to real customers, not just leaning on price increases. On top of that, Church & Dwight extended its long dividend record yet again. Although it is not quite a Dividend King, it has consistently raised its dividend for 29 years.
For investors, my advice here is straightforward: Treat Church & Dwight as a core holding in a consumer bucket. It's unlikely to deliver fireworks in a single year, but it keeps making acquisitions to deepen its understanding of existing categories.
#flashing #organic
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Church & Dwight has built its identity on everyday products like baking soda, laundry detergents, and cleaners that quietly show up in millions of homes. In May 2026, it moved to deepen that footprint by buying the Miss Mouth's Messy Eater brand, a fast-growing, non-toxic stain remover built for parents. It's a small thing on paper, but it fits this successful company's patterns: Keep layering niche, repeat-use products into an existing distribution machine instead of chasing flashy new categories.
The company's first-quarter 2026 update backs that strategy up. Organic sales rose 5% even though reported net sales were basically flat due to past portfolio pruning, per company management. Management described 2026 as a year of "volume-driven" organic growth, meaning they're focused on selling more units to real customers, not just leaning on price increases. On top of that, Church & Dwight extended its long dividend record yet again. Although it is not quite a Dividend King, it has consistently raised its dividend for 29 years.
For investors, my advice here is straightforward: Treat Church & Dwight as a core holding in a consumer bucket. It's unlikely to deliver fireworks in a single year, but it keeps making acquisitions to deepen its understanding of existing categories.
#flashing #organic

3 days ago
Whirlpool already cut its dividend 49% then skipped a payment entirely, while KHC's yield is inflated by a 55% decade-long price collapse with frozen payouts since 2019.
IEP's 29% yield masks two prior cuts and a 68% cash drop year over year, while UPS's quarterly operating cash flow fell $469 million short of its dividend payout.
A collapsing share price mechanically inflates yield, making high-yield stocks look attractive precisely when the underlying business is deteriorating most.
Just released. Our ******* ysts combed the entire stock market and named the ten best stocks to buy right now, and Kraft Heinz didn't make the cut. Enter your email to see the names that beat KHC. The report is free. Enter your email and see if any of your stocks made the cut.
Yield is a promise, not a payment. When a stock advertises a payout that looks two or three times the market average, it usually means the market has already decided something is wrong. The screen below flags six US-listed names where the numbers behind the yield show real strain: shrinking cash flow, stretched coverage, or a share price that collapsed and inflated the yield mechanically. None of these companies has announced a cut. Each has warning signs a retirement-focused reader should understand before buying the yield.
#inflated
IEP's 29% yield masks two prior cuts and a 68% cash drop year over year, while UPS's quarterly operating cash flow fell $469 million short of its dividend payout.
A collapsing share price mechanically inflates yield, making high-yield stocks look attractive precisely when the underlying business is deteriorating most.
Just released. Our ******* ysts combed the entire stock market and named the ten best stocks to buy right now, and Kraft Heinz didn't make the cut. Enter your email to see the names that beat KHC. The report is free. Enter your email and see if any of your stocks made the cut.
Yield is a promise, not a payment. When a stock advertises a payout that looks two or three times the market average, it usually means the market has already decided something is wrong. The screen below flags six US-listed names where the numbers behind the yield show real strain: shrinking cash flow, stretched coverage, or a share price that collapsed and inflated the yield mechanically. None of these companies has announced a cut. Each has warning signs a retirement-focused reader should understand before buying the yield.
#inflated

3 days ago
During market uncertainty, cautious investors may feel compelled to sell everything while they wait for the dust to settle. But Ross Gerber believes that, to paraphrase Rudyard Kipling, if you can keep your head when everyone else is losing theirs, you'll reap even bigger rewards.
The Gerber Kawasaki CEO says that while inflation, higher bond yields, oil prices, and Federal Reserve rate hikes can pressure stocks, he does not think investors should abandon equities wholesale. Instead, he advocates for a more defensive approach.
He recommends investors trim holdings with valuations that look stretched relative to their growth, build reserves in cash and short-duration fixed income **** ets, and keep long-term positions in companies that he believes still have strong earnings support, such as Nvidia.
And for investors trying to navigate an environment where corporate earnings remain strong while macroeconomic risks pressure stock valuations, that distinction matters. Gerber's framework is less about calling the market's next move than deciding which risks a portfolio can absorb—and which positions still deserve capital.
Here is a closer look at Gerber's defensive-focused strategy.
#gerber #pressure #still
The Gerber Kawasaki CEO says that while inflation, higher bond yields, oil prices, and Federal Reserve rate hikes can pressure stocks, he does not think investors should abandon equities wholesale. Instead, he advocates for a more defensive approach.
He recommends investors trim holdings with valuations that look stretched relative to their growth, build reserves in cash and short-duration fixed income **** ets, and keep long-term positions in companies that he believes still have strong earnings support, such as Nvidia.
And for investors trying to navigate an environment where corporate earnings remain strong while macroeconomic risks pressure stock valuations, that distinction matters. Gerber's framework is less about calling the market's next move than deciding which risks a portfolio can absorb—and which positions still deserve capital.
Here is a closer look at Gerber's defensive-focused strategy.
#gerber #pressure #still


3 days ago
On September 9, 2026, Academy Sports and Outdoors, Inc. (NASDAQ:ASO) posted second-quarter results for the period ended August 1, 2026. Net sales rose 3.0% to $1.65 billion, adjusted earnings per share climbed 19.1% to $2.31 from $1.94, and gross margin widened 440 basis points to 40.4%. Management lifted full-year adjusted EPS guidance to $6.50 to $6.90 and gross margin guidance to 35.5% to 36.0%. What the quarter did not deliver was a positive comp, which fell 0.4%.
Telsey Advisory came away seeing nothing that changes the thesis, calling the risk-reward attractive and pushing its target on Academy Sports and Outdoors, Inc. (NASDAQ:ASO) to $63 from $60 while staying at Outperform.
Wells Fargo's Ike Boruchow described himself as cautiously optimistic at current levels, arguing that both the quarter itself and management's forward commentary delivered upside surprise; his target moved to $55 from $50, though the rating stayed Equal Weight.
Barclays **** yst Adrienne Yih focused on the fact that Academy Sports and Outdoors, Inc. (NASDAQ:ASO) held its fiscal 2026 sales and comp guidance despite a tougher consumer backdrop and sequential demand deceleration, lifting her target to $53 from $50 at Equal Weight.
Supporting the case: e-commerce sales grew 12.8%, Sports and Recreation rose 6%, myAcademy loyalty membership passed 15 million, and the company raised adjusted free cash flow guidance to $300 million to $350 million after repurchasing $182.1 million of stock in the first half.
#sports #guidance #sales #target
Telsey Advisory came away seeing nothing that changes the thesis, calling the risk-reward attractive and pushing its target on Academy Sports and Outdoors, Inc. (NASDAQ:ASO) to $63 from $60 while staying at Outperform.
Wells Fargo's Ike Boruchow described himself as cautiously optimistic at current levels, arguing that both the quarter itself and management's forward commentary delivered upside surprise; his target moved to $55 from $50, though the rating stayed Equal Weight.
Barclays **** yst Adrienne Yih focused on the fact that Academy Sports and Outdoors, Inc. (NASDAQ:ASO) held its fiscal 2026 sales and comp guidance despite a tougher consumer backdrop and sequential demand deceleration, lifting her target to $53 from $50 at Equal Weight.
Supporting the case: e-commerce sales grew 12.8%, Sports and Recreation rose 6%, myAcademy loyalty membership passed 15 million, and the company raised adjusted free cash flow guidance to $300 million to $350 million after repurchasing $182.1 million of stock in the first half.
#sports #guidance #sales #target


3 days ago
Industrial automation company Rockwell (ROK) has joined Project Glasswing, Anthropic's initiative focused on using advanced artificial intelligence (AI) to improve cybersecurity across critical infrastructure. For Rockwell, this is especially relevant because its systems sit inside factories, warehouses, semiconductor plants, and other industrial operations.
The timing also matters. ROK stock has already had a strong run this year, while its latest results showed solid demand and expanding margins. But shares have pulled back from their June 52-week high of $497.36. That leaves investors asking whether Project Glasswing can become another growth driver or simply adds another layer to Rockwell's long-term technology story.
Mark Cuban Says He Was Dizzy for Months, So He Built a VR Fix That Does at Home 'Much Of What A 180k Machine' Does
Bank of America Just Declared a 'Generational Entry Point' in U.S. Bonds. Why Investors Should Be Backing Up the Truck on Treasuries Here.
Nvidia, OpenAI, and Oracle's $745B Financing Circle Just Hit Its First Stress Test: A Fed Rate Hike
#june #cuban
The timing also matters. ROK stock has already had a strong run this year, while its latest results showed solid demand and expanding margins. But shares have pulled back from their June 52-week high of $497.36. That leaves investors asking whether Project Glasswing can become another growth driver or simply adds another layer to Rockwell's long-term technology story.
Mark Cuban Says He Was Dizzy for Months, So He Built a VR Fix That Does at Home 'Much Of What A 180k Machine' Does
Bank of America Just Declared a 'Generational Entry Point' in U.S. Bonds. Why Investors Should Be Backing Up the Truck on Treasuries Here.
Nvidia, OpenAI, and Oracle's $745B Financing Circle Just Hit Its First Stress Test: A Fed Rate Hike
#june #cuban



4 days ago
Aristotle International Equity Fund, sub-advised by Aristotle Capital Management, LLC, released its second-quarter 2026 investor letter. The letter can be downloaded here. Global equity markets reached record highs in Q2, with the MSCI ACWI Index rising 14.93%, while global fixed income grew modestly by 0.87%. Geopolitical tensions, particularly in the Middle East, affected energy markets and investor sentiment, highlighting volatility and fragility in global supply. Central banks reacted variably to inflationary pressures, with the ECB raising rates amidst concerns of stagflation, while the Fed and Bank of England held rates steady. Despite economic challenges, robust earnings continued in Europe and Asia, driven by AI infrastructure demand. The Aristotle International Equity Fund (Class I-2) recorded an 8.40% return in the quarter, underperforming both the MSCI EAFE Index, which returned 10.82%, and the MSCI ACWI ex USA Index, which returned 14.49%. Going forward, the fund remains focused on quality investments as geopolitical and macroeconomic complexities make forecasting returns challenging. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its second-quarter 2026 investor letter, Aristotle International Equity Fund highlighted Unilever PLC (NYSE:UL). Unilever PLC (NYSE:UL) is a British consumer goods giant, that sell products across food, homecare, beauty, and personal care categories. On September 17, 2026, Unilever PLC (NYSE:UL) closed at $62.22 per share. Over the past month, Unilever PLC (NYSE:UL) declined 2.99%, but its shares are down 5.09% over the past year. Unilever PLC (NYSE:UL) has a market capitalization of $133.98 billion, and its stock has traded within a 52-week range of $54.75 to $74.98.
Aristotle International Equity Fund stated the following regarding Unilever PLC (NYSE:UL) in its Q2 2026 investor letter:
"We first invested in Unilever PLC (NYSE:UL), the global consumer staples company, in the second quarter of 2013. We have long been attracted to the company's broad portfolio of leading personal care and food brands (such as Dove, Knorr and Axe), global scale, significant emerging markets exposure and strong position across everyday use categories. Over our more than decade-long holding period, Unilever strengthened and simplified its portfolio, divesting lower-growth food ***** ets, improving efficiency, increasing focus behind its largest brands and shifting the business toward faster-growing, higher-margin beauty, wellbeing, personal care and home care categories. More recently, the separation of the ice cream business and continued reshaping of the food portfolio have further narrowed Unilever's strategic focus. While we continue to view the remaining Unilever franchise as high quality, we believe the more compelling opportunity now resides in the independent ice cream business, where dedicated management and a category-specific strategy should provide a clearer pa
In its second-quarter 2026 investor letter, Aristotle International Equity Fund highlighted Unilever PLC (NYSE:UL). Unilever PLC (NYSE:UL) is a British consumer goods giant, that sell products across food, homecare, beauty, and personal care categories. On September 17, 2026, Unilever PLC (NYSE:UL) closed at $62.22 per share. Over the past month, Unilever PLC (NYSE:UL) declined 2.99%, but its shares are down 5.09% over the past year. Unilever PLC (NYSE:UL) has a market capitalization of $133.98 billion, and its stock has traded within a 52-week range of $54.75 to $74.98.
Aristotle International Equity Fund stated the following regarding Unilever PLC (NYSE:UL) in its Q2 2026 investor letter:
"We first invested in Unilever PLC (NYSE:UL), the global consumer staples company, in the second quarter of 2013. We have long been attracted to the company's broad portfolio of leading personal care and food brands (such as Dove, Knorr and Axe), global scale, significant emerging markets exposure and strong position across everyday use categories. Over our more than decade-long holding period, Unilever strengthened and simplified its portfolio, divesting lower-growth food ***** ets, improving efficiency, increasing focus behind its largest brands and shifting the business toward faster-growing, higher-margin beauty, wellbeing, personal care and home care categories. More recently, the separation of the ice cream business and continued reshaping of the food portfolio have further narrowed Unilever's strategic focus. While we continue to view the remaining Unilever franchise as high quality, we believe the more compelling opportunity now resides in the independent ice cream business, where dedicated management and a category-specific strategy should provide a clearer pa
4 days ago
CorpGov is pleased to share the final agenda for the 2nd LA CorpGov Forum, to be held on Friday, Sept. 18, 2026 at The Huntington Library in San Marino, California. The conference registration will begin at 1:00pm and feature an afternoon of panels, firesides and networking, followed by a reception at 5:00pm with ***** tails and hors d'oeuvres in the Garden Court.
This event will bring together members of the financial community from both LA and beyond to join panels focused on the finance of entertainment and media, sports, along with capital markets and shareholder activism.
We invite institutional investors and corporate executives to attend and they may register at the link below. For more information, please email EditorCorpGov.com.
2:00PM: Best Practices in Sports Investing
Thomas W. Hulick, CEO, Managing Partner, Strategy ***** et Managers
#sports #Friday #library #california
This event will bring together members of the financial community from both LA and beyond to join panels focused on the finance of entertainment and media, sports, along with capital markets and shareholder activism.
We invite institutional investors and corporate executives to attend and they may register at the link below. For more information, please email EditorCorpGov.com.
2:00PM: Best Practices in Sports Investing
Thomas W. Hulick, CEO, Managing Partner, Strategy ***** et Managers
#sports #Friday #library #california


4 days ago
Watch Highlights From the 2025 Palm Beach CorpGov Forum:
CorpGov, IPO Edge and PE Edge will host the sixth annual Palm Beach CorpGov Forum on November 4-5, 2026, at the Palm Beach Lake Pavilion and The Cove Club, both located waterfront with sweeping views of Palm Beach Island, along with a reception at Cucina Palm Beach. The Forum will feature a VC-focused keynote panel on Wednesday evening and a full day of panels on Thursday, with networking events both nights.
Our audience will include approximately 300 attendees including institutional investors, board directors, family offices/HNWIs, attorneys, investment bankers and key advisors. For sponsorship, speaker or media enquiries, email EditorCorpGov.com
The event will be digitized into reports published on CorpGov and by its content partners (under relevant company stock tickers) Yahoo Finance, Bloomberg Terminals, Reuters via LSEG Workspace, and AlphaSense, and filmed with multiple 4K video cameras and professional editing.
Preliminary Agenda
#beach #corpgov #watch
CorpGov, IPO Edge and PE Edge will host the sixth annual Palm Beach CorpGov Forum on November 4-5, 2026, at the Palm Beach Lake Pavilion and The Cove Club, both located waterfront with sweeping views of Palm Beach Island, along with a reception at Cucina Palm Beach. The Forum will feature a VC-focused keynote panel on Wednesday evening and a full day of panels on Thursday, with networking events both nights.
Our audience will include approximately 300 attendees including institutional investors, board directors, family offices/HNWIs, attorneys, investment bankers and key advisors. For sponsorship, speaker or media enquiries, email EditorCorpGov.com
The event will be digitized into reports published on CorpGov and by its content partners (under relevant company stock tickers) Yahoo Finance, Bloomberg Terminals, Reuters via LSEG Workspace, and AlphaSense, and filmed with multiple 4K video cameras and professional editing.
Preliminary Agenda
#beach #corpgov #watch


4 days ago
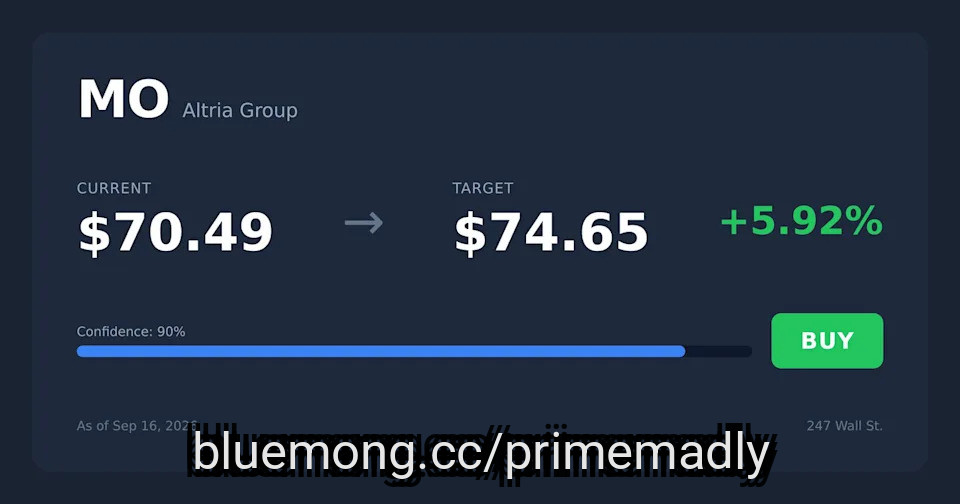
BTI yields 5.83% and beats MO on growth, trading at a cheaper forward P/E of 11 with EPS guidance of 5 to 8% versus Altria's 2.5 to 5.5%.
Altria wins on income reliability, having raised its dividend 60 times in 56 years with a 6.10% yield paid in dollars with zero currency risk.
BTI's Modern Oral segment surged 47% while Altria's nicotine pouch share fell 4 points and cigarette volumes dropped 10% in 2025.
Read More: Learn 7 secret wealth tips high net worth investors use that most investors miss (sponsor)
For a retirement-focused investor weighing high-yield tobacco names, the question is direct: British American Tobacco (NYSE:BTI) or Altria Group (NYSE:MO), which screens better for income investors right now? Both throw off cash, both trade at single-digit-to-low-teens forward earnings, and both are racing to replace shrinking combustible volumes with nicotine pouches, vapor, and heated tobacco. But when you line them up on the metrics that actually matter for a retiree cashing checks, one name comes out ahead.
#tobacco
Altria wins on income reliability, having raised its dividend 60 times in 56 years with a 6.10% yield paid in dollars with zero currency risk.
BTI's Modern Oral segment surged 47% while Altria's nicotine pouch share fell 4 points and cigarette volumes dropped 10% in 2025.
Read More: Learn 7 secret wealth tips high net worth investors use that most investors miss (sponsor)
For a retirement-focused investor weighing high-yield tobacco names, the question is direct: British American Tobacco (NYSE:BTI) or Altria Group (NYSE:MO), which screens better for income investors right now? Both throw off cash, both trade at single-digit-to-low-teens forward earnings, and both are racing to replace shrinking combustible volumes with nicotine pouches, vapor, and heated tobacco. But when you line them up on the metrics that actually matter for a retiree cashing checks, one name comes out ahead.
#tobacco


4 days ago
Brace for minor market tremors now that the Fed has hiked interest rates by 0.25%.
Although if history holds up, any losses could prove short-lived.
The S&P 500 (^GSPC) has declined by an average of 4.0% over the six weeks following the first Fed rate hike of a cycle across seven such episodes since 1988, per new ****** ysis from strategists at The Kobeissi Letter.
Stocks recovered all of those losses over the next five to six weeks on average.
In the six months following the first interest rate hike, the S&P 500 returned 4% on average. After 12 months, the S&P 500's average gain tallied 9%. Positive returns have occurred in every episode except 2022 over the 12 months.
"Fed rate hikes have historically been great buying opportunities," the strategists added.
Read more: Follow live coverage of the Fed meeting
The decision by the Fed to lift rates comes as sticky inflation readings — from the CPI to PPI — and rising energy costs force central bankers back into tightening mode. The rate hike marks the central bank's first interest rate increase since July 2023.
Investors are also focused on the updated economic projections and the Fed's "dot plot" to gauge future moves on rates — said dot plot didn't rule out one more hike this year. A hawkish dot plot as was received and follow up commentary from Fed Chairman Kevin Warsh could further elevate borrowing costs and pressure stocks initially around the world.
#rate #hike #first #plot
Although if history holds up, any losses could prove short-lived.
The S&P 500 (^GSPC) has declined by an average of 4.0% over the six weeks following the first Fed rate hike of a cycle across seven such episodes since 1988, per new ****** ysis from strategists at The Kobeissi Letter.
Stocks recovered all of those losses over the next five to six weeks on average.
In the six months following the first interest rate hike, the S&P 500 returned 4% on average. After 12 months, the S&P 500's average gain tallied 9%. Positive returns have occurred in every episode except 2022 over the 12 months.
"Fed rate hikes have historically been great buying opportunities," the strategists added.
Read more: Follow live coverage of the Fed meeting
The decision by the Fed to lift rates comes as sticky inflation readings — from the CPI to PPI — and rising energy costs force central bankers back into tightening mode. The rate hike marks the central bank's first interest rate increase since July 2023.
Investors are also focused on the updated economic projections and the Fed's "dot plot" to gauge future moves on rates — said dot plot didn't rule out one more hike this year. A hawkish dot plot as was received and follow up commentary from Fed Chairman Kevin Warsh could further elevate borrowing costs and pressure stocks initially around the world.
#rate #hike #first #plot


4 days ago
Autonomous vehicle company May Mobility is merging with a special purpose acquisition company (SPAC) and will become a publicly traded company. It's a deal that could raise more than $300 million for May Mobility at a valuation of $1.4 billion, the company said Wednesday.
Once the merger is complete, May Mobility said it will be the first public company in the U.S. that is focused entirely on autonomous ride-hailing vehicles. This is meant to differentiate it from a number of other public companies working on autonomy, including Tesla, Rivian, Alphabet (with Waymo), and trucking-focused Aurora and Kodiak.
The move sets up May Mobility to be a test of the stock market's appetite for pure-play robotaxi ventures.
It will also be a test of May Mobility's approach to autonomy, which it pitches as "asset-light" and "partnership-first." Instead of owning and operating the robotaxis, May Mobility's business revolves around selling its autonomous vehicles to its fleet partners over time while maintaining control of any remote supervision and software updates. In exchange, May Mobility receives either fixed fees or per-trip licensing fees.
Founded in 2017, May Mobility currently operates autonomous Toyota Siennas in three locations in the U.S. It has a partnership with Lyft in Atlanta, and offers rides in two cities — Eden Prairie and Grand Rapids — in Minnesota.
#company #autonomous #focused
Once the merger is complete, May Mobility said it will be the first public company in the U.S. that is focused entirely on autonomous ride-hailing vehicles. This is meant to differentiate it from a number of other public companies working on autonomy, including Tesla, Rivian, Alphabet (with Waymo), and trucking-focused Aurora and Kodiak.
The move sets up May Mobility to be a test of the stock market's appetite for pure-play robotaxi ventures.
It will also be a test of May Mobility's approach to autonomy, which it pitches as "asset-light" and "partnership-first." Instead of owning and operating the robotaxis, May Mobility's business revolves around selling its autonomous vehicles to its fleet partners over time while maintaining control of any remote supervision and software updates. In exchange, May Mobility receives either fixed fees or per-trip licensing fees.
Founded in 2017, May Mobility currently operates autonomous Toyota Siennas in three locations in the U.S. It has a partnership with Lyft in Atlanta, and offers rides in two cities — Eden Prairie and Grand Rapids — in Minnesota.
#company #autonomous #focused


4 days ago
On August 5, Kinetik Holdings Inc. (NYSE:KNTK) reported the strongest quarterly results in company history and raised its full-year 2026 guidance. The Permian-focused midstream operator posted net income, including noncontrolling interest, of $123.1 million for the quarter ended June 30, while Adjusted EBITDA climbed to $280.8 million. Management didn't stop at celebrating the number. It used the quarter as the launchpad for a string of expansion decisions that stretch out to 2028.
The Midstream Logistics segment, Kinetik's largest, grew Adjusted EBITDA 35% year over year to $204.8 million in the second quarter, even though processed natural gas volumes held flat at 1.74 Bcf/d. That flat number actually undersells the quarter. It came despite roughly 250 million cubic feet per day of gas that had been shut in because of weak Waha-area pricing, with stronger natural gas liquid recoveries, condensate yields, and favorable commodity spreads carrying the segment instead.
Management is betting the growth continues well past 2026. In May, Kinetik reached a final investment decision on Kings Landing II, a roughly $260 million project that will lift sour gas processing capacity across the company's Delaware North complex above 700 MMcf/d and push total system capacity to 2.7 Bcf/d when it comes online in mid-2028, earlier than previously communicated. The ECCC Pipeline, which links the system's northern and southern halves between Eddy and Culberson Counties, is now in service, and right-of-way work has already begun on a follow-on expansion for 2027.
Kinetik also locked in new firm Gulf Coast access for residue gas starting in 2027 and signed fresh natural gas liquids transport agreements, both aimed at getting better prices for the gas it moves. On the back of that momentum, Kinetik raised its full-year 2026 Adjusted EBITDA guidance to a range of $1.04 billion to $1.1 billion, a 7% ***** p from the guidance it issued in February.
Not every part of the business is moving in the same direction. The Pipeline Transportation segment posted Adjusted EBITDA of $83.0 million in the quarter, down 14% year over year, a decline the company attributes to last year's divestiture of its equity stake in EPIC Crude Holdings. That sale removed a source of cash flow the rest of the business now has to make up for. Kinetik also expects gas curtailments to keep running at an average of 25 million cubic feet per day through the second half of 2026, on top of the Waha-driven shut-ins that already weighed on the quarter. Its own pricing ***** umptions underline the regional problem: the company is now modeling Waha Hub natural gas at negative $0.26 per MMBtu for the full year, meaning gas in parts of the Permian is priced so low that moving it out of the basin is the whole game.
#quarter
The Midstream Logistics segment, Kinetik's largest, grew Adjusted EBITDA 35% year over year to $204.8 million in the second quarter, even though processed natural gas volumes held flat at 1.74 Bcf/d. That flat number actually undersells the quarter. It came despite roughly 250 million cubic feet per day of gas that had been shut in because of weak Waha-area pricing, with stronger natural gas liquid recoveries, condensate yields, and favorable commodity spreads carrying the segment instead.
Management is betting the growth continues well past 2026. In May, Kinetik reached a final investment decision on Kings Landing II, a roughly $260 million project that will lift sour gas processing capacity across the company's Delaware North complex above 700 MMcf/d and push total system capacity to 2.7 Bcf/d when it comes online in mid-2028, earlier than previously communicated. The ECCC Pipeline, which links the system's northern and southern halves between Eddy and Culberson Counties, is now in service, and right-of-way work has already begun on a follow-on expansion for 2027.
Kinetik also locked in new firm Gulf Coast access for residue gas starting in 2027 and signed fresh natural gas liquids transport agreements, both aimed at getting better prices for the gas it moves. On the back of that momentum, Kinetik raised its full-year 2026 Adjusted EBITDA guidance to a range of $1.04 billion to $1.1 billion, a 7% ***** p from the guidance it issued in February.
Not every part of the business is moving in the same direction. The Pipeline Transportation segment posted Adjusted EBITDA of $83.0 million in the quarter, down 14% year over year, a decline the company attributes to last year's divestiture of its equity stake in EPIC Crude Holdings. That sale removed a source of cash flow the rest of the business now has to make up for. Kinetik also expects gas curtailments to keep running at an average of 25 million cubic feet per day through the second half of 2026, on top of the Waha-driven shut-ins that already weighed on the quarter. Its own pricing ***** umptions underline the regional problem: the company is now modeling Waha Hub natural gas at negative $0.26 per MMBtu for the full year, meaning gas in parts of the Permian is priced so low that moving it out of the basin is the whole game.
#quarter

4 days ago
On September 14, Radiant Logistics (NYSEAMERICAN:RLGT) held its fourth fiscal quarter earnings call, and the headline numbers landed harder than a typical logistics update. Net income jumped 53.1% to $7.5 million for the quarter ended June 30, while revenue climbed 18.5% to $261.4 million. Look past that one quarter, though, and the picture gets more complicated, because full-year adjusted profitability actually fell. That gap between a blowout quarter and a softer year is what makes this name worth a closer look.
The fourth fiscal quarter was strong from top to bottom. Adjusted EBITDA rose 31.6% to $10.4 million, margin expanded 240 basis points to 15.5%, and adjusted net income climbed 34.5% to $7.4 million, all against organic revenue growth of 8%. Management credited the acceleration to US forwarding operations and international airfreight, including work supporting disaster relief after typhoon activity hit the Western Pacific earlier this year, plus airfreight demand tied to capital flows into global data center buildouts.
The balance sheet backs up the story. Radiant enters fiscal 2027 with zero net debt, $25.6 million in cash as of June 30, and a $200 million senior credit facility that was extended and restated in August, pushing maturity out to August 7, 2031, while its acquisition-focused accordion grew to $100 million from $75 million. On the domestic side, capacity has been exiting the truckload and intermodal markets, and spot rates and tender rejections moved higher late in the quarter. Radiant also launched a new independent agent program at Radiant Road & Rail during the quarter, extending its freight forwarding agent network into truck brokerage and intermodal, while Navegate is gaining traction, with one enterprise customer now managing more than 1,400 vendors on the platform.
The full-year numbers tell a different story than the quarter does. Revenue rose just 3.5% to $934.4 million from $902.7 million, a fraction of the fourth quarter's 18.5% pace, and full-year net income grew a modest 8.7% to $18.8 million. Full-year adjusted EBITDA actually fell 5.4% to $36.7 million from $38.8 million, and that figure included a $1.3 million First Brands adjustment. Strip that out and normalized adjusted EBITDA comes in at $35.4 million, an even steeper decline than the headline number suggests.
The operating backdrop stays complicated too. Ocean shipping routes remain disrupted by the closure of the Strait of Hormuz and continued Houthi activity affecting Suez Canal transits, keeping capacity tight on key trade lanes. US tariff policy is generating elevated IEEPA-related filing activity, and Canada put new retaliatory tariff measures into effect in early September, adding fresh complexity for shippers moving goods across that border. Management itself acknowledged that the domestic truck brokerage improvement seen late in the fourth quarter is not yet fully reflected in the reported results.
#quarter #revenue
The fourth fiscal quarter was strong from top to bottom. Adjusted EBITDA rose 31.6% to $10.4 million, margin expanded 240 basis points to 15.5%, and adjusted net income climbed 34.5% to $7.4 million, all against organic revenue growth of 8%. Management credited the acceleration to US forwarding operations and international airfreight, including work supporting disaster relief after typhoon activity hit the Western Pacific earlier this year, plus airfreight demand tied to capital flows into global data center buildouts.
The balance sheet backs up the story. Radiant enters fiscal 2027 with zero net debt, $25.6 million in cash as of June 30, and a $200 million senior credit facility that was extended and restated in August, pushing maturity out to August 7, 2031, while its acquisition-focused accordion grew to $100 million from $75 million. On the domestic side, capacity has been exiting the truckload and intermodal markets, and spot rates and tender rejections moved higher late in the quarter. Radiant also launched a new independent agent program at Radiant Road & Rail during the quarter, extending its freight forwarding agent network into truck brokerage and intermodal, while Navegate is gaining traction, with one enterprise customer now managing more than 1,400 vendors on the platform.
The full-year numbers tell a different story than the quarter does. Revenue rose just 3.5% to $934.4 million from $902.7 million, a fraction of the fourth quarter's 18.5% pace, and full-year net income grew a modest 8.7% to $18.8 million. Full-year adjusted EBITDA actually fell 5.4% to $36.7 million from $38.8 million, and that figure included a $1.3 million First Brands adjustment. Strip that out and normalized adjusted EBITDA comes in at $35.4 million, an even steeper decline than the headline number suggests.
The operating backdrop stays complicated too. Ocean shipping routes remain disrupted by the closure of the Strait of Hormuz and continued Houthi activity affecting Suez Canal transits, keeping capacity tight on key trade lanes. US tariff policy is generating elevated IEEPA-related filing activity, and Canada put new retaliatory tariff measures into effect in early September, adding fresh complexity for shippers moving goods across that border. Management itself acknowledged that the domestic truck brokerage improvement seen late in the fourth quarter is not yet fully reflected in the reported results.
#quarter #revenue

4 days ago
Parnassus Investments, an investment management company, released the "Parnassus Growth Equity Fund" second-quarter 2026 investor letter. The letter can be downloaded here. During the quarter, the Fund (Investor Shares) returned 17.49% (net of fees), outperforming the Russell 1000 Growth Index's 16.74%. Holdings in Information Technology and Consumer Discretionary sectors boosted relative returns, while Communication Services and Financials holdings detracted. For the year-to-date period, the Fund returned 6.17% (net of fees), outperforming the Russell 1000 Growth's 5.33%. The firm remains constructively bullish on U.S. equities and continues to be selective, valuation-sensitive, and focused on disruptive growth opportunities through active stock selection. Growth stocks advanced during the second quarter, as the Russell 1000 Growth Index generated strong double-digit returns driven by increased confidence in the durability of the ongoing artificial intelligence (AI) infrastructure build-out. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its second-quarter 2026 investor letter, Parnassus Growth Equity Fund highlighted Sandisk Corporation (NASDAQ:SNDK) as a newly added position. Sandisk Corporation (NASDAQ:SNDK) develops, manufactures, and sells data storage devices and solutions using NAND flash technology in the United States and internationally. On September 15, 2026, Sandisk Corporation (NASDAQ:SNDK) closed at $1,530.90 per share. Over the past month, Sandisk Corporation (NASDAQ:SNDK) declined 2.32%, but its shares are up 1,530.74% over the past year. Sandisk Corporation (NASDAQ:SNDK) has a market capitalization of $224.15 billion, and its stock has traded within a 52-week range of $90.22 to $2,354.39.
Parnassus Growth Equity Fund stated the following regarding Sandisk Corporation (NASDAQ:SNDK) in its Q2 2026 investor letter:
"Other positions added during the quarter included Sandisk Corporation (NASDAQ:SNDK), a leader in flash memory solutions; Comfort Systems, a mechanical, electrical and plumbing contractor. Sandisk makes NAND flash memory, which is seeing a surge in demand from data centers and AI workloads. While NAND remains cyclical, we believe the combination of accelerating AI-driven storage demand and constrained supply provides an attractive opportunity to participate in the current upcycle."
Sandisk Corporation (NASDAQ:SNDK) is on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 128 hedge fund portfolios held Sandisk Corporation (NASDAQ:SNDK) at the end of the second quarter which was 114 in the previous quarter. While we acknowledge the potential of Sandisk Corporation (NASDAQ:SNDK) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our fre
In its second-quarter 2026 investor letter, Parnassus Growth Equity Fund highlighted Sandisk Corporation (NASDAQ:SNDK) as a newly added position. Sandisk Corporation (NASDAQ:SNDK) develops, manufactures, and sells data storage devices and solutions using NAND flash technology in the United States and internationally. On September 15, 2026, Sandisk Corporation (NASDAQ:SNDK) closed at $1,530.90 per share. Over the past month, Sandisk Corporation (NASDAQ:SNDK) declined 2.32%, but its shares are up 1,530.74% over the past year. Sandisk Corporation (NASDAQ:SNDK) has a market capitalization of $224.15 billion, and its stock has traded within a 52-week range of $90.22 to $2,354.39.
Parnassus Growth Equity Fund stated the following regarding Sandisk Corporation (NASDAQ:SNDK) in its Q2 2026 investor letter:
"Other positions added during the quarter included Sandisk Corporation (NASDAQ:SNDK), a leader in flash memory solutions; Comfort Systems, a mechanical, electrical and plumbing contractor. Sandisk makes NAND flash memory, which is seeing a surge in demand from data centers and AI workloads. While NAND remains cyclical, we believe the combination of accelerating AI-driven storage demand and constrained supply provides an attractive opportunity to participate in the current upcycle."
Sandisk Corporation (NASDAQ:SNDK) is on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 128 hedge fund portfolios held Sandisk Corporation (NASDAQ:SNDK) at the end of the second quarter which was 114 in the previous quarter. While we acknowledge the potential of Sandisk Corporation (NASDAQ:SNDK) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our fre

4 days ago
Parnassus Investments, an investment management company, released the "Parnassus Growth Equity Fund" second-quarter 2026 investor letter. The letter can be downloaded here. During the quarter, the Fund (Investor Shares) returned 17.49% (net of fees), outperforming the Russell 1000 Growth Index's 16.74%. Holdings in Information Technology and Consumer Discretionary sectors boosted relative returns, while Communication Services and Financials holdings detracted. For the year-to-date period, the Fund returned 6.17% (net of fees), outperforming the Russell 1000 Growth's 5.33%. The firm remains constructively bullish on U.S. equities and continues to be selective, valuation-sensitive, and focused on disruptive growth opportunities through active stock selection. Growth stocks advanced during the second quarter, as the Russell 1000 Growth Index generated strong double-digit returns driven by increased confidence in the durability of the ongoing artificial intelligence (AI) infrastructure build-out. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its second-quarter 2026 investor letter, Parnassus Growth Equity Fund highlighted Brown & Brown, Inc. (NYSE:BRO). Brown & Brown, Inc. (NYSE:BRO) is a leading insurance brokerage firm operating through Retail and Specialty Distribution segments. On September 15, 2026, Brown & Brown, Inc. (NYSE:BRO) closed at $67.23 per share, reflecting a market capitalization of $22.5 billion. Brown & Brown, Inc. (NYSE:BRO) posted a one‑month return of -6.29%, while its shares lost 27.35% over the past 52 weeks.
Parnassus Growth Equity Fund stated the following regarding Brown & Brown, Inc. (NYSE:BRO) in its Q2 2026 investor letter:
"We sold Brown & Brown Inc. during the quarter. Brown & Brown, Inc. (NYSE:BRO) remains a high-quality business, but we see rising near term risks as the company navigates an industry downturn, integrates a large acquisition and works to close an AI capability gap versus larger peers."
Brown & Brown, Inc. (NYSE:BRO) is not on our list of 40 Most Popular Stocks Among Hedge Funds Heading Into 2026. According to our database, 44 hedge fund portfolios held Brown & Brown, Inc. (NYSE:BRO) at the end of the second quarter, compared to 41 in the previous quarter. While we acknowledge the potential of Brown & Brown, Inc. (NYSE:BRO) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#quarter #letter
In its second-quarter 2026 investor letter, Parnassus Growth Equity Fund highlighted Brown & Brown, Inc. (NYSE:BRO). Brown & Brown, Inc. (NYSE:BRO) is a leading insurance brokerage firm operating through Retail and Specialty Distribution segments. On September 15, 2026, Brown & Brown, Inc. (NYSE:BRO) closed at $67.23 per share, reflecting a market capitalization of $22.5 billion. Brown & Brown, Inc. (NYSE:BRO) posted a one‑month return of -6.29%, while its shares lost 27.35% over the past 52 weeks.
Parnassus Growth Equity Fund stated the following regarding Brown & Brown, Inc. (NYSE:BRO) in its Q2 2026 investor letter:
"We sold Brown & Brown Inc. during the quarter. Brown & Brown, Inc. (NYSE:BRO) remains a high-quality business, but we see rising near term risks as the company navigates an industry downturn, integrates a large acquisition and works to close an AI capability gap versus larger peers."
Brown & Brown, Inc. (NYSE:BRO) is not on our list of 40 Most Popular Stocks Among Hedge Funds Heading Into 2026. According to our database, 44 hedge fund portfolios held Brown & Brown, Inc. (NYSE:BRO) at the end of the second quarter, compared to 41 in the previous quarter. While we acknowledge the potential of Brown & Brown, Inc. (NYSE:BRO) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#quarter #letter

4 days ago
Parnassus Investments, an investment management company, released the "Parnassus Growth Equity Fund" second-quarter 2026 investor letter. The letter can be downloaded here. During the quarter, the Fund (Investor Shares) returned 17.49% (net of fees), outperforming the Russell 1000 Growth Index's 16.74%. Holdings in Information Technology and Consumer Discretionary sectors boosted relative returns, while Communication Services and Financials holdings detracted. For the year-to-date period, the Fund returned 6.17% (net of fees), outperforming the Russell 1000 Growth's 5.33%. The firm remains constructively bullish on U.S. equities and continues to be selective, valuation-sensitive, and focused on disruptive growth opportunities through active stock selection. Growth stocks advanced during the second quarter, as the Russell 1000 Growth Index generated strong double-digit returns driven by increased confidence in the durability of the ongoing artificial intelligence (AI) infrastructure build-out. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its second-quarter 2026 investor letter, Parnassus Growth Equity Fund highlighted Comfort Systems USA, Inc. (NYSE:FIX) as a new position. Comfort Systems USA, Inc. (NYSE:FIX) is a leading mechanical and electrical installation, renovation, maintenance, repair, and replacement services provider to commercial, industrial, and institutional customers. On September 15, 2026, Comfort Systems USA, Inc. (NYSE:FIX) closed at $1,576.78 per share. Over the past month, Comfort Systems USA, Inc. (NYSE:FIX) declined 5.15% and its shares gained 110.86% over the past 52 weeks. Comfort Systems USA, Inc. (NYSE:FIX) has a market capitalization of $55.49 billion.
Parnassus Growth Equity Fund stated the following regarding Comfort Systems USA, Inc. (NYSE:FIX) in its Q2 2026 investor letter:
"Other positions added during the quarter included Comfort Systems, a mechanical, electrical and plumbing contractor. Comfort Systems USA, Inc. (NYSE:FIX) is a mechanical, electrical and plumbing contractor that provides the skilled labor that's essential for building increasingly complex data centers, where demand continues to accelerate alongside AI investment."
Comfort Systems USA, Inc. (NYSE:FIX) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 83 hedge fund portfolios held Comfort Systems USA, Inc. (NYSE:FIX) at the end of the second quarter which was 80 in the previous quarter. While we acknowledge the potential of Comfort Systems USA, Inc. (NYSE:FIX) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#systems #parnassus
In its second-quarter 2026 investor letter, Parnassus Growth Equity Fund highlighted Comfort Systems USA, Inc. (NYSE:FIX) as a new position. Comfort Systems USA, Inc. (NYSE:FIX) is a leading mechanical and electrical installation, renovation, maintenance, repair, and replacement services provider to commercial, industrial, and institutional customers. On September 15, 2026, Comfort Systems USA, Inc. (NYSE:FIX) closed at $1,576.78 per share. Over the past month, Comfort Systems USA, Inc. (NYSE:FIX) declined 5.15% and its shares gained 110.86% over the past 52 weeks. Comfort Systems USA, Inc. (NYSE:FIX) has a market capitalization of $55.49 billion.
Parnassus Growth Equity Fund stated the following regarding Comfort Systems USA, Inc. (NYSE:FIX) in its Q2 2026 investor letter:
"Other positions added during the quarter included Comfort Systems, a mechanical, electrical and plumbing contractor. Comfort Systems USA, Inc. (NYSE:FIX) is a mechanical, electrical and plumbing contractor that provides the skilled labor that's essential for building increasingly complex data centers, where demand continues to accelerate alongside AI investment."
Comfort Systems USA, Inc. (NYSE:FIX) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 83 hedge fund portfolios held Comfort Systems USA, Inc. (NYSE:FIX) at the end of the second quarter which was 80 in the previous quarter. While we acknowledge the potential of Comfort Systems USA, Inc. (NYSE:FIX) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#systems #parnassus
4 days ago
Parnassus Investments, an investment management company, released the "Parnassus Growth Equity Fund" second-quarter 2026 investor letter. The letter can be downloaded here. During the quarter, the Fund (Investor Shares) returned 17.49% (net of fees), outperforming the Russell 1000 Growth Index's 16.74%. Holdings in Information Technology and Consumer Discretionary sectors boosted relative returns, while Communication Services and Financials holdings detracted. For the year-to-date period, the Fund returned 6.17% (net of fees), outperforming the Russell 1000 Growth's 5.33%. The firm remains constructively bullish on U.S. equities and continues to be selective, valuation-sensitive, and focused on disruptive growth opportunities through active stock selection. Growth stocks advanced during the second quarter, as the Russell 1000 Growth Index generated strong double-digit returns driven by increased confidence in the durability of the ongoing artificial intelligence (AI) infrastructure build-out. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its second-quarter 2026 investor letter, Parnassus Growth Equity Fund highlighted Insmed Incorporated (NASDAQ:INSM). The Fund exited its position in Insmed Incorporated (NASDAQ:INSM), a clinical-stage biotechnology company that develops and commercializes therapies for patients with serious and rare diseases, during the quarter. On September 15, 2026, Insmed Incorporated (NASDAQ:INSM) closed at $119.92 per share. Over the past month, Insmed Incorporated (NASDAQ:INSM) declined 7.49%, but its shares are down 16.51% over the past year. Insmed Incorporated (NASDAQ:INSM) has a market capitalization of $26.19 billion, and its stock has traded within a 52-week range of $90.39 and $212.75.
Parnassus Growth Equity Fund stated the following regarding Insmed Incorporated (NASDAQ:INSM) in its Q2 2026 investor letter:
"Insmed Incorporated (NASDAQ:INSM)shares fell after sales of the biopharmaceutical company's new lung drug Brinsupri fell short of ****** ysts' expectations. We exited the position during the quarter. Insmed's thesis had largely played out following positive TPIP data and upward revisions to Brinsupri sales. We redeployed capital to Twist Bioscience, which offers a longer runway for growth."
Insmed Incorporated (NASDAQ:INSM) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 88 hedge fund portfolios held Insmed Incorporated (NASDAQ:INSM) at the end of the second quarter, compared to 67 in the previous quarter. While we acknowledge the potential of Insmed Incorporated (NASDAQ:INSM) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#Growth #parnassus
In its second-quarter 2026 investor letter, Parnassus Growth Equity Fund highlighted Insmed Incorporated (NASDAQ:INSM). The Fund exited its position in Insmed Incorporated (NASDAQ:INSM), a clinical-stage biotechnology company that develops and commercializes therapies for patients with serious and rare diseases, during the quarter. On September 15, 2026, Insmed Incorporated (NASDAQ:INSM) closed at $119.92 per share. Over the past month, Insmed Incorporated (NASDAQ:INSM) declined 7.49%, but its shares are down 16.51% over the past year. Insmed Incorporated (NASDAQ:INSM) has a market capitalization of $26.19 billion, and its stock has traded within a 52-week range of $90.39 and $212.75.
Parnassus Growth Equity Fund stated the following regarding Insmed Incorporated (NASDAQ:INSM) in its Q2 2026 investor letter:
"Insmed Incorporated (NASDAQ:INSM)shares fell after sales of the biopharmaceutical company's new lung drug Brinsupri fell short of ****** ysts' expectations. We exited the position during the quarter. Insmed's thesis had largely played out following positive TPIP data and upward revisions to Brinsupri sales. We redeployed capital to Twist Bioscience, which offers a longer runway for growth."
Insmed Incorporated (NASDAQ:INSM) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 88 hedge fund portfolios held Insmed Incorporated (NASDAQ:INSM) at the end of the second quarter, compared to 67 in the previous quarter. While we acknowledge the potential of Insmed Incorporated (NASDAQ:INSM) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#Growth #parnassus

4 days ago
AI data centers are facing growing power constraints, and the issue is becoming increasingly urgent. New utility capacity can take years to develop and bring online, but hyperscalers cannot afford to wait that long to support their growing computing needs. That gap between supply and demand creates an opportunity for Bloom Energy (BE), which is focused on delivering power where and when hyperscalers like Microsoft (MSFT), Amazon (AMZN), and Alphabet (GOOG) (GOOGL) require it. The fundamentals are now starting to provide support for the growing optimism around its opportunity.
Bloom Energy's technology stands out because it can address the AI power challenge on a much shorter timeline. The company's solid-oxide fuel cells are manufactured in factories and can be moved where required. They can also be deployed much faster than traditional power infrastructure. Instead of waiting years for grid upgrades or additional turbine capacity, data center developers can install Bloom Energy's systems and bring power online in a much shorter timeframe. As AI infrastructure expands, that speed has helped the company establish itself as an increasingly important on-site power vendor. All major U.S. hyperscalers are also providing validation of its position.
Why UBS Just Turned Bearish on NuScale Power Stock
Crude Oil Prices Retreat as Supply Fears Ease
Crude Prices Soar as Global Oil Supplies Continue to Tighten
#bloom #crude
Bloom Energy's technology stands out because it can address the AI power challenge on a much shorter timeline. The company's solid-oxide fuel cells are manufactured in factories and can be moved where required. They can also be deployed much faster than traditional power infrastructure. Instead of waiting years for grid upgrades or additional turbine capacity, data center developers can install Bloom Energy's systems and bring power online in a much shorter timeframe. As AI infrastructure expands, that speed has helped the company establish itself as an increasingly important on-site power vendor. All major U.S. hyperscalers are also providing validation of its position.
Why UBS Just Turned Bearish on NuScale Power Stock
Crude Oil Prices Retreat as Supply Fears Ease
Crude Prices Soar as Global Oil Supplies Continue to Tighten
#bloom #crude


4 days ago
Parnassus Investments, an investment management company, released the "Parnassus Growth Equity Fund" second-quarter 2026 investor letter. The letter can be downloaded here. During the quarter, the Fund (Investor Shares) returned 17.49% (net of fees), outperforming the Russell 1000 Growth Index's 16.74%. Holdings in Information Technology and Consumer Discretionary sectors boosted relative returns, while Communication Services and Financials holdings detracted. For the year-to-date period, the Fund returned 6.17% (net of fees), outperforming the Russell 1000 Growth's 5.33%. The firm remains constructively bullish on U.S. equities and continues to be selective, valuation-sensitive, and focused on disruptive growth opportunities through active stock selection. Growth stocks advanced during the second quarter, as the Russell 1000 Growth Index generated strong double-digit returns driven by increased confidence in the durability of the ongoing artificial intelligence (AI) infrastructure build-out. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its second-quarter 2026 investor letter, Parnassus Growth Equity Fund highlighted Medline Inc. (NASDAQ:MDLN). Medline Inc. (NASDAQ:MDLN) manufactures med-surg products serving hospitals, surgery centers, physician offices, post-acute facilities, and nursing home sites of care. On September 15, 2026, Medline Inc. (NASDAQ:MDLN) closed at $36.59 per share. Over the past month, Medline Inc. (NASDAQ:MDLN) declined 4.23%, and YTD its shares lost 22.68%. Medline Inc. has a market capitalization of $42.22 billion.
Parnassus Growth Equity Fund stated the following regarding Medline Inc. (NASDAQ:MDLN) in its Q2 2026 investor letter:
"Medline Inc. (NASDAQ:MDLN) shares declined as medical technology stocks broadly came under pressure. The company also faced near term concerns surrounding tariffs and higher transportation costs, though we remain confident in its long-term competitive positioning."
Medline Inc. (NASDAQ:MDLN) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 52 hedge fund portfolios held Medline Inc. (NASDAQ:MDLN) at the end of the second quarter which was 65 in the previous quarter. While we acknowledge the potential of Medline Inc. (NASDAQ:MDLN) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#medline #NASDAQ #fund #parnassus
In its second-quarter 2026 investor letter, Parnassus Growth Equity Fund highlighted Medline Inc. (NASDAQ:MDLN). Medline Inc. (NASDAQ:MDLN) manufactures med-surg products serving hospitals, surgery centers, physician offices, post-acute facilities, and nursing home sites of care. On September 15, 2026, Medline Inc. (NASDAQ:MDLN) closed at $36.59 per share. Over the past month, Medline Inc. (NASDAQ:MDLN) declined 4.23%, and YTD its shares lost 22.68%. Medline Inc. has a market capitalization of $42.22 billion.
Parnassus Growth Equity Fund stated the following regarding Medline Inc. (NASDAQ:MDLN) in its Q2 2026 investor letter:
"Medline Inc. (NASDAQ:MDLN) shares declined as medical technology stocks broadly came under pressure. The company also faced near term concerns surrounding tariffs and higher transportation costs, though we remain confident in its long-term competitive positioning."
Medline Inc. (NASDAQ:MDLN) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 52 hedge fund portfolios held Medline Inc. (NASDAQ:MDLN) at the end of the second quarter which was 65 in the previous quarter. While we acknowledge the potential of Medline Inc. (NASDAQ:MDLN) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#medline #NASDAQ #fund #parnassus

4 days ago
Parnassus Investments, an investment management company, released the "Parnassus Growth Equity Fund" second-quarter 2026 investor letter. The letter can be downloaded here. During the quarter, the Fund (Investor Shares) returned 17.49% (net of fees), outperforming the Russell 1000 Growth Index's 16.74%. Holdings in Information Technology and Consumer Discretionary sectors boosted relative returns, while Communication Services and Financials holdings detracted. For the year-to-date period, the Fund returned 6.17% (net of fees), outperforming the Russell 1000 Growth's 5.33%. The firm remains constructively bullish on U.S. equities and continues to be selective, valuation-sensitive, and focused on disruptive growth opportunities through active stock selection. Growth stocks advanced during the second quarter, as the Russell 1000 Growth Index generated strong double-digit returns driven by increased confidence in the durability of the ongoing artificial intelligence (AI) infrastructure build-out. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its second-quarter 2026 investor letter, Parnassus Growth Equity Fund highlighted Lumentum Holdings Inc. (NASDAQ:LITE). Lumentum Holdings Inc. (NASDAQ:LITE) is a leading technology company that manufactures and sells optical and photonic products. On September 15, 2026, Lumentum Holdings Inc. closed at $838.96 per share. Over the past month, Lumentum Holdings Inc. gained 6.57%, and its shares are up 439.98% over the past year. Lumentum Holdings Inc. has a market capitalization of $75.25 billion, and its stock has traded within a 52-week range of $144.52 to $1,085.68.
Parnassus Growth Equity Fund stated the following regarding Lumentum Holdings Inc. (NASDAQ:LITE) in its Q2 2026 investor letter:
"Lumentum Holdings Inc. (NASDAQ:LITE) offers exposure to a key bottleneck in AI infrastructure, optical networking, as rising data demand drives a shift away from copper-based systems. Its components enable faster, more efficient data transfer and benefit from strong competitive advantages, including deep technical expertise and high switching costs once embedded in customer platforms."
Lumentum Holdings Inc. (NASDAQ:LITE) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 111 hedge fund portfolios held Lumentum Holdings Inc. (NASDAQ:LITE) at the end of the second quarter, down from 123 in the previous quarter. While we acknowledge the potential of Lumentum Holdings Inc. (NASDAQ:LITE) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#Growth #fund #quarter #parnassus
In its second-quarter 2026 investor letter, Parnassus Growth Equity Fund highlighted Lumentum Holdings Inc. (NASDAQ:LITE). Lumentum Holdings Inc. (NASDAQ:LITE) is a leading technology company that manufactures and sells optical and photonic products. On September 15, 2026, Lumentum Holdings Inc. closed at $838.96 per share. Over the past month, Lumentum Holdings Inc. gained 6.57%, and its shares are up 439.98% over the past year. Lumentum Holdings Inc. has a market capitalization of $75.25 billion, and its stock has traded within a 52-week range of $144.52 to $1,085.68.
Parnassus Growth Equity Fund stated the following regarding Lumentum Holdings Inc. (NASDAQ:LITE) in its Q2 2026 investor letter:
"Lumentum Holdings Inc. (NASDAQ:LITE) offers exposure to a key bottleneck in AI infrastructure, optical networking, as rising data demand drives a shift away from copper-based systems. Its components enable faster, more efficient data transfer and benefit from strong competitive advantages, including deep technical expertise and high switching costs once embedded in customer platforms."
Lumentum Holdings Inc. (NASDAQ:LITE) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 111 hedge fund portfolios held Lumentum Holdings Inc. (NASDAQ:LITE) at the end of the second quarter, down from 123 in the previous quarter. While we acknowledge the potential of Lumentum Holdings Inc. (NASDAQ:LITE) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#Growth #fund #quarter #parnassus

4 days ago
Parnassus Investments, an investment management company, released the "Parnassus Growth Equity Fund" second-quarter 2026 investor letter. The letter can be downloaded here. During the quarter, the Fund (Investor Shares) returned 17.49% (net of fees), outperforming the Russell 1000 Growth Index's 16.74%. Holdings in Information Technology and Consumer Discretionary sectors boosted relative returns, while Communication Services and Financials holdings detracted. For the year-to-date period, the Fund returned 6.17% (net of fees), outperforming the Russell 1000 Growth's 5.33%. The firm remains constructively bullish on U.S. equities and continues to be selective, valuation-sensitive, and focused on disruptive growth opportunities through active stock selection. Growth stocks advanced during the second quarter, as the Russell 1000 Growth Index generated strong double-digit returns driven by increased confidence in the durability of the ongoing artificial intelligence (AI) infrastructure build-out. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its second-quarter 2026 investor letter, Parnassus Growth Equity Fund highlighted Twist Bioscience Corporation (NASDAQ:TWST) as a new addition. Twist Bioscience Corporation (NASDAQ:TWST) is a leading biotechnology company specializing in the manufacture and sale of synthetic DNA-based products. On September 15, 2026, Twist Bioscience Corporation (NASDAQ:TWST) closed at $138.10 per share. Over the past month, Twist Bioscience Corporation (NASDAQ:TWST) returned 2.97% while its shares gained 443.64% over the past 52 weeks. Twist Bioscience Corporation (NASDAQ:TWST) has a market capitalization of $9.09 billion and its stock has traded within a 52-week range of $23.30 and $155.44.
Parnassus Growth Equity Fund stated the following regarding Twist Bioscience Corporation (NASDAQ:TWST) in its Q2 2026 investor letter:
"During the quarter, we added Twist Bioscience Corporation (NASDAQ:TWST), a biotechnology company with a proprietary silicon-based DNA synthesis platform. Twist Bioscience provides exposure to two powerful long-term trends in Health Care, AI-supported drug discovery and next-generation sequencing. The company's proprietary silicon-based DNA synthesis platform enables higher throughput and lower costs than traditional methods, creating a durable competitive advantage and positioning Twist to take share in a growing market."
Twist Bioscience Corporation (NASDAQ:TWST) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 42 hedge fund portfolios held Twist Bioscience Corporation (NASDAQ:TWST) at the end of the second quarter which was 30 in the previous quarter. While we acknowledge the potential of Twist Bioscience Corporation (NASDAQ:TWST) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands
In its second-quarter 2026 investor letter, Parnassus Growth Equity Fund highlighted Twist Bioscience Corporation (NASDAQ:TWST) as a new addition. Twist Bioscience Corporation (NASDAQ:TWST) is a leading biotechnology company specializing in the manufacture and sale of synthetic DNA-based products. On September 15, 2026, Twist Bioscience Corporation (NASDAQ:TWST) closed at $138.10 per share. Over the past month, Twist Bioscience Corporation (NASDAQ:TWST) returned 2.97% while its shares gained 443.64% over the past 52 weeks. Twist Bioscience Corporation (NASDAQ:TWST) has a market capitalization of $9.09 billion and its stock has traded within a 52-week range of $23.30 and $155.44.
Parnassus Growth Equity Fund stated the following regarding Twist Bioscience Corporation (NASDAQ:TWST) in its Q2 2026 investor letter:
"During the quarter, we added Twist Bioscience Corporation (NASDAQ:TWST), a biotechnology company with a proprietary silicon-based DNA synthesis platform. Twist Bioscience provides exposure to two powerful long-term trends in Health Care, AI-supported drug discovery and next-generation sequencing. The company's proprietary silicon-based DNA synthesis platform enables higher throughput and lower costs than traditional methods, creating a durable competitive advantage and positioning Twist to take share in a growing market."
Twist Bioscience Corporation (NASDAQ:TWST) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 42 hedge fund portfolios held Twist Bioscience Corporation (NASDAQ:TWST) at the end of the second quarter which was 30 in the previous quarter. While we acknowledge the potential of Twist Bioscience Corporation (NASDAQ:TWST) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands


4 days ago
Weitz Investment Management, an investment management firm, released its second-quarter Q2 2026 investor letter for the "Multi Cap Equity Fund". The letter can be downloaded here. The Multi Cap Equity Fund's Institutional Class returned 7.90% in Q2, underperforming the Bloomberg U.S. 3000 Index's 15.71% gain. Markets rose in the quarter on hopes of de-escalating Middle East tensions and easing oil flow. Investor focus shifted back to artificial intelligence, despite component shortages like processing chips affecting profits and valuations. Valuation-sensitive investors are selective within the AI sector, in contrast to valuation-agnostic indexes that adopt a more relaxed strategy. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its second-quarter 2026 investor letter, Weitz Multi Cap Equity Fund highlighted Charter Communications, Inc. (NASDAQ:CHTR). Charter Communications, Inc. (NASDAQ:CHTR) is a US-based broadband connectivity company. On September 15, 2026, Charter Communications, Inc. closed at $141.20 per share. Over the past month, Charter Communications, Inc. declined 7.39% and its shares lost 47.32% over the past 52 weeks. Charter Communications, Inc. has a market capitalization of $24.73 billion and its stock has traded within a 52-week range of $111.55 and $285.82.
Weitz Multi Cap Equity Fund stated the following regarding Charter Communications, Inc. (NASDAQ:CHTR) in its Q2 2026 investor letter:
"Charter Communications, Inc. (NASDAQ:CHTR) (the principal **** et of portfolio holding Liberty Broadband) shares were weak as investors remain laser-focused on the impact of competition in Charter's core broadband market. Although the stock price has not yet improved, we remain constructive and believe Charter's growing wireless business, forecasted reduction in investment spending and impending combination with **** provide reasons for optimism."
Charter Communications, Inc. (NASDAQ:CHTR) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 63 hedge fund portfolios held Charter Communications, Inc. (NASDAQ:CHTR) at the end of the second quarter which was 48 in the previous quarter. While we acknowledge the potential of Charter Communications, Inc. (NASDAQ:CHTR) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#communications #quarter #investor
In its second-quarter 2026 investor letter, Weitz Multi Cap Equity Fund highlighted Charter Communications, Inc. (NASDAQ:CHTR). Charter Communications, Inc. (NASDAQ:CHTR) is a US-based broadband connectivity company. On September 15, 2026, Charter Communications, Inc. closed at $141.20 per share. Over the past month, Charter Communications, Inc. declined 7.39% and its shares lost 47.32% over the past 52 weeks. Charter Communications, Inc. has a market capitalization of $24.73 billion and its stock has traded within a 52-week range of $111.55 and $285.82.
Weitz Multi Cap Equity Fund stated the following regarding Charter Communications, Inc. (NASDAQ:CHTR) in its Q2 2026 investor letter:
"Charter Communications, Inc. (NASDAQ:CHTR) (the principal **** et of portfolio holding Liberty Broadband) shares were weak as investors remain laser-focused on the impact of competition in Charter's core broadband market. Although the stock price has not yet improved, we remain constructive and believe Charter's growing wireless business, forecasted reduction in investment spending and impending combination with **** provide reasons for optimism."
Charter Communications, Inc. (NASDAQ:CHTR) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 63 hedge fund portfolios held Charter Communications, Inc. (NASDAQ:CHTR) at the end of the second quarter which was 48 in the previous quarter. While we acknowledge the potential of Charter Communications, Inc. (NASDAQ:CHTR) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#communications #quarter #investor


4 days ago
With a market cap of $27.1 billion, DTE Energy Company (DTE) is a diversified energy company engaged in energy-related businesses and services across the United States. Its operations include electric and natural gas utilities serving millions of customers in Michigan, along with businesses focused on custom energy solutions, renewable energy, and energy marketing and trading.
Companies worth more than $10 billion are generally labeled as "large-cap" stocks and DTE Energy fits this criterion perfectly. DTE Energy is also committed to accelerating carbon reduction, supporting community development, and promoting economic progress through philanthropy, education, employment initiatives, and volunteerism
Billionaire Charlie Munger, Who Died at 99, Skipped Insurance on His Mansion Since He Could Just Write a Check to Rebuild — 'All Intelligent People Do It My Way'
Nvidia CEO Jensen Huang Just Dropped Huge News for This Cybersecurity Stock
How to Play GME Stock as GameStop CEO Ryan Cohen Buys $20.3 Million in Shares
#energy #billion #businesses #states
Companies worth more than $10 billion are generally labeled as "large-cap" stocks and DTE Energy fits this criterion perfectly. DTE Energy is also committed to accelerating carbon reduction, supporting community development, and promoting economic progress through philanthropy, education, employment initiatives, and volunteerism
Billionaire Charlie Munger, Who Died at 99, Skipped Insurance on His Mansion Since He Could Just Write a Check to Rebuild — 'All Intelligent People Do It My Way'
Nvidia CEO Jensen Huang Just Dropped Huge News for This Cybersecurity Stock
How to Play GME Stock as GameStop CEO Ryan Cohen Buys $20.3 Million in Shares
#energy #billion #businesses #states

4 days ago
Invesco Aerospace & Defense ETF (NYSEMKT:PPA) offers a long track record and broad industrial exposure, while Global X Defense Tech ETF (NYSEMKT:SHLD) provides a lower-cost, technology-focused approach to the defense sector.
Defense spending often stays resilient throughout various economic cycles, making aerospace and defense exchange-traded funds a popular choice for investors seeking sector-specific growth. While both funds target the same broad industry, they differ in their approach to legacy hardware versus emerging technologies and software-defined systems. This comparison looks at how the veteran PPA stacks up against the newer SHLD.
Metric
SHLD
PPA
#approach
Defense spending often stays resilient throughout various economic cycles, making aerospace and defense exchange-traded funds a popular choice for investors seeking sector-specific growth. While both funds target the same broad industry, they differ in their approach to legacy hardware versus emerging technologies and software-defined systems. This comparison looks at how the veteran PPA stacks up against the newer SHLD.
Metric
SHLD
PPA
#approach