21 days ago
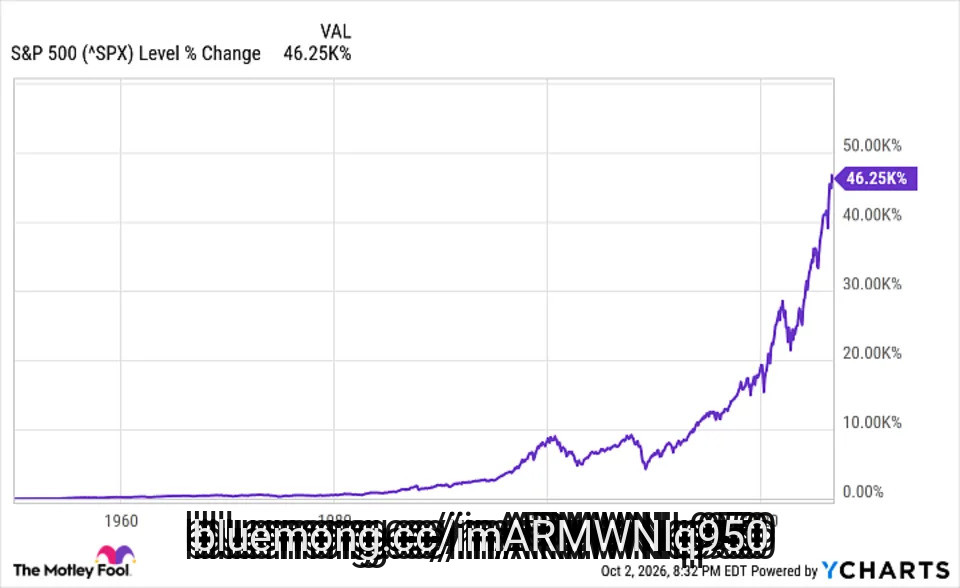
For decades, no investment portfolio has been more closely watched by investors than Berkshire Hathaway's (NYSE:BRKA)(NYSE:BRKB). Now-retired CEO Warren Buffett always had a knack for spotting amazing deals hiding in plain sight, leading to a greater-than-6,000,000% outperformance of the S&P 500 (SNPINDEX:^GSPC) since the mid-1960s.
But investors might not realize that a "secret" Buffett portfolio exists within Berkshire Hathaway. In the June-ended quarter, this $863 million portfolio sent shares of artificial intelligence (AI) superstars Alphabet (NASDAQ:GOOGL)(NASDAQ:GOOG) and Broadcom (NASDAQ:AVGO) packing. Meanwhile, this under-the-radar fund has built up a significant position in two S&P 500 index funds: the State Street SPDR S&P 500 ETF Trust (NYSEMKT:SPY) and the Vanguard S&P 500 ETF (NYSEMKT:VOO).
Missed AI's "Act 1"? Act 2 Could Be 14x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our ****** ysts, we're only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
Image source: Getty Images.
In 1998, Buffett's Berkshire acquired reinsurance company General Re for about $22 billion in an all-stock deal. While the reinsurance operations were the crown jewel of this buyout, General Re also owned a specialty investment firm, New England ****** et Management (NEAM). When the deal closed in December 1998, NEAM became a subsidiary of Berkshire Hathaway.
#Portfolio #buffett #general #neam

27 days ago
Two years before Erika Hammond joined Season 16 of The Real Housewives of New York City, she made headlines for her extremely lavish wedding to husband Ankur Jain. In April 2024, the couple tied the knot at the base of the Great Pyramids in Egypt.
Now, their relationship is back in the spotlight on RHONY, and from Hammond's Bravo bio, it seems that their wealth will be highlighted on the show. "[She has] built a life surrounded by extraordinary luxury complete with her own private island, where she whisks the women away for a one-of-a-kind getaway," the bio reads.
Below, we rounded up everything to know about Jain's company and billionaire status, as well as his relationship with the new Bravo star. Scroll down for more.
Jain is an entrepreneur and investor who is the founder and CEO of Bilt Rewards, a company that allows users to earn points on rent. Per Jain's website, the company has grown to a valuation of $1.5 billion since it launched in June 2021.
He was previously the chief product officer at Tinder, a dating app that acquired his company, Humin. In 2017, he founded Kairos, "a venture studio for young entrepreneurs that helped launch and grow its partner companies to over $6.5 billion."
#housewives


1 month ago
Vista Gold Corp. (NYSEAMERICAN:VGZ) announced on September 21 that it had agreed to be acquired by Artemis Gold Inc. (TSXV:ARTG). Under the agreement signed September 20, shareholders would receive 0.0966 buyer common shares for each existing common share and own approximately 5% of the combined company. That ownership calculation excludes the buyer's existing 4.95% stake in Vista Gold Corp. (NYSEAMERICAN:VGZ), which it intends to cancel at completion.
For shareholders, the trade-off is a smaller interest in a larger mining business with an operating ***** et and development expertise. The central question is whether that combination can supply the capital and execution needed to bring Australia's Mt Todd gold project into production.
Artemis Gold Inc. (TSXV:ARTG) operates the Blackwater mine in British Columbia and expects its future cash generation to support Mt Todd. That offers Vista Gold a potential funding source alongside a team experienced in building and operating mines.
The financial starting point explains the appeal. Vista Gold Corp. (NYSEAMERICAN:VGZ) ended June 2026 with $49.5 million in cash and no debt. Management described that cash as sufficient for interim development objectives. Joining an operating producer could broaden the resources available for the much larger task of construction.
The acquisition requires no cash consideration or new acquisition debt. Preserving the buyer's financial capacity could leave more room for investment, although the share exchange itself does not raise construction funding.
#cash

1 month ago
On September 17, Coherent Corp. (NYSE:COHR) announced an upgraded Pluggable Optical Line System that covers the full C-band and fits in a compact QSFP module, the same slot ordinary transceivers use. That is a lot of networking gear shrunk into a plug, and it follows a quarter of 34% revenue growth. Here is what the launch means, and where the stock's story gets harder to read.
Start with what the product does. The upgraded system can pack 32 wavelengths onto a single pair of fibers, which Coherent says adds up to as much as 25.6Tbps of traffic on links running 2km to 200km. It is designed for the latest 800G coherent optics, and it configures itself, handling link setup and laser safety without a technician tuning each connection. Coherent also says the system is generally available and already shipping in high volume, in 400G and 800G versions that work with existing network setups. Madhu Krishnaswamy, who runs the company's telecom transport unit, describes the goal as easing the usual trade-off between raw performance and operational simplicity.
The launch also sits on top of a business that is already moving. On August 12, Coherent reported results for its fiscal fourth quarter, which ended June 30: revenue of $2.05 billion, up 34% from a year earlier. Non-GAAP earnings per share rose to $1.74 from $1.00, and CEO Jim Anderson noted that for the full year, that measure grew more than twice as fast as revenue. Management guided to revenue of $2.2 billion to $2.4 billion for the first quarter of fiscal 2027, and Anderson says AI data centers are increasingly moving from copper to optical links.
Now look at the two versions of profit. Coherent's non-GAAP earnings came to $1.74 per share, but under GAAP the figure was $1.19. The gap comes from items management leaves out, including stock-based pay, amortization on acquired intangibles, and restructuring and integration costs. Operating margin shows it more clearly, at 21.8% on a non-GAAP basis and 12.4% under GAAP. Some of those costs are non-cash, but they are real, and anyone anchoring on the higher figure is skipping them.
Then there is how much weight this launch can carry. The announcement puts no sales figure on the product, so its contribution to a company that booked $2.05 billion in a quarter cannot be sized from what has been published. The bullish story also rests on management's own read of where AI networks are headed, and on a capacity build-out that CFO Sherri Luther says gets priority in spending. Money spent on capacity only pays off if the demand management describes keeps arriving.
#gaap #revenue #launch #anderson

1 month ago
Lindblad Expeditions Holdings, Inc. (NASDAQ:LIND) announced on September 15 that it had acquired 60% of White Desert Antarctica and its new aviation travel business, Echo Charlie. Consideration comprises approximately $61 million in cash, plus approximately $6 million relating to acquired cash, subject to working-capital, cash, and indebtedness adjustments.
The purchase broadens the travel portfolio beyond expedition cruises. For investors, the test is whether additional bookings and cash generation justify the acquisition price and subsequent investment.
White Desert takes guests into Antarctica's interior, including the Geographic South Pole. Echo Charlie offers journeys aboard a restored DC-3 aircraft carrying 12 guests. These experiences add distinctive products that Lindblad Expeditions Holdings, Inc. (NASDAQ:LIND) could market to existing adventure travelers.
Cross-selling could reduce marketing costs per booking and encourage repeat travel across the portfolio. Established customer relationships provide a starting point; the financial benefit depends on generating additional profitable departures.
The company already operates a growing land-travel business. Second-quarter Land Experiences revenue increased 23% to $70.0 million, driven by additional trips and higher pricing. That provides a relevant commercial foundation for the expansion.
#additional

1 month ago
SPX Technologies, Inc. (NYSE:SPXC) announced on September 15 that it completed the acquisition of FIS Water, LLC for approximately $410 million in cash, including certain tax attributes. The acquired business is expected to generate approximately $105 million of revenue in 2026.
That is FIS Water's full-year revenue forecast; its contribution to consolidated 2026 results will reflect the ownership period. The stated cash consideration equals approximately 3.9 times expected annual revenue, making profitability and cash conversion central to the investment case.
FIS Water expands the products SPX Technologies, Inc. (NYSE:SPXC) can supply to cooling customers. Its filtration and flow-control products remove solids, maintain water quality, and regulate water movement in commercial and industrial cooling systems, including data centers.
The business has joined the HVAC segment, covering heating, ventilation and air conditioning, within its Cooling operations. Its products complement existing cooling-tower offerings, while its valves and actuators also fit the recently acquired Neptronic controls business.
The strategic attraction is customer overlap. Management identified shared customers, engineering specifications and sales channels, and plans to use its global distribution and equipment-manufacturer relationships to support growth.
#cooling #NYSE

1 month ago
California Resources Corporation (NYSE:CRC) announced on September 17 that it had agreed to sell its Uinta Basin **** ets, located mostly in Utah and Colorado, to an undisclosed buyer for $90 million in cash. The company had come to own the Uinta **** ets, which span about 100,000 net acres, after it acquired Berry Corp last year. However, CRC considered them non-core to its operations. The net proceeds from the sale will be used for shareholder returns and other corporate purposes.
Francisco Leon, President and CEO of California Resources Corporation, commented:
"Today's transaction strengthens our business. The monetization of our Uinta Basin **** ets sharpens our focus on California and captures additional value from the Berry merger. This transaction enhances our capital allocation flexibility, allowing us to invest in higher-return opportunities within the Golden State and supports our shareholder return strategy. The sale also helps offset the purchase price of our recent midstream transaction."
The transaction is expected to close by year-end, subject to the receipt of certain third-party consents and other customary conditions.
The sale will allow CRC to redeploy the $90 million toward **** ets that are central to its operating strategy while avoiding additional capital commitments to Uinta. The company already stated in its Q2 earnings call that Uinta has higher capital intensity, higher break-evens, lower crude quality, higher transportation and operating costs, and steeper declines. Therefore, the sale removes a portfolio distraction at a time when CRC is concentrating investment in California infrastructure and production.
#uinta #assets #transaction #capital
1 month ago
Enbridge Inc. (NYSE:ENB) has declined by around 17% since hitting its record high in May, likely as a result of rising bond yields, lack of visibility on the company's 5% growth guidance through the end of the decade, and the recently closed equity offering intended to fund the midstream operator's strategic acquisitions.
However, BMO Capital sees this pullback as an opportunity and on September 15, the firm upgraded ENB from 'Market Perform' to 'Outperform', while also slightly raising its price target from C$79 to C$79.50. The target boost implies an upside of 18% from the current levels.
The **** yst believes that Enbridge's scale, limited commodity exposure, and diversified **** ets are underappreciated. BMO also cited the company's improving visibility on growth, robust backlog, opportunistic acquisitions, and improved balance sheet as reasons behind the upgrade.
Enbridge's aggressive expansion strategy adds significantly to its bull case. The company announced on September 9 that it would acquire Tallgrass Energy's crude oil business for $2.55 billion in cash, expanding its US liquids pipeline network by buying a majority stake in the Pony Express Pipeline and other **** ets. The midstream operator expects the acquisition to be accretive to distributable cash flow per share in the first full year of ownership.
Similarly, Enbridge announced last month that it had agreed to acquire Salt Creek Midstream's crude oil gathering business for $600 million in cash, further bolstering its presence in the prolific Permian Basin. The acquired **** ets have an average remaining contract life of about 10 years, providing stable long-term cash flows.
#visibility #target


1 month ago
On August 6, Wheaton Precious Metals (NYSE:WPM) reported second-quarter net earnings of $543 million on $929 million of revenue, both records. Through the first half, net earnings rose 106% to $1.1 billion. During the quarter, the company also made net upfront cash payments of $4.5 billion relative to mineral stream interests, and it now carries $2.0 billion of total debt against $100 million of cash on hand. Here is what that trade looks like up close.
Start with what the streaming model does when prices climb. Wheaton sold 14% more gold equivalent ounces than a year ago, but the average realized gold equivalent price jumped 61% in Q2, and that higher price explains most of the revenue surge. Costs per ounce rose from $406 to $568, yet the cash operating margin per ounce still grew 65% to $3,875, faster than gold itself appreciated. Operating cash flow hit $650 million in the quarter and $1.4 billion for the half.
The second argument is that plenty of growth hasn't arrived yet. Only about 3% of this year's production comes from **** ets still in construction or ramp-up, and the company forecasts a rise of roughly 50% to 1,200,000 gold equivalent ounces by 2030. Some of that ramp has dates attached. Ivanhoe now expects commercial production at Platreef in the fourth quarter of 2026, and Montage Gold is targeting first gold at Koné in late Q4. Effective April 1, Wheaton expanded its share of silver production from Antamina from 33.75% to 67.5% through the newly acquired BHP Antamina PMPA.
Growth on this scale wasn't free. Wheaton had no bank debt at the end of 2025. On April 1, it drew $1.5 billion on a new two-year term loan to help pay for Antamina, and finance costs that were negligible a year ago now take a real bite. Net debt stands at $1.9 billion. Taxes are heavier too. Wheaton paid $109 million of global minimum tax on June 24, and another Cdn$346 million is due around March 31, 2027.
Operations also gave investors a few reasons for caution. Gold ounces produced slipped 2.6% year over year, so the 6% rise in gold equivalent production leaned heavily on the Antamina purchase. Gold output at Salobo fell 11% on lower grades. At Constancia, it fell 35% after mining at the higher-grade Pampacancha pit finished in the fourth quarter of 2025. Hemlo Mining said on July 20 that its second-quarter output fell below the first quarter's, and Rio2 said on May 15 that Fenix missed planned tonnes and grade in Q1. And because the revenue jump came mainly from price, the same leverage works in reverse if metals slip.
#wheaton

1 month ago
Meta Platforms, Inc. (NASDAQ:META) is taking another step toward monetizing artificial intelligence beyond its core advertising business. On September 9, the company acquired AI startup Stilla.ai.
The acquisition will strengthen the company's agentic AI capabilities as it moves to capitalize on growing demand for AI agents that can handle business transactions. Plans are underway to integrate Stilla.ai's team and technology into Meta Business Agent, which already helps businesses interact with customers across various platforms.
Stilla.ai's technology could help Meta's Business Agent enable more sophisticated interactions between customers and AI agents across its messaging platforms. In the long term, customers could use AI agents to inquire about products, discuss pricing, and potentially complete purchases without leaving Meta's ecosystem.
Such capabilities could result in new monetization opportunities as the company faces increasing pressure to generate returns from its substantial artificial intelligence investments. Rather than relying exclusively on AI to improve advertising efficiency, Meta could use AI to facilitate transactions and capture value from the commercial activity taking place across its platforms.
The acquisition could help the company build an AI-driven commerce layer across its massive messaging ecosystem. The company has access to billions of users across Facebook, Instagram, Messenger, and WhatsApp, while millions of businesses already use its platforms to communicate with customers.
#customers #agents


1 month ago
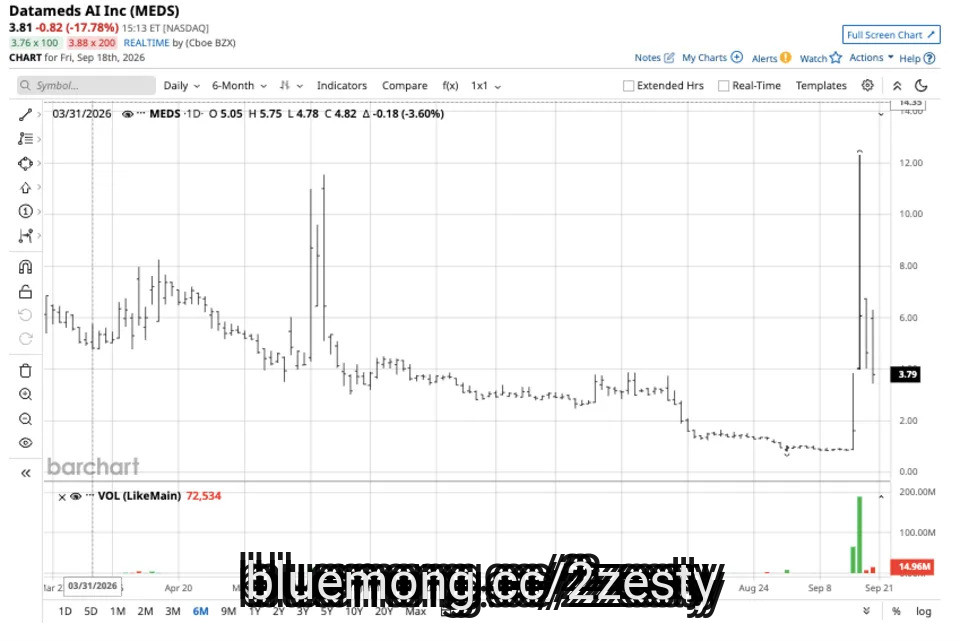
DataMEDS AI (MEDS) announced on Sept. 15 that it acquired Helomics and a lab services business, sparking a huge rally in MEDS stock. Shares of MEDS stock gained 87% on Sept. 15 and 275% in the following session. Like the lab services unit, Helomics was sold by Axe Compute (AGPU) and utilizes artificial intelligence (AI) for cancer diagnostics and treatment.
Generally, I'm a big fan of using AI in medicine, and a fan of the companies that do so. In fact, I own two stocks — Schrodinger (SDGR) and Radnet (RDNT) — that specialize in this area; Schrodinger uses AI to help speed up the drug-discovery process, while many of Radnet's diagnostic medical devices utilize AI.
Elon Musk, Who Became the World's First Trillionaire, Still Sleeps in a Tiny $50,000 House Where His Mom Uses the Garage — 'It's Kinda Awesome Though'
How to Play AMZN Stock as Amazon Unveils Project Mercury
JPMorgan Gives Up Forecasting Iran War Endgame as Trump Tells Reporters 'Anything Could Happen With Me'
#meds #shares


1 month ago
Investing in high-yield dividend stocks can be a solid portfolio move and give investors some nice supplemental income. However, not all dividend stocks are created equal. Two dividend stocks I'd be buying now are Energy Transfer (NYSE: ET) and Verizon (NYSE: VZ), while one I would avoid is Pfizer (NYSE: PFE).
Let's take a closer look at each, starting with why I'd avoid investing in Pfizer.
Missed AI's "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our **** ysts, we're only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
At one point, Pfizer was as blue chip of a pharmaceutical company as there was. However, the stock's 6.2% yield and cheap valuation reflect a company facing challenges ahead.
Pfizer took on significant debt when it acquired Seagen for $43 billion in December 2023 to strengthen its oncology portfolio. That has left the company with over $60 billion in debt and high interest expenses. The company paid out $9.7 billion in dividends last year while generating $9.1 billion in free cash flow, so it paid out more in dividends than it generated in cash. That has continued through the first six months of 2026.
#NYSE #stocks #missed #high

1 month ago
On September 15, Arthur J. Gallagher & Co. (NYSE:AJG) announced that it had bought McMillan Insurance & Bonding Inc., an Englewood, Colorado, firm that operates as Innovise Business Consultants. Gallagher did not say what it paid. On its own, the deal is a footnote. But it is one of many, and the way those deals show up in earnings is where the debate over this stock really lives.
On July 30, Gallagher reported results for the quarter ended June 30, and the top line was hard to argue with. Revenue from its combined Brokerage and Risk Management businesses grew 24%, and organic growth, which leaves out acquisitions, was 6%. That second number shows clients are staying and spending. It was not confined to one corner, either, since organic fees in the risk management arm rose 12%. Management adds that retention is strong and customers want broader help from the platform. Adjusted earnings per share climbed to $2.84 from $2.30, which means growth is reaching profit once one-time acquisition costs are set aside.
Innovise fits the pattern. It sells surety bonds and commercial insurance brokerage with a focus on manufacturing, energy, construction and real estate, and Chairman and CEO J. Patrick Gallagher, Jr. said that niche expertise adds depth in Colorado. Jason McMillan's team will move into Gallagher's Denver office and work under Bret VanderVoort, who oversees retail property/casualty brokerage for the Western Zone. Buying specialists and folding them into existing offices is a repeatable playbook, and Gallagher closed 14 brokerage acquisitions in the first six months of 2026.
Now look at reported earnings, because that is where you see the cost. Diluted earnings per share fell to $1.25, from $1.40 in the second quarter of 2025, even though revenue jumped. Much of the gap between reported and adjusted results is the price of buying growth. Amortization of acquired intangibles alone weighs on brokerage net earnings by $218 million, up from $130 million a year ago, and integration costs rose as well. Adjusted figures set those aside, but they are real expenses, and they keep landing as long as Gallagher keeps buying.
Margins tell a similar story. The brokerage segment's adjusted EBITDAC margin, a stand-in for operating profit, slipped to 33.3% from 36.1%. Gallagher points to last year's interest income on cash raised for the ***** uredPartners deal, which closed in the third quarter of 2025, plus seasonality and newly added tuck-ins. That is a fair explanation. But the debt behind the deal is still here, including $9.55 billion of public debt, plus more in private placements and on a credit line. And the deal flow is thinner: brokerage acquisitions closed in the first six months of 2026 carried $107 million of annualized revenue, versus $354 million a year earlier, which puts more weight on organic growth.
#Growth


1 month ago
On September 17, Coherent Corp. (NYSE:COHR) announced an upgraded Pluggable Optical Line System that covers the full C-band and fits in a compact QSFP module, the same slot ordinary transceivers use. That is a lot of networking gear shrunk into a plug, and it follows a quarter of 34% revenue growth. Here is what the launch means, and where the stock's story gets harder to read.
Start with what the product does. The upgraded system can pack 32 wavelengths onto a single pair of fibers, which Coherent says adds up to as much as 25.6Tbps of traffic on links running 2km to 200km. It is designed for the latest 800G coherent optics, and it configures itself, handling link setup and laser safety without a technician tuning each connection. Coherent also says the system is generally available and already shipping in high volume, in 400G and 800G versions that work with existing network setups. Madhu Krishnaswamy, who runs the company's telecom transport unit, describes the goal as easing the usual trade-off between raw performance and operational simplicity.
The launch also sits on top of a business that is already moving. On August 12, Coherent reported results for its fiscal fourth quarter, which ended June 30: revenue of $2.05 billion, up 34% from a year earlier. Non-GAAP earnings per share rose to $1.74 from $1.00, and CEO Jim Anderson noted that for the full year, that measure grew more than twice as fast as revenue. Management guided to revenue of $2.2 billion to $2.4 billion for the first quarter of fiscal 2027, and Anderson says AI data centers are increasingly moving from copper to optical links.
Now look at the two versions of profit. Coherent's non-GAAP earnings came to $1.74 per share, but under GAAP the figure was $1.19. The gap comes from items management leaves out, including stock-based pay, amortization on acquired intangibles, and restructuring and integration costs. Operating margin shows it more clearly, at 21.8% on a non-GAAP basis and 12.4% under GAAP. Some of those costs are non-cash, but they are real, and anyone anchoring on the higher figure is skipping them.
Then there is how much weight this launch can carry. The announcement puts no sales figure on the product, so its contribution to a company that booked $2.05 billion in a quarter cannot be sized from what has been published. The bullish story also rests on management's own read of where AI networks are headed, and on a capacity build-out that CFO Sherri Luther says gets priority in spending. Money spent on capacity only pays off if the demand management describes keeps arriving.
#quarter #launch #anderson

1 month ago
High Tide Inc. (NASDAQ:HITI) reported record fiscal third-quarter revenue of C$198.8 million on September 14, up 33% year over year. Operating income increased 133% to C$8.7 million for the quarter ended July 31, 2026, yet net cash provided by operating activities slipped to C$10.1 million from C$10.7 million.
High Tide Inc. (NASDAQ:HITI) generated C$11.9 million of operating cash flow before changes in non-cash working capital, up 44%. Working capital then absorbed C$1.8 million, compared with a C$2.4 million release a year earlier. That approximately C$4.2 million unfavorable swing outweighed the improvement before working-capital movements. The question is whether expansion will keep requiring a larger cash commitment.
High Tide Inc. (NASDAQ:HITI) is translating sales growth into stronger operating profitability. Operating income represented approximately 4.4% of revenue, compared with 2.5% a year earlier. That improvement gives the business more room to absorb the costs of expansion.
High Tide Inc. (NASDAQ:HITI) opened four Canadian stores and acquired four more during the quarter. Its German medical-cannabis subsidiary, Remexian, generated C$38.2 million in revenue, up from C$31.6 million sequentially. Remexian distributed 10.2 tonnes, a 35% sequential increase. Both markets offer opportunities to build sales across a larger operating base.
High Tide Inc. (NASDAQ:HITI) also improved operating cash flow to C$4.4 million in the second quarter. For the first nine months, operating cash flow reached C$20.4 million versus C$19.6 million a year earlier. Those comparisons show that the quarterly year-over-year decline sits alongside improving cash generation over other periods.
#high


1 month ago
Logistic Properties of the Americas (NYSEAMERICAN:LPA) moved closer to selling Parque Logístico Lima Sur after Peru's antitrust authority, INDECOPI, approved the transaction on September 11. FIBRA Prime would acquire the entire 1.3-million-square-foot logistics park for $145 million. Customary administrative closing matters remain outstanding.
Management expects approximately $85 million of net proceeds after debt repayment and before taxes, with Mexico the intended destination. Approval advances the financing of that expansion, while the investment case rests on replacing an established income stream.
Lima Sur generated $10.3 million of cash net operating income, or cash NOI, during the 12 months ended March 31, 2026. Cash NOI is a company-defined non-IFRS measure of property income after operating expenses, adjusted to remove straight-line rental accounting. It excludes corporate overhead, financing costs, income taxes, and other non-property items.
Logistic Properties of the Americas (NYSEAMERICAN:LPA) has demonstrated an ability to develop, lease and operate logistics ***** ets. Second-quarter revenue increased 26.1% to $14.7 million, while stabilized portfolio occupancy reached 100% as of June 30.
Mexico already contributes revenue. Two properties acquired in Puebla in August 2025 generated approximately $0.5 million during the second quarter. That provides an operating foothold for deploying proceeds.
#cash #logistic #nyseamerican #Mexico

1 month ago
Alcoa Corporation (NYSE:AA) priced $2.6 billion of acquisition financing on September 9, 2026, through two wholly owned subsidiaries. Alumina Pty Ltd will issue $1.5 billion of 6.625% notes due 2034, while Alcoa Nederland Holding B.V. will issue $1.1 billion of 6.875% notes due 2036. Alcoa Corporation (NYSE:AA) and certain subsidiaries will guarantee the notes on a senior unsecured basis.
The tranches imply annual coupons of $99.375 million and $75.625 million, respectively, totaling exactly $175 million. Settlement is expected on September 23. Net proceeds and cash on hand would fund the approximately $3.1 billion cash portion of the South32 Limited (ASX:S32) ****** et acquisition, plus related fees and expenses.
For Alcoa Corporation (NYSE:AA), successful settlement would secure longer-dated funding and allow termination of the remaining 364-day bridge commitments. Maturities in 2034 and 2036 give management time to integrate the ****** ets before principal comes due.
The operating opportunity lies in linking additional bauxite resources, alumina refining and aluminum production. Better coordination could strengthen feedstock security and improve purchasing, logistics and plant economics. Acquired earnings and operating improvements could produce recurring cash to service the debt while funding reinvestment.
Fixed coupons also make the interest burden predictable. Strong ****** et performance could support debt reduction and give shareholders a growing share of incremental cash generation.
#notes #september

1 month ago
AeroVironment, Inc. (NASDAQ:AVAV) reported on September 9, 2026, that revenue for fiscal Q1 2027, ended August 1, 2026, increased 6% to $480.5 million. Funded backlog reached approximately $1.5 billion at quarter-end, up from $1.2 billion at April 30, 2026. This represents remaining work under firm customer orders with funding already appropriated, providing a concrete base for future revenue.
Non-GAAP adjusted diluted earnings were $0.59 per share, excluding acquired-intangible amortization, purchase-accounting adjustments, acquisition expenses, and net gains and losses on equity-method and equity-security investments. Adjusted EPS retains net interest income. The GAAP result was a $5.1 million net loss, or $0.10 per diluted share. The question is whether the expanding order base can produce stronger operating earnings and cash generation.
Bookings reached $683 million, producing a book-to-bill ratio of 1.4, calculated as bookings divided by revenue. Bookings measure authorized contract awards and modifications and can include work whose funding has not yet been obligated. The ratio indicates that new business exceeded revenue recognized during the quarter.
AeroVironment, Inc. (NASDAQ:AVAV) is also translating demand into sales in Autonomous Systems, where revenue rose 21% to $346 million. That provides operating evidence behind the opportunity in unmanned aircraft and precision-strike systems.
Management maintained fiscal 2027 revenue guidance of $2.125 billion to $2.225 billion, and non-GAAP adjusted EBITDA of $305 million to $325 million. Adjusted EBITDA excludes net interest income or expense, taxes, depreciation and amortization from net income and further adjusts for stock compensation, acquisition expenses, cloud-computing amortization, net gains and losses on equity-method and equity-security investments, and other specified items.
#Equity


1 month ago
Jim Cramer sees Seneca Foods Corporation (NASDAQ:SENEA) as an attractive food stock after its sharp rally, but he wants investors to leave room for a further pullback. During the September 10 episode of Mad Money, he noted that the shares had recently fallen about 11% from their high the previous week. He added:
Looking at the chart, you'd think this was an AI data center company. The stock's up 256% over the past three years, nearly 70% year to date.
Cramer said its appeal starts with its exposure to both branded and private-label products:
They don't care whether you're buying the premium nationally branded stuff or the cheap private-label knockoffs because they package everything.
Seneca reported fiscal first-quarter 2027 revenue of $405.2 million, up 36.2% year over year, while diluted EPS increased to $2.85 from $2.14. Management attributed the revenue growth to the Green Giant U.S. frozen acquisition, private-label growth and the timing of contract-packaging sales. Cramer credited the Green Giant transaction with helping drive the improvement after Seneca acquired B&G Foods' U.S. frozen business in March.
#seneca #giant


1 month ago
This story was originally published on CFO Dive. To receive daily news and insights, subscribe to our free daily CFO Dive newsletter.
Stewart Grierson took the fifth CFO seat of his career this summer, joining Austin, Texas-based AI development company Anaconda.
In addition to his two decades of experience in the data infrastructure sector, Grierson brings to his new post all the experience gained after helping to complete multiple initial public offerings: Like when serving as the CFO of the security management company ArcSight, which went public and then was acquired in 2010 by HP in a $1.5 billion transaction.
Yet Grierson in a recent interview said taking Anaconda or any company public has never been an end goal for him, **** erting that it is just one path that any company may take as it evolves and grows.
"We have shareholders who will want liquidity at some point and I think my background gives [Anaconda] the optionality" of either looking at public markets in the futuure or taking other routes, including private equity investments or acquisitions, Grierson told CFO Dive.
#taking

1 month ago
Kimberly-Clark Corporation (NASDAQ:KMB) is preparing **** et sales to address EU antitrust concerns surrounding its planned $40 billion acquisition of Kenvue, according to Reuters. The company is reportedly seeking to offer remedies that could secure European Commission approval by the September 29 deadline, avoiding a more extensive four-month investigation. Similar regulatory concerns have already emerged in Australia, where the deal received conditional approval after Kimberly-Clark agreed to divest Kenvue's Carefree and Stayfree brands.
The transaction is strategically important because it would create a consumer-health and personal-care company with approximately $32 billion of annual revenue and $7 billion of adjusted EBITDA. Kimberly-Clark Corporation (NASDAQ:KMB) expects about $1.9 billion of annual cost synergies and $500 million of revenue synergies, although it expects to invest roughly $2.5 billion in cash to achieve the cost savings. Therefore, the scale of any EU divestitures will be critical to determining whether Kimberly-Clark can retain the expected economic benefits of the deal.
The strongest bullish argument is that Kimberly-Clark Corporation (NASDAQ:KMB) is actively working toward a regulatory solution rather than allowing the EU review to threaten the transaction. If the company can satisfy regulators through limited **** et sales, it could preserve the majority of Kenvue's revenue and earnings while moving ahead with the combination. The expected $1.9 billion in annual cost savings represents a substantial earnings opportunity relative to the combined company's roughly $7 billion adjusted EBITDA target, giving Kimberly-Clark significant potential to improve margins and cash generation after integration.
The Australian precedent also suggests that targeted divestitures could be sufficient to resolve competition concerns without materially undermining the broader deal. Securing EU approval by September 29 would be particularly positive because it would remove a major source of uncertainty and allow Kimberly-Clark Corporation (NASDAQ:KMB) to focus on integration and synergy execution. With Kenvue adding major brands across consumer health and personal care, successful completion could also broaden Kimberly-Clark's portfolio and reduce its reliance on its existing product categories.
The biggest risk is that the EU requires more substantial **** et sales than Kimberly-Clark Corporation (NASDAQ:KMB) currently expects. Giving up attractive Kenvue brands or businesses in Europe could reduce the revenue and EBITDA acquired through the transaction, while Kimberly-Clark would still have to bear much of the financing, transaction, and integration burden. That could make the $40 billion purchase price less attractive on a risk-adjusted basis, particularly if the divested **** ets are among Kenvue's stronger European businesses.
#kimberly #revenue #ebitda


1 month ago
Apollo Global Management, Inc. (NYSE:APO) is reportedly in talks to acquire Johnson & Johnson (NYSE:JNJ) DePuy Synthes orthopedics business in a transaction that could value the unit at close to $20 billion, according to Bloomberg, as reported by Reuters. J&J generated $9.3 billion of revenue from the orthopedics business in 2025, making the potential transaction material for both companies. The discussions could reach an agreement within weeks, although J&J is also considering a public-market spin-off. This is consistent with J&J's October 2025 decision to separate DePuy Synthes within an expected 18-to-24-month timeframe and shift its MedTech portfolio toward higher-growth, higher-margin businesses.
For Apollo Global Management, Inc. (NYSE:APO), the attraction is the opportunity to acquire a large, established medical-device franchise with substantial recurring demand from joint-replacement and surgical procedures. A roughly $20 billion valuation against $9.3 billion of 2025 revenue implies a price-to-sales multiple of about 2.2x, giving Apollo room to pursue operational improvements, portfolio rationalization, and margin expansion if the business is acquired at an attractive valuation.
DePuy Synthes also has meaningful scale and leading positions across major orthopedics categories, while J&J has recently invested in technologies that could strengthen the franchise, including an agreement covering Gemtrack tracking technology for robotic and navigation-assisted joint procedures and the acquisition of Expanding Innovations for expandable spine implants. Apollo is also entering the potential deal from a position of considerable financial scale: it had approximately $1.05 trillion of ***** ets under management as of June 30, 2026, with $198 billion in equity strategies and $849 billion in credit strategies. Its second-quarter results included $111 billion of gross capital deployment, demonstrating the capacity to execute large transactions.
For Johnson & Johnson (NYSE:JNJ), a sale could accelerate the portfolio transformation that management has already identified as a strategic priority while potentially delivering a sizeable upfront cash inflow. J&J explicitly said its planned orthopedics separation should increase the company's top-line growth and operating margins by allowing it to concentrate on Oncology, Immunology, Neuroscience, Cardiovascular, Surgery and Vision.
The company has also been restructuring orthopedics, with $307 million of restructuring expense in 2025, following $167 million in 2024 and $319 million in 2023, primarily tied to market and product exits. A sale could therefore remove a business that has required restructuring resources while allowing J&J to redeploy capital toward areas it views as higher growth and higher margin.
#billion #depuy

1 month ago
The aerospace industry is evolving as Boeing (NYSE:BA) attempts a massive operational turnaround while Rocket Lab (NASDAQ:RKLB) rapidly expands its footprint across the global ******* e economy.
Boeing remains a dominant force in commercial aviation and defense, whereas Rocket Lab specializes in small-satellite launches and ******* ecraft components. Investors often compare them to decide between an established giant recovering from crisis and a high-growth challenger in the private ******* e sector.
Boeing operates as a massive player among defense stocks and commercial aviation leaders, manufacturing everything from the 737 Max to advanced military rotorcraft. The company generates revenue through commercial aircraft sales, defense contracts with the U.S. Department of Defense and NASA, and global services. Customer concentration like this adds a layer of risk to the business. In 2025, the company acquired Spirit AeroSystems to address long-standing quality issues, providing transition services to other buyers like Airbus (OTC:EADSF).
In FY 2025, revenue reached nearly $89.5 billion, representing a growth of roughly 34.5% over the previous year. The company reported a net income of approximately $2.2 billion, a significant recovery from the net loss of nearly $11.8 billion in FY 2024. This improvement in the net margin to 2.5% suggests the company is beginning to stabilize its bottom line after years of heavy losses.
As of its December 2025 balance sheet, Boeing carries a debt-to-equity ratio of nearly 10.0x, a measure comparing total debt to shareholder equity that indicates a heavy reliance on borrowing. The company reported a current ratio of nearly 1.2x, which measures a company's ability to cover its short-term debts with liquid ******* ets. Note that stock-based compensation represented roughly 40% of operating cash flow, which inflates reported cash generation since SBC is a non-cash expense added back in the cash flow statement. The company also generated a negative free cash flow of approximately $1.9 billion, representing operating cash minus spending on physical ******* ets.
#boeing #nearly #rocket

1 month ago
Kimberly-Clark Corporation (NASDAQ:KMB) is preparing ***** et sales to address EU antitrust concerns surrounding its planned $40 billion acquisition of Kenvue, according to Reuters. The company is reportedly seeking to offer remedies that could secure European Commission approval by the September 29 deadline, avoiding a more extensive four-month investigation. Similar regulatory concerns have already emerged in Australia, where the deal received conditional approval after Kimberly-Clark agreed to divest Kenvue's Carefree and Stayfree brands.
The transaction is strategically important because it would create a consumer-health and personal-care company with approximately $32 billion of annual revenue and $7 billion of adjusted EBITDA. Kimberly-Clark Corporation (NASDAQ:KMB) expects about $1.9 billion of annual cost synergies and $500 million of revenue synergies, although it expects to invest roughly $2.5 billion in cash to achieve the cost savings. Therefore, the scale of any EU divestitures will be critical to determining whether Kimberly-Clark can retain the expected economic benefits of the deal.
The strongest bullish argument is that Kimberly-Clark Corporation (NASDAQ:KMB) is actively working toward a regulatory solution rather than allowing the EU review to threaten the transaction. If the company can satisfy regulators through limited ***** et sales, it could preserve the majority of Kenvue's revenue and earnings while moving ahead with the combination. The expected $1.9 billion in annual cost savings represents a substantial earnings opportunity relative to the combined company's roughly $7 billion adjusted EBITDA target, giving Kimberly-Clark significant potential to improve margins and cash generation after integration.
The Australian precedent also suggests that targeted divestitures could be sufficient to resolve competition concerns without materially undermining the broader deal. Securing EU approval by September 29 would be particularly positive because it would remove a major source of uncertainty and allow Kimberly-Clark Corporation (NASDAQ:KMB) to focus on integration and synergy execution. With Kenvue adding major brands across consumer health and personal care, successful completion could also broaden Kimberly-Clark's portfolio and reduce its reliance on its existing product categories.
The biggest risk is that the EU requires more substantial ***** et sales than Kimberly-Clark Corporation (NASDAQ:KMB) currently expects. Giving up attractive Kenvue brands or businesses in Europe could reduce the revenue and EBITDA acquired through the transaction, while Kimberly-Clark would still have to bear much of the financing, transaction, and integration burden. That could make the $40 billion purchase price less attractive on a risk-adjusted basis, particularly if the divested ***** ets are among Kenvue's stronger European businesses.
#revenue


1 month ago
Apollo Global Management, Inc. (NYSE:APO) is reportedly in talks to acquire Johnson & Johnson (NYSE:JNJ) DePuy Synthes orthopedics business in a transaction that could value the unit at close to $20 billion, according to Bloomberg, as reported by Reuters. J&J generated $9.3 billion of revenue from the orthopedics business in 2025, making the potential transaction material for both companies. The discussions could reach an agreement within weeks, although J&J is also considering a public-market spin-off. This is consistent with J&J's October 2025 decision to separate DePuy Synthes within an expected 18-to-24-month timeframe and shift its MedTech portfolio toward higher-growth, higher-margin businesses.
For Apollo Global Management, Inc. (NYSE:APO), the attraction is the opportunity to acquire a large, established medical-device franchise with substantial recurring demand from joint-replacement and surgical procedures. A roughly $20 billion valuation against $9.3 billion of 2025 revenue implies a price-to-sales multiple of about 2.2x, giving Apollo room to pursue operational improvements, portfolio rationalization, and margin expansion if the business is acquired at an attractive valuation.
DePuy Synthes also has meaningful scale and leading positions across major orthopedics categories, while J&J has recently invested in technologies that could strengthen the franchise, including an agreement covering Gemtrack tracking technology for robotic and navigation-assisted joint procedures and the acquisition of Expanding Innovations for expandable spine implants. Apollo is also entering the potential deal from a position of considerable financial scale: it had approximately $1.05 trillion of **** ets under management as of June 30, 2026, with $198 billion in equity strategies and $849 billion in credit strategies. Its second-quarter results included $111 billion of gross capital deployment, demonstrating the capacity to execute large transactions.
For Johnson & Johnson (NYSE:JNJ), a sale could accelerate the portfolio transformation that management has already identified as a strategic priority while potentially delivering a sizeable upfront cash inflow. J&J explicitly said its planned orthopedics separation should increase the company's top-line growth and operating margins by allowing it to concentrate on Oncology, Immunology, Neuroscience, Cardiovascular, Surgery and Vision.
The company has also been restructuring orthopedics, with $307 million of restructuring expense in 2025, following $167 million in 2024 and $319 million in 2023, primarily tied to market and product exits. A sale could therefore remove a business that has required restructuring resources while allowing J&J to redeploy capital toward areas it views as higher growth and higher margin.
#NYSE #johnson
1 month ago
OpenAI acquired Glass Imaging, a startup developing AI-powered smartphone camera technology, in a deal valued at over $300 million, according to The Wall Street Journal. The purchase price represents a significant jump from the roughly $100 million valuation Glass Imaging carried in a funding round last year.
Glass Imaging was founded in 2019 by Ziv Attar and Tom Bishop, two former Apple engineers who worked on the company's Portrait Mode feature. The Los Altos, California-based company had raised about $30 million from investors including GV, Alphabet's venture arm, and Insight Partners before the acquisition.
Glass Imaging's approach differs from conventional AI photo editing: instead of processing images after the fact, the company teaches neural networks the specific optical properties of each camera system so that picture quality is improved as the shot is taken, according to The Wall Street Journal. The company's goal is to produce image quality comparable to a DSLR camera from a smartphone. Its zoom-imaging technology was featured in a line of phones from Chinese smartphone brand Honor.
OpenAI's plans for Glass Imaging are unclear. The company is also developing a device with Jony Ive, the former Apple designer behind the iPhone. OpenAI brought on Ive in 2025 through its $6.5 billion purchase of io Products, and his responsibilities span hardware development alongside broader efforts to define how AI products will look and function.
A spokesperson for OpenAI had not provided a statement by the time of publication, according to TechCrunch. The company has made several other acquisitions recently, including an internet talk show called TBPN and an open-source developer tools startup, according to The Wall Street Journal. OpenAI is also preparing for an initial public offering expected next year.
#according #journal

1 month ago
Ocean Power Technologies Inc (NYSE-A:OPTT) reported first-quarter fiscal 2027 revenue of $1.7 million, up 44% from a year earlier, as the company expanded its work with US defense and security customers and moved forward with a strategic review process.
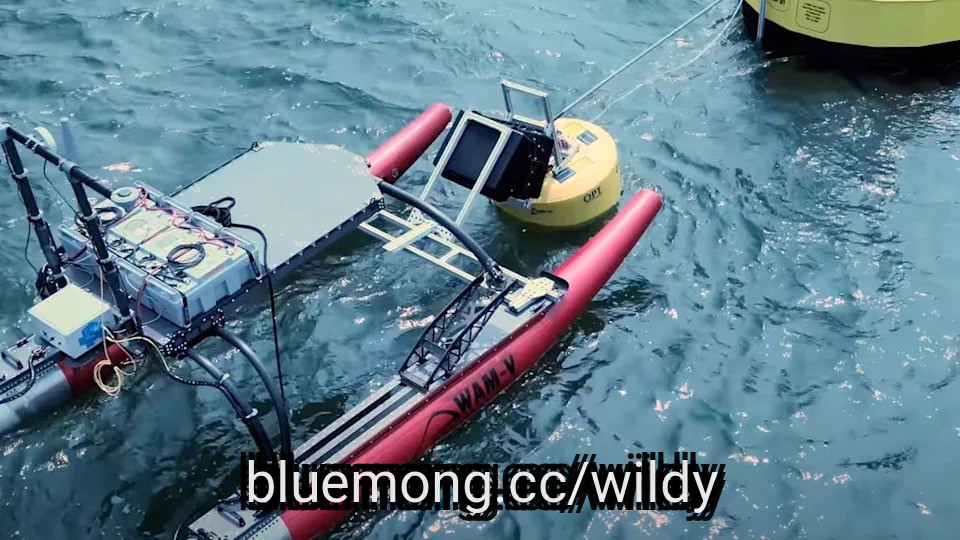
Ocean Power Technologies ran three PowerBuoy systems off Southern California for a U.S. Department of Homeland Security maritime domain awareness program, integrated with Anduril's Lattice platform and including a deployment beyond 1,000 meters depth, calling it the company's largest deployment and recurring revenue contract to date.
Ocean Power Technologies also deployed a PowerBuoy system off New Jersey for Rutgers University and delivered a WAM-V unmanned surface vehicle to Stevens Institute of Technology within five weeks of receiving the order.
The company demonstrated autonomous docking, charging and redeployment of a WAM-V, a capability it is working to integrate with the PowerBuoy platform to support longer autonomous missions. It also acquired subsea developmental technology ****** ets from Columbia Power Technologies, extending its capabilities from the ocean surface to the seabed.
Ocean Power Technologies achieved Cybersecurity Maturity Model Certification Level 2 compliance, positioning it to pursue defense programs requiring protection of controlled unclassified information. After the quarter ended, the company was selected as one of six potential awardees under a $40 million multiple-award contract supporting the Naval Oceanographic Office, creating an opportunity to compete for ocean-floor mapping task orders using unmanned surface vehicles.
#ocean #power #technologies #powerbuoy

1 month ago
AI investors are weighing warnings from technology executives about the safety risks posed by the rapid advancement of artificial intelligence. However, some believe that slowing AI development could leave the US behind China and other competitors in the global race. Brad Gerstner, founder and CEO of Altimeter Capital, said on CNBC that he supports AI safety measures but believes some fears are being exaggerated to advance a political agenda.
"I've not talked to a single person in AI who says, full steam ahead, disregard safety," Gerstner said. "It turns out we all care about kids. We all care about the future of the country. We know the massive benefits it offers, but we also want to take the extra time to make sure that we do this safely. But what I didn't like this week is these hyperbolic scare tactics, which I think are hiding behind a political agenda. We learn that all of this catastrophizing about data centers may in fact, have had support from the CCP. Right? So I want a little investigation. Who is behind all of this negativity? Is it coordinated? Right? Where is the money coming from?"
Altimeter's second-quarter 13F filings show that the fund opened new positions in several technology and AI-related companies, including Qualcomm (QCOM) and Micron Technology (MU).
Altimeter bought 1.88 million Qualcomm shares valued at about $347.9 million as of June 30. The position accounted for 3.54% of the fund's reported US equity portfolio. It also acquired 209,520 Micron shares worth roughly $241.8 million, representing 2.46% of the portfolio.
Brad Gerstner of Altimeter Capital
#behind #qualcomm

1 month ago
NFP, the Aon-owned property and casualty (P&C) broker and benefits consultant, has acquired Moores Insurance Management, a multi-disciplinary risk management company based in Minnesota, US.
Established in 1987, Moores works with high-net-worth (HNW) individuals and businesses in 43 states, offering P&C insurance services to both commercial and personal-risk clients.
Under the agreement, Moores CEO Mark Moores will take on the role of senior vice-president, commercial P&C at NFP, reporting to Amanda Ruback, the company's managing director of P&C for the central region.
NFP personal risk president Brett Woodward said: "Moores is a long-standing risk management firm and this addition further establishes our presence in the Minnesota market and positions us well to continue delivering P&C insurance solutions for high-net-worth and commercial clients."
Jack Moores, who serves as president of Moores, will join NFP as senior vice-president of personal lines.
#moores

1 month ago
CINCINNATI (AP) — The Los Angeles Dodgers clinched their 14th consecutive playoff berth with a 4-1 win over the Cincinnati Reds on Monday night behind Tarik Skubal's seven shutout innings and home runs by Kyle Tucker and Teoscar Hernández.
Los Angeles tied the record set by Atlanta from 1991 through 2005.
The two-time defending World Series champions cut their magic number to three for a fifth straight NL West ****** le and 13th in 14 seasons. The Dodgers became the third team ****** ured of a playoff spot after Milwaukee and Tampa Bay.
Skubal (10-7) allowed three hits, struck out nine and walked one as he gained his second win against Cincinnati in seven days. Skubal allowed two runs in 7 1/3 innings in a 3-2 victory on Sept. 8.
He is 3-2 with a 2.52 ERA in eight starts since the Dodgers (91-59) acquired him from Detroit Tigers on Aug. 2.
#Dodgers #playoff #seven