29 days ago
Kohl's is rolling out steep discounts for customers as it struggles to turn around its sales.
The department store chain revealed in its most recent earnings report that its comparable sales decreased 0.9% year over year in the second quarter of 2026, while recent Placer.ai data showed overall visits to Kohl's stores declined 1.4%.
Kohl's CEO Michael Bender said on the August earnings call that the company is "operating in a challenging macroeconomic environment" where customers are "experiencing persistent financial pressures from inflation in their everyday expenses, like gas and food."
Against this backdrop, Kohl's has taken several steps to make its merchandise more affordable. It introduced Deal Bar and Toy Towers in stores earlier this year, featuring products priced below $10. It also priced thousands of back-to-school items under $25 in July.
In its latest effort to win over price-conscious customers, Kohl's has made its annual Kohl's Deal Days savings event more generous this year.
#year #deal #recent #placer
The department store chain revealed in its most recent earnings report that its comparable sales decreased 0.9% year over year in the second quarter of 2026, while recent Placer.ai data showed overall visits to Kohl's stores declined 1.4%.
Kohl's CEO Michael Bender said on the August earnings call that the company is "operating in a challenging macroeconomic environment" where customers are "experiencing persistent financial pressures from inflation in their everyday expenses, like gas and food."
Against this backdrop, Kohl's has taken several steps to make its merchandise more affordable. It introduced Deal Bar and Toy Towers in stores earlier this year, featuring products priced below $10. It also priced thousands of back-to-school items under $25 in July.
In its latest effort to win over price-conscious customers, Kohl's has made its annual Kohl's Deal Days savings event more generous this year.
#year #deal #recent #placer

1 month ago
This story was originally published on Grocery Dive. To receive daily news and insights, subscribe to our free daily Grocery Dive newsletter.
Editor's note: This story is developing and will be updated.
Brian Monahan, the head of Albertsons' retail media division, has left the company, Albertsons confirmed to Grocery Dive on Monday.
Monahan served as senior vice president of Albertsons Media Collective for just over a year. Albertsons stated its retail media division will now report to Chief Marketing Officer Emily Turner.
Monahan's departure, which was first reported by Adweek, comes as Albertsons looks to remain a leader in retail media innovation and improve declining comparable-store sales.
#Media #grocery #monahan #division
Editor's note: This story is developing and will be updated.
Brian Monahan, the head of Albertsons' retail media division, has left the company, Albertsons confirmed to Grocery Dive on Monday.
Monahan served as senior vice president of Albertsons Media Collective for just over a year. Albertsons stated its retail media division will now report to Chief Marketing Officer Emily Turner.
Monahan's departure, which was first reported by Adweek, comes as Albertsons looks to remain a leader in retail media innovation and improve declining comparable-store sales.
#Media #grocery #monahan #division



1 month ago
Prince William has paid homage to the "incomparable" Dame Deborah James in a moving video message.
The Prince of Wales, 44, made a surprise appearance in a pre-recorded message at the inaugural Bowelbabe Fund Rebel Ball in London on what would have been the campaigner's 45th birthday.
He recalled: "What struck me was Deborah's positivity and humour in the face of adversity – what she liked to call 'rebellious hope'".
He described Dame Deborah, who died in 2022, as "an amazing woman" and said her Bowelbabe Fund for Cancer Research UK had achieved so much in the last four-and-a-half years, investing in pioneering research that was "giving more people more time with the ones they love".
Prince William addressed the room with a pre-recorded message (@ Simon Way)
#dame #james
The Prince of Wales, 44, made a surprise appearance in a pre-recorded message at the inaugural Bowelbabe Fund Rebel Ball in London on what would have been the campaigner's 45th birthday.
He recalled: "What struck me was Deborah's positivity and humour in the face of adversity – what she liked to call 'rebellious hope'".
He described Dame Deborah, who died in 2022, as "an amazing woman" and said her Bowelbabe Fund for Cancer Research UK had achieved so much in the last four-and-a-half years, investing in pioneering research that was "giving more people more time with the ones they love".
Prince William addressed the room with a pre-recorded message (@ Simon Way)
#dame #james



2 months ago
On September 9, 2026, Signet Jewelers Limited (NYSE:SIG) reported second-quarter net profit of more than $52 million, reversing a net loss of over $9 million a year earlier, with adjusted earnings per share of $2.19 beating ***** yst estimates of $1.72 by a wide margin. It sent shares up as much as 24% in trading.
The parent of Kay Jewelers, Zales, and Jared also raised its full-year profit guidance for the second time this fiscal year. It also extended its consumer credit partnership with Bread Financial through 2035, a deal it said includes new profit-sharing terms expected to make more than $1 billion in incremental value over time.
Signet Jewelers Limited (NYSE:SIG) is showing demand improvement across its core jewelry brands. Same-store sales increased 2.2% in the second quarter, beating Wall Street's 1.9% expectation. Management reported positive comparable sales across all three months of the quarter. Performance also improved across Kay, Zales, Jared, and Blue Nile. It shows the recovery extends beyond a single brand or temporary sales spike.
Margin expansion is allowing Signet to make substantially stronger earnings despite limited revenue growth. Adjusted operating margin expanded 140 basis points to 7%, while adjusted EPS reached $2.19, well above ***** ysts' $1.74 estimate. Stronger bridal and timepiece sales, tighter inventory management, and operating improvements helped Signet expand profitability. Redesigned Kay and Jared websites provide additional opportunities to back up digital sales.
Signet's higher earnings outlook and shareholder returns solidify the investment case. The company raised full-year adjusted EPS guidance to $10.45-$12.15 versus $9.20-$11.00 and plans a $125 million accelerated share repurchase program. Signet also extended its consumer-credit partnership with Bread Financial through 2035. It added improved technology and data ***** ytics while supporting customer financing and marketing capabilities over the long term.
#adjusted #jewelers #limited
The parent of Kay Jewelers, Zales, and Jared also raised its full-year profit guidance for the second time this fiscal year. It also extended its consumer credit partnership with Bread Financial through 2035, a deal it said includes new profit-sharing terms expected to make more than $1 billion in incremental value over time.
Signet Jewelers Limited (NYSE:SIG) is showing demand improvement across its core jewelry brands. Same-store sales increased 2.2% in the second quarter, beating Wall Street's 1.9% expectation. Management reported positive comparable sales across all three months of the quarter. Performance also improved across Kay, Zales, Jared, and Blue Nile. It shows the recovery extends beyond a single brand or temporary sales spike.
Margin expansion is allowing Signet to make substantially stronger earnings despite limited revenue growth. Adjusted operating margin expanded 140 basis points to 7%, while adjusted EPS reached $2.19, well above ***** ysts' $1.74 estimate. Stronger bridal and timepiece sales, tighter inventory management, and operating improvements helped Signet expand profitability. Redesigned Kay and Jared websites provide additional opportunities to back up digital sales.
Signet's higher earnings outlook and shareholder returns solidify the investment case. The company raised full-year adjusted EPS guidance to $10.45-$12.15 versus $9.20-$11.00 and plans a $125 million accelerated share repurchase program. Signet also extended its consumer-credit partnership with Bread Financial through 2035. It added improved technology and data ***** ytics while supporting customer financing and marketing capabilities over the long term.
#adjusted #jewelers #limited

2 months ago
On September 9, 2026, Jersey Mike's Subs Inc. (NYSE:JMKE) reported its first quarterly results as a public company, with total revenue up 10% year over year to $208 million and same-store sales accelerating to 2.3% growth from 1.7% in the prior quarter. It was primarily driven by transaction growth even as the restaurant industry faced weak traffic trends. Net income fell to $37 million from $59 million a year earlier. It showed non-routine expenses, advertising fund timing, and higher interest costs following the company's July initial public offering, partially offset by a $14 million gain on the sale of corporate-owned stores.
Jersey Mike's Subs Inc. (NYSE:JMKE) is gaining customers while its brand remains a major competitive advantage. The firm added 83 stores in the second quarter. It grew its customer base and increased systemwide sales 10% to $1.21 billion. Jersey Mike's also earned the No. 1 ranking among U.S. quick-service restaurant brands in the 2026 American Customer Satisfaction Index, surpassing Chick-fil-A after 11 consecutive years at the top. It gives the newly public company a strong foundation for continued customer and franchisee growth.
The business has substantial whitespace for long-term unit growth. Jersey Mike's ended the quarter with 3,378 locations and maintains a domestic development pipeline of more than 1,600 stores, with more than 90% of that pipeline coming from existing franchisees. Management estimates that the U.S. market could eventually support roughly 7,500 locations and sees potential to reach approximately 15,000 stores globally. It gives the business a long runway for franchise-led revenue and royalty growth.
Digital engagement and transaction growth give Jersey Mike's more avenues to increase sales. Digital sales represented 43% of systemwide sales in the second quarter, up from 41% a year earlier. Same-store sales increased 2.3% mainly because customers placed more transactions. Jersey Mike's also had more than 12.5 million active MyMike's loyalty members in 2025. It provides the company with a large customer database that it can use to increase frequency and personalize marketing as it expands.
Jersey Mike's Subs Inc. (NYSE:JMKE) still faces a significant profitability challenge despite its revenue growth. Second-quarter revenue jumped 10% to $208 million. However, net income fell 37% to $37 million from $59 million a year earlier. Management attributed part of the decline to advertising-fund timing and higher interest expense. It shows that revenue growth has not yet translated into comparable bottom-line growth for shareholders.
#million #customer
Jersey Mike's Subs Inc. (NYSE:JMKE) is gaining customers while its brand remains a major competitive advantage. The firm added 83 stores in the second quarter. It grew its customer base and increased systemwide sales 10% to $1.21 billion. Jersey Mike's also earned the No. 1 ranking among U.S. quick-service restaurant brands in the 2026 American Customer Satisfaction Index, surpassing Chick-fil-A after 11 consecutive years at the top. It gives the newly public company a strong foundation for continued customer and franchisee growth.
The business has substantial whitespace for long-term unit growth. Jersey Mike's ended the quarter with 3,378 locations and maintains a domestic development pipeline of more than 1,600 stores, with more than 90% of that pipeline coming from existing franchisees. Management estimates that the U.S. market could eventually support roughly 7,500 locations and sees potential to reach approximately 15,000 stores globally. It gives the business a long runway for franchise-led revenue and royalty growth.
Digital engagement and transaction growth give Jersey Mike's more avenues to increase sales. Digital sales represented 43% of systemwide sales in the second quarter, up from 41% a year earlier. Same-store sales increased 2.3% mainly because customers placed more transactions. Jersey Mike's also had more than 12.5 million active MyMike's loyalty members in 2025. It provides the company with a large customer database that it can use to increase frequency and personalize marketing as it expands.
Jersey Mike's Subs Inc. (NYSE:JMKE) still faces a significant profitability challenge despite its revenue growth. Second-quarter revenue jumped 10% to $208 million. However, net income fell 37% to $37 million from $59 million a year earlier. Management attributed part of the decline to advertising-fund timing and higher interest expense. It shows that revenue growth has not yet translated into comparable bottom-line growth for shareholders.
#million #customer

2 months ago
On September 4, 2026, the Wall Street Journal reported that Starbucks Corporation (NASDAQ:SBUX)' longtime chai latte devotees have turned against the company's reformulated recipe, introduced in March. It reduced sweetener and shifted from a pre-made concentrate to a new base with just two grams of sugar.
Customers have signed petitions, flooded Starbucks' corporate lines, and taken to Reddit and store review sites demanding the original formula back. Starbucks says the change gives customers more control over sweetness and has introduced new variations like Mango Cream Chai and Pumpkin Cream Chai.
Starbucks Corporation (NASDAQ:SBUX)' broader turnaround remains intact despite the backlash over its chai reformulation. Global comparable sales increased 7.9% in fiscal Q3, with comparable transactions rising 4.2%. The company raised its fiscal 2026 adjusted EPS guidance to $2.55-$2.65 from $2.25-$2.45. Stronger customer traffic and higher earnings give investors evidence that one unpopular menu change has not derailed the recovery.
The chai backlash appears concentrated among loyal customers of one product rather than across Starbucks' broader customer base. The business introduced the new chai formula as part of a personalization strategy. Customers can customize sweetness and other ingredients. If Starbucks keeps transaction growth across its wider menu, the business could improve its product economics without materially damaging overall customer demand.
Starbucks is improving profitability while it executes its turnaround. Non-GAAP operating margin expanded 430 basis points year over year to 14.4% in fiscal Q3, while North America revenue increased 7% to $7.4 billion. These results give investors evidence that the company can improve margins and sales even as it experiments with its menu and customer experience.
#customer
Customers have signed petitions, flooded Starbucks' corporate lines, and taken to Reddit and store review sites demanding the original formula back. Starbucks says the change gives customers more control over sweetness and has introduced new variations like Mango Cream Chai and Pumpkin Cream Chai.
Starbucks Corporation (NASDAQ:SBUX)' broader turnaround remains intact despite the backlash over its chai reformulation. Global comparable sales increased 7.9% in fiscal Q3, with comparable transactions rising 4.2%. The company raised its fiscal 2026 adjusted EPS guidance to $2.55-$2.65 from $2.25-$2.45. Stronger customer traffic and higher earnings give investors evidence that one unpopular menu change has not derailed the recovery.
The chai backlash appears concentrated among loyal customers of one product rather than across Starbucks' broader customer base. The business introduced the new chai formula as part of a personalization strategy. Customers can customize sweetness and other ingredients. If Starbucks keeps transaction growth across its wider menu, the business could improve its product economics without materially damaging overall customer demand.
Starbucks is improving profitability while it executes its turnaround. Non-GAAP operating margin expanded 430 basis points year over year to 14.4% in fiscal Q3, while North America revenue increased 7% to $7.4 billion. These results give investors evidence that the company can improve margins and sales even as it experiments with its menu and customer experience.
#customer

2 months ago
On September 3, 2026, lululemon athletica inc. (NASDAQ:LULU) reported second-quarter fiscal 2026 results for the period ended August 2, 2026. Net revenue fell 4% to $2.4 billion, missing the $2.46 billion ****** ysts expected, and comparable sales dropped 10% on a constant dollar basis. Management cut full-year revenue guidance to a decline of 5% to 7%, down from a prior forecast of flat to down 1%, and lowered full-year earnings per share guidance to $9.48 to $9.73 from its prior forecast of $10.95 to $11.15, compared with $13.26 earned in fiscal 2025. Shares fell about 18% in extended trading. Incoming CEO Heidi O'Neill was set to start the following week.
Photo by Ian Deng Quddu on Unsplash
Citi's cut to $117 from $130 came with a Neutral rating and the observation that the stock's risk-reward is "slightly more favorable" after the selloff, even though the firm called fiscal 2027 visibility "very unclear." The operational bright spots are real.
lululemon athletica inc. (NASDAQ:LULU) increased its chase volume, the supply chain capability that lets it reorder fast-moving styles quickly, by about 20% this year, and away-from-body styles including the Groove Wide-Leg, Align Foldover Jogger, Breezily, and an updated Dance Studio Pant are trending well as shoppers shift from tight-fitting leggings. The brand's community pull held up too.
The SeaWheeze Half Marathon and Festival returned in August for the first time since 2019, drawing nearly 10,000 runners from 24 countries and roughly 14,000 festival attendees, while more than 85,000 people from 120 countries joined the companion Strava challenge, strong enough that Lululemon already committed to bringing the event back next summer. Rest of World revenue, spanning EMEA and APAC, grew 5% on a reported basis, and the company ended the quarter with $1.4 billion in cash and no outstanding borrowings.
#revenue #billion #NASDAQ
Photo by Ian Deng Quddu on Unsplash
Citi's cut to $117 from $130 came with a Neutral rating and the observation that the stock's risk-reward is "slightly more favorable" after the selloff, even though the firm called fiscal 2027 visibility "very unclear." The operational bright spots are real.
lululemon athletica inc. (NASDAQ:LULU) increased its chase volume, the supply chain capability that lets it reorder fast-moving styles quickly, by about 20% this year, and away-from-body styles including the Groove Wide-Leg, Align Foldover Jogger, Breezily, and an updated Dance Studio Pant are trending well as shoppers shift from tight-fitting leggings. The brand's community pull held up too.
The SeaWheeze Half Marathon and Festival returned in August for the first time since 2019, drawing nearly 10,000 runners from 24 countries and roughly 14,000 festival attendees, while more than 85,000 people from 120 countries joined the companion Strava challenge, strong enough that Lululemon already committed to bringing the event back next summer. Rest of World revenue, spanning EMEA and APAC, grew 5% on a reported basis, and the company ended the quarter with $1.4 billion in cash and no outstanding borrowings.
#revenue #billion #NASDAQ


2 months ago
On September 9, 2026, Reuters reported that CEO Brian Niccol's first two years as Starbucks Corporation (NASDAQ:SBUX) CEO have succeeded in bringing customers back to the coffee chain. Comparable sales rose 7.9% in the fiscal third quarter for a fourth straight quarter of improvement, but his "Back to Starbucks" restructuring has raised costs and squeezed margins along the way. Global operating margin has fallen to 12.9% from 15.8% two years earlier. Niccol, who marks his second anniversary in the role, now faces pressure to convert the sales recovery into the sustainable profit growth investors are demanding.
Niccol's turnaround strategy has already restored customer momentum at Starbucks Corporation (NASDAQ:SBUX). The "Back to Starbucks" strategy reversed six consecutive quarters of declining comparable sales as the company focused on reducing wait times, simplifying menus, improving store ambiance, and increasing staffing. Starbucks has moved beyond the sales deterioration that preceded Niccol's tenure. It gives investors a stronger foundation for the next phase of the turnaround. If management can sustain traffic gains while improving productivity, the sales recovery could provide a path toward stronger earnings growth.
The China joint venture with Boyu Capital gives Starbucks a more capital-efficient way to participate in China's growth. Starbucks sold control of its China retail operations to Boyu. It retained a 40% stake and continues to own and license its brand and intellectual property. The structure reduces Starbucks' direct capital requirements while allowing it to retain economic exposure to the Chinese market. Reuters cited ****** ysts who said the arrangement leaves Starbucks well positioned to convert stronger organic sales growth into profit growth, which could support returns as the recovery progresses.
Starbucks now has an opportunity to turn its customer investments into margin expansion. The firm committed at least $500 million toward labor as part of the restructuring. Niccol prioritized staffing and store improvements to rebuild the customer experience. That spending helped help the sales recovery. But it also pushed global operating margins down to 12.9% from 15.8% over two years. With sales now improving, management can focus more heavily on productivity, cost control, and operating leverage. It creates an opportunity for stronger earnings if it can improve margins without damaging customer traffic.
Labor tensions could undermine Starbucks Corporation (NASDAQ:SBUX)' recovery and keep costs elevated. Starbucks has yet to reach a first contract with its U.S. barista union. The union called for a consumer boycott in August. Negotiations or labor actions could disrupt store operations, increase labor costs, and create reputational pressure just as Starbucks tries to improve profitability. Therefore, investors face a risk that labor issues could offset some of the productivity gains management needs to expand margins.
#
Niccol's turnaround strategy has already restored customer momentum at Starbucks Corporation (NASDAQ:SBUX). The "Back to Starbucks" strategy reversed six consecutive quarters of declining comparable sales as the company focused on reducing wait times, simplifying menus, improving store ambiance, and increasing staffing. Starbucks has moved beyond the sales deterioration that preceded Niccol's tenure. It gives investors a stronger foundation for the next phase of the turnaround. If management can sustain traffic gains while improving productivity, the sales recovery could provide a path toward stronger earnings growth.
The China joint venture with Boyu Capital gives Starbucks a more capital-efficient way to participate in China's growth. Starbucks sold control of its China retail operations to Boyu. It retained a 40% stake and continues to own and license its brand and intellectual property. The structure reduces Starbucks' direct capital requirements while allowing it to retain economic exposure to the Chinese market. Reuters cited ****** ysts who said the arrangement leaves Starbucks well positioned to convert stronger organic sales growth into profit growth, which could support returns as the recovery progresses.
Starbucks now has an opportunity to turn its customer investments into margin expansion. The firm committed at least $500 million toward labor as part of the restructuring. Niccol prioritized staffing and store improvements to rebuild the customer experience. That spending helped help the sales recovery. But it also pushed global operating margins down to 12.9% from 15.8% over two years. With sales now improving, management can focus more heavily on productivity, cost control, and operating leverage. It creates an opportunity for stronger earnings if it can improve margins without damaging customer traffic.
Labor tensions could undermine Starbucks Corporation (NASDAQ:SBUX)' recovery and keep costs elevated. Starbucks has yet to reach a first contract with its U.S. barista union. The union called for a consumer boycott in August. Negotiations or labor actions could disrupt store operations, increase labor costs, and create reputational pressure just as Starbucks tries to improve profitability. Therefore, investors face a risk that labor issues could offset some of the productivity gains management needs to expand margins.
#

2 months ago
Vera Bradley, Inc. (NASDAQ:VRA) reported on September 15 that fiscal 2027 second-quarter revenue from continuing operations increased 1.1% to $71.6 million. For the quarter ended August 1, 2026, GAAP operating income from continuing operations reached $4.2 million, compared with a $4.6 million loss a year earlier.
However, gross profit included a $7.7 million tariff refund relating to prior-period imports. Subtracting that benefit from reported operating income, with all other items unchanged, produces an illustrative operating loss of approximately $3.5 million and an operating margin of negative 4.9%.
The quarter therefore shows improving customer demand alongside an earnings recovery that still depends heavily on refunds.
Direct-channel performance gives Vera Bradley, Inc. (NASDAQ:VRA) tangible evidence of customer traction. Direct revenue increased 8.0% to $65.4 million, while comparable sales rose 9.2%. Management attributed the comparable-sales improvement to better e-commerce conversion and higher average transaction values across direct channels.
That combination matters because stronger conversion means more shoppers complete purchases, while larger transactions support revenue without requiring equivalent growth in customer traffic. Continued momentum could help spread store, distribution, and corporate costs across a larger sales base.
#bradley
However, gross profit included a $7.7 million tariff refund relating to prior-period imports. Subtracting that benefit from reported operating income, with all other items unchanged, produces an illustrative operating loss of approximately $3.5 million and an operating margin of negative 4.9%.
The quarter therefore shows improving customer demand alongside an earnings recovery that still depends heavily on refunds.
Direct-channel performance gives Vera Bradley, Inc. (NASDAQ:VRA) tangible evidence of customer traction. Direct revenue increased 8.0% to $65.4 million, while comparable sales rose 9.2%. Management attributed the comparable-sales improvement to better e-commerce conversion and higher average transaction values across direct channels.
That combination matters because stronger conversion means more shoppers complete purchases, while larger transactions support revenue without requiring equivalent growth in customer traffic. Continued momentum could help spread store, distribution, and corporate costs across a larger sales base.
#bradley


2 months ago
Interested in O'Reilly Automotive, Inc.? Here are five stocks we like better.
Record store expansion: O'Reilly plans to open 232 stores in 2026, its highest annual total, supported by new distribution capacity and growth opportunities across underserved U.S. markets.
International growth: The company expects to open 20–25 stores in Mexico, where it sees potential for more than 1,000 locations over time, and plans to add three to five Canadian stores while developing its platform.
Demand and competitive advantages: Comparable-store sales rose 7% through the second quarter, while O'Reilly highlighted its inventory network, promote-from-within culture, proprietary brands exceeding 55% of sales, and opportunities from an aging and increasingly complex vehicle fleet.
Hitting the Brakes: Is O'Reilly's Stock a Breakdown or a Buy?
#stores #open #Growth #interested
Record store expansion: O'Reilly plans to open 232 stores in 2026, its highest annual total, supported by new distribution capacity and growth opportunities across underserved U.S. markets.
International growth: The company expects to open 20–25 stores in Mexico, where it sees potential for more than 1,000 locations over time, and plans to add three to five Canadian stores while developing its platform.
Demand and competitive advantages: Comparable-store sales rose 7% through the second quarter, while O'Reilly highlighted its inventory network, promote-from-within culture, proprietary brands exceeding 55% of sales, and opportunities from an aging and increasingly complex vehicle fleet.
Hitting the Brakes: Is O'Reilly's Stock a Breakdown or a Buy?
#stores #open #Growth #interested

2 months ago
On September 16, IDEXX Laboratories (NASDAQ:IDXX) announced it had bought CoVetAI, a fast-growing veterinary software company whose tool listens during appointments and organizes what gets said and done. It sounds like a productivity gadget. But IDEXX is pitching it as a way to put the right patient details in front of a vet at the moment they decide what to test. The price was not disclosed, so the strategy is the story.
Start with the customer base IDEXX already has. More than 10,000 clinics worldwide run on its cloud practice software, and CoVet will plug into that system, including a link to IDEXX VetConnect PLUS. That hands a new product a ready audience. CoVet also works with practice systems IDEXX does not make, and IDEXX plans to keep supporting rival scribes, so the tool can reach clinics and regions the company does not serve today.
Then there is the engine this could feed. On August 4, IDEXX reported second-quarter revenue growth of 10%, and its recurring diagnostics business grew 11%, powered by higher volumes. That says vets are already running more tests, which is the behavior a smarter workflow tool is meant to encourage. The company also placed more than 1,600 inVue Dx ****** yzers in the quarter, lifting the installed base past 9,000, and it counts that instrument among its AI-driven products. Software and hardware are pointing in the same direction.
The biggest problem is what we can't see. Without deal terms, there is no way to judge what IDEXX paid or how much CoVet matters to earnings. And the company describes the payoff in future tense, saying these capabilities can raise diagnostic use over time. That is a hope, not a result yet. CoVet's openness to other systems cuts both ways too. It widens reach, but it also means a clinic can use CoVet without going deeper into IDEXX's ecosystem.
The second quarter also needs a careful read. Earnings per share rose 18%, but that included tax benefits from stock-based pay and a currency boost, and growth on a comparable basis was 15%. Some of the gain, in other words, did not come from selling more to vets. IDEXX also says it is spending more on commercial and innovation priorities, so its higher full-year earnings outlook comes with added costs attached.
#company #software #earnings #already
Start with the customer base IDEXX already has. More than 10,000 clinics worldwide run on its cloud practice software, and CoVet will plug into that system, including a link to IDEXX VetConnect PLUS. That hands a new product a ready audience. CoVet also works with practice systems IDEXX does not make, and IDEXX plans to keep supporting rival scribes, so the tool can reach clinics and regions the company does not serve today.
Then there is the engine this could feed. On August 4, IDEXX reported second-quarter revenue growth of 10%, and its recurring diagnostics business grew 11%, powered by higher volumes. That says vets are already running more tests, which is the behavior a smarter workflow tool is meant to encourage. The company also placed more than 1,600 inVue Dx ****** yzers in the quarter, lifting the installed base past 9,000, and it counts that instrument among its AI-driven products. Software and hardware are pointing in the same direction.
The biggest problem is what we can't see. Without deal terms, there is no way to judge what IDEXX paid or how much CoVet matters to earnings. And the company describes the payoff in future tense, saying these capabilities can raise diagnostic use over time. That is a hope, not a result yet. CoVet's openness to other systems cuts both ways too. It widens reach, but it also means a clinic can use CoVet without going deeper into IDEXX's ecosystem.
The second quarter also needs a careful read. Earnings per share rose 18%, but that included tax benefits from stock-based pay and a currency boost, and growth on a comparable basis was 15%. Some of the gain, in other words, did not come from selling more to vets. IDEXX also says it is spending more on commercial and innovation priorities, so its higher full-year earnings outlook comes with added costs attached.
#company #software #earnings #already


2 months ago
One of the biggest stories in markets this year has been how stubborn inflation remains. Geopolitical tension in the Middle East spurred the Consumer Price Index (CPI) in March, which rose 3.4% year over year in August. However, even before this conflict, the CPI was still well above the Federal Reserve's 2% target.
The market is starting to believe that inflation will stick around for a lot longer than initially expected. This could explain why Treasury yields, particularly for 10-, 20-, and 30-year terms, have risen significantly in the past 12 months. The **** umption is that interest rates will stay elevated for an extended time, at least compared to most of the 2010s.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Income investors looking to allocate capital are now faced with a crucial decision, one that might have been easier to make in the past. Is it smart to put money in dividend stalwarts, such as Coca-Cola (NYSE: KO) and Procter & Gamble (NYSE: PG)? Or should U.S. government bonds be on your shopping list?
As of this writing on the morning of Sept. 16, the 10-year Treasury yields just under 5%. At the same time, investors can earn more than 5.3% on 20-year and 30-year bonds. For the sake of this **** ysis, I believe it's best to focus on the 10-year Treasury, as this is a reasonable holding period that's also comparable to long-term stock investing.
#time #flashing
The market is starting to believe that inflation will stick around for a lot longer than initially expected. This could explain why Treasury yields, particularly for 10-, 20-, and 30-year terms, have risen significantly in the past 12 months. The **** umption is that interest rates will stay elevated for an extended time, at least compared to most of the 2010s.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Income investors looking to allocate capital are now faced with a crucial decision, one that might have been easier to make in the past. Is it smart to put money in dividend stalwarts, such as Coca-Cola (NYSE: KO) and Procter & Gamble (NYSE: PG)? Or should U.S. government bonds be on your shopping list?
As of this writing on the morning of Sept. 16, the 10-year Treasury yields just under 5%. At the same time, investors can earn more than 5.3% on 20-year and 30-year bonds. For the sake of this **** ysis, I believe it's best to focus on the 10-year Treasury, as this is a reasonable holding period that's also comparable to long-term stock investing.
#time #flashing

2 months ago
McDonald's (MCD) stock fell 14.2% over the past 12 months, versus roughly 14.3% for the S&P 500, and now sits near its 52-week low. Over roughly the same stretch, management changed how it explains weak traffic. It used to point at customers outside its control. It now points at its own restaurants, and that makes the stock a different bet.
Who Did McDonald's Say Was Pulling Back?
About a year ago, on the second-quarter 2025 call, the lead worry sat outside the company. The CEO put it this way: "Visits across the industry by low-income consumers once again declined by double digits." The value message of that period leaned on core menu pricing, which management said shapes how customers judge value most.
So What Does McDonald's Say Went Wrong Instead?
In the latest call, for the second quarter of 2026, low-income consumers did not come up by name. The backdrop still comes up: industry traffic in several of its largest markets stayed flat to negative. The lead, though, is a miss of its own making. U.S. comparable sales grew 0.8%, and the CEO said the company did not execute at the level it needed.
#TRAFFIC
Who Did McDonald's Say Was Pulling Back?
About a year ago, on the second-quarter 2025 call, the lead worry sat outside the company. The CEO put it this way: "Visits across the industry by low-income consumers once again declined by double digits." The value message of that period leaned on core menu pricing, which management said shapes how customers judge value most.
So What Does McDonald's Say Went Wrong Instead?
In the latest call, for the second quarter of 2026, low-income consumers did not come up by name. The backdrop still comes up: industry traffic in several of its largest markets stayed flat to negative. The lead, though, is a miss of its own making. U.S. comparable sales grew 0.8%, and the CEO said the company did not execute at the level it needed.
#TRAFFIC

2 months ago
On September 10, 2026, The Lovesac Company (NASDAQ:LOVE) reported second-quarter fiscal 2027 results for the period ended August 2, 2026. Net sales rose 0.4% to $161.2 million, a record for the quarter, and the company swung to net income of $7.4 million, or $0.51 per diluted share, from a loss of $6.7 million a year earlier. Inside that $0.51 sits $0.86 of net benefit from IEEPA tariff refunds. Omni-channel comparable sales fell 1.9%.
Canaccord's Maria Ripps read the quarter as in line, with revenue and adjusted EBITDA both landing within guidance and near consensus while tariff refunds pushed gross margin and earnings above expectations; she cut the firm's target on The Lovesac Company (NASDAQ:LOVE) to $20 from $22 but held the Buy rating.
Roth Capital's Matt Koranda also called the quarter in line with consensus, though he flagged omni-channel comps trending modestly negative on soft lower-end consumer demand. He lowered the firm's target on The Lovesac Company (NASDAQ:LOVE) to $20 from $22 as well, keeping a Buy rating, and noted that management reset full-year guidance lower on a tough demand environment and modest product launch delays.
DA Davidson offered a similar interpretation of the lower guidance, arguing that the reset reflects the new CFO's approach more than a deterioration in the underlying business. The firm said the CFO, who joined during the quarter, appears to be establishing more conservative expectations that could restore a beat-and-raise pattern the stock had lacked. DA Davidson lowered its target on The Lovesac Company (NASDAQ:LOVE) to $18 from $20 while maintaining its Buy rating.
The operating case rests on the high end: configurations above $6,000 grew double digits against a tough comparison, showroom net sales rose 4.6% to $114.1 million on 14 net new locations, and Snugg helped push other products revenue up 198.2%. Lovesac ended the quarter with $68.8 million in cash and no debt.
#quarter
Canaccord's Maria Ripps read the quarter as in line, with revenue and adjusted EBITDA both landing within guidance and near consensus while tariff refunds pushed gross margin and earnings above expectations; she cut the firm's target on The Lovesac Company (NASDAQ:LOVE) to $20 from $22 but held the Buy rating.
Roth Capital's Matt Koranda also called the quarter in line with consensus, though he flagged omni-channel comps trending modestly negative on soft lower-end consumer demand. He lowered the firm's target on The Lovesac Company (NASDAQ:LOVE) to $20 from $22 as well, keeping a Buy rating, and noted that management reset full-year guidance lower on a tough demand environment and modest product launch delays.
DA Davidson offered a similar interpretation of the lower guidance, arguing that the reset reflects the new CFO's approach more than a deterioration in the underlying business. The firm said the CFO, who joined during the quarter, appears to be establishing more conservative expectations that could restore a beat-and-raise pattern the stock had lacked. DA Davidson lowered its target on The Lovesac Company (NASDAQ:LOVE) to $18 from $20 while maintaining its Buy rating.
The operating case rests on the high end: configurations above $6,000 grew double digits against a tough comparison, showroom net sales rose 4.6% to $114.1 million on 14 net new locations, and Snugg helped push other products revenue up 198.2%. Lovesac ended the quarter with $68.8 million in cash and no debt.
#quarter


2 months ago
Dave & Buster's Entertainment, Inc. (NASDAQ:PLAY) reported a widening split between dining and entertainment in its September 14 second-quarter results. Food-and-beverage revenue increased to $211.5 million from $192.9 million, while entertainment revenue fell to $332.6 million from $364.5 million.
For the fiscal quarter ended August 4, 2026, total revenue declined 2.4% to $544.1 million. Operating income dropped to $19.4 million from $53 million. The GAAP net loss was $12.5 million, versus net income of $11.4 million a year earlier. Stronger restaurant sales are providing support, but the investment question is whether they can also bring customers back to the games.
Food-and-beverage revenue grew approximately 9.6%, giving Dave & Buster's Entertainment, Inc. (NASDAQ:PLAY) an identifiable source of momentum. A more appealing dining experience could encourage repeat visits, group occasions, and longer stays, creating additional opportunities to sell entertainment.
Management reported ongoing growth in food-and-beverage and special-events sales, alongside improving comparable-sales trends in July and the third quarter to date. That suggests the recovery effort has some traction beyond a single revenue category, although the later sales improvement was not quantified.
Management also said remodeled locations continued to outperform the system on comparable sales. That supports selective investment in existing venues, provided the additional revenue earns adequate returns on remodeling costs.
#entertainment #dave
For the fiscal quarter ended August 4, 2026, total revenue declined 2.4% to $544.1 million. Operating income dropped to $19.4 million from $53 million. The GAAP net loss was $12.5 million, versus net income of $11.4 million a year earlier. Stronger restaurant sales are providing support, but the investment question is whether they can also bring customers back to the games.
Food-and-beverage revenue grew approximately 9.6%, giving Dave & Buster's Entertainment, Inc. (NASDAQ:PLAY) an identifiable source of momentum. A more appealing dining experience could encourage repeat visits, group occasions, and longer stays, creating additional opportunities to sell entertainment.
Management reported ongoing growth in food-and-beverage and special-events sales, alongside improving comparable-sales trends in July and the third quarter to date. That suggests the recovery effort has some traction beyond a single revenue category, although the later sales improvement was not quantified.
Management also said remodeled locations continued to outperform the system on comparable sales. That supports selective investment in existing venues, provided the additional revenue earns adequate returns on remodeling costs.
#entertainment #dave

2 months ago
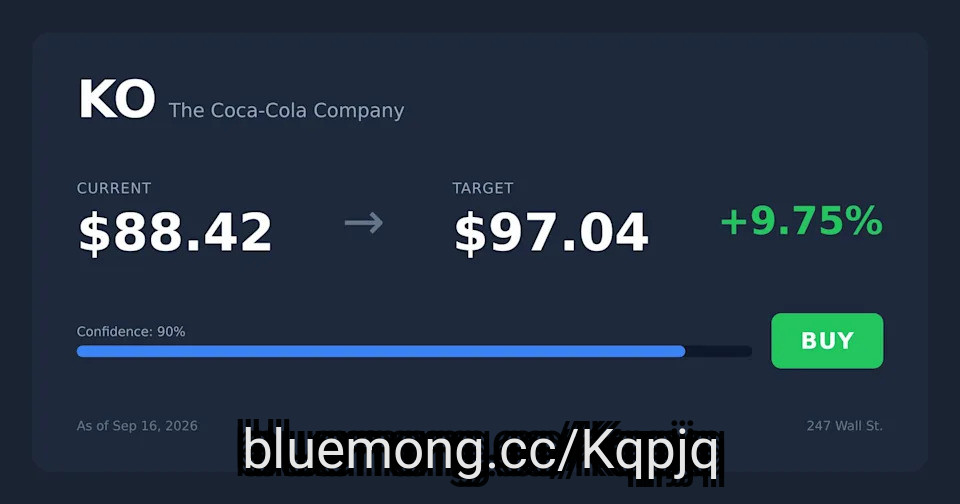
KO beat the S&P 500 over one and five years, returning 37% and 85% respectively, backed by 63 straight years of dividend raises.
At a P/E of 29 and P/FCF of 72 with shares near their $91.94 52-week high, Coca-Cola's valuation leaves little room for error.
Read More: Avoid these 13 retirement mistakes before they derail your future (sponsor)
If you bought Coca-Cola (NYSE:KO) a decade ago, you bought a business that has spent the intervening years quietly reinventing its balance sheet while doing what it always does: raising the dividend. 2025 marked the 63rd consecutive year of dividend increases, cementing Coca-Cola's status as a dividend king.
The past two years have been eventful. CEO James Quincey handed the reins to Henrique Braun in 2026, and the company has pushed hard on refranchising bottlers, including a pending sale of Coca-Cola Beverages Africa. Q4 2025 absorbed a $960M BODYARMOR impairment, but 2026 has been a different story. Q2 delivered EPS of $0.97, revenue of $13.38B (+6.7% YoY), and 5% unit case volume growth, aided by the FIFA World Cup marketing push. Management now guides to comparable EPS growth of 9% to 10% for the year.
#Dividend #cola #year
At a P/E of 29 and P/FCF of 72 with shares near their $91.94 52-week high, Coca-Cola's valuation leaves little room for error.
Read More: Avoid these 13 retirement mistakes before they derail your future (sponsor)
If you bought Coca-Cola (NYSE:KO) a decade ago, you bought a business that has spent the intervening years quietly reinventing its balance sheet while doing what it always does: raising the dividend. 2025 marked the 63rd consecutive year of dividend increases, cementing Coca-Cola's status as a dividend king.
The past two years have been eventful. CEO James Quincey handed the reins to Henrique Braun in 2026, and the company has pushed hard on refranchising bottlers, including a pending sale of Coca-Cola Beverages Africa. Q4 2025 absorbed a $960M BODYARMOR impairment, but 2026 has been a different story. Q2 delivered EPS of $0.97, revenue of $13.38B (+6.7% YoY), and 5% unit case volume growth, aided by the FIFA World Cup marketing push. Management now guides to comparable EPS growth of 9% to 10% for the year.
#Dividend #cola #year

2 months ago
On September 14, Dave & Buster's Entertainment (NASDAQ:PLAY) reported second-quarter fiscal 2026 results that read like two different companies at once. Revenue fell, and the company posted a net loss for the period ended August 4, yet comparable sales, which had been sliding for more than a year, kept getting less bad every month from June through the first five weeks of the third quarter. New CEO Darin Harper is betting that improvement compounds into something bigger.
The clearest evidence is the trend line itself. Comparable store sales fell 5.4% in the first quarter of fiscal 2026, then 2.9% in the second quarter, then just 1.6% in July after a 5% decline in June, and Harper said trends improved further over the first five weeks of the third quarter. Food and beverage sales are moving in the opposite direction entirely, up 7.6% in the quarter and positive for five straight quarters, helped by the Eat & Play Combo, a bundled meal and game credit offer sold through kiosks. Special event sales have now grown for seven consecutive quarters.
Behind that shift sits a rebuilt leadership bench. Dave & Buster's went more than a year without a chief marketing officer, and Harper has since added a CMO, a chief operations officer, a chief technology officer, and a chief legal officer since taking over. The company also leaned on new content, launching 10 games and attractions this year, including tie-ins with Mandalorian and Grogu, John Wick and Stranger Things, after research found more than 70% of guests said new games would bring them back more often. Changes to game pricing pushed play and dwell time up 16% to 20% or more. Six remodeled stores are already outperforming the rest of the chain, and management says the newest remodel template costs less to build than the last one. Net capital spending dropped to $127.6 million through the first half of the year from $155.4 million, and adjusted free cash flow swung to positive $19.5 million from negative $36.5 million, a $56 million improvement.
The headline figures were still rough. Total revenue slipped 2.4% to $544.1 million from $557.4 million a year earlier, and adjusted EBITDA dropped to $98.9 million, an 18.2% margin, from $129.8 million and a 23.3% margin. On a GAAP basis, the company posted a net loss of $12.5 million, or $0.36 per diluted share, versus net income of $11.4 million in the same quarter last year. About $15 million of the EBITDA decline came from items management calls non-normalized, including a $10 million noncash deferral adjustment that did not repeat this year, $3 million in extra preopening costs and $2 million in higher insurance expenses, but even stripped of those, the underlying decline was still roughly $16 million.
#year #first #harper #play
The clearest evidence is the trend line itself. Comparable store sales fell 5.4% in the first quarter of fiscal 2026, then 2.9% in the second quarter, then just 1.6% in July after a 5% decline in June, and Harper said trends improved further over the first five weeks of the third quarter. Food and beverage sales are moving in the opposite direction entirely, up 7.6% in the quarter and positive for five straight quarters, helped by the Eat & Play Combo, a bundled meal and game credit offer sold through kiosks. Special event sales have now grown for seven consecutive quarters.
Behind that shift sits a rebuilt leadership bench. Dave & Buster's went more than a year without a chief marketing officer, and Harper has since added a CMO, a chief operations officer, a chief technology officer, and a chief legal officer since taking over. The company also leaned on new content, launching 10 games and attractions this year, including tie-ins with Mandalorian and Grogu, John Wick and Stranger Things, after research found more than 70% of guests said new games would bring them back more often. Changes to game pricing pushed play and dwell time up 16% to 20% or more. Six remodeled stores are already outperforming the rest of the chain, and management says the newest remodel template costs less to build than the last one. Net capital spending dropped to $127.6 million through the first half of the year from $155.4 million, and adjusted free cash flow swung to positive $19.5 million from negative $36.5 million, a $56 million improvement.
The headline figures were still rough. Total revenue slipped 2.4% to $544.1 million from $557.4 million a year earlier, and adjusted EBITDA dropped to $98.9 million, an 18.2% margin, from $129.8 million and a 23.3% margin. On a GAAP basis, the company posted a net loss of $12.5 million, or $0.36 per diluted share, versus net income of $11.4 million in the same quarter last year. About $15 million of the EBITDA decline came from items management calls non-normalized, including a $10 million noncash deferral adjustment that did not repeat this year, $3 million in extra preopening costs and $2 million in higher insurance expenses, but even stripped of those, the underlying decline was still roughly $16 million.
#year #first #harper #play

2 months ago
On the September 11 episode of Mad Money, Jim Cramer expressed strong optimism for Brinker International, Inc. (NYSE:EAT) ahead of its upcoming **** yst presentation, as he said:
Thursday, we have two important **** yst meetings. Brinker... We have them all the time on the show. Brinker, you know, is Chili's, and the company never fails to wow me. I think this meeting will be no exception.
Brinker International, Inc. (NYSE:EAT) continues to demonstrate operational strength across the casual dining sector, driven by sustained customer traffic and menu innovation at Chili's Grill & Bar. In its fourth quarter of fiscal 2026, the company generated $1.54 billion in total revenue, bringing full-year revenues to $5.81 billion. Adjusted earnings per share for the quarter reached $3.07, representing a 23% year-over-year increase.
Chili's reported a 5.6% increase in comparable store sales, marking its 21st consecutive quarter of positive same-store sales growth. The sustained momentum has been supported by the ongoing success of the $10.99 "3 for Me" everyday value platform as well as targeted menu launches, including the Big Crispy Chicken Sandwich, which helped support traffic as Chili's continued positioning its value proposition against fast-food offerings. According to the company's CEO Kevin Hochman, the Big Crispy Chicken Sandwich "overdelivered" on the management's estimates.
Despite consistent top-line momentum, Brinker International, Inc. (NYSE:EAT) faces ongoing execution risks **** ociated with sticky cost inflation and broader macroeconomic pressures on consumer spending. Elevated wholesale prices for core commodities, especially beef and produce, continue to weigh on restaurant operating costs, while wage growth across regional markets keeps labor expenses elevated.
#elevated #analyst
Thursday, we have two important **** yst meetings. Brinker... We have them all the time on the show. Brinker, you know, is Chili's, and the company never fails to wow me. I think this meeting will be no exception.
Brinker International, Inc. (NYSE:EAT) continues to demonstrate operational strength across the casual dining sector, driven by sustained customer traffic and menu innovation at Chili's Grill & Bar. In its fourth quarter of fiscal 2026, the company generated $1.54 billion in total revenue, bringing full-year revenues to $5.81 billion. Adjusted earnings per share for the quarter reached $3.07, representing a 23% year-over-year increase.
Chili's reported a 5.6% increase in comparable store sales, marking its 21st consecutive quarter of positive same-store sales growth. The sustained momentum has been supported by the ongoing success of the $10.99 "3 for Me" everyday value platform as well as targeted menu launches, including the Big Crispy Chicken Sandwich, which helped support traffic as Chili's continued positioning its value proposition against fast-food offerings. According to the company's CEO Kevin Hochman, the Big Crispy Chicken Sandwich "overdelivered" on the management's estimates.
Despite consistent top-line momentum, Brinker International, Inc. (NYSE:EAT) faces ongoing execution risks **** ociated with sticky cost inflation and broader macroeconomic pressures on consumer spending. Elevated wholesale prices for core commodities, especially beef and produce, continue to weigh on restaurant operating costs, while wage growth across regional markets keeps labor expenses elevated.
#elevated #analyst

2 months ago
Ethereum's native token, Ether (ETH), is showing signs of underperformance against Bitcoin (BTC), with a bearish double-top setup emerging just as the US Senate's failure to advance the CLARITY Act adds fresh uncertainty to the crypto market.
Ether was trading near 0.03167 BTC on Sept. 16, after failing to sustain its latest advance against Bitcoin.
The ETH/BTC daily chart shows two comparable peaks near 0.03344 BTC, one formed in August and another in September. Together, they resemble a potential double top, a bearish reversal structure that typically develops when buyers repeatedly fail to push price through the same resistance area.
Its neckline sits around 0.03078 BTC, meaning ETH/BTC would need a decisive daily close below that level to validate the breakdown.
If that happens, subtracting the pattern's maximum height from the neckline produces a downside target near 0.0283 BTC. That would represent a decline of roughly 10% from current levels, signaling further Ethereum underperformance relative to Bitcoin.
#Bitcoin #underperformance #daily #neckline
Ether was trading near 0.03167 BTC on Sept. 16, after failing to sustain its latest advance against Bitcoin.
The ETH/BTC daily chart shows two comparable peaks near 0.03344 BTC, one formed in August and another in September. Together, they resemble a potential double top, a bearish reversal structure that typically develops when buyers repeatedly fail to push price through the same resistance area.
Its neckline sits around 0.03078 BTC, meaning ETH/BTC would need a decisive daily close below that level to validate the breakdown.
If that happens, subtracting the pattern's maximum height from the neckline produces a downside target near 0.0283 BTC. That would represent a decline of roughly 10% from current levels, signaling further Ethereum underperformance relative to Bitcoin.
#Bitcoin #underperformance #daily #neckline



2 months ago
The House of Representatives on Tuesday passed a bipartisan bill aimed at shielding Americans from increased electricity costs **** ociated with data centers being built across the country.
The Ratepayer Protection Act, which passed with an overwhelming 417-3 majority, "ensures American families are not left footing the bill for the grid upgrades and new energy generation required to operate large data centers," Republican Rep. Gabe Evans, one of the bill's sponsors, said ahead of the vote.
The bill now moves to the Senate, where its prospects of passing are uncertain.
The Ratepayer Protection Act is the first major piece of legislation taken up by Congress to address the growing public discontent over the mass buildout of data centers among the American public. Even if it passes, though, it won't directly set the rates that data center operators pay for their electricity.
Congress doesn't have the power to compel utilities to set higher rates for the facilities. Only states have that authority. What the Ratepayer Protection Act would do is compel state utility regulators to consider adopting a federal standard under which large data centers would cover the extra costs of upgrades. The bill is comparable to a proclamation signed by President Trump earlier this year that established a similar voluntary pledge for tech companies.
#passed
The Ratepayer Protection Act, which passed with an overwhelming 417-3 majority, "ensures American families are not left footing the bill for the grid upgrades and new energy generation required to operate large data centers," Republican Rep. Gabe Evans, one of the bill's sponsors, said ahead of the vote.
The bill now moves to the Senate, where its prospects of passing are uncertain.
The Ratepayer Protection Act is the first major piece of legislation taken up by Congress to address the growing public discontent over the mass buildout of data centers among the American public. Even if it passes, though, it won't directly set the rates that data center operators pay for their electricity.
Congress doesn't have the power to compel utilities to set higher rates for the facilities. Only states have that authority. What the Ratepayer Protection Act would do is compel state utility regulators to consider adopting a federal standard under which large data centers would cover the extra costs of upgrades. The bill is comparable to a proclamation signed by President Trump earlier this year that established a similar voluntary pledge for tech companies.
#passed



2 months ago
Wolfe Research upgraded two prominent pharmaceutical companies to Outperform on August 13. The firm upgraded both Biogen Inc. (NASDAQ:BIIB) and AbbVie Inc. (NYSE:ABBV)'s ratings from Peer Perform, with Wolfe ***** igning them similar $300 price targets. The firm's logic in each case was based on a comparable set of factors: pipelines that the market appears to undervalue, and valuations that Wolfe believes are too low given each company's growth track.
Wolfe's thesis for Biogen Inc. (NASDAQ:BIIB) is mainly based on late-stage clinical programs, which it believes the stock has yet to reflect. The firm focused on two experimental therapies in particular, both of which have key late-stage clinical readouts expected over the coming year: litifilimab, which Wolfe believes could be the first biologic approved for cutaneous lupus erythematosus, and felzartamab, which the firm claims represents a bigger commercial opportunity in antibody-mediated transplant rejection than Wall Street currently thinks.
Wolfe also cited Biogen's acquisition of Apellis Pharmaceuticals as strengthening its near-term revenue base through the FDA-approved drugs Empaveli and Syfovre. That move is part of an overall pattern of Biogen Inc. (NASDAQ:BIIB) diversifying beyond its core neurology brand, with the company completing its acquisition of RayThera on August 6, adding another early-stage immunology platform to its pipeline.
Wolfe's Biogen Inc. (NASDAQ:BIIB) thesis is incomplete without valuation. The firm believes the stock is trading at a discount to the broader market, despite the company's development on Leqembi, its Alzheimer's medication, and what Wolfe described as solid commercial execution overall.
AbbVie's upgrade is based on a slightly different premise: patent strength and cash generation rather than simple clinical events. Wolfe stated that AbbVie's 2027 earnings multiple of 14.6x seemed too low for a company that forecasts high-single-digit revenue growth for the rest of the decade. AbbVie's patent position, according to Wolfe, sets the company apart from its competitors in a way that the market has yet to completely price in.
#wolfe #firm #market #clinical
Wolfe's thesis for Biogen Inc. (NASDAQ:BIIB) is mainly based on late-stage clinical programs, which it believes the stock has yet to reflect. The firm focused on two experimental therapies in particular, both of which have key late-stage clinical readouts expected over the coming year: litifilimab, which Wolfe believes could be the first biologic approved for cutaneous lupus erythematosus, and felzartamab, which the firm claims represents a bigger commercial opportunity in antibody-mediated transplant rejection than Wall Street currently thinks.
Wolfe also cited Biogen's acquisition of Apellis Pharmaceuticals as strengthening its near-term revenue base through the FDA-approved drugs Empaveli and Syfovre. That move is part of an overall pattern of Biogen Inc. (NASDAQ:BIIB) diversifying beyond its core neurology brand, with the company completing its acquisition of RayThera on August 6, adding another early-stage immunology platform to its pipeline.
Wolfe's Biogen Inc. (NASDAQ:BIIB) thesis is incomplete without valuation. The firm believes the stock is trading at a discount to the broader market, despite the company's development on Leqembi, its Alzheimer's medication, and what Wolfe described as solid commercial execution overall.
AbbVie's upgrade is based on a slightly different premise: patent strength and cash generation rather than simple clinical events. Wolfe stated that AbbVie's 2027 earnings multiple of 14.6x seemed too low for a company that forecasts high-single-digit revenue growth for the rest of the decade. AbbVie's patent position, according to Wolfe, sets the company apart from its competitors in a way that the market has yet to completely price in.
#wolfe #firm #market #clinical


2 months ago
Inquiring about Walmart Inc. (NASDAQ:WMT) on September 10, a caller asked if they should "keep it." Mad Money host Jim Cramer replied:
I got to tell you, this one is a short and long-term, okay? Short-term, I think I know what Walmart's doing. I think that they're letting their customers have a big break. They're not passing along all of these costs. That is going to earn them tremendous love when things get better. So the wise situation is to say this: Walmart trades at 36 times earnings. It deserves to trade lower just because of what's happening at the company now and higher what's happening at the company when this inflation bout ends. So you buy some at $106, $105, and then buy some at $95. And yes, it could trade to $95. It does not have yield support. This is not like Target, which had that yield support. Target's doing better than Walmart right now. It is.
Walmart Inc.'s (NASDAQ:WMT) second-quarter fiscal 2027 revenue rose 5.9% year over year to $187.9 billion, while global e-commerce sales increased 23%. Global advertising revenue rose 38%, and membership-fee revenue increased 17% globally. Walmart U.S. comparable sales, excluding fuel, grew 2.6%. The company is also using tariff refunds to support lower prices. It said tariff refunds increased its gross profit rate during the quarter, while price investments partially offset the benefit.
Target Corporation (NYSE:TGT) has stronger recent comparable-sales momentum. Its second-quarter sales rose 5.3%, comparable sales increased 3.8%, and traffic rose 3.6%. The company also raised its full-year sales-growth outlook to approximately 5%. Its second-quarter GAAP and adjusted EPS were $4.11, including a $1.65 benefit from tariff refunds. Excluding tariff refunds, GAAP and adjusted EPS increased 20% year over year. CEO Michael Fiddelke said Target had reduced prices on more than 10,000 frequently purchased items over the past year and acknowledged that "there's still meaningful work ahead."
Walmart Inc.'s (NASDAQ:WMT) biggest risk is valuation. Its premium forward PE of 36.76 leaves the stock more exposed if U.S. comparable-sales growth remains modest while the company continues investing in prices. Walmart's 2.6% U.S. comparable-sales growth also trails Target's 3.8%.
#increased #rose
I got to tell you, this one is a short and long-term, okay? Short-term, I think I know what Walmart's doing. I think that they're letting their customers have a big break. They're not passing along all of these costs. That is going to earn them tremendous love when things get better. So the wise situation is to say this: Walmart trades at 36 times earnings. It deserves to trade lower just because of what's happening at the company now and higher what's happening at the company when this inflation bout ends. So you buy some at $106, $105, and then buy some at $95. And yes, it could trade to $95. It does not have yield support. This is not like Target, which had that yield support. Target's doing better than Walmart right now. It is.
Walmart Inc.'s (NASDAQ:WMT) second-quarter fiscal 2027 revenue rose 5.9% year over year to $187.9 billion, while global e-commerce sales increased 23%. Global advertising revenue rose 38%, and membership-fee revenue increased 17% globally. Walmart U.S. comparable sales, excluding fuel, grew 2.6%. The company is also using tariff refunds to support lower prices. It said tariff refunds increased its gross profit rate during the quarter, while price investments partially offset the benefit.
Target Corporation (NYSE:TGT) has stronger recent comparable-sales momentum. Its second-quarter sales rose 5.3%, comparable sales increased 3.8%, and traffic rose 3.6%. The company also raised its full-year sales-growth outlook to approximately 5%. Its second-quarter GAAP and adjusted EPS were $4.11, including a $1.65 benefit from tariff refunds. Excluding tariff refunds, GAAP and adjusted EPS increased 20% year over year. CEO Michael Fiddelke said Target had reduced prices on more than 10,000 frequently purchased items over the past year and acknowledged that "there's still meaningful work ahead."
Walmart Inc.'s (NASDAQ:WMT) biggest risk is valuation. Its premium forward PE of 36.76 leaves the stock more exposed if U.S. comparable-sales growth remains modest while the company continues investing in prices. Walmart's 2.6% U.S. comparable-sales growth also trails Target's 3.8%.
#increased #rose

2 months ago
Dick's Sporting Goods has been one of the big success stories in the brick-and-mortar retail ***** e.
At a time when many rivals have been shrinking their physical store counts, the sporting goods giant has leaned into stores, creating new experiential concepts and generally rethinking its retail strategy.
The chain has selectively built House of Sport locations that offer running tracks, batting cages, golf simulators, and other interactive options.
"House of Sport locations now seeing 5-6 times the number of visits per location compared to the rest of the chain. For reference, the average ***** 's Sporting Goods store is roughly 50K square feet square feet compared to 100K-120K square feet for House of Sport, indicating that House of Sport is also outperforming on a visit per square foot basis," according to 2024 data from Placer.ai.
That's a win, and the overall company delivered a nearly 5% comparable store sales gain in the second quarter. Chairman Edward Stack celebrated that success during the chain's second-quarter earnings call.
#square
At a time when many rivals have been shrinking their physical store counts, the sporting goods giant has leaned into stores, creating new experiential concepts and generally rethinking its retail strategy.
The chain has selectively built House of Sport locations that offer running tracks, batting cages, golf simulators, and other interactive options.
"House of Sport locations now seeing 5-6 times the number of visits per location compared to the rest of the chain. For reference, the average ***** 's Sporting Goods store is roughly 50K square feet square feet compared to 100K-120K square feet for House of Sport, indicating that House of Sport is also outperforming on a visit per square foot basis," according to 2024 data from Placer.ai.
That's a win, and the overall company delivered a nearly 5% comparable store sales gain in the second quarter. Chairman Edward Stack celebrated that success during the chain's second-quarter earnings call.
#square

2 months ago
This story was originally published on CRE Daily. Join 70,000+ commercial real estate professionals getting daily news, market insights, and industry **** ysis delivered straight to their inbox with the free CRE Daily newsletter.
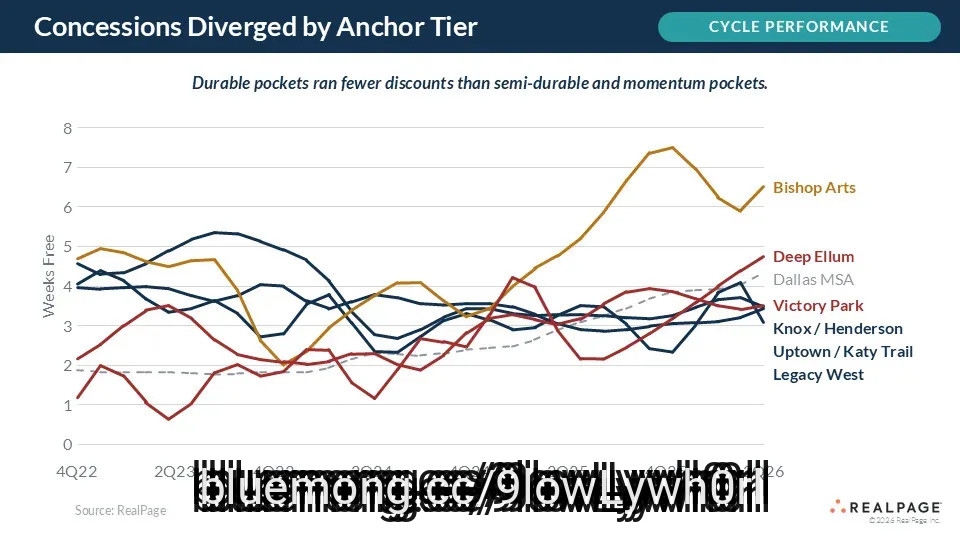
Legacy West apartments average $1,845 a month, a 9% premium over comparable Dallas properties that's smaller than any other demand pocket RealPage tracks, yet the submarket needs the fewest concessions to stay leased.
The pocket posted 95.5% occupancy in the second quarter, two points above the Dallas metro average, anchored by roughly 12,000 corporate jobs from employers including Toyota, JPMorgan Chase, and Frito-Lay.
Because Legacy West's strength rests on continued corporate expansion rather than a larger price premium, its durability depends on employers in the Plano-Frisco corridor keeping up their hiring pace.
Apartments in Legacy West command the smallest rent premium of any demand pocket in the Dallas metro, yet the submarket needs fewer concessions to stay full than any of its peers, according to RealPage. The corporate-anchored district straddling the Plano-Frisco border averaged $1,845 in effective rent in the second quarter, a 9% premium over comparable metro properties. That's the smallest premium among the demand pockets RealPage tracks across Dallas, even though Legacy West's occupancy and leasing strength outperform them.
#legacy #dallas #demand
Legacy West apartments average $1,845 a month, a 9% premium over comparable Dallas properties that's smaller than any other demand pocket RealPage tracks, yet the submarket needs the fewest concessions to stay leased.
The pocket posted 95.5% occupancy in the second quarter, two points above the Dallas metro average, anchored by roughly 12,000 corporate jobs from employers including Toyota, JPMorgan Chase, and Frito-Lay.
Because Legacy West's strength rests on continued corporate expansion rather than a larger price premium, its durability depends on employers in the Plano-Frisco corridor keeping up their hiring pace.
Apartments in Legacy West command the smallest rent premium of any demand pocket in the Dallas metro, yet the submarket needs fewer concessions to stay full than any of its peers, according to RealPage. The corporate-anchored district straddling the Plano-Frisco border averaged $1,845 in effective rent in the second quarter, a 9% premium over comparable metro properties. That's the smallest premium among the demand pockets RealPage tracks across Dallas, even though Legacy West's occupancy and leasing strength outperform them.
#legacy #dallas #demand

2 months ago
On September 9, American Eagle Outfitters Inc. (NYSE:AEO) revealed results for its fiscal 2026 second quarter. The company achieved an 8% year-over-year topline growth with net revenue figures of $1.38 billion. The second quarter operating profit jumped up to $211 million compared to $103 million during the same period last year. As a result, diluted earnings per share for the quarter stood at $0.79 in comparison with $0.45 for Q2 FY25. This led to a $21 million distribution to shareholders with a dividend payout of $0.125 per share.
Africa Studio/Shutterstock.com
A resilient performance during the second quarter was primarily driven by robust momentum within the Aerie sub-brand and OFFLINE collection. There was a 6% year-over-year growth in company-wide comparable sales, whereas the Aerie's comparable sales picked up by 19%. Total gross profit for the quarter reached $672 million, which shows a 34% increase against $500 million for Q2 FY25. This pushed Q2 gross margins to 48.7%, a jump of 980 basis points relative to the previous year's quarter, despite 330 basis points deleveraging across the merchandise margins. Compared to an 8% operating margin in Q2 FY25, the company posted 15.3% margin in the recent period.
Even with a slight dip in comparable sales, the American Eagle brand also exhibited some encouraging signs. It posted sequential gains from the previous quarter, which marks the fourth consecutive quarter of expansion across menswear.
Results for the reported period were bolstered by $196 million in International Emergency Economic Powers Act (IEEPA) tariff refunds, which also included interest payments. This resulted in an additional $35 million in incentive compensation set aside by the company, which affected both gross profit and SG&A. After taking these additional expenses into consideration, the overall operating income gains related to tariff refunds amounted to $161 million.
#comparable
Africa Studio/Shutterstock.com
A resilient performance during the second quarter was primarily driven by robust momentum within the Aerie sub-brand and OFFLINE collection. There was a 6% year-over-year growth in company-wide comparable sales, whereas the Aerie's comparable sales picked up by 19%. Total gross profit for the quarter reached $672 million, which shows a 34% increase against $500 million for Q2 FY25. This pushed Q2 gross margins to 48.7%, a jump of 980 basis points relative to the previous year's quarter, despite 330 basis points deleveraging across the merchandise margins. Compared to an 8% operating margin in Q2 FY25, the company posted 15.3% margin in the recent period.
Even with a slight dip in comparable sales, the American Eagle brand also exhibited some encouraging signs. It posted sequential gains from the previous quarter, which marks the fourth consecutive quarter of expansion across menswear.
Results for the reported period were bolstered by $196 million in International Emergency Economic Powers Act (IEEPA) tariff refunds, which also included interest payments. This resulted in an additional $35 million in incentive compensation set aside by the company, which affected both gross profit and SG&A. After taking these additional expenses into consideration, the overall operating income gains related to tariff refunds amounted to $161 million.
#comparable


2 months ago
Our ****** ysts just identified a stock with the potential to be the next Nvidia. Tell us how you invest and we'll show you why it's our #1 pick. Tap here.
Delivered total revenue growth of 1.1%, marking the second consecutive quarter of expansion as the Project Sunshine transformation gains traction.
Direct segment revenue grew 8% with comparable sales up 9.2%, serving as the primary indicator of customer resonance with new product and marketing strategies.
Gross margin expanded by more than 40 basis points (excluding tariff refunds) through disciplined pricing, promotion governance, and improved product ****** ortment productivity.
Indirect channel revenue contracted 39% due to intentional shifts in marketplace strategy and a strategic reduction in liquidation sales to protect brand equity.
#tell
Delivered total revenue growth of 1.1%, marking the second consecutive quarter of expansion as the Project Sunshine transformation gains traction.
Direct segment revenue grew 8% with comparable sales up 9.2%, serving as the primary indicator of customer resonance with new product and marketing strategies.
Gross margin expanded by more than 40 basis points (excluding tariff refunds) through disciplined pricing, promotion governance, and improved product ****** ortment productivity.
Indirect channel revenue contracted 39% due to intentional shifts in marketplace strategy and a strategic reduction in liquidation sales to protect brand equity.
#tell
2 months ago
On September 10, Canaccord cut its price target for The Lovesac Company (NASDAQ:LOVE) from $22 to $20 but maintained its Buy rating on the stock. This update came after the company reported its financial results for the second quarter of fiscal 2027, which ended August 2, 2026.
Canaccord noted that the company's fiscal Q2 results were in line with expectations. Revenue and adjusted EBITDA were both within the company's guidance and close to consensus estimates. The company received $21 million in IEEPA tariff refunds, which helped lift gross margins and earnings above consensus.
The Lovesac Company (NASDAQ:LOVE) reported net sales 0.4% higher than the prior-year period. This slight increase was mainly driven by 14 net new showrooms, although this was partly offset by a 1.9% decline in omni-channel comparable net sales and the closure of the company's Best Buy shop-in-shop locations. During the quarter, the company opened five additional showrooms and closed two.
The company reported net income of $7.4 million in the second quarter, compared with a net loss of $6.7 million in the same period last year. Operating income also improved to $10.9 million from an operating loss of $8.8 million a year earlier.
Gross profit rose 21.7% year-over-year while gross margin expanded to 68.4% of net sales from 56.4%, an increase of 1,200 basis points. The improvement was largely driven by IEEPA tariff recoveries, which contributed 1,240 basis points to gross margin. Excluding those recoveries, gross margin was 56.0%, down 40 basis points from the prior-year period.
#year #sales #period
Canaccord noted that the company's fiscal Q2 results were in line with expectations. Revenue and adjusted EBITDA were both within the company's guidance and close to consensus estimates. The company received $21 million in IEEPA tariff refunds, which helped lift gross margins and earnings above consensus.
The Lovesac Company (NASDAQ:LOVE) reported net sales 0.4% higher than the prior-year period. This slight increase was mainly driven by 14 net new showrooms, although this was partly offset by a 1.9% decline in omni-channel comparable net sales and the closure of the company's Best Buy shop-in-shop locations. During the quarter, the company opened five additional showrooms and closed two.
The company reported net income of $7.4 million in the second quarter, compared with a net loss of $6.7 million in the same period last year. Operating income also improved to $10.9 million from an operating loss of $8.8 million a year earlier.
Gross profit rose 21.7% year-over-year while gross margin expanded to 68.4% of net sales from 56.4%, an increase of 1,200 basis points. The improvement was largely driven by IEEPA tariff recoveries, which contributed 1,240 basis points to gross margin. Excluding those recoveries, gross margin was 56.0%, down 40 basis points from the prior-year period.
#year #sales #period

2 months ago
On September 10, Zumiez Inc. (NASDAQ:ZUMZ) reported weaker-than-expected results for its second quarter ended August 1, 2026, with the results falling short of Wall Street estimates and sending the stock lower.
For the second quarter of fiscal 2026, Zumiez Inc. (NASDAQ:ZUMZ) reported net sales of $209 million, down 2.5% year-over-year. Comparable sales declined 2.1%, with the weakness mainly coming from the US. Canada, Europe, and Australia all had positive comparable sales growth for the quarter. The company said it saw strong sales growth across its international markets, but softer domestic sales and lower foot traffic weighed on overall results.
The company also posted a net loss of $2.7 million, or $0.17 per share, compared with a net loss of $1.0 million, or $0.06 per share, in the second quarter of fiscal 2025.
Third-Quarter Outlook Disappoints, But Is It All Bad?
Zumiez Inc. (NASDAQ:ZUMZ) introduced third-quarter guidance, which also failed to provide much relief as it came in below Wall Street expectations. For the three months ending October 31, 2026, the company expects net sales of $222 million to $226 million, while earnings per share are projected to range from $0.00 to $0.10.
#quarter #sales
For the second quarter of fiscal 2026, Zumiez Inc. (NASDAQ:ZUMZ) reported net sales of $209 million, down 2.5% year-over-year. Comparable sales declined 2.1%, with the weakness mainly coming from the US. Canada, Europe, and Australia all had positive comparable sales growth for the quarter. The company said it saw strong sales growth across its international markets, but softer domestic sales and lower foot traffic weighed on overall results.
The company also posted a net loss of $2.7 million, or $0.17 per share, compared with a net loss of $1.0 million, or $0.06 per share, in the second quarter of fiscal 2025.
Third-Quarter Outlook Disappoints, But Is It All Bad?
Zumiez Inc. (NASDAQ:ZUMZ) introduced third-quarter guidance, which also failed to provide much relief as it came in below Wall Street expectations. For the three months ending October 31, 2026, the company expects net sales of $222 million to $226 million, while earnings per share are projected to range from $0.00 to $0.10.
#quarter #sales

2 months ago
Jim Cramer raised concerns about The TJX Companies, Inc. (NYSE:TJX) during the September 10 episode of Mad Money, as he said:
We had our CNBC Investing Club meeting today… I review each of the Charitable Trust positions on the call. This time, it was pretty clinical until I got to TJX, the off-price retailer. Candidly, I lost it on TJX. I've owned the stock for the Trust for as long as I can remember, and I've never felt so worried about this franchise. They have a bunch of divisions, but the biggest one, Marmaxx, consisting of TJ Maxx and Marshalls, really blew it. Management told us that they had figured out what had gone wrong and they've already fixed it, but because of competitive reasons or whatever, they wouldn't tell us what went wrong and they wouldn't tell us how they fixed it. I found that infuriating…
I came close to saying, forget it, Jim, it's retail. Sometimes retail is seductive. I love my local TJ Maxx, and I think Home Goods is a fun place to shop. The company's almost always about the best in the industry, crushing Burlington and Ross Stores. But this time, shockingly, Ross Stores upside surprised. It crushed TJX, much better than expected... So why bother sticking your neck out for something in this group? Simple. Because some of the greatest stories of all time have come from retail. Costco's been an incredible long-term performer. Walmart's been terrific. And TJX, it's been a wonder, one of the best stocks ever.
Could they really suddenly have lost it? Did they go all LULU? I don't think so. What happens, though, is you have to be conscious that TJX is right now being buffeted by its group, which is trading down because of the decline in discretionary income from the tax that is higher gasoline. We can't tell how much of its underperformance comes from that alone or maybe the mistakes that management made and says they've corrected. In other words, these retail stocks are very hard to own, even as they seem so easy to grasp.
TJX Companies, Inc. (NYSE:TJX) reported second-quarter fiscal 2027 sales of $15.18 billion, up 5% year over year, while consolidated comparable sales increased 4%. Adjusted diluted EPS rose 11% to $1.22, and the company raised its full-year diluted EPS outlook to $5.31-$5.36, or $5.15-$5.20 excluding an expected $0.16 net benefit from tariff refunds. The weakness was concentrated in Marmaxx, which includes TJ Maxx, Marshalls and Sierra. Comparable sales increased just 1%, down from 6% in the first quarter, while HomeGoods, TJX Canada and TJX International each posted comparable-sales growth of 6% or more.
#year
We had our CNBC Investing Club meeting today… I review each of the Charitable Trust positions on the call. This time, it was pretty clinical until I got to TJX, the off-price retailer. Candidly, I lost it on TJX. I've owned the stock for the Trust for as long as I can remember, and I've never felt so worried about this franchise. They have a bunch of divisions, but the biggest one, Marmaxx, consisting of TJ Maxx and Marshalls, really blew it. Management told us that they had figured out what had gone wrong and they've already fixed it, but because of competitive reasons or whatever, they wouldn't tell us what went wrong and they wouldn't tell us how they fixed it. I found that infuriating…
I came close to saying, forget it, Jim, it's retail. Sometimes retail is seductive. I love my local TJ Maxx, and I think Home Goods is a fun place to shop. The company's almost always about the best in the industry, crushing Burlington and Ross Stores. But this time, shockingly, Ross Stores upside surprised. It crushed TJX, much better than expected... So why bother sticking your neck out for something in this group? Simple. Because some of the greatest stories of all time have come from retail. Costco's been an incredible long-term performer. Walmart's been terrific. And TJX, it's been a wonder, one of the best stocks ever.
Could they really suddenly have lost it? Did they go all LULU? I don't think so. What happens, though, is you have to be conscious that TJX is right now being buffeted by its group, which is trading down because of the decline in discretionary income from the tax that is higher gasoline. We can't tell how much of its underperformance comes from that alone or maybe the mistakes that management made and says they've corrected. In other words, these retail stocks are very hard to own, even as they seem so easy to grasp.
TJX Companies, Inc. (NYSE:TJX) reported second-quarter fiscal 2027 sales of $15.18 billion, up 5% year over year, while consolidated comparable sales increased 4%. Adjusted diluted EPS rose 11% to $1.22, and the company raised its full-year diluted EPS outlook to $5.31-$5.36, or $5.15-$5.20 excluding an expected $0.16 net benefit from tariff refunds. The weakness was concentrated in Marmaxx, which includes TJ Maxx, Marshalls and Sierra. Comparable sales increased just 1%, down from 6% in the first quarter, while HomeGoods, TJX Canada and TJX International each posted comparable-sales growth of 6% or more.
#year


2 months ago
The Kroger Co. (NYSE:KR) cut its full-year 2026 identical-sales forecast excluding fuel to 0.2%–0.8% from 1%–2%, reflecting a sharper-than-expected slowdown in consumer demand. Second-quarter identical sales rose just 0.2%, down from 3.4% a year earlier and below the 0.9% ****** yst estimate.
The weakness reflects pressure on middle- and lower-income consumers, while a Cyclospora outbreak reduced quarterly identical sales by roughly 35 basis points and Medicare prescription-drug pricing changes created an approximately 140-basis-point headwind for pharmacy revenue. Importantly, Kroger maintained its full-year adjusted FIFO operating-profit forecast of $5.0 billion–$5.2 billion and delivered adjusted EPS of $1.09, ahead of the $1.06 consensus.
The strongest bullish argument is that The Kroger Co. (NYSE:KR) is currently protecting earnings despite the deterioration in sales momentum. Second-quarter adjusted EPS increased 5% year over year to $1.09, while adjusted FIFO operating profit was $1.076 billion. Kroger's gross margin rate actually increased by 13 basis points, although the overall gross-margin percentage was 22.4% versus 22.5% a year earlier, suggesting that pricing, sourcing, and cost-management initiatives are helping offset weaker volumes. The company's higher-margin businesses are also becoming increasingly important: adjusted e-commerce sales grew 20% in the quarter, and Kroger Precision Marketing profit increased 24%. That mix shift gives Kroger an earnings lever even when supermarket traffic and comparable sales are weak.
There is also evidence that management is actively responding to the competitive pressure rather than simply accepting slower growth. CEO Greg Foran has been pursuing tighter sourcing, simpler operations and lower prices, with Reuters reporting plans to cut prices across thousands of products to regain shoppers from Walmart, Costco and Aldi. The Kroger Co. (NYSE:KR)'s balance sheet provides room to fund that strategy: its net debt-to-adjusted-EBITDA ratio was 1.91x, below its stated target range of 2.30x–2.50x, while the company repurchased $1.0 billion of shares in the second quarter and $1.2 billion year to date. It also raised its dividend 11%, marking the 20th consecutive year of increases. If sales stabilize while e-commerce, retail media and cost efficiencies continue expanding, the unchanged $5.0 billion–$5.2 billion operating-profit forecast could prove more important to valuation than the reduced top-line outlook.
#year
The weakness reflects pressure on middle- and lower-income consumers, while a Cyclospora outbreak reduced quarterly identical sales by roughly 35 basis points and Medicare prescription-drug pricing changes created an approximately 140-basis-point headwind for pharmacy revenue. Importantly, Kroger maintained its full-year adjusted FIFO operating-profit forecast of $5.0 billion–$5.2 billion and delivered adjusted EPS of $1.09, ahead of the $1.06 consensus.
The strongest bullish argument is that The Kroger Co. (NYSE:KR) is currently protecting earnings despite the deterioration in sales momentum. Second-quarter adjusted EPS increased 5% year over year to $1.09, while adjusted FIFO operating profit was $1.076 billion. Kroger's gross margin rate actually increased by 13 basis points, although the overall gross-margin percentage was 22.4% versus 22.5% a year earlier, suggesting that pricing, sourcing, and cost-management initiatives are helping offset weaker volumes. The company's higher-margin businesses are also becoming increasingly important: adjusted e-commerce sales grew 20% in the quarter, and Kroger Precision Marketing profit increased 24%. That mix shift gives Kroger an earnings lever even when supermarket traffic and comparable sales are weak.
There is also evidence that management is actively responding to the competitive pressure rather than simply accepting slower growth. CEO Greg Foran has been pursuing tighter sourcing, simpler operations and lower prices, with Reuters reporting plans to cut prices across thousands of products to regain shoppers from Walmart, Costco and Aldi. The Kroger Co. (NYSE:KR)'s balance sheet provides room to fund that strategy: its net debt-to-adjusted-EBITDA ratio was 1.91x, below its stated target range of 2.30x–2.50x, while the company repurchased $1.0 billion of shares in the second quarter and $1.2 billion year to date. It also raised its dividend 11%, marking the 20th consecutive year of increases. If sales stabilize while e-commerce, retail media and cost efficiencies continue expanding, the unchanged $5.0 billion–$5.2 billion operating-profit forecast could prove more important to valuation than the reduced top-line outlook.
#year