

4 days ago
Some offers on this page are from advertisers who pay us, which may affect which products we write about, but not our recommendations. See our Advertiser Disclosure.
A health savings account (HSA) is a type of account that lets you save — and potentially invest — for healthcare expenses while earning tax benefits along the way. Depending on your financial situation and immediate medical needs, an HSA can even be a valuable retirement planning tool. But HSAs aren't available to everyone. Continue reading to learn how HSAs work, their rules, and pros and cons.
A health savings account is a tax-advantaged account you can use to pay for qualifying medical expenses, including prescription medications, eyeglasses, doctor's visits, and more. Some HSAs function like a savings account, while others give you the option to invest your funds for future use.
HSAs are known for their triple tax advantage: You fund them with pre-tax dollars, your contributions grow tax-free, and withdrawals are tax-free as long as you use them for qualifying medical expenses. For this reason, HSAs can be a valuable retirement savings tool if you don't need the funds to pay for immediate medical needs.
Unlike flexible spending accounts (FSAs), HSA contributions don't expire at the end of the year. This means you can contribute to your account year after year without the need to "use it or lose it." HSAs aren't subject to required minimum distributions, either.
#account #medical #year
A health savings account (HSA) is a type of account that lets you save — and potentially invest — for healthcare expenses while earning tax benefits along the way. Depending on your financial situation and immediate medical needs, an HSA can even be a valuable retirement planning tool. But HSAs aren't available to everyone. Continue reading to learn how HSAs work, their rules, and pros and cons.
A health savings account is a tax-advantaged account you can use to pay for qualifying medical expenses, including prescription medications, eyeglasses, doctor's visits, and more. Some HSAs function like a savings account, while others give you the option to invest your funds for future use.
HSAs are known for their triple tax advantage: You fund them with pre-tax dollars, your contributions grow tax-free, and withdrawals are tax-free as long as you use them for qualifying medical expenses. For this reason, HSAs can be a valuable retirement savings tool if you don't need the funds to pay for immediate medical needs.
Unlike flexible spending accounts (FSAs), HSA contributions don't expire at the end of the year. This means you can contribute to your account year after year without the need to "use it or lose it." HSAs aren't subject to required minimum distributions, either.
#account #medical #year

4 days ago
Ethereum ETFs posted $824.41 million in inflows during the week of August 24–28, their strongest five-day total on record, followed by another $218.40 million the subsequent week.
The $24.29 million outflow on September 8 was concentrated in Grayscale's funds, while Fidelity's FETH attracted $9.89 million and BlackRock's ETHA recorded no outflow.
The latest outflow looks more like a pause than a reversal, but sustained withdrawals from ETHA or FETH, combined with a deeper ETH price decline, would be a stronger warning sign.
Just released. Our ***** ysts combed the entire stock market and named the ten best stocks to buy right now. The report is free. Enter your email and see if any of your stocks made the cut.
Ethereum (CRYPTO:ETH) Exchange Traded Fundss recorded a $24.29 million net outflow on September 8, 2026, their second outflow day since a five-day run in late August that brought in $824.41 million, the funds' strongest week on record.
#week #strongest
The $24.29 million outflow on September 8 was concentrated in Grayscale's funds, while Fidelity's FETH attracted $9.89 million and BlackRock's ETHA recorded no outflow.
The latest outflow looks more like a pause than a reversal, but sustained withdrawals from ETHA or FETH, combined with a deeper ETH price decline, would be a stronger warning sign.
Just released. Our ***** ysts combed the entire stock market and named the ten best stocks to buy right now. The report is free. Enter your email and see if any of your stocks made the cut.
Ethereum (CRYPTO:ETH) Exchange Traded Fundss recorded a $24.29 million net outflow on September 8, 2026, their second outflow day since a five-day run in late August that brought in $824.41 million, the funds' strongest week on record.
#week #strongest


4 days ago
A $400,000 inherited IRA can become much more expensive if you get the withdrawal timing wrong. Many non-spouse beneficiaries must empty the account within 10 years, and some also have annual RMDs. Delaying distributions could concentrate more taxable income into later years and potentially push more of your money into higher tax brackets.
For many non-spouse beneficiaries, an inherited IRA must be emptied by December 31 of the year containing the 10th1 anniversary of the original owner's death. Certain beneficiaries qualify for different rules.
The 10-year deadline may not be the only requirement. If the original owner died on or after their required beginning date, a non-spouse beneficiary subject to the 10-year rule generally must also take annual RMDs during the 10-year period.
Missing a required distribution can trigger an excise tax of up to 25% of the amount not withdrawn. This makes it important to know whether annual withdrawals apply instead of ****** uming you can leave the entire account untouched until year 10.
Traditional inherited IRA distributions are generally taxed as ordinary income. Leaving a large amount until the final years could force you to withdraw more at once, potentially pushing more of the $400,000 into higher tax brackets.
#year #spouse #beneficiaries #account
For many non-spouse beneficiaries, an inherited IRA must be emptied by December 31 of the year containing the 10th1 anniversary of the original owner's death. Certain beneficiaries qualify for different rules.
The 10-year deadline may not be the only requirement. If the original owner died on or after their required beginning date, a non-spouse beneficiary subject to the 10-year rule generally must also take annual RMDs during the 10-year period.
Missing a required distribution can trigger an excise tax of up to 25% of the amount not withdrawn. This makes it important to know whether annual withdrawals apply instead of ****** uming you can leave the entire account untouched until year 10.
Traditional inherited IRA distributions are generally taxed as ordinary income. Leaving a large amount until the final years could force you to withdraw more at once, potentially pushing more of the $400,000 into higher tax brackets.
#year #spouse #beneficiaries #account


0.00$ raised of 0.00$ goal
0 donations
0.00$
to go

4 days ago
SmartAsset and Yahoo Finance LLC may earn commission or revenue through links in the content below.
I'm turning 68 shortly and plan to wait to claim my Social Security at age 70 to maximize the monthly benefit. I also plan to retire at the end of the year, if not sooner (so in three months or less). Does withdrawing from my traditional IRAs (current balance is $215,000) to reduce the income tax on my RMDs outweigh the benefit of keeping those withdrawals invested and growing tax-deferred? My understanding is that if I withdraw amounts up to my standard deduction, then those amounts would be tax-free.
– Austen
Retirement withdrawals, Social Security benefits, required minimum distribution (RMDs), taxes … there are a lot of moving parts when it comes to making decisions about your retirement income. Reducing the amount of money that's subject to RMDs can help minimize your taxes once they kick in. This may also help avoid taxes on your Social Security benefits.
If you don't need the money now, but want to reduce RMDs later, one of the best moves might be converting a portion of your IRA to a Roth IRA each year. That can help reduce future required withdrawals and allow your money to grow tax-free, though there can be tax consequences for certain withdrawals. (A financial advisor can help guide you through the Roth conversion process and potentially avoid unwanted tax consequences.)
#Help #taxes #roth #Retirement
I'm turning 68 shortly and plan to wait to claim my Social Security at age 70 to maximize the monthly benefit. I also plan to retire at the end of the year, if not sooner (so in three months or less). Does withdrawing from my traditional IRAs (current balance is $215,000) to reduce the income tax on my RMDs outweigh the benefit of keeping those withdrawals invested and growing tax-deferred? My understanding is that if I withdraw amounts up to my standard deduction, then those amounts would be tax-free.
– Austen
Retirement withdrawals, Social Security benefits, required minimum distribution (RMDs), taxes … there are a lot of moving parts when it comes to making decisions about your retirement income. Reducing the amount of money that's subject to RMDs can help minimize your taxes once they kick in. This may also help avoid taxes on your Social Security benefits.
If you don't need the money now, but want to reduce RMDs later, one of the best moves might be converting a portion of your IRA to a Roth IRA each year. That can help reduce future required withdrawals and allow your money to grow tax-free, though there can be tax consequences for certain withdrawals. (A financial advisor can help guide you through the Roth conversion process and potentially avoid unwanted tax consequences.)
#Help #taxes #roth #Retirement

0.00$ raised of 0.00$ goal
0 donations
0.00$
to go

4 days ago
SmartAsset and Yahoo Finance LLC may earn commission or revenue through links in the content below.
High-income households can use what's called a "backdoor Roth" to utilize a Roth IRA despite the program's standard income restrictions. This can be an effective way to build a tax-free stream of income for your retirement, and it is a completely legal strategy.
Whether this method will reduce your taxes depends heavily on your tax rates now versus what you'll pay in retirement. For some high-earners, a Roth IRA can actually be a money loser if it means you end up spending more on taxes today than you will save on taxes in retirement.
Do you have questions about taxes and retirement planning? Speak with a financial advisor today.
A Roth IRA is what's called a "post-tax" retirement account. This means that you contribute to it with money that you've already paid taxes on. Then, in retirement, you make withdrawals on both your contributions and any growth completely tax-free. The idea is that it's more expensive upfront to build a Roth IRA compared with a pre-tax portfolio like a traditional IRA or 401(k), but you save taxes on your portfolio at its peak value as a retiree.
#Retirement #completely
High-income households can use what's called a "backdoor Roth" to utilize a Roth IRA despite the program's standard income restrictions. This can be an effective way to build a tax-free stream of income for your retirement, and it is a completely legal strategy.
Whether this method will reduce your taxes depends heavily on your tax rates now versus what you'll pay in retirement. For some high-earners, a Roth IRA can actually be a money loser if it means you end up spending more on taxes today than you will save on taxes in retirement.
Do you have questions about taxes and retirement planning? Speak with a financial advisor today.
A Roth IRA is what's called a "post-tax" retirement account. This means that you contribute to it with money that you've already paid taxes on. Then, in retirement, you make withdrawals on both your contributions and any growth completely tax-free. The idea is that it's more expensive upfront to build a Roth IRA compared with a pre-tax portfolio like a traditional IRA or 401(k), but you save taxes on your portfolio at its peak value as a retiree.
#Retirement #completely
0.00$ raised of 0.00$ goal
0 donations
0.00$
to go

7 days ago
Selling a home for $890,000 leaves roughly $328,000 taxable after the $500,000 joint exclusion, adding $9,240 in Medicare surcharges two years later.
Section 121's $500,000 joint exclusion ceiling hasn't risen with inflation since 1997, leaving longtime homeowners exposed to large taxable gains on ordinary homes.
Rebuilding cost basis with documented improvements, deferring optional IRA withdrawals, and budgeting for the Medicare surcharge from proceeds reduces the sale's financial impact.
Many financial professionals are salespeople paid on what they push, not whether you end up wealthier. A fiduciary is the opposite. The SEC legally requires them to put your interests first. Advisor.com's free matching tool pairs you with vetted fiduciaries from major national firms, all in under three minutes. See who you match with today.
For more than 40 years, the house did exactly what its owners hoped it would do. A couple who paid $62,000 for their home in 1984 closes on the sale this year at $890,000. The IRS lets them exclude up to $500,000 of gain under Internal Revenue Code Section 121. Any taxable gain left after the exclusion, basis adjustments and selling expenses flows into adjusted gross income (AGI). That figure helps determine the modified adjusted gross income (MAGI) Social Security uses to calculate Medicare's income-related monthly adjustment amount (IRMAA) two years later. The sale closes in 2026. The Medicare bill arrives in 2028.
#medicare #years #selling #later
Section 121's $500,000 joint exclusion ceiling hasn't risen with inflation since 1997, leaving longtime homeowners exposed to large taxable gains on ordinary homes.
Rebuilding cost basis with documented improvements, deferring optional IRA withdrawals, and budgeting for the Medicare surcharge from proceeds reduces the sale's financial impact.
Many financial professionals are salespeople paid on what they push, not whether you end up wealthier. A fiduciary is the opposite. The SEC legally requires them to put your interests first. Advisor.com's free matching tool pairs you with vetted fiduciaries from major national firms, all in under three minutes. See who you match with today.
For more than 40 years, the house did exactly what its owners hoped it would do. A couple who paid $62,000 for their home in 1984 closes on the sale this year at $890,000. The IRS lets them exclude up to $500,000 of gain under Internal Revenue Code Section 121. Any taxable gain left after the exclusion, basis adjustments and selling expenses flows into adjusted gross income (AGI). That figure helps determine the modified adjusted gross income (MAGI) Social Security uses to calculate Medicare's income-related monthly adjustment amount (IRMAA) two years later. The sale closes in 2026. The Medicare bill arrives in 2028.
#medicare #years #selling #later


8 days ago
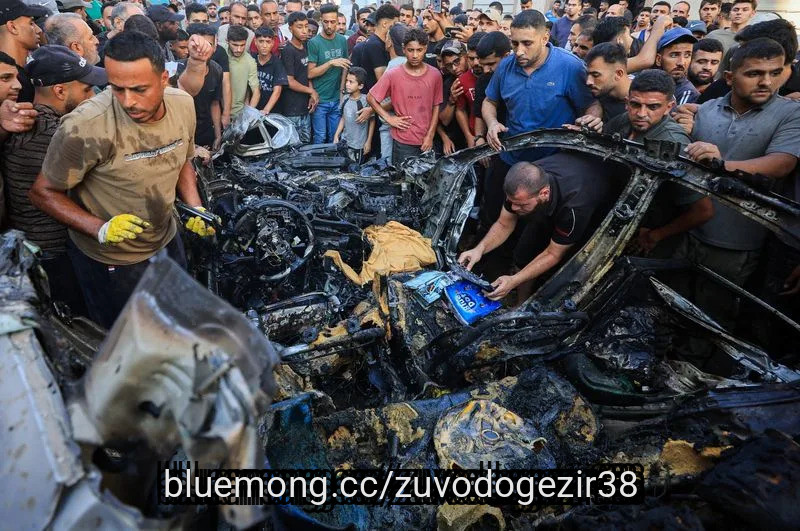
CAIRO, Sept 6 (Reuters) - An Israeli strike killed a man and his teenage daughter in the Gaza Strip on Sunday, health officials said.
Mohamed Abu Selmia, head of Al Shifa Hospital, the enclave's largest medical facility, said the airstrike hit a vehicle in western Gaza City, killing Youssef Akila and his daughter, Wafaa, and wounding six others.
The Israeli military did not immediately comment on the incident.
An October 2025 U.S.-backed ceasefire halted major fighting in the territory, but it failed to end strikes by the Israeli military, which it said aimed to thwart attacks by Hamas and other Gaza militants.
Hamas accuses Israel of violating the ceasefire and undermining efforts to implement U.S. President Donald Trump's broader plan to end the Gaza conflict, which also includes Israeli withdrawals and Hamas disarmament.
#israeli #hamas #sept #strip
Mohamed Abu Selmia, head of Al Shifa Hospital, the enclave's largest medical facility, said the airstrike hit a vehicle in western Gaza City, killing Youssef Akila and his daughter, Wafaa, and wounding six others.
The Israeli military did not immediately comment on the incident.
An October 2025 U.S.-backed ceasefire halted major fighting in the territory, but it failed to end strikes by the Israeli military, which it said aimed to thwart attacks by Hamas and other Gaza militants.
Hamas accuses Israel of violating the ceasefire and undermining efforts to implement U.S. President Donald Trump's broader plan to end the Gaza conflict, which also includes Israeli withdrawals and Hamas disarmament.
#israeli #hamas #sept #strip

9 days ago
A $500,000 balance yields just $20,000 annually at the 4% withdrawal rate, yet still surpasses the median 65+ retirement account balance of $103,202.
Traditional 401(k) withdrawals count as ordinary income and can trigger taxation on up to 85% of Social Security benefits, raising the real cost of each dollar withdrawn.
A paid-off home, a cash reserve of one to two years, and delaying Social Security to capture the roughly 8% annual benefit increase each do more for lifetime income than portfolio size alone.
Read More: Learn 7 secret wealth tips high net worth investors use that most investors miss (sponsor)
Half a million dollars in retirement savings may sound modest when headlines are full of seven-figure nest eggs. But measured against what real retirees have actually accumulated, it is a substantial sum. Vanguard's 2026 How America Saves report shows that for participants aged 65 and older, the median account balance was $103,202 in 2025, with an average of $330,186. Transamerica's most recent survey put median Baby Boomer household retirement savings at $270,000. So a reader sitting on $500,000 is ahead of the typical retiree. The real planning question is what that balance can actually deliver in monthly income once you factor in withdrawal math, taxes, and Medicare.
#Retirement
Traditional 401(k) withdrawals count as ordinary income and can trigger taxation on up to 85% of Social Security benefits, raising the real cost of each dollar withdrawn.
A paid-off home, a cash reserve of one to two years, and delaying Social Security to capture the roughly 8% annual benefit increase each do more for lifetime income than portfolio size alone.
Read More: Learn 7 secret wealth tips high net worth investors use that most investors miss (sponsor)
Half a million dollars in retirement savings may sound modest when headlines are full of seven-figure nest eggs. But measured against what real retirees have actually accumulated, it is a substantial sum. Vanguard's 2026 How America Saves report shows that for participants aged 65 and older, the median account balance was $103,202 in 2025, with an average of $330,186. Transamerica's most recent survey put median Baby Boomer household retirement savings at $270,000. So a reader sitting on $500,000 is ahead of the typical retiree. The real planning question is what that balance can actually deliver in monthly income once you factor in withdrawal math, taxes, and Medicare.
#Retirement


9 days ago
Delaying the first RMD to April 1 stacks two distributions on one tax return, potentially bundling over $150,000 in income for a $2 million IRA.
Medicare sets 2028 premiums using 2026 income, so a bunched RMD year can trigger IRMAA surcharges costing a married couple nearly $5,770 extra annually.
Taking the first RMD by December 31 instead of April 1 keeps both distributions on separate returns and eliminates the income-stacking problem entirely.
Read More: Learn 7 ways to generate income with a $1,000,000+ portfolio (sponsor)
A retiree turned 73 in 2025 and used the option Congress left him. Instead of taking his first required minimum distribution (RMD) by December 31, he delayed it until April 1, 2026. The second RMD was still due December 31, 2026. Two withdrawals landed on one tax return, and Medicare does not care that the first one "belonged" to 2025. Both dollars became 2026 income. The April deadline bought three months. It did not buy another tax year.
#taking #instead
Medicare sets 2028 premiums using 2026 income, so a bunched RMD year can trigger IRMAA surcharges costing a married couple nearly $5,770 extra annually.
Taking the first RMD by December 31 instead of April 1 keeps both distributions on separate returns and eliminates the income-stacking problem entirely.
Read More: Learn 7 ways to generate income with a $1,000,000+ portfolio (sponsor)
A retiree turned 73 in 2025 and used the option Congress left him. Instead of taking his first required minimum distribution (RMD) by December 31, he delayed it until April 1, 2026. The second RMD was still due December 31, 2026. Two withdrawals landed on one tax return, and Medicare does not care that the first one "belonged" to 2025. Both dollars became 2026 income. The April deadline bought three months. It did not buy another tax year.
#taking #instead

11 days ago
A $500,000 pre-tax 401(k) overstates real value because withdrawals face ordinary income tax at rates up to 37%, plus state taxes on top.
After divorce, the Section 121 home-sale exclusion drops from $500,000 to $250,000, exposing any appreciation above that cap to capital gains tax.
Unlike a home in a soft 4-million-sale market, a 401(k) lets its owner time withdrawals and Roth conversions to minimize taxes in low-income years.
Read More: Learn 7 ways to generate income with a $1,000,000+ portfolio (sponsor)
Divorce settlements often treat ***** ets as equal, but they are not. A $500,000 house and a $500,000 pre-tax 401(k) might look identical on a worksheet, and courts often treat them that way, but the two numbers could not be more different. One is roughly what you see. The other is a gross figure that shrinks the moment you touch it. The hidden rule inside every traditional 401(k) is that the IRS is a silent co-owner, and no divorce decree can change that.
#withdrawals
After divorce, the Section 121 home-sale exclusion drops from $500,000 to $250,000, exposing any appreciation above that cap to capital gains tax.
Unlike a home in a soft 4-million-sale market, a 401(k) lets its owner time withdrawals and Roth conversions to minimize taxes in low-income years.
Read More: Learn 7 ways to generate income with a $1,000,000+ portfolio (sponsor)
Divorce settlements often treat ***** ets as equal, but they are not. A $500,000 house and a $500,000 pre-tax 401(k) might look identical on a worksheet, and courts often treat them that way, but the two numbers could not be more different. One is roughly what you see. The other is a gross figure that shrinks the moment you touch it. The hidden rule inside every traditional 401(k) is that the IRS is a silent co-owner, and no divorce decree can change that.
#withdrawals


12 days ago
The SECURE Act forces most non-spouse inherited IRA beneficiaries to fully empty the account within 10 years, with no life-expectancy stretch available.
Waiting until year 10 to withdraw a full inherited IRA balance stacks ordinary income on top of salary, pushing marginal rates to 32%.
Spreading withdrawals across all 10 years to fill the 22% and 24% brackets avoids the single-year income spike that triggers higher rates.
Read More: Learn 7 ways to generate income with a $1,000,000+ portfolio (sponsor)
An inherited IRA is a retirement account passed to a beneficiary after the original owner dies. When the beneficiary is an adult child, the rules governing how quickly the money must be withdrawn have changed significantly under the SECURE Act. The scenario in the headline- a son who inherited a $220,000 IRA at age 60, deferred withdrawals, and then faced a forced distribution in year 10 that landed him in the 32% federal bracket- sits on a specific IRS rule that many beneficiaries misread.
#income
Waiting until year 10 to withdraw a full inherited IRA balance stacks ordinary income on top of salary, pushing marginal rates to 32%.
Spreading withdrawals across all 10 years to fill the 22% and 24% brackets avoids the single-year income spike that triggers higher rates.
Read More: Learn 7 ways to generate income with a $1,000,000+ portfolio (sponsor)
An inherited IRA is a retirement account passed to a beneficiary after the original owner dies. When the beneficiary is an adult child, the rules governing how quickly the money must be withdrawn have changed significantly under the SECURE Act. The scenario in the headline- a son who inherited a $220,000 IRA at age 60, deferred withdrawals, and then faced a forced distribution in year 10 that landed him in the 32% federal bracket- sits on a specific IRS rule that many beneficiaries misread.
#income


13 days ago
IRA withdrawals cannot satisfy 401(k) RMDs. Each 401(k) requires its own separate distribution, no matter how much you pull from the IRA.
Missing a 401(k) RMD triggers a 25% excise tax, but filing Form 5329 within two years cuts that penalty to 10%.
Rolling old 401(k)s into a single traditional IRA via direct trustee-to-trustee transfer reduces multiple RMD calculations to one annual withdrawal.
Read More: Learn 7 ways to generate income with a $1,000,000+ portfolio (sponsor)
At age 73, retirement savers face a firm deadline set by the IRS. That is when Required Minimum Distributions begin under the SECURE 2.0 Act, and the IRS begins expecting a slice of the pre-tax money that has been growing untouched for decades. The mechanics look simple on paper: calculate the amount, take the withdrawal, and report it on the tax return. Real accounts complicate that picture, and one woman's story shows why.
#withdrawal #missing
Missing a 401(k) RMD triggers a 25% excise tax, but filing Form 5329 within two years cuts that penalty to 10%.
Rolling old 401(k)s into a single traditional IRA via direct trustee-to-trustee transfer reduces multiple RMD calculations to one annual withdrawal.
Read More: Learn 7 ways to generate income with a $1,000,000+ portfolio (sponsor)
At age 73, retirement savers face a firm deadline set by the IRS. That is when Required Minimum Distributions begin under the SECURE 2.0 Act, and the IRS begins expecting a slice of the pre-tax money that has been growing untouched for decades. The mechanics look simple on paper: calculate the amount, take the withdrawal, and report it on the tax return. Real accounts complicate that picture, and one woman's story shows why.
#withdrawal #missing
14 days ago
Forty-two states don't tax Social Security benefits, giving many retirees a break on at least one major source of income.
Some states also exempt pension income, retirement account withdrawals, or military retirement pay from state taxes.
Nine states have no broad individual income tax, though retirees may still face property, sales, or other state and local taxes.
After a lifetime of contributing to Social Security, building up a retirement plan, or earning a pension, you may be bracing for a big tax hit in retirement. But state taxes vary widely, and many retirees get a break: 42 states don't tax Social Security income, 37 don't tax most military retirement pay, and 16 exempt pension income from state taxes.
Nine states go even further by not imposing a broad individual income tax at all. That can make a meaningful difference in how much retirement income you get to keep, though property, sales, and other taxes still matter when deciding where to live.
#income #don 't #pension
Some states also exempt pension income, retirement account withdrawals, or military retirement pay from state taxes.
Nine states have no broad individual income tax, though retirees may still face property, sales, or other state and local taxes.
After a lifetime of contributing to Social Security, building up a retirement plan, or earning a pension, you may be bracing for a big tax hit in retirement. But state taxes vary widely, and many retirees get a break: 42 states don't tax Social Security income, 37 don't tax most military retirement pay, and 16 exempt pension income from state taxes.
Nine states go even further by not imposing a broad individual income tax at all. That can make a meaningful difference in how much retirement income you get to keep, though property, sales, and other taxes still matter when deciding where to live.
#income #don 't #pension

16 days ago
A direct trustee-to-trustee rollover moves a pension lump sum like $812,000 into a traditional IRA with zero withholding and no current tax.
An indirect rollover triggers mandatory 20% federal withholding, and you must replace the withheld cash within 60 days or owe taxes and penalties.
SECURE 2.0 pushes the RMD start age to 73 or 75 depending on birth year, eventually forcing taxable withdrawals from the rolled-over balance.
Read More: Learn 7 ways to generate income with a $1,000,000+ portfolio (sponsor)
If your employer just dropped pension buyout paperwork on your desk and asked whether you want a monthly check for life or a one-time lump sum, there is a detail buried in the tax code that most retirees trip over right at the finish line. You can move the entire lump sum into a traditional IRA through a direct rollover, and the IRS will not collect a dime until you start taking money out. But mess up the execution, and the same move can trigger automatic withholding and a tax bill you never should have seen in the first place.
#lump #direct #pension
An indirect rollover triggers mandatory 20% federal withholding, and you must replace the withheld cash within 60 days or owe taxes and penalties.
SECURE 2.0 pushes the RMD start age to 73 or 75 depending on birth year, eventually forcing taxable withdrawals from the rolled-over balance.
Read More: Learn 7 ways to generate income with a $1,000,000+ portfolio (sponsor)
If your employer just dropped pension buyout paperwork on your desk and asked whether you want a monthly check for life or a one-time lump sum, there is a detail buried in the tax code that most retirees trip over right at the finish line. You can move the entire lump sum into a traditional IRA through a direct rollover, and the IRS will not collect a dime until you start taking money out. But mess up the execution, and the same move can trigger automatic withholding and a tax bill you never should have seen in the first place.
#lump #direct #pension


16 days ago
Moneywise and Yahoo Finance LLC may earn commission or revenue through links in the content below.
Tapping into your 401(k) early to deal with debt or emergency bills may seem like a savvy move, but two of the biggest names in retirement planning are sounding the alarm about doing so.
Fidelity, one of the largest 401(k) plan administrators in the country, and AARP, the nation's leading advocacy group for older Americans, are both warning workers that early withdrawals can wipe out a significant chunk of their savings overnight.
Jeff Bezos backs a platform that lets anyone invest in rental homes for as little as $100 — 6 ways to build wealth like a landlord without actually being one
JPMorgan sees gold hitting $5,000/oz by Q4 — and savvy investors are protecting their wealth with a tax-advantaged Gold IRA. Get your free guide from Priority Gold
#savvy #moneywise #tapping
Tapping into your 401(k) early to deal with debt or emergency bills may seem like a savvy move, but two of the biggest names in retirement planning are sounding the alarm about doing so.
Fidelity, one of the largest 401(k) plan administrators in the country, and AARP, the nation's leading advocacy group for older Americans, are both warning workers that early withdrawals can wipe out a significant chunk of their savings overnight.
Jeff Bezos backs a platform that lets anyone invest in rental homes for as little as $100 — 6 ways to build wealth like a landlord without actually being one
JPMorgan sees gold hitting $5,000/oz by Q4 — and savvy investors are protecting their wealth with a tax-advantaged Gold IRA. Get your free guide from Priority Gold
#savvy #moneywise #tapping

17 days ago
Moneywise and Yahoo Finance LLC may earn commission or revenue through links in the content below.
Tapping into your 401(k) early to deal with debt or emergency bills may seem like a savvy move, but two of the biggest names in retirement planning are sounding the alarm about doing so.
Fidelity, one of the largest 401(k) plan administrators in the country, and AARP, the nation's leading advocacy group for older Americans, are both warning workers that early withdrawals can wipe out a significant chunk of their savings overnight.
Jeff Bezos backs a platform that lets anyone invest in rental homes for as little as $100 — 6 ways to build wealth like a landlord without actually being one
JPMorgan sees gold hitting $5,000/oz by Q4 — and savvy investors are protecting their wealth with a tax-advantaged Gold IRA. Get your free guide from Priority Gold
#Gold #fidelity #aarp
Tapping into your 401(k) early to deal with debt or emergency bills may seem like a savvy move, but two of the biggest names in retirement planning are sounding the alarm about doing so.
Fidelity, one of the largest 401(k) plan administrators in the country, and AARP, the nation's leading advocacy group for older Americans, are both warning workers that early withdrawals can wipe out a significant chunk of their savings overnight.
Jeff Bezos backs a platform that lets anyone invest in rental homes for as little as $100 — 6 ways to build wealth like a landlord without actually being one
JPMorgan sees gold hitting $5,000/oz by Q4 — and savvy investors are protecting their wealth with a tax-advantaged Gold IRA. Get your free guide from Priority Gold
#Gold #fidelity #aarp

18 days ago
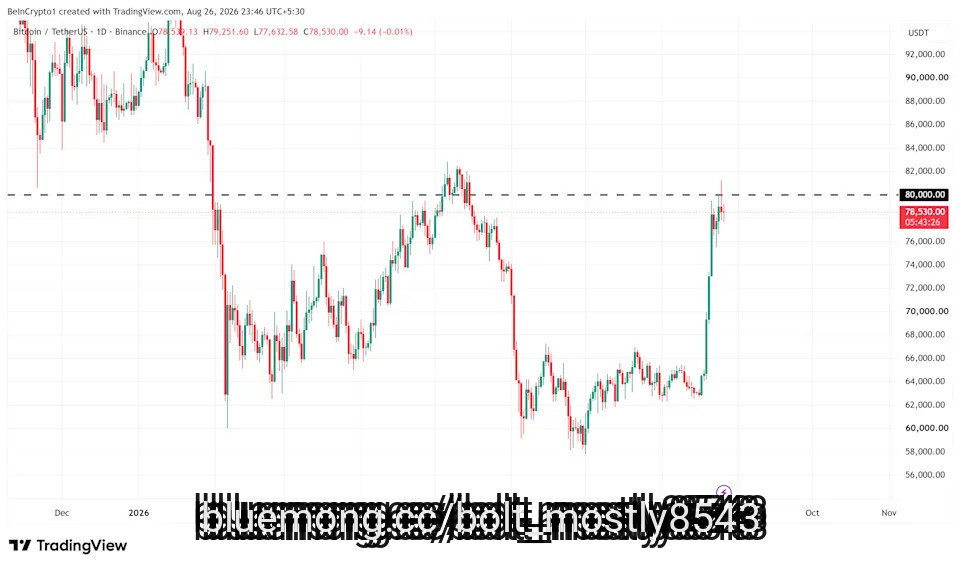
Andy Baehr, GSR's managing director of **** et management, says bitcoin's $80,000 breakout marks a new market regime. He argues the crypto trading firm watched a stagnant summer flip into real momentum within days.
Baehr spent 25 years on Wall Street derivatives desks, including Morgan Stanley and Credit Suisse, before crossing into digital **** ets. He served as the Executive Director of Equity Derivatives at Morgan Stanley between 2006 and 2007.
Bitcoin (BTC) briefly , topping out at $reclaimed $80,000 this week, topping out at $81,272 on Monday. It marked the first time since May that the pioneer crypto tested this threshold.
Baehr had urged patience through what he called a "super slow summer" of thin volumes and muted price action. The stagnation was measurable. Digital **** et funds bled a record $8 billion across eight straight weeks of ETF withdrawals before demand returned.
Then the mood turned fast. News of Treasury buybacks in long-dated bonds arrived alongside a planned White House gathering of crypto executives. Industry leaders were meeting in Jackson Hole as the headlines hit, Baehr recalled.
#Crypto #morgan #derivatives #digital
Baehr spent 25 years on Wall Street derivatives desks, including Morgan Stanley and Credit Suisse, before crossing into digital **** ets. He served as the Executive Director of Equity Derivatives at Morgan Stanley between 2006 and 2007.
Bitcoin (BTC) briefly , topping out at $reclaimed $80,000 this week, topping out at $81,272 on Monday. It marked the first time since May that the pioneer crypto tested this threshold.
Baehr had urged patience through what he called a "super slow summer" of thin volumes and muted price action. The stagnation was measurable. Digital **** et funds bled a record $8 billion across eight straight weeks of ETF withdrawals before demand returned.
Then the mood turned fast. News of Treasury buybacks in long-dated bonds arrived alongside a planned White House gathering of crypto executives. Industry leaders were meeting in Jackson Hole as the headlines hit, Baehr recalled.
#Crypto #morgan #derivatives #digital

20 days ago
Money entering crypto ETFs over their first two years meant institutions were arriving, and institutions arriving meant more demand for crypto. However, mid-2026 has made that relationship considerably more complicated.
Digital ***** et investment products went through eight consecutive weeks of withdrawals totalling a record $8 billion before inflows returned in July and early August. By August 7, the same products had recorded five consecutive positive weeks, including around $1.05 billion during the first week of August.
U.S. spot Bitcoin ETFs show the reversal particularly well. They attracted roughly $865 million between August 3 and August 7, followed by a combined net withdrawal of about $198 million from August 10 through August 12.
ETFs remain a major source of crypto demand. Their behaviour increasingly resembles other large investment vehicles, however: investors buy when risk looks attractive and redeem when it does not.
BeInCrypto asked executives from Wirex, Zoomex and Phemex what recent flows reveal about investor demand, how ETFs have affected crypto trading, and whether another generation of altcoin funds can reproduce Bitcoin's success.
#august #Crypto #meant #investment
Digital ***** et investment products went through eight consecutive weeks of withdrawals totalling a record $8 billion before inflows returned in July and early August. By August 7, the same products had recorded five consecutive positive weeks, including around $1.05 billion during the first week of August.
U.S. spot Bitcoin ETFs show the reversal particularly well. They attracted roughly $865 million between August 3 and August 7, followed by a combined net withdrawal of about $198 million from August 10 through August 12.
ETFs remain a major source of crypto demand. Their behaviour increasingly resembles other large investment vehicles, however: investors buy when risk looks attractive and redeem when it does not.
BeInCrypto asked executives from Wirex, Zoomex and Phemex what recent flows reveal about investor demand, how ETFs have affected crypto trading, and whether another generation of altcoin funds can reproduce Bitcoin's success.
#august #Crypto #meant #investment

20 days ago
SmartAsset and Yahoo Finance LLC may earn commission or revenue through links in the content below.
Late-in-life Roth conversions can take some tricky math.
As you approach retirement, one of the most important questions will be how to manage the taxes on your retirement income. For households that rely on pre-tax portfolios, like a 401(k) or a traditional IRA, this means anticipating ordinary income taxes on all of your withdrawals. It also means anticipating the necessary withdrawals **** ociated with the IRS' Required Minimum Distributions (RMD) rule.
As a result, it's common for people in their 60s to at least consider converting their money to a Roth IRA. This can have significant upsides. It will eliminate your taxes in retirement, along with your RMD requirements, and will even improve the after-tax value of your estate.
The problem is that, as you close in on retirement, a Roth conversion can get very expensive. You will pay quite a lot of up-front conversion taxes in exchange for those long-term income tax savings.
#roth #income #means #finance
Late-in-life Roth conversions can take some tricky math.
As you approach retirement, one of the most important questions will be how to manage the taxes on your retirement income. For households that rely on pre-tax portfolios, like a 401(k) or a traditional IRA, this means anticipating ordinary income taxes on all of your withdrawals. It also means anticipating the necessary withdrawals **** ociated with the IRS' Required Minimum Distributions (RMD) rule.
As a result, it's common for people in their 60s to at least consider converting their money to a Roth IRA. This can have significant upsides. It will eliminate your taxes in retirement, along with your RMD requirements, and will even improve the after-tax value of your estate.
The problem is that, as you close in on retirement, a Roth conversion can get very expensive. You will pay quite a lot of up-front conversion taxes in exchange for those long-term income tax savings.
#roth #income #means #finance

21 days ago
Retired married couples can withdraw ~$46,700 from a traditional IRA tax-free by stacking three 2026 deductions, including $32,200 standard and $12,000 in new senior deductions.
Most retirees skip this window by ****** uming all IRA withdrawals trigger taxes, waiting for forced RMDs at 73 when rates can reach 22% or higher.
Couples can use the window to reinvest IRA funds in a brokerage account or convert to Roth, both strategies carrying zero federal tax owed.
Are you ahead, or behind on retirement? SmartAsset's free tool can match you with a financial advisor in minutes to help you answer that today. Each advisor has been carefully vetted, and must act in your best interests. Don't waste another minute; learn more here.
Every January, a specific window opens for retired married couples: they can pull roughly $46,700 out of a traditional IRA, count it as ordinary income, and owe nothing in federal tax. The window closes on December 31. Most couples do not use it, and the mechanics of why they leave it unused, and what it costs them later, are the actual story.
#advisor
Most retirees skip this window by ****** uming all IRA withdrawals trigger taxes, waiting for forced RMDs at 73 when rates can reach 22% or higher.
Couples can use the window to reinvest IRA funds in a brokerage account or convert to Roth, both strategies carrying zero federal tax owed.
Are you ahead, or behind on retirement? SmartAsset's free tool can match you with a financial advisor in minutes to help you answer that today. Each advisor has been carefully vetted, and must act in your best interests. Don't waste another minute; learn more here.
Every January, a specific window opens for retired married couples: they can pull roughly $46,700 out of a traditional IRA, count it as ordinary income, and owe nothing in federal tax. The window closes on December 31. Most couples do not use it, and the mechanics of why they leave it unused, and what it costs them later, are the actual story.
#advisor
21 days ago
If you retire with $1 million, your nest egg should safely be able to produce somewhere around $40,000 in income for your first year of retirement, with withdrawals adjusted in subsequent years to account for inflation. That's based on the 4% rule, a common rule of thumb for setting a safe withdrawal rate.
Many people set the goal of saving $1 million for retirement because it's a simple number to work toward. But is it actually a realistic goal? How much would you have to save to hit the target?
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
If you want to end up with $1 million at retirement, you'll likely need to save consistently throughout your entire career in order to make that feasible. The specific amount, however, will vary depending on when you start saving and the returns you expect to earn.
The table below shows the different monthly amounts you will need to invest to reach $1 million by age 67, which is the full retirement age for Social Security for anyone who was born in 1960 or later. It ******* umes that you will earn a 10% average annual return, which is a reasonable ******* umption for many retirement savers based on the historical returns provided by the S&P 500.
#many #based
Many people set the goal of saving $1 million for retirement because it's a simple number to work toward. But is it actually a realistic goal? How much would you have to save to hit the target?
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
If you want to end up with $1 million at retirement, you'll likely need to save consistently throughout your entire career in order to make that feasible. The specific amount, however, will vary depending on when you start saving and the returns you expect to earn.
The table below shows the different monthly amounts you will need to invest to reach $1 million by age 67, which is the full retirement age for Social Security for anyone who was born in 1960 or later. It ******* umes that you will earn a 10% average annual return, which is a reasonable ******* umption for many retirement savers based on the historical returns provided by the S&P 500.
#many #based

28 days ago
Social Security's earnings test ignores 401(k) withdrawals entirely, counting only wages and net self-employment income against the 2026 limit of $24,480.
A $70,000 traditional 401(k) withdrawal enters IRS provisional income calculations, potentially making up to 85% of Social Security benefits taxable at ordinary rates.
Large 401(k) distributions can trigger IRMAA Medicare premium surcharges with a two-year delay, so a 2026 withdrawal may raise 2028 Part B and Part D costs.
Many financial professionals are salespeople paid on what they push, not whether you end up wealthier. A fiduciary is the opposite. The SEC legally requires them to put your interests first. Advisor.com's free matching tool pairs you with vetted fiduciaries from major national firms, all in under three minutes. See who you match with today.
Picture a 63-year-old who left his full-time shop job last year, started drawing Social Security early, and now picks up welding and small fabrication work from his garage. In a single year, he withdraws $70,000 from a traditional 401(k) to cover the mortgage and buy a truck. After business expenses, his welding work produces $10,000 in net self-employment earnings. He ***** umes the government sees $80,000 in income. Social Security does not. Its retirement earnings test looks only at the $10,000.
#security #year #income #part
A $70,000 traditional 401(k) withdrawal enters IRS provisional income calculations, potentially making up to 85% of Social Security benefits taxable at ordinary rates.
Large 401(k) distributions can trigger IRMAA Medicare premium surcharges with a two-year delay, so a 2026 withdrawal may raise 2028 Part B and Part D costs.
Many financial professionals are salespeople paid on what they push, not whether you end up wealthier. A fiduciary is the opposite. The SEC legally requires them to put your interests first. Advisor.com's free matching tool pairs you with vetted fiduciaries from major national firms, all in under three minutes. See who you match with today.
Picture a 63-year-old who left his full-time shop job last year, started drawing Social Security early, and now picks up welding and small fabrication work from his garage. In a single year, he withdraws $70,000 from a traditional 401(k) to cover the mortgage and buy a truck. After business expenses, his welding work produces $10,000 in net self-employment earnings. He ***** umes the government sees $80,000 in income. Social Security does not. Its retirement earnings test looks only at the $10,000.
#security #year #income #part
1 month ago
The HSA is the only account delivering all three tax advantages: deductible contributions (including FICA savings), tax-free growth, and tax-free qualified withdrawals.
Invest HSA funds in equity index funds, pay current medical bills from cash, and save receipts to reimburse yourself tax-free decades later.
After 65, HSA medical withdrawals don't count toward MAGI, helping retirees dodge IRMAA surcharges that add hundreds per month to Medicare premiums.
Are you ahead, or behind on retirement? SmartAsset's free tool can match you with a financial advisor in minutes to help you answer that today. Each advisor has been carefully vetted, and must act in your best interests. Don't waste another minute; learn more here.
Walk into any physician lounge and you'll hear the same advice from the partners closing in on 60: fund the match in your 401(k), then send the next dollar to your Health Savings Account before you finish the deferral. The HSA is the only account in the federal code that escapes tax three separate times, and the people who do tax math for a living treat it accordingly.
#free #don 't #only #three
Invest HSA funds in equity index funds, pay current medical bills from cash, and save receipts to reimburse yourself tax-free decades later.
After 65, HSA medical withdrawals don't count toward MAGI, helping retirees dodge IRMAA surcharges that add hundreds per month to Medicare premiums.
Are you ahead, or behind on retirement? SmartAsset's free tool can match you with a financial advisor in minutes to help you answer that today. Each advisor has been carefully vetted, and must act in your best interests. Don't waste another minute; learn more here.
Walk into any physician lounge and you'll hear the same advice from the partners closing in on 60: fund the match in your 401(k), then send the next dollar to your Health Savings Account before you finish the deferral. The HSA is the only account in the federal code that escapes tax three separate times, and the people who do tax math for a living treat it accordingly.
#free #don 't #only #three


1 month ago
Culture Secretary Lisa Nandy says women's footballers should not be "penalised" by a potential boycott of next month's Under-20 Women's World Cup, as hosts Poland say they have received no notice of any withdrawals from European teams.
European governing body Uefa and its 55 members have threatened to boycott Fifa competitions over its president Gianni Infantino's plan to sell off stakes in the World Cup.
Poland are due to host the tournament from 5-27 September, but are not the only Uefa nation involved - with England, Italy, Spain, Portugal and France all due to take part.
The Polish Football ***** ociation (PZPN) told BBC Sport on Tuesday that it had so far "not received any information regarding the possible withdrawal of any participating team from the tournament".
It added: "We believe that the current situation will be resolved swiftly, allowing young players from across the world to compete in Poland.
#secretary
European governing body Uefa and its 55 members have threatened to boycott Fifa competitions over its president Gianni Infantino's plan to sell off stakes in the World Cup.
Poland are due to host the tournament from 5-27 September, but are not the only Uefa nation involved - with England, Italy, Spain, Portugal and France all due to take part.
The Polish Football ***** ociation (PZPN) told BBC Sport on Tuesday that it had so far "not received any information regarding the possible withdrawal of any participating team from the tournament".
It added: "We believe that the current situation will be resolved swiftly, allowing young players from across the world to compete in Poland.
#secretary
1 month ago
Medicare's two-year lookback means a 2026 distribution sets 2028 premiums, costing married couples up to $1,783 yearly once MAGI exceeds $137,000.
Crossing $109,000 MAGI can make 85% of Social Security taxable, stacking costs that push the effective marginal rate on 401(k) withdrawals toward 40%.
Retirees can limit surcharges by modeling MAGI below thresholds, using QCDs up to $111,000 from an IRA, or filing Form SSA-44 after life-changing events.
Are you ahead, or behind on retirement? SmartAsset's free tool can match you with a financial advisor in minutes to help you answer that today. Each advisor has been carefully vetted, and must act in your best interests. Don't waste another minute; learn more here.
A 66-year-old retiree with $1.4 million in a traditional 401(k) pulls $60,000 in 2026 to renovate a kitchen. Combined with $28,000 in Social Security and a modest pension, modified adjusted gross income lands at $112,000. Nothing dramatic happens on the 1040. In January 2028, the Medicare bill jumps.
#security #year
Crossing $109,000 MAGI can make 85% of Social Security taxable, stacking costs that push the effective marginal rate on 401(k) withdrawals toward 40%.
Retirees can limit surcharges by modeling MAGI below thresholds, using QCDs up to $111,000 from an IRA, or filing Form SSA-44 after life-changing events.
Are you ahead, or behind on retirement? SmartAsset's free tool can match you with a financial advisor in minutes to help you answer that today. Each advisor has been carefully vetted, and must act in your best interests. Don't waste another minute; learn more here.
A 66-year-old retiree with $1.4 million in a traditional 401(k) pulls $60,000 in 2026 to renovate a kitchen. Combined with $28,000 in Social Security and a modest pension, modified adjusted gross income lands at $112,000. Nothing dramatic happens on the 1040. In January 2028, the Medicare bill jumps.
#security #year


1 month ago
In the study, the 4% rule carried a growing risk of depletion, while a full annuity sacrificed liquidity and any remaining balance.
Putting 50% of savings into an annuity earned the highest score, pairing strong income with money left for emergencies or heirs.
The study used a simple immediate annuity, not one of the more complex products commonly marketed to retirees.
For decades, one widely used retirement guideline has suggested withdrawing a set percentage in year one, typically 4%, then increasing that dollar amount annually to keep pace with inflation. But a new study found that neither this approach nor putting an entire portfolio into an annuity, produced the strongest overall result. The highest-scoring strategy used some of both.
Retirement income does not have to be an either-or choice between portfolio withdrawals and an annuity. This study suggests that combining the two may provide income security while preserving money for unexpected expenses or heirs.
#annuity
Putting 50% of savings into an annuity earned the highest score, pairing strong income with money left for emergencies or heirs.
The study used a simple immediate annuity, not one of the more complex products commonly marketed to retirees.
For decades, one widely used retirement guideline has suggested withdrawing a set percentage in year one, typically 4%, then increasing that dollar amount annually to keep pace with inflation. But a new study found that neither this approach nor putting an entire portfolio into an annuity, produced the strongest overall result. The highest-scoring strategy used some of both.
Retirement income does not have to be an either-or choice between portfolio withdrawals and an annuity. This study suggests that combining the two may provide income security while preserving money for unexpected expenses or heirs.
#annuity


1 month ago
Washington Saves launches July 1, 2027, automatically enrolling workers without employer retirement plans into an IRA at a default contribution rate ranging from 3% to 7%.
Choosing a Roth over a traditional auto-IRA keeps withdrawals tax-free and invisible to the Social Security formula that determines benefit taxation.
Even modest savings before full retirement age can fund delayed Social Security claiming, worth roughly 8% more per year than filing early.
Are you ahead, or behind on retirement? SmartAsset's free tool can match you with a financial advisor in minutes to help you answer that today. Each advisor has been carefully vetted, and must act in your best interests. Don't waste another minute; learn more here.
Picture a 59-year-old woman in Tacoma who has waited tables, run a register, and answered phones at a seven-person insurance office. Decades of steady work, zero years with a 401(k). Her retirement plan has always been Social Security. Then a letter arrives from her employer explaining that starting July 1, 2027, she is being automatically signed up for something called Washington Saves.
#Retirement #Social #free
Choosing a Roth over a traditional auto-IRA keeps withdrawals tax-free and invisible to the Social Security formula that determines benefit taxation.
Even modest savings before full retirement age can fund delayed Social Security claiming, worth roughly 8% more per year than filing early.
Are you ahead, or behind on retirement? SmartAsset's free tool can match you with a financial advisor in minutes to help you answer that today. Each advisor has been carefully vetted, and must act in your best interests. Don't waste another minute; learn more here.
Picture a 59-year-old woman in Tacoma who has waited tables, run a register, and answered phones at a seven-person insurance office. Decades of steady work, zero years with a 401(k). Her retirement plan has always been Social Security. Then a letter arrives from her employer explaining that starting July 1, 2027, she is being automatically signed up for something called Washington Saves.
#Retirement #Social #free

1 month ago
There's a new king of PFL, at least that's what he self-procclaims.
Regardless of whether you're the biggest supporter or biggest skeptic, there's no denying Moustapha Diakhate made an impact Friday at PFL New York.
From the opening entrance to the post-fight interview, Diakhate (6-0-1) turned some heads at UBS Arena in Elmont, N.Y. Diakhate entered with drummers, decked out in traditional Senegalese garb. With a jingasa hat, chains, and blond hair, the visuals Diakhate created were not run-of-the-mill.
"The clothes I wore, they were original from the King of Senegal," Diakhate told reporters after the fight (h/t Home of Fight). "Putting the clothes on me, I represented more my people and the kings of Senegal. ... Everybody says to me, 'Moustapha, why don't you go and do a movie?' I say, 'Maybe, one day.' I'm Moustapha Diakhate. I don't have an inspiration. I'm my inspiration. I try representing my people of Senegal, Africa. You know, 'Wakanda forever'? Let's go."
When it came time to fight, Diakhate delivered. He finished short-notice replacement Darryl Walker with ground-and-pound punches at 2:35 of Round 1. It was quite the exclamation point on a week full of uncertainty after multiple opponent withdrawals.
#diakhate #clothes
Regardless of whether you're the biggest supporter or biggest skeptic, there's no denying Moustapha Diakhate made an impact Friday at PFL New York.
From the opening entrance to the post-fight interview, Diakhate (6-0-1) turned some heads at UBS Arena in Elmont, N.Y. Diakhate entered with drummers, decked out in traditional Senegalese garb. With a jingasa hat, chains, and blond hair, the visuals Diakhate created were not run-of-the-mill.
"The clothes I wore, they were original from the King of Senegal," Diakhate told reporters after the fight (h/t Home of Fight). "Putting the clothes on me, I represented more my people and the kings of Senegal. ... Everybody says to me, 'Moustapha, why don't you go and do a movie?' I say, 'Maybe, one day.' I'm Moustapha Diakhate. I don't have an inspiration. I'm my inspiration. I try representing my people of Senegal, Africa. You know, 'Wakanda forever'? Let's go."
When it came time to fight, Diakhate delivered. He finished short-notice replacement Darryl Walker with ground-and-pound punches at 2:35 of Round 1. It was quite the exclamation point on a week full of uncertainty after multiple opponent withdrawals.
#diakhate #clothes


1 month ago
Patrick Cantlay became the fifth player to withdraw from this week's Wyndham Championship since the field was announced at the traditional PGA Tour Friday deadline.
Cantlay tied for eighth Sunday at the Rocket Classic, his fourth top 10 and ninth top 25 of the 2026 season. He's currently 41st in the FedEx Cup Playoffs standings, which puts him through to not only the first postseason event next week, the FedEx St. Jude Championship, but also Week 2's BMW Championship.
If PGA Tour players WD before a tournament starts, they're not required to provide a reason.
Other Wyndham withdrawals since the field was announced:
Saturday, Aug. 1: Kristoffer Reitan (WD), Kristoffer Ventura (IN); Brendon Todd (WD), Matt Kuchar (IN)
#championship #week #field #announced
Cantlay tied for eighth Sunday at the Rocket Classic, his fourth top 10 and ninth top 25 of the 2026 season. He's currently 41st in the FedEx Cup Playoffs standings, which puts him through to not only the first postseason event next week, the FedEx St. Jude Championship, but also Week 2's BMW Championship.
If PGA Tour players WD before a tournament starts, they're not required to provide a reason.
Other Wyndham withdrawals since the field was announced:
Saturday, Aug. 1: Kristoffer Reitan (WD), Kristoffer Ventura (IN); Brendon Todd (WD), Matt Kuchar (IN)
#championship #week #field #announced

1 month ago
Washington Saves launches July 1, 2027, automatically enrolling workers without employer retirement plans into an IRA at a default contribution rate ranging from 3% to 7%.
Choosing a Roth over a traditional auto-IRA keeps withdrawals tax-free and invisible to the Social Security formula that determines benefit taxation.
Even modest savings before full retirement age can fund delayed Social Security claiming, worth roughly 8% more per year than filing early.
Are you ahead, or behind on retirement? SmartAsset's free tool can match you with a financial advisor in minutes to help you answer that today. Each advisor has been carefully vetted, and must act in your best interests. Don't waste another minute; learn more here.
Picture a 59-year-old woman in Tacoma who has waited tables, run a register, and answered phones at a seven-person insurance office. Decades of steady work, zero years with a 401(k). Her retirement plan has always been Social Security. Then a letter arrives from her employer explaining that starting July 1, 2027, she is being automatically signed up for something called Washington Saves.
#security #july #free #year
Choosing a Roth over a traditional auto-IRA keeps withdrawals tax-free and invisible to the Social Security formula that determines benefit taxation.
Even modest savings before full retirement age can fund delayed Social Security claiming, worth roughly 8% more per year than filing early.
Are you ahead, or behind on retirement? SmartAsset's free tool can match you with a financial advisor in minutes to help you answer that today. Each advisor has been carefully vetted, and must act in your best interests. Don't waste another minute; learn more here.
Picture a 59-year-old woman in Tacoma who has waited tables, run a register, and answered phones at a seven-person insurance office. Decades of steady work, zero years with a 401(k). Her retirement plan has always been Social Security. Then a letter arrives from her employer explaining that starting July 1, 2027, she is being automatically signed up for something called Washington Saves.
#security #july #free #year


