14 hours ago
Corning Incorporated (GLW), the 175-year-old materials science giant based in Corning, New York, has become one of the more surprising beneficiaries of the artificial intelligence infrastructure buildout. Best known for its glass, ceramics, and optical technology innovations, Corning now plays a critical behind-the-scenes role as the dominant supplier of optical fiber powering hyperscale data centers and AI networks. The company has locked in major long-term supply agreements with tech heavyweights including Apple (AAPL), Meta (META), Nvidia (NVDA), Amazon (AMZN), and Verizon (VZ).
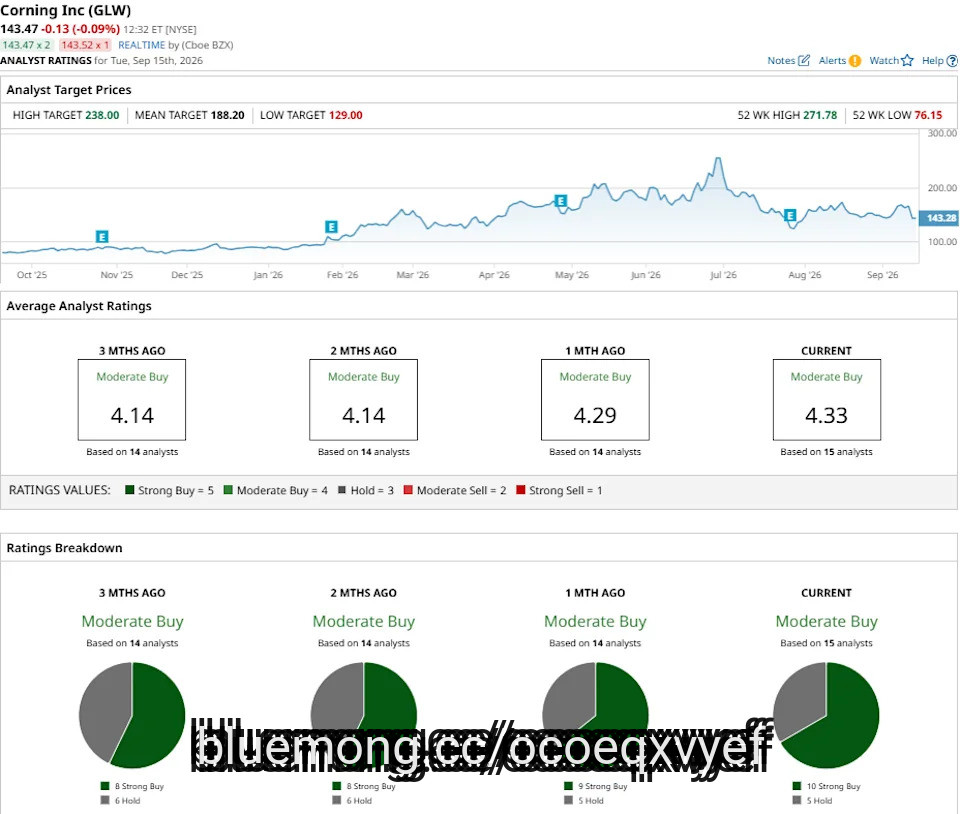
Corning stock has swung wildly of late, recently trading near $144 after plunging more than 13% in a single session following news of a $2 billion at-the-market equity offering arranged with Goldman Sachs, a move that reignited investor concerns over shareholder dilution. Shares now sit roughly in the middle of a wide 52-week range spanning $75.77 to $271.78, capturing a dramatic round trip. Corning suffered its worst monthly drop in 24 years this past July, only to rebound 8% in early September after unveiling a multibillion-dollar, 80-million-mile fiber supply deal with Verizon.
Billionaire Charlie Munger, Who Died at 99, Skipped Insurance on His Mansion Since He Could Just Write a Check to Rebuild — 'All Intelligent People Do It My Way'
Why It's Time to Load Up on Nvidia Stock
The Case for Selling CrowdStrike Stock
#meta #fiber
Corning stock has swung wildly of late, recently trading near $144 after plunging more than 13% in a single session following news of a $2 billion at-the-market equity offering arranged with Goldman Sachs, a move that reignited investor concerns over shareholder dilution. Shares now sit roughly in the middle of a wide 52-week range spanning $75.77 to $271.78, capturing a dramatic round trip. Corning suffered its worst monthly drop in 24 years this past July, only to rebound 8% in early September after unveiling a multibillion-dollar, 80-million-mile fiber supply deal with Verizon.
Billionaire Charlie Munger, Who Died at 99, Skipped Insurance on His Mansion Since He Could Just Write a Check to Rebuild — 'All Intelligent People Do It My Way'
Why It's Time to Load Up on Nvidia Stock
The Case for Selling CrowdStrike Stock
#meta #fiber


2 days ago
Eli Lilly and Company (NYSE:LLY) says its newly launched oral obesity drug Foundayo has captured more than 30% of new U.S. patients starting oral weight-loss medicines, a notable early gain against Novo Nordisk's Wegovy pill. Reuters reports that Wegovy initially held roughly 90% of the oral market, making Lilly's rapid share capture an important sign that the oral GLP-1 market is becoming a two-player competition rather than a Novo-dominated segment. The broader U.S. obesity-drug market is expected to exceed $100 billion annually by 2030, with oral treatments potentially accounting for more than one-third of GLP-1 use.
The timing is strategically important for Lilly because Foundayo was only launched in the U.S. in April 2026. The drug starts at $149 per month for self-pay patients and can cost as little as $25 for eligible commercially insured patients, while Medicare beneficiaries can access it through the GLP-1 Bridge program at $50 per month. Lilly's SEC filing says Mounjaro and Zepbound already represented 65% of its revenue in the first six months of 2026, highlighting both the importance of the incretin franchise and the opportunity for Foundayo to broaden Lilly's cardiometabolic revenue base.
The strongest bullish implication is that Foundayo appears to be overcoming the biggest behavioral barrier in obesity treatment: patients' preference for an oral medicine over an injection. Capturing more than 30% of new oral patients only months after launch suggests Eli Lilly and Company (NYSE:LLY) is establishing meaningful competitive positioning before the oral GLP-1 market fully scales. Foundayo's formulation also has a practical advantage because it can be taken at any time of day without food or water restrictions, while Lilly's clinical data showed an average 27.3-pound, or 12.4%, weight reduction at the highest dose among patients who remained on treatment in ATTAIN-1.
The commercial opportunity could become considerably larger if Foundayo gains indications beyond obesity. Lilly reported that in the ACHIEVE-3 trial, Foundayo produced a 57.1% greater relative reduction in A1C and a 73.6% greater relative reduction in body weight compared with oral semaglutide 14 mg. Lilly submitted Foundayo for type 2 diabetes in the U.S., EU, and **** an, potentially expanding the addressable market beyond weight management.
The early oral-market traction also complements Eli Lilly and Company (NYSE:LLY)'s existing injectable franchise rather than simply cannibalizing it. A Lilly trial found that patients switching from maximum-tolerated Wegovy to Foundayo maintained all but 0.9 kg of their previous weight loss after one year, while patients switching from maximum-dose Zepbound to Foundayo maintained all but 5.0 kg. That suggests Foundayo could serve as a maintenance or lower-burden treatment within Lilly's broader obesity portfolio, increasing lifetime value per patient rather than limiting the opportunity to new prescriptions.
#patients #weight #c
The timing is strategically important for Lilly because Foundayo was only launched in the U.S. in April 2026. The drug starts at $149 per month for self-pay patients and can cost as little as $25 for eligible commercially insured patients, while Medicare beneficiaries can access it through the GLP-1 Bridge program at $50 per month. Lilly's SEC filing says Mounjaro and Zepbound already represented 65% of its revenue in the first six months of 2026, highlighting both the importance of the incretin franchise and the opportunity for Foundayo to broaden Lilly's cardiometabolic revenue base.
The strongest bullish implication is that Foundayo appears to be overcoming the biggest behavioral barrier in obesity treatment: patients' preference for an oral medicine over an injection. Capturing more than 30% of new oral patients only months after launch suggests Eli Lilly and Company (NYSE:LLY) is establishing meaningful competitive positioning before the oral GLP-1 market fully scales. Foundayo's formulation also has a practical advantage because it can be taken at any time of day without food or water restrictions, while Lilly's clinical data showed an average 27.3-pound, or 12.4%, weight reduction at the highest dose among patients who remained on treatment in ATTAIN-1.
The commercial opportunity could become considerably larger if Foundayo gains indications beyond obesity. Lilly reported that in the ACHIEVE-3 trial, Foundayo produced a 57.1% greater relative reduction in A1C and a 73.6% greater relative reduction in body weight compared with oral semaglutide 14 mg. Lilly submitted Foundayo for type 2 diabetes in the U.S., EU, and **** an, potentially expanding the addressable market beyond weight management.
The early oral-market traction also complements Eli Lilly and Company (NYSE:LLY)'s existing injectable franchise rather than simply cannibalizing it. A Lilly trial found that patients switching from maximum-tolerated Wegovy to Foundayo maintained all but 0.9 kg of their previous weight loss after one year, while patients switching from maximum-dose Zepbound to Foundayo maintained all but 5.0 kg. That suggests Foundayo could serve as a maintenance or lower-burden treatment within Lilly's broader obesity portfolio, increasing lifetime value per patient rather than limiting the opportunity to new prescriptions.
#patients #weight #c


2 days ago
With Agentic AI accelerating CPU server chip demand, Wall Street believes Advanced Micro Devices, Inc. (NASDAQ:AMD) is one of the primary beneficiaries taking share. On September 9, Piper Sandler ******* yst David O'Connor initiated coverage on AMD (NASDAQ: AMD) with an Overweight rating and a $600 price target.
Analyst O'Connor estimates revenue for FY26-30 to grow at a 50% CAGR, while earnings per share compound at 65%.
The server-CPU share gain story for AMD is simple, Agentic AI is expected to increase demand for server CPUs. This is because the workloads require continuous control-plane activity, API calls, database queries and tool execution. AMD will benefit from this use based on its high-frequency and general-purpose processors with its Venice portfolio.
Even AMD executives have highlighted that AMD is now transitioning from merely a semiconductor supplier to a provider of rack-scale systems and software. It is also positioning its server CPU portfolio for increased demand from agentic AI workloads.
The company reported second-quarter revenue of $11.5 billion, beating ******* yst estimates. This includes $6.7 billion from data centers, up 107% year-over-year. The segment performance was attributed to EPYC processors and Instinct GPUs.
#workloads
Analyst O'Connor estimates revenue for FY26-30 to grow at a 50% CAGR, while earnings per share compound at 65%.
The server-CPU share gain story for AMD is simple, Agentic AI is expected to increase demand for server CPUs. This is because the workloads require continuous control-plane activity, API calls, database queries and tool execution. AMD will benefit from this use based on its high-frequency and general-purpose processors with its Venice portfolio.
Even AMD executives have highlighted that AMD is now transitioning from merely a semiconductor supplier to a provider of rack-scale systems and software. It is also positioning its server CPU portfolio for increased demand from agentic AI workloads.
The company reported second-quarter revenue of $11.5 billion, beating ******* yst estimates. This includes $6.7 billion from data centers, up 107% year-over-year. The segment performance was attributed to EPYC processors and Instinct GPUs.
#workloads


2 days ago
Eli Lilly and Company (NYSE:LLY) says its newly launched oral obesity drug Foundayo has captured more than 30% of new U.S. patients starting oral weight-loss medicines, a notable early gain against Novo Nordisk's Wegovy pill. Reuters reports that Wegovy initially held roughly 90% of the oral market, making Lilly's rapid share capture an important sign that the oral GLP-1 market is becoming a two-player competition rather than a Novo-dominated segment. The broader U.S. obesity-drug market is expected to exceed $100 billion annually by 2030, with oral treatments potentially accounting for more than one-third of GLP-1 use.
The timing is strategically important for Lilly because Foundayo was only launched in the U.S. in April 2026. The drug starts at $149 per month for self-pay patients and can cost as little as $25 for eligible commercially insured patients, while Medicare beneficiaries can access it through the GLP-1 Bridge program at $50 per month. Lilly's SEC filing says Mounjaro and Zepbound already represented 65% of its revenue in the first six months of 2026, highlighting both the importance of the incretin franchise and the opportunity for Foundayo to broaden Lilly's cardiometabolic revenue base.
The strongest bullish implication is that Foundayo appears to be overcoming the biggest behavioral barrier in obesity treatment: patients' preference for an oral medicine over an injection. Capturing more than 30% of new oral patients only months after launch suggests Eli Lilly and Company (NYSE:LLY) is establishing meaningful competitive positioning before the oral GLP-1 market fully scales. Foundayo's formulation also has a practical advantage because it can be taken at any time of day without food or water restrictions, while Lilly's clinical data showed an average 27.3-pound, or 12.4%, weight reduction at the highest dose among patients who remained on treatment in ATTAIN-1.
The commercial opportunity could become considerably larger if Foundayo gains indications beyond obesity. Lilly reported that in the ACHIEVE-3 trial, Foundayo produced a 57.1% greater relative reduction in A1C and a 73.6% greater relative reduction in body weight compared with oral semaglutide 14 mg. Lilly submitted Foundayo for type 2 diabetes in the U.S., EU, and ***** an, potentially expanding the addressable market beyond weight management.
The early oral-market traction also complements Eli Lilly and Company (NYSE:LLY)'s existing injectable franchise rather than simply cannibalizing it. A Lilly trial found that patients switching from maximum-tolerated Wegovy to Foundayo maintained all but 0.9 kg of their previous weight loss after one year, while patients switching from maximum-dose Zepbound to Foundayo maintained all but 5.0 kg. That suggests Foundayo could serve as a maintenance or lower-burden treatment within Lilly's broader obesity portfolio, increasing lifetime value per patient rather than limiting the opportunity to new prescriptions.
#weight
The timing is strategically important for Lilly because Foundayo was only launched in the U.S. in April 2026. The drug starts at $149 per month for self-pay patients and can cost as little as $25 for eligible commercially insured patients, while Medicare beneficiaries can access it through the GLP-1 Bridge program at $50 per month. Lilly's SEC filing says Mounjaro and Zepbound already represented 65% of its revenue in the first six months of 2026, highlighting both the importance of the incretin franchise and the opportunity for Foundayo to broaden Lilly's cardiometabolic revenue base.
The strongest bullish implication is that Foundayo appears to be overcoming the biggest behavioral barrier in obesity treatment: patients' preference for an oral medicine over an injection. Capturing more than 30% of new oral patients only months after launch suggests Eli Lilly and Company (NYSE:LLY) is establishing meaningful competitive positioning before the oral GLP-1 market fully scales. Foundayo's formulation also has a practical advantage because it can be taken at any time of day without food or water restrictions, while Lilly's clinical data showed an average 27.3-pound, or 12.4%, weight reduction at the highest dose among patients who remained on treatment in ATTAIN-1.
The commercial opportunity could become considerably larger if Foundayo gains indications beyond obesity. Lilly reported that in the ACHIEVE-3 trial, Foundayo produced a 57.1% greater relative reduction in A1C and a 73.6% greater relative reduction in body weight compared with oral semaglutide 14 mg. Lilly submitted Foundayo for type 2 diabetes in the U.S., EU, and ***** an, potentially expanding the addressable market beyond weight management.
The early oral-market traction also complements Eli Lilly and Company (NYSE:LLY)'s existing injectable franchise rather than simply cannibalizing it. A Lilly trial found that patients switching from maximum-tolerated Wegovy to Foundayo maintained all but 0.9 kg of their previous weight loss after one year, while patients switching from maximum-dose Zepbound to Foundayo maintained all but 5.0 kg. That suggests Foundayo could serve as a maintenance or lower-burden treatment within Lilly's broader obesity portfolio, increasing lifetime value per patient rather than limiting the opportunity to new prescriptions.
#weight
6 days ago
Updated Sept 11, 2026, 1:55 pm EDT / Original Sept 11, 2026, 7:30 am EDT
The grocery giant now expects same-store sales excluding fuel to rise between 0.2% and 0.8% for the fiscal year, down from a prior range of 1% to 2% growth. The new guidance includes a hit of roughly 140 basis points tied to the Inflation Reduction Act, which lowered prescription drug prices for Medicare beneficiaries and impacted pharmacy revenue. Management separately reaffirmed its earnings guidance of $5.10 to $5.30 a share for the fiscal year.
Copyright ©2026 Dow Jones & Company, Inc. All Rights Reserved. 87990cbe856818d5eddac44c7b1cdeb8
#inflation #medicare
The grocery giant now expects same-store sales excluding fuel to rise between 0.2% and 0.8% for the fiscal year, down from a prior range of 1% to 2% growth. The new guidance includes a hit of roughly 140 basis points tied to the Inflation Reduction Act, which lowered prescription drug prices for Medicare beneficiaries and impacted pharmacy revenue. Management separately reaffirmed its earnings guidance of $5.10 to $5.30 a share for the fiscal year.
Copyright ©2026 Dow Jones & Company, Inc. All Rights Reserved. 87990cbe856818d5eddac44c7b1cdeb8
#inflation #medicare

8 days ago
Broadcom Inc. (NASDAQ:AVGO) could be one of the biggest beneficiaries of Anthropic's accelerating compute requirements. The opportunity comes amid growing concerns that Google's decision to develop more of its chips internally could threaten Broadcom's custom silicon business.
However, Macquarie ****** yst Arthur Lai argued on September 3 that many of these concerns may already be priced in. The stock is down by about 24% from its all-time high, while Google's work with MediaTek and its expanding relationship with Marvell have added to concerns about Broadcom losing share in future TPU programs.
According to Lai, the recent weakness could create an attractive entry point as Broadcom positions itself to capture what could become a $40 billion opportunity from Anthropic.
In April, Anthropic announced an expanded partnership with Google and Broadcom to secure next-generation TPU capacity. Anthropic plans to use its computing infrastructure to accelerate training and inference for its Claude family of artificial intelligence models as demand for AI applications continues to grow.
The partnership could provide Broadcom with an important avenue for expanding its custom AI semiconductor business. The company has also been expanding its AI infrastructure capabilities through partnerships with major financial institutions. Together with Apollo and Blackstone, it launched an AI XPV platform designed to support more than 20 gigawatts of compute capacity.
#broadcom #Opportunity #custom #business
However, Macquarie ****** yst Arthur Lai argued on September 3 that many of these concerns may already be priced in. The stock is down by about 24% from its all-time high, while Google's work with MediaTek and its expanding relationship with Marvell have added to concerns about Broadcom losing share in future TPU programs.
According to Lai, the recent weakness could create an attractive entry point as Broadcom positions itself to capture what could become a $40 billion opportunity from Anthropic.
In April, Anthropic announced an expanded partnership with Google and Broadcom to secure next-generation TPU capacity. Anthropic plans to use its computing infrastructure to accelerate training and inference for its Claude family of artificial intelligence models as demand for AI applications continues to grow.
The partnership could provide Broadcom with an important avenue for expanding its custom AI semiconductor business. The company has also been expanding its AI infrastructure capabilities through partnerships with major financial institutions. Together with Apollo and Blackstone, it launched an AI XPV platform designed to support more than 20 gigawatts of compute capacity.
#broadcom #Opportunity #custom #business


8 days ago
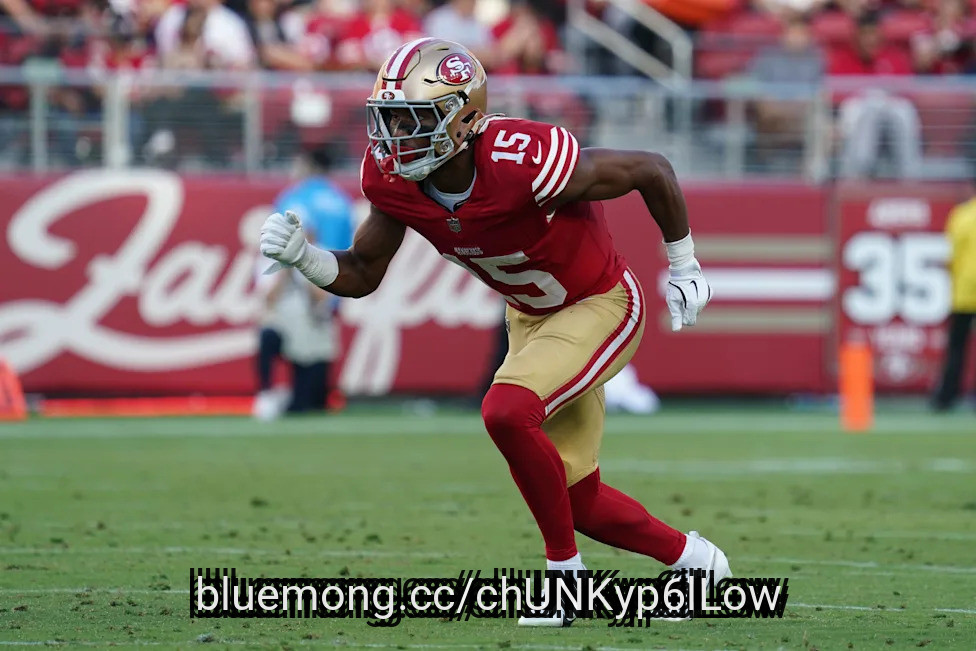
Updating a previous report, San Francisco 49ers WR De'Zhaun Stribling (ankle) will not return to the Week 1 game against the Los Angeles Rams after exiting with an ankle injury.
SOURCE: San Francisco 49ers
Why it Matters: With Stribling officially ruled out for the remainder of the opener, fantasy owners now have to wonder if he will miss extended time. Expect Demarcus Robinson and Deebo Samuel to be among the main beneficiaries if Stribling has a prolonged absence.
This article originally appeared on USA TODAY: De'Zhaun Stribling won't return to opener
#de 'zhaun #return #week
SOURCE: San Francisco 49ers
Why it Matters: With Stribling officially ruled out for the remainder of the opener, fantasy owners now have to wonder if he will miss extended time. Expect Demarcus Robinson and Deebo Samuel to be among the main beneficiaries if Stribling has a prolonged absence.
This article originally appeared on USA TODAY: De'Zhaun Stribling won't return to opener
#de 'zhaun #return #week
0.00$ raised of 0.00$ goal
0 donations
0.00$
to go

8 days ago
A $400,000 inherited IRA can become much more expensive if you get the withdrawal timing wrong. Many non-spouse beneficiaries must empty the account within 10 years, and some also have annual RMDs. Delaying distributions could concentrate more taxable income into later years and potentially push more of your money into higher tax brackets.
For many non-spouse beneficiaries, an inherited IRA must be emptied by December 31 of the year containing the 10th1 anniversary of the original owner's death. Certain beneficiaries qualify for different rules.
The 10-year deadline may not be the only requirement. If the original owner died on or after their required beginning date, a non-spouse beneficiary subject to the 10-year rule generally must also take annual RMDs during the 10-year period.
Missing a required distribution can trigger an excise tax of up to 25% of the amount not withdrawn. This makes it important to know whether annual withdrawals apply instead of ****** uming you can leave the entire account untouched until year 10.
Traditional inherited IRA distributions are generally taxed as ordinary income. Leaving a large amount until the final years could force you to withdraw more at once, potentially pushing more of the $400,000 into higher tax brackets.
#year #spouse #beneficiaries #account
For many non-spouse beneficiaries, an inherited IRA must be emptied by December 31 of the year containing the 10th1 anniversary of the original owner's death. Certain beneficiaries qualify for different rules.
The 10-year deadline may not be the only requirement. If the original owner died on or after their required beginning date, a non-spouse beneficiary subject to the 10-year rule generally must also take annual RMDs during the 10-year period.
Missing a required distribution can trigger an excise tax of up to 25% of the amount not withdrawn. This makes it important to know whether annual withdrawals apply instead of ****** uming you can leave the entire account untouched until year 10.
Traditional inherited IRA distributions are generally taxed as ordinary income. Leaving a large amount until the final years could force you to withdraw more at once, potentially pushing more of the $400,000 into higher tax brackets.
#year #spouse #beneficiaries #account


0.00$ raised of 0.00$ goal
0 donations
0.00$
to go
11 days ago
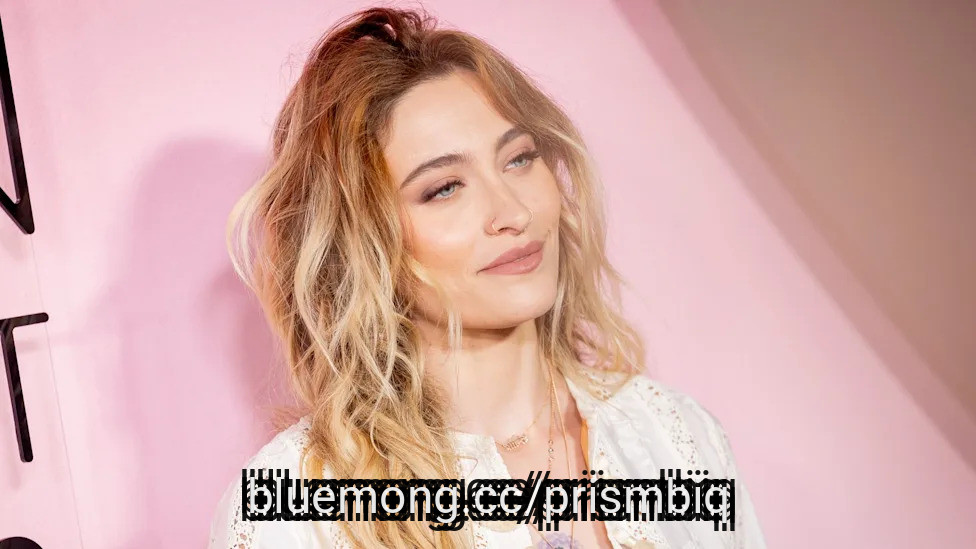
Paris Jackson didn't get to enjoy her father Michael Jackson's Neverland Ranch. The 28-year-old star, the daughter of the late King of Pop and his second wife, Debbie Rowe, has revealed that she and her siblings, Prince, 29, and Bigi, 24, never got the chance to enjoy the California property's features, such as the private amusement park, zoo, and movie theater.
Speaking on the Call Her Daddy podcast, Paris explained: "I didn't grow up there. "It was only the first few years of my life that I was there." In fact, Paris revealed that she and her siblings were told that Neverland's "attractions" were only to be enjoyed by underprivileged and sick children.
Prince Jackson, Paris Jackson, and Bigi Jackson are beneficiaries of the estate (@ Getty)
You may also like
Paris Jackson accuses paparazzi of causing her long-term trauma
#jackson #enjoy #revealed
Speaking on the Call Her Daddy podcast, Paris explained: "I didn't grow up there. "It was only the first few years of my life that I was there." In fact, Paris revealed that she and her siblings were told that Neverland's "attractions" were only to be enjoyed by underprivileged and sick children.
Prince Jackson, Paris Jackson, and Bigi Jackson are beneficiaries of the estate (@ Getty)
You may also like
Paris Jackson accuses paparazzi of causing her long-term trauma
#jackson #enjoy #revealed
14 days ago
Eagle Capital Management, an investment management company, released its second quarter 2026 investor letter. A copy of the letter can be downloaded here. In the quarter, Eagle Capital Management discussed how enthusiasm around AI capital spending has driven strong S&P 500 earnings growth while also increasing risks from elevated valuations, concentrated demand, and aggressive investment ***** umptions. Eagle remains a strong believer in AI but prefers constructing a portfolio that can perform across multiple outcomes rather than relying on one forecast. The firm believes current earnings can overstate underlying economics because semiconductor equipment is depreciated over several years, while free cash flow growth remains much weaker. It also expects competition and additional capacity across AI labs, hyperscalers, and semiconductors to eventually create winners and losers. These dynamics are encouraging Eagle to recycle capital toward attractive opportunities outside the most crowded AI trades while maintaining selective exposure to high-quality beneficiaries. The portfolio trades at a 20% market discount with faster expected EPS growth. Please review the Strategy's top five holdings for key selections in 2026.
In its second-quarter 2026 investor letter, Eagle Capital Management highlighted Danaher Corporation (NYSE:DHR). Danaher Corporation (NYSE:DHR) is a healthcare and life science tools company operating through Biotechnology, Life Sciences, and Diagnostics segments. On September 02, 2026, Danaher Corporation (NYSE:DHR) closed at $209.91 per share. Over the past month, Danaher Corporation (NYSE:DHR) returned 4.97%, and its shares gained 5.47% over the past 52 weeks. Danaher Corporation (NYSE:DHR) has a market capitalization of $147.56 billion.
Eagle Capital Management stated the following regarding Danaher Corporation (NYSE:DHR) in its Q2 2026 investor letter:
"High quality with low volatility (24% of capital): London Stock Exchange, Danaher Corporation (NYSE:DHR), S&P Global, Mastercard, A.J. Gallagher: Approximately a quarter of Eagle's portfolio is spread across a handful of superb businesses that exhibit high and stable margins, strong returns on capital, wide competitive advantages, and well above GDP growth. We expect the group to deftly navigate the integration of AI into their markets. Most operate with a combination of oligopoly/monopoly ***** ets, network effects, or regulatory moats. Danaher is a leading life sciences company, selling a broad mix of consumables and tooling for biological R&D and drug production.
A few years ago, these stocks were priced for perfection. Their attractive characteristics were prized, and the group traded at more than 30x earnings. Over the past five years, the businesses have grown significantly, while the stocks have de rated. Today, the group trades at a high teen multiple. In a market that is growing EPS at nearly 20%, their steady growth isn't scarce. However, as earnings in the economy nor
In its second-quarter 2026 investor letter, Eagle Capital Management highlighted Danaher Corporation (NYSE:DHR). Danaher Corporation (NYSE:DHR) is a healthcare and life science tools company operating through Biotechnology, Life Sciences, and Diagnostics segments. On September 02, 2026, Danaher Corporation (NYSE:DHR) closed at $209.91 per share. Over the past month, Danaher Corporation (NYSE:DHR) returned 4.97%, and its shares gained 5.47% over the past 52 weeks. Danaher Corporation (NYSE:DHR) has a market capitalization of $147.56 billion.
Eagle Capital Management stated the following regarding Danaher Corporation (NYSE:DHR) in its Q2 2026 investor letter:
"High quality with low volatility (24% of capital): London Stock Exchange, Danaher Corporation (NYSE:DHR), S&P Global, Mastercard, A.J. Gallagher: Approximately a quarter of Eagle's portfolio is spread across a handful of superb businesses that exhibit high and stable margins, strong returns on capital, wide competitive advantages, and well above GDP growth. We expect the group to deftly navigate the integration of AI into their markets. Most operate with a combination of oligopoly/monopoly ***** ets, network effects, or regulatory moats. Danaher is a leading life sciences company, selling a broad mix of consumables and tooling for biological R&D and drug production.
A few years ago, these stocks were priced for perfection. Their attractive characteristics were prized, and the group traded at more than 30x earnings. Over the past five years, the businesses have grown significantly, while the stocks have de rated. Today, the group trades at a high teen multiple. In a market that is growing EPS at nearly 20%, their steady growth isn't scarce. However, as earnings in the economy nor

14 days ago
Eagle Capital Management, an investment management company, released its second quarter 2026 investor letter. A copy of the letter can be downloaded here. In the quarter, Eagle Capital Management discussed how enthusiasm around AI capital spending has driven strong S&P 500 earnings growth while also increasing risks from elevated valuations, concentrated demand, and aggressive investment ****** umptions. Eagle remains a strong believer in AI but prefers constructing a portfolio that can perform across multiple outcomes rather than relying on one forecast. The firm believes current earnings can overstate underlying economics because semiconductor equipment is depreciated over several years, while free cash flow growth remains much weaker. It also expects competition and additional capacity across AI labs, hyperscalers, and semiconductors to eventually create winners and losers. These dynamics are encouraging Eagle to recycle capital toward attractive opportunities outside the most crowded AI trades while maintaining selective exposure to high-quality beneficiaries. The portfolio trades at a 20% market discount with faster expected EPS growth. Please review the Strategy's top five holdings for key selections in 2026.
In its second-quarter 2026 investor letter, Eagle Capital Management highlighted Mastercard Incorporated (NYSE:MA). Mastercard Incorporated (NYSE:MA) is a leading global payment technology company that provides transaction processing and other payment-related products and services. On September 02, 2026, Mastercard Incorporated (NYSE:MA) closed at $588.14 per share. Over the past month, Mastercard Incorporated (NYSE:MA) returned 2.12% while its shares lost 1.26% over the past 52 weeks. Mastercard Incorporated (NYSE:MA) has a market capitalization of $515.22 billion.
Eagle Capital Management stated the following regarding Mastercard Incorporated (NYSE:MA) in its Q2 2026 investor letter:
High quality with low volatility (24% of capital): London Stock Exchange, Danaher, S&P Global, Mastercard Incorporated (NYSE:MA), A.J. Gallagher: Approximately a quarter of Eagle's portfolio is spread across a handful of superb businesses that exhibit high and stable margins, strong returns on capital, wide competitive advantages, and well above GDP growth. We expect the group to deftly navigate the integration of AI into their markets. Most operate with a combination of oligopoly/monopoly ****** ets, network effects, or regulatory moats. Mastercard operates as part of a global duopoly of payment rails and standards.
A few years ago, these stocks were priced for perfection. Their attractive characteristics were prized, and the group traded at more than 30x earnings. Over the past five years, the businesses have grown significantly, while the stocks have de rated. Today, the group trades at a high teen multiple. In a market that is growing EPS at nearly 20%, their steady growth isn't scarce. However, as earnings in the economy normalize back towards m
In its second-quarter 2026 investor letter, Eagle Capital Management highlighted Mastercard Incorporated (NYSE:MA). Mastercard Incorporated (NYSE:MA) is a leading global payment technology company that provides transaction processing and other payment-related products and services. On September 02, 2026, Mastercard Incorporated (NYSE:MA) closed at $588.14 per share. Over the past month, Mastercard Incorporated (NYSE:MA) returned 2.12% while its shares lost 1.26% over the past 52 weeks. Mastercard Incorporated (NYSE:MA) has a market capitalization of $515.22 billion.
Eagle Capital Management stated the following regarding Mastercard Incorporated (NYSE:MA) in its Q2 2026 investor letter:
High quality with low volatility (24% of capital): London Stock Exchange, Danaher, S&P Global, Mastercard Incorporated (NYSE:MA), A.J. Gallagher: Approximately a quarter of Eagle's portfolio is spread across a handful of superb businesses that exhibit high and stable margins, strong returns on capital, wide competitive advantages, and well above GDP growth. We expect the group to deftly navigate the integration of AI into their markets. Most operate with a combination of oligopoly/monopoly ****** ets, network effects, or regulatory moats. Mastercard operates as part of a global duopoly of payment rails and standards.
A few years ago, these stocks were priced for perfection. Their attractive characteristics were prized, and the group traded at more than 30x earnings. Over the past five years, the businesses have grown significantly, while the stocks have de rated. Today, the group trades at a high teen multiple. In a market that is growing EPS at nearly 20%, their steady growth isn't scarce. However, as earnings in the economy normalize back towards m

14 days ago
Eagle Capital Management, an investment management company, released its second quarter 2026 investor letter. A copy of the letter can be downloaded here. In the quarter, Eagle Capital Management discussed how enthusiasm around AI capital spending has driven strong S&P 500 earnings growth while also increasing risks from elevated valuations, concentrated demand, and aggressive investment ****** umptions. Eagle remains a strong believer in AI but prefers constructing a portfolio that can perform across multiple outcomes rather than relying on one forecast. The firm believes current earnings can overstate underlying economics because semiconductor equipment is depreciated over several years, while free cash flow growth remains much weaker. It also expects competition and additional capacity across AI labs, hyperscalers, and semiconductors to eventually create winners and losers. These dynamics are encouraging Eagle to recycle capital toward attractive opportunities outside the most crowded AI trades while maintaining selective exposure to high-quality beneficiaries. The portfolio trades at a 20% market discount with faster expected EPS growth. Please review the Strategy's top five holdings for key selections in 2026.
In its second-quarter 2026 investor letter, Eagle Capital Management highlighted Arthur J. Gallagher & Co. (NYSE:AJG). Arthur J. Gallagher & Co. (NYSE:AJG) provides insurance and reinsurance brokerage, consulting, and third-party property/casualty claims settlement and administration services to entities and individuals. On September 02, 2026, Arthur J. Gallagher & Co. (NYSE:AJG) closed at $264.46 per share. Over the past month, Arthur J. Gallagher & Co. (NYSE:AJG) was up 5.05%, while its shares lost 11.91% over the past 52 weeks. Arthur J. Gallagher & Co. (NYSE:AJG) has a market capitalization of $67.78 billion.
Eagle Capital Management stated the following regarding Arthur J. Gallagher & Co. (NYSE:AJG) in its Q2 2026 investor letter:
"High quality with low volatility (24% of capital): London Stock Exchange, Danaher, S&P Global, Mastercard, A.J. Gallagher: Approximately a quarter of Eagle's portfolio is spread across a handful of superb businesses that exhibit high and stable margins, strong returns on capital, wide competitive advantages, and well above GDP growth. We expect the group to deftly navigate the integration of AI into their markets. Most operate with a combination of oligopoly/monopoly ****** ets, network effects, or regulatory moats. A.J. Gallagher is a commercial insurance broker that continues to gain share in a consolidating industry.
A few years ago, these stocks were priced for perfection. Their attractive characteristics were prized, and the group traded at more than 30x earnings. Over the past five years, the businesses have grown significantly, while the stocks have de rated. Today, the group trades at a high teen multiple. In a market that is growing EPS at nearly 20%, their steady growth isn't scarce. Howev
In its second-quarter 2026 investor letter, Eagle Capital Management highlighted Arthur J. Gallagher & Co. (NYSE:AJG). Arthur J. Gallagher & Co. (NYSE:AJG) provides insurance and reinsurance brokerage, consulting, and third-party property/casualty claims settlement and administration services to entities and individuals. On September 02, 2026, Arthur J. Gallagher & Co. (NYSE:AJG) closed at $264.46 per share. Over the past month, Arthur J. Gallagher & Co. (NYSE:AJG) was up 5.05%, while its shares lost 11.91% over the past 52 weeks. Arthur J. Gallagher & Co. (NYSE:AJG) has a market capitalization of $67.78 billion.
Eagle Capital Management stated the following regarding Arthur J. Gallagher & Co. (NYSE:AJG) in its Q2 2026 investor letter:
"High quality with low volatility (24% of capital): London Stock Exchange, Danaher, S&P Global, Mastercard, A.J. Gallagher: Approximately a quarter of Eagle's portfolio is spread across a handful of superb businesses that exhibit high and stable margins, strong returns on capital, wide competitive advantages, and well above GDP growth. We expect the group to deftly navigate the integration of AI into their markets. Most operate with a combination of oligopoly/monopoly ****** ets, network effects, or regulatory moats. A.J. Gallagher is a commercial insurance broker that continues to gain share in a consolidating industry.
A few years ago, these stocks were priced for perfection. Their attractive characteristics were prized, and the group traded at more than 30x earnings. Over the past five years, the businesses have grown significantly, while the stocks have de rated. Today, the group trades at a high teen multiple. In a market that is growing EPS at nearly 20%, their steady growth isn't scarce. Howev
14 days ago
Eagle Capital Management, an investment management company, released its second quarter 2026 investor letter. A copy of the letter can be downloaded here. In the quarter, Eagle Capital Management discussed how enthusiasm around AI capital spending has driven strong S&P 500 earnings growth while also increasing risks from elevated valuations, concentrated demand, and aggressive investment ******* umptions. Eagle remains a strong believer in AI but prefers constructing a portfolio that can perform across multiple outcomes rather than relying on one forecast. The firm believes current earnings can overstate underlying economics because semiconductor equipment is depreciated over several years, while free cash flow growth remains much weaker. It also expects competition and additional capacity across AI labs, hyperscalers, and semiconductors to eventually create winners and losers. These dynamics are encouraging Eagle to recycle capital toward attractive opportunities outside the most crowded AI trades while maintaining selective exposure to high quality beneficiaries. The portfolio trades at a 20% market discount with faster expected EPS growth. Please review the Strategy's top five holdings for key selections.
In its second-quarter 2026 investor letter, Eagle Capital Management highlighted UnitedHealth Group Incorporated (NYSE:UNH). UnitedHealth Group Incorporated (NYSE:UNH), a diversified healthcare company, contributed 2.5% to the Fund's performance during the quarter. On September 02, 2026, UnitedHealth Group Incorporated (NYSE:UNH) closed at $399.66 per share. Over the past month UnitedHealth Group Incorporated (NYSE:UNH) was down 1.07%, and its shares gained 28.76% over the past 52 weeks. UnitedHealth Group Incorporated (NYSE:UNH) has a market capitalization of $358.73 billion and its stock has traded within a 52-week range of $255.97 - $461.62.
Eagle Capital Management stated the following regarding UnitedHealth Group Incorporated (NYSE:UNH) in its Q2 2026 investor letter:
"Managed care (13% of capital): UnitedHealth Group Incorporated (NYSE:UNH), Humana, Elevance: These managed care companies have significant scale advantages in a consolidated industry that outgrows the overall economy. The industry moves with its own cycle and, over the last several years, has faced cost/price pressures in Medicare Advantage and Medicaid. Even the largest firms are earning poor margins, and some weaker firms are unprofitable. We believe conditions have bottomed out and that we are transitioning to a multi-year improvement in margins and earnings. Al-driven technology projects can both reduce costs and improve service quality. Since returning as CEO at UnitedHealth last year, Stephen Hemsley and the management team have been correcting some of the company's missteps. Recent results provide growing evidence that the turnaround is well on track. We expect EPS growth of 15-20% over the next several years, driven by moderate revenue growth and significantly e
In its second-quarter 2026 investor letter, Eagle Capital Management highlighted UnitedHealth Group Incorporated (NYSE:UNH). UnitedHealth Group Incorporated (NYSE:UNH), a diversified healthcare company, contributed 2.5% to the Fund's performance during the quarter. On September 02, 2026, UnitedHealth Group Incorporated (NYSE:UNH) closed at $399.66 per share. Over the past month UnitedHealth Group Incorporated (NYSE:UNH) was down 1.07%, and its shares gained 28.76% over the past 52 weeks. UnitedHealth Group Incorporated (NYSE:UNH) has a market capitalization of $358.73 billion and its stock has traded within a 52-week range of $255.97 - $461.62.
Eagle Capital Management stated the following regarding UnitedHealth Group Incorporated (NYSE:UNH) in its Q2 2026 investor letter:
"Managed care (13% of capital): UnitedHealth Group Incorporated (NYSE:UNH), Humana, Elevance: These managed care companies have significant scale advantages in a consolidated industry that outgrows the overall economy. The industry moves with its own cycle and, over the last several years, has faced cost/price pressures in Medicare Advantage and Medicaid. Even the largest firms are earning poor margins, and some weaker firms are unprofitable. We believe conditions have bottomed out and that we are transitioning to a multi-year improvement in margins and earnings. Al-driven technology projects can both reduce costs and improve service quality. Since returning as CEO at UnitedHealth last year, Stephen Hemsley and the management team have been correcting some of the company's missteps. Recent results provide growing evidence that the turnaround is well on track. We expect EPS growth of 15-20% over the next several years, driven by moderate revenue growth and significantly e
14 days ago
Eagle Capital Management, an investment management company, released its second quarter 2026 investor letter. A copy of the letter can be downloaded here. In the quarter, Eagle Capital Management discussed how enthusiasm around AI capital spending has driven strong S&P 500 earnings growth while also increasing risks from elevated valuations, concentrated demand, and aggressive investment **** umptions. Eagle remains a strong believer in AI but prefers constructing a portfolio that can perform across multiple outcomes rather than relying on one forecast. The firm believes current earnings can overstate underlying economics because semiconductor equipment is depreciated over several years, while free cash flow growth remains much weaker. It also expects competition and additional capacity across AI labs, hyperscalers, and semiconductors to eventually create winners and losers. These dynamics are encouraging Eagle to recycle capital toward attractive opportunities outside the most crowded AI trades while maintaining selective exposure to high-quality beneficiaries. The portfolio trades at a 20% market discount with faster expected EPS growth. Please review the Strategy's top five holdings for key selections in 2026.
In its second-quarter 2026 investor letter, Eagle Capital Management highlighted S&P Global Inc. (NYSE:SPGI). S&P Global Inc. is a financial services and **** ytics company that provides benchmarks, data, **** ytics, and workflow solutions in the global capital, energy, commodity, and automotive markets. On September 02, 2026, S&P Global Inc. closed at $431.71 per share, reflecting a market capitalization of $127.27 billion. S&P Global Inc. posted a one‑month return of 6.40%, while its shares lost 14.62% over the past 52 weeks.
Eagle Capital Management stated the following regarding S&P Global Inc. (NYSE:SPGI) in its Q2 2026 investor letter:
"High quality with low volatility (24% of capital): London Stock Exchange, Danaher, S&P Global Inc. (NYSE:SPGI), Mastercard, A.J. Gallagher: Approximately a quarter of Eagle's portfolio is spread across a handful of superb businesses that exhibit high and stable margins, strong returns on capital, wide competitive advantages, and well above GDP growth. We expect the group to deftly navigate the integration of AI into their markets. Most operate with a combination of oligopoly/monopoly **** ets, network effects, or regulatory moats. S&P Global owns the S&P ratings franchise, S&P Indexes, Platts, and Capital IQ.
A few years ago, these stocks were priced for perfection. Their attractive characteristics were prized, and the group traded at more than 30x earnings. Over the past five years, the businesses have grown significantly, while the stocks have de rated. Today, the group trades at a high teen multiple. In a market that is growing EPS at nearly 20%, their steady growth isn't scarce. However, as earnings in the economy normalize back towards mid businesses should demonstrate significant outperfor
In its second-quarter 2026 investor letter, Eagle Capital Management highlighted S&P Global Inc. (NYSE:SPGI). S&P Global Inc. is a financial services and **** ytics company that provides benchmarks, data, **** ytics, and workflow solutions in the global capital, energy, commodity, and automotive markets. On September 02, 2026, S&P Global Inc. closed at $431.71 per share, reflecting a market capitalization of $127.27 billion. S&P Global Inc. posted a one‑month return of 6.40%, while its shares lost 14.62% over the past 52 weeks.
Eagle Capital Management stated the following regarding S&P Global Inc. (NYSE:SPGI) in its Q2 2026 investor letter:
"High quality with low volatility (24% of capital): London Stock Exchange, Danaher, S&P Global Inc. (NYSE:SPGI), Mastercard, A.J. Gallagher: Approximately a quarter of Eagle's portfolio is spread across a handful of superb businesses that exhibit high and stable margins, strong returns on capital, wide competitive advantages, and well above GDP growth. We expect the group to deftly navigate the integration of AI into their markets. Most operate with a combination of oligopoly/monopoly **** ets, network effects, or regulatory moats. S&P Global owns the S&P ratings franchise, S&P Indexes, Platts, and Capital IQ.
A few years ago, these stocks were priced for perfection. Their attractive characteristics were prized, and the group traded at more than 30x earnings. Over the past five years, the businesses have grown significantly, while the stocks have de rated. Today, the group trades at a high teen multiple. In a market that is growing EPS at nearly 20%, their steady growth isn't scarce. However, as earnings in the economy normalize back towards mid businesses should demonstrate significant outperfor

14 days ago
Eagle Capital Management, an investment management company, released its second quarter 2026 investor letter. A copy of the letter can be downloaded here. In the quarter, Eagle Capital Management discussed how enthusiasm around AI capital spending has driven strong S&P 500 earnings growth while also increasing risks from elevated valuations, concentrated demand, and aggressive investment ***** umptions. Eagle remains a strong believer in AI but prefers constructing a portfolio that can perform across multiple outcomes rather than relying on one forecast. The firm believes current earnings can overstate underlying economics because semiconductor equipment is depreciated over several years, while free cash flow growth remains much weaker. It also expects competition and additional capacity across AI labs, hyperscalers, and semiconductors to eventually create winners and losers. These dynamics are encouraging Eagle to recycle capital toward attractive opportunities outside the most crowded AI trades while maintaining selective exposure to high-quality beneficiaries. The portfolio trades at a 20% market discount with faster expected EPS growth. Please review the Strategy's top five holdings for key selections in 2026.
In its second-quarter 2026 investor letter, Eagle Capital Management highlighted Humana Inc. (NYSE:HUM). Humana Inc. (NYSE:HUM) is an American insurance company that provides medical and specialty insurance products. On September 02, 2026, Humana Inc. (NYSE:HUM) closed at $400.97 per share. Over the past month, Humana Inc. (NYSE:HUM) returned 9.18%, and its shares gained 28.52% over the past 52 weeks. Humana Inc. (NYSE:HUM) has a market capitalization of $48.15 billion with a 52-week trading range between $163.11 and $428.88.
Eagle Capital Management stated the following regarding Humana Inc. (NYSE:HUM) in its Q2 2026 investor letter:
"Managed care (13% of capital): UnitedHealth Group, Humana Inc. (NYSE:HUM), Elevance: These managed care companies have significant scale advantages in a consolidated industry that outgrows the overall economy. The industry moves with its own cycle and, over the last several years, has faced cost/price pressures in Medicare Advantage and Medicaid. Even the largest firms are earning poor margins, and some weaker firms are unprofitable. We believe conditions have bottomed out and that we are transitioning to a multi-year improvement in margins and earnings. Al-driven technology projects can both reduce costs and improve service quality. Humana is also making good strides, and we expect significantly improved Star ratings for the company later this year. We expect EPS growth of 15-20% over the next several years, driven by moderate revenue growth and significantly expanding margins."
#eagle
In its second-quarter 2026 investor letter, Eagle Capital Management highlighted Humana Inc. (NYSE:HUM). Humana Inc. (NYSE:HUM) is an American insurance company that provides medical and specialty insurance products. On September 02, 2026, Humana Inc. (NYSE:HUM) closed at $400.97 per share. Over the past month, Humana Inc. (NYSE:HUM) returned 9.18%, and its shares gained 28.52% over the past 52 weeks. Humana Inc. (NYSE:HUM) has a market capitalization of $48.15 billion with a 52-week trading range between $163.11 and $428.88.
Eagle Capital Management stated the following regarding Humana Inc. (NYSE:HUM) in its Q2 2026 investor letter:
"Managed care (13% of capital): UnitedHealth Group, Humana Inc. (NYSE:HUM), Elevance: These managed care companies have significant scale advantages in a consolidated industry that outgrows the overall economy. The industry moves with its own cycle and, over the last several years, has faced cost/price pressures in Medicare Advantage and Medicaid. Even the largest firms are earning poor margins, and some weaker firms are unprofitable. We believe conditions have bottomed out and that we are transitioning to a multi-year improvement in margins and earnings. Al-driven technology projects can both reduce costs and improve service quality. Humana is also making good strides, and we expect significantly improved Star ratings for the company later this year. We expect EPS growth of 15-20% over the next several years, driven by moderate revenue growth and significantly expanding margins."
#eagle


14 days ago
Sands Capital, an investment management company, released its "Sands Capital Select Growth Fund" Q2 2026 investor letter. The letter can be downloaded here. Select Growth Fund targets U.S. businesses driving significant structural change through disruptive innovation. The fund returned 23.2% in the quarter, outperforming the Russell 1000 Growth Index's 16.7% gain. U.S. large-cap growth equities rebounded sharply, driven by improving corporate fundamentals and renewed investor confidence in AI, despite geopolitical uncertainties. However, the market's gains were narrow, concentrated among AI beneficiaries. The portfolio's success stemmed from strength in AI infrastructure holdings, especially memory and storage, supported by better pricing and tightening supply. As AI development advances, continuous demand for compute capacity is expected, prompting investments in memory, CPUs, AI chips, and semiconductor manufacturing to address emerging bottlenecks essential for scaling AI. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Sands Capital Select Growth Fund highlighted DoorDash, Inc. (NASDAQ:DASH). DoorDash, Inc. (NASDAQ:DASH) is a US-based leading online food ordering and delivery platform. On September 2, 2026, DoorDash, Inc. (NASDAQ:DASH) closed at $226.24 per share. DoorDash, Inc. (NASDAQ:DASH) returned 8.87% over the past month, while its shares lost 9.06% over the past 52 weeks. DoorDash, Inc. (NASDAQ:DASH) has a market capitalization of $98.04 billion.
Sands Capital Select Growth Fund stated the following regarding DoorDash, Inc. (NASDAQ:DASH) in its Q2 2026 investor letter:
"The sales of DoorDash, Inc. (NASDAQ:DASH) and Nu Holdings reflected the high bar for inclusion in a concentrated portfolio of roughly 30 businesses. We continue to view both companies as high-quality businesses and will monitor them closely but believe the portfolio would be better served by reallocating capital toward AI infrastructure beneficiaries and other idiosyncratic growth opportunities."
DoorDash, Inc. (NASDAQ:DASH) is on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 107 hedge fund portfolios held DoorDash, Inc. (NASDAQ:DASH) at the end of the second quarter which was 117 in the previous quarter. While we acknowledge the potential of DoorDash, Inc. (NASDAQ:DASH) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#doordash #dash #letter
In its second-quarter 2026 investor letter, Sands Capital Select Growth Fund highlighted DoorDash, Inc. (NASDAQ:DASH). DoorDash, Inc. (NASDAQ:DASH) is a US-based leading online food ordering and delivery platform. On September 2, 2026, DoorDash, Inc. (NASDAQ:DASH) closed at $226.24 per share. DoorDash, Inc. (NASDAQ:DASH) returned 8.87% over the past month, while its shares lost 9.06% over the past 52 weeks. DoorDash, Inc. (NASDAQ:DASH) has a market capitalization of $98.04 billion.
Sands Capital Select Growth Fund stated the following regarding DoorDash, Inc. (NASDAQ:DASH) in its Q2 2026 investor letter:
"The sales of DoorDash, Inc. (NASDAQ:DASH) and Nu Holdings reflected the high bar for inclusion in a concentrated portfolio of roughly 30 businesses. We continue to view both companies as high-quality businesses and will monitor them closely but believe the portfolio would be better served by reallocating capital toward AI infrastructure beneficiaries and other idiosyncratic growth opportunities."
DoorDash, Inc. (NASDAQ:DASH) is on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 107 hedge fund portfolios held DoorDash, Inc. (NASDAQ:DASH) at the end of the second quarter which was 117 in the previous quarter. While we acknowledge the potential of DoorDash, Inc. (NASDAQ:DASH) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#doordash #dash #letter

14 days ago
Sands Capital, an investment management company, released its "Sands Capital Select Growth Fund" Q2 2026 investor letter. The letter can be downloaded here. Select Growth Fund targets U.S. businesses driving significant structural change through disruptive innovation. The fund returned 23.2% in the quarter, outperforming the Russell 1000 Growth Index's 16.7% gain. U.S. large-cap growth equities rebounded sharply, driven by improving corporate fundamentals and renewed investor confidence in AI, despite geopolitical uncertainties. However, the market's gains were narrow, concentrated among AI beneficiaries. The portfolio's success stemmed from strength in AI infrastructure holdings, especially memory and storage, supported by better pricing and tightening supply. As AI development advances, continuous demand for compute capacity is expected, prompting investments in memory, CPUs, AI chips, and semiconductor manufacturing to address emerging bottlenecks essential for scaling AI. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Sands Capital Select Growth Fund highlighted Micron Technology, Inc. (NASDAQ:MU). Micron Technology, Inc. (NASDAQ:MU) is a leading semiconductor company manufacturing memory and storage products. On September 02, 2026, Micron Technology, Inc. (NASDAQ:MU) closed at $956.08 per share. Over the past month, Micron Technology, Inc. (NASDAQ:MU) returned 8.46%, but its shares are up 669.73% over the past year. Micron Technology, Inc. (NASDAQ:MU) has a market capitalization of $1.08 trillion, and its stock has traded within a 52-week range of $118.52 to $1,255.00.
Sands Capital Select Growth Fund stated the following regarding Micron Technology, Inc. (NASDAQ:MU) in its Q2 2026 investor letter:
"Micron Technology, Inc. (NASDAQ:MU) and SanDisk increased the portfolio's exposure to memory, which has become a critical bottleneck in the AI infrastructure stack. Agentic AI systems require greater context, faster retrieval, and more persistent memory, increasing demand for DRAM, high-bandwidth memory, and NAND. At the same time, advanced memory remains difficult, capital intensive, and time consuming to manufacture. The industry has also become more consolidated and disciplined, which should limit the speed of supply response. We believe this combination of accelerating demand and constrained supply can support stronger pricing, better margins, and a more durable earnings cycle for leading memory providers."
#NASDAQ #fund #sands #investor
In its second-quarter 2026 investor letter, Sands Capital Select Growth Fund highlighted Micron Technology, Inc. (NASDAQ:MU). Micron Technology, Inc. (NASDAQ:MU) is a leading semiconductor company manufacturing memory and storage products. On September 02, 2026, Micron Technology, Inc. (NASDAQ:MU) closed at $956.08 per share. Over the past month, Micron Technology, Inc. (NASDAQ:MU) returned 8.46%, but its shares are up 669.73% over the past year. Micron Technology, Inc. (NASDAQ:MU) has a market capitalization of $1.08 trillion, and its stock has traded within a 52-week range of $118.52 to $1,255.00.
Sands Capital Select Growth Fund stated the following regarding Micron Technology, Inc. (NASDAQ:MU) in its Q2 2026 investor letter:
"Micron Technology, Inc. (NASDAQ:MU) and SanDisk increased the portfolio's exposure to memory, which has become a critical bottleneck in the AI infrastructure stack. Agentic AI systems require greater context, faster retrieval, and more persistent memory, increasing demand for DRAM, high-bandwidth memory, and NAND. At the same time, advanced memory remains difficult, capital intensive, and time consuming to manufacture. The industry has also become more consolidated and disciplined, which should limit the speed of supply response. We believe this combination of accelerating demand and constrained supply can support stronger pricing, better margins, and a more durable earnings cycle for leading memory providers."
#NASDAQ #fund #sands #investor


14 days ago
Moneywise and Yahoo Finance LLC may earn commission or revenue through links in the content below.
For millions of seniors across the country, Social Security is the bedrock of their retirement. After decades of paying into the system, these seniors are finally getting what they were promised: a steady and inflation-hedged stream of monthly payments.
On average, a retired beneficiary receives $2,085.98 a month from the program, according to the Social Security Administration's (SSA's) Monthly Statistical Snapshot for July (1). But the actual amount received by beneficiaries has a wide range depending on their age of claim, work history and other factors.
Jeff Bezos backs a platform that lets anyone invest in rental homes for as little as $100 — 6 ways to build wealth like a landlord without actually being one
JPMorgan sees gold hitting $5,000/oz by Q4 — and savvy investors are protecting their wealth with a tax-advantaged Gold IRA. Get your free guide from Priority Gold
#seniors
For millions of seniors across the country, Social Security is the bedrock of their retirement. After decades of paying into the system, these seniors are finally getting what they were promised: a steady and inflation-hedged stream of monthly payments.
On average, a retired beneficiary receives $2,085.98 a month from the program, according to the Social Security Administration's (SSA's) Monthly Statistical Snapshot for July (1). But the actual amount received by beneficiaries has a wide range depending on their age of claim, work history and other factors.
Jeff Bezos backs a platform that lets anyone invest in rental homes for as little as $100 — 6 ways to build wealth like a landlord without actually being one
JPMorgan sees gold hitting $5,000/oz by Q4 — and savvy investors are protecting their wealth with a tax-advantaged Gold IRA. Get your free guide from Priority Gold
#seniors

15 days ago
Investors are awaiting the fourth-quarter earnings release of cybersecurity firm Zscaler (ZS), which is scheduled for Sept. 3, after the market closes. Ahead of that, investors have lifted the company's stock, expecting the earnings to provide tailwinds.
Cybersecurity spending is expected to be a priority in this era of artificial intelligence (AI). Recently, a series of AI hacking incidents brought the importance of cybersecurity to the forefront. Therefore, there's a chance that while chips and data centers were the biggest beneficiaries of the first wave of the AI boom, cybersecurity could steal that spot in the next wave and experience a spending boom.
Dear GameStop Stock Fans, Mark Your Calendars for September 8
Why ***** ysts Think Sellas Life Sciences Stock Can Gain 150% From Here
Jensen Huang: Nvidia's Vera Rubin Platform Turns Electricity Into a $40 Billion Cash Machine
#spending
Cybersecurity spending is expected to be a priority in this era of artificial intelligence (AI). Recently, a series of AI hacking incidents brought the importance of cybersecurity to the forefront. Therefore, there's a chance that while chips and data centers were the biggest beneficiaries of the first wave of the AI boom, cybersecurity could steal that spot in the next wave and experience a spending boom.
Dear GameStop Stock Fans, Mark Your Calendars for September 8
Why ***** ysts Think Sellas Life Sciences Stock Can Gain 150% From Here
Jensen Huang: Nvidia's Vera Rubin Platform Turns Electricity Into a $40 Billion Cash Machine
#spending


15 days ago
Artisan Partners, an investment management company, released its second-quarter 2026 investor commentary for the "Artisan Global Opportunities Strategy". The letter can be downloaded here. Global equities rebounded sharply during the quarter, with the MSCI ACWI Index returning 15.3% as resilient economic growth, strong corporate earnings, and continued enthusiasm around artificial intelligence supported markets despite persistent inflation, higher bond yields, and geopolitical uncertainty. The portfolio reported strong absolute returns of 12.65% (net) but underperformed the benchmark, mainly because of its underweight exposure to information technology and overweight position in health care. Strong stock selection in technology and energy partially offset these headwinds. The fund continues to see attractive long-term opportunities across AI infrastructure, health care and consumer internet, while remaining disciplined on valuation as several AI-related stocks have appreciated sharply. Management remains focused on durable franchises with identifiable profit cycles and attractive long-term earnings potential. Also, check the Strategy's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Artisan Global Opportunities Strategy highlighted Corning Incorporated (NYSE:GLW) as a new position. Corning Incorporated (NYSE:GLW) is a technology company that operates through optical communication, display technologies, environmental technologies, specialty materials, and life sciences business segments. On September 01, 2026, Corning Incorporated (NYSE:GLW) closed at $145.56 per share. Corning Incorporated (NYSE:GLW) declined 8.08% over the past month, while its shares gained 107.73% over the past 52 weeks. Corning Incorporated (NYSE:GLW) has a market capitalization of $125.38 billion with a 52-week trading range between $66.14 - $271.78.
Artisan Global Opportunities Strategy stated the following regarding Corning Incorporated (NYSE:GLW) in its Q2 2026 investor letter:
"During the quarter, we initiated positions in Corning Incorporated (NYSE:GLW). Corning and STMicroelectronics represent earlier stage semiconductor supply chain opportunities that we believe will see growing demand as AI infrastructure spending broadens beyond today's most obvious beneficiaries. In both cases, we see a potential opportunity for higher value, higher margin products as data centers require greater optical connectivity, semiconductor content and related infrastructure. Corning is a leading global supplier of specialty glass and optical connectivity solutions. We initiated a GardenSM position because we believe Corning is well positioned to meet rising optical connectivity needs as AI infrastructure shifts toward larger clusters and scale-up architectures. While we are not early to the story, we believe the company's fiber capacity, US-based manufacturing footprint and ability to deliver higher complexity optical solutions to hyperscaler
In its second-quarter 2026 investor letter, Artisan Global Opportunities Strategy highlighted Corning Incorporated (NYSE:GLW) as a new position. Corning Incorporated (NYSE:GLW) is a technology company that operates through optical communication, display technologies, environmental technologies, specialty materials, and life sciences business segments. On September 01, 2026, Corning Incorporated (NYSE:GLW) closed at $145.56 per share. Corning Incorporated (NYSE:GLW) declined 8.08% over the past month, while its shares gained 107.73% over the past 52 weeks. Corning Incorporated (NYSE:GLW) has a market capitalization of $125.38 billion with a 52-week trading range between $66.14 - $271.78.
Artisan Global Opportunities Strategy stated the following regarding Corning Incorporated (NYSE:GLW) in its Q2 2026 investor letter:
"During the quarter, we initiated positions in Corning Incorporated (NYSE:GLW). Corning and STMicroelectronics represent earlier stage semiconductor supply chain opportunities that we believe will see growing demand as AI infrastructure spending broadens beyond today's most obvious beneficiaries. In both cases, we see a potential opportunity for higher value, higher margin products as data centers require greater optical connectivity, semiconductor content and related infrastructure. Corning is a leading global supplier of specialty glass and optical connectivity solutions. We initiated a GardenSM position because we believe Corning is well positioned to meet rising optical connectivity needs as AI infrastructure shifts toward larger clusters and scale-up architectures. While we are not early to the story, we believe the company's fiber capacity, US-based manufacturing footprint and ability to deliver higher complexity optical solutions to hyperscaler

15 days ago
Baron Capital, an investment management company, released its second-quarter 2026 investor letter for its "Baron Global Opportunity Fund". The letter can be downloaded here. The fund achieved a strong quarter, gaining 26.7% (Institutional Shares), exceeding a 14.9% gain for the MSCI ACWI Index (the Index), and a 19.8% gain for the MSCI ACWI Growth Index. YTD, the Fund is up 20.6% compared to gains of 11.3% and 10.6% for the benchmarks, respectively. In mid-2026, market patterns show similarities to the previous year, following three years of over 25% gains driven by a healthy economy and AI investments. Elevated geopolitical risks persisted, with a pullback likely. A tariff-related market dip was followed by a recovery, reflecting a growing market indifference to geopolitical uncertainties. Similarly, airstrikes against Iran and subsequent tension led to an initial market sell-off, yet a lull in hostilities led to a strong market rally. The Fund noted significant outperformance, credited to stock selection and sector allocation, with 1,173bps of overall outperformance relative to the Index. It excelled in developed markets while underperforming in emerging markets, particularly due to a spectacular rise in Korea. The Fund remains optimistic about its investments and seeks attractive opportunities. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Baron Global Opportunity Fund highlighted CrowdStrike Holdings, Inc. (NASDAQ:CRWD). CrowdStrike Holdings, Inc. (NASDAQ:CRWD), a leading cybersecurity technology company, contributed 2.23% to the fund's performance this quarter. On September 1, 2026, CrowdStrike Holdings, Inc. (NASDAQ:CRWD) closed at $215.07 per share. Over the past month, CrowdStrike Holdings, Inc. (NASDAQ:CRWD) declined 2.01%, but its shares are up 99.08% over the past year. CrowdStrike Holdings, Inc. (NASDAQ:CRWD) has a market capitalization of $220.22 billion.
Baron Global Opportunity Fund stated the following regarding CrowdStrike Holdings, Inc. (NASDAQ:CRWD) in its Q2 2026 investor letter:
"Leading cloud-native cybersecurity platform CrowdStrike Holdings, Inc. (NASDAQ:CRWD) contributed to performance during the quarter with the stock up 95.6% as the market increasingly recognized the company as one of the primary beneficiaries of enterprise AI adoption. As organizations increasingly adopt AI, cybersecurity has moved to the forefront of C-suite concerns, and CrowdStrike is well positioned to potentially benefit as a leading platform with unmatched data and a large installed base that helps it defend better against breaches. That standing was reinforced when CrowdStrike was named a launch partner in major AI-industry security collaborations, including Anthropic's Project Glasswing and OpenAI's Trusted Access for Cyber program, underscoring its role in addressing new security challenges created by AI. This is already translating into demand. CrowdStrike's AI detection
In its second-quarter 2026 investor letter, Baron Global Opportunity Fund highlighted CrowdStrike Holdings, Inc. (NASDAQ:CRWD). CrowdStrike Holdings, Inc. (NASDAQ:CRWD), a leading cybersecurity technology company, contributed 2.23% to the fund's performance this quarter. On September 1, 2026, CrowdStrike Holdings, Inc. (NASDAQ:CRWD) closed at $215.07 per share. Over the past month, CrowdStrike Holdings, Inc. (NASDAQ:CRWD) declined 2.01%, but its shares are up 99.08% over the past year. CrowdStrike Holdings, Inc. (NASDAQ:CRWD) has a market capitalization of $220.22 billion.
Baron Global Opportunity Fund stated the following regarding CrowdStrike Holdings, Inc. (NASDAQ:CRWD) in its Q2 2026 investor letter:
"Leading cloud-native cybersecurity platform CrowdStrike Holdings, Inc. (NASDAQ:CRWD) contributed to performance during the quarter with the stock up 95.6% as the market increasingly recognized the company as one of the primary beneficiaries of enterprise AI adoption. As organizations increasingly adopt AI, cybersecurity has moved to the forefront of C-suite concerns, and CrowdStrike is well positioned to potentially benefit as a leading platform with unmatched data and a large installed base that helps it defend better against breaches. That standing was reinforced when CrowdStrike was named a launch partner in major AI-industry security collaborations, including Anthropic's Project Glasswing and OpenAI's Trusted Access for Cyber program, underscoring its role in addressing new security challenges created by AI. This is already translating into demand. CrowdStrike's AI detection

15 days ago
Sands Capital, an investment management company, released its "Sands Capital Select Growth Fund" Q2 2026 investor letter. The letter can be downloaded here. Select Growth Fund targets U.S. businesses driving significant structural change through disruptive innovation. The fund returned 23.2% in the quarter, outperforming the Russell 1000 Growth Index's 16.7%. U.S. large-cap growth equities rebounded sharply, driven by improving corporate fundamentals and renewed investor confidence in AI, despite geopolitical uncertainties. However, the market's gains were narrow, concentrated among AI beneficiaries. The portfolio's success stemmed from strength in AI infrastructure holdings, especially memory and storage, supported by better pricing and tightening supply. As AI development advances, continuous demand for compute capacity is expected, prompting investments in memory, CPUs, AI chips, and semiconductor manufacturing to address emerging bottlenecks essential for scaling AI. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Sands Capital Select Growth Fund highlighted Intercontinental Exchange, Inc. (NYSE:ICE), a US-based financial services company that provides technology, data, and market infrastructure to financial institutions, corporations, and government entities. On September 1, 2026, Intercontinental Exchange, Inc. (NYSE:ICE) closed at $159.60 per share. Over the past month, Intercontinental Exchange, Inc. (NYSE:ICE) returned 4.85%, while its shares have declined 10.30% in the last 52 weeks. Intercontinental Exchange, Inc. (NYSE:ICE) has a market capitalization of $89.6 billion, and its stock has traded within a 52-week range of $121.79 to $177.00.
Sands Capital Select Growth Fund stated the following regarding Intercontinental Exchange, Inc. (NYSE:ICE) in its Q2 2026 investor letter:
"Intercontinental Exchange, Inc. (NYSE:ICE) is one of the world's largest operators of financial exchanges and clearinghouses. Shares declined as investor concerns around AI disruption in ICE's Mortgage business and potential competition from perpetual futures contracts weighed on the stock. Much of the underperformance appears to reflect multiple compression rather than a weakening of fundamentals, which remain solid. In our view, the market is overestimating the risk that AI will displace ICE Mortgage. The business is not simply a workflow solution; it is a platform that connects lenders, data vendors, and other participants required to originate, sell, and service mortgages, while also serving as a system of record for a significant portion of the U.S. mortgage ecosystem. We also believe concerns around perpetual futures competition are overstated, as the structure of these products may limit their use in institutional hedging and risk management, particularly before accounting for liquidity. As such, we believe the recent sell-off more than discounts these risks."
#investor
In its second-quarter 2026 investor letter, Sands Capital Select Growth Fund highlighted Intercontinental Exchange, Inc. (NYSE:ICE), a US-based financial services company that provides technology, data, and market infrastructure to financial institutions, corporations, and government entities. On September 1, 2026, Intercontinental Exchange, Inc. (NYSE:ICE) closed at $159.60 per share. Over the past month, Intercontinental Exchange, Inc. (NYSE:ICE) returned 4.85%, while its shares have declined 10.30% in the last 52 weeks. Intercontinental Exchange, Inc. (NYSE:ICE) has a market capitalization of $89.6 billion, and its stock has traded within a 52-week range of $121.79 to $177.00.
Sands Capital Select Growth Fund stated the following regarding Intercontinental Exchange, Inc. (NYSE:ICE) in its Q2 2026 investor letter:
"Intercontinental Exchange, Inc. (NYSE:ICE) is one of the world's largest operators of financial exchanges and clearinghouses. Shares declined as investor concerns around AI disruption in ICE's Mortgage business and potential competition from perpetual futures contracts weighed on the stock. Much of the underperformance appears to reflect multiple compression rather than a weakening of fundamentals, which remain solid. In our view, the market is overestimating the risk that AI will displace ICE Mortgage. The business is not simply a workflow solution; it is a platform that connects lenders, data vendors, and other participants required to originate, sell, and service mortgages, while also serving as a system of record for a significant portion of the U.S. mortgage ecosystem. We also believe concerns around perpetual futures competition are overstated, as the structure of these products may limit their use in institutional hedging and risk management, particularly before accounting for liquidity. As such, we believe the recent sell-off more than discounts these risks."
#investor


15 days ago
Sands Capital, an investment management company, released its "Sands Capital Select Growth Fund" Q2 2026 investor letter. The letter can be downloaded here. Select Growth Fund targets U.S. businesses driving significant structural change through disruptive innovation. The fund returned 23.2% in the quarter, outperforming the Russell 1000 Growth Index's 16.7%. U.S. large-cap growth equities rebounded sharply, driven by improving corporate fundamentals and renewed investor confidence in AI, despite geopolitical uncertainties. However, the market's gains were narrow, concentrated among AI beneficiaries. The portfolio's success stemmed from strength in AI infrastructure holdings, especially memory and storage, supported by better pricing and tightening supply. As AI development advances, continuous demand for compute capacity is expected, prompting investments in memory, CPUs, AI chips, and semiconductor manufacturing to address emerging bottlenecks essential for scaling AI. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Sands Capital Select Growth Fund highlighted Sphere Entertainment Co. (NYSE:SPHR). Sphere Entertainment Co. (NYSE:SPHR) is a US-based live entertainment and media company. On September 1, 2026, Sphere Entertainment Co. (NYSE:SPHR) closed at $133.30 per share, reflecting a market capitalization of $4.79 billion. Sphere Entertainment Co. (NYSE:SPHR) posted a one-month return of -17.02%, while its shares gained 175.53% over the past 52 weeks.
Sands Capital Select Growth Fund stated the following regarding Sphere Entertainment Co. (NYSE:SPHR) in its Q2 2026 investor letter:
"Sphere Entertainment Co. (NYSE:SPHR) and ****** e Exploration Technologies (SpaceX) were added as more idiosyncratic growth opportunities. Sphere is creating a new category of immersive live entertainment, where we believe premium in-person experiences may become more valuable as digital content becomes increasingly abundant. Its Las Vegas venue combines live events, original content, and proprietary technology, creating the potential for high utilization and attractive venue-level economics. Over time, the investment case depends on Sphere's ability to scale beyond Las Vegas through additional venues, licensing, and high-margin content monetization."
Sphere Entertainment Co. (NYSE:SPHR) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 1 hedge fund portfolios held Sphere Entertainment Co. (NYSE:SPHR) at the end of the second quarter, which was 2 in the previous quarter. While we acknowledge the potential of Sphere Entertainment Co. (NYSE:SPHR) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#NYSE #s
In its second-quarter 2026 investor letter, Sands Capital Select Growth Fund highlighted Sphere Entertainment Co. (NYSE:SPHR). Sphere Entertainment Co. (NYSE:SPHR) is a US-based live entertainment and media company. On September 1, 2026, Sphere Entertainment Co. (NYSE:SPHR) closed at $133.30 per share, reflecting a market capitalization of $4.79 billion. Sphere Entertainment Co. (NYSE:SPHR) posted a one-month return of -17.02%, while its shares gained 175.53% over the past 52 weeks.
Sands Capital Select Growth Fund stated the following regarding Sphere Entertainment Co. (NYSE:SPHR) in its Q2 2026 investor letter:
"Sphere Entertainment Co. (NYSE:SPHR) and ****** e Exploration Technologies (SpaceX) were added as more idiosyncratic growth opportunities. Sphere is creating a new category of immersive live entertainment, where we believe premium in-person experiences may become more valuable as digital content becomes increasingly abundant. Its Las Vegas venue combines live events, original content, and proprietary technology, creating the potential for high utilization and attractive venue-level economics. Over time, the investment case depends on Sphere's ability to scale beyond Las Vegas through additional venues, licensing, and high-margin content monetization."
Sphere Entertainment Co. (NYSE:SPHR) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 1 hedge fund portfolios held Sphere Entertainment Co. (NYSE:SPHR) at the end of the second quarter, which was 2 in the previous quarter. While we acknowledge the potential of Sphere Entertainment Co. (NYSE:SPHR) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#NYSE #s

15 days ago
Sands Capital, an investment management company, released its "Sands Capital Select Growth Fund" Q2 2026 investor letter. The letter can be downloaded here. Select Growth Fund targets U.S. businesses driving significant structural change through disruptive innovation. The fund returned 23.2% in the quarter, outperforming the Russell 1000 Growth Index at 16.7%. U.S. large-cap growth equities rebounded sharply, driven by improving corporate fundamentals and renewed investor confidence in AI, despite geopolitical uncertainties. However, the market's gains were narrow, concentrated among AI beneficiaries. The portfolio's success stemmed from strength in AI infrastructure holdings, especially memory and storage, supported by better pricing and tightening supply. As AI development advances, continuous demand for compute capacity is expected, prompting investments in memory, CPUs, AI chips, and semiconductor manufacturing to address emerging bottlenecks essential for scaling AI. Also, check the fund's top five holdings to see its best picks in 2026.
In its Q2 2026 investor letter, Sands Capital Select Growth Fund highlighted Carpenter Technology Corporation (NYSE:CRS), a specialty metals manufacturer serving diversified industries. Carpenter Technology Corporation (NYSE:CRS), held since 2025 with a 4.2% portfolio weight, contributed 1.7% to the Fund's performance this quarter. On September 1, 2026, Carpenter Technology Corporation (NYSE:CRS) closed at $473.06 per share. Over the past month, Carpenter Technology Corporation (NYSE:CRS) declined 17.06%, while its shares are up 100.69% over the past year. Carpenter Technology Corporation (NYSE:CRS) has a market capitalization of $23.44 billion, and its stock has traded within a 52-week range of $228.00 to $625.99.
Sands Capital Select Growth Fund stated the following regarding Carpenter Technology Corporation (NYSE:CRS) in its Q2 2026 investor letter:
"Carpenter Technology Corporation (NYSE:CRS) is a leading supplier of specialty nickel alloys for the aerospace industry. Fiscal third quarter results reinforced our margin thesis as the company demonstrated significant operating leverage as the aerospace equipment cycle continued to recover. Specialty Alloys Operations generated an 86 percent incremental margin in a quarter when volume grew at its strongest rate since the post-COVID aerospace recovery. In our view, the results helped validate that Carpenter's earnings power can continue to expand as the business benefits from improving volume, pricing, and mix. We maintain conviction, supported by Carpenter Technology's specialized materials leadership, pricing power, and exposure to a multiyear aerospace production recovery."
#technology #corporation #capital #select
In its Q2 2026 investor letter, Sands Capital Select Growth Fund highlighted Carpenter Technology Corporation (NYSE:CRS), a specialty metals manufacturer serving diversified industries. Carpenter Technology Corporation (NYSE:CRS), held since 2025 with a 4.2% portfolio weight, contributed 1.7% to the Fund's performance this quarter. On September 1, 2026, Carpenter Technology Corporation (NYSE:CRS) closed at $473.06 per share. Over the past month, Carpenter Technology Corporation (NYSE:CRS) declined 17.06%, while its shares are up 100.69% over the past year. Carpenter Technology Corporation (NYSE:CRS) has a market capitalization of $23.44 billion, and its stock has traded within a 52-week range of $228.00 to $625.99.
Sands Capital Select Growth Fund stated the following regarding Carpenter Technology Corporation (NYSE:CRS) in its Q2 2026 investor letter:
"Carpenter Technology Corporation (NYSE:CRS) is a leading supplier of specialty nickel alloys for the aerospace industry. Fiscal third quarter results reinforced our margin thesis as the company demonstrated significant operating leverage as the aerospace equipment cycle continued to recover. Specialty Alloys Operations generated an 86 percent incremental margin in a quarter when volume grew at its strongest rate since the post-COVID aerospace recovery. In our view, the results helped validate that Carpenter's earnings power can continue to expand as the business benefits from improving volume, pricing, and mix. We maintain conviction, supported by Carpenter Technology's specialized materials leadership, pricing power, and exposure to a multiyear aerospace production recovery."
#technology #corporation #capital #select


15 days ago
Sands Capital, an investment management company, released its "Sands Capital Select Growth Fund" Q2 2026 investor letter. The letter can be downloaded here. Select Growth Fund targets U.S. businesses driving significant structural change through disruptive innovation. The fund returned 23.2% in the quarter, outperforming the Russell 1000 Growth Index's 16.7%. U.S. large-cap growth equities rebounded sharply, driven by improving corporate fundamentals and renewed investor confidence in AI, despite geopolitical uncertainties. However, the market's gains were narrow, concentrated among AI beneficiaries. The portfolio's success stemmed from strength in AI infrastructure holdings, especially memory and storage, supported by better pricing and tightening supply. As AI development advances, continuous demand for compute capacity is expected, prompting investments in memory, CPUs, AI chips, and semiconductor manufacturing to address emerging bottlenecks essential for scaling AI. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Sands Capital Select Growth Fund highlighted Lam Research Corporation (NASDAQ:LRCX), a leading semiconductor equipment company that supplies semiconductor processing equipment. Lam Research Corporation (NASDAQ:LRCX), with a 4.7% portfolio weight, contributed 2.2% to the Fund's performance this quarter. On September 1, 2026, Lam Research Corporation (NASDAQ:LRCX) closed at $290.20 per share. Over the past month, Lam Research Corporation (NASDAQ:LRCX) declined 5.60%, but its shares are up 196.91% over the past year. Lam Research Corporation (NASDAQ:LRCX) has a market capitalization of $363.13 billion.
Sands Capital Select Growth Fund stated the following regarding Lam Research Corporation (NASDAQ:LRCX) in its Q2 2026 investor letter:
"Lam Research Corporation (NASDAQ:LRCX) is a leading global provider of semiconductor fabrication equipment. Shares of the business benefited from renewed confidence in semiconductor capital spending and the rising complexity of chip manufacturing. In the first quarter, revenue grew 24 percent and adjusted earnings per share grew 42 percent year over year, while June-quarter guidance exceeded consensus expectations. The company is a critical supplier of etch and deposition equipment, both of which become increasingly important as memory architectures and leading-edge semiconductor manufacturing grow more complex. We believe Lam's exposure to high-bandwidth memory, advanced NAND, and a recovering memory investment cycle gives it a differentiated role within the AI infrastructure supply chain."
#NASDAQ #fund #select
In its second-quarter 2026 investor letter, Sands Capital Select Growth Fund highlighted Lam Research Corporation (NASDAQ:LRCX), a leading semiconductor equipment company that supplies semiconductor processing equipment. Lam Research Corporation (NASDAQ:LRCX), with a 4.7% portfolio weight, contributed 2.2% to the Fund's performance this quarter. On September 1, 2026, Lam Research Corporation (NASDAQ:LRCX) closed at $290.20 per share. Over the past month, Lam Research Corporation (NASDAQ:LRCX) declined 5.60%, but its shares are up 196.91% over the past year. Lam Research Corporation (NASDAQ:LRCX) has a market capitalization of $363.13 billion.
Sands Capital Select Growth Fund stated the following regarding Lam Research Corporation (NASDAQ:LRCX) in its Q2 2026 investor letter:
"Lam Research Corporation (NASDAQ:LRCX) is a leading global provider of semiconductor fabrication equipment. Shares of the business benefited from renewed confidence in semiconductor capital spending and the rising complexity of chip manufacturing. In the first quarter, revenue grew 24 percent and adjusted earnings per share grew 42 percent year over year, while June-quarter guidance exceeded consensus expectations. The company is a critical supplier of etch and deposition equipment, both of which become increasingly important as memory architectures and leading-edge semiconductor manufacturing grow more complex. We believe Lam's exposure to high-bandwidth memory, advanced NAND, and a recovering memory investment cycle gives it a differentiated role within the AI infrastructure supply chain."
#NASDAQ #fund #select

15 days ago
Sands Capital, an investment management company, released its "Sands Capital Select Growth Fund" Q2 2026 investor letter. The letter can be downloaded here. Select Growth Fund targets U.S. businesses driving significant structural change through disruptive innovation. The fund returned 23.2% in the quarter, outperforming the Russell 1000 Growth Index's 16.7%. U.S. large-cap growth equities rebounded sharply, driven by improving corporate fundamentals and renewed investor confidence in AI, despite geopolitical uncertainties. However, the market's gains were narrow, concentrated among AI beneficiaries. The portfolio's success stemmed from strength in AI infrastructure holdings, especially memory and storage, supported by better pricing and tightening supply. As AI development advances, continuous demand for compute capacity is expected, prompting investments in memory, CPUs, AI chips, and semiconductor manufacturing to address emerging bottlenecks essential for scaling AI. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Sands Capital Select Growth Fund highlighted Shopify Inc. (NASDAQ:SHOP). Shopify Inc. (NASDAQ:SHOP), a Canada-based e-commerce technology company that provides a cloud-based platform for individuals and companies to create and manage their operations, detracted from performance in the quarter. On September 01, 2026, Shopify Inc. (NASDAQ:SHOP) closed at $139.82 per share. Over the past month, Shopify Inc. (NASDAQ:SHOP) declined 3.06%, and its shares are down 0.29% over the past year. Shopify Inc. (NASDAQ:SHOP) has a market capitalization of $181.44 billion, and its stock has traded within a 52-week range of $94.00 to $182.19.
Sands Capital Select Growth Fund stated the following regarding Shopify Inc. (NASDAQ:SHOP) in its Q2 2026 investor letter:
"Shopify Inc. (NASDAQ:SHOP) is a leading global ecommerce platform enabling the next generation of retail. Shares declined as concerns around AI-related expenses and forward guidance overshadowed strong quarterly results. Revenue grew 32 percent, the company's fastest growth rate since 2021, supported by strength in North America and higher payments penetration. Investors focused on rising LLM costs ***** ociated with Sidekick, Shopify's AI ***** istant, and second-quarter guidance that implied sequential deceleration. In our view, these concerns are manageable. Shopify is embedding AI into its platform to improve merchant productivity, product discovery, conversion, and win rates, creating potential latent pricing power over time. Early traction is encouraging, with Sidekick usage up 400 percent and Campaigns usage up 300 percent year over year. We maintain conviction in Shopify's long-term growth, supported by enterprise adoption, international expansion, rising take rate, and AI-driven discovery and product enhancements."
#shop
In its second-quarter 2026 investor letter, Sands Capital Select Growth Fund highlighted Shopify Inc. (NASDAQ:SHOP). Shopify Inc. (NASDAQ:SHOP), a Canada-based e-commerce technology company that provides a cloud-based platform for individuals and companies to create and manage their operations, detracted from performance in the quarter. On September 01, 2026, Shopify Inc. (NASDAQ:SHOP) closed at $139.82 per share. Over the past month, Shopify Inc. (NASDAQ:SHOP) declined 3.06%, and its shares are down 0.29% over the past year. Shopify Inc. (NASDAQ:SHOP) has a market capitalization of $181.44 billion, and its stock has traded within a 52-week range of $94.00 to $182.19.
Sands Capital Select Growth Fund stated the following regarding Shopify Inc. (NASDAQ:SHOP) in its Q2 2026 investor letter:
"Shopify Inc. (NASDAQ:SHOP) is a leading global ecommerce platform enabling the next generation of retail. Shares declined as concerns around AI-related expenses and forward guidance overshadowed strong quarterly results. Revenue grew 32 percent, the company's fastest growth rate since 2021, supported by strength in North America and higher payments penetration. Investors focused on rising LLM costs ***** ociated with Sidekick, Shopify's AI ***** istant, and second-quarter guidance that implied sequential deceleration. In our view, these concerns are manageable. Shopify is embedding AI into its platform to improve merchant productivity, product discovery, conversion, and win rates, creating potential latent pricing power over time. Early traction is encouraging, with Sidekick usage up 400 percent and Campaigns usage up 300 percent year over year. We maintain conviction in Shopify's long-term growth, supported by enterprise adoption, international expansion, rising take rate, and AI-driven discovery and product enhancements."
#shop


15 days ago
Sands Capital, an investment management company, released its "Sands Capital Select Growth Fund" Q2 2026 investor letter. The letter can be downloaded here. Select Growth Fund targets U.S. businesses driving significant structural change through disruptive innovation. The fund returned 23.2% in the quarter, outperforming the Russell 1000 Growth Index's 16.7%. U.S. large-cap growth equities rebounded sharply, driven by improving corporate fundamentals and renewed investor confidence in AI, despite geopolitical uncertainties. However, the market's gains were narrow, concentrated among AI beneficiaries. The portfolio's success stemmed from strength in AI infrastructure holdings, especially memory and storage, supported by better pricing and tightening supply. As AI development advances, continuous demand for compute capacity is expected, prompting investments in memory, CPUs, AI chips, and semiconductor manufacturing to address emerging bottlenecks essential for scaling AI. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Sands Capital Technology Innovators Fund highlighted Spotify Technology S.A. (NYSE:SPOT). Spotify Technology S.A. (NYSE:SPOT) is a leading audio streaming subscription service provider monetizing through paid premium subscriptions and an ad-supported model. On September 1, 2026, Spotify Technology S.A. (NYSE:SPOT) closed at $544.15 per share. Over the past month, Spotify Technology S.A. (NYSE:SPOT) returned 12.84%, but its shares are down 21.97% over the past year. Spotify Technology S.A. (NYSE:SPOT) has a market capitalization of $111.86 billion, and its stock has traded within a 52-week range of $405.00 to $745.00.
Sands Capital Technology Innovators Fund stated the following regarding Spotify Technology S.A. (NYSE:SPOT) in its Q2 2026 investor letter:
"Spotify Technology S.A. (NYSE:SPOT) shares declined following first-quarter results after management guided margins lower due to a near-term increase in operating expenses. In our view, this spending reflects investment in future product development rather than a structurally higher cost base and likely signals the early stages of a new AI-enabled product cycle. Spotify's 2026 investor day helped address concerns around AI by reinforcing that AI could expand, rather than impair, the business model. Management highlighted a path to mid teens revenue growth through 2030, supported by new monetization opportunities, including AI music features, Audiobook+, and personal podcasts. The Universal Music Group partnership also provides a potential path to turn AI music into a paid feature. We believe Spotify's scale, pricing power, and distribution advantage position it to convert AI-enabled products into higher revenue per user and long-term margin expansion."
#spotify
In its second-quarter 2026 investor letter, Sands Capital Technology Innovators Fund highlighted Spotify Technology S.A. (NYSE:SPOT). Spotify Technology S.A. (NYSE:SPOT) is a leading audio streaming subscription service provider monetizing through paid premium subscriptions and an ad-supported model. On September 1, 2026, Spotify Technology S.A. (NYSE:SPOT) closed at $544.15 per share. Over the past month, Spotify Technology S.A. (NYSE:SPOT) returned 12.84%, but its shares are down 21.97% over the past year. Spotify Technology S.A. (NYSE:SPOT) has a market capitalization of $111.86 billion, and its stock has traded within a 52-week range of $405.00 to $745.00.
Sands Capital Technology Innovators Fund stated the following regarding Spotify Technology S.A. (NYSE:SPOT) in its Q2 2026 investor letter:
"Spotify Technology S.A. (NYSE:SPOT) shares declined following first-quarter results after management guided margins lower due to a near-term increase in operating expenses. In our view, this spending reflects investment in future product development rather than a structurally higher cost base and likely signals the early stages of a new AI-enabled product cycle. Spotify's 2026 investor day helped address concerns around AI by reinforcing that AI could expand, rather than impair, the business model. Management highlighted a path to mid teens revenue growth through 2030, supported by new monetization opportunities, including AI music features, Audiobook+, and personal podcasts. The Universal Music Group partnership also provides a potential path to turn AI music into a paid feature. We believe Spotify's scale, pricing power, and distribution advantage position it to convert AI-enabled products into higher revenue per user and long-term margin expansion."
#spotify

15 days ago
The SECURE Act forces most non-spouse inherited IRA beneficiaries to fully empty the account within 10 years, with no life-expectancy stretch available.
Waiting until year 10 to withdraw a full inherited IRA balance stacks ordinary income on top of salary, pushing marginal rates to 32%.
Spreading withdrawals across all 10 years to fill the 22% and 24% brackets avoids the single-year income spike that triggers higher rates.
Read More: Learn 7 ways to generate income with a $1,000,000+ portfolio (sponsor)
An inherited IRA is a retirement account passed to a beneficiary after the original owner dies. When the beneficiary is an adult child, the rules governing how quickly the money must be withdrawn have changed significantly under the SECURE Act. The scenario in the headline- a son who inherited a $220,000 IRA at age 60, deferred withdrawals, and then faced a forced distribution in year 10 that landed him in the 32% federal bracket- sits on a specific IRS rule that many beneficiaries misread.
#income
Waiting until year 10 to withdraw a full inherited IRA balance stacks ordinary income on top of salary, pushing marginal rates to 32%.
Spreading withdrawals across all 10 years to fill the 22% and 24% brackets avoids the single-year income spike that triggers higher rates.
Read More: Learn 7 ways to generate income with a $1,000,000+ portfolio (sponsor)
An inherited IRA is a retirement account passed to a beneficiary after the original owner dies. When the beneficiary is an adult child, the rules governing how quickly the money must be withdrawn have changed significantly under the SECURE Act. The scenario in the headline- a son who inherited a $220,000 IRA at age 60, deferred withdrawals, and then faced a forced distribution in year 10 that landed him in the 32% federal bracket- sits on a specific IRS rule that many beneficiaries misread.
#income


16 days ago
Hotchkis & Wiley, an investment management company, released its second-quarter 2026 investor letter for the "Large Cap Fundamental Value Fund." A copy can be downloaded here. Equity markets posted strong returns, with the Russell 1000 Value Index rising by 13.9%, although many individual stocks lagged. Notably, semiconductor stocks and AI-related sectors saw exceptional gains. The rally appeared speculative, marked by a stark difference in performance between high-beta and low-volatility stocks, along with momentum stocks outperforming the market significantly. Despite heightened enthusiasm for AI investments, concerns arise over inflated valuations reminiscent of the dot-com era. While there is substantial capital investment in AI, future earnings growth must justify these expenditures. The fund maintains a cautious approach towards perceived beneficiaries of AI, suggesting that select high-quality businesses with reasonable valuations may be better positioned. Historical trends suggest that speculative markets often revert to valuations based on fundamental economic realities, and the chosen investments are believed to be well-prepared for such a shift. The fund underperformed the index in the quarter and returned 5.69% vs. 13.87% for the Russell 1000 Value Index, largely due to a lack of exposure to high-performing sectors like semiconductors, while stock selection in healthcare provided a positive contribution. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Hotchkis & Wiley Large Cap Fundamental Value Fund highlighted Elevance Health, Inc. (NYSE:ELV) as a notable contributor. Elevance Health, Inc. (NYSE:ELV) is a US-based health benefits company. On August 31, 2026, Elevance Health, Inc. (NYSE:ELV) closed at $392.54 per share. Over the past month, Elevance Health, Inc. (NYSE:ELV) reported 3.85%, but its shares are up 21.78% over the past year. Elevance Health, Inc. (NYSE:ELV) has a market capitalization of $85.13 billion, and its stock has traded within a 52-week range of $274.84 to $436.24.
Hotchkis & Wiley Large Cap Fundamental Value Fund stated the following regarding Elevance Health, Inc. (NYSE:ELV) in its Q2 2026 investor letter:
"Elevance Health, Inc. (NYSE:ELV) is the second largest health insurer, and one of the largest commercial insurers in the United States. Shares rose during the quarter after the company reported quarterly earnings that beat consensus estimates. It was further supported by news that the US agreed to increase 2027 payments for private Medicare Advantage plans above the initial proposal. The company is priced at a discount to the market, driven by skepticism surrounding margins and growth, despite being a superior business that grows above GDP while returning most of its cash to shareholders."
#NYSE #fund #fundamental #wiley
In its second-quarter 2026 investor letter, Hotchkis & Wiley Large Cap Fundamental Value Fund highlighted Elevance Health, Inc. (NYSE:ELV) as a notable contributor. Elevance Health, Inc. (NYSE:ELV) is a US-based health benefits company. On August 31, 2026, Elevance Health, Inc. (NYSE:ELV) closed at $392.54 per share. Over the past month, Elevance Health, Inc. (NYSE:ELV) reported 3.85%, but its shares are up 21.78% over the past year. Elevance Health, Inc. (NYSE:ELV) has a market capitalization of $85.13 billion, and its stock has traded within a 52-week range of $274.84 to $436.24.
Hotchkis & Wiley Large Cap Fundamental Value Fund stated the following regarding Elevance Health, Inc. (NYSE:ELV) in its Q2 2026 investor letter:
"Elevance Health, Inc. (NYSE:ELV) is the second largest health insurer, and one of the largest commercial insurers in the United States. Shares rose during the quarter after the company reported quarterly earnings that beat consensus estimates. It was further supported by news that the US agreed to increase 2027 payments for private Medicare Advantage plans above the initial proposal. The company is priced at a discount to the market, driven by skepticism surrounding margins and growth, despite being a superior business that grows above GDP while returning most of its cash to shareholders."
#NYSE #fund #fundamental #wiley

16 days ago
Hotchkis & Wiley, an investment management company, released its second-quarter 2026 investor letter for the "Large Cap Fundamental Value Fund." A copy can be downloaded here. Equity markets posted strong returns, with the Russell 1000 Value Index rising by 13.9%, although many individual stocks lagged. Notably, semiconductor stocks and AI-related sectors saw exceptional gains. The rally appeared speculative, marked by a stark difference in performance between high-beta and low-volatility stocks, along with momentum stocks outperforming the market significantly. Despite heightened enthusiasm for AI investments, concerns arise over inflated valuations reminiscent of the dot-com era. While there is substantial capital investment in AI, future earnings growth must justify these expenditures. The fund maintains a cautious approach towards perceived beneficiaries of AI, suggesting that select high-quality businesses with reasonable valuations may be better positioned. Historical trends suggest that speculative markets often revert to valuations based on fundamental economic realities, and the chosen investments are believed to be well-prepared for such a shift. The fund underperformed the index in the quarter and returned 5.69% vs. 13.87% for the Russell 1000 Value Index, largely due to a lack of exposure to high-performing sectors like semiconductors, while stock selection in healthcare provided a positive contribution. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Hotchkis & Wiley Large Cap Fundamental Value Fund highlighted F5, Inc. (NASDAQ:FFIV) as one of its leading individual contributors. F5, Inc. (NASDAQ:FFIV) offers multi-cloud application security and delivery solutions. On August 31, 2026, F5, Inc. (NASDAQ:FFIV) closed at $407.13 per share. Over the past month, F5, Inc. (NASDAQ:FFIV) declined 3.41%, while its shares are up 29.82% over the past year. F5, Inc. (NASDAQ:FFIV) has a market capitalization of $23.05 billion, and its stock has traded within a 52-week range of $223.76 to $435.00.
Hotchkis & Wiley Large Cap Fundamental Value Fund stated the following regarding F5, Inc. (NASDAQ:FFIV) in its Q2 2026 investor letter:
"F5, Inc. (NASDAQ:FFIV) sells application networking and security software as well as data center appliances. The company's stock rose after it posted good quarterly results and raised both its revenue and EPS guidance. The company is misunderstood and gets incorrectly classified as a legacy IT hardware vendor, resulting in an attractive valuation for a company with better-than-average fundamental risk ratings. F5 has over 50% market share in traditional ADCs (application delivery controllers), along with various multi-cloud networking and application security products."
#ffiv
In its second-quarter 2026 investor letter, Hotchkis & Wiley Large Cap Fundamental Value Fund highlighted F5, Inc. (NASDAQ:FFIV) as one of its leading individual contributors. F5, Inc. (NASDAQ:FFIV) offers multi-cloud application security and delivery solutions. On August 31, 2026, F5, Inc. (NASDAQ:FFIV) closed at $407.13 per share. Over the past month, F5, Inc. (NASDAQ:FFIV) declined 3.41%, while its shares are up 29.82% over the past year. F5, Inc. (NASDAQ:FFIV) has a market capitalization of $23.05 billion, and its stock has traded within a 52-week range of $223.76 to $435.00.
Hotchkis & Wiley Large Cap Fundamental Value Fund stated the following regarding F5, Inc. (NASDAQ:FFIV) in its Q2 2026 investor letter:
"F5, Inc. (NASDAQ:FFIV) sells application networking and security software as well as data center appliances. The company's stock rose after it posted good quarterly results and raised both its revenue and EPS guidance. The company is misunderstood and gets incorrectly classified as a legacy IT hardware vendor, resulting in an attractive valuation for a company with better-than-average fundamental risk ratings. F5 has over 50% market share in traditional ADCs (application delivery controllers), along with various multi-cloud networking and application security products."
#ffiv