2 days ago
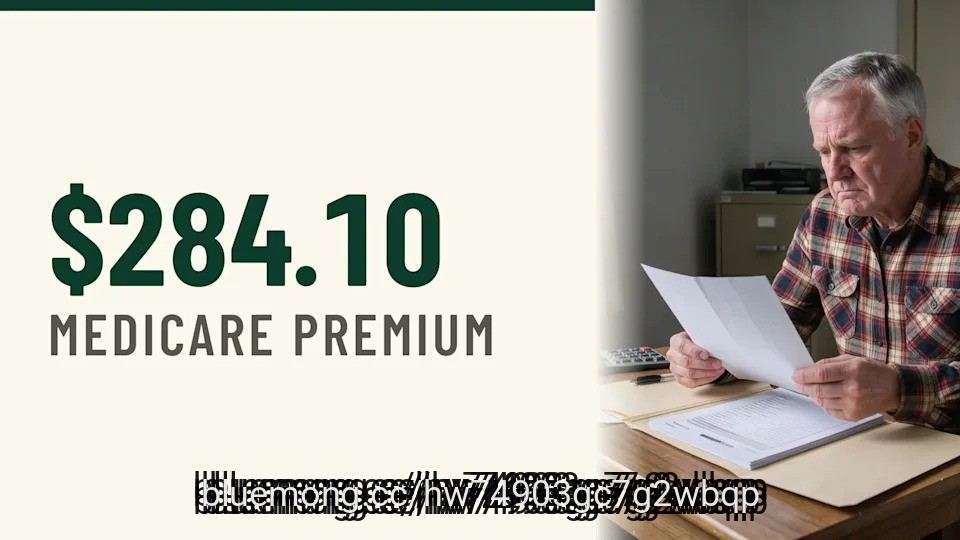
Medicare's two-year lookback rule means a retiree's $120,000 annual 401(k) withdrawals at 63 and 64 set his Part B premiums at 65 and 66.
A $120,000 withdrawal pushes a single filer $11,000 over the IRMAA threshold, raising Part B premiums to $284.10 monthly and costing roughly $2,297 extra over two years.
Covering part of living expenses with cash savings or qualified Roth withdrawals instead of 401(k) funds can keep reported MAGI below the surcharge threshold entirely.
Americans who work with a financial advisor have saved more than twice as much for retirement, on average. Find out what one could change for you: SmartAsset's free quiz matches you with up to three vetted fiduciary advisors in about five minutes. (Sponsor)
A 62-year-old leaves his job with a large traditional 401(k) and a simple plan. He will draw $120,000 a year to live on, then start Social Security at 67. He sees ages 63 and 64 as silent bridge years. Medicare will use income from those years to calculate his first two premium bills, something he may not have anticipated.
#premiums #covering #roth
A $120,000 withdrawal pushes a single filer $11,000 over the IRMAA threshold, raising Part B premiums to $284.10 monthly and costing roughly $2,297 extra over two years.
Covering part of living expenses with cash savings or qualified Roth withdrawals instead of 401(k) funds can keep reported MAGI below the surcharge threshold entirely.
Americans who work with a financial advisor have saved more than twice as much for retirement, on average. Find out what one could change for you: SmartAsset's free quiz matches you with up to three vetted fiduciary advisors in about five minutes. (Sponsor)
A 62-year-old leaves his job with a large traditional 401(k) and a simple plan. He will draw $120,000 a year to live on, then start Social Security at 67. He sees ages 63 and 64 as silent bridge years. Medicare will use income from those years to calculate his first two premium bills, something he may not have anticipated.
#premiums #covering #roth

2 days ago
The 2026 midterm results are in, and the Democrats won in a landslide. So what does this mean for Sandisk (NASDAQ:SNDK) stock? Apparently, nothing good.
Shares of the NAND flash memory giant sold off 8.6% through 11:50 a.m. ET Wednesday as nervous investors wonder what a sea change in government might mean for artificial intelligence data centers -- and for Sandisk's sales of memory to outfit them.
Missed AI's "Act 1"? Act 2 Could Be 16x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our ****** ysts, we're only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
Image source: Getty Images.
StreetInsider.com is blaming the midterm election results for "renewed selling pressure" on AI and memory chip stocks. As the thinking goes, "potential tighter oversight of AI infrastructure and data-center expansion" would be bad news for memory sales growth, and a Democratic Congress is seen as more likely to pass such regulations than the former Republican-led Congress was. And some Wall Street ****** ysts agree. As the election approached, Fox Advisors downgraded Sandisk stock to equalweight, and Wells Fargo cut its price target on the stock.
#Stock #midterm
Shares of the NAND flash memory giant sold off 8.6% through 11:50 a.m. ET Wednesday as nervous investors wonder what a sea change in government might mean for artificial intelligence data centers -- and for Sandisk's sales of memory to outfit them.
Missed AI's "Act 1"? Act 2 Could Be 16x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our ****** ysts, we're only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
Image source: Getty Images.
StreetInsider.com is blaming the midterm election results for "renewed selling pressure" on AI and memory chip stocks. As the thinking goes, "potential tighter oversight of AI infrastructure and data-center expansion" would be bad news for memory sales growth, and a Democratic Congress is seen as more likely to pass such regulations than the former Republican-led Congress was. And some Wall Street ****** ysts agree. As the election approached, Fox Advisors downgraded Sandisk stock to equalweight, and Wells Fargo cut its price target on the stock.
#Stock #midterm

2 days ago
Converting your 401(k) to a Roth portfolio will allow you to entirely avoid RMDs. This is a legitimate form of tax planning. However, often there's a difference between whether you can do something and whether you should; whether it's allowed, and whether it's in your long-term best interest.
For example, say that you're 62 years old. You have $1.6 million in a 401(k). If you convert this portfolio to a Roth IRA 10% at a time, you can avoid required minimum distributions on your $1.6 million. However, particularly for households approaching retirement, a Roth conversion may result in a net-loss. There's a chance that the tax costs of making those conversions will outweigh the tax benefits of avoiding minimum distributions.
Here are some things to consider. Also consider matching with a fiduciary financial advisor who can help you weigh your options.
Starting at age 73 (or 75 starting in 2023), the IRS requires you to begin taking regular, minimum withdrawals from every pre-tax retirement account. This includes 401(k) and traditional IRA portfolios. These withdrawals are known as RMDs.
The exact amount you must take is based on the portfolio's total value on January 1 and your age. You have until the end of each year to make the withdrawal, so you can take your minimum distribution in any amount at any time by or before December 31. If you don't take your minimum distribution, the IRS charges a tax penalty typically worth 25% of the amount not withdrawn.
#rmds #avoid
For example, say that you're 62 years old. You have $1.6 million in a 401(k). If you convert this portfolio to a Roth IRA 10% at a time, you can avoid required minimum distributions on your $1.6 million. However, particularly for households approaching retirement, a Roth conversion may result in a net-loss. There's a chance that the tax costs of making those conversions will outweigh the tax benefits of avoiding minimum distributions.
Here are some things to consider. Also consider matching with a fiduciary financial advisor who can help you weigh your options.
Starting at age 73 (or 75 starting in 2023), the IRS requires you to begin taking regular, minimum withdrawals from every pre-tax retirement account. This includes 401(k) and traditional IRA portfolios. These withdrawals are known as RMDs.
The exact amount you must take is based on the portfolio's total value on January 1 and your age. You have until the end of each year to make the withdrawal, so you can take your minimum distribution in any amount at any time by or before December 31. If you don't take your minimum distribution, the IRS charges a tax penalty typically worth 25% of the amount not withdrawn.
#rmds #avoid

2 days ago
My wife and I are elderly. I have an individual retirement account (IRA) worth about $100,000, and we have a trust set up through our children to protect our ****** ets. If one or both of us have to go into a nursing home, can they take our IRA? What do we need to do to protect it?
-Dawn
Long-term care (LTC), which may include nursing home stays, is expensive and can quickly suck up savings you may have intended for something else.
How do you prevent that from happening? The specific answer depends on variables you didn't reveal. But in my experience, when people talk about "protecting" ****** ets from LTC costs, they often have Medicaid in mind. So what does that look like? (And if you need more help planning for long-term care costs, consider working with a financial advisor).
Qualifying for Long-Term Care Through Medicaid
#term #protect #home
-Dawn
Long-term care (LTC), which may include nursing home stays, is expensive and can quickly suck up savings you may have intended for something else.
How do you prevent that from happening? The specific answer depends on variables you didn't reveal. But in my experience, when people talk about "protecting" ****** ets from LTC costs, they often have Medicaid in mind. So what does that look like? (And if you need more help planning for long-term care costs, consider working with a financial advisor).
Qualifying for Long-Term Care Through Medicaid
#term #protect #home

29 days ago
For an average single person planning to stop working at 64, a $1.2 million 401(k) account and $2,800 Social Security benefit could provide enough income to make ends meet during retirement. Widely used guidelines suggest your annual income may be around $81,600, which may or may not be more than your annual expenses. Much depends on individual circumstances, including the kind of retirement lifestyle you desire, your location and future trends of inflation, taxes and investment returns. To get a comprehensive workup of your retirement budget, take the question to a financial advisor.
Income and expenses represent the two sides of your retirement budget. Both are equally important and decisions you make regarding either can affect the overall accuracy and dependability of the budget.
You can estimate expenses by using averages for typical retirees or by considering specifics of your situation with estimate for categories such as housing, healthcare and taxes. Similarly, you can estimate future income with general guidelines or by accounting for specifics such as your personal investment preferences.
In your case, we'll start with income since we have information about that. Despite the possibility that Social Security benefits will be cut by about 20% after 2035, your $2,800 Social Security benefit can probably be relied upon. And benefits are indexed to a cost-of-living benchmark, providing protection against inflation.
Note, however, that if you wait to claim benefits, your monthly amount will increase every year until you are 70. By claiming at age 64 rather than waiting until your full retirement age of 67, you are receiving 20% less. If you wait until age 70, you'll get 24% more than at 67. And you'll receive the higher amount, adjusted annually for cost of living, as long as you live.
#Retirement #benefits
Income and expenses represent the two sides of your retirement budget. Both are equally important and decisions you make regarding either can affect the overall accuracy and dependability of the budget.
You can estimate expenses by using averages for typical retirees or by considering specifics of your situation with estimate for categories such as housing, healthcare and taxes. Similarly, you can estimate future income with general guidelines or by accounting for specifics such as your personal investment preferences.
In your case, we'll start with income since we have information about that. Despite the possibility that Social Security benefits will be cut by about 20% after 2035, your $2,800 Social Security benefit can probably be relied upon. And benefits are indexed to a cost-of-living benchmark, providing protection against inflation.
Note, however, that if you wait to claim benefits, your monthly amount will increase every year until you are 70. By claiming at age 64 rather than waiting until your full retirement age of 67, you are receiving 20% less. If you wait until age 70, you'll get 24% more than at 67. And you'll receive the higher amount, adjusted annually for cost of living, as long as you live.
#Retirement #benefits

29 days ago
Moneywise and Yahoo Finance LLC may earn commission or revenue through links in the content below.
If you've been worried sick about higher prices, one of Wall Street's most-watched bulls has a message for you: relief may be on the way.
"I think the probabilities are really high. It's going to drop," Tom Lee, co-founder of Fundstrat Global Advisors, said of inflation in a Sept. 25 interview.
Jeff Bezos backs a platform that lets anyone invest in rental homes for as little as $100 — 6 ways to build wealth like a landlord without actually being one
A single line on your car insurance policy could be inflating your premium by up to 30% — here's what to change
#finance #earn
If you've been worried sick about higher prices, one of Wall Street's most-watched bulls has a message for you: relief may be on the way.
"I think the probabilities are really high. It's going to drop," Tom Lee, co-founder of Fundstrat Global Advisors, said of inflation in a Sept. 25 interview.
Jeff Bezos backs a platform that lets anyone invest in rental homes for as little as $100 — 6 ways to build wealth like a landlord without actually being one
A single line on your car insurance policy could be inflating your premium by up to 30% — here's what to change
#finance #earn


30 days ago
The stock market has its dips, but historically, Apple (APPL) stock has done well for investors. As of Oct. 1, it traded for $330.32 — a nearly 30% yearly increase, according to Yahoo Finance. Take it back further to 2016, and the stock has gone up by a little over 1,063%.
As a new investor, you might be thinking Apple stock is the perfect buy. However, as with any other investment, it's not without risk. These are some of the most common mistakes investors make when buying stocks, according to financial advisors Ed Peagler and Xintian **** .
As per J.P. Morgan, the general advice when it comes to stocks is to put no more than 10% to 20% of your total portfolio in one stock. Of course, when you see the numbers rising on a particular stock, it's easy to get excited and make investment choices based on that.
This can be a mistake, though.
"Apple is a spectacular company that most people already know and love. It's no surprise, then, that many individuals end up with too large a position in their overall portfolio. And they don't feel like they have a high concentration stock because it's Apple. They trust it," said Xintian **** , CPA, senior tax manager at Alexander Accountants, CPAs. "But high concentration is high concentration. And it amplifies the risk of an unsafe, underestimated stock."
#concentration #according
As a new investor, you might be thinking Apple stock is the perfect buy. However, as with any other investment, it's not without risk. These are some of the most common mistakes investors make when buying stocks, according to financial advisors Ed Peagler and Xintian **** .
As per J.P. Morgan, the general advice when it comes to stocks is to put no more than 10% to 20% of your total portfolio in one stock. Of course, when you see the numbers rising on a particular stock, it's easy to get excited and make investment choices based on that.
This can be a mistake, though.
"Apple is a spectacular company that most people already know and love. It's no surprise, then, that many individuals end up with too large a position in their overall portfolio. And they don't feel like they have a high concentration stock because it's Apple. They trust it," said Xintian **** , CPA, senior tax manager at Alexander Accountants, CPAs. "But high concentration is high concentration. And it amplifies the risk of an unsafe, underestimated stock."
#concentration #according


30 days ago
Retirement isn't supposed to be a financial obstacle course. But for many retirees, it becomes one — not because they didn't save enough, but because they're avoiding the very decisions that could protect what they've already built. Small postponements and wishful thinking can quietly spiral into serious money problems.
Financial advisors see it happen again and again: retirees who put off critical decisions until the damage is done. Here are five avoidance moves that consistently undermine retirement security.
Without a realistic retirement plan, it's easy to spend more than your savings can actually support.
"What makes this especially difficult is that the conversation goes beyond just the numbers," explained Linda Grizely, financial wellness and behavioral finance speaker. "It can feel like a judgment about lifestyle, independence and past financial choices."
Most retirees keep doing what feels comfortable and hope it works out. Instead, Grizely recommended mapping your cash flow, spending, income, investments, taxes and account withdrawal strategy. Revisit this at least annually and whenever spending, markets, taxes, health or life circumstances shift.
#retirees #grizely #spending
Financial advisors see it happen again and again: retirees who put off critical decisions until the damage is done. Here are five avoidance moves that consistently undermine retirement security.
Without a realistic retirement plan, it's easy to spend more than your savings can actually support.
"What makes this especially difficult is that the conversation goes beyond just the numbers," explained Linda Grizely, financial wellness and behavioral finance speaker. "It can feel like a judgment about lifestyle, independence and past financial choices."
Most retirees keep doing what feels comfortable and hope it works out. Instead, Grizely recommended mapping your cash flow, spending, income, investments, taxes and account withdrawal strategy. Revisit this at least annually and whenever spending, markets, taxes, health or life circumstances shift.
#retirees #grizely #spending

30 days ago
SmartAsset and Yahoo Finance LLC may earn commission or revenue through links in the content below.
Deciding how much to withdraw from your retirement accounts means finding a balance between enjoying life and making your money last. Taking too little leaves you with unused savings, while taking too much risks running out of money later. Taxes also affect how much you can actually spend. To help you create a retirement budget, let's break down the example of a 67-year-old with $870,000 in a 401(k), $120,000 in an IRA and $26,400 annually from Social Security. Here's what a withdrawal plan could look based on two rates.
A financial advisor can help you create a withdrawal strategy that balances your lifestyle needs, tax impacts and long-term retirement goals.
A 401(k) and a traditional IRA are both retirement accounts funded with pre-tax dollars. Contributions are deducted from your taxable income, allowing you to grow savings faster because the money enters the account before taxes. In retirement, however, all withdrawals are taxed as ordinary income. This includes both the money you contributed and the investment earnings.
This is different from a Roth IRA, which is funded with after-tax dollars. You do not receive an upfront tax deduction for contributions. The benefit comes later: withdrawals in retirement are tax-free, including both contributions and earnings.
#taking #taxes #later #Help
Deciding how much to withdraw from your retirement accounts means finding a balance between enjoying life and making your money last. Taking too little leaves you with unused savings, while taking too much risks running out of money later. Taxes also affect how much you can actually spend. To help you create a retirement budget, let's break down the example of a 67-year-old with $870,000 in a 401(k), $120,000 in an IRA and $26,400 annually from Social Security. Here's what a withdrawal plan could look based on two rates.
A financial advisor can help you create a withdrawal strategy that balances your lifestyle needs, tax impacts and long-term retirement goals.
A 401(k) and a traditional IRA are both retirement accounts funded with pre-tax dollars. Contributions are deducted from your taxable income, allowing you to grow savings faster because the money enters the account before taxes. In retirement, however, all withdrawals are taxed as ordinary income. This includes both the money you contributed and the investment earnings.
This is different from a Roth IRA, which is funded with after-tax dollars. You do not receive an upfront tax deduction for contributions. The benefit comes later: withdrawals in retirement are tax-free, including both contributions and earnings.
#taking #taxes #later #Help


1 month ago
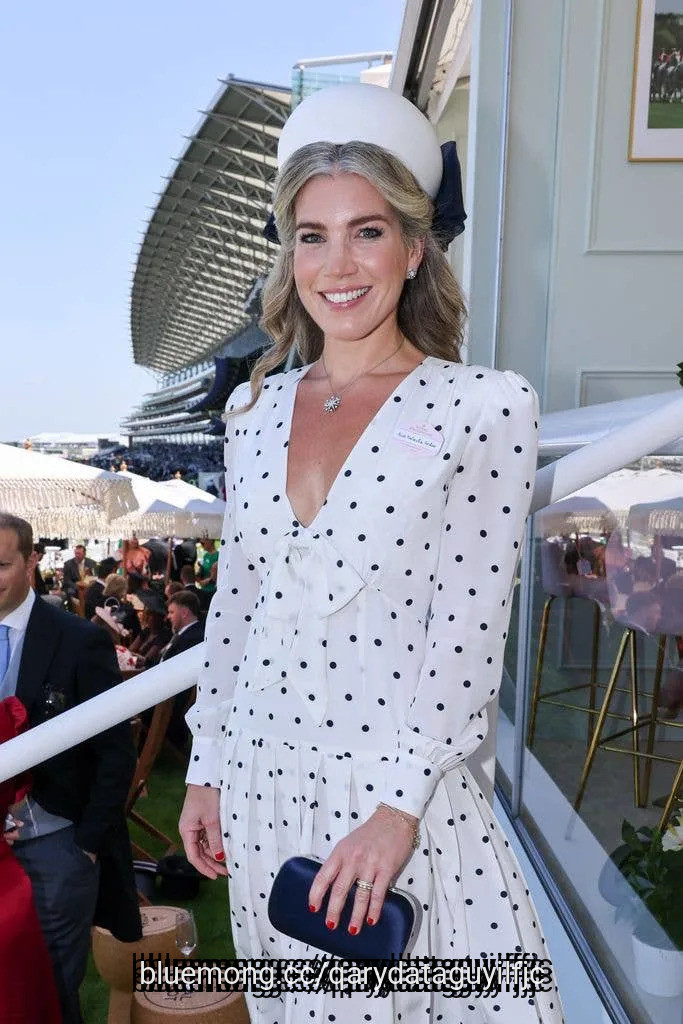
The Princess of Wales' long-time former stylist, Natasha Archer, shared a reflective post after stepping down as the mother-of-three's personal ***** istant in 2025.
Natasha went on to launch her own eponymous, bespoke advisory styling company. Taking to her professional Instagram account, alongside a stunning photograph of herself in a sleek white suit, she penned:
"One year into Natasha Archer, it feels like a lovely moment to say ***** o again. I've loved working with new clients, helping them build wardrobes that reflect who they are and feel confident in how they present themselves," she mused.
"My purpose remains the same: thoughtful, discreet guidance to elevate your wardrobe and help you feel ***** ured and at your best," she added.
"As we step into a busy season, I'm looking forward to new introductions and all that's still to come.",
#archer #princess #i 've #time
Natasha went on to launch her own eponymous, bespoke advisory styling company. Taking to her professional Instagram account, alongside a stunning photograph of herself in a sleek white suit, she penned:
"One year into Natasha Archer, it feels like a lovely moment to say ***** o again. I've loved working with new clients, helping them build wardrobes that reflect who they are and feel confident in how they present themselves," she mused.
"My purpose remains the same: thoughtful, discreet guidance to elevate your wardrobe and help you feel ***** ured and at your best," she added.
"As we step into a busy season, I'm looking forward to new introductions and all that's still to come.",
#archer #princess #i 've #time
1 month ago
AbbVie Inc. (NYSE:ABBV) was trading at around $263 on October 5, up 14.18% over twelve months. Its payout ratio is 190.40%. The company distributes nearly twice what it reports as profit.
A dividend that large is either about to be cut or is being paid out of something the earnings line does not show.
READ ALSO: Here is Why Tripadvisor (TRIP) is a Bad Investment at Today's Price
AbbVie reported net income of $6.27 billion and generated $16.87 billion of free cash flow. Dividends are paid from the second number, so a ratio measured against the first is describing depressed earnings rather than a company living beyond its means.
The margins show what depresses them. Operating margin is 40.04%. Net margin is 9.80%. Thirty points vanish between those lines, and where they vanish matters. Costs that high sitting below the operating line are not the business failing to earn. They are the amortization of a drug portfolio AbbVie bought rather than discovered, plus interest on the debt that bought it.
#paid
A dividend that large is either about to be cut or is being paid out of something the earnings line does not show.
READ ALSO: Here is Why Tripadvisor (TRIP) is a Bad Investment at Today's Price
AbbVie reported net income of $6.27 billion and generated $16.87 billion of free cash flow. Dividends are paid from the second number, so a ratio measured against the first is describing depressed earnings rather than a company living beyond its means.
The margins show what depresses them. Operating margin is 40.04%. Net margin is 9.80%. Thirty points vanish between those lines, and where they vanish matters. Costs that high sitting below the operating line are not the business failing to earn. They are the amortization of a drug portfolio AbbVie bought rather than discovered, plus interest on the debt that bought it.
#paid

1 month ago
Dividend-paying stocks are taking a beating as surging Treasury yields make bonds a more competitive income source, creating a difficult environment for baby boomers who lean on dividend funds and individual stocks to cover living expenses in retirement.
Utilities, real estate, and materials have all experienced share-price declines as climbing bond yields have drawn income-seeking investors away from dividend stocks. The 10-year Treasury yield has remained north of 5%, recently hovering between 5.2% and 5.3%, while the 20-year has hit 5.68% and the 30-year has reached 5.62% — marks last seen more than two decades ago, according to Benzinga.
The pain shows up clearly in fund performance. The Invesco S&P 500 High Dividend Low Volatility ETF (SPHD) lost 7.59% over the trailing month, and the iShares Select Dividend ETF (DVY) shed 6.02% in the same window, according to CNBC. The Vanguard High Dividend Yield Index ETF (VYM) gave back 3.85% over the past month. The WisdomTree U.S. Quality Dividend Growth Fund (DGRW) stands apart, with its heavy tilt toward technology helping limit its one-month loss to just 0.81%.
The Federal Reserve raised its overnight rate by a quarter percentage point on Sept. 16, and markets are pricing in additional increases, keeping pressure on rate-sensitive dividend sectors. The 10-year yield touched 5.342% and the 30-year reached 5.683%, their highest marks in 24 years, driven in part by rising public debt, geopolitical tensions, and the prospect of a prolonged high-rate environment.
Despite the pressure, financial advisors caution retirees against making reactive moves. "The worst thing that a retiree could do is sell a high-quality dividend payer at depressed prices to chase income somewhere else in the stock market just to get higher yield," Timothy Chubb, chief investment officer at Girard, a Univest Wealth Division, told CNBC. Chubb said he would rather own a company growing 4% to 5% annually with a 3% dividend yield than pursue an 8% yield from a deteriorating business.
#Dividend #yield #month #treasury
Utilities, real estate, and materials have all experienced share-price declines as climbing bond yields have drawn income-seeking investors away from dividend stocks. The 10-year Treasury yield has remained north of 5%, recently hovering between 5.2% and 5.3%, while the 20-year has hit 5.68% and the 30-year has reached 5.62% — marks last seen more than two decades ago, according to Benzinga.
The pain shows up clearly in fund performance. The Invesco S&P 500 High Dividend Low Volatility ETF (SPHD) lost 7.59% over the trailing month, and the iShares Select Dividend ETF (DVY) shed 6.02% in the same window, according to CNBC. The Vanguard High Dividend Yield Index ETF (VYM) gave back 3.85% over the past month. The WisdomTree U.S. Quality Dividend Growth Fund (DGRW) stands apart, with its heavy tilt toward technology helping limit its one-month loss to just 0.81%.
The Federal Reserve raised its overnight rate by a quarter percentage point on Sept. 16, and markets are pricing in additional increases, keeping pressure on rate-sensitive dividend sectors. The 10-year yield touched 5.342% and the 30-year reached 5.683%, their highest marks in 24 years, driven in part by rising public debt, geopolitical tensions, and the prospect of a prolonged high-rate environment.
Despite the pressure, financial advisors caution retirees against making reactive moves. "The worst thing that a retiree could do is sell a high-quality dividend payer at depressed prices to chase income somewhere else in the stock market just to get higher yield," Timothy Chubb, chief investment officer at Girard, a Univest Wealth Division, told CNBC. Chubb said he would rather own a company growing 4% to 5% annually with a 3% dividend yield than pursue an 8% yield from a deteriorating business.
#Dividend #yield #month #treasury

1 month ago
SmartAsset and Yahoo Finance LLC may earn commission or revenue through links in the content below.
During most of the decades you are preparing financially for retirement, you are likely focused on saving as close as you can get to the recommended amount, without worrying too much about the details. As you approach retirement, however, it's a good idea to look more closely at what might be a realistic retirement budget. At age 62, with $890,000 in a 401(k) account, $115,000 in a Roth IRA and accounting for Social Security benefits, you can likely generate enough income to cover typical retiree lifestyle expenses. Your individual needs may vary, of course, but there are likely moves you can make now and in retirement to give you the flexibility you'll need to fund a comfortable and secure retirement.
Consider speaking with a financial advisor for help building an effective retirement strategy.
A typical retirement budget starts with the income side and Social Security benefits represent an important part of that for a large majority of retirees. Social Security is lifelong, guaranteed by the U.S. government and includes annual cost-of-living adjustments to keep up with inflation. The amount of your specific benefit is controlled by your work history and age at claiming. ****** uming your current income is $90,000 annually, here are estimates of your annual Social Security benefit based on your age when you start claiming benefits:
Age
#annual
During most of the decades you are preparing financially for retirement, you are likely focused on saving as close as you can get to the recommended amount, without worrying too much about the details. As you approach retirement, however, it's a good idea to look more closely at what might be a realistic retirement budget. At age 62, with $890,000 in a 401(k) account, $115,000 in a Roth IRA and accounting for Social Security benefits, you can likely generate enough income to cover typical retiree lifestyle expenses. Your individual needs may vary, of course, but there are likely moves you can make now and in retirement to give you the flexibility you'll need to fund a comfortable and secure retirement.
Consider speaking with a financial advisor for help building an effective retirement strategy.
A typical retirement budget starts with the income side and Social Security benefits represent an important part of that for a large majority of retirees. Social Security is lifelong, guaranteed by the U.S. government and includes annual cost-of-living adjustments to keep up with inflation. The amount of your specific benefit is controlled by your work history and age at claiming. ****** uming your current income is $90,000 annually, here are estimates of your annual Social Security benefit based on your age when you start claiming benefits:
Age
#annual

1 month ago
New Generation Collective, a new initiative dedicated to helping young people in the entertainment, music and creator economy navigate growing up in the public eye, launched Tuesday. The initiative was announced during the inaugural summit for Hollywood & Mind in New York City. The Kids Mental Health Foundation, founded by Nationwide Children's Hospital, was also on hand at the summit to participate in the announcement.
The founding advisory board for the collective includes several entertainers and family members who have firsthand experience growing up in the public eye, including children's mental health advocate Angel Carter Conrad; the production company Artists for Artists; actor and singer Logan Henderson; actress and singer Isabela Merced; actor Kel Mitchell; actress and filmmaker Soleil Moon Frye; Carmela Wallace, mother of Juice WRLD and founder of Live Free 999; actor Hudson Yang; and actress and singer Breanna Yde. Additional members will be announced at a later date.
New Generation Collective was founded by Lilah Kojoori, a children's entertainment communications executive who departed her role as vice president of communications for Nickelodeon and Paramount+ Kids and Family last year. The organization draws on more than 20 years of experience working with young performers and their families.
Logo for the Next Generation Collective, founded by Lilah Kojoori. (Next Generation Collective)
The organization is designed to give young people, their families and the professionals who support them access to mental health experts through the Kids Mental Health Foundation. It also connects young performers with entertainment industry leaders who can offer guidance on mental health, boundaries and the realities of working on set, performing, creating content and building a public profile at a young age. The initiative will serve as an additional resource for studios, productions, agencies, managers and platforms supporting young talent
#mental
The founding advisory board for the collective includes several entertainers and family members who have firsthand experience growing up in the public eye, including children's mental health advocate Angel Carter Conrad; the production company Artists for Artists; actor and singer Logan Henderson; actress and singer Isabela Merced; actor Kel Mitchell; actress and filmmaker Soleil Moon Frye; Carmela Wallace, mother of Juice WRLD and founder of Live Free 999; actor Hudson Yang; and actress and singer Breanna Yde. Additional members will be announced at a later date.
New Generation Collective was founded by Lilah Kojoori, a children's entertainment communications executive who departed her role as vice president of communications for Nickelodeon and Paramount+ Kids and Family last year. The organization draws on more than 20 years of experience working with young performers and their families.
Logo for the Next Generation Collective, founded by Lilah Kojoori. (Next Generation Collective)
The organization is designed to give young people, their families and the professionals who support them access to mental health experts through the Kids Mental Health Foundation. It also connects young performers with entertainment industry leaders who can offer guidance on mental health, boundaries and the realities of working on set, performing, creating content and building a public profile at a young age. The initiative will serve as an additional resource for studios, productions, agencies, managers and platforms supporting young talent
#mental



1 month ago
Wealthy baby boomers have spent decades building their fortunes—and the foundations, donor-advised funds, and giving traditions that come with them. But as the $124 trillion Great Wealth Transfer gets underway, a growing share of the older generation isn't so sure their kids will carry on tradition the way they hope.
Fewer than half of wealthy Americans (47%) believe the next generation is prepared to take on family philanthropic causes, down from 55% in 2024, according to research from Bank of America released last week. The share of parents who believe their children share their commitment to giving back fell even more sharply to 65% from 76%. The bank surveyed more than 1,430 wealthy individuals in the U.S. aged 21 or older with at least $3 million in investable ******* ets, excluding primary residence.
The confidence gap in philanthropy mirrors a broader anxiety wealth advisors have noticed about whether heirs are ready for any of it.
"This is a very real concern I'm hearing from ultra-affluent families right now," Tom Thiegs, managing director of leadership and legacy at Ascent Private Capital Management with U.S. Bank, told Fortune of parents' fears that wealth could dampen their children's drive. Trent Von Ahsen of Cedar Point Capital Partners also told Fortune his clients are leaning on mentorship and phased wealth transfers rather than lump-sum inheritances.
But the irony is younger donors are, by several of the study's measures, more engaged donors than older generations. Gen Z and millennial donors support an average of 12 charitable causes, compared with eight among wealth donors overall. They're also roughly twice as likely to use a donor-advised fund, and 87% say honoring their family's philanthropic tradition is important. Meanwhile, 86% say it's equally important to establish their own charitable identity.
#advised
Fewer than half of wealthy Americans (47%) believe the next generation is prepared to take on family philanthropic causes, down from 55% in 2024, according to research from Bank of America released last week. The share of parents who believe their children share their commitment to giving back fell even more sharply to 65% from 76%. The bank surveyed more than 1,430 wealthy individuals in the U.S. aged 21 or older with at least $3 million in investable ******* ets, excluding primary residence.
The confidence gap in philanthropy mirrors a broader anxiety wealth advisors have noticed about whether heirs are ready for any of it.
"This is a very real concern I'm hearing from ultra-affluent families right now," Tom Thiegs, managing director of leadership and legacy at Ascent Private Capital Management with U.S. Bank, told Fortune of parents' fears that wealth could dampen their children's drive. Trent Von Ahsen of Cedar Point Capital Partners also told Fortune his clients are leaning on mentorship and phased wealth transfers rather than lump-sum inheritances.
But the irony is younger donors are, by several of the study's measures, more engaged donors than older generations. Gen Z and millennial donors support an average of 12 charitable causes, compared with eight among wealth donors overall. They're also roughly twice as likely to use a donor-advised fund, and 87% say honoring their family's philanthropic tradition is important. Meanwhile, 86% say it's equally important to establish their own charitable identity.
#advised

1 month ago
Former White House press secretary Karoline Leavitt will provide commentary across the Fox News lineup. (Alex Brandon/AP Photo)
Former White House press secretary Karoline Leavitt is joining Fox News Channel as an on-air contributor, FOX News Media CEO Suzanne Scott announced on Monday.
Leavitt, 29, who will provide commentary across the Fox News lineup, starts on Nov. 1. She most recently served as the 36th White House press secretary during President Donald Trump’s second administration, from January 2025 until August 2026.
"Karoline’s firsthand experience in the White House and on the presidential campaign trail gives her a distinct understanding of today’s political landscape. We look forward to her providing our audience with authentic and sharp insight across all FOX News Media platforms," Scott said in a statement.
TRUMP SAYS KAROLINE LEAVITT WILL LEAVE WHITE HOUSE PRESS SECRETARY ROLE, BECOME OUTSIDE ADVISOR
#karoline #press #secretary
Former White House press secretary Karoline Leavitt is joining Fox News Channel as an on-air contributor, FOX News Media CEO Suzanne Scott announced on Monday.
Leavitt, 29, who will provide commentary across the Fox News lineup, starts on Nov. 1. She most recently served as the 36th White House press secretary during President Donald Trump’s second administration, from January 2025 until August 2026.
"Karoline’s firsthand experience in the White House and on the presidential campaign trail gives her a distinct understanding of today’s political landscape. We look forward to her providing our audience with authentic and sharp insight across all FOX News Media platforms," Scott said in a statement.
TRUMP SAYS KAROLINE LEAVITT WILL LEAVE WHITE HOUSE PRESS SECRETARY ROLE, BECOME OUTSIDE ADVISOR
#karoline #press #secretary



1 month ago
Meanwhile, flood watches are in effect along the Gulf Coast and in Florida.
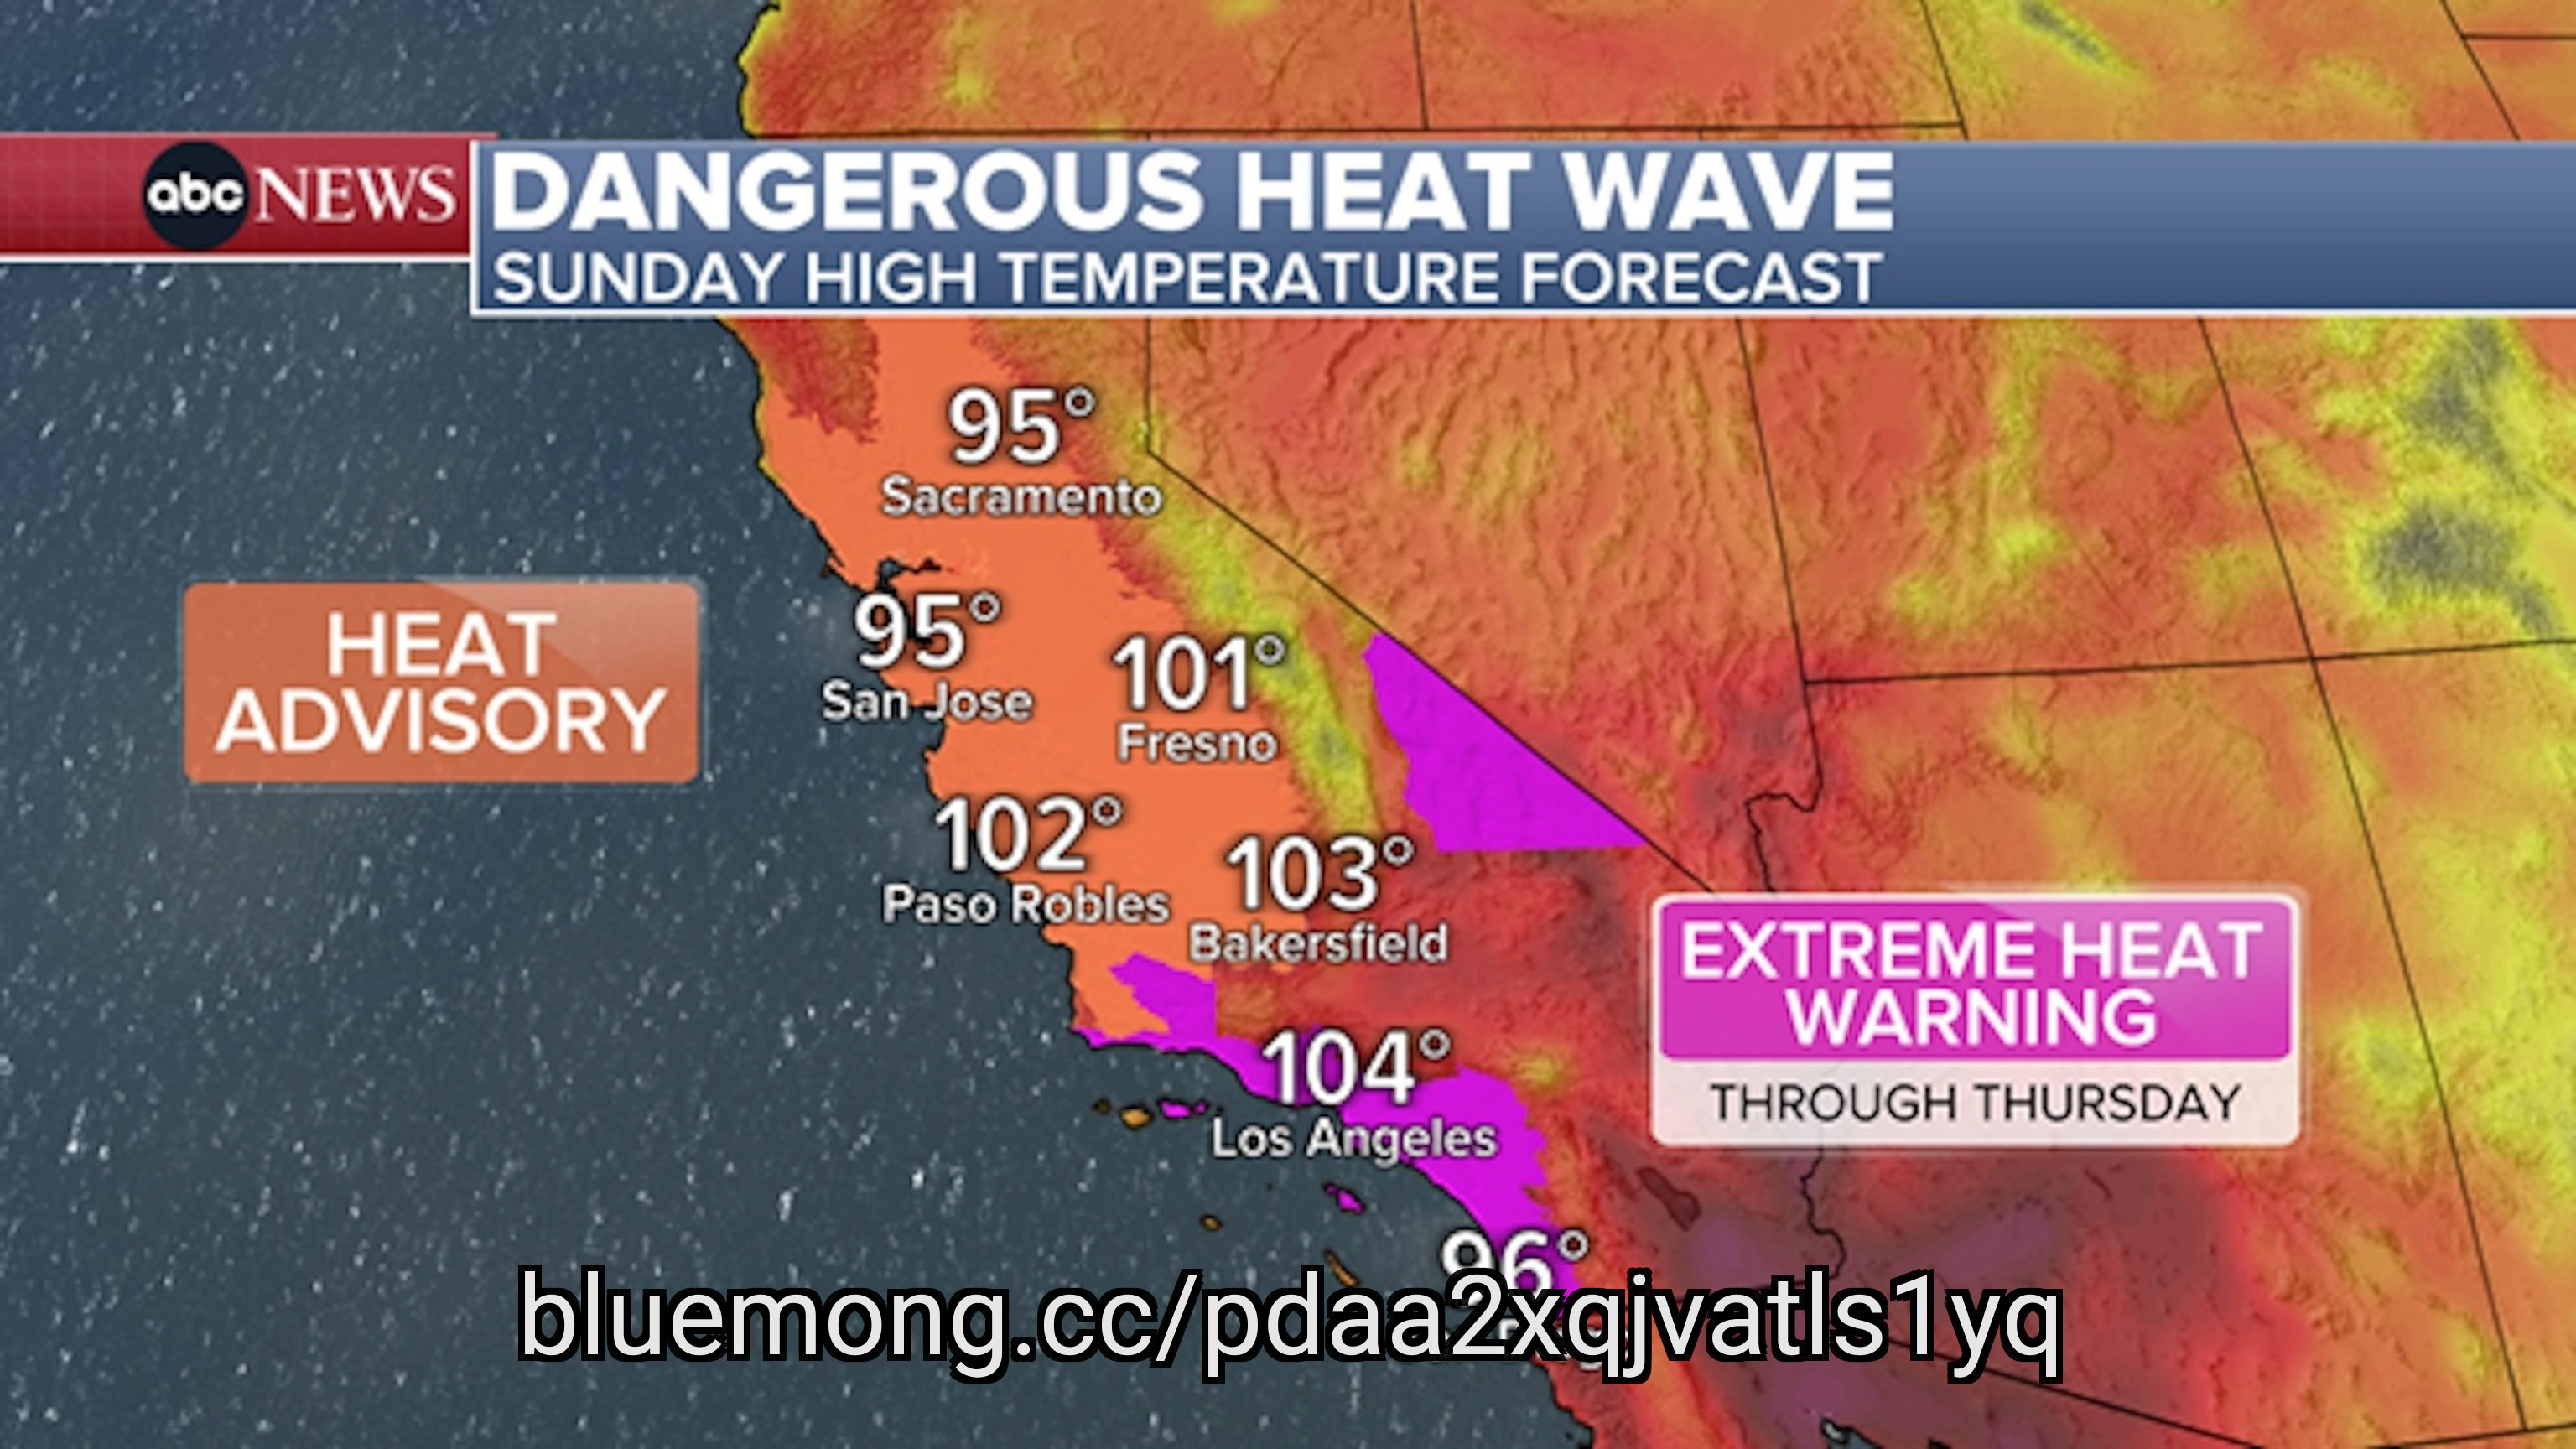
More than 35 million people are under heat alerts on Sunday afternoon as a dangerous multi-day October heat wave continues across nearly all of California.
Temperatures are expected to soar up to 20 degrees above normal for this time of year, into the 90s and 100s, from Northern California, including the San Francisco Bay Area, to the Mexico border.
In some areas of California, especially urban areas, warm nights will provide little to no relief.
Los Angeles and San Diego remain under an extreme heat warning, with heat advisories posted on Sunday for San Francisco and Sacramento.
#california
More than 35 million people are under heat alerts on Sunday afternoon as a dangerous multi-day October heat wave continues across nearly all of California.
Temperatures are expected to soar up to 20 degrees above normal for this time of year, into the 90s and 100s, from Northern California, including the San Francisco Bay Area, to the Mexico border.
In some areas of California, especially urban areas, warm nights will provide little to no relief.
Los Angeles and San Diego remain under an extreme heat warning, with heat advisories posted on Sunday for San Francisco and Sacramento.
#california


2 months ago
Claiming Social Security at 62 gives you three extra years of payments, but each monthly check is permanently smaller than it would be if you had waited until 65. Delaying benefits means giving up that early income in exchange for a larger monthly payment later. The break-even point shows when those larger checks catch up to the benefits collected by claiming early. Comparing that crossover age with your income needs, life expectancy and other retirement resources can help put the tradeoff in context.
A financial advisor can review a range of retirement strategies with you, including your optimum retirement age.
Social Security benefits can generally begin at age 62. However, starting before full retirement age (FRA) permanently reduces the monthly amount you receive. FRA depends on your birth year and ranges from 66 to 67 for workers approaching retirement today. For anyone born in 1960 or later, FRA is 67.
The Social Security Administration calculates early-claiming reductions based on how many months before FRA you begin collecting benefits. For the first 36 months before FRA, the benefit is generally reduced by 5/9 of 1% for each month. If you claim more than 36 months early, the reduction for those additional months is generally 5/12 of 1% per month.1
For a worker with an FRA of 67, claiming at 62 generally results in a 30% reduction. This means the worker receives about 70% of the benefit they would have received at FRA. Someone entitled to $2,500 per month at 67, for example, would receive approximately $1,750 per month by claiming at 62.
#Retirement
A financial advisor can review a range of retirement strategies with you, including your optimum retirement age.
Social Security benefits can generally begin at age 62. However, starting before full retirement age (FRA) permanently reduces the monthly amount you receive. FRA depends on your birth year and ranges from 66 to 67 for workers approaching retirement today. For anyone born in 1960 or later, FRA is 67.
The Social Security Administration calculates early-claiming reductions based on how many months before FRA you begin collecting benefits. For the first 36 months before FRA, the benefit is generally reduced by 5/9 of 1% for each month. If you claim more than 36 months early, the reduction for those additional months is generally 5/12 of 1% per month.1
For a worker with an FRA of 67, claiming at 62 generally results in a 30% reduction. This means the worker receives about 70% of the benefit they would have received at FRA. Someone entitled to $2,500 per month at 67, for example, would receive approximately $1,750 per month by claiming at 62.
#Retirement

2 months ago
Choosing between claiming Social Security at 62 or waiting until 70 can create a wide gap in your monthly income. Starting early gives you more years of payments, while delaying may increase the amount of each check. The tradeoff comes down to how long you expect to collect benefits and how much income you need along the way. Comparing the break-even point can help show when waiting may produce more ****** ulative benefits.
A financial advisor can help you plan for retirement at any age.
The size of your monthly retirement check largely depends on the age at which you start collecting. Your earnings history establishes the foundation for your payment, but when you claim affects the portion you receive each month.
Age 62 is generally the earliest you can begin collecting Social Security retirement benefits. Claiming that early comes with a permanent reduction in your monthly payment. Social Security calculates the reduction based on how many months before your full retirement age (FRA) you begin receiving benefits.
For people born in 1960 or later, FRA is 67. In that case, claiming at 62 means starting benefits 60 months early. This generally reduces a worker's retirement benefit by 30% compared with the amount available at FRA. For example, someone entitled to $2,000 per month at FRA would receive approximately $1,400 at 62, before considering other adjustments.1
#monthly #early #starting #income
A financial advisor can help you plan for retirement at any age.
The size of your monthly retirement check largely depends on the age at which you start collecting. Your earnings history establishes the foundation for your payment, but when you claim affects the portion you receive each month.
Age 62 is generally the earliest you can begin collecting Social Security retirement benefits. Claiming that early comes with a permanent reduction in your monthly payment. Social Security calculates the reduction based on how many months before your full retirement age (FRA) you begin receiving benefits.
For people born in 1960 or later, FRA is 67. In that case, claiming at 62 means starting benefits 60 months early. This generally reduces a worker's retirement benefit by 30% compared with the amount available at FRA. For example, someone entitled to $2,000 per month at FRA would receive approximately $1,400 at 62, before considering other adjustments.1
#monthly #early #starting #income


2 months ago
Automattic has a new interim chief financial officer: Jeremy Klaperman, the CFO of the company's WordPress VIP Enterprise business unit. The news, shared internally on Friday, follows last week's attempted ouster of Automattic CEO Matt Mullenweg, which ultimately resulted in the departure of the board members who voted him out and other executives, including then-CFO Mark Davies. Davies was briefly interim CEO before Mullenweg retook the position.
In a Slack post, Mullenweg shared that Klaperman had previously acted as Automattic CFO when Davies had been on sabbatical. He noted that the board — whose new members have yet to be announced — will still need to evaluate internal and external candidates for the position before a final decision is made.
In addition, Mullenweg said in the post that a candidate to become the company's chief legal officer had also just verbally accepted the position, replacing Chief Legal Officer Andy Missan, who has also since left the company alongside Davies. TechCrunch recently reported that Davies and Missan had signed reciprocal severance deals during Mullenweg's 33-hour leave of absence before he returned as CEO.
"I have 100% confidence in our cash and financial position," Mullenweg's post concluded, adding "There is still work to do, but everything is within our control and depends only on Automattic's ability to execute."
In subsequent updates, Mullenweg also said to "stay tuned" for board announcements, and noted that special advisor and creator of Wolfram|Alpha, Stephen Wolfram, will continue in his position. The company's next board meeting is scheduled for September 23.
#klaperman
In a Slack post, Mullenweg shared that Klaperman had previously acted as Automattic CFO when Davies had been on sabbatical. He noted that the board — whose new members have yet to be announced — will still need to evaluate internal and external candidates for the position before a final decision is made.
In addition, Mullenweg said in the post that a candidate to become the company's chief legal officer had also just verbally accepted the position, replacing Chief Legal Officer Andy Missan, who has also since left the company alongside Davies. TechCrunch recently reported that Davies and Missan had signed reciprocal severance deals during Mullenweg's 33-hour leave of absence before he returned as CEO.
"I have 100% confidence in our cash and financial position," Mullenweg's post concluded, adding "There is still work to do, but everything is within our control and depends only on Automattic's ability to execute."
In subsequent updates, Mullenweg also said to "stay tuned" for board announcements, and noted that special advisor and creator of Wolfram|Alpha, Stephen Wolfram, will continue in his position. The company's next board meeting is scheduled for September 23.
#klaperman


2 months ago
Evereve, the women's fashion retailer based in Endina, Minn., has named style and creative director Sarah Clary as advisory chief creative officer.
In her advisory role, she will help shape Evereve's creative direction and brand storytelling, beginning with the company's fall campaign, "Jeans That Make Me Feel ____."
More from WWD
Peter Arnold Promoted to President of Fashion Scholarship Fund
Designers & Agents Wraps Up Successful Show Amid NYFW Hustle
#fashion
In her advisory role, she will help shape Evereve's creative direction and brand storytelling, beginning with the company's fall campaign, "Jeans That Make Me Feel ____."
More from WWD
Peter Arnold Promoted to President of Fashion Scholarship Fund
Designers & Agents Wraps Up Successful Show Amid NYFW Hustle
#fashion

2 months ago
SEIC provides investment processing, management, and operational platforms for private banks, financial advisors, institutional investors, and financial managers. SEIC's second-quarter fiscal 2026 report showed revenue of $641.6 million (a 14.7% year-over-year gain), adjusted per-share earnings of $1.66 (a 38% rise), $207 million in operating income (a 36% jump) – all of which were quarterly records – and the company has nearly $400 million in cash for more growth ahead.
It's no wonder SEIC shares are up 28% so far this year – and they could rise more. MoneyFlows data shows how Big Money investors are again betting heavily on the stock
Institutional volumes reveal plenty. Over the last year, SEIC has enjoyed strong investor demand, which we believe to be institutional support.
Each green bar signals unusually large volumes in SEIC shares. They reflect our proprietary inflow signal, pushing the stock higher:
Plenty of financials names are under accumulation right now. But there's a powerful fundamental story happening with SEI.
#institutional #investors #Stock
It's no wonder SEIC shares are up 28% so far this year – and they could rise more. MoneyFlows data shows how Big Money investors are again betting heavily on the stock
Institutional volumes reveal plenty. Over the last year, SEIC has enjoyed strong investor demand, which we believe to be institutional support.
Each green bar signals unusually large volumes in SEIC shares. They reflect our proprietary inflow signal, pushing the stock higher:
Plenty of financials names are under accumulation right now. But there's a powerful fundamental story happening with SEI.
#institutional #investors #Stock



2 months ago
Concerned about an AI bubble? Sign up for The Daily Upside for smart and actionable market news, built for investors.
There's a lot we can't predict, like the outcome of the midterm elections, who will make it to the Super Bowl or whether Taylor Swift was actually hinting at a new album release in that Emmy's sketch. But when it comes to what our retirement looks like, we can certainly try.
Many retirement plans offer predictive tools that can help savers forecast their future balances, retirement readiness, income replacement rates and more. Participants, however, aren't happy with the options: J.D. Power's recent survey of digital experience satisfaction for retirement plans found that predictive tools were the lowest-performing attribute.
"The technology in the 401(k) is seriously behind what people are used to in their consumer life," said Fred Barstein, CEO of The Retirement Advisor University. When the underlying technology structure is old and **** bersome, it's hard for the tools to be as effective as they could be.
Sign up for The Daily Upside at no cost for premium **** ysis on all your favorite stocks.
#tools #sign #upside #like
There's a lot we can't predict, like the outcome of the midterm elections, who will make it to the Super Bowl or whether Taylor Swift was actually hinting at a new album release in that Emmy's sketch. But when it comes to what our retirement looks like, we can certainly try.
Many retirement plans offer predictive tools that can help savers forecast their future balances, retirement readiness, income replacement rates and more. Participants, however, aren't happy with the options: J.D. Power's recent survey of digital experience satisfaction for retirement plans found that predictive tools were the lowest-performing attribute.
"The technology in the 401(k) is seriously behind what people are used to in their consumer life," said Fred Barstein, CEO of The Retirement Advisor University. When the underlying technology structure is old and **** bersome, it's hard for the tools to be as effective as they could be.
Sign up for The Daily Upside at no cost for premium **** ysis on all your favorite stocks.
#tools #sign #upside #like
2 months ago
Concerned about an AI bubble? Sign up for The Daily Upside for smart and actionable market news, built for investors.
Let's just come right out and say it: It's a good time to sell a registered investment advisor practice.
We've all read headlines about sky-high multiples and firm owners fielding multiple calls a day from potential suitors. It's an environment where successful founders can generate tremendous value from selling their firms. The process isn't simple, however, and there are pitfalls that owners can stumble into, potentially robbing them of hard-earned enterprise value.
Adam Lewis, partner at Vedder Price, talked through these dynamics this week during a standing-room only session at the Future Proof Festival in Huntington Beach, California. While he advises on M&A across multiple industries, the world of wealth management stands apart in 2026 as the "strongest by far" in terms of dealmaking activity. The entrance of private equity buyers in the RIA **** e has been particularly significant, with the heightened competition among buyers helping ramp up valuations. It's a great environment for sellers who hope to monetize their life's work to fund their retirement lifestyle and potentially create intergenerational wealth, Lewis said. But it's important to be diligent and bring the right expertise to the table during the negotiation process.
Sign up for The Daily Upside at no cost for premium **** ysis on all your favorite stocks.
#lewis
Let's just come right out and say it: It's a good time to sell a registered investment advisor practice.
We've all read headlines about sky-high multiples and firm owners fielding multiple calls a day from potential suitors. It's an environment where successful founders can generate tremendous value from selling their firms. The process isn't simple, however, and there are pitfalls that owners can stumble into, potentially robbing them of hard-earned enterprise value.
Adam Lewis, partner at Vedder Price, talked through these dynamics this week during a standing-room only session at the Future Proof Festival in Huntington Beach, California. While he advises on M&A across multiple industries, the world of wealth management stands apart in 2026 as the "strongest by far" in terms of dealmaking activity. The entrance of private equity buyers in the RIA **** e has been particularly significant, with the heightened competition among buyers helping ramp up valuations. It's a great environment for sellers who hope to monetize their life's work to fund their retirement lifestyle and potentially create intergenerational wealth, Lewis said. But it's important to be diligent and bring the right expertise to the table during the negotiation process.
Sign up for The Daily Upside at no cost for premium **** ysis on all your favorite stocks.
#lewis

2 months ago
Concerned about an AI bubble? Sign up for The Daily Upside for smart and actionable market news, built for investors.
A mind is a terrible thing to waste, but college is awfully expensive.
Depending on where someone goes to school, they can be left with a lot of debt — an albatross that can hang around their neck for decades. Among 401(k) plan participants in their 40s, those with student loan debt had median retirement account balances roughly 45% lower than those without, according to a new report from the Employee Benefit Research Institute.
The best option is to figure out scholarships, financial aid, debt timelines and what school makes financial sense before going to college. But that's not reality for many clients, leaving advisors to help fit student debt into a financial plan that balances both loans and savings. "The biggest mistake I see is treating student loans as an all-or-nothing problem," said Corinna Rose, a CFP with Bell Investment Advisors. "Many borrowers think they need to eliminate every dollar of debt before they can start investing."
Sign up for The Daily Upside at no cost for premium ******* ysis on all your favorite stocks.
#student #sign #many
A mind is a terrible thing to waste, but college is awfully expensive.
Depending on where someone goes to school, they can be left with a lot of debt — an albatross that can hang around their neck for decades. Among 401(k) plan participants in their 40s, those with student loan debt had median retirement account balances roughly 45% lower than those without, according to a new report from the Employee Benefit Research Institute.
The best option is to figure out scholarships, financial aid, debt timelines and what school makes financial sense before going to college. But that's not reality for many clients, leaving advisors to help fit student debt into a financial plan that balances both loans and savings. "The biggest mistake I see is treating student loans as an all-or-nothing problem," said Corinna Rose, a CFP with Bell Investment Advisors. "Many borrowers think they need to eliminate every dollar of debt before they can start investing."
Sign up for The Daily Upside at no cost for premium ******* ysis on all your favorite stocks.
#student #sign #many

2 months ago
On September 9, 2026, Academy Sports and Outdoors, Inc. (NASDAQ:ASO) posted second-quarter results for the period ended August 1, 2026. Net sales rose 3.0% to $1.65 billion, adjusted earnings per share climbed 19.1% to $2.31 from $1.94, and gross margin widened 440 basis points to 40.4%. Management lifted full-year adjusted EPS guidance to $6.50 to $6.90 and gross margin guidance to 35.5% to 36.0%. What the quarter did not deliver was a positive comp, which fell 0.4%.
Telsey Advisory came away seeing nothing that changes the thesis, calling the risk-reward attractive and pushing its target on Academy Sports and Outdoors, Inc. (NASDAQ:ASO) to $63 from $60 while staying at Outperform.
Wells Fargo's Ike Boruchow described himself as cautiously optimistic at current levels, arguing that both the quarter itself and management's forward commentary delivered upside surprise; his target moved to $55 from $50, though the rating stayed Equal Weight.
Barclays **** yst Adrienne Yih focused on the fact that Academy Sports and Outdoors, Inc. (NASDAQ:ASO) held its fiscal 2026 sales and comp guidance despite a tougher consumer backdrop and sequential demand deceleration, lifting her target to $53 from $50 at Equal Weight.
Supporting the case: e-commerce sales grew 12.8%, Sports and Recreation rose 6%, myAcademy loyalty membership passed 15 million, and the company raised adjusted free cash flow guidance to $300 million to $350 million after repurchasing $182.1 million of stock in the first half.
#sports #guidance #sales #target
Telsey Advisory came away seeing nothing that changes the thesis, calling the risk-reward attractive and pushing its target on Academy Sports and Outdoors, Inc. (NASDAQ:ASO) to $63 from $60 while staying at Outperform.
Wells Fargo's Ike Boruchow described himself as cautiously optimistic at current levels, arguing that both the quarter itself and management's forward commentary delivered upside surprise; his target moved to $55 from $50, though the rating stayed Equal Weight.
Barclays **** yst Adrienne Yih focused on the fact that Academy Sports and Outdoors, Inc. (NASDAQ:ASO) held its fiscal 2026 sales and comp guidance despite a tougher consumer backdrop and sequential demand deceleration, lifting her target to $53 from $50 at Equal Weight.
Supporting the case: e-commerce sales grew 12.8%, Sports and Recreation rose 6%, myAcademy loyalty membership passed 15 million, and the company raised adjusted free cash flow guidance to $300 million to $350 million after repurchasing $182.1 million of stock in the first half.
#sports #guidance #sales #target

2 months ago
President attacks insiders who revealed details of Iran briefing with Tulsi Gabbard to Wall Street Journal last month, threatening repercussions
I would like to be emailed about offers, events and updates from The Independent. Read our Privacy notice
President Donald Trump has lashed out at leakers in his own administration after a series of behind-the-scenes reports on the Iran war.
As the conflict Trump claimed would be over in six weeks drags into its seventh month, insiders have repeatedly claimed the president was warned against taking action by his own advisors.
#Iran #claimed #street
I would like to be emailed about offers, events and updates from The Independent. Read our Privacy notice
President Donald Trump has lashed out at leakers in his own administration after a series of behind-the-scenes reports on the Iran war.
As the conflict Trump claimed would be over in six weeks drags into its seventh month, insiders have repeatedly claimed the president was warned against taking action by his own advisors.
#Iran #claimed #street



2 months ago
Wealthfront Corporation (NASDAQ:WLTH) reported on September 9 that fiscal second-quarter revenue increased 1% to $91.9 million, despite platform ***** ets rising 12% to $99 billion. The quarter ended July 31, 2026. Funded clients increased 14% to 1.51 million, and platform ***** ets surpassed $100 billion by the end of August.
Platform ***** ets measure financial ***** ets held in client accounts. Their growth reflects both net deposits and market movements, so the headline increase does not represent new client money alone.
Adjusted EBITDA declined 15% to $38.1 million, with its margin falling to 41% from 49%. Wealthfront Corporation (NASDAQ:WLTH) defines this non-GAAP measure as net income excluding interest expense, income taxes, depreciation and amortization, stock-based compensation, fair-value changes in convertible notes, warrant liabilities and simple agreements for future equity, and nonrecurring expenses. Adjusted EBITDA margin divides that figure by revenue.
The advisory business is translating ***** et growth into revenue. Investment advisory ***** ets increased 30% to $54.1 billion, while advisory revenue rose 31% to $28.8 million. Those results show that the expanding investment business is generating a larger recurring fee stream.
For Wealthfront Corporation (NASDAQ:WLTH), this creates an opportunity to deepen client relationships as savings move toward longer-term investment goals. A growing advisory base could support more durable relationships, provided clients remain invested and continue contributing.
#wealthfront #revenue #platform #investment
Platform ***** ets measure financial ***** ets held in client accounts. Their growth reflects both net deposits and market movements, so the headline increase does not represent new client money alone.
Adjusted EBITDA declined 15% to $38.1 million, with its margin falling to 41% from 49%. Wealthfront Corporation (NASDAQ:WLTH) defines this non-GAAP measure as net income excluding interest expense, income taxes, depreciation and amortization, stock-based compensation, fair-value changes in convertible notes, warrant liabilities and simple agreements for future equity, and nonrecurring expenses. Adjusted EBITDA margin divides that figure by revenue.
The advisory business is translating ***** et growth into revenue. Investment advisory ***** ets increased 30% to $54.1 billion, while advisory revenue rose 31% to $28.8 million. Those results show that the expanding investment business is generating a larger recurring fee stream.
For Wealthfront Corporation (NASDAQ:WLTH), this creates an opportunity to deepen client relationships as savings move toward longer-term investment goals. A growing advisory base could support more durable relationships, provided clients remain invested and continue contributing.
#wealthfront #revenue #platform #investment



2 months ago
Watch Highlights From the 2025 Palm Beach CorpGov Forum:
CorpGov, IPO Edge and PE Edge will host the sixth annual Palm Beach CorpGov Forum on November 4-5, 2026, at the Palm Beach Lake Pavilion and The Cove Club, both located waterfront with sweeping views of Palm Beach Island, along with a reception at Cucina Palm Beach. The Forum will feature a VC-focused keynote panel on Wednesday evening and a full day of panels on Thursday, with networking events both nights.
Our audience will include approximately 300 attendees including institutional investors, board directors, family offices/HNWIs, attorneys, investment bankers and key advisors. For sponsorship, speaker or media enquiries, email EditorCorpGov.com
The event will be digitized into reports published on CorpGov and by its content partners (under relevant company stock tickers) Yahoo Finance, Bloomberg Terminals, Reuters via LSEG Workspace, and AlphaSense, and filmed with multiple 4K video cameras and professional editing.
Preliminary Agenda
#beach #corpgov #watch
CorpGov, IPO Edge and PE Edge will host the sixth annual Palm Beach CorpGov Forum on November 4-5, 2026, at the Palm Beach Lake Pavilion and The Cove Club, both located waterfront with sweeping views of Palm Beach Island, along with a reception at Cucina Palm Beach. The Forum will feature a VC-focused keynote panel on Wednesday evening and a full day of panels on Thursday, with networking events both nights.
Our audience will include approximately 300 attendees including institutional investors, board directors, family offices/HNWIs, attorneys, investment bankers and key advisors. For sponsorship, speaker or media enquiries, email EditorCorpGov.com
The event will be digitized into reports published on CorpGov and by its content partners (under relevant company stock tickers) Yahoo Finance, Bloomberg Terminals, Reuters via LSEG Workspace, and AlphaSense, and filmed with multiple 4K video cameras and professional editing.
Preliminary Agenda
#beach #corpgov #watch