7 days ago
Landen Lewis produced one of the strongest recovery performances in Friday's Love's RV Stop 225 at Talladega Superspeedway, finishing sixth after starting 30th. The Niece Motorsports driver overcame a difficult qualifying effort and advanced 24 positions during the chaotic 86-lap event.
Lewis initially faced the challenge of working through a competitive field while navigating the changing drafting lanes. However, his No. 45 Chevrolet demonstrated impressive speed during the middle stages, allowing him to move toward the front. Lewis finished sixth in Stage 2, earning five additional points while establishing himself among the contenders.
He continued running competitively during the final stage, briefly leading the outside drafting lane as Tanner Gray challenged from the inside. The race's changing circumstances provided opportunities to gain positions, and Lewis avoided the accidents that eliminated several other drivers.
When the event entered overtime, Lewis remained among the leading competitors and positioned himself to capitalize on the final-lap battle. He ultimately finished sixth, just 0.272 seconds behind winner Sammy Smith. The result earned Lewis 36 points and marked another impressive performance during his part-time Truck Series campaign.
His ability to advance from 30th to sixth demonstrated the strength of his Chevrolet and his ability to compete in superspeedway racing.
#lewis #changing #drafting
Lewis initially faced the challenge of working through a competitive field while navigating the changing drafting lanes. However, his No. 45 Chevrolet demonstrated impressive speed during the middle stages, allowing him to move toward the front. Lewis finished sixth in Stage 2, earning five additional points while establishing himself among the contenders.
He continued running competitively during the final stage, briefly leading the outside drafting lane as Tanner Gray challenged from the inside. The race's changing circumstances provided opportunities to gain positions, and Lewis avoided the accidents that eliminated several other drivers.
When the event entered overtime, Lewis remained among the leading competitors and positioned himself to capitalize on the final-lap battle. He ultimately finished sixth, just 0.272 seconds behind winner Sammy Smith. The result earned Lewis 36 points and marked another impressive performance during his part-time Truck Series campaign.
His ability to advance from 30th to sixth demonstrated the strength of his Chevrolet and his ability to compete in superspeedway racing.
#lewis #changing #drafting

28 days ago
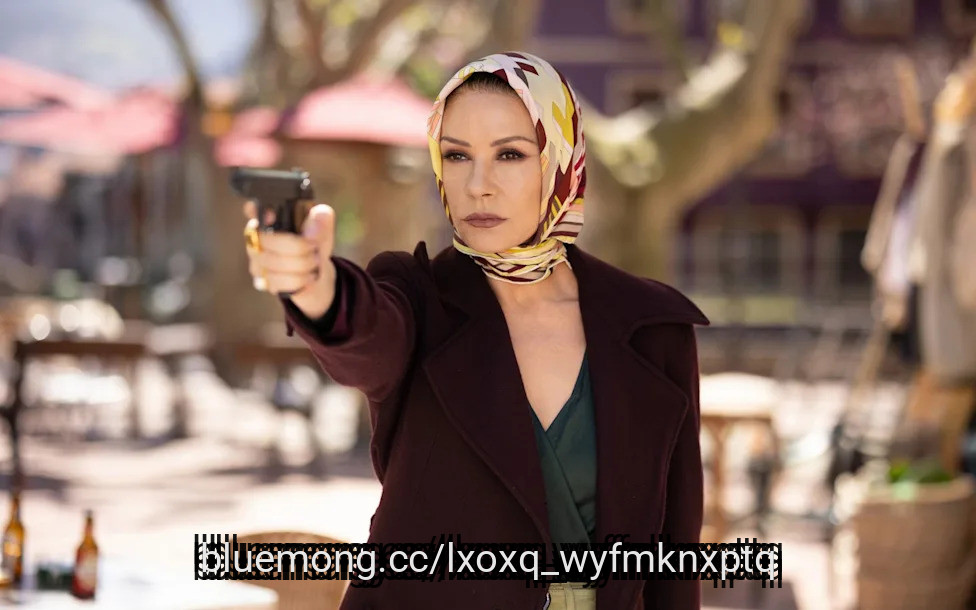
Adriana La Cerva in The Sopranos. Ginger McKenna in Casino. Sofía Vergara's Griselda Blanco. For decades, the mob wife has been the archetypal anti-heroine – all fur, animal print and knee-high boots. Now Catherine Zeta-Jones has joined the ranks.
Shedding the gothic lace and American drawl of Morticia Addams in Netflix's Wednesday, Swansea-born Zeta-Jones is using her real Welsh accent on screen for the first time in Prime Video's revenge thriller Kill Jackie. She plays Jackie Price, an ex-cocaine dealer whose quiet life unravels when one routine decision ends with an elite squad of ******* assins hired to kill her.
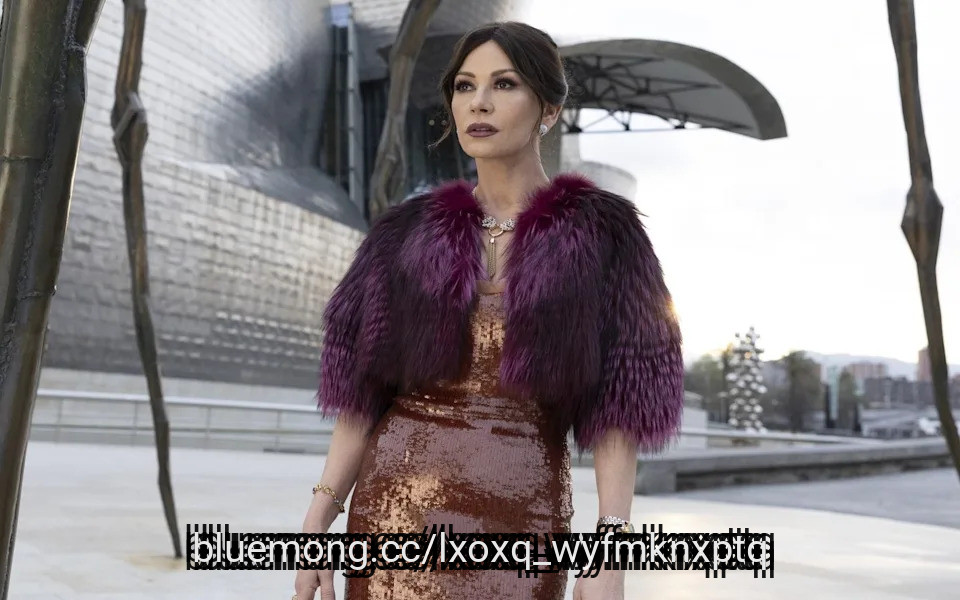
Unsurprisingly, the series is already drawing comparisons with the BBC's Killing Eve. The series shares a director (Damon Thomas), a dark, twisted humour and puts a fierce, quirky woman at its centre. But the strongest link may be the wardrobe.
Just as Villanelle's Molly Goddard tulle dress became a character in its own right, Jackie's wardrobe – built on an enticing mix of British designers, vintage and second-hand – is every bit as scene-stealing, and serves as inspiration for how we'll want to dress this autumn.
Jodie Comer as Villanelle wearing the memorable Molly Goddard tulle dress - Robert Viglasky/BBC
#goddard #kill #series
Shedding the gothic lace and American drawl of Morticia Addams in Netflix's Wednesday, Swansea-born Zeta-Jones is using her real Welsh accent on screen for the first time in Prime Video's revenge thriller Kill Jackie. She plays Jackie Price, an ex-cocaine dealer whose quiet life unravels when one routine decision ends with an elite squad of ******* assins hired to kill her.
Unsurprisingly, the series is already drawing comparisons with the BBC's Killing Eve. The series shares a director (Damon Thomas), a dark, twisted humour and puts a fierce, quirky woman at its centre. But the strongest link may be the wardrobe.
Just as Villanelle's Molly Goddard tulle dress became a character in its own right, Jackie's wardrobe – built on an enticing mix of British designers, vintage and second-hand – is every bit as scene-stealing, and serves as inspiration for how we'll want to dress this autumn.
Jodie Comer as Villanelle wearing the memorable Molly Goddard tulle dress - Robert Viglasky/BBC
#goddard #kill #series

29 days ago
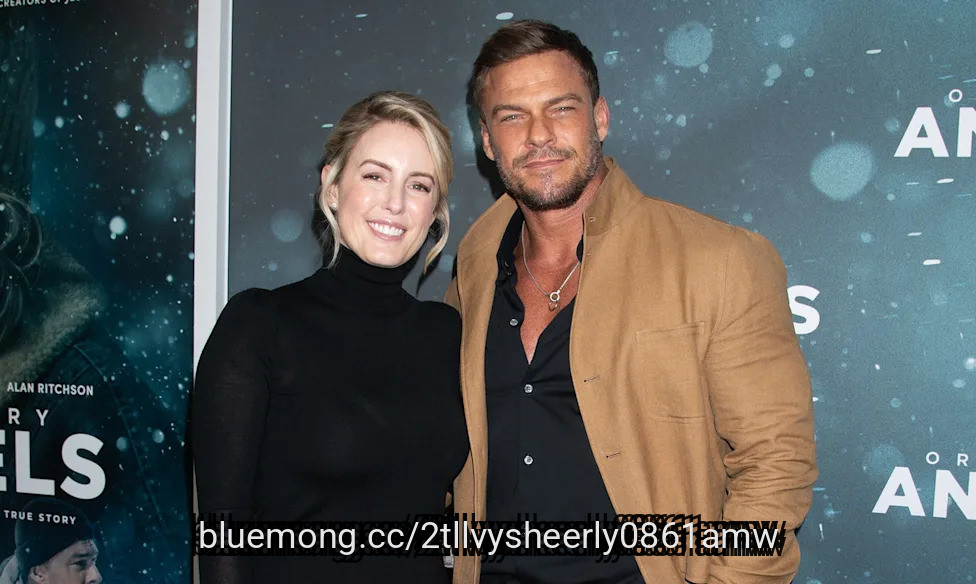
Alan Ritchson and his wife, Catherine, are putting a positive spin on their shock divorce, but friends of the former couple are bracing themselves for a messy situation in the months ahead, a source tells the National Enquirer.
"People around Alan were pretty shocked at the timing of this break-up, especially because being an involved, sensitive dad has been central to Alan's identity for so long," reveals the source. "That's still the thing he's most broken up about with this divorce: it's going to mean less time with [sons Calem, Edan and Amory] and there's almost nothing he can do about that."
After twenty years of marriage, the Reacher star, 43, and his writer-producer wife, 42, announced their split in a joint Instagram post on September 12, pledging to become the "strongest co-parents" they can be. "We also want to give each other room to grow into the people we are becoming," the statement read.
"[Alan] was quite protective of Catherine and the kids when the Reacher series first got started, and then the show kind of took over everything and made him richer and way more famous than he ever expected," admits the source. "It's a lot to go through in just a few short years, and Alan's insane training schedule, completely apart from the long filming days, didn't make things easier."
ZUMAPRESS.com / MEGA
#source #reacher #divorce
"People around Alan were pretty shocked at the timing of this break-up, especially because being an involved, sensitive dad has been central to Alan's identity for so long," reveals the source. "That's still the thing he's most broken up about with this divorce: it's going to mean less time with [sons Calem, Edan and Amory] and there's almost nothing he can do about that."
After twenty years of marriage, the Reacher star, 43, and his writer-producer wife, 42, announced their split in a joint Instagram post on September 12, pledging to become the "strongest co-parents" they can be. "We also want to give each other room to grow into the people we are becoming," the statement read.
"[Alan] was quite protective of Catherine and the kids when the Reacher series first got started, and then the show kind of took over everything and made him richer and way more famous than he ever expected," admits the source. "It's a lot to go through in just a few short years, and Alan's insane training schedule, completely apart from the long filming days, didn't make things easier."
ZUMAPRESS.com / MEGA
#source #reacher #divorce


30 days ago
Procter & Gamble has raised its dividend for 70 straight years while Johnson & Johnson covers its roughly $12.6 billion dividend run rate 1.56 times with free cash flow.
Coca-Cola posted its strongest Trademark volume growth in 17 years, and ADP's operating cash flow covers its dividend more than twice over while still funding buybacks.
Lowe's carries the lowest payout ratio in the group at 41% and trades at just 15 times earnings after falling 24% year to date.
Read More: Learn 7 ways to generate income with a $1,000,000+ portfolio (sponsor)
Yield is relatively easy to find. A dividend that keeps arriving through recessions, patent cliffs and housing slumps is much harder to find, and that kind of reliability is the hook for this group. Every name below covers its payout with real cash flow, has a long record of raises and keeps its payout ratio at a level that leaves room for mistakes. Procter & Gamble (NYSE:PG) sets the standard: management says its latest increase marks the 70th consecutive year of dividend increases and 136th consecutive year of dividend payments, putting it firmly in the Dividend Kings club (we ranked ten of them by valuation in a free report here). The other four pair long dividend records with cash flow that covers the payout.
#cash #year #procter #gamble
Coca-Cola posted its strongest Trademark volume growth in 17 years, and ADP's operating cash flow covers its dividend more than twice over while still funding buybacks.
Lowe's carries the lowest payout ratio in the group at 41% and trades at just 15 times earnings after falling 24% year to date.
Read More: Learn 7 ways to generate income with a $1,000,000+ portfolio (sponsor)
Yield is relatively easy to find. A dividend that keeps arriving through recessions, patent cliffs and housing slumps is much harder to find, and that kind of reliability is the hook for this group. Every name below covers its payout with real cash flow, has a long record of raises and keeps its payout ratio at a level that leaves room for mistakes. Procter & Gamble (NYSE:PG) sets the standard: management says its latest increase marks the 70th consecutive year of dividend increases and 136th consecutive year of dividend payments, putting it firmly in the Dividend Kings club (we ranked ten of them by valuation in a free report here). The other four pair long dividend records with cash flow that covers the payout.
#cash #year #procter #gamble

30 days ago
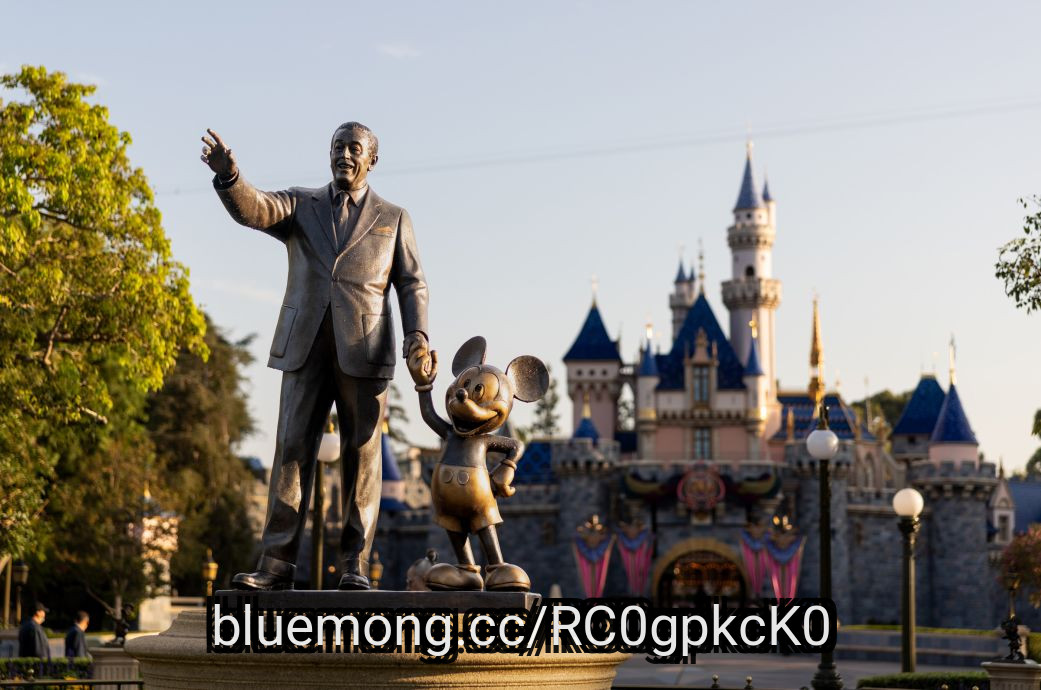
Disney raised prices on many of its theme park offerings today, coinciding with the start of the company’s new fiscal year. But consumers aren’t pushing back the way they did a few years ago.
Disney’s price hikes are an annual October ritual for the company, and it’s always a tricky balancing act between increasing revenue and consumers’ willingness to pay.
Many ticket types, passes and add-ons at Disneyland are not increasing at all this time. But premium products are getting more expensive, like the highest-level, skip-the-line service at Walt Disney World, which could now run just shy of the $500 mark during peak demand.
It’s a reflection of the company’s strategy: Spread the price boosts across different audiences, while leaving bottom-tier prices - like the slowest season, one-day, one-park tickets - unchanged.
Its theme parks strategy, Disney said, has evolved over time. Higher-priced premium products and add-ons, alongside targeted discounts and a refresh of older attractions, allowed the company this summer to generate the strongest parks and cruises revenue in two years.
#disney #company #consumers
Disney’s price hikes are an annual October ritual for the company, and it’s always a tricky balancing act between increasing revenue and consumers’ willingness to pay.
Many ticket types, passes and add-ons at Disneyland are not increasing at all this time. But premium products are getting more expensive, like the highest-level, skip-the-line service at Walt Disney World, which could now run just shy of the $500 mark during peak demand.
It’s a reflection of the company’s strategy: Spread the price boosts across different audiences, while leaving bottom-tier prices - like the slowest season, one-day, one-park tickets - unchanged.
Its theme parks strategy, Disney said, has evolved over time. Higher-priced premium products and add-ons, alongside targeted discounts and a refresh of older attractions, allowed the company this summer to generate the strongest parks and cruises revenue in two years.
#disney #company #consumers



1 month ago
Kanye West and Bianca Censori made a rare public appearance alongside North West over the weekend. Consequently, the teenager drew plenty of attention during the family outing. The trio attended the ComplexCon 2026 10-Year Anniversary Festival in Los Angeles. During the event, North appeared noticeably taller than her stepmother.
According to The Sun, Kanye West attended ComplexCon 2026 at the Los Angeles Convention Center with his wife, Bianca Censori, and his 13-year-old daughter, North West. The family reportedly arrived with a large security team and spent time exploring the festival while interacting with fans.
North stood out with bright blue hair, a black outfit, and bold makeup, while Bianca opted for a more covered-up look than her usual public style. The outlet noted that North appeared to tower over her stepmother during the outing, quickly becoming one of the most talked-about moments from the family's appearance.
Additional photos from the event showed Kanye and Bianca coordinating in black leather outfits as they walked around the convention with North. The trio was seen checking out attractions and greeting attendees throughout the festival.
The outing came shortly after Kim Kardashian opened up about raising her children in the public eye. Speaking to The Times, Kardashian admitted she worries about the pressures of fame for her children. She particularly harbors concerns for North, who has shown the strongest interest in being in the spotlight.
#bianca #kanye #outing #censori
According to The Sun, Kanye West attended ComplexCon 2026 at the Los Angeles Convention Center with his wife, Bianca Censori, and his 13-year-old daughter, North West. The family reportedly arrived with a large security team and spent time exploring the festival while interacting with fans.
North stood out with bright blue hair, a black outfit, and bold makeup, while Bianca opted for a more covered-up look than her usual public style. The outlet noted that North appeared to tower over her stepmother during the outing, quickly becoming one of the most talked-about moments from the family's appearance.
Additional photos from the event showed Kanye and Bianca coordinating in black leather outfits as they walked around the convention with North. The trio was seen checking out attractions and greeting attendees throughout the festival.
The outing came shortly after Kim Kardashian opened up about raising her children in the public eye. Speaking to The Times, Kardashian admitted she worries about the pressures of fame for her children. She particularly harbors concerns for North, who has shown the strongest interest in being in the spotlight.
#bianca #kanye #outing #censori


1 month ago
Costco is famously rooted in Washington state, with its headquarters in Kirkland (which is also the name of its signature brand) and its first official store operating out of Seattle's industrial SoDo neighborhood. But did you know that the wholesale club behemoth can trace its true origins much further south, and to a famous connection? As it turns out, a line can be drawn from Costco to Howard Hughes, the famous movie producer, aviator, and eccentric business tycoon.
Among his many properties, Hughes once owned a rather large warehouse in San Diego, California, that was eventually turned into an early wholesale store called Price Club. It went on to merge with Costco in the 1990s, forever cementing the Costco-Hughes connection. Sure, it may not be the strongest celebrity-Costco connection ever, and Hughes himself never set foot inside one of the chain's stores, but it's one that Costco can be proud to have as part of its storied history nonetheless.
Read more: 9 Store-Bought Canned Chili Brands Ranked Worst To Best
Bettmann/Getty Images
While it's unclear exactly how long Howard Hughes' San Diego building served as a hangar, or if any remodeling was done prior to its wholesale club days, what is known is that it reopened as Price Club in the summer of 1976 after being purchased by local businessman Sol Price and his son, Robert. It looks pretty similar today compared to old photos of the building in its Price Club days and as an aviation hangar, with its vaulted ceilings and massive walls. The coolest part though? If you're a history buff in San Diego, you can actually go shop at the Costco that once housed Hughes' airplanes (assuming you're also a Costco member, of course). The store sits on Morena Boulevard, at the exact same address as its preceding incarnations.
#price #connection #famous
Among his many properties, Hughes once owned a rather large warehouse in San Diego, California, that was eventually turned into an early wholesale store called Price Club. It went on to merge with Costco in the 1990s, forever cementing the Costco-Hughes connection. Sure, it may not be the strongest celebrity-Costco connection ever, and Hughes himself never set foot inside one of the chain's stores, but it's one that Costco can be proud to have as part of its storied history nonetheless.
Read more: 9 Store-Bought Canned Chili Brands Ranked Worst To Best
Bettmann/Getty Images
While it's unclear exactly how long Howard Hughes' San Diego building served as a hangar, or if any remodeling was done prior to its wholesale club days, what is known is that it reopened as Price Club in the summer of 1976 after being purchased by local businessman Sol Price and his son, Robert. It looks pretty similar today compared to old photos of the building in its Price Club days and as an aviation hangar, with its vaulted ceilings and massive walls. The coolest part though? If you're a history buff in San Diego, you can actually go shop at the Costco that once housed Hughes' airplanes (assuming you're also a Costco member, of course). The store sits on Morena Boulevard, at the exact same address as its preceding incarnations.
#price #connection #famous



1 month ago
SK Hynix is exploring something it has never done before: manufacturing memory chips in the United States.
Reuters reported on September 16 that the Korean memory giant is discussing several possibilities with Intel Corporation (NASDAQ:INTC), including leasing part of Intel's long-delayed Ohio complex or forming a venture involving Intel and large cloud customers. SK Hynix said no specific plan has been finalized.
For Micron Technology, Inc. (NASDAQ:MU), the talks matter because one of its strongest strategic advantages is being the major U.S.-based memory producer while AI has made DRAM and HBM increasingly scarce.
Intel has committed enormous capital to Ohio, with the broader project potentially reaching around $100 billion over time. Delays have pushed planned production into the next decade. A tenant or joint-venture partner could therefore help Intel share the financial burden of developing the Ohio site rather than relying entirely on its own foundry demand to justify the buildout.
That is the bull case. The bear case is that exploratory talks are a long way from revenue. Bringing advanced Korean memory production to the U.S. could face cost problems, technology-transfer restrictions and objections from Seoul. Intel still needs its core manufacturing roadmap to work.
#long
Reuters reported on September 16 that the Korean memory giant is discussing several possibilities with Intel Corporation (NASDAQ:INTC), including leasing part of Intel's long-delayed Ohio complex or forming a venture involving Intel and large cloud customers. SK Hynix said no specific plan has been finalized.
For Micron Technology, Inc. (NASDAQ:MU), the talks matter because one of its strongest strategic advantages is being the major U.S.-based memory producer while AI has made DRAM and HBM increasingly scarce.
Intel has committed enormous capital to Ohio, with the broader project potentially reaching around $100 billion over time. Delays have pushed planned production into the next decade. A tenant or joint-venture partner could therefore help Intel share the financial burden of developing the Ohio site rather than relying entirely on its own foundry demand to justify the buildout.
That is the bull case. The bear case is that exploratory talks are a long way from revenue. Bringing advanced Korean memory production to the U.S. could face cost problems, technology-transfer restrictions and objections from Seoul. Intel still needs its core manufacturing roadmap to work.
#long
2 months ago
Microsoft's (NASDAQ:MSFT) fiscal 2026, which ended June 30, was arguably the strongest year in the software giant's history. Revenue grew 18% to $331.8 billion. Net income jumped 31% year over year, to $133.7 billion.
Micron Technology (NASDAQ:MU) is approaching that number from a different direction. The memory specialist earned $8.5 billion in its fiscal 2025.
Missed AI's "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our ***** ysts, we're only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
But for the fiscal fourth quarter of 2026, which ended in early September, management guided to earnings of $30.73 per diluted share, plus or minus $1.00, on a generally accepted accounting principles (GAAP) basis. On about 1.15 billion diluted shares, the guidance works out to about $35 billion of profit in one quarter (about four times what the whole prior fiscal year produced).
Here's my prediction: In fiscal 2027, Micron will earn more than Microsoft. That means beating the year Microsoft is now in, not the one it just reported. It's a bold call, and it relies almost entirely on the price of memory.
#Microsoft #quarter
Micron Technology (NASDAQ:MU) is approaching that number from a different direction. The memory specialist earned $8.5 billion in its fiscal 2025.
Missed AI's "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our ***** ysts, we're only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
But for the fiscal fourth quarter of 2026, which ended in early September, management guided to earnings of $30.73 per diluted share, plus or minus $1.00, on a generally accepted accounting principles (GAAP) basis. On about 1.15 billion diluted shares, the guidance works out to about $35 billion of profit in one quarter (about four times what the whole prior fiscal year produced).
Here's my prediction: In fiscal 2027, Micron will earn more than Microsoft. That means beating the year Microsoft is now in, not the one it just reported. It's a bold call, and it relies almost entirely on the price of memory.
#Microsoft #quarter

2 months ago
Veteran ******* yst Jim Cramer sees something in Apple's (AAPL) latest launch that is more than a reason for its customers to buy another replacement phone.
After visiting Apple's Manhattan store, the CNBC host praised the iPhone 18 but reserved his strongest enthusiasm for the foldable Duo. He plans to buy it as a second phone, a distinction that gives his excitement an intriguing business angle.
Apple shares have already gained around 23.6% this year through September 18, raising the stakes for turning product excitement into sales.
For context, Apple unveiled its iPhone 18 Pro lineup and first foldable iPhone on September 9. The Pro models reached stores on September 18; Duo availability follows on October 23.
For Cramer, the bigger opportunity goes beyond better cameras and battery life. His reaction suggests Apple could give loyal customers a fresh reason to spend, even when their existing phones still work perfectly well.
#reason #phone #veteran
After visiting Apple's Manhattan store, the CNBC host praised the iPhone 18 but reserved his strongest enthusiasm for the foldable Duo. He plans to buy it as a second phone, a distinction that gives his excitement an intriguing business angle.
Apple shares have already gained around 23.6% this year through September 18, raising the stakes for turning product excitement into sales.
For context, Apple unveiled its iPhone 18 Pro lineup and first foldable iPhone on September 9. The Pro models reached stores on September 18; Duo availability follows on October 23.
For Cramer, the bigger opportunity goes beyond better cameras and battery life. His reaction suggests Apple could give loyal customers a fresh reason to spend, even when their existing phones still work perfectly well.
#reason #phone #veteran

2 months ago
Definium Therapeutics, Inc. (NASDAQ:DFTX) has now delivered a third consecutive positive Phase 3 readout for its LSD-based medication, the second in generalized anxiety disorder. The result puts the company on a viable route toward a potential FDA approval of an LSD-based treatment for generalized anxiety disorder, and considering how closely psychedelic stocks have historically traded on each other's data, the reading carries far more weight than Definium's own ticker.
On September 14, Definium Therapeutics, Inc. (NASDAQ:DFTX) announced that its drug DT120, an orally disintegrating tablet formulation of LSD, was successful in Panorama, the company's second late-stage anxiety trial. Over 12 weeks, patients who received a 100-microgram dose experienced a 9.8-point decline on the Hamilton Anxiety Rating Scale, a typical clinical measure, compared to a 4.7-point drop with placebo.
The resulting 5.1-point placebo-adjusted improvement is similar to what the company's first pivotal anxiety trial, Voyage, showed back in August: an 11.6-point improvement versus 6.2 for placebo, a 5.4-point separation that Jefferies called one of the strongest placebo-adjusted efficacy results ever seen in generalized anxiety disorder, and that Stifel simply described as "a clean win."
Psychedelic equities have a history of trading as a group rather than as individual names, and this tendency applies both ways. In February 2026, when Compass Pathways, the sector's other clinical leader developing a psilocybin-based drug for treatment-resistant depression, reported positive late-stage data, shares of Definium Therapeutics, Inc. (NASDAQ:DFTX), Atai Beckley, GH Research, and Helus Pharma all rose, some by double digits.
That correlation is significant here because Definium's win is an independent validation of the broader therapeutic argument on which Compass and others are betting: a single dose of a classic psychedelic, administered in a controlled clinical setting, can produce lasting improvements in serious mental health conditions via pathways different from existing SSRIs and other standard-of-care drugs.
#definium #placebo
On September 14, Definium Therapeutics, Inc. (NASDAQ:DFTX) announced that its drug DT120, an orally disintegrating tablet formulation of LSD, was successful in Panorama, the company's second late-stage anxiety trial. Over 12 weeks, patients who received a 100-microgram dose experienced a 9.8-point decline on the Hamilton Anxiety Rating Scale, a typical clinical measure, compared to a 4.7-point drop with placebo.
The resulting 5.1-point placebo-adjusted improvement is similar to what the company's first pivotal anxiety trial, Voyage, showed back in August: an 11.6-point improvement versus 6.2 for placebo, a 5.4-point separation that Jefferies called one of the strongest placebo-adjusted efficacy results ever seen in generalized anxiety disorder, and that Stifel simply described as "a clean win."
Psychedelic equities have a history of trading as a group rather than as individual names, and this tendency applies both ways. In February 2026, when Compass Pathways, the sector's other clinical leader developing a psilocybin-based drug for treatment-resistant depression, reported positive late-stage data, shares of Definium Therapeutics, Inc. (NASDAQ:DFTX), Atai Beckley, GH Research, and Helus Pharma all rose, some by double digits.
That correlation is significant here because Definium's win is an independent validation of the broader therapeutic argument on which Compass and others are betting: a single dose of a classic psychedelic, administered in a controlled clinical setting, can produce lasting improvements in serious mental health conditions via pathways different from existing SSRIs and other standard-of-care drugs.
#definium #placebo


2 months ago
On August 10, Ferguson Enterprises Inc. (NYSE:FERG) reported results for the quarter ended June 30, and the numbers show a company growing straight through a soft housing market. Sales rose 4.6% to $8.8 billion, and management lifted its outlook for the full year. But profit grew more slowly than sales, and that gap is what makes this report worth a closer look.
The strongest engine was non-residential work, where US revenue jumped 8% on share gains in what management called a mixed market. Large capital projects are part of the story, with open order volumes growing and bidding activity strong, so there is a pipeline behind the current numbers. Housing, roughly half of revenue, is the weak spot. Yet residential sales still rose 2% in the US even though new construction is weak and repair work is soft, which means Ferguson is beating its markets rather than riding them.
Capital deployment is the second pillar. Ferguson closed five acquisitions in the quarter, and on July 13, it announced a deal for FWI Holdings, known as FloWorks, an industrial distributor of valves and flow-control products that is expected to close in the third quarter. The eight deals announced this year carry about $1.4 billion in annualized revenue, a second growth path alongside organic sales. Net debt sits at 1.3 times adjusted EBITDA, a level management calls strong. The company also returned cash, buying back $202 million of stock in the quarter and declaring a $0.89 dividend payable October 7 to holders of record on August 21. Management raised its full-year sales outlook to mid-single-digit growth, before counting FloWorks.
Start with the gap between sales and profit. Adjusted operating profit rose 2.9%, behind the 4.6% sales gain, and gross margin slipped 20 basis points to 31.0%. Ferguson notes that last year's gross margin was temporarily lifted by the timing of supplier price increases, which is fair context, but the direction is still down. Reported earnings per share of $3.43 rose 6.9%, while the adjusted figure of $3.39 grew a slower 5.3%.
Then there are the soft spots. About half of revenue comes from residential markets that management describes as subdued, so a 2% gain there is modest. Canada's sales slipped 1.9%, with a business divestment outweighing organic growth, and management calls the market there challenging, especially in residential. Management also describes the economic environment as uncertain, and the margin part of the guidance raise is small. The low end of the adjusted operating margin range moved from 9.4% to 9.5%, while the top stayed at 9.8%. The guidance also leaves out FloWorks, and net debt to adjusted EBITDA is 1.3 times, against 1.2 times a year ago.
#management
The strongest engine was non-residential work, where US revenue jumped 8% on share gains in what management called a mixed market. Large capital projects are part of the story, with open order volumes growing and bidding activity strong, so there is a pipeline behind the current numbers. Housing, roughly half of revenue, is the weak spot. Yet residential sales still rose 2% in the US even though new construction is weak and repair work is soft, which means Ferguson is beating its markets rather than riding them.
Capital deployment is the second pillar. Ferguson closed five acquisitions in the quarter, and on July 13, it announced a deal for FWI Holdings, known as FloWorks, an industrial distributor of valves and flow-control products that is expected to close in the third quarter. The eight deals announced this year carry about $1.4 billion in annualized revenue, a second growth path alongside organic sales. Net debt sits at 1.3 times adjusted EBITDA, a level management calls strong. The company also returned cash, buying back $202 million of stock in the quarter and declaring a $0.89 dividend payable October 7 to holders of record on August 21. Management raised its full-year sales outlook to mid-single-digit growth, before counting FloWorks.
Start with the gap between sales and profit. Adjusted operating profit rose 2.9%, behind the 4.6% sales gain, and gross margin slipped 20 basis points to 31.0%. Ferguson notes that last year's gross margin was temporarily lifted by the timing of supplier price increases, which is fair context, but the direction is still down. Reported earnings per share of $3.43 rose 6.9%, while the adjusted figure of $3.39 grew a slower 5.3%.
Then there are the soft spots. About half of revenue comes from residential markets that management describes as subdued, so a 2% gain there is modest. Canada's sales slipped 1.9%, with a business divestment outweighing organic growth, and management calls the market there challenging, especially in residential. Management also describes the economic environment as uncertain, and the margin part of the guidance raise is small. The low end of the adjusted operating margin range moved from 9.4% to 9.5%, while the top stayed at 9.8%. The guidance also leaves out FloWorks, and net debt to adjusted EBITDA is 1.3 times, against 1.2 times a year ago.
#management

2 months ago
Concerned about an AI bubble? Sign up for The Daily Upside for smart and actionable market news, built for investors.
Let's just come right out and say it: It's a good time to sell a registered investment advisor practice.
We've all read headlines about sky-high multiples and firm owners fielding multiple calls a day from potential suitors. It's an environment where successful founders can generate tremendous value from selling their firms. The process isn't simple, however, and there are pitfalls that owners can stumble into, potentially robbing them of hard-earned enterprise value.
Adam Lewis, partner at Vedder Price, talked through these dynamics this week during a standing-room only session at the Future Proof Festival in Huntington Beach, California. While he advises on M&A across multiple industries, the world of wealth management stands apart in 2026 as the "strongest by far" in terms of dealmaking activity. The entrance of private equity buyers in the RIA **** e has been particularly significant, with the heightened competition among buyers helping ramp up valuations. It's a great environment for sellers who hope to monetize their life's work to fund their retirement lifestyle and potentially create intergenerational wealth, Lewis said. But it's important to be diligent and bring the right expertise to the table during the negotiation process.
Sign up for The Daily Upside at no cost for premium **** ysis on all your favorite stocks.
#lewis
Let's just come right out and say it: It's a good time to sell a registered investment advisor practice.
We've all read headlines about sky-high multiples and firm owners fielding multiple calls a day from potential suitors. It's an environment where successful founders can generate tremendous value from selling their firms. The process isn't simple, however, and there are pitfalls that owners can stumble into, potentially robbing them of hard-earned enterprise value.
Adam Lewis, partner at Vedder Price, talked through these dynamics this week during a standing-room only session at the Future Proof Festival in Huntington Beach, California. While he advises on M&A across multiple industries, the world of wealth management stands apart in 2026 as the "strongest by far" in terms of dealmaking activity. The entrance of private equity buyers in the RIA **** e has been particularly significant, with the heightened competition among buyers helping ramp up valuations. It's a great environment for sellers who hope to monetize their life's work to fund their retirement lifestyle and potentially create intergenerational wealth, Lewis said. But it's important to be diligent and bring the right expertise to the table during the negotiation process.
Sign up for The Daily Upside at no cost for premium **** ysis on all your favorite stocks.
#lewis

2 months ago
Stocks slid Wednesday afternoon after Federal Reserve Chair Kevin Warsh followed the central bank's first rate hike in three years with a press conference that hinted it wouldn't be the last.
The S&P 500 dropped 1%, heading toward its lowest close since July. The Dow Jones Industrial Average fell 1.7%, or more than 700 points, with financial shares leading the decline. The Nasdaq Composite fell 0.8%. The 10-year Treasury yield held near 5% a day after touching its highest level since 2007, and the dollar index climbed 0.6% to its strongest since late July.
Markets had priced in the quarter-point increase itself and initially took it in stride. All three indexes were higher before the 2 p.m. decision. The selling started during the press conference.
Warsh was on a tightrope going in. The question was whether he'd frame the hike as a one-off adjustment—which risked the bond market reading it as too little to deter inflation—or as the start of a longer cycle. He did neither, and instead went in a more hawkish direction. "I would be hard pressed to describe broad financial conditions as restrictive," he said in his opening remarks. "This view was widely shared by the committee, so we removed a dose of accommodation."
That's a new way of describing a rate hike, and one investors aren't used to. Under his predecessor, Jerome Powell, the Fed called policy "modestly restrictive," meaning rates were already high enough to slow the economy. Warsh was saying that at 3.5%–3.75%, they weren't—and by implication, one quarter point may not have gotten them there either. Asked directly, he declined to say whether policy is restrictive now.
#hike #press
The S&P 500 dropped 1%, heading toward its lowest close since July. The Dow Jones Industrial Average fell 1.7%, or more than 700 points, with financial shares leading the decline. The Nasdaq Composite fell 0.8%. The 10-year Treasury yield held near 5% a day after touching its highest level since 2007, and the dollar index climbed 0.6% to its strongest since late July.
Markets had priced in the quarter-point increase itself and initially took it in stride. All three indexes were higher before the 2 p.m. decision. The selling started during the press conference.
Warsh was on a tightrope going in. The question was whether he'd frame the hike as a one-off adjustment—which risked the bond market reading it as too little to deter inflation—or as the start of a longer cycle. He did neither, and instead went in a more hawkish direction. "I would be hard pressed to describe broad financial conditions as restrictive," he said in his opening remarks. "This view was widely shared by the committee, so we removed a dose of accommodation."
That's a new way of describing a rate hike, and one investors aren't used to. Under his predecessor, Jerome Powell, the Fed called policy "modestly restrictive," meaning rates were already high enough to slow the economy. Warsh was saying that at 3.5%–3.75%, they weren't—and by implication, one quarter point may not have gotten them there either. Asked directly, he declined to say whether policy is restrictive now.
#hike #press

2 months ago
Cerebras Systems (NASDAQ:CBRS) has been cut in half. Shares of the artificial intelligence (AI) computing specialist peaked at $386.34 on their first day of trading in May, a day after the company priced its initial public offering (IPO) at $185 and raised $6.4 billion. As of this writing, the stock trades around $184 -- about 52% below the high, and just under that IPO price.
A decline like that usually follows a stumble: a guidance cut, a lost customer, a bad quarter. Cerebras hasn't had one. Shares dropped double digits anyway the day after its mid-August update, arguably the company's strongest yet and one in which management raised its outlook for the year.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Yet even at half price, the stock costs about 145 times the earnings **** ysts expect the company to generate next year.
What did the fall reprice -- the business, or just the price tag?
#signal #company #half
A decline like that usually follows a stumble: a guidance cut, a lost customer, a bad quarter. Cerebras hasn't had one. Shares dropped double digits anyway the day after its mid-August update, arguably the company's strongest yet and one in which management raised its outlook for the year.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Yet even at half price, the stock costs about 145 times the earnings **** ysts expect the company to generate next year.
What did the fall reprice -- the business, or just the price tag?
#signal #company #half

2 months ago
On August 5, Kinetik Holdings Inc. (NYSE:KNTK) reported the strongest quarterly results in company history and raised its full-year 2026 guidance. The Permian-focused midstream operator posted net income, including noncontrolling interest, of $123.1 million for the quarter ended June 30, while Adjusted EBITDA climbed to $280.8 million. Management didn't stop at celebrating the number. It used the quarter as the launchpad for a string of expansion decisions that stretch out to 2028.
The Midstream Logistics segment, Kinetik's largest, grew Adjusted EBITDA 35% year over year to $204.8 million in the second quarter, even though processed natural gas volumes held flat at 1.74 Bcf/d. That flat number actually undersells the quarter. It came despite roughly 250 million cubic feet per day of gas that had been shut in because of weak Waha-area pricing, with stronger natural gas liquid recoveries, condensate yields, and favorable commodity spreads carrying the segment instead.
Management is betting the growth continues well past 2026. In May, Kinetik reached a final investment decision on Kings Landing II, a roughly $260 million project that will lift sour gas processing capacity across the company's Delaware North complex above 700 MMcf/d and push total system capacity to 2.7 Bcf/d when it comes online in mid-2028, earlier than previously communicated. The ECCC Pipeline, which links the system's northern and southern halves between Eddy and Culberson Counties, is now in service, and right-of-way work has already begun on a follow-on expansion for 2027.
Kinetik also locked in new firm Gulf Coast access for residue gas starting in 2027 and signed fresh natural gas liquids transport agreements, both aimed at getting better prices for the gas it moves. On the back of that momentum, Kinetik raised its full-year 2026 Adjusted EBITDA guidance to a range of $1.04 billion to $1.1 billion, a 7% ***** p from the guidance it issued in February.
Not every part of the business is moving in the same direction. The Pipeline Transportation segment posted Adjusted EBITDA of $83.0 million in the quarter, down 14% year over year, a decline the company attributes to last year's divestiture of its equity stake in EPIC Crude Holdings. That sale removed a source of cash flow the rest of the business now has to make up for. Kinetik also expects gas curtailments to keep running at an average of 25 million cubic feet per day through the second half of 2026, on top of the Waha-driven shut-ins that already weighed on the quarter. Its own pricing ***** umptions underline the regional problem: the company is now modeling Waha Hub natural gas at negative $0.26 per MMBtu for the full year, meaning gas in parts of the Permian is priced so low that moving it out of the basin is the whole game.
#quarter
The Midstream Logistics segment, Kinetik's largest, grew Adjusted EBITDA 35% year over year to $204.8 million in the second quarter, even though processed natural gas volumes held flat at 1.74 Bcf/d. That flat number actually undersells the quarter. It came despite roughly 250 million cubic feet per day of gas that had been shut in because of weak Waha-area pricing, with stronger natural gas liquid recoveries, condensate yields, and favorable commodity spreads carrying the segment instead.
Management is betting the growth continues well past 2026. In May, Kinetik reached a final investment decision on Kings Landing II, a roughly $260 million project that will lift sour gas processing capacity across the company's Delaware North complex above 700 MMcf/d and push total system capacity to 2.7 Bcf/d when it comes online in mid-2028, earlier than previously communicated. The ECCC Pipeline, which links the system's northern and southern halves between Eddy and Culberson Counties, is now in service, and right-of-way work has already begun on a follow-on expansion for 2027.
Kinetik also locked in new firm Gulf Coast access for residue gas starting in 2027 and signed fresh natural gas liquids transport agreements, both aimed at getting better prices for the gas it moves. On the back of that momentum, Kinetik raised its full-year 2026 Adjusted EBITDA guidance to a range of $1.04 billion to $1.1 billion, a 7% ***** p from the guidance it issued in February.
Not every part of the business is moving in the same direction. The Pipeline Transportation segment posted Adjusted EBITDA of $83.0 million in the quarter, down 14% year over year, a decline the company attributes to last year's divestiture of its equity stake in EPIC Crude Holdings. That sale removed a source of cash flow the rest of the business now has to make up for. Kinetik also expects gas curtailments to keep running at an average of 25 million cubic feet per day through the second half of 2026, on top of the Waha-driven shut-ins that already weighed on the quarter. Its own pricing ***** umptions underline the regional problem: the company is now modeling Waha Hub natural gas at negative $0.26 per MMBtu for the full year, meaning gas in parts of the Permian is priced so low that moving it out of the basin is the whole game.
#quarter


2 months ago
Alluvium **** et Management, an **** et management company, released its "Conventum – Alluvium Global Fund" second-quarter 2026 investor letter. The letter can be downloaded here. The second quarter reflected a sharp shift from geopolitical uncertainty and oil market volatility to a powerful equity rally led by semiconductor companies. Despite the broader market strength, the Fund declined 1.4% in EUR terms, 2.2% in USD terms, and 3.9% in AUD terms. Portfolio results were mixed, with Alphabet benefiting from strong Cloud growth, while Robert Half, H&R Block and other holdings posted solid gains. However, cable businesses and several healthcare and consumer holdings weighed on performance. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Conventum – Alluvium Global Fund highlighted Alphabet Inc. (NASDAQ:GOOG). Alphabet Inc. (NASDAQ:GOOG), the parent company of Google, offers various platforms and services, including online search and advertising, cloud solutions, and artificial intelligence. On September 15, 2026, Alphabet Inc. (NASDAQ:GOOG) closed at $341.43 per share, reflecting a market capitalization of $4.2 trillion. Alphabet Inc. (NASDAQ:GOOG) posted a one-month return of -0.08%, while its shares gained 36.65% over the past 52 weeks.
Conventum – Alluvium Global Fund stated the following regarding Alphabet Inc. (NASDAQ:GOOG) in its Q2 2026 investor letter:
"Alphabet Inc. (NASDAQ:GOOG) was the Fund's strongest performer over the quarter, up 24.4%. There's little to add from our last report, except that its 22% revenue growth exceeded our expectations, and it seems it can't keep up with demand, hence it has increased, yet again (and somewhat worryingly) its capital expenditure to budget (to USD 190b) and expects further increases next year."
Alphabet Inc. (NASDAQ:GOOG) ranks 7th on our list of 40 Most Popular Stocks Among Hedge Funds. As per our database, 195 hedge fund portfolios held Alphabet Inc. (NASDAQ:GOOG) at the end of the second quarter, which was 201 in the previous quarter. While we acknowledge the potential of Alphabet Inc. (NASDAQ:GOOG) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#alphabet #NASDAQ #quarter #conventum
In its second-quarter 2026 investor letter, Conventum – Alluvium Global Fund highlighted Alphabet Inc. (NASDAQ:GOOG). Alphabet Inc. (NASDAQ:GOOG), the parent company of Google, offers various platforms and services, including online search and advertising, cloud solutions, and artificial intelligence. On September 15, 2026, Alphabet Inc. (NASDAQ:GOOG) closed at $341.43 per share, reflecting a market capitalization of $4.2 trillion. Alphabet Inc. (NASDAQ:GOOG) posted a one-month return of -0.08%, while its shares gained 36.65% over the past 52 weeks.
Conventum – Alluvium Global Fund stated the following regarding Alphabet Inc. (NASDAQ:GOOG) in its Q2 2026 investor letter:
"Alphabet Inc. (NASDAQ:GOOG) was the Fund's strongest performer over the quarter, up 24.4%. There's little to add from our last report, except that its 22% revenue growth exceeded our expectations, and it seems it can't keep up with demand, hence it has increased, yet again (and somewhat worryingly) its capital expenditure to budget (to USD 190b) and expects further increases next year."
Alphabet Inc. (NASDAQ:GOOG) ranks 7th on our list of 40 Most Popular Stocks Among Hedge Funds. As per our database, 195 hedge fund portfolios held Alphabet Inc. (NASDAQ:GOOG) at the end of the second quarter, which was 201 in the previous quarter. While we acknowledge the potential of Alphabet Inc. (NASDAQ:GOOG) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#alphabet #NASDAQ #quarter #conventum

2 months ago
Is there anything prettier than a consistently uptrending stock price chart? I'm drawn to these types of charts. I've always thought a consistent uptrend is an indication of strong buying power for a stock. However, while I can tell you if a chart looks like a consistent, methodical trend, it's hard to define it using data, which is necessary to create an indicator. That's why, until now, I've never put numbers behind my theory.
I won't go into the details, but using moving averages over various time frames, I've created a ranking system for stocks with the most consistent uptrends and downtrends over the past three months. Using this ranking system, Docusign (DOCU) is one of the top uptrending stocks. That's a pretty chart, if I do say so myself. When I see a chart like this, I think, why would it stop now?
In this week's article, I'll test my theory with actual numbers and see if DOCU and other stocks like it are good bets, like my instincts have always led me to believe.
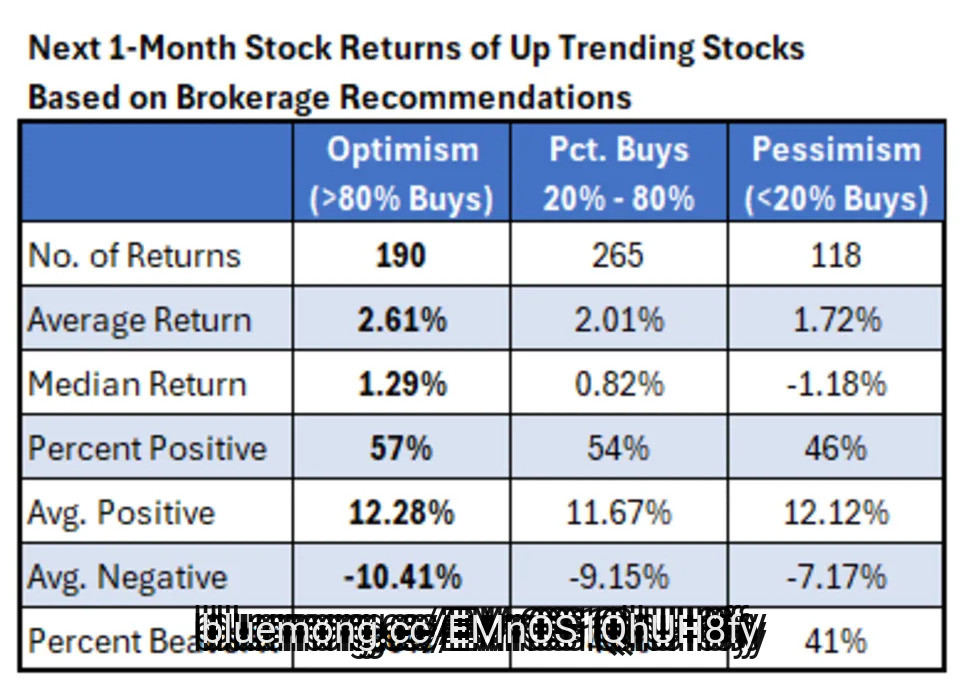
For this study, I went back to 2024 and picked the 18th of each month, which corresponds to the end of this week. I used my trend ranking system to find the 30 stocks in the strongest uptrends and the 30 in the most consistent downtrends. Then, I tracked how each group performed over the next month of trading. The table below summarizes the results.
My instincts look correct based on the average returns of the stocks. The top uptrending stocks averaged a return of 2.15% over the next month, while the most consistently downtrending stocks averaged a return of 1.57%. The other stocks averaged 1.84%, falling between the two groups.
#like #using
I won't go into the details, but using moving averages over various time frames, I've created a ranking system for stocks with the most consistent uptrends and downtrends over the past three months. Using this ranking system, Docusign (DOCU) is one of the top uptrending stocks. That's a pretty chart, if I do say so myself. When I see a chart like this, I think, why would it stop now?
In this week's article, I'll test my theory with actual numbers and see if DOCU and other stocks like it are good bets, like my instincts have always led me to believe.
For this study, I went back to 2024 and picked the 18th of each month, which corresponds to the end of this week. I used my trend ranking system to find the 30 stocks in the strongest uptrends and the 30 in the most consistent downtrends. Then, I tracked how each group performed over the next month of trading. The table below summarizes the results.
My instincts look correct based on the average returns of the stocks. The top uptrending stocks averaged a return of 2.15% over the next month, while the most consistently downtrending stocks averaged a return of 1.57%. The other stocks averaged 1.84%, falling between the two groups.
#like #using

2 months ago
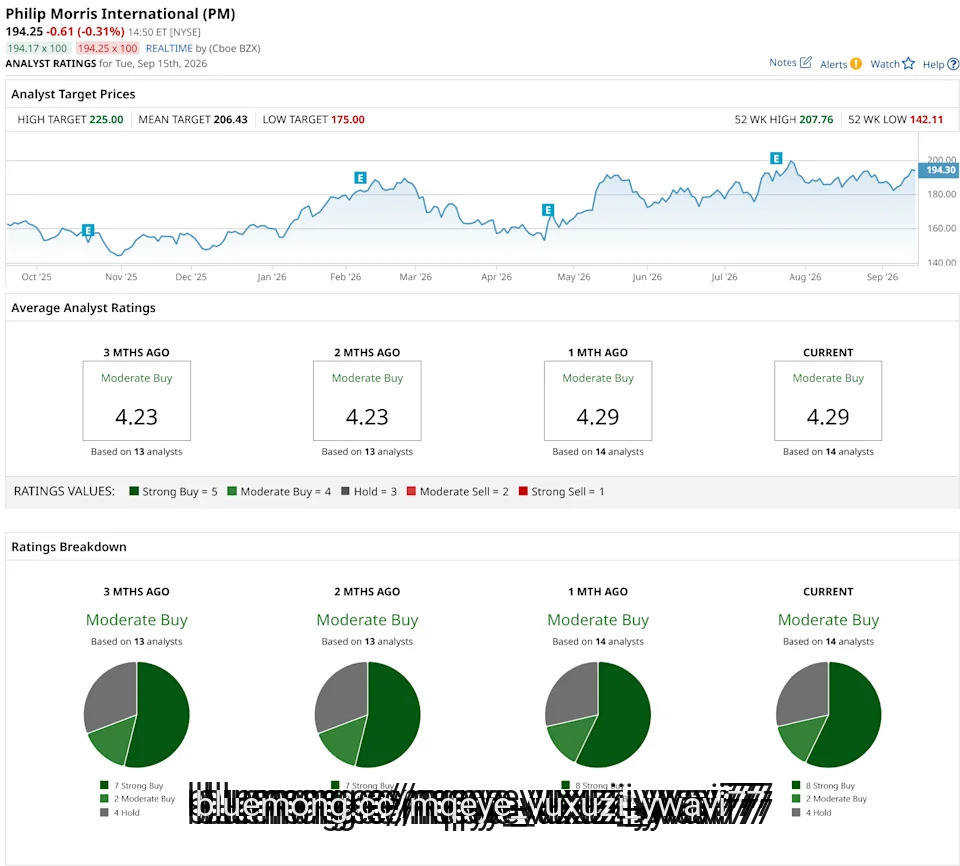
President Trump has nominated Nicole Saphier as Surgeon General, and she has revealed her investment portfolio, which includes tobacco stocks Philip Morris International (PM), Altria Group (MO), and British American Tobacco (BTI). If confirmed in the hearing scheduled for Sept. 16, Saphier would divest these holdings no later than 90 days after her confirmation, as part of an ethics agreement. This clearly avoids conflicts of interest with the role's public health mandate.
Meanwhile, the tobacco market is transforming, with smoke-free products gaining prominence. Bank of America's four‑week scanner data through May 30 showed that most U.S. tobacco categories continued to lose volume, while oral nicotine products remained the sector's strongest growth area.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Billionaire Charlie Munger, Who Died at 99, Skipped Insurance on His Mansion Since He Could Just Write a Check to Rebuild — 'All Intelligent People Do It My Way'
The EV Bubble Has Burst. How to Play Rivian Stock Now.
#philip
Meanwhile, the tobacco market is transforming, with smoke-free products gaining prominence. Bank of America's four‑week scanner data through May 30 showed that most U.S. tobacco categories continued to lose volume, while oral nicotine products remained the sector's strongest growth area.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Billionaire Charlie Munger, Who Died at 99, Skipped Insurance on His Mansion Since He Could Just Write a Check to Rebuild — 'All Intelligent People Do It My Way'
The EV Bubble Has Burst. How to Play Rivian Stock Now.
#philip


2 months ago
In XRP news today, its 30-day liquidity index on Binance has climbed to 0.0675, the highest reading in about six months. Its 30-day turnover recovered to approximately $4.6 billion after sinking to between $2 billion and $3 billion during July and August.
The rebound signals that XRP liquidity conditions have meaningfully improved, but a deeper order book supports both accumulation and distribution equally well, and is leaving the question of which side actually controls this market unanswered.
The liquidity index measures how easily traders can move XRP in and out of positions without moving the price against themselves, calculated against how quickly XRP turns over relative to what Binance holds on its books. A rising reading means faster turnover and tighter execution, which is exactly what the data shows.
XRP closed August up about 28.5%, its strongest August performance since 2021, while U.S. spot XRP ETF products pulled in $153.55 million of inflows that month.
Now, the flow data from the end of last week complicates a clean bullish read. More than 91 million XRP moved into Binance on the 11th, and over 113 million XRP moved out, both six-month highs in single-day volume. Withdrawals outpaced deposits by 22.7 million XRP, yet Binance's total XRP holdings rose just 0.43% over the full week.
#reading
The rebound signals that XRP liquidity conditions have meaningfully improved, but a deeper order book supports both accumulation and distribution equally well, and is leaving the question of which side actually controls this market unanswered.
The liquidity index measures how easily traders can move XRP in and out of positions without moving the price against themselves, calculated against how quickly XRP turns over relative to what Binance holds on its books. A rising reading means faster turnover and tighter execution, which is exactly what the data shows.
XRP closed August up about 28.5%, its strongest August performance since 2021, while U.S. spot XRP ETF products pulled in $153.55 million of inflows that month.
Now, the flow data from the end of last week complicates a clean bullish read. More than 91 million XRP moved into Binance on the 11th, and over 113 million XRP moved out, both six-month highs in single-day volume. Withdrawals outpaced deposits by 22.7 million XRP, yet Binance's total XRP holdings rose just 0.43% over the full week.
#reading


2 months ago
The exchange-traded fund (ETF) market's August numbers look flawless on the surface, until you look at where the money actually went.
The industry held $16.4 trillion in ******* ets through August 31, 2026, with $180 billion in fresh capital pouring in that month alone, 3.8 times the historical August average and the strongest August on record for fund inflows, State Street reported.
New fund creation has been equally prolific, with 1,023 ETFs debuting in the first eight months of 2026, a 52% jump from the previous year's pace.
Active strategies represent more than 80% of the year's new products, and about 25% of August's 134 launches used leveraged or inverse structures, FactSet noted.
Among August's new launches were 18 single-stock ETFs, most of them targeting semiconductor companies to tap into the artificial intelligence infrastructure buildout.
#august #state #street #exchange
The industry held $16.4 trillion in ******* ets through August 31, 2026, with $180 billion in fresh capital pouring in that month alone, 3.8 times the historical August average and the strongest August on record for fund inflows, State Street reported.
New fund creation has been equally prolific, with 1,023 ETFs debuting in the first eight months of 2026, a 52% jump from the previous year's pace.
Active strategies represent more than 80% of the year's new products, and about 25% of August's 134 launches used leveraged or inverse structures, FactSet noted.
Among August's new launches were 18 single-stock ETFs, most of them targeting semiconductor companies to tap into the artificial intelligence infrastructure buildout.
#august #state #street #exchange
2 months ago
A European independent power producer is expanding its ******* et base on the continent. Israel-headquartered Econergy on September 15 said it is entering the French market with a €134-million ($155 million) acquisition of Escofi, a private wind energy platform of about 740 MW.Econergy, which has offices across Europe, said the deal significantly expands the company's European wind ******* et base, bringing its total renewable portfolio to 13 GW. Escofi, founded in 1988, originates, finances, builds, and operates onshore wind projects, with its wind energy portfolio across four development stages: 128 MW in commercial operation, 34 MW under construction, 147 MW in advanced development stage (with building permits and grid connection approvals in place and construction due to commence between 2028 and 2030), and 432 MW in early and mid-stage development.Escofi's portfolio is concentrated in the Hauts-de-France and Grand Est regions of northern France, which officials said have the strongest onshore wind conditions and regulatory environments in the country.
More than 90% of Escofi's operational and under-construction capacity benefits from 20-year contracted revenues under France's Contracts for Difference (CfDs) regime, providing a stable, long-term revenue stream for the portfolio. Escofi in July of this year secured additional CfDs for three more projects totaling 46 MW at prices above €80/MWh ($92/MWh) for 20-year terms, further strengthening the portfolio's contracted revenue base."The acquisition of Escofi is a significant strategic step for Econergy, establishing our presence in France and materially expanding our European wind platform," said Eyal Podhorzer, CEO of Econergy. "Escofi brings us a proven, 37-year-old French onshore wind operator with a high-quality operational fleet and a strong pipeline of projects with 20-year CfD revenues located in the best wind regions in France. Combined with our existing European platform, this gives Econergy a stronger and more geographically diversified base of long-term, contracted cash flows to build on."Escofi's 309 MW of operational, under-construction, and advanced-development projects are expected to generate annual revenues of €59-65 million and EBITDA of €47-53 million on a representative-year basis. By 2030, on completion of the projects under construction and the 147-MW advanced pipeline, Escofi's operational capacity is expected to reach about 300 MW, with project-level EBITDA of about €42–44 million. Escofi's effective ownership across projects stands at about 91%, and the 432-MW early- and mid-stage pipeline provides the platform's long-term growth runway, according to the company.
#econergy
More than 90% of Escofi's operational and under-construction capacity benefits from 20-year contracted revenues under France's Contracts for Difference (CfDs) regime, providing a stable, long-term revenue stream for the portfolio. Escofi in July of this year secured additional CfDs for three more projects totaling 46 MW at prices above €80/MWh ($92/MWh) for 20-year terms, further strengthening the portfolio's contracted revenue base."The acquisition of Escofi is a significant strategic step for Econergy, establishing our presence in France and materially expanding our European wind platform," said Eyal Podhorzer, CEO of Econergy. "Escofi brings us a proven, 37-year-old French onshore wind operator with a high-quality operational fleet and a strong pipeline of projects with 20-year CfD revenues located in the best wind regions in France. Combined with our existing European platform, this gives Econergy a stronger and more geographically diversified base of long-term, contracted cash flows to build on."Escofi's 309 MW of operational, under-construction, and advanced-development projects are expected to generate annual revenues of €59-65 million and EBITDA of €47-53 million on a representative-year basis. By 2030, on completion of the projects under construction and the 147-MW advanced pipeline, Escofi's operational capacity is expected to reach about 300 MW, with project-level EBITDA of about €42–44 million. Escofi's effective ownership across projects stands at about 91%, and the 432-MW early- and mid-stage pipeline provides the platform's long-term growth runway, according to the company.
#econergy


2 months ago
Auxier ******* et Management, an investment advisory firm, released its second-quarter 2026 investor letter. The letter can be downloaded here. Following a strong rebound from the first-quarter decline, the S&P 500 gained 15.2% as accelerating capital spending toward artificial intelligence infrastructure drove significant gains across technology hardware companies. Semiconductor and data-center-related businesses benefited from supply constraints and strong demand, while enterprise software remained under pressure as investors reassessed AI disruption risks and compressed valuations. In the quarter, Auxier Focus Fund's Investor Class gained 8.82% and 10.70% for the six months ended June 30, 2026. Despite strong earnings growth across the broader market, Auxier highlighted concerns around rising margin debt, increased leverage, and elevated capital flows into high-growth technology areas that could amplify future volatility. The firm continues to focus on identifying enduring businesses with strong competitive advantages, resilient cash flows, and sustainable long-term growth potential. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Auxier ******* et Management highlighted Caterpillar Inc. (NYSE:CAT). Caterpillar Inc. (NYSE:CAT) is a leading manufacturer of construction and mining equipment, off-highway diesel and natural gas engines, industrial gas turbines, and diesel-electric locomotives. On September 14, 2026, Caterpillar Inc. (NYSE:CAT) closed at $784.00 per share. Over the past month, Caterpillar Inc. (NYSE:CAT) declined 7.12%, but its shares are up 77.23% over the past year. Caterpillar Inc. (NYSE:CAT) has a market capitalization of $360.39 billion, and its stock has traded within a 52-week range of $423.32 to $1,073.46.
Auxier ******* et Management stated the following regarding Caterpillar Inc. (NYSE:CAT) in its Q2 2026 investor letter:
"Industrials were the strongest performing sector during the quarter. Tech-facing industrial players benefited from a shift in investor focus toward AI buildout rather than the development of AI models. Caterpillar Inc. (NYSE:CAT) and Gates also benefited indirectly from the expansion of AI infrastructure, particularly through increased demand for energy generation and cooling capacity in data centers."
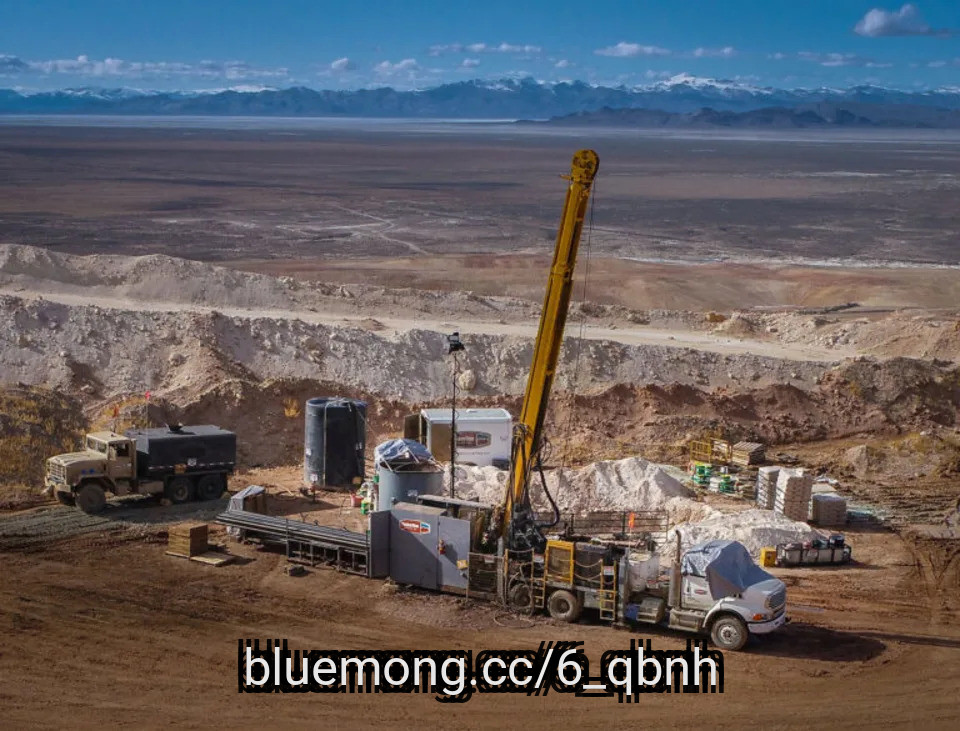
Photo from Hycroft Mining website
#letter
In its second-quarter 2026 investor letter, Auxier ******* et Management highlighted Caterpillar Inc. (NYSE:CAT). Caterpillar Inc. (NYSE:CAT) is a leading manufacturer of construction and mining equipment, off-highway diesel and natural gas engines, industrial gas turbines, and diesel-electric locomotives. On September 14, 2026, Caterpillar Inc. (NYSE:CAT) closed at $784.00 per share. Over the past month, Caterpillar Inc. (NYSE:CAT) declined 7.12%, but its shares are up 77.23% over the past year. Caterpillar Inc. (NYSE:CAT) has a market capitalization of $360.39 billion, and its stock has traded within a 52-week range of $423.32 to $1,073.46.
Auxier ******* et Management stated the following regarding Caterpillar Inc. (NYSE:CAT) in its Q2 2026 investor letter:
"Industrials were the strongest performing sector during the quarter. Tech-facing industrial players benefited from a shift in investor focus toward AI buildout rather than the development of AI models. Caterpillar Inc. (NYSE:CAT) and Gates also benefited indirectly from the expansion of AI infrastructure, particularly through increased demand for energy generation and cooling capacity in data centers."
Photo from Hycroft Mining website
#letter

2 months ago
Auxier ******* et Management, an investment advisory firm, released its second-quarter 2026 investor letter. The letter can be downloaded here. Following a strong rebound from the first-quarter decline, the S&P 500 gained 15.2% as accelerating capital spending toward artificial intelligence infrastructure drove significant gains across technology hardware companies. Semiconductor and data-center-related businesses benefited from supply constraints and strong demand, while enterprise software remained under pressure as investors reassessed AI disruption risks and compressed valuations. In the quarter, Auxier Focus Fund's Investor Class gained 8.82% and 10.70% for the six months ended June 30, 2026. Despite strong earnings growth across the broader market, Auxier highlighted concerns around rising margin debt, increased leverage, and elevated capital flows into high-growth technology areas that could amplify future volatility. The firm continues to focus on identifying enduring businesses with strong competitive advantages, resilient cash flows, and sustainable long-term growth potential. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Auxier ******* et Management highlighted Gates Industrial Corporation Ltd. (NYSE:GTES). Gates Industrial Corporation Ltd. (NYSE:GTES) is a leading manufacturer of engineered power transmission and fluid power solutions. On September 14, 2026, Gates Industrial Corporation Ltd. (NYSE:GTES) closed at $25.42 per share. Over the past month, Gates Industrial Corporation Ltd. (NYSE:GTES) declined 6.17%, and its shares gained 0.77% over the past 52 weeks. Gates Industrial Corporation Ltd. (NYSE:GTES) has a market capitalization of $6.44 billion, and its stock has traded within a 52-week range of $20.88 and $30.34.
Auxier ******* et Management stated the following regarding Gates Industrial Corporation Ltd. (NYSE:GTES) in its Q2 2026 investor letter:
"Industrials were the strongest performing sector during the quarter. Tech-facing industrial players benefited from a shift in investor focus toward AI buildout rather than the development of AI models. Caterpillar and Gates Industrial Corporation Ltd. (NYSE:GTES) Ltd. (NYSE:GTES) also benefited indirectly from the expansion of AI infrastructure, particularly through increased demand for energy generation and cooling capacity in data centers."
Gates Industrial Corporation Ltd. (NYSE:GTES) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 36 hedge fund portfolios held Gates Industrial Corporation Ltd. (NYSE:GTES) at the end of the second quarter which was 37 in the previous quarter. While we acknowledge the potential of Gates Industrial Corporation Ltd. (NYSE:GTES) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from
In its second-quarter 2026 investor letter, Auxier ******* et Management highlighted Gates Industrial Corporation Ltd. (NYSE:GTES). Gates Industrial Corporation Ltd. (NYSE:GTES) is a leading manufacturer of engineered power transmission and fluid power solutions. On September 14, 2026, Gates Industrial Corporation Ltd. (NYSE:GTES) closed at $25.42 per share. Over the past month, Gates Industrial Corporation Ltd. (NYSE:GTES) declined 6.17%, and its shares gained 0.77% over the past 52 weeks. Gates Industrial Corporation Ltd. (NYSE:GTES) has a market capitalization of $6.44 billion, and its stock has traded within a 52-week range of $20.88 and $30.34.
Auxier ******* et Management stated the following regarding Gates Industrial Corporation Ltd. (NYSE:GTES) in its Q2 2026 investor letter:
"Industrials were the strongest performing sector during the quarter. Tech-facing industrial players benefited from a shift in investor focus toward AI buildout rather than the development of AI models. Caterpillar and Gates Industrial Corporation Ltd. (NYSE:GTES) Ltd. (NYSE:GTES) also benefited indirectly from the expansion of AI infrastructure, particularly through increased demand for energy generation and cooling capacity in data centers."
Gates Industrial Corporation Ltd. (NYSE:GTES) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 36 hedge fund portfolios held Gates Industrial Corporation Ltd. (NYSE:GTES) at the end of the second quarter which was 37 in the previous quarter. While we acknowledge the potential of Gates Industrial Corporation Ltd. (NYSE:GTES) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from


2 months ago
Reddit (RDDT) stock finally gave investors something to cheer about. Shares jumped about 6% on Sept. 10 after Piper Sandler data showed Reddit's user base grew 8% month over month in August. That marked the company's strongest monthly gain of 2026 and a sharp reversal from the roughly 2% decline in July.
The move also snapped a four-session losing streak. But there's still a major problem. Reddit shares remain down 30% in 2026 and down roughly 38% over the past year. The big question now is whether August marked the beginning of a real turnaround or just another short-lived bounce. Let's take a closer look.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Morgan Stanley Doubles Down on Apple Stock as New Offerings Become 'More Exciting'
The EV Bubble Has Burst. How to Play Rivian Stock Now.
#Stock
The move also snapped a four-session losing streak. But there's still a major problem. Reddit shares remain down 30% in 2026 and down roughly 38% over the past year. The big question now is whether August marked the beginning of a real turnaround or just another short-lived bounce. Let's take a closer look.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Morgan Stanley Doubles Down on Apple Stock as New Offerings Become 'More Exciting'
The EV Bubble Has Burst. How to Play Rivian Stock Now.
#Stock

2 months ago
BioNTech SE (NASDAQ:BNTX) reported that its investigational lung-cancer drug gotistobart produced a clinically meaningful overall-survival benefit in the Phase 3 PRESERVE-003 trial in patients with metastatic squamous non-small cell lung cancer whose disease had progressed after prior immunotherapy and chemotherapy. Reuters said gotistobart nearly doubled survival compared with standard-of-care chemotherapy, strengthening the case for the drug as a potential chemotherapy-free treatment in a population with significant unmet need.
The result builds on earlier Stage 1 data, where gotistobart reduced the risk of death by 54% versus docetaxel, with a hazard ratio of 0.46. Median overall survival was not yet reached for gotistobart versus 9.95 months for docetaxel, while the 12-month progression-free survival rate was 25.2% versus 0%. BioNTech is now awaiting the pivotal Stage 2 readout, making the latest result important not only for the drug's approval prospects but also for the credibility of BioNTech's broader transition from a COVID-vaccine company toward a multi-product oncology business.
The strongest bullish argument is that gotistobart now has repeated evidence of a meaningful survival advantage in a difficult-to-treat lung-cancer population. The earlier Stage 1 dataset showed 55.6% of patients alive in the gotistobart arm versus 23.8% with docetaxel, alongside a 54% reduction in the risk of death. The latest Phase 3 update reinforces that signal rather than introducing an entirely new hypothesis. If the pivotal Stage 2 data confirm the benefit, BioNTech SE (NASDAQ:BNTX) could have a differentiated therapy capable of competing on survival rather than simply response rates, potentially supporting meaningful pricing power and a commercially attractive oncology franchise.
The result also strengthens BioNTech's broader oncology strategy because gotistobart is one piece of a much larger pipeline rather than a standalone bet. BioNTech says it has 14 ongoing pivotal trials and more than 10 novel combination programs, while its lung-cancer strategy spans more than 16 ongoing clinical trials and five Phase 3 programs. Gotistobart's success therefore provides validation for the company's immuno-oncology capabilities, while other ****** ets such as pumitamig and antibody-drug conjugates advance toward additional indications. BioNTech has identified 17+ late-stage or pivotal readouts through 2030+, creating the possibility that a successful gotistobart launch becomes the first major commercial proof point in its planned transition to a multi-product oncology company.
#stage #survival
The result builds on earlier Stage 1 data, where gotistobart reduced the risk of death by 54% versus docetaxel, with a hazard ratio of 0.46. Median overall survival was not yet reached for gotistobart versus 9.95 months for docetaxel, while the 12-month progression-free survival rate was 25.2% versus 0%. BioNTech is now awaiting the pivotal Stage 2 readout, making the latest result important not only for the drug's approval prospects but also for the credibility of BioNTech's broader transition from a COVID-vaccine company toward a multi-product oncology business.
The strongest bullish argument is that gotistobart now has repeated evidence of a meaningful survival advantage in a difficult-to-treat lung-cancer population. The earlier Stage 1 dataset showed 55.6% of patients alive in the gotistobart arm versus 23.8% with docetaxel, alongside a 54% reduction in the risk of death. The latest Phase 3 update reinforces that signal rather than introducing an entirely new hypothesis. If the pivotal Stage 2 data confirm the benefit, BioNTech SE (NASDAQ:BNTX) could have a differentiated therapy capable of competing on survival rather than simply response rates, potentially supporting meaningful pricing power and a commercially attractive oncology franchise.
The result also strengthens BioNTech's broader oncology strategy because gotistobart is one piece of a much larger pipeline rather than a standalone bet. BioNTech says it has 14 ongoing pivotal trials and more than 10 novel combination programs, while its lung-cancer strategy spans more than 16 ongoing clinical trials and five Phase 3 programs. Gotistobart's success therefore provides validation for the company's immuno-oncology capabilities, while other ****** ets such as pumitamig and antibody-drug conjugates advance toward additional indications. BioNTech has identified 17+ late-stage or pivotal readouts through 2030+, creating the possibility that a successful gotistobart launch becomes the first major commercial proof point in its planned transition to a multi-product oncology company.
#stage #survival

2 months ago
Eli Lilly and Company (NYSE:LLY) says its newly launched oral obesity drug Foundayo has captured more than 30% of new U.S. patients starting oral weight-loss medicines, a notable early gain against Novo Nordisk's Wegovy pill. Reuters reports that Wegovy initially held roughly 90% of the oral market, making Lilly's rapid share capture an important sign that the oral GLP-1 market is becoming a two-player competition rather than a Novo-dominated segment. The broader U.S. obesity-drug market is expected to exceed $100 billion annually by 2030, with oral treatments potentially accounting for more than one-third of GLP-1 use.
The timing is strategically important for Lilly because Foundayo was only launched in the U.S. in April 2026. The drug starts at $149 per month for self-pay patients and can cost as little as $25 for eligible commercially insured patients, while Medicare beneficiaries can access it through the GLP-1 Bridge program at $50 per month. Lilly's SEC filing says Mounjaro and Zepbound already represented 65% of its revenue in the first six months of 2026, highlighting both the importance of the incretin franchise and the opportunity for Foundayo to broaden Lilly's cardiometabolic revenue base.
The strongest bullish implication is that Foundayo appears to be overcoming the biggest behavioral barrier in obesity treatment: patients' preference for an oral medicine over an injection. Capturing more than 30% of new oral patients only months after launch suggests Eli Lilly and Company (NYSE:LLY) is establishing meaningful competitive positioning before the oral GLP-1 market fully scales. Foundayo's formulation also has a practical advantage because it can be taken at any time of day without food or water restrictions, while Lilly's clinical data showed an average 27.3-pound, or 12.4%, weight reduction at the highest dose among patients who remained on treatment in ATTAIN-1.
The commercial opportunity could become considerably larger if Foundayo gains indications beyond obesity. Lilly reported that in the ACHIEVE-3 trial, Foundayo produced a 57.1% greater relative reduction in A1C and a 73.6% greater relative reduction in body weight compared with oral semaglutide 14 mg. Lilly submitted Foundayo for type 2 diabetes in the U.S., EU, and **** an, potentially expanding the addressable market beyond weight management.
The early oral-market traction also complements Eli Lilly and Company (NYSE:LLY)'s existing injectable franchise rather than simply cannibalizing it. A Lilly trial found that patients switching from maximum-tolerated Wegovy to Foundayo maintained all but 0.9 kg of their previous weight loss after one year, while patients switching from maximum-dose Zepbound to Foundayo maintained all but 5.0 kg. That suggests Foundayo could serve as a maintenance or lower-burden treatment within Lilly's broader obesity portfolio, increasing lifetime value per patient rather than limiting the opportunity to new prescriptions.
#patients #weight #c
The timing is strategically important for Lilly because Foundayo was only launched in the U.S. in April 2026. The drug starts at $149 per month for self-pay patients and can cost as little as $25 for eligible commercially insured patients, while Medicare beneficiaries can access it through the GLP-1 Bridge program at $50 per month. Lilly's SEC filing says Mounjaro and Zepbound already represented 65% of its revenue in the first six months of 2026, highlighting both the importance of the incretin franchise and the opportunity for Foundayo to broaden Lilly's cardiometabolic revenue base.
The strongest bullish implication is that Foundayo appears to be overcoming the biggest behavioral barrier in obesity treatment: patients' preference for an oral medicine over an injection. Capturing more than 30% of new oral patients only months after launch suggests Eli Lilly and Company (NYSE:LLY) is establishing meaningful competitive positioning before the oral GLP-1 market fully scales. Foundayo's formulation also has a practical advantage because it can be taken at any time of day without food or water restrictions, while Lilly's clinical data showed an average 27.3-pound, or 12.4%, weight reduction at the highest dose among patients who remained on treatment in ATTAIN-1.
The commercial opportunity could become considerably larger if Foundayo gains indications beyond obesity. Lilly reported that in the ACHIEVE-3 trial, Foundayo produced a 57.1% greater relative reduction in A1C and a 73.6% greater relative reduction in body weight compared with oral semaglutide 14 mg. Lilly submitted Foundayo for type 2 diabetes in the U.S., EU, and **** an, potentially expanding the addressable market beyond weight management.
The early oral-market traction also complements Eli Lilly and Company (NYSE:LLY)'s existing injectable franchise rather than simply cannibalizing it. A Lilly trial found that patients switching from maximum-tolerated Wegovy to Foundayo maintained all but 0.9 kg of their previous weight loss after one year, while patients switching from maximum-dose Zepbound to Foundayo maintained all but 5.0 kg. That suggests Foundayo could serve as a maintenance or lower-burden treatment within Lilly's broader obesity portfolio, increasing lifetime value per patient rather than limiting the opportunity to new prescriptions.
#patients #weight #c


2 months ago
Kimberly-Clark Corporation (NASDAQ:KMB) is preparing **** et sales to address EU antitrust concerns surrounding its planned $40 billion acquisition of Kenvue, according to Reuters. The company is reportedly seeking to offer remedies that could secure European Commission approval by the September 29 deadline, avoiding a more extensive four-month investigation. Similar regulatory concerns have already emerged in Australia, where the deal received conditional approval after Kimberly-Clark agreed to divest Kenvue's Carefree and Stayfree brands.
The transaction is strategically important because it would create a consumer-health and personal-care company with approximately $32 billion of annual revenue and $7 billion of adjusted EBITDA. Kimberly-Clark Corporation (NASDAQ:KMB) expects about $1.9 billion of annual cost synergies and $500 million of revenue synergies, although it expects to invest roughly $2.5 billion in cash to achieve the cost savings. Therefore, the scale of any EU divestitures will be critical to determining whether Kimberly-Clark can retain the expected economic benefits of the deal.
The strongest bullish argument is that Kimberly-Clark Corporation (NASDAQ:KMB) is actively working toward a regulatory solution rather than allowing the EU review to threaten the transaction. If the company can satisfy regulators through limited **** et sales, it could preserve the majority of Kenvue's revenue and earnings while moving ahead with the combination. The expected $1.9 billion in annual cost savings represents a substantial earnings opportunity relative to the combined company's roughly $7 billion adjusted EBITDA target, giving Kimberly-Clark significant potential to improve margins and cash generation after integration.
The Australian precedent also suggests that targeted divestitures could be sufficient to resolve competition concerns without materially undermining the broader deal. Securing EU approval by September 29 would be particularly positive because it would remove a major source of uncertainty and allow Kimberly-Clark Corporation (NASDAQ:KMB) to focus on integration and synergy execution. With Kenvue adding major brands across consumer health and personal care, successful completion could also broaden Kimberly-Clark's portfolio and reduce its reliance on its existing product categories.
The biggest risk is that the EU requires more substantial **** et sales than Kimberly-Clark Corporation (NASDAQ:KMB) currently expects. Giving up attractive Kenvue brands or businesses in Europe could reduce the revenue and EBITDA acquired through the transaction, while Kimberly-Clark would still have to bear much of the financing, transaction, and integration burden. That could make the $40 billion purchase price less attractive on a risk-adjusted basis, particularly if the divested **** ets are among Kenvue's stronger European businesses.
#kimberly #revenue #ebitda
The transaction is strategically important because it would create a consumer-health and personal-care company with approximately $32 billion of annual revenue and $7 billion of adjusted EBITDA. Kimberly-Clark Corporation (NASDAQ:KMB) expects about $1.9 billion of annual cost synergies and $500 million of revenue synergies, although it expects to invest roughly $2.5 billion in cash to achieve the cost savings. Therefore, the scale of any EU divestitures will be critical to determining whether Kimberly-Clark can retain the expected economic benefits of the deal.
The strongest bullish argument is that Kimberly-Clark Corporation (NASDAQ:KMB) is actively working toward a regulatory solution rather than allowing the EU review to threaten the transaction. If the company can satisfy regulators through limited **** et sales, it could preserve the majority of Kenvue's revenue and earnings while moving ahead with the combination. The expected $1.9 billion in annual cost savings represents a substantial earnings opportunity relative to the combined company's roughly $7 billion adjusted EBITDA target, giving Kimberly-Clark significant potential to improve margins and cash generation after integration.
The Australian precedent also suggests that targeted divestitures could be sufficient to resolve competition concerns without materially undermining the broader deal. Securing EU approval by September 29 would be particularly positive because it would remove a major source of uncertainty and allow Kimberly-Clark Corporation (NASDAQ:KMB) to focus on integration and synergy execution. With Kenvue adding major brands across consumer health and personal care, successful completion could also broaden Kimberly-Clark's portfolio and reduce its reliance on its existing product categories.
The biggest risk is that the EU requires more substantial **** et sales than Kimberly-Clark Corporation (NASDAQ:KMB) currently expects. Giving up attractive Kenvue brands or businesses in Europe could reduce the revenue and EBITDA acquired through the transaction, while Kimberly-Clark would still have to bear much of the financing, transaction, and integration burden. That could make the $40 billion purchase price less attractive on a risk-adjusted basis, particularly if the divested **** ets are among Kenvue's stronger European businesses.
#kimberly #revenue #ebitda

2 months ago
Broyhill ***** et Management, a Charlotte-based firm, issued its second-quarter 2026 investor letter, which is available for download here. The Broyhill Equity Composite gained 8.8% in Q2, trailing the MSCI All Country World Index's 15.1% and the MSCI ACWI Value Index's 10.8%. For the first half, the Composite returned 2.3%, versus 11.5% for the Index. The letter highlights that a significant portion of the shortfall occurred in April due to market dynamics and geopolitical events, with tech, particularly semiconductors, driving recent gains. Broyhill notes its lack of direct semiconductor exposure but acknowledges potential interest in the sector if opportunities arise, maintaining its investment philosophy focused on capital protection in fragile market conditions. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Broyhill ***** et Management highlighted Masco Corporation (NYSE:MAS). Masco Corporation (NYSE:MAS), a US-based home improvement and building products manufacturer, contributed positively to performance this quarter. On September 14, 2026, Masco Corporation (NYSE:MAS) closed at $69.41 per share. Over the past month, Masco Corporation (NYSE:MAS) declined 5.41%, but its shares are down 5.31% over the past year. Masco Corporation (NYSE:MAS) has a market capitalization of $13.69 billion, and its stock has traded within a 52-week range of $58.16 to $83.64.
Broyhill ***** et Management stated the following regarding Masco Corporation (NYSE:MAS) in its Q2 2026 investor letter:
"Masco Corporation (NYSE:MAS) gained 37%, the best result in the portfolio, and was initiated in the first quarter as one of two investments in the depressed housing sector. The quarter was plumbing-led and, more to the point, volume-led, with the strongest volume growth since the end of the pandemic and pricing intact. Management raised the topline outlook, took out delayed-draw leverage to repurchase stock, and increased the buyback guide by $200 million, to more than $800 million against a $2 billion authorization. Earlier in the quarter, our investment team also attended Masco's investor day and was able to interact with management at the event."
Masco Corporation (NYSE:MAS) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 46 hedge fund portfolios held Masco Corporation (NYSE:MAS) at the end of the second quarter, compared to 42 in the previous quarter. While we acknowledge the potential of Masco Corporation (NYSE:MAS) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#corporation #letter
In its second-quarter 2026 investor letter, Broyhill ***** et Management highlighted Masco Corporation (NYSE:MAS). Masco Corporation (NYSE:MAS), a US-based home improvement and building products manufacturer, contributed positively to performance this quarter. On September 14, 2026, Masco Corporation (NYSE:MAS) closed at $69.41 per share. Over the past month, Masco Corporation (NYSE:MAS) declined 5.41%, but its shares are down 5.31% over the past year. Masco Corporation (NYSE:MAS) has a market capitalization of $13.69 billion, and its stock has traded within a 52-week range of $58.16 to $83.64.
Broyhill ***** et Management stated the following regarding Masco Corporation (NYSE:MAS) in its Q2 2026 investor letter:
"Masco Corporation (NYSE:MAS) gained 37%, the best result in the portfolio, and was initiated in the first quarter as one of two investments in the depressed housing sector. The quarter was plumbing-led and, more to the point, volume-led, with the strongest volume growth since the end of the pandemic and pricing intact. Management raised the topline outlook, took out delayed-draw leverage to repurchase stock, and increased the buyback guide by $200 million, to more than $800 million against a $2 billion authorization. Earlier in the quarter, our investment team also attended Masco's investor day and was able to interact with management at the event."
Masco Corporation (NYSE:MAS) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 46 hedge fund portfolios held Masco Corporation (NYSE:MAS) at the end of the second quarter, compared to 42 in the previous quarter. While we acknowledge the potential of Masco Corporation (NYSE:MAS) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#corporation #letter

2 months ago
The Kroger Co. (NYSE:KR) cut its full-year 2026 identical-sales forecast excluding fuel to 0.2%–0.8% from 1%–2%, reflecting a sharper-than-expected slowdown in consumer demand. Second-quarter identical sales rose just 0.2%, down from 3.4% a year earlier and below the 0.9% ****** yst estimate.
The weakness reflects pressure on middle- and lower-income consumers, while a Cyclospora outbreak reduced quarterly identical sales by roughly 35 basis points and Medicare prescription-drug pricing changes created an approximately 140-basis-point headwind for pharmacy revenue. Importantly, Kroger maintained its full-year adjusted FIFO operating-profit forecast of $5.0 billion–$5.2 billion and delivered adjusted EPS of $1.09, ahead of the $1.06 consensus.
The strongest bullish argument is that The Kroger Co. (NYSE:KR) is currently protecting earnings despite the deterioration in sales momentum. Second-quarter adjusted EPS increased 5% year over year to $1.09, while adjusted FIFO operating profit was $1.076 billion. Kroger's gross margin rate actually increased by 13 basis points, although the overall gross-margin percentage was 22.4% versus 22.5% a year earlier, suggesting that pricing, sourcing, and cost-management initiatives are helping offset weaker volumes. The company's higher-margin businesses are also becoming increasingly important: adjusted e-commerce sales grew 20% in the quarter, and Kroger Precision Marketing profit increased 24%. That mix shift gives Kroger an earnings lever even when supermarket traffic and comparable sales are weak.
There is also evidence that management is actively responding to the competitive pressure rather than simply accepting slower growth. CEO Greg Foran has been pursuing tighter sourcing, simpler operations and lower prices, with Reuters reporting plans to cut prices across thousands of products to regain shoppers from Walmart, Costco and Aldi. The Kroger Co. (NYSE:KR)'s balance sheet provides room to fund that strategy: its net debt-to-adjusted-EBITDA ratio was 1.91x, below its stated target range of 2.30x–2.50x, while the company repurchased $1.0 billion of shares in the second quarter and $1.2 billion year to date. It also raised its dividend 11%, marking the 20th consecutive year of increases. If sales stabilize while e-commerce, retail media and cost efficiencies continue expanding, the unchanged $5.0 billion–$5.2 billion operating-profit forecast could prove more important to valuation than the reduced top-line outlook.
#year
The weakness reflects pressure on middle- and lower-income consumers, while a Cyclospora outbreak reduced quarterly identical sales by roughly 35 basis points and Medicare prescription-drug pricing changes created an approximately 140-basis-point headwind for pharmacy revenue. Importantly, Kroger maintained its full-year adjusted FIFO operating-profit forecast of $5.0 billion–$5.2 billion and delivered adjusted EPS of $1.09, ahead of the $1.06 consensus.
The strongest bullish argument is that The Kroger Co. (NYSE:KR) is currently protecting earnings despite the deterioration in sales momentum. Second-quarter adjusted EPS increased 5% year over year to $1.09, while adjusted FIFO operating profit was $1.076 billion. Kroger's gross margin rate actually increased by 13 basis points, although the overall gross-margin percentage was 22.4% versus 22.5% a year earlier, suggesting that pricing, sourcing, and cost-management initiatives are helping offset weaker volumes. The company's higher-margin businesses are also becoming increasingly important: adjusted e-commerce sales grew 20% in the quarter, and Kroger Precision Marketing profit increased 24%. That mix shift gives Kroger an earnings lever even when supermarket traffic and comparable sales are weak.
There is also evidence that management is actively responding to the competitive pressure rather than simply accepting slower growth. CEO Greg Foran has been pursuing tighter sourcing, simpler operations and lower prices, with Reuters reporting plans to cut prices across thousands of products to regain shoppers from Walmart, Costco and Aldi. The Kroger Co. (NYSE:KR)'s balance sheet provides room to fund that strategy: its net debt-to-adjusted-EBITDA ratio was 1.91x, below its stated target range of 2.30x–2.50x, while the company repurchased $1.0 billion of shares in the second quarter and $1.2 billion year to date. It also raised its dividend 11%, marking the 20th consecutive year of increases. If sales stabilize while e-commerce, retail media and cost efficiencies continue expanding, the unchanged $5.0 billion–$5.2 billion operating-profit forecast could prove more important to valuation than the reduced top-line outlook.
#year