7 days ago
Lots of investors keep coming back to dividend stocks for a pretty simple reason: While the market is often busy chasing whatever happens to be hot that week, a growing dividend is something a company actually has to earn. It has to generate the cash to keep paying investors quarter after quarter, year after year.
That makes dividends especially appealing when the market and the economy feel like they're being pulled in every direction. A company can dress up a press release, but it can't fake the cash sitting in its bank account. When it comes time to pay a dividend, the money is either there or it isn't.
Missed AI's "Act 1"? Act 2 Could Be 14x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our ****** ysts, we're only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
What interests me most, though, aren't necessarily the big, well-known dividend payers. I'm more interested in the companies flying under the radar that have increased their payouts for decades while also making meaningful changes to their underlying businesses today. These four companies fit that description.
Universal (NYSE: UVV) is the highest yielder here, paying out around 7.4% at recent prices, and it has raised its dividend for 56 consecutive years. This raise makes it a Dividend King, a company that has delivered 50 or more years of annual dividend increases. Universal isn't a cigarette maker, but it is the world's largest leaf tobacco exporter and importer. It supplies tobacco companies rather than selling to smokers directly, which is why it rarely shows up in articles about tobacco stocks.
#market
7 days ago
Robert Kelker-Kelly complained of chest pain shortly before becoming unresponsive at his Missouri home, according to police. The former Days of Our Lives actor died at 62.
Officers and paramedics were called to his home in St. Peters, a suburb of St. Louis, at around 8:15 p.m. on Saturday, Oct. 3.
Lt. Melissa Doss of the St. Peters Police Department told Entertainment Weekly that nothing suspicious was noted at the scene and that the circumstances appeared consistent with a medical event.
The emergency was dispatched as a cardiac arrest, but officials have not announced an underlying cause of death.
Dispatch audio obtained by TMZ indicated that Kelker-Kelly had been found in bed and that the caller could not move him. CPR was already underway while police and emergency medical personnel were responding.
#kelly #peters #home #days
8 days ago
Before we get worried about recessions or market crashes, let's put a 10% drop in context. Going back to 1980, the S&P 500 has fallen 10% or more in roughly half of all calendar years, and a correction of that size has historically shown up about once every 12 to 18 months.
What makes a 10% decline packed into a single month unusual isn't the size of the drop, it's the speed: that kind of compressed move tends to show up during sudden shocks rather than the slower grind most corrections take. Even so, it's happened before, and the market has recovered every time.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
My goal here isn't to predict whether October brings one. It's to point to three consumer businesses whose underlying demand doesn't particularly care what the stock market does that month.
Procter & Gamble (NYSE: PG) makes Tide, Pampers, Crest, and Gillette. These products are the kind of household basics people buy again almost automatically, recession or not. That steadiness shows up in the numbers. P&G generated more than $87 billion in revenue in its 2026 fiscal year and returned over $15 billion to shareholders through dividends and buybacks.
#market #flashing #every #month

13 days ago
Rebel Wilson is facing a new sanctions motion in her Los Angeles defamation battle with three producers of The Deb.
Amanda Ghost, Gregor Cameron and Vince Holden accuse Wilson of giving false sworn testimony, withholding documents and mishandling evidence during pretrial discovery. Their lawyers characterize the alleged conduct as a "fraud on the court" and are asking Judge Thomas Long to impose penalties.
Wilson's attorney, Allyson Katherine Thompson, disputes the accusations. She told MyNewsLA that the motion is another attempt to malign Wilson and described it as "gamesmanship" in a heavily contested case.
The sanctions motion is scheduled for an Oct. 22 hearing. The producers' underlying defamation case against Wilson is currently scheduled for trial in Los Angeles in January 2027.
One of the examples in the motion concerns a demand letter tied to the dispute.
#amanda


23 days ago
Morgan Stanley has cut Novo Nordisk A/S (NYSE:NVO) to Underweight on September 11, 2026. Semaglutide, the underlying molecule for Wegovy and Ozempic, generates roughly 75% of 2026 revenue. Morgan Stanley models that it will still represent 59% of total sales when its patent protection expires in 2031. And according to the firm, the valuation does not price in the impact it has on Novo's terminal value. The stock, currently trading at 10.6x earnings and down 33% from its 52-week high, slipped another 2% following the call. At this point, the question isn't about whether the patent cliff is real or not, but whether the 10x multiple reflects an actual bargain.
Semaglutide loses exclusivity in Europe in 2031 and the US in 2032. And Morgan Stanley believes Novo's oral-obesity business, projected to reach $10 billion by 2031, could not offset the pricing collapse after the arrival of generics. Growth decelerates to a 4% compound rate between 2027 and 2030. If the deceleration continues, it will justify 10x earnings as a fair price instead of a cheap one.
The 10.6x multiple already prices aggressive pessimism into a market leader of one of the fastest-growing drug classes in history. Morgan Stanley fueled the pessimism by discounting a 2031 cliff five years earlier. However, pharmaceutical patent expirations frequently face extensions and prove difficult to time. Second, the ***** umption that oral obesity treatments cannot offset patent losses relies on oral semaglutide being the bridge. But Novo's next-generation portfolio, including CagriSema and amycretin, offers a significant defense against the patent cliff. This remains unproven, however, specifically after CagriSema's earlier weight-loss data failed to impress, yet Morgan Stanley's terminal-value model discounts this pipeline almost entirely. The company is also expanding its franchise. On September 7, the STEP Young trial hit its endpoint in children aged six to twelve, strengthening the base its successors inherit.
The smart money is leaning in. As per the Insider Monkey database, 59 hedge funds held NVO in the second quarter of 2026, up from 55 in the first, indicating a slight increase in the modest institutional interest in the stock. Short interest on the ADR is negligible at about 0.7%. The positioning reflects a beaten-down value stock quietly seeing institutional accumulation while Wall Street turns increasingly bearish.
#semaglutide #oral

24 days ago
On September 16, Air Products (NYSE:APD) said it had signed a long-term deal to supply high-purity gases to a leading chipmaker, backed by roughly $250 million of its own money in Arizona. It is the company's second semiconductor supply win, and the two projects together carry more than $900 million of investment. That is a notable turn for a company that has been pulling back from big clean-energy projects.
The Arizona project plays to what Air Products already does. It will build, own, and operate the equipment, from hydrogen generation units and carbon dioxide purification to bulk supply for three gases: helium, hydrogen, and carbon dioxide. That means the customer's gas supply runs through equipment Air Products owns. Supply is targeted to start in phases, so the buildout can move alongside the customer's expansion plans. And this is familiar ground. Air Products has supplied electronics makers for more than 40 years, and its Chandler facility has served the Phoenix chip cluster since 1981, with a pipeline system carrying ultra-high purity nitrogen around the area.
The core business gives the deal a solid floor. In the fiscal third quarter, reported on July 30, adjusted earnings per share rose 12% to $3.47, and management lifted its full-year outlook to an adjusted $13.39 to $13.49 per share. Margins widened as well, so growth is showing up as profit. Chips appear elsewhere in the results too, since the company announced a deal to build four large air separation units to serve a chipmaker's growth in Taiwan.
The cost of the pivot is hard to ignore. On June 30, Air Products announced it would not go ahead with its Louisiana Clean Energy Complex and would discontinue a zero-carbon liquid hydrogen facility in Casa Grande, Arizona, plus other smaller clean energy distribution projects. The exits triggered roughly $2.9 billion in pre-tax charges, which is why the company posted a GAAP loss of $6.47 per share in the third quarter even as its underlying earnings grew. Adjusted results leave that hit out, but the GAAP numbers show what the retreat cost.
Owning the ****** ets also means funding them. Air Products expects about $3.5 billion of capital spending in fiscal 2026, and the Arizona plant alone is a commitment of approximately $250 million, with supply arriving in phases. The release also leaves gaps: it does not name the customer or say how long the contract runs, so the length of the revenue stream is unclear. Elsewhere, Europe's operating income rose only 2% as costs climbed, and management says it is still cautious about the economic backdrop.
#clean #adjusted

24 days ago
Moneywise and Yahoo Finance LLC may earn commission or revenue through links in the content below.
The future of America's social safety net is hanging in limbo as the underlying trust fund reserves for Social Security benefits will be depleted in just six years.
And not only is the U.S. government not offering solutions for the funding crisis, it's actually making the problem worse — even if there's money on the table for retirees as a result.
Jeff Bezos backs a platform that lets anyone invest in rental homes for as little as $100 — 6 ways to build wealth like a landlord without actually being one
A single line on your car insurance policy could be inflating your premium by up to 30% — here's what to change
#actually #moneywise #bezos #commission

24 days ago
GDEV Inc. (NASDAQ:GDEV) saw a year-on-year drop in bookings from both its in-app purchases and advertising, during the second quarter fiscal 2026. Consequently, the quarterly revenue figure of $94 million was down 22% compared to Q2 FY25. On the flip side, SG&A expenses and costs related to platform commissions were lower relative to the corresponding period last year. Along with other factors, the lower cost base helped GDEV report $20 million in net profit, up from $17 million in the second quarter of 2025.
Copyright: artush / 123RF Stock Photo
Breaking down the expenses, selling and marketing costs came down by 38% compared to the same quarter last year, clocking in at $33 million. It reflects on management's continued focus on deploying an efficient approach for its user acquisition initiatives. The approach is based on a more targeted performance marketing across certain channels that lead to durable high-value users, instead of broader campaigns for near-term benefits.
The reported quarter marked a turnaround related to the equity accounted ******* ociates. These contributed a $2 million profit share, which was a reversal from a $2 million loss share in Q2 FY25. Most notably, cash flows from operating activities turned from negative $10 million in Q2 FY25 to positive $10 million in the reported period.
Several operating metrics weakened during the reported quarter. Monthly paying users dropped by 23% year-over-year, along with a 15% decline for the entire first half. This was the major underlying reason for a sluggish performance in bookings, which stood at $73 million and $156 million for the second quarter and first half of the year, respectively. These fell short in comparison to $92 million and $173 million recorded in the corresponding periods last year. GDEV also said the decline in first-half platform commissions was driven by lower revenues recognized from PC platforms, while PC's share of bookings fell to 36% from 39%.
#million #lower
24 days ago
Affirm Holdings, Inc. (NASDAQ:AFRM) has underperformed the broader market year to date, but the tide is slowly turning. Robust growth in interest-bearing loans, a strategic partnership with Shopify in Australia, and accelerating volumes at Amazon provide multiple avenues for continued growth.
On September 12, Goldman Sachs raised its price target to $115 from $106, citing improving underlying fundamentals. The hike follows the company's impressive fourth-quarter fiscal 2026 results, with revenues surging 33% to $1.2 billion and operating income rising $89 million to $147 million.
The robust revenue growth came as the company continued to attract more business interest-bearing loans. Interest income rose 35% in the fourth quarter, in line with a 33% increase in average net loans held for investment partners. More importantly, 80% of Affirm's direct-to-consumer product loans carried interest at quarter-end, giving the company an increasingly meaningful source of recurring interest income.
The investment bank has also touted the growth opportunity around Affirm Card, which is helping the company expand its relationship with consumers beyond individual BNPL transactions. Active cardholders more than doubled to 5.2 million, resulting in a 124% increase in Card GMV to $2.8 billion.
Management has already hinted at continued upside momentum by estimating a massive increase in GMV to $64 billion in fiscal 2027 and an adjusted operating margin of 30.5%. Against this backdrop, Wolfe Research ****** yst Darrin Peller upgraded the stock to Outperform with a $90 price target. According to the ****** yst, Affirm Holdings is a winner in the point-of-sale financing ****** e.
#interest #billion #company

24 days ago
On September 18, Prudential Financial (NYSE:PRU) announced it will sell every share it holds in Alexforbes, a company listed on the Johannesburg Stock Exchange. Two buyers are splitting the stake. Alexforbes will repurchase roughly 372.8 million shares itself, and ARC AF Holdings will take about 74.1 million more. The package is worth about $185 million, a small number for a company managing $1.642 trillion. But the message matters more than the money. A plan Prudential laid out in August is now turning into signed agreements.
The logic is easy to follow. Prudential wants to operate in fewer places and put its money, people and attention where it thinks it can win for years. Andy Sullivan, the chief executive, says the aim is to lean harder on ***** et management, retirement and protection, and get those units working together more closely. David Legher, who leads emerging markets, called Alexforbes a successful investment, so this reads as a planned exit rather than a retreat from a problem.
The core business is giving management room to be choosy. On August 4, Prudential reported second-quarter net income of $985 million, up from $533 million a year earlier. That happened even though a charge from the yearly ***** umption update grew to $299 million from $134 million, so the underlying engine ran strong enough to absorb a bigger hit. The company also returned $743 million to shareholders in the quarter and held $4.2 billion in highly liquid ***** ets at the parent level. That does not look like a seller in a hurry.
Start with what has not happened yet. The deals are expected to close in the first half of 2027, and they still need Alexforbes shareholders to approve the buyback, along with regulatory sign-off. Until then, $185 million is an agreed price, not cash in the bank. Prudential also said New Veld's involvement continues before completion, so the company stays tied to the ***** et for now.
Then there is the size. Set against those trillions in ***** ets, this sale will not move results either way. Its value is strategic, and strategy takes years to judge. Prudential is giving up a foothold in a partnership it called important, and its remaining businesses have their own snags. Sales in Prudential of ***** an are suspended, and management said that weighed on international results even as earnings held up.
#august #money

25 days ago
Whirlpool already cut its dividend 49% then skipped a payment entirely, while KHC's yield is inflated by a 55% decade-long price collapse with frozen payouts since 2019.
IEP's 29% yield masks two prior cuts and a 68% cash drop year over year, while UPS's quarterly operating cash flow fell $469 million short of its dividend payout.
A collapsing share price mechanically inflates yield, making high-yield stocks look attractive precisely when the underlying business is deteriorating most.
Just released. Our ******* ysts combed the entire stock market and named the ten best stocks to buy right now, and Kraft Heinz didn't make the cut. Enter your email to see the names that beat KHC. The report is free. Enter your email and see if any of your stocks made the cut.
Yield is a promise, not a payment. When a stock advertises a payout that looks two or three times the market average, it usually means the market has already decided something is wrong. The screen below flags six US-listed names where the numbers behind the yield show real strain: shrinking cash flow, stretched coverage, or a share price that collapsed and inflated the yield mechanically. None of these companies has announced a cut. Each has warning signs a retirement-focused reader should understand before buying the yield.
#inflated

25 days ago
Bonds should be an essential part of a well-balanced portfolio. Factual differences between the Schwab Long-Term U.S. Treasury ETF (NYSEMKT:SCHQ) and the State Street SPDR Portfolio Long Term Corporate Bond ETF (NYSEMKT:SPLB) center on credit quality, as the Schwab fund tracks government debt while the State Street fund targets investment-grade corporate bonds.
Investors seeking exposure to long-dated fixed income typically choose between government-backed securities and corporate credit. While both funds focus on maturities exceeding 10 years, they offer significantly different risk-reward profiles based on their underlying debt issuers and the credit risk investors are willing to accept for higher income.
Metric
SPLB
SCHQ
#nysemkt #state

25 days ago
Concerned about an AI bubble? Sign up for The Daily Upside for smart and actionable market news, built for investors.
There's a lot we can't predict, like the outcome of the midterm elections, who will make it to the Super Bowl or whether Taylor Swift was actually hinting at a new album release in that Emmy's sketch. But when it comes to what our retirement looks like, we can certainly try.
Many retirement plans offer predictive tools that can help savers forecast their future balances, retirement readiness, income replacement rates and more. Participants, however, aren't happy with the options: J.D. Power's recent survey of digital experience satisfaction for retirement plans found that predictive tools were the lowest-performing attribute.
"The technology in the 401(k) is seriously behind what people are used to in their consumer life," said Fred Barstein, CEO of The Retirement Advisor University. When the underlying technology structure is old and **** bersome, it's hard for the tools to be as effective as they could be.
Sign up for The Daily Upside at no cost for premium **** ysis on all your favorite stocks.
#tools #sign #upside #like
25 days ago
Interested in HCA Healthcare, Inc.? Here are five stocks we like better.
Exchange-related pressure is weighing on HCA's 2026 outlook: The expiration of enhanced tax credits is pushing some patients into uninsured status, with estimated full-year impact of $1 billion to $1.2 billion and slower elective-care utilization.
State supplemental payments and underlying demand provide offsets: HCA expects a $300 million to $500 million net benefit from state programs, while insured business excluding exchange plans grew 3.2% and adjusted admissions increased 2.7% in the second quarter.
HCA is pursuing long-term growth through capacity and efficiency investments: The company is expanding outpatient facilities, improving patient throughput and cost management, and maintaining a target of 4% to 6% long-term revenue growth with stable margins.
Healthcare Added 35,200 Jobs—3 Stocks Positioned to Benefit
#healthcare #Growth

25 days ago
QQQI holders forfeited roughly $11 per share in total return versus QQQ over 31 months, equal to about $2,194 on a $10,000 stake.
Nearly 99% of QQQI's 2025 distributions were return of capital, meaning investors received their own money back, not income, with a shrinking cost basis.
QQQM and JEPQ serve as alternative ways to access the same underlying index.
Read More: Learn 7 secret wealth tips high net worth investors use that most investors miss (sponsor)
Every month, a NEOS Nasdaq-100 High Income ETF (NASDAQ:QQQI) holder gets a distribution check. In August 2026, it was $0.6518 per share. The annualized forward rate sits at $7.8216. The check feels like income, but the total-return record tells a different story. Since QQQI's first ex-dividend date, holders have quietly foregone roughly $10.97 per share in total return compared to a matching Nasdaq-100 position that costs a fraction to own.
#high

25 days ago
On September 10, 2026, The Lovesac Company (NASDAQ:LOVE) reported second-quarter fiscal 2027 results for the period ended August 2, 2026. Net sales rose 0.4% to $161.2 million, a record for the quarter, and the company swung to net income of $7.4 million, or $0.51 per diluted share, from a loss of $6.7 million a year earlier. Inside that $0.51 sits $0.86 of net benefit from IEEPA tariff refunds. Omni-channel comparable sales fell 1.9%.
Canaccord's Maria Ripps read the quarter as in line, with revenue and adjusted EBITDA both landing within guidance and near consensus while tariff refunds pushed gross margin and earnings above expectations; she cut the firm's target on The Lovesac Company (NASDAQ:LOVE) to $20 from $22 but held the Buy rating.
Roth Capital's Matt Koranda also called the quarter in line with consensus, though he flagged omni-channel comps trending modestly negative on soft lower-end consumer demand. He lowered the firm's target on The Lovesac Company (NASDAQ:LOVE) to $20 from $22 as well, keeping a Buy rating, and noted that management reset full-year guidance lower on a tough demand environment and modest product launch delays.
DA Davidson offered a similar interpretation of the lower guidance, arguing that the reset reflects the new CFO's approach more than a deterioration in the underlying business. The firm said the CFO, who joined during the quarter, appears to be establishing more conservative expectations that could restore a beat-and-raise pattern the stock had lacked. DA Davidson lowered its target on The Lovesac Company (NASDAQ:LOVE) to $18 from $20 while maintaining its Buy rating.
The operating case rests on the high end: configurations above $6,000 grew double digits against a tough comparison, showroom net sales rose 4.6% to $114.1 million on 14 net new locations, and Snugg helped push other products revenue up 198.2%. Lovesac ended the quarter with $68.8 million in cash and no debt.
#quarter

25 days ago
Virtus Investment Partners, Inc. (NYSE:VRTS) reported on September 11 that preliminary ****** ets under management, or AUM, totaled $147.501 billion at August-end, compared with $148.874 billion at July-end. That represents a $1.373 billion decline, or approximately 0.9%.
Management identified net outflows in institutional accounts, retail separate accounts, U.S. retail funds and global funds, partly offset by positive flows into exchange-traded funds, or ETFs, and tender-offer funds.
Positive market performance partly offset net outflows. The $1.373 billion AUM decline therefore differs from net client withdrawals, which the announcement did not quantify. The underlying business question is whether products attracting new money can become large enough to stabilize the revenue base.
Virtus Investment Partners, Inc. (NYSE:VRTS) has identifiable sources of customer demand. Positive net flows into ETFs and tender-offer funds provide a route toward a more balanced product mix.
ETF demand also appeared in the second quarter, when these products attracted $0.3 billion of net inflows. August's positive flows suggest the opportunity extends beyond a single reporting period.
#virtus #investment #partners
25 days ago
Updated Sept. 17, 2026 2:46 pm ET
Listen
(3 min)
1443 ET – Precious metal futures settle higher in New York, recovering from a swoon in the wake of yesterday’s Federal Reserve interest-rate increase. “My sense is that they will lag while we’re in a rate-hiking cycle, and right now we’re fairly clearly in a rate-hiking cycle,” says David Russell, global head of market strategy at TradeStation. There are a lot of arguments in favor of gold, in terms of central bank buying and an alternative to the dollar, but the current macro environment “is not in any way textbook favorable for gold and silver,” he adds. Front-month gold settles up 0.3% to $4,360.20 a troy ounce, and silver rises 1.8% to $65.47 a troy ounce. (anthony.harrupwsj.com)
1118 ET – Gold futures recover losses that followed the Fed’s rate hike as Treasury yields move lower and the dollar slips, while oil prices extend their pullback to a second day. “Gold is rangebound with two-way risk, but the large bull market we had seen earlier in the year is considered on pause for now,” Pepperstone strategist Ahmad ******* iri says in a note. The bull market could continue at some stage with underlying drivers such as central bank demand, macro uncertainty, and fiscal concerns, he says. But “the path of oil prices and their transmission into Fed policy remains the single most important variable from now till year-end.” The December contract is up 0.4% in New York at $4,404.90 a troy ounce. Silver rises 2.3% to $66.44 a troy ounce. (anthony.harrupwsj.com)
#Gold #york #futures



25 days ago
Exodus Movement, Inc. (NYSEAMERICAN:EXOD) reported on September 11 that August payment-processing gross transaction volume reached $356.8 million, up from $338.0 million in July. Monthly active cards declined to 757,900 from 783,600.
Separately, Web3 exchange-provider processed volume increased to $376.8 million from $314.8 million, while reported monthly active users remained at 1.4 million. The figures show stronger transaction activity alongside fewer active cards and a stable reported user count.
The question is whether that activity produces enough revenue to improve profitability while Exodus Movement, Inc. (NYSEAMERICAN:EXOD) integrates Monavate and reduces costs.
Payment growth persists after adjusting for currency translation. Exodus Movement, Inc. (NYSEAMERICAN:EXOD) converted sterling payment volumes into dollars using average rates of $1.35 per pound for August and $1.34 for July. Reversing those conversions implies approximately 4.8% growth in underlying sterling volume, compared with 5.6% in reported dollars. Both calculations use rounded disclosed figures.
Web3 exchange-provider volume increased approximately 19.7%. XO Swap partners contributed 23% of volume in both months. The unchanged reported share suggests both the partner channel and the remaining business contributed to growth.
#reported #exodus #nyseamerican
26 days ago
Johnson & Johnson (JNJ) has been a rewarding stock to hold, up about 53% over the past year against about 17% for the S&P 500. The change worth noticing over that stretch is quieter than the price. Management said sales still rose 5.6% despite a STELARA drag of about 460 basis points. Management is encouraging investors to evaluate the company's underlying momentum by presenting growth rates that exclude STELARA alongside its reported figures.
A year and a half ago, that drag was the headline. Management's own framing of the first quarter of 2025 noted an approximate 810 basis point headwind on Innovative Medicine sales.
By the second quarter of 2026, that segment-level drag remained heavy at roughly 760 basis points (or about 460 basis points across the total enterprise), yet management's emphasis shifted to highlighting double-digit operational growth excluding STELARA
The exclusion is not a rounding adjustment. STELARA sales fell 55.7% in the second quarter of 2026, and management put that drag at about 460 basis points of the whole company's 5.6% operational sales growth.
Two products show what the replacement looks like. TREMFYA booked $2 billion of sales in the second quarter of 2026, up over 70%, and management says ulcerative colitis and Crohn's disease are the major drivers of that growth. ICOTYDE, a recently launched once-daily pill for psoriasis, is the second, which leadership has highlighted as a key pipeline priority for the immunology business.
#sales #basis #drag #quarter


26 days ago
The Federal Reserve raised its benchmark interest rate by a quarter percentage point on Wednesday, the first increase since July 2023, with Fed Chair Kevin Warsh saying inflation has been "too high ... for too long."
The decision, reached by a unanimous 12-0 vote of the Federal Open Market Committee, brings the federal funds rate to a new target range of 3.75%–4%. The Fed's post-meeting statement pointed to persistent price pressures and a durable economy, declaring: "Inflation remains elevated. Today's policy action will support a timelier return to the Committee's 2 percent goal. The Committee will deliver price stability."
At a news conference following the decision, Warsh said the Fed needed to be confident "that underlying inflation is moving to our objective clearly and at sufficient speed," adding that the FOMC had determined "this standard has not been satisfied." He pointed to three converging factors — a robust labor market, inflation still running above target, and ongoing conflict in the Middle East — as driving the committee's unanimous vote.
The Dow Jones Industrial Average shed more than 400 points in afternoon trading following the Fed's move. The S&P 500 and the tech-heavy Nasdaq Composite also slumped.
Updated economic projections released Wednesday showed FOMC participants nudged their inflation forecasts higher. The median projection for headline PCE inflation this year rose to 3.7% and core PCE to 3.4%, each up 0.1 percentage point from the June forecast, the Fed said. Officials do not expect inflation to return to the 2% target until 2029. The median unemployment rate projection for 2026 fell to 4.1%, down from 4.3% in June, while the GDP growth outlook rose to 2.3% from 2.2%.
#federal #rate #committee

26 days ago
This story was originally published on Multifamily Dive. To receive daily news and insights, subscribe to our free daily Multifamily Dive newsletter.
For the first time in more than three years, the Federal Open Market Committee raised interest rates, following its two-day September meeting on Wednesday.
In a unanimous vote, the FOMC raised the target range for the federal funds rate by 25 basis points to 3.75% to 4%.
"This summer's inflation readings do not tell me that underlying trends have meaningfully improved," Kevin Warsh, chair of the Federal Reserve, said in a press conference following the announcement.
Despite persistent concern about inflation and the rate hike, multifamily executives thought the near-term impact on the market would be limited, as they kept their focus on Treasury rates.
#rate

26 days ago
On September 14, Dave & Buster's Entertainment (NASDAQ:PLAY) reported second-quarter fiscal 2026 results that read like two different companies at once. Revenue fell, and the company posted a net loss for the period ended August 4, yet comparable sales, which had been sliding for more than a year, kept getting less bad every month from June through the first five weeks of the third quarter. New CEO Darin Harper is betting that improvement compounds into something bigger.
The clearest evidence is the trend line itself. Comparable store sales fell 5.4% in the first quarter of fiscal 2026, then 2.9% in the second quarter, then just 1.6% in July after a 5% decline in June, and Harper said trends improved further over the first five weeks of the third quarter. Food and beverage sales are moving in the opposite direction entirely, up 7.6% in the quarter and positive for five straight quarters, helped by the Eat & Play Combo, a bundled meal and game credit offer sold through kiosks. Special event sales have now grown for seven consecutive quarters.
Behind that shift sits a rebuilt leadership bench. Dave & Buster's went more than a year without a chief marketing officer, and Harper has since added a CMO, a chief operations officer, a chief technology officer, and a chief legal officer since taking over. The company also leaned on new content, launching 10 games and attractions this year, including tie-ins with Mandalorian and Grogu, John Wick and Stranger Things, after research found more than 70% of guests said new games would bring them back more often. Changes to game pricing pushed play and dwell time up 16% to 20% or more. Six remodeled stores are already outperforming the rest of the chain, and management says the newest remodel template costs less to build than the last one. Net capital spending dropped to $127.6 million through the first half of the year from $155.4 million, and adjusted free cash flow swung to positive $19.5 million from negative $36.5 million, a $56 million improvement.
The headline figures were still rough. Total revenue slipped 2.4% to $544.1 million from $557.4 million a year earlier, and adjusted EBITDA dropped to $98.9 million, an 18.2% margin, from $129.8 million and a 23.3% margin. On a GAAP basis, the company posted a net loss of $12.5 million, or $0.36 per diluted share, versus net income of $11.4 million in the same quarter last year. About $15 million of the EBITDA decline came from items management calls non-normalized, including a $10 million noncash deferral adjustment that did not repeat this year, $3 million in extra preopening costs and $2 million in higher insurance expenses, but even stripped of those, the underlying decline was still roughly $16 million.
#year #first #harper #play
27 days ago
Stock futures are higher after two days of losses for major indexes as traders await the Federal Reserve's decision on interest rates; the Fed is widely expected to raise its benchmark interest rate for the first time in three years to tame inflation; the European Union could add Canada as an "associate member" amid the country's growing trade war with the Trump administration; shares of SK Hynix and Intel are climbing following a report that the companies could partner to build chips in the U.S.; and retail sales data is due this morning. Here's what you need to know today.
Stock futures are rising this morning ahead of the highly anticipated Federal Reserve decision on interest rates. Dow Jones Industrial Average and S&P 500 futures were each up 0.3% in recent trading while futures tracking the tech-heavy Nasdaq added 0.6%. The major indexes fell Tuesday for the second straight session as oil prices and government bond yields rose. WTI crude oil futures were recently down more more than 2% at $103.50 per barrel after hitting a fresh four-month high yesterday. The yield on the 10-year Treasury note was at 4.97%, after jumping as high as 5.04% in yesterday's session, the highest point since the financial crisis of 2007. Bitcoin was holding steady at $76,100, after the cryptocurrency slumped yesterday as the Clarity Act failed to pass through a cloture vote in the Senate. Gold futures were up 1% to $4,390 an ounce.
The Federal Reserve's policy committee will wrap up its two-day meeting this afternoon amid expectations that the central bank will hike its benchmark rate for the first time in three years to address mounting inflationary pressure. The Federal Open Market Committee's decision is scheduled to be released at 2:00 p.m. ET, along with quarterly economic projections from FOMC members. Fed Chair Kevin Warsh, who took over the top position in May, has said repeatedly the Fed is squarely focussed on bringing inflation down to the Fed's target. Recent inflation data has confirmed that price pressures persist as oil prices rise owing to the Iran war. Investors will be looking for additional insights from Warsh, who is scheduled to speak at a press conference half an hour after the decision is announced. A rate hike is meant to raise borrowing costs, slowing economic activity such that inflation moderates. The challenge the Fed faces is that it can't address the underlying causes of the inflation, including the Iran war, tariffs and rampant corporate spending on AI.
#interest

27 days ago
You can find original article here WealthManagement. Subscribe to our free daily WealthManagement newsletters.
Columbia Threadneedle Investments and alternative ******* et manager Hamilton Lane announced a strategic collaboration to deliver new investment products for the wealth channel. An interval fund combining public and private equity exposure, currently awaiting SEC approval, will likely be the first product launched through the two firms' partnership.
Columbia Threadneedle brings its public markets expertise, multi-asset investment capabilities and strategic distribution relationships to the collaboration. Hamilton Lane specializes in alternatives, with an established private markets platform, investment sourcing capabilities and data ******* ytics expertise.
Columbia Threadneedle filed a preliminary registration statement with the SEC for the Columbia Hamilton Lane Growth Innovation Fund, a public-private growth equity interval fund. If the fund is approved by the SEC, it will be offered to the wealth channel through financial advisors.
According to the filing, the fund will focus on capital appreciation, allocating at least 80% of its net ******* ets to investments in growth innovation companies. The fund will be roughly evenly split in exposure to publicly traded securities and private ******* ets. At least 40% of the fund's ******* ets will be invested in underlying funds managed by Hamilton Lane.
#lane
27 days ago
Our **** ysts just identified a stock with the potential to be the next Nvidia. Tell us how you invest and we'll show you why it's our #1 pick. Tap here.
Trustpilot's underlying business is still growing quickly, with revenue up 23%, bookings up 22% and adjusted EBITDA climbing 46% in the first half. But investors instead focused on a surprise statutory loss, several one-off charges and management's decision to leave full-year guidance unchanged after a huge run in the shares.
Trustpilot shares fell as much as 20% after the online review platform reported strong first-half growth but delivered a messier bottom line than investors had expected.
Revenue increased 23% to $151.4 million in the six months to June, equivalent to 19% growth at constant currencies, while bookings rose 22% to $171.2 million.
Adjusted EBITDA climbed 46% to a record $26.3 million and the margin expanded to 17.4%, although the profit figure came in slightly below the $27 million company-compiled consensus.
#ebitda #bookings #investors

27 days ago
This story was originally published on Bisnow, the newsroom global commercial real estate reads first. To receive daily news and ******* ysis, subscribe to Bisnow's free suite of newsletters.
A pair of national real estate investment managers closed their U.S. office credit fund with $1.1B in investor commitments.
Hines and Rialto Capital secured 126 investors for their Hines Rialto Credit Partners, a co-general partnership focused on U.S. office credit investments. The fund required a minimum investment of $100K, according to a filing with the U.S. Securities and Exchange Commission.
With the rapid growth of private credit, Hines said it believes investors are searching for real estate credit strategies grounded in specialized underwriting and deep market knowledge.
"Yield alone does not tell you the quality of the risk," Alfonso Munk, Hines' global co-head of investment management, said in a statement. "In real estate credit, understanding the underlying ******* et — what it is worth, how it performs and how it may hold up under pressure — is becoming increasingly important as the market works through a significant refinancing cycle."
#real #rialto
27 days ago
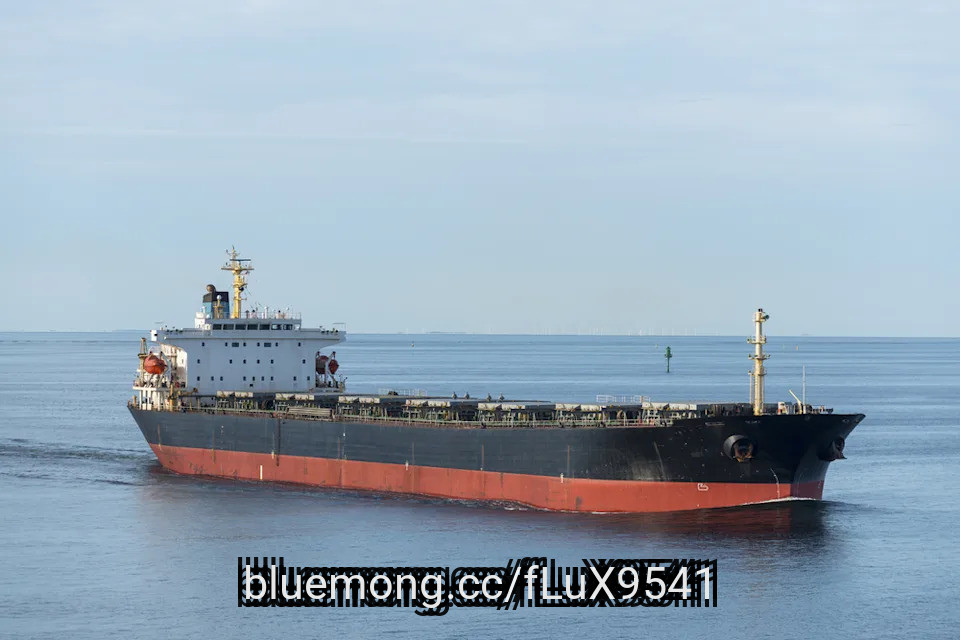
On September 10, Imperial Petroleum Inc. (NASDAQ:IMPP), a company involved in seaborne transportation of crude oil, dry bulk, and petroleum products, released its second quarter results. With a topline figure of $87.1 million, the company delivered record quarterly revenue, which also resulted in 139.9% year-over-year growth. Imperial's adjusted EBITDA for the second quarter stood at $41.7 million, while the Q2 adjusted net income of $35.3 million exhibited around 163% growth in comparison with Q2 FY25.
Ralf Gosch/Shutterstock.com
Several factors contributed to the second quarter topline growth. A 6.9 vessel rise in the company's average fleet size was the primary growth enabler. Other factors include encouraging dynamics across the drybulk segment, and higher rates for both drybulk and tankers amid the geopolitical uncertainties. Operating income for the quarter jumped to a near-record level of $33.4 million, which translates into a 307.3% growth relative to Q2 FY25. Imperial posted an adjusted EPS of $0.76 for the reported quarter, which almost doubled compared to the same quarter a year prior.
At the back of efficient fleet management, management remained focus on strengthening its financial position. The company ended the quarter with no debt, and its liquidity position also remained resilient. Cash and cash equivalents, including time deposits, increased from $179.1 million at the end of 2025 to $245.2 million as of June 30, 2026. The company added that its cash base had increased further to approximately $260 million as of the September 10 results release.
Certain areas of weakness warrant a closer examination. During the reported quarter, fleet operational utilization went down from 83.1% in prior year's second quarter to 73.5%. There was a substantial increase in some of the underlying operating expenses. For instance, the vessel operating expense stood at $14.4 million compared to $8.4 million during Q2 FY25. This $6 million rise can be attributed to Imperial's larger fleet size. Similarly, the voyage expenses also jumped from $10.7 million in last year's Q2 to $22.1 million for Q2 FY26. The incremental voyage expenses stemmed from higher bunkers' rates, as well as a 58.4% jump in spot days.
#fleet
27 days ago
Novo Nordisk A/S (NYSE:NVO)'s decision to rebrand its day-to-day identity as "Novo" and launch a cultural reset is primarily a strategic response to the company's loss of momentum in the obesity-drug market, rather than a financial restructuring in itself. Reuters reports that the company is trying to regain competitiveness as pressure from Eli Lilly intensifies. The move comes as Novo prepares to unveil new strategic ambitions at its September 21 Capital Markets Day, making the cultural reset potentially important if it leads to faster decision-making, stronger commercial execution and a more aggressive R&D approach.
The underlying business still has substantial scale to protect. Novo generated DKK 309.1 billion of 2025 sales and DKK 127.7 billion of operating profit, while obesity-care sales rose 31% at constant exchange rates to DKK 82.3 billion. However, the company also spent around DKK 8 billion on its transformation in 2025, and its diabetes value-market share fell 3.6 percentage points to 30.1%. The reset therefore comes at a critical point: Novo remains the global obesity-market leader, with a 59.6% branded-volume share in 2025, but Lilly is rapidly narrowing the competitive gap.
A successful cultural reset could improve Novo Nordisk A/S (NYSE:NVO)'s execution at a time when the company needs to convert its scientific and commercial ******* ets into faster growth. Reuters reported that CEO Mike Doustdar is already seeking to accelerate R&D and streamline decision-making following investor concerns about the pipeline and competition from Lilly. If the reorganization reduces internal bureaucracy and improves the speed of clinical, regulatory and commercial decisions, it could help Novo extract more value from its existing obesity portfolio while advancing next-generation treatments before the semaglutide patent cliff expected early next decade.
The company also has ******* ets that give a cultural and operational reset something concrete to build around. Wegovy was available in 52 countries by the end of 2025, while the company's higher-dose Wegovy achieved 20.7% weight loss in Phase 3 studies and its oral Wegovy achieved 16.6% weight loss. More recently, Wegovy received approval in China for MASH, expanding its potential beyond weight management and cardiovascular benefits into another large metabolic-disease market. If Novo Nordisk A/S (NYSE:NVO) can combine these products with better execution, the reset could support higher patient volumes and extend the commercial life of its GLP-1 franchise, helping defend revenue and cash flow despite pricing pressure.
#nordisk #lilly
27 days ago
Colgate-Palmolive Company (NYSE:CL) is reportedly exploring the sale of several mass-market personal care brands, including Softsoap, Irish Spring and Speed Stick, in a portfolio reshaping effort that could generate more than $1 billion. The company is working with Goldman Sachs on the potential divestiture. Personal care accounted for roughly 17% of Colgate-Palmolive's 2025 net sales, or about $3.5 billion, while oral care remains the company's largest business.
The move comes as Colgate faces pressure in its North American business. Although the company recently reported a 4.9% increase in net sales, organic sales in North America declined 3%, highlighting competitive pressure in a mature market. The strategy is also consistent with a broader consumer-goods shift toward simplifying portfolios and concentrating capital on higher-growth categories. Unilever, Nestlé, and other major consumer companies have similarly been selling slower-growing or non-core businesses.
The biggest positive is that Colgate-Palmolive Company (NYSE:CL) could become a more focused and potentially higher-quality business. Selling brands that no longer fit its highest-priority growth areas would allow management to concentrate capital, marketing spending, and management attention on oral care, pet nutrition, and other businesses where Colgate has stronger competitive advantages. The company's decision would therefore be less about abandoning personal care altogether and more about improving the quality of the remaining portfolio.
A sale could also unlock meaningful shareholder value. If the divestitures generate more than $1 billion, Colgate would have additional capital that could be used for debt reduction, share repurchases, acquisitions, or investment behind its strongest brands. In a mature consumer-staples company, disciplined capital allocation can have an outsized impact on earnings growth and shareholder returns. There is also evidence that portfolio simplification is becoming increasingly attractive across the consumer-goods industry. The Wall Street Journal has highlighted how companies such as Unilever and Nestlé are shedding businesses that add complexity without providing sufficient growth. The underlying argument is that the benefits of owning a very broad portfolio have diminished as consumer preferences become more fragmented and smaller brands become better at responding to trends.
Most importantly, the divestiture could improve Colgate-Palmolive Company (NYSE:CL)'s strategic focus at a time when North American competition is challenging. Rather than allocating resources to defend slower-growing personal-care brands, management could direct investment toward categories and geographies with better long-term growth prospects. That could ultimately support margins and organic growth even if the immediate revenue base becomes smaller.
#personal #NYSE #Portfolio