

29 days ago
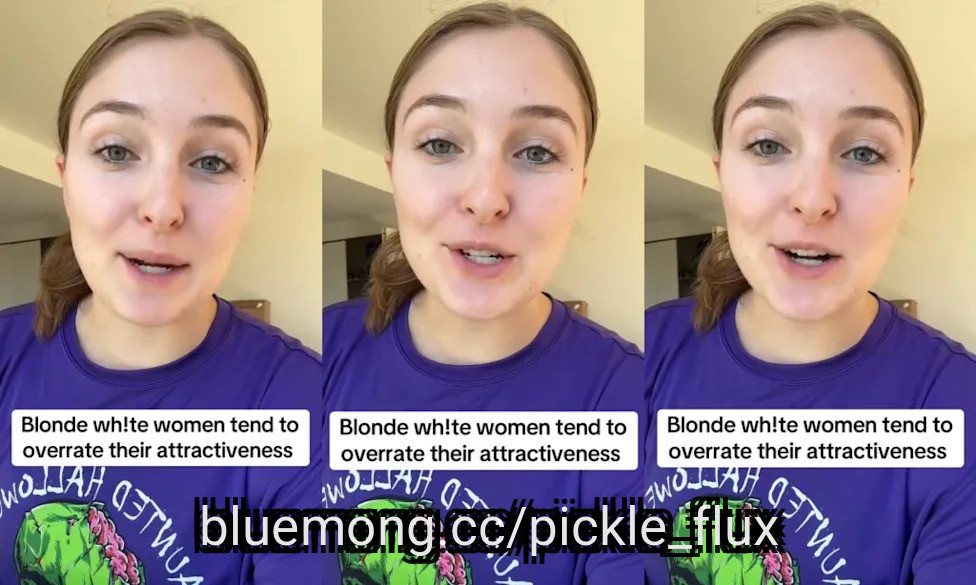
A TikTok influencer has said that white women, especially blond-haired women, have an overly inflated sense of their looks, stating that this mentality causes much animosity in her video.
Kylie Brewer named the video "Blonde wh!te women tend to overrate their attractiveness." This is the sequel to her earlier video, where she said white men overestimate their looks.
Brewer claims that lots of white women find it hard to understand that other people might not think of them as the ultimate choice.
"If you tell them that you don't think that, that's the most attractive type of person out there, they literally cannot imagine it because for them, their experience of what they think is colorism is between blonde and brunettes," Brewer said.
"And white women get incredibly territorial over blond hair and over men in general," she added.
#blonde
Kylie Brewer named the video "Blonde wh!te women tend to overrate their attractiveness." This is the sequel to her earlier video, where she said white men overestimate their looks.
Brewer claims that lots of white women find it hard to understand that other people might not think of them as the ultimate choice.
"If you tell them that you don't think that, that's the most attractive type of person out there, they literally cannot imagine it because for them, their experience of what they think is colorism is between blonde and brunettes," Brewer said.
"And white women get incredibly territorial over blond hair and over men in general," she added.
#blonde

2 months ago
Whirlpool already cut its dividend 49% then skipped a payment entirely, while KHC's yield is inflated by a 55% decade-long price collapse with frozen payouts since 2019.
IEP's 29% yield masks two prior cuts and a 68% cash drop year over year, while UPS's quarterly operating cash flow fell $469 million short of its dividend payout.
A collapsing share price mechanically inflates yield, making high-yield stocks look attractive precisely when the underlying business is deteriorating most.
Just released. Our ******* ysts combed the entire stock market and named the ten best stocks to buy right now, and Kraft Heinz didn't make the cut. Enter your email to see the names that beat KHC. The report is free. Enter your email and see if any of your stocks made the cut.
Yield is a promise, not a payment. When a stock advertises a payout that looks two or three times the market average, it usually means the market has already decided something is wrong. The screen below flags six US-listed names where the numbers behind the yield show real strain: shrinking cash flow, stretched coverage, or a share price that collapsed and inflated the yield mechanically. None of these companies has announced a cut. Each has warning signs a retirement-focused reader should understand before buying the yield.
#inflated
IEP's 29% yield masks two prior cuts and a 68% cash drop year over year, while UPS's quarterly operating cash flow fell $469 million short of its dividend payout.
A collapsing share price mechanically inflates yield, making high-yield stocks look attractive precisely when the underlying business is deteriorating most.
Just released. Our ******* ysts combed the entire stock market and named the ten best stocks to buy right now, and Kraft Heinz didn't make the cut. Enter your email to see the names that beat KHC. The report is free. Enter your email and see if any of your stocks made the cut.
Yield is a promise, not a payment. When a stock advertises a payout that looks two or three times the market average, it usually means the market has already decided something is wrong. The screen below flags six US-listed names where the numbers behind the yield show real strain: shrinking cash flow, stretched coverage, or a share price that collapsed and inflated the yield mechanically. None of these companies has announced a cut. Each has warning signs a retirement-focused reader should understand before buying the yield.
#inflated


2 months ago
On August 6, James Hardie Industries (NYSE:JHX) reported results for the quarter ended June 30 and beat its own numbers by enough to raise guidance just three months into the fiscal year. Net sales jumped 64% year over year to $1.475 billion, adjusted EBITDA climbed 79% to $422.1 million, and both figures came in ahead of what management had originally guided investors to expect. For a company that closed a transformative acquisition less than a year earlier, that kind of overshoot forces a reassessment of the growth story ahead.
The headline growth number is inflated by the AZEK Exteriors deal folded into the base, so the more telling figure is the 12% pro forma net sales growth, which also beat original guidance. Siding & Trim, the core fiber cement business, posted organic net sales growth of 20% as North American fiber cement volumes returned to growth for the first time in several quarters. CEO Aaron Erter tied that to share gains against vinyl and other competing materials, along with programs like ColorPlus and Expanded Statement drawing more of the higher-end repair and remodel market. Adjusted EBITDA margin in that segment expanded 140 basis points to 33.5%, powered by favorable pricing, cheaper raw materials, and continued savings from the company's Hardie Manufacturing Operating System even as freight costs rose.
Management also said cost synergies from the AZEK integration are running ahead of schedule and revenue synergies are on track, evidenced by newly expanded nationwide distribution partnerships with Boise Cascade and other regional distributors. In Deck, Rail & Accessories, sell-through accelerated every month of the quarter and outpaced shipments, pulling channel inventory back to normal levels and setting up a cleaner back half of the year. Free cash flow more than doubled to $254.2 million, and the company used the cash to pay down $400 million of senior unsecured notes.
Erter was careful to frame the beat as execution rather than a healthier market, telling investors the company is "not ***** uming a housing market improvement" for the rest of fiscal 2027. Part of the quarter's strength came from an easy comparison, since channel inventory was deliberately reduced a year earlier, and management said that benefit is expected to moderate as the year goes on. Deck, Rail & Accessories net sales actually fell 5% on a pro forma basis because the company intentionally cut production to work down channel inventory, leaving the segment with an operating loss of $3.3 million for the quarter.
#Growth #sales #management
The headline growth number is inflated by the AZEK Exteriors deal folded into the base, so the more telling figure is the 12% pro forma net sales growth, which also beat original guidance. Siding & Trim, the core fiber cement business, posted organic net sales growth of 20% as North American fiber cement volumes returned to growth for the first time in several quarters. CEO Aaron Erter tied that to share gains against vinyl and other competing materials, along with programs like ColorPlus and Expanded Statement drawing more of the higher-end repair and remodel market. Adjusted EBITDA margin in that segment expanded 140 basis points to 33.5%, powered by favorable pricing, cheaper raw materials, and continued savings from the company's Hardie Manufacturing Operating System even as freight costs rose.
Management also said cost synergies from the AZEK integration are running ahead of schedule and revenue synergies are on track, evidenced by newly expanded nationwide distribution partnerships with Boise Cascade and other regional distributors. In Deck, Rail & Accessories, sell-through accelerated every month of the quarter and outpaced shipments, pulling channel inventory back to normal levels and setting up a cleaner back half of the year. Free cash flow more than doubled to $254.2 million, and the company used the cash to pay down $400 million of senior unsecured notes.
Erter was careful to frame the beat as execution rather than a healthier market, telling investors the company is "not ***** uming a housing market improvement" for the rest of fiscal 2027. Part of the quarter's strength came from an easy comparison, since channel inventory was deliberately reduced a year earlier, and management said that benefit is expected to moderate as the year goes on. Deck, Rail & Accessories net sales actually fell 5% on a pro forma basis because the company intentionally cut production to work down channel inventory, leaving the segment with an operating loss of $3.3 million for the quarter.
#Growth #sales #management


2 months ago
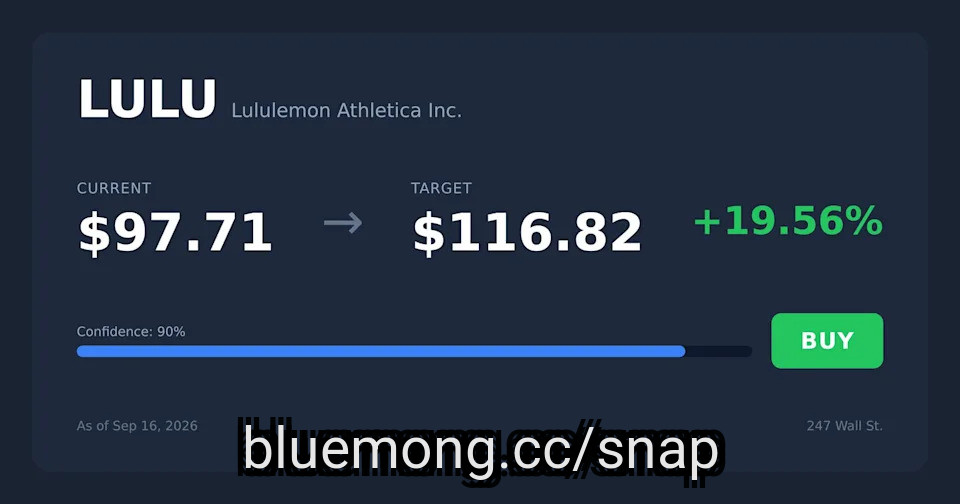
Lululemon fell 18% after Meghan Frank delivered a second guidance cut, dropping the full-year EPS outlook to roughly $9.60 from last year's $13.26.
Nike fell 10% and On Holding dropped 14% over the same month, suggesting athletic-apparel sector headwinds extend well beyond Lululemon alone.
An 86-cent tariff refund inflated Q2 EPS but won't recur, making Lululemon's reported profit look cleaner than the challenge facing incoming CEO Heidi O'Neill.
Just released. Our ***** ysts combed the entire stock market and named the ten best stocks to buy right now, and Lululemon didn't make the cut. Enter your email to see the names that beat LULU. The report is free. Enter your email and see if any of your stocks made the cut.
Lululemon Athletica (NASDAQ:LULU) stock is under sustained pressure after a September earnings update that lowered management's outlook for the year. Retail broadly softened alongside it, and the broad market held up better, which frames the question of how much of the damage is company-specific and how much is sector-wide. Peer moves are part of that same picture, since athletic-apparel names moved lower together across the past month.
#lululemon #enter #outlook
Nike fell 10% and On Holding dropped 14% over the same month, suggesting athletic-apparel sector headwinds extend well beyond Lululemon alone.
An 86-cent tariff refund inflated Q2 EPS but won't recur, making Lululemon's reported profit look cleaner than the challenge facing incoming CEO Heidi O'Neill.
Just released. Our ***** ysts combed the entire stock market and named the ten best stocks to buy right now, and Lululemon didn't make the cut. Enter your email to see the names that beat LULU. The report is free. Enter your email and see if any of your stocks made the cut.
Lululemon Athletica (NASDAQ:LULU) stock is under sustained pressure after a September earnings update that lowered management's outlook for the year. Retail broadly softened alongside it, and the broad market held up better, which frames the question of how much of the damage is company-specific and how much is sector-wide. Peer moves are part of that same picture, since athletic-apparel names moved lower together across the past month.
#lululemon #enter #outlook


2 months ago
As I write this on Sunday night, all but one Week 1 game is comfortably in the books, and as is always the case on opening weekend, we encountered a slew of surprises. Some promising, others concerning and many that may have affected our outlook on a player or an offense. We're all doing our best not to overreact to one Sunday (and one Wednesday and one Thursday), but some of these shifting perspectives are bound to have permanent ramifications.
Join or create a Yahoo Fantasy Football league for the 2026 NFL season
With that in mind, I've compiled the (first) full weekly fantasy football stock report. These are the most notable risers and fallers heading into Week 2.
Ankle sprain, schmankle schprain (sorry, editors). Ashton Jeanty looked incredible on Sunday and had absolutely no limitations on his workload. He handled 23 carries and had six catches, totaling 147 yards while scoring twice through the air. He totaled 74 rushing yards after contact and scored both of his receiving touchdowns from the 13-yard line. Translation? The second-year RB's upside is arguably somewhere in the Christian McCaffrey stratosphere. The one caveat to all of this, of course, is that he did it against the Miami Dolphins. We'll see whether things change in Week 2 against the Chargers. But for now, Jeanty looks fully healthy and completely dominant, and anyone who got him at the "ankle sprain discount" is doing cartwheels.
At just 61% rostered on Yahoo, Jalen ******* er was closer to being a waiver-wire player than a fantasy stud. Not anymore. The third-year wideout led the Panthers with nine targets, eight catches, 138 receiving yards and two touchdowns, finishing as the WR1 overall on Sunday (29.8 fantasy points). He ran the second-most routes on the team (32), behind Tetairoa McMillan (36), and averaged 13.8 air yards per target and 4.31 yards per route run. He made a very strong opening argument to be a 1B to McMillan's 1A this season. And while all of Carolina's numbers were inflated by this barn-burner of a game with Chicago, ******* er had flashed late last year and looks like a legitimate third-year breakout candidate. He'll be among the most-added players on waivers this week (despite starting at 61%) and should be at least a FLEX consideration until further notice.
#yards
Join or create a Yahoo Fantasy Football league for the 2026 NFL season
With that in mind, I've compiled the (first) full weekly fantasy football stock report. These are the most notable risers and fallers heading into Week 2.
Ankle sprain, schmankle schprain (sorry, editors). Ashton Jeanty looked incredible on Sunday and had absolutely no limitations on his workload. He handled 23 carries and had six catches, totaling 147 yards while scoring twice through the air. He totaled 74 rushing yards after contact and scored both of his receiving touchdowns from the 13-yard line. Translation? The second-year RB's upside is arguably somewhere in the Christian McCaffrey stratosphere. The one caveat to all of this, of course, is that he did it against the Miami Dolphins. We'll see whether things change in Week 2 against the Chargers. But for now, Jeanty looks fully healthy and completely dominant, and anyone who got him at the "ankle sprain discount" is doing cartwheels.
At just 61% rostered on Yahoo, Jalen ******* er was closer to being a waiver-wire player than a fantasy stud. Not anymore. The third-year wideout led the Panthers with nine targets, eight catches, 138 receiving yards and two touchdowns, finishing as the WR1 overall on Sunday (29.8 fantasy points). He ran the second-most routes on the team (32), behind Tetairoa McMillan (36), and averaged 13.8 air yards per target and 4.31 yards per route run. He made a very strong opening argument to be a 1B to McMillan's 1A this season. And while all of Carolina's numbers were inflated by this barn-burner of a game with Chicago, ******* er had flashed late last year and looks like a legitimate third-year breakout candidate. He'll be among the most-added players on waivers this week (despite starting at 61%) and should be at least a FLEX consideration until further notice.
#yards



2 months ago
BAGHDAD (AP) — Iraq's government raced Saturday to contain the fallout after local Iran-backed militias were accused of attacking and shuttering a key Saudi pipeline.
Though an umbrella group of Iran-backed militias in Iraq denied their involvement, Iraq's government confirmed the attacks had originated from its territory. The government pledged to investigate and dismissed two senior officials.
The country is under mounting pressure to prevent local militias from aiding other Iran proxy groups across the region. The Iraqi government has set a Sept. 30 deadline for nonstate groups to disarm, but several of the most powerful militias have said they will not comply.
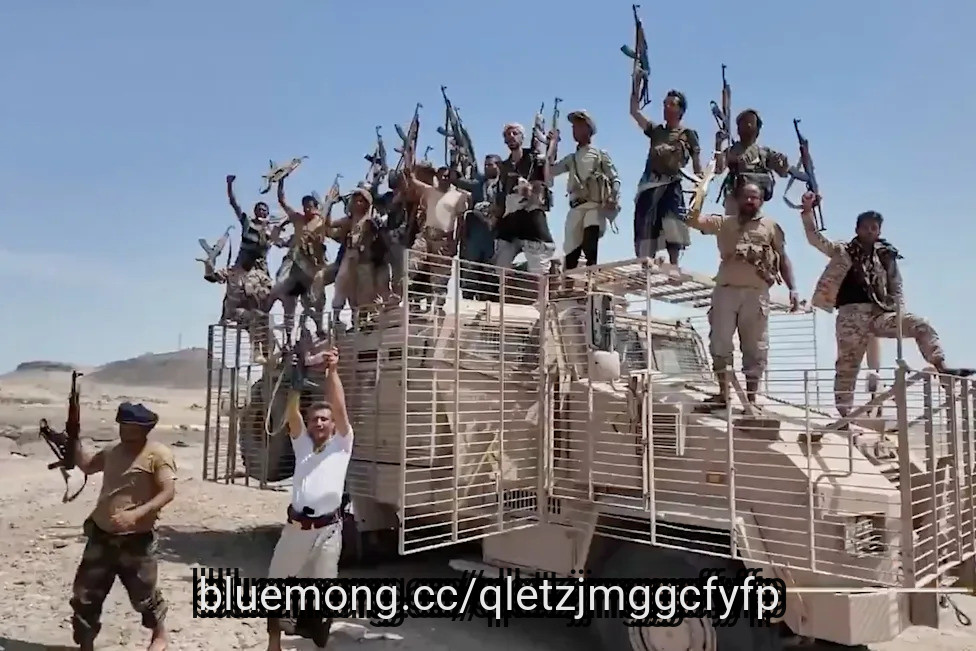
Pressure to disarm the militias is especially acute as the Iran-backed Houthi rebels make an advance across Yemen's west coast in a major setback to the Saudi-backed coalition that risks escalating the war in the region. The Houthis on Friday seized an island in the Bab el-Mandeb Strait, a key shipping lane through which around 12% of global trade passes.
Their virtual control of the strait could send global oil prices — already inflated by the six-month Iran-U.S. war — spiraling. The strait has become a vital commercial lane for Saudi oil ever since the Iran war disrupted shipping in the Strait of Hormuz.
#saudi #across
Though an umbrella group of Iran-backed militias in Iraq denied their involvement, Iraq's government confirmed the attacks had originated from its territory. The government pledged to investigate and dismissed two senior officials.
The country is under mounting pressure to prevent local militias from aiding other Iran proxy groups across the region. The Iraqi government has set a Sept. 30 deadline for nonstate groups to disarm, but several of the most powerful militias have said they will not comply.
Pressure to disarm the militias is especially acute as the Iran-backed Houthi rebels make an advance across Yemen's west coast in a major setback to the Saudi-backed coalition that risks escalating the war in the region. The Houthis on Friday seized an island in the Bab el-Mandeb Strait, a key shipping lane through which around 12% of global trade passes.
Their virtual control of the strait could send global oil prices — already inflated by the six-month Iran-U.S. war — spiraling. The strait has become a vital commercial lane for Saudi oil ever since the Iran war disrupted shipping in the Strait of Hormuz.
#saudi #across


2 months ago
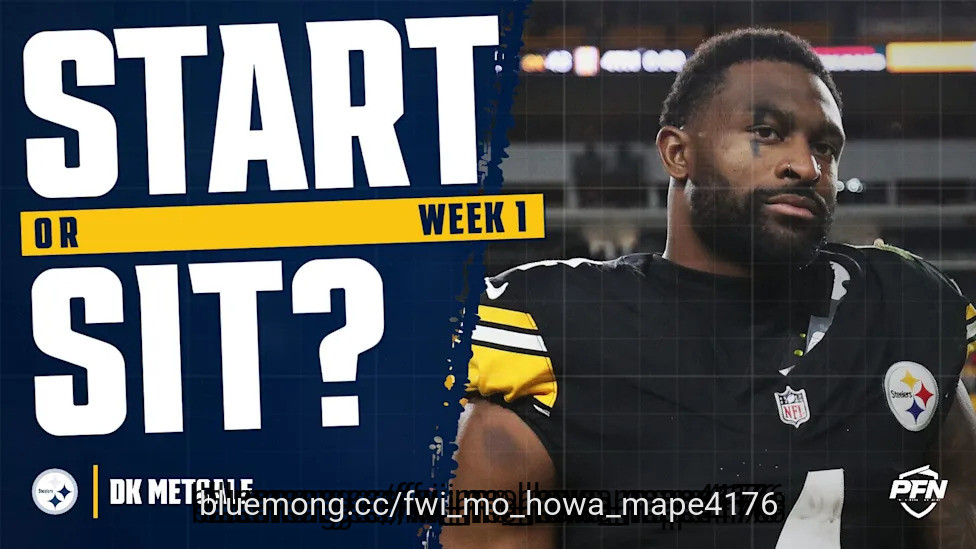
Metcalf sits 34th among wide receivers in PFN's Week 1 rankings, which is what happens after the worst season of your career. The Falcons allowed seven receivers to clear 20 PPR points last season, so the setup is there, and so is the Michael Pittman theory. I'm going to be a week or two late to this party rather than early.
Let's call a spade a spade: Metcalf is coming off of the worst season of his career. His 850 yards were a new low-water mark and even that was inflated by two games where he had superhero singular plays that lifted his stat line (274 yards in games against the Ravens and Vikings, 576 in his other 13, good for just 44.3 yards per contest).
Aaron Rodgers is back at the helm and the team added Michael Pittman this offseason, a receiver who has effectively made a career off of what the Steelers asked of Metcalf in his first season with the franchise: short targets and hope.
SET YOUR LINEUPS: PFN's Free Fantasy Football Start/Sit Optimizer
Metcalf's 11.3 aDOT was, you guessed it, the lowest of his career, and featured just 24.2% of his looks coming deep downfield (15 or more yards), a rate that stood at 43.5% in 2024 with Seattle.
#season #week #receivers
Let's call a spade a spade: Metcalf is coming off of the worst season of his career. His 850 yards were a new low-water mark and even that was inflated by two games where he had superhero singular plays that lifted his stat line (274 yards in games against the Ravens and Vikings, 576 in his other 13, good for just 44.3 yards per contest).
Aaron Rodgers is back at the helm and the team added Michael Pittman this offseason, a receiver who has effectively made a career off of what the Steelers asked of Metcalf in his first season with the franchise: short targets and hope.
SET YOUR LINEUPS: PFN's Free Fantasy Football Start/Sit Optimizer
Metcalf's 11.3 aDOT was, you guessed it, the lowest of his career, and featured just 24.2% of his looks coming deep downfield (15 or more yards), a rate that stood at 43.5% in 2024 with Seattle.
#season #week #receivers

2 months ago
Interested in Qualcomm Incorporated? Here are five stocks we like better.
Qualcomm's Amazon agreement gives its data center strategy a major anchor beyond smartphones.
Amazon's warrants are tied to up to $60 billion in potential purchases over a decade, making the deal meaningful but gradual.
Qualcomm's valuation still trails many AI infrastructure peers, but dilution risk and execution timing remain important factors.
Investors continue to seek disciplined strategies to participate in the evolving artificial intelligence (AI) economy without paying inflated multiples for standard graphics hardware. Capital remains focused on businesses positioned to sustain steady enterprise workload expansion while maintaining reasonable valuation metrics.
#interested #qualcomm
Qualcomm's Amazon agreement gives its data center strategy a major anchor beyond smartphones.
Amazon's warrants are tied to up to $60 billion in potential purchases over a decade, making the deal meaningful but gradual.
Qualcomm's valuation still trails many AI infrastructure peers, but dilution risk and execution timing remain important factors.
Investors continue to seek disciplined strategies to participate in the evolving artificial intelligence (AI) economy without paying inflated multiples for standard graphics hardware. Capital remains focused on businesses positioned to sustain steady enterprise workload expansion while maintaining reasonable valuation metrics.
#interested #qualcomm

2 months ago
In 2026, the Cubs' starters have been a major storyline. While the bullpen's struggle is the biggest issue, the rotation has been concerning. The pitching struggles have severely impacted the team in the second half of the season. When looking at the playoff picture, their lead has diminished, and both San Diego and Arizona are within three games of Chicago. However, there is hope for the Cubs starters.
Chicago has had a very up-and-down year from their starters. Injuries have plagued the team, as nearly all pitchers miss time. A busy trade deadline had things looking promising. While a few have had good starts, the team has struggled to find consistency. That said, the Cubs' starter hierarchy has clearly shifted. If Chicago wishes to make a run in the playoffs, relying on the top three Cubs starters needs to be the move.
Clay Holmes has been the top Cubs starter since he joined the team. With Chicago, he is 2-3 with a 3.51 ERA. The ERA is inflated by his last start, in which he allowed eight runs in 4.1 innings. Without that game, he was showing his ace potential. Down the stretch of the season, Holmes will need to show his talent and give the Cubs valuable length.
The other newcomer, Kevin Gausman, has also been solid since joining Chicago. His most recent start against the Brewers was rough, allowing six earned runs. He has had mixed results in his seven starts, with a 5.31 ERA. However, he is giving good length, going six or seven innings in most starts. Additionally, his valuable playoff experience makes him a key piece of the Cubs rotation.
Of the three starters, Matthew Boyd is the only one who has been with them all year. Boyd has struggled with injuries and inconsistency, but still has given valuable innings. Like Gausman, he can go fairly deep into games. He is 8-4 with a 4.03 ERA in 109.1 innings. His experience with Chicago could see him start one of the first two games come playoff time.
#innings #playoff
Chicago has had a very up-and-down year from their starters. Injuries have plagued the team, as nearly all pitchers miss time. A busy trade deadline had things looking promising. While a few have had good starts, the team has struggled to find consistency. That said, the Cubs' starter hierarchy has clearly shifted. If Chicago wishes to make a run in the playoffs, relying on the top three Cubs starters needs to be the move.
Clay Holmes has been the top Cubs starter since he joined the team. With Chicago, he is 2-3 with a 3.51 ERA. The ERA is inflated by his last start, in which he allowed eight runs in 4.1 innings. Without that game, he was showing his ace potential. Down the stretch of the season, Holmes will need to show his talent and give the Cubs valuable length.
The other newcomer, Kevin Gausman, has also been solid since joining Chicago. His most recent start against the Brewers was rough, allowing six earned runs. He has had mixed results in his seven starts, with a 5.31 ERA. However, he is giving good length, going six or seven innings in most starts. Additionally, his valuable playoff experience makes him a key piece of the Cubs rotation.
Of the three starters, Matthew Boyd is the only one who has been with them all year. Boyd has struggled with injuries and inconsistency, but still has given valuable innings. Like Gausman, he can go fairly deep into games. He is 8-4 with a 4.03 ERA in 109.1 innings. His experience with Chicago could see him start one of the first two games come playoff time.
#innings #playoff

0.00$ raised of 0.00$ goal
0 donations
0.00$
to go

2 months ago
Hotchkis & Wiley, an investment management company, released its second-quarter 2026 investor letter for the "Large Cap Fundamental Value Fund." A copy can be downloaded here. Equity markets posted strong returns, with the Russell 1000 Value Index rising by 13.9%, although many individual stocks lagged. Notably, semiconductor stocks and AI-related sectors saw exceptional gains. The rally appeared speculative, marked by a stark difference in performance between high-beta and low-volatility stocks, along with momentum stocks outperforming the market significantly. Despite heightened enthusiasm for AI investments, concerns arise over inflated valuations reminiscent of the dot-com era. While there is substantial capital investment in AI, future earnings growth must justify these expenditures. The fund maintains a cautious approach towards perceived beneficiaries of AI, suggesting that select high-quality businesses with reasonable valuations may be better positioned. Historical trends suggest that speculative markets often revert to valuations based on fundamental economic realities, and the chosen investments are believed to be well-prepared for such a shift. The fund underperformed the index in the quarter and returned 5.69% vs. 13.87% for the Russell 1000 Value Index, largely due to a lack of exposure to high-performing sectors like semiconductors, while stock selection in healthcare provided a positive contribution. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Hotchkis & Wiley Large Cap Fundamental Value Fund highlighted Elevance Health, Inc. (NYSE:ELV) as a notable contributor. Elevance Health, Inc. (NYSE:ELV) is a US-based health benefits company. On August 31, 2026, Elevance Health, Inc. (NYSE:ELV) closed at $392.54 per share. Over the past month, Elevance Health, Inc. (NYSE:ELV) reported 3.85%, but its shares are up 21.78% over the past year. Elevance Health, Inc. (NYSE:ELV) has a market capitalization of $85.13 billion, and its stock has traded within a 52-week range of $274.84 to $436.24.
Hotchkis & Wiley Large Cap Fundamental Value Fund stated the following regarding Elevance Health, Inc. (NYSE:ELV) in its Q2 2026 investor letter:
"Elevance Health, Inc. (NYSE:ELV) is the second largest health insurer, and one of the largest commercial insurers in the United States. Shares rose during the quarter after the company reported quarterly earnings that beat consensus estimates. It was further supported by news that the US agreed to increase 2027 payments for private Medicare Advantage plans above the initial proposal. The company is priced at a discount to the market, driven by skepticism surrounding margins and growth, despite being a superior business that grows above GDP while returning most of its cash to shareholders."
#NYSE #fund #fundamental #wiley
In its second-quarter 2026 investor letter, Hotchkis & Wiley Large Cap Fundamental Value Fund highlighted Elevance Health, Inc. (NYSE:ELV) as a notable contributor. Elevance Health, Inc. (NYSE:ELV) is a US-based health benefits company. On August 31, 2026, Elevance Health, Inc. (NYSE:ELV) closed at $392.54 per share. Over the past month, Elevance Health, Inc. (NYSE:ELV) reported 3.85%, but its shares are up 21.78% over the past year. Elevance Health, Inc. (NYSE:ELV) has a market capitalization of $85.13 billion, and its stock has traded within a 52-week range of $274.84 to $436.24.
Hotchkis & Wiley Large Cap Fundamental Value Fund stated the following regarding Elevance Health, Inc. (NYSE:ELV) in its Q2 2026 investor letter:
"Elevance Health, Inc. (NYSE:ELV) is the second largest health insurer, and one of the largest commercial insurers in the United States. Shares rose during the quarter after the company reported quarterly earnings that beat consensus estimates. It was further supported by news that the US agreed to increase 2027 payments for private Medicare Advantage plans above the initial proposal. The company is priced at a discount to the market, driven by skepticism surrounding margins and growth, despite being a superior business that grows above GDP while returning most of its cash to shareholders."
#NYSE #fund #fundamental #wiley

2 months ago
Hotchkis & Wiley, an investment management company, released its second-quarter 2026 investor letter for the "Large Cap Fundamental Value Fund." A copy can be downloaded here. Equity markets posted strong returns, with the Russell 1000 Value Index rising by 13.9%, although many individual stocks lagged. Notably, semiconductor stocks and AI-related sectors saw exceptional gains. The rally appeared speculative, marked by a stark difference in performance between high-beta and low-volatility stocks, along with momentum stocks outperforming the market significantly. Despite heightened enthusiasm for AI investments, concerns arise over inflated valuations reminiscent of the dot-com era. While there is substantial capital investment in AI, future earnings growth must justify these expenditures. The fund maintains a cautious approach towards perceived beneficiaries of AI, suggesting that select high-quality businesses with reasonable valuations may be better positioned. Historical trends suggest that speculative markets often revert to valuations based on fundamental economic realities, and the chosen investments are believed to be well-prepared for such a shift. The fund underperformed the index in the quarter and returned 5.69% vs. 13.87% for the Russell 1000 Value Index, largely due to a lack of exposure to high-performing sectors like semiconductors, while stock selection in healthcare provided a positive contribution. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Hotchkis & Wiley Large Cap Fundamental Value Fund highlighted F5, Inc. (NASDAQ:FFIV) as one of its leading individual contributors. F5, Inc. (NASDAQ:FFIV) offers multi-cloud application security and delivery solutions. On August 31, 2026, F5, Inc. (NASDAQ:FFIV) closed at $407.13 per share. Over the past month, F5, Inc. (NASDAQ:FFIV) declined 3.41%, while its shares are up 29.82% over the past year. F5, Inc. (NASDAQ:FFIV) has a market capitalization of $23.05 billion, and its stock has traded within a 52-week range of $223.76 to $435.00.
Hotchkis & Wiley Large Cap Fundamental Value Fund stated the following regarding F5, Inc. (NASDAQ:FFIV) in its Q2 2026 investor letter:
"F5, Inc. (NASDAQ:FFIV) sells application networking and security software as well as data center appliances. The company's stock rose after it posted good quarterly results and raised both its revenue and EPS guidance. The company is misunderstood and gets incorrectly classified as a legacy IT hardware vendor, resulting in an attractive valuation for a company with better-than-average fundamental risk ratings. F5 has over 50% market share in traditional ADCs (application delivery controllers), along with various multi-cloud networking and application security products."
#ffiv
In its second-quarter 2026 investor letter, Hotchkis & Wiley Large Cap Fundamental Value Fund highlighted F5, Inc. (NASDAQ:FFIV) as one of its leading individual contributors. F5, Inc. (NASDAQ:FFIV) offers multi-cloud application security and delivery solutions. On August 31, 2026, F5, Inc. (NASDAQ:FFIV) closed at $407.13 per share. Over the past month, F5, Inc. (NASDAQ:FFIV) declined 3.41%, while its shares are up 29.82% over the past year. F5, Inc. (NASDAQ:FFIV) has a market capitalization of $23.05 billion, and its stock has traded within a 52-week range of $223.76 to $435.00.
Hotchkis & Wiley Large Cap Fundamental Value Fund stated the following regarding F5, Inc. (NASDAQ:FFIV) in its Q2 2026 investor letter:
"F5, Inc. (NASDAQ:FFIV) sells application networking and security software as well as data center appliances. The company's stock rose after it posted good quarterly results and raised both its revenue and EPS guidance. The company is misunderstood and gets incorrectly classified as a legacy IT hardware vendor, resulting in an attractive valuation for a company with better-than-average fundamental risk ratings. F5 has over 50% market share in traditional ADCs (application delivery controllers), along with various multi-cloud networking and application security products."
#ffiv

2 months ago
Hotchkis & Wiley, an investment management company, released its second-quarter 2026 investor letter for the "Large Cap Fundamental Value Fund." A copy can be downloaded here. Equity markets posted strong returns, with the Russell 1000 Value Index rising by 13.9%, although many individual stocks lagged. Notably, semiconductor stocks and AI-related sectors saw exceptional gains. The rally appeared speculative, marked by a stark difference in performance between high-beta and low-volatility stocks, along with momentum stocks outperforming the market significantly. Despite heightened enthusiasm for AI investments, concerns arise over inflated valuations reminiscent of the dot-com era. While there is substantial capital investment in AI, future earnings growth must justify these expenditures. The fund maintains a cautious approach towards perceived beneficiaries of AI, suggesting that select high-quality businesses with reasonable valuations may be better positioned. Historical trends suggest that speculative markets often revert to valuations based on fundamental economic realities, and the chosen investments are believed to be well-prepared for such a shift. The fund underperformed the index in the quarter and returned 5.69% vs. 13.87% for the Russell 1000 Value Index, largely due to a lack of exposure to high-performing sectors like semiconductors, while stock selection in healthcare provided a positive contribution. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Hotchkis & Wiley Large Cap Fundamental Value Fund highlighted Workday, Inc. (NASDAQ:WDAY). Workday, Inc. (NASDAQ:WDAY), a leading enterprise software company that provides cloud applications for human resources and financial management, detracted from performance this quarter. On August 31, 2026, Workday, Inc. (NASDAQ:WDAY) closed at $197.45 per share. Over the past month, Workday, Inc. (NASDAQ:WDAY) returned 15.87%, but its shares are down 13.29% over the past year. Workday, Inc. (NASDAQ:WDAY) has a market capitalization of $47.59 billion.
Hotchkis & Wiley Large Cap Fundamental Value Fund stated the following regarding Workday, Inc. (NASDAQ:WDAY) in its Q2 2026 investor letter:
Workday, Inc. (NASDAQ:WDAY) is a leader in cloud software for back-office business functions, spanning human capital management (HCM), financial management, and adjacent ERP (enterprise resource planning) products, with 60% of the Fortune 500 as HCM customers. Shares declined over the period, pressured by investor concerns that AI could disrupt application software vendors. The most recent quarter, however, did not show evidence of this. Subscription revenue grew 14%, 12-month backlog grew 16%, retention remained industry leading, margins expanded, and management reiterated full-year subscription revenue guidance while raising operating margin guidance. AI adoption also appears to be progressing, with Workday-developed agents now used by more
In its second-quarter 2026 investor letter, Hotchkis & Wiley Large Cap Fundamental Value Fund highlighted Workday, Inc. (NASDAQ:WDAY). Workday, Inc. (NASDAQ:WDAY), a leading enterprise software company that provides cloud applications for human resources and financial management, detracted from performance this quarter. On August 31, 2026, Workday, Inc. (NASDAQ:WDAY) closed at $197.45 per share. Over the past month, Workday, Inc. (NASDAQ:WDAY) returned 15.87%, but its shares are down 13.29% over the past year. Workday, Inc. (NASDAQ:WDAY) has a market capitalization of $47.59 billion.
Hotchkis & Wiley Large Cap Fundamental Value Fund stated the following regarding Workday, Inc. (NASDAQ:WDAY) in its Q2 2026 investor letter:
Workday, Inc. (NASDAQ:WDAY) is a leader in cloud software for back-office business functions, spanning human capital management (HCM), financial management, and adjacent ERP (enterprise resource planning) products, with 60% of the Fortune 500 as HCM customers. Shares declined over the period, pressured by investor concerns that AI could disrupt application software vendors. The most recent quarter, however, did not show evidence of this. Subscription revenue grew 14%, 12-month backlog grew 16%, retention remained industry leading, margins expanded, and management reiterated full-year subscription revenue guidance while raising operating margin guidance. AI adoption also appears to be progressing, with Workday-developed agents now used by more

2 months ago
In a summer of highly-inflated transfer fees, value has become increasingly hard to determine.
On one hand, the Iliman Ndiaye is a player of superlative skill, evasive, quick and wonderfully entertaining with the ball at his feet.
Ndiaye was responsible for 73 of Everton's 250 completed dribbles last season, the highest share of any Premier League player.
Everton fans may also point to recent moves in the Premier League involving Manchester City, such as the sale of Savio to Tottenham for an initial £75m, as further evidence that the club should have demanded more for Ndiaye.
On the other hand, Everton are effectively quadrupling the initial £16m they paid Marseille to sign Ndiaye two years ago for a player whose underlying numbers, at this stage at least, are not truly elite.
#premier #everton #hand #manchester
On one hand, the Iliman Ndiaye is a player of superlative skill, evasive, quick and wonderfully entertaining with the ball at his feet.
Ndiaye was responsible for 73 of Everton's 250 completed dribbles last season, the highest share of any Premier League player.
Everton fans may also point to recent moves in the Premier League involving Manchester City, such as the sale of Savio to Tottenham for an initial £75m, as further evidence that the club should have demanded more for Ndiaye.
On the other hand, Everton are effectively quadrupling the initial £16m they paid Marseille to sign Ndiaye two years ago for a player whose underlying numbers, at this stage at least, are not truly elite.
#premier #everton #hand #manchester

2 months ago
The U.S. Federal Trade Commission, joined by 22 states, has sued Amazon.com, Inc. (NASDAQ:AMZN) over allegations that the company secretly inflated prices in its advertising auctions for more than seven years. The FTC alleges that Amazon used an undisclosed "soft reserve price" to raise the amount advertisers paid above what competitive bidding would have produced.
According to the complaint, the practice affected more than one million brands and sellers and may have generated tens of billions of dollars in additional revenue for Amazon. The FTC also alleges that the pricing changes became increasingly aggressive, with advertisers paying their own bids roughly 80% of the time for Sponsored Products by 2024.
Amazon.com, Inc. (NASDAQ:AMZN) disputes the allegations, arguing that the FTC misunderstands how its advertising auctions work and that its pricing practices improve ad relevance and value for advertisers.
Photo by Bryan Angelo on Unsplash
The biggest positive for Amazon.com, Inc. (NASDAQ:AMZN) is that the lawsuit does not immediately undermine the underlying strength of its advertising business. Amazon generated about $68 billion in advertising revenue in 2025, making advertising an increasingly important and high-margin contributor to the company's overall profitability.
#amazon #amzn #allegations
According to the complaint, the practice affected more than one million brands and sellers and may have generated tens of billions of dollars in additional revenue for Amazon. The FTC also alleges that the pricing changes became increasingly aggressive, with advertisers paying their own bids roughly 80% of the time for Sponsored Products by 2024.
Amazon.com, Inc. (NASDAQ:AMZN) disputes the allegations, arguing that the FTC misunderstands how its advertising auctions work and that its pricing practices improve ad relevance and value for advertisers.
Photo by Bryan Angelo on Unsplash
The biggest positive for Amazon.com, Inc. (NASDAQ:AMZN) is that the lawsuit does not immediately undermine the underlying strength of its advertising business. Amazon generated about $68 billion in advertising revenue in 2025, making advertising an increasingly important and high-margin contributor to the company's overall profitability.
#amazon #amzn #allegations

2 months ago
Hotchkis & Wiley, an investment management company, released its second-quarter 2026 investor letter for the "Large Cap Fundamental Value Fund." A copy can be downloaded here. Equity markets posted strong returns, with the Russell 1000 Value Index rising by 13.9%, although many individual stocks lagged. Notably, semiconductor stocks and AI-related sectors saw exceptional gains. The rally appeared speculative, marked by a stark difference in performance between high-beta and low-volatility stocks, along with momentum stocks outperforming the market significantly. Despite heightened enthusiasm for AI investments, concerns arise over inflated valuations reminiscent of the dot-com era. While there is substantial capital investment in AI, future earnings growth must justify these expenditures. The fund maintains a cautious approach towards perceived beneficiaries of AI, suggesting that select high-quality businesses with reasonable valuations may be better positioned. Historical trends suggest that speculative markets often revert to valuations based on fundamental economic realities, and the chosen investments are believed to be well-prepared for such a shift. The fund underperformed the index in the quarter and returned 5.69% vs. 13.87% for the Russell 1000 Value Index, largely due to a lack of exposure to high-performing sectors like semiconductors, while stock selection in healthcare provided a positive contribution. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Hotchkis & Wiley Large Cap Fundamental Value Fund highlighted Elevance Health, Inc. (NYSE:ELV) as a notable contributor. Elevance Health, Inc. (NYSE:ELV) is a US-based health benefits company. On August 31, 2026, Elevance Health, Inc. (NYSE:ELV) closed at $392.54 per share. Over the past month, Elevance Health, Inc. (NYSE:ELV) reported 3.85%, but its shares are up 21.78% over the past year. Elevance Health, Inc. (NYSE:ELV) has a market capitalization of $85.13 billion, and its stock has traded within a 52-week range of $274.84 to $436.24.
Hotchkis & Wiley Large Cap Fundamental Value Fund stated the following regarding Elevance Health, Inc. (NYSE:ELV) in its Q2 2026 investor letter:
"Elevance Health, Inc. (NYSE:ELV) is the second largest health insurer, and one of the largest commercial insurers in the United States. Shares rose during the quarter after the company reported quarterly earnings that beat consensus estimates. It was further supported by news that the US agreed to increase 2027 payments for private Medicare Advantage plans above the initial proposal. The company is priced at a discount to the market, driven by skepticism surrounding margins and growth, despite being a superior business that grows above GDP while returning most of its cash to shareholders."
#value #company
In its second-quarter 2026 investor letter, Hotchkis & Wiley Large Cap Fundamental Value Fund highlighted Elevance Health, Inc. (NYSE:ELV) as a notable contributor. Elevance Health, Inc. (NYSE:ELV) is a US-based health benefits company. On August 31, 2026, Elevance Health, Inc. (NYSE:ELV) closed at $392.54 per share. Over the past month, Elevance Health, Inc. (NYSE:ELV) reported 3.85%, but its shares are up 21.78% over the past year. Elevance Health, Inc. (NYSE:ELV) has a market capitalization of $85.13 billion, and its stock has traded within a 52-week range of $274.84 to $436.24.
Hotchkis & Wiley Large Cap Fundamental Value Fund stated the following regarding Elevance Health, Inc. (NYSE:ELV) in its Q2 2026 investor letter:
"Elevance Health, Inc. (NYSE:ELV) is the second largest health insurer, and one of the largest commercial insurers in the United States. Shares rose during the quarter after the company reported quarterly earnings that beat consensus estimates. It was further supported by news that the US agreed to increase 2027 payments for private Medicare Advantage plans above the initial proposal. The company is priced at a discount to the market, driven by skepticism surrounding margins and growth, despite being a superior business that grows above GDP while returning most of its cash to shareholders."
#value #company
2 months ago
Hotchkis & Wiley, an investment management company, released its second-quarter 2026 investor letter for the "Large Cap Fundamental Value Fund." A copy can be downloaded here. Equity markets posted strong returns, with the Russell 1000 Value Index rising by 13.9%, although many individual stocks lagged. Notably, semiconductor stocks and AI-related sectors saw exceptional gains. The rally appeared speculative, marked by a stark difference in performance between high-beta and low-volatility stocks, along with momentum stocks outperforming the market significantly. Despite heightened enthusiasm for AI investments, concerns arise over inflated valuations reminiscent of the dot-com era. While there is substantial capital investment in AI, future earnings growth must justify these expenditures. The fund maintains a cautious approach towards perceived beneficiaries of AI, suggesting that select high-quality businesses with reasonable valuations may be better positioned. Historical trends suggest that speculative markets often revert to valuations based on fundamental economic realities, and the chosen investments are believed to be well-prepared for such a shift. The fund underperformed the index in the quarter and returned 5.69% vs. 13.87% for the Russell 1000 Value Index, largely due to a lack of exposure to high-performing sectors like semiconductors, while stock selection in healthcare provided a positive contribution. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Hotchkis & Wiley Large Cap Fundamental Value Fund highlighted Workday, Inc. (NASDAQ:WDAY). Workday, Inc. (NASDAQ:WDAY), a leading enterprise software company that provides cloud applications for human resources and financial management, detracted from performance this quarter. On August 31, 2026, Workday, Inc. (NASDAQ:WDAY) closed at $197.45 per share. Over the past month, Workday, Inc. (NASDAQ:WDAY) returned 15.87%, but its shares are down 13.29% over the past year. Workday, Inc. (NASDAQ:WDAY) has a market capitalization of $47.59 billion.
Hotchkis & Wiley Large Cap Fundamental Value Fund stated the following regarding Workday, Inc. (NASDAQ:WDAY) in its Q2 2026 investor letter:
Workday, Inc. (NASDAQ:WDAY) is a leader in cloud software for back-office business functions, spanning human capital management (HCM), financial management, and adjacent ERP (enterprise resource planning) products, with 60% of the Fortune 500 as HCM customers. Shares declined over the period, pressured by investor concerns that AI could disrupt application software vendors. The most recent quarter, however, did not show evidence of this. Subscription revenue grew 14%, 12-month backlog grew 16%, retention remained industry leading, margins expanded, and management reiterated full-year subscription revenue guidance while raising operating margin guidance. AI adoption also appears to be progressing, with Workday-developed agents now used by more
In its second-quarter 2026 investor letter, Hotchkis & Wiley Large Cap Fundamental Value Fund highlighted Workday, Inc. (NASDAQ:WDAY). Workday, Inc. (NASDAQ:WDAY), a leading enterprise software company that provides cloud applications for human resources and financial management, detracted from performance this quarter. On August 31, 2026, Workday, Inc. (NASDAQ:WDAY) closed at $197.45 per share. Over the past month, Workday, Inc. (NASDAQ:WDAY) returned 15.87%, but its shares are down 13.29% over the past year. Workday, Inc. (NASDAQ:WDAY) has a market capitalization of $47.59 billion.
Hotchkis & Wiley Large Cap Fundamental Value Fund stated the following regarding Workday, Inc. (NASDAQ:WDAY) in its Q2 2026 investor letter:
Workday, Inc. (NASDAQ:WDAY) is a leader in cloud software for back-office business functions, spanning human capital management (HCM), financial management, and adjacent ERP (enterprise resource planning) products, with 60% of the Fortune 500 as HCM customers. Shares declined over the period, pressured by investor concerns that AI could disrupt application software vendors. The most recent quarter, however, did not show evidence of this. Subscription revenue grew 14%, 12-month backlog grew 16%, retention remained industry leading, margins expanded, and management reiterated full-year subscription revenue guidance while raising operating margin guidance. AI adoption also appears to be progressing, with Workday-developed agents now used by more


2 months ago
Hotchkis & Wiley, an investment management company, released its second-quarter 2026 investor letter for the "Large Cap Fundamental Value Fund." A copy can be downloaded here. Equity markets posted strong returns, with the Russell 1000 Value Index rising by 13.9%, although many individual stocks lagged. Notably, semiconductor stocks and AI-related sectors saw exceptional gains. The rally appeared speculative, marked by a stark difference in performance between high-beta and low-volatility stocks, along with momentum stocks outperforming the market significantly. Despite heightened enthusiasm for AI investments, concerns arise over inflated valuations reminiscent of the dot-com era. While there is substantial capital investment in AI, future earnings growth must justify these expenditures. The fund maintains a cautious approach towards perceived beneficiaries of AI, suggesting that select high-quality businesses with reasonable valuations may be better positioned. Historical trends suggest that speculative markets often revert to valuations based on fundamental economic realities, and the chosen investments are believed to be well-prepared for such a shift. The fund underperformed the index in the quarter and returned 5.69% vs. 13.87% for the Russell 1000 Value Index, largely due to a lack of exposure to high-performing sectors like semiconductors, while stock selection in healthcare provided a positive contribution. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Hotchkis & Wiley Large Cap Fundamental Value Fund highlighted F5, Inc. (NASDAQ:FFIV) as one of its leading individual contributors. F5, Inc. (NASDAQ:FFIV) offers multi-cloud application security and delivery solutions. On August 31, 2026, F5, Inc. (NASDAQ:FFIV) closed at $407.13 per share. Over the past month, F5, Inc. (NASDAQ:FFIV) declined 3.41%, while its shares are up 29.82% over the past year. F5, Inc. (NASDAQ:FFIV) has a market capitalization of $23.05 billion, and its stock has traded within a 52-week range of $223.76 to $435.00.
Hotchkis & Wiley Large Cap Fundamental Value Fund stated the following regarding F5, Inc. (NASDAQ:FFIV) in its Q2 2026 investor letter:
"F5, Inc. (NASDAQ:FFIV) sells application networking and security software as well as data center appliances. The company's stock rose after it posted good quarterly results and raised both its revenue and EPS guidance. The company is misunderstood and gets incorrectly classified as a legacy IT hardware vendor, resulting in an attractive valuation for a company with better-than-average fundamental risk ratings. F5 has over 50% market share in traditional ADCs (application delivery controllers), along with various multi-cloud networking and application security products."
#application
In its second-quarter 2026 investor letter, Hotchkis & Wiley Large Cap Fundamental Value Fund highlighted F5, Inc. (NASDAQ:FFIV) as one of its leading individual contributors. F5, Inc. (NASDAQ:FFIV) offers multi-cloud application security and delivery solutions. On August 31, 2026, F5, Inc. (NASDAQ:FFIV) closed at $407.13 per share. Over the past month, F5, Inc. (NASDAQ:FFIV) declined 3.41%, while its shares are up 29.82% over the past year. F5, Inc. (NASDAQ:FFIV) has a market capitalization of $23.05 billion, and its stock has traded within a 52-week range of $223.76 to $435.00.
Hotchkis & Wiley Large Cap Fundamental Value Fund stated the following regarding F5, Inc. (NASDAQ:FFIV) in its Q2 2026 investor letter:
"F5, Inc. (NASDAQ:FFIV) sells application networking and security software as well as data center appliances. The company's stock rose after it posted good quarterly results and raised both its revenue and EPS guidance. The company is misunderstood and gets incorrectly classified as a legacy IT hardware vendor, resulting in an attractive valuation for a company with better-than-average fundamental risk ratings. F5 has over 50% market share in traditional ADCs (application delivery controllers), along with various multi-cloud networking and application security products."
#application


2 months ago
NFL All-Overpaid team: Zay Flowers, Deshaun Watson headline players with worst contracts originally appeared on The Sporting News. Add The Sporting News as a Preferred Source by clicking here.
The NFL is all about value.
As a salary-capped league, front offices only have so much flexibility to work with each season. And while that salary cap has skyrocketed over the years, now at $301.2 million per team for the 2026 season, markets have been dictated by positional value. Superstar quarterbacks and pass rushers come at a premium, running backs have been seeing somewhat of a financial resurgence after years of struggles, while special teams players are usually given whatever is left over.
Like any sports league, however, there are some players who don't provide their franchises the kind of value their significant contracts would indicate, especially compared to their positional peers. Whether due to injuries, poor performance or off-the-field issues, an inflated contract can handicap an NFL team, and there are plenty of them across the league.
Here's a look at The Sporting News' All-Overpaid team entering the 2026 NFL season.
#sporting #players #value
The NFL is all about value.
As a salary-capped league, front offices only have so much flexibility to work with each season. And while that salary cap has skyrocketed over the years, now at $301.2 million per team for the 2026 season, markets have been dictated by positional value. Superstar quarterbacks and pass rushers come at a premium, running backs have been seeing somewhat of a financial resurgence after years of struggles, while special teams players are usually given whatever is left over.
Like any sports league, however, there are some players who don't provide their franchises the kind of value their significant contracts would indicate, especially compared to their positional peers. Whether due to injuries, poor performance or off-the-field issues, an inflated contract can handicap an NFL team, and there are plenty of them across the league.
Here's a look at The Sporting News' All-Overpaid team entering the 2026 NFL season.
#sporting #players #value



2 months ago
Interested in Dollar General Corporation? Here are five stocks we like better.
Many retailers beat earnings estimates last week, but one-time tariff refunds inflated results and masked underlying weakness in some cases.
Dollar General and Best Buy delivered high-quality beats, with strong comp sales growth that held up even after stripping out minimal tariff-refund contributions.
Williams-Sonoma outperformed a weak home furnishings sector with accelerating comp sales and raised margin guidance that excluded any ****** umed tariff refunds.
The retail sector was one of the biggest winners in earnings season, which was especially evident in some of the reports that rolled in last week. Eight major retailers reported earnings within 48 hours, and nearly all beat on headline numbers. But headline numbers rarely tell the story, and this quarter was especially deceiving. Tariff refunds have done to earnings what steroids did to baseball players in the 1990s, and these juiced results can mask underlying weakness.
#retailers #last #results
Many retailers beat earnings estimates last week, but one-time tariff refunds inflated results and masked underlying weakness in some cases.
Dollar General and Best Buy delivered high-quality beats, with strong comp sales growth that held up even after stripping out minimal tariff-refund contributions.
Williams-Sonoma outperformed a weak home furnishings sector with accelerating comp sales and raised margin guidance that excluded any ****** umed tariff refunds.
The retail sector was one of the biggest winners in earnings season, which was especially evident in some of the reports that rolled in last week. Eight major retailers reported earnings within 48 hours, and nearly all beat on headline numbers. But headline numbers rarely tell the story, and this quarter was especially deceiving. Tariff refunds have done to earnings what steroids did to baseball players in the 1990s, and these juiced results can mask underlying weakness.
#retailers #last #results


2 months ago
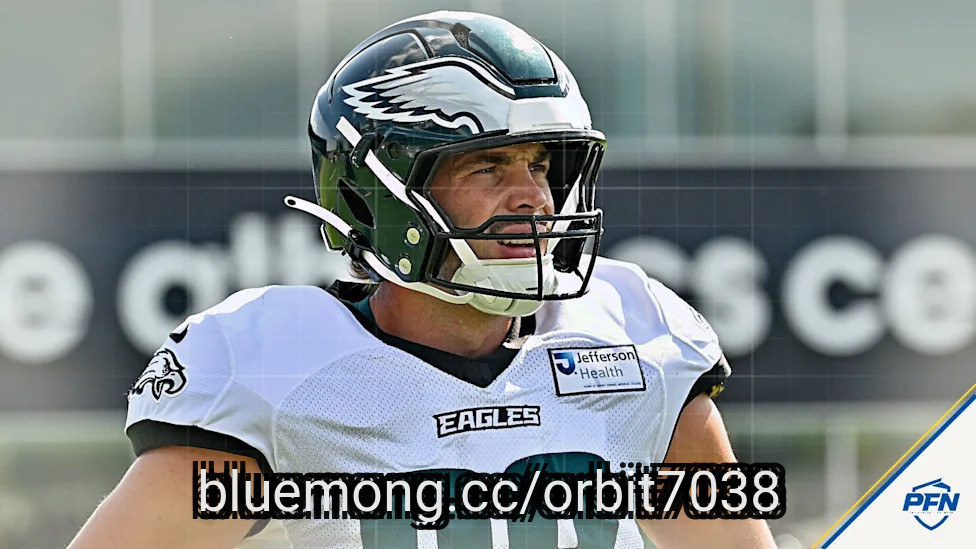
Dallas Goedert is entering his ninth season with the Philadelphia Eagles. Now, at 31 years old, he is coming off the best fantasy year of his career. With A.J. Brown gone and a rookie tight end in the building, should fantasy managers be drafting Goedert in 2026?
I expected to be out on Goedert this season.
The reason is that his 2025 breakout was almost entirely a mirage. Goedert averaged 12.3 fantasy points per game, and that figure was inflated by an absurd 11 touchdowns. Nothing else about his profile actually changed.
START PREPARING: PFN's FREE Fantasy Draft Simulator
His targets and yards landed right in his usual range. His yards per reception was a career-low 9.9. He simply happened to find the end zone six more times than he ever had before. For context on how extreme that was, you would have to add up his previous four seasons combined to exceed last year's touchdown total.
#goedert #Career #yards #dallas
I expected to be out on Goedert this season.
The reason is that his 2025 breakout was almost entirely a mirage. Goedert averaged 12.3 fantasy points per game, and that figure was inflated by an absurd 11 touchdowns. Nothing else about his profile actually changed.
START PREPARING: PFN's FREE Fantasy Draft Simulator
His targets and yards landed right in his usual range. His yards per reception was a career-low 9.9. He simply happened to find the end zone six more times than he ever had before. For context on how extreme that was, you would have to add up his previous four seasons combined to exceed last year's touchdown total.
#goedert #Career #yards #dallas

2 months ago
On August 14, RLX Technology (NYSE:RLX) reported second-quarter results that told two different stories at once. International sales climbed to roughly 70% of revenue as the company absorbed a new European distribution partner, even as trade normalization back home pulled growth down from where the year started. RLX is no longer just an e-vapor device maker. It is trying to become a diversified, direct-to-retail nicotine platform before its home market tightens further.
Net revenues reached RMB1.01 billion in the second quarter, up 14.8% year over year, powered by international volume growth and the contribution of a company RLX acquired in May 2025. Gross margin expanded to 35.4% from 27.5% a year earlier, a jump management credited to supply chain optimization and a better mix of products and geographies. Non-GAAP income from operations rose 28.8% to RMB149.6 million, marking the 11th straight quarter of positive non-GAAP operating profit.
In July 2026, RLX took a 51% controlling stake in a Western European distributor that reaches 30,000 retail endpoints and runs a digital ordering platform connecting 20,000 independent merchants, a deal management framed as the next step in building direct retail relationships rather than depending on layers of wholesalers. CEO Kate ****** argued that as vaping hardware becomes commoditized, "competition is shifting from pure product development to route-to-market execution."
The company is also leaning into modern oral nicotine pouches as a new growth line and is building a manufacturing hub in Southeast Asia to produce them at scale, all while sitting on RMB13.9 billion in total capital resources as of June 30, 2026.
The same quarter that produced margin expansion also produced warning signs closer to home. Mainland China revenue is now expected to be roughly flat for the full year, and Sam Tsang, the company's head of capital markets, said the "procedural time line for government approval has become more conservative" as domestic enforcement tightens. Revenue and margins both moderated sequentially from the first quarter, which had been inflated by a shipment pull-forward tied to regulatory export changes, and management flagged that the elevated 35.4% margin should settle into a lower range going forward.
#revenue #retail
Net revenues reached RMB1.01 billion in the second quarter, up 14.8% year over year, powered by international volume growth and the contribution of a company RLX acquired in May 2025. Gross margin expanded to 35.4% from 27.5% a year earlier, a jump management credited to supply chain optimization and a better mix of products and geographies. Non-GAAP income from operations rose 28.8% to RMB149.6 million, marking the 11th straight quarter of positive non-GAAP operating profit.
In July 2026, RLX took a 51% controlling stake in a Western European distributor that reaches 30,000 retail endpoints and runs a digital ordering platform connecting 20,000 independent merchants, a deal management framed as the next step in building direct retail relationships rather than depending on layers of wholesalers. CEO Kate ****** argued that as vaping hardware becomes commoditized, "competition is shifting from pure product development to route-to-market execution."
The company is also leaning into modern oral nicotine pouches as a new growth line and is building a manufacturing hub in Southeast Asia to produce them at scale, all while sitting on RMB13.9 billion in total capital resources as of June 30, 2026.
The same quarter that produced margin expansion also produced warning signs closer to home. Mainland China revenue is now expected to be roughly flat for the full year, and Sam Tsang, the company's head of capital markets, said the "procedural time line for government approval has become more conservative" as domestic enforcement tightens. Revenue and margins both moderated sequentially from the first quarter, which had been inflated by a shipment pull-forward tied to regulatory export changes, and management flagged that the elevated 35.4% margin should settle into a lower range going forward.
#revenue #retail


2 months ago
In a conference long known for its stout defenses, being recognized as the top player on that side of the ball is no easy feat. The last five winners reflect that. Since 2021, the last four winners of the award — Aidan Hutchinson (Michigan), Jack Campbell (Iowa), Jer'Zhan Newton (Illinois), and Abdul Carter (Penn State) — have made their presence felt on Sundays in the NFL. Caleb Downs, who is the most recent winner, was selected No. 11 overall by the Dallas Cowboys and could be in for a highly impactful rookie campaign.
Typically, I like to present a list of options and riddle the breakdown with several pumpfakes that'll make you believe I'm picking that player to take home the award later this year. Not this time.
2026 Big Ten Defensive Player of the Year: EDGE Anthony Smith, Minnesota
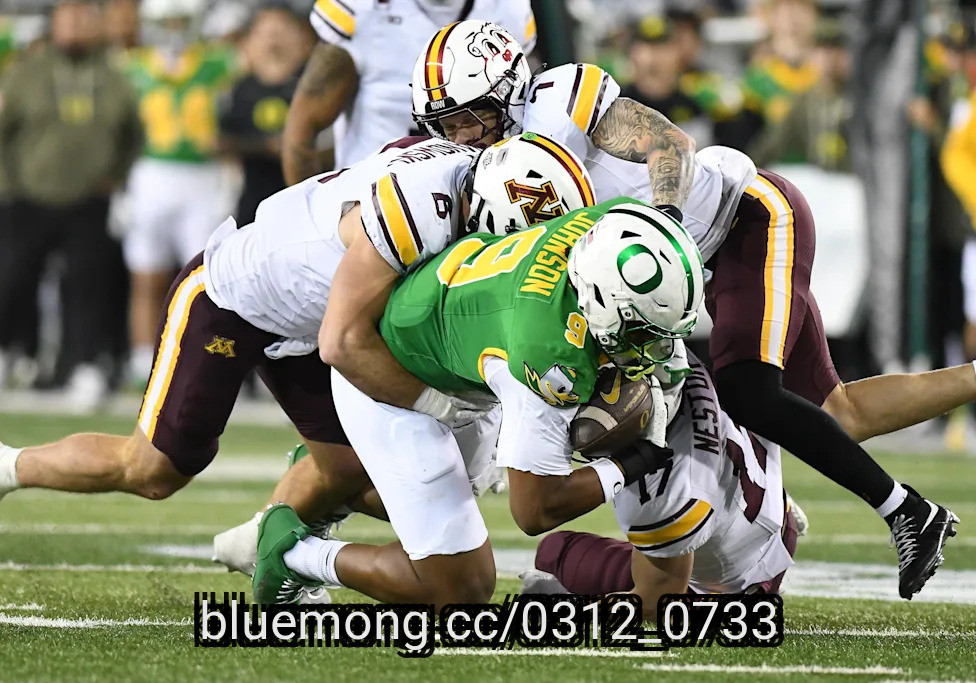
Last season, Smith was a disruptor. He finished the year with 21 solo tackles and 12.5 sacks. Those numbers are sometimes inflated in blowout wins against non-Power Five opponents, but that wasn't the case for Smith. The Golden Gophers opened the season against Buffalo and Northwestern State (FCS). Smith had just two sacks during that stretch, despite the victory over NWSU coming in the form of a 66-0 shellacking. He did add two sacks against a Non-Power Five foe, but that was in the Rate Bowl against New Mexico, so you can't dock him there.
Smith isn't my pick because he's the best defender. Nor is he my pick because Cleveland.com has the same projection. The team with the most candidates is Oregon. If the Ducks live up to expectations, they'll boast one of the most balanced defenses. With their mixture of talent and depth, we probably won't see any extraordinary stat lines from a Duck defender. This is where Smith benefits. If the award is not given to the best defender on the best defensive team, the second qualifier will boil down to numbers. Smith has already proven that he's capable of posting big ones.
#last #defender
Typically, I like to present a list of options and riddle the breakdown with several pumpfakes that'll make you believe I'm picking that player to take home the award later this year. Not this time.
2026 Big Ten Defensive Player of the Year: EDGE Anthony Smith, Minnesota
Last season, Smith was a disruptor. He finished the year with 21 solo tackles and 12.5 sacks. Those numbers are sometimes inflated in blowout wins against non-Power Five opponents, but that wasn't the case for Smith. The Golden Gophers opened the season against Buffalo and Northwestern State (FCS). Smith had just two sacks during that stretch, despite the victory over NWSU coming in the form of a 66-0 shellacking. He did add two sacks against a Non-Power Five foe, but that was in the Rate Bowl against New Mexico, so you can't dock him there.
Smith isn't my pick because he's the best defender. Nor is he my pick because Cleveland.com has the same projection. The team with the most candidates is Oregon. If the Ducks live up to expectations, they'll boast one of the most balanced defenses. With their mixture of talent and depth, we probably won't see any extraordinary stat lines from a Duck defender. This is where Smith benefits. If the award is not given to the best defender on the best defensive team, the second qualifier will boil down to numbers. Smith has already proven that he's capable of posting big ones.
#last #defender

2 months ago
On August 18, Keysight Technologies (NYSE:KEYS) delivered a fiscal third quarter that beat the high end of its own guidance across the board. Revenue climbed 36% year over year to $1.85 billion, non-GAAP earnings per share jumped 79% to $3.07, and orders topped $2 billion for the second straight quarter. Management raised its outlook for both the fourth quarter and the full fiscal year, pointing to demand tied to artificial intelligence infrastructure, defense modernization, and next-generation communications standards. The results position Keysight as one of the more direct ways to invest in the testing and validation side of the AI buildout, a corner of the market most investors rarely think about.
Orders reached $2.091 billion in the quarter, up 56% on a reported basis, the second straight quarter above the $2 billion mark. Wireline orders more than doubled year over year as customers scaled out AI data center infrastructure, and Commercial Communications crossed $1 billion in quarterly revenue for the first time, up 56%, while revenue from wireline products outpaced wireless within that segment for the first time. The Electronic Industrial Solutions Group posted a record $501 million in revenue, up 21%, with double-digit order growth across general electronics, semiconductors, and automotive and energy. Aerospace, defense and government revenue grew 14% to $339 million as spending shifted toward lower-cost autonomous platforms, including UAVs and low earth orbit satellite constellations built by venture-funded defense technology firms.
Profitability expanded right alongside the growth: operating margin hit 33.2%, up 820 basis points and above the company's long-term target range of 31% to 32%, while free cash flow rose to $403 million from $291 million a year earlier. The company also added nearly 3,000 new customers so far this fiscal year, a group that has already contributed more than $100 million in new business, and said July was its busiest month yet for incoming sales opportunities, pushing the trailing 12-month pipeline to a record. Further out, the 3GPP standards body confirmed in June that the first 6G standard is targeted for March 2029, a milestone management said is already moving customers from exploratory research into funded development work.
CFO Neil Dougherty tempered the enthusiasm, warning that supply availability remains "a governor of our ability to convert demand into revenue" over the next several quarters, meaning orders are outrunning what the company can actually ship and book as revenue right now. He also noted that one-time tariff impacts in fiscal 2026 inflated this year's profitability in ways that are not expected to repeat in fiscal 2027. That combination, a backlog constrained by supply and a margin base partly lifted by tariffs, complicates how much of this quarter's strength carries forward unchanged. The integration of recent acquisitions is also still working through the system.
#quarter #billion #m
Orders reached $2.091 billion in the quarter, up 56% on a reported basis, the second straight quarter above the $2 billion mark. Wireline orders more than doubled year over year as customers scaled out AI data center infrastructure, and Commercial Communications crossed $1 billion in quarterly revenue for the first time, up 56%, while revenue from wireline products outpaced wireless within that segment for the first time. The Electronic Industrial Solutions Group posted a record $501 million in revenue, up 21%, with double-digit order growth across general electronics, semiconductors, and automotive and energy. Aerospace, defense and government revenue grew 14% to $339 million as spending shifted toward lower-cost autonomous platforms, including UAVs and low earth orbit satellite constellations built by venture-funded defense technology firms.
Profitability expanded right alongside the growth: operating margin hit 33.2%, up 820 basis points and above the company's long-term target range of 31% to 32%, while free cash flow rose to $403 million from $291 million a year earlier. The company also added nearly 3,000 new customers so far this fiscal year, a group that has already contributed more than $100 million in new business, and said July was its busiest month yet for incoming sales opportunities, pushing the trailing 12-month pipeline to a record. Further out, the 3GPP standards body confirmed in June that the first 6G standard is targeted for March 2029, a milestone management said is already moving customers from exploratory research into funded development work.
CFO Neil Dougherty tempered the enthusiasm, warning that supply availability remains "a governor of our ability to convert demand into revenue" over the next several quarters, meaning orders are outrunning what the company can actually ship and book as revenue right now. He also noted that one-time tariff impacts in fiscal 2026 inflated this year's profitability in ways that are not expected to repeat in fiscal 2027. That combination, a backlog constrained by supply and a margin base partly lifted by tariffs, complicates how much of this quarter's strength carries forward unchanged. The integration of recent acquisitions is also still working through the system.
#quarter #billion #m

2 months ago
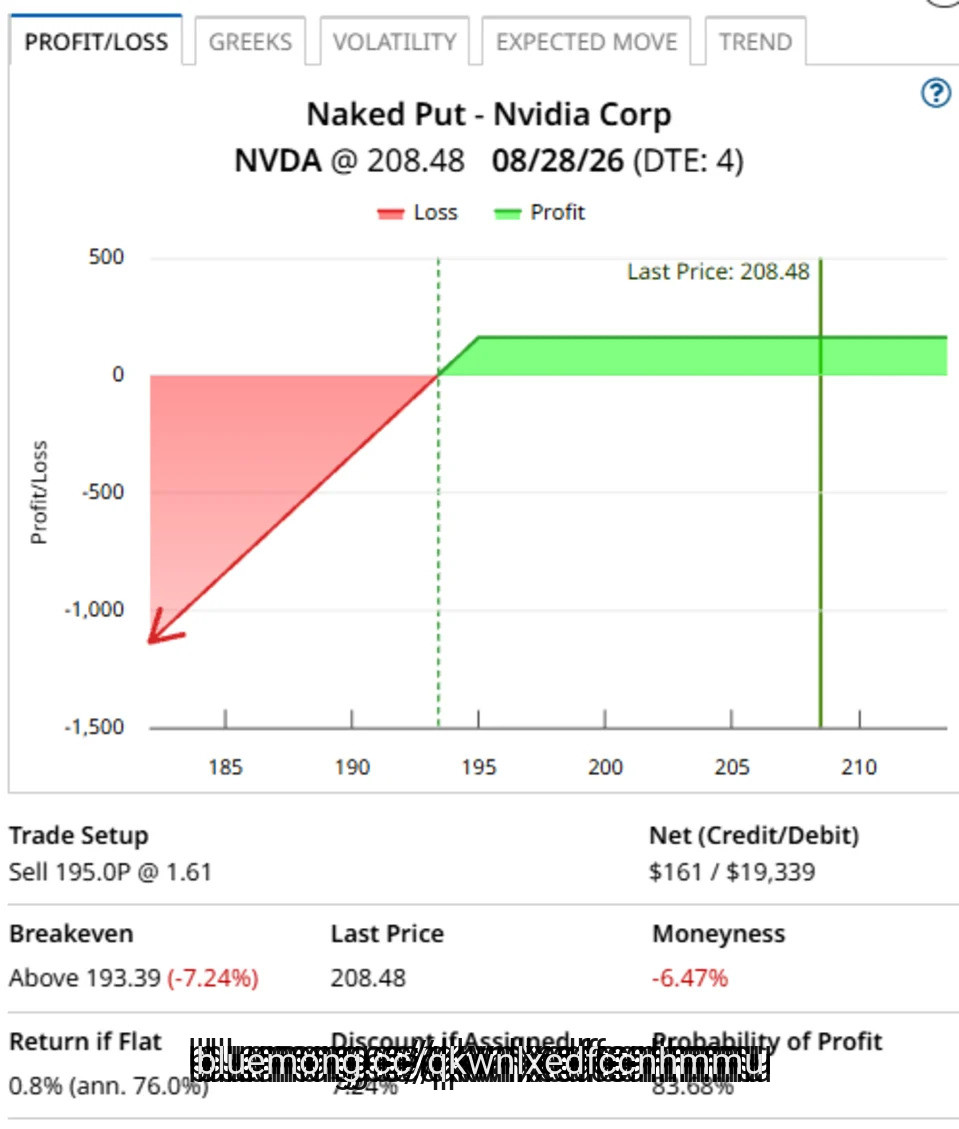
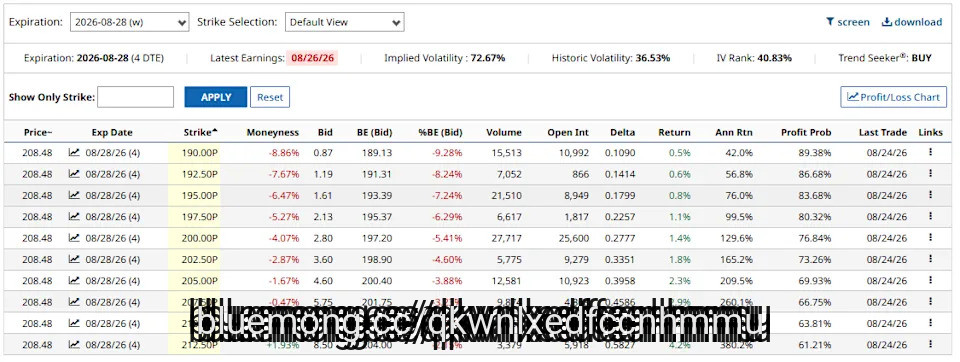
Selling put options before a company's earnings announcement can be a valid strategy for options traders seeking to capitalize on higher than normal volatility.
One of the primary reasons traders may consider selling a Nvidia (NVDA) put option before their earnings announcement on Friday is the elevated implied volatility. Earnings reports can trigger significant price movements, and this volatility results in an increase in option premiums. By selling the put option before the announcement, traders aim to capitalize on the inflated premium, especially if they believe that the stock will remain above the strike price by the option's expiration date.
QQQ is Still in a Negative Gamma Regime. Here's How a 'Put Wall' and Fibonacci Support Could Come Into Play.
Huge, Unusual Put and Call Option Volume in Intel - Investors Bullish as INTC Drops
Why the China-Led Weakness in NXP Semiconductors Stock Could Open Doors for Speculators
#earnings #announcement #traders #price
One of the primary reasons traders may consider selling a Nvidia (NVDA) put option before their earnings announcement on Friday is the elevated implied volatility. Earnings reports can trigger significant price movements, and this volatility results in an increase in option premiums. By selling the put option before the announcement, traders aim to capitalize on the inflated premium, especially if they believe that the stock will remain above the strike price by the option's expiration date.
QQQ is Still in a Negative Gamma Regime. Here's How a 'Put Wall' and Fibonacci Support Could Come Into Play.
Huge, Unusual Put and Call Option Volume in Intel - Investors Bullish as INTC Drops
Why the China-Led Weakness in NXP Semiconductors Stock Could Open Doors for Speculators
#earnings #announcement #traders #price
2 months ago
The freight market has seen a brutal downturn, with an astounding 85% failure rate for new carriers in the past three years. Kirk Mann, EVP & GM of Transportation and Vendor Solutions at Mitsubishi HC Capital America, dives into why this cycle was the longest, the impact of over-financed ****** ets, and what it means for the future of freight demand and equipment financing. Learn how lenders navigate this volatile landscape and what's next for carrier growth.
The average three-year failure rate for motor carriers with fewer than two years of operating experience and their own ICC authority hit 85% during the prolonged freight downturn, according to Kirk Mann, EVP & GM of Transportation and Vendor Solutions at Mitsubishi HC Capital. Mann shared the figure in a FreightWaves interview, offering one of the starkest measures yet of how the roughly three-and-a-half-year downturn devastated the smallest participants in the for-hire trucking market.
The elevated failure rate traces directly to the equipment bubble that inflated during 2021 and 2022. Mann recalled a conversation with his chief risk officer in which they discussed a four-year-old Freightliner Cascadia with fewer than 500,000 miles — an ****** et the risk officer valued at roughly $45,000 but that the company was financing at $100,000 to $110,000. FreightWaves data showed pre-COVID prices on five-year-old equipment running around $34,000, climbing to as high as $120,000 at the peak. Carriers that entered the business buying equipment at those inflated values were immediately underwater when rates collapsed.
"I remember we were way bubble. It was an ****** et bubble of enormous proportions," Mann said.
When defaults mounted, Mitsubishi HC Capital leaned on workout tools rather than immediate repossession. Mann said the company restructured approximately 75% of its loans during its 2020 customer ****** istance program launched at the onset of COVID-19, and that 95% of those borrowers resumed payments within 90 days. Even so, the lender accumulated repossessed inventory it held "for quite a long time" before conditions improved enough to move units through dealer networks, auctions, and internal sales channels.
#freight
The average three-year failure rate for motor carriers with fewer than two years of operating experience and their own ICC authority hit 85% during the prolonged freight downturn, according to Kirk Mann, EVP & GM of Transportation and Vendor Solutions at Mitsubishi HC Capital. Mann shared the figure in a FreightWaves interview, offering one of the starkest measures yet of how the roughly three-and-a-half-year downturn devastated the smallest participants in the for-hire trucking market.
The elevated failure rate traces directly to the equipment bubble that inflated during 2021 and 2022. Mann recalled a conversation with his chief risk officer in which they discussed a four-year-old Freightliner Cascadia with fewer than 500,000 miles — an ****** et the risk officer valued at roughly $45,000 but that the company was financing at $100,000 to $110,000. FreightWaves data showed pre-COVID prices on five-year-old equipment running around $34,000, climbing to as high as $120,000 at the peak. Carriers that entered the business buying equipment at those inflated values were immediately underwater when rates collapsed.
"I remember we were way bubble. It was an ****** et bubble of enormous proportions," Mann said.
When defaults mounted, Mitsubishi HC Capital leaned on workout tools rather than immediate repossession. Mann said the company restructured approximately 75% of its loans during its 2020 customer ****** istance program launched at the onset of COVID-19, and that 95% of those borrowers resumed payments within 90 days. Even so, the lender accumulated repossessed inventory it held "for quite a long time" before conditions improved enough to move units through dealer networks, auctions, and internal sales channels.
#freight

2 months ago
With the Mariners showing no consistent signs in the second half that they'd put their first-half struggles behind them, many fans have put to bed their hopes for the playoffs, especially as the team entered into this particularly grueling stretch of a long road trip combined with playing three very tough NL teams: the Brewers, Cubs, and now the Phillies. Both the Brewers and Cubs series featured brutal, humiliating losses, the Brewers a historic 22-0 drubbing and the Cubs – despite a series win thanks to scraping out wins in the first two games – a game that saw multiple position players have to take the mound in a 19-2 loss. But just as the Mariners bounced back to ******* a game from the Brewers after making team history (derogatory), they again bounced back tonight to surprise the Phillies with a dominant 9-2 win that also made history (complimentary).
It certainly didn't look like things were going to go this way. The game got off to a rough start for Logan Gilbert, who walked Kyle Schwarber on five pitches to lead off the game. He struck out Trea Turner on a spicy 98 mph heater, but then surrendered back-to-back singles to Bryce Harper and Luis Arraez to load the bases with just one out. To Gilbert's credit, though, he didn't wilt under pressure, continuing to execute pitch after pitch. Alex Boehm hit into an RBI groundout on a slow roller that could have been an inning-ending double play, and then Gilbert bullied Bryson Stott on four pitches, striking him out on another spicy heater. In the end, the Phillies only got one run out of all that traffic, and the only real damage was done to Logan's pitch count, at 29.
But Zack Wheeler had his own struggles in the bottom of the first, and would finish the inning with a similarly inflated pitch count (33) but significantly more damage on the scoreboard thanks to two Mariners home runs. MULTI-run home runs, even, which is delightful. Randy Arozarena led off the game with a walk, followed by a sharply-hit single from Dominic Canzone (110 EV), and then Julio Rodríguez – who scuffled in the Cubs series, going 1-for-13 with seven strikeouts – tattooed a splitter that caught too much plate for a home run into the visitor's bullpen.
Your browser does not support the video tag. Download the video.
And then, and this is the part you'll really like, the Mariners didn't stop there. So often we've seen this team score a few early and then take their foot off the gas. Instead, they kept the pressure on Wheeler in the first, with Josh Naylor singling into right field (but then getting thrown out and also bonked on the head trying to stretch it into a double, no Josh!), and then Taylor Ward refusing to chase off the plate for a walk to extend Wheeler's inning. That brought up Cal Raleigh, and Wheeler tried to dispense of him with a fastball up, a pitch Cal has been consistently missing this season. He did not miss this one:
#game #first #Phillies #back
It certainly didn't look like things were going to go this way. The game got off to a rough start for Logan Gilbert, who walked Kyle Schwarber on five pitches to lead off the game. He struck out Trea Turner on a spicy 98 mph heater, but then surrendered back-to-back singles to Bryce Harper and Luis Arraez to load the bases with just one out. To Gilbert's credit, though, he didn't wilt under pressure, continuing to execute pitch after pitch. Alex Boehm hit into an RBI groundout on a slow roller that could have been an inning-ending double play, and then Gilbert bullied Bryson Stott on four pitches, striking him out on another spicy heater. In the end, the Phillies only got one run out of all that traffic, and the only real damage was done to Logan's pitch count, at 29.
But Zack Wheeler had his own struggles in the bottom of the first, and would finish the inning with a similarly inflated pitch count (33) but significantly more damage on the scoreboard thanks to two Mariners home runs. MULTI-run home runs, even, which is delightful. Randy Arozarena led off the game with a walk, followed by a sharply-hit single from Dominic Canzone (110 EV), and then Julio Rodríguez – who scuffled in the Cubs series, going 1-for-13 with seven strikeouts – tattooed a splitter that caught too much plate for a home run into the visitor's bullpen.
Your browser does not support the video tag. Download the video.
And then, and this is the part you'll really like, the Mariners didn't stop there. So often we've seen this team score a few early and then take their foot off the gas. Instead, they kept the pressure on Wheeler in the first, with Josh Naylor singling into right field (but then getting thrown out and also bonked on the head trying to stretch it into a double, no Josh!), and then Taylor Ward refusing to chase off the plate for a walk to extend Wheeler's inning. That brought up Cal Raleigh, and Wheeler tried to dispense of him with a fastball up, a pitch Cal has been consistently missing this season. He did not miss this one:
#game #first #Phillies #back
3 months ago
Atletico Madrid are moving with some urgency in the transfer market, and Nicolas Jackson has emerged as a serious target. According to Marca, Mateu Alemany travelled to London on Thursday in an attempt to push discussions forward for the Chelsea forward, with Atletico seeking attacking help after an injury to Alexander Sorloth and with Julian Alvarez still short of top condition.
This is the sort of deal that makes sense on several levels, even if the mechanics look awkward. Atletico want another forward, Jackson knows Spanish football, and Chelsea have a squad that still feels crowded in key attacking areas. The issue, as ever, is cost. Atletico have already stretched themselves after the Cristian Romero deal, reported as £33 million plus £7 million in variables, so any move for Jackson appears dependent on favourable terms.
That means a loan is the obvious route, with Atletico reportedly hoping Chelsea would cover part of the player's salary. In plain terms, they want quality without paying the full freight. Clubs across Europe are trying the same trick, because the market is inflated and proven attacking players are expensive.
Marca's report places Jackson among the preferred options inside the Metropolitano. There are other names under consideration, but his profile is clear. He has pace, he attacks **** e, and he already showed in Spain that he can trouble defenders at a high level. His rise at Villarreal earned him a move to Chelsea for around £37 million after Bournemouth failed to complete a transfer for him earlier in that season.
Photo IMAGO
#jackson #deal
This is the sort of deal that makes sense on several levels, even if the mechanics look awkward. Atletico want another forward, Jackson knows Spanish football, and Chelsea have a squad that still feels crowded in key attacking areas. The issue, as ever, is cost. Atletico have already stretched themselves after the Cristian Romero deal, reported as £33 million plus £7 million in variables, so any move for Jackson appears dependent on favourable terms.
That means a loan is the obvious route, with Atletico reportedly hoping Chelsea would cover part of the player's salary. In plain terms, they want quality without paying the full freight. Clubs across Europe are trying the same trick, because the market is inflated and proven attacking players are expensive.
Marca's report places Jackson among the preferred options inside the Metropolitano. There are other names under consideration, but his profile is clear. He has pace, he attacks **** e, and he already showed in Spain that he can trouble defenders at a high level. His rise at Villarreal earned him a move to Chelsea for around £37 million after Bournemouth failed to complete a transfer for him earlier in that season.
Photo IMAGO
#jackson #deal


3 months ago
Many stocks on the Nasdaq exchange are trading at extremely high valuations. That can make picking stocks to buy there a challenge, as many of them may be due for significant corrections due to their inflated price tags. Below, however, I'm going to look at three of the cheapest stocks on the Nasdaq-100 index, which, based on their expected future profits, appear to be bargain buys, and I'll look at why they appear to be so cheap and why they may be trading at discounts.
Micron Technology (NASDAQ:MU), PDD Holdings(NASDAQ:PDD) , and Adobe (NASDAQ:ADBE) all appear to be trading at dirt cheap valuations. Are they incredible buys right now, or is there more to the story with their seeming low prices?
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Image source: Getty Images.
What's intriguing about Micron Technology is that it has generated massive gains over the past year -- up around 660%. Normally, when that happens, a stock's valuation becomes rich, and it looks to run out of room to rise higher. But with Micron, that doesn't appear to be the case. Based on ******* yst projections, it's trading at a forward price-to-earnings (P/E) multiple of just 6.5. By comparison, the average stock on the S&P 500 trades at a forward earnings multiple of 21. Micron, it seems, may still be due to rise higher.
#appear
Micron Technology (NASDAQ:MU), PDD Holdings(NASDAQ:PDD) , and Adobe (NASDAQ:ADBE) all appear to be trading at dirt cheap valuations. Are they incredible buys right now, or is there more to the story with their seeming low prices?
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Image source: Getty Images.
What's intriguing about Micron Technology is that it has generated massive gains over the past year -- up around 660%. Normally, when that happens, a stock's valuation becomes rich, and it looks to run out of room to rise higher. But with Micron, that doesn't appear to be the case. Based on ******* yst projections, it's trading at a forward price-to-earnings (P/E) multiple of just 6.5. By comparison, the average stock on the S&P 500 trades at a forward earnings multiple of 21. Micron, it seems, may still be due to rise higher.
#appear


3 months ago
CAIRO (AP) — Palestinians face inflated prices for groceries and batteries, hospitals have turned to smugglers for medicine and equipment, Israeli soldiers and other middlemen are accused of pocketing millions of dollars, and the Hamas-led government takes a cut as the smuggling of goods restricted by Israel into the Gaza Strip has boomed, according to an ******* ociated Press investigation based on court documents and interviews with traders, truckers and officials.
Cigarettes and tobacco — banned from entry to Gaza since the start of the Israel-Hamas war in October 2023 — rake in the biggest profits for smugglers and merchants, officials and residents say. But everything from iPhones and solar panels to fuel and anesthetics are also brought into the tiny coastal territory illegally. Israel restricts quantities of some goods and bans others outright. It defines many as "dual use" — including concrete, vehicle parts and X-ray machines — ******* erting they could be repurposed by Hamas militants for military functions.
To build a picture of the illicit trade, The ******* ociated Press ******* yzed Israeli court documents and spoke to five major traders who import smuggled goods, three merchants who sell them, and two truckers — all on condition of anonymity because of their roles in the illegal smuggling business and concerns about their safety in Gaza. AP also interviewed four Palestinian officials, two on condition of anonymity because of worries about retribution from Israel, Hamas or merchants; two U.N. officials, on condition of anonymity over concern for their jobs; and a dozen Palestinian residents, who spoke about how they get everyday items and their skyrocketing costs.
AP found a rush from all sides to profit off the tight restrictions imposed by Israel on Gaza and its 2 million residents, most of whom have been displaced by the war. Smuggling rings — which have long flourished, circumventing two decades of Israeli blockades and building a network of businessmen and collaborators — pull in millions of dollars. Payoffs go to Israeli troops, drivers, warehouse workers and others on both sides of the border, according to traders and court documents.
"The occupation has left no other option before us. Smuggling has become routine," one trader said, noting that some in Israel's military are willing to help — for a price. "We benefit, they benefit and the people in Gaza benefit because we provide goods, including food, to the market."
#israeli #smuggling
Cigarettes and tobacco — banned from entry to Gaza since the start of the Israel-Hamas war in October 2023 — rake in the biggest profits for smugglers and merchants, officials and residents say. But everything from iPhones and solar panels to fuel and anesthetics are also brought into the tiny coastal territory illegally. Israel restricts quantities of some goods and bans others outright. It defines many as "dual use" — including concrete, vehicle parts and X-ray machines — ******* erting they could be repurposed by Hamas militants for military functions.
To build a picture of the illicit trade, The ******* ociated Press ******* yzed Israeli court documents and spoke to five major traders who import smuggled goods, three merchants who sell them, and two truckers — all on condition of anonymity because of their roles in the illegal smuggling business and concerns about their safety in Gaza. AP also interviewed four Palestinian officials, two on condition of anonymity because of worries about retribution from Israel, Hamas or merchants; two U.N. officials, on condition of anonymity over concern for their jobs; and a dozen Palestinian residents, who spoke about how they get everyday items and their skyrocketing costs.
AP found a rush from all sides to profit off the tight restrictions imposed by Israel on Gaza and its 2 million residents, most of whom have been displaced by the war. Smuggling rings — which have long flourished, circumventing two decades of Israeli blockades and building a network of businessmen and collaborators — pull in millions of dollars. Payoffs go to Israeli troops, drivers, warehouse workers and others on both sides of the border, according to traders and court documents.
"The occupation has left no other option before us. Smuggling has become routine," one trader said, noting that some in Israel's military are willing to help — for a price. "We benefit, they benefit and the people in Gaza benefit because we provide goods, including food, to the market."
#israeli #smuggling



3 months ago
The price of the brick keeps going up. According to the Times of London, Tottenham Hotspur's pursuit of Brazilian winger Savinho could cost them as much as £85m. This particular transfer saga has now gone on for a year after Spurs expressed their interest and came close to signing Savinho last summer before City pulled the plug on negotiations.
The new £85m figure comes as almost a throwaway line in an article about City's overall transfer business and their continued attempt to refresh the squad under new head coach Enzo Maresco.
City are in talks with Tottenham Hotspur over the potential sale of Savinho for £85million while Nico González's situation is being monitored by several interested parties. The club also lost two of their top earners over the summer after Bernardo Silva and John Stones left for Real Madrid and Inter Milan respectively on free transfers.
I swear I can remember a time when the price for Savinho was rumored to be around £60m-65m. The delay in coming to an agreement appears to be mostly on the City side of negotiations — there are reports that Maresca has been delaying deciding whether Savinho is in his plans or not; meanwhile it's been clear for a while now that Savinho is of great interest to Spurs and is one of Roberto De Zerbi's top transfer targets, which no doubt has inflated the price. (This is why you don't tip your hand in negotiations.)
Meanwhile, rarely has a player made it so clear that he wants to leave and join Tottenham Hotspur. His social media has included commenting on and befriending numerous Spurs player accounts, and he's refused to train a couple of times now (though City has attributed this, plus his absence from the Community Shield squad, as "illness).
#negotiations #times
The new £85m figure comes as almost a throwaway line in an article about City's overall transfer business and their continued attempt to refresh the squad under new head coach Enzo Maresco.
City are in talks with Tottenham Hotspur over the potential sale of Savinho for £85million while Nico González's situation is being monitored by several interested parties. The club also lost two of their top earners over the summer after Bernardo Silva and John Stones left for Real Madrid and Inter Milan respectively on free transfers.
I swear I can remember a time when the price for Savinho was rumored to be around £60m-65m. The delay in coming to an agreement appears to be mostly on the City side of negotiations — there are reports that Maresca has been delaying deciding whether Savinho is in his plans or not; meanwhile it's been clear for a while now that Savinho is of great interest to Spurs and is one of Roberto De Zerbi's top transfer targets, which no doubt has inflated the price. (This is why you don't tip your hand in negotiations.)
Meanwhile, rarely has a player made it so clear that he wants to leave and join Tottenham Hotspur. His social media has included commenting on and befriending numerous Spurs player accounts, and he's refused to train a couple of times now (though City has attributed this, plus his absence from the Community Shield squad, as "illness).
#negotiations #times


