

1 day ago
Hewlett Packard Enterprise Company (HPE) is becoming a major beneficiary of the enterprise artificial intelligence (AI) infrastructure growth. While many companies are working on AI applications, Hewlett Packard primarily focuses on infrastructure, supplying servers, networking, and other technology essential for large-scale AI deployment.
The company's latest quarterly results showed rising demand, with both revenue and profit exceeding **** yst expectations and robust growth across all segments. Its integration of Juniper Networks has further strengthened the company's position in AI networking, giving the company greater access to the infrastructure needs driven by AI's rapid growth.
Billionaire Charlie Munger, Who Died at 99, Skipped Insurance on His Mansion Since He Could Just Write a Check to Rebuild — 'All Intelligent People Do It My Way'
Nvidia CEO Jensen Huang Just Dropped Huge News for This Cybersecurity Stock
How to Play GME Stock as GameStop CEO Ryan Cohen Buys $20.3 Million in Shares
#infrastructure #company #juniper
The company's latest quarterly results showed rising demand, with both revenue and profit exceeding **** yst expectations and robust growth across all segments. Its integration of Juniper Networks has further strengthened the company's position in AI networking, giving the company greater access to the infrastructure needs driven by AI's rapid growth.
Billionaire Charlie Munger, Who Died at 99, Skipped Insurance on His Mansion Since He Could Just Write a Check to Rebuild — 'All Intelligent People Do It My Way'
Nvidia CEO Jensen Huang Just Dropped Huge News for This Cybersecurity Stock
How to Play GME Stock as GameStop CEO Ryan Cohen Buys $20.3 Million in Shares
#infrastructure #company #juniper


7 days ago
Junipero Serra takes on St. Mary's (Stockton) tonight as the 2026 high school football schedule ramps up across the country.
Searching for how to watch the game live?
Fans can stream the California high school football game live on the NFHS Network from a laptop, mobile device or even Smart TV apps like Amazon Fire, Apple TV, Google TV and Roku.
Don't miss a moment of the game with on-demand replays, too.
Ahead of the kickoff, here's what to know about the Junipero Serra vs. St. Mary's (Stockton) clash.
#game #stockton #Football #searching
Searching for how to watch the game live?
Fans can stream the California high school football game live on the NFHS Network from a laptop, mobile device or even Smart TV apps like Amazon Fire, Apple TV, Google TV and Roku.
Don't miss a moment of the game with on-demand replays, too.
Ahead of the kickoff, here's what to know about the Junipero Serra vs. St. Mary's (Stockton) clash.
#game #stockton #Football #searching


8 days ago
Hewlett Packard Enterprise Company (NYSE:HPE) announced an expanded collaboration with Oracle Corporation (NYSE:ORCL) on September 2 to scale Oracle's global AI infrastructure using HPE Juniper Networking across Oracle Cloud Infrastructure (OCI) data centers. The partnership builds on over a decade of joint engineering, leveraging HPE's routing and switching platforms to support OCI's expanding gigawatt-scale GPU superclusters. To align long-term incentives, HPE issued stock warrants to Oracle.
Following the announcement, Wall Street delivered fast price target hikes: Barclays' Tim Long raised HPE's target by $12 to $79 (Overweight), citing server upside and robust margins, while Morgan Stanley's Sanjit Singh boosted Oracle's target by $3 to $210 (Equal Weight), noting a tactically positive setup driven by GPUaaS demand.
Hewlett Packard Enterprise Company (NYSE:HPE) and Oracle both delivered strong results, although Oracle operates at a significantly larger scale. HPE reported record Q3 2026 revenue of $12.2 billion, up 34% year over year, driven by strong server demand and a 74.9% increase in Networking revenue to $2.9 billion. GAAP diluted EPS reached $1.06, while strong execution led management to raise full-year FY26 revenue growth guidance to 34%-37% and its free cash flow target to at least $3.75 billion.
Oracle Corporation (NYSE:ORCL), meanwhile, ended fiscal 2026 with record Q4 revenue of $19.2 billion, up 21% year over year, and full-year revenue of $67.4 billion, up 17%. Q4 Cloud Infrastructure (IaaS) revenue surged 93% to $5.8 billion, while full-year GAAP EPS rose 34% to $5.83 and Remaining Performance Obligations (RPO) jumped 363% to $638 billion.
Overall, ORCL leads in hyper-growth and long-term backlog, reinforcing its position as the stronger software and cloud play, while HPE is demonstrating stronger near-term hardware momentum and attractive cash flow generation for value-oriented investors.
#billion #revenue #infrastructure
Following the announcement, Wall Street delivered fast price target hikes: Barclays' Tim Long raised HPE's target by $12 to $79 (Overweight), citing server upside and robust margins, while Morgan Stanley's Sanjit Singh boosted Oracle's target by $3 to $210 (Equal Weight), noting a tactically positive setup driven by GPUaaS demand.
Hewlett Packard Enterprise Company (NYSE:HPE) and Oracle both delivered strong results, although Oracle operates at a significantly larger scale. HPE reported record Q3 2026 revenue of $12.2 billion, up 34% year over year, driven by strong server demand and a 74.9% increase in Networking revenue to $2.9 billion. GAAP diluted EPS reached $1.06, while strong execution led management to raise full-year FY26 revenue growth guidance to 34%-37% and its free cash flow target to at least $3.75 billion.
Oracle Corporation (NYSE:ORCL), meanwhile, ended fiscal 2026 with record Q4 revenue of $19.2 billion, up 21% year over year, and full-year revenue of $67.4 billion, up 17%. Q4 Cloud Infrastructure (IaaS) revenue surged 93% to $5.8 billion, while full-year GAAP EPS rose 34% to $5.83 and Remaining Performance Obligations (RPO) jumped 363% to $638 billion.
Overall, ORCL leads in hyper-growth and long-term backlog, reinforcing its position as the stronger software and cloud play, while HPE is demonstrating stronger near-term hardware momentum and attractive cash flow generation for value-oriented investors.
#billion #revenue #infrastructure


10 days ago
Harbor Funds, an investment management company, released its Q2 2026 investor letter for "Harbor Mid Cap Value Fund". The letter can be downloaded here. Global equities experienced a sharp rally in Q2 2026, with the S&P 500 returning 15.2%, its strongest quarter since 2020, driven by a shift from software to hardware in the Artificial Intelligence capital spending cycle. Small caps outperformed large caps, with the Russell 2000® gaining 21.5% compared to the Russell 1000's 15.1%. Growth stocks led within large caps, while Information Technology rose about 33%, contributing significantly to the S&P 500's return. The Harbor Mid Cap Value Fund returned 13.99%, outperforming its benchmark, the Russell Midcap Value Index. Strong stock selection in Consumer Discretionary, Real Estate, and Financials contributed positively, although an underweight in Information Technology negatively impacted results. Despite ongoing economic uncertainties, the investment philosophy remains committed to a disciplined value approach. Check the fund's top five holdings for its best picks in 2026.
In its second-quarter 2026 investor letter, Harbor Mid Cap Fund highlighted Hewlett Packard Enterprise Company (NYSE:HPE). Hewlett Packard Enterprise Company (NYSE:HPE), US based information technology company that specialized on developing intelligent solutions, positively contributed to the fund's performance this quarter. On September 04, 2026, Hewlett Packard Enterprise Company (NYSE:HPE) closed at $52.00 per share. Over the past month, Hewlett Packard Enterprise Company (NYSE:HPE) declined 2.31%, but its shares are up 127.30% over the past year. Hewlett Packard Enterprise Company (NYSE:HPE) has a market capitalization of $69.03 billion, and its stock has traded within a 52-week range of $19.84 to $64.25.
Harbor Mid Cap Fund stated the following regarding Hewlett Packard Enterprise Company (NYSE:HPE) in its Q2 2026 investor letter:
"The top contributors in the second quarter included three Information Technology holdings: TD Synnex, Arrow Electronics, and Hewlett Packard Enterprise Company (NYSE:HPE). Hewlett Packard Enterprise was up nearly 90% due to surging AI server demand and a successful integration of its Juniper Networks acquisition. The company reported record revenue with earnings per share significantly beating estimates."
Hewlett Packard Enterprise Company (NYSE:HPE) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 85 hedge fund portfolios held Hewlett Packard Enterprise Company (NYSE:HPE) at the end of the second quarter, up from 58 in the previous quarter. While we acknowledge the potential of Hewlett Packard Enterprise Company (NYSE:HPE) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on t
In its second-quarter 2026 investor letter, Harbor Mid Cap Fund highlighted Hewlett Packard Enterprise Company (NYSE:HPE). Hewlett Packard Enterprise Company (NYSE:HPE), US based information technology company that specialized on developing intelligent solutions, positively contributed to the fund's performance this quarter. On September 04, 2026, Hewlett Packard Enterprise Company (NYSE:HPE) closed at $52.00 per share. Over the past month, Hewlett Packard Enterprise Company (NYSE:HPE) declined 2.31%, but its shares are up 127.30% over the past year. Hewlett Packard Enterprise Company (NYSE:HPE) has a market capitalization of $69.03 billion, and its stock has traded within a 52-week range of $19.84 to $64.25.
Harbor Mid Cap Fund stated the following regarding Hewlett Packard Enterprise Company (NYSE:HPE) in its Q2 2026 investor letter:
"The top contributors in the second quarter included three Information Technology holdings: TD Synnex, Arrow Electronics, and Hewlett Packard Enterprise Company (NYSE:HPE). Hewlett Packard Enterprise was up nearly 90% due to surging AI server demand and a successful integration of its Juniper Networks acquisition. The company reported record revenue with earnings per share significantly beating estimates."
Hewlett Packard Enterprise Company (NYSE:HPE) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 85 hedge fund portfolios held Hewlett Packard Enterprise Company (NYSE:HPE) at the end of the second quarter, up from 58 in the previous quarter. While we acknowledge the potential of Hewlett Packard Enterprise Company (NYSE:HPE) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on t

12 days ago
Hewlett Packard Enterprise said on September 2 that Oracle may deploy its Juniper networking equipment across Oracle Cloud Infrastructure data centers under a multi-year collaboration. The potential footprint includes PTX and MX routing plus QFX and EX switching, along with support and financing. Hewlett Packard Enterprise Company (NYSE:HPE) also issued warrants to Oracle Corporation (NYSE:ORCL), making the arrangement strategically important without turning every possible deployment into booked revenue.
For HPE, the bull case is that AI clusters are becoming networking systems, not merely collections of GPUs. Training at enormous scale requires fast links inside a data center and between facilities. Juniper gives HPE credible routing and switching ******* ets, while Oracle supplies a demanding reference customer. Insider Monkey counted 85 hedge funds holding HPE at June 30, up from 58 at March 31. Elliott Management held 32,271,985 shares after increasing its disclosed position by 18% during the quarter.
The bear case is conversion. The release describes potential deployments and several product families but discloses neither guaranteed purchase volume nor revenue. Warrants can align the customer while diluting existing owners if exercised. HPE also must integrate Juniper, defend margins, and compete with entrenched networking vendors while customers bargain aggressively over large orders.
Oracle's advantage is supply-chain flexibility. Adding HPE gives OCI another route to build high-bandwidth infrastructure as AI demand strains capacity. Oracle can combine cloud contracts, database relationships, and financing to pull customers onto its infrastructure. Hedge-fund participation remained broad: 119 funds held Oracle Corporation (NYSE:ORCL) in Q2, up from 115 in Q1. Fisher ******* et Management reported 13,261,451 shares, 39% more than in the previous filing.
Oracle still carries the heavier capital burden. Data centers require chips, land, power, and debt-funded construction before contracted demand becomes cash. A networking partnership improves execution options but does not protect returns if utilization or pricing disappoints.
#oracle #Networking #NYSE #enterprise
For HPE, the bull case is that AI clusters are becoming networking systems, not merely collections of GPUs. Training at enormous scale requires fast links inside a data center and between facilities. Juniper gives HPE credible routing and switching ******* ets, while Oracle supplies a demanding reference customer. Insider Monkey counted 85 hedge funds holding HPE at June 30, up from 58 at March 31. Elliott Management held 32,271,985 shares after increasing its disclosed position by 18% during the quarter.
The bear case is conversion. The release describes potential deployments and several product families but discloses neither guaranteed purchase volume nor revenue. Warrants can align the customer while diluting existing owners if exercised. HPE also must integrate Juniper, defend margins, and compete with entrenched networking vendors while customers bargain aggressively over large orders.
Oracle's advantage is supply-chain flexibility. Adding HPE gives OCI another route to build high-bandwidth infrastructure as AI demand strains capacity. Oracle can combine cloud contracts, database relationships, and financing to pull customers onto its infrastructure. Hedge-fund participation remained broad: 119 funds held Oracle Corporation (NYSE:ORCL) in Q2, up from 115 in Q1. Fisher ******* et Management reported 13,261,451 shares, 39% more than in the previous filing.
Oracle still carries the heavier capital burden. Data centers require chips, land, power, and debt-funded construction before contracted demand becomes cash. A networking partnership improves execution options but does not protect returns if utilization or pricing disappoints.
#oracle #Networking #NYSE #enterprise
16 days ago
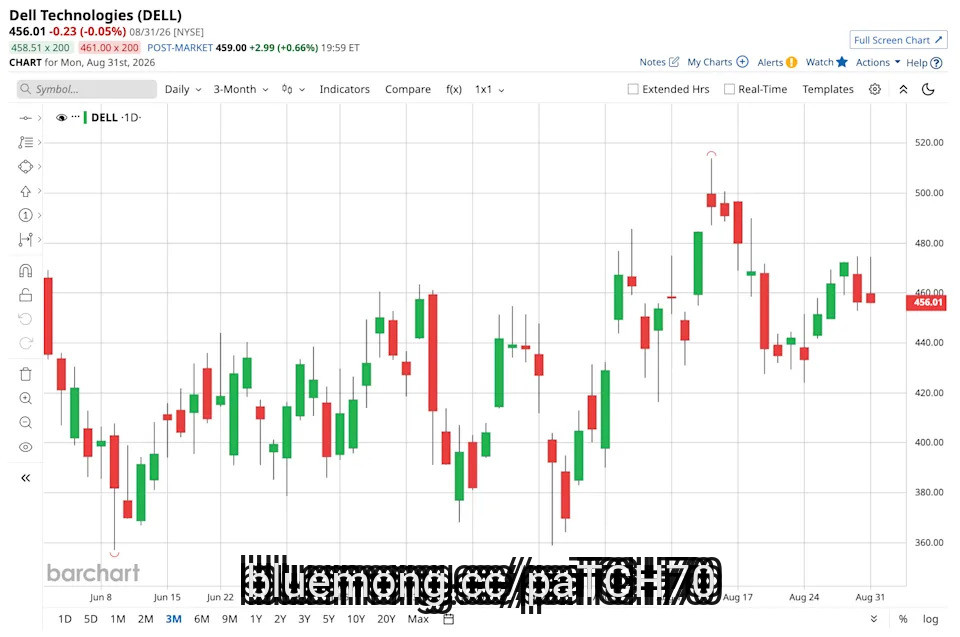
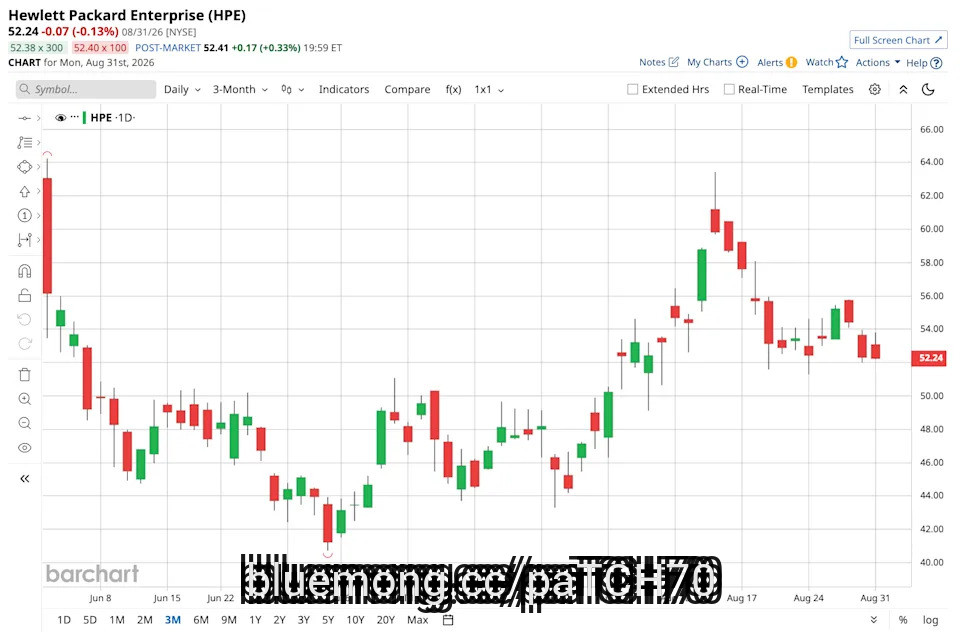
Dell Technologies (DELL) and Hewlett Packard Enterprise (HPE) report within a day of each other this week. Dell goes first on Sept. 1, followed by HPE on Sept. 2. J.P. Morgan expects both to lift guidance again, helped by strong AI server demand and steady demand for ordinary, non-AI gear. ****** ysts estimate revenue of $44.5 billion and adjusted EPS of $4.92 for Dell and revenue of $11.94 billion and adjusted EPS of $0.93 for HPE. Both stocks rose sharply after their last reports, and the market is expecting more good news again. That is why I think the headline beat matters less this time around.
Dell has already set the bar high. During its last quarterly release, it lifted the full-year revenue outlook from $140 billion to $167 billion and nearly doubled its GAAP EPS guidance to a $17.31 midpoint. Its AI backlog sits at $51 billion, with AI revenue guided to $60 billion for the year. Another raise is widely expected, and the stock is priced for it. HPE is coming off with similar momentum. In June, it posted record revenue and margins, raised its full-year outlook, and pulled its fiscal 2028 profit target forward by two full years. A lot of that comes from Juniper. HPE's networking carries far richer margins than servers do. So Dell is the bigger growth story, while HPE is quietly building the better-quality one.
Dear Sandisk Stock Fans, Mark Your Calendars for August 31
Bill Gates Says 'We Need Time to Prepare' for an Economic Upheaval — Especially the $20-an-Hour Workers Being Replaced by $10-an-Hour Robots
Dear Palantir Stock Fans, Here's What Maven's Billion-Dollar ARR Means for PLTR
#dear #fans
Dell has already set the bar high. During its last quarterly release, it lifted the full-year revenue outlook from $140 billion to $167 billion and nearly doubled its GAAP EPS guidance to a $17.31 midpoint. Its AI backlog sits at $51 billion, with AI revenue guided to $60 billion for the year. Another raise is widely expected, and the stock is priced for it. HPE is coming off with similar momentum. In June, it posted record revenue and margins, raised its full-year outlook, and pulled its fiscal 2028 profit target forward by two full years. A lot of that comes from Juniper. HPE's networking carries far richer margins than servers do. So Dell is the bigger growth story, while HPE is quietly building the better-quality one.
Dear Sandisk Stock Fans, Mark Your Calendars for August 31
Bill Gates Says 'We Need Time to Prepare' for an Economic Upheaval — Especially the $20-an-Hour Workers Being Replaced by $10-an-Hour Robots
Dear Palantir Stock Fans, Here's What Maven's Billion-Dollar ARR Means for PLTR
#dear #fans
17 days ago
Hims & Hers Health, Inc. (NYSE:HIMS) has entered Australia, marking its first expansion into the Asia-Pacific market. The move follows its acquisition of Australian digital-health platform Eucalyptus, which includes men's health brand Pilot and women's health brand Juniper. Hims is initially rolling out weight-loss and men's health treatments, with plans to introduce women's health services later this year.
The Australian launch allows Hims & Hers Health, Inc. (NYSE:HIMS) to replicate its U.S. and European model in another large, digitally connected healthcare market. It also gives the company access to local infrastructure and clinical expertise rather than requiring it to build the business entirely from scratch. The company has said international expansion has already helped increase monthly revenue per subscriber by 21% year over year, although international growth has also pressured gross margins.
Australia could become another meaningful growth engine for Hims & Hers Health, Inc. (NYSE:HIMS) as the company expands beyond its core U.S. market. The acquisition of Eucalyptus gives Hims an established local presence, existing brands and clinicians, which should reduce some of the execution risk normally ******* ociated with entering a new country.
The opportunity is particularly attractive because Hims can introduce multiple healthcare categories rather than relying on a single product. Weight loss, men's health, and eventually women's health give the company several avenues to increase customer acquisition and spending per subscriber. Combining services Australians previously purchased separately could also increase customer lifetime value.
The Australian market could also strengthen Hims' international scale. The company has already expanded into Europe through its acquisition of Zava, and Australia provides another market in which the company can leverage its technology, brand and telehealth infrastructure. If Hims & Hers Health, Inc. (NYSE:HIMS) can successfully replicate its customer-acquisition model internationally, the Australian business could become an important contributor toward its long-term $6.5 billion revenue target for 2030.
#Health #company #acquisition #australia
The Australian launch allows Hims & Hers Health, Inc. (NYSE:HIMS) to replicate its U.S. and European model in another large, digitally connected healthcare market. It also gives the company access to local infrastructure and clinical expertise rather than requiring it to build the business entirely from scratch. The company has said international expansion has already helped increase monthly revenue per subscriber by 21% year over year, although international growth has also pressured gross margins.
Australia could become another meaningful growth engine for Hims & Hers Health, Inc. (NYSE:HIMS) as the company expands beyond its core U.S. market. The acquisition of Eucalyptus gives Hims an established local presence, existing brands and clinicians, which should reduce some of the execution risk normally ******* ociated with entering a new country.
The opportunity is particularly attractive because Hims can introduce multiple healthcare categories rather than relying on a single product. Weight loss, men's health, and eventually women's health give the company several avenues to increase customer acquisition and spending per subscriber. Combining services Australians previously purchased separately could also increase customer lifetime value.
The Australian market could also strengthen Hims' international scale. The company has already expanded into Europe through its acquisition of Zava, and Australia provides another market in which the company can leverage its technology, brand and telehealth infrastructure. If Hims & Hers Health, Inc. (NYSE:HIMS) can successfully replicate its customer-acquisition model internationally, the Australian business could become an important contributor toward its long-term $6.5 billion revenue target for 2030.
#Health #company #acquisition #australia


1 month ago
Sometimes, putting out a sign actually works.
Young adults at the LGBTQ+ program Summer of Sass got quite the surprise Friday when Dylan Mulvaney unexpectedly showed up at the organization's annual Strawberry Social fundraiser in Provincetown.
It started when Salem, a Summer of Sass participant who works at the Provincetown Theater, learned that the transgender actress and influencer was in town and planned to attend a nearby show that night. Salem had an idea: Why not invite her to the Strawberry Social?
Juniper Kristal Starling, another participant, suggested putting up signs leading to the Sass House.
"Ultimately, I don't think anyone expected it to work," Juniper tells Out.
#sass #provincetown #participant
Young adults at the LGBTQ+ program Summer of Sass got quite the surprise Friday when Dylan Mulvaney unexpectedly showed up at the organization's annual Strawberry Social fundraiser in Provincetown.
It started when Salem, a Summer of Sass participant who works at the Provincetown Theater, learned that the transgender actress and influencer was in town and planned to attend a nearby show that night. Salem had an idea: Why not invite her to the Strawberry Social?
Juniper Kristal Starling, another participant, suggested putting up signs leading to the Sass House.
"Ultimately, I don't think anyone expected it to work," Juniper tells Out.
#sass #provincetown #participant



2 months ago
Deep Sail Capital Partners, an investment management company, released its second-quarter 2026 investor letter. A copy of the letter can be downloaded here. In the second quarter, the fund significantly outperformed both of its benchmarks, the Russell 2000 Mid Cap Growth Index and the Russell 2000 Index, returning 41.6% net of fees while averaging 88% net long exposure. YTD, the fund returned 16.5% net of fees. long portfolio significantly outperformed both benchmarks, while the short portfolio was mixed in the quarter. The letter states that there was a notable performance push in Q1, which was reflected in Q2, driven by both the Iran War and idiosyncratic impacts on positions in the fund. In addition, please check the Fund's top five holdings to know its best picks in 2026.
In its Q2 2026 investor letter, Deep Sail Capital Partners highlighted Celestica Inc. (NYSE:CLS). Celestica Inc. (NYSE:CLS) is a leading technology and electronic manufacturing services company that offers supply chain solutions across multiple countries. On July 22, 2026, Celestica Inc. (NYSE:CLS) closed at $335.50 per share, reflecting a market capitalization of $38.57 billion. Celestica Inc. (NYSE:CLS) posted a one-month return of -7.17%, while its shares gained 104.60% over the past 52 weeks.
Deep Sail Capital Partners stated the following regarding Celestica Inc. (NYSE:CLS) in its Q2 2026 investor update:
"Celestica Inc. (NYSE:CLS) has transitioned from its legacy roots as an IBM captive manufacturer to become a design and technology integration leader within the AI and cloud infrastructure ***** e. Celestica was founded in 1994 as a subsidiary of IBM Canada. It was subsequently acquired by PE, and then IPOed in the late 1990s. The company's strategy from there was an acquisition model for the next two decades, acquiring various electronics and computer peripherals manufacturing and supply companies, highly tied to major OEMs like IBM, Avaya, and Lucent. At the beginning of the AI boom, the company found itself incredibly well positioned to provide specialized design, operational, and engineering services to large technology companies looking to build data centers or ***** ociated integrated rack systems.
The business segments of Celestica are split into two highly specialized operational segments: Advanced Technology Solutions (ATS) and Connectivity & Cloud Solutions (CCS). Within the CCS segment, the company serves enterprise AI companies and the hyperscalers, including Google, Meta, Dell, HPE, IBM, Juniper Networks, and Oracle Corporation, among others. Within the ATS segment, Celestica supports highly complex capital equipment, aerospace, and defense programs for Tier-1 customers such as Applied Materials, Honeywell, Lam Research, and Raytheon..." (Click here to read the full text)
#deep #solutions
In its Q2 2026 investor letter, Deep Sail Capital Partners highlighted Celestica Inc. (NYSE:CLS). Celestica Inc. (NYSE:CLS) is a leading technology and electronic manufacturing services company that offers supply chain solutions across multiple countries. On July 22, 2026, Celestica Inc. (NYSE:CLS) closed at $335.50 per share, reflecting a market capitalization of $38.57 billion. Celestica Inc. (NYSE:CLS) posted a one-month return of -7.17%, while its shares gained 104.60% over the past 52 weeks.
Deep Sail Capital Partners stated the following regarding Celestica Inc. (NYSE:CLS) in its Q2 2026 investor update:
"Celestica Inc. (NYSE:CLS) has transitioned from its legacy roots as an IBM captive manufacturer to become a design and technology integration leader within the AI and cloud infrastructure ***** e. Celestica was founded in 1994 as a subsidiary of IBM Canada. It was subsequently acquired by PE, and then IPOed in the late 1990s. The company's strategy from there was an acquisition model for the next two decades, acquiring various electronics and computer peripherals manufacturing and supply companies, highly tied to major OEMs like IBM, Avaya, and Lucent. At the beginning of the AI boom, the company found itself incredibly well positioned to provide specialized design, operational, and engineering services to large technology companies looking to build data centers or ***** ociated integrated rack systems.
The business segments of Celestica are split into two highly specialized operational segments: Advanced Technology Solutions (ATS) and Connectivity & Cloud Solutions (CCS). Within the CCS segment, the company serves enterprise AI companies and the hyperscalers, including Google, Meta, Dell, HPE, IBM, Juniper Networks, and Oracle Corporation, among others. Within the ATS segment, Celestica supports highly complex capital equipment, aerospace, and defense programs for Tier-1 customers such as Applied Materials, Honeywell, Lam Research, and Raytheon..." (Click here to read the full text)
#deep #solutions


2 months ago
Madison Small Cap Fund, managed by Madison Funds, released its Q2 2026 investor letter. A copy of the letter can be downloaded fhere. The small-cap market showed exceptional strength in Q2, largely due to anticipated peace in the Middle East. The Russell 2000 Index began to rally, propelled by Information Technology, Health Care, and Industrials. The Madison Small Cap Fund (Class I) returned 12.7% in the quarter, underperforming the Russell 2000's 21.5% and Russell 2500's 20.2%. While strong gains were seen in Info Tech investments, recent investments in underperforming software companies negatively impacted overall performance. Nevertheless, confidence in the long-term potential of these software investments remains high. The firm is optimistic about small caps, noting their recent outperformance over large caps, recovery in certain software sectors, and improvements in some housing stocks toward the end of the second quarter. Please review the Fund's top five holdings to gain insights into their key selections for 2026.
In its Q2 2026 investor letter, Madison Small Cap Fund highlighted Extreme Networks, Inc. (NASDAQ:EXTR). Extreme Networks, Inc. (NASDAQ:EXTR) is a cloud driven enterprise networking company that develops and markets network infrastructure equipment and related software. On July 16, 2026, Extreme Networks, Inc. (NASDAQ:EXTR) closed at $29.76 per share, reflecting a market capitalization of $3.93 billion. Extreme Networks, Inc. (NASDAQ:EXTR) posted a one-month return of -3.92%, while its shares gained 71.86% over the past 52 weeks.
Madison Small Cap Fund stated the following regarding Extreme Networks, Inc. (NASDAQ:EXTR) in its Q2 2026 investor update:
"Extreme Networks, Inc. (NASDAQ:EXTR) (market capitalization of ~$4 billion) is a global provider of cloud driven enterprise networking solutions. The company designs and manufactures wired and wireless LAN (local area network) hardware, software-defined networking (SDN) fabric, and cloud-native management tools. They enable critical connectivity for high density, high-security environments, including professional sports stadiums, healthcare systems, and large-scale government and private enterprises. Extreme has successfully pivoted from a legacy hardware vendor to a cloud-managed, software-defined platform, creating deep "stickiness" within its customer base. In enterprise networking, the "specification moat" is significant. Once an organization builds its network fabric and security policies within Extreme's cloud dashboard, the operational risk and cost of migrating to a competitor are prohibitively high. Their strategy of offering superior simplicity and faster deployment times allows them to aggressively take market share from slower-moving, larger incumbents like Cisco and Juniper. The current industry-wide transition to Wi-Fi 7 is a catalyst, as these new hardware deployments inherently drive higher attach rates for Extreme's cloud-management software. We also believe th
In its Q2 2026 investor letter, Madison Small Cap Fund highlighted Extreme Networks, Inc. (NASDAQ:EXTR). Extreme Networks, Inc. (NASDAQ:EXTR) is a cloud driven enterprise networking company that develops and markets network infrastructure equipment and related software. On July 16, 2026, Extreme Networks, Inc. (NASDAQ:EXTR) closed at $29.76 per share, reflecting a market capitalization of $3.93 billion. Extreme Networks, Inc. (NASDAQ:EXTR) posted a one-month return of -3.92%, while its shares gained 71.86% over the past 52 weeks.
Madison Small Cap Fund stated the following regarding Extreme Networks, Inc. (NASDAQ:EXTR) in its Q2 2026 investor update:
"Extreme Networks, Inc. (NASDAQ:EXTR) (market capitalization of ~$4 billion) is a global provider of cloud driven enterprise networking solutions. The company designs and manufactures wired and wireless LAN (local area network) hardware, software-defined networking (SDN) fabric, and cloud-native management tools. They enable critical connectivity for high density, high-security environments, including professional sports stadiums, healthcare systems, and large-scale government and private enterprises. Extreme has successfully pivoted from a legacy hardware vendor to a cloud-managed, software-defined platform, creating deep "stickiness" within its customer base. In enterprise networking, the "specification moat" is significant. Once an organization builds its network fabric and security policies within Extreme's cloud dashboard, the operational risk and cost of migrating to a competitor are prohibitively high. Their strategy of offering superior simplicity and faster deployment times allows them to aggressively take market share from slower-moving, larger incumbents like Cisco and Juniper. The current industry-wide transition to Wi-Fi 7 is a catalyst, as these new hardware deployments inherently drive higher attach rates for Extreme's cloud-management software. We also believe th


2 months ago
Keeping Wrigley Field green takes more than sunshine and a dedicated grounds crew.
It also takes water -- and one Cubs employee found a creative way to conserve it.
Water conservation is a key part of the Chicago Cubs' sustainability efforts, and because Wrigley Field is more than 100 years old, the team has had to think outside the box.
That creativity led ***** istant Groundskeeper Graham Flora to look to his own backyard for inspiration.
While tending to the juniper plants that cascade down the ballpark's bleacher sections, Flora noticed an opportunity high above the field. At the top of Wrigley's iconic 60-foot scoreboard, rainwater from the roof drains away after storms.
It also takes water -- and one Cubs employee found a creative way to conserve it.
Water conservation is a key part of the Chicago Cubs' sustainability efforts, and because Wrigley Field is more than 100 years old, the team has had to think outside the box.
That creativity led ***** istant Groundskeeper Graham Flora to look to his own backyard for inspiration.
While tending to the juniper plants that cascade down the ballpark's bleacher sections, Flora noticed an opportunity high above the field. At the top of Wrigley's iconic 60-foot scoreboard, rainwater from the roof drains away after storms.


2 months ago
Hewlett Packard Enterprise Co (NYSE:HPE) is one of the best stocks to buy according to David Greenspan's Slate Path Capital. HPE stock has gained more than 80% year-to-date and more than doubled over the past year. ******* ysts see more upside potential in the stock, projecting a 50% rise from the current level. Some 58 hedge funds are backing HPE stock.
Hewlett Packard Enterprise Co (NYSE:HPE) is expanding the market reach of its networking business following its acquisition of Juniper Networks. On June 30, HPE's technology distributor, ScanSource, said that it was adding Juniper products to the portfolio of HPE networking solutions it distributes.
ScanSource has been helping HPE to get a wide variety of its products to the market. It is a foundational channel partner that has been distributing HPE Aruba networking products across the US for nearly two decades. ScanSource said it would distribute Juniper products through its Launch Point program, which provides marketing strategies and sales support.
HPE's networking portfolio includes an AI-enabled platform for managing wireless, wireline, and software-defined networks.
Texas-based Hewlett Packard Enterprise Co (NYSE:HPE) is a global technology company that provides a broad array of enterprise-grade solutions. It provides IT infrastructure, cloud computing, AI deployment, storage, and networking solutions to businesses and governments.
Hewlett Packard Enterprise Co (NYSE:HPE) is expanding the market reach of its networking business following its acquisition of Juniper Networks. On June 30, HPE's technology distributor, ScanSource, said that it was adding Juniper products to the portfolio of HPE networking solutions it distributes.
ScanSource has been helping HPE to get a wide variety of its products to the market. It is a foundational channel partner that has been distributing HPE Aruba networking products across the US for nearly two decades. ScanSource said it would distribute Juniper products through its Launch Point program, which provides marketing strategies and sales support.
HPE's networking portfolio includes an AI-enabled platform for managing wireless, wireline, and software-defined networks.
Texas-based Hewlett Packard Enterprise Co (NYSE:HPE) is a global technology company that provides a broad array of enterprise-grade solutions. It provides IT infrastructure, cloud computing, AI deployment, storage, and networking solutions to businesses and governments.

3 months ago
Hewlett Packard Enterprise Company (NYSE:HPE) is one of the best AI networking stocks to buy according to ***** ysts. The company gave investors a fresh AI networking update on June 1, when it reported fiscal second-quarter revenue of $10.7 billion, up 40% from the prior-year period.
The strongest signal came from HPE's networking business. Networking revenue reached $2.7 billion in the quarter, up 148.2% year over year, while Data Center Networking revenue rose 233.3% to $320 million. Cloud & AI revenue also reached $7.7 billion, up 22.9% from the prior-year period, supported by stronger server demand.
The numbers are relevant to the AI networking theme because HPE is no longer just a server and hybrid-cloud story. Its expanded networking portfolio, strengthened by Juniper, gives it exposure to campus, branch, routing, security, and data-center networking demand as enterprises build infrastructure for AI workloads. HPE also raised its fiscal 2026 revenue growth outlook to 29% to 33% and lifted its Networking segment growth outlook to 72% to 75%.
Hewlett Packard Enterprise Company (NYSE:HPE) is an enterprise technology company that brings together AI, cloud, and networking solutions to help organizations modernize infrastructure and improve operational performance.
While we acknowledge the potential of HPE as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
The strongest signal came from HPE's networking business. Networking revenue reached $2.7 billion in the quarter, up 148.2% year over year, while Data Center Networking revenue rose 233.3% to $320 million. Cloud & AI revenue also reached $7.7 billion, up 22.9% from the prior-year period, supported by stronger server demand.
The numbers are relevant to the AI networking theme because HPE is no longer just a server and hybrid-cloud story. Its expanded networking portfolio, strengthened by Juniper, gives it exposure to campus, branch, routing, security, and data-center networking demand as enterprises build infrastructure for AI workloads. HPE also raised its fiscal 2026 revenue growth outlook to 29% to 33% and lifted its Networking segment growth outlook to 72% to 75%.
Hewlett Packard Enterprise Company (NYSE:HPE) is an enterprise technology company that brings together AI, cloud, and networking solutions to help organizations modernize infrastructure and improve operational performance.
While we acknowledge the potential of HPE as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.


3 months ago
Stan Honda/AFP via Getty Images
This story originally appeared on The 19th.
For Juniper Simonis, that night in 2012 replays like the start of a favorite movie. It’s a warm summer evening, and she’s speeding through Ithaca, New York, on her bike. The wind is in her hair — at least as much as it could be under a bike helmet. Mariee Siou, the American folk singer, is blasting through her headphones.
The moment is memorable because of the feelings of freedom and hope sparked by an email she has just received. It says that the Ithaca League of Women Rollers derby team voted to allow her to play.
“As somebody who played sports and was queer, but those were two very separate parts of my life, the promise and the opportunity … to integrate those was very hopeful for me.”
This story originally appeared on The 19th.
For Juniper Simonis, that night in 2012 replays like the start of a favorite movie. It’s a warm summer evening, and she’s speeding through Ithaca, New York, on her bike. The wind is in her hair — at least as much as it could be under a bike helmet. Mariee Siou, the American folk singer, is blasting through her headphones.
The moment is memorable because of the feelings of freedom and hope sparked by an email she has just received. It says that the Ithaca League of Women Rollers derby team voted to allow her to play.
“As somebody who played sports and was queer, but those were two very separate parts of my life, the promise and the opportunity … to integrate those was very hopeful for me.”


3 months ago
Hewlett Packard Enterprise Company (NYSE:HPE) has gained more than 60% during the last month, making it one of the Best Performing Stocks in May. Recently, on June 3, Goldman Sachs raised the price target on the stock from $32 to $79 and maintained a Buy rating on the shares.
The increased price target comes after Hewlett Packard Enterprise Company (NYSE:HPE) posted strong earnings for its fiscal second quarter of 2026. During the quarter, the company posted record revenue of $10.7 billion, reflecting 40% year-over-year increase and ahead of the consensus of $9.76 billion. Hewlett also posted all-time highs in gross margin, non-GAAP EPS, and free cash flow for the second quarter. Management highlighted profitability as GAAP gross margins reached 36.5% after increasing 810 basis points year-over-year.
The revenue was driven by the networking segment, which grew 148% year-over-year to $2.7 billion. The growth in this segment was aided by Juniper Networks’ acquisition. Moreover, the data center networking alone skyrocketed 233%, and the cloud & AI segment grew 23% to $7.7 billion, with server revenue up 33%. Based on the strong momentum, HPE raised its full-year fiscal 2026 guidance and now projects revenue growth of 29% to 33% and free cash flow of at least $3.5 billion.
Goldman Sachs noted that they have increased confidence in the company’s differentiated position in the AI infrastructure buildout, following the Q2 results.
Hewlett Packard Enterprise Company (NYSE:HPE) operates as a global technology provider focused on intelligent solutions. Its platforms help customers capture, ****** yze, and act on data from edge to cloud. The customer base ranges from small and medium-sized businesses to large enterprises and government organizations.
The increased price target comes after Hewlett Packard Enterprise Company (NYSE:HPE) posted strong earnings for its fiscal second quarter of 2026. During the quarter, the company posted record revenue of $10.7 billion, reflecting 40% year-over-year increase and ahead of the consensus of $9.76 billion. Hewlett also posted all-time highs in gross margin, non-GAAP EPS, and free cash flow for the second quarter. Management highlighted profitability as GAAP gross margins reached 36.5% after increasing 810 basis points year-over-year.
The revenue was driven by the networking segment, which grew 148% year-over-year to $2.7 billion. The growth in this segment was aided by Juniper Networks’ acquisition. Moreover, the data center networking alone skyrocketed 233%, and the cloud & AI segment grew 23% to $7.7 billion, with server revenue up 33%. Based on the strong momentum, HPE raised its full-year fiscal 2026 guidance and now projects revenue growth of 29% to 33% and free cash flow of at least $3.5 billion.
Goldman Sachs noted that they have increased confidence in the company’s differentiated position in the AI infrastructure buildout, following the Q2 results.
Hewlett Packard Enterprise Company (NYSE:HPE) operates as a global technology provider focused on intelligent solutions. Its platforms help customers capture, ****** yze, and act on data from edge to cloud. The customer base ranges from small and medium-sized businesses to large enterprises and government organizations.


3 months ago
Hewlett Packard Enterprise Company (NYSE:HPE) has gained more than 60% during the last month, making it one of the Best Performing Stocks in May. Recently, on June 3, Goldman Sachs raised the price target on the stock from $32 to $79 and maintained a Buy rating on the shares.
The increased price target comes after Hewlett Packard Enterprise Company (NYSE:HPE) posted strong earnings for its fiscal second quarter of 2026. During the quarter, the company posted record revenue of $10.7 billion, reflecting 40% year-over-year increase and ahead of the consensus of $9.76 billion. Hewlett also posted all-time highs in gross margin, non-GAAP EPS, and free cash flow for the second quarter. Management highlighted profitability as GAAP gross margins reached 36.5% after increasing 810 basis points year-over-year.
The revenue was driven by the networking segment, which grew 148% year-over-year to $2.7 billion. The growth in this segment was aided by Juniper Networks’ acquisition. Moreover, the data center networking alone skyrocketed 233%, and the cloud & AI segment grew 23% to $7.7 billion, with server revenue up 33%. Based on the strong momentum, HPE raised its full-year fiscal 2026 guidance and now projects revenue growth of 29% to 33% and free cash flow of at least $3.5 billion.
Goldman Sachs noted that they have increased confidence in the company’s differentiated position in the AI infrastructure buildout, following the Q2 results.
Hewlett Packard Enterprise Company (NYSE:HPE) operates as a global technology provider focused on intelligent solutions. Its platforms help customers capture, ****** yze, and act on data from edge to cloud. The customer base ranges from small and medium-sized businesses to large enterprises and government organizations.
The increased price target comes after Hewlett Packard Enterprise Company (NYSE:HPE) posted strong earnings for its fiscal second quarter of 2026. During the quarter, the company posted record revenue of $10.7 billion, reflecting 40% year-over-year increase and ahead of the consensus of $9.76 billion. Hewlett also posted all-time highs in gross margin, non-GAAP EPS, and free cash flow for the second quarter. Management highlighted profitability as GAAP gross margins reached 36.5% after increasing 810 basis points year-over-year.
The revenue was driven by the networking segment, which grew 148% year-over-year to $2.7 billion. The growth in this segment was aided by Juniper Networks’ acquisition. Moreover, the data center networking alone skyrocketed 233%, and the cloud & AI segment grew 23% to $7.7 billion, with server revenue up 33%. Based on the strong momentum, HPE raised its full-year fiscal 2026 guidance and now projects revenue growth of 29% to 33% and free cash flow of at least $3.5 billion.
Goldman Sachs noted that they have increased confidence in the company’s differentiated position in the AI infrastructure buildout, following the Q2 results.
Hewlett Packard Enterprise Company (NYSE:HPE) operates as a global technology provider focused on intelligent solutions. Its platforms help customers capture, ****** yze, and act on data from edge to cloud. The customer base ranges from small and medium-sized businesses to large enterprises and government organizations.


7 months ago
A dinosaur road trip through the American West
RED FLEET STATE PARK, Utah - A three-toed footprint appeared in the rock, slightly longer than my hiking boot.
The outlines weren’t crisp, but the impression was deep enough to collect sand grains and pebbles. This impression is estimated to be between 157 million years old and 206 million years old.
Subscribe to The Post Most newsletter for the most important and interesting stories from The Washington Post.
After a one-mile desert hike through scattered sagebrush, juniper trees and cactus, I found proof of dinosaurs.
More footprints - fai
RED FLEET STATE PARK, Utah - A three-toed footprint appeared in the rock, slightly longer than my hiking boot.
The outlines weren’t crisp, but the impression was deep enough to collect sand grains and pebbles. This impression is estimated to be between 157 million years old and 206 million years old.
Subscribe to The Post Most newsletter for the most important and interesting stories from The Washington Post.
After a one-mile desert hike through scattered sagebrush, juniper trees and cactus, I found proof of dinosaurs.
More footprints - fai





