

10 mins. ago
Toast (NYSE: TOST) is a leading provider of financial technology services for businesses in the restaurant industry. The business is growing rapidly and still seems to have a long runway for expansion, but some of its business segments are carrying a lot more weight on the profitability front than others.
In the second quarter, Toast's revenue grew 23% to reach roughly $1.91 billion. Meanwhile, the business posted net income of $154 million in the period -- good for a margin of roughly 80.7%. The company's payments business once again did the heavy lifting in driving profits, but the picture is also more nuanced.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
In the second quarter, the financial technology solutions segment that includes Toast's payments business accounted for $1.57 billion of its overall sales in the period -- roughly 82.2% of the total pie. While the segment's total cost of revenue accounted for roughly $1.21 billion of the total $1.39 billion cost of sales in the quarter, it was still central to the business's gross profit of roughly $516 million in the quarter.
Notably, the company's hardware and professional services segment had a substantially negative gross margin in Q2. While the unit posted revenue of roughly $48 million in the period, it had a cost of revenue of $116 million -- and that doesn't factor in operating expenses for the segment.
#business
In the second quarter, Toast's revenue grew 23% to reach roughly $1.91 billion. Meanwhile, the business posted net income of $154 million in the period -- good for a margin of roughly 80.7%. The company's payments business once again did the heavy lifting in driving profits, but the picture is also more nuanced.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
In the second quarter, the financial technology solutions segment that includes Toast's payments business accounted for $1.57 billion of its overall sales in the period -- roughly 82.2% of the total pie. While the segment's total cost of revenue accounted for roughly $1.21 billion of the total $1.39 billion cost of sales in the quarter, it was still central to the business's gross profit of roughly $516 million in the quarter.
Notably, the company's hardware and professional services segment had a substantially negative gross margin in Q2. While the unit posted revenue of roughly $48 million in the period, it had a cost of revenue of $116 million -- and that doesn't factor in operating expenses for the segment.
#business


16 mins. ago
Private equity dealmakers in the US are poised for higher borrowing costs as the Federal Reserve on Wednesday raised interest rates for the first time since 2023.
The rate-setting committee unanimously agreed to raise the benchmark interest rate by a quarter of a percentage point, and officials largely agreed that, at the current trend, one more hike would be needed in 2026.
The decision lifted the federal funds rate to a target range of 3.75% to 4%, in line with market expectations heading into the September meeting.
Kyle Walters, a PE ******* yst at PitchBook, described the rate hike as "directionally negative for PE exit activity," though it is unlikely to cause significant damage on its own.
"The larger question is whether this rate hike is a one-off or if more are to follow. If it's the latter, that would have a more negative impact on monetization efforts, as most LBO debt is floating rate, which results in higher interest expense on these companies, and can damage the financial statements prospective buyers look at."
#interest #damage #reserve
The rate-setting committee unanimously agreed to raise the benchmark interest rate by a quarter of a percentage point, and officials largely agreed that, at the current trend, one more hike would be needed in 2026.
The decision lifted the federal funds rate to a target range of 3.75% to 4%, in line with market expectations heading into the September meeting.
Kyle Walters, a PE ******* yst at PitchBook, described the rate hike as "directionally negative for PE exit activity," though it is unlikely to cause significant damage on its own.
"The larger question is whether this rate hike is a one-off or if more are to follow. If it's the latter, that would have a more negative impact on monetization efforts, as most LBO debt is floating rate, which results in higher interest expense on these companies, and can damage the financial statements prospective buyers look at."
#interest #damage #reserve



29 mins. ago
Some offers on this page are from advertisers who pay us, which may affect which products we write about, but not our recommendations. See our Advertiser Disclosure.
The Federal Reserve raised interest rates on Wednesday, marking its first hike in more than three years, in a move that will likely make borrowing more expensive while giving savers a modest boost.
Fed Chairman Kevin Warsh and the Federal Open Market Committee announced a widely expected quarter-point rate increase and indicated another to come.
The stock market's reaction to the Fed's announcement is likely to draw the most headlines, and John Shugar, a partner at Goldman Sachs, leans toward an optimistic scenario.
"You basically have a market where all of the heavy lifting has actually been done on the earnings side," Shugar said in an **** ysis. He points to "terrific opportunities" in various AI consumer sectors, though "over the next few weeks, we may have a lot more speed **** ps."
#shugar #reserve #kevin
The Federal Reserve raised interest rates on Wednesday, marking its first hike in more than three years, in a move that will likely make borrowing more expensive while giving savers a modest boost.
Fed Chairman Kevin Warsh and the Federal Open Market Committee announced a widely expected quarter-point rate increase and indicated another to come.
The stock market's reaction to the Fed's announcement is likely to draw the most headlines, and John Shugar, a partner at Goldman Sachs, leans toward an optimistic scenario.
"You basically have a market where all of the heavy lifting has actually been done on the earnings side," Shugar said in an **** ysis. He points to "terrific opportunities" in various AI consumer sectors, though "over the next few weeks, we may have a lot more speed **** ps."
#shugar #reserve #kevin


32 mins. ago
Oil markets appear to have reached the inflection point that many ***** ysts had predicted weeks ago as the Middle East conflict re-escalated with no diplomatic push in sight and global inventories continue to slump.
Oil prices are back above $100 per barrel, lifting diesel and gasoline prices, including in the United States.
The Trump Administration is looking to downplay the price spikes it sees as only temporary. Prices would "drop like a rock" when the Iran war ends, U.S. President Donald Trump said, but he appears to have acknowledged that there may be no respite before the mid-term elections in early November.
Meanwhile, the record-high diesel prices and the highest gasoline prices for this time of year on record could do damage to the economy and consumer spending.
On Tuesday evening, the U.S. average diesel price hit $6.301 per gallon while gasoline prices jumped to an average of $4.355 per gallon, according to GasBuddy data.
#prices #Trump #price #record
Oil prices are back above $100 per barrel, lifting diesel and gasoline prices, including in the United States.
The Trump Administration is looking to downplay the price spikes it sees as only temporary. Prices would "drop like a rock" when the Iran war ends, U.S. President Donald Trump said, but he appears to have acknowledged that there may be no respite before the mid-term elections in early November.
Meanwhile, the record-high diesel prices and the highest gasoline prices for this time of year on record could do damage to the economy and consumer spending.
On Tuesday evening, the U.S. average diesel price hit $6.301 per gallon while gasoline prices jumped to an average of $4.355 per gallon, according to GasBuddy data.
#prices #Trump #price #record

1 hr. ago
The biggest return in the U.S. market this year came from the cost of moving oil across the ocean.
The Breakwave Tanker Shipping ETF (BWET) has climbed about 3,600% since the start of the year. That makes it the top-performing non-leveraged fund in the country, ahead of every AI and energy trade that grabbed headlines.
BWET now trades near $726 a share, up from under $20 in January. The huge increase traces back to one event that reshaped global shipping, and it carries a warning for anyone tempted to buy in now.
BWET tracks the price of moving oil by sea. It does that by holding short-dated freight futures, which are contracts that lock in the future cost of renting an oil tanker.
About 90% of the fund follows shipping agreements with the biggest tankers on the route from the Middle East to China. Those agreements lift BWET whenever hiring rates increase.
#cost #agreements
The Breakwave Tanker Shipping ETF (BWET) has climbed about 3,600% since the start of the year. That makes it the top-performing non-leveraged fund in the country, ahead of every AI and energy trade that grabbed headlines.
BWET now trades near $726 a share, up from under $20 in January. The huge increase traces back to one event that reshaped global shipping, and it carries a warning for anyone tempted to buy in now.
BWET tracks the price of moving oil by sea. It does that by holding short-dated freight futures, which are contracts that lock in the future cost of renting an oil tanker.
About 90% of the fund follows shipping agreements with the biggest tankers on the route from the Middle East to China. Those agreements lift BWET whenever hiring rates increase.
#cost #agreements


2 hours ago
Sept 16 (Reuters) - Top U.S. banks raised their prime lending rate on Wednesday after the Federal Reserve lifted its benchmark interest rate, a move that would increase borrowing costs for consumers and businesses with loans.
Following the Fed's first rate hike since 2023, the prime rate of JPMorgan , Bank of America, Citigroup, Wells Fargo, KeyCorp, Huntington Bancshares, Fifth Third Bancorp and Truist Financial from Thursday will rise to 7% from 6.75%.
The Fed raised rates by a quarter of a percentage point on Wednesday and flagged further increases in borrowing costs in the coming months as policymakers focus on addressing persistent inflation.
Shares of big banks ended lower amid broader weakness in U.S. stocks. BofA closed down 2.7%, Citi 2.4%, Wells Fargo 3%, and JPMorgan 1%. Morgan Stanley slipped 1.9% and Goldman Sachs fell 4%.
The prime rate, which follows the federal funds rate, is used by U.S. banks as a reference for setting rates on many financial products such as credit cards and personal loans.
#prime #jpmorgan #raised
Following the Fed's first rate hike since 2023, the prime rate of JPMorgan , Bank of America, Citigroup, Wells Fargo, KeyCorp, Huntington Bancshares, Fifth Third Bancorp and Truist Financial from Thursday will rise to 7% from 6.75%.
The Fed raised rates by a quarter of a percentage point on Wednesday and flagged further increases in borrowing costs in the coming months as policymakers focus on addressing persistent inflation.
Shares of big banks ended lower amid broader weakness in U.S. stocks. BofA closed down 2.7%, Citi 2.4%, Wells Fargo 3%, and JPMorgan 1%. Morgan Stanley slipped 1.9% and Goldman Sachs fell 4%.
The prime rate, which follows the federal funds rate, is used by U.S. banks as a reference for setting rates on many financial products such as credit cards and personal loans.
#prime #jpmorgan #raised

2 hours ago
Argentina's controversial right-wing president, Javier Milei, slashed inflation with a brutal dose of economic austerity, but this came at a steep social cost. The cost of living is spiraling higher, fueling household debt, loan delinquencies, and economic hardship. Industrial output, since Milei took office, has declined sharply, with local companies closing at an alarming rate. While parts of the economy are falling into chaos, Argentina's oil and gas sector is experiencing a generational boom driven by the Vaca Muerta shale.
Argentina's vital hydrocarbon sector continues to surge, with oil production hitting yet another record in July 2026. Output reached 902,920 barrels per day, almost 1% above June and 12% higher than a year earlier, marking the country's highest oil production on record. Natural gas production has also expanded strongly, although output slipped 0.5% month over month and 1.6% year over year in July to average 5.6 billion cubic feet per day. That modest setback barely dents the bigger picture: economically crucial gas production has surged 21% over the past five years.
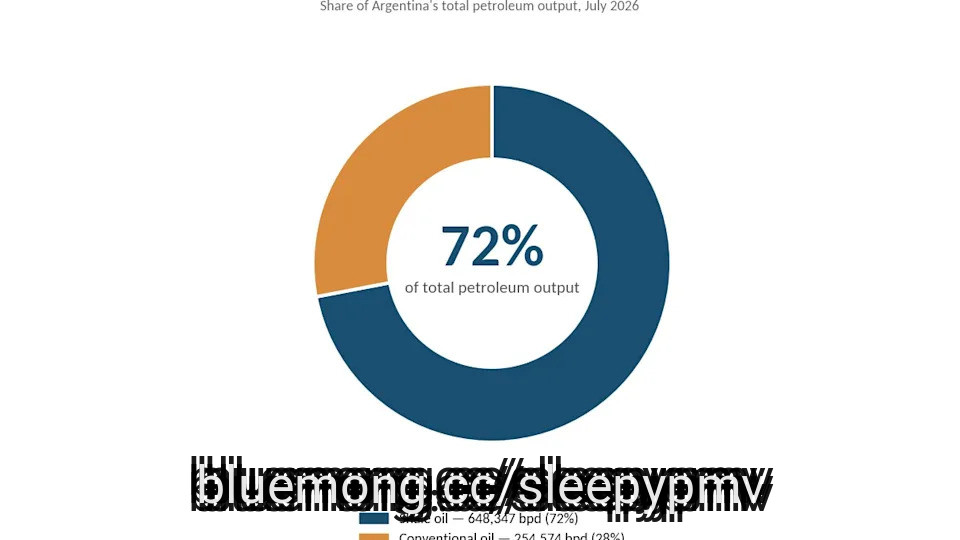
It is the ongoing and growing exploitation of the Vaca Muerta shale, situated in northern Patagonia in Neuquén Province which is responsible for Argentina's booming oil and natural gas complex. For July 2026, shale oil production rose by 1.2% month over month and a whopping 26% year over year to an all-time high of 648,347 barrels per day. As a result, shale oil now comprises a record 72% of Argentina's total petroleum output. This is also responsible for bolstering energy security in the Americas.
Shale gas production is also expanding at a healthy clip. For July 2026, Argentina lifted an average of 3.9 billion cubic feet per day of the fossil, which, despite being nearly 1% less than a month prior, was almost 4% higher year over year. That is the second-highest monthly shale gas production ever recorded. It was only eclipsed by June 2026 output, which hit 3.94 billion cubic feet per day. Shale gas now makes up 70% of Argentina's natural gas output, which is the highest level ever recorded.
Shale oil and gas production will keep growing at a solid pace, with Argentina on track to become a pure unconventional producer. You see, conventional oil output is in decline and has been for over a decade. Argentina's conventional fields are well past their prime, in many cases having hit peak production a decade ago with output now truly in decline. Government data shows July 2026 conventional oil production of 254,574 barrels per day, which is 2% lower than a month prior and 13% less year over year, indicating conventional oil output is 50% lower than a decade ago.
#shale #july #higher #record
Argentina's vital hydrocarbon sector continues to surge, with oil production hitting yet another record in July 2026. Output reached 902,920 barrels per day, almost 1% above June and 12% higher than a year earlier, marking the country's highest oil production on record. Natural gas production has also expanded strongly, although output slipped 0.5% month over month and 1.6% year over year in July to average 5.6 billion cubic feet per day. That modest setback barely dents the bigger picture: economically crucial gas production has surged 21% over the past five years.
It is the ongoing and growing exploitation of the Vaca Muerta shale, situated in northern Patagonia in Neuquén Province which is responsible for Argentina's booming oil and natural gas complex. For July 2026, shale oil production rose by 1.2% month over month and a whopping 26% year over year to an all-time high of 648,347 barrels per day. As a result, shale oil now comprises a record 72% of Argentina's total petroleum output. This is also responsible for bolstering energy security in the Americas.
Shale gas production is also expanding at a healthy clip. For July 2026, Argentina lifted an average of 3.9 billion cubic feet per day of the fossil, which, despite being nearly 1% less than a month prior, was almost 4% higher year over year. That is the second-highest monthly shale gas production ever recorded. It was only eclipsed by June 2026 output, which hit 3.94 billion cubic feet per day. Shale gas now makes up 70% of Argentina's natural gas output, which is the highest level ever recorded.
Shale oil and gas production will keep growing at a solid pace, with Argentina on track to become a pure unconventional producer. You see, conventional oil output is in decline and has been for over a decade. Argentina's conventional fields are well past their prime, in many cases having hit peak production a decade ago with output now truly in decline. Government data shows July 2026 conventional oil production of 254,574 barrels per day, which is 2% lower than a month prior and 13% less year over year, indicating conventional oil output is 50% lower than a decade ago.
#shale #july #higher #record

5 hours ago
Brace for minor market tremors now that the Fed has hiked interest rates by 0.25%.
Although if history holds up, any losses could prove short-lived.
The S&P 500 (^GSPC) has declined by an average of 4.0% over the six weeks following the first Fed rate hike of a cycle across seven such episodes since 1988, per new ****** ysis from strategists at The Kobeissi Letter.
Stocks recovered all of those losses over the next five to six weeks on average.
In the six months following the first interest rate hike, the S&P 500 returned 4% on average. After 12 months, the S&P 500's average gain tallied 9%. Positive returns have occurred in every episode except 2022 over the 12 months.
"Fed rate hikes have historically been great buying opportunities," the strategists added.
Read more: Follow live coverage of the Fed meeting
The decision by the Fed to lift rates comes as sticky inflation readings — from the CPI to PPI — and rising energy costs force central bankers back into tightening mode. The rate hike marks the central bank's first interest rate increase since July 2023.
Investors are also focused on the updated economic projections and the Fed's "dot plot" to gauge future moves on rates — said dot plot didn't rule out one more hike this year. A hawkish dot plot as was received and follow up commentary from Fed Chairman Kevin Warsh could further elevate borrowing costs and pressure stocks initially around the world.
#rate #hike #first #plot
Although if history holds up, any losses could prove short-lived.
The S&P 500 (^GSPC) has declined by an average of 4.0% over the six weeks following the first Fed rate hike of a cycle across seven such episodes since 1988, per new ****** ysis from strategists at The Kobeissi Letter.
Stocks recovered all of those losses over the next five to six weeks on average.
In the six months following the first interest rate hike, the S&P 500 returned 4% on average. After 12 months, the S&P 500's average gain tallied 9%. Positive returns have occurred in every episode except 2022 over the 12 months.
"Fed rate hikes have historically been great buying opportunities," the strategists added.
Read more: Follow live coverage of the Fed meeting
The decision by the Fed to lift rates comes as sticky inflation readings — from the CPI to PPI — and rising energy costs force central bankers back into tightening mode. The rate hike marks the central bank's first interest rate increase since July 2023.
Investors are also focused on the updated economic projections and the Fed's "dot plot" to gauge future moves on rates — said dot plot didn't rule out one more hike this year. A hawkish dot plot as was received and follow up commentary from Fed Chairman Kevin Warsh could further elevate borrowing costs and pressure stocks initially around the world.
#rate #hike #first #plot


6 hours ago
Some offers on this page are from advertisers who pay us, which may affect which products we write about, but not our recommendations. See our Advertiser Disclosure.
The Federal Reserve raised interest rates on Wednesday, marking its first hike in more than three years, in a move that will likely make borrowing more expensive while giving savers a modest boost.
Fed Chairman Kevin Warsh and the Federal Open Market Committee announced a widely expected quarter-point rate increase and indicated another to come.
The stock market's reaction to the Fed's announcement is likely to draw the most headlines, and John Shugar, a partner at Goldman Sachs, leans toward an optimistic scenario.
"You basically have a market where all of the heavy lifting has actually been done on the earnings side," Shugar said in an ***** ysis. He points to "terrific opportunities" in various AI consumer sectors, though "over the next few weeks, we may have a lot more speed ***** ps."
#shugar #market #disclosure #chairman
The Federal Reserve raised interest rates on Wednesday, marking its first hike in more than three years, in a move that will likely make borrowing more expensive while giving savers a modest boost.
Fed Chairman Kevin Warsh and the Federal Open Market Committee announced a widely expected quarter-point rate increase and indicated another to come.
The stock market's reaction to the Fed's announcement is likely to draw the most headlines, and John Shugar, a partner at Goldman Sachs, leans toward an optimistic scenario.
"You basically have a market where all of the heavy lifting has actually been done on the earnings side," Shugar said in an ***** ysis. He points to "terrific opportunities" in various AI consumer sectors, though "over the next few weeks, we may have a lot more speed ***** ps."
#shugar #market #disclosure #chairman

11 hours ago
On August 5, Kinetik Holdings Inc. (NYSE:KNTK) reported the strongest quarterly results in company history and raised its full-year 2026 guidance. The Permian-focused midstream operator posted net income, including noncontrolling interest, of $123.1 million for the quarter ended June 30, while Adjusted EBITDA climbed to $280.8 million. Management didn't stop at celebrating the number. It used the quarter as the launchpad for a string of expansion decisions that stretch out to 2028.
The Midstream Logistics segment, Kinetik's largest, grew Adjusted EBITDA 35% year over year to $204.8 million in the second quarter, even though processed natural gas volumes held flat at 1.74 Bcf/d. That flat number actually undersells the quarter. It came despite roughly 250 million cubic feet per day of gas that had been shut in because of weak Waha-area pricing, with stronger natural gas liquid recoveries, condensate yields, and favorable commodity spreads carrying the segment instead.
Management is betting the growth continues well past 2026. In May, Kinetik reached a final investment decision on Kings Landing II, a roughly $260 million project that will lift sour gas processing capacity across the company's Delaware North complex above 700 MMcf/d and push total system capacity to 2.7 Bcf/d when it comes online in mid-2028, earlier than previously communicated. The ECCC Pipeline, which links the system's northern and southern halves between Eddy and Culberson Counties, is now in service, and right-of-way work has already begun on a follow-on expansion for 2027.
Kinetik also locked in new firm Gulf Coast access for residue gas starting in 2027 and signed fresh natural gas liquids transport agreements, both aimed at getting better prices for the gas it moves. On the back of that momentum, Kinetik raised its full-year 2026 Adjusted EBITDA guidance to a range of $1.04 billion to $1.1 billion, a 7% ***** p from the guidance it issued in February.
Not every part of the business is moving in the same direction. The Pipeline Transportation segment posted Adjusted EBITDA of $83.0 million in the quarter, down 14% year over year, a decline the company attributes to last year's divestiture of its equity stake in EPIC Crude Holdings. That sale removed a source of cash flow the rest of the business now has to make up for. Kinetik also expects gas curtailments to keep running at an average of 25 million cubic feet per day through the second half of 2026, on top of the Waha-driven shut-ins that already weighed on the quarter. Its own pricing ***** umptions underline the regional problem: the company is now modeling Waha Hub natural gas at negative $0.26 per MMBtu for the full year, meaning gas in parts of the Permian is priced so low that moving it out of the basin is the whole game.
#quarter
The Midstream Logistics segment, Kinetik's largest, grew Adjusted EBITDA 35% year over year to $204.8 million in the second quarter, even though processed natural gas volumes held flat at 1.74 Bcf/d. That flat number actually undersells the quarter. It came despite roughly 250 million cubic feet per day of gas that had been shut in because of weak Waha-area pricing, with stronger natural gas liquid recoveries, condensate yields, and favorable commodity spreads carrying the segment instead.
Management is betting the growth continues well past 2026. In May, Kinetik reached a final investment decision on Kings Landing II, a roughly $260 million project that will lift sour gas processing capacity across the company's Delaware North complex above 700 MMcf/d and push total system capacity to 2.7 Bcf/d when it comes online in mid-2028, earlier than previously communicated. The ECCC Pipeline, which links the system's northern and southern halves between Eddy and Culberson Counties, is now in service, and right-of-way work has already begun on a follow-on expansion for 2027.
Kinetik also locked in new firm Gulf Coast access for residue gas starting in 2027 and signed fresh natural gas liquids transport agreements, both aimed at getting better prices for the gas it moves. On the back of that momentum, Kinetik raised its full-year 2026 Adjusted EBITDA guidance to a range of $1.04 billion to $1.1 billion, a 7% ***** p from the guidance it issued in February.
Not every part of the business is moving in the same direction. The Pipeline Transportation segment posted Adjusted EBITDA of $83.0 million in the quarter, down 14% year over year, a decline the company attributes to last year's divestiture of its equity stake in EPIC Crude Holdings. That sale removed a source of cash flow the rest of the business now has to make up for. Kinetik also expects gas curtailments to keep running at an average of 25 million cubic feet per day through the second half of 2026, on top of the Waha-driven shut-ins that already weighed on the quarter. Its own pricing ***** umptions underline the regional problem: the company is now modeling Waha Hub natural gas at negative $0.26 per MMBtu for the full year, meaning gas in parts of the Permian is priced so low that moving it out of the basin is the whole game.
#quarter


14 hours ago
Alluvium **** et Management, an **** et management company, released its "Conventum – Alluvium Global Fund" second-quarter 2026 investor letter. The letter can be downloaded here. The second quarter reflected a sharp shift from geopolitical uncertainty and oil market volatility to a powerful equity rally led by semiconductor companies. Despite the broader market strength, the Fund declined 1.4% in EUR terms, 2.2% in USD terms, and 3.9% in AUD terms. Portfolio results were mixed, with Alphabet benefiting from strong Cloud growth, while Robert Half, H&R Block and other holdings posted solid gains. However, cable businesses and several healthcare and consumer holdings weighed on performance. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Conventum – Alluvium Global Fund highlighted Liberty Capital Corporation (NASDAQ:GLIBK). Liberty Capital Corporation (NASDAQ:GLIBK) is a communication services company that provides a range of data, wireless, video, voice, and managed services. GCI Liberty, Inc. rebranded to Liberty Capital Corporation (NASDAQ:GLIBK) in May 2026. On September 15, 2026, Liberty Capital Corporation (NASDAQ:GLIBK) closed at $25.55 per share. Over the past month, Liberty Capital Corporation (NASDAQ:GLIBK) declined 1.50% and its shares lost 27.02% over the past 52 weeks. Liberty Capital Corporation (NASDAQ:GLIBK) has a market capitalization of $1.02 billion, and its stock trades within a 52-week range of $19.30 and $41.18.
Conventum – Alluvium Global Fund stated the following regarding Liberty Capital Corporation (NASDAQ:GLIBK) in its Q2 2026 investor letter:
"GCI Liberty, the Alaskan cable business that was spun out of Liberty Broadband, has been renamed Liberty Capital Corporation (NASDAQ:GLIBK) (to reflect a future which is expected to include a broader array of businesses, and with its legacy GCI Alaska cable business being the solid "cash cow"). It fell 40.6%. There was plenty of news. Most notable was its USD 360m acquisition of Quintillion, which owns around 3,000 kilometres of fibre cable and plans to expand it by a further 2,500 kilometres or so. This perfectly aligns with Liberty's GCI operations. We understand Quintillion generates around USD 55-60m in revenue and USD 30m in free cash. We would expect significant synergies (reportedly around USD 20m) so we have little doubt that the deal adds value. And in fact, when we incorporate it into our model, the valuation uplift is around 35%. Management also decided to retreat from the competitive and low margin video business. And finally, Liberty Capital had intended to acquire an interest in Liberty Latin America by striking a deal for an initial 6% stake and building on that by buying John Malone's interest. For some reason this did not proceed which perhaps spooked the market. With the share price falling (to levels approximating half our valuation), and encouraged by its CEO buying shares, we increased our
In its second-quarter 2026 investor letter, Conventum – Alluvium Global Fund highlighted Liberty Capital Corporation (NASDAQ:GLIBK). Liberty Capital Corporation (NASDAQ:GLIBK) is a communication services company that provides a range of data, wireless, video, voice, and managed services. GCI Liberty, Inc. rebranded to Liberty Capital Corporation (NASDAQ:GLIBK) in May 2026. On September 15, 2026, Liberty Capital Corporation (NASDAQ:GLIBK) closed at $25.55 per share. Over the past month, Liberty Capital Corporation (NASDAQ:GLIBK) declined 1.50% and its shares lost 27.02% over the past 52 weeks. Liberty Capital Corporation (NASDAQ:GLIBK) has a market capitalization of $1.02 billion, and its stock trades within a 52-week range of $19.30 and $41.18.
Conventum – Alluvium Global Fund stated the following regarding Liberty Capital Corporation (NASDAQ:GLIBK) in its Q2 2026 investor letter:
"GCI Liberty, the Alaskan cable business that was spun out of Liberty Broadband, has been renamed Liberty Capital Corporation (NASDAQ:GLIBK) (to reflect a future which is expected to include a broader array of businesses, and with its legacy GCI Alaska cable business being the solid "cash cow"). It fell 40.6%. There was plenty of news. Most notable was its USD 360m acquisition of Quintillion, which owns around 3,000 kilometres of fibre cable and plans to expand it by a further 2,500 kilometres or so. This perfectly aligns with Liberty's GCI operations. We understand Quintillion generates around USD 55-60m in revenue and USD 30m in free cash. We would expect significant synergies (reportedly around USD 20m) so we have little doubt that the deal adds value. And in fact, when we incorporate it into our model, the valuation uplift is around 35%. Management also decided to retreat from the competitive and low margin video business. And finally, Liberty Capital had intended to acquire an interest in Liberty Latin America by striking a deal for an initial 6% stake and building on that by buying John Malone's interest. For some reason this did not proceed which perhaps spooked the market. With the share price falling (to levels approximating half our valuation), and encouraged by its CEO buying shares, we increased our

14 hours ago
Rocket Lab (RKLB) stock has traded between $39.48 and $150.23 over the past 52 weeks. It now sits about 58% below its 52-week high, and anyone who bought twelve months ago is still up about 19%. None of that tells you what you would be buying today. Rocket Lab sells two quite different things, and the one its name points at is the smaller of them.
In Q2 2026 the ****** e Systems segment brought in $189.5 million. Launch Services brought in $44.6 million, down 30% from the previous quarter despite a similar number of launches. Management attributes that drop to accounting rather than lost work, because revenue from those launches is recognized over time and much of it had already been booked.
So Rocket Lab earns most of its revenue building satellites and their parts. Electron flew its 16th mission of 2026 in September. Launch is a real franchise, and it is not where most of the money comes from.
The stock trades at 52 times sales, against 3.1 for the S&P 500, on revenue of about $0.8 billion over the trailing twelve months. At this valuation, investors are largely pricing in future execution on the Neutron medium-lift rocket and the financial impact of the pending Iridium acquisition, rather than current satellite production alone. Management targets delivery to the pad in Q4 2026, and says the window for a launch before the end of 2026 is narrowing.
And you are paying for Iridium, which Rocket Lab has agreed to buy and expects to close in mid-2027. Iridium, a global satellite communications network, serves more than 2.5 million subscribers and delivered over $870 million of revenue in its past year. That is more than Rocket Lab's whole trailing twelve months. Management calls it a relatively slow-growing business that brings profit rather than a hole in the income statement.
#million #management #revenue
In Q2 2026 the ****** e Systems segment brought in $189.5 million. Launch Services brought in $44.6 million, down 30% from the previous quarter despite a similar number of launches. Management attributes that drop to accounting rather than lost work, because revenue from those launches is recognized over time and much of it had already been booked.
So Rocket Lab earns most of its revenue building satellites and their parts. Electron flew its 16th mission of 2026 in September. Launch is a real franchise, and it is not where most of the money comes from.
The stock trades at 52 times sales, against 3.1 for the S&P 500, on revenue of about $0.8 billion over the trailing twelve months. At this valuation, investors are largely pricing in future execution on the Neutron medium-lift rocket and the financial impact of the pending Iridium acquisition, rather than current satellite production alone. Management targets delivery to the pad in Q4 2026, and says the window for a launch before the end of 2026 is narrowing.
And you are paying for Iridium, which Rocket Lab has agreed to buy and expects to close in mid-2027. Iridium, a global satellite communications network, serves more than 2.5 million subscribers and delivered over $870 million of revenue in its past year. That is more than Rocket Lab's whole trailing twelve months. Management calls it a relatively slow-growing business that brings profit rather than a hole in the income statement.
#million #management #revenue


15 hours ago
By Anna Szymanski
Sept 16 (Reuters) - An unsettled few days set the scene for the week's main event: the Federal Reserve's policy decision. Markets overwhelmingly expect a quarter-point rate hike, the central bank's first since 2023, against the backdrop of resurgent oil prices and a 10-year Treasury yield that's recently breached the important 5% mark.
A rate increase could put Fed Chair Kevin Warsh on a collision course with the White House, given President Donald Trump's continued preference for easing policy. But given all the economic data supporting calls for a hike, Warsh risks losing credibility if the central bank stays on hold.
Today's decision - and the messaging surrounding it - will be a major test for Warsh. The Fed chair struck a hawkish tone at Jackson Hole last month and, with U.S. inflation still running above target and the unemployment rate still low, policymakers risk undermining their credibility if they don't follow through and lift the benchmark rate to the 3.75%-4.00% range.
That's as Donald Trump continues to push for the U.S. to have the lowest borrowing costs in the world. The U.S. president recently threatened to stop trading with some countries if the Fed does not cut rates, though markets have not taken that threat very seriously.
#rate #markets #president #decision
Sept 16 (Reuters) - An unsettled few days set the scene for the week's main event: the Federal Reserve's policy decision. Markets overwhelmingly expect a quarter-point rate hike, the central bank's first since 2023, against the backdrop of resurgent oil prices and a 10-year Treasury yield that's recently breached the important 5% mark.
A rate increase could put Fed Chair Kevin Warsh on a collision course with the White House, given President Donald Trump's continued preference for easing policy. But given all the economic data supporting calls for a hike, Warsh risks losing credibility if the central bank stays on hold.
Today's decision - and the messaging surrounding it - will be a major test for Warsh. The Fed chair struck a hawkish tone at Jackson Hole last month and, with U.S. inflation still running above target and the unemployment rate still low, policymakers risk undermining their credibility if they don't follow through and lift the benchmark rate to the 3.75%-4.00% range.
That's as Donald Trump continues to push for the U.S. to have the lowest borrowing costs in the world. The U.S. president recently threatened to stop trading with some countries if the Fed does not cut rates, though markets have not taken that threat very seriously.
#rate #markets #president #decision

1 day ago
The U.S. fuel crisis stemming from the ongoing war in Iran has now reached the retail shelf, with Costco Wholesale (COST) nearly doubling the price of its Kirkland Signature full-synthetic motor oil from roughly $30 to $58 per 5-quart two-pack, while simultaneously capping purchases at two units per membership every seven days.
It's an extraordinary move for a retailer whose entire brand identity rests on bulk buying at deep discounts, and it signals that severe supply chain disruptions are spreading well beyond the gasoline pump.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Crude Prices Soar as Global Oil Supplies Continue to Tighten
Middle East Supply Constraints Lift Crude Oil Prices
#supply #wholesale
It's an extraordinary move for a retailer whose entire brand identity rests on bulk buying at deep discounts, and it signals that severe supply chain disruptions are spreading well beyond the gasoline pump.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Crude Prices Soar as Global Oil Supplies Continue to Tighten
Middle East Supply Constraints Lift Crude Oil Prices
#supply #wholesale


1 day ago
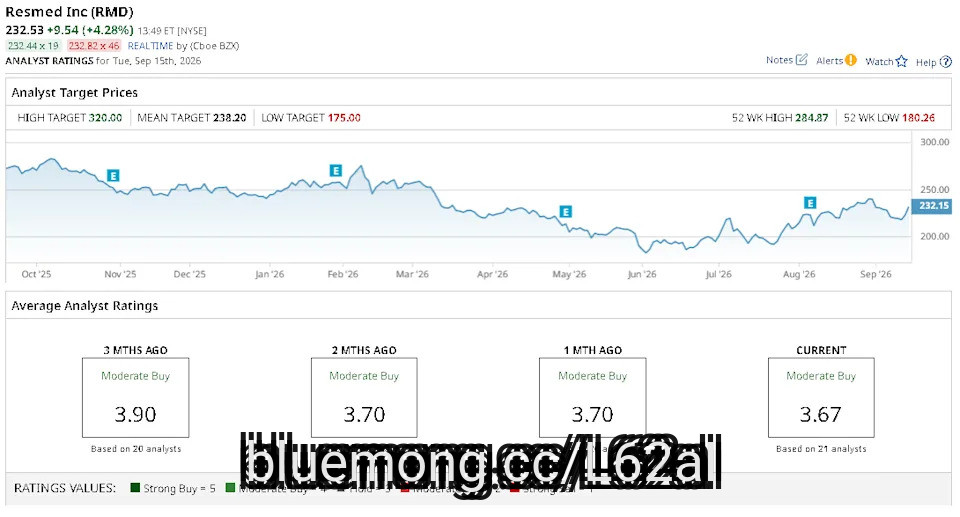
ResMed (RMD) shares are pushing higher on Tuesday after a senior RBC Capital Markets ****** yst upgraded the medical equipment specialist to an "Outperform" rating. In his research note, Craig Wong-Pan cited RMD's robust Q4 performance as he lifted his price target as well to $262, indicating potential upside of nearly 10% from here.
Note that ResMed stock has already been in a massive uptrend in recent months, currently trading about 28% above its June low.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Billionaire Charlie Munger, Who Died at 99, Skipped Insurance on His Mansion Since He Could Just Write a Check to Rebuild — 'All Intelligent People Do It My Way'
1 'Strong Buy' Dividend Stock Offering a 6.3% Yield Right Now
#markets
Note that ResMed stock has already been in a massive uptrend in recent months, currently trading about 28% above its June low.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Billionaire Charlie Munger, Who Died at 99, Skipped Insurance on His Mansion Since He Could Just Write a Check to Rebuild — 'All Intelligent People Do It My Way'
1 'Strong Buy' Dividend Stock Offering a 6.3% Yield Right Now
#markets


1 day ago
Bond traders are pricing in a Federal Reserve interest-rate hike Wednesday with a level of conviction that has proven right for decades. Interest-rate swaps tied to Fed meeting dates show traders see more than a 90% chance that Fed Chairman Kevin Warsh and his colleagues will lift the benchmark policy rate by a quarter point from the current 3.5%-3.75% range. That equates to roughly 23 basis points of tightening priced in. Kitty Richards Senior Fellow at the Groundwork Collaborative joined Balance of Power saying it will be difficult for the Fed to not raise rates.
#rate
#rate


1 day ago
October WTI crude oil (CLV26) closed up +4.44 (+4.38%) on Tuesday, and October RBOB gasoline (RBV26) closed up +0.1481 (+4.46%).
Crude oil and gasoline prices rallied sharply for a second day on Tuesday, with crude posting a 3.75-month high and gasoline posting a 3-week high. Supply risks are underpinning crude oil prices as energy exports from the Middle East remain limited, tightening global supplies.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Crude Prices Soar as Global Oil Supplies Continue to Tighten
Middle East Supply Constraints Lift Crude Oil Prices
#supply
Crude oil and gasoline prices rallied sharply for a second day on Tuesday, with crude posting a 3.75-month high and gasoline posting a 3-week high. Supply risks are underpinning crude oil prices as energy exports from the Middle East remain limited, tightening global supplies.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Crude Prices Soar as Global Oil Supplies Continue to Tighten
Middle East Supply Constraints Lift Crude Oil Prices
#supply


1 day ago
October Nymex natural gas (NGV26) on Tuesday closed up +0.023 (+0.79%).
Nat-gas prices finished higher on Tuesday on the outlook for above-average US temperatures, which should boost nat-gas demand from electricity providers as air conditioning use is expected to increase. The Commodity Weather Group said Tuesday that above-average temperatures are expected across the South and Southeast through September 29.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Crude Prices Soar as Global Oil Supplies Continue to Tighten
Middle East Supply Constraints Lift Crude Oil Prices
#tuesday #average #october
Nat-gas prices finished higher on Tuesday on the outlook for above-average US temperatures, which should boost nat-gas demand from electricity providers as air conditioning use is expected to increase. The Commodity Weather Group said Tuesday that above-average temperatures are expected across the South and Southeast through September 29.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Crude Prices Soar as Global Oil Supplies Continue to Tighten
Middle East Supply Constraints Lift Crude Oil Prices
#tuesday #average #october

1 day ago
NuScale Power Corporation (SMR) stands out as America's leading developer of small modular reactors (SMRs), building light-water nuclear systems designed to deliver reliable, carbon-free baseload power. Its core product, the NuScale Power Module, targets a wide range of applications, from traditional electricity generation to industrial decarbonization, AI data center power supply, and hydrogen production. Notably, NuScale remains the only SMR developer to secure Standard Design Approval from the U.S. Nuclear Regulatory Commission, a regulatory milestone that continues to anchor its competitive positioning in the emerging advanced nuclear industry.
NuScale's stock has been anything but stable. Over the past 52 weeks, shares have traded across an enormous range, from a low of $7.21 to a high of $57.42, before settling closer to $10.81. That volatility stems from a mix of factors: heavy retail investor interest, elevated short interest fueling sharp swings in both directions, and macroeconomic shifts in interest rates that disproportionately affect capital-intensive, pre-revenue growth companies. Compared to the Russell 2000, a benchmark of diversified, largely profitable small-cap stocks, NuScale carries a significantly higher beta and downside risk, reflecting its speculative, early-stage commercialization profile.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Crude Prices Soar as Global Oil Supplies Continue to Tighten
Middle East Supply Constraints Lift Crude Oil Prices
#nuclear #crude
NuScale's stock has been anything but stable. Over the past 52 weeks, shares have traded across an enormous range, from a low of $7.21 to a high of $57.42, before settling closer to $10.81. That volatility stems from a mix of factors: heavy retail investor interest, elevated short interest fueling sharp swings in both directions, and macroeconomic shifts in interest rates that disproportionately affect capital-intensive, pre-revenue growth companies. Compared to the Russell 2000, a benchmark of diversified, largely profitable small-cap stocks, NuScale carries a significantly higher beta and downside risk, reflecting its speculative, early-stage commercialization profile.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Crude Prices Soar as Global Oil Supplies Continue to Tighten
Middle East Supply Constraints Lift Crude Oil Prices
#nuclear #crude



1 day ago
GE Aerospace (GE) trades near $318, up 13.4% over the past twelve months. Behind that price sits a commercial services backlog of roughly $170 billion, work on engines already flying. The easy read is that the good news is in the price, and the coming three years just work that backlog off. A three-year scenario on the company's own numbers puts a size on what is left.
Revenue does most of the work. The scenario grows it 17.4% a year for three years, down from the 21.7% pace of the past twelve months, and net margin recovers some of the ground it has lost. Together they lift earnings about 67%.
The constraint is not demand. Management said in July that what lies ahead is much more a supply-side challenge than a demand one. Spare parts delinquencies, shipments held up for want of material, grew 20% sequentially in the second quarter of 2026.
GE Aerospace agreed in September to buy the castings maker Consolidated Precision Products. The deal shows where the bottleneck sits.
Then the multiple takes its cut. The scenario trims the P/E from 36.8x to 32.9x, because a slower revenue pace will not support what the market pays today. On those ******* umptions the stock would be worth about $475 in three years, roughly 50% above today.
#aerospace #revenue #price
Revenue does most of the work. The scenario grows it 17.4% a year for three years, down from the 21.7% pace of the past twelve months, and net margin recovers some of the ground it has lost. Together they lift earnings about 67%.
The constraint is not demand. Management said in July that what lies ahead is much more a supply-side challenge than a demand one. Spare parts delinquencies, shipments held up for want of material, grew 20% sequentially in the second quarter of 2026.
GE Aerospace agreed in September to buy the castings maker Consolidated Precision Products. The deal shows where the bottleneck sits.
Then the multiple takes its cut. The scenario trims the P/E from 36.8x to 32.9x, because a slower revenue pace will not support what the market pays today. On those ******* umptions the stock would be worth about $475 in three years, roughly 50% above today.
#aerospace #revenue #price


1 day ago
During the September 10 episode of Mad Money, a caller inquired about Mad Money host Jim Cramer's confidence that Arista Networks, Inc. (NYSE:ANET) will not go down the same path as Ciena Corporation. He replied:
Okay, so let me just tell you, Arista is up a lot this year. My confidence is with Jayshree Ullall. I think she's amazing and I think it every time the stock has dipped, if you've noticed it. Since her tenure began, you have to buy it, and I'm not backing away from that. I feel the same way I do now, the way I did, oh man, how many years ago when we first met her. She is money, and the company's fantastic.
In its second quarter, the company shattered records by delivering its first-ever $3 billion quarter, reporting $3.036 billion in revenue, a 38% year-over-year and over 12% sequential increase. Management lifted its full-year 2026 revenue guidance to approximately $12.6 billion, representing roughly 40% annual top-line growth. The acceleration is supported by deep integration into cloud architectures, where Arista Networks, Inc. (NYSE:ANET) expects its dedicated AI fabrics revenue to reach at least $3.5 billion in 2026, supported by more than 100 **** ulative Etherlink customers.
Bottom-line performance remains equally strong, with non-GAAP diluted earnings per share reaching $1.02, driven by a 49.9% non-GAAP operating margin and $1.3 billion in non-GAAP quarterly net income. Arista Networks, Inc. (NYSE:ANET) ended the quarter with roughly $13.3 billion in cash and marketable securities, offering substantial liquidity. However, its $9.7 billion of non-cancellable purchase commitments also increase working-capital and inventory risk as the company secures components ahead of expected AI demand.
The company's financial results remain heavily tied to two hyperscale customers. According to its 10-K filings, Microsoft accounted for 26%, and Meta Platforms generated 16% of total revenue in fiscal 2025, bringing combined spending from these two cloud giants to 42%. It leaves Arista Networks, Inc. (NYSE:ANET) vulnerable to sudden capital expenditure adjustments, vendor diversification shifts, or project delays by its core buyers.
#billion #NYSE #year
Okay, so let me just tell you, Arista is up a lot this year. My confidence is with Jayshree Ullall. I think she's amazing and I think it every time the stock has dipped, if you've noticed it. Since her tenure began, you have to buy it, and I'm not backing away from that. I feel the same way I do now, the way I did, oh man, how many years ago when we first met her. She is money, and the company's fantastic.
In its second quarter, the company shattered records by delivering its first-ever $3 billion quarter, reporting $3.036 billion in revenue, a 38% year-over-year and over 12% sequential increase. Management lifted its full-year 2026 revenue guidance to approximately $12.6 billion, representing roughly 40% annual top-line growth. The acceleration is supported by deep integration into cloud architectures, where Arista Networks, Inc. (NYSE:ANET) expects its dedicated AI fabrics revenue to reach at least $3.5 billion in 2026, supported by more than 100 **** ulative Etherlink customers.
Bottom-line performance remains equally strong, with non-GAAP diluted earnings per share reaching $1.02, driven by a 49.9% non-GAAP operating margin and $1.3 billion in non-GAAP quarterly net income. Arista Networks, Inc. (NYSE:ANET) ended the quarter with roughly $13.3 billion in cash and marketable securities, offering substantial liquidity. However, its $9.7 billion of non-cancellable purchase commitments also increase working-capital and inventory risk as the company secures components ahead of expected AI demand.
The company's financial results remain heavily tied to two hyperscale customers. According to its 10-K filings, Microsoft accounted for 26%, and Meta Platforms generated 16% of total revenue in fiscal 2025, bringing combined spending from these two cloud giants to 42%. It leaves Arista Networks, Inc. (NYSE:ANET) vulnerable to sudden capital expenditure adjustments, vendor diversification shifts, or project delays by its core buyers.
#billion #NYSE #year
1 day ago
On September 10, Canaccord cut its price target for The Lovesac Company (NASDAQ:LOVE) from $22 to $20 but maintained its Buy rating on the stock. This update came after the company reported its financial results for the second quarter of fiscal 2027, which ended August 2, 2026.
Canaccord noted that the company's fiscal Q2 results were in line with expectations. Revenue and adjusted EBITDA were both within the company's guidance and close to consensus estimates. The company received $21 million in IEEPA tariff refunds, which helped lift gross margins and earnings above consensus.
The Lovesac Company (NASDAQ:LOVE) reported net sales 0.4% higher than the prior-year period. This slight increase was mainly driven by 14 net new showrooms, although this was partly offset by a 1.9% decline in omni-channel comparable net sales and the closure of the company's Best Buy shop-in-shop locations. During the quarter, the company opened five additional showrooms and closed two.
The company reported net income of $7.4 million in the second quarter, compared with a net loss of $6.7 million in the same period last year. Operating income also improved to $10.9 million from an operating loss of $8.8 million a year earlier.
Gross profit rose 21.7% year-over-year while gross margin expanded to 68.4% of net sales from 56.4%, an increase of 1,200 basis points. The improvement was largely driven by IEEPA tariff recoveries, which contributed 1,240 basis points to gross margin. Excluding those recoveries, gross margin was 56.0%, down 40 basis points from the prior-year period.
#year #sales #period
Canaccord noted that the company's fiscal Q2 results were in line with expectations. Revenue and adjusted EBITDA were both within the company's guidance and close to consensus estimates. The company received $21 million in IEEPA tariff refunds, which helped lift gross margins and earnings above consensus.
The Lovesac Company (NASDAQ:LOVE) reported net sales 0.4% higher than the prior-year period. This slight increase was mainly driven by 14 net new showrooms, although this was partly offset by a 1.9% decline in omni-channel comparable net sales and the closure of the company's Best Buy shop-in-shop locations. During the quarter, the company opened five additional showrooms and closed two.
The company reported net income of $7.4 million in the second quarter, compared with a net loss of $6.7 million in the same period last year. Operating income also improved to $10.9 million from an operating loss of $8.8 million a year earlier.
Gross profit rose 21.7% year-over-year while gross margin expanded to 68.4% of net sales from 56.4%, an increase of 1,200 basis points. The improvement was largely driven by IEEPA tariff recoveries, which contributed 1,240 basis points to gross margin. Excluding those recoveries, gross margin was 56.0%, down 40 basis points from the prior-year period.
#year #sales #period
1 day ago
If you bought Meta Platforms (META) for its advertising engine, the engine still runs: revenue rose 28% year over year in the June 2026 quarter, and its Advantage+ automated campaigns keep growing. What has changed is where the cash goes afterward. The question for a holder is whether Meta is still the business you bought.
Over the twelve months through the June 2026 quarter, capital spending took 39.1% of revenue, against 18.5% across Meta's history. That money buys servers, data centers and network infrastructure. In late July 2026, Meta also announced a venture with BlackRock to develop a 1 gigawatt data center in El Paso, Texas. The plan is to keep going: management narrowed its 2026 capital-spending range by lifting the bottom of it.
Less cash is left over. TTM free-cash-flow margin is 18.0%, against 32.8% across its history, so on each dollar of sales Meta keeps a little more than half the free cash it used to.
Borrowing fills part of the gap. Debt has risen to 25.0% of total ******* ets, against a historical 7.0%, and the CFO says Meta is adding more debt to lower its cost of capital. Meta still holds more cash and marketable securities than debt.
Together, those three readings are the most unusual combination Meta has shown in 14 years. Taken with the 2026 spending floor that management has raised, the combination reads as a change in the business rather than one quarter of noise.
#quarter #spending #bought #engine
Over the twelve months through the June 2026 quarter, capital spending took 39.1% of revenue, against 18.5% across Meta's history. That money buys servers, data centers and network infrastructure. In late July 2026, Meta also announced a venture with BlackRock to develop a 1 gigawatt data center in El Paso, Texas. The plan is to keep going: management narrowed its 2026 capital-spending range by lifting the bottom of it.
Less cash is left over. TTM free-cash-flow margin is 18.0%, against 32.8% across its history, so on each dollar of sales Meta keeps a little more than half the free cash it used to.
Borrowing fills part of the gap. Debt has risen to 25.0% of total ******* ets, against a historical 7.0%, and the CFO says Meta is adding more debt to lower its cost of capital. Meta still holds more cash and marketable securities than debt.
Together, those three readings are the most unusual combination Meta has shown in 14 years. Taken with the 2026 spending floor that management has raised, the combination reads as a change in the business rather than one quarter of noise.
#quarter #spending #bought #engine


1 day ago
October WTI crude oil (CLV26) is up +3.30 (+3.25%) on Monday, and October RBOB gasoline (RBV26) is up +0.1164 (+3.51%).
Crude oil and gasoline prices are sharply higher today, with crude just below Monday's 3.75-month high. Supply risks are underpinning crude oil prices as crude exports from the Middle East remain limited, tightening global supplies.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Middle East Supply Constraints Lift Crude Oil Prices
Crude Prices Surge as Saudi Arabia Closes its East-West Pipeline
#middle
Crude oil and gasoline prices are sharply higher today, with crude just below Monday's 3.75-month high. Supply risks are underpinning crude oil prices as crude exports from the Middle East remain limited, tightening global supplies.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Middle East Supply Constraints Lift Crude Oil Prices
Crude Prices Surge as Saudi Arabia Closes its East-West Pipeline
#middle

1 day ago
U.S. stocks fell Tuesday as the 10-year Treasury yield climbed above 5% for the first time since 2007, with investors awaiting a Federal Reserve interest-rate decision expected Wednesday.
The Dow Jones Industrial Average dropped roughly 449 points, or 0.86%. The S&P 500 fell about 0.34% and the Nasdaq Composite declined 0.48%. The 10-year Treasury yield rose as high as 5.041% before pulling back to trade around 5.011%.
Oil prices extended gains after Saudi Arabia shut a key pipeline that bypasses the Strait of Hormuz. Brent crude futures for November delivery rose about 1.6% to trade above $107 a barrel, while West Texas Intermediate futures climbed to above $103.
Fed funds futures point to roughly a 90% to 93% probability that the Fed raises its benchmark rate by a quarter percentage point on Wednesday, which would lift the upper bound of the target range to 4%, according to The Wall Street Journal. That probability was roughly 59% a week ago.
Christopher Hodge, chief economist for the U.S. at Natixis CIB Americas, said in a note that he expects Fed Chair Kevin Warsh to signal the rate move is not a commitment to further hikes. "We also think that he will emphasize that this decision was discrete and does not pre-commit the Fed to any actions in subsequent meetings, giving him and the Committee maximum flexibility to respond to shocks," Hodge said, according to CNBC.
#rate
The Dow Jones Industrial Average dropped roughly 449 points, or 0.86%. The S&P 500 fell about 0.34% and the Nasdaq Composite declined 0.48%. The 10-year Treasury yield rose as high as 5.041% before pulling back to trade around 5.011%.
Oil prices extended gains after Saudi Arabia shut a key pipeline that bypasses the Strait of Hormuz. Brent crude futures for November delivery rose about 1.6% to trade above $107 a barrel, while West Texas Intermediate futures climbed to above $103.
Fed funds futures point to roughly a 90% to 93% probability that the Fed raises its benchmark rate by a quarter percentage point on Wednesday, which would lift the upper bound of the target range to 4%, according to The Wall Street Journal. That probability was roughly 59% a week ago.
Christopher Hodge, chief economist for the U.S. at Natixis CIB Americas, said in a note that he expects Fed Chair Kevin Warsh to signal the rate move is not a commitment to further hikes. "We also think that he will emphasize that this decision was discrete and does not pre-commit the Fed to any actions in subsequent meetings, giving him and the Committee maximum flexibility to respond to shocks," Hodge said, according to CNBC.
#rate


1 day ago
Oracle Corporation (NYSE:ORCL) is increasing the expected cost of its fiscal 2026 restructuring plan by about $700 million to roughly $2.8 billion as it simultaneously ramps up spending to capture demand for AI cloud services. The additional costs include severance, contract terminations and other exit expenses, with some restructuring directly linked to adopting AI across parts of the organization.
Oracle had already recorded $1.8 billion of restructuring expenses in fiscal 2026, compared with $299 million in fiscal 2025, showing how materially the company is accelerating its operational transformation. The restructuring comes alongside an unusually large AI investment cycle. Oracle booked more than $30 billion of new AI cloud contracts in its latest quarter, lifting its remaining performance obligations/revenue backlog to $664 billion, while roughly half of that backlog is expected to convert into revenue over the next 36 months.
The strongest bull argument is that the additional restructuring expense is part of a broader shift toward a higher-growth cloud and AI business rather than simply a deterioration in cost control. Oracle Corporation (NYSE:ORCL)'s restructuring program is explicitly aimed at improving efficiency while reallocating resources toward cloud-based offerings and second-generation cloud infrastructure. If the $2.8 billion restructuring program reduces lower-growth costs and enables Oracle to redirect personnel and capital toward AI infrastructure, the near-term earnings pressure could support stronger operating leverage later as cloud revenue scales.
More importantly, the restructuring is occurring against evidence that AI demand is already translating into contracted revenue. Oracle added more than $30 billion of AI cloud contracts in one quarter, pushing its backlog to $664 billion, above the $639.89 billion ******* yst estimate. Management said most of the newly contracted revenue would not require substantial incremental capital because customers are using prepayments or supplying their own hardware. That is particularly important because Oracle's biggest weakness has been the mismatch between rapid infrastructure investment and current cash generation. If customer-funded capacity continues to reduce Oracle's upfront capital burden, the company could convert its huge backlog into revenue without proportionally increasing its cash burn.
The early financial evidence also supports the possibility that the AI strategy is beginning to improve Oracle's growth profile. Revenue in the recent quarter rose 30% year over year to $19.3 billion, adjusted EPS reached $1.92 versus the $1.74 ******* yst consensus, and Oracle Corporation (NYSE:ORCL) raised its fiscal 2027 adjusted EPS forecast from $8.05 to $8.10. Meanwhile, first-quarter free cash flow of negative $5.4 billion was substantially better than both the expected negative $9.56 billion and the previous-quarter negative $11.48 billion. If this trajectory continues, the $700
Oracle had already recorded $1.8 billion of restructuring expenses in fiscal 2026, compared with $299 million in fiscal 2025, showing how materially the company is accelerating its operational transformation. The restructuring comes alongside an unusually large AI investment cycle. Oracle booked more than $30 billion of new AI cloud contracts in its latest quarter, lifting its remaining performance obligations/revenue backlog to $664 billion, while roughly half of that backlog is expected to convert into revenue over the next 36 months.
The strongest bull argument is that the additional restructuring expense is part of a broader shift toward a higher-growth cloud and AI business rather than simply a deterioration in cost control. Oracle Corporation (NYSE:ORCL)'s restructuring program is explicitly aimed at improving efficiency while reallocating resources toward cloud-based offerings and second-generation cloud infrastructure. If the $2.8 billion restructuring program reduces lower-growth costs and enables Oracle to redirect personnel and capital toward AI infrastructure, the near-term earnings pressure could support stronger operating leverage later as cloud revenue scales.
More importantly, the restructuring is occurring against evidence that AI demand is already translating into contracted revenue. Oracle added more than $30 billion of AI cloud contracts in one quarter, pushing its backlog to $664 billion, above the $639.89 billion ******* yst estimate. Management said most of the newly contracted revenue would not require substantial incremental capital because customers are using prepayments or supplying their own hardware. That is particularly important because Oracle's biggest weakness has been the mismatch between rapid infrastructure investment and current cash generation. If customer-funded capacity continues to reduce Oracle's upfront capital burden, the company could convert its huge backlog into revenue without proportionally increasing its cash burn.
The early financial evidence also supports the possibility that the AI strategy is beginning to improve Oracle's growth profile. Revenue in the recent quarter rose 30% year over year to $19.3 billion, adjusted EPS reached $1.92 versus the $1.74 ******* yst consensus, and Oracle Corporation (NYSE:ORCL) raised its fiscal 2027 adjusted EPS forecast from $8.05 to $8.10. Meanwhile, first-quarter free cash flow of negative $5.4 billion was substantially better than both the expected negative $9.56 billion and the previous-quarter negative $11.48 billion. If this trajectory continues, the $700
1 day ago
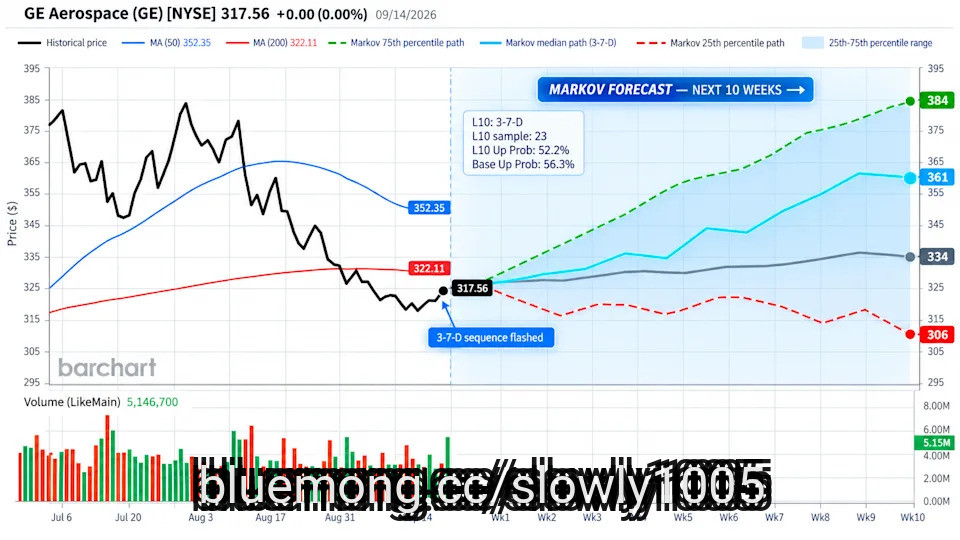
Browsing through the available strike selections for month-of-October bull call spreads, it's impossible to ignore one glaring idea for GE Aerospace (GE). With a maximum payout of 222.58% in exchange for a net debit (cash outlay) of $310, the risk-reward profile seems unusually favorable. Of course, Wall Street isn't in the business of giving traders a free lunch — and that's where the problem with GE stock lies.
While the breakeven price of $333.10 represents "only" a 5% lift from the current spot price, the implied probability of this threshold (derived from the Black-Scholes family of calculations) sits at 29.6%. Again, that's just to break even. If you want to be fully profitable, GE Aerospace stock must trigger the $340 second-leg strike price.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
What Old-School Chart **** ysis and Gamma Exposure Tell Us About QQQ This Fed Week
Unusually High Volume in Deep Out-of-the-Money Vertiv Call Options Shows Investors Bullish on VRT
#price #call #unusually #browsing
While the breakeven price of $333.10 represents "only" a 5% lift from the current spot price, the implied probability of this threshold (derived from the Black-Scholes family of calculations) sits at 29.6%. Again, that's just to break even. If you want to be fully profitable, GE Aerospace stock must trigger the $340 second-leg strike price.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
What Old-School Chart **** ysis and Gamma Exposure Tell Us About QQQ This Fed Week
Unusually High Volume in Deep Out-of-the-Money Vertiv Call Options Shows Investors Bullish on VRT
#price #call #unusually #browsing

1 day ago
The 10-year U.S. Treasury yield ($TNX) surged to 5.041% earlier today, marking its highest level since July 2007 and representing an 86-basis-point climb since the start of 2026. This 19-year high in benchmark borrowing costs has arrived at a critical juncture, with the Federal Reserve commencing its two-day policy meeting Tuesday and a rate decision expected Wednesday afternoon.
Markets are pricing in a 92.7% probability of a 25-basis-point hike, per CME's FedWatch Tool, which would lift the federal funds target range to 3.75%-4.00%. That overwhelming consensus in favor of a rate hike is a dramatic shift from roughly 59% just one week ago.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Middle East Supply Constraints Lift Crude Oil Prices
Crude Prices Soar as Global Oil Supplies Continue to Tighten
#prices #year #point #rate
Markets are pricing in a 92.7% probability of a 25-basis-point hike, per CME's FedWatch Tool, which would lift the federal funds target range to 3.75%-4.00%. That overwhelming consensus in favor of a rate hike is a dramatic shift from roughly 59% just one week ago.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Middle East Supply Constraints Lift Crude Oil Prices
Crude Prices Soar as Global Oil Supplies Continue to Tighten
#prices #year #point #rate


1 day ago
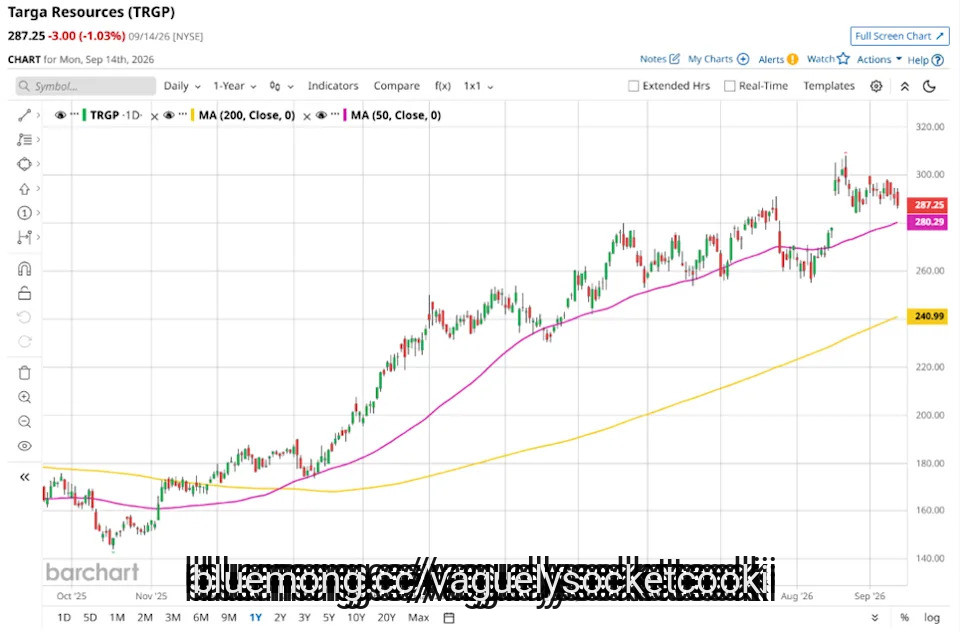
Targa Resources Corp. (TRGP), headquartered in Houston, Texas, owns, operates, acquires, and develops a portfolio of complementary domestic infrastructure ***** ets. Valued at $62.2 billion by market cap, the company's ***** ets connect natural gas and NGLs to domestic and international markets with growing demand for cleaner fuels and feedstocks.
Companies worth $10 billion or more are generally described as "large-cap stocks," and TRGP perfectly fits that description, with its market cap exceeding this mark, underscoring its size, influence, and dominance within the oil & gas midstream industry. TRGP benefits from strategic positioning in key shale plays including Permian, STACK, SCOOP, and Bakken, giving it a competitive edge in midstream. Its diversified service portfolio, including the Grand Prix NGL pipeline and Mont Belvieu fractionation capacity, underpins a strong market presence and stable revenue base.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Middle East Supply Constraints Lift Crude Oil Prices
Crude Prices Soar as Global Oil Supplies Continue to Tighten
#market
Companies worth $10 billion or more are generally described as "large-cap stocks," and TRGP perfectly fits that description, with its market cap exceeding this mark, underscoring its size, influence, and dominance within the oil & gas midstream industry. TRGP benefits from strategic positioning in key shale plays including Permian, STACK, SCOOP, and Bakken, giving it a competitive edge in midstream. Its diversified service portfolio, including the Grand Prix NGL pipeline and Mont Belvieu fractionation capacity, underpins a strong market presence and stable revenue base.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Middle East Supply Constraints Lift Crude Oil Prices
Crude Prices Soar as Global Oil Supplies Continue to Tighten
#market


1 day ago
If you bought Meta Platforms (META) for its advertising engine, the engine still runs: revenue rose 28% year over year in the June 2026 quarter, and its Advantage+ automated campaigns keep growing. What has changed is where the cash goes afterward. The question for a holder is whether Meta is still the business you bought.
Over the twelve months through the June 2026 quarter, capital spending took 39.1% of revenue, against 18.5% across Meta's history. That money buys servers, data centers and network infrastructure. In late July 2026, Meta also announced a venture with BlackRock to develop a 1 gigawatt data center in El Paso, Texas. The plan is to keep going: management narrowed its 2026 capital-spending range by lifting the bottom of it.
Less cash is left over. TTM free-cash-flow margin is 18.0%, against 32.8% across its history, so on each dollar of sales Meta keeps a little more than half the free cash it used to.
Borrowing fills part of the gap. Debt has risen to 25.0% of total **** ets, against a historical 7.0%, and the CFO says Meta is adding more debt to lower its cost of capital. Meta still holds more cash and marketable securities than debt.
Together, those three readings are the most unusual combination Meta has shown in 14 years. Taken with the 2026 spending floor that management has raised, the combination reads as a change in the business rather than one quarter of noise.
#meta #cash
Over the twelve months through the June 2026 quarter, capital spending took 39.1% of revenue, against 18.5% across Meta's history. That money buys servers, data centers and network infrastructure. In late July 2026, Meta also announced a venture with BlackRock to develop a 1 gigawatt data center in El Paso, Texas. The plan is to keep going: management narrowed its 2026 capital-spending range by lifting the bottom of it.
Less cash is left over. TTM free-cash-flow margin is 18.0%, against 32.8% across its history, so on each dollar of sales Meta keeps a little more than half the free cash it used to.
Borrowing fills part of the gap. Debt has risen to 25.0% of total **** ets, against a historical 7.0%, and the CFO says Meta is adding more debt to lower its cost of capital. Meta still holds more cash and marketable securities than debt.
Together, those three readings are the most unusual combination Meta has shown in 14 years. Taken with the 2026 spending floor that management has raised, the combination reads as a change in the business rather than one quarter of noise.
#meta #cash




