3 hours ago
Following an impressive second quarter FY27, Navan Inc. (NASDAQ:NAVN) announced its acquisition of BoomPop, an AI-powered meetings and events platform that has been recognized by Inc. as one of the fastest-growing private companies in America. Launched in 2023, BoomPop offers end-to-end event management solutions to enterprises, by leveraging artificial intelligence capabilities. Its offerings cover the entire spectrum of event management procedures including venue selection, vendor sourcing, contractual agreement, payments, and more. For Navan, this deal build on an existing alliance between the two entities, which was announced earlier in February. It marks the company's strategic push to expand its footprint across the meetings and events segment, where a large chunk of the spending is still done outside managed platforms.
LStockStudio/Shutterstock.com
The BoomPop acquisition follows a persistent enterprise market momentum reported by the company in its second quarter results, allowing Navan to enter into collaborative agreements with several leading companies during the quarter. These included Enbridge, Ingersoll Rand, ****** mins, and Evotec. Navan also concluded the deal to acquire Smartrips, a well-reputed travel management business, with the aim of bolstering its presence across a rapidly-growing Latin American market.
Notably, Navan registered adjusted net income of $14 million during the second quarter compared to an $8 million loss in Q2 FY26. It came at the back of year-over-year growth figures of 39% and 35% for subscription revenue and usage revenue, respectively.
Through full integration of BoomPop's staff and technology, Navan intends to expand its current meetings and events operations, accelerate its product development timeline, and satisfy growing customer interest. The company aims to deliver a more seamless experience covering travel, expense, meetings, and events.
#navan
LStockStudio/Shutterstock.com
The BoomPop acquisition follows a persistent enterprise market momentum reported by the company in its second quarter results, allowing Navan to enter into collaborative agreements with several leading companies during the quarter. These included Enbridge, Ingersoll Rand, ****** mins, and Evotec. Navan also concluded the deal to acquire Smartrips, a well-reputed travel management business, with the aim of bolstering its presence across a rapidly-growing Latin American market.
Notably, Navan registered adjusted net income of $14 million during the second quarter compared to an $8 million loss in Q2 FY26. It came at the back of year-over-year growth figures of 39% and 35% for subscription revenue and usage revenue, respectively.
Through full integration of BoomPop's staff and technology, Navan intends to expand its current meetings and events operations, accelerate its product development timeline, and satisfy growing customer interest. The company aims to deliver a more seamless experience covering travel, expense, meetings, and events.
#navan


14 hours ago
The Justice Department's push to pursue a sweeping conspiracy probe into former officials behind investigations targeting President Donald Trump has descended into turmoil and possibly new delays following the abrupt resignation of the top prosecutor overseeing the probe.
Joe diGenova, the Washington lawyer and former top prosecutor leading the South Florida-based investigation, resigned a day after a tense phone call Wednesday with Attorney General Todd Blanche, according to two people familiar with the matter. The final clash centered on diGenova's effort to block lawyers dispatched by Justice Department headquarters from ***** isting the probe, following broader disagreements with top Justice officials over its pace.
Among the disputes that added to tensions between diGenova and his bosses in Washington was diGenova's request for a high-security room known as a SCIF to be built at the Fort Pierce office, to make it easier for the prosecution team to store highly classified materials, two people familiar with the investigation told CNN. The team worked in an office with a special room where sensitive, but not the highest-classified, evidence could be handled. Justice Department officials told diGenova he and his team should use a SCIF at an FBI office miles away, two people familiar with the investigation told CNN.
DiGenova also pressed for more lawyers for his team. Justice officials pushed back on any claims that he was denied resources, according to two people familiar with the investigation.
For more than a year, Justice Department officials have pushed to bring criminal charges against former CIA director John Brennan, who is accused of making false statements to Congress and has been the subject of the president's ire for years. Since diGenova joined the probe in April, he's chosen to pursue a broader set of charges against several of Trump's political critics — including Brennan — who were involved in investigations of him over the past decade.
#officials #familiar #department
Joe diGenova, the Washington lawyer and former top prosecutor leading the South Florida-based investigation, resigned a day after a tense phone call Wednesday with Attorney General Todd Blanche, according to two people familiar with the matter. The final clash centered on diGenova's effort to block lawyers dispatched by Justice Department headquarters from ***** isting the probe, following broader disagreements with top Justice officials over its pace.
Among the disputes that added to tensions between diGenova and his bosses in Washington was diGenova's request for a high-security room known as a SCIF to be built at the Fort Pierce office, to make it easier for the prosecution team to store highly classified materials, two people familiar with the investigation told CNN. The team worked in an office with a special room where sensitive, but not the highest-classified, evidence could be handled. Justice Department officials told diGenova he and his team should use a SCIF at an FBI office miles away, two people familiar with the investigation told CNN.
DiGenova also pressed for more lawyers for his team. Justice officials pushed back on any claims that he was denied resources, according to two people familiar with the investigation.
For more than a year, Justice Department officials have pushed to bring criminal charges against former CIA director John Brennan, who is accused of making false statements to Congress and has been the subject of the president's ire for years. Since diGenova joined the probe in April, he's chosen to pursue a broader set of charges against several of Trump's political critics — including Brennan — who were involved in investigations of him over the past decade.
#officials #familiar #department



15 hours ago
Argentina's state-controlled energy company YPF is close to signing several LNG sales agreements for its planned Argentina LNG project as it races toward a final investment decision later this year.
YPF CEO Horacio Marín said at the Gastech conference in Bangkok that the company expects to sign two or three LNG contracts covering between 0.5 million and 1.5 million tonnes per year each. YPF aims to have the agreements secured before partners make a final investment decision in November.
The $24-billion Argentina LNG development, backed by YPF, Italy's Eni and Abu Dhabi's XRG, is designed to turn the vast Vaca Muerta shale formation into a major source of LNG for international markets.
The initial development will feature two floating LNG facilities with combined capacity of 12 million tonnes per year, with potential expansion to 18 million tonnes. A dedicated 527-kilometer pipeline will transport gas from Vaca Muerta to the Atlantic coast in Río Negro province. YPF says the development will also include gas treatment and liquids infrastructure.
Eni and XRG each hold approximately 32% interests in the upstream blocks feeding the development, with YPF holding 36%.
#development #year #tonnes #muerta
YPF CEO Horacio Marín said at the Gastech conference in Bangkok that the company expects to sign two or three LNG contracts covering between 0.5 million and 1.5 million tonnes per year each. YPF aims to have the agreements secured before partners make a final investment decision in November.
The $24-billion Argentina LNG development, backed by YPF, Italy's Eni and Abu Dhabi's XRG, is designed to turn the vast Vaca Muerta shale formation into a major source of LNG for international markets.
The initial development will feature two floating LNG facilities with combined capacity of 12 million tonnes per year, with potential expansion to 18 million tonnes. A dedicated 527-kilometer pipeline will transport gas from Vaca Muerta to the Atlantic coast in Río Negro province. YPF says the development will also include gas treatment and liquids infrastructure.
Eni and XRG each hold approximately 32% interests in the upstream blocks feeding the development, with YPF holding 36%.
#development #year #tonnes #muerta


16 hours ago
TotalEnergies SE (NYSE:TTE) plans to invest $10 billion alongside its partners in Angola over the next five years, with the goal of maintaining and potentially increasing its oil production in the country. TotalEnergies currently produces around 450,000 barrels per day in Angola, making it the country's largest oil operator and accounting for more than 40% of its total output.
The investment will go toward existing operations, new exploration, and projects aimed at replacing production from Angola's aging offshore fields. One of the biggest projects in the pipeline is the $6 billion Kaminho development, which is expected to start producing oil in 2028. TotalEnergies SE (NYSE:TTE) is also expanding its exploration efforts after signing agreements for two additional offshore blocks. On top of that, the company recently announced a new discovery in Block 17 that could add roughly 6,000 barrels per day to production.
The investment strengthens TotalEnergies SE (NYSE:TTE)'s position in one of Africa's key oil-producing markets and, perhaps more importantly, helps protect a major source of existing production. With around 450,000 barrels per day already coming from Angola, simply keeping output at current levels could continue to provide a meaningful contribution to the company's upstream cash flow. Any additional production from new discoveries and projects would offer further upside.
The current oil-price environment also works in TotalEnergies' favor. Brent crude recently climbed above $100 a barrel amid supply concerns and geopolitical tensions and is currently trading near this range. If prices remain elevated, projects designed to maintain or increase Angolan production could generate strong returns and make the company's investment more attractive.
There are also signs that TotalEnergies SE (NYSE:TTE) is doing more than just trying to slow production declines. Its recent Acacia-5 discovery in Block 17 could add around 6,000 barrels per day, while the company is expanding its exploration presence through new offshore blocks in the Lower Congo Basin. Angola's efforts to reform its oil sector and attract more exploration investment could also create a more favorable environment for TotalEnergies over the longer term.
#investment #offshore
The investment will go toward existing operations, new exploration, and projects aimed at replacing production from Angola's aging offshore fields. One of the biggest projects in the pipeline is the $6 billion Kaminho development, which is expected to start producing oil in 2028. TotalEnergies SE (NYSE:TTE) is also expanding its exploration efforts after signing agreements for two additional offshore blocks. On top of that, the company recently announced a new discovery in Block 17 that could add roughly 6,000 barrels per day to production.
The investment strengthens TotalEnergies SE (NYSE:TTE)'s position in one of Africa's key oil-producing markets and, perhaps more importantly, helps protect a major source of existing production. With around 450,000 barrels per day already coming from Angola, simply keeping output at current levels could continue to provide a meaningful contribution to the company's upstream cash flow. Any additional production from new discoveries and projects would offer further upside.
The current oil-price environment also works in TotalEnergies' favor. Brent crude recently climbed above $100 a barrel amid supply concerns and geopolitical tensions and is currently trading near this range. If prices remain elevated, projects designed to maintain or increase Angolan production could generate strong returns and make the company's investment more attractive.
There are also signs that TotalEnergies SE (NYSE:TTE) is doing more than just trying to slow production declines. Its recent Acacia-5 discovery in Block 17 could add around 6,000 barrels per day, while the company is expanding its exploration presence through new offshore blocks in the Lower Congo Basin. Angola's efforts to reform its oil sector and attract more exploration investment could also create a more favorable environment for TotalEnergies over the longer term.
#investment #offshore


2 days ago
Private equity advisers are racing to leverage AI and automate the services they provide to fund managers and their investors. Law firms, such as Kirkland & Ellis, have been among the most active adopters.
The dominant name in private fund formation and sponsor-backed M&A, the firm rolled out its own AI platform in June, built with Palantir and designed to reshape the repetitive, boilerplate elements of fund formation work, such as drafting limited partnership agreements, closing investor commitments and conducting compliance.
Earlier this year, Kirkland reportedly earmarked $500 million to develop a proprietary AI tool over three to four years, no small sum even for a law firm that generated $10.6 billion in annual revenue last year.
Erica Berthou
Erica Berthou, a partner at Kirkland and a member of the firm's executive committee, recently spoke with PitchBook about how AI could reshape the practice of law—including how it will change the economics of legal work—and how the adoption of AI may affect practitioners, especially the young talent.
#kirkland #private
The dominant name in private fund formation and sponsor-backed M&A, the firm rolled out its own AI platform in June, built with Palantir and designed to reshape the repetitive, boilerplate elements of fund formation work, such as drafting limited partnership agreements, closing investor commitments and conducting compliance.
Earlier this year, Kirkland reportedly earmarked $500 million to develop a proprietary AI tool over three to four years, no small sum even for a law firm that generated $10.6 billion in annual revenue last year.
Erica Berthou
Erica Berthou, a partner at Kirkland and a member of the firm's executive committee, recently spoke with PitchBook about how AI could reshape the practice of law—including how it will change the economics of legal work—and how the adoption of AI may affect practitioners, especially the young talent.
#kirkland #private


3 days ago
Lil Durk has been cleared of every charge in the federal murder-for-hire trial that drew packed courtrooms, celebrity spectators and crowds of supporters to downtown Los Angeles.
A federal jury found the 33-year-old Chicago rapper, whose legal name is Durk Banks, not guilty on September 11 after three days of deliberations. The case centered on an August 2022 attack targeting rapper Quando Rondo that instead killed Rondo's 24-year-old cousin, Saviay'a Robinson, according to The ******* ociated Press.
Prosecutors accused Durk of financing and directing the attack in retaliation for the 2020 killing of his close friend Dayvon "King Von" Bennett. Durk's lawyers argued that former ******* istant Kavon Grant organized the plot without the rapper's knowledge and attacked the credibility of cooperating witnesses who had reached plea agreements with the government.
Durk was not released after the verdict. He remains in federal custody because he faces a separate trial involving murder-related racketeering and firearms allegations, with jury selection currently scheduled to begin October 5.
Durk had faced five counts: conspiracy to commit stalking, stalking using a dangerous weapon, stalking resulting in death, conspiracy to use interstate commerce facilities to commit murder-for-hire resulting in death and use of interstate commerce facilities to commit murder-for-hire resulting in death.
#commit #stalking
A federal jury found the 33-year-old Chicago rapper, whose legal name is Durk Banks, not guilty on September 11 after three days of deliberations. The case centered on an August 2022 attack targeting rapper Quando Rondo that instead killed Rondo's 24-year-old cousin, Saviay'a Robinson, according to The ******* ociated Press.
Prosecutors accused Durk of financing and directing the attack in retaliation for the 2020 killing of his close friend Dayvon "King Von" Bennett. Durk's lawyers argued that former ******* istant Kavon Grant organized the plot without the rapper's knowledge and attacked the credibility of cooperating witnesses who had reached plea agreements with the government.
Durk was not released after the verdict. He remains in federal custody because he faces a separate trial involving murder-related racketeering and firearms allegations, with jury selection currently scheduled to begin October 5.
Durk had faced five counts: conspiracy to commit stalking, stalking using a dangerous weapon, stalking resulting in death, conspiracy to use interstate commerce facilities to commit murder-for-hire resulting in death and use of interstate commerce facilities to commit murder-for-hire resulting in death.
#commit #stalking


3 days ago
Henry Winkler is "still working on his perspective" about his relationship with Tom Hanks.
Winkler, 80, gained notoriety for playing Arthur "Fonzie" Fonzarelli on Happy Days, and first crossed paths with Hanks when the now-70-year-old actor landed a guest star role in a 1982 episode of the sitcom.
Hanks went on to star in movies and the pair briefly reunited in 1989 when Winkler signed on to direct Turner & Hooch, only to leave the project soon after due to on-set disagreements.
In September 2026, Winkler talked about his experience working on the movie and his ongoing tension with Hanks on In Depth With Graham Bensinger.
He explained that he worked with Hanks "before he was a movie star," but hinted that he wasn't sure what went wrong with their relationship, as years later, the actor did not seem interested in reuniting.
#winkler #relationship #actor
Winkler, 80, gained notoriety for playing Arthur "Fonzie" Fonzarelli on Happy Days, and first crossed paths with Hanks when the now-70-year-old actor landed a guest star role in a 1982 episode of the sitcom.
Hanks went on to star in movies and the pair briefly reunited in 1989 when Winkler signed on to direct Turner & Hooch, only to leave the project soon after due to on-set disagreements.
In September 2026, Winkler talked about his experience working on the movie and his ongoing tension with Hanks on In Depth With Graham Bensinger.
He explained that he worked with Hanks "before he was a movie star," but hinted that he wasn't sure what went wrong with their relationship, as years later, the actor did not seem interested in reuniting.
#winkler #relationship #actor

3 days ago
Deutsche Bank Aktiengesellschaft (NYSE:DB) said on September 7 that it had settled a Frankfurt lawsuit brought by former banker Dario Schiraldi, according to Reuters. He had sought €152 million in damages, but the settlement amount was not disclosed. The bank said the agreement would have only a small financial effect on third-quarter earnings.
The distinction matters: €152 million was the claim, while the payment remains confidential. The earnings impact also does not establish the cash cost, because a settlement payment may discharge a liability for which an expense was recognized earlier.
Four former employees continue to pursue claims exceeding £600 million in London. The Frankfurt agreement therefore reduces the number of unresolved cases without establishing the cost of resolving the wider dispute.
Deutsche Bank Aktiengesellschaft (NYSE:DB) has removed one source of litigation uncertainty. The Frankfurt court confirmed that Schiraldi withdrew his case ahead of the scheduled hearing. Investors now have management's ***** sment of a limited near-term earnings effect instead of an unresolved damages demand.
The agreement also shows that negotiated resolutions are possible. It was the second settlement involving the six former employees who brought related claims. Further agreements could reduce litigation costs and management distraction if acceptable terms can be reached.
#million
The distinction matters: €152 million was the claim, while the payment remains confidential. The earnings impact also does not establish the cash cost, because a settlement payment may discharge a liability for which an expense was recognized earlier.
Four former employees continue to pursue claims exceeding £600 million in London. The Frankfurt agreement therefore reduces the number of unresolved cases without establishing the cost of resolving the wider dispute.
Deutsche Bank Aktiengesellschaft (NYSE:DB) has removed one source of litigation uncertainty. The Frankfurt court confirmed that Schiraldi withdrew his case ahead of the scheduled hearing. Investors now have management's ***** sment of a limited near-term earnings effect instead of an unresolved damages demand.
The agreement also shows that negotiated resolutions are possible. It was the second settlement involving the six former employees who brought related claims. Further agreements could reduce litigation costs and management distraction if acceptable terms can be reached.
#million


3 days ago
Pampa Energía S.A. (NYSE:PAM) is seeking investors for a potential data center near its Loma de la Lata power plant in Patagonia. Investors favor a 20-to-40-MW pilot, with potential electricity demand reaching up to 500 MW after expansion. Electrical infrastructure for the full concept could cost almost $900 million, according to a September 7 Reuters report.
The Reuters report did not identify an anchor customer, committed financing, or a final investment decision. The electrical estimate does not establish the total development budget or the amount Pampa Energía S.A. (NYSE:PAM) would invest. Those distinctions matter when ****** sing the potential shareholder return.
Pampa Energía S.A. (NYSE:PAM) could turn proximity to generation and gas resources into a commercial advantage. Locating computing demand beside an energy complex offers a starting point for coordinating fuel supply, power delivery, and future expansion.
The attraction for shareholders would be dependable electricity sales under contracts that compensate Pampa Energía S.A. (NYSE:PAM) for the infrastructure and operating risks it ****** umes. A customer with strong credit and a long-term commitment could improve revenue visibility and support financing.
Pampa Energía S.A. (NYSE:PAM) is quoting energy prices to interested parties and aims to reach initial agreements by the end of 2026, according to Reuters. That provides a near-term commercial milestone.
#Potential #electrical #power
The Reuters report did not identify an anchor customer, committed financing, or a final investment decision. The electrical estimate does not establish the total development budget or the amount Pampa Energía S.A. (NYSE:PAM) would invest. Those distinctions matter when ****** sing the potential shareholder return.
Pampa Energía S.A. (NYSE:PAM) could turn proximity to generation and gas resources into a commercial advantage. Locating computing demand beside an energy complex offers a starting point for coordinating fuel supply, power delivery, and future expansion.
The attraction for shareholders would be dependable electricity sales under contracts that compensate Pampa Energía S.A. (NYSE:PAM) for the infrastructure and operating risks it ****** umes. A customer with strong credit and a long-term commitment could improve revenue visibility and support financing.
Pampa Energía S.A. (NYSE:PAM) is quoting energy prices to interested parties and aims to reach initial agreements by the end of 2026, according to Reuters. That provides a near-term commercial milestone.
#Potential #electrical #power

3 days ago
Tamboran Resources Corporation (NYSE:TBN) announced September 7 that it and Daly Waters Energy, LP had begun gas sales from the Shenandoah South Pilot Project into Australia's Northern Territory network. The deliveries mark the Beetaloo Basin's first gas sales and move the project into revenue generation.
The Sturt Plateau Compression Facility has a capacity of approximately 48.5 million cubic feet per day. Contracted supply of approximately 38.8 million cubic feet per day is expected by early 2027 under a long-term take-or-pay agreement with the Northern Territory Government. These are gross project volumes. Commissioning gas receives a discounted price because supply remains interruptible.
Tamboran Resources Corporation (NYSE:TBN) now has a working route from wells through processing infrastructure to a customer. All five wells on the Shenandoah South 2 pad have been drilled, stimulated and connected to the facility. Initial deliveries reduce uncertainty around the physical connection between the resource and its market.
Contracted demand equals 80% of stated processing capacity, providing a substantial foundation for utilization once production reaches the target. Take-or-pay agreements generally require buyers to pay for committed volumes even if they do not take delivery, subject to contractual conditions.
The gas sales agreement specifies a fixed price with annual adjustments linked to Australia's Consumer Price Index. That structure provides more revenue visibility than relying entirely on spot-market demand, although the price remains confidential.
#corporation
The Sturt Plateau Compression Facility has a capacity of approximately 48.5 million cubic feet per day. Contracted supply of approximately 38.8 million cubic feet per day is expected by early 2027 under a long-term take-or-pay agreement with the Northern Territory Government. These are gross project volumes. Commissioning gas receives a discounted price because supply remains interruptible.
Tamboran Resources Corporation (NYSE:TBN) now has a working route from wells through processing infrastructure to a customer. All five wells on the Shenandoah South 2 pad have been drilled, stimulated and connected to the facility. Initial deliveries reduce uncertainty around the physical connection between the resource and its market.
Contracted demand equals 80% of stated processing capacity, providing a substantial foundation for utilization once production reaches the target. Take-or-pay agreements generally require buyers to pay for committed volumes even if they do not take delivery, subject to contractual conditions.
The gas sales agreement specifies a fixed price with annual adjustments linked to Australia's Consumer Price Index. That structure provides more revenue visibility than relying entirely on spot-market demand, although the price remains confidential.
#corporation


4 days ago
Kelly Osbourne loves her mother, but she is not pretending they agree on everything.
Asked directly about Sharon Osbourne's support for British activist Tommy Robinson during an interview with Attitude at London's National Television Awards, Kelly gave an equally direct answer: "I don't agree with my mum, no."
Kelly acknowledged that political disagreements can be uncomfortable inside a family. She said Sharon is entitled to her own opinions, but made clear that her mother's position is "not for me."
The conversation then moved beyond Robinson to Kelly's relationship with the LGBTQ+ community and her mother's views on trans issues. Kelly credited drag queens with teaching her makeup, the trans community with teaching her about bravery and RuPaul's Drag Race with influencing how she presents herself.
The issue Attitude put to Kelly dates back to April, when Sharon's official Instagram account commented "See you at the march" beneath a video promoting Robinson's Unite the Kingdom event in London.
#teaching
Asked directly about Sharon Osbourne's support for British activist Tommy Robinson during an interview with Attitude at London's National Television Awards, Kelly gave an equally direct answer: "I don't agree with my mum, no."
Kelly acknowledged that political disagreements can be uncomfortable inside a family. She said Sharon is entitled to her own opinions, but made clear that her mother's position is "not for me."
The conversation then moved beyond Robinson to Kelly's relationship with the LGBTQ+ community and her mother's views on trans issues. Kelly credited drag queens with teaching her makeup, the trans community with teaching her about bravery and RuPaul's Drag Race with influencing how she presents herself.
The issue Attitude put to Kelly dates back to April, when Sharon's official Instagram account commented "See you at the march" beneath a video promoting Robinson's Unite the Kingdom event in London.
#teaching


4 days ago
Wall Street has bid up defense contractors on geopolitical tensions alongside expanded missile-defense funding, but Northrop Grumman Corporation (NYSE:NOC) remains an outlier. On September 4, 2026, the company secured a $508.5 million Missile Defense Agency contract for ICBM and IRBM target flight-test support running through 2035. The non-competitive contract follows the $3 billion (approx.) in framework agreements to expand solid-rocket-motor production for PAC-3 and THAAD interceptors. Despite these bookings, stock slipped 2.5% to $515. The stock is trading near 16 times earnings and 33% below its peak, making Northrop one of the lowest-multiple prime defense contractors.
Northrop is one of the largest-cap defense contractors with exposure to Golden Dome through ******* e sensors and interceptors, while the Sentinel ICBM and the B-21 bomber provide additional exposure to broader U.S. strategic modernization. The recent bookings back that up: the $508.5 million MDA award, the ~$3 billion PAC-3 and THAAD agreements that will double and triple solid-rocket-motor capacity, and $1.4 billion of IBCS-related U.S. and Polish air-and-missile-defense awards announced in 2025. The latest MDA contract includes cost-plus, cost-reimbursable, and fixed-price-incentive elements, which reduce some financial exposure compared with purely fixed-price development work. Long-term missile-shield funding, however, remains tied to both political and defense bets. Legislative approval introduces timing risk, but the bull thesis is already working.
Execution problems explain the valuation discount. The Sentinel ICBM program triggered a critical Nunn-McCurdy breach after projected costs rose 81% to roughly $141 billion, forcing a Pentagon program restructuring. Concurrently, low-rate initial production on the B-21 bomber generated approximately $2 billion in pre-tax charges on fixed-price commitments. Management must demonstrate that these losses have ceased. Till then, multiple expansion will remain limited. Lockheed trades at roughly 19 times earnings compared with Northrop at about 16 times.
Institutional positioning does not point to aggressiveness in short trades. Our Insider Monkey database tracked 59 hedge funds holding NOC in the second quarter of 2026, compared to 62 in the first quarter. Short interest sits at 1.7% of the float, representing a low number of bets against the stock. Paired with -0.11 beta and a 1.9% dividend yield, the stock offers portfolio diversification at a discounted entry multiple.
#northrop
Northrop is one of the largest-cap defense contractors with exposure to Golden Dome through ******* e sensors and interceptors, while the Sentinel ICBM and the B-21 bomber provide additional exposure to broader U.S. strategic modernization. The recent bookings back that up: the $508.5 million MDA award, the ~$3 billion PAC-3 and THAAD agreements that will double and triple solid-rocket-motor capacity, and $1.4 billion of IBCS-related U.S. and Polish air-and-missile-defense awards announced in 2025. The latest MDA contract includes cost-plus, cost-reimbursable, and fixed-price-incentive elements, which reduce some financial exposure compared with purely fixed-price development work. Long-term missile-shield funding, however, remains tied to both political and defense bets. Legislative approval introduces timing risk, but the bull thesis is already working.
Execution problems explain the valuation discount. The Sentinel ICBM program triggered a critical Nunn-McCurdy breach after projected costs rose 81% to roughly $141 billion, forcing a Pentagon program restructuring. Concurrently, low-rate initial production on the B-21 bomber generated approximately $2 billion in pre-tax charges on fixed-price commitments. Management must demonstrate that these losses have ceased. Till then, multiple expansion will remain limited. Lockheed trades at roughly 19 times earnings compared with Northrop at about 16 times.
Institutional positioning does not point to aggressiveness in short trades. Our Insider Monkey database tracked 59 hedge funds holding NOC in the second quarter of 2026, compared to 62 in the first quarter. Short interest sits at 1.7% of the float, representing a low number of bets against the stock. Paired with -0.11 beta and a 1.9% dividend yield, the stock offers portfolio diversification at a discounted entry multiple.
#northrop

7 days ago
On August 4, Essential Utilities (NYSE:WTRG) reported second-quarter results that read like two different stories stapled together. Revenue climbed, the dividend grew for the 36th time in 35 years, and the merger with American Water inched closer to the finish line. But earnings per share actually dipped from a year earlier, and the company had to strip out merger costs just to show flat profitability. For a utility this steady, that split is worth a closer look.
Essential's regulated water segment posted revenue of $357.5 million in the quarter, up 7.6% from $332.3 million a year earlier, and the whole company's first-half revenue climbed 7.2% to nearly $1.4 billion. Much of that growth came from rate cases: state regulators approved $43.9 million in new annual water revenue across Pennsylvania, Illinois, Ohio, North Carolina and Indiana, plus $12.7 million more for the gas business in Kentucky and Pennsylvania. Another $79.7 million in water rate requests and a $163.2 million gas case in Pennsylvania, tied to replacing aging pipelines, are still working through the process.
The company keeps buying its way into new customers, too. In May, it closed a $4.9 million wastewater deal in Bastrop County, Texas, and it has signed agreements worth roughly $282 million to add over 200,000 more customers in Pennsylvania, Texas, North Carolina and New Jersey, including the $276.5 million purchase of Philadelphia-area sewer authority DELCORA. Since 2015, acquisitions have added more than 138,000 customers to Essential's base.
Layer on the pending American Water merger, which cleared Virginia and Ohio regulators this year after nearly unanimous shareholder approval in February, and Essential is positioning itself as a much larger multi-state utility by early 2027. The board's decision to raise the dividend 5.25% to $0.3606 per share, continuing a streak of 36 increases over 35 years, signals confidence that this growth is durable.
Look past the top line and the picture gets less flattering. Second quarter net income actually fell to $105.7 million from $107.8 million a year ago, pulling GAAP earnings per share down to $0.37 from $0.38. Essential had to report an adjusted $0.38 figure just to exclude merger-related costs and show earnings roughly matching last year's. The slide is sharper over six months: net income dropped to $330.1 million, or $1.16 per share, from $391.6 million, or $1.41 per share, in the first half of 2025.
#water #pennsylvania
Essential's regulated water segment posted revenue of $357.5 million in the quarter, up 7.6% from $332.3 million a year earlier, and the whole company's first-half revenue climbed 7.2% to nearly $1.4 billion. Much of that growth came from rate cases: state regulators approved $43.9 million in new annual water revenue across Pennsylvania, Illinois, Ohio, North Carolina and Indiana, plus $12.7 million more for the gas business in Kentucky and Pennsylvania. Another $79.7 million in water rate requests and a $163.2 million gas case in Pennsylvania, tied to replacing aging pipelines, are still working through the process.
The company keeps buying its way into new customers, too. In May, it closed a $4.9 million wastewater deal in Bastrop County, Texas, and it has signed agreements worth roughly $282 million to add over 200,000 more customers in Pennsylvania, Texas, North Carolina and New Jersey, including the $276.5 million purchase of Philadelphia-area sewer authority DELCORA. Since 2015, acquisitions have added more than 138,000 customers to Essential's base.
Layer on the pending American Water merger, which cleared Virginia and Ohio regulators this year after nearly unanimous shareholder approval in February, and Essential is positioning itself as a much larger multi-state utility by early 2027. The board's decision to raise the dividend 5.25% to $0.3606 per share, continuing a streak of 36 increases over 35 years, signals confidence that this growth is durable.
Look past the top line and the picture gets less flattering. Second quarter net income actually fell to $105.7 million from $107.8 million a year ago, pulling GAAP earnings per share down to $0.37 from $0.38. Essential had to report an adjusted $0.38 figure just to exclude merger-related costs and show earnings roughly matching last year's. The slide is sharper over six months: net income dropped to $330.1 million, or $1.16 per share, from $391.6 million, or $1.41 per share, in the first half of 2025.
#water #pennsylvania
7 days ago
Stewart ***** et Management's flagship portfolio returned 15.97%, net of fees, in the second quarter, and the S&P 500 Index gained 15.20%. YTD, it appreciated 5.37%, net of fees, and the S&P 500 Index gained 10.21%. The letter can be downloaded here. Despite geopolitical uncertainties, share prices surged higher as emerging prospects for a ceasefire in the Middle East restored market composure and investor optimism for continued earnings growth in the second half of the year. Volatility in share prices was noted, particularly tied to industrial trends like AI, with comparisons made to the internet boom and personal computer adoption. Despite concerns about extreme valuations and potential corrections, the conclusion is that strong earnings growth is fundamental to rising share prices, emphasizing the importance of investing in robust businesses. Please check the fund's top five holdings for its best picks in 2026.
In its second-quarter 2026 investor letter, Stewart ***** et Management highlighted Lumentum Holdings Inc. (NASDAQ:LITE). Lumentum Holdings Inc. (NASDAQ:LITE) is a leading technology company that manufactures and sells optical and photonic products. On September 04, 2026, Lumentum Holdings Inc. (NASDAQ:LITE) closed at $881.26 per share. Over the past month, Lumentum Holdings Inc. (NASDAQ:LITE) gained 13.83%, and its shares are up 519.81% over the past year. Lumentum Holdings Inc. (NASDAQ:LITE) has a market capitalization of $79.05 billion, and its stock has traded within a 52-week range of $144.52 to $1,085.68.
Stewart ***** et Management stated the following regarding Lumentum Holdings Inc. (NASDAQ:LITE) in its Q2 2026 investor letter:
"During the quarter we initiated a small investment in Lumentum Holdings Inc. (NASDAQ:LITE), a leader in optical networking — the hardware that moves data between AI chips, servers, and data centers. We believe AI infrastructure spending is driving an optical upgrade cycle from which Lumentum may benefit. Demand outstrips supply, and customer agreements now extend through 2027 as data centers grow in number and size. Capturing this opportunity requires execution on capacity expansion and continued hyperscaler willingness to invest in AI infrastructure. The primary risks ***** ociated with the company are its concentration of revenue from a small number of customers, product timelines shifting and emerging technologies. However, we believe that the positives noted above outweigh these risks."
Lumentum Holdings Inc. (NASDAQ:LITE) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 111 hedge fund portfolios held Lumentum Holdings Inc. (NASDAQ:LITE) at the end of the second quarter, down from 123 in the previous quarter. While we acknowledge the potential of Lumentum Holdings Inc. (NASDAQ:LITE) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that a
In its second-quarter 2026 investor letter, Stewart ***** et Management highlighted Lumentum Holdings Inc. (NASDAQ:LITE). Lumentum Holdings Inc. (NASDAQ:LITE) is a leading technology company that manufactures and sells optical and photonic products. On September 04, 2026, Lumentum Holdings Inc. (NASDAQ:LITE) closed at $881.26 per share. Over the past month, Lumentum Holdings Inc. (NASDAQ:LITE) gained 13.83%, and its shares are up 519.81% over the past year. Lumentum Holdings Inc. (NASDAQ:LITE) has a market capitalization of $79.05 billion, and its stock has traded within a 52-week range of $144.52 to $1,085.68.
Stewart ***** et Management stated the following regarding Lumentum Holdings Inc. (NASDAQ:LITE) in its Q2 2026 investor letter:
"During the quarter we initiated a small investment in Lumentum Holdings Inc. (NASDAQ:LITE), a leader in optical networking — the hardware that moves data between AI chips, servers, and data centers. We believe AI infrastructure spending is driving an optical upgrade cycle from which Lumentum may benefit. Demand outstrips supply, and customer agreements now extend through 2027 as data centers grow in number and size. Capturing this opportunity requires execution on capacity expansion and continued hyperscaler willingness to invest in AI infrastructure. The primary risks ***** ociated with the company are its concentration of revenue from a small number of customers, product timelines shifting and emerging technologies. However, we believe that the positives noted above outweigh these risks."
Lumentum Holdings Inc. (NASDAQ:LITE) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 111 hedge fund portfolios held Lumentum Holdings Inc. (NASDAQ:LITE) at the end of the second quarter, down from 123 in the previous quarter. While we acknowledge the potential of Lumentum Holdings Inc. (NASDAQ:LITE) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that a
7 days ago
Turkish Airlines will become Liverpool's new front-of-shirt sponsor from the start of the 2027/28 season, the Premier League giants announced on Tuesday.
No fee was disclosed by the club, but the BBC reported that the five-year deal was worth £300 million ($406 million) in total.
A contract worth more than £60 million a season, would represent an increase on the current £50 million-per-season deal with retail bank Standard Chartered, who have been the Reds' front-of-shirt sponsor since 2010.
Liverpool's new deal is believed to be the most lucrative purely front-of-shirt agreement in Premier League history, with **** nal and Manchester City's agreements with Emirates and Etihad Airways respectively also involving stadium naming rights.
By contrast, six-time European champions Liverpool's home ground is still solely known by its original name of Anfield.
#million #front #sponsor #worth
No fee was disclosed by the club, but the BBC reported that the five-year deal was worth £300 million ($406 million) in total.
A contract worth more than £60 million a season, would represent an increase on the current £50 million-per-season deal with retail bank Standard Chartered, who have been the Reds' front-of-shirt sponsor since 2010.
Liverpool's new deal is believed to be the most lucrative purely front-of-shirt agreement in Premier League history, with **** nal and Manchester City's agreements with Emirates and Etihad Airways respectively also involving stadium naming rights.
By contrast, six-time European champions Liverpool's home ground is still solely known by its original name of Anfield.
#million #front #sponsor #worth


8 days ago
NRG Energy gained 6.4% and Constellation Energy rose 4.9% on September 4 while the S&P 500 fell 0.4%. The gains were consistent with the broader AI-power trade where data-center projects increasingly depend on generators that can add reliable capacity, navigate interconnection queues, and sign contracts before construction. NRG Energy, Inc. (NYSE:NRG) and Constellation Energy Corporation (NASDAQ:CEG) offer different versions of that opportunity.
NRG is advancing a Bring Your Own Power strategy with a hyperscaler for a 1.2-gigawatt combined-cycle gas project in Texas. It also brought a 415-megawatt facility into commercial operation and reported $1.03 billion of second-quarter free cash flow before growth investments. The bull case is speed: pairing contracted data-center load with dispatchable generation can bypass part of the grid bottleneck. The bear case is project execution, fuel exposure, financing, and the possibility that forecast load never materializes.
Insider Monkey counted 59 hedge funds holding NRG Energy, Inc. (NYSE:NRG) at June 30, down from 76 at March 31. Israel Englander's Millennium Management nevertheless disclosed 4,257,712 shares, 115% more than in Q1. The contrast between a falling fund count and one manager's larger position argues against treating institutional sentiment as uniform.
Constellation brings the largest U.S. nuclear fleet plus gas **** ets acquired with Calpine. It raised full-year adjusted operating EPS guidance to $11.50 to $12.50 and said it had signed another 920 megawatts of long-term power agreements. The bull case is scarce around-the-clock clean generation. The bear case includes plant outages, regulatory intervention, integration risk, and the danger of overpaying to expand capacity during a demand boom.
Seventy-three hedge funds held Constellation Energy Corporation (NASDAQ:CEG) in Q2, down from 79 in Q1. Philippe Laffont's Coatue Management disclosed 4,632,475 shares at quarter-end; the available profile did not show a usable sequential activity figure, so no motive or timing is inferred.
#energy #management
NRG is advancing a Bring Your Own Power strategy with a hyperscaler for a 1.2-gigawatt combined-cycle gas project in Texas. It also brought a 415-megawatt facility into commercial operation and reported $1.03 billion of second-quarter free cash flow before growth investments. The bull case is speed: pairing contracted data-center load with dispatchable generation can bypass part of the grid bottleneck. The bear case is project execution, fuel exposure, financing, and the possibility that forecast load never materializes.
Insider Monkey counted 59 hedge funds holding NRG Energy, Inc. (NYSE:NRG) at June 30, down from 76 at March 31. Israel Englander's Millennium Management nevertheless disclosed 4,257,712 shares, 115% more than in Q1. The contrast between a falling fund count and one manager's larger position argues against treating institutional sentiment as uniform.
Constellation brings the largest U.S. nuclear fleet plus gas **** ets acquired with Calpine. It raised full-year adjusted operating EPS guidance to $11.50 to $12.50 and said it had signed another 920 megawatts of long-term power agreements. The bull case is scarce around-the-clock clean generation. The bear case includes plant outages, regulatory intervention, integration risk, and the danger of overpaying to expand capacity during a demand boom.
Seventy-three hedge funds held Constellation Energy Corporation (NASDAQ:CEG) in Q2, down from 79 in Q1. Philippe Laffont's Coatue Management disclosed 4,632,475 shares at quarter-end; the available profile did not show a usable sequential activity figure, so no motive or timing is inferred.
#energy #management

8 days ago
On September 2, ChargePoint Holdings, Inc (NYSE:CHPT) reported stronger-than-expected results for the second quarter of fiscal 2027. Revenue and the company's loss per share both came in better than Wall Street expectations and the company also reported record non-GAAP gross margin while also highlighting continued progress across its charging business.
Q2 revenue increased 18% year-over-year to $116.1 million, exceeding the $105.2 million ****** yst estimate. ChargePoint Holdings, Inc (NYSE:CHPT) reported an adjusted loss of 35 cents per share, compared with ****** ysts' expectations for a loss of 85 cents per share, according to average estimates compiled by LSEG.
The company also benefited from higher North American home-charging sales, which helped push revenue above expectations. Networked charging systems revenue was up 25% year-over-year as it reached $62.9 million. Subscription revenue increased 10% to $43.7 million. Additionally, the company reported a 78% improvement in its non-GAAP adjusted EBITDA loss, which narrowed sharply to $4.8 million from $22.1 million in the same quarter last year.
ChargePoint Holdings, Inc (NYSE:CHPT) expanded its commercial relationships during the quarter as it extended its long-standing partnership with Mercedes-Benz through a new agreement covering charging solutions for fleet operators in the UK and Germany. The company also announced agreements with Optimus Energy Solutions and Onvo that are expected to add hundreds of new charging ports across the eastern US.
The company also appointed automotive industry veteran John Saffrett as Executive Vice President and Managing Director for Europe, where he will be overseeing sales, customer relationships, partnerships, and market expansion.
#revenue #holdings #chpt
Q2 revenue increased 18% year-over-year to $116.1 million, exceeding the $105.2 million ****** yst estimate. ChargePoint Holdings, Inc (NYSE:CHPT) reported an adjusted loss of 35 cents per share, compared with ****** ysts' expectations for a loss of 85 cents per share, according to average estimates compiled by LSEG.
The company also benefited from higher North American home-charging sales, which helped push revenue above expectations. Networked charging systems revenue was up 25% year-over-year as it reached $62.9 million. Subscription revenue increased 10% to $43.7 million. Additionally, the company reported a 78% improvement in its non-GAAP adjusted EBITDA loss, which narrowed sharply to $4.8 million from $22.1 million in the same quarter last year.
ChargePoint Holdings, Inc (NYSE:CHPT) expanded its commercial relationships during the quarter as it extended its long-standing partnership with Mercedes-Benz through a new agreement covering charging solutions for fleet operators in the UK and Germany. The company also announced agreements with Optimus Energy Solutions and Onvo that are expected to add hundreds of new charging ports across the eastern US.
The company also appointed automotive industry veteran John Saffrett as Executive Vice President and Managing Director for Europe, where he will be overseeing sales, customer relationships, partnerships, and market expansion.
#revenue #holdings #chpt

8 days ago
On August 4, Essential Utilities (NYSE:WTRG) reported second-quarter results that read like two different stories stapled together. Revenue climbed, the dividend grew for the 36th time in 35 years, and the merger with American Water inched closer to the finish line. But earnings per share actually dipped from a year earlier, and the company had to strip out merger costs just to show flat profitability. For a utility this steady, that split is worth a closer look.
Essential's regulated water segment posted revenue of $357.5 million in the quarter, up 7.6% from $332.3 million a year earlier, and the whole company's first-half revenue climbed 7.2% to nearly $1.4 billion. Much of that growth came from rate cases: state regulators approved $43.9 million in new annual water revenue across Pennsylvania, Illinois, Ohio, North Carolina and Indiana, plus $12.7 million more for the gas business in Kentucky and Pennsylvania. Another $79.7 million in water rate requests and a $163.2 million gas case in Pennsylvania, tied to replacing aging pipelines, are still working through the process.
The company keeps buying its way into new customers, too. In May, it closed a $4.9 million wastewater deal in Bastrop County, Texas, and it has signed agreements worth roughly $282 million to add over 200,000 more customers in Pennsylvania, Texas, North Carolina and New Jersey, including the $276.5 million purchase of Philadelphia-area sewer authority DELCORA. Since 2015, acquisitions have added more than 138,000 customers to Essential's base.
Layer on the pending American Water merger, which cleared Virginia and Ohio regulators this year after nearly unanimous shareholder approval in February, and Essential is positioning itself as a much larger multi-state utility by early 2027. The board's decision to raise the dividend 5.25% to $0.3606 per share, continuing a streak of 36 increases over 35 years, signals confidence that this growth is durable.
Look past the top line and the picture gets less flattering. Second quarter net income actually fell to $105.7 million from $107.8 million a year ago, pulling GAAP earnings per share down to $0.37 from $0.38. Essential had to report an adjusted $0.38 figure just to exclude merger-related costs and show earnings roughly matching last year's. The slide is sharper over six months: net income dropped to $330.1 million, or $1.16 per share, from $391.6 million, or $1.41 per share, in the first half of 2025.
#million #revenue #merger #year
Essential's regulated water segment posted revenue of $357.5 million in the quarter, up 7.6% from $332.3 million a year earlier, and the whole company's first-half revenue climbed 7.2% to nearly $1.4 billion. Much of that growth came from rate cases: state regulators approved $43.9 million in new annual water revenue across Pennsylvania, Illinois, Ohio, North Carolina and Indiana, plus $12.7 million more for the gas business in Kentucky and Pennsylvania. Another $79.7 million in water rate requests and a $163.2 million gas case in Pennsylvania, tied to replacing aging pipelines, are still working through the process.
The company keeps buying its way into new customers, too. In May, it closed a $4.9 million wastewater deal in Bastrop County, Texas, and it has signed agreements worth roughly $282 million to add over 200,000 more customers in Pennsylvania, Texas, North Carolina and New Jersey, including the $276.5 million purchase of Philadelphia-area sewer authority DELCORA. Since 2015, acquisitions have added more than 138,000 customers to Essential's base.
Layer on the pending American Water merger, which cleared Virginia and Ohio regulators this year after nearly unanimous shareholder approval in February, and Essential is positioning itself as a much larger multi-state utility by early 2027. The board's decision to raise the dividend 5.25% to $0.3606 per share, continuing a streak of 36 increases over 35 years, signals confidence that this growth is durable.
Look past the top line and the picture gets less flattering. Second quarter net income actually fell to $105.7 million from $107.8 million a year ago, pulling GAAP earnings per share down to $0.37 from $0.38. Essential had to report an adjusted $0.38 figure just to exclude merger-related costs and show earnings roughly matching last year's. The slide is sharper over six months: net income dropped to $330.1 million, or $1.16 per share, from $391.6 million, or $1.41 per share, in the first half of 2025.
#million #revenue #merger #year

8 days ago
The dispute surrounding Ahmed Sayed "Zizo" has moved beyond the football authorities after Zamalek treasurer Hossam El-Mandouh revealed plans to raise questions over player contracts in Parliament.
El-Mandouh, who is also a member of the Egyptian House of Representatives, believes the figures surrounding Zizo's contract warrant further scrutiny and has called for state intervention in reviewing footballers' agreements.
Photo by Stefan Koops/EYE4IMAGES/NurPhoto via Getty Images
El-Mandouh's comments centre on an alleged difference between the amount a player requested from Zamalek and the value of the contract registered with the Egyptian Football **** ociation.
"There was a player who asked us (Zamalek) for 80 million pounds per season, and then we hear that his contract at the Football **** ociation is only 5 million pounds. So is this something logical?"
#zamalek #contract #surrounding #million
El-Mandouh, who is also a member of the Egyptian House of Representatives, believes the figures surrounding Zizo's contract warrant further scrutiny and has called for state intervention in reviewing footballers' agreements.
Photo by Stefan Koops/EYE4IMAGES/NurPhoto via Getty Images
El-Mandouh's comments centre on an alleged difference between the amount a player requested from Zamalek and the value of the contract registered with the Egyptian Football **** ociation.
"There was a player who asked us (Zamalek) for 80 million pounds per season, and then we hear that his contract at the Football **** ociation is only 5 million pounds. So is this something logical?"
#zamalek #contract #surrounding #million



9 days ago
Shares of NuScale Power (NYSE:SMR) trade around $9.63 as of this writing, down about 83% from their $57.42 52-week high.
But the demand that sent nuclear stocks soaring in the first place hasn't reversed. Constellation Energy (NASDAQ:CEG), for instance, reported an additional 920 megawatts of long-term power purchase agreements alongside its second-quarter results.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
In other words, the crash and the demand can both be true at once, because these companies do very different jobs. NuScale designs reactors, Cameco (NYSE:CCJ) sells the fuel, and Constellation already sells the power. A $2,000 investment split across the three buys three different claims on the same electricity demand.
Image source: The Motley Fool.
#power #constellation #down #first
But the demand that sent nuclear stocks soaring in the first place hasn't reversed. Constellation Energy (NASDAQ:CEG), for instance, reported an additional 920 megawatts of long-term power purchase agreements alongside its second-quarter results.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
In other words, the crash and the demand can both be true at once, because these companies do very different jobs. NuScale designs reactors, Cameco (NYSE:CCJ) sells the fuel, and Constellation already sells the power. A $2,000 investment split across the three buys three different claims on the same electricity demand.
Image source: The Motley Fool.
#power #constellation #down #first

9 days ago
Wall Street delivered a sharp split on September 4. The S&P 500 fell 0.4% after a stronger-than-expected jobs report lifted rate concerns, but Sandisk jumped 11.9% and Micron gained 6.1%. The divergence matters because it was not a broad risk-on move. The pattern was consistent with investors rotating toward memory and storage suppliers that help keep AI systems fed with data. That put Sandisk Corporation (NASDAQ:SNDK) and Micron Technology, Inc. (NASDAQ:MU) at the center of the session.
Source: Sandisk Corporation
Sandisk offers the purer NAND and flash-storage argument. Its August results established data center as a key growth pillar, and management said it had signed five more new-business-model agreements since April. The bull case is that AI expands high-value enterprise storage demand while tighter supply supports pricing. The bear case is cyclicality: customer agreements cannot eliminate inventory swings, pricing reversals, or the execution risk that comes with a newly independent public company.
Professional ownership broadened before Friday's rally. Insider Monkey counted 128 hedge funds holding Sandisk Corporation (NASDAQ:SNDK) at June 30, up from 114 at March 31. Leopold Aschenbrenner's Situational Awareness LP disclosed 2,495,344 shares, about 119% more than the 1,140,119 shares reported in Q1. Those filings are quarter-end snapshots and do not show what the funds did during the September move.
Micron supplies both high-bandwidth memory and conventional DRAM and NAND. Its fiscal third-quarter revenue reached $41.46 billion, while Cloud Memory revenue rose to $13.77 billion and Core Data Center revenue to $11.52 billion. That operating leverage is the bull case. The counterargument is that extraordinary margins invite capacity additions, and today's scarcity economics may normalize faster than investors expect.
#sandisk #corporation #center #storage
Source: Sandisk Corporation
Sandisk offers the purer NAND and flash-storage argument. Its August results established data center as a key growth pillar, and management said it had signed five more new-business-model agreements since April. The bull case is that AI expands high-value enterprise storage demand while tighter supply supports pricing. The bear case is cyclicality: customer agreements cannot eliminate inventory swings, pricing reversals, or the execution risk that comes with a newly independent public company.
Professional ownership broadened before Friday's rally. Insider Monkey counted 128 hedge funds holding Sandisk Corporation (NASDAQ:SNDK) at June 30, up from 114 at March 31. Leopold Aschenbrenner's Situational Awareness LP disclosed 2,495,344 shares, about 119% more than the 1,140,119 shares reported in Q1. Those filings are quarter-end snapshots and do not show what the funds did during the September move.
Micron supplies both high-bandwidth memory and conventional DRAM and NAND. Its fiscal third-quarter revenue reached $41.46 billion, while Cloud Memory revenue rose to $13.77 billion and Core Data Center revenue to $11.52 billion. That operating leverage is the bull case. The counterargument is that extraordinary margins invite capacity additions, and today's scarcity economics may normalize faster than investors expect.
#sandisk #corporation #center #storage

9 days ago
On August 5, Southwest Gas Holdings (NYSE:SWX) reported second quarter results for the period ended June 30 and reaffirmed its full year 2026 guidance. Net income attributable to the company reached $42.1 million, a sharp turnaround from a $40.2 million loss in the same quarter of 2025. But the number that stood out was the Great Basin 2028 Expansion Project, where contracted demand has grown enough that management now expects capital costs of $2.3 billion instead of the $1.7 billion baked into current five year guidance.
Southwest Gas's growth story increasingly runs through Nevada. Binding precedent agreements for the Great Basin 2028 Expansion Project have grown to roughly 1 billion cubic feet per day of contracted demand, and the company has fielded another 1.8 billion cubic feet of expressions of interest for phases running from 2029 through 2035. Based on that demand, management now projects an annual margin of $270 million to $300 million once the pipeline is in service, on capital investment of about $2.3 billion.
Regulators have been cooperating too. California's Public Utilities Commission approved the non-cost-of-capital pieces of Southwest Gas's rate case, adding roughly $40 million of incremental annual revenue and triggering recognition of $9.7 million of previously deferred first-quarter income. Nevada regulators approved a Triennial Resource Plan with prudency pre-determinations for about $186 million of capital spending, and the company filed for a general rate case increase of roughly $74 million.
Arizona's new System Integrity Mechanism, effective April 1 this year, lets Southwest Gas recover safety and reliability spending faster, up to a $50 million annual cap. The company put $520 million into its network in the first six months of 2026, including $115 million toward Great Basin, and closed the quarter with $270.5 million in cash and nearly $1 billion in available liquidity.
Look past the headline swing to profit, and the picture gets murkier. The core natural gas distribution segment actually earned less this quarter, with its contribution to net income falling from $45.6 million a year earlier to $40.8 million, and its adjusted net income slipping from $33.7 million to $31 million. Depreciation and amortization rose $8.7 million, or 13%, as gas plant in service grew 7% year over year, a reminder that heavy pipeline spending shows up in expenses well before it shows up in rates.
#million #company #basin
Southwest Gas's growth story increasingly runs through Nevada. Binding precedent agreements for the Great Basin 2028 Expansion Project have grown to roughly 1 billion cubic feet per day of contracted demand, and the company has fielded another 1.8 billion cubic feet of expressions of interest for phases running from 2029 through 2035. Based on that demand, management now projects an annual margin of $270 million to $300 million once the pipeline is in service, on capital investment of about $2.3 billion.
Regulators have been cooperating too. California's Public Utilities Commission approved the non-cost-of-capital pieces of Southwest Gas's rate case, adding roughly $40 million of incremental annual revenue and triggering recognition of $9.7 million of previously deferred first-quarter income. Nevada regulators approved a Triennial Resource Plan with prudency pre-determinations for about $186 million of capital spending, and the company filed for a general rate case increase of roughly $74 million.
Arizona's new System Integrity Mechanism, effective April 1 this year, lets Southwest Gas recover safety and reliability spending faster, up to a $50 million annual cap. The company put $520 million into its network in the first six months of 2026, including $115 million toward Great Basin, and closed the quarter with $270.5 million in cash and nearly $1 billion in available liquidity.
Look past the headline swing to profit, and the picture gets murkier. The core natural gas distribution segment actually earned less this quarter, with its contribution to net income falling from $45.6 million a year earlier to $40.8 million, and its adjusted net income slipping from $33.7 million to $31 million. Depreciation and amortization rose $8.7 million, or 13%, as gas plant in service grew 7% year over year, a reminder that heavy pipeline spending shows up in expenses well before it shows up in rates.
#million #company #basin


10 days ago
C3.ai's fiscal first-quarter results replaced a speculative earnings setup with a mixed turnaround test. The company reported $52.4 million of revenue, within its $50 million to $54 million guidance but down 25% from $70.3 million a year earlier. Subscription revenue was $49.2 million, or 94% of total revenue, compared with $60.3 million in the prior-year quarter. C3.ai, Inc. (NYSE:AI) therefore stabilized within management's lowered expectations, without yet returning to growth.
There were encouraging operating signals. Bookings increased 73% sequentially, the company signed 22 agreements, and free cash flow improved to positive $2.1 million from negative $34.3 million a year earlier. Its non-GAAP operating loss narrowed 33% sequentially to $36.2 million. Management guided fiscal second-quarter revenue to $51 million to $55 million and maintained full-year revenue guidance of $210 million to $240 million. Still, both ranges imply that a rapid return to the prior year's scale is unlikely.
Those figures complicate, rather than erase, DA Davidson ***** yst Lucky Schreiner's bearish case. In a September 1 note, Schreiner reiterated an Underperform rating and a $7 target, while seeing possible professional-services upside and stabilization in subscription trends. Revenue landed near the middle of guidance, and subscription revenue represented a larger share of the mix. However, stabilization at a much lower level is not the same as renewed expansion.
The bearish evidence remains substantial. GAAP gross margin was only 32%, and the company posted a $92.8 million GAAP net loss, or $0.60 per share. C3.ai, Inc. (NYSE:AI) still competes against cloud providers, data platforms, and customers building applications internally. Better bookings and cash flow must translate into durable subscription growth and improving margins before the results demonstrate an economic turnaround.
Hedge funds showed cautious improvement rather than conviction. Insider Monkey counted 29 hedge funds holding the shares in Q2, up from 25 in Q1. Point72 ***** et Management increased its position 154% to 568,406 shares. That is notable, but 13F filings reveal positions rather than investment rationales.
#gaap #company #guidance #NYSE
There were encouraging operating signals. Bookings increased 73% sequentially, the company signed 22 agreements, and free cash flow improved to positive $2.1 million from negative $34.3 million a year earlier. Its non-GAAP operating loss narrowed 33% sequentially to $36.2 million. Management guided fiscal second-quarter revenue to $51 million to $55 million and maintained full-year revenue guidance of $210 million to $240 million. Still, both ranges imply that a rapid return to the prior year's scale is unlikely.
Those figures complicate, rather than erase, DA Davidson ***** yst Lucky Schreiner's bearish case. In a September 1 note, Schreiner reiterated an Underperform rating and a $7 target, while seeing possible professional-services upside and stabilization in subscription trends. Revenue landed near the middle of guidance, and subscription revenue represented a larger share of the mix. However, stabilization at a much lower level is not the same as renewed expansion.
The bearish evidence remains substantial. GAAP gross margin was only 32%, and the company posted a $92.8 million GAAP net loss, or $0.60 per share. C3.ai, Inc. (NYSE:AI) still competes against cloud providers, data platforms, and customers building applications internally. Better bookings and cash flow must translate into durable subscription growth and improving margins before the results demonstrate an economic turnaround.
Hedge funds showed cautious improvement rather than conviction. Insider Monkey counted 29 hedge funds holding the shares in Q2, up from 25 in Q1. Point72 ***** et Management increased its position 154% to 568,406 shares. That is notable, but 13F filings reveal positions rather than investment rationales.
#gaap #company #guidance #NYSE

10 days ago
We ran an **** ysis based on Insider Monkey's proprietary database to see which real estate stocks billionaire-led funds held at the end of the second quarter. We narrowed the list to names paying dividend yields above 5%. Two stood out.
VICI Properties Inc. (NYSE:VICI) came in first. A total of 22 billionaire-led funds held stakes in the company at the end of the second quarter. VICI owns casino and gaming real estate and leases the properties back to operators under triple-net agreements, which means tenants cover taxes, insurance and maintenance. It has a dividend yield of about 7%.
Gaming and Leisure Properties, Inc. (NASDAQ:GLPI) was in about 19 billionaire-led fund portfolios as of the end of the June quarter, up from 16 in the first quarter. The stock has a dividend yield of about 7.5%. In this article, we will focus on Gaming and Leisure Properties, Inc. (NASDAQ:GLPI).
Gaming and Leisure Properties, Inc. (NASDAQ:GLPI) is a REIT focusing on casino properties. In the most recent quarter, its revenue rose about 9% year over year and beat estimates. Management raised its full-year fiscal 2026 outlook for adjusted funds from operations.
Photo by Breno **** is on Unsplash
#quarter #NASDAQ #Dividend
VICI Properties Inc. (NYSE:VICI) came in first. A total of 22 billionaire-led funds held stakes in the company at the end of the second quarter. VICI owns casino and gaming real estate and leases the properties back to operators under triple-net agreements, which means tenants cover taxes, insurance and maintenance. It has a dividend yield of about 7%.
Gaming and Leisure Properties, Inc. (NASDAQ:GLPI) was in about 19 billionaire-led fund portfolios as of the end of the June quarter, up from 16 in the first quarter. The stock has a dividend yield of about 7.5%. In this article, we will focus on Gaming and Leisure Properties, Inc. (NASDAQ:GLPI).
Gaming and Leisure Properties, Inc. (NASDAQ:GLPI) is a REIT focusing on casino properties. In the most recent quarter, its revenue rose about 9% year over year and beat estimates. Management raised its full-year fiscal 2026 outlook for adjusted funds from operations.
Photo by Breno **** is on Unsplash
#quarter #NASDAQ #Dividend

11 days ago
On August 25, Electromed (NASDAQ:ELMD) reported fiscal fourth-quarter results that extended a streak few small-cap medical device companies can claim: fifteen consecutive quarters of year-over-year revenue and profit growth. Net revenue hit a record $19.4 million, up 11.6% from a year earlier, and diluted earnings per share climbed to $0.39 from $0.25. Those headline numbers look clean, but they arrive alongside a leadership change and a hospital business moving in the opposite direction, which makes the quarter more complicated than the growth streak suggests.
Home care is still the whole story here. Home care revenue reached $17.7 million in the quarter, up 15.2% year over year, and for the full fiscal year it grew 16.3% to $66.6 million. That growth is coming from efficiency, not just headcount: on an annualized basis, home care revenue worked out to $1,145,000 per rep, above the company's own target range of $1 million to $1.1 million. Electromed ended the year with 64 direct sales reps and is targeting 67 filled territories for fiscal 2027, including two hospital account liaisons meant to catch patients as they move from acute care into home-based therapy.
The addressable market behind that growth still looks large. Management estimates roughly 1 million people in the U.S. carry a bronchiectasis diagnosis, yet only about 16% currently use high-frequency chest wall oscillation therapy, leaving close to 800,000 diagnosed patients untreated, plus more than 4 million additional people who may have the condition without a diagnosis at all. Payer access has kept pace with that opportunity.
Electromed closed the fiscal year with 87% of US covered lives under contract after signing 40 new payer agreements and adding 6 million covered lives. Its Smart Order e-prescribing tool handled 45% of fourth-quarter orders and shipped them noticeably faster than fax submissions, which matters as CMS rules phase out fax-based ordering by May 2028. All of this sits on a debt-free balance sheet, with cash growing to $20.5 million even after $3.9 million in share repurchases during the year.
The weaker spots are easy to miss next to those numbers. Hospital revenue fell 29% in the fourth quarter, which CEO James Cunniff attributed to a sales cycle that is "inherently less predictable than our other channels." The distributor channel grew just 2% in the quarter, and combined, the non-home care business grew only 6.7% for the full year versus 16.3% in home care, meaning nearly all of Electromed's growth is coming from one channel. SG&A expenses rose 8.7% to $42.7 million for the year, driven mainly by higher sales, marketing, and reimbursement compensation, and accounts receivable climbed to $29.8 million from $24.7 million as the business scaled up.
#quarter #Growth #electromed #hospital
Home care is still the whole story here. Home care revenue reached $17.7 million in the quarter, up 15.2% year over year, and for the full fiscal year it grew 16.3% to $66.6 million. That growth is coming from efficiency, not just headcount: on an annualized basis, home care revenue worked out to $1,145,000 per rep, above the company's own target range of $1 million to $1.1 million. Electromed ended the year with 64 direct sales reps and is targeting 67 filled territories for fiscal 2027, including two hospital account liaisons meant to catch patients as they move from acute care into home-based therapy.
The addressable market behind that growth still looks large. Management estimates roughly 1 million people in the U.S. carry a bronchiectasis diagnosis, yet only about 16% currently use high-frequency chest wall oscillation therapy, leaving close to 800,000 diagnosed patients untreated, plus more than 4 million additional people who may have the condition without a diagnosis at all. Payer access has kept pace with that opportunity.
Electromed closed the fiscal year with 87% of US covered lives under contract after signing 40 new payer agreements and adding 6 million covered lives. Its Smart Order e-prescribing tool handled 45% of fourth-quarter orders and shipped them noticeably faster than fax submissions, which matters as CMS rules phase out fax-based ordering by May 2028. All of this sits on a debt-free balance sheet, with cash growing to $20.5 million even after $3.9 million in share repurchases during the year.
The weaker spots are easy to miss next to those numbers. Hospital revenue fell 29% in the fourth quarter, which CEO James Cunniff attributed to a sales cycle that is "inherently less predictable than our other channels." The distributor channel grew just 2% in the quarter, and combined, the non-home care business grew only 6.7% for the full year versus 16.3% in home care, meaning nearly all of Electromed's growth is coming from one channel. SG&A expenses rose 8.7% to $42.7 million for the year, driven mainly by higher sales, marketing, and reimbursement compensation, and accounts receivable climbed to $29.8 million from $24.7 million as the business scaled up.
#quarter #Growth #electromed #hospital


11 days ago
Florida-headquartered ONE Nuclear Energy said the company has executed a binding letter of intent (LOI) that would provide site control for development of Project Cayman, a 2.88-GW gas-fired power plant and 700-MW/2.88 GWh battery energy storage system (BESS) sited alongside a data center complex.The LOI was signed with what One Nuclear in an August 31 news release called a "prominent Louisiana landowner group." The company said the strategy aligns with Louisiana utility Entergy's continuing buildout of regional electricity transmission infrastructure."Project Cayman, with its 2.88-GW power capacity, demonstrates that One Nuclear is committed to supporting the future economic development of one of Louisiana's most important industrial regions," said Richard Taylor, CEO of One Nuclear. "The project will deliver the reliable energy needed to support new investment, create jobs, expand the local tax base and generate additional funding for community priorities and critical infrastructure."
Project Cayman is located near the RiverPlex MegaPark, a 17,000-acre heavy industrial site on the west bank of the Mississippi River in Ascension Parish, Louisiana. The location is northeast of ****** eX's recently announced $100-billion project to build its largest launch facility yet, called Starbase, Louisiana, in coastal Vermilion Parish. Project Cayman, along with serving data centers, is expected to support regional economic development for other industrial projects.One Nuclear said it will hold a series of public information meetings with local parishes, governmental agencies, and other project stakeholders from now through the end of the year.
[evtx_block slug="dpx-26-textblock"]
"ONE Nuclear is proud to invest in the region to support the rapidly growing energy needs created by other recently announced developments such as the ****** eX Starbase project and Hyundai's $5.8-billion steel mill," said Taylor. The company did not disclose details about the data center development, including the companies involved.
One Nuclear supports advanced small modular nuclear reactor (SMR) technology along with utility-scale gas-fired power plants. It currently has projects in Washington state, Texas, and New Mexico. The company has said its strategy is to build natural gas-fired generation to serve industrial sites that could later transition to the use of nuclear power through SMRs.Louisiana officials, unlike those in some other states, have signaled their support for data centers. Several major projects are underway or planned. Tech giant Meta is developing a 5-GW campus in Richland Parish. Amazon Web Services earlier this year said the company plans to invest $12 billion to build data center campuses in northwest Louisiana.Meta last year signed power purchase agreements with Treaty Oak Clean Energy for solar power in Louisiana. Entergy Louisiana in 2024 said it would build gigawatts of new natural gas-fired power generation to support Meta's operations in the sta
Project Cayman is located near the RiverPlex MegaPark, a 17,000-acre heavy industrial site on the west bank of the Mississippi River in Ascension Parish, Louisiana. The location is northeast of ****** eX's recently announced $100-billion project to build its largest launch facility yet, called Starbase, Louisiana, in coastal Vermilion Parish. Project Cayman, along with serving data centers, is expected to support regional economic development for other industrial projects.One Nuclear said it will hold a series of public information meetings with local parishes, governmental agencies, and other project stakeholders from now through the end of the year.
[evtx_block slug="dpx-26-textblock"]
"ONE Nuclear is proud to invest in the region to support the rapidly growing energy needs created by other recently announced developments such as the ****** eX Starbase project and Hyundai's $5.8-billion steel mill," said Taylor. The company did not disclose details about the data center development, including the companies involved.
One Nuclear supports advanced small modular nuclear reactor (SMR) technology along with utility-scale gas-fired power plants. It currently has projects in Washington state, Texas, and New Mexico. The company has said its strategy is to build natural gas-fired generation to serve industrial sites that could later transition to the use of nuclear power through SMRs.Louisiana officials, unlike those in some other states, have signaled their support for data centers. Several major projects are underway or planned. Tech giant Meta is developing a 5-GW campus in Richland Parish. Amazon Web Services earlier this year said the company plans to invest $12 billion to build data center campuses in northwest Louisiana.Meta last year signed power purchase agreements with Treaty Oak Clean Energy for solar power in Louisiana. Entergy Louisiana in 2024 said it would build gigawatts of new natural gas-fired power generation to support Meta's operations in the sta
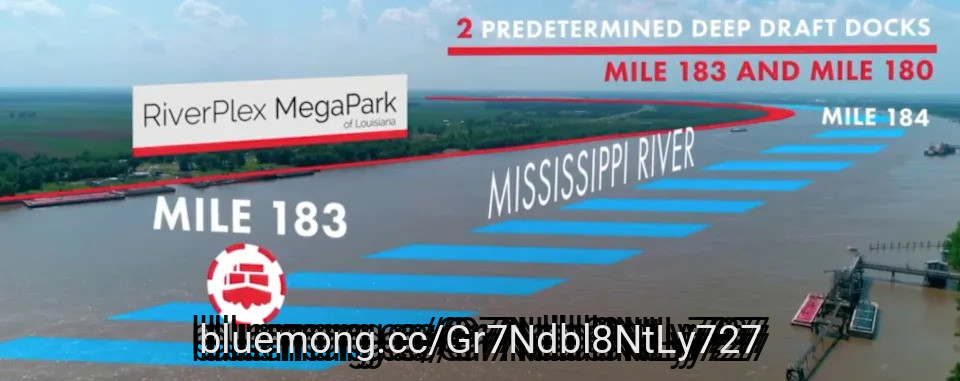
11 days ago
Chevron will invest more than $7 billion in Venezuela over the next five years and more than double its oil production in the country to about 600,000 barrels per day, Reuters reported Wednesday.
The investment follows new agreements with Venezuela that give Chevron improved fiscal, commercial and legal terms and additional acreage in the Orinoco Belt. Chevron said its three Venezuelan joint ventures will invest the money through 2031, with total production costs remaining below $20 per barrel.
Chevron currently produces about 290,000 bpd in Venezuela, all of which is exported to the United States, according to Reuters. Venezuela is producing about 1.1 million to 1.2 million bpd, down from more than 3 million bpd in the late 1990s.
The new acreage includes the Carabobo-1 and Carabobo-2-South-A areas in the Orinoco Belt, ******* igned to Petroindependencia, the joint venture in which Chevron holds a 49% interest. Chevron also increased its Petroindependencia stake to 49% in April and received rights to develop the Ayacucho 8 area next to its Petropiar venture. Its three Venezuelan joint ventures have increased production by 15% so far this year.
Wednesday's announcement puts a dollar figure and production target on the Chevron agreements that were nearing completion earlier this week. Those agreements were previously described only as being of "significant size," with Chevron seeking additional Orinoco Belt acreage.
#venezuela #joint #reuters
The investment follows new agreements with Venezuela that give Chevron improved fiscal, commercial and legal terms and additional acreage in the Orinoco Belt. Chevron said its three Venezuelan joint ventures will invest the money through 2031, with total production costs remaining below $20 per barrel.
Chevron currently produces about 290,000 bpd in Venezuela, all of which is exported to the United States, according to Reuters. Venezuela is producing about 1.1 million to 1.2 million bpd, down from more than 3 million bpd in the late 1990s.
The new acreage includes the Carabobo-1 and Carabobo-2-South-A areas in the Orinoco Belt, ******* igned to Petroindependencia, the joint venture in which Chevron holds a 49% interest. Chevron also increased its Petroindependencia stake to 49% in April and received rights to develop the Ayacucho 8 area next to its Petropiar venture. Its three Venezuelan joint ventures have increased production by 15% so far this year.
Wednesday's announcement puts a dollar figure and production target on the Chevron agreements that were nearing completion earlier this week. Those agreements were previously described only as being of "significant size," with Chevron seeking additional Orinoco Belt acreage.
#venezuela #joint #reuters

11 days ago
PACS Group, Inc. (NYSE:PACS) shares rose 3.3% in premarket trading on Wednesday after the company announced definitive agreements to acquire the operations of 32 skilled nursing facilities in Florida and completed additional facility acquisitions from Eduro Healthcare.
The Florida facilities comprise 4,049 licensed skilled nursing beds and will be leased from Omega Healthcare Investors, Inc. (NYSE:OHI).
The transaction is expected to close during the fourth quarter, subject to customary closing conditions.
The planned acquisition will mark PACS Group's entry into Florida, extending its southern U.S. operations beyond its existing presence in Texas, South Carolina, Tennessee and Kentucky.
According to PACS, the 32 facilities are integrated into healthcare networks across Florida.
#healthcare #nursing #wednesday
The Florida facilities comprise 4,049 licensed skilled nursing beds and will be leased from Omega Healthcare Investors, Inc. (NYSE:OHI).
The transaction is expected to close during the fourth quarter, subject to customary closing conditions.
The planned acquisition will mark PACS Group's entry into Florida, extending its southern U.S. operations beyond its existing presence in Texas, South Carolina, Tennessee and Kentucky.
According to PACS, the 32 facilities are integrated into healthcare networks across Florida.
#healthcare #nursing #wednesday

12 days ago
The wait for the new team format is finally over. The WTGL has officially locked in a start date and a major media rights deal that puts the league on national television. This is a concrete plan to get women's golf in front of millions of viewers, not just another press release. Broadcast rights for the competition have been locked in by TMRW Sports via multi-year agreements with ESPN and Scripps Sports/ION, signaling genuine confidence in the product. Although the complete schedule is still confidential, the league is scheduled to debut on Sunday, Nov. 8. This date aligns with the final round of the LPGA's TOTO ****** an Classic, providing the new league with a high-profile opening night.
Matches and shoulder programming will appear on ABC, ESPN, and ESPN2. On ION, the league joins a strong lineup of women's sports including the WNBA, NWSL, and PWHL. This distribution reaches 128 million homes nationally. It's a massive step up from streaming-only launches. The deal mirrors the success of the men's TGL, which ESPN has called home since its inaugural 2024-25 season. The infrastructure is ready. The players are set. Now the cameras just need to roll.
According to reports, the announcement came just two days after WTGL revealed the official rosters for the league's five teams. November will mark the league's start at the SoFi Center located in Palm Beach Gardens, Florida. The regular season runs through November and December with a round-robin format. The postseason features single-elimination semifinals and a best-of-three finals. This structure creates a clear path to a champion, forcing teams to think about how they win a series rather than just a single tournament.
The broadcast partners are already on board. "We are genuinely excited to be the home for WTGL as it launches its inaugural season this fall," said Rosalyn Durant, executive vice president, programming and acquisitions, in a release. She added that bringing the league to fans continues a commitment to growing women's sports and supports the belief in the momentum of women's golf. While production details, the on-air talent list, and the full schedule are set for later announcement, the platform is ready.
The roster depth is significant. An inaugural season field of 25 players has been established by the league, comprising individuals with 112 LPGA Tour victories and 15 major championships. However, the real story is the format. Just three players from every five-player roster are eligible to compete in a match. Before the shot clock starts or the Hammer comes into play, a coach must decide who plays and which two sit. This lineup card determines whether team golf gains substance or merely resembles individual golfers wearing matching shirts.
#sports #golf #inaugural #players
Matches and shoulder programming will appear on ABC, ESPN, and ESPN2. On ION, the league joins a strong lineup of women's sports including the WNBA, NWSL, and PWHL. This distribution reaches 128 million homes nationally. It's a massive step up from streaming-only launches. The deal mirrors the success of the men's TGL, which ESPN has called home since its inaugural 2024-25 season. The infrastructure is ready. The players are set. Now the cameras just need to roll.
According to reports, the announcement came just two days after WTGL revealed the official rosters for the league's five teams. November will mark the league's start at the SoFi Center located in Palm Beach Gardens, Florida. The regular season runs through November and December with a round-robin format. The postseason features single-elimination semifinals and a best-of-three finals. This structure creates a clear path to a champion, forcing teams to think about how they win a series rather than just a single tournament.
The broadcast partners are already on board. "We are genuinely excited to be the home for WTGL as it launches its inaugural season this fall," said Rosalyn Durant, executive vice president, programming and acquisitions, in a release. She added that bringing the league to fans continues a commitment to growing women's sports and supports the belief in the momentum of women's golf. While production details, the on-air talent list, and the full schedule are set for later announcement, the platform is ready.
The roster depth is significant. An inaugural season field of 25 players has been established by the league, comprising individuals with 112 LPGA Tour victories and 15 major championships. However, the real story is the format. Just three players from every five-player roster are eligible to compete in a match. Before the shot clock starts or the Hammer comes into play, a coach must decide who plays and which two sit. This lineup card determines whether team golf gains substance or merely resembles individual golfers wearing matching shirts.
#sports #golf #inaugural #players


12 days ago
Hewlett Packard Enterprise raised its fiscal 2026 revenue growth forecast to a range of 34% to 37%, up from a prior range of 29% to 33%, after reporting record quarterly sales driven by demand for AI servers and networking equipment.
Third-quarter revenue rose 34% from a year earlier to $12.2 billion, the company said. HPE also raised its adjusted earnings per share forecast for the full year to between $3.75 and $3.85, up from a prior range of $3.35 to $3.45.
HPE stock fell more than 5% in extended trading after the results were released. Although revenue beat the consensus ******* yst estimate, it missed the mark for investors who had anticipated even stronger results, according to Bloomberg.
Server revenue climbed 35% to $6.8 billion in the quarter. Networking revenue jumped 75% to $2.9 billion, driven by data center networking that more than doubled and a 270% surge in routing revenue, the company said.
Supply constraints remain a limiting factor. Chief Executive Officer Antonio Neri said on a conference call that HPE is working with partners to secure additional multiyear supply agreements, according to Bloomberg. Chief Financial Officer Marie Myers told Reuters that memory tops the list of constrained components, with NAND, CPUs, and drives also creating shortfalls, and that the company has entered into extended supply agreements to shore up access to critical parts. "Demand is far outstripping supply," Myers said.
#Networking #range
Third-quarter revenue rose 34% from a year earlier to $12.2 billion, the company said. HPE also raised its adjusted earnings per share forecast for the full year to between $3.75 and $3.85, up from a prior range of $3.35 to $3.45.
HPE stock fell more than 5% in extended trading after the results were released. Although revenue beat the consensus ******* yst estimate, it missed the mark for investors who had anticipated even stronger results, according to Bloomberg.
Server revenue climbed 35% to $6.8 billion in the quarter. Networking revenue jumped 75% to $2.9 billion, driven by data center networking that more than doubled and a 270% surge in routing revenue, the company said.
Supply constraints remain a limiting factor. Chief Executive Officer Antonio Neri said on a conference call that HPE is working with partners to secure additional multiyear supply agreements, according to Bloomberg. Chief Financial Officer Marie Myers told Reuters that memory tops the list of constrained components, with NAND, CPUs, and drives also creating shortfalls, and that the company has entered into extended supply agreements to shore up access to critical parts. "Demand is far outstripping supply," Myers said.
#Networking #range