7 days ago
Princess Eugenie's close ties with Meghan Markle have reportedly raised concerns that she could potentially be a "double agent." The daughter of Andrew Mountbatten-Windsor and Sarah Ferguson is known to be close to both the Waleses and the Sussexes. Hence, sources claim that some palace insiders believe she cannot keep one foot in both camps and may eventually have to choose a side.
Princess Eugenie may need to decide whether she is on Meghan Markle's side or not. The 36-year-old shares a good bond with Meghan and Prince Harry, as well as Prince William and Kate Middleton. Now that Meghan and Harry are back in Britain for an extended stay, people are eager to see how their bond with Eugenie develops.
However, a source told Woman's Day that Meghan and Eugenie haven't seen much of each other recently. The reason, according to the source, is that both women are extremely busy. However, the source noted that it could also be a conscious decision on Eugenie's part. They reportedly believe that she may want to distance herself from Meghan.
After the large-scale controversy last year, Eugenie's parents, Andrew Mountbatten-Windsor and Sarah Ferguson, were asked to leave the Royal Lodge. In fact, Andrew was even stripped of his ****** les. However, the ****** les of Eugenie and Princess Beatrice remained intact. Keeping that in mind, the source said that the growing consensus is that Eugenie wants to maintain friendly ties with the royals. If she is seen spending too much time with Meghan, it may not be a good look for her.
The source continued that palace insiders feel she "can't continue to have the best of both worlds." The insider added, "If she wants to stay on decent terms with the likes of William and Kate then she can't be seen as this double agent type of figure." Hence, they believe that she now needs to pick a side.
#meghan #andrew #seen

17 days ago
MACOM Technology Solutions is suddenly giving investors two numbers to think about: its stock has more than doubled over the past year, and its newest optical components push data rates toward another doubling.
asharkyu/Shutterstock.com
MACOM Technology Solutions Holdings, Inc. (NASDAQ:MTSI) announced a 3.2-terabit optical chipset on September 17 built around eight 448-Gbps PAM-4 channels. A day later, BMO Capital upgraded the shares to Outperform with a $335 target, arguing that a 36% decline from the May peak had compressed MACOM's forward valuation to roughly 29 times earnings while data-center fundamentals remained intact.
That puts Coherent Corp. (NYSE:COHR) directly in the conversation because both companies supply the optical connectivity needed to keep larger AI clusters fed with data.
MACOM's new platform combines drivers, photodiodes and transimpedance amplifiers for next-generation optical modules. The company says the components are already available, rather than merely a research roadmap.
#data #macom #holdings #NASDAQ
24 days ago
On September 4, 2026, the Wall Street Journal reported that Starbucks Corporation (NASDAQ:SBUX)' longtime chai latte devotees have turned against the company's reformulated recipe, introduced in March. It reduced sweetener and shifted from a pre-made concentrate to a new base with just two grams of sugar.
Customers have signed petitions, flooded Starbucks' corporate lines, and taken to Reddit and store review sites demanding the original formula back. Starbucks says the change gives customers more control over sweetness and has introduced new variations like Mango Cream Chai and Pumpkin Cream Chai.
Starbucks Corporation (NASDAQ:SBUX)' broader turnaround remains intact despite the backlash over its chai reformulation. Global comparable sales increased 7.9% in fiscal Q3, with comparable transactions rising 4.2%. The company raised its fiscal 2026 adjusted EPS guidance to $2.55-$2.65 from $2.25-$2.45. Stronger customer traffic and higher earnings give investors evidence that one unpopular menu change has not derailed the recovery.
The chai backlash appears concentrated among loyal customers of one product rather than across Starbucks' broader customer base. The business introduced the new chai formula as part of a personalization strategy. Customers can customize sweetness and other ingredients. If Starbucks keeps transaction growth across its wider menu, the business could improve its product economics without materially damaging overall customer demand.
Starbucks is improving profitability while it executes its turnaround. Non-GAAP operating margin expanded 430 basis points year over year to 14.4% in fiscal Q3, while North America revenue increased 7% to $7.4 billion. These results give investors evidence that the company can improve margins and sales even as it experiments with its menu and customer experience.
#customer
25 days ago
Benzinga and Yahoo Finance LLC may earn commission or revenue on some items through the links below.
Brad Gerstner says leading AI labs need to lift their combined annualized revenue from roughly $100 billion to at least $180 billion by year-end to keep the AI trade intact.
The Altimeter Capital founder, whose firm held nearly $1.9 billion of Nvidia Corp. (NASDAQ:NVDA) shares at the end of June, called AI lab revenue "the single most important data point in the market today" at the All-In Summit.
Gerstner estimated that Anthropic, OpenAI and **** eX (NASDAQ:SPCX), which owns xAI, had a combined run rate of roughly $100 billion based on figures circulating in July.
Gerstner said the companies need to reach at least $180 billion by year-end, up about 80% from his July estimate, "just to keep the AI trade intact."
#NASDAQ #combined #least #year
28 days ago
Broyhill ***** et Management, a Charlotte-based firm, issued its second-quarter 2026 investor letter, which is available for download here. The Broyhill Equity Composite gained 8.8% in Q2, trailing the MSCI All Country World Index's 15.1% and the MSCI ACWI Value Index's 10.8%. For the first half, the Composite returned 2.3%, versus 11.5% for the Index. The letter highlights that a significant portion of the shortfall occurred in April due to market dynamics and geopolitical events, with tech, particularly semiconductors, driving recent gains. Broyhill notes its lack of direct semiconductor exposure but acknowledges potential interest in the sector if opportunities arise, maintaining its investment philosophy focused on capital protection in fragile market conditions. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Broyhill ***** et Management highlighted Masco Corporation (NYSE:MAS). Masco Corporation (NYSE:MAS), a US-based home improvement and building products manufacturer, contributed positively to performance this quarter. On September 14, 2026, Masco Corporation (NYSE:MAS) closed at $69.41 per share. Over the past month, Masco Corporation (NYSE:MAS) declined 5.41%, but its shares are down 5.31% over the past year. Masco Corporation (NYSE:MAS) has a market capitalization of $13.69 billion, and its stock has traded within a 52-week range of $58.16 to $83.64.
Broyhill ***** et Management stated the following regarding Masco Corporation (NYSE:MAS) in its Q2 2026 investor letter:
"Masco Corporation (NYSE:MAS) gained 37%, the best result in the portfolio, and was initiated in the first quarter as one of two investments in the depressed housing sector. The quarter was plumbing-led and, more to the point, volume-led, with the strongest volume growth since the end of the pandemic and pricing intact. Management raised the topline outlook, took out delayed-draw leverage to repurchase stock, and increased the buyback guide by $200 million, to more than $800 million against a $2 billion authorization. Earlier in the quarter, our investment team also attended Masco's investor day and was able to interact with management at the event."
Masco Corporation (NYSE:MAS) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 46 hedge fund portfolios held Masco Corporation (NYSE:MAS) at the end of the second quarter, compared to 42 in the previous quarter. While we acknowledge the potential of Masco Corporation (NYSE:MAS) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#corporation #letter

29 days ago
XRP dropped 9% on the CLARITY Act's Senate failure, but Coinbase fell 9%, more exposed to the rulebook the bill would have set.
XRP retains its SEC-CFTC commodity classification and 5 live spot ETFs with $1.7 billion in net inflows, keeping its legal floor intact.
XRP has underperformed Bitcoin on every rate release this month, with $1.25 as the critical support heading into the Fed's afternoon decision.
Read More: Learn 7 secret wealth tips high net worth investors use that most investors miss (sponsor)
On Monday, XRP (CRYPTO:XRP) surged 9.8% to $1.49, while Ripple CEO Brad Garlinghouse told the Senate that "the world was watching." However, two days later, the Senate failed to open debate on the CLARITY Act, and XRP fell to $1.28.
#senate #fell #learn #Monday

1 month ago
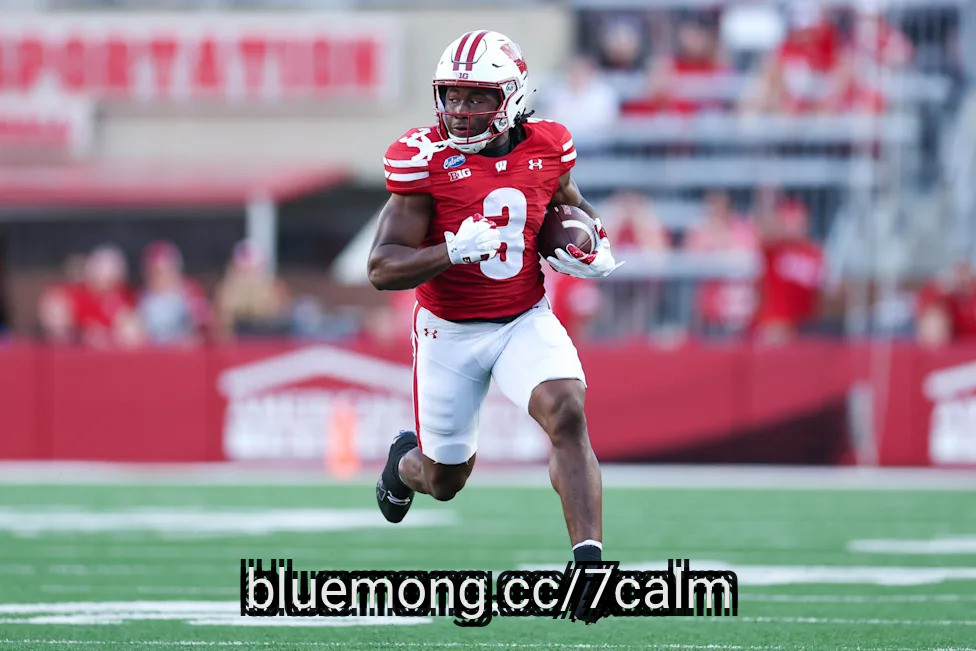
We now know what time and how to watch the Homecoming clash between Penn State and Wisconsin on Saturday, September 26th. Earlier today, it was announced via the official PSU Football social media accounts that the Nittany Lions will face the Badgers at Beaver Stadium in a 5:00 PM EST kickoff that will be streaming on Peacock.
Understandably, this is frustrating news for those who don't already have a Peacock subscription and don't feel like plunking down additional money for another monthly streaming subscription just to watch one game. That being said, games that air on Peacock also air simultaneously on NBC Sports Network, a channel that is readily available on Comcast Xfinity, YouTubeTV, and Fubo. So, if you already are a subscriber to one of those aforementioned streaming services, you should be good to go.
The last time these two teams collided was on October 26th, 2024, when PSU went into Camp Randall Stadium for a nighttime showdown that saw Beau Pribula step in for an injured Drew Allar after halftime and along with a pick-six by Jaylen Reed and some strong running from Kaytron Allen, help guide the Nittany Lions to a 28-13 win to keep their College Football Playoff hopes intact.
#Football #already
1 month ago
Hub Group anticipates receiving a delisting notification from Nasdaq following delays in submitting its financial reports, which stemmed from an accounting error identified earlier this year. The company missed a Monday deadline to comply with Nasdaq's financial reporting requirements. It will ask for a hearing to keep its stock listing intact and plans to seek a further extension of the filing requirements.
The company said receipt of the letter doesn't mean shares will immediately stop trading, and that the hearing request will automatically stay a delisting for 15 calendar days. It will also ask for shares not to be delisted during the hearing process, which can take approximately 30 to 45 days to commence following the request.
"While there can be no ***** urances, the Company expects that the Company's Class A common stock will continue to trade on the Nasdaq Global Select Market during the hearing process," a Monday news release stated. "In addition, the Company expects to present to the Nasdaq Hearings Panel a compelling plan to regain full compliance with Nasdaq's continued listing requirements and to secure sufficient time to execute such plan."
Hub Group (NASDAQ: HUBG) announced in February that it had identified a $77-million understatement in purchased transportation expenses during the first three quarters of 2025, and that it was delaying fourth-quarter and full-year 2025 financial reporting. It said in May that "prematurely or incorrectly recognized" transactions were also discovered during 2023 and 2024, and that those periods, along with the first three quarters of 2025, would need to be restated.
It plans to complete the restatement process and file results for the outstanding periods during the fourth quarter. Shares of HUBG were off 6.2% in early trading on Monday compared to the S&P 500, which was down 0.6%.
#NASDAQ #shares #process

1 month ago
Interested in Intuitive Surgical, Inc.? Here are five stocks we like better.
Global procedure growth remains intact despite a recent U.S. slowdown and Affordable Care Act-related uncertainty; Intuitive Surgical maintained its 13.5%–15.5% global procedure-growth outlook, expecting results near the midpoint.
Ambulatory surgery centers and international markets remain important expansion opportunities, with second-quarter system placements rising in the U.S. and abroad. However, China remains pressured by local competition and slower tenders, with improved visibility not expected until 2027.
Future growth could come from da Vinci 5 upgrades, Force Feedback instruments, new procedures and sites of care, and AI services such as Case Insights. The company also reported strong financial performance, including 21% revenue growth and operating and free-cash-flow margins above historical averages.
This AI ETF Is Missing the Biggest AI Winners
#affordable
1 month ago
Unlike Medicare Advantage, Medigap offers no recurring annual shopping window, so health conditions can permanently lock policyholders into higher premiums.
The one-time federal Medigap Open Enrollment Period lasts just six months starting at age 65; after that, most states allow medical underwriting.
Never cancel an existing Medigap policy before a replacement is confirmed in writing, since a declined application leaves the original coverage intact.
Are you ahead, or behind on retirement? SmartAsset's free tool can match you with a financial advisor in minutes to help you answer that today. Each advisor has been carefully vetted, and must act in your best interests. Don't waste another minute; learn more here.
A 72-year-old in Ohio opens a December rate notice and finds that her Medigap Plan G premium is rising again in January, the fourth increase in four years. Her broker finds a competitor charging $40 less each month.
#finds #period
1 month ago
So often pitchers' duels don't really stand up to the hype, but today's matchup between two former Stetson Hatters – the Mariners' Logan Gilbert and the Rangers' Jacob deGrom – delivered on all that promise and then some. The two pitchers combined for 23 strikeouts, and deGrom carried a perfect game through five innings. In true pitching duel style, it looked like the pitcher who blinked first would come out on the short end, but despite Logan Gilbert making a couple of mistakes, his offense was able to pick him up and deliver him the win. Bragging rights are fun; wins are better. (Gilbert also gets the honor of leading MLB in whiffs today: 24 to deGrom's 20, despite having one fewer strikeout than deGrom.)
This all being said, it was a slog for the Mariners early on. The best at-bat the first time through the order for the Mariners went to – surprise, surprise – Cal Raleigh, who battled deGrom for nine pitches before striking out on deGrom's fastest fastball of the day, a 99.6 mph heater (my campaign for decimal points on the ribbon board in the stadium, which read 100, continues unabated). But the Mariners did fight deGrom, getting themselves into good counts and forcing him into the zone; he finished the second inning at 37 pitches, compared to Gilbert's 24.
But it only took two pitches to offset that work in the third. Nicky Lopez was able to take 96 up and in from Gilbert and find a hole on the infield, and one batter later, with two outs, Joc Pederson jumped a first-pitch slider for a two-run homer. It wasn't a terrible pitch from Gilbert, away from Pederson but probably still too much on the plate; Gilbert had struck Pederson out on the slider in his first at-bat. The slider was particularly nasty today, with an eye-popping 75% whiff rate. He led with the pitch, throwing it 40 times, 12 times to start off an at-bat, which feels like a different sequence than he's used. Gilbert credits Cal for coming up with a good game plan, especially after he felt like he fell into some predictable patterns in his last time out against the A's.
"Like with Joc, we got him with the slider early, so he probably thought we were going to it next time," explained Gilbert. "But then also other guys, we went heavy spin, like with Duran, and then next time went three or four straight fastballs. So I think we did a good job there. They're trying to look at how we're probably scouting them, and then next time through, maybe pitch them different. I think Cal did a good job there."
But deGrom was just as tough on the other side. After striking out eight times in the first three innings, the Mariners hitters decided to try a different strategy the second time through the order. That also didn't work, as they let deGrom cruise through the fourth on nine pitches, keeping his perfect game intact.
#degrom #like #pitch

0.00$ raised of 0.00$ goal
0 donations
0.00$
to go
1 month ago
The Denver Broncos have named their team captains for the 2026 season and, in doing so, have followed the same approach that they took in the offseason: sticking with what worked.
The Broncos made few changes to their roster this offseason, believing the group in place was good enough to win a Super Bowl and wanted to keep as much of that intact as possible. The same can be said for the team captains.
The Broncos chose the same eight team captains that they had last season, with one addition. Special teams ace and reserve safety Devon Key was added as a special teams captain.
"He was a[n All-Pro] special teamer a year ago, and I think it's the respect of his teammates," coach Sean Payton said of Key being voted a captain. "He's someone that he'll play on defense as well, but just his production I think and his consistency."
Denver quarterback Bo Nix echoed his coach's remarks.
#season
0.00$ raised of 0.00$ goal
0 donations
0.00$
to go
1 month ago
Seattle quarterback Sam Darnold received good news Thursday about the right hip injury he suffered in a Seahawks NFL victory over New England, but a return timetable remains uncertain.
Seahawks coach Mike Macdonald told Seattle radio station KIRO on Thursday that Darnold's injury is a muscle strain rather than joint damage after Seattle's 13-10 home win over the Patriots on Wednesday.
While multiple reports said Darnold is expected to miss next week's game against Arizona, Darnold has likely avoided a long-term absence.
Darnold exited the NFL 2026 season opener after only five plays because of a hip injury suffered when he was sacked, limping to the locker room.
"The hip is intact and it's good. It's more of like a muscle thing," Macdonald said. "So that's good news."
#england
0.00$ raised of 0.00$ goal
0 donations
0.00$
to go
1 month ago
TeraWulf fell 4% to $16.50, APLD dropped 3%, and IREN slid 2%, all on broad profit-taking after strong YTD gains with no new company catalysts.
The Bitcoin mining ETF WGMI dropped 4% while QQQ fell just 0.4%, confirming the selloff is a group rotation, not broad tech weakness.
Paul Meeks initiated TeraWulf with a Buy and $19 target, while a 20-year Anthropic deal worth $19 billion in contracted revenue remains fully intact.
Just released. Our ******* ysts combed the entire stock market and named the ten best stocks to buy right now, and Iren didn't make the cut. Enter your email to see the names that beat IREN. The report is free. Enter your email and see if any of your stocks made the cut.
Shares of TeraWulf (NASDAQ:WULF) are down 4% to $16.50 in Thursday's midday session, trimming a slice of what's been a 43.6% year-to-date advance for the stock. The pullback is showing up across the miner-turned-AI-infrastructure cohort, and there's no fresh company disclosure to pin it on.
#enter #broad
0.00$ raised of 0.00$ goal
0 donations
0.00$
to go
1 month ago
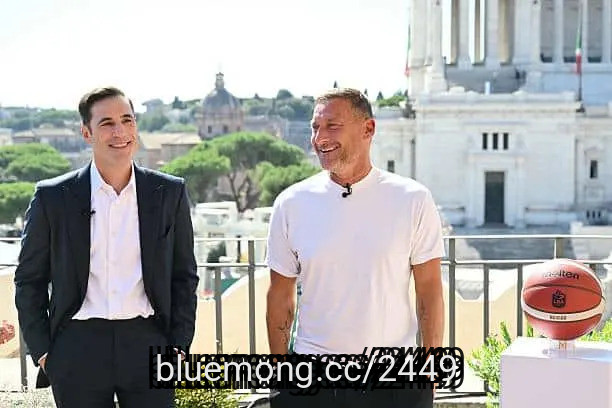
Roma is in, but Francesco Totti prefers not to rush things.
The former Giallorossi captain, now an advisor for Maxima Roma, spoke to Rai Sport on the sidelines of the presentation of the capital's basketball team, also focusing on the ***** le race.
Regarding the potential battle for first place, Totti names two teams but postpones any decision: "Roma and Inter are the candidates for the ***** le, we're not saying anything and we'll wait for the rest of the season. We'll see in 10 or 15 matchdays."
Meanwhile, his bond with the Giallorossi remains intact. Totti doesn't hide his satisfaction with the team's start and reiterates what Roma means to him: "I will never put Roma aside, it's my skin. We're here, we've started well, and I hope it can continue at this level."
The former number 10 then rejected the idea that the new adventure could be a response to those who didn't involve him in other projects: "Am I taking revenge on those who didn't seek me out? It's not a reprisal, but a project that's excited me. I'm happy because for me, sport comes first."
#giallorossi #we 're #we 'll

1 month ago
CNBC reported that Chris Churchman, The Goldman Sachs Group, Inc. (NYSE:GS) partner who leads the bank's Marquee digital platform for institutional clients, warned that AI's spread across Wall Street risks eroding the reasoning skills of the next generation of bankers.
Churchman said on Goldman's internal "Exchanges" podcast, "There's a huge danger here that in the era of AI, we outsource our reasoning to these models, and we have cognitive atrophy that stops us being able to reason from first principles ourselves." He compared it to how GPS and search engines eroded navigation skills and said much of banking's knowledge is learned only "by doing." Churchman said the firm has not yet determined how it will manage the transition.
The Goldman Sachs Group, Inc. (NYSE:GS) is surfacing this risk proactively, through its own senior AI leadership, rather than being caught off guard by it later. Having the executive who leads Marquee flag the danger publicly signals internal scrutiny that could help Goldman build safeguards into its AI rollout before problems show up in deal execution. It is an advantage over firms deploying AI without asking the same questions.
The near-term efficiency case for AI remains fully intact regardless of the long-term talent question. CNBC itself framed the tradeoff as a "devil's bargain" that could make the industry more profitable today while potentially eroding the talent it needs for tomorrow. It means Goldman still captures AI's productivity benefits now even as it works out the downstream risk.
Marquee itself is a genuine strategic **** et getting AI investment. The platform, through which hedge funds and other large institutional clients access Goldman's market data, research, **** ytics, and execution tools, is being built out with AI features, which positions it as a differentiated offering for Goldman's most valuable client relationships.
#churchman #marquee #cnbc #sachs
1 month ago
On September 4, Bruker (NASDAQ:BRKR) said its energy and supercon technologies unit, Bruker Energy & Supercon Technologies (or BEST), had struck a supply collaboration with Luvata Materials & Solutions to scale up production of RRP superconductors for magnetic confinement fusion. The deal lands right as governments and private developers from Europe to South Korea race to build fusion demonstration plants, and it comes a month after Bruker's core scientific instruments business showed its first real signs of stabilizing. Two very different stories are converging inside one stock.
The Luvata tie-up is not Bruker's first rodeo in fusion. BEST and Luvata previously supplied materials and expertise to ITER, the international fusion megaproject, and to the Wendelstein 7-X stellarator, two of the most advanced superconducting plasma facilities ever built. Their RRP superconductors, wires built with the Rod-Restack Process to withstand field strengths between 12 and 20 Tesla, already run inside CERN's Large Hadron Collider and in ultra-high field NMR magnets. That track record matters now because fusion programs are ramping across Europe, the Americas, China, ***** an and South Korea, and Gauss Fusion has already begun evaluating RRP superconductors for its Gauss Industrial Demonstrator and GIGA power plant platform.
The segment is already delivering. On August 4, Bruker reported that BEST revenue climbed 11.9% year over year to $74.2 million in the second quarter, with organic growth of 8.9% net of intercompany eliminations, while first-half BEST revenue rose 12.3% to $141 million. That growth showed up in Bruker's bottom line too. Non-GAAP operating margin expanded to 14.1% from 9% a year earlier, and non-GAAP diluted earnings per share grew to $0.49 from $0.32, results strong enough that management kept its full-year non-GAAP EPS growth target of 15% to 17% intact.
None of that shows up on a GAAP basis. Bruker's second-quarter GAAP operating results swung to a $65.3 million loss, versus $11.9 million of GAAP operating income a year earlier, dragged down largely by a $134.9 million non-cash goodwill charge. GAAP diluted earnings per share swung to a loss of $0.41 from a profit of $0.05, and for the first half of 2026 the company posted a GAAP diluted loss per share of $0.39. Impairments do not spend cash, but they are a reminder that some of what Bruker paid for in past acquisitions is now being written down.
#fusion

1 month ago
On September 4, Bruker (NASDAQ:BRKR) said its energy and supercon technologies unit, Bruker Energy & Supercon Technologies (or BEST), had struck a supply collaboration with Luvata Materials & Solutions to scale up production of RRP superconductors for magnetic confinement fusion. The deal lands right as governments and private developers from Europe to South Korea race to build fusion demonstration plants, and it comes a month after Bruker's core scientific instruments business showed its first real signs of stabilizing. Two very different stories are converging inside one stock.
The Luvata tie-up is not Bruker's first rodeo in fusion. BEST and Luvata previously supplied materials and expertise to ITER, the international fusion megaproject, and to the Wendelstein 7-X stellarator, two of the most advanced superconducting plasma facilities ever built. Their RRP superconductors, wires built with the Rod-Restack Process to withstand field strengths between 12 and 20 Tesla, already run inside CERN's Large Hadron Collider and in ultra-high field NMR magnets. That track record matters now because fusion programs are ramping across Europe, the Americas, China, **** an and South Korea, and Gauss Fusion has already begun evaluating RRP superconductors for its Gauss Industrial Demonstrator and GIGA power plant platform.
The segment is already delivering. On August 4, Bruker reported that BEST revenue climbed 11.9% year over year to $74.2 million in the second quarter, with organic growth of 8.9% net of intercompany eliminations, while first-half BEST revenue rose 12.3% to $141 million. That growth showed up in Bruker's bottom line too. Non-GAAP operating margin expanded to 14.1% from 9% a year earlier, and non-GAAP diluted earnings per share grew to $0.49 from $0.32, results strong enough that management kept its full-year non-GAAP EPS growth target of 15% to 17% intact.
None of that shows up on a GAAP basis. Bruker's second-quarter GAAP operating results swung to a $65.3 million loss, versus $11.9 million of GAAP operating income a year earlier, dragged down largely by a $134.9 million non-cash goodwill charge. GAAP diluted earnings per share swung to a loss of $0.41 from a profit of $0.05, and for the first half of 2026 the company posted a GAAP diluted loss per share of $0.39. Impairments do not spend cash, but they are a reminder that some of what Bruker paid for in past acquisitions is now being written down.
#gaap #bruker #million #already
1 month ago
On paper, it could appear as though the league was taking away the 2029 Clippers pick the Sixers had the right to swap. But a league source confirmed a report from PhillyVoice that said the NBA was taking away a first-round pick the Pacers owe the Clippers from the Ivica Zubac trade and was not touching the Clippers' own pick, meaning the Sixers' right to swap that pick remains intact.
This article originally appeared on Hoops Hype: A league source confirmed a report from PhillyVoice …
#clippers #league
This article originally appeared on Hoops Hype: A league source confirmed a report from PhillyVoice …
#clippers #league

1 month ago
Davis says the NBA picked him over other retired players mentioned in the investigation, leading him to spend nearly two years in prison in addition to three years of supervision. Big Baby expressed his frustration with the process that led to his imprisonment while others mentioned in the indictment, including his former Boston Celtics teammates Kendrick Perkins and Tony Allen, didn't, he explained, per Locked In with Ian Bick. "They literally wanted to make me out to be an example. There was a lot of people that got investigated," Davis said. "Kendrick Perkins, you see him on ESPN. Tony Allen—he was literally the third person on the indictment, with his wife. He's not walking in jail. Darius Miles—he's not walking in jail. And these guys got money, like thousands of dollars. How'd I end up in jail and these guys are on probation/walking free; their whole life is still intact. "I think the NBA let the feds pick who they wanted to choose. 180 people were investigated/supenoed. We didn't hear about all those people. We just heard about the 22 people that got caught, or that got jammed in the situation. A lot of people pleaded out. They didn't go to jail. They didn't even go get time served."
This article originally appeared on Hoops Hype: Glen Davis on spending time in prison while Kendrick Perkins, Tony Allen were free: 'They literally wanted to make me out to be an example'
#literally
This article originally appeared on Hoops Hype: Glen Davis on spending time in prison while Kendrick Perkins, Tony Allen were free: 'They literally wanted to make me out to be an example'
#literally

1 month ago
Snowflake recently delivered one of its strongest quarters in years, prompting Wall Street to take notice.
In an investor note shared with me, Morgan Stanley ***** yst Sanjit Singh raised his price target on the cloud data company to $470 from $300, keeping his "Overweight" rating intact.
Valued at a market cap of $106 billion, SNOW stock is priced at $356 at the time of writing. Over the last three years, SNOW stock has more than doubled.
A higher stock price target comes after Snowflake posted its third straight quarter of accelerating revenue growth, a trend that's rare for a company of its size.
Singh called it "an AI-powered growth flywheel that is still in the early innings."
#snowflake #snow #years #target

1 month ago
Baron Capital, an investment management company, released its second-quarter 2026 investor letter for its "Baron Fifth Avenue Growth Fund". The letter can be downloaded here. The fund achieved a strong quarter, gaining 24.6% (Institutional Shares), outperforming the Russell 1000 Growth Index (16.7%) and the S&P 500 (15.2%). Year to date, it's up 11.7%, surpassing its benchmarks. The first half of 2026 mirrored the previous year, with a 10.4% drawdown in Q1 due to geopolitical tensions, similar to last year's tariff-related decline. However, the fund rebounded with a 24.6% gain in Q2 after a cease-fire and declining oil prices. Stock selection drove the outperformance, contributing 940bps, while sector allocation detracted 152bps. In a volatile market, the firm remains focused on identifying high-quality, competitively advantaged companies and is optimistic about long-term prospects, investing when prices align with intrinsic values. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Baron Fifth Avenue Growth Fund highlighted Coupang, Inc. (NYSE:CPNG). Coupang, Inc. (NYSE:CPNG), a Korean technology and e-commerce platform that operates through Product Commerce and Developing Offerings segments, detracted from the fund's performance this quarter. On August 31, 2026, Coupang, Inc. (NYSE:CPNG) closed at $16.06 per share. Over the past month, Coupang, Inc. (NYSE:CPNG) declined 4.29%, and its shares are down 43.47% over the past year. Coupang, Inc. (NYSE:CPNG) has a market capitalization of $28.87 billion, and its stock has traded within a 52-week range of $14.92 to $34.08.
Baron Fifth Avenue Growth Fund stated the following regarding Coupang, Inc. (NYSE:CPNG) in its Q2 2026 investor letter:
"Coupang, Inc. (NYSE:CPNG), Korea's largest e-commerce platform, detracted from performance with shares down 7.7%. The stock came under pressure following first-quarter results, where in-line revenue was overshadowed by softer second-quarter guidance as capacity and supply chain investments made ahead of Coupang's 2025 data breach weighed on margins while customer volumes recovered. Sentiment was further weighed down by a record KRW 624.7 billion (about US $430 million) privacy fine stemming from an investigation into the breach, while a rotation of fast money into AI and semiconductor names added to the weakness. Despite these headwinds, our conviction remains intact. We view the margin pressure as temporary, and the fine removes a key overhang and reinforces our belief that the breach does not reflect a structural loss of market share. By the end of April, Coupang recovered roughly 80% of the post-breach decline in WOW Membership (its paid subscription program), with returning members resuming prior spending levels. We continue to view Coupang as a competitively advantaged e-commerce business gaining share in its core market while scaling Taiwan operations."
#fund #baron

1 month ago
Riverwater Partners, an investment management company, released its 'Small Cap Strategy' Q2 2026 investor letter. The letter can be downloaded here. The Small Cap Strategy underperformed the Russell 2000 in the second quarter as the benchmark experienced one of its strongest risk-on rallies in recent memory, although the strategy remained ahead year-to-date. The quarter was defined by accelerating AI investment, energy market disruptions, and renewed investor appetite for higher-beta stocks, creating headwinds for the firm's quality-focused approach and healthcare positioning. Despite this, stock selection contributed positively in energy, materials, and financials, while healthcare and consumer discretionary detracted due to the fund's disciplined avoidance of speculative businesses. Looking ahead, the firm remains cautiously optimistic, focusing on opportunities created by market dislocations, including AI infrastructure enablers, select consumer companies, healthcare innovators, and energy businesses trading below intrinsic value. The strategy continues to emphasize high-quality companies with strong management teams and attractive valuations, positioning the portfolio for a potential rotation away from speculative market leadership. In addition, please check the Strategy's top five holdings to know its best picks in 2026.
In its second-quarter 2026 investor letter, Riverwater Partners Small Cap Strategy highlighted Grand Canyon Education, Inc. (NASDAQ:LOPE). Grand Canyon Education, Inc. (NASDAQ:LOPE), a US-based education services company, detracted from performance this quarter. On August 31, 2026, Grand Canyon Education, Inc. (NASDAQ:LOPE) closed at $148.13 per share. Grand Canyon Education, Inc. (NASDAQ:LOPE) fell 1.77% over the past month, and its shares are down 27.09% over the past 52 weeks. Grand Canyon Education, Inc. (NASDAQ:LOPE) has a market capitalization of around $3.86 billion with a 52-week trading range between $134.27 - $223.04.
Riverwater Partners Small Cap Strategy stated the following regarding Grand Canyon Education, Inc. (NASDAQ:LOPE) in its Q2 2026 investor letter:
"Grand Canyon Education, Inc. (NASDAQ:LOPE), the education services provider, declined approximately 16% and was the portfolio's largest detractor. Our investment thesis remains intact; LOPE's steady, profitable, countercyclical enrollment business was simply left behind in a market that rewarded beta and speculation. Enrollment trends and cash generation remain consistent with our expectations, and we continue to hold the position."
#Education #lope #market #partners

1 month ago
Hotchkis & Wiley, an investment management company, released its second-quarter 2026 investor letter for the "Global Value Fund." The letter can be downloaded here. In Q2 2026, the MSCI World Index rose by +13.8% and the MSCI World Value Index by +9.2%, despite challenges like rising inflation and the Iran conflict. The US now comprises about 71% of the MSCI World Index, with notable gains in semiconductor and AI-related stocks, some exceeding 100%. The market showed speculative behavior, especially with high-beta and momentum stocks outperforming significantly. While enthusiasm for AI drove investor leverage, many stocks are trading at elevated multiples reminiscent of the dot-com era. Concerns about sustainability arise as earnings growth is heavily tied to AI data centers. Preference is shifting to high-quality businesses in sectors like enterprise software and healthcare, which are perceived as more stable. Defensive sectors have been underinvested, offering potential opportunities. The fund achieved a return of 9.97% in the quarter, surpassing the MSCI World Value Index, with healthcare as a key contributor. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Hotchkis & Wiley Global Value Fund noted that Alphabet Inc. (NASDAQ:GOOGL) detracted from performance due to its underweight position in the stock. Alphabet Inc. (NASDAQ:GOOGL), the parent company of Google, offers various platforms and services, including online search and advertising, cloud solutions, and artificial intelligence. On September 1, 2026, Alphabet Inc. (NASDAQ:GOOGL) closed at $335.02 per share. Over the past month, Alphabet Inc. (NASDAQ:GOOGL) declined 7.56%, but its shares are up 45.24% over the past year. Alphabet Inc. (NASDAQ:GOOGL) has a market capitalization of $4.09 trillion.
Hotchkis & Wiley Global Value Fund stated the following regarding Alphabet Inc. (NASDAQ:GOOGL) in its Q2 2026 investor letter:
"Alphabet Inc. (NASDAQ:GOOGL) is a holding company whose primary subsidiary is Google, whose Search business makes it one of the largest advertising companies in the world. Alphabet's other businesses are its enterprise cloud platform and venture-stage companies collectively reported as "Other Bets." We believe Alphabet's valuation remain good given its improving growth prospects. Although the stock rose during the quarter, it detracted from relative performance because we were underweight compared to the benchmark. Our investment thesis remains intact."
#index #hotchkis

1 month ago
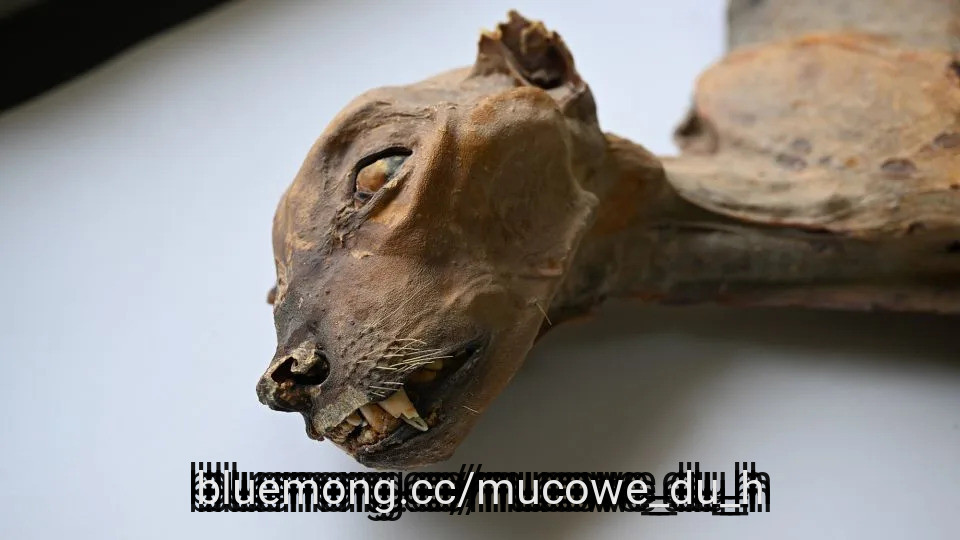
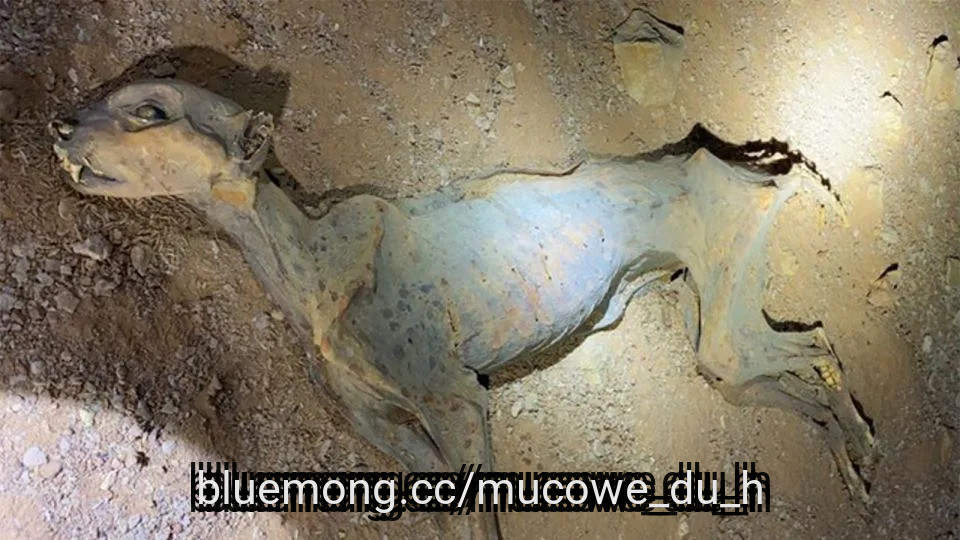
When scientists with the National Center for Wildlife in Saudi Arabia were surveying caves in search of wildlife in 2022 and 2023, they came across something unexpected: seven naturally mummified cheetahs in five caves near the northern city of Arar. The remains were largely intact with well-preserved soft tissue and skeletons.
Now, an ******* ysis of three of the mummies' DNA has revealed something that could help reintroduce cheetahs to the Arabian Peninsula wilderness, researchers say.
Cheetahs once inhabited much of Africa and parts of Asia, but now they are found in only 9% of their historic range. It was previously believed that the Asiatic cheetah, called Acinonyx jubatus venaticus, was the only subspecies ever present in Saudi Arabia. The species is now critically endangered, with a small wild population remaining in Iran. Across the peninsula, cheetahs were deemed locally extinct in the 1970s.
But when the researchers ******* yzed three of the mummies, they found that two of the oldest specimens were genetically closer to the subspecies Acinonyx jubatus hecki, known as the Northwest African cheetah.
The findings, published in January in the journal Communications Earth & Environment, reveal that at least two subspecies of cheetah once roamed the Arabian Peninsula. The discovery could help reintroduction efforts as scientists now know which cheetah lineages once lived in the peninsula and have evidence of their success in the area.
#cheetahs #cheetah #once #arabia
1 month ago
Meta Platforms (NASDAQ:META) has faced at least two significant issues over the past year that have weighed on its stock. First, many investors aren't convinced that its massive artificial intelligence (AI)-related spending will yield the kind of return the company is hoping for. And since these investments are shrinking margins and earnings, skeptics have been running for the hills.
Second, Meta Platforms has faced lawsuits over its social media websites and apps. Plaintiffs allege that they have harmed users, especially younger users. The good news for Meta is that the company has made significant progress in overcoming one of these headwinds while keeping its core business mostly intact.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Image source: The Motley Fool.
A coalition of U.S. states and territories was suing Meta Platforms in lawsuits over social media addiction. On Aug. 26, they agreed to a settlement worth up to $17.1 billion that Meta will pay. The tech giant will also be required to install stronger guardrails to protect young users across its apps. These will include daily usage limits, the ability to opt out of personalized algorithms, and stricter parental controls.
#platforms #NVIDIA #company #users
1 month ago
Baron Capital, an investment management company, released its second-quarter 2026 investor letter for its "Baron Fifth Avenue Growth Fund". The letter can be downloaded here. The fund achieved a strong quarter, gaining 24.6% (Institutional Shares), outperforming the Russell 1000 Growth Index (16.7%) and the S&P 500 (15.2%). Year to date, it's up 11.7%, surpassing its benchmarks. The first half of 2026 mirrored the previous year, with a 10.4% drawdown in Q1 due to geopolitical tensions, similar to last year's tariff-related decline. However, the fund rebounded with a 24.6% gain in Q2 after a cease-fire and declining oil prices. Stock selection drove the outperformance, contributing 940bps, while sector allocation detracted 152bps. In a volatile market, the firm remains focused on identifying high-quality, competitively advantaged companies and is optimistic about long-term prospects, investing when prices align with intrinsic values. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Baron Fifth Avenue Growth Fund highlighted Coupang, Inc. (NYSE:CPNG). Coupang, Inc. (NYSE:CPNG), a Korean technology and e-commerce platform that operates through Product Commerce and Developing Offerings segments, detracted from the fund's performance this quarter. On August 31, 2026, Coupang, Inc. (NYSE:CPNG) closed at $16.06 per share. Over the past month, Coupang, Inc. (NYSE:CPNG) declined 4.29%, and its shares are down 43.47% over the past year. Coupang, Inc. (NYSE:CPNG) has a market capitalization of $28.87 billion, and its stock has traded within a 52-week range of $14.92 to $34.08.
Baron Fifth Avenue Growth Fund stated the following regarding Coupang, Inc. (NYSE:CPNG) in its Q2 2026 investor letter:
"Coupang, Inc. (NYSE:CPNG), Korea's largest e-commerce platform, detracted from performance with shares down 7.7%. The stock came under pressure following first-quarter results, where in-line revenue was overshadowed by softer second-quarter guidance as capacity and supply chain investments made ahead of Coupang's 2025 data breach weighed on margins while customer volumes recovered. Sentiment was further weighed down by a record KRW 624.7 billion (about US $430 million) privacy fine stemming from an investigation into the breach, while a rotation of fast money into AI and semiconductor names added to the weakness. Despite these headwinds, our conviction remains intact. We view the margin pressure as temporary, and the fine removes a key overhang and reinforces our belief that the breach does not reflect a structural loss of market share. By the end of April, Coupang recovered roughly 80% of the post-breach decline in WOW Membership (its paid subscription program), with returning members resuming prior spending levels. We continue to view Coupang as a competitively advantaged e-commerce business gaining share in its core market while scaling Taiwan operations."
#coupang #NYSE #letter

1 month ago
Riverwater Partners, an investment management company, released its 'Small Cap Strategy' Q2 2026 investor letter. The letter can be downloaded here. The Small Cap Strategy underperformed the Russell 2000 in the second quarter as the benchmark experienced one of its strongest risk-on rallies in recent memory, although the strategy remained ahead year-to-date. The quarter was defined by accelerating AI investment, energy market disruptions, and renewed investor appetite for higher-beta stocks, creating headwinds for the firm's quality-focused approach and healthcare positioning. Despite this, stock selection contributed positively in energy, materials, and financials, while healthcare and consumer discretionary detracted due to the fund's disciplined avoidance of speculative businesses. Looking ahead, the firm remains cautiously optimistic, focusing on opportunities created by market dislocations, including AI infrastructure enablers, select consumer companies, healthcare innovators, and energy businesses trading below intrinsic value. The strategy continues to emphasize high-quality companies with strong management teams and attractive valuations, positioning the portfolio for a potential rotation away from speculative market leadership. In addition, please check the Strategy's top five holdings to know its best picks in 2026.
In its second-quarter 2026 investor letter, Riverwater Partners Small Cap Strategy highlighted Grand Canyon Education, Inc. (NASDAQ:LOPE). Grand Canyon Education, Inc. (NASDAQ:LOPE), a US-based education services company, detracted from performance this quarter. On August 31, 2026, Grand Canyon Education, Inc. (NASDAQ:LOPE) closed at $148.13 per share. Grand Canyon Education, Inc. (NASDAQ:LOPE) fell 1.77% over the past month, and its shares are down 27.09% over the past 52 weeks. Grand Canyon Education, Inc. (NASDAQ:LOPE) has a market capitalization of around $3.86 billion with a 52-week trading range between $134.27 - $223.04.
Riverwater Partners Small Cap Strategy stated the following regarding Grand Canyon Education, Inc. (NASDAQ:LOPE) in its Q2 2026 investor letter:
"Grand Canyon Education, Inc. (NASDAQ:LOPE), the education services provider, declined approximately 16% and was the portfolio's largest detractor. Our investment thesis remains intact; LOPE's steady, profitable, countercyclical enrollment business was simply left behind in a market that rewarded beta and speculation. Enrollment trends and cash generation remain consistent with our expectations, and we continue to hold the position."
#strategy #market #riverwater #partners
1 month ago
Knicks projected to part ways with key 2026 NBA Championship piece originally appeared on The Sporting News. Add The Sporting News as a Preferred Source by clicking here.
A rare phenomenon in the NBA is when a team keeps its championship squad intact for a back-to-back run. The New York Knicks, led by Jalen Brunson, do not have that luxury heading into the 2026-27 season. They already lost Mitchell Robinson to the Boston Celtics; the next domino is about to fall. That's because James Dolan has made it clear the franchise can compete, but only with certain salary cap stipulations. So, who's the person predicted to leave the Knicks? Miles McBride.
James Dolan has made things clear to Leon Rose: the Knicks can compete as long as their salaries do not hit the second apron. As a consequence, Jalen Brunson lost a screener and fair rebounder in Mitchell Robinson during the offseason. With this pattern looming, Miles McBride is the next candidate to leave.
The Knicks and McBride had an extension deadline in mid-August if they wanted him to settle for a cheaper deal. As expected, the young guard has not signed and will play out the last year of his deal with the Knicks. All signs point to the Knicks seeing McBride walk in NBA Free Agency and not getting any value in return, via James L. Edwards III of The Athletic.
More: Shannon Sharpe argues Jalen Brunson's championship is more impressive than SGA's MVP
#knicks


1 month ago
The Tennessee ******* ans' initial 53-man roster stayed intact for all of 19 hours.
The ******* ans have been granted the rights to three players via the NFL waiver wire on Aug. 31, bringing in new faces who haven't been on the squad throughout the offseason. Players claimed off waivers must be signed directly to the active roster, so the ******* ans will have to make corresponding roster moves to make ******* e.
The players the ******* ans have signed are LB Owen Pappoe, DB Melvin Smith and DT ******* r Stackhouse.
Per NFL rules, the ******* ans trimmed their active roster down from 91 players to 53 players on Aug. 30, parting ways with some well-known players including former starting QB Will Levis. The roster is fluid, though, and the ******* ans can continue to tinker with players and placements up to the day before the season opener against the New York Jets on Sept. 13. The ******* ans will also be able to build their 17-player practice squad here in the coming hours now that waivers have been cleared, and plan to bring back several of the young options they waived on Aug. 30 into the fold.
Get to know the ******* ans' latest waiver claim adds below:
#Titans #waiver #make