4 days ago
MACOM Technology Solutions is suddenly giving investors two numbers to think about: its stock has more than doubled over the past year, and its newest optical components push data rates toward another doubling.
asharkyu/Shutterstock.com
MACOM Technology Solutions Holdings, Inc. (NASDAQ:MTSI) announced a 3.2-terabit optical chipset on September 17 built around eight 448-Gbps PAM-4 channels. A day later, BMO Capital upgraded the shares to Outperform with a $335 target, arguing that a 36% decline from the May peak had compressed MACOM's forward valuation to roughly 29 times earnings while data-center fundamentals remained intact.
That puts Coherent Corp. (NYSE:COHR) directly in the conversation because both companies supply the optical connectivity needed to keep larger AI clusters fed with data.
MACOM's new platform combines drivers, photodiodes and transimpedance amplifiers for next-generation optical modules. The company says the components are already available, rather than merely a research roadmap.
#data #macom #holdings #NASDAQ
11 days ago
For the recently reported second quarter, PicS N.V. (NASDAQ:PICS) outperformed relative to its previous guidance across all profitability metrics. The total account base for the company went up to 70.4 million during the second quarter, showcasing a 10% jump from the prior year. Moving on to the bottom line figures, the adjusted earnings before tax, without factoring in costs ******* ociated with stock-based compensation came in at R$291 million for the quarter. This represented a 2.1% outperformance relative to the company's R$285 million guidance. Similarly, compared to the R$245 million projection, adjusted net income for the period actually stood 15.5% higher at R$283 million.
welcomia/Shutterstock.com
The second quarter concluded with strong financial and operating momentum for PicS. The company recorded a 9% annual and 2% sequential growth in its client base, which went up to 45.4 million active users. The total credit portfolio jumped to R$31.9 billion, exceeding management's guidance by 3%. This outperformance came due to a higher number of mature credit card cohorts, and accelerated origination within secured and partly secured categories. An additional factor that accounted for the credit portfolio growth was management's measured expansion into higher risk areas such as newer platform credit and private payroll lending.
Managerial revenue rose to R$3,730 million, topping guidance by 3.6%, and net interest income reached R$2,002 million, 5.4% above projections, boosted by growing credit income. Total cash in totaled R$136.4 billion, up 17% from a year earlier and 9% from the previous quarter, with customers bringing in an average of approximately R$45.4 billion to the platform each month. Total deposits climbed to R$35.8 billion, a 45% yearly jump and 10% quarterly rise.
Some concerns related to the company's loan portfolio emerged during the quarter. Non-performing loans more than 90 days overdue increased to 9.8% of the credit portfolio during the quarter, up 93 basis points sequentially. Stage 3 exposure, which includes a broader set of credit-impaired loans, reached 12.9% of the total credit portfolio.
#million #credit #quarter #Portfolio
11 days ago
On September 14, Evercore ISI raised its price target for Netflix, Inc. (NASDAQ:NFLX) from $100 to $110 while maintaining its Outperform rating. The research firm rolled its valuation framework forward to 2028 and applied a multiple of 25 times its 2028 EPS estimate.
The new price target represents more than 40% upside from the share price of $76.41 as of September 16. However, the stock has declined about 16% year-to-date and remains well below its 52-week high of $124.86.
Evercore ISI conducted its 58th quarterly US survey and 12th semi-annual ****** an survey on Netflix, Inc. (NASDAQ:NFLX), which showed multi-year high penetration of 63% in the US and a record-high 22% penetration in ****** an.
Japan also showed strong subscriber engagement as 58% of subscribers said they were slightly or not at all likely to cancel. Subscriber satisfaction in ****** an also reached 67%.
The company's new ads plan also showed encouraging signs in ****** an. About 66% of new ads plan subscribers were either former Netflix users or people who were new to Netflix.
#high

12 days ago
On September 9, 2026, Chewy, Inc. (NYSE:CHWY) reported fiscal second-quarter net sales of $3.33 billion, up 7.3% year over year, and adjusted earnings per share of $0.36, nearly double the roughly $0.18 ******* ysts had expected, prompting the company to raise its full-year revenue and profitability outlook. CEO Sumit Singh said the broader pet market did not meaningfully recover during the quarter but also did not deteriorate further, with Chewy continuing to outperform the category by two to three times through share gains across its established and newer businesses.
Chewy, Inc. (NYSE:CHWY)'s recurring revenue base is solid. It gives the company greater visibility into future sales. Autoship sales jumped by 9.3% year over year to $2.82 billion and represented 84.6% of total net sales. The growing contribution from subscription-based purchases gives Chewy a more predictable revenue stream and reduces its exposure to fluctuations in discretionary pet spending.
Chewy is also building growth engines beyond its core retail business. Chewy Health, which includes veterinary care and pharmacy services, delivered triple-digit revenue growth. Specialty categories such as equine and exotics recorded a seventh consecutive quarter of mid-double-digit growth. These businesses give Chewy additional opportunities to increase customer spending and diversify its sources of revenue as the overall pet market matures.
Chewy is combining customer growth with stronger profitability and shareholder returns. The firm added 208,000 net active customers during the quarter. It takes its customer base to 21.7 million while returning $200 million to shareholders through share repurchases. Management also noted structural SG&A leverage, automation, and AI-driven cost reductions as contributors to margin expansion. It shows that Chewy can improve earnings while investing in customer acquisition and growth.
Part of Chewy, Inc. (NYSE:CHWY)'s profitability improvement came from benefits that may not recur. CFO Chris Deppe said the quarter's profitability upside included about $10 million from timing benefits and more than $5 million from discrete benefits. Those items boosted the latest results but do not provide a recurring earnings contribution. It means investors may need to lower their expectations for the pace of margin expansion in future quarters.
#customer

12 days ago
Phillips 66 (NYSE:PSX) has been on a strong rally this year, posting gains of over 110% since the beginning of 2026. The outperformance has been driven by an unusually sharp surge in global refining margins amid the war in the Middle East, which has significantly tightened the world's refining capacity and reduced supplies of gasoline, diesel, and jet fuel.
Given Phillips 66's substantial outperformance compared to the wider market, investors may be questioning whether the stock's record-setting run has reached its peak. However, the ****** ysts over at BMO Capital see further upside ahead. On September 17, the firm raised its price target on PSX from $260 to $310, while maintaining an 'Outperform' rating on the shares. The target boost implies an upside of 13% from the current levels and even exceeds the stock's all-time high of over $274 achieved earlier this month.
BMO Capital highlighted Phillips 66's integrated business model, noting that it has gained momentum and outperformed its individual segments, supported by strong execution across the portfolio. While Refining and Renewables remain the cyclical leaders, BMO also sees a favorable medium-term growth outlook for the company's Midstream business.
BMO Capital's vote of confidence comes amid a broader optimism surrounding Phillips 66, with ****** ysts from Morgan Stanley, Raymon James, UBS, and several others also improving their respective outlooks on PSX. This suggests that Wall Street expects the ongoing refining upcycle to last longer than previously expected, particularly following the renewed escalations between Iran and the United States.
The supply disruptions now extend beyond the troubled region, as a recent wave of Ukrainian attacks on Russian refineries has further reduced global refining capacity and provided further support to margins.
#further #margins #amid
12 days ago
Targa Resources Corp. (NYSE:TRGP) has significantly outperformed the wider market this year, posting gains of over 56% since the beginning of 2026. A major catalyst behind this growth was the 20-year fee-based agreement that the company signed with ExxonMobil last month.
While there are concerns that the stock's rally may have topped out, the **** ysts over at TD Cowen see further growth ahead. On September 18, the firm upgraded TRGP from 'Hold' to Buy', while also boosting its price target from $275 to $350. The revised target implies an upside of almost 20% from the current levels and even exceeds the stock's record high of just under $308 achieved last month.
TD Cowen cited Targa's expected Permian Basin wet gas growth and peer-leading EBITDA growth for the upgrade. The **** yst expects the company's free cash flow yield to rise from 6% in 2026 to more than 10% in 2028, compared with an estimated 8.5% FCF yield for peers in 2030. The improvement is expected to be driven by EBITDA growth from new processing plants and the completion of a major capital project in the Speedway NGL pipeline.
According to TD Cowen, a key driver for Targa's growth is the rising wet gas production in the Permian, which means that the **** yst's thesis is tied to physical volume growth rather than simply a higher-commodity price **** umption.
Targa's recently announced deal with ExxonMobil provides greater visibility into future volumes and infrastructure demand. The company has also planned three new natural gas processing plants in the Permian Delaware as part of the deal, with an aggregate capacity of roughly 825 MMcf/day. Targa expects this agreement to add significantly to its "strong growth rate well into the next decade and bolster its outlook for durable and growing adjusted free cash flow over the long term".
#exxonmobil #ebitda
12 days ago
Marathon Petroleum Corporation (NYSE:MPC) has substantially outperformed the wider market this year, supported by an unusually sharp surge in global refining margins as the prolonged Iran crisis has significantly tightened global refining capacity and reduced supplies of gasoline, diesel, and jet fuel.
With Marathon up by over 150% since the beginning of 2026, there are now concerns that the stock may have topped out. However, the ****** ysts over at Morgan Stanley are convinced that the rally still has further room to run. On September 14, Morgan Stanley ****** yst Joe Laetsch significantly raised the firm's price target on MPC from $265 to $453, while reaffirming an 'Overweight' rating on the shares.
The target boost reflects an upside of over 9% from the current price level and even exceeds the stock's record high of just under $411 per share achieved earlier this month. The Morgan Stanley update comes amid broader Wall Street optimism surrounding the American refining giant, with ****** ysts from Raymon James, UBS, and several others also improving their respective outlooks on MPC.
Morgan Stanley's vote of confidence suggests that Wall Street expects the ongoing refining upcycle to last longer than previously expected, especially given the fresh wave of attacks between Washington and Tehran. Even if the conflict in the Middle East subsides, the region's refined fuel output is expected to remain relatively tight, since the damaged or idled refineries in the Middle East are likely to take some time to return to full operations.
As the largest refiner by volume in the United States, Marathon has significant operating leverage to capitalize on the current high-margin environment. The company already demonstrated its ability to translate the high crack spreads into material earnings when it delivered an almost fourfold increase in profits in the second quarter.
#morgan #marathon #stanley #middle

12 days ago
Enbridge Inc. (NYSE:ENB) has declined by around 17% since hitting its record high in May, likely as a result of rising bond yields, lack of visibility on the company's 5% growth guidance through the end of the decade, and the recently closed equity offering intended to fund the midstream operator's strategic acquisitions.
However, BMO Capital sees this pullback as an opportunity and on September 15, the firm upgraded ENB from 'Market Perform' to 'Outperform', while also slightly raising its price target from C$79 to C$79.50. The target boost implies an upside of 18% from the current levels.
The **** yst believes that Enbridge's scale, limited commodity exposure, and diversified **** ets are underappreciated. BMO also cited the company's improving visibility on growth, robust backlog, opportunistic acquisitions, and improved balance sheet as reasons behind the upgrade.
Enbridge's aggressive expansion strategy adds significantly to its bull case. The company announced on September 9 that it would acquire Tallgrass Energy's crude oil business for $2.55 billion in cash, expanding its US liquids pipeline network by buying a majority stake in the Pony Express Pipeline and other **** ets. The midstream operator expects the acquisition to be accretive to distributable cash flow per share in the first full year of ownership.
Similarly, Enbridge announced last month that it had agreed to acquire Salt Creek Midstream's crude oil gathering business for $600 million in cash, further bolstering its presence in the prolific Permian Basin. The acquired **** ets have an average remaining contract life of about 10 years, providing stable long-term cash flows.
#visibility #target

12 days ago
Pricing alone does not decide where people buy their clothes.
With a number of retail chains competing for the off-price, on-trend fashion crown, it's easy for one brand to fall out of favor. Consumers seem to have an enduring love for Marshalls and TJ Maxx, while the popularity of Ross Dress for Less has grown steadily in recent years.
These brands drive sales by foot traffic, and that's a battle the aforementioned chains have been winning.
"Off-price apparel remained on solid footing in Q2 2026, with Ross leading the segment. Visits to Ross Dress for Less rose 16.4% year over year (YoY), while dd's DISCOUNTS grew 8.4%. TJX's TJ Maxx and Marshalls, meanwhile, saw visits hover around last year's levels — significantly outperforming traditional apparel, which declined 3.5% YoY," according to data from Placer.ai.
In the battle for customers looking for deals on trendy, fashionable clothes, Cato has been struggling, and now plans to close about 15% of its retail stores.
#less #retail

12 days ago
Affirm Holdings, Inc. (NASDAQ:AFRM) has underperformed the broader market year to date, but the tide is slowly turning. Robust growth in interest-bearing loans, a strategic partnership with Shopify in Australia, and accelerating volumes at Amazon provide multiple avenues for continued growth.
On September 12, Goldman Sachs raised its price target to $115 from $106, citing improving underlying fundamentals. The hike follows the company's impressive fourth-quarter fiscal 2026 results, with revenues surging 33% to $1.2 billion and operating income rising $89 million to $147 million.
The robust revenue growth came as the company continued to attract more business interest-bearing loans. Interest income rose 35% in the fourth quarter, in line with a 33% increase in average net loans held for investment partners. More importantly, 80% of Affirm's direct-to-consumer product loans carried interest at quarter-end, giving the company an increasingly meaningful source of recurring interest income.
The investment bank has also touted the growth opportunity around Affirm Card, which is helping the company expand its relationship with consumers beyond individual BNPL transactions. Active cardholders more than doubled to 5.2 million, resulting in a 124% increase in Card GMV to $2.8 billion.
Management has already hinted at continued upside momentum by estimating a massive increase in GMV to $64 billion in fiscal 2027 and an adjusted operating margin of 30.5%. Against this backdrop, Wolfe Research ****** yst Darrin Peller upgraded the stock to Outperform with a $90 price target. According to the ****** yst, Affirm Holdings is a winner in the point-of-sale financing ****** e.
#interest #billion #company


12 days ago
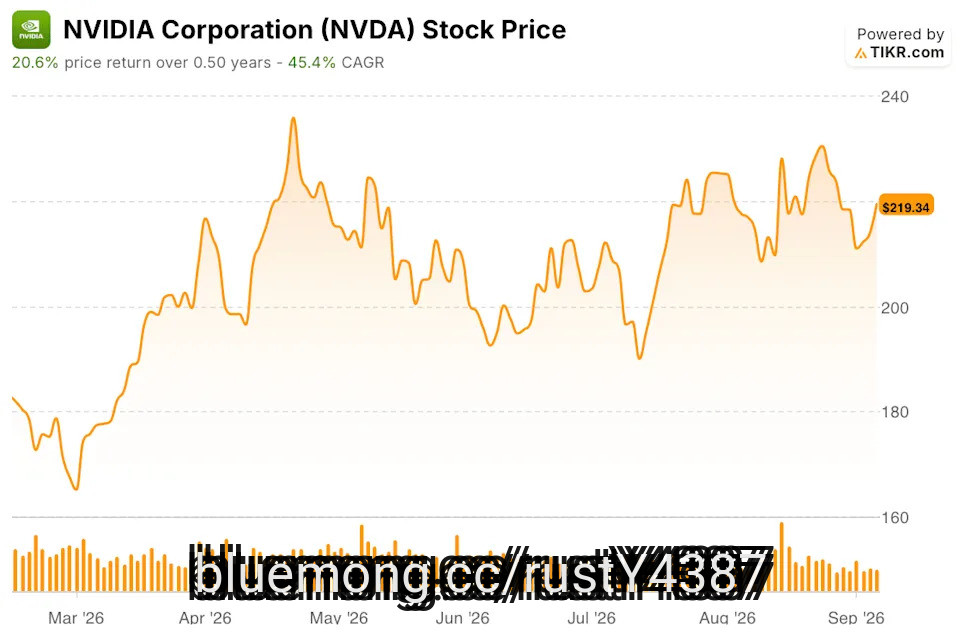
Six-Month Run: NVDA stock has climbed 20.6% since mid-March, a 45.4% annualized pace, even as the S&P 500 wobbled under the Fed's rate hike and a 10-year Treasury yield near 5%.
Model Verdict: TIKR's model puts fair value at $643, implying 193% total return by early 2031.
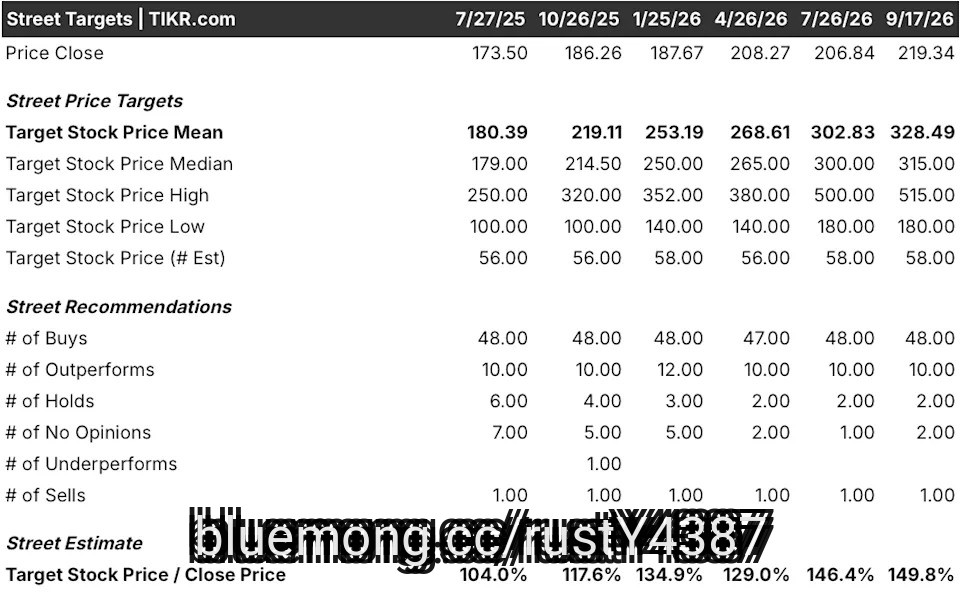
Coverage Split: Nvidia stock carries 48 buy ratings, 10 outperforms, 2 holds, 2 no opinions and 1 sell, with a mean target of $328, 50% above the current price.
Supply Squeeze: Nvidia guided to roughly 70% revenue growth for fiscal 2028 on demand it calls supply-constrained, with cloud industry backlog above $2 trillion.
Nvidia (NVDA) stock has climbed 20.6% since mid-March, a 45.4% annualized pace, while the Federal Reserve's first rate hike in more than three years pushed the 10-year Treasury yield toward 5% and dragged the S&P 500 into back-to-back weekly declines. Most of the market treated the hike as a reason to sell. Nvidia stock kept climbing anyway.
#march #model #supply #since
12 days ago
The first full week of trading in September didn't give Zscaler (NASDAQ: ZS) investors much to celebrate. During the shortened trading week that followed Labor Day, Zscaler dropped about 3%. This week, however, is a very different story, thanks to a firm providing an auspicious outlook for the cybersecurity stock.
According to data provided by S&P Global Market Intelligence, Zscaler shares were up 20.7% from the end of trading last Friday through 3:37 p.m. today.
Missed AI's "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our ******* ysts, we're only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
Maintaining its outperform rating, Bernstein hiked its price target on Zscaler stock to $298 from $224 on Thursday morning. Based on Zscaler's closing price of $191.58 on Wednesday, the Bernstein price target implies 56% upside.
According to Thefly.com, Bernstein based its improved outlook on the belief that there's growing positive market sentiment toward cybersecurity stocks. In addition, Bernstein notes that cybersecurity stocks it had previously identified as "too cheap" are now reasonable valued, yet Zscaler is one option that still provides material upside.
#week
12 days ago
One of the world's largest companies has become a cash-return machine of historic scale, but its engine is now facing a serious test.
With Apple (AAPL) stock trading near $337 a share, an owner might ask a simple question. The company has returned a fortune in cash while the stock has dramatically outperformed the market; was holding worth it, and can this machine keep running?
Over the last five years, Apple sent $510.4 billion in cash back to its shareholders. That sum, equal to about 10.3% of the company's current market value, is the largest capital return of any U.S. company Trefis tracks over that period. The question is what that extraordinary payout says about the business today.
The money printer is Apple's core business, which generated $136.68 billion in free cash flow over the last twelve months. In its most recent quarter, the company reported record June-quarter revenue, with iPhone sales growing 22% and Mac sales growing an impressive 29% from a year ago. Management noted that the iPhone and Mac were "both doing remarkably better than we thought they would do."
That operational strength funds the shareholder returns. The five-year payout was heavily weighted toward share repurchases, which totaled $434.5 billion, with another $75.9 billion paid in dividends. Apple's absolute dollar payout stands alone, even though the 10.3% of market value it returned sits well below the 16.9% median for S&P 500 companies.
#market

12 days ago
Pricing alone does not decide where people buy their clothes.
With a number of retail chains competing for the off-price, on-trend fashion crown, it's easy for one brand to fall out of favor. Consumers seem to have an enduring love for Marshalls and TJ Maxx, while the popularity of Ross Dress for Less has grown steadily in recent years.
These brands drive sales by foot traffic, and that's a battle the aforementioned chains have been winning.
"Off-price apparel remained on solid footing in Q2 2026, with Ross leading the segment. Visits to Ross Dress for Less rose 16.4% year over year (YoY), while dd's DISCOUNTS grew 8.4%. TJX's TJ Maxx and Marshalls, meanwhile, saw visits hover around last year's levels — significantly outperforming traditional apparel, which declined 3.5% YoY," according to data from Placer.ai.
In the battle for customers looking for deals on trendy, fashionable clothes, Cato has been struggling, and now plans to close about 15% of its retail stores.
#price
13 days ago
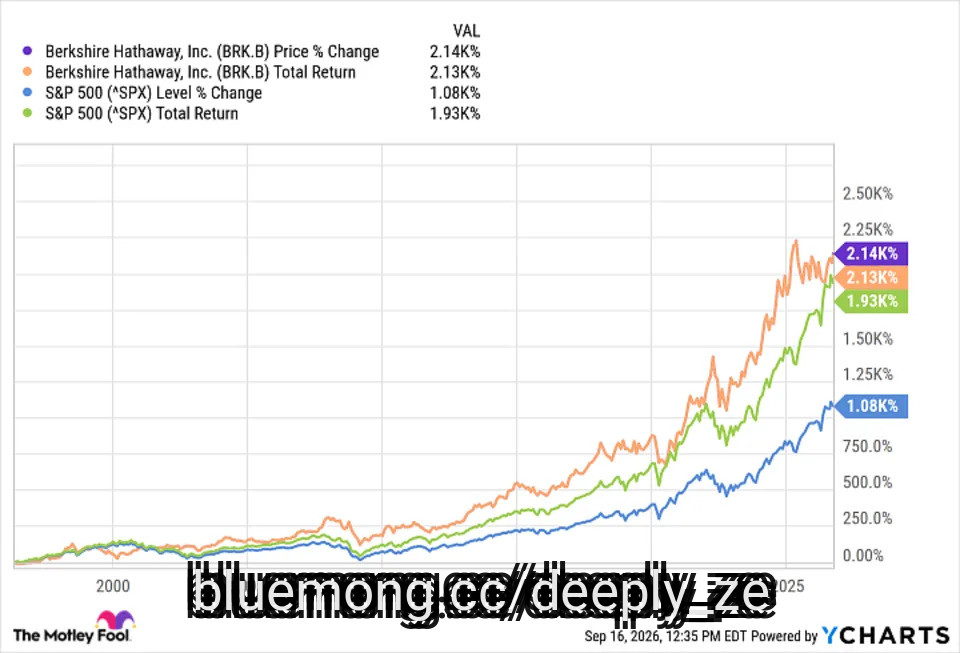
Experienced investors know the advantages of buying and holding S&P 500 index funds like the Vanguard S&P 500 ETF (NYSEMKT: VOO) or the SPDR S&P 500 ETF Trust (NYSEMKT: SPY). Not only are they super simple, but statistically speaking, you're likely to get better performance from them than you are by picking individual stocks or by owning an actively managed fund.
Nevertheless, given its long-term (and often market-beating) track record, even the most disciplined of investors might have the itch to step into a stake in Berkshire Hathaway (NYSE: BRKA) (NYSE: BRKB). But is it actually the better buy?
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Berkshire Hathaway is a conglomerate consisting of several dozen reliable cash-producing businesses as well as a portfolio of hand-picked stocks. Brought to prominence by Warren Buffett, the company's flexible structure has enabled its shares to consistently outperform the S&P 500 since Buffett first took the helm in 1965.
It hasn't beaten the market every year since then, to be clear. Some years it did. Other years it didn't. It typically achieved the feat in five-year time frames.
#signal #years #buffett #flashing

13 days ago
On September 14, Evercore ISI raised its price target for Netflix, Inc. (NASDAQ:NFLX) from $100 to $110 while maintaining its Outperform rating. The research firm rolled its valuation framework forward to 2028 and applied a multiple of 25 times its 2028 EPS estimate.
The new price target represents more than 40% upside from the share price of $76.41 as of September 16. However, the stock has declined about 16% year-to-date and remains well below its 52-week high of $124.86.
Evercore ISI conducted its 58th quarterly US survey and 12th semi-annual **** an survey on Netflix, Inc. (NASDAQ:NFLX), which showed multi-year high penetration of 63% in the US and a record-high 22% penetration in **** an.
Japan also showed strong subscriber engagement as 58% of subscribers said they were slightly or not at all likely to cancel. Subscriber satisfaction in **** an also reached 67%.
The company's new ads plan also showed encouraging signs in **** an. About 66% of new ads plan subscribers were either former Netflix users or people who were new to Netflix.
#netflix #price #september #evercore


13 days ago
For the recently reported second quarter, PicS N.V. (NASDAQ:PICS) outperformed relative to its previous guidance across all profitability metrics. The total account base for the company went up to 70.4 million during the second quarter, showcasing a 10% jump from the prior year. Moving on to the bottom line figures, the adjusted earnings before tax, without factoring in costs ****** ociated with stock-based compensation came in at R$291 million for the quarter. This represented a 2.1% outperformance relative to the company's R$285 million guidance. Similarly, compared to the R$245 million projection, adjusted net income for the period actually stood 15.5% higher at R$283 million.
welcomia/Shutterstock.com
The second quarter concluded with strong financial and operating momentum for PicS. The company recorded a 9% annual and 2% sequential growth in its client base, which went up to 45.4 million active users. The total credit portfolio jumped to R$31.9 billion, exceeding management's guidance by 3%. This outperformance came due to a higher number of mature credit card cohorts, and accelerated origination within secured and partly secured categories. An additional factor that accounted for the credit portfolio growth was management's measured expansion into higher risk areas such as newer platform credit and private payroll lending.
Managerial revenue rose to R$3,730 million, topping guidance by 3.6%, and net interest income reached R$2,002 million, 5.4% above projections, boosted by growing credit income. Total cash in totaled R$136.4 billion, up 17% from a year earlier and 9% from the previous quarter, with customers bringing in an average of approximately R$45.4 billion to the platform each month. Total deposits climbed to R$35.8 billion, a 45% yearly jump and 10% quarterly rise.
Some concerns related to the company's loan portfolio emerged during the quarter. Non-performing loans more than 90 days overdue increased to 9.8% of the credit portfolio during the quarter, up 93 basis points sequentially. Stage 3 exposure, which includes a broader set of credit-impaired loans, reached 12.9% of the total credit portfolio.
#million #total
13 days ago
AGNC Investment (NASDAQ: AGNC) completed its IPO in May 2008 at $20 per share. Today, shares of the mortgage REIT trade at around $10 per share, a staggering 50% below their IPO price.
However, the company's monthly dividends have more than offset the slump in its share price. AGNC has paid out over $50 per share in ****** ulative dividends since its IPO, more than double its IPO price. With dividends reinvested, it has significantly outperformed mortgage REITs and other financial stocks since its IPO.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
AGNC Investment's founders formed it in the depths of the financial crisis, seeing an opportunity to create a leading Agency MBS (mortgage-backed securities guaranteed against credit losses by government agencies like Fannie Mae). It invests in Agency MBS on a leveraged basis, primarily through repurchase agreements, and uses dynamic risk management strategies to navigate market risks, including interest rate changes.
The company has had to maneuver around several market cycles, unexpected events, and market volatility over the years, which have weighed on its investment returns and earnings. AGNC Investment has still managed to significantly expand its Agency MBS portfolio (it reached $97.2 billion at the end of the second quarter), financed primarily by selling stock. As a result, its shares outstanding have risen a staggering 7,660% since its IPO. This combination of earnings volatility and dilution is why its share prices have fallen 50% since the IPO.
#since #agency #dividends



13 days ago
The Magnificent 7 stocks are having a tough ride in 2026, and only Apple (AAPL) is outperforming the Nasdaq 100 Index ($IUXX). Digging deeper, Nvidia (NVDA) is the only other constituent that is up in double digits. Despite its recent rally, Tesla (TSLA) is still down over 18% year-to-date (YTD) and is the worst-performing Mag 7 stock.
The price action is not difficult to explain. Investors are now getting increasingly wary of tech companies' ever-rising capex to build artificial intelligence (AI) infrastructure. Apple was an outlier in the AI buildout race and is now sitting pretty as investors realize that waiting it out wasn't exactly a bad move on the iPhone maker's part.
Mark Cuban Says He Was Dizzy for Months, So He Built a VR Fix That Does at Home 'Much Of What A 180k Machine' Does
Bank of America Just Declared a 'Generational Entry Point' in U.S. Bonds. Why Investors Should Be Backing Up the Truck on Treasuries Here.
Nvidia, OpenAI, and Oracle's $745B Financing Circle Just Hit Its First Stress Test: A Fed Rate Hike
#aapl #iuxx


13 days ago
On September 10, 2026, Copart, Inc. (NASDAQ:CPRT) reported fourth-quarter results for the period ended July 31, 2026, and used the call to announce an all-cash acquisition of digital auto marketplace ACV Auctions. Revenue grew 2.4% to $1.2 billion, but gross profit fell 5.5% to $481.4 million and net income dropped 17.4% to $327.4 million. Diluted EPS came in at $0.35 against $0.41 a year earlier.
Wall Street spent the following days separating the deal from the quarter.
Barrington's Gary Prestopino saw enough in the transaction to move off the sidelines, upgrading Copart, Inc. (NASDAQ:CPRT) to Outperform from Market Perform with a $40 target. His argument is that combining Copart's physical network with ACV's digital marketplace, at an implied equity value of $1.9 billion or $10.50 per share in cash, creates an end-to-end remarketing platform and opens a new growth vector in dealer-to-dealer and commercial vehicle auctions.
JPMorgan's Jash Patwa had already upgraded Copart, Inc. (NASDAQ:CPRT) to Overweight from Neutral ahead of the print, raising his target to $40 from $32 on encouraging salvage industry channel checks, web scraping data showing Copart gaining share with a carrier across several states, and a collision cycle he sees turning more favorable as insurance penetration recovers.
Freedom Broker, which trimmed its target to $36 from $39 while keeping a Buy rating, called the report mixed but framed the ACV move as a strong pivot toward digital marketplace expansion.
#NASDAQ #cprt #auctions

13 days ago
On September 9, 2026, Academy Sports and Outdoors, Inc. (NASDAQ:ASO) posted second-quarter results for the period ended August 1, 2026. Net sales rose 3.0% to $1.65 billion, adjusted earnings per share climbed 19.1% to $2.31 from $1.94, and gross margin widened 440 basis points to 40.4%. Management lifted full-year adjusted EPS guidance to $6.50 to $6.90 and gross margin guidance to 35.5% to 36.0%. What the quarter did not deliver was a positive comp, which fell 0.4%.
Telsey Advisory came away seeing nothing that changes the thesis, calling the risk-reward attractive and pushing its target on Academy Sports and Outdoors, Inc. (NASDAQ:ASO) to $63 from $60 while staying at Outperform.
Wells Fargo's Ike Boruchow described himself as cautiously optimistic at current levels, arguing that both the quarter itself and management's forward commentary delivered upside surprise; his target moved to $55 from $50, though the rating stayed Equal Weight.
Barclays **** yst Adrienne Yih focused on the fact that Academy Sports and Outdoors, Inc. (NASDAQ:ASO) held its fiscal 2026 sales and comp guidance despite a tougher consumer backdrop and sequential demand deceleration, lifting her target to $53 from $50 at Equal Weight.
Supporting the case: e-commerce sales grew 12.8%, Sports and Recreation rose 6%, myAcademy loyalty membership passed 15 million, and the company raised adjusted free cash flow guidance to $300 million to $350 million after repurchasing $182.1 million of stock in the first half.
#sports #guidance #sales #target

13 days ago
Dave & Buster's Entertainment, Inc. (NASDAQ:PLAY) reported a widening split between dining and entertainment in its September 14 second-quarter results. Food-and-beverage revenue increased to $211.5 million from $192.9 million, while entertainment revenue fell to $332.6 million from $364.5 million.
For the fiscal quarter ended August 4, 2026, total revenue declined 2.4% to $544.1 million. Operating income dropped to $19.4 million from $53 million. The GAAP net loss was $12.5 million, versus net income of $11.4 million a year earlier. Stronger restaurant sales are providing support, but the investment question is whether they can also bring customers back to the games.
Food-and-beverage revenue grew approximately 9.6%, giving Dave & Buster's Entertainment, Inc. (NASDAQ:PLAY) an identifiable source of momentum. A more appealing dining experience could encourage repeat visits, group occasions, and longer stays, creating additional opportunities to sell entertainment.
Management reported ongoing growth in food-and-beverage and special-events sales, alongside improving comparable-sales trends in July and the third quarter to date. That suggests the recovery effort has some traction beyond a single revenue category, although the later sales improvement was not quantified.
Management also said remodeled locations continued to outperform the system on comparable sales. That supports selective investment in existing venues, provided the additional revenue earns adequate returns on remodeling costs.
#entertainment #dave

14 days ago
Over the last seven years, I've **** yzed hundreds of stocks and cryptocurrencies to see if they might be worth an investment. At the end of the day, I only end up buying a select few, like two of my longtime favorites, Costco Wholesale (NASDAQ: COST) and Apple (NASDAQ: AAPL).
Here's an abridged version of my research process -- hopefully it'll contain something useful to adapt as your own.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
I typically start by getting the lay of the land regarding the company in question.
Step zero is comparing the stock's total returns to the S&P 500 over a range of different periods, starting from one month and extending to five years. Ideally, like both Apple and Costco, the company being evaluated will have outperformed the index over the last five years.
#NASDAQ #flashing #total

14 days ago
Teck Resources Ltd (NYSE:TECK) stock's pullback from its Sept. 8 record high of $72.56 has found support at the 60-, 80-, and 100-day moving averages. The 100-day trendline in particular is a historically bullish signal that presents an intriguing 'buy the dip' angle.
Per Schaeffer's Senior Quantitative ******* yst Rocky White, TECK has traded within 0.75 times the 100-day moving average's 20-day average true range (ATR) after spending at least 80% of the previous two weeks and 80% of the prior 42 trading sessions above the trendline. This setup has occurred eight other times over the last decade, after which the stock was higher one month later 75% of the time, averaging a large 13.8% gain.
Short interest accounts for a healthy 7.5% of the stock's available float, leaving ample sideline buying power should some of these bearish bets begin to unwind. TECK's 14-day Relative Strength Index (RSI) of 28.4 also sits in "oversold" territory, which often precedes a short-term bounce.
Plus, TECK's Schaeffer's Volatility Scorecard (SVS) sits at 81 out of 100, suggesting the shares have tended to outperform options traders' volatility expectations during the past year.
#resources

14 days ago
GE Vernova Inc (NYSE:GEV) rebounded with Bernstein's backing after an earlier sell-off that followed broader concerns about technology infrastructure spending.
Shares were up 6% at $933.94 during afternoon trading on Wednesday, outpacing the utilities sector's reported 1.24% advance.
GE Vernova also ranked among the three leading stocks by turnover in the utilities sector as its shares recovered from prior-session declines.
Bernstein reaffirmed its "outperform" rating, highlighting electrification demand beyond immediate artificial intelligence data center needs.
The brokerage said utility-driven power grid upgrades, energy security and decarbonization initiatives accounted for the majority of electrification orders.
#backing

14 days ago
Our **** ysts just identified a stock with the potential to be the next Nvidia. Tell us how you invest and we'll show you why it's our #1 pick. Tap here.
Achieved group-adjusted EBITDA break-even just 15 months post-acquisition by applying Mytheresa's 'secret sauce'—focusing on top-tier customers, full-price selling, and rigorous cost discipline—to the distressed YNAP business.
Mytheresa reached a EUR 1 billion milestone in FY 2026, outperforming the industry through superior customer economics where top customers (4.8% of base) generated 48.4% of total GMV.
NET-A-PORTER and MR PORTER reached a strategic inflection point, returning to top-line growth and positive adjusted EBITDA in Q4 by pivoting from promotional discounting to editorial-led luxury discovery.
YOOX's turnaround is being driven by a deliberate retreat from high-cost overseas markets to focus on a 'healthy core' in Europe, resulting in losses being cut nearly in half compared to the prior year.
#porter #customers #cost #reached
15 days ago
Parnassus Investments, an investment management company, released the "Parnassus Growth Equity Fund" second-quarter 2026 investor letter. The letter can be downloaded here. During the quarter, the Fund (Investor Shares) returned 17.49% (net of fees), outperforming the Russell 1000 Growth Index's 16.74%. Holdings in Information Technology and Consumer Discretionary sectors boosted relative returns, while Communication Services and Financials holdings detracted. For the year-to-date period, the Fund returned 6.17% (net of fees), outperforming the Russell 1000 Growth's 5.33%. The firm remains constructively bullish on U.S. equities and continues to be selective, valuation-sensitive, and focused on disruptive growth opportunities through active stock selection. Growth stocks advanced during the second quarter, as the Russell 1000 Growth Index generated strong double-digit returns driven by increased confidence in the durability of the ongoing artificial intelligence (AI) infrastructure build-out. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its second-quarter 2026 investor letter, Parnassus Growth Equity Fund highlighted Sandisk Corporation (NASDAQ:SNDK) as a newly added position. Sandisk Corporation (NASDAQ:SNDK) develops, manufactures, and sells data storage devices and solutions using NAND flash technology in the United States and internationally. On September 15, 2026, Sandisk Corporation (NASDAQ:SNDK) closed at $1,530.90 per share. Over the past month, Sandisk Corporation (NASDAQ:SNDK) declined 2.32%, but its shares are up 1,530.74% over the past year. Sandisk Corporation (NASDAQ:SNDK) has a market capitalization of $224.15 billion, and its stock has traded within a 52-week range of $90.22 to $2,354.39.
Parnassus Growth Equity Fund stated the following regarding Sandisk Corporation (NASDAQ:SNDK) in its Q2 2026 investor letter:
"Other positions added during the quarter included Sandisk Corporation (NASDAQ:SNDK), a leader in flash memory solutions; Comfort Systems, a mechanical, electrical and plumbing contractor. Sandisk makes NAND flash memory, which is seeing a surge in demand from data centers and AI workloads. While NAND remains cyclical, we believe the combination of accelerating AI-driven storage demand and constrained supply provides an attractive opportunity to participate in the current upcycle."
Sandisk Corporation (NASDAQ:SNDK) is on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 128 hedge fund portfolios held Sandisk Corporation (NASDAQ:SNDK) at the end of the second quarter which was 114 in the previous quarter. While we acknowledge the potential of Sandisk Corporation (NASDAQ:SNDK) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our fre

15 days ago
Parnassus Investments, an investment management company, released the "Parnassus Growth Equity Fund" second-quarter 2026 investor letter. The letter can be downloaded here. During the quarter, the Fund (Investor Shares) returned 17.49% (net of fees), outperforming the Russell 1000 Growth Index's 16.74%. Holdings in Information Technology and Consumer Discretionary sectors boosted relative returns, while Communication Services and Financials holdings detracted. For the year-to-date period, the Fund returned 6.17% (net of fees), outperforming the Russell 1000 Growth's 5.33%. The firm remains constructively bullish on U.S. equities and continues to be selective, valuation-sensitive, and focused on disruptive growth opportunities through active stock selection. Growth stocks advanced during the second quarter, as the Russell 1000 Growth Index generated strong double-digit returns driven by increased confidence in the durability of the ongoing artificial intelligence (AI) infrastructure build-out. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its second-quarter 2026 investor letter, Parnassus Growth Equity Fund highlighted Brown & Brown, Inc. (NYSE:BRO). Brown & Brown, Inc. (NYSE:BRO) is a leading insurance brokerage firm operating through Retail and Specialty Distribution segments. On September 15, 2026, Brown & Brown, Inc. (NYSE:BRO) closed at $67.23 per share, reflecting a market capitalization of $22.5 billion. Brown & Brown, Inc. (NYSE:BRO) posted a one‑month return of -6.29%, while its shares lost 27.35% over the past 52 weeks.
Parnassus Growth Equity Fund stated the following regarding Brown & Brown, Inc. (NYSE:BRO) in its Q2 2026 investor letter:
"We sold Brown & Brown Inc. during the quarter. Brown & Brown, Inc. (NYSE:BRO) remains a high-quality business, but we see rising near term risks as the company navigates an industry downturn, integrates a large acquisition and works to close an AI capability gap versus larger peers."
Brown & Brown, Inc. (NYSE:BRO) is not on our list of 40 Most Popular Stocks Among Hedge Funds Heading Into 2026. According to our database, 44 hedge fund portfolios held Brown & Brown, Inc. (NYSE:BRO) at the end of the second quarter, compared to 41 in the previous quarter. While we acknowledge the potential of Brown & Brown, Inc. (NYSE:BRO) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#quarter #letter
15 days ago
On September 14, Dave & Buster's Entertainment (NASDAQ:PLAY) reported second-quarter fiscal 2026 results that read like two different companies at once. Revenue fell, and the company posted a net loss for the period ended August 4, yet comparable sales, which had been sliding for more than a year, kept getting less bad every month from June through the first five weeks of the third quarter. New CEO Darin Harper is betting that improvement compounds into something bigger.
The clearest evidence is the trend line itself. Comparable store sales fell 5.4% in the first quarter of fiscal 2026, then 2.9% in the second quarter, then just 1.6% in July after a 5% decline in June, and Harper said trends improved further over the first five weeks of the third quarter. Food and beverage sales are moving in the opposite direction entirely, up 7.6% in the quarter and positive for five straight quarters, helped by the Eat & Play Combo, a bundled meal and game credit offer sold through kiosks. Special event sales have now grown for seven consecutive quarters.
Behind that shift sits a rebuilt leadership bench. Dave & Buster's went more than a year without a chief marketing officer, and Harper has since added a CMO, a chief operations officer, a chief technology officer, and a chief legal officer since taking over. The company also leaned on new content, launching 10 games and attractions this year, including tie-ins with Mandalorian and Grogu, John Wick and Stranger Things, after research found more than 70% of guests said new games would bring them back more often. Changes to game pricing pushed play and dwell time up 16% to 20% or more. Six remodeled stores are already outperforming the rest of the chain, and management says the newest remodel template costs less to build than the last one. Net capital spending dropped to $127.6 million through the first half of the year from $155.4 million, and adjusted free cash flow swung to positive $19.5 million from negative $36.5 million, a $56 million improvement.
The headline figures were still rough. Total revenue slipped 2.4% to $544.1 million from $557.4 million a year earlier, and adjusted EBITDA dropped to $98.9 million, an 18.2% margin, from $129.8 million and a 23.3% margin. On a GAAP basis, the company posted a net loss of $12.5 million, or $0.36 per diluted share, versus net income of $11.4 million in the same quarter last year. About $15 million of the EBITDA decline came from items management calls non-normalized, including a $10 million noncash deferral adjustment that did not repeat this year, $3 million in extra preopening costs and $2 million in higher insurance expenses, but even stripped of those, the underlying decline was still roughly $16 million.
#year #first #harper #play
15 days ago
Parnassus Investments, an investment management company, released the "Parnassus Growth Equity Fund" second-quarter 2026 investor letter. The letter can be downloaded here. During the quarter, the Fund (Investor Shares) returned 17.49% (net of fees), outperforming the Russell 1000 Growth Index's 16.74%. Holdings in Information Technology and Consumer Discretionary sectors boosted relative returns, while Communication Services and Financials holdings detracted. For the year-to-date period, the Fund returned 6.17% (net of fees), outperforming the Russell 1000 Growth's 5.33%. The firm remains constructively bullish on U.S. equities and continues to be selective, valuation-sensitive, and focused on disruptive growth opportunities through active stock selection. Growth stocks advanced during the second quarter, as the Russell 1000 Growth Index generated strong double-digit returns driven by increased confidence in the durability of the ongoing artificial intelligence (AI) infrastructure build-out. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its second-quarter 2026 investor letter, Parnassus Growth Equity Fund highlighted Comfort Systems USA, Inc. (NYSE:FIX) as a new position. Comfort Systems USA, Inc. (NYSE:FIX) is a leading mechanical and electrical installation, renovation, maintenance, repair, and replacement services provider to commercial, industrial, and institutional customers. On September 15, 2026, Comfort Systems USA, Inc. (NYSE:FIX) closed at $1,576.78 per share. Over the past month, Comfort Systems USA, Inc. (NYSE:FIX) declined 5.15% and its shares gained 110.86% over the past 52 weeks. Comfort Systems USA, Inc. (NYSE:FIX) has a market capitalization of $55.49 billion.
Parnassus Growth Equity Fund stated the following regarding Comfort Systems USA, Inc. (NYSE:FIX) in its Q2 2026 investor letter:
"Other positions added during the quarter included Comfort Systems, a mechanical, electrical and plumbing contractor. Comfort Systems USA, Inc. (NYSE:FIX) is a mechanical, electrical and plumbing contractor that provides the skilled labor that's essential for building increasingly complex data centers, where demand continues to accelerate alongside AI investment."
Comfort Systems USA, Inc. (NYSE:FIX) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 83 hedge fund portfolios held Comfort Systems USA, Inc. (NYSE:FIX) at the end of the second quarter which was 80 in the previous quarter. While we acknowledge the potential of Comfort Systems USA, Inc. (NYSE:FIX) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#systems #parnassus