

2 months ago
Sempra (NYSE:SRE) added a long-term customer commitment on September 14, when its infrastructure subsidiary announced a 20-year sales and purchase agreement with Petróleo Brasileiro S.A. - Petrobras (NYSE:PBR). The agreement covers approximately 0.8 million tonnes annually of liquefied natural gas, or LNG.
Supply will come from the subsidiary's contracted liquefaction capacity at Port Arthur LNG Phase 2 in Texas. The project is under construction, with trains 3 and 4 expected to begin commercial operations in 2030 and 2031, respectively. The agreement improves visibility into future sales, while the earnings contribution depends on delivery and contract economics.
Petróleo Brasileiro S.A. - Petrobras (NYSE:PBR) becomes the infrastructure subsidiary's first South American LNG customer. That broadens the geographic base of buyers and establishes a commercial relationship extending over two decades.
For Sempra (NYSE:SRE), the practical benefit is an external buyer for part of the subsidiary's contracted capacity. Securing that relationship before startup could reduce the need to find buyers for the covered volumes as production approaches, while supporting longer-term supply planning.
The annual commitment equals approximately 6.2% of Phase 2's planned 13-million-tonne annual capacity. This provides a measure of scale, although it does not establish the percentage of capacity still available for sale.
#agreement #petr #supply #term
Supply will come from the subsidiary's contracted liquefaction capacity at Port Arthur LNG Phase 2 in Texas. The project is under construction, with trains 3 and 4 expected to begin commercial operations in 2030 and 2031, respectively. The agreement improves visibility into future sales, while the earnings contribution depends on delivery and contract economics.
Petróleo Brasileiro S.A. - Petrobras (NYSE:PBR) becomes the infrastructure subsidiary's first South American LNG customer. That broadens the geographic base of buyers and establishes a commercial relationship extending over two decades.
For Sempra (NYSE:SRE), the practical benefit is an external buyer for part of the subsidiary's contracted capacity. Securing that relationship before startup could reduce the need to find buyers for the covered volumes as production approaches, while supporting longer-term supply planning.
The annual commitment equals approximately 6.2% of Phase 2's planned 13-million-tonne annual capacity. This provides a measure of scale, although it does not establish the percentage of capacity still available for sale.
#agreement #petr #supply #term

2 months ago
On August 6, Wheaton Precious Metals (NYSE:WPM) reported second-quarter net earnings of $543 million on $929 million of revenue, both records. Through the first half, net earnings rose 106% to $1.1 billion. During the quarter, the company also made net upfront cash payments of $4.5 billion relative to mineral stream interests, and it now carries $2.0 billion of total debt against $100 million of cash on hand. Here is what that trade looks like up close.
Start with what the streaming model does when prices climb. Wheaton sold 14% more gold equivalent ounces than a year ago, but the average realized gold equivalent price jumped 61% in Q2, and that higher price explains most of the revenue surge. Costs per ounce rose from $406 to $568, yet the cash operating margin per ounce still grew 65% to $3,875, faster than gold itself appreciated. Operating cash flow hit $650 million in the quarter and $1.4 billion for the half.
The second argument is that plenty of growth hasn't arrived yet. Only about 3% of this year's production comes from **** ets still in construction or ramp-up, and the company forecasts a rise of roughly 50% to 1,200,000 gold equivalent ounces by 2030. Some of that ramp has dates attached. Ivanhoe now expects commercial production at Platreef in the fourth quarter of 2026, and Montage Gold is targeting first gold at Koné in late Q4. Effective April 1, Wheaton expanded its share of silver production from Antamina from 33.75% to 67.5% through the newly acquired BHP Antamina PMPA.
Growth on this scale wasn't free. Wheaton had no bank debt at the end of 2025. On April 1, it drew $1.5 billion on a new two-year term loan to help pay for Antamina, and finance costs that were negligible a year ago now take a real bite. Net debt stands at $1.9 billion. Taxes are heavier too. Wheaton paid $109 million of global minimum tax on June 24, and another Cdn$346 million is due around March 31, 2027.
Operations also gave investors a few reasons for caution. Gold ounces produced slipped 2.6% year over year, so the 6% rise in gold equivalent production leaned heavily on the Antamina purchase. Gold output at Salobo fell 11% on lower grades. At Constancia, it fell 35% after mining at the higher-grade Pampacancha pit finished in the fourth quarter of 2025. Hemlo Mining said on July 20 that its second-quarter output fell below the first quarter's, and Rio2 said on May 15 that Fenix missed planned tonnes and grade in Q1. And because the revenue jump came mainly from price, the same leverage works in reverse if metals slip.
#wheaton
Start with what the streaming model does when prices climb. Wheaton sold 14% more gold equivalent ounces than a year ago, but the average realized gold equivalent price jumped 61% in Q2, and that higher price explains most of the revenue surge. Costs per ounce rose from $406 to $568, yet the cash operating margin per ounce still grew 65% to $3,875, faster than gold itself appreciated. Operating cash flow hit $650 million in the quarter and $1.4 billion for the half.
The second argument is that plenty of growth hasn't arrived yet. Only about 3% of this year's production comes from **** ets still in construction or ramp-up, and the company forecasts a rise of roughly 50% to 1,200,000 gold equivalent ounces by 2030. Some of that ramp has dates attached. Ivanhoe now expects commercial production at Platreef in the fourth quarter of 2026, and Montage Gold is targeting first gold at Koné in late Q4. Effective April 1, Wheaton expanded its share of silver production from Antamina from 33.75% to 67.5% through the newly acquired BHP Antamina PMPA.
Growth on this scale wasn't free. Wheaton had no bank debt at the end of 2025. On April 1, it drew $1.5 billion on a new two-year term loan to help pay for Antamina, and finance costs that were negligible a year ago now take a real bite. Net debt stands at $1.9 billion. Taxes are heavier too. Wheaton paid $109 million of global minimum tax on June 24, and another Cdn$346 million is due around March 31, 2027.
Operations also gave investors a few reasons for caution. Gold ounces produced slipped 2.6% year over year, so the 6% rise in gold equivalent production leaned heavily on the Antamina purchase. Gold output at Salobo fell 11% on lower grades. At Constancia, it fell 35% after mining at the higher-grade Pampacancha pit finished in the fourth quarter of 2025. Hemlo Mining said on July 20 that its second-quarter output fell below the first quarter's, and Rio2 said on May 15 that Fenix missed planned tonnes and grade in Q1. And because the revenue jump came mainly from price, the same leverage works in reverse if metals slip.
#wheaton

2 months ago
High Tide Inc. (NASDAQ:HITI) reported record fiscal third-quarter revenue of C$198.8 million on September 14, up 33% year over year. Operating income increased 133% to C$8.7 million for the quarter ended July 31, 2026, yet net cash provided by operating activities slipped to C$10.1 million from C$10.7 million.
High Tide Inc. (NASDAQ:HITI) generated C$11.9 million of operating cash flow before changes in non-cash working capital, up 44%. Working capital then absorbed C$1.8 million, compared with a C$2.4 million release a year earlier. That approximately C$4.2 million unfavorable swing outweighed the improvement before working-capital movements. The question is whether expansion will keep requiring a larger cash commitment.
High Tide Inc. (NASDAQ:HITI) is translating sales growth into stronger operating profitability. Operating income represented approximately 4.4% of revenue, compared with 2.5% a year earlier. That improvement gives the business more room to absorb the costs of expansion.
High Tide Inc. (NASDAQ:HITI) opened four Canadian stores and acquired four more during the quarter. Its German medical-cannabis subsidiary, Remexian, generated C$38.2 million in revenue, up from C$31.6 million sequentially. Remexian distributed 10.2 tonnes, a 35% sequential increase. Both markets offer opportunities to build sales across a larger operating base.
High Tide Inc. (NASDAQ:HITI) also improved operating cash flow to C$4.4 million in the second quarter. For the first nine months, operating cash flow reached C$20.4 million versus C$19.6 million a year earlier. Those comparisons show that the quarterly year-over-year decline sits alongside improving cash generation over other periods.
#high
High Tide Inc. (NASDAQ:HITI) generated C$11.9 million of operating cash flow before changes in non-cash working capital, up 44%. Working capital then absorbed C$1.8 million, compared with a C$2.4 million release a year earlier. That approximately C$4.2 million unfavorable swing outweighed the improvement before working-capital movements. The question is whether expansion will keep requiring a larger cash commitment.
High Tide Inc. (NASDAQ:HITI) is translating sales growth into stronger operating profitability. Operating income represented approximately 4.4% of revenue, compared with 2.5% a year earlier. That improvement gives the business more room to absorb the costs of expansion.
High Tide Inc. (NASDAQ:HITI) opened four Canadian stores and acquired four more during the quarter. Its German medical-cannabis subsidiary, Remexian, generated C$38.2 million in revenue, up from C$31.6 million sequentially. Remexian distributed 10.2 tonnes, a 35% sequential increase. Both markets offer opportunities to build sales across a larger operating base.
High Tide Inc. (NASDAQ:HITI) also improved operating cash flow to C$4.4 million in the second quarter. For the first nine months, operating cash flow reached C$20.4 million versus C$19.6 million a year earlier. Those comparisons show that the quarterly year-over-year decline sits alongside improving cash generation over other periods.
#high


2 months ago
Indian automotive supplier Uno Minda has announced four capacity expansion and consolidation projects across its component businesses, with a combined proposed investment of about Rs14.15bn ($147.5m).
The projects span the company's two-wheeler alloy wheels, aluminium casting, moulding, and interior, exterior parts and sealing systems operations, although details have so far been provided for two of them.
One of the projects concerns a new greenfield aluminium casting plant in Hosur, Tamil Nadu, after expansion **** e at the company's existing Hosur facility was used up.
This business supplies parts for two-wheelers, four-wheelers and commercial vehicles for both combustion-engine and electric vehicle platforms.
The project is expected to involve an additional investment of Rs5.10bn and increase capacity at the site from about 13,000 metric tonnes to a peak of 30,000 metric tonnes.
#projects #aluminium #casting
The projects span the company's two-wheeler alloy wheels, aluminium casting, moulding, and interior, exterior parts and sealing systems operations, although details have so far been provided for two of them.
One of the projects concerns a new greenfield aluminium casting plant in Hosur, Tamil Nadu, after expansion **** e at the company's existing Hosur facility was used up.
This business supplies parts for two-wheelers, four-wheelers and commercial vehicles for both combustion-engine and electric vehicle platforms.
The project is expected to involve an additional investment of Rs5.10bn and increase capacity at the site from about 13,000 metric tonnes to a peak of 30,000 metric tonnes.
#projects #aluminium #casting

2 months ago
Our ******* ysts just identified a stock with the potential to be the next Nvidia. Tell us how you invest and we'll show you why it's our #1 pick. Tap here.
French manufacturing giant Vallourec has secured the entire carbon-steel line pipe and external coating scope for Petrobras's Sepia 2 offshore development, covering roughly 130 kilometers of subsea infrastructure.
The contract strengthens its position in Brazil's technically demanding pre-salt market and gives investors another reason to believe the group's offshore order book still has room to grow.
Vallourec shares rose around 6% after the premium pipe manufacturer announced a major contract with Subsea7 for the Sepia 2 project in Brazil's Santos Basin.
The agreement covers roughly 130 kilometers of rigid risers and flowlines, representing more than 15,000 tonnes of carbon-steel seamless line pipe designed for highly corrosive environments.
#roughly
French manufacturing giant Vallourec has secured the entire carbon-steel line pipe and external coating scope for Petrobras's Sepia 2 offshore development, covering roughly 130 kilometers of subsea infrastructure.
The contract strengthens its position in Brazil's technically demanding pre-salt market and gives investors another reason to believe the group's offshore order book still has room to grow.
Vallourec shares rose around 6% after the premium pipe manufacturer announced a major contract with Subsea7 for the Sepia 2 project in Brazil's Santos Basin.
The agreement covers roughly 130 kilometers of rigid risers and flowlines, representing more than 15,000 tonnes of carbon-steel seamless line pipe designed for highly corrosive environments.
#roughly

2 months ago
Our ****** ysts just identified a stock with the potential to be the next Nvidia. Tell us how you invest and we'll show you why it's our #1 pick. Tap here.
Saleable coal production grew 8% to 11.5 million tonnes, exceeding guidance due to the successful ramp-up of New Acland and Bengalla returning to nameplate capacity.
Management attributed the 10% decline in average realized price to $145 per tonne to broader market cyclicality, though low-cost ****** ets maintained a resilient $45 per tonne margin.
Bengalla's performance was impacted by a temporary increase in strip ratio and pit resequencing following significant weather events late in the 2025 financial year.
The group shifted its primary safety metric to High Potential Event Frequency Rate (HPEFR) to focus on preventing fatal or life-altering risks rather than just traditional injury counts.
#tell #Event
Saleable coal production grew 8% to 11.5 million tonnes, exceeding guidance due to the successful ramp-up of New Acland and Bengalla returning to nameplate capacity.
Management attributed the 10% decline in average realized price to $145 per tonne to broader market cyclicality, though low-cost ****** ets maintained a resilient $45 per tonne margin.
Bengalla's performance was impacted by a temporary increase in strip ratio and pit resequencing following significant weather events late in the 2025 financial year.
The group shifted its primary safety metric to High Potential Event Frequency Rate (HPEFR) to focus on preventing fatal or life-altering risks rather than just traditional injury counts.
#tell #Event
2 months ago
Our **** ysts just identified a stock with the potential to be the next Nvidia. Tell us how you invest and we'll show you why it's our #1 pick. Tap here.
Saleable coal production grew 8% to 11.5 million tonnes, exceeding guidance due to the successful ramp-up of New Acland and Bengalla returning to nameplate capacity.
Management attributed the 10% decline in average realized price to $145 per tonne to broader market cyclicality, though low-cost **** ets maintained a resilient $45 per tonne margin.
Bengalla's performance was impacted by a temporary increase in strip ratio and pit resequencing following significant weather events late in the 2025 financial year.
The group shifted its primary safety metric to High Potential Event Frequency Rate (HPEFR) to focus on preventing fatal or life-altering risks rather than just traditional injury counts.
#tonne #saleable #acland
Saleable coal production grew 8% to 11.5 million tonnes, exceeding guidance due to the successful ramp-up of New Acland and Bengalla returning to nameplate capacity.
Management attributed the 10% decline in average realized price to $145 per tonne to broader market cyclicality, though low-cost **** ets maintained a resilient $45 per tonne margin.
Bengalla's performance was impacted by a temporary increase in strip ratio and pit resequencing following significant weather events late in the 2025 financial year.
The group shifted its primary safety metric to High Potential Event Frequency Rate (HPEFR) to focus on preventing fatal or life-altering risks rather than just traditional injury counts.
#tonne #saleable #acland

2 months ago
Indian automotive supplier Uno Minda has announced four capacity expansion and consolidation projects across its component businesses, with a combined proposed investment of about Rs14.15bn ($147.5m).
The projects span the company's two-wheeler alloy wheels, aluminium casting, moulding, and interior, exterior parts and sealing systems operations, although details have so far been provided for two of them.
One of the projects concerns a new greenfield aluminium casting plant in Hosur, Tamil Nadu, after expansion ******* e at the company's existing Hosur facility was used up.
This business supplies parts for two-wheelers, four-wheelers and commercial vehicles for both combustion-engine and electric vehicle platforms.
The project is expected to involve an additional investment of Rs5.10bn and increase capacity at the site from about 13,000 metric tonnes to a peak of 30,000 metric tonnes.
#expansion #parts
The projects span the company's two-wheeler alloy wheels, aluminium casting, moulding, and interior, exterior parts and sealing systems operations, although details have so far been provided for two of them.
One of the projects concerns a new greenfield aluminium casting plant in Hosur, Tamil Nadu, after expansion ******* e at the company's existing Hosur facility was used up.
This business supplies parts for two-wheelers, four-wheelers and commercial vehicles for both combustion-engine and electric vehicle platforms.
The project is expected to involve an additional investment of Rs5.10bn and increase capacity at the site from about 13,000 metric tonnes to a peak of 30,000 metric tonnes.
#expansion #parts

2 months ago
Our ******* ysts just identified a stock with the potential to be the next Nvidia. Tell us how you invest and we'll show you why it's our #1 pick. Tap here.
French manufacturing giant Vallourec has secured the entire carbon-steel line pipe and external coating scope for Petrobras's Sepia 2 offshore development, covering roughly 130 kilometers of subsea infrastructure.
The contract strengthens its position in Brazil's technically demanding pre-salt market and gives investors another reason to believe the group's offshore order book still has room to grow.
Vallourec shares rose around 6% after the premium pipe manufacturer announced a major contract with Subsea7 for the Sepia 2 project in Brazil's Santos Basin.
The agreement covers roughly 130 kilometers of rigid risers and flowlines, representing more than 15,000 tonnes of carbon-steel seamless line pipe designed for highly corrosive environments.
#pipe #vallourec #roughly
French manufacturing giant Vallourec has secured the entire carbon-steel line pipe and external coating scope for Petrobras's Sepia 2 offshore development, covering roughly 130 kilometers of subsea infrastructure.
The contract strengthens its position in Brazil's technically demanding pre-salt market and gives investors another reason to believe the group's offshore order book still has room to grow.
Vallourec shares rose around 6% after the premium pipe manufacturer announced a major contract with Subsea7 for the Sepia 2 project in Brazil's Santos Basin.
The agreement covers roughly 130 kilometers of rigid risers and flowlines, representing more than 15,000 tonnes of carbon-steel seamless line pipe designed for highly corrosive environments.
#pipe #vallourec #roughly


2 months ago
Argentina's state-controlled energy company YPF is close to signing several LNG sales agreements for its planned Argentina LNG project as it races toward a final investment decision later this year.
YPF CEO Horacio Marín said at the Gastech conference in Bangkok that the company expects to sign two or three LNG contracts covering between 0.5 million and 1.5 million tonnes per year each. YPF aims to have the agreements secured before partners make a final investment decision in November.
The $24-billion Argentina LNG development, backed by YPF, Italy's Eni and Abu Dhabi's XRG, is designed to turn the vast Vaca Muerta shale formation into a major source of LNG for international markets.
The initial development will feature two floating LNG facilities with combined capacity of 12 million tonnes per year, with potential expansion to 18 million tonnes. A dedicated 527-kilometer pipeline will transport gas from Vaca Muerta to the Atlantic coast in Río Negro province. YPF says the development will also include gas treatment and liquids infrastructure.
Eni and XRG each hold approximately 32% interests in the upstream blocks feeding the development, with YPF holding 36%.
#development #year #tonnes #muerta
YPF CEO Horacio Marín said at the Gastech conference in Bangkok that the company expects to sign two or three LNG contracts covering between 0.5 million and 1.5 million tonnes per year each. YPF aims to have the agreements secured before partners make a final investment decision in November.
The $24-billion Argentina LNG development, backed by YPF, Italy's Eni and Abu Dhabi's XRG, is designed to turn the vast Vaca Muerta shale formation into a major source of LNG for international markets.
The initial development will feature two floating LNG facilities with combined capacity of 12 million tonnes per year, with potential expansion to 18 million tonnes. A dedicated 527-kilometer pipeline will transport gas from Vaca Muerta to the Atlantic coast in Río Negro province. YPF says the development will also include gas treatment and liquids infrastructure.
Eni and XRG each hold approximately 32% interests in the upstream blocks feeding the development, with YPF holding 36%.
#development #year #tonnes #muerta

2 months ago
ExxonMobil Holdings Corporation (NYSE:XOM) agreed to increase its Papua LNG interest from 28.7% to 34.1% and ***** ume operatorship, as disclosed on September 7. The proposed ownership percentages reflect Papua New Guinea's state participation rights.
Papua LNG targets a fourth-quarter 2026 final investment decision, or FID. Santos Limited (ASX:STO) disclosed FID as a closing condition for its own stake acquisition; the operatorship announcement did not specify an equivalent condition.
TotalEnergies SE (NYSE:TTE) said redesign and contractor rebidding had reduced estimated development spending by nearly $4 billion since 2024 to approximately $14 billion. The project would produce 5.6 million tonnes of liquefied natural gas annually. The question is whether that smaller budget can support attractive returns through construction and an uncertain LNG market.
ExxonMobil Holdings Corporation (NYSE:XOM) already operates neighboring PNG LNG. Combining operatorship could improve coordination during construction and operations, including the redesigned handling of upstream condensate. That gives the proposed efficiency gains a practical basis in existing infrastructure and local experience.
The cost reduction is substantial. Mechanically, nearly $4 billion off an approximately $18 billion previous estimate represents about 22%. For ExxonMobil Holdings Corporation (NYSE:XOM), lower development spending would reduce the capital required to generate each future dollar of project cash flow, ***** uming production and operating economics hold.
#holdings #operatorship
Papua LNG targets a fourth-quarter 2026 final investment decision, or FID. Santos Limited (ASX:STO) disclosed FID as a closing condition for its own stake acquisition; the operatorship announcement did not specify an equivalent condition.
TotalEnergies SE (NYSE:TTE) said redesign and contractor rebidding had reduced estimated development spending by nearly $4 billion since 2024 to approximately $14 billion. The project would produce 5.6 million tonnes of liquefied natural gas annually. The question is whether that smaller budget can support attractive returns through construction and an uncertain LNG market.
ExxonMobil Holdings Corporation (NYSE:XOM) already operates neighboring PNG LNG. Combining operatorship could improve coordination during construction and operations, including the redesigned handling of upstream condensate. That gives the proposed efficiency gains a practical basis in existing infrastructure and local experience.
The cost reduction is substantial. Mechanically, nearly $4 billion off an approximately $18 billion previous estimate represents about 22%. For ExxonMobil Holdings Corporation (NYSE:XOM), lower development spending would reduce the capital required to generate each future dollar of project cash flow, ***** uming production and operating economics hold.
#holdings #operatorship

2 months ago
Good morning everyone and welcome to Fitzie's gaming corner, where your hoddler-in-chief talks about video and **** ogue games.
There's an exciting new PC game coming out soon: Guild Wars 3.
It's official. #GW3 is a thing – we are developing Guild Wars 3! https://t.co/yKMu6euKg2 pic.twitter.com/7nkR6TBt8v
Guild Wars is what is called an MMORPG – or "massively multiplayer online role-playing game" – that's like a cooler version of World of Warcraft. It's got these cool characters and no subscription model, which means it's far more accessible.
Your hoddler-in-chief used to play Guild Wars all the time. First the OG when it came out in 2007 and then when Guild Wars 2 was released in 2012. I spent a tonne of hours playing it until it reached a point where my computer's RAM could no longer support it.
#game #playing #mmorpg #World
There's an exciting new PC game coming out soon: Guild Wars 3.
It's official. #GW3 is a thing – we are developing Guild Wars 3! https://t.co/yKMu6euKg2 pic.twitter.com/7nkR6TBt8v
Guild Wars is what is called an MMORPG – or "massively multiplayer online role-playing game" – that's like a cooler version of World of Warcraft. It's got these cool characters and no subscription model, which means it's far more accessible.
Your hoddler-in-chief used to play Guild Wars all the time. First the OG when it came out in 2007 and then when Guild Wars 2 was released in 2012. I spent a tonne of hours playing it until it reached a point where my computer's RAM could no longer support it.
#game #playing #mmorpg #World

2 months ago
Russian oil producer Rosneft has commenced oil shipments from its Vostok Oil project following a commissioning ceremony overseen by Russian President Vladimir Putin via video link.
The first oil from the development was loaded onto the Valentin Pikul Arc7-class Arctic tanker at the Bukhta Sever port.
Rosneft CEO Igor Sechin and Russian Deputy Prime Minister Alexander Novak also participated in the event.
The Vostok Oil project consolidates a number of significant oil and gas deposits in the northern Krasnoyarsk Territory.
Rosneft estimates the project's resource base at seven billion tonnes (bt) of oil with sulphur content ranging between 0.01% and 0.1%.
#russian #rosneft #president
The first oil from the development was loaded onto the Valentin Pikul Arc7-class Arctic tanker at the Bukhta Sever port.
Rosneft CEO Igor Sechin and Russian Deputy Prime Minister Alexander Novak also participated in the event.
The Vostok Oil project consolidates a number of significant oil and gas deposits in the northern Krasnoyarsk Territory.
Rosneft estimates the project's resource base at seven billion tonnes (bt) of oil with sulphur content ranging between 0.01% and 0.1%.
#russian #rosneft #president
2 months ago
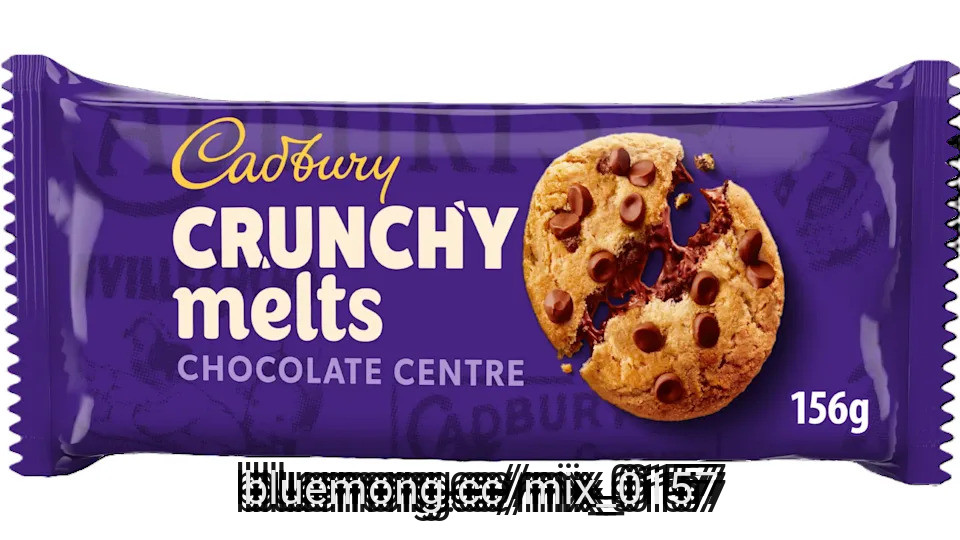
Mondelēz International has substituted rigid polyethylene terephthalate (PET) trays with FSC-certified paper trays across its main cookie lines in Europe within the biscuits segment, according to a press release posted on My News Desk.
The switch applies to more than 115 products sold under eight brands. These include Cadbury, Chips Ahoy!, Freia, Lacta and Marabou.
These items are distributed in more than 25 European countries, including France, Germany, Ireland, the Nordic region, Poland, Spain and the UK.
The project covers approximately 28,000 tonnes of cookies made each year.
Mondelēz estimates the move will cut the use of virgin plastic by 2,200tpa, which is around 80% less than the previous tray format.
#mondel #chips #ahoy #lacta
The switch applies to more than 115 products sold under eight brands. These include Cadbury, Chips Ahoy!, Freia, Lacta and Marabou.
These items are distributed in more than 25 European countries, including France, Germany, Ireland, the Nordic region, Poland, Spain and the UK.
The project covers approximately 28,000 tonnes of cookies made each year.
Mondelēz estimates the move will cut the use of virgin plastic by 2,200tpa, which is around 80% less than the previous tray format.
#mondel #chips #ahoy #lacta

2 months ago
Moneywise and Yahoo Finance LLC may earn commission or revenue through links in the content below.
The Dutch central bank has moved roughly $11.6 billion worth of gold (1) out of the United States and Canada as "increasing geopolitical unrest" pushes another European country to strengthen its "crisis preparedness."
Between March and August, De Nederlandsche Bank transferred 86 metric tonnes (2) of bullion from New York and Ottawa to London, where gold can be traded more quickly during an emergency.
Jeff Bezos backs a platform that lets anyone invest in rental homes for as little as $100 — 6 ways to build wealth like a landlord without actually being one
JPMorgan sees gold hitting $5,000/oz by Q4 — and savvy investors are protecting their wealth with a tax-advantaged Gold IRA. Get your free guide from Priority Gold
#finance #dutch
The Dutch central bank has moved roughly $11.6 billion worth of gold (1) out of the United States and Canada as "increasing geopolitical unrest" pushes another European country to strengthen its "crisis preparedness."
Between March and August, De Nederlandsche Bank transferred 86 metric tonnes (2) of bullion from New York and Ottawa to London, where gold can be traded more quickly during an emergency.
Jeff Bezos backs a platform that lets anyone invest in rental homes for as little as $100 — 6 ways to build wealth like a landlord without actually being one
JPMorgan sees gold hitting $5,000/oz by Q4 — and savvy investors are protecting their wealth with a tax-advantaged Gold IRA. Get your free guide from Priority Gold
#finance #dutch

2 months ago
Lake Victoria Gold Ltd. (TSXV:LVG) (OTCQB:LVGLF) (FSE:E1K) reported high-grade, near-surface gold intercepts from drilling at its Imwelo Gold Project in Tanzania, adding new data to the company's ongoing work to refine the project's initial mining area and processing plans.
The latest drilling at Area C, the planned initial open-pit area, returned 28.71 grams per tonne (g/t) gold over 2.75 metres from 21 metres in hole IMWDR029. A second hole, IMWDR028, intersected 12.20 g/t gold over 4.50 metres from 32 metres.
Individual quartz-vein samples within those intervals returned much higher grades, including 142.90 g/t gold over 0.50 metres in IMWDR029 and 124.83 g/t over 0.40 metres in IMWDR028.
The results are from eight HQ diamond drill holes covering 225 metres across roughly 240 metres of strike in Area C. Four holes encountered voids **** ociated with historical artisanal mining, where parts of the shallow mineralized zone had already been removed.
The company said the drilling will help refine detailed mine planning and future grade-control work. Reported intercepts are down-hole lengths, and true widths have not yet been established.
#imwdr029
The latest drilling at Area C, the planned initial open-pit area, returned 28.71 grams per tonne (g/t) gold over 2.75 metres from 21 metres in hole IMWDR029. A second hole, IMWDR028, intersected 12.20 g/t gold over 4.50 metres from 32 metres.
Individual quartz-vein samples within those intervals returned much higher grades, including 142.90 g/t gold over 0.50 metres in IMWDR029 and 124.83 g/t over 0.40 metres in IMWDR028.
The results are from eight HQ diamond drill holes covering 225 metres across roughly 240 metres of strike in Area C. Four holes encountered voids **** ociated with historical artisanal mining, where parts of the shallow mineralized zone had already been removed.
The company said the drilling will help refine detailed mine planning and future grade-control work. Reported intercepts are down-hole lengths, and true widths have not yet been established.
#imwdr029

2 months ago
Our ******* ysts just identified a stock with the potential to be the next Nvidia. Tell us how you invest and we'll show you why it's our #1 pick. Tap here.
Nobody announces that they've stopped trusting you. They just start moving things out on weekday afternoons, a carload at a time, and by the time you notice, the good coat is already somewhere else. Central banks do this too but their subtle breaking up with you involves armored trucks, an ocean, and a press release that leans very hard on the word "logistics."
Between March and August, the Dutch central bank moved 86 tonnes of gold out of New York and Ottawa and into London. It called the project "crisis preparedness" and cited "increasing geopolitical unrest," which is central banker for saying the quiet part at a normal indoor volume.
De Nederlandsche Bank, DNB to its friends, closed 2025 sitting on 612.4 tonnes of gold worth €72.2 billion ($83.7 billion). About 31.3% of it lived in New York and another 19.7% in Ottawa, roughly 313 tonnes parked in North America. The 86 tonnes that left is a bit more than a quarter of that pile.
Roughly 59 tonnes never went anywhere at all. DNB sold that gold in New York and bought the same quantity in London, which is the bullion version of Venmo-ing a friend instead of driving across state lines with a duffel bag. The other 27-odd tonnes actually traveled, first from New York and Ottawa to DNB's own vault in the Dutch town of Zeist, then an equivalent amount from Zeist onward to London. The gold, in other words, flew with a layover. Structuring it that way let the bank skip melting down and re-casting bars to meet London's standards, which costs real money and carries the always-unwelcome risk of finishing the process with less gold than it started with.
#york #central #bank #roughly
Nobody announces that they've stopped trusting you. They just start moving things out on weekday afternoons, a carload at a time, and by the time you notice, the good coat is already somewhere else. Central banks do this too but their subtle breaking up with you involves armored trucks, an ocean, and a press release that leans very hard on the word "logistics."
Between March and August, the Dutch central bank moved 86 tonnes of gold out of New York and Ottawa and into London. It called the project "crisis preparedness" and cited "increasing geopolitical unrest," which is central banker for saying the quiet part at a normal indoor volume.
De Nederlandsche Bank, DNB to its friends, closed 2025 sitting on 612.4 tonnes of gold worth €72.2 billion ($83.7 billion). About 31.3% of it lived in New York and another 19.7% in Ottawa, roughly 313 tonnes parked in North America. The 86 tonnes that left is a bit more than a quarter of that pile.
Roughly 59 tonnes never went anywhere at all. DNB sold that gold in New York and bought the same quantity in London, which is the bullion version of Venmo-ing a friend instead of driving across state lines with a duffel bag. The other 27-odd tonnes actually traveled, first from New York and Ottawa to DNB's own vault in the Dutch town of Zeist, then an equivalent amount from Zeist onward to London. The gold, in other words, flew with a layover. Structuring it that way let the bank skip melting down and re-casting bars to meet London's standards, which costs real money and carries the always-unwelcome risk of finishing the process with less gold than it started with.
#york #central #bank #roughly

2 months ago
On September 1, Sasol Limited (NYSE:SSL) posted fiscal 2026 results that looked nothing like the shaky operator investors have grown used to. Net debt fell to its lowest level in ten years, Secunda output hit a five-year high, and adjusted EBITDA jumped 17% year over year to ZAR 61 billion. The numbers suggest a turnaround that finally has traction, even as chemical markets stay stuck in a rut.
The clearest thread running through the quarter is that Sasol's core Southern African operations are simply working better than they have in years. Secunda production reached 7.26 million tonnes, a five-year high, driven by improved coal quality and gas availability after the company installed a destoning plant that pushed sinks below 12%. That reliability helped cut the Southern African oil breakeven to $49 per barrel. Management is also weaning the business off external coal, planning to cut purchases from 8.8 million tonnes down to a range of 5 million to 7 million tonnes in fiscal 2027 as own production climbs toward 34 million tonnes by 2028.
The balance sheet tells a similar story. Net debt dropped 11% to $3.3 billion, and available liquidity rose 21% to roughly $5 billion after a bond swap that better matched debt currency to cash generation. Free cash flow of ZAR 11.9 billion was actually up 26% once you strip out a one-time legal settlement from the prior year. International Chemicals, long the drag on the portfolio, posted $604 million in adjusted EBITDA on a 7% cut in fixed costs and a stronger fourth quarter market. Retail fuel market share climbed to 13% from 9% five years ago, and renewable capacity reached 500 megawatts on the way to a 2 gigawatt target by 2030.
Not everything is fixed. Sasol lost two colleagues during the year, a reminder that operational improvement has not erased safety risk. Currency remains a persistent headwind, with CFO Walt Bruns noting that "the stronger rand remained a significant earnings headwind given the U.S. dollar-linked nature of much of our revenue." That same stronger rand outlook, combined with weaker long-term polyethylene pricing, drove impairments on the Secunda liquid fuels refinery and the South African polyethylene unit.
Management was explicit that global chemical markets have not turned a corner, warning that "excess capacity and weaker demand" continue pressuring prices with only a gradual recovery expected. Working capital also ran hot at 18.3% of trailing turnover, above the 15.5% to 16.5% target range, due to pricing volatility and elevated inventory. Fiscal 2027 capital spending guidance of ZAR 23 billion to ZAR 26 billion is also higher than the year just completed, and dividends stay off the table until net debt is sustainably below $3 billion, a threshold the company has approached but not yet crossed.
#debt #fiscal #years #five
The clearest thread running through the quarter is that Sasol's core Southern African operations are simply working better than they have in years. Secunda production reached 7.26 million tonnes, a five-year high, driven by improved coal quality and gas availability after the company installed a destoning plant that pushed sinks below 12%. That reliability helped cut the Southern African oil breakeven to $49 per barrel. Management is also weaning the business off external coal, planning to cut purchases from 8.8 million tonnes down to a range of 5 million to 7 million tonnes in fiscal 2027 as own production climbs toward 34 million tonnes by 2028.
The balance sheet tells a similar story. Net debt dropped 11% to $3.3 billion, and available liquidity rose 21% to roughly $5 billion after a bond swap that better matched debt currency to cash generation. Free cash flow of ZAR 11.9 billion was actually up 26% once you strip out a one-time legal settlement from the prior year. International Chemicals, long the drag on the portfolio, posted $604 million in adjusted EBITDA on a 7% cut in fixed costs and a stronger fourth quarter market. Retail fuel market share climbed to 13% from 9% five years ago, and renewable capacity reached 500 megawatts on the way to a 2 gigawatt target by 2030.
Not everything is fixed. Sasol lost two colleagues during the year, a reminder that operational improvement has not erased safety risk. Currency remains a persistent headwind, with CFO Walt Bruns noting that "the stronger rand remained a significant earnings headwind given the U.S. dollar-linked nature of much of our revenue." That same stronger rand outlook, combined with weaker long-term polyethylene pricing, drove impairments on the Secunda liquid fuels refinery and the South African polyethylene unit.
Management was explicit that global chemical markets have not turned a corner, warning that "excess capacity and weaker demand" continue pressuring prices with only a gradual recovery expected. Working capital also ran hot at 18.3% of trailing turnover, above the 15.5% to 16.5% target range, due to pricing volatility and elevated inventory. Fiscal 2027 capital spending guidance of ZAR 23 billion to ZAR 26 billion is also higher than the year just completed, and dividends stay off the table until net debt is sustainably below $3 billion, a threshold the company has approached but not yet crossed.
#debt #fiscal #years #five

2 months ago
Cheniere Energy, Inc. (NYSE:LNG) is substantially completing the Corpus Christi Stage 3 expansion, with contractor Bechtel handing over the seventh and final liquefaction train. The project adds more than 10 million tonnes per annum (mtpa) of LNG capacity, lifting Cheniere's overall production capacity to roughly 56 mtpa, an increase of more than 20%.
The timing is favorable because Cheniere is entering a period of higher production while global LNG demand remains strong. In its latest quarterly results, Cheniere raised its 2026 adjusted EBITDA guidance to $7.9 billion-$8.4 billion, from $7.25 billion-$7.75 billion previously. The company also said it expects higher exports as its expansion projects ramp up. The company is not finished expanding Corpus Christi. It is also developing Midscale Trains 8 and 9, while the U.S. Energy Department has authorized additional exports from those trains.
The biggest positive is that Cheniere now has additional LNG capacity coming online at an established export facility. The completion of Stage 3 allows Cheniere to increase volumes without having to build an entirely new LNG terminal from scratch. The company expects increased exports next year as it benefits from a full year of production from its expansion projects. That creates a relatively straightforward growth path: more LNG volumes can generate more revenue, while the existing infrastructure and long-term commercial arrangements can support attractive cash generation.
Cheniere Energy, Inc. (NYSE:LNG) is positioned to benefit from continued growth in LNG consumption, particularly in Europe and Asia. U.S. LNG deliveries to Asia reached a quarterly record of 11 million metric tons in Q2 2026, while Cheniere continues to see strong demand and competitive pricing in new contract negotiations. The company's scale also gives it an advantage as global buyers seek reliable LNG supplies. The U.S. has become the world's largest LNG exporter, with Cheniere playing a central role in that export growth.
The completion of Stage 3 further increases the gap between Cheniere and competing U.S. LNG exporters. The project takes Corpus Christi's production capabilities to a much higher level and gives Cheniere greater exposure to international LNG demand. This scale can also improve the company's ability to serve customers across different markets and capture attractive destination pricing. Cheniere has historically used strong cash generation to return capital to shareholders while continuing to invest in expansion. The company is balancing shareholder returns with investments in additional production capacity.
#production #capacity #company
The timing is favorable because Cheniere is entering a period of higher production while global LNG demand remains strong. In its latest quarterly results, Cheniere raised its 2026 adjusted EBITDA guidance to $7.9 billion-$8.4 billion, from $7.25 billion-$7.75 billion previously. The company also said it expects higher exports as its expansion projects ramp up. The company is not finished expanding Corpus Christi. It is also developing Midscale Trains 8 and 9, while the U.S. Energy Department has authorized additional exports from those trains.
The biggest positive is that Cheniere now has additional LNG capacity coming online at an established export facility. The completion of Stage 3 allows Cheniere to increase volumes without having to build an entirely new LNG terminal from scratch. The company expects increased exports next year as it benefits from a full year of production from its expansion projects. That creates a relatively straightforward growth path: more LNG volumes can generate more revenue, while the existing infrastructure and long-term commercial arrangements can support attractive cash generation.
Cheniere Energy, Inc. (NYSE:LNG) is positioned to benefit from continued growth in LNG consumption, particularly in Europe and Asia. U.S. LNG deliveries to Asia reached a quarterly record of 11 million metric tons in Q2 2026, while Cheniere continues to see strong demand and competitive pricing in new contract negotiations. The company's scale also gives it an advantage as global buyers seek reliable LNG supplies. The U.S. has become the world's largest LNG exporter, with Cheniere playing a central role in that export growth.
The completion of Stage 3 further increases the gap between Cheniere and competing U.S. LNG exporters. The project takes Corpus Christi's production capabilities to a much higher level and gives Cheniere greater exposure to international LNG demand. This scale can also improve the company's ability to serve customers across different markets and capture attractive destination pricing. Cheniere has historically used strong cash generation to return capital to shareholders while continuing to invest in expansion. The company is balancing shareholder returns with investments in additional production capacity.
#production #capacity #company


2 months ago
Almonty Industries Inc. (NASDAQ:ALM) began a 36-month share-repurchase authorization on August 24 that permits the company to buy up to 14.4 million common shares, representing approximately 5% of shares outstanding as of August 14, for as much as US$300 million.
The headline amount overstates what Almonty Industries Inc. (NASDAQ:ALM) would spend at its current valuation. At the August 24 closing price of $18.28, repurchasing the full 14.4 million shares would cost approximately $263.2 million before transaction costs. The share limit would become the binding constraint unless the average purchase price exceeds roughly $20.83.
The buyback is financially plausible because Almonty Industries Inc. (NASDAQ:ALM) ended June with C$1.23 billion of cash. First-half operating cash flow reached C$31.6 million, compared with a C$14.9 million outflow a year earlier, while second-quarter revenue increased to C$43.0 million from C$7.2 million.
Sangdong is also moving beyond construction. Almonty Industries Inc. (NASDAQ:ALM) began feeding stockpiled ore into the processing plant in June to produce saleable tungsten concentrate. Phase I is designed for approximately 640,000 tonnes of annual ore throughput, and the planned Phase II expansion could increase capacity to approximately 1.2 million tonnes.
If management is correct that the market undervalues Sangdong's future cash flow, retiring shares before the mine reaches full output could increase each remaining shareholder's participation in that growth. Almonty Industries Inc. (NASDAQ:ALM) also has flexibility to spread purchases across three years rather than committing the entire amount immediately.
#million #phase
The headline amount overstates what Almonty Industries Inc. (NASDAQ:ALM) would spend at its current valuation. At the August 24 closing price of $18.28, repurchasing the full 14.4 million shares would cost approximately $263.2 million before transaction costs. The share limit would become the binding constraint unless the average purchase price exceeds roughly $20.83.
The buyback is financially plausible because Almonty Industries Inc. (NASDAQ:ALM) ended June with C$1.23 billion of cash. First-half operating cash flow reached C$31.6 million, compared with a C$14.9 million outflow a year earlier, while second-quarter revenue increased to C$43.0 million from C$7.2 million.
Sangdong is also moving beyond construction. Almonty Industries Inc. (NASDAQ:ALM) began feeding stockpiled ore into the processing plant in June to produce saleable tungsten concentrate. Phase I is designed for approximately 640,000 tonnes of annual ore throughput, and the planned Phase II expansion could increase capacity to approximately 1.2 million tonnes.
If management is correct that the market undervalues Sangdong's future cash flow, retiring shares before the mine reaches full output could increase each remaining shareholder's participation in that growth. Almonty Industries Inc. (NASDAQ:ALM) also has flexibility to spread purchases across three years rather than committing the entire amount immediately.
#million #phase

2 months ago
Greatland Resources Ltd (AIM:GGP, OTC:GRLGF, ASX:GGP) has delivered a net profit after tax of A$862 million in its first full financial year owning the Telfer gold-copper operation, supported by strong production, higher metal prices and substantial cash generation.
Revenue for the year to June 30, 2026, reached A$2.26 billion, up 136%, while EBITDA increased 186% to A$1.33 billion. Free cash flow jumped 413% to A$737 million, helping lift closing cash to $1.29 billion.
The company sold 326,859 ounces of gold at an average realised price of A$6,223 an ounce and 14,730 tonnes of copper at an average A$14,895 a tonne.
Telfer produced 328,987 ounces of gold and 14,594 tonnes of copper during the year at an all-in sustaining cost of A$2,179 per ounce.
Gold production rose 66% compared with the previous period, while gold sales increased 81%. The comparison reflects only around seven months of Telfer ownership in the prior year following Greatland's acquisition in December 2024.
Greatland processed 19.2 million tonnes during the year at an average grade of 0.58 g/t gold and 0.1% copper, achieving gold recovery of 88%.
#year #telfer #cash #greatland
Revenue for the year to June 30, 2026, reached A$2.26 billion, up 136%, while EBITDA increased 186% to A$1.33 billion. Free cash flow jumped 413% to A$737 million, helping lift closing cash to $1.29 billion.
The company sold 326,859 ounces of gold at an average realised price of A$6,223 an ounce and 14,730 tonnes of copper at an average A$14,895 a tonne.
Telfer produced 328,987 ounces of gold and 14,594 tonnes of copper during the year at an all-in sustaining cost of A$2,179 per ounce.
Gold production rose 66% compared with the previous period, while gold sales increased 81%. The comparison reflects only around seven months of Telfer ownership in the prior year following Greatland's acquisition in December 2024.
Greatland processed 19.2 million tonnes during the year at an average grade of 0.58 g/t gold and 0.1% copper, achieving gold recovery of 88%.
#year #telfer #cash #greatland



2 months ago
First Phosphate Corp (NASDAQ:PHOS) (OTC:FRSPF) on Monday filed an updated technical report revealing resource expansion at its Bégin-Lamarche project in Quebec, Canada.
The latest mineral resource estimate highlights a 378% surge in indicated resources compared to the company's initial ****** sment released on September 9, 2024.
The updated estimate demonstrates substantial resource growth for the deposit, located 50 kilometers northwest of Saguenay.
The technical report outlines 6.2 million tonnes of measured pit-constrained resources grading at 7.70% phosphate.
Furthermore, indicated resources reached 198.5 million tonnes at a 6.00% grade, while inferred resources hit 89.5 million tonnes at 6.16%.
#resources #resource #tonnes #estimate
The latest mineral resource estimate highlights a 378% surge in indicated resources compared to the company's initial ****** sment released on September 9, 2024.
The updated estimate demonstrates substantial resource growth for the deposit, located 50 kilometers northwest of Saguenay.
The technical report outlines 6.2 million tonnes of measured pit-constrained resources grading at 7.70% phosphate.
Furthermore, indicated resources reached 198.5 million tonnes at a 6.00% grade, while inferred resources hit 89.5 million tonnes at 6.16%.
#resources #resource #tonnes #estimate


2 months ago
German ice cream maker Florida Eis is expanding local production capacity with a new factory in Schönebeck (Elbe).
On Thursday (20 August), Florida Eis said the new plant in Schönebeck's West Industrial Park on Wilhelm-Dümling-Straße will be designed to produce around 5,000 metric tonnes of ice cream each year.
Operations are due to start in 2028.
The company plans to spend about €25m ($29.1m) on the factory, which will include a roughly 4,000-square-metre production hall, logistics areas, and an office building with an ice cream parlour and a factory outlet.
In a separate statement to Just Food, the company said the new factory is intended to ease capacity constraints at its current plant in Berlin-Spandau, where it has operated since it was founded in 1927.
#factory #capacity #plant #thursday
On Thursday (20 August), Florida Eis said the new plant in Schönebeck's West Industrial Park on Wilhelm-Dümling-Straße will be designed to produce around 5,000 metric tonnes of ice cream each year.
Operations are due to start in 2028.
The company plans to spend about €25m ($29.1m) on the factory, which will include a roughly 4,000-square-metre production hall, logistics areas, and an office building with an ice cream parlour and a factory outlet.
In a separate statement to Just Food, the company said the new factory is intended to ease capacity constraints at its current plant in Berlin-Spandau, where it has operated since it was founded in 1927.
#factory #capacity #plant #thursday


3 months ago
On August 13, Golar LNG (NASDAQ:GLNG) used its second-quarter earnings call to announce a fourth floating LNG unit, an order signed just hours before the call began. The Mark II vessel will be built at CIMC Raffles Shipyard in China and delivered within 2029, making it the earliest available liquefaction capacity anywhere in the world. Combined with an EBITDA backlog of $17 billion already locked in through Hilli, Gimi, and the FLNG Esperanza, the announcement reframes Golar as a company still adding capacity rather than one just running out its existing fleet.
The new order lifts Golar's controlled liquefaction capacity by 41%, from 8.6 million tonnes to more than 12 million tonnes once fully delivered. Management said that if the unit is chartered on terms similar to last year's Esperanza deal, annual earnings capacity could rise 50%, pushing run-rate EBITDA past $1.2 billion by 2030. That confidence rests on a shipyard bottleneck.
Samsung, the industry's biggest builder, isn't expected to have open capacity until 2031, and Wison in China is on track to book its next two large units, leaving it committed well into the next decade. Seatrium and CIMC, the only two yards actively converting FLNG units right now, have built exclusively for Golar. The operating record backs up the growth pitch. Hilli finished its eight-year Cameroon contract with 100% economic uptime and 156 cargoes delivered, Gimi produced 15% above its contracted volume in the quarter, and the Esperanza conversion is 74% complete and still on budget. Commodity-linked income is already showing up in the numbers: Hilli's contribution jumped to $37 million in the quarter from $10 million in the first quarter, helping push EBITDA up 20% sequentially to $127 million.
Growth at this pace isn't free. The CapEx budget for the fourth FLNG unit came in around $2.45 billion, roughly 10% above the $2.2 billion spent on Esperanza, a jump management tied to inflation in long-lead equipment like turbines and dual-fuel engines, parts now being bid up by AI data center and aircraft manufacturers too. That new unit also has no charter yet, so the 50% earnings boost management is pointing to is a target, not a locked-in number.
Meanwhile, Golar is still equity funding Esperanza, having put in $1.3 billion of its $2.2 billion budget, while carrying net interest-bearing debt of about $1.8 billion. Executives are counting on refinancing Hilli and locking in long-term financing for Esperanza to free up roughly $2.3 billion in liquidity, transactions that are still in progress rather than done. The commodity exposure that flatters earnings when LNG prices are high works the same way in reverse. Management's own sensitivity table shows EBITDA falling back toward $1.2 billion if prices settle near $8 per million BTU, well below the $1.9 billion implied by today's $15 forward price. And the disruption at Qatar's Ras Laffan facility, which knocked out an estimated 17 million tonnes of capacity for three
The new order lifts Golar's controlled liquefaction capacity by 41%, from 8.6 million tonnes to more than 12 million tonnes once fully delivered. Management said that if the unit is chartered on terms similar to last year's Esperanza deal, annual earnings capacity could rise 50%, pushing run-rate EBITDA past $1.2 billion by 2030. That confidence rests on a shipyard bottleneck.
Samsung, the industry's biggest builder, isn't expected to have open capacity until 2031, and Wison in China is on track to book its next two large units, leaving it committed well into the next decade. Seatrium and CIMC, the only two yards actively converting FLNG units right now, have built exclusively for Golar. The operating record backs up the growth pitch. Hilli finished its eight-year Cameroon contract with 100% economic uptime and 156 cargoes delivered, Gimi produced 15% above its contracted volume in the quarter, and the Esperanza conversion is 74% complete and still on budget. Commodity-linked income is already showing up in the numbers: Hilli's contribution jumped to $37 million in the quarter from $10 million in the first quarter, helping push EBITDA up 20% sequentially to $127 million.
Growth at this pace isn't free. The CapEx budget for the fourth FLNG unit came in around $2.45 billion, roughly 10% above the $2.2 billion spent on Esperanza, a jump management tied to inflation in long-lead equipment like turbines and dual-fuel engines, parts now being bid up by AI data center and aircraft manufacturers too. That new unit also has no charter yet, so the 50% earnings boost management is pointing to is a target, not a locked-in number.
Meanwhile, Golar is still equity funding Esperanza, having put in $1.3 billion of its $2.2 billion budget, while carrying net interest-bearing debt of about $1.8 billion. Executives are counting on refinancing Hilli and locking in long-term financing for Esperanza to free up roughly $2.3 billion in liquidity, transactions that are still in progress rather than done. The commodity exposure that flatters earnings when LNG prices are high works the same way in reverse. Management's own sensitivity table shows EBITDA falling back toward $1.2 billion if prices settle near $8 per million BTU, well below the $1.9 billion implied by today's $15 forward price. And the disruption at Qatar's Ras Laffan facility, which knocked out an estimated 17 million tonnes of capacity for three


3 months ago
BHP and SiTration, a Massachusetts Institute of Technology (MIT) spin-out, are planning to conduct two pilot programmes of copper recovery technology at BHP's site in the Globe-Miami district of Arizona, US.
The companies aim to demonstrate a method for producing copper domestically by extracting it from legacy mining water at the historic Copper Cities site.
The initial phase of the pilot will focus on a small-scale trial, running over one month.
Later this year, the project is expected to expand, with a larger deployment planned to produce up to two tonnes (t) of commercial-scale copper cathodes for two months.
Copper Cities was an active mine that produced nearly 400,000t of copper between the 1950s and early 1980s.
#scale #sitration
The companies aim to demonstrate a method for producing copper domestically by extracting it from legacy mining water at the historic Copper Cities site.
The initial phase of the pilot will focus on a small-scale trial, running over one month.
Later this year, the project is expected to expand, with a larger deployment planned to produce up to two tonnes (t) of commercial-scale copper cathodes for two months.
Copper Cities was an active mine that produced nearly 400,000t of copper between the 1950s and early 1980s.
#scale #sitration

3 months ago
Argentina LNG, the liquefied natural gas project backed by YPF, Eni and Abu Dhabi-based XRG, has applied for inclusion in Argentina's Large Investment Incentive Regime, or RIGI, as the partners work toward a final investment decision by the end of 2026.
The proposed integrated development would connect natural gas production from Argentina's Vaca Muerta shale formation with processing, transportation and LNG export infrastructure. The project calls for two floating LNG vessels offshore Río Negro province with combined liquefaction capacity of 12 million tonnes per year.
YPF said in a separate project announcement that total spending over the life of Argentina LNG could reach $51 billion, making it the largest project submitted under the RIGI framework to date. The company expects the two floating LNG units to begin operations around 2031.
RIGI was established to encourage large-scale investments in Argentina by providing qualifying projects with long-term fiscal, customs and foreign-exchange benefits and greater regulatory stability. For Argentina LNG, securing those terms would help underpin the financing of a capital-intensive project intended largely for export markets.
The application follows several steps by the partners to deepen their involvement in the project. YPF, Eni and XRG signed a binding joint development agreement in February to advance engineering, commercial and financing work for the 12-million-tonne-per-year development.
#project #rigi #export
The proposed integrated development would connect natural gas production from Argentina's Vaca Muerta shale formation with processing, transportation and LNG export infrastructure. The project calls for two floating LNG vessels offshore Río Negro province with combined liquefaction capacity of 12 million tonnes per year.
YPF said in a separate project announcement that total spending over the life of Argentina LNG could reach $51 billion, making it the largest project submitted under the RIGI framework to date. The company expects the two floating LNG units to begin operations around 2031.
RIGI was established to encourage large-scale investments in Argentina by providing qualifying projects with long-term fiscal, customs and foreign-exchange benefits and greater regulatory stability. For Argentina LNG, securing those terms would help underpin the financing of a capital-intensive project intended largely for export markets.
The application follows several steps by the partners to deepen their involvement in the project. YPF, Eni and XRG signed a binding joint development agreement in February to advance engineering, commercial and financing work for the 12-million-tonne-per-year development.
#project #rigi #export


3 months ago
Nutrien (NYSE:NTR) held its second-quarter 2026 earnings call on August 6. The headline numbers show a company leaning on its potash strength to offset a ****** pier nitrogen and phosphate picture, while still finding room to raise guidance in one segment and cut spending in another.
Nutrien posted record potash sales volumes in the first half of 2026 and raised the bottom end of its full-year potash sales guidance to a range of 14.2 million to 14.8 million tonnes. Potash generated $658 million in adjusted EBITDA during the quarter, and the company kept controllable cash costs flat year over year while targeting below $60 per tonne for the full year. Automation now covers 53% of ore tonnes mined in the first half, already past the target management set at its 2024 Investor Day. Canpotex is fully committed to third-quarter volumes, and management pointed to a favorable response to its domestic summer fill program.
Beyond the mine, Nutrien trimmed its 2026 capital expenditure guidance by $50 million to a range of $1.95 billion to $2.05 billion, and lifted first-half share repurchases 26% over the prior year, stepping up the pace to roughly $75 million a month in the third quarter. Retail adjusted EBITDA climbed 4% in the first half to $1.24 billion, driven by a 10% jump in proprietary crop nutrients gross margin and sales volumes for certain nutritional products that nearly tenfolded from a year earlier. The company has also generated about $1 billion in gross divestiture proceeds since the fourth quarter of 2024, including roughly $90 million in new agreements since June 2026, and said it received numerous nonbinding bids as it reviews strategic alternatives for its phosphate business.
Nitrogen sales volumes fell from the prior year, with no production from Trinidad or New Madrid, planned maintenance at Carseland, and deferred customer purchases late in the quarter as market volatility picked up. Only about 35% of total nitrogen segment volumes were sold ahead of the onset of the Middle East conflict, leaving more of the book exposed to a choppier pricing environment. Global urea prices dropped in the back half of the second quarter during a seasonal demand lull that geopolitical developments made worse, even as management says trade flow disruptions, production outages, and elevated energy prices firmed up fundamentals again in the third quarter.
Phosphate adjusted EBITDA declined in the quarter because of elevated sulfur costs that Nutrien described as placing unsustainable pressure on producer margins across the industry. Nitrogen segment adjusted EBITDA came in at $635 million for the quarter, and the company still has turnarounds planned at its Lima and Redwater facilities in the third quarter, adding to the operational moving parts already at play from the Carseland work completed earlier in the year.
#year
Nutrien posted record potash sales volumes in the first half of 2026 and raised the bottom end of its full-year potash sales guidance to a range of 14.2 million to 14.8 million tonnes. Potash generated $658 million in adjusted EBITDA during the quarter, and the company kept controllable cash costs flat year over year while targeting below $60 per tonne for the full year. Automation now covers 53% of ore tonnes mined in the first half, already past the target management set at its 2024 Investor Day. Canpotex is fully committed to third-quarter volumes, and management pointed to a favorable response to its domestic summer fill program.
Beyond the mine, Nutrien trimmed its 2026 capital expenditure guidance by $50 million to a range of $1.95 billion to $2.05 billion, and lifted first-half share repurchases 26% over the prior year, stepping up the pace to roughly $75 million a month in the third quarter. Retail adjusted EBITDA climbed 4% in the first half to $1.24 billion, driven by a 10% jump in proprietary crop nutrients gross margin and sales volumes for certain nutritional products that nearly tenfolded from a year earlier. The company has also generated about $1 billion in gross divestiture proceeds since the fourth quarter of 2024, including roughly $90 million in new agreements since June 2026, and said it received numerous nonbinding bids as it reviews strategic alternatives for its phosphate business.
Nitrogen sales volumes fell from the prior year, with no production from Trinidad or New Madrid, planned maintenance at Carseland, and deferred customer purchases late in the quarter as market volatility picked up. Only about 35% of total nitrogen segment volumes were sold ahead of the onset of the Middle East conflict, leaving more of the book exposed to a choppier pricing environment. Global urea prices dropped in the back half of the second quarter during a seasonal demand lull that geopolitical developments made worse, even as management says trade flow disruptions, production outages, and elevated energy prices firmed up fundamentals again in the third quarter.
Phosphate adjusted EBITDA declined in the quarter because of elevated sulfur costs that Nutrien described as placing unsustainable pressure on producer margins across the industry. Nitrogen segment adjusted EBITDA came in at $635 million for the quarter, and the company still has turnarounds planned at its Lima and Redwater facilities in the third quarter, adding to the operational moving parts already at play from the Carseland work completed earlier in the year.
#year

3 months ago
London BTC Company Ltd (LSE:BTC, OTCQB: VINZF) is expanding the scope of its Nevada exploration strategy to include antimony, adding exposure to the US-designated critical mineral alongside the gold and silver potential already identified across its growing project portfolio.
The company's antimony will now form part of ongoing exploration targeting in Nevada, where London BTC has ***** embled a portfolio of early-stage precious metals projects through its wholly owned US subsidiary, Tethered Gold LLC.
The move broadens a strategy that has so far concentrated on gold and silver, with recent work producing high-grade surface results from several projects.
At the Amonett-Frank Gold-Silver Project in Pershing County, recent ***** ays returned gold grades of up to 143.1 grams per tonne (g/t), the highest recorded to date across London BTC's US portfolio.
Black Star has also returned surface ***** ays of up to 16.23 g/t gold and 50.5 g/t silver, with mineralisation identified across 2 target areas separated by around 2.5 kilometres.
#london
The company's antimony will now form part of ongoing exploration targeting in Nevada, where London BTC has ***** embled a portfolio of early-stage precious metals projects through its wholly owned US subsidiary, Tethered Gold LLC.
The move broadens a strategy that has so far concentrated on gold and silver, with recent work producing high-grade surface results from several projects.
At the Amonett-Frank Gold-Silver Project in Pershing County, recent ***** ays returned gold grades of up to 143.1 grams per tonne (g/t), the highest recorded to date across London BTC's US portfolio.
Black Star has also returned surface ***** ays of up to 16.23 g/t gold and 50.5 g/t silver, with mineralisation identified across 2 target areas separated by around 2.5 kilometres.
#london
3 months ago
Our ******* ysts just identified a stock with the potential to be the next Nvidia. Tell us how you invest and we'll show you why it's our #1 pick. Tap here.
Secured a firm order for a fourth FLNG unit (Mark II design) with CIMC Raffles, increasing controlled liquefaction capacity by 41% to over 12 million tonnes.
Performance attribution for the quarter was driven by Hilli's 100% economic uptime over its 8-year Cameroon contract and Gimi overproducing 15% against contractual volumes.
Strategic positioning focuses on being the only 'FLNG as a service' provider, capturing demand for supply diversification following geopolitical disruptions in major export hubs like Qatar.
Management attributes the decision to proceed with a Mark II design to strong charter engagement and superior economics regarding CapEx per tonne and OpEx per MMBtu.
#mark #NVIDIA #tell #cimc
Secured a firm order for a fourth FLNG unit (Mark II design) with CIMC Raffles, increasing controlled liquefaction capacity by 41% to over 12 million tonnes.
Performance attribution for the quarter was driven by Hilli's 100% economic uptime over its 8-year Cameroon contract and Gimi overproducing 15% against contractual volumes.
Strategic positioning focuses on being the only 'FLNG as a service' provider, capturing demand for supply diversification following geopolitical disruptions in major export hubs like Qatar.
Management attributes the decision to proceed with a Mark II design to strong charter engagement and superior economics regarding CapEx per tonne and OpEx per MMBtu.
#mark #NVIDIA #tell #cimc


3 months ago
Andoni Iraola still has a lot of work to do to his team.
The Spaniard may have already welcomed three new players to his ranks but, with how poor Liverpool were last term, they need more than just three players adding to their ranks.
Their attack and defence need a complete revamp and, while Jeremy Jacquet and Ronald Araujo will certainly help them do that, another player who could play anywhere across the back four would be helpful.
Of course, that's a lot to ask for in a player these days but, since Joe Gomez is so injury **** e, it's clear that Liverpool need a replacement for him too.
Despite their defence needing tonnes of work, their attacking line could also do with another new signing or two as well.
#ranks
The Spaniard may have already welcomed three new players to his ranks but, with how poor Liverpool were last term, they need more than just three players adding to their ranks.
Their attack and defence need a complete revamp and, while Jeremy Jacquet and Ronald Araujo will certainly help them do that, another player who could play anywhere across the back four would be helpful.
Of course, that's a lot to ask for in a player these days but, since Joe Gomez is so injury **** e, it's clear that Liverpool need a replacement for him too.
Despite their defence needing tonnes of work, their attacking line could also do with another new signing or two as well.
#ranks



