
1 month ago
Pricing alone does not decide where people buy their clothes.
With a number of retail chains competing for the off-price, on-trend fashion crown, it's easy for one brand to fall out of favor. Consumers seem to have an enduring love for Marshalls and TJ Maxx, while the popularity of Ross Dress for Less has grown steadily in recent years.
These brands drive sales by foot traffic, and that's a battle the aforementioned chains have been winning.
"Off-price apparel remained on solid footing in Q2 2026, with Ross leading the segment. Visits to Ross Dress for Less rose 16.4% year over year (YoY), while dd's DISCOUNTS grew 8.4%. TJX's TJ Maxx and Marshalls, meanwhile, saw visits hover around last year's levels — significantly outperforming traditional apparel, which declined 3.5% YoY," according to data from Placer.ai.
In the battle for customers looking for deals on trendy, fashionable clothes, Cato has been struggling, and now plans to close about 15% of its retail stores.
#price
With a number of retail chains competing for the off-price, on-trend fashion crown, it's easy for one brand to fall out of favor. Consumers seem to have an enduring love for Marshalls and TJ Maxx, while the popularity of Ross Dress for Less has grown steadily in recent years.
These brands drive sales by foot traffic, and that's a battle the aforementioned chains have been winning.
"Off-price apparel remained on solid footing in Q2 2026, with Ross leading the segment. Visits to Ross Dress for Less rose 16.4% year over year (YoY), while dd's DISCOUNTS grew 8.4%. TJX's TJ Maxx and Marshalls, meanwhile, saw visits hover around last year's levels — significantly outperforming traditional apparel, which declined 3.5% YoY," according to data from Placer.ai.
In the battle for customers looking for deals on trendy, fashionable clothes, Cato has been struggling, and now plans to close about 15% of its retail stores.
#price
1 month ago
On August 5, Cencora (NYSE:COR) reported results for its fiscal third quarter, which closed on June 30, and the headline numbers looked clean. Revenue rose 5.1% to $84.8 billion, adjusted earnings per share climbed 12.0% to $4.48, and management raised its full-year adjusted EPS outlook to $17.75 to $17.95. The company also repurchased $1 billion of its own stock during the quarter. But the profit story has moving parts, and a few of them pull in opposite directions.
Start with the gap between profit growth and sales growth. Adjusted operating income rose 17.0% while revenue grew only 5.1%. Much of the help came from gross profit, which jumped 23.2% on an adjusted basis as both segments contributed and the OneOncology acquisition in February lifted margins in the US business. In plain terms, adjusted gross margin widened 61 basis points to 4.16%, so the company keeps more gross profit from every dollar it sells.
The strength was not confined to one corner, either. US Healthcare Solutions grew operating income 15.9% on higher pharmaceutical sales and the OneOncology deal, while specialty volume to health systems and physician groups lifted its revenue. International Healthcare Solutions did better still, with operating income up 20.8% on strength in European distribution and global specialty logistics. Management also put cash to work, completing in one quarter the $1 billion of buybacks it had expected to finish by the close of calendar 2026. The board declared a $0.60 quarterly dividend as well, payable August 31, to holders of record on August 14.
Growth is costing more than it first appears. Adjusted operating expenses jumped 26.8%, faster than adjusted gross profit, because OneOncology brought expenses along with its profits. Even so, adjusted operating income amounts to just 1.46% of revenue, a thin cushion on a business this large. Financing adds weight too. Cencora funded part of the purchase with new senior notes plus variable-rate term loans, and net interest expense rose $58.9 million from a year earlier.
The sales mix carries its own drag. GLP-1 drugs for diabetes and weight loss are adding to revenue, but they earn lower gross margins, so each dollar of that growth is worth less to profit. Meanwhile, an oncology customer Cencora lost in 2025, and lower sales to a large mail order customer both held back US revenue, as did lower manufacturer prices on some brand pharmaceuticals. Cencora is also exploring strategic alternatives for a group of other businesses, and its April divestiture of US Consulting Services trimmed consulting sales.
#profit #operating #Growth #august
Start with the gap between profit growth and sales growth. Adjusted operating income rose 17.0% while revenue grew only 5.1%. Much of the help came from gross profit, which jumped 23.2% on an adjusted basis as both segments contributed and the OneOncology acquisition in February lifted margins in the US business. In plain terms, adjusted gross margin widened 61 basis points to 4.16%, so the company keeps more gross profit from every dollar it sells.
The strength was not confined to one corner, either. US Healthcare Solutions grew operating income 15.9% on higher pharmaceutical sales and the OneOncology deal, while specialty volume to health systems and physician groups lifted its revenue. International Healthcare Solutions did better still, with operating income up 20.8% on strength in European distribution and global specialty logistics. Management also put cash to work, completing in one quarter the $1 billion of buybacks it had expected to finish by the close of calendar 2026. The board declared a $0.60 quarterly dividend as well, payable August 31, to holders of record on August 14.
Growth is costing more than it first appears. Adjusted operating expenses jumped 26.8%, faster than adjusted gross profit, because OneOncology brought expenses along with its profits. Even so, adjusted operating income amounts to just 1.46% of revenue, a thin cushion on a business this large. Financing adds weight too. Cencora funded part of the purchase with new senior notes plus variable-rate term loans, and net interest expense rose $58.9 million from a year earlier.
The sales mix carries its own drag. GLP-1 drugs for diabetes and weight loss are adding to revenue, but they earn lower gross margins, so each dollar of that growth is worth less to profit. Meanwhile, an oncology customer Cencora lost in 2025, and lower sales to a large mail order customer both held back US revenue, as did lower manufacturer prices on some brand pharmaceuticals. Cencora is also exploring strategic alternatives for a group of other businesses, and its April divestiture of US Consulting Services trimmed consulting sales.
#profit #operating #Growth #august

2 months ago
Dave & Buster's Entertainment, Inc. (NASDAQ:PLAY) reported a widening split between dining and entertainment in its September 14 second-quarter results. Food-and-beverage revenue increased to $211.5 million from $192.9 million, while entertainment revenue fell to $332.6 million from $364.5 million.
For the fiscal quarter ended August 4, 2026, total revenue declined 2.4% to $544.1 million. Operating income dropped to $19.4 million from $53 million. The GAAP net loss was $12.5 million, versus net income of $11.4 million a year earlier. Stronger restaurant sales are providing support, but the investment question is whether they can also bring customers back to the games.
Food-and-beverage revenue grew approximately 9.6%, giving Dave & Buster's Entertainment, Inc. (NASDAQ:PLAY) an identifiable source of momentum. A more appealing dining experience could encourage repeat visits, group occasions, and longer stays, creating additional opportunities to sell entertainment.
Management reported ongoing growth in food-and-beverage and special-events sales, alongside improving comparable-sales trends in July and the third quarter to date. That suggests the recovery effort has some traction beyond a single revenue category, although the later sales improvement was not quantified.
Management also said remodeled locations continued to outperform the system on comparable sales. That supports selective investment in existing venues, provided the additional revenue earns adequate returns on remodeling costs.
#entertainment #dave
For the fiscal quarter ended August 4, 2026, total revenue declined 2.4% to $544.1 million. Operating income dropped to $19.4 million from $53 million. The GAAP net loss was $12.5 million, versus net income of $11.4 million a year earlier. Stronger restaurant sales are providing support, but the investment question is whether they can also bring customers back to the games.
Food-and-beverage revenue grew approximately 9.6%, giving Dave & Buster's Entertainment, Inc. (NASDAQ:PLAY) an identifiable source of momentum. A more appealing dining experience could encourage repeat visits, group occasions, and longer stays, creating additional opportunities to sell entertainment.
Management reported ongoing growth in food-and-beverage and special-events sales, alongside improving comparable-sales trends in July and the third quarter to date. That suggests the recovery effort has some traction beyond a single revenue category, although the later sales improvement was not quantified.
Management also said remodeled locations continued to outperform the system on comparable sales. That supports selective investment in existing venues, provided the additional revenue earns adequate returns on remodeling costs.
#entertainment #dave
2 months ago
Alluvium ****** et Management, an ****** et management company, released its "Conventum – Alluvium Global Fund" second-quarter 2026 investor letter. The letter can be downloaded here. The second quarter reflected a sharp shift from geopolitical uncertainty and oil market volatility to a powerful equity rally led by semiconductor companies. Despite the broader market strength, the Fund declined 1.4% in EUR terms, 2.2% in USD terms, and 3.9% in AUD terms. Portfolio results were mixed, with Alphabet benefiting from strong Cloud growth, while Robert Half, H&R Block, and other holdings posted solid gains. However, cable businesses and several healthcare and consumer holdings weighed on performance. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Conventum – Alluvium Global Fund highlighted Ryanair Holdings plc (NASDAQ:RYAAY). Headquartered in Swords, Ireland, Ryanair Holdings plc (NASDAQ:RYAAY) provides scheduled passenger airline services. On September 15, 2026, Ryanair Holdings plc (NASDAQ:RYAAY) closed at $51.95 per share. Over the past month, Ryanair Holdings plc (NASDAQ:RYAAY) declined 5.18%, and its shares lost 9.81% over the past 52 weeks. Ryanair Holdings plc (NASDAQ:RYAAY) has a market capitalization of $26.32 billion and its stock has traded within a 52-week range of $51.68 and $74.24.
Conventum – Alluvium Global Fund stated the following regarding Ryanair Holdings plc (NASDAQ:RYAAY) in its Q2 2026 investor letter:
"Similarly with Ryanair Holdings plc (NASDAQ:RYAAY) (up 14.6%) its share price was faltering and we added to our position, but it since bounced back to account for more than 10% of the Fund, so in this case we were forced to sell a little. It now accounts for 9.9% of the Fund."
Ryanair Holdings plc (NASDAQ:RYAAY) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 23 hedge fund portfolios held Ryanair Holdings plc (NASDAQ:RYAAY) at the end of the second quarter which was 29 in the previous quarter. While we acknowledge the potential of Ryanair Holdings plc (NASDAQ:RYAAY) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#NASDAQ #ryaay #conventum #global
In its second-quarter 2026 investor letter, Conventum – Alluvium Global Fund highlighted Ryanair Holdings plc (NASDAQ:RYAAY). Headquartered in Swords, Ireland, Ryanair Holdings plc (NASDAQ:RYAAY) provides scheduled passenger airline services. On September 15, 2026, Ryanair Holdings plc (NASDAQ:RYAAY) closed at $51.95 per share. Over the past month, Ryanair Holdings plc (NASDAQ:RYAAY) declined 5.18%, and its shares lost 9.81% over the past 52 weeks. Ryanair Holdings plc (NASDAQ:RYAAY) has a market capitalization of $26.32 billion and its stock has traded within a 52-week range of $51.68 and $74.24.
Conventum – Alluvium Global Fund stated the following regarding Ryanair Holdings plc (NASDAQ:RYAAY) in its Q2 2026 investor letter:
"Similarly with Ryanair Holdings plc (NASDAQ:RYAAY) (up 14.6%) its share price was faltering and we added to our position, but it since bounced back to account for more than 10% of the Fund, so in this case we were forced to sell a little. It now accounts for 9.9% of the Fund."
Ryanair Holdings plc (NASDAQ:RYAAY) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 23 hedge fund portfolios held Ryanair Holdings plc (NASDAQ:RYAAY) at the end of the second quarter which was 29 in the previous quarter. While we acknowledge the potential of Ryanair Holdings plc (NASDAQ:RYAAY) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#NASDAQ #ryaay #conventum #global
2 months ago
Broyhill ***** et Management, a Charlotte-based firm, issued its second-quarter 2026 investor letter, which is available for download here. The Broyhill Equity Composite gained 8.8% in Q2, trailing the MSCI All Country World Index's 15.1% and the MSCI ACWI Value Index's 10.8%. For the first half, the Composite returned 2.3%, versus 11.5% for the Index. The letter highlights that a significant portion of the shortfall occurred in April due to market dynamics and geopolitical events, with tech, particularly semiconductors, driving recent gains. Broyhill notes its lack of direct semiconductor exposure but acknowledges potential interest in the sector if opportunities arise, maintaining its investment philosophy focused on capital protection in fragile market conditions. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Broyhill ***** et Management highlighted The Middleby Corporation (NASDAQ:MIDD). The Middleby Corporation (NASDAQ:MIDD), a leading player in the foodservice industry, contributed positively to performance during the quarter. On September 14, 2026, The Middleby Corporation (NASDAQ:MIDD) closed at $109.72 per share. Over the past month, The Middleby Corporation (NASDAQ:MIDD) declined 3.75%, but its shares are up 1.27% over the past year. The Middleby Corporation (NASDAQ:MIDD) has a market capitalization of $78.51 billion, and its stock has traded within a 52-week range of $89.14 to $148.55.
Broyhill ***** et Management stated the following regarding The Middleby Corporation (NASDAQ:MIDD) in its Q2 2026 investor letter:
"The Middleby Corporation (NASDAQ:MIDD) gained 31%. Commercial Foodservice grew organic revenue 8% as chains returned to growth and management raised full-year guidance by roughly 4%. More important was the structural progress: the Food Processing separation was confirmed at the May investor day (which our investment team attended) and completed on July 6th, creating Midera. Following the majority sale of the residential business earlier this year, what remains is a cleaner business with leverage approaching 2.5x."
The Middleby Corporation (NASDAQ:MIDD) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 42 hedge fund portfolios held The Middleby Corporation (NASDAQ:MIDD) at the end of the second quarter which was 35 in the previous quarter. While we acknowledge the potential of The Middleby Corporation (NASDAQ:MIDD) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#NASDAQ #midd #asset
In its second-quarter 2026 investor letter, Broyhill ***** et Management highlighted The Middleby Corporation (NASDAQ:MIDD). The Middleby Corporation (NASDAQ:MIDD), a leading player in the foodservice industry, contributed positively to performance during the quarter. On September 14, 2026, The Middleby Corporation (NASDAQ:MIDD) closed at $109.72 per share. Over the past month, The Middleby Corporation (NASDAQ:MIDD) declined 3.75%, but its shares are up 1.27% over the past year. The Middleby Corporation (NASDAQ:MIDD) has a market capitalization of $78.51 billion, and its stock has traded within a 52-week range of $89.14 to $148.55.
Broyhill ***** et Management stated the following regarding The Middleby Corporation (NASDAQ:MIDD) in its Q2 2026 investor letter:
"The Middleby Corporation (NASDAQ:MIDD) gained 31%. Commercial Foodservice grew organic revenue 8% as chains returned to growth and management raised full-year guidance by roughly 4%. More important was the structural progress: the Food Processing separation was confirmed at the May investor day (which our investment team attended) and completed on July 6th, creating Midera. Following the majority sale of the residential business earlier this year, what remains is a cleaner business with leverage approaching 2.5x."
The Middleby Corporation (NASDAQ:MIDD) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 42 hedge fund portfolios held The Middleby Corporation (NASDAQ:MIDD) at the end of the second quarter which was 35 in the previous quarter. While we acknowledge the potential of The Middleby Corporation (NASDAQ:MIDD) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#NASDAQ #midd #asset

2 months ago
Some offers on this page are from advertisers who pay us, which may affect which products we write about, but not our recommendations. See our Advertiser Disclosure.
The national average rate for a 30-year fixed mortgage has crossed 7%. However, there is a way to lower your mortgage costs: a buydown interest rate.
With this method, you pay more at closing to lower your mortgage interest rate. While it costs more money up front, it can lead to greater savings over the life of the loan. But it's a more beneficial tactic if you plan to stay in the home for a while — the longer you keep the mortgage, the more you'll save by buying down the rate.
While there are perks to having a lower mortgage rate, there are also factors to consider before buying down your interest rate.
When you buy down your mortgage rate, you pay extra money at closing to purchase points that essentially lower your interest rate.
#closing
The national average rate for a 30-year fixed mortgage has crossed 7%. However, there is a way to lower your mortgage costs: a buydown interest rate.
With this method, you pay more at closing to lower your mortgage interest rate. While it costs more money up front, it can lead to greater savings over the life of the loan. But it's a more beneficial tactic if you plan to stay in the home for a while — the longer you keep the mortgage, the more you'll save by buying down the rate.
While there are perks to having a lower mortgage rate, there are also factors to consider before buying down your interest rate.
When you buy down your mortgage rate, you pay extra money at closing to purchase points that essentially lower your interest rate.
#closing


0.00$ raised of 0.00$ goal
0 donations
0.00$
to go
2 months ago
Coca-Cola (NYSE: KO) is one of the best-known companies in the world, thanks to its namesake beverage brand, so it needs little introduction. However, what's most impressive right now is the stock's performance. It is up 28% over the past year, as of this writing. The average consumer staples stock is only up 5% over that span. Even the S&P 500 index (SNPINDEX: ^GSPC) is "only" up 20%. After a run like that, is Coca-Cola a buy, hold, or sell?
Coca-Cola is a well-run business. It is one of the world's largest consumer staples companies. It is globally diversified and has industry-leading capabilities in distribution, marketing, and innovation. The company's fundamental strength is evident in its status as a Dividend King, with 64 consecutive annual dividend increases. The only consumer staples peer with a better record is Procter & Gamble (NYSE: PG), but P&G doesn't make food. So, Coca-Cola is the food company with the best dividend record.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
If you want to own industry-leading businesses, Coca-Cola should be on your short list. And, with an above-market yield of 2.4%, you could easily justify adding it to your portfolio. That's particularly true given recent results, with organic revenue growth of 6% in the second quarter of 2026, even as consumers tighten their belts. In fact, Coca-Cola raised its full-year guidance despite the broader food industry's struggles.
Certainly, if you have owned Coca-Cola for years, selling it right when it is performing so well as a business probably isn't something you should be considering. Unless, of course, the stock's valuation was running ahead of its historical norms. But that's not the case.
#staples
Coca-Cola is a well-run business. It is one of the world's largest consumer staples companies. It is globally diversified and has industry-leading capabilities in distribution, marketing, and innovation. The company's fundamental strength is evident in its status as a Dividend King, with 64 consecutive annual dividend increases. The only consumer staples peer with a better record is Procter & Gamble (NYSE: PG), but P&G doesn't make food. So, Coca-Cola is the food company with the best dividend record.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
If you want to own industry-leading businesses, Coca-Cola should be on your short list. And, with an above-market yield of 2.4%, you could easily justify adding it to your portfolio. That's particularly true given recent results, with organic revenue growth of 6% in the second quarter of 2026, even as consumers tighten their belts. In fact, Coca-Cola raised its full-year guidance despite the broader food industry's struggles.
Certainly, if you have owned Coca-Cola for years, selling it right when it is performing so well as a business probably isn't something you should be considering. Unless, of course, the stock's valuation was running ahead of its historical norms. But that's not the case.
#staples

2 months ago
Pre-approval signals you likely qualify, but no underwriter has verified your income, debts, or employment, so it is far from a guaranteed loan.
Full underwriting approval verifies income, employment, credit, and ******* ets, but can still carry conditions that must be resolved before closing.
Even after full approval, taking on new debt, switching jobs, or a failed appraisal can derail your mortgage before closing day.
Just released. Our ******* ysts combed the entire stock market and named the ten best stocks to buy right now. The report is free. Enter your email and see if any of your stocks made the cut.
Getting approved for a mortgage is one of the first major steps in the home-buying process. But it's not always so easy and usually comes with a lot of paperwork. Lenders need to know you are a reliable borrower. They want to review your finances to make sure you can comfortably afford the loan. This means you need to provide documented proof of your income, employment history, savings, and existing debt. Having these documents ready ahead of time can make the mortgage process faster and more manageable. While every lender will have slightly different requirements, these are the most common documents a lender will ask for.
#approval #loan #stocks
Full underwriting approval verifies income, employment, credit, and ******* ets, but can still carry conditions that must be resolved before closing.
Even after full approval, taking on new debt, switching jobs, or a failed appraisal can derail your mortgage before closing day.
Just released. Our ******* ysts combed the entire stock market and named the ten best stocks to buy right now. The report is free. Enter your email and see if any of your stocks made the cut.
Getting approved for a mortgage is one of the first major steps in the home-buying process. But it's not always so easy and usually comes with a lot of paperwork. Lenders need to know you are a reliable borrower. They want to review your finances to make sure you can comfortably afford the loan. This means you need to provide documented proof of your income, employment history, savings, and existing debt. Having these documents ready ahead of time can make the mortgage process faster and more manageable. While every lender will have slightly different requirements, these are the most common documents a lender will ask for.
#approval #loan #stocks
2 months ago
This story was originally published on FSR. To receive daily news and insights, subscribe to our free daily FS Insider.
More than half a decade after the pandemic fundamentally changed how consumers interact with restaurants, delivery has moved well beyond the "turn it on" phase for full-service operators. The focus now is less on adding a sales channel than on optimizing one that touches the kitchen, labor model, guest relationship, and broader tech stack.
"We look at it a little differently nowadays," says Jason Saposnik, VP of information technology for FSC Franchise Co., the parent company of Beef 'O' Brady's, The Brass Tap, and Newk's Eatery. "Early on, the focus was more about just growing delivery sales. Now, we're a lot more focused on whether those sales are profitable, how the restaurants can handle that increased volume, and whether customers are actually getting the same great experience."
The first major improvement in delivery operations was straightforward: getting orders into the restaurant without forcing employees to act as the integration layer.
Saposnik recalls an earlier "tablet ******* " environment in which teams monitored separate devices for DoorDash, Uber Eats, and other channels, then manually entered orders into the POS. "That created all sorts of issues for missed orders and mistakes and delays," he says. "Now, everything just flows into the POS and into the kitchen correctly."
#getting
More than half a decade after the pandemic fundamentally changed how consumers interact with restaurants, delivery has moved well beyond the "turn it on" phase for full-service operators. The focus now is less on adding a sales channel than on optimizing one that touches the kitchen, labor model, guest relationship, and broader tech stack.
"We look at it a little differently nowadays," says Jason Saposnik, VP of information technology for FSC Franchise Co., the parent company of Beef 'O' Brady's, The Brass Tap, and Newk's Eatery. "Early on, the focus was more about just growing delivery sales. Now, we're a lot more focused on whether those sales are profitable, how the restaurants can handle that increased volume, and whether customers are actually getting the same great experience."
The first major improvement in delivery operations was straightforward: getting orders into the restaurant without forcing employees to act as the integration layer.
Saposnik recalls an earlier "tablet ******* " environment in which teams monitored separate devices for DoorDash, Uber Eats, and other channels, then manually entered orders into the POS. "That created all sorts of issues for missed orders and mistakes and delays," he says. "Now, everything just flows into the POS and into the kitchen correctly."
#getting

2 months ago
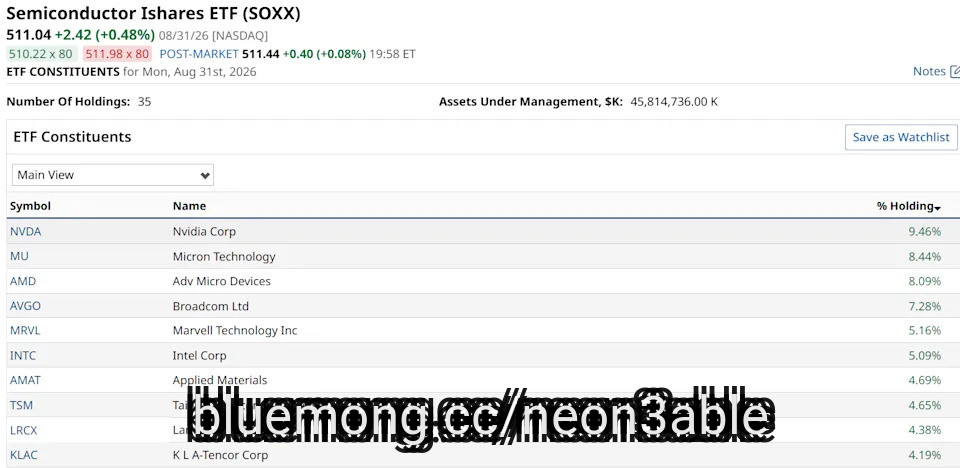
I have a chart that will knock your socks off. It's none other than the very popular iShares Semiconductor ETF (SOXX), and I've marked in purple a very important point in the long up cycle. That's a triangle, or wedge. And if SOXX breaks down through it without an instant recovery, it could open the stock market floodgates.
For now, it is simply a marker. And it won't take long to resolve, one way or the other. That's the usual nature of this type of pattern, once it hits that most narrow section at the far right of the chart.
Dear Sandisk Stock Fans, Mark Your Calendars for August 31
Bill Gates Says 'We Need Time to Prepare' for an Economic Upheaval — Especially the $20-an-Hour Workers Being Replaced by $10-an-Hour Robots
Dear Palantir Stock Fans, Here's What Maven's Billion-Dollar ARR Means for PLTR
#fans #semiconductor #i 've
For now, it is simply a marker. And it won't take long to resolve, one way or the other. That's the usual nature of this type of pattern, once it hits that most narrow section at the far right of the chart.
Dear Sandisk Stock Fans, Mark Your Calendars for August 31
Bill Gates Says 'We Need Time to Prepare' for an Economic Upheaval — Especially the $20-an-Hour Workers Being Replaced by $10-an-Hour Robots
Dear Palantir Stock Fans, Here's What Maven's Billion-Dollar ARR Means for PLTR
#fans #semiconductor #i 've

2 months ago
When it comes to profiting from the current AI boom, you don't necessarily have to invest in the central players. Sure, the likes of Nvidia (NVDA), Micron (MU), and TSMC (TSM) are raking in the money and giving shareholders triple-digit returns.
But sometimes, the better opportunities lie with the companies serving as the foundation of the AI boom. The ones supplying the materials, equipment, and infrastructure that make up the rest of data centers.
Tired of missing midday reversals? The FREE Barchart Brief newsletter keeps you in the know. Sign up now!
That brings us to an interesting matchup in that AI infrastructure play. One company is providing connectivity materials that all data centers need to move all their information across, well, everywhere, while the other supplies the equipment to the chipmakers themselves.
Both companies are pillars of the AI boom, but they're supporting different sides of the sector.
#boom #infrastructure #data
But sometimes, the better opportunities lie with the companies serving as the foundation of the AI boom. The ones supplying the materials, equipment, and infrastructure that make up the rest of data centers.
Tired of missing midday reversals? The FREE Barchart Brief newsletter keeps you in the know. Sign up now!
That brings us to an interesting matchup in that AI infrastructure play. One company is providing connectivity materials that all data centers need to move all their information across, well, everywhere, while the other supplies the equipment to the chipmakers themselves.
Both companies are pillars of the AI boom, but they're supporting different sides of the sector.
#boom #infrastructure #data

2 months ago
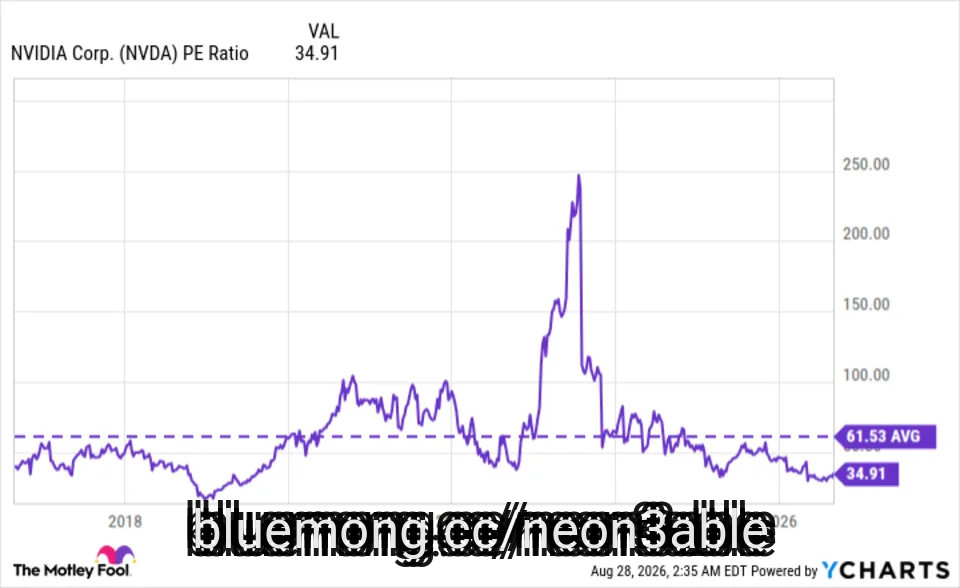
After the close of trading on Aug. 26, Nvidia (NASDAQ: NVDA) reported a set of operating results for its fiscal 2027 second quarter (ended July 26, 2026) that blew away Wall Street's expectations, and the company also unexpectedly offered some very bullish forward revenue guidance for fiscal 2028. As a result, Nvidia's stock price soared by almost 9% the very next day.
There is a long list of reasons why Nvidia stock is still a buy, but there is also room for caution right now, particularly surrounding the deals that management is cutting with many of the company's biggest artificial intelligence (AI) customers. So, before investors buy the stock, here's a breakdown of the good news and the bad news.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Nvidia supplies the world's best graphics processing units (GPUs) for data centers, which are the main chips used in AI training and inference workloads. The company's new Vera Rubin systems, which include Rubin GPUs, Vera central processors (CPUs), and a series of advanced networking components, provide up to 30 times more performance per megawatt than its previous Blackwell Ultra systems, highlighting the sheer pace of innovation.
Nvidia says Vera Rubin systems will also reduce inference token costs by a staggering 97% compared to Blackwell Ultra. Inference tokens are the text, images, or computer code generated by an AI model in response to a query, so these new chips will dramatically reduce the cost of deploying AI software. This might encourage more AI usage while making data center operators more profitable, which will only increase demand for Nvidia's chips.
#gpus
There is a long list of reasons why Nvidia stock is still a buy, but there is also room for caution right now, particularly surrounding the deals that management is cutting with many of the company's biggest artificial intelligence (AI) customers. So, before investors buy the stock, here's a breakdown of the good news and the bad news.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Nvidia supplies the world's best graphics processing units (GPUs) for data centers, which are the main chips used in AI training and inference workloads. The company's new Vera Rubin systems, which include Rubin GPUs, Vera central processors (CPUs), and a series of advanced networking components, provide up to 30 times more performance per megawatt than its previous Blackwell Ultra systems, highlighting the sheer pace of innovation.
Nvidia says Vera Rubin systems will also reduce inference token costs by a staggering 97% compared to Blackwell Ultra. Inference tokens are the text, images, or computer code generated by an AI model in response to a query, so these new chips will dramatically reduce the cost of deploying AI software. This might encourage more AI usage while making data center operators more profitable, which will only increase demand for Nvidia's chips.
#gpus
2 months ago
Interested in Red Violet, Inc.? Here are five stocks we like better.
Red Violet is expanding its AI-powered identity intelligence platform across collections, investigations, financial and corporate risk, emerging markets and real estate, serving more than 10,000 customers and an estimated $10 billion total addressable market.
The company is broadening its FOREWARN safety application beyond real estate into home healthcare, while continuing to grow its law-enforcement presence and other public-sector opportunities.
Red Violet raised approximately $115 million in equity to fund acquisitions, sales initiatives and organic growth. Management is targeting gross margins above 90% and adjusted EBITDA margins of 60% to 65% as revenue scales on its largely fixed-cost platform.
Are These 3 Under-the-Radar AI Stocks the Next Big Growth Stories?
#stocks #Growth
Red Violet is expanding its AI-powered identity intelligence platform across collections, investigations, financial and corporate risk, emerging markets and real estate, serving more than 10,000 customers and an estimated $10 billion total addressable market.
The company is broadening its FOREWARN safety application beyond real estate into home healthcare, while continuing to grow its law-enforcement presence and other public-sector opportunities.
Red Violet raised approximately $115 million in equity to fund acquisitions, sales initiatives and organic growth. Management is targeting gross margins above 90% and adjusted EBITDA margins of 60% to 65% as revenue scales on its largely fixed-cost platform.
Are These 3 Under-the-Radar AI Stocks the Next Big Growth Stories?
#stocks #Growth
2 months ago
Circle Internet Group (NYSE:CRCL) share price surged amid a broad cryptocurrency rally following a White House meeting with industry executives, with lower Treasury yields and expanded government bond buybacks also supporting risk ***** ets. President Donald Trump urged Congress to pass a "fair version" of the CLARITY Act.
The meeting strengthened the policy narrative without changing Circle's immediate economics. Circle Internet Group (NYSE:CRCL) ended the second quarter with $73.3 billion of USDC in circulation, up 19% year over year. Reserve income still represented $668 million of its $701 million in total revenue and reserve income.
The central question is whether clearer rules can expand USDC adoption quickly enough to reduce Circle's dependence on short-term interest rates.
USDC activity continues to expand faster than Circle Internet Group (NYSE:CRCL)'s reported revenue. Onchain transaction volume increased 151% to $14.8 trillion during the second quarter, while average USDC circulation grew 25% to a record $76.5 billion.
The CLARITY Act would complement the GENIUS Act, the federal payment-stablecoin framework enacted in 2025, by addressing broader digital-asset market structure and SEC/CFTC jurisdiction. For Circle Internet Group (NYSE:CRCL), more predictable rules could make banks, payment companies and ***** et managers more comfortable building products around USDC.
#internet #meeting #second
The meeting strengthened the policy narrative without changing Circle's immediate economics. Circle Internet Group (NYSE:CRCL) ended the second quarter with $73.3 billion of USDC in circulation, up 19% year over year. Reserve income still represented $668 million of its $701 million in total revenue and reserve income.
The central question is whether clearer rules can expand USDC adoption quickly enough to reduce Circle's dependence on short-term interest rates.
USDC activity continues to expand faster than Circle Internet Group (NYSE:CRCL)'s reported revenue. Onchain transaction volume increased 151% to $14.8 trillion during the second quarter, while average USDC circulation grew 25% to a record $76.5 billion.
The CLARITY Act would complement the GENIUS Act, the federal payment-stablecoin framework enacted in 2025, by addressing broader digital-asset market structure and SEC/CFTC jurisdiction. For Circle Internet Group (NYSE:CRCL), more predictable rules could make banks, payment companies and ***** et managers more comfortable building products around USDC.
#internet #meeting #second
2 months ago
Most Americans will never use Palantir's Maven software, but they are paying more and more taxes for it.
William Blair ****** yst Louie DiPalma reiterated an Outperform rating on Palantir Technologies (PLTR) on the back of the company's Maven Smart System, which he said looks to be approaching a $1 billion annual revenue run rate and could eventually secure formal program-of-record status in the U.S. defense establishment.
It's an estimate that counts since Maven isn't just another corporate chatbot. It's an AI-enabled military intelligence and data system.
William Blair said Maven looks to be on target for a $1 billion annual revenue run rate, with use rising at the Pentagon.
Beyond that, the Pentagon is already heavily involved. The Army awarded Palantir a $795 million contract amendment in May 2025 for the Maven Smart System software licenses, with work through May 2029.
#maven #system
William Blair ****** yst Louie DiPalma reiterated an Outperform rating on Palantir Technologies (PLTR) on the back of the company's Maven Smart System, which he said looks to be approaching a $1 billion annual revenue run rate and could eventually secure formal program-of-record status in the U.S. defense establishment.
It's an estimate that counts since Maven isn't just another corporate chatbot. It's an AI-enabled military intelligence and data system.
William Blair said Maven looks to be on target for a $1 billion annual revenue run rate, with use rising at the Pentagon.
Beyond that, the Pentagon is already heavily involved. The Army awarded Palantir a $795 million contract amendment in May 2025 for the Maven Smart System software licenses, with work through May 2029.
#maven #system

2 months ago
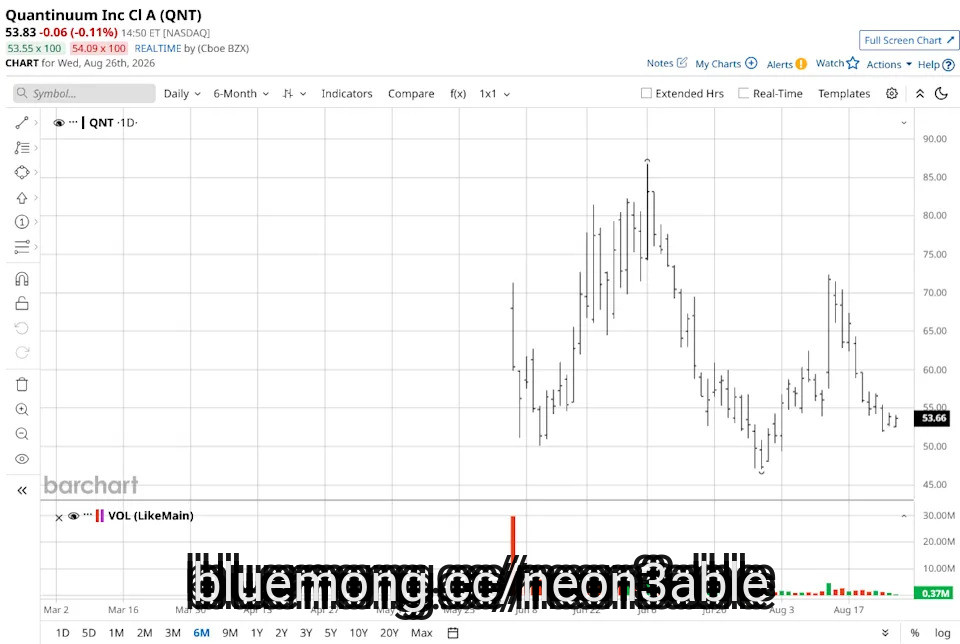
There's a great deal to like about quantum firm D-Wave (QBTS), including its promising technologies, its rapidly growing bookings and backlog, the investment that it received from the U.S. government, and its impressive list of customers.
However, Quantinuum (QNT), whose IPO was launched by majority owner Honeywell (HON), also has all of these attributes. However, its revenue, backlog, and cash reserves are meaningfully larger than those of D-Wave. Due to these points, I view QNT stock as the better, safer pick for investors for now.
Walmart Stock Is More Expensive Than Nvidia Amid Earnings Miss
SpaceX Stock Just Crashed Below Its IPO Price: Here's the Bull Case ******* ody Can Ignore
A Major Bitcoin Short Squeeze Is Taking MicroStrategy Stock Higher. What Comes Next.
#Stock #wave #backlog
However, Quantinuum (QNT), whose IPO was launched by majority owner Honeywell (HON), also has all of these attributes. However, its revenue, backlog, and cash reserves are meaningfully larger than those of D-Wave. Due to these points, I view QNT stock as the better, safer pick for investors for now.
Walmart Stock Is More Expensive Than Nvidia Amid Earnings Miss
SpaceX Stock Just Crashed Below Its IPO Price: Here's the Bull Case ******* ody Can Ignore
A Major Bitcoin Short Squeeze Is Taking MicroStrategy Stock Higher. What Comes Next.
#Stock #wave #backlog

2 months ago
Sandhill Investment Management, an investment management company, released its second quarter 2026 investor letter. A copy of the letter can be downloaded here. The letter highlighted a strong second quarter for equity markets, with the S&P 500 up about 15% and projected earnings growth at the fastest rate in five years. Despite challenges like tensions with Iran and lower oil prices, the semiconductor sector and AI advancements drove significant stock price increases. In fixed income, rising yields have made corporate bonds appealing, offering over 5% returns. However, consumer sentiment is waning, and the savings rate is at a six-decade low, raising caution about the economy. Investment trends suggest that while overall market valuations are high, quality businesses present selective opportunities for long-term gains amidst short-term volatility. Also, check the fund's top five holdings to see its best picks in 2026.
In its Q2 2026 investor letter, Sandhill Investment Management highlighted Forgent Power Solutions, Inc. (NYSE:FPS) as a new holdings. Forgent Power Solutions, Inc. (NYSE:FPS) is a leading industrial company that designs and manufactures electrical distribution equipment used in data centers, the power grid, and energy-intensive industrial facilities. On August 26, 2026, Forgent Power Solutions, Inc. (NYSE:FPS) closed at $32.21 per share, reflecting a market capitalization of $9.80 billion. Forgent Power Solutions, Inc. (NYSE:FPS) posted a one-month return of -3.22%.
Sandhill Investment Management stated the following regarding Forgent Power Solutions, Inc. (NYSE:FPS) in its Q2 2026 investor letter:
"Despite the elevated broad market valuation and the caution related to the consumer, quality businesses are being valued more cheaply than they have been in a long time, and we are putting capital to work. We remain selective, but individual businesses are presenting compelling value.
We also initiated a position in Forgent Power Solutions, Inc. (NYSE:FPS), a newly public manufacturer of electrical distribution equipment, including transformers, switchgear and prefabricated power systems for data centers and the broader electric grid. As AI infrastructure spending accelerates, power equipment has become a critical constraint on new data center capacity. Forgent's ability to provide an integrated range of electrical products positions it well as customers seek faster and more coordinated solutions. Forgent, by contrast, is a newly public company that remains less widely followed despite strong long-term growth prospects and a valuation that leaves room for upside."
#power #NYSE #letter #company
In its Q2 2026 investor letter, Sandhill Investment Management highlighted Forgent Power Solutions, Inc. (NYSE:FPS) as a new holdings. Forgent Power Solutions, Inc. (NYSE:FPS) is a leading industrial company that designs and manufactures electrical distribution equipment used in data centers, the power grid, and energy-intensive industrial facilities. On August 26, 2026, Forgent Power Solutions, Inc. (NYSE:FPS) closed at $32.21 per share, reflecting a market capitalization of $9.80 billion. Forgent Power Solutions, Inc. (NYSE:FPS) posted a one-month return of -3.22%.
Sandhill Investment Management stated the following regarding Forgent Power Solutions, Inc. (NYSE:FPS) in its Q2 2026 investor letter:
"Despite the elevated broad market valuation and the caution related to the consumer, quality businesses are being valued more cheaply than they have been in a long time, and we are putting capital to work. We remain selective, but individual businesses are presenting compelling value.
We also initiated a position in Forgent Power Solutions, Inc. (NYSE:FPS), a newly public manufacturer of electrical distribution equipment, including transformers, switchgear and prefabricated power systems for data centers and the broader electric grid. As AI infrastructure spending accelerates, power equipment has become a critical constraint on new data center capacity. Forgent's ability to provide an integrated range of electrical products positions it well as customers seek faster and more coordinated solutions. Forgent, by contrast, is a newly public company that remains less widely followed despite strong long-term growth prospects and a valuation that leaves room for upside."
#power #NYSE #letter #company

2 months ago
By Mike Scarcella
WASHINGTON, Aug 25 (Reuters) - Alphabet's Google on Tuesday expanded its Gemini Enterprise artificial intelligence platform with new tools for lawyers and law firms, accelerating a race among technology companies to meet legal sector demand for AI.
The company said its Gemini Enterprise for Legal would help law firms use AI to manage routine and complex work to allow lawyers to focus on higher-value services, while keeping their data secure and confidential.
The new plug-in for Gemini Enterprise includes integration with legal software and data platforms and a stable of AI agents that Google said can handle specialized legal and administrative functions without significant human oversight.
Alphabet launched Gemini Enterprise for business customers in October, in a bid to attract more corporate clients with its AI offerings. Google Cloud has become one of Alphabet's fastest-growing businesses.
#lawyers #firms #data
WASHINGTON, Aug 25 (Reuters) - Alphabet's Google on Tuesday expanded its Gemini Enterprise artificial intelligence platform with new tools for lawyers and law firms, accelerating a race among technology companies to meet legal sector demand for AI.
The company said its Gemini Enterprise for Legal would help law firms use AI to manage routine and complex work to allow lawyers to focus on higher-value services, while keeping their data secure and confidential.
The new plug-in for Gemini Enterprise includes integration with legal software and data platforms and a stable of AI agents that Google said can handle specialized legal and administrative functions without significant human oversight.
Alphabet launched Gemini Enterprise for business customers in October, in a bid to attract more corporate clients with its AI offerings. Google Cloud has become one of Alphabet's fastest-growing businesses.
#lawyers #firms #data

2 months ago
Updated Aug 25, 2026, 1:40 pm EDT / Original Aug 24, 2026, 4:40 pm EDT
Traders are increasingly betting that the Federal Reserve will raise interest rates at the end of this year and early 2027, and it is time to start looking at the sectors that will benefit.
Copyright ©2026 Dow Jones & Company, Inc. All Rights Reserved. 87990cbe856818d5eddac44c7b1cdeb8
#rights #increasingly
Traders are increasingly betting that the Federal Reserve will raise interest rates at the end of this year and early 2027, and it is time to start looking at the sectors that will benefit.
Copyright ©2026 Dow Jones & Company, Inc. All Rights Reserved. 87990cbe856818d5eddac44c7b1cdeb8
#rights #increasingly

2 months ago
Joshua Allen Franks, Senior Vice President of Operations at e.l.f. Beauty, Inc. (NYSE:ELF), sold 5,718 shares of common stock at $100.00 per share on August 19, 2026 according to a recent SEC Form 4 filing.
Metric
Value
Transaction value
$571,800
#joshua #president #beauty
Metric
Value
Transaction value
$571,800
#joshua #president #beauty

2 months ago
This story was originally published on Construction Dive. To receive daily news and insights, subscribe to our free daily Construction Dive newsletter.
Robots are gaining steam in the construction industry, with two announcements this week highlighting the demand for these solutions on jobsites.
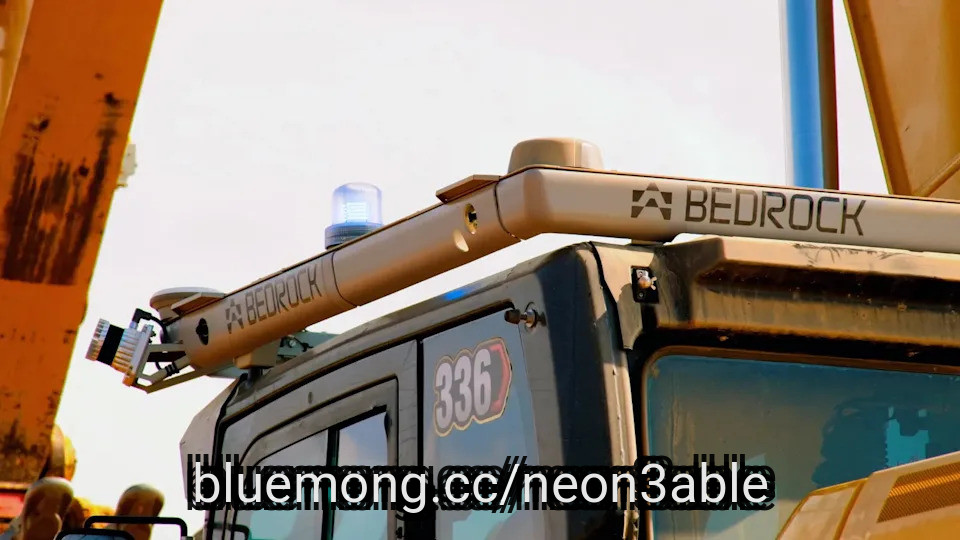
On Monday, global investment behemoth SoftBank threw its weight behind Gravis Robotics in a $200 million Series A funding round. That same day, Bedrock Robotics, founded by alumni from robotaxi firm Waymo, announced its machines were doing work on real jobsites for established contractors, including Sundt Construction and Zachry Construction.
Those are only the latest developments in the sector. Last year, "robot brain" maker FieldAI raised $405 million across two consecutive funding rounds. And Bedrock's latest jobsite announcement followed its February funding news, where it raised $270 million in a Series B round.
The focus on robots in construction demonstrates not only a desire from legacy investors to pursue automation in the sector, but the need of contractors to find labor — human or otherwise — to complete jobs. As Bedrock CEO Boris Sofman told Construction Dive earlier this week, "We are seeing increasing projects with millions of cubic yards of earth to be moved."
#robotics #week
Robots are gaining steam in the construction industry, with two announcements this week highlighting the demand for these solutions on jobsites.
On Monday, global investment behemoth SoftBank threw its weight behind Gravis Robotics in a $200 million Series A funding round. That same day, Bedrock Robotics, founded by alumni from robotaxi firm Waymo, announced its machines were doing work on real jobsites for established contractors, including Sundt Construction and Zachry Construction.
Those are only the latest developments in the sector. Last year, "robot brain" maker FieldAI raised $405 million across two consecutive funding rounds. And Bedrock's latest jobsite announcement followed its February funding news, where it raised $270 million in a Series B round.
The focus on robots in construction demonstrates not only a desire from legacy investors to pursue automation in the sector, but the need of contractors to find labor — human or otherwise — to complete jobs. As Bedrock CEO Boris Sofman told Construction Dive earlier this week, "We are seeing increasing projects with millions of cubic yards of earth to be moved."
#robotics #week
3 months ago
IM Cannabis (NASDAQ:IMCC) has entered into a definitive agreement to sell IMC Holdings and its European-focused **** ets to Slil.com Holding, a transaction management expects to improve shareholders' equity by approximately C$3 million while reducing liabilities and simplifying the company's structure.
The proposed European **** et sale would leave IM Cannabis focused on its Israeli medical cannabis operations, but investors must also weigh the company's stated financial difficulties and the related-party nature of the deal.
IM Cannabis (NASDAQ:IMCC) expects the transaction to improve shareholders' equity by approximately C$3 million based on management's current pro forma **** ysis.
Slil will **** ume retained liabilities of up to approximately C$9.4 million, unless the parties mutually agree to an adjustment.
The consideration also includes C$3 million of advance payments previously made to IM Cannabis by Slil and an affiliate.
#Cannabis #european
The proposed European **** et sale would leave IM Cannabis focused on its Israeli medical cannabis operations, but investors must also weigh the company's stated financial difficulties and the related-party nature of the deal.
IM Cannabis (NASDAQ:IMCC) expects the transaction to improve shareholders' equity by approximately C$3 million based on management's current pro forma **** ysis.
Slil will **** ume retained liabilities of up to approximately C$9.4 million, unless the parties mutually agree to an adjustment.
The consideration also includes C$3 million of advance payments previously made to IM Cannabis by Slil and an affiliate.
#Cannabis #european
3 months ago
On August 7, Sylvamo (NYSE:SLVM) reported its second-quarter 2026 financial results. Sequential adjusted EBITDA jumped to $60 million, more than double the prior quarter's total, but margin stayed thin at 7%. Free cash flow stayed negative at $23 million, though that marked a real improvement from the quarter before. CEO John Sims called 2026 a transition year, shaped by the end of a supply agreement and an extended mill outage. The real question is whether the back half delivers the turnaround management is promising.
Price and mix gains added $32 million to EBITDA in the quarter, as Sylvamo pushed through uncoated freesheet price increases across every region it serves. Europe got a fresh increase in mid-June, with realization continuing through the third quarter, while Latin America should benefit from seasonally stronger second-half demand plus ongoing price hikes to export customers there and in the Middle East and Africa. North America's backdrop has shifted too: International Paper's Riverdale mill conversion pulled 7% of annual uncoated freesheet industry capacity offline, giving Sylvamo more room to raise prices at home.
Altogether, management expects $75 million to $85 million of price and mix benefit in the second half versus the first. The Eastover mill investments add another lever: a paper machine speed-up will add 60,000 tons of annual capacity once it wraps during the fourth-quarter outage, and a new sheeter has already cleared acceptance testing and arrived in the U.S. Those projects, plus a warehouse sale-leaseback deal, are projected to generate $55 million a year in benefits, with $30 million to $40 million landing as soon as 2027.
While sequential operating metrics moved higher, earnings remained constrained. Adjusted operating earnings came in at $0.03 per share, weighed down by $24 million in planned maintenance outage costs as scheduled downtime ran across all regions. Sylvamo expects roughly $5 million more of unfavorable maintenance impact in the second half while it takes extended downtime at Eastover to finish the paper machine work. Input and transportation costs were also a $2 million drag, with fiber costs climbing in Latin America and freight costs rising in North America, partly offset by the non-repeat of a one-time $10 million charge tied to International Paper's Riverdale mill.
Management also flagged the Middle East conflict as an ongoing drag on energy, chemicals and transportation costs in every region. Imports into North America ticked up in the quarter too, a response to a new 10% tariff threshold on global shipments, which could complicate the pricing gains tied to reduced domestic supply. Second-half volume will also be trimmed by lost Riverdale-related tons and the extended Eastover outage in the fourth quarter.
#million #sylvamo #costs
Price and mix gains added $32 million to EBITDA in the quarter, as Sylvamo pushed through uncoated freesheet price increases across every region it serves. Europe got a fresh increase in mid-June, with realization continuing through the third quarter, while Latin America should benefit from seasonally stronger second-half demand plus ongoing price hikes to export customers there and in the Middle East and Africa. North America's backdrop has shifted too: International Paper's Riverdale mill conversion pulled 7% of annual uncoated freesheet industry capacity offline, giving Sylvamo more room to raise prices at home.
Altogether, management expects $75 million to $85 million of price and mix benefit in the second half versus the first. The Eastover mill investments add another lever: a paper machine speed-up will add 60,000 tons of annual capacity once it wraps during the fourth-quarter outage, and a new sheeter has already cleared acceptance testing and arrived in the U.S. Those projects, plus a warehouse sale-leaseback deal, are projected to generate $55 million a year in benefits, with $30 million to $40 million landing as soon as 2027.
While sequential operating metrics moved higher, earnings remained constrained. Adjusted operating earnings came in at $0.03 per share, weighed down by $24 million in planned maintenance outage costs as scheduled downtime ran across all regions. Sylvamo expects roughly $5 million more of unfavorable maintenance impact in the second half while it takes extended downtime at Eastover to finish the paper machine work. Input and transportation costs were also a $2 million drag, with fiber costs climbing in Latin America and freight costs rising in North America, partly offset by the non-repeat of a one-time $10 million charge tied to International Paper's Riverdale mill.
Management also flagged the Middle East conflict as an ongoing drag on energy, chemicals and transportation costs in every region. Imports into North America ticked up in the quarter too, a response to a new 10% tariff threshold on global shipments, which could complicate the pricing gains tied to reduced domestic supply. Second-half volume will also be trimmed by lost Riverdale-related tons and the extended Eastover outage in the fourth quarter.
#million #sylvamo #costs

3 months ago
AGTHX owns $6 billion in private AI stakes like Anthropic and OpenAI, unavailable to index funds, and returned 87% over three years vs. SPY's 72%.
The A share load of up to 5.75% can cost retail buyers thousands upfront, making GAFFX the cleaner entry for fee-based advisory clients.
Act now: the ****** yst who called NVIDIA in 2010 just named his top 10 AI stocks — and AGTHX didn't make the cut. Grab the names FREE today.
The Growth Fund of America manages $360.9 billion in net ****** ets as of May 31, 2026, which is roughly the GDP of a mid-sized country parked inside a single actively managed mutual fund. That is a strange headline in an era when index funds were supposed to have won the argument. Yet Growth Fund of America (NASDAQ:AGTHX) keeps holding its ****** ets, keeps writing checks to private AI companies, and over the last three years has quietly done something its skeptics said active managers no longer could.
Run by Capital Group under the American Funds brand, AGTHX is a large-cap growth fund with 332 positions spread across US mega-caps, international semiconductors, private tech, and a slug of cash. The A share class is the flagship retail vehicle and the one most 401(k) participants know. Capital Group does not disclose the expense ratio in the snapshot data reviewed here, so investors should confirm the current figure and any sales charge directly on the fund's prospectus before buying.
#Growth
The A share load of up to 5.75% can cost retail buyers thousands upfront, making GAFFX the cleaner entry for fee-based advisory clients.
Act now: the ****** yst who called NVIDIA in 2010 just named his top 10 AI stocks — and AGTHX didn't make the cut. Grab the names FREE today.
The Growth Fund of America manages $360.9 billion in net ****** ets as of May 31, 2026, which is roughly the GDP of a mid-sized country parked inside a single actively managed mutual fund. That is a strange headline in an era when index funds were supposed to have won the argument. Yet Growth Fund of America (NASDAQ:AGTHX) keeps holding its ****** ets, keeps writing checks to private AI companies, and over the last three years has quietly done something its skeptics said active managers no longer could.
Run by Capital Group under the American Funds brand, AGTHX is a large-cap growth fund with 332 positions spread across US mega-caps, international semiconductors, private tech, and a slug of cash. The A share class is the flagship retail vehicle and the one most 401(k) participants know. Capital Group does not disclose the expense ratio in the snapshot data reviewed here, so investors should confirm the current figure and any sales charge directly on the fund's prospectus before buying.
#Growth
3 months ago
New York-based Colgate-Palmolive Company (CL) manufactures and sells consumer products in the United States and internationally. The company has a market cap of $71.9 billion and operates through two segments: Oral, Personal and Home Care; and Pet Nutrition, and offers toothpaste, toothbrushes, mouthwash, bar and liquid hand soaps, shower gels, shampoos, conditioners, deodorants and antiperspirants, and other products.
CL shares have lagged behind the broader market over the past year, surging 7.6% compared to the S&P 500 Index's ($SPX) 21.8% surge. However, in 2026, the stock has grown by nearly 13.7%, outperforming the SPX's 11% rise.
General Motors vs. Ford: 1 Auto Giant Is Winning the EV Race
1 ******* anese Company Just Waved a Red Flag for Micron Stock. How to Play It Here.
Billionaire Ken Griffin Just Saved Situational Awareness, But Here's What a Rescue Call From Citadel Really Sounds Like — 'I… Heard the Grim Reaper's Scythe'
#products #market
CL shares have lagged behind the broader market over the past year, surging 7.6% compared to the S&P 500 Index's ($SPX) 21.8% surge. However, in 2026, the stock has grown by nearly 13.7%, outperforming the SPX's 11% rise.
General Motors vs. Ford: 1 Auto Giant Is Winning the EV Race
1 ******* anese Company Just Waved a Red Flag for Micron Stock. How to Play It Here.
Billionaire Ken Griffin Just Saved Situational Awareness, But Here's What a Rescue Call From Citadel Really Sounds Like — 'I… Heard the Grim Reaper's Scythe'
#products #market


3 months ago
Family game nights are often an excuse to relax, blow off steam and have fun. Unless, perhaps, you're Jamie Dimon.
The 70-year-old chairman and CEO of JPMorgan Chase recently revealed on an episode of The Master Investor Podcast with Wilfred Frost that, as a kid, he played an investing game with his dad that makes Monopoly sound as quaint as Go Fish.
Jeff Bezos backs a platform that lets anyone invest in rental homes for as little as $100 — 6 ways to build wealth like a landlord without actually being one
Dave Ramsey warns nearly 50% of Americans are making 1 big Social Security mistake. Here's what it is and 3 simple steps to fix it ASAP
Millionaires under 43 hold only 25% of their wealth in stocks. Here's where their money is actually going
#game #actually
The 70-year-old chairman and CEO of JPMorgan Chase recently revealed on an episode of The Master Investor Podcast with Wilfred Frost that, as a kid, he played an investing game with his dad that makes Monopoly sound as quaint as Go Fish.
Jeff Bezos backs a platform that lets anyone invest in rental homes for as little as $100 — 6 ways to build wealth like a landlord without actually being one
Dave Ramsey warns nearly 50% of Americans are making 1 big Social Security mistake. Here's what it is and 3 simple steps to fix it ASAP
Millionaires under 43 hold only 25% of their wealth in stocks. Here's where their money is actually going
#game #actually


3 months ago
Access to this page has been denied because we believe you are using automation tools to browse the website.
This may happen as a result of the following:
Please make sure that Javascript and cookies are enabled on your browser and that you are not blocking them from loading.
Reference ID: #42303c08 -8aa9-11f1-93c8-0bac019917c9
#believe
This may happen as a result of the following:
Please make sure that Javascript and cookies are enabled on your browser and that you are not blocking them from loading.
Reference ID: #42303c08 -8aa9-11f1-93c8-0bac019917c9
#believe
3 months ago
DIVO delivers a 6.4% monthly yield from 40 blue-chip dividend payers layered with covered-call premiums, returning 65% over five years.
JPM and CAT anchor DIVO's distribution, with JPM posting $21 billion in Q2 net income and CAT sustaining dividends uninterrupted for over 25 years.
Act now: the **** yst who called NVIDIA in 2010 just named his top 10 AI stocks — and Microsoft didn't make the cut. Grab the names FREE today.
Amplify CWP Enhanced Dividend Income ETF (NYSEARCA:DIVO) pays a 6.4% distribution yield in monthly installments, with the latest payout of $0.18284 per share hitting accounts on June 30, 2026. DIVO attracts income investors seeking monthly distributions without relying entirely on options-income funds that sacrifice growth for yield. The core question is whether the distribution is backed by durable cash flow from blue-chip holdings or masks instability.
This is an actively managed portfolio of roughly 40 large-cap dividend payers, with the top 10 accounting for roughly 49% of **** ets. Sector weights lean toward financials at 24%, technology at 15%, and industrials at 13%. The manager collects ordinary dividends, then writes covered calls on selected positions when volatility makes premiums attractive, layering options income on top. The blended payout flows to shareholders monthly.
#divo
JPM and CAT anchor DIVO's distribution, with JPM posting $21 billion in Q2 net income and CAT sustaining dividends uninterrupted for over 25 years.
Act now: the **** yst who called NVIDIA in 2010 just named his top 10 AI stocks — and Microsoft didn't make the cut. Grab the names FREE today.
Amplify CWP Enhanced Dividend Income ETF (NYSEARCA:DIVO) pays a 6.4% distribution yield in monthly installments, with the latest payout of $0.18284 per share hitting accounts on June 30, 2026. DIVO attracts income investors seeking monthly distributions without relying entirely on options-income funds that sacrifice growth for yield. The core question is whether the distribution is backed by durable cash flow from blue-chip holdings or masks instability.
This is an actively managed portfolio of roughly 40 large-cap dividend payers, with the top 10 accounting for roughly 49% of **** ets. Sector weights lean toward financials at 24%, technology at 15%, and industrials at 13%. The manager collects ordinary dividends, then writes covered calls on selected positions when volatility makes premiums attractive, layering options income on top. The blended payout flows to shareholders monthly.
#divo

3 months ago
NOBL's equal weighting across 70 holdings and a 44% fund-level payout ratio give its 2% yield a durable, compounding foundation.
CVX posted negative Q1 free cash flow and a 37% net income drop, but its 1.4% weight limits damage to ***** L's income stream.
JNJ and KO anchor the income story with 64 and 60-plus consecutive dividend raises and payout ratios comfortably below 65%.
Act now: the ***** yst who called NVIDIA in 2010 just named his top 10 AI stocks — and Johnson & Johnson didn't make the cut. Grab the names FREE today.
The ProShares S&P 500 Dividend Aristocrats ETF (CBOE:NOBL) pays a roughly 2% dividend yield built on a portfolio of 70 holdings, each of which has raised its dividend for at least 25 consecutive years. Income investors buy ***** L for a specific promise: that the underlying companies are so entrenched in their markets that quarterly dividend growth continues through recessions, inflation shocks, and rate cycles. That promise faces a test in mid-2026, especially across the five holdings most investors watch as bellwethers for the group.
#Dividend #income #across #consecutive
CVX posted negative Q1 free cash flow and a 37% net income drop, but its 1.4% weight limits damage to ***** L's income stream.
JNJ and KO anchor the income story with 64 and 60-plus consecutive dividend raises and payout ratios comfortably below 65%.
Act now: the ***** yst who called NVIDIA in 2010 just named his top 10 AI stocks — and Johnson & Johnson didn't make the cut. Grab the names FREE today.
The ProShares S&P 500 Dividend Aristocrats ETF (CBOE:NOBL) pays a roughly 2% dividend yield built on a portfolio of 70 holdings, each of which has raised its dividend for at least 25 consecutive years. Income investors buy ***** L for a specific promise: that the underlying companies are so entrenched in their markets that quarterly dividend growth continues through recessions, inflation shocks, and rate cycles. That promise faces a test in mid-2026, especially across the five holdings most investors watch as bellwethers for the group.
#Dividend #income #across #consecutive