22 days ago
The bond-market rout of 2026 may be jolting markets, but it's also gaining a important following among savers and the risk-averse.
Wall Street has been gripped by the volatile moves in bond yields over the past few weeks. The all-important 10-year Treasury yield BX:TMUBMUSD10Y was up another 3.4 basis points on Monday to 5.35%, it highest level since April 2002, according to Dow Jones Market Data.
My wife never went back to work after raising our kids. Do I have to share my retirement savings 50/50?
Go ahead and get that poetry degree. Republican law won't prevent people with humanities majors from getting student loans.
That's raised the costs of new mortgages, corporate borrowing and financing the $40 trillion national debt. It also has many bond portfolios sitting in a sea of red ink for 2026, with the bond market's equivalent of the S&P 500 SPX — the Bloomberg U.S. Aggregate Index's — total return having turned negative. Bond yields and prices move in the opposite direction.
#bond #treasury #tmubmusd10y



1 month ago
On September 8, 2026, Reuters reported that Paramount Skydance Corporation (NASDAQ:PSKY) said California Attorney General Rob Bonta made television statements that contradict his own legal arguments against Paramount's request for a $1.88 billion bond in the ongoing court fight over its roughly $110 billion acquisition of Warner Bros. Discovery, Inc. (NASDAQ:WBD).
Bonta's office has argued the bond is unnecessary because Paramount voluntarily agreed to pause the deal's closing rather than wait for a court injunction. But Paramount described that same pause as equivalent to an injunction in media interviews, which it argues legally requires the states to post a bond under antitrust law. A hearing is scheduled for September 24.
Paramount Skydance Corporation (NASDAQ:PSKY) could protect a significant portion of its financial position if the court grants its $1.88 billion bond request. Paramount says the delay could cost it about $1.3 billion in fees to Warner Bros. Discovery shareholders by the time the case concludes in April 2027. A bond would give Paramount a potential path to recover those losses if it ultimately defeats the states' challenge. It reduces the financial damage from a prolonged legal process.
Warner Bros. Discovery, Inc. (NASDAQ:WBD) is receiving financial protection from the transaction's delay through Paramount's ticking fees. Paramount agreed to pay WBD shareholders approximately $7 million per day starting October 1 if the transaction does not close, creating a growing payment obligation for Paramount. It is also providing WBD shareholders with compensation for waiting. The arrangement gives WBD a financial benefit from the prolonged closing process even as the companies await a final legal resolution.
The legal dispute has not eliminated the strategic rationale for combining the two media companies. Paramount argues that the merger would strengthen the film and television industry and lead to more content while giving the combined company greater scale to compete with Netflix and Disney. For Paramount, completing the acquisition would speed up David Ellison's plan to build a larger media competitor. WBD shareholders would receive the transaction consideration rather than remain exposed to the company's standalone turnaround.
#paramount


1 month ago
Vera Bradley, Inc. (NASDAQ:VRA) reported on September 15 that fiscal 2027 second-quarter revenue from continuing operations increased 1.1% to $71.6 million. For the quarter ended August 1, 2026, GAAP operating income from continuing operations reached $4.2 million, compared with a $4.6 million loss a year earlier.
However, gross profit included a $7.7 million tariff refund relating to prior-period imports. Subtracting that benefit from reported operating income, with all other items unchanged, produces an illustrative operating loss of approximately $3.5 million and an operating margin of negative 4.9%.
The quarter therefore shows improving customer demand alongside an earnings recovery that still depends heavily on refunds.
Direct-channel performance gives Vera Bradley, Inc. (NASDAQ:VRA) tangible evidence of customer traction. Direct revenue increased 8.0% to $65.4 million, while comparable sales rose 9.2%. Management attributed the comparable-sales improvement to better e-commerce conversion and higher average transaction values across direct channels.
That combination matters because stronger conversion means more shoppers complete purchases, while larger transactions support revenue without requiring equivalent growth in customer traffic. Continued momentum could help spread store, distribution, and corporate costs across a larger sales base.
#bradley


1 month ago
On August 6, Wheaton Precious Metals (NYSE:WPM) reported second-quarter net earnings of $543 million on $929 million of revenue, both records. Through the first half, net earnings rose 106% to $1.1 billion. During the quarter, the company also made net upfront cash payments of $4.5 billion relative to mineral stream interests, and it now carries $2.0 billion of total debt against $100 million of cash on hand. Here is what that trade looks like up close.
Start with what the streaming model does when prices climb. Wheaton sold 14% more gold equivalent ounces than a year ago, but the average realized gold equivalent price jumped 61% in Q2, and that higher price explains most of the revenue surge. Costs per ounce rose from $406 to $568, yet the cash operating margin per ounce still grew 65% to $3,875, faster than gold itself appreciated. Operating cash flow hit $650 million in the quarter and $1.4 billion for the half.
The second argument is that plenty of growth hasn't arrived yet. Only about 3% of this year's production comes from **** ets still in construction or ramp-up, and the company forecasts a rise of roughly 50% to 1,200,000 gold equivalent ounces by 2030. Some of that ramp has dates attached. Ivanhoe now expects commercial production at Platreef in the fourth quarter of 2026, and Montage Gold is targeting first gold at Koné in late Q4. Effective April 1, Wheaton expanded its share of silver production from Antamina from 33.75% to 67.5% through the newly acquired BHP Antamina PMPA.
Growth on this scale wasn't free. Wheaton had no bank debt at the end of 2025. On April 1, it drew $1.5 billion on a new two-year term loan to help pay for Antamina, and finance costs that were negligible a year ago now take a real bite. Net debt stands at $1.9 billion. Taxes are heavier too. Wheaton paid $109 million of global minimum tax on June 24, and another Cdn$346 million is due around March 31, 2027.
Operations also gave investors a few reasons for caution. Gold ounces produced slipped 2.6% year over year, so the 6% rise in gold equivalent production leaned heavily on the Antamina purchase. Gold output at Salobo fell 11% on lower grades. At Constancia, it fell 35% after mining at the higher-grade Pampacancha pit finished in the fourth quarter of 2025. Hemlo Mining said on July 20 that its second-quarter output fell below the first quarter's, and Rio2 said on May 15 that Fenix missed planned tonnes and grade in Q1. And because the revenue jump came mainly from price, the same leverage works in reverse if metals slip.
#wheaton

1 month ago
On September 16, Evolution Petroleum Corporation (NYSEAMERICAN:EPM) held its fiscal fourth-quarter and full-year 2026 earnings call, and the numbers told a story of a company climbing out of a rough patch. Revenue jumped 20% sequentially to $24.2 million as oil prices realized before hedge settlements shot up 49% year over year to $90.74 a barrel. Adjusted EBITDA more than doubled to $6.5 million. After a bruising third quarter, the fourth quarter finally looked like the recovery management had promised investors back in May.
The fourth-quarter turnaround wasn't just about crude. NGL prices realized $32.49 a barrel, up 27% year over year, and because Evolution leaves its NGL production entirely unhedged, every dollar of that gain flowed straight through. That combination of higher liquids pricing, growing production, and the roll-off of a prior-period transportation adjustment at the Delhi Field pushed operating cash flow to $6.8 million in the quarter, nearly double the $3.5 million generated in the third quarter.
Behind the quarterly numbers sits a longer-term shift in how Evolution makes money. The company closed a roughly $16 million acquisition of mineral and royalty acreage in the Permian's Midland Basin after the fiscal year ended, adding about 3,420 net royalty acres and more than 200 barrels of oil equivalent per day of current production, all without Evolution spending a dime on development. That mirrors what's already happening in the SCOOP/STACK play, where fourth-quarter production climbed 14% year over year to 1,275 BOE per day while unit operating costs fell to $10.33 a barrel. Evolution also replaced more than 100% of the 2.6 million barrels of oil equivalent it produced during the year, ending fiscal 2026 with 27.2 million barrels of proved reserves, an outcome that matters directly to a dividend now in its 52nd consecutive quarter.
Not every part of the business bounced back. Average daily production fell 4% year over year to 6,901 barrels of oil equivalent per day, largely because the flush production from new Chaveroo wells that boosted last year's fourth quarter has since tapered off. Natural gas pricing remained the softest spot in the portfolio, especially at the Jonah Field, where CEO Kelly Loyd said "regional differentials have weighed on realizations" even as broader demand for gas keeps growing. CFO Ryan Stash noted that stronger oil and NGL results helped offset "continued weakness in natural gas realizations, particularly at Jonah."
#barrel


1 month ago
On August 6, APA Corporation (NASDAQ:APA) held its second-quarter earnings call, and one number stood out from the rest. The oil and gas producer is now holding its Permian oil production steady with four drilling rigs, half the eight it once estimated it would need. Adjusted production of 347,000 barrels of oil equivalent per day beat management's own guidance, free cash flow kept climbing, and the balance sheet is healing faster than planned. That combination is the story of the quarter.
APA raised its full-year US oil guidance to 123,000 barrels per day, up from an original 120,000, while holding its capital budget at $1.3 billion despite higher diesel and other input costs. Management also lifted its cost-savings target to $500 million in annualized run-rate savings by year-end, up from the $450 million goal it set at the start of the year.
That flexibility is showing up in cash flow. Free cash flow hit $738 million in the second quarter, pushing the first half of 2026 past $1.2 billion, which topped what APA generated in each of the past three full years. The company returned $189 million of that to shareholders through dividends and the repurchase of 2.8 million shares at an average price of $35.26, continuing a streak of returning at least 60% of free cash flow to investors every year since 2021.
The balance sheet is moving just as fast. Net debt stood at $3.3 billion at quarter-end after APA repaid $752 million of bonds in the first half, including $673 million in the second quarter alone, cutting total debt by $2.3 billion since the end of 2024 and lowering annualized interest expense by roughly $175 million. Management now expects to hit its $3 billion net debt target in 2027, well ahead of the three- to four-year window it laid out when the goal was first announced.
Further out, APA is building option value beyond its core Permian and Egypt ****** ets. It agreed to acquire Savant Alaska for $70 million, picking up an airstrip, a dock, and a pipeline connection into the Trans Alaska system to support two exploration wells planned for 2027. In Uruguay, ENI signed on as a partner in Block 6, funding a significant share of the first exploration well while APA keeps 60% ownership. In Suriname, the GranMorgu project remains on budget for first oil in mid-2028.
#billion

1 month ago
On August 18, Amer Sports (NYSE:AS) reported second-quarter results that beat its own guidance and then raised the bar for the rest of the year. Revenue climbed 32% to $1.63 billion, adjusted operating profit nearly tripled, and every region and segment posted double-digit growth. Diluted earnings per share reached $0.18, up from a much smaller figure a year earlier. What stands out about August 18 is not just the size of the beat but how broad it was.
Technical Apparel grew 32% to $674 million, led by Arc'teryx and backed by a 17% omni-comp gain across owned stores and e-commerce. Outdoor Performance grew even faster, up 37% to $569 million, driven by Salomon Softgoods. Ball & Racquet Sports rose 24% to $390 million on the strength of Wilson Tennis 360. CEO James Zheng pointed to strong double-digit growth across every segment, geography, and channel as the reason for confidence in the outlook.
That confidence showed up in the numbers: Amer Sports raised full-year 2026 guidance to roughly 24% reported revenue growth, a gross margin of 60.5% to 61.0%, an operating margin of 14.2% to 14.5%, and diluted EPS of $1.27 to $1.30. The balance sheet backs up the reinvestment CFO Andrew Page described, with $573 million in net cash and $720 million in cash and equivalents at quarter-end.
Some of the second quarter's biggest numbers lean on a one-time tailwind. Gross margin expanded 710 basis points to 65.6%, but 390 of those points came from net tariff refunds. Operating margin's 820 basis point jump included the same 390-point benefit. The effect is largest in Ball & Racquet Sports, where adjusted segment operating margin rose 1,300 basis points to 17.2%, yet 970 of those points came from tariff refunds alone. Selling, general and administrative expenses rose 30% to $909 million, and on an adjusted basis SG&A grew 33%, faster than revenue itself.
Inventories climbed 19% year over year to $1,897 million. The guidance for the next quarter also points to a slower pace: third quarter revenue growth is guided at 18% to 20%, well below the 32% just reported, with gross margin guided down to about 59.0% and net finance cost alone guided to $15 million to $20 million, against roughly $85 million for the entire year.
#revenue #basis


1 month ago
On September 15, Jazz Pharmaceuticals plc (NASDAQ:JAZZ) completed its acquisition of privately held Actio Biosciences for $820 million upfront, adding a clinical-stage epilepsy drug called ABS-1230 to its rare disease pipeline. The deal lands weeks after Jazz posted its highest quarterly revenue ever on August 3, and raised its full-year guidance, so a fresh acquisition now sits on top of a business that was already accelerating. The question for investors is whether that combination adds up to durable growth or just a bigger bill.
ABS-1230 targets KCNT1-related epilepsy, a rare and hard-to-treat form of the disease. In an early clinical proof-of-concept trial, children who received the drug experienced meaningful seizure reductions, and preclinical testing showed it inhibited KCNT1 across every pathogenic mutation researchers evaluated, hinting it could work across the whole patient population rather than a narrow subset. The FDA has already granted ABS-1230 Orphan Drug, Rare Pediatric Disease and Fast Track designations, and accepted it into the agency's Rare Disease Evidence Principles process, a set of regulatory advantages that can speed a drug toward approval.
The acquisition also arrives while Jazz's existing business is firing on multiple cylinders. Second-quarter revenue climbed 16% year over year to $1.2 billion, the company's highest quarterly total on record, and management raised full-year 2026 revenue guidance to a range of $4.6 billion to $4.75 billion. Growth was not confined to one product. Xywav sales rose 13% to $471 million on 525 net new patients, Epidiolex grew 16% to $292 million, and Zepzelca jumped 42% to $106 million. Zanidatamab, sold as Ziihera in biliary tract cancer, also received Breakthrough Therapy designation from the FDA for a form of colorectal cancer, adding another avenue for the oncology franchise Jazz has been building beyond its epilepsy and sleep businesses.
None of that came free. The $820 million upfront payment for Actio lands on top of $4.4 billion in long-term debt that Jazz already carried as of June 30, even after the company used part of its cash to repay $1.0 billion of exchangeable notes that matured this year. Cash, equivalents and investments stood at $2.2 billion at that point, meaning the Actio payment alone accounts for a meaningful share of the company's liquid resources.
Jazz's recent history also shows how acquisitions can distort the bottom line before they pay off. A $905.4 million in-process research and development charge tied to the 2025 Chimerix acquisition pushed second-quarter 2025 GAAP earnings to a loss of $11.74 per share, and a smaller $77 million IPR&D charge from the AbCellera and Werewolf deals still dented second-quarter 2026 results. ABS-1230 itself remains early, with only proof-of-concept data in hand and no late-stage trial results yet. The portfolio is not without setbacks, either. Jazz is moving to voluntarily drop the second-line indication for Zepzelca in meta

1 month ago
The temporary closure of the key onshore pipeline Saudi Arabia uses to bypass the Strait of Hormuz has added another shock to an oil market already struggling with six months of Middle East supply disruptions.
And the damage now appears to be more extensive than initially believed.
Three pumping stations along Saudi Arabia's East-West pipeline were damaged in last week's attack, Reuters reported on Thursday, citing satellite imagery and industry sources. Earlier ***** sments had identified damage at two stations. Three sources told Reuters that repairs could take five to six weeks, although partial pumping could resume sooner.
Before the attack, the system was moving between 4 million and 5 million barrels per day (bpd), equivalent to roughly 4%–5% of global oil supply. Its total capacity is around 7 million bpd, including approximately 2 million bpd supplied to refineries.
Saudi Arabia shut the pipeline following multiple attacks on September 10. Satellite imagery previously published by MizarVision showed extensive fire and structural damage around pumping stations along the route.
#million #pumping #arabia
1 month ago
The Children's Place, Inc. (NASDAQ:PLCE) reported on September 14 that fiscal second-quarter net sales declined 18.9% year over year to $241.8 million. Reported gross margin rose to 34.4% from 34.0% a year earlier for the quarter ended August 1, 2026.
The apparent margin improvement depended heavily on $39 million of tariff refunds recognized as a reduction of cost of sales. That benefit was equivalent to nearly 47% of reported gross profit of $83.3 million.
Management said gross margin excluding the refunds declined 1,550 basis points, or 15.5 percentage points, year over year. This non-GAAP comparison removes the cost-of-sales benefit. The central question is whether inventory cleanup can establish a healthier operating base.
The Children's Place, Inc. (NASDAQ:PLCE) reduced inventory to $340.2 million, down 23.2% from $442.7 million a year earlier. A smaller inventory position allows management to improve the merchandise mix and reduce future exposure to aging products.
Clearing excess stock can release working capital and create room for products better aligned with demand. The eventual benefit depends on rebuilding sales with less discounting, but reducing the stock burden is a useful starting point.
#reported #Margin
1 month ago
Seagate Technology Holdings plc (NASDAQ:STX) announced on September 9 that its subsidiary, Seagate HDD Cayman, completed the redemption and exchange of its remaining 3.50% exchangeable senior notes due 2028 on September 8. Approximately $150.7 million of principal was retired through a settlement involving approximately $150.97 million in cash and 1,647,862 ordinary shares.
For notes submitted for exchange, principal was paid in cash, and the exchange obligation above principal was settled in shares, with cash for fractional shares where applicable. The share delivery therefore satisfied an existing contractual obligation.
Seagate Technology Holdings plc (NASDAQ:STX) has removed a 2028 maturity and the remaining settlement uncertainty attached to this instrument. Based on the approximately $150.7 million principal balance and 3.50% coupon, the transaction eliminates roughly $5.3 million of annual stated interest. That is a calculated annualized saving before taxes and any interest income lost on the cash used.
Recent cash generation supports the ability to absorb the payment. As of July 3, 2026, Seagate Technology Holdings plc (NASDAQ:STX) reported $1.704 billion in cash and cash equivalents. Fiscal fourth-quarter free cash flow was $1.118 billion. This company-defined non-GAAP measure is operating cash flow less acquisitions of property, equipment, and leasehold improvements.
The settlement cash payment equals approximately 8.9% of that reported cash balance. Although the July figure predates settlement, it provides a useful measure of the transaction's scale.
#technology #million #exchange

1 month ago
American Tower Corporation (NYSE:AMT) priced $1.6 billion of senior notes on September 9: $500 million at 5.300% due 2031, $500 million at 5.560% due 2033, and $600 million at 5.750% due 2036. Once issued, the three tranches would carry combined annual coupons of $88.8 million, equivalent to a weighted average coupon of 5.55%.
American Tower Corporation (NYSE:AMT) expects approximately $1.580 billion in net proceeds. It intends to use $600 million to repay 1.450% notes due in 2026, with additional proceeds designated for revolving-credit debt and general corporate purposes. The financing exchanges a near-term repayment requirement and some revolving debt for longer fixed-rate obligations.
The investment question is whether greater funding certainty compensates for the higher cash-interest commitment.
American Tower Corporation (NYSE:AMT) would remove a $600 million maturity falling due this year once the planned repayment occurs. That reduces exposure to having to refinance the obligation closer to its deadline, when borrowing conditions could be less favorable.
The new maturities also distribute principal repayments across 2031, 2033 and 2036. For American Tower Corporation (NYSE:AMT), a spread of repayment dates can support financial planning across its communications-site and data-center portfolio. Fixed coupons make the cost of this funding predictable.
#tower


1 month ago
On August 25, Aptiv (NYSE:APTV) said it will support NVIDIA's newly announced Jetson Orin Nano 2 processor, extending a partnership that already covers the more powerful Jetson Thor platform. The move puts Aptiv squarely inside the buildout of "physical AI," the term for machines like drones, robots, and industrial systems that need to sense and react to the real world in real time. For a company still just months removed from spinning off its electrical distribution business, betting on edge robotics is a statement about where it thinks the next decade of growth actually lives.
NVIDIA's Jetson Orin Nano 2 packs 78 TOPS of processing power into an 8GB, 8-core Arm chip that doubles the inference speed of its predecessor while cutting power draw by 40% at equivalent performance. That kind of efficiency gain matters for battery-powered devices like delivery drones and mobile robots, where every watt saved extends run time. Aptiv isn't just supplying compute support; it is layering in its PULSE surround-view camera and radar system for 360-degree sensing, its Gen 8 radar for object detection in tough conditions, and Wind River software to handle the unglamorous but essential work of long-term maintenance and security updates. That full-stack approach is the pitch: instead of stitching together sensors, chips, and software from separate vendors, customers get one partner who can carry a device from prototype to a fleet running in the field.
The timing lines up with what Aptiv reported in its second-quarter results on August 4, 2026. Revenue reached $3.3 billion, up 2%, while adjusted EBITDA climbed to $613 million from $547 million a year earlier, pushing margins to 18.7% from 17.1%. CEO Kevin Clark pointed to double-digit growth in non-automotive revenue, progress moving robotics from partnership talks to actual commercial deployments, and a major drone industry win secured in early July. North America sales rose 10% and Asia Pacific grew 6%, including 5% growth in China, giving the company some geographic momentum to lean on as it chases this new business line.
The quarter wasn't clean underneath the headline numbers. Free cash flow came in at just $12 million in the second quarter, down from $219 million a year earlier, and the first half of 2026 actually posted negative free cash flow of $196 million versus a positive $264 million a year ago. Operating cash flow from continuing operations fell to $82 million for the first half, down sharply from $531 million. Management also flagged automotive demand and customer mix as an incremental headwind, a reminder that Aptiv's legacy business still carries real weight even as it chases robotics and drones. EMEA revenue dropped 8%, and South America fell 4% in the quarter, both drags even as North America and Asia Pacific grew.
#jetson #robotics
1 month ago
Updated on: September 16, 2026 / 5:45 PM EDT / CBS/AP
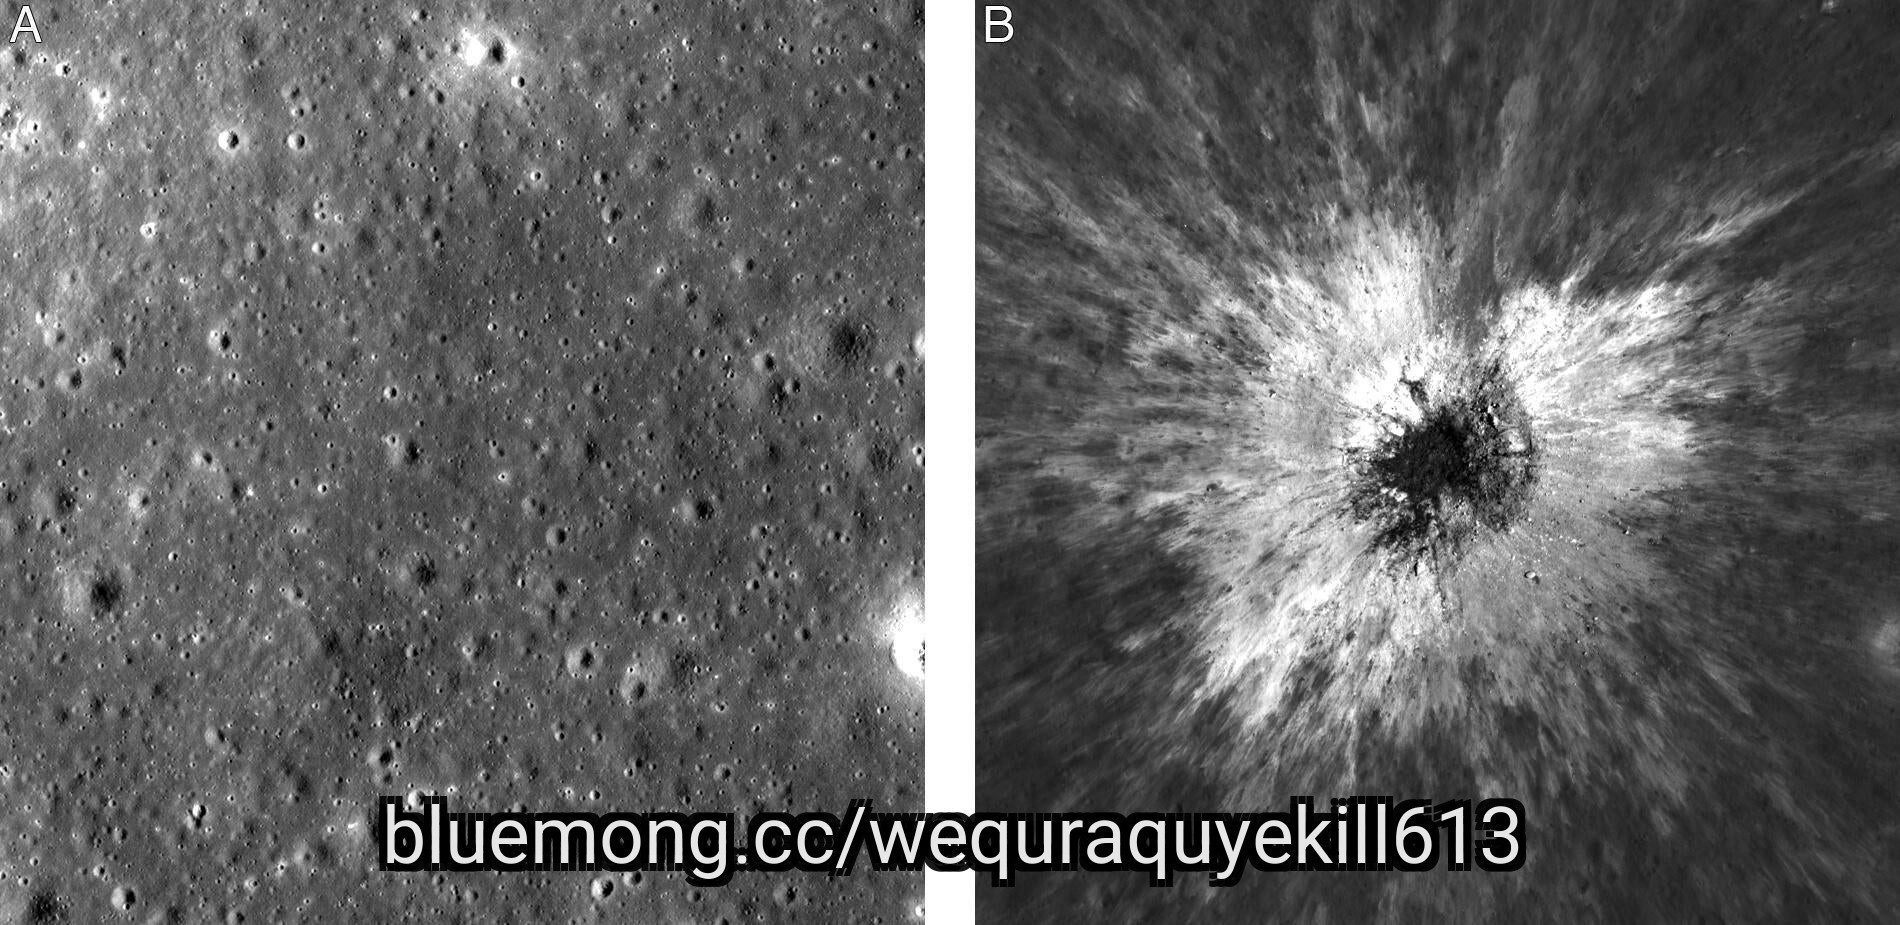
Scientists have discovered a crater on the moon that's bigger than the Roman Colosseum and is the result of a powerful impact two years ago that initially went undetected.
The steep-sided hole measured about 728 feet across, the length of two football fields, and up to 141 feet deep, equivalent to three vertically stacked yellow school buses, according to NASA. It's the solar system's biggest known impact crater carved out in recent times.
Such a large-scale event is estimated to occur only once every 132 years, researchers said, making this a treasure trove of information as NASA prepares to build a base for astronauts on the moon.
"This event constitutes a statistically rare, effectively once-in-a-lifetime observation," the scientists wrote in one of two studies appearing on the subject Wednesday in the journal Science Advances.
#crater

1 month ago
Our **** ysts just identified a stock with the potential to be the next Nvidia. Tell us how you invest and we'll show you why it's our #1 pick. Tap here.
Trustpilot's underlying business is still growing quickly, with revenue up 23%, bookings up 22% and adjusted EBITDA climbing 46% in the first half. But investors instead focused on a surprise statutory loss, several one-off charges and management's decision to leave full-year guidance unchanged after a huge run in the shares.
Trustpilot shares fell as much as 20% after the online review platform reported strong first-half growth but delivered a messier bottom line than investors had expected.
Revenue increased 23% to $151.4 million in the six months to June, equivalent to 19% growth at constant currencies, while bookings rose 22% to $171.2 million.
Adjusted EBITDA climbed 46% to a record $26.3 million and the margin expanded to 17.4%, although the profit figure came in slightly below the $27 million company-compiled consensus.
#ebitda #bookings #investors


1 month ago
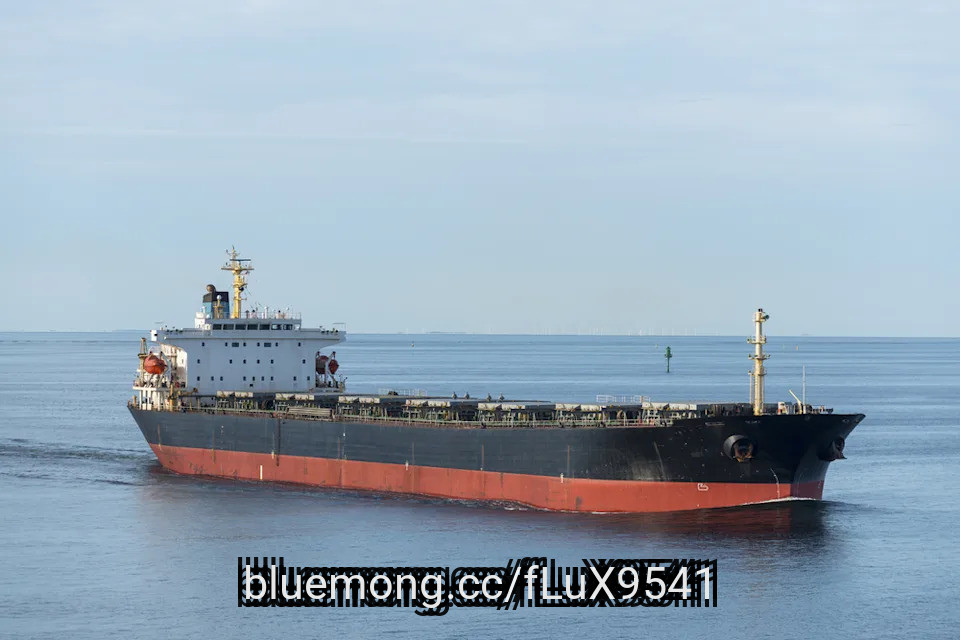
On September 10, Imperial Petroleum Inc. (NASDAQ:IMPP), a company involved in seaborne transportation of crude oil, dry bulk, and petroleum products, released its second quarter results. With a topline figure of $87.1 million, the company delivered record quarterly revenue, which also resulted in 139.9% year-over-year growth. Imperial's adjusted EBITDA for the second quarter stood at $41.7 million, while the Q2 adjusted net income of $35.3 million exhibited around 163% growth in comparison with Q2 FY25.
Ralf Gosch/Shutterstock.com
Several factors contributed to the second quarter topline growth. A 6.9 vessel rise in the company's average fleet size was the primary growth enabler. Other factors include encouraging dynamics across the drybulk segment, and higher rates for both drybulk and tankers amid the geopolitical uncertainties. Operating income for the quarter jumped to a near-record level of $33.4 million, which translates into a 307.3% growth relative to Q2 FY25. Imperial posted an adjusted EPS of $0.76 for the reported quarter, which almost doubled compared to the same quarter a year prior.
At the back of efficient fleet management, management remained focus on strengthening its financial position. The company ended the quarter with no debt, and its liquidity position also remained resilient. Cash and cash equivalents, including time deposits, increased from $179.1 million at the end of 2025 to $245.2 million as of June 30, 2026. The company added that its cash base had increased further to approximately $260 million as of the September 10 results release.
Certain areas of weakness warrant a closer examination. During the reported quarter, fleet operational utilization went down from 83.1% in prior year's second quarter to 73.5%. There was a substantial increase in some of the underlying operating expenses. For instance, the vessel operating expense stood at $14.4 million compared to $8.4 million during Q2 FY25. This $6 million rise can be attributed to Imperial's larger fleet size. Similarly, the voyage expenses also jumped from $10.7 million in last year's Q2 to $22.1 million for Q2 FY26. The incremental voyage expenses stemmed from higher bunkers' rates, as well as a 58.4% jump in spot days.
#fleet
1 month ago
On August 25, Aptiv (NYSE:APTV) said it will support NVIDIA's newly announced Jetson Orin Nano 2 processor, extending a partnership that already covers the more powerful Jetson Thor platform. The move puts Aptiv squarely inside the buildout of "physical AI," the term for machines like drones, robots, and industrial systems that need to sense and react to the real world in real time. For a company still just months removed from spinning off its electrical distribution business, betting on edge robotics is a statement about where it thinks the next decade of growth actually lives.
NVIDIA's Jetson Orin Nano 2 packs 78 TOPS of processing power into an 8GB, 8-core Arm chip that doubles the inference speed of its predecessor while cutting power draw by 40% at equivalent performance. That kind of efficiency gain matters for battery-powered devices like delivery drones and mobile robots, where every watt saved extends run time. Aptiv isn't just supplying compute support; it is layering in its PULSE surround-view camera and radar system for 360-degree sensing, its Gen 8 radar for object detection in tough conditions, and Wind River software to handle the unglamorous but essential work of long-term maintenance and security updates. That full-stack approach is the pitch: instead of stitching together sensors, chips, and software from separate vendors, customers get one partner who can carry a device from prototype to a fleet running in the field.
The timing lines up with what Aptiv reported in its second-quarter results on August 4, 2026. Revenue reached $3.3 billion, up 2%, while adjusted EBITDA climbed to $613 million from $547 million a year earlier, pushing margins to 18.7% from 17.1%. CEO Kevin Clark pointed to double-digit growth in non-automotive revenue, progress moving robotics from partnership talks to actual commercial deployments, and a major drone industry win secured in early July. North America sales rose 10% and Asia Pacific grew 6%, including 5% growth in China, giving the company some geographic momentum to lean on as it chases this new business line.
The quarter wasn't clean underneath the headline numbers. Free cash flow came in at just $12 million in the second quarter, down from $219 million a year earlier, and the first half of 2026 actually posted negative free cash flow of $196 million versus a positive $264 million a year ago. Operating cash flow from continuing operations fell to $82 million for the first half, down sharply from $531 million. Management also flagged automotive demand and customer mix as an incremental headwind, a reminder that Aptiv's legacy business still carries real weight even as it chases robotics and drones. EMEA revenue dropped 8%, and South America fell 4% in the quarter, both drags even as North America and Asia Pacific grew.
#America #real


1 month ago
On September 10, Tsakos Energy Navigation (NYSE:TEN) reported a first half of 2026 that reads like a fantasy year for a decades-old tanker operator. Net income hit $228 million, more than triple what the company earned over the same six months a year earlier, while diluted EPS climbed to $7.12 from $1.70. Behind those numbers sits a rare combination: a fleet locked into billions in forward earnings, war-driven cargo detours pushing rates higher, and a newbuilding bet that has already paid off before half the ships have even hit the water.
The earnings power came from two directions at once. The average time charter equivalent rate rose 41% to $43,503 a day in the first half, and profit-sharing contracts on nine large vessels brought in $71 million, up from just $10 million a year earlier. Even with six vessels pulled from service for scheduled dry docks, the fleet still ran at 96.5% utilization. Second-quarter results followed the same pattern, with net income of $139.3 million, which included a $38 million gain on ******* et sales, and earnings per share of $4.40 against $0.67 in last year's second quarter.
Tsakos is also sitting on a fleet renewal bet that already worked out. Since the start of 2023, the company has sold 20 tankers averaging 17.3 years old and replaced them with 35 vessels averaging just half a year old. Its 26-ship newbuilding program, contracted for about $3.1 billion, is now valued roughly 30% above that cost, and CEO Nikolas Tsakos said the VLCCs in that order book have nearly doubled in price since they were placed. With $466 million in cash and forward committed earnings of roughly $3.5 billion, management has room to raise its dividend, which already paid out $1.60 per share this year, and is weighing whether to redeem $120 million of 9.25% preferred shares, a move it estimates could add $0.30 to $0.40 to EPS.
That performance came against a backdrop the company would rather not have. President George Saroglou said vessels have been attacked, and seafarers hurt or killed trying to keep global trade moving through the Strait of Hormuz, where a ceasefire unraveled roughly halfway through its planned 60-day run and a US naval presence now tries to manage safe passage. Tsakos has chosen to route around the strait entirely rather than put crews through the toll those attacks take.
The cost side is climbing too. Bunker prices jumped about 25%, pushing first-half voyage expenses to $82 million from $68 million, and operating expenses rose to $111 million from $102 million on higher dry-docking costs and inflation. Total debt reached $2.1 billion at the end of June, up from $1.8 billion a year earlier, as the company finances its newbuilding program. And while profit-sharing revenue jumped, the operating days tied to those market-related contracts actually fell 22%, meaning a smaller slice of the fleet is left exposed to capture further spot-rate gains if the tanker market keeps running hot.
#billion

1 month ago
Nasdaq-listed DeFi Development Corp (NASDAQ: $DFDV) has increased its Solana (CRYPTO: $SOL) treasury by 55,491 SOL, bringing its total holdings to about 2.39 million SOL and SOL equivalents.
The company said Monday that its treasury has grown roughly 2% since August 27 as it resumed regular Solana purchases and continued generating yield from its holdings. DeFi Development Corp is now the second-largest public-company holder of Solana after Forward Industries.
Alongside the treasury increase, the company established a $300 million at-the-market offering for its CHAD perpetual preferred stock. The Variable Rate Series C Perpetual Preferred Stock carries an initial annual dividend rate of 13%. DeFi Development said it plans to issue the shares at or above their $10 par value, with most of the proceeds expected to fund additional SOL purchases.
More From Cryptoprowl:
MEXC Launches Earn Plus With Limited-Time Event Offering Up to 800% APR Booster
#NASDAQ #offering

1 month ago
Costco has raised the price of its Kirkland Signature full-synthetic motor oil and begun limiting how much any one member can purchase, as a global lubricant shortage tied to the ongoing Middle East conflict pushes crude oil toward $100 a barrel.
That 10-quart case — two 5-quart bottles, enough for a typical V6 or V8 oil change — has jumped to $57.99, compared with the roughly $30 price members had grown accustomed to paying, according to The Drive. Stores are capping purchases at two units per customer per week. The retailer has also imposed a five-per-member limit on Mobil 1, with six quarts of that brand running $44.
The rationing reflects pressure from multiple directions. The connection to fuel prices runs through the refinery: base oil shares its crude-oil origins with gasoline and diesel, so when margins on finished fuel are strong, refiners have a financial reason to favor fuel production over lubricant stock, according to The Auto Wire. EIA data showed the gasoline crack spread sitting roughly a dollar per gallon higher than where it stood at the same point in 2025, a gap that has squeezed base oil availability and pushed its price upward.
Regulatory and licensing costs add a separate layer of expense. The Kirkland 5W-30 displays the dexos1 Gen 3 certification, GM's proprietary specification, and earning that mark is not free — manufacturers must put their formulation through GM's independent testing protocol and obtain a license from the automaker, paying separately for each product and each unit sold, according to The Auto Wire. Layered on top of that is an industry-wide burden: when the API SP category took effect around 2020, it introduced seven additional laboratory tests with no equivalent in the previous standard, among them a procedure targeting low-speed pre-ignition, the knock-like detonation problem **** ociated with modern turbocharged, direct-injection engines.
The supply squeeze is unfolding against a backdrop of a worsening global oil deficit. The International Energy Agency cut its 2026 global oil supply forecast to 102 million barrels per day in August, projecting a deficit of 1.8 million barrels per day in the third quarter — more than double its prior estimate. **** ulative global inventory draws since the start of the U.S.-Iran conflict have reached more than 500 million barrels, and Chevron CEO Mike Wirth said last week that the cushions that had softened earlier price increases have been exhausted. U.S. diesel prices crossed $6 per gallon for the first time, sitting at $6.06 as of Monday, an 8-cent increase from Sunday and 21 cents above week-earlier levels, according to AAA.
#barrels #wire


2 months ago
Jim Cramer sees Enterprise Products Partners L.P. (NYSE:EPD) as a major beneficiary of the disruption surrounding the Strait of Hormuz, as he said during the September 8 episode of Mad Money:
When I wrote How to Make Money in Any Market… I didn't know that Enterprise Products Partners was going to be the, maybe the single biggest pipeline winner in this country thanks to the war. I didn't see that war coming. The CEO of Enterprise, Jim Teague, has raised awareness for the company's profit opportunity because of the Hormuz closing. The margins of some of its liquids, like ethane to ethylene, ethylene to polyethylene, have soared. As Teague says, the Houston Ship Channel is now just as important as the Strait of Hormuz. Now, there's an endorsement. Stock yields 5.8%.
Enterprise Products Partners L.P. (NYSE:EPD) reported record second-quarter adjusted EBITDA of $2.8 billion, up 17% year over year, while operational distributable cash flow reached a record $2.3 billion, up 21%. Moreover, pipeline volumes reached a record 14.7 million barrels of oil equivalent per day, up 8%, while marine-terminal volumes increased 33% to 2.8 million barrels per day. Co-Chief Executive Officer James Teague said:
Volumes at our marine terminals have returned to normal levels in June and July after the initial rush to backfill volumes affected by hostilities in the Middle East in April and May.
In July, Enterprise Products Partners L.P. (NYSE:EPD) declared a quarterly distribution of $0.56 per unit, or $2.24 annualized, a 2.8% increase from a year earlier. At EPD's September 8 closing price of $38.83, that equates to a yield of approximately 5.8%. The company has increased its distribution for 27 consecutive years. The company's latest investor materials show $6.5 billion of major capital projects under construction. It expects 2026 organic growth capital spending, net of ***** et-sale proceeds, of $2.9 billion to $3.4 billion. The company retained $1.1 billion of DCF for internally funded growth capital expenditures and buybacks.
#partners #hormuz

2 months ago
Mexico's government is slashing financial ******* istance for the state energy major by as much as 70% despite Pemex's continued struggle to pay down debt and boost production. The decision rests on expectations that the company will benefit from the oil and gas price rally spurred by the U.S. and Israeli war against Iran.
Per a Bloomberg report from this week, the government of Mexico sees Pemex posting a rare cash surplus of some 95 billion pesos, or around $5.63 billion, as a result of the oil price rally. Based on those expectations, the Scheinbaum government stipulated financial help of just 81 billion pesos for the company in next year's budget, equivalent to some $4.8 billion. This was down by 70% from this year.
"We said that by 2027, support for Pemex would be very limited, and that's indeed the case," President Sheinbaum told media this week. "Pemex now receives very little support from the Mexican government, and its own finances will sustain its development."
Mexico's energy major is the most indebted company in the world, with a load of some $105 billion as of mid-2025, of which some $20 billion is in unpaid bills to suppliers. Since then, the company has managed to reduce the debt pile to some $79 billion as of the end of the first quarter of this year. The company said in a news release at the time that this was the lowest its debt has been since 2014.
Meanwhile, however, boosting refining output has turned out to be a challenge, and issues with crude quality—including high water content—have alienated key buyers over the past couple of years. The previous administration of Mexico focused on supporting the company by turning it back into a monopoly on the Mexican energy market. The Scheinbaum government, on the other hand, moved to open up the Mexican oil industry to other players as well, launching a new contract framework for joint ventures, the so-called mixed contracts. In mixed development allocations, Pemex can enter into an agreement with one or more private firms.
#PEMEX #government #scheinbaum #since


2 months ago
ExxonMobil Holdings Corporation (NYSE:XOM) agreed to increase its Papua LNG interest from 28.7% to 34.1% and ***** ume operatorship, as disclosed on September 7. The proposed ownership percentages reflect Papua New Guinea's state participation rights.
Papua LNG targets a fourth-quarter 2026 final investment decision, or FID. Santos Limited (ASX:STO) disclosed FID as a closing condition for its own stake acquisition; the operatorship announcement did not specify an equivalent condition.
TotalEnergies SE (NYSE:TTE) said redesign and contractor rebidding had reduced estimated development spending by nearly $4 billion since 2024 to approximately $14 billion. The project would produce 5.6 million tonnes of liquefied natural gas annually. The question is whether that smaller budget can support attractive returns through construction and an uncertain LNG market.
ExxonMobil Holdings Corporation (NYSE:XOM) already operates neighboring PNG LNG. Combining operatorship could improve coordination during construction and operations, including the redesigned handling of upstream condensate. That gives the proposed efficiency gains a practical basis in existing infrastructure and local experience.
The cost reduction is substantial. Mechanically, nearly $4 billion off an approximately $18 billion previous estimate represents about 22%. For ExxonMobil Holdings Corporation (NYSE:XOM), lower development spending would reduce the capital required to generate each future dollar of project cash flow, ***** uming production and operating economics hold.
#holdings #operatorship

2 months ago
Intellia Therapeutics, Inc. (NASDAQ:NTLA) entered a five-year senior secured credit facility with OrbiMed for up to $400 million and drew $75 million at closing. The remaining $325 million depends on milestones or further lender agreement.
The facility bears interest at an annual rate equal to the greater of 3% or the one-month Secured Overnight Financing Rate, plus 6.15%, payable monthly. The formula sets a 9.15% minimum. Applying that floor to the initial borrowing produces approximately $6.9 million of article-calculated annual interest before commitment, administrative, undrawn-amount, and facility fees.
The financing arrives as Intellia Therapeutics, Inc. (NASDAQ:NTLA) prepares for a potential U.S. launch of lonvoguran ziclumeran, or lonvo-z, for hereditary angioedema. Intellia Therapeutics, Inc. (NASDAQ:NTLA) held $628.4 million of cash, cash equivalents, and marketable securities as of June 30, but reported a $106.6 million second-quarter net loss.
The staged structure gives Intellia Therapeutics, Inc. (NASDAQ:NTLA) capital without issuing equity at closing and avoids drawing the full amount before milestones that could support additional debt.
A second $75 million tranche becomes available at the option of Intellia Therapeutics, Inc. (NASDAQ:NTLA) if the FDA approves the biologics license application for lonvo-z before a specified date. Three further $40 million tranches depend on lonvo-z revenue targets, while another $30 million requires an equity-fundraising milestone. This links most committed borrowing capacity to regulatory and commercial progress.
#million #therapeutics #ntla #lonvo

2 months ago
By Sai Ishwarbharath B and Abhirami G
BENGALURU, Sept 10 (Reuters) - Wipro's AI initiatives have increased productivity equivalent to the output of 20,000 employees, who have since been redeployed within the Indian IT firm, its chief technology officer said.
The comments come as India's $315 billion software services industry grapples with adoption of AI, which is reshaping hiring, software development and contracts.
Wipro, with about 243,000 employees in June, is shifting to a "human-AI operating model," with more than 100,000 employees receiving advanced AI-related training and certifications, Sandhya Arun said in an interview.
"It could be the same engineer managing a bunch of agents, deployed on other projects or being trained for some other role. It doesn't necessarily mean person-to-person replacement by an agent."
#employees #ishwarbharath


2 months ago
On August 11, Humana Inc. (NYSE:HUM) announced that its Medicaid plan, Humana Healthy Horizons in Indiana, is collaborating with HealthStream, Inc. (NASDAQ:HSTM). The partnership expands access to workforce training for caregivers, aiming to recruit and retain talent in rural and underserved communities. While one provides healthcare coverage and the other builds the software to train healthcare workers, both companies are capitalizing on the industry's critical focus: solving caregiving shortages and optimizing healthcare delivery.
HealthStream emerges as the operationally cleaner, higher-growth performer, while Humana continues to navigate a more complex transition marked by regulatory and profitability pressures. Humana Inc. (NYSE:HUM) reported Q2 2026 GAAP EPS of $5.73 and adjusted EPS of $7.61, with an Insurance segment GAAP benefit ratio of 91.2%. The company reaffirmed its full-year adjusted EPS guidance of at least $9.00 but lowered its FY 2026 GAAP EPS forecast to at least $6.52 from $8.36, reflecting non-cash adjustments and value creation charges. Although individual Medicare Advantage membership is expected to grow approximately 25% in 2026, lower Star Ratings remain a significant drag on profitability.
HealthStream, Inc. (NASDAQ:HSTM), meanwhile, delivered record Q2 2026 results, with revenue rising 12.5% year over year to $83.7 million. Operating income increased 41.4% to $8.3 million, while net income climbed 23.8% to $6.7 million, or $0.23 per diluted share. Adjusted EBITDA also increased 16.9% to $20.6 million. The company's debt-free balance sheet, supported by $66.7 million in cash and cash equivalents, further strengthens its financial flexibility. While Humana operates at substantially greater scale, HealthStream is demonstrating stronger operational leverage, margin expansion, and balance sheet flexibility.
Humana's bull case is supported by strong Medicare Advantage membership growth, with the company targeting a 25% increase in 2026, alongside strategic expansion of its CenterWell primary care business and state Medicaid footprint, including its recent Illinois win. These initiatives could strengthen its long-term recovery and expand its addressable market. However, the bear case centers on elevated medical benefit ratios, which reached 91.2% in Q2, as well as regulatory pressures in Medicaid and continued Medicare Star Ratings headwinds. These factors could further squeeze margins and weigh on net earnings.
#healthcare #year
2 months ago
Gasoline has never cost this much in September, while diesel prices touched a new record on Wednesday as crude oil topped $100 a barrel.
"Gasoline prices in the USA are the highest ever for this time of year," Andy Lipow of Lipow Oil ***** ociates said.
While Brent crude (BZ=F) has edged past $100 for the first time in two months, the pain at the pump is even greater. Energy bottlenecks tied to the US-Iran conflict, and refining constraints have pushed crack spreads — the gap between crude and refined fuel prices — to new highs.
Consumers are effectively paying the equivalent of $177 a barrel for gasoline and $250 a barrel for diesel, according to Lipow's ***** ysis.
"Those high prices are starting to impact demand," he said.
#Diesel


2 months ago
Comstock Resources, Inc. (NYSE:CRK) signed a nonbinding letter of intent under which SOCAR would pay $1.65 billion in cash, subject to customary adjustments. SOCAR would acquire non-operated working interests representing 20% of the Legacy Haynesville and 15% of the Western Haynesville upstream interests held by Comstock Resources, Inc. (NYSE:CRK). SOCAR would also acquire 15% of the 73% ownership interest held by Comstock Resources, Inc. (NYSE:CRK) in Pinnacle Gas Services.
The letter of intent requires good-faith negotiations but does not obligate completion. The parties are targeting a definitive agreement by October 31, 2026, and closing by year-end, subject to negotiations, approvals, and customary conditions.
Separately, a Jerry Jones family partnership will fund 85% of the drilling and completion costs for 18 Western Haynesville wells and 80% for nine Legacy Haynesville wells. The total 27-well program is expected to cost approximately $450 million over 12 months. After a 15% return on investment, 50% of the interest covered by the venture will revert to Comstock Resources, Inc. (NYSE:CRK).
If the SOCAR transaction closes, Comstock Resources, Inc. (NYSE:CRK) estimates that the proceeds would reduce company-defined non-GAAP net debt from $3.1 billion to $1.5 billion as of June 30, 2026. Net debt is calculated as total debt less cash and cash equivalents. The approximately $1.6 billion reduction would nearly halve the measure and could improve financial flexibility.
The drilling venture allows development to continue without equivalent near-term cash funding. Following completion of the SOCAR transaction, Comstock Resources, Inc. (NYSE:CRK) would retain operatorship of the upstream ****** ets and control of Pinnacle Gas Services. Drilling should provide volumes to Pinnacle and help delineate the 545,000 net acres in the Western Haynesville.
#SOCAR
0.00$ raised of 0.00$ goal
0 donations
0.00$
to go
2 months ago
SpaceX must pull off rocket reusability if the company is to reach a stratospheric market valuation in the not-too-distant future.
"A successful investment case in ****** eX at the current $2 trillion enterprise value rests almost entirely on a single admittedly massive engineering bottleneck: Starship reusability (i.e. 20-50 flights per Starship with relatively inexpensive and quick refurbishment/redeployment)," Pivotal Research Group ****** yst Jeffrey Wlodarczak wrote in a note on Tuesday. "If Elon Musk can solve for this fundamental issue it potentially drives down the cost of launches to ****** e to the equivalent of terrestrial freight opening up an unarguably massive opportunity."
Wlodarczak initiated coverage of ****** eX with a Buy rating and $220 price target.
That massive opportunity, Wlodarczak said, includes Starlink taking a material share of the wireless industry and serving as a ****** e monopoly, with others having to pay ****** eX for entry.
"In the end, investors are debating xAI, Colossus, and Starlink take-rates," Wlodarczak added. "Those matter only after Starship works. Our $220 target is a call on reuse 20–50 flights per vehicle, cheap refurb, fast turnaround. If that is solved, the rest of the model can happen. If it is not, SPCX is a different and much smaller company."
#SpaceX



2 months ago
On August 5, OraSure Technologies (NASDAQ:OSUR) reported second-quarter 2026 results that included its first GAAP net income in years, a headline number of $6.2 million versus a $19.7 million loss a year earlier. Revenue of $30.6 million beat the company's own guidance range and climbed 9.7% from the prior quarter. But look past the top line and the story splits in two, one part driven by real operating progress, the other by an accounting adjustment tied to a regulatory setback.
Some of this quarter's improvement came from actual operations. Gross margin expanded to 43.5% on a GAAP basis, up from 42.1% a year earlier, and non-GAAP gross margin rose to 44.2% from 43.2%. Diagnostics revenue grew 1% year over year to $19.4 million, helped by higher syphilis test sales and the addition of BioMedomics' Sickle SCAN product line. OraSure also picked up two regulatory wins during the quarter. In June 2026, the FDA cleared its Colli-Pee Dx urine collection kit for use with Roche's **** ually transmitted infection tests, letting patients collect samples at home instead of in a clinic.
The following month, the FDA granted Emergency Use Authorization for the second-generation OraQuick Ebola 2.0 Rapid Antigen Test, which can detect all four Ebola virus strains known to cause disease in humans. Cash used in operating activities improved to $23.8 million over the first six months of 2026, down from $30 million a year earlier, a sign the cash burn is easing. The company also kept buying back stock, repurchasing $22 million of shares, or 7.7 million shares, against its $40 million authorization, retiring more than 10% of shares outstanding.
The GAAP profit that headlines this quarter didn't come from the business getting more profitable. It came almost entirely from a $22.6 million reduction in a contingent consideration liability, an accounting entry triggered when OraSure updated its regulatory submission plan for the CT/NG test on its Sherlock platform. Strip that adjustment out and the underlying trend looks different. Non-GAAP operating loss widened to $14.7 million from $13.2 million a year earlier, and non-GAAP net loss came in at $13.8 million, roughly in line with last year's $14.2 million loss. The regulatory event behind that accounting gain is itself a setback.
In July, OraSure withdrew its InteliQuick CT/NG molecular self-test submission after receiving FDA feedback, meaning the product's path to market is now delayed while the company prepares a future resubmission. Total revenue for the quarter was still down 2% year over year, and core revenue, which excludes COVID-19 and Risk **** sment Testing, was flat. Six-month revenue fell 4% to $58.6 million. Sample Management Solutions revenue stayed flat year over year at $9.9 million, showing no growth driver of its own. Cash and equivalents fell to $161 million at quarter-end from $199.3 million at the end of 2025, pulled down by continued buybacks and cash used in operations.
#year #gaap #reven