1 month ago
For the recently reported second quarter, PicS N.V. (NASDAQ:PICS) outperformed relative to its previous guidance across all profitability metrics. The total account base for the company went up to 70.4 million during the second quarter, showcasing a 10% jump from the prior year. Moving on to the bottom line figures, the adjusted earnings before tax, without factoring in costs ******* ociated with stock-based compensation came in at R$291 million for the quarter. This represented a 2.1% outperformance relative to the company's R$285 million guidance. Similarly, compared to the R$245 million projection, adjusted net income for the period actually stood 15.5% higher at R$283 million.
welcomia/Shutterstock.com
The second quarter concluded with strong financial and operating momentum for PicS. The company recorded a 9% annual and 2% sequential growth in its client base, which went up to 45.4 million active users. The total credit portfolio jumped to R$31.9 billion, exceeding management's guidance by 3%. This outperformance came due to a higher number of mature credit card cohorts, and accelerated origination within secured and partly secured categories. An additional factor that accounted for the credit portfolio growth was management's measured expansion into higher risk areas such as newer platform credit and private payroll lending.
Managerial revenue rose to R$3,730 million, topping guidance by 3.6%, and net interest income reached R$2,002 million, 5.4% above projections, boosted by growing credit income. Total cash in totaled R$136.4 billion, up 17% from a year earlier and 9% from the previous quarter, with customers bringing in an average of approximately R$45.4 billion to the platform each month. Total deposits climbed to R$35.8 billion, a 45% yearly jump and 10% quarterly rise.
Some concerns related to the company's loan portfolio emerged during the quarter. Non-performing loans more than 90 days overdue increased to 9.8% of the credit portfolio during the quarter, up 93 basis points sequentially. Stage 3 exposure, which includes a broader set of credit-impaired loans, reached 12.9% of the total credit portfolio.
#million #credit #quarter #Portfolio
welcomia/Shutterstock.com
The second quarter concluded with strong financial and operating momentum for PicS. The company recorded a 9% annual and 2% sequential growth in its client base, which went up to 45.4 million active users. The total credit portfolio jumped to R$31.9 billion, exceeding management's guidance by 3%. This outperformance came due to a higher number of mature credit card cohorts, and accelerated origination within secured and partly secured categories. An additional factor that accounted for the credit portfolio growth was management's measured expansion into higher risk areas such as newer platform credit and private payroll lending.
Managerial revenue rose to R$3,730 million, topping guidance by 3.6%, and net interest income reached R$2,002 million, 5.4% above projections, boosted by growing credit income. Total cash in totaled R$136.4 billion, up 17% from a year earlier and 9% from the previous quarter, with customers bringing in an average of approximately R$45.4 billion to the platform each month. Total deposits climbed to R$35.8 billion, a 45% yearly jump and 10% quarterly rise.
Some concerns related to the company's loan portfolio emerged during the quarter. Non-performing loans more than 90 days overdue increased to 9.8% of the credit portfolio during the quarter, up 93 basis points sequentially. Stage 3 exposure, which includes a broader set of credit-impaired loans, reached 12.9% of the total credit portfolio.
#million #credit #quarter #Portfolio

1 month ago
Huntington Bancshares Incorporated (NASDAQ:HBAN) dropped 5.55% to $15.82 on September 16, 2026, close to its 52-week low. The price movement was triggered by a profit warning at a Barclays conference. Huntington brought down its 2027 EPS guidance from above $1.90 to the range of $1.75-$1.83, and its 2026 net interest income growth from 39%-43% to roughly 35%. What matters more than these numbers is the reason behind them. Deposit costs are rising, and loan pricing is tightening, and it landed on the day the Fed delivered its first interest rate hike since 2023. The drop therefore raises the question: is this an oversold bank or the opening crack in regional-bank margins?
A well-run bank has just lowered its guidance, citing intense competition for deposits and loans. If Huntington feels the margin pressure, then it is likely that its peers feel the same. This explains why Fifth Third shares slid 4.1% on the same afternoon alongside the whole financials group. The Fed's new hike makes the environment more unfavorable for the group in the near term. While rate increases eventually lift ***** et yields, banks must immediately offer higher deposit yields to retain balances, squeezing net interest margins in the near term. Furthermore, accelerated commercial real estate loan payoffs reduced total earning ***** ets, though these early payoffs lower credit risk on the loan book.
The selloff leans too much into the reset. A move to $1.75-$1.83 from above $1.90 is a modest single-digit trim. Huntington sustains its profit as well as its operational performance. Loans reached $189 billion from $50 billion in 2015. Deposits touched $222 billion. And one of the company's biggest growth engines, value-added fee income, compounded at a 14% annual rate since mid-2024, with year-to-date growth near 32%. The income helps offset a notable portion of the spread pressure and offers a competitive edge against pure spread lenders.
A higher-for-longer rate environment carries trade-offs for commercial banks. It drives up deposit expenses, reflecting the margin pressure Huntington reported. It also expands loan yields as credit ***** ets reprice. Deposit beta determines the net effect by measuring how much of each benchmark rate increase the bank transfers to depositors. After the rate hikes, deposit costs typically rise further, so betting on a near-term peak takes some faith. A lower beta allows fee revenue to support earnings, whereas a higher beta keeps the squeeze sustained over multiple quarters.
#bank #interest #Growth
A well-run bank has just lowered its guidance, citing intense competition for deposits and loans. If Huntington feels the margin pressure, then it is likely that its peers feel the same. This explains why Fifth Third shares slid 4.1% on the same afternoon alongside the whole financials group. The Fed's new hike makes the environment more unfavorable for the group in the near term. While rate increases eventually lift ***** et yields, banks must immediately offer higher deposit yields to retain balances, squeezing net interest margins in the near term. Furthermore, accelerated commercial real estate loan payoffs reduced total earning ***** ets, though these early payoffs lower credit risk on the loan book.
The selloff leans too much into the reset. A move to $1.75-$1.83 from above $1.90 is a modest single-digit trim. Huntington sustains its profit as well as its operational performance. Loans reached $189 billion from $50 billion in 2015. Deposits touched $222 billion. And one of the company's biggest growth engines, value-added fee income, compounded at a 14% annual rate since mid-2024, with year-to-date growth near 32%. The income helps offset a notable portion of the spread pressure and offers a competitive edge against pure spread lenders.
A higher-for-longer rate environment carries trade-offs for commercial banks. It drives up deposit expenses, reflecting the margin pressure Huntington reported. It also expands loan yields as credit ***** ets reprice. Deposit beta determines the net effect by measuring how much of each benchmark rate increase the bank transfers to depositors. After the rate hikes, deposit costs typically rise further, so betting on a near-term peak takes some faith. A lower beta allows fee revenue to support earnings, whereas a higher beta keeps the squeeze sustained over multiple quarters.
#bank #interest #Growth

1 month ago
Robinhood Markets (NASDAQ:HOOD) ended August with $384 billion in Total Platform **** ets, its term for everything customers hold on the platform -- up 8% from July and 26% from a year earlier, according to operating data published Sept. 10.
The next big round number, $500 billion, sits about 30% away. I think Robinhood gets there at some point during 2027.
Missed AI's "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our **** ysts, we're only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
The reason isn't a bold **** umption about markets or a bet on a new product taking off. Customers' own deposits carry the platform most of the way, and the market only has to cover a modest gap.
Image source: Getty Images.
#billion #think #NASDAQ
The next big round number, $500 billion, sits about 30% away. I think Robinhood gets there at some point during 2027.
Missed AI's "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our **** ysts, we're only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
The reason isn't a bold **** umption about markets or a bet on a new product taking off. Customers' own deposits carry the platform most of the way, and the market only has to cover a modest gap.
Image source: Getty Images.
#billion #think #NASDAQ

2 months ago
For the recently reported second quarter, PicS N.V. (NASDAQ:PICS) outperformed relative to its previous guidance across all profitability metrics. The total account base for the company went up to 70.4 million during the second quarter, showcasing a 10% jump from the prior year. Moving on to the bottom line figures, the adjusted earnings before tax, without factoring in costs ****** ociated with stock-based compensation came in at R$291 million for the quarter. This represented a 2.1% outperformance relative to the company's R$285 million guidance. Similarly, compared to the R$245 million projection, adjusted net income for the period actually stood 15.5% higher at R$283 million.
welcomia/Shutterstock.com
The second quarter concluded with strong financial and operating momentum for PicS. The company recorded a 9% annual and 2% sequential growth in its client base, which went up to 45.4 million active users. The total credit portfolio jumped to R$31.9 billion, exceeding management's guidance by 3%. This outperformance came due to a higher number of mature credit card cohorts, and accelerated origination within secured and partly secured categories. An additional factor that accounted for the credit portfolio growth was management's measured expansion into higher risk areas such as newer platform credit and private payroll lending.
Managerial revenue rose to R$3,730 million, topping guidance by 3.6%, and net interest income reached R$2,002 million, 5.4% above projections, boosted by growing credit income. Total cash in totaled R$136.4 billion, up 17% from a year earlier and 9% from the previous quarter, with customers bringing in an average of approximately R$45.4 billion to the platform each month. Total deposits climbed to R$35.8 billion, a 45% yearly jump and 10% quarterly rise.
Some concerns related to the company's loan portfolio emerged during the quarter. Non-performing loans more than 90 days overdue increased to 9.8% of the credit portfolio during the quarter, up 93 basis points sequentially. Stage 3 exposure, which includes a broader set of credit-impaired loans, reached 12.9% of the total credit portfolio.
#million #total
welcomia/Shutterstock.com
The second quarter concluded with strong financial and operating momentum for PicS. The company recorded a 9% annual and 2% sequential growth in its client base, which went up to 45.4 million active users. The total credit portfolio jumped to R$31.9 billion, exceeding management's guidance by 3%. This outperformance came due to a higher number of mature credit card cohorts, and accelerated origination within secured and partly secured categories. An additional factor that accounted for the credit portfolio growth was management's measured expansion into higher risk areas such as newer platform credit and private payroll lending.
Managerial revenue rose to R$3,730 million, topping guidance by 3.6%, and net interest income reached R$2,002 million, 5.4% above projections, boosted by growing credit income. Total cash in totaled R$136.4 billion, up 17% from a year earlier and 9% from the previous quarter, with customers bringing in an average of approximately R$45.4 billion to the platform each month. Total deposits climbed to R$35.8 billion, a 45% yearly jump and 10% quarterly rise.
Some concerns related to the company's loan portfolio emerged during the quarter. Non-performing loans more than 90 days overdue increased to 9.8% of the credit portfolio during the quarter, up 93 basis points sequentially. Stage 3 exposure, which includes a broader set of credit-impaired loans, reached 12.9% of the total credit portfolio.
#million #total

2 months ago
One of the challenges for nontraditional fintech lenders has been the expense **** ociated with lending.
Because most of them do not have bank charters, they must partner with a traditional third-party bank to fund their loans. However, they must pay a fee or provide a cut of interest income earned on every loan they make using a third party. That eats into their profits.
Missed AI's "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our **** ysts, we're only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
A federal bank charter would allow the fintechs to take deposits, because without one, they cannot. The deposits serve as an internal funding source, as loans can be made from the deposit base. With an internal funding source, these fintechs do not have to get third-party funding for loans, which, in turn, allows them to save on fees and collect all of the interest income.
Since fintechs started popping up more frequently over the past five or six years, federal regulators have been reluctant to grant bank charters to fintechs, imposing stringent requirements. But that has changed over the past couple of years as restrictions have eased. There has been a surge in the number of fintechs applying for, and getting, bank charters.
#Fintechs #missed #interest
Because most of them do not have bank charters, they must partner with a traditional third-party bank to fund their loans. However, they must pay a fee or provide a cut of interest income earned on every loan they make using a third party. That eats into their profits.
Missed AI's "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our **** ysts, we're only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
A federal bank charter would allow the fintechs to take deposits, because without one, they cannot. The deposits serve as an internal funding source, as loans can be made from the deposit base. With an internal funding source, these fintechs do not have to get third-party funding for loans, which, in turn, allows them to save on fees and collect all of the interest income.
Since fintechs started popping up more frequently over the past five or six years, federal regulators have been reluctant to grant bank charters to fintechs, imposing stringent requirements. But that has changed over the past couple of years as restrictions have eased. There has been a surge in the number of fintechs applying for, and getting, bank charters.
#Fintechs #missed #interest


2 months ago
Some offers on this page are from advertisers who pay us, which may affect which products we write about, but not our recommendations. See our Advertiser Disclosure.
Maybe you only think about the Federal Reserve when interest rate decisions make headlines. However, the Fed does much more than that, and it often impacts Americans' personal finances.
Discover how Fed rate moves affect your money.
The Federal Reserve acts as a bank for banks. It holds bank deposits, lends money to financial institutions, and facilitates the process by which banks borrow funds from each other.
The Federal Reserve also ensures the smooth operation of the banking system and guides the nation's economy by managing U.S. currency and by steering interest rates.
#affect #interest #advertiser
Maybe you only think about the Federal Reserve when interest rate decisions make headlines. However, the Fed does much more than that, and it often impacts Americans' personal finances.
Discover how Fed rate moves affect your money.
The Federal Reserve acts as a bank for banks. It holds bank deposits, lends money to financial institutions, and facilitates the process by which banks borrow funds from each other.
The Federal Reserve also ensures the smooth operation of the banking system and guides the nation's economy by managing U.S. currency and by steering interest rates.
#affect #interest #advertiser


2 months ago
Wealthfront Corporation (NASDAQ:WLTH) reported on September 9 that fiscal second-quarter revenue increased 1% to $91.9 million, despite platform ***** ets rising 12% to $99 billion. The quarter ended July 31, 2026. Funded clients increased 14% to 1.51 million, and platform ***** ets surpassed $100 billion by the end of August.
Platform ***** ets measure financial ***** ets held in client accounts. Their growth reflects both net deposits and market movements, so the headline increase does not represent new client money alone.
Adjusted EBITDA declined 15% to $38.1 million, with its margin falling to 41% from 49%. Wealthfront Corporation (NASDAQ:WLTH) defines this non-GAAP measure as net income excluding interest expense, income taxes, depreciation and amortization, stock-based compensation, fair-value changes in convertible notes, warrant liabilities and simple agreements for future equity, and nonrecurring expenses. Adjusted EBITDA margin divides that figure by revenue.
The advisory business is translating ***** et growth into revenue. Investment advisory ***** ets increased 30% to $54.1 billion, while advisory revenue rose 31% to $28.8 million. Those results show that the expanding investment business is generating a larger recurring fee stream.
For Wealthfront Corporation (NASDAQ:WLTH), this creates an opportunity to deepen client relationships as savings move toward longer-term investment goals. A growing advisory base could support more durable relationships, provided clients remain invested and continue contributing.
#wealthfront #revenue #platform #investment
Platform ***** ets measure financial ***** ets held in client accounts. Their growth reflects both net deposits and market movements, so the headline increase does not represent new client money alone.
Adjusted EBITDA declined 15% to $38.1 million, with its margin falling to 41% from 49%. Wealthfront Corporation (NASDAQ:WLTH) defines this non-GAAP measure as net income excluding interest expense, income taxes, depreciation and amortization, stock-based compensation, fair-value changes in convertible notes, warrant liabilities and simple agreements for future equity, and nonrecurring expenses. Adjusted EBITDA margin divides that figure by revenue.
The advisory business is translating ***** et growth into revenue. Investment advisory ***** ets increased 30% to $54.1 billion, while advisory revenue rose 31% to $28.8 million. Those results show that the expanding investment business is generating a larger recurring fee stream.
For Wealthfront Corporation (NASDAQ:WLTH), this creates an opportunity to deepen client relationships as savings move toward longer-term investment goals. A growing advisory base could support more durable relationships, provided clients remain invested and continue contributing.
#wealthfront #revenue #platform #investment


2 months ago
Interested in Truist Financial Corporation? Here are five stocks we like better.
Truist will sell its $5.5 billion near-prime auto loan portfolio and exit its Regional Acceptance Corporation business, which was roughly break-even despite high loan yields. The transaction is expected to modestly improve earnings, tangible book value and credit metrics.
The bank reaffirmed its financial outlook, including third-quarter net interest income growth of about 1.5%, full-year growth of 1% to 1.5%, and its $5 billion share-repurchase plan. The sale is expected to generate approximately $950 million in capital but reduce net interest margin by 4 to 5 basis points.
New CEO Mike Lyons is accelerating a broader portfolio and capital-allocation review, with Truist emphasizing relationship banking, deposits, commercial lending, payments, wealth management and potentially credit cards, mortgages and home equity lending.
Smart Money Shifts: U.S. Bancorp Pairs Tech With Yield
#truist #financial #loan #credit
Truist will sell its $5.5 billion near-prime auto loan portfolio and exit its Regional Acceptance Corporation business, which was roughly break-even despite high loan yields. The transaction is expected to modestly improve earnings, tangible book value and credit metrics.
The bank reaffirmed its financial outlook, including third-quarter net interest income growth of about 1.5%, full-year growth of 1% to 1.5%, and its $5 billion share-repurchase plan. The sale is expected to generate approximately $950 million in capital but reduce net interest margin by 4 to 5 basis points.
New CEO Mike Lyons is accelerating a broader portfolio and capital-allocation review, with Truist emphasizing relationship banking, deposits, commercial lending, payments, wealth management and potentially credit cards, mortgages and home equity lending.
Smart Money Shifts: U.S. Bancorp Pairs Tech With Yield
#truist #financial #loan #credit


2 months ago
When a caller inquired about SoFi Technologies, Inc. (NASDAQ:SOFI) during the September 10 episode of Mad Money, Jim Cramer commented:
Well, you know, it's a financial tech. It's a bank, but let's put it this way: It's doing as well as it can, but it has a very high price-to-earnings multiple versus the others in its cohort. So, it's going to mark time until the earnings continue to go up. I do like the company. I like the management. I wouldn't mind you owning it for the long term.
SoFi Technologies, Inc. (NASDAQ:SOFI) reported record second-quarter adjusted net revenue of $1.2 billion, up 40% year over year, while GAAP net income rose 61% to $156.6 million. Adjusted EBITDA increased 44% to $358 million. Loan originations reached a record $14.8 billion, while members increased 35% to 15.8 million and deposits reached $45.5 billion. Moreover, at the September 8 Goldman Sachs conference, CFO Chris Lapointe said SoFi generated approximately 40% year-over-year revenue growth in each of the first two quarters and approximately 30% adjusted EBITDA margins. He also said the company had outpaced the Rule of 40 for 20 consecutive quarters. Additionally, the company raised its 2026 adjusted net revenue outlook to $4.75 billion to $4.85 billion but maintained its adjusted EPS outlook at $0.60.
A concern is that SoFi Technologies, Inc.'s (NASDAQ:SOFI) earnings growth may not be sufficient to justify the multiple investors are paying. SoFi is trading at a premium valuation compared to its traditional banking peers, with Yahoo Finance's latest data showing a trailing P/E of 35.12 and a forward P/E of 21.51. That valuation leaves the shares sensitive to a slowdown in earnings growth. Credit performance is another important consideration as SoFi expands its lending business. For the six months ended June 30, total net charge-offs were $406.1 million, up $77.2 million from the prior-year period, while the total net charge-off ratio declined to 1.91% from 2.24%. The increase in charge-offs was driven primarily by higher personal-loan net charge-offs and student-loan net charge-offs, reflecting growth in average loans.
According to Insider Monkey, which tracks more than 1,000 hedge funds, 44 hedge funds held SoFi in Q2, down from 47 in Q1. Its short interest stood at about 14% to 15% of the float. SoFi Technologies, Inc.'s (NASDAQ:SOFI) growth and improving profitability give Cramer's long-term view a fundamental basis, but its valuation still leaves the stock dependent on continued earnings growth. The company's ability to turn strong revenue and loan growth into higher earnings will remain important to the stock's valuation.
#earnings #adjusted #million #charge
Well, you know, it's a financial tech. It's a bank, but let's put it this way: It's doing as well as it can, but it has a very high price-to-earnings multiple versus the others in its cohort. So, it's going to mark time until the earnings continue to go up. I do like the company. I like the management. I wouldn't mind you owning it for the long term.
SoFi Technologies, Inc. (NASDAQ:SOFI) reported record second-quarter adjusted net revenue of $1.2 billion, up 40% year over year, while GAAP net income rose 61% to $156.6 million. Adjusted EBITDA increased 44% to $358 million. Loan originations reached a record $14.8 billion, while members increased 35% to 15.8 million and deposits reached $45.5 billion. Moreover, at the September 8 Goldman Sachs conference, CFO Chris Lapointe said SoFi generated approximately 40% year-over-year revenue growth in each of the first two quarters and approximately 30% adjusted EBITDA margins. He also said the company had outpaced the Rule of 40 for 20 consecutive quarters. Additionally, the company raised its 2026 adjusted net revenue outlook to $4.75 billion to $4.85 billion but maintained its adjusted EPS outlook at $0.60.
A concern is that SoFi Technologies, Inc.'s (NASDAQ:SOFI) earnings growth may not be sufficient to justify the multiple investors are paying. SoFi is trading at a premium valuation compared to its traditional banking peers, with Yahoo Finance's latest data showing a trailing P/E of 35.12 and a forward P/E of 21.51. That valuation leaves the shares sensitive to a slowdown in earnings growth. Credit performance is another important consideration as SoFi expands its lending business. For the six months ended June 30, total net charge-offs were $406.1 million, up $77.2 million from the prior-year period, while the total net charge-off ratio declined to 1.91% from 2.24%. The increase in charge-offs was driven primarily by higher personal-loan net charge-offs and student-loan net charge-offs, reflecting growth in average loans.
According to Insider Monkey, which tracks more than 1,000 hedge funds, 44 hedge funds held SoFi in Q2, down from 47 in Q1. Its short interest stood at about 14% to 15% of the float. SoFi Technologies, Inc.'s (NASDAQ:SOFI) growth and improving profitability give Cramer's long-term view a fundamental basis, but its valuation still leaves the stock dependent on continued earnings growth. The company's ability to turn strong revenue and loan growth into higher earnings will remain important to the stock's valuation.
#earnings #adjusted #million #charge


2 months ago
In XRP news today, its 30-day liquidity index on Binance has climbed to 0.0675, the highest reading in about six months. Its 30-day turnover recovered to approximately $4.6 billion after sinking to between $2 billion and $3 billion during July and August.
The rebound signals that XRP liquidity conditions have meaningfully improved, but a deeper order book supports both accumulation and distribution equally well, and is leaving the question of which side actually controls this market unanswered.
The liquidity index measures how easily traders can move XRP in and out of positions without moving the price against themselves, calculated against how quickly XRP turns over relative to what Binance holds on its books. A rising reading means faster turnover and tighter execution, which is exactly what the data shows.
XRP closed August up about 28.5%, its strongest August performance since 2021, while U.S. spot XRP ETF products pulled in $153.55 million of inflows that month.
Now, the flow data from the end of last week complicates a clean bullish read. More than 91 million XRP moved into Binance on the 11th, and over 113 million XRP moved out, both six-month highs in single-day volume. Withdrawals outpaced deposits by 22.7 million XRP, yet Binance's total XRP holdings rose just 0.43% over the full week.
#reading
The rebound signals that XRP liquidity conditions have meaningfully improved, but a deeper order book supports both accumulation and distribution equally well, and is leaving the question of which side actually controls this market unanswered.
The liquidity index measures how easily traders can move XRP in and out of positions without moving the price against themselves, calculated against how quickly XRP turns over relative to what Binance holds on its books. A rising reading means faster turnover and tighter execution, which is exactly what the data shows.
XRP closed August up about 28.5%, its strongest August performance since 2021, while U.S. spot XRP ETF products pulled in $153.55 million of inflows that month.
Now, the flow data from the end of last week complicates a clean bullish read. More than 91 million XRP moved into Binance on the 11th, and over 113 million XRP moved out, both six-month highs in single-day volume. Withdrawals outpaced deposits by 22.7 million XRP, yet Binance's total XRP holdings rose just 0.43% over the full week.
#reading


2 months ago
On September 10, Imperial Petroleum Inc. (NASDAQ:IMPP), a company involved in seaborne transportation of crude oil, dry bulk, and petroleum products, released its second quarter results. With a topline figure of $87.1 million, the company delivered record quarterly revenue, which also resulted in 139.9% year-over-year growth. Imperial's adjusted EBITDA for the second quarter stood at $41.7 million, while the Q2 adjusted net income of $35.3 million exhibited around 163% growth in comparison with Q2 FY25.
Ralf Gosch/Shutterstock.com
Several factors contributed to the second quarter topline growth. A 6.9 vessel rise in the company's average fleet size was the primary growth enabler. Other factors include encouraging dynamics across the drybulk segment, and higher rates for both drybulk and tankers amid the geopolitical uncertainties. Operating income for the quarter jumped to a near-record level of $33.4 million, which translates into a 307.3% growth relative to Q2 FY25. Imperial posted an adjusted EPS of $0.76 for the reported quarter, which almost doubled compared to the same quarter a year prior.
At the back of efficient fleet management, management remained focus on strengthening its financial position. The company ended the quarter with no debt, and its liquidity position also remained resilient. Cash and cash equivalents, including time deposits, increased from $179.1 million at the end of 2025 to $245.2 million as of June 30, 2026. The company added that its cash base had increased further to approximately $260 million as of the September 10 results release.
Certain areas of weakness warrant a closer examination. During the reported quarter, fleet operational utilization went down from 83.1% in prior year's second quarter to 73.5%. There was a substantial increase in some of the underlying operating expenses. For instance, the vessel operating expense stood at $14.4 million compared to $8.4 million during Q2 FY25. This $6 million rise can be attributed to Imperial's larger fleet size. Similarly, the voyage expenses also jumped from $10.7 million in last year's Q2 to $22.1 million for Q2 FY26. The incremental voyage expenses stemmed from higher bunkers' rates, as well as a 58.4% jump in spot days.
#fleet
Ralf Gosch/Shutterstock.com
Several factors contributed to the second quarter topline growth. A 6.9 vessel rise in the company's average fleet size was the primary growth enabler. Other factors include encouraging dynamics across the drybulk segment, and higher rates for both drybulk and tankers amid the geopolitical uncertainties. Operating income for the quarter jumped to a near-record level of $33.4 million, which translates into a 307.3% growth relative to Q2 FY25. Imperial posted an adjusted EPS of $0.76 for the reported quarter, which almost doubled compared to the same quarter a year prior.
At the back of efficient fleet management, management remained focus on strengthening its financial position. The company ended the quarter with no debt, and its liquidity position also remained resilient. Cash and cash equivalents, including time deposits, increased from $179.1 million at the end of 2025 to $245.2 million as of June 30, 2026. The company added that its cash base had increased further to approximately $260 million as of the September 10 results release.
Certain areas of weakness warrant a closer examination. During the reported quarter, fleet operational utilization went down from 83.1% in prior year's second quarter to 73.5%. There was a substantial increase in some of the underlying operating expenses. For instance, the vessel operating expense stood at $14.4 million compared to $8.4 million during Q2 FY25. This $6 million rise can be attributed to Imperial's larger fleet size. Similarly, the voyage expenses also jumped from $10.7 million in last year's Q2 to $22.1 million for Q2 FY26. The incremental voyage expenses stemmed from higher bunkers' rates, as well as a 58.4% jump in spot days.
#fleet

2 months ago
The CoinEx crypto exchange is shutting down its operations after nine years, citing a "prolonged" crypto market downturn, shrinking trading activity and rising compliance costs across major jurisdictions.
The exchange said the wind-down will begin on Sep. 15, with services being withdrawn in stages before the platform closes completely on Dec. 22.
Related: Coinbase CEO doubles down on bullish Bitcoin target
CoinEx will immediately stop new user registrations, referral commissions and several new product subscriptions. Futures markets are moving into reduce-only mode, while no new orders will be accepted for margin trading, loans, staking, earn products and several other services.
All non-spot services are scheduled to end on Sep. 22. On-chain deposits will also close that day, with the exception of deposits in CoinEx Token, or CET, which will remain available until Sep. 29.
#Services #exchange #trading
The exchange said the wind-down will begin on Sep. 15, with services being withdrawn in stages before the platform closes completely on Dec. 22.
Related: Coinbase CEO doubles down on bullish Bitcoin target
CoinEx will immediately stop new user registrations, referral commissions and several new product subscriptions. Futures markets are moving into reduce-only mode, while no new orders will be accepted for margin trading, loans, staking, earn products and several other services.
All non-spot services are scheduled to end on Sep. 22. On-chain deposits will also close that day, with the exception of deposits in CoinEx Token, or CET, which will remain available until Sep. 29.
#Services #exchange #trading

2 months ago
The White House said Tuesday that banning yield on stablecoins would do little to increase bank lending, pushing back against estimates that stablecoin rewards could result in large amounts of deposits leaving the traditional banking system.
In an update to an April ****** ysis by the Council of Economic Advisers (CEA), the White House said eliminating stablecoin yield would increase bank lending by about $2.1 billion under its baseline ****** umptions. That represents just 0.02% of outstanding bank loans.
Community banks would account for roughly $500 million of the additional lending, or about 0.03% of their loan books, according to the ****** ysis.
More From Cryptoprowl:
MEXC Launches Earn Plus With Limited-Time Event Offering Up to 800% APR Booster
#yield #increase #tuesday
In an update to an April ****** ysis by the Council of Economic Advisers (CEA), the White House said eliminating stablecoin yield would increase bank lending by about $2.1 billion under its baseline ****** umptions. That represents just 0.02% of outstanding bank loans.
Community banks would account for roughly $500 million of the additional lending, or about 0.03% of their loan books, according to the ****** ysis.
More From Cryptoprowl:
MEXC Launches Earn Plus With Limited-Time Event Offering Up to 800% APR Booster
#yield #increase #tuesday


2 months ago
Some offers on this page are from advertisers who pay us, which may affect which products we write about, but not our recommendations. See our Advertiser Disclosure.
If you're looking for safe ways to grow your money and protect your savings, a high-yield savings account (HYSA) can be a great option. However, it's important to be aware that there are certain instances when you could lose money. So if you plan on opening a high-yield savings account, be sure you understand how to protect your principal and earned interest.
High-yield savings accounts are like traditional savings accounts except that they offer above-average interest rates. These accounts are available from banks and credit unions, particularly online financial institutions. The higher interest rate means you earn more on your deposited funds over time, allowing your savings to grow faster.
If you open an account with a federally insured financial institution, your savings account deposits are protected in case the institution fails. With banks, deposits are protected by the Federal Deposit Insurance Corporation (FDIC) up to $250,000 per institution, per depositor, per ownership category. With credit unions, deposits are similarly insured by the National Credit Union Administration.
Read more: High-yield savings account vs. traditional savings account: Which one is better?
#high #credit #interest
If you're looking for safe ways to grow your money and protect your savings, a high-yield savings account (HYSA) can be a great option. However, it's important to be aware that there are certain instances when you could lose money. So if you plan on opening a high-yield savings account, be sure you understand how to protect your principal and earned interest.
High-yield savings accounts are like traditional savings accounts except that they offer above-average interest rates. These accounts are available from banks and credit unions, particularly online financial institutions. The higher interest rate means you earn more on your deposited funds over time, allowing your savings to grow faster.
If you open an account with a federally insured financial institution, your savings account deposits are protected in case the institution fails. With banks, deposits are protected by the Federal Deposit Insurance Corporation (FDIC) up to $250,000 per institution, per depositor, per ownership category. With credit unions, deposits are similarly insured by the National Credit Union Administration.
Read more: High-yield savings account vs. traditional savings account: Which one is better?
#high #credit #interest


2 months ago
Block, Inc. (NYSE:XYZ) is taking another step toward consolidating its digital **** et operations under a federal regulatory framework. On September 8, it filed an application with the Office of the Comptroller of the Currency (OCC) to charter Builders Bank & Trust, N.A.
If chartered, the Builders Bank & Trust could become an important part of Block's digital **** et custody infrastructure, giving the company a federally supervised framework for custody and related services involving bitcoin and stablecoins.
Builders Bank & Trust would be an uninsured national trust bank, meaning it would not accept deposits or make traditional loans. Instead, its focus would be on fiduciary and custody services, allowing Block to build specialized infrastructure for safeguarding digital **** ets.
The structure could be particularly valuable as Block, Inc. (NYSE:XYZ) seeks to expand its institutional customer base. A federally supervised custody operation could give larger financial institutions greater confidence in Block's ability to safeguard Bitcoin and other digital **** ets.
Stablecoins represent a potentially important opportunity for Block, particularly through its Cash App ecosystem. A regulated custody infrastructure could eventually support broader stablecoin-related products and payments if Block chooses to expand further in this area.
#Bitcoin
If chartered, the Builders Bank & Trust could become an important part of Block's digital **** et custody infrastructure, giving the company a federally supervised framework for custody and related services involving bitcoin and stablecoins.
Builders Bank & Trust would be an uninsured national trust bank, meaning it would not accept deposits or make traditional loans. Instead, its focus would be on fiduciary and custody services, allowing Block to build specialized infrastructure for safeguarding digital **** ets.
The structure could be particularly valuable as Block, Inc. (NYSE:XYZ) seeks to expand its institutional customer base. A federally supervised custody operation could give larger financial institutions greater confidence in Block's ability to safeguard Bitcoin and other digital **** ets.
Stablecoins represent a potentially important opportunity for Block, particularly through its Cash App ecosystem. A regulated custody infrastructure could eventually support broader stablecoin-related products and payments if Block chooses to expand further in this area.
#Bitcoin


2 months ago
U.S. Bancorp (NYSE:USB) has raised its quarterly dividend by 3.8% to $0.54 per share. That brings the annualized payout at $2.16 and the yield at 3.5%.
For income-focused investors, the increase adds to the bank's appeal. But the more important point is what supports the higher payout.
U.S. Bancorp enters the second half of 2026 on firm footing. The bank's latest results show accelerating earnings, strong loan growth, and a solid capital position.
U.S. Bancorp (NYSE:USB)'s revenue increased 10% YoY in Q2 to a record $7.7 billion. Net interest margin jumped to 2.79%, up from 2.66% a year ago. That helped push the net income attributable to the bank up 20% to $2.18 billion. Diluted EPS rose 21.6% to $1.35.
The bank's balance sheet also continued to expand. Average loans increased 7.1% to $405.5 billion, supported by strong commercial, commercial real estate and credit card lending activity. Average deposits increased 2.4% to $515.1 billion, providing low-cost funding for the loan growth.
#Growth
For income-focused investors, the increase adds to the bank's appeal. But the more important point is what supports the higher payout.
U.S. Bancorp enters the second half of 2026 on firm footing. The bank's latest results show accelerating earnings, strong loan growth, and a solid capital position.
U.S. Bancorp (NYSE:USB)'s revenue increased 10% YoY in Q2 to a record $7.7 billion. Net interest margin jumped to 2.79%, up from 2.66% a year ago. That helped push the net income attributable to the bank up 20% to $2.18 billion. Diluted EPS rose 21.6% to $1.35.
The bank's balance sheet also continued to expand. Average loans increased 7.1% to $405.5 billion, supported by strong commercial, commercial real estate and credit card lending activity. Average deposits increased 2.4% to $515.1 billion, providing low-cost funding for the loan growth.
#Growth

2 months ago
First Citizens BancShares, Inc. (NASDAQ:FCNCA), through its First-Citizens Bank & Trust Company subsidiary, completed the acquisition of 138 BMO Bank N.A. branches on September 4. The locations span 11 states across the Midwest, Great Plains and West.
The completion announcement did not disclose final transferred balances. At the announcement, First Citizens BancShares, Inc. (NASDAQ:FCNCA) expected to ****** ume approximately $5.7 billion of deposits and acquire $1.1 billion of loans. Its July 2026 update lowered those estimates to $5.3 billion and $700 million, respectively. Both estimates imply roughly $4.6 billion of net liquidity. That difference represents funding capacity, not transaction income, and remains subject to final balances and acquisition accounting.
The deposit franchise could be the transaction's most valuable ****** et. At announcement, the acquired deposits carried a weighted average rate of 1.43%, with 21% in noninterest-bearing demand accounts. First Citizens BancShares, Inc. (NASDAQ:FCNCA) reported a 2.07% average total deposit cost in the second quarter of 2026. Retaining the acquired accounts near their original pricing could lower the consolidated funding cost.
The 138 branches also establish or deepen a presence across 11 states. The original transaction presentation identified approximately $1.0 billion of wealth ****** ets under management, creating opportunities to cross-sell commercial lending, treasury services, and wealth products. Retaining branch personnel could help preserve local relationships.
First Citizens BancShares, Inc. (NASDAQ:FCNCA) can deploy the surplus funding in several ways. As of June 30, 2026, the company held $151.03 billion of loans and $32.19 billion of borrowings, including a $28.42 billion purchase money note owed to the Federal Deposit Insurance Corporation. The acquired liquidity could support loan growth, replace more expensive funding, or be invested in securities. The original presentation projected immediate earnings-per-share accretion and an approximately 27-basis-point reduction in the Common Equity Tier 1 capital ratio.
#billion #first #citizens
The completion announcement did not disclose final transferred balances. At the announcement, First Citizens BancShares, Inc. (NASDAQ:FCNCA) expected to ****** ume approximately $5.7 billion of deposits and acquire $1.1 billion of loans. Its July 2026 update lowered those estimates to $5.3 billion and $700 million, respectively. Both estimates imply roughly $4.6 billion of net liquidity. That difference represents funding capacity, not transaction income, and remains subject to final balances and acquisition accounting.
The deposit franchise could be the transaction's most valuable ****** et. At announcement, the acquired deposits carried a weighted average rate of 1.43%, with 21% in noninterest-bearing demand accounts. First Citizens BancShares, Inc. (NASDAQ:FCNCA) reported a 2.07% average total deposit cost in the second quarter of 2026. Retaining the acquired accounts near their original pricing could lower the consolidated funding cost.
The 138 branches also establish or deepen a presence across 11 states. The original transaction presentation identified approximately $1.0 billion of wealth ****** ets under management, creating opportunities to cross-sell commercial lending, treasury services, and wealth products. Retaining branch personnel could help preserve local relationships.
First Citizens BancShares, Inc. (NASDAQ:FCNCA) can deploy the surplus funding in several ways. As of June 30, 2026, the company held $151.03 billion of loans and $32.19 billion of borrowings, including a $28.42 billion purchase money note owed to the Federal Deposit Insurance Corporation. The acquired liquidity could support loan growth, replace more expensive funding, or be invested in securities. The original presentation projected immediate earnings-per-share accretion and an approximately 27-basis-point reduction in the Common Equity Tier 1 capital ratio.
#billion #first #citizens


2 months ago
After signing what President Donald Trump touted as "the biggest oil deal in world history" to take majority control of 65 billion barrels of proven crude oil reserves in Venezuela, the U.S. Administration is setting its sights on the South American country's potentially vast gold and critical minerals wealth.
The Trump Administration is weighing measures to involve U.S. companies in Venezuela's gold and critical minerals and has held initial meetings with firms to see if there is interest in engaging in the Venezuelan mining sector, sources with knowledge of the plans told Reuters this week.
Securing gold and critical minerals from Venezuela could help the U.S. with its supply of metals crucial for defense technology and applications that don't depend on China. Moreover, greater access for U.S. and Western firms in Venezuela's minerals sector would further undermine Chinese and Russian influence in the country, which the ousted Venezuelan leader, Nicolas Maduro, deposed and arrested by the U.S. in January, had enjoyed.
"We are all watching the oil situation closely and recognize there could be a parallel track with critical minerals," an executive from a critical minerals firm who met with the U.S. Administration about Venezuela, told Reuters.
However, the path to mining Venezuela's minerals would not be as straightforward as it arguably is for the oil reserves. Operators generally know how much crude oil Venezuela has (the biggest reserves in the world), but no one really knows the reserves and mining potential of the gold and critical minerals deposits.
#venezuela
The Trump Administration is weighing measures to involve U.S. companies in Venezuela's gold and critical minerals and has held initial meetings with firms to see if there is interest in engaging in the Venezuelan mining sector, sources with knowledge of the plans told Reuters this week.
Securing gold and critical minerals from Venezuela could help the U.S. with its supply of metals crucial for defense technology and applications that don't depend on China. Moreover, greater access for U.S. and Western firms in Venezuela's minerals sector would further undermine Chinese and Russian influence in the country, which the ousted Venezuelan leader, Nicolas Maduro, deposed and arrested by the U.S. in January, had enjoyed.
"We are all watching the oil situation closely and recognize there could be a parallel track with critical minerals," an executive from a critical minerals firm who met with the U.S. Administration about Venezuela, told Reuters.
However, the path to mining Venezuela's minerals would not be as straightforward as it arguably is for the oil reserves. Operators generally know how much crude oil Venezuela has (the biggest reserves in the world), but no one really knows the reserves and mining potential of the gold and critical minerals deposits.
#venezuela

2 months ago
Strategy, formerly MicroStrategy, says 91% of its balance sheet rests on money **** ody can take back. JPMorgan runs on deposits customers can pull any day. Strategy calls that the safer design.
The claim comes from a slide that the company put in front of investors. It puts Strategy's short-term funding gap at zero and JPMorgan's at negative $1.2 trillion. Strategy wrote those definitions itself.
"MSTR inverts TradFi," says Strategy.
Follow us on X to get the latest news as it happens
Banks borrow short, lend long, and deposits can vanish in a day. Additionally, sometimes loans take years to come back, which is why insurance, regulators and central bank credit exist to cover that gap.
#follow
The claim comes from a slide that the company put in front of investors. It puts Strategy's short-term funding gap at zero and JPMorgan's at negative $1.2 trillion. Strategy wrote those definitions itself.
"MSTR inverts TradFi," says Strategy.
Follow us on X to get the latest news as it happens
Banks borrow short, lend long, and deposits can vanish in a day. Additionally, sometimes loans take years to come back, which is why insurance, regulators and central bank credit exist to cover that gap.
#follow


2 months ago
Block has applied to the Office of the Comptroller of the Currency for a national trust bank charter, the payments company behind Square and Cash App said on Tuesday.
Builders Bank & Trust would be uninsured and non-depository, taking no deposits and making no loans. Its business would be custody of Bitcoin and other digital ***** ets, executing customer buy and sell orders on a riskless principal basis, and stablecoin settlement.
Block has run digital ***** et services for about eight years under more than 50 state money transmitter and virtual currency licenses, the application says, handling around $10.7 billion in Bitcoin transaction volume in 2025 and serving about two million monthly crypto users through Cash App by the second quarter. A federal charter, Block says, would let it support those activities "through a consistent national framework as the business scales."
Builders Bank would be headquartered in Sioux Falls, South Dakota, with no branches. All five proposed directors live elsewhere, and Block has asked the OCC to waive the rule requiring one to live within 100 miles. Lee Woolley, Block's digital ***** et strategy lead and a former Northern Trust and BNY Mellon executive, would chair it and serve as chief executive.
Dorsey himself is not among the organizers, directors or senior executives, and appears in the filing only as Block's co-founder. The business plan and capital figures went in as confidential exhibits, and the bank cannot open unless the OCC approves.
#block #digital #national
Builders Bank & Trust would be uninsured and non-depository, taking no deposits and making no loans. Its business would be custody of Bitcoin and other digital ***** ets, executing customer buy and sell orders on a riskless principal basis, and stablecoin settlement.
Block has run digital ***** et services for about eight years under more than 50 state money transmitter and virtual currency licenses, the application says, handling around $10.7 billion in Bitcoin transaction volume in 2025 and serving about two million monthly crypto users through Cash App by the second quarter. A federal charter, Block says, would let it support those activities "through a consistent national framework as the business scales."
Builders Bank would be headquartered in Sioux Falls, South Dakota, with no branches. All five proposed directors live elsewhere, and Block has asked the OCC to waive the rule requiring one to live within 100 miles. Lee Woolley, Block's digital ***** et strategy lead and a former Northern Trust and BNY Mellon executive, would chair it and serve as chief executive.
Dorsey himself is not among the organizers, directors or senior executives, and appears in the filing only as Block's co-founder. The business plan and capital figures went in as confidential exhibits, and the bank cannot open unless the OCC approves.
#block #digital #national
0.00$ raised of 0.00$ goal
0 donations
0.00$
to go

2 months ago
Russian oil producer Rosneft has commenced oil shipments from its Vostok Oil project following a commissioning ceremony overseen by Russian President Vladimir Putin via video link.
The first oil from the development was loaded onto the Valentin Pikul Arc7-class Arctic tanker at the Bukhta Sever port.
Rosneft CEO Igor Sechin and Russian Deputy Prime Minister Alexander Novak also participated in the event.
The Vostok Oil project consolidates a number of significant oil and gas deposits in the northern Krasnoyarsk Territory.
Rosneft estimates the project's resource base at seven billion tonnes (bt) of oil with sulphur content ranging between 0.01% and 0.1%.
#russian #rosneft #president
The first oil from the development was loaded onto the Valentin Pikul Arc7-class Arctic tanker at the Bukhta Sever port.
Rosneft CEO Igor Sechin and Russian Deputy Prime Minister Alexander Novak also participated in the event.
The Vostok Oil project consolidates a number of significant oil and gas deposits in the northern Krasnoyarsk Territory.
Rosneft estimates the project's resource base at seven billion tonnes (bt) of oil with sulphur content ranging between 0.01% and 0.1%.
#russian #rosneft #president
2 months ago
USA Rare Earth (NASDAQ: USAR) is quickly becoming one of America's most strategically important mining companies, at least if the economy, technology, and national security count for anything.
Why all the attention? Two words: rare earths. Indeed, rare-earth metals, as their name suggests, are a class of elements that are tough to find in economically useful deposits. They are essential to everything from smartphones and electric vehicles (EVs) to fighter jets and guided missiles, and China controls most of the world's capacity to process them.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
USA Rare Earth is one of only a handful of American companies that control a rare-earth deposit on American soil. Its goal is to extract rare-earth elements from a deposit in Texas, process and separate them domestically, and turn them into permanent magnets for American companies out of its factory in Oklahoma.
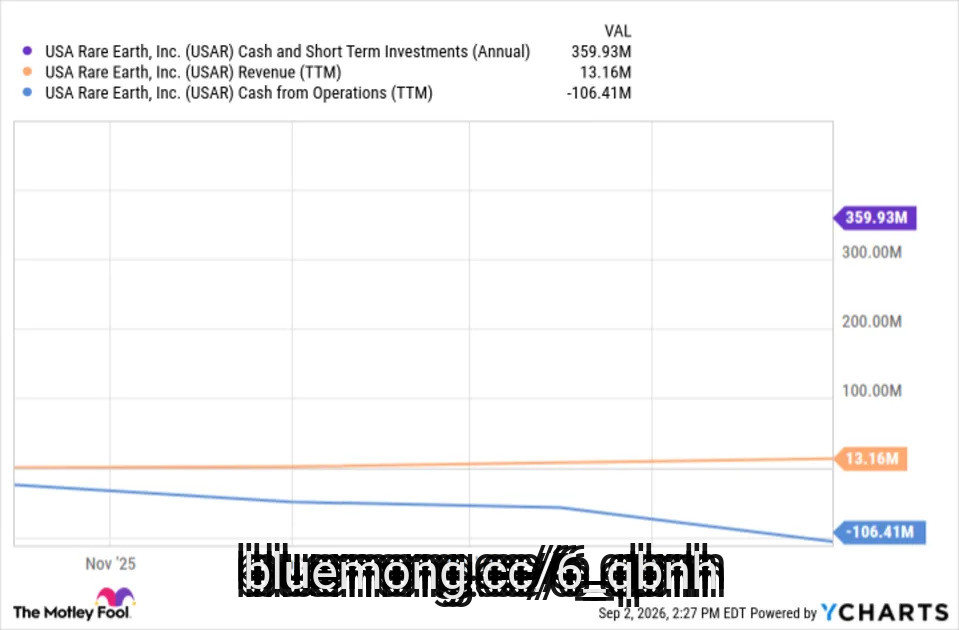
For some time, this has been at the heart of USA Rare Earth's growth thesis; none of it is new. What is new, however, is its pending acquisition of Serra Verde, which could turn USA Rare Earth from a would-be miner with an uncertain start date into the owner of an operating rare-earth mine. That deal will likely close before its next earnings report -- expected in early November -- and could set the stage for a huge rally.
#american #Companies #time
Why all the attention? Two words: rare earths. Indeed, rare-earth metals, as their name suggests, are a class of elements that are tough to find in economically useful deposits. They are essential to everything from smartphones and electric vehicles (EVs) to fighter jets and guided missiles, and China controls most of the world's capacity to process them.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
USA Rare Earth is one of only a handful of American companies that control a rare-earth deposit on American soil. Its goal is to extract rare-earth elements from a deposit in Texas, process and separate them domestically, and turn them into permanent magnets for American companies out of its factory in Oklahoma.
For some time, this has been at the heart of USA Rare Earth's growth thesis; none of it is new. What is new, however, is its pending acquisition of Serra Verde, which could turn USA Rare Earth from a would-be miner with an uncertain start date into the owner of an operating rare-earth mine. That deal will likely close before its next earnings report -- expected in early November -- and could set the stage for a huge rally.
#american #Companies #time

2 months ago
JEPQ, DGRW, and JAAA together can convert a $250,000 life insurance lump sum into monthly deposits that replicate a working spouse's paycheck.
A $100,000 JEPQ allocation buys roughly 1,695 shares at $59, generating $8.46 annualized per share in monthly income with 18% yearly price gains.
JAAA's AAA-rated CLO holdings pay $2.70 per share annually with near-zero volatility, acting as the stable floor when equity markets drop.
Read More: Avoid these 13 retirement mistakes before they derail your future (sponsor)
Six weeks ago, the insurance company wired $250,000 into your checking account, and there it sits, earning almost nothing while you try to remember what day it is. That is fine. Life insurance death benefits are generally income-tax-free to the beneficiary, and no rule says grieving people have to make portfolio decisions on a schedule. When you are ready, though, three funds can turn that lump sum into a monthly deposit that behaves a lot like the paycheck your spouse used to bring home: JPMorgan Nasdaq Equity Premium Income ETF (NASDAQ:JEPQ), WisdomTree U.S. Quality Dividend Growth Fund (NASDAQ:DGRW), and Janus Henderson AAA CLO ETF (NYSEARCA:JAAA).
#life
A $100,000 JEPQ allocation buys roughly 1,695 shares at $59, generating $8.46 annualized per share in monthly income with 18% yearly price gains.
JAAA's AAA-rated CLO holdings pay $2.70 per share annually with near-zero volatility, acting as the stable floor when equity markets drop.
Read More: Avoid these 13 retirement mistakes before they derail your future (sponsor)
Six weeks ago, the insurance company wired $250,000 into your checking account, and there it sits, earning almost nothing while you try to remember what day it is. That is fine. Life insurance death benefits are generally income-tax-free to the beneficiary, and no rule says grieving people have to make portfolio decisions on a schedule. When you are ready, though, three funds can turn that lump sum into a monthly deposit that behaves a lot like the paycheck your spouse used to bring home: JPMorgan Nasdaq Equity Premium Income ETF (NASDAQ:JEPQ), WisdomTree U.S. Quality Dividend Growth Fund (NASDAQ:DGRW), and Janus Henderson AAA CLO ETF (NYSEARCA:JAAA).
#life

2 months ago
Some offers on this page are from advertisers who pay us, which may affect which products we write about, but not our recommendations. See our Advertiser Disclosure.
Summary: Bread Savings, formerly known as Comenity Direct, is a division of Bread Financial — a financial services company that offers personal and business banking products.
The high-yield savings account from Bread currently offers a competitive 4% APY (interest is compounded daily and credited monthly) with no monthly fees. The minimum opening deposit is $100. Bread Savings offers free ACH transfers, free online statements, free incoming wire transfers, and unlimited deposits via mobile check capture and ACH transfer.
Bread Savings offers CDs with terms ranging from three months to five years, and rates up to 4.15% APY. The minimum opening deposit for CDs is $1,500. There are no monthly maintenance fees. Interest is compounded daily and credited monthly.
Bread Savings does not charge many fees. However, you may be charged the following fees for specific services:
#financial
Summary: Bread Savings, formerly known as Comenity Direct, is a division of Bread Financial — a financial services company that offers personal and business banking products.
The high-yield savings account from Bread currently offers a competitive 4% APY (interest is compounded daily and credited monthly) with no monthly fees. The minimum opening deposit is $100. Bread Savings offers free ACH transfers, free online statements, free incoming wire transfers, and unlimited deposits via mobile check capture and ACH transfer.
Bread Savings offers CDs with terms ranging from three months to five years, and rates up to 4.15% APY. The minimum opening deposit for CDs is $1,500. There are no monthly maintenance fees. Interest is compounded daily and credited monthly.
Bread Savings does not charge many fees. However, you may be charged the following fees for specific services:
#financial


2 months ago
Some offers on this page are from advertisers who pay us, which may affect which products we write about, but not our recommendations. See our Advertiser Disclosure.
No doubt you've seen an "FDIC-insured" or "Member FDIC" sign on the wall of a bank or at the bottom of a bank website homepage. Almost all banks, including online banks, are insured by the Federal Deposit Insurance Corporation (FDIC).
The FDIC is an independent government agency that insures money people deposit at a bank. If the bank fails, the FDIC repays up to $250,000 per person, per ownership category at each FDIC-insured bank.
The FDIC was created in 1933 in response to the turmoil of the 1929 stock market crash. Following the crash, people rushed to withdraw their money from banks. As a result of these bank runs, as many as 9,000 banks failed and $7 billion dollars in deposits were lost, wiping out the life savings of millions of Americans.
President Franklin D. Roosevelt signed the Banking Act of 1933, establishing the FDIC to restore trust in the US banking system. The FDIC reports that since then, no one has lost any FDIC-insured money due to a bank failure.
#fdic #bank #money #crash
No doubt you've seen an "FDIC-insured" or "Member FDIC" sign on the wall of a bank or at the bottom of a bank website homepage. Almost all banks, including online banks, are insured by the Federal Deposit Insurance Corporation (FDIC).
The FDIC is an independent government agency that insures money people deposit at a bank. If the bank fails, the FDIC repays up to $250,000 per person, per ownership category at each FDIC-insured bank.
The FDIC was created in 1933 in response to the turmoil of the 1929 stock market crash. Following the crash, people rushed to withdraw their money from banks. As a result of these bank runs, as many as 9,000 banks failed and $7 billion dollars in deposits were lost, wiping out the life savings of millions of Americans.
President Franklin D. Roosevelt signed the Banking Act of 1933, establishing the FDIC to restore trust in the US banking system. The FDIC reports that since then, no one has lost any FDIC-insured money due to a bank failure.
#fdic #bank #money #crash

2 months ago
Artisan Partners, an investment management company, released its second-quarter 2026 investor commentary for the "Artisan Global Opportunities Strategy". The letter can be downloaded here. Global equities rebounded sharply during the quarter, with the MSCI ACWI Index returning 15.3% as resilient economic growth, strong corporate earnings, and continued enthusiasm around artificial intelligence supported markets despite persistent inflation, higher bond yields, and geopolitical uncertainty. The portfolio reported strong absolute returns of 12.65% (net) but underperformed the benchmark, mainly because of its underweight exposure to information technology and overweight position in health care. Strong stock selection in technology and energy partially offset these headwinds. The fund continues to see attractive long-term opportunities across AI infrastructure, health care and consumer internet, while remaining disciplined on valuation as several AI-related stocks have appreciated sharply. Management remains focused on durable franchises with identifiable profit cycles and attractive long-term earnings potential. Also, check the Strategy's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Artisan Global Opportunities Strategy highlighted Robinhood Markets, Inc. (NASDAQ:HOOD) as a new holding. Robinhood Markets, Inc. (NASDAQ:HOOD) is a US-based financial services company that provides a trading platform for stocks, exchange-traded funds, American depository receipts, options, gold, and cryptocurrencies. On September 01, 2026, Robinhood Markets, Inc. (NASDAQ:HOOD) closed at $103.51 per share. Robinhood Markets, Inc. (NASDAQ:HOOD) returned 14.18% over the past month and its shares have gained 5.10% over the past 52 weeks. Robinhood Markets, Inc. (NASDAQ:HOOD) has a market capitalization of $93.06 billion.
Artisan Global Opportunities Strategy stated the following regarding Robinhood Markets, Inc. (NASDAQ:HOOD) in its Q2 2026 investor letter:
"During the quarter, we initiated positions in Robinhood Markets, Inc. (NASDAQ:HOOD). Robinhood Markets operates a financial services platform offering brokerage, cash management and other investing products. We initiated a GardenSM position following share price weakness driven in part by lower crypto prices, which we viewed as an attractive entry point into a business with a long runway for growth. Despite the crypto headwind, Robinhood has continued to grow deposits at a strong rate, reflecting the platform's ability to attract and retain customer ***** ets. We believe Robinhood can continue gaining market share in the retail wealth market through its leadership in active trading and by expanding its suite of retirement, banking, lending and credit products. As the company has gained market share and increased its base of long-term customer ***** ets, we see a multiyear opportunity for potential revenue growth and margin expansion."
#opportunities #strong #strategy
In its second-quarter 2026 investor letter, Artisan Global Opportunities Strategy highlighted Robinhood Markets, Inc. (NASDAQ:HOOD) as a new holding. Robinhood Markets, Inc. (NASDAQ:HOOD) is a US-based financial services company that provides a trading platform for stocks, exchange-traded funds, American depository receipts, options, gold, and cryptocurrencies. On September 01, 2026, Robinhood Markets, Inc. (NASDAQ:HOOD) closed at $103.51 per share. Robinhood Markets, Inc. (NASDAQ:HOOD) returned 14.18% over the past month and its shares have gained 5.10% over the past 52 weeks. Robinhood Markets, Inc. (NASDAQ:HOOD) has a market capitalization of $93.06 billion.
Artisan Global Opportunities Strategy stated the following regarding Robinhood Markets, Inc. (NASDAQ:HOOD) in its Q2 2026 investor letter:
"During the quarter, we initiated positions in Robinhood Markets, Inc. (NASDAQ:HOOD). Robinhood Markets operates a financial services platform offering brokerage, cash management and other investing products. We initiated a GardenSM position following share price weakness driven in part by lower crypto prices, which we viewed as an attractive entry point into a business with a long runway for growth. Despite the crypto headwind, Robinhood has continued to grow deposits at a strong rate, reflecting the platform's ability to attract and retain customer ***** ets. We believe Robinhood can continue gaining market share in the retail wealth market through its leadership in active trading and by expanding its suite of retirement, banking, lending and credit products. As the company has gained market share and increased its base of long-term customer ***** ets, we see a multiyear opportunity for potential revenue growth and margin expansion."
#opportunities #strong #strategy


2 months ago
For years, the world's largest banks watched stablecoins from the sidelines, treating them as a threat to deposits and traditional payment rails. That era appears to be over.
A consortium of 21 financial institutions, including Goldman Sachs, Bank of America, Citigroup, Deutsche Bank, UBS, Wells Fargo, Barclays and Santander, is planning to form a company that would issue a stablecoin pegged to the U.S. dollar, with a launch targeted for the first half of 2027, according to Reuters.
A stablecoin is a digital token designed to hold a steady value, typically backed one-to-one by a traditional currency like the U.S. dollar, and used for payments, trading and moving money across borders.
Related: 50 major hacks cost crypto investors $136M in August
The effort started smaller.
#goldman #sachs #wells
A consortium of 21 financial institutions, including Goldman Sachs, Bank of America, Citigroup, Deutsche Bank, UBS, Wells Fargo, Barclays and Santander, is planning to form a company that would issue a stablecoin pegged to the U.S. dollar, with a launch targeted for the first half of 2027, according to Reuters.
A stablecoin is a digital token designed to hold a steady value, typically backed one-to-one by a traditional currency like the U.S. dollar, and used for payments, trading and moving money across borders.
Related: 50 major hacks cost crypto investors $136M in August
The effort started smaller.
#goldman #sachs #wells
2 months ago
Some offers on this page are from advertisers who pay us, which may affect which products we write about, but not our recommendations. See our Advertiser Disclosure.
Airbnb doesn't have its own credit card, but you can use certain rewards credit cards to help cover your Airbnb expenses or earn more on your stays. This could help you save money if you're a frequent Airbnb guest.
Why we like it: The Capital One Venture Rewards lets you redeem miles toward past travel purchases, often including Airbnb stays. This allows you to completely cover your Airbnb purchase using credit card rewards, which isn't an option on every rewards card.
Read our full Capital One Venture Rewards review
Why we like it: The Chase Sapphire Preferred provides 2x points on eligible Airbnb purchases, and it's easy to redeem Chase Ultimate Rewards points for Airbnb stays. You can redeem rewards for Airbnb gift cards, statement credits to cover your balance after paying for a stay, or deposits into an eligible bank account.
#rewards #venture #chase
Airbnb doesn't have its own credit card, but you can use certain rewards credit cards to help cover your Airbnb expenses or earn more on your stays. This could help you save money if you're a frequent Airbnb guest.
Why we like it: The Capital One Venture Rewards lets you redeem miles toward past travel purchases, often including Airbnb stays. This allows you to completely cover your Airbnb purchase using credit card rewards, which isn't an option on every rewards card.
Read our full Capital One Venture Rewards review
Why we like it: The Chase Sapphire Preferred provides 2x points on eligible Airbnb purchases, and it's easy to redeem Chase Ultimate Rewards points for Airbnb stays. You can redeem rewards for Airbnb gift cards, statement credits to cover your balance after paying for a stay, or deposits into an eligible bank account.
#rewards #venture #chase
2 months ago
Some offers on this page are from advertisers who pay us, which may affect which products we write about, but not our recommendations. See our Advertiser Disclosure.
Automating your savings contributions is one way to ensure you save consistently and effortlessly. However, if you're going to put your savings on autopilot, it's important to do it the right way.
Automating your savings means setting up a system where a portion of your income is regularly transferred to a savings account or investment account without any manual effort on your part.
For example, you could have your employer direct a percentage of your paycheck to your retirement account. Or you could set up a monthly transfer from your checking account to your savings account.
And considering that some savings accounts still offer interest rates as high as 4% (or even more in some cases), you want to make sure you're making regular deposits to your account and taking advantage of that compound interest.
#account #you 're #advertiser #offers
Automating your savings contributions is one way to ensure you save consistently and effortlessly. However, if you're going to put your savings on autopilot, it's important to do it the right way.
Automating your savings means setting up a system where a portion of your income is regularly transferred to a savings account or investment account without any manual effort on your part.
For example, you could have your employer direct a percentage of your paycheck to your retirement account. Or you could set up a monthly transfer from your checking account to your savings account.
And considering that some savings accounts still offer interest rates as high as 4% (or even more in some cases), you want to make sure you're making regular deposits to your account and taking advantage of that compound interest.
#account #you 're #advertiser #offers

2 months ago
By Jonathan Stempel
Aug 31 (Reuters) - A U.S. judge said the former parent of Silicon Valley Bank cannot pursue a $1.71 billion claim against the FDIC stemming from the bank's March 2023 collapse, one of the largest U.S. bank failures.
In a 206-page decision on Friday, U.S. District Judge Beth Labson Freeman in San Jose, California, held that a trust that took over the parent's claims was responsible for former executives' ill-fated decisions to try boosting profit by investing heavily in long-term government bonds and mortgage-backed securities.
Silicon Valley Bank collapsed after rising interest rates caused at least $4.52 billion of losses in the bank's investment portfolio, sparking a bank run that disrupted many technology startups whose deposits it held.
Most of the bank's deposits were uninsured. The bank's demise presaged the collapses of two other large lenders in 2023, Signature Bank and First Republic Bank.
#former #deposits
Aug 31 (Reuters) - A U.S. judge said the former parent of Silicon Valley Bank cannot pursue a $1.71 billion claim against the FDIC stemming from the bank's March 2023 collapse, one of the largest U.S. bank failures.
In a 206-page decision on Friday, U.S. District Judge Beth Labson Freeman in San Jose, California, held that a trust that took over the parent's claims was responsible for former executives' ill-fated decisions to try boosting profit by investing heavily in long-term government bonds and mortgage-backed securities.
Silicon Valley Bank collapsed after rising interest rates caused at least $4.52 billion of losses in the bank's investment portfolio, sparking a bank run that disrupted many technology startups whose deposits it held.
Most of the bank's deposits were uninsured. The bank's demise presaged the collapses of two other large lenders in 2023, Signature Bank and First Republic Bank.
#former #deposits