3 days ago
Packers' Jordan Love highlights what offense needs to reach its full potential appeared first on ClutchPoints. Add ClutchPoints as a Preferred Source by clicking here.
The Green Bay Packers have had some ups and downs this season. More recently, it's been more ups than downs. Jordan Love and the Packers picked up a big win on Sunday Night Football over the Dallas Cowboys. However, even this win wasn't without some pain points.
The Packers offense has been under some real scrutiny this season. Green Bay has had some big moments offensively. In other times, though, they've looked either sluggish at best or straight bad at worst. After Sunday's win, Love spoke about what needs to happen for this offense to find consistent success.
"I still think there's so much more out there for us as an offense, and once we get that run game really going and solidified, it'll help a lot of areas," the Green Bay signal-caller said, via Packer Dispatch writer Zach Jacobson.
Watch sports LIVE with fuboTV (free trial)
#packers #green #clutchpoints #preferred

13 days ago
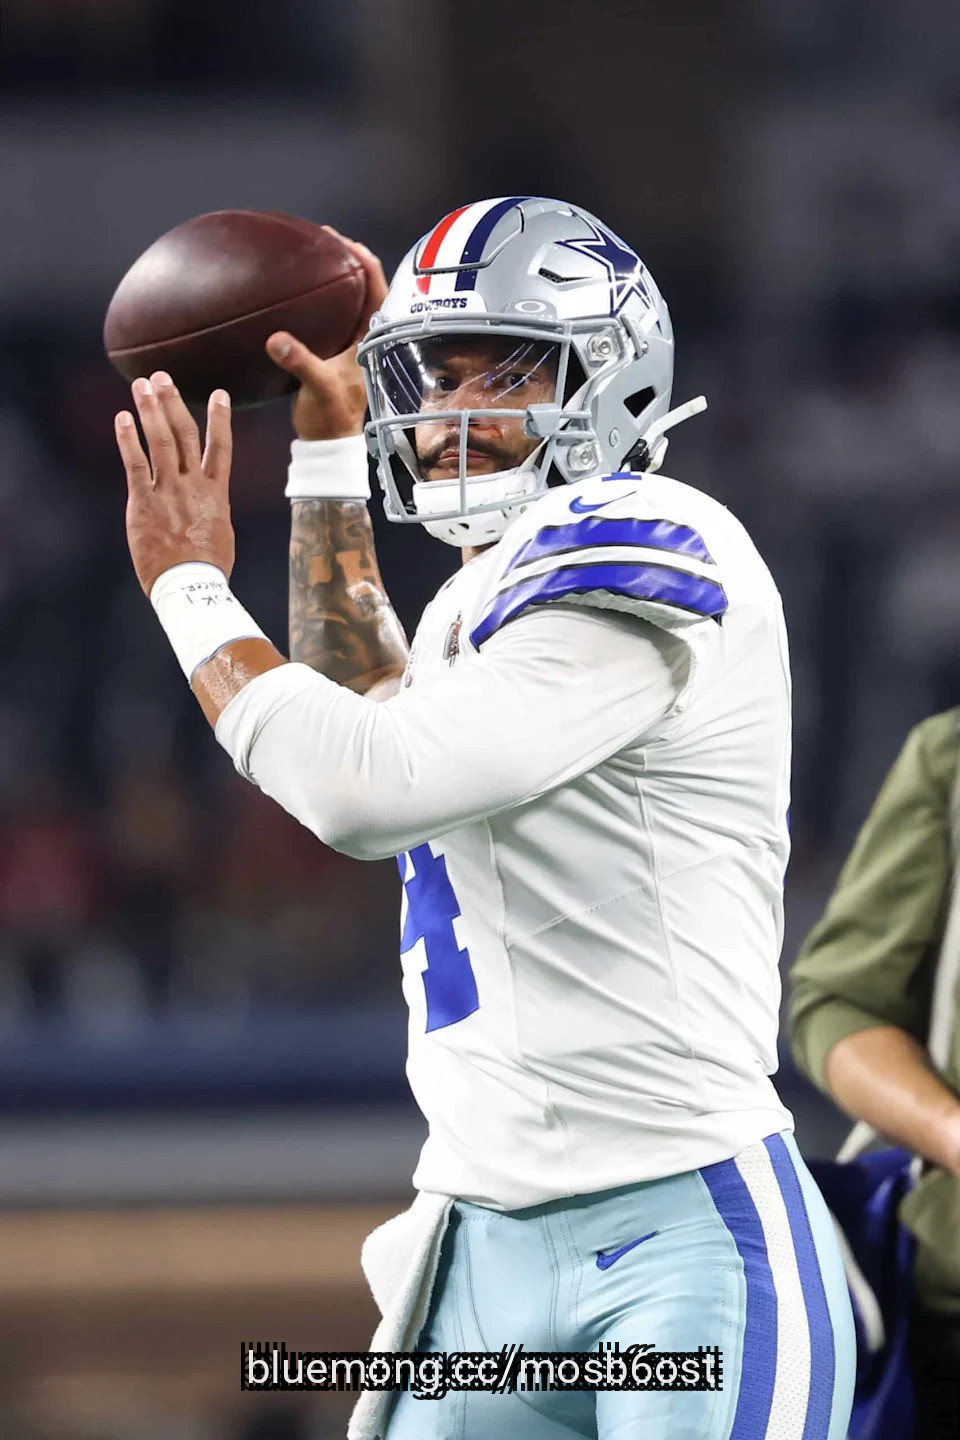
Actor C.W. Morgan has passed away at the age of 72. He was known for playing Billy Loomis' father in Scream and Scream 3. According to medical reports, Morgan died on August 30, 2026, though the reason has not been disclosed.
The confirmation of his death comes from Los Angeles County Medical Examiner records seen by TMZ and Entertainment Weekly. According to the records, Morgan died in a bathroom in Los Angeles. An LAPD spokesperson told TMZ that the death appears to be a result of natural causes.
Morgan was born in Bisbee, Arizona, and began his acting career in entertainment by starring in the 1991 TV series, Midnight Caller. Following that, he appeared in the 1992 TV movie, The Last of His Tribe. Besides the Scream movies, Morgan has also appeared in the film Metro and the TV show Nash Bridges as himself. In addition to his film and television work, he also lent his voice to the 1997 video game, The Last Express.
While his appearances were brief, his character, Hank Loomis, holds great importance to Scream fans. In the original film, it is revealed that Hank had an affair with Sidney Prescott's mother, which eventually led to his son, Billy, becoming Ghostface.
Morgan's daughter, Renata Macfie, paid tribute to the actor on Facebook. "I'm never going to have the right words for this post. Losing you has left the biggest hole in my heart. I will carry on our Mulholland drives and our Starbucks outings. I'm grateful and lucky to have had you as my daddy. My Guck. Rest easy, bubby. Life will never be the same without you and your poorly timed jokes that I inherited from you. Love you endlessly (no more fighting about that anymore, I win)."
#hank

14 days ago
When a caller mentioned that they are thinking about adding to their position in Simon Property Group, Inc. (NYSE:SPG) during the October 2 episode of Mad Money, Jim Cramer commented:
I think you're absolutely right... I want you to add to the Simon Property Group... What a great man he (David Simon, previous CEO) was, and he built a fabulous company, and you should buy more of it.
A September 8 question about buying Simon Property Group led Cramer to bring another real estate stock into the conversation.
Simon Property Group, Inc. (NYSE:SPG) reported second-quarter real estate funds from operations of $3.29 per diluted share, up 7.9% year-over-year. Domestic property net operating income increased 8.5%. Occupancy at its U.S. malls and premium outlets remained at 96%, while base minimum rent increased 6.3% to $62.42 per square foot. Management raised its full-year real estate funds from operations outlook to $13.20 - $13.30 per share. These figures show rent and property-income growth without requiring an increase in occupancy. Leasing activity also remained substantial. During the earnings call, management reported signing approximately 1,200 leases covering more than 4.8 million square feet, with new-deal volume increasing more than 20%.
Stable occupancy does not mean every tenant is healthy. Simon Property Group, Inc. (NYSE:SPG) absorbed approximately one million square feet of ****** e returned through retailer bankruptcies during the quarter. Management said it successfully re-leased the ****** e, helping maintain occupancy. That shows leasing strength, but also a reminder of the work required to preserve rental income. Additional retailer failures could bring more vacancies and replacement costs, even when demand for the properties remains sound.
#occupancy #NYSE #management #estate
14 days ago
WASHINGTON (AP) — The Federal Communications Commission is considering a request by a conservative group to loosen rules on political robocalls, including those with artificial intelligence-generated voices, before November's midterm elections.
Federal law currently bans most robocalls to cellphones unless the caller gets consent beforehand. The petition calls for a waiver that would allow political groups to use artificial or prerecorded voices in unsolicited wireless calls.
The Republican-led FCC advanced the request for public comment and could rule on it as soon as late October.
Consumer advocacy groups warn the proposed change could trigger a surge of unwanted, partisan and potentially misleading automated calls in the critical final days of the election, which will determine which party controls Congress for the final two years of President Donald Trump's term.
The potential perils became evident two years ago during the presidential primary season when thousands of voters in New Hampshire received a robocall with an AI-generated voice of then-President Joe Biden. The call suggested voters should forgo casting a ballot in the primary and "save" their votes for the general election.
#federal #robocalls #artificial #generated

15 days ago
Robert Kelker-Kelly complained of chest pain shortly before becoming unresponsive at his Missouri home, according to police. The former Days of Our Lives actor died at 62.
Officers and paramedics were called to his home in St. Peters, a suburb of St. Louis, at around 8:15 p.m. on Saturday, Oct. 3.
Lt. Melissa Doss of the St. Peters Police Department told Entertainment Weekly that nothing suspicious was noted at the scene and that the circumstances appeared consistent with a medical event.
The emergency was dispatched as a cardiac arrest, but officials have not announced an underlying cause of death.
Dispatch audio obtained by TMZ indicated that Kelker-Kelly had been found in bed and that the caller could not move him. CPR was already underway while police and emergency medical personnel were responding.
#kelly #peters #home #days
1 month ago
On the Sept. 3, 2026 episode of The Ramsey Show, a Houston caller named Nathan asked whether he should use his savings to clear a mortgage he described as a "whatever, 2% mortgage or something." He had about $280,000 left on it and roughly $346,000 in liquid ******* ets, most of it cash and the rest in a taxable brokerage account. Dave Ramsey told him to do it, and to do it that night.
Five months earlier, Ramsey had told a caller in almost the same position the opposite. On April 1, 2026, a web engineer earning around $600,000 a year called in about three weeks after being laid off, sitting on enough cash to clear a San Francisco, California mortgage. "When you're in the middle of a storm, you do temporary things," Ramsey said. "Hold on to the cash. We're not gonna pay off the house because we may not be staying in the house."
Here's Another Little-Known Firm Jensen Huang's Nvidia Is Quietly Backing
MediaTek Is Stepping Up Competition Against Qualcomm With a New 2-Nanometer Chip. What This Means for QCOM Stock.
1 Year Into the Microsoft Deal, IREN Is Delivering and a Rally May Follow Soon
#mortgage #told

1 month ago
Toward the end of the lightning round on September 17, a caller asked for Mad Money's host Jim Cramer's thoughts on Iron Mountain Incorporated (NYSE:IRM), and he replied:
It's been an incredible stock. It's a real estate investment trust, basically. And you know, we know that they shred, 3% yield, down 20 points from its high. I think it's a buy.
Iron Mountain Incorporated (NYSE:IRM) operates a highly durable business model centered on physical records management, secure document destruction, and expanding digital infrastructure. In Q2, total revenue reached $2.03 billion, representing an 18.7% increase year-over-year and 16.8% organic growth. The core physical storage business provides reliable cash flow, with storage rental revenue expanding 11.5% year-over-year excluding foreign-exchange effects across a global customer base of 240,000. Adjusted funds from operations grew 17% to $432.7 million, or $1.44 per share.
At the same time, management has channeled capital into scaling higher-growth segments, including digital solutions, ***** et lifecycle management, and data center operations. The data center segment posted 39% revenue growth during the second quarter, securing 110 megawatts in new leases through July and increasing power capacity across major enterprise markets. Operating as a real estate investment trust, the company maintains a quarterly dividend of $0.864 per share, offering shareholders a forward yield of over 3%.
On the other hand, Iron Mountain Incorporated (NYSE:IRM) faces risks inherent to capital-intensive real estate infrastructure expansion. Rapid buildouts of data center power capacity demand substantial capital expenditure, leading to elevated leverage across the balance sheet. Long-term debt, net of the current portion, reached approximately $17.1 billion at the end of the second quarter, increasing sensitivity to interest rate fluctuations and refinancing costs.
#revenue #Growth
1 month ago
Ramsey warns that depreciating ****** ets like cars erode wealth, and 84% of millionaires credited ditching car payments as key to building it.
A $30,000 car loses roughly $18,000 in value within five years, and average annual ownership costs hit $11,577, making cars a major wealth drag.
Since Micah maxes retirement accounts, carries zero debt, and pays cash, buying the sports car is defensible if he maintains those financial habits.
Two retirees, same $1 million, same 4% rule, buy one finished with $1.4 million, the other hit $0 in 12 years. Our free reader guide explains the flaw that separated them, and the income-first method built to avoid it.
A caller to the Dave Ramsey Show recently sparked a pointed conversation about cars, wealth, and what it actually means to earn a solid income. The caller was Micah, a 24-year-old earning $80,000 per year. He maxes out both his 401(k) and IRA and carries zero debt. His question was simple: he has $30,000 in cash and wants to put it toward a 2019 Nissan 370Z as a weekend car, but he wonders whether investing the money instead would serve him better long-term.
#zero
1 month ago
Starting the lightning round on September 14, when a caller inquired about SentinelOne, Inc. (NYSE:S), Mad Money host Jim Cramer remarked:
No, look, I think you don't need, look, my Charitable Trust owns both Palo Alto and CrowdStrike. It's already too many. I think either one of those two is superior to letter S.
The latest results show a large difference in scale. SentinelOne's fiscal second-quarter 2027 revenue rose 21% year over year to $292 million, while annualized recurring revenue increased 22% to $1.218 billion. Palo Alto Networks, Inc.'s (NASDAQ:PANW) fiscal fourth-quarter 2026 revenue rose 34% to $3.41 billion, while Next-Generation Security ARR increased 63% to $9.10 billion. Additionally, we have discussed CRWD in our recent article, "Jim Cramer Highlights CrowdStrike (CRWD) as AI Security Concerns Lift Cybersecurity Stocks."
SentinelOne, Inc. (NYSE:S) non-GAAP operating margin reached 10% in fiscal Q2 2027, up from 2% a year earlier, while its GAAP operating margin improved to negative 31% from negative 33%. The company guided for fiscal third-quarter revenue of $309 million to $311 million and full-year revenue of $1.202 billion to $1.207 billion.
Palo Alto Networks, Inc. (NASDAQ:PANW) reported approximately $1 billion of non-GAAP operating income in its fiscal fourth quarter of 2026, compared with $768 million a year earlier. Adjusted free cash flow reached approximately $1.3 billion, while GAAP operating income was $172 million versus $497 million a year earlier. Palo Alto CEO Nikesh Arora said in the September 1 earnings release that the latest advances in AI are "elevating cybersecurity to the top of the CIO priority list."
#billion #year #gaap #operating

1 month ago
During the September 11 episode of Mad Money, a caller asked whether to buy, sell, or hold shares of The Kraft Heinz Company (NYSE:KHC). Jim Cramer replied:
No, I don't want you to do that… And I'll tell you why. Because it's not that I believe in the greater man theory, but this Steve Cahillane, who's the CEO, he saved Kellogg and made people a ton of money. He's going to do the same thing with Kraft Heinz. Let's give him a chance. Let's give him six months, okay? I think he'd appreciate that if we give him six months. He's been here for a while, and he's a… person [who] really likes to... [take] action. Don't leave it. Please don't leave Kraft Heinz.
The comments build on his June 2 view that he was willing to "take on the risk" of owning Kraft Heinz because of Cahillane's record at Kellogg. At the time, however, Cramer said he had "not all that much faith in Kraft or Heinz after previous management gutted the company."
The Kraft Heinz Company's (NYSE:KHC) second-quarter results show why the turnaround remains unfinished. Net sales fell 1.4% year over year to $6.26 billion, while organic net sales declined 1.3%. Adjusted operating income fell 18.4% to $1 billion, while North American sales declined 2.7%. Management raised its 2026 organic net-sales outlook to a decline of 0.5% to 2%, from the previous range of a 1.5% to 3.5% decline. It also increased incremental investment by $100 million to approximately $700 million in 2026, with the company targeting a return to volume-led, sustainable and profitable growth.
On September 2, Kraft Heinz said it will hold an Investor Day on November 12 to present its long-term strategy for "sustainable volume-led and profitable growth." Cahillane said, "Our brand investments are gaining traction and driving improved performance."
#kraft #give #september

1 month ago
On September 11, a caller praised The Boeing Company's (NYSE:BA) CEO and asked when the company would overcome the ongoing labor uncertainty and finally move beyond years of sideways stock performance. Mad Money host Jim Cramer replied:
I think that Boeing is ready to go up. But here's the problem. Every time crude goes up a dollar, the stock goes down a dollar. And that, think about it, that was actually the ratio. I did some work on this. And because today crude was down, Boeing went up $5... No, it's so stupid because, in truth, the airlines need more planes because the planes are more fuel-efficient. So they actually do better in this environment, but ******* ody cares. They know that airlines have to borrow money to buy planes and rates are higher, and they think that oil somehow's bad. But what ends up happening is the stock does nothing. I think it's about to go up because I think oil might be peaking unless there's some catastrophe over there.
The Boeing Company's (NYSE:BA) second-quarter results showed improving cash generation, but profitability remained weak. Revenue rose 8% year over year to $24.6 billion, while operating cash flow reached $1.4 billion and free cash flow was $631 million. Its total backlog reached a record $715 billion, including more than 6,200 commercial airplanes. CEO Kelly Ortberg said, "We're ramping up production just as we planned. That's driving higher revenues and improved cash flow." He also said there's more work ahead to ramp production, complete commercial-aircraft certifications and uphold customer commitments. Boeing said the 737-7 and 737-10 had completed flight testing, with deliveries expected to begin in 2027.
The Boeing Company's (NYSE:BA) large backlog has yet to translate into consistent commercial-aircraft profitability, leaving execution and margins as important concerns for investors. Commercial Airplanes delivered 171 aircraft in the second quarter but still posted a $322 million operating loss and a negative 2.7% operating margin. It also reported a $428 million GAAP net loss.
The balance sheet leaves less room for further setbacks. The company ended June with $45.9 billion of consolidated debt against $20 billion of cash and investments in marketable securities. The FAA certified the 737-7 on August 3, while Boeing continues working toward certification of the 737-10. First deliveries of the variants are expected in 2027. The company also recorded $280 million of losses on the VC-25B program in the quarter.
#boeing #cash #commercial
1 month ago
At 60, Stephen has $40,000 saved against a $680,000 benchmark, plus $32,000 in debt draining his recovery runway.
Rachel Cruze and George Kamel told Stephen to stop funding his daughter and eliminate debt before rebuilding retirement savings.
Workers aged 60 to 63 can contribute up to $35,750 annually to a 401(k), a catch-up window that Stephen must use before it closes at age 64.
Read More: Learn 7 ways to generate income with a $1,000,000+ portfolio (sponsor)
A 60-year-old caller named Stephen phoned The Ramsey Show from Portland and laid out a balance sheet that would make anyone flinch: $40,000 left in retirement, no liquid savings, a $27,000 loan on a 4Runner worth about what he owes, $5,000 in credit card debt, and an $85,000 salary he took after quitting a more stressful job. He said he had drained the retirement account to put his daughter through school and pay off a $25,000 IRS bill he insists "wasn't mine."
#stephen #Retirement #workers

1 month ago
When a caller inquired about SoFi Technologies, Inc. (NASDAQ:SOFI) during the September 10 episode of Mad Money, Jim Cramer commented:
Well, you know, it's a financial tech. It's a bank, but let's put it this way: It's doing as well as it can, but it has a very high price-to-earnings multiple versus the others in its cohort. So, it's going to mark time until the earnings continue to go up. I do like the company. I like the management. I wouldn't mind you owning it for the long term.
SoFi Technologies, Inc. (NASDAQ:SOFI) reported record second-quarter adjusted net revenue of $1.2 billion, up 40% year over year, while GAAP net income rose 61% to $156.6 million. Adjusted EBITDA increased 44% to $358 million. Loan originations reached a record $14.8 billion, while members increased 35% to 15.8 million and deposits reached $45.5 billion. Moreover, at the September 8 Goldman Sachs conference, CFO Chris Lapointe said SoFi generated approximately 40% year-over-year revenue growth in each of the first two quarters and approximately 30% adjusted EBITDA margins. He also said the company had outpaced the Rule of 40 for 20 consecutive quarters. Additionally, the company raised its 2026 adjusted net revenue outlook to $4.75 billion to $4.85 billion but maintained its adjusted EPS outlook at $0.60.
A concern is that SoFi Technologies, Inc.'s (NASDAQ:SOFI) earnings growth may not be sufficient to justify the multiple investors are paying. SoFi is trading at a premium valuation compared to its traditional banking peers, with Yahoo Finance's latest data showing a trailing P/E of 35.12 and a forward P/E of 21.51. That valuation leaves the shares sensitive to a slowdown in earnings growth. Credit performance is another important consideration as SoFi expands its lending business. For the six months ended June 30, total net charge-offs were $406.1 million, up $77.2 million from the prior-year period, while the total net charge-off ratio declined to 1.91% from 2.24%. The increase in charge-offs was driven primarily by higher personal-loan net charge-offs and student-loan net charge-offs, reflecting growth in average loans.
According to Insider Monkey, which tracks more than 1,000 hedge funds, 44 hedge funds held SoFi in Q2, down from 47 in Q1. Its short interest stood at about 14% to 15% of the float. SoFi Technologies, Inc.'s (NASDAQ:SOFI) growth and improving profitability give Cramer's long-term view a fundamental basis, but its valuation still leaves the stock dependent on continued earnings growth. The company's ability to turn strong revenue and loan growth into higher earnings will remain important to the stock's valuation.
#earnings #adjusted #million #charge

1 month ago
Answering a caller's query about The Procter & Gamble Company (NYSE:PG) during the lightning round of the September 10 episode of Mad Money, Jim Cramer said:
It's a tough stock. It's a tough stock because they don't have the growth that I want. They do have the 3% yield, but that's not enough. So, I'm going to say, you know, we sold it for the club. Don't look back.
The Procter & Gamble Company's (NYSE:PG) upside relies on elite operational execution and pricing power in high-margin categories. Continuous supply chain savings and an aggressive premiumization push toward items like Tide PODS help protect profitability. Combined with strong free cash flow productivity, management returned roughly $15 billion in FY 2026 through dividends and share buybacks, ensuring a steady earnings floor despite slow top-line growth.
The primary headwind is weak top-line momentum, with organic sales flat in the second quarter as challenging consumer trends, particularly in the U.S., weighed on growth. Foreign exchange friction and cost pressures further cap near-term earnings acceleration. Additionally, while the stock offers a reliable 3% dividend yield, that income profile creates a steep opportunity cost when risk-free ******* ets and higher-growth stocks offer attractive returns. We recently discussed what Cramer thinks is the ideal valuation for a good entry point in our article, "Jim Cramer Discusses Procter & Gamble (PG) Valuation and Growth."
According to Insider Monkey's data, 83 hedge funds had a stake in The Procter & Gamble Company (NYSE:PG) in Q2 compared to 78 in the prior quarter. Short percentage of the float is 1.21%, showing its status as a defensive holding rather than a short target. While the company provides exceptional balance sheet stability and reliable cash returns for defensive portfolios, its modest top-line growth trajectory and premium valuation continue to test investor patience, validating Cramer's decision to reallocate capital toward faster-moving opportunities.
#company

1 month ago
Inquiring about Walmart Inc. (NASDAQ:WMT) on September 10, a caller asked if they should "keep it." Mad Money host Jim Cramer replied:
I got to tell you, this one is a short and long-term, okay? Short-term, I think I know what Walmart's doing. I think that they're letting their customers have a big break. They're not passing along all of these costs. That is going to earn them tremendous love when things get better. So the wise situation is to say this: Walmart trades at 36 times earnings. It deserves to trade lower just because of what's happening at the company now and higher what's happening at the company when this inflation bout ends. So you buy some at $106, $105, and then buy some at $95. And yes, it could trade to $95. It does not have yield support. This is not like Target, which had that yield support. Target's doing better than Walmart right now. It is.
Walmart Inc.'s (NASDAQ:WMT) second-quarter fiscal 2027 revenue rose 5.9% year over year to $187.9 billion, while global e-commerce sales increased 23%. Global advertising revenue rose 38%, and membership-fee revenue increased 17% globally. Walmart U.S. comparable sales, excluding fuel, grew 2.6%. The company is also using tariff refunds to support lower prices. It said tariff refunds increased its gross profit rate during the quarter, while price investments partially offset the benefit.
Target Corporation (NYSE:TGT) has stronger recent comparable-sales momentum. Its second-quarter sales rose 5.3%, comparable sales increased 3.8%, and traffic rose 3.6%. The company also raised its full-year sales-growth outlook to approximately 5%. Its second-quarter GAAP and adjusted EPS were $4.11, including a $1.65 benefit from tariff refunds. Excluding tariff refunds, GAAP and adjusted EPS increased 20% year over year. CEO Michael Fiddelke said Target had reduced prices on more than 10,000 frequently purchased items over the past year and acknowledged that "there's still meaningful work ahead."
Walmart Inc.'s (NASDAQ:WMT) biggest risk is valuation. Its premium forward PE of 36.76 leaves the stock more exposed if U.S. comparable-sales growth remains modest while the company continues investing in prices. Walmart's 2.6% U.S. comparable-sales growth also trails Target's 3.8%.
#increased #rose
1 month ago
During the September 10 episode of Mad Money, a caller inquired about Mad Money host Jim Cramer's confidence that Arista Networks, Inc. (NYSE:ANET) will not go down the same path as Ciena Corporation. He replied:
Okay, so let me just tell you, Arista is up a lot this year. My confidence is with Jayshree Ullall. I think she's amazing and I think it every time the stock has dipped, if you've noticed it. Since her tenure began, you have to buy it, and I'm not backing away from that. I feel the same way I do now, the way I did, oh man, how many years ago when we first met her. She is money, and the company's fantastic.
In its second quarter, the company shattered records by delivering its first-ever $3 billion quarter, reporting $3.036 billion in revenue, a 38% year-over-year and over 12% sequential increase. Management lifted its full-year 2026 revenue guidance to approximately $12.6 billion, representing roughly 40% annual top-line growth. The acceleration is supported by deep integration into cloud architectures, where Arista Networks, Inc. (NYSE:ANET) expects its dedicated AI fabrics revenue to reach at least $3.5 billion in 2026, supported by more than 100 **** ulative Etherlink customers.
Bottom-line performance remains equally strong, with non-GAAP diluted earnings per share reaching $1.02, driven by a 49.9% non-GAAP operating margin and $1.3 billion in non-GAAP quarterly net income. Arista Networks, Inc. (NYSE:ANET) ended the quarter with roughly $13.3 billion in cash and marketable securities, offering substantial liquidity. However, its $9.7 billion of non-cancellable purchase commitments also increase working-capital and inventory risk as the company secures components ahead of expected AI demand.
The company's financial results remain heavily tied to two hyperscale customers. According to its 10-K filings, Microsoft accounted for 26%, and Meta Platforms generated 16% of total revenue in fiscal 2025, bringing combined spending from these two cloud giants to 42%. It leaves Arista Networks, Inc. (NYSE:ANET) vulnerable to sudden capital expenditure adjustments, vendor diversification shifts, or project delays by its core buyers.
#billion #NYSE #year
1 month ago
On September 10, a caller outlined a detailed financial thesis showing Micron Technology, Inc. (NASDAQ:MU) reaching $1,400 and asked whether the **** ysis held water. In response, Mad Money host Jim Cramer said:
I mean, that's a remarkable **** ysis. It's spot on in every single number. Every single thing you said is true, which is why my Charitable Trust owns it, and why we are buying it aggressively. And by the way, can I just say if you listen to what… [the caller] said, he put some money away. He was fortunate enough to have money, which I know not everybody can have, but he had money. He put it in an individual stock. Now, if he put it in an index fund, he'd make some money, but he got really rich. And part of my job is not just to get you rich, but to hopefully get you really rich.
Micron Technology, Inc. (NASDAQ:MU) stands as one of three primary global manufacturers of dynamic random-access memory (DRAM) and NAND flash memory, positioning it at the center of the ongoing expansion in artificial intelligence infrastructure. Because advanced AI workloads require significantly higher memory bandwidth, demand has surged for Micron's High-Bandwidth Memory (HBM3E) architecture, which is integrated directly into top-tier AI graphics processors and data center accelerators. With memory production capacity for advanced AI chips remaining constrained industry-wide, Micron has secured long-term purchase agreements that cover its HBM output through 2026 and into 2027, providing visibility into top-line revenue growth.
Driven by accelerated AI server adoption and broader pricing recovery across traditional DRAM and NAND markets, it reported extraordinary growth in fiscal Q3. Revenue surged to $41.46 billion, more than quadrupling the $9.30 billion generated in the same period last year and stepping up sharply from $23.86 billion in the prior quarter. The company demonstrated exceptional operating leverage during the period, posting GAAP net income of $28.24 billion ($24.67 per diluted share) and non-GAAP net income of $28.86 billion ($25.11 per diluted share). Operating cash flow also scaled quickly, reaching $25.39 billion compared to $11.90 billion in the prior quarter and $4.61 billion in the prior-year period.
Despite its strong position in the AI supply chain, Micron Technology, Inc. (NASDAQ:MU) operates in a historically cyclical memory industry with some operational and market risks. Memory chip pricing remains sensitive to industry-wide supply-and-demand imbalances, where oversupply can rapidly compress profit margins during broader downturns in consumer electronics demand or corporate IT spending.
#billion #memory #NASDAQ #industry

1 month ago
During the September 10 episode of Mad Money, a caller questioned whether recent vertical integration by industrial competitors and market selloffs warranted a lower valuation for Howmet Aerospace Inc.'s (NYSE:HWM) economic moat, or if demand remained strong enough to make the pullback an overreaction. Jim Cramer replied:
Now, look, I'll tell you, here's the problem… It's a fastener company, and it frankly is, most times, very commodity-oriented business, and it happens to sell at 44 times earnings, and we don't want to pay that for commodities even though the business is strong. I think people are saying, "Wait a second, that's too much to pay, and I'm going to wait till it goes lower." And if you look at the chart, it does seem like it is going lower.
Howmet Aerospace Inc. (NYSE:HWM) occupies a sole-source or primary-supplier position across critical narrowbody and widebody aircraft programs, providing single-crystal turbine blades, advanced structural castings, and **** anium fasteners. Approval and qualification requirements, manufacturing complexity, and a limited supplier base can make alternative sources difficult to establish quickly. That gives the company strong pricing power on both new plane parts and higher-margin replacement spares.
The structural advantages of Howmet Aerospace Inc.'s (NYSE:HWM) business model can be seen in its Q2 financial results. Revenue surged over 24% year-over-year (21% organically) to $2.55 billion, driven by a 28% jump in commercial aerospace revenue, a 38% expansion in industrial gas turbines, and an 11% gain in defense aerospace. The core Engine Products division recorded third-party sales of $1.37 billion, up 32% year-over-year, while segment adjusted EBITDA margins expanded by 470 basis points to 37.7%.
Despite its market positioning, Howmet Aerospace Inc. (NYSE:HWM) carries valuation risks that advise a cautious approach. Trading at elevated EV/EBITDA and forward P/E multiples relative to traditional industrial peers, the stock leaves little margin for operational missteps. Capital expenditures are projected to exceed $500 million in 2026 as the company builds out production capacity for next-generation engine components and gas turbines, reducing near-term free cash conversion flexibility.
#lower #ebitda
1 month ago
Packers news: Will Jordan Love survive Green Bay's o-line? Dan Orlovsky has concerns appeared first on ClutchPoints. Add ClutchPoints as a Preferred Source by clicking here.
After allowing 22 unanswered points in the fourth quarter on Sunday, the Green Bay Packers suffered a 39-22 Week 1 loss to the Minnesota Vikings. While there were some bright spots throughout the contest, one notable weakness was the pass protection. It was so poor that former quarterback turned NFL ***** yst Dan Orlovsky revealed he's concerned about Jordan Love for the rest of the season.
During ESPN's pregame show for "Monday Night Football," Orlovsky implored that the Packers' offensive line has to improve. If not, the club's 27-year-old signal-caller may not survive the 2026-27 campaign.
"He won't survive," Orlovsky said. "This offensive line, if they don't get better, [Jordan Love] won't survive. The only reason it's even a game is because he was sensational early on. I mean, just unbelievable throw after unbelievable throw… I think the most concerning thing is it was, overall, team-wise, [a] very undisciplined performance… [A] divisional opponent that [Matt] LaFleur and them should know better.
Watch sports LIVE with fuboTV (free trial)
#green #clutchpoints

1 month ago
Dave Ramsey told caller Hazel her secret teen payments aren't a money problem but a marriage problem requiring full financial transparency and counseling.
Secret spending makes joint wealth-building impossible. Hiding $400 monthly from a spouse means losing its compounding potential in a Roth IRA or 529.
Transparency alone flips the outcome: a joint kid-support budget lets both spouses plan together, while secret contributions force decisions based on false information.
Read More: Learn 7 ways to generate income with a $1,000,000+ portfolio (sponsor)
On the September 9 episode of The Ramsey Show, a caller named Hazel admitted she has been slipping money to her three teenagers from a prior marriage, quietly, from her own account, because her husband of almost seven years refuses to help pay for their sports and school costs. Dave Ramsey did not reach for a spreadsheet. He told her: "You don't have a combining money problem and you don't have a who pays for what problem. You have a marriage problem."
#problem #secret

1 month ago
Toward the end of the lightning round on September 8, when a caller inquired about AstraZeneca PLC (NYSE:AZN), Mad Money host Jim Cramer commented:
Alright, now, AstraZeneca reminds me of a company, it's not unlike Novartis. I'm a little nervous about it. It's been missing some of its trials. I don't think COPD is enough to change my mind… I am not going to put my money on AstraZeneca.
AstraZeneca PLC (NYSE:AZN) maintains a solid financial foundation supported by steady top-line growth and disciplined cost management. In its second-quarter report, the company generated total revenue of $15.38 billion, marking a 6.4% increase compared to the same period last year. Adjusted earnings per share reached $2.63, outperforming ****** yst consensus estimates.
The profitability was driven by strong global demand for core oncology and rare disease treatments, which successfully offset revenue headwinds from generic competition affecting older blockbusters like Farxiga and Brilinta. With a net margin hovering around 17.02% and management reiterating its full-year guidance for mid-to-high single-digit revenue growth along with low double-digit core EPS expansion, the core business continues to demonstrate commercial resilience.
The primary driver behind the skepticism could be based on tangible execution risks and regulatory hurdles that threaten AstraZeneca PLC's (NYSE:AZN) long-term top line. A significant blow to the rare disease division came when anselamimab failed to achieve statistical significance for the primary endpoint in the overall AL amyloidosis population in the Phase III CARES program, although AstraZeneca reported encouraging results in a prespecified subgroup of patients with kappa light-chain amyloidosis.
#management
1 month ago
On September 8, a caller inquired if Trinity Industries, Inc. (NYSE:TRN) is worth looking at after its recent pullback. Mad Money host Jim Cramer replied:
Yes, Railcar, shouldn't be down this much. I like your thinking. You waited for the big hit. Now, it's in a good place. I would pull the trigger.
Trinity Industries, Inc. (NYSE:TRN) has faced a sharp correction, pulling back significantly from its 52-week high of $38.31. Despite this downward pressure, the company's fundamental **** et base remains exceptionally stable. In its second-quarter earnings report, the company posted total revenues of $485 million and diluted earnings per share from continuing operations of $1.25, with earnings benefiting from a $132 million non-cash pre-tax gain tied to the Napier Park railcar partnership transaction.
The leasing and services segment continues to support the business, posting a robust fleet utilization rate of 97.3% and an improved lease renewal success rate of 75%. In addition, the Future Lease Rate Differential improved to +3.5%, showing healthy pricing power on expiring contracts. Management reaffirmed its full-year EPS guidance of $2.20 to $2.40, supported by a solid railcar backlog standing at $1.6 billion.
The primary catalyst for Trinity Industries, Inc.'s (NYSE:TRN) recent sell-off stems from margin compression within the Rail Products manufacturing division. Operating margins in manufacturing faced pressure from an unplanned production interruption at the Longview manufacturing facility and temporary realignment expenses tied to the company's Mexican footprint. These localized execution issues overshadowed a strong quarterly performance in leasing, causing the stock to drift below both its 50-day and 200-day moving average.
#trinity
1 month ago
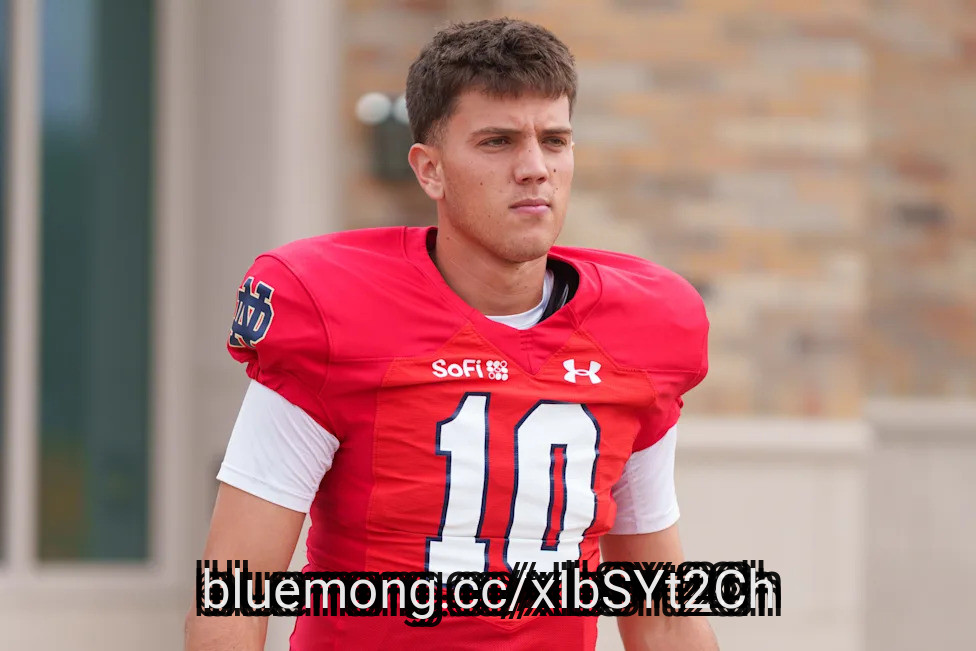
SOUTH BEND — Notre Dame football's trio of backup quarterbacks entered the 2026 season with zero college snaps to their credit.
That changed Saturday, Sept. 12 against overmatched Rice, when preseason Heisman Trophy candidate CJ Carr gave way to No. 2 quarterback Noah Grubbs with the Irish leading 49-0 at the 9:22 mark of the third quarter.
Here are three things to know about Grubbs, a freshman from Lake Mary, FL.
No, he isn't. At 6-foot-4 and 210 pounds, Grubbs' physical measurements are an exact match for fellow first-year signal caller Teddy Jarrard.
Both Carr and second-year man Blake Hebert are listed at 6-2 and right around the same weight: Carr tips the scales at 215 pounds while Hebert is listed at 216.
#pounds
1 month ago
We've got a game that counts on our hands Sunday afternoon, when the Commanders play the Eagles in Philadelphia.
In a word: Finally.
The 2026 NFL regular season is here, where we finally see what all those free-agent signings, NFL draft picks new play callers can do for a Commanders team looking to rebound from a 5-12 showing.
Starting the season against host Philadelphia is no easy task. It will require quality and consistent execution from both sides of the football, winning tough matchups and finding a way to pull through at the end.
We could pick darn near anyone as a key player in this matchup, but we'll stick to five Commanders (not named Jayden Daniels) to watch heading into this NFC East clash:
#Eagles #starting

1 month ago
When you're overmatched as the Carolina Panthers may be on Sunday against the Chicago Bears—sometimes, you have to pick your battles. Stopping everything that head coach and play-caller Ben Johnson wants to do offensively simply isn't realistic given the schematic and talent mismatch on that side of the ball.
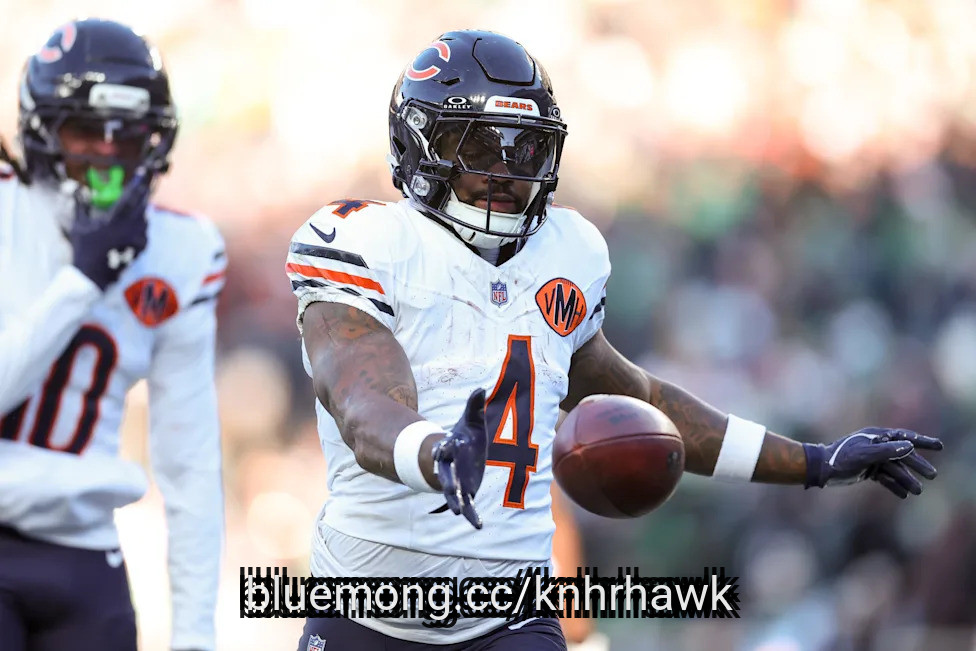
However, if the Panthers are going to defy the odds and their sorry Week 1 history to pull off a win, they have to find a way to make Chicago's offense one-dimensional. And the quickest way to do that is by shutting down the Bears' ground game, which is led by running back D'Andre Swift.
Last season, Swift led the Bears with 1,087 rushing yards and nine touchdowns. Backup Kyle Monangai ranked second with 783 rushing yards to go with five scores on the ground. As a team, Chicago ranked third in the NFL with 144.5 rushing yards per game.
Containing that potent rushing attack will be easier said than done, but it's critical that the Panthers find a way to do so. While defensive coordinator Ejiro Evero will direct the symphony from the sideline, it'll be Pro Bowl inside linebacker Devin Lloyd—who was signed to a three-year, $42 million pact this offseason—who shoulders most of the responsibilities on the field.
Lloyd will likely be the first defender to meet Swift or Monangai once they break past the line of scrimmage, and how well he tackles will play a big role in deciding who wins those matchups.
#swift #rushing #monangai
1 month ago
Texas A&M's six remaining home games during the 2026 season will serve as critical recruiting opportunities for coach Mike Elko and his staff, especially in the 2028 recruiting cycle, as five-star quarterback Donald Tabron III and four-star Edge Chance Archangel serve as the lone commits in the class and will make their way back to campus this fall.
Plenty of intriguing names in the cycle will visit this weekend when the Aggies host Arizona State on Saturday afternoon, while five-star wide receiver Braylon Clark recently placed Texas A&M in his top 12 program list and will visit College Station on October 3 when the Aggies host Arkansas.
Under Mike Elko, Texas A&M has developed NFL talent at nearly every position, especially after a record-tying 10 players were selected in the 2026 NFL Draft back in late April. Elko's background as one of the best defensive coordinators in the country, currently serving as the Aggies' defensive playcaller, has continued to make its way to the eyes and ears of up-and-coming defenders, including 2028 four-star Edge David Dotson.
During his recent interview with Rivals insider Sam Spiegelman, Dotson named Texas A&M among several programs that "have his attention" heading into the fall months.
"Texas, Oklahoma, SMU, Texas A&M, Ohio State, Michigan, Georgia, LSU, and Alabama all have my attention," Dotson continued. "They've each shown me why they want me and how I could fit into their program. The relationships with the coaches, player development, culture, academics, and overall fit are all important to me."
#star #aggies #elko


1 month ago
The Philadelphia Eagles enter Week 1 as favorites over the Washington Commanders, but divisional familiarity and several offseason changes could make Sunday's opener difficult.
Here are five concerns entering the matchup.
Daniels can extend plays and punish undisciplined pass-rush lanes. Philadelphia must pressure him without creating easy escape routes.
The Commanders ranked fourth with 134.7 rushing yards per game, while Philadelphia finished 22nd in run defense. Jacory Croskey-Merritt, Rachaad White and Daniels give Washington several options.
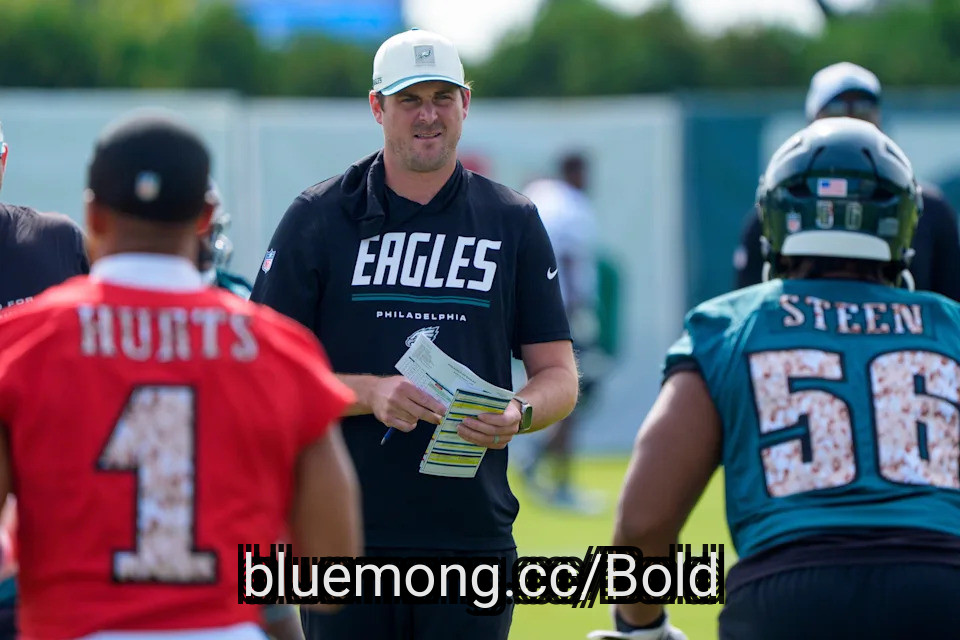
The Eagles are playing their first meaningful game with Sean Mannion calling plays. Hurts must adjust to having his offensive coordinator in the booth as the unit establishes its identity under a new play-caller.
#Eagles #plays

1 month ago
As players, David Blough and Sean Mannion never played together, or faced off against each other, not as starting quarterbacks, anyway. But they're set to square off in Week 1 as two of the most intriguing — and most untested — offensive coordinators in the NFL this season as Blough's Washington Commanders open the 2026 NFL season on the road against Mannion's Philadelphia Eagles.
Both were career backup quarterbacks, with a combined 10 NFL starts between them. Each spent time on three or more teams' rosters and practice squads as players. Blough once essentially replaced Mannion with the Minnesota Vikings in 2022. Both ended their playing days following the 2023 season, transitioned to coaching and have been thrust into coveted OC roles early in their coaching careers — and both before the age of 35. They're part of a new group of younger and inexperienced play-callers.
Are they ready for the challenge? Their paths to answering that question start Sunday at Lincoln Financial Field.
They've worked with some of the same coaches throughout their career, or at least some of the same core offensive philosophies. Some of the challenges they're facing in their new jobs and the ideas they want to incorporate are similar, too.
Join or create a Yahoo Fantasy Football league for the 2026 NFL season
#offensive #Career #same

1 month ago
On September 3, a caller asked whether to rotate out of artificial intelligence stocks and add to Eli Lilly and Company (NYSE:LLY) rather than chase Johnson & Johnson (NYSE:JNJ) or Cardinal Health (NYSE:CAH). Mad Money host Jim Cramer said:
Well, I'll tell you… I think it's always good to look at Lilly as a stock that I think has a lot of things that are going well, but I want to wait. Well, actually, you know, tell you the truth… It's pulled back. I think you're fine, I think you're fine to add some. I'm going to okay that. And I understand JNJ's moved a great deal. It's been a great club hit and Cardinal has been terrific, too. So, thank you for referencing those two really good ones.
Cramer was also asked to rank J&J, Lilly, and Pfizer Inc. (NYSE:PFE) by another caller. He said:
Okay, so let's take them. J&J is best of breed, AAA balance sheet, 18 drugs… You're not going to have any expiration problems, okay? Lilly has one huge drug that we know is going to be a franchise for many, many years. I do like a diversifying pattern more. And Pfizer's starting to creep up and is playing catch-up, but I need a reason to recommend it. So I'm going to say J&J and Lilly and then Pfizer.
The latest results largely explain the differences in Cramer's ranking. Eli Lilly and Company (NYSE:LLY) has the strongest growth profile by a wide margin. Second-quarter revenue jumped 48% to $23 billion, while reported EPS increased 26% to $7.94 and non-GAAP EPS rose 33% to $8.38. Mounjaro revenue rose 91% to $9.9 billion, while US Zepbound revenue increased 44% to $4.9 billion. The company also raised its 2026 revenue guidance to $85 billion-$87 billion.
#NYSE #billion #company #well

1 month ago
Answering a caller's query about Box, Inc. (NYSE:BOX) during the lightning round of Mad Money on September 3, Jim Cramer commented:
Box is finally, after multiple years, it is finally breaking out. It has good storage. People like storage. It's got a good CEO in Aaron Levie. It's just never been exciting to people. It's finally starting to get some mojo. I think it's okay to own. It's done nothing for years.
Cramer's perspective highlights a shifting narrative for a cloud pioneer that has historically traded in a tight range. In its fiscal second-quarter 2027 report, Box, Inc. (NYSE:BOX) posted revenue of $321.1 million, marking a 9.2% year-over-year increase that topped Wall Street expectations by over $2 million. Adjusted earnings per share reached $0.40, in line with consensus forecasts, while management raised full-year revenue guidance to approximately $1.29 billion. The core demand is supported by expanding adoption of higher-tier Box Suites, which now account for 69% of revenue, along with early traction in AI-driven document tools that help enterprises modernize legacy storage workflows.
Despite recent top-line acceleration, Box, Inc. (NYSE:BOX) operates in a fiercely competitive market dominated by massive tech ecosystems like Microsoft OneDrive and Google Drive, and other specialized rivals such as Dropbox. While quarterly growth has stabilized, Box's multi-year annual growth rate has historically lagged behind high-flying software peers. Furthermore, Box still needs to sustain its recent growth acceleration while investing in AI capabilities.
As per Insider Monkey's data of over 1000 hedge funds, 37 hedge funds had a stake in Box, Inc. (NYSE:BOX) in Q2 compared to 36 in Q1, highlighting steady institutional backing from long-term ***** et managers. Arrowstreet Capital remained the company's top hedge fund holder in Q2 with 4.3 million shares. Additionally, it is worth noting that another significant shareholder, Citadel Investment Group increased its position in the stock by 60% to over 3.7 million shares. The short percentage of float sits at 14.26%, which shows a notable segment of the market remains unconvinced about the sustainability of the breakout.
#NYSE #year #people