7 hours ago
For the recently reported second quarter, PicS N.V. (NASDAQ:PICS) outperformed relative to its previous guidance across all profitability metrics. The total account base for the company went up to 70.4 million during the second quarter, showcasing a 10% jump from the prior year. Moving on to the bottom line figures, the adjusted earnings before tax, without factoring in costs ****** ociated with stock-based compensation came in at R$291 million for the quarter. This represented a 2.1% outperformance relative to the company's R$285 million guidance. Similarly, compared to the R$245 million projection, adjusted net income for the period actually stood 15.5% higher at R$283 million.
welcomia/Shutterstock.com
The second quarter concluded with strong financial and operating momentum for PicS. The company recorded a 9% annual and 2% sequential growth in its client base, which went up to 45.4 million active users. The total credit portfolio jumped to R$31.9 billion, exceeding management's guidance by 3%. This outperformance came due to a higher number of mature credit card cohorts, and accelerated origination within secured and partly secured categories. An additional factor that accounted for the credit portfolio growth was management's measured expansion into higher risk areas such as newer platform credit and private payroll lending.
Managerial revenue rose to R$3,730 million, topping guidance by 3.6%, and net interest income reached R$2,002 million, 5.4% above projections, boosted by growing credit income. Total cash in totaled R$136.4 billion, up 17% from a year earlier and 9% from the previous quarter, with customers bringing in an average of approximately R$45.4 billion to the platform each month. Total deposits climbed to R$35.8 billion, a 45% yearly jump and 10% quarterly rise.
Some concerns related to the company's loan portfolio emerged during the quarter. Non-performing loans more than 90 days overdue increased to 9.8% of the credit portfolio during the quarter, up 93 basis points sequentially. Stage 3 exposure, which includes a broader set of credit-impaired loans, reached 12.9% of the total credit portfolio.
#million #total
welcomia/Shutterstock.com
The second quarter concluded with strong financial and operating momentum for PicS. The company recorded a 9% annual and 2% sequential growth in its client base, which went up to 45.4 million active users. The total credit portfolio jumped to R$31.9 billion, exceeding management's guidance by 3%. This outperformance came due to a higher number of mature credit card cohorts, and accelerated origination within secured and partly secured categories. An additional factor that accounted for the credit portfolio growth was management's measured expansion into higher risk areas such as newer platform credit and private payroll lending.
Managerial revenue rose to R$3,730 million, topping guidance by 3.6%, and net interest income reached R$2,002 million, 5.4% above projections, boosted by growing credit income. Total cash in totaled R$136.4 billion, up 17% from a year earlier and 9% from the previous quarter, with customers bringing in an average of approximately R$45.4 billion to the platform each month. Total deposits climbed to R$35.8 billion, a 45% yearly jump and 10% quarterly rise.
Some concerns related to the company's loan portfolio emerged during the quarter. Non-performing loans more than 90 days overdue increased to 9.8% of the credit portfolio during the quarter, up 93 basis points sequentially. Stage 3 exposure, which includes a broader set of credit-impaired loans, reached 12.9% of the total credit portfolio.
#million #total

16 hours ago
On September 15, Jazz Pharmaceuticals plc (NASDAQ:JAZZ) completed its acquisition of privately held Actio Biosciences for $820 million upfront, adding a clinical-stage epilepsy drug called ABS-1230 to its rare disease pipeline. The deal lands weeks after Jazz posted its highest quarterly revenue ever on August 3, and raised its full-year guidance, so a fresh acquisition now sits on top of a business that was already accelerating. The question for investors is whether that combination adds up to durable growth or just a bigger bill.
ABS-1230 targets KCNT1-related epilepsy, a rare and hard-to-treat form of the disease. In an early clinical proof-of-concept trial, children who received the drug experienced meaningful seizure reductions, and preclinical testing showed it inhibited KCNT1 across every pathogenic mutation researchers evaluated, hinting it could work across the whole patient population rather than a narrow subset. The FDA has already granted ABS-1230 Orphan Drug, Rare Pediatric Disease and Fast Track designations, and accepted it into the agency's Rare Disease Evidence Principles process, a set of regulatory advantages that can speed a drug toward approval.
The acquisition also arrives while Jazz's existing business is firing on multiple cylinders. Second-quarter revenue climbed 16% year over year to $1.2 billion, the company's highest quarterly total on record, and management raised full-year 2026 revenue guidance to a range of $4.6 billion to $4.75 billion. Growth was not confined to one product. Xywav sales rose 13% to $471 million on 525 net new patients, Epidiolex grew 16% to $292 million, and Zepzelca jumped 42% to $106 million. Zanidatamab, sold as Ziihera in biliary tract cancer, also received Breakthrough Therapy designation from the FDA for a form of colorectal cancer, adding another avenue for the oncology franchise Jazz has been building beyond its epilepsy and sleep businesses.
None of that came free. The $820 million upfront payment for Actio lands on top of $4.4 billion in long-term debt that Jazz already carried as of June 30, even after the company used part of its cash to repay $1.0 billion of exchangeable notes that matured this year. Cash, equivalents and investments stood at $2.2 billion at that point, meaning the Actio payment alone accounts for a meaningful share of the company's liquid resources.
Jazz's recent history also shows how acquisitions can distort the bottom line before they pay off. A $905.4 million in-process research and development charge tied to the 2025 Chimerix acquisition pushed second-quarter 2025 GAAP earnings to a loss of $11.74 per share, and a smaller $77 million IPR&D charge from the AbCellera and Werewolf deals still dented second-quarter 2026 results. ABS-1230 itself remains early, with only proof-of-concept data in hand and no late-stage trial results yet. The portfolio is not without setbacks, either. Jazz is moving to voluntarily drop the second-line indication for Zepzelca in meta
ABS-1230 targets KCNT1-related epilepsy, a rare and hard-to-treat form of the disease. In an early clinical proof-of-concept trial, children who received the drug experienced meaningful seizure reductions, and preclinical testing showed it inhibited KCNT1 across every pathogenic mutation researchers evaluated, hinting it could work across the whole patient population rather than a narrow subset. The FDA has already granted ABS-1230 Orphan Drug, Rare Pediatric Disease and Fast Track designations, and accepted it into the agency's Rare Disease Evidence Principles process, a set of regulatory advantages that can speed a drug toward approval.
The acquisition also arrives while Jazz's existing business is firing on multiple cylinders. Second-quarter revenue climbed 16% year over year to $1.2 billion, the company's highest quarterly total on record, and management raised full-year 2026 revenue guidance to a range of $4.6 billion to $4.75 billion. Growth was not confined to one product. Xywav sales rose 13% to $471 million on 525 net new patients, Epidiolex grew 16% to $292 million, and Zepzelca jumped 42% to $106 million. Zanidatamab, sold as Ziihera in biliary tract cancer, also received Breakthrough Therapy designation from the FDA for a form of colorectal cancer, adding another avenue for the oncology franchise Jazz has been building beyond its epilepsy and sleep businesses.
None of that came free. The $820 million upfront payment for Actio lands on top of $4.4 billion in long-term debt that Jazz already carried as of June 30, even after the company used part of its cash to repay $1.0 billion of exchangeable notes that matured this year. Cash, equivalents and investments stood at $2.2 billion at that point, meaning the Actio payment alone accounts for a meaningful share of the company's liquid resources.
Jazz's recent history also shows how acquisitions can distort the bottom line before they pay off. A $905.4 million in-process research and development charge tied to the 2025 Chimerix acquisition pushed second-quarter 2025 GAAP earnings to a loss of $11.74 per share, and a smaller $77 million IPR&D charge from the AbCellera and Werewolf deals still dented second-quarter 2026 results. ABS-1230 itself remains early, with only proof-of-concept data in hand and no late-stage trial results yet. The portfolio is not without setbacks, either. Jazz is moving to voluntarily drop the second-line indication for Zepzelca in meta


16 hours ago
Picture a snowy mountain slope in France or an elite tennis court during a grand slam. Whether it is an Arc'teryx jacket designed for the harshest alpine conditions or a Wilson racket in the hands of a professional, Amer Sports (NYSE:AS) equips the world's most demanding athletes. The company functions as a global powerhouse in athletic gear and apparel, operating a premium multi-brand platform that spans from high-end technical clothing to specialized sports equipment. With its current stock price at $27.26 as of Sept. 16, 2026, the company has seen the stock decline 26% over the past year, reflecting the market's digestion of its rapid post-IPO scaling.
Our proprietary Hidden Gems scoring system **** igns Amer Sports an overall Superscore of 75 out of 100, placing it in the Above Average category. This score ranks the company in the Top ~21% of every company we evaluate, ahead of roughly 79 out of every 100 firms we score. The Superscore serves as a data-driven starting point, and this article examines both the operational momentum fueling its recent success and the structural hurdles that keep the company below top-tier rankings, helping you weigh these signals against your own research.
Strong revenue momentum: The company achieved 27% year-over-year revenue growth in 2025, reaching $6.6 billion as it successfully scaled its brand-led platform across global markets.
Effective channel pivot: Direct-to-consumer revenue surged 43% in 2025, allowing the company to capture higher margins and deepen its direct relationship with premium consumers.
Expanding operational efficiency: Adjusted EBITDA margins widened to 18% in 2025, demonstrating that the company's shared infrastructure strategy is successfully converting scale into bottom-line profitability.
#company #sports #global #premium
Our proprietary Hidden Gems scoring system **** igns Amer Sports an overall Superscore of 75 out of 100, placing it in the Above Average category. This score ranks the company in the Top ~21% of every company we evaluate, ahead of roughly 79 out of every 100 firms we score. The Superscore serves as a data-driven starting point, and this article examines both the operational momentum fueling its recent success and the structural hurdles that keep the company below top-tier rankings, helping you weigh these signals against your own research.
Strong revenue momentum: The company achieved 27% year-over-year revenue growth in 2025, reaching $6.6 billion as it successfully scaled its brand-led platform across global markets.
Effective channel pivot: Direct-to-consumer revenue surged 43% in 2025, allowing the company to capture higher margins and deepen its direct relationship with premium consumers.
Expanding operational efficiency: Adjusted EBITDA margins widened to 18% in 2025, demonstrating that the company's shared infrastructure strategy is successfully converting scale into bottom-line profitability.
#company #sports #global #premium


16 hours ago
On August 6, Millicom International Cellular (NASDAQ:TIGO) released its second-quarter 2026 results, and the numbers pulled in two directions at once. Revenue jumped 59.4% year over year to $2.18 billion, while Adjusted EBITDA crossed $1 billion for the first time in the company's history at $1.01 billion, up 58% from a year earlier. Yet net profit attributable to company owners fell 83.9% to just $109 million. Investors weighing this quarter have to decide which of those two stories actually describes the business.
The headline figures are hard to ignore. Service revenue reached $2.04 billion in the quarter, up 60.1% year over year, while H1 2026 revenue climbed to $4.16 billion from $2.74 billion a year earlier, a 52.3% increase. Equity free cash flow hit a quarterly record of $327 million, up 50.1% from a year ago, and leverage actually fell to 2.73x even after Millicom absorbed acquisitions in Colombia, Ecuador and Uruguay. That combination, rising cash generation alongside falling leverage during an acquisition spree, is the kind of signal that tends to matter more than a single quarter's headline growth rate.
Management is backing that signal with cash. Millicom already declared a $3.00 per share dividend in May, to be paid out quarterly over the next 12 months, and on August 5, the board approved an additional interim dividend of $1.50 per share, split into two $0.75 installments due January 15, 2027, and April 15, 2027. The company also raised its full-year 2026 equity free cash flow guidance from at least $900 million to around $1.1 billion, while lowering its year-end leverage target from about 2.5x to below 2.5x. CEO Marcelo Benitez pointed to Ecuador and Uruguay as evidence the integration playbook works, saying both markets have reached margins and cash generation broadly in line with the Millicom average, with Colombia and Chile now showing early improvement on the same path.
Strip out the acquisitions, and the picture looks far less dramatic. Organic revenue growth was just 4.3% in the quarter and 4.2% for the first half, a fraction of the 59.4% and 52.3% reported figures. Most of what shows up in the headline number is Millicom buying its way to a bigger top line, not the existing business accelerating on its own.
The profit line raises a separate question. Net profit attributable to company owners dropped to $109 million from $676 million a year earlier, and the first-half figure fell 74.9% to $218 million from $869 million, even as EBITDA and cash flow set records over the same stretch. That gap between a surging EBITDA number and a collapsing bottom line is the kind of divergence that deserves scrutiny rather than a shrug. Capital spending is climbing too, up 51.2% to $234 million in the quarter and 48.8% to $426 million for the half, running well ahead of the organic growth rate it is meant to fund. And the balance sheet is still in motion: in July 2026, Bolivia took on five new local bank loans totaling roughly $44 millio
The headline figures are hard to ignore. Service revenue reached $2.04 billion in the quarter, up 60.1% year over year, while H1 2026 revenue climbed to $4.16 billion from $2.74 billion a year earlier, a 52.3% increase. Equity free cash flow hit a quarterly record of $327 million, up 50.1% from a year ago, and leverage actually fell to 2.73x even after Millicom absorbed acquisitions in Colombia, Ecuador and Uruguay. That combination, rising cash generation alongside falling leverage during an acquisition spree, is the kind of signal that tends to matter more than a single quarter's headline growth rate.
Management is backing that signal with cash. Millicom already declared a $3.00 per share dividend in May, to be paid out quarterly over the next 12 months, and on August 5, the board approved an additional interim dividend of $1.50 per share, split into two $0.75 installments due January 15, 2027, and April 15, 2027. The company also raised its full-year 2026 equity free cash flow guidance from at least $900 million to around $1.1 billion, while lowering its year-end leverage target from about 2.5x to below 2.5x. CEO Marcelo Benitez pointed to Ecuador and Uruguay as evidence the integration playbook works, saying both markets have reached margins and cash generation broadly in line with the Millicom average, with Colombia and Chile now showing early improvement on the same path.
Strip out the acquisitions, and the picture looks far less dramatic. Organic revenue growth was just 4.3% in the quarter and 4.2% for the first half, a fraction of the 59.4% and 52.3% reported figures. Most of what shows up in the headline number is Millicom buying its way to a bigger top line, not the existing business accelerating on its own.
The profit line raises a separate question. Net profit attributable to company owners dropped to $109 million from $676 million a year earlier, and the first-half figure fell 74.9% to $218 million from $869 million, even as EBITDA and cash flow set records over the same stretch. That gap between a surging EBITDA number and a collapsing bottom line is the kind of divergence that deserves scrutiny rather than a shrug. Capital spending is climbing too, up 51.2% to $234 million in the quarter and 48.8% to $426 million for the half, running well ahead of the organic growth rate it is meant to fund. And the balance sheet is still in motion: in July 2026, Bolivia took on five new local bank loans totaling roughly $44 millio


20 hours ago
SGOV, JPST, and VTIP create a layered cash reserve covering one to five years, shielding equities from forced sales in a bear market.
Drawdowns from 2000 to 2007 and 2008 to 2013 both lasted multiple years, proving one year of T-bills forces equity sales at the worst possible time.
VTIP adjusts principal with CPI and delivers a 2.42% real yield, protecting purchasing power when inflation surprises retirees in years four and five.
Read More: Learn 7 secret wealth tips high net worth investors use that most investors miss (sponsor)
You retired into a market that rewards patience and punishes forced sellers. The bucket strategy answers a single question: how much of your spending can you cover without touching stocks when the S&P falls 30%? Guess one year, and a prolonged drawdown forces you to sell equities at the bottom. Guess five, and you drag on returns. The middle path is a laddered cash reserve, and three ETFs do the heavy lifting: iShares 0-3 Month Treasury Bond ETF (NYSEARCA:SGOV), JPMorgan Ultra-Short Income ETF (NYSEARCA:JPST), and Vanguard Short-Term Inflation-Protected Securities ETF (NASDAQ:VTIP).
#vtip
Drawdowns from 2000 to 2007 and 2008 to 2013 both lasted multiple years, proving one year of T-bills forces equity sales at the worst possible time.
VTIP adjusts principal with CPI and delivers a 2.42% real yield, protecting purchasing power when inflation surprises retirees in years four and five.
Read More: Learn 7 secret wealth tips high net worth investors use that most investors miss (sponsor)
You retired into a market that rewards patience and punishes forced sellers. The bucket strategy answers a single question: how much of your spending can you cover without touching stocks when the S&P falls 30%? Guess one year, and a prolonged drawdown forces you to sell equities at the bottom. Guess five, and you drag on returns. The middle path is a laddered cash reserve, and three ETFs do the heavy lifting: iShares 0-3 Month Treasury Bond ETF (NYSEARCA:SGOV), JPMorgan Ultra-Short Income ETF (NYSEARCA:JPST), and Vanguard Short-Term Inflation-Protected Securities ETF (NASDAQ:VTIP).
#vtip

22 hours ago
In late 2022, OpenAI released ChatGPT, and within months the bottom rung of the tech-industry career ladder started to disappear. Graduates who majored in computer science and other AI-exposed fields are increasingly missing out on the jobs they trained for, and a chunk of them are landing behind restaurant counters and retail registers instead, according to two Census Bureau papers.
An April 2026 Census paper tracked matched employer-employee records and found that hiring of workers ages 22 to 24 fell sharply in the industries most exposed to AI, while hiring in less-exposed industries held steady. Employment for early-career workers in the most AI-exposed fifth of industries dropped 12% over the ten quarters after ChatGPT's release. Lee Tucker, one of the coauthors of the paper, said "the decline in hires is the primary cause" of that rate of unemployment, not people losing jobs they already had.
That mattered most for one type of graduate. The most AI-exposed industries, Tucker found, cluster heavily around software and information-technology work, which are the very fields computer science and other highly AI-exposed majors are built to feed into.
A second paper from last week, also coauthored by Tucker, follows the graduates of the most AI-exposed decile of college majors. Their odds of holding a job one quarter after graduation fell by five percentage points, and full-quarter initial earnings dropped 13% following ChatGPT's release. A 13% earnings decline is roughly the size economists would expect from graduating into a severe recession—except there wasn't one, since the rest of the labor market held up fine.
Young grads still need to work and still have jobs, even if they've received highly exposed degrees. So the decline in earnings is less about a lack of employment and more about pursuing lower-wage occupations to make ends meet.
#graduates
An April 2026 Census paper tracked matched employer-employee records and found that hiring of workers ages 22 to 24 fell sharply in the industries most exposed to AI, while hiring in less-exposed industries held steady. Employment for early-career workers in the most AI-exposed fifth of industries dropped 12% over the ten quarters after ChatGPT's release. Lee Tucker, one of the coauthors of the paper, said "the decline in hires is the primary cause" of that rate of unemployment, not people losing jobs they already had.
That mattered most for one type of graduate. The most AI-exposed industries, Tucker found, cluster heavily around software and information-technology work, which are the very fields computer science and other highly AI-exposed majors are built to feed into.
A second paper from last week, also coauthored by Tucker, follows the graduates of the most AI-exposed decile of college majors. Their odds of holding a job one quarter after graduation fell by five percentage points, and full-quarter initial earnings dropped 13% following ChatGPT's release. A 13% earnings decline is roughly the size economists would expect from graduating into a severe recession—except there wasn't one, since the rest of the labor market held up fine.
Young grads still need to work and still have jobs, even if they've received highly exposed degrees. So the decline in earnings is less about a lack of employment and more about pursuing lower-wage occupations to make ends meet.
#graduates

2 days ago
Some offers on this page are from advertisers who pay us, which may affect which products we write about, but not our recommendations. See our Advertiser Disclosure.
The Federal Reserve — the country's central bank — periodically adjusts its target rate to keep the economy running smoothly and consumer prices in check. When the federal funds rate moves up or down, so do the interest rates on bank accounts and loans.
In other words, changes in the Fed's rate impact how much your savings can grow and how much you pay to borrow money.
So how does today's federal funds rate compare to past years? Here's a look at historical Fed interest rates so you can better understand how your bottom line is affected.
The federal funds rate is set by the Federal Reserve and dictates what a bank can charge another bank for ultra-short-term loans (usually overnight) in order to meet reserve requirements. It's expressed as a range, and financial institutions can negotiate a specific rate between each other within that range.
#reserve #funds #rates #range
The Federal Reserve — the country's central bank — periodically adjusts its target rate to keep the economy running smoothly and consumer prices in check. When the federal funds rate moves up or down, so do the interest rates on bank accounts and loans.
In other words, changes in the Fed's rate impact how much your savings can grow and how much you pay to borrow money.
So how does today's federal funds rate compare to past years? Here's a look at historical Fed interest rates so you can better understand how your bottom line is affected.
The federal funds rate is set by the Federal Reserve and dictates what a bank can charge another bank for ultra-short-term loans (usually overnight) in order to meet reserve requirements. It's expressed as a range, and financial institutions can negotiate a specific rate between each other within that range.
#reserve #funds #rates #range


2 days ago
Palantir Technologies (PLTR) trades near $172.56, and the options market has already drawn the year ahead in dollars. The one-year band runs from $96.77 at the floor to $307.69 at the ceiling. That is not a forecast. It is the size of the uncertainty you are holding, and it raises a question about position size rather than direction.
What You Are Actually Risking On A Palantir Position
That range is where the options market puts roughly a two-in-three chance over the twelve months ahead. On a $10,000 holding, that is about $4,400 at risk down to the floor. Up to the ceiling there is about $7,800 of room. The two sides are not the same size because a stock cannot fall below zero but can rise without limit.
Outside that band sit two tails: roughly a one-in-six chance the stock finishes above the ceiling, and the same chance it finishes below the floor. So $96.77 is the edge of the ordinary, not the bottom of it.
Palantir Has Been Moving More Than Its Options Imply
#options #position
What You Are Actually Risking On A Palantir Position
That range is where the options market puts roughly a two-in-three chance over the twelve months ahead. On a $10,000 holding, that is about $4,400 at risk down to the floor. Up to the ceiling there is about $7,800 of room. The two sides are not the same size because a stock cannot fall below zero but can rise without limit.
Outside that band sit two tails: roughly a one-in-six chance the stock finishes above the ceiling, and the same chance it finishes below the floor. So $96.77 is the edge of the ordinary, not the bottom of it.
Palantir Has Been Moving More Than Its Options Imply
#options #position


2 days ago
Freight fraud risks and carrier vetting are the focus as Highway Chief Commercial Officer Michael Caney joins FreightWaves Today. He breaks down what brokers, carriers and shippers need to watch right now when onboarding and monitoring capacity.If you work fraud prevention, carrier compliance or network procurement, this conversation gets straight to the operational takeaway without the fluff.#FreightFraud #CarrierVetting #SupplyChain
Carrier-vetting platform Highway is putting its balance sheet behind its fraud-detection product: if a broker moves freight using Highway's guarantee standard and loses a load, Highway writes a check for $100,000. The company's chief commercial officer said the program covers the vast majority of carrier capacity in North America — and has paid out only once across roughly one million loads.
Of the approximately 175,000 carriers that move freight for freight brokers, Highway says more than 82% qualify for the guarantee tier. "What I would tell you is the industry keeps trying to solve for the bottom 18% of the market," the CCO said. "And what we're saying is if you will just move your freight to this cohort of carriers, which is the majority of capacity in North America, not only will you be fine, but Highway will stand behind it with a performance guarantee."
"The average cargo theft is not the $100,000, it's $250,000. This idea that a motor carrier can just show up and say, hey man, I'm gonna need this cargo, it's $250 grand, I'm good for it, is bananas."
The single payout to date stemmed from an identity-design flaw tied to California's non-domiciled limited-term licensing rules. A fraudulent carrier obtained a new license through California's process, resubmitted in Highway's system, and the alert dropped off before the bug was caught and fixed — costing Highway $100,000. The CCO described theft events as a "Swiss cheese" of compounding decisions rather than a single failure point, and said Highway continuously monitors for ownership changes, inbox compromises, and cyber anomalies within the guarantee framework.
#carriers #capacity #America
Carrier-vetting platform Highway is putting its balance sheet behind its fraud-detection product: if a broker moves freight using Highway's guarantee standard and loses a load, Highway writes a check for $100,000. The company's chief commercial officer said the program covers the vast majority of carrier capacity in North America — and has paid out only once across roughly one million loads.
Of the approximately 175,000 carriers that move freight for freight brokers, Highway says more than 82% qualify for the guarantee tier. "What I would tell you is the industry keeps trying to solve for the bottom 18% of the market," the CCO said. "And what we're saying is if you will just move your freight to this cohort of carriers, which is the majority of capacity in North America, not only will you be fine, but Highway will stand behind it with a performance guarantee."
"The average cargo theft is not the $100,000, it's $250,000. This idea that a motor carrier can just show up and say, hey man, I'm gonna need this cargo, it's $250 grand, I'm good for it, is bananas."
The single payout to date stemmed from an identity-design flaw tied to California's non-domiciled limited-term licensing rules. A fraudulent carrier obtained a new license through California's process, resubmitted in Highway's system, and the alert dropped off before the bug was caught and fixed — costing Highway $100,000. The CCO described theft events as a "Swiss cheese" of compounding decisions rather than a single failure point, and said Highway continuously monitors for ownership changes, inbox compromises, and cyber anomalies within the guarantee framework.
#carriers #capacity #America


2 days ago
Some offers on this page are from advertisers who pay us, which may affect which products we write about, but not our recommendations. See our Advertiser Disclosure.
The Federal Reserve — the country's central bank — periodically adjusts its target rate to keep the economy running smoothly and consumer prices in check. When the federal funds rate moves up or down, so do the interest rates on bank accounts and loans.
In other words, changes in the Fed's rate impact how much your savings can grow and how much you pay to borrow money.
So how does today's federal funds rate compare to past years? Here's a look at historical Fed interest rates so you can better understand how your bottom line is affected.
The federal funds rate is set by the Federal Reserve and dictates what a bank can charge another bank for ultra-short-term loans (usually overnight) in order to meet reserve requirements. It's expressed as a range, and financial institutions can negotiate a specific rate between each other within that range.
#federal #funds #rates
The Federal Reserve — the country's central bank — periodically adjusts its target rate to keep the economy running smoothly and consumer prices in check. When the federal funds rate moves up or down, so do the interest rates on bank accounts and loans.
In other words, changes in the Fed's rate impact how much your savings can grow and how much you pay to borrow money.
So how does today's federal funds rate compare to past years? Here's a look at historical Fed interest rates so you can better understand how your bottom line is affected.
The federal funds rate is set by the Federal Reserve and dictates what a bank can charge another bank for ultra-short-term loans (usually overnight) in order to meet reserve requirements. It's expressed as a range, and financial institutions can negotiate a specific rate between each other within that range.
#federal #funds #rates

2 days ago
On September 14, Radiant Logistics (NYSEAMERICAN:RLGT) held its fourth fiscal quarter earnings call, and the headline numbers landed harder than a typical logistics update. Net income jumped 53.1% to $7.5 million for the quarter ended June 30, while revenue climbed 18.5% to $261.4 million. Look past that one quarter, though, and the picture gets more complicated, because full-year adjusted profitability actually fell. That gap between a blowout quarter and a softer year is what makes this name worth a closer look.
The fourth fiscal quarter was strong from top to bottom. Adjusted EBITDA rose 31.6% to $10.4 million, margin expanded 240 basis points to 15.5%, and adjusted net income climbed 34.5% to $7.4 million, all against organic revenue growth of 8%. Management credited the acceleration to US forwarding operations and international airfreight, including work supporting disaster relief after typhoon activity hit the Western Pacific earlier this year, plus airfreight demand tied to capital flows into global data center buildouts.
The balance sheet backs up the story. Radiant enters fiscal 2027 with zero net debt, $25.6 million in cash as of June 30, and a $200 million senior credit facility that was extended and restated in August, pushing maturity out to August 7, 2031, while its acquisition-focused accordion grew to $100 million from $75 million. On the domestic side, capacity has been exiting the truckload and intermodal markets, and spot rates and tender rejections moved higher late in the quarter. Radiant also launched a new independent agent program at Radiant Road & Rail during the quarter, extending its freight forwarding agent network into truck brokerage and intermodal, while Navegate is gaining traction, with one enterprise customer now managing more than 1,400 vendors on the platform.
The full-year numbers tell a different story than the quarter does. Revenue rose just 3.5% to $934.4 million from $902.7 million, a fraction of the fourth quarter's 18.5% pace, and full-year net income grew a modest 8.7% to $18.8 million. Full-year adjusted EBITDA actually fell 5.4% to $36.7 million from $38.8 million, and that figure included a $1.3 million First Brands adjustment. Strip that out and normalized adjusted EBITDA comes in at $35.4 million, an even steeper decline than the headline number suggests.
The operating backdrop stays complicated too. Ocean shipping routes remain disrupted by the closure of the Strait of Hormuz and continued Houthi activity affecting Suez Canal transits, keeping capacity tight on key trade lanes. US tariff policy is generating elevated IEEPA-related filing activity, and Canada put new retaliatory tariff measures into effect in early September, adding fresh complexity for shippers moving goods across that border. Management itself acknowledged that the domestic truck brokerage improvement seen late in the fourth quarter is not yet fully reflected in the reported results.
#quarter #revenue
The fourth fiscal quarter was strong from top to bottom. Adjusted EBITDA rose 31.6% to $10.4 million, margin expanded 240 basis points to 15.5%, and adjusted net income climbed 34.5% to $7.4 million, all against organic revenue growth of 8%. Management credited the acceleration to US forwarding operations and international airfreight, including work supporting disaster relief after typhoon activity hit the Western Pacific earlier this year, plus airfreight demand tied to capital flows into global data center buildouts.
The balance sheet backs up the story. Radiant enters fiscal 2027 with zero net debt, $25.6 million in cash as of June 30, and a $200 million senior credit facility that was extended and restated in August, pushing maturity out to August 7, 2031, while its acquisition-focused accordion grew to $100 million from $75 million. On the domestic side, capacity has been exiting the truckload and intermodal markets, and spot rates and tender rejections moved higher late in the quarter. Radiant also launched a new independent agent program at Radiant Road & Rail during the quarter, extending its freight forwarding agent network into truck brokerage and intermodal, while Navegate is gaining traction, with one enterprise customer now managing more than 1,400 vendors on the platform.
The full-year numbers tell a different story than the quarter does. Revenue rose just 3.5% to $934.4 million from $902.7 million, a fraction of the fourth quarter's 18.5% pace, and full-year net income grew a modest 8.7% to $18.8 million. Full-year adjusted EBITDA actually fell 5.4% to $36.7 million from $38.8 million, and that figure included a $1.3 million First Brands adjustment. Strip that out and normalized adjusted EBITDA comes in at $35.4 million, an even steeper decline than the headline number suggests.
The operating backdrop stays complicated too. Ocean shipping routes remain disrupted by the closure of the Strait of Hormuz and continued Houthi activity affecting Suez Canal transits, keeping capacity tight on key trade lanes. US tariff policy is generating elevated IEEPA-related filing activity, and Canada put new retaliatory tariff measures into effect in early September, adding fresh complexity for shippers moving goods across that border. Management itself acknowledged that the domestic truck brokerage improvement seen late in the fourth quarter is not yet fully reflected in the reported results.
#quarter #revenue


2 days ago
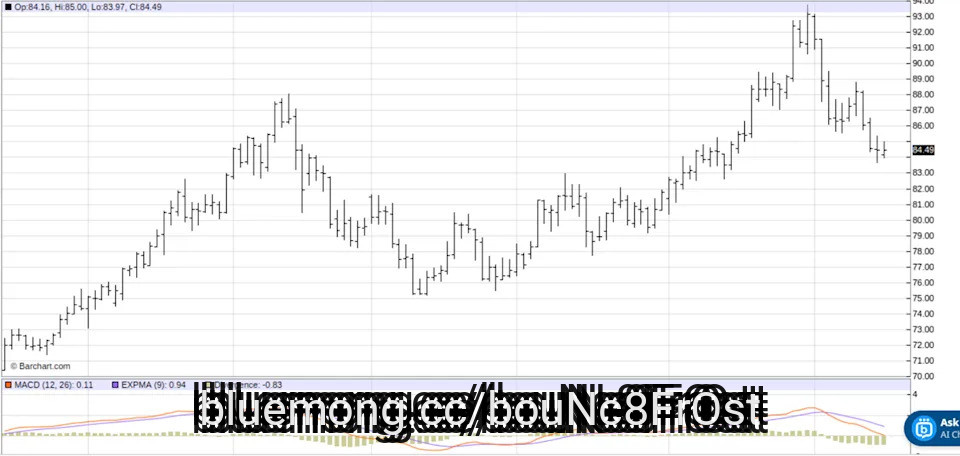
December cotton (CTZ26) futures present a selling opportunity on more price weakness.
See on the daily bar chart for December cotton futures that prices are trending down and have just hit a four-week low. See, too, at the bottom of the chart that the moving average convergence divergence (MACD) indicator is in a bearish posture as the blue MACD line is below the red trigger line and both lines are trending down. The bears have the near-term technical advantage as the trend is now their friend.
Coffee Prices Retreat on Ideal Growing Weather in Brazil and Vietnam
Cocoa Prices Fall on Signs of Adequate Supplies
Signs of Adequate Supplies Weigh on Cocoa Prices
#prices #macd #supplies
See on the daily bar chart for December cotton futures that prices are trending down and have just hit a four-week low. See, too, at the bottom of the chart that the moving average convergence divergence (MACD) indicator is in a bearish posture as the blue MACD line is below the red trigger line and both lines are trending down. The bears have the near-term technical advantage as the trend is now their friend.
Coffee Prices Retreat on Ideal Growing Weather in Brazil and Vietnam
Cocoa Prices Fall on Signs of Adequate Supplies
Signs of Adequate Supplies Weigh on Cocoa Prices
#prices #macd #supplies


2 days ago
This story was originally published on CFO.com. To receive daily news and insights, subscribe to our free daily CFO.com newsletter.
Is there a disconnect between finance teams and procurement teams? A new survey of 2,005 procurement leaders in the U.S. and the U.K. suggests there is for some companies, and it may ultimately be affecting their bottom lines.
Released Tuesday, the report from California-based contract lifecycle management company Agiloft showed that about one in 10 respondents said they have no shared metrics between chief procurement officers and CFOs. The lack of shared metrics was cited among the biggest obstacles preventing companies from "closing the gap between what procurement negotiates and what finance realizes."
Other barriers cited were lack of contract data visibility, selected by 14% of respondents, along with manual processes that create exceptions that go unseen (23%).
Agiloft's survey included responses gathered from 2,005 chief procurement officers and other procurement leaders Aug. 5-20.
#procurement
Is there a disconnect between finance teams and procurement teams? A new survey of 2,005 procurement leaders in the U.S. and the U.K. suggests there is for some companies, and it may ultimately be affecting their bottom lines.
Released Tuesday, the report from California-based contract lifecycle management company Agiloft showed that about one in 10 respondents said they have no shared metrics between chief procurement officers and CFOs. The lack of shared metrics was cited among the biggest obstacles preventing companies from "closing the gap between what procurement negotiates and what finance realizes."
Other barriers cited were lack of contract data visibility, selected by 14% of respondents, along with manual processes that create exceptions that go unseen (23%).
Agiloft's survey included responses gathered from 2,005 chief procurement officers and other procurement leaders Aug. 5-20.
#procurement


3 days ago
Some offers on this page are from advertisers who pay us, which may affect which products we write about, but not our recommendations. See our Advertiser Disclosure.
At the beginning of 2026, the biggest question surrounding the Federal Reserve and interest rates was whether the Fed would cut its target rate at some point this year. However, it's become increasingly clear that a rate cut won't happen any time soon. In fact, it's possible that the Fed may increase its benchmark rate before the year is over.
Following the Federal Open Market Committee (FOMC)'s most recent meeting in July, under the leadership of new Fed Chair Kevin Warsh, the committee announced its decision to maintain the target range for the federal funds rate at 3.50%-3.75%.
In its statement, the committee noted that "inflation remains elevated relative to the Committee's 2 percent goal, in part reflecting supply shocks that have driven price increases in certain sectors, including energy. The Committee will deliver price stability."
The Fed has not cut rates since late 2025, yet interest rates on consumer loans and bank accounts steadily decreased throughout 2026 — at least, until recently. Recent rate increases are a sign that the market is already pricing in a rate hike. And with a few more Fed meetings on the calendar for the remainder of 2026, consumers are wondering how potential rate changes could impact their bottom lines.
#year
At the beginning of 2026, the biggest question surrounding the Federal Reserve and interest rates was whether the Fed would cut its target rate at some point this year. However, it's become increasingly clear that a rate cut won't happen any time soon. In fact, it's possible that the Fed may increase its benchmark rate before the year is over.
Following the Federal Open Market Committee (FOMC)'s most recent meeting in July, under the leadership of new Fed Chair Kevin Warsh, the committee announced its decision to maintain the target range for the federal funds rate at 3.50%-3.75%.
In its statement, the committee noted that "inflation remains elevated relative to the Committee's 2 percent goal, in part reflecting supply shocks that have driven price increases in certain sectors, including energy. The Committee will deliver price stability."
The Fed has not cut rates since late 2025, yet interest rates on consumer loans and bank accounts steadily decreased throughout 2026 — at least, until recently. Recent rate increases are a sign that the market is already pricing in a rate hike. And with a few more Fed meetings on the calendar for the remainder of 2026, consumers are wondering how potential rate changes could impact their bottom lines.
#year

3 days ago
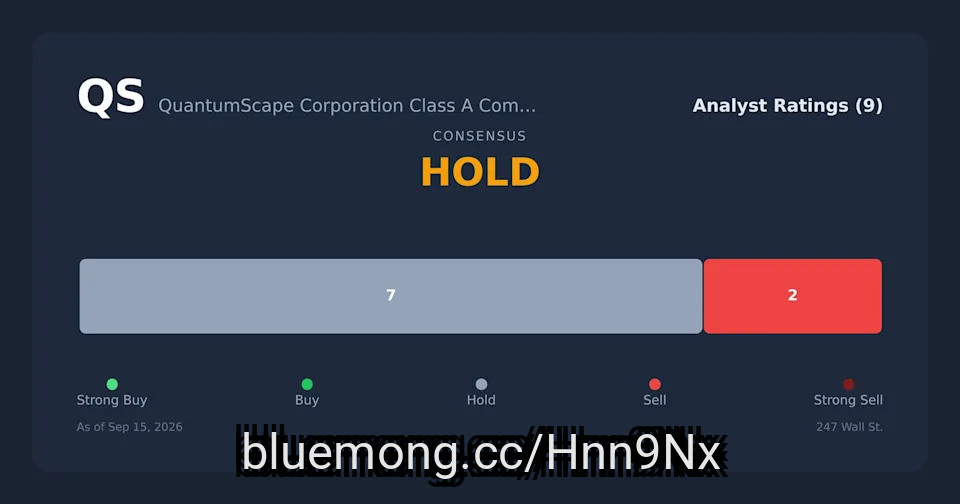
QS stock has fallen 51% year to date to near its 52-week low of $4.77, despite a Q2 earnings beat and $859 million in liquidity.
Enovix and Eos Energy are down 59% and 65% YTD as battery ETF LIT gained 8%, showing the market penalizing pre-revenue companies.
No **** ysts rate QS a buy, and production milestones stretch well into the late 2020s, yet Honda's rigorous technology validation strengthens the long-duration bull case.
Read More: Avoid these 13 retirement mistakes before they derail your future (sponsor)
Shares of QuantumScape (NYSE:QS) are down 1% to $5.14 in Tuesday afternoon trading, extending a slide that has left the solid-state battery developer down 51% year to date. QuantumScape stock now trades near the bottom of a 52-week range that topped $19 last fall.
#Stock #date #near #week
Enovix and Eos Energy are down 59% and 65% YTD as battery ETF LIT gained 8%, showing the market penalizing pre-revenue companies.
No **** ysts rate QS a buy, and production milestones stretch well into the late 2020s, yet Honda's rigorous technology validation strengthens the long-duration bull case.
Read More: Avoid these 13 retirement mistakes before they derail your future (sponsor)
Shares of QuantumScape (NYSE:QS) are down 1% to $5.14 in Tuesday afternoon trading, extending a slide that has left the solid-state battery developer down 51% year to date. QuantumScape stock now trades near the bottom of a 52-week range that topped $19 last fall.
#Stock #date #near #week



3 days ago
Accenture (ACN) stock trades near $195, and the options market prices roughly a two-in-three chance that it ends the coming twelve months between about $123 and about $308. That floor is about where the stock bottomed over the past year, and the ceiling is above the high it has already given back. For a holder, the question is whether a band that wide is more than you signed up for.
How Much Of Your Position Is On The Table Each Way?
The floor sits about 37% below today's price, a fall of $71.59, and the ceiling about 58% above it, a rise of $113.12. The bigger upside figure is not a lean: a share price can rise without limit and cannot fall below zero, so the band is always wider in dollars on the way up.
Has Accenture Stock Moved This Much Before?
It has. The stock traded between $122.96 and $282.71 over the past 52 weeks, and it lost 17.5% over the trailing twelve months while the S&P 500 gained 17%. Realized volatility over that year was 44.9%, and the one-year options carry implied volatility of 45.5%, a ratio of 1.01. The chain is pricing another year of movement about the size of the last one.
#twelve #floor
How Much Of Your Position Is On The Table Each Way?
The floor sits about 37% below today's price, a fall of $71.59, and the ceiling about 58% above it, a rise of $113.12. The bigger upside figure is not a lean: a share price can rise without limit and cannot fall below zero, so the band is always wider in dollars on the way up.
Has Accenture Stock Moved This Much Before?
It has. The stock traded between $122.96 and $282.71 over the past 52 weeks, and it lost 17.5% over the trailing twelve months while the S&P 500 gained 17%. Realized volatility over that year was 44.9%, and the one-year options carry implied volatility of 45.5%, a ratio of 1.01. The chain is pricing another year of movement about the size of the last one.
#twelve #floor

3 days ago
Our **** ysts just identified a stock with the potential to be the next Nvidia. Tell us how you invest and we'll show you why it's our #1 pick. Tap here.
Trustpilot's underlying business is still growing quickly, with revenue up 23%, bookings up 22% and adjusted EBITDA climbing 46% in the first half. But investors instead focused on a surprise statutory loss, several one-off charges and management's decision to leave full-year guidance unchanged after a huge run in the shares.
Trustpilot shares fell as much as 20% after the online review platform reported strong first-half growth but delivered a messier bottom line than investors had expected.
Revenue increased 23% to $151.4 million in the six months to June, equivalent to 19% growth at constant currencies, while bookings rose 22% to $171.2 million.
Adjusted EBITDA climbed 46% to a record $26.3 million and the margin expanded to 17.4%, although the profit figure came in slightly below the $27 million company-compiled consensus.
#ebitda #bookings #investors
Trustpilot's underlying business is still growing quickly, with revenue up 23%, bookings up 22% and adjusted EBITDA climbing 46% in the first half. But investors instead focused on a surprise statutory loss, several one-off charges and management's decision to leave full-year guidance unchanged after a huge run in the shares.
Trustpilot shares fell as much as 20% after the online review platform reported strong first-half growth but delivered a messier bottom line than investors had expected.
Revenue increased 23% to $151.4 million in the six months to June, equivalent to 19% growth at constant currencies, while bookings rose 22% to $171.2 million.
Adjusted EBITDA climbed 46% to a record $26.3 million and the margin expanded to 17.4%, although the profit figure came in slightly below the $27 million company-compiled consensus.
#ebitda #bookings #investors


3 days ago
During the September 10 episode of Mad Money, a caller inquired about Mad Money host Jim Cramer's confidence that Arista Networks, Inc. (NYSE:ANET) will not go down the same path as Ciena Corporation. He replied:
Okay, so let me just tell you, Arista is up a lot this year. My confidence is with Jayshree Ullall. I think she's amazing and I think it every time the stock has dipped, if you've noticed it. Since her tenure began, you have to buy it, and I'm not backing away from that. I feel the same way I do now, the way I did, oh man, how many years ago when we first met her. She is money, and the company's fantastic.
In its second quarter, the company shattered records by delivering its first-ever $3 billion quarter, reporting $3.036 billion in revenue, a 38% year-over-year and over 12% sequential increase. Management lifted its full-year 2026 revenue guidance to approximately $12.6 billion, representing roughly 40% annual top-line growth. The acceleration is supported by deep integration into cloud architectures, where Arista Networks, Inc. (NYSE:ANET) expects its dedicated AI fabrics revenue to reach at least $3.5 billion in 2026, supported by more than 100 **** ulative Etherlink customers.
Bottom-line performance remains equally strong, with non-GAAP diluted earnings per share reaching $1.02, driven by a 49.9% non-GAAP operating margin and $1.3 billion in non-GAAP quarterly net income. Arista Networks, Inc. (NYSE:ANET) ended the quarter with roughly $13.3 billion in cash and marketable securities, offering substantial liquidity. However, its $9.7 billion of non-cancellable purchase commitments also increase working-capital and inventory risk as the company secures components ahead of expected AI demand.
The company's financial results remain heavily tied to two hyperscale customers. According to its 10-K filings, Microsoft accounted for 26%, and Meta Platforms generated 16% of total revenue in fiscal 2025, bringing combined spending from these two cloud giants to 42%. It leaves Arista Networks, Inc. (NYSE:ANET) vulnerable to sudden capital expenditure adjustments, vendor diversification shifts, or project delays by its core buyers.
#billion #NYSE #year
Okay, so let me just tell you, Arista is up a lot this year. My confidence is with Jayshree Ullall. I think she's amazing and I think it every time the stock has dipped, if you've noticed it. Since her tenure began, you have to buy it, and I'm not backing away from that. I feel the same way I do now, the way I did, oh man, how many years ago when we first met her. She is money, and the company's fantastic.
In its second quarter, the company shattered records by delivering its first-ever $3 billion quarter, reporting $3.036 billion in revenue, a 38% year-over-year and over 12% sequential increase. Management lifted its full-year 2026 revenue guidance to approximately $12.6 billion, representing roughly 40% annual top-line growth. The acceleration is supported by deep integration into cloud architectures, where Arista Networks, Inc. (NYSE:ANET) expects its dedicated AI fabrics revenue to reach at least $3.5 billion in 2026, supported by more than 100 **** ulative Etherlink customers.
Bottom-line performance remains equally strong, with non-GAAP diluted earnings per share reaching $1.02, driven by a 49.9% non-GAAP operating margin and $1.3 billion in non-GAAP quarterly net income. Arista Networks, Inc. (NYSE:ANET) ended the quarter with roughly $13.3 billion in cash and marketable securities, offering substantial liquidity. However, its $9.7 billion of non-cancellable purchase commitments also increase working-capital and inventory risk as the company secures components ahead of expected AI demand.
The company's financial results remain heavily tied to two hyperscale customers. According to its 10-K filings, Microsoft accounted for 26%, and Meta Platforms generated 16% of total revenue in fiscal 2025, bringing combined spending from these two cloud giants to 42%. It leaves Arista Networks, Inc. (NYSE:ANET) vulnerable to sudden capital expenditure adjustments, vendor diversification shifts, or project delays by its core buyers.
#billion #NYSE #year

3 days ago
If you bought Meta Platforms (META) for its advertising engine, the engine still runs: revenue rose 28% year over year in the June 2026 quarter, and its Advantage+ automated campaigns keep growing. What has changed is where the cash goes afterward. The question for a holder is whether Meta is still the business you bought.
Over the twelve months through the June 2026 quarter, capital spending took 39.1% of revenue, against 18.5% across Meta's history. That money buys servers, data centers and network infrastructure. In late July 2026, Meta also announced a venture with BlackRock to develop a 1 gigawatt data center in El Paso, Texas. The plan is to keep going: management narrowed its 2026 capital-spending range by lifting the bottom of it.
Less cash is left over. TTM free-cash-flow margin is 18.0%, against 32.8% across its history, so on each dollar of sales Meta keeps a little more than half the free cash it used to.
Borrowing fills part of the gap. Debt has risen to 25.0% of total ******* ets, against a historical 7.0%, and the CFO says Meta is adding more debt to lower its cost of capital. Meta still holds more cash and marketable securities than debt.
Together, those three readings are the most unusual combination Meta has shown in 14 years. Taken with the 2026 spending floor that management has raised, the combination reads as a change in the business rather than one quarter of noise.
#quarter #spending #bought #engine
Over the twelve months through the June 2026 quarter, capital spending took 39.1% of revenue, against 18.5% across Meta's history. That money buys servers, data centers and network infrastructure. In late July 2026, Meta also announced a venture with BlackRock to develop a 1 gigawatt data center in El Paso, Texas. The plan is to keep going: management narrowed its 2026 capital-spending range by lifting the bottom of it.
Less cash is left over. TTM free-cash-flow margin is 18.0%, against 32.8% across its history, so on each dollar of sales Meta keeps a little more than half the free cash it used to.
Borrowing fills part of the gap. Debt has risen to 25.0% of total ******* ets, against a historical 7.0%, and the CFO says Meta is adding more debt to lower its cost of capital. Meta still holds more cash and marketable securities than debt.
Together, those three readings are the most unusual combination Meta has shown in 14 years. Taken with the 2026 spending floor that management has raised, the combination reads as a change in the business rather than one quarter of noise.
#quarter #spending #bought #engine


3 days ago
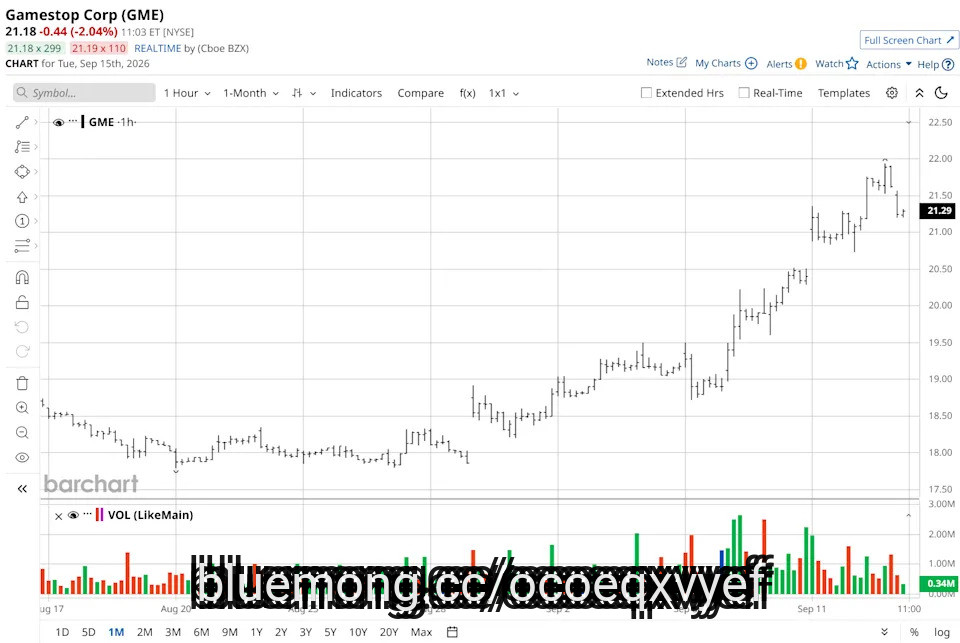
GameStop (GME) is a Grapevine, Texas-based specialty retailer operating stores and e-commerce platforms under the GameStop, EB Games, and Micromania banners across the U.S., Canada, Australia, and Europe. Once known primarily as a video game and electronics retailer, GameStop has diversified aggressively under Executive Chairman Ryan Cohen, expanding into collectibles, trading cards, pop culture merchandise, and even cryptocurrency and equity investments. The company has become a prominent "meme stock," attracting substantial retail investor attention while pursuing an unconventional capital allocation strategy that includes bitcoin holdings and a sizable equity stake in eBay (EBAY), positioning GameStop as much an investment vehicle as a traditional retailer.
GameStop stock recently traded around $21.15, near the bottom of its 52-week range of $17.79 to $28.10 and below its 200-day moving average. Shares have pulled back significantly from their 2025 meme-stock highs, weighed down by declining video game sales, ongoing store closures, and investor skepticism toward the company's diversification into digital ***** ets and equity investments. The stock did see brief bursts of retail-trader enthusiasm this year, including renewed meme-stock speculation tied to its proposed eBay acquisition, though shares have remained volatile and range-bound as GameStop's core retail business continues shrinking alongside its growing collectibles and investment segments.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Morgan Stanley Doubles Down on Apple Stock as New Offerings Become 'More Exciting'
The EV Bubble Has Burst. How to Play Rivian Stock Now.
#shares
GameStop stock recently traded around $21.15, near the bottom of its 52-week range of $17.79 to $28.10 and below its 200-day moving average. Shares have pulled back significantly from their 2025 meme-stock highs, weighed down by declining video game sales, ongoing store closures, and investor skepticism toward the company's diversification into digital ***** ets and equity investments. The stock did see brief bursts of retail-trader enthusiasm this year, including renewed meme-stock speculation tied to its proposed eBay acquisition, though shares have remained volatile and range-bound as GameStop's core retail business continues shrinking alongside its growing collectibles and investment segments.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Morgan Stanley Doubles Down on Apple Stock as New Offerings Become 'More Exciting'
The EV Bubble Has Burst. How to Play Rivian Stock Now.
#shares

3 days ago
If you bought Meta Platforms (META) for its advertising engine, the engine still runs: revenue rose 28% year over year in the June 2026 quarter, and its Advantage+ automated campaigns keep growing. What has changed is where the cash goes afterward. The question for a holder is whether Meta is still the business you bought.
Over the twelve months through the June 2026 quarter, capital spending took 39.1% of revenue, against 18.5% across Meta's history. That money buys servers, data centers and network infrastructure. In late July 2026, Meta also announced a venture with BlackRock to develop a 1 gigawatt data center in El Paso, Texas. The plan is to keep going: management narrowed its 2026 capital-spending range by lifting the bottom of it.
Less cash is left over. TTM free-cash-flow margin is 18.0%, against 32.8% across its history, so on each dollar of sales Meta keeps a little more than half the free cash it used to.
Borrowing fills part of the gap. Debt has risen to 25.0% of total **** ets, against a historical 7.0%, and the CFO says Meta is adding more debt to lower its cost of capital. Meta still holds more cash and marketable securities than debt.
Together, those three readings are the most unusual combination Meta has shown in 14 years. Taken with the 2026 spending floor that management has raised, the combination reads as a change in the business rather than one quarter of noise.
#meta #cash
Over the twelve months through the June 2026 quarter, capital spending took 39.1% of revenue, against 18.5% across Meta's history. That money buys servers, data centers and network infrastructure. In late July 2026, Meta also announced a venture with BlackRock to develop a 1 gigawatt data center in El Paso, Texas. The plan is to keep going: management narrowed its 2026 capital-spending range by lifting the bottom of it.
Less cash is left over. TTM free-cash-flow margin is 18.0%, against 32.8% across its history, so on each dollar of sales Meta keeps a little more than half the free cash it used to.
Borrowing fills part of the gap. Debt has risen to 25.0% of total **** ets, against a historical 7.0%, and the CFO says Meta is adding more debt to lower its cost of capital. Meta still holds more cash and marketable securities than debt.
Together, those three readings are the most unusual combination Meta has shown in 14 years. Taken with the 2026 spending floor that management has raised, the combination reads as a change in the business rather than one quarter of noise.
#meta #cash


3 days ago
The aerospace industry is evolving as Boeing (NYSE:BA) attempts a massive operational turnaround while Rocket Lab (NASDAQ:RKLB) rapidly expands its footprint across the global ******* e economy.
Boeing remains a dominant force in commercial aviation and defense, whereas Rocket Lab specializes in small-satellite launches and ******* ecraft components. Investors often compare them to decide between an established giant recovering from crisis and a high-growth challenger in the private ******* e sector.
Boeing operates as a massive player among defense stocks and commercial aviation leaders, manufacturing everything from the 737 Max to advanced military rotorcraft. The company generates revenue through commercial aircraft sales, defense contracts with the U.S. Department of Defense and NASA, and global services. Customer concentration like this adds a layer of risk to the business. In 2025, the company acquired Spirit AeroSystems to address long-standing quality issues, providing transition services to other buyers like Airbus (OTC:EADSF).
In FY 2025, revenue reached nearly $89.5 billion, representing a growth of roughly 34.5% over the previous year. The company reported a net income of approximately $2.2 billion, a significant recovery from the net loss of nearly $11.8 billion in FY 2024. This improvement in the net margin to 2.5% suggests the company is beginning to stabilize its bottom line after years of heavy losses.
As of its December 2025 balance sheet, Boeing carries a debt-to-equity ratio of nearly 10.0x, a measure comparing total debt to shareholder equity that indicates a heavy reliance on borrowing. The company reported a current ratio of nearly 1.2x, which measures a company's ability to cover its short-term debts with liquid ******* ets. Note that stock-based compensation represented roughly 40% of operating cash flow, which inflates reported cash generation since SBC is a non-cash expense added back in the cash flow statement. The company also generated a negative free cash flow of approximately $1.9 billion, representing operating cash minus spending on physical ******* ets.
#boeing #nearly #rocket
Boeing remains a dominant force in commercial aviation and defense, whereas Rocket Lab specializes in small-satellite launches and ******* ecraft components. Investors often compare them to decide between an established giant recovering from crisis and a high-growth challenger in the private ******* e sector.
Boeing operates as a massive player among defense stocks and commercial aviation leaders, manufacturing everything from the 737 Max to advanced military rotorcraft. The company generates revenue through commercial aircraft sales, defense contracts with the U.S. Department of Defense and NASA, and global services. Customer concentration like this adds a layer of risk to the business. In 2025, the company acquired Spirit AeroSystems to address long-standing quality issues, providing transition services to other buyers like Airbus (OTC:EADSF).
In FY 2025, revenue reached nearly $89.5 billion, representing a growth of roughly 34.5% over the previous year. The company reported a net income of approximately $2.2 billion, a significant recovery from the net loss of nearly $11.8 billion in FY 2024. This improvement in the net margin to 2.5% suggests the company is beginning to stabilize its bottom line after years of heavy losses.
As of its December 2025 balance sheet, Boeing carries a debt-to-equity ratio of nearly 10.0x, a measure comparing total debt to shareholder equity that indicates a heavy reliance on borrowing. The company reported a current ratio of nearly 1.2x, which measures a company's ability to cover its short-term debts with liquid ******* ets. Note that stock-based compensation represented roughly 40% of operating cash flow, which inflates reported cash generation since SBC is a non-cash expense added back in the cash flow statement. The company also generated a negative free cash flow of approximately $1.9 billion, representing operating cash minus spending on physical ******* ets.
#boeing #nearly #rocket

3 days ago
GameStop (GME) is a Grapevine, Texas-based specialty retailer operating stores and e-commerce platforms under the GameStop, EB Games, and Micromania banners across the U.S., Canada, Australia, and Europe. Once known primarily as a video game and electronics retailer, GameStop has diversified aggressively under Executive Chairman Ryan Cohen, expanding into collectibles, trading cards, pop culture merchandise, and even cryptocurrency and equity investments. The company has become a prominent "meme stock," attracting substantial retail investor attention while pursuing an unconventional capital allocation strategy that includes bitcoin holdings and a sizable equity stake in eBay (EBAY), positioning GameStop as much an investment vehicle as a traditional retailer.
GameStop stock recently traded around $21.15, near the bottom of its 52-week range of $17.79 to $28.10 and below its 200-day moving average. Shares have pulled back significantly from their 2025 meme-stock highs, weighed down by declining video game sales, ongoing store closures, and investor skepticism toward the company's diversification into digital **** ets and equity investments. The stock did see brief bursts of retail-trader enthusiasm this year, including renewed meme-stock speculation tied to its proposed eBay acquisition, though shares have remained volatile and range-bound as GameStop's core retail business continues shrinking alongside its growing collectibles and investment segments.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Morgan Stanley Doubles Down on Apple Stock as New Offerings Become 'More Exciting'
The EV Bubble Has Burst. How to Play Rivian Stock Now.
#Equity
GameStop stock recently traded around $21.15, near the bottom of its 52-week range of $17.79 to $28.10 and below its 200-day moving average. Shares have pulled back significantly from their 2025 meme-stock highs, weighed down by declining video game sales, ongoing store closures, and investor skepticism toward the company's diversification into digital **** ets and equity investments. The stock did see brief bursts of retail-trader enthusiasm this year, including renewed meme-stock speculation tied to its proposed eBay acquisition, though shares have remained volatile and range-bound as GameStop's core retail business continues shrinking alongside its growing collectibles and investment segments.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Morgan Stanley Doubles Down on Apple Stock as New Offerings Become 'More Exciting'
The EV Bubble Has Burst. How to Play Rivian Stock Now.
#Equity
3 days ago
On September 14, Radiant Logistics (NYSEAMERICAN:RLGT) held its fourth fiscal quarter earnings call, and the headline numbers landed harder than a typical logistics update. Net income jumped 53.1% to $7.5 million for the quarter ended June 30, while revenue climbed 18.5% to $261.4 million. Look past that one quarter, though, and the picture gets more complicated, because full-year adjusted profitability actually fell. That gap between a blowout quarter and a softer year is what makes this name worth a closer look.
The fourth fiscal quarter was strong from top to bottom. Adjusted EBITDA rose 31.6% to $10.4 million, margin expanded 240 basis points to 15.5%, and adjusted net income climbed 34.5% to $7.4 million, all against organic revenue growth of 8%. Management credited the acceleration to US forwarding operations and international airfreight, including work supporting disaster relief after typhoon activity hit the Western Pacific earlier this year, plus airfreight demand tied to capital flows into global data center buildouts.
The balance sheet backs up the story. Radiant enters fiscal 2027 with zero net debt, $25.6 million in cash as of June 30, and a $200 million senior credit facility that was extended and restated in August, pushing maturity out to August 7, 2031, while its acquisition-focused accordion grew to $100 million from $75 million. On the domestic side, capacity has been exiting the truckload and intermodal markets, and spot rates and tender rejections moved higher late in the quarter. Radiant also launched a new independent agent program at Radiant Road & Rail during the quarter, extending its freight forwarding agent network into truck brokerage and intermodal, while Navegate is gaining traction, with one enterprise customer now managing more than 1,400 vendors on the platform.
The full-year numbers tell a different story than the quarter does. Revenue rose just 3.5% to $934.4 million from $902.7 million, a fraction of the fourth quarter's 18.5% pace, and full-year net income grew a modest 8.7% to $18.8 million. Full-year adjusted EBITDA actually fell 5.4% to $36.7 million from $38.8 million, and that figure included a $1.3 million First Brands adjustment. Strip that out and normalized adjusted EBITDA comes in at $35.4 million, an even steeper decline than the headline number suggests.
The operating backdrop stays complicated too. Ocean shipping routes remain disrupted by the closure of the Strait of Hormuz and continued Houthi activity affecting Suez Canal transits, keeping capacity tight on key trade lanes. US tariff policy is generating elevated IEEPA-related filing activity, and Canada put new retaliatory tariff measures into effect in early September, adding fresh complexity for shippers moving goods across that border. Management itself acknowledged that the domestic truck brokerage improvement seen late in the fourth quarter is not yet fully reflected in the reported results.
#million #quarter #revenue #fiscal
The fourth fiscal quarter was strong from top to bottom. Adjusted EBITDA rose 31.6% to $10.4 million, margin expanded 240 basis points to 15.5%, and adjusted net income climbed 34.5% to $7.4 million, all against organic revenue growth of 8%. Management credited the acceleration to US forwarding operations and international airfreight, including work supporting disaster relief after typhoon activity hit the Western Pacific earlier this year, plus airfreight demand tied to capital flows into global data center buildouts.
The balance sheet backs up the story. Radiant enters fiscal 2027 with zero net debt, $25.6 million in cash as of June 30, and a $200 million senior credit facility that was extended and restated in August, pushing maturity out to August 7, 2031, while its acquisition-focused accordion grew to $100 million from $75 million. On the domestic side, capacity has been exiting the truckload and intermodal markets, and spot rates and tender rejections moved higher late in the quarter. Radiant also launched a new independent agent program at Radiant Road & Rail during the quarter, extending its freight forwarding agent network into truck brokerage and intermodal, while Navegate is gaining traction, with one enterprise customer now managing more than 1,400 vendors on the platform.
The full-year numbers tell a different story than the quarter does. Revenue rose just 3.5% to $934.4 million from $902.7 million, a fraction of the fourth quarter's 18.5% pace, and full-year net income grew a modest 8.7% to $18.8 million. Full-year adjusted EBITDA actually fell 5.4% to $36.7 million from $38.8 million, and that figure included a $1.3 million First Brands adjustment. Strip that out and normalized adjusted EBITDA comes in at $35.4 million, an even steeper decline than the headline number suggests.
The operating backdrop stays complicated too. Ocean shipping routes remain disrupted by the closure of the Strait of Hormuz and continued Houthi activity affecting Suez Canal transits, keeping capacity tight on key trade lanes. US tariff policy is generating elevated IEEPA-related filing activity, and Canada put new retaliatory tariff measures into effect in early September, adding fresh complexity for shippers moving goods across that border. Management itself acknowledged that the domestic truck brokerage improvement seen late in the fourth quarter is not yet fully reflected in the reported results.
#million #quarter #revenue #fiscal


5 days ago
As you may have heard, Pete Alonso returned with his new team to Citi Field tonight, and the Mets lost to the Orioles 2-1. Although Jonah Tong pitched admirably, the Mets could not capitalize on their six hits and left nine runners on base.
After Jonah Tong struck out Dylan Beavers to lead off the first inning, Alonso stepped up to thunderous applause, cheers, and chants of his name. He flied out to Carson Benge in right field, but that did not dampen the enthusiasm of the crowd. Tong then retired Gunnar Henderson as well for a 1-2-3 start to his day. In the bottom of the inning, Francisco Lindor walked to lead off, but Juan Soto popped out, and Bo Bichette grounded into a double play for the second and third outs to end the inning.
At the top of the second inning, Jackson Holliday looped a one-out single into right field. He reached second on a passed ball by Francisco Alvarez, which had popped out of Alvarez's glove. It proved costly when Heston Kjerstad drilled a double into right field past Brett Baty. The ball made a weird hop past Baty, and Holliday scored the first run of the game. When the Mets came to bat in the second, they loaded the bases with two outs. Marcus Semien drilled a single down the left-field line, and then A.J. Ewing and Baty walked. Unfortunately, they were all stranded when Alvarez struck out on a foul tip for the third out, and the second inning ended with the score Orioles 1, Mets 0.
Alonso drew a two-out walk in the third inning, but was stranded there when Tong struck out Henderson. At the bottom of the third, Juan Soto smacked a one-out single into right field. Benge sneaked a single past third base, but both runners were again stranded when Jared Young grounded out for the third out. At the top of the fourth inning, Holliday hit a ground ball straight to Semien, but Semien could not get it out of his glove in a timely manner, and Holliday made it to first base safely. He was stranded as well, though. At the bottom of the inning, Ewing drilled a home run into right field. Alvarez smacked a ground ball to third base that Coby Mayo initially fielded but bobbled, allowing Alvarez to reach base safely on an infield hit. However, he was also stranded when Lindor struck out, leaving the score Mets 1, Orioles 1, at the end of the fourth inning.
To lead off the fifth inning, Colton Cowser hit a single that Semien knocked down but couldn't get to first base in time. The next three batters went down in order. Soto walked to lead off the bottom of the fifth and, with two outs, stole second base. Young also drew a walk, but Semien grounded out to end the rally attempt there. Tong came back out for the top of the sixth inning and only needed six pitches to retire the three batters he saw. Josh Walker replaced Brandon Young for the Orioles at the bottom of the sixth, and he also worked a 1-2-3 inning. The score remained 1-1.
#field
After Jonah Tong struck out Dylan Beavers to lead off the first inning, Alonso stepped up to thunderous applause, cheers, and chants of his name. He flied out to Carson Benge in right field, but that did not dampen the enthusiasm of the crowd. Tong then retired Gunnar Henderson as well for a 1-2-3 start to his day. In the bottom of the inning, Francisco Lindor walked to lead off, but Juan Soto popped out, and Bo Bichette grounded into a double play for the second and third outs to end the inning.
At the top of the second inning, Jackson Holliday looped a one-out single into right field. He reached second on a passed ball by Francisco Alvarez, which had popped out of Alvarez's glove. It proved costly when Heston Kjerstad drilled a double into right field past Brett Baty. The ball made a weird hop past Baty, and Holliday scored the first run of the game. When the Mets came to bat in the second, they loaded the bases with two outs. Marcus Semien drilled a single down the left-field line, and then A.J. Ewing and Baty walked. Unfortunately, they were all stranded when Alvarez struck out on a foul tip for the third out, and the second inning ended with the score Orioles 1, Mets 0.
Alonso drew a two-out walk in the third inning, but was stranded there when Tong struck out Henderson. At the bottom of the third, Juan Soto smacked a one-out single into right field. Benge sneaked a single past third base, but both runners were again stranded when Jared Young grounded out for the third out. At the top of the fourth inning, Holliday hit a ground ball straight to Semien, but Semien could not get it out of his glove in a timely manner, and Holliday made it to first base safely. He was stranded as well, though. At the bottom of the inning, Ewing drilled a home run into right field. Alvarez smacked a ground ball to third base that Coby Mayo initially fielded but bobbled, allowing Alvarez to reach base safely on an infield hit. However, he was also stranded when Lindor struck out, leaving the score Mets 1, Orioles 1, at the end of the fourth inning.
To lead off the fifth inning, Colton Cowser hit a single that Semien knocked down but couldn't get to first base in time. The next three batters went down in order. Soto walked to lead off the bottom of the fifth and, with two outs, stole second base. Young also drew a walk, but Semien grounded out to end the rally attempt there. Tong came back out for the top of the sixth inning and only needed six pitches to retire the three batters he saw. Josh Walker replaced Brandon Young for the Orioles at the bottom of the sixth, and he also worked a 1-2-3 inning. The score remained 1-1.
#field
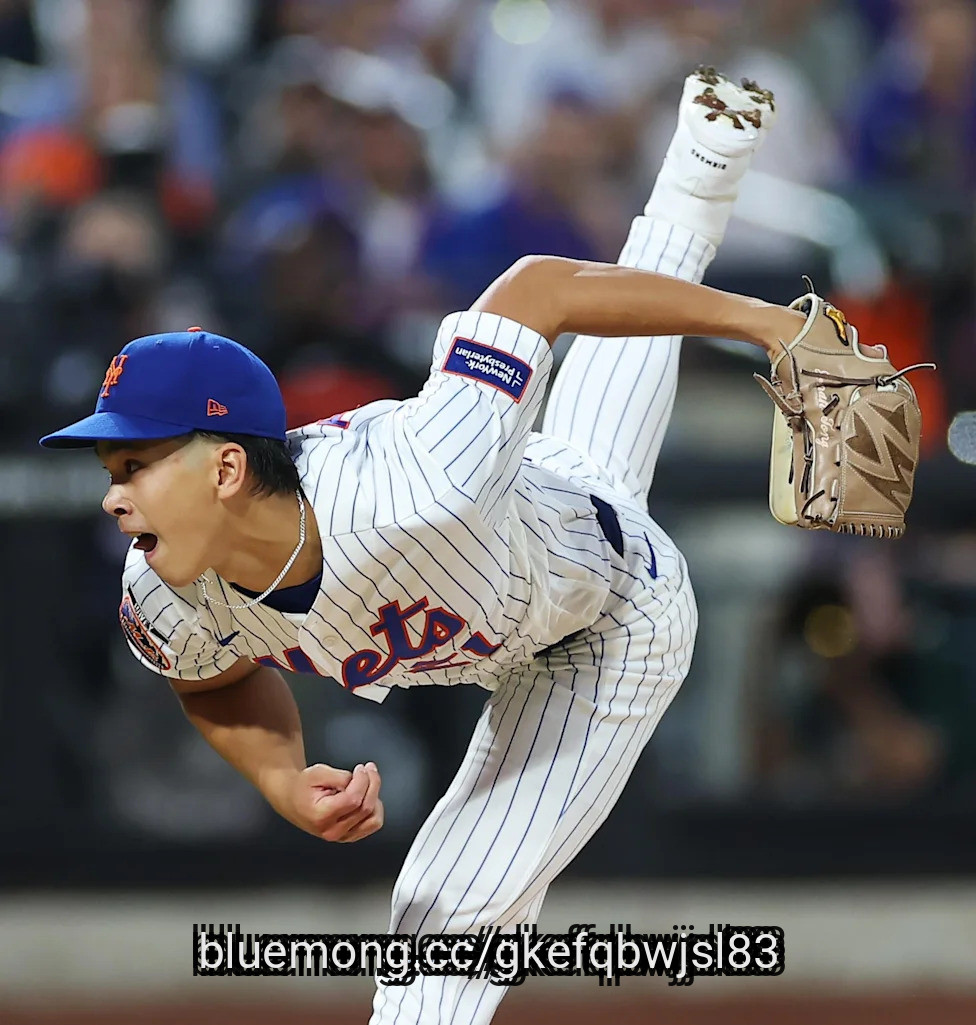

5 days ago
Dispatch.com readers can vote for their favorite boys high school athletes of the week on their desktop, the Dispatch.com mobile web or Dispatch app once per hour by scrolling down to ballots listed below.
Deadline is 4 p.m. Friday, Sept. 18.
The Ohio State University Wexner Medical Center high school Athlete of the Week voting occurs each week during high school sports competition and recognizes athletes across all sports.
Last week's Athlete of the Week: Berlin's Ethan Litton voted Boys Athlete of the Week presented by Wexner Medical Center
If you can't see the ballot when you scroll to the bottom of this story, try refreshing the link or clearing the cache in your browser. You do not have to be a subscriber to vote.
#wexner #medical
Deadline is 4 p.m. Friday, Sept. 18.
The Ohio State University Wexner Medical Center high school Athlete of the Week voting occurs each week during high school sports competition and recognizes athletes across all sports.
Last week's Athlete of the Week: Berlin's Ethan Litton voted Boys Athlete of the Week presented by Wexner Medical Center
If you can't see the ballot when you scroll to the bottom of this story, try refreshing the link or clearing the cache in your browser. You do not have to be a subscriber to vote.
#wexner #medical
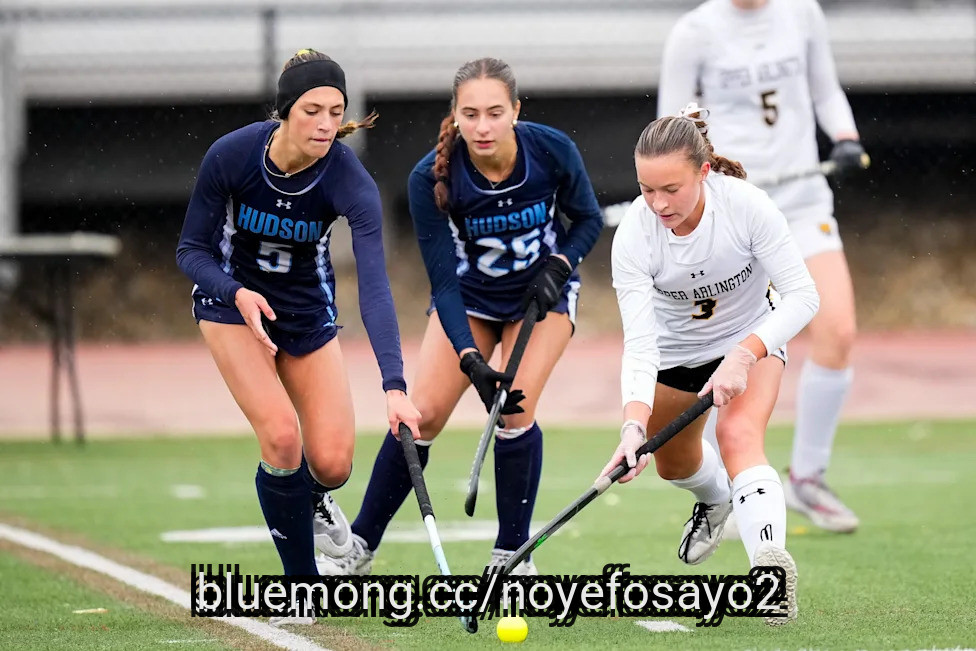

5 days ago
Duke basketball coach Jon Scheyer addressed the reports linking him to the NBA during the offseason.
The Blue Devils head coach was reportedly linked to Dallas Mavericks through the offseason as a potential replacement for Jason Kidd. The Mavericks ultimately hired former Michigan coach Dusty May.
Scheyer discussed the NBA interest on the Glue Guys Podcast on Monday, Sept. 14.
"If anybody that knows me, I wouldn't be able to live with myself not seeing this thing through, that's just the bottom line," Scheyer said. "I'm at a one-of-one place where (it's) not often you get your dream job when you're 33, and that's what happened to me."
Scheyer took over for Mike Krzyzewski in 2022 after spending nine seasons on his predecessor's staff. A former Duke national champion and two-time team captain, Scheyer is entering his fifth season as the program's head coach. He owns a 124-25 career record, the most wins by any Division I head coach in their first four seasons, and has led the Blue Devils to three ACC Tournament championships, three NCAA Elite Eight appearances and one Final Four.
#duke
The Blue Devils head coach was reportedly linked to Dallas Mavericks through the offseason as a potential replacement for Jason Kidd. The Mavericks ultimately hired former Michigan coach Dusty May.
Scheyer discussed the NBA interest on the Glue Guys Podcast on Monday, Sept. 14.
"If anybody that knows me, I wouldn't be able to live with myself not seeing this thing through, that's just the bottom line," Scheyer said. "I'm at a one-of-one place where (it's) not often you get your dream job when you're 33, and that's what happened to me."
Scheyer took over for Mike Krzyzewski in 2022 after spending nine seasons on his predecessor's staff. A former Duke national champion and two-time team captain, Scheyer is entering his fifth season as the program's head coach. He owns a 124-25 career record, the most wins by any Division I head coach in their first four seasons, and has led the Blue Devils to three ACC Tournament championships, three NCAA Elite Eight appearances and one Final Four.
#duke

5 days ago
On August 6, The RealReal (NASDAQ:REAL) reported second quarter results that beat its own outlook and pushed the resale luxury marketplace to raise its full year guidance. Gross merchandise value hit an all time high of $617 million, up 22% from a year earlier, and management pointed to four straight quarters of GMV growth above 20%. But a wider net loss sitting next to those record numbers complicates the story for anyone weighing the stock today.
The headline number is GMV of $617 million for the quarter ended June 30, up 22% year over year, with total revenue climbing 17% to $193 million. Consignment revenue grew 15% while Direct Revenue, the company's owned inventory channel, grew 26%, showing both sides of the business contributing to the acceleration. Profitability moved in the same direction. Gross margin reached 74.4%, up 10 basis points from a year ago, and Adjusted EBITDA margin jumped to 7%, a 290 basis point improvement that management called nearly 300 basis points of expansion.
The buyer base backs up the growth story rather than just the pricing. Trailing twelve-month active buyers rose 11% to 1,107,000, and average order value climbed 13% to $659, meaning existing shoppers are spending meaningfully more per transaction, not just showing up more often. That combination gave management enough confidence to raise full-year guidance to $2.54 billion to $2.57 billion in GMV and $788 million to $797 million in total revenue, alongside third-quarter Adjusted EBITDA guidance of $13.5 million to $14.5 million.
Despite the operating improvements, GAAP losses widened. Net loss came in at $27 million, or 14.1% of total revenue, compared to $11 million, or 6.9% of total revenue, a year earlier. GAAP basic net loss per share was $0.23 versus $0.10 in the prior year period, and diluted net loss per share was $0.23 versus $0.13. Much of that swing traces to a $(18.6) million non-cash adjustment tied to the change in fair value of warrant liability, a factor unrelated to how the underlying business performed. On a non-GAAP basis, basic and diluted net loss per share actually narrowed to $0.01 from $0.06, underscoring how much of the GAAP gap is accounting rather than operations.
There is also a transparency wrinkle in the guidance itself. The RealReal said it has not reconciled its forward-looking Adjusted EBITDA figures to GAAP net income or loss, citing components like payroll tax expense on employee stock transactions that it cannot predict with reasonable certainty. That leaves investors trusting a non-GAAP target without the usual bridge back to the bottom line.
#adjusted
The headline number is GMV of $617 million for the quarter ended June 30, up 22% year over year, with total revenue climbing 17% to $193 million. Consignment revenue grew 15% while Direct Revenue, the company's owned inventory channel, grew 26%, showing both sides of the business contributing to the acceleration. Profitability moved in the same direction. Gross margin reached 74.4%, up 10 basis points from a year ago, and Adjusted EBITDA margin jumped to 7%, a 290 basis point improvement that management called nearly 300 basis points of expansion.
The buyer base backs up the growth story rather than just the pricing. Trailing twelve-month active buyers rose 11% to 1,107,000, and average order value climbed 13% to $659, meaning existing shoppers are spending meaningfully more per transaction, not just showing up more often. That combination gave management enough confidence to raise full-year guidance to $2.54 billion to $2.57 billion in GMV and $788 million to $797 million in total revenue, alongside third-quarter Adjusted EBITDA guidance of $13.5 million to $14.5 million.
Despite the operating improvements, GAAP losses widened. Net loss came in at $27 million, or 14.1% of total revenue, compared to $11 million, or 6.9% of total revenue, a year earlier. GAAP basic net loss per share was $0.23 versus $0.10 in the prior year period, and diluted net loss per share was $0.23 versus $0.13. Much of that swing traces to a $(18.6) million non-cash adjustment tied to the change in fair value of warrant liability, a factor unrelated to how the underlying business performed. On a non-GAAP basis, basic and diluted net loss per share actually narrowed to $0.01 from $0.06, underscoring how much of the GAAP gap is accounting rather than operations.
There is also a transparency wrinkle in the guidance itself. The RealReal said it has not reconciled its forward-looking Adjusted EBITDA figures to GAAP net income or loss, citing components like payroll tax expense on employee stock transactions that it cannot predict with reasonable certainty. That leaves investors trusting a non-GAAP target without the usual bridge back to the bottom line.
#adjusted

5 days ago
On August 5, Clear Channel Outdoor Holdings Inc. (NYSE:CCO) reported second-quarter results that showed the billboard and airport advertising company accelerating just as it prepares to leave the public markets. On February 9, Clear Channel agreed to be acquired by an investor consortium advised by Mubadala Capital for $2.43 per share, a deal stockholders approved on May 12, and one expected to close by the end of the third quarter of 2026. Because of the pending Merger, Clear Channel skipped its usual earnings call and offered no forward guidance.
Consolidated revenue climbed 8.7% to $438.0 million in the quarter and 10.2% to $811.9 million over the first half, with the 2026 FIFA World Cup pulling in extra advertising spend across both of Clear Channel's segments. The America division, which houses the roadside billboard and street furniture business, grew revenue 7% to $324.3 million as demand from technology advertisers in the San Francisco/Bay Area market broadened out and digital billboard revenue rose 7.2% to $122 million. Airports revenue jumped 14% to $113.6 million, helped by strong demand at San Francisco
International Airport and digital sales that climbed 15.6% to $73.4 million, with national advertisers now accounting for 57.8% of that segment's revenue. Profitability grew even faster than the top line. Adjusted EBITDA rose 11.6% to $143.4 million for the quarter and 19% to $247.3 million for the first half, while Airports Segment Adjusted EBITDA jumped 22.8% to $29.9 million. Adjusted Funds From Operations climbed 61.6% to $44.9 million in the quarter, and for the first half it went from just $5 million a year ago to $51.5 million. On August 4, Clear Channel also closed the sale of its Spain business for about $132.3 million, proceeds it plans to put toward paying down debt.
The growth did not reach the bottom line. Clear Channel posted a loss from continuing operations of $10 million in the quarter, reversing a $6.3 million profit a year earlier, and the consolidated net loss came to $5 million versus net income of $10.6 million in the same period of 2025. Over six months, the loss from continuing operations widened 21.4% to $59.4 million. Costs rose alongside revenue. Direct operating and SG&A expenses increased 5.9% for the quarter, and Airports site lease expense alone jumped 12.0% to $67.1 million on higher minimum guaranteed payments and the renewed contract with the Metropolitan Washington Airports Authority.
#channel #revenue #airports #operations
Consolidated revenue climbed 8.7% to $438.0 million in the quarter and 10.2% to $811.9 million over the first half, with the 2026 FIFA World Cup pulling in extra advertising spend across both of Clear Channel's segments. The America division, which houses the roadside billboard and street furniture business, grew revenue 7% to $324.3 million as demand from technology advertisers in the San Francisco/Bay Area market broadened out and digital billboard revenue rose 7.2% to $122 million. Airports revenue jumped 14% to $113.6 million, helped by strong demand at San Francisco
International Airport and digital sales that climbed 15.6% to $73.4 million, with national advertisers now accounting for 57.8% of that segment's revenue. Profitability grew even faster than the top line. Adjusted EBITDA rose 11.6% to $143.4 million for the quarter and 19% to $247.3 million for the first half, while Airports Segment Adjusted EBITDA jumped 22.8% to $29.9 million. Adjusted Funds From Operations climbed 61.6% to $44.9 million in the quarter, and for the first half it went from just $5 million a year ago to $51.5 million. On August 4, Clear Channel also closed the sale of its Spain business for about $132.3 million, proceeds it plans to put toward paying down debt.
The growth did not reach the bottom line. Clear Channel posted a loss from continuing operations of $10 million in the quarter, reversing a $6.3 million profit a year earlier, and the consolidated net loss came to $5 million versus net income of $10.6 million in the same period of 2025. Over six months, the loss from continuing operations widened 21.4% to $59.4 million. Costs rose alongside revenue. Direct operating and SG&A expenses increased 5.9% for the quarter, and Airports site lease expense alone jumped 12.0% to $67.1 million on higher minimum guaranteed payments and the renewed contract with the Metropolitan Washington Airports Authority.
#channel #revenue #airports #operations

5 days ago
Week 1 was a great reminder of why we all love fantasy football.
At quarterback, Bryce Young scored more points than Drake Maye, Baker Mayfield, Matthew Stafford, Kyler Murray and Sam Darnold combined. At running back, two Bears finished inside the top-10 while Christian McCaffrey was out-carried by a rookie. The current WR1, Jalen ****** er, had more fantasy points than Puka Nacua, DeVonta Smith, Drake London, George Pickens and Ja'Marr Chase combined. Finally, the currently list of TE1s includes Mike Gesicki, Pat Freiermuth, T.J. Hockenson, Noah Fant, Cole Kmet and Kenyon Sadiq. Fun.
Thankfully, we can already start looking ahead to Week 2.
Here's an early look at Week 2 fantasy football rankings. Toggle between standard, half PPR (point per reception) and full PPR to see where players rank in your league's format. Scroll to the bottom to view the complete rankings.
Our team at USA TODAY Sports has you covered with plenty of content to help with your Week 2 waiver wire and roster decisions. Looking for up-to-date player news? We've got it. Wondering who the best waiver-wire claims are? We have that covered, so you can make your pickups. Need to know what players you can drop? We have that as well. We also have a list of the eight best buy low/sell high candidates and our biggest winners and losers from Week 1.
#drake #looking #Football #list
At quarterback, Bryce Young scored more points than Drake Maye, Baker Mayfield, Matthew Stafford, Kyler Murray and Sam Darnold combined. At running back, two Bears finished inside the top-10 while Christian McCaffrey was out-carried by a rookie. The current WR1, Jalen ****** er, had more fantasy points than Puka Nacua, DeVonta Smith, Drake London, George Pickens and Ja'Marr Chase combined. Finally, the currently list of TE1s includes Mike Gesicki, Pat Freiermuth, T.J. Hockenson, Noah Fant, Cole Kmet and Kenyon Sadiq. Fun.
Thankfully, we can already start looking ahead to Week 2.
Here's an early look at Week 2 fantasy football rankings. Toggle between standard, half PPR (point per reception) and full PPR to see where players rank in your league's format. Scroll to the bottom to view the complete rankings.
Our team at USA TODAY Sports has you covered with plenty of content to help with your Week 2 waiver wire and roster decisions. Looking for up-to-date player news? We've got it. Wondering who the best waiver-wire claims are? We have that covered, so you can make your pickups. Need to know what players you can drop? We have that as well. We also have a list of the eight best buy low/sell high candidates and our biggest winners and losers from Week 1.
#drake #looking #Football #list