1 hr. ago
Rick Ross was arrested in Florida and booked into jail on Thursday, Oct. 1, on charges of battery by strangulation and misdemeanor battery charges
A judge ordered the rapper to stay away from his accuser, identified as J.K. in court documents
Ross pleaded not guilty as his attorney called the allegations false and questioned his ex-girlfriend's motivations
Rick Ross was arrested on domestic violence-related charges days after his ex-girlfriend Jazzma Kendrick claimed that the rapper was physically abusive toward her.
The rapper, whose legal name is William Leonard Roberts II, was booked into jail in Florida on Thursday, Oct. 1, on charges of felony battery by strangulation and misdemeanor battery, according to Miami-Dade County court records reviewed by PEOPLE.
#battery #rick #thursday #booked


8 hours ago
Joe Burrow's girlfriend Olivia Ponton delivers her scorching 'hot take' on cheating appeared first on ClutchPoints. Add ClutchPoints as a Preferred Source by clicking here.
Cincinnati Bengals quarterback Joe Burrow's personal life has remained largely private, which is why he was initially upset when his relationship with social media influencer and model Olivia Ponton became public knowledge back in 2024. As Burrow is set to continue the Bengals' strong start to the season, Ponton recently revealed details about how she no longer tolerates infidelity in relationships.
Speaking on her "Booked & Busy" podcast, Ponton revealed how she has been cheated on multiple times in the past when she was longer, per New York Post.
"I have been cheated on in all of my past relationships. Literally every single one of them. All of them," she said.
Watch sports LIVE with fuboTV (free trial)
#clutchpoints #revealed #past #preferred
9 hours ago
Rick Ross' attorney brought up his client's celebrity status while asking for a quick release from custody. The judge made it clear that fame would not change how she treated him. The rapper appeared by video before Miami-Dade Judge Mindy Glazer on Thursday following his arrest on domestic violence-related battery charges. When his lawyer requested an expedited release for safety reasons, Glazer responded that she had "no idea" who Ross was. Ross has pleaded not guilty and maintains his innocence.
Spread Pictures / MEGA
Attorney Steve Sadow identified Ross by his legal name, William Leonard Roberts II, while asking the judge to speed up his release. "Mr. Roberts is a celebrity. I don't know to whatever degree Your Honor can, but I'd ask that his release be expedited," Sadow said.
The attorney argued that a faster release would be in his client's best interest. Glazer addressed Ross directly in her response. "Hi Mr. Roberts. I have no idea who you are, except as somebody here in the court who's going to be treated fairly, just like everybody here," she said.
Ross had been booked around 6:10 a.m. Thursday before making his video appearance. His bond was set at $4,000 for the felony battery by strangulation charge and $1,000 for the misdemeanor battery charge.
#release #glazer #Attorney #celebrity


9 hours ago
Rick Ross (born William Roberts) was arrested and booked on a pair of domestic battery charges in Miami Beach on Thursday (Oct. 1). When Rozay was remotely arraigned while still in custody hours later, the rapper's attorney, Bradley **** nstein, asked Judge Mindy Glazer for an expedited release process due to Ross' celebrity status.
TMZ obtained footage from the courtroom, which saw Judge Glazer explaining how she had no inkling who Rick Ross was, but promised him a fair process.
More from Billboard
Rick Ross Arrested on Battery & Domestic Violence Charges in Miami Beach, Pleads Not Guilty
Rick Ross Talks 'Port of Miami,' His Business Hustle & New Album 'Set In Stone'
#beach #glazer #battery


10 hours ago
Rick Ross was arrested in Miami Beach on Thursday on two domestic violence-related battery charges stemming from an alleged incident at his home in August. The rapper, whose legal name is William Roberts II, faces one felony count of battery by strangulation and one misdemeanor battery charge.
Ross voluntarily surrendered to Miami Beach police and was booked into the Turner Guilford Knight Correctional Center shortly after 6 a.m. on October 1. CBS12 reported from Miami-Dade court records that Ross and attorney Bradley ****** nstein filed a written plea of not guilty and demanded a jury trial.
Ross later bonded out and denied the allegations while speaking to reporters outside the jail. "I'm totally innocent of these fabricated allegations made against me," he said, according to WSVN 7News. His legal team has likewise said he is being wrongfully accused and asked that the case be allowed to proceed without prejudgment.
The arrest report describes an alleged August 28 confrontation involving a woman who said she had been in a relationship with Ross and living with him. The allegations have not been adjudicated, and Ross is presumed innocent unless proven guilty in court.
According to the arrest affidavit reviewed by CBS12, the woman went to Miami Beach police on September 29 to report an incident she said had occurred about a month earlier. She told investigators that Ross became angry after seeing an Instagram photograph in which she had been tagged and questioned her about another person.
#beach #august #according #alleged


11 hours ago
Rick Ross (born William Roberts) was arrested in Miami Beach on Thursday morning (Oct. 1) on a pair of battery charges, including battery by strangulation charge, according to Miami-Dade County jail records.
Rozay's record shows both counts are domestic violence-related charges, and the rapper was given a $5,000 bond. Ross was booked into the Turner Guilford Knight Correctional Center at 6:10 a.m. ET on Thursday.
More from Billboard
Every Guest Ye Brought Out During Night 2 of His Star-Studded Homecoming Show in Chicago
Rick Ross Plots Port of Miami 20th Anniversary Orchestra Tour: See the Dates
#Miami #battery #william #dade

12 hours ago
Rapper Rick Ross appeared in court Thursday after he was arrested on two domestic violence charges.
The "Hustlin'" rapper, whose legal name is William Leonard Roberts, voluntarily surrendered to police in Miami Beach early Thursday morning and was booked into jail on charges of felony battery by strangulation and misdemeanor battery, according to the Miami Beach Police Department.
In court, Ross' attorney submitted a not guilty plea on his behalf.
Obtained by ABC News - PHOTO: William Leonard Roberts II Known as Rick Ross in a video grab og a court livestream, OCt. 1, 2026.
The judge ordered Ross to stay away from the accuser, who was not publicly identified, and set bond at $5,000.
#ross #roberts #beach #rapper

13 hours ago
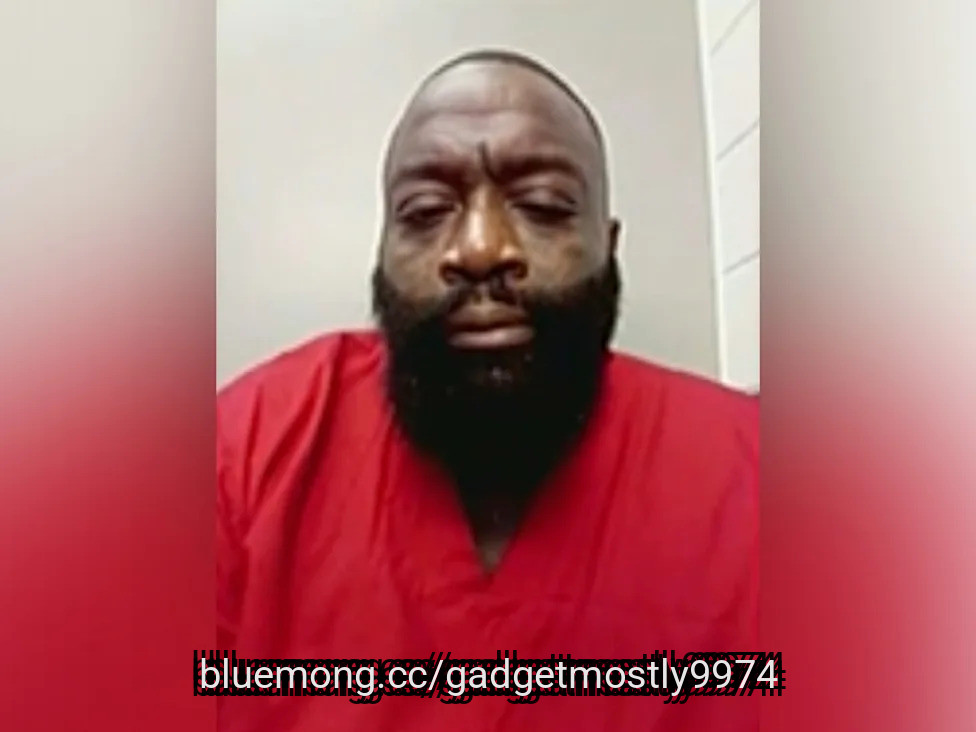
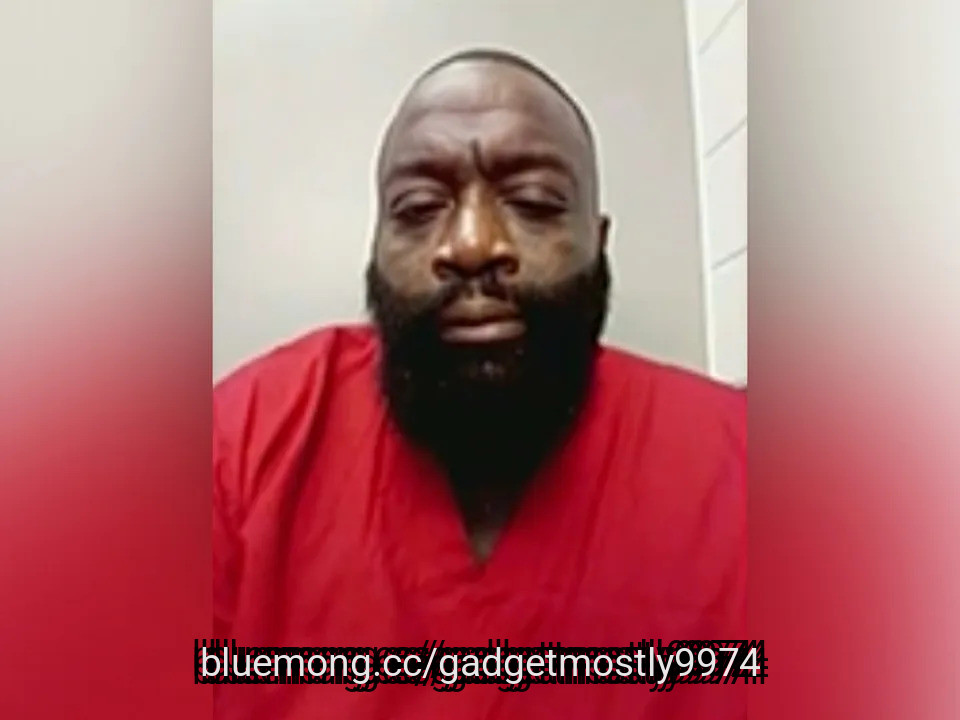
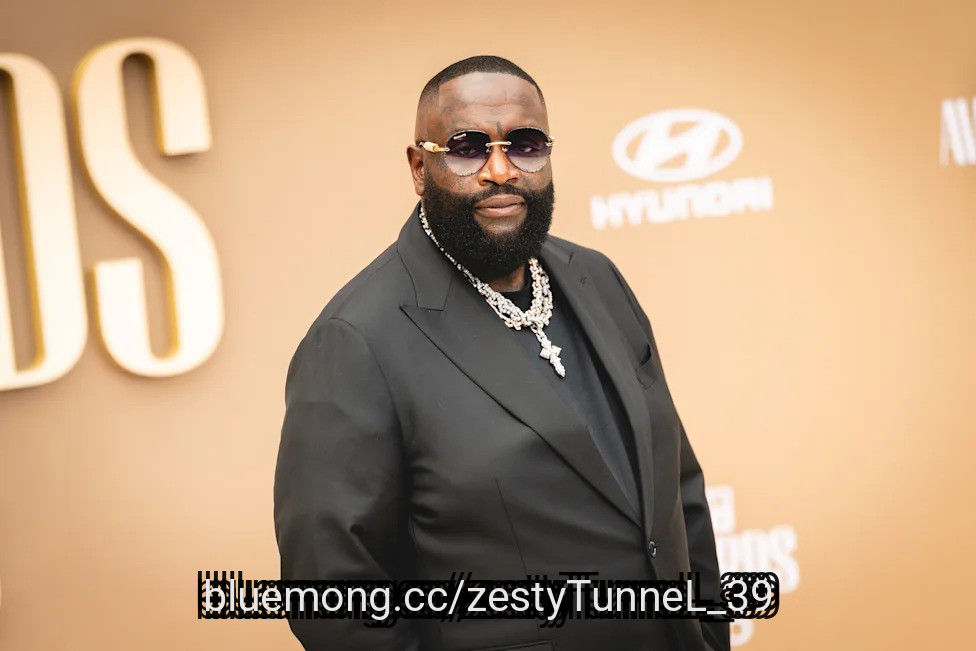
Rick Ross was arrested Thursday morning in Miami Beach on domestic violence charges including a felony count of battery by strangulation.
The rapper, born William Roberts II, voluntarily surrendered to Miami Beach Police headquarters, and was soon after booked into the Turner Guilford Knight Correctional Center, the Sun Sentinel reports. Ross was charged with one felony count of battery by strangulation and one misdemeanor count of battery. His bond was set at $6,000.
More from Rolling Stone
French Montana, Max B, and Rick Ross Perform at BET Awards 2026
Rick Ross on New Book, NA Spirits, and Exercising With a Joint and Luc Belaire
#battery #Miami #felony #strangulation
13 hours ago
Rick Ross has been arrested on domestic violence charges in Florida.
The rapper was arrested by Miami Beach police in the early hours of Thursday on domestic violence charges, including felony battery by strangulation, according to Miami-Dade jail and court records.
The 50-year-old, whose legal name is William Leonard Roberts, was booked into the Turner Guilford Knight Correctional Center at 6.10am.
He faces two charges listed as involving domestic violence, including one felony count of battery by strangulation and one misdemeanour count of battery.
The Grammy nominee reportedly turned himself in to police on Thursday after an ex-girlfriend alerted them on Tuesday, claiming he had been violent with her on 28 August.
The woman reportedly told police that Ross allegedly woke her up while she was sleeping and was physical with her while in a "jealous rage" over a photo she was tagged in on social media, according to TMZ.
#domestic #police #battery #Miami

14 hours ago
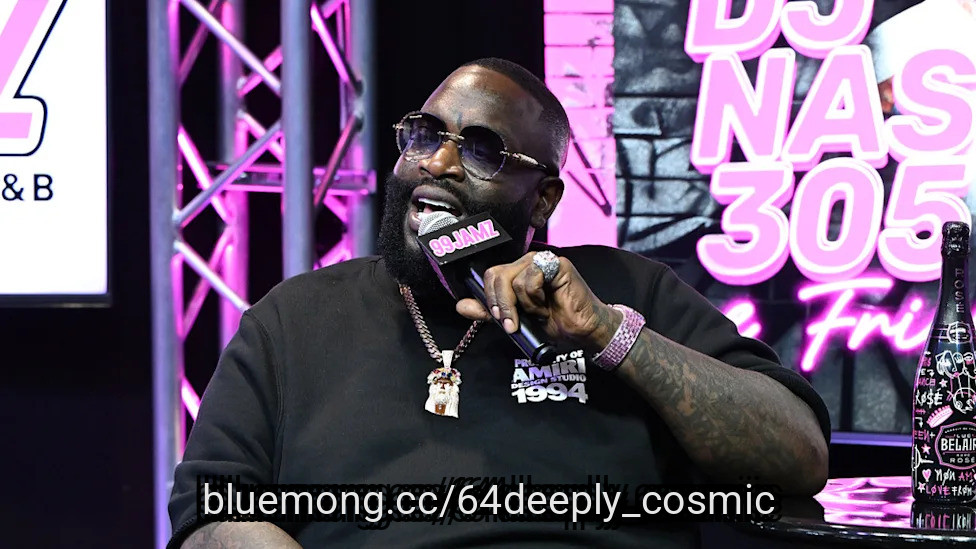
A woman who reported to the police that Rick Ross allegedly committed domestic violence against her is revealed to be the rapper's former girlfriend by TMZ, just a few hours after Ross himself surrendered on the domestic violence allegations.
Rick Ross, whose real name is William Leonard Roberts II and who is 50 years old, turned himself in to Miami Beach police early Thursday morning. According to the documents provided by the county jail and court, Ross has been charged with felony battery by strangulation and misdemeanor battery related to domestic violence and booked into the Turner Guilford Knight Correctional Center at 6:10 a.m. He has posted a $6,000 bond for his release: $5,000 for the felony and $1,000 for the misdemeanor.
The sources in law enforcement, cited by TMZ, claimed that the woman contacted the police on Tuesday, roughly a month after the alleged **** ault. The website has not disclosed the complainant's identity, and authorities have not yet released the arrest affidavit.
As TMZ reports, the woman said that the alleged **** ault took place on August 28th, when Ross woke her up over a photo she had been tagged in on social media.
According to the woman, Ross demanded explanations from her about lying to him, slapped her in the face, and accused her of having affairs with other men. She told the police that he hit her every time she denied it. Moreover, the woman claimed that Ross struck her in the chest several times, choked her till she could not breathe, yanked her ponytail, and pushed her against the wall. Then she showed the photos of the injuries to the police, according to TMZ.
#ross #woman #domestic

11 days ago
On September 17, Coherent Corp. (NYSE:COHR) announced an upgraded Pluggable Optical Line System that covers the full C-band and fits in a compact QSFP module, the same slot ordinary transceivers use. That is a lot of networking gear shrunk into a plug, and it follows a quarter of 34% revenue growth. Here is what the launch means, and where the stock's story gets harder to read.
Start with what the product does. The upgraded system can pack 32 wavelengths onto a single pair of fibers, which Coherent says adds up to as much as 25.6Tbps of traffic on links running 2km to 200km. It is designed for the latest 800G coherent optics, and it configures itself, handling link setup and laser safety without a technician tuning each connection. Coherent also says the system is generally available and already shipping in high volume, in 400G and 800G versions that work with existing network setups. Madhu Krishnaswamy, who runs the company's telecom transport unit, describes the goal as easing the usual trade-off between raw performance and operational simplicity.
The launch also sits on top of a business that is already moving. On August 12, Coherent reported results for its fiscal fourth quarter, which ended June 30: revenue of $2.05 billion, up 34% from a year earlier. Non-GAAP earnings per share rose to $1.74 from $1.00, and CEO Jim Anderson noted that for the full year, that measure grew more than twice as fast as revenue. Management guided to revenue of $2.2 billion to $2.4 billion for the first quarter of fiscal 2027, and Anderson says AI data centers are increasingly moving from copper to optical links.
Now look at the two versions of profit. Coherent's non-GAAP earnings came to $1.74 per share, but under GAAP the figure was $1.19. The gap comes from items management leaves out, including stock-based pay, amortization on acquired intangibles, and restructuring and integration costs. Operating margin shows it more clearly, at 21.8% on a non-GAAP basis and 12.4% under GAAP. Some of those costs are non-cash, but they are real, and anyone anchoring on the higher figure is skipping them.
Then there is how much weight this launch can carry. The announcement puts no sales figure on the product, so its contribution to a company that booked $2.05 billion in a quarter cannot be sized from what has been published. The bullish story also rests on management's own read of where AI networks are headed, and on a capacity build-out that CFO Sherri Luther says gets priority in spending. Money spent on capacity only pays off if the demand management describes keeps arriving.
#gaap #revenue #launch #anderson

12 days ago
Rocket Lab (RKLB) has gained 9.5% over the last five trading days, while the S&P 500 added 0.6%. A week like that pulls money in. The stock is still about 55% below its 52-week high. The run is not the question. What matters for your money is what this stock does to your portfolio when the market moves, because it travels about four times as far as the index in both directions.
On days the S&P 500 rose over the past year, Rocket Lab captured about 381% of the gain. On days the index fell, it absorbed about 403% of the loss. The down days take slightly more than the up days give.
That is leverage on the market rather than a cushion. Over the past five years Rocket Lab ran 79.2% annualized volatility against 17.2% for the S&P 500, and its daily moves tracked the index at a correlation of 0.46 over those five years.
A moderate correlation and a swing that size sit together. Correlation asks whether the stock and the index move the same way, not how far. A good part of what Rocket Lab does is its own.
Look at what you own. Rocket Lab booked a record $234 million of revenue in Q2 2026, up 62% from the same quarter a year earlier, and it has just flown its 16th Electron mission of 2026.
#days
12 days ago
Super Micro Computer (SMCI) stock rose 9.5% on Thursday, September 17, closing just over $40. The move followed a bullish call on how big the market for AI servers gets. That call may well be right. But it answers a question Super Micro's own results never raised. That is why one big session tells you less than it looks like it does.
Analysts at Goldman Sachs said the addressable market for AI servers will expand aggressively through the end of the decade. That is a forecast about an industry rather than about one manufacturer. Another account of Thursday morning's climb credited a broader equity rebound after Wednesday afternoon's Federal Reserve rate decision, not the forecast. Hewlett Packard Enterprise (HPE) jumped 8.0% the same day against the S&P 500's 1.1% gain, showing that capital was rotating heavily into primary AI server makers.
Company-specific headlines that day ran the other way: after the close, a shareholder rights law firm issued a press release soliciting clients for a potential investigation into company management.
A bigger market is not what this company is short of. In its fiscal fourth quarter, ended June 2026, Super Micro booked over $60 billion of new orders. That backlog underpins management's fiscal 2027 revenue guidance of $65 billion to $72 billion—up sharply from the $39 billion booked over the prior twelve months, but spread out as delivery and deployment constraints allow customers to take delivery.
What it is short of is customers ready to take delivery. Super Micro sells data center building block solutions, which bundle the servers with the power, cooling, networking and software around them. The company's manufacturing capability is on track to include more than 3,000 direct liquid-cooled racks a month.
#forecast


13 days ago
On September 17, Coherent Corp. (NYSE:COHR) announced an upgraded Pluggable Optical Line System that covers the full C-band and fits in a compact QSFP module, the same slot ordinary transceivers use. That is a lot of networking gear shrunk into a plug, and it follows a quarter of 34% revenue growth. Here is what the launch means, and where the stock's story gets harder to read.
Start with what the product does. The upgraded system can pack 32 wavelengths onto a single pair of fibers, which Coherent says adds up to as much as 25.6Tbps of traffic on links running 2km to 200km. It is designed for the latest 800G coherent optics, and it configures itself, handling link setup and laser safety without a technician tuning each connection. Coherent also says the system is generally available and already shipping in high volume, in 400G and 800G versions that work with existing network setups. Madhu Krishnaswamy, who runs the company's telecom transport unit, describes the goal as easing the usual trade-off between raw performance and operational simplicity.
The launch also sits on top of a business that is already moving. On August 12, Coherent reported results for its fiscal fourth quarter, which ended June 30: revenue of $2.05 billion, up 34% from a year earlier. Non-GAAP earnings per share rose to $1.74 from $1.00, and CEO Jim Anderson noted that for the full year, that measure grew more than twice as fast as revenue. Management guided to revenue of $2.2 billion to $2.4 billion for the first quarter of fiscal 2027, and Anderson says AI data centers are increasingly moving from copper to optical links.
Now look at the two versions of profit. Coherent's non-GAAP earnings came to $1.74 per share, but under GAAP the figure was $1.19. The gap comes from items management leaves out, including stock-based pay, amortization on acquired intangibles, and restructuring and integration costs. Operating margin shows it more clearly, at 21.8% on a non-GAAP basis and 12.4% under GAAP. Some of those costs are non-cash, but they are real, and anyone anchoring on the higher figure is skipping them.
Then there is how much weight this launch can carry. The announcement puts no sales figure on the product, so its contribution to a company that booked $2.05 billion in a quarter cannot be sized from what has been published. The bullish story also rests on management's own read of where AI networks are headed, and on a capacity build-out that CFO Sherri Luther says gets priority in spending. Money spent on capacity only pays off if the demand management describes keeps arriving.
#quarter #launch #anderson

14 days ago
Johnson & Johnson (JNJ) has been a rewarding stock to hold, up about 53% over the past year against about 17% for the S&P 500. The change worth noticing over that stretch is quieter than the price. Management said sales still rose 5.6% despite a STELARA drag of about 460 basis points. Management is encouraging investors to evaluate the company's underlying momentum by presenting growth rates that exclude STELARA alongside its reported figures.
A year and a half ago, that drag was the headline. Management's own framing of the first quarter of 2025 noted an approximate 810 basis point headwind on Innovative Medicine sales.
By the second quarter of 2026, that segment-level drag remained heavy at roughly 760 basis points (or about 460 basis points across the total enterprise), yet management's emphasis shifted to highlighting double-digit operational growth excluding STELARA
The exclusion is not a rounding adjustment. STELARA sales fell 55.7% in the second quarter of 2026, and management put that drag at about 460 basis points of the whole company's 5.6% operational sales growth.
Two products show what the replacement looks like. TREMFYA booked $2 billion of sales in the second quarter of 2026, up over 70%, and management says ulcerative colitis and Crohn's disease are the major drivers of that growth. ICOTYDE, a recently launched once-daily pill for psoriasis, is the second, which leadership has highlighted as a key pipeline priority for the immunology business.
#sales #basis #drag #quarter

14 days ago
GE Aerospace (GE) has more engine work booked than it can currently perform, and that visibility is much of why people own the shares. The option chain does not treat the stock as settled. At about $307, contracts running twelve months out carry a band from near $216.93 to near $434.6, with roughly a two-in-three chance the stock finishes inside it.
Read that band as money. The ceiling near $434.6 sits about 41.5% above today's price, and the floor near $216.93 sits about 29.4% below it. Whatever money you have in GE, the options market prices about $90 of every $307 coming off, or about $128 going on, inside twelve months.
The two distances are not equal. A share price cannot fall below zero while nothing caps the upside, so the ceiling always sits further out than the floor. That is arithmetic rather than a view on GE.
The floor is the half worth sitting with. Near $216.93, it is well below $272.91, the lowest GE has traded in the past 52 weeks. The chain is not forecasting that price. It prices twelve months as long enough to reach it.
A range is only wide relative to something. The stock's realized volatility over the trailing year, meaning how far it has actually moved, was 33.2%, and the options quote 34.6%. The market is charging about what this stock already delivers.
#near #sits #floor #band
14 days ago
Rocket Lab (RKLB) stock has traded between $39.48 and $150.23 over the past 52 weeks. It now sits about 58% below its 52-week high, and anyone who bought twelve months ago is still up about 19%. None of that tells you what you would be buying today. Rocket Lab sells two quite different things, and the one its name points at is the smaller of them.
In Q2 2026 the ****** e Systems segment brought in $189.5 million. Launch Services brought in $44.6 million, down 30% from the previous quarter despite a similar number of launches. Management attributes that drop to accounting rather than lost work, because revenue from those launches is recognized over time and much of it had already been booked.
So Rocket Lab earns most of its revenue building satellites and their parts. Electron flew its 16th mission of 2026 in September. Launch is a real franchise, and it is not where most of the money comes from.
The stock trades at 52 times sales, against 3.1 for the S&P 500, on revenue of about $0.8 billion over the trailing twelve months. At this valuation, investors are largely pricing in future execution on the Neutron medium-lift rocket and the financial impact of the pending Iridium acquisition, rather than current satellite production alone. Management targets delivery to the pad in Q4 2026, and says the window for a launch before the end of 2026 is narrowing.
And you are paying for Iridium, which Rocket Lab has agreed to buy and expects to close in mid-2027. Iridium, a global satellite communications network, serves more than 2.5 million subscribers and delivered over $870 million of revenue in its past year. That is more than Rocket Lab's whole trailing twelve months. Management calls it a relatively slow-growing business that brings profit rather than a hole in the income statement.
#million #management #revenue

15 days ago
Oracle Corporation (NYSE:ORCL) is increasing the expected cost of its fiscal 2026 restructuring plan by about $700 million to roughly $2.8 billion as it simultaneously ramps up spending to capture demand for AI cloud services. The additional costs include severance, contract terminations and other exit expenses, with some restructuring directly linked to adopting AI across parts of the organization.
Oracle had already recorded $1.8 billion of restructuring expenses in fiscal 2026, compared with $299 million in fiscal 2025, showing how materially the company is accelerating its operational transformation. The restructuring comes alongside an unusually large AI investment cycle. Oracle booked more than $30 billion of new AI cloud contracts in its latest quarter, lifting its remaining performance obligations/revenue backlog to $664 billion, while roughly half of that backlog is expected to convert into revenue over the next 36 months.
The strongest bull argument is that the additional restructuring expense is part of a broader shift toward a higher-growth cloud and AI business rather than simply a deterioration in cost control. Oracle Corporation (NYSE:ORCL)'s restructuring program is explicitly aimed at improving efficiency while reallocating resources toward cloud-based offerings and second-generation cloud infrastructure. If the $2.8 billion restructuring program reduces lower-growth costs and enables Oracle to redirect personnel and capital toward AI infrastructure, the near-term earnings pressure could support stronger operating leverage later as cloud revenue scales.
More importantly, the restructuring is occurring against evidence that AI demand is already translating into contracted revenue. Oracle added more than $30 billion of AI cloud contracts in one quarter, pushing its backlog to $664 billion, above the $639.89 billion ******* yst estimate. Management said most of the newly contracted revenue would not require substantial incremental capital because customers are using prepayments or supplying their own hardware. That is particularly important because Oracle's biggest weakness has been the mismatch between rapid infrastructure investment and current cash generation. If customer-funded capacity continues to reduce Oracle's upfront capital burden, the company could convert its huge backlog into revenue without proportionally increasing its cash burn.
The early financial evidence also supports the possibility that the AI strategy is beginning to improve Oracle's growth profile. Revenue in the recent quarter rose 30% year over year to $19.3 billion, adjusted EPS reached $1.92 versus the $1.74 ******* yst consensus, and Oracle Corporation (NYSE:ORCL) raised its fiscal 2027 adjusted EPS forecast from $8.05 to $8.10. Meanwhile, first-quarter free cash flow of negative $5.4 billion was substantially better than both the expected negative $9.56 billion and the previous-quarter negative $11.48 billion. If this trajectory continues, the $700
15 days ago
ASML Holding N.V. (NASDAQ:ASML) is examining ways to produce more than 110 EUV lithography systems in 2028, according to JPMorgan ***** ysts following a meeting with CFO Roger Dassen. The company is already nearly sold out for 2027 and expects to produce at least 80 EUV systems that year, meaning output above 110 in 2028 would represent at least a 37.5% increase from the 2027 level. JPMorgan said the main constraint has shifted toward ***** embly speed rather than the availability of critical components, suggesting ASML believes additional capacity can be unlocked through manufacturing and ***** embly improvements.
The potential increase is being driven primarily by AI-related demand. ASML's existing EUV machines, which cost roughly $200 million each, are essential for manufacturing leading-edge AI processors, while customers including TSMC, Samsung, SK Hynix and Intel are expanding advanced-chip capacity. Reuters reported separately that virtually all of ASML's EUV production capacity is booked through 2027, while the company has begun construction of a new Eindhoven facility designed to accelerate tool ***** embly and eventually accommodate up to 20,000 workers.
The strongest bullish implication is that ASML Holding N.V. (NASDAQ:ASML) may be able to convert exceptionally strong demand into higher unit volumes rather than simply relying on price increases. Moving from at least 80 EUV systems in 2027 to more than 110 in 2028 would materially expand the number of high-value systems ASML can monetize. This comes after the company already raised its 2026 revenue outlook to €43 billion–€45 billion, compared with its previous €36 billion–€40 billion range, while targeting a 54%–56% gross margin. Reuters also reported that second-quarter revenue reached €9.3 billion with a 54% gross margin, demonstrating that stronger AI-driven demand is already translating into financial performance.
The longer-term competitive position is particularly favorable because ASML Holding N.V. (NASDAQ:ASML) effectively has no commercial competitor in EUV. JPMorgan estimates that ASML held 94% of the overall lithography market in 2025, while Reuters describes the company as having maintained a monopoly in EUV since the late 2010s. At the same time, customers are committing to ASML's next-generation High-NA technology: the machines cost approximately $400 million, can print features about 40% smaller than existing EUV systems, and TSMC, Samsung, and SK Hynix have all established plans for production adoption. If AI chip demand remains strong enough to support both higher low-NA volumes and eventual High-NA adoption, ASML could see a multi-year increase in system shipments, revenue, and potentially cash generation while strengthening its already exceptional competitive moat.
#company

15 days ago
Oracle Corporation (NYSE:ORCL) is increasing the expected cost of its fiscal 2026 restructuring plan by about $700 million to roughly $2.8 billion as it simultaneously ramps up spending to capture demand for AI cloud services. The additional costs include severance, contract terminations and other exit expenses, with some restructuring directly linked to adopting AI across parts of the organization.
Oracle had already recorded $1.8 billion of restructuring expenses in fiscal 2026, compared with $299 million in fiscal 2025, showing how materially the company is accelerating its operational transformation. The restructuring comes alongside an unusually large AI investment cycle. Oracle booked more than $30 billion of new AI cloud contracts in its latest quarter, lifting its remaining performance obligations/revenue backlog to $664 billion, while roughly half of that backlog is expected to convert into revenue over the next 36 months.
The strongest bull argument is that the additional restructuring expense is part of a broader shift toward a higher-growth cloud and AI business rather than simply a deterioration in cost control. Oracle Corporation (NYSE:ORCL)'s restructuring program is explicitly aimed at improving efficiency while reallocating resources toward cloud-based offerings and second-generation cloud infrastructure. If the $2.8 billion restructuring program reduces lower-growth costs and enables Oracle to redirect personnel and capital toward AI infrastructure, the near-term earnings pressure could support stronger operating leverage later as cloud revenue scales.
More importantly, the restructuring is occurring against evidence that AI demand is already translating into contracted revenue. Oracle added more than $30 billion of AI cloud contracts in one quarter, pushing its backlog to $664 billion, above the $639.89 billion ****** yst estimate. Management said most of the newly contracted revenue would not require substantial incremental capital because customers are using prepayments or supplying their own hardware. That is particularly important because Oracle's biggest weakness has been the mismatch between rapid infrastructure investment and current cash generation. If customer-funded capacity continues to reduce Oracle's upfront capital burden, the company could convert its huge backlog into revenue without proportionally increasing its cash burn.
The early financial evidence also supports the possibility that the AI strategy is beginning to improve Oracle's growth profile. Revenue in the recent quarter rose 30% year over year to $19.3 billion, adjusted EPS reached $1.92 versus the $1.74 ****** yst consensus, and Oracle Corporation (NYSE:ORCL) raised its fiscal 2027 adjusted EPS forecast from $8.05 to $8.10. Meanwhile, first-quarter free cash flow of negative $5.4 billion was substantially better than both the expected negative $9.56 billion and the previous-quarter negative $11.48 billion. If this trajectory continues, the $700 mi
17 days ago
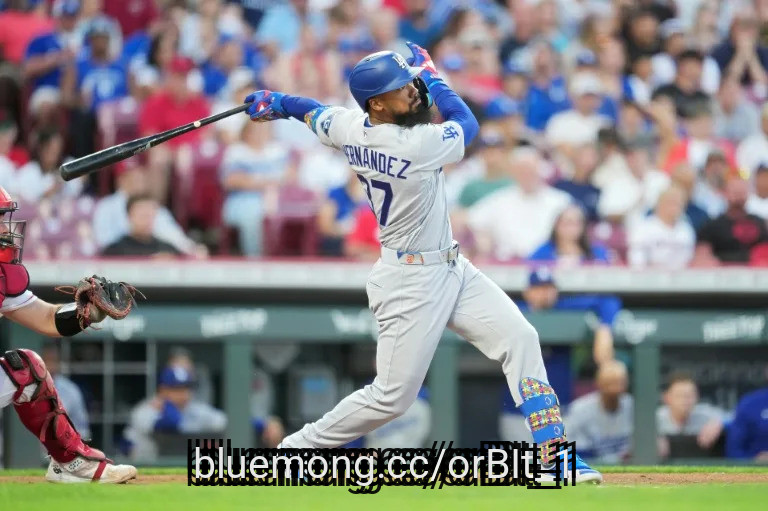
The Los Angeles Dodgers, seeking a third straight World Series crown, booked their playoff berth Monday with a 4-1 win over the Cincinnati Reds.
With a 91-59 record and 12 games remaining in the regular season, the Dodgers are now ****** ured of at least a wild card series place, as they pursue a historic three-peat as MLB champions.
The Dodgers are currently in position for one of the National League's top-two seeds -- who receive first-round byes and hosting rights in the division series -- along with the Milwaukee Brewers, who are also ****** ured of post-season action.
Over in the American League, the Tampa Bay Rays have already qualified.
The free-spending Dodgers beat the New York Yankees in the 2024 World Series and triumphed over the Toronto Blue Jays last year.
#series #World
17 days ago
On August 4, Willis Lease Finance Corporation (NASDAQ:WLFC) reported second-quarter results that pulled in two directions at once. The lessor of commercial aircraft engines grew its operating business at a healthy clip, yet net income fell by more than half, a split that makes this quarter harder to read than the headline suggests.
Income from operations climbed 20.2% to $34.0 million in the quarter ended June 30, 2026, and the engine underneath that number is lease rent revenue, which rose 6.7% to $77.1 million as the average size of Willis Lease's portfolio expanded from a year earlier. Over the first six months of 2026, lease rent revenue is up 10.4% to $154.5 million, a steadier pace than the quarterly figure alone implies.
The company's trading business added to that. Willis Lease booked a $32.0 million gain on the sale of leased equipment, up 16.2%, after selling 21 engines and other parts and equipment during the quarter, compared with 14 engines and two airframes a year earlier. That kind of turnover matters for a leasing company, since selling ****** ets at a gain confirms that engine values in the market are holding up.
The bigger story sits in how Willis Lease is expanding beyond its own balance sheet. ****** ets under management, which folds in the company's on-balance-sheet fleet along with its Willis Aviation Capital business, grew 21% year over year to $4.4 billion. CEO Austin C. Willis tied that growth directly to building out Willis Aviation Capital, and the fee income backs that up: management and advisory fees jumped 113.4% to $5.5 million in the quarter and 194.9% to $13.4 million over six months. Two new investment fund partnerships, one with Liberty Mutual Investments that began operating in March 2026 and one with Blackstone Credit & Insurance that started in April 2026, are the mechanics behind that shift toward managing other people's capital rather than only deploying its own.
Net income attributable to common shareholders fell 51.2% to $28.7 million, and diluted earnings per share dropped from $2.81 to $1.31. Some of that gap traces to a tough comparison rather than a weaker quarter, since the second quarter of 2025 included a $43.0 million gain from the sale of the BAML business that had no counterpart this year. Willis Lease also recognized a $5.4 million loss on debt extinguishment in the quarter, and $12.4 million over six months, a cost tied to refinancing that simply was not there in 2025.
#lease #capital #months
17 days ago
On September 10, LightPath Technologies (NASDAQ:LPTH) reported fiscal fourth-quarter and full-year results that turned a multiyear strategic bet into a financial statement. Revenue nearly doubled for the year, margins expanded, and the company walked away from its last manufacturing ties to China. For a small-cap optics supplier that spent years explaining a strategy, this was the quarter the strategy started explaining itself.
Annual revenue climbed 92.7% to $71.7 million from $37.2 million, and the fourth quarter alone hit a record $21.2 million, up 73.8% year over year. That growth is not just volume. Full-year gross margin expanded to 36% from 27.2%, and the fourth quarter came in even higher at 39.4%, because ****** emblies, modules and cameras now make up 44% of annual sales instead of being sold as raw components.
CEO Sam Rubin said the shift reflects both a change in what LightPath sells and better execution on what it already made, noting every one of its four product groups improved margin for the year. Backlog finished at $110.9 million, up 197% from $37.4 million a year earlier, with $85.6 million of it scheduled for delivery within 12 months. Weeks after the fiscal year closed, the company booked another $24 million in counter-UAS orders, and some of those programs have already moved to monthly delivery cadences of tens of units.
LightPath also completed its exit from China, selling its subsidiary there for $4.5 million paid out over five years, leaving the company with no manufacturing footprint in a country that increasingly can't supply the defense primes it depends on. That matters because defense programs face a deadline this decade to source optics away from covered nations, and qualification cycles run two to three years, meaning the sourcing decisions being made now will determine who wins contracts in 2029 and 2030.
The company's fourth-quarter net loss narrowed to $4.1 million from $7.1 million a year earlier, but full-year operating expenses jumped to $45.5 million from $22 million, and $15.6 million of that was a noncash charge tied to G5 Infrared outperforming the earnout targets set at acquisition. Management called that charge mostly behind the business now that the final G5 payout has been accrued for January 2027, but it is a reminder that acquisition accounting can swing the income statement even when operations are healthy.
#year #quarter #China
17 days ago
On September 10, MasterCraft Boat Holdings (NASDAQ:MCFT) reported a fiscal fourth quarter that looked nothing like the one a year earlier. Adjusted EBITDA more than doubled, margins expanded across the legacy business, and the company closed out a year defined by its May 15 acquisition of Marine Products Corporation. But buried inside those same results was a $10.1 million writedown that tells a very different story about one corner of the business.
MasterCraft's core boat business is the reason the quarter worked at all. Legacy net sales, meaning the business before the acquisition, climbed 21.5% year over year to $96.6 million in the fourth quarter, powered by the next generation X Series lineup and less discounting at the dealer level. That combination of volume and pricing pushed legacy adjusted EBITDA margin up 730 basis points to 19.3%, up from 12% a year earlier. Once the newly acquired Chaparral and Robalo brands are added in, which contributed for only six weeks after the deal closed on May 15, consolidated fourth quarter net sales reached $129.9 million, up 63.4%, and adjusted EBITDA hit $20.5 million, up 114.9%.
The company also cleaned up its channel. Dealer field inventory for the legacy business fell 30% year over year, with turnover now running ahead of pre-pandemic levels, a sign dealers are selling boats rather than sitting on them. Full-year adjusted net income reached $30.2 million, or $1.76 per diluted share, up from $15.1 million, or $0.92 per share, in fiscal 2025. The company generated $22.3 million in free cash flow for the year and, as of June 30, held $43.9 million in cash, zero debt, and a fully available $75 million credit line. MasterCraft's own retail sales grew low single digits for the year even as the broader powerboat industry fell mid to high single digits, and the newer Robalo brand posted high single-digit retail growth in the fishing boat category.
The picture gets murkier once you look past the flagship brand. The Leisure segment, home to the Crest and Balise pontoon boats, saw fourth-quarter sales fall 11.2% year over year to $12.1 million, and the company booked a $10.1 million non-cash impairment against Crest brand ******* ets tied to what management called current category conditions. On a GAAP basis, that charge combined with acquisition costs and purchase accounting adjustments turned the quarter into a net loss of $7 million, or $0.35 per diluted share, compared to net income of $5.5 million a year earlier. Operating expenses rose $23.1 million in the quarter, including $5.9 million in transaction costs tied to the acquisition.
#million #legacy

18 days ago
Broadcom's AI revenue surged 221% year over year with a forward P/E of 19, making it cheaper than Nvidia despite a similar growth trajectory.
TSMC revenue rose 53% year over year at a forward P/E of 20, and Dell booked a record $61B in AI orders last quarter.
Just released. Our ******* ysts combed the entire stock market and named the ten best stocks to buy right now, and NVIDIA didn't make the cut. Enter your email to see the names that beat NVDA. The report is free. Enter your email and see if any of your stocks made the cut.
On a recent Earn Your Leisure episode, hosts Troy Millings and Rashaad Bilal split openly on where the next dollar of AI value accrues. Millings argued for names outside the Magnificent 7 and made Broadcom's custom accelerator business the centerpiece of the case. Bilal countered that "you have to go with the people who are on the leaderboard," naming Taiwan Semiconductor (NYSE:TSM), Nvidia (NASDAQ:NVDA), Micron (NASDAQ:MU), Apple (NASDAQ:AAPL), Alphabet (NASDAQ:GOOG, NASDAQ:GOOGL), Microsoft (NASDAQ:MSFT), and the Nasdaq 100.
I find Millings the more persuasive of the two. Broadcom (NASDAQ:AVGO) posted AI semiconductor revenue of $16.7 billion in the third quarter of fiscal 2026, up 221% year over year, and guided the fourth quarter to $21.7 billion, up 236%. On the earnings call, Hock Tan sketched a trajectory to roughly $115 billion in fiscal 2027 and $230 billion in fiscal 2028.
#NVIDIA #billion #enter


18 days ago
SPY surged 11% year-to-date while home prices hit all-time highs, powering a record $12.5 trillion single-quarter wealth gain to $185.7 trillion total.
The personal saving rate collapsed to 2.8% from 5.8% a year ago as Americans spend paper gains concentrated among the wealthiest households.
Household net worth hit 571% of GDP, just shy of the 574% record that previously preceded the Fed's most aggressive rate-hiking cycle in four decades.
Just released. Our ***** ysts combed the entire stock market and named the ten best stocks to buy right now. The report is free. Enter your email and see if any of your stocks made the cut.
American households just booked the largest quarterly wealth gain in history, and most Americans do not feel any richer. Federal Reserve data released this month shows U.S. household net worth jumped $12.5 trillion in the second quarter of 2026, reaching a record $185.7 trillion. That single-quarter increase exceeds the annual gross domestic product of every country on earth except the United States and China. It is the eleventh straight quarter of gains, a streak that has added $43.4 trillion to household balance sheets and pushed ***** ulative wealth creation since the 2020 pandemic to $83.9 trillion. Yet the University of Michigan's consumer sentiment index came in at 55.2 in July, a level the survey's own interpretation guide classifies as recessionary.
#trillion #quarter #record #year
18 days ago
Lyft, Inc. (NASDAQ:LYFT) has begun offering Waymo's fully autonomous robotaxi rides directly through its app in Nashville, marking the first market where Waymo vehicles can be booked through both the Waymo and Lyft apps. Lyft users requesting Standard, Priority Pickup, Wait & Save, or Extra Comfort rides within the designated Nashville service area can be matched with a Waymo vehicle at no additional cost.
The rollout also gives Lyft a larger role in the autonomous-vehicle ecosystem through its Flexdrive subsidiary, which will manage charging, cleaning and maintenance for Waymo's fleet. Reuters previously reported that the Nashville partnership was intended to become Waymo's first commercial deployment through Lyft's ride-hailing network.
paul-hanaoka-D-qq7W751vs-unsplash
The partnership could strengthen Lyft, Inc. (NASDAQ:LYFT)'s long-term position in a ride-hailing industry that is increasingly moving toward autonomous vehicles. Rather than spending heavily to develop its own robotaxi technology, Lyft can leverage Waymo's autonomous-driving capabilities while providing the customer base, app infrastructure, and fleet-management services needed to put those vehicles to work. This ****** et-light approach could allow Lyft to participate in the growth of robotaxis without bearing the enormous technological costs and risks ****** ociated with developing a self-driving system internally.
The bigger opportunity is Flexdrive. Lyft is not simply sending customers to Waymo; its subsidiary is taking responsibility for keeping Waymo vehicles operational in Nashville. Lyft says its new 80,000-square-foot facility will support more than 70 full-time positions and help optimize vehicle availability. If this operating model proves successful, Lyft could potentially become a valuable infrastructure and fleet-management partner as Waymo expands into additional markets. That would give Lyft another potential revenue opportunity beyond traditional ride commissions.
#vehicle #fleet #ride #NASDAQ

19 days ago
Charleston White, comedian and social media star, allegedly ****** aulted and robbed a woman.
This happened during the same weekend when the comedian was arrested on battery charges in South Florida.
Kay Pretty alleged on her Instagram on September 12, 2026, that she kept silent for too long. According to her story, White punched her in the face while she was sleeping, insulted her, said she was worthless, and tried to drive her away from the house they both lived in. The woman added that he had physically ****** aulted her the previous night as well.
"I have a lot to say about Charleston, from abusing me physically, mentally, emotionally, financially, and spiritually, to stealing my money, my jewelry, my clothes, my bags," she wrote. "He has disrespected me for the last time, and I won't stand for it anymore. I hope he gets what he deserves and rots in jail."
White, 49, was arrested Saturday by the Hollywood Police Department and booked into the Broward County jail on the misdemeanor charge of touch or strike battery, according to TMZ reports that referenced the jail records. The records list the case as pending trial with bond at $0. Until the case goes to court and the judge sets the bond, the comedian stays in jail. The details of the alleged battery incident aren't disclosed.
#comedian #battery
20 days ago
Ben Shelton has been handed a potential blow ahead of his US Open final against Alexander Zverev, with girlfriend Trinity Rodman unlikely to be in the stands because of a scheduling clash.
The American tennis star booked his place in his first Grand Slam final by beating Frances Tiafoe 4-6, 6-3, 6-3, 7-5 on Friday night at Arthur Ashe Stadium.
Shelton now faces Zverev on Sunday with a chance to become the first American man to win a Grand Slam since Andy Roddick in 2003. However, he will have to overcome a difficult record against the German.
Photo by Christian Kaspar-Bartke/Getty Images
Rodman is scheduled to play for Washington Spirit against Boston Legacy FC in an NWSL away game on Sunday, with kick-off at 1pm local time.
#slam


20 days ago
"IndoNinja" goes again.
Top Ultimate Fighting Championship (UFC) Flyweight prospect Bilal Hasan has booked his second official Octagon appearance, colliding with Luis Gurule at UFC 334 on Sat., Nov. 14, 2026, inside Madison Square Garden in New York City.
MMA Fighting was first to report the news.
Hasan (10-0) burst onto the UFC scene in style, scoring a 45-second knockout over Mridul Saikia during Week 1 of Contender Series Season 10 to earn his contract.
Just 18 days later, Hasan made his official UFC debut at UFC Shanghai, brutally knocking out fellow undefeated newcomer Nilson Rojas in the second round (watch highlights).
#bilal