

2 days ago
When Christmas rolls around, my wife puts out a very small tree and some stuffed ornaments we bought a few years ago at Target. That's a pretty modest approach to decorating for the holidays compared to many of our neighbors.
At the house we just moved out of, some homes added tasteful lights, others opted for religious displays, and a few opted for a whole lot of inflatables. In some cases, the spending was significant, although many of the items were reused year after year.
Decorations are a small but meaningful part of holiday spending.
Americans planned to spend an average of $1,172 on travel, $632 on gifts, $351 on entertaining, and $227 on decorations, according to a BMO survey conducted before the 2024 holiday season.
Getting those items may be more of a challenge this year, as Gordon Companies, which runs a number of Christmas-themed websites and lists Target, Kohl's, Home Depot, Walmart, Amazon, Lowe's, and Michaels as retail partners, has filed for Chapter 11 bankruptcy.
#christmas #decorations #opted #items
At the house we just moved out of, some homes added tasteful lights, others opted for religious displays, and a few opted for a whole lot of inflatables. In some cases, the spending was significant, although many of the items were reused year after year.
Decorations are a small but meaningful part of holiday spending.
Americans planned to spend an average of $1,172 on travel, $632 on gifts, $351 on entertaining, and $227 on decorations, according to a BMO survey conducted before the 2024 holiday season.
Getting those items may be more of a challenge this year, as Gordon Companies, which runs a number of Christmas-themed websites and lists Target, Kohl's, Home Depot, Walmart, Amazon, Lowe's, and Michaels as retail partners, has filed for Chapter 11 bankruptcy.
#christmas #decorations #opted #items

2 days ago
On September 8, 2026, Reuters reported that ASML Holding N.V. (NASDAQ:ASML) plans to work with major customers. It includes Taiwan Semiconductor Manufacturing Company Limited (NYSE:TSM), Nvidia, Intel, Samsung, and SK Hynix to adapt its next-generation "High NA" extreme ultraviolet lithography tools so they can print larger data-center chips. It addresses a current limitation where the newer machines use a smaller mask than ASML's widely deployed standard EUV tools.
ASML targets a pilot production line using the larger masks by 2031 and high-volume manufacturing readiness by 2033. Chief technology officer Marco Pieters said these changes could lift the productivity of these systems by roughly 40%.
The larger-mask project could create a new growth opportunity for ASML Holding N.V. (NASDAQ:ASML) while helping TSMC manufacture larger AI chips more efficiently. ASML plans to use its High NA EUV tools to handle chips as large as today's biggest data-center processors. The business expects the larger masks to increase system productivity by 40%. It could scale up demand for its next-generation equipment and help TSMC improve the economics of producing increasingly large and complex chips.
Taiwan Semiconductor Manufacturing Company Limited (NYSE:TSM)'s planned use gives ASML a clear path toward commercializing the technology. TSMC plans to introduce High NA EUV into advanced-node high-volume production from 2030. ASML aims to show its larger-mask technology through a pilot line in 2031. TSMC's commitment could give ASML greater visibility into future equipment demand. Early use could help TSMC maintain its advanced-chip manufacturing advantage.
The collaboration could solidify both companies' positions as chipmakers develop larger and more powerful processors. ASML can extend its High NA roadmap beyond its current chip-size limitation. TSMC can prepare its manufacturing processes for the next generation of AI chips. The partnership gives ASML an opportunity to deepen its relationship with one of its largest customers and gives TSMC access to a technology that could support future advanced-chip production.
#asml #technology #plans #next
ASML targets a pilot production line using the larger masks by 2031 and high-volume manufacturing readiness by 2033. Chief technology officer Marco Pieters said these changes could lift the productivity of these systems by roughly 40%.
The larger-mask project could create a new growth opportunity for ASML Holding N.V. (NASDAQ:ASML) while helping TSMC manufacture larger AI chips more efficiently. ASML plans to use its High NA EUV tools to handle chips as large as today's biggest data-center processors. The business expects the larger masks to increase system productivity by 40%. It could scale up demand for its next-generation equipment and help TSMC improve the economics of producing increasingly large and complex chips.
Taiwan Semiconductor Manufacturing Company Limited (NYSE:TSM)'s planned use gives ASML a clear path toward commercializing the technology. TSMC plans to introduce High NA EUV into advanced-node high-volume production from 2030. ASML aims to show its larger-mask technology through a pilot line in 2031. TSMC's commitment could give ASML greater visibility into future equipment demand. Early use could help TSMC maintain its advanced-chip manufacturing advantage.
The collaboration could solidify both companies' positions as chipmakers develop larger and more powerful processors. ASML can extend its High NA roadmap beyond its current chip-size limitation. TSMC can prepare its manufacturing processes for the next generation of AI chips. The partnership gives ASML an opportunity to deepen its relationship with one of its largest customers and gives TSMC access to a technology that could support future advanced-chip production.
#asml #technology #plans #next


2 days ago
LifeMD, Inc. (NASDAQ:LFMD) announced an exclusive healthcare collaboration on September 15 that initially makes virtual-health membership benefits available to approximately 29 million eligible AT&T wireless and fiber customers across 11 states. Customers must be 18 or older, and some services have additional eligibility and state restrictions. A nationwide expansion planned for January 2027 would extend eligibility beyond 100 million customers.
The $19 monthly membership fee is waived, but customers must enroll. Visits, prescriptions, and other services remain separately payable. For LifeMD, Inc. (NASDAQ:LFMD), the opportunity is converting access to a large audience into recurring demand for paid care.
The partnership gives LifeMD, Inc. (NASDAQ:LFMD) a distribution channel through the website, mobile app and customer-benefits program of AT&T Inc. (NYSE:T). Reaching customers through an established relationship could reduce reliance on advertising and lower acquisition costs per paying patient.
Removing the membership charge also reduces the financial commitment required to try the service. Announced visit prices start at $29 for message-based care, $49 for urgent and primary care video visits, and $79 for specialty care. Customers may use insurance, Medicare, or discounted cash-pay rates for visits and prescriptions.
LifeMD, Inc. (NASDAQ:LFMD) could benefit from repeat consultations and prescription fulfillment when clinically appropriate. Primary care, chronic-condition management and other services create opportunities for continuing patient relationships. If satisfied patients return, the revenue earned over those relationships could exceed the cost of acquiring and serving them.
#Services
The $19 monthly membership fee is waived, but customers must enroll. Visits, prescriptions, and other services remain separately payable. For LifeMD, Inc. (NASDAQ:LFMD), the opportunity is converting access to a large audience into recurring demand for paid care.
The partnership gives LifeMD, Inc. (NASDAQ:LFMD) a distribution channel through the website, mobile app and customer-benefits program of AT&T Inc. (NYSE:T). Reaching customers through an established relationship could reduce reliance on advertising and lower acquisition costs per paying patient.
Removing the membership charge also reduces the financial commitment required to try the service. Announced visit prices start at $29 for message-based care, $49 for urgent and primary care video visits, and $79 for specialty care. Customers may use insurance, Medicare, or discounted cash-pay rates for visits and prescriptions.
LifeMD, Inc. (NASDAQ:LFMD) could benefit from repeat consultations and prescription fulfillment when clinically appropriate. Primary care, chronic-condition management and other services create opportunities for continuing patient relationships. If satisfied patients return, the revenue earned over those relationships could exceed the cost of acquiring and serving them.
#Services


2 days ago
Sempra (NYSE:SRE) added a long-term customer commitment on September 14, when its infrastructure subsidiary announced a 20-year sales and purchase agreement with Petróleo Brasileiro S.A. - Petrobras (NYSE:PBR). The agreement covers approximately 0.8 million tonnes annually of liquefied natural gas, or LNG.
Supply will come from the subsidiary's contracted liquefaction capacity at Port Arthur LNG Phase 2 in Texas. The project is under construction, with trains 3 and 4 expected to begin commercial operations in 2030 and 2031, respectively. The agreement improves visibility into future sales, while the earnings contribution depends on delivery and contract economics.
Petróleo Brasileiro S.A. - Petrobras (NYSE:PBR) becomes the infrastructure subsidiary's first South American LNG customer. That broadens the geographic base of buyers and establishes a commercial relationship extending over two decades.
For Sempra (NYSE:SRE), the practical benefit is an external buyer for part of the subsidiary's contracted capacity. Securing that relationship before startup could reduce the need to find buyers for the covered volumes as production approaches, while supporting longer-term supply planning.
The annual commitment equals approximately 6.2% of Phase 2's planned 13-million-tonne annual capacity. This provides a measure of scale, although it does not establish the percentage of capacity still available for sale.
#agreement #petr #supply #term
Supply will come from the subsidiary's contracted liquefaction capacity at Port Arthur LNG Phase 2 in Texas. The project is under construction, with trains 3 and 4 expected to begin commercial operations in 2030 and 2031, respectively. The agreement improves visibility into future sales, while the earnings contribution depends on delivery and contract economics.
Petróleo Brasileiro S.A. - Petrobras (NYSE:PBR) becomes the infrastructure subsidiary's first South American LNG customer. That broadens the geographic base of buyers and establishes a commercial relationship extending over two decades.
For Sempra (NYSE:SRE), the practical benefit is an external buyer for part of the subsidiary's contracted capacity. Securing that relationship before startup could reduce the need to find buyers for the covered volumes as production approaches, while supporting longer-term supply planning.
The annual commitment equals approximately 6.2% of Phase 2's planned 13-million-tonne annual capacity. This provides a measure of scale, although it does not establish the percentage of capacity still available for sale.
#agreement #petr #supply #term

2 days ago
Bloom Energy Corporation (NYSE:BE) garnered significant investor attention after it unveiled a new 800V DC-native fuel-cell power architecture on September 16, designed to supply continuous direct current to the next generation of AI data centers.
These solid-oxide fuel cells can generate continuous 800V DC power natively, rather than producing AC power that then has to be converted into DC that AI computing equipment ultimately consumes. This potentially removes several conversion stages, such as transformers and switchgear, thus lowering capital cost and energy losses.
Bloom claims that its technology can cut non-compute capital expenditures for a 1 GW data center by $3.6 billion, or 27%, and lower five-year total cost of ownership by $5.5 billion, or 9%, compared to traditional AC-based infrastructure.
With this technology, Bloom Energy is targeting one of the biggest bottlenecks in the ongoing AI boom – securing large amounts of reliable power quickly and economically. If 800V DC becomes widely adopted across AI data centers, the company will benefit not only from the soaring power demand, but also from a broader shift in how that power is generated and delivered.
Bloom Energy pointed to Nvidia's planned adoption of 800V DC architecture beginning with Rubin Ultra and Kyber systems as an indication of where data center power infrastructure is heading. In its 2026 Mid-Year Data Center Power Report, Bloom claimed that data center leaders expect DC-based architectures to account for 58% of new deployments by 2030, potentially creating a significant market for technologies designed around direct-current power delivery.
#energy #architecture
These solid-oxide fuel cells can generate continuous 800V DC power natively, rather than producing AC power that then has to be converted into DC that AI computing equipment ultimately consumes. This potentially removes several conversion stages, such as transformers and switchgear, thus lowering capital cost and energy losses.
Bloom claims that its technology can cut non-compute capital expenditures for a 1 GW data center by $3.6 billion, or 27%, and lower five-year total cost of ownership by $5.5 billion, or 9%, compared to traditional AC-based infrastructure.
With this technology, Bloom Energy is targeting one of the biggest bottlenecks in the ongoing AI boom – securing large amounts of reliable power quickly and economically. If 800V DC becomes widely adopted across AI data centers, the company will benefit not only from the soaring power demand, but also from a broader shift in how that power is generated and delivered.
Bloom Energy pointed to Nvidia's planned adoption of 800V DC architecture beginning with Rubin Ultra and Kyber systems as an indication of where data center power infrastructure is heading. In its 2026 Mid-Year Data Center Power Report, Bloom claimed that data center leaders expect DC-based architectures to account for 58% of new deployments by 2030, potentially creating a significant market for technologies designed around direct-current power delivery.
#energy #architecture


2 days ago
Targa Resources Corp. (NYSE:TRGP) has significantly outperformed the wider market this year, posting gains of over 56% since the beginning of 2026. A major catalyst behind this growth was the 20-year fee-based agreement that the company signed with ExxonMobil last month.
While there are concerns that the stock's rally may have topped out, the **** ysts over at TD Cowen see further growth ahead. On September 18, the firm upgraded TRGP from 'Hold' to Buy', while also boosting its price target from $275 to $350. The revised target implies an upside of almost 20% from the current levels and even exceeds the stock's record high of just under $308 achieved last month.
TD Cowen cited Targa's expected Permian Basin wet gas growth and peer-leading EBITDA growth for the upgrade. The **** yst expects the company's free cash flow yield to rise from 6% in 2026 to more than 10% in 2028, compared with an estimated 8.5% FCF yield for peers in 2030. The improvement is expected to be driven by EBITDA growth from new processing plants and the completion of a major capital project in the Speedway NGL pipeline.
According to TD Cowen, a key driver for Targa's growth is the rising wet gas production in the Permian, which means that the **** yst's thesis is tied to physical volume growth rather than simply a higher-commodity price **** umption.
Targa's recently announced deal with ExxonMobil provides greater visibility into future volumes and infrastructure demand. The company has also planned three new natural gas processing plants in the Permian Delaware as part of the deal, with an aggregate capacity of roughly 825 MMcf/day. Targa expects this agreement to add significantly to its "strong growth rate well into the next decade and bolster its outlook for durable and growing adjusted free cash flow over the long term".
#exxonmobil #ebitda
While there are concerns that the stock's rally may have topped out, the **** ysts over at TD Cowen see further growth ahead. On September 18, the firm upgraded TRGP from 'Hold' to Buy', while also boosting its price target from $275 to $350. The revised target implies an upside of almost 20% from the current levels and even exceeds the stock's record high of just under $308 achieved last month.
TD Cowen cited Targa's expected Permian Basin wet gas growth and peer-leading EBITDA growth for the upgrade. The **** yst expects the company's free cash flow yield to rise from 6% in 2026 to more than 10% in 2028, compared with an estimated 8.5% FCF yield for peers in 2030. The improvement is expected to be driven by EBITDA growth from new processing plants and the completion of a major capital project in the Speedway NGL pipeline.
According to TD Cowen, a key driver for Targa's growth is the rising wet gas production in the Permian, which means that the **** yst's thesis is tied to physical volume growth rather than simply a higher-commodity price **** umption.
Targa's recently announced deal with ExxonMobil provides greater visibility into future volumes and infrastructure demand. The company has also planned three new natural gas processing plants in the Permian Delaware as part of the deal, with an aggregate capacity of roughly 825 MMcf/day. Targa expects this agreement to add significantly to its "strong growth rate well into the next decade and bolster its outlook for durable and growing adjusted free cash flow over the long term".
#exxonmobil #ebitda

2 days ago
On September 17, Ferrari N.V. (NYSE:RACE) announced a partnership with the technology company Rakuten Group, Inc., effective January 1, 2027. The announcement gives no scope and no price tag, so it works better as a signal than as a number. The real substance sits in the results Ferrari posted on July 30, when it raised its 2026 guidance because buyers are ordering more personalization than the company expected.
In the second quarter, revenue rose 8%, but operating profit rose 10%, which means each euro of sales is leaving more behind. Ferrari credits a richer mix of cars, with the F80 helping, along with more buyers paying up for personalization. Strip out currency swings, and the gap widens, with revenue up 11% and operating profit up 16%. Deliveries of the Purosangue and the 296 Speciale family grew even in the middle of a planned model changeover.
Cash and demand back that up. Industrial free cash flow jumped 39% to €276 million, and Ferrari also returned more than €800 million to shareholders through a dividend and buybacks. Racing helped too, as higher sponsorships and engine rentals to other Formula 1 teams lifted revenue. Meanwhile, the order book covers 2027 in full, and the new 12Cilindri Manuale is already fully allocated, which is about as strong a demand signal as a carmaker can send. Those trends are why revenue guidance moved up to about €7.60 billion from about €7.50 billion.
Part of the strength is timing. Operating profit got a boost from temporarily lower depreciation and amortization while Ferrari swaps out models, and the company says those charges will climb once the new cars enter production. Net profit also leaned on a 23.0% tax rate, which reflects an estimated benefit from the new Patent Box. Neither says much about how profitable the cars themselves are.
Costs are climbing too. Higher industrial and marketing expenses weighed on operating profit, EBITDA margin slipped to 39.0% from 39.7% a year earlier, and management expects heavier brand, racing and digital spending for the year. Currency is a drag as well, mostly from the dollar and the yen, which is why 11% growth at constant currency shrank to 8% as reported. Deliveries totaled 3,366 cars while the 296 GTS, Roma Spider and SF90 XX family wound down, and sponsorship, commercial and brand revenue grew just 2%. And the whole outlook leans on current visibility into the Middle East crisis, which Ferrari cannot control.
#Ferrari
In the second quarter, revenue rose 8%, but operating profit rose 10%, which means each euro of sales is leaving more behind. Ferrari credits a richer mix of cars, with the F80 helping, along with more buyers paying up for personalization. Strip out currency swings, and the gap widens, with revenue up 11% and operating profit up 16%. Deliveries of the Purosangue and the 296 Speciale family grew even in the middle of a planned model changeover.
Cash and demand back that up. Industrial free cash flow jumped 39% to €276 million, and Ferrari also returned more than €800 million to shareholders through a dividend and buybacks. Racing helped too, as higher sponsorships and engine rentals to other Formula 1 teams lifted revenue. Meanwhile, the order book covers 2027 in full, and the new 12Cilindri Manuale is already fully allocated, which is about as strong a demand signal as a carmaker can send. Those trends are why revenue guidance moved up to about €7.60 billion from about €7.50 billion.
Part of the strength is timing. Operating profit got a boost from temporarily lower depreciation and amortization while Ferrari swaps out models, and the company says those charges will climb once the new cars enter production. Net profit also leaned on a 23.0% tax rate, which reflects an estimated benefit from the new Patent Box. Neither says much about how profitable the cars themselves are.
Costs are climbing too. Higher industrial and marketing expenses weighed on operating profit, EBITDA margin slipped to 39.0% from 39.7% a year earlier, and management expects heavier brand, racing and digital spending for the year. Currency is a drag as well, mostly from the dollar and the yen, which is why 11% growth at constant currency shrank to 8% as reported. Deliveries totaled 3,366 cars while the 296 GTS, Roma Spider and SF90 XX family wound down, and sponsorship, commercial and brand revenue grew just 2%. And the whole outlook leans on current visibility into the Middle East crisis, which Ferrari cannot control.
#Ferrari

2 days ago
On August 6, Wheaton Precious Metals (NYSE:WPM) reported second-quarter net earnings of $543 million on $929 million of revenue, both records. Through the first half, net earnings rose 106% to $1.1 billion. During the quarter, the company also made net upfront cash payments of $4.5 billion relative to mineral stream interests, and it now carries $2.0 billion of total debt against $100 million of cash on hand. Here is what that trade looks like up close.
Start with what the streaming model does when prices climb. Wheaton sold 14% more gold equivalent ounces than a year ago, but the average realized gold equivalent price jumped 61% in Q2, and that higher price explains most of the revenue surge. Costs per ounce rose from $406 to $568, yet the cash operating margin per ounce still grew 65% to $3,875, faster than gold itself appreciated. Operating cash flow hit $650 million in the quarter and $1.4 billion for the half.
The second argument is that plenty of growth hasn't arrived yet. Only about 3% of this year's production comes from **** ets still in construction or ramp-up, and the company forecasts a rise of roughly 50% to 1,200,000 gold equivalent ounces by 2030. Some of that ramp has dates attached. Ivanhoe now expects commercial production at Platreef in the fourth quarter of 2026, and Montage Gold is targeting first gold at Koné in late Q4. Effective April 1, Wheaton expanded its share of silver production from Antamina from 33.75% to 67.5% through the newly acquired BHP Antamina PMPA.
Growth on this scale wasn't free. Wheaton had no bank debt at the end of 2025. On April 1, it drew $1.5 billion on a new two-year term loan to help pay for Antamina, and finance costs that were negligible a year ago now take a real bite. Net debt stands at $1.9 billion. Taxes are heavier too. Wheaton paid $109 million of global minimum tax on June 24, and another Cdn$346 million is due around March 31, 2027.
Operations also gave investors a few reasons for caution. Gold ounces produced slipped 2.6% year over year, so the 6% rise in gold equivalent production leaned heavily on the Antamina purchase. Gold output at Salobo fell 11% on lower grades. At Constancia, it fell 35% after mining at the higher-grade Pampacancha pit finished in the fourth quarter of 2025. Hemlo Mining said on July 20 that its second-quarter output fell below the first quarter's, and Rio2 said on May 15 that Fenix missed planned tonnes and grade in Q1. And because the revenue jump came mainly from price, the same leverage works in reverse if metals slip.
#wheaton
Start with what the streaming model does when prices climb. Wheaton sold 14% more gold equivalent ounces than a year ago, but the average realized gold equivalent price jumped 61% in Q2, and that higher price explains most of the revenue surge. Costs per ounce rose from $406 to $568, yet the cash operating margin per ounce still grew 65% to $3,875, faster than gold itself appreciated. Operating cash flow hit $650 million in the quarter and $1.4 billion for the half.
The second argument is that plenty of growth hasn't arrived yet. Only about 3% of this year's production comes from **** ets still in construction or ramp-up, and the company forecasts a rise of roughly 50% to 1,200,000 gold equivalent ounces by 2030. Some of that ramp has dates attached. Ivanhoe now expects commercial production at Platreef in the fourth quarter of 2026, and Montage Gold is targeting first gold at Koné in late Q4. Effective April 1, Wheaton expanded its share of silver production from Antamina from 33.75% to 67.5% through the newly acquired BHP Antamina PMPA.
Growth on this scale wasn't free. Wheaton had no bank debt at the end of 2025. On April 1, it drew $1.5 billion on a new two-year term loan to help pay for Antamina, and finance costs that were negligible a year ago now take a real bite. Net debt stands at $1.9 billion. Taxes are heavier too. Wheaton paid $109 million of global minimum tax on June 24, and another Cdn$346 million is due around March 31, 2027.
Operations also gave investors a few reasons for caution. Gold ounces produced slipped 2.6% year over year, so the 6% rise in gold equivalent production leaned heavily on the Antamina purchase. Gold output at Salobo fell 11% on lower grades. At Constancia, it fell 35% after mining at the higher-grade Pampacancha pit finished in the fourth quarter of 2025. Hemlo Mining said on July 20 that its second-quarter output fell below the first quarter's, and Rio2 said on May 15 that Fenix missed planned tonnes and grade in Q1. And because the revenue jump came mainly from price, the same leverage works in reverse if metals slip.
#wheaton

3 days ago
On September 18, Prudential Financial (NYSE:PRU) announced it will sell every share it holds in Alexforbes, a company listed on the Johannesburg Stock Exchange. Two buyers are splitting the stake. Alexforbes will repurchase roughly 372.8 million shares itself, and ARC AF Holdings will take about 74.1 million more. The package is worth about $185 million, a small number for a company managing $1.642 trillion. But the message matters more than the money. A plan Prudential laid out in August is now turning into signed agreements.
The logic is easy to follow. Prudential wants to operate in fewer places and put its money, people and attention where it thinks it can win for years. Andy Sullivan, the chief executive, says the aim is to lean harder on ***** et management, retirement and protection, and get those units working together more closely. David Legher, who leads emerging markets, called Alexforbes a successful investment, so this reads as a planned exit rather than a retreat from a problem.
The core business is giving management room to be choosy. On August 4, Prudential reported second-quarter net income of $985 million, up from $533 million a year earlier. That happened even though a charge from the yearly ***** umption update grew to $299 million from $134 million, so the underlying engine ran strong enough to absorb a bigger hit. The company also returned $743 million to shareholders in the quarter and held $4.2 billion in highly liquid ***** ets at the parent level. That does not look like a seller in a hurry.
Start with what has not happened yet. The deals are expected to close in the first half of 2027, and they still need Alexforbes shareholders to approve the buyback, along with regulatory sign-off. Until then, $185 million is an agreed price, not cash in the bank. Prudential also said New Veld's involvement continues before completion, so the company stays tied to the ***** et for now.
Then there is the size. Set against those trillions in ***** ets, this sale will not move results either way. Its value is strategic, and strategy takes years to judge. Prudential is giving up a foothold in a partnership it called important, and its remaining businesses have their own snags. Sales in Prudential of ***** an are suspended, and management said that weighed on international results even as earnings held up.
#august #money
The logic is easy to follow. Prudential wants to operate in fewer places and put its money, people and attention where it thinks it can win for years. Andy Sullivan, the chief executive, says the aim is to lean harder on ***** et management, retirement and protection, and get those units working together more closely. David Legher, who leads emerging markets, called Alexforbes a successful investment, so this reads as a planned exit rather than a retreat from a problem.
The core business is giving management room to be choosy. On August 4, Prudential reported second-quarter net income of $985 million, up from $533 million a year earlier. That happened even though a charge from the yearly ***** umption update grew to $299 million from $134 million, so the underlying engine ran strong enough to absorb a bigger hit. The company also returned $743 million to shareholders in the quarter and held $4.2 billion in highly liquid ***** ets at the parent level. That does not look like a seller in a hurry.
Start with what has not happened yet. The deals are expected to close in the first half of 2027, and they still need Alexforbes shareholders to approve the buyback, along with regulatory sign-off. Until then, $185 million is an agreed price, not cash in the bank. Prudential also said New Veld's involvement continues before completion, so the company stays tied to the ***** et for now.
Then there is the size. Set against those trillions in ***** ets, this sale will not move results either way. Its value is strategic, and strategy takes years to judge. Prudential is giving up a foothold in a partnership it called important, and its remaining businesses have their own snags. Sales in Prudential of ***** an are suspended, and management said that weighed on international results even as earnings held up.
#august #money

3 days ago
Leaving $650,000 in IRAs untouched for 11 years grew the balance to $1.11 million, forcing a $42,000 first-year RMD on top of pension income.
The couple missed 11 years of Roth conversion opportunities at the 12% rate, pushing RMD dollars into the 22% bracket instead.
When one spouse dies, the survivor files under single brackets where the 22% rate starts at $50,400, making the same RMD far more costly.
Two retirees, same $1 million, same 4% rule, buy one finished with $1.4 million, the other hit $0 in 12 years. Our free reader guide explains the flaw that separated them, and the income-first method built to avoid it.
Let's start by considering a couple retiring at 62. His pension covers the mortgage, the groceries, the property tax, and the trip to see the grandkids twice a year. Two traditional IRAs, hers and his, hold a combined $650,000 on the day they stop working, and they never take a distribution. Now imagine that eleven quiet years have passed, and then the first required minimum distribution letter arrives, followed by a second, and the number attached to those letters is larger than either of them planned for.
#iras
The couple missed 11 years of Roth conversion opportunities at the 12% rate, pushing RMD dollars into the 22% bracket instead.
When one spouse dies, the survivor files under single brackets where the 22% rate starts at $50,400, making the same RMD far more costly.
Two retirees, same $1 million, same 4% rule, buy one finished with $1.4 million, the other hit $0 in 12 years. Our free reader guide explains the flaw that separated them, and the income-first method built to avoid it.
Let's start by considering a couple retiring at 62. His pension covers the mortgage, the groceries, the property tax, and the trip to see the grandkids twice a year. Two traditional IRAs, hers and his, hold a combined $650,000 on the day they stop working, and they never take a distribution. Now imagine that eleven quiet years have passed, and then the first required minimum distribution letter arrives, followed by a second, and the number attached to those letters is larger than either of them planned for.
#iras
3 days ago
On August 6, APA Corporation (NASDAQ:APA) held its second-quarter earnings call, and one number stood out from the rest. The oil and gas producer is now holding its Permian oil production steady with four drilling rigs, half the eight it once estimated it would need. Adjusted production of 347,000 barrels of oil equivalent per day beat management's own guidance, free cash flow kept climbing, and the balance sheet is healing faster than planned. That combination is the story of the quarter.
APA raised its full-year US oil guidance to 123,000 barrels per day, up from an original 120,000, while holding its capital budget at $1.3 billion despite higher diesel and other input costs. Management also lifted its cost-savings target to $500 million in annualized run-rate savings by year-end, up from the $450 million goal it set at the start of the year.
That flexibility is showing up in cash flow. Free cash flow hit $738 million in the second quarter, pushing the first half of 2026 past $1.2 billion, which topped what APA generated in each of the past three full years. The company returned $189 million of that to shareholders through dividends and the repurchase of 2.8 million shares at an average price of $35.26, continuing a streak of returning at least 60% of free cash flow to investors every year since 2021.
The balance sheet is moving just as fast. Net debt stood at $3.3 billion at quarter-end after APA repaid $752 million of bonds in the first half, including $673 million in the second quarter alone, cutting total debt by $2.3 billion since the end of 2024 and lowering annualized interest expense by roughly $175 million. Management now expects to hit its $3 billion net debt target in 2027, well ahead of the three- to four-year window it laid out when the goal was first announced.
Further out, APA is building option value beyond its core Permian and Egypt ****** ets. It agreed to acquire Savant Alaska for $70 million, picking up an airstrip, a dock, and a pipeline connection into the Trans Alaska system to support two exploration wells planned for 2027. In Uruguay, ENI signed on as a partner in Block 6, funding a significant share of the first exploration well while APA keeps 60% ownership. In Suriname, the GranMorgu project remains on budget for first oil in mid-2028.
#billion
APA raised its full-year US oil guidance to 123,000 barrels per day, up from an original 120,000, while holding its capital budget at $1.3 billion despite higher diesel and other input costs. Management also lifted its cost-savings target to $500 million in annualized run-rate savings by year-end, up from the $450 million goal it set at the start of the year.
That flexibility is showing up in cash flow. Free cash flow hit $738 million in the second quarter, pushing the first half of 2026 past $1.2 billion, which topped what APA generated in each of the past three full years. The company returned $189 million of that to shareholders through dividends and the repurchase of 2.8 million shares at an average price of $35.26, continuing a streak of returning at least 60% of free cash flow to investors every year since 2021.
The balance sheet is moving just as fast. Net debt stood at $3.3 billion at quarter-end after APA repaid $752 million of bonds in the first half, including $673 million in the second quarter alone, cutting total debt by $2.3 billion since the end of 2024 and lowering annualized interest expense by roughly $175 million. Management now expects to hit its $3 billion net debt target in 2027, well ahead of the three- to four-year window it laid out when the goal was first announced.
Further out, APA is building option value beyond its core Permian and Egypt ****** ets. It agreed to acquire Savant Alaska for $70 million, picking up an airstrip, a dock, and a pipeline connection into the Trans Alaska system to support two exploration wells planned for 2027. In Uruguay, ENI signed on as a partner in Block 6, funding a significant share of the first exploration well while APA keeps 60% ownership. In Suriname, the GranMorgu project remains on budget for first oil in mid-2028.
#billion
3 days ago
On September 8, 2026, the Wall Street Journal reported United Natural Foods, Inc. (NYSE:UNFI)'s fiscal fourth-quarter results, in which adjusted earnings per share of $0.69 beat ***** yst expectations even as revenue of $7.64 billion came in below consensus.
The grocery wholesaler guided for fiscal 2027 net sales of $31.2 billion to $31.8 billion, a return to growth after full-year fiscal 2026 sales declined 2% to $31.2 billion. The business said full-year adjusted EBITDA rose 27% to $701 million and free cash flow hit a record $323 million as it continued executing what CEO Sandy Douglas called its second year of a value-creation strategy.
United Natural Foods, Inc. (NYSE:UNFI)'s turnaround is improving the financial metrics that matter most for a food distributor. Full-year adjusted EBITDA increased 27%. Net debt fell by $295 million and net leverage improved to 2.2 times. The stronger balance sheet gives UNFI more financial flexibility as it works to return to sales growth.
UNFI's natural-products business is providing an important growth engine. Fourth-quarter natural-products sales increased 6.6%, even as conventional-products sales declined 8.6%. The stronger performance in natural products backs up UNFI's strategy of expanding business with customers that can drive growth as the business restructures its operations.
Management also expects fiscal 2027 sales to reach $31.2 billion to $31.8 billion, up from $31.15 billion in fiscal 2026. Adjusted EPS should reach $3.00 to $3.50 versus $2.65 previously. Management anticipates about 10 basis points of margin expansion at the midpoint, which could help UNFI reach its fiscal 2028 margin target a year earlier than planned.
#billion
The grocery wholesaler guided for fiscal 2027 net sales of $31.2 billion to $31.8 billion, a return to growth after full-year fiscal 2026 sales declined 2% to $31.2 billion. The business said full-year adjusted EBITDA rose 27% to $701 million and free cash flow hit a record $323 million as it continued executing what CEO Sandy Douglas called its second year of a value-creation strategy.
United Natural Foods, Inc. (NYSE:UNFI)'s turnaround is improving the financial metrics that matter most for a food distributor. Full-year adjusted EBITDA increased 27%. Net debt fell by $295 million and net leverage improved to 2.2 times. The stronger balance sheet gives UNFI more financial flexibility as it works to return to sales growth.
UNFI's natural-products business is providing an important growth engine. Fourth-quarter natural-products sales increased 6.6%, even as conventional-products sales declined 8.6%. The stronger performance in natural products backs up UNFI's strategy of expanding business with customers that can drive growth as the business restructures its operations.
Management also expects fiscal 2027 sales to reach $31.2 billion to $31.8 billion, up from $31.15 billion in fiscal 2026. Adjusted EPS should reach $3.00 to $3.50 versus $2.65 previously. Management anticipates about 10 basis points of margin expansion at the midpoint, which could help UNFI reach its fiscal 2028 margin target a year earlier than planned.
#billion

3 days ago
Intel (NASDAQ: INTC) stock jumped roughly 7.6% on Thursday after news broke yesterday of a possible deal that would see SK Hynix's memory chips fabricated in Intel's Ohio factories.
The S&P 500 and the Nasdaq Composite rose 1.1% and 1.7%, respectively, on Thursday.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Reuters reported on Sept. 16 that SK Hynix is discussing either leasing part of Intel's planned Ohio facility or forming a venture with Intel and others. The talks are exploratory, and no formal deal has been made, but the possibility of a deal has been enough to boost Intel for two sessions in a row.
If a deal materializes, it could be a significant one for the U.S. chipmaker's Foundry business, which has struggled. The company considered selling it off before CEO Lip-Bu Tan made it a core part of his turnaround efforts after years of underperformance.
#signal #thursday #flashing #years
The S&P 500 and the Nasdaq Composite rose 1.1% and 1.7%, respectively, on Thursday.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Reuters reported on Sept. 16 that SK Hynix is discussing either leasing part of Intel's planned Ohio facility or forming a venture with Intel and others. The talks are exploratory, and no formal deal has been made, but the possibility of a deal has been enough to boost Intel for two sessions in a row.
If a deal materializes, it could be a significant one for the U.S. chipmaker's Foundry business, which has struggled. The company considered selling it off before CEO Lip-Bu Tan made it a core part of his turnaround efforts after years of underperformance.
#signal #thursday #flashing #years


4 days ago
Uber Technologies Inc. (NYSE:UBER) has secured Madrid as the fourth city covered by its partnership with WeRide, bringing Spain into its rapidly expanding autonomous vehicle network. The company's broader AV strategy covers more than 30 partners, while Uber expects to commit more than $10 billion across AV investments, infrastructure, and vehicle offtake over the coming years. At the center of that strategy is Uber's decision not to build self-driving technology itself. Instead, the company wants to become the indispensable demand layer for whichever AV providers ultimately emerge as winners. Yet the diversification strategy is facing pressure in key areas. One of its most prominent AV partners is pulling back, while another remains under an active safety investigation.
Uber, WeRide, and AVOMO have secured Spain's first national permit covering level 4 autonomous passenger vehicles. The permit was issued by Spain's Directorate General of Traffic and allows the companies to begin deployment preparations on public roads in Madrid. Under the permit, WeRide can test its GXR vehicles and conduct roadmapping throughout Madrid in preparation for a commercial launch planned for year-end. The rollout will begin with 20 vehicles, each supervised by an in-car specialist, operating across high-demand areas of Greater Madrid. Madrid becomes the fourth city included in the Uber-WeRide partnership, which plans to reach 15 cities globally by 2030. The expansion also fits Uber's broader ******* et-light AV strategy, which includes more than 30 partnerships while Uber expects to commit over $10 billion across AV investments, infrastructure, and vehicle offtake over the coming years.
The diversification of Uber's AV network does not eliminate risks from individual partners. Uber and Waymo confirmed in late June that their Phoenix partnership had ended, while Waymo is reportedly considering a broader exit from its relationship with Uber. This comes even as Uber executives have publicly criticized Waymo's model while investing substantial capital in competing fleets. Avride is facing a separate challenge, with the NHTSA investigating the Uber AV partner after multiple crashes. At the same time, Tesla is ramping up its own Cybercab fleet, while Waymo has raised $16 billion to accelerate its independent growth. Together, these moves could reduce Waymo's reliance on Uber while increasing competitive pressure on Uber's AV platform.
#madrid #waymo
Uber, WeRide, and AVOMO have secured Spain's first national permit covering level 4 autonomous passenger vehicles. The permit was issued by Spain's Directorate General of Traffic and allows the companies to begin deployment preparations on public roads in Madrid. Under the permit, WeRide can test its GXR vehicles and conduct roadmapping throughout Madrid in preparation for a commercial launch planned for year-end. The rollout will begin with 20 vehicles, each supervised by an in-car specialist, operating across high-demand areas of Greater Madrid. Madrid becomes the fourth city included in the Uber-WeRide partnership, which plans to reach 15 cities globally by 2030. The expansion also fits Uber's broader ******* et-light AV strategy, which includes more than 30 partnerships while Uber expects to commit over $10 billion across AV investments, infrastructure, and vehicle offtake over the coming years.
The diversification of Uber's AV network does not eliminate risks from individual partners. Uber and Waymo confirmed in late June that their Phoenix partnership had ended, while Waymo is reportedly considering a broader exit from its relationship with Uber. This comes even as Uber executives have publicly criticized Waymo's model while investing substantial capital in competing fleets. Avride is facing a separate challenge, with the NHTSA investigating the Uber AV partner after multiple crashes. At the same time, Tesla is ramping up its own Cybercab fleet, while Waymo has raised $16 billion to accelerate its independent growth. Together, these moves could reduce Waymo's reliance on Uber while increasing competitive pressure on Uber's AV platform.
#madrid #waymo

4 days ago
Guardian Metal Resources PLC (NYSEAMERICAN:GMTL) reported its first Good Hope drilling results on September 14, adding exploration potential to the Pilot Mountain tungsten project in Nevada. Hole GH26-01 returned a 12.95-meter downhole interval grading 0.79% tungsten trioxide, or WO3, starting at 12.19 meters. GH26-02 intersected 13.11 meters at 0.42% WO3 from 2.13 meters.
The holes were twinned, with GH26-02 redrilling the upper portion where core had not been recovered. Good Hope and the separate Tremor discovery remain outside the resource base supporting the existing pre-feasibility study. The investment question is whether additional mineralization can improve project returns without slowing development.
Shallow mineralization offers a potential route to additional feed that could be accessible early in a future mining sequence. Good Hope sits approximately 1.1 to 1.3 kilometers from the existing resource areas, making its possible integration worth evaluating alongside the planned operation.
The June pre-feasibility study models an eight-year open-pit operation based on Desert Scheelite and Garnet. If further work establishes economic resources at Good Hope or Tremor, additional feed could extend that operating life or improve the sequence in which material reaches the processing plant.
For Guardian Metal Resources PLC (NYSEAMERICAN:GMTL), the potential benefit is better use of infrastructure already contemplated for Pilot Mountain. That would depend on recoverable metal, processing compatibility, and the additional capital required to bring the new zones into production.
#hope #resources #guardian
The holes were twinned, with GH26-02 redrilling the upper portion where core had not been recovered. Good Hope and the separate Tremor discovery remain outside the resource base supporting the existing pre-feasibility study. The investment question is whether additional mineralization can improve project returns without slowing development.
Shallow mineralization offers a potential route to additional feed that could be accessible early in a future mining sequence. Good Hope sits approximately 1.1 to 1.3 kilometers from the existing resource areas, making its possible integration worth evaluating alongside the planned operation.
The June pre-feasibility study models an eight-year open-pit operation based on Desert Scheelite and Garnet. If further work establishes economic resources at Good Hope or Tremor, additional feed could extend that operating life or improve the sequence in which material reaches the processing plant.
For Guardian Metal Resources PLC (NYSEAMERICAN:GMTL), the potential benefit is better use of infrastructure already contemplated for Pilot Mountain. That would depend on recoverable metal, processing compatibility, and the additional capital required to bring the new zones into production.
#hope #resources #guardian

4 days ago
The intelligence report, circulated across the US military this spring in the midst of the war with Iran, immediately set off alarm bells: A Chinese ship in the Middle East was transporting components of a nuclear weapons program.
The US military swung into action with plans to intercept the vessel, according to four sources familiar with the episode. According to two of the sources, armed members of the US military were preparing to board the ship. Military planes were in the air, one of those sources and another source familiar with the incident said.
It was only just before the planned operation that officials dug deeper into the report put together by a special operations command ****** yst and found it had been generated with the help of artificial intelligence (AI) — and that a chatbot the ****** yst had used inaccurately identified the material the ship was carrying. CNN was not able to learn what the misidentified cargo was.
The report, according to one of the sources, was “entirely false.” But it also “almost started a war,” the source said. Any US operation against a Chinese vessel could have risked spiraling into an armed conflict between the two nations.
Across the US military and the intelligence community, officials are pushing to weave AI into nearly every facet of their work, from ****** yzing the huge volumes of raw intelligence the US collects and selecting targets for strikes, to more mundane applications like managing budgeting, logistics and supply chains.
#intelligence #ship #familiar
The US military swung into action with plans to intercept the vessel, according to four sources familiar with the episode. According to two of the sources, armed members of the US military were preparing to board the ship. Military planes were in the air, one of those sources and another source familiar with the incident said.
It was only just before the planned operation that officials dug deeper into the report put together by a special operations command ****** yst and found it had been generated with the help of artificial intelligence (AI) — and that a chatbot the ****** yst had used inaccurately identified the material the ship was carrying. CNN was not able to learn what the misidentified cargo was.
The report, according to one of the sources, was “entirely false.” But it also “almost started a war,” the source said. Any US operation against a Chinese vessel could have risked spiraling into an armed conflict between the two nations.
Across the US military and the intelligence community, officials are pushing to weave AI into nearly every facet of their work, from ****** yzing the huge volumes of raw intelligence the US collects and selecting targets for strikes, to more mundane applications like managing budgeting, logistics and supply chains.
#intelligence #ship #familiar

4 days ago
He was the sole holdout on a 12-person jury who otherwise voted to acquit Lindsay Clancy of murdering her three children — frustrating the defense and causing a mistrial.
After seven days of deliberations, and with specific instructions from Judge William Sullivan to follow the letter of the law on reasonable doubt, the jury said it still had one holdout who refused to budge. A mistrial was declared on Sept. 4.
Now, the lone juror, named Michael Desronvil, has come forward to share his side of the story, saying that he "didn't have any doubts" that Clancy was criminally responsible for the killings.
In a statement shared with Yahoo on Sept. 18 by his attorney Edward Andrew Paltzik, Desronvil said: "I didn't have any doubts. As I tried to explain different possible theories during deliberation, I kept getting cut off as if I had doubts based on the evidence presented.
"Based on all the physical evidence, key witnesses, and what the prosecution presented, I thought it was enough proof that she (Clancy) knew exactly what she was doing and planned."
#clancy #evidence
After seven days of deliberations, and with specific instructions from Judge William Sullivan to follow the letter of the law on reasonable doubt, the jury said it still had one holdout who refused to budge. A mistrial was declared on Sept. 4.
Now, the lone juror, named Michael Desronvil, has come forward to share his side of the story, saying that he "didn't have any doubts" that Clancy was criminally responsible for the killings.
In a statement shared with Yahoo on Sept. 18 by his attorney Edward Andrew Paltzik, Desronvil said: "I didn't have any doubts. As I tried to explain different possible theories during deliberation, I kept getting cut off as if I had doubts based on the evidence presented.
"Based on all the physical evidence, key witnesses, and what the prosecution presented, I thought it was enough proof that she (Clancy) knew exactly what she was doing and planned."
#clancy #evidence


4 days ago
On September 11, a caller praised The Boeing Company's (NYSE:BA) CEO and asked when the company would overcome the ongoing labor uncertainty and finally move beyond years of sideways stock performance. Mad Money host Jim Cramer replied:
I think that Boeing is ready to go up. But here's the problem. Every time crude goes up a dollar, the stock goes down a dollar. And that, think about it, that was actually the ratio. I did some work on this. And because today crude was down, Boeing went up $5... No, it's so stupid because, in truth, the airlines need more planes because the planes are more fuel-efficient. So they actually do better in this environment, but ******* ody cares. They know that airlines have to borrow money to buy planes and rates are higher, and they think that oil somehow's bad. But what ends up happening is the stock does nothing. I think it's about to go up because I think oil might be peaking unless there's some catastrophe over there.
The Boeing Company's (NYSE:BA) second-quarter results showed improving cash generation, but profitability remained weak. Revenue rose 8% year over year to $24.6 billion, while operating cash flow reached $1.4 billion and free cash flow was $631 million. Its total backlog reached a record $715 billion, including more than 6,200 commercial airplanes. CEO Kelly Ortberg said, "We're ramping up production just as we planned. That's driving higher revenues and improved cash flow." He also said there's more work ahead to ramp production, complete commercial-aircraft certifications and uphold customer commitments. Boeing said the 737-7 and 737-10 had completed flight testing, with deliveries expected to begin in 2027.
The Boeing Company's (NYSE:BA) large backlog has yet to translate into consistent commercial-aircraft profitability, leaving execution and margins as important concerns for investors. Commercial Airplanes delivered 171 aircraft in the second quarter but still posted a $322 million operating loss and a negative 2.7% operating margin. It also reported a $428 million GAAP net loss.
The balance sheet leaves less room for further setbacks. The company ended June with $45.9 billion of consolidated debt against $20 billion of cash and investments in marketable securities. The FAA certified the 737-7 on August 3, while Boeing continues working toward certification of the 737-10. First deliveries of the variants are expected in 2027. The company also recorded $280 million of losses on the VC-25B program in the quarter.
#boeing #cash #commercial
I think that Boeing is ready to go up. But here's the problem. Every time crude goes up a dollar, the stock goes down a dollar. And that, think about it, that was actually the ratio. I did some work on this. And because today crude was down, Boeing went up $5... No, it's so stupid because, in truth, the airlines need more planes because the planes are more fuel-efficient. So they actually do better in this environment, but ******* ody cares. They know that airlines have to borrow money to buy planes and rates are higher, and they think that oil somehow's bad. But what ends up happening is the stock does nothing. I think it's about to go up because I think oil might be peaking unless there's some catastrophe over there.
The Boeing Company's (NYSE:BA) second-quarter results showed improving cash generation, but profitability remained weak. Revenue rose 8% year over year to $24.6 billion, while operating cash flow reached $1.4 billion and free cash flow was $631 million. Its total backlog reached a record $715 billion, including more than 6,200 commercial airplanes. CEO Kelly Ortberg said, "We're ramping up production just as we planned. That's driving higher revenues and improved cash flow." He also said there's more work ahead to ramp production, complete commercial-aircraft certifications and uphold customer commitments. Boeing said the 737-7 and 737-10 had completed flight testing, with deliveries expected to begin in 2027.
The Boeing Company's (NYSE:BA) large backlog has yet to translate into consistent commercial-aircraft profitability, leaving execution and margins as important concerns for investors. Commercial Airplanes delivered 171 aircraft in the second quarter but still posted a $322 million operating loss and a negative 2.7% operating margin. It also reported a $428 million GAAP net loss.
The balance sheet leaves less room for further setbacks. The company ended June with $45.9 billion of consolidated debt against $20 billion of cash and investments in marketable securities. The FAA certified the 737-7 on August 3, while Boeing continues working toward certification of the 737-10. First deliveries of the variants are expected in 2027. The company also recorded $280 million of losses on the VC-25B program in the quarter.
#boeing #cash #commercial

4 days ago
American Tower Corporation (NYSE:AMT) priced $1.6 billion of senior notes on September 9: $500 million at 5.300% due 2031, $500 million at 5.560% due 2033, and $600 million at 5.750% due 2036. Once issued, the three tranches would carry combined annual coupons of $88.8 million, equivalent to a weighted average coupon of 5.55%.
American Tower Corporation (NYSE:AMT) expects approximately $1.580 billion in net proceeds. It intends to use $600 million to repay 1.450% notes due in 2026, with additional proceeds designated for revolving-credit debt and general corporate purposes. The financing exchanges a near-term repayment requirement and some revolving debt for longer fixed-rate obligations.
The investment question is whether greater funding certainty compensates for the higher cash-interest commitment.
American Tower Corporation (NYSE:AMT) would remove a $600 million maturity falling due this year once the planned repayment occurs. That reduces exposure to having to refinance the obligation closer to its deadline, when borrowing conditions could be less favorable.
The new maturities also distribute principal repayments across 2031, 2033 and 2036. For American Tower Corporation (NYSE:AMT), a spread of repayment dates can support financial planning across its communications-site and data-center portfolio. Fixed coupons make the cost of this funding predictable.
#tower
American Tower Corporation (NYSE:AMT) expects approximately $1.580 billion in net proceeds. It intends to use $600 million to repay 1.450% notes due in 2026, with additional proceeds designated for revolving-credit debt and general corporate purposes. The financing exchanges a near-term repayment requirement and some revolving debt for longer fixed-rate obligations.
The investment question is whether greater funding certainty compensates for the higher cash-interest commitment.
American Tower Corporation (NYSE:AMT) would remove a $600 million maturity falling due this year once the planned repayment occurs. That reduces exposure to having to refinance the obligation closer to its deadline, when borrowing conditions could be less favorable.
The new maturities also distribute principal repayments across 2031, 2033 and 2036. For American Tower Corporation (NYSE:AMT), a spread of repayment dates can support financial planning across its communications-site and data-center portfolio. Fixed coupons make the cost of this funding predictable.
#tower


4 days ago
Sunbelt Rentals Holdings, Inc. (NYSE:SUNB) reported on September 9 that fiscal first-quarter revenue increased 11.2% to $3.115 billion, including $2.927 billion of rental revenue, up 12.5%. The quarter ended July 31, 2026.
Management raised fiscal 2027 rental-revenue growth guidance to 7% through 10%, while increasing planned net rental-equipment capital expenditures to $2.4 billion through $2.8 billion. Demand supports expansion, but investors need to ****** s how much cash remains after funding the fleet.
North America Specialty rental revenue grew 25.3%, giving Sunbelt Rentals Holdings, Inc. (NYSE:SUNB) a strong source of growth beyond general equipment rentals. Specialized services can deepen customer relationships and create opportunities to supply several needs on the same project.
The company estimated that the FIFA World Cup contributed 2.5 percentage points to quarterly rental-revenue growth. Serving complex events demonstrates the commercial value of a broad equipment network. The investment opportunity is to turn that capability into recurring work across industrial, energy and construction customers.
Adjusted EBITDA increased 8.7% to $1.315 billion. This company-defined non-GAAP measure adds taxes, net interest, depreciation, amortization, stock-based compensation and specified restructuring costs to net income. Its margin is adjusted EBITDA divided by revenue.
#rentals
Management raised fiscal 2027 rental-revenue growth guidance to 7% through 10%, while increasing planned net rental-equipment capital expenditures to $2.4 billion through $2.8 billion. Demand supports expansion, but investors need to ****** s how much cash remains after funding the fleet.
North America Specialty rental revenue grew 25.3%, giving Sunbelt Rentals Holdings, Inc. (NYSE:SUNB) a strong source of growth beyond general equipment rentals. Specialized services can deepen customer relationships and create opportunities to supply several needs on the same project.
The company estimated that the FIFA World Cup contributed 2.5 percentage points to quarterly rental-revenue growth. Serving complex events demonstrates the commercial value of a broad equipment network. The investment opportunity is to turn that capability into recurring work across industrial, energy and construction customers.
Adjusted EBITDA increased 8.7% to $1.315 billion. This company-defined non-GAAP measure adds taxes, net interest, depreciation, amortization, stock-based compensation and specified restructuring costs to net income. Its margin is adjusted EBITDA divided by revenue.
#rentals

4 days ago
Anthropic, one of the world's fastest-growing AI companies, announced on June 1 that it had filed a confidential Form S-1 with the SEC for its planned IPO. It could price its offering by the end of the year, and it's reportedly targeting a valuation of $2 trillion -- which would surpass **** eX's (NASDAQ: SPCX) $1.77 trillion to become the biggest IPO in history. That's more than double the valuation of $965 billion it reached after its last private funding round in May.
Should investors chase Anthropic's eagerly anticipated IPO, or should they wait for the initial hype to die down? Let's see what investors should know before it goes public.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Anthropic's annualized run rate exceeded $65 billion at the end of July, compared to roughly $9 billion at the end of 2025. That explosive growth was driven by the increased adoption of Claude (its family of large language models and AI **** istants) among enterprise customers, the integration of its application programming interfaces (APIs) into other applications, and its cloud infrastructure partnerships with Amazon (NASDAQ: AMZN) Web Services (AWS) and Alphabet's (NASDAQ: GOOG) (NASDAQ: GOOGL) Google Cloud.
Amazon and Alphabet both hold double-digit stakes in Anthropic, so its upcoming IPO could significantly boost their profits. Nvidia (NASDAQ: NVDA) has also reportedly been mulling a $10 billion investment in Anthropic's IPO to fortify its software optimization partnership and supply chain ties.
#NASDAQ
Should investors chase Anthropic's eagerly anticipated IPO, or should they wait for the initial hype to die down? Let's see what investors should know before it goes public.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Anthropic's annualized run rate exceeded $65 billion at the end of July, compared to roughly $9 billion at the end of 2025. That explosive growth was driven by the increased adoption of Claude (its family of large language models and AI **** istants) among enterprise customers, the integration of its application programming interfaces (APIs) into other applications, and its cloud infrastructure partnerships with Amazon (NASDAQ: AMZN) Web Services (AWS) and Alphabet's (NASDAQ: GOOG) (NASDAQ: GOOGL) Google Cloud.
Amazon and Alphabet both hold double-digit stakes in Anthropic, so its upcoming IPO could significantly boost their profits. Nvidia (NASDAQ: NVDA) has also reportedly been mulling a $10 billion investment in Anthropic's IPO to fortify its software optimization partnership and supply chain ties.
#NASDAQ


4 days ago
Evommune, Inc. (NYSE:EVMN) announced on September 8 that EVO756 missed its primary endpoint in a randomized, double-blind, placebo-controlled Phase 2b trial involving 121 adults with moderate-to-severe atopic dermatitis. The primary measure was the percentage change from baseline in Eczema Area and Severity Index, or EASI, at week 12. No tested dose met the primary or secondary endpoints, and development in that indication will stop.
Evommune, Inc. (NYSE:EVMN) had already discontinued EVO756 for chronic spontaneous urticaria following a June trial failure. Development continues in migraine prevention. The setbacks place greater weight on EVO301, which has positive Phase 2a eczema data and a Phase 2b study planned for mid-2027.
Evommune, Inc. (NYSE:EVMN) has clinical evidence supporting its next eczema program. In February, the company reported that EVO301 met the primary endpoint in a randomized, double-blind, placebo-controlled Phase 2a trial involving 70 adults. Participants received two intravenous doses or placebo over a 12-week study.
Evommune, Inc. (NYSE:EVMN) reported a 55% EASI reduction with EVO301 versus 22% with placebo at week 12, a difference of 33 percentage points. The study met its prespecified Bayesian success criterion, and a separate conventional ****** ysis showed statistical significance at p
Evommune, Inc. (NYSE:EVMN) had already discontinued EVO756 for chronic spontaneous urticaria following a June trial failure. Development continues in migraine prevention. The setbacks place greater weight on EVO301, which has positive Phase 2a eczema data and a Phase 2b study planned for mid-2027.
Evommune, Inc. (NYSE:EVMN) has clinical evidence supporting its next eczema program. In February, the company reported that EVO301 met the primary endpoint in a randomized, double-blind, placebo-controlled Phase 2a trial involving 70 adults. Participants received two intravenous doses or placebo over a 12-week study.
Evommune, Inc. (NYSE:EVMN) reported a 55% EASI reduction with EVO301 versus 22% with placebo at week 12, a difference of 33 percentage points. The study met its prespecified Bayesian success criterion, and a separate conventional ****** ysis showed statistical significance at p


4 days ago
The Williams Companies, Inc. (NYSE:WMB) lost a key New Jersey water-quality certification for Northeast Supply Enhancement, or NESE, after a September 8 federal appeals court ruling reported by Reuters on September 9. The Third Circuit vacated the certification and returned the matter to state regulators. The Williams Companies, Inc. (NYSE:WMB) said that, at this time, it did not expect the ruling to adversely affect construction or the anticipated in-service timeline.
The project, which Reuters described as costing approximately $1 billion, expands the existing Transco network through Pennsylvania, New Jersey and New York. The Williams Companies, Inc. (NYSE:WMB) continues to target fourth-quarter 2027 service. The investment question is whether the permit review can be resolved quickly enough to protect both that schedule and the economics of the investment.
The commercial rationale rests on delivering additional gas into a constrained market. The Williams Companies, Inc. (NYSE:WMB) says demand continues to grow in areas including Brooklyn, Queens, Staten Island and Long Island. Planned capacity of approximately 400,000 dekatherms per day would expand the system's ability to serve those markets.
NESE also builds on existing infrastructure. The Williams Companies, Inc. (NYSE:WMB) plans pipeline loops, compressor work, and connections to the Transco system. Those connections give the added capacity access to an established transportation network and regional delivery points, although substantial construction remains necessary.
The remand leaves a route for reconsideration by New Jersey regulators. For The Williams Companies, Inc. (NYSE:WMB), the favorable scenario is a replacement certification that addresses the court's findings without requiring substantial redesign or disrupting the construction sequence.
#williams #NYSE #jersey #construction
The project, which Reuters described as costing approximately $1 billion, expands the existing Transco network through Pennsylvania, New Jersey and New York. The Williams Companies, Inc. (NYSE:WMB) continues to target fourth-quarter 2027 service. The investment question is whether the permit review can be resolved quickly enough to protect both that schedule and the economics of the investment.
The commercial rationale rests on delivering additional gas into a constrained market. The Williams Companies, Inc. (NYSE:WMB) says demand continues to grow in areas including Brooklyn, Queens, Staten Island and Long Island. Planned capacity of approximately 400,000 dekatherms per day would expand the system's ability to serve those markets.
NESE also builds on existing infrastructure. The Williams Companies, Inc. (NYSE:WMB) plans pipeline loops, compressor work, and connections to the Transco system. Those connections give the added capacity access to an established transportation network and regional delivery points, although substantial construction remains necessary.
The remand leaves a route for reconsideration by New Jersey regulators. For The Williams Companies, Inc. (NYSE:WMB), the favorable scenario is a replacement certification that addresses the court's findings without requiring substantial redesign or disrupting the construction sequence.
#williams #NYSE #jersey #construction

5 days ago
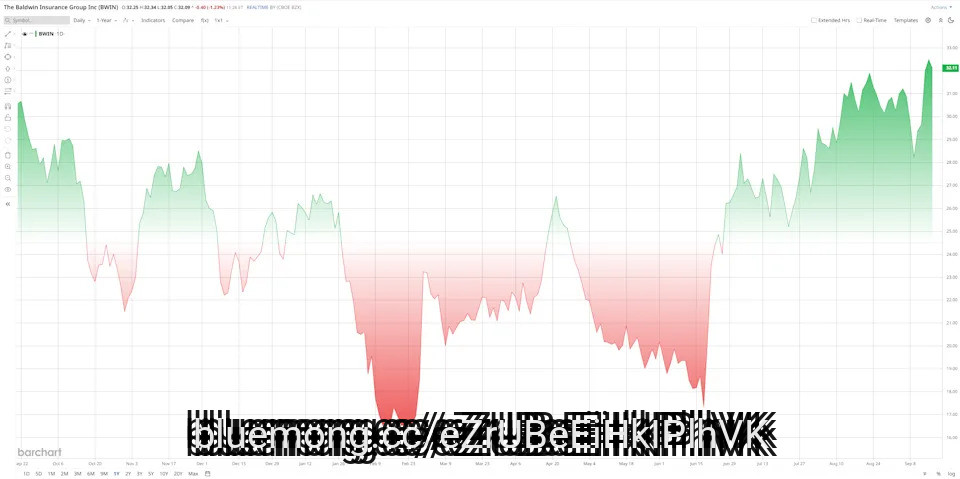
The Baldwin Insurance Group (BWIN) is suddenly in the spotlight after Michael Dell's family office and Sequence Holdings agreed to take the insurance broker private in a deal valued at about $7.7 billion. The offer calls for $32.50 in cash for each share. That represents an 88% premium to Baldwin's unaffected June 17 closing price. Shares jumped 7.5% to $31.89 after the deal was announced on Sept. 14.
For investors, the story is now less about what Baldwin might be worth as a standalone public company and more about whether the proposed transaction closes as planned. The deal also gives Baldwin access to long-duration capital outside the public markets. That could help the company keep investing in acquisitions, technology, and artificial intelligence without the same pressure to deliver results every quarter.
Billionaire Charlie Munger, Who Died at 99, Skipped Insurance on His Mansion Since He Could Just Write a Check to Rebuild — 'All Intelligent People Do It My Way'
The Case for Selling CrowdStrike Stock
Dear Tesla Stock Fans, Mark Your Calendars for October 1
#sequence
For investors, the story is now less about what Baldwin might be worth as a standalone public company and more about whether the proposed transaction closes as planned. The deal also gives Baldwin access to long-duration capital outside the public markets. That could help the company keep investing in acquisitions, technology, and artificial intelligence without the same pressure to deliver results every quarter.
Billionaire Charlie Munger, Who Died at 99, Skipped Insurance on His Mansion Since He Could Just Write a Check to Rebuild — 'All Intelligent People Do It My Way'
The Case for Selling CrowdStrike Stock
Dear Tesla Stock Fans, Mark Your Calendars for October 1
#sequence

5 days ago
Federal officials acknowledge that President Donald Trump’s planned triumphal arch will unavoidably harm historic sites if built as planned, but they say the project must move forward, according to a National Park Service document and emails obtained by The Washington Post.
Trump’s 250-foot-tall proposed arch would be built in Memorial Circle, a traffic roundabout tucked inside Washington’s boundaries near Arlington National Cemetery. Historic preservationists, veterans groups and others have called on the administration to shrink the monument’s planned size or build it elsewhere, warning that the towering structure would overshadow the cemetery, interrupt the solemn corridor that was intended between the cemetery and the Lincoln Memorial, and create other disruptions.
National Park Service officials agree that the arch would adversely affect the cemetery, the Lincoln Memorial and several dozen other historic sites.
The “adverse effects cannot be fully avoided,” Park Service officials wrote in a document circulated Tuesday and obtained by The Washington Post. But, they said, the project cannot be constructed somewhere else because “the proposed location at Memorial Circle is central to the undertaking,” according to the NPS document.
The document is a proposed agreement that the administration wants local historic-preservation officers to sign onto as part of a federally required process to offer feedback on the project.
#national #document
Trump’s 250-foot-tall proposed arch would be built in Memorial Circle, a traffic roundabout tucked inside Washington’s boundaries near Arlington National Cemetery. Historic preservationists, veterans groups and others have called on the administration to shrink the monument’s planned size or build it elsewhere, warning that the towering structure would overshadow the cemetery, interrupt the solemn corridor that was intended between the cemetery and the Lincoln Memorial, and create other disruptions.
National Park Service officials agree that the arch would adversely affect the cemetery, the Lincoln Memorial and several dozen other historic sites.
The “adverse effects cannot be fully avoided,” Park Service officials wrote in a document circulated Tuesday and obtained by The Washington Post. But, they said, the project cannot be constructed somewhere else because “the proposed location at Memorial Circle is central to the undertaking,” according to the NPS document.
The document is a proposed agreement that the administration wants local historic-preservation officers to sign onto as part of a federally required process to offer feedback on the project.
#national #document

5 days ago
Small modular reactors, or SMRs, are essentially miniature nuclear power plants. They can be built faster than larger conventional nuclear facilities. And while typically more expensive on a per-megawatt basis, upfront capital investment can also be much lower than that of traditional nuclear plants.
While the concept of SMRs has been around for decades, only two SMR systems have ever been commercialized -- one in Russia, the other in China. Both of those systems are relatively small in generating capacity.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
A new age for SMRs, however, is upon us. The AI industry needs more power quickly to support scaling trillions of dollars in data center infrastructure. Nuclear power can provide large amounts of stable baseload power with minimal refueling needs. And while SMRs are typically higher cost on a per-megawatt basis, the speed of construction of these smaller nuclear systems is highly attractive in today's environment.
The European Investment Bank -- the lending arm of the European Union -- is recognizing the potential of SMRs. On Sept. 4, the group announced a €40 million loan to Steady Energy, an SMR developer based in Finland. According to Reuters, "The loan is the first in a pipeline of SMR investments the EIB has planned."
#smrs #power #small
While the concept of SMRs has been around for decades, only two SMR systems have ever been commercialized -- one in Russia, the other in China. Both of those systems are relatively small in generating capacity.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
A new age for SMRs, however, is upon us. The AI industry needs more power quickly to support scaling trillions of dollars in data center infrastructure. Nuclear power can provide large amounts of stable baseload power with minimal refueling needs. And while SMRs are typically higher cost on a per-megawatt basis, the speed of construction of these smaller nuclear systems is highly attractive in today's environment.
The European Investment Bank -- the lending arm of the European Union -- is recognizing the potential of SMRs. On Sept. 4, the group announced a €40 million loan to Steady Energy, an SMR developer based in Finland. According to Reuters, "The loan is the first in a pipeline of SMR investments the EIB has planned."
#smrs #power #small
5 days ago
Enova International Inc (NYSE:ENVA) withdrew regulatory applications for its planned Grasshopper Bancorp acquisition on Tuesday, sending shares sharply lower despite reaffirmed growth forecasts and plans for faster buybacks.
Shares fell 25% to $169.50 following the company's acquisition update.
The technology and ******* ytics company pulled applications with the Office of the Comptroller of the Currency and the Federal Reserve after reviewing the transaction and bank approval process.
CEO Steve Cunningham said withdrawing the applications was the best choice for Enova and its shareholders, adding that the company can keep growing without becoming a bank.
He argued that banking rules have not kept pace with the credit needs of consumers and small businesses that banks do not adequately serve.
#acquisition #bank #international
Shares fell 25% to $169.50 following the company's acquisition update.
The technology and ******* ytics company pulled applications with the Office of the Comptroller of the Currency and the Federal Reserve after reviewing the transaction and bank approval process.
CEO Steve Cunningham said withdrawing the applications was the best choice for Enova and its shareholders, adding that the company can keep growing without becoming a bank.
He argued that banking rules have not kept pace with the credit needs of consumers and small businesses that banks do not adequately serve.
#acquisition #bank #international

6 days ago
This story was originally published on Food Dive. To receive daily news and insights, subscribe to our free daily Food Dive newsletter.
Coca-Cola said the beverage giant and its bottlers will invest $10 billion in U.S. infrastructure by 2030 to meet growing demand for its offerings.
The system-wide investments include a mix of new and previously announced projects that will expand production, distribution and office facilities, according to a Tuesday press release.
This includes a bottling distribution facility in Rancho Cucamonga, California; a bottling plant in Colorado Springs, Colorado; a manufacturing plant in Indianapolis; a Coca-Cola United campus in Birmingham, Alabama; a Fairlife plant in Coopersville, Michigan; and a distribution center in Orlando.
Other investments are planned for St. Cloud, Minnesota, and at a Fairlife plant in Webster, New York. Additional investments will be made during the next four years, a Coca-Cola spokesperson said in an email.
#Colorado
Coca-Cola said the beverage giant and its bottlers will invest $10 billion in U.S. infrastructure by 2030 to meet growing demand for its offerings.
The system-wide investments include a mix of new and previously announced projects that will expand production, distribution and office facilities, according to a Tuesday press release.
This includes a bottling distribution facility in Rancho Cucamonga, California; a bottling plant in Colorado Springs, Colorado; a manufacturing plant in Indianapolis; a Coca-Cola United campus in Birmingham, Alabama; a Fairlife plant in Coopersville, Michigan; and a distribution center in Orlando.
Other investments are planned for St. Cloud, Minnesota, and at a Fairlife plant in Webster, New York. Additional investments will be made during the next four years, a Coca-Cola spokesperson said in an email.
#Colorado

6 days ago
BioNTech SE (NASDAQ:BNTX) reported that its investigational lung-cancer drug gotistobart produced a clinically meaningful overall-survival benefit in the Phase 3 PRESERVE-003 trial in patients with metastatic squamous non-small cell lung cancer whose disease had progressed after prior immunotherapy and chemotherapy. Reuters said gotistobart nearly doubled survival compared with standard-of-care chemotherapy, strengthening the case for the drug as a potential chemotherapy-free treatment in a population with significant unmet need.
The result builds on earlier Stage 1 data, where gotistobart reduced the risk of death by 54% versus docetaxel, with a hazard ratio of 0.46. Median overall survival was not yet reached for gotistobart versus 9.95 months for docetaxel, while the 12-month progression-free survival rate was 25.2% versus 0%. BioNTech is now awaiting the pivotal Stage 2 readout, making the latest result important not only for the drug's approval prospects but also for the credibility of BioNTech's broader transition from a COVID-vaccine company toward a multi-product oncology business.
The strongest bullish argument is that gotistobart now has repeated evidence of a meaningful survival advantage in a difficult-to-treat lung-cancer population. The earlier Stage 1 dataset showed 55.6% of patients alive in the gotistobart arm versus 23.8% with docetaxel, alongside a 54% reduction in the risk of death. The latest Phase 3 update reinforces that signal rather than introducing an entirely new hypothesis. If the pivotal Stage 2 data confirm the benefit, BioNTech SE (NASDAQ:BNTX) could have a differentiated therapy capable of competing on survival rather than simply response rates, potentially supporting meaningful pricing power and a commercially attractive oncology franchise.
The result also strengthens BioNTech's broader oncology strategy because gotistobart is one piece of a much larger pipeline rather than a standalone bet. BioNTech says it has 14 ongoing pivotal trials and more than 10 novel combination programs, while its lung-cancer strategy spans more than 16 ongoing clinical trials and five Phase 3 programs. Gotistobart's success therefore provides validation for the company's immuno-oncology capabilities, while other ****** ets such as pumitamig and antibody-drug conjugates advance toward additional indications. BioNTech has identified 17+ late-stage or pivotal readouts through 2030+, creating the possibility that a successful gotistobart launch becomes the first major commercial proof point in its planned transition to a multi-product oncology company.
#stage #survival
The result builds on earlier Stage 1 data, where gotistobart reduced the risk of death by 54% versus docetaxel, with a hazard ratio of 0.46. Median overall survival was not yet reached for gotistobart versus 9.95 months for docetaxel, while the 12-month progression-free survival rate was 25.2% versus 0%. BioNTech is now awaiting the pivotal Stage 2 readout, making the latest result important not only for the drug's approval prospects but also for the credibility of BioNTech's broader transition from a COVID-vaccine company toward a multi-product oncology business.
The strongest bullish argument is that gotistobart now has repeated evidence of a meaningful survival advantage in a difficult-to-treat lung-cancer population. The earlier Stage 1 dataset showed 55.6% of patients alive in the gotistobart arm versus 23.8% with docetaxel, alongside a 54% reduction in the risk of death. The latest Phase 3 update reinforces that signal rather than introducing an entirely new hypothesis. If the pivotal Stage 2 data confirm the benefit, BioNTech SE (NASDAQ:BNTX) could have a differentiated therapy capable of competing on survival rather than simply response rates, potentially supporting meaningful pricing power and a commercially attractive oncology franchise.
The result also strengthens BioNTech's broader oncology strategy because gotistobart is one piece of a much larger pipeline rather than a standalone bet. BioNTech says it has 14 ongoing pivotal trials and more than 10 novel combination programs, while its lung-cancer strategy spans more than 16 ongoing clinical trials and five Phase 3 programs. Gotistobart's success therefore provides validation for the company's immuno-oncology capabilities, while other ****** ets such as pumitamig and antibody-drug conjugates advance toward additional indications. BioNTech has identified 17+ late-stage or pivotal readouts through 2030+, creating the possibility that a successful gotistobart launch becomes the first major commercial proof point in its planned transition to a multi-product oncology company.
#stage #survival

6 days ago
Kimberly-Clark Corporation (NASDAQ:KMB) is preparing **** et sales to address EU antitrust concerns surrounding its planned $40 billion acquisition of Kenvue, according to Reuters. The company is reportedly seeking to offer remedies that could secure European Commission approval by the September 29 deadline, avoiding a more extensive four-month investigation. Similar regulatory concerns have already emerged in Australia, where the deal received conditional approval after Kimberly-Clark agreed to divest Kenvue's Carefree and Stayfree brands.
The transaction is strategically important because it would create a consumer-health and personal-care company with approximately $32 billion of annual revenue and $7 billion of adjusted EBITDA. Kimberly-Clark Corporation (NASDAQ:KMB) expects about $1.9 billion of annual cost synergies and $500 million of revenue synergies, although it expects to invest roughly $2.5 billion in cash to achieve the cost savings. Therefore, the scale of any EU divestitures will be critical to determining whether Kimberly-Clark can retain the expected economic benefits of the deal.
The strongest bullish argument is that Kimberly-Clark Corporation (NASDAQ:KMB) is actively working toward a regulatory solution rather than allowing the EU review to threaten the transaction. If the company can satisfy regulators through limited **** et sales, it could preserve the majority of Kenvue's revenue and earnings while moving ahead with the combination. The expected $1.9 billion in annual cost savings represents a substantial earnings opportunity relative to the combined company's roughly $7 billion adjusted EBITDA target, giving Kimberly-Clark significant potential to improve margins and cash generation after integration.
The Australian precedent also suggests that targeted divestitures could be sufficient to resolve competition concerns without materially undermining the broader deal. Securing EU approval by September 29 would be particularly positive because it would remove a major source of uncertainty and allow Kimberly-Clark Corporation (NASDAQ:KMB) to focus on integration and synergy execution. With Kenvue adding major brands across consumer health and personal care, successful completion could also broaden Kimberly-Clark's portfolio and reduce its reliance on its existing product categories.
The biggest risk is that the EU requires more substantial **** et sales than Kimberly-Clark Corporation (NASDAQ:KMB) currently expects. Giving up attractive Kenvue brands or businesses in Europe could reduce the revenue and EBITDA acquired through the transaction, while Kimberly-Clark would still have to bear much of the financing, transaction, and integration burden. That could make the $40 billion purchase price less attractive on a risk-adjusted basis, particularly if the divested **** ets are among Kenvue's stronger European businesses.
#kimberly #revenue #ebitda
The transaction is strategically important because it would create a consumer-health and personal-care company with approximately $32 billion of annual revenue and $7 billion of adjusted EBITDA. Kimberly-Clark Corporation (NASDAQ:KMB) expects about $1.9 billion of annual cost synergies and $500 million of revenue synergies, although it expects to invest roughly $2.5 billion in cash to achieve the cost savings. Therefore, the scale of any EU divestitures will be critical to determining whether Kimberly-Clark can retain the expected economic benefits of the deal.
The strongest bullish argument is that Kimberly-Clark Corporation (NASDAQ:KMB) is actively working toward a regulatory solution rather than allowing the EU review to threaten the transaction. If the company can satisfy regulators through limited **** et sales, it could preserve the majority of Kenvue's revenue and earnings while moving ahead with the combination. The expected $1.9 billion in annual cost savings represents a substantial earnings opportunity relative to the combined company's roughly $7 billion adjusted EBITDA target, giving Kimberly-Clark significant potential to improve margins and cash generation after integration.
The Australian precedent also suggests that targeted divestitures could be sufficient to resolve competition concerns without materially undermining the broader deal. Securing EU approval by September 29 would be particularly positive because it would remove a major source of uncertainty and allow Kimberly-Clark Corporation (NASDAQ:KMB) to focus on integration and synergy execution. With Kenvue adding major brands across consumer health and personal care, successful completion could also broaden Kimberly-Clark's portfolio and reduce its reliance on its existing product categories.
The biggest risk is that the EU requires more substantial **** et sales than Kimberly-Clark Corporation (NASDAQ:KMB) currently expects. Giving up attractive Kenvue brands or businesses in Europe could reduce the revenue and EBITDA acquired through the transaction, while Kimberly-Clark would still have to bear much of the financing, transaction, and integration burden. That could make the $40 billion purchase price less attractive on a risk-adjusted basis, particularly if the divested **** ets are among Kenvue's stronger European businesses.
#kimberly #revenue #ebitda


