6 days ago
On September 14, Evercore ISI raised its price target for Netflix, Inc. (NASDAQ:NFLX) from $100 to $110 while maintaining its Outperform rating. The research firm rolled its valuation framework forward to 2028 and applied a multiple of 25 times its 2028 EPS estimate.
The new price target represents more than 40% upside from the share price of $76.41 as of September 16. However, the stock has declined about 16% year-to-date and remains well below its 52-week high of $124.86.
Evercore ISI conducted its 58th quarterly US survey and 12th semi-annual ****** an survey on Netflix, Inc. (NASDAQ:NFLX), which showed multi-year high penetration of 63% in the US and a record-high 22% penetration in ****** an.
Japan also showed strong subscriber engagement as 58% of subscribers said they were slightly or not at all likely to cancel. Subscriber satisfaction in ****** an also reached 67%.
The company's new ads plan also showed encouraging signs in ****** an. About 66% of new ads plan subscribers were either former Netflix users or people who were new to Netflix.
#high
The new price target represents more than 40% upside from the share price of $76.41 as of September 16. However, the stock has declined about 16% year-to-date and remains well below its 52-week high of $124.86.
Evercore ISI conducted its 58th quarterly US survey and 12th semi-annual ****** an survey on Netflix, Inc. (NASDAQ:NFLX), which showed multi-year high penetration of 63% in the US and a record-high 22% penetration in ****** an.
Japan also showed strong subscriber engagement as 58% of subscribers said they were slightly or not at all likely to cancel. Subscriber satisfaction in ****** an also reached 67%.
The company's new ads plan also showed encouraging signs in ****** an. About 66% of new ads plan subscribers were either former Netflix users or people who were new to Netflix.
#high
6 days ago
On September 9, 2026, Casey's General Stores, Inc. (NASDAQ:CASY) reported fiscal first-quarter revenue of $5.68 billion, up 24.3% year over year, and earnings per share of $7.37, beating the $6.78 ******* yst consensus. Yet shares fell roughly 10-15% after same-store sales grew just 3.2%, below the 3.8% Wall Street had expected.
CEO Darren Rebelez described a "volatile" fuel environment during the quarter. Same-store fuel gallons sold declined 0.3% as elevated prices pushed customers toward fewer gallons per visit, more frequent trips, and cheaper fuel grades.
Fuel profitability more than offset softer gallon volumes. Fuel gross profit jumped 19.6% to $446.9 million as the fuel margin expanded to 47.8 cents per gallon from 41.0 cents a year earlier. It shows Casey's General Stores, Inc. (NASDAQ:CASY)'s pricing discipline can protect profitability even when customers buy fewer gallons. Prepared food added another source of margin strength, with same-store sales rising 4.8% and margins expanding to 59.3% from 58.0%.
Strong earnings growth gives Casey's a solid start to fiscal 2027. EBITDA grew 17.1% to $485.1 million, while net income rose 27.1% to $273.7 million. It shows that Casey's can grow earnings despite softer same-store sales. The firm also delivered $5.68 billion of revenue, up 24% year over year and above the $5.56 billion ******* yst estimate. It gives investors evidence that the overall business remains capable of producing strong growth.
Casey's is expanding its store base and integrating Fikes. The business said the Fikes integration remains ahead of schedule and maintained its plan to open at least 120 stores in fiscal 2027 through construction and acquisitions. Ongoing unit growth can expand Casey's geographic reach, increase purchasing scale, and support long-term revenue growth even if mature-store sales remain uneven.
#fuel #revenue
CEO Darren Rebelez described a "volatile" fuel environment during the quarter. Same-store fuel gallons sold declined 0.3% as elevated prices pushed customers toward fewer gallons per visit, more frequent trips, and cheaper fuel grades.
Fuel profitability more than offset softer gallon volumes. Fuel gross profit jumped 19.6% to $446.9 million as the fuel margin expanded to 47.8 cents per gallon from 41.0 cents a year earlier. It shows Casey's General Stores, Inc. (NASDAQ:CASY)'s pricing discipline can protect profitability even when customers buy fewer gallons. Prepared food added another source of margin strength, with same-store sales rising 4.8% and margins expanding to 59.3% from 58.0%.
Strong earnings growth gives Casey's a solid start to fiscal 2027. EBITDA grew 17.1% to $485.1 million, while net income rose 27.1% to $273.7 million. It shows that Casey's can grow earnings despite softer same-store sales. The firm also delivered $5.68 billion of revenue, up 24% year over year and above the $5.56 billion ******* yst estimate. It gives investors evidence that the overall business remains capable of producing strong growth.
Casey's is expanding its store base and integrating Fikes. The business said the Fikes integration remains ahead of schedule and maintained its plan to open at least 120 stores in fiscal 2027 through construction and acquisitions. Ongoing unit growth can expand Casey's geographic reach, increase purchasing scale, and support long-term revenue growth even if mature-store sales remain uneven.
#fuel #revenue

6 days ago
On September 9, 2026, Reuters reported that Amazon.com, Inc. (NASDAQ:AMZN) raised £4.25 billion, or about $5.76 billion, in its first-ever sterling bond sale, slightly more than initially expected, as part of a four-tranche deal spanning 3 to 19 years. Final investor demand came in at more than £10.65 billion, roughly 2.5 times the amount raised, but that was notably lower than the demand Alphabet saw for its own sterling debut in February, a sign ******* ysts said shows hyperscaler borrowing may be starting to test the limits of investor appetite.
Amazon.com, Inc. (NASDAQ:AMZN)'s first sterling bond sale shows that investors still have a strong appetite for its debt. The firm raised $5.8 billion through the offering, and demand reached roughly 2.5 times the amount available. The sterling market also has relatively limited supply of large technology-company debt. It could back up demand for future Amazon issuance in the currency. Strong demand gives Amazon another funding channel as it finances its large-scale AI and cloud infrastructure investments.
Amazon can put the proceeds toward AWS, its fastest-growing major business. AWS revenue increased 36.7% year over year in the second quarter. It marks its fastest growth rate in 18 quarters as demand for AI infrastructure accelerated. Funding more data centers, computing capacity and related infrastructure could allow Amazon to capture more of that demand. If AWS sustains its growth while making strong operating profits, the additional debt could support investments in one of Amazon's most important long-term earnings drivers.
The sterling offering diversifies Amazon's funding base as its capital requirements grow. Amazon issued four tranches with maturities ranging from three to 19 years. It gives the business access to UK investors while adding sterling financing alongside its existing dollar, euro, Swiss franc and yen debt. This overall investor base gives Amazon greater flexibility to raise capital across different markets and currencies. So diversification could become more valuable as Amazon funds an unprecedented AI infrastructure buildout without relying entirely on one debt market.
Amazon.com, Inc. (NASDAQ:AMZN)'s weaker reception compared with Alphabet signals that investors may demand higher borrowing costs from hyperscalers. Amazon's sterling offering attracted about 2.5 times coverage, below Alphabet's roughly 3.5 times coverage for its recent euro bond sale. The difference shows that demand for hyperscaler debt is not unlimited. If investor appetite continues to weaken, Amazon could face higher yields on future borrowing, increasing the cost of financing its AI infrastructure expansion.
#sterling #infrastructure #NASDAQ #amzn
Amazon.com, Inc. (NASDAQ:AMZN)'s first sterling bond sale shows that investors still have a strong appetite for its debt. The firm raised $5.8 billion through the offering, and demand reached roughly 2.5 times the amount available. The sterling market also has relatively limited supply of large technology-company debt. It could back up demand for future Amazon issuance in the currency. Strong demand gives Amazon another funding channel as it finances its large-scale AI and cloud infrastructure investments.
Amazon can put the proceeds toward AWS, its fastest-growing major business. AWS revenue increased 36.7% year over year in the second quarter. It marks its fastest growth rate in 18 quarters as demand for AI infrastructure accelerated. Funding more data centers, computing capacity and related infrastructure could allow Amazon to capture more of that demand. If AWS sustains its growth while making strong operating profits, the additional debt could support investments in one of Amazon's most important long-term earnings drivers.
The sterling offering diversifies Amazon's funding base as its capital requirements grow. Amazon issued four tranches with maturities ranging from three to 19 years. It gives the business access to UK investors while adding sterling financing alongside its existing dollar, euro, Swiss franc and yen debt. This overall investor base gives Amazon greater flexibility to raise capital across different markets and currencies. So diversification could become more valuable as Amazon funds an unprecedented AI infrastructure buildout without relying entirely on one debt market.
Amazon.com, Inc. (NASDAQ:AMZN)'s weaker reception compared with Alphabet signals that investors may demand higher borrowing costs from hyperscalers. Amazon's sterling offering attracted about 2.5 times coverage, below Alphabet's roughly 3.5 times coverage for its recent euro bond sale. The difference shows that demand for hyperscaler debt is not unlimited. If investor appetite continues to weaken, Amazon could face higher yields on future borrowing, increasing the cost of financing its AI infrastructure expansion.
#sterling #infrastructure #NASDAQ #amzn
6 days ago
RF Industries, Ltd. (NASDAQ:RFIL) reported stronger fiscal third-quarter results on September 14. Revenue increased 21% to $23.96 million for the quarter ended July 31, 2026, while operating income reached approximately $1.8 million, compared with $720,000 a year earlier.
The next question is whether new orders can sustain that performance. Quarterly bookings totaled $22.5 million, below revenue. Backlog stood at $18.6 million at quarter-end and increased to $19.8 million by September 14.
Bookings measure new orders, including modifications or cancellations of earlier orders. Backlog represents orders received for which revenue has yet to be recognized.
RF Industries, Ltd. (NASDAQ:RFIL) improved both sales and profitability. Gross margin increased to 35.6% from 34% a year earlier, helping operating income grow much faster than revenue.
Management attributes the margin expansion to a shift toward customized cabling and integrated systems. These offerings involve more engineering and larger projects than traditional component sales. Competing on technical capability and customer requirements could support stronger relationships and repeat business.
#earlier
The next question is whether new orders can sustain that performance. Quarterly bookings totaled $22.5 million, below revenue. Backlog stood at $18.6 million at quarter-end and increased to $19.8 million by September 14.
Bookings measure new orders, including modifications or cancellations of earlier orders. Backlog represents orders received for which revenue has yet to be recognized.
RF Industries, Ltd. (NASDAQ:RFIL) improved both sales and profitability. Gross margin increased to 35.6% from 34% a year earlier, helping operating income grow much faster than revenue.
Management attributes the margin expansion to a shift toward customized cabling and integrated systems. These offerings involve more engineering and larger projects than traditional component sales. Competing on technical capability and customer requirements could support stronger relationships and repeat business.
#earlier

6 days ago
As a Californian, I can say this: If there are two industries that residents of the Golden State really don't like, it's insurance providers and utilities.
Interestingly, with the state considering wildfire reform legislation, those industries are at odds with one another. That's material for investors considering stocks such as PG&E (NYSE: PCG). The company known to California customers as Pacific Gas & Electric is one of the four major investor-owned utilities in the state, and due to the state having some of the highest utility rates in the U.S., PG&E and friends don't have a lot of fans in the state.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Of course, investing isn't a popularity contest. There are plenty of stocks that are often vilified in the court of public opinion that also deliver compelling returns. This year, oil equities certainly check that box. But the biggest risk to prospective PG&E investors isn't how Californians feel about the utility. It's the goings-on in Sacramento.
For those who are new to utility stocks, the primary reasons investors have embraced this sector over the years are above-average dividend yields, below-average risk profiles, and, more recently, inroads to the artificial intelligence (AI) trade.
#state #signal
Interestingly, with the state considering wildfire reform legislation, those industries are at odds with one another. That's material for investors considering stocks such as PG&E (NYSE: PCG). The company known to California customers as Pacific Gas & Electric is one of the four major investor-owned utilities in the state, and due to the state having some of the highest utility rates in the U.S., PG&E and friends don't have a lot of fans in the state.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Of course, investing isn't a popularity contest. There are plenty of stocks that are often vilified in the court of public opinion that also deliver compelling returns. This year, oil equities certainly check that box. But the biggest risk to prospective PG&E investors isn't how Californians feel about the utility. It's the goings-on in Sacramento.
For those who are new to utility stocks, the primary reasons investors have embraced this sector over the years are above-average dividend yields, below-average risk profiles, and, more recently, inroads to the artificial intelligence (AI) trade.
#state #signal
6 days ago
Moneywise and Yahoo Finance LLC may earn commission or revenue through links in the content below.
Losing your job at age 60 is difficult enough. Losing it when you've saved practically nothing for retirement can turn the next few years into a financial scramble.
Consider George, a single man from Little Rock, Ark., who found himself in that position after losing his job in a company restructuring. At 60, he was still two years away from being eligible to claim Social Security and five years away from Medicare eligibility — with little retirement savings to fall back on.
Jeff Bezos backs a platform that lets anyone invest in rental homes for as little as $100 — 6 ways to build wealth like a landlord without actually being one
A single line on your car insurance policy could be inflating your premium by up to 30% — here's what to change
#single
Losing your job at age 60 is difficult enough. Losing it when you've saved practically nothing for retirement can turn the next few years into a financial scramble.
Consider George, a single man from Little Rock, Ark., who found himself in that position after losing his job in a company restructuring. At 60, he was still two years away from being eligible to claim Social Security and five years away from Medicare eligibility — with little retirement savings to fall back on.
Jeff Bezos backs a platform that lets anyone invest in rental homes for as little as $100 — 6 ways to build wealth like a landlord without actually being one
A single line on your car insurance policy could be inflating your premium by up to 30% — here's what to change
#single

6 days ago
Moneywise and Yahoo Finance LLC may earn commission or revenue through links in the content below.
The Social Security trust fund is projected to be depleted by the end of 2032 — at which point benefits could be automatically cut by as much as 22% on average, according to the 2026 Trustees Report (1) put out by the Social Security Administration (SSA).
Now, two Democrat lawmakers have proposed a solution that would not only avoid the cut but also boost benefits for some older Americans on the program.
Jeff Bezos backs a platform that lets anyone invest in rental homes for as little as $100 — 6 ways to build wealth like a landlord without actually being one
A single line on your car insurance policy could be inflating your premium by up to 30% — here's what to change
#Social #benefits #democrat
The Social Security trust fund is projected to be depleted by the end of 2032 — at which point benefits could be automatically cut by as much as 22% on average, according to the 2026 Trustees Report (1) put out by the Social Security Administration (SSA).
Now, two Democrat lawmakers have proposed a solution that would not only avoid the cut but also boost benefits for some older Americans on the program.
Jeff Bezos backs a platform that lets anyone invest in rental homes for as little as $100 — 6 ways to build wealth like a landlord without actually being one
A single line on your car insurance policy could be inflating your premium by up to 30% — here's what to change
#Social #benefits #democrat

6 days ago
On August 20, Royal Caribbean Group (NYSE:RCL) said it had completed a sale of $1.25 billion of notes that carry a 5.55% coupon and come due on January 20, 2034. The money is earmarked first for floating-rate term loans, with anything left over used to repay or refinance other debt, and the offering rode on a shelf registration filed on February 29, 2024. That sounds like routine upkeep. But next to an earnings beat and a flat third-quarter pricing outlook, the deal gives you a handy lens on where the company stands.
Start with the debt itself. Swapping floating-rate borrowings for notes with a stated 5.550% coupon takes some interest-rate guesswork out of the picture, and the notes don't mature until January 20, 2034. That matters because $2.7 billion comes due in 2027 and $3.4 billion in 2028. Against those bills, the company held $6.9 billion of liquidity as of June 30, and it added $250 million to its revolving credit line in July.
The business generating the cash is running well. On July 28, Royal Caribbean reported second-quarter adjusted earnings of $4.21 per share, ahead of its own guidance on stronger last-minute demand, lower costs, and better results from joint ventures. Management then raised full-year adjusted EPS guidance to a range of $17.73 to $17.87, which implies 14% growth. It also kept returning cash to shareholders in the second quarter, through $404 million of dividends and $199 million of buybacks. Booking volumes are running above last year, and 2027 bookings are tracking ahead of past years, even on routes that geopolitical events hit in 2026.
Beat or not, that $4.21 is still below the $4.38 from the same quarter in 2025. Costs excluding fuel per passenger cruise day rose 4.4%, and the cost beat came largely from the timing of expenses. Then there is pricing, where the story gets less rosy. Third-quarter net yields are guided to roughly flat against 2025 while capacity grows 8.5%, so the expected 8% revenue growth comes from more capacity, not from better yields. Management also says prolonged geopolitical activity has dented bookings on select itineraries. It calls the hit modest, but it is now built into guidance.
The refinancing also doesn't shrink the debt pile. New notes pay off old borrowings, so the total owed stays roughly where it was, and the company still expects net interest of $980 million to $990 million this year. Add roughly $4.7 billion of capital spending in 2026, mostly for new ships and destination projects, and it is clear this business needs a steady supply of capital. The April ship orders, Icon VI and Icon VII, extend that appetite, though their financing is already committed.
#billion #quarter #company #year
Start with the debt itself. Swapping floating-rate borrowings for notes with a stated 5.550% coupon takes some interest-rate guesswork out of the picture, and the notes don't mature until January 20, 2034. That matters because $2.7 billion comes due in 2027 and $3.4 billion in 2028. Against those bills, the company held $6.9 billion of liquidity as of June 30, and it added $250 million to its revolving credit line in July.
The business generating the cash is running well. On July 28, Royal Caribbean reported second-quarter adjusted earnings of $4.21 per share, ahead of its own guidance on stronger last-minute demand, lower costs, and better results from joint ventures. Management then raised full-year adjusted EPS guidance to a range of $17.73 to $17.87, which implies 14% growth. It also kept returning cash to shareholders in the second quarter, through $404 million of dividends and $199 million of buybacks. Booking volumes are running above last year, and 2027 bookings are tracking ahead of past years, even on routes that geopolitical events hit in 2026.
Beat or not, that $4.21 is still below the $4.38 from the same quarter in 2025. Costs excluding fuel per passenger cruise day rose 4.4%, and the cost beat came largely from the timing of expenses. Then there is pricing, where the story gets less rosy. Third-quarter net yields are guided to roughly flat against 2025 while capacity grows 8.5%, so the expected 8% revenue growth comes from more capacity, not from better yields. Management also says prolonged geopolitical activity has dented bookings on select itineraries. It calls the hit modest, but it is now built into guidance.
The refinancing also doesn't shrink the debt pile. New notes pay off old borrowings, so the total owed stays roughly where it was, and the company still expects net interest of $980 million to $990 million this year. Add roughly $4.7 billion of capital spending in 2026, mostly for new ships and destination projects, and it is clear this business needs a steady supply of capital. The April ship orders, Icon VI and Icon VII, extend that appetite, though their financing is already committed.
#billion #quarter #company #year
6 days ago
Moneywise and Yahoo Finance LLC may earn commission or revenue through links in the content below.
The future of America's social safety net is hanging in limbo as the underlying trust fund reserves for Social Security benefits will be depleted in just six years.
And not only is the U.S. government not offering solutions for the funding crisis, it's actually making the problem worse — even if there's money on the table for retirees as a result.
Jeff Bezos backs a platform that lets anyone invest in rental homes for as little as $100 — 6 ways to build wealth like a landlord without actually being one
A single line on your car insurance policy could be inflating your premium by up to 30% — here's what to change
#actually #moneywise #bezos #commission
The future of America's social safety net is hanging in limbo as the underlying trust fund reserves for Social Security benefits will be depleted in just six years.
And not only is the U.S. government not offering solutions for the funding crisis, it's actually making the problem worse — even if there's money on the table for retirees as a result.
Jeff Bezos backs a platform that lets anyone invest in rental homes for as little as $100 — 6 ways to build wealth like a landlord without actually being one
A single line on your car insurance policy could be inflating your premium by up to 30% — here's what to change
#actually #moneywise #bezos #commission

6 days ago
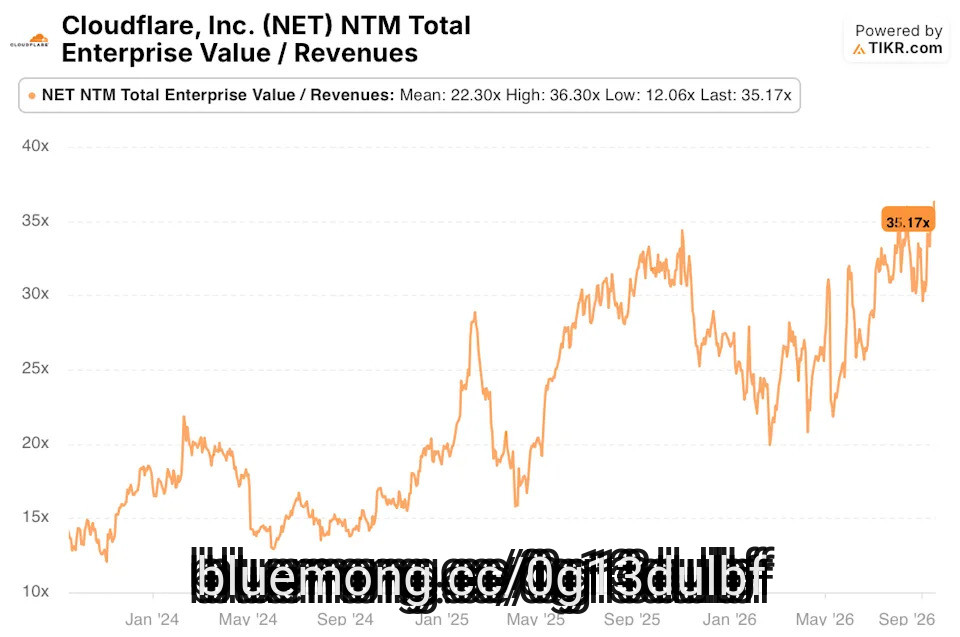
Cloudflare's Q2 beat and reaccelerating growth (36% revenue growth, 120% net dollar retention, record large customer adds) pushed NET stock to new highs, but the market has already paid up: NTM EV/Revenue sits at 35.17x, just below its all-time high of 36.30x and well above its roughly two-year average of 22.30x.
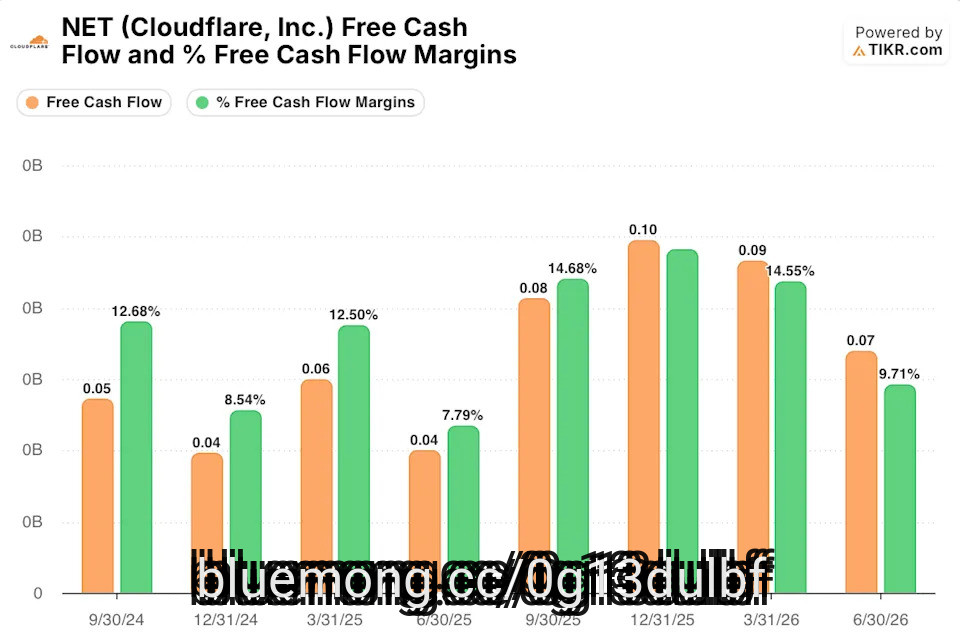
Free cash flow margin, the exact metric management points to as evidence of a credible path to GAAP profitability by 2028, has fallen for two straight quarters, from 14.55% in Q1 2026 to 9.71% in Q2 2026, even as severance and restructuring costs climbed toward $165 million for the year.
President Michelle Zatlyn, CFO Thomas Seifert, and director John Graham-Cumming all sold stock in August and September, Zatlyn alone disposing of roughly $44 million across two separate filings, while the company also raised $2.175 billion in convertible debt despite already holding $4.2 billion in cash.
Street consensus, which saw NET stock as 13% to 22% undervalued for most of late 2025 and early 2026, has now caught up: the mean ****** yst target of $336.81 sits just 4% above the September 18 close of $323.60, a far thinner cushion than investors had earlier in the rally.
Cloudflare's second quarter gave bulls plenty to like. Revenue grew 36% year over year to $696.1 million, beating the $665.5 million ****** yst estimate. The company added a record 986 large customers over the trailing year and net dollar retention accelerated to 120%, up six points from a year earlier. Management used that momentum to lean harder into its Act 4 story, the plan to turn Cloudflare's network into infrastructure for agentic commerce through products like Monetization Gateway, Wallets, and cloudflare.pay.
#revenue #dollar
Free cash flow margin, the exact metric management points to as evidence of a credible path to GAAP profitability by 2028, has fallen for two straight quarters, from 14.55% in Q1 2026 to 9.71% in Q2 2026, even as severance and restructuring costs climbed toward $165 million for the year.
President Michelle Zatlyn, CFO Thomas Seifert, and director John Graham-Cumming all sold stock in August and September, Zatlyn alone disposing of roughly $44 million across two separate filings, while the company also raised $2.175 billion in convertible debt despite already holding $4.2 billion in cash.
Street consensus, which saw NET stock as 13% to 22% undervalued for most of late 2025 and early 2026, has now caught up: the mean ****** yst target of $336.81 sits just 4% above the September 18 close of $323.60, a far thinner cushion than investors had earlier in the rally.
Cloudflare's second quarter gave bulls plenty to like. Revenue grew 36% year over year to $696.1 million, beating the $665.5 million ****** yst estimate. The company added a record 986 large customers over the trailing year and net dollar retention accelerated to 120%, up six points from a year earlier. Management used that momentum to lean harder into its Act 4 story, the plan to turn Cloudflare's network into infrastructure for agentic commerce through products like Monetization Gateway, Wallets, and cloudflare.pay.
#revenue #dollar

6 days ago
On August 6, Wheaton Precious Metals (NYSE:WPM) reported second-quarter net earnings of $543 million on $929 million of revenue, both records. Through the first half, net earnings rose 106% to $1.1 billion. During the quarter, the company also made net upfront cash payments of $4.5 billion relative to mineral stream interests, and it now carries $2.0 billion of total debt against $100 million of cash on hand. Here is what that trade looks like up close.
Start with what the streaming model does when prices climb. Wheaton sold 14% more gold equivalent ounces than a year ago, but the average realized gold equivalent price jumped 61% in Q2, and that higher price explains most of the revenue surge. Costs per ounce rose from $406 to $568, yet the cash operating margin per ounce still grew 65% to $3,875, faster than gold itself appreciated. Operating cash flow hit $650 million in the quarter and $1.4 billion for the half.
The second argument is that plenty of growth hasn't arrived yet. Only about 3% of this year's production comes from **** ets still in construction or ramp-up, and the company forecasts a rise of roughly 50% to 1,200,000 gold equivalent ounces by 2030. Some of that ramp has dates attached. Ivanhoe now expects commercial production at Platreef in the fourth quarter of 2026, and Montage Gold is targeting first gold at Koné in late Q4. Effective April 1, Wheaton expanded its share of silver production from Antamina from 33.75% to 67.5% through the newly acquired BHP Antamina PMPA.
Growth on this scale wasn't free. Wheaton had no bank debt at the end of 2025. On April 1, it drew $1.5 billion on a new two-year term loan to help pay for Antamina, and finance costs that were negligible a year ago now take a real bite. Net debt stands at $1.9 billion. Taxes are heavier too. Wheaton paid $109 million of global minimum tax on June 24, and another Cdn$346 million is due around March 31, 2027.
Operations also gave investors a few reasons for caution. Gold ounces produced slipped 2.6% year over year, so the 6% rise in gold equivalent production leaned heavily on the Antamina purchase. Gold output at Salobo fell 11% on lower grades. At Constancia, it fell 35% after mining at the higher-grade Pampacancha pit finished in the fourth quarter of 2025. Hemlo Mining said on July 20 that its second-quarter output fell below the first quarter's, and Rio2 said on May 15 that Fenix missed planned tonnes and grade in Q1. And because the revenue jump came mainly from price, the same leverage works in reverse if metals slip.
#wheaton
Start with what the streaming model does when prices climb. Wheaton sold 14% more gold equivalent ounces than a year ago, but the average realized gold equivalent price jumped 61% in Q2, and that higher price explains most of the revenue surge. Costs per ounce rose from $406 to $568, yet the cash operating margin per ounce still grew 65% to $3,875, faster than gold itself appreciated. Operating cash flow hit $650 million in the quarter and $1.4 billion for the half.
The second argument is that plenty of growth hasn't arrived yet. Only about 3% of this year's production comes from **** ets still in construction or ramp-up, and the company forecasts a rise of roughly 50% to 1,200,000 gold equivalent ounces by 2030. Some of that ramp has dates attached. Ivanhoe now expects commercial production at Platreef in the fourth quarter of 2026, and Montage Gold is targeting first gold at Koné in late Q4. Effective April 1, Wheaton expanded its share of silver production from Antamina from 33.75% to 67.5% through the newly acquired BHP Antamina PMPA.
Growth on this scale wasn't free. Wheaton had no bank debt at the end of 2025. On April 1, it drew $1.5 billion on a new two-year term loan to help pay for Antamina, and finance costs that were negligible a year ago now take a real bite. Net debt stands at $1.9 billion. Taxes are heavier too. Wheaton paid $109 million of global minimum tax on June 24, and another Cdn$346 million is due around March 31, 2027.
Operations also gave investors a few reasons for caution. Gold ounces produced slipped 2.6% year over year, so the 6% rise in gold equivalent production leaned heavily on the Antamina purchase. Gold output at Salobo fell 11% on lower grades. At Constancia, it fell 35% after mining at the higher-grade Pampacancha pit finished in the fourth quarter of 2025. Hemlo Mining said on July 20 that its second-quarter output fell below the first quarter's, and Rio2 said on May 15 that Fenix missed planned tonnes and grade in Q1. And because the revenue jump came mainly from price, the same leverage works in reverse if metals slip.
#wheaton

6 days ago
This page either does not exist or is currently unavailable.
From here you can either hit the "back" ****** on on your browser to return to the previous page, or visit the ABCNews.com Home Page. You can also search for something on our site below.
#exist #currently
From here you can either hit the "back" ****** on on your browser to return to the previous page, or visit the ABCNews.com Home Page. You can also search for something on our site below.
#exist #currently


6 days ago
Benzinga and Yahoo Finance LLC may earn commission or revenue on some items through the links below.
It's been a bloodbath for Hunter Biden's Laptop (LAPTOP) memecoin since its launch a week ago, far worse than that of President Donald Trump's memecoin in its debut week.
LAPTOP launched on Base, a Layer 2 blockchain developed by Coinbase Global Inc., at roughly $37, according to CoinMarketCap. Within minutes, it surged to a record high of $401.12, pushing its market cap to $50 billion.
However, the frenzy was short-lived.
Don't Miss:
#laptop #week #finance #president
It's been a bloodbath for Hunter Biden's Laptop (LAPTOP) memecoin since its launch a week ago, far worse than that of President Donald Trump's memecoin in its debut week.
LAPTOP launched on Base, a Layer 2 blockchain developed by Coinbase Global Inc., at roughly $37, according to CoinMarketCap. Within minutes, it surged to a record high of $401.12, pushing its market cap to $50 billion.
However, the frenzy was short-lived.
Don't Miss:
#laptop #week #finance #president
7 days ago
Benzinga and Yahoo Finance LLC may earn commission or revenue on some items through the links below.
Humanoid robots are showing meaningful progress beyond controlled demonstrations, with advances in autonomy, dexterity, and the ability to perform repetitive real-world tasks. But widespread commercial deployment still remains a work in progress.
After spending a week meeting with leading robotics labs, engineers and investors across the San Francisco Bay Area, researchers found that most humanoid robots remain in development, training, and tele-operated demonstrations. Where real-world deployments exist, they are generally closer to pilots than clear return-on-investment opportunities, according to a report published Wednesday by Citrini Research.
Don't Miss:
A single bad hire can set a startup back years. Here are the 5 hires founders most often misjudge — and why
#robots
Humanoid robots are showing meaningful progress beyond controlled demonstrations, with advances in autonomy, dexterity, and the ability to perform repetitive real-world tasks. But widespread commercial deployment still remains a work in progress.
After spending a week meeting with leading robotics labs, engineers and investors across the San Francisco Bay Area, researchers found that most humanoid robots remain in development, training, and tele-operated demonstrations. Where real-world deployments exist, they are generally closer to pilots than clear return-on-investment opportunities, according to a report published Wednesday by Citrini Research.
Don't Miss:
A single bad hire can set a startup back years. Here are the 5 hires founders most often misjudge — and why
#robots


7 days ago
Eli Lilly (LLY) trades near $1,150, up about 52% over the past year, and is now worth more than a trillion dollars. At that size the easy read is that the big money has been made. But Lilly has barely started selling Foundayo, its oral obesity medicine, outside the United States. So how much is left? The scenario below starts from Lilly's own trailing numbers, but the growth, margin, and multiple it ***** umes are ours. It is not a forecast and not a price target.
Almost all of the upside is revenue. The scenario caps growth at 30% a year. That is well below the 49.6% Lilly grew over the past twelve months, though only a little below the roughly 32% pace of its own 2026 guide. Revenue still climbs from $79.7 billion to $175.0 billion by year three.
The engine is incretins. Mounjaro and Zepbound together made $14.9 billion in the second quarter of 2026, $6.3 billion more than a year earlier. Net margin eases to 30.7% in the scenario, so earnings roughly double.
Then the multiple takes its cut. Lilly's P/E of 38.5x already sits below its three-year average of 68.9x, and the scenario trims it further to 33.6x because slower growth will not support even today's multiple. On those ***** umptions the stock would be worth about $2,024 in three years, roughly 76% above today.
LLY
#below #roughly #revenue
Almost all of the upside is revenue. The scenario caps growth at 30% a year. That is well below the 49.6% Lilly grew over the past twelve months, though only a little below the roughly 32% pace of its own 2026 guide. Revenue still climbs from $79.7 billion to $175.0 billion by year three.
The engine is incretins. Mounjaro and Zepbound together made $14.9 billion in the second quarter of 2026, $6.3 billion more than a year earlier. Net margin eases to 30.7% in the scenario, so earnings roughly double.
Then the multiple takes its cut. Lilly's P/E of 38.5x already sits below its three-year average of 68.9x, and the scenario trims it further to 33.6x because slower growth will not support even today's multiple. On those ***** umptions the stock would be worth about $2,024 in three years, roughly 76% above today.
LLY
#below #roughly #revenue

7 days ago
Rocket Lab (RKLB) has gained 9.5% over the last five trading days, while the S&P 500 added 0.6%. A week like that pulls money in. The stock is still about 55% below its 52-week high. The run is not the question. What matters for your money is what this stock does to your portfolio when the market moves, because it travels about four times as far as the index in both directions.
On days the S&P 500 rose over the past year, Rocket Lab captured about 381% of the gain. On days the index fell, it absorbed about 403% of the loss. The down days take slightly more than the up days give.
That is leverage on the market rather than a cushion. Over the past five years Rocket Lab ran 79.2% annualized volatility against 17.2% for the S&P 500, and its daily moves tracked the index at a correlation of 0.46 over those five years.
A moderate correlation and a swing that size sit together. Correlation asks whether the stock and the index move the same way, not how far. A good part of what Rocket Lab does is its own.
Look at what you own. Rocket Lab booked a record $234 million of revenue in Q2 2026, up 62% from the same quarter a year earlier, and it has just flown its 16th Electron mission of 2026.
#days
On days the S&P 500 rose over the past year, Rocket Lab captured about 381% of the gain. On days the index fell, it absorbed about 403% of the loss. The down days take slightly more than the up days give.
That is leverage on the market rather than a cushion. Over the past five years Rocket Lab ran 79.2% annualized volatility against 17.2% for the S&P 500, and its daily moves tracked the index at a correlation of 0.46 over those five years.
A moderate correlation and a swing that size sit together. Correlation asks whether the stock and the index move the same way, not how far. A good part of what Rocket Lab does is its own.
Look at what you own. Rocket Lab booked a record $234 million of revenue in Q2 2026, up 62% from the same quarter a year earlier, and it has just flown its 16th Electron mission of 2026.
#days

7 days ago
Benzinga and Yahoo Finance LLC may earn commission or revenue on some items through the links below.
The Securities and Exchange Commission (SEC) is seeking interviews with current and former Guggenheim Investments employees as regulators deepen inquiries into CEO Mark Walter's business.
The SEC is specifically looking at people who have managed insurance-company ******* et portfolios, sources familiar with the matter told Bloomberg. Some individuals contacted by the agency are hiring lawyers to help them respond to confidential inquiries.
The request for interviews suggests that regulators are continuing to scrutinize the billionaire's business empire despite public ******* urances from Guggenheim officials and TWG Holdings, Walter's holding company, that they are cooperating and working with the government on its inquiries.
Read Also:Deal Dispatch: Egg Maker Vital Farms Considers Sale, Blackstone Buys Flow Control, Kennedy Center Troubles
#regulators #securities
The Securities and Exchange Commission (SEC) is seeking interviews with current and former Guggenheim Investments employees as regulators deepen inquiries into CEO Mark Walter's business.
The SEC is specifically looking at people who have managed insurance-company ******* et portfolios, sources familiar with the matter told Bloomberg. Some individuals contacted by the agency are hiring lawyers to help them respond to confidential inquiries.
The request for interviews suggests that regulators are continuing to scrutinize the billionaire's business empire despite public ******* urances from Guggenheim officials and TWG Holdings, Walter's holding company, that they are cooperating and working with the government on its inquiries.
Read Also:Deal Dispatch: Egg Maker Vital Farms Considers Sale, Blackstone Buys Flow Control, Kennedy Center Troubles
#regulators #securities

7 days ago
(Table below reflects daily flows on September 17, 2026 and **** et totals as of that date.)
ETF Brand League Table
Welcome to the etf.com league table. On this page, you'll find the U.S. ETF market through different lenses: brand and issuer. What's the difference? The brand is what the ETF says on the tin. For example, "iShares" is the brand of issuer "BlackRock's" ETFs. Because many issuers license their ETF infrastructure to third parties, we present the data in both ways. The identification of the correct brand and legal issuer is done by our key data provider, FactSet.
Brand
AUM ($, mm)
#league #welcome #etfs
ETF Brand League Table
Welcome to the etf.com league table. On this page, you'll find the U.S. ETF market through different lenses: brand and issuer. What's the difference? The brand is what the ETF says on the tin. For example, "iShares" is the brand of issuer "BlackRock's" ETFs. Because many issuers license their ETF infrastructure to third parties, we present the data in both ways. The identification of the correct brand and legal issuer is done by our key data provider, FactSet.
Brand
AUM ($, mm)
#league #welcome #etfs

7 days ago
A crypto whale appears to be shifting a large portion of its portfolio from Bitcoin into Ethereum.
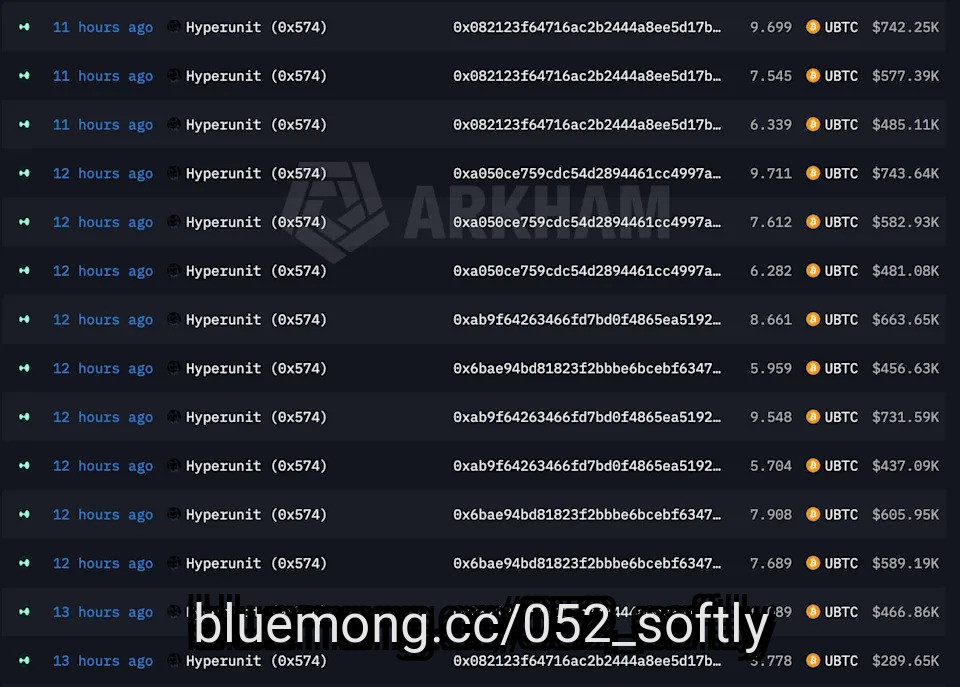
According to blockchain ***** ytics platform Lookonchain, 11 newly created wallets suspected to belong to the same whale, sold 602 BTC and bought 18,780 ETH on Hyperliquid over the past three days. Both sides of the transactions were worth roughly $45.83 million, indicating a large-scale portfolio rebalancing.
At press time, Bitcoin was trading around $81,001, up nearly 5.5% over the past 24 hours, while Ether was around $2,594, gaining about 5%.
JPMorgan says one ***** et class could soon beat gold
Kevin O'Leary has a warning on Washington's tax plans
#whale #Portfolio #ethereum #lookonchain
According to blockchain ***** ytics platform Lookonchain, 11 newly created wallets suspected to belong to the same whale, sold 602 BTC and bought 18,780 ETH on Hyperliquid over the past three days. Both sides of the transactions were worth roughly $45.83 million, indicating a large-scale portfolio rebalancing.
At press time, Bitcoin was trading around $81,001, up nearly 5.5% over the past 24 hours, while Ether was around $2,594, gaining about 5%.
JPMorgan says one ***** et class could soon beat gold
Kevin O'Leary has a warning on Washington's tax plans
#whale #Portfolio #ethereum #lookonchain



7 days ago
In June, ****** eX (NASDAQ: SPCX) successfully completed its blockbuster IPO, raising more than $85 billion. In the days that followed, ****** eX's market cap soared from an initial IPO valuation of $1.77 trillion to nearly $2.8 trillion. Shares corrected hard after the surge, however, and ****** eX's valuation now hovers just below $2 trillion -- a 36% decline versus the company's all-time high.
Morgan Stanley (NYSE: MS) ****** ysts remain unfazed regarding the ****** e stock's long-term growth potential. On Sept. 15, the bank reiterated its "buy" rating on shares, affirming its $300 price target. That price target implies more than 100% in near-term upside over the next 12 months.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Why does Morgan Stanley remain so bullish? The answer might surprise you.
Morgan Stanley appears all-in on the ****** e economy. The bank, in many ways, predicted ****** eX's meteoric rise years before much of the public caught on.
#trillion #valuation
Morgan Stanley (NYSE: MS) ****** ysts remain unfazed regarding the ****** e stock's long-term growth potential. On Sept. 15, the bank reiterated its "buy" rating on shares, affirming its $300 price target. That price target implies more than 100% in near-term upside over the next 12 months.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Why does Morgan Stanley remain so bullish? The answer might surprise you.
Morgan Stanley appears all-in on the ****** e economy. The bank, in many ways, predicted ****** eX's meteoric rise years before much of the public caught on.
#trillion #valuation


7 days ago
Benzinga and Yahoo Finance LLC may earn commission or revenue on some items through the links below.
Ripple-backed XRP treasury company Evernorth Holdings has lined up $30 million in new financing as it prepares to go public through a merger with Armada Acquisition Corp. II (NASDAQ:XRPN).
The deal would bring Evernorth onto Nasdaq under the XRPN ticker, giving public-market investors exposure to a company built around accumulating XRP (CRYPTO: XRP) and deploying it across the XRP ecosystem.
Evernorth said the new financing may be used to buy more XRP and fund other ecosystem investments. The $30 million arrives when the merger closes, which the company expects in the fourth quarter.
Evernorth and an affiliate held 473.1 million XRP at the end of 2025. At around $1.38 per token, $30 million would buy roughly another 21.7 million XRP, or less than 5% of that existing position.
#financing #merger
Ripple-backed XRP treasury company Evernorth Holdings has lined up $30 million in new financing as it prepares to go public through a merger with Armada Acquisition Corp. II (NASDAQ:XRPN).
The deal would bring Evernorth onto Nasdaq under the XRPN ticker, giving public-market investors exposure to a company built around accumulating XRP (CRYPTO: XRP) and deploying it across the XRP ecosystem.
Evernorth said the new financing may be used to buy more XRP and fund other ecosystem investments. The $30 million arrives when the merger closes, which the company expects in the fourth quarter.
Evernorth and an affiliate held 473.1 million XRP at the end of 2025. At around $1.38 per token, $30 million would buy roughly another 21.7 million XRP, or less than 5% of that existing position.
#financing #merger
7 days ago
One of the world's largest companies has become a cash-return machine of historic scale, but its engine is now facing a serious test.
With Apple (AAPL) stock trading near $337 a share, an owner might ask a simple question. The company has returned a fortune in cash while the stock has dramatically outperformed the market; was holding worth it, and can this machine keep running?
Over the last five years, Apple sent $510.4 billion in cash back to its shareholders. That sum, equal to about 10.3% of the company's current market value, is the largest capital return of any U.S. company Trefis tracks over that period. The question is what that extraordinary payout says about the business today.
The money printer is Apple's core business, which generated $136.68 billion in free cash flow over the last twelve months. In its most recent quarter, the company reported record June-quarter revenue, with iPhone sales growing 22% and Mac sales growing an impressive 29% from a year ago. Management noted that the iPhone and Mac were "both doing remarkably better than we thought they would do."
That operational strength funds the shareholder returns. The five-year payout was heavily weighted toward share repurchases, which totaled $434.5 billion, with another $75.9 billion paid in dividends. Apple's absolute dollar payout stands alone, even though the 10.3% of market value it returned sits well below the 16.9% median for S&P 500 companies.
#market
With Apple (AAPL) stock trading near $337 a share, an owner might ask a simple question. The company has returned a fortune in cash while the stock has dramatically outperformed the market; was holding worth it, and can this machine keep running?
Over the last five years, Apple sent $510.4 billion in cash back to its shareholders. That sum, equal to about 10.3% of the company's current market value, is the largest capital return of any U.S. company Trefis tracks over that period. The question is what that extraordinary payout says about the business today.
The money printer is Apple's core business, which generated $136.68 billion in free cash flow over the last twelve months. In its most recent quarter, the company reported record June-quarter revenue, with iPhone sales growing 22% and Mac sales growing an impressive 29% from a year ago. Management noted that the iPhone and Mac were "both doing remarkably better than we thought they would do."
That operational strength funds the shareholder returns. The five-year payout was heavily weighted toward share repurchases, which totaled $434.5 billion, with another $75.9 billion paid in dividends. Apple's absolute dollar payout stands alone, even though the 10.3% of market value it returned sits well below the 16.9% median for S&P 500 companies.
#market

7 days ago
Xenon Pharmaceuticals (XENE) shares crashed on Friday after the biopharmaceutical firm said it has paused new patient enrollment in its clinical trials evaluating azetukalner. As investors responded to the setback involving XENE's lead drug candidate for major depressive disorder, its relative strength index (RSI) slipped into the early teens, indicating extremely oversold conditions.
Following today's decline, Xenon Pharmaceuticals stock is trading nearly 40% below its year-to-date high.
Bank of America Just Declared a 'Generational Entry Point' in U.S. Bonds. Why Investors Should Be Backing Up the Truck on Treasuries Here.
Mark Cuban Says He Was Dizzy for Months, So He Built a VR Fix That Does at Home 'Much Of What A 180k Machine' Does
JPMorgan Gives Up Forecasting Iran War Endgame as Trump Tells Reporters 'Anything Could Happen With Me'
#xene #following #America
Following today's decline, Xenon Pharmaceuticals stock is trading nearly 40% below its year-to-date high.
Bank of America Just Declared a 'Generational Entry Point' in U.S. Bonds. Why Investors Should Be Backing Up the Truck on Treasuries Here.
Mark Cuban Says He Was Dizzy for Months, So He Built a VR Fix That Does at Home 'Much Of What A 180k Machine' Does
JPMorgan Gives Up Forecasting Iran War Endgame as Trump Tells Reporters 'Anything Could Happen With Me'
#xene #following #America


7 days ago
Benzinga and Yahoo Finance LLC may earn commission or revenue on some items through the links below.
Brad Gerstner says leading AI labs need to lift their combined annualized revenue from roughly $100 billion to at least $180 billion by year-end to keep the AI trade intact.
The Altimeter Capital founder, whose firm held nearly $1.9 billion of Nvidia Corp. (NASDAQ:NVDA) shares at the end of June, called AI lab revenue "the single most important data point in the market today" at the All-In Summit.
Gerstner estimated that Anthropic, OpenAI and **** eX (NASDAQ:SPCX), which owns xAI, had a combined run rate of roughly $100 billion based on figures circulating in July.
Gerstner said the companies need to reach at least $180 billion by year-end, up about 80% from his July estimate, "just to keep the AI trade intact."
#NASDAQ #combined #least #year
Brad Gerstner says leading AI labs need to lift their combined annualized revenue from roughly $100 billion to at least $180 billion by year-end to keep the AI trade intact.
The Altimeter Capital founder, whose firm held nearly $1.9 billion of Nvidia Corp. (NASDAQ:NVDA) shares at the end of June, called AI lab revenue "the single most important data point in the market today" at the All-In Summit.
Gerstner estimated that Anthropic, OpenAI and **** eX (NASDAQ:SPCX), which owns xAI, had a combined run rate of roughly $100 billion based on figures circulating in July.
Gerstner said the companies need to reach at least $180 billion by year-end, up about 80% from his July estimate, "just to keep the AI trade intact."
#NASDAQ #combined #least #year
7 days ago
Barclays ******* yst Simon Coles says the recent pullback in Tower Semiconductor (TSEM) shares is an opportunity to load up on a quality name at a meaningful discount. In a research note this morning, Coles ******* umed coverage of the independent specialty foundry with an "Overweight" rating and a $310 price target that signals potential upside of nearly 40% from here.
Tower Semiconductor stock has been in a sharp downtrend in recent months, currently trading about 30% below its June high.
Bank of America Just Declared a 'Generational Entry Point' in U.S. Bonds. Why Investors Should Be Backing Up the Truck on Treasuries Here.
Mark Cuban Says He Was Dizzy for Months, So He Built a VR Fix That Does at Home 'Much Of What A 180k Machine' Does
JPMorgan Gives Up Forecasting Iran War Endgame as Trump Tells Reporters 'Anything Could Happen With Me'
#tower #recent #simon #tsem
Tower Semiconductor stock has been in a sharp downtrend in recent months, currently trading about 30% below its June high.
Bank of America Just Declared a 'Generational Entry Point' in U.S. Bonds. Why Investors Should Be Backing Up the Truck on Treasuries Here.
Mark Cuban Says He Was Dizzy for Months, So He Built a VR Fix That Does at Home 'Much Of What A 180k Machine' Does
JPMorgan Gives Up Forecasting Iran War Endgame as Trump Tells Reporters 'Anything Could Happen With Me'
#tower #recent #simon #tsem


7 days ago
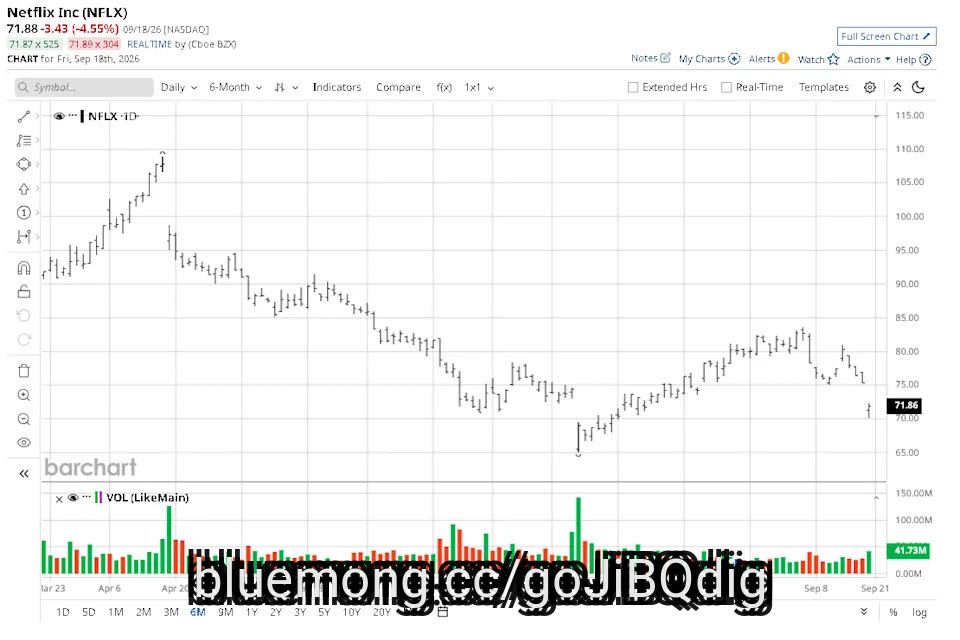
Netflix (NFLX) shares are on track to record their worst year since 2022, but a senior Wells Fargo ******* yst, Steven Cahall, cautions against hoping for a swift recovery. In his latest research note, Cahall downgraded the streaming giant to "Underweight" and slashed his price target to $57, indicating potential downside of another 20% from here.
At the time of writing, Netflix stock is already trading about 35% below its year-to-date high.
Bank of America Just Declared a 'Generational Entry Point' in U.S. Bonds. Why Investors Should Be Backing Up the Truck on Treasuries Here.
Mark Cuban Says He Was Dizzy for Months, So He Built a VR Fix That Does at Home 'Much Of What A 180k Machine' Does
JPMorgan Gives Up Forecasting Iran War Endgame as Trump Tells Reporters 'Anything Could Happen With Me'
#netflix #wells #fargo #steven
At the time of writing, Netflix stock is already trading about 35% below its year-to-date high.
Bank of America Just Declared a 'Generational Entry Point' in U.S. Bonds. Why Investors Should Be Backing Up the Truck on Treasuries Here.
Mark Cuban Says He Was Dizzy for Months, So He Built a VR Fix That Does at Home 'Much Of What A 180k Machine' Does
JPMorgan Gives Up Forecasting Iran War Endgame as Trump Tells Reporters 'Anything Could Happen With Me'
#netflix #wells #fargo #steven

7 days ago
Jim Cramer put Intel Corporation (NASDAQ:INTC) and Micron Technology, Inc. (NASDAQ:MU) at the top of his technology stock list during the September 17 episode of Mad Money, as he said:
Yesterday, I said that people would buy tech. We got that in spades today. I continue to recommend the cybersecurity stocks, and I'd add Okta to the list because rogue agents cannot be stopped unless we can identify them first. That's Okta's job. I still think that Intel, as I tell club members, is the best stock in show, and Micron, number two… Both their products are in short supply. I just bought some Micron, candidly.
Intel Corporation's (NASDAQ:INTC) second-quarter revenue rose 25% year over year to $16.1 billion, while Data Center and AI revenue increased 59% to $6.3 billion. Intel Products generated $4.8 billion of operating income in the second quarter, up from $2.7 billion a year earlier, while Data Center and AI operating income increased $1.8 billion to $2.5 billion.
The company said client supply constraints are expected to ease in the second half of 2026, while industry-wide constraints affecting Data Center and AI products are expected to persist into 2027.
Micron Technology, Inc.'s (NASDAQ:MU) fiscal third-quarter GAAP operating margin reached 80.4%, up from 67.6% in the prior quarter and 23.3% a year earlier. Its non-GAAP operating margin was 81.2%. Operating cash flow reached $25.4 billion. The company also said DRAM inventories were "very tight and below 120 days."
#NASDAQ #operating #year #data
Yesterday, I said that people would buy tech. We got that in spades today. I continue to recommend the cybersecurity stocks, and I'd add Okta to the list because rogue agents cannot be stopped unless we can identify them first. That's Okta's job. I still think that Intel, as I tell club members, is the best stock in show, and Micron, number two… Both their products are in short supply. I just bought some Micron, candidly.
Intel Corporation's (NASDAQ:INTC) second-quarter revenue rose 25% year over year to $16.1 billion, while Data Center and AI revenue increased 59% to $6.3 billion. Intel Products generated $4.8 billion of operating income in the second quarter, up from $2.7 billion a year earlier, while Data Center and AI operating income increased $1.8 billion to $2.5 billion.
The company said client supply constraints are expected to ease in the second half of 2026, while industry-wide constraints affecting Data Center and AI products are expected to persist into 2027.
Micron Technology, Inc.'s (NASDAQ:MU) fiscal third-quarter GAAP operating margin reached 80.4%, up from 67.6% in the prior quarter and 23.3% a year earlier. Its non-GAAP operating margin was 81.2%. Operating cash flow reached $25.4 billion. The company also said DRAM inventories were "very tight and below 120 days."
#NASDAQ #operating #year #data

7 days ago
Happy Friday, traders. Welcome to our weekly market wrap, where we take a look back at these last five trading days with a focus on the market news, economic data, and headlines that had the most impact on gold prices and other key correlated ****** ets—and may continue to in the future.
So, what kind of week has it been?
Gold took a more volatile path than expected but rebounded from a post-FOMC low near $4,260/oz to trade just above $4,350/oz shortly after the US market open on Friday, putting the yellow metal in position for a moderate weekly gain.
The Federal Reserve delivered the week's main event on Wednesday, unanimously raising policy rates by 25 basis points. Gold's sharp initial drop appeared tied less to the hike itself than to projections showing elevated inflation expectations and another 25-basis-point increase before the end of 2026.
Thursday brought the countermove as crude oil slid back toward and then below $100 per barrel, US Treasury yields eased, and gold recovered to around $4,360/oz. The Bank of ****** an's overnight rate hike to 1.25% added another tailwind into Friday.
#Friday #weekly #welcome
So, what kind of week has it been?
Gold took a more volatile path than expected but rebounded from a post-FOMC low near $4,260/oz to trade just above $4,350/oz shortly after the US market open on Friday, putting the yellow metal in position for a moderate weekly gain.
The Federal Reserve delivered the week's main event on Wednesday, unanimously raising policy rates by 25 basis points. Gold's sharp initial drop appeared tied less to the hike itself than to projections showing elevated inflation expectations and another 25-basis-point increase before the end of 2026.
Thursday brought the countermove as crude oil slid back toward and then below $100 per barrel, US Treasury yields eased, and gold recovered to around $4,360/oz. The Bank of ****** an's overnight rate hike to 1.25% added another tailwind into Friday.
#Friday #weekly #welcome
7 days ago
Meta Platforms (META) has spent most of 2026 trading near $648 while the business behind it delivered record quarterly revenue. That growing mismatch has drawn a wave of ******* ysts who believe the stock is meaningfully underpriced.
Second-quarter revenue reached $60.8 billion, up 28% year over year, with a 31% operating margin, Meta's earnings press release confirmed.
At a forward price-to-earnings (P/E) ratio of 19, the stock trades below the S&P 500's approximately 22 times forward earnings.
Reaching $900 would require roughly 39% upside from current levels. Whether the target is realistic depends on how quickly Meta's artificial intelligence spending produces revenue beyond its advertising business.
Meta's advertising technology is producing gains that rival any growth story in big tech. Internal model upgrades drove an 8.3% lift in ad clicks and a 15.7% conversion gain on Facebook last quarter, 24/7 Wall St reported.
#business #year
Second-quarter revenue reached $60.8 billion, up 28% year over year, with a 31% operating margin, Meta's earnings press release confirmed.
At a forward price-to-earnings (P/E) ratio of 19, the stock trades below the S&P 500's approximately 22 times forward earnings.
Reaching $900 would require roughly 39% upside from current levels. Whether the target is realistic depends on how quickly Meta's artificial intelligence spending produces revenue beyond its advertising business.
Meta's advertising technology is producing gains that rival any growth story in big tech. Internal model upgrades drove an 8.3% lift in ad clicks and a 15.7% conversion gain on Facebook last quarter, 24/7 Wall St reported.
#business #year
7 days ago
On September 14, Evercore ISI raised its price target for Netflix, Inc. (NASDAQ:NFLX) from $100 to $110 while maintaining its Outperform rating. The research firm rolled its valuation framework forward to 2028 and applied a multiple of 25 times its 2028 EPS estimate.
The new price target represents more than 40% upside from the share price of $76.41 as of September 16. However, the stock has declined about 16% year-to-date and remains well below its 52-week high of $124.86.
Evercore ISI conducted its 58th quarterly US survey and 12th semi-annual **** an survey on Netflix, Inc. (NASDAQ:NFLX), which showed multi-year high penetration of 63% in the US and a record-high 22% penetration in **** an.
Japan also showed strong subscriber engagement as 58% of subscribers said they were slightly or not at all likely to cancel. Subscriber satisfaction in **** an also reached 67%.
The company's new ads plan also showed encouraging signs in **** an. About 66% of new ads plan subscribers were either former Netflix users or people who were new to Netflix.
#netflix #price #september #evercore
The new price target represents more than 40% upside from the share price of $76.41 as of September 16. However, the stock has declined about 16% year-to-date and remains well below its 52-week high of $124.86.
Evercore ISI conducted its 58th quarterly US survey and 12th semi-annual **** an survey on Netflix, Inc. (NASDAQ:NFLX), which showed multi-year high penetration of 63% in the US and a record-high 22% penetration in **** an.
Japan also showed strong subscriber engagement as 58% of subscribers said they were slightly or not at all likely to cancel. Subscriber satisfaction in **** an also reached 67%.
The company's new ads plan also showed encouraging signs in **** an. About 66% of new ads plan subscribers were either former Netflix users or people who were new to Netflix.
#netflix #price #september #evercore