1 day ago
On August 5, Clear Channel Outdoor Holdings Inc. (NYSE:CCO) reported second-quarter results that showed the billboard and airport advertising company accelerating just as it prepares to leave the public markets. On February 9, Clear Channel agreed to be acquired by an investor consortium advised by Mubadala Capital for $2.43 per share, a deal stockholders approved on May 12, and one expected to close by the end of the third quarter of 2026. Because of the pending Merger, Clear Channel skipped its usual earnings call and offered no forward guidance.
Consolidated revenue climbed 8.7% to $438.0 million in the quarter and 10.2% to $811.9 million over the first half, with the 2026 FIFA World Cup pulling in extra advertising spend across both of Clear Channel's segments. The America division, which houses the roadside billboard and street furniture business, grew revenue 7% to $324.3 million as demand from technology advertisers in the San Francisco/Bay Area market broadened out and digital billboard revenue rose 7.2% to $122 million. Airports revenue jumped 14% to $113.6 million, helped by strong demand at San Francisco
International Airport and digital sales that climbed 15.6% to $73.4 million, with national advertisers now accounting for 57.8% of that segment's revenue. Profitability grew even faster than the top line. Adjusted EBITDA rose 11.6% to $143.4 million for the quarter and 19% to $247.3 million for the first half, while Airports Segment Adjusted EBITDA jumped 22.8% to $29.9 million. Adjusted Funds From Operations climbed 61.6% to $44.9 million in the quarter, and for the first half it went from just $5 million a year ago to $51.5 million. On August 4, Clear Channel also closed the sale of its Spain business for about $132.3 million, proceeds it plans to put toward paying down debt.
The growth did not reach the bottom line. Clear Channel posted a loss from continuing operations of $10 million in the quarter, reversing a $6.3 million profit a year earlier, and the consolidated net loss came to $5 million versus net income of $10.6 million in the same period of 2025. Over six months, the loss from continuing operations widened 21.4% to $59.4 million. Costs rose alongside revenue. Direct operating and SG&A expenses increased 5.9% for the quarter, and Airports site lease expense alone jumped 12.0% to $67.1 million on higher minimum guaranteed payments and the renewed contract with the Metropolitan Washington Airports Authority.
#channel #revenue #airports #operations
Consolidated revenue climbed 8.7% to $438.0 million in the quarter and 10.2% to $811.9 million over the first half, with the 2026 FIFA World Cup pulling in extra advertising spend across both of Clear Channel's segments. The America division, which houses the roadside billboard and street furniture business, grew revenue 7% to $324.3 million as demand from technology advertisers in the San Francisco/Bay Area market broadened out and digital billboard revenue rose 7.2% to $122 million. Airports revenue jumped 14% to $113.6 million, helped by strong demand at San Francisco
International Airport and digital sales that climbed 15.6% to $73.4 million, with national advertisers now accounting for 57.8% of that segment's revenue. Profitability grew even faster than the top line. Adjusted EBITDA rose 11.6% to $143.4 million for the quarter and 19% to $247.3 million for the first half, while Airports Segment Adjusted EBITDA jumped 22.8% to $29.9 million. Adjusted Funds From Operations climbed 61.6% to $44.9 million in the quarter, and for the first half it went from just $5 million a year ago to $51.5 million. On August 4, Clear Channel also closed the sale of its Spain business for about $132.3 million, proceeds it plans to put toward paying down debt.
The growth did not reach the bottom line. Clear Channel posted a loss from continuing operations of $10 million in the quarter, reversing a $6.3 million profit a year earlier, and the consolidated net loss came to $5 million versus net income of $10.6 million in the same period of 2025. Over six months, the loss from continuing operations widened 21.4% to $59.4 million. Costs rose alongside revenue. Direct operating and SG&A expenses increased 5.9% for the quarter, and Airports site lease expense alone jumped 12.0% to $67.1 million on higher minimum guaranteed payments and the renewed contract with the Metropolitan Washington Airports Authority.
#channel #revenue #airports #operations

2 days ago
Sept 14 (Reuters) - Dominion Energy and NextEra Energy on Monday said they would establish a Virginia supplier program worth up to $1 billion annually for five years if their proposed merger is approved.
They announced merger plans in May, as rising power demand from data centers, electric vehicles and other industries drives a renewed wave of utility consolidation.
• NextEra and Dominion said the new program would direct spending toward contractors, suppliers and service providers in Virginia.
• They proposed extending monthly $10 bill credits to four years from two and increasing Dominion's low-income financial ***** istance by $100 million through 2038.
• The commitments include a $100 million workforce development fund, an annual energy summit in the state and maintaining the current employee headcount there for five years.
#energy #nextera #merger
They announced merger plans in May, as rising power demand from data centers, electric vehicles and other industries drives a renewed wave of utility consolidation.
• NextEra and Dominion said the new program would direct spending toward contractors, suppliers and service providers in Virginia.
• They proposed extending monthly $10 bill credits to four years from two and increasing Dominion's low-income financial ***** istance by $100 million through 2038.
• The commitments include a $100 million workforce development fund, an annual energy summit in the state and maintaining the current employee headcount there for five years.
#energy #nextera #merger


2 days ago
SWKS surged 27% in a month to $88.35, now trading above its $68.35 consensus ****** yst target with most ****** ysts rating it Hold or worse.
The Qorvo merger could unlock $500M+ in synergies, but a regulatory delay leaves Skyworks holding $2B in new debt against shrinking revenue.
At 46x trailing P/E with 14 downward EPS revisions and the CFO selling into the rally, momentum is doing all the heavy lifting.
Just released. Our ****** ysts combed the entire stock market and named the ten best stocks to buy right now, and Skyworks Solutions didn't make the cut. Enter your email to see the names that beat SWKS. The report is free. Enter your email and see if any of your stocks made the cut.
At $88.35, Skyworks Solutions (NASDAQ:SWKS) is a Hold. The stock has ripped past its consensus ****** yst price target of $68.35, and with a pending merger, a fresh capital allocation framework, and a mixed fundamental picture, the case for chasing here is as thin as the case for stepping in front of the momentum.
#skyworks #solutions #analyst #target
The Qorvo merger could unlock $500M+ in synergies, but a regulatory delay leaves Skyworks holding $2B in new debt against shrinking revenue.
At 46x trailing P/E with 14 downward EPS revisions and the CFO selling into the rally, momentum is doing all the heavy lifting.
Just released. Our ****** ysts combed the entire stock market and named the ten best stocks to buy right now, and Skyworks Solutions didn't make the cut. Enter your email to see the names that beat SWKS. The report is free. Enter your email and see if any of your stocks made the cut.
At $88.35, Skyworks Solutions (NASDAQ:SWKS) is a Hold. The stock has ripped past its consensus ****** yst price target of $68.35, and with a pending merger, a fresh capital allocation framework, and a mixed fundamental picture, the case for chasing here is as thin as the case for stepping in front of the momentum.
#skyworks #solutions #analyst #target

3 days ago
Skyworks Solutions (SWKS) shares rallied and printed a new 52-week high on Sept. 11 after chief executive Phil Brace said the pending merger with Qorvo has entered its final phases. As investors cheered the disclosure, SWKS's relative strength index (RSI) soared into the early 80s, indicating overbought conditions that often trigger profit-taking in the near term.
Including today's gains, Skyworks stock is up more than 50% versus its low in mid-July.
GME Stock Jumps as GameStop CEO Ryan Cohen Buys $20 Million Worth of Shares
Cathie Wood Just Bet $45 Million on This Beaten-Down ***** e Stock. Wall Street Sees 70% Upside.
Rocket Lab Stock Just Scored a New Bullish Rating
#swks
Including today's gains, Skyworks stock is up more than 50% versus its low in mid-July.
GME Stock Jumps as GameStop CEO Ryan Cohen Buys $20 Million Worth of Shares
Cathie Wood Just Bet $45 Million on This Beaten-Down ***** e Stock. Wall Street Sees 70% Upside.
Rocket Lab Stock Just Scored a New Bullish Rating
#swks

5 days ago
Oklo (NYSE: OKLO), a developer of microreactors for nuclear power plants, has been a divisive stock since its market debut. After going public through a merger with a special purpose acquisition company (SPAC) on May 10, 2024, Oklo started trading at $15.50 per share.
It soared to a record high of $174.14 on Oct. 14, 2025, but it now trades at about $43. Wall Street's average price target for the stock is about $75. Let's see why Oklo's stock went through so many wild swings -- and where I think it will actually end up by the end of 2026.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Oklo's Aurora microreactor, which is much smaller than conventional nuclear reactors, only generates 1.5 MWe per unit. However, its modular design allows it to be deployed alongside additional reactors to generate up to 75 MWe per "Powerhouse" power plant. That's tiny compared to a conventional nuclear power plant, which typically generates at least 1,000 MWe, but Aurora's Powerhouse plants can be deployed on less land in remote, off-grid areas.
The Aurora also uses metallic uranium fuel pellets, which are denser, have higher thermal resistance, and are cheaper to produce than the uranium dioxide fuel pellets that power conventional reactors. By recycling its pellets in a closed loop, the Aurora can last for a decade without refueling. Conventional reactors are still refueled in stages every two years.
#conventional #reactors #signal
It soared to a record high of $174.14 on Oct. 14, 2025, but it now trades at about $43. Wall Street's average price target for the stock is about $75. Let's see why Oklo's stock went through so many wild swings -- and where I think it will actually end up by the end of 2026.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Oklo's Aurora microreactor, which is much smaller than conventional nuclear reactors, only generates 1.5 MWe per unit. However, its modular design allows it to be deployed alongside additional reactors to generate up to 75 MWe per "Powerhouse" power plant. That's tiny compared to a conventional nuclear power plant, which typically generates at least 1,000 MWe, but Aurora's Powerhouse plants can be deployed on less land in remote, off-grid areas.
The Aurora also uses metallic uranium fuel pellets, which are denser, have higher thermal resistance, and are cheaper to produce than the uranium dioxide fuel pellets that power conventional reactors. By recycling its pellets in a closed loop, the Aurora can last for a decade without refueling. Conventional reactors are still refueled in stages every two years.
#conventional #reactors #signal


6 days ago
Tyrone All-Ireland winner Conor Meyler said his concern over the planned merger of the GAA, Camogie ******* ociation and Ladies Gaelic Football ******* ociation [LGFA] is that the issue "is going to be thrown to the wayside again".
In February 2024, the three bodies announced plans to merge into one organisation by 2027.
However, in recent days, chairperson of the Steering Group Dr Mary McAleese stepped down, while a recent letter sent by the GAA's Integration Committee said it could no longer commit to that timeline.
"I don't doubt her [McAleese's] ability and leadership in any stretch," Meyler told BBC Sport NI's Mark Sidebottom.
"I just don't think she surrounded herself with the right board composition to actually get it done or she didn't have the power in the position to actually get things done within the three ******* ociations that she wanted and that's probably really disappointing because I know she was wholeheartedly going into this trying to make it happen.
#actually #tyrone
In February 2024, the three bodies announced plans to merge into one organisation by 2027.
However, in recent days, chairperson of the Steering Group Dr Mary McAleese stepped down, while a recent letter sent by the GAA's Integration Committee said it could no longer commit to that timeline.
"I don't doubt her [McAleese's] ability and leadership in any stretch," Meyler told BBC Sport NI's Mark Sidebottom.
"I just don't think she surrounded herself with the right board composition to actually get it done or she didn't have the power in the position to actually get things done within the three ******* ociations that she wanted and that's probably really disappointing because I know she was wholeheartedly going into this trying to make it happen.
#actually #tyrone

0.00$ raised of 0.00$ goal
0 donations
0.00$
to go

6 days ago
Arcosa, Inc. (NYSE:ACA) shareholders approved the proposed acquisition by CRH plc (NYSE:CRH) on September 4. The merger agreement received 39,595,867 votes in favor, compared with 66,113 against and 16,786 abstentions. Approximately 39.7 million shares, representing 80.8% of shares outstanding as of the record date, were present or represented by proxy.
The vote satisfies a major condition for the all-cash transaction. CRH plc (NYSE:CRH) agreed to pay $150 per share, valuing Arcosa, Inc. (NYSE:ACA) at an enterprise value of approximately $8.5 billion. The companies continue to expect a first-quarter 2027 closing, subject to required regulatory approvals and other customary conditions.
CRH plc (NYSE:CRH) described the valuation as 11.5 times estimated 2026 adjusted EBITDA, a company-defined non-GAAP measure, including $175 million of targeted annual run-rate cost synergies expected by year three. CRH plc (NYSE:CRH) defines adjusted EBITDA as earnings from continuing operations before interest, taxes, depreciation, depletion and amortization, with exclusions for impairments, divestitures and investments, equity-method results, substantial acquisition costs and specified pension items.
The result removes the principal seller-side approval risk. The merger no longer depends on another shareholder meeting, and support was decisive among the shares represented. Financing appears less exposed than regulatory clearance: CRH plc (NYSE:CRH) plans to use available cash and committed debt financing, while completion is not subject to a financing condition.
The strategic rationale is tangible. Arcosa, Inc. (NYSE:ACA) would add 109 quarries and yards, nine asphalt plants, 19 terminals and approximately 35 million tons of 2025 aggregates shipments. CRH plc (NYSE:CRH) expects more than 265 million tons of combined annualized aggregates production. Arcosa, Inc. (NYSE:ACA) also brings engineered structures serving grid modernization, electrification and data-center construction.
#NYSE #represented
The vote satisfies a major condition for the all-cash transaction. CRH plc (NYSE:CRH) agreed to pay $150 per share, valuing Arcosa, Inc. (NYSE:ACA) at an enterprise value of approximately $8.5 billion. The companies continue to expect a first-quarter 2027 closing, subject to required regulatory approvals and other customary conditions.
CRH plc (NYSE:CRH) described the valuation as 11.5 times estimated 2026 adjusted EBITDA, a company-defined non-GAAP measure, including $175 million of targeted annual run-rate cost synergies expected by year three. CRH plc (NYSE:CRH) defines adjusted EBITDA as earnings from continuing operations before interest, taxes, depreciation, depletion and amortization, with exclusions for impairments, divestitures and investments, equity-method results, substantial acquisition costs and specified pension items.
The result removes the principal seller-side approval risk. The merger no longer depends on another shareholder meeting, and support was decisive among the shares represented. Financing appears less exposed than regulatory clearance: CRH plc (NYSE:CRH) plans to use available cash and committed debt financing, while completion is not subject to a financing condition.
The strategic rationale is tangible. Arcosa, Inc. (NYSE:ACA) would add 109 quarries and yards, nine asphalt plants, 19 terminals and approximately 35 million tons of 2025 aggregates shipments. CRH plc (NYSE:CRH) expects more than 265 million tons of combined annualized aggregates production. Arcosa, Inc. (NYSE:ACA) also brings engineered structures serving grid modernization, electrification and data-center construction.
#NYSE #represented

0.00$ raised of 0.00$ goal
0 donations
0.00$
to go
6 days ago
SWKS surged 9% and QRVO gained 6% as CEO Phil Brace confirmed China's SAMR review hit its final phase, targeting a year-end close.
SOXX dropped 2% on the same session, isolating the rally as merger-arb repricing, with AAPL the largest customer for both companies post-merger.
Just released. Our ***** ysts combed the entire stock market and named the ten best stocks to buy right now, and Skyworks Solutions didn't make the cut. Enter your email to see the names that beat SWKS. The report is free. Enter your email and see if any of your stocks made the cut.
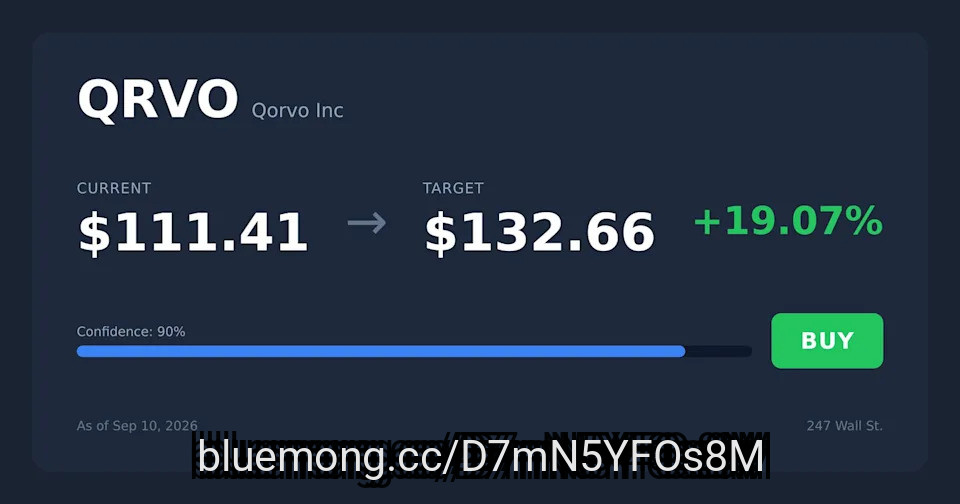
Shares of Skyworks Solutions (NASDAQ:SWKS) are up 10% to $84.24 in Thursday midday trade, while Qorvo (NASDAQ:QRVO) stock is climbing 6% to $111.49. The paired rally arrives on a session when the broader chip complex is red, which frames the move as merger-arb repricing driven by transaction odds.
The iShares Semiconductor ETF (NASDAQ:SOXX) is down 2%. Meanwhile, the Invesco QQQ Trust (NASDAQ:QQQ) is off 0.9%, so the divergence between the two RF names and the wider market isn't subtle.
#soxx #enter
SOXX dropped 2% on the same session, isolating the rally as merger-arb repricing, with AAPL the largest customer for both companies post-merger.
Just released. Our ***** ysts combed the entire stock market and named the ten best stocks to buy right now, and Skyworks Solutions didn't make the cut. Enter your email to see the names that beat SWKS. The report is free. Enter your email and see if any of your stocks made the cut.
Shares of Skyworks Solutions (NASDAQ:SWKS) are up 10% to $84.24 in Thursday midday trade, while Qorvo (NASDAQ:QRVO) stock is climbing 6% to $111.49. The paired rally arrives on a session when the broader chip complex is red, which frames the move as merger-arb repricing driven by transaction odds.
The iShares Semiconductor ETF (NASDAQ:SOXX) is down 2%. Meanwhile, the Invesco QQQ Trust (NASDAQ:QQQ) is off 0.9%, so the divergence between the two RF names and the wider market isn't subtle.
#soxx #enter


0.00$ raised of 0.00$ goal
0 donations
0.00$
to go

8 days ago
On August 4, Essential Utilities (NYSE:WTRG) reported second-quarter results that read like two different stories stapled together. Revenue climbed, the dividend grew for the 36th time in 35 years, and the merger with American Water inched closer to the finish line. But earnings per share actually dipped from a year earlier, and the company had to strip out merger costs just to show flat profitability. For a utility this steady, that split is worth a closer look.
Essential's regulated water segment posted revenue of $357.5 million in the quarter, up 7.6% from $332.3 million a year earlier, and the whole company's first-half revenue climbed 7.2% to nearly $1.4 billion. Much of that growth came from rate cases: state regulators approved $43.9 million in new annual water revenue across Pennsylvania, Illinois, Ohio, North Carolina and Indiana, plus $12.7 million more for the gas business in Kentucky and Pennsylvania. Another $79.7 million in water rate requests and a $163.2 million gas case in Pennsylvania, tied to replacing aging pipelines, are still working through the process.
The company keeps buying its way into new customers, too. In May, it closed a $4.9 million wastewater deal in Bastrop County, Texas, and it has signed agreements worth roughly $282 million to add over 200,000 more customers in Pennsylvania, Texas, North Carolina and New Jersey, including the $276.5 million purchase of Philadelphia-area sewer authority DELCORA. Since 2015, acquisitions have added more than 138,000 customers to Essential's base.
Layer on the pending American Water merger, which cleared Virginia and Ohio regulators this year after nearly unanimous shareholder approval in February, and Essential is positioning itself as a much larger multi-state utility by early 2027. The board's decision to raise the dividend 5.25% to $0.3606 per share, continuing a streak of 36 increases over 35 years, signals confidence that this growth is durable.
Look past the top line and the picture gets less flattering. Second quarter net income actually fell to $105.7 million from $107.8 million a year ago, pulling GAAP earnings per share down to $0.37 from $0.38. Essential had to report an adjusted $0.38 figure just to exclude merger-related costs and show earnings roughly matching last year's. The slide is sharper over six months: net income dropped to $330.1 million, or $1.16 per share, from $391.6 million, or $1.41 per share, in the first half of 2025.
#water #pennsylvania
Essential's regulated water segment posted revenue of $357.5 million in the quarter, up 7.6% from $332.3 million a year earlier, and the whole company's first-half revenue climbed 7.2% to nearly $1.4 billion. Much of that growth came from rate cases: state regulators approved $43.9 million in new annual water revenue across Pennsylvania, Illinois, Ohio, North Carolina and Indiana, plus $12.7 million more for the gas business in Kentucky and Pennsylvania. Another $79.7 million in water rate requests and a $163.2 million gas case in Pennsylvania, tied to replacing aging pipelines, are still working through the process.
The company keeps buying its way into new customers, too. In May, it closed a $4.9 million wastewater deal in Bastrop County, Texas, and it has signed agreements worth roughly $282 million to add over 200,000 more customers in Pennsylvania, Texas, North Carolina and New Jersey, including the $276.5 million purchase of Philadelphia-area sewer authority DELCORA. Since 2015, acquisitions have added more than 138,000 customers to Essential's base.
Layer on the pending American Water merger, which cleared Virginia and Ohio regulators this year after nearly unanimous shareholder approval in February, and Essential is positioning itself as a much larger multi-state utility by early 2027. The board's decision to raise the dividend 5.25% to $0.3606 per share, continuing a streak of 36 increases over 35 years, signals confidence that this growth is durable.
Look past the top line and the picture gets less flattering. Second quarter net income actually fell to $105.7 million from $107.8 million a year ago, pulling GAAP earnings per share down to $0.37 from $0.38. Essential had to report an adjusted $0.38 figure just to exclude merger-related costs and show earnings roughly matching last year's. The slide is sharper over six months: net income dropped to $330.1 million, or $1.16 per share, from $391.6 million, or $1.41 per share, in the first half of 2025.
#water #pennsylvania

8 days ago
United Airlines Holdings, Inc. (NASDAQ:UAL) CEO Scott Kirby told CNBC he wants to expand United's presence at New York's John F. Kennedy International Airport, returning to the congested airport through a new partnership with JetBlue Airways, American's former partner, as early as next year.
Kirby said he is also preparing for how artificial intelligence will change the airline industry. CNBC reported that Kirby, who was fired by American Airlines a decade ago when he served as its president, has floated megamerger ideas with both Delta and American over the past year but has so far been rebuffed, with antitrust experts skeptical the combinations could happen. He said he remains uninterested in acquiring a smaller carrier. United currently ranks as the second most profitable U.S. airline behind Delta, with American a "distant third."
United Airlines Holdings, Inc. (NASDAQ:UAL) has a concrete opportunity to strengthen its position at JFK through its partnership with JetBlue. Re-entering one of the country's most valuable and slot-constrained airports would give United incremental access to a market where it has struggled to compete. The partnership could also weaken American's competitive position by pulling JetBlue away from its previous relationship with American.
United also has the financial strength to pursue an ambitious growth strategy. The airline ranks as the second-most profitable U.S. carrier behind Delta, giving CEO Scott Kirby greater flexibility to invest in network expansion, technology, and other long-term opportunities. That financial position gives United more room to pursue transformative moves without relying solely on defensive strategies.
Kirby's comments on M&A also suggest that United wants to pursue scale selectively rather than chase every available acquisition. He has expressed little interest in buying a smaller carrier while discussing the possibility of much larger combinations with Delta or American. That approach could help United focus its capital and management resources on deals that could materially strengthen its competitive position.
#kirby
Kirby said he is also preparing for how artificial intelligence will change the airline industry. CNBC reported that Kirby, who was fired by American Airlines a decade ago when he served as its president, has floated megamerger ideas with both Delta and American over the past year but has so far been rebuffed, with antitrust experts skeptical the combinations could happen. He said he remains uninterested in acquiring a smaller carrier. United currently ranks as the second most profitable U.S. airline behind Delta, with American a "distant third."
United Airlines Holdings, Inc. (NASDAQ:UAL) has a concrete opportunity to strengthen its position at JFK through its partnership with JetBlue. Re-entering one of the country's most valuable and slot-constrained airports would give United incremental access to a market where it has struggled to compete. The partnership could also weaken American's competitive position by pulling JetBlue away from its previous relationship with American.
United also has the financial strength to pursue an ambitious growth strategy. The airline ranks as the second-most profitable U.S. carrier behind Delta, giving CEO Scott Kirby greater flexibility to invest in network expansion, technology, and other long-term opportunities. That financial position gives United more room to pursue transformative moves without relying solely on defensive strategies.
Kirby's comments on M&A also suggest that United wants to pursue scale selectively rather than chase every available acquisition. He has expressed little interest in buying a smaller carrier while discussing the possibility of much larger combinations with Delta or American. That approach could help United focus its capital and management resources on deals that could materially strengthen its competitive position.
#kirby
8 days ago
Reuters reported that Solstice Advanced Materials, Inc. (NASDAQ:SOLS) and Element Solutions Inc (NYSE:ESI) mutually agreed to terminate their $14.5 billion merger agreement, the companies said on August 27, citing feedback from shareholders on both sides who preferred each to stay independent. Neither side will pay a termination fee.
Solstice Chairman Rajeev Gautam said the company valued that feedback, including shareholders' "excitement about Solstice's strategy and growth trajectory as an independent company." Solstice's board also authorized its first-ever buyback, up to $500 million, and reaffirmed its recently raised guidance. Solstice shares jumped 15% in after-hours trading, while Element gained 4%. The deal, announced July 6 just 10 months after Solstice's Honeywell spin-off, would have combined Solstice's refrigerants and specialty materials businesses with Element's electronics chemicals operations, paying Element holders $10 cash plus 0.5 Solstice shares per share. The original announcement got a rough welcome: Solstice fell nearly 15% that day, which CEO David Sewell blamed on arbitrage trading, not doubts about the deal.
Both companies continue to perform strongly on their own. Solstice's second-quarter net sales rose 11% to $1.148 billion, and the company raised its full-year sales guidance to $4.125 billion-$4.185 billion. Element delivered an even stronger quarter, with record net sales up 56% to $978 million and full-year adjusted EBITDA guidance raised to $690 million-$710 million.
Solstice Advanced Materials, Inc. (NASDAQ:SOLS) sheds significant deal risk by walking away. The termination removes the financing and merger risks linked to the acquisition and eliminates the need to use the $4.685 billion bridge facility. It also lets Solstice maintain its 1.3x net leverage. Its new $500 million buyback, the company's first ever, also gives Solstice a direct way to return capital to shareholders while it focuses on organic growth.
Element Solutions Inc (NYSE:ESI) also maintains the strengths that its shareholders wanted to preserve. Chairman Ian Ashken said investors valued Element's management team, culture, and existing business portfolio. CEO Benjamin Gliklich said the company's growth remains compelling. Remaining independent allows Element to continue investing in its existing businesses and pursuing its own growth strategy without taking on the risks of a larger combination.
#billion #million #Growth
Solstice Chairman Rajeev Gautam said the company valued that feedback, including shareholders' "excitement about Solstice's strategy and growth trajectory as an independent company." Solstice's board also authorized its first-ever buyback, up to $500 million, and reaffirmed its recently raised guidance. Solstice shares jumped 15% in after-hours trading, while Element gained 4%. The deal, announced July 6 just 10 months after Solstice's Honeywell spin-off, would have combined Solstice's refrigerants and specialty materials businesses with Element's electronics chemicals operations, paying Element holders $10 cash plus 0.5 Solstice shares per share. The original announcement got a rough welcome: Solstice fell nearly 15% that day, which CEO David Sewell blamed on arbitrage trading, not doubts about the deal.
Both companies continue to perform strongly on their own. Solstice's second-quarter net sales rose 11% to $1.148 billion, and the company raised its full-year sales guidance to $4.125 billion-$4.185 billion. Element delivered an even stronger quarter, with record net sales up 56% to $978 million and full-year adjusted EBITDA guidance raised to $690 million-$710 million.
Solstice Advanced Materials, Inc. (NASDAQ:SOLS) sheds significant deal risk by walking away. The termination removes the financing and merger risks linked to the acquisition and eliminates the need to use the $4.685 billion bridge facility. It also lets Solstice maintain its 1.3x net leverage. Its new $500 million buyback, the company's first ever, also gives Solstice a direct way to return capital to shareholders while it focuses on organic growth.
Element Solutions Inc (NYSE:ESI) also maintains the strengths that its shareholders wanted to preserve. Chairman Ian Ashken said investors valued Element's management team, culture, and existing business portfolio. CEO Benjamin Gliklich said the company's growth remains compelling. Remaining independent allows Element to continue investing in its existing businesses and pursuing its own growth strategy without taking on the risks of a larger combination.
#billion #million #Growth

8 days ago
VadimNemkov will defend his Professional Fighters League heavyweight championship againstSergeyBilostenniy in November.
The promotion recently announced that former Bellatorchamp Nemkov (20-2) will meet the No. 3-ranked Bilostenniy (15-4)in the main event of PFL Dubai on Nov. 14 at Coca-Cola Arena.
Nemkov, a protégé of FedorEmelianenko, moved up to heavyweight in 2024 and captured PFLgold last December.
Bilostenniy is 4-1 in the PFL and has earned notable finishes overKarlWilliams, TyrellFortune and former PFL champion RenanFerreira. Like Nemkov, he trains under the Team Fedor bannerand has previously shared training camps with the champion.
This marks the first PFL main event in Dubai since the promotion'smerger with Most Valuable Promotions.
"Dubai has become a special city for PFL and the site of someunforgettable moments in our history," PFL CEO John Martin said ina press release. "Both fighters have roots in Team Fedor andrepresent the next generation of Russia's storied heavyweighttradition and now they'll meet to determine who sits atop one ofthe most prestigious divisions in combat sports."
#nemkov #team #former #main
The promotion recently announced that former Bellatorchamp Nemkov (20-2) will meet the No. 3-ranked Bilostenniy (15-4)in the main event of PFL Dubai on Nov. 14 at Coca-Cola Arena.
Nemkov, a protégé of FedorEmelianenko, moved up to heavyweight in 2024 and captured PFLgold last December.
Bilostenniy is 4-1 in the PFL and has earned notable finishes overKarlWilliams, TyrellFortune and former PFL champion RenanFerreira. Like Nemkov, he trains under the Team Fedor bannerand has previously shared training camps with the champion.
This marks the first PFL main event in Dubai since the promotion'smerger with Most Valuable Promotions.
"Dubai has become a special city for PFL and the site of someunforgettable moments in our history," PFL CEO John Martin said ina press release. "Both fighters have roots in Team Fedor andrepresent the next generation of Russia's storied heavyweighttradition and now they'll meet to determine who sits atop one ofthe most prestigious divisions in combat sports."
#nemkov #team #former #main

9 days ago
On August 4, Essential Utilities (NYSE:WTRG) reported second-quarter results that read like two different stories stapled together. Revenue climbed, the dividend grew for the 36th time in 35 years, and the merger with American Water inched closer to the finish line. But earnings per share actually dipped from a year earlier, and the company had to strip out merger costs just to show flat profitability. For a utility this steady, that split is worth a closer look.
Essential's regulated water segment posted revenue of $357.5 million in the quarter, up 7.6% from $332.3 million a year earlier, and the whole company's first-half revenue climbed 7.2% to nearly $1.4 billion. Much of that growth came from rate cases: state regulators approved $43.9 million in new annual water revenue across Pennsylvania, Illinois, Ohio, North Carolina and Indiana, plus $12.7 million more for the gas business in Kentucky and Pennsylvania. Another $79.7 million in water rate requests and a $163.2 million gas case in Pennsylvania, tied to replacing aging pipelines, are still working through the process.
The company keeps buying its way into new customers, too. In May, it closed a $4.9 million wastewater deal in Bastrop County, Texas, and it has signed agreements worth roughly $282 million to add over 200,000 more customers in Pennsylvania, Texas, North Carolina and New Jersey, including the $276.5 million purchase of Philadelphia-area sewer authority DELCORA. Since 2015, acquisitions have added more than 138,000 customers to Essential's base.
Layer on the pending American Water merger, which cleared Virginia and Ohio regulators this year after nearly unanimous shareholder approval in February, and Essential is positioning itself as a much larger multi-state utility by early 2027. The board's decision to raise the dividend 5.25% to $0.3606 per share, continuing a streak of 36 increases over 35 years, signals confidence that this growth is durable.
Look past the top line and the picture gets less flattering. Second quarter net income actually fell to $105.7 million from $107.8 million a year ago, pulling GAAP earnings per share down to $0.37 from $0.38. Essential had to report an adjusted $0.38 figure just to exclude merger-related costs and show earnings roughly matching last year's. The slide is sharper over six months: net income dropped to $330.1 million, or $1.16 per share, from $391.6 million, or $1.41 per share, in the first half of 2025.
#million #revenue #merger #year
Essential's regulated water segment posted revenue of $357.5 million in the quarter, up 7.6% from $332.3 million a year earlier, and the whole company's first-half revenue climbed 7.2% to nearly $1.4 billion. Much of that growth came from rate cases: state regulators approved $43.9 million in new annual water revenue across Pennsylvania, Illinois, Ohio, North Carolina and Indiana, plus $12.7 million more for the gas business in Kentucky and Pennsylvania. Another $79.7 million in water rate requests and a $163.2 million gas case in Pennsylvania, tied to replacing aging pipelines, are still working through the process.
The company keeps buying its way into new customers, too. In May, it closed a $4.9 million wastewater deal in Bastrop County, Texas, and it has signed agreements worth roughly $282 million to add over 200,000 more customers in Pennsylvania, Texas, North Carolina and New Jersey, including the $276.5 million purchase of Philadelphia-area sewer authority DELCORA. Since 2015, acquisitions have added more than 138,000 customers to Essential's base.
Layer on the pending American Water merger, which cleared Virginia and Ohio regulators this year after nearly unanimous shareholder approval in February, and Essential is positioning itself as a much larger multi-state utility by early 2027. The board's decision to raise the dividend 5.25% to $0.3606 per share, continuing a streak of 36 increases over 35 years, signals confidence that this growth is durable.
Look past the top line and the picture gets less flattering. Second quarter net income actually fell to $105.7 million from $107.8 million a year ago, pulling GAAP earnings per share down to $0.37 from $0.38. Essential had to report an adjusted $0.38 figure just to exclude merger-related costs and show earnings roughly matching last year's. The slide is sharper over six months: net income dropped to $330.1 million, or $1.16 per share, from $391.6 million, or $1.41 per share, in the first half of 2025.
#million #revenue #merger #year


11 days ago
Actress and liberal activist Jane Fonda had some surprisingly positive things to say about Paramount Skydance CEO David Ellison despite her complete opposition to a merger between Paramount and Warner Bros. Discovery.
Fonda took questions this week at the DVF Awards charity gala held during the Venice Film Festival, and she said she likes Ellison "very much," which makes her vocal opposition to his $111 billion merger a bit awkward.
"It's sad for me because I like David Ellison very much," Fonda said, according to Variety.
The 88-year-old actress noted Ellison's Skydance financed her Netflix series Grace and Frankie which ended in 2022.
"David's Skydance financed Grace and Frankie, my seven-year-long run for Netflix, and I got to know him, and I like him. But that doesn't change things. This is not a personal thing. This is what it will do to the entertainment industry, which is already suffering terribly," Fonda said.
#ellison #netflix
Fonda took questions this week at the DVF Awards charity gala held during the Venice Film Festival, and she said she likes Ellison "very much," which makes her vocal opposition to his $111 billion merger a bit awkward.
"It's sad for me because I like David Ellison very much," Fonda said, according to Variety.
The 88-year-old actress noted Ellison's Skydance financed her Netflix series Grace and Frankie which ended in 2022.
"David's Skydance financed Grace and Frankie, my seven-year-long run for Netflix, and I got to know him, and I like him. But that doesn't change things. This is not a personal thing. This is what it will do to the entertainment industry, which is already suffering terribly," Fonda said.
#ellison #netflix


11 days ago
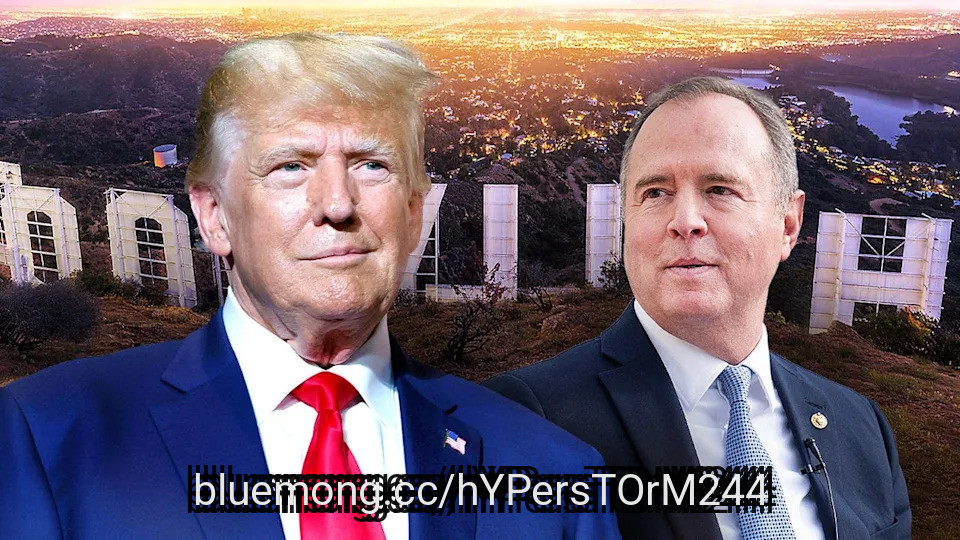
EXCLUSIVE: President Donald Trump has gained several unlikely allies, including the man who led his first impeachment trial, in a major push to bring motion picture production back to California from other countries.
Sen. Adam Schiff, D-Calif., who represented studio-heavy Burbank in Congress, was joined by Reps. Ilhan Omar, D-Minn., and Nancy Pelosi, D-Calif., in echoing support for Trump's federal tax incentive plan to draw major film projects back to where it began.
"We've been promoting that for a long time. I'm glad he finally arrived at it," Pelosi told Fox News Digital when asked about the plan on the Capitol grounds.
Paramount Escalates Threat To Leave California As Dem Ag's Antitrust Lawsuit Stalls Warner Bros Merger
President Donald Trump has found an unlikely ally in his push for incentives to bring back the film industry to Hollywood: Sen. Adam Schiff, D-Calif.
#calif #adam
Sen. Adam Schiff, D-Calif., who represented studio-heavy Burbank in Congress, was joined by Reps. Ilhan Omar, D-Minn., and Nancy Pelosi, D-Calif., in echoing support for Trump's federal tax incentive plan to draw major film projects back to where it began.
"We've been promoting that for a long time. I'm glad he finally arrived at it," Pelosi told Fox News Digital when asked about the plan on the Capitol grounds.
Paramount Escalates Threat To Leave California As Dem Ag's Antitrust Lawsuit Stalls Warner Bros Merger
President Donald Trump has found an unlikely ally in his push for incentives to bring back the film industry to Hollywood: Sen. Adam Schiff, D-Calif.
#calif #adam



11 days ago
Benzinga and Yahoo Finance LLC may earn commission or revenue on some items through the links below.
Yorkville Ives' Partner and Senior Managing Director, Dan Ives, expects Apple Inc.'s new CEO John Ternus to usher in mergers and acquisitions, the crucial "missing piece" for the tech giant to compete in the accelerating artificial intelligence arms race.
While former CEO Tim Cook is widely regarded as a "Mount Rushmore Hall of Fame CEO," Ives argued that Apple's previous strategy may have caused the company to miss out on certain growth opportunities over the last decade. With Ternus at the helm, investors can expect a distinct strategic shift.
Don't Miss:
A single bad hire can set a startup back years. Here are the 5 hires founders most often misjudge — and why
#director
Yorkville Ives' Partner and Senior Managing Director, Dan Ives, expects Apple Inc.'s new CEO John Ternus to usher in mergers and acquisitions, the crucial "missing piece" for the tech giant to compete in the accelerating artificial intelligence arms race.
While former CEO Tim Cook is widely regarded as a "Mount Rushmore Hall of Fame CEO," Ives argued that Apple's previous strategy may have caused the company to miss out on certain growth opportunities over the last decade. With Ternus at the helm, investors can expect a distinct strategic shift.
Don't Miss:
A single bad hire can set a startup back years. Here are the 5 hires founders most often misjudge — and why
#director


11 days ago
With about 40% short interest, SoundHound AI (NASDAQ: SOUN) is one of the most shorted stocks in the market. The company has been growing its revenue quickly, but a pending merger with troubled LivePerson (NASDAQ: LPSN) has investors betting against the stock. However, heavy short interest is a double-edged sword.
If a stock has high short interest, there is usually a bearish case to be made against it. In the case of SoundHound AI, its merger with LivePerson will bring considerable debt and a business currently in decline. There is also a good chance that SoundHound AI will seek a future equity raise to pay off the debt it is taking on as part of the deal, as it has stated it will work to quickly retire the debt through a combination of cash and stock.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
The flip side is that heavily shorted stocks can see huge short squeezes if they can prove the skeptics wrong. With LivePerson, SoundHound AI is gaining access to a large, established, albeit declining, customer base, especially in call centers and the customer service ***** e.
Its goal will be to retain these customers and switch them to its more comprehensive and higher-priced AI voice technology and agentic AI platform. If the company can stabilize churn and upsell customers, this deal could be a huge boon for this growth stock.
#Stock #NVIDIA #interest #NASDAQ
If a stock has high short interest, there is usually a bearish case to be made against it. In the case of SoundHound AI, its merger with LivePerson will bring considerable debt and a business currently in decline. There is also a good chance that SoundHound AI will seek a future equity raise to pay off the debt it is taking on as part of the deal, as it has stated it will work to quickly retire the debt through a combination of cash and stock.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
The flip side is that heavily shorted stocks can see huge short squeezes if they can prove the skeptics wrong. With LivePerson, SoundHound AI is gaining access to a large, established, albeit declining, customer base, especially in call centers and the customer service ***** e.
Its goal will be to retain these customers and switch them to its more comprehensive and higher-priced AI voice technology and agentic AI platform. If the company can stabilize churn and upsell customers, this deal could be a huge boon for this growth stock.
#Stock #NVIDIA #interest #NASDAQ

11 days ago
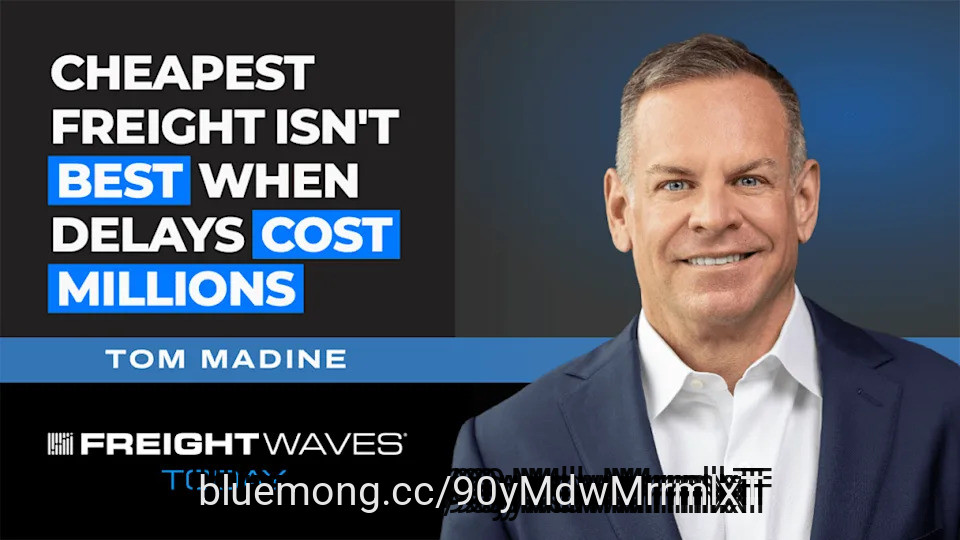
Cheapest freight isn't always best, especially when a late shipment can cost millions. ShipStation Global CEO Tom Madine breaks down why SMB shippers need parcel, LTL and truckload in one workflow, and why better freight decisions now matter more than just lower rates. From the merger that created ShipStation Global to adding more modes into the platform, this conversation gets into where shipping tech is heading, how data shapes carrier selection, and what smaller shippers actually need from logistics partners. #FreightTech #LTL #SupplyChain
ShipStation Global is formally launching its less-than-truckload product, marking the first tangible freight expansion since the merger of software provider Auctane, formerly the parent of the Stamps.com andShipStation,and WWEX Group, which previously housed freight brokerages like Worldwide Express. The company's CEO said the rollout represents the opening move in a broader strategy to let small and midsize shippers purchase and manage all transportation modes through a single platform.
"Today's the first day we've really launched the LTL product," said Tom Madine, CEO of ShipStation Global, noting the company plans to add truckload, final mile, and eventually ocean and forwarding capabilities after establishing its inland position.
The strategic rationale centers on eliminating the workflow gap that forced ShipStation users to leave the platform whenever they needed to move freight beyond parcel. Customer surveys repeatedly flagged the absence of additional modes as the top improvement request, he said. With LTL now integrated, shippers can manage inbound inventory movements alongside outbound parcel without switching systems.
"Cheapest is not always best…But at the same time, you don't want to overpay," Madine said, illustrating the point with a customer whose engine shipments carry multi-million-dollar consequences if delayed.
#madine #shippers #parcel #cheapest
ShipStation Global is formally launching its less-than-truckload product, marking the first tangible freight expansion since the merger of software provider Auctane, formerly the parent of the Stamps.com andShipStation,and WWEX Group, which previously housed freight brokerages like Worldwide Express. The company's CEO said the rollout represents the opening move in a broader strategy to let small and midsize shippers purchase and manage all transportation modes through a single platform.
"Today's the first day we've really launched the LTL product," said Tom Madine, CEO of ShipStation Global, noting the company plans to add truckload, final mile, and eventually ocean and forwarding capabilities after establishing its inland position.
The strategic rationale centers on eliminating the workflow gap that forced ShipStation users to leave the platform whenever they needed to move freight beyond parcel. Customer surveys repeatedly flagged the absence of additional modes as the top improvement request, he said. With LTL now integrated, shippers can manage inbound inventory movements alongside outbound parcel without switching systems.
"Cheapest is not always best…But at the same time, you don't want to overpay," Madine said, illustrating the point with a customer whose engine shipments carry multi-million-dollar consequences if delayed.
#madine #shippers #parcel #cheapest
11 days ago
Small and midsize shippers are often forced to stitch together various tools for parcel labels, freight quotes, tracking, and much more. The fragmentation gets more expensive as a business grows past pure e-commerce, since the moment a merchant needs to move inventory between warehouses or ship a pallet instead of a box, they're forced out of whatever platform runs their day-to-day shipping and into unfamiliar territory.
ShipStation Global CEO Tom Madine has built the company's post-merger strategy around closing that gap, knowing that the same merchants who came to the platform for parcel labels are increasingly buying freight, too, and would rather not leave the software to do it.
The LTL rollout is the first major product integration since Thoma Bravo acquired WWEX Group (parent of Worldwide Express, GlobalTranz, Unishippers, JEAR Logistics and BLX Logistics) and merged it with Auctane, the parent company of ShipStation, this past June. The combination created ShipStation Global, a company now valued at roughly $12 billion. CEO Tom Madine described the logic of putting the two businesses together as less about scale for its own sake and more about closing a gap both companies kept running into with customers.
"If you think about an e-commerce merchant that's selling through multiple channels, using multiple carriers with inventory in multiple places, it makes that a much more seamless and stress-free process for them, and allows them to manage everything through a single pane of glass," Madine said of the legacy ShipStation product, before pointing to what it had been missing. "There's nothing else like it on the market."
According to Madine, that gap had shown up repeatedly in customer surveys. "One of the most common requests that ShipStation would get in the legacy Auctane world was, 'When are you going to add other modes to the platform?'" he said. "Prior to today, if you were a ShipStation user, you were managing your entire workflow in ShipStation, except when you needed to move freight." Merchants who needed to move inventory between warehouses had to leave the platform entirely, log into a separate freight system, and reconcile the two.
#freight #inventory #multiple #auctane
ShipStation Global CEO Tom Madine has built the company's post-merger strategy around closing that gap, knowing that the same merchants who came to the platform for parcel labels are increasingly buying freight, too, and would rather not leave the software to do it.
The LTL rollout is the first major product integration since Thoma Bravo acquired WWEX Group (parent of Worldwide Express, GlobalTranz, Unishippers, JEAR Logistics and BLX Logistics) and merged it with Auctane, the parent company of ShipStation, this past June. The combination created ShipStation Global, a company now valued at roughly $12 billion. CEO Tom Madine described the logic of putting the two businesses together as less about scale for its own sake and more about closing a gap both companies kept running into with customers.
"If you think about an e-commerce merchant that's selling through multiple channels, using multiple carriers with inventory in multiple places, it makes that a much more seamless and stress-free process for them, and allows them to manage everything through a single pane of glass," Madine said of the legacy ShipStation product, before pointing to what it had been missing. "There's nothing else like it on the market."
According to Madine, that gap had shown up repeatedly in customer surveys. "One of the most common requests that ShipStation would get in the legacy Auctane world was, 'When are you going to add other modes to the platform?'" he said. "Prior to today, if you were a ShipStation user, you were managing your entire workflow in ShipStation, except when you needed to move freight." Merchants who needed to move inventory between warehouses had to leave the platform entirely, log into a separate freight system, and reconcile the two.
#freight #inventory #multiple #auctane

11 days ago
As electricity demand surges amid AI data center growth, two utility companies stand out. NextEra Energy (NYSE: NEE) and Constellation Energy (NASDAQ: CEG) are both incredibly strong businesses, but are taking different approaches to this new chapter in North American power.
NextEra is both a traditional utility provider and a powerhouse in renewable energy. It is planning to spend $94 billion through 2030 in an aggressive push to build out its footprint. In May, the energy giant announced an all-stock agreement to acquire Dominion Energy. This deal will make NextEra the world's largest utility business, but the megamerger is facing intense regulatory scrutiny.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
The company's dividend yield is holding strong at over 3%. The stock has risen just 2% this year. NextEra is a reliable income producer, but could see substantial growth through the early 2030s.
Constellation's approach is completely different from NextEra's. Constellation is the largest nuclear power operator in the U.S. It's also an independent power producer, meaning it sells electricity on the open market and not through a regulated utility model. This gives it greater pricing volatility, but potentially more upside.
#energy #flashing
NextEra is both a traditional utility provider and a powerhouse in renewable energy. It is planning to spend $94 billion through 2030 in an aggressive push to build out its footprint. In May, the energy giant announced an all-stock agreement to acquire Dominion Energy. This deal will make NextEra the world's largest utility business, but the megamerger is facing intense regulatory scrutiny.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
The company's dividend yield is holding strong at over 3%. The stock has risen just 2% this year. NextEra is a reliable income producer, but could see substantial growth through the early 2030s.
Constellation's approach is completely different from NextEra's. Constellation is the largest nuclear power operator in the U.S. It's also an independent power producer, meaning it sells electricity on the open market and not through a regulated utility model. This gives it greater pricing volatility, but potentially more upside.
#energy #flashing

12 days ago
On August 5, LiveRamp (NYSE:RAMP) reported first-quarter fiscal 2027 results for the period ended June 30, and the numbers looked less like a company coasting toward a sale than one hitting its stride. Revenue rose 10% to $214 million, but the more striking move was further down the income statement, where operating income more than doubled. LiveRamp skipped its usual earnings call this quarter, a direct result of its pending acquisition by Publicis Groupe, but that silence has not slowed the underlying business.
GAAP operating income jumped to $20 million from $7 million a year earlier, pushing operating margin up six points to 9%. Non-GAAP operating income rose 41% to $50 million, with margin expanding five points to 24%, meaning more of every new revenue dollar is dropping to profit rather than being spent to chase it. Diluted earnings per share more than doubled on a GAAP basis to $0.28 from $0.12, while operating cash flow flipped from a $16 million outflow a year ago to $17 million generated this quarter.
LiveRamp is also positioning itself inside the AI advertising buildout rather than at its edges. The company launched LiveRamp Agent Builders, a program pulling outside AI agents into its network for planning and measurement work, and added integrations tied to OpenAI's advertising tools, Databricks' new Agentic Customer Data Platform, and Adobe's commerce content pipeline, alongside a measurement partnership with DoorDash. None of that shows up in a revenue line yet, but customer behavior already reflects some payoff. LiveRamp ended the quarter with 132 customers paying more than $1 million a year, up from 127, and subscription net retention held at 103%. Annualized recurring revenue grew 7% to $539 million, and Data Marketplace revenue climbed 13% to $40 million.
None of that operational improvement changes the number shareholders actually care about: $38.50 a share, the all-cash price Publicis Groupe agreed to pay when the deal was announced on May 17, 2026. However much operating income grows from here, the merger agreement fixes what LiveRamp holders collect if the transaction closes, so this quarter's beat does not translate into upside for anyone holding the stock for the buyout. LiveRamp also confirmed it will not hold a conference call or issue guidance while the deal is pending, which limits how much investors can independently verify beyond what is in this release.
The transaction still has to clear a shareholder vote scheduled for August 17, and closing remains subject to customary conditions even though management called it on track for before the end of calendar 2026. That leaves a few weeks of real, if narrow, uncertainty. The growth numbers are also decelerating slightly at the edges: total revenue grew 10% this quarter versus 11% in the prior year period, and subscription revenue growth slowed to 8% from 10%. Marketplace and Other revenue, the more variable, usage-driven part of the business, is doing more of the work
GAAP operating income jumped to $20 million from $7 million a year earlier, pushing operating margin up six points to 9%. Non-GAAP operating income rose 41% to $50 million, with margin expanding five points to 24%, meaning more of every new revenue dollar is dropping to profit rather than being spent to chase it. Diluted earnings per share more than doubled on a GAAP basis to $0.28 from $0.12, while operating cash flow flipped from a $16 million outflow a year ago to $17 million generated this quarter.
LiveRamp is also positioning itself inside the AI advertising buildout rather than at its edges. The company launched LiveRamp Agent Builders, a program pulling outside AI agents into its network for planning and measurement work, and added integrations tied to OpenAI's advertising tools, Databricks' new Agentic Customer Data Platform, and Adobe's commerce content pipeline, alongside a measurement partnership with DoorDash. None of that shows up in a revenue line yet, but customer behavior already reflects some payoff. LiveRamp ended the quarter with 132 customers paying more than $1 million a year, up from 127, and subscription net retention held at 103%. Annualized recurring revenue grew 7% to $539 million, and Data Marketplace revenue climbed 13% to $40 million.
None of that operational improvement changes the number shareholders actually care about: $38.50 a share, the all-cash price Publicis Groupe agreed to pay when the deal was announced on May 17, 2026. However much operating income grows from here, the merger agreement fixes what LiveRamp holders collect if the transaction closes, so this quarter's beat does not translate into upside for anyone holding the stock for the buyout. LiveRamp also confirmed it will not hold a conference call or issue guidance while the deal is pending, which limits how much investors can independently verify beyond what is in this release.
The transaction still has to clear a shareholder vote scheduled for August 17, and closing remains subject to customary conditions even though management called it on track for before the end of calendar 2026. That leaves a few weeks of real, if narrow, uncertainty. The growth numbers are also decelerating slightly at the edges: total revenue grew 10% this quarter versus 11% in the prior year period, and subscription revenue growth slowed to 8% from 10%. Marketplace and Other revenue, the more variable, usage-driven part of the business, is doing more of the work

12 days ago
Chances are, if you have watched a YouTube video, you have come across one where the creator is recording their experiences through a small, handheld camera. Usually, it is a GoPro (GPRO). And it is in the news now because prominent YouTuber and filmmaker Markiplier (also known as Mark Fischbach) has become the single largest shareholder of the company. Additionally, the company has now entered into a $285 million merger agreement with photonics company Starman Optical.
Aimed at expanding GoPro's reach in the AI and defense market, Starman CEO Charles Tebele said, "Advanced optics and imaging are essential to AI, national security, and the broader economy, yet much of the critical hardware supporting these technologies continues to be manufactured overseas. The combination of GoPro's world-class optical expertise and intellectual property with Starman's advanced transceiver capabilities and U.S. manufacturing platform creates a unique opportunity. Together, we intend to bring production of these critical components back to the United States."
Dear GameStop Stock Fans, Mark Your Calendars for September 8
Why **** ysts Think Sellas Life Sciences Stock Can Gain 150% From Here
Jensen Huang: Nvidia's Vera Rubin Platform Turns Electricity Into a $40 Billion Cash Machine
#advanced #platform #critical
Aimed at expanding GoPro's reach in the AI and defense market, Starman CEO Charles Tebele said, "Advanced optics and imaging are essential to AI, national security, and the broader economy, yet much of the critical hardware supporting these technologies continues to be manufactured overseas. The combination of GoPro's world-class optical expertise and intellectual property with Starman's advanced transceiver capabilities and U.S. manufacturing platform creates a unique opportunity. Together, we intend to bring production of these critical components back to the United States."
Dear GameStop Stock Fans, Mark Your Calendars for September 8
Why **** ysts Think Sellas Life Sciences Stock Can Gain 150% From Here
Jensen Huang: Nvidia's Vera Rubin Platform Turns Electricity Into a $40 Billion Cash Machine
#advanced #platform #critical


12 days ago
A banner flew over Paramount Studios that read, "Ellison is Trump's b----."
David Ellison, the CEO of Paramount Skydance, has courted controversy for leading the attempted takeover of Warner Bros. Discovery.
Ellison has denied reports that he **** ured Donald Trump he would tweak CNN to the president's liking should he gain control over the news network via the merger.
Paramount Skydance CEO David Ellison can't even look up to the heavens to escape criticism.
The embattled head of the media conglomerate was the subject of a vulgar message that was printed in capital letters and flown over Paramount Studios in Los Angeles on Thursday. "Ellison is Trump's b----!" read the message on a banner that a plane dragged back and forth across the airspace over the movie studio.
#message
David Ellison, the CEO of Paramount Skydance, has courted controversy for leading the attempted takeover of Warner Bros. Discovery.
Ellison has denied reports that he **** ured Donald Trump he would tweak CNN to the president's liking should he gain control over the news network via the merger.
Paramount Skydance CEO David Ellison can't even look up to the heavens to escape criticism.
The embattled head of the media conglomerate was the subject of a vulgar message that was printed in capital letters and flown over Paramount Studios in Los Angeles on Thursday. "Ellison is Trump's b----!" read the message on a banner that a plane dragged back and forth across the airspace over the movie studio.
#message



12 days ago
QuantumScape (NASDAQ: QS), a developer of solid-state batteries, went public through a merger with a special purpose acquisition company (SPAC) on Nov. 27, 2020. Its stock opened at $24.80 on its first day and closed at an all-time high of $131.67 on Dec. 22, 2020.
Before going public, QuantumScape claimed it could commercialize its first batteries by 2024, and that its revenue would soar from $14 million in 2024 to $275 million in 2026. But as of this writing, it hasn't commercialized any batteries nor generated any meaningful revenue yet.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
That's why QuantumScape's stock plummeted 96% to its current price of about $5. Will it bounce back next year as it makes more progress toward launching its first batteries?
QuantumScape's solid-state batteries have higher charging capacities, shorter charging times, and better thermal resistance than liquid-based lithium-ion batteries. But they're also more expensive and challenging to manufacture than their lithium-ion counterparts.
#batteries
Before going public, QuantumScape claimed it could commercialize its first batteries by 2024, and that its revenue would soar from $14 million in 2024 to $275 million in 2026. But as of this writing, it hasn't commercialized any batteries nor generated any meaningful revenue yet.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
That's why QuantumScape's stock plummeted 96% to its current price of about $5. Will it bounce back next year as it makes more progress toward launching its first batteries?
QuantumScape's solid-state batteries have higher charging capacities, shorter charging times, and better thermal resistance than liquid-based lithium-ion batteries. But they're also more expensive and challenging to manufacture than their lithium-ion counterparts.
#batteries

12 days ago
USA Rare Earth (NASDAQ: USAR) is a critical minerals specialist that went public through a merger with special purpose acquisition company (SPAC) Inflection Point Acquisition Corp. II in March 2025. The company saw some volatile trading in the months immediately following its debut, but it went on to hit a lifetime high in October of that year following reports that the company was discussing a potential partnership with the White House and rumors that the U.S. government could take a stake in the business.
In January 2026, USA Rare Earth actually did announce that the U.S. government was establishing a roughly 10% ownership stake in the company that could expand to 16% with the exercise of warrants -- but its share price has still fallen far below the high it hit last year. As of this writing, the stock is down roughly 53.5% from that valuation peak. In other words, a $10,000 investment made in the stock at that point would now be worth roughly $4,650.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
While the U.S. government's desire to increase its ability to source critical minerals domestically and reduce its dependence on minerals from China presents a potentially powerful catalyst for USA Rare Earth's business, the company is still in a relatively early stage of expanding its operations. Along those lines, the company generated just $11.5 million in revenue across the first half of this year. Meanwhile, the mining and processing player has a market capitalization of roughly $4.4 billion.
The company's move to acquire Brazilian rare-earth specialist Serra Verde in a roughly $2.8 billion deal should dramatically expand USA Rare Earth's sales footprint and earnings potential, but the deal being primarily funded with stock also means that shareholders will see significant dilution. USA Rare Earth has growth opportunities on the horizon that could help it bounce back and climb well above its past valuation peak, but investors should approach the stock with the understanding that it's a speculative bet.
#rare #roughly #NVIDIA #year
In January 2026, USA Rare Earth actually did announce that the U.S. government was establishing a roughly 10% ownership stake in the company that could expand to 16% with the exercise of warrants -- but its share price has still fallen far below the high it hit last year. As of this writing, the stock is down roughly 53.5% from that valuation peak. In other words, a $10,000 investment made in the stock at that point would now be worth roughly $4,650.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
While the U.S. government's desire to increase its ability to source critical minerals domestically and reduce its dependence on minerals from China presents a potentially powerful catalyst for USA Rare Earth's business, the company is still in a relatively early stage of expanding its operations. Along those lines, the company generated just $11.5 million in revenue across the first half of this year. Meanwhile, the mining and processing player has a market capitalization of roughly $4.4 billion.
The company's move to acquire Brazilian rare-earth specialist Serra Verde in a roughly $2.8 billion deal should dramatically expand USA Rare Earth's sales footprint and earnings potential, but the deal being primarily funded with stock also means that shareholders will see significant dilution. USA Rare Earth has growth opportunities on the horizon that could help it bounce back and climb well above its past valuation peak, but investors should approach the stock with the understanding that it's a speculative bet.
#rare #roughly #NVIDIA #year

13 days ago
Interested in Union Pacific Corporation? Here are five stocks we like better.
STB review is advancing: Union Pacific said the Surface Transportation Board's 12-month review of its proposed Norfolk Southern merger began after the application was accepted on May 28, 2026. The company expects the deal could close in the third or fourth quarter of 2027.
Projected merger benefits remain substantial: Union Pacific estimates the combination could remove 2.1 million truckloads from highways annually, generate $3.5 billion in shipper savings, and deliver approximately $1.8 billion in annual revenue synergies plus $1 billion in cost synergies.
Competitive concerns are being addressed: The company has proposed pricing and service protections for shippers and reached agreements with Canadian National intended to ease concentration concerns and expand routing options. Executives said they remain confident the merger will meet the STB's public-interest requirements.
Buffett Spent 60 Years Ignoring Tech and the Bill Is Coming Due
#pacific #billion #remain #concerns
STB review is advancing: Union Pacific said the Surface Transportation Board's 12-month review of its proposed Norfolk Southern merger began after the application was accepted on May 28, 2026. The company expects the deal could close in the third or fourth quarter of 2027.
Projected merger benefits remain substantial: Union Pacific estimates the combination could remove 2.1 million truckloads from highways annually, generate $3.5 billion in shipper savings, and deliver approximately $1.8 billion in annual revenue synergies plus $1 billion in cost synergies.
Competitive concerns are being addressed: The company has proposed pricing and service protections for shippers and reached agreements with Canadian National intended to ease concentration concerns and expand routing options. Executives said they remain confident the merger will meet the STB's public-interest requirements.
Buffett Spent 60 Years Ignoring Tech and the Bill Is Coming Due
#pacific #billion #remain #concerns


13 days ago
Symbotic (NASDAQ: SYM), a developer of autonomous warehouse robots, went public through a merger with a special purpose acquisition company (SPAC) on June 8, 2022. It started trading at $10.51 per share, closed at a record high of $87.30 on Nov. 26, 2025, but now trades at $38.
Symbotic is still a divisive stock. The bulls are impressed by its robust revenue growth, its expanding margins, and its growing backlog -- which reached $22.5 billion in its latest quarter. But the bears will warn you that it's overly dependent on Walmart (NASDAQ: WMT) and that many investors overlook that customer concentration risk.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Walmart is Symbotic's largest customer and one of its top investors. The world's largest retailer accounted for 85% of its revenue in fiscal 2025 (which ended last September), driven by a long-term contract to automate all of its U.S. regional distribution centers through 2037.
Symbotic also acquired Walmart's own robotics division in early 2025, and the two companies have been co-developing automated micro-fulfillment systems for its brick-and-mortar stores. In other words, Symbotic wouldn't exist in its current form without Walmart's support.
#NVIDIA #walmart #flashing #revenue
Symbotic is still a divisive stock. The bulls are impressed by its robust revenue growth, its expanding margins, and its growing backlog -- which reached $22.5 billion in its latest quarter. But the bears will warn you that it's overly dependent on Walmart (NASDAQ: WMT) and that many investors overlook that customer concentration risk.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Walmart is Symbotic's largest customer and one of its top investors. The world's largest retailer accounted for 85% of its revenue in fiscal 2025 (which ended last September), driven by a long-term contract to automate all of its U.S. regional distribution centers through 2037.
Symbotic also acquired Walmart's own robotics division in early 2025, and the two companies have been co-developing automated micro-fulfillment systems for its brick-and-mortar stores. In other words, Symbotic wouldn't exist in its current form without Walmart's support.
#NVIDIA #walmart #flashing #revenue

13 days ago
There's a list of celebrities supporting Mark Ruffalo after the "Avengers" star's latest anti-Israel bombast.
Gina Carano might have settled for just one A-list defender. Or even a D-list dweller.
Ruffalo's chronic anti-Israel rhetoric finally caught up with the 58-year-old actor. Several Jewish groups chastised his recent anti-Paramount merger rhetoric wrapped in what some called antisemitic tropes.
"Larry Ellison will own most of 'Para Bros.' Larry is a classic Oligarch. They are crushing workers and consolidating the wealth of the world for their own power and concentrated dominance."
There's a list of celebrities supporting Mark Ruffalo after the "Avengers" star's latest anti-Israel bombast. WireImage
#Israel #ruffalo #larry #supporting
Gina Carano might have settled for just one A-list defender. Or even a D-list dweller.
Ruffalo's chronic anti-Israel rhetoric finally caught up with the 58-year-old actor. Several Jewish groups chastised his recent anti-Paramount merger rhetoric wrapped in what some called antisemitic tropes.
"Larry Ellison will own most of 'Para Bros.' Larry is a classic Oligarch. They are crushing workers and consolidating the wealth of the world for their own power and concentrated dominance."
There's a list of celebrities supporting Mark Ruffalo after the "Avengers" star's latest anti-Israel bombast. WireImage
#Israel #ruffalo #larry #supporting

14 days ago
George Clooney is the latest addition to Mark Ruffalo's defense team!
The A-list actor has come to his pal's rescue as he continues to come under fire for allegedly conveying antisemitic views towards the Paramount merger with Warner Bros Discovery.
Mark Ruffalo has previously warned about the adoption of Oracle technology because of their affiliation with Israeli military operations in the wake of the CEO funding Paramount's latest venture.
Xavier Collin/Image Press Agency/MEGA
The movie star broke his silence during a press conference at the Venice Film Festival as he was set to receive the Golden Lion for lifetime achievement. He was asked to give his 2 cents on Paramount's criticism of Ruffalo, to which he reiterated his support for Ruffalo's ability to speak freely.
#george
The A-list actor has come to his pal's rescue as he continues to come under fire for allegedly conveying antisemitic views towards the Paramount merger with Warner Bros Discovery.
Mark Ruffalo has previously warned about the adoption of Oracle technology because of their affiliation with Israeli military operations in the wake of the CEO funding Paramount's latest venture.
Xavier Collin/Image Press Agency/MEGA
The movie star broke his silence during a press conference at the Venice Film Festival as he was set to receive the Golden Lion for lifetime achievement. He was asked to give his 2 cents on Paramount's criticism of Ruffalo, to which he reiterated his support for Ruffalo's ability to speak freely.
#george



14 days ago
George Clooney is coming to Mark Ruffalo's defense after the 13 Going on 30 star, 58, faced backlash for his criticism of the proposed Paramount-Warner Bros. merger.
Clooney, 65, was on hand at the Venice Film Festival Wednesday, September 2 — where he was accepting the Golden Lion for Lifetime Achievement Award on the festival's opening day — and he was asked about the state of politics in America and the rise of AI, particularly when it comes to Paramount's ongoing attempt to merge with Warner Bros.
That's when the Oscar winner came to the defense of Ruffalo, who was accused by Paramount of "antisemitic tropes" after the Marvel star attacked the deal over its potential consequences for Hollywood, accusing David Ellison, CEO of Paramount Skydance, and the Ellison family of being complicit in the ongoing conflict in Palestine.
"I support Mark Ruffalo's ability to speak freely," Clooney told Variety when asked about the controversy. "It's ridiculous. We're not going to ban speech. I believe in free speech even when I completely disagree with it. That's important. In fact, it's part of how democracy works."
"There're gonna be people tonight in the room that are gonna disagree with most everything I say or stand for. Fair enough, that's how it's supposed to be," he continued. "We're supposed to argue these things out and come to a conclusion based on the information we take in. So I will always support Mark Ruffalo's ability to speak freely. I like him; he's a good man."
#mark #going
Clooney, 65, was on hand at the Venice Film Festival Wednesday, September 2 — where he was accepting the Golden Lion for Lifetime Achievement Award on the festival's opening day — and he was asked about the state of politics in America and the rise of AI, particularly when it comes to Paramount's ongoing attempt to merge with Warner Bros.
That's when the Oscar winner came to the defense of Ruffalo, who was accused by Paramount of "antisemitic tropes" after the Marvel star attacked the deal over its potential consequences for Hollywood, accusing David Ellison, CEO of Paramount Skydance, and the Ellison family of being complicit in the ongoing conflict in Palestine.
"I support Mark Ruffalo's ability to speak freely," Clooney told Variety when asked about the controversy. "It's ridiculous. We're not going to ban speech. I believe in free speech even when I completely disagree with it. That's important. In fact, it's part of how democracy works."
"There're gonna be people tonight in the room that are gonna disagree with most everything I say or stand for. Fair enough, that's how it's supposed to be," he continued. "We're supposed to argue these things out and come to a conclusion based on the information we take in. So I will always support Mark Ruffalo's ability to speak freely. I like him; he's a good man."
#mark #going