

9 mins. ago
The price of Bitcoin (CRYPTO: $BTC) and other cryptocurrencies strengthened heading into the weekend after a volatile week dominated by an interest rate hike from the U.S. Federal Reserve
On the afternoon of Sept. 18, Bitcoin was up 6% and trading at $80,850 U.S. The largest cryptocurrency had been trading near $75,000 U.S. on the eve of the U.S. interest rate decision on Sept. 16. Other digital ****** ets were gaining strength at week's end, with Ethereum (CRYPTO: $ETH) also up 6% and Solana's (CRYPTO: $SOL) price rising 11%.
It's proving to be a quick recovery for digital ****** ets after the U.S. central bank raised its trendsetting Fed Funds Rate by 25 basis points, its first hike in three years. Crypto appears to be staging a relief rally as the market welcomes slightly higher interest rates that are used to dampen inflation.
More From Cryptoprowl:
U.S. Regulators Push Crypto Rules As Clarity Act Stalls
#sept #digital
On the afternoon of Sept. 18, Bitcoin was up 6% and trading at $80,850 U.S. The largest cryptocurrency had been trading near $75,000 U.S. on the eve of the U.S. interest rate decision on Sept. 16. Other digital ****** ets were gaining strength at week's end, with Ethereum (CRYPTO: $ETH) also up 6% and Solana's (CRYPTO: $SOL) price rising 11%.
It's proving to be a quick recovery for digital ****** ets after the U.S. central bank raised its trendsetting Fed Funds Rate by 25 basis points, its first hike in three years. Crypto appears to be staging a relief rally as the market welcomes slightly higher interest rates that are used to dampen inflation.
More From Cryptoprowl:
U.S. Regulators Push Crypto Rules As Clarity Act Stalls
#sept #digital

50 mins. ago
Benzinga and Yahoo Finance LLC may earn commission or revenue on some items through the links below.
The Securities and Exchange Commission (SEC) is seeking interviews with current and former Guggenheim Investments employees as regulators deepen inquiries into CEO Mark Walter's business.
The SEC is specifically looking at people who have managed insurance-company ******* et portfolios, sources familiar with the matter told Bloomberg. Some individuals contacted by the agency are hiring lawyers to help them respond to confidential inquiries.
The request for interviews suggests that regulators are continuing to scrutinize the billionaire's business empire despite public ******* urances from Guggenheim officials and TWG Holdings, Walter's holding company, that they are cooperating and working with the government on its inquiries.
Read Also:Deal Dispatch: Egg Maker Vital Farms Considers Sale, Blackstone Buys Flow Control, Kennedy Center Troubles
#regulators #securities
The Securities and Exchange Commission (SEC) is seeking interviews with current and former Guggenheim Investments employees as regulators deepen inquiries into CEO Mark Walter's business.
The SEC is specifically looking at people who have managed insurance-company ******* et portfolios, sources familiar with the matter told Bloomberg. Some individuals contacted by the agency are hiring lawyers to help them respond to confidential inquiries.
The request for interviews suggests that regulators are continuing to scrutinize the billionaire's business empire despite public ******* urances from Guggenheim officials and TWG Holdings, Walter's holding company, that they are cooperating and working with the government on its inquiries.
Read Also:Deal Dispatch: Egg Maker Vital Farms Considers Sale, Blackstone Buys Flow Control, Kennedy Center Troubles
#regulators #securities

4 hours ago
FleetCor and CEO Ronald Clarke agreed to a $100 million payment resolving Federal Trade Commission litigation. The settlement follows years of court action over hidden charges involving commercial fuel cards. Harm reached tens of thousands among small-business customers seeking lower operating costs. Regulators say promised savings disappeared beneath undisclosed billing practices.
Federal regulators accused FleetCor, which now operates as Corpay, of imposing unauthorized fees totaling hundreds of millions. Investigators found improper late penalties despite timely remittance or company barriers that prevented payment. Officials cited misleading claims about gas savings, fraud controls, plus card-related expenses. Those practices harmed operators across the United States, according to a 2019 complaint.
Regulators found FleetCor often waited several billing cycles before adding many charges. Delayed timing made extra costs harder for customers to notice. Invoices omitted fee disclosures, pushing account holders toward separate management reports. Even those documents obscured some amounts among unrelated details or excluded them entirely.
"FleetCor deceived its small business customers by promising fuel savings that never materialized," Christopher Mufarrige said. He directs FTC's Bureau of Consumer Protection. Agency officials also criticized hidden and unauthorized charges. Settlement terms channel restitution toward harmed account holders.
In 2023, one federal district court granted summary judgment to the FTC on every count. Its ruling found hidden charges and false representations involving savings, fees, plus fraud-control features. Permanent injunction terms barred FleetCor from billing without informed consent alongside clear disclosures. That order also prohibited deceptive fuel-card claims or hiding material information behind hyperlinks.
#fleetcor #savings
Federal regulators accused FleetCor, which now operates as Corpay, of imposing unauthorized fees totaling hundreds of millions. Investigators found improper late penalties despite timely remittance or company barriers that prevented payment. Officials cited misleading claims about gas savings, fraud controls, plus card-related expenses. Those practices harmed operators across the United States, according to a 2019 complaint.
Regulators found FleetCor often waited several billing cycles before adding many charges. Delayed timing made extra costs harder for customers to notice. Invoices omitted fee disclosures, pushing account holders toward separate management reports. Even those documents obscured some amounts among unrelated details or excluded them entirely.
"FleetCor deceived its small business customers by promising fuel savings that never materialized," Christopher Mufarrige said. He directs FTC's Bureau of Consumer Protection. Agency officials also criticized hidden and unauthorized charges. Settlement terms channel restitution toward harmed account holders.
In 2023, one federal district court granted summary judgment to the FTC on every count. Its ruling found hidden charges and false representations involving savings, fees, plus fraud-control features. Permanent injunction terms barred FleetCor from billing without informed consent alongside clear disclosures. That order also prohibited deceptive fuel-card claims or hiding material information behind hyperlinks.
#fleetcor #savings



4 hours ago
Coinbase Global (NASDAQ: $COIN) has filed for regulatory approval to list perpetual futures tied to individual large-cap U.S. stocks, opening the door to 24/7 leveraged trading of shares such as Apple, Microsoft, Tesla and Nvidia on a regulated U.S. platform.
The exchange plans to offer contracts linked to roughly 50 to 60 major stocks, with trading potentially starting later this year if regulators approve the products, according to The Wall Street Journal.
Perpetual futures, commonly known as perps, are derivatives that do not have an expiration date. Traders can keep positions open indefinitely, while leverage can magnify both gains and losses.
More From Cryptoprowl:
U.S. Regulators Push Crypto Rules As Clarity Act Stalls
#perpetual #global #coin
The exchange plans to offer contracts linked to roughly 50 to 60 major stocks, with trading potentially starting later this year if regulators approve the products, according to The Wall Street Journal.
Perpetual futures, commonly known as perps, are derivatives that do not have an expiration date. Traders can keep positions open indefinitely, while leverage can magnify both gains and losses.
More From Cryptoprowl:
U.S. Regulators Push Crypto Rules As Clarity Act Stalls
#perpetual #global #coin


14 hours ago
One of the challenges for nontraditional fintech lenders has been the expense **** ociated with lending.
Because most of them do not have bank charters, they must partner with a traditional third-party bank to fund their loans. However, they must pay a fee or provide a cut of interest income earned on every loan they make using a third party. That eats into their profits.
Missed AI's "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our **** ysts, we're only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
A federal bank charter would allow the fintechs to take deposits, because without one, they cannot. The deposits serve as an internal funding source, as loans can be made from the deposit base. With an internal funding source, these fintechs do not have to get third-party funding for loans, which, in turn, allows them to save on fees and collect all of the interest income.
Since fintechs started popping up more frequently over the past five or six years, federal regulators have been reluctant to grant bank charters to fintechs, imposing stringent requirements. But that has changed over the past couple of years as restrictions have eased. There has been a surge in the number of fintechs applying for, and getting, bank charters.
#Fintechs #missed #interest
Because most of them do not have bank charters, they must partner with a traditional third-party bank to fund their loans. However, they must pay a fee or provide a cut of interest income earned on every loan they make using a third party. That eats into their profits.
Missed AI's "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our **** ysts, we're only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
A federal bank charter would allow the fintechs to take deposits, because without one, they cannot. The deposits serve as an internal funding source, as loans can be made from the deposit base. With an internal funding source, these fintechs do not have to get third-party funding for loans, which, in turn, allows them to save on fees and collect all of the interest income.
Since fintechs started popping up more frequently over the past five or six years, federal regulators have been reluctant to grant bank charters to fintechs, imposing stringent requirements. But that has changed over the past couple of years as restrictions have eased. There has been a surge in the number of fintechs applying for, and getting, bank charters.
#Fintechs #missed #interest


2 days ago
Fox Corporation (NASDAQ:FOXA) disclosed on September 9 that the U.S. Department of Justice issued a second request for information concerning the proposed acquisition of Roku, Inc. (NASDAQ:ROKU). Cooperation with the review continues, and the expected closing remains in the first half of 2027, according to The Wall Street Journal.
A second request extends the premerger waiting period while regulators seek additional documents and data. For investors, the question is whether Fox Corporation (NASDAQ:FOXA) can preserve the acquisition's streaming benefits through a potentially longer review and any conditions attached to clearance.
The strategic fit centers on combining content with distribution. Roku, Inc. (NASDAQ:ROKU) reaches more than 100 million households globally and would provide Fox Corporation (NASDAQ:FOXA) with an established connected-television platform, advertising technology and direct consumer relationships.
That reach could create additional opportunities to promote live news, sports and streaming services. For advertisers, a broader combination of content, audience data and campaign tools could make the combined offering more useful, provided integration improves targeting and measurement.
The commercial opportunity also extends beyond audience growth. Better advertising monetization and more efficient promotion of streaming services could improve the value generated from existing viewers. Household reach provides the starting point; advertising revenue, engagement and customer acquisition costs would determine the financial payoff.
#advertising #second #request #review
A second request extends the premerger waiting period while regulators seek additional documents and data. For investors, the question is whether Fox Corporation (NASDAQ:FOXA) can preserve the acquisition's streaming benefits through a potentially longer review and any conditions attached to clearance.
The strategic fit centers on combining content with distribution. Roku, Inc. (NASDAQ:ROKU) reaches more than 100 million households globally and would provide Fox Corporation (NASDAQ:FOXA) with an established connected-television platform, advertising technology and direct consumer relationships.
That reach could create additional opportunities to promote live news, sports and streaming services. For advertisers, a broader combination of content, audience data and campaign tools could make the combined offering more useful, provided integration improves targeting and measurement.
The commercial opportunity also extends beyond audience growth. Better advertising monetization and more efficient promotion of streaming services could improve the value generated from existing viewers. Household reach provides the starting point; advertising revenue, engagement and customer acquisition costs would determine the financial payoff.
#advertising #second #request #review


2 days ago
The Williams Companies, Inc. (NYSE:WMB) lost a key New Jersey water-quality certification for Northeast Supply Enhancement, or NESE, after a September 8 federal appeals court ruling reported by Reuters on September 9. The Third Circuit vacated the certification and returned the matter to state regulators. The Williams Companies, Inc. (NYSE:WMB) said that, at this time, it did not expect the ruling to adversely affect construction or the anticipated in-service timeline.
The project, which Reuters described as costing approximately $1 billion, expands the existing Transco network through Pennsylvania, New Jersey and New York. The Williams Companies, Inc. (NYSE:WMB) continues to target fourth-quarter 2027 service. The investment question is whether the permit review can be resolved quickly enough to protect both that schedule and the economics of the investment.
The commercial rationale rests on delivering additional gas into a constrained market. The Williams Companies, Inc. (NYSE:WMB) says demand continues to grow in areas including Brooklyn, Queens, Staten Island and Long Island. Planned capacity of approximately 400,000 dekatherms per day would expand the system's ability to serve those markets.
NESE also builds on existing infrastructure. The Williams Companies, Inc. (NYSE:WMB) plans pipeline loops, compressor work, and connections to the Transco system. Those connections give the added capacity access to an established transportation network and regional delivery points, although substantial construction remains necessary.
The remand leaves a route for reconsideration by New Jersey regulators. For The Williams Companies, Inc. (NYSE:WMB), the favorable scenario is a replacement certification that addresses the court's findings without requiring substantial redesign or disrupting the construction sequence.
#williams #NYSE #jersey #construction
The project, which Reuters described as costing approximately $1 billion, expands the existing Transco network through Pennsylvania, New Jersey and New York. The Williams Companies, Inc. (NYSE:WMB) continues to target fourth-quarter 2027 service. The investment question is whether the permit review can be resolved quickly enough to protect both that schedule and the economics of the investment.
The commercial rationale rests on delivering additional gas into a constrained market. The Williams Companies, Inc. (NYSE:WMB) says demand continues to grow in areas including Brooklyn, Queens, Staten Island and Long Island. Planned capacity of approximately 400,000 dekatherms per day would expand the system's ability to serve those markets.
NESE also builds on existing infrastructure. The Williams Companies, Inc. (NYSE:WMB) plans pipeline loops, compressor work, and connections to the Transco system. Those connections give the added capacity access to an established transportation network and regional delivery points, although substantial construction remains necessary.
The remand leaves a route for reconsideration by New Jersey regulators. For The Williams Companies, Inc. (NYSE:WMB), the favorable scenario is a replacement certification that addresses the court's findings without requiring substantial redesign or disrupting the construction sequence.
#williams #NYSE #jersey #construction


2 days ago
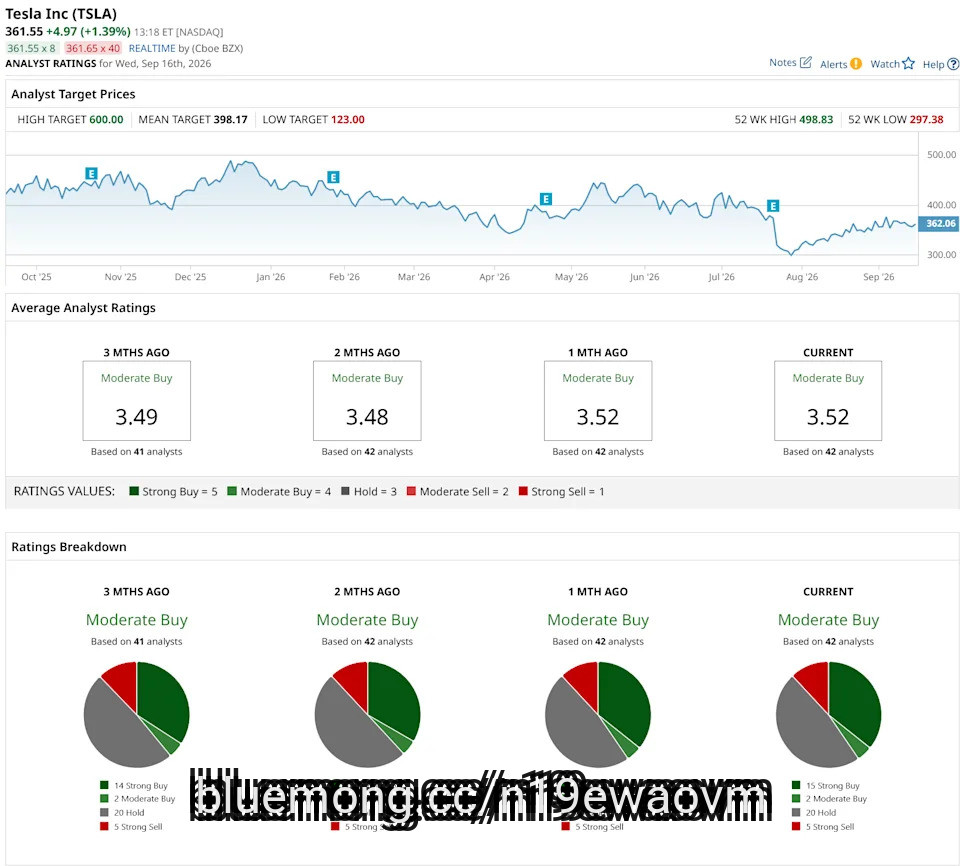
Tesla (TSLA) has had a rough 2026. The stock is down about 20% year-to-date (YTD), falling from $458.34 on the first trading day of the year to $297.38 in late July. That is a decline of more than 27% from peak to trough.
Its much-publicized Cybercab launch also disappointed investors. Tesla launched the robotaxi service in Austin on Sept. 3 with only 45 vehicles registered in Texas. The stock then dropped nearly 6% the next day, wiping out its 5.4% pre-launch gain, after federal safety regulators opened an audit into about 1,000 steering-wheel-free vehicles. Tesla's Model Y-based driverless ride service is still limited to seven U.S. metro areas.
Billionaire Charlie Munger, Who Died at 99, Skipped Insurance on His Mansion Since He Could Just Write a Check to Rebuild — 'All Intelligent People Do It My Way'
Why It's Time to Load Up on Nvidia Stock
The Case for Selling CrowdStrike Stock
#tesla #Tsla
Its much-publicized Cybercab launch also disappointed investors. Tesla launched the robotaxi service in Austin on Sept. 3 with only 45 vehicles registered in Texas. The stock then dropped nearly 6% the next day, wiping out its 5.4% pre-launch gain, after federal safety regulators opened an audit into about 1,000 steering-wheel-free vehicles. Tesla's Model Y-based driverless ride service is still limited to seven U.S. metro areas.
Billionaire Charlie Munger, Who Died at 99, Skipped Insurance on His Mansion Since He Could Just Write a Check to Rebuild — 'All Intelligent People Do It My Way'
Why It's Time to Load Up on Nvidia Stock
The Case for Selling CrowdStrike Stock
#tesla #Tsla


2 days ago
If online prediction markets are correct, the Democrats are likely to win back the House and Senate in November. On Polymarket, there's currently a 53% chance of a Democratic sweep.
If you're a crypto investor, that outcome could have important consequences for your portfolio. That's especially the case if Democrats delay, roll back, or block important pro-crypto legislation. With that in mind, here's one crypto to buy and one crypto to sell.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
My one crypto to buy is Bitcoin (CRYPTO: BTC). It is still the most popular cryptocurrency, accounting for a whopping 60% of the crypto market's total $2.6 trillion market cap. As Bitcoin goes, so goes the crypto market.
As a result, Bitcoin currently has the support of both Wall Street and the White House, so any political fallout from the midterm elections in the event of a Democratic sweep should be minimal. Regulators already agree that Bitcoin is a commodity, not a security. Thus, even if the Clarity Act does not pass this year, it shouldn't have a direct impact on the regulatory status of Bitcoin and how institutional investors view it.
#NVIDIA #flashing #total
If you're a crypto investor, that outcome could have important consequences for your portfolio. That's especially the case if Democrats delay, roll back, or block important pro-crypto legislation. With that in mind, here's one crypto to buy and one crypto to sell.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
My one crypto to buy is Bitcoin (CRYPTO: BTC). It is still the most popular cryptocurrency, accounting for a whopping 60% of the crypto market's total $2.6 trillion market cap. As Bitcoin goes, so goes the crypto market.
As a result, Bitcoin currently has the support of both Wall Street and the White House, so any political fallout from the midterm elections in the event of a Democratic sweep should be minimal. Regulators already agree that Bitcoin is a commodity, not a security. Thus, even if the Clarity Act does not pass this year, it shouldn't have a direct impact on the regulatory status of Bitcoin and how institutional investors view it.
#NVIDIA #flashing #total

3 days ago
The House of Representatives on Tuesday passed a bipartisan bill aimed at shielding Americans from increased electricity costs **** ociated with data centers being built across the country.
The Ratepayer Protection Act, which passed with an overwhelming 417-3 majority, "ensures American families are not left footing the bill for the grid upgrades and new energy generation required to operate large data centers," Republican Rep. Gabe Evans, one of the bill's sponsors, said ahead of the vote.
The bill now moves to the Senate, where its prospects of passing are uncertain.
The Ratepayer Protection Act is the first major piece of legislation taken up by Congress to address the growing public discontent over the mass buildout of data centers among the American public. Even if it passes, though, it won't directly set the rates that data center operators pay for their electricity.
Congress doesn't have the power to compel utilities to set higher rates for the facilities. Only states have that authority. What the Ratepayer Protection Act would do is compel state utility regulators to consider adopting a federal standard under which large data centers would cover the extra costs of upgrades. The bill is comparable to a proclamation signed by President Trump earlier this year that established a similar voluntary pledge for tech companies.
#passed
The Ratepayer Protection Act, which passed with an overwhelming 417-3 majority, "ensures American families are not left footing the bill for the grid upgrades and new energy generation required to operate large data centers," Republican Rep. Gabe Evans, one of the bill's sponsors, said ahead of the vote.
The bill now moves to the Senate, where its prospects of passing are uncertain.
The Ratepayer Protection Act is the first major piece of legislation taken up by Congress to address the growing public discontent over the mass buildout of data centers among the American public. Even if it passes, though, it won't directly set the rates that data center operators pay for their electricity.
Congress doesn't have the power to compel utilities to set higher rates for the facilities. Only states have that authority. What the Ratepayer Protection Act would do is compel state utility regulators to consider adopting a federal standard under which large data centers would cover the extra costs of upgrades. The bill is comparable to a proclamation signed by President Trump earlier this year that established a similar voluntary pledge for tech companies.
#passed


3 days ago
Two former Robinhood engineers were charged with fraud on Tuesday in a Hyperliquid insider trading case, accused of buying futures contracts before their employer announced new token listings.
Hefu Chai, 36, and Huaisong Xiang, 30, each face one count of violating the Commodity Exchange Act and one count of wire fraud. Prosecutors say the pair made more than $50,000 apiece.
"Robinhood takes market integrity seriously and has zero tolerance for insider trading. We have robust insider trading policies and procedures in place, including for new crypto listings. We immediately investigated and reported this matter to law enforcement and regulators, and will continue to cooperate with the investigations," a Robinhood spokesperson told BeInCrypto.
Follow us on X to get the latest news as it happens
Hyperliquid runs a decentralized exchange built around perpetual futures. These are leveraged bets on a token's price that never expire, so a trader can hold the position indefinitely.
#robinhood #exchange #tuesday
Hefu Chai, 36, and Huaisong Xiang, 30, each face one count of violating the Commodity Exchange Act and one count of wire fraud. Prosecutors say the pair made more than $50,000 apiece.
"Robinhood takes market integrity seriously and has zero tolerance for insider trading. We have robust insider trading policies and procedures in place, including for new crypto listings. We immediately investigated and reported this matter to law enforcement and regulators, and will continue to cooperate with the investigations," a Robinhood spokesperson told BeInCrypto.
Follow us on X to get the latest news as it happens
Hyperliquid runs a decentralized exchange built around perpetual futures. These are leveraged bets on a token's price that never expire, so a trader can hold the position indefinitely.
#robinhood #exchange #tuesday


3 days ago
Kimberly-Clark Corporation (NASDAQ:KMB) is preparing **** et sales to address EU antitrust concerns surrounding its planned $40 billion acquisition of Kenvue, according to Reuters. The company is reportedly seeking to offer remedies that could secure European Commission approval by the September 29 deadline, avoiding a more extensive four-month investigation. Similar regulatory concerns have already emerged in Australia, where the deal received conditional approval after Kimberly-Clark agreed to divest Kenvue's Carefree and Stayfree brands.
The transaction is strategically important because it would create a consumer-health and personal-care company with approximately $32 billion of annual revenue and $7 billion of adjusted EBITDA. Kimberly-Clark Corporation (NASDAQ:KMB) expects about $1.9 billion of annual cost synergies and $500 million of revenue synergies, although it expects to invest roughly $2.5 billion in cash to achieve the cost savings. Therefore, the scale of any EU divestitures will be critical to determining whether Kimberly-Clark can retain the expected economic benefits of the deal.
The strongest bullish argument is that Kimberly-Clark Corporation (NASDAQ:KMB) is actively working toward a regulatory solution rather than allowing the EU review to threaten the transaction. If the company can satisfy regulators through limited **** et sales, it could preserve the majority of Kenvue's revenue and earnings while moving ahead with the combination. The expected $1.9 billion in annual cost savings represents a substantial earnings opportunity relative to the combined company's roughly $7 billion adjusted EBITDA target, giving Kimberly-Clark significant potential to improve margins and cash generation after integration.
The Australian precedent also suggests that targeted divestitures could be sufficient to resolve competition concerns without materially undermining the broader deal. Securing EU approval by September 29 would be particularly positive because it would remove a major source of uncertainty and allow Kimberly-Clark Corporation (NASDAQ:KMB) to focus on integration and synergy execution. With Kenvue adding major brands across consumer health and personal care, successful completion could also broaden Kimberly-Clark's portfolio and reduce its reliance on its existing product categories.
The biggest risk is that the EU requires more substantial **** et sales than Kimberly-Clark Corporation (NASDAQ:KMB) currently expects. Giving up attractive Kenvue brands or businesses in Europe could reduce the revenue and EBITDA acquired through the transaction, while Kimberly-Clark would still have to bear much of the financing, transaction, and integration burden. That could make the $40 billion purchase price less attractive on a risk-adjusted basis, particularly if the divested **** ets are among Kenvue's stronger European businesses.
#kimberly #revenue #ebitda
The transaction is strategically important because it would create a consumer-health and personal-care company with approximately $32 billion of annual revenue and $7 billion of adjusted EBITDA. Kimberly-Clark Corporation (NASDAQ:KMB) expects about $1.9 billion of annual cost synergies and $500 million of revenue synergies, although it expects to invest roughly $2.5 billion in cash to achieve the cost savings. Therefore, the scale of any EU divestitures will be critical to determining whether Kimberly-Clark can retain the expected economic benefits of the deal.
The strongest bullish argument is that Kimberly-Clark Corporation (NASDAQ:KMB) is actively working toward a regulatory solution rather than allowing the EU review to threaten the transaction. If the company can satisfy regulators through limited **** et sales, it could preserve the majority of Kenvue's revenue and earnings while moving ahead with the combination. The expected $1.9 billion in annual cost savings represents a substantial earnings opportunity relative to the combined company's roughly $7 billion adjusted EBITDA target, giving Kimberly-Clark significant potential to improve margins and cash generation after integration.
The Australian precedent also suggests that targeted divestitures could be sufficient to resolve competition concerns without materially undermining the broader deal. Securing EU approval by September 29 would be particularly positive because it would remove a major source of uncertainty and allow Kimberly-Clark Corporation (NASDAQ:KMB) to focus on integration and synergy execution. With Kenvue adding major brands across consumer health and personal care, successful completion could also broaden Kimberly-Clark's portfolio and reduce its reliance on its existing product categories.
The biggest risk is that the EU requires more substantial **** et sales than Kimberly-Clark Corporation (NASDAQ:KMB) currently expects. Giving up attractive Kenvue brands or businesses in Europe could reduce the revenue and EBITDA acquired through the transaction, while Kimberly-Clark would still have to bear much of the financing, transaction, and integration burden. That could make the $40 billion purchase price less attractive on a risk-adjusted basis, particularly if the divested **** ets are among Kenvue's stronger European businesses.
#kimberly #revenue #ebitda


3 days ago
Kimberly-Clark Corporation (NASDAQ:KMB) is preparing ***** et sales to address EU antitrust concerns surrounding its planned $40 billion acquisition of Kenvue, according to Reuters. The company is reportedly seeking to offer remedies that could secure European Commission approval by the September 29 deadline, avoiding a more extensive four-month investigation. Similar regulatory concerns have already emerged in Australia, where the deal received conditional approval after Kimberly-Clark agreed to divest Kenvue's Carefree and Stayfree brands.
The transaction is strategically important because it would create a consumer-health and personal-care company with approximately $32 billion of annual revenue and $7 billion of adjusted EBITDA. Kimberly-Clark Corporation (NASDAQ:KMB) expects about $1.9 billion of annual cost synergies and $500 million of revenue synergies, although it expects to invest roughly $2.5 billion in cash to achieve the cost savings. Therefore, the scale of any EU divestitures will be critical to determining whether Kimberly-Clark can retain the expected economic benefits of the deal.
The strongest bullish argument is that Kimberly-Clark Corporation (NASDAQ:KMB) is actively working toward a regulatory solution rather than allowing the EU review to threaten the transaction. If the company can satisfy regulators through limited ***** et sales, it could preserve the majority of Kenvue's revenue and earnings while moving ahead with the combination. The expected $1.9 billion in annual cost savings represents a substantial earnings opportunity relative to the combined company's roughly $7 billion adjusted EBITDA target, giving Kimberly-Clark significant potential to improve margins and cash generation after integration.
The Australian precedent also suggests that targeted divestitures could be sufficient to resolve competition concerns without materially undermining the broader deal. Securing EU approval by September 29 would be particularly positive because it would remove a major source of uncertainty and allow Kimberly-Clark Corporation (NASDAQ:KMB) to focus on integration and synergy execution. With Kenvue adding major brands across consumer health and personal care, successful completion could also broaden Kimberly-Clark's portfolio and reduce its reliance on its existing product categories.
The biggest risk is that the EU requires more substantial ***** et sales than Kimberly-Clark Corporation (NASDAQ:KMB) currently expects. Giving up attractive Kenvue brands or businesses in Europe could reduce the revenue and EBITDA acquired through the transaction, while Kimberly-Clark would still have to bear much of the financing, transaction, and integration burden. That could make the $40 billion purchase price less attractive on a risk-adjusted basis, particularly if the divested ***** ets are among Kenvue's stronger European businesses.
#revenue
The transaction is strategically important because it would create a consumer-health and personal-care company with approximately $32 billion of annual revenue and $7 billion of adjusted EBITDA. Kimberly-Clark Corporation (NASDAQ:KMB) expects about $1.9 billion of annual cost synergies and $500 million of revenue synergies, although it expects to invest roughly $2.5 billion in cash to achieve the cost savings. Therefore, the scale of any EU divestitures will be critical to determining whether Kimberly-Clark can retain the expected economic benefits of the deal.
The strongest bullish argument is that Kimberly-Clark Corporation (NASDAQ:KMB) is actively working toward a regulatory solution rather than allowing the EU review to threaten the transaction. If the company can satisfy regulators through limited ***** et sales, it could preserve the majority of Kenvue's revenue and earnings while moving ahead with the combination. The expected $1.9 billion in annual cost savings represents a substantial earnings opportunity relative to the combined company's roughly $7 billion adjusted EBITDA target, giving Kimberly-Clark significant potential to improve margins and cash generation after integration.
The Australian precedent also suggests that targeted divestitures could be sufficient to resolve competition concerns without materially undermining the broader deal. Securing EU approval by September 29 would be particularly positive because it would remove a major source of uncertainty and allow Kimberly-Clark Corporation (NASDAQ:KMB) to focus on integration and synergy execution. With Kenvue adding major brands across consumer health and personal care, successful completion could also broaden Kimberly-Clark's portfolio and reduce its reliance on its existing product categories.
The biggest risk is that the EU requires more substantial ***** et sales than Kimberly-Clark Corporation (NASDAQ:KMB) currently expects. Giving up attractive Kenvue brands or businesses in Europe could reduce the revenue and EBITDA acquired through the transaction, while Kimberly-Clark would still have to bear much of the financing, transaction, and integration burden. That could make the $40 billion purchase price less attractive on a risk-adjusted basis, particularly if the divested ***** ets are among Kenvue's stronger European businesses.
#revenue


8 days ago
Cryptocurrency exchange Bybit plans to launch a new super app in Europe that will offer both a regular bank account and stock and crypto trading.
The privately held Dubai-based firm, which claims to have more than 80 million users worldwide, has been granted an electronic money institution license by European regulators.
That will enable Bybit, which also holds a Markets in Crypto ******* ets (MiCA) license in Austria, to launch the new super app for the European market.
More From Cryptoprowl:
MEXC Launches Earn Plus With Limited-Time Event Offering Up to 800% APR Booster
#super #license #Europe #Dubai
The privately held Dubai-based firm, which claims to have more than 80 million users worldwide, has been granted an electronic money institution license by European regulators.
That will enable Bybit, which also holds a Markets in Crypto ******* ets (MiCA) license in Austria, to launch the new super app for the European market.
More From Cryptoprowl:
MEXC Launches Earn Plus With Limited-Time Event Offering Up to 800% APR Booster
#super #license #Europe #Dubai


9 days ago
Strategy, formerly MicroStrategy, says 91% of its balance sheet rests on money **** ody can take back. JPMorgan runs on deposits customers can pull any day. Strategy calls that the safer design.
The claim comes from a slide that the company put in front of investors. It puts Strategy's short-term funding gap at zero and JPMorgan's at negative $1.2 trillion. Strategy wrote those definitions itself.
"MSTR inverts TradFi," says Strategy.
Follow us on X to get the latest news as it happens
Banks borrow short, lend long, and deposits can vanish in a day. Additionally, sometimes loans take years to come back, which is why insurance, regulators and central bank credit exist to cover that gap.
#follow
The claim comes from a slide that the company put in front of investors. It puts Strategy's short-term funding gap at zero and JPMorgan's at negative $1.2 trillion. Strategy wrote those definitions itself.
"MSTR inverts TradFi," says Strategy.
Follow us on X to get the latest news as it happens
Banks borrow short, lend long, and deposits can vanish in a day. Additionally, sometimes loans take years to come back, which is why insurance, regulators and central bank credit exist to cover that gap.
#follow

9 days ago
The artificial intelligence (AI) boom is fueling a nuclear renaissance. For the industry to grow, massive amounts of energy-intensive compute power will need to be built. As a low-carbon, high-baseload energy source, nuclear power is a promising solution.
NuScale Power (NYSE: SMR) is the only small modular reactor (SMR) developer in the U.S. approved by regulators to construct an SMR facility. SMRs are ideal for the AI data center build-out, given that they can be built more quickly and at a lower cost than conventional nuclear plants. This smaller footprint allows an SMR to be constructed near the data center infrastructure itself.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Despite growth potential, NuScale shares are down 40% this year. Skepticism is reasonable. Only two SMR systems currently exist worldwide. NuScale has never commercialized any of its SMR designs. Plus, the company already experienced a sizable failure in 2023 when its biggest customer (at the time) canceled its project.
While NuScale operates in an industry that should see long-term growth, the nuclear stock's future may hinge on a single upcoming catalyst.
#nuclear
NuScale Power (NYSE: SMR) is the only small modular reactor (SMR) developer in the U.S. approved by regulators to construct an SMR facility. SMRs are ideal for the AI data center build-out, given that they can be built more quickly and at a lower cost than conventional nuclear plants. This smaller footprint allows an SMR to be constructed near the data center infrastructure itself.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Despite growth potential, NuScale shares are down 40% this year. Skepticism is reasonable. Only two SMR systems currently exist worldwide. NuScale has never commercialized any of its SMR designs. Plus, the company already experienced a sizable failure in 2023 when its biggest customer (at the time) canceled its project.
While NuScale operates in an industry that should see long-term growth, the nuclear stock's future may hinge on a single upcoming catalyst.
#nuclear


11 days ago
On August 4, Essential Utilities (NYSE:WTRG) reported second-quarter results that read like two different stories stapled together. Revenue climbed, the dividend grew for the 36th time in 35 years, and the merger with American Water inched closer to the finish line. But earnings per share actually dipped from a year earlier, and the company had to strip out merger costs just to show flat profitability. For a utility this steady, that split is worth a closer look.
Essential's regulated water segment posted revenue of $357.5 million in the quarter, up 7.6% from $332.3 million a year earlier, and the whole company's first-half revenue climbed 7.2% to nearly $1.4 billion. Much of that growth came from rate cases: state regulators approved $43.9 million in new annual water revenue across Pennsylvania, Illinois, Ohio, North Carolina and Indiana, plus $12.7 million more for the gas business in Kentucky and Pennsylvania. Another $79.7 million in water rate requests and a $163.2 million gas case in Pennsylvania, tied to replacing aging pipelines, are still working through the process.
The company keeps buying its way into new customers, too. In May, it closed a $4.9 million wastewater deal in Bastrop County, Texas, and it has signed agreements worth roughly $282 million to add over 200,000 more customers in Pennsylvania, Texas, North Carolina and New Jersey, including the $276.5 million purchase of Philadelphia-area sewer authority DELCORA. Since 2015, acquisitions have added more than 138,000 customers to Essential's base.
Layer on the pending American Water merger, which cleared Virginia and Ohio regulators this year after nearly unanimous shareholder approval in February, and Essential is positioning itself as a much larger multi-state utility by early 2027. The board's decision to raise the dividend 5.25% to $0.3606 per share, continuing a streak of 36 increases over 35 years, signals confidence that this growth is durable.
Look past the top line and the picture gets less flattering. Second quarter net income actually fell to $105.7 million from $107.8 million a year ago, pulling GAAP earnings per share down to $0.37 from $0.38. Essential had to report an adjusted $0.38 figure just to exclude merger-related costs and show earnings roughly matching last year's. The slide is sharper over six months: net income dropped to $330.1 million, or $1.16 per share, from $391.6 million, or $1.41 per share, in the first half of 2025.
#water #pennsylvania
Essential's regulated water segment posted revenue of $357.5 million in the quarter, up 7.6% from $332.3 million a year earlier, and the whole company's first-half revenue climbed 7.2% to nearly $1.4 billion. Much of that growth came from rate cases: state regulators approved $43.9 million in new annual water revenue across Pennsylvania, Illinois, Ohio, North Carolina and Indiana, plus $12.7 million more for the gas business in Kentucky and Pennsylvania. Another $79.7 million in water rate requests and a $163.2 million gas case in Pennsylvania, tied to replacing aging pipelines, are still working through the process.
The company keeps buying its way into new customers, too. In May, it closed a $4.9 million wastewater deal in Bastrop County, Texas, and it has signed agreements worth roughly $282 million to add over 200,000 more customers in Pennsylvania, Texas, North Carolina and New Jersey, including the $276.5 million purchase of Philadelphia-area sewer authority DELCORA. Since 2015, acquisitions have added more than 138,000 customers to Essential's base.
Layer on the pending American Water merger, which cleared Virginia and Ohio regulators this year after nearly unanimous shareholder approval in February, and Essential is positioning itself as a much larger multi-state utility by early 2027. The board's decision to raise the dividend 5.25% to $0.3606 per share, continuing a streak of 36 increases over 35 years, signals confidence that this growth is durable.
Look past the top line and the picture gets less flattering. Second quarter net income actually fell to $105.7 million from $107.8 million a year ago, pulling GAAP earnings per share down to $0.37 from $0.38. Essential had to report an adjusted $0.38 figure just to exclude merger-related costs and show earnings roughly matching last year's. The slide is sharper over six months: net income dropped to $330.1 million, or $1.16 per share, from $391.6 million, or $1.41 per share, in the first half of 2025.
#water #pennsylvania

12 days ago
Oracle (ORCL) has enough on its plate heading into earnings week. Now Brussels wants a word.
European antitrust regulators are quietly examining how Oracle licenses its software, and the timing could hardly be more inconvenient for shareholders.
The stock trades near $158.78, down about 19% so far in 2026 and roughly 54% below its 52-week high of $345.72.
Investors were already nervous about Oracle's debt-heavy artificial intelligence (AI) buildout. This regulatory question adds to the list of worries.
The European Commission is gathering information from Oracle's customers and rivals to decide whether its cloud software terms unfairly lock clients in, Reuters reported.
#european #enough
European antitrust regulators are quietly examining how Oracle licenses its software, and the timing could hardly be more inconvenient for shareholders.
The stock trades near $158.78, down about 19% so far in 2026 and roughly 54% below its 52-week high of $345.72.
Investors were already nervous about Oracle's debt-heavy artificial intelligence (AI) buildout. This regulatory question adds to the list of worries.
The European Commission is gathering information from Oracle's customers and rivals to decide whether its cloud software terms unfairly lock clients in, Reuters reported.
#european #enough


12 days ago
Federal regulators said the two crew members aboard the Amazon cargo jet that crashed at Miami International Airport on Sunday survived the accident.
The National Transportation Safety Board (NTSB) provided the update during a Sunday press conference after officials said the cargo plane overran the runway and caught fire while landing. The crash killed five people and injured five others, authorities said Sunday.
The jet collided with two vehicles carrying at least eight occupants, according to NTSB Chairwoman Jennifer Homendy.
Seven of the victims were in a van that was struck and "torn apart" on airport grounds, Homendy said. The 2012 white Ford Econoline van was owned by Ocean Service Corporation, a contract cleaning company that provides services for airlines, she said.
Amazon Cargo Plane Overruns Miami Airport Runway And Strikes 'Multiple' Vehicles; 5 Dead, 5 Injured
#homendy
The National Transportation Safety Board (NTSB) provided the update during a Sunday press conference after officials said the cargo plane overran the runway and caught fire while landing. The crash killed five people and injured five others, authorities said Sunday.
The jet collided with two vehicles carrying at least eight occupants, according to NTSB Chairwoman Jennifer Homendy.
Seven of the victims were in a van that was struck and "torn apart" on airport grounds, Homendy said. The 2012 white Ford Econoline van was owned by Ocean Service Corporation, a contract cleaning company that provides services for airlines, she said.
Amazon Cargo Plane Overruns Miami Airport Runway And Strikes 'Multiple' Vehicles; 5 Dead, 5 Injured
#homendy


13 days ago
On August 4, Essential Utilities (NYSE:WTRG) reported second-quarter results that read like two different stories stapled together. Revenue climbed, the dividend grew for the 36th time in 35 years, and the merger with American Water inched closer to the finish line. But earnings per share actually dipped from a year earlier, and the company had to strip out merger costs just to show flat profitability. For a utility this steady, that split is worth a closer look.
Essential's regulated water segment posted revenue of $357.5 million in the quarter, up 7.6% from $332.3 million a year earlier, and the whole company's first-half revenue climbed 7.2% to nearly $1.4 billion. Much of that growth came from rate cases: state regulators approved $43.9 million in new annual water revenue across Pennsylvania, Illinois, Ohio, North Carolina and Indiana, plus $12.7 million more for the gas business in Kentucky and Pennsylvania. Another $79.7 million in water rate requests and a $163.2 million gas case in Pennsylvania, tied to replacing aging pipelines, are still working through the process.
The company keeps buying its way into new customers, too. In May, it closed a $4.9 million wastewater deal in Bastrop County, Texas, and it has signed agreements worth roughly $282 million to add over 200,000 more customers in Pennsylvania, Texas, North Carolina and New Jersey, including the $276.5 million purchase of Philadelphia-area sewer authority DELCORA. Since 2015, acquisitions have added more than 138,000 customers to Essential's base.
Layer on the pending American Water merger, which cleared Virginia and Ohio regulators this year after nearly unanimous shareholder approval in February, and Essential is positioning itself as a much larger multi-state utility by early 2027. The board's decision to raise the dividend 5.25% to $0.3606 per share, continuing a streak of 36 increases over 35 years, signals confidence that this growth is durable.
Look past the top line and the picture gets less flattering. Second quarter net income actually fell to $105.7 million from $107.8 million a year ago, pulling GAAP earnings per share down to $0.37 from $0.38. Essential had to report an adjusted $0.38 figure just to exclude merger-related costs and show earnings roughly matching last year's. The slide is sharper over six months: net income dropped to $330.1 million, or $1.16 per share, from $391.6 million, or $1.41 per share, in the first half of 2025.
#million #revenue #merger #year
Essential's regulated water segment posted revenue of $357.5 million in the quarter, up 7.6% from $332.3 million a year earlier, and the whole company's first-half revenue climbed 7.2% to nearly $1.4 billion. Much of that growth came from rate cases: state regulators approved $43.9 million in new annual water revenue across Pennsylvania, Illinois, Ohio, North Carolina and Indiana, plus $12.7 million more for the gas business in Kentucky and Pennsylvania. Another $79.7 million in water rate requests and a $163.2 million gas case in Pennsylvania, tied to replacing aging pipelines, are still working through the process.
The company keeps buying its way into new customers, too. In May, it closed a $4.9 million wastewater deal in Bastrop County, Texas, and it has signed agreements worth roughly $282 million to add over 200,000 more customers in Pennsylvania, Texas, North Carolina and New Jersey, including the $276.5 million purchase of Philadelphia-area sewer authority DELCORA. Since 2015, acquisitions have added more than 138,000 customers to Essential's base.
Layer on the pending American Water merger, which cleared Virginia and Ohio regulators this year after nearly unanimous shareholder approval in February, and Essential is positioning itself as a much larger multi-state utility by early 2027. The board's decision to raise the dividend 5.25% to $0.3606 per share, continuing a streak of 36 increases over 35 years, signals confidence that this growth is durable.
Look past the top line and the picture gets less flattering. Second quarter net income actually fell to $105.7 million from $107.8 million a year ago, pulling GAAP earnings per share down to $0.37 from $0.38. Essential had to report an adjusted $0.38 figure just to exclude merger-related costs and show earnings roughly matching last year's. The slide is sharper over six months: net income dropped to $330.1 million, or $1.16 per share, from $391.6 million, or $1.41 per share, in the first half of 2025.
#million #revenue #merger #year

14 days ago
On August 5, Southwest Gas Holdings (NYSE:SWX) reported second quarter results for the period ended June 30 and reaffirmed its full year 2026 guidance. Net income attributable to the company reached $42.1 million, a sharp turnaround from a $40.2 million loss in the same quarter of 2025. But the number that stood out was the Great Basin 2028 Expansion Project, where contracted demand has grown enough that management now expects capital costs of $2.3 billion instead of the $1.7 billion baked into current five year guidance.
Southwest Gas's growth story increasingly runs through Nevada. Binding precedent agreements for the Great Basin 2028 Expansion Project have grown to roughly 1 billion cubic feet per day of contracted demand, and the company has fielded another 1.8 billion cubic feet of expressions of interest for phases running from 2029 through 2035. Based on that demand, management now projects an annual margin of $270 million to $300 million once the pipeline is in service, on capital investment of about $2.3 billion.
Regulators have been cooperating too. California's Public Utilities Commission approved the non-cost-of-capital pieces of Southwest Gas's rate case, adding roughly $40 million of incremental annual revenue and triggering recognition of $9.7 million of previously deferred first-quarter income. Nevada regulators approved a Triennial Resource Plan with prudency pre-determinations for about $186 million of capital spending, and the company filed for a general rate case increase of roughly $74 million.
Arizona's new System Integrity Mechanism, effective April 1 this year, lets Southwest Gas recover safety and reliability spending faster, up to a $50 million annual cap. The company put $520 million into its network in the first six months of 2026, including $115 million toward Great Basin, and closed the quarter with $270.5 million in cash and nearly $1 billion in available liquidity.
Look past the headline swing to profit, and the picture gets murkier. The core natural gas distribution segment actually earned less this quarter, with its contribution to net income falling from $45.6 million a year earlier to $40.8 million, and its adjusted net income slipping from $33.7 million to $31 million. Depreciation and amortization rose $8.7 million, or 13%, as gas plant in service grew 7% year over year, a reminder that heavy pipeline spending shows up in expenses well before it shows up in rates.
#million #company #basin
Southwest Gas's growth story increasingly runs through Nevada. Binding precedent agreements for the Great Basin 2028 Expansion Project have grown to roughly 1 billion cubic feet per day of contracted demand, and the company has fielded another 1.8 billion cubic feet of expressions of interest for phases running from 2029 through 2035. Based on that demand, management now projects an annual margin of $270 million to $300 million once the pipeline is in service, on capital investment of about $2.3 billion.
Regulators have been cooperating too. California's Public Utilities Commission approved the non-cost-of-capital pieces of Southwest Gas's rate case, adding roughly $40 million of incremental annual revenue and triggering recognition of $9.7 million of previously deferred first-quarter income. Nevada regulators approved a Triennial Resource Plan with prudency pre-determinations for about $186 million of capital spending, and the company filed for a general rate case increase of roughly $74 million.
Arizona's new System Integrity Mechanism, effective April 1 this year, lets Southwest Gas recover safety and reliability spending faster, up to a $50 million annual cap. The company put $520 million into its network in the first six months of 2026, including $115 million toward Great Basin, and closed the quarter with $270.5 million in cash and nearly $1 billion in available liquidity.
Look past the headline swing to profit, and the picture gets murkier. The core natural gas distribution segment actually earned less this quarter, with its contribution to net income falling from $45.6 million a year earlier to $40.8 million, and its adjusted net income slipping from $33.7 million to $31 million. Depreciation and amortization rose $8.7 million, or 13%, as gas plant in service grew 7% year over year, a reminder that heavy pipeline spending shows up in expenses well before it shows up in rates.
#million #company #basin


15 days ago
US-based electric utility PG&E and its subsidiary the Pacific Gas and Electric Company have announced a strategic review of the organisation's energy business structure and financing, alongside plans to defer approximately $2bn in planned investment in 2027.
The company stated that the moves are intended to help maintain essential safety investments and compliance standards while reducing near-term borrowing costs for California customers.
A newly formed Strategic Review Committee made up of four independent directors from PG&E's board will lead the review.
The committee will evaluate regulatory, financial, operational and strategic alternatives to determine the best organisation and financing structure for the company.
PG&E said the review will include consultations with regulators, policymakers and stakeholders in California and focus on achieving a financially sound, investment-grade status.
#california
The company stated that the moves are intended to help maintain essential safety investments and compliance standards while reducing near-term borrowing costs for California customers.
A newly formed Strategic Review Committee made up of four independent directors from PG&E's board will lead the review.
The committee will evaluate regulatory, financial, operational and strategic alternatives to determine the best organisation and financing structure for the company.
PG&E said the review will include consultations with regulators, policymakers and stakeholders in California and focus on achieving a financially sound, investment-grade status.
#california


16 days ago
Ondo Finance has filed three comment letters with the Securities and Exchange Commission (SEC) and the Commodity Futures Trading Commission (CFTC), arguing that existing U.S. regulations already have room for products built on blockchain technology, they just need to be applied differently.
The letters, published Sep. 2, cover three separate rulemaking areas: perpetual futures product definitions, portfolio margining, and market data reporting.
Each letter addresses a different rule, but the underlying argument is the same across all three: regulators should judge whether a system works, not whether it looks like the one it's replacing.
Related: Cathie Wood buys millions in popular crypto stock on Chelsea FC deal
Perpetual futures, or "perps," are contracts that let traders bet on an ***** et's price without the contract ever expiring. Traditional futures use expiration dates to force prices to converge with the underlying ***** et.
#commission #whether #finance
The letters, published Sep. 2, cover three separate rulemaking areas: perpetual futures product definitions, portfolio margining, and market data reporting.
Each letter addresses a different rule, but the underlying argument is the same across all three: regulators should judge whether a system works, not whether it looks like the one it's replacing.
Related: Cathie Wood buys millions in popular crypto stock on Chelsea FC deal
Perpetual futures, or "perps," are contracts that let traders bet on an ***** et's price without the contract ever expiring. Traditional futures use expiration dates to force prices to converge with the underlying ***** et.
#commission #whether #finance

16 days ago
Financial regulators warn about nearly everything. That is the job.
Most of those warnings sound alike after a while, which is why the useful signal is rarely the warning itself.
It is the ranking.
Twice a year, ahead of the G20 finance ministers and central bank governors' meetings, the Financial Stability Board sends a letter laying out what is most likely to break next in the global financial system.
Those letters tend to open with the same cast of characters. Sovereign debt markets. Private credit. ***** et valuations that have run ahead of themselves. Borrowed money sitting somewhere ***** ody has checked recently.
#twice #stability
Most of those warnings sound alike after a while, which is why the useful signal is rarely the warning itself.
It is the ranking.
Twice a year, ahead of the G20 finance ministers and central bank governors' meetings, the Financial Stability Board sends a letter laying out what is most likely to break next in the global financial system.
Those letters tend to open with the same cast of characters. Sovereign debt markets. Private credit. ***** et valuations that have run ahead of themselves. Borrowed money sitting somewhere ***** ody has checked recently.
#twice #stability

16 days ago
By Nupur Anand
NEW YORK, Sept 2 (Reuters) - A Democratic U.S. senator has pressed Capital One Financial for details about an internal anti-money laundering review that the bank said last month led it to close accounts linked to President Donald Trump and his businesses.
In a letter sent to Capital One CEO Richard Fairbank on Tuesday evening and first reported by Reuters, Senator Maggie Hassan, a New Hampshire Democrat, asked for documents describing the transactions, alerts and other factors that prompted the review, as well as any communications with law enforcement or regulators related to the matter.
"The American people deserve to know," wrote Hassan, the top Democrat on the Joint Economic Committee.
Capital One declined to comment.
#reuters #democrat #anand #york
NEW YORK, Sept 2 (Reuters) - A Democratic U.S. senator has pressed Capital One Financial for details about an internal anti-money laundering review that the bank said last month led it to close accounts linked to President Donald Trump and his businesses.
In a letter sent to Capital One CEO Richard Fairbank on Tuesday evening and first reported by Reuters, Senator Maggie Hassan, a New Hampshire Democrat, asked for documents describing the transactions, alerts and other factors that prompted the review, as well as any communications with law enforcement or regulators related to the matter.
"The American people deserve to know," wrote Hassan, the top Democrat on the Joint Economic Committee.
Capital One declined to comment.
#reuters #democrat #anand #york

16 days ago
By Nupur Anand
NEW YORK, Sept 2 (Reuters) - A Democratic U.S. senator has pressed Capital One Financial for details about an internal anti-money laundering review that the bank said last month led it to close accounts linked to President Donald Trump and his businesses.
In a letter sent to Capital One CEO Richard Fairbank on Tuesday evening and first reported by Reuters, Senator Maggie Hassan, a New Hampshire Democrat, asked for documents describing the transactions, alerts and other factors that prompted the review, as well as any communications with law enforcement or regulators related to the matter.
"The American people deserve to know," wrote Hassan, the top Democrat on the Joint Economic Committee.
Capital One declined to comment.
#capital #nupur #sept
NEW YORK, Sept 2 (Reuters) - A Democratic U.S. senator has pressed Capital One Financial for details about an internal anti-money laundering review that the bank said last month led it to close accounts linked to President Donald Trump and his businesses.
In a letter sent to Capital One CEO Richard Fairbank on Tuesday evening and first reported by Reuters, Senator Maggie Hassan, a New Hampshire Democrat, asked for documents describing the transactions, alerts and other factors that prompted the review, as well as any communications with law enforcement or regulators related to the matter.
"The American people deserve to know," wrote Hassan, the top Democrat on the Joint Economic Committee.
Capital One declined to comment.
#capital #nupur #sept


17 days ago
On August 12, Royalty Pharma (NASDAQ:RPRX) agreed to pay Zealand Pharma $100 million for the rights to future royalties on rusfertide, an experimental treatment for a rare blood disorder called polycythemia vera. It is Royalty Pharma's second collaboration with Zealand, and it arrives just as rusfertide awaits a decision from the FDA. For a company that makes its living buying pieces of other companies' drugs, the timing says a lot about how it weighs risk against reward before a regulatory verdict even lands.
Royalty Pharma's business depends on picking the right moment to buy into a drug's future, and this deal fits that pattern. Under the agreement, $50 million changes hands at closing and the remaining $50 million arrives on the first anniversary, in exchange for a 1% royalty on rusfertide's global sales plus any regulatory and commercial milestones. Rusfertide, a once-weekly self-injected therapy that mimics the hormone hepcidin to control iron levels in polycythemia vera patients, already has an FDA goal date set for the third quarter of 2026, with Takeda lined up to handle commercialization worldwide. That is a near-term catalyst most royalty purchases do not carry.
The broader portfolio backs up the confidence. Royalty Receipts grew 14% to $768 million in the second quarter of 2026, lifted by Tremfya, Voranigo, Imdelltra and Evrysdi, and the company raised its full-year 2026 guidance for Portfolio Receipts to a range of $3.4 billion to $3.5 billion, the second increase this year. Capital deployment has already topped $1 billion in 2026, including a July 2026 royalty purchase tied to AstraZeneca's cliramitug, pushing the development-stage pipeline to 19 potential therapies. Even after repaying a $380 million term loan in July 2026, Royalty Pharma still paid a quarterly dividend of $0.235 per share and bought back $45 million of stock in the second quarter alone.
Not every royalty ages well, and Royalty Pharma's own numbers show it. Promacta royalties fell 75% in the second quarter of 2026 to just $8 million as US generic competition took hold, and Imbruvica payments slipped 16% to $36 million, a reminder that patent cliffs eventually catch up to even the steadiest cash flows. That same risk sits underneath every new deal the company signs, including the one with Zealand.
The rusfertide agreement carries its own strings. Royalty Pharma's 1% royalty stops scaling once global sales pass $1.5 billion, at which point Zealand keeps a 0.25% cut and Royalty Pharma only 0.75%, so the largest commercial outcomes get split rather than fully captured. And rusfertide still has not cleared the FDA. The agency's goal date only falls in the third quarter of 2026, meaning the second $50 million payment is committed before regulators finish their review. Layer that onto a balance sheet carrying $9.2 billion in total debt principal against $812 million of cash as of June 30, 2026, and it becomes clear this is a company funding new bets with borrowed as w
Royalty Pharma's business depends on picking the right moment to buy into a drug's future, and this deal fits that pattern. Under the agreement, $50 million changes hands at closing and the remaining $50 million arrives on the first anniversary, in exchange for a 1% royalty on rusfertide's global sales plus any regulatory and commercial milestones. Rusfertide, a once-weekly self-injected therapy that mimics the hormone hepcidin to control iron levels in polycythemia vera patients, already has an FDA goal date set for the third quarter of 2026, with Takeda lined up to handle commercialization worldwide. That is a near-term catalyst most royalty purchases do not carry.
The broader portfolio backs up the confidence. Royalty Receipts grew 14% to $768 million in the second quarter of 2026, lifted by Tremfya, Voranigo, Imdelltra and Evrysdi, and the company raised its full-year 2026 guidance for Portfolio Receipts to a range of $3.4 billion to $3.5 billion, the second increase this year. Capital deployment has already topped $1 billion in 2026, including a July 2026 royalty purchase tied to AstraZeneca's cliramitug, pushing the development-stage pipeline to 19 potential therapies. Even after repaying a $380 million term loan in July 2026, Royalty Pharma still paid a quarterly dividend of $0.235 per share and bought back $45 million of stock in the second quarter alone.
Not every royalty ages well, and Royalty Pharma's own numbers show it. Promacta royalties fell 75% in the second quarter of 2026 to just $8 million as US generic competition took hold, and Imbruvica payments slipped 16% to $36 million, a reminder that patent cliffs eventually catch up to even the steadiest cash flows. That same risk sits underneath every new deal the company signs, including the one with Zealand.
The rusfertide agreement carries its own strings. Royalty Pharma's 1% royalty stops scaling once global sales pass $1.5 billion, at which point Zealand keeps a 0.25% cut and Royalty Pharma only 0.75%, so the largest commercial outcomes get split rather than fully captured. And rusfertide still has not cleared the FDA. The agency's goal date only falls in the third quarter of 2026, meaning the second $50 million payment is committed before regulators finish their review. Layer that onto a balance sheet carrying $9.2 billion in total debt principal against $812 million of cash as of June 30, 2026, and it becomes clear this is a company funding new bets with borrowed as w

18 days ago
Tiger Global Management made a dramatic-looking second-quarter rotation within AI. Its August 14 filing showed the fund cutting Alphabet Inc. (NASDAQ:GOOGL) by 45.4%, from 10.63 million shares to 5.81 million, while opening a position in Advanced Micro Devices, Inc. (NASDAQ:AMD). The trade shifts some exposure from a giant platform funding AI infrastructure to a chip supplier seeking share within it. Yet Alphabet remained a large holding, so this is better understood as rebalancing than abandonment.
A financial ****** yst presenting a chart of insurance solutions to a boardroom.
Alphabet Inc. (NASDAQ:GOOGL) still has a formidable bull case. Google Cloud grew 82%, and the company can distribute AI across search, advertising, productivity software, and enterprise services. Its models, custom chips, data, and global user base create several paths to returns. The bear case is the cost and uncertainty of defending those businesses. Capital spending is surging while AI answers may alter search economics and regulators challenge the platform's advantages.
Advanced Micro Devices, Inc. (NASDAQ:AMD) provides a more focused route to the same demand. Its second-quarter revenue rose 50%, with data-center revenue up 107%, as Instinct accelerators and EPYC processors gained momentum. If hyperscalers insist on multiple suppliers, AMD can grow faster than total AI spending. It also faces the harder competitive task: Nvidia's software ecosystem remains dominant, and customers developing internal chips can limit the merchant opportunity.
The filing changes the composition of Tiger's reported positions, but it does not disclose why the fund made either move. Alphabet owns demand and distribution but must prove huge investments strengthen its core economics. AMD sells into that investment wave but must win deployments against powerful alternatives. One can benefit from lower chip prices while the other needs sufficient pricing and share. Holding both, even at different weights, captures the expansion while acknowledging that value may migrate across the stack. The next confirmation should come from cloud margins and accelerator deployment growth rather than portfolio symbolism.
#devices #global #made
A financial ****** yst presenting a chart of insurance solutions to a boardroom.
Alphabet Inc. (NASDAQ:GOOGL) still has a formidable bull case. Google Cloud grew 82%, and the company can distribute AI across search, advertising, productivity software, and enterprise services. Its models, custom chips, data, and global user base create several paths to returns. The bear case is the cost and uncertainty of defending those businesses. Capital spending is surging while AI answers may alter search economics and regulators challenge the platform's advantages.
Advanced Micro Devices, Inc. (NASDAQ:AMD) provides a more focused route to the same demand. Its second-quarter revenue rose 50%, with data-center revenue up 107%, as Instinct accelerators and EPYC processors gained momentum. If hyperscalers insist on multiple suppliers, AMD can grow faster than total AI spending. It also faces the harder competitive task: Nvidia's software ecosystem remains dominant, and customers developing internal chips can limit the merchant opportunity.
The filing changes the composition of Tiger's reported positions, but it does not disclose why the fund made either move. Alphabet owns demand and distribution but must prove huge investments strengthen its core economics. AMD sells into that investment wave but must win deployments against powerful alternatives. One can benefit from lower chip prices while the other needs sufficient pricing and share. Holding both, even at different weights, captures the expansion while acknowledging that value may migrate across the stack. The next confirmation should come from cloud margins and accelerator deployment growth rather than portfolio symbolism.
#devices #global #made

18 days ago
IPO Edge hosted a fireside chat on Aug. 26 at Nasdaq MarketSite with Brittany Kaiser, Chief Executive Officer of Alpha Compute Corp. (Nasdaq: ALP). The in-person interview was joined by Editor-in-Chief John Jannarone and they discussed how the company is building the infrastructure AI runs on with a focus on data privacy, and how its vertically integrated business model is boosting compute revenue.
About Brittany Kaiser
Brittany Kaiser is Chief Executive Officer of Alpha Compute Corp. (Nasdaq: ALP), where she leads strategy in confidential computing, data sovereignty, and AI infrastructure. A globally recognized authority on data rights, digital **** ets, and AI governance, she became a leading voice in the modern privacy movement after serving as a whistleblower in the Cambridge **** ytica scandal.
Kaiser is the author of the international bestseller Targeted and the principal subject of the Emmy- and BAFTA-nominated Netflix documentary The Great Hack. She has advised U.S. congressional committees, governments, and regulators on data ownership, digital **** et policy, and responsible AI, and co-authored legislation shaping the digital economy. A serial entrepreneur and advocate, she is also Co-Founder and President of the Own Your Data Foundation and a sought-after keynote speaker worldwide.
About Alpha Compute Corp (Nasdaq: ALP)
Alpha Compute Corp. (Nasdaq: ALP) is a vertically integrated AI infrastructure company specializing in GPU-as-a-service and AI Confidential Compute. Alpha Compute's mission is to support clients, subsidiaries, and partners across critical sectors including: finance, defense, intelligence, and media with the essential framework for any organization requiring secure, confidential computing environments. For more information, please visit: https://www.alphacompute.a...
Alpha Compute Corp is domiciled in the British Virgin Islands with offices in New York, Los Angeles, Miami, Amsterdam and Toronto. Alpha Compute is a founding partner of the Right2Compute Coalition; more information is available at www.right2compute.com.
#compute #alpha #chief #infrastructure
About Brittany Kaiser
Brittany Kaiser is Chief Executive Officer of Alpha Compute Corp. (Nasdaq: ALP), where she leads strategy in confidential computing, data sovereignty, and AI infrastructure. A globally recognized authority on data rights, digital **** ets, and AI governance, she became a leading voice in the modern privacy movement after serving as a whistleblower in the Cambridge **** ytica scandal.
Kaiser is the author of the international bestseller Targeted and the principal subject of the Emmy- and BAFTA-nominated Netflix documentary The Great Hack. She has advised U.S. congressional committees, governments, and regulators on data ownership, digital **** et policy, and responsible AI, and co-authored legislation shaping the digital economy. A serial entrepreneur and advocate, she is also Co-Founder and President of the Own Your Data Foundation and a sought-after keynote speaker worldwide.
About Alpha Compute Corp (Nasdaq: ALP)
Alpha Compute Corp. (Nasdaq: ALP) is a vertically integrated AI infrastructure company specializing in GPU-as-a-service and AI Confidential Compute. Alpha Compute's mission is to support clients, subsidiaries, and partners across critical sectors including: finance, defense, intelligence, and media with the essential framework for any organization requiring secure, confidential computing environments. For more information, please visit: https://www.alphacompute.a...
Alpha Compute Corp is domiciled in the British Virgin Islands with offices in New York, Los Angeles, Miami, Amsterdam and Toronto. Alpha Compute is a founding partner of the Right2Compute Coalition; more information is available at www.right2compute.com.
#compute #alpha #chief #infrastructure
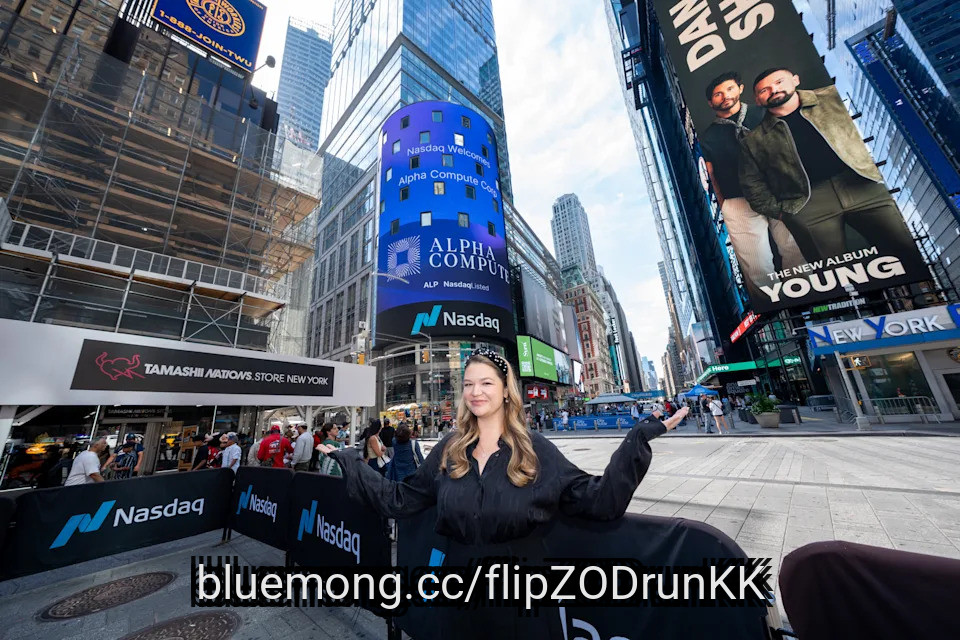

18 days ago
Our **** ysts just identified a stock with the potential to be the next Nvidia. Tell us how you invest and we'll show you why it's our #1 pick. Tap here.
Switzerland wants UBS to be safer after Credit Suisse blew up. UBS says too much safety could make it less competitive. Now lawmakers are trying to mix a regulatory **** tail that protects taxpayers without turning the country's last megabank into a padded cell with a banking license.
Swiss lawmakers are expected to send a softened banking reform proposal to the upper house of parliament, as the country tries to settle one of the biggest questions left by the Credit Suisse collapse: how much capital should UBS be forced to hold?
The Swiss government originally wanted UBS to hold about $20 billion in additional Common Equity Tier 1 capital. CET1 is the hard stuff: high-quality equity capital that absorbs losses first and gives regulators comfort when a bank gets into trouble.
The proposed requirement followed UBS's emergency takeover of Credit Suisse in 2023. That deal stopped one crisis, but created another problem. Switzerland now has one giant globally important bank, and regulators want to make sure taxpayers are not dragged back into another rescue.
#make
Switzerland wants UBS to be safer after Credit Suisse blew up. UBS says too much safety could make it less competitive. Now lawmakers are trying to mix a regulatory **** tail that protects taxpayers without turning the country's last megabank into a padded cell with a banking license.
Swiss lawmakers are expected to send a softened banking reform proposal to the upper house of parliament, as the country tries to settle one of the biggest questions left by the Credit Suisse collapse: how much capital should UBS be forced to hold?
The Swiss government originally wanted UBS to hold about $20 billion in additional Common Equity Tier 1 capital. CET1 is the hard stuff: high-quality equity capital that absorbs losses first and gives regulators comfort when a bank gets into trouble.
The proposed requirement followed UBS's emergency takeover of Credit Suisse in 2023. That deal stopped one crisis, but created another problem. Switzerland now has one giant globally important bank, and regulators want to make sure taxpayers are not dragged back into another rescue.
#make



