

6 days ago
OpenAI launched a product on Thursday called ChatGPT for Financial Services, a version of its enterprise tool tailored to handle tasks traditionally performed by entry-level investment bankers, including company research, financial data ***** ysis, and pitchbook creation.
According to CNBC, the product was developed alongside Morgan Stanley and Evercore as design partners, is built on top of ChatGPT Work, and is powered by GPT-6 Astra, the most capable model in OpenAI's current lineup. It is initially aimed at investment banking and equity research teams.
"We're effectively teaching ChatGPT to research like an ***** yst and back up its conclusions like an ***** yst as well," Nick Turley, OpenAI's vice president of product, told CNBC during a briefing announcing the product.
Unlike the standard ChatGPT Work offering, the financial services version connects directly to data from LSEG, Daloopa, and Pitchbook — giving the system ready access to financial statements and earnings transcripts — and can also tap into a firm's existing data subscriptions automatically, according to CNBC. The product also includes sourcing tools that link figures directly to underlying filings, chart verification functionality, and permission controls designed to safeguard confidential deal information.
In a live demo, Turley walked through the platform's capabilities as it examined a prospective M&A target, drew financial figures from industry-standard data sources, and generated a formatted PowerPoint presentation styled to a bank's existing template, according to CNBC.
#according
According to CNBC, the product was developed alongside Morgan Stanley and Evercore as design partners, is built on top of ChatGPT Work, and is powered by GPT-6 Astra, the most capable model in OpenAI's current lineup. It is initially aimed at investment banking and equity research teams.
"We're effectively teaching ChatGPT to research like an ***** yst and back up its conclusions like an ***** yst as well," Nick Turley, OpenAI's vice president of product, told CNBC during a briefing announcing the product.
Unlike the standard ChatGPT Work offering, the financial services version connects directly to data from LSEG, Daloopa, and Pitchbook — giving the system ready access to financial statements and earnings transcripts — and can also tap into a firm's existing data subscriptions automatically, according to CNBC. The product also includes sourcing tools that link figures directly to underlying filings, chart verification functionality, and permission controls designed to safeguard confidential deal information.
In a live demo, Turley walked through the platform's capabilities as it examined a prospective M&A target, drew financial figures from industry-standard data sources, and generated a formatted PowerPoint presentation styled to a bank's existing template, according to CNBC.
#according

0.00$ raised of 0.00$ goal
0 donations
0.00$
to go

11 days ago
Shares of Apple Inc. (NASDAQ:AAPL) have performed well so far this year. As of September 2, the stock has gained nearly 20% year-to-date, compared with an 11.78% rise in the broader S&P 500 Index. However, **** ysts remain divided on the company's outlook.
App Store Weakness Raises Concerns
On September 2, Evercore ISI reiterated its Outperform rating on the stock with a $365 price target following August App Store revenue data.
App Store revenue fell 1% year-over-year in August, marking the first year-over-year decline since November 2022 and the sixth consecutive month of deceleration. Gaming revenue declined about 10% year-over-year in August after seeing a fall of 8% in July.
U.S. App Store revenue declined for the sixth consecutive month, seeing a 10% year-over-year fall in August. Evercore ISI warned that continued weakness in App Store revenues could make it more difficult for Apple Inc. (NASDAQ:AAPL) to achieve double-digit Services growth. However, the research firm noted that the company has been able to offset softer App Store trends with faster-growing areas of its Services business.
#year #aapl #september #evercore
App Store Weakness Raises Concerns
On September 2, Evercore ISI reiterated its Outperform rating on the stock with a $365 price target following August App Store revenue data.
App Store revenue fell 1% year-over-year in August, marking the first year-over-year decline since November 2022 and the sixth consecutive month of deceleration. Gaming revenue declined about 10% year-over-year in August after seeing a fall of 8% in July.
U.S. App Store revenue declined for the sixth consecutive month, seeing a 10% year-over-year fall in August. Evercore ISI warned that continued weakness in App Store revenues could make it more difficult for Apple Inc. (NASDAQ:AAPL) to achieve double-digit Services growth. However, the research firm noted that the company has been able to offset softer App Store trends with faster-growing areas of its Services business.
#year #aapl #september #evercore

11 days ago
Duolingo shares rose about 7% on September 1 after Evercore ISI upgraded the stock from In Line to Outperform and doubled its price target from $105 to $210. From the prior closing level, the new objective implied roughly 42% upside. The **** yst's central argument was that competitive fears around general-purpose products such as ChatGPT had become exaggerated. Duolingo, Inc. (NASDAQ:DUOL) still owns a habit-forming consumer product, a global brand, and a large base of learners who want structure rather than an open-ended chatbot.
Andrey_Popov/Shutterstock.com
That distinction matters. A language model can explain grammar, simulate conversation, and create personalized exercises, but it does not automatically reproduce Duolingo's streaks, curriculum, social reinforcement, or mobile distribution. Duolingo can also use the same models to create content faster and improve speaking practice. Evercore raised its 2027 and 2028 earnings estimates, suggesting that AI may support engagement and operating leverage instead of simply eroding the moat.
The bear case is not imaginary. Chatbots are improving quickly, and voice interaction makes free-form tutoring more natural. Consumers can divide their time among many inexpensive applications, while Duolingo must keep spending on product development and marketing to remain distinctive. A doubled price target following a major decline may signal that expectations became too low, but it does not prove that competitive pressure has peaked. Valuation can still compress if user growth or bookings slow.
Hedge funds leaned modestly more bullish in Q2. Insider Monkey counted 39 funds holding Duolingo, Inc. (NASDAQ:DUOL), up from 37 in Q1. AQR Capital Management increased its stake more than twentyfold to 2,332,543 shares, one of the quarter's clearest institutional changes. The filing cannot show whether that was a long-term conviction bet, a quantitative signal, or a hedge.
#NASDAQ #duol #hedge #price
Andrey_Popov/Shutterstock.com
That distinction matters. A language model can explain grammar, simulate conversation, and create personalized exercises, but it does not automatically reproduce Duolingo's streaks, curriculum, social reinforcement, or mobile distribution. Duolingo can also use the same models to create content faster and improve speaking practice. Evercore raised its 2027 and 2028 earnings estimates, suggesting that AI may support engagement and operating leverage instead of simply eroding the moat.
The bear case is not imaginary. Chatbots are improving quickly, and voice interaction makes free-form tutoring more natural. Consumers can divide their time among many inexpensive applications, while Duolingo must keep spending on product development and marketing to remain distinctive. A doubled price target following a major decline may signal that expectations became too low, but it does not prove that competitive pressure has peaked. Valuation can still compress if user growth or bookings slow.
Hedge funds leaned modestly more bullish in Q2. Insider Monkey counted 39 funds holding Duolingo, Inc. (NASDAQ:DUOL), up from 37 in Q1. AQR Capital Management increased its stake more than twentyfold to 2,332,543 shares, one of the quarter's clearest institutional changes. The filing cannot show whether that was a long-term conviction bet, a quantitative signal, or a hedge.
#NASDAQ #duol #hedge #price


15 days ago
After a banner second quarter earnings season helped push stocks to new highs this summer, there is a new combination at play that could aid the bull run going into the fall — provided oil prices don't explode above $100 a barrel and a hawkish Fed Chairman Kevin Warsh doesn't begin a rate-hiking cycle.
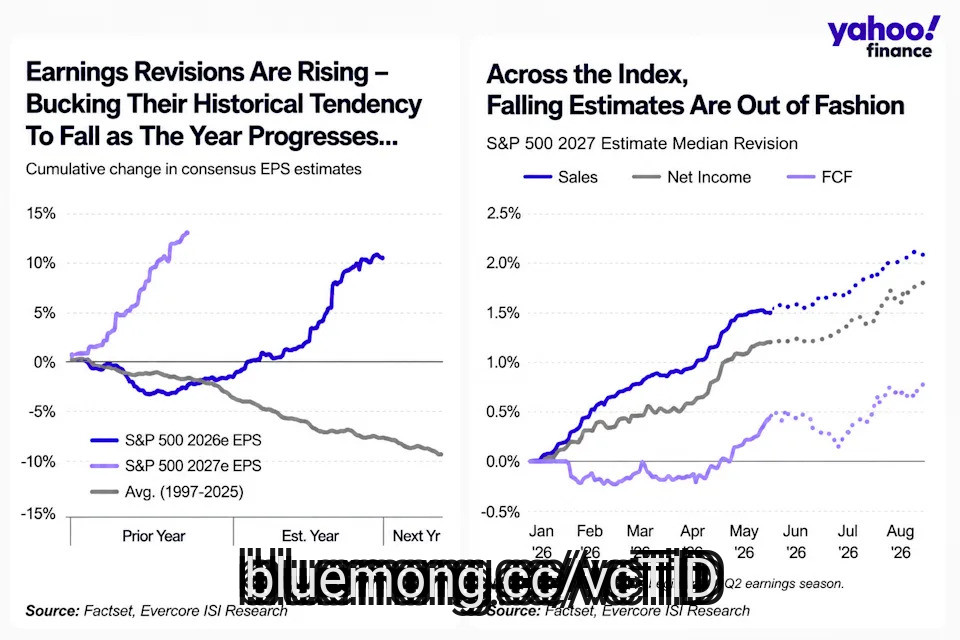
The next stock catalyst is the one-two punch of rising ***** yst profit estimates and fewer estimate cuts.
Earnings are bucking the seasonal revision trend and continuing to inflect upward, Evercore ISI strategist Julian Emanuel pointed out in a new note (see the chart below).
What's more, estimates for the median stock in the S&P 500 (^GSPC) have risen across top-line growth, bottom-line earnings, and free cash flow returns.
"We are living in extraordinary times," Emanuel wrote.
#Stock
The next stock catalyst is the one-two punch of rising ***** yst profit estimates and fewer estimate cuts.
Earnings are bucking the seasonal revision trend and continuing to inflect upward, Evercore ISI strategist Julian Emanuel pointed out in a new note (see the chart below).
What's more, estimates for the median stock in the S&P 500 (^GSPC) have risen across top-line growth, bottom-line earnings, and free cash flow returns.
"We are living in extraordinary times," Emanuel wrote.
#Stock

17 days ago
Revolution Medicines, Inc. (NASDAQ:RVMD) touched an all-time high above $224 on August 27, 2026, following FDA approval of Rasonque (daraxonrasib) – the first broad RAS-targeted therapy cleared for metastatic pancreatic cancer. Creating a milestone, the approval came roughly five weeks after filing under the agency's national priority voucher. The pivotal RASolute 302 trial nearly doubled median overall survival, to 13.2 months from 6.7 on chemotherapy. While the clinical benefit is substantial, a $47 billion valuation suggests the market had already priced in this success.
RVMD carries essentially no product revenue yet. Its price rests entirely on the future. Evercore ISI has raised the next-year sales estimate for Rasonque to ~$2.4 billion. Additionally, the $47 billion valuation discounts much of a long-term pancreatic opportunity which the Evercore **** yst estimates Rasonque could generate about $15.1 billion in pancreatic-cancer sales by 2034. However, a few details complicate this math. First, the approved label applies strictly to second-line or multiagent-ineligible patients. The front-line indication represents the larger market opportunity but remains pending, meaning a notable portion of the TAM is not yet accessible. Second, RVMD's current valuation also sits well above the $28 billion–$32 billion takeover valuation reportedly discussed with Merck earlier this year. Bulls argue lung and colorectal trials justify the $47 billion beyond pancreatic cancer, though that pipeline potential remains unproven.
That matters because Revolution Medicines must now execute its first commercial launch independently in one of oncology's most challenging indications characterized by short survival, high patient frailty, and a U.S. list price of $39,800 for a 30-day supply. Commercialization will require heavy spending. The second-quarter net loss widened to $644 million, and full-year operating expense guidance increased to between $2.1 and $2.2 billion. While a $3.9 billion cash balance and up to $1.5 billion in committed royalty financing fund the launch, operational execution remains the primary risk.
Insiders were net sellers of roughly $21.5 million over the past 90 days with zero buying. Hedge fund data on the stock is flat. As per the Insider Monkey database, 105 funds held RVMD in the second quarter of 2026, modestly down from 106 in the first, indicating strong conviction among institutional investors. Short interest sits near 6% of float, representing a modest level of bets against the stock.
#first
RVMD carries essentially no product revenue yet. Its price rests entirely on the future. Evercore ISI has raised the next-year sales estimate for Rasonque to ~$2.4 billion. Additionally, the $47 billion valuation discounts much of a long-term pancreatic opportunity which the Evercore **** yst estimates Rasonque could generate about $15.1 billion in pancreatic-cancer sales by 2034. However, a few details complicate this math. First, the approved label applies strictly to second-line or multiagent-ineligible patients. The front-line indication represents the larger market opportunity but remains pending, meaning a notable portion of the TAM is not yet accessible. Second, RVMD's current valuation also sits well above the $28 billion–$32 billion takeover valuation reportedly discussed with Merck earlier this year. Bulls argue lung and colorectal trials justify the $47 billion beyond pancreatic cancer, though that pipeline potential remains unproven.
That matters because Revolution Medicines must now execute its first commercial launch independently in one of oncology's most challenging indications characterized by short survival, high patient frailty, and a U.S. list price of $39,800 for a 30-day supply. Commercialization will require heavy spending. The second-quarter net loss widened to $644 million, and full-year operating expense guidance increased to between $2.1 and $2.2 billion. While a $3.9 billion cash balance and up to $1.5 billion in committed royalty financing fund the launch, operational execution remains the primary risk.
Insiders were net sellers of roughly $21.5 million over the past 90 days with zero buying. Hedge fund data on the stock is flat. As per the Insider Monkey database, 105 funds held RVMD in the second quarter of 2026, modestly down from 106 in the first, indicating strong conviction among institutional investors. Short interest sits near 6% of float, representing a modest level of bets against the stock.
#first

19 days ago
Boston Scientific (BSX) stock crumbled Wednesday after the company said a cybersecurity incident interrupted its ability to process and ship customer orders.
The medical devices company said the incident disrupted certain IT systems worldwide. It's working with third-party security experts to contain the threat and restore systems, but didn't offer a timeline for a return to regular operations.
Shares tumbled 3.4%, closing at 48.17. After years 13 years of climbing, Boston Scientific stock began a precipitous decline last December. Shares have lost about 49.5% this year, as of Wednesday's close.
Evercore ISI **** yst Vijay **** ar noted Stryker (SYK) had a cybersecurity incident earlier in the year. It was identified on March 11 and resolved about three weeks later on April 1. The Stryker incident was related to a Microsoft (MSFT) system.
Both companies noted the incidents led to order processing and shipping disruptions.
#scientific #Cybersecurity #systems
The medical devices company said the incident disrupted certain IT systems worldwide. It's working with third-party security experts to contain the threat and restore systems, but didn't offer a timeline for a return to regular operations.
Shares tumbled 3.4%, closing at 48.17. After years 13 years of climbing, Boston Scientific stock began a precipitous decline last December. Shares have lost about 49.5% this year, as of Wednesday's close.
Evercore ISI **** yst Vijay **** ar noted Stryker (SYK) had a cybersecurity incident earlier in the year. It was identified on March 11 and resolved about three weeks later on April 1. The Stryker incident was related to a Microsoft (MSFT) system.
Both companies noted the incidents led to order processing and shipping disruptions.
#scientific #Cybersecurity #systems

20 days ago
Nvidia (NVDA) being more generous with dividends and stock buybacks could be a nice catalyst for the stock, just as it has been for Apple (AAPL).
The AI chip darling returned a record $26 billion to shareholders in its second fiscal quarter, $20 billion through share repurchases and $6 billion by way of a $0.25 a share quarterly dividend. Relative to its plan to return 50% or more of free cash flow to shareholders, Nvidia has returned 60% year to date.
Executives said the company intends to increase capital returns going forward.
"We forecast Nvidia to return $115 billion in cash to shareholders in 2026 and $230b billion in 2027, which we expect will translate to P/E multiple expansion, similar to what happened to Apple in 2015," Evercore ISI ******* yst Mark Lipacis wrote in a note on Thursday.
Lipacis pointed out in the chart below that after five years of compression, Apple's price-to-earnings ratio began expanding with increases in its capital returns program.
#billion #lipacis #returned #cash
The AI chip darling returned a record $26 billion to shareholders in its second fiscal quarter, $20 billion through share repurchases and $6 billion by way of a $0.25 a share quarterly dividend. Relative to its plan to return 50% or more of free cash flow to shareholders, Nvidia has returned 60% year to date.
Executives said the company intends to increase capital returns going forward.
"We forecast Nvidia to return $115 billion in cash to shareholders in 2026 and $230b billion in 2027, which we expect will translate to P/E multiple expansion, similar to what happened to Apple in 2015," Evercore ISI ******* yst Mark Lipacis wrote in a note on Thursday.
Lipacis pointed out in the chart below that after five years of compression, Apple's price-to-earnings ratio began expanding with increases in its capital returns program.
#billion #lipacis #returned #cash



27 days ago
NVDA posted 85% revenue growth and MSFT's Azure crossed $100B annually, but Emanuel says what has peaked is the growth rate itself, not earnings.
Widening investment-grade tech spreads, driven by Microsoft's $175B CapEx and massive AI borrowing, are the clearest signal the buildout is straining balance sheets.
Act now: the ****** yst who called NVIDIA in 2010 just named his top 10 AI stocks — and Microsoft didn't make the cut. Grab the names FREE today.
Julian Emanuel, Evercore ISI's chief equity derivatives and quantitative strategist, said on CNBC this week that megacap tech results this quarter were "breathtaking" and then said, "the other side of breathtaking is it is likely to be as good as it gets." In the same breath, he told viewers to stay long on technology into 2027.
The tension resolves once you separate two ideas that usually get mashed together. Peak growth rate refers to the second derivative, meaning the rate of improvement.
#rate #Tech #azure #widening
Widening investment-grade tech spreads, driven by Microsoft's $175B CapEx and massive AI borrowing, are the clearest signal the buildout is straining balance sheets.
Act now: the ****** yst who called NVIDIA in 2010 just named his top 10 AI stocks — and Microsoft didn't make the cut. Grab the names FREE today.
Julian Emanuel, Evercore ISI's chief equity derivatives and quantitative strategist, said on CNBC this week that megacap tech results this quarter were "breathtaking" and then said, "the other side of breathtaking is it is likely to be as good as it gets." In the same breath, he told viewers to stay long on technology into 2027.
The tension resolves once you separate two ideas that usually get mashed together. Peak growth rate refers to the second derivative, meaning the rate of improvement.
#rate #Tech #azure #widening


1 month ago
Jenna O'Malley/PitchBook News
In the first half of 2026, a record number of private equity managers used continuation funds to return cash to their investors without having to sell companies. They also moved to capture a bigger slice of returns when that sale eventually comes.
By dollar volume, around 35% of continuation funds closing in the first six months of the year had premium economics, colloquially known as super carry, baked into their fund documents, according to investment bank Evercore. This compares with 15% in the bank's full-year 2025 survey.
While there is no single definition of what constitutes super carry, Evercore, the most active broker of continuation fund deals, defines it as terms that allow a fund manager to claim more than 20% of the profit generated by a deal.
The highest level of carry observed in a 2025 study of continuation funds by law firm Morgan Lewis was 30%. The firm, which often represents institutional investors in secondary deals, also noted that three-quarters of continuation funds had tiered carry structures. For example, in the case of a fund employing super carry, a 2x return might net the manager a 20% profit share, with a 3x return bringing it 30%.
#continuation #carry #funds
In the first half of 2026, a record number of private equity managers used continuation funds to return cash to their investors without having to sell companies. They also moved to capture a bigger slice of returns when that sale eventually comes.
By dollar volume, around 35% of continuation funds closing in the first six months of the year had premium economics, colloquially known as super carry, baked into their fund documents, according to investment bank Evercore. This compares with 15% in the bank's full-year 2025 survey.
While there is no single definition of what constitutes super carry, Evercore, the most active broker of continuation fund deals, defines it as terms that allow a fund manager to claim more than 20% of the profit generated by a deal.
The highest level of carry observed in a 2025 study of continuation funds by law firm Morgan Lewis was 30%. The firm, which often represents institutional investors in secondary deals, also noted that three-quarters of continuation funds had tiered carry structures. For example, in the case of a fund employing super carry, a 2x return might net the manager a 20% profit share, with a 3x return bringing it 30%.
#continuation #carry #funds


1 month ago
Roger Altman of Evercore (EVR) argues the S&P 500, up 10% year to date and 18% over 12 months, is shrugging off every macro headwind.
Goldman Sachs (GS) flags hyperscaler capex has consumed roughly 95% of operating cash flows, with projected AI spending reaching $2.1 trillion through 2027.
Record corporate profits of $4,427 billion in Q1 2026, up 13% year over year, powered 86% of S&P 500 companies to beat consensus estimates.
Act now: the **** yst who called NVIDIA in 2010 just named his top 10 AI stocks — and Evercore didn't make the cut. Grab the names FREE today.
Roger Altman, founder and senior chairman of Evercore (NYSE:EVR), made an appearance on CNBC on August 3 to argue that the stock market is absorbing every macro punch thrown at it.
#altman #every #Macro #sachs
Goldman Sachs (GS) flags hyperscaler capex has consumed roughly 95% of operating cash flows, with projected AI spending reaching $2.1 trillion through 2027.
Record corporate profits of $4,427 billion in Q1 2026, up 13% year over year, powered 86% of S&P 500 companies to beat consensus estimates.
Act now: the **** yst who called NVIDIA in 2010 just named his top 10 AI stocks — and Evercore didn't make the cut. Grab the names FREE today.
Roger Altman, founder and senior chairman of Evercore (NYSE:EVR), made an appearance on CNBC on August 3 to argue that the stock market is absorbing every macro punch thrown at it.
#altman #every #Macro #sachs

2 months ago
Alphabet (GOOG, GOOGL) earnings out later today will likely mark a moment of truth for tech investors.
That is, whether to stick with a renewed "Magnificent Seven" bull trade or buy the steep sell-off in semiconductor stocks and perhaps load back up on both by the year's end.
Quick insight: Over the past month, the performance gap between semiconductor stocks and Magnificent Seven stocks has expanded, as seen in the Yahoo Finance AlphaSpace chart below.
The Magnificent Seven comprises Apple (AAPL), Alphabet, Microsoft (MSFT), Amazon (AMZN), Meta (META), Tesla (TSLA), and Nvidia (NVDA).
The divergence reflects investor indecision on whether the previously virtuous circular relationship between chips and hyperscaler capex is sustainable, given that hyperscaler forward free cash flow is likely to turn negative in this quarter, Evercore ISI strategist Julian Emanuel explained in a new note on Wednesday.
#semiconductor
That is, whether to stick with a renewed "Magnificent Seven" bull trade or buy the steep sell-off in semiconductor stocks and perhaps load back up on both by the year's end.
Quick insight: Over the past month, the performance gap between semiconductor stocks and Magnificent Seven stocks has expanded, as seen in the Yahoo Finance AlphaSpace chart below.
The Magnificent Seven comprises Apple (AAPL), Alphabet, Microsoft (MSFT), Amazon (AMZN), Meta (META), Tesla (TSLA), and Nvidia (NVDA).
The divergence reflects investor indecision on whether the previously virtuous circular relationship between chips and hyperscaler capex is sustainable, given that hyperscaler forward free cash flow is likely to turn negative in this quarter, Evercore ISI strategist Julian Emanuel explained in a new note on Wednesday.
#semiconductor


2 months ago
Single-asset continuation funds carried secondary deal volume to a first-half record in 2026, according to one of the most active intermediaries in the ***** e.
The total surpassed $120 billion in the first six months of the year, a 20% jump over H1 2025, the previous record, according to Evercore.
GP-led transactions, which are centered on one or a small number of companies, accounted for 53.7% of deal volume as sponsors turned to the vehicles to generate distributions for investors and get more time to hold onto "trophy" ***** ets.
That's a switch-up from years prior, when LP-led transactions accounted for the largest share of deal volume, driven by favorable pricing and muted distributions, per Evercore's data. Such deals involve acquiring stakes in private funds, typically offloaded by institutional investors.
In H1 2026, single ***** et continuation vehicles accounted for $34 billion of deal value, representing over half of the GP-led volume in the period. Evercore attributed this to sponsors wanting to extend ownership of their highest-conviction ***** ets.
#volume
The total surpassed $120 billion in the first six months of the year, a 20% jump over H1 2025, the previous record, according to Evercore.
GP-led transactions, which are centered on one or a small number of companies, accounted for 53.7% of deal volume as sponsors turned to the vehicles to generate distributions for investors and get more time to hold onto "trophy" ***** ets.
That's a switch-up from years prior, when LP-led transactions accounted for the largest share of deal volume, driven by favorable pricing and muted distributions, per Evercore's data. Such deals involve acquiring stakes in private funds, typically offloaded by institutional investors.
In H1 2026, single ***** et continuation vehicles accounted for $34 billion of deal value, representing over half of the GP-led volume in the period. Evercore attributed this to sponsors wanting to extend ownership of their highest-conviction ***** ets.
#volume


2 months ago
Wall Street staged a comeback as dip buyers emerged, lifting stocks amid rally in chipmakers on bets the artificial-intelligence trade that's powered the bull market has more room to run.Julian Emanuel, Chief Equity & Quantitative Strategist at Evercore ISI, joins to talk tech volatility, the intact bull market, and earnings season.
#Equity
#Equity


2 months ago
Intuitive Surgical, Inc. (NASDAQ:ISRG) is one of the 8 Worst Blue Chip Stocks to Buy Now.
On July 9, 2026, BMO Capital ****** yst Vik Chopra initiated coverage of Intuitive Surgical, Inc. (NASDAQ:ISRG) with an Outperform rating and $518 price target. Chopra said the da Vinci 5 upgrade cycle remains in the early innings, procedure growth is broadening into new specialties and geographies, and the earnings stream is "durable and visible."
On July 6, Evercore ISI lowered the firm's price target on Intuitive Surgical to $430 from $480 and kept an In Line rating on the shares. Evercore ISI said its Q2 preview for MedTech, Life Sciences Tools, and Diagnostics highlights generally healthy procedure volumes and capital expenditure trends across the sector.
Last month, BofA ****** yst Travis Steed lowered the firm's price target on Intuitive Surgical to $515 from $520 and kept a Buy rating on the shares. Steed noted that BofA's services team continues to highlight a lower utilization environment and took a more conservative view on 2027 medtech company estimates, given that valuations already reflect utilization risk. Steed also ****** umed inflation will be more of a headwind in 2027, with less margin expansion for medtech, and lowered 2027 estimates across the firm's larger-cap coverage with exposure to utilization and inflation.
Intuitive Surgical, Inc. (NASDAQ:ISRG) develops, manufactures, and markets products that enable physicians and healthcare providers to enhance the quality of and access to minimally invasive care in the United States and internationally.
On July 9, 2026, BMO Capital ****** yst Vik Chopra initiated coverage of Intuitive Surgical, Inc. (NASDAQ:ISRG) with an Outperform rating and $518 price target. Chopra said the da Vinci 5 upgrade cycle remains in the early innings, procedure growth is broadening into new specialties and geographies, and the earnings stream is "durable and visible."
On July 6, Evercore ISI lowered the firm's price target on Intuitive Surgical to $430 from $480 and kept an In Line rating on the shares. Evercore ISI said its Q2 preview for MedTech, Life Sciences Tools, and Diagnostics highlights generally healthy procedure volumes and capital expenditure trends across the sector.
Last month, BofA ****** yst Travis Steed lowered the firm's price target on Intuitive Surgical to $515 from $520 and kept a Buy rating on the shares. Steed noted that BofA's services team continues to highlight a lower utilization environment and took a more conservative view on 2027 medtech company estimates, given that valuations already reflect utilization risk. Steed also ****** umed inflation will be more of a headwind in 2027, with less margin expansion for medtech, and lowered 2027 estimates across the firm's larger-cap coverage with exposure to utilization and inflation.
Intuitive Surgical, Inc. (NASDAQ:ISRG) develops, manufactures, and markets products that enable physicians and healthcare providers to enhance the quality of and access to minimally invasive care in the United States and internationally.


2 months ago
Abbott Laboratories (NYSE:ABT) is one of the Best Monopoly Stocks to Buy According to Hedge Funds. On June 30, Baird initiated coverage on the company's stock with an "Outperform" rating, setting a price objective of $121.00. The firm sees Abbott Laboratories (NYSE:ABT)'s portfolio as delivering steady top-line and earnings growth over the upcoming several years. As per the firm, the company's medical device segment is expected to see an above-peer growth trajectory.
The company's diagnostics, nutrition, and established pharmaceutical offerings enhance Abbott Laboratories (NYSE:ABT)'s reach throughout the healthcare spectrum. As per the firm, there is a clearer path to upside in FY 2027 and FY 2028, with new products and indication opportunities layering in, and Exact Sciences integration and synergies contributing to the results.
In a different update, Evercore ISI **** yst Vijay **** ar reduced the firm's price objective on Abbott Laboratories (NYSE:ABT)'s stock to $112 from $120 and maintained an "Outperform" rating. The firm's Q2 preview for MedTech, Life Sciences Tools, and Diagnostics demonstrates healthy procedure volumes as well as capex trends throughout the sector.
Abbott Laboratories (NYSE:ABT) is engaged in discovering, developing, manufacturing, and selling health care products.
While we acknowledge the potential of ABT as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
The company's diagnostics, nutrition, and established pharmaceutical offerings enhance Abbott Laboratories (NYSE:ABT)'s reach throughout the healthcare spectrum. As per the firm, there is a clearer path to upside in FY 2027 and FY 2028, with new products and indication opportunities layering in, and Exact Sciences integration and synergies contributing to the results.
In a different update, Evercore ISI **** yst Vijay **** ar reduced the firm's price objective on Abbott Laboratories (NYSE:ABT)'s stock to $112 from $120 and maintained an "Outperform" rating. The firm's Q2 preview for MedTech, Life Sciences Tools, and Diagnostics demonstrates healthy procedure volumes as well as capex trends throughout the sector.
Abbott Laboratories (NYSE:ABT) is engaged in discovering, developing, manufacturing, and selling health care products.
While we acknowledge the potential of ABT as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.


2 months ago
Apple Inc. (NASDAQ:AAPL) is one of the 10 Best Stocks to Buy in 2026 According to Billionaire D.E. Shaw.
Consumer electronics giant Apple Inc. (NASDAQ:AAPL)'s shares are up by 48.9% over the past year and by 16,9% year-to-date. Evercore ISI discussed the firm on June 25th, as it kept a $365 share price target and an Overweight rating on the stock. The coverage came after Apple Inc. (NASDAQ:AAPL) made a major announcement due to the ongoing historic shortages in the memory market. This announcement saw the firm increase its product prices across the board due to the pricey memory chips. Everocre remarked that the price hikes showed that even Apple Inc. (NASDAQ:AAPL), despite its heft, was not immune to component pricing pressures.
Giuseppe Costantino/Shutterstock.com
A few days earlier, on June 22nd, KGI Securities had downgraded the shares. It had cut the rating to Hold from Outperform and kept a $315 share price target. More recently, Apple Inc. (NASDAQ:AAPL) has been in the news due to a historic leak of details about its iPhone 18. The upcoming smartphone's pictures, supplier list and other details were leaked after India's Tata Electronics was targeted by a cyberattack.
While we acknowledge the risk and potential of AAPL as an investment, our conviction lies in the belief that some AI stocks hold greater promise for delivering higher returns and doing so within a shorter time frame. If you are looking for an AI stock that is more promising than AAPL and that has 10,000% upside potential, check out our report about the cheapest AI stock.
Consumer electronics giant Apple Inc. (NASDAQ:AAPL)'s shares are up by 48.9% over the past year and by 16,9% year-to-date. Evercore ISI discussed the firm on June 25th, as it kept a $365 share price target and an Overweight rating on the stock. The coverage came after Apple Inc. (NASDAQ:AAPL) made a major announcement due to the ongoing historic shortages in the memory market. This announcement saw the firm increase its product prices across the board due to the pricey memory chips. Everocre remarked that the price hikes showed that even Apple Inc. (NASDAQ:AAPL), despite its heft, was not immune to component pricing pressures.
Giuseppe Costantino/Shutterstock.com
A few days earlier, on June 22nd, KGI Securities had downgraded the shares. It had cut the rating to Hold from Outperform and kept a $315 share price target. More recently, Apple Inc. (NASDAQ:AAPL) has been in the news due to a historic leak of details about its iPhone 18. The upcoming smartphone's pictures, supplier list and other details were leaked after India's Tata Electronics was targeted by a cyberattack.
While we acknowledge the risk and potential of AAPL as an investment, our conviction lies in the belief that some AI stocks hold greater promise for delivering higher returns and doing so within a shorter time frame. If you are looking for an AI stock that is more promising than AAPL and that has 10,000% upside potential, check out our report about the cheapest AI stock.

2 months ago
Credo Technology Group Holding Ltd (NASDAQ:CRDO) is one of the best performing AI stocks over the last 3 years, with a 3Y CAGR of 153%. On July 6, William Blair **** yst Sebastien Naji named Credo his top semiconductor pick for the next six months. That followed several constructive June calls. Evercore ISI **** yst Mark Lipacis initiated coverage on June 22 with an Outperform rating and a $325 target, describing Credo as an AI-connectivity leader moving from a mainly copper portfolio toward a combined copper-and-optical offering.
The same day, Stifel **** yst Tore Svanberg maintained a Buy rating and raised his target to $350 from $250 after management meetings, citing the company's vertically integrated, system-level approach across both technologies. Bank of America kept Buy on June 26. The common thread is that larger AI clusters require more high-speed, energy-efficient connections. Credo's active electrical cables, digital signal processors and optical products address that need. Risks include customer concentration, rapid interface transitions, and expectations that already **** ume substantial growth.
Credo Technology Group Holding Ltd (NASDAQ:CRDO) provides high-speed connectivity solutions, including active electrical cables, digital signal processors, retimers, SerDes chiplets, and optical components for hyperscale, cloud, and AI networks.
While we acknowledge the potential of CRDO as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
READ NEXT: 33 Stocks That Should Double in 3 Years and Cathie Wood 2026 Portfolio: 10 Best Stocks to Buy.
The same day, Stifel **** yst Tore Svanberg maintained a Buy rating and raised his target to $350 from $250 after management meetings, citing the company's vertically integrated, system-level approach across both technologies. Bank of America kept Buy on June 26. The common thread is that larger AI clusters require more high-speed, energy-efficient connections. Credo's active electrical cables, digital signal processors and optical products address that need. Risks include customer concentration, rapid interface transitions, and expectations that already **** ume substantial growth.
Credo Technology Group Holding Ltd (NASDAQ:CRDO) provides high-speed connectivity solutions, including active electrical cables, digital signal processors, retimers, SerDes chiplets, and optical components for hyperscale, cloud, and AI networks.
While we acknowledge the potential of CRDO as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
READ NEXT: 33 Stocks That Should Double in 3 Years and Cathie Wood 2026 Portfolio: 10 Best Stocks to Buy.

2 months ago
Twist Bioscience Corporation (NASDAQ:TWST) is one of the 10 Best Performing American Stocks in June 2026.
On July 6, 2026, Evercore ISI downgraded Twist Bioscience Corporation (NASDAQ:TWST) to In Line from Outperform with a price target of $102, up from $66. Evercore ISI said Twist has been one of the best performers in life science tools, up more than 200% year-to-date, with most of the move, or 85%, coming since its May 21 ***** yst day on optimism around AI-driven order momentum. The firm said it is taking some profits after the rally.
On June 29, Guggenheim raised the firm's price target on Twist Bioscience to $107 from $60 and kept a Buy rating on the shares. Guggenheim adjusted models and forecasts for select companies in its diagnostics and life sciences tools coverage after meetings with management teams.
Pixabay/Public Domain
On June 24, Barclays ***** yst Luke Sergott raised the firm's price target on Twist Bioscience to $95 from $65 and kept an Overweight rating on the shares. Sergott adjusted targets in the life science and diagnostic tools ***** e as part of a Q2 preview, noting that tools are "gaining favor among healthcare subsectors." Barclays expects in-line to modest beats in Q2 for the group.
On July 6, 2026, Evercore ISI downgraded Twist Bioscience Corporation (NASDAQ:TWST) to In Line from Outperform with a price target of $102, up from $66. Evercore ISI said Twist has been one of the best performers in life science tools, up more than 200% year-to-date, with most of the move, or 85%, coming since its May 21 ***** yst day on optimism around AI-driven order momentum. The firm said it is taking some profits after the rally.
On June 29, Guggenheim raised the firm's price target on Twist Bioscience to $107 from $60 and kept a Buy rating on the shares. Guggenheim adjusted models and forecasts for select companies in its diagnostics and life sciences tools coverage after meetings with management teams.
Pixabay/Public Domain
On June 24, Barclays ***** yst Luke Sergott raised the firm's price target on Twist Bioscience to $95 from $65 and kept an Overweight rating on the shares. Sergott adjusted targets in the life science and diagnostic tools ***** e as part of a Q2 preview, noting that tools are "gaining favor among healthcare subsectors." Barclays expects in-line to modest beats in Q2 for the group.


2 months ago
Fiserv (FISV) stock rose Tuesday on a report that the financial services company could sell its debit card payment processing network to a group of banks.
The banks interested in acquiring Fiserv's debit network include JPMorgan Chase (JPM), Bank of America (BAC), Wells Fargo (WFC) and PNC Financial Services Group (PNC), the Wall Street Journal reported.
At William Blair, ***** yst Andrew Jeffrey said a deal is unlikely. "A deal seems unlikely given regulatory and likely large merchant pushback," he said in a report. "We also note that by aiding large banks, Fiserv could alienate its community bank and credit union customer base, beneficiaries of Durbin debit regulations."
Fiserv provides payments and financial technology for banking and commerce, billing and point-of-sale transactions. The chief executive of Fiserv, Mike Lyons, recently resigned, sparking a sell-off. Takis Georgakopoulos, who had served as chief operating officer and copresident, was named CEO.
At Evercore ISI, ***** yst Adam Frisch also doubts a debit network deal will get done with the banks.
The banks interested in acquiring Fiserv's debit network include JPMorgan Chase (JPM), Bank of America (BAC), Wells Fargo (WFC) and PNC Financial Services Group (PNC), the Wall Street Journal reported.
At William Blair, ***** yst Andrew Jeffrey said a deal is unlikely. "A deal seems unlikely given regulatory and likely large merchant pushback," he said in a report. "We also note that by aiding large banks, Fiserv could alienate its community bank and credit union customer base, beneficiaries of Durbin debit regulations."
Fiserv provides payments and financial technology for banking and commerce, billing and point-of-sale transactions. The chief executive of Fiserv, Mike Lyons, recently resigned, sparking a sell-off. Takis Georgakopoulos, who had served as chief operating officer and copresident, was named CEO.
At Evercore ISI, ***** yst Adam Frisch also doubts a debit network deal will get done with the banks.


2 months ago
Apple Inc. (NASDAQ:AAPL) is one of the Best AI and Technology Stocks to Buy Now. On June 25, Evercore ISI maintained an "Outperform" rating on the company's stock with a price objective of $365. This comes after the company announced price increases throughout select Mac, iPad, and home devices. Apple Inc. (NASDAQ:AAPL) increased the prices across the product lineup, with these increases ranging between 17% to 25% on base-model Mac as well as iPad configurations.
The decision comes after the recent comments from its CEO regarding the memory supply constraints. It seems that the price hikes are due to the increased memory costs as DRAM and NAND pricing are now multiples higher compared to the previous year and significantly above levels at the beginning of the year when the company refreshed the product lines.
Furthermore, the firm stated that the intra-cycle price hike demonstrates that the magnitude and pace of cost pressure surpassed Apple Inc. (NASDAQ:AAPL)'s capability to absorb it. Even though the price increases are expected to support gross margins, intra-cycle hikes might lead to demand friction throughout Macs and iPads.
Apple Inc. (NASDAQ:AAPL) designs, manufactures, and markets smartphones, personal computers, tablets, wearables, and home accessories.
While we acknowledge the potential of AAPL as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
The decision comes after the recent comments from its CEO regarding the memory supply constraints. It seems that the price hikes are due to the increased memory costs as DRAM and NAND pricing are now multiples higher compared to the previous year and significantly above levels at the beginning of the year when the company refreshed the product lines.
Furthermore, the firm stated that the intra-cycle price hike demonstrates that the magnitude and pace of cost pressure surpassed Apple Inc. (NASDAQ:AAPL)'s capability to absorb it. Even though the price increases are expected to support gross margins, intra-cycle hikes might lead to demand friction throughout Macs and iPads.
Apple Inc. (NASDAQ:AAPL) designs, manufactures, and markets smartphones, personal computers, tablets, wearables, and home accessories.
While we acknowledge the potential of AAPL as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.

3 months ago
AvalonBay Communities, Inc. (NYSE:AVB) is one of the 10 Interest Rate Sensitive Stocks to Buy Now.
On June 16, 2026, Truist raised its price target on AvalonBay Communities, Inc. (NYSE:AVB) to $202 from $201 and kept a Buy rating. Truist adjusted its model with expectations for 1.3% year-over-year same-store revenue growth in 2026 and 3.9% expense growth, resulting in 0.2% same-store net operating income growth. The firm said this is consistent with management's down 0.7% to up 1.3% guidance range.
On June 10, Mizuho raised its price target on AvalonBay to $192 from $189 and kept a Neutral rating. Mizuho adjusted targets in the apartment real estate investment trust group, saying an improved macro backdrop and "supportive" private market data have raised expectations. The firm said Sunbelt names should be near-term relative winners.
On June 8, Evercore ISI raised its price target on AvalonBay Communities, Inc. (NYSE:AVB) to $198 from $191 and kept an In Line rating after the annual NAREIT Conference.
AvalonBay Communities, Inc. (NYSE:AVB) is an equity REIT that develops, redevelops, acquires, and manages communities in leading metropolitan areas.
On June 16, 2026, Truist raised its price target on AvalonBay Communities, Inc. (NYSE:AVB) to $202 from $201 and kept a Buy rating. Truist adjusted its model with expectations for 1.3% year-over-year same-store revenue growth in 2026 and 3.9% expense growth, resulting in 0.2% same-store net operating income growth. The firm said this is consistent with management's down 0.7% to up 1.3% guidance range.
On June 10, Mizuho raised its price target on AvalonBay to $192 from $189 and kept a Neutral rating. Mizuho adjusted targets in the apartment real estate investment trust group, saying an improved macro backdrop and "supportive" private market data have raised expectations. The firm said Sunbelt names should be near-term relative winners.
On June 8, Evercore ISI raised its price target on AvalonBay Communities, Inc. (NYSE:AVB) to $198 from $191 and kept an In Line rating after the annual NAREIT Conference.
AvalonBay Communities, Inc. (NYSE:AVB) is an equity REIT that develops, redevelops, acquires, and manages communities in leading metropolitan areas.

3 months ago
Cousins Properties Incorporated (NYSE:CUZ) is one of the 10 Interest Rate Sensitive Stocks to Buy Now.
On June 26, 2026, Truist ******* yst Michael Lewis raised the firm's price target on Cousins Properties Incorporated (NYSE:CUZ) to $30 from $24 and kept a Hold rating as part of a broader note on Office REITs. Lewis said Truist had been hesitant to become more constructive on the group several months ago, citing lackluster cash flow, weak job growth, private credit concerns, the start of the war in Iran contributing to higher inflation and interest rates, and the threat of AI to office-using employment.
Since then, Truist said job growth has improved a bit, private credit concerns have taken a back seat, and healthy leasing activity has led many investors to shift their view of AI from a job-killer to a driver of additional office leasing in some markets.
Earlier in June, Evercore ISI raised its price target on Cousins Properties Incorporated (NYSE:CUZ) to $30 from $29 previously and kept an Outperform rating on the shares after the annual NAREIT Conference.
Cousins Properties Incorporated (NYSE:CUZ) is a fully integrated, self-administered, and self-managed real estate investment trust.
On June 26, 2026, Truist ******* yst Michael Lewis raised the firm's price target on Cousins Properties Incorporated (NYSE:CUZ) to $30 from $24 and kept a Hold rating as part of a broader note on Office REITs. Lewis said Truist had been hesitant to become more constructive on the group several months ago, citing lackluster cash flow, weak job growth, private credit concerns, the start of the war in Iran contributing to higher inflation and interest rates, and the threat of AI to office-using employment.
Since then, Truist said job growth has improved a bit, private credit concerns have taken a back seat, and healthy leasing activity has led many investors to shift their view of AI from a job-killer to a driver of additional office leasing in some markets.
Earlier in June, Evercore ISI raised its price target on Cousins Properties Incorporated (NYSE:CUZ) to $30 from $29 previously and kept an Outperform rating on the shares after the annual NAREIT Conference.
Cousins Properties Incorporated (NYSE:CUZ) is a fully integrated, self-administered, and self-managed real estate investment trust.


3 months ago
Cousins Properties Incorporated (NYSE:CUZ) is one of the 10 Interest Rate Sensitive Stocks to Buy Now.
On June 26, 2026, Truist ******* yst Michael Lewis raised the firm's price target on Cousins Properties Incorporated (NYSE:CUZ) to $30 from $24 and kept a Hold rating as part of a broader note on Office REITs. Lewis said Truist had been hesitant to become more constructive on the group several months ago, citing lackluster cash flow, weak job growth, private credit concerns, the start of the war in Iran contributing to higher inflation and interest rates, and the threat of AI to office-using employment.
Since then, Truist said job growth has improved a bit, private credit concerns have taken a back seat, and healthy leasing activity has led many investors to shift their view of AI from a job-killer to a driver of additional office leasing in some markets.
Earlier in June, Evercore ISI raised its price target on Cousins Properties Incorporated (NYSE:CUZ) to $30 from $29 previously and kept an Outperform rating on the shares after the annual NAREIT Conference.
Cousins Properties Incorporated (NYSE:CUZ) is a fully integrated, self-administered, and self-managed real estate investment trust.
On June 26, 2026, Truist ******* yst Michael Lewis raised the firm's price target on Cousins Properties Incorporated (NYSE:CUZ) to $30 from $24 and kept a Hold rating as part of a broader note on Office REITs. Lewis said Truist had been hesitant to become more constructive on the group several months ago, citing lackluster cash flow, weak job growth, private credit concerns, the start of the war in Iran contributing to higher inflation and interest rates, and the threat of AI to office-using employment.
Since then, Truist said job growth has improved a bit, private credit concerns have taken a back seat, and healthy leasing activity has led many investors to shift their view of AI from a job-killer to a driver of additional office leasing in some markets.
Earlier in June, Evercore ISI raised its price target on Cousins Properties Incorporated (NYSE:CUZ) to $30 from $29 previously and kept an Outperform rating on the shares after the annual NAREIT Conference.
Cousins Properties Incorporated (NYSE:CUZ) is a fully integrated, self-administered, and self-managed real estate investment trust.

3 months ago
Fermi Inc. (NASDAQ:FRMI) is one of the 10 Best New Stocks to Buy Other Than ***** eX.
On June 23, 2026, Stifel lowered its price target on Fermi Inc. (NASDAQ:FRMI) to $17 from $29 and kept a Buy rating. Stifel said Fermi has apparently made progress in the background after months of post-IPO uncertainty, but the continued wait for a firm contract with an initial tenant has "clearly delayed the story and rattled our valuation." The firm updated its forecasts and said Fermi remains "a high-risk, high-reward, pre-revenue story."
On June 11, Citizens said The Information's report that OpenAI is in talks to lease a 10-gigawatt data center in Ohio through funding provided by Nvidia bodes well for Fermi. Citizens said the report improves the likelihood of a significant signed lease for Fermi as the company seeks its first lease for its developing 11 GW natural gas-powered complex. Fermi shares were up 13% to $6.35 following Citizens' note.
Pixabay/Public Domain
Last month, Evercore ISI ***** yst Nicholas Amicucci downgraded Fermi to In Line from Outperform with a price target of $11, down from $20. Amicucci said the downgrade is "not a rejection" of the long-term scarcity value of Project Matador or the broader power-demand thesis, but reflects a changed underwriting standard. Amicucci said Fermi 2.0 is "credible evidence" that a reset has begun, but not yet proof that it has worked.
On June 23, 2026, Stifel lowered its price target on Fermi Inc. (NASDAQ:FRMI) to $17 from $29 and kept a Buy rating. Stifel said Fermi has apparently made progress in the background after months of post-IPO uncertainty, but the continued wait for a firm contract with an initial tenant has "clearly delayed the story and rattled our valuation." The firm updated its forecasts and said Fermi remains "a high-risk, high-reward, pre-revenue story."
On June 11, Citizens said The Information's report that OpenAI is in talks to lease a 10-gigawatt data center in Ohio through funding provided by Nvidia bodes well for Fermi. Citizens said the report improves the likelihood of a significant signed lease for Fermi as the company seeks its first lease for its developing 11 GW natural gas-powered complex. Fermi shares were up 13% to $6.35 following Citizens' note.
Pixabay/Public Domain
Last month, Evercore ISI ***** yst Nicholas Amicucci downgraded Fermi to In Line from Outperform with a price target of $11, down from $20. Amicucci said the downgrade is "not a rejection" of the long-term scarcity value of Project Matador or the broader power-demand thesis, but reflects a changed underwriting standard. Amicucci said Fermi 2.0 is "credible evidence" that a reset has begun, but not yet proof that it has worked.

3 months ago
Apple Inc. (NASDAQ:AAPL) is one of the 15 Best AI Stocks That Will Make You Rich in 10 Years.
On June 26, 2026, Bloomberg's Mark Gurman reported that Apple Inc. (NASDAQ:AAPL) is planning a major change to its Mac chip roadmap, citing people with knowledge of the matter. Apple is expected to launch a base M6 chip for entry-level Macs as early as this year while skipping M6 Pro and Max variants. Higher-end performance upgrades are instead expected to be reserved for an AI-focused M7 generation in 2027, with more significant computing and graphics advances. Gurman wrote that the shift should help meet demand for on-device AI capabilities and more graphics-intensive software.
On June 25, Evercore ISI noted that Apple made the "rare move" of raising prices intra-cycle across select Macs, iPads, and home devices. The firm called the hikes "a surprise," saying increases of 17% to 25% across the core Mac and iPad lineup should help protect gross margins but could create demand friction. Evercore ISI maintained an Outperform rating and $365 price target on Apple shares, which were down about 5% to $277.65 in morning trading.
Earlier, Apple confirmed price hikes on several MacBook and iPad products, saying the consumer electronics industry is facing an "unprecedented challenge" as AI data center growth drives higher memory and storage demand. Apple said it had "reached a point" where it needed to raise prices on some products, while noting it is working to find solutions.
Giuseppe Costantino/Shutterstock.com
On June 26, 2026, Bloomberg's Mark Gurman reported that Apple Inc. (NASDAQ:AAPL) is planning a major change to its Mac chip roadmap, citing people with knowledge of the matter. Apple is expected to launch a base M6 chip for entry-level Macs as early as this year while skipping M6 Pro and Max variants. Higher-end performance upgrades are instead expected to be reserved for an AI-focused M7 generation in 2027, with more significant computing and graphics advances. Gurman wrote that the shift should help meet demand for on-device AI capabilities and more graphics-intensive software.
On June 25, Evercore ISI noted that Apple made the "rare move" of raising prices intra-cycle across select Macs, iPads, and home devices. The firm called the hikes "a surprise," saying increases of 17% to 25% across the core Mac and iPad lineup should help protect gross margins but could create demand friction. Evercore ISI maintained an Outperform rating and $365 price target on Apple shares, which were down about 5% to $277.65 in morning trading.
Earlier, Apple confirmed price hikes on several MacBook and iPad products, saying the consumer electronics industry is facing an "unprecedented challenge" as AI data center growth drives higher memory and storage demand. Apple said it had "reached a point" where it needed to raise prices on some products, while noting it is working to find solutions.
Giuseppe Costantino/Shutterstock.com


3 months ago
Credo Technology Group Holding Ltd (NASDAQ:CRDO) is one of the top trending US stocks to buy now. Stifel lifted the price target on Credo Technology Group Holding Ltd (NASDAQ:CRDO) to $350 from $250 on June 22 and maintained a Buy rating on the shares. The firm reported that, after hosting CEO Bill Brennan and CFO Dan Fleming for two days of meetings, it concluded that management's message centered on a vertically integrated, system-level approach across both copper and optical connectivity.
Credo Technology Group Holding Ltd (NASDAQ:CRDO) also received a rating update from Evercore ISI the same day. The firm initiated coverage of the stock with an Outperform rating and set a price target of $325. It told investors that it senses that while the company is viewed as a copper-based AI-connectivity play, the firm believes that the company will be increasingly viewed as a broad copper plus optical AI-connectivity play as it executes its optical roadmap. Evercore further stated that near term, it models 100% and 60% growth for its AEC solutions in calendar year 2026 and 2027, respectively, and longer term, it models $13-plus in 2028 EPS, 40% higher than Street estimates.
Credo Technology Group Holding Ltd (NASDAQ:CRDO) develops connectivity solutions and products for the data infrastructure market, with its products including integrated circuits, active electrical cables, and SerDes chiplets.
While we acknowledge the potential of CRDO as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
READ NEXT: 15 Stocks That Will Make You Rich in 10 Years AND 12 Best Stocks That Will Always Grow.
Credo Technology Group Holding Ltd (NASDAQ:CRDO) also received a rating update from Evercore ISI the same day. The firm initiated coverage of the stock with an Outperform rating and set a price target of $325. It told investors that it senses that while the company is viewed as a copper-based AI-connectivity play, the firm believes that the company will be increasingly viewed as a broad copper plus optical AI-connectivity play as it executes its optical roadmap. Evercore further stated that near term, it models 100% and 60% growth for its AEC solutions in calendar year 2026 and 2027, respectively, and longer term, it models $13-plus in 2028 EPS, 40% higher than Street estimates.
Credo Technology Group Holding Ltd (NASDAQ:CRDO) develops connectivity solutions and products for the data infrastructure market, with its products including integrated circuits, active electrical cables, and SerDes chiplets.
While we acknowledge the potential of CRDO as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
READ NEXT: 15 Stocks That Will Make You Rich in 10 Years AND 12 Best Stocks That Will Always Grow.


3 months ago
Credo Technology Group Holding Ltd (NASDAQ:CRDO) is one of the top trending US stocks to buy now. Stifel lifted the price target on Credo Technology Group Holding Ltd (NASDAQ:CRDO) to $350 from $250 on June 22 and maintained a Buy rating on the shares. The firm reported that, after hosting CEO Bill Brennan and CFO Dan Fleming for two days of meetings, it concluded that management's message centered on a vertically integrated, system-level approach across both copper and optical connectivity.
Credo Technology Group Holding Ltd (NASDAQ:CRDO) also received a rating update from Evercore ISI the same day. The firm initiated coverage of the stock with an Outperform rating and set a price target of $325. It told investors that it senses that while the company is viewed as a copper-based AI-connectivity play, the firm believes that the company will be increasingly viewed as a broad copper plus optical AI-connectivity play as it executes its optical roadmap. Evercore further stated that near term, it models 100% and 60% growth for its AEC solutions in calendar year 2026 and 2027, respectively, and longer term, it models $13-plus in 2028 EPS, 40% higher than Street estimates.
Credo Technology Group Holding Ltd (NASDAQ:CRDO) develops connectivity solutions and products for the data infrastructure market, with its products including integrated circuits, active electrical cables, and SerDes chiplets.
While we acknowledge the potential of CRDO as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
READ NEXT: 15 Stocks That Will Make You Rich in 10 Years AND 12 Best Stocks That Will Always Grow.
Credo Technology Group Holding Ltd (NASDAQ:CRDO) also received a rating update from Evercore ISI the same day. The firm initiated coverage of the stock with an Outperform rating and set a price target of $325. It told investors that it senses that while the company is viewed as a copper-based AI-connectivity play, the firm believes that the company will be increasingly viewed as a broad copper plus optical AI-connectivity play as it executes its optical roadmap. Evercore further stated that near term, it models 100% and 60% growth for its AEC solutions in calendar year 2026 and 2027, respectively, and longer term, it models $13-plus in 2028 EPS, 40% higher than Street estimates.
Credo Technology Group Holding Ltd (NASDAQ:CRDO) develops connectivity solutions and products for the data infrastructure market, with its products including integrated circuits, active electrical cables, and SerDes chiplets.
While we acknowledge the potential of CRDO as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
READ NEXT: 15 Stocks That Will Make You Rich in 10 Years AND 12 Best Stocks That Will Always Grow.


3 months ago
Credo Tech (NASDAQ:CRDO) is one of the 15 AI Stocks ****** ysts Are Watching: Microsoft, Nvidia, and More.
On June 22, Evercore ISI ****** yst Mark Lipacis initiates coverage on Credo Tech (NASDAQ:CRDO) with an Outperform rating and a $325 price target. ****** ysts at the firm believe that Credo could increasingly benefit from growth in optical connectivity.
Currently, it is mostly known for its copper-based AI connectivity products because it created the active electric cable, or AEC, interconnect standard and developed a reliable full system solution combing both whole cable and chips instead of just chips.
However, we believe it will be increasingly viewed as a broad copper + optical AI-connectivity play as it prosecutes its optical roadmap, which includes optical DSPs, Silicon Photonics ICs, microLED cables and most importantly its ZFOptics modules, where consistent with its AEC playbook, it is also taking a systems approach.
The firm believes that Credo's current total addressable market of roughly $5 billion to $10 billion could expand by 10 to 20 times due to its product roadmap. The firm models 100% and 60% growth for its AEC solutions during 2026 and 2027. Meanwhile, it believes that CRDO's optical portfolio could accelerate and contribute up to 25% of revenues in 2027.
On June 22, Evercore ISI ****** yst Mark Lipacis initiates coverage on Credo Tech (NASDAQ:CRDO) with an Outperform rating and a $325 price target. ****** ysts at the firm believe that Credo could increasingly benefit from growth in optical connectivity.
Currently, it is mostly known for its copper-based AI connectivity products because it created the active electric cable, or AEC, interconnect standard and developed a reliable full system solution combing both whole cable and chips instead of just chips.
However, we believe it will be increasingly viewed as a broad copper + optical AI-connectivity play as it prosecutes its optical roadmap, which includes optical DSPs, Silicon Photonics ICs, microLED cables and most importantly its ZFOptics modules, where consistent with its AEC playbook, it is also taking a systems approach.
The firm believes that Credo's current total addressable market of roughly $5 billion to $10 billion could expand by 10 to 20 times due to its product roadmap. The firm models 100% and 60% growth for its AEC solutions during 2026 and 2027. Meanwhile, it believes that CRDO's optical portfolio could accelerate and contribute up to 25% of revenues in 2027.

3 months ago
Nike (NYSE:NKE) shares slipped 1.4% in premarket trading on Tuesday after Evercore ISI downgraded the sportswear giant to In Line from Outperform and reduced its price target to $46 from $57.
The brokerage cited weakening sales trends, limited product innovation and growing concerns that Nike may need to lower market expectations ahead of a key investor event later this year.
Nearly two years into Nike's turnaround strategy, Evercore said its latest channel checks continue to reveal signs of pressure across several important parts of the business.
The firm pointed to worsening conditions in U.S. lifestyle and family retail channels, where order cancellations and delayed purchases are reportedly exceeding company expectations.
Analysts also highlighted softer demand for recent Jordan retro product launches and supply chain disruptions in Europe that have delayed the arrival of World Cup-related merchandise.
The brokerage cited weakening sales trends, limited product innovation and growing concerns that Nike may need to lower market expectations ahead of a key investor event later this year.
Nearly two years into Nike's turnaround strategy, Evercore said its latest channel checks continue to reveal signs of pressure across several important parts of the business.
The firm pointed to worsening conditions in U.S. lifestyle and family retail channels, where order cancellations and delayed purchases are reportedly exceeding company expectations.
Analysts also highlighted softer demand for recent Jordan retro product launches and supply chain disruptions in Europe that have delayed the arrival of World Cup-related merchandise.


3 months ago
Meta Platforms, Inc. (NASDAQ:META) is one of the Best Data Center Stocks That Are Cheaper Than the S&P 500. Wall Street is bullish on the stock as the ****** ysts' 12-month average price target suggests more than 41.83% upside from the current level.
Recently, on June 17, Evercore ISI reiterated a Buy rating on Meta Platforms, Inc. (NASDAQ:META) with a price target of $930. A few days earlier, on June 9, Truist also reiterated a Buy rating on the stock with a $840 price target. The positive ratings are based on the company's launch of new paid subscription plans.
Meta introduced consumer and business subscriptions across its Family of Apps, alongside a new Meta One AI subscription suite. Moreover, App-level Plus plans are rolling out across Facebook, Instagram, and WhatsApp. Meta One AI tiers combine app perks with expanded Meta AI access, while business and creator tiers add verification, discovery tools, insights, and workflow features.
Evercore ISI sees the move as a move to diversify revenue. The firm expects a modest revenue impact but a more meaningful boost to operating income over time, given the high-margin nature of subscriptions. Near-term impact is expected to be limited due to phased availability and likely low initial conversion rates. That said, the firm notes that even modest penetration across Meta's 3.6 billion-plus daily user base could eventually build into a significant high-margin revenue stream.
On the other hand, Truist estimates the subscription business could generate over $20 billion in high-margin revenue by fiscal 2030, representing roughly 5% of total revenue. The projection ****** umes user penetration of around 3%, in line with Google's current subscription rate. The firm sees subscriptions as a growth extender, helping Meta sustain momentum beyond its already strong digital advertising performance.
Recently, on June 17, Evercore ISI reiterated a Buy rating on Meta Platforms, Inc. (NASDAQ:META) with a price target of $930. A few days earlier, on June 9, Truist also reiterated a Buy rating on the stock with a $840 price target. The positive ratings are based on the company's launch of new paid subscription plans.
Meta introduced consumer and business subscriptions across its Family of Apps, alongside a new Meta One AI subscription suite. Moreover, App-level Plus plans are rolling out across Facebook, Instagram, and WhatsApp. Meta One AI tiers combine app perks with expanded Meta AI access, while business and creator tiers add verification, discovery tools, insights, and workflow features.
Evercore ISI sees the move as a move to diversify revenue. The firm expects a modest revenue impact but a more meaningful boost to operating income over time, given the high-margin nature of subscriptions. Near-term impact is expected to be limited due to phased availability and likely low initial conversion rates. That said, the firm notes that even modest penetration across Meta's 3.6 billion-plus daily user base could eventually build into a significant high-margin revenue stream.
On the other hand, Truist estimates the subscription business could generate over $20 billion in high-margin revenue by fiscal 2030, representing roughly 5% of total revenue. The projection ****** umes user penetration of around 3%, in line with Google's current subscription rate. The firm sees subscriptions as a growth extender, helping Meta sustain momentum beyond its already strong digital advertising performance.


