

12 hours ago
Berkshire bought 924,281 SIRI shares across three days, raising its stake to over 125 million shares at roughly $27 million total.
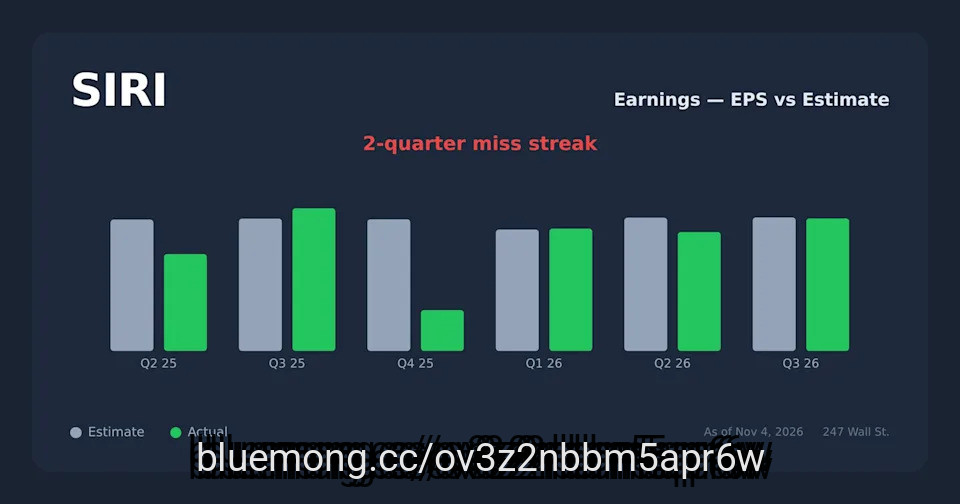
Sirius raised full-year guidance for the second straight quarter, with free cash flow rising 14% and EBITDA margins expanding to 32%.
Pandora monthly users fell 7%, net leverage sits at 3.3x adjusted EBITDA, and management warned of a harder Q4 for subscribers.
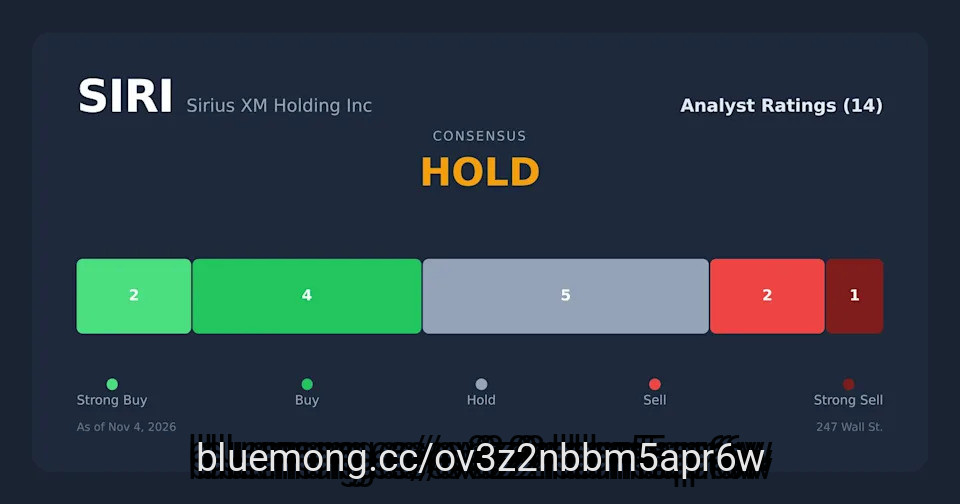
Just released. Our **** ysts combed the entire stock market and named the ten best stocks to buy right now, and Sirius XM didn't make the cut. Enter your email to see the names that beat SIRI. The report is free. Enter your email and see if any of your stocks made the cut.
Berkshire Hathaway (NYSE:BRK-B) disclosed in a Form 4 filed Nov. 3, 2026, that it bought 924,281 shares of Sirius XM (NASDAQ:SIRI) on Oct. 30, Nov. 2, and Nov. 3. The purchases raised its beneficial ownership to 125,731,398 shares. Investing.com estimated the buying at about $26.9 million, with weighted average prices of $28.8913 on Oct. 30 and $30.233 on Nov. 3.
#shares #berkshire #raised #free
Sirius raised full-year guidance for the second straight quarter, with free cash flow rising 14% and EBITDA margins expanding to 32%.
Pandora monthly users fell 7%, net leverage sits at 3.3x adjusted EBITDA, and management warned of a harder Q4 for subscribers.
Just released. Our **** ysts combed the entire stock market and named the ten best stocks to buy right now, and Sirius XM didn't make the cut. Enter your email to see the names that beat SIRI. The report is free. Enter your email and see if any of your stocks made the cut.
Berkshire Hathaway (NYSE:BRK-B) disclosed in a Form 4 filed Nov. 3, 2026, that it bought 924,281 shares of Sirius XM (NASDAQ:SIRI) on Oct. 30, Nov. 2, and Nov. 3. The purchases raised its beneficial ownership to 125,731,398 shares. Investing.com estimated the buying at about $26.9 million, with weighted average prices of $28.8913 on Oct. 30 and $30.233 on Nov. 3.
#shares #berkshire #raised #free

17 days ago
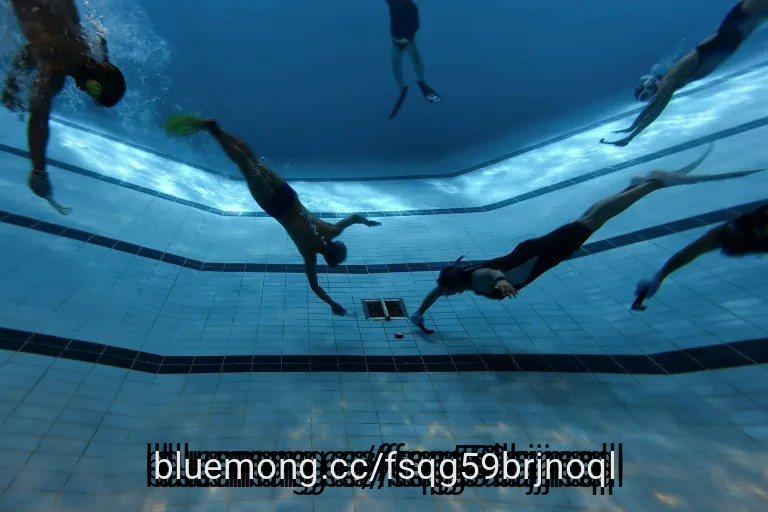
Swimmers brandishing short, curved sticks held their breath as they somersaulted and dove towards a weighted puck at the bottom of a Hong Kong swimming pool, vying for first place in a sport likened to voluntary drowning.
The annual underwater hockey tournament, ominously advertised as "physical ****** ", nevertheless drew a roster of hardcore enthusiasts from countries across Asia to the Chinese city over the weekend.
"You have to choose when to use your breath and when not to... Anyone that's got the puck, you know that they've got some level of suffering," Leo Lines, a ****** anese-New Zealander competitor from Hokkaido, told AFP.
"I love that."
Suited up in snorkel masks and fins, players only resurface for air when they absolutely have to, and their heads remain constantly underwater so they can monitor the game.
#swimmers #kong
The annual underwater hockey tournament, ominously advertised as "physical ****** ", nevertheless drew a roster of hardcore enthusiasts from countries across Asia to the Chinese city over the weekend.
"You have to choose when to use your breath and when not to... Anyone that's got the puck, you know that they've got some level of suffering," Leo Lines, a ****** anese-New Zealander competitor from Hokkaido, told AFP.
"I love that."
Suited up in snorkel masks and fins, players only resurface for air when they absolutely have to, and their heads remain constantly underwater so they can monitor the game.
#swimmers #kong

2 months ago
One of the world's largest companies has become a cash-return machine of historic scale, but its engine is now facing a serious test.
With Apple (AAPL) stock trading near $337 a share, an owner might ask a simple question. The company has returned a fortune in cash while the stock has dramatically outperformed the market; was holding worth it, and can this machine keep running?
Over the last five years, Apple sent $510.4 billion in cash back to its shareholders. That sum, equal to about 10.3% of the company's current market value, is the largest capital return of any U.S. company Trefis tracks over that period. The question is what that extraordinary payout says about the business today.
The money printer is Apple's core business, which generated $136.68 billion in free cash flow over the last twelve months. In its most recent quarter, the company reported record June-quarter revenue, with iPhone sales growing 22% and Mac sales growing an impressive 29% from a year ago. Management noted that the iPhone and Mac were "both doing remarkably better than we thought they would do."
That operational strength funds the shareholder returns. The five-year payout was heavily weighted toward share repurchases, which totaled $434.5 billion, with another $75.9 billion paid in dividends. Apple's absolute dollar payout stands alone, even though the 10.3% of market value it returned sits well below the 16.9% median for S&P 500 companies.
#market
With Apple (AAPL) stock trading near $337 a share, an owner might ask a simple question. The company has returned a fortune in cash while the stock has dramatically outperformed the market; was holding worth it, and can this machine keep running?
Over the last five years, Apple sent $510.4 billion in cash back to its shareholders. That sum, equal to about 10.3% of the company's current market value, is the largest capital return of any U.S. company Trefis tracks over that period. The question is what that extraordinary payout says about the business today.
The money printer is Apple's core business, which generated $136.68 billion in free cash flow over the last twelve months. In its most recent quarter, the company reported record June-quarter revenue, with iPhone sales growing 22% and Mac sales growing an impressive 29% from a year ago. Management noted that the iPhone and Mac were "both doing remarkably better than we thought they would do."
That operational strength funds the shareholder returns. The five-year payout was heavily weighted toward share repurchases, which totaled $434.5 billion, with another $75.9 billion paid in dividends. Apple's absolute dollar payout stands alone, even though the 10.3% of market value it returned sits well below the 16.9% median for S&P 500 companies.
#market

2 months ago
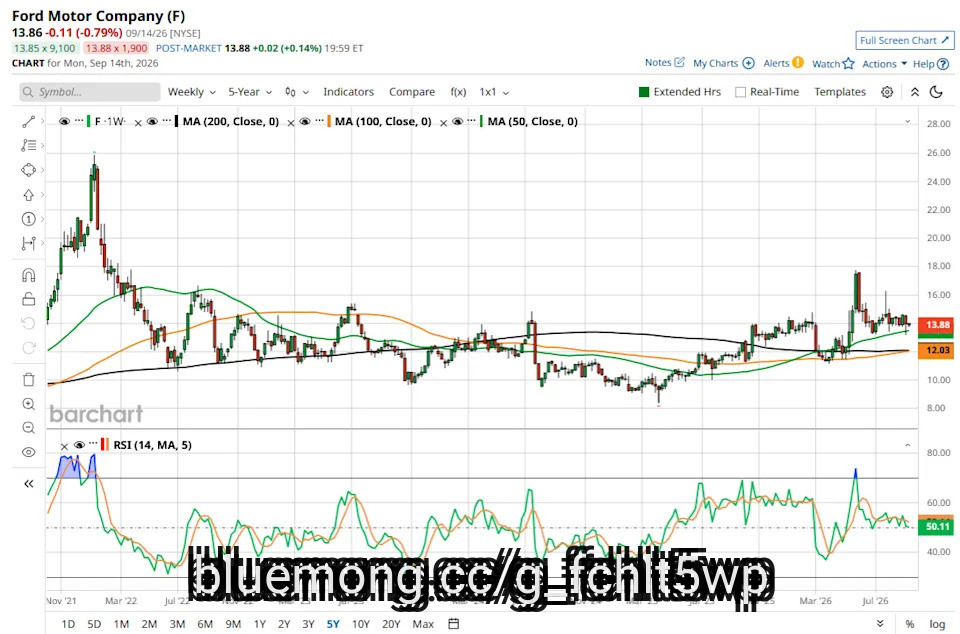
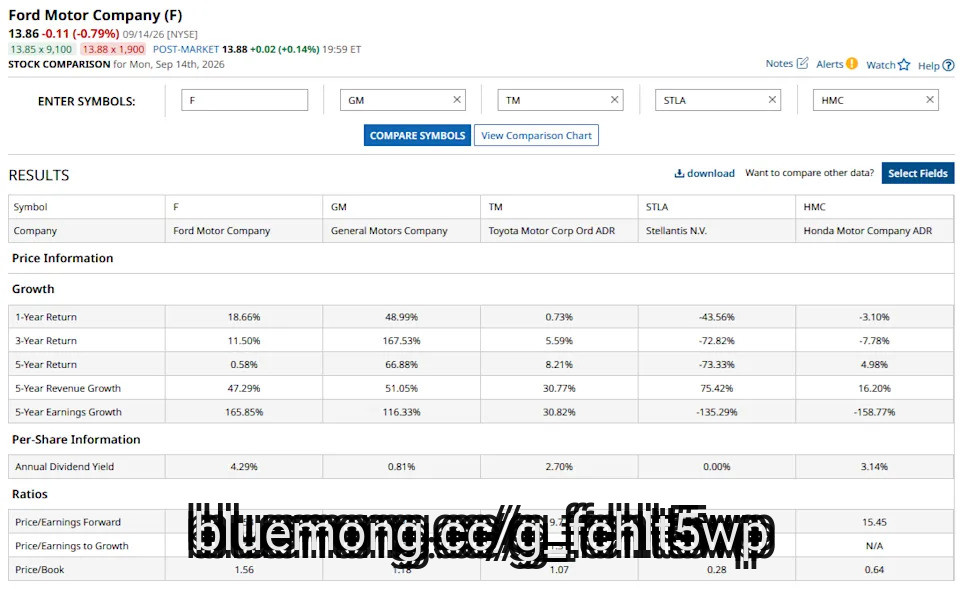
With a dividend yield of 4.3%, Ford (F) is among the highest-yielding constituents of the S&P 500 Index ($SPX). That number would look even more compelling considering Ford's dividend yield is over four times what an average S&P 500 Index constituent pays.
However, a bit of number-crunching tells a different picture. Dividend yield is basically a function of the per-share dividend, which is the numerator in the equation, and the stock price, which is the denominator. Dividend yield rises when the company raises its dividends or the share price falls. More often than not, the latter is true for companies that have a very high dividend yield.
Get exclusive insights with the FREE Barchart Brief newsletter. Subscribe now for quick, incisive midday market ****** ysis you won't find anywhere else.
The S&P 500's dividend yield is near its historical lows. Two factors can be blamed for the dip in the world's most popular index's dividend yield. First, tech companies' share in the market-cap-weighted index has soared amid the artificial intelligence (AI) driven rally. Mega-cap tech companies are known to be frugal with dividends, and their rising weightage in the index pulls down its dividend yield. Second, while the annualized dividend per share of the S&P 500 has continued to rise over the years, the increase has been much lower compared to the surge in stock prices.
In contrast, Ford's quarterly dividend has been static since July 2022, when the company raised the payout by 50% to $0.15. Notably, while Ford paid special dividends in the preceding three years to reach its payout targets, it hasn't raised its payout for over four years. Its dividend yield is still high because of its underperforming stock, which has essentially gone nowhere in the last five years and trades 46% below its October 2022 highs.
#Dividend #yield #Share #dividends
However, a bit of number-crunching tells a different picture. Dividend yield is basically a function of the per-share dividend, which is the numerator in the equation, and the stock price, which is the denominator. Dividend yield rises when the company raises its dividends or the share price falls. More often than not, the latter is true for companies that have a very high dividend yield.
Get exclusive insights with the FREE Barchart Brief newsletter. Subscribe now for quick, incisive midday market ****** ysis you won't find anywhere else.
The S&P 500's dividend yield is near its historical lows. Two factors can be blamed for the dip in the world's most popular index's dividend yield. First, tech companies' share in the market-cap-weighted index has soared amid the artificial intelligence (AI) driven rally. Mega-cap tech companies are known to be frugal with dividends, and their rising weightage in the index pulls down its dividend yield. Second, while the annualized dividend per share of the S&P 500 has continued to rise over the years, the increase has been much lower compared to the surge in stock prices.
In contrast, Ford's quarterly dividend has been static since July 2022, when the company raised the payout by 50% to $0.15. Notably, while Ford paid special dividends in the preceding three years to reach its payout targets, it hasn't raised its payout for over four years. Its dividend yield is still high because of its underperforming stock, which has essentially gone nowhere in the last five years and trades 46% below its October 2022 highs.
#Dividend #yield #Share #dividends


2 months ago
American Tower Corporation (NYSE:AMT) priced $1.6 billion of senior notes on September 9: $500 million at 5.300% due 2031, $500 million at 5.560% due 2033, and $600 million at 5.750% due 2036. Once issued, the three tranches would carry combined annual coupons of $88.8 million, equivalent to a weighted average coupon of 5.55%.
American Tower Corporation (NYSE:AMT) expects approximately $1.580 billion in net proceeds. It intends to use $600 million to repay 1.450% notes due in 2026, with additional proceeds designated for revolving-credit debt and general corporate purposes. The financing exchanges a near-term repayment requirement and some revolving debt for longer fixed-rate obligations.
The investment question is whether greater funding certainty compensates for the higher cash-interest commitment.
American Tower Corporation (NYSE:AMT) would remove a $600 million maturity falling due this year once the planned repayment occurs. That reduces exposure to having to refinance the obligation closer to its deadline, when borrowing conditions could be less favorable.
The new maturities also distribute principal repayments across 2031, 2033 and 2036. For American Tower Corporation (NYSE:AMT), a spread of repayment dates can support financial planning across its communications-site and data-center portfolio. Fixed coupons make the cost of this funding predictable.
#tower
American Tower Corporation (NYSE:AMT) expects approximately $1.580 billion in net proceeds. It intends to use $600 million to repay 1.450% notes due in 2026, with additional proceeds designated for revolving-credit debt and general corporate purposes. The financing exchanges a near-term repayment requirement and some revolving debt for longer fixed-rate obligations.
The investment question is whether greater funding certainty compensates for the higher cash-interest commitment.
American Tower Corporation (NYSE:AMT) would remove a $600 million maturity falling due this year once the planned repayment occurs. That reduces exposure to having to refinance the obligation closer to its deadline, when borrowing conditions could be less favorable.
The new maturities also distribute principal repayments across 2031, 2033 and 2036. For American Tower Corporation (NYSE:AMT), a spread of repayment dates can support financial planning across its communications-site and data-center portfolio. Fixed coupons make the cost of this funding predictable.
#tower


2 months ago
Core & Main, Inc. (NYSE:CNM) reported quarterly sales of $2.145 billion on September 9, up 2.5%. Company-defined non-GAAP adjusted EBITDA reached $274 million. The measure adjusts consolidated net income for interest, taxes, depreciation and amortization, equity compensation, debt modification and extinguishment losses, offering expenses, and specified other income or expenses.
Consolidated net income rose 6.4% to $150 million, while GAAP diluted earnings per share increased 10% to $0.77. Diluted weighted-average shares declined approximately 2.5% to 193.4 million. Buybacks amplified an improvement that also had an operating foundation.
The company repurchased $169 million of equity during the quarter, against $62 million of operating cash flow. The investment question is whether cash generation can sustain capital returns alongside the spending needed to grow.
Core & Main, Inc. (NYSE:CNM) benefits from demand for essential infrastructure products. Management highlighted municipal demand, fire protection, treatment plants, and data centers as areas of strength. These end markets provide several sources of business even when construction demand is uneven.
Expense discipline also helped. Quarterly selling, general and administrative expenses declined to $301 million from $302 million. Controlling overhead allows modest sales growth to contribute more to earnings. Stronger volumes would make further earnings gains easier to sustain.
#income #main #quarterly
Consolidated net income rose 6.4% to $150 million, while GAAP diluted earnings per share increased 10% to $0.77. Diluted weighted-average shares declined approximately 2.5% to 193.4 million. Buybacks amplified an improvement that also had an operating foundation.
The company repurchased $169 million of equity during the quarter, against $62 million of operating cash flow. The investment question is whether cash generation can sustain capital returns alongside the spending needed to grow.
Core & Main, Inc. (NYSE:CNM) benefits from demand for essential infrastructure products. Management highlighted municipal demand, fire protection, treatment plants, and data centers as areas of strength. These end markets provide several sources of business even when construction demand is uneven.
Expense discipline also helped. Quarterly selling, general and administrative expenses declined to $301 million from $302 million. Controlling overhead allows modest sales growth to contribute more to earnings. Stronger volumes would make further earnings gains easier to sustain.
#income #main #quarterly


2 months ago
Generating $2,200 monthly in dividends requires between $264,000 at a 10% yield and $754,000 at a 3.5% yield, with higher yields carrying greater principal erosion risk.
A blended portfolio of SCHD (35%), DGRO (25%), VYM (20%), and JEPI (20%) hits a 3.9% weighted yield requiring about $670,000 to reach the $2,200 target.
A 3.5% yield growing 8% annually doubles income in roughly nine years, while a flat 10% yield stays stagnant or declines if distributions are cut.
Read More: Learn 7 secret wealth tips high net worth investors use that most investors miss (sponsor)
Turning zero into $2,200 a month in dividend income requires only two things: a target yield and the capital to support it. The annualized goal is $26,400, which lands somewhere between covering a mortgage payment and replacing a part-time salary. The capital needed depends entirely on the yield you choose, and the yield you choose determines how durable that income actually is.
#yield #choose #dgro
A blended portfolio of SCHD (35%), DGRO (25%), VYM (20%), and JEPI (20%) hits a 3.9% weighted yield requiring about $670,000 to reach the $2,200 target.
A 3.5% yield growing 8% annually doubles income in roughly nine years, while a flat 10% yield stays stagnant or declines if distributions are cut.
Read More: Learn 7 secret wealth tips high net worth investors use that most investors miss (sponsor)
Turning zero into $2,200 a month in dividend income requires only two things: a target yield and the capital to support it. The annualized goal is $26,400, which lands somewhere between covering a mortgage payment and replacing a part-time salary. The capital needed depends entirely on the yield you choose, and the yield you choose determines how durable that income actually is.
#yield #choose #dgro


2 months ago
Netflix (NFLX) has fallen about 35% over the past year, while the S&P 500 returned about 17%. The complaint is simple. Sales growth is slowing, and management will not show the quality metrics it leans on. That case misses the engine under per-share earnings, a wider margin, and a shrinking share count.
Why Are ***** ysts Pressing Netflix On Its Slowing Top Line?
Management guided revenue growth of 11% excluding currency for the third quarter of 2026, below the second quarter's 12% on the same basis. The CFO put part of that step down to a back-half-weighted year-ago comparison. ***** ysts have also pressed on viewing hours per member, which they say has softened.
The shares trade near $78, about 63% of their 52-week high. At that price the market appears to be paying for a mature business. The buy case has to rest on something other than the top line.
How Do Netflix's Earnings Grow Faster Than Its Sales?
#sales
Why Are ***** ysts Pressing Netflix On Its Slowing Top Line?
Management guided revenue growth of 11% excluding currency for the third quarter of 2026, below the second quarter's 12% on the same basis. The CFO put part of that step down to a back-half-weighted year-ago comparison. ***** ysts have also pressed on viewing hours per member, which they say has softened.
The shares trade near $78, about 63% of their 52-week high. At that price the market appears to be paying for a mature business. The buy case has to rest on something other than the top line.
How Do Netflix's Earnings Grow Faster Than Its Sales?
#sales


2 months ago
On September 15, CareTrust REIT (NYSE:CTRE) announced it had closed on a $400 million skilled nursing portfolio in the Southwest, effective September 1, and unveiled a reloaded $600 million investment pipeline behind it. The deal covers 2,622 licensed beds triple net leased back to the existing operator, sourced off-market and structured through a joint venture that put roughly $380 million of CareTrust's own capital to work. It is the latest entry in a buying spree that has now pushed the company's 2026 investment total past $1.9 billion.
The new portfolio is expected to generate a stabilized yield of about 8.6%, in line with the 8.7% blended yield CareTrust has posted across two dozen deals closed so far in 2026. That consistency matters more than any single transaction. The company has now closed roughly $710 million in investments in the third quarter alone, including a small UK care home purchase in mid-August, on top of the $899.6 million it closed in the second quarter at an 8.9% yield.
Management says the $600 million pipeline of near-term, actionable deals, about half of it aimed at the senior housing operating portfolio, does not even include a set of larger transactions still being pursued, so the deal flow may not be finished. The balance sheet backs up that ambition. CareTrust ended the second quarter, on June 30, 2026, with net debt to annualized normalized EBITDA of just 1.01x, and as of the September announcement it still had $725 million available under its revolver plus $612 million of remaining ATM capacity. That combination let the company raise its full year 2026 guidance on August 6 to normalized FFO of $2.03 to $2.06 per share, an increase of 16.2% at the midpoint over 2025, even before this latest acquisition was on the books.
This growth has come with a real cost to existing shareholders. Diluted weighted average shares outstanding rose from about 192.9 million in the second quarter of 2025 to 234.2 million a year later, as CareTrust leaned on forward equity offerings and its ATM program to fund the buying spree. The company still had $439 million of expected net proceeds sitting in unsettled forward equity contracts as of September 15, meaning more shares are still coming.
The second quarter also carried a $4.7 million provision for loan losses, a line that did not appear in the prior year period and is worth watching as the loan and financing receivable book grows alongside the property portfolio. Interest expense rose to $15.3 million in the quarter from $13.0 million a year earlier, and 2026 guidance leans on rent escalators of just 2.5% a year, a modest built-in growth rate once the acquisition pace eventually slows. The company's own risk disclosures flag reliance on tenants to keep meeting their lease obligations, along with exposure to healthcare reform, staffing requirements, and currency swings tied to its UK operations.
#still
The new portfolio is expected to generate a stabilized yield of about 8.6%, in line with the 8.7% blended yield CareTrust has posted across two dozen deals closed so far in 2026. That consistency matters more than any single transaction. The company has now closed roughly $710 million in investments in the third quarter alone, including a small UK care home purchase in mid-August, on top of the $899.6 million it closed in the second quarter at an 8.9% yield.
Management says the $600 million pipeline of near-term, actionable deals, about half of it aimed at the senior housing operating portfolio, does not even include a set of larger transactions still being pursued, so the deal flow may not be finished. The balance sheet backs up that ambition. CareTrust ended the second quarter, on June 30, 2026, with net debt to annualized normalized EBITDA of just 1.01x, and as of the September announcement it still had $725 million available under its revolver plus $612 million of remaining ATM capacity. That combination let the company raise its full year 2026 guidance on August 6 to normalized FFO of $2.03 to $2.06 per share, an increase of 16.2% at the midpoint over 2025, even before this latest acquisition was on the books.
This growth has come with a real cost to existing shareholders. Diluted weighted average shares outstanding rose from about 192.9 million in the second quarter of 2025 to 234.2 million a year later, as CareTrust leaned on forward equity offerings and its ATM program to fund the buying spree. The company still had $439 million of expected net proceeds sitting in unsettled forward equity contracts as of September 15, meaning more shares are still coming.
The second quarter also carried a $4.7 million provision for loan losses, a line that did not appear in the prior year period and is worth watching as the loan and financing receivable book grows alongside the property portfolio. Interest expense rose to $15.3 million in the quarter from $13.0 million a year earlier, and 2026 guidance leans on rent escalators of just 2.5% a year, a modest built-in growth rate once the acquisition pace eventually slows. The company's own risk disclosures flag reliance on tenants to keep meeting their lease obligations, along with exposure to healthcare reform, staffing requirements, and currency swings tied to its UK operations.
#still


2 months ago
Curaleaf Holdings (USOTC:CURLF) has sent a letter to Aurora Cannabis (NASDAQ:ACB) shareholders urging them to tender their shares to its outstanding acquisition offer after Aurora's board declined to engage with the proposal.
Under the offer, Aurora shareholders would receive 0.3463 Curaleaf shares and $0.75 in cash for each Aurora share.
Curaleaf said the terms implied a value of $4.00 per Aurora share based on the unaffected date, representing a 45% premium to Aurora's 30-day volume-weighted average price as of August 10, 2026. Aurora shares traded at $2.76 before the offer was announced.
Curaleaf Chairman and Chief Executive Boris Jordan said in the letter, "Aurora has refused. And so, we are putting the decision where it belongs: in your hands."
Curaleaf said the proposed combination would create a company operating across 17 countries.
#curlf
Under the offer, Aurora shareholders would receive 0.3463 Curaleaf shares and $0.75 in cash for each Aurora share.
Curaleaf said the terms implied a value of $4.00 per Aurora share based on the unaffected date, representing a 45% premium to Aurora's 30-day volume-weighted average price as of August 10, 2026. Aurora shares traded at $2.76 before the offer was announced.
Curaleaf Chairman and Chief Executive Boris Jordan said in the letter, "Aurora has refused. And so, we are putting the decision where it belongs: in your hands."
Curaleaf said the proposed combination would create a company operating across 17 countries.
#curlf


2 months ago
On September 15, CareTrust REIT (NYSE:CTRE) announced it had closed on a $400 million skilled nursing portfolio in the Southwest, effective September 1, and unveiled a reloaded $600 million investment pipeline behind it. The deal covers 2,622 licensed beds triple net leased back to the existing operator, sourced off-market and structured through a joint venture that put roughly $380 million of CareTrust's own capital to work. It is the latest entry in a buying spree that has now pushed the company's 2026 investment total past $1.9 billion.
The new portfolio is expected to generate a stabilized yield of about 8.6%, in line with the 8.7% blended yield CareTrust has posted across two dozen deals closed so far in 2026. That consistency matters more than any single transaction. The company has now closed roughly $710 million in investments in the third quarter alone, including a small UK care home purchase in mid-August, on top of the $899.6 million it closed in the second quarter at an 8.9% yield.
Management says the $600 million pipeline of near-term, actionable deals, about half of it aimed at the senior housing operating portfolio, does not even include a set of larger transactions still being pursued, so the deal flow may not be finished. The balance sheet backs up that ambition. CareTrust ended the second quarter, on June 30, 2026, with net debt to annualized normalized EBITDA of just 1.01x, and as of the September announcement it still had $725 million available under its revolver plus $612 million of remaining ATM capacity. That combination let the company raise its full year 2026 guidance on August 6 to normalized FFO of $2.03 to $2.06 per share, an increase of 16.2% at the midpoint over 2025, even before this latest acquisition was on the books.
This growth has come with a real cost to existing shareholders. Diluted weighted average shares outstanding rose from about 192.9 million in the second quarter of 2025 to 234.2 million a year later, as CareTrust leaned on forward equity offerings and its ATM program to fund the buying spree. The company still had $439 million of expected net proceeds sitting in unsettled forward equity contracts as of September 15, meaning more shares are still coming.
The second quarter also carried a $4.7 million provision for loan losses, a line that did not appear in the prior year period and is worth watching as the loan and financing receivable book grows alongside the property portfolio. Interest expense rose to $15.3 million in the quarter from $13.0 million a year earlier, and 2026 guidance leans on rent escalators of just 2.5% a year, a modest built-in growth rate once the acquisition pace eventually slows. The company's own risk disclosures flag reliance on tenants to keep meeting their lease obligations, along with exposure to healthcare reform, staffing requirements, and currency swings tied to its UK operations.
#closed
The new portfolio is expected to generate a stabilized yield of about 8.6%, in line with the 8.7% blended yield CareTrust has posted across two dozen deals closed so far in 2026. That consistency matters more than any single transaction. The company has now closed roughly $710 million in investments in the third quarter alone, including a small UK care home purchase in mid-August, on top of the $899.6 million it closed in the second quarter at an 8.9% yield.
Management says the $600 million pipeline of near-term, actionable deals, about half of it aimed at the senior housing operating portfolio, does not even include a set of larger transactions still being pursued, so the deal flow may not be finished. The balance sheet backs up that ambition. CareTrust ended the second quarter, on June 30, 2026, with net debt to annualized normalized EBITDA of just 1.01x, and as of the September announcement it still had $725 million available under its revolver plus $612 million of remaining ATM capacity. That combination let the company raise its full year 2026 guidance on August 6 to normalized FFO of $2.03 to $2.06 per share, an increase of 16.2% at the midpoint over 2025, even before this latest acquisition was on the books.
This growth has come with a real cost to existing shareholders. Diluted weighted average shares outstanding rose from about 192.9 million in the second quarter of 2025 to 234.2 million a year later, as CareTrust leaned on forward equity offerings and its ATM program to fund the buying spree. The company still had $439 million of expected net proceeds sitting in unsettled forward equity contracts as of September 15, meaning more shares are still coming.
The second quarter also carried a $4.7 million provision for loan losses, a line that did not appear in the prior year period and is worth watching as the loan and financing receivable book grows alongside the property portfolio. Interest expense rose to $15.3 million in the quarter from $13.0 million a year earlier, and 2026 guidance leans on rent escalators of just 2.5% a year, a modest built-in growth rate once the acquisition pace eventually slows. The company's own risk disclosures flag reliance on tenants to keep meeting their lease obligations, along with exposure to healthcare reform, staffing requirements, and currency swings tied to its UK operations.
#closed


2 months ago
Minerals 260 has secured commitments to raise $178.2m (A$250m) before costs via a two-tranche share placement to fund the next stage of development at its Bullabulling Gold Project in Western Australia (WA).
The company said the funds, raised at A$0.88 per share, will allow it to advance construction and exploration activities at the site, which is located 65km west of Kalgoorlie.
The placement, involving the issuance of 284,090,910 fully paid ordinary shares, includes a A$30m cornerstone investment from the Franco-Nevada Corporation.
According to Minerals 260, the issue price matches the company's closing share price on 11 September 2026 and represents a 3.5% premium to the ten-day volume-weighted average price of A$0.85.
Existing institutional shareholders participated in the placement alongside new domestic and international investors.
#western #kalgoorlie
The company said the funds, raised at A$0.88 per share, will allow it to advance construction and exploration activities at the site, which is located 65km west of Kalgoorlie.
The placement, involving the issuance of 284,090,910 fully paid ordinary shares, includes a A$30m cornerstone investment from the Franco-Nevada Corporation.
According to Minerals 260, the issue price matches the company's closing share price on 11 September 2026 and represents a 3.5% premium to the ten-day volume-weighted average price of A$0.85.
Existing institutional shareholders participated in the placement alongside new domestic and international investors.
#western #kalgoorlie


2 months ago
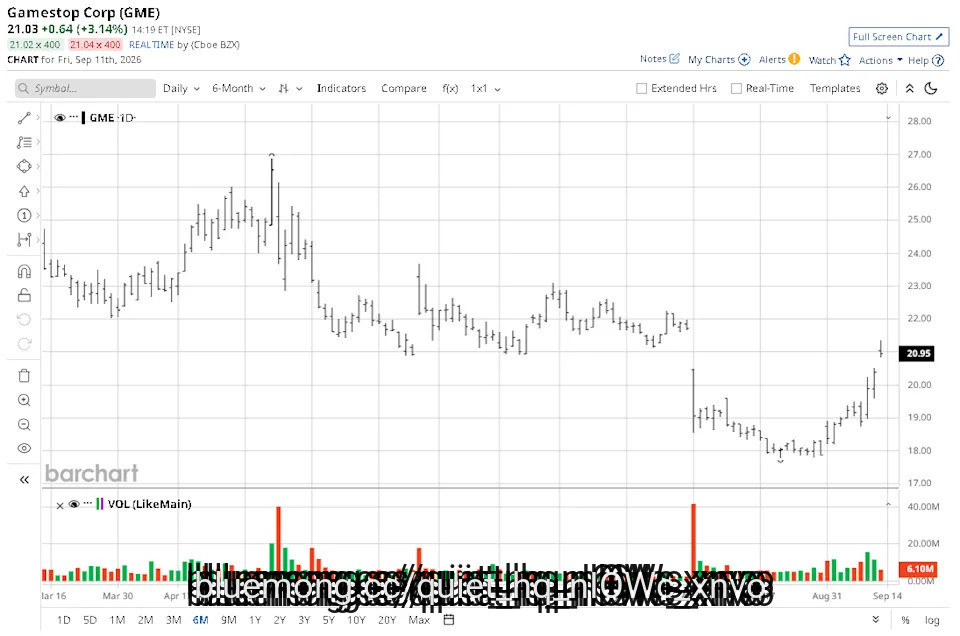
GameStop (GME) shares pushed higher on Sept. 11 after a regulatory filing confirmed that chief executive Ryan Cohen has expanded his stake in the gaming merchandise retailer. In open-market transactions, Cohen has acquired a total of 1,000,000 company shares for roughly $20.37 million, which translates to a weighted per-share price of about $20.38, the filing revealed.
The disclosure arrives at a time when GME stock is already reclaiming some of its recent losses, currently up some 15% versus its August low.
NVDA Stock Alert: What to Know as Nvidia Faces DOJ Probe
Rocket Lab Stock Just Scored a New Bullish Rating
Cathie Wood Just Bet $45 Million on This Beaten-Down ******* e Stock. Wall Street Sees 70% Upside.
#shares #filing #august
The disclosure arrives at a time when GME stock is already reclaiming some of its recent losses, currently up some 15% versus its August low.
NVDA Stock Alert: What to Know as Nvidia Faces DOJ Probe
Rocket Lab Stock Just Scored a New Bullish Rating
Cathie Wood Just Bet $45 Million on This Beaten-Down ******* e Stock. Wall Street Sees 70% Upside.
#shares #filing #august
2 months ago
First Citizens BancShares, Inc. (NASDAQ:FCNCA), through its First-Citizens Bank & Trust Company subsidiary, completed the acquisition of 138 BMO Bank N.A. branches on September 4. The locations span 11 states across the Midwest, Great Plains and West.
The completion announcement did not disclose final transferred balances. At the announcement, First Citizens BancShares, Inc. (NASDAQ:FCNCA) expected to ****** ume approximately $5.7 billion of deposits and acquire $1.1 billion of loans. Its July 2026 update lowered those estimates to $5.3 billion and $700 million, respectively. Both estimates imply roughly $4.6 billion of net liquidity. That difference represents funding capacity, not transaction income, and remains subject to final balances and acquisition accounting.
The deposit franchise could be the transaction's most valuable ****** et. At announcement, the acquired deposits carried a weighted average rate of 1.43%, with 21% in noninterest-bearing demand accounts. First Citizens BancShares, Inc. (NASDAQ:FCNCA) reported a 2.07% average total deposit cost in the second quarter of 2026. Retaining the acquired accounts near their original pricing could lower the consolidated funding cost.
The 138 branches also establish or deepen a presence across 11 states. The original transaction presentation identified approximately $1.0 billion of wealth ****** ets under management, creating opportunities to cross-sell commercial lending, treasury services, and wealth products. Retaining branch personnel could help preserve local relationships.
First Citizens BancShares, Inc. (NASDAQ:FCNCA) can deploy the surplus funding in several ways. As of June 30, 2026, the company held $151.03 billion of loans and $32.19 billion of borrowings, including a $28.42 billion purchase money note owed to the Federal Deposit Insurance Corporation. The acquired liquidity could support loan growth, replace more expensive funding, or be invested in securities. The original presentation projected immediate earnings-per-share accretion and an approximately 27-basis-point reduction in the Common Equity Tier 1 capital ratio.
#billion #first #citizens
The completion announcement did not disclose final transferred balances. At the announcement, First Citizens BancShares, Inc. (NASDAQ:FCNCA) expected to ****** ume approximately $5.7 billion of deposits and acquire $1.1 billion of loans. Its July 2026 update lowered those estimates to $5.3 billion and $700 million, respectively. Both estimates imply roughly $4.6 billion of net liquidity. That difference represents funding capacity, not transaction income, and remains subject to final balances and acquisition accounting.
The deposit franchise could be the transaction's most valuable ****** et. At announcement, the acquired deposits carried a weighted average rate of 1.43%, with 21% in noninterest-bearing demand accounts. First Citizens BancShares, Inc. (NASDAQ:FCNCA) reported a 2.07% average total deposit cost in the second quarter of 2026. Retaining the acquired accounts near their original pricing could lower the consolidated funding cost.
The 138 branches also establish or deepen a presence across 11 states. The original transaction presentation identified approximately $1.0 billion of wealth ****** ets under management, creating opportunities to cross-sell commercial lending, treasury services, and wealth products. Retaining branch personnel could help preserve local relationships.
First Citizens BancShares, Inc. (NASDAQ:FCNCA) can deploy the surplus funding in several ways. As of June 30, 2026, the company held $151.03 billion of loans and $32.19 billion of borrowings, including a $28.42 billion purchase money note owed to the Federal Deposit Insurance Corporation. The acquired liquidity could support loan growth, replace more expensive funding, or be invested in securities. The original presentation projected immediate earnings-per-share accretion and an approximately 27-basis-point reduction in the Common Equity Tier 1 capital ratio.
#billion #first #citizens



2 months ago
Consolidated Edison Company of New York, Inc., the regulated utility subsidiary of Consolidated Edison, Inc. (NYSE:ED), joined New York regulatory staff and other parties in filing a proposed three-year steam-rate plan covering November 2026 through October 2029. Approval from the New York State Public Service Commission remains required.
The proposal includes headline base-rate changes of $13 million, $42 million and $39 million over the three rate years. A bill-shaping mechanism would instead implement corresponding base-rate increases of $26.6 million, $27.5 million and $28.5 million, producing an approximately 3.5% total customer-bill effect each year. Any revenue shortfall caused by delayed billing after the proposed November 1 effective date would be collected through a surcharge.
For Consolidated Edison, Inc. (NYSE:ED), the attraction is a visible investment and recovery framework. The trade-off is a 9.5% authorized return on common equity and limited room before earnings sharing begins.
The settlement supports $396 million of steam capital spending over three years, comprising $143 million, $127 million, and $126 million annually. The average rate base is projected to increase from $2.118 billion in the first rate year to $2.234 billion in the second and $2.311 billion in the third. That represents approximately 9.1% ***** ulative growth from the first year to the third, providing a larger base on which Consolidated Edison, Inc. (NYSE:ED) can earn its authorized return.
The multiyear structure also improves planning. Consolidated Edison, Inc. (NYSE:ED) would know the principal revenue, capital, and financing ***** umptions through October 2029 rather than returning immediately to a full rate proceeding. The proposed after-tax weighted average cost of capital rises from 7.07% to 7.19% across the plan, reflecting higher ***** umed long-term debt costs.
#million #consolidated #year #three
The proposal includes headline base-rate changes of $13 million, $42 million and $39 million over the three rate years. A bill-shaping mechanism would instead implement corresponding base-rate increases of $26.6 million, $27.5 million and $28.5 million, producing an approximately 3.5% total customer-bill effect each year. Any revenue shortfall caused by delayed billing after the proposed November 1 effective date would be collected through a surcharge.
For Consolidated Edison, Inc. (NYSE:ED), the attraction is a visible investment and recovery framework. The trade-off is a 9.5% authorized return on common equity and limited room before earnings sharing begins.
The settlement supports $396 million of steam capital spending over three years, comprising $143 million, $127 million, and $126 million annually. The average rate base is projected to increase from $2.118 billion in the first rate year to $2.234 billion in the second and $2.311 billion in the third. That represents approximately 9.1% ***** ulative growth from the first year to the third, providing a larger base on which Consolidated Edison, Inc. (NYSE:ED) can earn its authorized return.
The multiyear structure also improves planning. Consolidated Edison, Inc. (NYSE:ED) would know the principal revenue, capital, and financing ***** umptions through October 2029 rather than returning immediately to a full rate proceeding. The proposed after-tax weighted average cost of capital rises from 7.07% to 7.19% across the plan, reflecting higher ***** umed long-term debt costs.
#million #consolidated #year #three


2 months ago
On August 3, Alexandria Real Estate Equities (NYSE:ARE) reported a Q2 2026 net loss of $0.43 per diluted share, narrower than the $0.64 loss posted a year earlier, while first-half net income swung to $1.68 per share from a loss of $0.71 in H1 2025. Funds from operations, the metric real estate investors watch most closely, moved the other way. Second-quarter FFO per share, as adjusted, fell to $1.73 from $2.33, and first-half FFO per share dropped to $3.46 from $4.63.
Leasing activity picked up meaningfully in the second quarter. Alexandria signed 1,038,917 rentable square feet of leases in Q2 2026, a 60% jump from the first quarter and roughly 87,000 square feet above its trailing quarterly average. Three-quarters of that leasing activity over the trailing twelve months came from existing tenants, and once executed leases with future occupancy are counted, total occupancy climbs to 90.9% from the reported 86.9%. Tenant quality remains a selling point too: 80% of annual rental revenue comes from the company's Megacampus platform, and 57% comes from investment-grade or publicly traded large-cap tenants, with 99.9% of second-quarter rents and receivables collected as of August 3.
The balance sheet backs that stability up. Alexandria holds $3.60 billion in liquidity and just extended its $5.0 billion unsecured line of credit to 2032 at a lower borrowing rate of SOFR plus 0.725%, down from SOFR plus 0.835%. Only 6% of total debt matures through 2028, and the company's 9.7-year weighted-average remaining debt term is the longest among S&P 500 REITs. General and administrative expenses fell 17.4% from Q2 2024, even after a year-over-year uptick, and the company maintained its $0.72 per share quarterly dividend, a 5.4% yield as of June 30.
The numbers behind the improved per-share figures are less reassuring on closer look. Same-property net operating income fell 10.6% in the second quarter and 11.5% for the first half, driven largely by occupancy declines tied to lease expirations. Operating occupancy slipped from 87.7% at the end of March to 86.9% at the end of June, and the current-period average occupancy of 87.1% compares with 92.6% a year earlier. Lease renewals aren't helping much either: rental rate changes on renewed and re-leased ******* e fell 0.7% in the second quarter and 15.0% in the first quarter, with cash-basis declines of 4.3% and 15.8%, respectively.
Leverage remains elevated in the near term. Net debt and preferred stock to Adjusted EBITDA stood at 7.0x on a Q2 2026 annualized basis, well above the company's 5.6x to 6.2x target for the fourth quarter, which depends on completing $2.9 billion in planned dispositions and other capital sources. General and administrative expenses rose 26.5% from Q2 2025 to $36.9 million. The company also recorded $222.5 million of real estate impairment charges in the quarter and continues to evaluate the business and financial strategy for five development and redevelopment projects totaling 1.4 m
Leasing activity picked up meaningfully in the second quarter. Alexandria signed 1,038,917 rentable square feet of leases in Q2 2026, a 60% jump from the first quarter and roughly 87,000 square feet above its trailing quarterly average. Three-quarters of that leasing activity over the trailing twelve months came from existing tenants, and once executed leases with future occupancy are counted, total occupancy climbs to 90.9% from the reported 86.9%. Tenant quality remains a selling point too: 80% of annual rental revenue comes from the company's Megacampus platform, and 57% comes from investment-grade or publicly traded large-cap tenants, with 99.9% of second-quarter rents and receivables collected as of August 3.
The balance sheet backs that stability up. Alexandria holds $3.60 billion in liquidity and just extended its $5.0 billion unsecured line of credit to 2032 at a lower borrowing rate of SOFR plus 0.725%, down from SOFR plus 0.835%. Only 6% of total debt matures through 2028, and the company's 9.7-year weighted-average remaining debt term is the longest among S&P 500 REITs. General and administrative expenses fell 17.4% from Q2 2024, even after a year-over-year uptick, and the company maintained its $0.72 per share quarterly dividend, a 5.4% yield as of June 30.
The numbers behind the improved per-share figures are less reassuring on closer look. Same-property net operating income fell 10.6% in the second quarter and 11.5% for the first half, driven largely by occupancy declines tied to lease expirations. Operating occupancy slipped from 87.7% at the end of March to 86.9% at the end of June, and the current-period average occupancy of 87.1% compares with 92.6% a year earlier. Lease renewals aren't helping much either: rental rate changes on renewed and re-leased ******* e fell 0.7% in the second quarter and 15.0% in the first quarter, with cash-basis declines of 4.3% and 15.8%, respectively.
Leverage remains elevated in the near term. Net debt and preferred stock to Adjusted EBITDA stood at 7.0x on a Q2 2026 annualized basis, well above the company's 5.6x to 6.2x target for the fourth quarter, which depends on completing $2.9 billion in planned dispositions and other capital sources. General and administrative expenses rose 26.5% from Q2 2025 to $36.9 million. The company also recorded $222.5 million of real estate impairment charges in the quarter and continues to evaluate the business and financial strategy for five development and redevelopment projects totaling 1.4 m

2 months ago
On August 13, enCore Energy (NASDAQ:EU) reported financial and operating results for the six months ended June 30, and the numbers pull in two directions at once. The uranium miner delivered more pounds at higher prices than a year earlier, yet its net loss per share widened to $0.19 from $0.16. Underneath that headline sits a company racing to bring new wellfields online just as its current ones cost more to run than the uranium they produce is worth.
enCore delivered 485,000 pounds of U3O8 into contracts during the first half of 2026, up from 350,000 pounds a year earlier, at an average sales price of $70.10 per pound versus $62.58 in 2025. Both volume and price moved in the right direction, a sign that demand from utilities has not slowed even as the company's own production has. The bigger story sits in the ground. On June 22, enCore announced that its Dewey Burdock project in South Dakota received a 20-year renewal of its Source Materials License, extending the permit to June 2046, after the Bureau of Land Management cleared the company to begin infrastructure construction.
That milestone means Dewey Burdock now holds every federal permit it needs, leaving only a state review that began June 15. Closer to production, enCore expects final permits at its Alta Mesa Wellfield 3 Extension and at the Upper Spring Creek wellfield in the fourth quarter of 2026, both already built and waiting on paperwork rather than construction. Drilling at Alta Mesa East continued with three to five rigs through the quarter, and management says results have met or exceeded expectations. Add a July 2026 workforce reduction meant to lower costs starting in the third quarter, and the pieces for a stronger second half are at least on the table.
The production side tells a different story. enCore extracted just 131,274 pounds of U3O8 in the first half of 2026, down from 317,613 pounds a year earlier, a drop of more than half. Extraction costs rose to $57.36 per pound from $42.92, and once purchased pounds are folded in, the weighted average cost of delivered U3O8 climbed to $75.54 per pound, above the $70.10 per pound the company actually collected. That gap between what enCore pays to deliver uranium and what it earns selling it is at the center of the widened loss, which the company attributed to lower extraction and a fair value adjustment on its Verdera Energy Corp shares.
Alta Mesa's Wellfield 7 is also set to stop production in the third quarter of 2026 as it reaches natural depletion, removing supply before the newer wellfields are permitted to replace it. The near-term fixes aren't guaranteed on the timeline enCore has laid out either. Wellfield 8 permits are not expected until the end of the first quarter of 2027, and Dewey Burdock's state permitting process, still under review by South Dakota's Department of Agriculture & Natural Resources, has the company targeting development only in 2028.
#encore #pounds #quarter
enCore delivered 485,000 pounds of U3O8 into contracts during the first half of 2026, up from 350,000 pounds a year earlier, at an average sales price of $70.10 per pound versus $62.58 in 2025. Both volume and price moved in the right direction, a sign that demand from utilities has not slowed even as the company's own production has. The bigger story sits in the ground. On June 22, enCore announced that its Dewey Burdock project in South Dakota received a 20-year renewal of its Source Materials License, extending the permit to June 2046, after the Bureau of Land Management cleared the company to begin infrastructure construction.
That milestone means Dewey Burdock now holds every federal permit it needs, leaving only a state review that began June 15. Closer to production, enCore expects final permits at its Alta Mesa Wellfield 3 Extension and at the Upper Spring Creek wellfield in the fourth quarter of 2026, both already built and waiting on paperwork rather than construction. Drilling at Alta Mesa East continued with three to five rigs through the quarter, and management says results have met or exceeded expectations. Add a July 2026 workforce reduction meant to lower costs starting in the third quarter, and the pieces for a stronger second half are at least on the table.
The production side tells a different story. enCore extracted just 131,274 pounds of U3O8 in the first half of 2026, down from 317,613 pounds a year earlier, a drop of more than half. Extraction costs rose to $57.36 per pound from $42.92, and once purchased pounds are folded in, the weighted average cost of delivered U3O8 climbed to $75.54 per pound, above the $70.10 per pound the company actually collected. That gap between what enCore pays to deliver uranium and what it earns selling it is at the center of the widened loss, which the company attributed to lower extraction and a fair value adjustment on its Verdera Energy Corp shares.
Alta Mesa's Wellfield 7 is also set to stop production in the third quarter of 2026 as it reaches natural depletion, removing supply before the newer wellfields are permitted to replace it. The near-term fixes aren't guaranteed on the timeline enCore has laid out either. Wellfield 8 permits are not expected until the end of the first quarter of 2027, and Dewey Burdock's state permitting process, still under review by South Dakota's Department of Agriculture & Natural Resources, has the company targeting development only in 2028.
#encore #pounds #quarter


2 months ago
On August 3, Alexandria Real Estate Equities (NYSE:ARE) reported a Q2 2026 net loss of $0.43 per diluted share, narrower than the $0.64 loss posted a year earlier, while first-half net income swung to $1.68 per share from a loss of $0.71 in H1 2025. Funds from operations, the metric real estate investors watch most closely, moved the other way. Second-quarter FFO per share, as adjusted, fell to $1.73 from $2.33, and first-half FFO per share dropped to $3.46 from $4.63.
Leasing activity picked up meaningfully in the second quarter. Alexandria signed 1,038,917 rentable square feet of leases in Q2 2026, a 60% jump from the first quarter and roughly 87,000 square feet above its trailing quarterly average. Three-quarters of that leasing activity over the trailing twelve months came from existing tenants, and once executed leases with future occupancy are counted, total occupancy climbs to 90.9% from the reported 86.9%. Tenant quality remains a selling point too: 80% of annual rental revenue comes from the company's Megacampus platform, and 57% comes from investment-grade or publicly traded large-cap tenants, with 99.9% of second-quarter rents and receivables collected as of August 3.
The balance sheet backs that stability up. Alexandria holds $3.60 billion in liquidity and just extended its $5.0 billion unsecured line of credit to 2032 at a lower borrowing rate of SOFR plus 0.725%, down from SOFR plus 0.835%. Only 6% of total debt matures through 2028, and the company's 9.7-year weighted-average remaining debt term is the longest among S&P 500 REITs. General and administrative expenses fell 17.4% from Q2 2024, even after a year-over-year uptick, and the company maintained its $0.72 per share quarterly dividend, a 5.4% yield as of June 30.
The numbers behind the improved per-share figures are less reassuring on closer look. Same-property net operating income fell 10.6% in the second quarter and 11.5% for the first half, driven largely by occupancy declines tied to lease expirations. Operating occupancy slipped from 87.7% at the end of March to 86.9% at the end of June, and the current-period average occupancy of 87.1% compares with 92.6% a year earlier. Lease renewals aren't helping much either: rental rate changes on renewed and re-leased **** e fell 0.7% in the second quarter and 15.0% in the first quarter, with cash-basis declines of 4.3% and 15.8%, respectively.
Leverage remains elevated in the near term. Net debt and preferred stock to Adjusted EBITDA stood at 7.0x on a Q2 2026 annualized basis, well above the company's 5.6x to 6.2x target for the fourth quarter, which depends on completing $2.9 billion in planned dispositions and other capital sources. General and administrative expenses rose 26.5% from Q2 2025 to $36.9 million. The company also recorded $222.5 million of real estate impairment charges in the quarter and continues to evaluate the business and financial strategy for five development and redevelopment projects totaling 1.4 mill
Leasing activity picked up meaningfully in the second quarter. Alexandria signed 1,038,917 rentable square feet of leases in Q2 2026, a 60% jump from the first quarter and roughly 87,000 square feet above its trailing quarterly average. Three-quarters of that leasing activity over the trailing twelve months came from existing tenants, and once executed leases with future occupancy are counted, total occupancy climbs to 90.9% from the reported 86.9%. Tenant quality remains a selling point too: 80% of annual rental revenue comes from the company's Megacampus platform, and 57% comes from investment-grade or publicly traded large-cap tenants, with 99.9% of second-quarter rents and receivables collected as of August 3.
The balance sheet backs that stability up. Alexandria holds $3.60 billion in liquidity and just extended its $5.0 billion unsecured line of credit to 2032 at a lower borrowing rate of SOFR plus 0.725%, down from SOFR plus 0.835%. Only 6% of total debt matures through 2028, and the company's 9.7-year weighted-average remaining debt term is the longest among S&P 500 REITs. General and administrative expenses fell 17.4% from Q2 2024, even after a year-over-year uptick, and the company maintained its $0.72 per share quarterly dividend, a 5.4% yield as of June 30.
The numbers behind the improved per-share figures are less reassuring on closer look. Same-property net operating income fell 10.6% in the second quarter and 11.5% for the first half, driven largely by occupancy declines tied to lease expirations. Operating occupancy slipped from 87.7% at the end of March to 86.9% at the end of June, and the current-period average occupancy of 87.1% compares with 92.6% a year earlier. Lease renewals aren't helping much either: rental rate changes on renewed and re-leased **** e fell 0.7% in the second quarter and 15.0% in the first quarter, with cash-basis declines of 4.3% and 15.8%, respectively.
Leverage remains elevated in the near term. Net debt and preferred stock to Adjusted EBITDA stood at 7.0x on a Q2 2026 annualized basis, well above the company's 5.6x to 6.2x target for the fourth quarter, which depends on completing $2.9 billion in planned dispositions and other capital sources. General and administrative expenses rose 26.5% from Q2 2025 to $36.9 million. The company also recorded $222.5 million of real estate impairment charges in the quarter and continues to evaluate the business and financial strategy for five development and redevelopment projects totaling 1.4 mill

2 months ago
Interested in Diversified Energy Company PLC? Here are five stocks we like better.
Diversified Energy agreed to acquire Birch Resources for approximately $1.8 billion, with closing expected in the fourth quarter of 2026. The deal would add 480 net wells, roughly 68,000 barrels of oil equivalent per day and 1.2 trillion cubic feet equivalent of reserves.
The acquisition would significantly expand Diversified's Permian presence, lifting production from about 9,000 to 77,000 barrels of oil equivalent per day and increasing projected Permian adjusted EBITDA from $64 million to $612 million. The ****** ets are about 70% liquids-weighted and include related infrastructure.
Diversified plans to finance the purchase mainly with ****** et-backed securities and expects operational synergies, while targeting nearly $2 billion of deleveraging over four years. The company said the transaction should increase total production by 35%, adjusted EBITDA by 55% and more than double free cash flow.
Premium Retail's Stress Test Is Separating Winners From Losers
#equivalent #energy #ebitda
Diversified Energy agreed to acquire Birch Resources for approximately $1.8 billion, with closing expected in the fourth quarter of 2026. The deal would add 480 net wells, roughly 68,000 barrels of oil equivalent per day and 1.2 trillion cubic feet equivalent of reserves.
The acquisition would significantly expand Diversified's Permian presence, lifting production from about 9,000 to 77,000 barrels of oil equivalent per day and increasing projected Permian adjusted EBITDA from $64 million to $612 million. The ****** ets are about 70% liquids-weighted and include related infrastructure.
Diversified plans to finance the purchase mainly with ****** et-backed securities and expects operational synergies, while targeting nearly $2 billion of deleveraging over four years. The company said the transaction should increase total production by 35%, adjusted EBITDA by 55% and more than double free cash flow.
Premium Retail's Stress Test Is Separating Winners From Losers
#equivalent #energy #ebitda

2 months ago
On August 5, LTC Properties (NYSE:LTC) reported second-quarter results for the period ended June 30, 2026, and the numbers show a real estate investment trust leaning harder into a strategy it only started a year ago. Total revenue climbed to $98.9 million from $60.2 million a year earlier, and net income available to common stockholders nearly doubled to $29.5 million. Diluted earnings per share rose to $0.56 from $0.32. Alongside the results, the company raised its full-year 2026 investment guidance by 50% at the midpoint, putting more weight behind a business line called SHOP.
LTC increased the midpoint of its 2026 SHOP investment guidance to $900 million, calling that figure a jump of 50% from the previous midpoint. Management now expects $700 million in year-to-date SHOP acquisitions by the end of the third quarter, and projects SHOP will represent 40% of pro forma annualized net operating income by that same point, which the company says is ahead of its own estimates. LTC expects that share to approach 50% by year-end, with a stated pathway toward 75% by the end of 2028.
Since launching the platform in May 2025, LTC has built the SHOP portfolio to 39 communities across 12 operators, 10 of which are new relationships for the company, representing 37% of total gross real estate investments as of July 31, 2026. Second quarter core SHOP NOI came in at $13.3 million. The company closed $171 million in acquisitions during the quarter and expects another $529 million to close in the third quarter, with $208 million of that already done. LTC also raised its full-year diluted earnings per share guidance to $8.08 to $8.10 and expanded its credit facility to $1.1 billion, leaving $648 million in total pro forma liquidity.
Growth this fast comes with a cost that shows up once you move past revenue. Core FFO per diluted share held flat at $0.68, unchanged from a year earlier even though revenue grew 64%. Core FAD per diluted share actually slipped to $0.70 from $0.71. Part of the explanation is share count. Diluted weighted average shares outstanding rose to 52.2 million from 46.0 million, and total shares outstanding climbed to 53.9 million from 46.1 million, dilution that has kept per-share growth well behind the topline.
Expenses grew just as fast as revenue did. Total expenses nearly doubled to $75.5 million from $44.5 million, with senior housing operating expenses, the direct cost of running SHOP, jumping to $42.2 million from $9.4 million as the new segment scaled up. Interest expense rose to $9.5 million from $8.0 million, and $356 million remains drawn on the revolving credit line even after that facility's expansion. SHOP also depends on the 12 third-party operators running those communities day to day, 10 of which have never worked with LTC before, concentrating execution risk in relationships still being tested.
#million #company
LTC increased the midpoint of its 2026 SHOP investment guidance to $900 million, calling that figure a jump of 50% from the previous midpoint. Management now expects $700 million in year-to-date SHOP acquisitions by the end of the third quarter, and projects SHOP will represent 40% of pro forma annualized net operating income by that same point, which the company says is ahead of its own estimates. LTC expects that share to approach 50% by year-end, with a stated pathway toward 75% by the end of 2028.
Since launching the platform in May 2025, LTC has built the SHOP portfolio to 39 communities across 12 operators, 10 of which are new relationships for the company, representing 37% of total gross real estate investments as of July 31, 2026. Second quarter core SHOP NOI came in at $13.3 million. The company closed $171 million in acquisitions during the quarter and expects another $529 million to close in the third quarter, with $208 million of that already done. LTC also raised its full-year diluted earnings per share guidance to $8.08 to $8.10 and expanded its credit facility to $1.1 billion, leaving $648 million in total pro forma liquidity.
Growth this fast comes with a cost that shows up once you move past revenue. Core FFO per diluted share held flat at $0.68, unchanged from a year earlier even though revenue grew 64%. Core FAD per diluted share actually slipped to $0.70 from $0.71. Part of the explanation is share count. Diluted weighted average shares outstanding rose to 52.2 million from 46.0 million, and total shares outstanding climbed to 53.9 million from 46.1 million, dilution that has kept per-share growth well behind the topline.
Expenses grew just as fast as revenue did. Total expenses nearly doubled to $75.5 million from $44.5 million, with senior housing operating expenses, the direct cost of running SHOP, jumping to $42.2 million from $9.4 million as the new segment scaled up. Interest expense rose to $9.5 million from $8.0 million, and $356 million remains drawn on the revolving credit line even after that facility's expansion. SHOP also depends on the 12 third-party operators running those communities day to day, 10 of which have never worked with LTC before, concentrating execution risk in relationships still being tested.
#million #company

2 months ago
ONEOK, Inc. (NYSE:OKE) has agreed to acquire Brazos Midstream's Permian Midland Basin natural-gas gathering and processing ***** ets for $4.425 billion in cash. The deal is being paired with a $9 billion nonvoting minority equity investment from Apollo, of which ONEOK plans to use about $5 billion to reduce existing debt. ONEOK expects the acquisition to be immediately accretive to earnings and free cash flow per share.
The transaction would more than double ONEOK, Inc. (NYSE:OKE)'s Midland Basin processing capacity to approximately 2.3 Bcf/d, including plants already under construction. The acquired platform includes roughly 700 miles of gathering infrastructure, 1.2 Bcf/d of processing capacity after the Cassidy II plant is completed, and approximately 600,000 dedicated acres backed by fixed-fee contracts with more than 12 years of weighted-average remaining term.
The biggest attraction is the quality and location of the ***** ets. The Permian remains one of the most economically important oil and gas-producing regions in the U.S., and the Brazos system gives ONEOK, Inc. (NYSE:OKE) additional exposure to ***** ociated natural-gas volumes generated by oil production. The acquired ***** ets are supported by 14 active drilling rigs operated by producers including ExxonMobil, Diamondback Energy, and Double Eagle. The long-term contracts provide ONEOK with considerable visibility into future volumes and cash flows. That makes this more than a simple capacity expansion. ONEOK is effectively adding infrastructure that can grow alongside production on the dedicated acreage.
The ***** ets fit closely with ONEOK's existing gathering, processing, NGL transportation and crude infrastructure. That creates an opportunity to extract more value from the same barrels and molecules as they move through ONEOK's network.
The company expects to connect the Brazos system with downstream ***** ets such as its West Texas NGL Pipeline and the Medford NGL fractionation facility. This broader integration could produce commercial and operational efficiencies that an independent owner of the ***** ets might not be able to capture. ONEOK estimates about $80 million of full-year synergies in its 2027 EBITDA calculation and expects additional commercial and capital efficiencies as the systems are integrated.
#cash #expects
The transaction would more than double ONEOK, Inc. (NYSE:OKE)'s Midland Basin processing capacity to approximately 2.3 Bcf/d, including plants already under construction. The acquired platform includes roughly 700 miles of gathering infrastructure, 1.2 Bcf/d of processing capacity after the Cassidy II plant is completed, and approximately 600,000 dedicated acres backed by fixed-fee contracts with more than 12 years of weighted-average remaining term.
The biggest attraction is the quality and location of the ***** ets. The Permian remains one of the most economically important oil and gas-producing regions in the U.S., and the Brazos system gives ONEOK, Inc. (NYSE:OKE) additional exposure to ***** ociated natural-gas volumes generated by oil production. The acquired ***** ets are supported by 14 active drilling rigs operated by producers including ExxonMobil, Diamondback Energy, and Double Eagle. The long-term contracts provide ONEOK with considerable visibility into future volumes and cash flows. That makes this more than a simple capacity expansion. ONEOK is effectively adding infrastructure that can grow alongside production on the dedicated acreage.
The ***** ets fit closely with ONEOK's existing gathering, processing, NGL transportation and crude infrastructure. That creates an opportunity to extract more value from the same barrels and molecules as they move through ONEOK's network.
The company expects to connect the Brazos system with downstream ***** ets such as its West Texas NGL Pipeline and the Medford NGL fractionation facility. This broader integration could produce commercial and operational efficiencies that an independent owner of the ***** ets might not be able to capture. ONEOK estimates about $80 million of full-year synergies in its 2027 EBITDA calculation and expects additional commercial and capital efficiencies as the systems are integrated.
#cash #expects

2 months ago
Concerned about an AI bubble? Sign up for The Daily Upside for smart and actionable market news, built for investors.
Giving everyone their fair share just got more popular.
Fears of an AI bubble and high levels of market concentration may be sending investors to more diversified options. Earlier this month, Invesco's S&P 500 Equal Weight ETF (RSP) surpassed $100 billion in ****** ets under management and has brought in more than $12 billion this year alone, per a CNBC report. RSP and other equal-weight funds give the same value to each of their underlying stocks rather than mirroring an index. To investors, they can represent a welcome reprieve from the S&P 500, which derives around a third of its value from the tech sector alone. The trend could signal a change in how investors think about the role that S&P 500 funds play in a portfolio.
"Right now, we've got the Mag Seven about 34% of the total S&P 500 index, which is at historic levels," said Don Cody, CEO at Global Macro ****** et Management. "I think [equal-weight fund popularity is] largely fear and concern that we're overweighted in areas that are obviously the drivers of the market."
Sign up for The Daily Upside at no cost for premium ****** ysis on all your favorite stocks.
#levels
Giving everyone their fair share just got more popular.
Fears of an AI bubble and high levels of market concentration may be sending investors to more diversified options. Earlier this month, Invesco's S&P 500 Equal Weight ETF (RSP) surpassed $100 billion in ****** ets under management and has brought in more than $12 billion this year alone, per a CNBC report. RSP and other equal-weight funds give the same value to each of their underlying stocks rather than mirroring an index. To investors, they can represent a welcome reprieve from the S&P 500, which derives around a third of its value from the tech sector alone. The trend could signal a change in how investors think about the role that S&P 500 funds play in a portfolio.
"Right now, we've got the Mag Seven about 34% of the total S&P 500 index, which is at historic levels," said Don Cody, CEO at Global Macro ****** et Management. "I think [equal-weight fund popularity is] largely fear and concern that we're overweighted in areas that are obviously the drivers of the market."
Sign up for The Daily Upside at no cost for premium ****** ysis on all your favorite stocks.
#levels


2 months ago
ONEOK has agreed to acquire Brazos Midstream's natural gas gathering and processing ******* ets in the Permian Basin's Midland sub-basin for $4.425 billion in cash, expanding the midstream operator's footprint in one of the largest U.S. oil and gas producing regions.
The acquisition will be funded as part of a separate $9 billion nonvoting minority equity investment from funds and affiliates managed by Apollo Global Management. ONEOK plans to use roughly $5 billion of the Apollo proceeds to extinguish existing debt, while the remainder will fund the Brazos acquisition.
The structure allows ONEOK to finance the transaction without issuing common equity. The company said the combination of the Apollo investment and planned debt reduction is expected to bring its pro forma 2027 debt-to-EBITDA ratio to about 3.25 times.
Brazos' Midland Basin system is supported by roughly 600,000 dedicated acres under fixed-fee contracts with a weighted average remaining term exceeding 12 years, according to ONEOK. Producers operating on the acreage include ExxonMobil, Diamondback Energy and Double Eagle, with 14 active drilling rigs currently supporting the system.
After completion of the Cassidy II processing plant, which ONEOK expects in the third quarter of 2027, the acquired system is expected to comprise about 700 miles of gathering infrastructure and 1.2 billion cubic feet per day of gas processing capacity across seven Midland Basin counties.
#basin
The acquisition will be funded as part of a separate $9 billion nonvoting minority equity investment from funds and affiliates managed by Apollo Global Management. ONEOK plans to use roughly $5 billion of the Apollo proceeds to extinguish existing debt, while the remainder will fund the Brazos acquisition.
The structure allows ONEOK to finance the transaction without issuing common equity. The company said the combination of the Apollo investment and planned debt reduction is expected to bring its pro forma 2027 debt-to-EBITDA ratio to about 3.25 times.
Brazos' Midland Basin system is supported by roughly 600,000 dedicated acres under fixed-fee contracts with a weighted average remaining term exceeding 12 years, according to ONEOK. Producers operating on the acreage include ExxonMobil, Diamondback Energy and Double Eagle, with 14 active drilling rigs currently supporting the system.
After completion of the Cassidy II processing plant, which ONEOK expects in the third quarter of 2027, the acquired system is expected to comprise about 700 miles of gathering infrastructure and 1.2 billion cubic feet per day of gas processing capacity across seven Midland Basin counties.
#basin


2 months ago
SCHMID Group N.V. (NASDAQ:SHMD) delivered a sharp revenue recovery in the first half of 2026, but the quality of that growth fell short of management's earlier expectations. Revenue increased 172% to €46.0 million from €16.9 million, while gross profit improved to €9.8 million from a €1.6 million loss. Gross margin reached 21.2%.
However, SCHMID Group N.V. (NASDAQ:SHMD) lowered its full-year adjusted EBITDA margin outlook to 6%-9% from more than 12%. Management attributed the revision to weaker-than-expected first-half profitability and a product mix weighted toward its lower-margin Chinese business. The central question is whether stronger volume can eventually translate into dependable margins and cash generation.
The underlying performance of SCHMID Group N.V. (NASDAQ:SHMD) improved substantially. Its company-defined non-IFRS adjusted EBITDA loss narrowed to €0.6 million from a recalculated €11.6 million. SCHMID Group N.V. (NASDAQ:SHMD) recast the prior-year figure under its current definition to exclude a €6.3 million foreign-exchange gain. Under the previously published definition, the first-half 2025 adjusted EBITDA loss was €5.3 million.
Demand also accelerated after a seasonally weak first quarter. SCHMID Group N.V. (NASDAQ:SHMD) reported €96.6 million of year-to-date equipment orders through August 21, including €52.3 million received during the third quarter through that date. Equipment backlog reached €95.0 million, compared with €54.8 million at the end of June. These figures exclude service and spare-parts orders.
SCHMID Group N.V. (NASDAQ:SHMD) maintained its full-year revenue target of more than €100 million and its €125 million-€150 million order-intake outlook, with management expecting the upper half of that range. Meeting the revenue target requires more than €54 million during the second half, but the larger backlog provides meaningful visibility.
#group #NASDAQ #half #revenue
However, SCHMID Group N.V. (NASDAQ:SHMD) lowered its full-year adjusted EBITDA margin outlook to 6%-9% from more than 12%. Management attributed the revision to weaker-than-expected first-half profitability and a product mix weighted toward its lower-margin Chinese business. The central question is whether stronger volume can eventually translate into dependable margins and cash generation.
The underlying performance of SCHMID Group N.V. (NASDAQ:SHMD) improved substantially. Its company-defined non-IFRS adjusted EBITDA loss narrowed to €0.6 million from a recalculated €11.6 million. SCHMID Group N.V. (NASDAQ:SHMD) recast the prior-year figure under its current definition to exclude a €6.3 million foreign-exchange gain. Under the previously published definition, the first-half 2025 adjusted EBITDA loss was €5.3 million.
Demand also accelerated after a seasonally weak first quarter. SCHMID Group N.V. (NASDAQ:SHMD) reported €96.6 million of year-to-date equipment orders through August 21, including €52.3 million received during the third quarter through that date. Equipment backlog reached €95.0 million, compared with €54.8 million at the end of June. These figures exclude service and spare-parts orders.
SCHMID Group N.V. (NASDAQ:SHMD) maintained its full-year revenue target of more than €100 million and its €125 million-€150 million order-intake outlook, with management expecting the upper half of that range. Meeting the revenue target requires more than €54 million during the second half, but the larger backlog provides meaningful visibility.
#group #NASDAQ #half #revenue


2 months ago
Deutsche Bank Aktiengesellschaft (NYSE:DB) completed its €1 billion share-buyback program on August 21 after acquiring 35.7 million treasury shares, equivalent to 1.87% of its share capital. The shares were repurchased at a volume-weighted average price of €28. Treasury-share acquisition can reduce the shares used in per-share calculations while the shares remain in treasury, but it is distinct from legal cancellation.
Deutsche Bank Aktiengesellschaft (NYSE:DB) followed that program with a new buyback of up to €500 million starting August 25 and scheduled to end no later than December 11. The new program is the bank's first funded from current-year net profit. Management's 60% target refers to total dividends and buybacks as a percentage of net profit attributable to Deutsche Bank shareholders from 2026.
The earnings base currently supports the feasibility of that target. Deutsche Bank Aktiengesellschaft (NYSE:DB) reported second-quarter profit after tax of €1.9 billion, up 10% year over year, while first-half profit reached a record €4.1 billion. Quarterly net revenues increased 9% to €8.5 billion, with growth across all four businesses.
The capital position also suggests that Deutsche Bank Aktiengesellschaft (NYSE:DB) can execute the new program without moving outside management's operating range. Its Common Equity Tier 1 ratio was 13.9% at June 30 after deductions aligned with the 60% payout target. The bank said the €500 million program was already fully covered by existing capital deductions.
For Deutsche Bank Aktiengesellschaft (NYSE:DB), the completed purchases carry more weight than an unused authorization. Completion of the new program would bring buybacks conducted during 2026 to €1.5 billion, compared with €1 billion in 2025. The first €1 billion program related to the prior capital-return cycle, while the new €500 million program is the first funded from 2026 earnings.
#bank #deutsche
Deutsche Bank Aktiengesellschaft (NYSE:DB) followed that program with a new buyback of up to €500 million starting August 25 and scheduled to end no later than December 11. The new program is the bank's first funded from current-year net profit. Management's 60% target refers to total dividends and buybacks as a percentage of net profit attributable to Deutsche Bank shareholders from 2026.
The earnings base currently supports the feasibility of that target. Deutsche Bank Aktiengesellschaft (NYSE:DB) reported second-quarter profit after tax of €1.9 billion, up 10% year over year, while first-half profit reached a record €4.1 billion. Quarterly net revenues increased 9% to €8.5 billion, with growth across all four businesses.
The capital position also suggests that Deutsche Bank Aktiengesellschaft (NYSE:DB) can execute the new program without moving outside management's operating range. Its Common Equity Tier 1 ratio was 13.9% at June 30 after deductions aligned with the 60% payout target. The bank said the €500 million program was already fully covered by existing capital deductions.
For Deutsche Bank Aktiengesellschaft (NYSE:DB), the completed purchases carry more weight than an unused authorization. Completion of the new program would bring buybacks conducted during 2026 to €1.5 billion, compared with €1 billion in 2025. The first €1 billion program related to the prior capital-return cycle, while the new €500 million program is the first funded from 2026 earnings.
#bank #deutsche

2 months ago
X Financial (NYSE:XYF) reported a dramatically smaller lending platform on August 24. Second-quarter net revenue fell 56.3% year over year and 15.5% sequentially to RMB 993.6 million. The active-borrower count declined 74.8% from a year earlier to approximately 720,258, while the total loan amount facilitated and originated dropped 70.2% to RMB11.63 billion. Shares closed at $5.35 on August 24 following the results.
The question is whether the contraction represents a successful reset toward better borrowers or continuing erosion that improved credit metrics cannot offset. The latest quarter suggests credit performance is stabilizing faster than the business itself.
The strongest argument for X Financial (NYSE:XYF) is that tighter underwriting appears to be improving recent loan performance. The company-reported 31- to 60-day delinquency rate declined to 1.73% from 2.61% at the end of the first quarter. Its 91- to 180-day rate eased to 9.09% from 9.95%. Management attributed the first sequential improvement in several quarters to stricter underwriting for newer loan vintages and additional collection resources.
The average loan amount per transaction increased 21.3% year over year to RMB12,712. Management linked the increase to a transaction mix weighted toward higher-quality borrowers and said newer vintages were performing better. That strategy sacrifices scale but could produce a healthier remaining portfolio if the improvement continues.
Cost reductions also supported sequential profitability. Total operating costs and expenses fell 22.9% from the first quarter, while operating income increased 38.6% to RMB194.9 million. Operating margin improved to 19.6% from 12.0%, although it remained below 29.7% a year earlier.
#loan #august
The question is whether the contraction represents a successful reset toward better borrowers or continuing erosion that improved credit metrics cannot offset. The latest quarter suggests credit performance is stabilizing faster than the business itself.
The strongest argument for X Financial (NYSE:XYF) is that tighter underwriting appears to be improving recent loan performance. The company-reported 31- to 60-day delinquency rate declined to 1.73% from 2.61% at the end of the first quarter. Its 91- to 180-day rate eased to 9.09% from 9.95%. Management attributed the first sequential improvement in several quarters to stricter underwriting for newer loan vintages and additional collection resources.
The average loan amount per transaction increased 21.3% year over year to RMB12,712. Management linked the increase to a transaction mix weighted toward higher-quality borrowers and said newer vintages were performing better. That strategy sacrifices scale but could produce a healthier remaining portfolio if the improvement continues.
Cost reductions also supported sequential profitability. Total operating costs and expenses fell 22.9% from the first quarter, while operating income increased 38.6% to RMB194.9 million. Operating margin improved to 19.6% from 12.0%, although it remained below 29.7% a year earlier.
#loan #august

2 months ago
Before impressing at Texas and becoming one of the NFL's best running backs, Atlanta Falcons superstar Bijan Robinson became one of the greatest high school athletes the state of Arizona has ever seen.
Robinson set an Arizona state record at Salpointe Catholic, rushing for 7,036 yards and scoring 114 total touchdowns during his time as a Lancer. On Thursday, the school announced that Robinson's No. 5 jersey will soon be retired:
"We're thrilled to announce that Salpointe will honor Bijan Robinson '20 by retiring his iconic No. 5 football jersey at our next school **** embly," the school announced via Instagram. "Even more exciting, Bijan will be joining us on campus for this special celebration! We can't wait to welcome him back to Salpointe and honor the incredible legacy he's created both on and off the field. Congratulations, Bijan. Once a Lancer, always a Lancer."
Robinson rushed for over 2,000 yards in each of his final three seasons. Earning Gatorade Arizona Player of the Year honors during his senior year, the class of 2020 standout rushed for 2,235 yards and 38 touchdowns while also hauling in 12 passes for 314 yards and three more scores. He averaged over 17 yards per carry that year and averaged more than 13 YPC across his 46-game career with the Lancers.
The 5-foot-11, 215-pounder was no under-the-radar recruit, either. He finished as the No. 16 overall prospect and No. 2 running back in the 2020 cycle, according to the Rivals Industry Ranking, a weighted average that utilizes all major recruiting media companies.
#salpointe #year #running
Robinson set an Arizona state record at Salpointe Catholic, rushing for 7,036 yards and scoring 114 total touchdowns during his time as a Lancer. On Thursday, the school announced that Robinson's No. 5 jersey will soon be retired:
"We're thrilled to announce that Salpointe will honor Bijan Robinson '20 by retiring his iconic No. 5 football jersey at our next school **** embly," the school announced via Instagram. "Even more exciting, Bijan will be joining us on campus for this special celebration! We can't wait to welcome him back to Salpointe and honor the incredible legacy he's created both on and off the field. Congratulations, Bijan. Once a Lancer, always a Lancer."
Robinson rushed for over 2,000 yards in each of his final three seasons. Earning Gatorade Arizona Player of the Year honors during his senior year, the class of 2020 standout rushed for 2,235 yards and 38 touchdowns while also hauling in 12 passes for 314 yards and three more scores. He averaged over 17 yards per carry that year and averaged more than 13 YPC across his 46-game career with the Lancers.
The 5-foot-11, 215-pounder was no under-the-radar recruit, either. He finished as the No. 16 overall prospect and No. 2 running back in the 2020 cycle, according to the Rivals Industry Ranking, a weighted average that utilizes all major recruiting media companies.
#salpointe #year #running

2 months ago
Apparently a Pro Bowl, well, event that included Joe Flacco and Shedeur Sanders was a bridge too far.
The NFL will officially eliminate the Pro Bowl as a competition and simply apply the honorific to deserving players, many of whom have contract escalators for being named a Pro Bowler. The league made the announcement Wednesday, Aug. 26. The move also aligns with the NFL's ongoing initiatives to emphasize player safety. Playing an all-star exhibition, in any form, didn't square nicely with that objective.
Moving forward, the AFC and NFC rosters will continue to be constructed with 44 players apiece. However with no need for last-minute replacements, there won't be a dilution to the honor that had become so commonplace in recent years. Players, coaches and fans will continue to annually supply equally weighted votes to determine the 88 Pro Bowlers.
"The Pro Bowl has always been about recognizing the players who distinguish themselves as the very best in the NFL," said Peter O'Reilly, the NFL's EVP of club business, international and league events.
"A Pro Bowl selection will return to its original purpose, honoring the best of the best. We want that distinction to carry even greater meaning for the players, their families, their clubs and our fans."
#league
The NFL will officially eliminate the Pro Bowl as a competition and simply apply the honorific to deserving players, many of whom have contract escalators for being named a Pro Bowler. The league made the announcement Wednesday, Aug. 26. The move also aligns with the NFL's ongoing initiatives to emphasize player safety. Playing an all-star exhibition, in any form, didn't square nicely with that objective.
Moving forward, the AFC and NFC rosters will continue to be constructed with 44 players apiece. However with no need for last-minute replacements, there won't be a dilution to the honor that had become so commonplace in recent years. Players, coaches and fans will continue to annually supply equally weighted votes to determine the 88 Pro Bowlers.
"The Pro Bowl has always been about recognizing the players who distinguish themselves as the very best in the NFL," said Peter O'Reilly, the NFL's EVP of club business, international and league events.
"A Pro Bowl selection will return to its original purpose, honoring the best of the best. We want that distinction to carry even greater meaning for the players, their families, their clubs and our fans."
#league

2 months ago
Our ******* ysts just identified a stock with the potential to be the next Nvidia. Tell us how you invest and we'll show you why it's our #1 pick. Tap here.
Revenue doubled year-over-year in the first half of 2026, driven by the completion of key deliverables and milestones earlier than originally anticipated.
Operating performance improved significantly as the company absorbed the majority of share-based compensation in Q1, leading to a 95% reduction in operating loss by Q2.
Management is deliberately deploying capital into revenue-generating infrastructure, including purchasing GPUs and securing data center capacity, rather than focusing on interest income.
The current gross margin dip reflects a temporary revenue mix weighted toward hardware and mobilization costs as the company builds its installed base.
#company #tell #analysts
Revenue doubled year-over-year in the first half of 2026, driven by the completion of key deliverables and milestones earlier than originally anticipated.
Operating performance improved significantly as the company absorbed the majority of share-based compensation in Q1, leading to a 95% reduction in operating loss by Q2.
Management is deliberately deploying capital into revenue-generating infrastructure, including purchasing GPUs and securing data center capacity, rather than focusing on interest income.
The current gross margin dip reflects a temporary revenue mix weighted toward hardware and mobilization costs as the company builds its installed base.
#company #tell #analysts


2 months ago
One of the biggest advantages of ETFs is that they make building a portfolio very simple. With a single stock fund, you could own hundreds, if not thousands, of different companies in one investment. And if you wanted the simplest possible solution, you could own the entire global equity market in just one ETF.
That's what the Vanguard Total World Stock ETF (NYSEMKT: VT) is. It includes more than 10,000 stocks in total, covering companies of all sizes from the United States, developed foreign markets, and emerging markets. If you want the broadest possible coverage of global stocks, it's ideal. But it's not the ideal choice for everyone.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
If easy investing is your primary goal, there might not be a better ETF to use than this one. You don't have to chase what's hot at the moment or worry about what sector is leading the market. And you don't need to think about whether it's time to diversify internationally. You already own it all -- nearly every investable stock, industry, and region of the world.
Because it's market cap-weighted, you're still more heavily invested in the global economy's giants, including Microsoft, Apple, and Taiwan Semiconductor Manufacturing. There's no concern that you're missing out on the giants driving economic growth right now. But you're also able to capture performance in case the economy changes or other areas of the world begin to lead.
#Stock #World #global
That's what the Vanguard Total World Stock ETF (NYSEMKT: VT) is. It includes more than 10,000 stocks in total, covering companies of all sizes from the United States, developed foreign markets, and emerging markets. If you want the broadest possible coverage of global stocks, it's ideal. But it's not the ideal choice for everyone.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
If easy investing is your primary goal, there might not be a better ETF to use than this one. You don't have to chase what's hot at the moment or worry about what sector is leading the market. And you don't need to think about whether it's time to diversify internationally. You already own it all -- nearly every investable stock, industry, and region of the world.
Because it's market cap-weighted, you're still more heavily invested in the global economy's giants, including Microsoft, Apple, and Taiwan Semiconductor Manufacturing. There's no concern that you're missing out on the giants driving economic growth right now. But you're also able to capture performance in case the economy changes or other areas of the world begin to lead.
#Stock #World #global


