

1 month ago
GE Vernova Inc. (NYSE:GEV) is one of Jim Cramer's favorite stocks. Throughout 2025, the CNBC TV host continued to heap praise on the firm. Cramer's praise came at a time when new-age nuclear power and quantum computing stocks were experiencing strong gains. Throughout this period, he continued to **** ert that GE Vernova Inc. (NYSE:GEV) was the only nuclear firm with a stable delivery timeline and the capacity to deliver. In his morning appearance on the 15th, Cramer discussed the recent dip in shares and worries about a slowdown in the AI buildout:
"One company, GE Vernova, which was hit incredibly hard, which actually builds these, was saying they're seeing an order acceleration. So I really doubt the idea there's going to be a decel. Now that stock got hammered yesterday, it's been a horrendous stock since we started getting this political controversy. But again I point out that you just hear no one say anything about pullback."
For GE Vernova Inc. (NYSE:GEV), as perhaps indicated by the share price movement, the narrative is driven by its backlog and overall exposure to AI's power generation demand. On this front, CEO Scott Strazik, another Cramer favorite, outlined during the firm's second quarter earnings that data center orders of $5 billion for H1 2026 had already doubled over the full year 2025 figures. Additionally, during Q2, the firm's total orders touched $24 billion to mark an 88% growth driven by its Power and Electrification segment. As a whole, GE Vernova Inc. (NYSE:GEV)'s Q2 revenue grew by 22% annually, while its overall backlog and electrification backlogs sat at $176 billion and $446 billion.
At the same time, with GE Vernova Inc. (NYSE:GEV) also relying on gas turbines for its business, the debate is also about whether exposure to AI can remove the inherent cyclicality in the business. Additionally, with data centers accounting for 40% of the Electrification business's orders, any slowdown in capex spending by big tech players could generate tailwinds for GE Vernova Inc. (NYSE:GEV). Similarly, while the data center business is booming and the gas generation business remains tied to prices and interest rates, the firm's wind business is a drag and expected to hurt the bottom line throughout 2026.
In Q2, 106 out of the 1,006 funds tracked by Insider Monkey had held a stake in GE Vernova Inc. (NYSE:GEV), which marked a dip over the 118 out of 1,022 funds in Q1. Whether the dip was due to the order mix and AI sentiment or due to profit taking, your guess is as good as ours. On the valuation front, GE Vernova Inc. (NYSE:GEV) trades at a forward P/E ratio of 35, while short interest as a percentage of float is 3.29%.
#vernova #business #throughout #data


1 month ago
Cybersecurity provider CrowdStrike Holdings, Inc. (NASDAQ:CRWD)'s shares are up by more than 100% year to date. With AI continuing to dominate the market narrative, the firm has found itself at the center of the industry's concerns about cybersecurity. While some, such as Anthropic's Dario Amodei, have claimed that their AI software is sufficient for cybersecurity purposes, others have argued that firms such as CrowdStrike Holdings, Inc. (NASDAQ:CRWD) will play a key role in the industry. Cramer is in the latter camp, and in his morning appearance on September 15th, the CNBC TV host discussed the recent discussions about AI being a threat:
"I had George Kurtz last night, who has partnered both with OpenAI and Anthropic. And he encouraged me to say look, they are doing a lot of things about safeguards. I think he was so much surprised, that there was so much doomsaying, of course, doomsaying being heavily refuted. Now there's a stock, remember that stock was up the most of any stock in the S&P."
While Cramer believes CrowdStrike Holdings, Inc. (NASDAQ:CRWD) will play an important role in cybersecurity in the AI era, the broader debate about the firm is about its AI-driven cybersecurity initiatives and whether they are sufficient to stay competitive and justify the eye-watering share price performance. On this front, the firm's annual recurring revenue (ARR) grew by 25% and net new ARR grew by 55% in its fiscal second quarter. Additionally, CrowdStrike Holdings, Inc. (NASDAQ:CRWD)'s net new ARR set a new record of $333 million. Cramer's bullishness on the firm is also matched by others, such as ******* ysts from Argus. Argus has set a $425 share price target for CrowdStrike Holdings, Inc. (NASDAQ:CRWD) and argued that growth in agentic AI use presents a major tailwind for the firm.
Yet, in a classic case of the bigger you are, the harder you fall, CrowdStrike Holdings, Inc. (NASDAQ:CRWD)'s massive growth creates risk. For its fiscal second quarter, the firm has guided net new ARR to range between $343 million and $347 million to imply growth ranging between 29% to 31%. Considering that the metric grew by 55% in Q1, the new figures do indicate a slowdown. As for catalysts from agentic AI, CrowdStrike Holdings, Inc. (NASDAQ:CRWD)'s next-gen SIEM (Security Information and Event Management) ending ARR grew by 60% to $695 million in the second quarter.
Hedge fund interest in CrowdStrike Holdings, Inc. (NASDAQ:CRWD) grew in Q2. According to Insider Monkey's data, 89 out of 1,006 funds had held a stake in the firm during the period. This marked a jump over the 89 out of the 1,022 funds in Q1. As for valuation, CrowdStrike Holdings, Inc. (NASDAQ:CRWD)'s forward P/E ratio of 188 is significantly higher than peer firm Palo Alto's 89 which should increase the pressure to maintain growth. Short interest as a percentage of float is 2.41% for CrowdStrike Holdings, Inc. (NASDAQ:CRWD) compared to 2.65% for Palo Alto.
#NASDAQ #firm #grew


1 month ago
Happy Friday, traders. Welcome to our weekly market wrap, where we take a look back at these last five trading days with a focus on the market news, economic data, and headlines that had the most impact on gold prices and other key correlated ****** ets—and may continue to in the future.
So, what kind of week has it been?
Gold took a more volatile path than expected but rebounded from a post-FOMC low near $4,260/oz to trade just above $4,350/oz shortly after the US market open on Friday, putting the yellow metal in position for a moderate weekly gain.
The Federal Reserve delivered the week's main event on Wednesday, unanimously raising policy rates by 25 basis points. Gold's sharp initial drop appeared tied less to the hike itself than to projections showing elevated inflation expectations and another 25-basis-point increase before the end of 2026.
Thursday brought the countermove as crude oil slid back toward and then below $100 per barrel, US Treasury yields eased, and gold recovered to around $4,360/oz. The Bank of ****** an's overnight rate hike to 1.25% added another tailwind into Friday.
#Friday #weekly #welcome

1 month ago
On August 18, Amer Sports (NYSE:AS) reported second-quarter results that beat its own guidance and then raised the bar for the rest of the year. Revenue climbed 32% to $1.63 billion, adjusted operating profit nearly tripled, and every region and segment posted double-digit growth. Diluted earnings per share reached $0.18, up from a much smaller figure a year earlier. What stands out about August 18 is not just the size of the beat but how broad it was.
Technical Apparel grew 32% to $674 million, led by Arc'teryx and backed by a 17% omni-comp gain across owned stores and e-commerce. Outdoor Performance grew even faster, up 37% to $569 million, driven by Salomon Softgoods. Ball & Racquet Sports rose 24% to $390 million on the strength of Wilson Tennis 360. CEO James Zheng pointed to strong double-digit growth across every segment, geography, and channel as the reason for confidence in the outlook.
That confidence showed up in the numbers: Amer Sports raised full-year 2026 guidance to roughly 24% reported revenue growth, a gross margin of 60.5% to 61.0%, an operating margin of 14.2% to 14.5%, and diluted EPS of $1.27 to $1.30. The balance sheet backs up the reinvestment CFO Andrew Page described, with $573 million in net cash and $720 million in cash and equivalents at quarter-end.
Some of the second quarter's biggest numbers lean on a one-time tailwind. Gross margin expanded 710 basis points to 65.6%, but 390 of those points came from net tariff refunds. Operating margin's 820 basis point jump included the same 390-point benefit. The effect is largest in Ball & Racquet Sports, where adjusted segment operating margin rose 1,300 basis points to 17.2%, yet 970 of those points came from tariff refunds alone. Selling, general and administrative expenses rose 30% to $909 million, and on an adjusted basis SG&A grew 33%, faster than revenue itself.
Inventories climbed 19% year over year to $1,897 million. The guidance for the next quarter also points to a slower pace: third quarter revenue growth is guided at 18% to 20%, well below the 32% just reported, with gross margin guided down to about 59.0% and net finance cost alone guided to $15 million to $20 million, against roughly $85 million for the entire year.
#revenue #basis

1 month ago
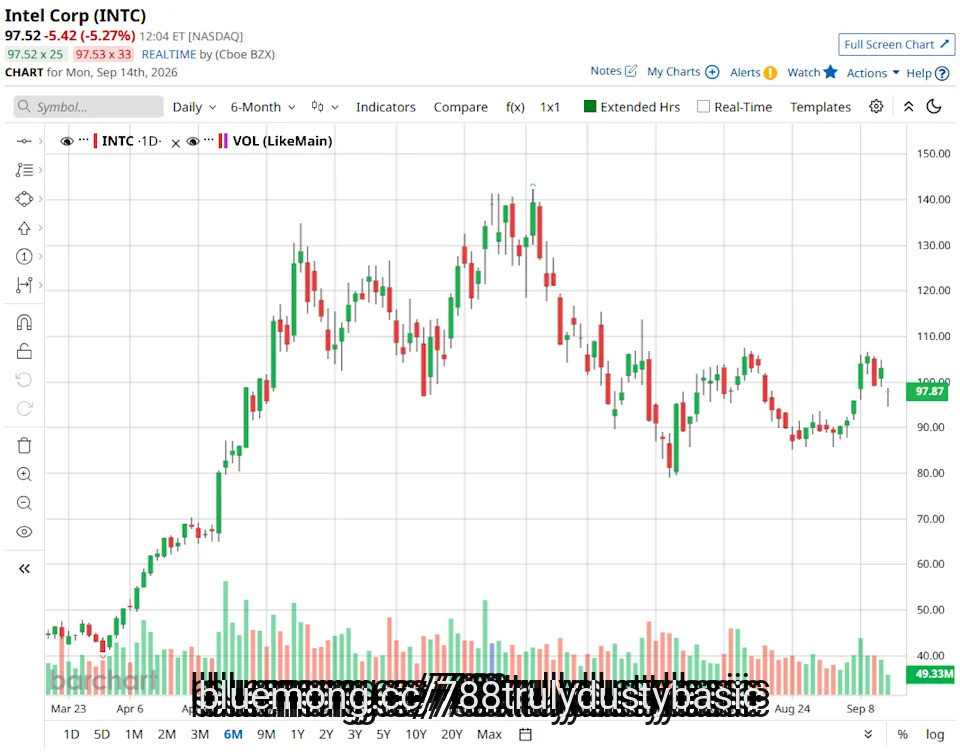
Mizuho has identified four clear tailwinds for Intel (INTC): ongoing CPU supply shortages, a stronger PC refresh cycle, accelerating demand for agentic AI, and growth in advanced packaging. Normally, such a setup would provide a reason to raise a price target. Instead, the firm cut its price target from $109 to $92, citing short-term multiple compression across Agentic AI stocks, and maintained a "Neutral" rating. The contradiction becomes more important because Intel's re-rating still depends on a foundry turnaround that has yet to prove itself.
Mizuho remains cautious on INTC stock despite outlining four separate tailwinds that could support the company's growth. The firm lowered its price target from $109 to $92 on Sept. 3, pointing to short-term multiple compression across agentic AI companies while keeping its "Neutral" rating unchanged. Mizuho **** yst Vijay Rakesh highlighted four developments that could support Intel's outlook. According to the **** yst, accelerating agentic AI demand could improve CPU-to-GPU ratios and drive additional server refreshers. Ongoing CPU supply constraints could also leave the company unable to fully meet demand through 2027. In addition, advanced packaging revenue is expected to reach $3.5 billion by 2029, with external foundry revenue potentially reaching a similar level through the 14A node. Finally, a stronger PC cycle could extend the upgrade cycle as corporate refreshes combine with ongoing memory tightness.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Billionaire Charlie Munger, Who Died at 99, Skipped Insurance on His Mansion Since He Could Just Write a Check to Rebuild — 'All Intelligent People Do It My Way'
The EV Bubble Has Burst. How to Play Rivian Stock Now.
#four


1 month ago
Shares of Nvidia Corp (NASDAQ:NVDA) stock are inching 0.4% higher to trade at $211.72 this afternoon, taking a breather after five-straight losing sessions, including yesterday's AI-induced selloff of 3.4%. The equity is still up 13.3% in 2026, however, and a rebound could soon be on the way, per a historically bullish trendline.
According to Schaeffer's Senior Quantitative ***** yst Rocky White, NVDA is trading within 0.75 times the 126-day moving average's 20-day average true range (ATR), after spending at least 80% of the previous two weeks and 80% of the prior 42 trading sessions above that trendline.
This setup has appeared 11 times over the last decade, after which the stock was higher one month later 82% of the time, averaging a 6.2% gain. From its current perch, a move of this caliber would put the equity just shy of $225.
NVDA sports a 50-day put/call volume ratio at the International Securities Exchange (ISE), Cboe Options Exchange (CBOE), and NASDAQ OMX PHLX (PHLX) that stands higher than 83% of readings from the past year. Should this bearish sentiment begin to unwind, it could trigger a new round of tailwinds for the shares.
Options are looking affordable as well. The stock's Schaeffer's Volatility Index (SVI) of 34% stands higher than just 2% of all other readings from the past year. In other words, near-term option traders are pricing in low volatility expectations at the moment.
#NASDAQ #cboe #phlx


2 months ago
Shopify (SHOP) stock opened higher on Wednesday after the e-commerce firm said it has acquired Tailwind Labs, the company behind the widely used Tailwind CSS. The announcement is significant for SHOP, given that Tailwind CSS is installed more than 110 million times per week and is used by prominent names like ChatGPT, Cloudflare (NET), Reddit (RDDT), and X.
That said, Shopify shares have reversed their intraday gains in recent hours and are now headed to end the Sept. 9 session down more than 5%.
'Not Tens Of Billions, But Tens Of Trillions': Nvidia CEO Jensen Huang Says AI Is Like the New Electricity and the Scale Is Unlike Any Tech in History
What It Means for MSFT Stock Investors as Microsoft Switches to 2 Business Segments
RKLB Stock Jumps as Rocket Lab Debuts New Solar Cell for ******* e
#tailwind #chatgpt



2 months ago
Lyft Inc (NASDAQ:LYFT) is slightly lower this afternoon, down 0.2% at $14.86. Heading for a fifth-straight daily drop, the Uber Technologies (UBER) rival is trading near its late-July lows, sporting a grim 23.3% year-to-date deficit. All may not be lost, however, as this pullback looks to be placing Lyft stock near a trendline with historically bullish implications.
According to Schaeffer's Senior Quantitative ****** yst Rocky White, LYFT shares are within 0.75 of their 126-day moving average's 20-day average true range (ATR), after remaining below it 80% of the time in the past two weeks and in 80% of the last 42 trading sessions.
This signal has occurred five times in the last 10 years, after which Lyft stock was higher one month later 60% of the time, averaging a 9.4% gain. From its current perch, a surge of this magnitude would put the shares back above the $16 area.
Put traders have been circling, per LYFT's 10-day put/call volume ratio at the International Securities Exchange (ISE), Chicago Board Options Exchange (CBOE), and NASDAQ OMX PHLX (PHLX), which stands higher than 76% of all other readings from the past year. Echoing this, the stock's Schaeffer's put/call open interest ratio (SOIR) of ranks higher than all other readings from the past 12 months. Should this bearish sentiment begin to unwind, it could trigger tailwinds for the shares.
Options are attractively priced as well, per the stock's Schaeffer's Volatility Index (SVI) of 51%, which stands higher than just 18% of all other readings from the past year, implying that near-term option traders are pricing in relatively low volatility expectations.
#lyft #higher #uber

0.00$ raised of 0.00$ goal
0 donations
0.00$
to go

2 months ago
Jeff Klingelhofer, CFA, Managing Director, Portfolio Manager & Senior Research **** yst, Securitized **** ets at Aristotle Pacific didn't set out to be a bond guy but a launchpad at PIMCO, stops in Tokyo and London, and a Chicago MBA detour into a scrappy five-person hedge fund rewired how he thinks about fixed income. The internship stuck, with Klingelhofer building out Thornburg's taxable fixed income desk from employee #3 to Head of Investments, before joining Aristotle Pacific in 2024. The firm is a 15-year-old franchise (formerly Pacific **** et Management) now running roughly $16 billion and, as of July 30, three brand-new ETFs: the Aristotle Core Plus Income ETF (ARCP), the Aristotle Multi-Sector Income ETF (ARMS), and the Aristotle Short Term Income ETF (SDUR).
The pitch isn't about taking on more risk to boost returns but about capturing returns with minimal risk, and that means shopping across every fixed income silo instead of hunting inside one. Klingelhofer gives the example of February 2020, when American Airlines' corporate bond and its aircraft-backed EETC both priced at 3.75% with the same issuer, same tenor, same yield. A month later, COVID hit and the corporate bond cratered to 27 cents on the dollar while the EETC held at 65 cents. Same company, wildly different outcomes because Wall Street desks looked at each instrument in isolation instead of comparing across the capital stack. That's the whole Aristotle Pacific thesis, and it's why he sees the same mispricing setting up today in data center financing.
The three funds slot into that framework by risk level, with SDUR as a low-duration, active-credit alternative to cash, ARCP as a core-bond upgrade aiming to beat the Agg by 100-150bps, and ARMS as the full relative-value expression targeting 250bps over a cycle with real flexibility to shift credit quality. Macro-wise, Klingelhofer thinks the market is underestimating new Fed Chair Warsh, who, unlike his predecessor, inherits a purely high-inflation world with no disinflationary tailwind. It means the firm is positioning the funds slightly long duration as a hedge against credit risk elsewhere in the book. His closing advice to advisors was a cautionary and practical one, that they shouldn't expect Aristotle to work in every environment (no fund does), and to pair its bottom-up process with top-down managers like PIMCO so the two zig and zag differently throughout market cycles.
To learn more about Aristotle Pacific, go here, or you can learn more about their new ETFs here.
#pacific #same #fixed


2 months ago
By Dhara Ranasinghe, Rae Wee and Atsuko Aoyama
LONDON/SINGAPORE/TOKYO, Sept 4 (Reuters) - Six weeks after hitting a four-decade low against the dollar, the tide appears to be turning for the battered yen as a host of factors finally smoke out traders who have spent years betting against the ****** anese currency.
While central bank rate hikes and record currency intervention have failed to provide lasting support for the yen, new tailwinds from capital repatriation, unwinding carry trades and U.S. political pressure are now giving short speculators cause to rethink their long-term game.
The yen is on track for a roughly 2% surge against the greenback this week — the most since a rare joint U.S. and ****** an intervention at the end of July to lift the yen.
"The market psychology around the yen appears to be changing," said Rong Ren Goh, a fixed income portfolio manager at Eastspring Investments. "Investors seem increasingly reluctant to aggressively short the JPY (yen), particularly with the prospect of a BOJ rate hike in September adding another layer of risk to the trade."
#currency #dhara #ranasinghe


2 months ago
On August 10, Joe Gomes from ***** le Capital reiterated his Outperform rating on CoreCivic Inc. (NYSE:CXW). In the process, the ***** yst increased his target price on the stock from $35 to $42, resulting in a revised upside potential in excess of 24% based on stock's closing price on August 27. This upward adjustment in price target came after an impressive second quarter print above management estimates. Let's explore the underlying drivers of this outperformance, and which additional factors are expected to shape up investor sentiment toward the stock.
Earlier in August, the company reported its second quarter results which exceeded management's expectations. Topline figures were recorded at $684.9 million, up by 27.3% compared to Q2 2025. Adjusted EBITDA of $109.4 million exhibited 5.9% year-on-year growth, while adjusted diluted EPS of $0.38 reflected a 5.6% growth compared to the same period last year. Such expansion in adjusted diluted EPS was supported by lower operating costs and slightly higher ICE populations, while strong federal revenue also contributed to growth. Following the quarter and subsequent facility sales, management raised its full-year 2026 guidance.
During 2026, CoreCivic has been focusing on strengthening its financial position while expanding its footprint as a federal detention operator. The company generated $734 million in gross proceeds from sales of Prairie Correctional Facility and Midwest Regional Reception Center, to the Department of Homeland Security. It expects to continue to operate both facilities under current arrangements, and was also awarded a new ICE contract to operate the 1,600 bed Prairie Correctional Facility till August 2031. The contract award offers potential for $75 million in revenue boost in the future once fully activated, with no material impact expected during 2026.
CoreCivic can benefit from this demand tailwind without the time and capital required to construct entirely new facilities, although activating idle sites still involves staffing and start-up costs. It also strengthens the company's position as a trusted partner for federal detention requirements, and might create potential opportunities for more contracts in the future.
The company has also taken an aggressive approach toward debt reduction and returning capital to shareholders. On August 10, it entered a $500 million accelerated share repurchase agreement, supported by the proceeds from recent facility sales. A portion of those sale proceeds was also utilized for $608.5 million debt repayment, which included early redemption of senior notes that were due in 2027.
#price

2 months ago
Bitcoin (BTC) mining name Riot Platforms Inc (NASDAQ:RIOT) is surging today, up 11.6% at $20.79 at last glance while Bitcoin taps three-month highs. Along with sector tailwinds, RIOT has its own bullish signal to keep an eye on as well.
According to Schaeffer's Senior Quantitative ******* yst Rocky White, Riot Platforms stock is trading within 0.75 times the 260-day moving averages' 20-day average true range (ATR), after spending at least 80% of the previous two weeks and 80% of the prior 42 trading sessions above that trendline. This setup has appeared six other times over the last decade, after which the stock was higher one month later 100% of the time, averaging a large 19.7% gain.
Short interest represents a hefty 14.35% of RIOT's available float, or more than 50 million shares, and would take shorts nearly three days to cover at the stock's average pace of trading. A move higher could pressure some of these bearish bettors to exit their positions, creating additional buying power.
Now also looks like a good time to weigh RIOT's next move with options. The stock's Schaeffer's Volatility Index (SVI) of 76% sits in the low 9th percentile of its annual range, suggesting options traders are pricing in relatively low volatility expectations at the moment. Plus, its Schaeffer's Volatility Scorecard (SVS) stands at 80 out of 100, indicating RIOT has tended to exceed option traders' volatility expectations during the past year.
#volatility #three #Stock #times


2 months ago
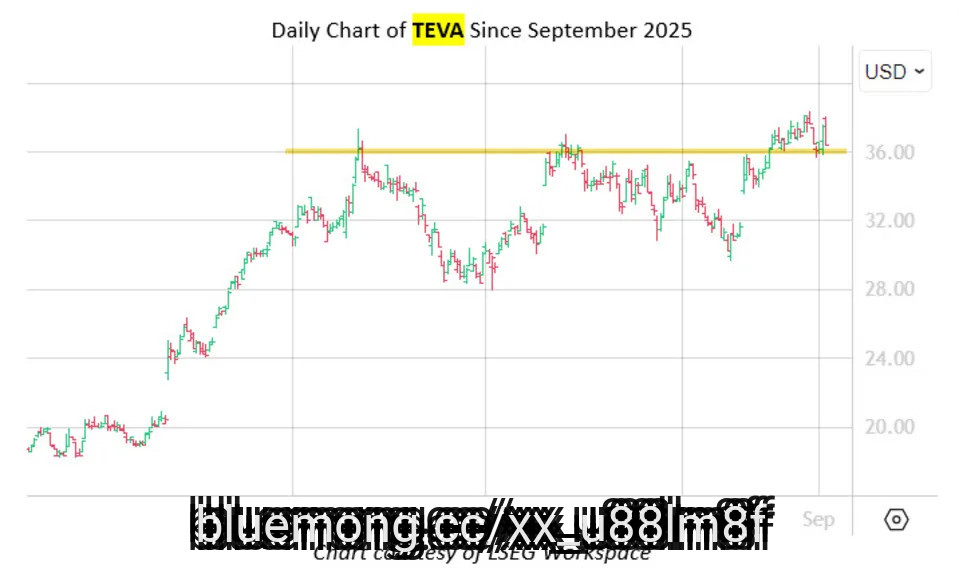
Teva Pharmaceuticals Industries (NYSE:TEVA) is moving 2.9% lower to trade at $36.41, pulling back from its Aug. 27, nearly nine-year high of $38.36. The $36 level looks to have moved in as a floor of support, a former level of resistance for the shares since late January. More gains could be on the table, however, with a fresh bull signal now flashing for the drug maker.
TEVA's long-term outperformance comes amid historically low implied volatility (IV). Specifically, the equity's current SVI of 29% stands in the low 5th percentile of its annual range.
According to data from Schaeffer's Senior Quantitative ******* yst Rocky White, there have been five instances in the past five years when the equity traded within 2% of its 52-week high, while its Schaeffer's Volatility Index (SVI) ranked in the 20th percentile of its annual range or lower.
TEVA was higher one month later 80% of the time after those signals, averaging a 5.5% gain. From its current perch, a shift of this amount would put the equity back above $38 -- within a chip-shot of its August peak.
Options traders are still not convinced. This is per the equity's 10-day put/call volume ratio at the International Securities Exchange (ISE), Cboe Options Exchange (CBOE), and NASDAQ OMX PHLX (PHLX), which sits higher than 96% of readings from the past year. Should this bearish sentiment begin to unwind, it could trigger more tailwinds for the shares.
#exchange

2 months ago
On August 26, Movado Group (NYSE:MOV) reported second-quarter fiscal 2027 results that pushed adjusted earnings per share to $0.54 from $0.23 a year earlier, while net sales climbed 4.9% to $169.8 million. The jewelry and watch company also confirmed it will stop issuing annual financial guidance going forward, choosing instead to focus commentary on near-term trends. For a business built on Swiss craftsmanship and a stable of licensed fashion brands, the quarter marked a fifth straight period of positive momentum, and it came with a few surprises tucked inside the numbers.
Some of the headline strength came from a one-time source: $3.2 million in IEEPA duty refunds tied to tariffs paid between February 2025 and May 2026, which lifted GAAP gross margin to 59.4% from 54.1%. But strip that out and adjusted gross margin still rose 340 basis points to 57.5%, driven by favorable channel and product mix, strategic pricing, and less discounting. Growth was broad rather than concentrated in one line item. US net sales rose 4.9%, international sales rose 4.9% as well (4.1% in constant currency), and Latin America and India posted particularly strong results.
Movado.com sales jumped 8%, and Olivia Burton sales grew 23%, powered by small-shaped watches focused on the U.K. and US markets. The company also flagged a resurgence in traditional watch interest among younger buyers, pointing to the Baby Face mini strap watch, which sold out more than 400 units on movado.com in under a month. Looking ahead, Movado is expanding its Tapestry partnership to launch Kate Spade watches starting next fiscal year. The balance sheet backs up the momentum, with $211.6 million in cash, no debt, and $16.6 million already returned to shareholders through dividends this year.
Not every piece of this quarter travels into the second half. Management was explicit that the favorable mix of lower duty rate inventory that padded margins is temporary and is not expected to continue, and second-half gross margin guidance of 55% to 56% reflects that normalization. Sallie DeMarsilis also noted that gross margin gains were partially offset by higher shipping costs tied to fuel surcharges and rising e-commerce volume.
Geographically, the Middle East remains a soft spot, with Efraim Grinberg citing tourism-related headwinds in a region still affected by regional conflict. Operating expenses rose to $85.7 million from $80.6 million, largely on higher performance-based compensation and marketing spend. There is also a smaller but notable item: a $0.2 million pretax charge tied to a misconduct investigation within a Dubai-based Swiss subsidiary branch. And while Movado expects to recover another $6.8 million in IEEPA duties, it has chosen not to recognize that gain until the cash actually arrives, a reminder that not all of this quarter's tailwind is guaranteed to repeat.
#second
2 months ago
Our **** ysts just identified a stock with the potential to be the next Nvidia. Tell us how you invest and we'll show you why it's our #1 pick. Tap here.
Achieved the highest second quarter net income per share in company history, attributed to disciplined operating teams and favorable market tailwinds.
Performance was significantly bolstered by Section 45Z production tax credits, which contributed approximately $18.4 million directly to gross profit during the quarter.
Gross profit grew approximately 144% year-over-year even when excluding the impact of 45Z tax credits, driven by stronger industry crush margins.
Operational success is supported by a robust balance sheet with no bank debt and $379.5 million in cash and short-term investments, allowing for internal funding of all growth projects.
#credits


2 months ago
Investors are awaiting the fourth-quarter earnings release of cybersecurity firm Zscaler (ZS), which is scheduled for Sept. 3, after the market closes. Ahead of that, investors have lifted the company's stock, expecting the earnings to provide tailwinds.
Cybersecurity spending is expected to be a priority in this era of artificial intelligence (AI). Recently, a series of AI hacking incidents brought the importance of cybersecurity to the forefront. Therefore, there's a chance that while chips and data centers were the biggest beneficiaries of the first wave of the AI boom, cybersecurity could steal that spot in the next wave and experience a spending boom.
Dear GameStop Stock Fans, Mark Your Calendars for September 8
Why ***** ysts Think Sellas Life Sciences Stock Can Gain 150% From Here
Jensen Huang: Nvidia's Vera Rubin Platform Turns Electricity Into a $40 Billion Cash Machine
#spending



2 months ago
Sandisk (NASDAQ: SNDK) stock has more than quintupled year to date, but despite those gains, its rally still doesn't appear to be over. The long-term tailwinds in the memory market just accelerated, and Sandisk is one of the best-positioned companies in the industry.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Investors have greatly underestimated the durability of the current memory chip boom, even the most bullish ones. Samsung (OTC: SSNLF) recently reported that three large customers had signed deals locking up 70% of its memory chip capacity through 2031: Nvidia (NASDAQ: NVDA), Microsoft (NASDAQ: MSFT), and Alphabet (NASDAQ: GOOG) (NASDAQ: GOOGL).
Those deals are a big catalyst for the entire memory sector, and while Samsung is the immediate beneficiary, Sandisk may emerge as the bigger winner. That's because Sandisk has been growing sales at a faster rate than Samsung, thanks to its NAND flash memory storage chips.
Samsung reported 130% year-over-year revenue growth in the second quarter, while Sandisk delivered 372% year-over-year revenue growth. Sandisk told investors in its 2026 Investor Day that it, too, is securing multiyear deals with its top customers. The Samsung news has further limited the volume of memory chips that will be available for future customers, which will make it easier for Sandisk to command higher prices and sign more attractive multiyear deals.
#samsung #deals #customers #flashing

2 months ago
KMI's 2% dividend raise earns a C+ while WMB's 5% raise and 52-year payment streak push it to an A-.
WMB carries 3.9x leverage after its $5.5 billion Momentum Midstream acquisition, though management expects deleveraging by 2028.
Just released. Our **** ysts combed the entire stock market and named the ten best stocks to buy right now. The report is free. Enter your email and see if any of your stocks made the cut.
Two natural gas pipeline giants just cut checks to shareholders, and the fine print reveals why they deserve very different dividend grades. Kinder Morgan (NYSE:KMI) sent investors $0.2975 per share on August 17, 2026, while Williams Companies (NYSE:WMB) most recently paid $0.525 per share on June 29, 2026, with another $0.525 payment scheduled for September 28. Same sector, same customer base, same natural gas tailwinds. Very different scorecards.
The gap comes down to growth rate, payout coverage, and streak length. One is compounding faster and covering the payout more comfortably. The other is running a tighter payout ratio with slower raises. Here is the grading.
#stocks



2 months ago
Our ****** ysts just identified a stock with the potential to be the next Nvidia. Tell us how you invest and we'll show you why it's our #1 pick. Tap here.
Record revenue and EPS were driven by the compounding benefits of a modernized operating model, enabling earnings to grow faster than revenue through significant operating leverage.
Management attributes the 122% growth in traditional servers to a structural shift where customers view IT as a value driver rather than a cost center, accelerating the refresh of an aged installed base.
AI server momentum is broadening across Neoclouds, sovereigns, and enterprise customers, with the customer count surpassing 6,500 as organizations move from design to production.
Storage returned to growth and share gains, fueled by strong demand for Dell IP products and early tailwinds from AI workloads requiring massive data movement and protection.
#Growth #management #storage

2 months ago
Kaiser Aluminum Corporation (NASDAQ:KALU) has pulled back sharply from its recent highs, but UBS sees the weakness as a buying opportunity. On August 31, UBS upgraded Kaiser Aluminum from Neutral to Buy and raised its price target to $184 from $179. ******* yst Alex Stansbury argued that the selloff has created an attractive entry point into a business with improving earnings power.
UBS's upgrade to Buy from Neutral is based on the view that Kaiser Aluminum Corporation (NASDAQ:KALU)'s recent pullback has created an attractive entry point rather than signaling a deterioration in the company's long-term earnings outlook. ******* yst Alex Stansbury raised the price target to $184 from $179, arguing that the selloff has created an opportunity to buy a business with improving earnings power.
The most important part of UBS's argument is that several of the pressures weighing on Kaiser's shares appear temporary. Stansbury specifically pointed to scrap as a meaningful tailwind while also saying that the company's underlying fundamentals are strengthening. That is important because UBS is not relying solely on higher aluminum prices to support its bullish view. Instead, the bank sees operational improvements and stronger end-market demand contributing to earnings growth.
UBS also highlighted the benefits of Kaiser's investments at Warrick and Trentwood. Those investments are increasingly relevant to the earnings story. Kaiser says its Warrick investment is designed to increase capacity for higher-margin coated packaging products, while its Trentwood modernization has focused on improving efficiency, capacity and the quality of products serving aerospace and general engineering customers.
The aerospace recovery is another key part of UBS's thesis. Stansbury pointed to the end of aerospace destocking and accelerating build rates, suggesting that an important headwind for Kaiser is beginning to reverse. That view is supported by Kaiser's latest results: the company said aerospace demand was strengthening as destocking eased, while second-quarter aerospace shipments increased year over year.
#kaiser #earnings #created #view


2 months ago
POET (NASDAQ: POET) secured a $50 million Lumilens purchase order, and our model sees 137% upside to a $17.74 BUY price target.
Lumentum (LITE) generates $1 billion quarterly on the same optical tailwind; Applied Optoelectronics (AAOI) proves hyperscale-qualified 800G suppliers command premium multiples.
POET holds $796 million in cash to fund its Malaysia production ramp, but four of its last five earnings reports missed estimates.
Act now: the ****** yst who called NVIDIA in 2010 just named his top 10 AI stocks — and Poet Technologies didn't make the cut. Grab the names FREE today.
POET Technologies (NASDAQ:POET) is a small-cap photonics designer building optical engines for 400G, 800G, and 1.6T data center interconnects, the plumbing hyperscalers need to move AI traffic without melting their power budgets. With a fresh $50 million purchase order from Lumilens in hand, our proprietary model sees room for a sharp re-rating.
#order

2 months ago
Moderna led the S&P 500 in August after reporting promising results from a late-stage trial of a personalized mRNA cancer vaccine it co-developed with Merck, according to CNBC. The data challenged years of skepticism about whether the company's mRNA technology could produce another major breakthrough following the decline of its Covid-19 vaccine business. "This is miraculous, so it got a miraculous welcome," CNBC's Jim Cramer said Monday.
Enterprise software stocks accounted for many of the index's other top performers. Palantir, Veeva Systems, Salesforce, and ServiceNow had each come under sustained selling pressure as investors grew skeptical that traditional software models could remain competitive against the backdrop of accelerating AI development, according to the outlet. Those declines were compounded by large short positions held by Situational Awareness, a leveraged hedge fund that had bet against software companies based on that thesis. When the fund was forced to unwind its trades in late July, those shorts became a tailwind for the stocks it had targeted. "As August comes to a grinding end, it's hard to believe that the reverberations of a hedge fund implosion could color so much of the month's action," Cramer said.
Situational Awareness, which was run by Leopold Aschenbrenner and peaked at $45 billion in **** ets at the start of July, lost roughly $35 billion after margin calls from prime brokers Bank of America, Goldman Sachs, and JPMorgan Chase forced a distressed sale of its publicly traded holdings to Ken Griffin's Citadel. The fund had used as much as 400% leverage and held large short positions in software names including Adobe alongside bullish bets on AI infrastructure stocks.
Among individual software stocks, Salesforce bounced back after better-than-expected quarterly results quieted fears of what Cramer called a "SaaSpocalypse," while ServiceNow gained ground after showing investors that AI could be folded into its platform without disrupting existing operations. Veeva Systems climbed in tandem with the wider software sector after the anticipated AI threat to its life sciences niche failed to materialize in any meaningful way. Gartner also joined the recovery, as worries that large AI models would erode the market for its research and advisory services turned out not to be borne out by the company's actual results.
Outside software, Newmont benefited from a recovery in gold prices, while Coinbase climbed as cryptocurrencies rebounded amid concerns about U.S. debt and government spending. Super Micro Computer and Sandisk also surged on strong demand for memory used in AI data centers.
#cramer
2 months ago
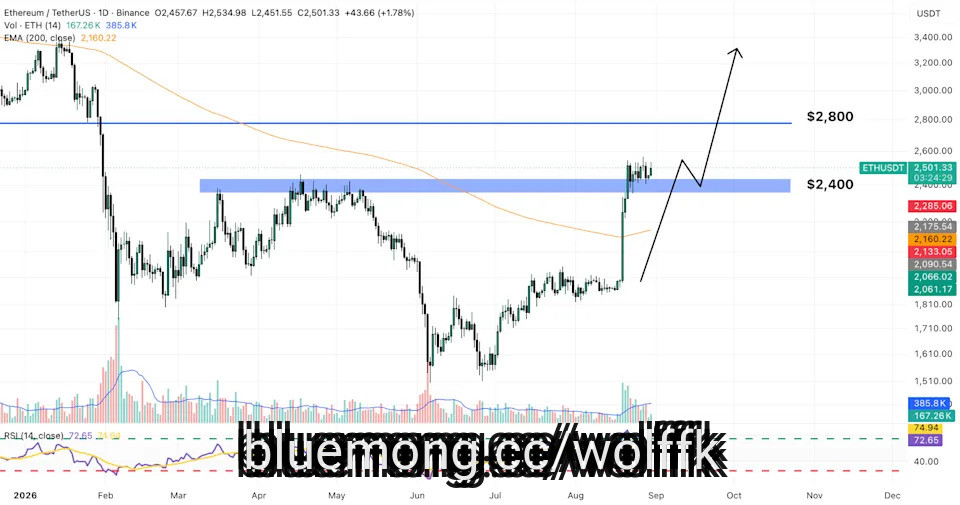
Ethereum (ETH) has jumped by 34% in the past 30 days, outpacing all other tokens in the top 5 during this period, after a couple of macro tailwinds.
The latest speech from the Chairman of the Federal Reserve, Kevin Warsh, during the Jackson Hole summit managed to pause the crypto rally but only temporarily, as most tokens have recovered during the weekend.
Trading volumes in the past 24 hours jumped by 39%, currently sitting at nearly $9 billion. This figure accounts for nearly 3% of the **** et's circulating market cap, indicating that the buying interest has subsided a bit.
Market sentiment improved dramatically in the past couple of weeks after the U.S. Securities and Exchange Commission (SEC) proposed a new set of rules for the crypto industry that front-run Congress's expected approval of the Clarity Act.
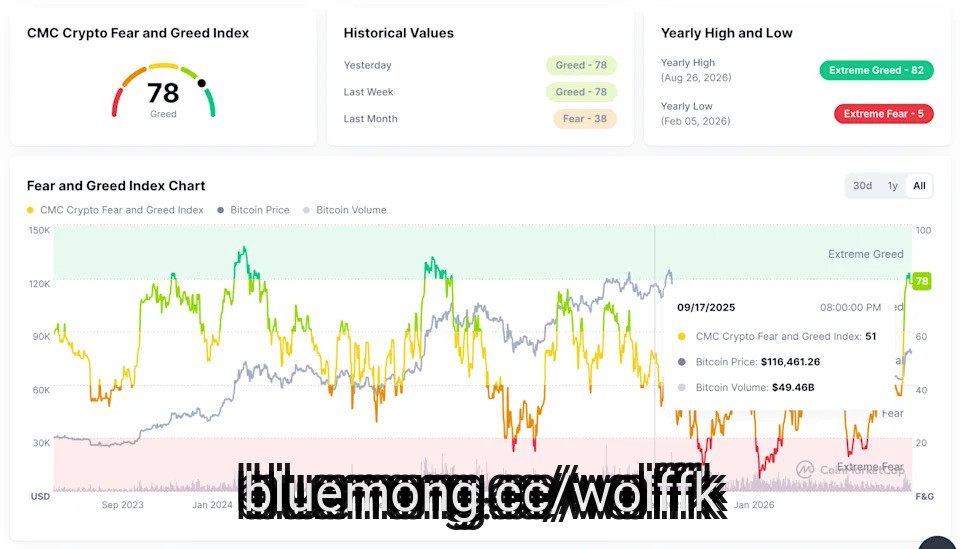
The Crypto Fear and Greed Index has jumped to 78, indicating that investors are in "Greed" mode. This is the highest reading since December 2024, back when the ETH was rallying to $4,000.
#jumped #tokens


2 months ago
On August 28, Pinterest (NYSE:PINS) said that the Chief Financial Officer, Julia Donnelly, will leave the company on October 30, kicking off an external search for her replacement. Vikram Naidu, the company's vice president of finance and business operations, will serve as interim principal financial officer in the meantime. Donnelly is departing to join a private, early-stage company after roughly three years in the role, a stretch CEO Bill Ready credited with 11 consecutive quarters of double-digit revenue growth. The timing puts a spotlight on whether Pinterest can keep that momentum going without her.
The financial picture Donnelly leaves behind is a strong one. In the second quarter of 2026, Pinterest generated $1.18 billion in revenue, up 18% year over year and the fourth straight quarter above $1 billion. Global monthly active users climbed to 640 million, an 11% increase and the eleventh consecutive quarter of double-digit user growth, with Gen Z now making up more than half the platform's user base.
The United States and Canada region, Pinterest's most lucrative market, shows the acceleration most clearly. Revenue there grew 18%, a five-point jump from the prior quarter, helped by a restructured sales team and tighter account coverage for mid-market advertisers. Average revenue per user in that region rose 14% to $8.30. Management has also leaned hard into artificial intelligence, rolling its conversational Pinterest ****** istant out to most US users by the end of July and pointing to open-source models that run at less than 8% of the cost of comparable closed systems.
Profitability improved alongside growth. Adjusted EBITDA reached $311 million, a 26% margin that expanded 130 basis points from a year earlier, and free cash flow totaled $1.3 billion over the trailing twelve months. Pinterest used some of that cash to retire nearly 111 million shares this year, spending more than $2 billion on buybacks.
Donnelly's exit adds a layer of uncertainty to a company that just forecast a deceleration. Pinterest's own guidance calls for third-quarter revenue growth of 13% to 15%, down from 18% in the second quarter, a slowdown management attributes to the shift in when Prime Day fell, a smaller currency tailwind, and continued pressure from Asia-based cross-border retailers hit by regulatory actions in Europe. Competition from Meta's Instagram for digital advertising dollars is compounding the squeeze.
#revenue #year #company


2 months ago
The Hershey Company (NYSE: HSY) is heading into the autumn months with the tailwinds of pricing power and seasonal demand. The one stat that makes the company hard to ignore right now is its revenue growth relative to cocoa costs, which have increased by more than 120% in the past six months.
One might think a triple-digit rise in the cost of a core ingredient would hurt business, but the company's second-quarter earnings showed net sales up 6.6% year over year. Adjusted earnings per share in Q2 rose a whopping 57% in the same time period. This demonstrates Hershey's brand strength and its ability to price products without scaring off customers.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Hershey's research found that 82% of parents are likely to purchase chocolate in October, and intend to buy gummies and sour candy even earlier in the season. In response, management is planning a "Hersheyween," which runs from the end of the summer into the fourth quarter. The promotion is Hershey's largest-ever Halloween lineup.
Hershey's stock trades at a slight premium to some of its peers in the packaged-goods industry, but the sweets company offers a tasty 3.2% dividend yield and decades of consistent payouts. Hershey is currently well below its 52-week high of $239. The stock is relatively flat year to date.
#company #hershey #earnings

2 months ago
Ross Stores, Inc. (NASDAQ:ROST) surged after raising its full-year fiscal 2026 earnings guidance. The off-price retailer boosted its FY26 EPS target to $8.61–$8.77 from $7.50–$7.74, cruising past consensus estimates of $7.82.
The primary catalyst was a stellar Q2 2026 report. Total sales rose 13% to $6.3 billion, beating estimates, while comparable-store sales jumped 10% versus 7.6% expected, driven primarily by customer traffic. Operating profits reached $1.1 billion, with operating margin expanding 610 basis points to include a 405 basis point boost from IEEPA tariff refunds. Reported diluted EPS reached $2.66 (vs. $1.56 a year ago), which included a $0.60 per share tariff refund benefit. Excluding this benefit, adjusted EPS came in at $2.06, still beating expectations driven by broad-based gains across customer demographics. The company also increased its fiscal 2026 store expansion plan to 115 new locations.
This performance brings up a core question: Does Ross Stores' double-digit comp growth signal sustainable market share gains, or will non-recurring tariff tailwinds and inventory buildup pressure future upside?
Wall Street **** ysts responded aggressively to the quarter. On August 21, Barclays **** yst Adrienne Yih raised the firm's price target on ROST to $298 from $260, keeping an Overweight rating. She cited the 10% comp beat, noting that Ross's "short-term execution gap versus peers remains wide" while trend strength has continued into Q3. The same day, Deutsche Bank raised its target to $294 from $283 with a Buy rating, highlighting that comp growth was driven by broad-based transaction gains and management's confidence in accelerating two-year comp momentum.
Operationally, Ross benefits from a scalable off-price model that efficiently sources excess inventory. Rapid turns and frequent product changes foster traffic and customer loyalty. Traffic gains across all merchandise categories indicate broad market share gains rather than reliance on a single segment. Furthermore, strong cash generation ($1.71 billion in H1 operating cash flow) supports store expansion, with 115 new openings planned for FY26, and continuous share buybacks without balance sheet strain.
#gains #Share #billion


2 months ago
Toast, Inc. (NYSE:TOST) delivered strong second-quarter 2026 financial results, highlighted by raised full-year guidance across key profitability metrics. The restaurant management software provider raised its full-year 2026 adjusted EBITDA outlook to $805 million–$825 million, up from its previous projection of $790 million–$810 million. Management also raised its guidance for recurring gross profit streams, defined as subscription services and financial technology solutions gross profit, to $2,325 million–$2,355 million (23%–25% year-over-year growth).
For Q2 2026, total revenue reached $1.90 billion, climbing 23% year-over-year, while total gross profit reached $516 million. GAAP net income rose sharply to $154 million ($0.26 per diluted share) from $80 million ($0.13 per share) in Q2 2025. Adjusted EBITDA reached $221 million, inclusive of a $10 million one-time benefit from tariff refunds, which management plans to reinvest into strategic growth initiatives. Operational expansion remained robust: Annualized Recurring Run-Rate (ARR) surged 25% year-over-year to $2.4 billion, supported by 22% growth in Gross Payment Volume (GPV) to $60.7 billion. The company added a record 9,500 net new locations in the quarter, bringing its global active footprint to approximately 180,000 locations.
This raises a core question: Does Toast, Inc. (NYSE:TOST)'s operational momentum and platform expansion justify a valuation premium, or will increasing market saturation and macroeconomic pressure on restaurant spending cap further upside?
Bulls emphasize Toast, Inc. (NYSE:TOST)'s industry-leading software adoption and expanding ecosystem. Following the Q2 report, on August 12, Truist raised its price target on Toast to $39 from $33 on August 12, maintaining a Buy rating. The firm noted higher recurring gross profit estimates driven by location net adds and rising subscription SaaS ARPU as new product launches ramp up. Operational tailwinds received another boost on August 10 when Adyen announced an expanded partnership with Toast into the U.S., supporting Toast's more than $215 billion in annual GPV across 180,000 locations and scaling its global processing capabilities.
Bears argue that persistent inflation and consumer spending fatigue could pressure restaurant transaction volumes, impacting Toast, Inc. (NYSE:TOST)'s payment processing revenues. While DA Davidson raised its price target to $34 from $30 on August 10 following the Q2 beat, the firm maintained a Neutral rating, pointing to a balanced risk-reward profile. Additionally, Toast's Q2 EPS of $0.26 came in below certain consensus estimates despite top-line beats, reflecting ongoing investments in international scaling, enterprise sales, and AI features like Toast IQ Grow. Free cash flow also slowed to $130 million in Q2 2026 from $208 million in the prior-year period.
#toast #gross #raised #billion

2 months ago
Tyson Foods, Inc. (NYSE:TSN) updated its fiscal 2026 outlook alongside its Q3 2026 financial report, raising its full-year revenue growth view to 2.5%–3.5% from its previous range of 2%–4%. The revised sales guidance reflects price increases across protein categories and operational execution, even as structural livestock constraints weigh on total volumes.
For Q3 2026, Tyson reported sales of $13.87 billion, flat year-over-year (or up 0.6% excluding a $98 million legal contingency accrual). GAAP operating income reached $362 million (up 39%), while adjusted operating income grew 8% to $547 million. GAAP EPS surged to $0.52 (up from $0.17), and adjusted EPS rose 9% to $0.99. Through nine months, sales reached $41.83 billion (up 3.1%), with GAAP operating income rising 17% to $1.10 billion and cash provided by operating activities reaching $1.47 billion. Segment performance diverged sharply: Chicken and Prepared Foods drove operating growth, offsetting an adjusted operating loss in the Beef segment.
This contrast brings up a critical question: Is Tyson Foods, Inc. (NYSE:TSN)'s diversified multi-protein model and core strength in chicken and branded prepared foods enough to protect corporate profits from deep, multi-year structural losses in its beef segment?
Bulls emphasize that Tyson Foods, Inc. (NYSE:TSN)'s non-beef operational tailwinds are proving resilient against wider agricultural cycles. Sustained volume growth in Chicken, combined with genetics-driven live performance and yield improvements, supported strong results, keeping management's full-year Chicken adjusted operating income guidance on track at $1.9 billion to $2.05 billion. In Prepared Foods, momentum across retail brands like Jimmy Dean and Hillshire Farm continues to drive market share gains. These factors are anchored by a solid financial base, including $913 million in nine-month free cash flow, debt reduction of $824 million, and $4.0 billion in total available liquidity.
Bears point out that persistent cattle herd shortages and high input costs are inflicting severe structural damage on Tyson's Beef segment, with management projecting a full-year segment operating loss of $(650) million to $(500) million. To shrink its struggling footprint, Tyson announced on August 13 that it is closing its Joslin, Illinois beef plant (which employs over 2,000 workers), selling its Pasco, Washington facility, and shutting a Utah packaging operation. ******* ysts have responded cautiously: on August 4, BofA lowered its price target on Tyson Foods to $65 from $68, maintaining a Neutral rating while trimming FY26–28 adjusted operating income estimates.
#beef #segment #income #adjusted

2 months ago
Broadcom's AI orders exceeded $30B this quarter while Micron secured ~$100B in contracted memory revenue through five-year take-or-pay deals.
Micron's HBM4 is ramping twice as fast as its predecessor, with DRAM prices jumping 60% sequentially and gross margins hitting a record 84.9%.
Act now: the ***** yst who called NVIDIA in 2010 just named his top 10 AI stocks — and Broadcom didn't make the cut. Grab the names FREE today.
Broadcom (NASDAQ:AVGO) and Micron Technology (NASDAQ:MU) delivered blockbuster quarters mapping onto the shift from AI training to inference and agentic workloads. Broadcom sells custom accelerators and networking silicon that stitch hyperscaler clusters together. Micron supplies the high-bandwidth memory those clusters need. Two different business models. One shared tailwind.
Broadcom's fiscal Q2 revenue hit $22.2 billion, up 48% year-on-year, with AI semiconductor revenue of $10.8 billion, up 143%. Hock Tan told investors "networking represented almost 40% of our Q2 AI revenue" and guided Q3 AI silicon to $16 billion, up over 200% year-on-year. Bookings were the headline: AI semiconductor orders exceeded $30 billion in the quarter, with programs now stretching to Google TPUs, Meta MTIA XPUs, OpenAI silicon, and Anthropic compute capacity.
#billion


2 months ago
The long-term growth story for nuclear power is clear. Artificial intelligence (AI) companies are scaling energy-intensive data center infrastructure as quickly as humanly possible. And the current energy grid isn't prepared for this unprecedented build-out. New energy sources will be needed quickly, and nuclear energy could deliver the reliable, low-carbon baseload power the AI industry craves.
NuScale Power (NYSE: SMR) has long appreciated this data center infrastructure demand tailwind. The company's small modular reactors (SMRs) are a great fit for adding large amounts of reliable power generation to the grid.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
This year, however, I think there's an even more exciting catalyst to pay attention to than general industry demand tailwinds.
NuScale remains the only nuclear developer in the U.S. approved by regulators to build an SMR system. But it has yet to even commercialize its approved designs. That could change later this year when the company suspects it could reach a power purchase agreement (PPA) with a major customer.
#signal #nuclear #data


