

10 hours ago
NFLX shares have fallen 33% year to date to near their 52-week low, despite a Q3 operating margin of 34.6% and a record $4.8 billion buyback quarter.
Netflix's 29% operating margin dwarfs Disney's (DIS) 15% and Spotify's (SPOT) 13%, yet its P/E multiple sits far closer to Disney's than Spotify's.
Just released. Our ******* ysts combed the entire stock market and named the ten best stocks to buy right now, and Netflix didn't make the cut. Enter your email to see the names that beat NFLX. The report is free. Enter your email and see if any of your stocks made the cut.
Netflix (NASDAQ:NFLX) spent 2026 extending its reach. It added live NFL games, built its own ad technology and brought outside networks onto its platform.
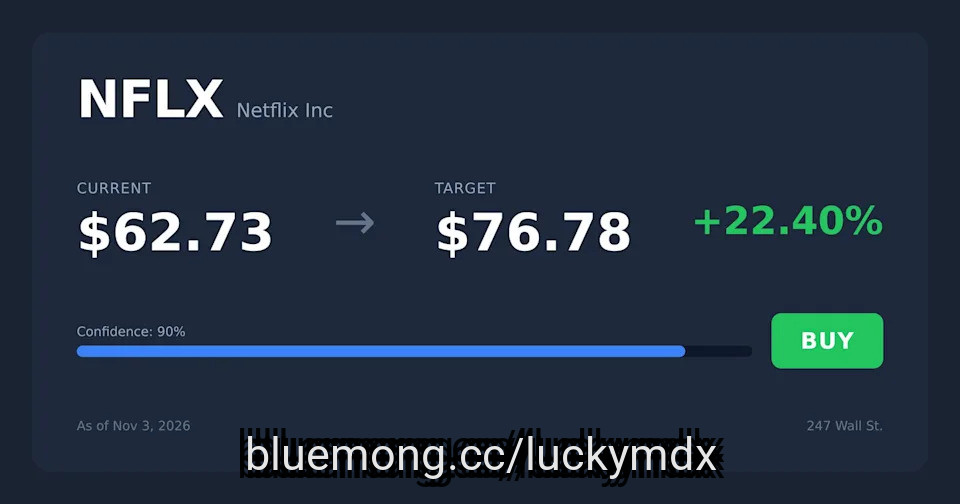
The stock fell anyway, and that gap is why the setup deserves a closer look. The 24/7 Wall St. price target for Netflix is $76.26, which means 22.9% upside from $62.05.
#netflix #Stock #spot
Netflix's 29% operating margin dwarfs Disney's (DIS) 15% and Spotify's (SPOT) 13%, yet its P/E multiple sits far closer to Disney's than Spotify's.
Just released. Our ******* ysts combed the entire stock market and named the ten best stocks to buy right now, and Netflix didn't make the cut. Enter your email to see the names that beat NFLX. The report is free. Enter your email and see if any of your stocks made the cut.
Netflix (NASDAQ:NFLX) spent 2026 extending its reach. It added live NFL games, built its own ad technology and brought outside networks onto its platform.
The stock fell anyway, and that gap is why the setup deserves a closer look. The 24/7 Wall St. price target for Netflix is $76.26, which means 22.9% upside from $62.05.
#netflix #Stock #spot

6 days ago
As we approach Gameweek 9 of the 2026/27 Fantasy Premier League campaign, getting your captaincy choice right is essential for driving your rank up the mini-league standings.
With key injuries shaking up forward lines, red-hot strikers in the form of their lives, and marquee fixtures dominating the schedule, fantasy managers have several intriguing routes to consider.
Below is our breakdown of the premier GW9 FPL captaincy pick options to help you make an informed decision before the deadline.
With João Pedro sidelined through injury and Cole Palmer searching for consistent rhythm, Morgan Rogers has stepped up as the central spark in Chelsea's attacking setup.
Operating with complete creative freedom, Rogers provides a dependable route to points as Chelsea travels to face a struggling Manchester United backline.
#gameweek #cole
With key injuries shaking up forward lines, red-hot strikers in the form of their lives, and marquee fixtures dominating the schedule, fantasy managers have several intriguing routes to consider.
Below is our breakdown of the premier GW9 FPL captaincy pick options to help you make an informed decision before the deadline.
With João Pedro sidelined through injury and Cole Palmer searching for consistent rhythm, Morgan Rogers has stepped up as the central spark in Chelsea's attacking setup.
Operating with complete creative freedom, Rogers provides a dependable route to points as Chelsea travels to face a struggling Manchester United backline.
#gameweek #cole


17 days ago
FC Barcelona will fly to Paris later today as they get set to take on PSG in the UEFA Champions League tomorrow night in one of the most highly anticipated encounters of the league phase of the competition.
Ahead of their trip to France, manager Hansi Flick has announced the squad list of players who will be available at his disposal for the blockbuster clash.
As expected, Barça go into the game without several key players as both Eric Garcia and Jules Kounde miss out after getting injured this past weekend against Real Betis.
Meanwhile, Andreas Christensen also remains unavailable as he continues his recovery from his injury.
The number of defensive absences have led to Flick calling up young prospect Alex Campos to the squad to face Luis Enrique's side. The 18-year-old is a part of the Barça Atletic and could get an opportunity in the senior setup.
#champions #ahead
Ahead of their trip to France, manager Hansi Flick has announced the squad list of players who will be available at his disposal for the blockbuster clash.
As expected, Barça go into the game without several key players as both Eric Garcia and Jules Kounde miss out after getting injured this past weekend against Real Betis.
Meanwhile, Andreas Christensen also remains unavailable as he continues his recovery from his injury.
The number of defensive absences have led to Flick calling up young prospect Alex Campos to the squad to face Luis Enrique's side. The 18-year-old is a part of the Barça Atletic and could get an opportunity in the senior setup.
#champions #ahead


27 days ago
Meghan Markle is reportedly facing fresh tensions with her US team after a promotional image for her As Ever brand drew criticism over its cooking setup. The reported fallout comes as the ******* ss of Sussex seeks to hire senior British staff. However, an insider claims her history of staff turnover could make it harder for her to attract experienced candidates.
According to sources cited by Naughty But Nice, Meghan Markle has grown frustrated with her US team after critics questioned an As Ever promotional cooking photo. The image appeared to show a gas stove that was switched off, leading critics to question the cooking setup. However, the photo alone does not confirm whether Meghan was actually cooking or whether she used the stove at another time.
An insider claimed Meghan expected her team to catch potential problems before the image reached the public. "She exploded," the source said. "It was, 'How did ******* ody catch this?' Meghan expects her team to protect her from exactly this kind of ridicule." However, her reaction may be making it harder for her to hire new staff. "She blames the American team when things go wrong, while prospective British employees are watching," the source explains. "Nobody wants to become the next person blamed — or the next departure that makes headlines."
Meghan is reportedly looking to strengthen her team in the UK, including by hiring an executive ******* istant. However, the insider claims that attracting experienced British candidates has become difficult because of the attention surrounding staff departures over the years. The source argued that a prestigious ******* le and the opportunity to work closely with Meghan may not be enough to convince top candidates to accept a role.
"Meghan can offer a glamorous ******* le, but the best people aren't biting," the insider told Naughty But Nice. "Her reputation gets there before the job offer does." The source added that prospective employees may wonder whether they would have a different experience from previous staff members. "People see the turnover and think, 'Why would it be different for me?'" the insider claimed.
#however
According to sources cited by Naughty But Nice, Meghan Markle has grown frustrated with her US team after critics questioned an As Ever promotional cooking photo. The image appeared to show a gas stove that was switched off, leading critics to question the cooking setup. However, the photo alone does not confirm whether Meghan was actually cooking or whether she used the stove at another time.
An insider claimed Meghan expected her team to catch potential problems before the image reached the public. "She exploded," the source said. "It was, 'How did ******* ody catch this?' Meghan expects her team to protect her from exactly this kind of ridicule." However, her reaction may be making it harder for her to hire new staff. "She blames the American team when things go wrong, while prospective British employees are watching," the source explains. "Nobody wants to become the next person blamed — or the next departure that makes headlines."
Meghan is reportedly looking to strengthen her team in the UK, including by hiring an executive ******* istant. However, the insider claims that attracting experienced British candidates has become difficult because of the attention surrounding staff departures over the years. The source argued that a prestigious ******* le and the opportunity to work closely with Meghan may not be enough to convince top candidates to accept a role.
"Meghan can offer a glamorous ******* le, but the best people aren't biting," the insider told Naughty But Nice. "Her reputation gets there before the job offer does." The source added that prospective employees may wonder whether they would have a different experience from previous staff members. "People see the turnover and think, 'Why would it be different for me?'" the insider claimed.
#however


1 month ago
Ben Affleck and Shakira may sound like the kind of unexpected celebrity pairing destined to dominate headlines, but there is one major problem with the story: they are not dating.
The speculation grew after The View co-host Ana Navarro revealed that she had once floated the idea of setting up the two newly single stars. Ben Affleck has now responded, and his reaction makes it clear that the matchmaking idea never turned into an actual romance.
(@ FilmMagic)
(@ Bruce Glikas/Getty Images)
In fact, Affleck said he had never even heard about the attempted setup until reporters brought it to his attention.
#idea #never #filmmagic #bruce
The speculation grew after The View co-host Ana Navarro revealed that she had once floated the idea of setting up the two newly single stars. Ben Affleck has now responded, and his reaction makes it clear that the matchmaking idea never turned into an actual romance.
(@ FilmMagic)
(@ Bruce Glikas/Getty Images)
In fact, Affleck said he had never even heard about the attempted setup until reporters brought it to his attention.
#idea #never #filmmagic #bruce



2 months ago
On September 17, Coherent Corp. (NYSE:COHR) announced an upgraded Pluggable Optical Line System that covers the full C-band and fits in a compact QSFP module, the same slot ordinary transceivers use. That is a lot of networking gear shrunk into a plug, and it follows a quarter of 34% revenue growth. Here is what the launch means, and where the stock's story gets harder to read.
Start with what the product does. The upgraded system can pack 32 wavelengths onto a single pair of fibers, which Coherent says adds up to as much as 25.6Tbps of traffic on links running 2km to 200km. It is designed for the latest 800G coherent optics, and it configures itself, handling link setup and laser safety without a technician tuning each connection. Coherent also says the system is generally available and already shipping in high volume, in 400G and 800G versions that work with existing network setups. Madhu Krishnaswamy, who runs the company's telecom transport unit, describes the goal as easing the usual trade-off between raw performance and operational simplicity.
The launch also sits on top of a business that is already moving. On August 12, Coherent reported results for its fiscal fourth quarter, which ended June 30: revenue of $2.05 billion, up 34% from a year earlier. Non-GAAP earnings per share rose to $1.74 from $1.00, and CEO Jim Anderson noted that for the full year, that measure grew more than twice as fast as revenue. Management guided to revenue of $2.2 billion to $2.4 billion for the first quarter of fiscal 2027, and Anderson says AI data centers are increasingly moving from copper to optical links.
Now look at the two versions of profit. Coherent's non-GAAP earnings came to $1.74 per share, but under GAAP the figure was $1.19. The gap comes from items management leaves out, including stock-based pay, amortization on acquired intangibles, and restructuring and integration costs. Operating margin shows it more clearly, at 21.8% on a non-GAAP basis and 12.4% under GAAP. Some of those costs are non-cash, but they are real, and anyone anchoring on the higher figure is skipping them.
Then there is how much weight this launch can carry. The announcement puts no sales figure on the product, so its contribution to a company that booked $2.05 billion in a quarter cannot be sized from what has been published. The bullish story also rests on management's own read of where AI networks are headed, and on a capacity build-out that CFO Sherri Luther says gets priority in spending. Money spent on capacity only pays off if the demand management describes keeps arriving.
#gaap #revenue #launch #anderson
Start with what the product does. The upgraded system can pack 32 wavelengths onto a single pair of fibers, which Coherent says adds up to as much as 25.6Tbps of traffic on links running 2km to 200km. It is designed for the latest 800G coherent optics, and it configures itself, handling link setup and laser safety without a technician tuning each connection. Coherent also says the system is generally available and already shipping in high volume, in 400G and 800G versions that work with existing network setups. Madhu Krishnaswamy, who runs the company's telecom transport unit, describes the goal as easing the usual trade-off between raw performance and operational simplicity.
The launch also sits on top of a business that is already moving. On August 12, Coherent reported results for its fiscal fourth quarter, which ended June 30: revenue of $2.05 billion, up 34% from a year earlier. Non-GAAP earnings per share rose to $1.74 from $1.00, and CEO Jim Anderson noted that for the full year, that measure grew more than twice as fast as revenue. Management guided to revenue of $2.2 billion to $2.4 billion for the first quarter of fiscal 2027, and Anderson says AI data centers are increasingly moving from copper to optical links.
Now look at the two versions of profit. Coherent's non-GAAP earnings came to $1.74 per share, but under GAAP the figure was $1.19. The gap comes from items management leaves out, including stock-based pay, amortization on acquired intangibles, and restructuring and integration costs. Operating margin shows it more clearly, at 21.8% on a non-GAAP basis and 12.4% under GAAP. Some of those costs are non-cash, but they are real, and anyone anchoring on the higher figure is skipping them.
Then there is how much weight this launch can carry. The announcement puts no sales figure on the product, so its contribution to a company that booked $2.05 billion in a quarter cannot be sized from what has been published. The bullish story also rests on management's own read of where AI networks are headed, and on a capacity build-out that CFO Sherri Luther says gets priority in spending. Money spent on capacity only pays off if the demand management describes keeps arriving.
#gaap #revenue #launch #anderson

2 months ago
On September 17, Coherent Corp. (NYSE:COHR) announced an upgraded Pluggable Optical Line System that covers the full C-band and fits in a compact QSFP module, the same slot ordinary transceivers use. That is a lot of networking gear shrunk into a plug, and it follows a quarter of 34% revenue growth. Here is what the launch means, and where the stock's story gets harder to read.
Start with what the product does. The upgraded system can pack 32 wavelengths onto a single pair of fibers, which Coherent says adds up to as much as 25.6Tbps of traffic on links running 2km to 200km. It is designed for the latest 800G coherent optics, and it configures itself, handling link setup and laser safety without a technician tuning each connection. Coherent also says the system is generally available and already shipping in high volume, in 400G and 800G versions that work with existing network setups. Madhu Krishnaswamy, who runs the company's telecom transport unit, describes the goal as easing the usual trade-off between raw performance and operational simplicity.
The launch also sits on top of a business that is already moving. On August 12, Coherent reported results for its fiscal fourth quarter, which ended June 30: revenue of $2.05 billion, up 34% from a year earlier. Non-GAAP earnings per share rose to $1.74 from $1.00, and CEO Jim Anderson noted that for the full year, that measure grew more than twice as fast as revenue. Management guided to revenue of $2.2 billion to $2.4 billion for the first quarter of fiscal 2027, and Anderson says AI data centers are increasingly moving from copper to optical links.
Now look at the two versions of profit. Coherent's non-GAAP earnings came to $1.74 per share, but under GAAP the figure was $1.19. The gap comes from items management leaves out, including stock-based pay, amortization on acquired intangibles, and restructuring and integration costs. Operating margin shows it more clearly, at 21.8% on a non-GAAP basis and 12.4% under GAAP. Some of those costs are non-cash, but they are real, and anyone anchoring on the higher figure is skipping them.
Then there is how much weight this launch can carry. The announcement puts no sales figure on the product, so its contribution to a company that booked $2.05 billion in a quarter cannot be sized from what has been published. The bullish story also rests on management's own read of where AI networks are headed, and on a capacity build-out that CFO Sherri Luther says gets priority in spending. Money spent on capacity only pays off if the demand management describes keeps arriving.
#quarter #launch #anderson
Start with what the product does. The upgraded system can pack 32 wavelengths onto a single pair of fibers, which Coherent says adds up to as much as 25.6Tbps of traffic on links running 2km to 200km. It is designed for the latest 800G coherent optics, and it configures itself, handling link setup and laser safety without a technician tuning each connection. Coherent also says the system is generally available and already shipping in high volume, in 400G and 800G versions that work with existing network setups. Madhu Krishnaswamy, who runs the company's telecom transport unit, describes the goal as easing the usual trade-off between raw performance and operational simplicity.
The launch also sits on top of a business that is already moving. On August 12, Coherent reported results for its fiscal fourth quarter, which ended June 30: revenue of $2.05 billion, up 34% from a year earlier. Non-GAAP earnings per share rose to $1.74 from $1.00, and CEO Jim Anderson noted that for the full year, that measure grew more than twice as fast as revenue. Management guided to revenue of $2.2 billion to $2.4 billion for the first quarter of fiscal 2027, and Anderson says AI data centers are increasingly moving from copper to optical links.
Now look at the two versions of profit. Coherent's non-GAAP earnings came to $1.74 per share, but under GAAP the figure was $1.19. The gap comes from items management leaves out, including stock-based pay, amortization on acquired intangibles, and restructuring and integration costs. Operating margin shows it more clearly, at 21.8% on a non-GAAP basis and 12.4% under GAAP. Some of those costs are non-cash, but they are real, and anyone anchoring on the higher figure is skipping them.
Then there is how much weight this launch can carry. The announcement puts no sales figure on the product, so its contribution to a company that booked $2.05 billion in a quarter cannot be sized from what has been published. The bullish story also rests on management's own read of where AI networks are headed, and on a capacity build-out that CFO Sherri Luther says gets priority in spending. Money spent on capacity only pays off if the demand management describes keeps arriving.
#quarter #launch #anderson

2 months ago
On September 2, 2026, Snowflake Inc. (NYSE:SNOW) reported second-quarter fiscal 2027 results for the period ended July 31, 2026. Revenue rose 35% to $1.55 billion against a $1.48 billion consensus, product revenue grew 37% to $1.49 billion, and adjusted earnings came in at $0.62 per share versus the $0.45 ******* ysts expected. Management raised full-year product revenue guidance to $6.07 billion from $5.84 billion. Shares surged more than 20% in extended trading, and within 48 hours eight firms had rewritten their models.
The size of the target revisions tells the story.
Argus ******* yst Joseph Bonner moved to $450 from $300, keeping a Buy rating and arguing that new AI products are driving sales, customer conversion, and retention while Snowflake Inc. (NYSE:SNOW) grows well above management's 30% north star target with expanding margins.
Goldman Sachs also went to $436 from $300, noting product revenue landed 5% above the Street and EBIT margins 270 basis points ahead, and said the stock reaction reflects a setup where estimates keep moving higher over the next 18 months.
JPMorgan lifted its target to $426 from $285 on a third straight quarter of product revenue acceleration, while Raymond James ******* yst Adam Tindle went to $425 from $275, framing Snowflake Inc. (NYSE:SNOW) as an AI-native control plane for enterprise workflows beyond ******* ytics.
#target
The size of the target revisions tells the story.
Argus ******* yst Joseph Bonner moved to $450 from $300, keeping a Buy rating and arguing that new AI products are driving sales, customer conversion, and retention while Snowflake Inc. (NYSE:SNOW) grows well above management's 30% north star target with expanding margins.
Goldman Sachs also went to $436 from $300, noting product revenue landed 5% above the Street and EBIT margins 270 basis points ahead, and said the stock reaction reflects a setup where estimates keep moving higher over the next 18 months.
JPMorgan lifted its target to $426 from $285 on a third straight quarter of product revenue acceleration, while Raymond James ******* yst Adam Tindle went to $425 from $275, framing Snowflake Inc. (NYSE:SNOW) as an AI-native control plane for enterprise workflows beyond ******* ytics.
#target

2 months ago
Apollo Global Management warned Wednesday that credit default swaps on hyperscaler debt are pricing in more risk. Chief economist Torsten Slok tied the shift to weakening credit fundamentals rather than routine bond-dealer hedging.
Hyperscalers are the cloud computing giants, including Amazon, Microsoft, Google, and Meta, that run the infrastructure behind the AI boom. They face a credit default swap (CDS) gap against bank debt, widened to about 60 basis points since October 2025.
Slok made the case in a Wednesday note reported by CNBC.
"What the market is repricing is hyperscaler credit fundamentals, namely a debt-financed AI capex cycle with rising leverage, negative free cash flow and uncertain payback on depreciating ****** ets."
Dan Alpert, founding managing partner of Westwood Capital, compared the setup to the run-up to the 2008 mortgage crisis. He said banks have since built far bigger equity buffers and are more diversified than they were then.
#slok
Hyperscalers are the cloud computing giants, including Amazon, Microsoft, Google, and Meta, that run the infrastructure behind the AI boom. They face a credit default swap (CDS) gap against bank debt, widened to about 60 basis points since October 2025.
Slok made the case in a Wednesday note reported by CNBC.
"What the market is repricing is hyperscaler credit fundamentals, namely a debt-financed AI capex cycle with rising leverage, negative free cash flow and uncertain payback on depreciating ****** ets."
Dan Alpert, founding managing partner of Westwood Capital, compared the setup to the run-up to the 2008 mortgage crisis. He said banks have since built far bigger equity buffers and are more diversified than they were then.
#slok
2 months ago
A UTMA custodial account requires no attorney, costs nothing to open, and lets married couples contribute $38,000 annually per grandchild without triggering gift-tax reporting.
VOO anchors the portfolio at 60-70% with a 0.03% expense ratio, while SCHG's 447% 10-year return earns it a 20-25% growth slice.
Custodial account funds legally become the grandchild's property at 18 or 21, so grandparents who want spending control should use a 529 instead.
Read More: Avoid these 13 retirement mistakes before they derail your future (sponsor)
You want to hand each grandchild a serious head start without the complicated legal setup. Skip the trust attorney. A custodial account under the Uniform Transfers to Minors Act (UTMA) can be opened in an afternoon at any major brokerage, and three low-cost ETFs can do the work for the next 15 to 20 years: the Vanguard S&P 500 ETF (NYSEARCA:VOO), the Schwab U.S. Large-Cap Growth ETF (NYSEARCA:SCHG), and the iShares Core MSCI Emerging Markets ETF (NYSEARCA:IEMG). Three tickers, one account per grandchild, and time on your side.
#custodial #three
VOO anchors the portfolio at 60-70% with a 0.03% expense ratio, while SCHG's 447% 10-year return earns it a 20-25% growth slice.
Custodial account funds legally become the grandchild's property at 18 or 21, so grandparents who want spending control should use a 529 instead.
Read More: Avoid these 13 retirement mistakes before they derail your future (sponsor)
You want to hand each grandchild a serious head start without the complicated legal setup. Skip the trust attorney. A custodial account under the Uniform Transfers to Minors Act (UTMA) can be opened in an afternoon at any major brokerage, and three low-cost ETFs can do the work for the next 15 to 20 years: the Vanguard S&P 500 ETF (NYSEARCA:VOO), the Schwab U.S. Large-Cap Growth ETF (NYSEARCA:SCHG), and the iShares Core MSCI Emerging Markets ETF (NYSEARCA:IEMG). Three tickers, one account per grandchild, and time on your side.
#custodial #three


2 months ago
Teck Resources Ltd (NYSE:TECK) stock's pullback from its Sept. 8 record high of $72.56 has found support at the 60-, 80-, and 100-day moving averages. The 100-day trendline in particular is a historically bullish signal that presents an intriguing 'buy the dip' angle.
Per Schaeffer's Senior Quantitative ******* yst Rocky White, TECK has traded within 0.75 times the 100-day moving average's 20-day average true range (ATR) after spending at least 80% of the previous two weeks and 80% of the prior 42 trading sessions above the trendline. This setup has occurred eight other times over the last decade, after which the stock was higher one month later 75% of the time, averaging a large 13.8% gain.
Short interest accounts for a healthy 7.5% of the stock's available float, leaving ample sideline buying power should some of these bearish bets begin to unwind. TECK's 14-day Relative Strength Index (RSI) of 28.4 also sits in "oversold" territory, which often precedes a short-term bounce.
Plus, TECK's Schaeffer's Volatility Scorecard (SVS) sits at 81 out of 100, suggesting the shares have tended to outperform options traders' volatility expectations during the past year.
#resources
Per Schaeffer's Senior Quantitative ******* yst Rocky White, TECK has traded within 0.75 times the 100-day moving average's 20-day average true range (ATR) after spending at least 80% of the previous two weeks and 80% of the prior 42 trading sessions above the trendline. This setup has occurred eight other times over the last decade, after which the stock was higher one month later 75% of the time, averaging a large 13.8% gain.
Short interest accounts for a healthy 7.5% of the stock's available float, leaving ample sideline buying power should some of these bearish bets begin to unwind. TECK's 14-day Relative Strength Index (RSI) of 28.4 also sits in "oversold" territory, which often precedes a short-term bounce.
Plus, TECK's Schaeffer's Volatility Scorecard (SVS) sits at 81 out of 100, suggesting the shares have tended to outperform options traders' volatility expectations during the past year.
#resources

2 months ago
Coherent jumped 6% and Lumentum climbed 5% with no catalyst, driven by short covering after both stocks fell sharply over the prior month.
SOXX gained only 2% and SPY just 0.3%, making the optics group's surge a positioning-only bounce confined to the sector, not a broad re-rating.
Just released. Our ******* ysts combed the entire stock market and named the ten best stocks to buy right now, and Coherent didn't make the cut. Enter your email to see the names that beat COHR. The report is free. Enter your email and see if any of your stocks made the cut.
Optics stocks are rebounding Wednesday morning without a fresh headline to point to, and the size of the group's move relative to the broader market is the story. The iShares Semiconductor ETF (NASDAQ:SOXX) is at $508.59, up 2%, while the SPDR S&P 500 ETF Trust (NYSEARCA:SPY) is at $759.69, up just 0.3%. The three optics names running today are outpacing both benchmarks by a wide margin.
Coherent Corp. (NYSE:COHR) stock is up 6% to $287.21 in Wednesday morning trading. The bounce arrives after a rough stretch. Coherent shares had fallen 12% over the past month heading into today's session, and that drawdown is the part of the setup that hasn't been undone.
#optics
SOXX gained only 2% and SPY just 0.3%, making the optics group's surge a positioning-only bounce confined to the sector, not a broad re-rating.
Just released. Our ******* ysts combed the entire stock market and named the ten best stocks to buy right now, and Coherent didn't make the cut. Enter your email to see the names that beat COHR. The report is free. Enter your email and see if any of your stocks made the cut.
Optics stocks are rebounding Wednesday morning without a fresh headline to point to, and the size of the group's move relative to the broader market is the story. The iShares Semiconductor ETF (NASDAQ:SOXX) is at $508.59, up 2%, while the SPDR S&P 500 ETF Trust (NYSEARCA:SPY) is at $759.69, up just 0.3%. The three optics names running today are outpacing both benchmarks by a wide margin.
Coherent Corp. (NYSE:COHR) stock is up 6% to $287.21 in Wednesday morning trading. The bounce arrives after a rough stretch. Coherent shares had fallen 12% over the past month heading into today's session, and that drawdown is the part of the setup that hasn't been undone.
#optics


2 months ago
Ethereum's native token, Ether (ETH), is showing signs of underperformance against Bitcoin (BTC), with a bearish double-top setup emerging just as the US Senate's failure to advance the CLARITY Act adds fresh uncertainty to the crypto market.
Ether was trading near 0.03167 BTC on Sept. 16, after failing to sustain its latest advance against Bitcoin.
The ETH/BTC daily chart shows two comparable peaks near 0.03344 BTC, one formed in August and another in September. Together, they resemble a potential double top, a bearish reversal structure that typically develops when buyers repeatedly fail to push price through the same resistance area.
Its neckline sits around 0.03078 BTC, meaning ETH/BTC would need a decisive daily close below that level to validate the breakdown.
If that happens, subtracting the pattern's maximum height from the neckline produces a downside target near 0.0283 BTC. That would represent a decline of roughly 10% from current levels, signaling further Ethereum underperformance relative to Bitcoin.
#Bitcoin #underperformance #daily #neckline
Ether was trading near 0.03167 BTC on Sept. 16, after failing to sustain its latest advance against Bitcoin.
The ETH/BTC daily chart shows two comparable peaks near 0.03344 BTC, one formed in August and another in September. Together, they resemble a potential double top, a bearish reversal structure that typically develops when buyers repeatedly fail to push price through the same resistance area.
Its neckline sits around 0.03078 BTC, meaning ETH/BTC would need a decisive daily close below that level to validate the breakdown.
If that happens, subtracting the pattern's maximum height from the neckline produces a downside target near 0.0283 BTC. That would represent a decline of roughly 10% from current levels, signaling further Ethereum underperformance relative to Bitcoin.
#Bitcoin #underperformance #daily #neckline


2 months ago
Lam Research Corporation (NASDAQ: LRCX) stock has struggled recently, shedding 16.6% in the last week alone. The shares have seen some volatility since their April-June rally peaked at a June 30 record high of $438.50. LRCX was last seen down 2.3% at $267.22 today, though it still boasts a roughly 56% year-to-date lead. Plus, the recent pullback has found support at the 200-day moving average, a trendline with historically bullish implications.
Per Schaeffer's Senior Quantitative ***** yst Rocky White, LRCX has traded within 0.75 times the 200-day moving average's 20-day average true range (ATR) after spending at least 80% of the previous two weeks and 80% of the prior 42 trading sessions above the trendline. This setup has occurred five other times over the last decade, after which the stock was higher one month later 80% of the time, averaging a 6.9% gain.
Furthermore, LRCX's 14-day Relative Strength Index (RSI) of 28.7 sits in "oversold" territory, which often precedes a short-term bounce.
#Stock #Research
Per Schaeffer's Senior Quantitative ***** yst Rocky White, LRCX has traded within 0.75 times the 200-day moving average's 20-day average true range (ATR) after spending at least 80% of the previous two weeks and 80% of the prior 42 trading sessions above the trendline. This setup has occurred five other times over the last decade, after which the stock was higher one month later 80% of the time, averaging a 6.9% gain.
Furthermore, LRCX's 14-day Relative Strength Index (RSI) of 28.7 sits in "oversold" territory, which often precedes a short-term bounce.
#Stock #Research


2 months ago
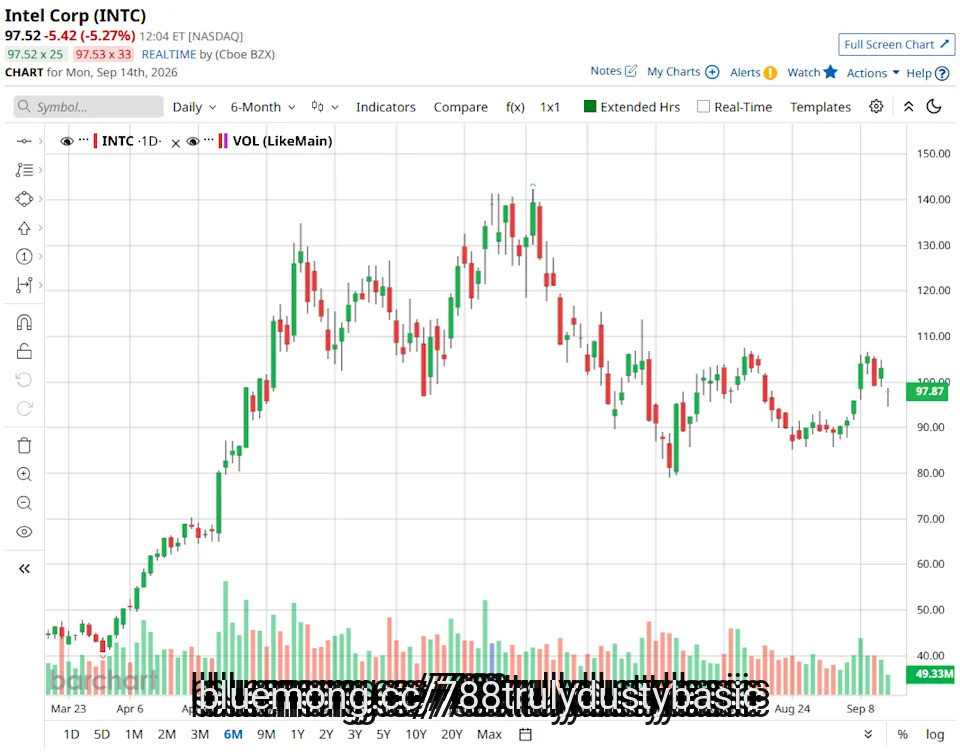
Mizuho has identified four clear tailwinds for Intel (INTC): ongoing CPU supply shortages, a stronger PC refresh cycle, accelerating demand for agentic AI, and growth in advanced packaging. Normally, such a setup would provide a reason to raise a price target. Instead, the firm cut its price target from $109 to $92, citing short-term multiple compression across Agentic AI stocks, and maintained a "Neutral" rating. The contradiction becomes more important because Intel's re-rating still depends on a foundry turnaround that has yet to prove itself.
Mizuho remains cautious on INTC stock despite outlining four separate tailwinds that could support the company's growth. The firm lowered its price target from $109 to $92 on Sept. 3, pointing to short-term multiple compression across agentic AI companies while keeping its "Neutral" rating unchanged. Mizuho **** yst Vijay Rakesh highlighted four developments that could support Intel's outlook. According to the **** yst, accelerating agentic AI demand could improve CPU-to-GPU ratios and drive additional server refreshers. Ongoing CPU supply constraints could also leave the company unable to fully meet demand through 2027. In addition, advanced packaging revenue is expected to reach $3.5 billion by 2029, with external foundry revenue potentially reaching a similar level through the 14A node. Finally, a stronger PC cycle could extend the upgrade cycle as corporate refreshes combine with ongoing memory tightness.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Billionaire Charlie Munger, Who Died at 99, Skipped Insurance on His Mansion Since He Could Just Write a Check to Rebuild — 'All Intelligent People Do It My Way'
The EV Bubble Has Burst. How to Play Rivian Stock Now.
#four
Mizuho remains cautious on INTC stock despite outlining four separate tailwinds that could support the company's growth. The firm lowered its price target from $109 to $92 on Sept. 3, pointing to short-term multiple compression across agentic AI companies while keeping its "Neutral" rating unchanged. Mizuho **** yst Vijay Rakesh highlighted four developments that could support Intel's outlook. According to the **** yst, accelerating agentic AI demand could improve CPU-to-GPU ratios and drive additional server refreshers. Ongoing CPU supply constraints could also leave the company unable to fully meet demand through 2027. In addition, advanced packaging revenue is expected to reach $3.5 billion by 2029, with external foundry revenue potentially reaching a similar level through the 14A node. Finally, a stronger PC cycle could extend the upgrade cycle as corporate refreshes combine with ongoing memory tightness.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Billionaire Charlie Munger, Who Died at 99, Skipped Insurance on His Mansion Since He Could Just Write a Check to Rebuild — 'All Intelligent People Do It My Way'
The EV Bubble Has Burst. How to Play Rivian Stock Now.
#four

2 months ago
Shares of Nvidia Corp (NASDAQ:NVDA) stock are inching 0.4% higher to trade at $211.72 this afternoon, taking a breather after five-straight losing sessions, including yesterday's AI-induced selloff of 3.4%. The equity is still up 13.3% in 2026, however, and a rebound could soon be on the way, per a historically bullish trendline.
According to Schaeffer's Senior Quantitative ***** yst Rocky White, NVDA is trading within 0.75 times the 126-day moving average's 20-day average true range (ATR), after spending at least 80% of the previous two weeks and 80% of the prior 42 trading sessions above that trendline.
This setup has appeared 11 times over the last decade, after which the stock was higher one month later 82% of the time, averaging a 6.2% gain. From its current perch, a move of this caliber would put the equity just shy of $225.
NVDA sports a 50-day put/call volume ratio at the International Securities Exchange (ISE), Cboe Options Exchange (CBOE), and NASDAQ OMX PHLX (PHLX) that stands higher than 83% of readings from the past year. Should this bearish sentiment begin to unwind, it could trigger a new round of tailwinds for the shares.
Options are looking affordable as well. The stock's Schaeffer's Volatility Index (SVI) of 34% stands higher than just 2% of all other readings from the past year. In other words, near-term option traders are pricing in low volatility expectations at the moment.
#NASDAQ #cboe #phlx
According to Schaeffer's Senior Quantitative ***** yst Rocky White, NVDA is trading within 0.75 times the 126-day moving average's 20-day average true range (ATR), after spending at least 80% of the previous two weeks and 80% of the prior 42 trading sessions above that trendline.
This setup has appeared 11 times over the last decade, after which the stock was higher one month later 82% of the time, averaging a 6.2% gain. From its current perch, a move of this caliber would put the equity just shy of $225.
NVDA sports a 50-day put/call volume ratio at the International Securities Exchange (ISE), Cboe Options Exchange (CBOE), and NASDAQ OMX PHLX (PHLX) that stands higher than 83% of readings from the past year. Should this bearish sentiment begin to unwind, it could trigger a new round of tailwinds for the shares.
Options are looking affordable as well. The stock's Schaeffer's Volatility Index (SVI) of 34% stands higher than just 2% of all other readings from the past year. In other words, near-term option traders are pricing in low volatility expectations at the moment.
#NASDAQ #cboe #phlx


2 months ago
Pfizer Inc. (NYSE:PFE) and Valneva SE (NASDAQ:VALN) reported on August 14 that the European Medicines Agency has validated the Marketing Authorization Application for PF-07307405, the companies' experimental Lyme disease vaccine candidate, and will now begin the official review.
For a vaccine candidate first proposed in a 2020 collaboration deal between Pfizer Inc. (NYSE:PFE) and French biotech Valneva SE (NASDAQ:VALN), this represents the formal transition from years of clinical development into European regulatory review.
The application is based on the Phase 3 VALOR trial, a placebo-controlled, randomized study of 9,437 participants aged five and older from high-incidence Lyme disease locations in US, Canada, and Europe. Participants got four doses on a phased schedule: one at months 0, 2, and 5-9, followed by a fourth dosage around a year later, shortly before the start of the next Lyme season. Topline data released in March 2026 demonstrated efficacy of over 70% in reducing confirmed Lyme disease cases, with the vaccine generally tolerated and no safety issues detected. However, the statistical picture was less clean than the headline efficacy suggests. The first prespecified **** ysis, which served as the primary endpoint, showed 73.2% efficacy but failed the trial's predefined statistical criterion because the lower bound of the 95% confidence interval was 15.8%, below the required 20%. A second prespecified **** ysis showed 74.8% efficacy and did meet that threshold.
Valneva SE (NASDAQ:VALN), the smallest of the two partners, views the vaccine as a clean competitive setup. According to the company, PF-07307405 is the most advanced Lyme disease vaccine candidate currently in clinical development, a rare spot in the vaccine industry where new entrants often face competition from existing treatments. Under the terms of the 2020 partnership and license agreement, Pfizer Inc. (NYSE:PFE) will have exclusive rights to produce and commercialize the vaccine if it is approved, while Valneva SE (NASDAQ:VALN) will benefit as a development partner.
The institutional stance is very different between the two companies, reflecting their very different sizes. Pfizer Inc. (NYSE:PFE) is still a strong name in the institutional **** e, with hedge fund ownership stable at 83 funds in the second quarter of 2026, the same as the first quarter, reflecting its position as a large, diversified pharmaceutical holding, rather than a name driven by a specific pipeline event. Valneva SE (NASDAQ:VALN), however, has little hedge fund exposure, with only 4 funds holding a position in the second quarter, up from 1 in the first quarter, reflecting the continued lack of visibility of the smaller partner among institutional investors.
#vaccine #pfizer #NYSE
For a vaccine candidate first proposed in a 2020 collaboration deal between Pfizer Inc. (NYSE:PFE) and French biotech Valneva SE (NASDAQ:VALN), this represents the formal transition from years of clinical development into European regulatory review.
The application is based on the Phase 3 VALOR trial, a placebo-controlled, randomized study of 9,437 participants aged five and older from high-incidence Lyme disease locations in US, Canada, and Europe. Participants got four doses on a phased schedule: one at months 0, 2, and 5-9, followed by a fourth dosage around a year later, shortly before the start of the next Lyme season. Topline data released in March 2026 demonstrated efficacy of over 70% in reducing confirmed Lyme disease cases, with the vaccine generally tolerated and no safety issues detected. However, the statistical picture was less clean than the headline efficacy suggests. The first prespecified **** ysis, which served as the primary endpoint, showed 73.2% efficacy but failed the trial's predefined statistical criterion because the lower bound of the 95% confidence interval was 15.8%, below the required 20%. A second prespecified **** ysis showed 74.8% efficacy and did meet that threshold.
Valneva SE (NASDAQ:VALN), the smallest of the two partners, views the vaccine as a clean competitive setup. According to the company, PF-07307405 is the most advanced Lyme disease vaccine candidate currently in clinical development, a rare spot in the vaccine industry where new entrants often face competition from existing treatments. Under the terms of the 2020 partnership and license agreement, Pfizer Inc. (NYSE:PFE) will have exclusive rights to produce and commercialize the vaccine if it is approved, while Valneva SE (NASDAQ:VALN) will benefit as a development partner.
The institutional stance is very different between the two companies, reflecting their very different sizes. Pfizer Inc. (NYSE:PFE) is still a strong name in the institutional **** e, with hedge fund ownership stable at 83 funds in the second quarter of 2026, the same as the first quarter, reflecting its position as a large, diversified pharmaceutical holding, rather than a name driven by a specific pipeline event. Valneva SE (NASDAQ:VALN), however, has little hedge fund exposure, with only 4 funds holding a position in the second quarter, up from 1 in the first quarter, reflecting the continued lack of visibility of the smaller partner among institutional investors.
#vaccine #pfizer #NYSE

2 months ago
Pfizer Inc. (NYSE:PFE) and Valneva SE (NASDAQ:VALN) reported on August 14 that the European Medicines Agency has validated the Marketing Authorization Application for PF-07307405, the companies' experimental Lyme disease vaccine candidate, and will now begin the official review.
For a vaccine candidate first proposed in a 2020 collaboration deal between Pfizer Inc. (NYSE:PFE) and French biotech Valneva SE (NASDAQ:VALN), this represents the formal transition from years of clinical development into European regulatory review.
The application is based on the Phase 3 VALOR trial, a placebo-controlled, randomized study of 9,437 participants aged five and older from high-incidence Lyme disease locations in US, Canada, and Europe. Participants got four doses on a phased schedule: one at months 0, 2, and 5-9, followed by a fourth dosage around a year later, shortly before the start of the next Lyme season. Topline data released in March 2026 demonstrated efficacy of over 70% in reducing confirmed Lyme disease cases, with the vaccine generally tolerated and no safety issues detected. However, the statistical picture was less clean than the headline efficacy suggests. The first prespecified **** ysis, which served as the primary endpoint, showed 73.2% efficacy but failed the trial's predefined statistical criterion because the lower bound of the 95% confidence interval was 15.8%, below the required 20%. A second prespecified **** ysis showed 74.8% efficacy and did meet that threshold.
Valneva SE (NASDAQ:VALN), the smallest of the two partners, views the vaccine as a clean competitive setup. According to the company, PF-07307405 is the most advanced Lyme disease vaccine candidate currently in clinical development, a rare spot in the vaccine industry where new entrants often face competition from existing treatments. Under the terms of the 2020 partnership and license agreement, Pfizer Inc. (NYSE:PFE) will have exclusive rights to produce and commercialize the vaccine if it is approved, while Valneva SE (NASDAQ:VALN) will benefit as a development partner.
The institutional stance is very different between the two companies, reflecting their very different sizes. Pfizer Inc. (NYSE:PFE) is still a strong name in the institutional **** e, with hedge fund ownership stable at 83 funds in the second quarter of 2026, the same as the first quarter, reflecting its position as a large, diversified pharmaceutical holding, rather than a name driven by a specific pipeline event. Valneva SE (NASDAQ:VALN), however, has little hedge fund exposure, with only 4 funds holding a position in the second quarter, up from 1 in the first quarter, reflecting the continued lack of visibility of the smaller partner among institutional investors.
#disease
For a vaccine candidate first proposed in a 2020 collaboration deal between Pfizer Inc. (NYSE:PFE) and French biotech Valneva SE (NASDAQ:VALN), this represents the formal transition from years of clinical development into European regulatory review.
The application is based on the Phase 3 VALOR trial, a placebo-controlled, randomized study of 9,437 participants aged five and older from high-incidence Lyme disease locations in US, Canada, and Europe. Participants got four doses on a phased schedule: one at months 0, 2, and 5-9, followed by a fourth dosage around a year later, shortly before the start of the next Lyme season. Topline data released in March 2026 demonstrated efficacy of over 70% in reducing confirmed Lyme disease cases, with the vaccine generally tolerated and no safety issues detected. However, the statistical picture was less clean than the headline efficacy suggests. The first prespecified **** ysis, which served as the primary endpoint, showed 73.2% efficacy but failed the trial's predefined statistical criterion because the lower bound of the 95% confidence interval was 15.8%, below the required 20%. A second prespecified **** ysis showed 74.8% efficacy and did meet that threshold.
Valneva SE (NASDAQ:VALN), the smallest of the two partners, views the vaccine as a clean competitive setup. According to the company, PF-07307405 is the most advanced Lyme disease vaccine candidate currently in clinical development, a rare spot in the vaccine industry where new entrants often face competition from existing treatments. Under the terms of the 2020 partnership and license agreement, Pfizer Inc. (NYSE:PFE) will have exclusive rights to produce and commercialize the vaccine if it is approved, while Valneva SE (NASDAQ:VALN) will benefit as a development partner.
The institutional stance is very different between the two companies, reflecting their very different sizes. Pfizer Inc. (NYSE:PFE) is still a strong name in the institutional **** e, with hedge fund ownership stable at 83 funds in the second quarter of 2026, the same as the first quarter, reflecting its position as a large, diversified pharmaceutical holding, rather than a name driven by a specific pipeline event. Valneva SE (NASDAQ:VALN), however, has little hedge fund exposure, with only 4 funds holding a position in the second quarter, up from 1 in the first quarter, reflecting the continued lack of visibility of the smaller partner among institutional investors.
#disease


2 months ago
Lululemon Athletica Inc. (NASDAQ:LULU) recently issued its second guidance cut of the year, and investors responded immediately by sending shares down roughly 18%. That selloff came despite an EPS beat, but the headline result was heavily supported by a tariff refund rather than underlying business strength. Brand sentiment, traffic, and leggings sales are all weakening across the company's two largest markets. The key issue for investors is no longer whether the quarter was weak, but whether the stock's low valuation and new CEO can provide the catalyst for a meaningful recovery.
Lululemon shares dropped 18% after the company lowered its full-year guidance for the second time this year. Revenue is now projected to range from $10.35 billion to $10.5 billion, while EPS guidance was reduced to $9.48 to $9.73. Both represent sharp reductions from its earlier guidance ranges. Second-quarter revenue was particularly weak, falling 4% to $2.4 billion and coming in below consensus estimates, while comparable sales dropped 9%, or 10% on a constant-dollar basis. According to the company, negative commentary had affected traffic in both the U.S. and China, while leggings sales slowed more than expected. Although reported EPS beat estimates, nearly all of that upside came from an $0.86 per share tariff refund. For the third quarter, management expects revenue to decline another 10% to 11%.
Lululemon still has several financial advantages that could support the business through its current slowdown. The company has no outstanding borrowings and maintains $1.4 billion in cash. First-half operating cash flow climbed to $589 million, more than double the prior year. Inventory per unit also declined roughly 7% year over year, reducing the risk of a margin-damaging clearance event. Meanwhile, shares have fallen over 50% year-to-date and now trade at a historically depressed valuation, potentially creating an out-of-favor-setup for investors. At the same time, management continued its buyback program, repurchasing $330 million worth of shares during the quarter.
The weakness in traffic and leggings sales cannot be ignored, and both remain serious concerns. However, the company has a debt-free balance sheet, stronger cash generation, and a valuation that already reflects much of the recent bad news. That gives Lululemon room to prove that its current struggles are mainly execution-related rather than signs of a structural decline.
#year #shares #company
Lululemon shares dropped 18% after the company lowered its full-year guidance for the second time this year. Revenue is now projected to range from $10.35 billion to $10.5 billion, while EPS guidance was reduced to $9.48 to $9.73. Both represent sharp reductions from its earlier guidance ranges. Second-quarter revenue was particularly weak, falling 4% to $2.4 billion and coming in below consensus estimates, while comparable sales dropped 9%, or 10% on a constant-dollar basis. According to the company, negative commentary had affected traffic in both the U.S. and China, while leggings sales slowed more than expected. Although reported EPS beat estimates, nearly all of that upside came from an $0.86 per share tariff refund. For the third quarter, management expects revenue to decline another 10% to 11%.
Lululemon still has several financial advantages that could support the business through its current slowdown. The company has no outstanding borrowings and maintains $1.4 billion in cash. First-half operating cash flow climbed to $589 million, more than double the prior year. Inventory per unit also declined roughly 7% year over year, reducing the risk of a margin-damaging clearance event. Meanwhile, shares have fallen over 50% year-to-date and now trade at a historically depressed valuation, potentially creating an out-of-favor-setup for investors. At the same time, management continued its buyback program, repurchasing $330 million worth of shares during the quarter.
The weakness in traffic and leggings sales cannot be ignored, and both remain serious concerns. However, the company has a debt-free balance sheet, stronger cash generation, and a valuation that already reflects much of the recent bad news. That gives Lululemon room to prove that its current struggles are mainly execution-related rather than signs of a structural decline.
#year #shares #company
2 months ago
Salesforce (CRM) trades at 20.6 times earnings, below the S&P 500 median of 22.6, after losing 2.8% over the past twelve months while the index gained 17.9%. A profitable software company priced under the market is the setup value buyers wait for. The question is whether that is a good business on sale or a fair price for a legacy platform facing disintermediation from next-generation AI architectures.
Salesforce sells the customer relationship software that companies run their sales and service teams on, and it owns Slack. Deutsche Telekom and FIFA both expanded their AI spending with Salesforce in fiscal Q2 2027. Revenue over the trailing twelve months was $43.94 billion, up 11.2%. The three-year average revenue growth rate is 9.9% a year—ahead of the S&P 500 median of 8.3%—making the last twelve months the faster of the two.
Free cash flow over the same window was $15.15 billion, a 7.6% yield on the market value. Operating margin over those twelve months is 21.5% against an S&P 500 median of 18.6%, and the margin did not thin against the year before.
Free cash flow in fiscal Q2 2027 was $1.1 billion, up 81% from a year earlier. That is one quarter. For the whole of fiscal 2027 management guides free cash flow growth of 4% to 5%, against revenue guided up 11% to 12%, so cash is set to grow at less than half the pace of the top line.
License revenue is a headwind and integration and ******* ytics revenue is volatile, management says, though both only partially offset growth in the newer lines. Near $243, the stock is just 8% off its 52-week high, though it remains about 33% below its two-year peak of $363.22: while the recent rally closed the immediate valuation gap, the longer-term discount reflects that structural hesitation hasn't fully cleared.
#cash #billion
Salesforce sells the customer relationship software that companies run their sales and service teams on, and it owns Slack. Deutsche Telekom and FIFA both expanded their AI spending with Salesforce in fiscal Q2 2027. Revenue over the trailing twelve months was $43.94 billion, up 11.2%. The three-year average revenue growth rate is 9.9% a year—ahead of the S&P 500 median of 8.3%—making the last twelve months the faster of the two.
Free cash flow over the same window was $15.15 billion, a 7.6% yield on the market value. Operating margin over those twelve months is 21.5% against an S&P 500 median of 18.6%, and the margin did not thin against the year before.
Free cash flow in fiscal Q2 2027 was $1.1 billion, up 81% from a year earlier. That is one quarter. For the whole of fiscal 2027 management guides free cash flow growth of 4% to 5%, against revenue guided up 11% to 12%, so cash is set to grow at less than half the pace of the top line.
License revenue is a headwind and integration and ******* ytics revenue is volatile, management says, though both only partially offset growth in the newer lines. Near $243, the stock is just 8% off its 52-week high, though it remains about 33% below its two-year peak of $363.22: while the recent rally closed the immediate valuation gap, the longer-term discount reflects that structural hesitation hasn't fully cleared.
#cash #billion

2 months ago
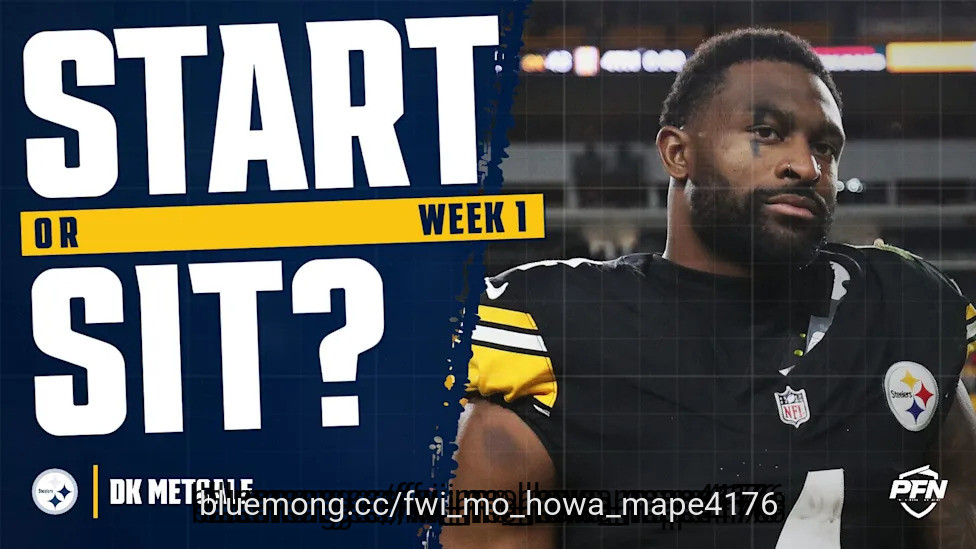
Metcalf sits 34th among wide receivers in PFN's Week 1 rankings, which is what happens after the worst season of your career. The Falcons allowed seven receivers to clear 20 PPR points last season, so the setup is there, and so is the Michael Pittman theory. I'm going to be a week or two late to this party rather than early.
Let's call a spade a spade: Metcalf is coming off of the worst season of his career. His 850 yards were a new low-water mark and even that was inflated by two games where he had superhero singular plays that lifted his stat line (274 yards in games against the Ravens and Vikings, 576 in his other 13, good for just 44.3 yards per contest).
Aaron Rodgers is back at the helm and the team added Michael Pittman this offseason, a receiver who has effectively made a career off of what the Steelers asked of Metcalf in his first season with the franchise: short targets and hope.
SET YOUR LINEUPS: PFN's Free Fantasy Football Start/Sit Optimizer
Metcalf's 11.3 aDOT was, you guessed it, the lowest of his career, and featured just 24.2% of his looks coming deep downfield (15 or more yards), a rate that stood at 43.5% in 2024 with Seattle.
#season #week #receivers
Let's call a spade a spade: Metcalf is coming off of the worst season of his career. His 850 yards were a new low-water mark and even that was inflated by two games where he had superhero singular plays that lifted his stat line (274 yards in games against the Ravens and Vikings, 576 in his other 13, good for just 44.3 yards per contest).
Aaron Rodgers is back at the helm and the team added Michael Pittman this offseason, a receiver who has effectively made a career off of what the Steelers asked of Metcalf in his first season with the franchise: short targets and hope.
SET YOUR LINEUPS: PFN's Free Fantasy Football Start/Sit Optimizer
Metcalf's 11.3 aDOT was, you guessed it, the lowest of his career, and featured just 24.2% of his looks coming deep downfield (15 or more yards), a rate that stood at 43.5% in 2024 with Seattle.
#season #week #receivers

2 months ago
The NASCAR O'Reilly Auto Parts Series returns to action Saturday night as the playoff battle continues at World Wide Technology Raceway in Madison, Illinois.
The Nu Way 225 is scheduled for 7:30 p.m. ET, with drivers looking to make a major statement as the championship fight begins to heat up. The race will be the second event of the 2026 O'Reilly Series chase.
World Wide Technology Raceway is one of the most difficult tracks on the O'Reilly Series schedule because of its unique layout.
The 1.25-mile oval features different corner characteristics, forcing teams to find a setup that works in both ends of the track. Drivers will also have to manage tire wear, track position and restarts throughout the night.
Gateway is a track where experience can make a major difference. With the championship battle underway, mistakes could become extremely costly.
#technology #night
The Nu Way 225 is scheduled for 7:30 p.m. ET, with drivers looking to make a major statement as the championship fight begins to heat up. The race will be the second event of the 2026 O'Reilly Series chase.
World Wide Technology Raceway is one of the most difficult tracks on the O'Reilly Series schedule because of its unique layout.
The 1.25-mile oval features different corner characteristics, forcing teams to find a setup that works in both ends of the track. Drivers will also have to manage tire wear, track position and restarts throughout the night.
Gateway is a track where experience can make a major difference. With the championship battle underway, mistakes could become extremely costly.
#technology #night


2 months ago
The brass at La Liga giants Real Madrid are ready to offer a significant salary increase to midfield standout Jude Bellingham. This comes as Florentino Pérez and co. prepare to ramp up efforts to tie the Englishman down for the long-term.
Bellingham is for his part of course fresh off a superb opening to the new campaign. After lighting up the World Cup with Thomas Tuchel's England, the former Borussia Dortmund man was quickly afforded a central berth in the setup of new Real Madrid boss José Mourinho.
And Bellingham has since responded with a string of fine performances, giving rise to four direct goal contributions in four La Liga appearances.
Widespread confirmation has in turn surfaced over recent days that the Bernabéu hierarchy are ready to afford their all-action engine room star a new contract.
And as alluded to above, on Friday, further insight into the situation has been provided. The info comes courtesy of Blancos journalist Jorge C Picon, who reports:
#bellingham #real #comes #jude
Bellingham is for his part of course fresh off a superb opening to the new campaign. After lighting up the World Cup with Thomas Tuchel's England, the former Borussia Dortmund man was quickly afforded a central berth in the setup of new Real Madrid boss José Mourinho.
And Bellingham has since responded with a string of fine performances, giving rise to four direct goal contributions in four La Liga appearances.
Widespread confirmation has in turn surfaced over recent days that the Bernabéu hierarchy are ready to afford their all-action engine room star a new contract.
And as alluded to above, on Friday, further insight into the situation has been provided. The info comes courtesy of Blancos journalist Jorge C Picon, who reports:
#bellingham #real #comes #jude


2 months ago
Former Australia opener David Warner found himself in a playful social media exchange with England's famous fan group, the Barmy Army, on Friday, and the banter quickly moved from Saim Ayub's ducks to Marnus Labuschagne's century drought, England's curfew troubles and Warner's long-running Stuart Broad problem.
It all started when the Barmy Army took a dig at Warner after Pakistan batter Saim Ayub registered a pair of ducks in the final Test against England at Edgbaston. The England fan group posted a statistic pointing out that Ayub had now registered a pair twice on English soil.
Replying to the Barmy Army, Warner wrote: "Interesting stat. When was the last time I went 42 innings without a Test hundred??"
The reference was not actually about Warner. The 42 innings was a cheeky dig at former Australia teammate Marnus Labuschagne, who had gone through a lengthy drought without a Test century. Labuschagne's last Test hundred came against England at Headingley in 2023, and his drought had stretched to 42 innings.
But he wasn't finished. Then came the curfew dig.
Warner followed his 42-innings reference with another jab: "Oh do you guys still have a curfew? Asking for a mate."
That was a reference to England's recent off-field disciplinary issues involving players breaking team curfew and going out drinking. The issue had become a talking point around the England setup, with fast bowler Brydon Carse among the players caught up in the recent controversy.
#australia
It all started when the Barmy Army took a dig at Warner after Pakistan batter Saim Ayub registered a pair of ducks in the final Test against England at Edgbaston. The England fan group posted a statistic pointing out that Ayub had now registered a pair twice on English soil.
Replying to the Barmy Army, Warner wrote: "Interesting stat. When was the last time I went 42 innings without a Test hundred??"
The reference was not actually about Warner. The 42 innings was a cheeky dig at former Australia teammate Marnus Labuschagne, who had gone through a lengthy drought without a Test century. Labuschagne's last Test hundred came against England at Headingley in 2023, and his drought had stretched to 42 innings.
But he wasn't finished. Then came the curfew dig.
Warner followed his 42-innings reference with another jab: "Oh do you guys still have a curfew? Asking for a mate."
That was a reference to England's recent off-field disciplinary issues involving players breaking team curfew and going out drinking. The issue had become a talking point around the England setup, with fast bowler Brydon Carse among the players caught up in the recent controversy.
#australia

2 months ago
Hewlett Packard Enterprise Company (NYSE:HPE) announced an expanded collaboration with Oracle Corporation (NYSE:ORCL) on September 2 to scale Oracle's global AI infrastructure using HPE Juniper Networking across Oracle Cloud Infrastructure (OCI) data centers. The partnership builds on over a decade of joint engineering, leveraging HPE's routing and switching platforms to support OCI's expanding gigawatt-scale GPU superclusters. To align long-term incentives, HPE issued stock warrants to Oracle.
Following the announcement, Wall Street delivered fast price target hikes: Barclays' Tim Long raised HPE's target by $12 to $79 (Overweight), citing server upside and robust margins, while Morgan Stanley's Sanjit Singh boosted Oracle's target by $3 to $210 (Equal Weight), noting a tactically positive setup driven by GPUaaS demand.
Hewlett Packard Enterprise Company (NYSE:HPE) and Oracle both delivered strong results, although Oracle operates at a significantly larger scale. HPE reported record Q3 2026 revenue of $12.2 billion, up 34% year over year, driven by strong server demand and a 74.9% increase in Networking revenue to $2.9 billion. GAAP diluted EPS reached $1.06, while strong execution led management to raise full-year FY26 revenue growth guidance to 34%-37% and its free cash flow target to at least $3.75 billion.
Oracle Corporation (NYSE:ORCL), meanwhile, ended fiscal 2026 with record Q4 revenue of $19.2 billion, up 21% year over year, and full-year revenue of $67.4 billion, up 17%. Q4 Cloud Infrastructure (IaaS) revenue surged 93% to $5.8 billion, while full-year GAAP EPS rose 34% to $5.83 and Remaining Performance Obligations (RPO) jumped 363% to $638 billion.
Overall, ORCL leads in hyper-growth and long-term backlog, reinforcing its position as the stronger software and cloud play, while HPE is demonstrating stronger near-term hardware momentum and attractive cash flow generation for value-oriented investors.
#billion #revenue #infrastructure
Following the announcement, Wall Street delivered fast price target hikes: Barclays' Tim Long raised HPE's target by $12 to $79 (Overweight), citing server upside and robust margins, while Morgan Stanley's Sanjit Singh boosted Oracle's target by $3 to $210 (Equal Weight), noting a tactically positive setup driven by GPUaaS demand.
Hewlett Packard Enterprise Company (NYSE:HPE) and Oracle both delivered strong results, although Oracle operates at a significantly larger scale. HPE reported record Q3 2026 revenue of $12.2 billion, up 34% year over year, driven by strong server demand and a 74.9% increase in Networking revenue to $2.9 billion. GAAP diluted EPS reached $1.06, while strong execution led management to raise full-year FY26 revenue growth guidance to 34%-37% and its free cash flow target to at least $3.75 billion.
Oracle Corporation (NYSE:ORCL), meanwhile, ended fiscal 2026 with record Q4 revenue of $19.2 billion, up 21% year over year, and full-year revenue of $67.4 billion, up 17%. Q4 Cloud Infrastructure (IaaS) revenue surged 93% to $5.8 billion, while full-year GAAP EPS rose 34% to $5.83 and Remaining Performance Obligations (RPO) jumped 363% to $638 billion.
Overall, ORCL leads in hyper-growth and long-term backlog, reinforcing its position as the stronger software and cloud play, while HPE is demonstrating stronger near-term hardware momentum and attractive cash flow generation for value-oriented investors.
#billion #revenue #infrastructure


2 months ago
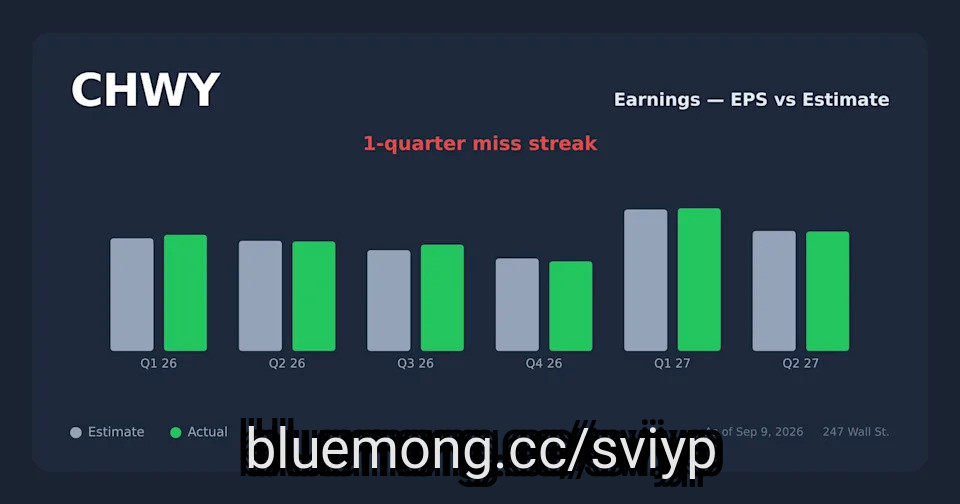
Chewy dropped 9% after free cash flow fell 15% to $89.5M despite beating revenue estimates, while Petco slid 6% on sector contagion.
Freshpet bucked the sector weakness, rising 2% on 15.5% revenue growth and a raised 2026 sales outlook.
Chewy's Autoship sales hit 84.6% of revenue with 21.7 million active customers, anchoring the bull case for its multi-quarter reinvestment cycle.
Just released. Our **** ysts combed the entire stock market and named the ten best stocks to buy right now, and Chewy didn't make the cut. Enter your email to see the names that beat CHWY. The report is free. Enter your email and see if any of your stocks made the cut.
Chewy (NYSE:CHWY) stock is down 11% midday on Wednesday to $20.68 after the online pet retailer reported fiscal Q2 2027 results that carried a free cash flow shortfall large enough to swamp a raised full-year outlook. The setup is unusual because both the revenue and the adjusted earnings landed close to where **** ysts had expected.
#enter #cash #raised #sales
Freshpet bucked the sector weakness, rising 2% on 15.5% revenue growth and a raised 2026 sales outlook.
Chewy's Autoship sales hit 84.6% of revenue with 21.7 million active customers, anchoring the bull case for its multi-quarter reinvestment cycle.
Just released. Our **** ysts combed the entire stock market and named the ten best stocks to buy right now, and Chewy didn't make the cut. Enter your email to see the names that beat CHWY. The report is free. Enter your email and see if any of your stocks made the cut.
Chewy (NYSE:CHWY) stock is down 11% midday on Wednesday to $20.68 after the online pet retailer reported fiscal Q2 2027 results that carried a free cash flow shortfall large enough to swamp a raised full-year outlook. The setup is unusual because both the revenue and the adjusted earnings landed close to where **** ysts had expected.
#enter #cash #raised #sales


2 months ago
Etsy Inc (NASDAQ:ETSY) stock is down 2.6% to trade at $70.20 today amid broader market pressure, though Argus reiterated its "buy" rating and lifted its price target to $89 from $67. The $70 level has served as both support and resistance in recent months and could provide a potential pivot point for the shares. What's more, the e-commerce name is now within striking distance of a historically bullish trendline.
According to Schaeffer's Senior Quantitative ***** yst Rocky White, Etsy stock is trading within 0.75 times the 100-day moving averages' 20-day average true range (ATR), after spending at least 80% of the previous two weeks and 80% of the prior 42 trading sessions above that trendline. This setup has appeared 13 other times over the last decade, after which the stock was higher one month later 77% of the time, averaging a 10.3% gain.
Short interest represents 10.8% of the stock's available float, and would take shorts over three days to cover at the stock's average pace of trading. A move higher could pressure some of these bearish bettors to exit their positions, creating additional buying power.
Now also looks like a good time to weigh in on ETSY's next move with options. The stock's Schaeffer's Volatility Index (SVI) of 49% sits in the low 10th percentile of its annual range, suggesting options traders are pricing in relatively low volatility expectations at the moment.
#trading #volatility #within
According to Schaeffer's Senior Quantitative ***** yst Rocky White, Etsy stock is trading within 0.75 times the 100-day moving averages' 20-day average true range (ATR), after spending at least 80% of the previous two weeks and 80% of the prior 42 trading sessions above that trendline. This setup has appeared 13 other times over the last decade, after which the stock was higher one month later 77% of the time, averaging a 10.3% gain.
Short interest represents 10.8% of the stock's available float, and would take shorts over three days to cover at the stock's average pace of trading. A move higher could pressure some of these bearish bettors to exit their positions, creating additional buying power.
Now also looks like a good time to weigh in on ETSY's next move with options. The stock's Schaeffer's Volatility Index (SVI) of 49% sits in the low 10th percentile of its annual range, suggesting options traders are pricing in relatively low volatility expectations at the moment.
#trading #volatility #within

2 months ago
Two wins in the Bundesliga, one in the cup, one in the UEFA Champions League – BVB have recently celebrated four consecutive victories. In the Bundesliga table, the Black and Yellows sit in third place with the maximum return of six points. Speaking about the clash against Villarreal FC (3:2) in midweek, BVB coach Niko Kovac said: "Of course, you expend a lot physically, but also mentally. Now it's about getting the mental side back under control immediately in order to switch back to the Bundesliga." His team are the favorites against the newly promoted side: "We're playing at home and we want to win, that's our goal." But: "There are no easy games in the Bundesliga. You have to approach them in a way that means you're fully there right away. That's why I want my boys to step on the gas from the first minute and get our fans behind us again as quickly as possible so that we can play successful football."
Nico Schlotterbeck and Ramy Bensebaini have returned to team training after their injuries and are available for the Paderborn match. "They are fit, healthy and ready to play this weekend. I can count on both of them," said Kovac. Konstantinos Karetsas will not be involved after having to be substituted in the game against Villarreal FC due to circulation problems. Read more now!
SC Paderborn have been promoted to the Bundesliga for the third time in the club's history. "A team with the ambition to stay in the league. We will certainly be facing a deep block from the opposition, who will want to hit on the counter," said Kovac. On matchday one, the team picked up a point away at FSV Mainz 05 (0:0) and then lost 1:0 at home to SC Freiburg. They currently sit 12th in the table. Despite 23 shots on goal, Paderborn have yet to score. Defensively, however, they have not allowed much either and have goalkeeper Nahuel Noll to thank, as he has conceded only one goal so far. Paderborn's Felix Götze (in the BVB youth setup until 2014) and Steffen Tigges (2019 to 2022) also wore the Black and Yellow shirt in the past.
BVB have never lost a competitive match against SC Paderborn: there have been two meetings in the DFB-Pokal, and on both occasions the Black and Yellows advanced to the next round. In the Bundesliga, Borussia have won two matches so far, while two others ended in draws. The last Bundesliga meeting at the end of May 2020 is especially memorable. In this ghost game in Paderborn played behind closed doors due to the coronavirus, the Black and Yellows produced a poor first half but improved after the break. All seven goals in the 6:1 victory came in the second half. It was the highest-scoring half of the 2019/20 season. For BVB, Jadon Sancho (3), Thorgan Hazard, Achraf Hakimi and Marcel Schmelzer, with the last goal of his professional career, were on target.Christina Reinke
This article was translated into English by Artificial Intelligence. You can read the original version in 🇩🇪 here.
#yellows #goal #half
Nico Schlotterbeck and Ramy Bensebaini have returned to team training after their injuries and are available for the Paderborn match. "They are fit, healthy and ready to play this weekend. I can count on both of them," said Kovac. Konstantinos Karetsas will not be involved after having to be substituted in the game against Villarreal FC due to circulation problems. Read more now!
SC Paderborn have been promoted to the Bundesliga for the third time in the club's history. "A team with the ambition to stay in the league. We will certainly be facing a deep block from the opposition, who will want to hit on the counter," said Kovac. On matchday one, the team picked up a point away at FSV Mainz 05 (0:0) and then lost 1:0 at home to SC Freiburg. They currently sit 12th in the table. Despite 23 shots on goal, Paderborn have yet to score. Defensively, however, they have not allowed much either and have goalkeeper Nahuel Noll to thank, as he has conceded only one goal so far. Paderborn's Felix Götze (in the BVB youth setup until 2014) and Steffen Tigges (2019 to 2022) also wore the Black and Yellow shirt in the past.
BVB have never lost a competitive match against SC Paderborn: there have been two meetings in the DFB-Pokal, and on both occasions the Black and Yellows advanced to the next round. In the Bundesliga, Borussia have won two matches so far, while two others ended in draws. The last Bundesliga meeting at the end of May 2020 is especially memorable. In this ghost game in Paderborn played behind closed doors due to the coronavirus, the Black and Yellows produced a poor first half but improved after the break. All seven goals in the 6:1 victory came in the second half. It was the highest-scoring half of the 2019/20 season. For BVB, Jadon Sancho (3), Thorgan Hazard, Achraf Hakimi and Marcel Schmelzer, with the last goal of his professional career, were on target.Christina Reinke
This article was translated into English by Artificial Intelligence. You can read the original version in 🇩🇪 here.
#yellows #goal #half

0.00$ raised of 0.00$ goal
0 donations
0.00$
to go
2 months ago
USAR drops 4% and MP Materials falls 5% as Trump-Xi summit hopes erode the scarcity premium driving domestic rare earth valuations.
REMX sinks 5% versus SPY's 0.5% dip, confirming a targeted sector repricing rather than a broad market risk-off move.
USA Rare Earth broke ground on a $1.2 billion South Carolina facility Wednesday, yet diplomatic headlines overshadowed the milestone the very next day.
Just released. Our ****** ysts combed the entire stock market and named the ten best stocks to buy right now, and MP Materials didn't make the cut. Enter your email to see the names that beat MP. The report is free. Enter your email and see if any of your stocks made the cut.
Domestic rare earth stocks are sliding Thursday midday as fresh diplomatic warming between Washington and Beijing chips away at the scarcity premium powering the trade. USA Rare Earth (NASDAQ:USAR) stock is down 4% to $16.36, and MP Materials (NYSE:MP) shares are down 5% to $51.85. Both names sit near the front of the U.S. critical-minerals theme and tend to move hard when the geopolitical setup shifts.
#market
REMX sinks 5% versus SPY's 0.5% dip, confirming a targeted sector repricing rather than a broad market risk-off move.
USA Rare Earth broke ground on a $1.2 billion South Carolina facility Wednesday, yet diplomatic headlines overshadowed the milestone the very next day.
Just released. Our ****** ysts combed the entire stock market and named the ten best stocks to buy right now, and MP Materials didn't make the cut. Enter your email to see the names that beat MP. The report is free. Enter your email and see if any of your stocks made the cut.
Domestic rare earth stocks are sliding Thursday midday as fresh diplomatic warming between Washington and Beijing chips away at the scarcity premium powering the trade. USA Rare Earth (NASDAQ:USAR) stock is down 4% to $16.36, and MP Materials (NYSE:MP) shares are down 5% to $51.85. Both names sit near the front of the U.S. critical-minerals theme and tend to move hard when the geopolitical setup shifts.
#market

0.00$ raised of 0.00$ goal
0 donations
0.00$
to go

2 months ago
Phillies news: Pitcher headed for intriguing role after injury return appeared first on ClutchPoints. Add ClutchPoints as a Preferred Source by clicking here.
The Philadelphia Phillies are preparing for another postseason push. Their starting pitching is set to lead the way, but the Phillies do have some overall uncertainty on the roster. One pitcher who could make an impact in a specific role once he returns from injury is Tanner Banks. According to MLB.com, Banks, who is recovering from a left forearm strain, is being built up for a long man role in the bullpen.
While most relievers pitch one inning in games, Banks could give the Phillies multiple innings in this role. He would likely be expected to throw anywhere from two to four innings depending on the situation of the game. For example, if a starter struggles and exits the game in the third inning, Banks could potentially save the bullpen and pitch into the sixth inning.
So, why is this role so important? After all, it isn't exactly the closer or setup man role in the bullpen. Well, starting pitchers do not always pitch especially late into games this late in the season. Managers are much more likely to turn to the bullpen earlier in games during the postseason.
Watch sports LIVE with fuboTV (free trial)
#pitch #clutchpoints
The Philadelphia Phillies are preparing for another postseason push. Their starting pitching is set to lead the way, but the Phillies do have some overall uncertainty on the roster. One pitcher who could make an impact in a specific role once he returns from injury is Tanner Banks. According to MLB.com, Banks, who is recovering from a left forearm strain, is being built up for a long man role in the bullpen.
While most relievers pitch one inning in games, Banks could give the Phillies multiple innings in this role. He would likely be expected to throw anywhere from two to four innings depending on the situation of the game. For example, if a starter struggles and exits the game in the third inning, Banks could potentially save the bullpen and pitch into the sixth inning.
So, why is this role so important? After all, it isn't exactly the closer or setup man role in the bullpen. Well, starting pitchers do not always pitch especially late into games this late in the season. Managers are much more likely to turn to the bullpen earlier in games during the postseason.
Watch sports LIVE with fuboTV (free trial)
#pitch #clutchpoints



