21 mins. ago
Dick's Sporting Goods has been one of the big success stories in the brick-and-mortar retail ***** e.
At a time when many rivals have been shrinking their physical store counts, the sporting goods giant has leaned into stores, creating new experiential concepts and generally rethinking its retail strategy.
The chain has selectively built House of Sport locations that offer running tracks, batting cages, golf simulators, and other interactive options.
"House of Sport locations now seeing 5-6 times the number of visits per location compared to the rest of the chain. For reference, the average ***** 's Sporting Goods store is roughly 50K square feet square feet compared to 100K-120K square feet for House of Sport, indicating that House of Sport is also outperforming on a visit per square foot basis," according to 2024 data from Placer.ai.
That's a win, and the overall company delivered a nearly 5% comparable store sales gain in the second quarter. Chairman Edward Stack celebrated that success during the chain's second-quarter earnings call.
#square
At a time when many rivals have been shrinking their physical store counts, the sporting goods giant has leaned into stores, creating new experiential concepts and generally rethinking its retail strategy.
The chain has selectively built House of Sport locations that offer running tracks, batting cages, golf simulators, and other interactive options.
"House of Sport locations now seeing 5-6 times the number of visits per location compared to the rest of the chain. For reference, the average ***** 's Sporting Goods store is roughly 50K square feet square feet compared to 100K-120K square feet for House of Sport, indicating that House of Sport is also outperforming on a visit per square foot basis," according to 2024 data from Placer.ai.
That's a win, and the overall company delivered a nearly 5% comparable store sales gain in the second quarter. Chairman Edward Stack celebrated that success during the chain's second-quarter earnings call.
#square


30 mins. ago
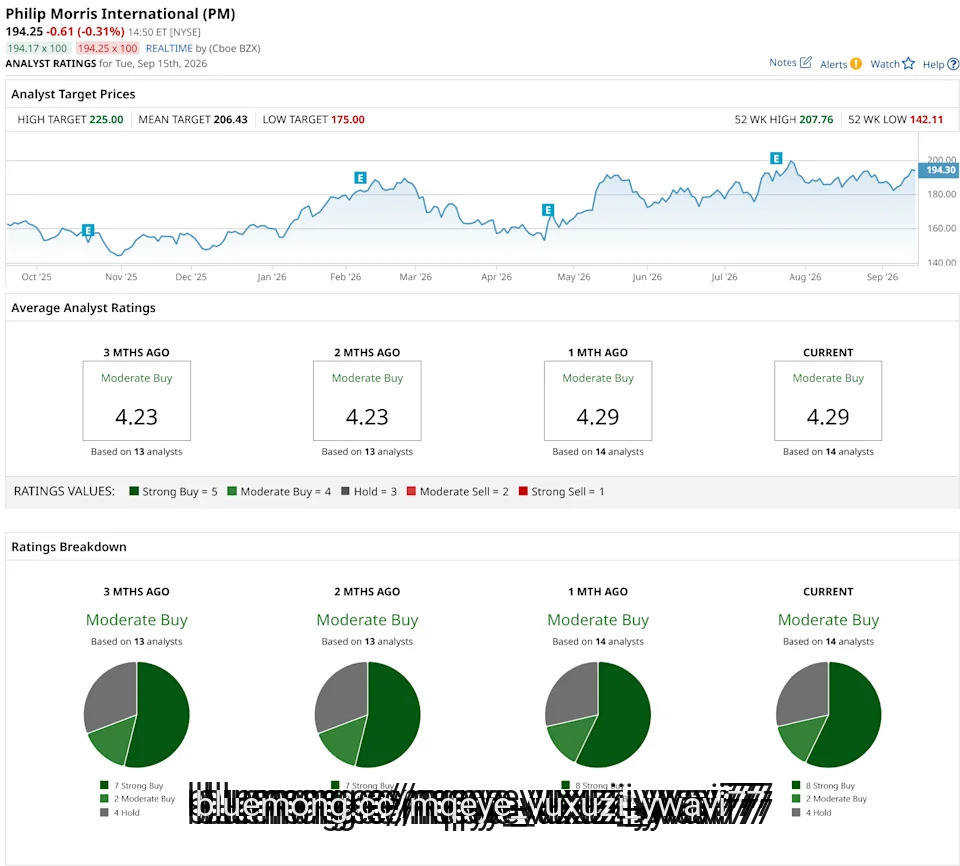
President Trump has nominated Nicole Saphier as Surgeon General, and she has revealed her investment portfolio, which includes tobacco stocks Philip Morris International (PM), Altria Group (MO), and British American Tobacco (BTI). If confirmed in the hearing scheduled for Sept. 16, Saphier would divest these holdings no later than 90 days after her confirmation, as part of an ethics agreement. This clearly avoids conflicts of interest with the role's public health mandate.
Meanwhile, the tobacco market is transforming, with smoke-free products gaining prominence. Bank of America's four‑week scanner data through May 30 showed that most U.S. tobacco categories continued to lose volume, while oral nicotine products remained the sector's strongest growth area.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Billionaire Charlie Munger, Who Died at 99, Skipped Insurance on His Mansion Since He Could Just Write a Check to Rebuild — 'All Intelligent People Do It My Way'
The EV Bubble Has Burst. How to Play Rivian Stock Now.
#philip
Meanwhile, the tobacco market is transforming, with smoke-free products gaining prominence. Bank of America's four‑week scanner data through May 30 showed that most U.S. tobacco categories continued to lose volume, while oral nicotine products remained the sector's strongest growth area.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Billionaire Charlie Munger, Who Died at 99, Skipped Insurance on His Mansion Since He Could Just Write a Check to Rebuild — 'All Intelligent People Do It My Way'
The EV Bubble Has Burst. How to Play Rivian Stock Now.
#philip

37 mins. ago
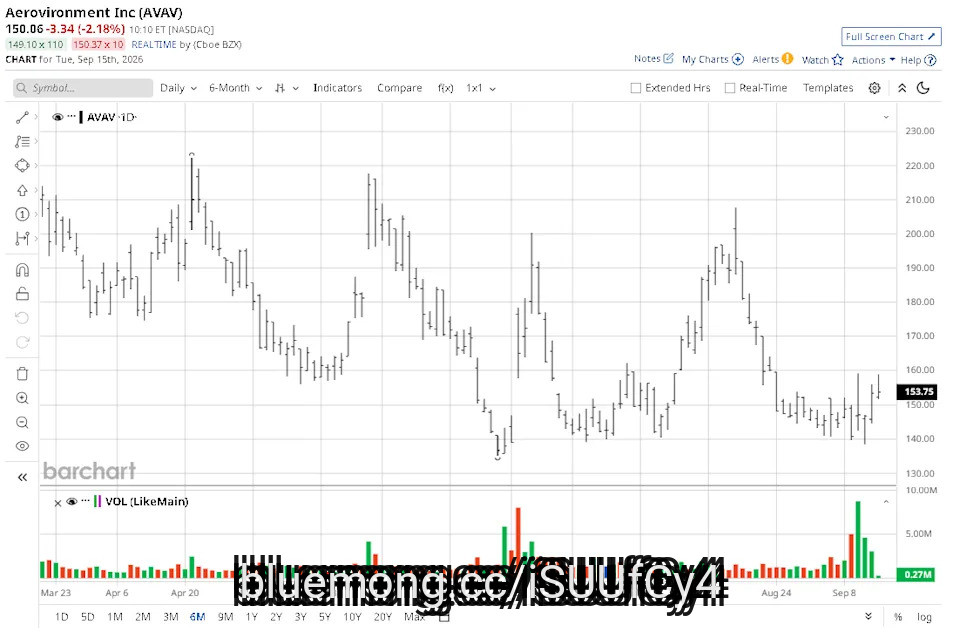
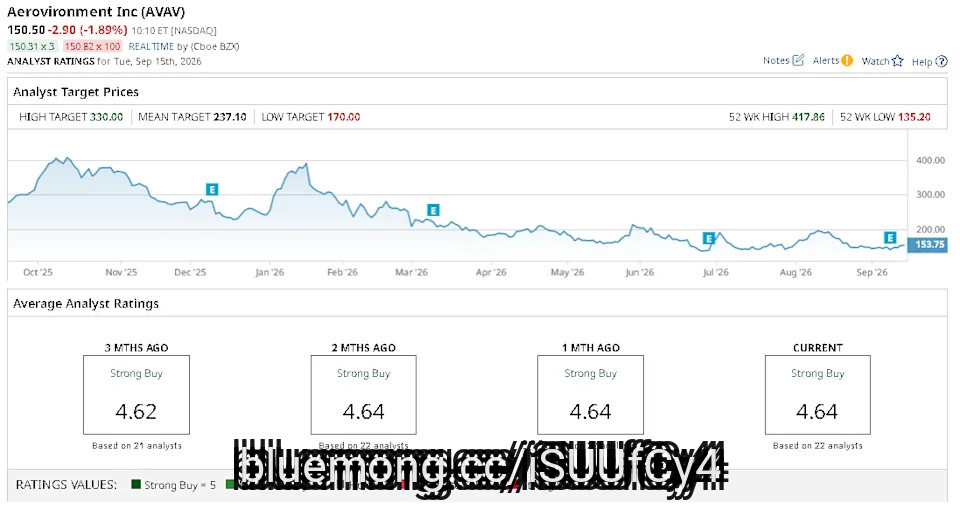
AeroVironment (AVAV) stock extended gains on Sept. 15 after the company's BlueHalo unit landed a landmark defense contract potentially worth up to $99.8 million. In its press release, AVAV said this new U.S. Air Force award — designed to advance military ******* e systems under the Leveraged Orbital Battlespace Optimization program — runs through August 2031.
The announcement arrives as AeroVironment shares are struggling to regain investor interest, currently down more than 60% versus their year-to-date high.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Billionaire Charlie Munger, Who Died at 99, Skipped Insurance on His Mansion Since He Could Just Write a Check to Rebuild — 'All Intelligent People Do It My Way'
The EV Bubble Has Burst. How to Play Rivian Stock Now.
#sept
The announcement arrives as AeroVironment shares are struggling to regain investor interest, currently down more than 60% versus their year-to-date high.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Billionaire Charlie Munger, Who Died at 99, Skipped Insurance on His Mansion Since He Could Just Write a Check to Rebuild — 'All Intelligent People Do It My Way'
The EV Bubble Has Burst. How to Play Rivian Stock Now.
#sept

52 mins. ago
Interested in Eli Lilly and Company? Here are five stocks we like better.
The healthcare sector offers options for investors of every age, combining high-growth drugmakers, defensive operators, and reliable dividend payers.
Eli Lilly suits younger investors with its obesity and diabetes drug pipeline driving growth, having gained nearly 34% since its April low.
UnitedHealth Group fits middle-aged investors with a turnaround story and rising dividend, while Johnson & Johnson's Dividend King status appeals to older, income-focused investors.
When it comes to investing, there is no one-size-fits-all approach. Strategies vary based on numerous factors, including but not limited to investors' risk tolerance, net worth, and age. When it comes to stock-picking, that last one is important.
#comes #here #april
The healthcare sector offers options for investors of every age, combining high-growth drugmakers, defensive operators, and reliable dividend payers.
Eli Lilly suits younger investors with its obesity and diabetes drug pipeline driving growth, having gained nearly 34% since its April low.
UnitedHealth Group fits middle-aged investors with a turnaround story and rising dividend, while Johnson & Johnson's Dividend King status appeals to older, income-focused investors.
When it comes to investing, there is no one-size-fits-all approach. Strategies vary based on numerous factors, including but not limited to investors' risk tolerance, net worth, and age. When it comes to stock-picking, that last one is important.
#comes #here #april

1 hr. ago
An AI approval in minutes means nothing if you retire before closing. Lenders must re-verify employment within 10 business days of the note date.
Retirement income like Social Security can replace a salary for qualifying purposes, and an SSA award letter alone may be enough to close.
A rate lock protects only the interest rate, so disclose your retirement date early and build the loan file around income that survives closing day.
Read More: Learn 7 ways to generate income with a $1,000,000+ portfolio (sponsor)
Mortgage lenders are racing to make refinancing feel almost instantaneous. Better.com says an initial approval can take as little as two minutes. For a borrower nearing retirement, that speed creates a strange new trap.
#approval
Retirement income like Social Security can replace a salary for qualifying purposes, and an SSA award letter alone may be enough to close.
A rate lock protects only the interest rate, so disclose your retirement date early and build the loan file around income that survives closing day.
Read More: Learn 7 ways to generate income with a $1,000,000+ portfolio (sponsor)
Mortgage lenders are racing to make refinancing feel almost instantaneous. Better.com says an initial approval can take as little as two minutes. For a borrower nearing retirement, that speed creates a strange new trap.
#approval

1 hr. ago
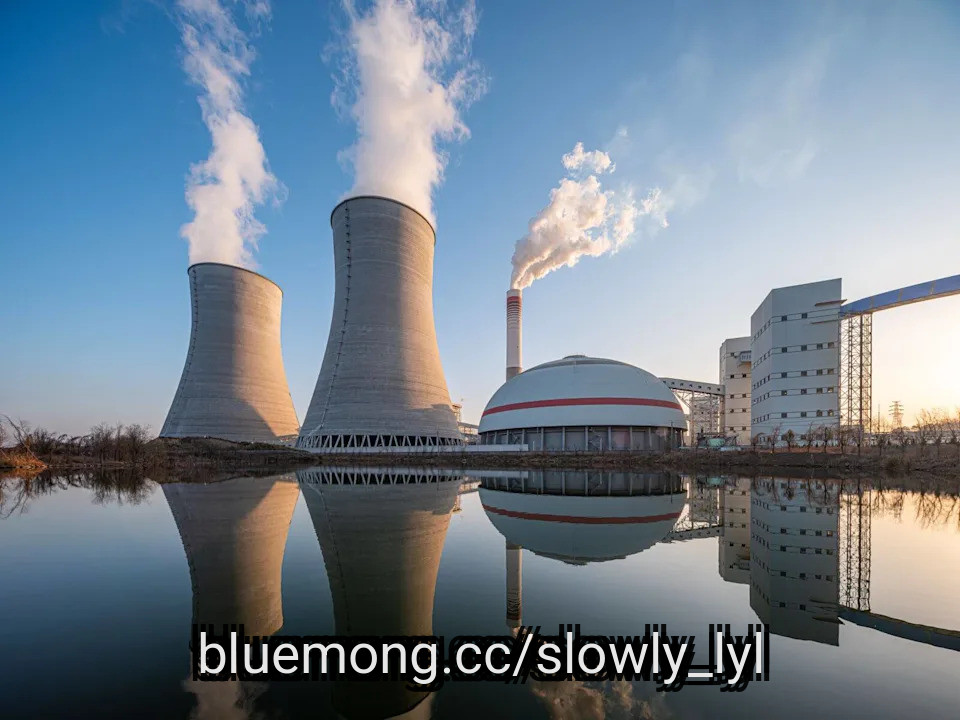
NuScale Power Corporation (SMR) stands out as America's leading developer of small modular reactors (SMRs), building light-water nuclear systems designed to deliver reliable, carbon-free baseload power. Its core product, the NuScale Power Module, targets a wide range of applications, from traditional electricity generation to industrial decarbonization, AI data center power supply, and hydrogen production. Notably, NuScale remains the only SMR developer to secure Standard Design Approval from the U.S. Nuclear Regulatory Commission, a regulatory milestone that continues to anchor its competitive positioning in the emerging advanced nuclear industry.
NuScale's stock has been anything but stable. Over the past 52 weeks, shares have traded across an enormous range, from a low of $7.21 to a high of $57.42, before settling closer to $10.81. That volatility stems from a mix of factors: heavy retail investor interest, elevated short interest fueling sharp swings in both directions, and macroeconomic shifts in interest rates that disproportionately affect capital-intensive, pre-revenue growth companies. Compared to the Russell 2000, a benchmark of diversified, largely profitable small-cap stocks, NuScale carries a significantly higher beta and downside risk, reflecting its speculative, early-stage commercialization profile.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Crude Prices Soar as Global Oil Supplies Continue to Tighten
Middle East Supply Constraints Lift Crude Oil Prices
#nuclear #crude
NuScale's stock has been anything but stable. Over the past 52 weeks, shares have traded across an enormous range, from a low of $7.21 to a high of $57.42, before settling closer to $10.81. That volatility stems from a mix of factors: heavy retail investor interest, elevated short interest fueling sharp swings in both directions, and macroeconomic shifts in interest rates that disproportionately affect capital-intensive, pre-revenue growth companies. Compared to the Russell 2000, a benchmark of diversified, largely profitable small-cap stocks, NuScale carries a significantly higher beta and downside risk, reflecting its speculative, early-stage commercialization profile.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Crude Prices Soar as Global Oil Supplies Continue to Tighten
Middle East Supply Constraints Lift Crude Oil Prices
#nuclear #crude



1 hr. ago
Some offers on this page are from advertisers who pay us, which may affect which products we write about, but not our recommendations. See our Advertiser Disclosure.
Yes, you can sometimes have two of the same credit card, but whether you're allowed to depends on the card issuer and the specific card. And even with issuers that allow you to have two of the same card, you're usually subject to limitations and restrictions.
Whether you can have two of the same credit card at one time depends on each credit card issuer's policies. Credit card issuers don't always make it clear that you can apply for the same card multiple times, so we reached out to several major credit card issuers. We asked them to clarify whether a customer could have two of the same card, and this is what we found:
Can you have 2 of the same credit card?
Yes
#same #whether #you 're #advertiser
Yes, you can sometimes have two of the same credit card, but whether you're allowed to depends on the card issuer and the specific card. And even with issuers that allow you to have two of the same card, you're usually subject to limitations and restrictions.
Whether you can have two of the same credit card at one time depends on each credit card issuer's policies. Credit card issuers don't always make it clear that you can apply for the same card multiple times, so we reached out to several major credit card issuers. We asked them to clarify whether a customer could have two of the same card, and this is what we found:
Can you have 2 of the same credit card?
Yes
#same #whether #you 're #advertiser


2 hours ago
Crypto markets and related stocks moved lower Tuesday as investors braced for two major Washington catalysts: a Senate vote on the CLARITY Act and the Federal Reserve's interest-rate decision Wednesday.
Bitcoin was trading around $76,431, down 2.19% over 24 hours, while Ether fell 1.8% to roughly $2,449 and Solana dropped 1.02% to about $100. The total crypto market capitalization declined 1.2% to $2.61 trillion.
Derivatives traders were also caught in the selloff. Roughly $384 million in crypto positions were liquidated over 24 hours, including about $195 million in longs and $189 million in shorts, while nearly $160 million was wiped out over the previous 12 hours.
Crypto-linked stocks were hit harder.
Related: CLARITY Act faces urgent Democratic counterproposal and growing opposition
#hours #tuesday
Bitcoin was trading around $76,431, down 2.19% over 24 hours, while Ether fell 1.8% to roughly $2,449 and Solana dropped 1.02% to about $100. The total crypto market capitalization declined 1.2% to $2.61 trillion.
Derivatives traders were also caught in the selloff. Roughly $384 million in crypto positions were liquidated over 24 hours, including about $195 million in longs and $189 million in shorts, while nearly $160 million was wiped out over the previous 12 hours.
Crypto-linked stocks were hit harder.
Related: CLARITY Act faces urgent Democratic counterproposal and growing opposition
#hours #tuesday

2 hours ago
Updated Sept 15, 2026, 1:23 pm EDT / Original Sept 15, 2026, 12:51 pm EDT
Nicholas Colas doesn’t see
5% Treasury yields
as a stock market spoiler. Instead, the co-founder of DataTrek Research sees them as a healthy reset of interest rates that could pave the way for more sustainable growth.
Copyright ©2026 Dow Jones & Company, Inc. All Rights Reserved. 87990cbe856818d5eddac44c7b1cdeb8
Rising oil prices and a 10-year Treasury yield climbing to around 5% have raised concerns about consumer spending and restaurant operating costs.
#nicholas
Nicholas Colas doesn’t see
5% Treasury yields
as a stock market spoiler. Instead, the co-founder of DataTrek Research sees them as a healthy reset of interest rates that could pave the way for more sustainable growth.
Copyright ©2026 Dow Jones & Company, Inc. All Rights Reserved. 87990cbe856818d5eddac44c7b1cdeb8
Rising oil prices and a 10-year Treasury yield climbing to around 5% have raised concerns about consumer spending and restaurant operating costs.
#nicholas

2 hours ago
This story was originally published on CRE Daily. Join 70,000+ commercial real estate professionals getting daily news, market insights, and industry **** ysis delivered straight to their inbox with the free CRE Daily newsletter.
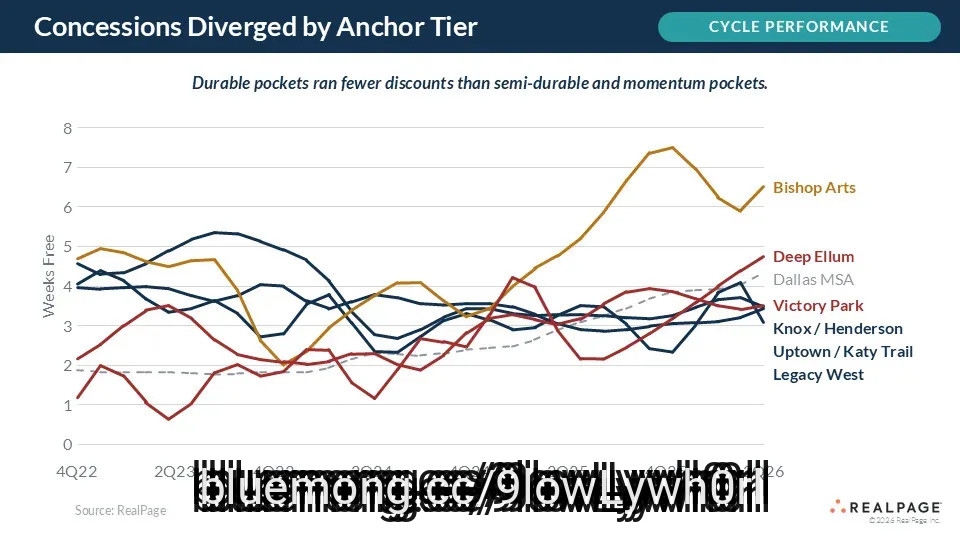
Legacy West apartments average $1,845 a month, a 9% premium over comparable Dallas properties that's smaller than any other demand pocket RealPage tracks, yet the submarket needs the fewest concessions to stay leased.
The pocket posted 95.5% occupancy in the second quarter, two points above the Dallas metro average, anchored by roughly 12,000 corporate jobs from employers including Toyota, JPMorgan Chase, and Frito-Lay.
Because Legacy West's strength rests on continued corporate expansion rather than a larger price premium, its durability depends on employers in the Plano-Frisco corridor keeping up their hiring pace.
Apartments in Legacy West command the smallest rent premium of any demand pocket in the Dallas metro, yet the submarket needs fewer concessions to stay full than any of its peers, according to RealPage. The corporate-anchored district straddling the Plano-Frisco border averaged $1,845 in effective rent in the second quarter, a 9% premium over comparable metro properties. That's the smallest premium among the demand pockets RealPage tracks across Dallas, even though Legacy West's occupancy and leasing strength outperform them.
#legacy #dallas #demand
Legacy West apartments average $1,845 a month, a 9% premium over comparable Dallas properties that's smaller than any other demand pocket RealPage tracks, yet the submarket needs the fewest concessions to stay leased.
The pocket posted 95.5% occupancy in the second quarter, two points above the Dallas metro average, anchored by roughly 12,000 corporate jobs from employers including Toyota, JPMorgan Chase, and Frito-Lay.
Because Legacy West's strength rests on continued corporate expansion rather than a larger price premium, its durability depends on employers in the Plano-Frisco corridor keeping up their hiring pace.
Apartments in Legacy West command the smallest rent premium of any demand pocket in the Dallas metro, yet the submarket needs fewer concessions to stay full than any of its peers, according to RealPage. The corporate-anchored district straddling the Plano-Frisco border averaged $1,845 in effective rent in the second quarter, a 9% premium over comparable metro properties. That's the smallest premium among the demand pockets RealPage tracks across Dallas, even though Legacy West's occupancy and leasing strength outperform them.
#legacy #dallas #demand

2 hours ago
Fast-growing stocks and artificial intelligence (AI) seem to go hand in hand, and there are several examples of stocks growing their revenue at 50%, 100%, or even 200%. But none quite touch how rapidly Nebius (NASDAQ: NBIS) is growing. During its most recent quarter, revenue rose by a jaw-dropping 454% year over year. What's even more impressive is that this growth rate is expected to last through the rest of the year, and 2027's will also be elevated.
It's starting to make a lot of sense that Nvidia (NASDAQ: NVDA) is investing in Nebius, and there's still a great buying opportunity here for investors.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Nebius is a neocloud business that provides AI-focused cloud computing power to its clients. Among its biggest clients are Meta Platforms and Microsoft, each of which has signed multi-year deals with Nebius to expand capacity. Both Microsoft and Meta have their own data centers, and Microsoft rents out its capacity to others, so why are they renting from Nebius?
Nebius' deal with Nvidia provides it with leading hardware before others, so it's a way to gain early access to the best computing units. Furthermore, these companies like having a bit of flexibility and not having to build too many data centers, as well as getting their hands on as much computing capacity as quickly as possible.
#Microsoft
It's starting to make a lot of sense that Nvidia (NASDAQ: NVDA) is investing in Nebius, and there's still a great buying opportunity here for investors.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Nebius is a neocloud business that provides AI-focused cloud computing power to its clients. Among its biggest clients are Meta Platforms and Microsoft, each of which has signed multi-year deals with Nebius to expand capacity. Both Microsoft and Meta have their own data centers, and Microsoft rents out its capacity to others, so why are they renting from Nebius?
Nebius' deal with Nvidia provides it with leading hardware before others, so it's a way to gain early access to the best computing units. Furthermore, these companies like having a bit of flexibility and not having to build too many data centers, as well as getting their hands on as much computing capacity as quickly as possible.
#Microsoft


2 hours ago
In some markets, it costs less to rent than to buy — by a lot. And it could be a great way to save a ton of money during your retirement years.
Mortgage and financial consultant Cody Schuiteboer of Best Interest Financial said many retirees never even consider renting as a serious option.
"There is an unshakeable mentality that buying is always the right choice, but the opposite is often true in retirement," he said. "If renting is actually cheaper in that market, renting lets retirees stretch their nest egg further."
MoneyLion ran the rent-versus-ownership numbers in the top retirement destinations along the East Coast and found the cities offering the greatest savings to renters. The homeownership numbers ****** umed a 10% down payment and a 6.53% interest rate, using average home price and rent numbers from Zillow.
Best of all, the following retirement hubs all have a total monthly expenditure cost under $4,000 according to BLS data, and adults over 65 make up at least 20% of the population.
#rent
Mortgage and financial consultant Cody Schuiteboer of Best Interest Financial said many retirees never even consider renting as a serious option.
"There is an unshakeable mentality that buying is always the right choice, but the opposite is often true in retirement," he said. "If renting is actually cheaper in that market, renting lets retirees stretch their nest egg further."
MoneyLion ran the rent-versus-ownership numbers in the top retirement destinations along the East Coast and found the cities offering the greatest savings to renters. The homeownership numbers ****** umed a 10% down payment and a 6.53% interest rate, using average home price and rent numbers from Zillow.
Best of all, the following retirement hubs all have a total monthly expenditure cost under $4,000 according to BLS data, and adults over 65 make up at least 20% of the population.
#rent

2 hours ago
On September 9, American Eagle Outfitters Inc. (NYSE:AEO) revealed results for its fiscal 2026 second quarter. The company achieved an 8% year-over-year topline growth with net revenue figures of $1.38 billion. The second quarter operating profit jumped up to $211 million compared to $103 million during the same period last year. As a result, diluted earnings per share for the quarter stood at $0.79 in comparison with $0.45 for Q2 FY25. This led to a $21 million distribution to shareholders with a dividend payout of $0.125 per share.
Africa Studio/Shutterstock.com
A resilient performance during the second quarter was primarily driven by robust momentum within the Aerie sub-brand and OFFLINE collection. There was a 6% year-over-year growth in company-wide comparable sales, whereas the Aerie's comparable sales picked up by 19%. Total gross profit for the quarter reached $672 million, which shows a 34% increase against $500 million for Q2 FY25. This pushed Q2 gross margins to 48.7%, a jump of 980 basis points relative to the previous year's quarter, despite 330 basis points deleveraging across the merchandise margins. Compared to an 8% operating margin in Q2 FY25, the company posted 15.3% margin in the recent period.
Even with a slight dip in comparable sales, the American Eagle brand also exhibited some encouraging signs. It posted sequential gains from the previous quarter, which marks the fourth consecutive quarter of expansion across menswear.
Results for the reported period were bolstered by $196 million in International Emergency Economic Powers Act (IEEPA) tariff refunds, which also included interest payments. This resulted in an additional $35 million in incentive compensation set aside by the company, which affected both gross profit and SG&A. After taking these additional expenses into consideration, the overall operating income gains related to tariff refunds amounted to $161 million.
#comparable
Africa Studio/Shutterstock.com
A resilient performance during the second quarter was primarily driven by robust momentum within the Aerie sub-brand and OFFLINE collection. There was a 6% year-over-year growth in company-wide comparable sales, whereas the Aerie's comparable sales picked up by 19%. Total gross profit for the quarter reached $672 million, which shows a 34% increase against $500 million for Q2 FY25. This pushed Q2 gross margins to 48.7%, a jump of 980 basis points relative to the previous year's quarter, despite 330 basis points deleveraging across the merchandise margins. Compared to an 8% operating margin in Q2 FY25, the company posted 15.3% margin in the recent period.
Even with a slight dip in comparable sales, the American Eagle brand also exhibited some encouraging signs. It posted sequential gains from the previous quarter, which marks the fourth consecutive quarter of expansion across menswear.
Results for the reported period were bolstered by $196 million in International Emergency Economic Powers Act (IEEPA) tariff refunds, which also included interest payments. This resulted in an additional $35 million in incentive compensation set aside by the company, which affected both gross profit and SG&A. After taking these additional expenses into consideration, the overall operating income gains related to tariff refunds amounted to $161 million.
#comparable

2 hours ago
Interested in Netflix, Inc.? Here are five stocks we like better.
Netflix received 25 negative revisions in 90 days, yet 54 **** ysts remain bullish, seeing over 20% upside despite reduced price targets.
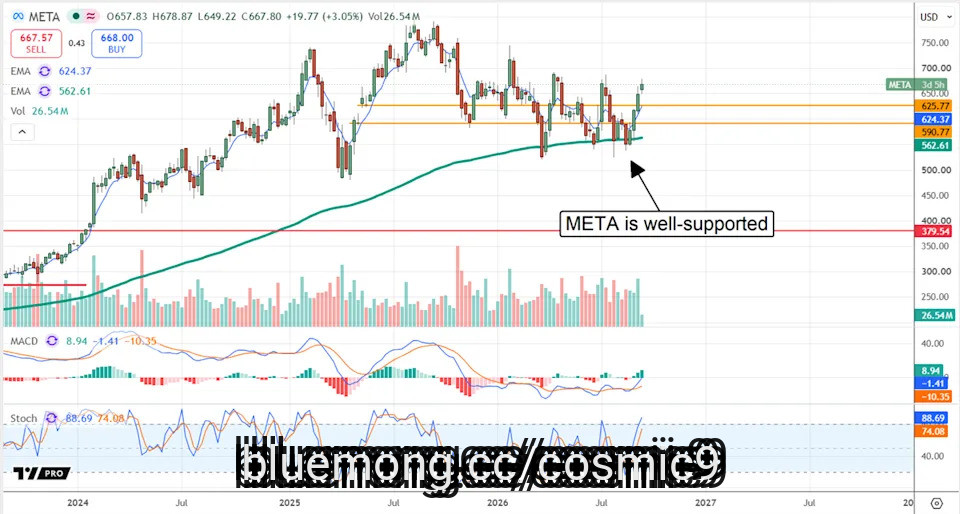
Meta Platforms faces 21 downgrades tied to rising CapEx and weak Q2 results, but **** ysts still rate it a Moderate Buy with about 20% upside.
Lululemon's downgrades reflect genuine fundamental deterioration, with 29 **** ysts giving it a consensus Reduce rating and mostly Hold or Sell ratings.
Downgrades rarely help bullish traders, hurting sentiment and price action—unless, of course, you're looking for a good stock to buy into. As always, it's the trend that matters, because a downgrade or price target reduction can mean different things in different situations.
#bullish #upside #interested #here
Netflix received 25 negative revisions in 90 days, yet 54 **** ysts remain bullish, seeing over 20% upside despite reduced price targets.
Meta Platforms faces 21 downgrades tied to rising CapEx and weak Q2 results, but **** ysts still rate it a Moderate Buy with about 20% upside.
Lululemon's downgrades reflect genuine fundamental deterioration, with 29 **** ysts giving it a consensus Reduce rating and mostly Hold or Sell ratings.
Downgrades rarely help bullish traders, hurting sentiment and price action—unless, of course, you're looking for a good stock to buy into. As always, it's the trend that matters, because a downgrade or price target reduction can mean different things in different situations.
#bullish #upside #interested #here



3 hours ago
There are plenty of reasons for investors to be nervous about stocks right now. Inflation remains stubbornly high. Treasury yields are climbing. And traders now see a 90% probability that the Federal Reserve raises interest rates at its September meeting this week.
Yet I'm still buying and holding the Vanguard Total Stock Market ETF (NYSEMKT: VTI).
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
The reason comes down to one thing. Corporate earnings are proving remarkably resilient and are projected to continue growing at a healthy rate through at least the end of 2027.
Stocks don't necessarily need falling interest rates to move higher. If corporate profits keep growing fast enough, earnings can push stock prices higher over the next six to 12 months.
#total #interest
Yet I'm still buying and holding the Vanguard Total Stock Market ETF (NYSEMKT: VTI).
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
The reason comes down to one thing. Corporate earnings are proving remarkably resilient and are projected to continue growing at a healthy rate through at least the end of 2027.
Stocks don't necessarily need falling interest rates to move higher. If corporate profits keep growing fast enough, earnings can push stock prices higher over the next six to 12 months.
#total #interest


3 hours ago
Interested in NVIDIA Corporation? Here are five stocks we like better.
NVIDIA released CUDA-Q Logical, an open-source software layer that links GPUs with quantum processors to solve practical error correction challenges.
Early testing by Fermilab and Sandia National Laboratories shows dramatic efficiency gains, including a seven-fold faster design cycle and reduced physical qubit requirements.
Quantum hardware firms IonQ, Rigetti Computing, and D-Wave Quantum could benefit as standardized software lowers development costs and enables deeper integration with NVIDIA's infrastructure.
Many investors view quantum hardware developers and classical semiconductor leaders as competing forces in high-performance computing. Recent developments demonstrate that the two architectures are becoming deeply interdependent.
#hardware #here
NVIDIA released CUDA-Q Logical, an open-source software layer that links GPUs with quantum processors to solve practical error correction challenges.
Early testing by Fermilab and Sandia National Laboratories shows dramatic efficiency gains, including a seven-fold faster design cycle and reduced physical qubit requirements.
Quantum hardware firms IonQ, Rigetti Computing, and D-Wave Quantum could benefit as standardized software lowers development costs and enables deeper integration with NVIDIA's infrastructure.
Many investors view quantum hardware developers and classical semiconductor leaders as competing forces in high-performance computing. Recent developments demonstrate that the two architectures are becoming deeply interdependent.
#hardware #here


3 hours ago
Alluvium ***** et Management, an ***** et management company, released its "Conventum – Alluvium Global Fund" second-quarter 2026 investor letter. The letter can be downloaded here. The second quarter reflected a sharp shift from geopolitical uncertainty and oil market volatility to a powerful equity rally led by semiconductor companies. Despite the broader market strength, the Fund declined 1.4% in EUR terms, 2.2% in USD terms, and 3.9% in AUD terms. Portfolio results were mixed, with Alphabet benefiting from strong Cloud growth, while Robert Half, H&R Block and other holdings posted solid gains. However, cable businesses and several healthcare and consumer holdings weighed on performance. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Conventum – Alluvium Global Fund highlighted Copart, Inc. (NASDAQ:CPRT). Copart, Inc. (NASDAQ:CPRT) is an online auction and vehicle remarketing services company. On September 14, 2026, Copart, Inc. (NASDAQ:CPRT) closed at $30.75 per share. Over the past month, Copart, Inc. (NASDAQ:CPRT) returned 0.14%, while its shares lost 32.24% over the past 52 weeks. Copart, Inc. (NASDAQ:CPRT) has a market capitalization of $29.65 billion, and its stock has traded within a 52-week range of $26.81 and $48.96.
Conventum – Alluvium Global Fund stated the following regarding Copart, Inc. (NASDAQ:CPRT) in its Q2 2026 investor letter:
"Once again, the most significant and interesting news for investors is a new position we initiated. On this occasion, it is Copart, Inc. (NASDAQ:CPRT, the car wrecker turned auction platform (down 15.1% over the quarter). Copart has grown from a small single auto salvage yard in Vallejo, California in 1982 to a car auction technology platform selling over 4 million cars per year, predominantly on behalf of large insurance companies. We were alerted to this business by our quantitative screen - where it appeared a compelling opportunity (ten year sales growth of 17.4% and 19.1% profit growth, negligible debt, and mid 30's returns on invested capital), so we explored the business in greater depth. Our synopsis: It is a top notch business operating in a duopoly, but with little scope for domestic growth significant enough to move the needle. Most of Copart's revenue stems from its services to insurance companies for selling their vehicles which they classify to be "total losses". So, when it comes to ***** ysing the long term viability of its business, we think there are two key considerations. There is the likely growth rate of automobile accidents. We expect this to gradually decline as a result of increased adoption of autonomous driving, which is known to have lower crash rates than human-driven vehicles. Then there is the proportion of future collisions that are likely to result in cars being classified as "total losses". We expect this will continue its long term upward trend (driven by increased technology and high repair cos
In its second-quarter 2026 investor letter, Conventum – Alluvium Global Fund highlighted Copart, Inc. (NASDAQ:CPRT). Copart, Inc. (NASDAQ:CPRT) is an online auction and vehicle remarketing services company. On September 14, 2026, Copart, Inc. (NASDAQ:CPRT) closed at $30.75 per share. Over the past month, Copart, Inc. (NASDAQ:CPRT) returned 0.14%, while its shares lost 32.24% over the past 52 weeks. Copart, Inc. (NASDAQ:CPRT) has a market capitalization of $29.65 billion, and its stock has traded within a 52-week range of $26.81 and $48.96.
Conventum – Alluvium Global Fund stated the following regarding Copart, Inc. (NASDAQ:CPRT) in its Q2 2026 investor letter:
"Once again, the most significant and interesting news for investors is a new position we initiated. On this occasion, it is Copart, Inc. (NASDAQ:CPRT, the car wrecker turned auction platform (down 15.1% over the quarter). Copart has grown from a small single auto salvage yard in Vallejo, California in 1982 to a car auction technology platform selling over 4 million cars per year, predominantly on behalf of large insurance companies. We were alerted to this business by our quantitative screen - where it appeared a compelling opportunity (ten year sales growth of 17.4% and 19.1% profit growth, negligible debt, and mid 30's returns on invested capital), so we explored the business in greater depth. Our synopsis: It is a top notch business operating in a duopoly, but with little scope for domestic growth significant enough to move the needle. Most of Copart's revenue stems from its services to insurance companies for selling their vehicles which they classify to be "total losses". So, when it comes to ***** ysing the long term viability of its business, we think there are two key considerations. There is the likely growth rate of automobile accidents. We expect this to gradually decline as a result of increased adoption of autonomous driving, which is known to have lower crash rates than human-driven vehicles. Then there is the proportion of future collisions that are likely to result in cars being classified as "total losses". We expect this will continue its long term upward trend (driven by increased technology and high repair cos


3 hours ago
Sept 15, 2026, 11:57 am EDT
Guggenheim ******* yst
Michael Ciarmoli
sees a lot of opportunity in the
beaten-up
defense sector. Monday, he launched coverage of almost two dozen stocks. He has a baker’s dozen buys, with some surprising price targets.
Copyright ©2026 Dow Jones & Company, Inc. All Rights Reserved. 87990cbe856818d5eddac44c7b1cdeb8
Higher borrowing costs could make it harder for restaurant chains to open new locations at the pace investors expect.
#dozen #guggenheim #jones #rights
Guggenheim ******* yst
Michael Ciarmoli
sees a lot of opportunity in the
beaten-up
defense sector. Monday, he launched coverage of almost two dozen stocks. He has a baker’s dozen buys, with some surprising price targets.
Copyright ©2026 Dow Jones & Company, Inc. All Rights Reserved. 87990cbe856818d5eddac44c7b1cdeb8
Higher borrowing costs could make it harder for restaurant chains to open new locations at the pace investors expect.
#dozen #guggenheim #jones #rights

3 hours ago
Auxier ******* et Management, an investment advisory firm, released its second-quarter 2026 investor letter. The letter can be downloaded here. Following a strong rebound from the first-quarter decline, the S&P 500 gained 15.2% as accelerating capital spending toward artificial intelligence infrastructure drove significant gains across technology hardware companies. Semiconductor and data-center-related businesses benefited from supply constraints and strong demand, while enterprise software remained under pressure as investors reassessed AI disruption risks and compressed valuations. In the quarter, Auxier Focus Fund's Investor Class gained 8.82% and 10.70% for the six months ended June 30, 2026. Despite strong earnings growth across the broader market, Auxier highlighted concerns around rising margin debt, increased leverage, and elevated capital flows into high-growth technology areas that could amplify future volatility. The firm continues to focus on identifying enduring businesses with strong competitive advantages, resilient cash flows, and sustainable long-term growth potential. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Auxier ******* et Management highlighted The Kroger Co. (NYSE:KR). The Kroger Co. (NYSE:KR) is a leading supermarket chain that operates combination food and drug stores, multi-department stores, marketplace stores, and price impact warehouses. On September 14, 2026, The Kroger Co. (NYSE:KR) closed at $60.91 per share. Over the past month, The Kroger Co. (NYSE:KR) returned 10.12%, but its shares are down 7.06% over the past year. The Kroger Co. (NYSE:KR) has a market capitalization of $37.32 billion, and its stock has traded within a 52-week range of $54.15 to $76.58.
Auxier ******* et Management stated the following regarding The Kroger Co. (NYSE:KR) in its Q2 2026 investor letter:
"Consumer staples underperformed during the quarter. Elevated inflation, high interest rates and rising gas prices contributed to lower consumer spending, impacting companies like The Kroger Co. (NYSE:KR) and PepsiCo. Although Kroger's stock has been weak, its new CEO Greg Foran brings exceptional leadership that promises positive change. While he was President of Walmart US from 2014-2019, the company achieved 20 consecutive quarters of same-store sales growth and scaled its online grocery pickup. Since joining Kroger he has aggressively reduced prices and boosted the growth in private label and organic offerings. The stock trades at a mere 12 times earnings which is a significant discount to both Costco and Walmart."
#Growth #asset
In its second-quarter 2026 investor letter, Auxier ******* et Management highlighted The Kroger Co. (NYSE:KR). The Kroger Co. (NYSE:KR) is a leading supermarket chain that operates combination food and drug stores, multi-department stores, marketplace stores, and price impact warehouses. On September 14, 2026, The Kroger Co. (NYSE:KR) closed at $60.91 per share. Over the past month, The Kroger Co. (NYSE:KR) returned 10.12%, but its shares are down 7.06% over the past year. The Kroger Co. (NYSE:KR) has a market capitalization of $37.32 billion, and its stock has traded within a 52-week range of $54.15 to $76.58.
Auxier ******* et Management stated the following regarding The Kroger Co. (NYSE:KR) in its Q2 2026 investor letter:
"Consumer staples underperformed during the quarter. Elevated inflation, high interest rates and rising gas prices contributed to lower consumer spending, impacting companies like The Kroger Co. (NYSE:KR) and PepsiCo. Although Kroger's stock has been weak, its new CEO Greg Foran brings exceptional leadership that promises positive change. While he was President of Walmart US from 2014-2019, the company achieved 20 consecutive quarters of same-store sales growth and scaled its online grocery pickup. Since joining Kroger he has aggressively reduced prices and boosted the growth in private label and organic offerings. The stock trades at a mere 12 times earnings which is a significant discount to both Costco and Walmart."
#Growth #asset

4 hours ago
Nvidia (NVDA) CEO Jensen Huang just dropped an interesting update on the company's growth. He said he believes the chip giant can grow revenue by 70% next year, a forecast that would take annual sales from roughly $400 billion to about $680 billion.
At first look, that sounds almost too ambitious, but Huang argues that Nvidia is still at the center of the artificial intelligence buildout, and demand for its computing systems remains far from saturated.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Morgan Stanley Doubles Down on Apple Stock as New Offerings Become 'More Exciting'
The EV Bubble Has Burst. How to Play Rivian Stock Now.
#billion #nvda #goldman #expects
At first look, that sounds almost too ambitious, but Huang argues that Nvidia is still at the center of the artificial intelligence buildout, and demand for its computing systems remains far from saturated.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Morgan Stanley Doubles Down on Apple Stock as New Offerings Become 'More Exciting'
The EV Bubble Has Burst. How to Play Rivian Stock Now.
#billion #nvda #goldman #expects

4 hours ago
Fidelity Investments, an investment management company, recently released its second-quarter 2026 investor letter for the "Fidelity Dividend Growth Fund". The letter can be downloaded here. The Fidelity Dividend Growth Fund is a diversified large-cap equity strategy focused on capital appreciation through investments in large- and mid-cap stocks with strong dividend growth prospects. The fund returned 17.05% in the quarter, outperforming the S&P 500 Index, which gained 15.20%. U.S. stocks experienced significant gains in Q2, driven by increased spending on artificial intelligence. Technology stocks gained 31.79%, mainly driven by semiconductor companies, while the index faced a slight decline in June as investors considered the sustainability of AI-related profits amidst rising interest rates. Despite recent turbulence from the Middle East conflict, the fund remains optimistic about key investment themes, particularly in artificial intelligence. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Fidelity Dividend Growth Fund highlighted Allison Transmission Holdings, Inc. (NYSE:ALSN). Allison Transmission Holdings, Inc. (NYSE:ALSN) is a manufacturer of commercial-duty automatic transmissions and hybrid propulsion systems for medium- and heavy-duty vehicles. On September 14, 2026, Allison Transmission Holdings, Inc. (NYSE:ALSN) closed at $123.49 per share. Over the past month, Allison Transmission Holdings, Inc. (NYSE:ALSN) declined 1.56%, but its shares are up 40.84% over the past year. Allison Transmission Holdings, Inc. (NYSE:ALSN) has a market capitalization of $10.2 billion, and its stock has traded within a 52-week range of $76.01 to $137.62.
Fidelity Dividend Growth Fund stated the following regarding Allison Transmission Holdings, Inc. (NYSE:ALSN) in its Q2 2026 investor letter:
"Elsewhere in the industrials sector, Allison Transmission Holdings, Inc. (NYSE:ALSN) was another meaningful overweight at the end of June. This provider of automatic transmissions for medium- and heavy-duty vehicles has continued to benefit from accelerating industrial activity, driven by federal support for infrastructure and onshoring. In January, the company completed a major acquisition with the purchase of the Off-Highway Drive & Motion Systems business of Dana Incorporated, a leading provider of drivetrain and propulsion solutions. We like the prospects for this acquisition."
Allison Transmission Holdings, Inc. (NYSE:ALSN) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 48 hedge fund portfolios held Allison Transmission Holdings, Inc. (NYSE:ALSN) at the end of the second quarter, which was 44 in the previous quarter. While we acknowledge the potential of Allison Transmission Holdings, Inc. (NYSE:ALSN) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely underval
In its second-quarter 2026 investor letter, Fidelity Dividend Growth Fund highlighted Allison Transmission Holdings, Inc. (NYSE:ALSN). Allison Transmission Holdings, Inc. (NYSE:ALSN) is a manufacturer of commercial-duty automatic transmissions and hybrid propulsion systems for medium- and heavy-duty vehicles. On September 14, 2026, Allison Transmission Holdings, Inc. (NYSE:ALSN) closed at $123.49 per share. Over the past month, Allison Transmission Holdings, Inc. (NYSE:ALSN) declined 1.56%, but its shares are up 40.84% over the past year. Allison Transmission Holdings, Inc. (NYSE:ALSN) has a market capitalization of $10.2 billion, and its stock has traded within a 52-week range of $76.01 to $137.62.
Fidelity Dividend Growth Fund stated the following regarding Allison Transmission Holdings, Inc. (NYSE:ALSN) in its Q2 2026 investor letter:
"Elsewhere in the industrials sector, Allison Transmission Holdings, Inc. (NYSE:ALSN) was another meaningful overweight at the end of June. This provider of automatic transmissions for medium- and heavy-duty vehicles has continued to benefit from accelerating industrial activity, driven by federal support for infrastructure and onshoring. In January, the company completed a major acquisition with the purchase of the Off-Highway Drive & Motion Systems business of Dana Incorporated, a leading provider of drivetrain and propulsion solutions. We like the prospects for this acquisition."
Allison Transmission Holdings, Inc. (NYSE:ALSN) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 48 hedge fund portfolios held Allison Transmission Holdings, Inc. (NYSE:ALSN) at the end of the second quarter, which was 44 in the previous quarter. While we acknowledge the potential of Allison Transmission Holdings, Inc. (NYSE:ALSN) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely underval

4 hours ago
Fidelity Investments, an investment management company, recently released its second-quarter 2026 investor letter for the "Fidelity Dividend Growth Fund". The letter can be downloaded here. The Fidelity Dividend Growth Fund is a diversified large-cap equity strategy focused on capital appreciation through investments in large- and mid-cap stocks with strong dividend growth prospects. The fund returned 17.05% in the quarter, outperforming the S&P 500 Index, which gained 15.20%. U.S. stocks experienced significant gains in Q2, driven by increased spending on artificial intelligence. Technology stocks gained 31.79%, mainly driven by semiconductor companies, while the index faced a slight decline in June as investors considered the sustainability of AI-related profits amidst rising interest rates. Despite recent turbulence from the Middle East conflict, the fund remains optimistic about key investment themes, particularly in artificial intelligence. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Fidelity Dividend Growth Fund highlighted Western Digital Corporation (NASDAQ:WDC). Western Digital Corporation (NASDAQ:WDC) is a data storage company that engages in the manufacturing and distribution of data storage devices and solutions based on hard disk drive (HDD) technology. On September 14, 2026, Western Digital Corporation (NASDAQ:WDC) closed at $426.94 per share. Over the past month, Western Digital Corporation (NASDAQ:WDC) declined 13.95%, and its shares are up 314.14% over the past year. Western Digital Corporation (NASDAQ:WDC) has a market capitalization of $153.93 billion, and its stock has traded within a 52-week range of $93.92 to $799.87.
Fidelity Dividend Growth Fund stated the following regarding Western Digital Corporation (NASDAQ:WDC) in its Q2 2026 investor letter:
"Among individual holdings, a sizable overweight in Western Digital Corporation (NASDAQ:WDC) (+140%) topped the list of relative contributors. In late April, the data-storage maker reported better-than-expected quarterly financial results, including higher earnings and gross profit margin. In its report, management said brisk demand for the firm's storage solutions for AI capabilities contributed to the solid quarter. Also, the company raised its financial guidance."
Western Digital Corporation (NASDAQ:WDC) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 98 hedge fund portfolios held Western Digital Corporation (NASDAQ:WDC) at the end of the second quarter, up from 83 in the previous quarter. While we acknowledge the potential of Western Digital Corporation (NASDAQ:WDC) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-te
In its second-quarter 2026 investor letter, Fidelity Dividend Growth Fund highlighted Western Digital Corporation (NASDAQ:WDC). Western Digital Corporation (NASDAQ:WDC) is a data storage company that engages in the manufacturing and distribution of data storage devices and solutions based on hard disk drive (HDD) technology. On September 14, 2026, Western Digital Corporation (NASDAQ:WDC) closed at $426.94 per share. Over the past month, Western Digital Corporation (NASDAQ:WDC) declined 13.95%, and its shares are up 314.14% over the past year. Western Digital Corporation (NASDAQ:WDC) has a market capitalization of $153.93 billion, and its stock has traded within a 52-week range of $93.92 to $799.87.
Fidelity Dividend Growth Fund stated the following regarding Western Digital Corporation (NASDAQ:WDC) in its Q2 2026 investor letter:
"Among individual holdings, a sizable overweight in Western Digital Corporation (NASDAQ:WDC) (+140%) topped the list of relative contributors. In late April, the data-storage maker reported better-than-expected quarterly financial results, including higher earnings and gross profit margin. In its report, management said brisk demand for the firm's storage solutions for AI capabilities contributed to the solid quarter. Also, the company raised its financial guidance."
Western Digital Corporation (NASDAQ:WDC) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 98 hedge fund portfolios held Western Digital Corporation (NASDAQ:WDC) at the end of the second quarter, up from 83 in the previous quarter. While we acknowledge the potential of Western Digital Corporation (NASDAQ:WDC) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-te

4 hours ago
Fidelity Investments, an investment management company, recently released its second-quarter 2026 investor letter for the "Fidelity Dividend Growth Fund". The letter can be downloaded here. The Fidelity Dividend Growth Fund is a diversified large-cap equity strategy focused on capital appreciation through investments in large- and mid-cap stocks with strong dividend growth prospects. The fund returned 17.05% in the quarter, outperforming the S&P 500 Index, which gained 15.20%. U.S. stocks experienced significant gains in Q2, driven by increased spending on artificial intelligence. Technology stocks gained 31.79%, mainly driven by semiconductor companies, while the index faced a slight decline in June as investors considered the sustainability of AI-related profits amidst rising interest rates. Despite recent turbulence from the Middle East conflict, the fund remains optimistic about key investment themes, particularly in artificial intelligence. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Fidelity Dividend Growth Fund highlighted Advanced Micro Devices, Inc. (NASDAQ:AMD). Advanced Micro Devices, Inc. (NASDAQ:AMD) is a leading semiconductor company that designs and manufactures AI accelerators, microprocessors, and graphics processing units. On September 14, 2026, Advanced Micro Devices, Inc. (NASDAQ:AMD) closed at $493.41 per share, reflecting a market capitalization of $805.61 billion. Over the past month, Advanced Micro Devices, Inc. (NASDAQ:AMD) returned 7.72%, but its shares are up 226.08% over the past year.
Fidelity Dividend Growth Fund stated the following regarding Advanced Micro Devices, Inc. (NASDAQ:AMD) in its Q2 2026 investor letter:
"On the other hand, security selection in industrials and materials meaningfully detracted for the quarter, along with a large overweight in the lagging energy sector. The five largest relative detractors were all strong-performing benchmark components in the technology sector that the fund didn't own during the quarter. For example, Advanced Micro Devices, Inc. (NASDAQ:AMD) (+186%) was the largest relative detractor for the period. AMD competes in many markets with Nvidia, which we preferred and has outperformed AMD in many recent quarters. Also, AMD pays no dividend, whereas Nvidia does. The past three months, though, AMD had by far the better return, aided by better-than-expected earnings for Q1 that were driven by accelerating demand for AI infrastructure."
#Dividend
In its second-quarter 2026 investor letter, Fidelity Dividend Growth Fund highlighted Advanced Micro Devices, Inc. (NASDAQ:AMD). Advanced Micro Devices, Inc. (NASDAQ:AMD) is a leading semiconductor company that designs and manufactures AI accelerators, microprocessors, and graphics processing units. On September 14, 2026, Advanced Micro Devices, Inc. (NASDAQ:AMD) closed at $493.41 per share, reflecting a market capitalization of $805.61 billion. Over the past month, Advanced Micro Devices, Inc. (NASDAQ:AMD) returned 7.72%, but its shares are up 226.08% over the past year.
Fidelity Dividend Growth Fund stated the following regarding Advanced Micro Devices, Inc. (NASDAQ:AMD) in its Q2 2026 investor letter:
"On the other hand, security selection in industrials and materials meaningfully detracted for the quarter, along with a large overweight in the lagging energy sector. The five largest relative detractors were all strong-performing benchmark components in the technology sector that the fund didn't own during the quarter. For example, Advanced Micro Devices, Inc. (NASDAQ:AMD) (+186%) was the largest relative detractor for the period. AMD competes in many markets with Nvidia, which we preferred and has outperformed AMD in many recent quarters. Also, AMD pays no dividend, whereas Nvidia does. The past three months, though, AMD had by far the better return, aided by better-than-expected earnings for Q1 that were driven by accelerating demand for AI infrastructure."
#Dividend


4 hours ago
Fidelity Investments, an investment management company, recently released its second-quarter 2026 investor letter for the "Fidelity Dividend Growth Fund". The letter can be downloaded here. The Fidelity Dividend Growth Fund is a diversified large-cap equity strategy focused on capital appreciation through investments in large- and mid-cap stocks with strong dividend growth prospects. The fund returned 17.05% in the quarter, outperforming the S&P 500 Index, which gained 15.20%. U.S. stocks experienced significant gains in Q2, driven by increased spending on artificial intelligence. Technology stocks gained 31.79%, mainly driven by semiconductor companies, while the index faced a slight decline in June as investors considered the sustainability of AI-related profits amidst rising interest rates. Despite recent turbulence from the Middle East conflict, the fund remains optimistic about key investment themes, particularly in artificial intelligence. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Fidelity Dividend Growth Fund highlighted Seagate Technology Holdings plc (NASDAQ:STX) as a notable performance contributor. Seagate Technology Holdings plc (NASDAQ:STX) is a data storage company providing data storage technology and infrastructure solutions. On September 14, 2026, Seagate Technology Holdings plc (NASDAQ:STX) closed at $805.55 per share. Over the past month, Seagate Technology Holdings plc (NASDAQ:STX) declined 10.86%, but its shares are up 281.54% over the past year. Seagate Technology Holdings plc (NASDAQ:STX) has a market capitalization of $183.18 billion, and its stock has traded within a 52-week range of $206.26 to $1,145.00.
Fidelity Dividend Growth Fund stated the following regarding Seagate Technology Holdings plc (NASDAQ:STX) in its Q2 2026 investor letter:
"Shares of Seagate Technology Holdings plc (NASDAQ:STX) gained about 147% the past three months. Seagate is one of the world's largest producers of digital storage and, along with Western Digital, one of two dominant makers of hard-disk drives. Exploding demand for HDDs used in AI capable data centers has led to surging sales and strong pricing power for the company. In its most recent quarterly filing in April, Seagate reported revenue, earnings and profitability that all exceeded consensus expectations, while raising financial guidance."
Seagate Technology Holdings plc (NASDAQ:STX) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 131 hedge fund portfolios held Seagate Technology Holdings plc (NASDAQ:STX) at the end of the second quarter, compared to 93 in the previous quarter. While we acknowledge the potential of Seagate Technology Holdings plc (NASDAQ:STX) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly f
In its second-quarter 2026 investor letter, Fidelity Dividend Growth Fund highlighted Seagate Technology Holdings plc (NASDAQ:STX) as a notable performance contributor. Seagate Technology Holdings plc (NASDAQ:STX) is a data storage company providing data storage technology and infrastructure solutions. On September 14, 2026, Seagate Technology Holdings plc (NASDAQ:STX) closed at $805.55 per share. Over the past month, Seagate Technology Holdings plc (NASDAQ:STX) declined 10.86%, but its shares are up 281.54% over the past year. Seagate Technology Holdings plc (NASDAQ:STX) has a market capitalization of $183.18 billion, and its stock has traded within a 52-week range of $206.26 to $1,145.00.
Fidelity Dividend Growth Fund stated the following regarding Seagate Technology Holdings plc (NASDAQ:STX) in its Q2 2026 investor letter:
"Shares of Seagate Technology Holdings plc (NASDAQ:STX) gained about 147% the past three months. Seagate is one of the world's largest producers of digital storage and, along with Western Digital, one of two dominant makers of hard-disk drives. Exploding demand for HDDs used in AI capable data centers has led to surging sales and strong pricing power for the company. In its most recent quarterly filing in April, Seagate reported revenue, earnings and profitability that all exceeded consensus expectations, while raising financial guidance."
Seagate Technology Holdings plc (NASDAQ:STX) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 131 hedge fund portfolios held Seagate Technology Holdings plc (NASDAQ:STX) at the end of the second quarter, compared to 93 in the previous quarter. While we acknowledge the potential of Seagate Technology Holdings plc (NASDAQ:STX) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly f

4 hours ago
Broyhill **** et Management, a Charlotte-based firm, issued its second-quarter 2026 investor letter, which is available for download here. The Broyhill Equity Composite gained 8.8% in Q2, trailing the MSCI All Country World Index's 15.1% and the MSCI ACWI Value Index's 10.8%. For the first half, the Composite returned 2.3%, versus 11.5% for the Index. The letter highlights that a significant portion of the shortfall occurred in April due to market dynamics and geopolitical events, with tech, particularly semiconductors, driving recent gains. Broyhill notes its lack of direct semiconductor exposure but acknowledges potential interest in the sector if opportunities arise, maintaining its investment philosophy focused on capital protection in fragile market conditions. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Broyhill **** et Management highlighted First Citizens BancShares, Inc. (NASDAQ:FCNCA). First Citizens BancShares, Inc. (NASDAQ:FCNCA) operates as the holding company for First-Citizens Bank & Trust Company, providing retail and commercial banking services. On September 14, 2026, First Citizens BancShares, Inc. (NASDAQ:FCNCA) closed at $2,173.88 per share. Over the past month, First Citizens BancShares, Inc. (NASDAQ:FCNCA) declined 1.03%, but its shares are up 17.10% over the past year. First Citizens BancShares, Inc. (NASDAQ:FCNCA) has a market capitalization of $24.55 billion, and its stock has traded within a 52-week range of $1,623.76 to $2,296.30.
Broyhill **** et Management stated the following regarding First Citizens BancShares, Inc. (NASDAQ:FCNCA) in its Q2 2026 investor letter:
"First Citizens BancShares, Inc. (NASDAQ:FCNCA), initiated in June, is a well-run company which we believe to be undervalued and with catalysts on the horizon. The company has retired almost 20% of its Class A shares since July 2024, and inside its roughly $25 billion market capitalization sits a rail leasing fleet of approximately 128,000 cars valued by the market at bank multiples. Management has proven themselves highly competent and highly aligned with shareholders, with the Holding family in key executive positions, owning over 20% of the economics and controlling roughly half the vote through their Class B shares. Much of what we are waiting on has a date attached to it: two separations have completed, and Masco and First Citizens are retiring shares at a pace that improves per-share value whether or not the multiples change."
#fcnca #market
In its second-quarter 2026 investor letter, Broyhill **** et Management highlighted First Citizens BancShares, Inc. (NASDAQ:FCNCA). First Citizens BancShares, Inc. (NASDAQ:FCNCA) operates as the holding company for First-Citizens Bank & Trust Company, providing retail and commercial banking services. On September 14, 2026, First Citizens BancShares, Inc. (NASDAQ:FCNCA) closed at $2,173.88 per share. Over the past month, First Citizens BancShares, Inc. (NASDAQ:FCNCA) declined 1.03%, but its shares are up 17.10% over the past year. First Citizens BancShares, Inc. (NASDAQ:FCNCA) has a market capitalization of $24.55 billion, and its stock has traded within a 52-week range of $1,623.76 to $2,296.30.
Broyhill **** et Management stated the following regarding First Citizens BancShares, Inc. (NASDAQ:FCNCA) in its Q2 2026 investor letter:
"First Citizens BancShares, Inc. (NASDAQ:FCNCA), initiated in June, is a well-run company which we believe to be undervalued and with catalysts on the horizon. The company has retired almost 20% of its Class A shares since July 2024, and inside its roughly $25 billion market capitalization sits a rail leasing fleet of approximately 128,000 cars valued by the market at bank multiples. Management has proven themselves highly competent and highly aligned with shareholders, with the Holding family in key executive positions, owning over 20% of the economics and controlling roughly half the vote through their Class B shares. Much of what we are waiting on has a date attached to it: two separations have completed, and Masco and First Citizens are retiring shares at a pace that improves per-share value whether or not the multiples change."
#fcnca #market
4 hours ago
Citigroup Inc. (NYSE:C)'s CFO Gonzalo Luchetti said the bank expects return on tangible common equity (RoTCE) to come in slightly above 11% in 2026, while also indicating that Citi will increase stock buybacks from the $13 billion repurchased in 2025. The bank plans to accelerate roughly $500 million of investment by year-end, including spending on severance and marketing intended to expand its credit-card and wealth-management businesses. Citi also expects to remove Banamex from its balance sheet in 2027, which will create an estimated $9 billion currency-translation adjustment loss.
The 11%+ target is meaningful because Citi's profitability has already improved materially. In the second quarter, Citi generated $24.8 billion of revenue, up 14% year over year, while net income rose 45% to $5.8 billion. Investment-banking revenue increased 44% to $1.55 billion, and net interest income increased 13%. Citi's SEC filing shows second-quarter RoTCE of 13.0%, versus 8.7% a year earlier, while the first half of 2026 produced a 13.1% RoTCE. The new guidance therefore suggests management believes profitability can remain above the longer-term 11%-13% RoTCE range Citi established for 2027-28, despite additional investment spending.
Kiev.Victor / Shutterstock.com
The bullish argument is that Citigroup Inc. (NYSE:C) appears to be converting its multiyear restructuring into higher returns while simultaneously returning more capital to shareholders. The move from 8.7% RoTCE in the second quarter of 2025 to 13.0% in the second quarter of 2026 represents a substantial improvement in capital efficiency. Citi's efficiency ratio also improved to 57.4% from 62.7%, indicating that revenue growth is increasingly translating into operating leverage rather than being absorbed by expenses. That is particularly relevant because management now intends to spend another roughly $500 million on severance, marketing, and growth initiatives; if these investments produce the intended expansion in cards and wealth management, they could support revenue growth without derailing the profitability trajectory.
Capital returns provide another positive lever. Citi repurchased $13 billion of stock in 2025 and now expects to increase that amount, while its June 2026 CET1 ratio remained 12.78%, comfortably above its 11.6% standardized regulatory requirement. Buybacks can reduce tangible common equity and shares outstanding, potentially supporting both RoTCE and per-share earnings when executed below intrinsic value. Citi's tangible book value per share had already risen 7% year over year to $100.89 by June 30, 2026. The combination of higher operating profitability, shrinking share count, and improving capital efficiency strengthens the case for a valuation re-rating if Citi can sustain returns above 11%.
#rotce #citi #management
The 11%+ target is meaningful because Citi's profitability has already improved materially. In the second quarter, Citi generated $24.8 billion of revenue, up 14% year over year, while net income rose 45% to $5.8 billion. Investment-banking revenue increased 44% to $1.55 billion, and net interest income increased 13%. Citi's SEC filing shows second-quarter RoTCE of 13.0%, versus 8.7% a year earlier, while the first half of 2026 produced a 13.1% RoTCE. The new guidance therefore suggests management believes profitability can remain above the longer-term 11%-13% RoTCE range Citi established for 2027-28, despite additional investment spending.
Kiev.Victor / Shutterstock.com
The bullish argument is that Citigroup Inc. (NYSE:C) appears to be converting its multiyear restructuring into higher returns while simultaneously returning more capital to shareholders. The move from 8.7% RoTCE in the second quarter of 2025 to 13.0% in the second quarter of 2026 represents a substantial improvement in capital efficiency. Citi's efficiency ratio also improved to 57.4% from 62.7%, indicating that revenue growth is increasingly translating into operating leverage rather than being absorbed by expenses. That is particularly relevant because management now intends to spend another roughly $500 million on severance, marketing, and growth initiatives; if these investments produce the intended expansion in cards and wealth management, they could support revenue growth without derailing the profitability trajectory.
Capital returns provide another positive lever. Citi repurchased $13 billion of stock in 2025 and now expects to increase that amount, while its June 2026 CET1 ratio remained 12.78%, comfortably above its 11.6% standardized regulatory requirement. Buybacks can reduce tangible common equity and shares outstanding, potentially supporting both RoTCE and per-share earnings when executed below intrinsic value. Citi's tangible book value per share had already risen 7% year over year to $100.89 by June 30, 2026. The combination of higher operating profitability, shrinking share count, and improving capital efficiency strengthens the case for a valuation re-rating if Citi can sustain returns above 11%.
#rotce #citi #management

4 hours ago
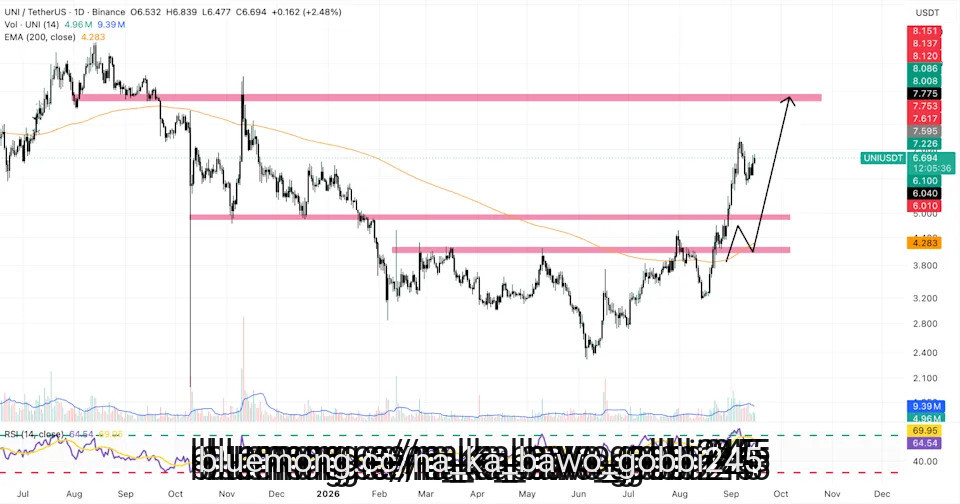
Uniswap (UNI) has jumped by more than 6% in the past 24 hours, and it is the best-performing token in the top 20, as on-chain data shows that protocol fees have exploded in September.
In the past 30 days alone, this token has doubled its value, primarily amid the success of its launch on the Robinhood Chain.
Trading volumes in the past 24 hours have surged by 80%, to nearly $640 million. At those levels, they account for almost 15% of the ****** et's circulating market cap.
UNI has managed to defy a challenging macroeconomic backdrop marked by expectations of multiple upcoming rate hikes.
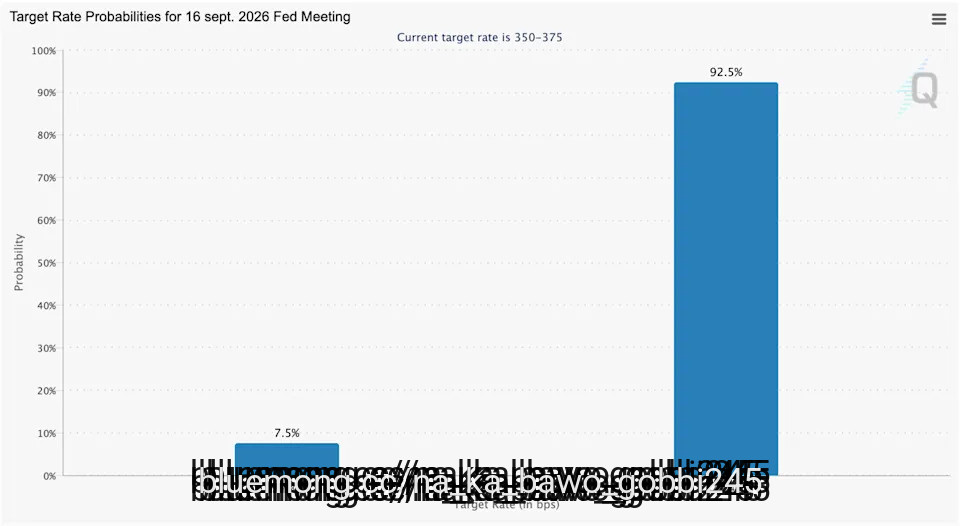
According to data from FedWatch, the Federal Reserve will increase interest rates by 25 basis points tomorrow. Meanwhile, it appears that ****** ysts are leaning toward a second rate increase in December, as high inflation in the United States persists.
#past #token #increase
In the past 30 days alone, this token has doubled its value, primarily amid the success of its launch on the Robinhood Chain.
Trading volumes in the past 24 hours have surged by 80%, to nearly $640 million. At those levels, they account for almost 15% of the ****** et's circulating market cap.
UNI has managed to defy a challenging macroeconomic backdrop marked by expectations of multiple upcoming rate hikes.
According to data from FedWatch, the Federal Reserve will increase interest rates by 25 basis points tomorrow. Meanwhile, it appears that ****** ysts are leaning toward a second rate increase in December, as high inflation in the United States persists.
#past #token #increase
5 hours ago
Bank of America Corporation (NYSE:BAC) expects third-quarter investment banking fees to fall by at least 10% year over year, which highlights a broader normalization across capital markets after an unusually strong first half of 2026. BofA expects investment banking fees of roughly $1.6 billion to $1.8 billion in the third quarter, compared with $2 billion a year earlier. CEO Brian Moynihan said the broader investment banking market is also down around 10%, suggesting that the softer quarter reflects a cooling in industry activity rather than a company-specific breakdown.
The comparison with the second quarter illustrates how sharp the normalization is. BofA's investment banking fees had risen 50% year over year to $2.1 billion in Q2, while sales and trading revenue reached a record $7.1 billion. The current outlook therefore represents a pullback from elevated levels rather than a reversal of the broader recovery in dealmaking. Global M&A activity remained substantial in the first half of 2026, with more than $3 trillion of announced transactions, providing evidence that corporate deal appetite has remained relatively healthy even as quarterly activity fluctuates.
Pixabay/Public Domain
From a longer-term perspective, the normalization does not necessarily undermine Bank of America Corporation (NYSE:BAC)'s capital-markets franchise. Investment banking revenues remain well above the depressed levels seen during the earlier downturn in deal activity, while the bank continues to have a substantial pipeline of potential transactions. Moynihan's comments that the pipeline remains strong suggest that some of the current weakness could reflect the timing of transactions rather than a fundamental loss of corporate demand for M&A, financing or advisory services.
BofA also has a diversified earnings base that makes it less dependent on any single capital-markets cycle. Its second-quarter net interest income increased 9% to $16 billion, while average loans and leases grew 8%. That provides a more stable source of revenue as investment banking normalizes. In this context, the Q3 decline can be viewed as a shift away from exceptionally strong capital-markets contributions rather than evidence that the bank's broader earnings trajectory has deteriorated.
#billion #year #rather
The comparison with the second quarter illustrates how sharp the normalization is. BofA's investment banking fees had risen 50% year over year to $2.1 billion in Q2, while sales and trading revenue reached a record $7.1 billion. The current outlook therefore represents a pullback from elevated levels rather than a reversal of the broader recovery in dealmaking. Global M&A activity remained substantial in the first half of 2026, with more than $3 trillion of announced transactions, providing evidence that corporate deal appetite has remained relatively healthy even as quarterly activity fluctuates.
Pixabay/Public Domain
From a longer-term perspective, the normalization does not necessarily undermine Bank of America Corporation (NYSE:BAC)'s capital-markets franchise. Investment banking revenues remain well above the depressed levels seen during the earlier downturn in deal activity, while the bank continues to have a substantial pipeline of potential transactions. Moynihan's comments that the pipeline remains strong suggest that some of the current weakness could reflect the timing of transactions rather than a fundamental loss of corporate demand for M&A, financing or advisory services.
BofA also has a diversified earnings base that makes it less dependent on any single capital-markets cycle. Its second-quarter net interest income increased 9% to $16 billion, while average loans and leases grew 8%. That provides a more stable source of revenue as investment banking normalizes. In this context, the Q3 decline can be viewed as a shift away from exceptionally strong capital-markets contributions rather than evidence that the bank's broader earnings trajectory has deteriorated.
#billion #year #rather

5 hours ago
Eli Lilly and Company (NYSE:LLY) says its newly launched oral obesity drug Foundayo has captured more than 30% of new U.S. patients starting oral weight-loss medicines, a notable early gain against Novo Nordisk's Wegovy pill. Reuters reports that Wegovy initially held roughly 90% of the oral market, making Lilly's rapid share capture an important sign that the oral GLP-1 market is becoming a two-player competition rather than a Novo-dominated segment. The broader U.S. obesity-drug market is expected to exceed $100 billion annually by 2030, with oral treatments potentially accounting for more than one-third of GLP-1 use.
The timing is strategically important for Lilly because Foundayo was only launched in the U.S. in April 2026. The drug starts at $149 per month for self-pay patients and can cost as little as $25 for eligible commercially insured patients, while Medicare beneficiaries can access it through the GLP-1 Bridge program at $50 per month. Lilly's SEC filing says Mounjaro and Zepbound already represented 65% of its revenue in the first six months of 2026, highlighting both the importance of the incretin franchise and the opportunity for Foundayo to broaden Lilly's cardiometabolic revenue base.
The strongest bullish implication is that Foundayo appears to be overcoming the biggest behavioral barrier in obesity treatment: patients' preference for an oral medicine over an injection. Capturing more than 30% of new oral patients only months after launch suggests Eli Lilly and Company (NYSE:LLY) is establishing meaningful competitive positioning before the oral GLP-1 market fully scales. Foundayo's formulation also has a practical advantage because it can be taken at any time of day without food or water restrictions, while Lilly's clinical data showed an average 27.3-pound, or 12.4%, weight reduction at the highest dose among patients who remained on treatment in ATTAIN-1.
The commercial opportunity could become considerably larger if Foundayo gains indications beyond obesity. Lilly reported that in the ACHIEVE-3 trial, Foundayo produced a 57.1% greater relative reduction in A1C and a 73.6% greater relative reduction in body weight compared with oral semaglutide 14 mg. Lilly submitted Foundayo for type 2 diabetes in the U.S., EU, and **** an, potentially expanding the addressable market beyond weight management.
The early oral-market traction also complements Eli Lilly and Company (NYSE:LLY)'s existing injectable franchise rather than simply cannibalizing it. A Lilly trial found that patients switching from maximum-tolerated Wegovy to Foundayo maintained all but 0.9 kg of their previous weight loss after one year, while patients switching from maximum-dose Zepbound to Foundayo maintained all but 5.0 kg. That suggests Foundayo could serve as a maintenance or lower-burden treatment within Lilly's broader obesity portfolio, increasing lifetime value per patient rather than limiting the opportunity to new prescriptions.
#patients #weight #c
The timing is strategically important for Lilly because Foundayo was only launched in the U.S. in April 2026. The drug starts at $149 per month for self-pay patients and can cost as little as $25 for eligible commercially insured patients, while Medicare beneficiaries can access it through the GLP-1 Bridge program at $50 per month. Lilly's SEC filing says Mounjaro and Zepbound already represented 65% of its revenue in the first six months of 2026, highlighting both the importance of the incretin franchise and the opportunity for Foundayo to broaden Lilly's cardiometabolic revenue base.
The strongest bullish implication is that Foundayo appears to be overcoming the biggest behavioral barrier in obesity treatment: patients' preference for an oral medicine over an injection. Capturing more than 30% of new oral patients only months after launch suggests Eli Lilly and Company (NYSE:LLY) is establishing meaningful competitive positioning before the oral GLP-1 market fully scales. Foundayo's formulation also has a practical advantage because it can be taken at any time of day without food or water restrictions, while Lilly's clinical data showed an average 27.3-pound, or 12.4%, weight reduction at the highest dose among patients who remained on treatment in ATTAIN-1.
The commercial opportunity could become considerably larger if Foundayo gains indications beyond obesity. Lilly reported that in the ACHIEVE-3 trial, Foundayo produced a 57.1% greater relative reduction in A1C and a 73.6% greater relative reduction in body weight compared with oral semaglutide 14 mg. Lilly submitted Foundayo for type 2 diabetes in the U.S., EU, and **** an, potentially expanding the addressable market beyond weight management.
The early oral-market traction also complements Eli Lilly and Company (NYSE:LLY)'s existing injectable franchise rather than simply cannibalizing it. A Lilly trial found that patients switching from maximum-tolerated Wegovy to Foundayo maintained all but 0.9 kg of their previous weight loss after one year, while patients switching from maximum-dose Zepbound to Foundayo maintained all but 5.0 kg. That suggests Foundayo could serve as a maintenance or lower-burden treatment within Lilly's broader obesity portfolio, increasing lifetime value per patient rather than limiting the opportunity to new prescriptions.
#patients #weight #c

5 hours ago
Novo Nordisk A/S (NYSE:NVO)'s decision to rebrand its day-to-day identity as "Novo" and launch a cultural reset is primarily a strategic response to the company's loss of momentum in the obesity-drug market, rather than a financial restructuring in itself. Reuters reports that the company is trying to regain competitiveness as pressure from Eli Lilly intensifies. The move comes as Novo prepares to unveil new strategic ambitions at its September 21 Capital Markets Day, making the cultural reset potentially important if it leads to faster decision-making, stronger commercial execution and a more aggressive R&D approach.
The underlying business still has substantial scale to protect. Novo generated DKK 309.1 billion of 2025 sales and DKK 127.7 billion of operating profit, while obesity-care sales rose 31% at constant exchange rates to DKK 82.3 billion. However, the company also spent around DKK 8 billion on its transformation in 2025, and its diabetes value-market share fell 3.6 percentage points to 30.1%. The reset therefore comes at a critical point: Novo remains the global obesity-market leader, with a 59.6% branded-volume share in 2025, but Lilly is rapidly narrowing the competitive gap.
A successful cultural reset could improve Novo Nordisk A/S (NYSE:NVO)'s execution at a time when the company needs to convert its scientific and commercial ******* ets into faster growth. Reuters reported that CEO Mike Doustdar is already seeking to accelerate R&D and streamline decision-making following investor concerns about the pipeline and competition from Lilly. If the reorganization reduces internal bureaucracy and improves the speed of clinical, regulatory and commercial decisions, it could help Novo extract more value from its existing obesity portfolio while advancing next-generation treatments before the semaglutide patent cliff expected early next decade.
The company also has ******* ets that give a cultural and operational reset something concrete to build around. Wegovy was available in 52 countries by the end of 2025, while the company's higher-dose Wegovy achieved 20.7% weight loss in Phase 3 studies and its oral Wegovy achieved 16.6% weight loss. More recently, Wegovy received approval in China for MASH, expanding its potential beyond weight management and cardiovascular benefits into another large metabolic-disease market. If Novo Nordisk A/S (NYSE:NVO) can combine these products with better execution, the reset could support higher patient volumes and extend the commercial life of its GLP-1 franchise, helping defend revenue and cash flow despite pricing pressure.
#nordisk #lilly
The underlying business still has substantial scale to protect. Novo generated DKK 309.1 billion of 2025 sales and DKK 127.7 billion of operating profit, while obesity-care sales rose 31% at constant exchange rates to DKK 82.3 billion. However, the company also spent around DKK 8 billion on its transformation in 2025, and its diabetes value-market share fell 3.6 percentage points to 30.1%. The reset therefore comes at a critical point: Novo remains the global obesity-market leader, with a 59.6% branded-volume share in 2025, but Lilly is rapidly narrowing the competitive gap.
A successful cultural reset could improve Novo Nordisk A/S (NYSE:NVO)'s execution at a time when the company needs to convert its scientific and commercial ******* ets into faster growth. Reuters reported that CEO Mike Doustdar is already seeking to accelerate R&D and streamline decision-making following investor concerns about the pipeline and competition from Lilly. If the reorganization reduces internal bureaucracy and improves the speed of clinical, regulatory and commercial decisions, it could help Novo extract more value from its existing obesity portfolio while advancing next-generation treatments before the semaglutide patent cliff expected early next decade.
The company also has ******* ets that give a cultural and operational reset something concrete to build around. Wegovy was available in 52 countries by the end of 2025, while the company's higher-dose Wegovy achieved 20.7% weight loss in Phase 3 studies and its oral Wegovy achieved 16.6% weight loss. More recently, Wegovy received approval in China for MASH, expanding its potential beyond weight management and cardiovascular benefits into another large metabolic-disease market. If Novo Nordisk A/S (NYSE:NVO) can combine these products with better execution, the reset could support higher patient volumes and extend the commercial life of its GLP-1 franchise, helping defend revenue and cash flow despite pricing pressure.
#nordisk #lilly