24 hours ago
Chief Executive Officer Lip-Bu Tan purchased 150,000 shares of common stock across multiple trades priced between $64.71 and $64.74.
The strategic share acquisition follows Intel's Q3 2026 earnings release, which showed $16.5 billion in revenue, but shares suffered a sharp after-hours plunge driven by conservative fourth-quarter sales forecasts.
Investors are weighing cooling artificial intelligence capital expenditure (capex) cycles following a Democratic wave in mid-term elections.
Intel's (INTC) chief executive officer and director Lip-Bu Tan acquired 150,000 shares of common stock worth $9.7 million on Nov. 2 via his family trust, according to a regulatory filing on Wednesday.
Tan bought the stock through several open-market transactions at prices ranging from $64.705 to $64.735; the total investment amounted to approximately $9.71 million. The move could be seen as a vote of confidence as the semiconductor giant navigates supply chain pressures, fabrication hurdles at its Israel facility, and shifting demand in the personal computer market.
#shares #executive #million #market
The strategic share acquisition follows Intel's Q3 2026 earnings release, which showed $16.5 billion in revenue, but shares suffered a sharp after-hours plunge driven by conservative fourth-quarter sales forecasts.
Investors are weighing cooling artificial intelligence capital expenditure (capex) cycles following a Democratic wave in mid-term elections.
Intel's (INTC) chief executive officer and director Lip-Bu Tan acquired 150,000 shares of common stock worth $9.7 million on Nov. 2 via his family trust, according to a regulatory filing on Wednesday.
Tan bought the stock through several open-market transactions at prices ranging from $64.705 to $64.735; the total investment amounted to approximately $9.71 million. The move could be seen as a vote of confidence as the semiconductor giant navigates supply chain pressures, fabrication hurdles at its Israel facility, and shifting demand in the personal computer market.
#shares #executive #million #market

2 days ago
Recent filings with the Securities and Exchange Commission show that Berkshire Hathaway purchased an additional $27 million in one of its top 20 holdings, SiriusXM (NASDAQ:SIRI).
The purchases were made between Oct. 30 and Nov. 3 for an average price of roughly $29 per share.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
The satellite radio company Sirius now accounts for 1.1% of Berkshire's massive, roughly $368 billion equity portfolio, and Berkshire controls over 37% of Sirius's outstanding shares.
Berkshire has owned a significant stake in Sirius for quite a while, but when Liberty Media split off Sirius XM and two of its tracking stocks in 2024, Berkshire went in again, purchasing another $1.2 billion of Sirius stock in early 2024.
#roughly
The purchases were made between Oct. 30 and Nov. 3 for an average price of roughly $29 per share.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
The satellite radio company Sirius now accounts for 1.1% of Berkshire's massive, roughly $368 billion equity portfolio, and Berkshire controls over 37% of Sirius's outstanding shares.
Berkshire has owned a significant stake in Sirius for quite a while, but when Liberty Media split off Sirius XM and two of its tracking stocks in 2024, Berkshire went in again, purchasing another $1.2 billion of Sirius stock in early 2024.
#roughly

7 days ago
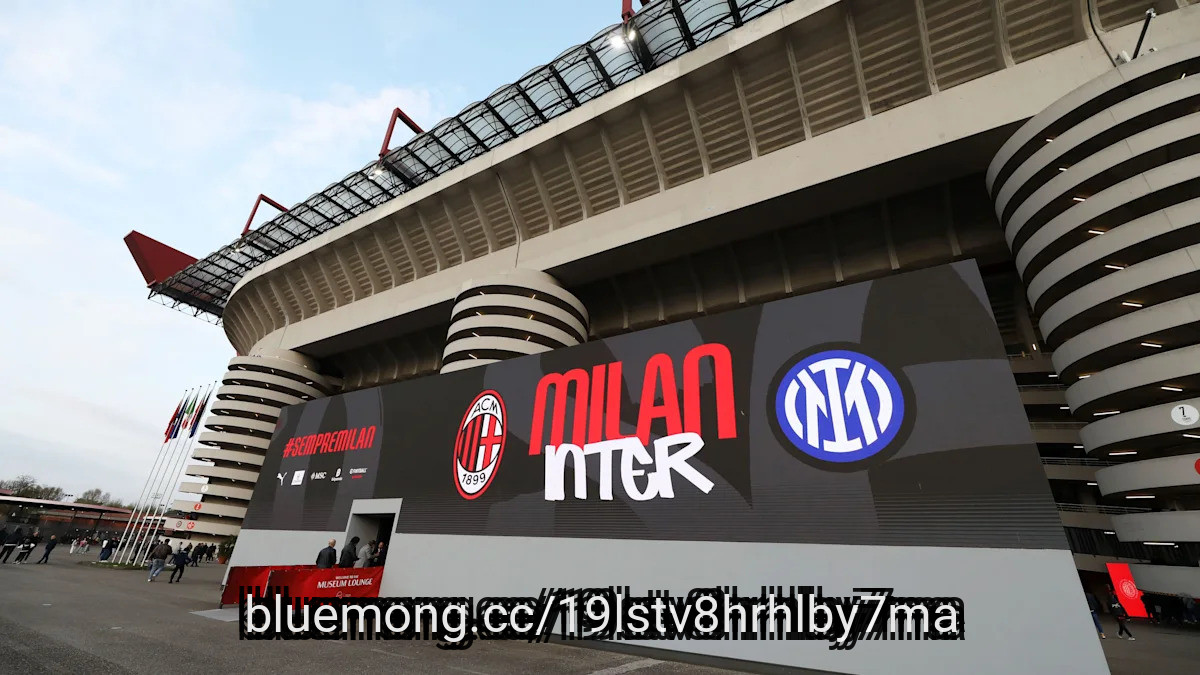
The iconic skyline of Milan is set for a historic transformation as the city's two footballing heavyweights prepare to move into a state-of-the-art new home. In a move that signals a massive shift in the financial landscape of Serie A, AC Milan and Inter have officially secured a record-breaking naming rights partnership with Italian insurance giant Generali for their future shared arena.
Milan and Inter have agreed a staggering 20-year naming rights contract with Generali, which ESPN reports is worth €650 million (£545m/$725m). The new 71,500-capacity venue will be officially known as the Generali Stadium, effectively replacing the historic San Siro. The clubs purchased the required land from the city last November for €197m, paving the way for the eventual demolition of their legendary current home.
Construction is targeted to begin in 2028, with the first matches scheduled for the 2031-32 campaign, pending necessary approvals. Spearheaded by respective ownership groups RedBird Capital Partners and Oaktree, the stadium project also anchors a wider urban regeneration plan featuring new retail, leisure, and green ******* es.
The massive financial commitment eclipses the $700m agreement struck by Crypto.com in 2021 for the Los Angeles arena shared by the Lakers and Kings. It stands as a monumental boost for the two Serie A giants as they look to modernise and bridge the matchday revenue gap with Europe's elite.
A new symbol for Milano.
A new home for future generations of fans.
Generali Stadium 🏟️GENERALI pic.twitter.com/c7D0827E7T
#generali #historic
Milan and Inter have agreed a staggering 20-year naming rights contract with Generali, which ESPN reports is worth €650 million (£545m/$725m). The new 71,500-capacity venue will be officially known as the Generali Stadium, effectively replacing the historic San Siro. The clubs purchased the required land from the city last November for €197m, paving the way for the eventual demolition of their legendary current home.
Construction is targeted to begin in 2028, with the first matches scheduled for the 2031-32 campaign, pending necessary approvals. Spearheaded by respective ownership groups RedBird Capital Partners and Oaktree, the stadium project also anchors a wider urban regeneration plan featuring new retail, leisure, and green ******* es.
The massive financial commitment eclipses the $700m agreement struck by Crypto.com in 2021 for the Los Angeles arena shared by the Lakers and Kings. It stands as a monumental boost for the two Serie A giants as they look to modernise and bridge the matchday revenue gap with Europe's elite.
A new symbol for Milano.
A new home for future generations of fans.
Generali Stadium 🏟️GENERALI pic.twitter.com/c7D0827E7T
#generali #historic

28 days ago
Taylor Swift and Travis Kelce seem to already be having issues with their new neighbors.
Earlier this year, it was reported by the Wall Street Journal that Kelce, 37, purchased a $5.35 million lakefront estate in Ohio, and now home renovations are underway.
The Daily Mail reported on Thursday, October 8, that a planning board meeting was held last month in the village of Bratenahl, just outside Cleveland, and a six-foot fence was unanimously approved despite some objections from those living close by, according to records.
A neighbor by the name of Katherine Bolton reportedly told the Architectural Review Board that Kelce's new purchase was a "tremendous blow" to "the peace and quiet in Bratenahl."
"There's a new owner, who is an absentee owner, who is not going to be here," she said, according to a record of the hearing obtained by the Mail. (The Kansas City Chiefs tight end and pop star, 36, weren't named.)
#bratenahl #reported #swift
Earlier this year, it was reported by the Wall Street Journal that Kelce, 37, purchased a $5.35 million lakefront estate in Ohio, and now home renovations are underway.
The Daily Mail reported on Thursday, October 8, that a planning board meeting was held last month in the village of Bratenahl, just outside Cleveland, and a six-foot fence was unanimously approved despite some objections from those living close by, according to records.
A neighbor by the name of Katherine Bolton reportedly told the Architectural Review Board that Kelce's new purchase was a "tremendous blow" to "the peace and quiet in Bratenahl."
"There's a new owner, who is an absentee owner, who is not going to be here," she said, according to a record of the hearing obtained by the Mail. (The Kansas City Chiefs tight end and pop star, 36, weren't named.)
#bratenahl #reported #swift



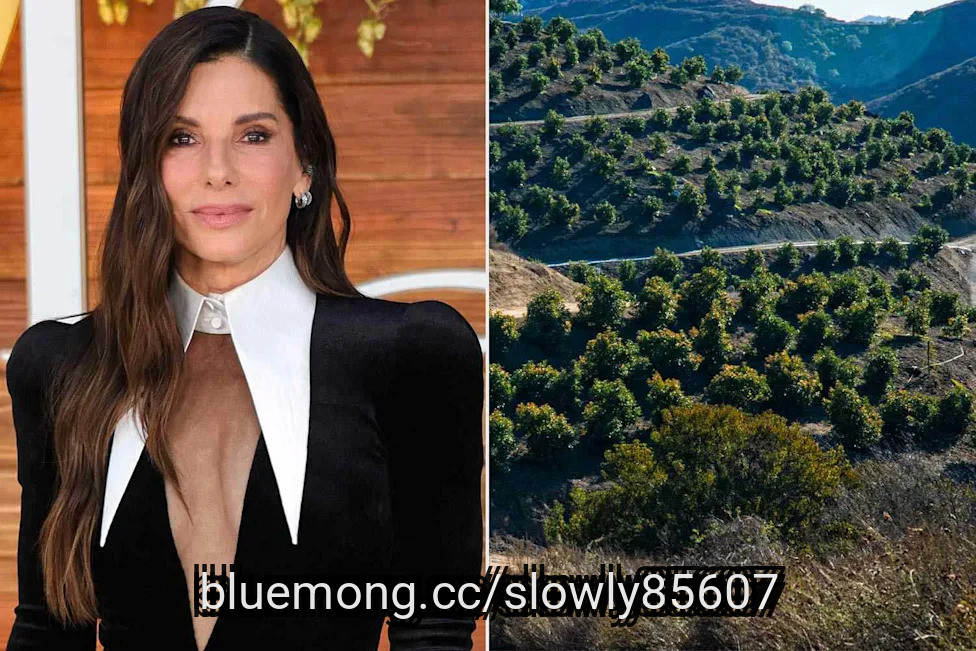
28 days ago
Sandra Bullock purchased her Valley Center property for $2.72 million in 2007, extensively renovating it
The estate featured 1,200 organic avocado trees, citrus groves, a saltwater pool and solar charging stations
She sold the property for $5.6 million in 2022 after it spent three weeks on the market
Years before she made her return to the big screen with Practical Magic 2, Sandra Bullock was making magic in another way — via her real estate holdings, which previously included a 91-acre Valley Center, Calif., property complete with an avocado tree farm (and 1,200 organic avocado trees).
The actress, 62, purchased the property in 2007 for $2.72 million via a trust, per Mansion Global, which cites property records.
#property #bullock #center
The estate featured 1,200 organic avocado trees, citrus groves, a saltwater pool and solar charging stations
She sold the property for $5.6 million in 2022 after it spent three weeks on the market
Years before she made her return to the big screen with Practical Magic 2, Sandra Bullock was making magic in another way — via her real estate holdings, which previously included a 91-acre Valley Center, Calif., property complete with an avocado tree farm (and 1,200 organic avocado trees).
The actress, 62, purchased the property in 2007 for $2.72 million via a trust, per Mansion Global, which cites property records.
#property #bullock #center

28 days ago
Taylor Swift and Travis Kelce's plans for a more private Ohio retreat have run into some very public objections. Neighbors of the $5.35 million Lake Erie estate are challenging proposed landscaping and fencing, raising concerns about a shared sewer line, wildlife, and how the changes could affect their longtime homes.
A six-foot fence has already received approval, but parts of the landscaping remain unresolved. The property's representatives, meanwhile, say they have adjusted the plans, paid for sewer repairs and added gates to accommodate residents.
ZUMAPRESS.com / MEGA
According to the Daily Mail, the dispute centers on an estate in Bratenahl, a village outside Cleveland. Property records cited by the outlet show that an LLC linked to Kelce purchased the mansion in March. The 21,000-square-foot property features eight bedrooms, 11 bathrooms, and a two-bedroom guest cottage. Built in 1895, it also has a former ballroom converted into a game room and home theater.
But proposed changes to the grounds have become a sticking point with nearby residents. Katherine Bolton, who has lived next door for 35 years, described news of the new owners as a "tremendous blow" to "the peace and quiet in Bratenahl."
#estate
A six-foot fence has already received approval, but parts of the landscaping remain unresolved. The property's representatives, meanwhile, say they have adjusted the plans, paid for sewer repairs and added gates to accommodate residents.
ZUMAPRESS.com / MEGA
According to the Daily Mail, the dispute centers on an estate in Bratenahl, a village outside Cleveland. Property records cited by the outlet show that an LLC linked to Kelce purchased the mansion in March. The 21,000-square-foot property features eight bedrooms, 11 bathrooms, and a two-bedroom guest cottage. Built in 1895, it also has a former ballroom converted into a game room and home theater.
But proposed changes to the grounds have become a sticking point with nearby residents. Katherine Bolton, who has lived next door for 35 years, described news of the new owners as a "tremendous blow" to "the peace and quiet in Bratenahl."
#estate



30 days ago
EPR Properties (NYSE: EPR) is a company focused on properties designed for experiential and educational purposes. One of the benefits of owning its stock has been its dividend, which has increased for four consecutive years.
EPR is a real estate investment trust (REIT), which means it must pay out at least 90% of its taxable net income as dividends to retain that status. That makes it highly likely that payouts will continue. As the dividend has become more generous, it might surprise investors how little it takes to generate more than $1,000 in annual dividends in this stock.
Missed AI's "Act 1"? Act 2 Could Be 14x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our **** ysts, we're only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
Working with whole shares, 269 shares purchased for $15,182 will generate $1,001 in annual dividends.
This amounts to an annual dividend of $3.72 per share with a yield of about 6.6%. That is far above the S&P 500 average of 1.1%. Moreover, it is one of the few stocks paying monthly dividends, which might make it especially appealing to income investors.
#Dividend #annual #missed
EPR is a real estate investment trust (REIT), which means it must pay out at least 90% of its taxable net income as dividends to retain that status. That makes it highly likely that payouts will continue. As the dividend has become more generous, it might surprise investors how little it takes to generate more than $1,000 in annual dividends in this stock.
Missed AI's "Act 1"? Act 2 Could Be 14x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our **** ysts, we're only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
Working with whole shares, 269 shares purchased for $15,182 will generate $1,001 in annual dividends.
This amounts to an annual dividend of $3.72 per share with a yield of about 6.6%. That is far above the S&P 500 average of 1.1%. Moreover, it is one of the few stocks paying monthly dividends, which might make it especially appealing to income investors.
#Dividend #annual #missed

1 month ago
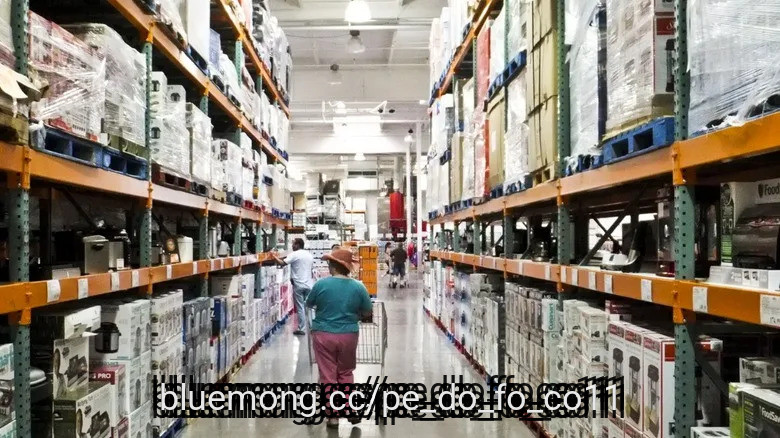
Costco is famously rooted in Washington state, with its headquarters in Kirkland (which is also the name of its signature brand) and its first official store operating out of Seattle's industrial SoDo neighborhood. But did you know that the wholesale club behemoth can trace its true origins much further south, and to a famous connection? As it turns out, a line can be drawn from Costco to Howard Hughes, the famous movie producer, aviator, and eccentric business tycoon.
Among his many properties, Hughes once owned a rather large warehouse in San Diego, California, that was eventually turned into an early wholesale store called Price Club. It went on to merge with Costco in the 1990s, forever cementing the Costco-Hughes connection. Sure, it may not be the strongest celebrity-Costco connection ever, and Hughes himself never set foot inside one of the chain's stores, but it's one that Costco can be proud to have as part of its storied history nonetheless.
Read more: 9 Store-Bought Canned Chili Brands Ranked Worst To Best
Bettmann/Getty Images
While it's unclear exactly how long Howard Hughes' San Diego building served as a hangar, or if any remodeling was done prior to its wholesale club days, what is known is that it reopened as Price Club in the summer of 1976 after being purchased by local businessman Sol Price and his son, Robert. It looks pretty similar today compared to old photos of the building in its Price Club days and as an aviation hangar, with its vaulted ceilings and massive walls. The coolest part though? If you're a history buff in San Diego, you can actually go shop at the Costco that once housed Hughes' airplanes (assuming you're also a Costco member, of course). The store sits on Morena Boulevard, at the exact same address as its preceding incarnations.
#price #connection #famous
Among his many properties, Hughes once owned a rather large warehouse in San Diego, California, that was eventually turned into an early wholesale store called Price Club. It went on to merge with Costco in the 1990s, forever cementing the Costco-Hughes connection. Sure, it may not be the strongest celebrity-Costco connection ever, and Hughes himself never set foot inside one of the chain's stores, but it's one that Costco can be proud to have as part of its storied history nonetheless.
Read more: 9 Store-Bought Canned Chili Brands Ranked Worst To Best
Bettmann/Getty Images
While it's unclear exactly how long Howard Hughes' San Diego building served as a hangar, or if any remodeling was done prior to its wholesale club days, what is known is that it reopened as Price Club in the summer of 1976 after being purchased by local businessman Sol Price and his son, Robert. It looks pretty similar today compared to old photos of the building in its Price Club days and as an aviation hangar, with its vaulted ceilings and massive walls. The coolest part though? If you're a history buff in San Diego, you can actually go shop at the Costco that once housed Hughes' airplanes (assuming you're also a Costco member, of course). The store sits on Morena Boulevard, at the exact same address as its preceding incarnations.
#price #connection #famous



1 month ago
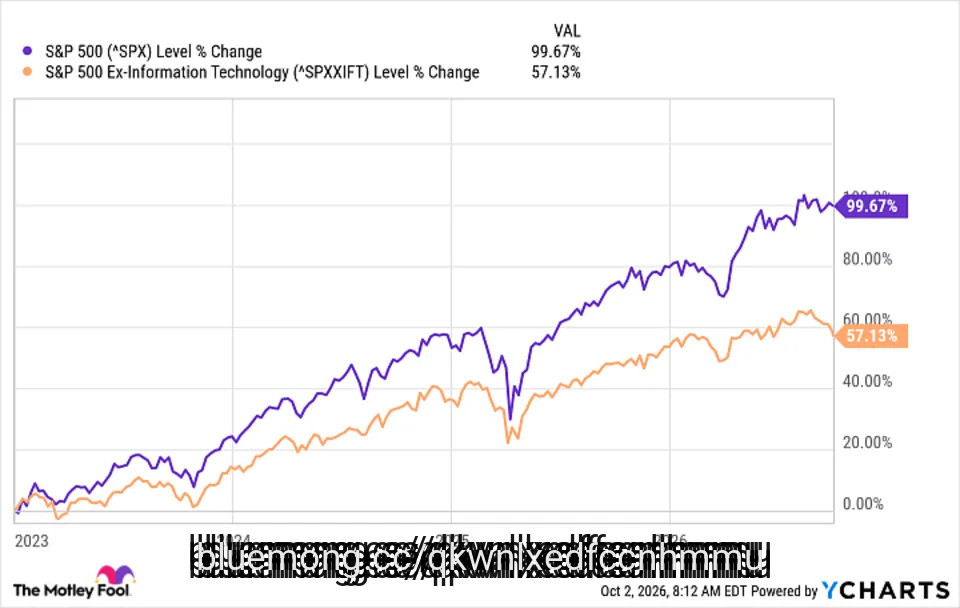
Warren Buffett stepped down from his role as the chief executive officer of Berkshire Hathaway (NYSE: BRKA)(NYSE: BRKB) at the end of 2025. During his 60-year tenure, he grew the company into a $1 trillion conglomerate with multiple wholly owned subsidiaries, a $350 billion stock portfolio, and over $350 billion in cash.
Had an investor purchased $500 worth of Berkshire shares when Buffett took the helm in 1965, thatr person would have been sitting on a whopping $24 million by the time Buffett stepped down. However, Buffett was a full-time professional investor, so he always knew the average person would struggle to replicate his results. That's why he regularly advocated for exchange-traded funds (ETF) that track a diversified index like the S&P 500 (SNPINDEX: ^GSPC).
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
In his 2013 annual letter to shareholders (published in February 2014), Buffett specifically recommended the Vanguard S&P 500 ETF (NYSEMKT: VOO) because of its exceptionally low fees. While young investors in their 20s and 30s can afford to take more risks, those in their 40s who want to achieve financial security heading into retirement might want to heed Buffett's advice. Here's why I'd buy the Vanguard ETF if I were in that age group.
The S&P 500 is made up of 500 American companies from 11 different sectors of the economy. It has a very strict entry criteria, requiring its members to maintain a market capitalization of at least $22.7 billion, and they must also generate positive earnings. But even after meeting those conditions, a special committee still has the final say over which companies make the cut.
#NVIDIA #signal #flashing
Had an investor purchased $500 worth of Berkshire shares when Buffett took the helm in 1965, thatr person would have been sitting on a whopping $24 million by the time Buffett stepped down. However, Buffett was a full-time professional investor, so he always knew the average person would struggle to replicate his results. That's why he regularly advocated for exchange-traded funds (ETF) that track a diversified index like the S&P 500 (SNPINDEX: ^GSPC).
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
In his 2013 annual letter to shareholders (published in February 2014), Buffett specifically recommended the Vanguard S&P 500 ETF (NYSEMKT: VOO) because of its exceptionally low fees. While young investors in their 20s and 30s can afford to take more risks, those in their 40s who want to achieve financial security heading into retirement might want to heed Buffett's advice. Here's why I'd buy the Vanguard ETF if I were in that age group.
The S&P 500 is made up of 500 American companies from 11 different sectors of the economy. It has a very strict entry criteria, requiring its members to maintain a market capitalization of at least $22.7 billion, and they must also generate positive earnings. But even after meeting those conditions, a special committee still has the final say over which companies make the cut.
#NVIDIA #signal #flashing


1 month ago
Frank Fitzpatrick bought ~200 shares of Berkshire Hathaway (BRK-B) at $40 in 1976, sold after 14 months when the stock doubled, then bought back in at a higher price.
Fitzpatrick used his Berkshire gains to buy a Lake Tahoe lakefront home, fund an education nonprofit, and leave shares to his two children.
Fitzpatrick's habit of running back to Berkshire despite a painful early exit shows temperament, not timing, drives long-term investing success.
Building a portfolio and living off one are two completely different skills, and almost ******* ody teaches the second. This problem is what The Definitive Guide to Retirement Income helps, and it is free today. Read more here. (Sponsor)
In 1995, a family gathered on the deck of a newly purchased lakefront home in Lake Tahoe, Nevada. According to The Wall Street Journal, they came together "for a group hug and said, 'Thank you, Warren'". The homeowner was Frank Fitzpatrick, a Lake Tahoe tax lawyer known to friends as "Forty-Dollar Frank."
#tahoe #shares
Fitzpatrick used his Berkshire gains to buy a Lake Tahoe lakefront home, fund an education nonprofit, and leave shares to his two children.
Fitzpatrick's habit of running back to Berkshire despite a painful early exit shows temperament, not timing, drives long-term investing success.
Building a portfolio and living off one are two completely different skills, and almost ******* ody teaches the second. This problem is what The Definitive Guide to Retirement Income helps, and it is free today. Read more here. (Sponsor)
In 1995, a family gathered on the deck of a newly purchased lakefront home in Lake Tahoe, Nevada. According to The Wall Street Journal, they came together "for a group hug and said, 'Thank you, Warren'". The homeowner was Frank Fitzpatrick, a Lake Tahoe tax lawyer known to friends as "Forty-Dollar Frank."
#tahoe #shares
1 month ago
Brian May is best known as Queen's legendary guitarist, but nature conservation is another important part of his life. May, who also earned his PhD in astrophysics and has helped NASA, loves this planet and all its wildlife.
In 2013, May announced that he had purchased 157 acres of land that was due to be developed into housing in Bere Regis, Dorset, England. He intended to transform it into a nature reserve where native British trees and wildlife could thrive.
During a July 2012 interview, May told The Sunday Times, "Queen is a huge part of my life, but I do have other interests. People know about the astrophysics, but I love gardening, too, and I've always been passionate about the welfare of our wonderful British wildlife."
Since then, the former farmland has been cultivated into a woodland wildlife sanctuary and animal rescue.
May worked with local residents and wildlife officials to make the plans for the nature reserve. In a February 2013 BBC interview, May shared his plans for the freshly purchased former farmland.
#wildlife #nature #part #astrophysics
In 2013, May announced that he had purchased 157 acres of land that was due to be developed into housing in Bere Regis, Dorset, England. He intended to transform it into a nature reserve where native British trees and wildlife could thrive.
During a July 2012 interview, May told The Sunday Times, "Queen is a huge part of my life, but I do have other interests. People know about the astrophysics, but I love gardening, too, and I've always been passionate about the welfare of our wonderful British wildlife."
Since then, the former farmland has been cultivated into a woodland wildlife sanctuary and animal rescue.
May worked with local residents and wildlife officials to make the plans for the nature reserve. In a February 2013 BBC interview, May shared his plans for the freshly purchased former farmland.
#wildlife #nature #part #astrophysics

1 month ago
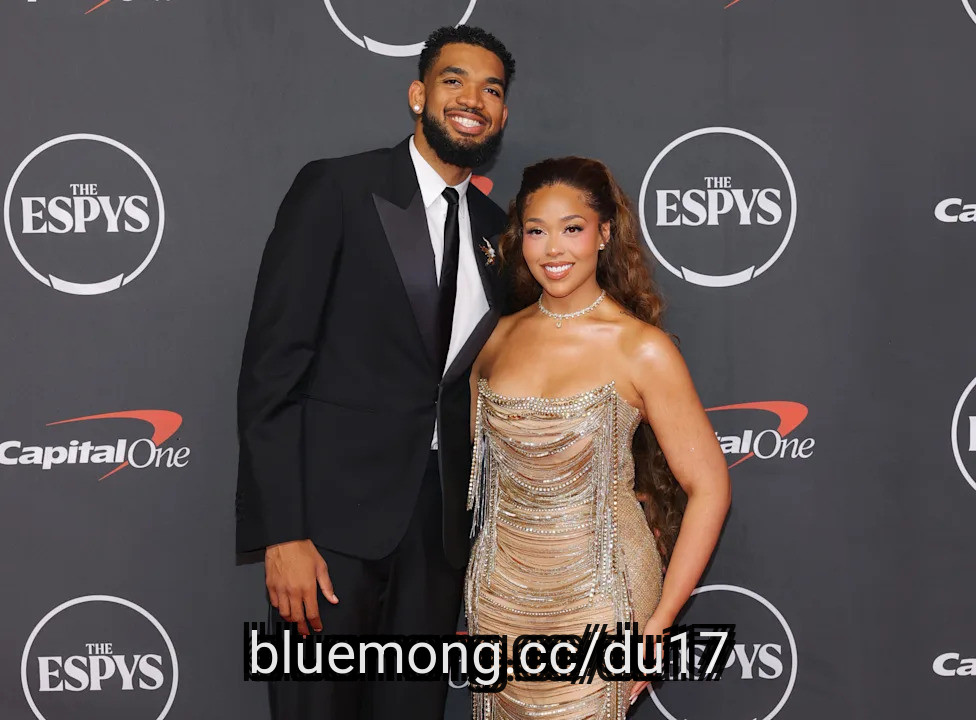
Jordyn Woods has spent much of her life in the spotlight, first as Kylie Jenner's longtime best friend and later as a model, entrepreneur and celebrity in her own right. From her Hollywood connections and family background to her relationship with NBA star Karl-Anthony Towns, Woods has built a life that extends far beyond her former ties to the Kardashian-Jenner family.
But how much do we really know about the life Woods has created for herself? From whether she grew up wealthy and where she lives today to the eye-catching engagement ring she received from Towns and her estimated net worth, here's everything to know about Jordyn Woods' life, career and finances.
Despite her close ties to the Kardashian-Jenner and Smith families, Jordyn Woods did not grow up in a wealthy celebrity household. Her father, John Woods, was a television sound engineer who worked on "The Fresh Prince of Bel-Air", while her mother, Elizabeth Woods, worked as a talent and brand manager. Her parents' careers gave Jordyn an early connection to Hollywood, and her family became particularly close with Will Smith and Jada Pinkett Smith through her father's work, according to People.
Jordyn has acknowledged that she had certain privileges growing up in California and being surrounded by successful people, but she has also pushed back against the idea that her family was wealthy. In a 2025 interview with Crystal Renee Hayslett, she explained that her father worked extremely hard to provide for their family and said that they "definitely struggled," emphasizing that being around wealthy people did not mean her family had the same financial resources.
Jordyn Woods currently lives in Los Angeles, California, with her husband, NBA star Karl-Anthony Towns. TMZ reports the couple purchased a $14 million home in the Los Angeles area, putting them among the city's many celebrity homeowners. Their move into the luxury property came as Woods continued to expand her career beyond social media, while Towns built his fortune through his NBA career.
#woods #jordyn #towns #smith
But how much do we really know about the life Woods has created for herself? From whether she grew up wealthy and where she lives today to the eye-catching engagement ring she received from Towns and her estimated net worth, here's everything to know about Jordyn Woods' life, career and finances.
Despite her close ties to the Kardashian-Jenner and Smith families, Jordyn Woods did not grow up in a wealthy celebrity household. Her father, John Woods, was a television sound engineer who worked on "The Fresh Prince of Bel-Air", while her mother, Elizabeth Woods, worked as a talent and brand manager. Her parents' careers gave Jordyn an early connection to Hollywood, and her family became particularly close with Will Smith and Jada Pinkett Smith through her father's work, according to People.
Jordyn has acknowledged that she had certain privileges growing up in California and being surrounded by successful people, but she has also pushed back against the idea that her family was wealthy. In a 2025 interview with Crystal Renee Hayslett, she explained that her father worked extremely hard to provide for their family and said that they "definitely struggled," emphasizing that being around wealthy people did not mean her family had the same financial resources.
Jordyn Woods currently lives in Los Angeles, California, with her husband, NBA star Karl-Anthony Towns. TMZ reports the couple purchased a $14 million home in the Los Angeles area, putting them among the city's many celebrity homeowners. Their move into the luxury property came as Woods continued to expand her career beyond social media, while Towns built his fortune through his NBA career.
#woods #jordyn #towns #smith

1 month ago
Legendary artist and musician YokoOno lives a reclusive life in her ninth decade. The 93-year-old ******* anese icon, best known for her marriage to and collaborations with her late husband John Lennon, has lived a life away from the public eye for several years.
Here's what we know about Yoko's life out of the spotlight now, from her home to her family…
For five decades, the musician lived in her famous apartment in New York in the exclusive Dakota building, outside where John was tragically shot and killed in 1980.
It was at this famous apartment that she hosted several of the world's elite and raised her son with John, although as it turns out, she's now found a new abode.
Per Daily Mail in 2023, Yoko moved out of her NYC digs for a massive 600-acre farm in upstate New York, a property she and the Beatles member purchased back in 1978.
#john #lived #apartment #yokoono
Here's what we know about Yoko's life out of the spotlight now, from her home to her family…
For five decades, the musician lived in her famous apartment in New York in the exclusive Dakota building, outside where John was tragically shot and killed in 1980.
It was at this famous apartment that she hosted several of the world's elite and raised her son with John, although as it turns out, she's now found a new abode.
Per Daily Mail in 2023, Yoko moved out of her NYC digs for a massive 600-acre farm in upstate New York, a property she and the Beatles member purchased back in 1978.
#john #lived #apartment #yokoono



1 month ago
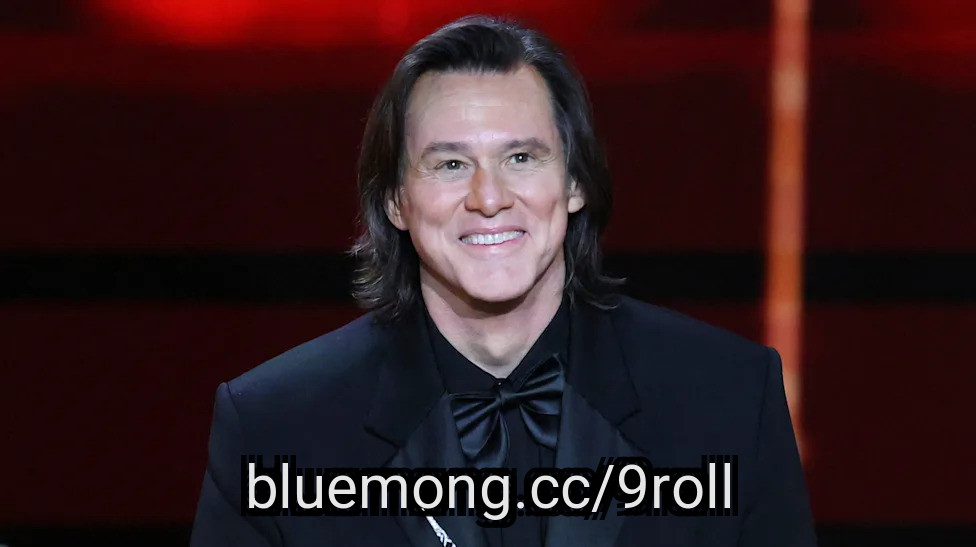
It looks like Jim Carrey is ready for his next chapter.
In Touch can confirm that the Mask star, 64, listed his three-bedroom, four-and-a-half-bathroom house in Hawaii for $35 million after it was revealed this week that he recently married girlfriend Min Ah in a small private ceremony in Los Angeles.
The actor purchased the 4,717-square-foot home, located roughly 170 feet along the water on Keawakapu Beach in Kihei, nearly a decade ago in November 2016 for $16.5 million.
Designed by Ike Kligerman Barkley, the primary residence sits under a thatched roof and is framed in Douglas fir and lined in woven bamboo, according to a listing. The great room rises into the trusses and opens fully to a covered stone lanai.
ZUMAPRESS.com / MEGA
#carrey #beach #november
In Touch can confirm that the Mask star, 64, listed his three-bedroom, four-and-a-half-bathroom house in Hawaii for $35 million after it was revealed this week that he recently married girlfriend Min Ah in a small private ceremony in Los Angeles.
The actor purchased the 4,717-square-foot home, located roughly 170 feet along the water on Keawakapu Beach in Kihei, nearly a decade ago in November 2016 for $16.5 million.
Designed by Ike Kligerman Barkley, the primary residence sits under a thatched roof and is framed in Douglas fir and lined in woven bamboo, according to a listing. The great room rises into the trusses and opens fully to a covered stone lanai.
ZUMAPRESS.com / MEGA
#carrey #beach #november


1 month ago
Devon Sawa and Macaulay Culkin's internet feud may be over, but one joke persists. Sawa recently opened up about a strange rivalry with Culkin, saying that the "Home Alone" star still owned a website with his name.
Sawa has revealed to E!'s Hot Goss that the playful feud dates back to when Culkin purchased a website connected to him. Culkin bought devonsawa.com around Sawa's birthday. He then proceeded to direct fans towards merchandise and jokes involving the actor.
"He and I had a internet beef," Sawa told E!'s Eyal Booker and Lonnie Marts IIV. "He bought devonsawa.com. He did that, and we did this photo shoot together, and then we just started pranking each other."
The rivalry ultimately "kind of faded out," but Culkin still owns devonsawa.com. "If you want to go to devonsawa.com, you will be purchasing everything from Macaulay Culkin," Sawa joked. "I can't believe I'm giving him free press." Despite the long time they spent trolling each other, Sawa heaped praise on his fellow former child star.
"He's amazing," he said.
#sawa #internet #feud #website
Sawa has revealed to E!'s Hot Goss that the playful feud dates back to when Culkin purchased a website connected to him. Culkin bought devonsawa.com around Sawa's birthday. He then proceeded to direct fans towards merchandise and jokes involving the actor.
"He and I had a internet beef," Sawa told E!'s Eyal Booker and Lonnie Marts IIV. "He bought devonsawa.com. He did that, and we did this photo shoot together, and then we just started pranking each other."
The rivalry ultimately "kind of faded out," but Culkin still owns devonsawa.com. "If you want to go to devonsawa.com, you will be purchasing everything from Macaulay Culkin," Sawa joked. "I can't believe I'm giving him free press." Despite the long time they spent trolling each other, Sawa heaped praise on his fellow former child star.
"He's amazing," he said.
#sawa #internet #feud #website


2 months ago
On August 5, Cencora (NYSE:COR) reported results for its fiscal third quarter, which closed on June 30, and the headline numbers looked clean. Revenue rose 5.1% to $84.8 billion, adjusted earnings per share climbed 12.0% to $4.48, and management raised its full-year adjusted EPS outlook to $17.75 to $17.95. The company also repurchased $1 billion of its own stock during the quarter. But the profit story has moving parts, and a few of them pull in opposite directions.
Start with the gap between profit growth and sales growth. Adjusted operating income rose 17.0% while revenue grew only 5.1%. Much of the help came from gross profit, which jumped 23.2% on an adjusted basis as both segments contributed and the OneOncology acquisition in February lifted margins in the US business. In plain terms, adjusted gross margin widened 61 basis points to 4.16%, so the company keeps more gross profit from every dollar it sells.
The strength was not confined to one corner, either. US Healthcare Solutions grew operating income 15.9% on higher pharmaceutical sales and the OneOncology deal, while specialty volume to health systems and physician groups lifted its revenue. International Healthcare Solutions did better still, with operating income up 20.8% on strength in European distribution and global specialty logistics. Management also put cash to work, completing in one quarter the $1 billion of buybacks it had expected to finish by the close of calendar 2026. The board declared a $0.60 quarterly dividend as well, payable August 31, to holders of record on August 14.
Growth is costing more than it first appears. Adjusted operating expenses jumped 26.8%, faster than adjusted gross profit, because OneOncology brought expenses along with its profits. Even so, adjusted operating income amounts to just 1.46% of revenue, a thin cushion on a business this large. Financing adds weight too. Cencora funded part of the purchase with new senior notes plus variable-rate term loans, and net interest expense rose $58.9 million from a year earlier.
The sales mix carries its own drag. GLP-1 drugs for diabetes and weight loss are adding to revenue, but they earn lower gross margins, so each dollar of that growth is worth less to profit. Meanwhile, an oncology customer Cencora lost in 2025, and lower sales to a large mail order customer both held back US revenue, as did lower manufacturer prices on some brand pharmaceuticals. Cencora is also exploring strategic alternatives for a group of other businesses, and its April divestiture of US Consulting Services trimmed consulting sales.
#adjusted #revenue #august
Start with the gap between profit growth and sales growth. Adjusted operating income rose 17.0% while revenue grew only 5.1%. Much of the help came from gross profit, which jumped 23.2% on an adjusted basis as both segments contributed and the OneOncology acquisition in February lifted margins in the US business. In plain terms, adjusted gross margin widened 61 basis points to 4.16%, so the company keeps more gross profit from every dollar it sells.
The strength was not confined to one corner, either. US Healthcare Solutions grew operating income 15.9% on higher pharmaceutical sales and the OneOncology deal, while specialty volume to health systems and physician groups lifted its revenue. International Healthcare Solutions did better still, with operating income up 20.8% on strength in European distribution and global specialty logistics. Management also put cash to work, completing in one quarter the $1 billion of buybacks it had expected to finish by the close of calendar 2026. The board declared a $0.60 quarterly dividend as well, payable August 31, to holders of record on August 14.
Growth is costing more than it first appears. Adjusted operating expenses jumped 26.8%, faster than adjusted gross profit, because OneOncology brought expenses along with its profits. Even so, adjusted operating income amounts to just 1.46% of revenue, a thin cushion on a business this large. Financing adds weight too. Cencora funded part of the purchase with new senior notes plus variable-rate term loans, and net interest expense rose $58.9 million from a year earlier.
The sales mix carries its own drag. GLP-1 drugs for diabetes and weight loss are adding to revenue, but they earn lower gross margins, so each dollar of that growth is worth less to profit. Meanwhile, an oncology customer Cencora lost in 2025, and lower sales to a large mail order customer both held back US revenue, as did lower manufacturer prices on some brand pharmaceuticals. Cencora is also exploring strategic alternatives for a group of other businesses, and its April divestiture of US Consulting Services trimmed consulting sales.
#adjusted #revenue #august

2 months ago
My husband, 59, and I, 55, are planning to retire over the next few years, and this is one of the biggest unknowns I'm struggling with. My mom had Alzheimer's disease and spent seven years in a really nice memory-care facility in a smaller town. It cost about $7,000 a month. Thankfully, my parents had purchased long-term-care insurance and had paid premiums for about 12 years.
My dad died shortly after being diagnosed with cancer, so his policy was never used. But my mom's policy ended up being worth its weight in gold. It essentially covered all of her care. By the time my mother died, the insurance company had paid out almost $600,000. We only paid about $100 a month for some extras. Needless to say, that experience has made me think.
The 10-year Treasury is having its worst run in over 100 years. Why investors are buying bonds anyway.
'I'm burned out': I'm constantly helping my cousin who is running out of money. Is it too much to expect his sister to help?
I've looked into long-term-care insurance, but the premiums are so incredibly expensive, and I worry about what they'll cost by the time it makes sense for me to seriously consider a policy. We're fortunate financially. After 35 years in the corporate grind, we'll have substantial retirement savings; we've always saved carefully; and we have no debt or mortgage.
#insurance #paid #term
My dad died shortly after being diagnosed with cancer, so his policy was never used. But my mom's policy ended up being worth its weight in gold. It essentially covered all of her care. By the time my mother died, the insurance company had paid out almost $600,000. We only paid about $100 a month for some extras. Needless to say, that experience has made me think.
The 10-year Treasury is having its worst run in over 100 years. Why investors are buying bonds anyway.
'I'm burned out': I'm constantly helping my cousin who is running out of money. Is it too much to expect his sister to help?
I've looked into long-term-care insurance, but the premiums are so incredibly expensive, and I worry about what they'll cost by the time it makes sense for me to seriously consider a policy. We're fortunate financially. After 35 years in the corporate grind, we'll have substantial retirement savings; we've always saved carefully; and we have no debt or mortgage.
#insurance #paid #term


2 months ago
On August 5, Cencora (NYSE:COR) reported results for its fiscal third quarter, which closed on June 30, and the headline numbers looked clean. Revenue rose 5.1% to $84.8 billion, adjusted earnings per share climbed 12.0% to $4.48, and management raised its full-year adjusted EPS outlook to $17.75 to $17.95. The company also repurchased $1 billion of its own stock during the quarter. But the profit story has moving parts, and a few of them pull in opposite directions.
Start with the gap between profit growth and sales growth. Adjusted operating income rose 17.0% while revenue grew only 5.1%. Much of the help came from gross profit, which jumped 23.2% on an adjusted basis as both segments contributed and the OneOncology acquisition in February lifted margins in the US business. In plain terms, adjusted gross margin widened 61 basis points to 4.16%, so the company keeps more gross profit from every dollar it sells.
The strength was not confined to one corner, either. US Healthcare Solutions grew operating income 15.9% on higher pharmaceutical sales and the OneOncology deal, while specialty volume to health systems and physician groups lifted its revenue. International Healthcare Solutions did better still, with operating income up 20.8% on strength in European distribution and global specialty logistics. Management also put cash to work, completing in one quarter the $1 billion of buybacks it had expected to finish by the close of calendar 2026. The board declared a $0.60 quarterly dividend as well, payable August 31, to holders of record on August 14.
Growth is costing more than it first appears. Adjusted operating expenses jumped 26.8%, faster than adjusted gross profit, because OneOncology brought expenses along with its profits. Even so, adjusted operating income amounts to just 1.46% of revenue, a thin cushion on a business this large. Financing adds weight too. Cencora funded part of the purchase with new senior notes plus variable-rate term loans, and net interest expense rose $58.9 million from a year earlier.
The sales mix carries its own drag. GLP-1 drugs for diabetes and weight loss are adding to revenue, but they earn lower gross margins, so each dollar of that growth is worth less to profit. Meanwhile, an oncology customer Cencora lost in 2025, and lower sales to a large mail order customer both held back US revenue, as did lower manufacturer prices on some brand pharmaceuticals. Cencora is also exploring strategic alternatives for a group of other businesses, and its April divestiture of US Consulting Services trimmed consulting sales.
#profit #operating #Growth #august
Start with the gap between profit growth and sales growth. Adjusted operating income rose 17.0% while revenue grew only 5.1%. Much of the help came from gross profit, which jumped 23.2% on an adjusted basis as both segments contributed and the OneOncology acquisition in February lifted margins in the US business. In plain terms, adjusted gross margin widened 61 basis points to 4.16%, so the company keeps more gross profit from every dollar it sells.
The strength was not confined to one corner, either. US Healthcare Solutions grew operating income 15.9% on higher pharmaceutical sales and the OneOncology deal, while specialty volume to health systems and physician groups lifted its revenue. International Healthcare Solutions did better still, with operating income up 20.8% on strength in European distribution and global specialty logistics. Management also put cash to work, completing in one quarter the $1 billion of buybacks it had expected to finish by the close of calendar 2026. The board declared a $0.60 quarterly dividend as well, payable August 31, to holders of record on August 14.
Growth is costing more than it first appears. Adjusted operating expenses jumped 26.8%, faster than adjusted gross profit, because OneOncology brought expenses along with its profits. Even so, adjusted operating income amounts to just 1.46% of revenue, a thin cushion on a business this large. Financing adds weight too. Cencora funded part of the purchase with new senior notes plus variable-rate term loans, and net interest expense rose $58.9 million from a year earlier.
The sales mix carries its own drag. GLP-1 drugs for diabetes and weight loss are adding to revenue, but they earn lower gross margins, so each dollar of that growth is worth less to profit. Meanwhile, an oncology customer Cencora lost in 2025, and lower sales to a large mail order customer both held back US revenue, as did lower manufacturer prices on some brand pharmaceuticals. Cencora is also exploring strategic alternatives for a group of other businesses, and its April divestiture of US Consulting Services trimmed consulting sales.
#profit #operating #Growth #august

2 months ago
Raffaele Zagari, a Director of Star Bulk Carriers Corp. (NASDAQ:SBLK), purchased 60,000 shares of common stock on September 15, 2026, according to a recent SEC Form 4 filing.
Metric
Value
Transaction value
$1.7 million
#corp
Metric
Value
Transaction value
$1.7 million
#corp

2 months ago
Core & Main, Inc. (NYSE:CNM) reported quarterly sales of $2.145 billion on September 9, up 2.5%. Company-defined non-GAAP adjusted EBITDA reached $274 million. The measure adjusts consolidated net income for interest, taxes, depreciation and amortization, equity compensation, debt modification and extinguishment losses, offering expenses, and specified other income or expenses.
Consolidated net income rose 6.4% to $150 million, while GAAP diluted earnings per share increased 10% to $0.77. Diluted weighted-average shares declined approximately 2.5% to 193.4 million. Buybacks amplified an improvement that also had an operating foundation.
The company repurchased $169 million of equity during the quarter, against $62 million of operating cash flow. The investment question is whether cash generation can sustain capital returns alongside the spending needed to grow.
Core & Main, Inc. (NYSE:CNM) benefits from demand for essential infrastructure products. Management highlighted municipal demand, fire protection, treatment plants, and data centers as areas of strength. These end markets provide several sources of business even when construction demand is uneven.
Expense discipline also helped. Quarterly selling, general and administrative expenses declined to $301 million from $302 million. Controlling overhead allows modest sales growth to contribute more to earnings. Stronger volumes would make further earnings gains easier to sustain.
#income #main #quarterly
Consolidated net income rose 6.4% to $150 million, while GAAP diluted earnings per share increased 10% to $0.77. Diluted weighted-average shares declined approximately 2.5% to 193.4 million. Buybacks amplified an improvement that also had an operating foundation.
The company repurchased $169 million of equity during the quarter, against $62 million of operating cash flow. The investment question is whether cash generation can sustain capital returns alongside the spending needed to grow.
Core & Main, Inc. (NYSE:CNM) benefits from demand for essential infrastructure products. Management highlighted municipal demand, fire protection, treatment plants, and data centers as areas of strength. These end markets provide several sources of business even when construction demand is uneven.
Expense discipline also helped. Quarterly selling, general and administrative expenses declined to $301 million from $302 million. Controlling overhead allows modest sales growth to contribute more to earnings. Stronger volumes would make further earnings gains easier to sustain.
#income #main #quarterly

2 months ago
Weitz Investment Management, an investment management firm, released its second-quarter Q2 2026 investor letter for the "Multi Cap Equity Fund". The letter can be downloaded here. The Multi Cap Equity Fund's Institutional Class returned 7.90% in Q2, underperforming the Bloomberg U.S. 3000 Index's 15.71% gain. Markets rose in the quarter on hopes of de-escalating Middle East tensions and easing oil flow. Investor focus shifted back to artificial intelligence, despite component shortages like processing chips affecting profits and valuations. Valuation-sensitive investors are selective within the AI sector, in contrast to valuation-agnostic indexes that adopt a more relaxed strategy. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its second-quarter 2026 investor letter, Weitz Multi Cap Equity Fund highlighted Mettler-Toledo International Inc. (NYSE:MTD). Mettler-Toledo International Inc. (NYSE:MTD) manufactures and supplies precision instruments and services in the Americas, Europe, Asia, and internationally. On September 15, 2026, Mettler-Toledo International Inc. (NYSE:MTD) closed at $1,330.40 per share. Over the past month, Mettler-Toledo International Inc. (NYSE:MTD) declined 6.64%, and its shares gained 4.43% over the past 52 weeks. Mettler-Toledo International Inc. (NYSE:MTD) has a market capitalization of $26.66 billion.
Weitz Multi Cap Equity Fund stated the following regarding Mettler-Toledo International Inc. (NYSE:MTD) in its Q2 2026 investor letter:
"Less familiar to shareholders may be our new position in Mettler-Toledo International Inc. (NYSE:MTD), a global supplier of precision measurement instruments across laboratory, industrial and food retailing applications where accuracy, reliability and regulatory compliance are vital. Its highly specialized sales and service organization is a key competitive advantage, working collaboratively with customers to optimize their workflows and improve productivity, reinforcing long-term customer relationships. We have long admired Mettler's business and purchased a small position during a brief period of price dislocation during the quarter."
Mettler-Toledo International Inc. (NYSE:MTD) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 48 hedge fund portfolios held Mettler-Toledo International Inc. (NYSE:MTD) at the end of the second quarter, down from 50 in the previous quarter. While we acknowledge the potential of Mettler-Toledo International Inc. (NYSE:MTD) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#mettler #quarter
In its second-quarter 2026 investor letter, Weitz Multi Cap Equity Fund highlighted Mettler-Toledo International Inc. (NYSE:MTD). Mettler-Toledo International Inc. (NYSE:MTD) manufactures and supplies precision instruments and services in the Americas, Europe, Asia, and internationally. On September 15, 2026, Mettler-Toledo International Inc. (NYSE:MTD) closed at $1,330.40 per share. Over the past month, Mettler-Toledo International Inc. (NYSE:MTD) declined 6.64%, and its shares gained 4.43% over the past 52 weeks. Mettler-Toledo International Inc. (NYSE:MTD) has a market capitalization of $26.66 billion.
Weitz Multi Cap Equity Fund stated the following regarding Mettler-Toledo International Inc. (NYSE:MTD) in its Q2 2026 investor letter:
"Less familiar to shareholders may be our new position in Mettler-Toledo International Inc. (NYSE:MTD), a global supplier of precision measurement instruments across laboratory, industrial and food retailing applications where accuracy, reliability and regulatory compliance are vital. Its highly specialized sales and service organization is a key competitive advantage, working collaboratively with customers to optimize their workflows and improve productivity, reinforcing long-term customer relationships. We have long admired Mettler's business and purchased a small position during a brief period of price dislocation during the quarter."
Mettler-Toledo International Inc. (NYSE:MTD) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 48 hedge fund portfolios held Mettler-Toledo International Inc. (NYSE:MTD) at the end of the second quarter, down from 50 in the previous quarter. While we acknowledge the potential of Mettler-Toledo International Inc. (NYSE:MTD) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#mettler #quarter


2 months ago
The fragment is from Book 12, when Zeus curses Odysseus' men for killing and eating Helios' sacred cattle.
A researcher was perusing a collection of old Egyptian texts in a Dutch library when he stumbled upon a torn piece of parchment containing a pivotal story: a section from Homer's "Odyssey." The fragment appears to be from a pocket edition of the epic produced in Egypt around A.D. 300.
The researcher, Mark de Kreij, a Greek literature expert and professor at Radboud University in the Netherlands, found the parchment while studying early Christian manuscripts that the Utrecht University library purchased in the mid-20th century, according to a Sept. 14 statement from Utrecht University. Among a collection of Egyptian and Greek texts, de Kreij found a tiny piece of parchment with words he recognized from Homer's epic.
"There are so many boring parts in the Odyssey," de Kreij told RTV Utrecht. "This happens to be a really fun passage."
#utrecht
A researcher was perusing a collection of old Egyptian texts in a Dutch library when he stumbled upon a torn piece of parchment containing a pivotal story: a section from Homer's "Odyssey." The fragment appears to be from a pocket edition of the epic produced in Egypt around A.D. 300.
The researcher, Mark de Kreij, a Greek literature expert and professor at Radboud University in the Netherlands, found the parchment while studying early Christian manuscripts that the Utrecht University library purchased in the mid-20th century, according to a Sept. 14 statement from Utrecht University. Among a collection of Egyptian and Greek texts, de Kreij found a tiny piece of parchment with words he recognized from Homer's epic.
"There are so many boring parts in the Odyssey," de Kreij told RTV Utrecht. "This happens to be a really fun passage."
#utrecht



2 months ago
Inquiring about Walmart Inc. (NASDAQ:WMT) on September 10, a caller asked if they should "keep it." Mad Money host Jim Cramer replied:
I got to tell you, this one is a short and long-term, okay? Short-term, I think I know what Walmart's doing. I think that they're letting their customers have a big break. They're not passing along all of these costs. That is going to earn them tremendous love when things get better. So the wise situation is to say this: Walmart trades at 36 times earnings. It deserves to trade lower just because of what's happening at the company now and higher what's happening at the company when this inflation bout ends. So you buy some at $106, $105, and then buy some at $95. And yes, it could trade to $95. It does not have yield support. This is not like Target, which had that yield support. Target's doing better than Walmart right now. It is.
Walmart Inc.'s (NASDAQ:WMT) second-quarter fiscal 2027 revenue rose 5.9% year over year to $187.9 billion, while global e-commerce sales increased 23%. Global advertising revenue rose 38%, and membership-fee revenue increased 17% globally. Walmart U.S. comparable sales, excluding fuel, grew 2.6%. The company is also using tariff refunds to support lower prices. It said tariff refunds increased its gross profit rate during the quarter, while price investments partially offset the benefit.
Target Corporation (NYSE:TGT) has stronger recent comparable-sales momentum. Its second-quarter sales rose 5.3%, comparable sales increased 3.8%, and traffic rose 3.6%. The company also raised its full-year sales-growth outlook to approximately 5%. Its second-quarter GAAP and adjusted EPS were $4.11, including a $1.65 benefit from tariff refunds. Excluding tariff refunds, GAAP and adjusted EPS increased 20% year over year. CEO Michael Fiddelke said Target had reduced prices on more than 10,000 frequently purchased items over the past year and acknowledged that "there's still meaningful work ahead."
Walmart Inc.'s (NASDAQ:WMT) biggest risk is valuation. Its premium forward PE of 36.76 leaves the stock more exposed if U.S. comparable-sales growth remains modest while the company continues investing in prices. Walmart's 2.6% U.S. comparable-sales growth also trails Target's 3.8%.
#increased #rose
I got to tell you, this one is a short and long-term, okay? Short-term, I think I know what Walmart's doing. I think that they're letting their customers have a big break. They're not passing along all of these costs. That is going to earn them tremendous love when things get better. So the wise situation is to say this: Walmart trades at 36 times earnings. It deserves to trade lower just because of what's happening at the company now and higher what's happening at the company when this inflation bout ends. So you buy some at $106, $105, and then buy some at $95. And yes, it could trade to $95. It does not have yield support. This is not like Target, which had that yield support. Target's doing better than Walmart right now. It is.
Walmart Inc.'s (NASDAQ:WMT) second-quarter fiscal 2027 revenue rose 5.9% year over year to $187.9 billion, while global e-commerce sales increased 23%. Global advertising revenue rose 38%, and membership-fee revenue increased 17% globally. Walmart U.S. comparable sales, excluding fuel, grew 2.6%. The company is also using tariff refunds to support lower prices. It said tariff refunds increased its gross profit rate during the quarter, while price investments partially offset the benefit.
Target Corporation (NYSE:TGT) has stronger recent comparable-sales momentum. Its second-quarter sales rose 5.3%, comparable sales increased 3.8%, and traffic rose 3.6%. The company also raised its full-year sales-growth outlook to approximately 5%. Its second-quarter GAAP and adjusted EPS were $4.11, including a $1.65 benefit from tariff refunds. Excluding tariff refunds, GAAP and adjusted EPS increased 20% year over year. CEO Michael Fiddelke said Target had reduced prices on more than 10,000 frequently purchased items over the past year and acknowledged that "there's still meaningful work ahead."
Walmart Inc.'s (NASDAQ:WMT) biggest risk is valuation. Its premium forward PE of 36.76 leaves the stock more exposed if U.S. comparable-sales growth remains modest while the company continues investing in prices. Walmart's 2.6% U.S. comparable-sales growth also trails Target's 3.8%.
#increased #rose
2 months ago
Citigroup Inc. (NYSE:C)'s CFO Gonzalo Luchetti said the bank expects return on tangible common equity (RoTCE) to come in slightly above 11% in 2026, while also indicating that Citi will increase stock buybacks from the $13 billion repurchased in 2025. The bank plans to accelerate roughly $500 million of investment by year-end, including spending on severance and marketing intended to expand its credit-card and wealth-management businesses. Citi also expects to remove Banamex from its balance sheet in 2027, which will create an estimated $9 billion currency-translation adjustment loss.
The 11%+ target is meaningful because Citi's profitability has already improved materially. In the second quarter, Citi generated $24.8 billion of revenue, up 14% year over year, while net income rose 45% to $5.8 billion. Investment-banking revenue increased 44% to $1.55 billion, and net interest income increased 13%. Citi's SEC filing shows second-quarter RoTCE of 13.0%, versus 8.7% a year earlier, while the first half of 2026 produced a 13.1% RoTCE. The new guidance therefore suggests management believes profitability can remain above the longer-term 11%-13% RoTCE range Citi established for 2027-28, despite additional investment spending.
Kiev.Victor / Shutterstock.com
The bullish argument is that Citigroup Inc. (NYSE:C) appears to be converting its multiyear restructuring into higher returns while simultaneously returning more capital to shareholders. The move from 8.7% RoTCE in the second quarter of 2025 to 13.0% in the second quarter of 2026 represents a substantial improvement in capital efficiency. Citi's efficiency ratio also improved to 57.4% from 62.7%, indicating that revenue growth is increasingly translating into operating leverage rather than being absorbed by expenses. That is particularly relevant because management now intends to spend another roughly $500 million on severance, marketing, and growth initiatives; if these investments produce the intended expansion in cards and wealth management, they could support revenue growth without derailing the profitability trajectory.
Capital returns provide another positive lever. Citi repurchased $13 billion of stock in 2025 and now expects to increase that amount, while its June 2026 CET1 ratio remained 12.78%, comfortably above its 11.6% standardized regulatory requirement. Buybacks can reduce tangible common equity and shares outstanding, potentially supporting both RoTCE and per-share earnings when executed below intrinsic value. Citi's tangible book value per share had already risen 7% year over year to $100.89 by June 30, 2026. The combination of higher operating profitability, shrinking share count, and improving capital efficiency strengthens the case for a valuation re-rating if Citi can sustain returns above 11%.
#rotce #citi #management
The 11%+ target is meaningful because Citi's profitability has already improved materially. In the second quarter, Citi generated $24.8 billion of revenue, up 14% year over year, while net income rose 45% to $5.8 billion. Investment-banking revenue increased 44% to $1.55 billion, and net interest income increased 13%. Citi's SEC filing shows second-quarter RoTCE of 13.0%, versus 8.7% a year earlier, while the first half of 2026 produced a 13.1% RoTCE. The new guidance therefore suggests management believes profitability can remain above the longer-term 11%-13% RoTCE range Citi established for 2027-28, despite additional investment spending.
Kiev.Victor / Shutterstock.com
The bullish argument is that Citigroup Inc. (NYSE:C) appears to be converting its multiyear restructuring into higher returns while simultaneously returning more capital to shareholders. The move from 8.7% RoTCE in the second quarter of 2025 to 13.0% in the second quarter of 2026 represents a substantial improvement in capital efficiency. Citi's efficiency ratio also improved to 57.4% from 62.7%, indicating that revenue growth is increasingly translating into operating leverage rather than being absorbed by expenses. That is particularly relevant because management now intends to spend another roughly $500 million on severance, marketing, and growth initiatives; if these investments produce the intended expansion in cards and wealth management, they could support revenue growth without derailing the profitability trajectory.
Capital returns provide another positive lever. Citi repurchased $13 billion of stock in 2025 and now expects to increase that amount, while its June 2026 CET1 ratio remained 12.78%, comfortably above its 11.6% standardized regulatory requirement. Buybacks can reduce tangible common equity and shares outstanding, potentially supporting both RoTCE and per-share earnings when executed below intrinsic value. Citi's tangible book value per share had already risen 7% year over year to $100.89 by June 30, 2026. The combination of higher operating profitability, shrinking share count, and improving capital efficiency strengthens the case for a valuation re-rating if Citi can sustain returns above 11%.
#rotce #citi #management

2 months ago
The Kroger Co. (NYSE:KR) cut its full-year 2026 identical-sales forecast excluding fuel to 0.2%–0.8% from 1%–2%, reflecting a sharper-than-expected slowdown in consumer demand. Second-quarter identical sales rose just 0.2%, down from 3.4% a year earlier and below the 0.9% ****** yst estimate.
The weakness reflects pressure on middle- and lower-income consumers, while a Cyclospora outbreak reduced quarterly identical sales by roughly 35 basis points and Medicare prescription-drug pricing changes created an approximately 140-basis-point headwind for pharmacy revenue. Importantly, Kroger maintained its full-year adjusted FIFO operating-profit forecast of $5.0 billion–$5.2 billion and delivered adjusted EPS of $1.09, ahead of the $1.06 consensus.
The strongest bullish argument is that The Kroger Co. (NYSE:KR) is currently protecting earnings despite the deterioration in sales momentum. Second-quarter adjusted EPS increased 5% year over year to $1.09, while adjusted FIFO operating profit was $1.076 billion. Kroger's gross margin rate actually increased by 13 basis points, although the overall gross-margin percentage was 22.4% versus 22.5% a year earlier, suggesting that pricing, sourcing, and cost-management initiatives are helping offset weaker volumes. The company's higher-margin businesses are also becoming increasingly important: adjusted e-commerce sales grew 20% in the quarter, and Kroger Precision Marketing profit increased 24%. That mix shift gives Kroger an earnings lever even when supermarket traffic and comparable sales are weak.
There is also evidence that management is actively responding to the competitive pressure rather than simply accepting slower growth. CEO Greg Foran has been pursuing tighter sourcing, simpler operations and lower prices, with Reuters reporting plans to cut prices across thousands of products to regain shoppers from Walmart, Costco and Aldi. The Kroger Co. (NYSE:KR)'s balance sheet provides room to fund that strategy: its net debt-to-adjusted-EBITDA ratio was 1.91x, below its stated target range of 2.30x–2.50x, while the company repurchased $1.0 billion of shares in the second quarter and $1.2 billion year to date. It also raised its dividend 11%, marking the 20th consecutive year of increases. If sales stabilize while e-commerce, retail media and cost efficiencies continue expanding, the unchanged $5.0 billion–$5.2 billion operating-profit forecast could prove more important to valuation than the reduced top-line outlook.
#year
The weakness reflects pressure on middle- and lower-income consumers, while a Cyclospora outbreak reduced quarterly identical sales by roughly 35 basis points and Medicare prescription-drug pricing changes created an approximately 140-basis-point headwind for pharmacy revenue. Importantly, Kroger maintained its full-year adjusted FIFO operating-profit forecast of $5.0 billion–$5.2 billion and delivered adjusted EPS of $1.09, ahead of the $1.06 consensus.
The strongest bullish argument is that The Kroger Co. (NYSE:KR) is currently protecting earnings despite the deterioration in sales momentum. Second-quarter adjusted EPS increased 5% year over year to $1.09, while adjusted FIFO operating profit was $1.076 billion. Kroger's gross margin rate actually increased by 13 basis points, although the overall gross-margin percentage was 22.4% versus 22.5% a year earlier, suggesting that pricing, sourcing, and cost-management initiatives are helping offset weaker volumes. The company's higher-margin businesses are also becoming increasingly important: adjusted e-commerce sales grew 20% in the quarter, and Kroger Precision Marketing profit increased 24%. That mix shift gives Kroger an earnings lever even when supermarket traffic and comparable sales are weak.
There is also evidence that management is actively responding to the competitive pressure rather than simply accepting slower growth. CEO Greg Foran has been pursuing tighter sourcing, simpler operations and lower prices, with Reuters reporting plans to cut prices across thousands of products to regain shoppers from Walmart, Costco and Aldi. The Kroger Co. (NYSE:KR)'s balance sheet provides room to fund that strategy: its net debt-to-adjusted-EBITDA ratio was 1.91x, below its stated target range of 2.30x–2.50x, while the company repurchased $1.0 billion of shares in the second quarter and $1.2 billion year to date. It also raised its dividend 11%, marking the 20th consecutive year of increases. If sales stabilize while e-commerce, retail media and cost efficiencies continue expanding, the unchanged $5.0 billion–$5.2 billion operating-profit forecast could prove more important to valuation than the reduced top-line outlook.
#year

2 months ago
Axon Enterprise (NASDAQ:AXON) shares fell 5% on Tuesday after the public safety technology company announced plans to offer $1 billion of 0% convertible senior notes due 2031.
The notes will be offered through a public offering registered under the Securities Act of 1933. Axon also expects to grant the underwriters an option to purchase up to an additional $150 million of notes to cover over-allotments.
The securities will mature on September 15, 2031, unless they are converted, redeemed or repurchased earlier. They will be senior unsecured obligations and will not carry regular interest.
Upon conversion, Axon may settle the notes in cash, shares of its common stock or a combination of the two, at the company's election.
Axon said it plans to use part of the net proceeds to fund capped call transactions ******* ociated with the offering.
#senior #enterprise
The notes will be offered through a public offering registered under the Securities Act of 1933. Axon also expects to grant the underwriters an option to purchase up to an additional $150 million of notes to cover over-allotments.
The securities will mature on September 15, 2031, unless they are converted, redeemed or repurchased earlier. They will be senior unsecured obligations and will not carry regular interest.
Upon conversion, Axon may settle the notes in cash, shares of its common stock or a combination of the two, at the company's election.
Axon said it plans to use part of the net proceeds to fund capped call transactions ******* ociated with the offering.
#senior #enterprise

2 months ago
Citigroup Inc. (NYSE:C)'s CFO Gonzalo Luchetti said the bank expects return on tangible common equity (RoTCE) to come in slightly above 11% in 2026, while also indicating that Citi will increase stock buybacks from the $13 billion repurchased in 2025. The bank plans to accelerate roughly $500 million of investment by year-end, including spending on severance and marketing intended to expand its credit-card and wealth-management businesses. Citi also expects to remove Banamex from its balance sheet in 2027, which will create an estimated $9 billion currency-translation adjustment loss.
The 11%+ target is meaningful because Citi's profitability has already improved materially. In the second quarter, Citi generated $24.8 billion of revenue, up 14% year over year, while net income rose 45% to $5.8 billion. Investment-banking revenue increased 44% to $1.55 billion, and net interest income increased 13%. Citi's SEC filing shows second-quarter RoTCE of 13.0%, versus 8.7% a year earlier, while the first half of 2026 produced a 13.1% RoTCE. The new guidance therefore suggests management believes profitability can remain above the longer-term 11%-13% RoTCE range Citi established for 2027-28, despite additional investment spending.
Kiev.Victor / Shutterstock.com
The bullish argument is that Citigroup Inc. (NYSE:C) appears to be converting its multiyear restructuring into higher returns while simultaneously returning more capital to shareholders. The move from 8.7% RoTCE in the second quarter of 2025 to 13.0% in the second quarter of 2026 represents a substantial improvement in capital efficiency. Citi's efficiency ratio also improved to 57.4% from 62.7%, indicating that revenue growth is increasingly translating into operating leverage rather than being absorbed by expenses. That is particularly relevant because management now intends to spend another roughly $500 million on severance, marketing, and growth initiatives; if these investments produce the intended expansion in cards and wealth management, they could support revenue growth without derailing the profitability trajectory.
Capital returns provide another positive lever. Citi repurchased $13 billion of stock in 2025 and now expects to increase that amount, while its June 2026 CET1 ratio remained 12.78%, comfortably above its 11.6% standardized regulatory requirement. Buybacks can reduce tangible common equity and shares outstanding, potentially supporting both RoTCE and per-share earnings when executed below intrinsic value. Citi's tangible book value per share had already risen 7% year over year to $100.89 by June 30, 2026. The combination of higher operating profitability, shrinking share count, and improving capital efficiency strengthens the case for a valuation re-rating if Citi can sustain returns above 11%.
#year #management
The 11%+ target is meaningful because Citi's profitability has already improved materially. In the second quarter, Citi generated $24.8 billion of revenue, up 14% year over year, while net income rose 45% to $5.8 billion. Investment-banking revenue increased 44% to $1.55 billion, and net interest income increased 13%. Citi's SEC filing shows second-quarter RoTCE of 13.0%, versus 8.7% a year earlier, while the first half of 2026 produced a 13.1% RoTCE. The new guidance therefore suggests management believes profitability can remain above the longer-term 11%-13% RoTCE range Citi established for 2027-28, despite additional investment spending.
Kiev.Victor / Shutterstock.com
The bullish argument is that Citigroup Inc. (NYSE:C) appears to be converting its multiyear restructuring into higher returns while simultaneously returning more capital to shareholders. The move from 8.7% RoTCE in the second quarter of 2025 to 13.0% in the second quarter of 2026 represents a substantial improvement in capital efficiency. Citi's efficiency ratio also improved to 57.4% from 62.7%, indicating that revenue growth is increasingly translating into operating leverage rather than being absorbed by expenses. That is particularly relevant because management now intends to spend another roughly $500 million on severance, marketing, and growth initiatives; if these investments produce the intended expansion in cards and wealth management, they could support revenue growth without derailing the profitability trajectory.
Capital returns provide another positive lever. Citi repurchased $13 billion of stock in 2025 and now expects to increase that amount, while its June 2026 CET1 ratio remained 12.78%, comfortably above its 11.6% standardized regulatory requirement. Buybacks can reduce tangible common equity and shares outstanding, potentially supporting both RoTCE and per-share earnings when executed below intrinsic value. Citi's tangible book value per share had already risen 7% year over year to $100.89 by June 30, 2026. The combination of higher operating profitability, shrinking share count, and improving capital efficiency strengthens the case for a valuation re-rating if Citi can sustain returns above 11%.
#year #management

2 months ago
Benzinga and Yahoo Finance LLC may earn commission or revenue on some items through the links below.
After watching home prices explode during the pandemic, one recent buyer has a question that probably sounds familiar to anyone who has looked at real estate lately: How can this possibly continue?
The buyer, who recently purchased a home in the Dallas-Fort Worth area, asked Reddit's r/RealEstate community where the ceiling is if home prices keep appreciating while incomes struggle to keep pace.
"At some point don't we just reach a point where no one can afford a home?" they asked. They were even worried that continued appreciation could eventually make their own home difficult to sell because there wouldn't be enough buyers who could afford it.
Don't Miss:
#point
After watching home prices explode during the pandemic, one recent buyer has a question that probably sounds familiar to anyone who has looked at real estate lately: How can this possibly continue?
The buyer, who recently purchased a home in the Dallas-Fort Worth area, asked Reddit's r/RealEstate community where the ceiling is if home prices keep appreciating while incomes struggle to keep pace.
"At some point don't we just reach a point where no one can afford a home?" they asked. They were even worried that continued appreciation could eventually make their own home difficult to sell because there wouldn't be enough buyers who could afford it.
Don't Miss:
#point

2 months ago
Lumson has purchased Lombardi Design and Manufacturing in the US, along with full ownership of Lombardi Design & MFG in Asia.
Financial terms of the deals remain undisclosed.
The deals form part of Lumson's wider international expansion plan and are intended to add to its industrial and technological capacity while extending its reach in primary packaging for the beauty and personal care sector.
With the two transactions, Lumson has a direct presence in Europe, North America and Asia.
The broader footprint will support work with international clients, help build industrial and commercial ties across markets, and open access to regions.
#financial #Europe
Financial terms of the deals remain undisclosed.
The deals form part of Lumson's wider international expansion plan and are intended to add to its industrial and technological capacity while extending its reach in primary packaging for the beauty and personal care sector.
With the two transactions, Lumson has a direct presence in Europe, North America and Asia.
The broader footprint will support work with international clients, help build industrial and commercial ties across markets, and open access to regions.
#financial #Europe