14 days ago
Definium Therapeutics, Inc. (NASDAQ:DFTX) has now delivered a third consecutive positive Phase 3 readout for its LSD-based medication, the second in generalized anxiety disorder. The result puts the company on a viable route toward a potential FDA approval of an LSD-based treatment for generalized anxiety disorder, and considering how closely psychedelic stocks have historically traded on each other's data, the reading carries far more weight than Definium's own ticker.
On September 14, Definium Therapeutics, Inc. (NASDAQ:DFTX) announced that its drug DT120, an orally disintegrating tablet formulation of LSD, was successful in Panorama, the company's second late-stage anxiety trial. Over 12 weeks, patients who received a 100-microgram dose experienced a 9.8-point decline on the Hamilton Anxiety Rating Scale, a typical clinical measure, compared to a 4.7-point drop with placebo.
The resulting 5.1-point placebo-adjusted improvement is similar to what the company's first pivotal anxiety trial, Voyage, showed back in August: an 11.6-point improvement versus 6.2 for placebo, a 5.4-point separation that Jefferies called one of the strongest placebo-adjusted efficacy results ever seen in generalized anxiety disorder, and that Stifel simply described as "a clean win."
Psychedelic equities have a history of trading as a group rather than as individual names, and this tendency applies both ways. In February 2026, when Compass Pathways, the sector's other clinical leader developing a psilocybin-based drug for treatment-resistant depression, reported positive late-stage data, shares of Definium Therapeutics, Inc. (NASDAQ:DFTX), Atai Beckley, GH Research, and Helus Pharma all rose, some by double digits.
That correlation is significant here because Definium's win is an independent validation of the broader therapeutic argument on which Compass and others are betting: a single dose of a classic psychedelic, administered in a controlled clinical setting, can produce lasting improvements in serious mental health conditions via pathways different from existing SSRIs and other standard-of-care drugs.
#definium #placebo


18 days ago
Liberty Media Formula One (FWONK) is increasingly looking like more than a fast-growing sports franchise — it is becoming a premium global media and entertainment ******* et. That view is gaining traction on Wall Street, with Jefferies initiating coverage of FWONK stock with a "Buy" rating and a $115 price target, implying about 22% potential upside from current levels. Jefferies views Formula One as a high-quality media and consumer-experiences business, supported by its premium sports ******* ets, ******* et-light model, and margin-expansion opportunity.
Jefferies believes that the company streamlining Formula One and MotoGP after the Liberty Live separation and MotoGP acquisition could improve how its allocates capital and executes. Moreover, ******* ysts highlighted Apple's (AAPL) new U.S. F1 media-rights deal for Apple TV, estimating it could add revenue of about $55 million annually through 2030. Overall, the firm expects revenue to grow to $5.84 billion in 2028, and adjusted OIBDA margins to expand to 27.2%.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Billionaire Charlie Munger, Who Died at 99, Skipped Insurance on His Mansion Since He Could Just Write a Check to Rebuild — 'All Intelligent People Do It My Way'
The EV Bubble Has Burst. How to Play Rivian Stock Now.
#liberty


20 days ago
September's debate over Chinese and American AI spending puts Alibaba Group Holding Limited (NYSE:BABA) and Amazon.com, Inc. (NASDAQ:AMZN) on opposite sides of the same investment question. Both report strong demand for computing services. Shareholders still need that demand to justify the infrastructure bill.
September 7 coverage of Jefferies' ***** ysis highlighted differences in spending intensity. The companies' own results suggest a more useful test than choosing a winner from headline capital expenditures: distinguish operating progress from cash committed ahead of future growth.
Alibaba's August 20 report showed June-quarter AI Cloud and Compute Services revenue increasing 45% to RMB48.44 billion. Segment adjusted EBITA reached RMB5.63 billion. The reporting group now combines its former Cloud Intelligence Group with T-Head, so investors should use the company's recast comparisons.
That operating improvement supports the case that computing demand can generate returns. It does not mean the spending cycle has already paid for itself. Group capital expenditures reached RMB67.68 billion, while free cash flow, a non-GAAP liquidity measure, was negative RMB44.67 billion for the quarter.
The opportunity is to keep expanding customer demand and utilization as new infrastructure becomes available. The risk is that cash outlays remain elevated while weaker returns elsewhere in the group reduce the room for error. Cloud growth alone cannot settle the value of the entire business.
#spending #cash #Services

30 days ago
Jefferies reiterated a Hold rating on Adobe Inc. (NASDAQ:ADBE) and raised the price target to $285 from $230 on August 30, citing expectations that the company will deliver results in line with expectations. The research firm has echoed the company's long-term prospects amid heightened focus on user acquisition and engagement.
During the second-quarter earnings call, management reiterated the new focus in response to the way artificial intelligence is changing the way users discover and buy creative and productivity tools. According to CEO Shantanu Narayen, AI is accelerating customer behavior, and Adobe must respond.
Therefore, the focus is on enabling friction-free onboarding for new users through "freemium" artificial intelligence offerings, rather than pushing them into direct paid journeys. Amid the new push, Jefferies expects Adobe to reiterate its fiscal 2026 outlook for 10.2% year-over-year growth in total ending ARR. The company also expects revenue of between $26.5 billion and $26.6 billion for fiscal 2026.
Adobe Inc. (NASDAQ:ADBE)'s opportunity hinges on its ability to turn Firefly, Acrobat AI, and AI-powered Creative Cloud features into monetized products, even as it focuses on attracting new users and enhancing engagement levels. The company is already seeing increasing Firefly adoption and AI-first ARR as Creative Cloud's huge installed base gives it millions of potential new AI customers.
Earlier on August 19, BofA reiterated an Underperform rating on Adobe and raised the price target to $220 from $190. BofA remains concerned that generative AI could pressure Adobe's longer-term growth as lower-cost, AI-native alternatives increase competition and Adobe's AI monetization has yet to materially accelerate overall growth. Additionally, its core products, including Photoshop, are under immense pressure from AI. Free or low cost AI native tools are making it harder for the company to expand its revenue base.
#adobe #creative #users #jefferies

30 days ago
On Aug. 30, Elon Musk tweeted that ***** eX (SPCX) will start casting its own gas turbine blades and vanes at a foundry in Texas. And when the richest man in the world makes a statement, the world takes notice. The market worried about the impact this could have on Howmet Aerospace (HWM), and its stock fell roughly 8% in a single trading session. The blades Musk wrote about sit in the hottest part of a turbine, and they are one of the main bottlenecks slowing down new power plants. Musk said building them in-house could bring turbines online up to 18 months sooner, feeding the power needs of ***** eX's AI data centers. Investors heard "new competitor" and sold. In my opinion, that may have been an overreaction.
The only reason ***** eX has to build its own foundry is that Howmet and the firms like it are sold out. Just four companies in the world cast these blades at scale, and together they control around 70% to 80% of the market. So several ***** ysts read the news as a sign of strength. Bernstein, which had lifted its price target to $328 just days earlier, called the selloff a buying opportunity. Citi and Jefferies pushed back too.
Nvidia CEO Jensen Huang Says His $3.5 Billion MediaTek Deal Is 'Not Circular' Because 'They Do Their Own Business'
Strategy's Strategy Appears to Have Failed, and the Outlook of MSTR Stock Is Unfavorable
A Potential ***** eX Deal Could Meaningfully Accelerate Growth for Technip Stock
#deal
1 month ago
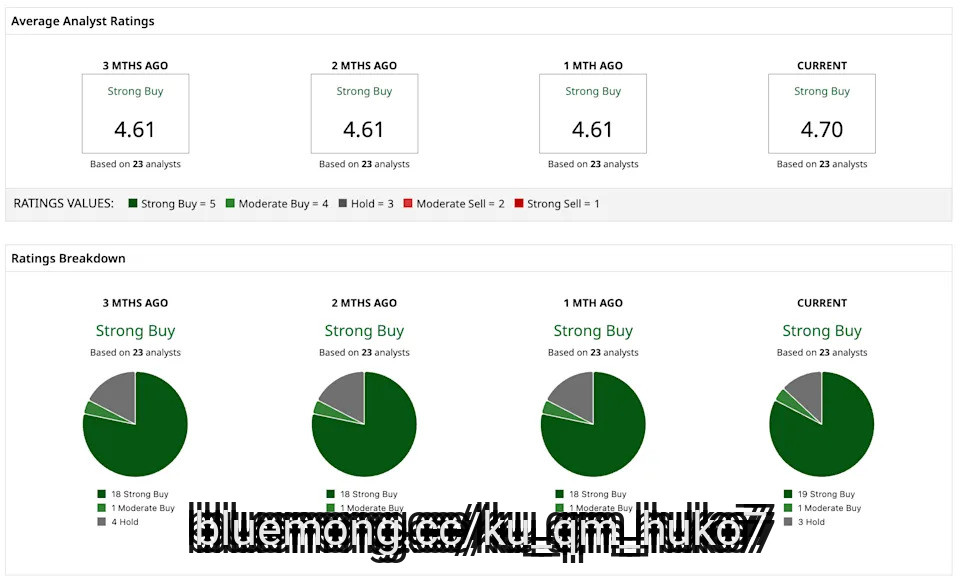
Palo Alto Networks (PANW) reports earnings on Sept. 1, and Wall Street has high expectations. In the week before its quarterly release, almost every day an **** yst firm raised its price target for the company. Benchmark started the rally by raising its price target on Aug. 24. J.P Morgan raised its price target on Aug. 25. Robert W. Baird raised it on Aug. 27. And Jefferies did the same on Aug. 28. All these firms kept a "Buy" rating on the stock. The optimism helped push PANW stock higher, and shares jumped roughly 13% in a single trading session.
The optimism is for a good reason. For the July quarter, management guided to revenue of around $3.35 billion, which would be an increase of approximately 32% from a year ago. Its next-generation security business, the subscription-based AI and cloud products, is expected to grow close to 60%. This will also be the first full quarter that includes CyberArk, the $25 billion identity security company Palo Alto recently bought. Its newest AI security product, Prisma AIRS, has also been the fastest-growing product in the company's history.
Jeff Bezos' Heartfelt Tribute to Dolly Parton Drew Brutal Backlash: 'Nobody Wanted to Hear This From You' — He Once Gave Her $100 Million for Charity
Intel vs. AMD: Why the Market Share Number Is Misleading
A $100 Billion Buildout In Louisiana Is Planned for Starship. What This Means for SPCX Stock.
#price #palo


1 month ago
Nike's (NKE) dreadful stretch of earnings under the thought-to-be savior CEO Elliott Hill may not be ending anytime soon, judging by what key partner ******* 's Sporting Goods (DKS) said this week.
"I think we have the [footwear] hangover right now," ******* 's Sporting Goods executive chairman Ed Stack told ******* ysts on his earnings call Tuesday. "We are going through that with these legacy silhouettes. The new styles of shoes that are coming out from brands across the board — whether it be Nike, whether it be Adidas, whether it be On, HOKA — we are going through that reset right now."
Lifestyle sneakers from Nike, with minimal fashion looks, have been solid performers for ******* 's in recent years, but they are quickly falling out of favor with consumers.
In turn, Nike is taking aggressive markdowns to clear slow-moving product. This has led competing brands to replicate these tactics, which is sparking a "domino effect of pricing pressure on styles of yesterday," Jefferies ******* yst Jonathan Matuszewski said.
"This is unfortunate for ******* 's given their high reliance on Nike and growing reliance on other emerging brands in recent years," Matuszewski wrote in a note.
#whether #goods #matuszewski #going

1 month ago
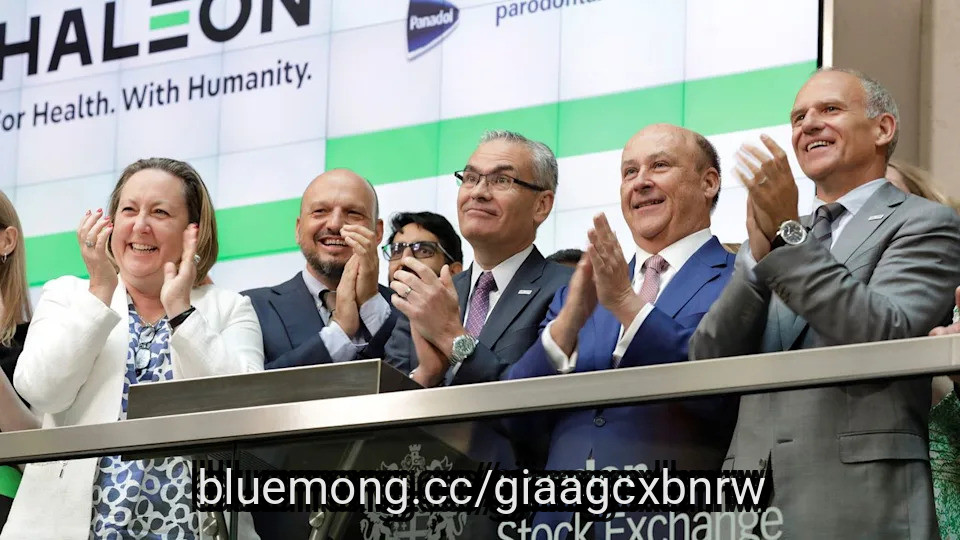
Jefferies has raised its price target for Haleon (Haleon PLC (LSE:HLN, NYSE:HLN), the consumer health company behind Sensodyne and Advil, to 410p from 400p, maintaining its Buy rating.
The broker highlighted a 70 basis point margin beat in the first half of the year, though it warned this revived concerns about whether Haleon was investing enough behind growth.
Haleon shares rose 0.28% to 364.10p in morning trading on Monday, after opening at 363.10p, with the stock reaching an intraday high of 364.50p.
Haleon delivered organic sales growth of 3.1% in the second quarter, split between a 1.7% rise in prices and a 1.4% increase in volumes.
Oral Health grew 6.2%, driven by the Sensodyne and Parodontax brands, while Pain Relief accelerated 4.6% on Voltaren gel expansion.
#Health #NYSE
1 month ago
On August 10, Jefferies downgraded Apple Inc. (NASDAQ:AAPL) to underperform from hold, cutting its price target to $263.66 from $285.56, implying roughly a 16% downside from Friday's close of $313.33. ******* yst Edison Lee said supply chain checks show Apple has canceled its planned all-glass 20th-anniversary iPhone, expected to launch in September 2027, due to poor production yield. Jefferies also trimmed its fiscal 2028 earnings forecast by 2.1%. Shares fell about 1.3% to 1.5% on the news.
Jefferies says Apple Inc. (NASDAQ:AAPL) has quietly canceled its marquee anniversary iPhone just as component costs are spiking industry-wide. That adds to a growing pile of Wall Street skepticism and raises a real question: is this the start of genuine cracks in Apple's pricing power, or just one bearish call against a stock still up double digits this year?
As of August 7, Apple is still up over 15% year-to-date, and the vast majority of Wall Street remains bullish, with 30 of 47 covering ******* ysts rating the stock buy or strong buy. The foldable iPhone debuting next month is Apple Inc. (NASDAQ:AAPL)'s biggest hardware redesign ever and gives the company a genuine new premium price anchor even with the all-glass model shelved. Despite an industry-wide memory shortage pushing prices higher across the smartphone market, Apple's brand loyalty gives it real room to pass through modest increases. Yahoo Finance tech editor Dan Howley noted that a roughly $100 price ******* p, spread across a phone's life and paid monthly, may not be enough to meaningfully change how people buy.
Six ******* ysts now carry sell-equivalent ratings on Apple, tying the highest count since 2012, and the stock's consensus recommendation of 3.88 out of 5 is its lowest since 2019. Fewer than 60% of ******* ysts recommend buying, well below megacap peers Microsoft, Amazon, and Nvidia, which are all backed by more than 90% of covering ******* ysts.
Jefferies argues the canceled all-glass model shows that "introducing new form factors" to justify higher prices is "more difficult than expected." The foldable iPhone is now the only near-term booster of higher prices. However, surging memory costs could push its starting price above $2,000, which Jefferies itself warns could make it a niche product with limited sales impact. This follows an earlier disappointment too: a soft sales forecast linked to component shortages already knocked the stock about 8% off its recent peak.
#NASDAQ


2 months ago
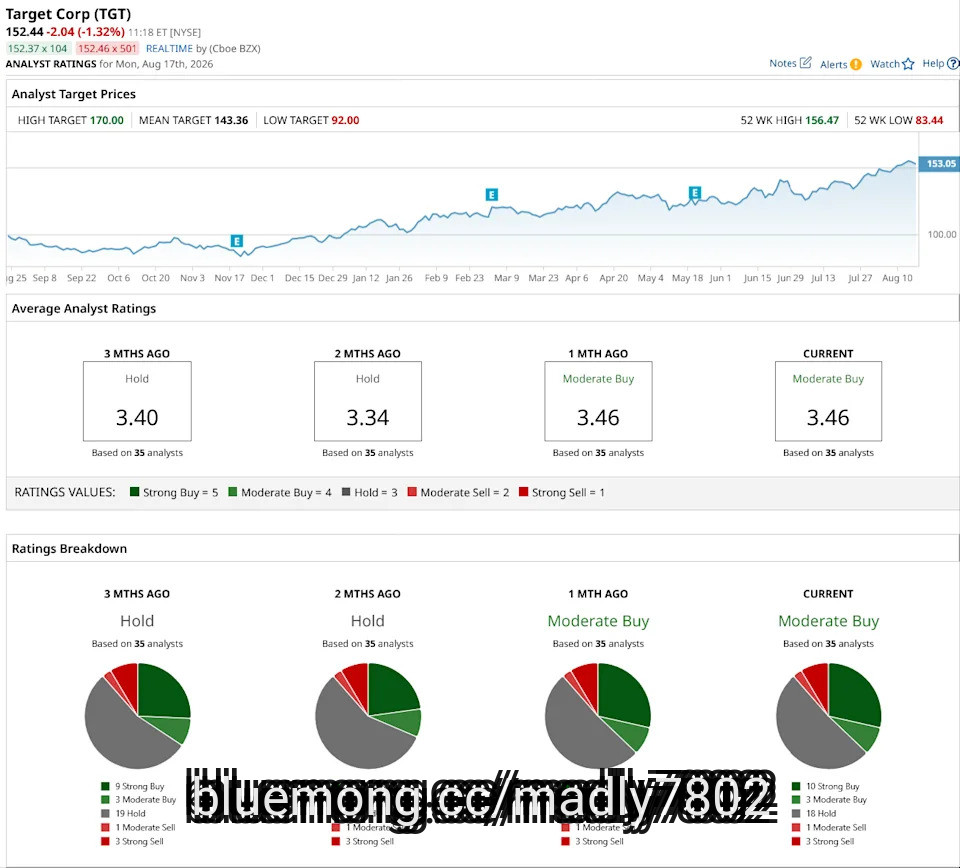
Target Corporation (TGT), a large U.S. retailer, is heading into its second-quarter earnings with strong momentum. TGT stock is up 56% year-to-date (YTD), touching a new 52-week high of $156.47 on Aug. 13. More importantly, Wall Street has high hopes that the company will beat estimates and has already started to price in that possibility. Many **** ysts have raised the target price for Target's stock.
Let's find out what **** ysts are expecting from Target this quarter.
Home Depot CEO Takes Medical Leave. What This Means for HD Stock Ahead of Earnings.
Tired of missing midday reversals? The FREE Barchart Brief newsletter keeps you in the know. Sign up now!
Analysts have been raising Target's price target before its Q2 earnings report on Aug. 19, believing its turnaround story is gaining momentum. Jefferies initiated coverage with a "Buy" rating and a $177 price target, which is the highest price estimate now, implying a 16% upside from current levels. Telsey Advisory has raised the price target to $170 while maintaining a "Buy" rating. Piper Sandler has lifted its target to $146 from $127, although it retained a "Hold" rating. Truist also moved its target to $147 from $130.
#high #raised


2 months ago
Okta (OKTA) stock has delivered one of the more striking moves in software this year. Its shares have climbed 93.8% over the past three months. That sharp re-rating has left the stock trading only 2.6% below its recent peak, even as investors continue to debate the durability of the next growth phase.
The latest spark came on Aug. 12, when Citizens JMP Securities upgraded Okta to "Market Outperform". With Okta scheduled to report fiscal second-quarter results after the close on Aug. 26, the upgrade lands at a moment when the market is especially focused on whether accelerating demand for securing AI agents can sustain the rally.
A $20 Billion Reason Why Intel Stock Is in Focus
Mark Cuban Says If You Win The Lottery, Don't Take The Lump Sum — And Tell People Who Ask for Money No, But 'Be Nice. No One Likes a Mean Billionaire'
Jefferies' Latest Warning on Palantir Sends Clear Message: Stay Cautious on PLTR Stock
#securities #outperform #reason


2 months ago
Five Below (FIVE) shares extended gains on Thursday after Jefferies issued a bullish note in favor of the Philadelphia-headquartered chain of discount retail stores. ***** yst Randal Konik upgraded FIVE this morning and raised his price target to $350, indicating potential upside of more than 40% from current levels.
Konik's research note arrives at a time when Five Below stock is already on an uptrend, currently up more than 35% versus its July low.
A $20 Billion Reason Why Intel Stock Is in Focus
Marvell Technology (MRVL) Stock Might Offer a Quick Bounce Before Earnings
Mark Cuban Says If You Win The Lottery, Don't Take The Lump Sum — And Tell People Who Ask for Money No, But 'Be Nice. No One Likes a Mean Billionaire'
#jefferies #konik


2 months ago
Jefferies initiated AEHR with a Buy rating and $175 target, calling its model conservative and excluding memory wins and AI customer upside.
COHU gained 151% and TER rose 112% year to date as AI chip complexity drives demand for more intensive semiconductor testing.
AEHR carries extreme valuation risk with a beta of 3.09, a recent 43% YoY revenue drop, and steady CEO and CFO insider selling.
Don't wait: the ****** yst who called NVIDIA in 2010 just revealed his top 10 AI stocks. See the full list FREE now.
Shares of Aehr Test Systems (NASDAQ:AEHR) are up roughly 8% in Friday midday, after a fresh Wall Street initiation lit another fire under one of 2026's most explosive small caps. The move extends a year-to-date advance of 510.7% and pushes the stock through its 52-week high of $133.35.
#date #free

2 months ago
Apple (NASDAQ:AAPL) shares are in the red today amid reports that rising memory costs could result in higher prices for the iPhone 18, while a Jefferies report indicated disappointing prospects for an all-glass iPhone. However, Gene Munster, managing partner at Deepwater ***** et Management, said in a recent program on CNBC that he still feels good about Apple and remains bullish on the stock.
Munster believes a potential increase in iPhone prices could actually help boost Apple's revenue growth, with limited impact on demand. At the core of his argument is his expectation of a strong upgrade cycle for Apple's iPhone business, which he believes could drive higher sales over the next several quarters. He also sees a broader consumer hardware upgrade cycle driven by personalized AI beginning around 2027, which he believes could create another major growth opportunity for Apple.
"There's going to be a massive upgrade cycle around consumer hardware," Munster said. "That's probably going to start 27 mid to late 27 and probably go for a few years. And that's based on personalized AI. That's going to do inference on device that's going to benefit Apple, that's going to benefit other hardware makers. And so when you put this together, I think shares are undervalued. And I think we're going to see a strong next 12 months."
Not all is good for Apple. The stock trades at around 35x forward earnings while growth is decelerating. Revenue growth is expected to fall back to single digits in FY27 once the current upgrade cycle matures. Q4 guidance already shows the slowdown starting, with revenue growth of 9% to 11% versus 16% in Q3. That makes Apple the slowest grower in the Magnificent Seven outside Tesla, yet it trades at the highest multiple. Meta grows over 20% at roughly 19x forward earnings. Alphabet trades at 18x. Amazon at 23x. Microsoft at 25x. Apple is at 35x.
Apple is losing the AI race and outsourcing its way through it. The new Siri runs on Google's Gemini model. Apple reportedly pays around $1 billion a year for it. Microsoft, Alphabet, and Amazon have ways to monetize their cloud platforms. Apple is renting intelligence from a direct competitor and has no clear way to make money off it.
#going #upgrade #around #believes

2 months ago
Five golds to be won on day two at Birmingham's Alexander Stadium - watch live on BBC One (UK only)
LIVE: Greatt Britain's Romell Glave and Jeremiah Azu win gold and silver in men's 100m as Italy's Marcell Jacobs pulls up halfway through
Netherlands' Nadine Vesser wins women's 100m hurdles by 0.001 seconds, GB's Marcia Sey finishes eighth
Greece's Miltiadis Tentoglou wins fourth men's long jump **** le
Local favourite Matthew Hudson-Smith second in his 400m semi-final, but Charlie Dobson and Ben Jefferies go out
#five #greatt #romell #jeremiah


2 months ago
Five golds to be won on day two of European Championships at Birmingham's Alexander Stadium - watch live on BBC TV (UK only)
LIVE: GB's Hannah Nuttall fifth in women's 5,000m final won by Italy's Nadia Battocletti
20:32: Men's 100m semi-finals featuring Italy's two-time champion Lamont Marcell Jacobs and GB's Romell Glave, Jeremiah Azu and Louie Hinchliffe
21:00: Men's 400m semi-finals with home favourite Matthew Hudson-Smith, Charlie Dobson and Ben Jefferies
21:30: Women's 100m hurdles final
#finals #five #stadium


2 months ago
AstraZeneca and Bristol Myers Squibb never held merger discussions and are not in talks now, a senior source close to the matter told Reuters on Wednesday.
"There is no deal between AstraZeneca and BMS. There never was a deal to be done, and there are no discussions between the companies," the source said, under the cover of anonymity. Neither company offered a comment when contacted by Reuters.
The denial came days after reports that the two pharmaceutical companies had been in preliminary discussions about a combination that could have created a company worth close to $400 billion. The Financial Times first reported the story. Reuters, which broke the Sunday story on the preliminary talks, noted at the time that it could not confirm whether those conversations were still active.
AstraZeneca shares dropped roughly 9% in the wake of the deal reports, while Bristol Myers Squibb shares weathered the news with relatively little movement.
When the merger reports first surfaced, as covered earlier this week, AstraZeneca stock tumbled as much as 7% on Monday. Bristol Myers Squibb stock rose 6% in U.S. premarket trading. **** ysts at Jefferies questioned the strategic rationale, writing that AstraZeneca was a company that did not need "financial engineering." Citi **** ysts called the reported talks a "surprise" given AstraZeneca's pipeline, according to CNBC.
#astrazeneca #bristol #reuters #reports

2 months ago
Ford Motor Company (F) has failed to attract many Wall Street players for most of the past year. Now one firm has decided to reconsider its stance on it.
Jefferies upgraded Ford to buy from hold on Monday, July 27, and raised its price target to $17.50 from $14.50.
The call landed one day before Ford reported its second-quarter results, and Jefferies' new target sat roughly 21% above where the stock traded early Monday, near $14.46.
The upgrade matters because Jefferies did not wait for the numbers to confirm the thesis. It bet that Ford's second quarter would mark the low point for margins and volume before things improve.
For anyone holding Ford, or watching it, the question was simple: Did the setup justify buying before the print? The July 28 report gave the first answer.
#company #wall


2 months ago
The AI buildout has resulted in an unanticipated casualty distant from Silicon Valley: telecom equipment manufacturers, who now compete with hyperscalers for the same memory chips. Three major companies, SK Hynix, Samsung, and Micron, control more than 95% of worldwide DRAM production, and as AI data centers use an increasing share of that output, memory chips used in telecom base stations become scarcer and more expensive as a direct result. That is the mechanism behind Telefonaktiebolaget LM Ericsson (NASDAQ:ERIC)'s worst single-day stock reaction in nearly three years.
The company's shares plunged about 12% on July 14, reaching their lowest level since February, after Ericsson warned that growing component costs, particularly memory chips, will affect margins in the future. Looking into Ericsson's Q2 2026 results, the market's harsh reaction was more about forward guidance rather than a breakdown in existing operational execution. Adjusted EPS was SEK 1.22 (~$0.13), which was in line with market expectations. Adjusted gross margin increased to 48.4%, a two-percentage-point year-over-year rise after normalizing for a prior-period IPR licensing settlement. Meanwhile, reported net sales declined 6% to SEK 52.7 billion ($5.62 billion), missing the SEK 53.71 billion forecast, while organic sales excluding currency and one-offs remained essentially flat.
What worried investors was guidance and cash flow, not the print itself. Free cash flow before M&A fell to SEK 0.4 billion from SEK 2.6 billion a year ago, owing to increased inventories being accumulated ahead of scheduled third-quarter deliveries. Management forecasted Q3 Networks adjusted gross margin to a range of 48% to 50%, a slight decrease from Q2 levels, noting a higher share of lower-margin network rollout projects and component inflation developing "gradually" during the second half of 2026 and into 2027.
Jefferies, which rated the stock at a Hold with a target price of 98 Kronor, framed the sales miss as being centered primarily on delayed India deliveries within the Networks division as opposed to broad-based demand weakness, and noted Ericsson is forecasting a stronger-than-seasonal third quarter as those delayed deliveries arrive.
The sudden selloff has generated an attractive valuation gap for long-term investors. Telefonaktiebolaget LM Ericsson (NASDAQ:ERIC) is currently trading at a 14.45x forward P/E multiple, representing a significant discount to key infrastructure rivals such as Nokia, which trade on similar 5G-cycle and edge-connectivity theses. The market's knee-jerk reaction appears to regard temporary component inflation as a permanent weakening of Ericsson's earnings potential, resulting in a clear disparity between price and underlying value.
#billion #adjusted #memory

2 months ago
Digital advertising spending in 2026 is expected to expand unevenly. According to the IAB's 2026 Outlook Study, overall US ad spend is projected to grow by 9.5% this year, with social media advertising growing 14.6%, well outperforming the broader industry. However, growth is not evenly spread across advertiser sizes, with larger consumer firms lowering marketing expenditure as one of the fastest ways to maintain profitability amid wary consumers and narrowing margins.
That's the backdrop in which Reddit, Inc. (NYSE:RDDT) is placing a significant bet: while the biggest social platforms compete for the same narrowing pool of massive brand advertisers, Reddit is slowly opening the door to small and medium-sized businesses that couldn't previously manage the cost of creating a personalized ad campaign.
That shift became clear when Reddit, Inc. (NYSE:RDDT) released a beta version of Reddit Community Intelligence on July 10, an AI-powered, free-form ad generator that provides advertisers with AI-generated creative recommendations customized to certain communities instead of forcing them to start from scratch. The tool is deliberately designed to make campaign creation easier for advertisers targeting community-specific audiences, which have traditionally found platform advertising too resource-intensive to bother with.
Wall Street research desks realized the structural significance of the self-service shift. On July 13, Citizens ***** yst Andrew Boone confirmed his Market Outperform rating and $240 price target for Reddit, Inc. (NYSE:RDDT), citing automated self-service technologies as a key revenue driver. Boone emphasized that lowering friction for smaller advertisers enables Reddit to capture previously untapped performance budgets, resulting in long-term, lower-funnel revenue streams.
Crucially, Reddit's advertising momentum was accelerating even before the Community Intelligence tool shipped. On July 10, Jefferies, drawing on conversations with agencies, added that Reddit, Inc. (NYSE:RDDT) continued to gain share in social media advertising through the second quarter. Agencies said that this was due to the platform's large and growing audience, growing reach, and more personalized targeting, a read that preceded the Community Intelligence launch and shows the platform was already winning before the tool even shipped.
#rddt #advertising #growing

2 months ago
After trying Meta Platforms' (META) AI glasses lineup, Wall Street ****** ysts have turned bullish on the company's hardware ambitions, a possible change of heart considering how much money Meta has lost on Reality Labs and virtual reality (VR). Improved cameras, comfortability, and enhanced audio were the main drivers of the positive reception. Jefferies ****** ysts believe the glasses could become a real new growth driver for the company after testing the Ray-Ban Meta Gen2, Oakley Meta, and Ray-Ban Display. But what caught my attention was not hidden in the product notes — it was in the price tags of $379, $499, and $799, respectively. This pricing points to a long-term strategy designed to generate repeat purchases over years, not a single sale.
Starting with the entry point, the Ray-Ban Meta Gen2 is only voice-first, camera-equipped, and with no display. Next, the Oakley Meta at $499 pushes into a sportier niche at a slightly higher price. Finally, at $799, the Ray-Ban Display with Neural band is Meta's top-of-the-line model — the only one with an actual screen and gesture control. This product lineup clearly shows something that Meta is trying to build on: Pulling customers up the ladder over successive purchases rather than selling them a single product once.
Ahead of Microsoft Earnings, Here's What Barchart Data Says Comes Next for MSFT Stock
Nasdaq Futures Plunge as Chip Selloff Rages On, FOMC Meeting and Earnings on Tap
Broadcom Leads 3 AI Stocks Quietly Raising Their Dividends, One by 161%
#product #next #earnings


2 months ago
Two Detroit automakers jumped Monday morning on positive ****** yst news. Jefferies upgraded both General Motors and Ford to buy ratings, from hold.
The investment firm raised General Motors' price target to $99 from $90; and Ford to $17.50, up from $14.50, according to theFly.com. The price targets imply a 12-month upside of 17% for GM and 21% for Ford, relative to where shares traded Monday morning.
The ****** yst action for both companies follows an extended period of hold ratings, and comes after both automakers in December incurred huge, multibillion write-offs related to a series of electric vehicle investments that didn't pan out.
Ford stock rose as much as 3% on Monday's news as it continues to hug its 50-day line, according to MarketSurge. Meanwhile, General Motors' 3.5% gain pushed it briefly above a buy point of 85.41 as it tinkers with a breakout from a flat base. Over the last 12 months, General Motors (GM) is up just under 60%. Ford (F) advanced roughly 28%.
#ford #automakers

2 months ago
The most talked about and market moving research calls around Wall Street are now in one place. Here are today's research calls that investors need to know, as compiled by The Fly.
Top 5 Upgrades:
Jefferies upgraded Verisk ****** ytics (VRSK) to Buy from Hold with a price target of $235, up from $192. Verisk's Q1 report "likely marks a trough," with its organic growth improving to 5% year-over-year in Q2, and accelerating further in the second half of 2026, the firm tells investors in a research note.
Morgan Stanley upgraded PayPay (PAYP) to Overweight from Equal Weight with a price target of $23, down from $24. The firm says that while the company's near-term catalysts remain limited, the stock's risk/reward suggests the upside potential outweighs downside risk.
Wolfe Research upgraded AT&T (T) to Outperform from Peer Perform with a $29 price target. The company's Q2 brought "stable and better than expected" unit economics, the firm tells investors in a research note.
KeyBanc upgraded Ameren (AEE) to Overweight from Sector Weight with a $122 price target. The firm believes increasing visibility around incremental load growth could position Ameren for a "meaningful earnings growth revision as early as this fall."
#Research #price #investors #Growth

2 months ago
Twilio Inc (NYSE:TWLO) is expected to deliver second quarter results that exceed expectations on revenue and operating income, with investors likely to focus on whether the communications software company's gross profit growth can remain in the mid-teens during the second half of the year, according to Jefferies ******* ysts.
Ahead of Twilio's August 6 earnings release, Jefferies wrote that it expects the company to post revenue and operating income above expectations, although it does not anticipate the same degree of outperformance as in the first quarter.
The firm added that while business fundamentals remain strong, the stock's premium valuation and heavy investor positioning could limit upside unless Twilio significantly raises its outlook.
Jefferies forecasts second-quarter revenue of $1.427 billion, up 16% year over year and broadly in line with consensus expectations and the company's guidance range of $1.42 billion to $1.43 billion.
The firm expects gross profit of $684 million, implying a gross margin of 47.9%, compared with consensus expectations of $690 million and a 48.3% margin. It projects operating income of $255 million, or a 17.9% operating margin, and earnings per share of $1.30, versus Wall Street expectations of $258 million in operating income and EPS of $1.33.
#expectations

2 months ago
Advanced Micro Devices (AMD) hosts its Advancing AI event in San Francisco on July 22-3, and Jefferies expects a busy day. ******* yst Blayne Curtis, who has a "Buy" rating and a $615 price target, thinks AMD will raise its estimate of the total market for its processors past $200 billion. He expects fresh details on the MI500 chips due after the current generation. The part investors will be keen on watching is the customer list. The ******* yst believes Microsoft (MSFT) is signed up for the MI450. There are also growing talks of a deal with Anthropic, which has reportedly been hiring engineers familiar with AMD's software.
The reason a new customer matters so much comes down to how AMD won the last two. To land OpenAI and Meta Platforms (META), each committing to six gigawatts of chips, AMD handed both companies warrants to buy up to 160 million shares. Combined, AMD has promised away about a fifth of itself to secure those orders.
Huge, Unusual Intel Options Volume Today Ahead of Earnings This Week
Intel Stock Is Down, But Put Premiums are High - Put Short Sellers Love the High Yields
The Number Tesla Stock Bulls Are Really Waiting for This Earnings Season Has Nothing to Do With Cars
#earnings #customer


2 months ago
This story was originally published on BioPharma Dive. To receive daily news and insights, subscribe to our free daily BioPharma Dive newsletter.
Novartis said second-quarter sales inched upward, beating **** yst expectations for a decline as demand for newer products helped offset generic competition for its former top-selling heart medication Entresto.
At constant exchange rates, net sales increased 1% to $14.4 billion, Novartis said Tuesday. That beat the consensus estimate of about $13.7 billion, Jefferies **** yst Michael Leuchten wrote in a note to clients. Core operating income reached $5.94 billion, topping the consensus estimate of $5.31 billion. Leuchten had expected core operating income of $5.16 billion on sales of $13.8 billion.
The Swiss drugmaker highlighted increases of more than 30% for "priority brands" including Kisqali, Kesimpta, Scemblix, Pluvicto and Leqvio. Revenue from Entresto plunged by half to $1.18 billion in the period, moving the drug down to fourth place on the list of Novartis' most lucrative products.
Already buffeted by Entresto losses in the U.S., Novartis is looking ahead to one of the most daunting patent cliffs in the pharmaceutical industry over the next five years, affecting all four of its top-selling medicines in the second quarter. Entresto is set to lose exclusivity in Europe in 2028. After that, U.S. patent expirations follow for its biggest moneymaker, Cosentyx, in 2029 and both Kesimpta and Kisqali in 2031.
#billion #biopharma #dive


3 months ago
Dan Ives logs into the Zoom call in a loud, tropical shirt, the word "Margaritaville" splashed across the chest. He has spent the better part of 25 years as one of Wall Street's most recognizable tech bulls — a go-to voice on everything from Apple to Nvidia, a prolific note-writer who repeated the phrase "fourth industrial revolution" and has been telling investors, through every dip and correction, that they're still in the early innings. He has made a lot of people a lot of money by being consistently, loudly optimistic about technology stocks.
Now he is doing what he spent a decade and a half telling everyone else to do.
"Look, I'm an example of what I've preached over the years that AI will ultimately create more jobs than what it takes away," he told me in an interview, several weeks after leaving Wedbush Securities to launch Yorkville Ives, what he calls a "modern merchant bank" with Yorkville Securities. "If it wasn't for the AI revolution and it wasn't for this period … I couldn't do something like this."
That's the short version of what happened. The longer version, Ives told Fortune, is that after 25 years covering other people's companies, he realized he had never actually built one himself — and he wanted to. "As an ***** yst I always talk about companies, whether good or bad, what they've done. But I've never built anything," he said. He has helped institutional investors make money and CEOs shape narratives, he added, but he felt the itch. "I wanted to get off the treadmill and actually build something myself."
The first question, though, is just what he is building, actually. Ives said he traces the merchant bank concept back to Thomas Weisel and the early Jefferies era of the 1990s — outfits that didn't just publish research but put their own capital into transactions. "A lot of banks … they won't put their own money [in], they don't have the capital," he said. "That to me is really the key in terms of the difference with a merchant bank versus a typical investment bank."

3 months ago
Sable Offshore Corp. (NYSE:SOC) is one of the 10 best stocks under $10 that could triple.
On July 6, Lloyd Byrne from Jefferies reduced Sable Offshore Corp.'s (NYSE:SOC) price target from $24 to $11. Despite such a huge downward adjustment, the price target still results in an upside potential of over 180%.
Pixabay/Public Domain
The ****** yst maintained a Buy rating on the stock despite some recent challenges, such as the dilution for current equity holders caused by the recent convertible notes offering. The offering was executed amid the company's failure to attain government support.
Earlier on July 1, Sable Offshore Corp. (NYSE:SOC) shared details around the company's recent public offerings. These involved 32,467,533 common shares, priced at $3.08 per share, and the issuance of 6.5% convertible senior notes with a $300 million principal amount due in 2031.

3 months ago
EQT Corporation (NYSE:EQT) is one of the 8 Worst Blue Chip Stocks to Buy Now.
On July 8, 2026, UBS lowered the firm's price target on EQT Corporation (NYSE:EQT) to $73 from $74 previously and kept a Buy rating on the shares.
On July 2, Jefferies **** yst Lloyd Byrne lowered the firm's price target on EQT Corporation (NYSE:EQT) to $75 from $77 and kept a Buy rating on the shares as part of a Q2 preview. Byrne said Jefferies expects EQT to post Q2 EBITDA of $1.13B, just below the consensus of $1.19B.
On June 30, Freedom Broker initiated coverage of EQT Corporation (NYSE:EQT) with a Buy rating and $79 price target on the shares. The firm said EQT is the largest U.S. natural gas producer and is positioned to benefit from improving natural gas market fundamentals.
EQT Corporation (NYSE:EQT) engages in the exploration, production, gathering, and transmission of hydrocarbons and natural gas.

3 months ago
Sable Offshore Corp. (NYSE:SOC) is one of the 10 best stocks under $10 that could triple.
On July 6, Lloyd Byrne from Jefferies reduced Sable Offshore Corp.'s (NYSE:SOC) price target from $24 to $11. Despite such a huge downward adjustment, the price target still results in an upside potential of over 180%.
Pixabay/Public Domain
The ****** yst maintained a Buy rating on the stock despite some recent challenges, such as the dilution for current equity holders caused by the recent convertible notes offering. The offering was executed amid the company's failure to attain government support.
Earlier on July 1, Sable Offshore Corp. (NYSE:SOC) shared details around the company's recent public offerings. These involved 32,467,533 common shares, priced at $3.08 per share, and the issuance of 6.5% convertible senior notes with a $300 million principal amount due in 2031.
On July 6, Lloyd Byrne from Jefferies reduced Sable Offshore Corp.'s (NYSE:SOC) price target from $24 to $11. Despite such a huge downward adjustment, the price target still results in an upside potential of over 180%.
Pixabay/Public Domain
The ****** yst maintained a Buy rating on the stock despite some recent challenges, such as the dilution for current equity holders caused by the recent convertible notes offering. The offering was executed amid the company's failure to attain government support.
Earlier on July 1, Sable Offshore Corp. (NYSE:SOC) shared details around the company's recent public offerings. These involved 32,467,533 common shares, priced at $3.08 per share, and the issuance of 6.5% convertible senior notes with a $300 million principal amount due in 2031.